Kansas City Southern — Merger or Acquisition (August 2021)
18 slides from Kansas City Southern's merger presentation, Aug 3, 2021
Slide 1: Combination of CN & Kansas City Southern: Creating the Premier Railway for the 21st Century
KANSAS CITY SOUTHERN Combination of CN & Kansas City Southern Creating the Premier Railway for the 21st Century August 2021
Slide 2: Forward Looking Statements
Forward Looking Statements Certain statements included in this presentation constitute “forward-looking statements” within the meaning of the United States Private Securities Litigation Reform Act of 1995 and under Canadian securities laws, including statements based on management’s assessment and a
Slide 3: No Offer or Solicitation
No Offer or Solicitation This presentation does not constitute an offer to sell or the solicitation of an offer to buy any securities or a solicitation of any vote or approval, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful p
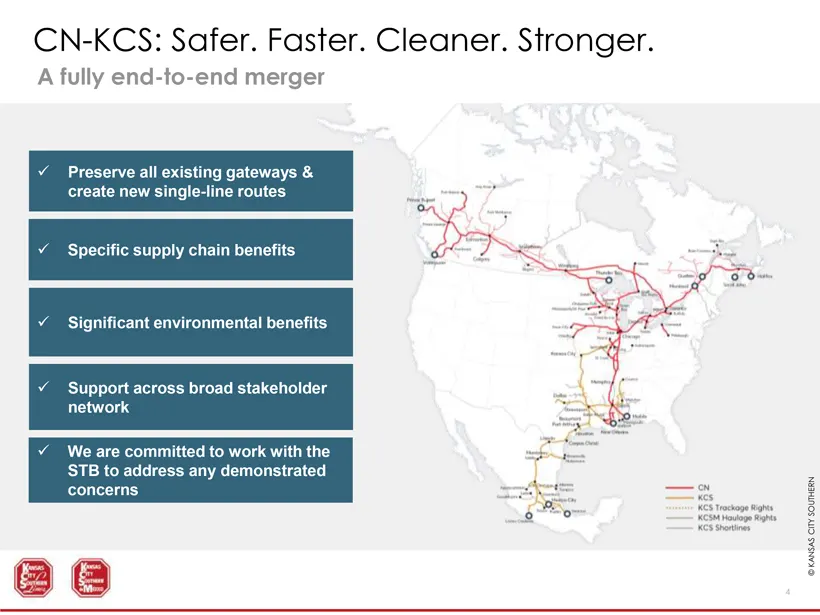
Slide 4: CN-KCS: Safer. Faster. Cleaner. Stronger.
CN-KCS: Safer. Faster. Cleaner. Stronger. A fully end-to-end merger ✓ Preserve all existing gateways & create new single-line routes ✓ Specific supply chain benefits ✓ Significant environmental benefits ✓ Support across broad stakeholder network ✓ We are committed to work with the STB to address any
Slide 5: Executive Summary
Executive Summary â–ª KCS Board of Directors continues to strongly recommend a vote “FOR” CN’s proposal â–ª CN’s $325 offer is clearly superior to CP’s inferior $275 proposal â–ª KCS Board terminated CP’s merger agreement in May and CP has chosen its own path of not revising its offer and collected
Slide 6: Compelling Value Proposition for KCS Shareholders
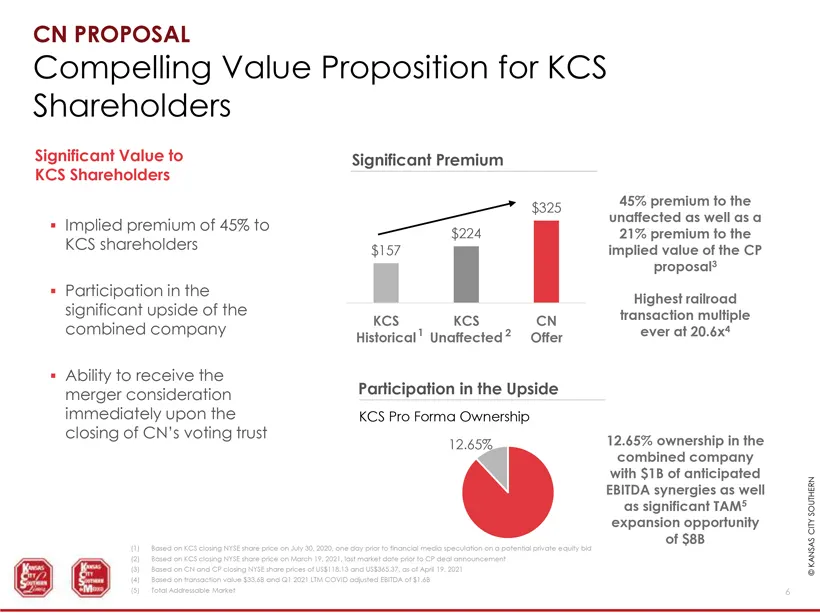
CN PROPOSAL Compelling Value Proposition for KCS Shareholders Significant Value to KCS Shareholders â–ª Implied premium of 45% to KCS shareholders â–ª Participation in the significant upside of the combined company â–ª Ability to receive the merger consideration immediately upon the closing of CN’s
Slide 7: Delivering EBITDA Synergies Approaching $1B
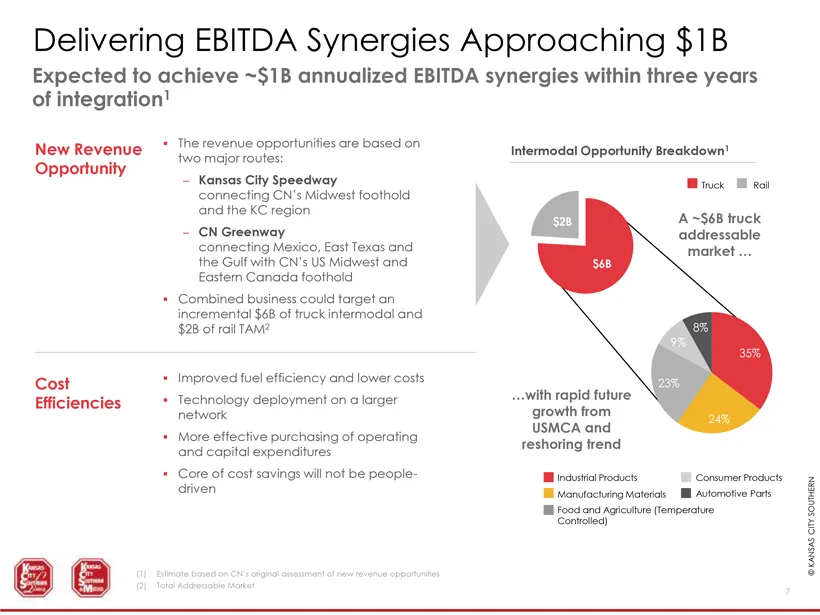
Delivering EBITDA Synergies Approaching $1B Expected to achieve ~$1B annualized EBITDA synergies within three years of integration1 New Revenue â–ª The revenue opportunities are based on two major routes: Opportunity – Kansas City Speedway connecting CN’s Midwest foothold and the KC region – CN Gree
Slide 8: CP Self-interested Attempt to Undermine CN's Superior Proposal
We Believe CP is Engaging in a Self-interested Attempt to Undermine CN’s Superior Proposal to the Detriment of KCS Shareholders â–ª CP chose not to exercise its right to match CN’s superior proposal when it had the chance under the terms of its initial merger contract â–ª Rather than improving its o
Slide 9: Enhancing Competition and Maximizing Customer Choice
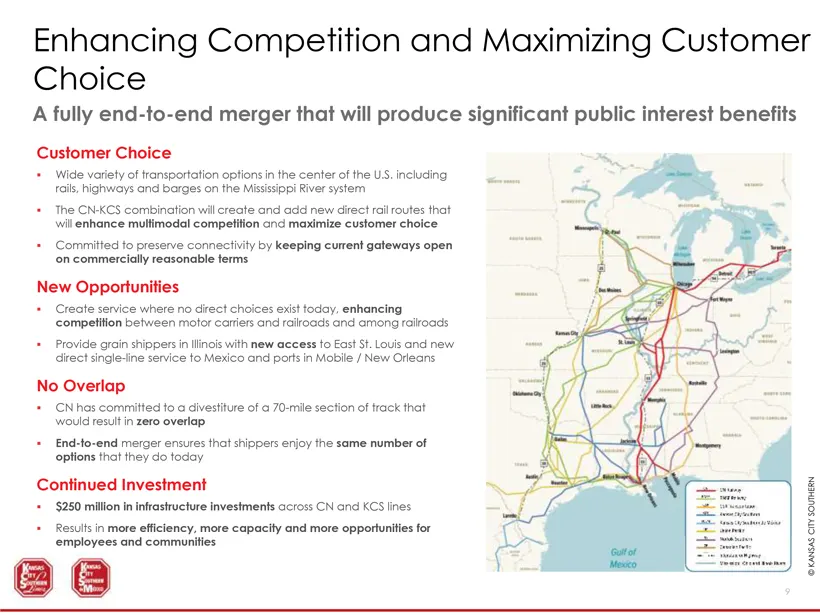
Enhancing Competition and Maximizing Customer Choice A fully end-to-end merger that will produce significant public interest benefits Customer Choice â–ª Wide variety of transportation options in the center of the U.S. including rails, highways and barges on the Mississippi River system â–ª The CN-K
Slide 10: CP's Claim of Reduced Shipper Competition Is Vastly Overstated
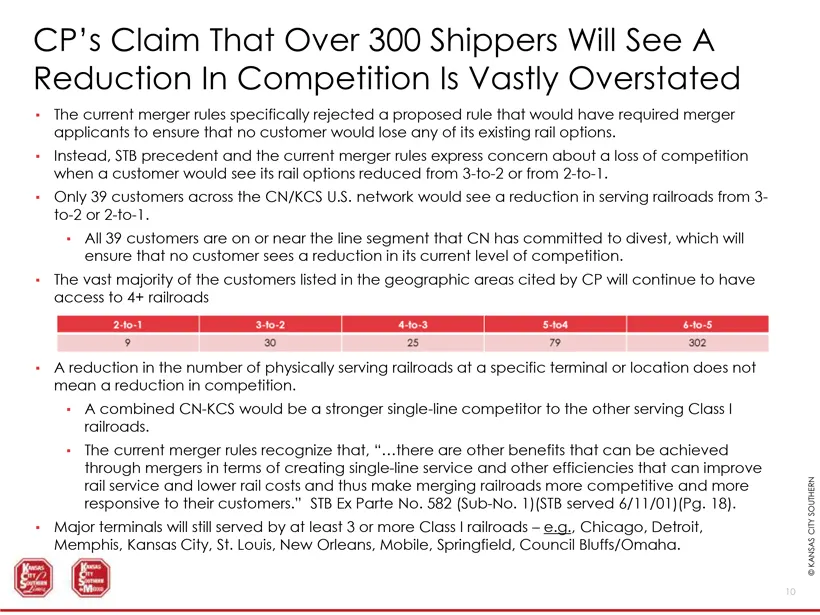
CP’s Claim That Over 300 Shippers Will See A Reduction In Competition Is Vastly Overstated â–ª The current merger rules specifically rejected a proposed rule that would have required merger applicants to ensure that no customer would lose any of its existing rail options. â–ª Instead, STB precedent
Slide 11: St. Louis Gains New Single Line Service
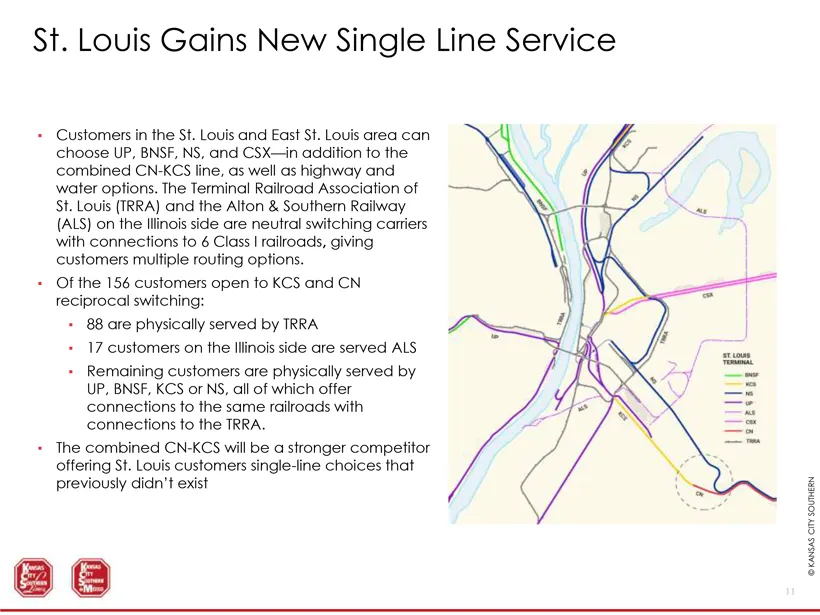
St. Louis Gains New Single Line Service â–ª Customers in the St. Louis and East St. Louis area can choose UP, BNSF, NS, and CSX—in addition to the combined CN-KCS line, as well as highway and water options. The Terminal Railroad Association of St. Louis (TRRA) and the Alton & Southern Railway (ALS)
Slide 12: Compelling Voting Trust Case
Compelling Voting Trust Case â–ª Voting Trust Rule — 49 CFR 1180.4(b)(4)(iv) “. . . In each proceeding involving a major transaction, applicants contemplating the use of a voting trust must explain how the trust would insulate them from an unlawful control violation and why their proposed use of the
Slide 13: STB Voting Trust Standard
STB Voting Trust Standard Voting Trust Review Governed By 49 U.S.C. §11324(b) and 49 CFR 1180.4(b)(iv). A voting trust will be approved if: i. The trust will insulate the seller from control of the buyer during the trust period; and ii. The trust is consistent with the public interest. This public i
Slide 14: CN-KCS Aligned with Executive Order Promoting Competition
CN-KCS is Aligned with Executive Order Promoting Competition in the American Economy â–ª The CN/KCS merger enhances competition and is fully consistent with President Biden’s Executive Order, which is focused on promoting a “fair, open and competitive marketplace.” â–ª STB’s current major merger rul
Slide 15: CN-KCS Better Offer, Better Partner, Better Railway, Best Solution
CN-KCS Better Offer, Better Partner, Better Railway, Best Solution â–ª Compelling Value Proposition for KCS Shareholders of $325 per share â–ª Safer, Faster, Cleaner, Stronger Railway â–ª End to End Merger Creates USMCA Railway â–ª Enhanced Competition, Increased Customer Choice – Will work with the
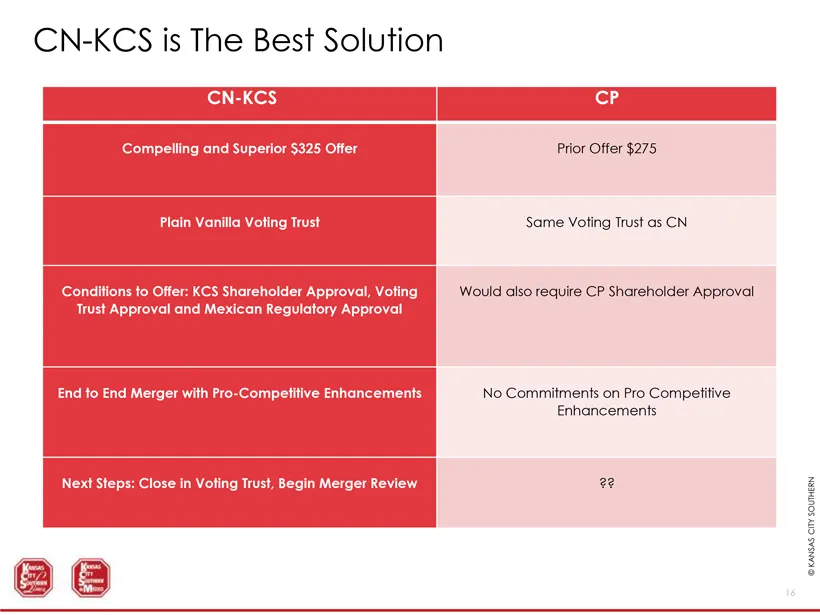
Slide 16: CN-KCS is The Best Solution
CN-KCS is The Best Solution CN-KCS CP Compelling and Superior $325 Offer Prior Offer $275 Plain Vanilla Voting Trust Same Voting Trust as CN Conditions to Offer: KCS Shareholder Approval, Voting Would also require CP Shareholder Approval Trust Approval and Mexican Regulatory Approval End to End Merg
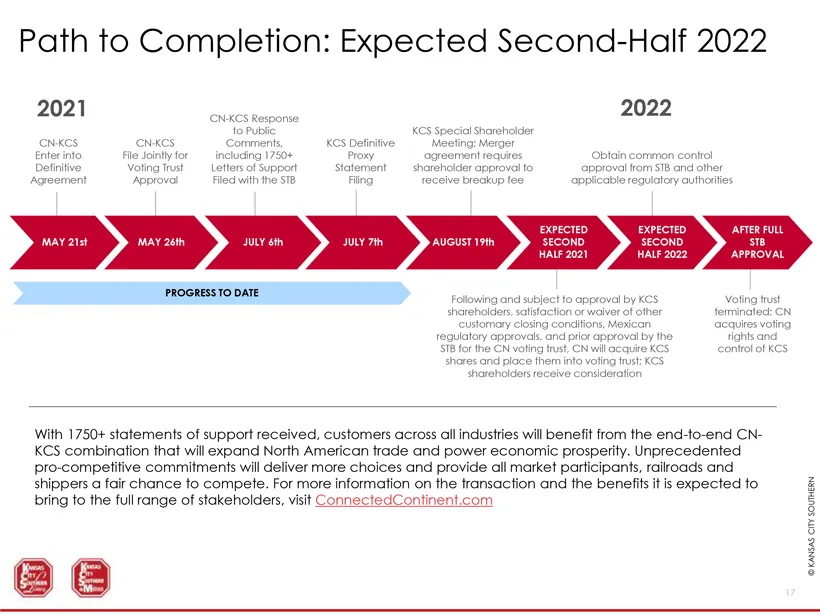
Slide 17: Path to Completion: Expected Second-Half 2022
Path to Completion: Expected Second-Half 2022 2021 2022 CN-KCS Response to Public KCS Special Shareholder CN-KCS CN-KCS Comments, KCS Definitive Meeting; Merger Enter into File Jointly for including 1750+ Proxy agreement requires Obtain common control Definitive Voting Trust Letters of Support State
Slide 18: connectedcontinent.com
connectedcontinent.com
Source: SEC EDGAR · 425 filed Aug 3, 2021
More decks from Kansas City Southern
 Merger or Acquisition (September 2021)9 slides · Sep 16, 2021
 Merger or Acquisition (September 2021)10 slides · Sep 1, 2021
 Merger or Acquisition (August 2021)12 slides · Aug 27, 2021
 Merger or Acquisition (August 2021)11 slides · Aug 17, 2021
 Merger or Acquisition (August 2021)13 slides · Aug 10, 2021
 Merger or Acquisition (August 2021)7 slides · Aug 5, 2021