Vodafone Idea Ltd · NSE:IDEA
Vodafone Idea — Investor Presentation (May 2024)
34 slides from Vodafone Idea's investor presentation, May 3, 2024
Slide 1: Vodafone Idea Limited
Vodafone Idea Limited May 3, 2024 1
Slide 2: Company Overview
Company Overview 2
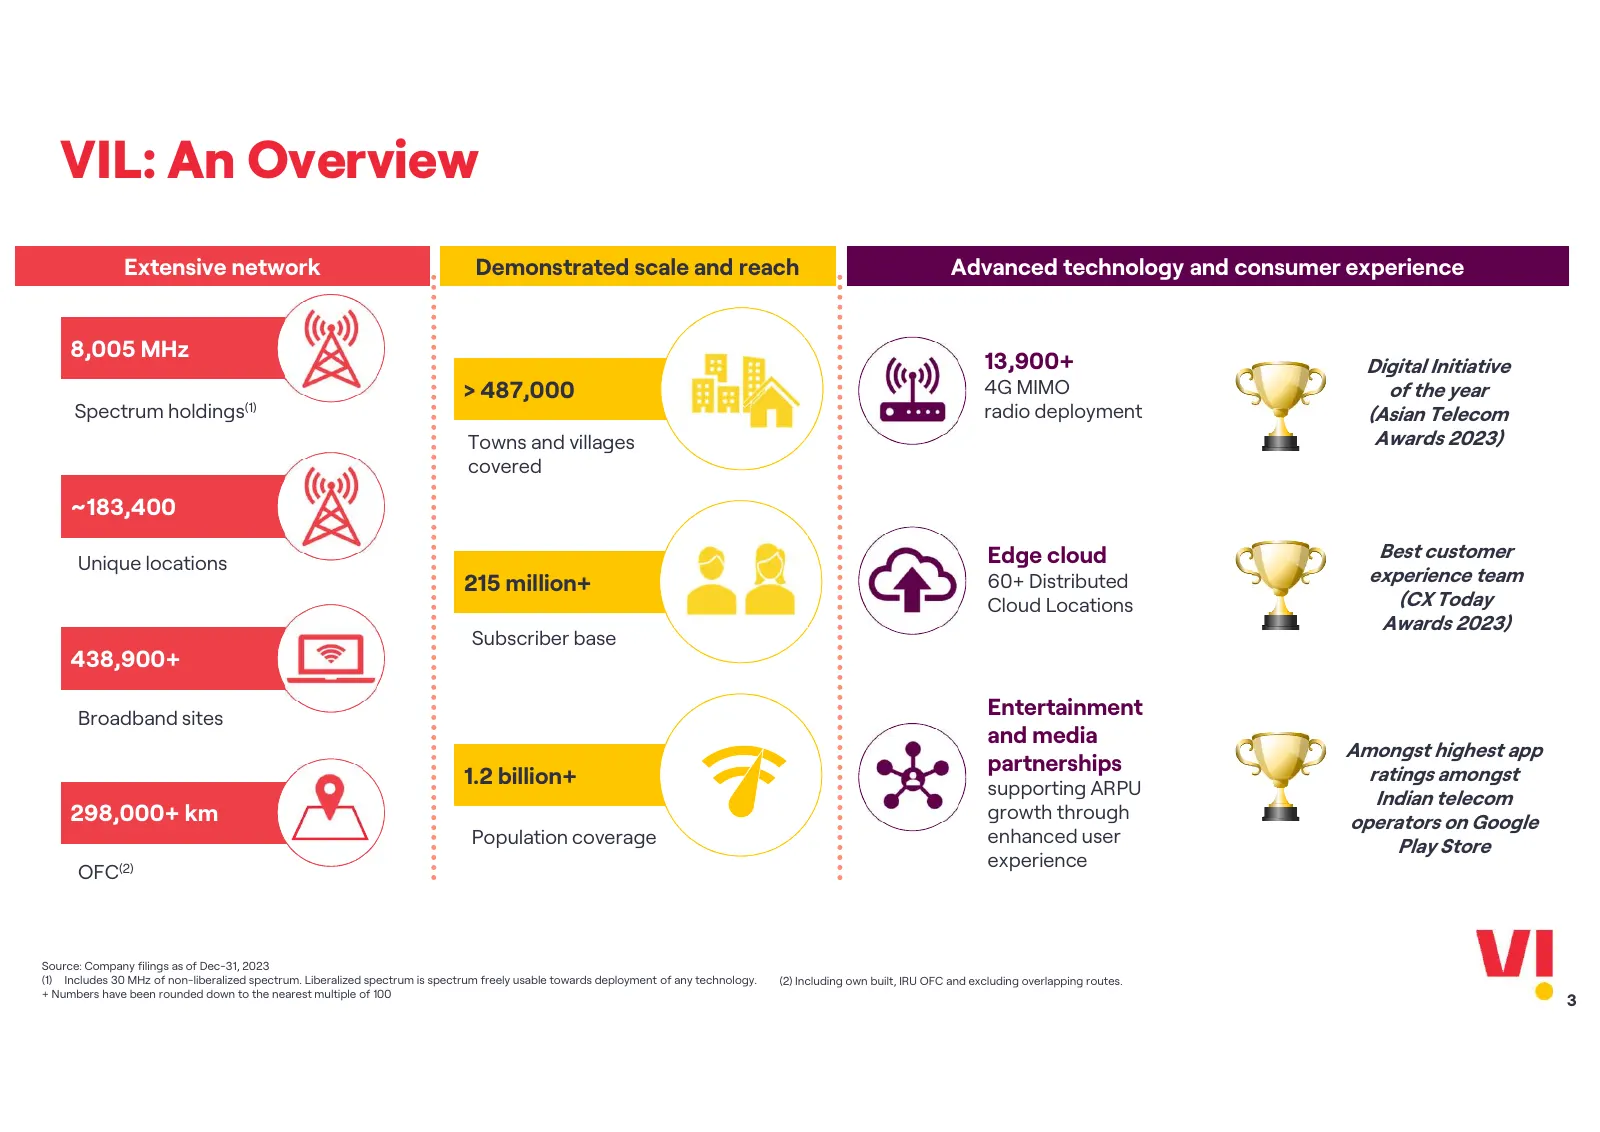
Slide 3: VIL: An Overview
VIL: An Overview Extensive network Demonstrated scale and reach Advanced technology and consumer experience 8,005 MHz 13,900+ Digital Initiative > 487,000 4G MIMO of the year Spectrum holdings(1) radio deployment (Asian Telecom Towns and villages Awards 2023) covered ~183,400 Edge cloud Best custome
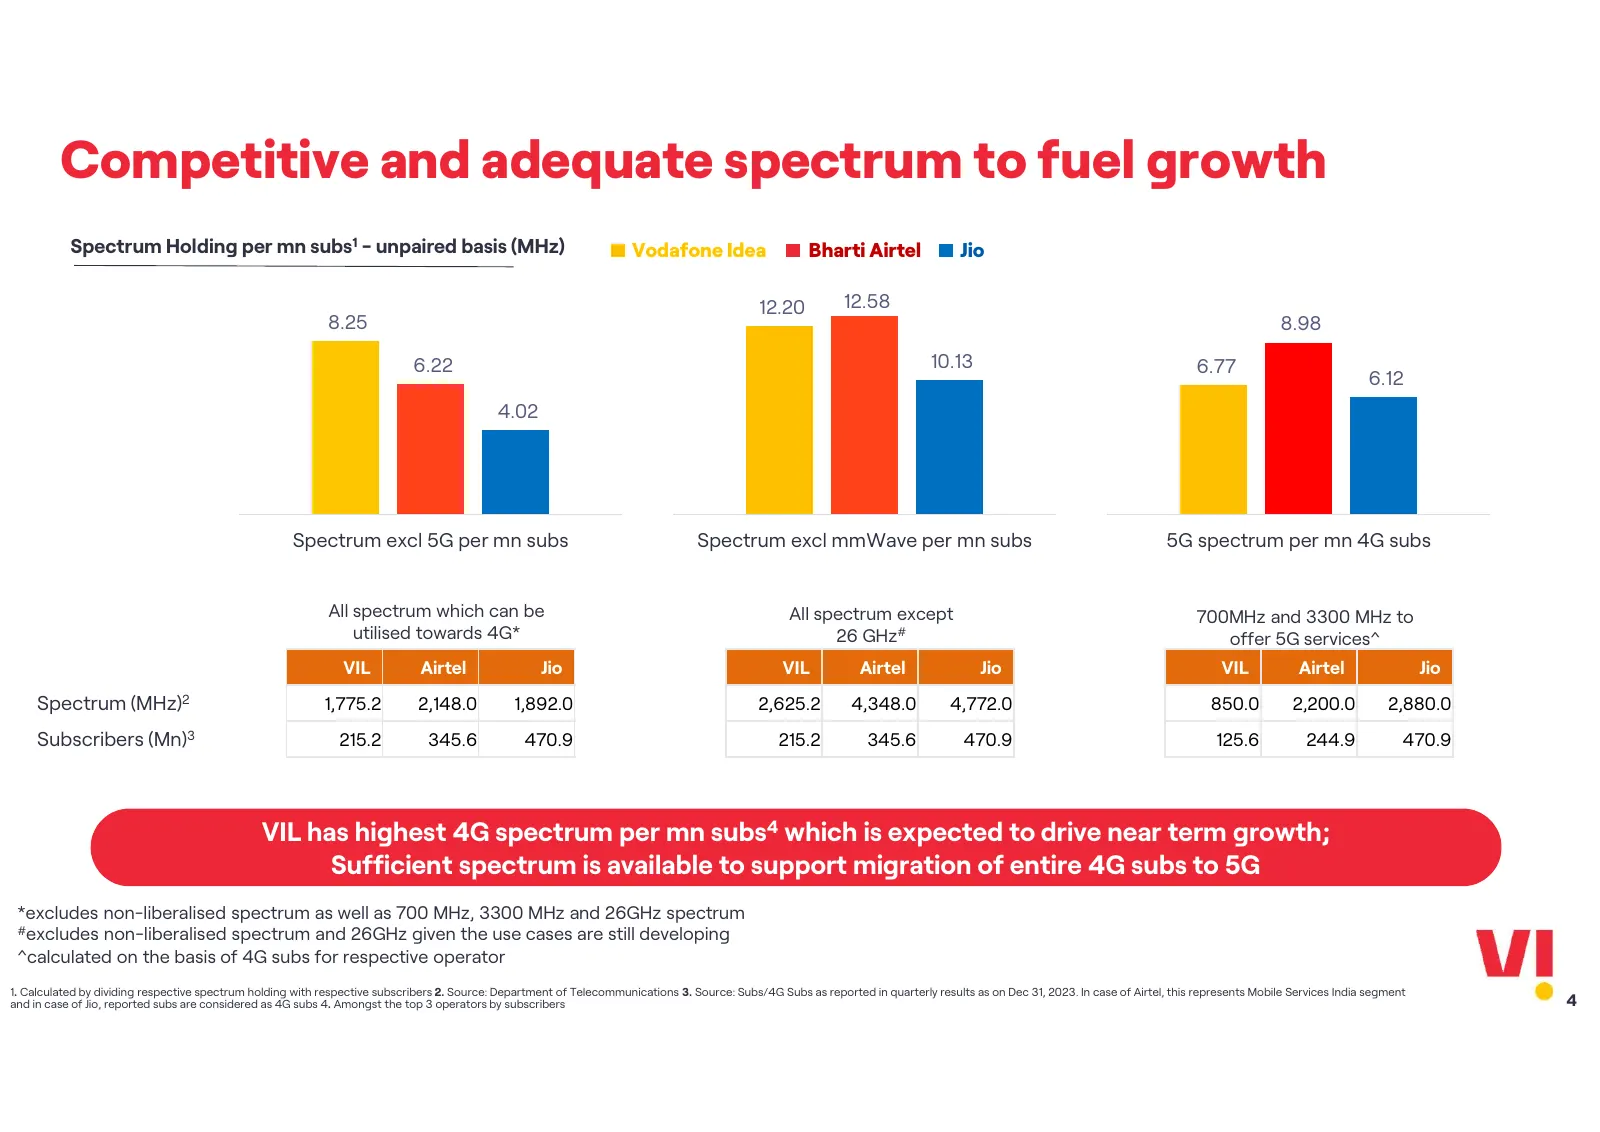
Slide 4: Competitive and adequate spectrum to fuel growth
Competitive and adequate spectrum to fuel growth Spectrum Holding per mn subs1 - unpaired basis (MHz) Vodafone Idea Bharti Airtel Jio 12.20 12.58 8.25 8.98 6.22 10.13 6.77 6.12 4.02 Spectrum excl 5G per mn subs Spectrum excl mmWave per mn subs 5G spectrum per mn 4G subs All spectrum which can be All
Slide 5: Trusted brand with strong proposition
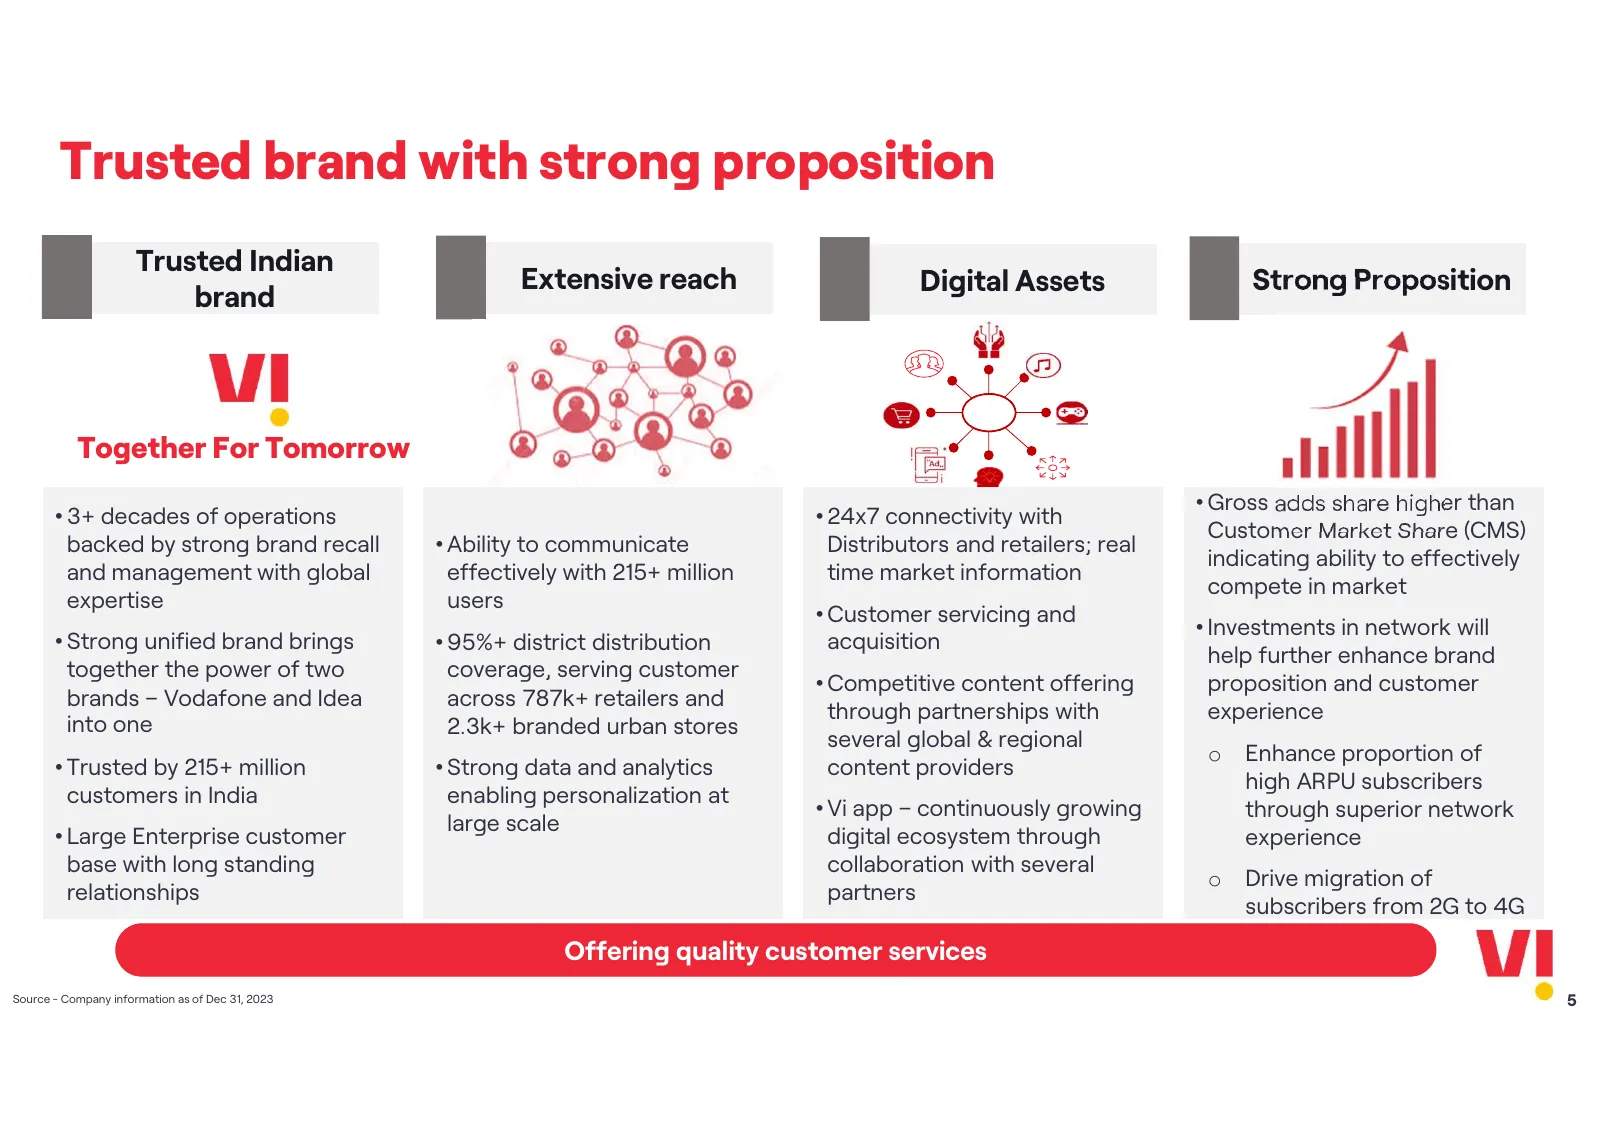
Trusted brand with strong proposition Trusted Indian Extensive reach Digital Assets Strong Proposition brand Together For Tomorrow • Gross adds share higher than • 3+ decades of operations • 24x7 connectivity with Customer Market Share (CMS) backed by strong brand recall • Ability to communicate Dis
Slide 6: Strong Promoters and Support from GOI
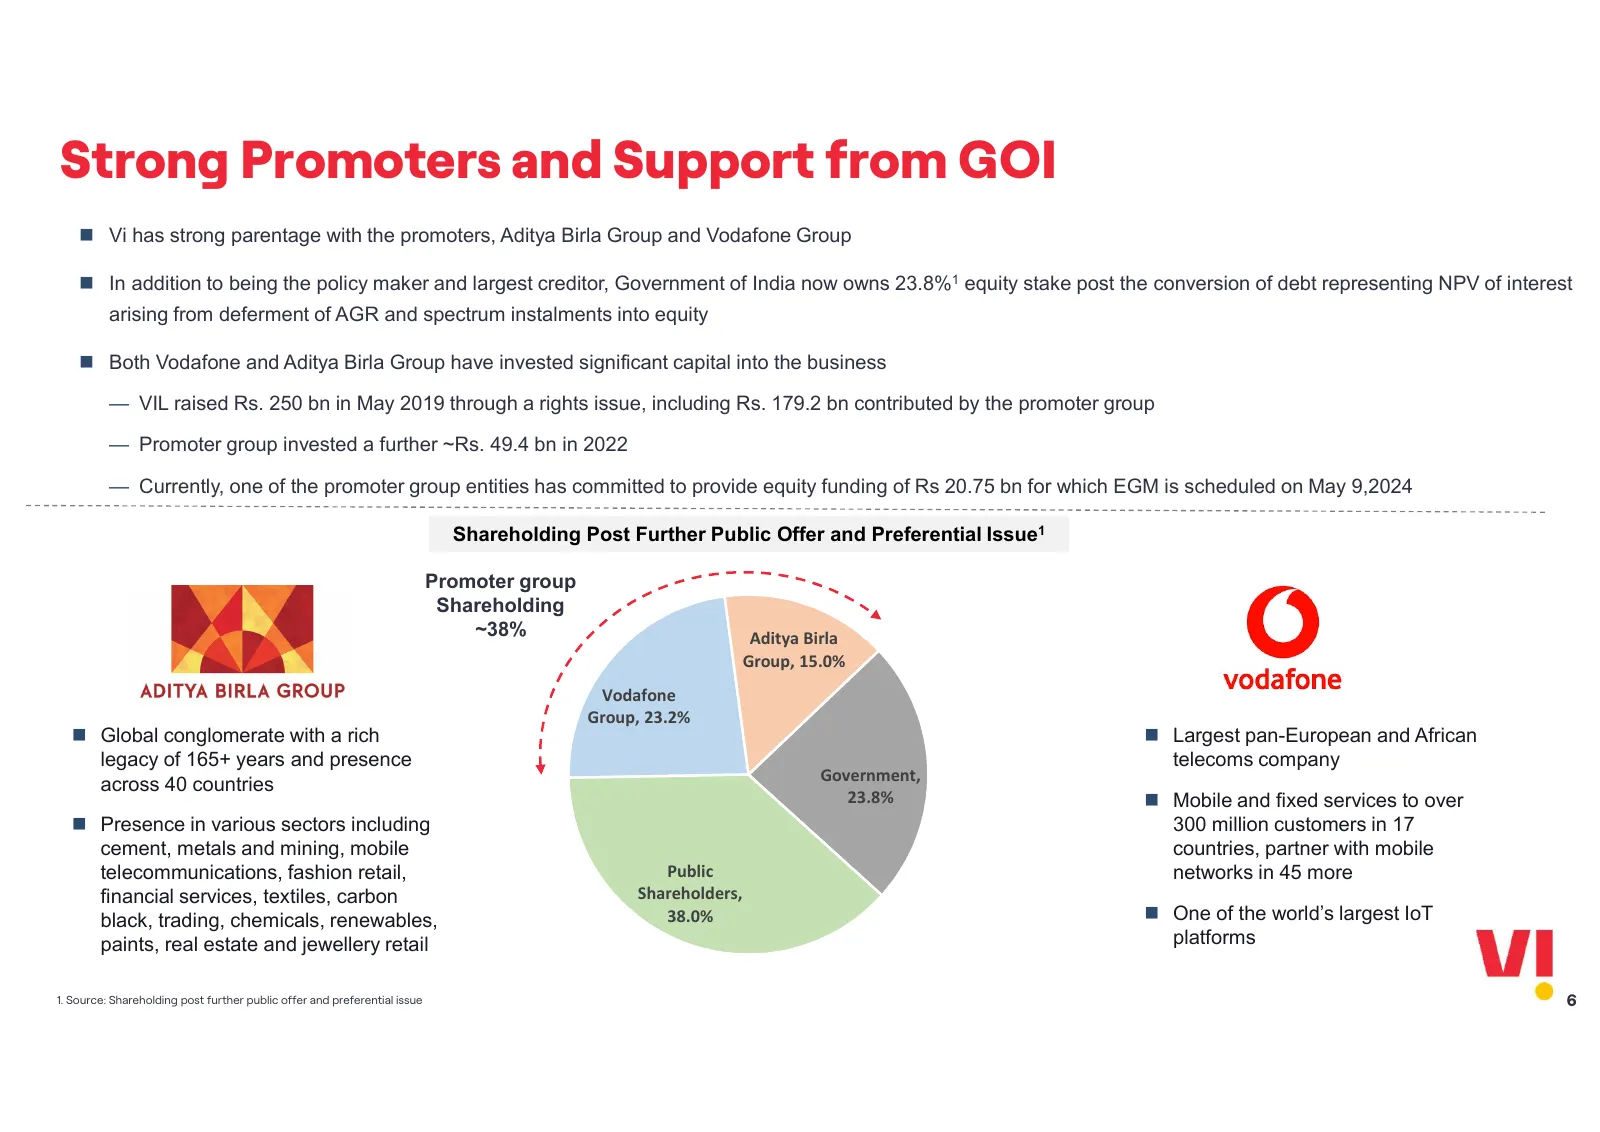
Strong Promoters and Support from GOI Vi has strong parentage with the promoters, Aditya Birla Group and Vodafone Group In addition to being the policy maker and largest creditor, Government of India now owns 23.8%1 equity stake post the conversion of debt representing NPV of interest arising fr
Slide 7: Growth Opportunities
Growth Opportunities 7
Slide 8: Growth potential in the Indian telecom sector (1/2)
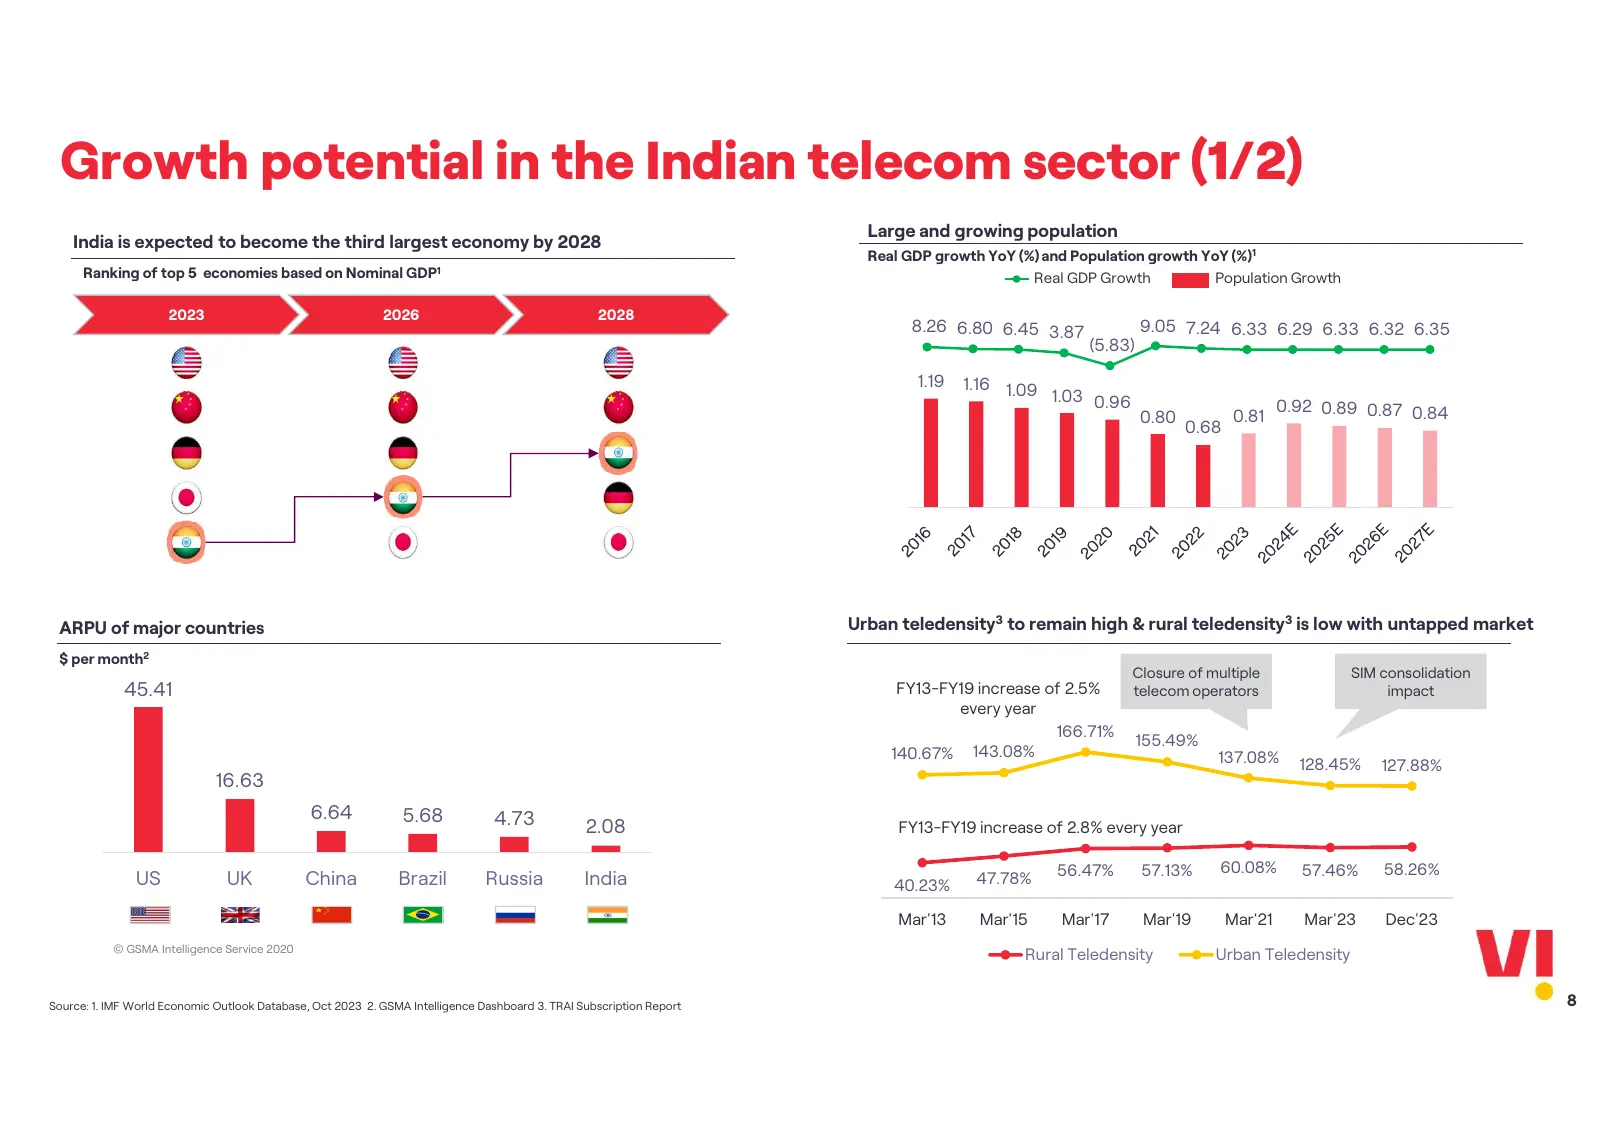
Growth potential in the Indian telecom sector (1/2) Large and growing population India is expected to become the third largest economy by 2028 Real GDP growth YoY (%) and Population growth YoY (%)1 Ranking of top 5 economies based on Nominal GDP1 Real GDP Growth Population Growth 2023 2026 2028 8.26
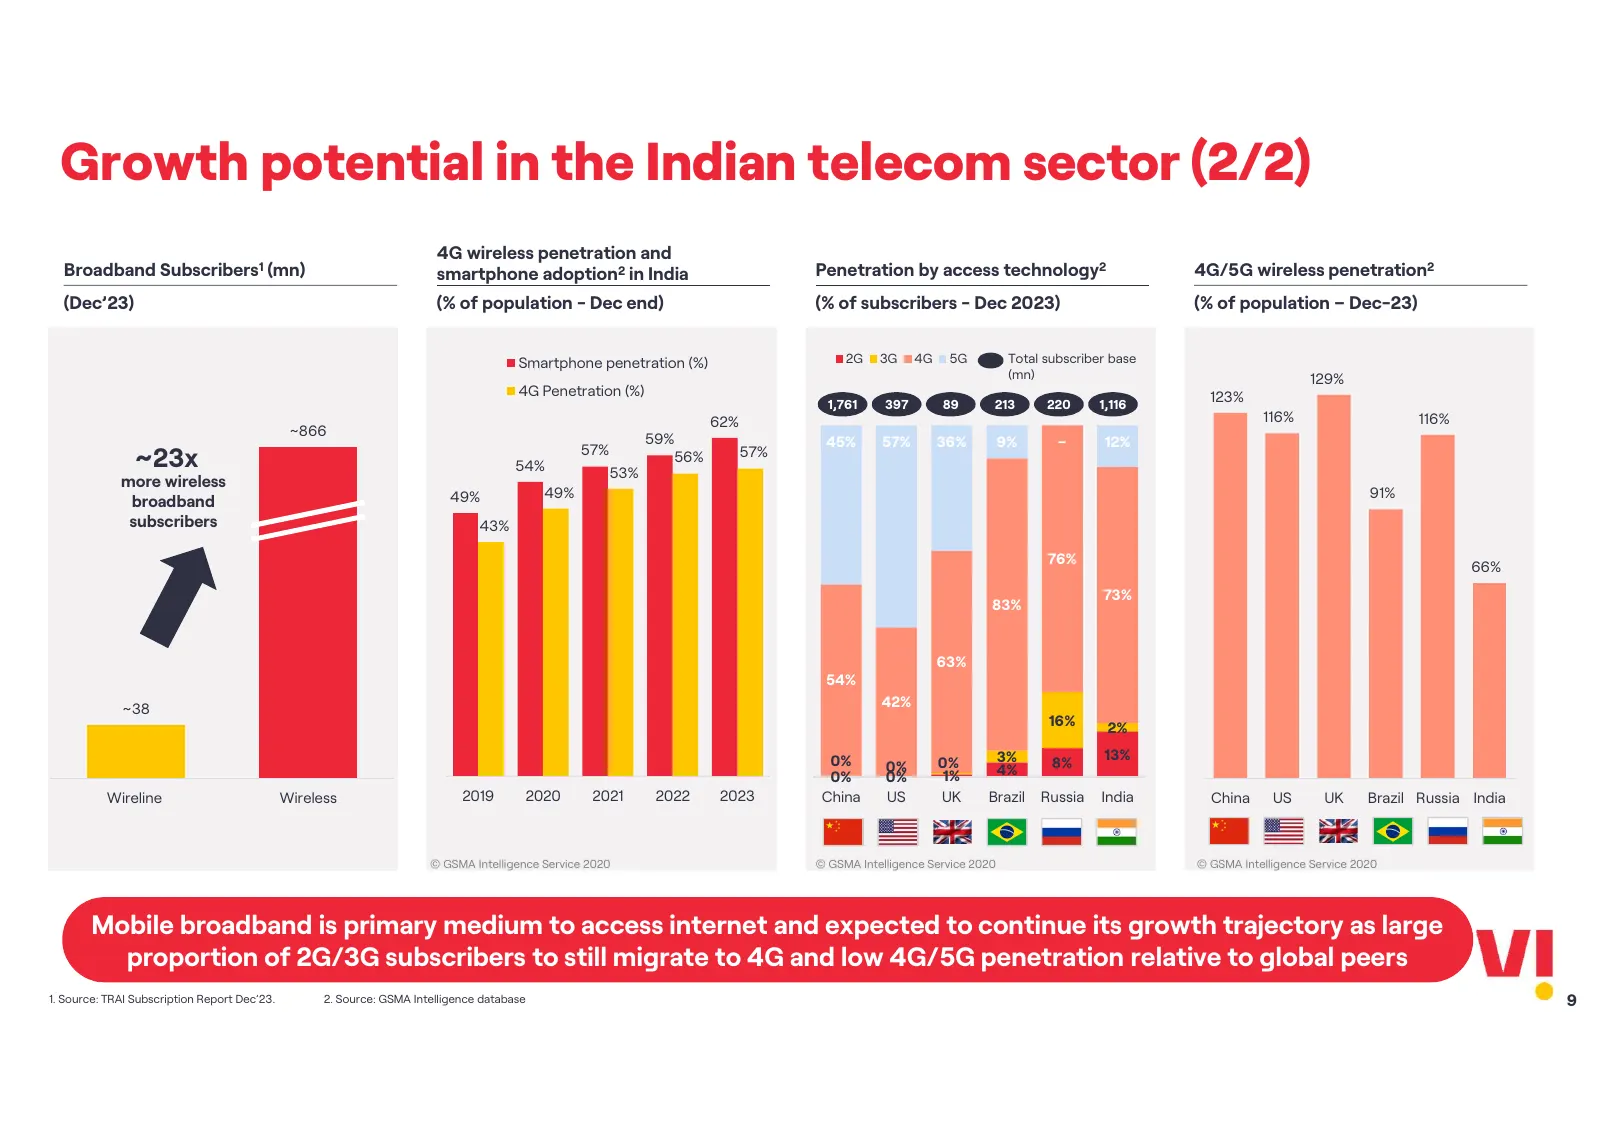
Slide 9: Growth potential in the Indian telecom sector (2/2)
Growth potential in the Indian telecom sector (2/2) 4G wireless penetration and Broadband Subscribers1 (mn) smartphone adoption2 in India Penetration by access technology2 4G/5G wireless penetration2 (Dec’23) (% of population - Dec end) (% of subscribers - Dec 2023) (% of population – Dec-23) Smartp
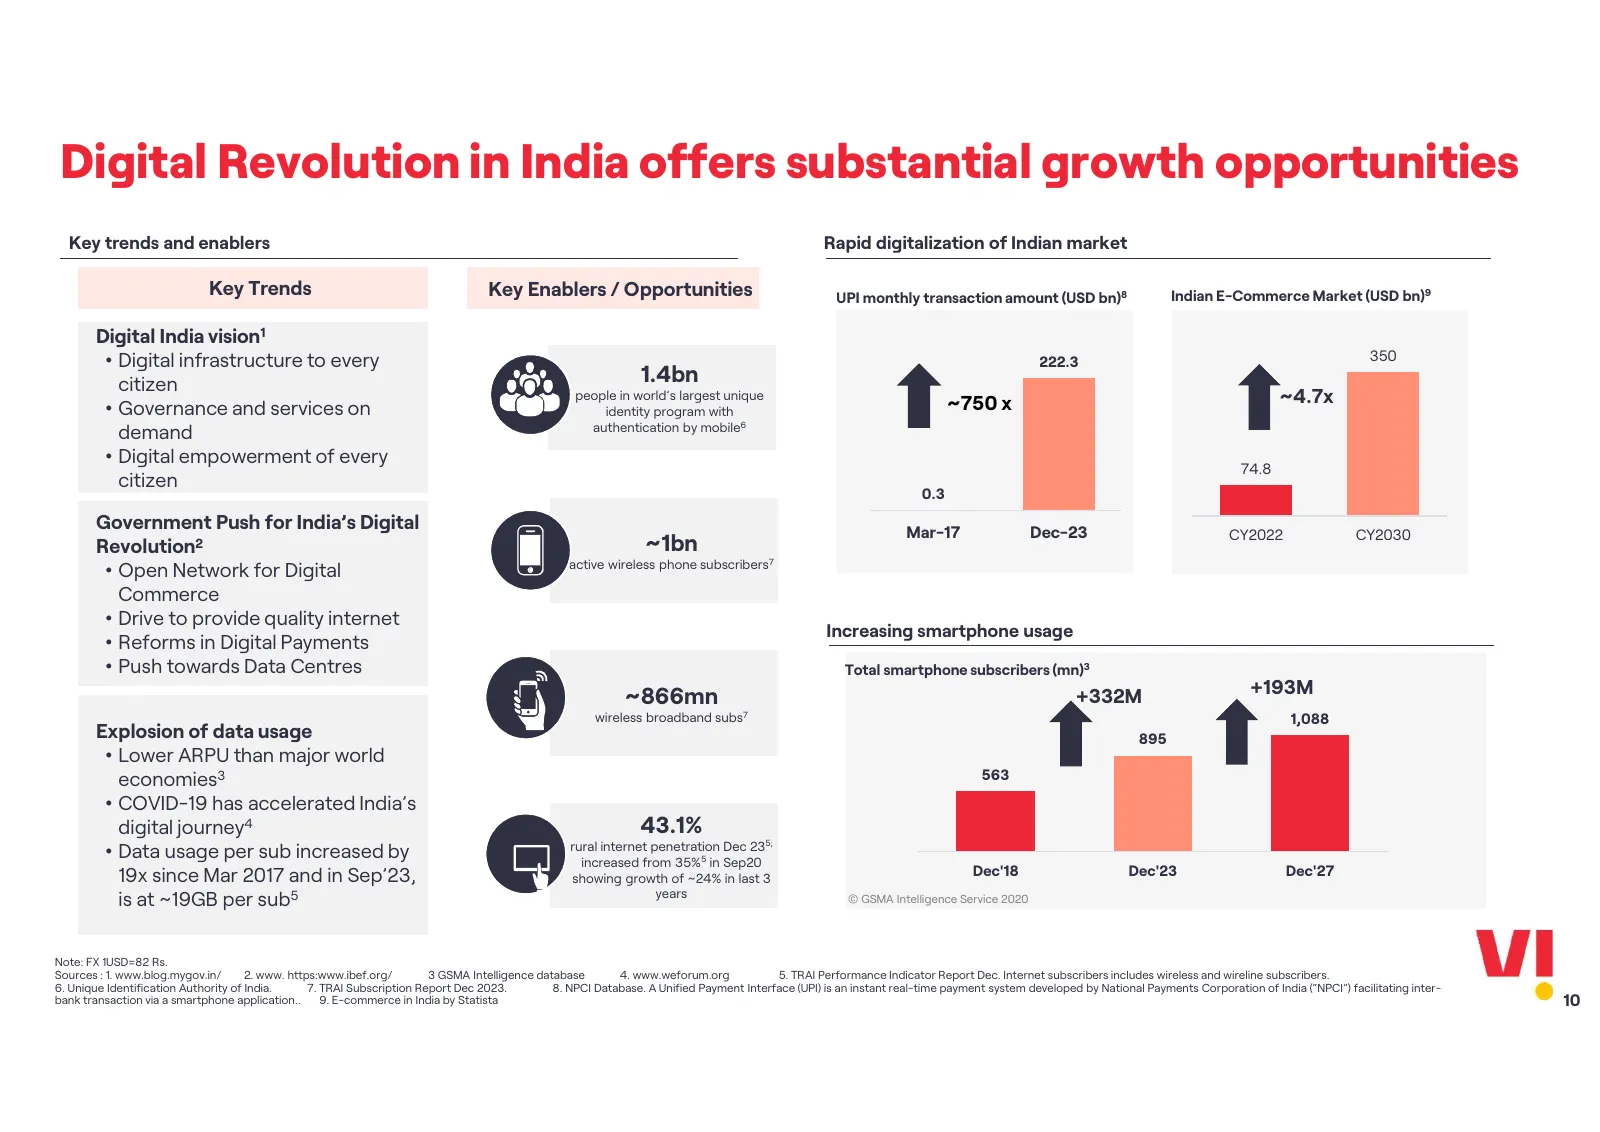
Slide 10: Digital Revolution in India offers substantial growth opportunities
Digital Revolution in India offers substantial growth opportunities Key trends and enablers Rapid digitalization of Indian market Key Trends Key Enablers / Opportunities UPI monthly transaction amount (USD bn)8 Indian E-Commerce Market (USD bn)9 Digital India vision1 • Digital infrastructure to ever
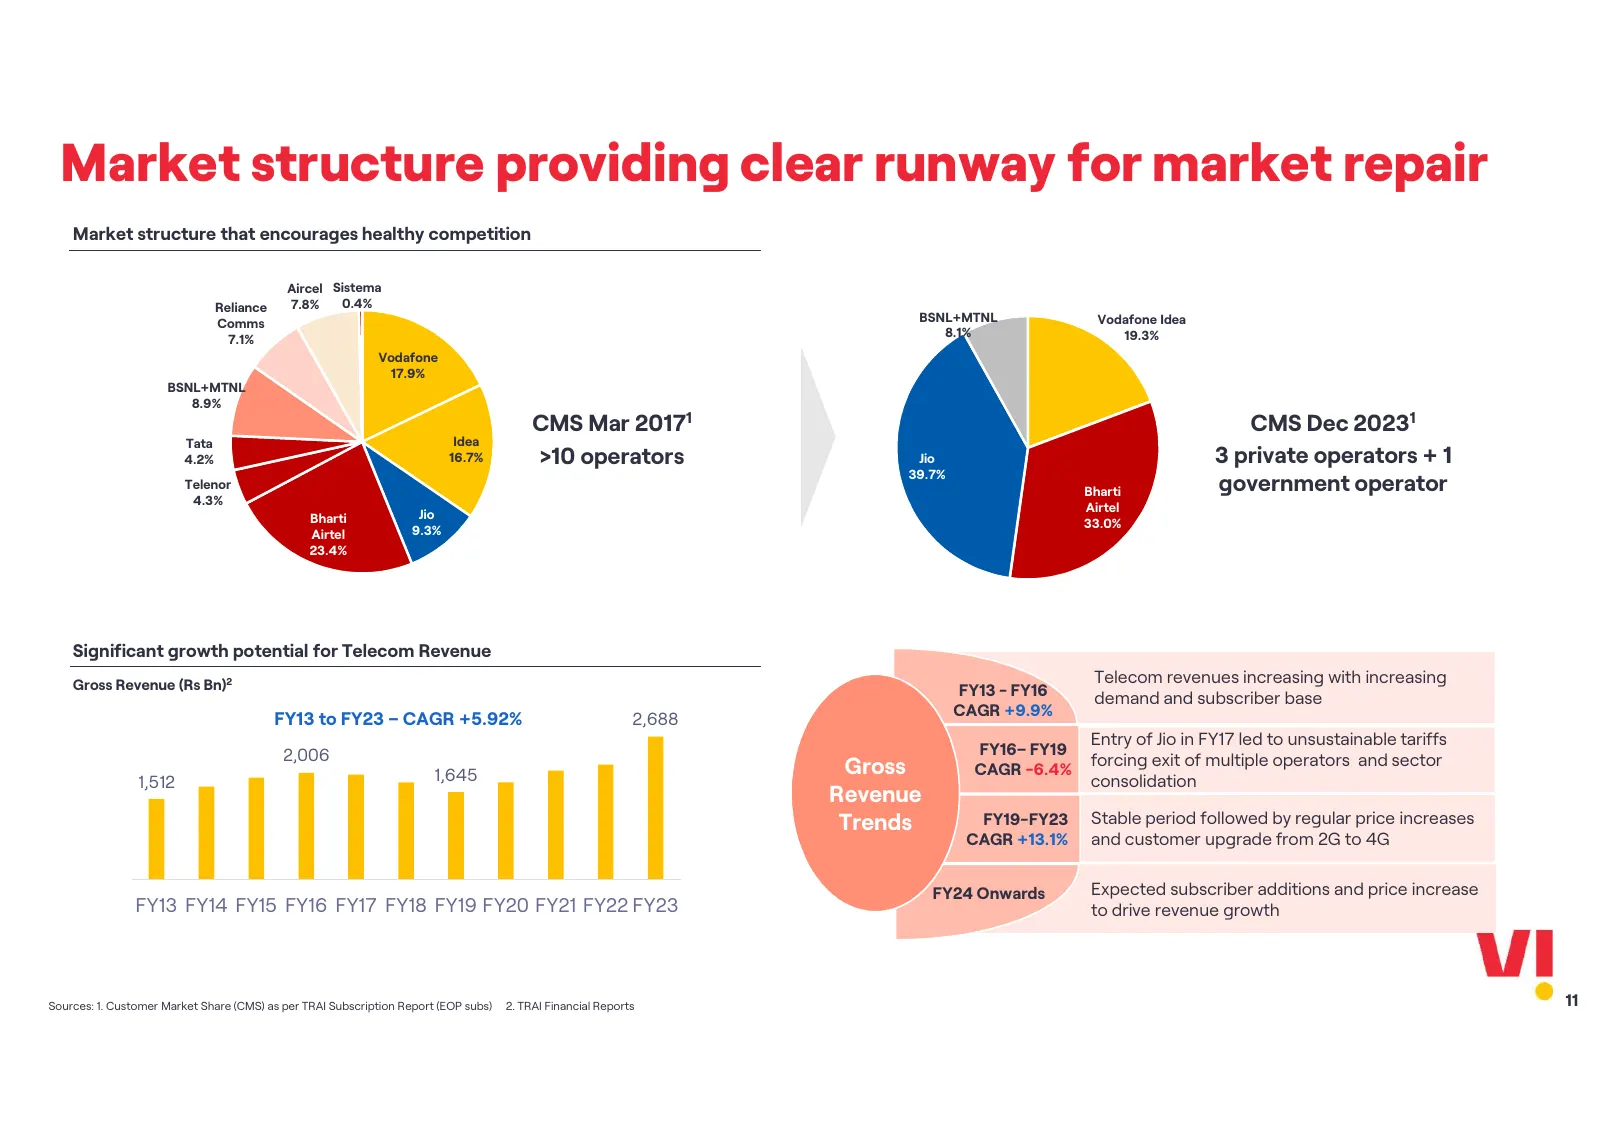
Slide 11: Market structure providing clear runway for market repair
Market structure providing clear runway for market repair Market structure that encourages healthy competition Aircel Sistema Reliance 7.8% 0.4% BSNL+MTNL Vodafone Idea Comms 8.1% 19.3% 7.1% Vodafone 17.9% BSNL+MTNL 8.9% CMS Mar 20171 CMS Dec 20231 Tata Idea 4.2% 16.7% >10 operators Jio 3 private op
Slide 12: VIL Strategy
VIL Strategy 12
Slide 13: Vodafone Idea Strategy
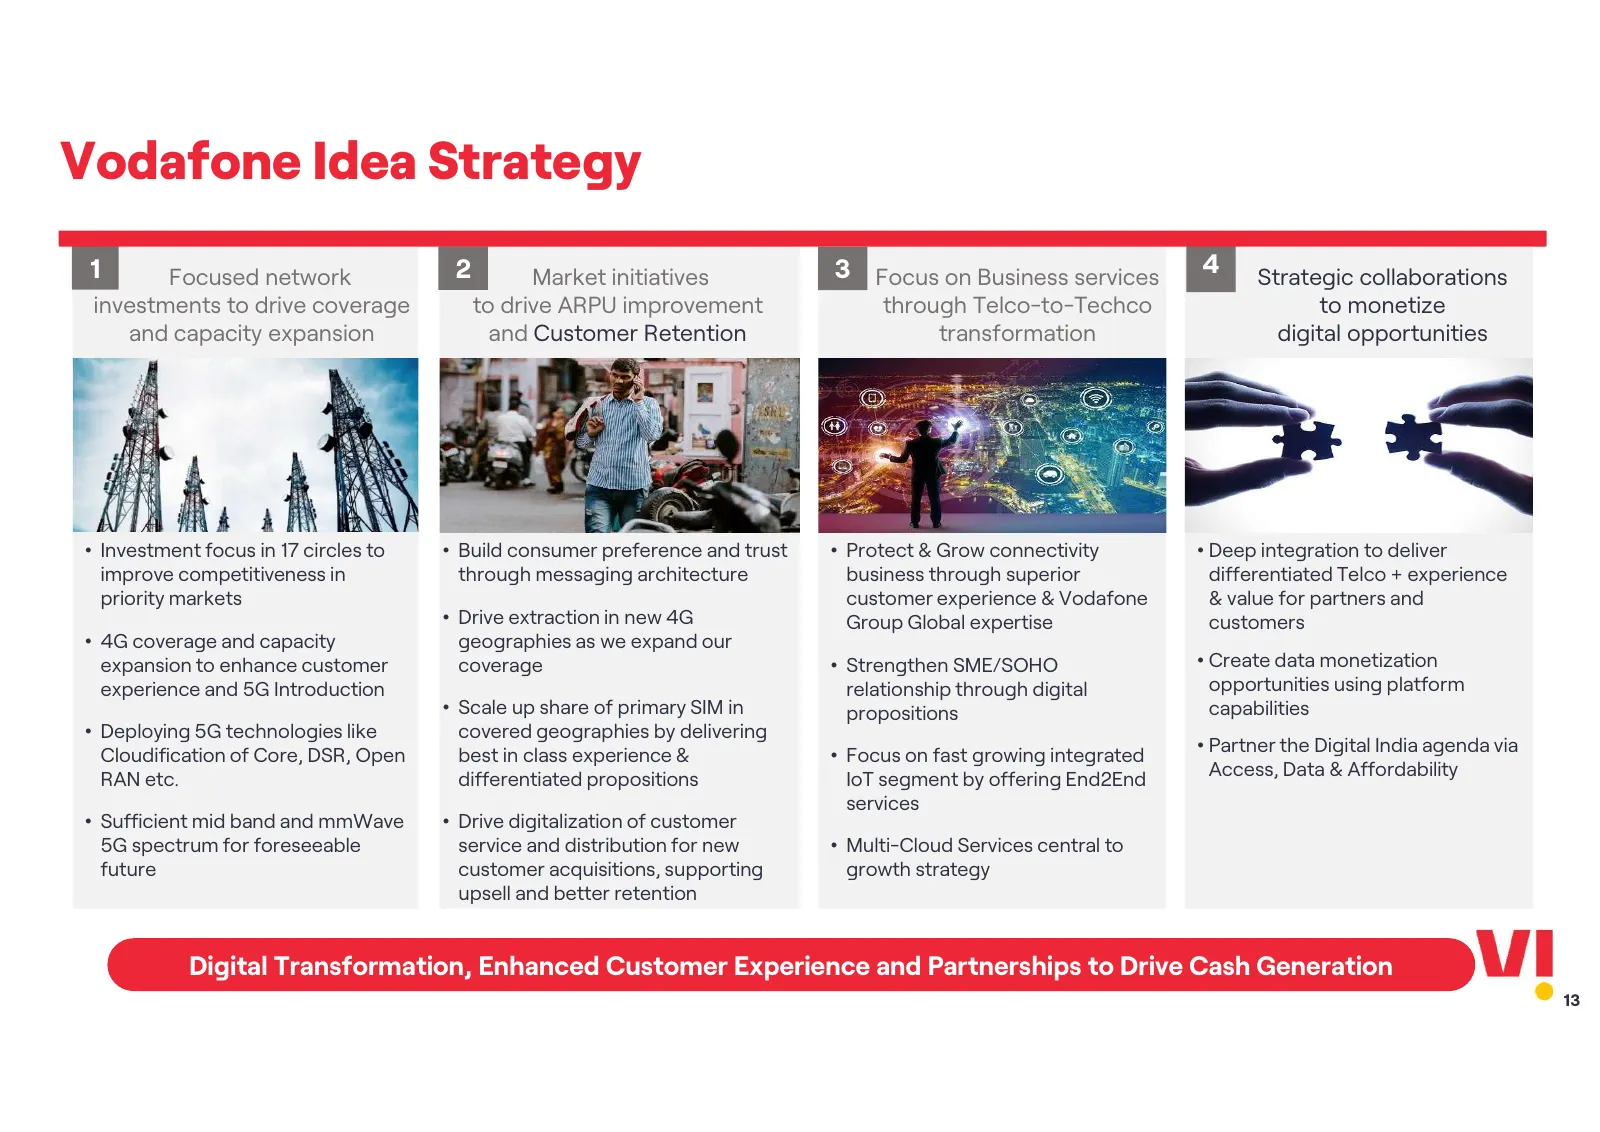
Vodafone Idea Strategy 1 Focused network 2 Market initiatives 3 Focus on Business services 4 Strategic collaborations investments to drive coverage to drive ARPU improvement through Telco-to-Techco to monetize and capacity expansion and Customer Retention transformation digital opportunities • Inves
Slide 14: Focused investments to drive coverage & capacity expansion
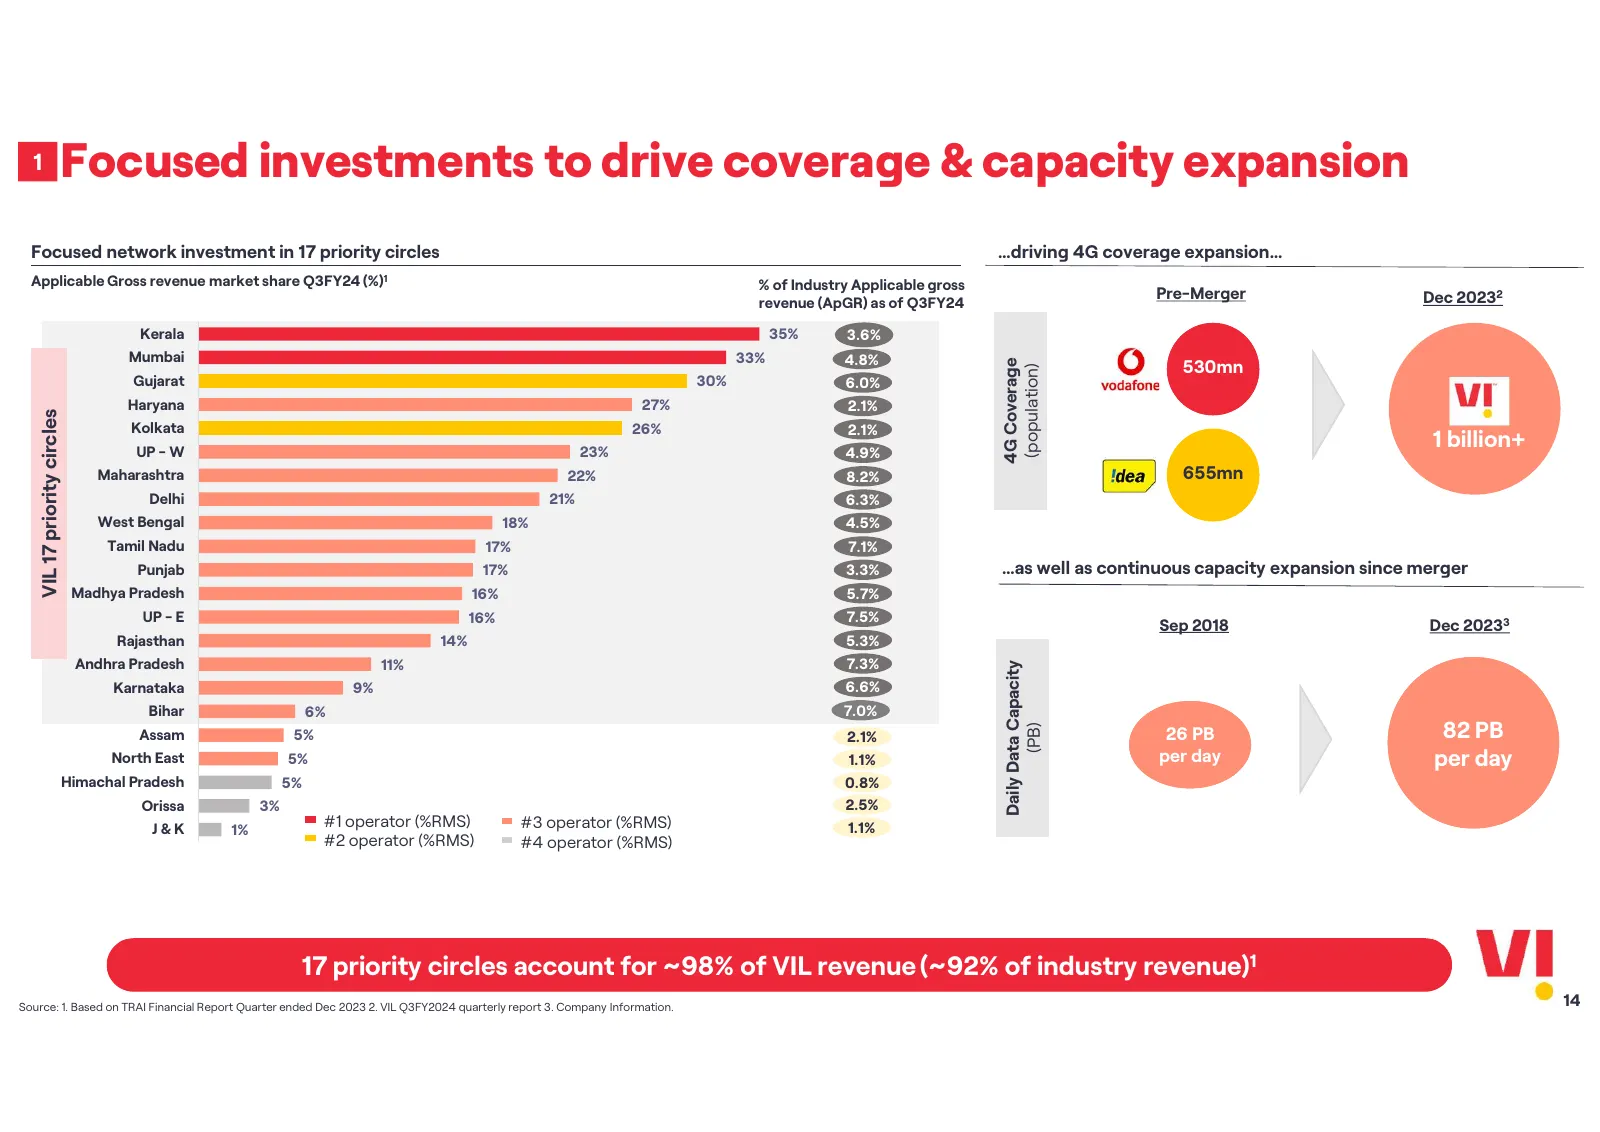
1 Focused investments to drive coverage & capacity expansion Focused network investment in 17 priority circles …driving 4G coverage expansion… Applicable Gross revenue market share Q3FY24 (%)1 % of Industry Applicable gross Pre-Merger Dec 20232 revenue (ApGR) as of Q3FY24 Kerala 35% 3.6% Mumbai 33%
Slide 15: Focused investments in priority circles
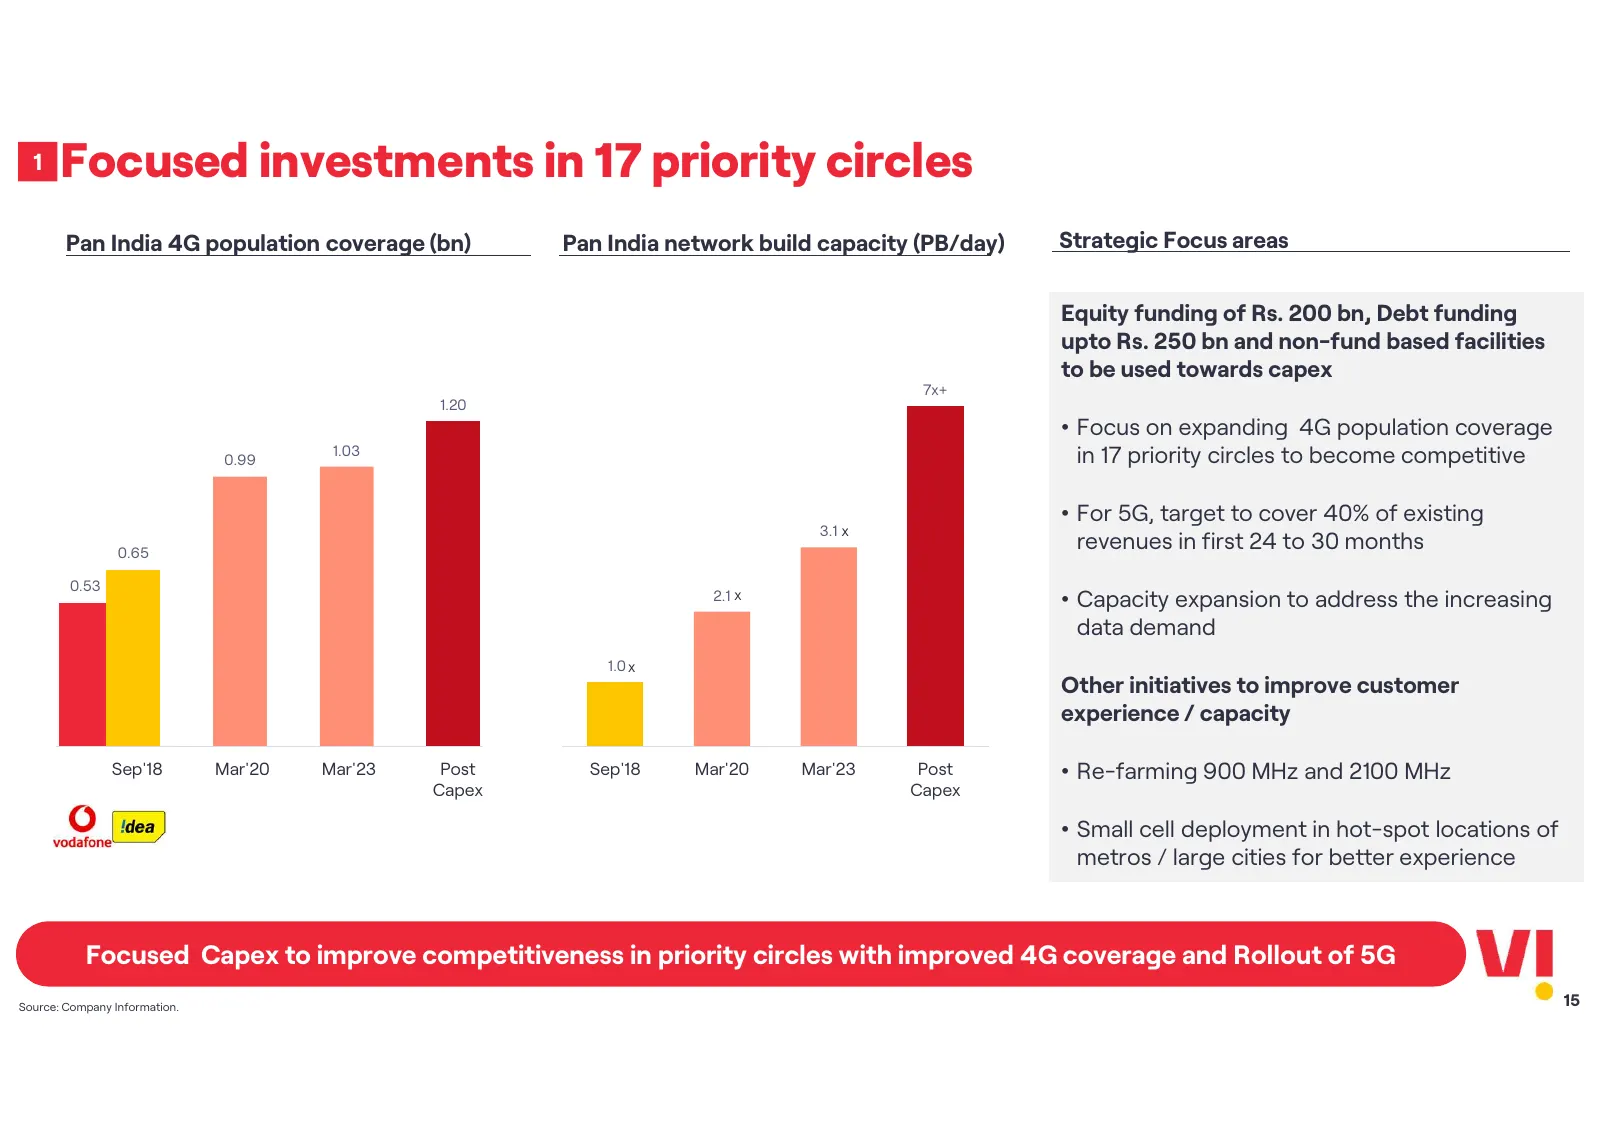
1 Focused investments in 17 priority circles Pan India 4G population coverage (bn) Pan India network build capacity (PB/day) Strategic Focus areas Equity funding of Rs. 200 bn, Debt funding upto Rs. 250 bn and non-fund based facilities to be used towards capex 7x+ 1.20 • Focus on expanding 4G popula
Slide 16: Existing network built on 5G-ready architecture
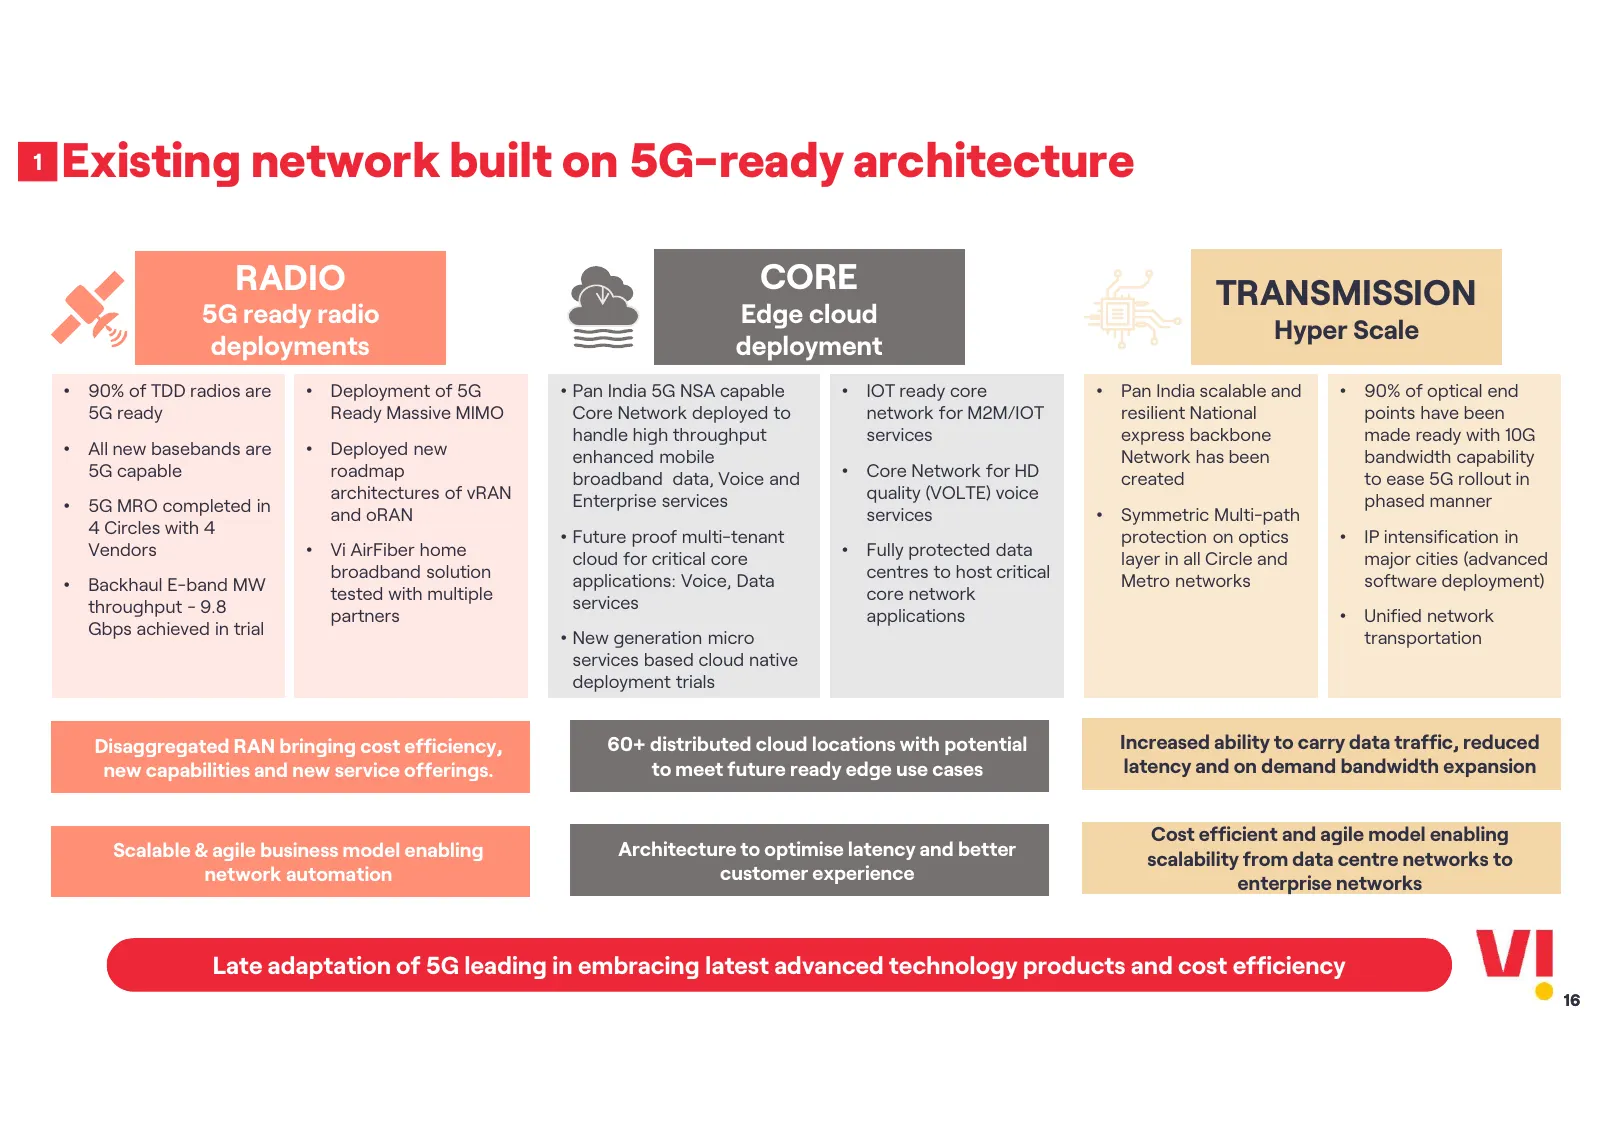
1 Existing network built on 5G-ready architecture RADIO CORE TRANSMISSION 5G ready radio Edge cloud Hyper Scale deployments deployment • 90% of TDD radios are • Deployment of 5G • Pan India 5G NSA capable • IOT ready core • Pan India scalable and • 90% of optical end 5G ready Ready Massive MIMO Core
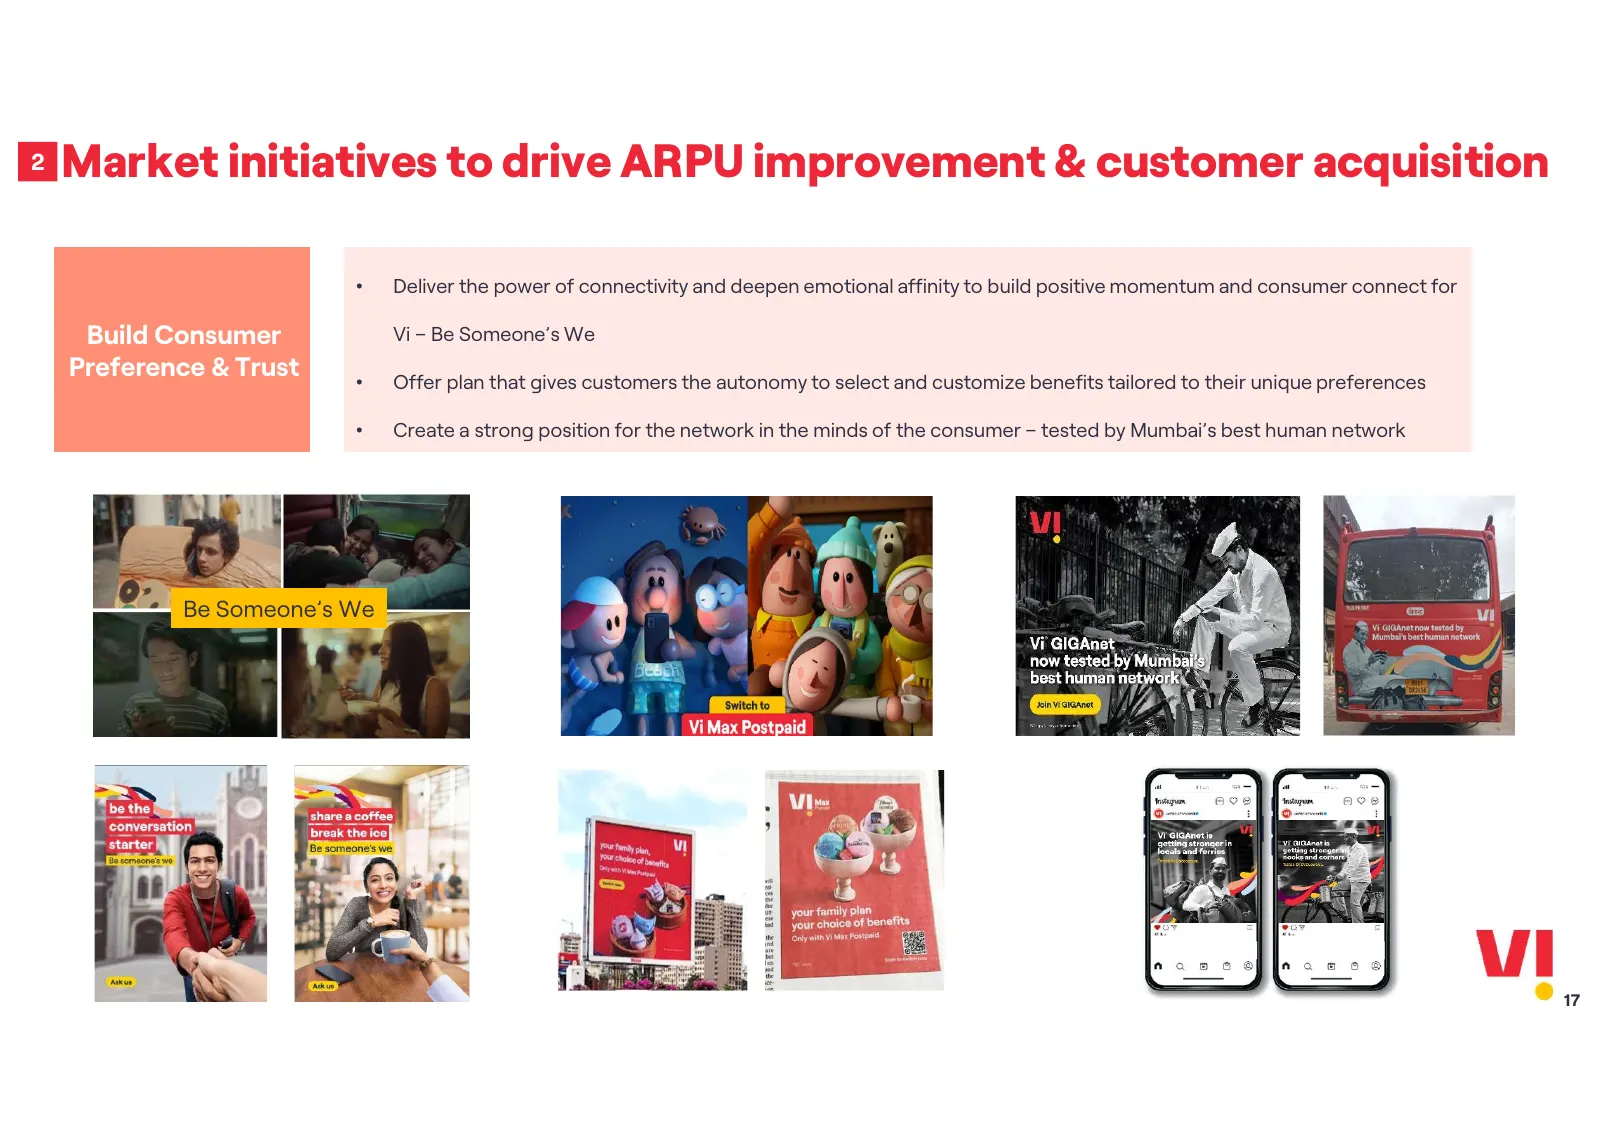
Slide 17: Market initiatives to drive ARPU improvement & customer acquisition
2 Market initiatives to drive ARPU improvement & customer acquisition • Deliver the power of connectivity and deepen emotional affinity to build positive momentum and consumer connect for Build Consumer Vi – Be Someone’s We Preference & Trust • Offer plan that gives customers the autonomy to select
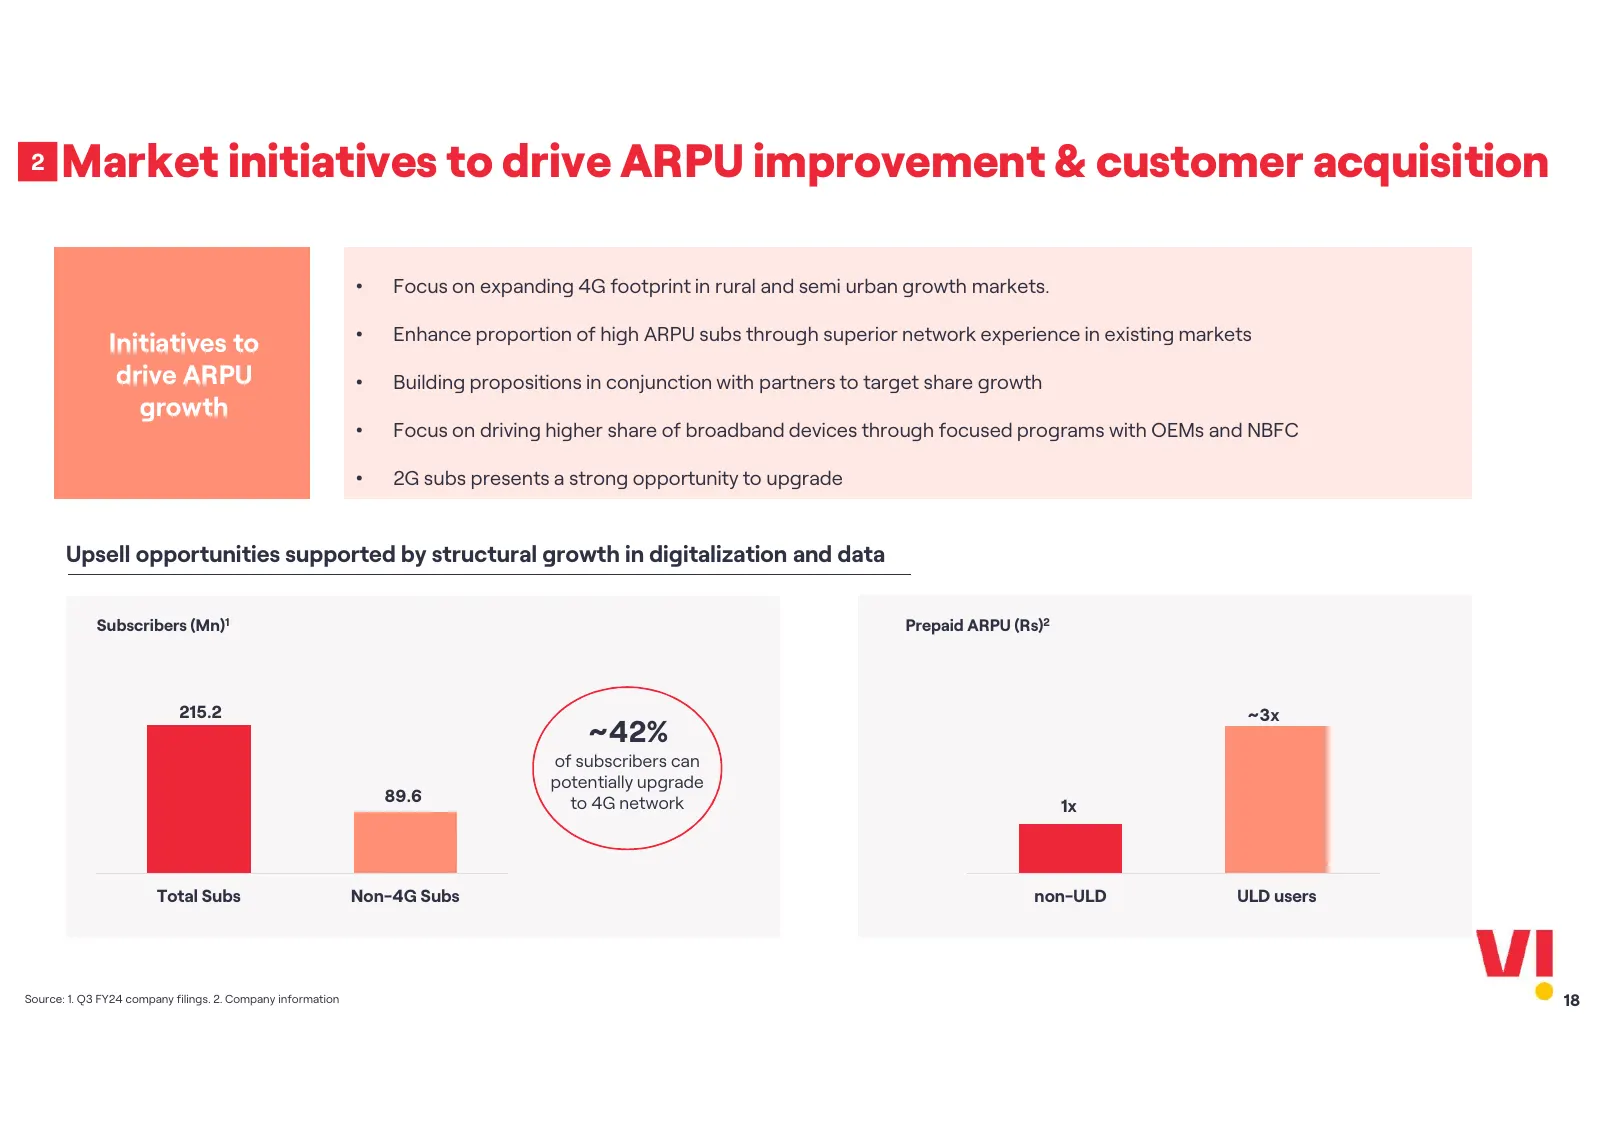
Slide 18: Market initiatives to drive ARPU improvement & customer acquisition
2 Market initiatives to drive ARPU improvement & customer acquisition • Focus on expanding 4G footprint in rural and semi urban growth markets. • Enhance proportion of high ARPU subs through superior network experience in existing markets Initiatives to drive ARPU • Building propositions in conjunct
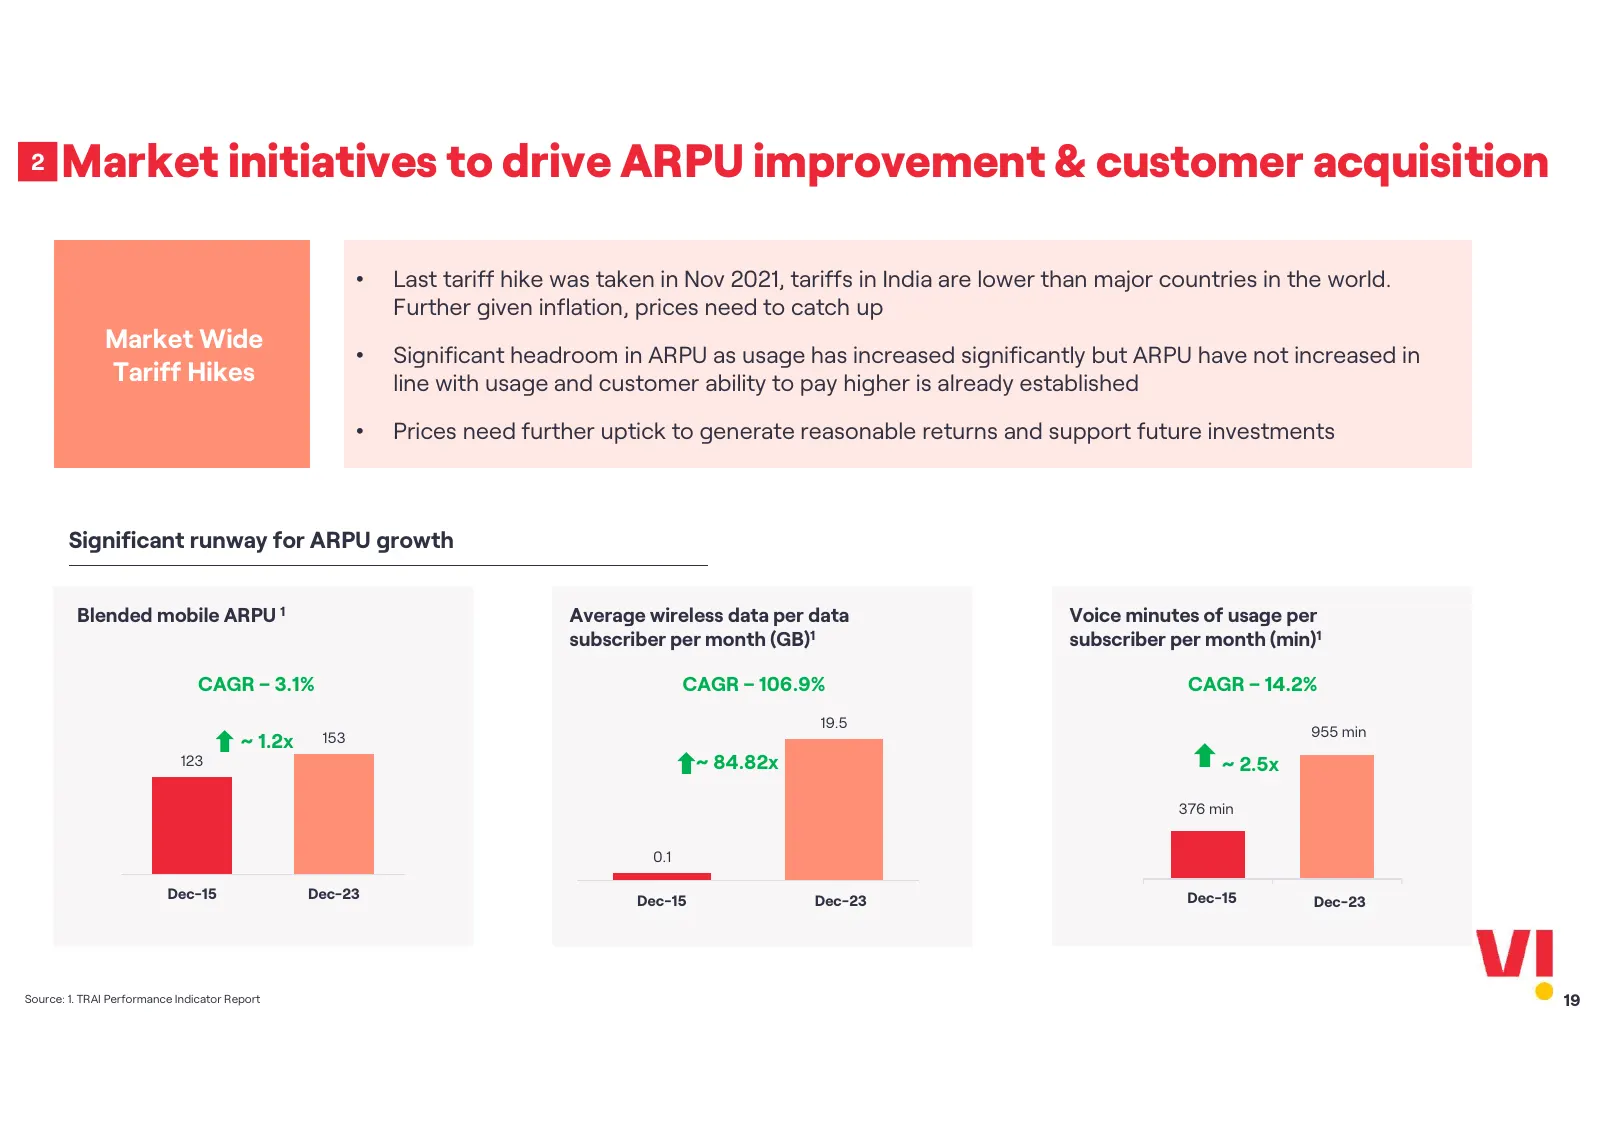
Slide 19: Market initiatives to drive ARPU improvement & customer acquisition
2 Market initiatives to drive ARPU improvement & customer acquisition • Last tariff hike was taken in Nov 2021, tariffs in India are lower than major countries in the world. Further given inflation, prices need to catch up Market Wide • Significant headroom in ARPU as usage has increased significant
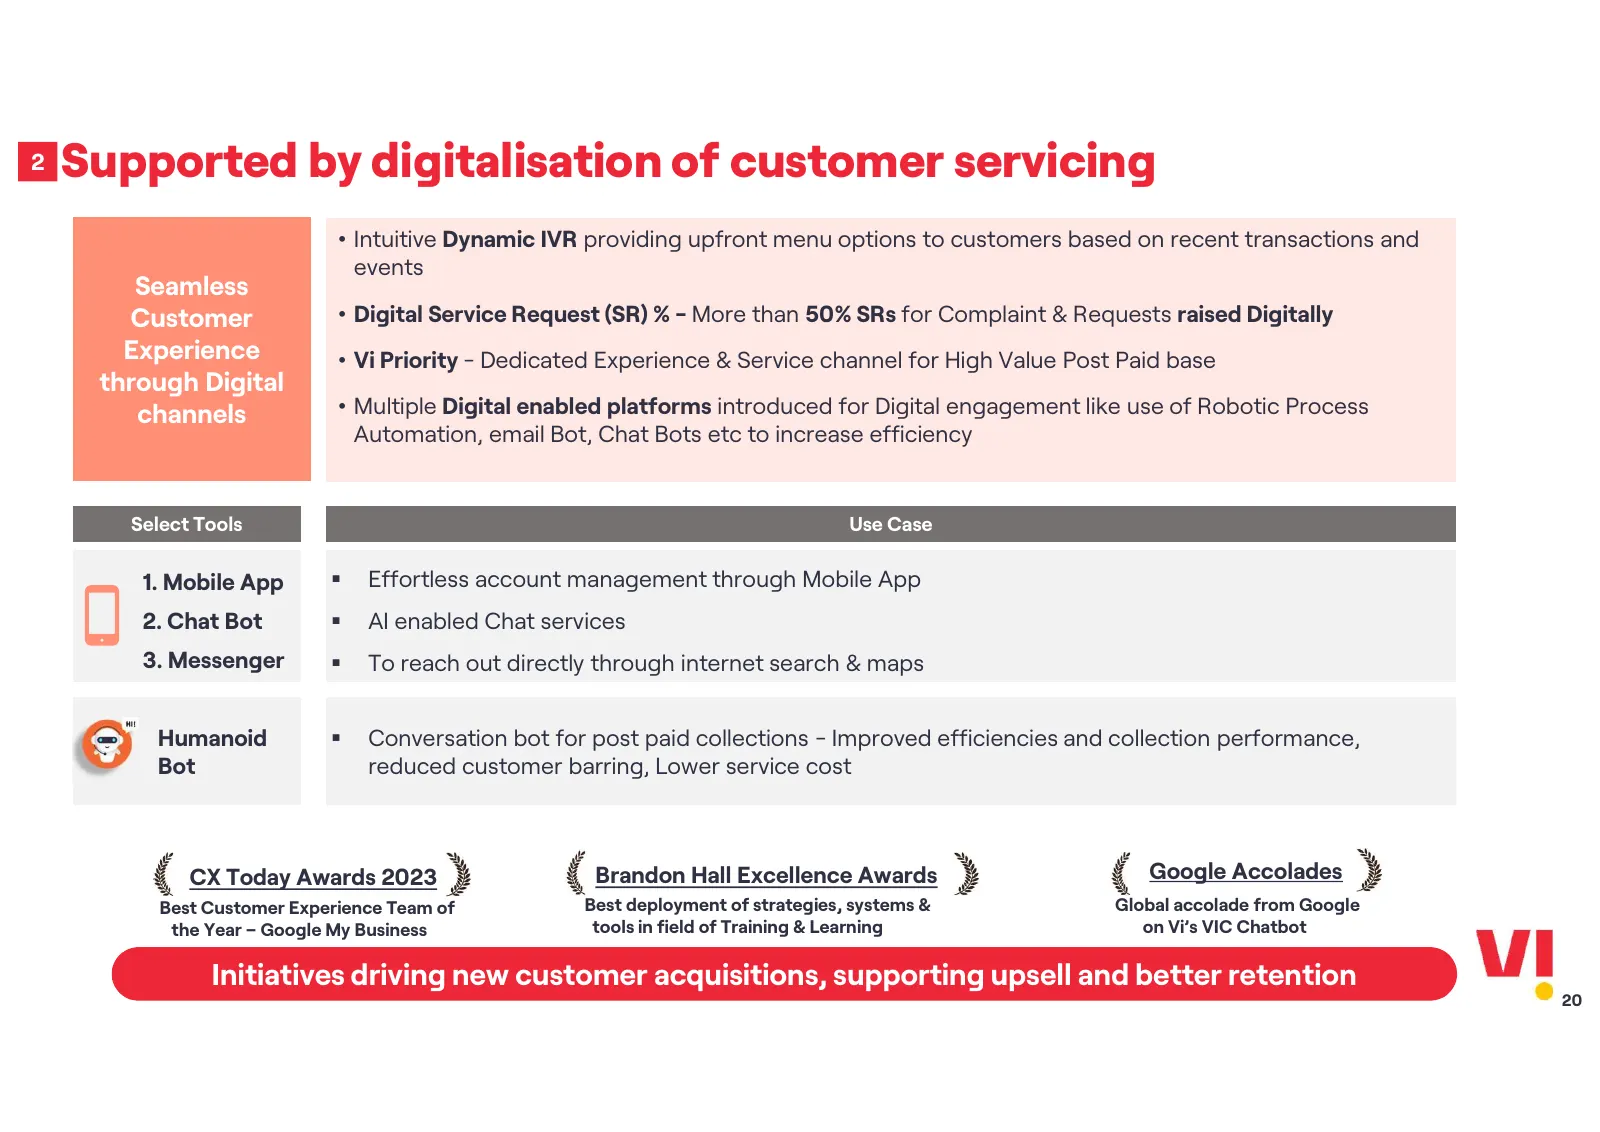
Slide 20: Supported by digitalisation of customer servicing
2 Supported by digitalisation of customer servicing • Intuitive Dynamic IVR providing upfront menu options to customers based on recent transactions and events Seamless Customer • Digital Service Request (SR) % - More than 50% SRs for Complaint & Requests raised Digitally Experience • Vi Priority -
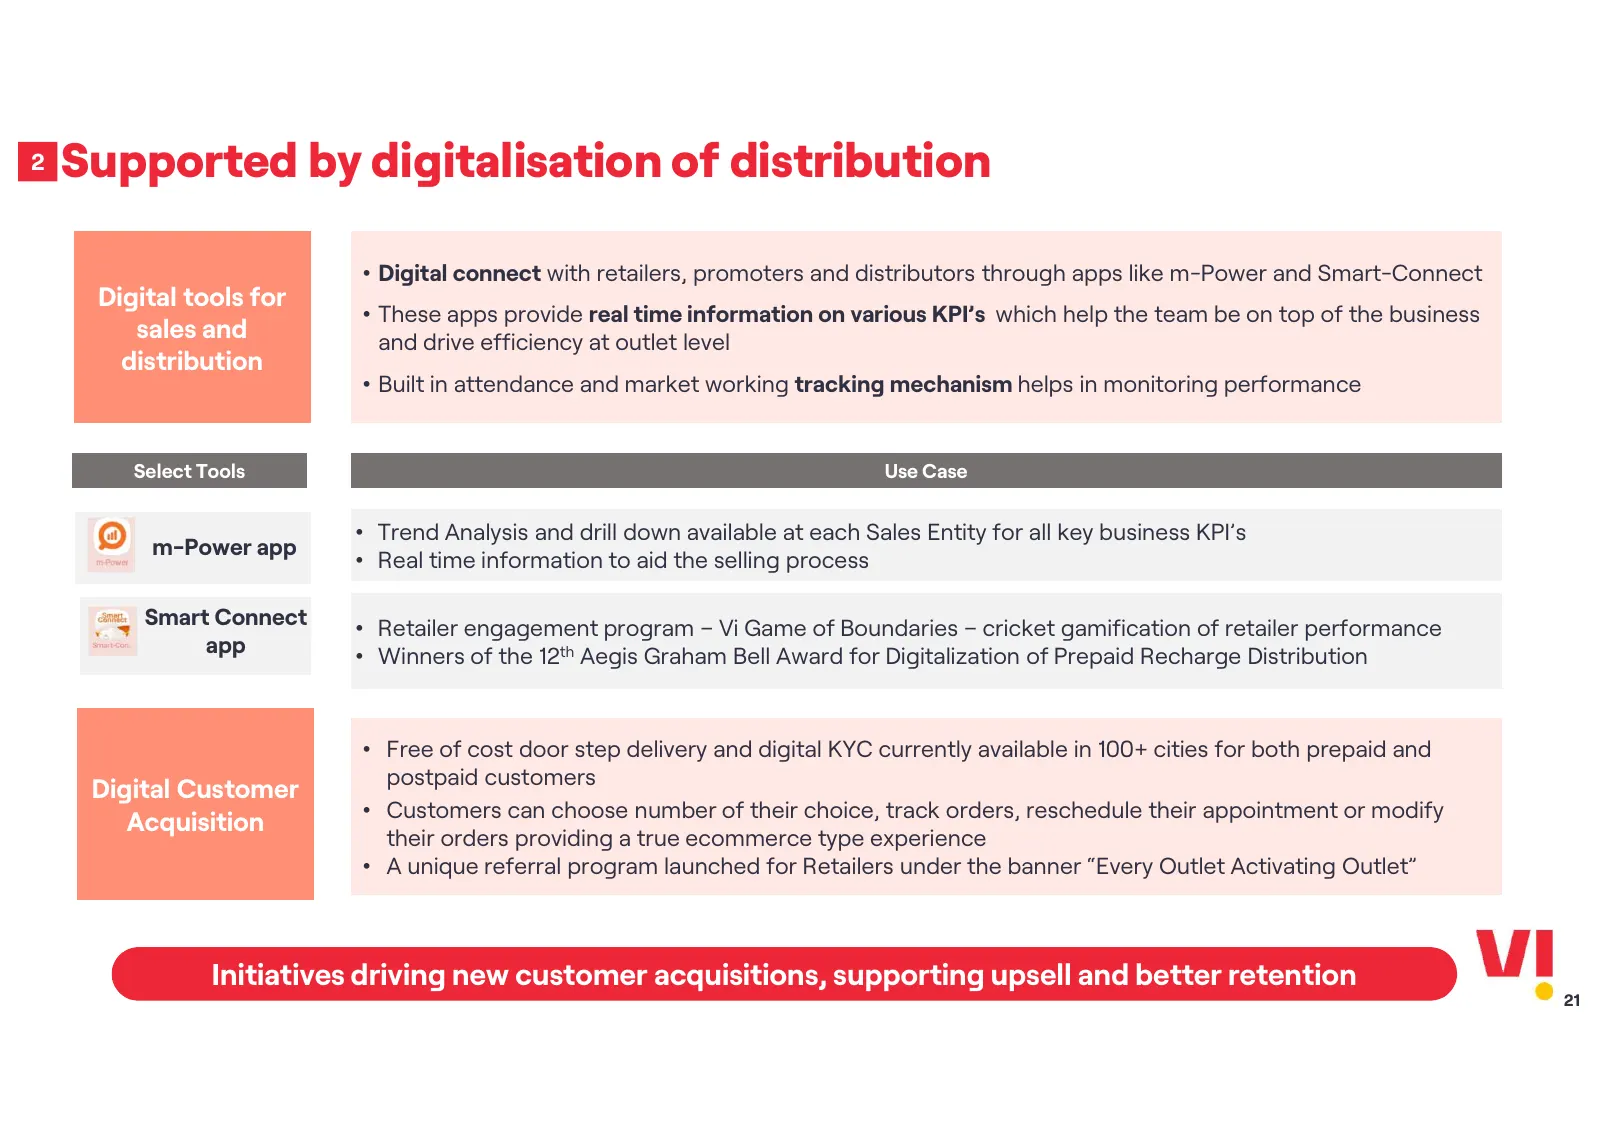
Slide 21: Supported by digitalisation of distribution
2 Supported by digitalisation of distribution • Digital connect with retailers, promoters and distributors through apps like m-Power and Smart-Connect Digital tools for • These apps provide real time information on various KPI’s which help the team be on top of the business sales and and drive effic
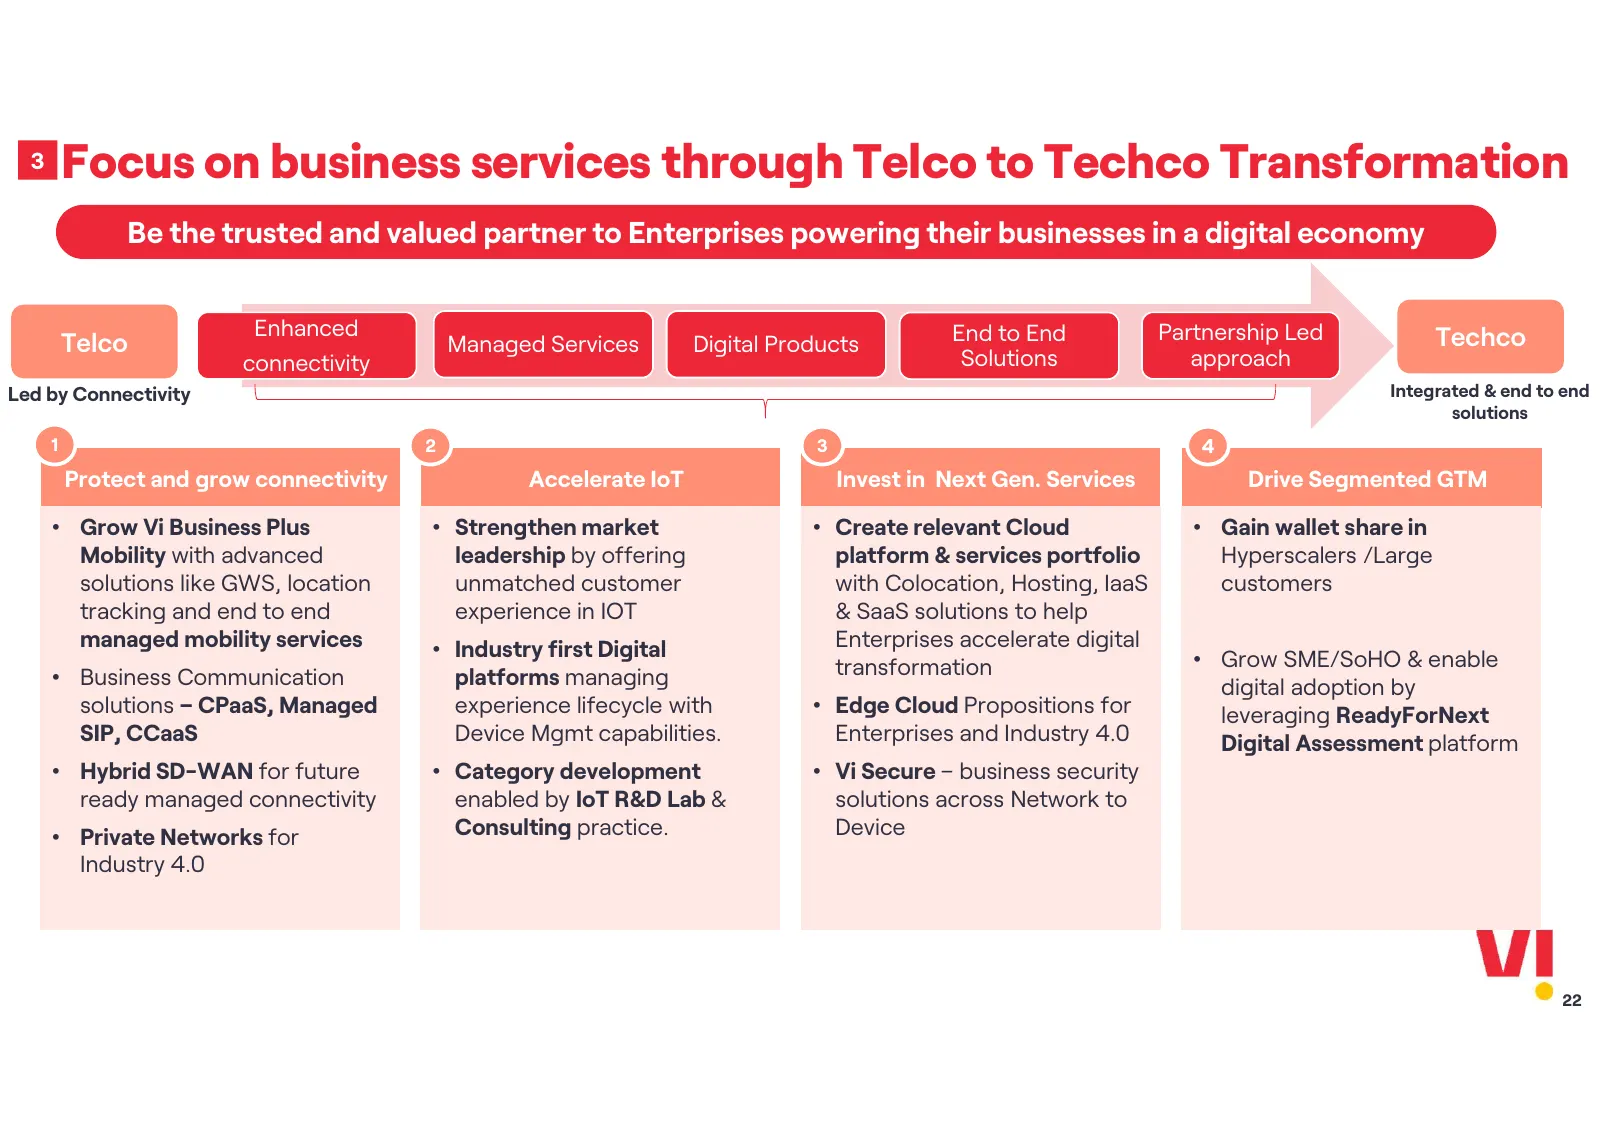
Slide 22: Focus on business services through Telco to Techco Transformation
3 Focus on business services through Telco to Techco Transformation Be the trusted and valued partner to Enterprises powering their businesses in a digital economy Enhanced End to End Partnership Led Techco Telco Managed Services Digital Products connectivity Solutions approach Led by Connectivity I
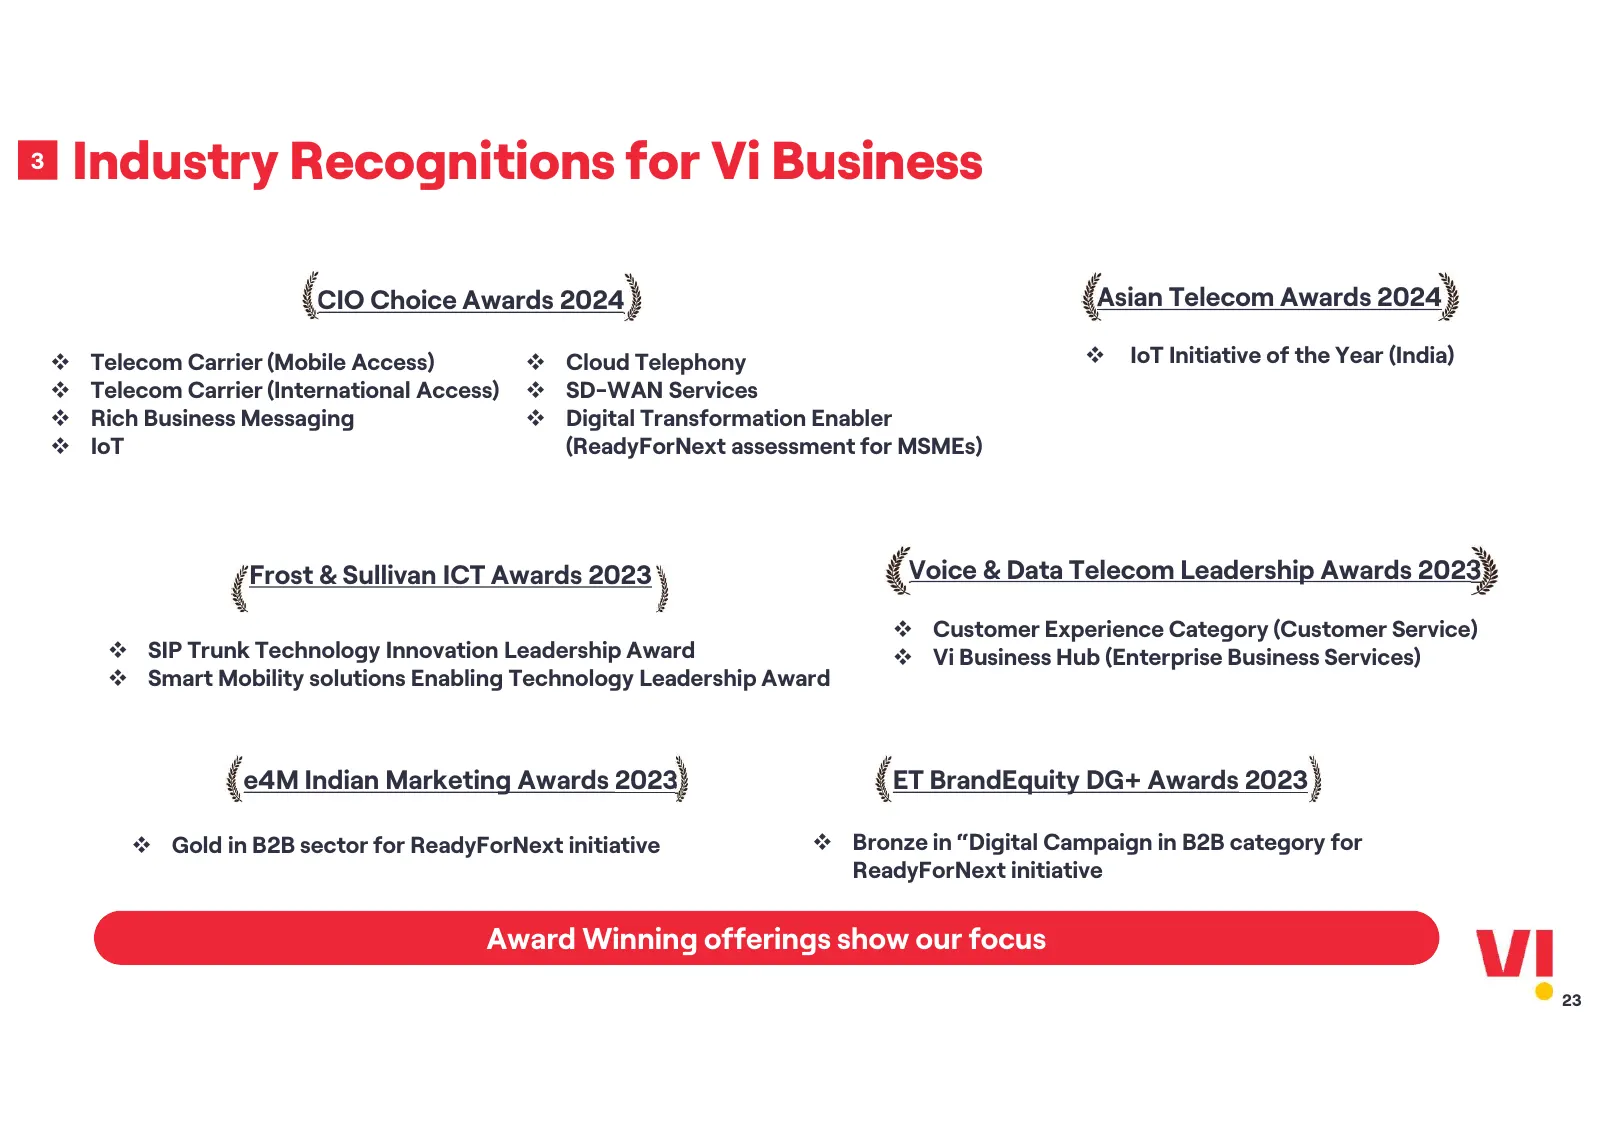
Slide 23: Industry Recognitions for Vi Business
3 Industry Recognitions for Vi Business CIO Choice Awards 2024 Asian Telecom Awards 2024 Telecom Carrier (Mobile Access) Cloud Telephony IoT Initiative of the Year (India) Telecom Carrier (International Access) SD-WAN Services Rich Business Messaging Digital Transformation Enabler Io
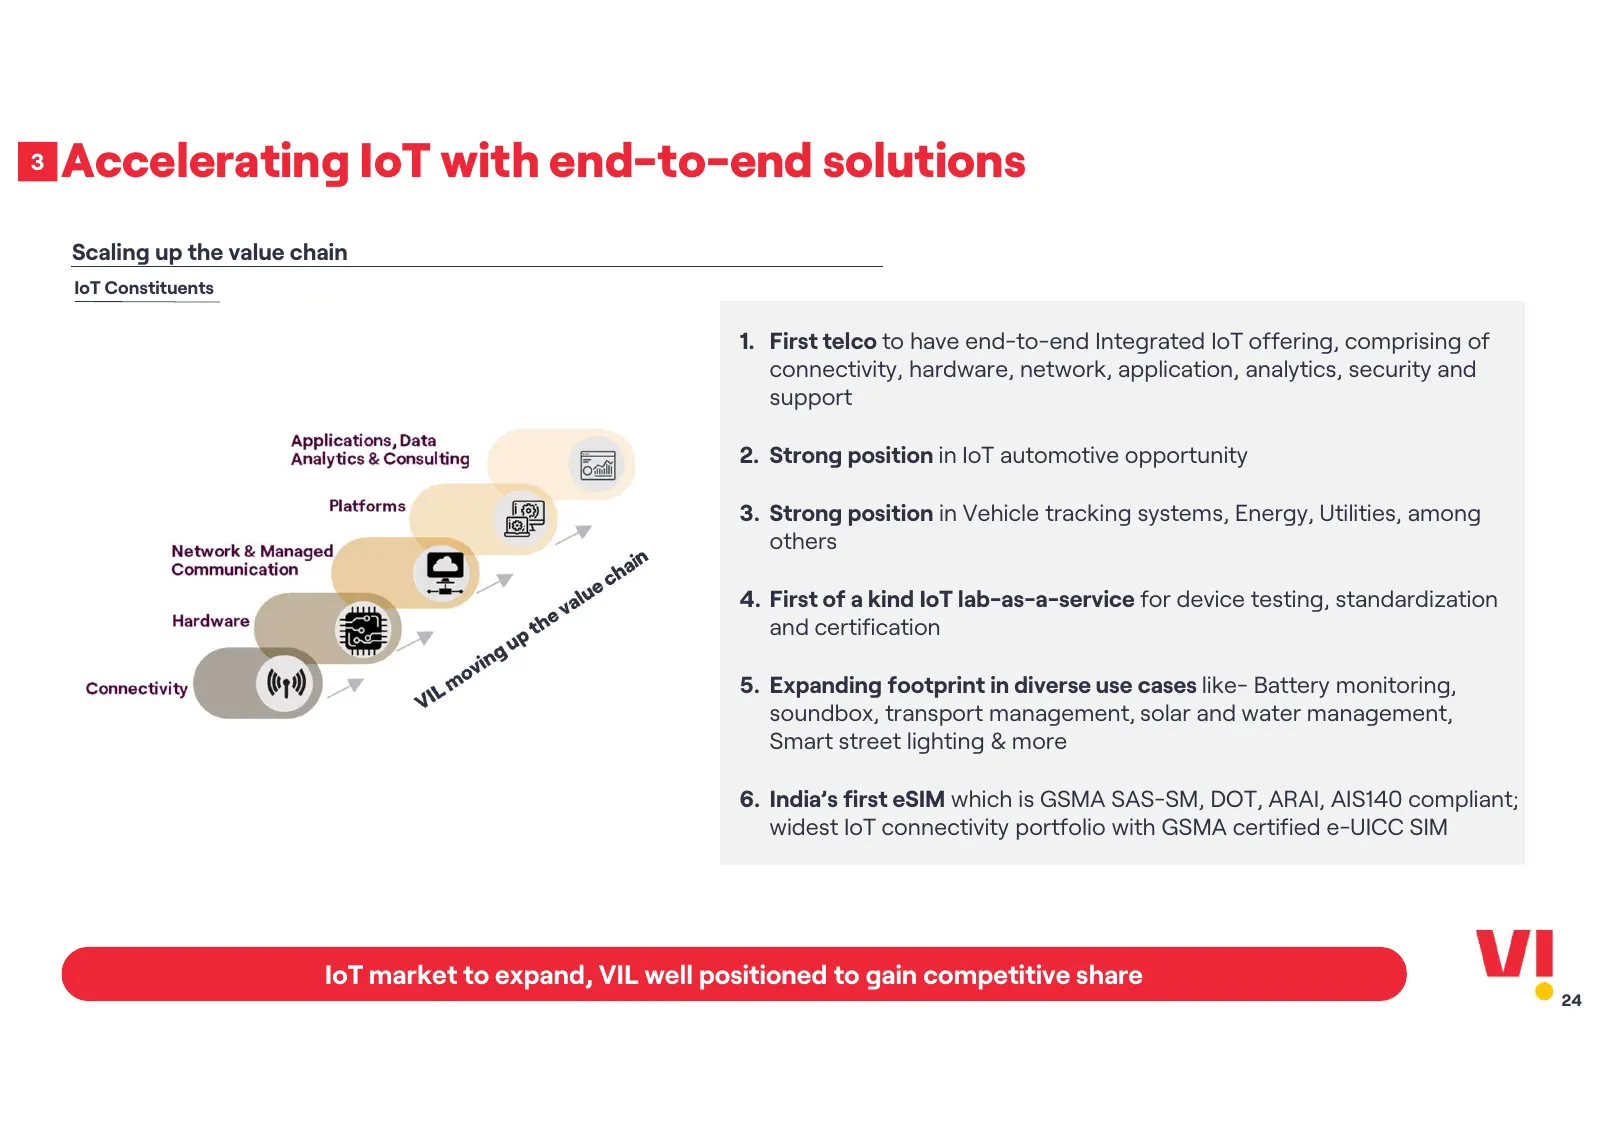
Slide 24: Accelerating IoT with end-to-end solutions
3 Accelerating IoT with end-to-end solutions Scaling up the value chain IoT Constituents 1. First telco to have end-to-end Integrated IoT offering, comprising of connectivity, hardware, network, application, analytics, security and support 2. Strong position in IoT automotive opportunity 3. Strong p
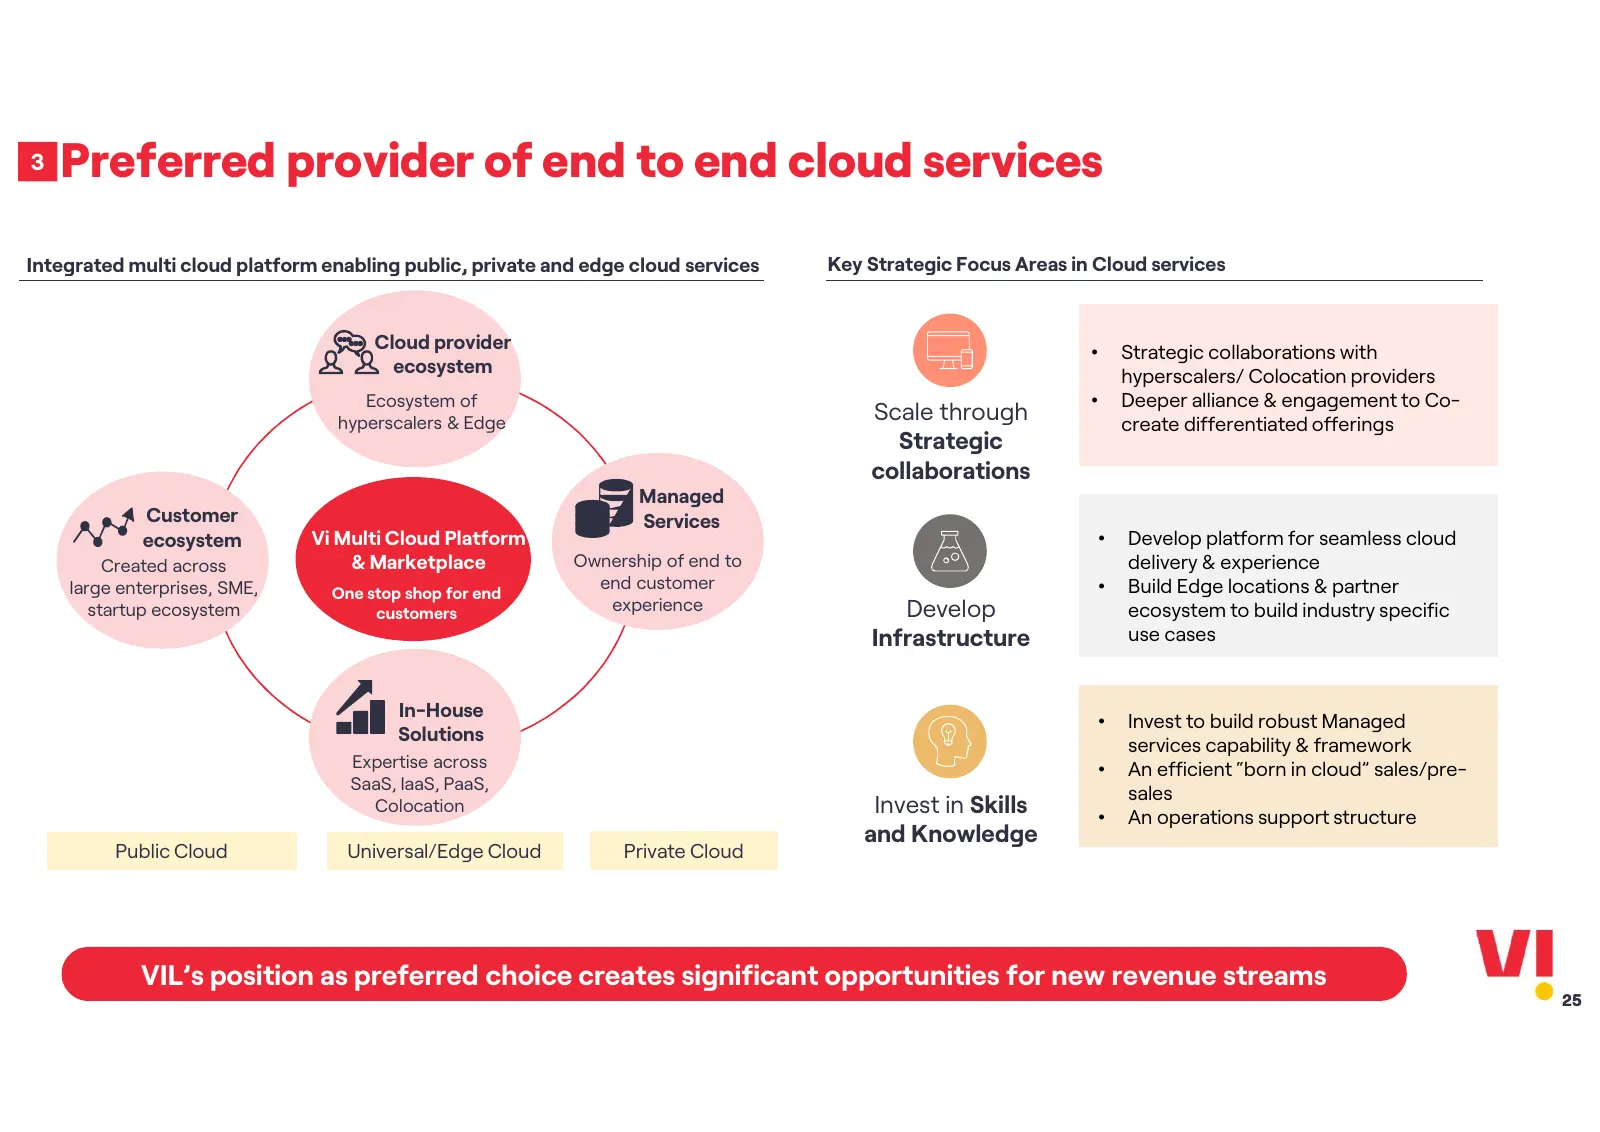
Slide 25: Preferred provider of end to end cloud services
3 Preferred provider of end to end cloud services Integrated multi cloud platform enabling public, private and edge cloud services Key Strategic Focus Areas in Cloud services Cloud provider • Strategic collaborations with ecosystem hyperscalers/ Colocation providers Ecosystem of • Deeper alliance &
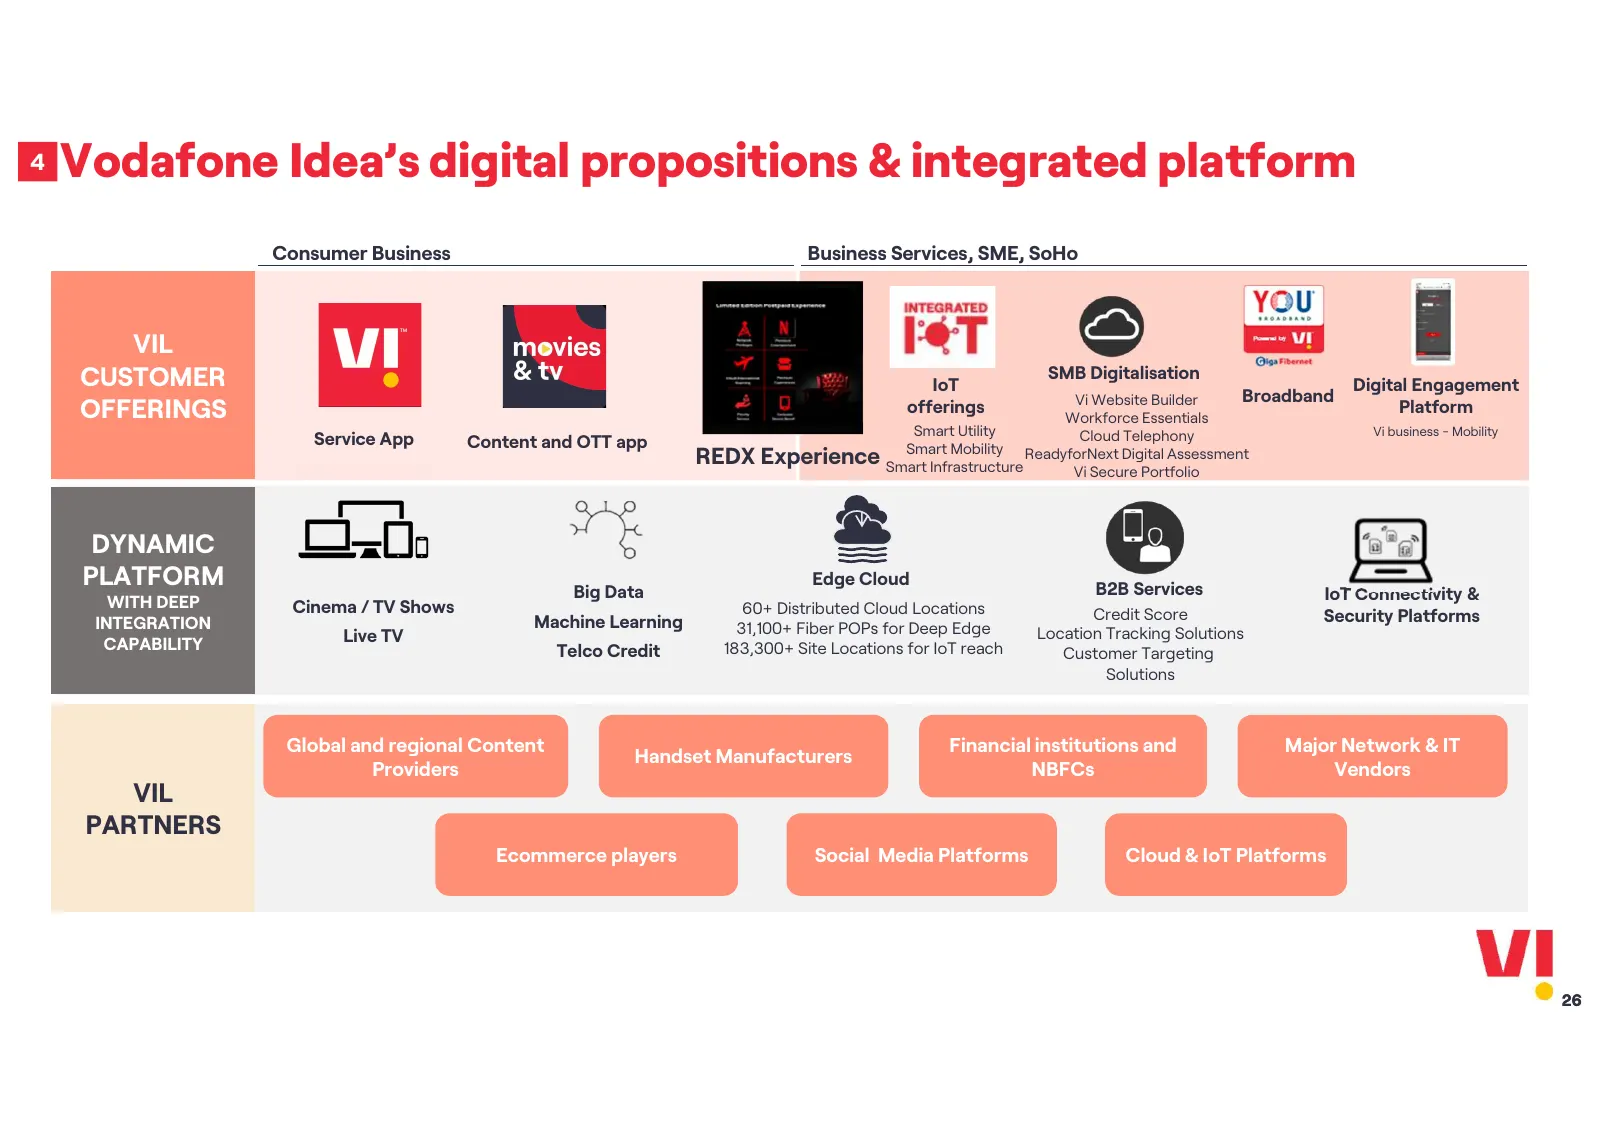
Slide 26: Vodafone Idea's digital propositions & integrated platform
4 Vodafone Idea’s digital propositions & integrated platform Consumer Business Business Services, SME, SoHo VIL CUSTOMER IoT SMB Digitalisation Digital Engagement Vi Website Builder Broadband OFFERINGS offerings Workforce Essentials Platform Smart Utility Cloud Telephony Vi business - Mobility Servi
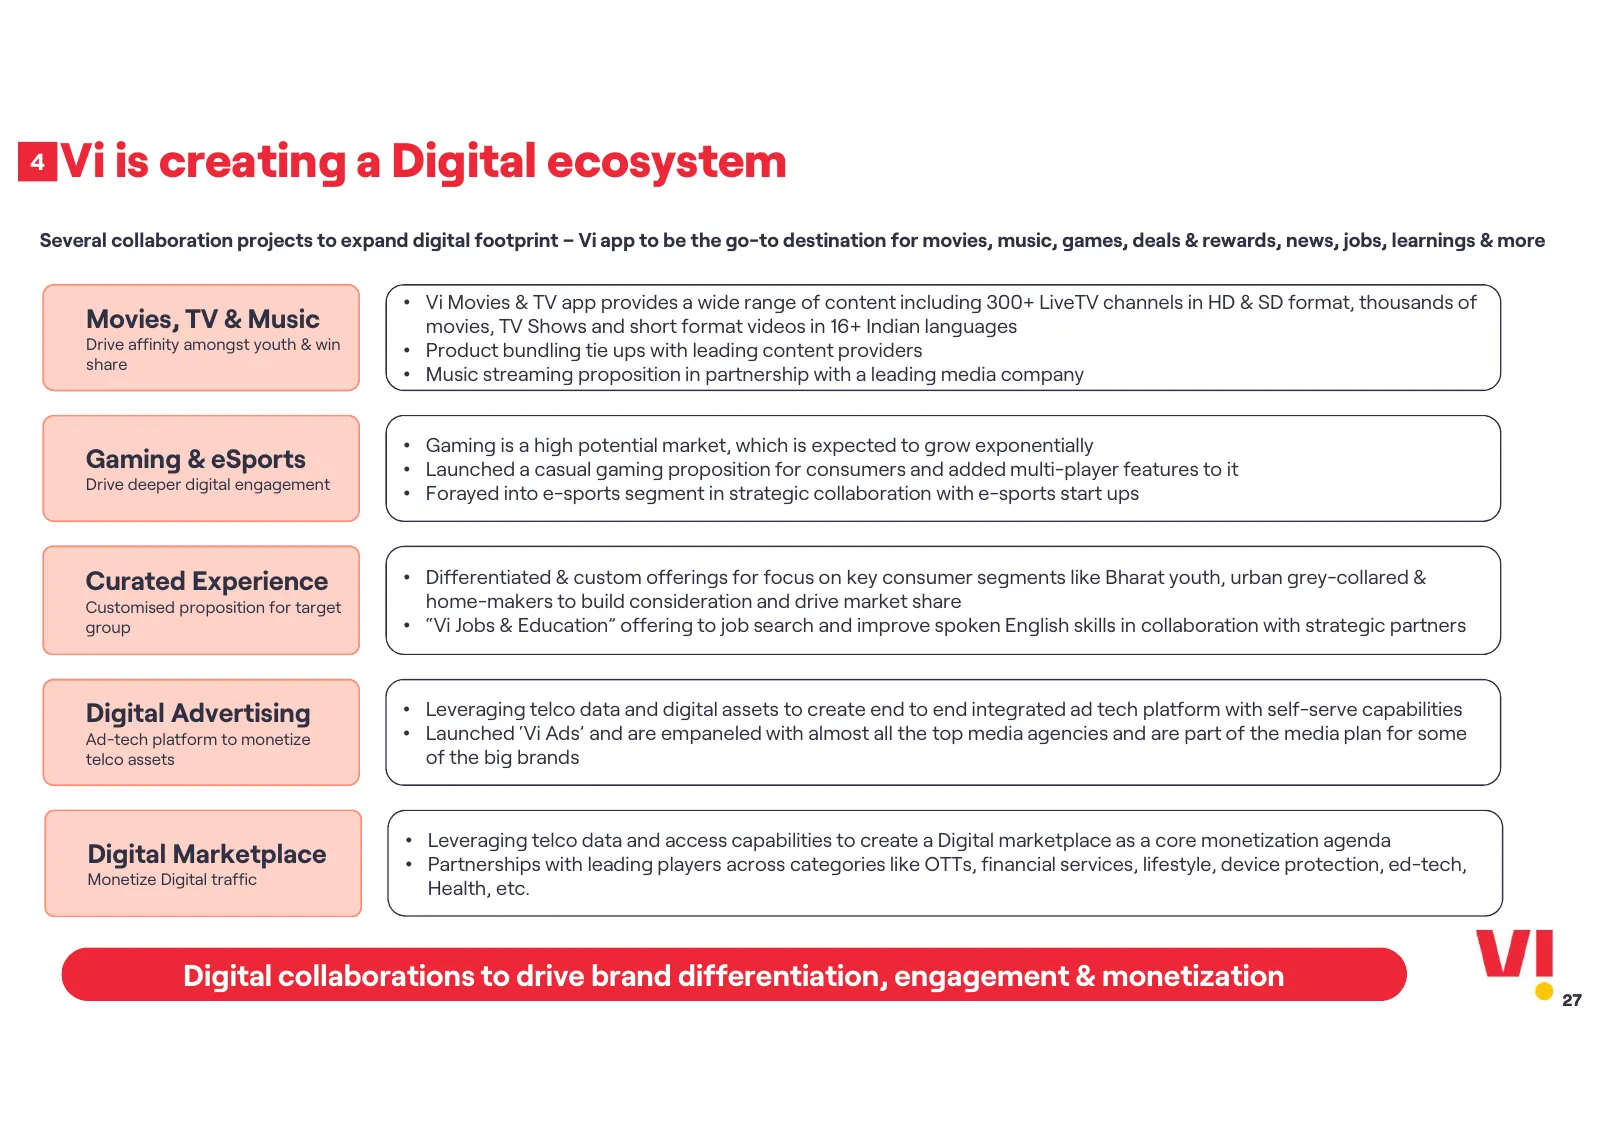
Slide 27: Vi is creating a Digital ecosystem
4 Vi is creating a Digital ecosystem Several collaboration projects to expand digital footprint – Vi app to be the go-to destination for movies, music, games, deals & rewards, news, jobs, learnings & more • Vi Movies & TV app provides a wide range of content including 300+ LiveTV channels in HD & SD
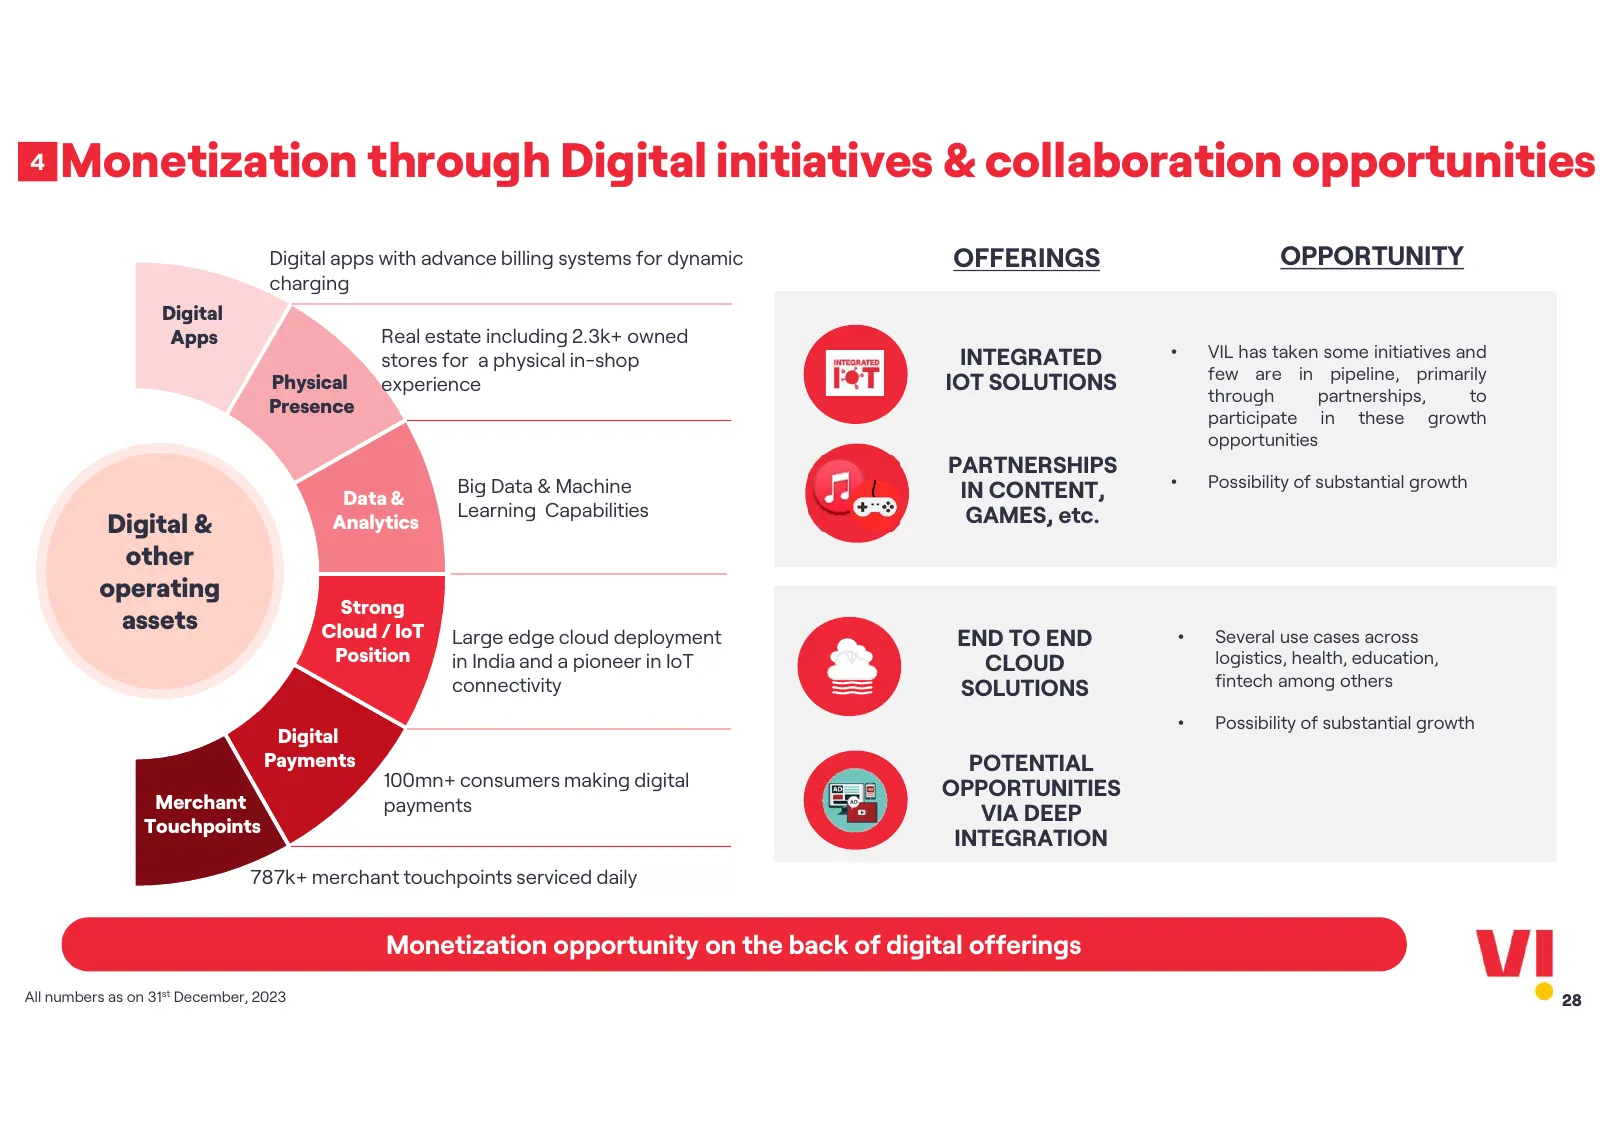
Slide 28: Monetization through Digital initiatives & collaboration opportunities
4 Monetization through Digital initiatives & collaboration opportunities Digital apps with advance billing systems for dynamic OFFERINGS OPPORTUNITY charging Digital Apps Real estate including 2.3k+ owned stores for a physical in-shop INTEGRATED • VIL has taken some initiatives and few are in pipeli
Slide 29: Q3FY24 Update
Q3FY24 Update 29
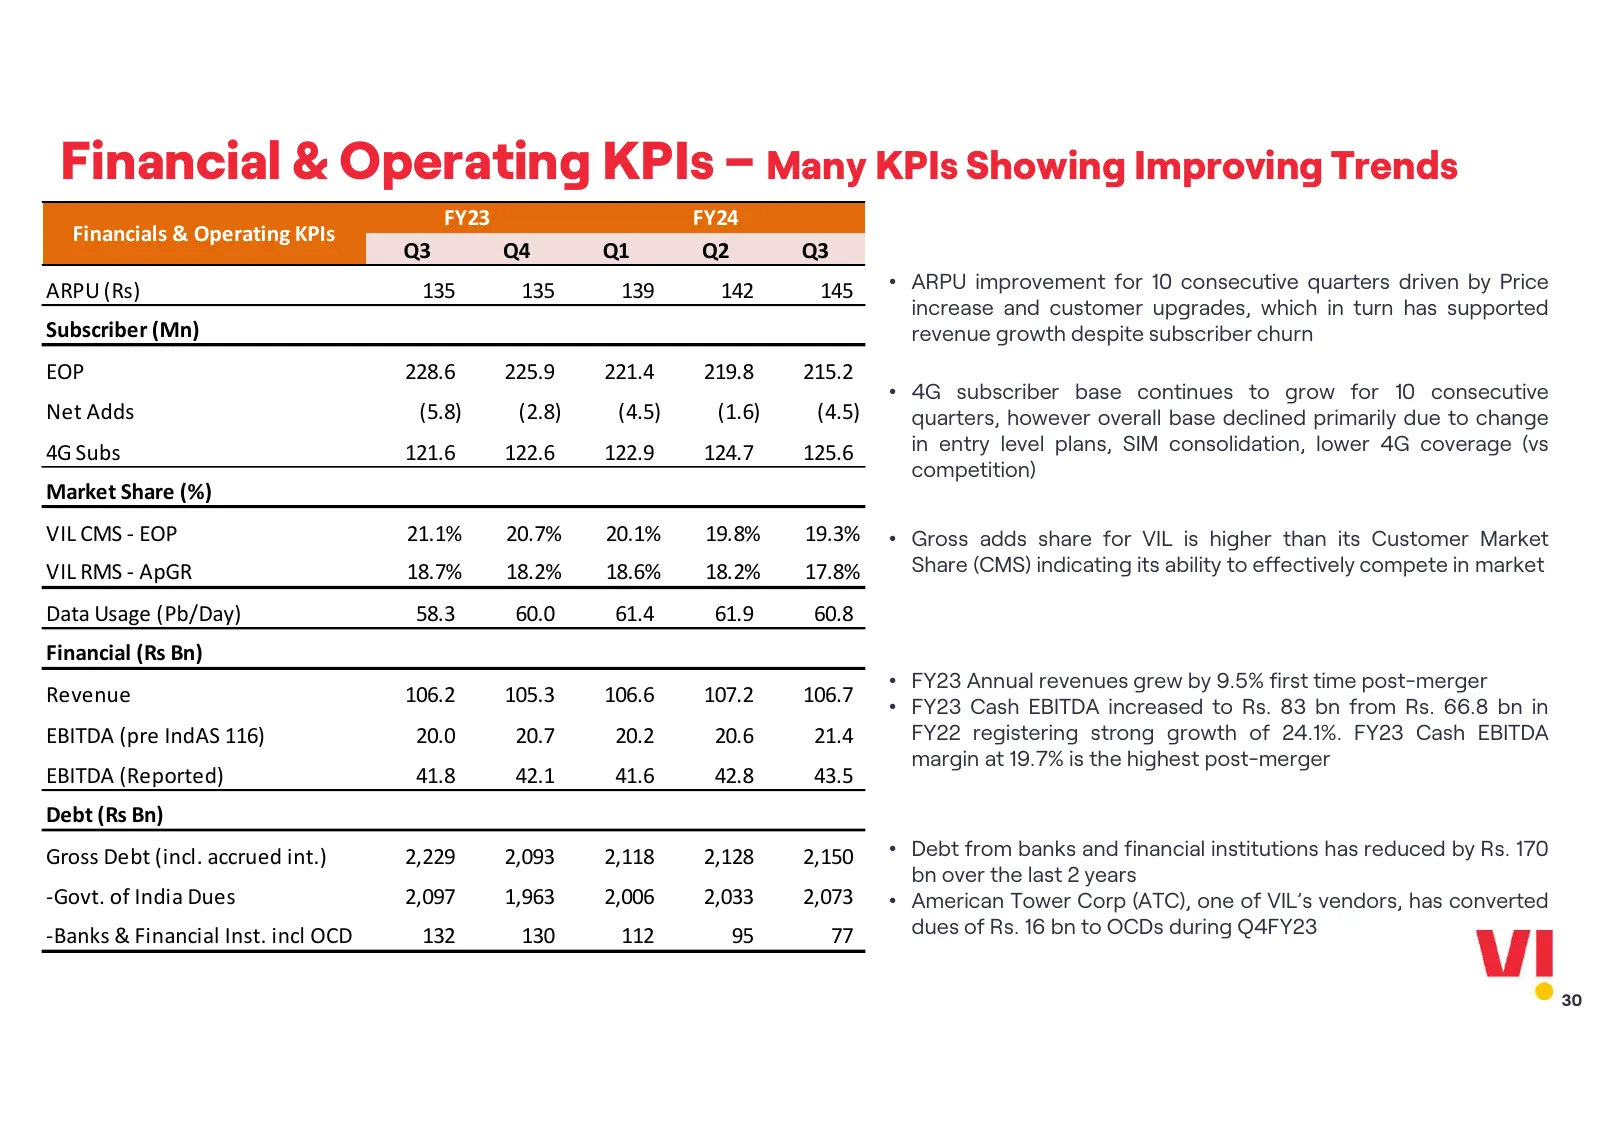
Slide 30: Financial & Operating KPIs – Many KPIs Showing Improving Trends
Financial & Operating KPIs – Many KPIs Showing Improving Trends FY23 FY24 Financials & Operating KPIs Q3 Q4 Q1 Q2 Q3 ARPU (Rs) 135 135 139 142 145 • ARPU improvement for 10 consecutive quarters driven by Price increase and customer upgrades, which in turn has supported Subscriber (Mn) revenue growth
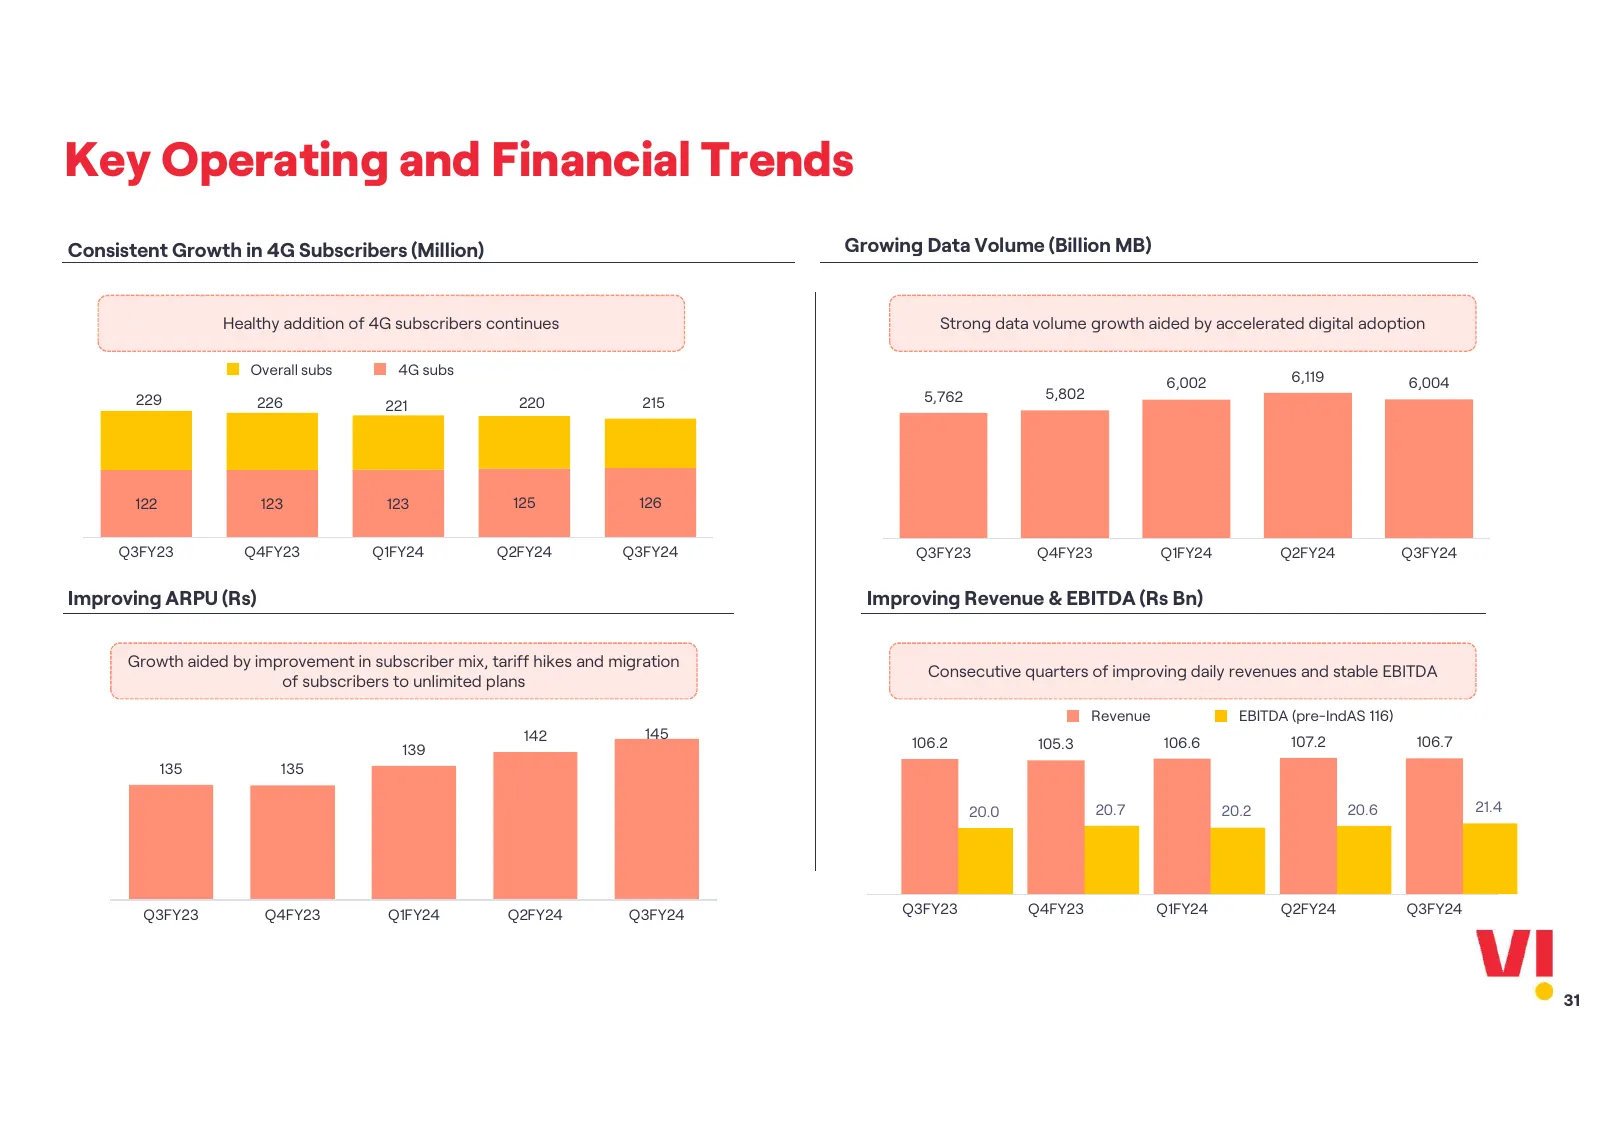
Slide 31: Key Operating and Financial Trends
Key Operating and Financial Trends Consistent Growth in 4G Subscribers (Million) Growing Data Volume (Billion MB) Healthy addition of 4G subscribers continues Strong data volume growth aided by accelerated digital adoption Overall subs 4G subs 6,119 6,002 6,004 229 5,762 5,802 226 221 220 215 122 12
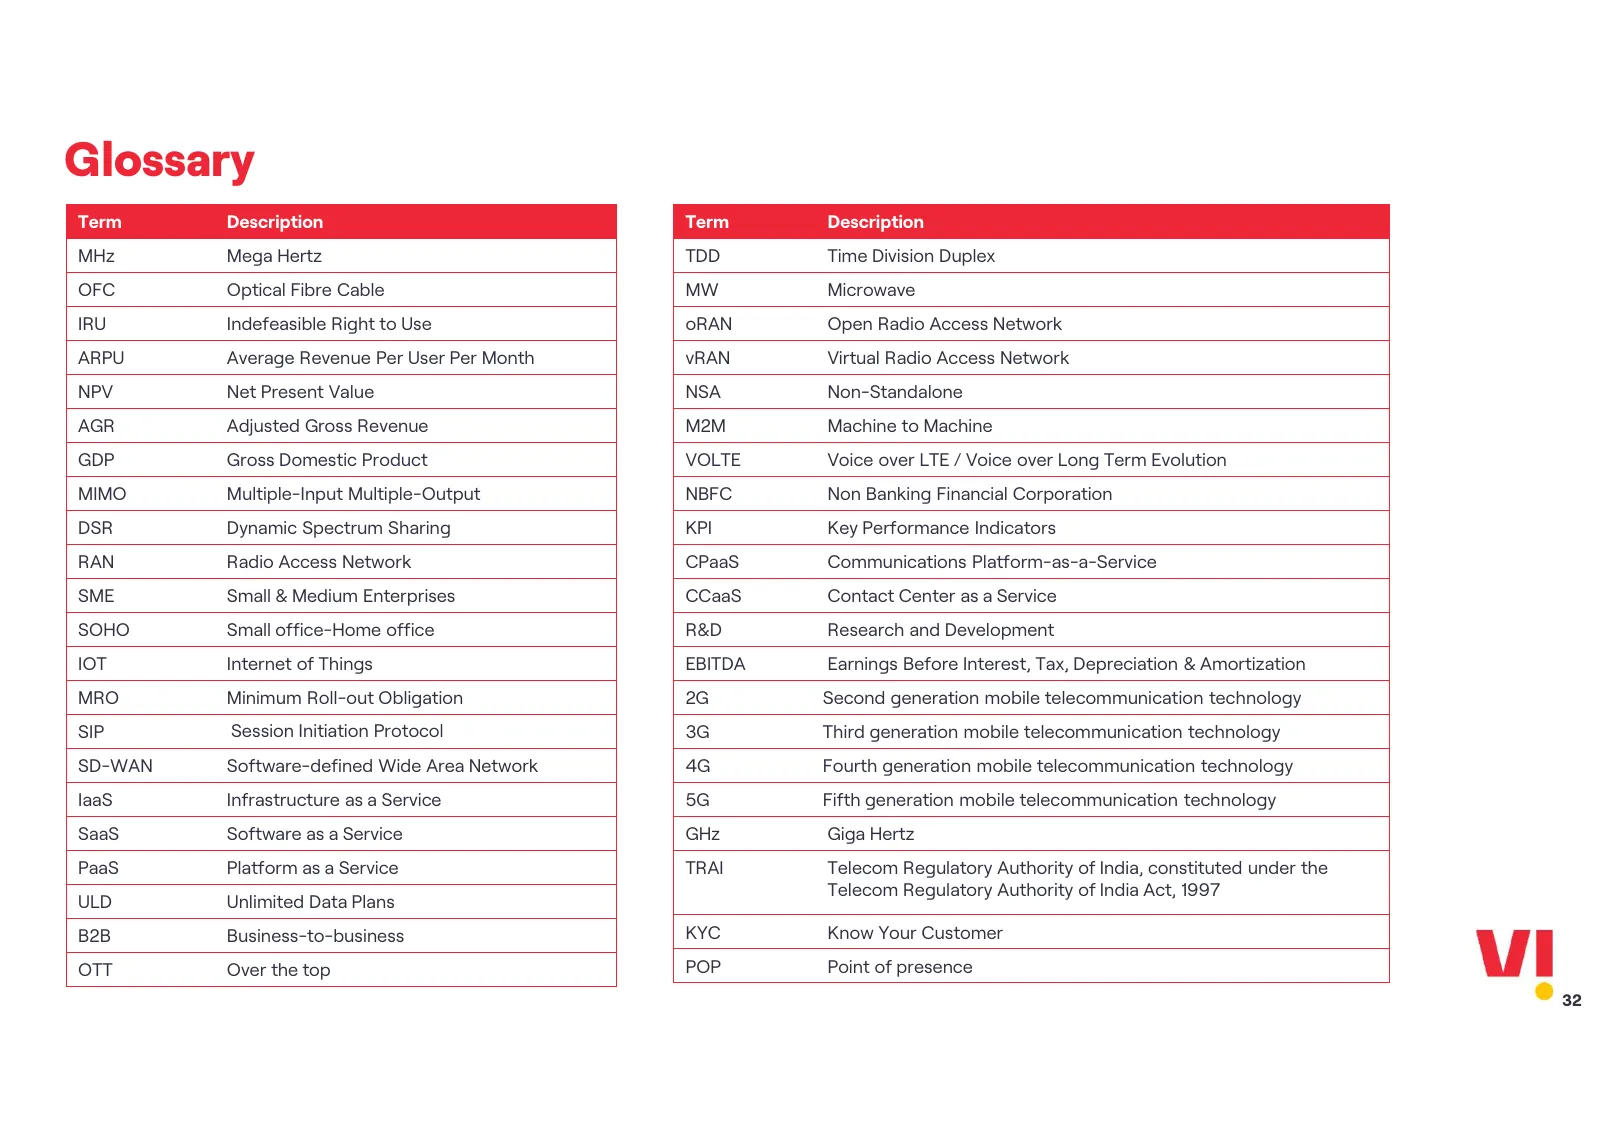
Slide 32: Glossary
Glossary Term Description Term Description MHz Mega Hertz TDD Time Division Duplex OFC Optical Fibre Cable MW Microwave IRU Indefeasible Right to Use oRAN Open Radio Access Network ARPU Average Revenue Per User Per Month vRAN Virtual Radio Access Network NPV Net Present Value NSA Non-Standalone AGR
Slide 33: Disclaimer
Disclaimer This presentation (“Presentation”) is issued by Vodafone Idea Limited (the “Company”) for general information purposes only, without regard to any specific objectives, suitability, financial situations and needs of any particular person. This Presentation does not constitute any recommend
Slide 34: Thank You
Thank You 34
Source: Internet Archive copy of myvi.in
More decks from Vodafone Idea Ltd
 Investor Presentation (November 2026)25 slides · Nov 12, 2026
 Investor Presentation (September 2026)21 slides · Sep 15, 2026
 Investor Presentation (June 2026)20 slides · Jun 30, 2026
 Investor Presentation (June 2026)19 slides · June 2026
 Investor Presentation (January 2026)31 slides · Jan 28, 2026
 Investor Presentation (January 2026)32 slides · Jan 28, 2026