Vodafone Idea Ltd · NSE:IDEA
Vodafone Idea — Investor Presentation (December 2020)
32 slides from Vodafone Idea's investor presentation, December 2020
Slide 1: Vodafone Idea Limited
VI Vodafone Idea Limited
Slide 2: Company Overview
Company Overview 2
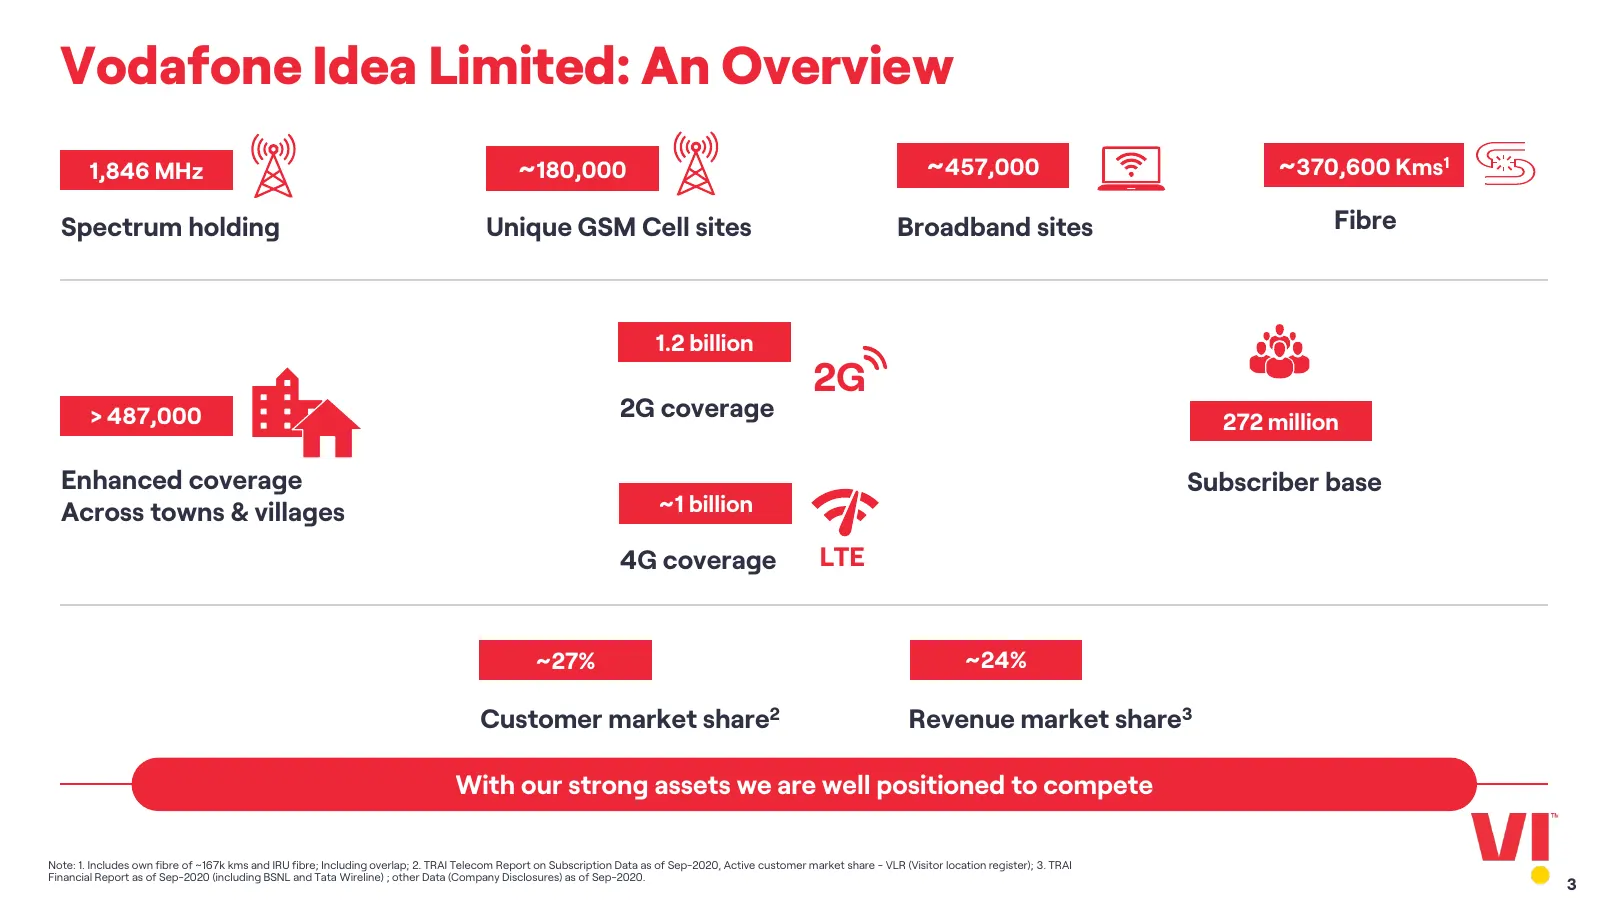
Slide 3: Vodafone Idea Limited: An Overview
Vodafone Idea Limited: An Overview 1,846 MHz ~180,000 ~457,000 ~370,600 Kms1 Spectrum holding Unique GSM Cell sites Broadband sites Fibre 1.2 billion 2G > 487,000 2G coverage 272 million Enhanced coverage Subscriber base Across towns & villages ~1 billion 4G coverage LTE ~27% ~24% Customer market sh
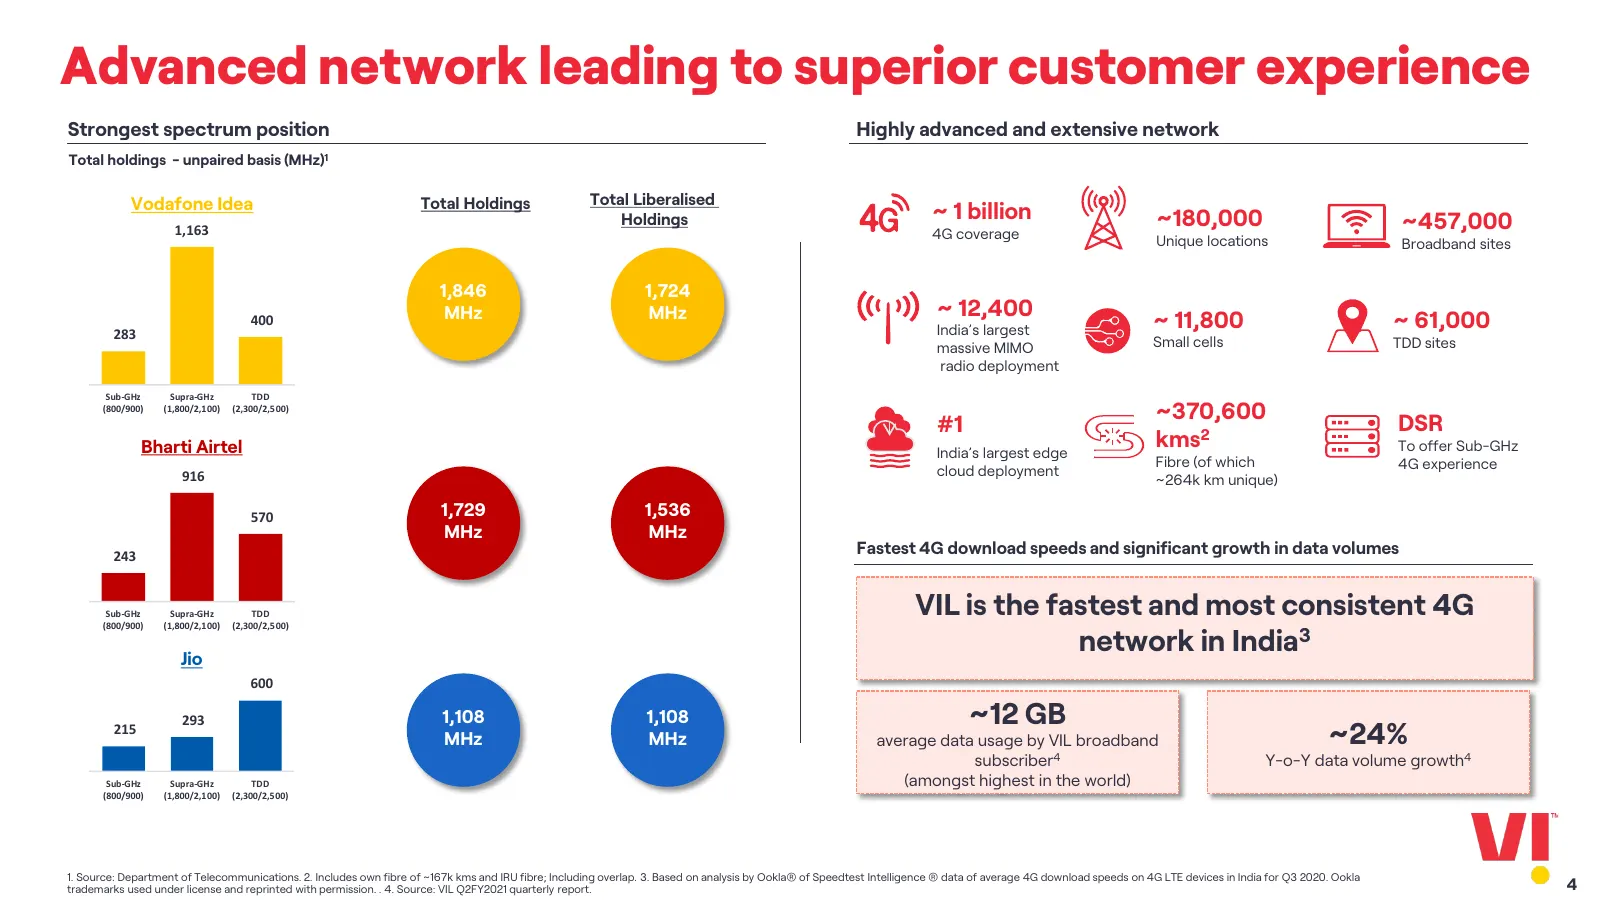
Slide 4: Advanced network leading to superior customer experience
Advanced network leading to superior customer experience Strongest spectrum position Highly advanced and extensive network Total holdings - unpaired basis (MHz)1 Vodafone Idea Total Holdings Total Liberalised Holdings ~ 1 billion ~180,000 ~457,000 1,163 4G coverage Unique locations Broadband sites 1
Slide 5: Strong market position in consumer, business services & IoT
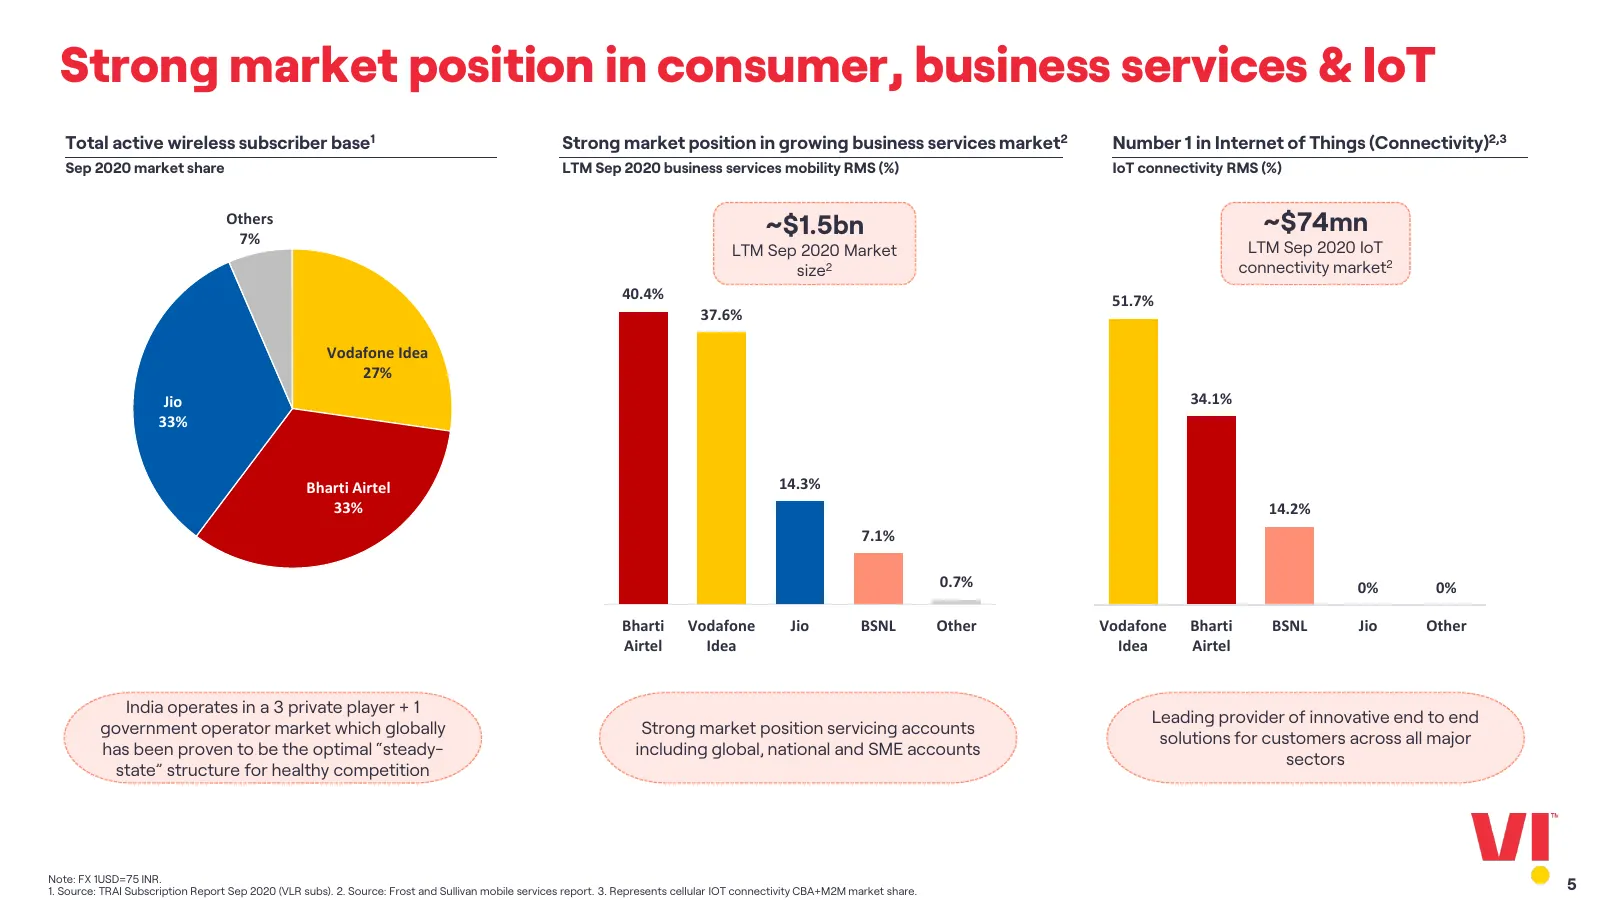
Strong market position in consumer, business services & IoT Total active wireless subscriber base1 Strong market position in growing business services market2 Number 1 in Internet of Things (Connectivity)2,3 Sep 2020 market share LTM Sep 2020 business services mobility RMS (%) IoT connectivity RMS (
Slide 6: Globally scaled subscriber base
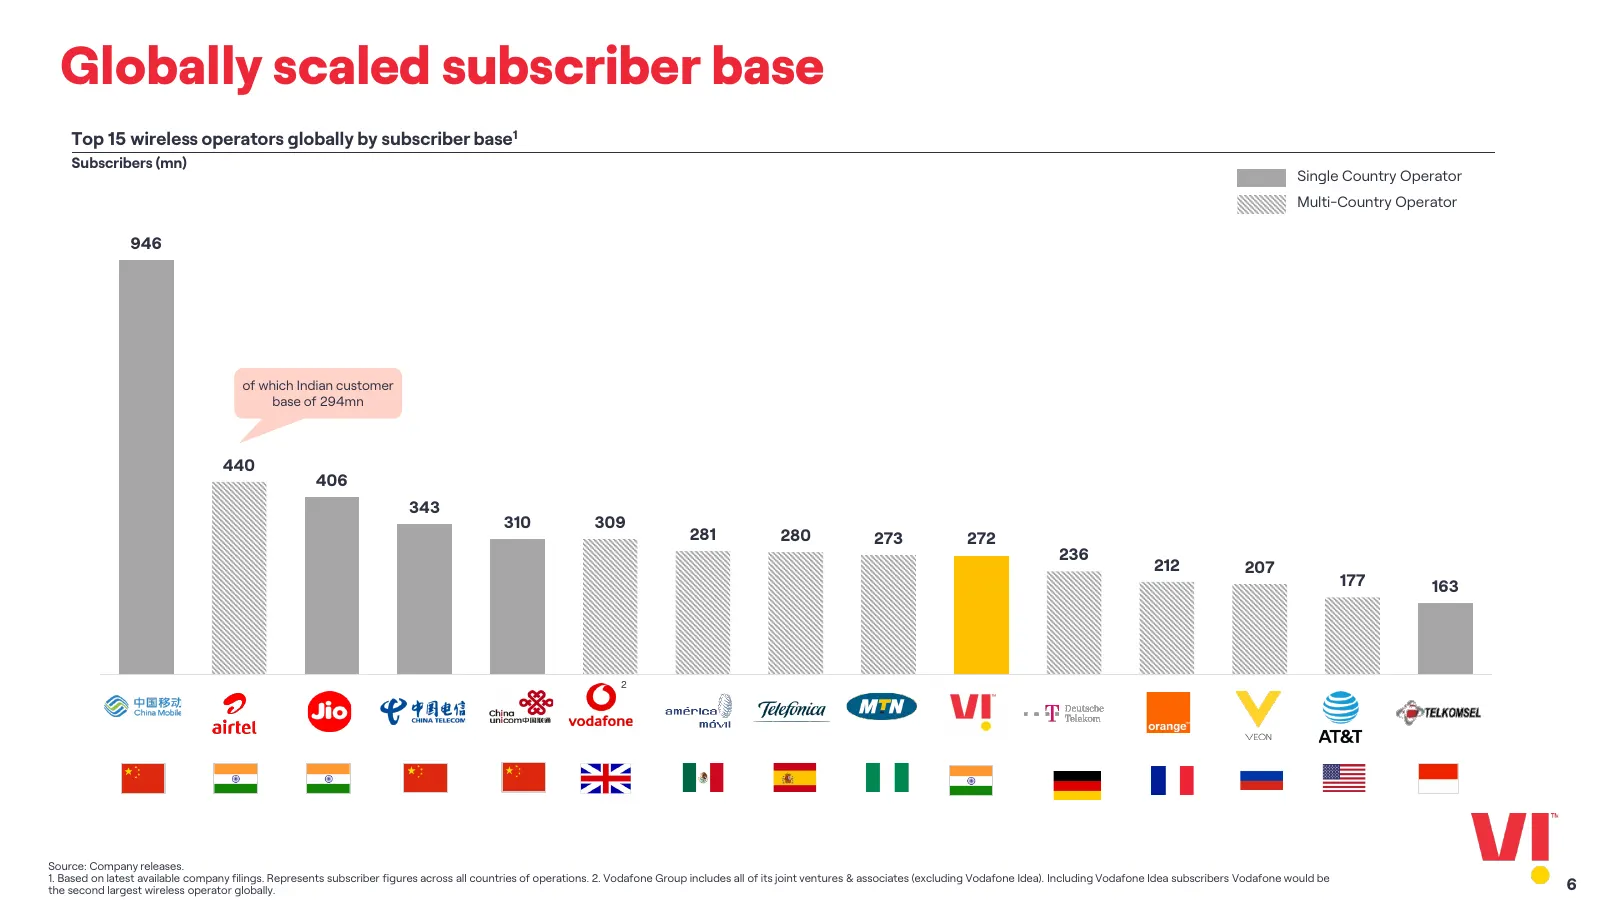
Globally scaled subscriber base Top 15 wireless operators globally by subscriber base1 Subscribers (mn) Single Country Operator Multi-Country Operator 946 of which Indian customer base of 294mn 440 406 343 310 309 281 280 273 272 236 212 207 177 163 2 Source: Company releases. 1. Based on latest ava
Slide 7: Strong new unified brand and other operating assets
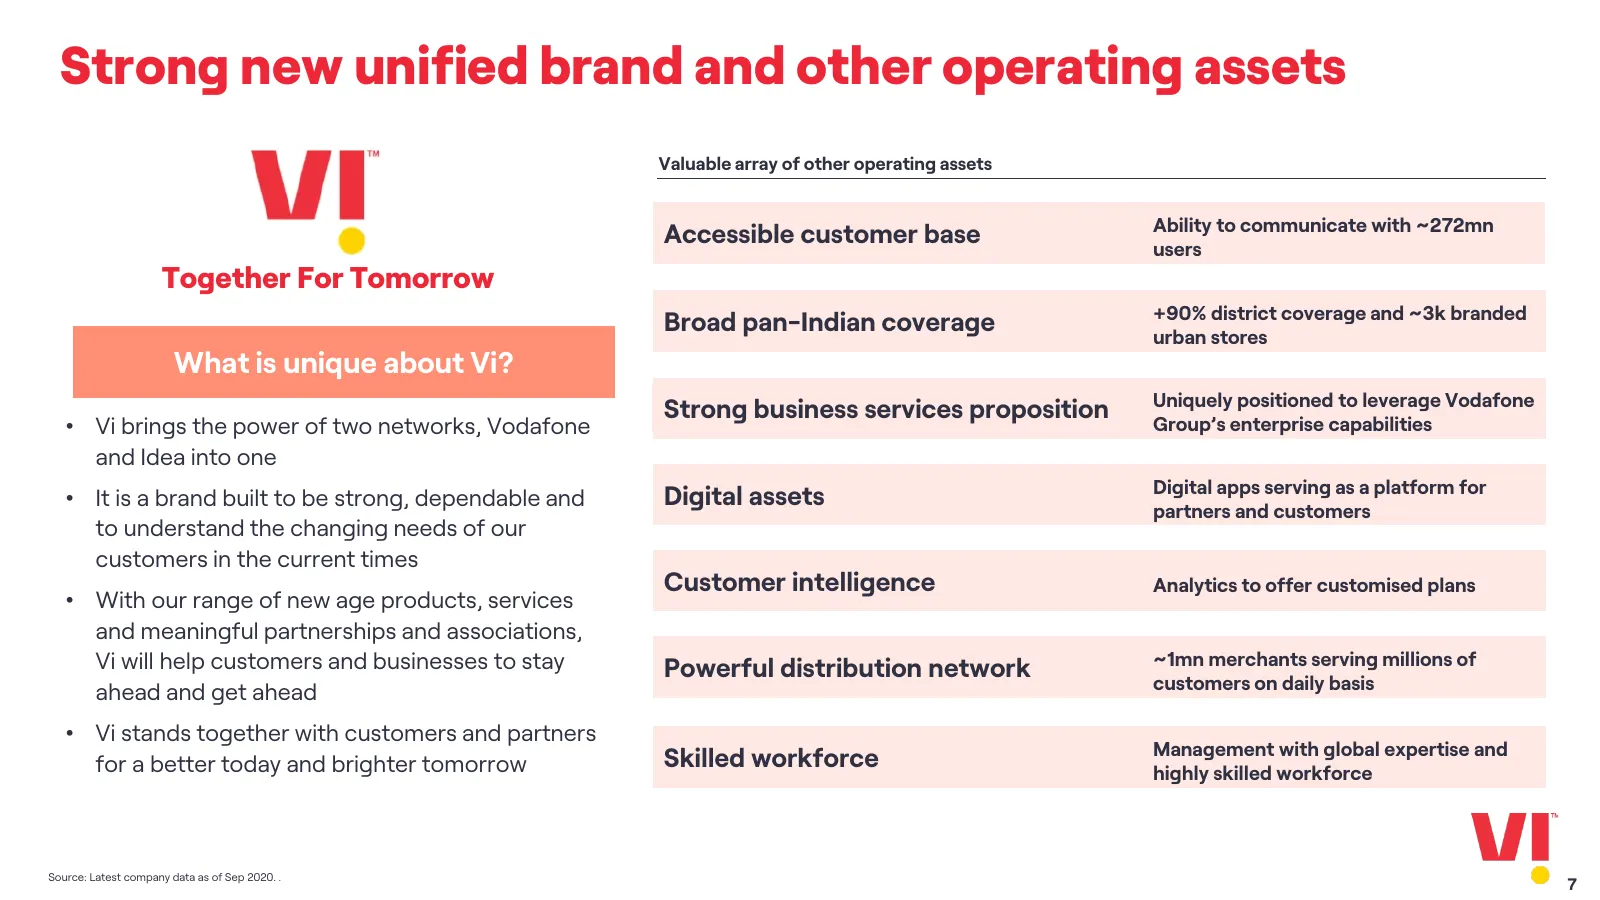
Strong new unified brand and other operating assets Valuable array of other operating assets Ability to communicate with ~272mn Accessible customer base users Together For Tomorrow +90% district coverage and ~3k branded Broad pan-Indian coverage urban stores What is unique about Vi? Uniquely positio
Slide 8: Growth Opportunities
Growth Opportunities 8
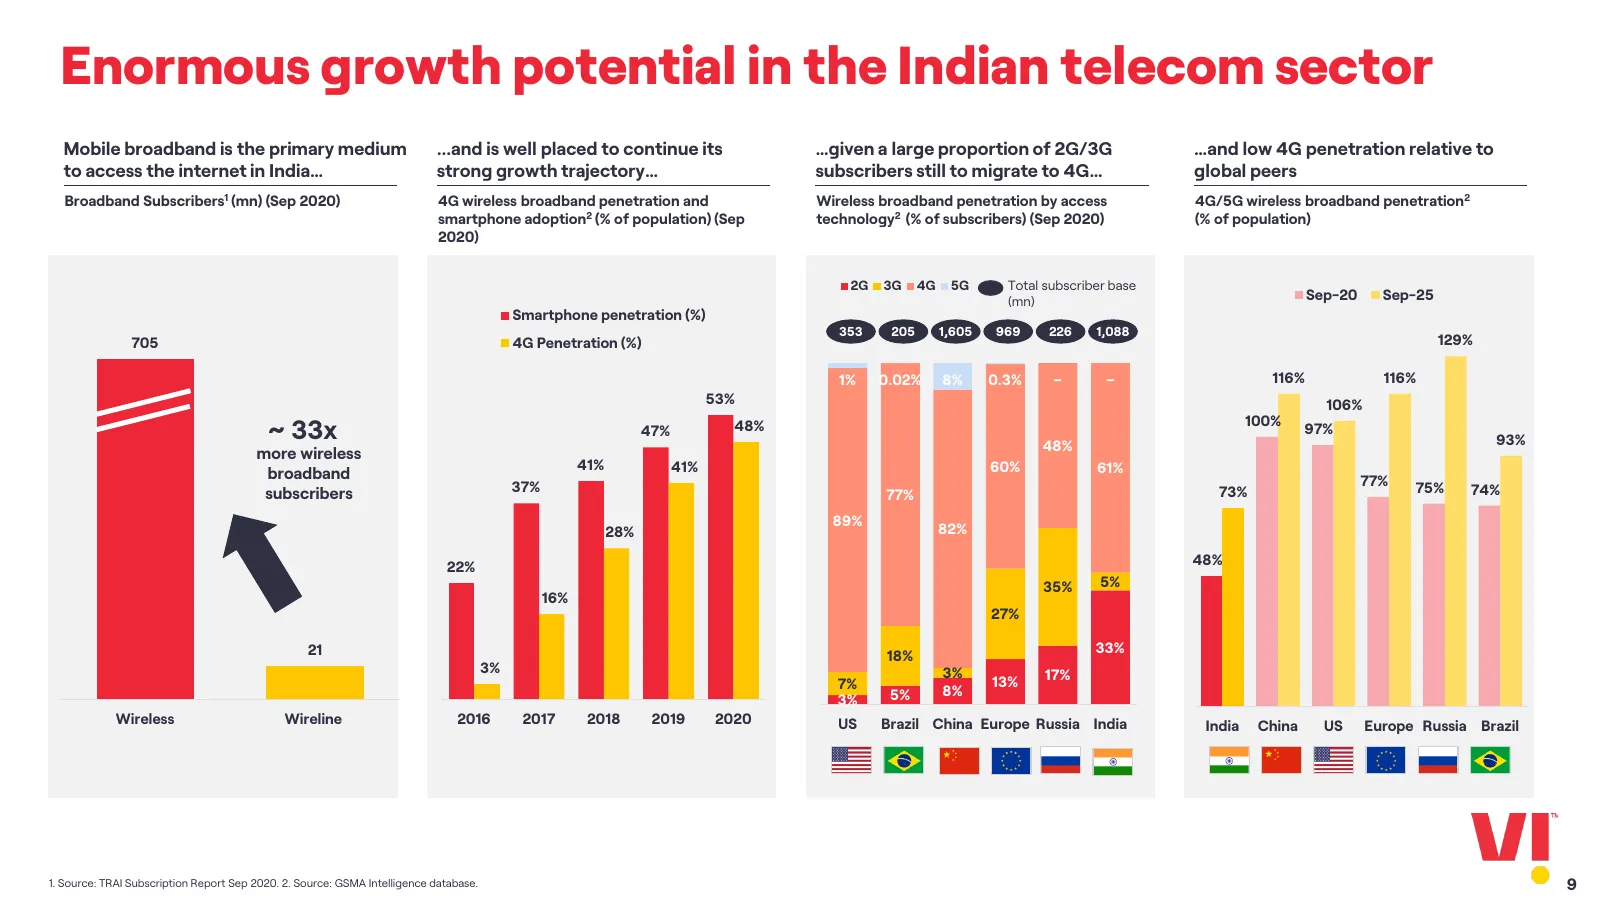
Slide 9: Enormous growth potential in the Indian telecom sector
Enormous growth potential in the Indian telecom sector Mobile broadband is the primary medium ...and is well placed to continue its …given a large proportion of 2G/3G …and low 4G penetration relative to to access the internet in India… strong growth trajectory… subscribers still to migrate to 4G… gl
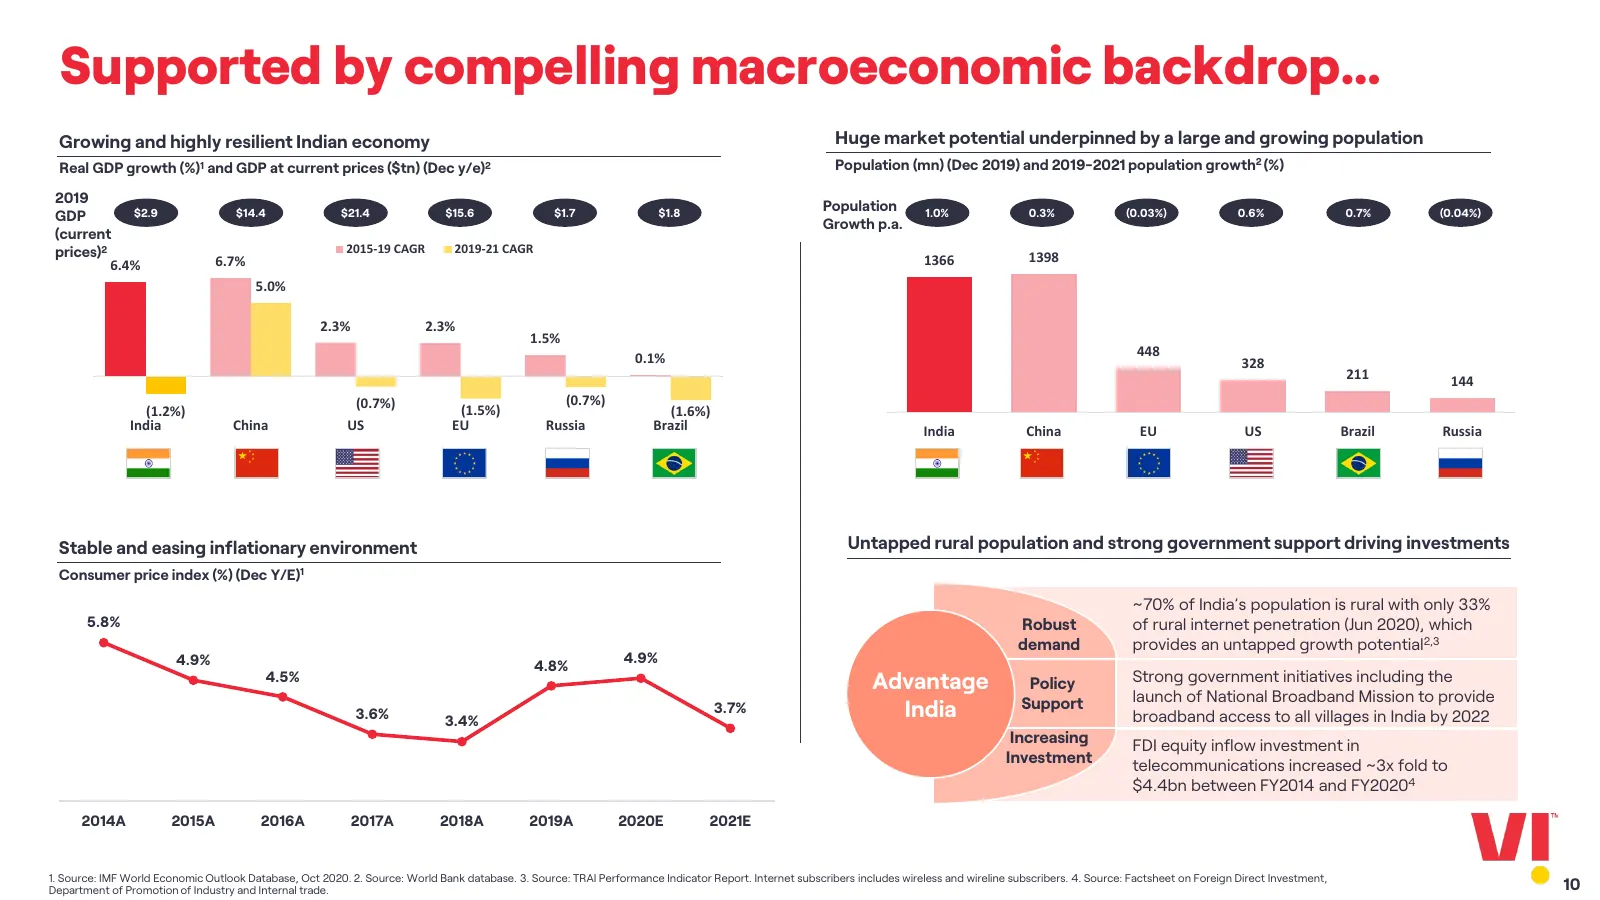
Slide 10: Supported by compelling macroeconomic backdrop…
Supported by compelling macroeconomic backdrop… Growing and highly resilient Indian economy Huge market potential underpinned by a large and growing population Real GDP growth (%)1 and GDP at current prices ($tn) (Dec y/e)2 Population (mn) (Dec 2019) and 2019-2021 population growth2 (%) 2019 Populat
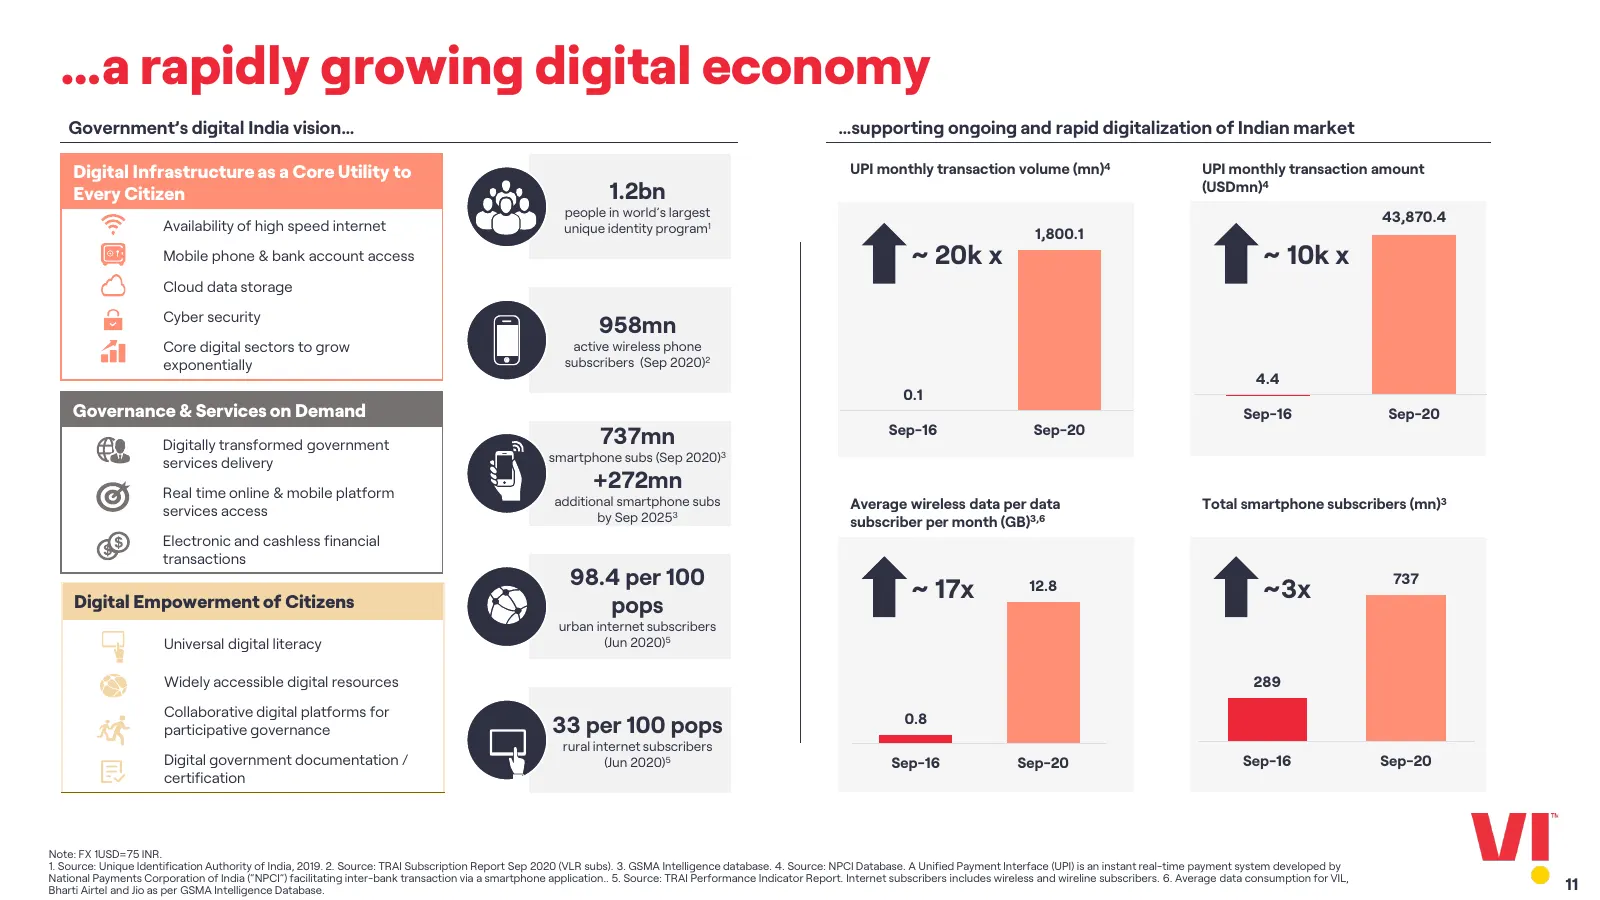
Slide 11: …a rapidly growing digital economy
…a rapidly growing digital economy Government’s digital India vision… …supporting ongoing and rapid digitalization of Indian market Digital Infrastructure as a Core Utility to UPI monthly transaction volume (mn)4 UPI monthly transaction amount Every Citizen 1.2bn (USDmn)4 people in world’s largest 4
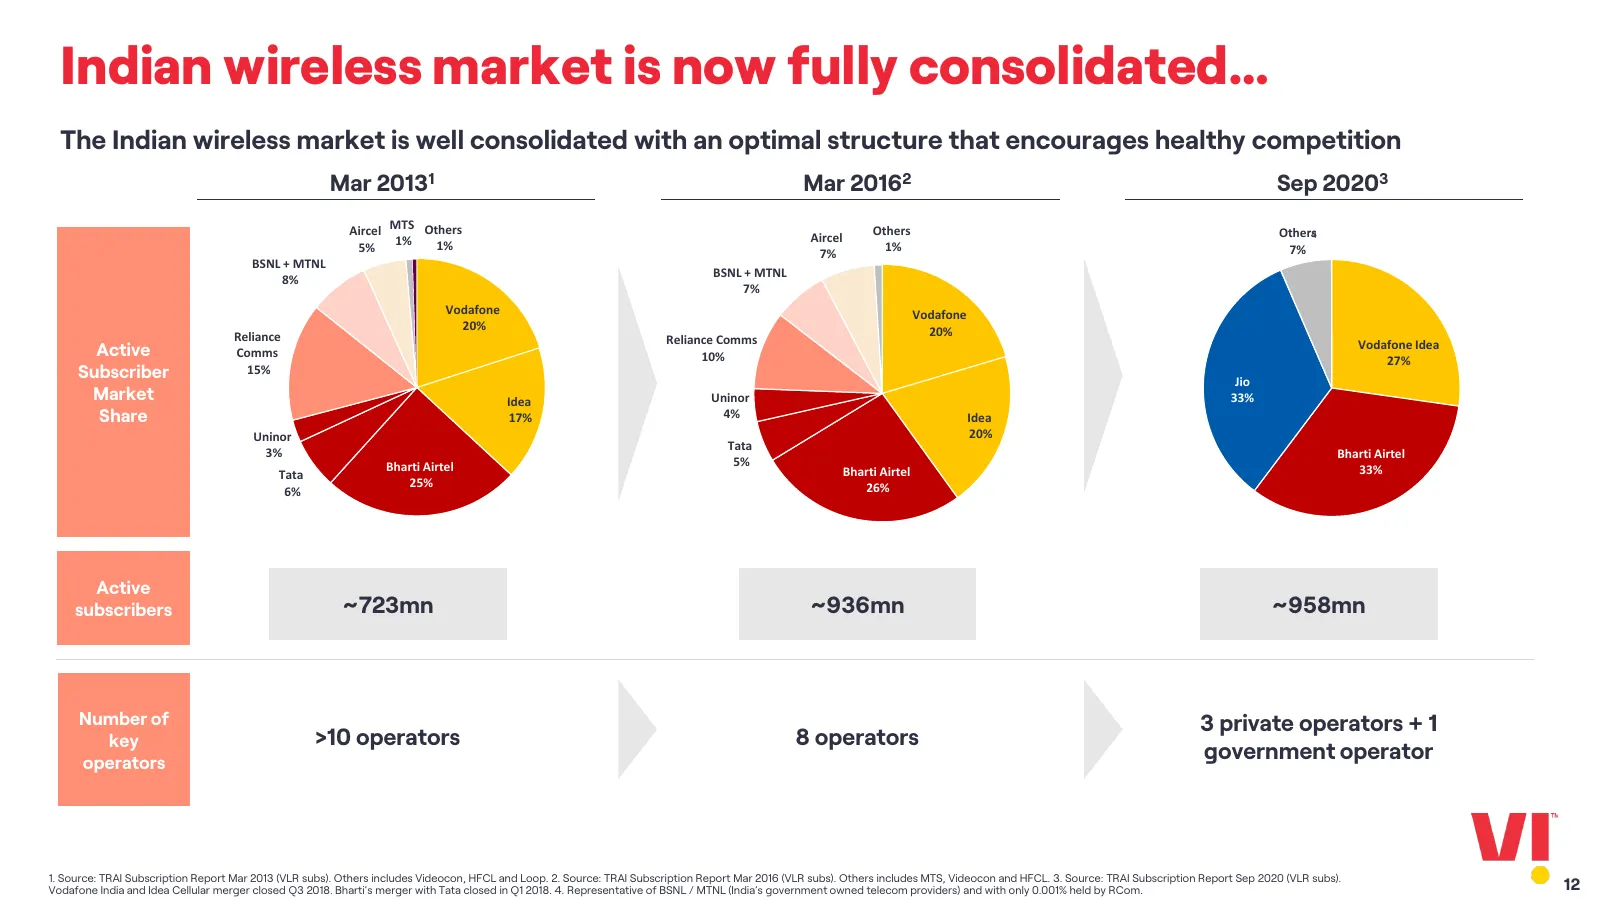
Slide 12: Indian wireless market is now fully consolidated…
Indian wireless market is now fully consolidated… The Indian wireless market is well consolidated with an optimal structure that encourages healthy competition Mar 20131 Mar 20162 Sep 20203 Aircel MTS Others Aircel Others Others4 5% 1% 1% 7% 1% 7% BSNL + MTNL BSNL + MTNL 8% 7% Vodafone Vodafone 20%
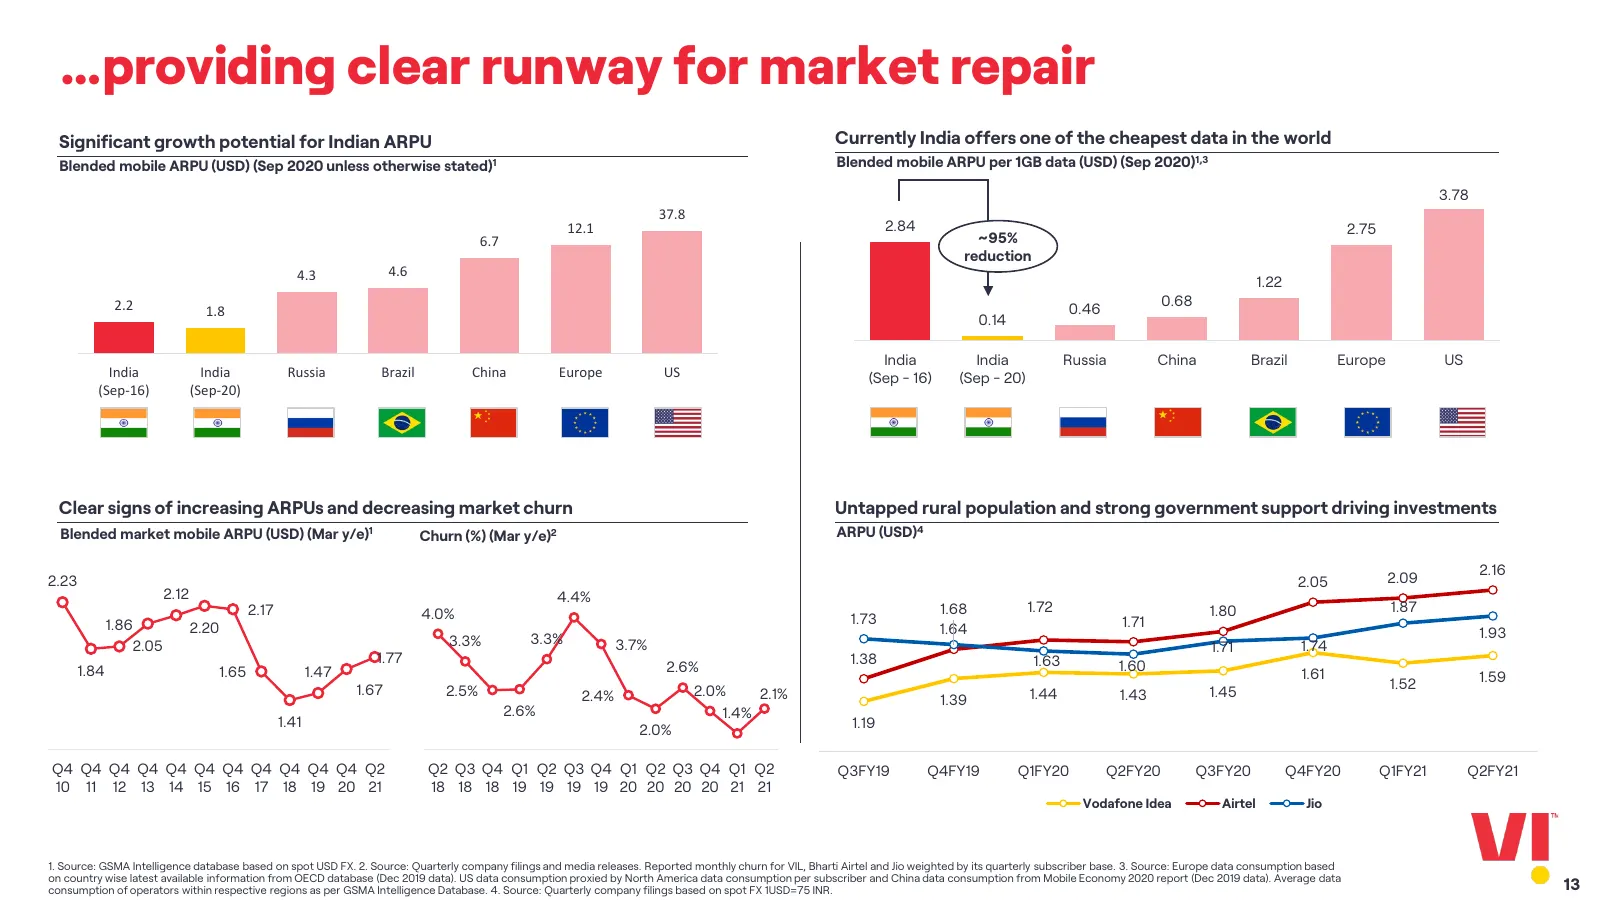
Slide 13: …providing clear runway for market repair
…providing clear runway for market repair Significant growth potential for Indian ARPU Currently India offers one of the cheapest data in the world Blended mobile ARPU (USD) (Sep 2020 unless otherwise stated)1 Blended mobile ARPU per 1GB data (USD) (Sep 2020)1,3 4.00 3.78 37.8 2.84 2.75 3.50 12.1 6.
Slide 14: VIL Strategy
VIL Strategy 14
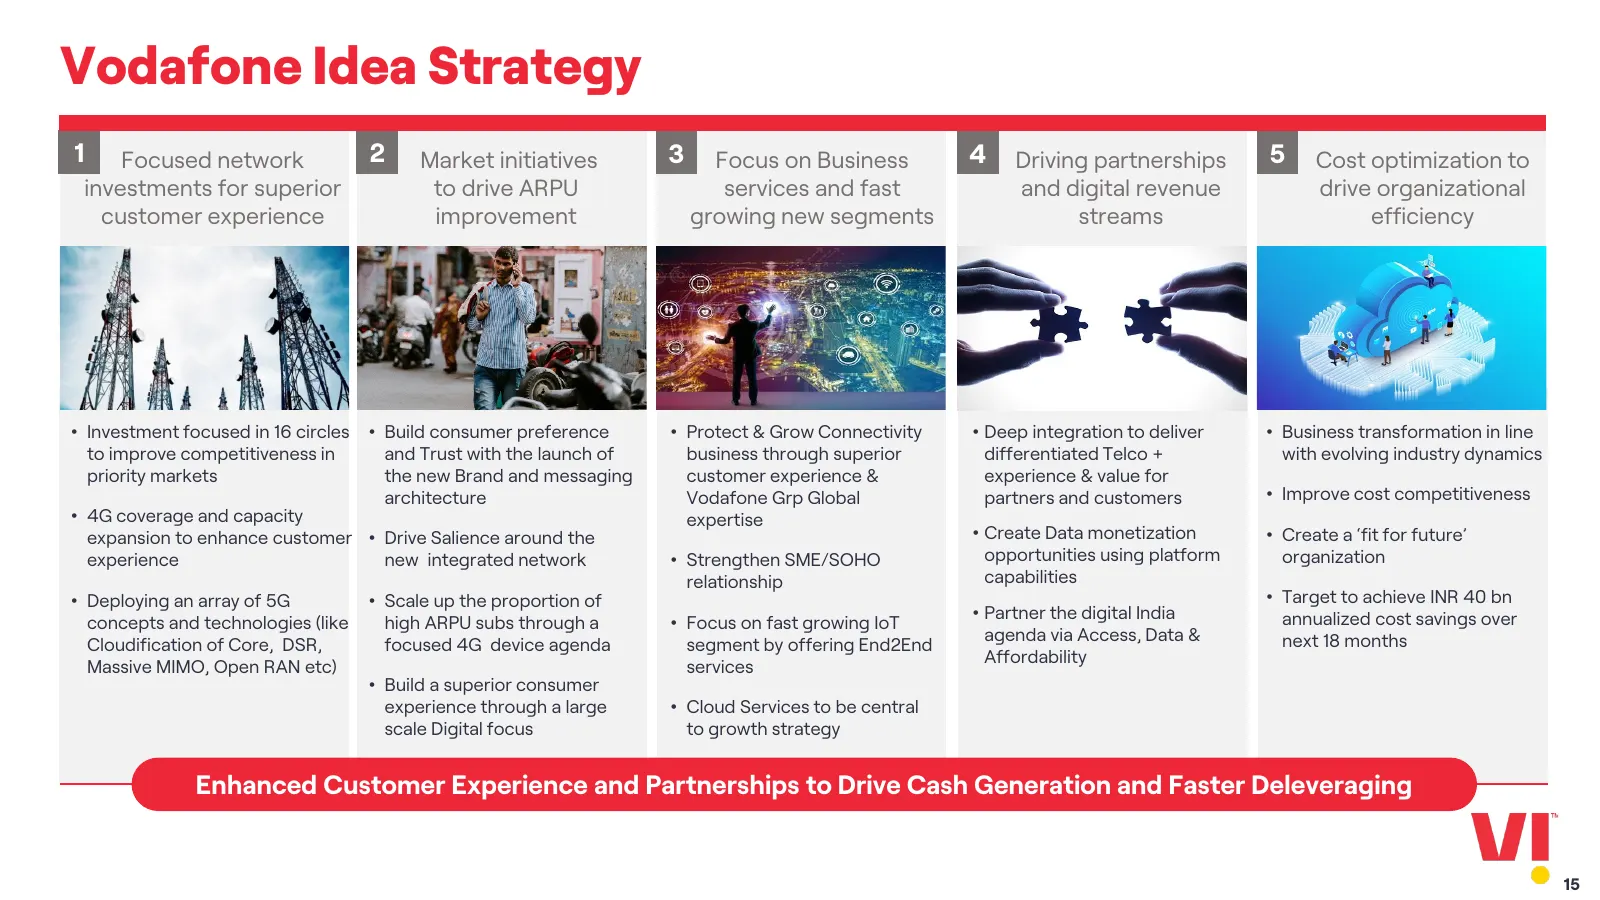
Slide 15: Vodafone Idea Strategy
Vodafone Idea Strategy 1 Focused network 2 Market initiatives 3 Focus on Business 4 Driving partnerships 5 Cost optimization to investments for superior to drive ARPU services and fast and digital revenue drive organizational customer experience improvement growing new segments streams efficiency •
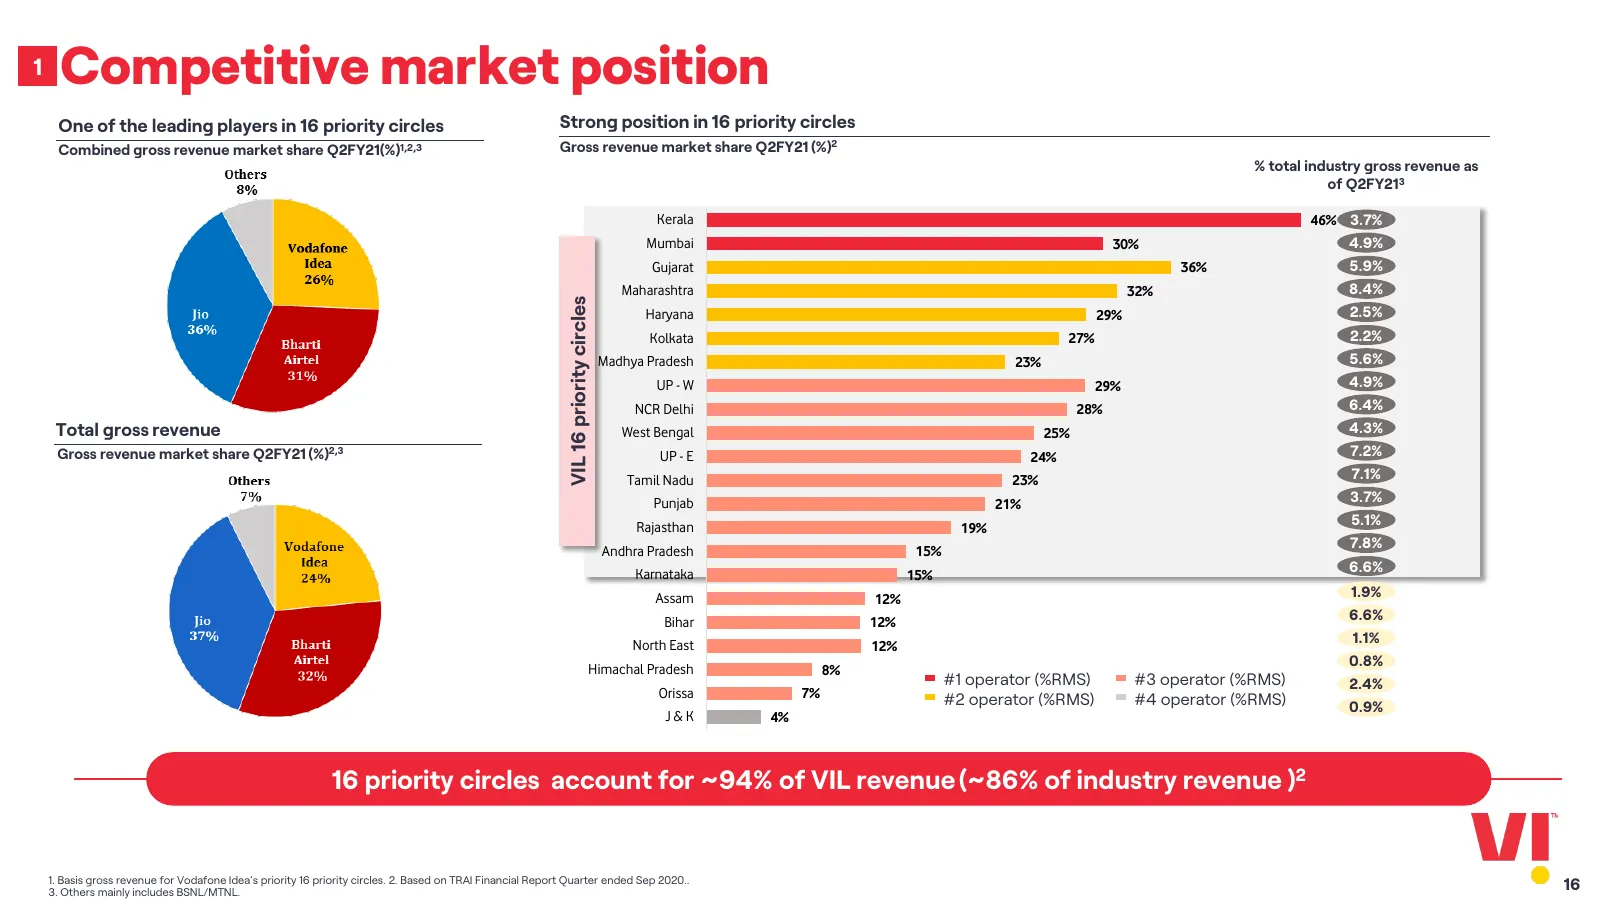
Slide 16: Competitive market position
1 Competitive market position One of the leading players in 16 priority circles Strong position in 16 priority circles Combined gross revenue market share Q2FY21(%)1,2,3 Gross revenue market share Q2FY21 (%)2 % total industry gross revenue as of Q2FY213 Kerala 46% 3.7% Mumbai 30% 4.9% Gujarat 36% 5.
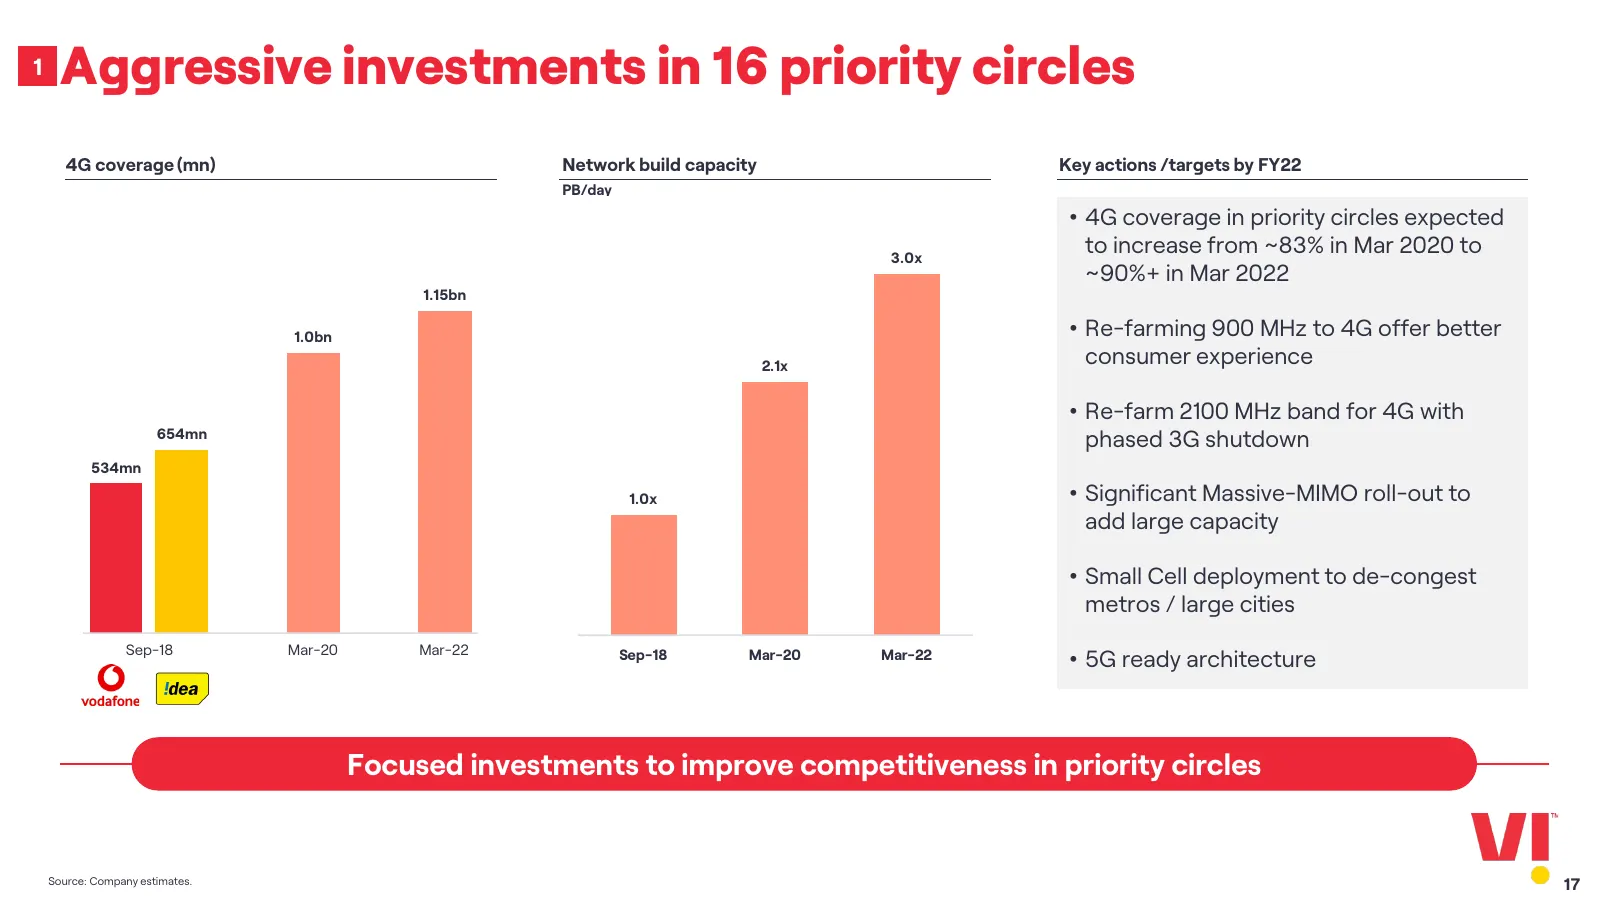
Slide 17: Aggressive investments in 16 priority circles
1 Aggressive investments in 16 priority circles 4G coverage (mn) Network build capacity Key actions /targets by FY22 PB/day • 4G coverage in priority circles expected 3.0x to increase from ~83% in Mar 2020 to ~90%+ in Mar 2022 1.15bn 1.0bn • Re-farming 900 MHz to 4G offer better 2.1x consumer experi
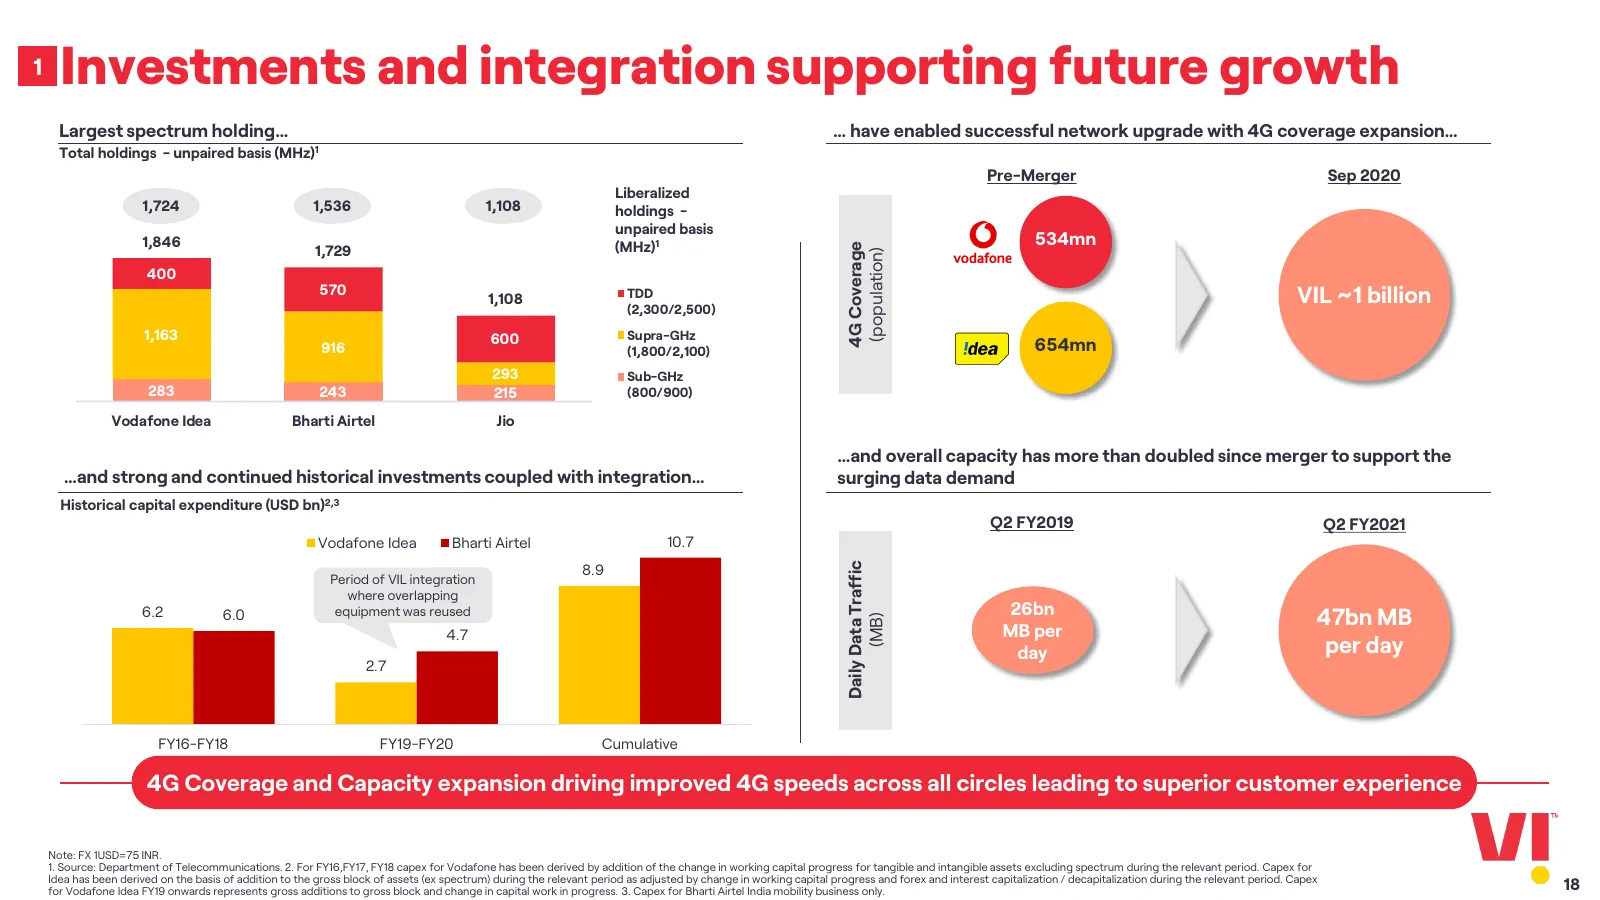
Slide 18: Investments and integration supporting future growth
1 Investments and integration supporting future growth Largest spectrum holding… … have enabled successful network upgrade with 4G coverage expansion… Total holdings - unpaired basis (MHz)1 Pre-Merger Sep 2020 Liberalized 1,724 1,536 1,108 holdings - unpaired basis 1,846 (MHz)1 534mn 1,729 4G Covera
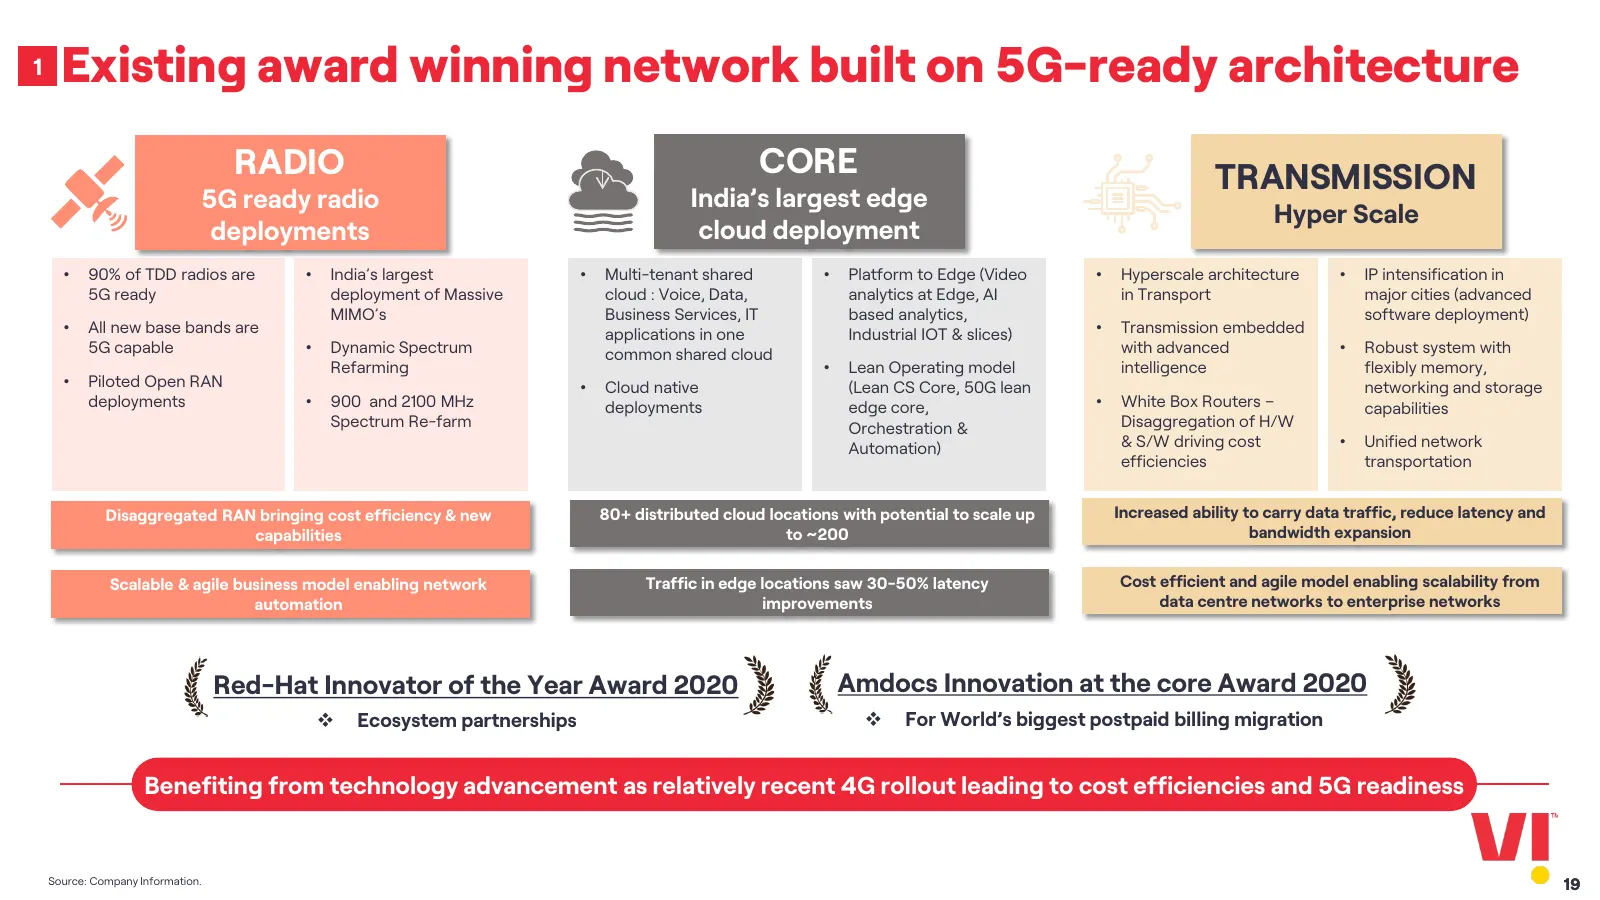
Slide 19: Existing award winning network built on 5G-ready architecture
1 Existing award winning network built on 5G-ready architecture RADIO CORE TRANSMISSION 5G ready radio India’s largest edge Hyper Scale deployments cloud deployment • 90% of TDD radios are • India’s largest • Multi-tenant shared • Platform to Edge (Video • Hyperscale architecture • IP intensificatio
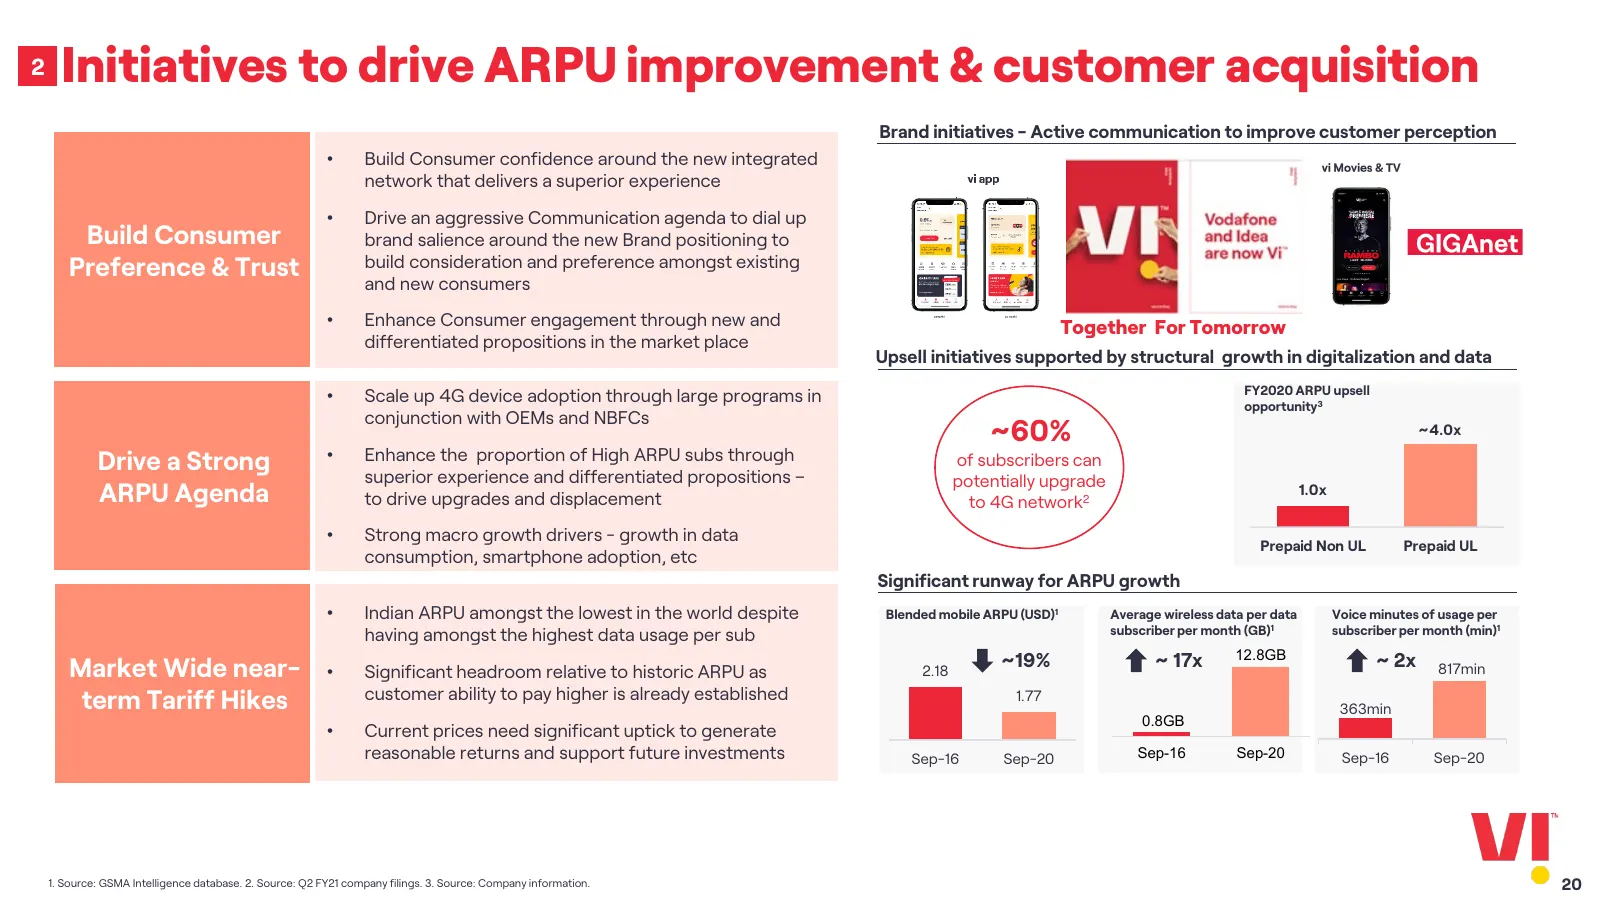
Slide 20: Initiatives to drive ARPU improvement & customer acquisition
2 Initiatives to drive ARPU improvement & customer acquisition Brand initiatives - Active communication to improve customer perception • Build Consumer confidence around the new integrated network that delivers a superior experience • Drive an aggressive Communication agenda to dial up Build Consume
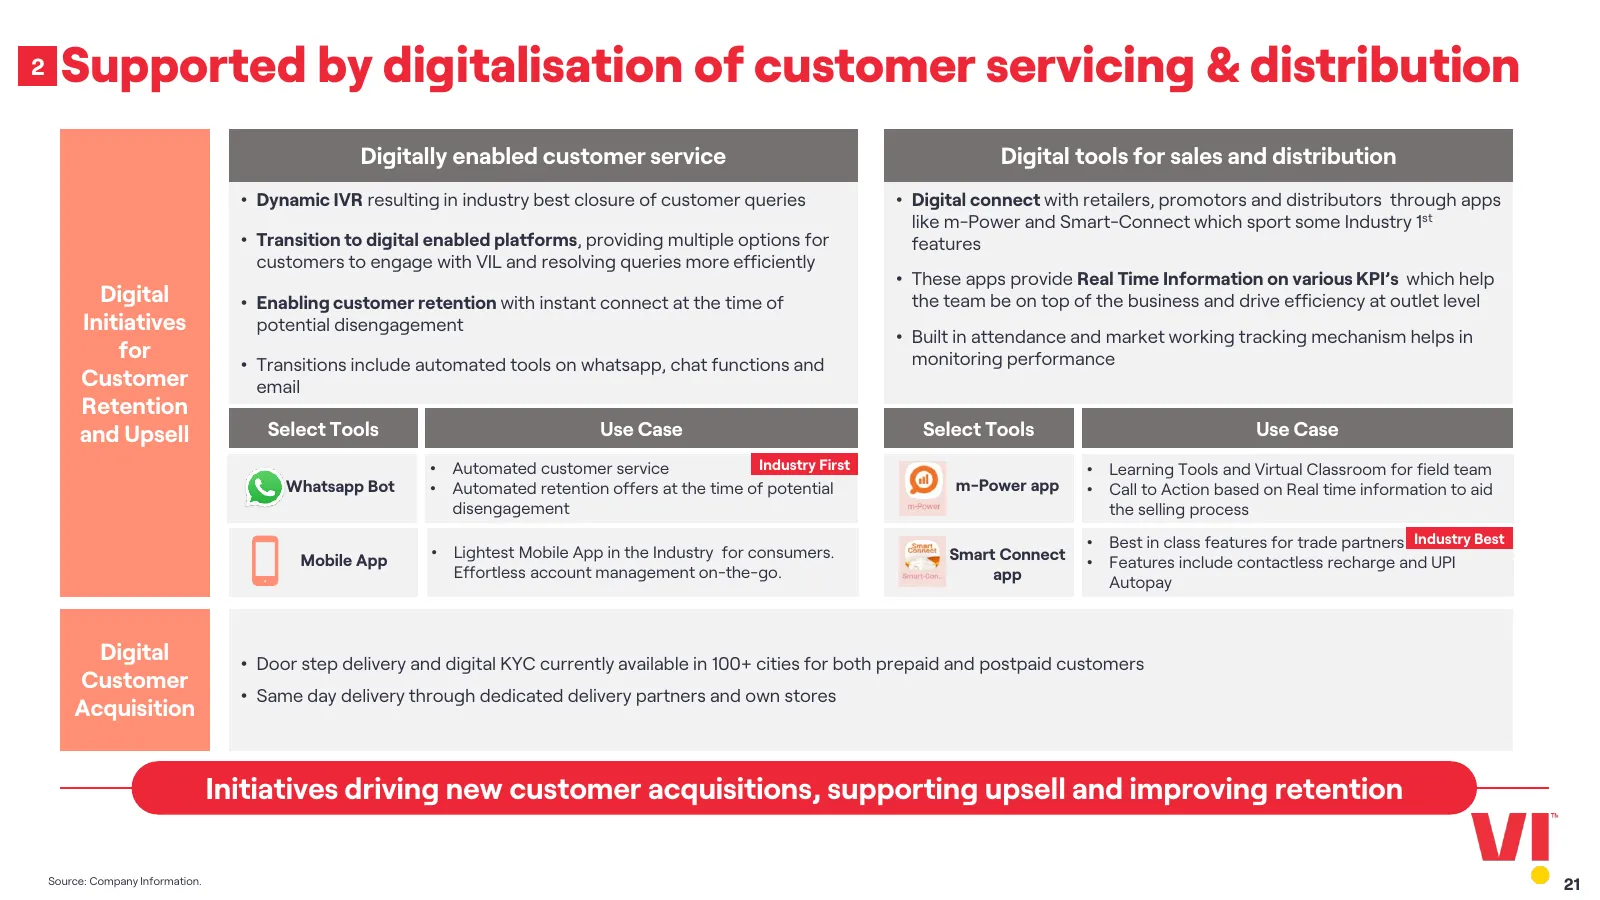
Slide 21: Supported by digitalisation of customer servicing & distribution
2 Supported by digitalisation of customer servicing & distribution Digitally enabled customer service Digital tools for sales and distribution • Dynamic IVR resulting in industry best closure of customer queries • Digital connect with retailers, promotors and distributors through apps like m-Power a
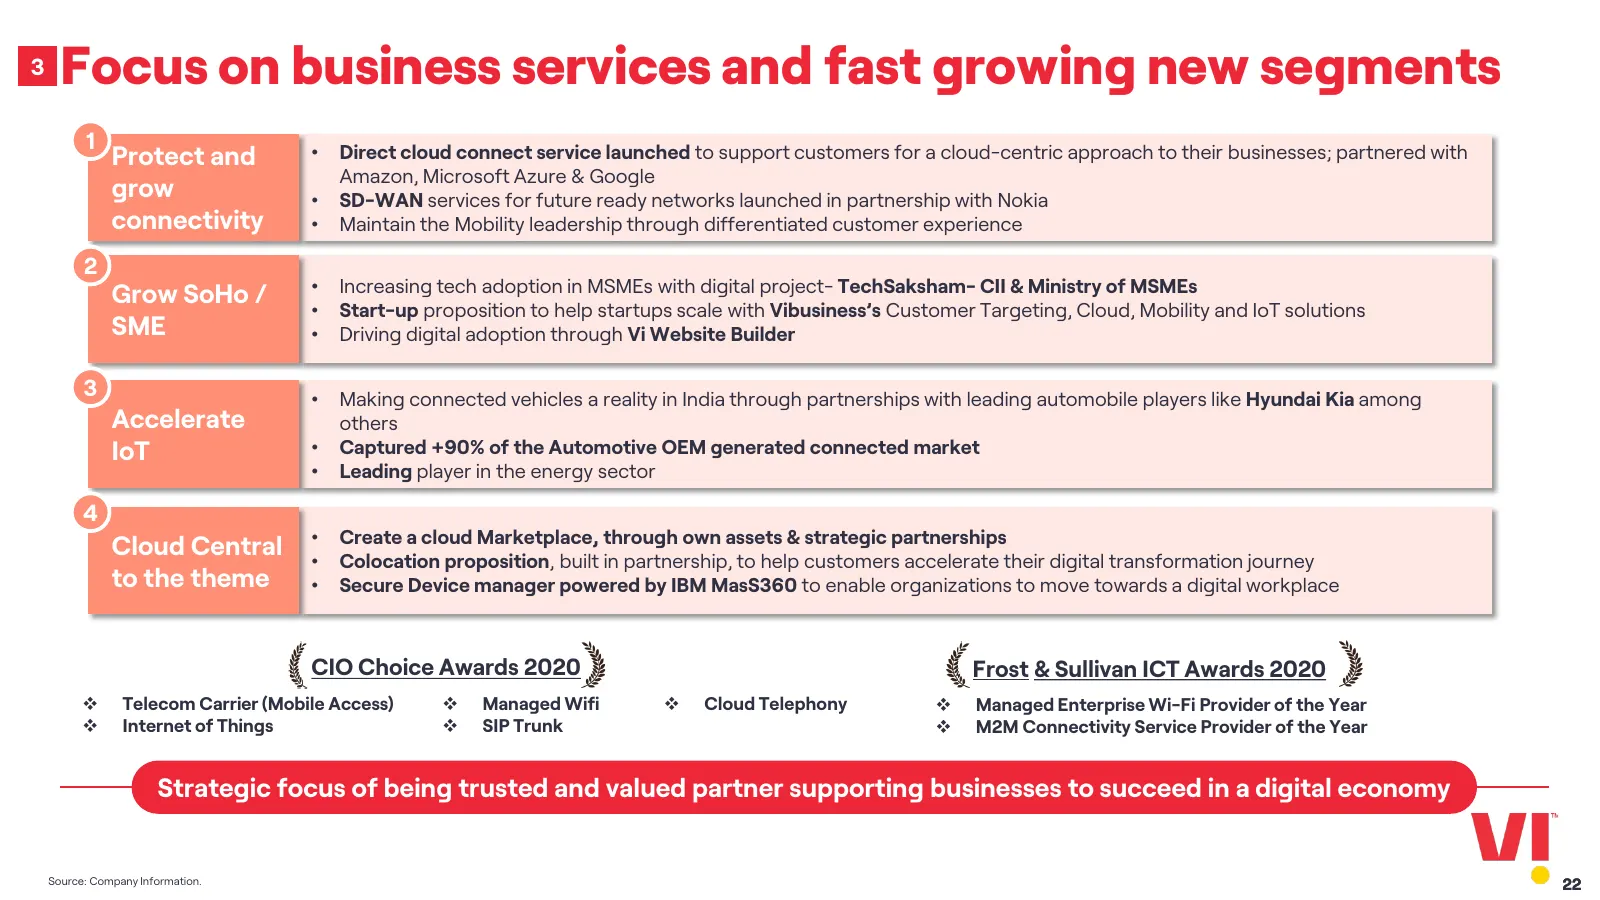
Slide 22: Focus on business services and fast growing new segments
3 Focus on business services and fast growing new segments 1 Protect and • Direct cloud connect service launched to support customers for a cloud-centric approach to their businesses; partnered with Amazon, Microsoft Azure & Google grow • SD-WAN services for future ready networks launched in partner
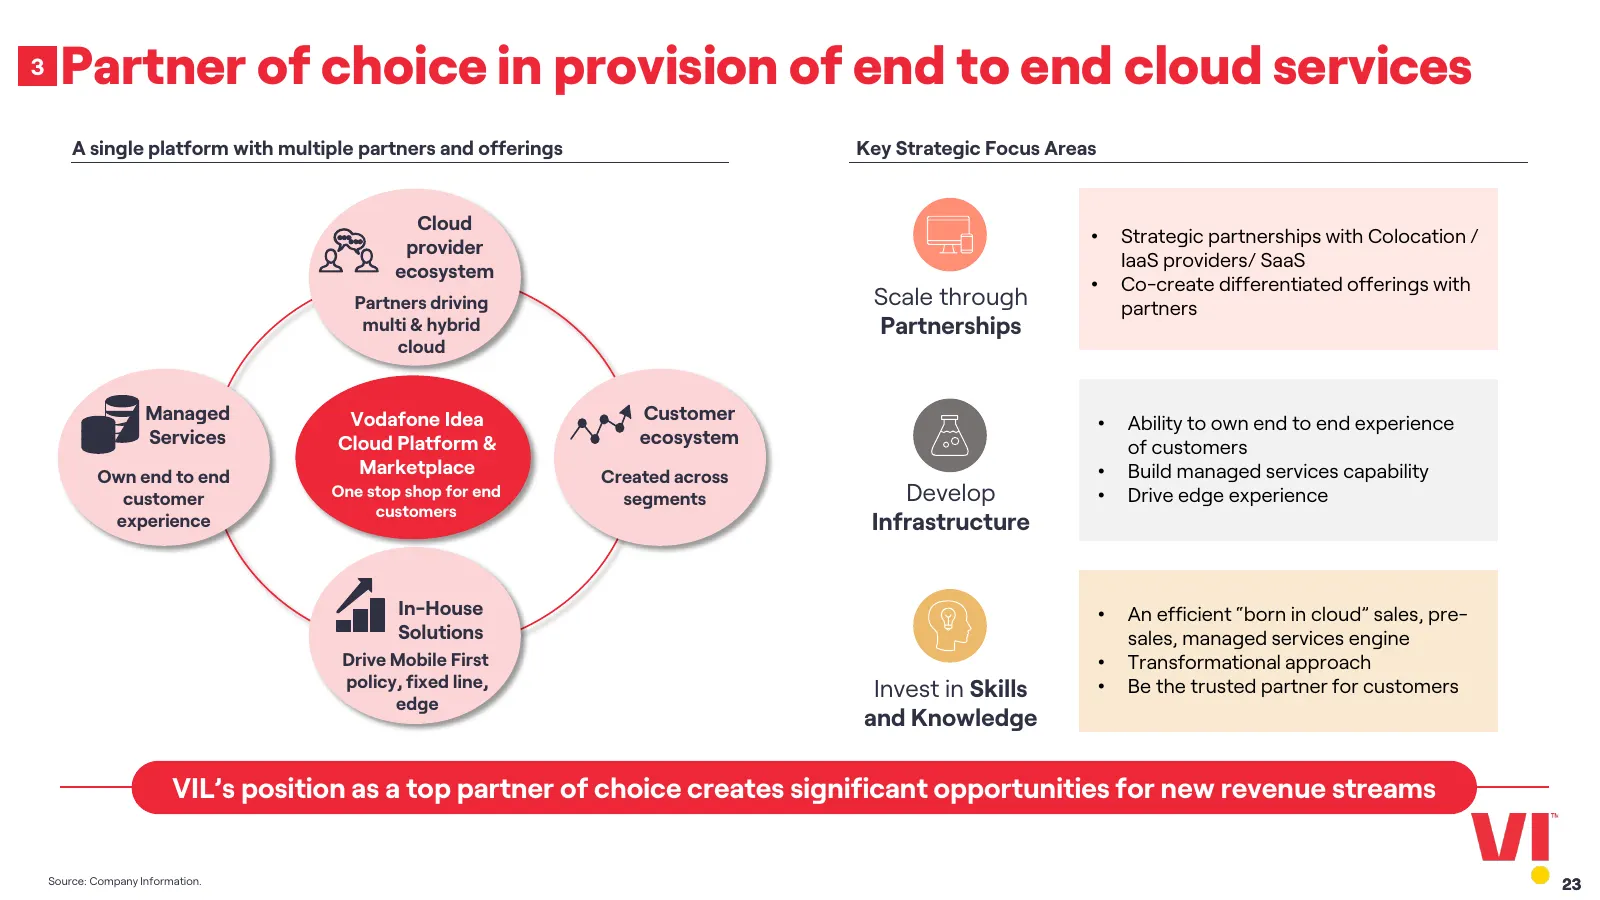
Slide 23: Partner of choice in provision of end to end cloud services
3 Partner of choice in provision of end to end cloud services A single platform with multiple partners and offerings Key Strategic Focus Areas Cloud • Strategic partnerships with Colocation / provider IaaS providers/ SaaS ecosystem • Co-create differentiated offerings with Partners driving Scale thr
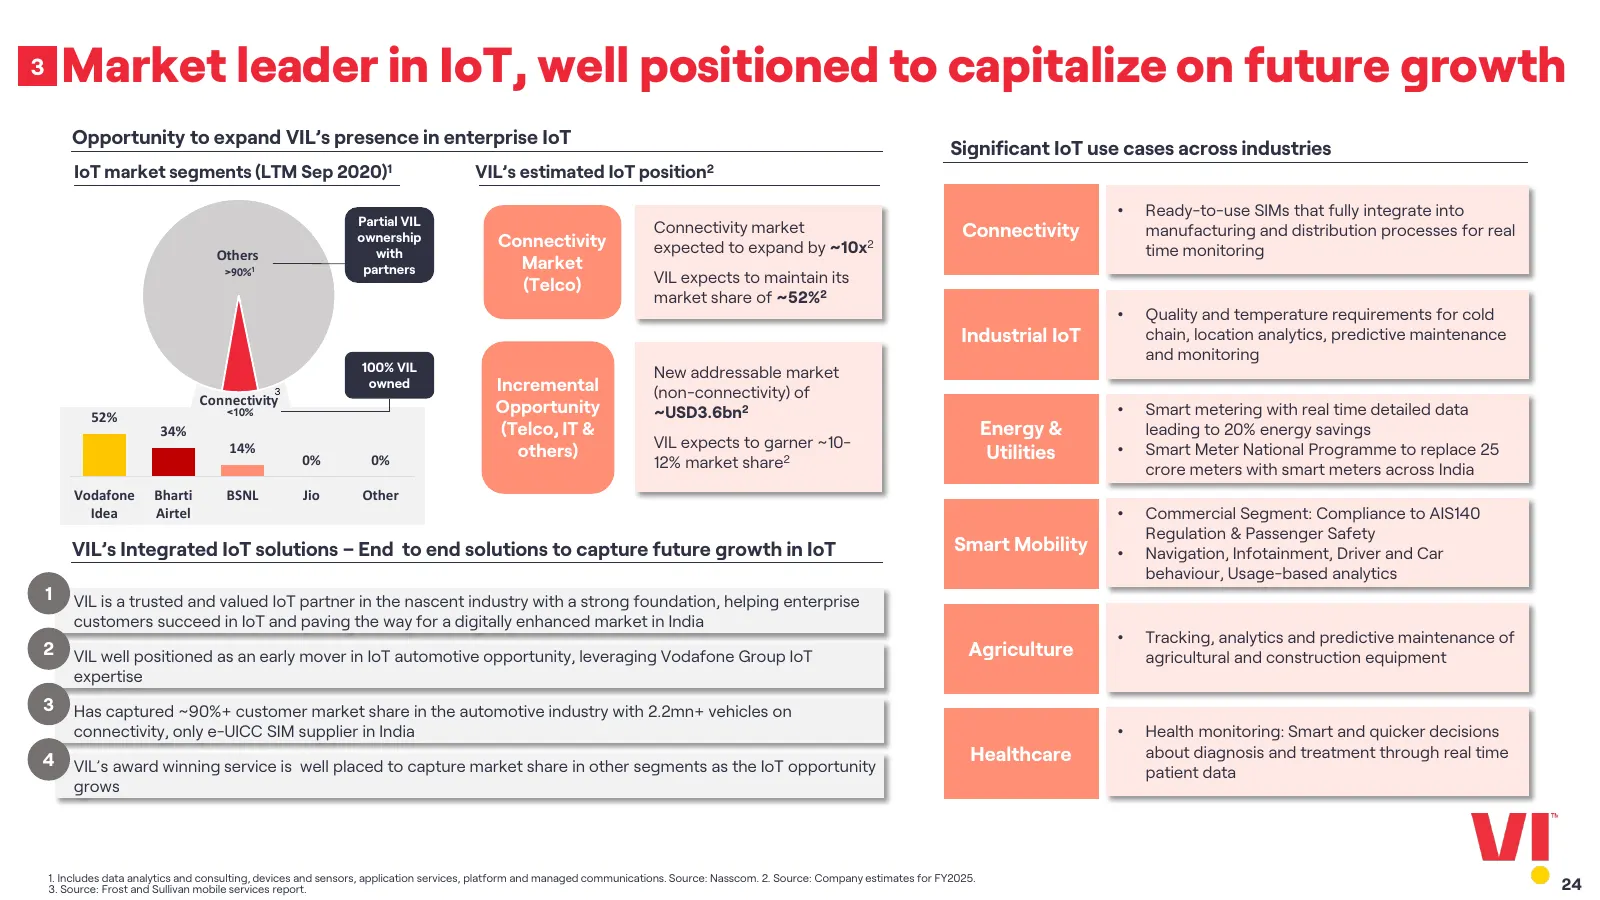
Slide 24: Market leader in IoT, well positioned to capitalize on future growth
3 Market leader in IoT, well positioned to capitalize on future growth Opportunity to expand VIL’s presence in enterprise IoT Significant IoT use cases across industries IoT market segments (LTM Sep 2020)1 VIL’s estimated IoT position2 • Ready-to-use SIMs that fully integrate into Partial VIL owners
Slide 25: Vodafone Idea's propositions & integrated platform
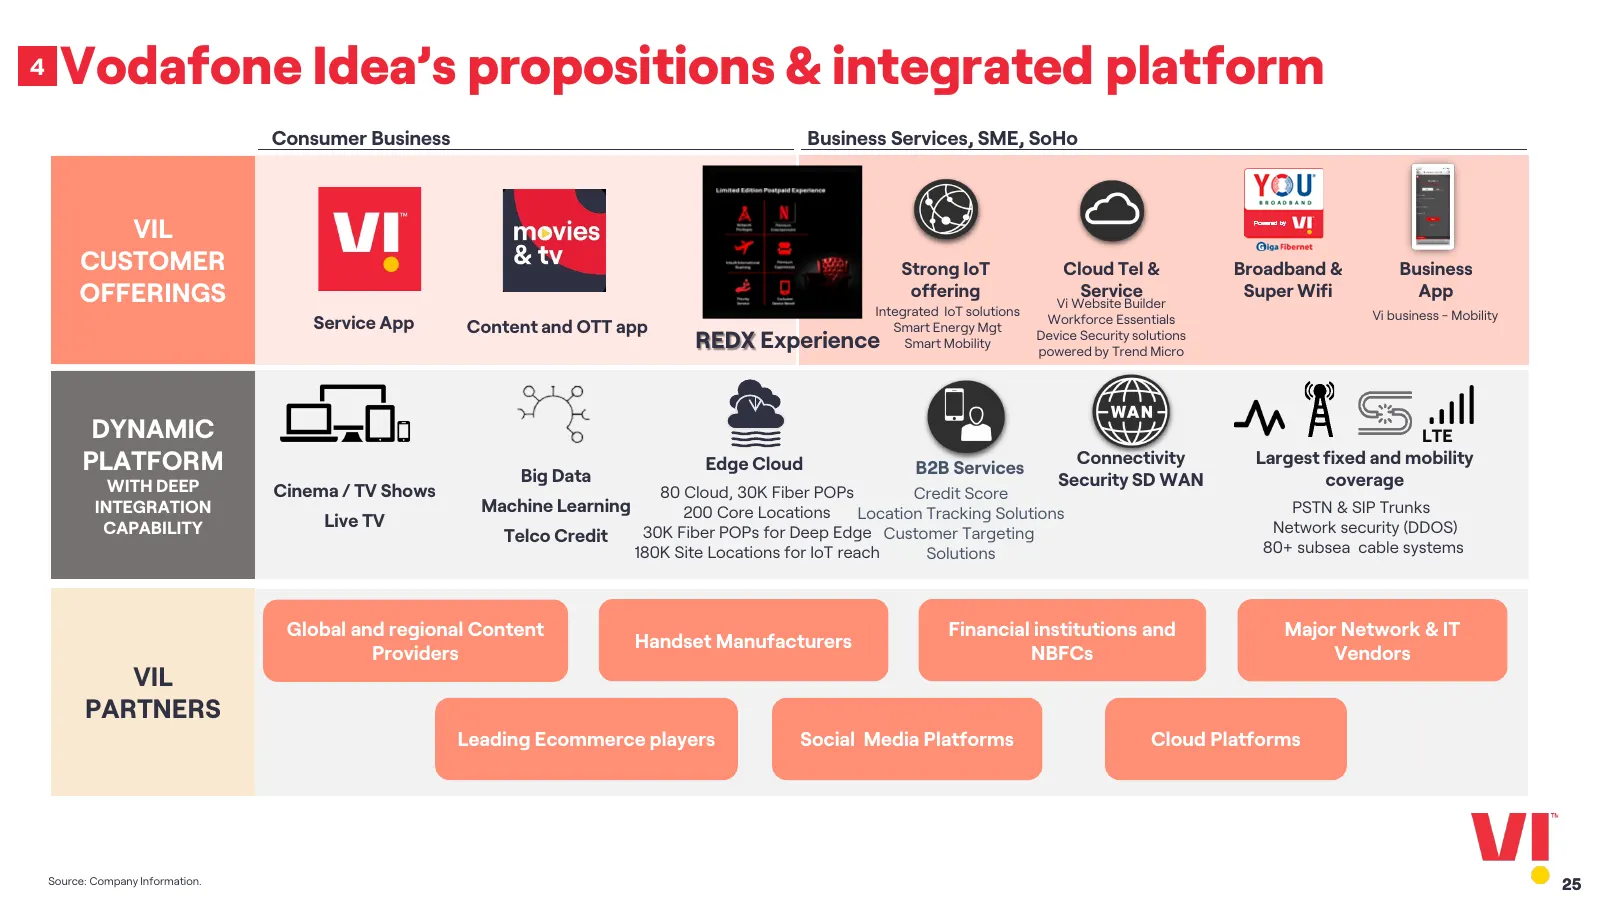
4 Vodafone Idea’s propositions & integrated platform Consumer Business Business Services, SME, SoHo VIL CUSTOMER Strong IoT Cloud Tel & Broadband & Business OFFERINGS offering Service Vi Website Builder Super Wifi App Integrated IoT solutions Vi business - Mobility Service App Content and OTT app Sm
Slide 26: Extensive partnership opportunities across industries
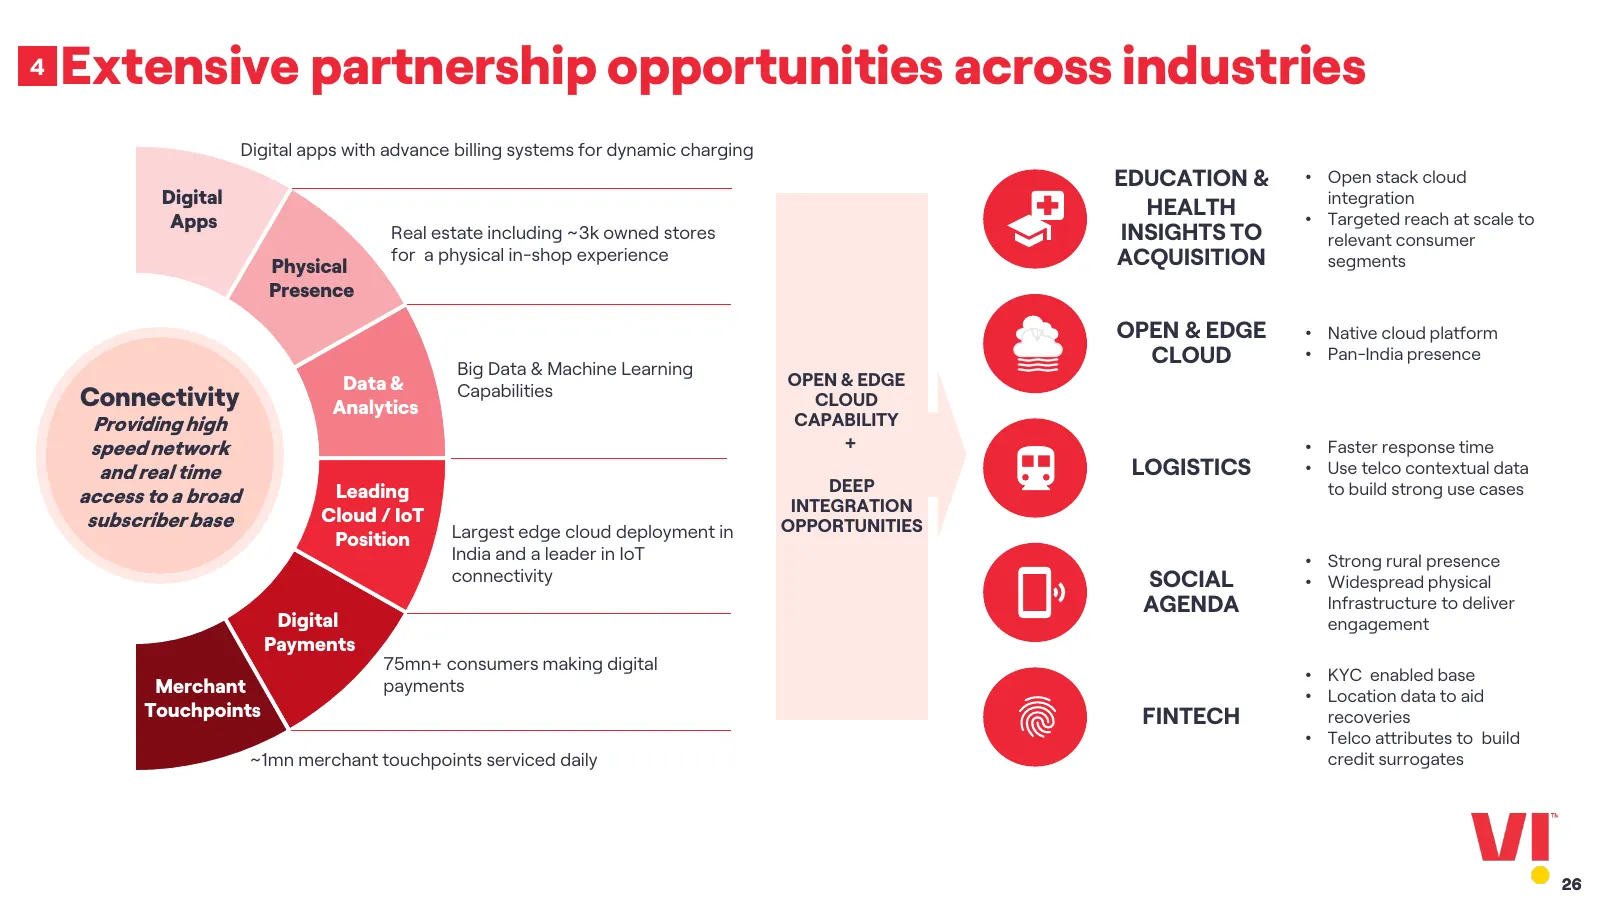
4 Extensive partnership opportunities across industries Digital apps with advance billing systems for dynamic charging EDUCATION & • Open stack cloud Digital integration HEALTH Apps • Targeted reach at scale to Real estate including ~3k owned stores INSIGHTS TO relevant consumer Physical for a physi
Slide 27: Cost optimization to drive organizational efficiency
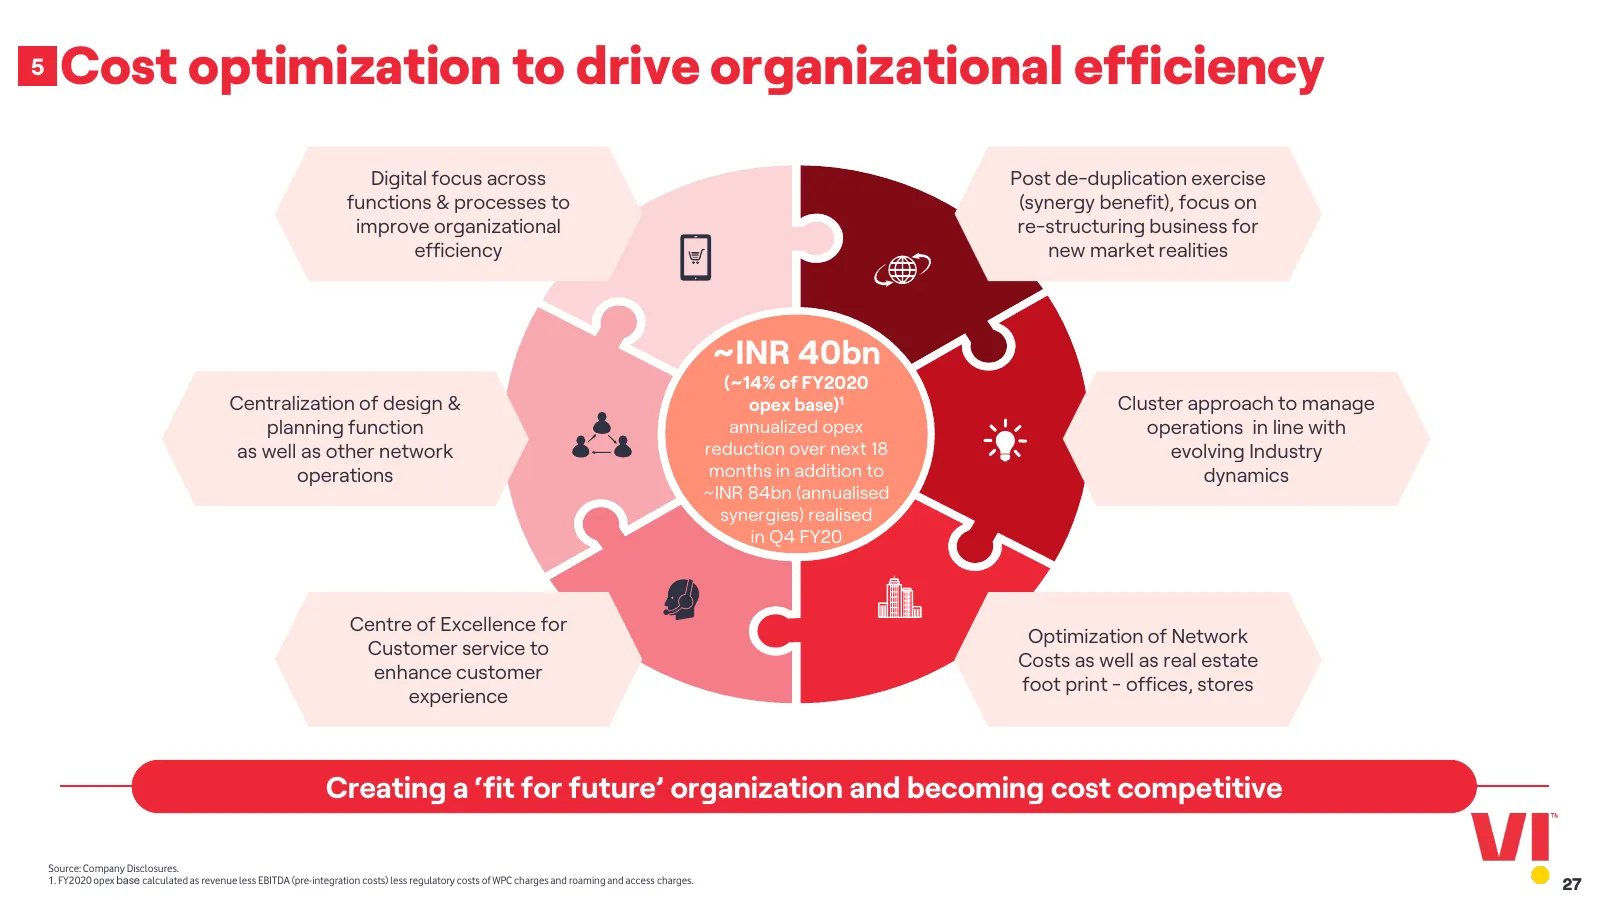
5 Cost optimization to drive organizational efficiency Digital focus across Post de-duplication exercise functions & processes to (synergy benefit), focus on improve organizational re-structuring business for efficiency new market realities ~INR 40bn (~14% of FY2020 Centralization of design & opex b
Slide 28: Q2FY21 Performance Review
Q2FY21 Performance Review 28
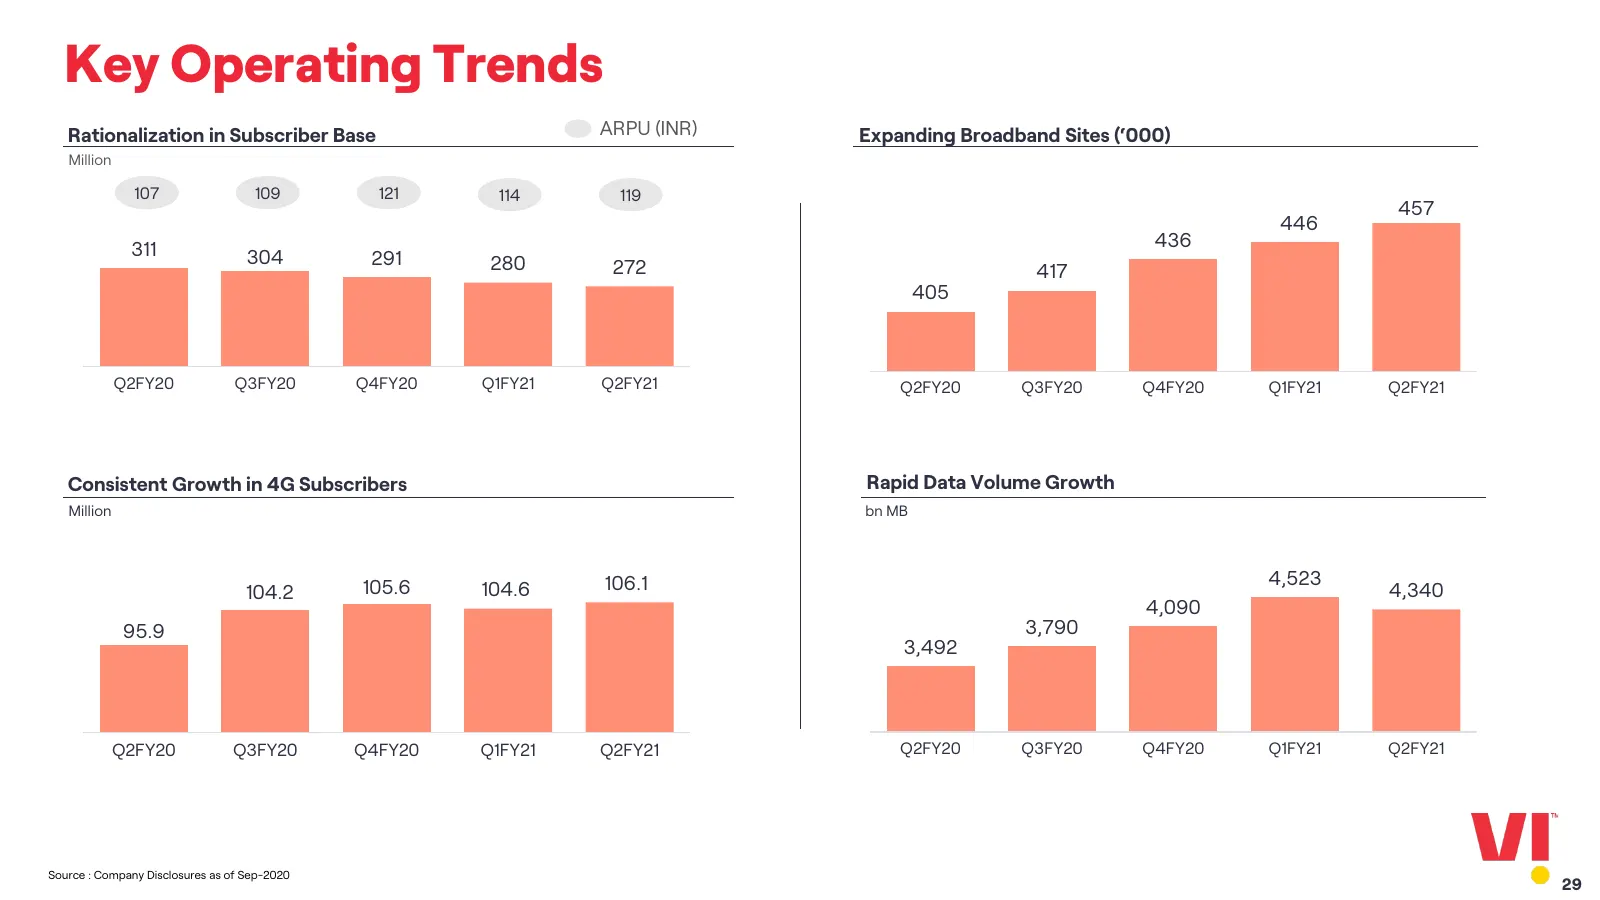
Slide 29: Key Operating Trends
Key Operating Trends Rationalization in Subscriber Base ARPU (INR) Expanding Broadband Sites (‘000) Million 107 109 121 114 119 457 446 311 436 304 291 280 272 417 405 Q2FY20 Q3FY20 Q4FY20 Q1FY21 Q2FY21 Q2FY20 Q3FY20 Q4FY20 Q1FY21 Q2FY21 Consistent Growth in 4G Subscribers Rapid Data Volume Growth M
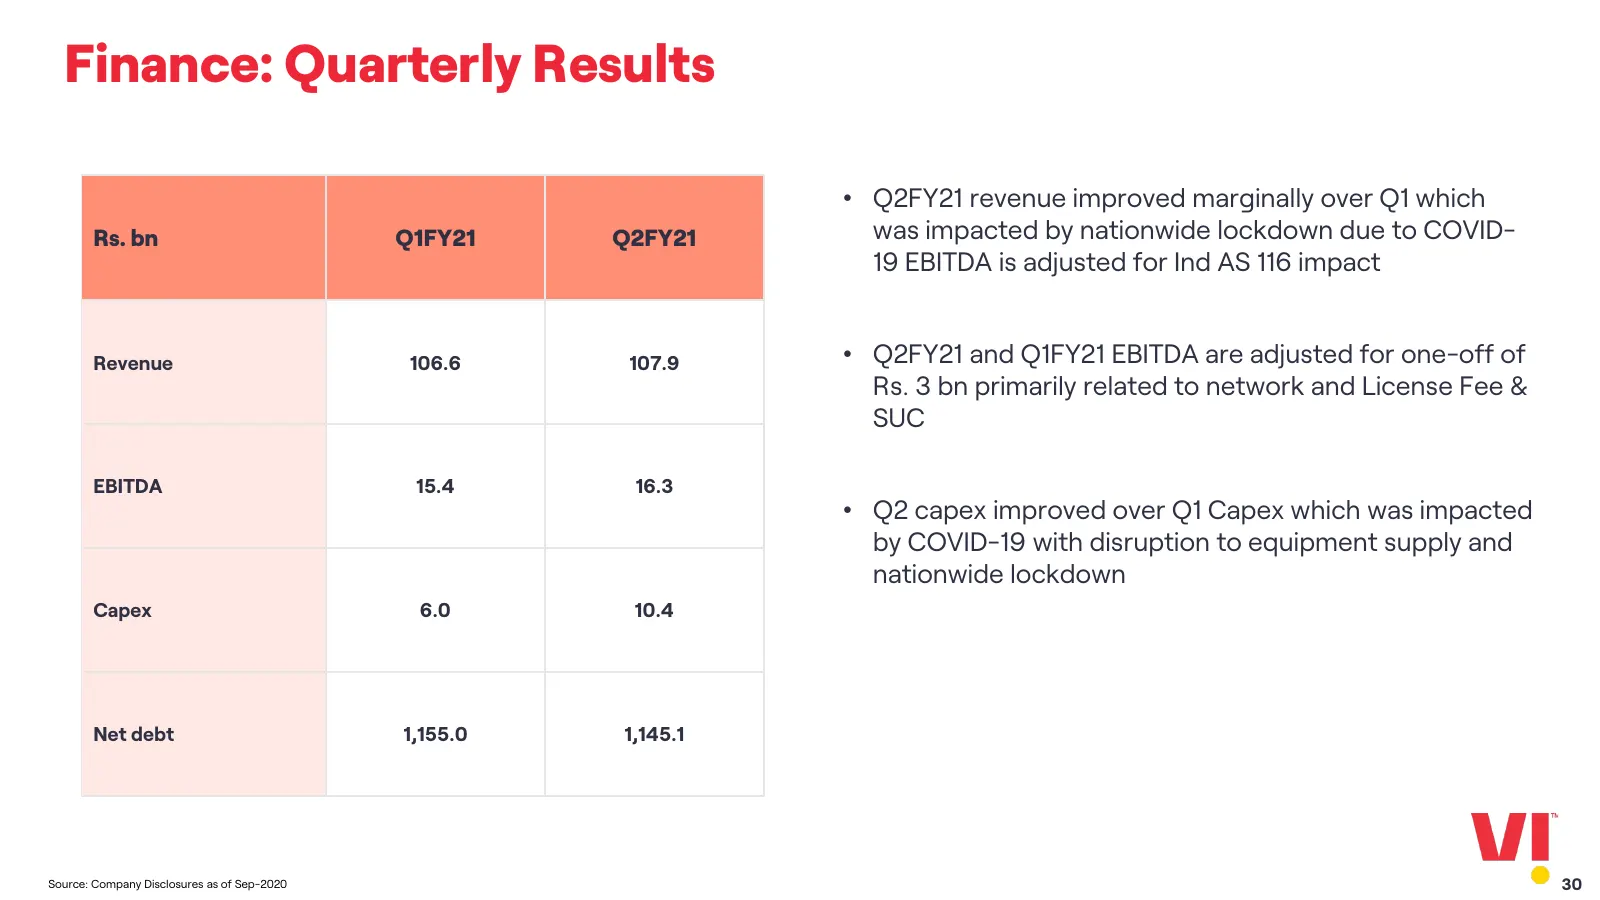
Slide 30: Finance: Quarterly Results
Finance: Quarterly Results • Q2FY21 revenue improved marginally over Q1 which Rs. bn Q1FY21 Q2FY21 was impacted by nationwide lockdown due to COVID- 19 EBITDA is adjusted for Ind AS 116 impact Revenue 106.6 107.9 • Q2FY21 and Q1FY21 EBITDA are adjusted for one-off of Rs. 3 bn primarily related to ne
Slide 31: Disclaimer
Disclaimer This presentation and accompanying slides (the “Presentation”) has been prepared by Vodafone India Limited (“Company”) and is not for release, distribution or publication, whether directly or indirectly, in whole or part, into or in any jurisdiction in which such release, distribution or
Slide 32: Thank You
Thank You 32
Source: Internet Archive copy of myvi.in
More decks from Vodafone Idea Ltd
 Investor Presentation (November 2026)25 slides · Nov 12, 2026
 Investor Presentation (September 2026)21 slides · Sep 15, 2026
 Investor Presentation (June 2026)20 slides · Jun 30, 2026
 Investor Presentation (June 2026)19 slides · June 2026
 Investor Presentation (January 2026)31 slides · Jan 28, 2026
 Investor Presentation (January 2026)32 slides · Jan 28, 2026