Air Transport Services Group Inc
Air Transport Services — Dahlman Rose & Co. Global Transportation Conference 2012
14 slides from Air Transport Services's conference presentation, Sep 6, 2012
Slide 1: Dahlman Rose & Co. Global Transportation Conference September 6, 2012
0 Dahlman Rose & Co. Global Transportation Conference September 6, 2012
Slide 2: Safe Harbor Statement
Safe Harbor Statement Except for historical information contained herein, the matters discussed in this presentation contain forward-looking statements that involve risks and uncertainties. There are a number of important factors that could cause Air Transport Services Group's ("ATSG's") actual resu
Slide 3: ATSG Strategy
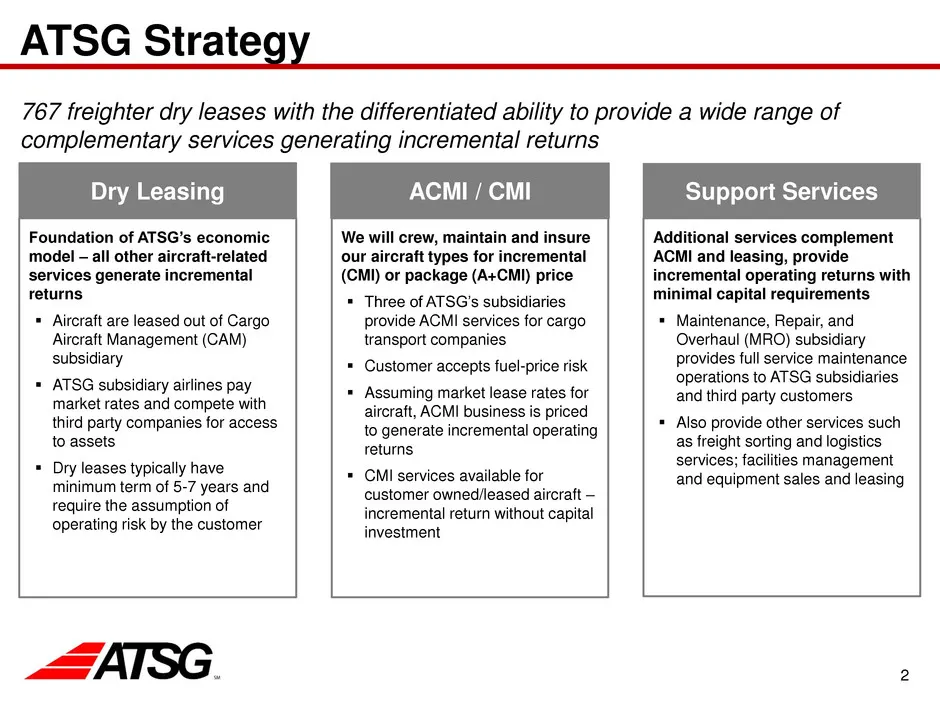
2 ATSG Strategy 767 freighter dry leases with the differentiated ability to provide a wide range of complementary services generating incremental returns Dry Leasing ACMI / CMI Support Services Foundation of ATSG’s economic model – all other aircraft-related services generate incremental returns A
Slide 4: ATSG Business Model
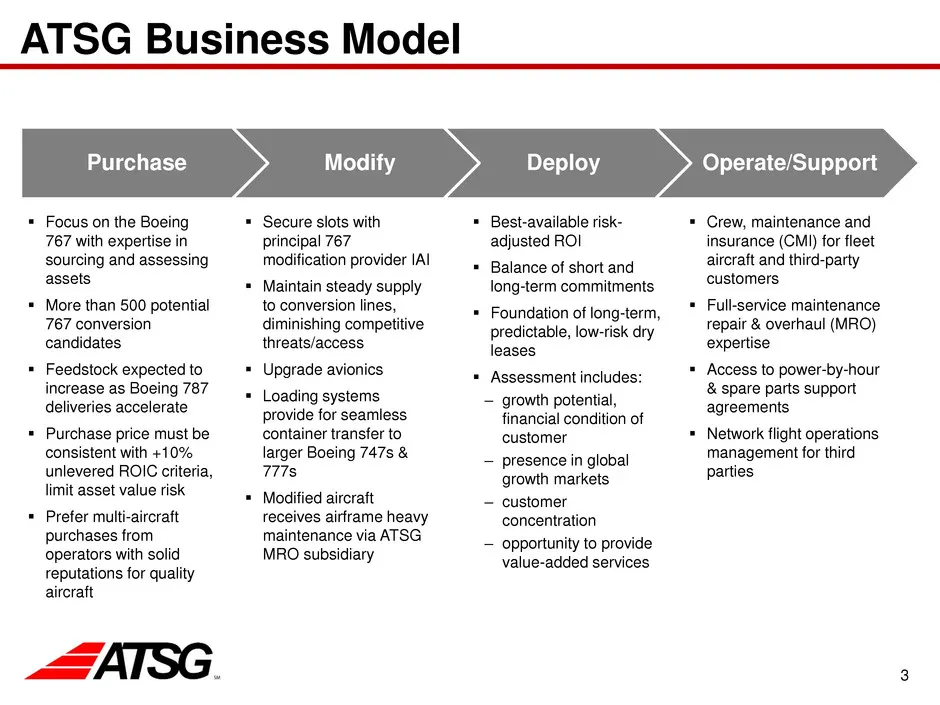
3 ATSG Business Model Purchase Modify Deploy Operate/Support Focus on the Boeing 767 with expertise in sourcing and assessing assets More than 500 potential 767 conversion candidates Feedstock expected to increase as Boeing 787 deliveries accelerate Purchase price must be consistent with +10
Slide 5: Transformation Drives Earnings Growth
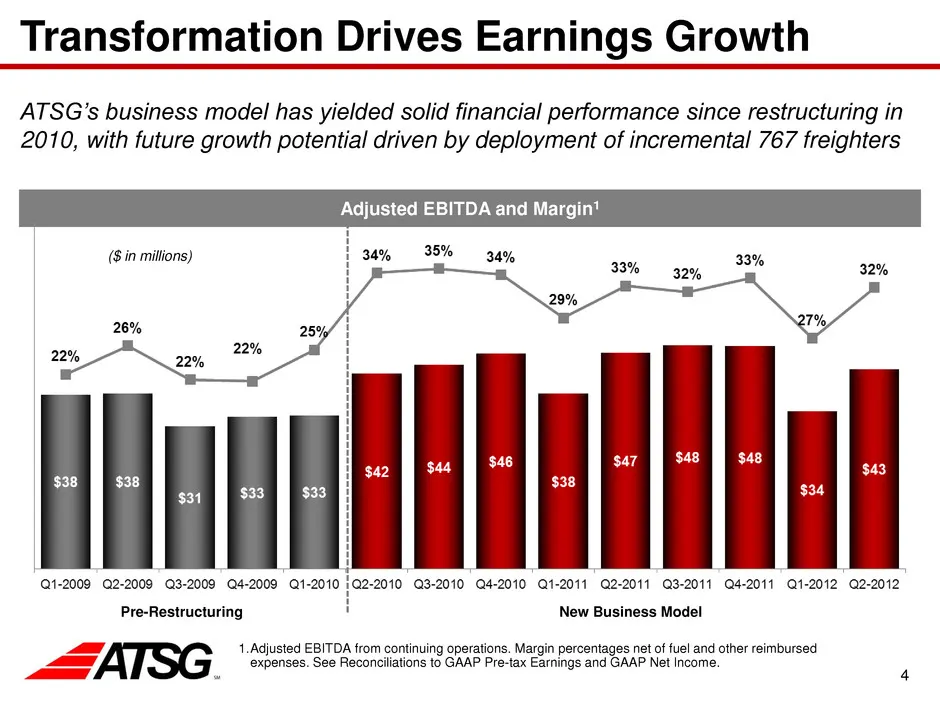
4 Transformation Drives Earnings Growth ATSG’s business model has yielded solid financial performance since restructuring in 2010, with future growth potential driven by deployment of incremental 767 freighters Adjusted EBITDA and Margin1 1.Adjusted EBITDA from continuing operations. Margin percenta
Slide 6: ATSG Investment Strategy
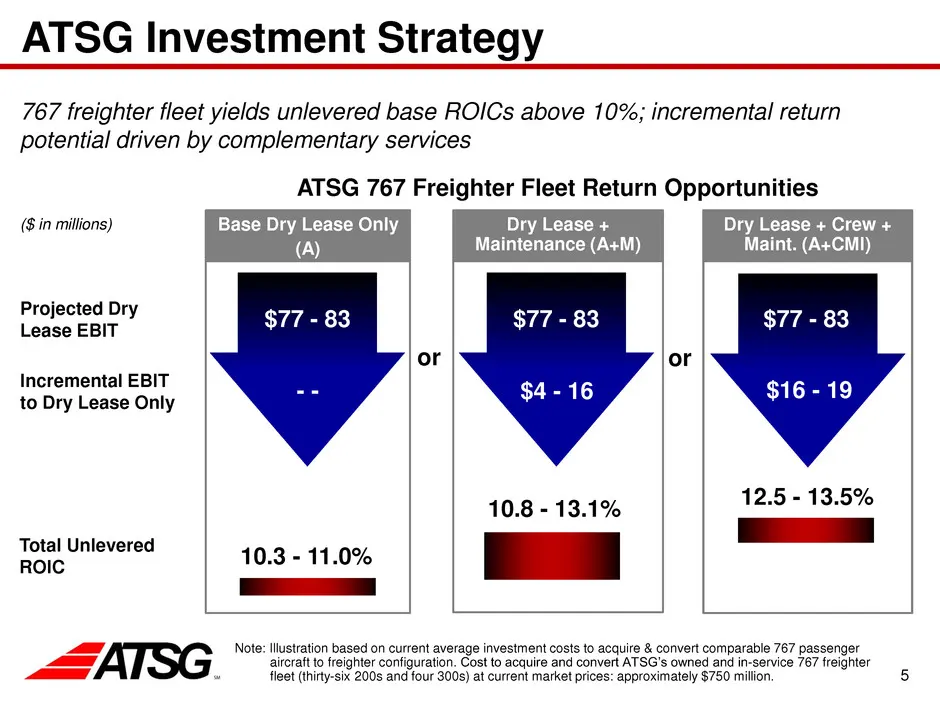
5 ATSG Investment Strategy 767 freighter fleet yields unlevered base ROICs above 10%; incremental return potential driven by complementary services Base Dry Lease Only (A) Dry Lease + Crew + Maint. (A+CMI) Dry Lease + Maintenance (A+M) Projected Dry Lease EBIT Incremental EBIT to Dry Lease Only Tota
Slide 7: First Half Financials
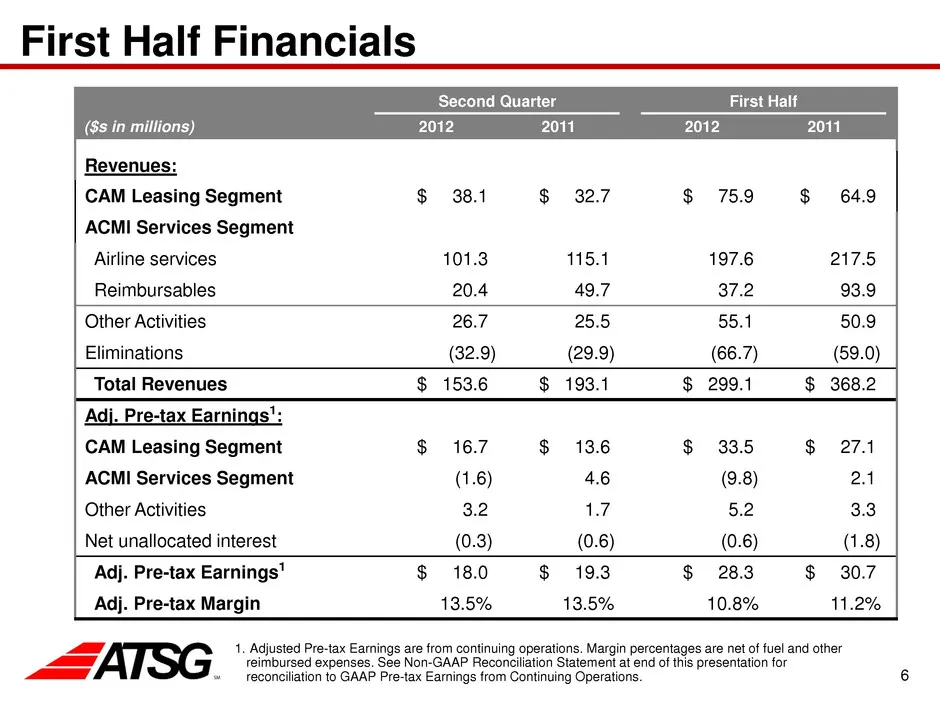
6 First Half Financials Second Quarter First Half ($s in millions) 2012 2011 2012 2011 Revenues: CAM Leasing Segment $ 38.1 $ 32.7 $ 75.9 $ 64.9 ACMI Services Segment Airline services 101.3 115.1 197.6 217.5 Reimbursables 20.4 49.7 37.2 93.9 Other Activities 26.7 25.5 55.1 50.9 Eliminations (32.9) (
Slide 8: Capital Base to Support Growth
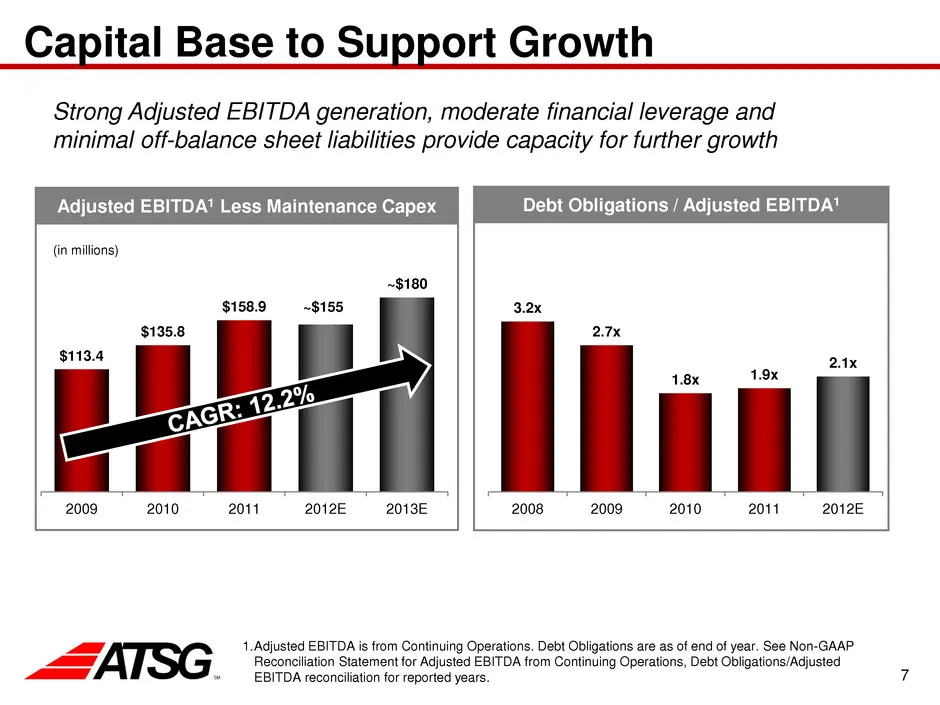
7 $113.4 $135.8 $158.9 ~$155 ~$180 2009 2010 2011 2012E 2013E Capital Base to Support Growth Strong Adjusted EBITDA generation, moderate financial leverage and minimal off-balance sheet liabilities provide capacity for further growth Debt Obligations / Adjusted EBITDA1 1.Adjusted EBITDA is from Cont
Slide 9: Unrivaled Leader in ACMI Medium Wide-body
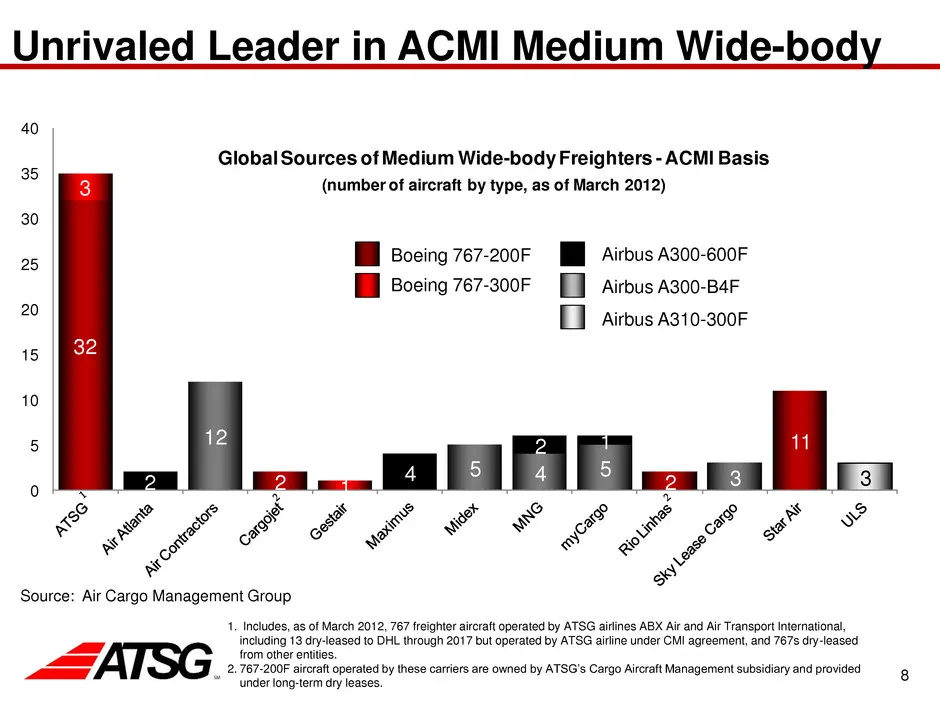
8 Unrivaled Leader in ACMI Medium Wide-body 32 2 2 11 3 1 12 5 4 5 32 4 2 1 3 0 5 10 15 20 25 30 35 40 Global Sources of Medium Wide-body Freighters - ACMI Basis (number of aircraft by type, as of March 2012) 1. Includes, as of March 2012, 767 freighter aircraft operated by ATSG airlines ABX Air and
Slide 10: Current Freighter Deployments
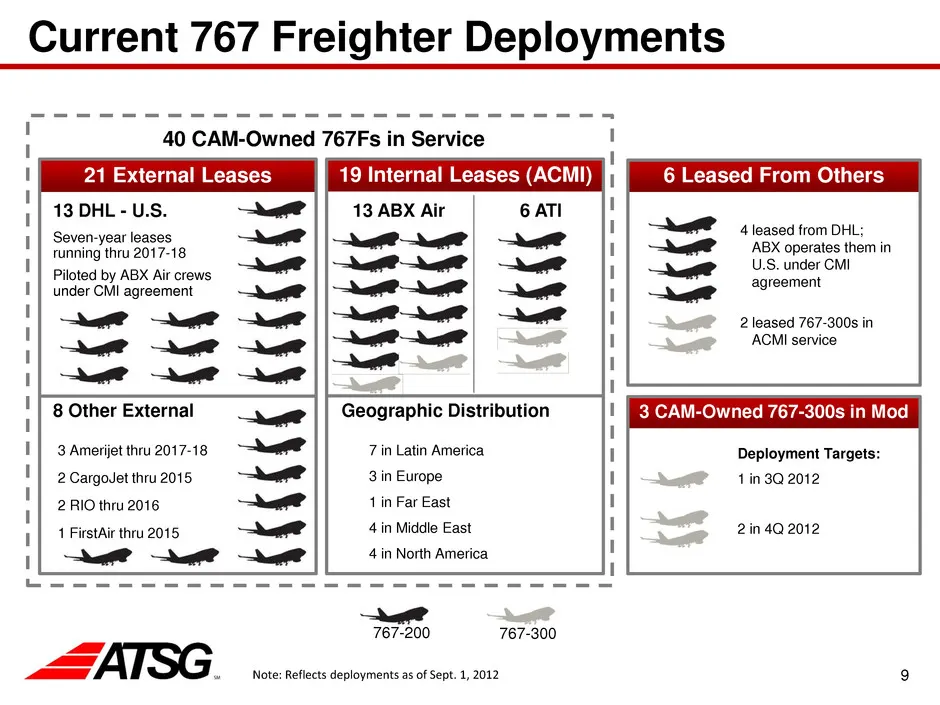
9 Current 767 Freighter Deployments 21 External Leases 19 Internal Leases (ACMI) 13 DHL - U.S. Seven-year leases running thru 2017-18 Piloted by ABX Air crews under CMI agreement 6 ATI Geographic Distribution 13 ABX Air 8 Other External 3 Amerijet thru 2017-18 2 CargoJet thru 2015 2 RIO thru 2016 1
Slide 11: ATSG's Global Opportunities
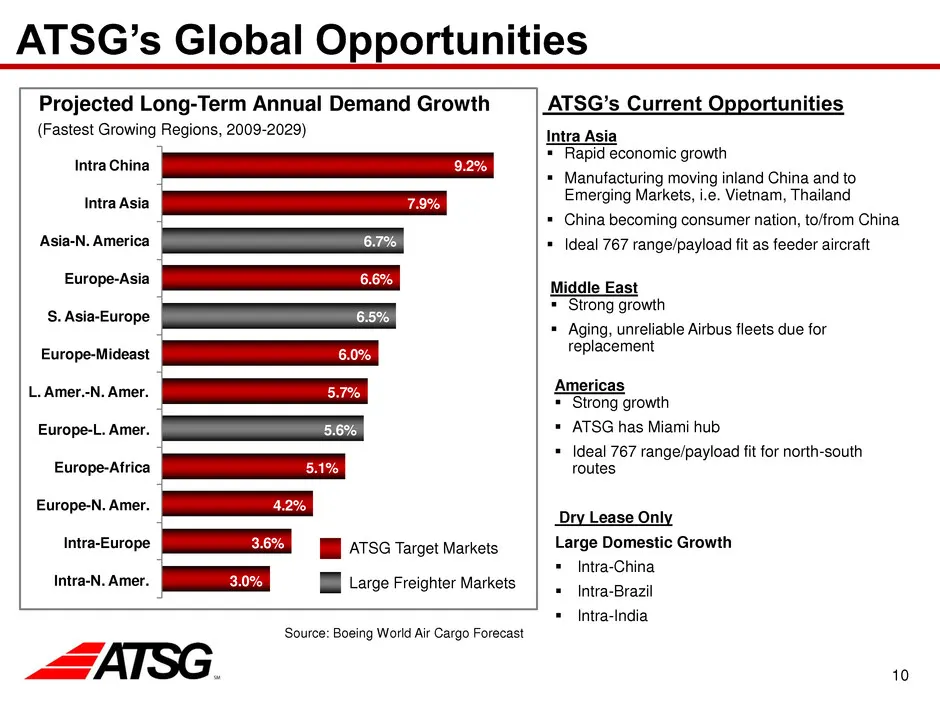
10 (Fastest Growing Regions, 2009-2029) ATSG’s Global Opportunities Projected Long-Term Annual Demand Growth Source: Boeing World Air Cargo Forecast Large Freighter Markets ATSG Target Markets Americas Strong growth ATSG has Miami hub Ideal 767 range/payload fit for north-south routes Intra As
Slide 12: New Combi Award Supports Investment
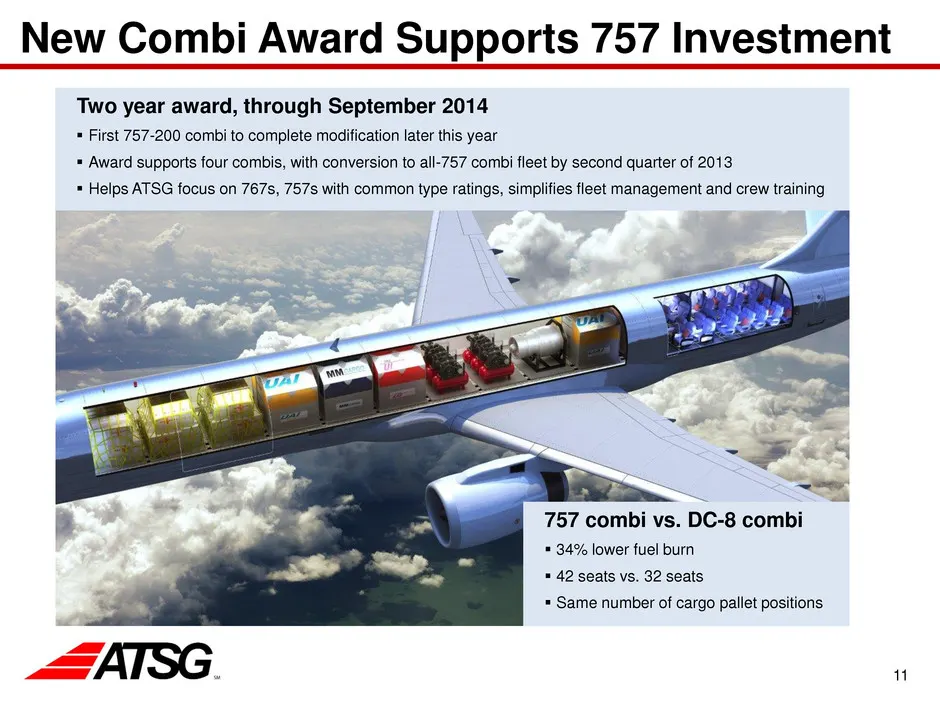
11 New Combi Award Supports 757 Investment 757 combi vs. DC-8 combi 34% lower fuel burn 42 seats vs. 32 seats Same number of cargo pallet positions Two year award, through September 2014 First 757-200 combi to complete modification later this year Award supports four combis, with conversio
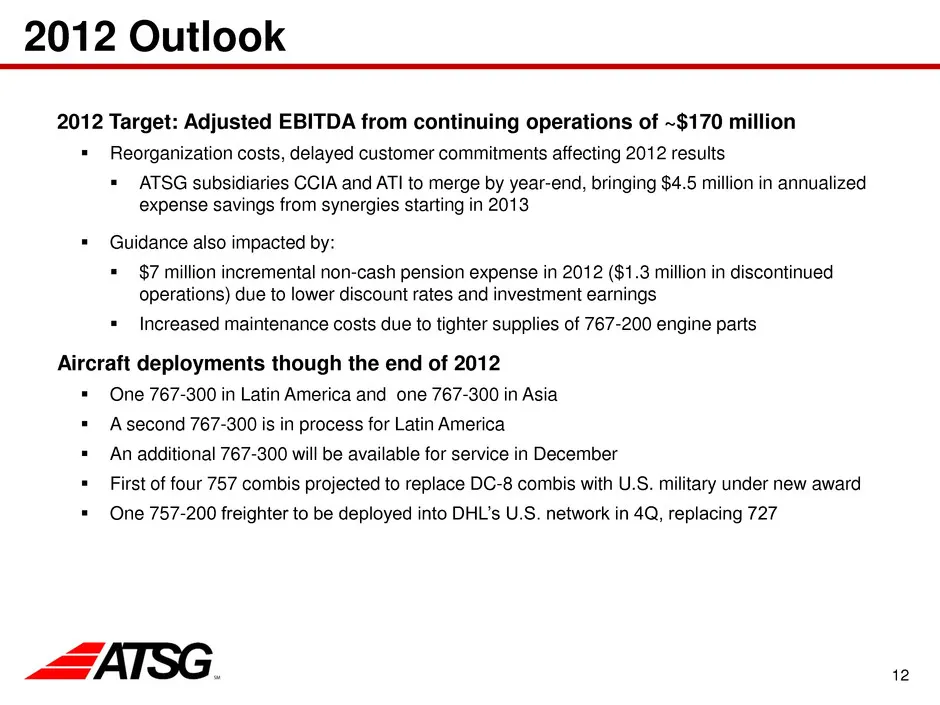
Slide 13: 2012 Outlook
12 2012 Outlook 2012 Target: Adjusted EBITDA from continuing operations of ~$170 million Reorganization costs, delayed customer commitments affecting 2012 results ATSG subsidiaries CCIA and ATI to merge by year-end, bringing $4.5 million in annualized expense savings from synergies starting in 2
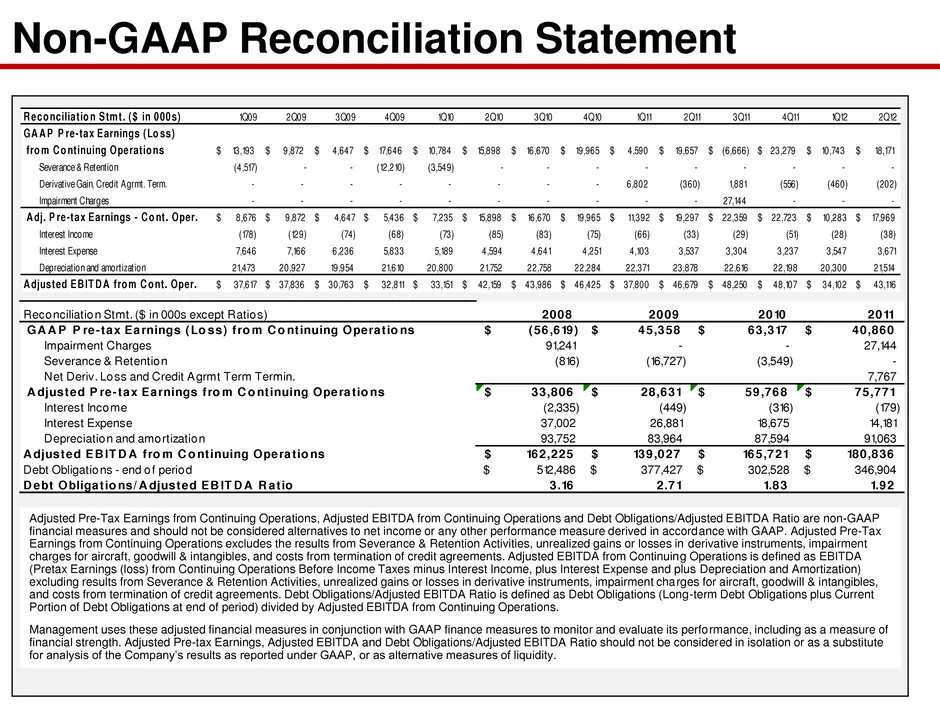
Slide 14: Non-GAAP Reconciliation Statement
13 Non-GAAP Reconciliation Statement 1Q09 2Q09 3Q09 4Q09 1Q10 2Q10 3Q10 4Q10 1Q11 2Q11 3Q11 4Q11 1Q12 2Q12 13,193$ 9,872$ 4,647$ 17,646$ 10,784$ 15,898$ 16,670$ 19,965$ 4,590$ 19,657$ (6,666)$ 23,279$ 10,743$ 18,171$ Severance & Retention (4,517) - - (12,210) (3,549) - - - - - - - - - Derivat ive Ga
Source: SEC EDGAR · 8-K filed Sep 6, 2012
More decks from Air Transport Services Group Inc
 Shareholder Meeting (May 2024)26 slides · May 23, 2024
 Stephens Annual Investment Conference 202321 slides · Nov 14, 2023
 Investor Day (September 2023)68 slides · Sep 27, 2023
 Shareholder Meeting (May 2023)25 slides · May 26, 2023
 Stifel conference (February 2023)15 slides · Feb 6, 2023
 Stifel 2020 Transportation & Logistics Conference18 slides · Feb 11, 2020