Hi-Crush Partners LP — Investor Presentation (February 2017)
17 slides from Hi-Crush Partners LP's investor presentation, Feb 23, 2017
Slide 1: Investor Presentation February 2017
INVESTOR PRESENTATION FEBRUARY 2017
Slide 2: Forward Looking Statements
Forward Looking Statements Some of the information included herein may contain forward-looking statements within the meaning of the federal securities laws. Forward- looking statements give our current expectations and may contain projections of results of operations or of financial condition, or fo
Slide 3: Offering Overview
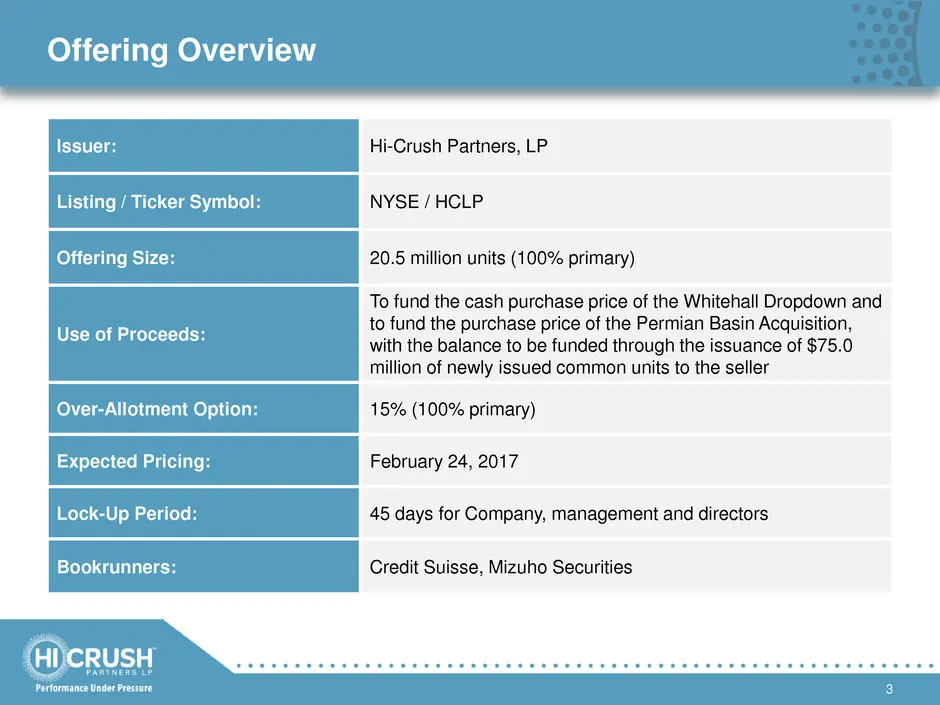
Offering Overview 3 Issuer: Hi-Crush Partners, LP Listing / Ticker Symbol: NYSE / HCLP Offering Size: 20.5 million units (100% primary) Use of Proceeds: To fund the cash purchase price of the Whitehall Dropdown and to fund the purchase price of the Permian Basin Acquisition, with the balance to be f
Slide 4: Sources, Uses, and Pro Forma Capitalization
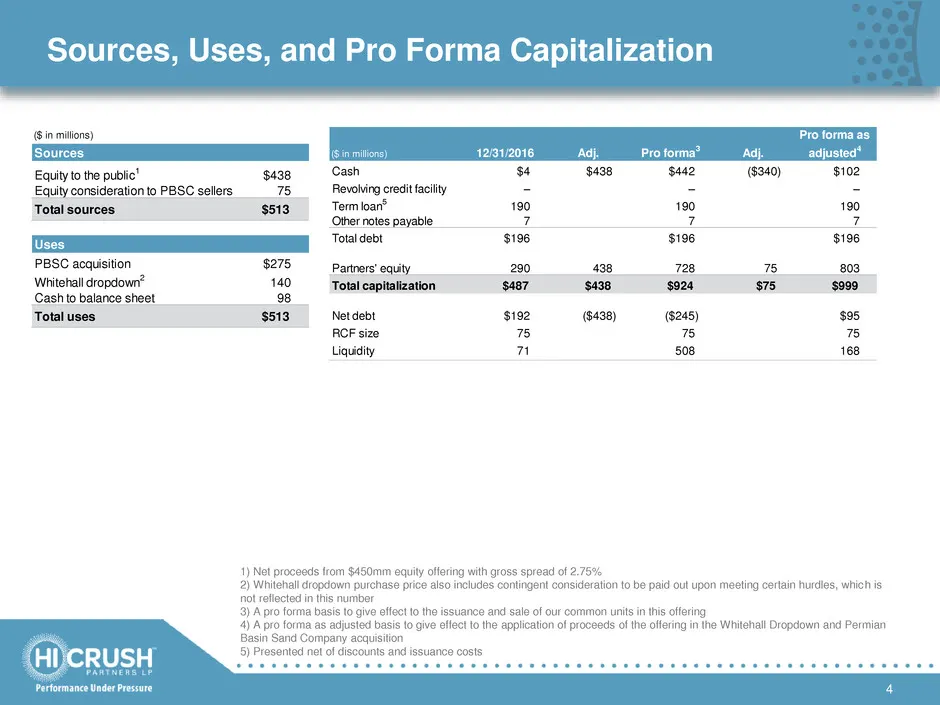
Sources, Uses, and Pro Forma Capitalization 4 ($ in millions) Sources Equity to the public 1 $438 Equity consideration to PBSC sellers 75 Total sources $513 Uses PBSC acquisition $275 Whitehall dropdown 2 140 Cash to balance sheet 98 Total uses $513 ($ in millions) 12/31/2016 Adj. Pro forma 3 Adj. P
Slide 5: Strategic Update
Strategic Update
Slide 6: Strategically Positioned in the Upswing
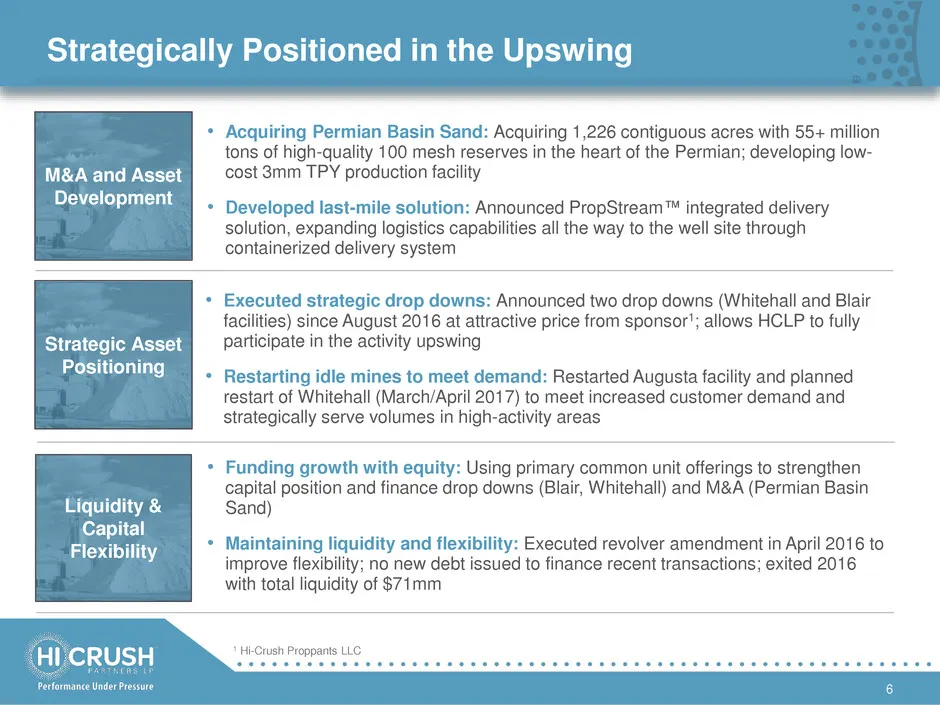
Strategically Positioned in the Upswing 6 Strategic Asset Positioning • Acquiring Permian Basin Sand: Acquiring 1,226 contiguous acres with 55+ million tons of high-quality 100 mesh reserves in the heart of the Permian; developing low- cost 3mm TPY production facility • Developed last-mile solution:
Slide 7: Permian Basin Sand Company Acquisition Overview
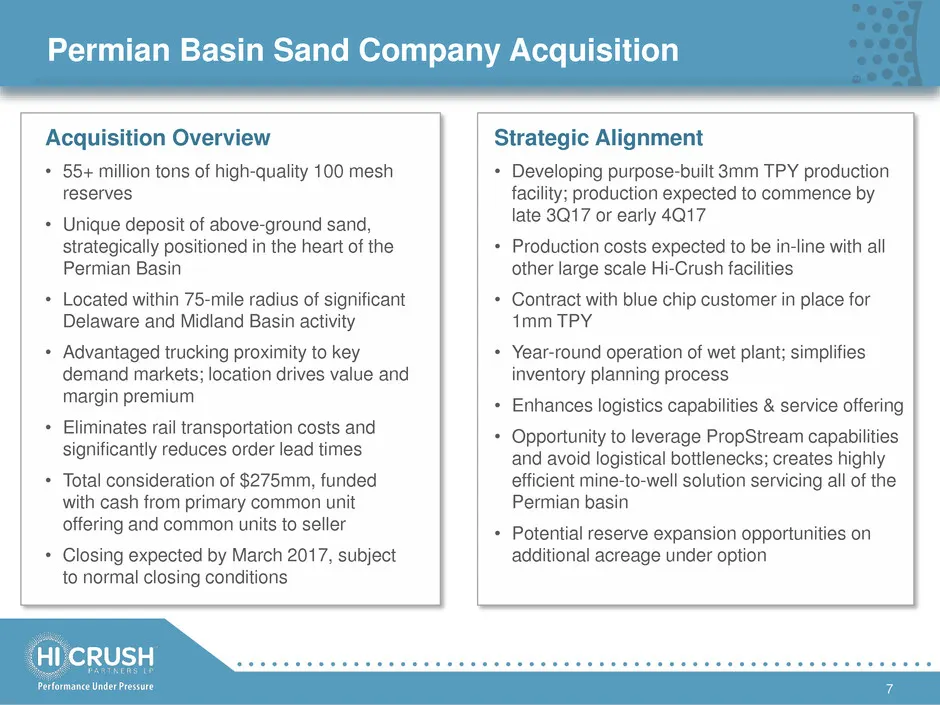
Permian Basin Sand Company Acquisition 7 Acquisition Overview • 55+ million tons of high-quality 100 mesh reserves • Unique deposit of above-ground sand, strategically positioned in the heart of the Permian Basin • Located within 75-mile radius of significant Delaware and Midland Basin activity • Ad
Slide 8: Optimally & Uniquely Positioned
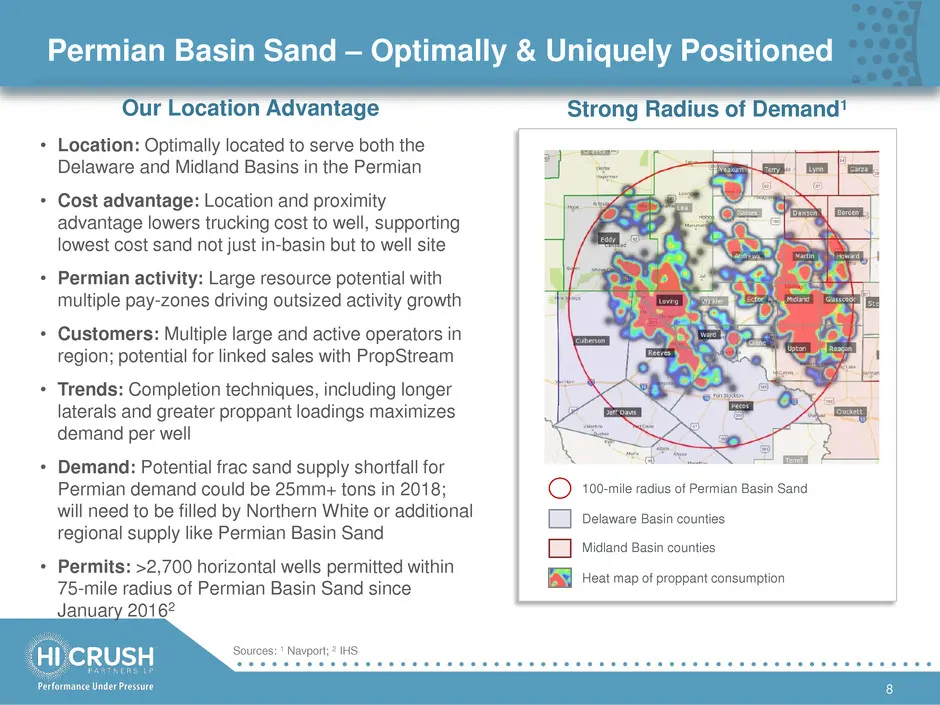
Permian Basin Sand – Optimally & Uniquely Positioned 8 • Location: Optimally located to serve both the Delaware and Midland Basins in the Permian • Cost advantage: Location and proximity advantage lowers trucking cost to well, supporting lowest cost sand not just in-basin but to well site • Permian
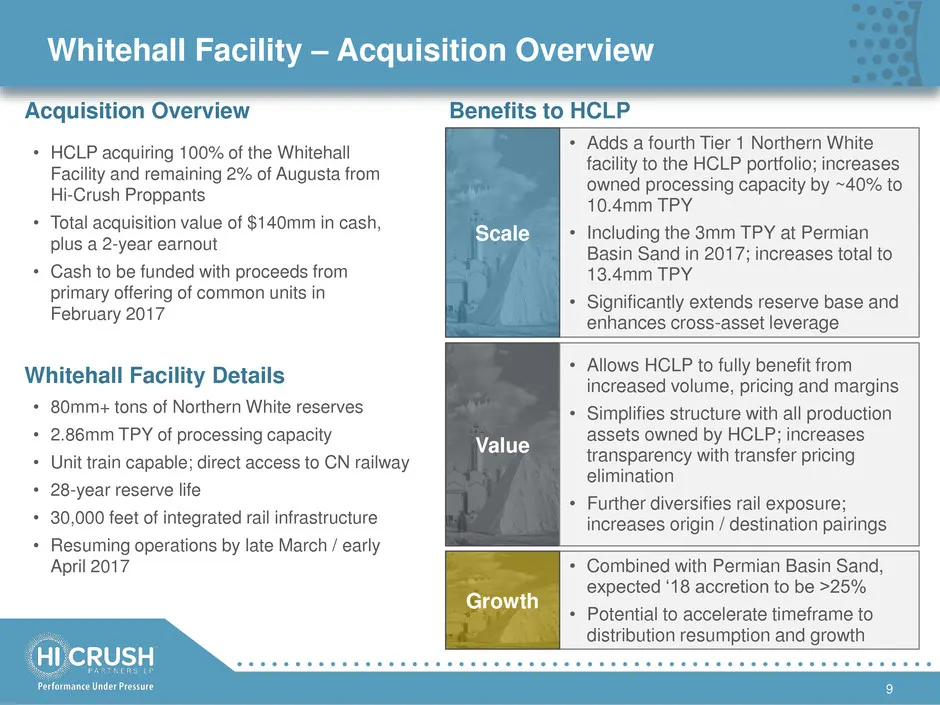
Slide 9: Whitehall Facility – Acquisition Overview
• Adds a fourth Tier 1 Northern White facility to the HCLP portfolio; increases owned processing capacity by ~40% to 10.4mm TPY • Including the 3mm TPY at Permian Basin Sand in 2017; increases total to 13.4mm TPY • Significantly extends reserve base and enhances cross-asset leverage Whitehall Facili
Slide 10: Business Updates
as Business Updates
Slide 11: Leveraging Our Competitive Advantages
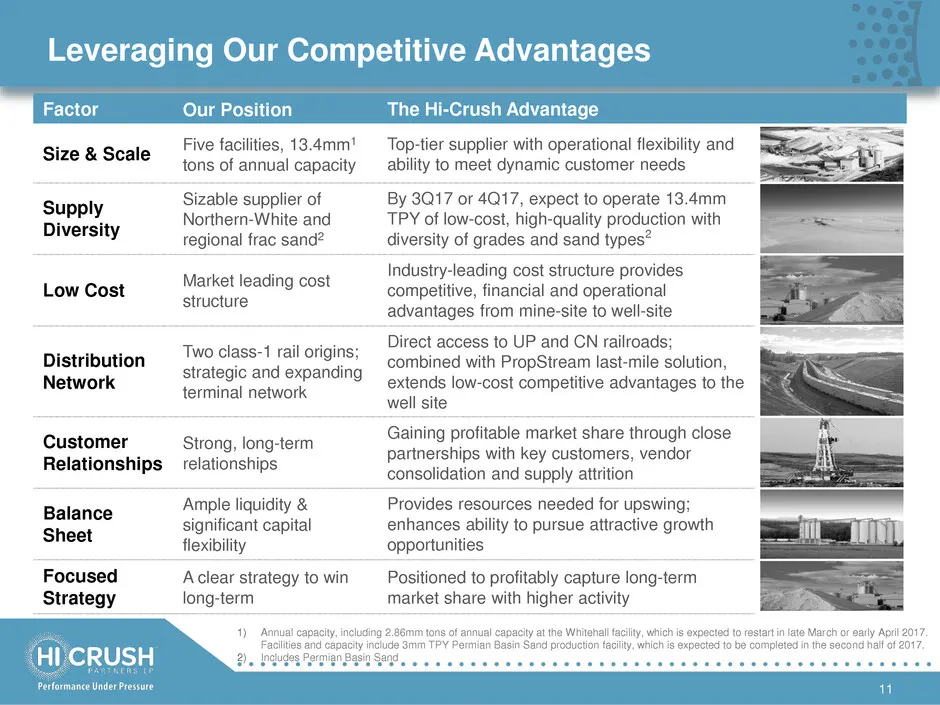
Leveraging Our Competitive Advantages 11 1) Annual capacity, including 2.86mm tons of annual capacity at the Whitehall facility, which is expected to restart in late March or early April 2017. Facilities and capacity include 3mm TPY Permian Basin Sand production facility, which is expected to be com
Slide 12: Hi-Crush's Portfolio of Processing Plant Assets
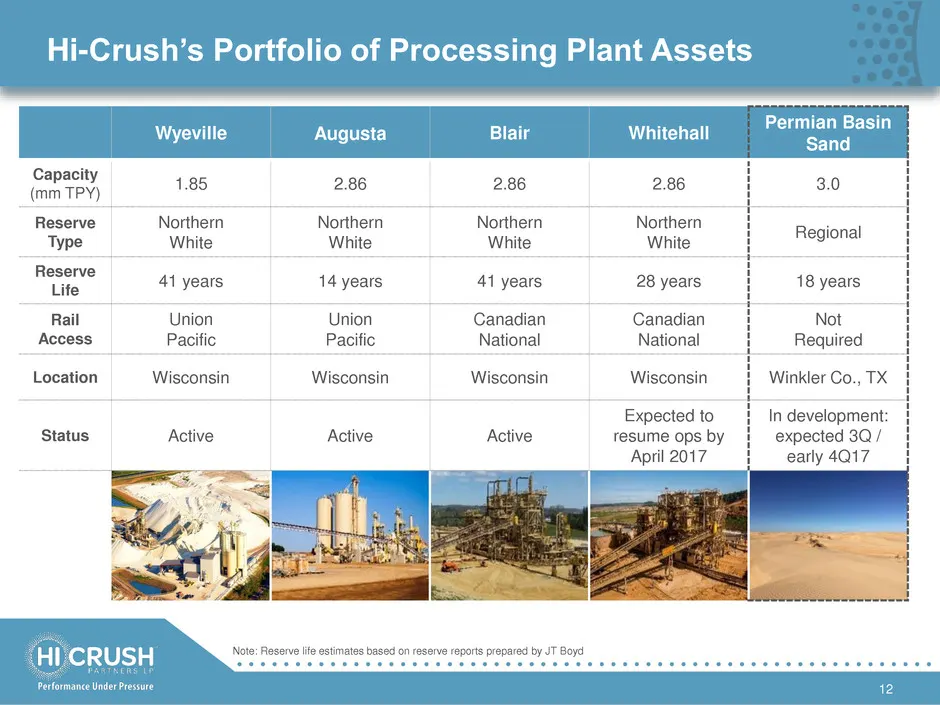
Hi-Crush’s Portfolio of Processing Plant Assets 12 Note: Reserve life estimates based on reserve reports prepared by JT Boyd Wyeville Augusta Blair Whitehall Permian Basin Sand Capacity (mm TPY) 1.85 2.86 2.86 2.86 3.0 Reserve Type Northern White Northern White Northern White Northern White Regional
Slide 13: Strong Frac Sand Fundamentals
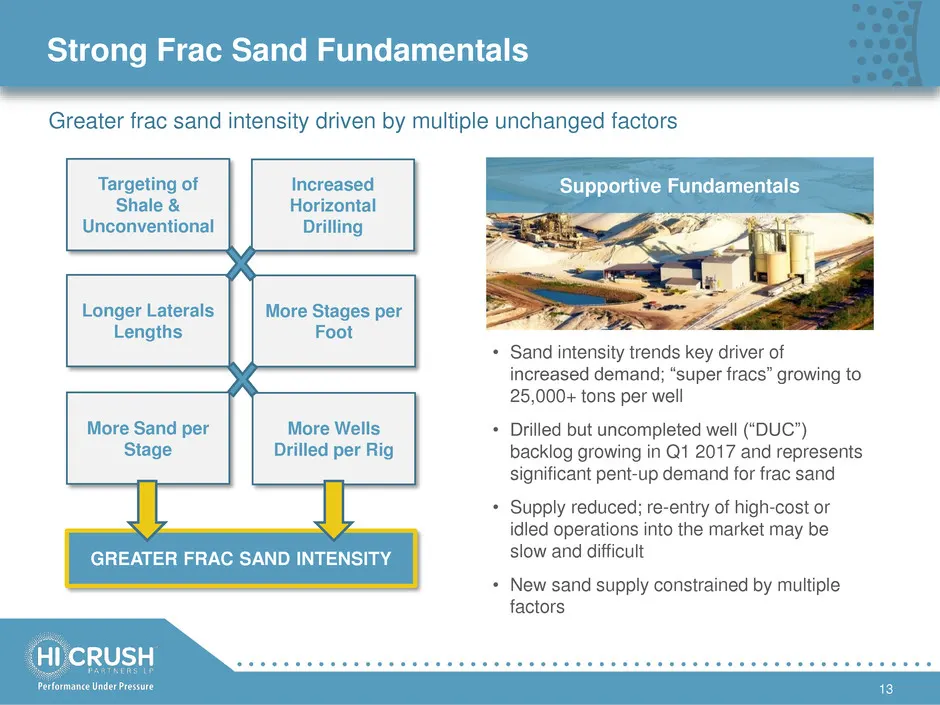
Strong Frac Sand Fundamentals 13 Supportive FundamentalsTargeting of Shale & Unconventional Increased Horizontal Drilling Longer Laterals Lengths More Stages per Foot More Sand per Stage More Wells Drilled per Rig GREATER FRAC SAND INTENSITY Greater frac sand intensity driven by multiple unchanged f
Slide 14: Leverage to Current Upcycle vs Prior Peak
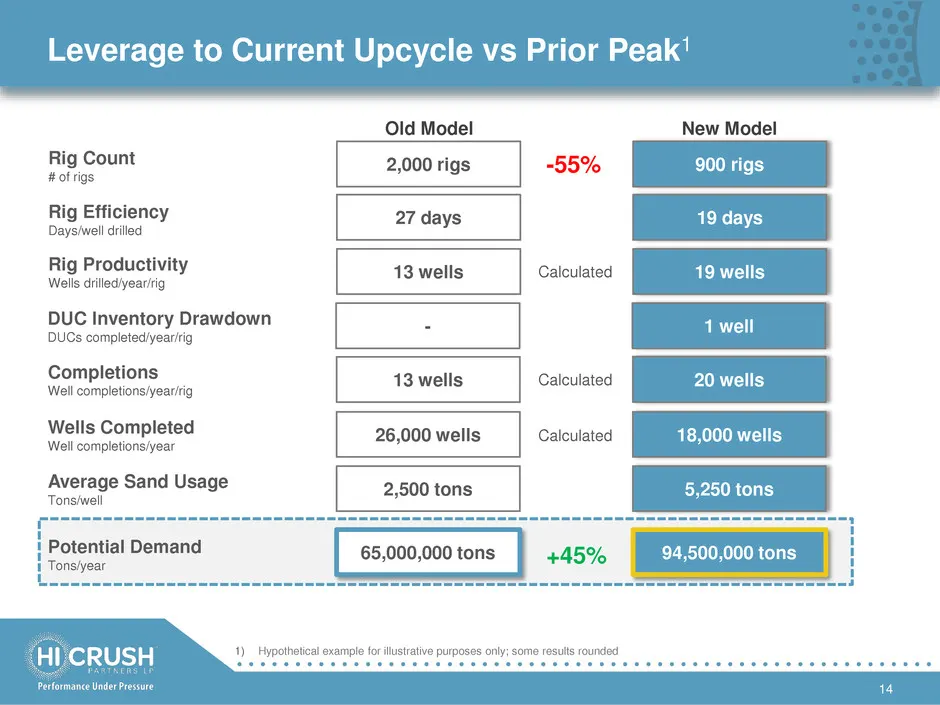
Leverage to Current Upcycle vs Prior Peak1 14 2,000 rigs 27 days 13 wells 13 wells 26,000 wells 2,500 tons 65,000,000 tons Rig Count # of rigs Rig Efficiency Days/well drilled Rig Productivity Wells drilled/year/rig Completions Well completions/year/rig Wells Completed Well completions/year Average
Slide 15: Logistics Flexibility Critical
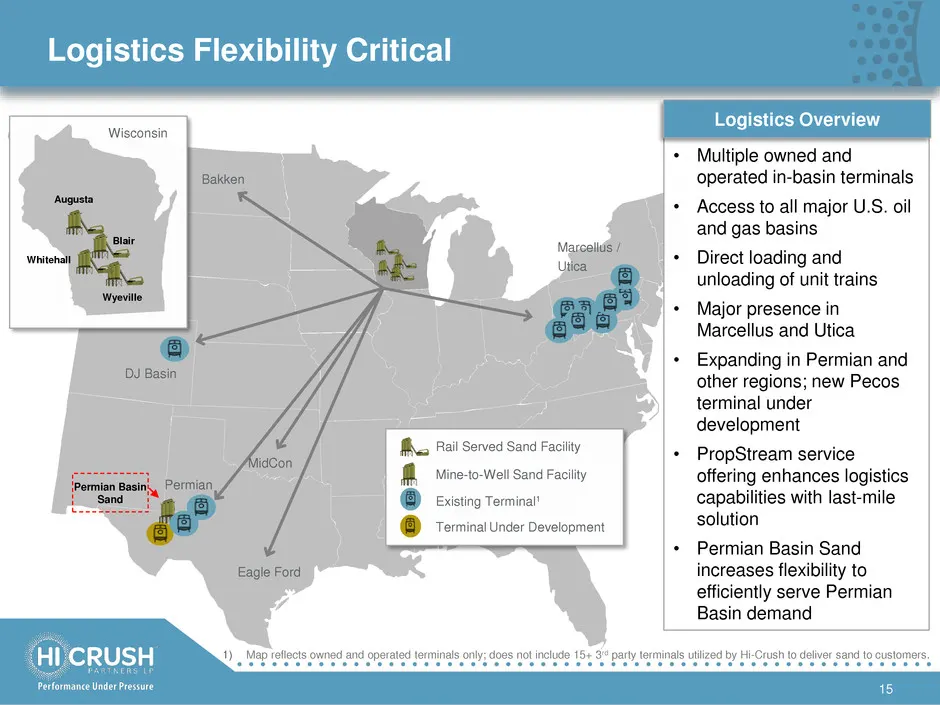
Logistics Flexibility Critical 15 1) Map reflects owned and operated terminals only; does not include 15+ 3rd party terminals utilized by Hi-Crush to deliver sand to customers. • Multiple owned and operated in-basin terminals • Access to all major U.S. oil and gas basins • Direct loading and unloadi
Slide 16: Pecos Terminal Further Enhances Texas Position
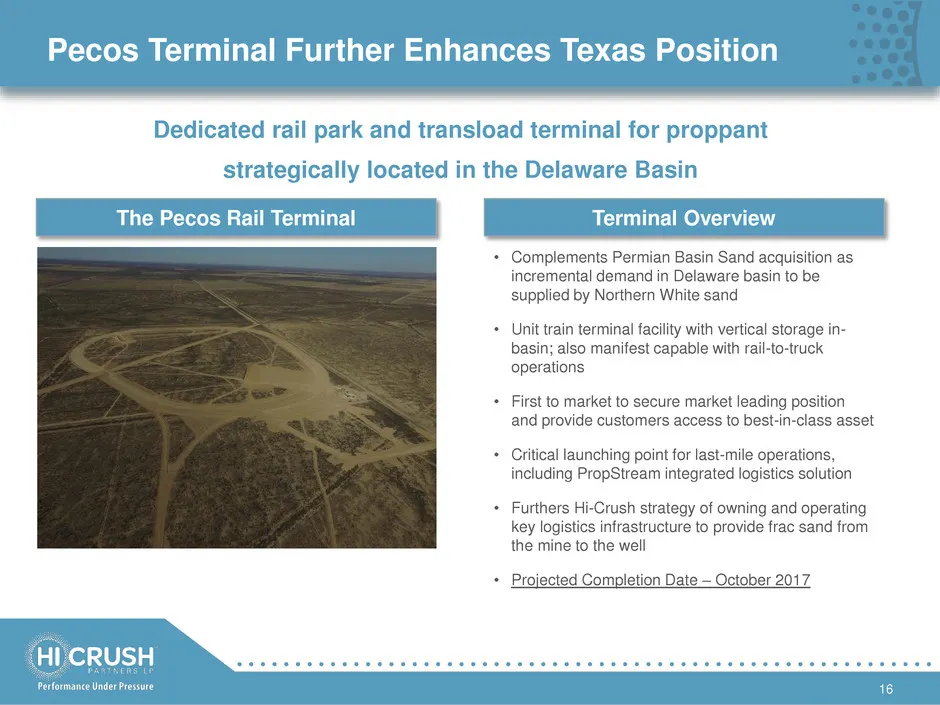
Pecos Terminal Further Enhances Texas Position 16 Terminal Overview • Complements Permian Basin Sand acquisition as incremental demand in Delaware basin to be supplied by Northern White sand • Unit train terminal facility with vertical storage in- basin; also manifest capable with rail-to-truck oper
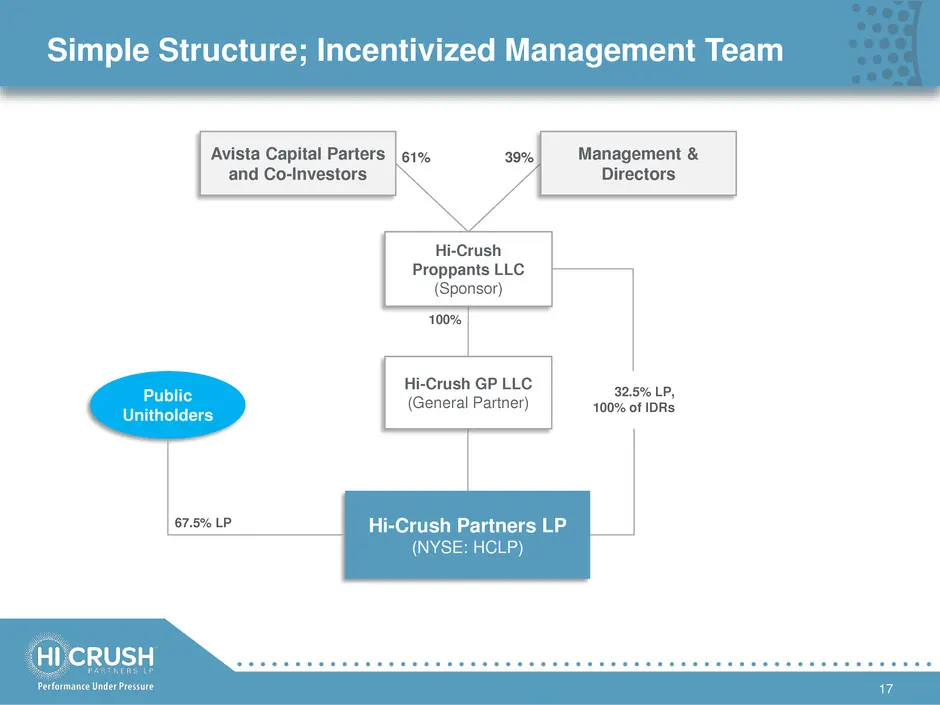
Slide 17: Simple Structure; Incentivized Management Team
Simple Structure; Incentivized Management Team 17 39%61% 100% 67.5% LP 32.5% LP, 100% of IDRs Hi-Crush Proppants LLC (Sponsor) Avista Capital Parters and Co-Investors Management & Directors Hi-Crush Partners LP (NYSE: HCLP) Public Unitholders Hi-Crush GP LLC (General Partner)
Source: SEC EDGAR · 8-K filed Feb 23, 2017
More decks from Hi-Crush Partners LP
 Q4 2019 Earnings Presentation21 slides · Feb 19, 2020
 Q3 2019 Earnings Presentation19 slides · Nov 5, 2019
 Q2 2019 Earnings Presentation25 slides · Aug 7, 2019
 Q1 2019 Earnings Presentation21 slides · May 7, 2019
 Q4 2018 Earnings Presentation29 slides · Feb 5, 2019
 Investor Presentation (January 2019)21 slides · Jan 7, 2019