Benefytt Technologies — Health Insurance Innovations — Investor Presentation (March 2016)
24 slides from Benefytt Technologies's investor presentation, Mar 9, 2016
Slide 1: Game-Changing Industry Leadership
Game-Changing Industry Leadership NASDAQ: HIIQ March 2016 Exhibit 99.1
Slide 2: Forward-looking statements disclosure
Certain statements included herein, including those that express management’s expectations or estimates of Health Insurance Innovations, Inc.’s (“HII”) future performance, constitute “forward-looking statements” within the meaning of applicable securities laws. These statements may include words suc
Slide 3: Health Insurance Innovations at a Glance
Health Insurance Innovations at a Glance Double-digit revenue growth for the past 3 years NASDAQ: HIIQ Founded 2008 IPO in February 2013 Development of top quality Health Insurance products HII takes no insurance risk Large captive distribution network Core Offices: Tampa, Florida Mountain View, Cal
Slide 4: Sustainable and Unique High Growth Platform
Sustainable and Unique High Growth Platform = Well Positioned for a Dynamic Market Leader in individual term policy design Proprietary, direct to consumer technology Strong, long standing carrier relationships Extensive, growing and scalable distribution network Seasoned management team poised for g
Slide 5: Untapped Market Opportunity
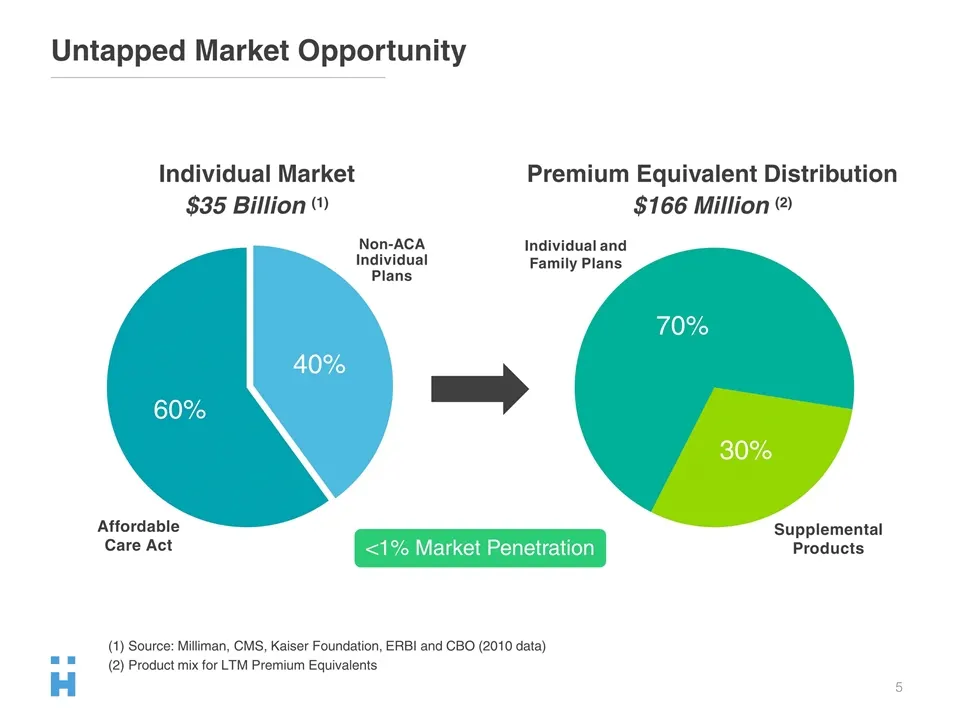
Untapped Market Opportunity Individual Market $35 Billion (1) Premium Equivalent Distribution $166 Million (2) <1% Market Penetration Affordable Care Act Non-ACA Individual Plans Individual and Family Plans Supplemental Products (1) Source: Milliman, CMS, Kaiser Foundation, ERBI and CBO (2010 data)
Slide 6: Demand Growth
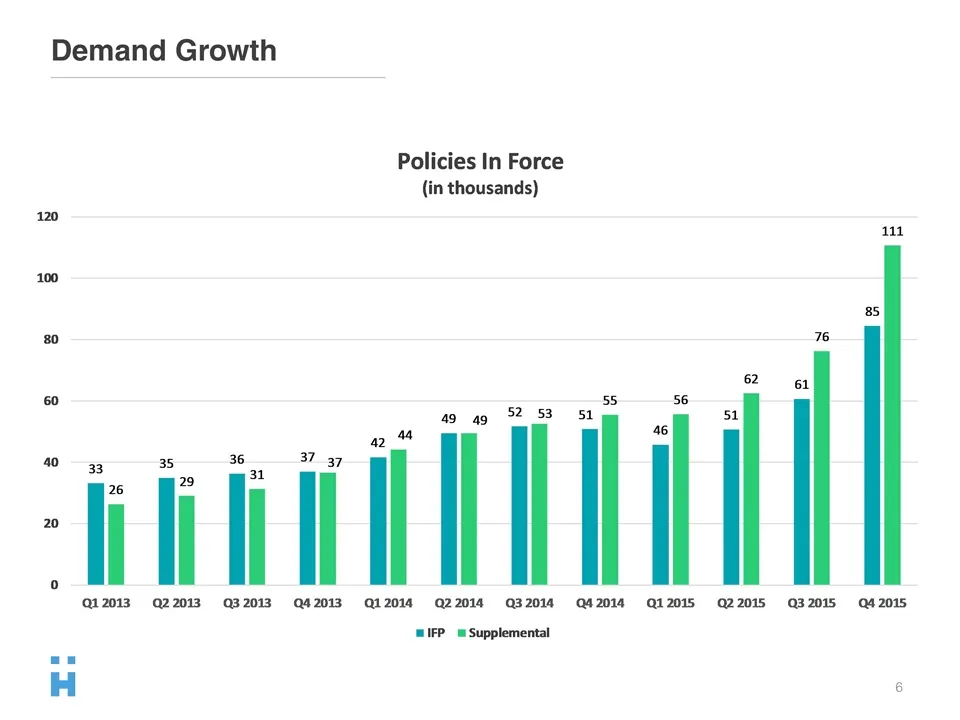
Demand Growth Policies In Force (in thousands) 85 76 62 gy 60 56 ag 52 53 51 46 I | | | | ° i i | | 012013 Q22013 Q32013 Q42013 Q12014 «Q22014 Q32014 42014 Q12015 Q22015 Q32015 42015 SIFP m= Supplemental oo
Slide 7: HII Operating Model
HII OPERATING MODEL
Slide 8: Innovate Top Quality Products & Product Bundles
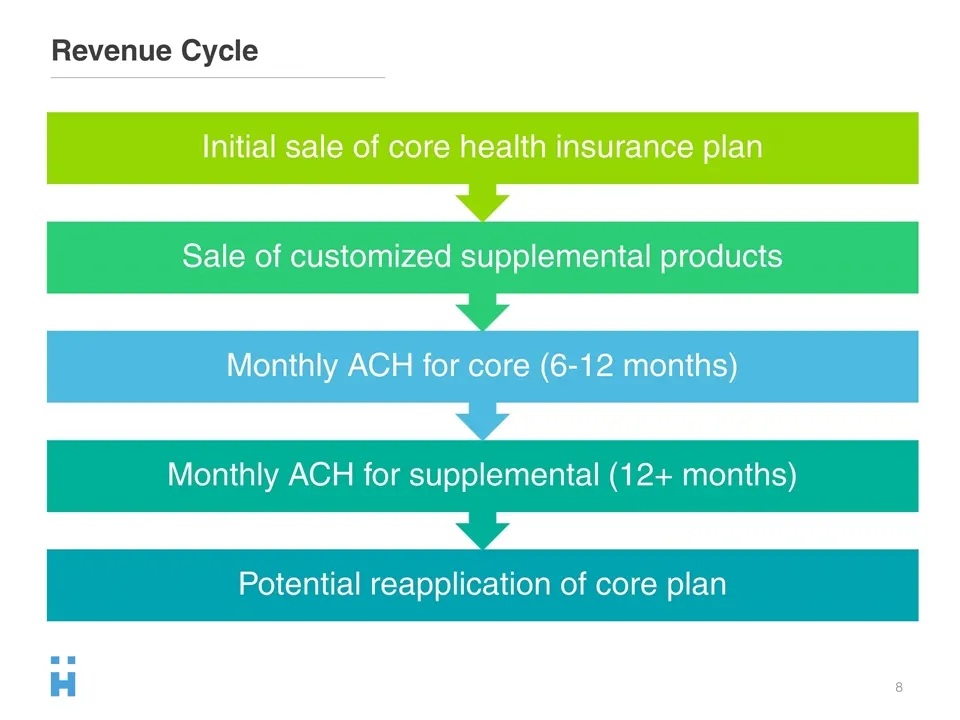
Innovate Top Quality Products & Product Bundles Revenue Cycle Initial sale of core health insurance plan Sale of customized supplemental products Monthly ACH for core (6-12 months) Monthly ACH for supplemental (12+ months) Potential reapplication of core plan
Slide 9: Individual Insurance Purchase Process
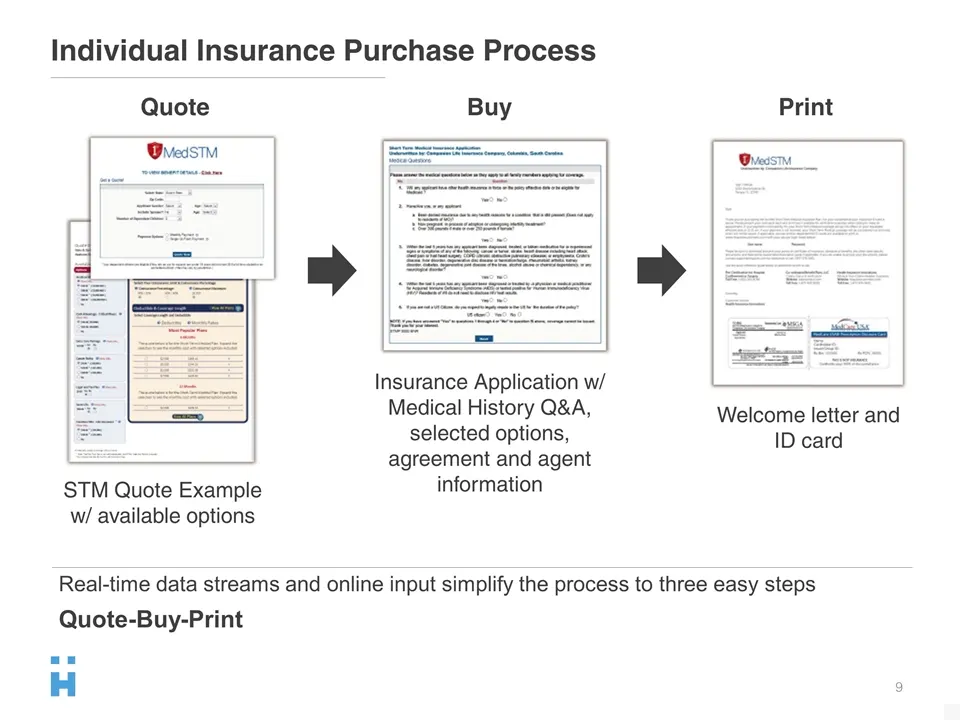
Individual Insurance Purchase Process Quote Buy Print STM Quote Example w/ available options Insurance Application w/ Medical History Q&A, selected options, agreement and agent information Welcome letter and ID card Real-time data streams and online input simplify the process to three easy steps Quo
Slide 10: Unique Platform With Proprietary Technology
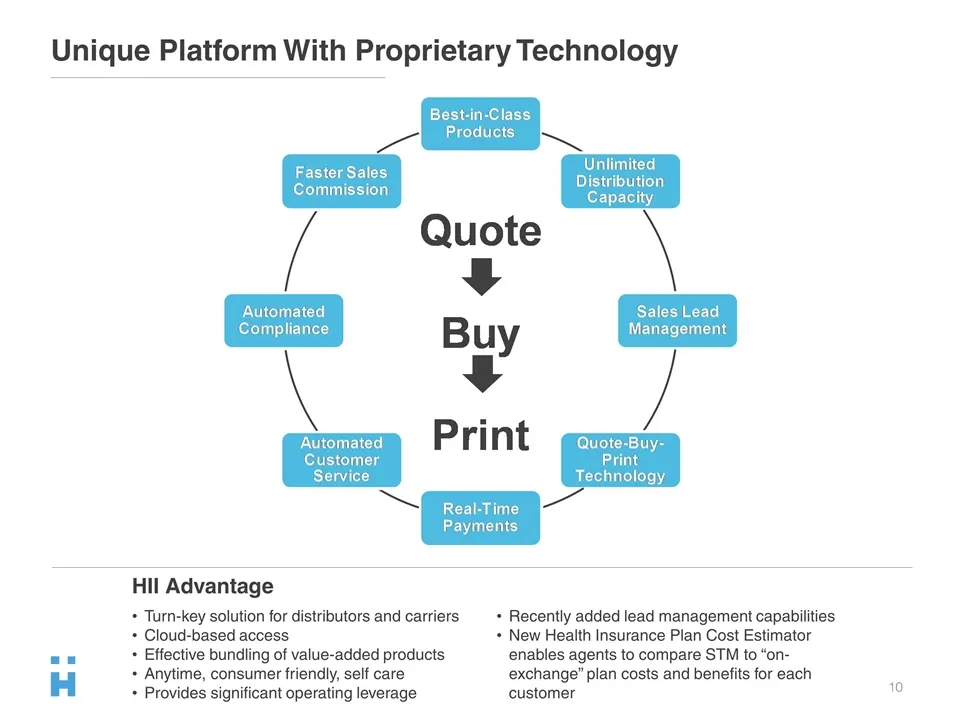
Unique Platform With Proprietary Technology HII Advantage Turn-key solution for distributors and carriers Cloud-based access Effective bundling of value-added products Anytime, consumer friendly, self care Provides significant operating leverage Recently added lead management capabilities New Health
Slide 11: Portfolio of Customized Products
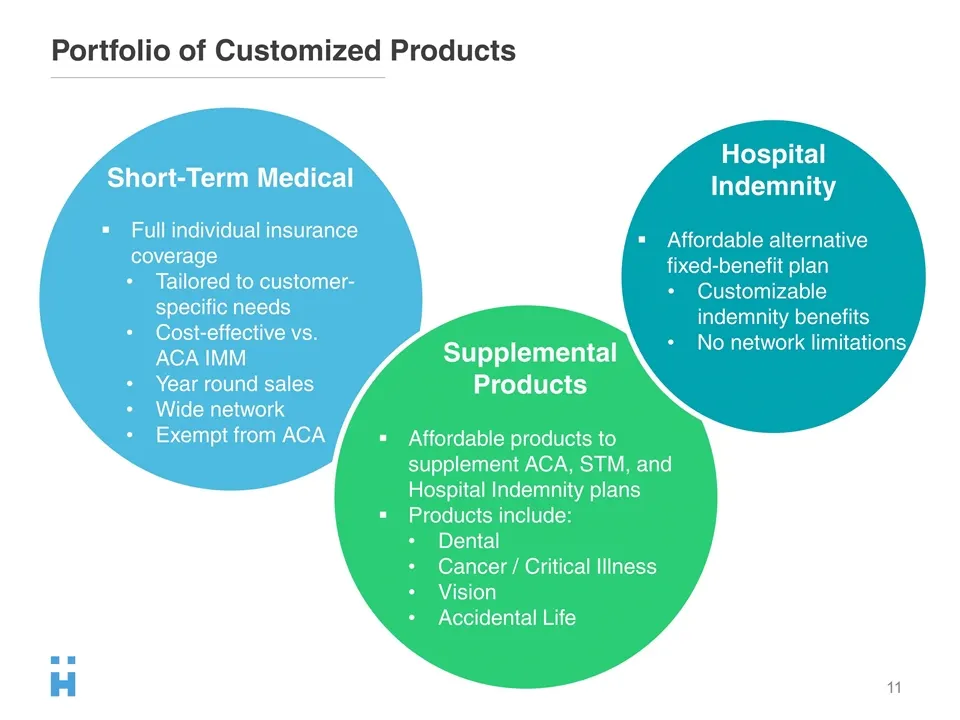
Portfolio of Customized Products Short-Term Medical Full individual insurance coverage Tailored to customer-specific needs Cost-effective vs. ACA IMM Year round sales Wide network Exempt from ACA Supplemental Products Affordable products to supplement ACA, STM, and Hospital Indemnity plans Products
Slide 12: Extensive and Growing Distribution Network
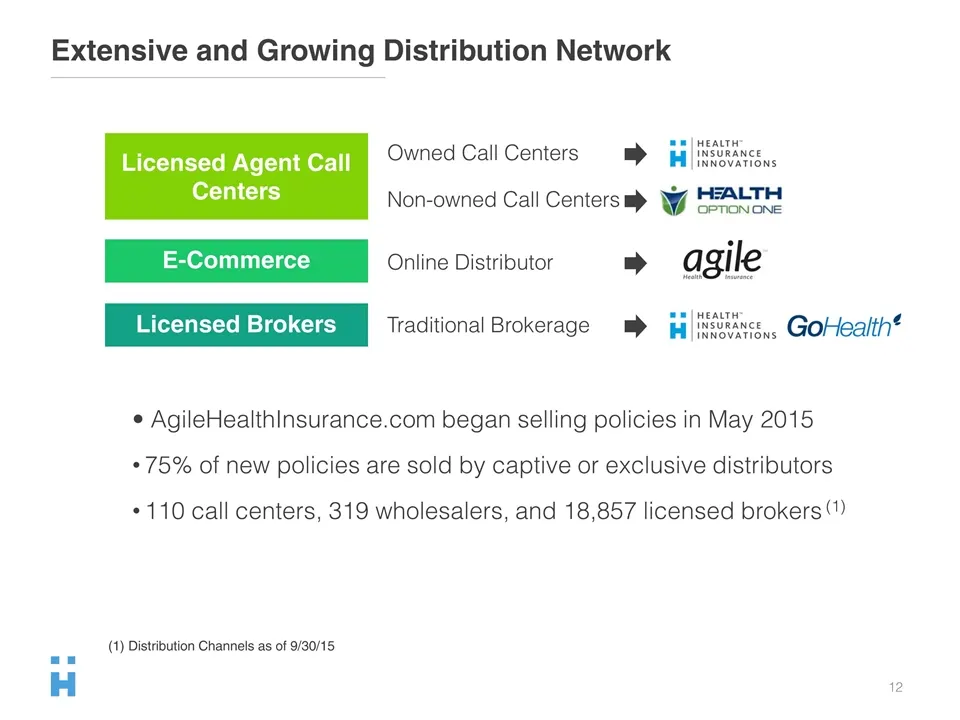
110 18,857 • AgileHealthInsurance.com began selling policies in May 2015 75% of new policies are sold by captive or exclusive distributors 110 call centers, 319 wholesalers, and 18,857 licensed brokers (1) Extensive and Growing Distribution Network Licensed Agent Call Centers Licensed Brokers Owned
Slide 13: Key partnerships with A to A++ Carriers
Key partnerships with A to A++ Carriers A.M. Best Ratings Carriers assume all underwriting risk and claims payment responsibility Innovative, customized, consumer-driven products Best-In-Class Carriers and Benefit Providers
Slide 14: Breadth of Product Offerings
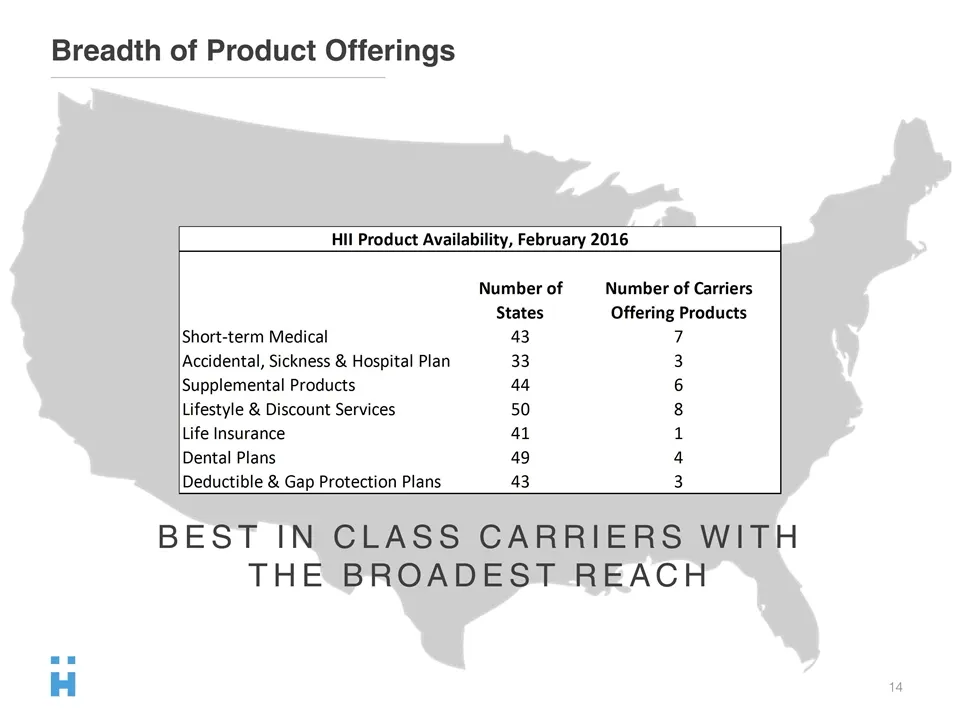
Breadth of Product Offerings BEST IN CLASS CARRIERS WITH THE BROADEST REACH
Slide 15: Emphasis on Innovation
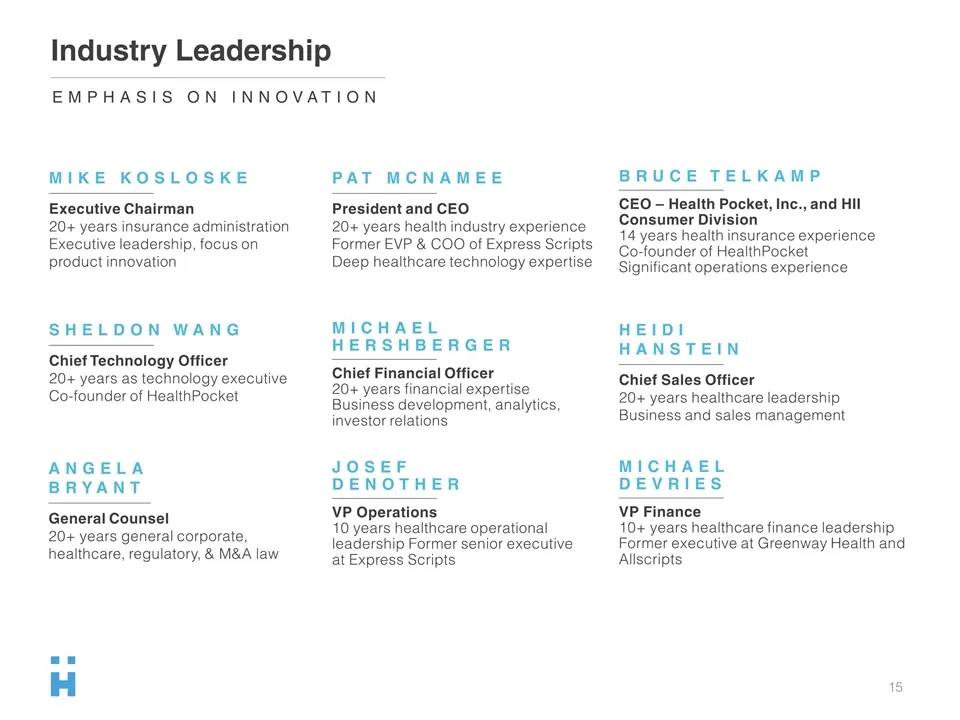
EMPHASIS ON INNOVATION MIKE KOSLOSKE ______________________________________ Executive Chairman 20+ years insurance administration Executive leadership, focus on product innovation PAT MCNAMEE ______________________________________ President and CEO 20+ years health industry experience Former EVP & C
Slide 16: Significant Improvement Since June 2015
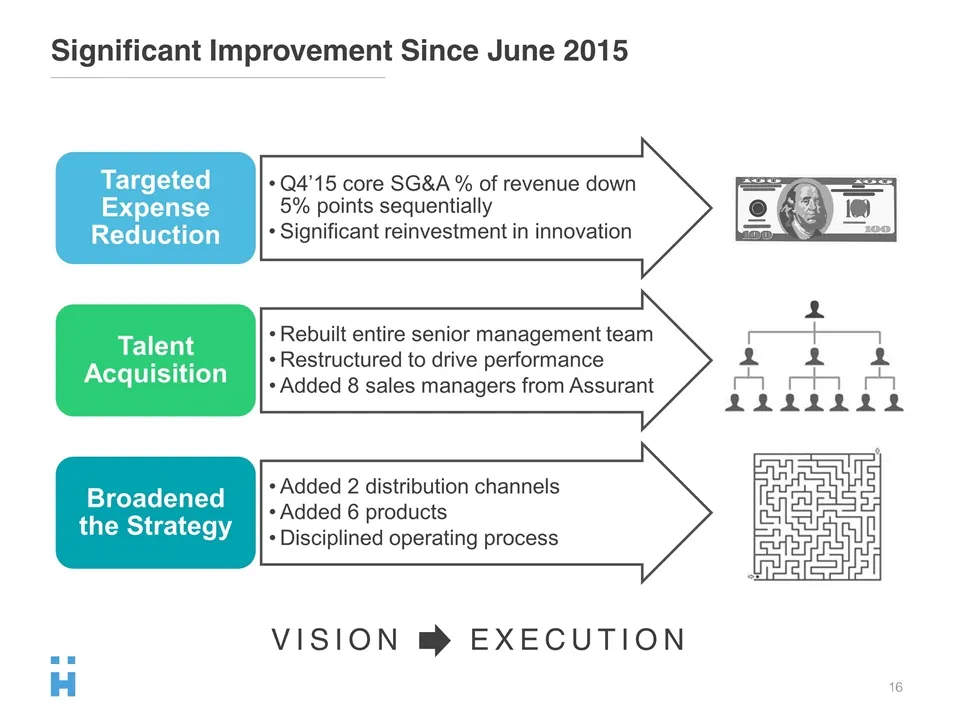
Significant Improvement Since June 2015 VISION EXECUTION Targeted Expense Reduction Q4’15 core SG&A % of revenue down 5% points sequentially Significant reinvestment in innovation Talent Acquisition Broadened the Strategy Rebuilt entire senior management team Added 8 sales managers from Assurant Res
Slide 17: Individual Health Insurance Company Comparison
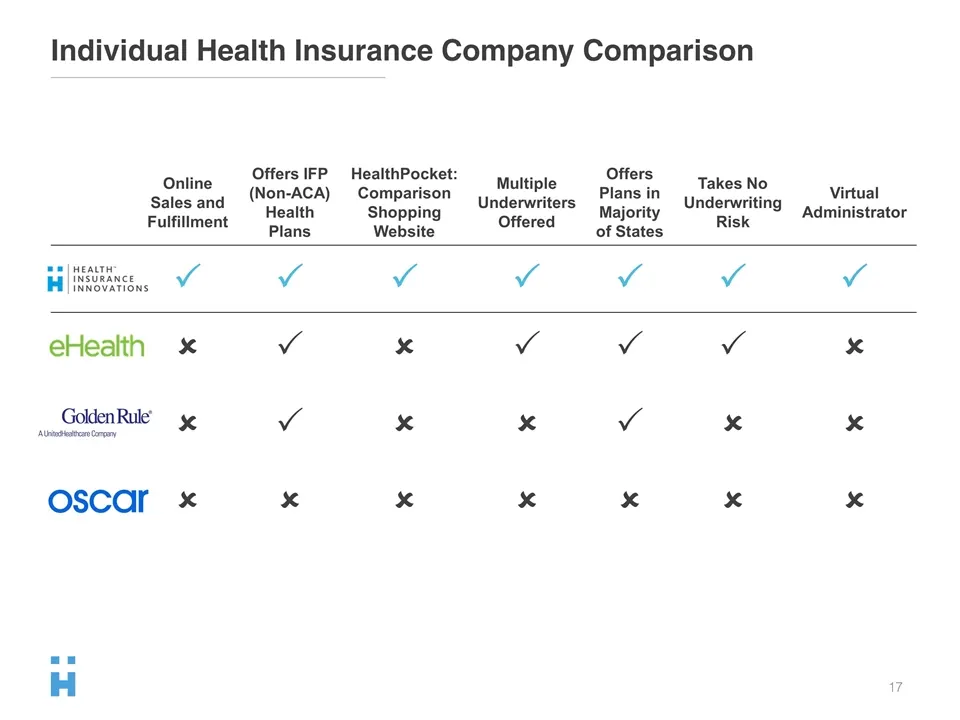
Individual Health Insurance Company Comparison Online Sales and Fulfillment Offers IFP (Non-ACA) Health Plans HealthPocket: Comparison Shopping Website Multiple Underwriters Offered Offers Plans in Majority of States Takes No Underwriting Risk Virtual Administrator HII P P P P P P P E- Health û P û
Slide 18: Growth Strategy
GROWTH STRATEGY
Slide 19: Track Record of Success With a Solid Trajectory
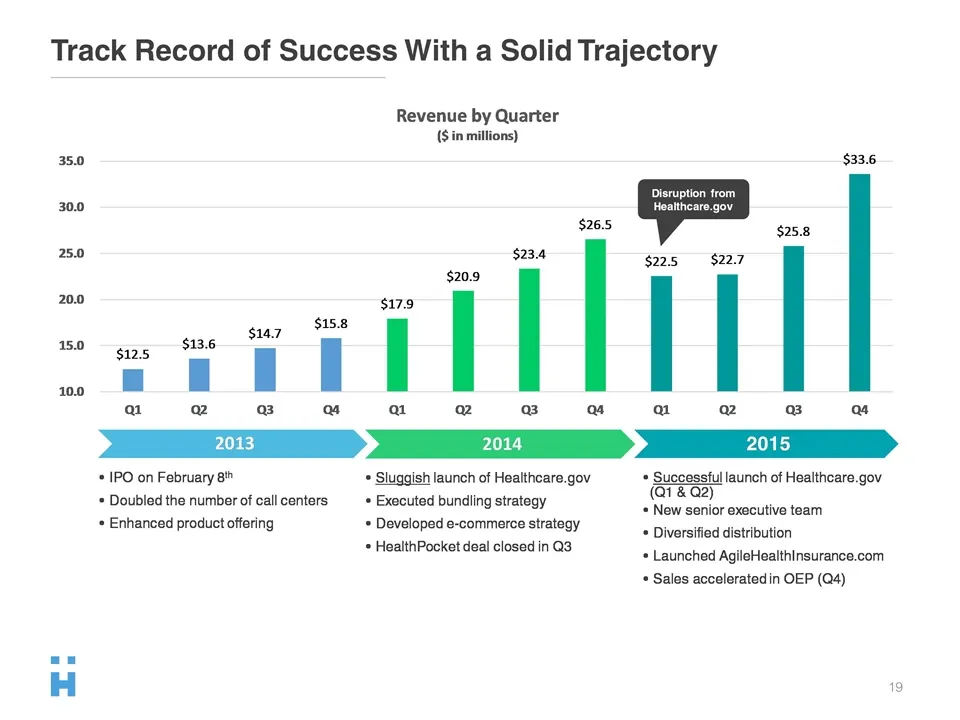
1 3 4 Track Record of Success With a Solid Trajectory
Slide 20: AgileHealthInsurance.com
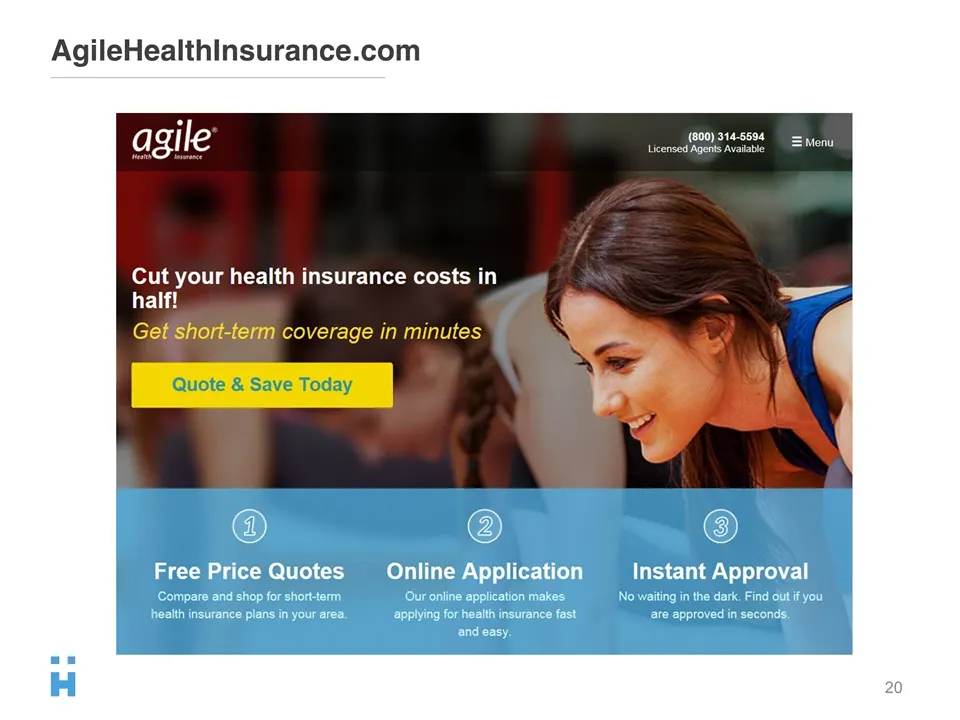
AgileHealthInsurance.com agile aes Cut your health insurance costs in half! Gefshort-term coverage in minutes
Slide 21: HII and HealthPocket
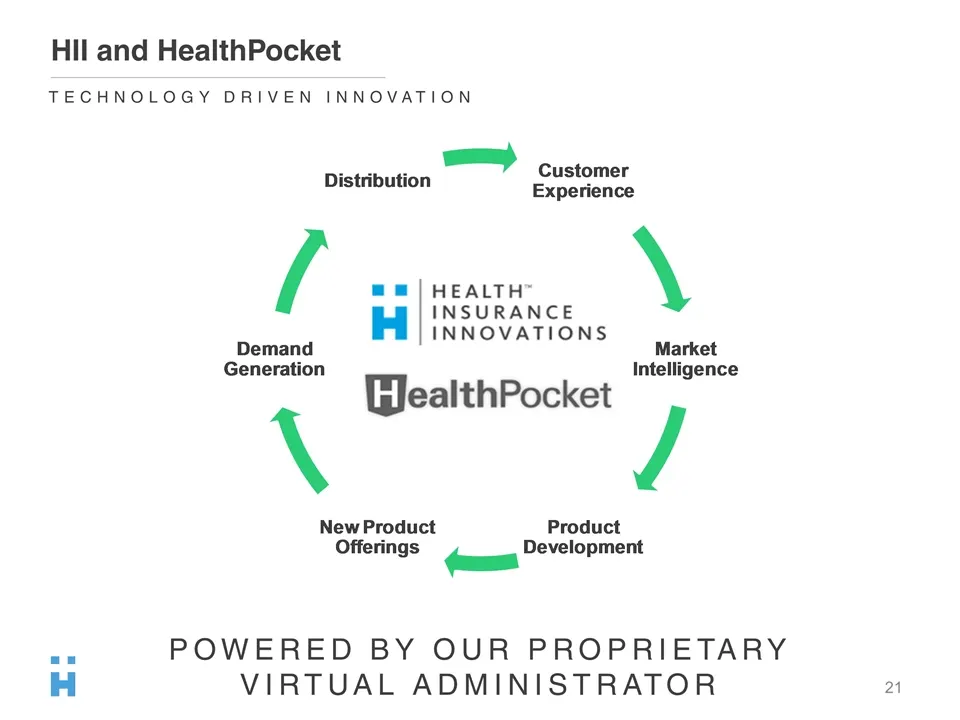
HII and HealthPocket POWERED BY OUR PROPRIETARY VIRTUAL ADMINISTRATOR TECHNOLOGY DRIVEN INNOVATION
Slide 22: HealthPocket Press References
HealthPocket Press References “In comparison, the average deductible for a bronze plan on the exchange — the least expensive coverage — was $5,081 for an individual and $10,386 for a family, according to HealthPocket” “Insurers will continue to limit their networks of health care providers, often by
Slide 23: Results and Outlook
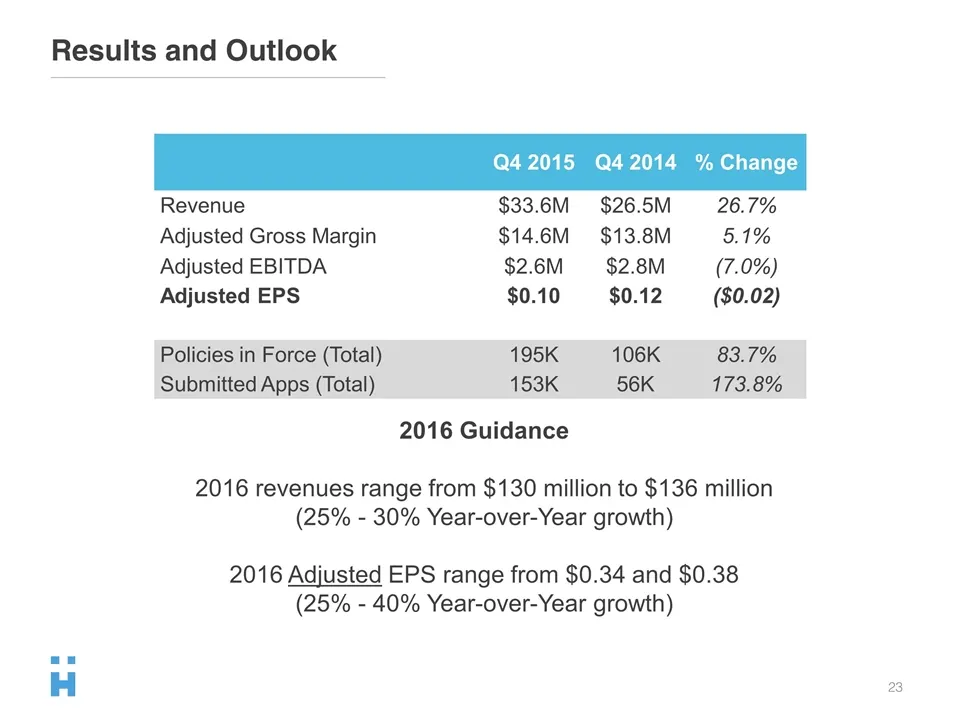
Results and Outlook Q4 2015 Q4 2014 % Change Revenue $33.6M $26.5M 26.7% Adjusted Gross Margin $14.6M $13.8M 5.1% Adjusted EBITDA $2.6M $2.8M (7.0%) Adjusted EPS $0.10 $0.12 ($0.02) Policies in Force (Total) 195K 106K 83.7% Submitted Apps (Total) 153K 56K 173.8% 2016 Guidance 2016 revenues range fro
Slide 24: Well Positioned for a Dynamic Market Leader
= Well Positioned for a Dynamic Market Leader in individual term policy design Proprietary, direct to consumer technology Strong, long standing carrier relationships Extensive, growing and scalable distribution network Seasoned management team poised for growth Sustainable and Unique High Growth Pla
Source: SEC EDGAR · 8-K filed Mar 9, 2016
More decks from Benefytt Technologies Inc
 Q1 2020 Earnings Presentation15 slides · May 7, 2020
 Health Insurance Innovations — Investor Presentation (August 2019)27 slides · Aug 20, 2019
 Health Insurance Innovations — Investor Presentation (May 2019)28 slides · May 22, 2019
 Health Insurance Innovations — Investor Presentation (January 2019)28 slides · Jan 7, 2019
 Health Insurance Innovations — Investor Presentation (September 2017)25 slides · Sep 25, 2017