Ellaktor SA · ATHEX:ELLAKTOR
Ellaktor SA — El.Tech. Anemos — FY2016 Earnings Presentation
13 slides from Ellaktor SA's earnings presentation, April 2017
Slide 1: FY 2016 Results
EL.TECH. ANEMOS MEMBER OF ELLAKTOR GROUP FY 2016 Results April 2017
Slide 2: Calendar of Main Events, 2016-04/2017
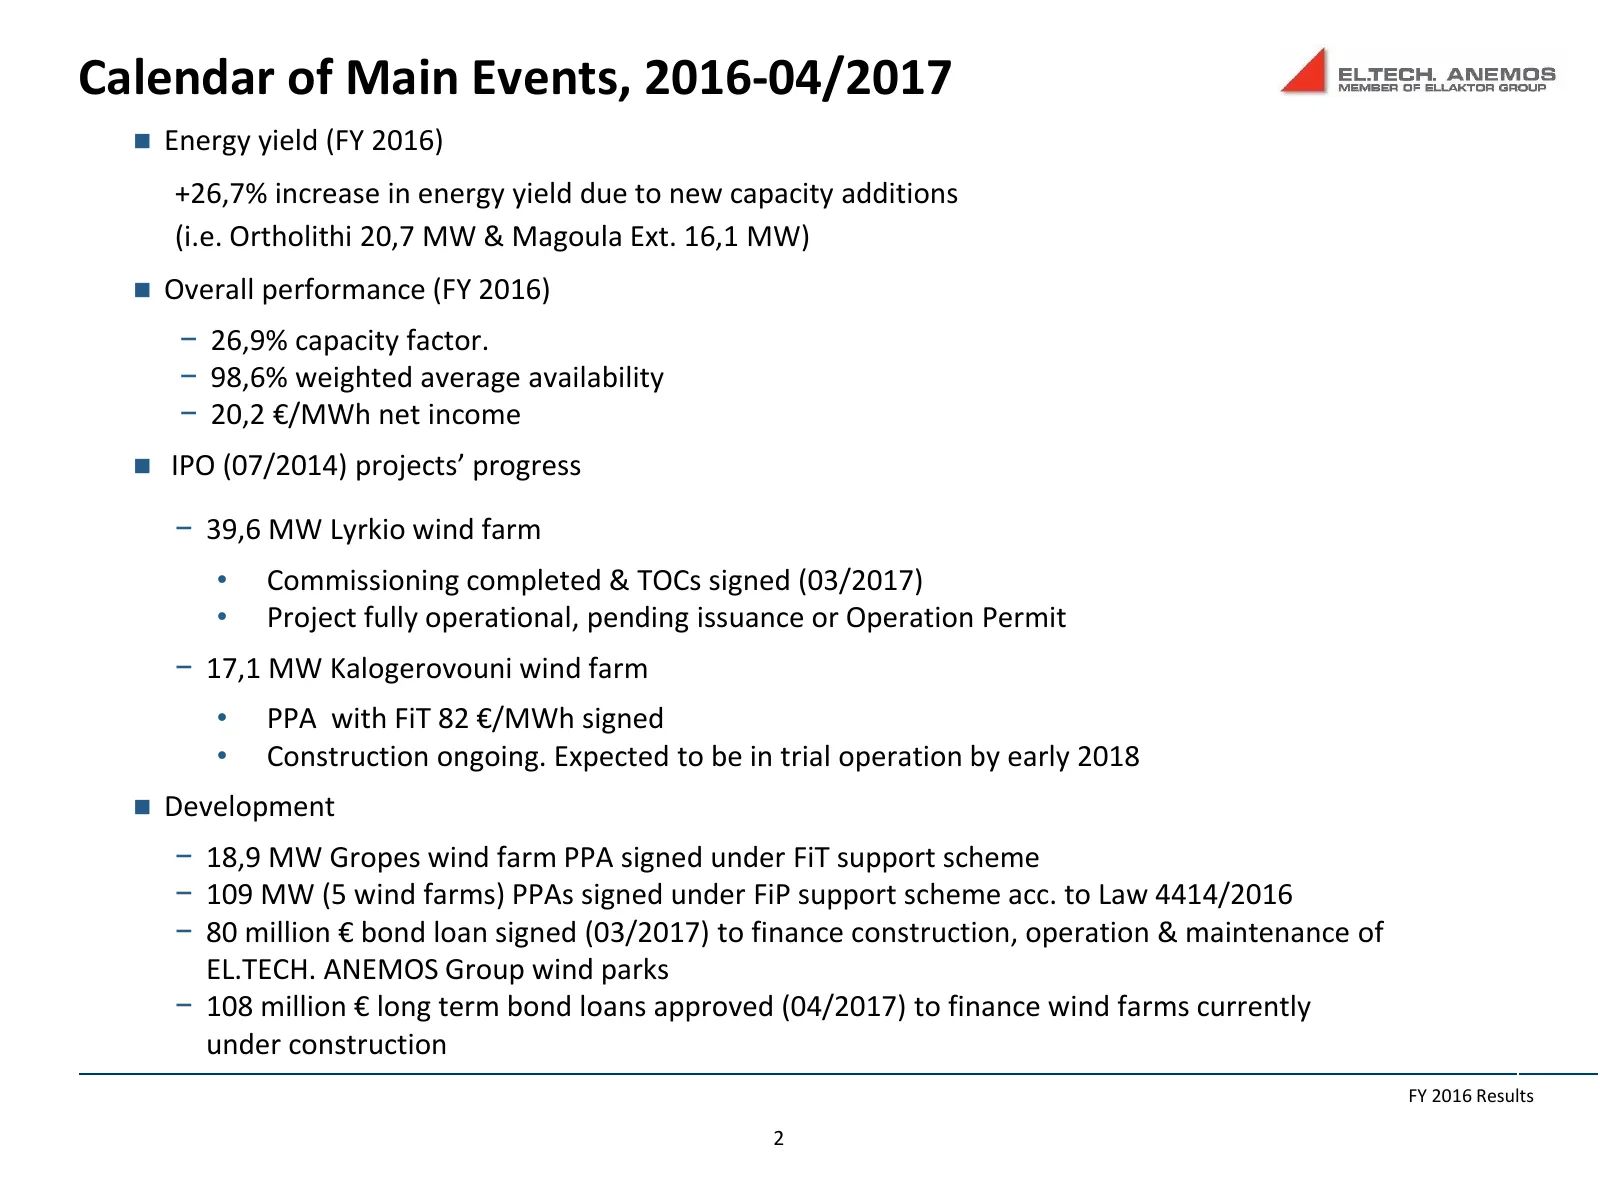
Calendar of Main Events, 2016-04/2017 Energy yield (FY 2016) +26,7% increase in energy yield due to new capacity additions (i.e. Ortholithi 20,7 MW & Magoula Ext. 16,1 MW) Overall performance (FY 2016) − 26,9% capacity factor. − 98,6% weighted average availability − 20,2 €/MWh net income IPO (
Slide 3: FY 2016 Economic Highlights
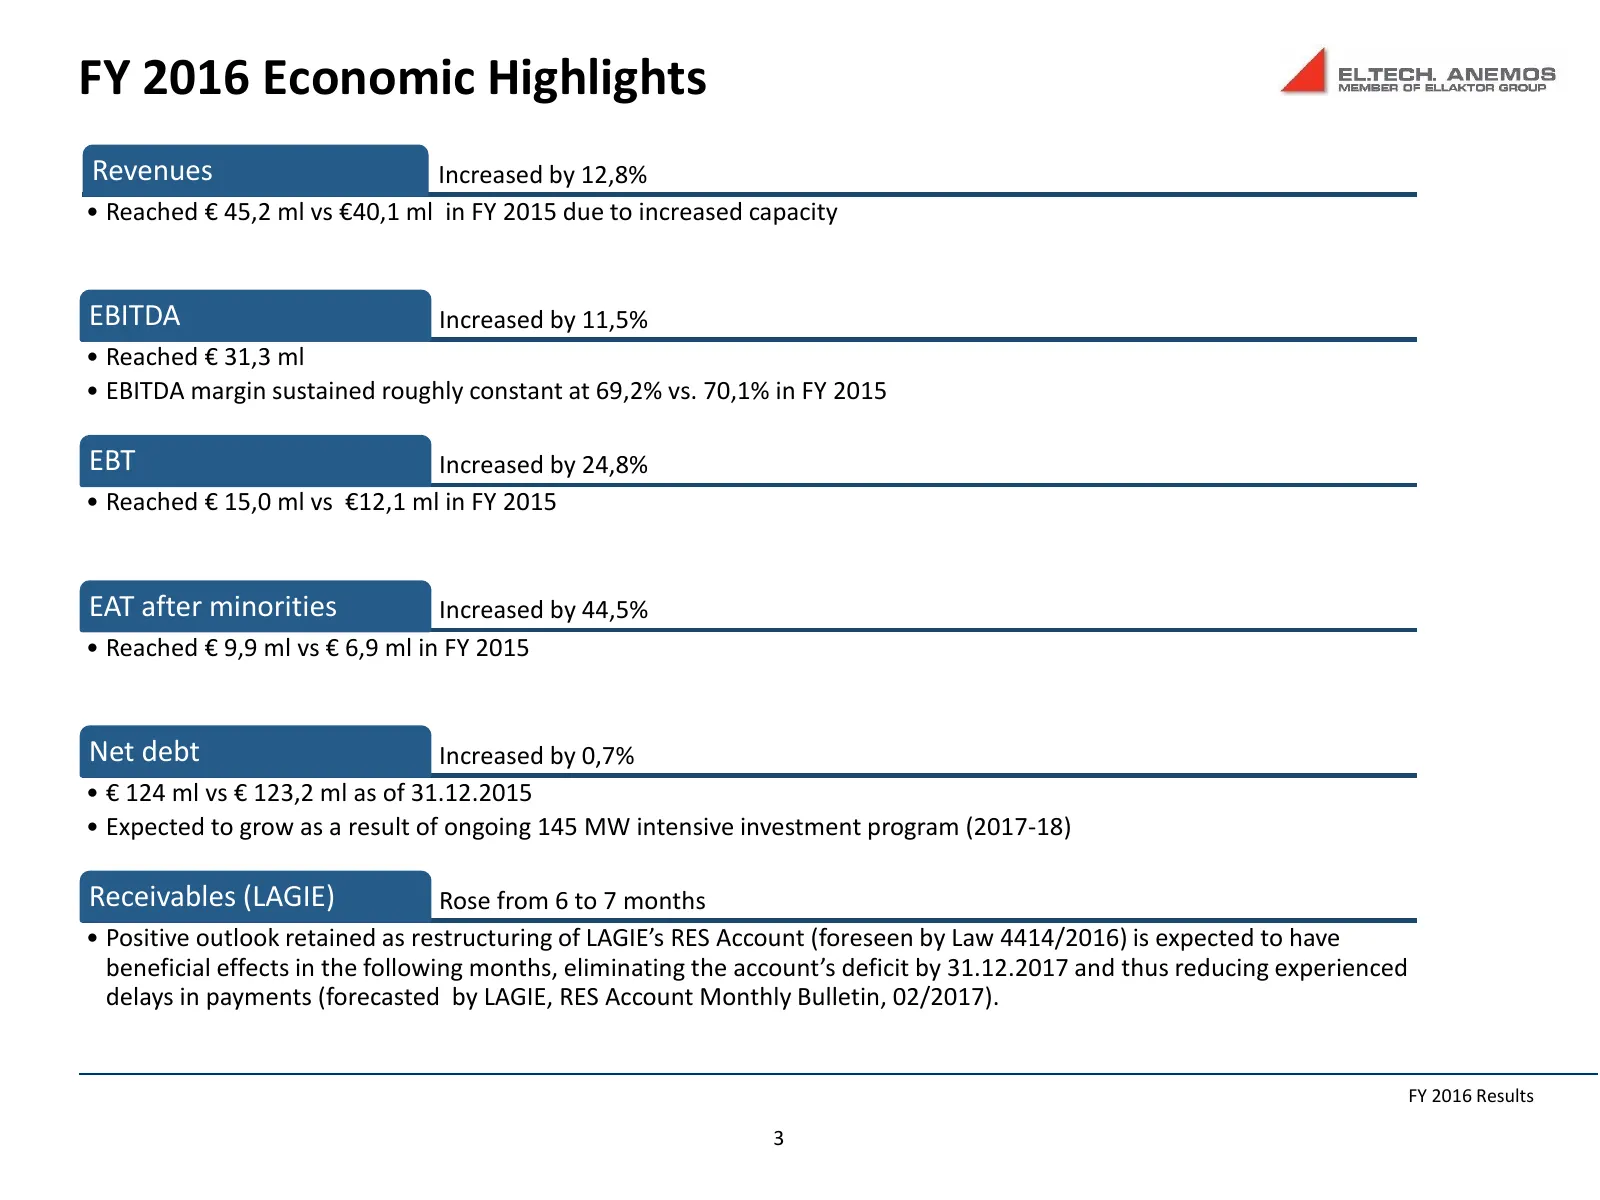
FY 2016 Economic Highlights Revenues Increased by 12,8% • Reached € 45,2 ml vs €40,1 ml in FY 2015 due to increased capacity EBITDA Increased by 11,5% • Reached € 31,3 ml • EBITDA margin sustained roughly constant at 69,2% vs. 70,1% in FY 2015 EBT Increased by 24,8% • Reached € 15,0 ml vs €12,1 ml i
Slide 4: Evolution of key P&L figures (IFRS in € ml)
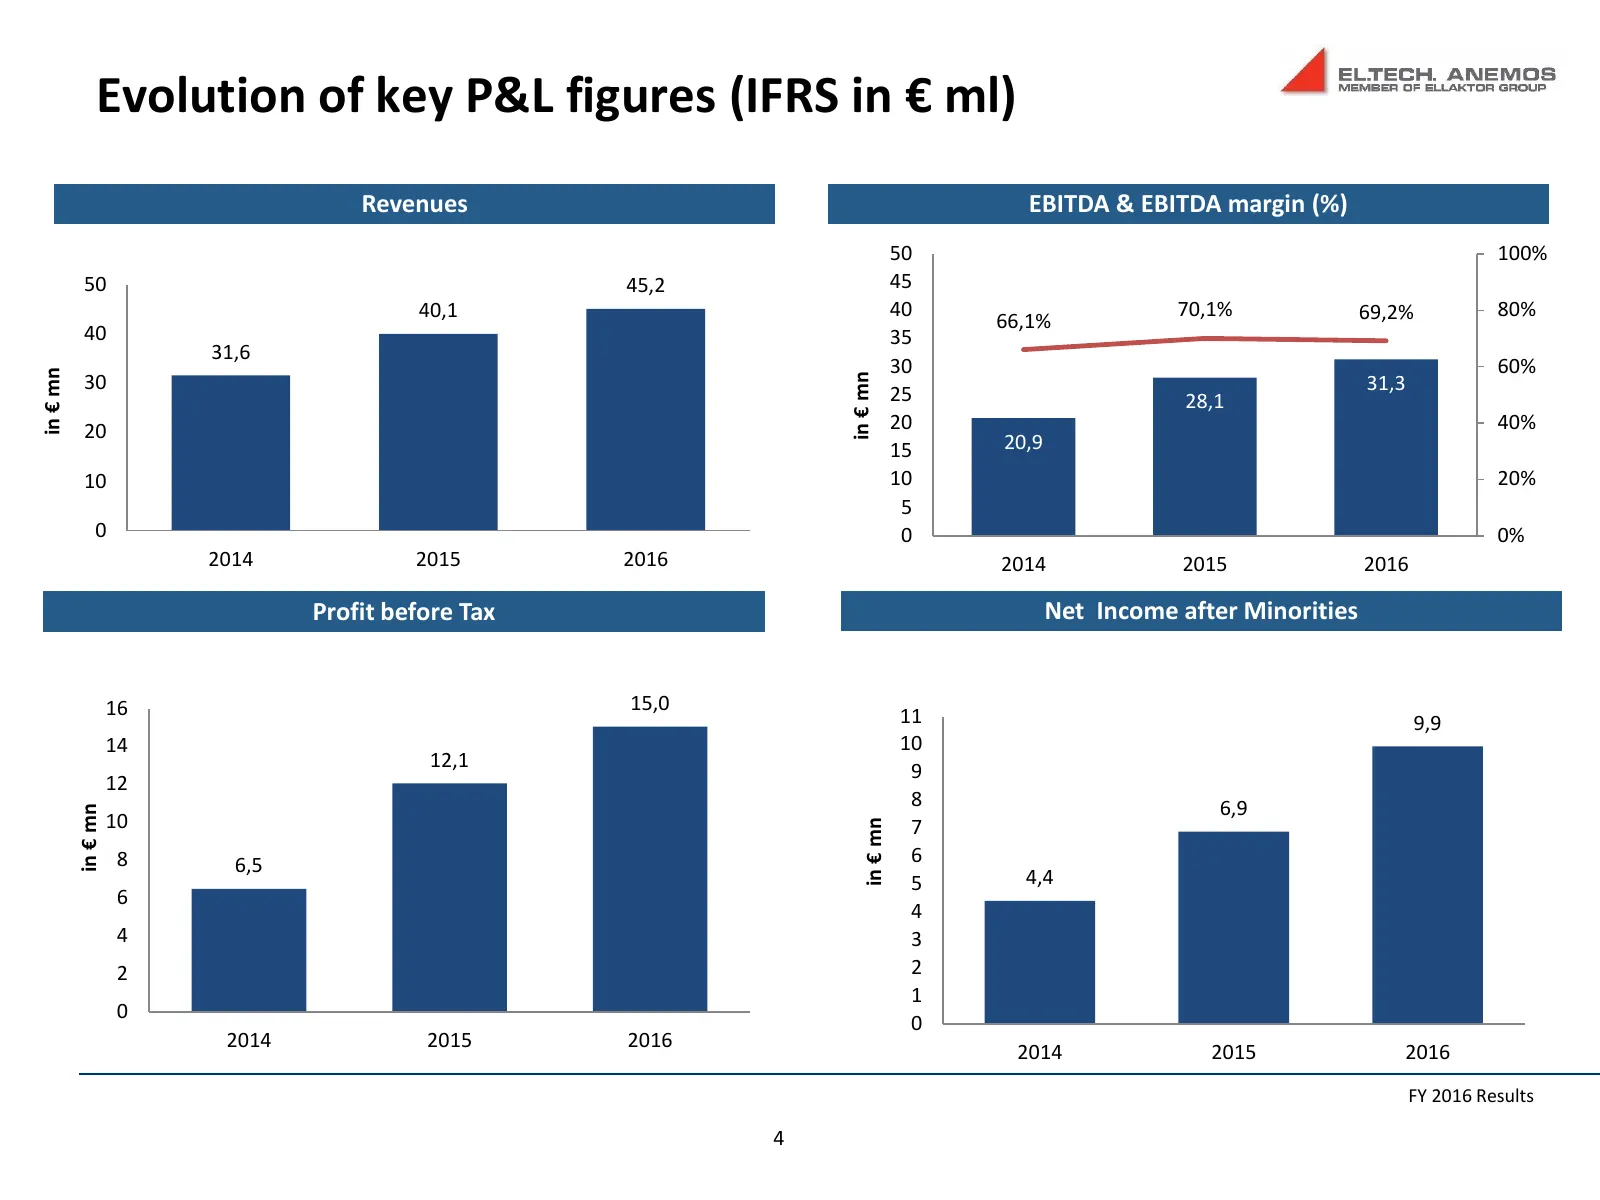
Evolution of key P&L figures (IFRS in € ml) Revenues EBITDA & EBITDA margin (%) 50 100% 50 45,2 45 40,1 40 70,1% 69,2% 80% 66,1% 40 35 31,6 30 60% in € mn in € mn 30 31,3 25 28,1 20 20 40% 15 20,9 10 10 20% 5 0 0 0% 2014 2015 2016 2014 2015 2016 Profit before Tax Net Income after Minorities 16 15,0
Slide 5: Evolution of key Balance Sheet figures (IFRS in € ml)
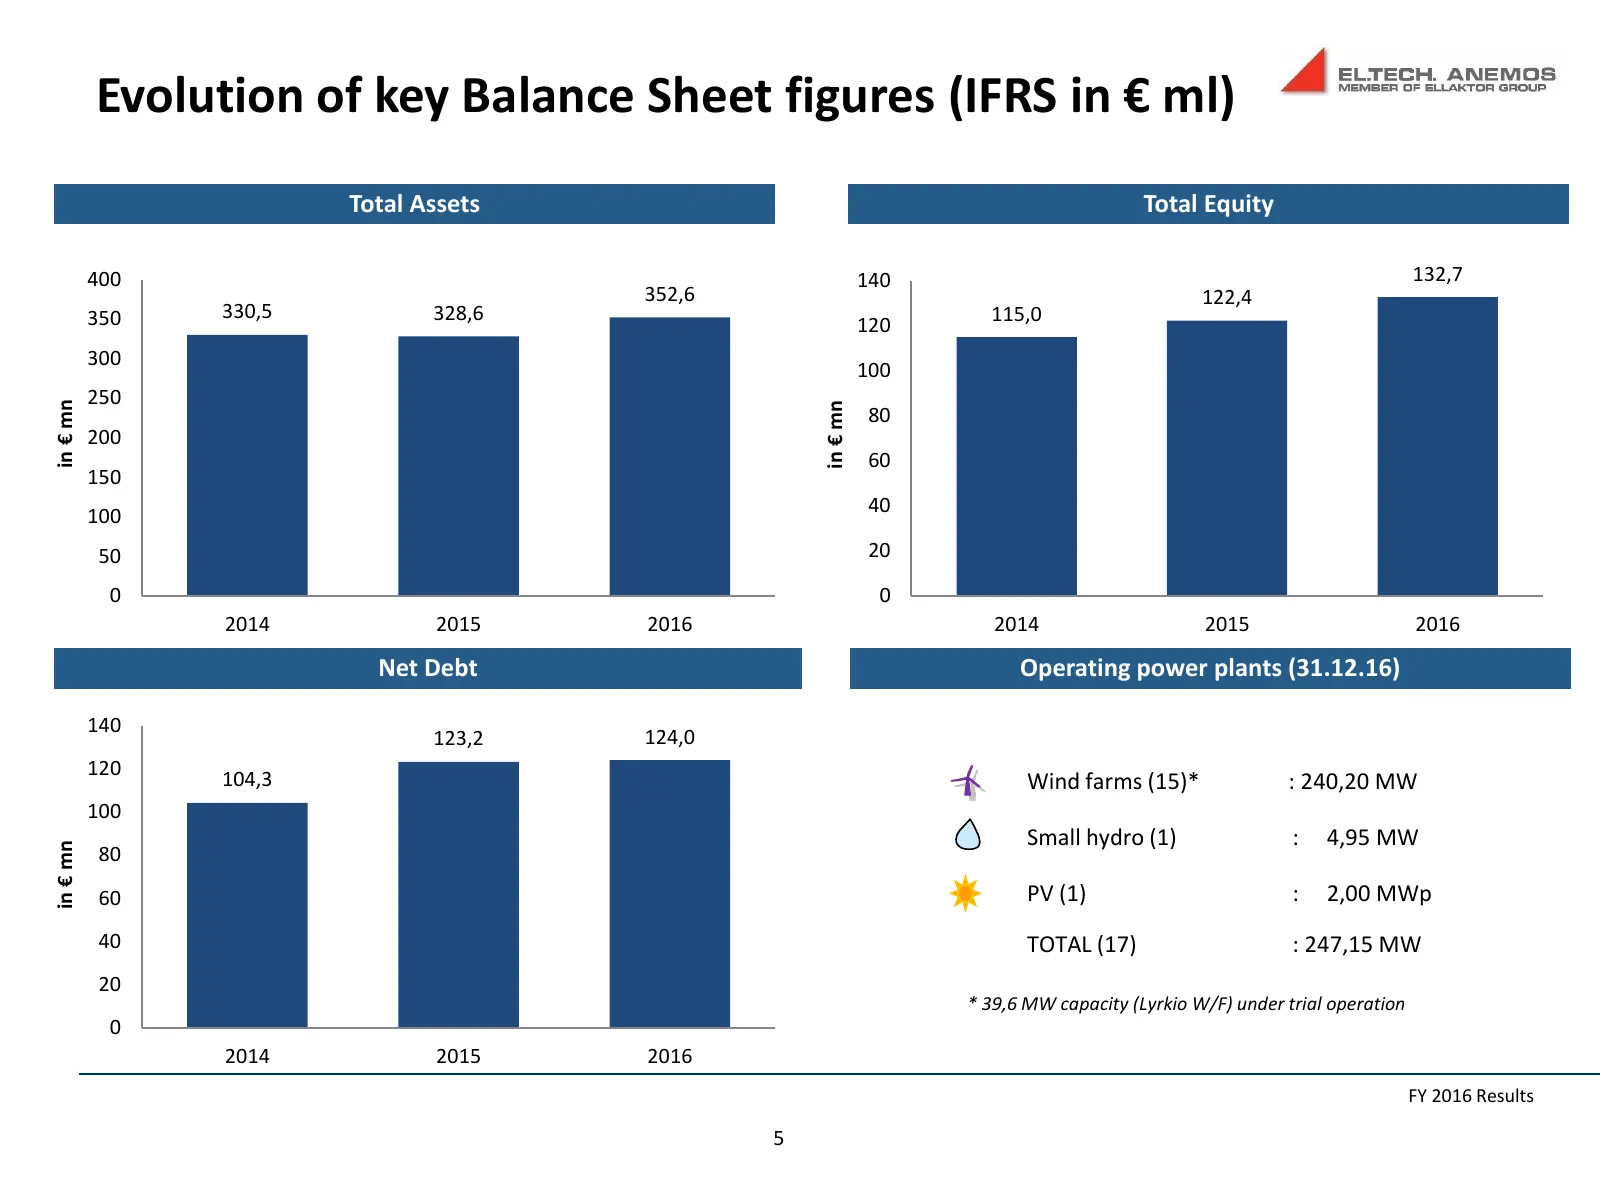
Evolution of key Balance Sheet figures (IFRS in € ml) Total Assets Total Equity 400 140 132,7 352,6 122,4 350 330,5 328,6 115,0 120 300 100 250 in € mn in € mn 80 200 60 150 100 40 50 20 0 0 2014 2015 2016 2014 2015 2016 Net Debt Operating power plants (31.12.16) 140 123,2 124,0 120 104,3 Wind farms
Slide 6: ANEMOS RES Asset Portfolio
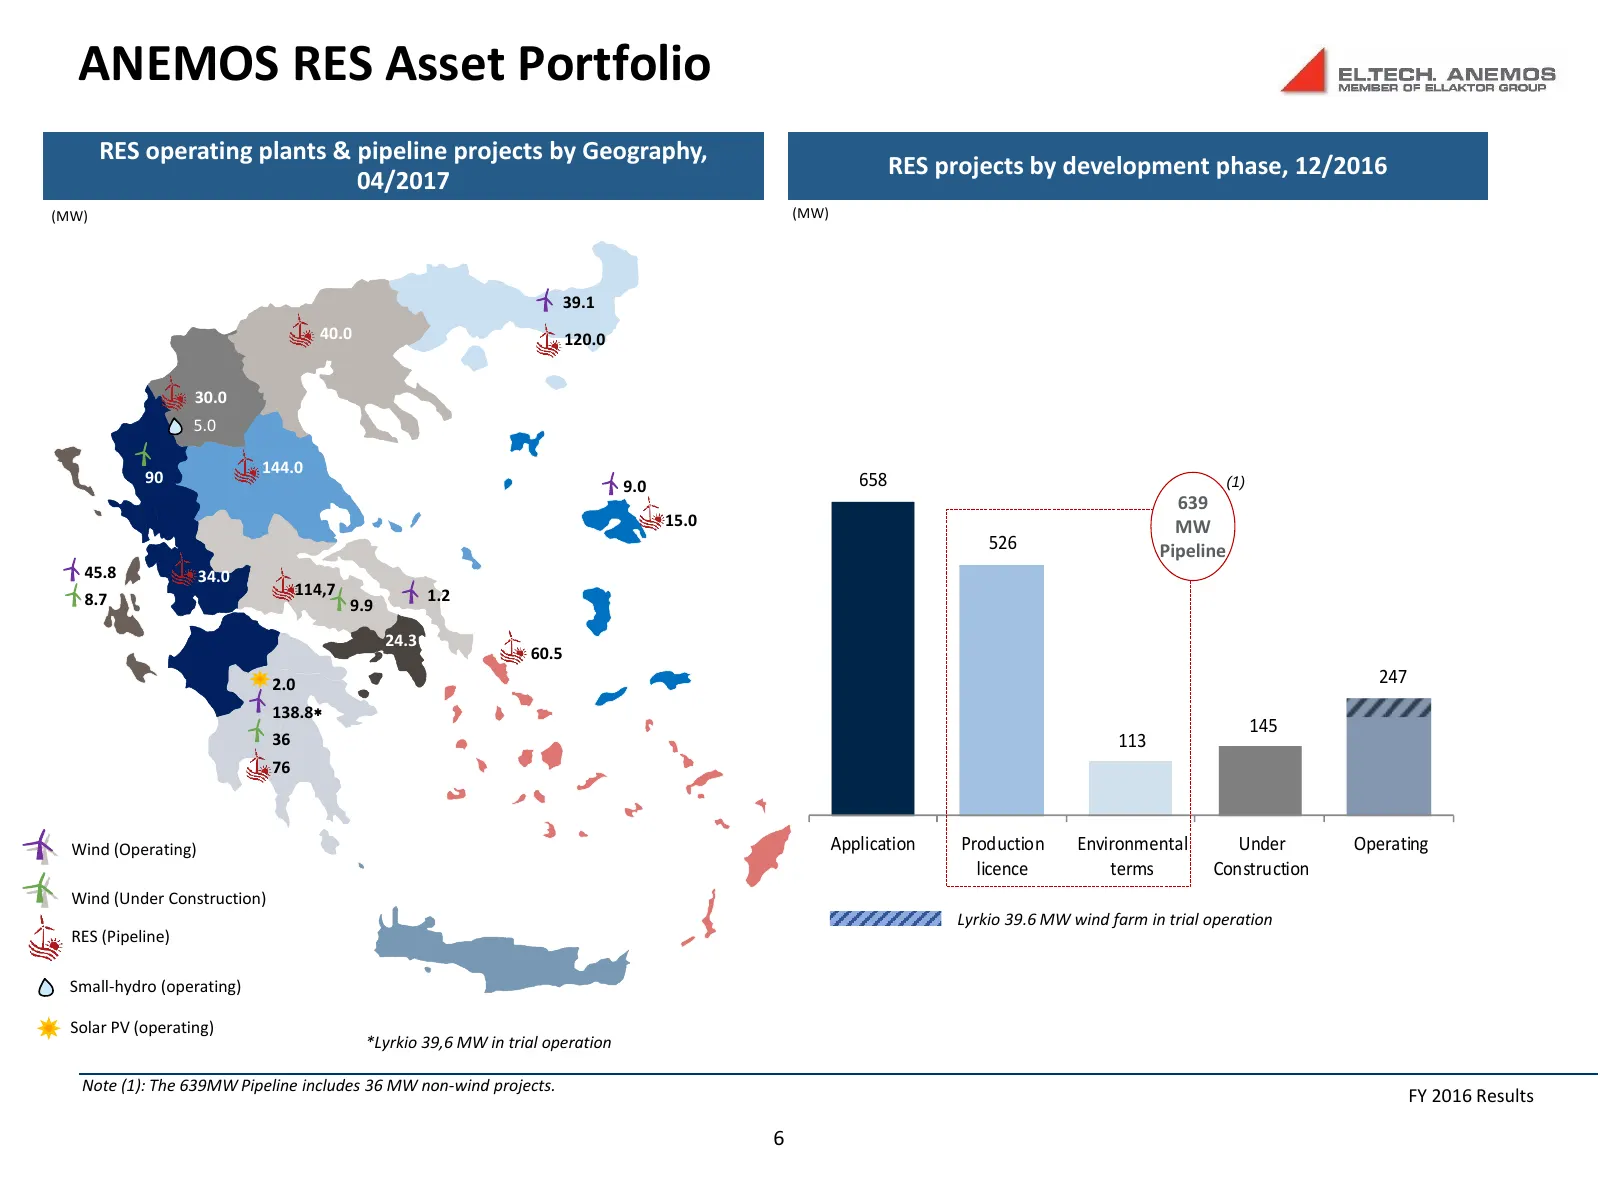
ANEMOS RES Asset Portfolio RES operating plants & pipeline projects by Geography, RES projects by development phase, 12/2016 04/2017 (MW) (MW) 39.1 40.0 120.0 30.0 5.0 144.0 90 9.0 658 (1) 639 15.0 MW 526 Pipeline 45.8 34.0 114,7 1.2 8.7 9.9 24.3 60.5 2.0 247 138.8 145 36 113 76 Wind (Operating) Ap
Slide 7: Strategy Going Forward – Maintain Growth Profile
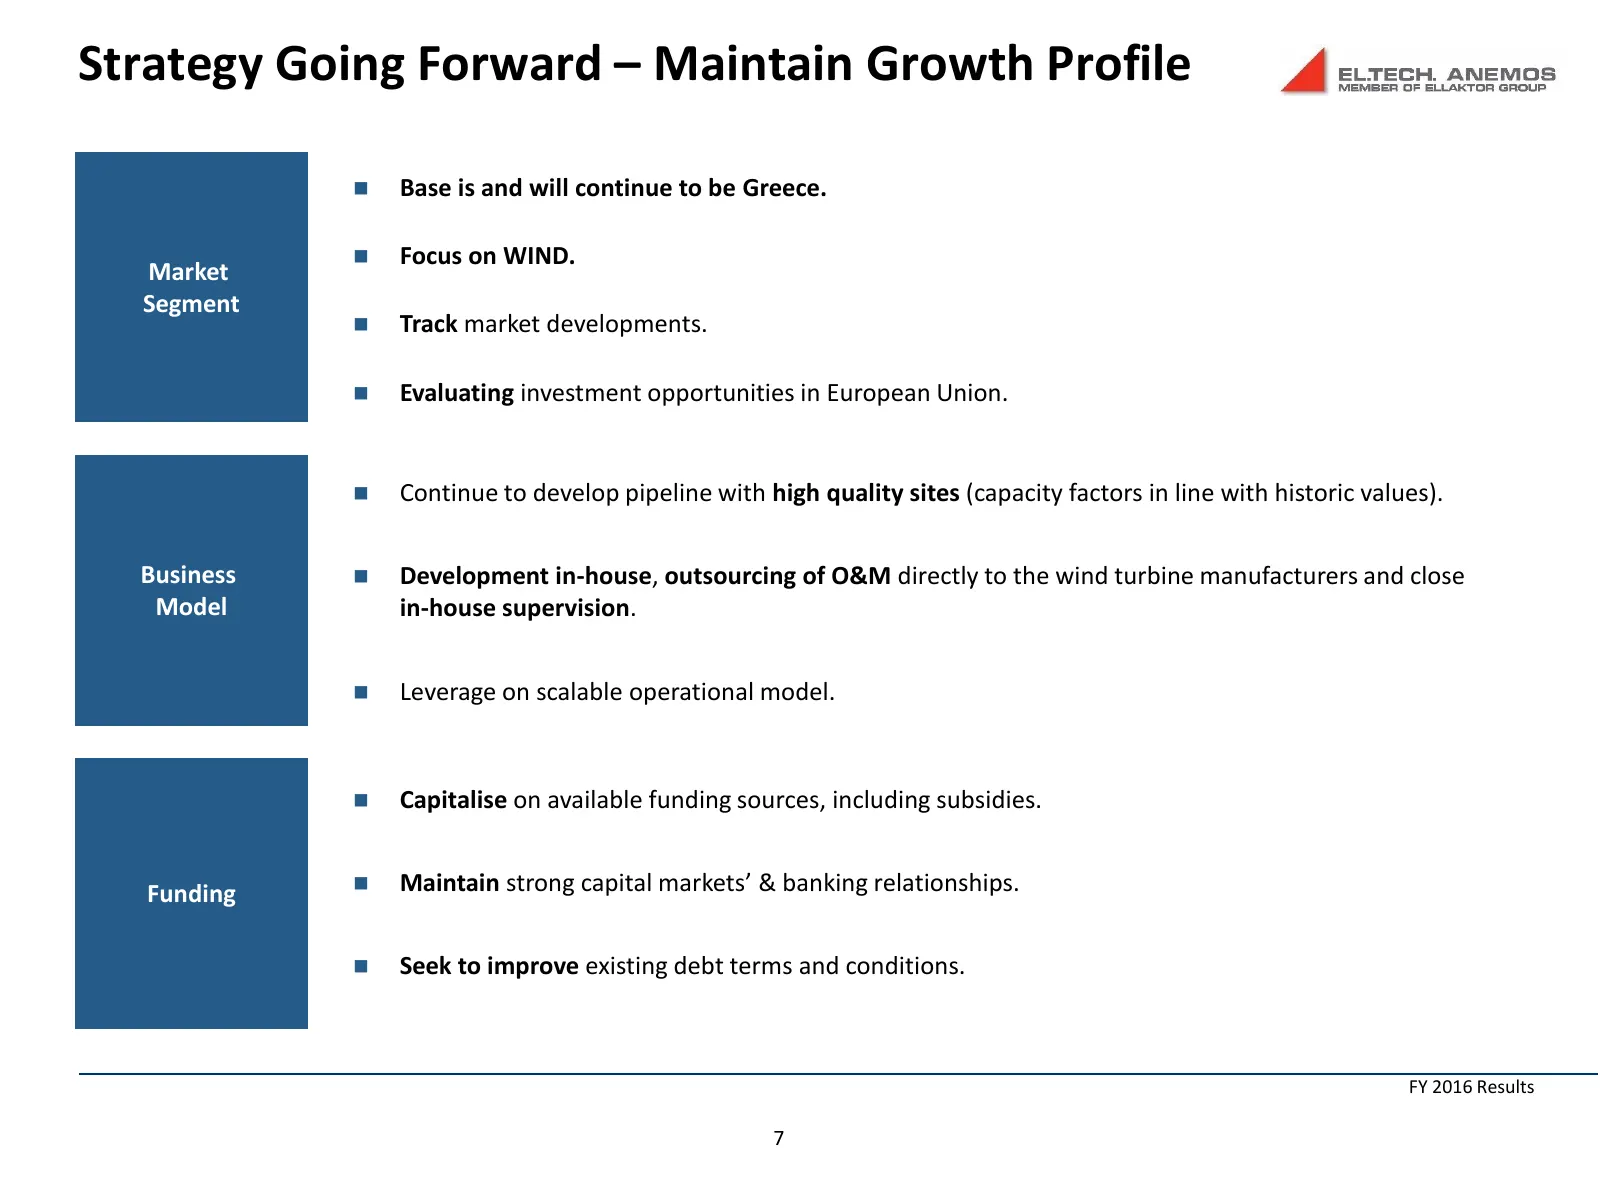
Strategy Going Forward – Maintain Growth Profile Base is and will continue to be Greece. Focus on WIND. Market Segment Track market developments. Evaluating investment opportunities in European Union. Continue to develop pipeline with high quality sites (capacity factors in line with histo
Slide 8: IPO Proceeds to finance wind farms of 93,5 MW
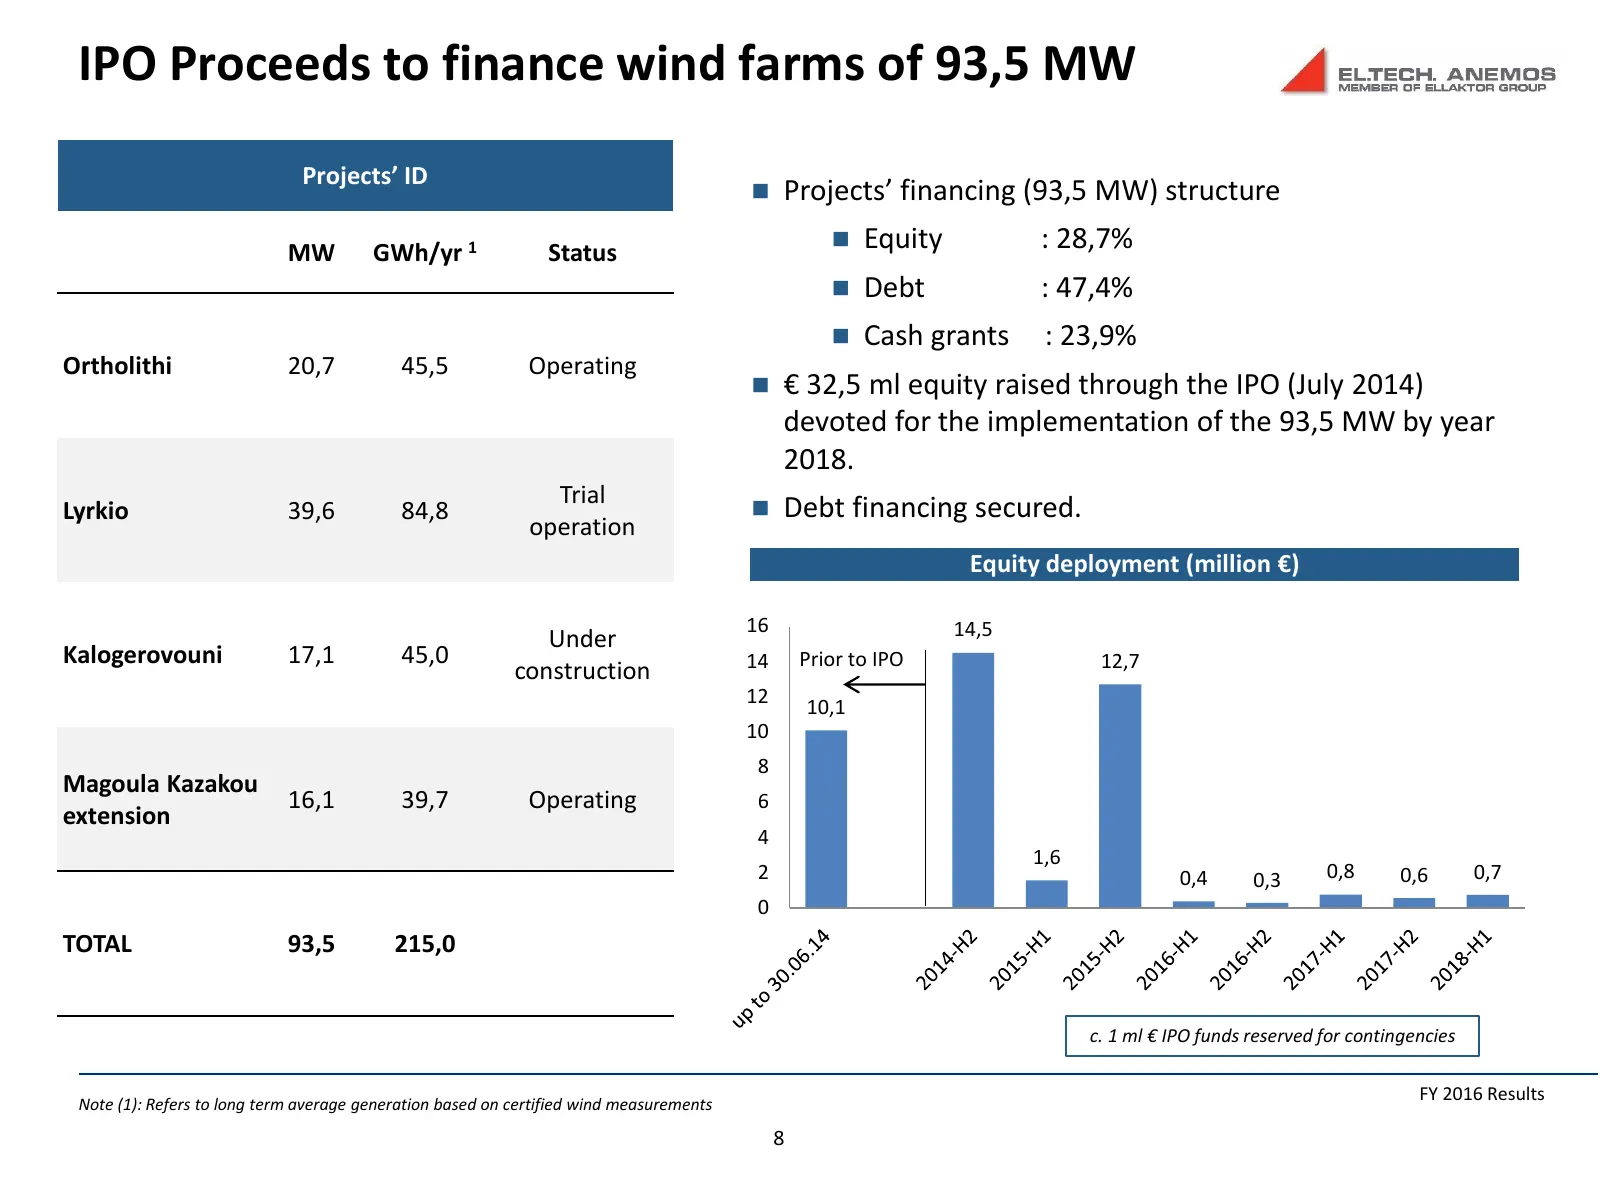
IPO Proceeds to finance wind farms of 93,5 MW Projects’ ID Projects’ financing (93,5 MW) structure Equity : 28,7% MW GWh/yr 1 Status Debt : 47,4% Cash grants : 23,9% Ortholithi 20,7 45,5 Operating € 32,5 ml equity raised through the IPO (July 2014) devoted for the implementation of the 93,
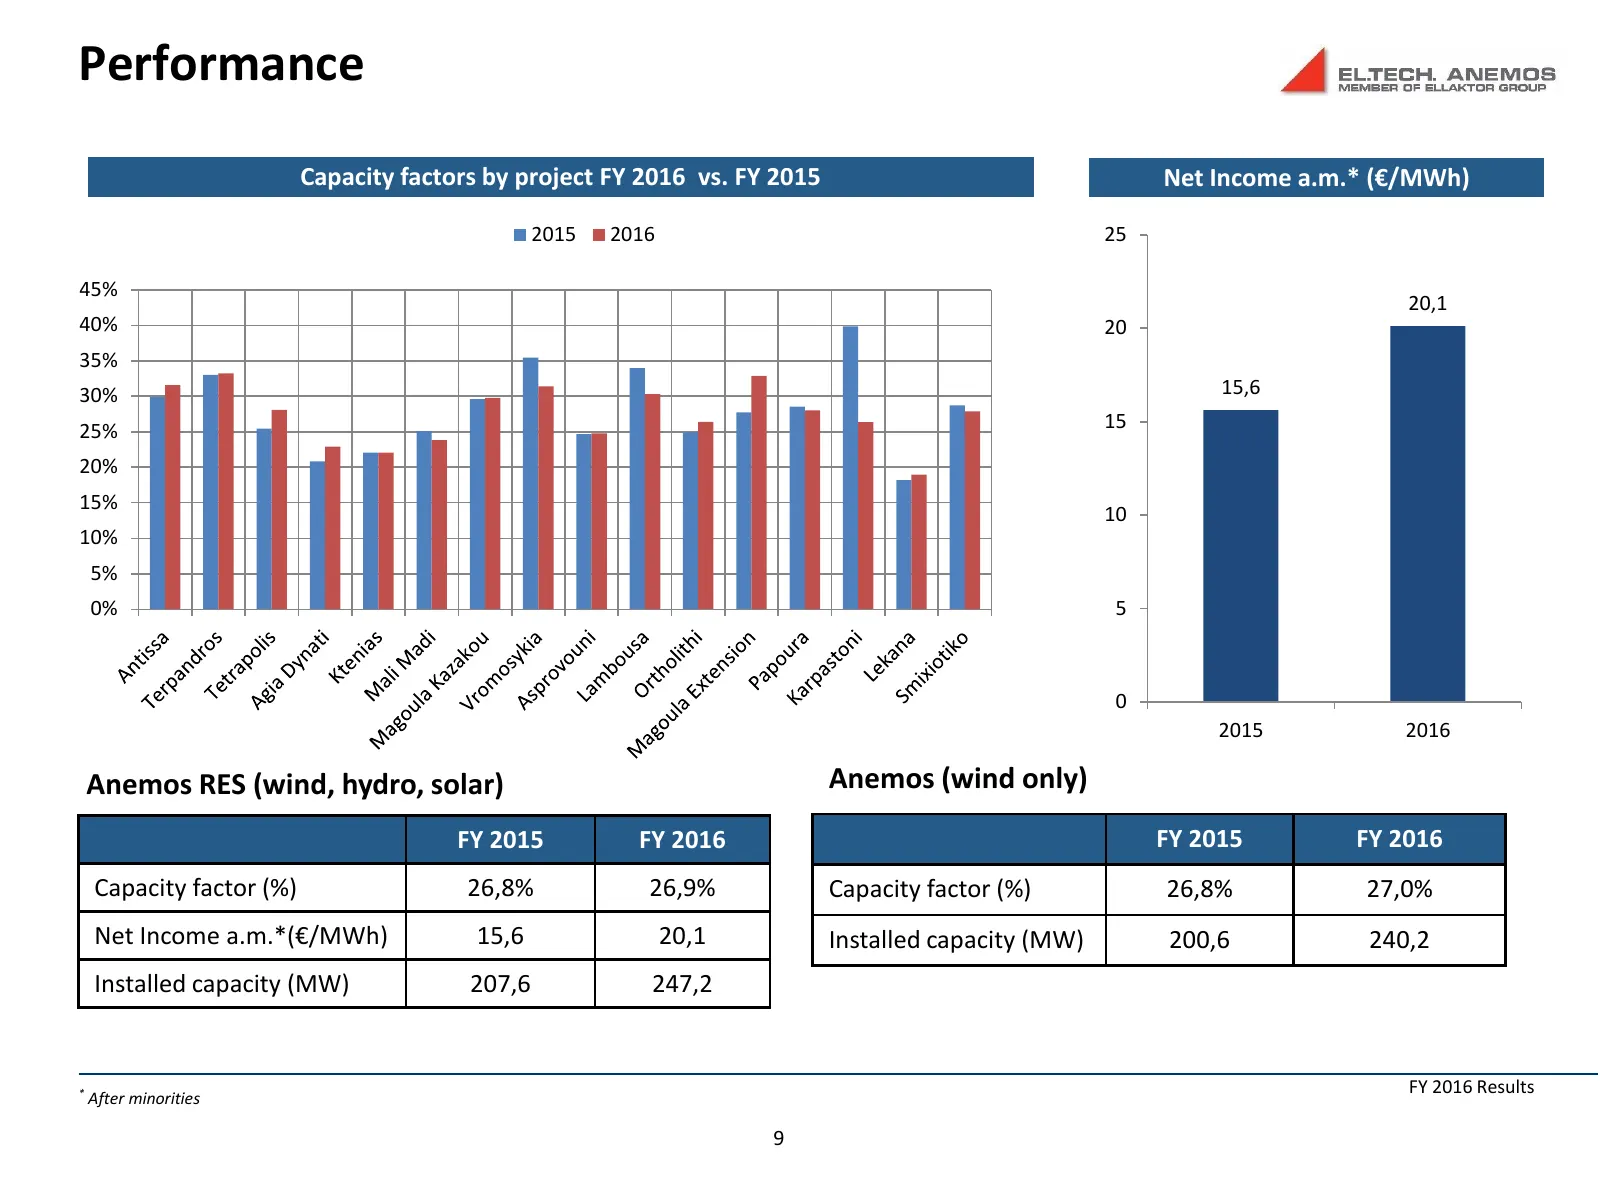
Slide 9: Performance
Performance Capacity factors by project FY 2016 vs. FY 2015 Net Income a.m.* (€/MWh) 2015 2016 25 45% 20,1 40% 20 35% 30% 15,6 25% 15 20% 15% 10 10% 5% 0% 5 0 2015 2016 Anemos RES (wind, hydro, solar) Anemos (wind only) FY 2015 FY 2016 FY 2015 FY 2016 Capacity factor (%) 26,8% 26,9% Capacity factor
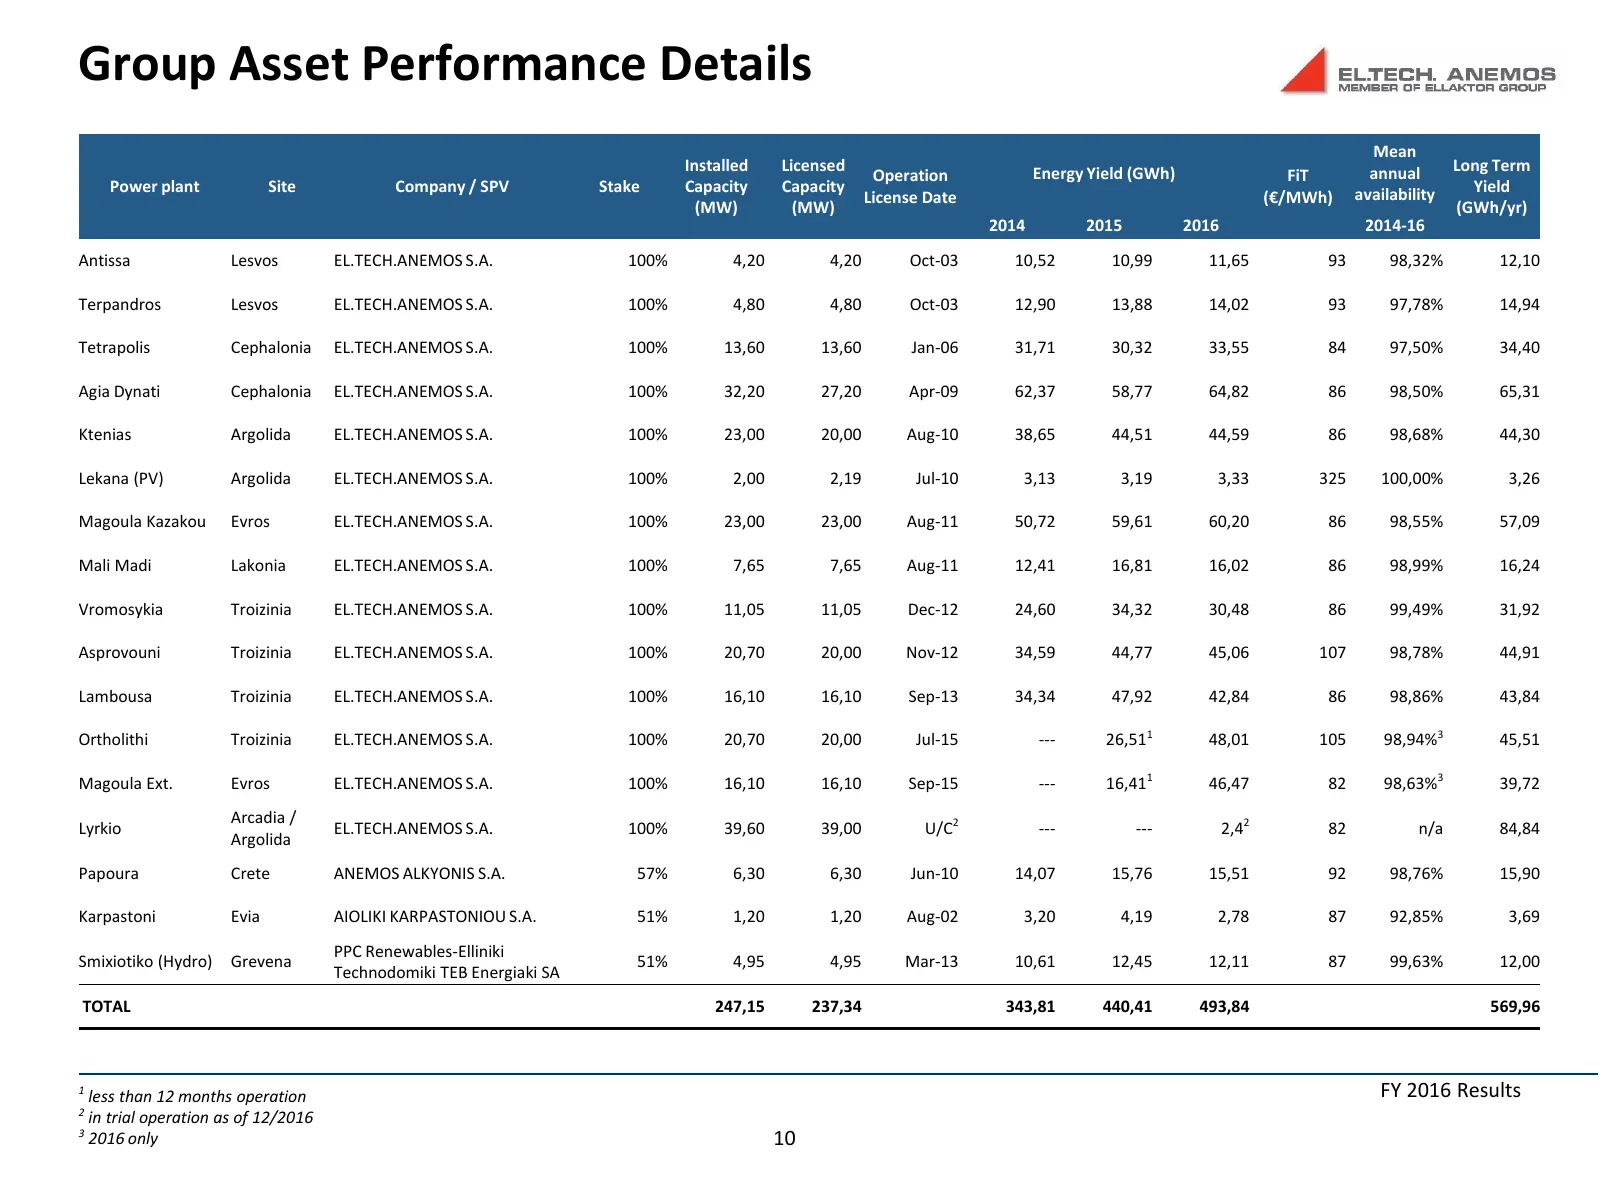
Slide 10: Group Asset Performance Details
Group Asset Performance Details Mean Installed Licensed Energy Yield (GWh) annual Long Term Operation FiT Power plant Site Company / SPV Stake Capacity Capacity availability Yield License Date (€/MWh) (MW) (MW) (GWh/yr) 2014 2015 2016 2014-16 Antissa Lesvos EL.TECH.ANEMOS S.A. 100% 4,20 4,20 Oct-03
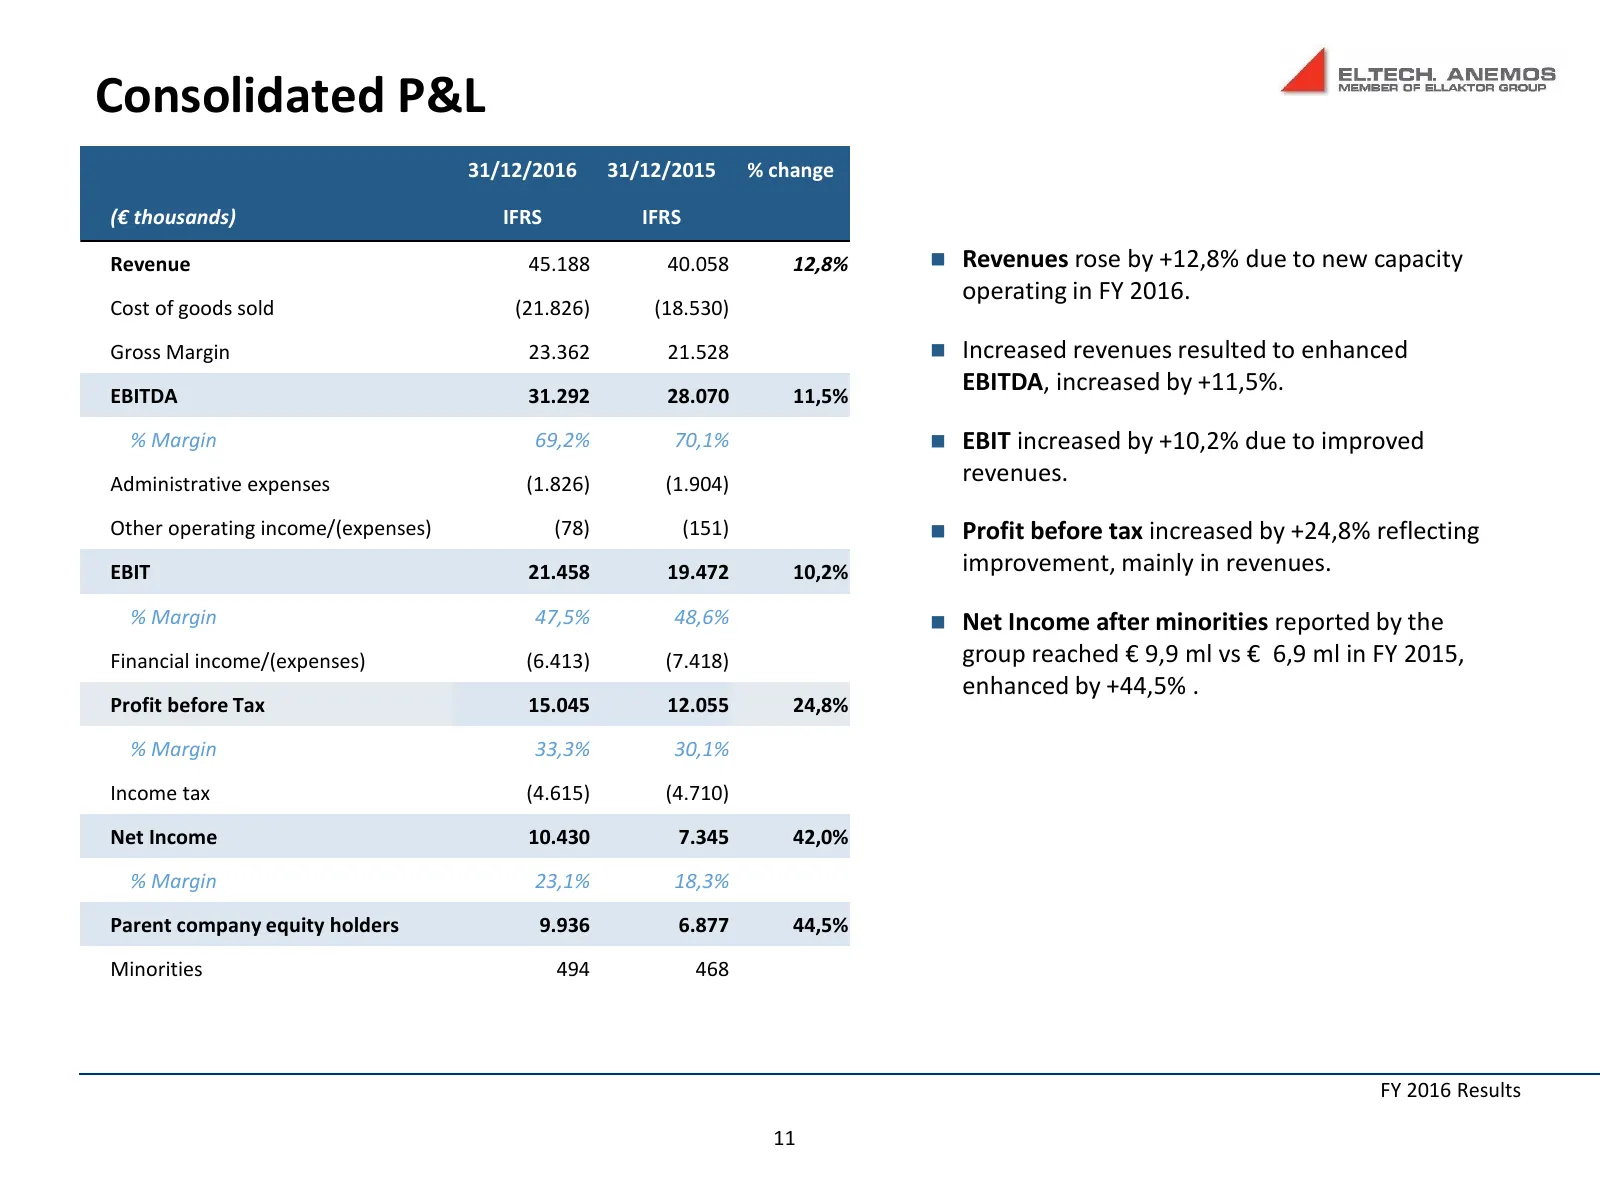
Slide 11: Consolidated P&L
Consolidated P&L 31/12/2016 31/12/2015 % change (€ thousands) IFRS IFRS Revenue 45.188 40.058 12,8% Revenues rose by +12,8% due to new capacity operating in FY 2016. Cost of goods sold (21.826) (18.530) Gross Margin 23.362 21.528 Increased revenues resulted to enhanced EBITDA 31.292 28.070 11,5%
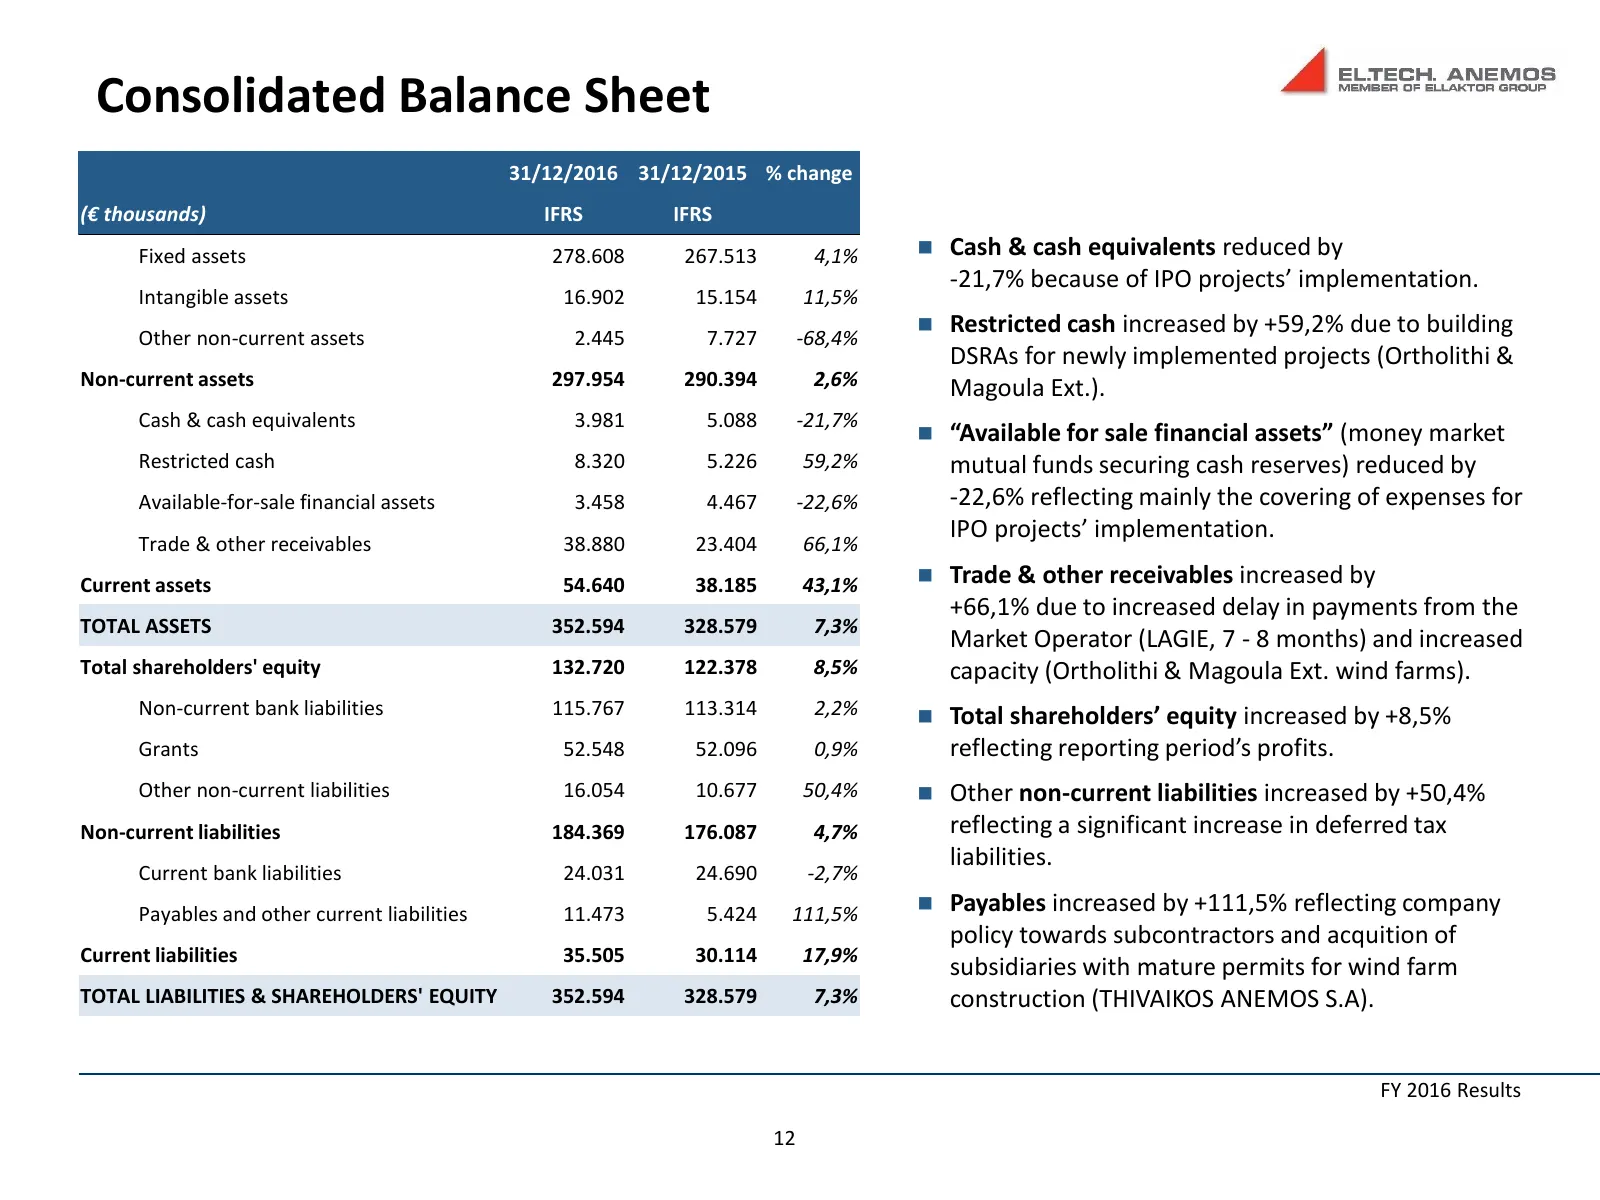
Slide 12: Consolidated Balance Sheet
Consolidated Balance Sheet 31/12/2016 31/12/2015 % change (€ thousands) IFRS IFRS Fixed assets 278.608 267.513 4,1% Cash & cash equivalents reduced by -21,7% because of IPO projects’ implementation. Intangible assets 16.902 15.154 11,5% Other non-current assets 2.445 7.727 -68,4% Restricted cash
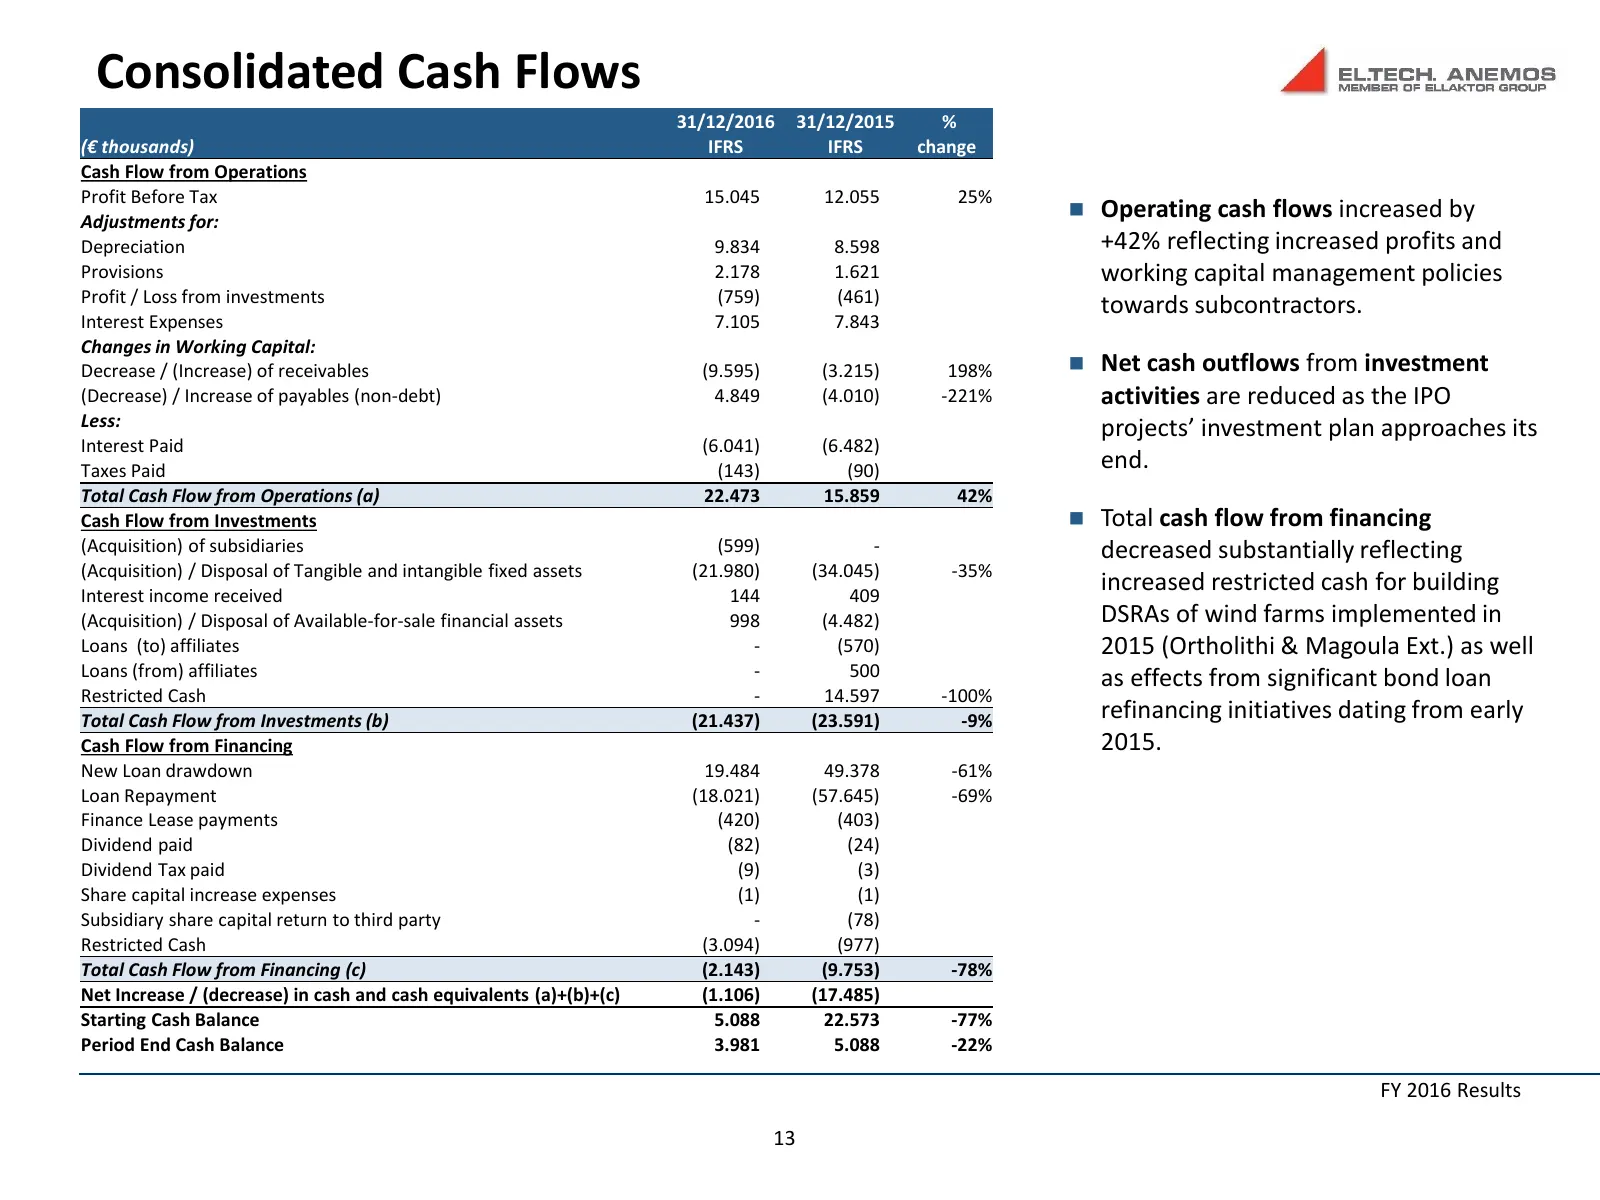
Slide 13: Consolidated Cash Flows
Consolidated Cash Flows 31/12/2016 31/12/2015 % (€ thousands) IFRS IFRS change Cash Flow from Operations Profit Before Tax 15.045 12.055 25% Adjustments for: Operating cash flows increased by Depreciation 9.834 8.598 +42% reflecting increased profits and Provisions 2.178 1.621 working capital mana
Source: Internet Archive copy of ellaktor.com
More decks from Ellaktor SA
 FY2025 Earnings Presentation23 slides · Apr 17, 2026
 FY2024 Earnings Presentation30 slides · Apr 24, 2025
 H1 2024 Earnings Presentation30 slides · Sep 12, 2024
 FY2023 Earnings Presentation32 slides · Apr 18, 2024
 9M 2023 Earnings Presentation31 slides · Nov 23, 2023
 9M 2023 Earnings Presentation48 slides · November 2023