Dyncorp International — Bear Stearns SMID Cap Conference (November 2006)
23 slides from Dyncorp International's conference presentation, Nov 14, 2006
Slide 1: Investor Presentation November 14, 2006
Investor Presentation November 14, 2006
Slide 2: Forward-Looking Statements
Forward-Looking Statements FORWARD-LOOKING STATEMENTS This presentation contains statements that may be considered forward looking within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, such as estimates of our Fourth Quarter Fiscal 20
Slide 3: Company Snapshot
Company Snapshot Global Headquarters: Falls Church, Virginia History: We trace our beginnings to 1946 IPO Date: May 4, 2006 FY End Date: Closest Friday to March 31st Yearly Revenue: $1.97 Billion (Year Ended March 31, 2006) First Half FY07 Revenue: $1,012.4 Million (Six months ended September 29, 20
Slide 4: Established & Strong Global Presence
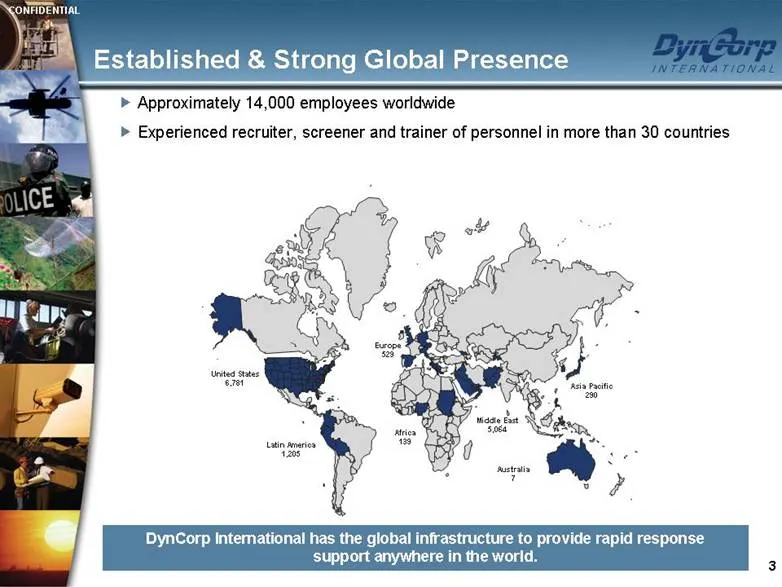
Established & Strong Global Presence Approximately 14,000 employees worldwide Experienced recruiter, screener and trainer of personnel in more than 30 countries United States 6,781 DynCorp International has the global infrastructure to provide rapid response support anywhere in the world. Latin Amer
Slide 5: Investment Highlights
Investment Highlights Unique Global Provider of Outsourced Technical Services Leading Market Position Strong, Long-Standing and Strong Customer Relationships Attractive Industry Fundamentals Diversified, Stable Platform for Growth Global Business Growth Opportunities Attractive Cash Flow Dynamics Ex
Slide 6: Unique Mission-Critical Service Provider
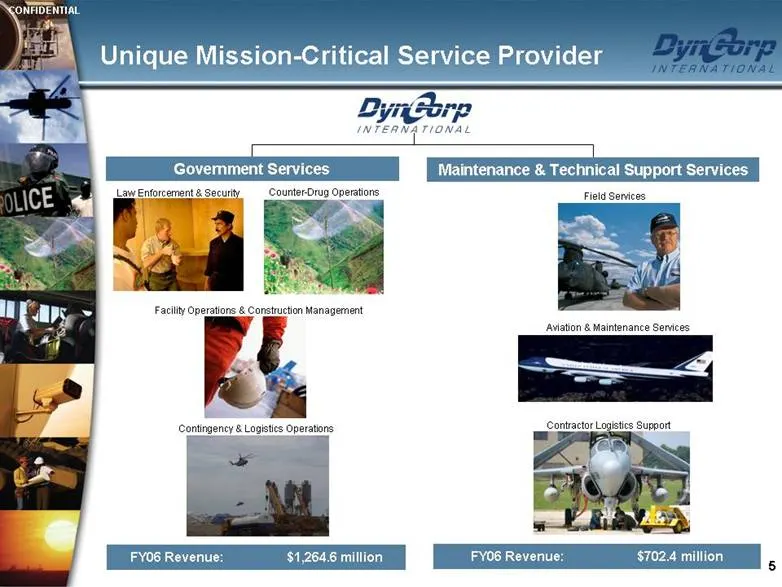
Government Services Law Enforcement & Security Counter-Drug Operations Facility Operations & Construction Management Contingency & Logistics Operations Aviation & Maintenance Services Unique Mission-Critical Service Provider Maintenance & Technical Support Services Field Services FY06 Revenue: $1,26
Slide 7: Five Core Service Offerings
Five Core Service Offerings Maintenance & Technical Support Services The Maintenance & Technical Support Services Group provides maintenance, modifications, repairs, and engineering and logistics support for various commercial and Department of Defense aircraft and weapons systems and associated sup
Slide 8: Leading Market Position
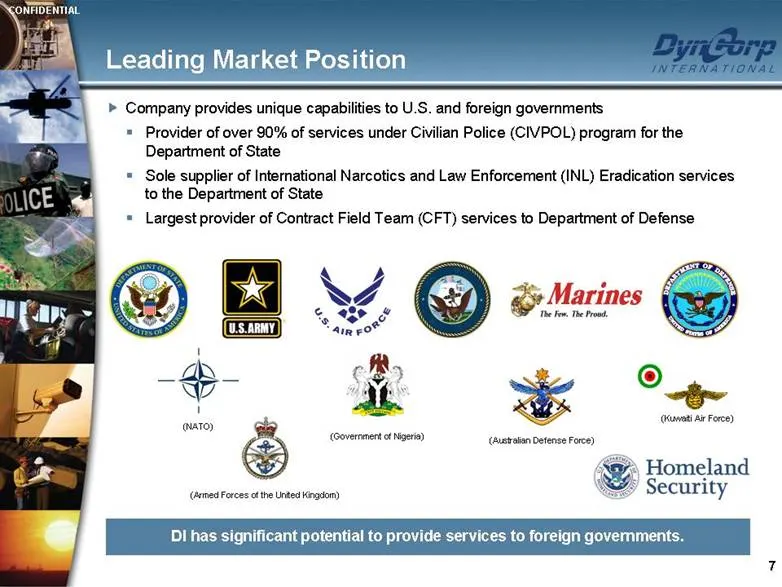
Leading Market Position DI has significant potential to provide services to foreign governments. Company provides unique capabilities to U.S. and foreign governments Provider of over 90% of services under Civilian Police (CIVPOL) program for the Department of State Sole supplier of International Nar
Slide 9: Key Government Services Contracts
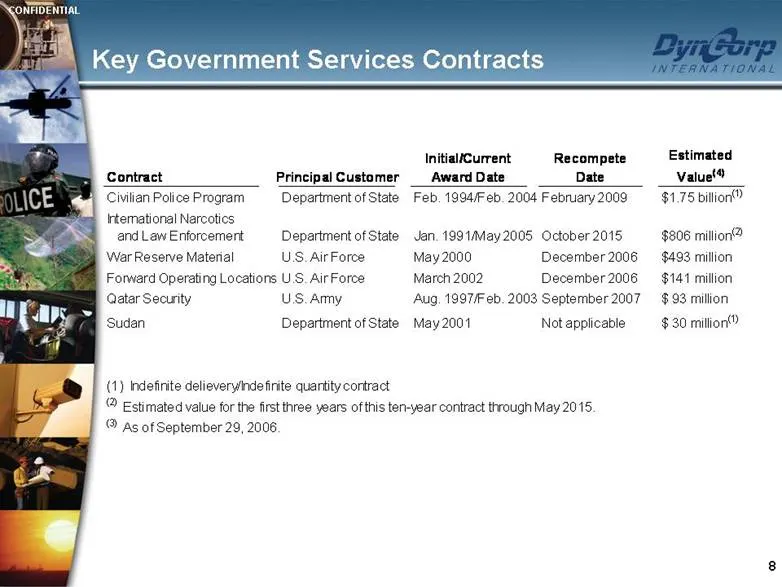
Key Government Services Contracts Contract Principal Customer Initial/Current Award Date Recompete Date Estimated Value (4) Civilian Police Program Department of State Feb. 1994/Feb. 2004 February 2009 $1.75 billion (1) International Narcotics and Law Enforcement Department of State Jan. 1991/May 20
Slide 10: Rising Number of IPLOs
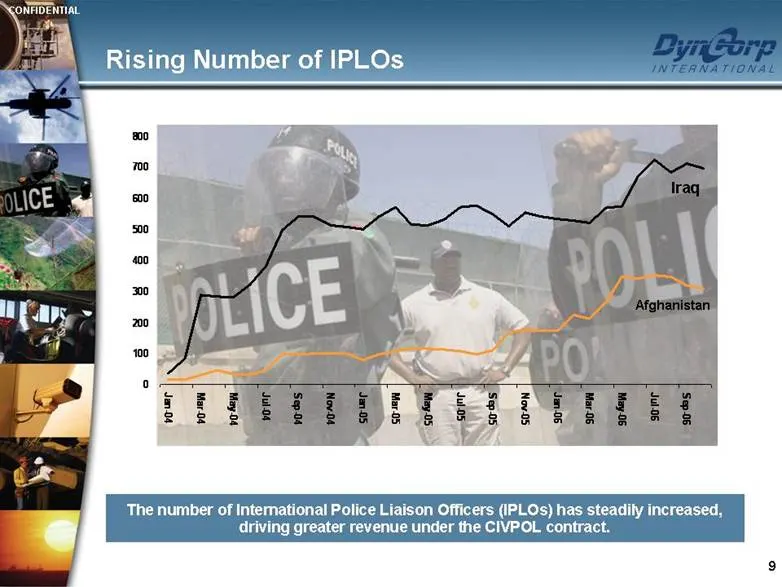
Rising Number of IPLOs The number of International Police Liaison Officers (IPLOs) has steadily increased, driving greater revenue under the CIVPOL contract. Afghanistan Iraq 0 100 200 300 400 500 600 700 800 Jan-04 Mar-04 May-04 Jul-04 Sep-04 Nov-04 Jan-05 Mar-05 May-05 Jul-05 Sep-05 Nov-05 Jan-06
Slide 11: Increasing Government & DoD Outsourcing
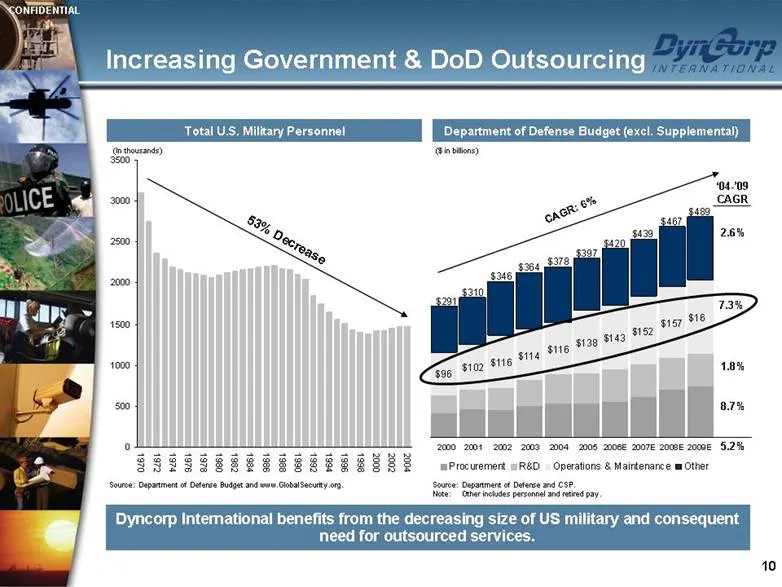
Increasing Government & DoD Outsourcing Department of Defense Budget (excl. Supplemental) ($ in billions) CAGR: 6% Source: Department of Defense and CSP. Note: Other includes personnel and retired pay. ‘04-’09 CAGR 2.6% 7.3% 1.8% 8.7% Dyncorp International benefits from the decreasing size of US mil
Slide 12: DI's Role Increases Post-Conflict
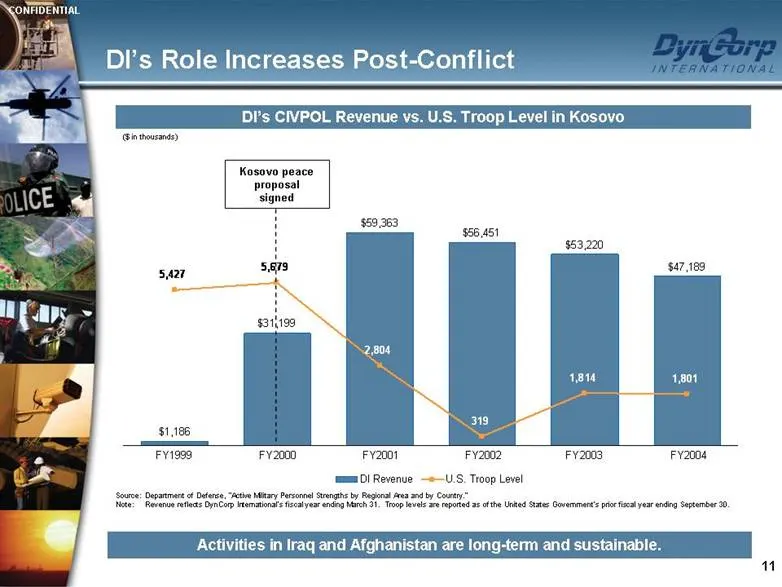
DI’s Role Increases Post-Conflict Activities in Iraq and Afghanistan are long-term and sustainable. DI’s CIVPOL Revenue vs. U.S. Troop Level in Kosovo ($ in thousands) Kosovo peace proposal signed Source: Department of Defense, “Active Military Personnel Strengths by Regional Area and by Country.” N
Slide 13: Key Maintenance and Technical Support Services Contracts
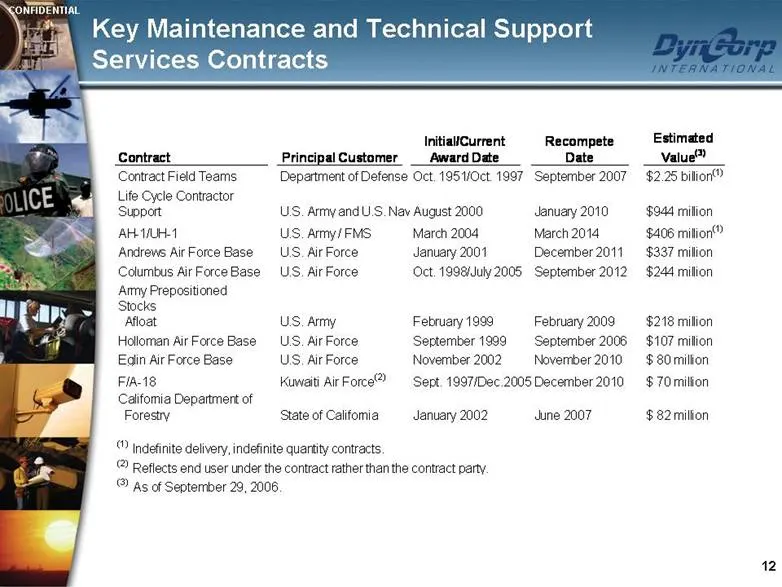
Key Maintenance and Technical Support Services Contracts Contract Principal Customer Initial/Current Award Date Recompete Date Estimated Value (3) Contract Field TeamsDepartment of DefenseOct. 1951/Oct. 1997September 2007$2.25 billion (1) Life Cycle Contractor SupportU.S. Army and U.S. NavyAugust 20
Slide 14: Domestic Growth Opportunities
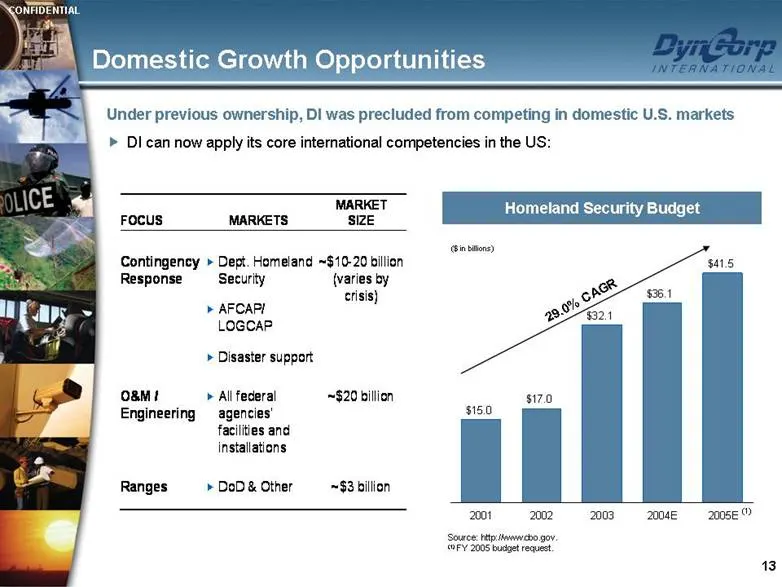
Domestic Growth Opportunities Under previous ownership, DI was precluded from competing in domestic U.S. markets DI can now apply its core international competencies in the US: Homeland Security Budget ($ in billions) Source: http://www.cbo.gov. (1) FY 2005 budget request. 29.0% CAGR $41.5 $36.1 $32
Slide 15: Financial Review
Financial Review
Slide 16: Revenue Breakdown
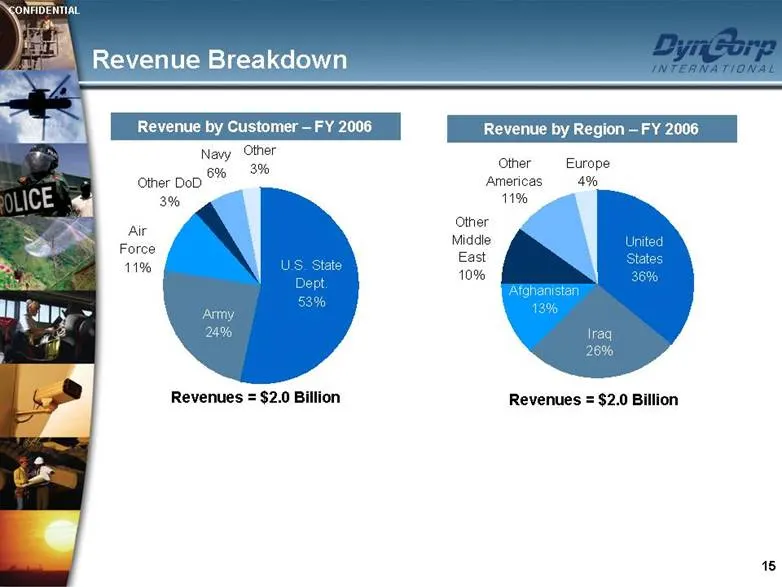
Revenue Breakdown Revenue by Customer – FY 2006 Revenue by Region – FY 2006 Revenues = $2.0 Billion Revenues = $2.0 Billion United States 36% Iraq 26% Afghanistan 13% Other Middle East 10% Other Americas 11% Europe 4% U.S. State Dept. 53% Army 24% Air Force 11% Other DoD 3% Navy 6% Other 3%
Slide 17: Historical Operating Performance
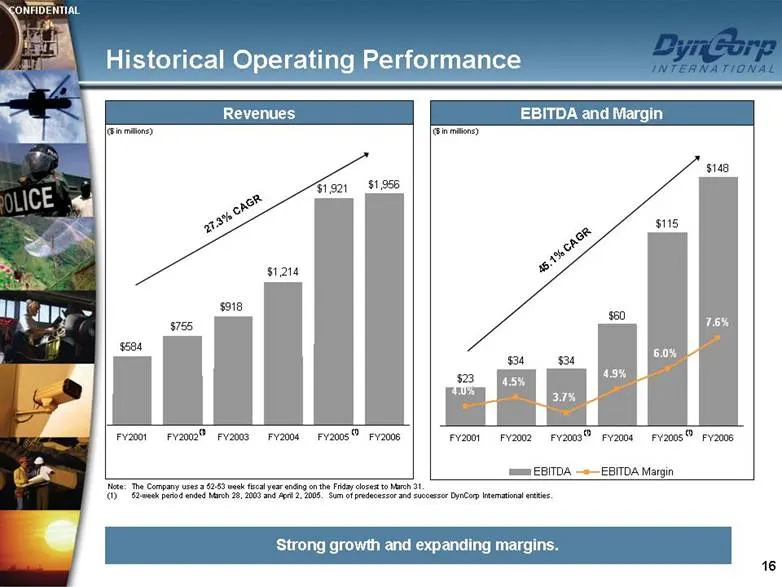
Historical Operating Performance Strong growth and expanding margins. Revenues EBITDA and Margin ($ in millions) 27.3% CAGR ($ in millions) 45.1% CAGR Note: The Company uses a 52-53 week fiscal year ending on the Friday closest to March 31. (1) 52-week period ended March 28, 2003 and April 2, 2005.
Slide 18: Current Year Operating Performance
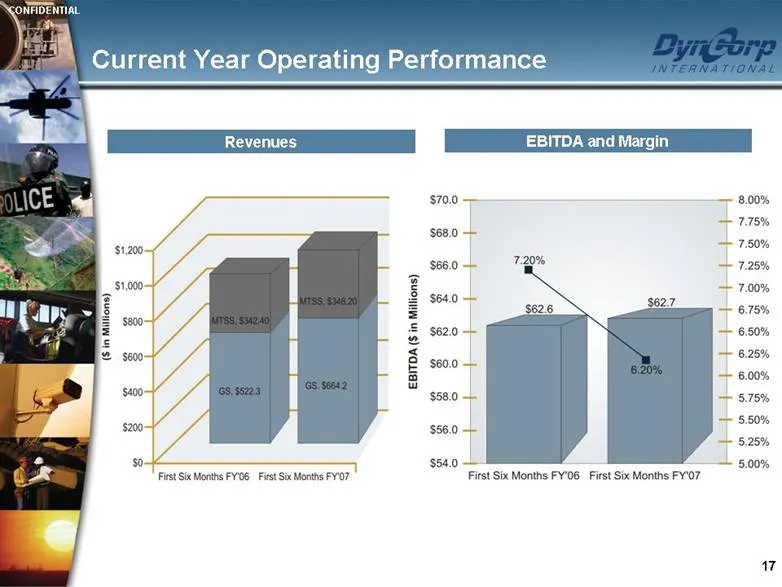
Current Year Operating Performance Revenues EBITDA and Margin
Slide 19: Total Debt and Leverage
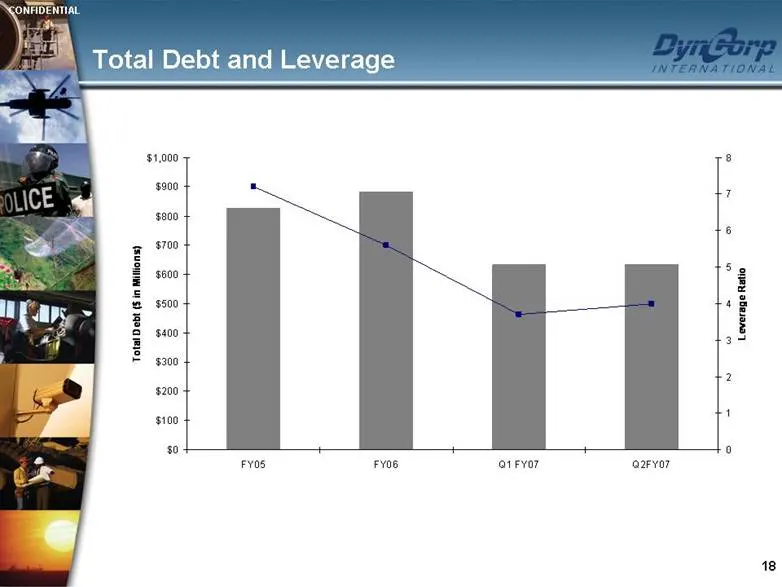
Total Debt and Leverage $0 $100 $200 $300 $400 $500 $600 $700 $800 $900 $1,000 FY05 FY06 Q1 FY07 Q2FY07 Total Debt ($ in Millions) 0 1 2 3 4 5 6 7 8 Leverage Ratio
Slide 20: Diversified, Stable Platform for Growth
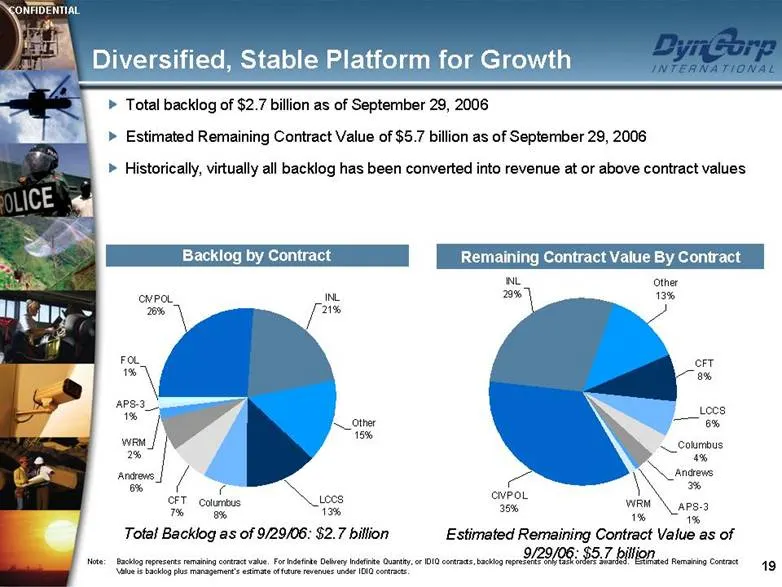
Diversified, Stable Platform for Growth Total backlog of $2.7 billion as of September 29, 2006 Estimated Remaining Contract Value of $5.7 billion as of September 29, 2006 Historically, virtually all backlog has been converted into revenue at or above contract values Backlog by Contract Remaining Con
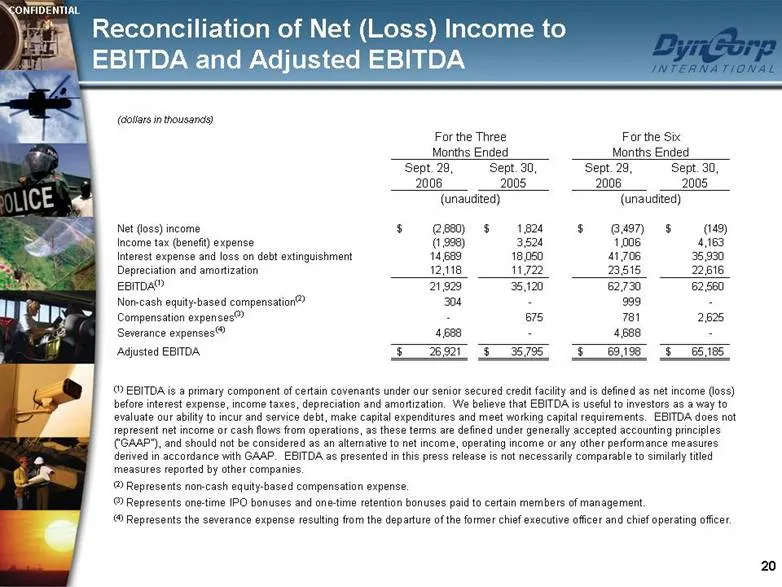
Slide 21: Reconciliation of Net (Loss) Income to EBITDA and Adjusted EBITDA
Reconciliation of Net (Loss) Income to EBITDA and Adjusted EBITDA (1) EBITDA is a primary component of certain covenants under our senior secured credit facility and is defined as net income (loss) before interest expense, income taxes, depreciation and amortization. We believe that EBITDA is useful
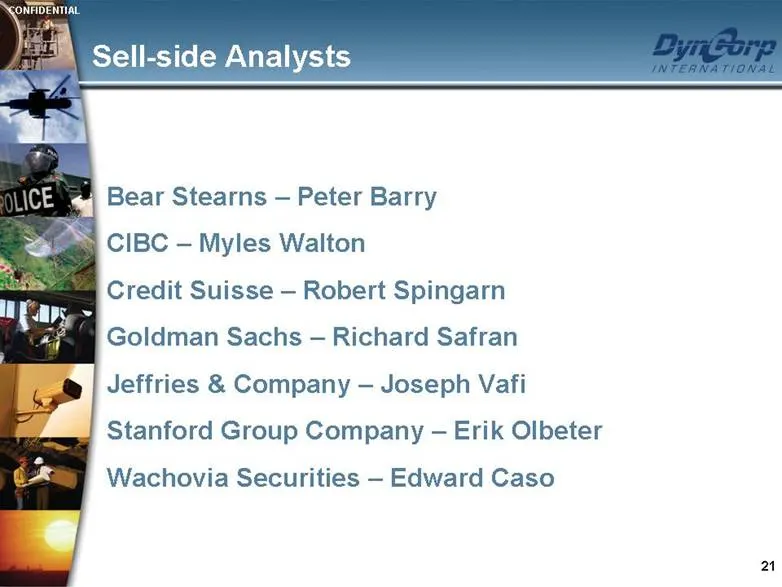
Slide 22: Sell-side Analysts
Sell-side Analysts Bear Stearns – Peter Barry CIBC – Myles Walton Credit Suisse – Robert Spingarn Goldman Sachs – Richard Safran Jeffries & Company – Joseph Vafi Stanford Group Company – Erik Olbeter Wachovia Securities – Edward Caso
Slide 23: Thank You For Your Interest
‘GONFIDENTIAL Thank You For Your Interest
Source: SEC EDGAR · 8-K filed Nov 14, 2006