Vistry Group PLC · LSE:VTY
Vistry — Investor Day (May 2021)
45 slides from Vistry's investor day presentation, May 25, 2021
Slide 1: Partnerships Briefing
Lea Castle, Kidderminster Partnerships Briefing 25th May 2021
Slide 2: Agenda
Kingfisher Green, Exeter Agenda • The Partnerships Model • Market Analysis and Capacity • Strategy and Growth • Partnerships in Action • Questions
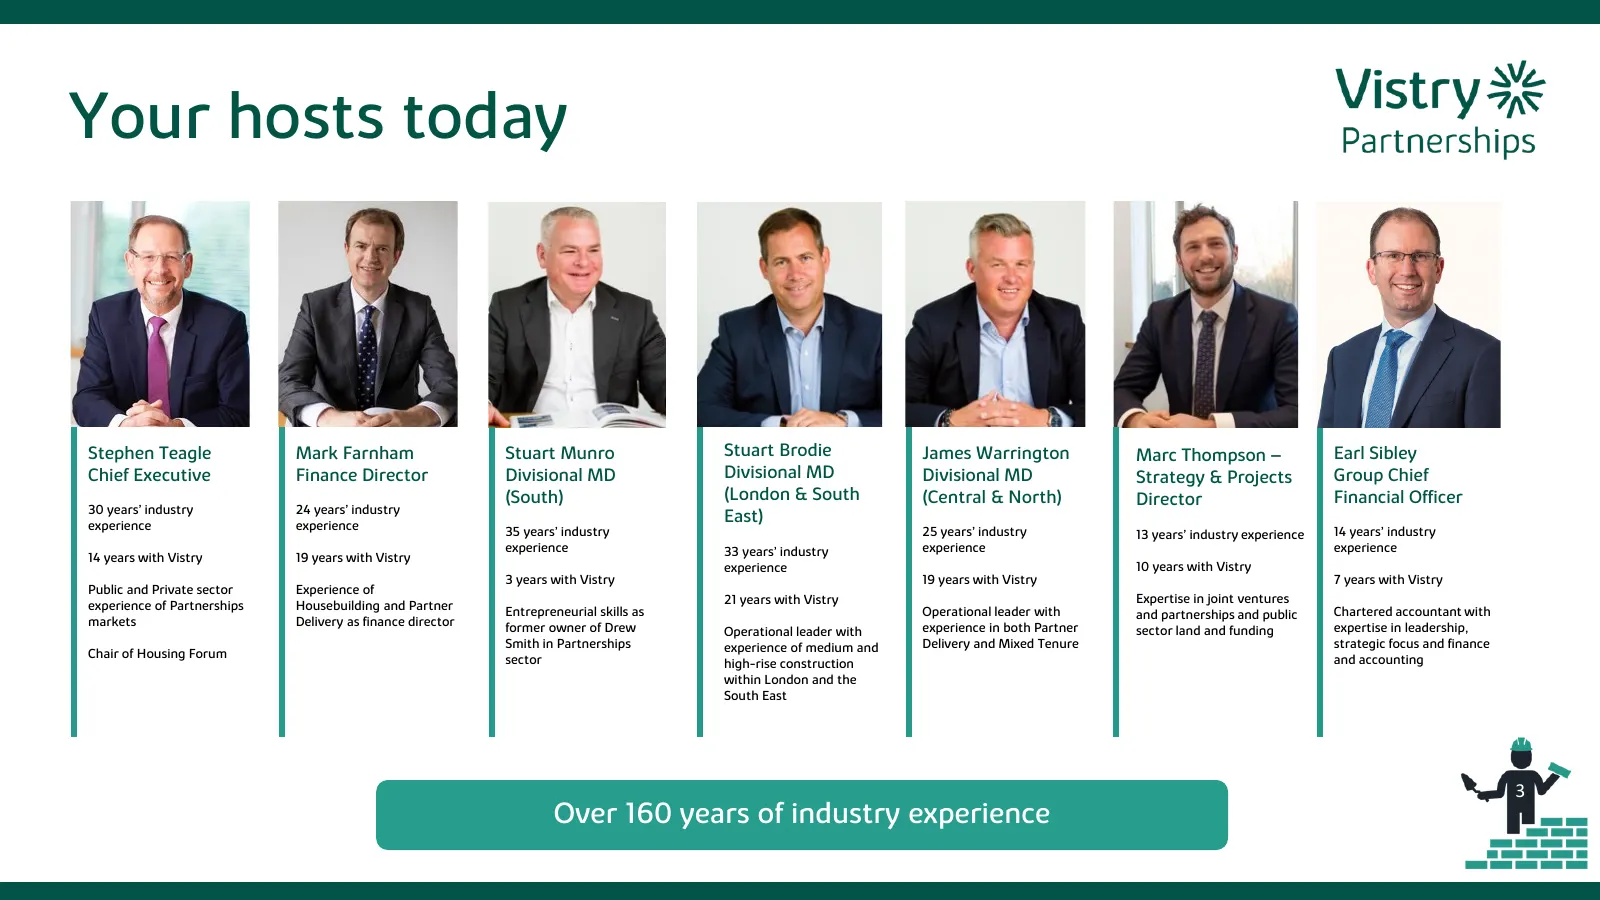
Slide 3: Your hosts today
Your hosts today Stephen Teagle Mark Farnham Stuart Munro Stuart Brodie James Warrington Marc Thompson – Earl Sibley Chief Executive Finance Director Divisional MD Divisional MD Divisional MD Strategy & Projects Group Chief (South) (London & South (Central & North) Director Financial Officer 30 year
Slide 4: The Partnerships Model
The Partnerships Change image/title Model BU to provide best Whoimage we are relevant to BU Blackberry Hill, Bristol
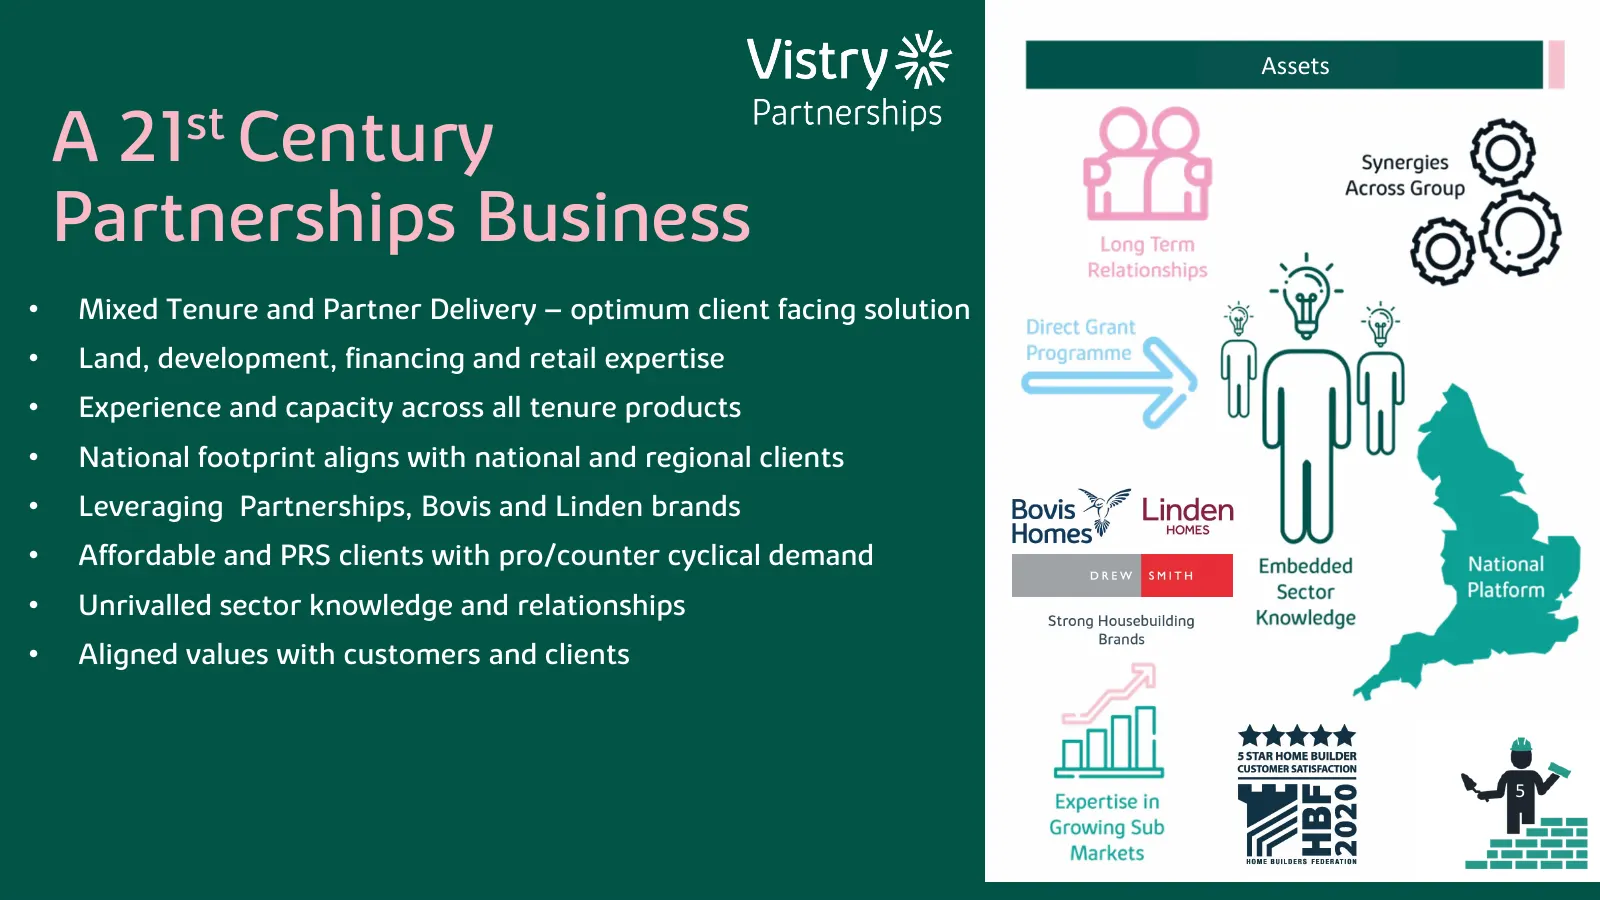
Slide 5: A 21st Century Partnerships Business
Assets A 21 Century st Partnerships Business A differentiated partnerships business with sector expertise • Mixed Tenure and Partner Delivery – optimum client facing solution • Land, development, financing and retail expertise • Experience and capacity across all tenure products • National footprint
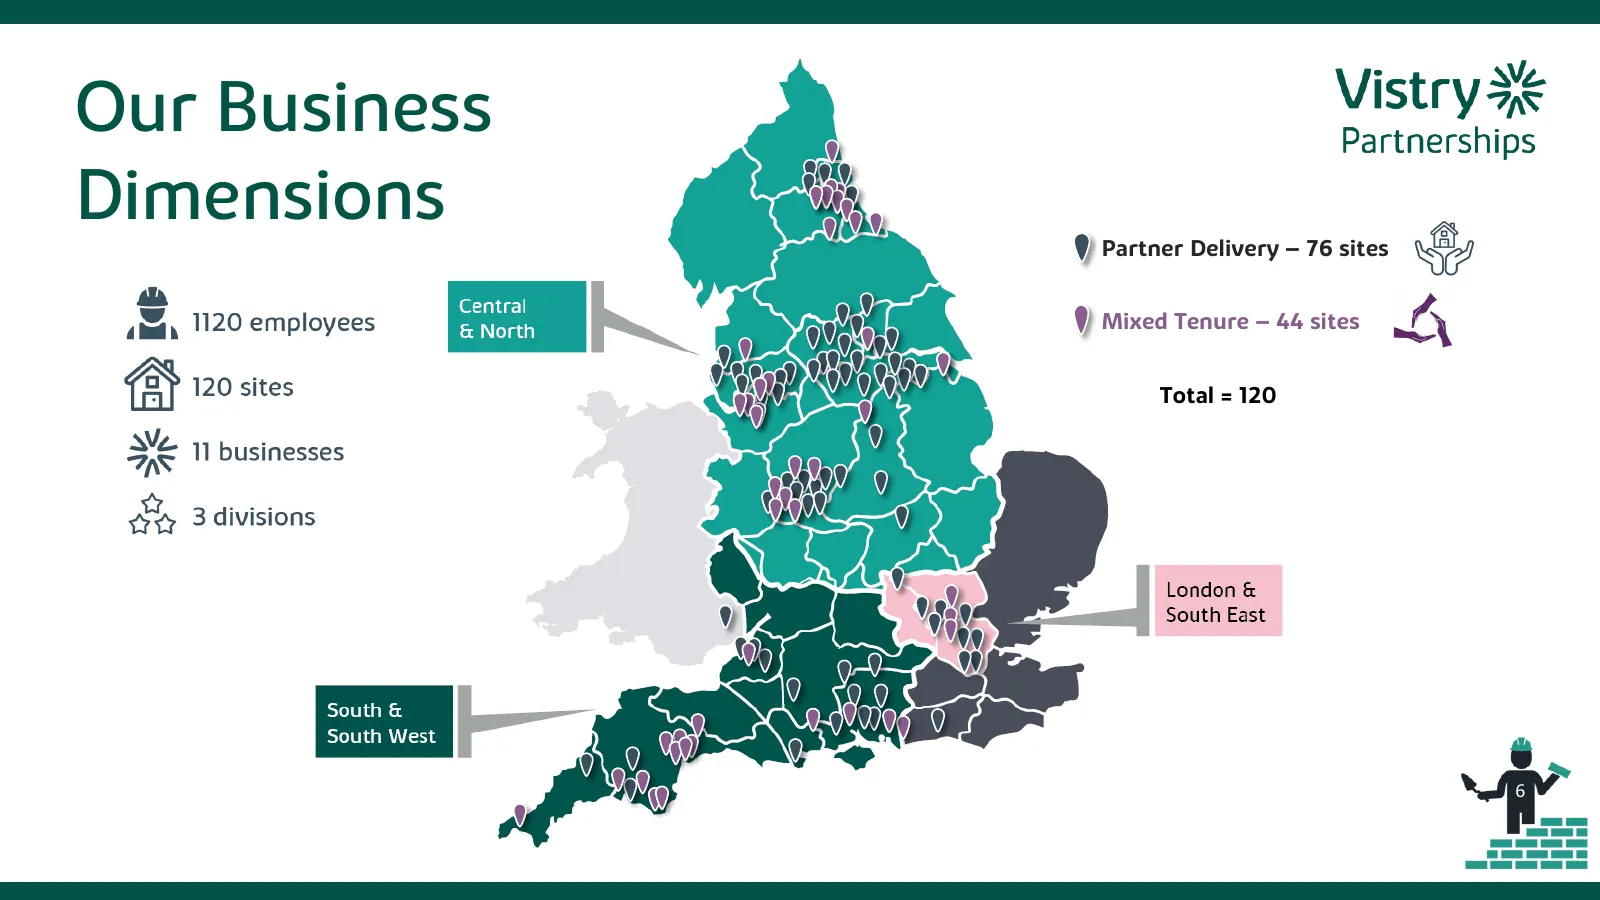
Slide 6: Our Business Dimensions
Our Business Dimensions Partner Delivery – 76 sites Mixed Tenure – 44 sites Total = 120 6
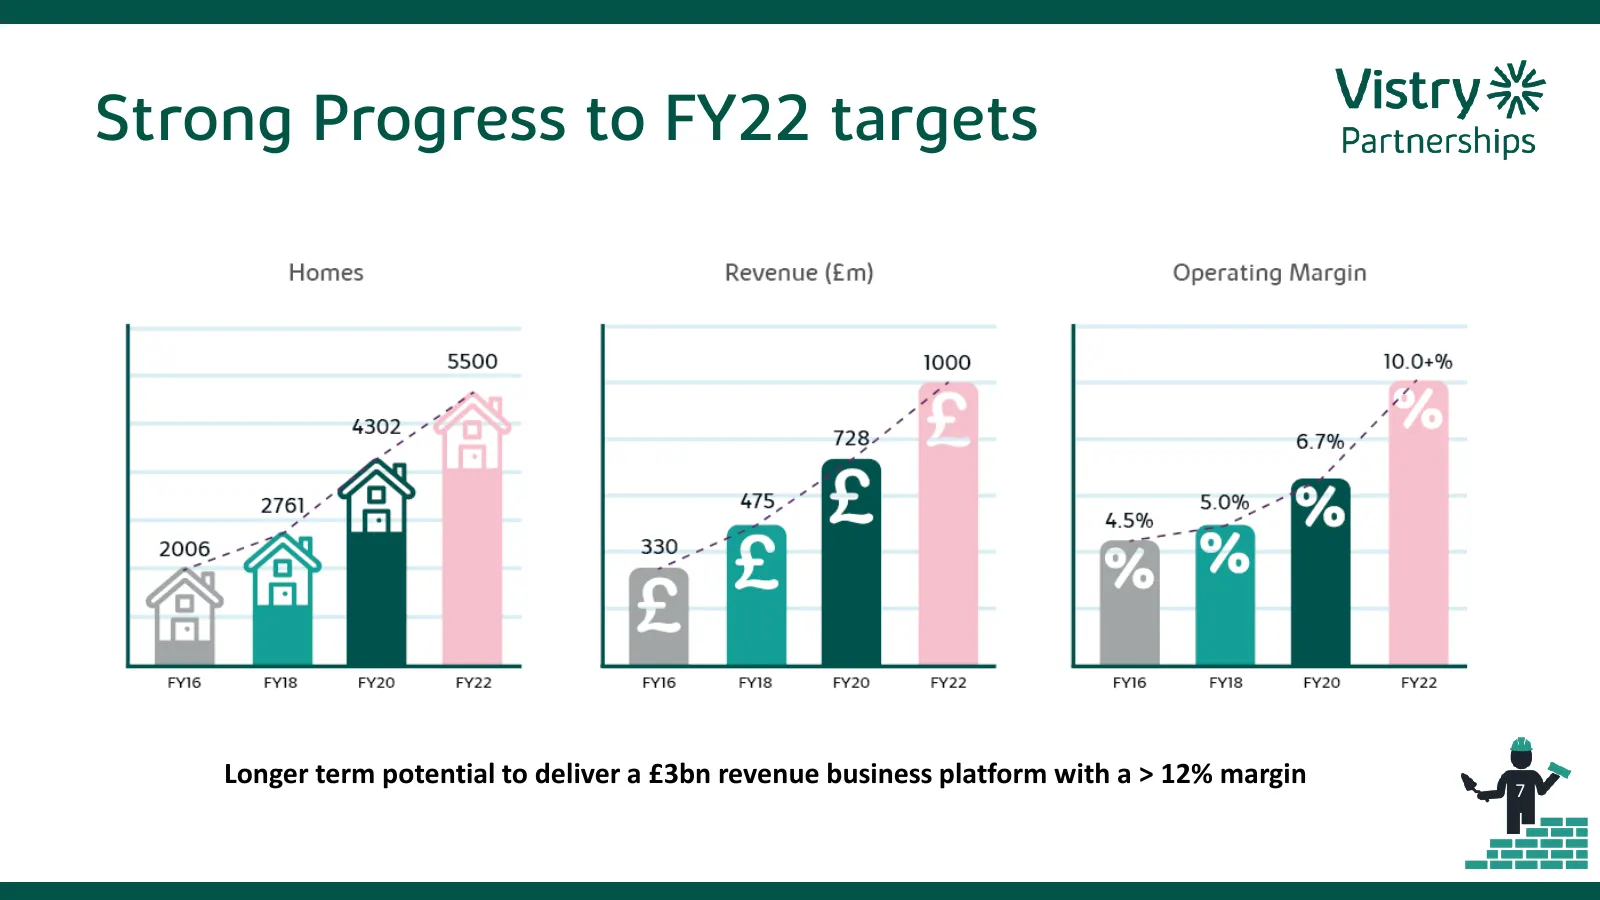
Slide 7: Strong Progress to FY22 targets
Strong Progress to FY22 targets * Longer term potential to deliver a £3bn revenue business platform with a > 12% margin 7
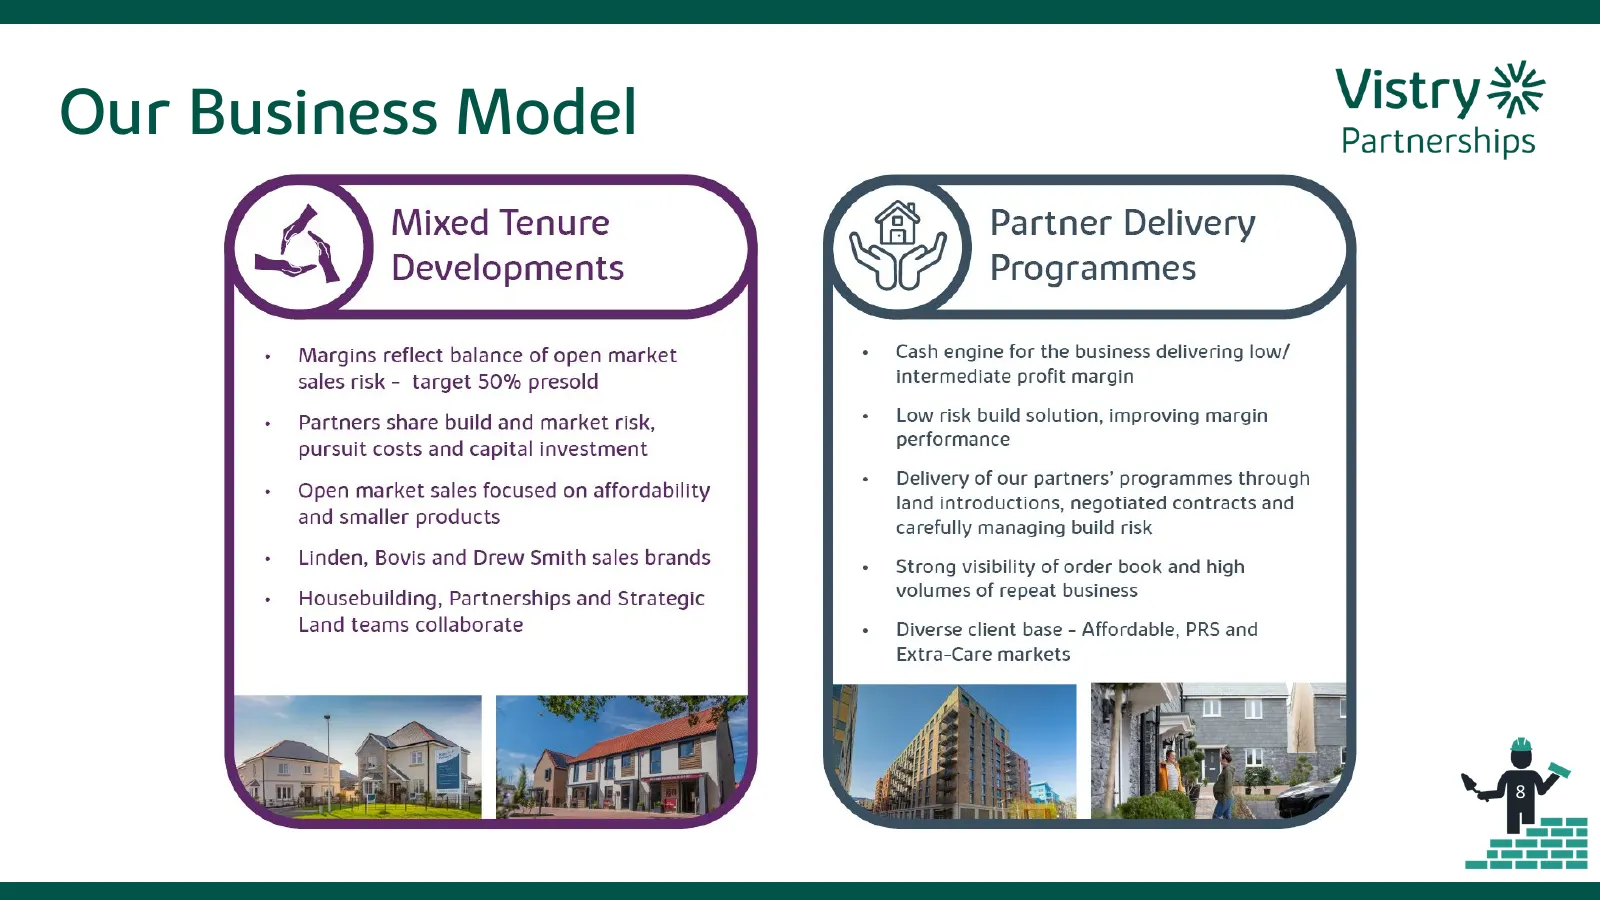
Slide 8: Our Business Model
Our Business Model Mixed Tenure Developments Margins reflect balance of open market sales risk - target 50% presold Partners share build and market risk, pursuit costs and capital investment Open market sales focused on affordability and smaller products Linden, Bovis and Drew Smith sales brands Hou
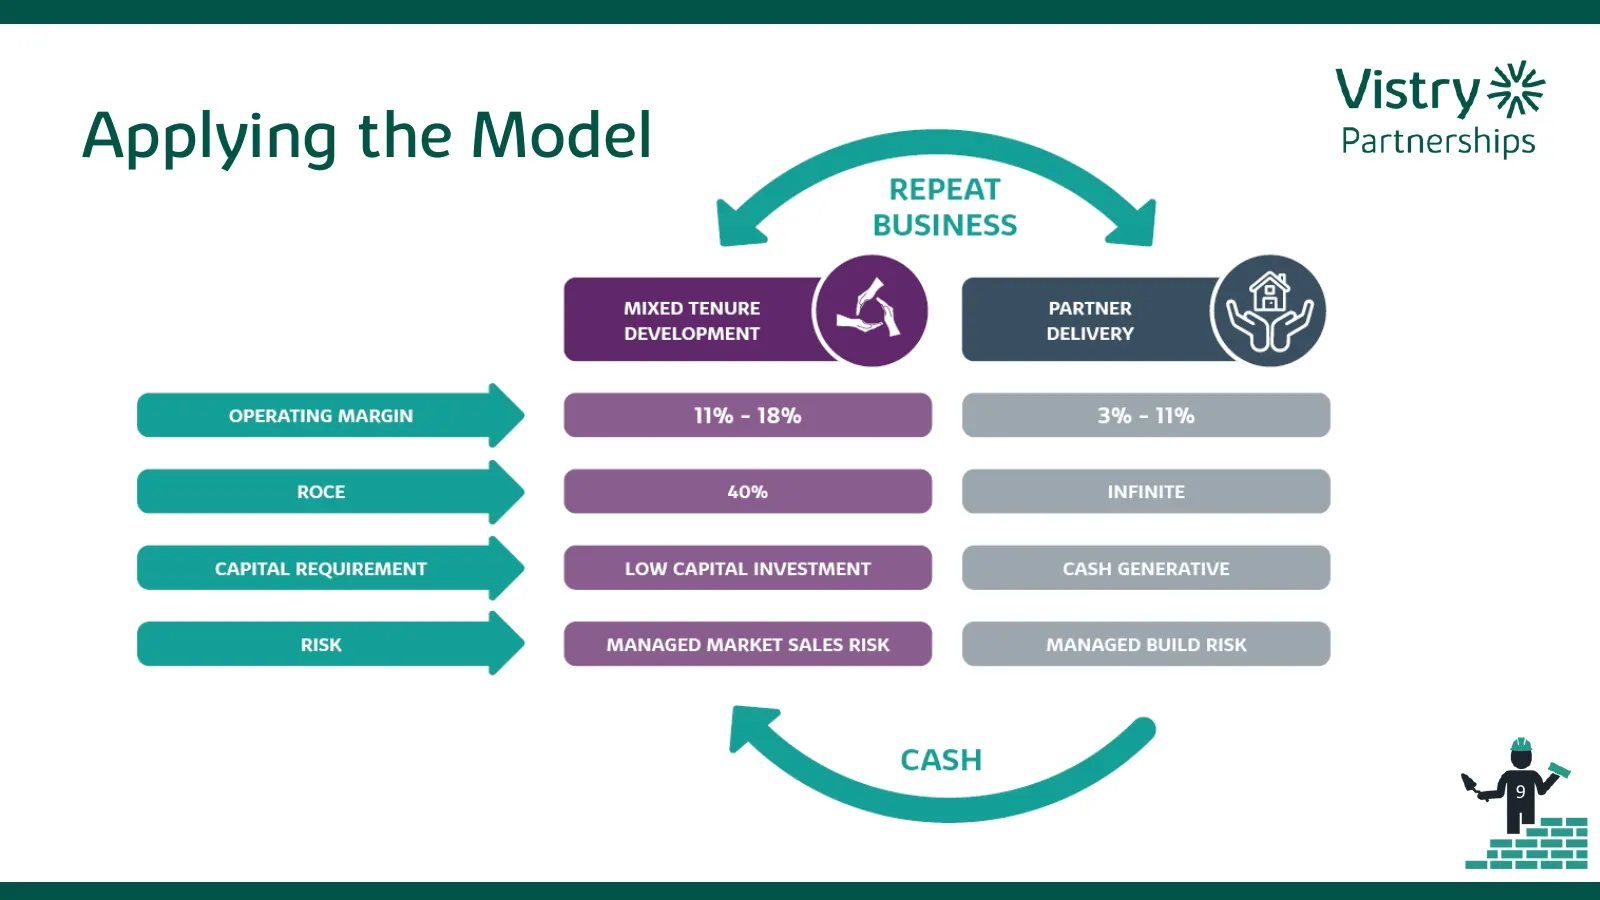
Slide 9: Applying the Model
. v Vistry 3< Partnerships Applying the Model REPEAT BUSINESS MIXED TENURE PARTNER DEVELOPMENT DELIVERY
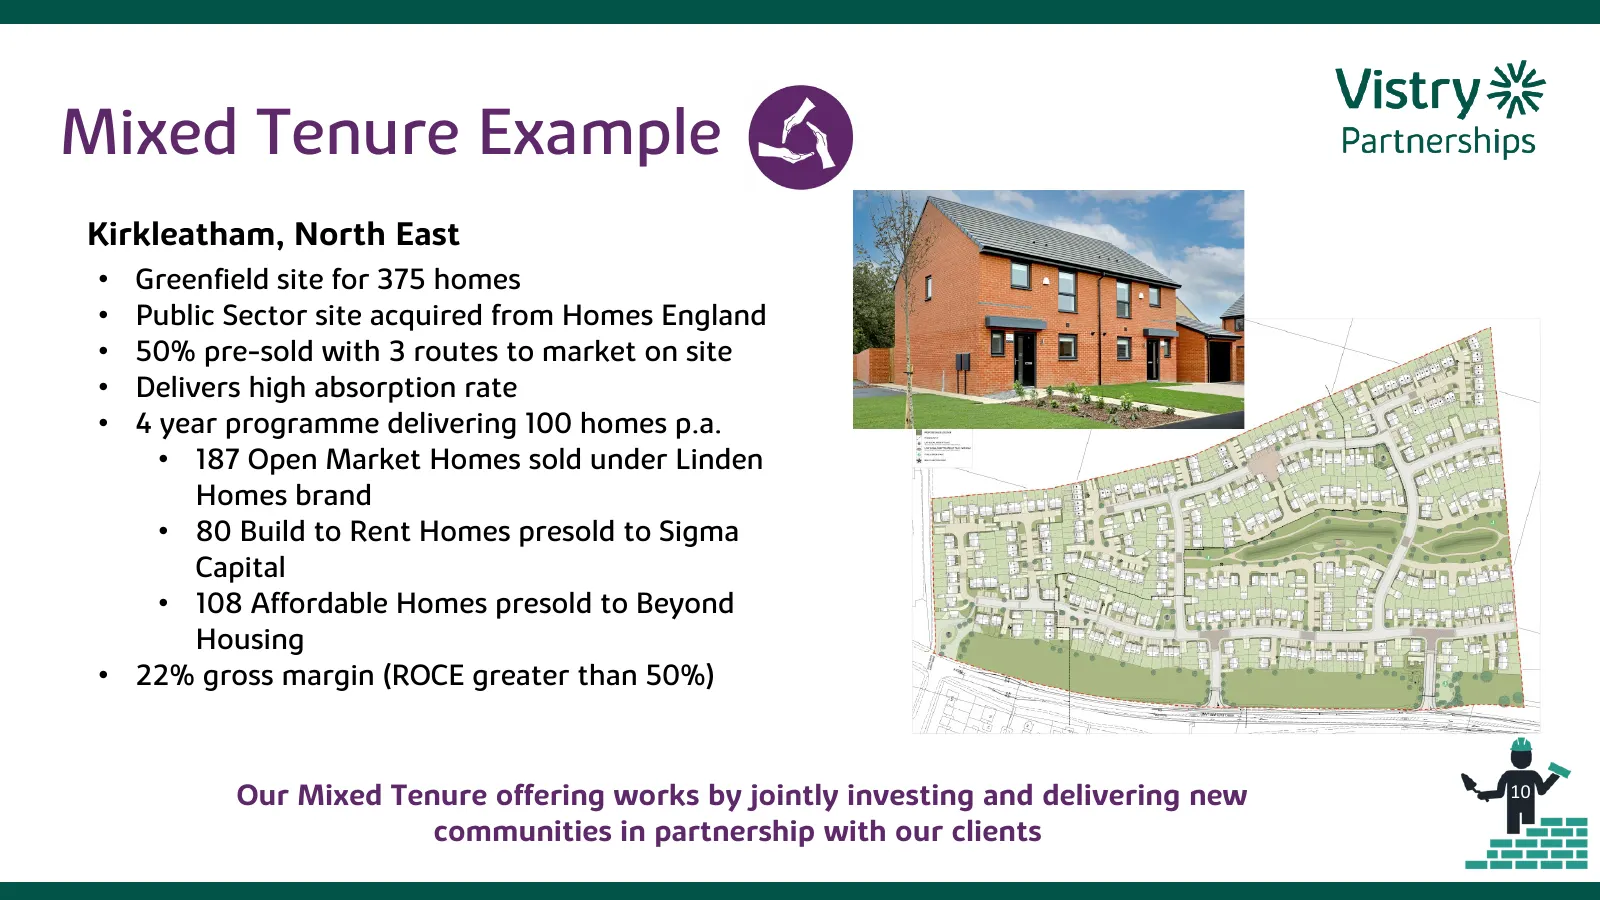
Slide 10: Mixed Tenure Example
Mixed Tenure Example Kirkleatham, North East • Greenfield site for 375 homes • Public Sector site acquired from Homes England • 50% pre-sold with 3 routes to market on site • Delivers high absorption rate • 4 year programme delivering 100 homes p.a. • 187 Open Market Homes sold under Linden Homes br
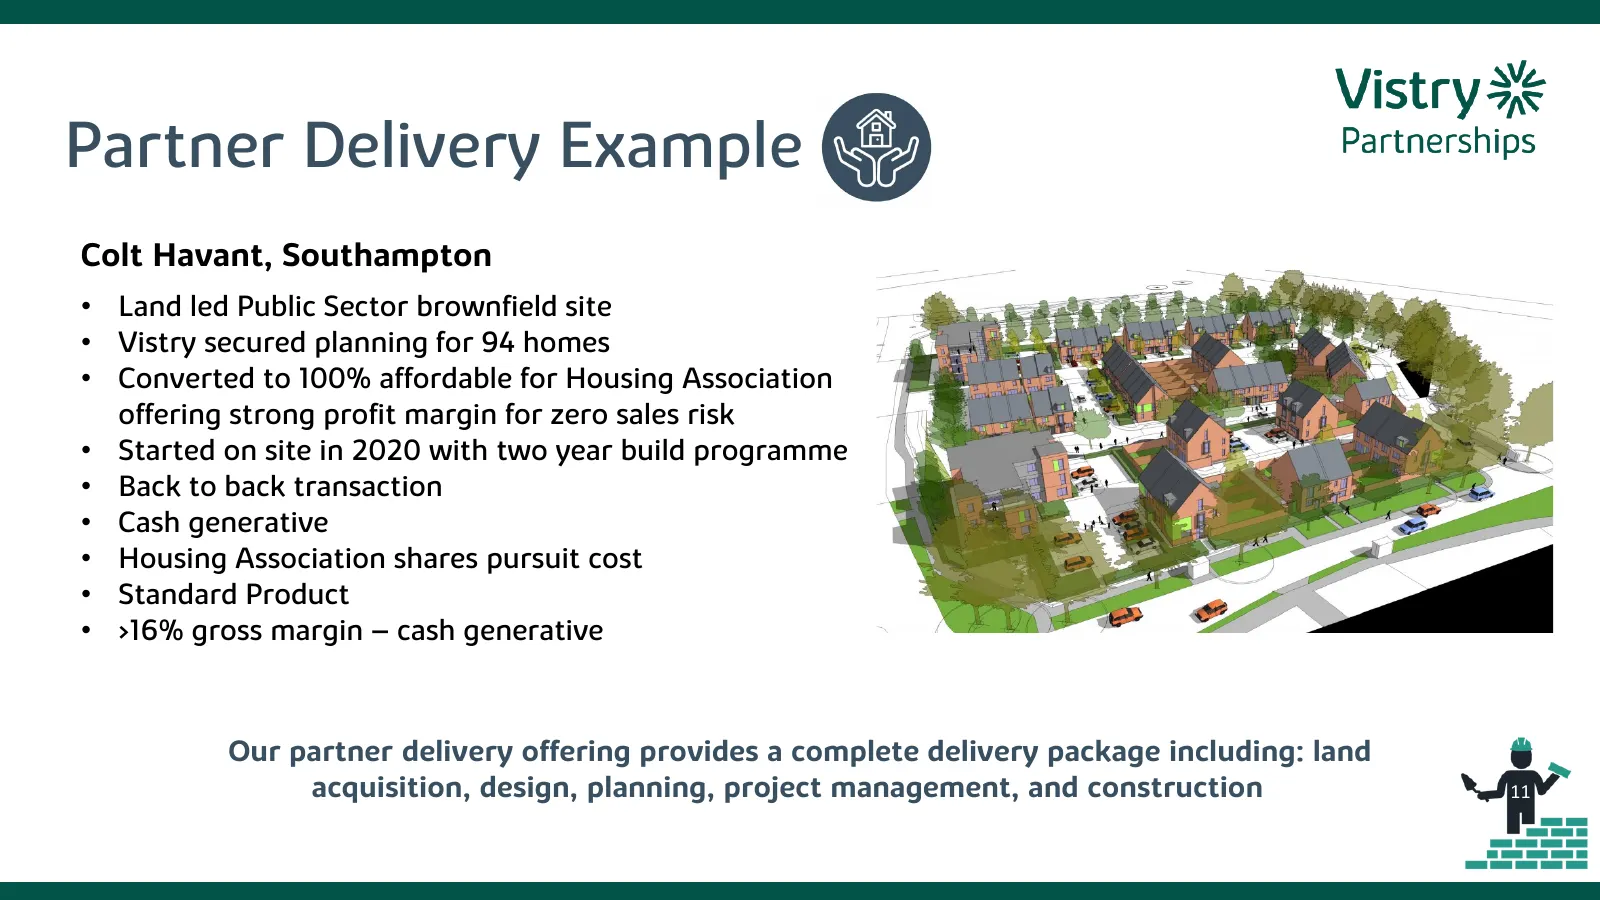
Slide 11: Partner Delivery Example
Partner Delivery Example Colt Havant, Southampton • Land led Public Sector brownfield site • Vistry secured planning for 94 homes • Converted to 100% affordable for Housing Association offering strong profit margin for zero sales risk • Started on site in 2020 with two year build programme • Back to
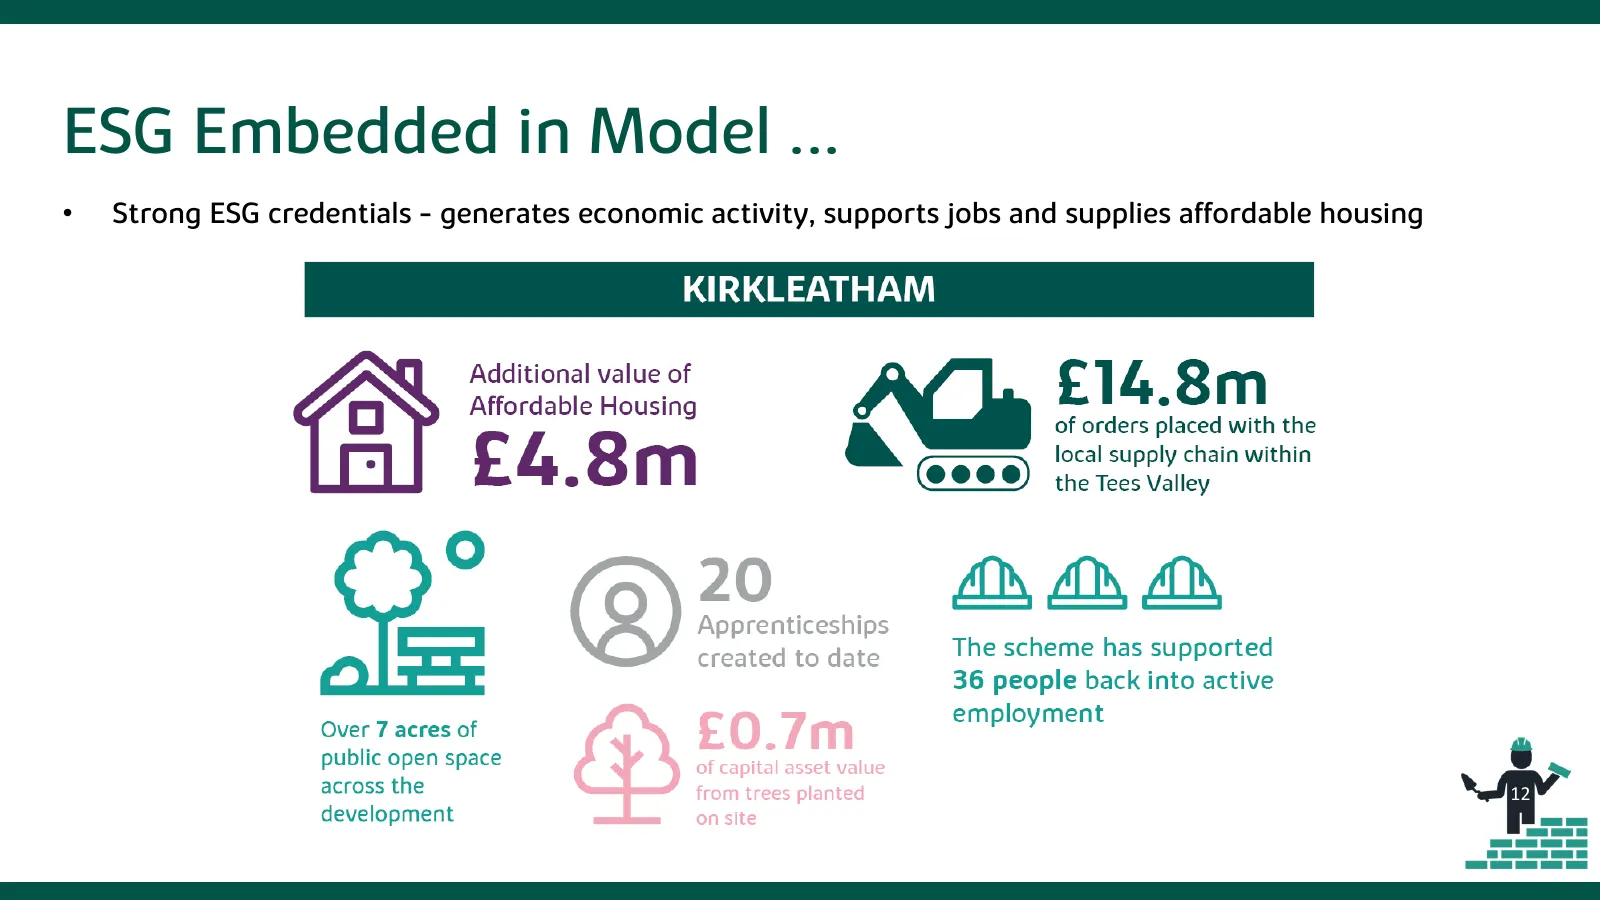
Slide 12: ESG Embedded in Model
ESG Embedded in Model ... • Strong ESG credentials - generates economic activity, supports jobs and supplies affordable housing 12
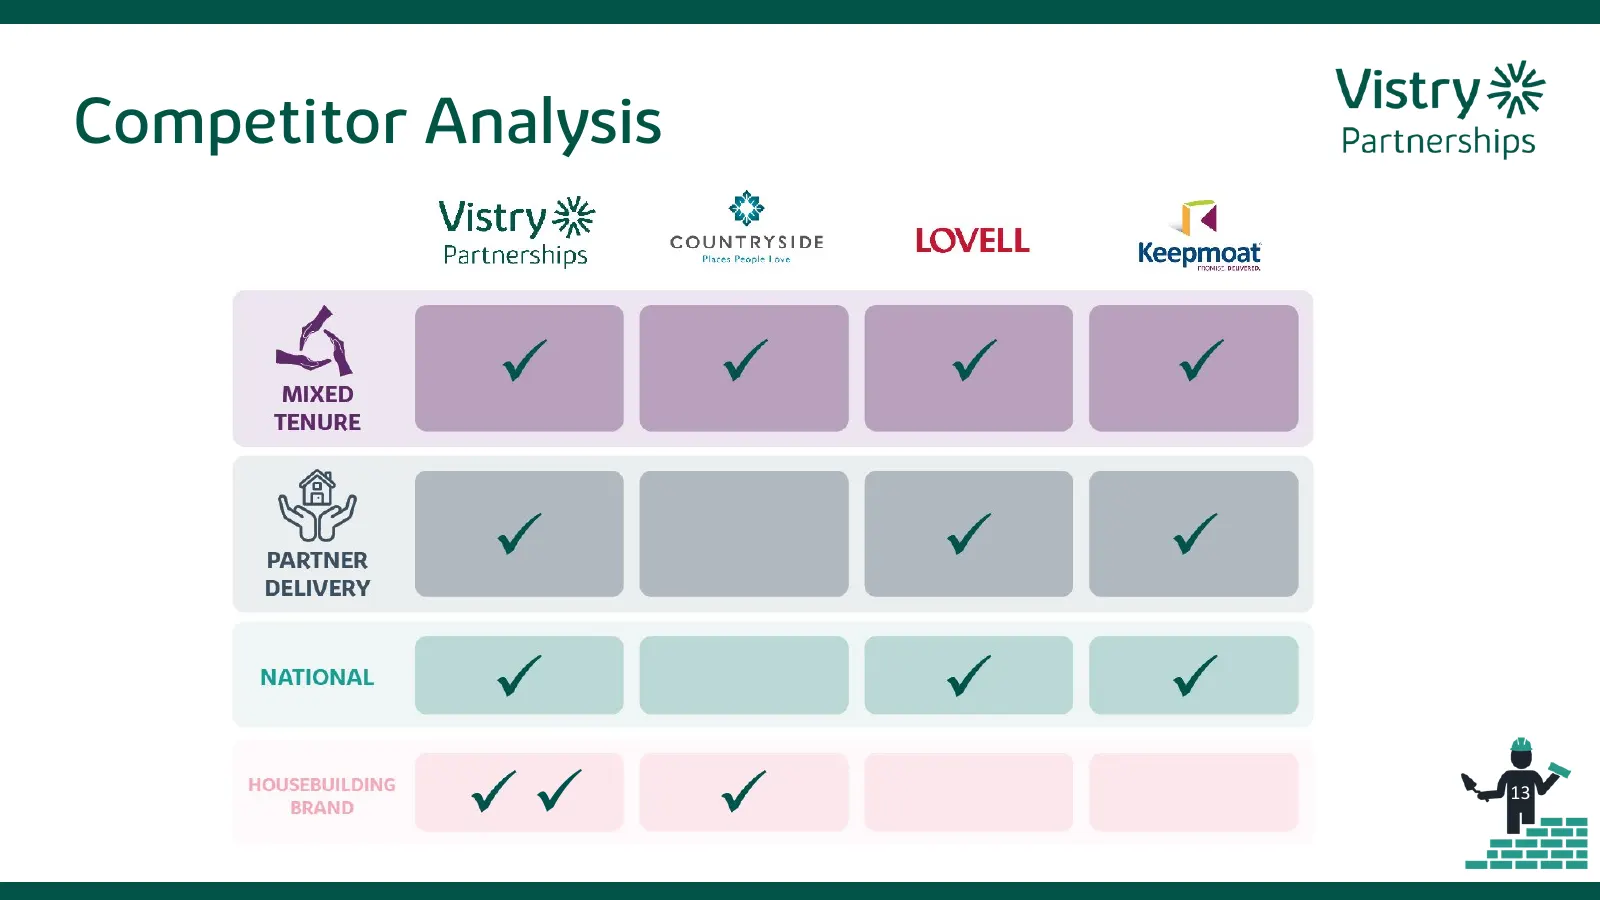
Slide 13: Competitor Analysis
; Vistry 3 Competitor Analysis manners F Me a Mey countmysioe — LOVELL =f meh MIXED TENURE iy a | | a a DELIVERY NATIONAL a A v Heteesnsnins Sf Vv v
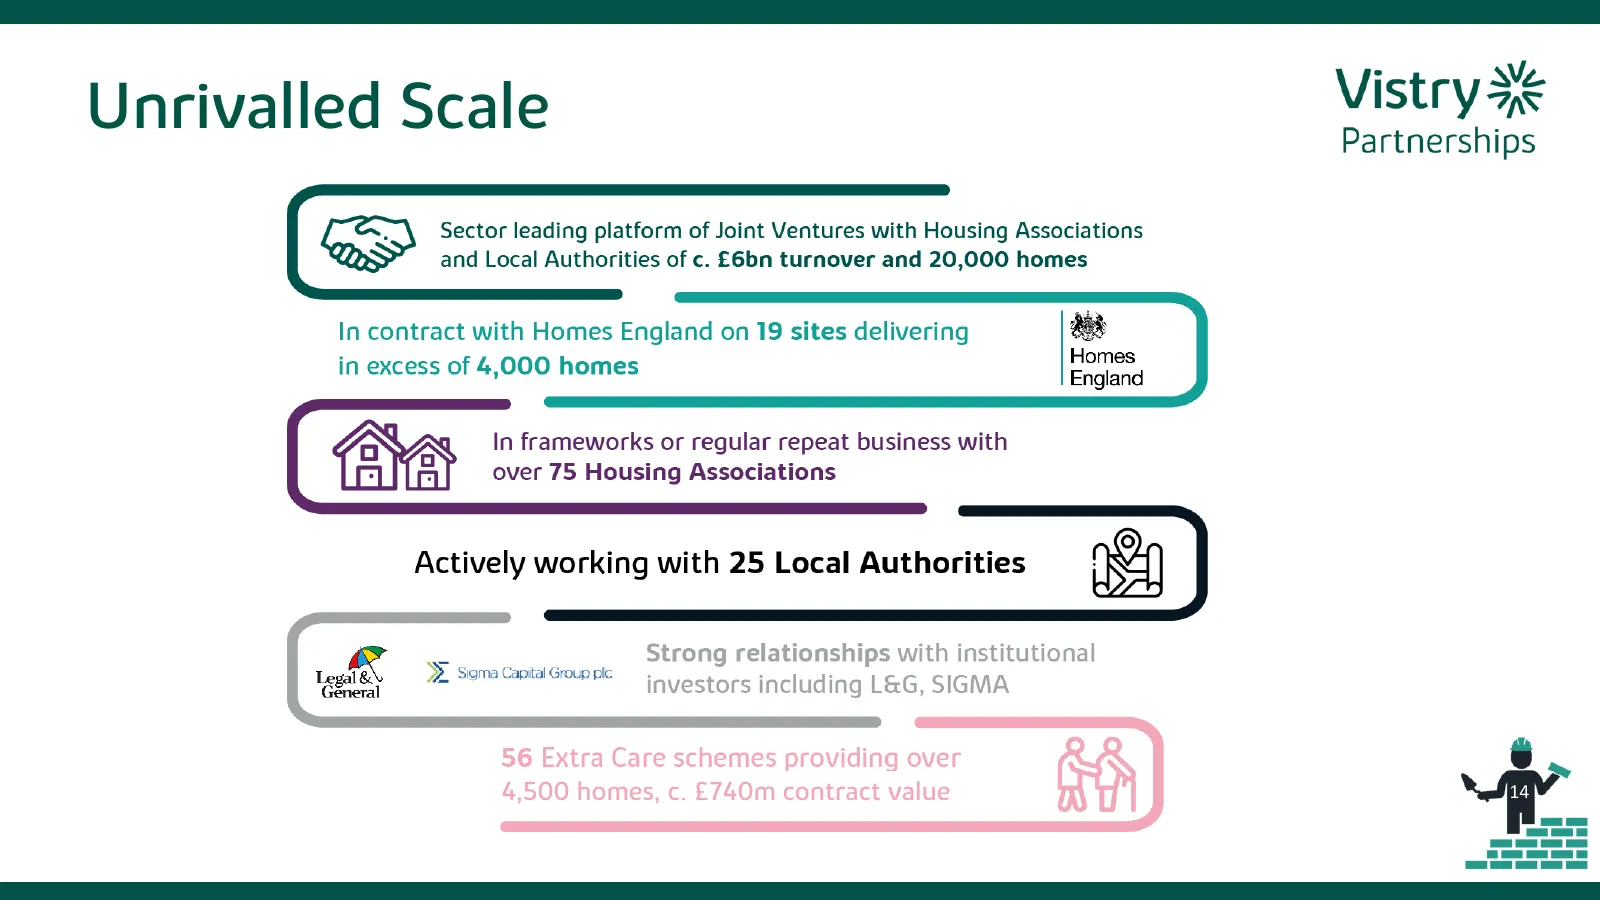
Slide 14: Unrivalled Scale
Unrivalled Scale 4,500 homes, c. £740m contract value 14
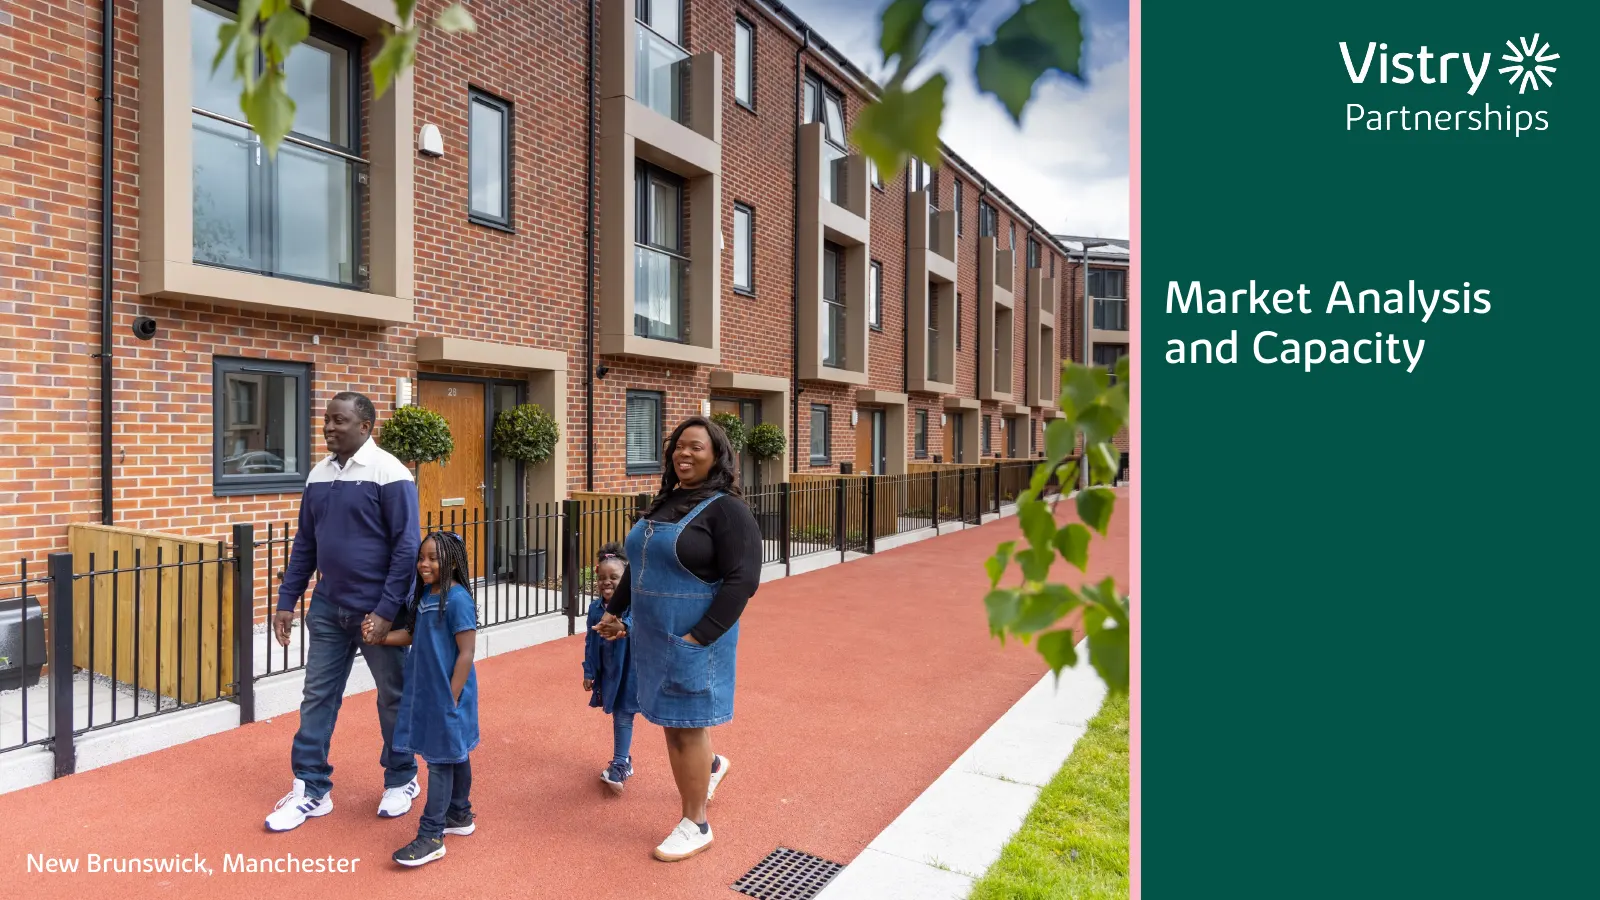
Slide 15: Market Analysis and Capacity
Market Analysis and Capacity Sherford, New Brunswick, Plymouth Manchester
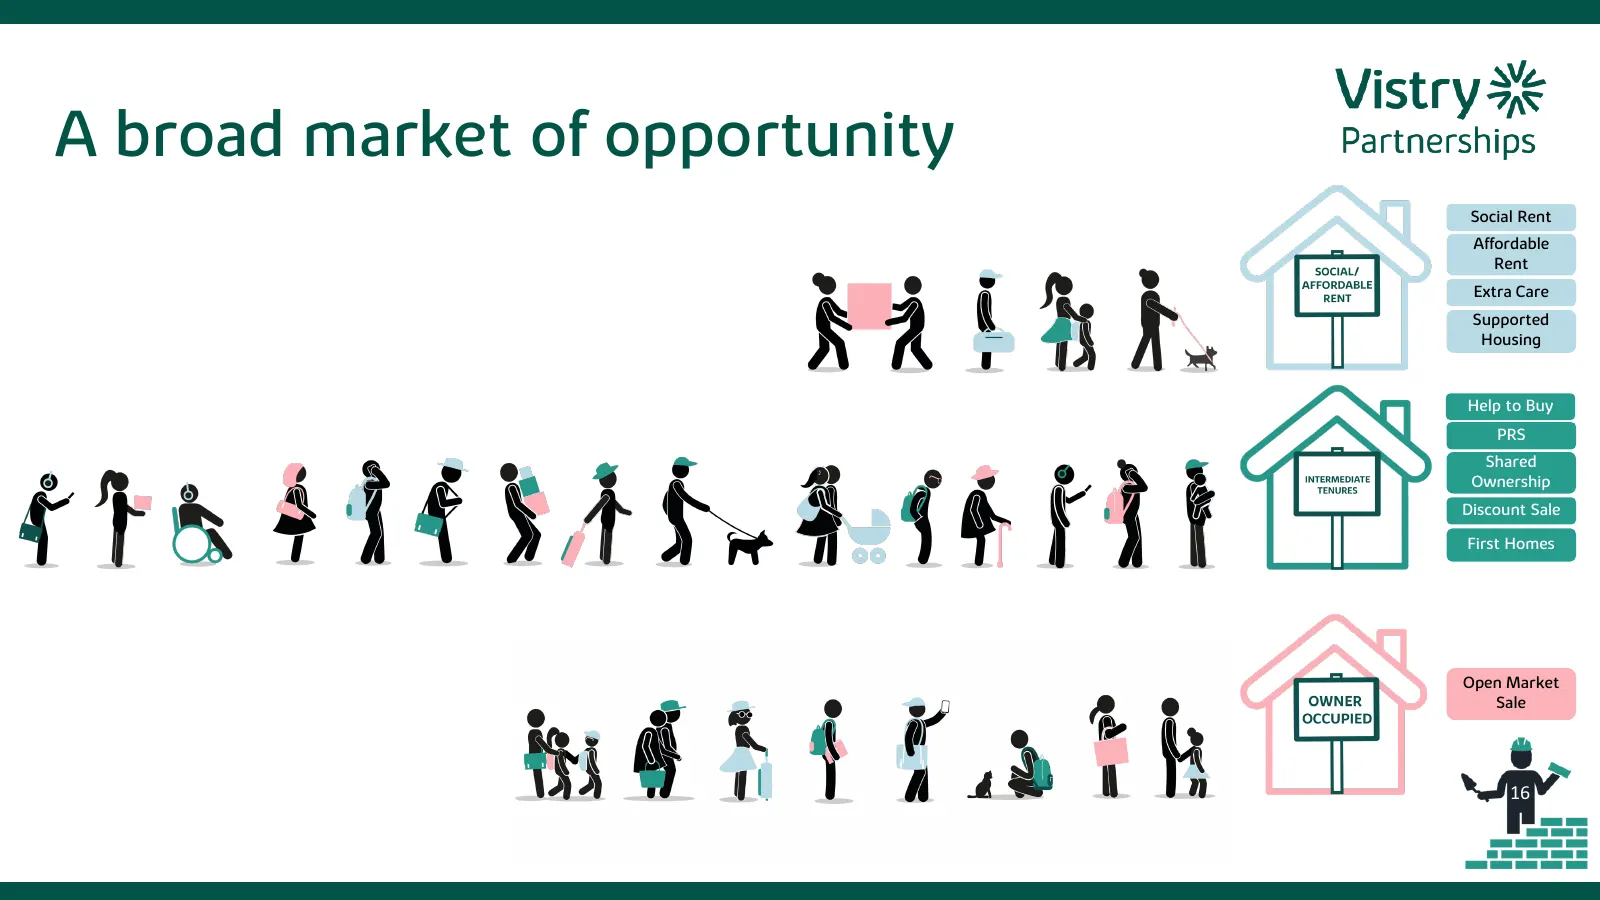
Slide 16: A broad market of opportunity
A broad market of opportunity Social Rent Affordable Rent Extra Care Supported Housing Help to Buy PRS Shared Ownership Discount Sale First Homes Open Market Sale 16
Slide 17: Market Opportunity
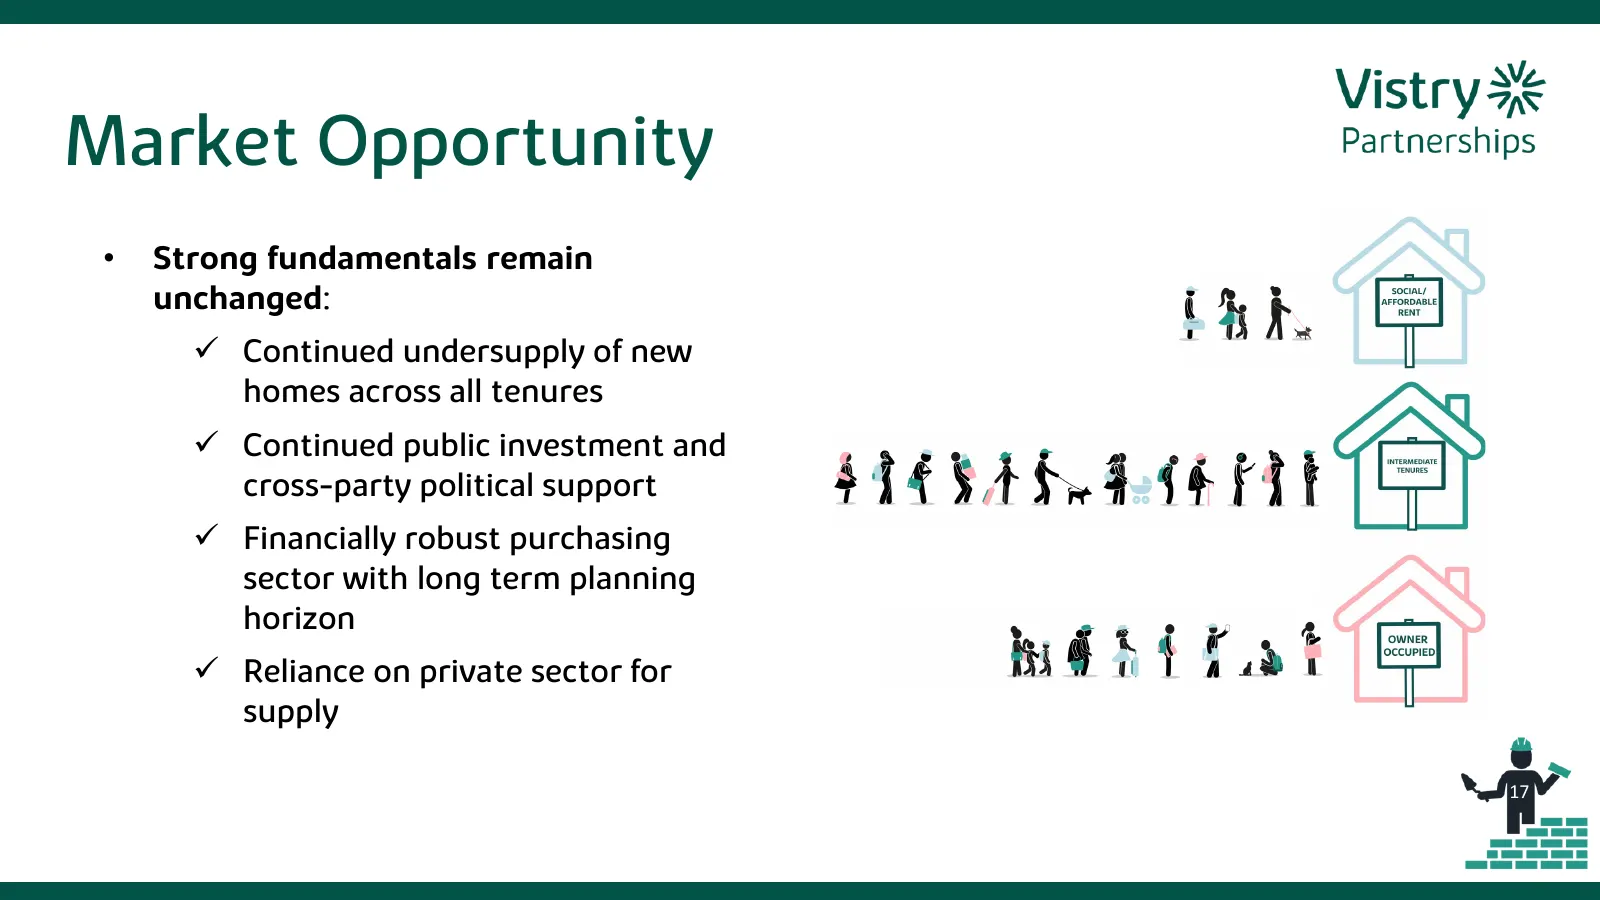
Market Opportunity • Strong fundamentals remain unchanged: Continued undersupply of new homes across all tenures Continued public investment and cross-party political support Financially robust purchasing sector with long term planning horizon Reliance on private sector for supply Reliance
Slide 18: Scale of Affordable Housing
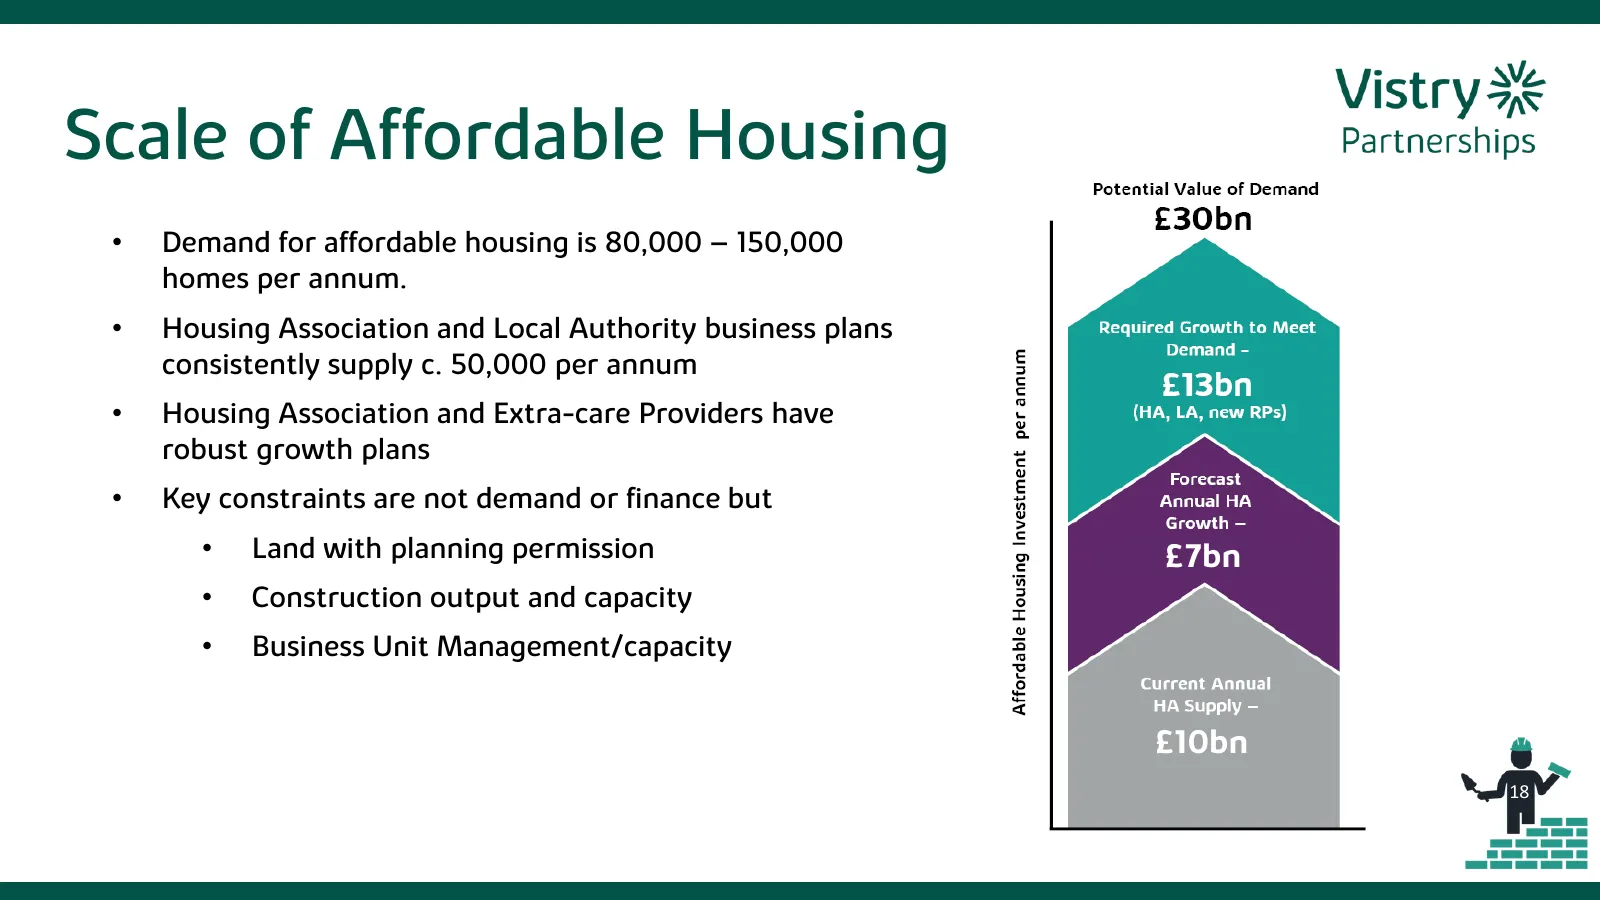
Scale of Affordable Housing • Demand for affordable housing is 80,000 – 150,000 homes per annum. • Housing Association and Local Authority business plans consistently supply c. 50,000 per annum • Housing Association and Extra-care Providers have robust growth plans • Key constraints are not demand o
Slide 19: Robust and Active Purchasing Sector
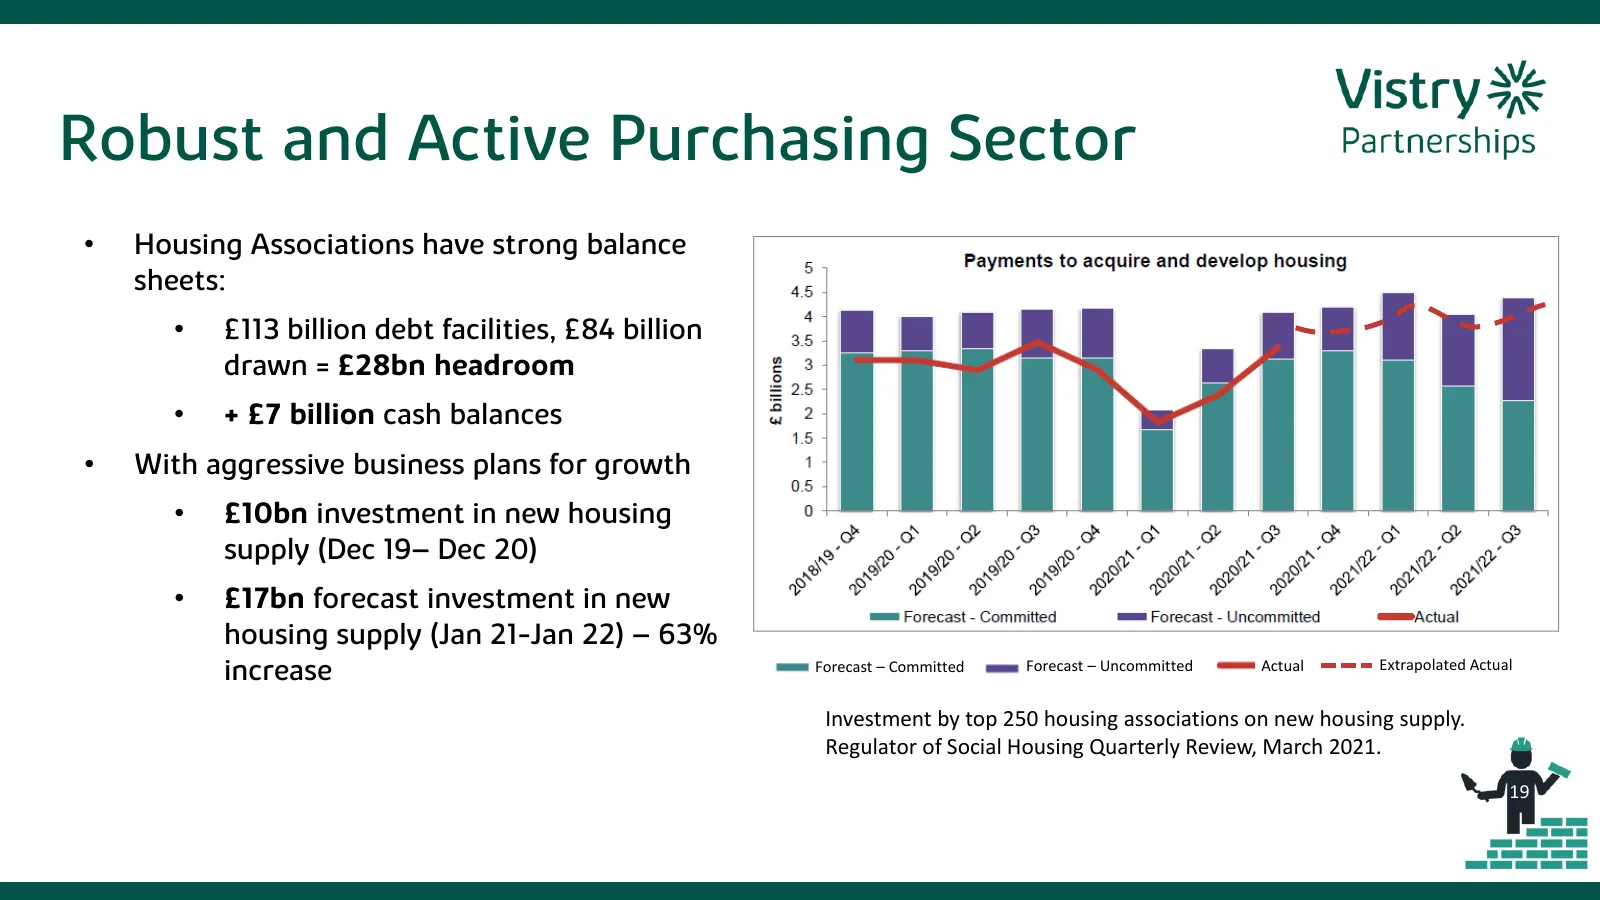
Robust and Active Purchasing Sector • Housing Associations have strong balance sheets: • £113 billion debt facilities, £84 billion drawn = £28bn headroom • + £7 billion cash balances • With aggressive business plans for growth • £10bn investment in new housing supply (Dec 19– Dec 20) • £17bn forecas
Slide 20: Government Funding Commitment
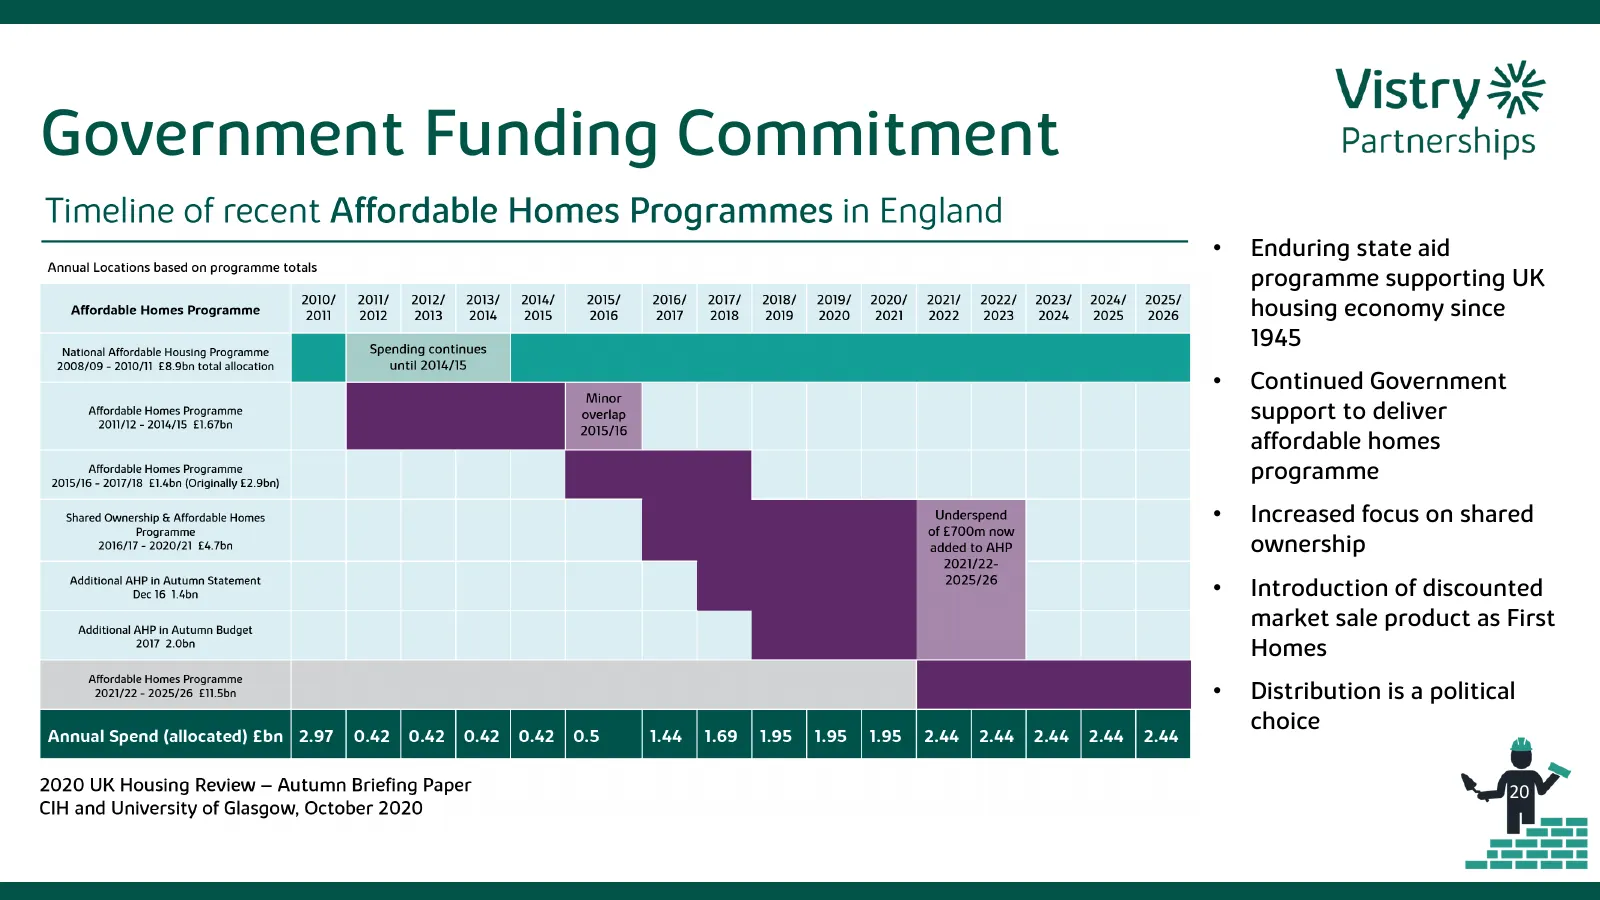
Government Funding Commitment • Enduring state aid programme supporting UK housing economy since 1945 • Continued Government support to deliver affordable homes programme • Increased focus on shared ownership • Introduction of discounted market sale product as First Homes • Distribution is a politic
Slide 21: Growth in Sub-Markets
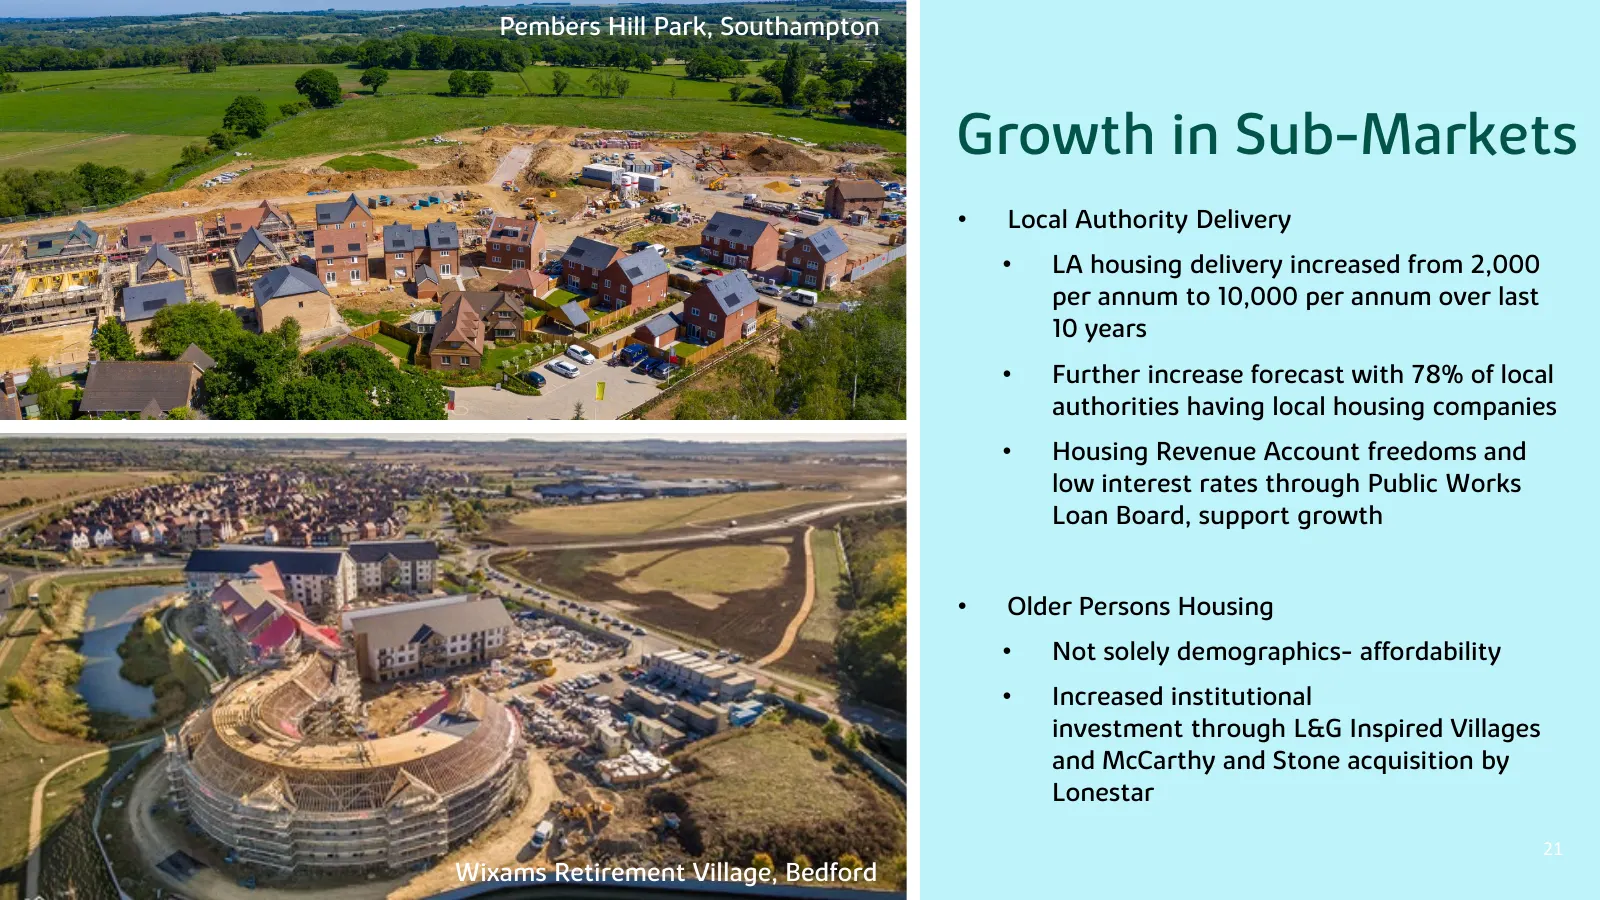
Pembers Hill Park, Southampton Growth in Sub-Markets • Local Authority Delivery • LA housing delivery increased from 2,000 per annum to 10,000 per annum over last 10 years • Further increase forecast with 78% of local authorities having local housing companies • Housing Revenue Account freedoms and
Slide 22: Growth in PRS
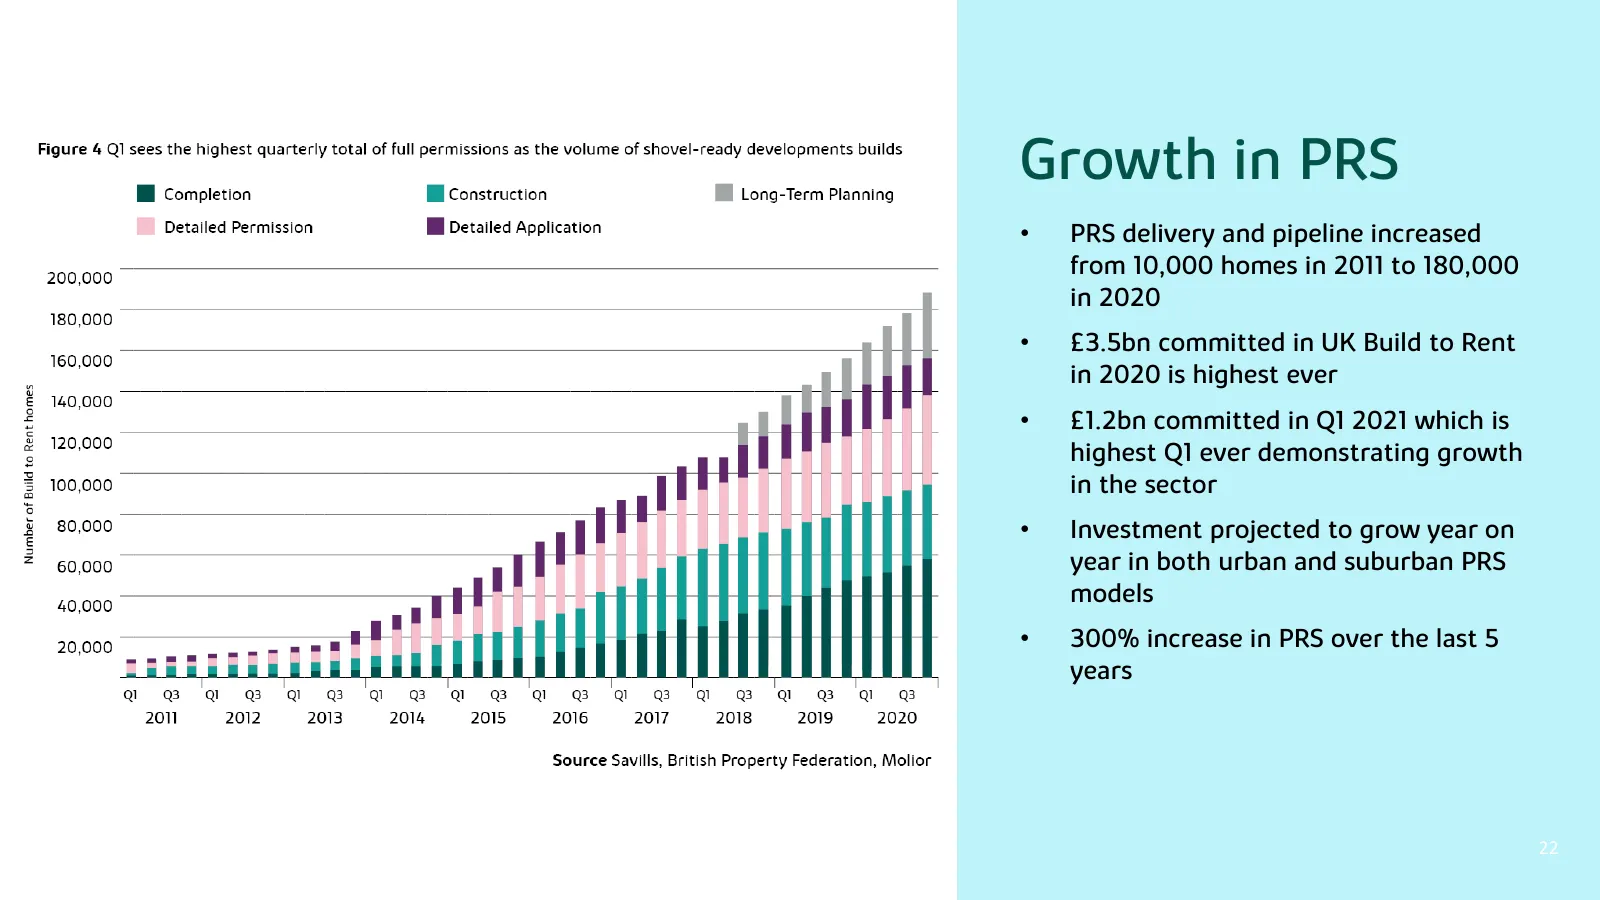
Growth in PRS • PRS delivery and pipeline increased from 10,000 homes in 2011 to 180,000 in 2020 • £3.5bn committed in UK Build to Rent in 2020 is highest ever • £1.2bn committed in Q1 2021 which is highest Q1 ever demonstrating growth in the sector • Investment projected to grow year on year in bot
Slide 23: Strategy and Growth
The Greens, Atherstone Strategy and Growth
Slide 24: Short term delivery – FY22
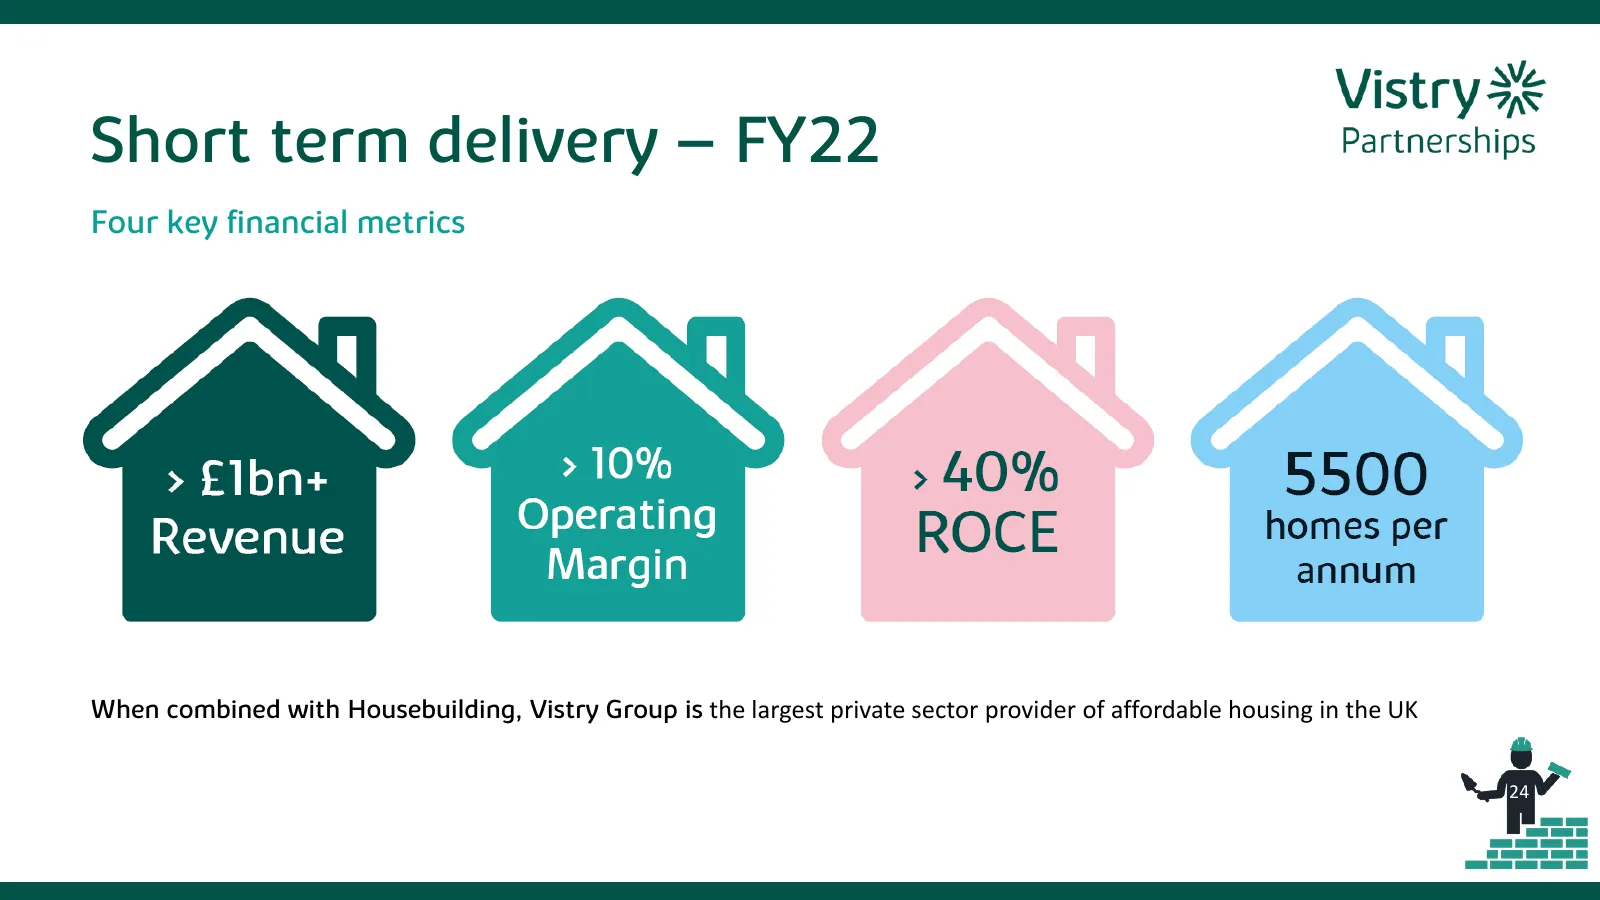
Short term delivery – FY22 Four key financial metrics When combined with Housebuilding, Vistry Group is the largest private sector provider of affordable housing in the UK 24
Slide 25: Strong Visibility of Future Years
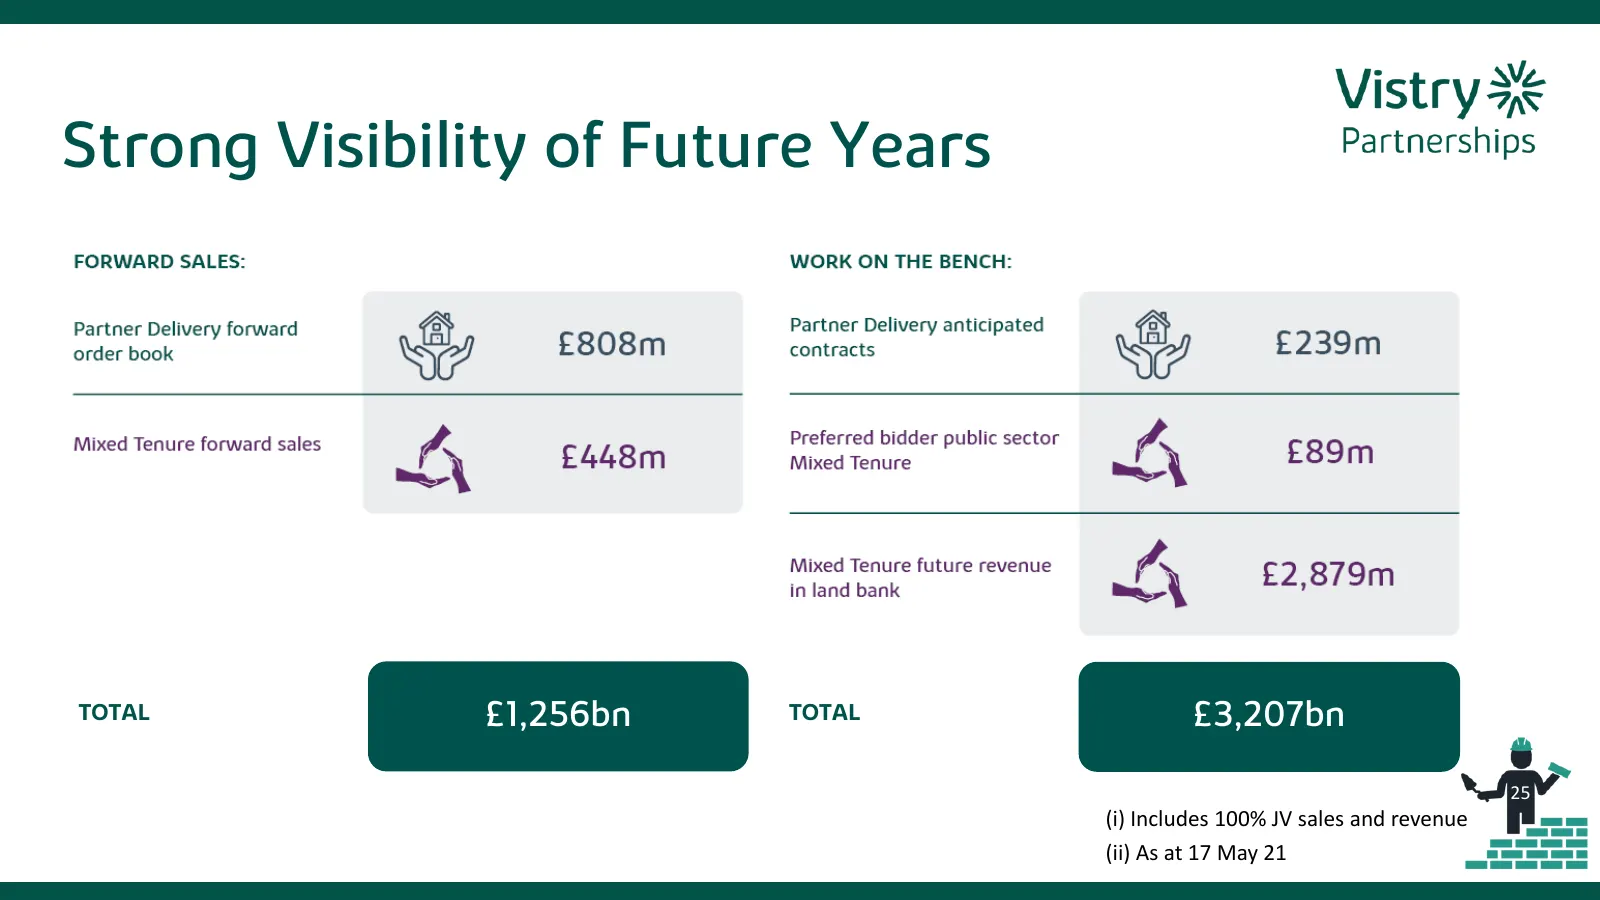
Strong Visibility of Future Years TOTAL £1,256bn TOTAL £3,207bn 25 (i) Includes 100% JV sales and revenue (ii) As at 17 May 21
Slide 26: Strategy for further growth
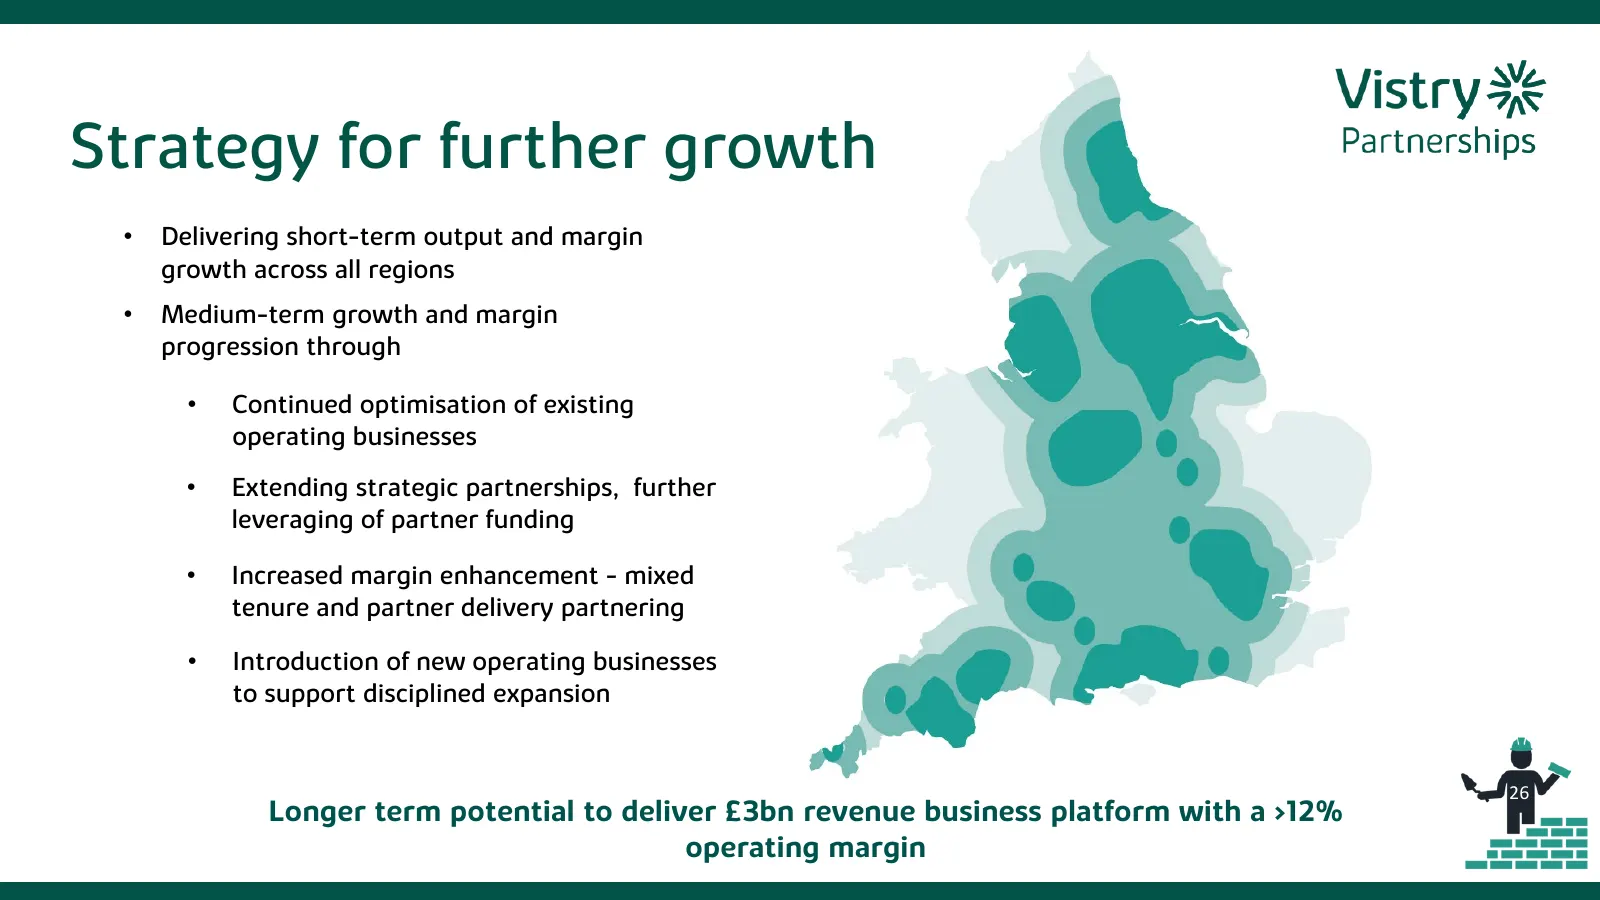
Strategy for further growth • Delivering short-term output and margin growth across all regions • Medium-term growth and margin progression through • Continued optimisation of existing operating businesses • Extending strategic partnerships, further leveraging of partner funding • Increased margin e
Slide 27: Optimisation of Business Platforms
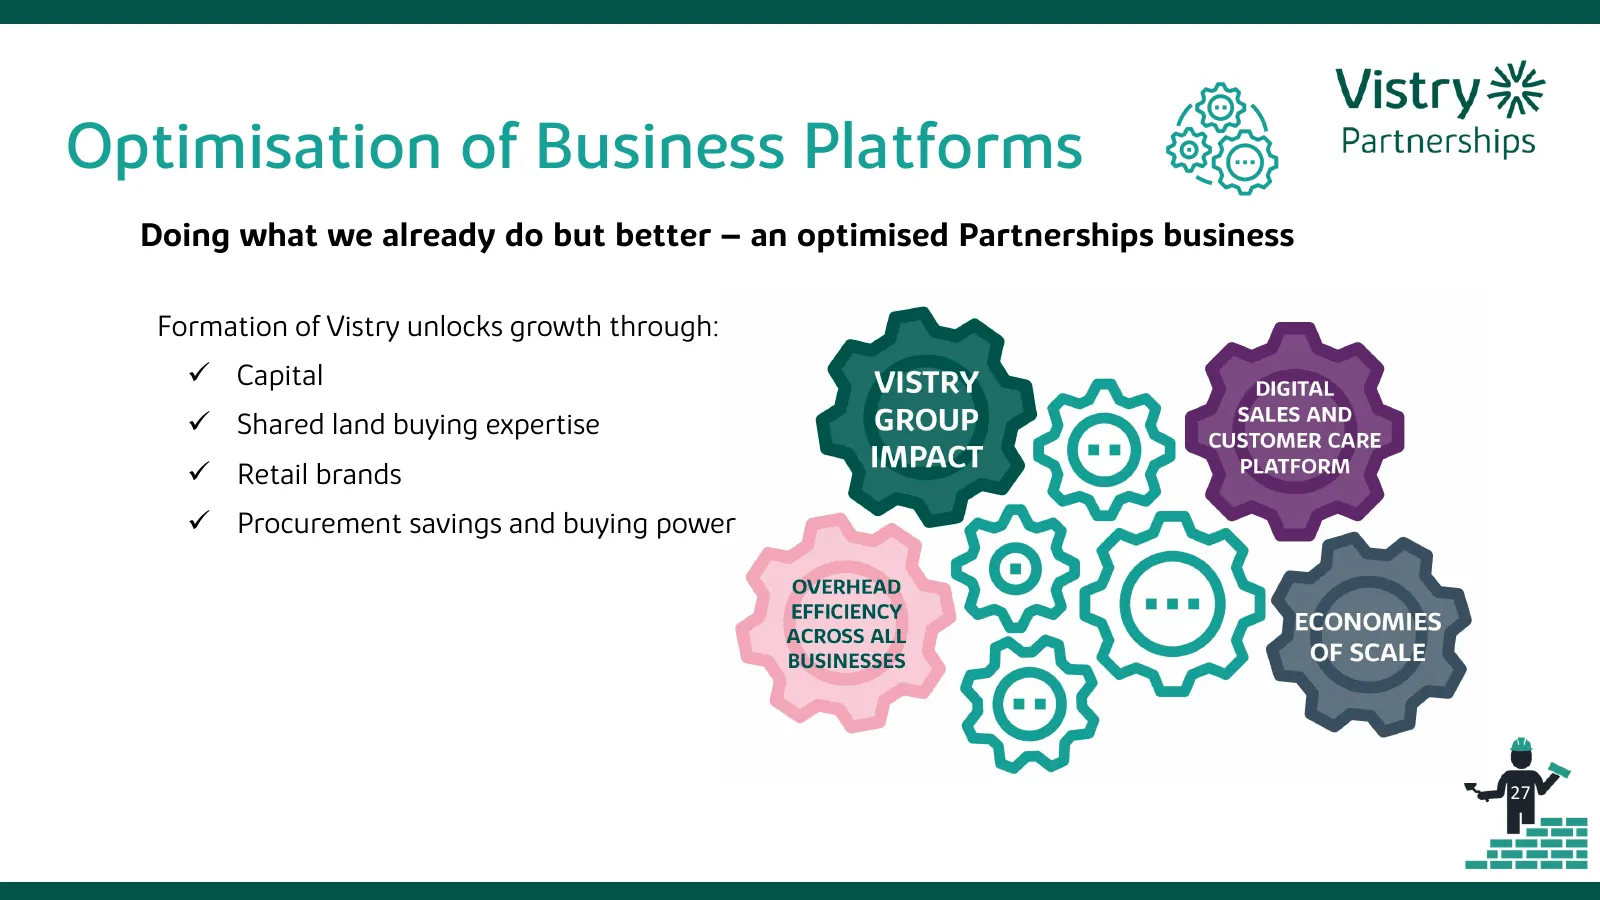
Optimisation of Business Platforms Doing what we already do but better – an optimised Partnerships business Formation of Vistry unlocks growth through: Capital Shared land buying expertise Retail brands Procurement savings and buying power 27
Slide 28: Strategic Alignment with Partners
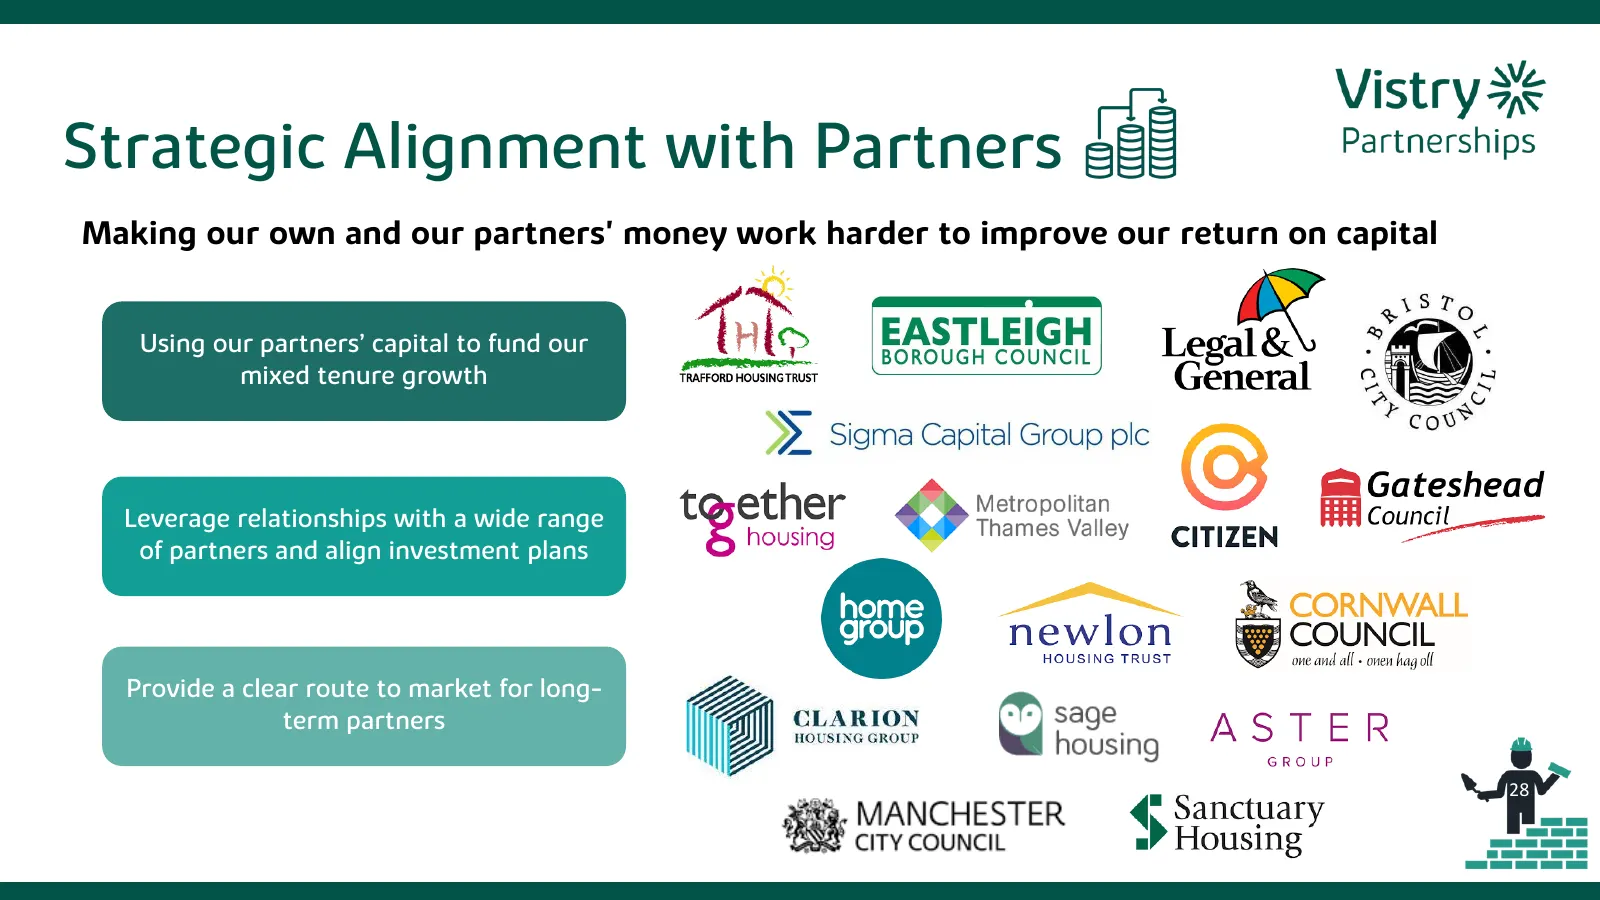
Strategic Alignment with Partners Making our own and our partners' money work harder to improve our return on capital Using our partners’ capital to fund our mixed tenure growth Leverage relationships with a wide range of partners and align investment plans Provide a clear route to market for long-
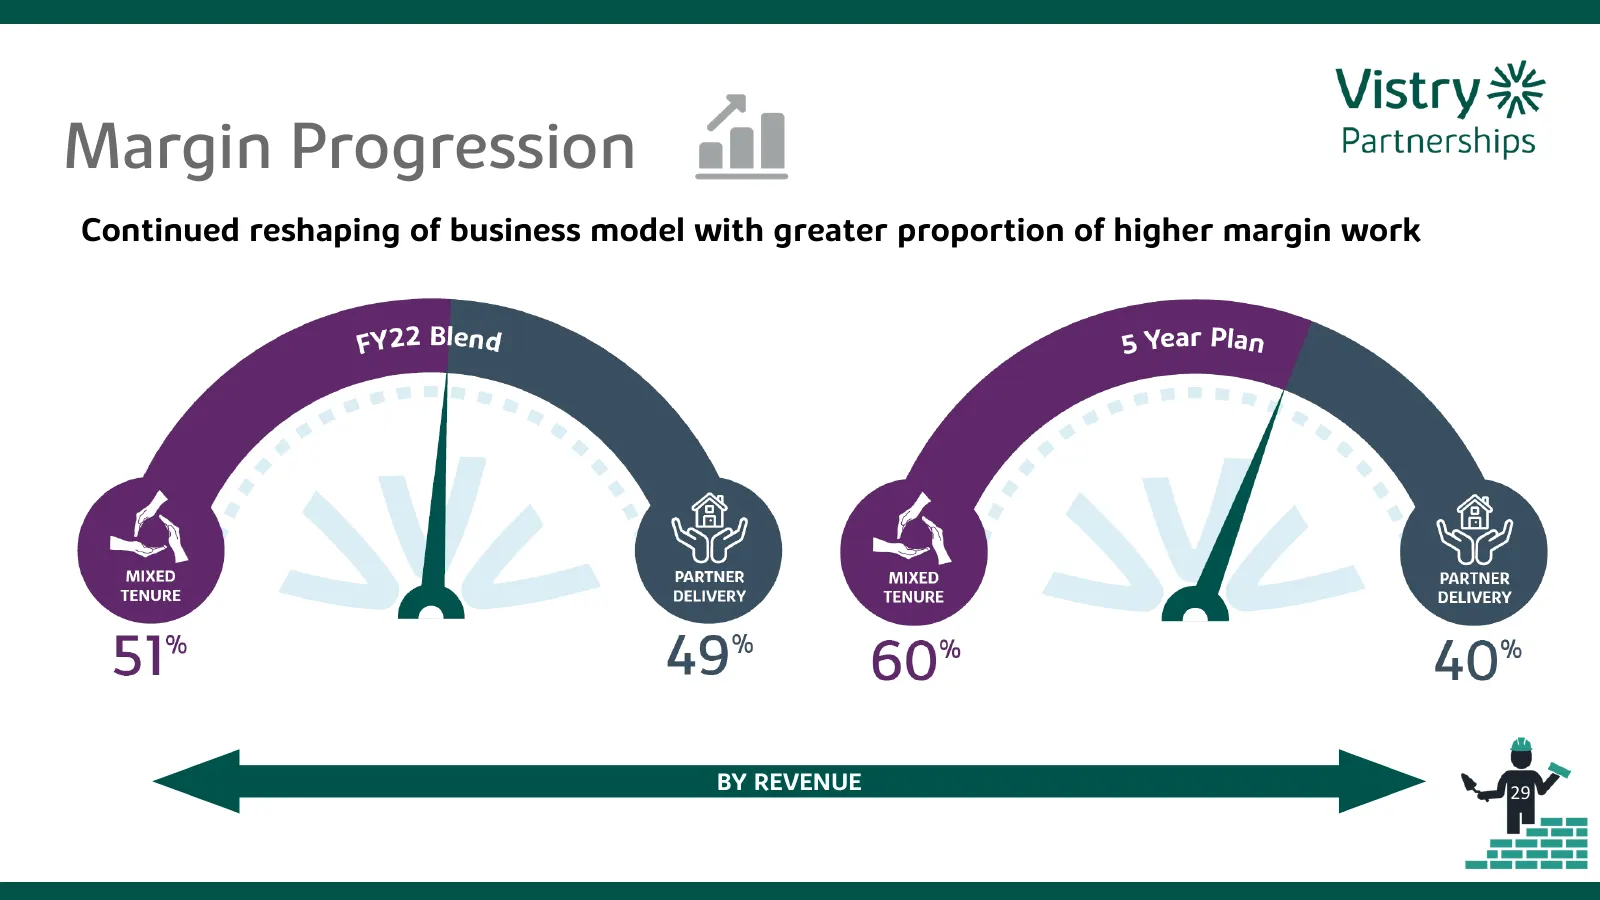
Slide 29: Margin Progression
Margin Progression Continued reshaping of business model with greater proportion of higher margin work 29
Slide 30: Partnerships in Action
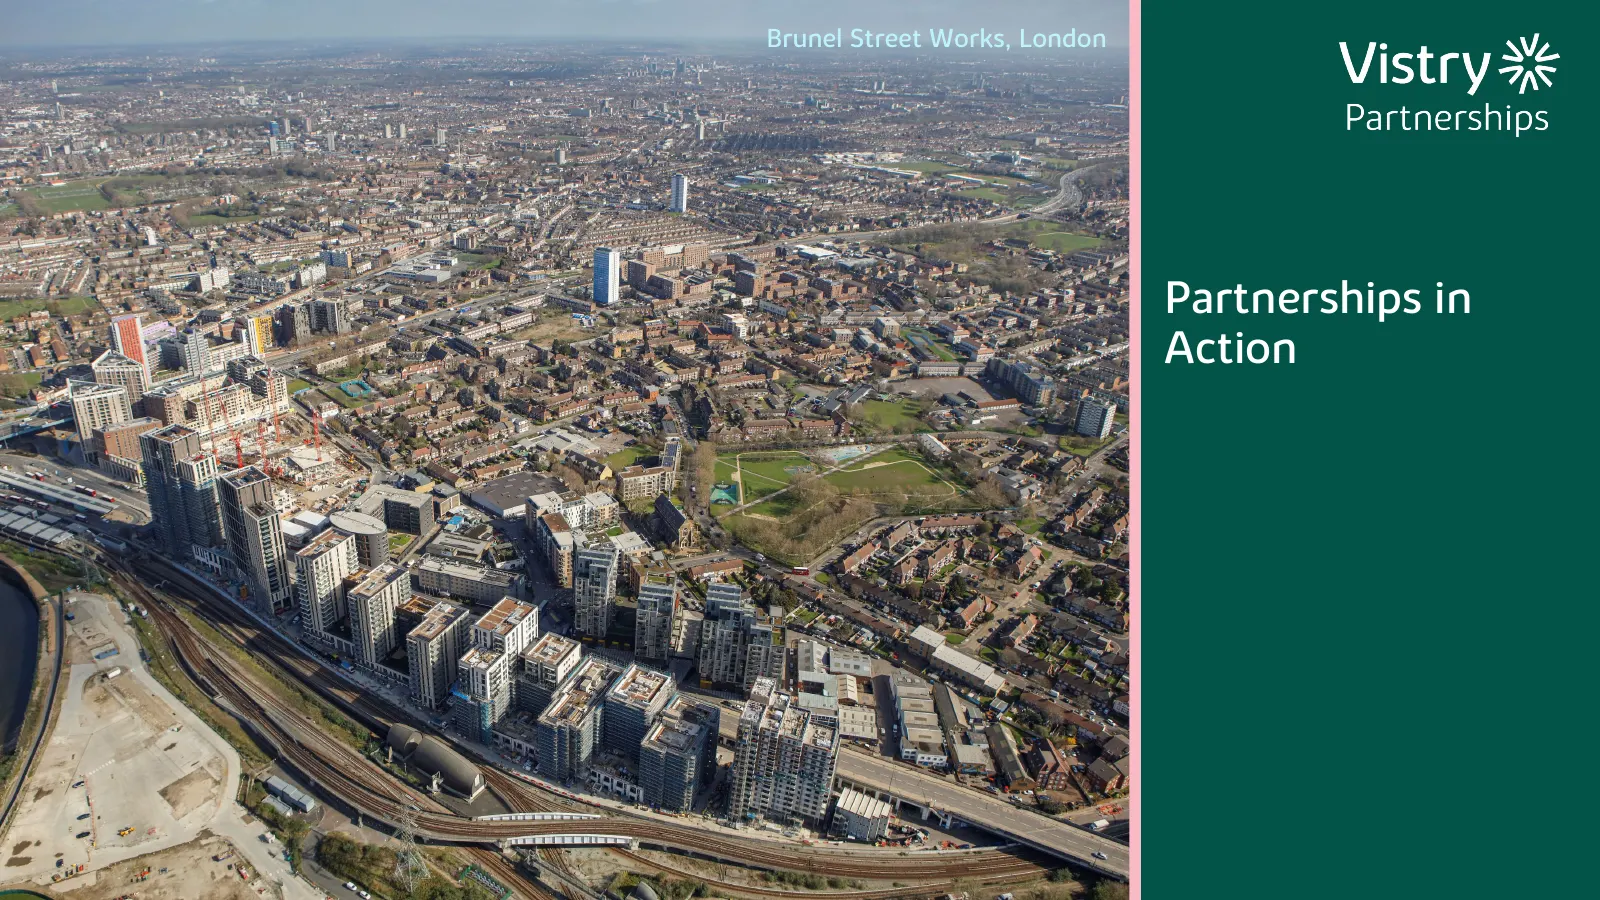
Brunel Street Works, London Partnerships in Action
Slide 31: Land Sourcing
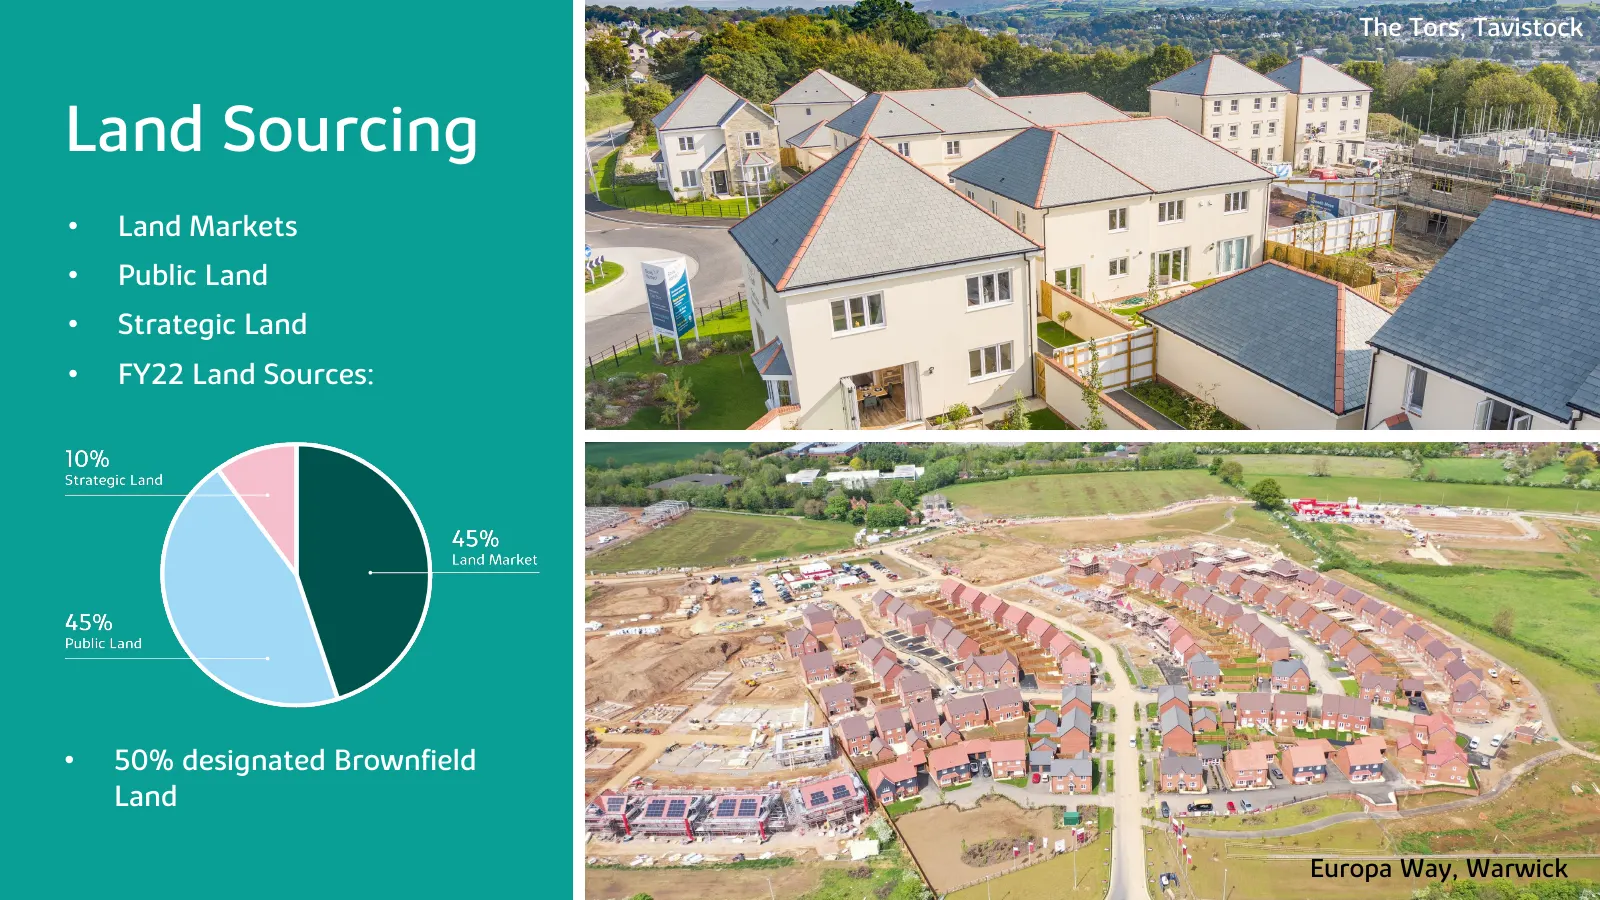
The Tors, Tavistock Land Sourcing • Land Markets • Public Land • Strategic Land • FY22 Land Sources: • 50% designated Brownfield Land Europa Way, Warwick
Slide 32: Lea Castle Joint Venture
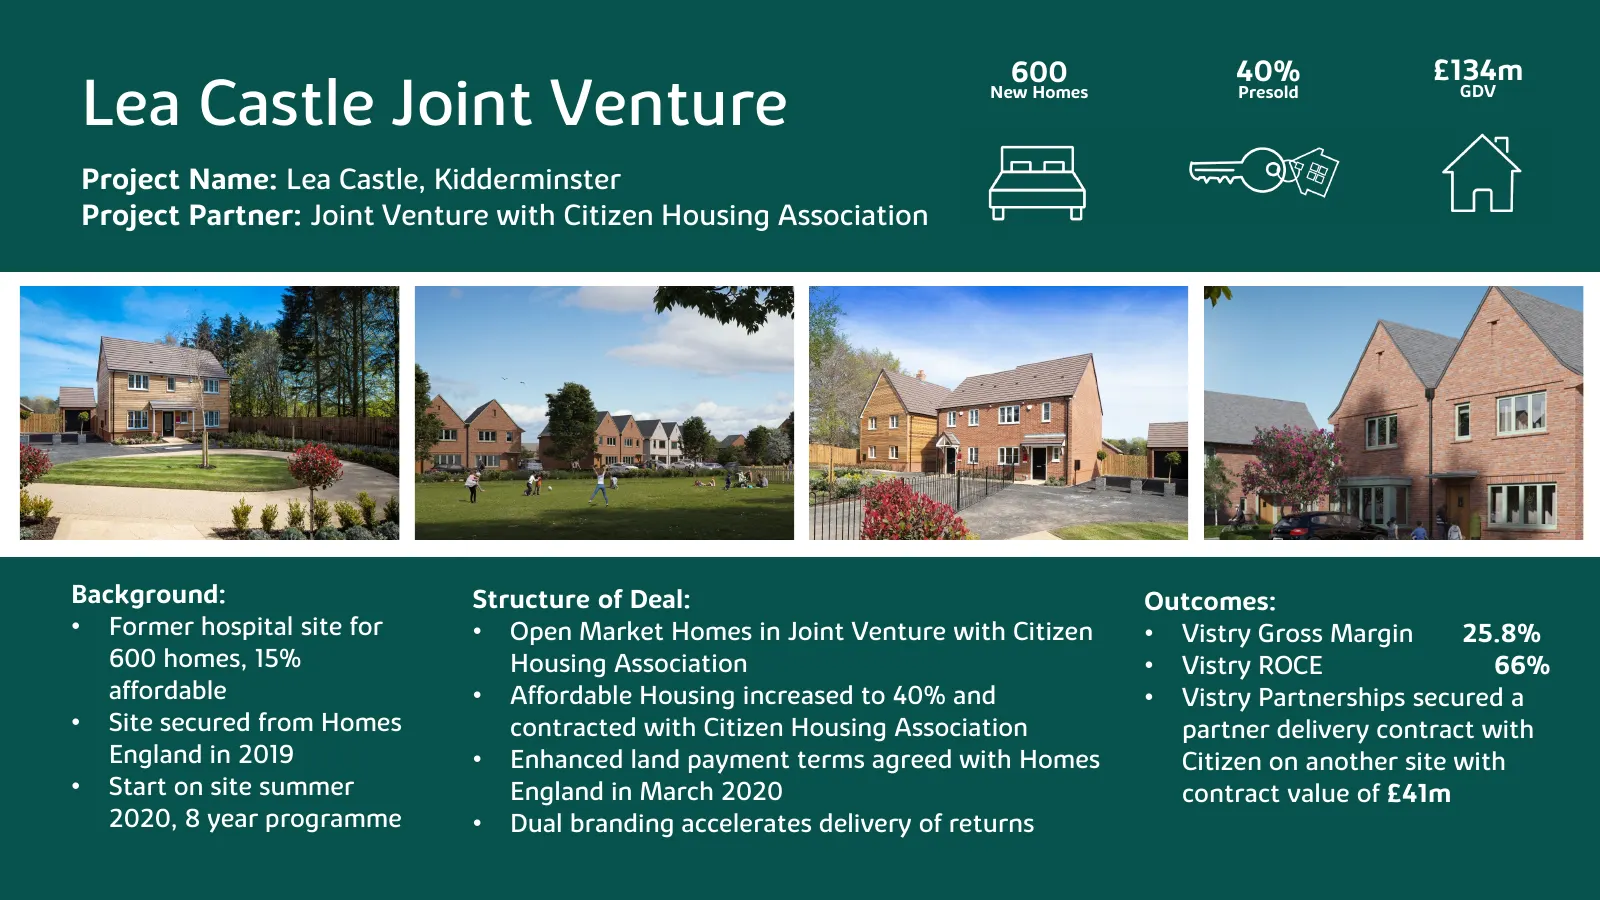
600 40% £134m Lea Castle Joint Venture New Homes Presold GDV Project Name: Lea Castle, Kidderminster Project Partner: Joint Venture with Citizen Housing Association Start on site Summer 2020, 8 year programme Background: Structure of Deal: Outcomes: • Former hospital site for • Open Market Homes in
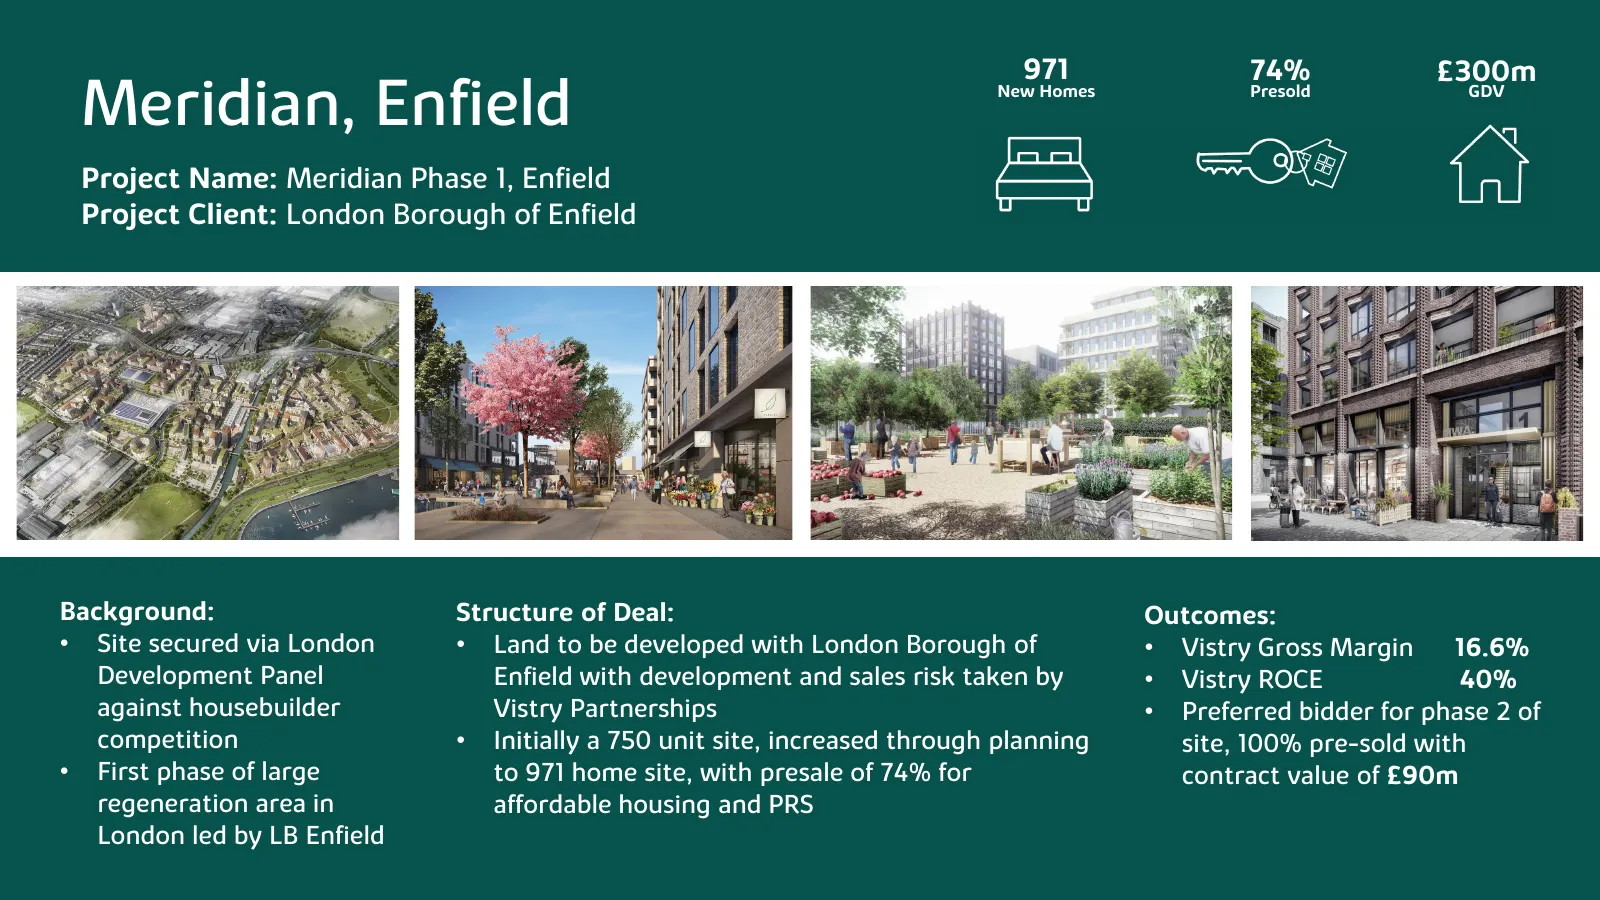
Slide 33: Meridian, Enfield
971 74% £300m Meridian, Enfield New Homes Presold GDV Project Name: Meridian Phase 1, Enfield Project Client: London Borough of Enfield Background: Structure of Deal: Outcomes: • Site secured via London • Land to be developed with London Borough of • Vistry Gross Margin 16.6% Development Panel Enfie
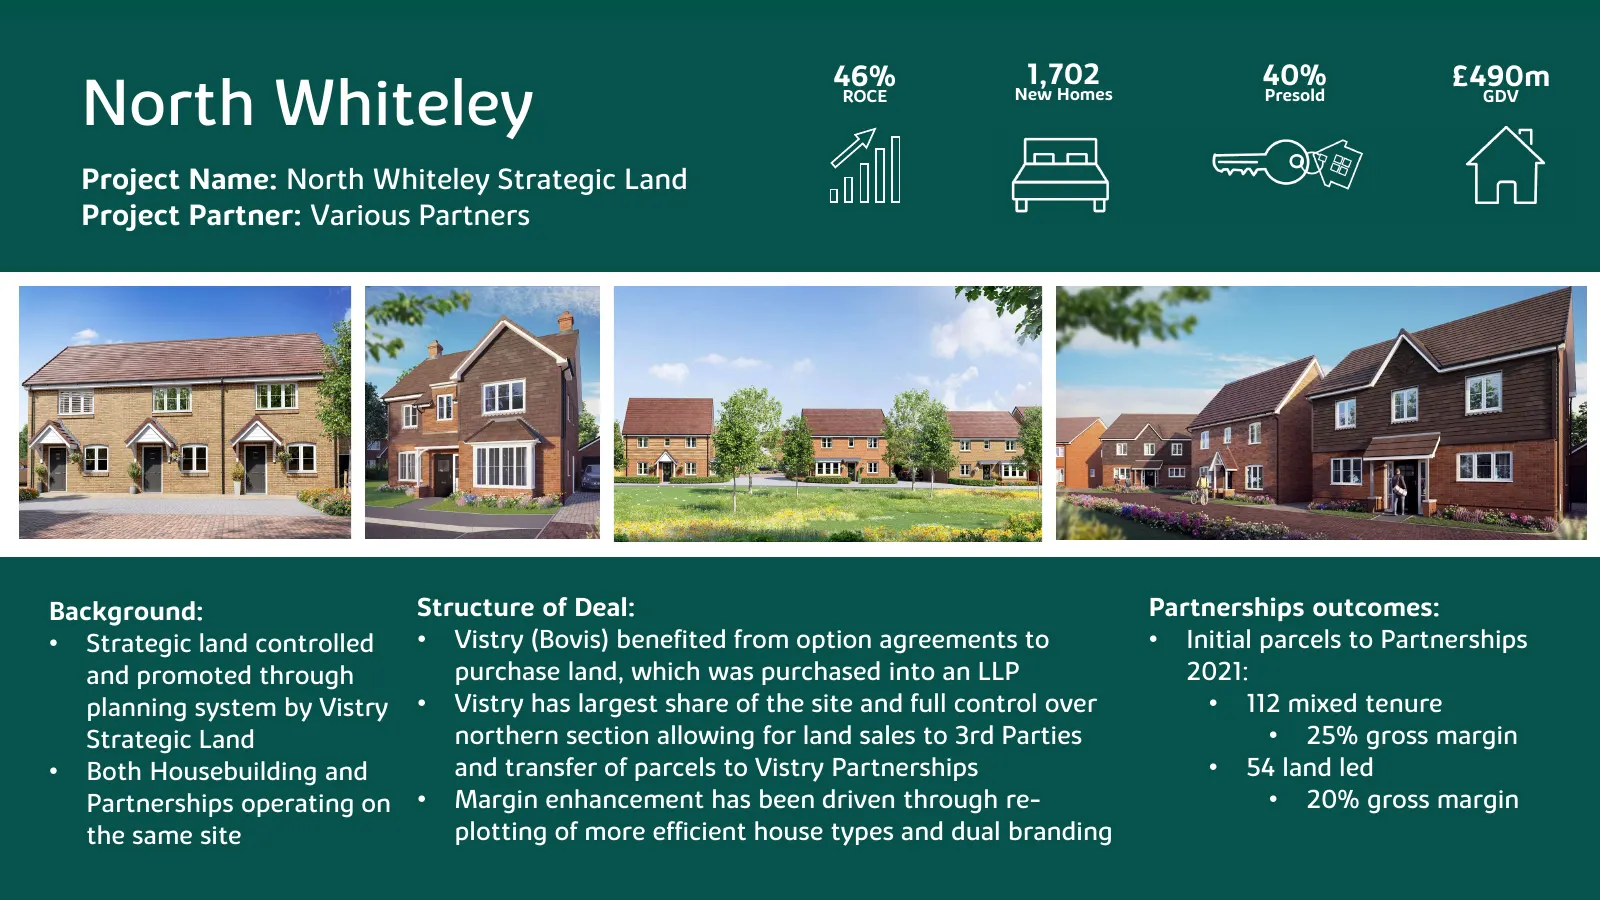
Slide 34: North Whiteley
46% 1,702 40% £490m North Whiteley ROCE New Homes Presold GDV Project Name: North Whiteley Strategic Land Project Partner: Various Partners Background: Structure of Deal: Partnerships outcomes: • Strategic land controlled • Vistry (Bovis) benefited from option agreements to • Initial parcels to Part
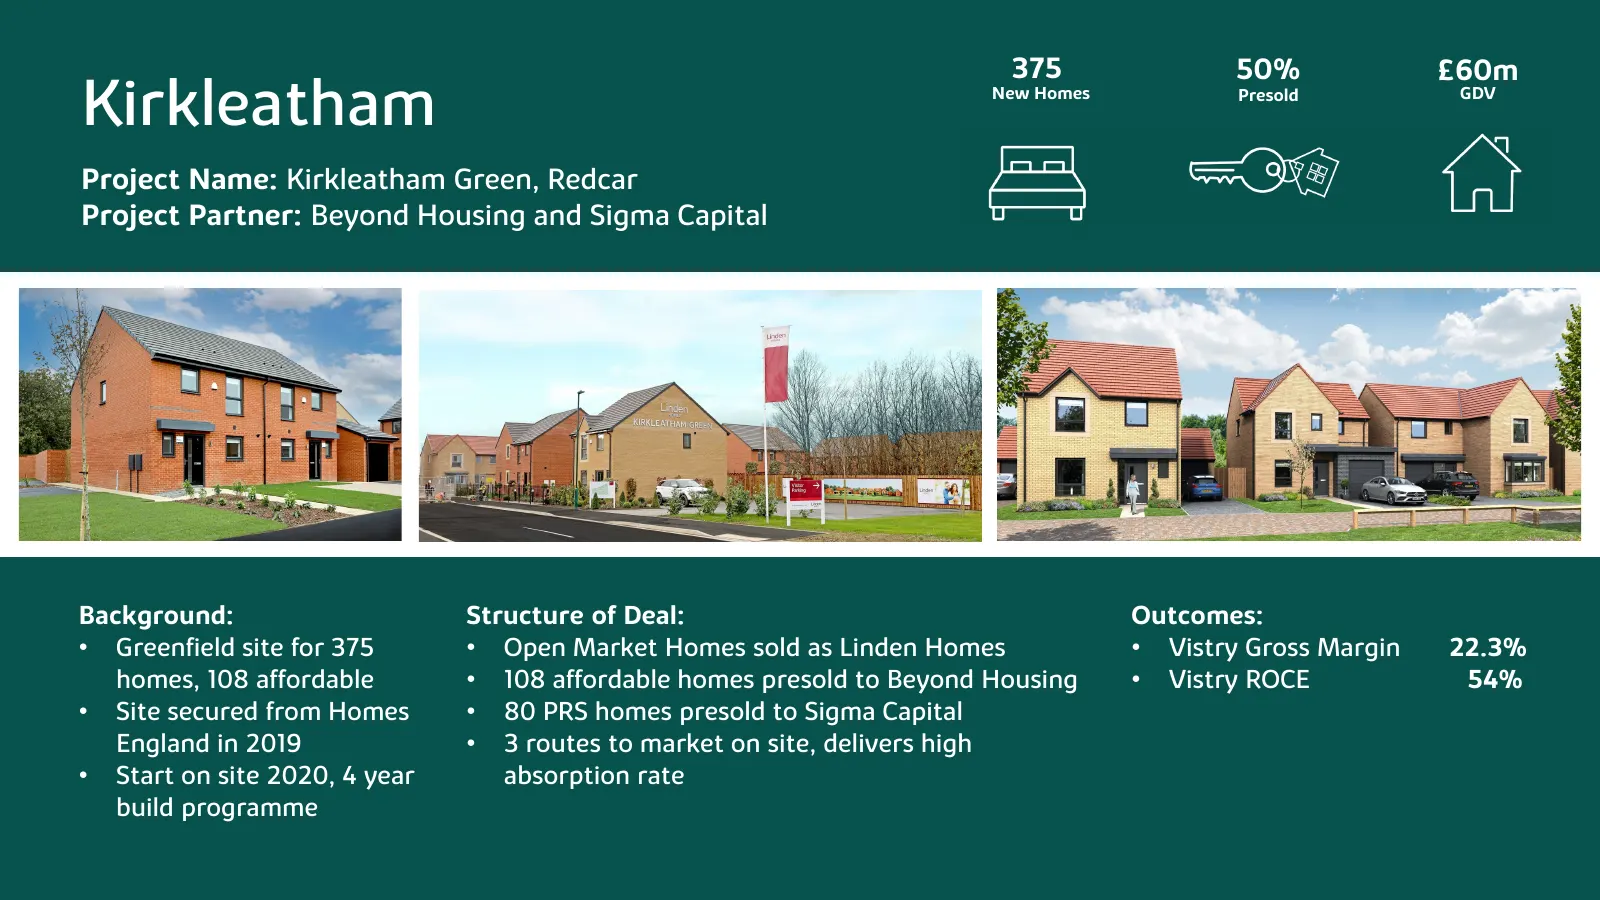
Slide 35: Kirkleatham
375 50% £60m Kirkleatham New Homes Presold GDV Project Name: Kirkleatham Green, Redcar Project Partner: Beyond Housing and Sigma Capital Start on site Summer 2020, 8 year programme Background: Structure of Deal: Outcomes: • Greenfield site for 375 • Open Market Homes sold as Linden Homes • Vistry Gr
Slide 36: Summary
The Tors, Tavistock Summary Perranporth, Cornwall
Slide 37: Outlook
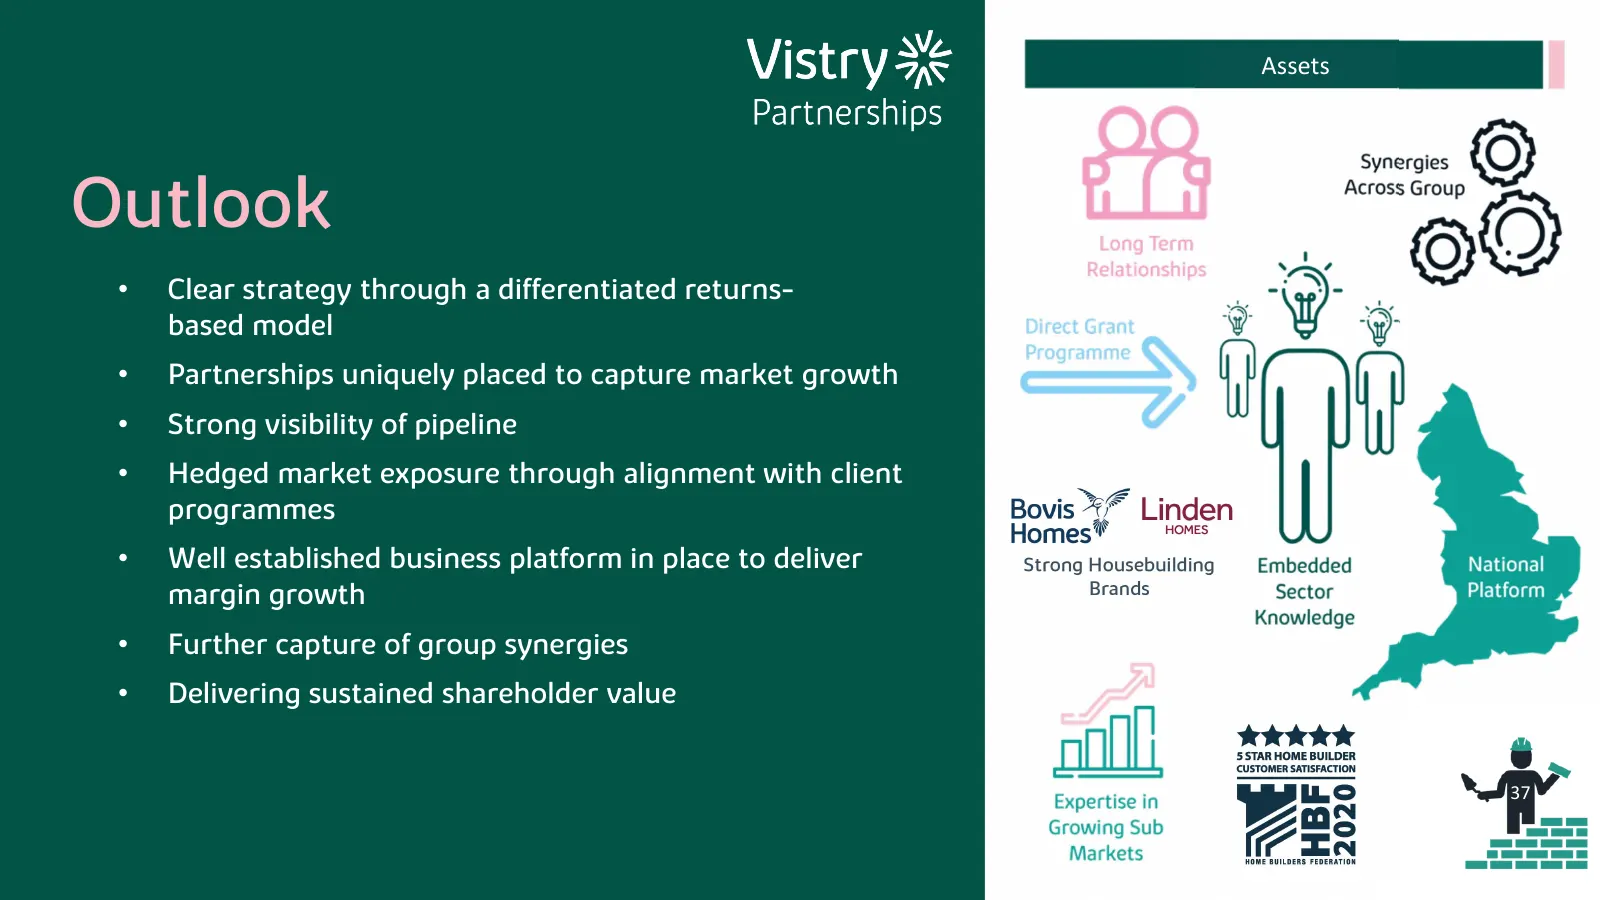
Assets Outlook A differentiated partnerships business with sector expertise • Clear strategy through a differentiated returns- based model • Partnerships uniquely placed to capture market growth • Strong visibility of pipeline • Hedged market exposure through alignment with client programmes • Well
Slide 38: Questions
Vistry 3 Partnerships Questions
Slide 39: Appendix
Vistry 3 Appendix Pannen a
Slide 40: Glossary of Key Terms – Key Stakeholders
Glossary of Key Terms – Key Stakeholders • Homes England – Government Agency with mission to accelerate housing delivery in England through the following interventions; Help to Buy, Affordable Housing and Housing Infrastructure Funding, Public Land disposals and other investment programmes. • Housin
Slide 41: Glossary of Key Terms – Affordable Housing
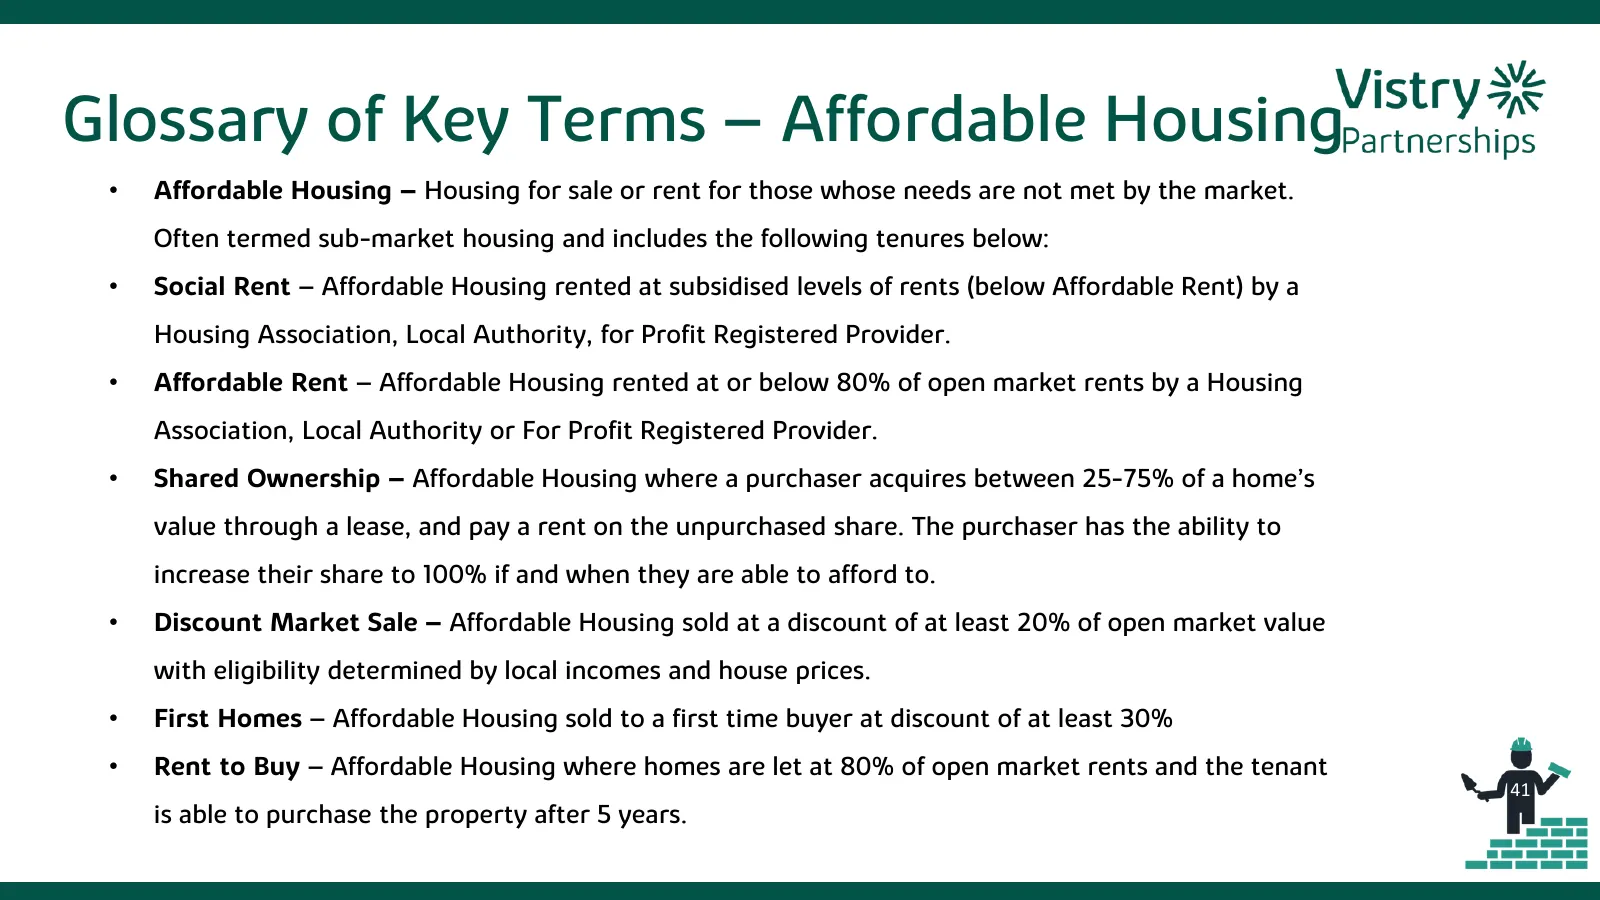
Glossary of Key Terms – Affordable Housing • Affordable Housing – Housing for sale or rent for those whose needs are not met by the market. Often termed sub-market housing and includes the following tenures below: • Social Rent – Affordable Housing rented at subsidised levels of rents (below Afforda
Slide 42: Glossary of Key Terms – Other Housing Tenures
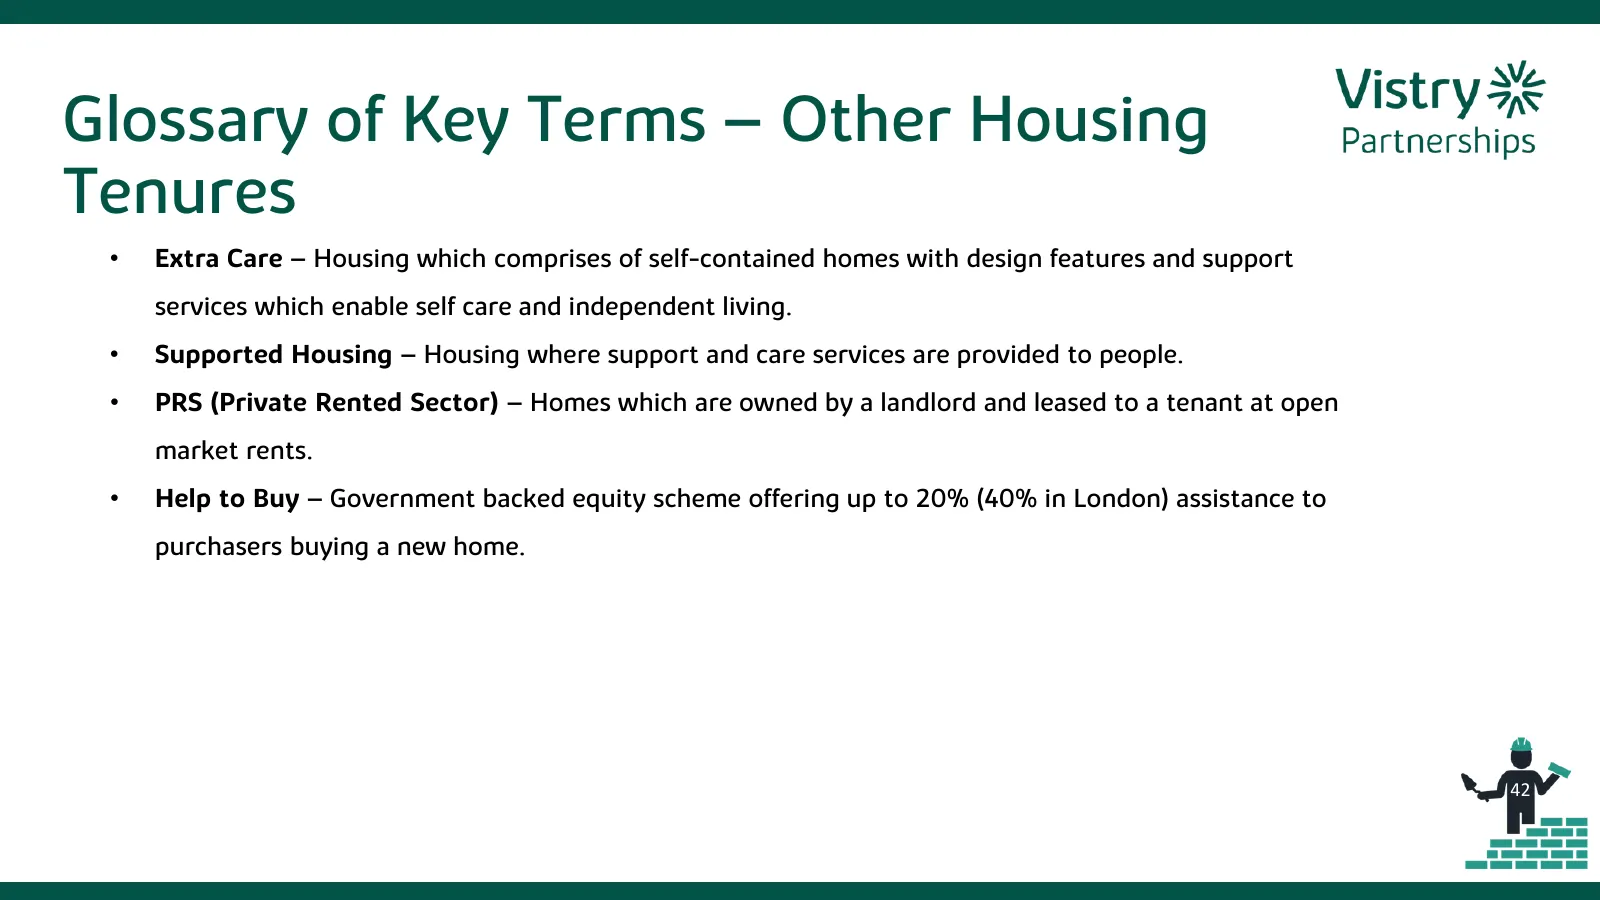
Glossary of Key Terms – Other Housing Tenures • Extra Care – Housing which comprises of self-contained homes with design features and support services which enable self care and independent living. • Supported Housing – Housing where support and care services are provided to people. • PRS (Private R
Slide 43: Glossary of Key Terms – Partner Delivery Terms
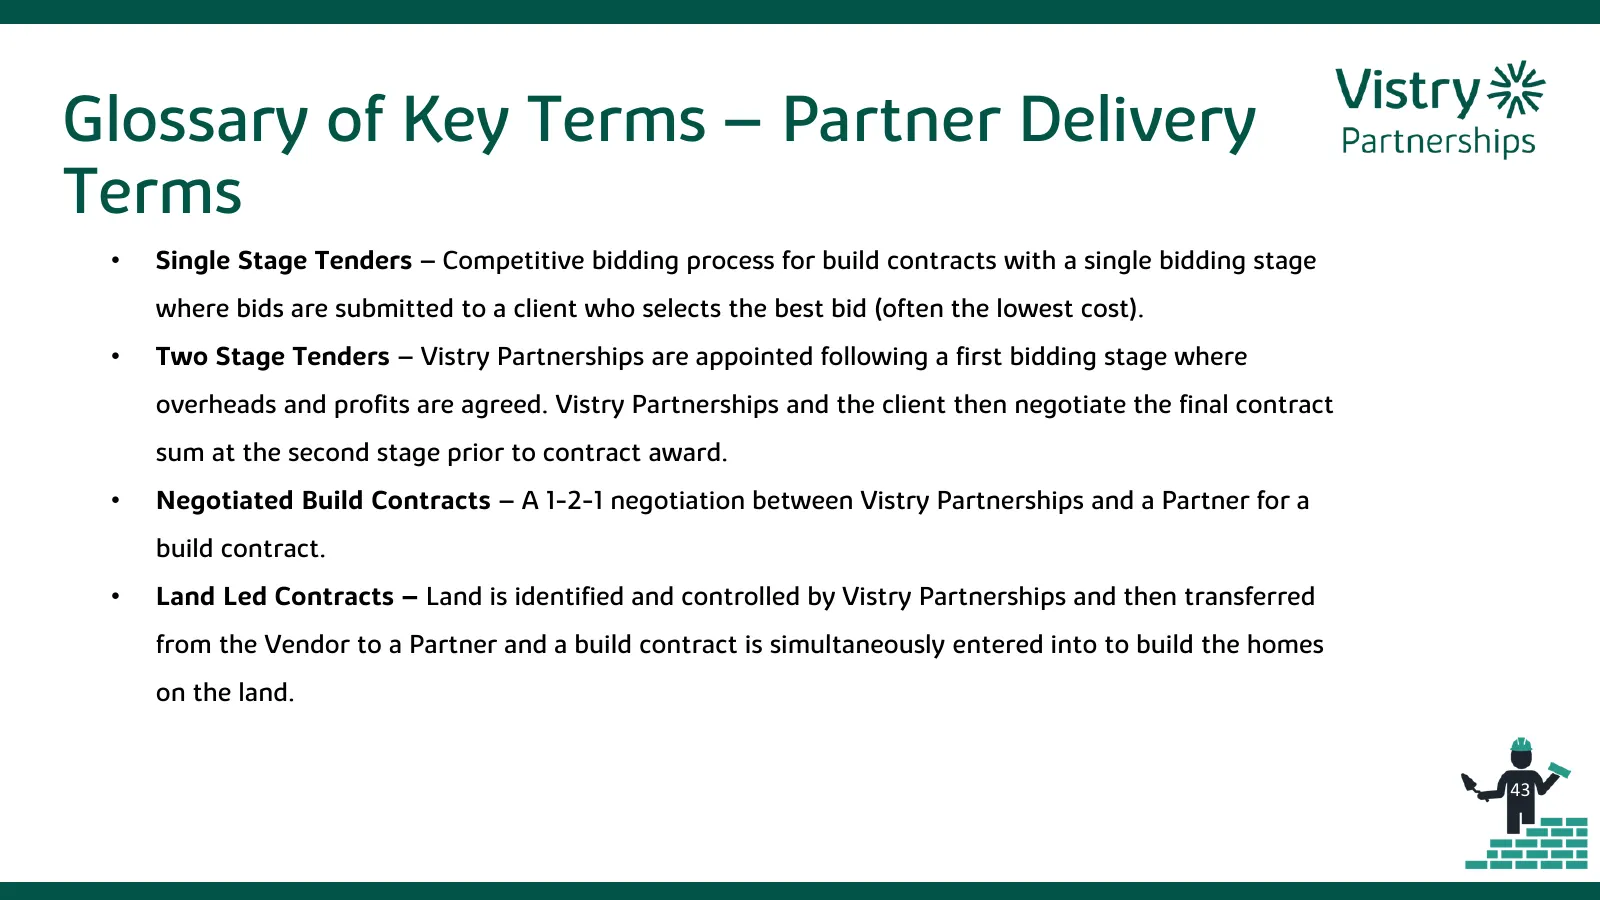
Glossary of Key Terms – Partner Delivery Terms • Single Stage Tenders – Competitive bidding process for build contracts with a single bidding stage where bids are submitted to a client who selects the best bid (often the lowest cost). • Two Stage Tenders – Vistry Partnerships are appointed following
Slide 44: Glossary of Key Terms – Other Terms
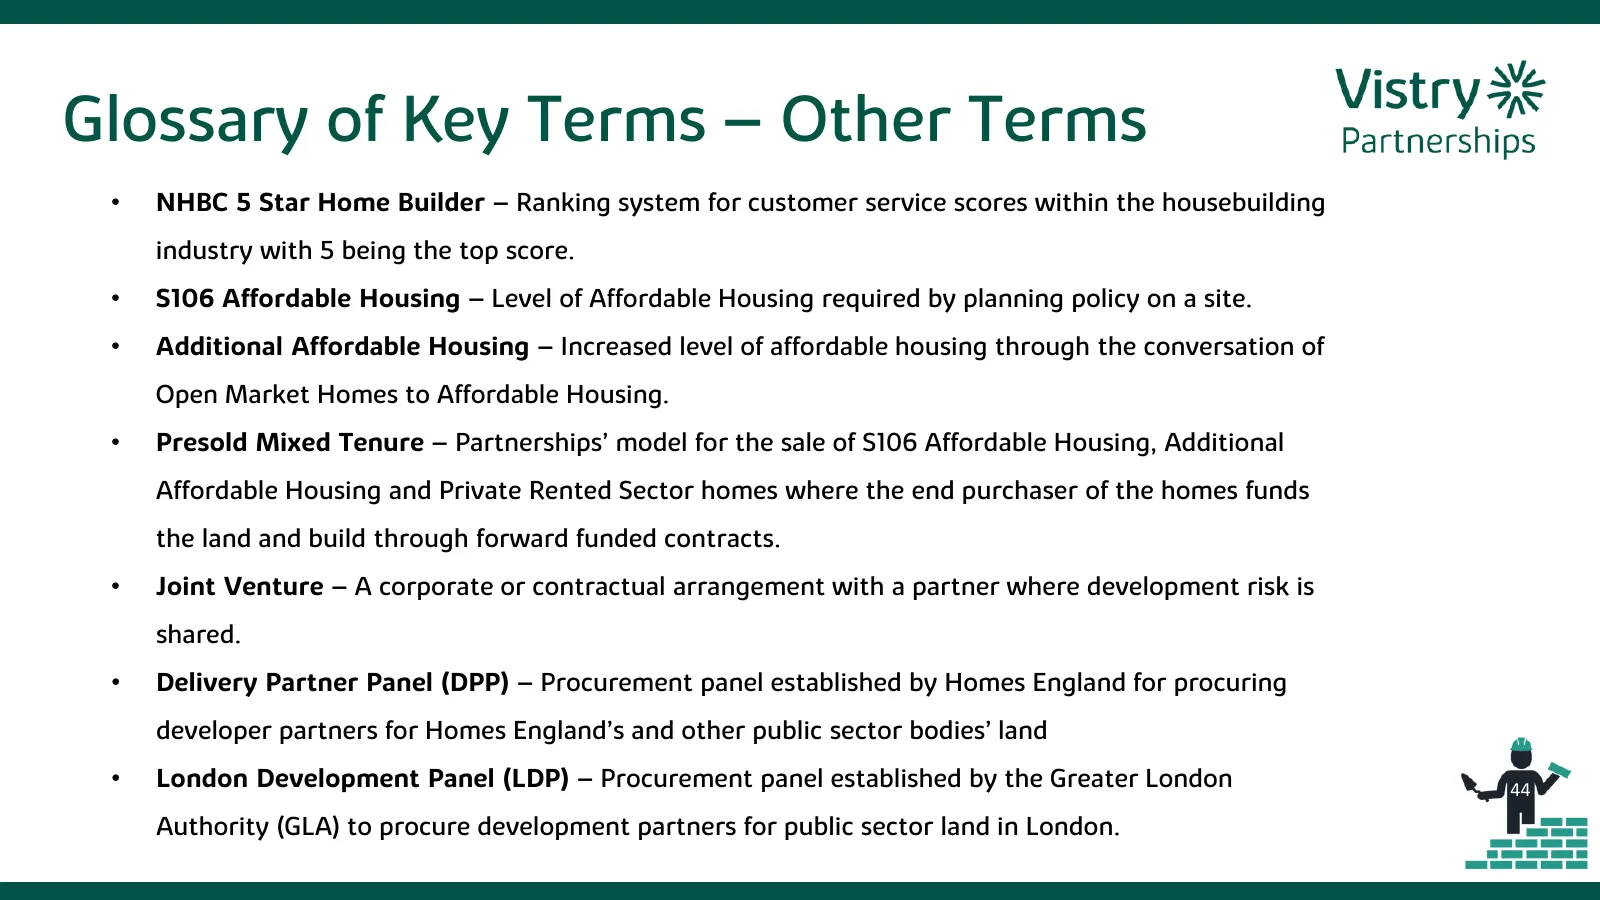
Glossary of Key Terms – Other Terms • NHBC 5 Star Home Builder – Ranking system for customer service scores within the housebuilding industry with 5 being the top score. • S106 Affordable Housing – Level of Affordable Housing required by planning policy on a site. • Additional Affordable Housing – I
Slide 45: Disclaimer – Important Notice
Disclaimer – Important Notice • Certain statements in this presentation are forward looking statements. • Forward looking statements involve evaluating a number of risks, uncertainties or assumptions that could cause actual results to differ materially from those expressed or implied by those statem
Source: company website
More decks from Vistry Group PLC
 H1 2026 Earnings Presentation93 slides · Sep 24, 2026
 FY2025 Earnings Presentation47 slides · Mar 4, 2026
 H1 2025 Earnings Presentation50 slides · Sep 10, 2025
 FY2024 Earnings Presentation52 slides · Mar 26, 2025
 H1 2024 Earnings Presentation58 slides · Sep 5, 2024
 FY2023 Earnings Presentation54 slides · Mar 14, 2024