Nedbank Group · JSE:NED
Nedbank — Investor Day (June 2014)
20 slides from Nedbank's investor day presentation, Jun 12, 2014
Slide 1: Renaissance Capital Business Banking Investor Day
NEDBANK GROUP LIMITED Renaissance Capital Business Banking Investor Day 12th June 2014
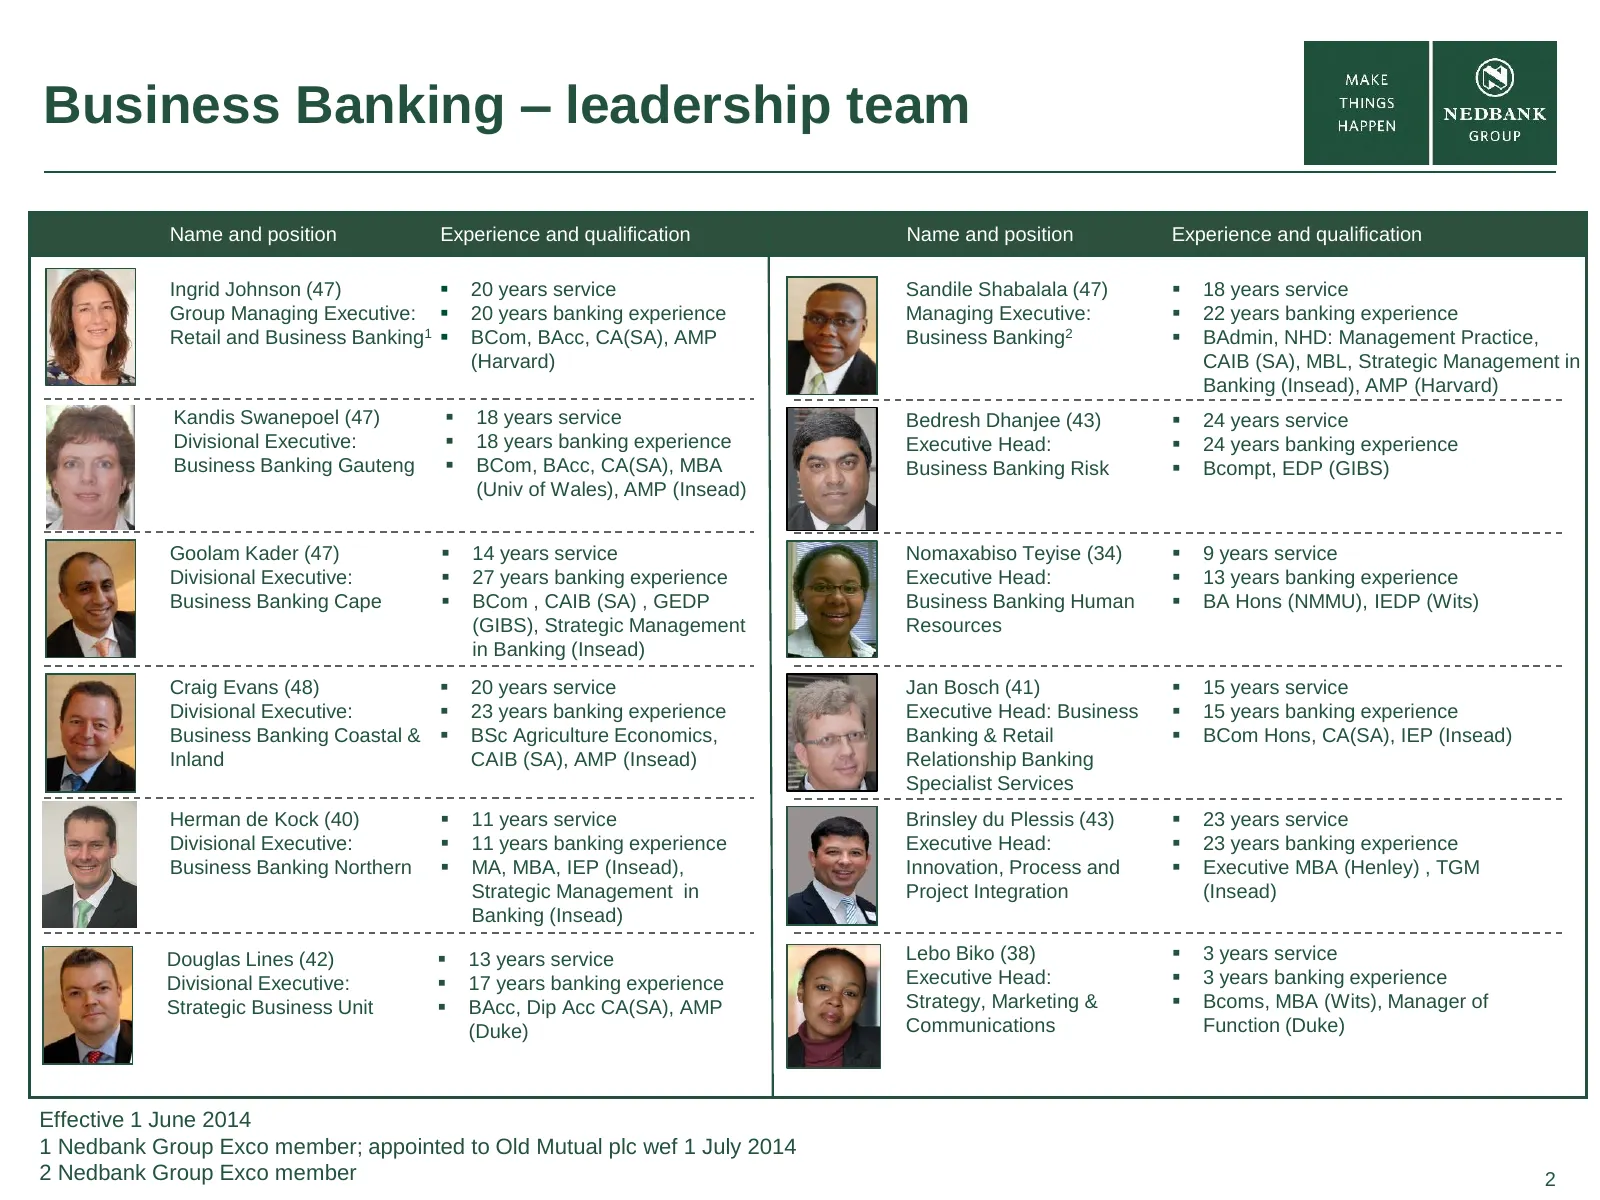
Slide 2: Business Banking – leadership team
Business Banking – leadership team Name and position Experience and qualification Name and position Experience and qualification Ingrid Johnson (47) 20 years service Sandile Shabalala (47) 18 years service Group Managing Executive: 20 years banking experience Managing Executive: 22 years ban
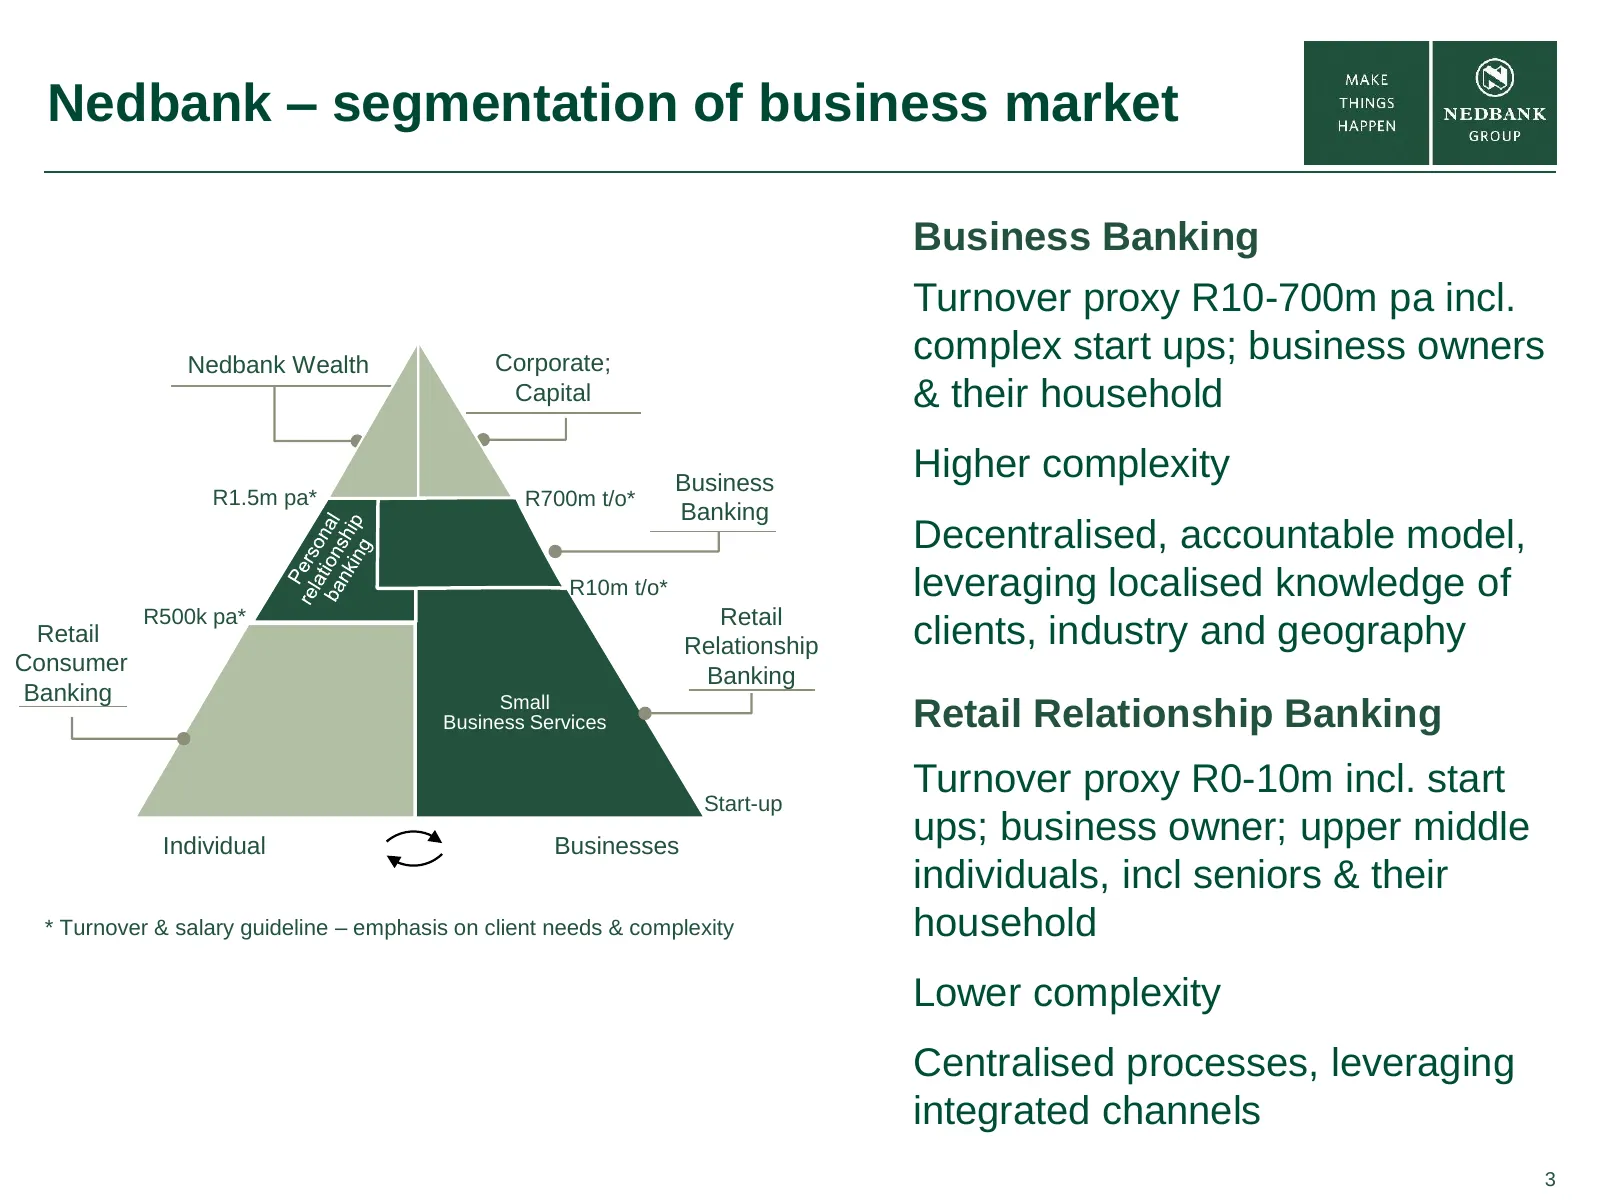
Slide 3: Nedbank – segmentation of business market
Nedbank – segmentation of business market Business Banking Turnover proxy R10-700m pa incl. Nedbank Wealth Corporate; complex start ups; business owners Capital & their household Business Higher complexity R1.5m pa* R700m t/o* Banking Decentralised, accountable model, R10m t/o* leveraging localised
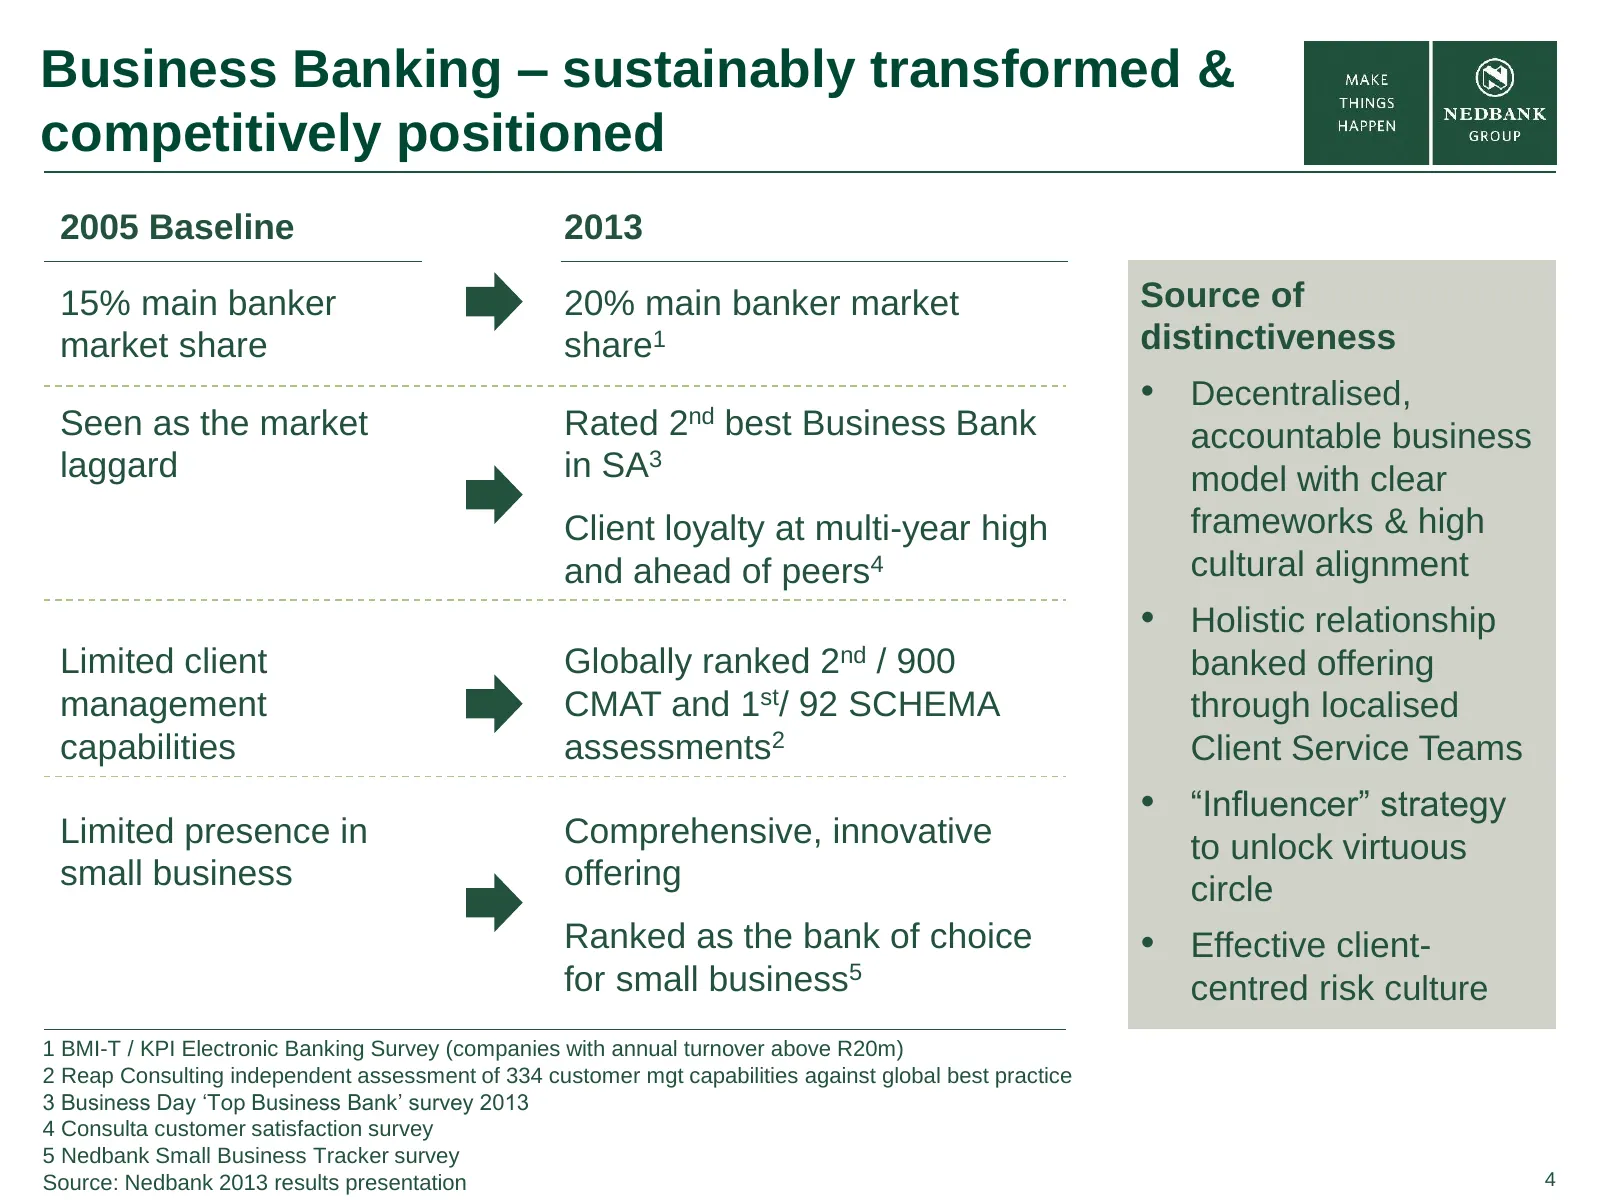
Slide 4: Business Banking – sustainably transformed & competitively positioned
Business Banking – sustainably transformed & competitively positioned 2005 Baseline 2013 15% main banker 20% main banker market Source of market share share1 distinctiveness • Decentralised, Seen as the market Rated 2nd best Business Bank accountable business laggard in SA3 model with clear Client l
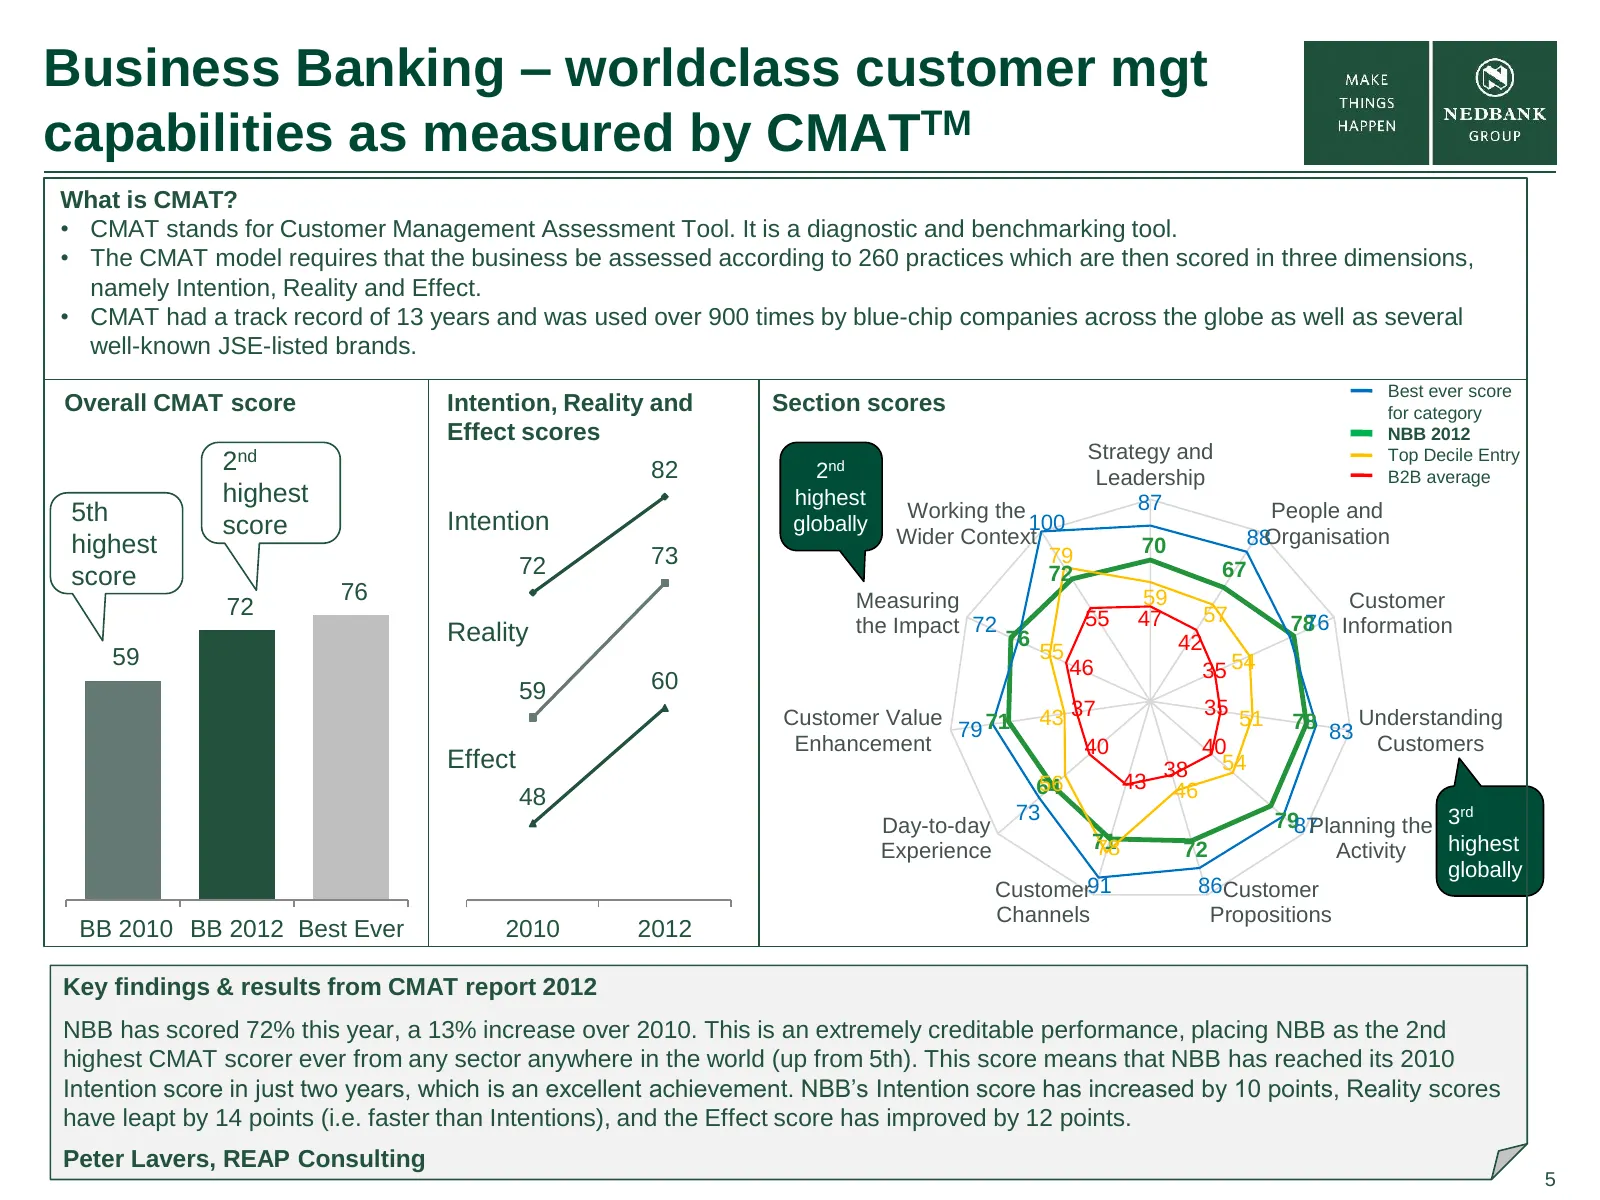
Slide 5: Business Banking – worldclass customer mgt capabilities as measured by CMAT
Business Banking – worldclass customer mgt capabilities as measured by CMATTM What is CMAT? • CMAT stands for Customer Management Assessment Tool. It is a diagnostic and benchmarking tool. • The CMAT model requires that the business be assessed according to 260 practices which are then scored in thr
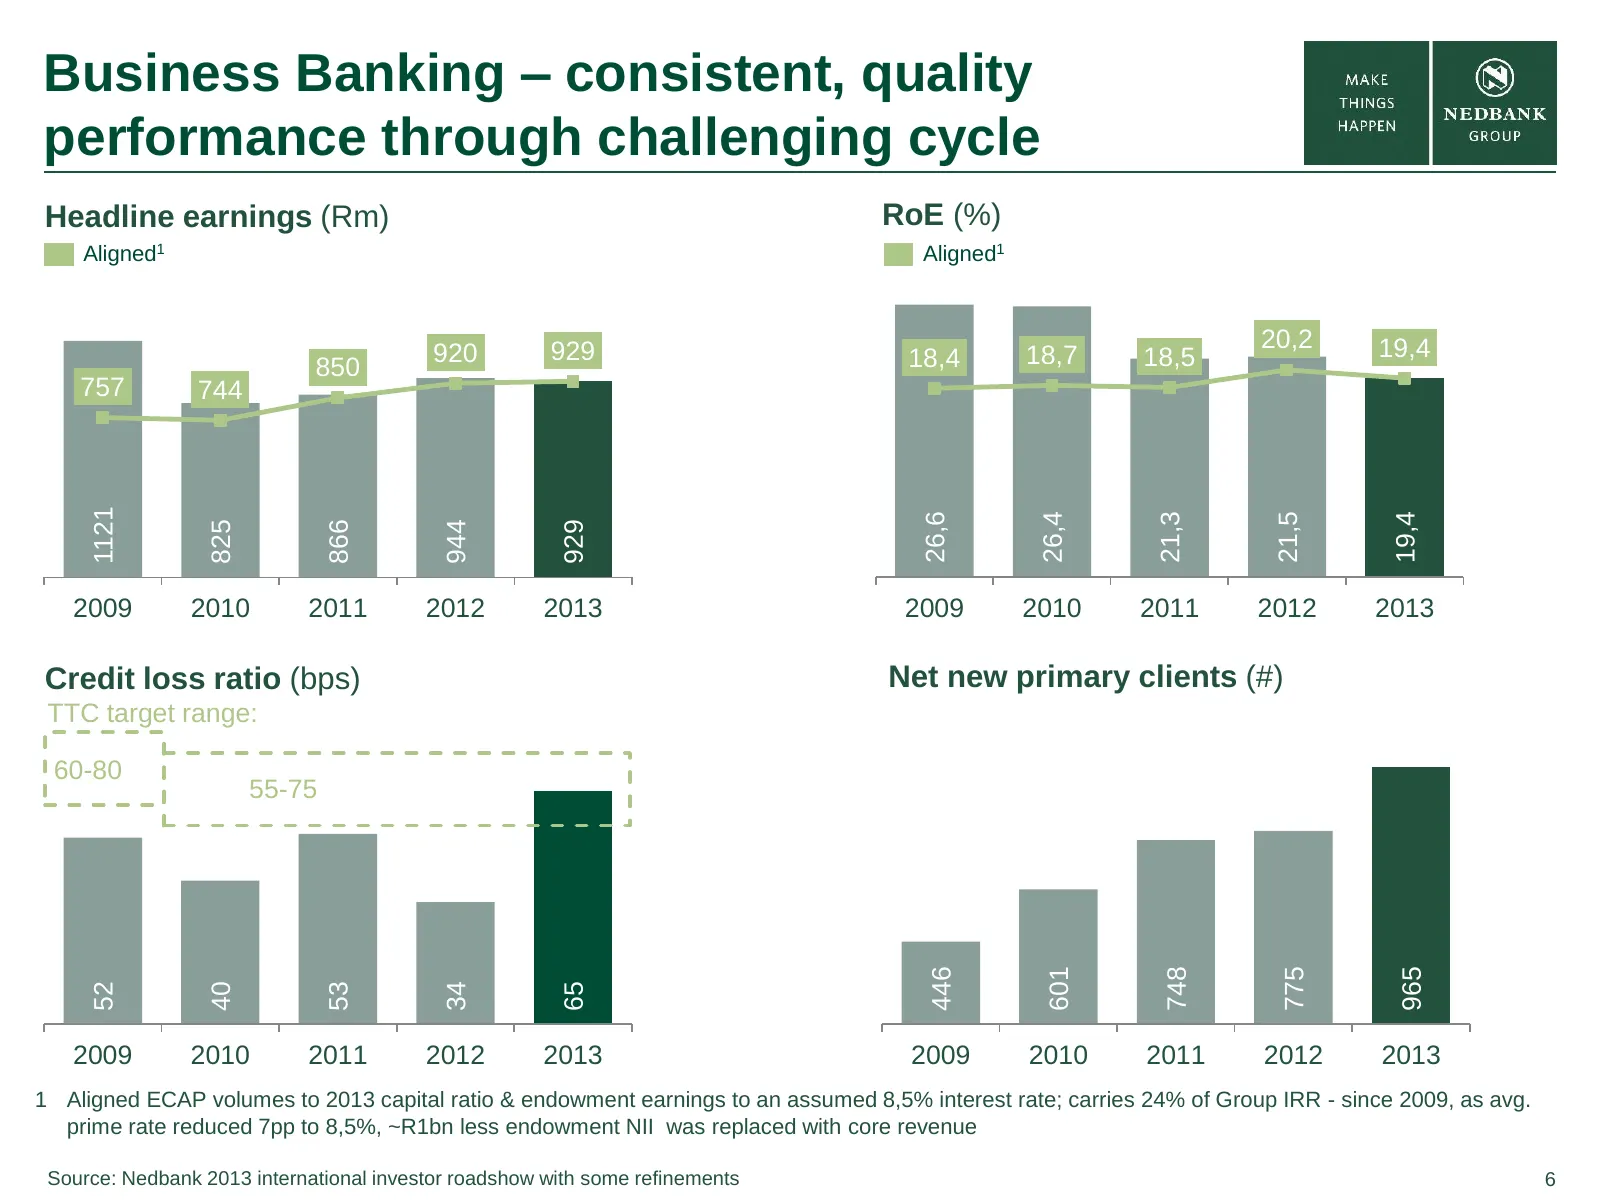
Slide 6: Business Banking – consistent, quality performance through challenging cycle
Business Banking – consistent, quality performance through challenging cycle Headline earnings (Rm) RoE (%) Aligned1 Aligned1 920 929 20,2 19,4 850 18,4 18,7 18,5 757 744 1121 26,6 26,4 21,3 21,5 19,4 825 866 944 929 2009 2010 2011 2012 2013 2009 2010 2011 2012 2013 Credit loss ratio (bps) Net new p
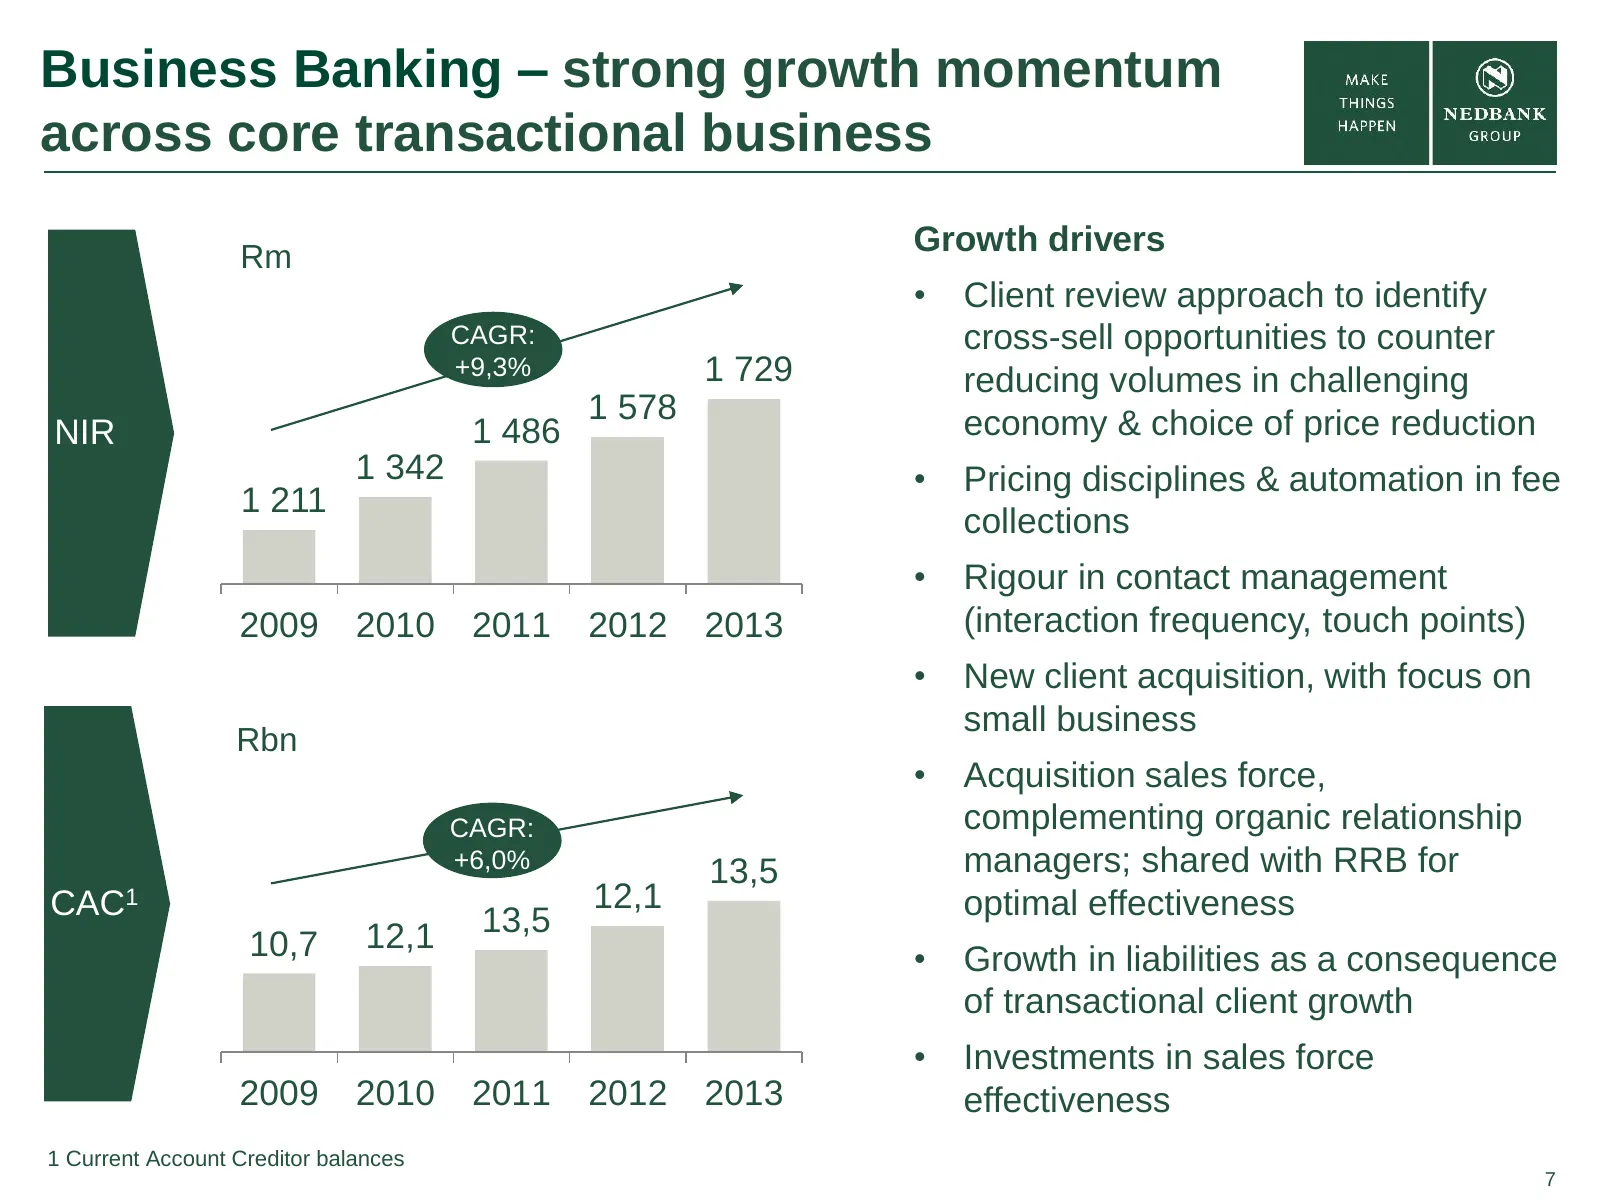
Slide 7: Business Banking – strong growth momentum across core transactional business
Business Banking – strong growth momentum across core transactional business Growth drivers Rm • Client review approach to identify CAGR: cross-sell opportunities to counter +9,3% 1 729 reducing volumes in challenging 1 578 economy & choice of price reduction NIR 1 486 1 342 • Pricing disciplines &
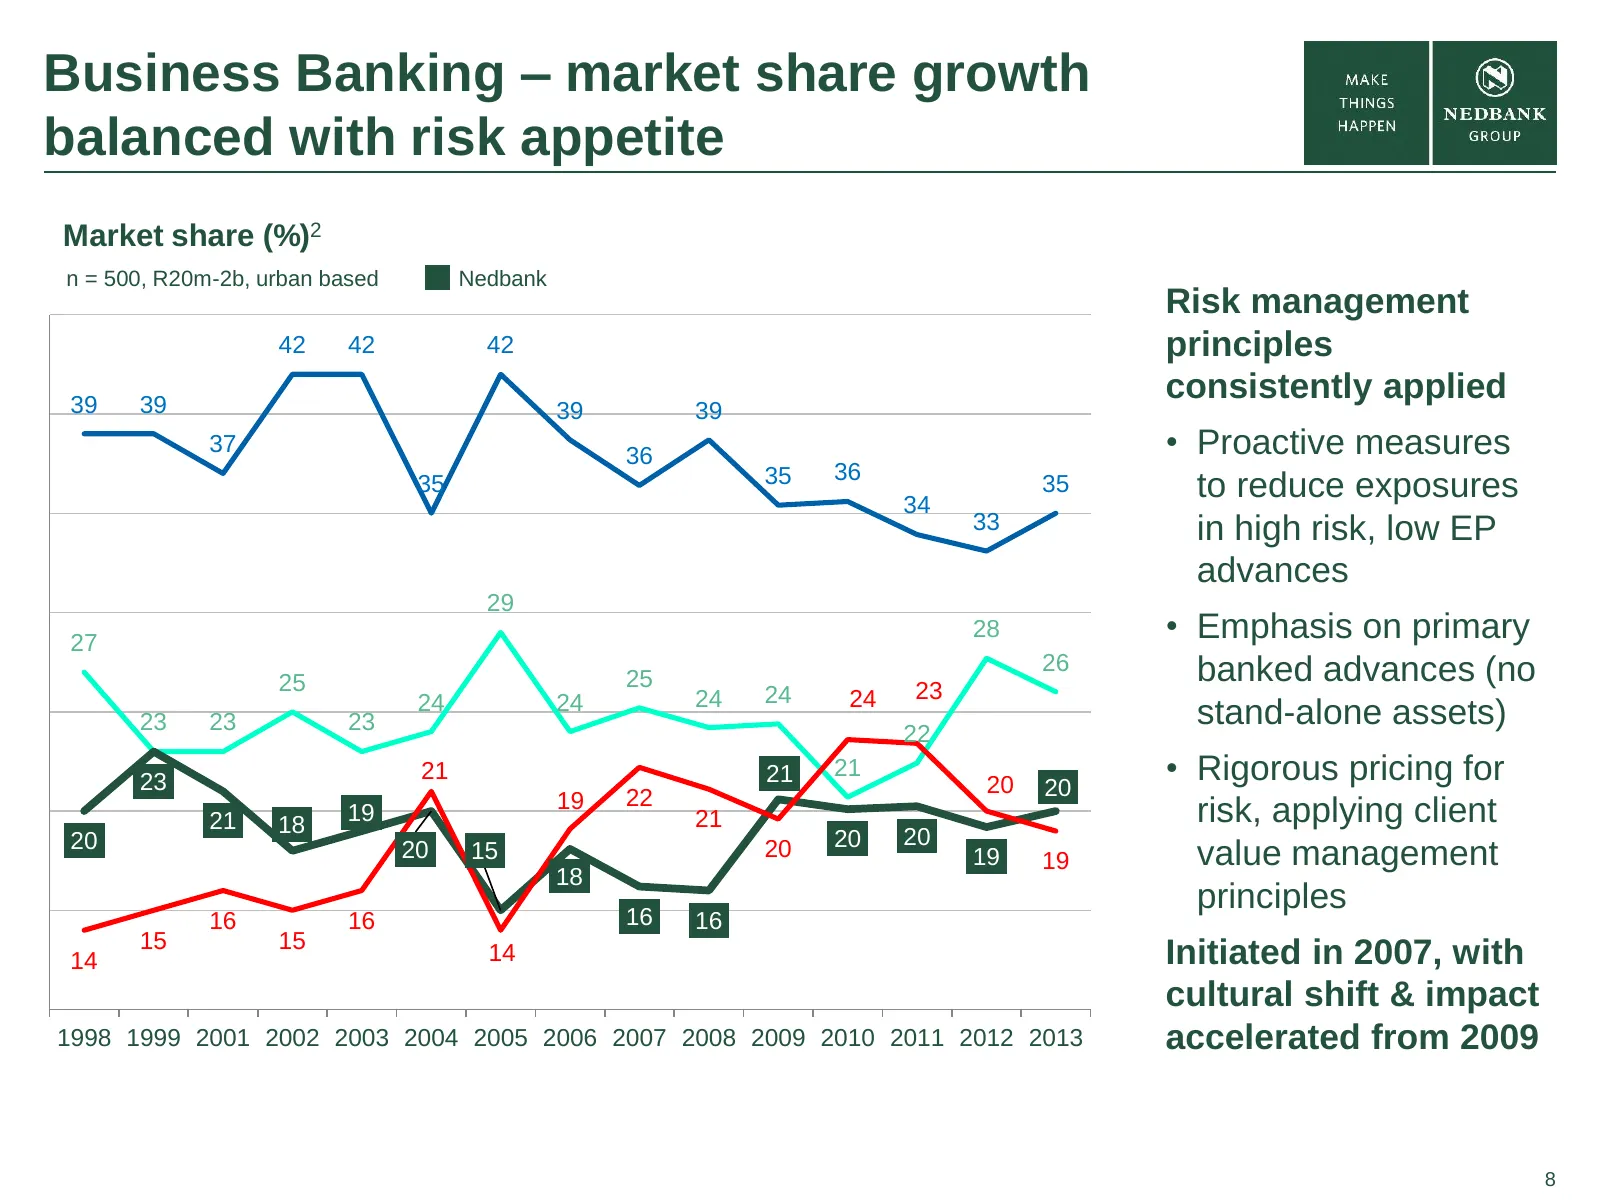
Slide 8: Business Banking – market share growth balanced with risk appetite
Business Banking – market share growth balanced with risk appetite Market share (%)2 n = 500, R20m-2b, urban based Nedbank Risk management 42 42 42 principles 39 39 consistently applied 39 39 37 36 • Proactive measures 35 36 35 34 35 to reduce exposures 33 in high risk, low EP advances 29 27 28 • Em
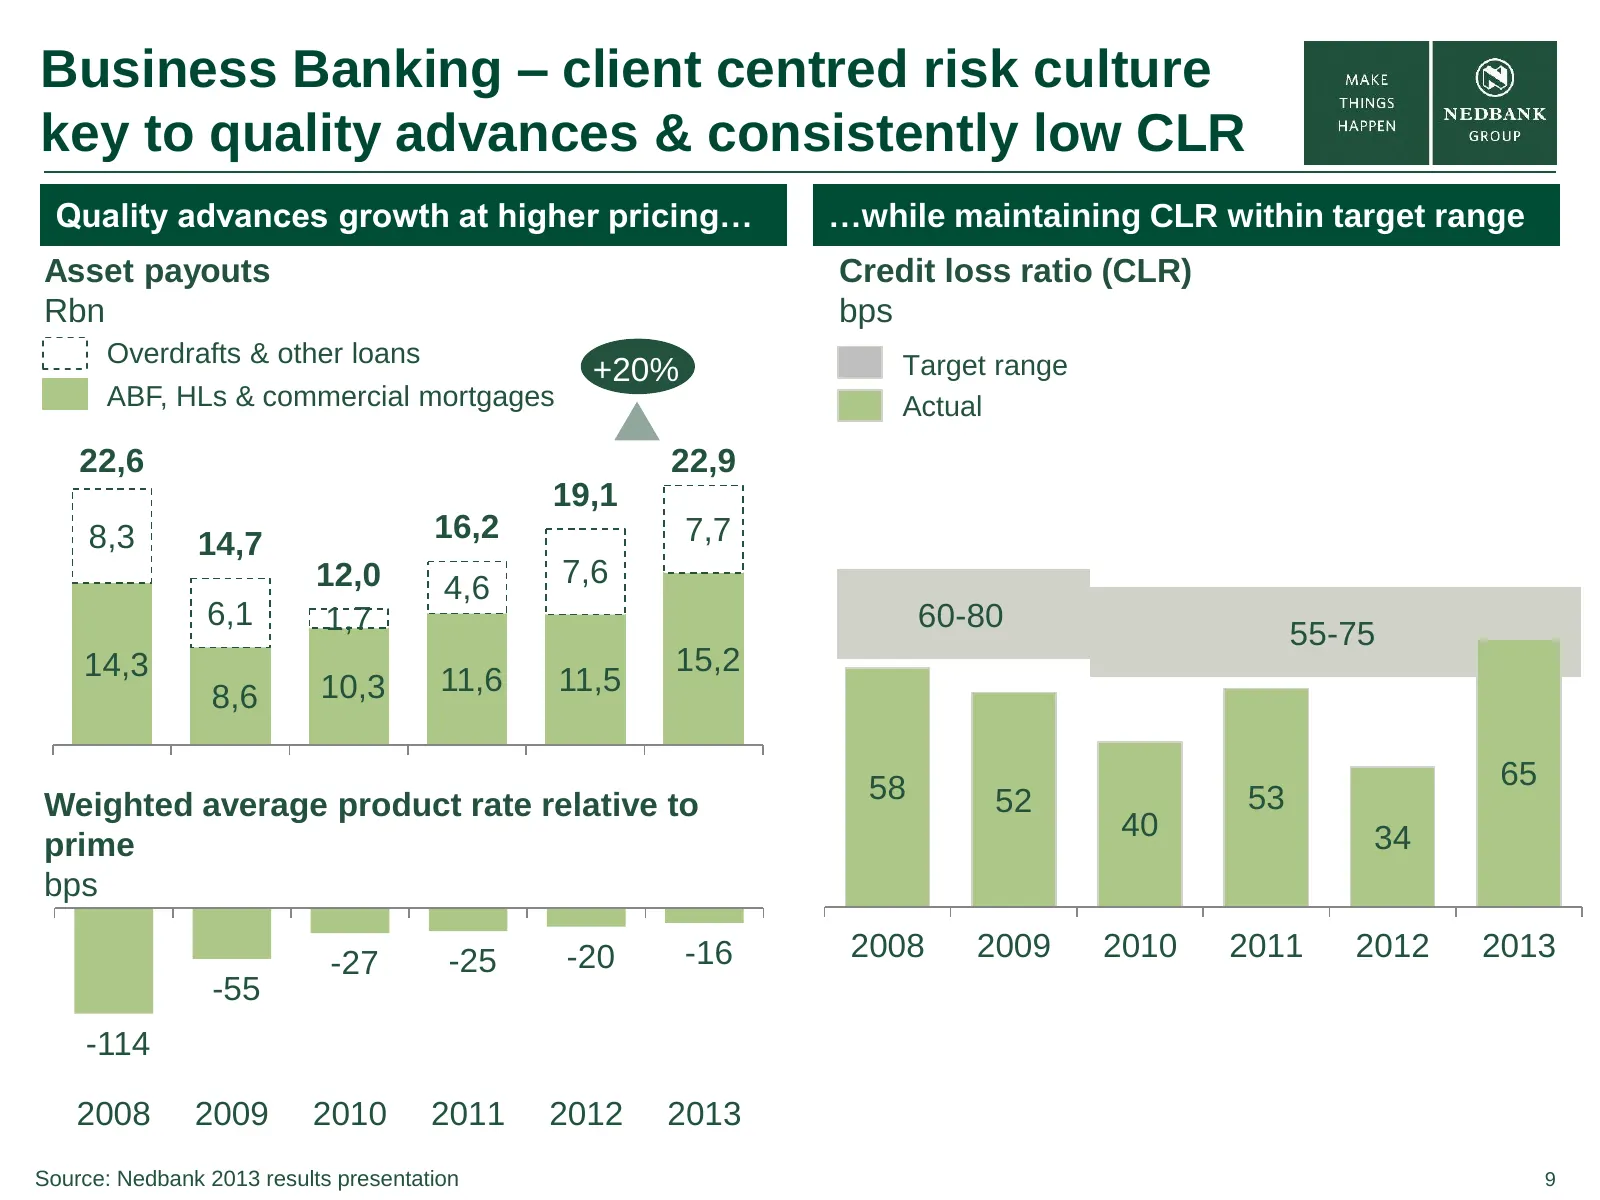
Slide 9: Business Banking – client centred risk culture
Business Banking – client centred risk culture key to quality advances & consistently low CLR Quality advances growth at higher pricing… …while maintaining CLR within target range Asset payouts Credit loss ratio (CLR) Rbn bps Overdrafts & other loans Target range +20% ABF, HLs & commercial mortgages
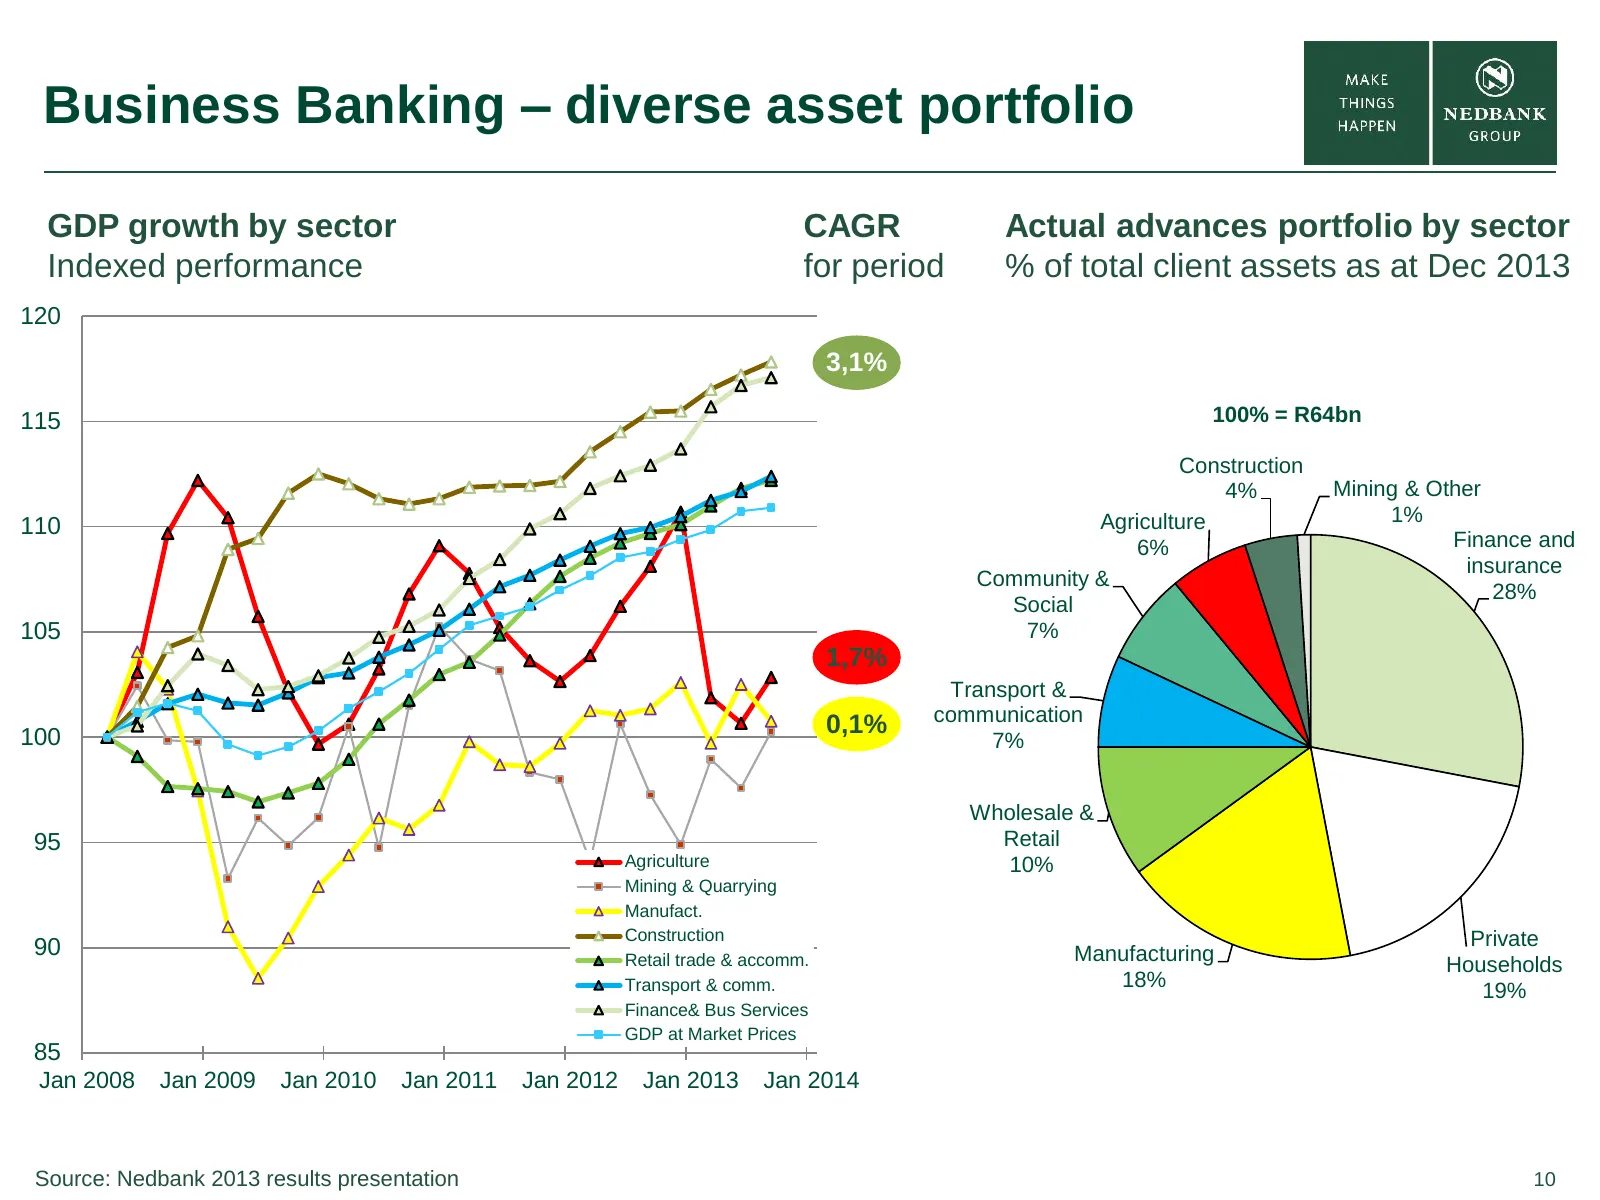
Slide 10: Business Banking – diverse asset portfolio
Business Banking – diverse asset portfolio GDP growth by sector CAGR Actual advances portfolio by sector Indexed performance for period % of total client assets as at Dec 2013 120 3,1% 115 100% = R64bn Construction 4% Mining & Other Agriculture 1% 110 6% Finance and insurance Community & 28% Social
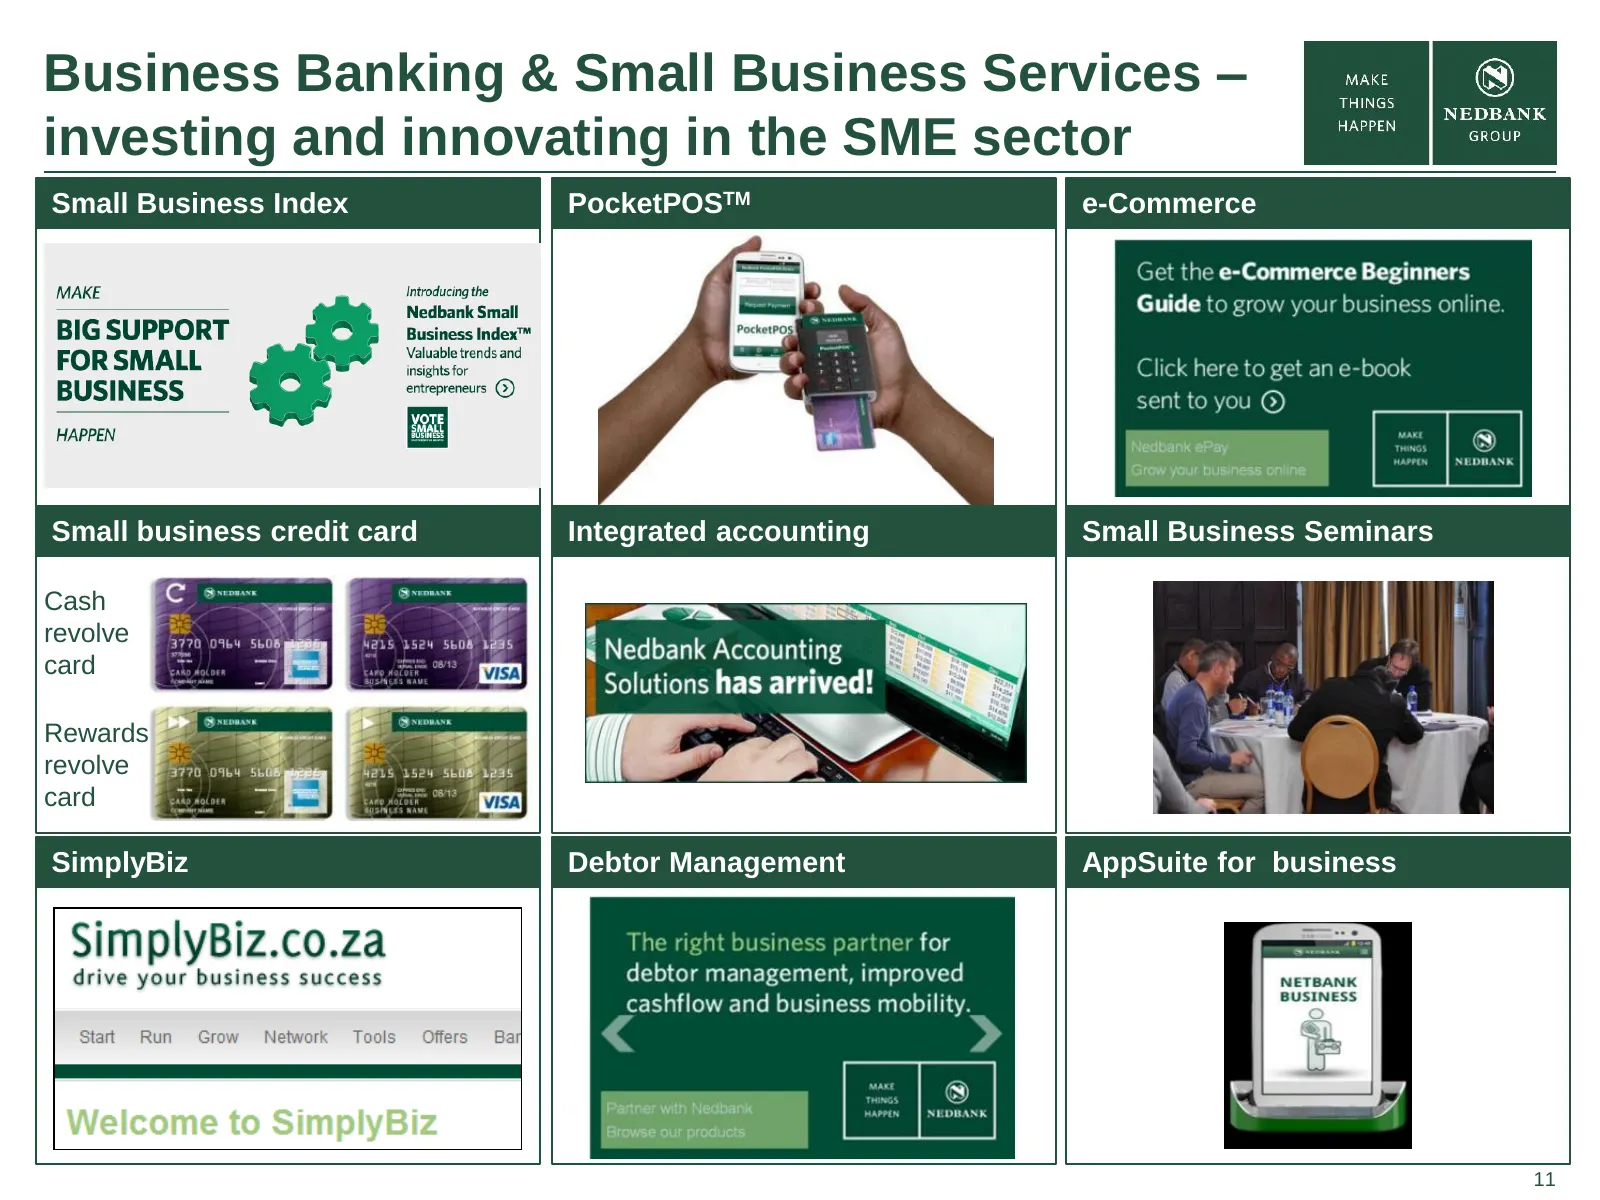
Slide 11: Business Banking & Small Business Services – investing and innovating in the SME sector
Business Banking & Small Business Services – investing and innovating in the SME sector Small Business Index PocketPOSTM e-Commerce Small business credit card Integrated accounting Small Business Seminars Cash revolve card Rewards revolve card SimplyBiz Debtor Management AppSuite for business 11
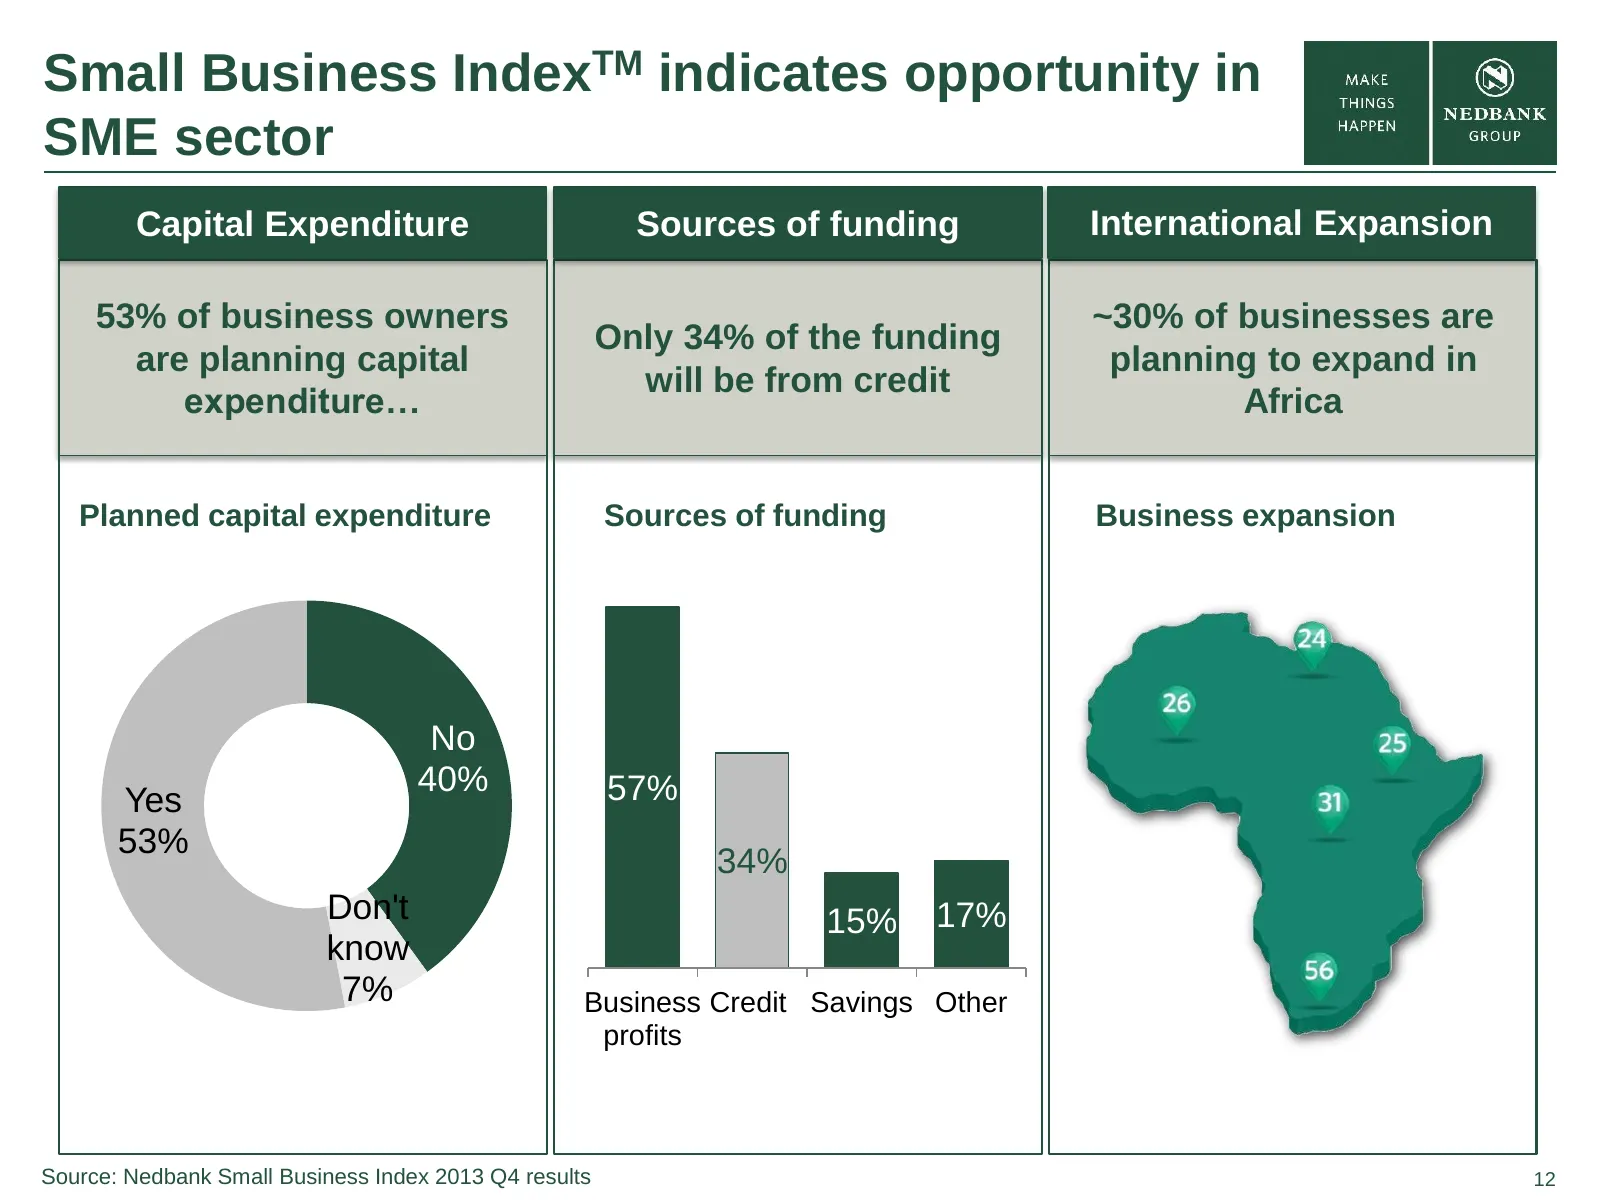
Slide 12: Small Business Index indicates opportunity in SME sector
Small Business IndexTM indicates opportunity in SME sector Capital Expenditure Sources of funding International Expansion 53% of business owners ~30% of businesses are Only 34% of the funding are planning capital planning to expand in will be from credit expenditure… Africa Planned capital expenditu
Slide 13: Small Business Services – well positioned for small business growth
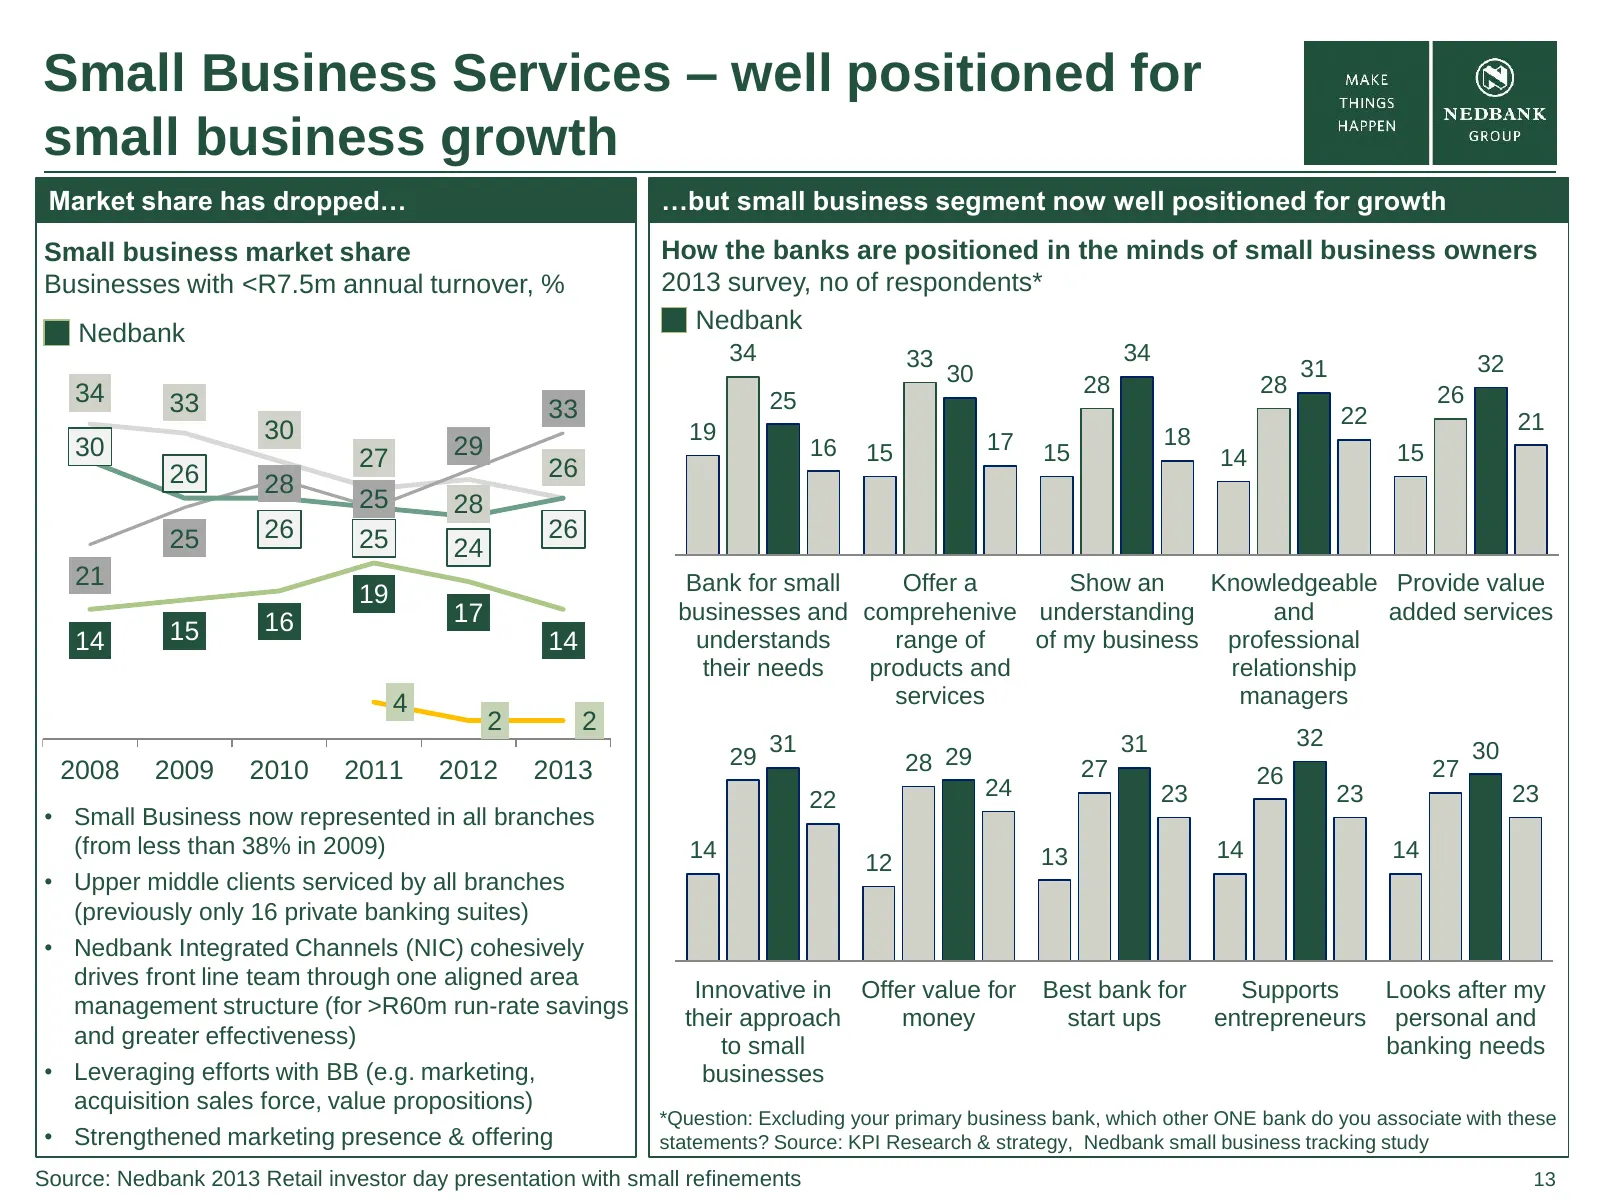
Small Business Services – well positioned for small business growth Market share has dropped… …but small business segment now well positioned for growth Small business market share How the banks are positioned in the minds of small business owners Businesses with <R7.5m annual turnover, % 2013 surve
Slide 14: Small Business Services – seamless professional offering to feed small business pipeline
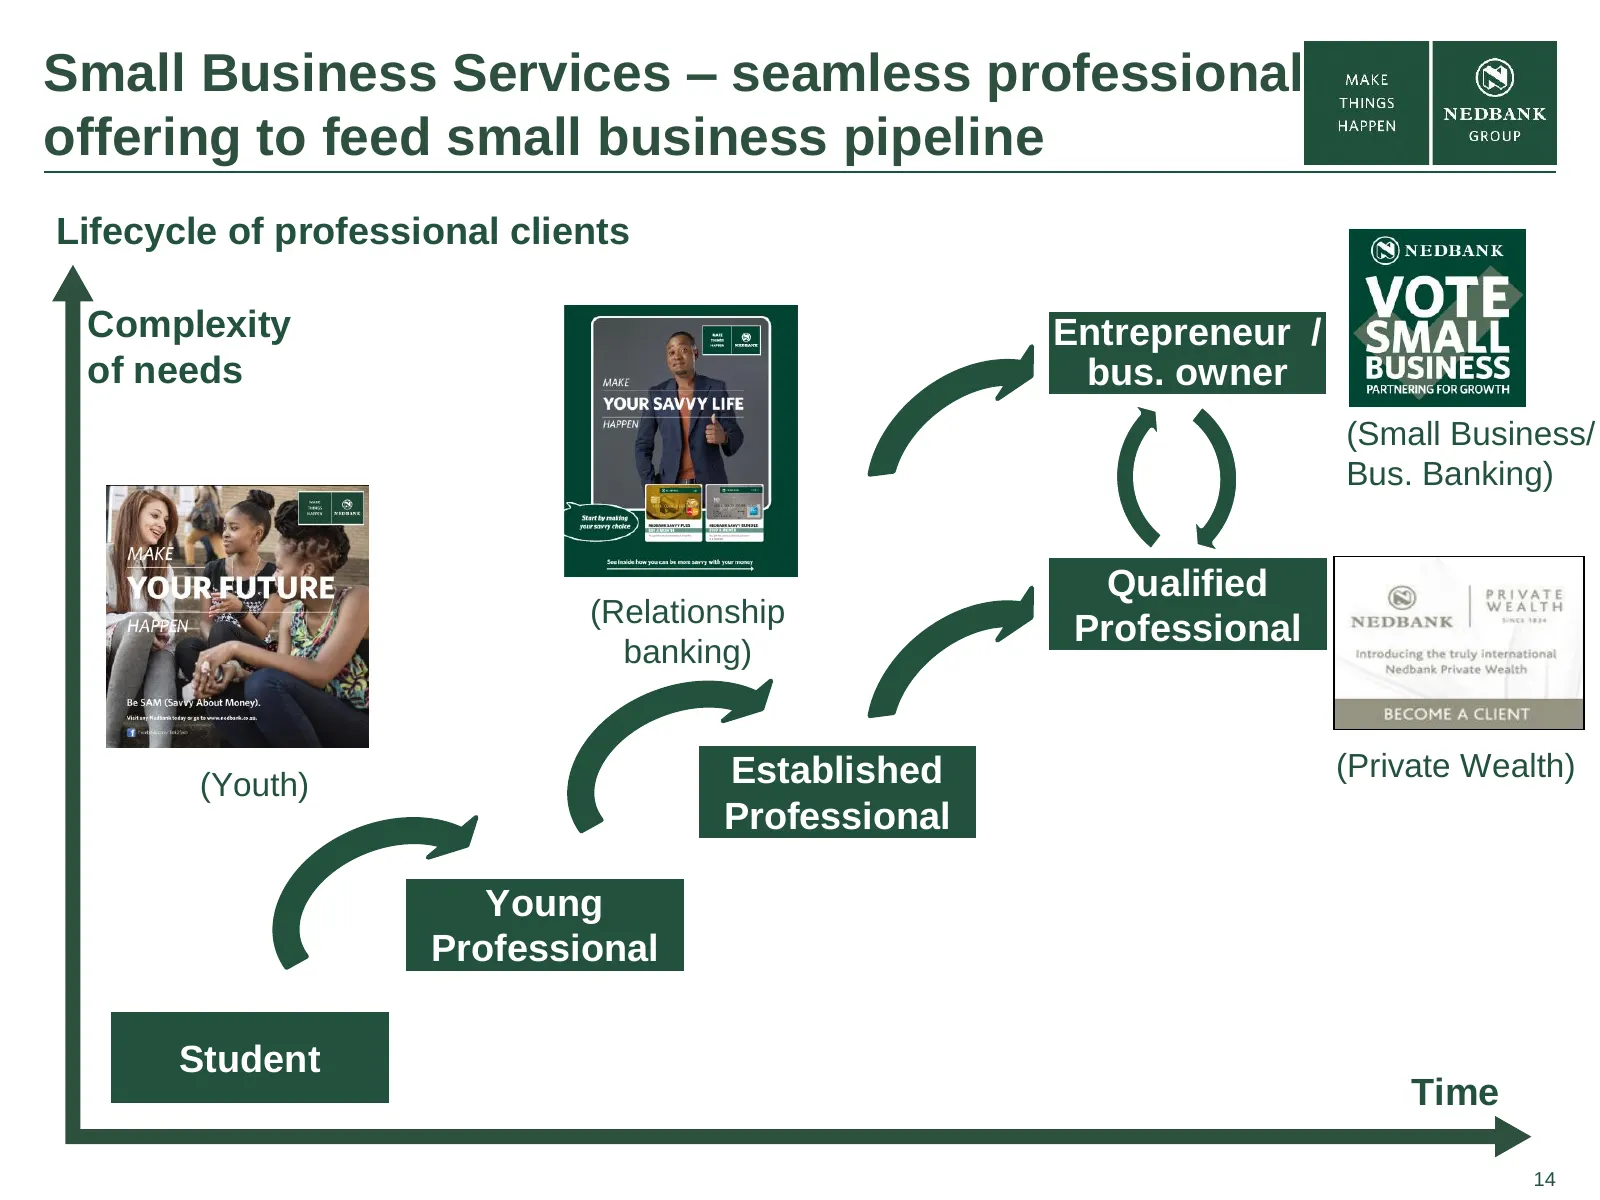
Small Business Services – seamless professional offering to feed small business pipeline Lifecycle of professional clients Complexity Entrepreneur / of needs bus. owner (Small Business/ Bus. Banking) Qualified (Relationship Professional banking) Established (Private Wealth) (Youth) Professional Youn
Slide 15: Retail & Business Banking – unlocking the virtuous circle of household & business
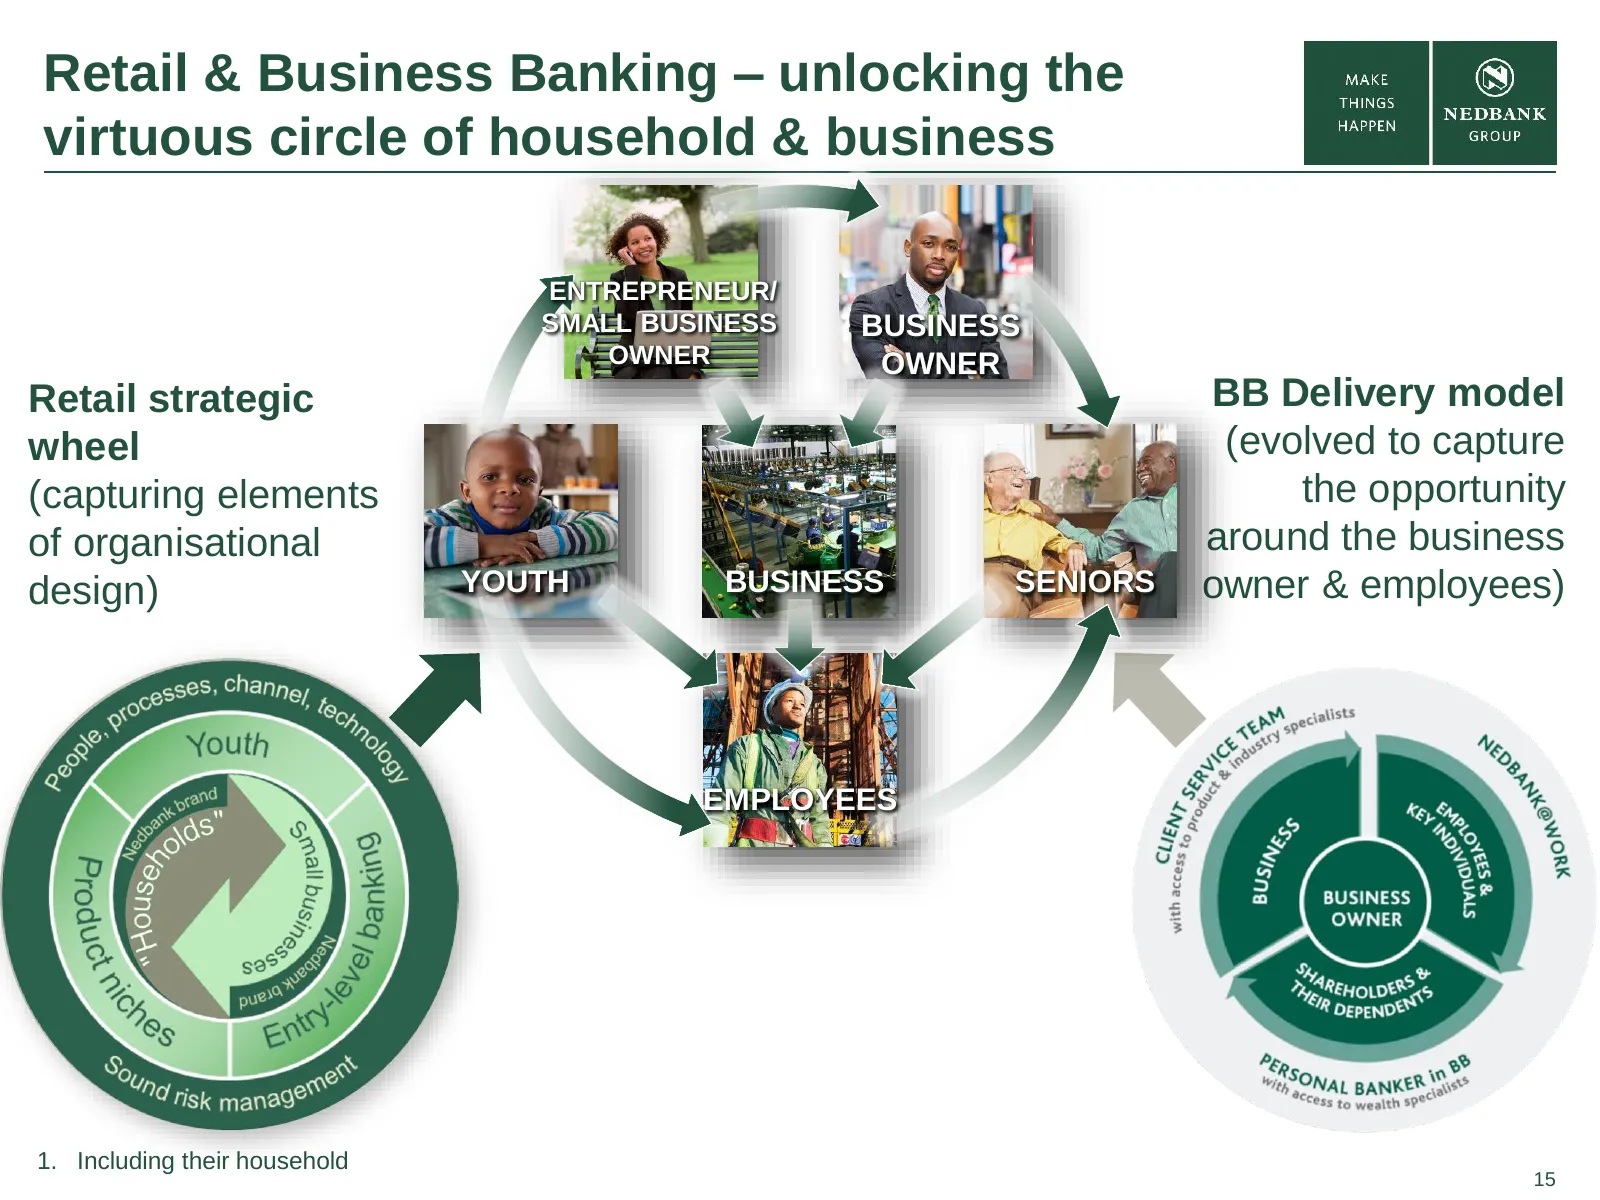
Retail & Business Banking – unlocking the virtuous circle of household & business ENTREPRENEUR/ SMALL BUSINESS BUSINESS OWNER OWNER Retail strategic BB Delivery model wheel (evolved to capture (capturing elements the opportunity of organisational around the business design) YOUTH BUSINESS SENIORS ow
Slide 16: Retail & Business Banking – leveraging key trends for distinctive positioning
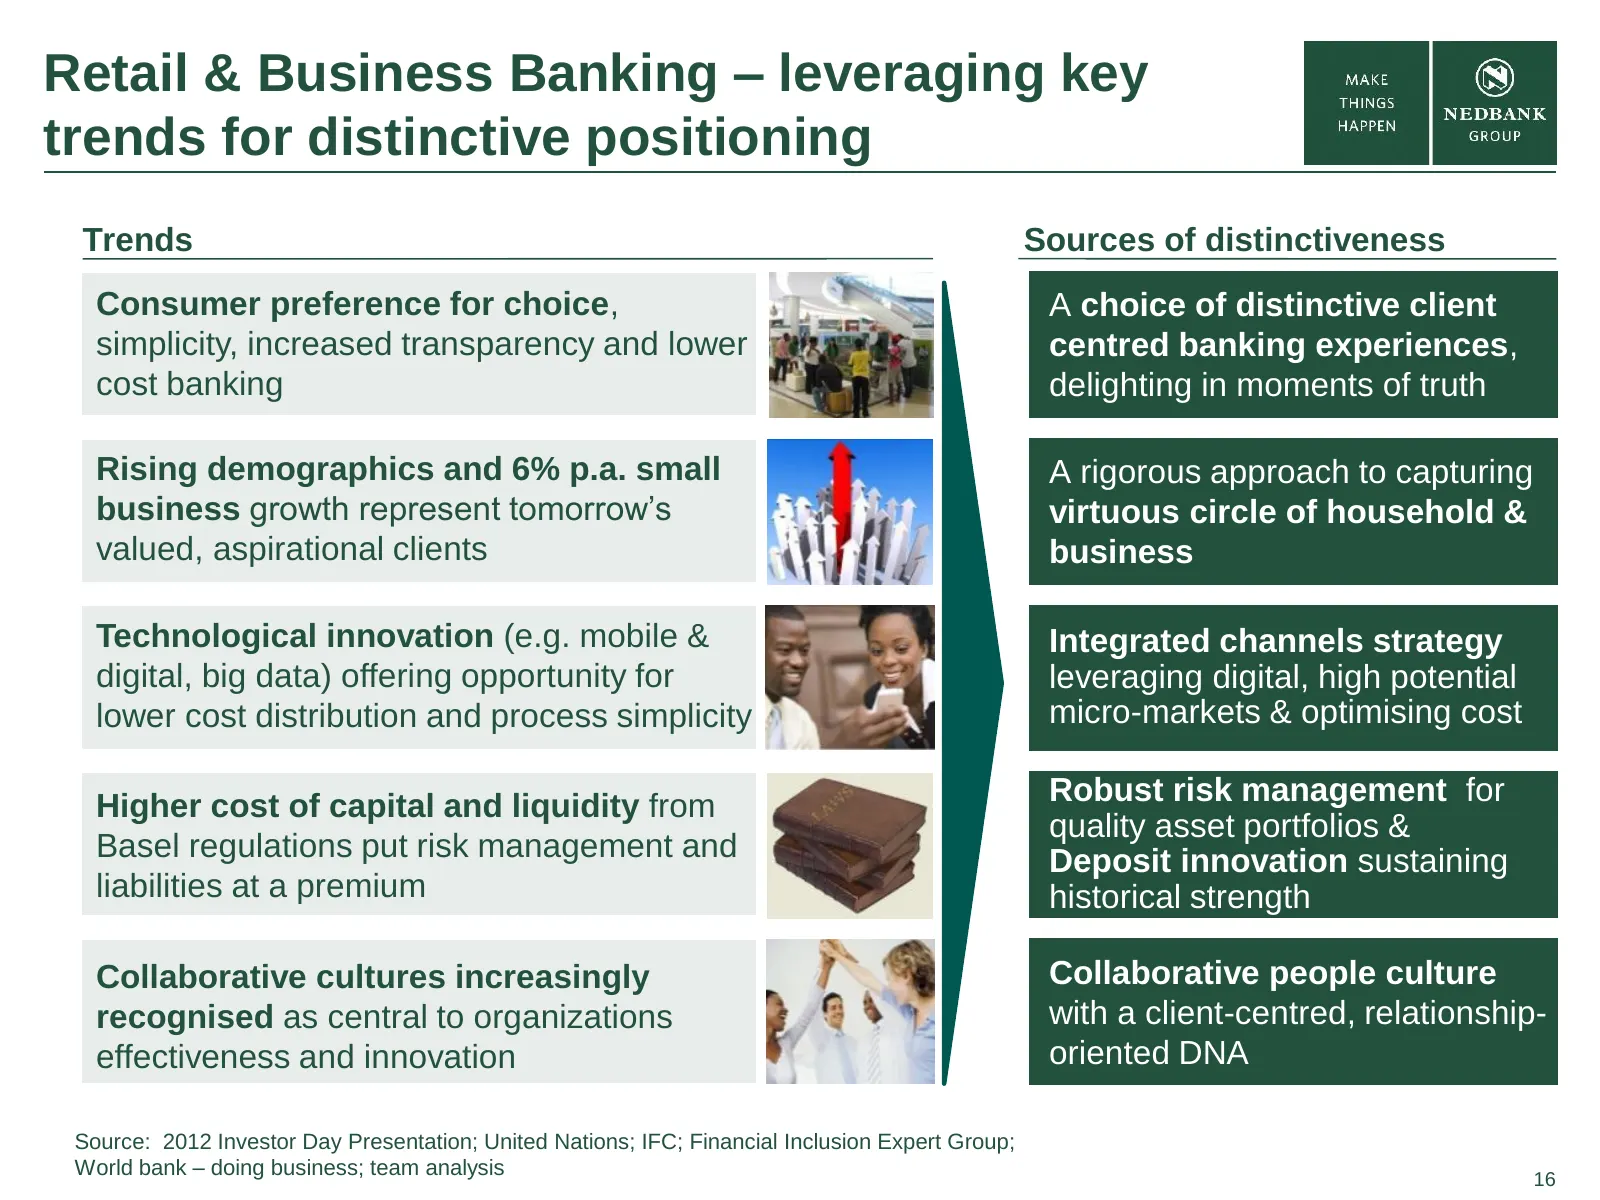
Retail & Business Banking – leveraging key trends for distinctive positioning Trends Sources of distinctiveness Consumer preference for choice, A choice of distinctive client simplicity, increased transparency and lower centred banking experiences, cost banking delighting in moments of truth Rising
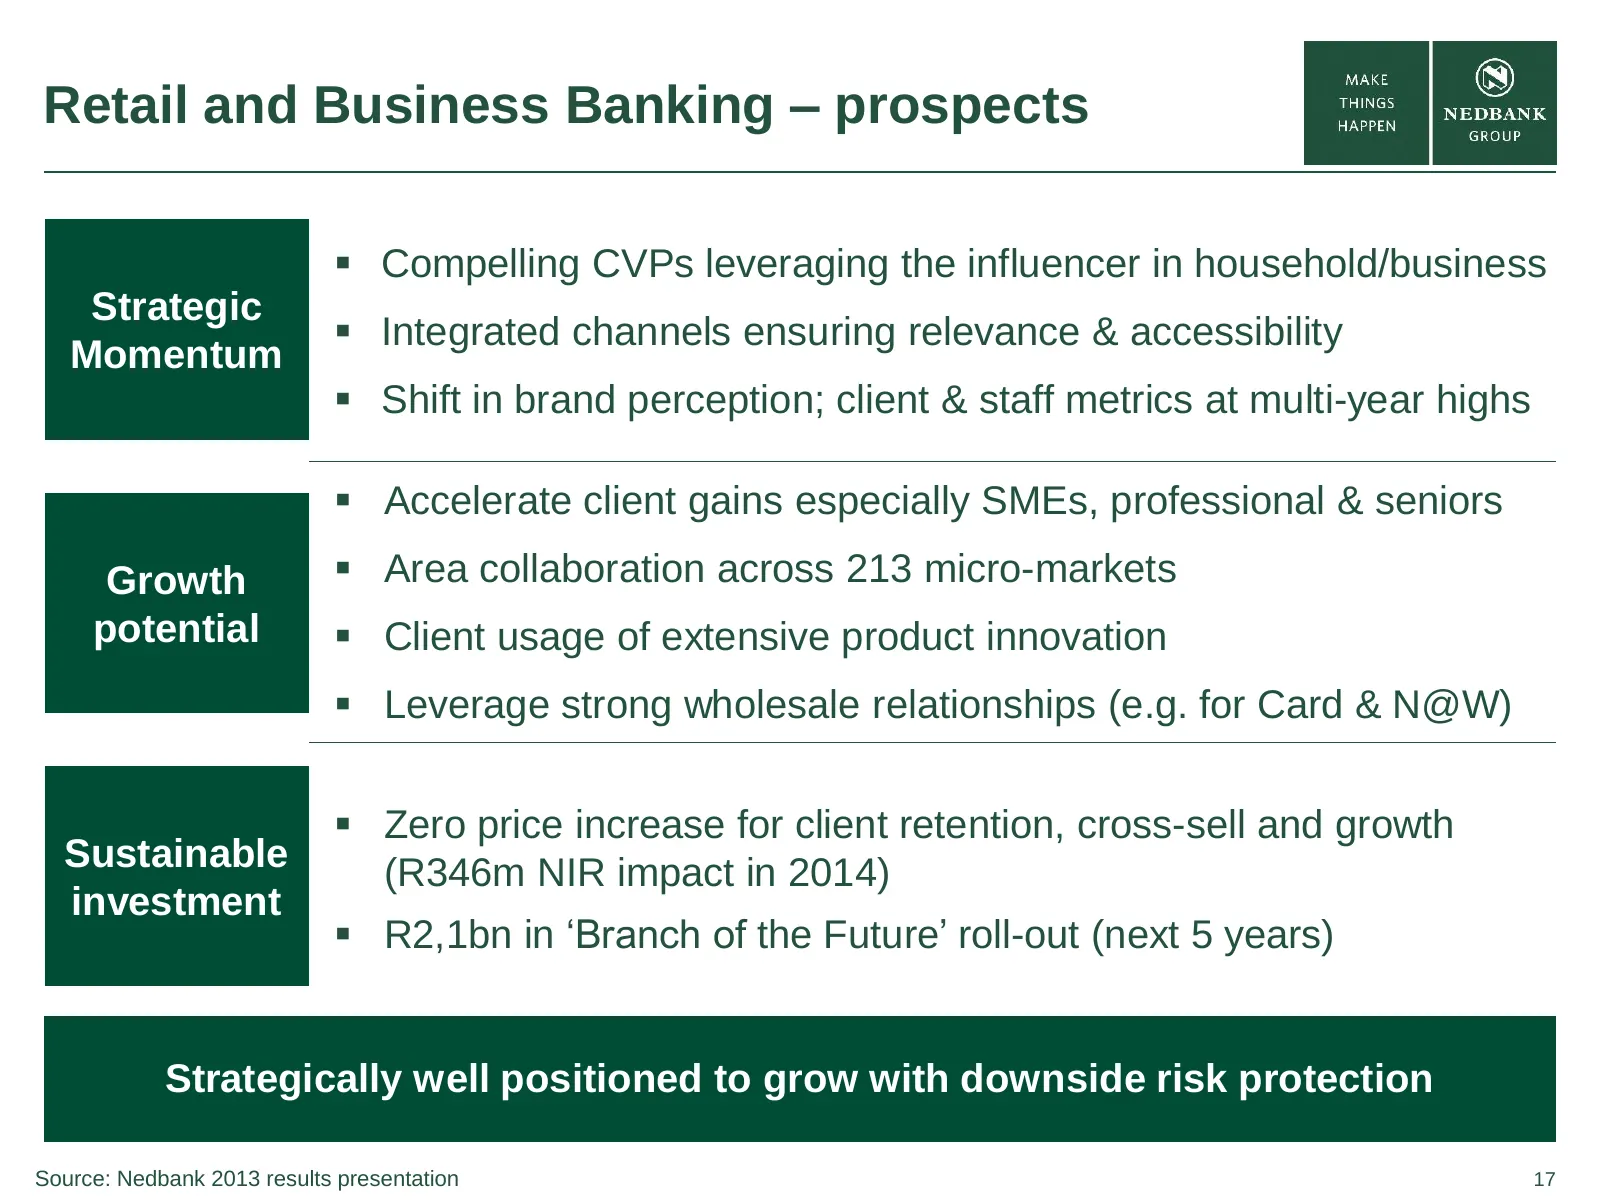
Slide 17: Retail and Business Banking – prospects
Retail and Business Banking – prospects Compelling CVPs leveraging the influencer in household/business Strategic Integrated channels ensuring relevance & accessibility Momentum Shift in brand perception; client & staff metrics at multi-year highs Accelerate client gains especially SMEs, pro
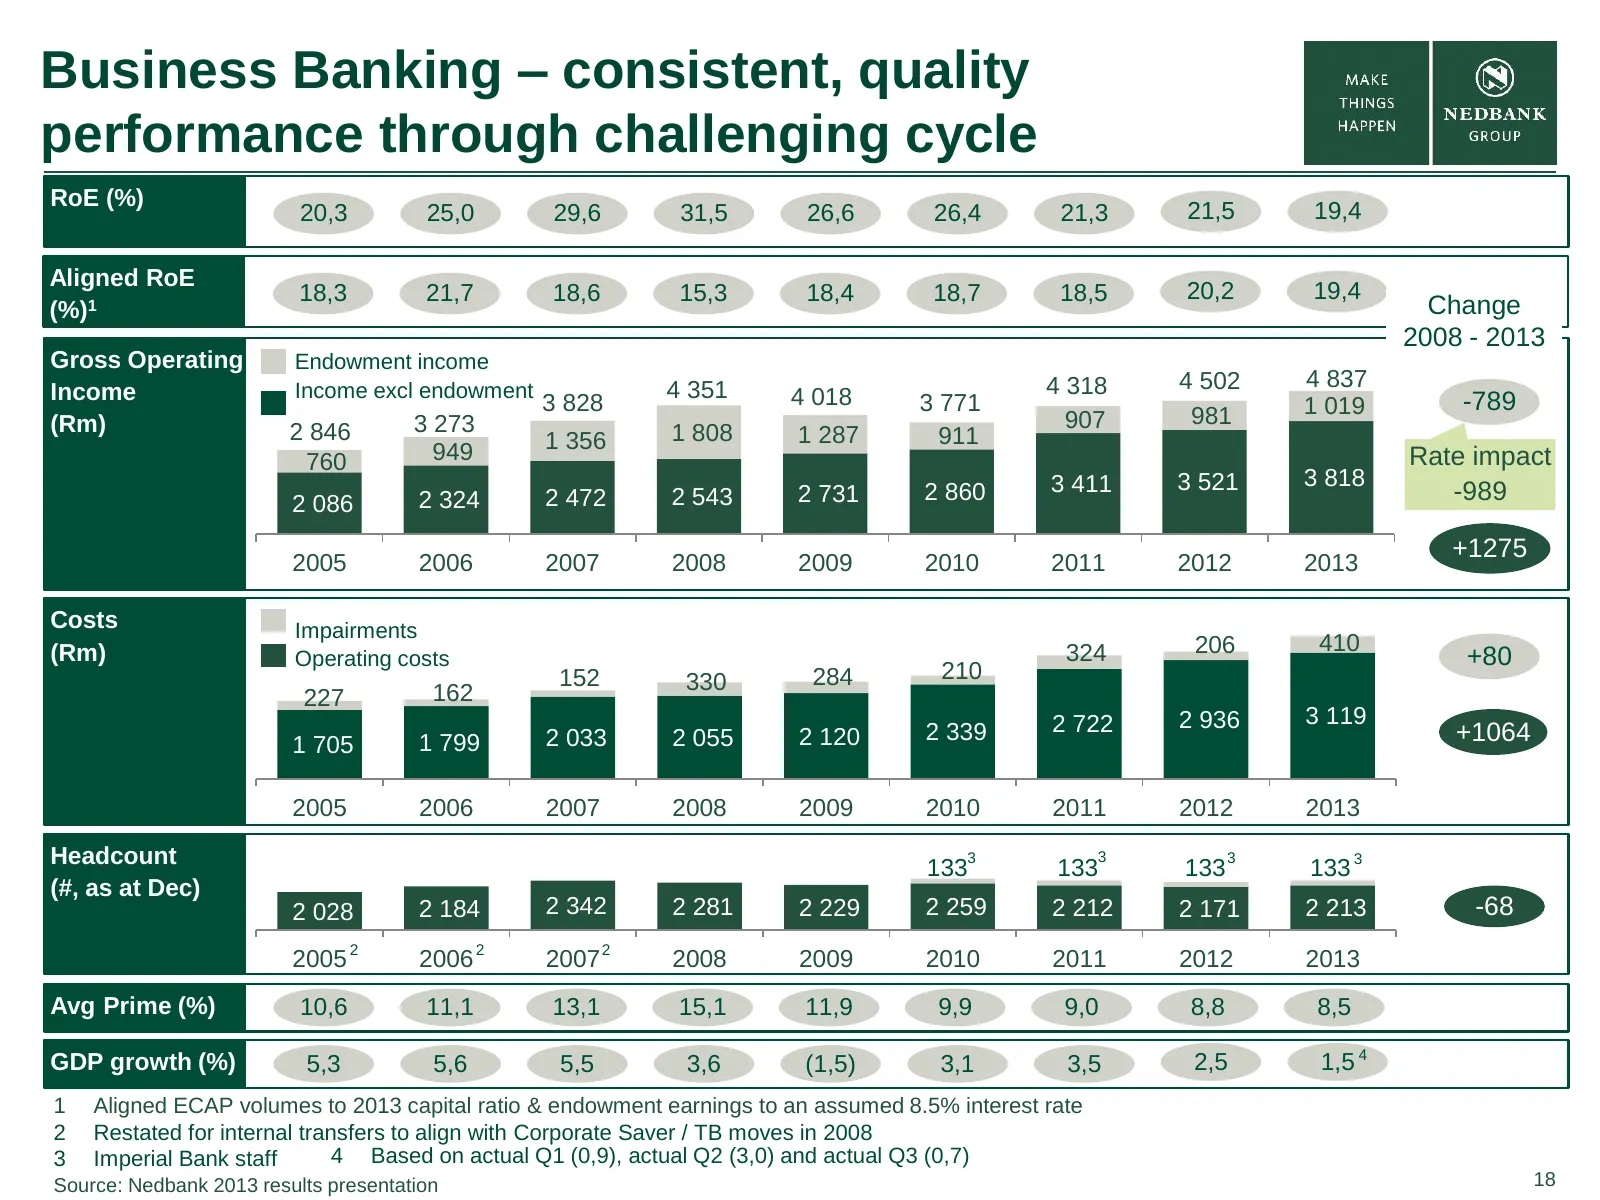
Slide 18: Business Banking – consistent, quality performance through challenging cycle
Business Banking – consistent, quality performance through challenging cycle RoE (%) 20,3 25,0 29,6 31,5 26,6 26,4 21,3 21,5 19,4 Aligned RoE 18,3 21,7 18,6 15,3 18,4 18,7 18,5 20,2 19,4 (%)1 Change 2008 - 2013 Gross Operating Endowment income Income excl endowment 4 351 4 318 4 502 4 837 Income 3 8
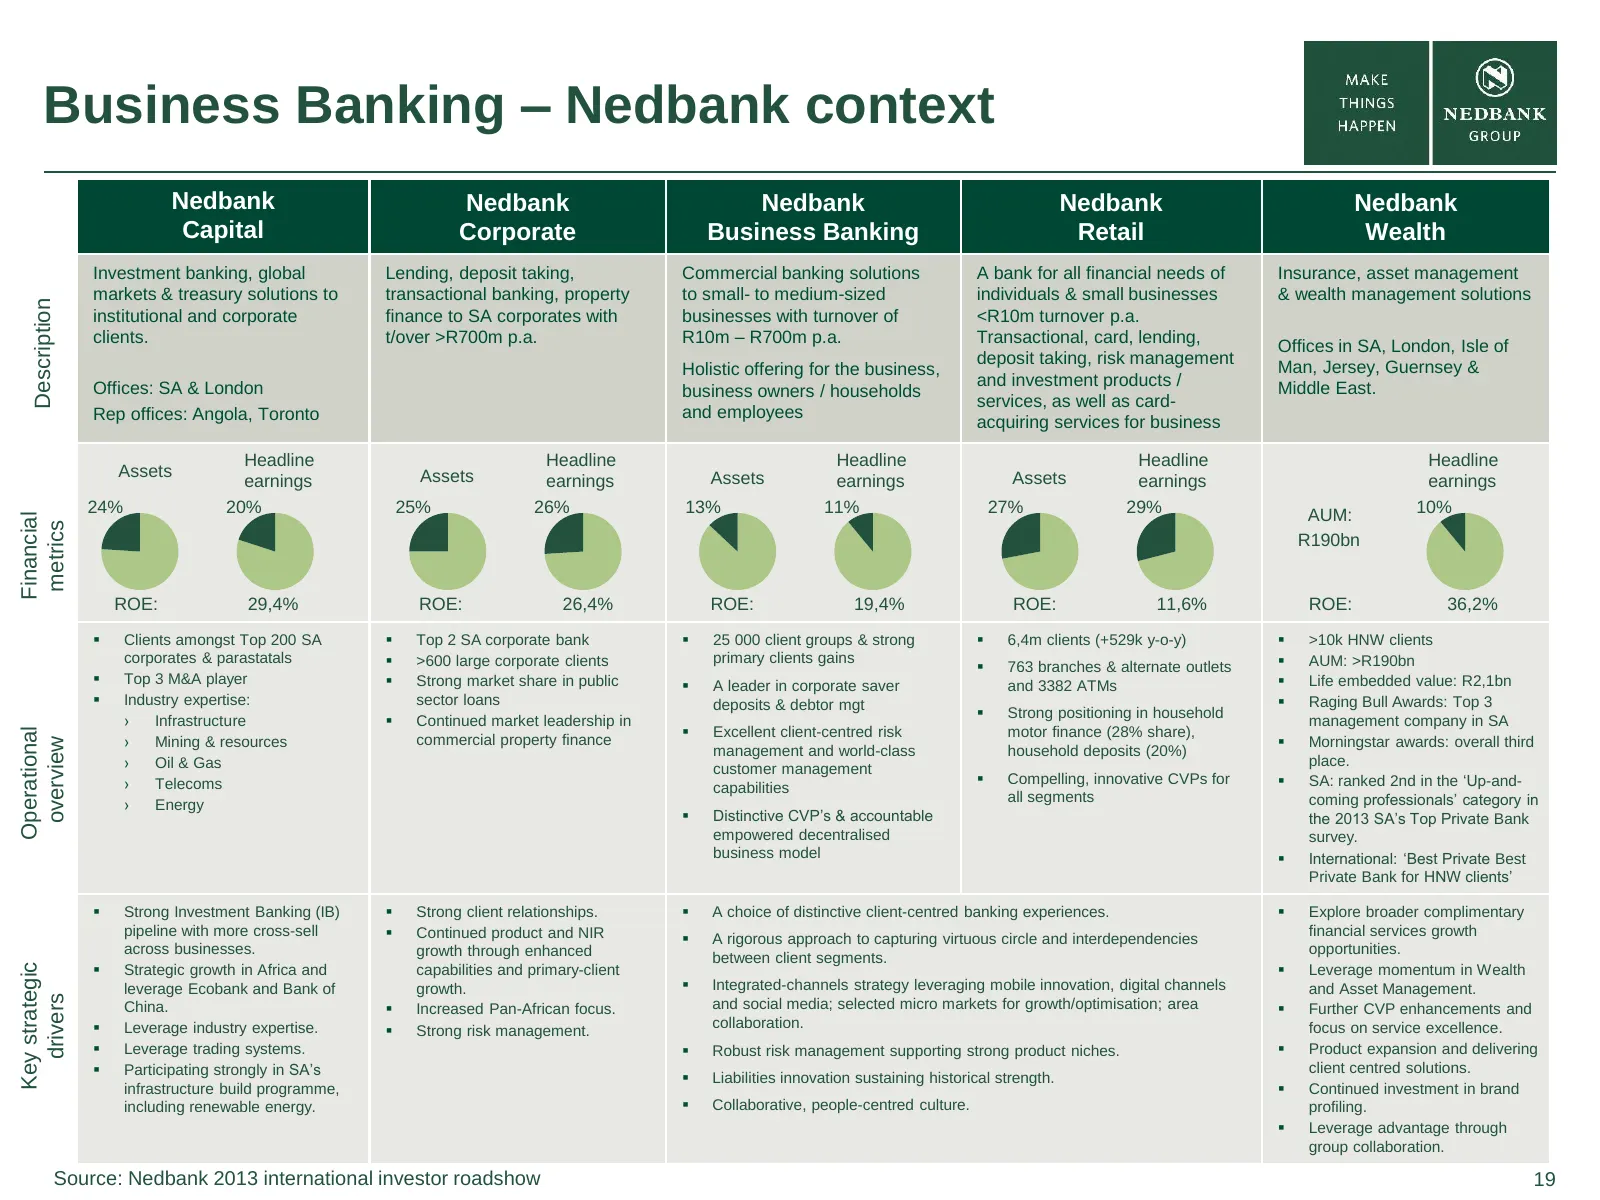
Slide 19: Nedbank operational context
Business Banking – Nedbank context Nedbank Nedbank Nedbank Nedbank Nedbank Capital Corporate Business Banking Retail Wealth Investment banking, global Lending, deposit taking, Commercial banking solutions A bank for all financial needs of Insurance, asset management markets & treasury solutions to t
Slide 20: Contact us & Disclaimer
Contact us & Disclaimer Nedbank Group Nedbank Investor Relations www.nedbankgroup.co.za Head of Investor Relations Nedbank Group Limited Alfred Visagie Tel: +27 (0) 11 294 4444 Direct tel: +27 (0) 11 295 6249 Physical address Cell: +27 (0) 82 855 4692 135 Rivonia Road Email: AlfredV@nedbank.co.za Sa
Source: Internet Archive copy of nedbank.co.za
More decks from Nedbank Group
 FY2025 Earnings Presentation50 slides · February 2026
 FY2024 Earnings Presentation63 slides · March 2025
 27th UBS SA Financial Services Conference 202424 slides · October 2024
 Investor Presentation (October 2024)20 slides · October 2024
 Emerge — Nedbank Investment Conference (2024)22 slides · Sep 10, 2024
 H1 2024 Earnings Presentation85 slides · Aug 6, 2024