NatWest Group PLC · LSE:NWG
NatWest — Investor Day (June 2021)
45 slides from NatWest's investor day presentation, Jun 29, 2021
Slide 1: Retail and Private Banking Investor Spotlight
Retail and Private Banking Investor Spotlight 29th June 2021
Slide 2: Forward-looking statements
Forward-looking statements The guidance, targets, expectations and trends discussed in this presentation represent NatWest Group management’s current ex pectations and are subject to change, including as a result of the factors described in the “Risk Factors” on pages 345-362 of the NatWest Group pl
Slide 3: David Lindberg, Retail Banking CEO
David Lindberg Retail Banking CEO 3
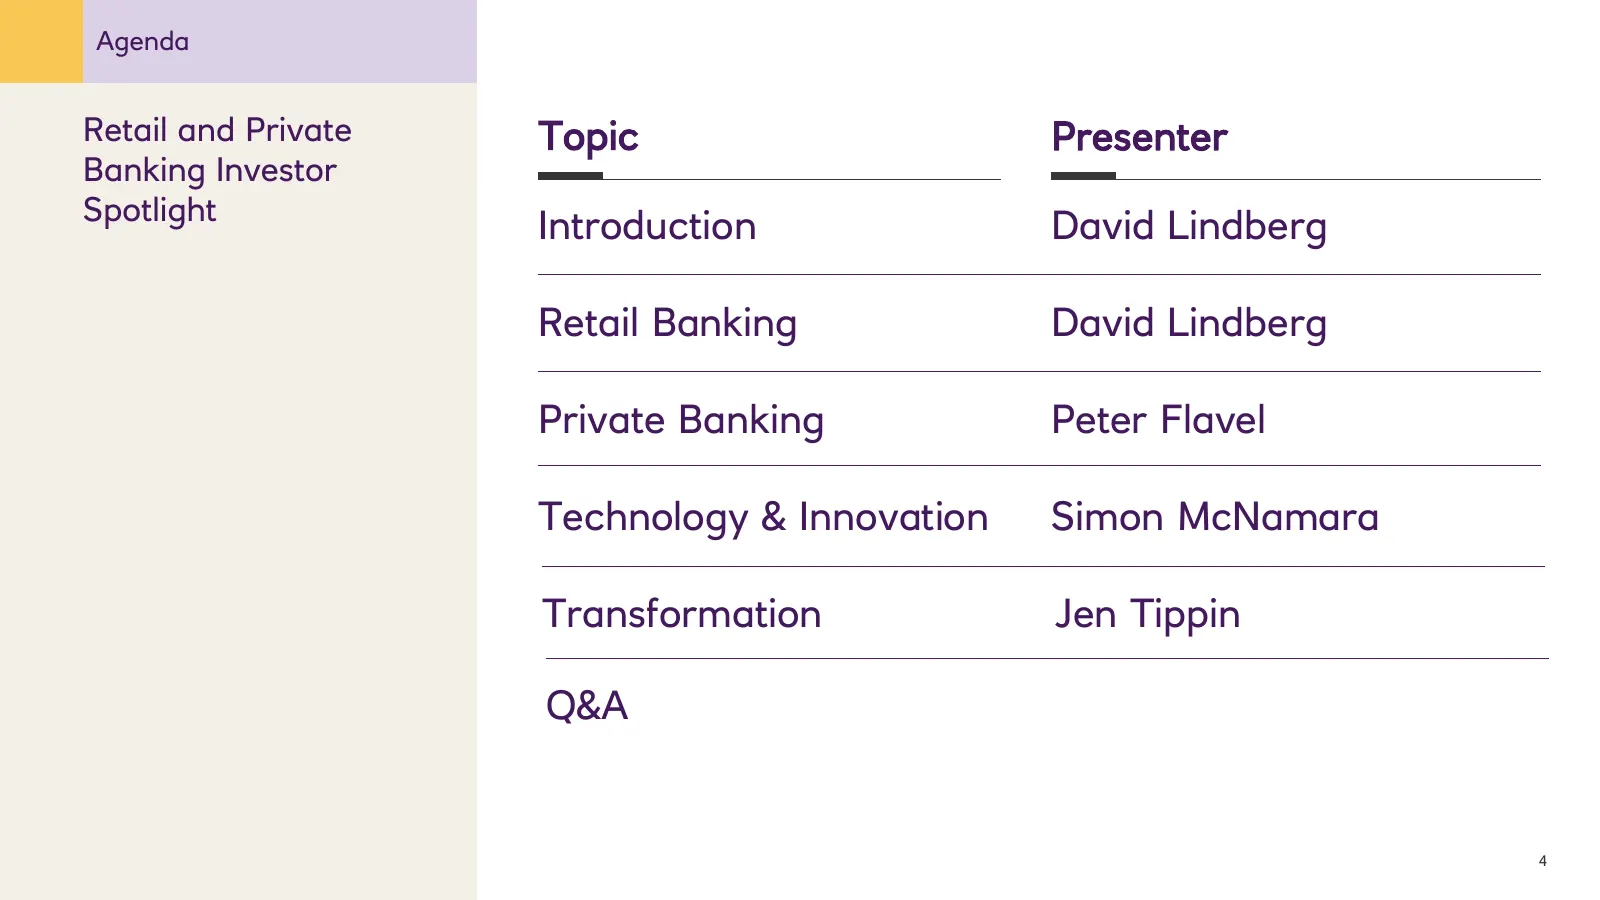
Slide 4: Agenda
Agenda Retail and Private Topic Presenter Banking Investor Spotlight Introduction David Lindberg Retail Banking David Lindberg Private Banking Peter Flavel Technology & Innovation Simon McNamara Transformation Jen Tippin Q&A 4
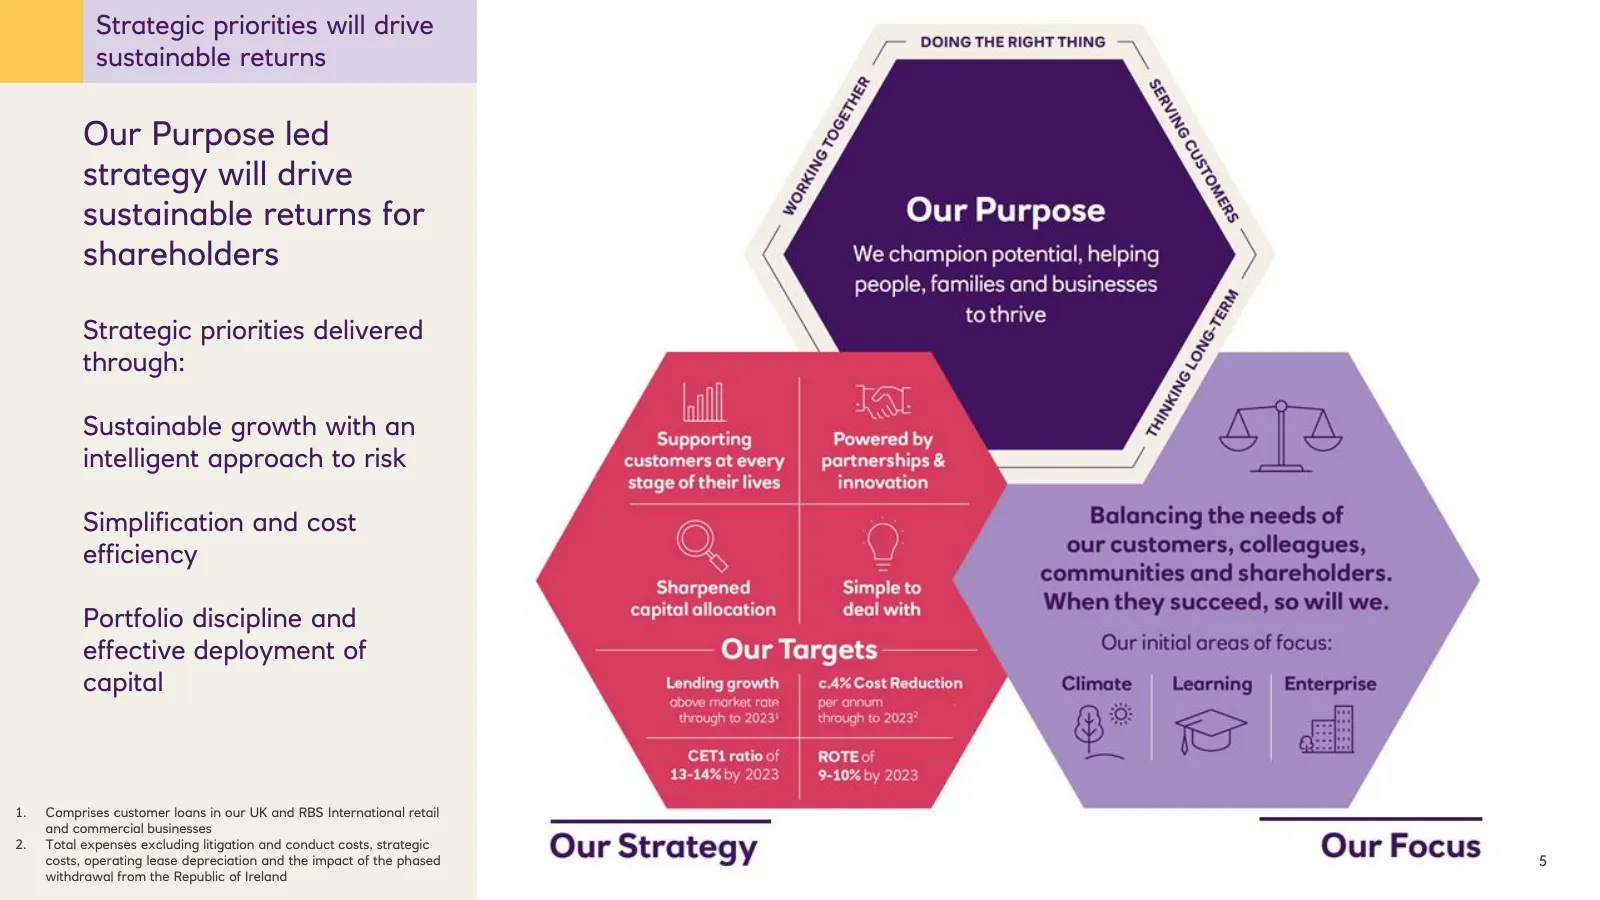
Slide 5: Strategic priorities will drive sustainable returns
Strategic priorities will drive sustainable returns Our Purpose led strategy will drive sustainable returns for shareholders Strategic priorities delivered through: Sustainable growth with an intelligent approach to risk Simplification and cost efficiency Portfolio discipline and effective deploymen
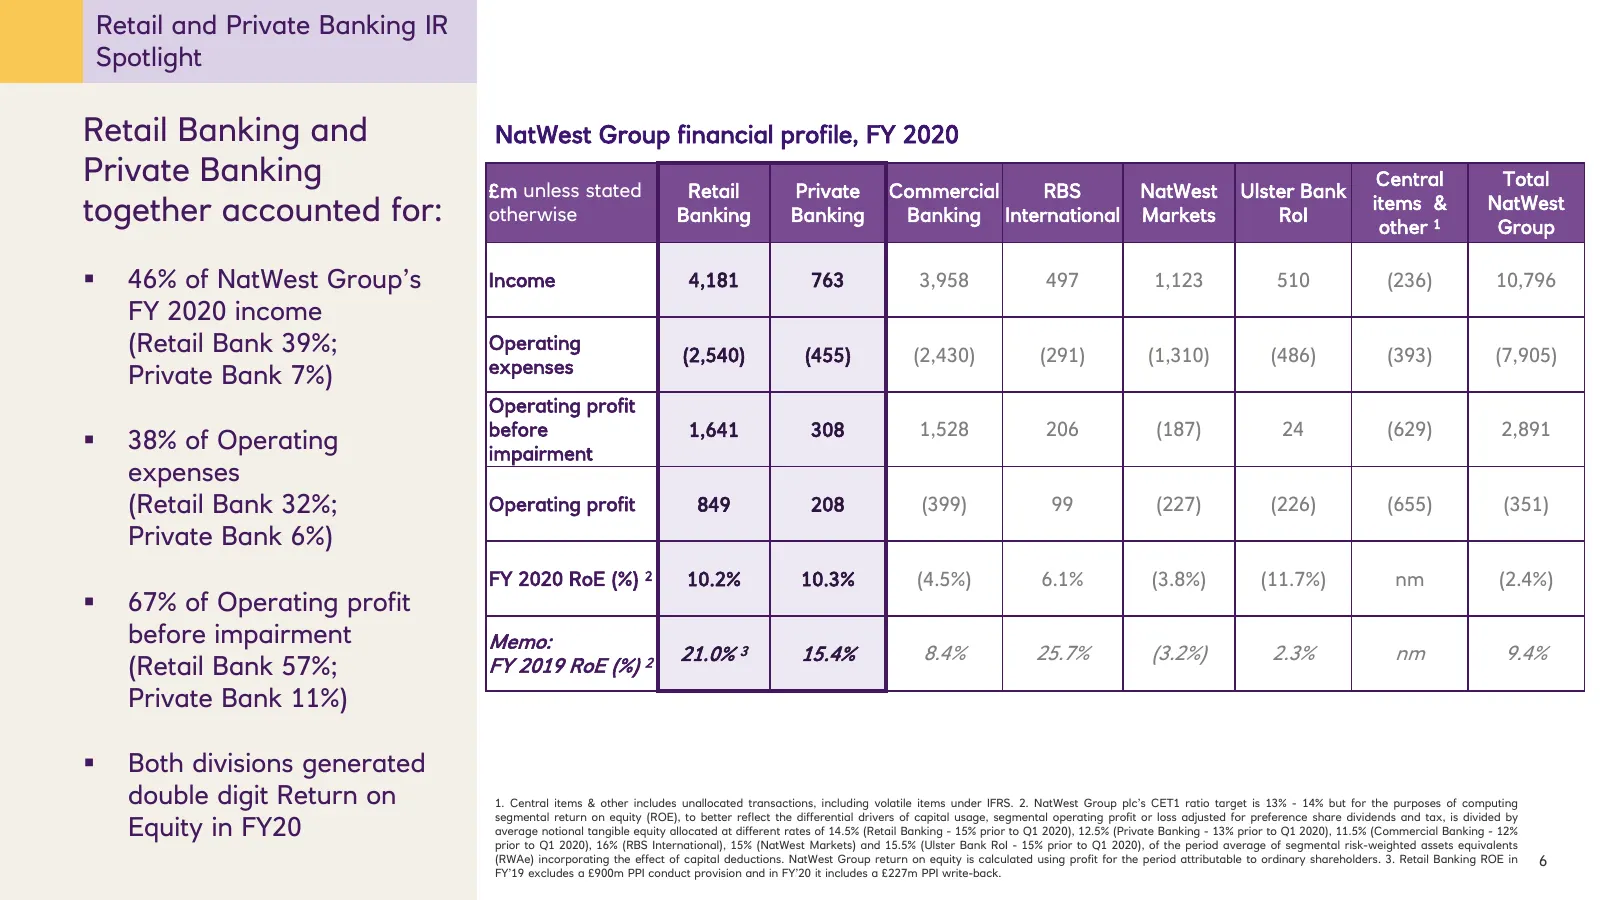
Slide 6: Retail and Private Banking financial profile, FY 2020
Retail and Private Banking IR Spotlight Retail Banking and NatWest Group financial profile, FY 2020 Private Banking £m unless stated Retail Private Commercial RBS NatWest Ulster Bank Central Total together accounted for: otherwise Banking Banking Banking International Markets RoI items & other 1 Nat
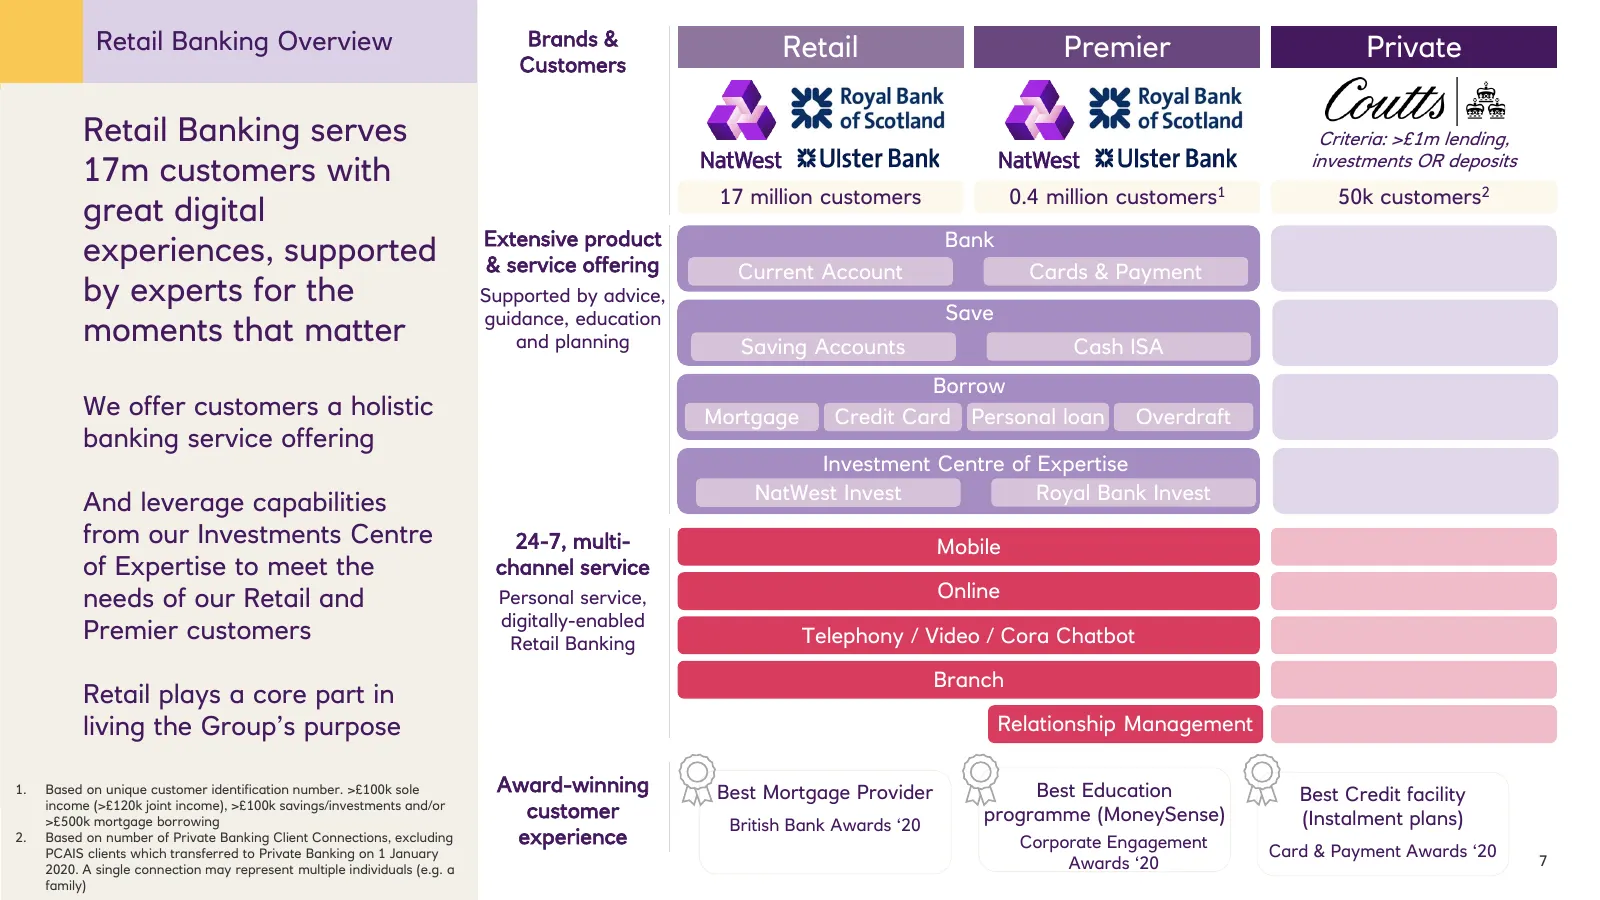
Slide 7: Retail Banking serves 17m customers with great digital experiences
Retail Banking Overview Brands & Retail Premier Private Customers Retail Banking serves Criteria: >£1m lending, investments OR deposits 17m customers with 17 million customers 0.4 million customers1 50k customers2 great digital Extensive product Bank experiences, supported & service offering Current
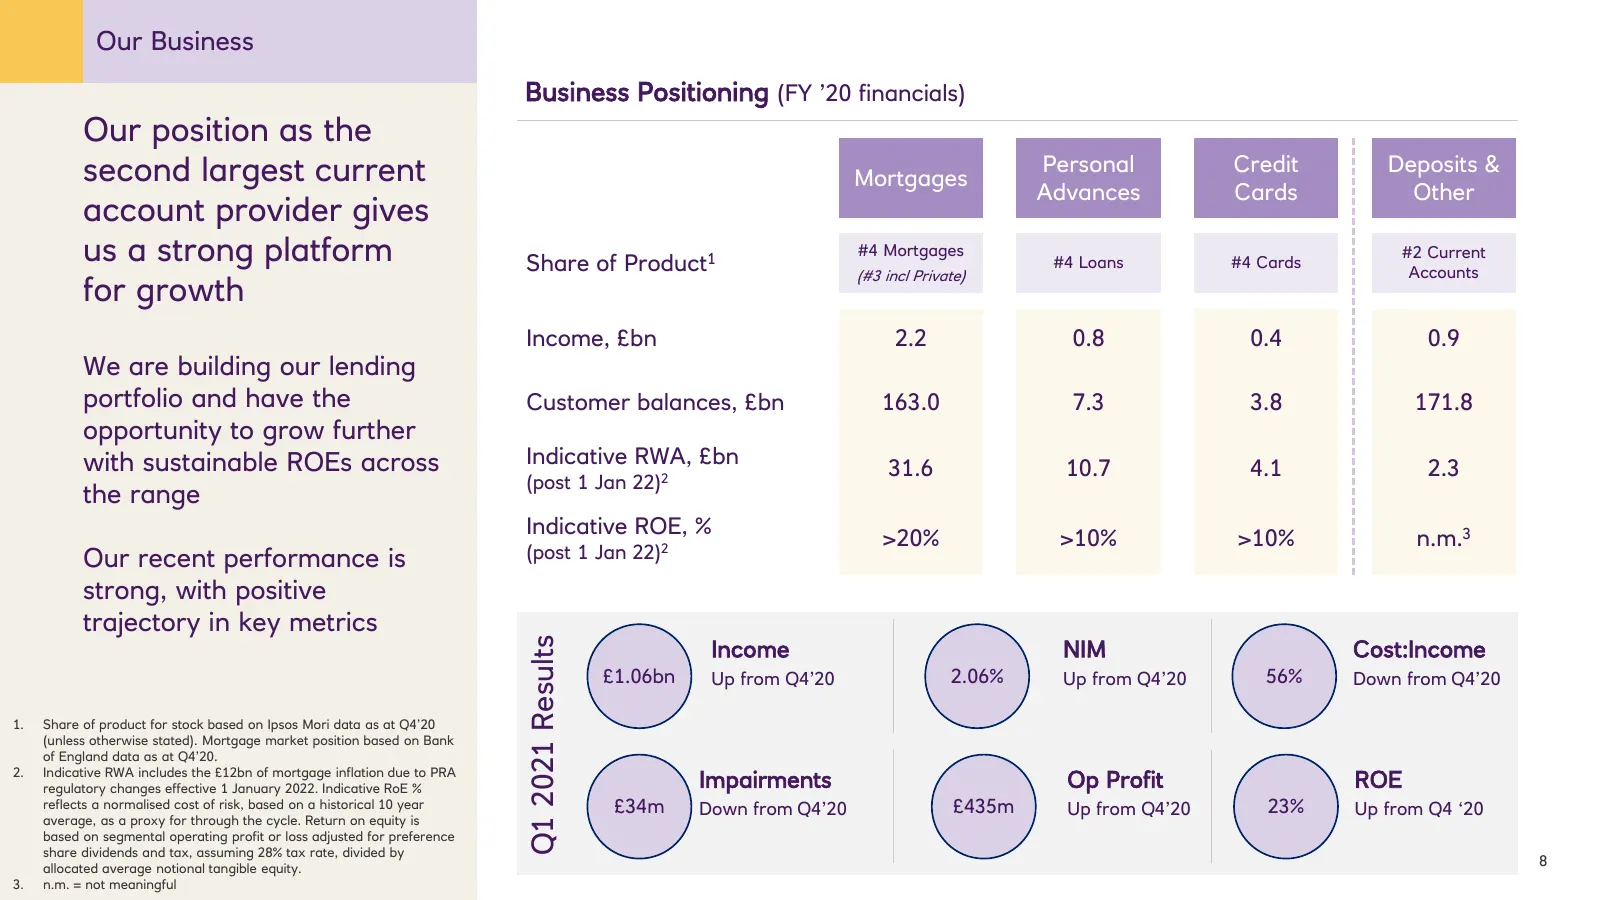
Slide 8: Our Business
Our Business Business Positioning (FY ’20 financials) Our position as the second largest current Mortgages Personal Credit Deposits & Advances Cards Other account provider gives us a strong platform Share of Product1 #4 Mortgages #4 Loans #4 Cards #2 Current (#3 incl Private) Accounts for growth Inc
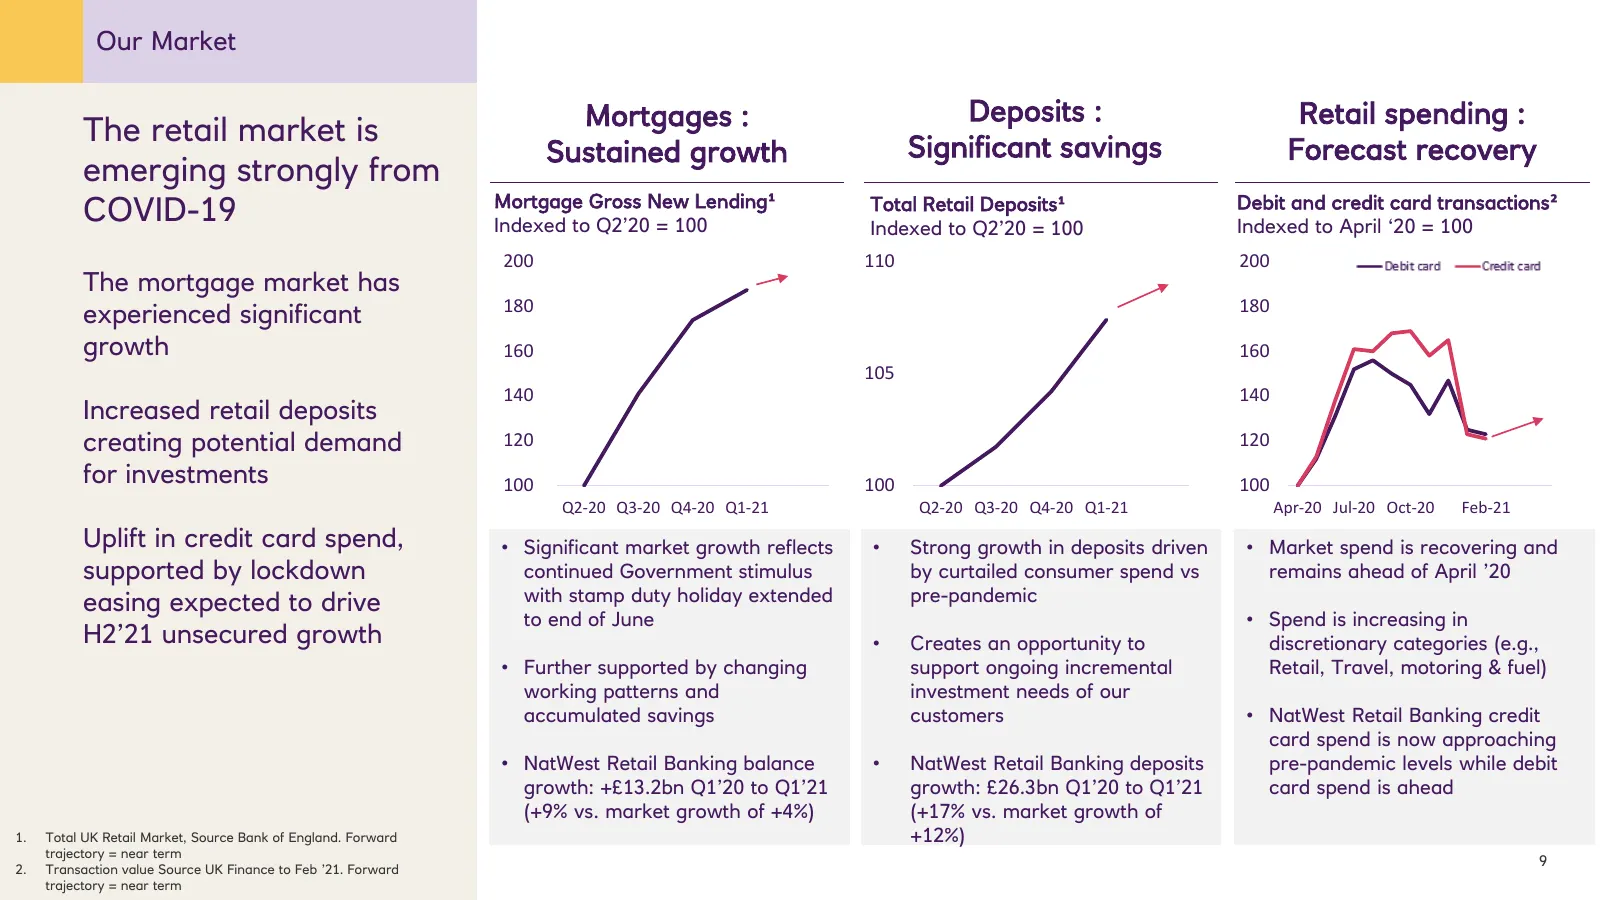
Slide 9: The retail market is emerging strongly from COVID-19
Our Market Mortgages : Deposits : Retail spending : The retail market is Significant savings Sustained growth Forecast recovery emerging strongly from Mortgage Gross New Lending¹ COVID-19 Indexed to Q2’20 = 100 Total Retail Deposits¹ Indexed to Q2’20 = 100 Debit and credit card transactions² Indexed
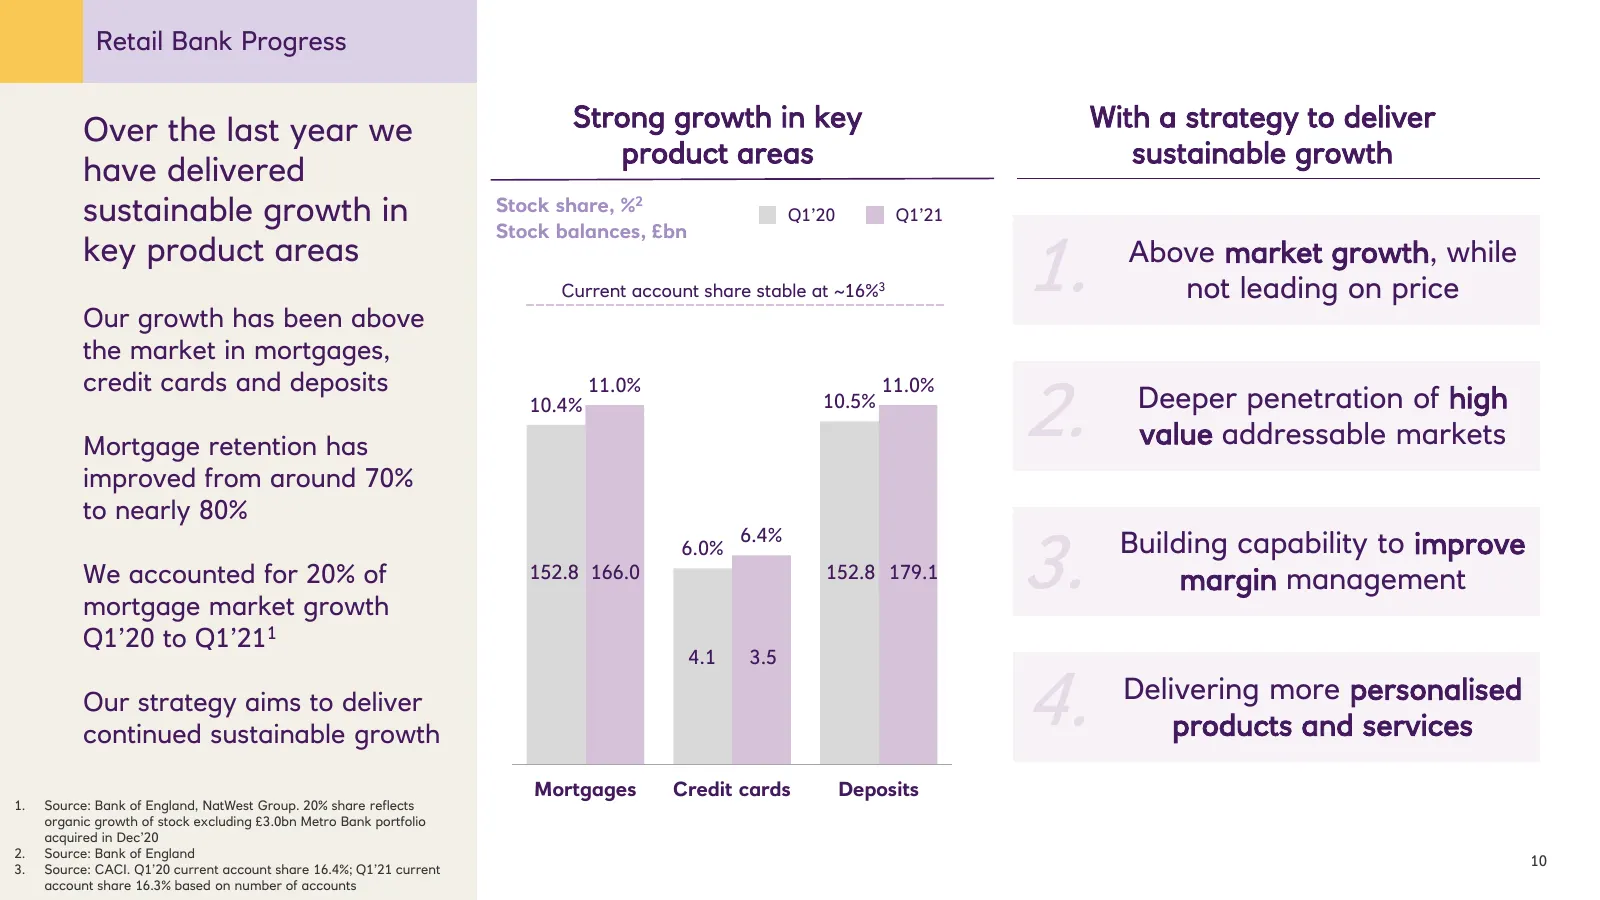
Slide 10: Retail Bank Progress
Retail Bank Progress Over the last year we Strong growth in key With a strategy to deliver product areas sustainable growth have delivered sustainable growth in Stock share, %2 Q1’20 Q1’21 1. Stock balances, £bn key product areas Above market growth, while Current account share stable at ~16%3 not l
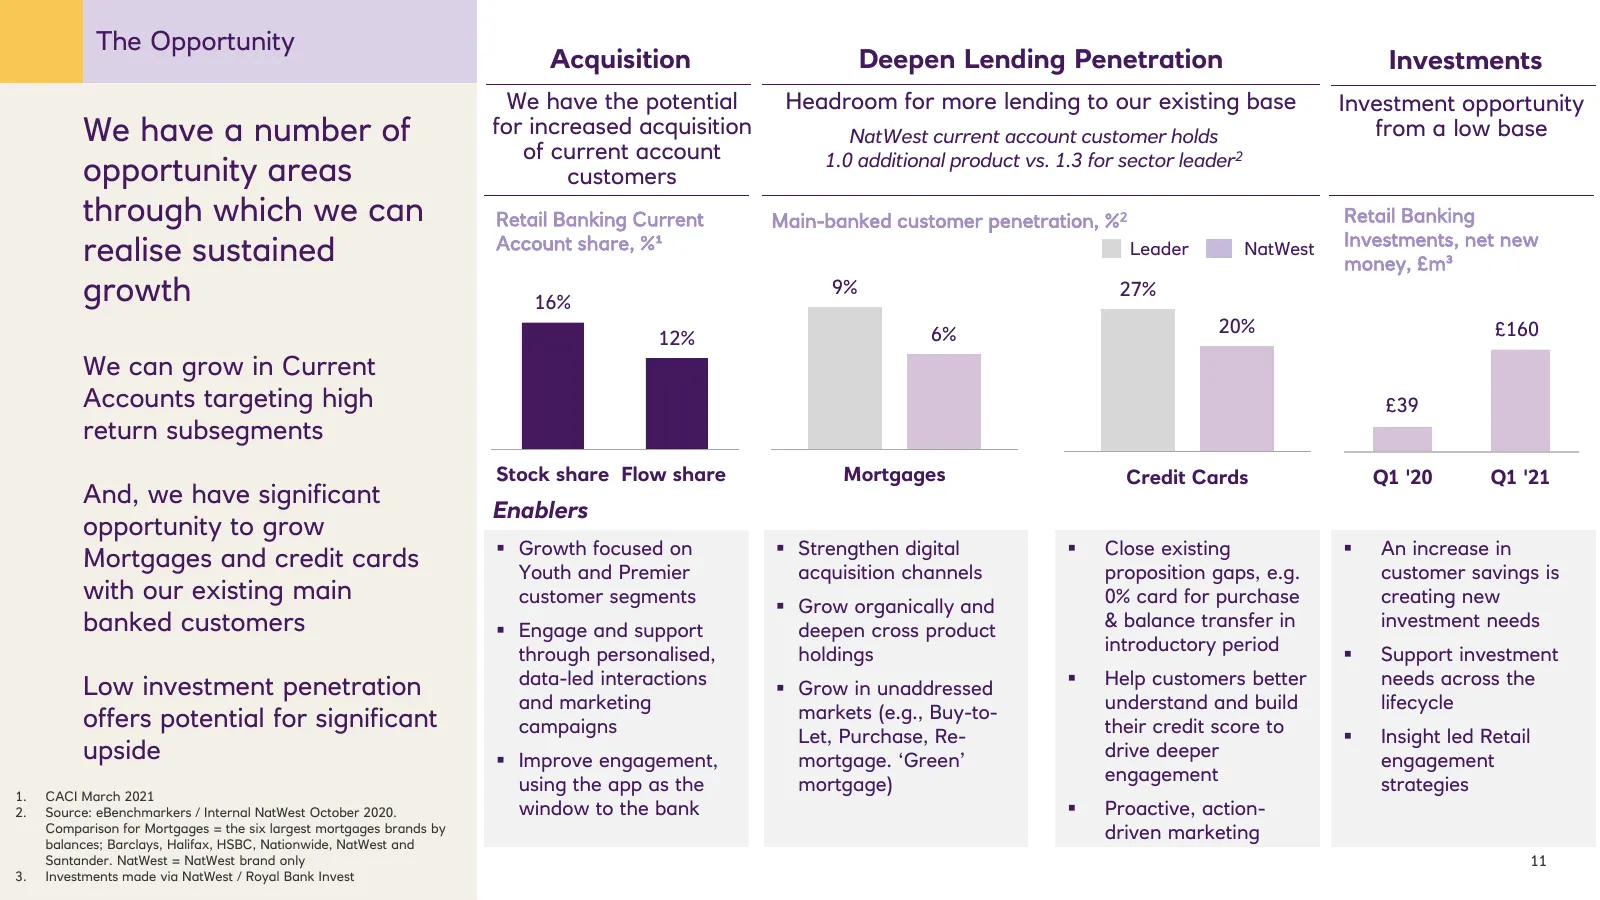
Slide 11: The Opportunity
The Opportunity Acquisition Deepen Lending Penetration Investments We have the potential Headroom for more lending to our existing base Investment opportunity We have a number of for increased acquisition NatWest current account customer holds from a low base of current account 1.0 additional produc
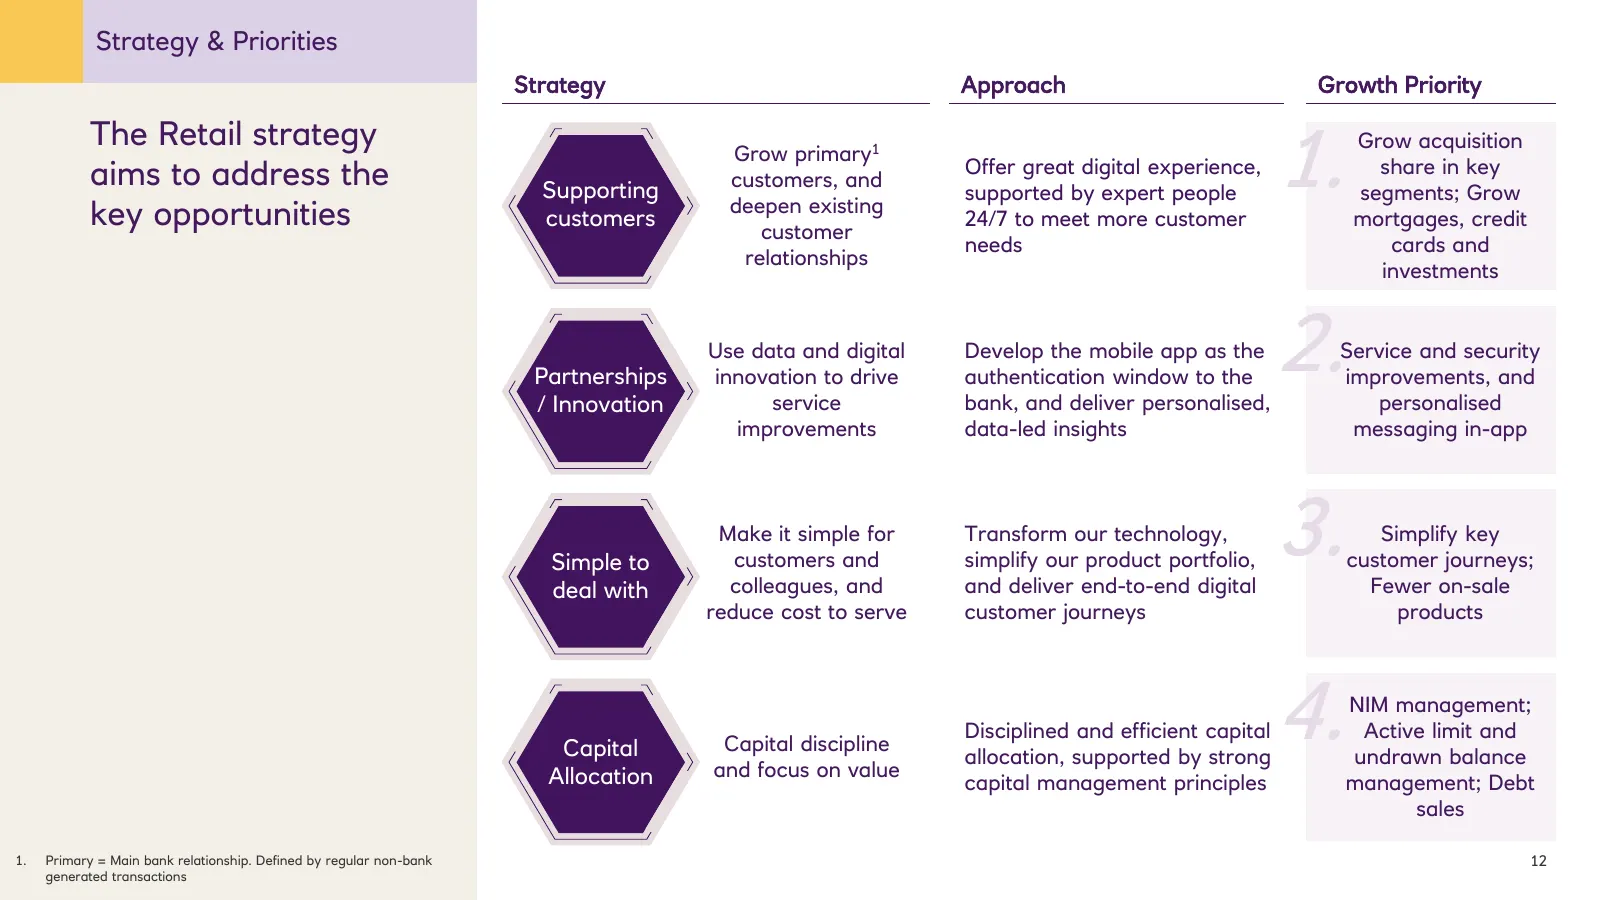
Slide 12: Strategy & Priorities
Strategy & Priorities Strategy Approach Growth Priority 1. The Retail strategy Grow primary1 Grow acquisition aims to address the Supporting customers, and Offer great digital experience, supported by expert people share in key segments; Grow deepen existing key opportunities customers customer 24/7
Slide 13: Supporting customers: great digital experience
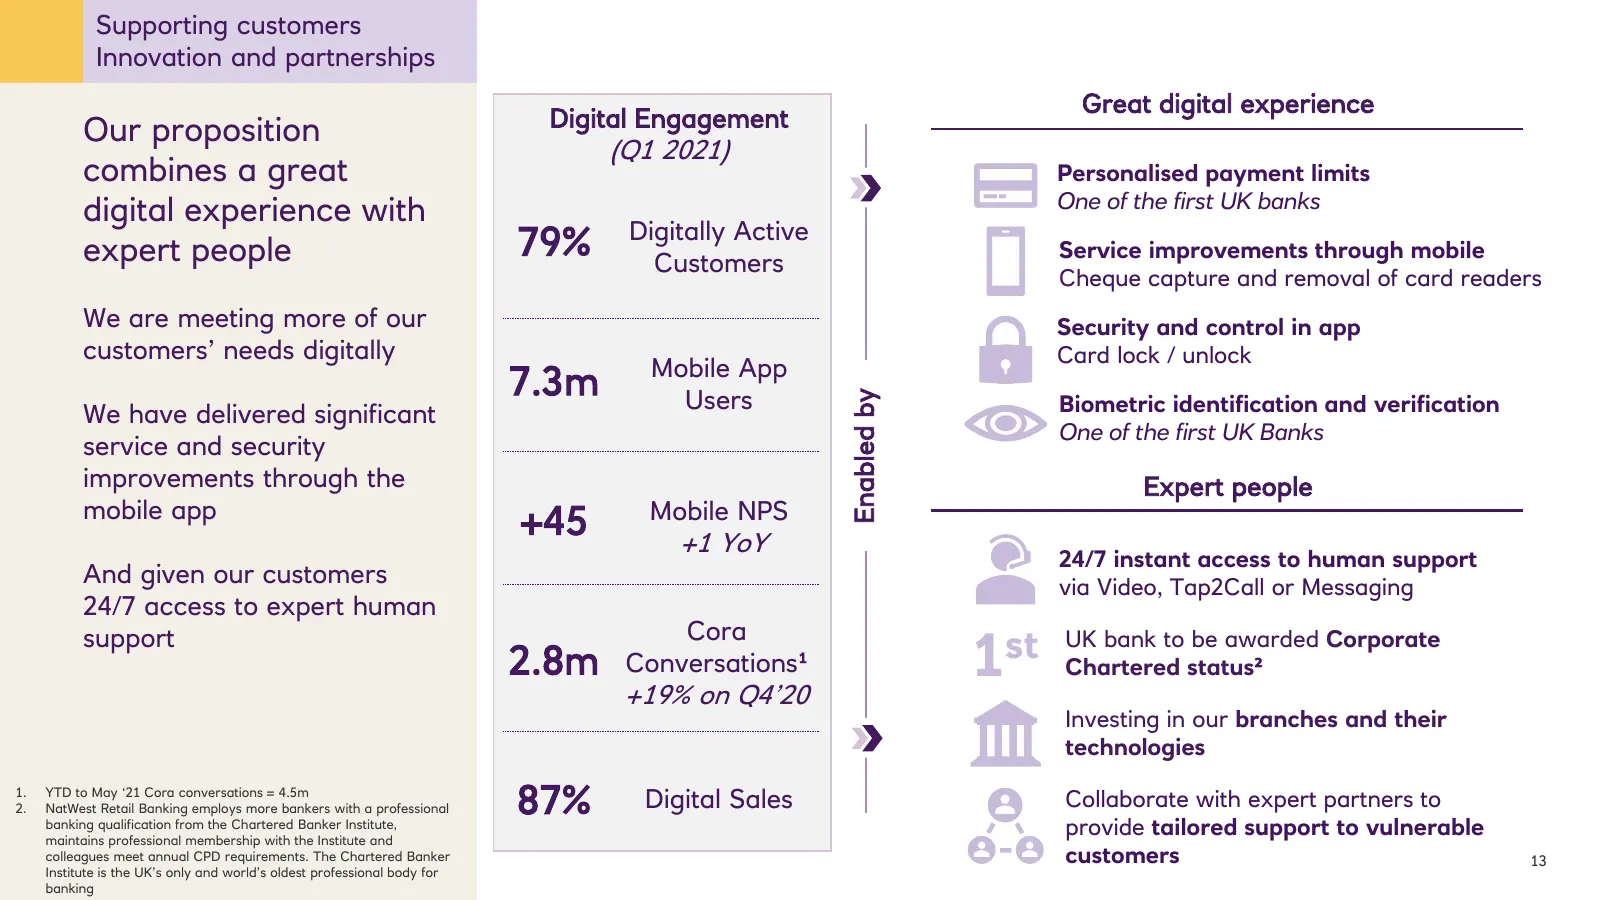
Supporting customers Innovation and partnerships Great digital experience Digital Engagement Our proposition (Q1 2021) combines a great Personalised payment limits One of the first UK banks digital experience with Digitally Active expert people 79% Customers Service improvements through mobile Chequ
Slide 14: Simple to deal with
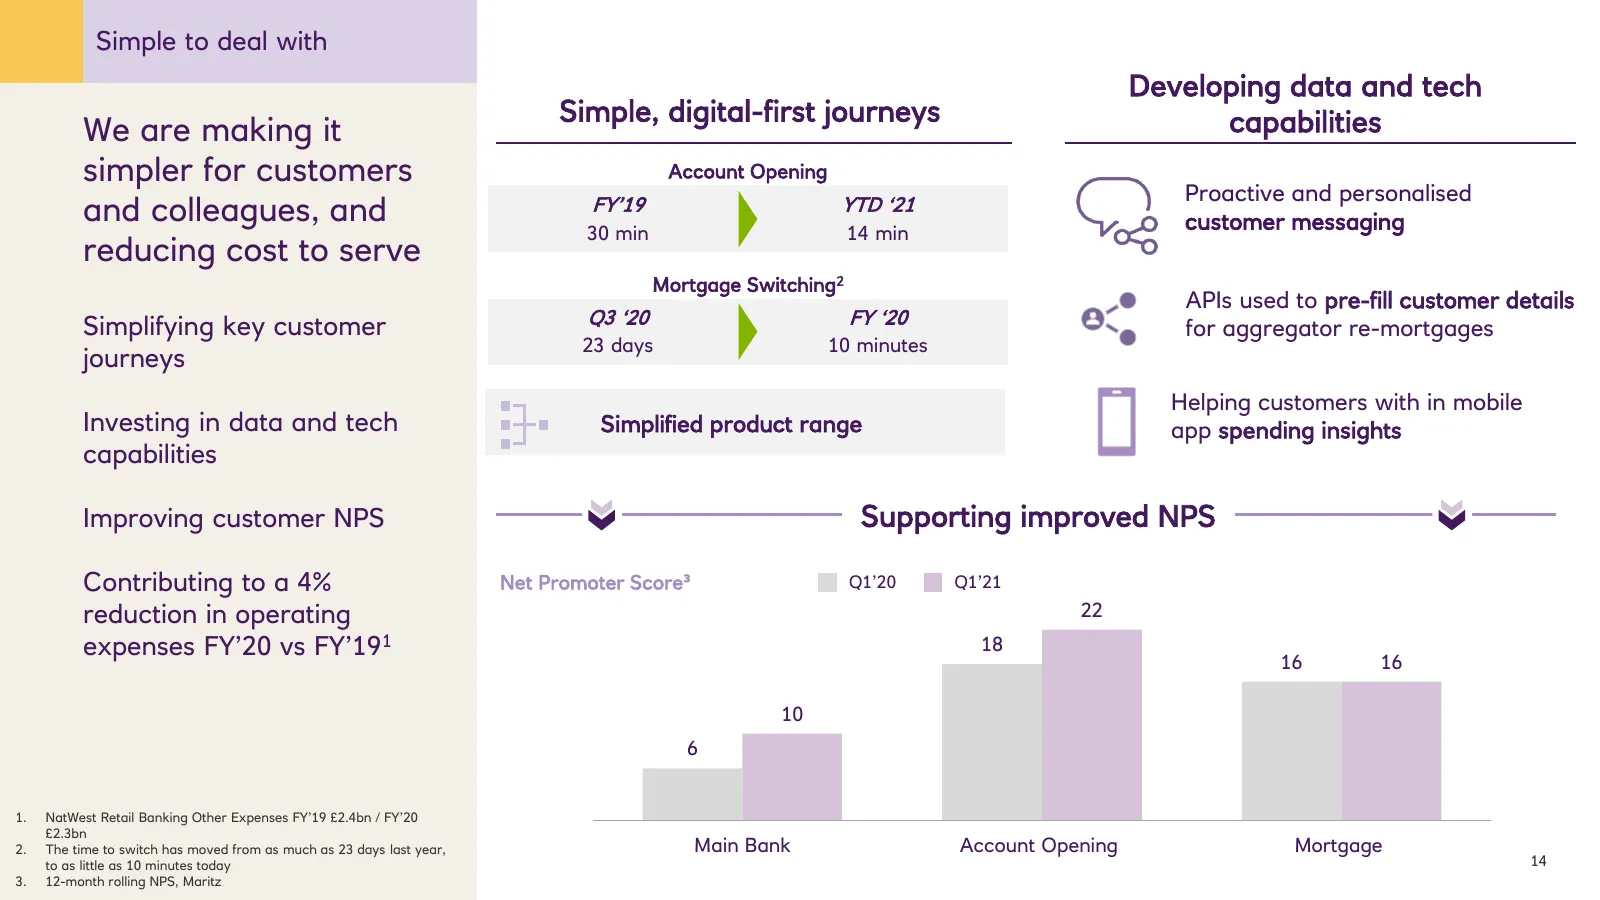
Simple to deal with Developing data and tech Simple, digital-first journeys capabilities We are making it simpler for customers Account Opening Proactive and personalised and colleagues, and FY’19 YTD ‘21 customer messaging 30 min 14 min reducing cost to serve Mortgage Switching2 APIs used to pre-fi
Slide 15: Capital Allocation
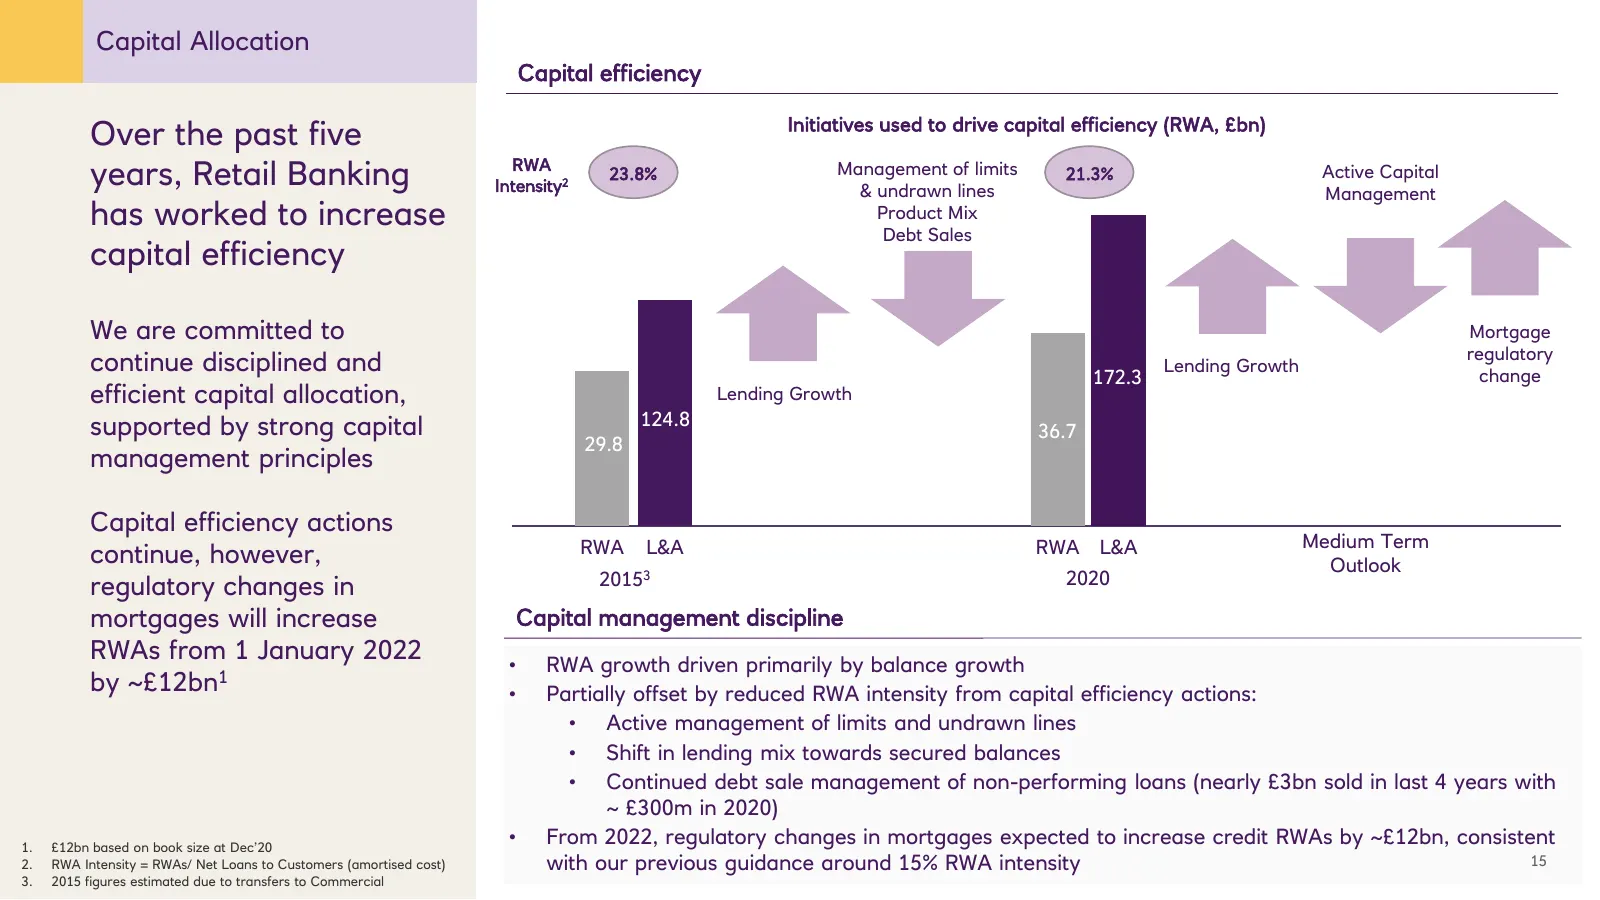
Capital Allocation Capital efficiency Initiatives used to drive capital efficiency (RWA, £bn) Over the past five years, Retail Banking RWA Intensity2 23.8% Management of limits & undrawn lines 21.3% Active Capital Management has worked to increase Product Mix Debt Sales capital efficiency We are com
Slide 16: Key financial highlights and outlook
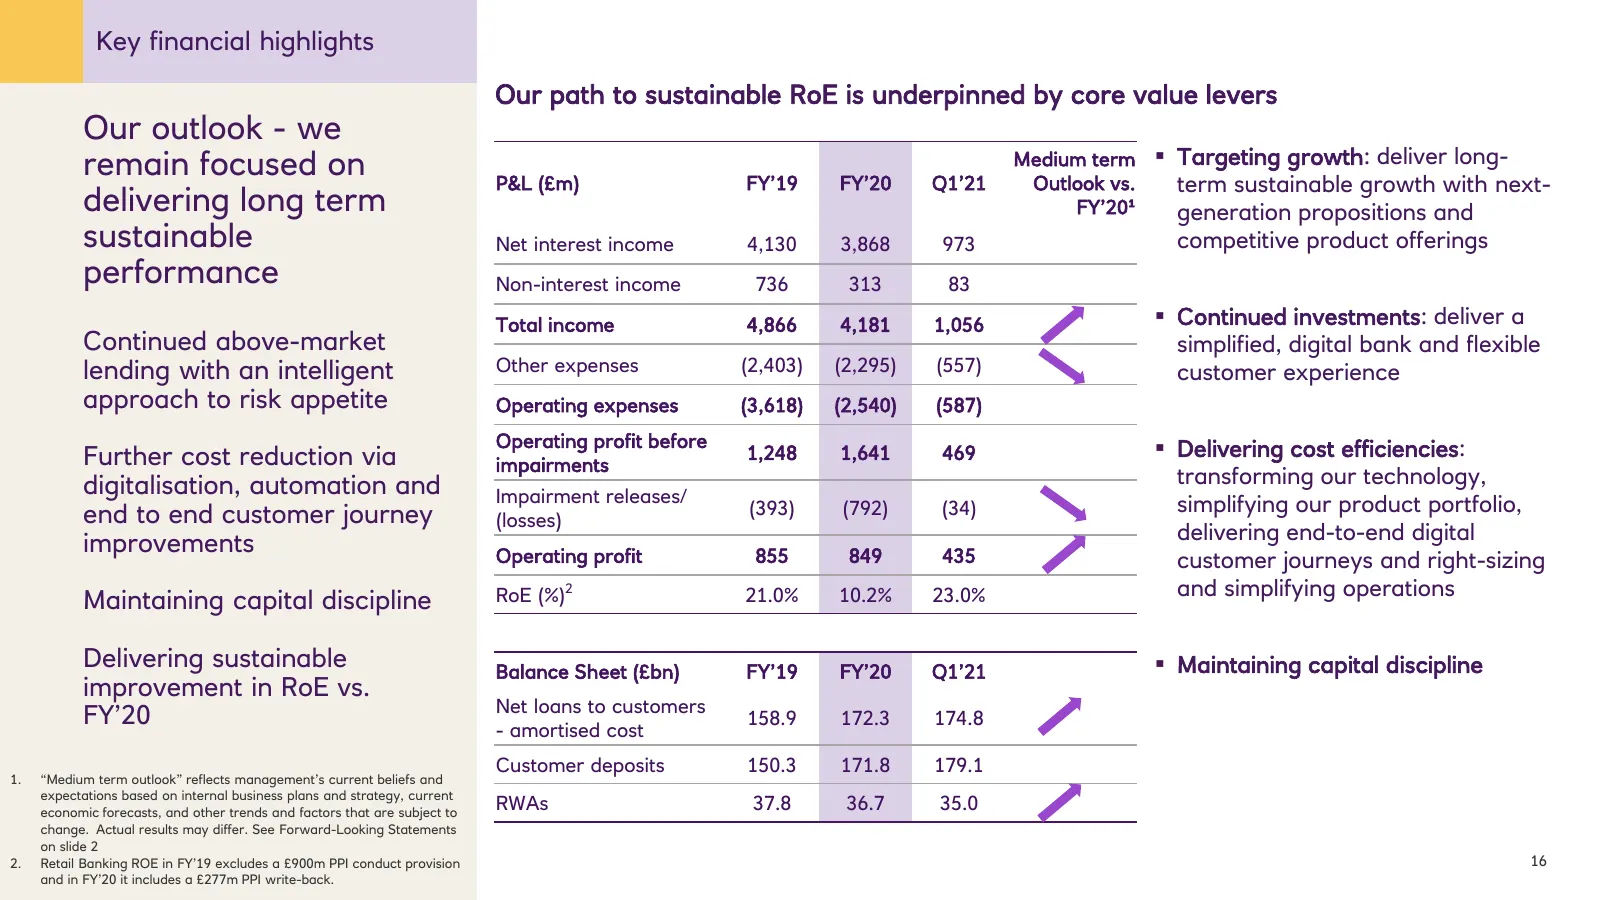
Key financial highlights Our path to sustainable RoE is underpinned by core value levers Our outlook - we remain focused on Medium term ▪ Targeting growth: deliver long- P&L (£m) FY’19 FY’20 Q1’21 Outlook vs. term sustainable growth with next- delivering long term FY’20¹ generation propositions and
Slide 17: Key messages
Key messages Retail Banking serves 17m customers with great digital experiences, supported 1. We are growing ahead of the market in key areas with sustainable ROE, and positive outlook by experts in the 2. moments that matter Our strategy focuses on unique opportunities to meet more of our customers
Slide 18: Peter Flavel, Private Banking CEO
Peter Flavel Private Banking CEO 18
Slide 19: Private Banking Overview
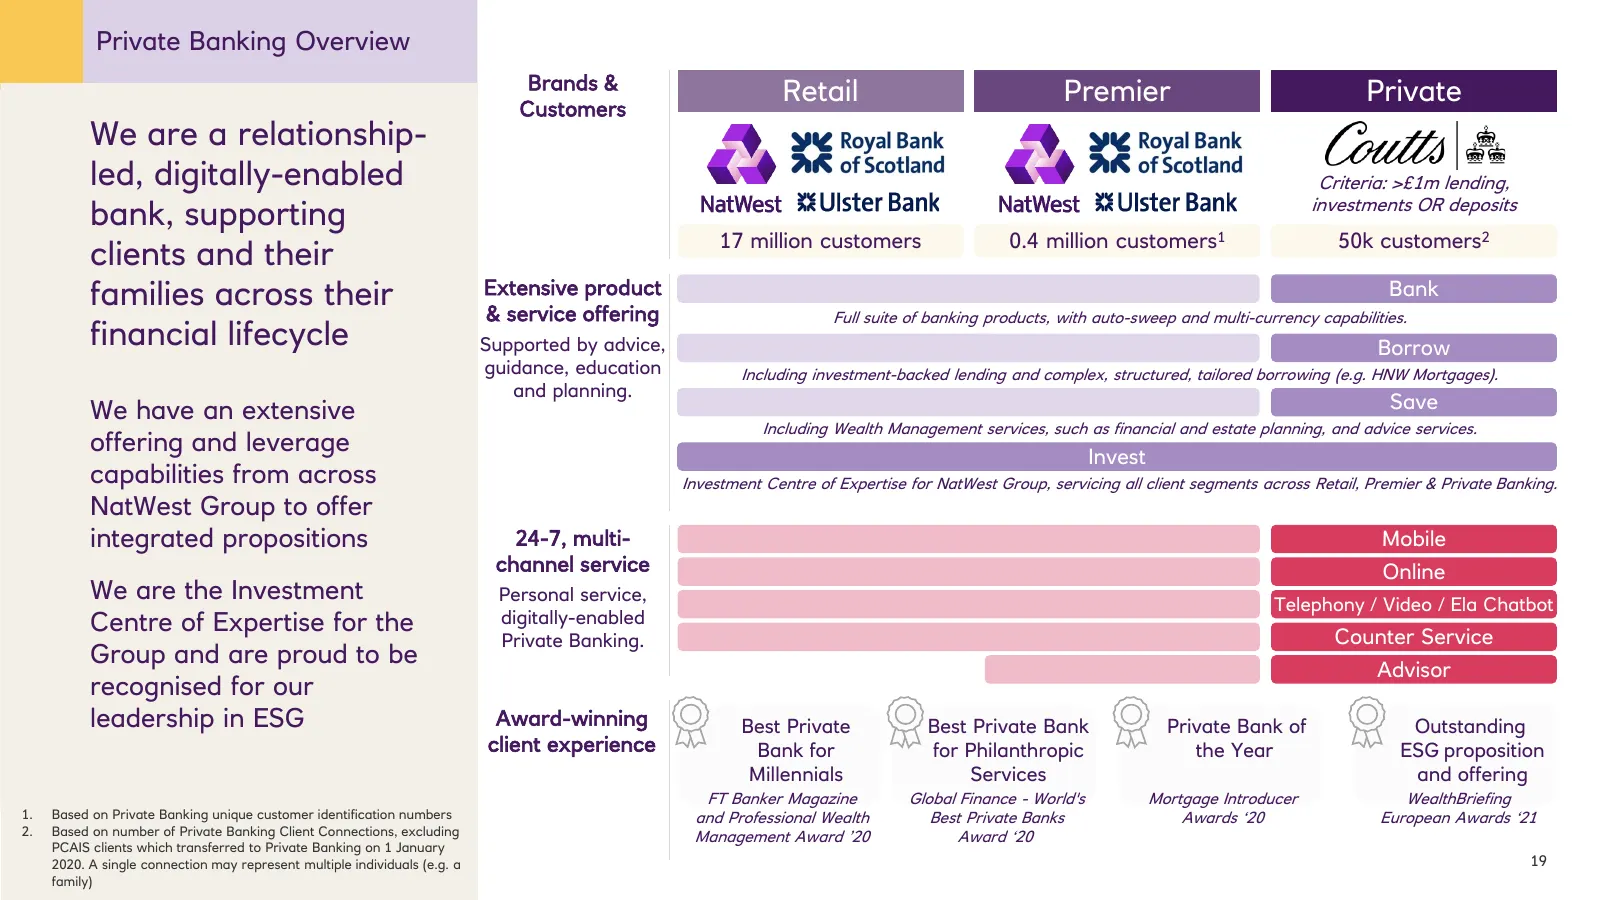
Private Banking Overview Brands & Customers Retail Premier Private We are a relationship- led, digitally-enabled Criteria: >£1m lending, investments OR deposits bank, supporting 17 million customers 0.4 million customers1 50k customers2 clients and their families across their Extensive product & ser
Slide 20: Strategy & Priorities
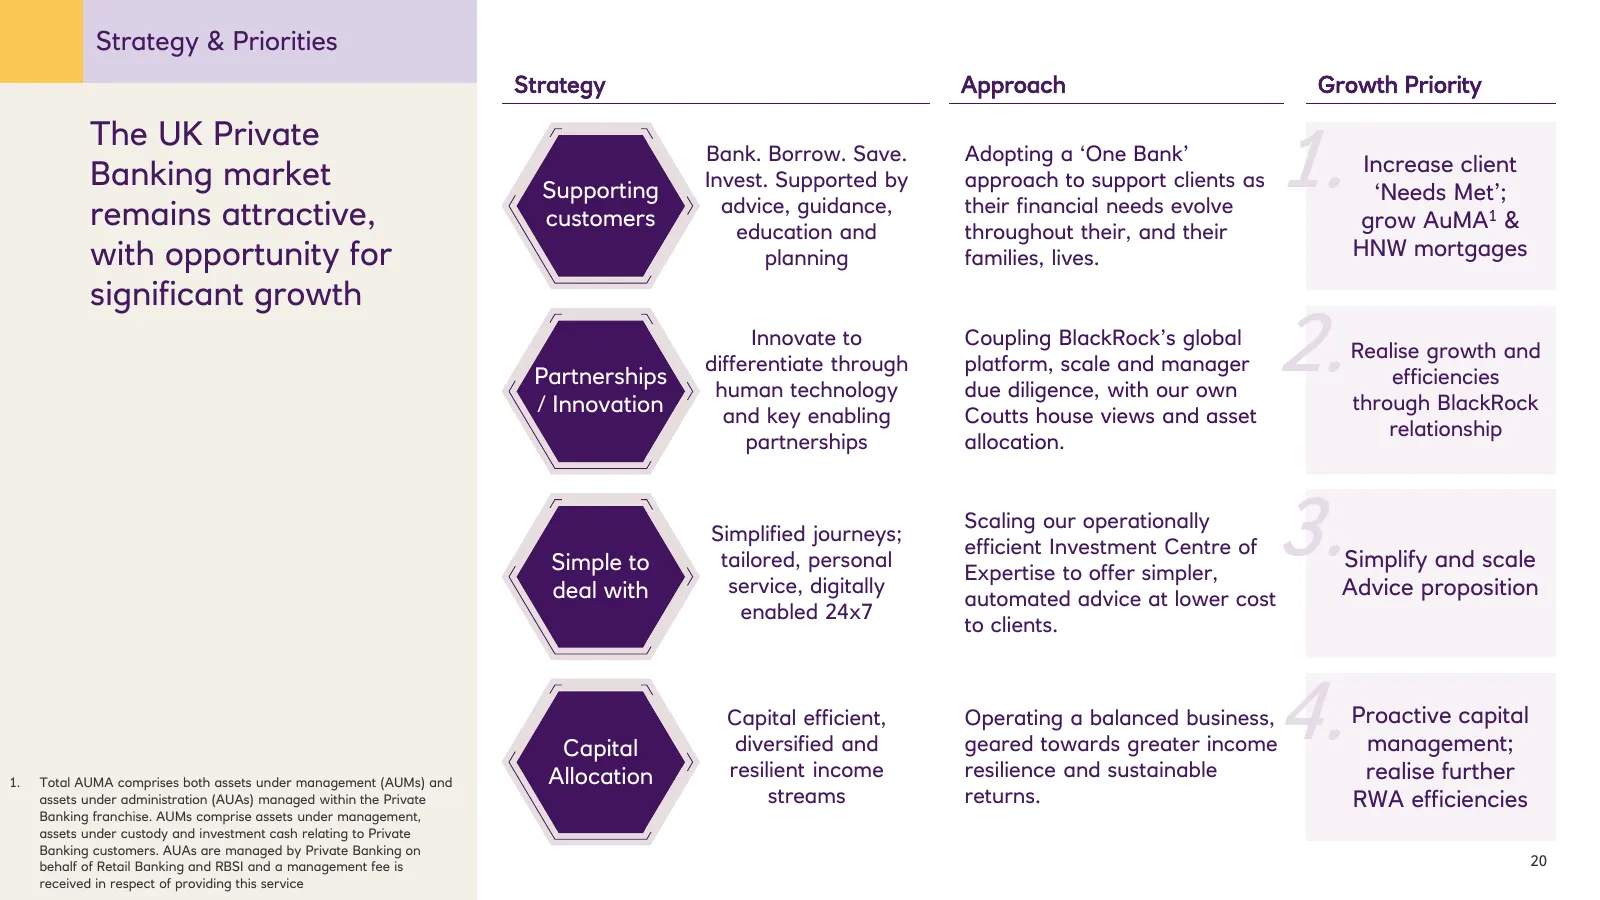
Strategy & Priorities Strategy Approach Growth Priority 1. The UK Private Bank. Borrow. Save. Adopting a ‘One Bank’ Increase client Banking market Supporting Invest. Supported by approach to support clients as ‘Needs Met’; advice, guidance, their financial needs evolve remains attractive, customers
Slide 21: Private Banking transformation over five years
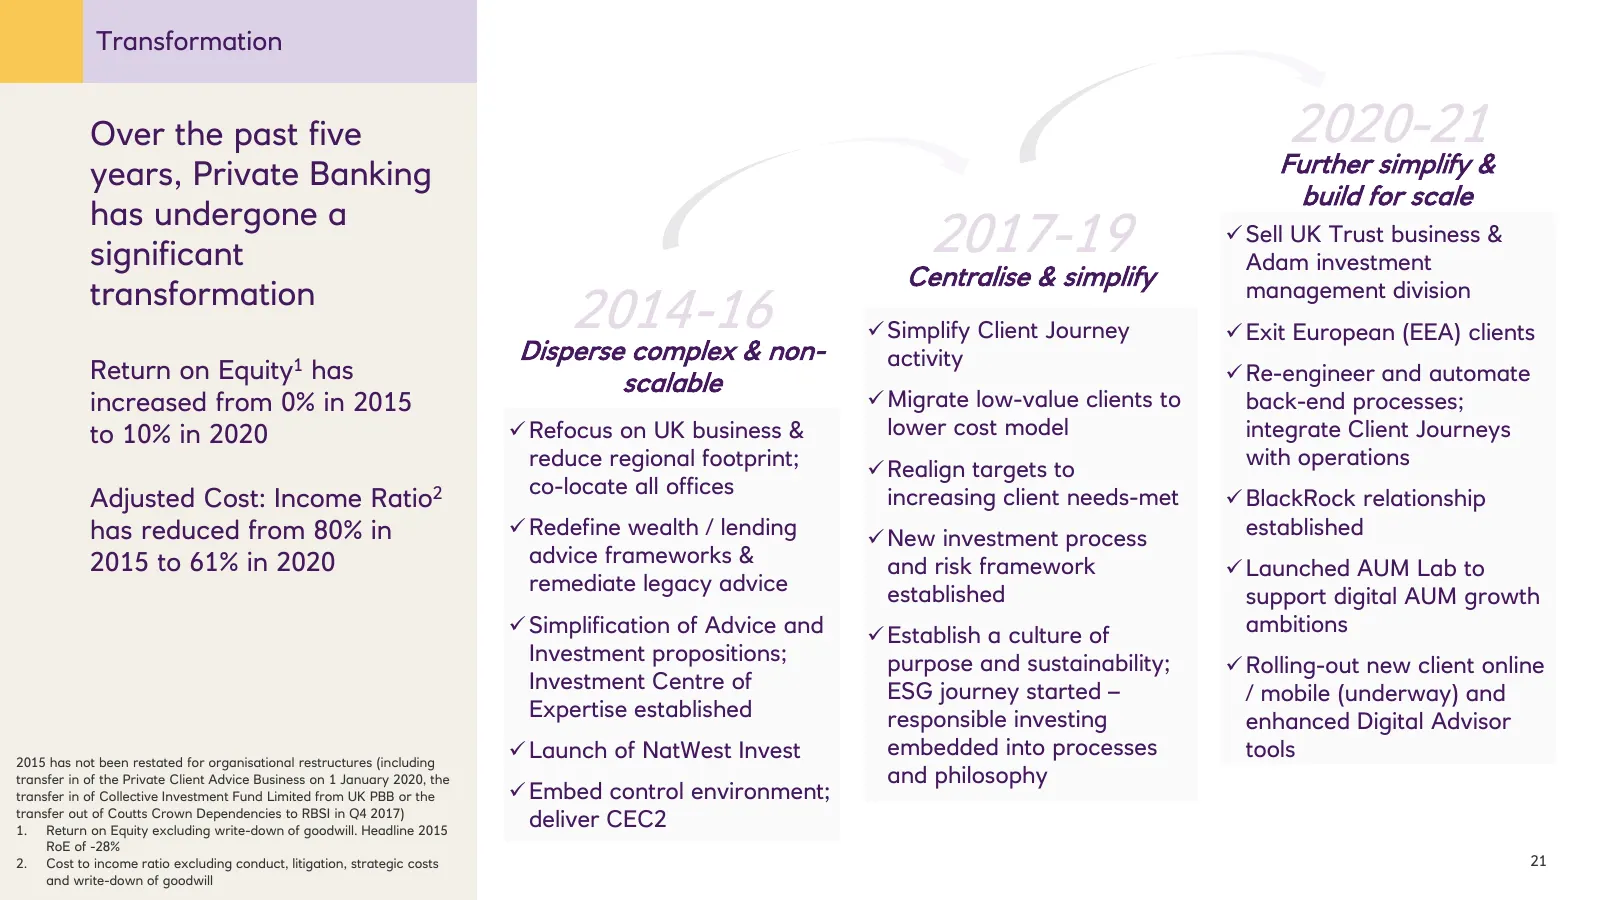
Transformation Over the past five 2020-21 years, Private Banking Further simplify & build for scale has undergone a significant 2017-19 ✓ Sell UK Trust business & Adam investment Centralise & simplify transformation 2014-16 management division ✓ Simplify Client Journey ✓ Exit European (EEA) clients
Slide 22: Private Banking continues to deliver strong volume growth
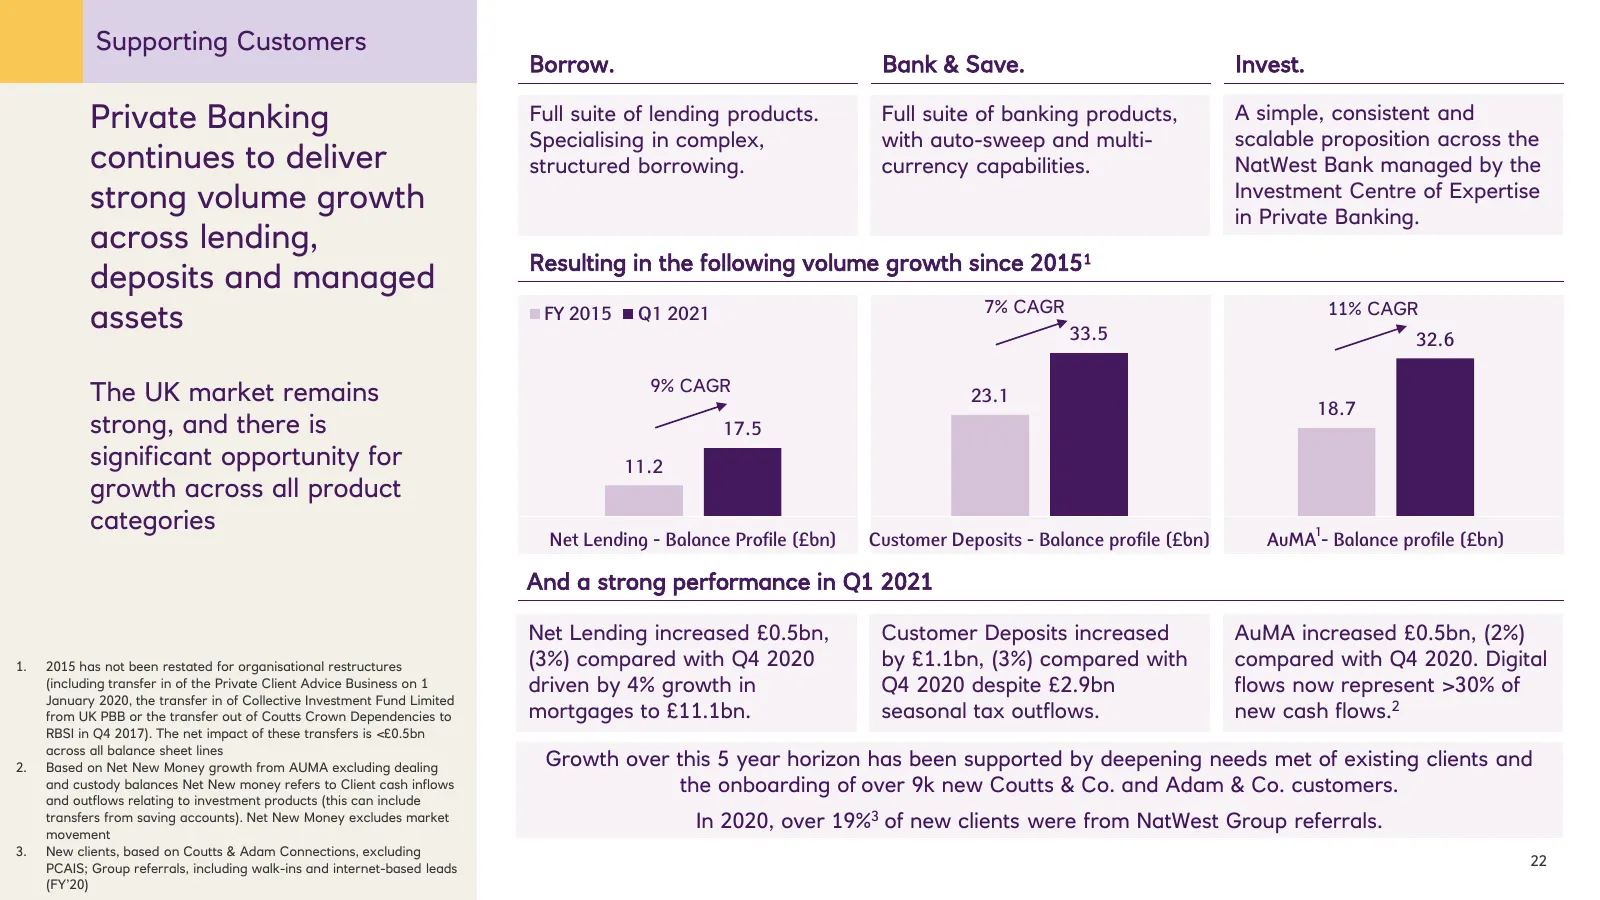
Supporting Customers Borrow. Bank & Save. Invest. Private Banking Full suite of lending products. Full suite of banking products, A simple, consistent and Specialising in complex, with auto-sweep and multi- scalable proposition across the continues to deliver structured borrowing. currency capabilit
Slide 23: Leveraging One Bank capabilities
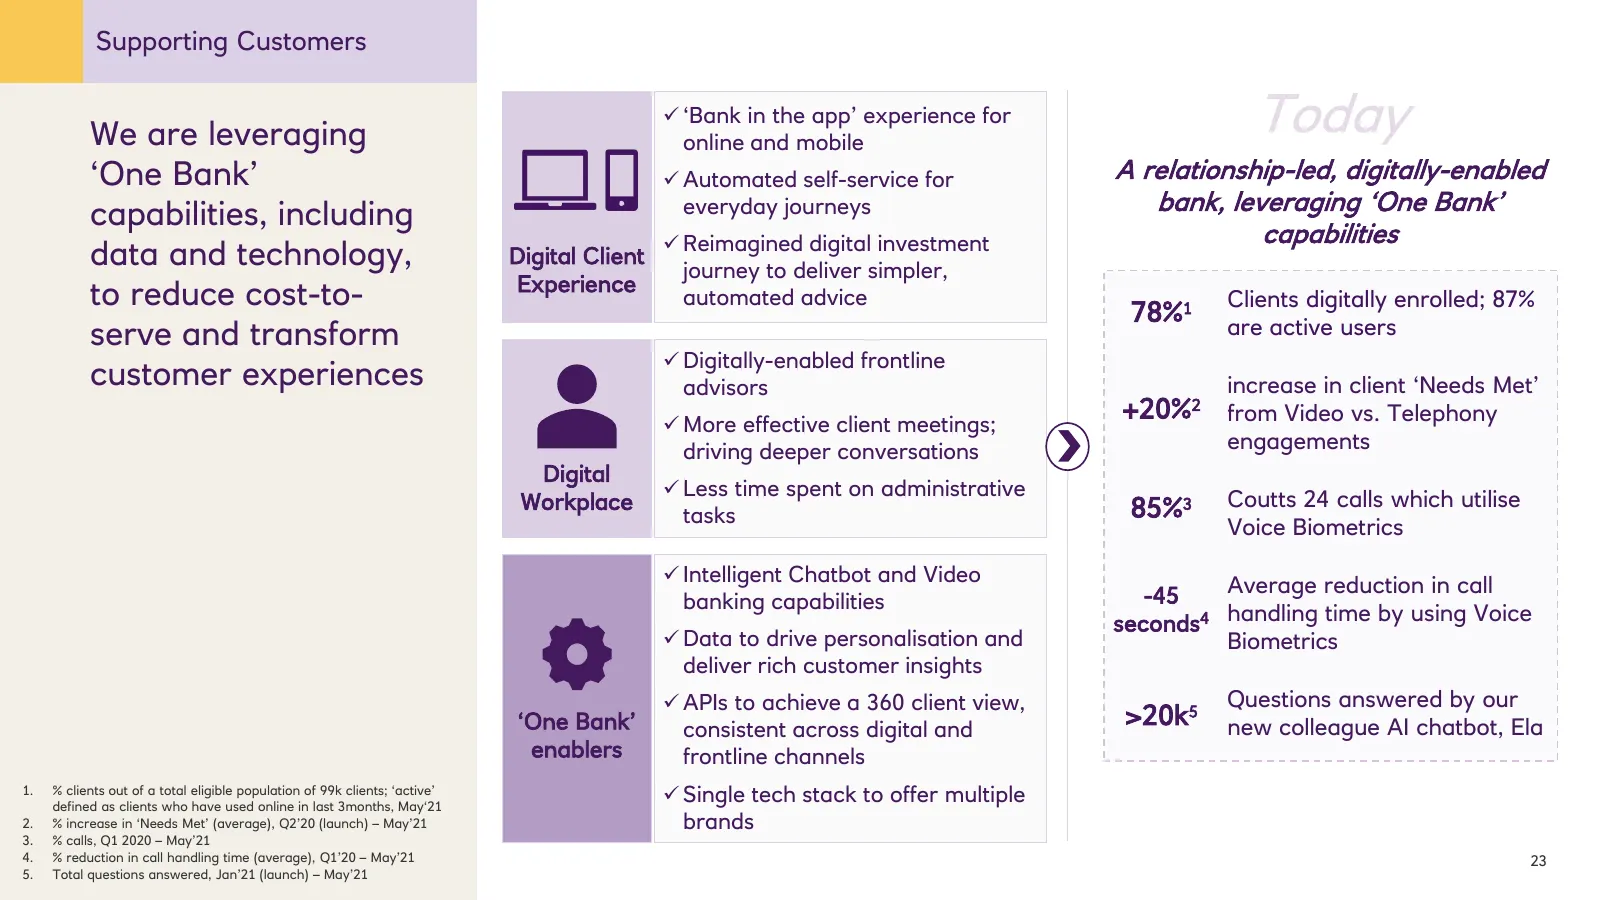
Supporting Customers We are leveraging ✓ ‘Bank in the app’ experience for online and mobile Today ‘One Bank’ ✓ Automated self-service for A relationship-led, digitally-enabled everyday journeys bank, leveraging ‘One Bank’ capabilities, including ✓ Reimagined digital investment capabilities data and
Slide 24: Transformed Investment business
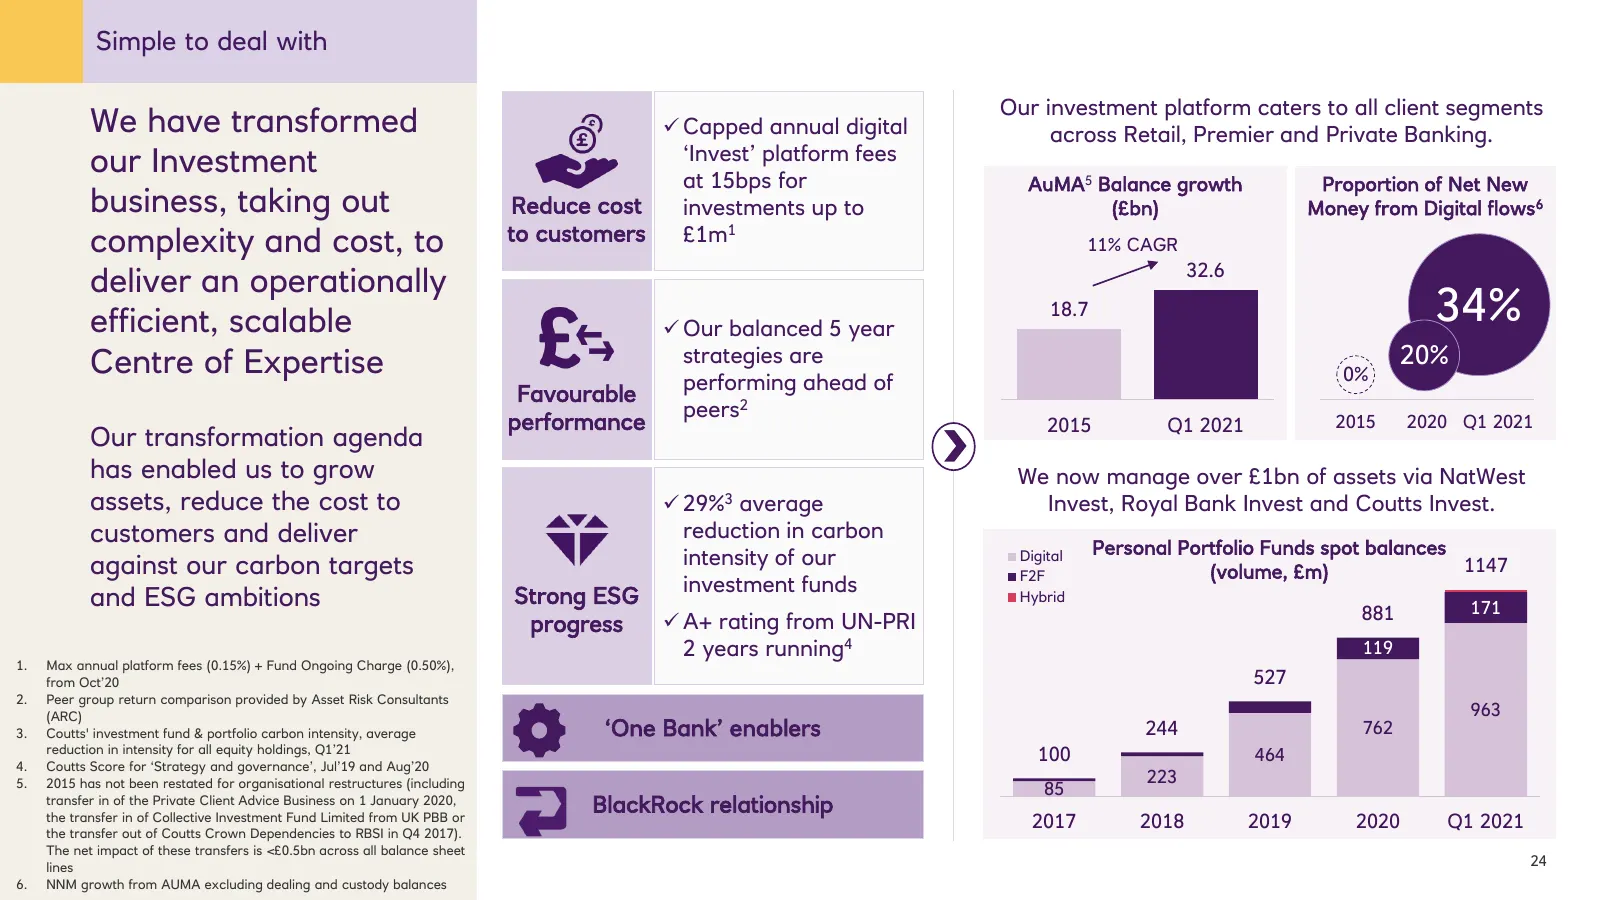
Simple to deal with Our investment platform caters to all client segments We have transformed ✓ Capped annual digital across Retail, Premier and Private Banking. ‘Invest’ platform fees our Investment at 15bps for AuMA5 Balance growth Proportion of Net New business, taking out Reduce cost investments
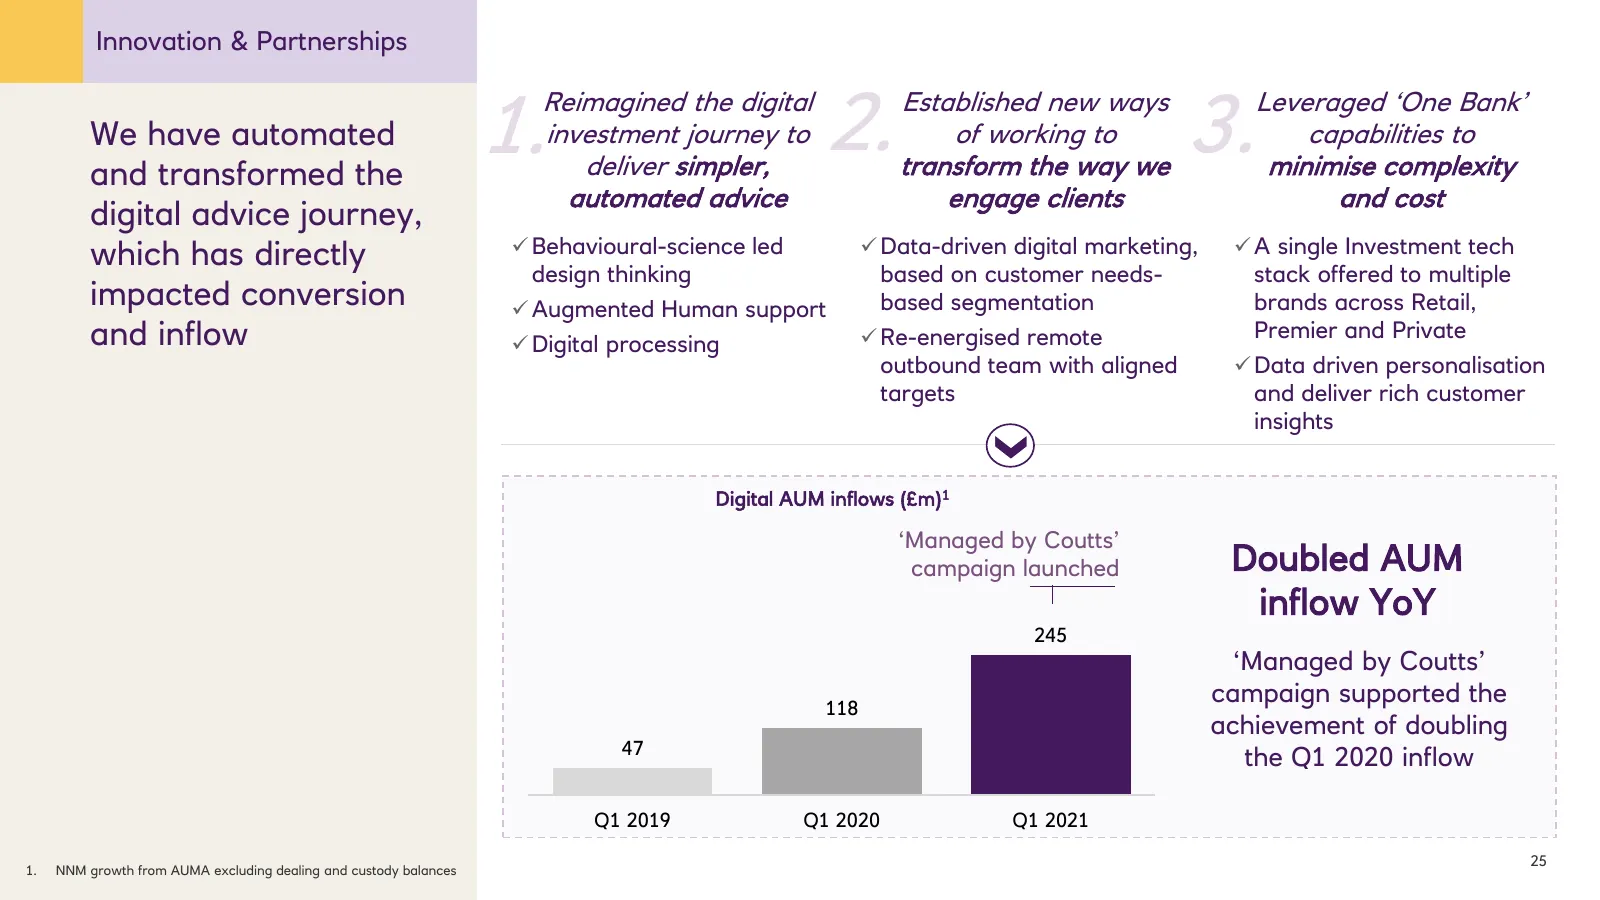
Slide 25: Automated and transformed digital advice journey
Innovation & Partnerships We have automated and transformed the 1.Reimagined the digital investment journey to deliver simpler, 2. Established new ways of working to transform the way we 3. Leveraged ‘One Bank’ capabilities to minimise complexity automated advice engage clients and cost digital advi
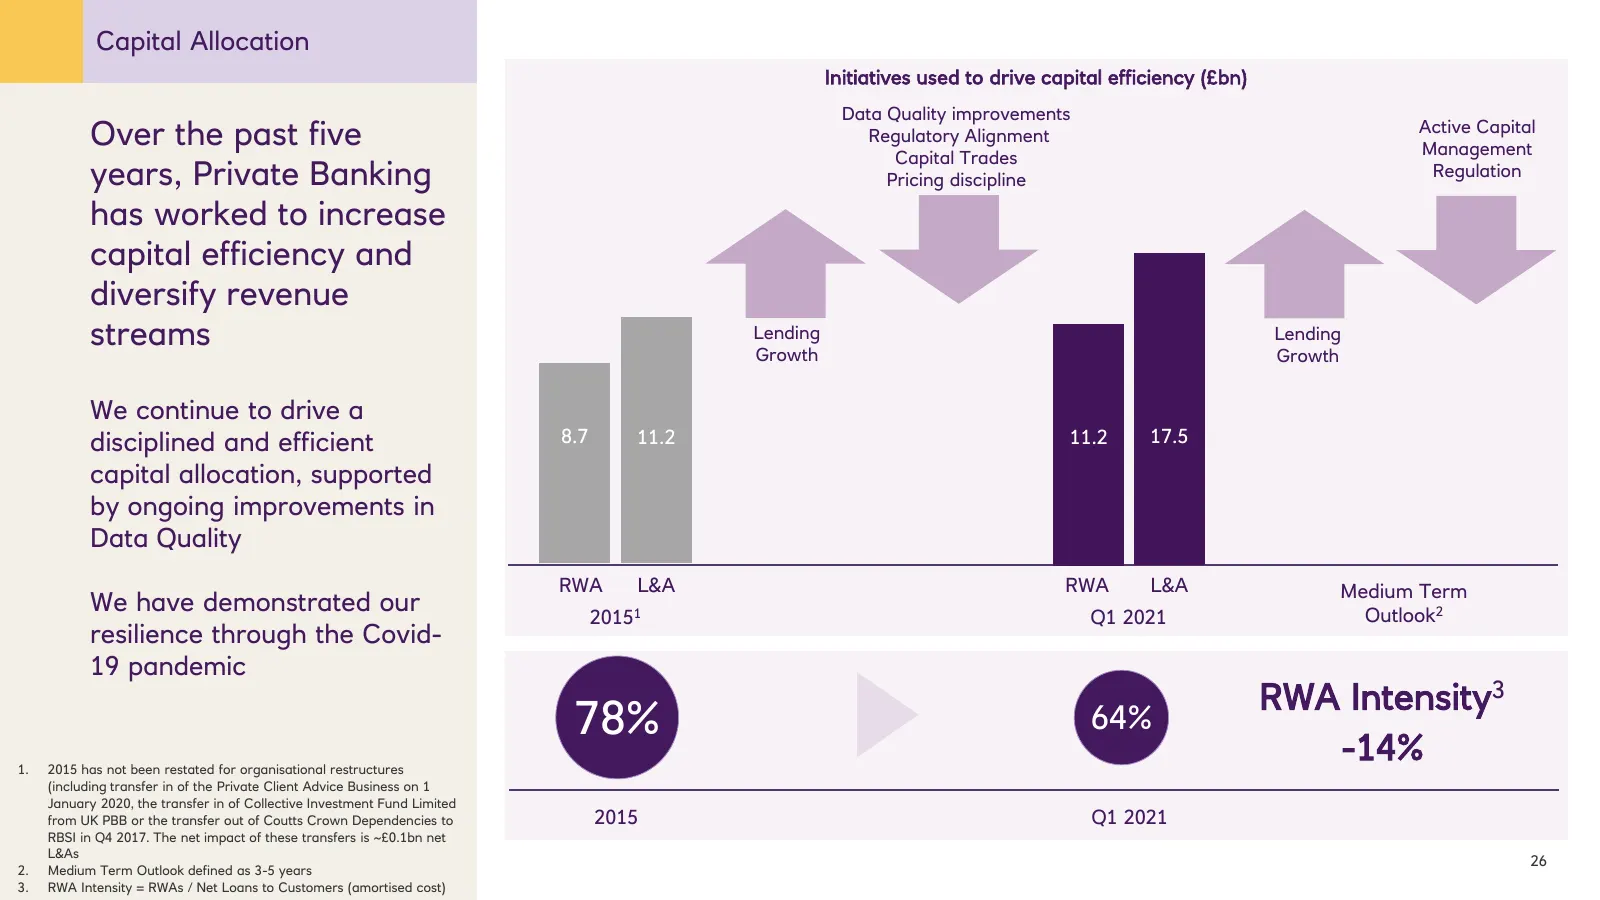
Slide 26: Capital Allocation
Capital Allocation Initiatives used to drive capital efficiency (£bn) Data Quality improvements Over the past five Regulatory Alignment Active Capital Management Capital Trades years, Private Banking Pricing discipline Regulation has worked to increase capital efficiency and diversify revenue stream
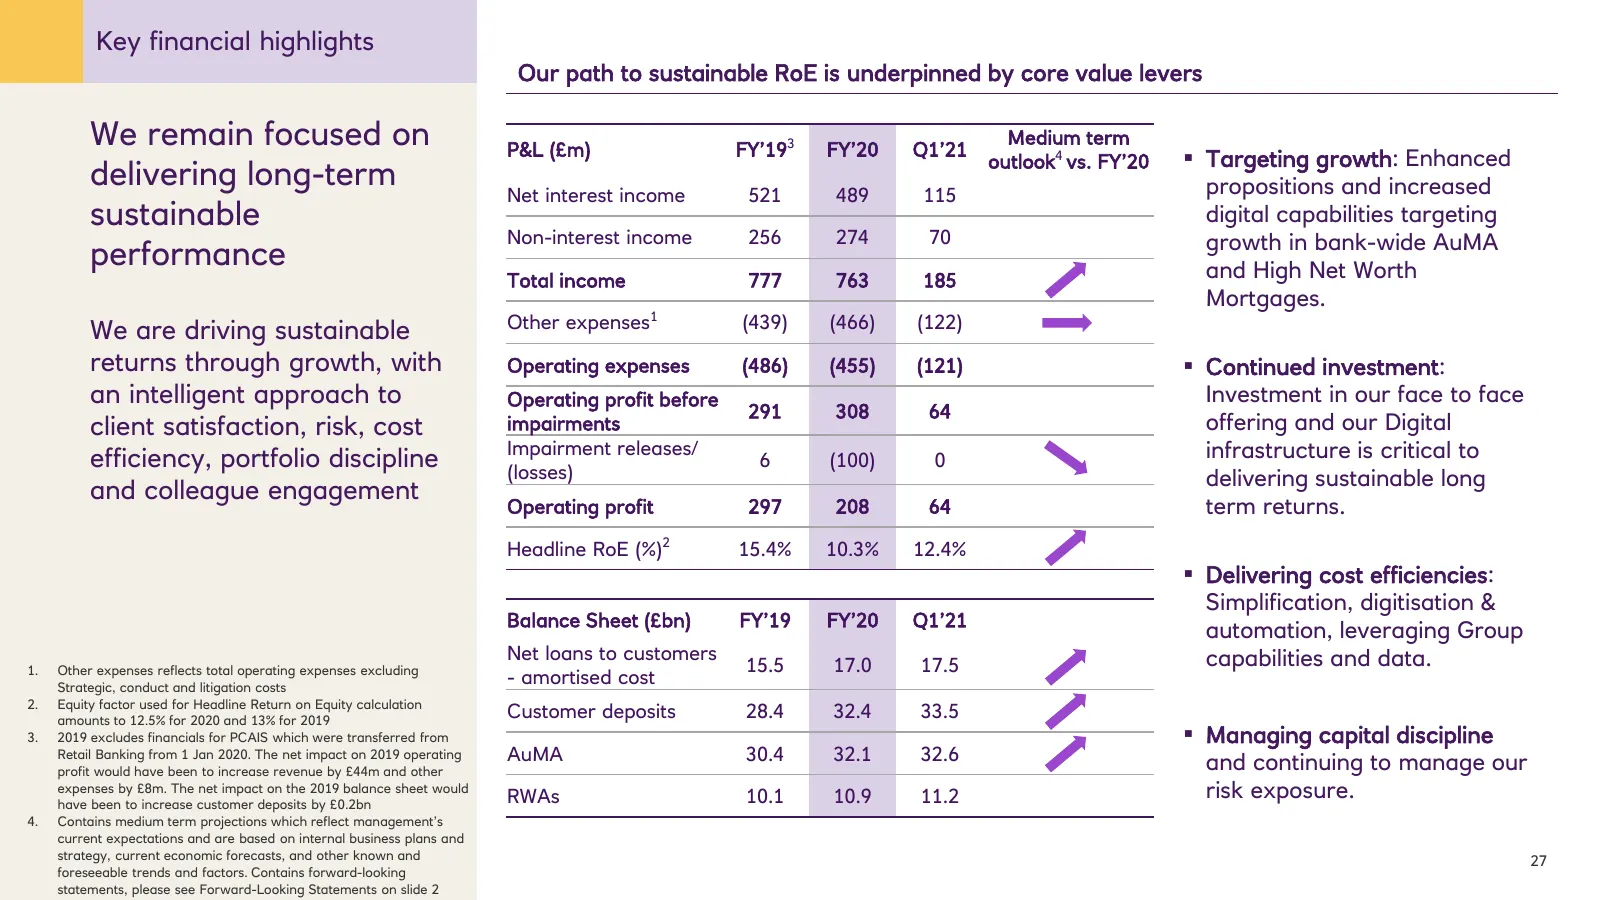
Slide 27: Key financial highlights
Key financial highlights Our path to sustainable RoE is underpinned by core value levers We remain focused on P&L (£m) FY’193 FY’20 Q1’21 Medium term outlook4 vs. FY’20 ▪ Targeting growth: Enhanced delivering long-term propositions and increased Net interest income 521 489 115 sustainable digital ca
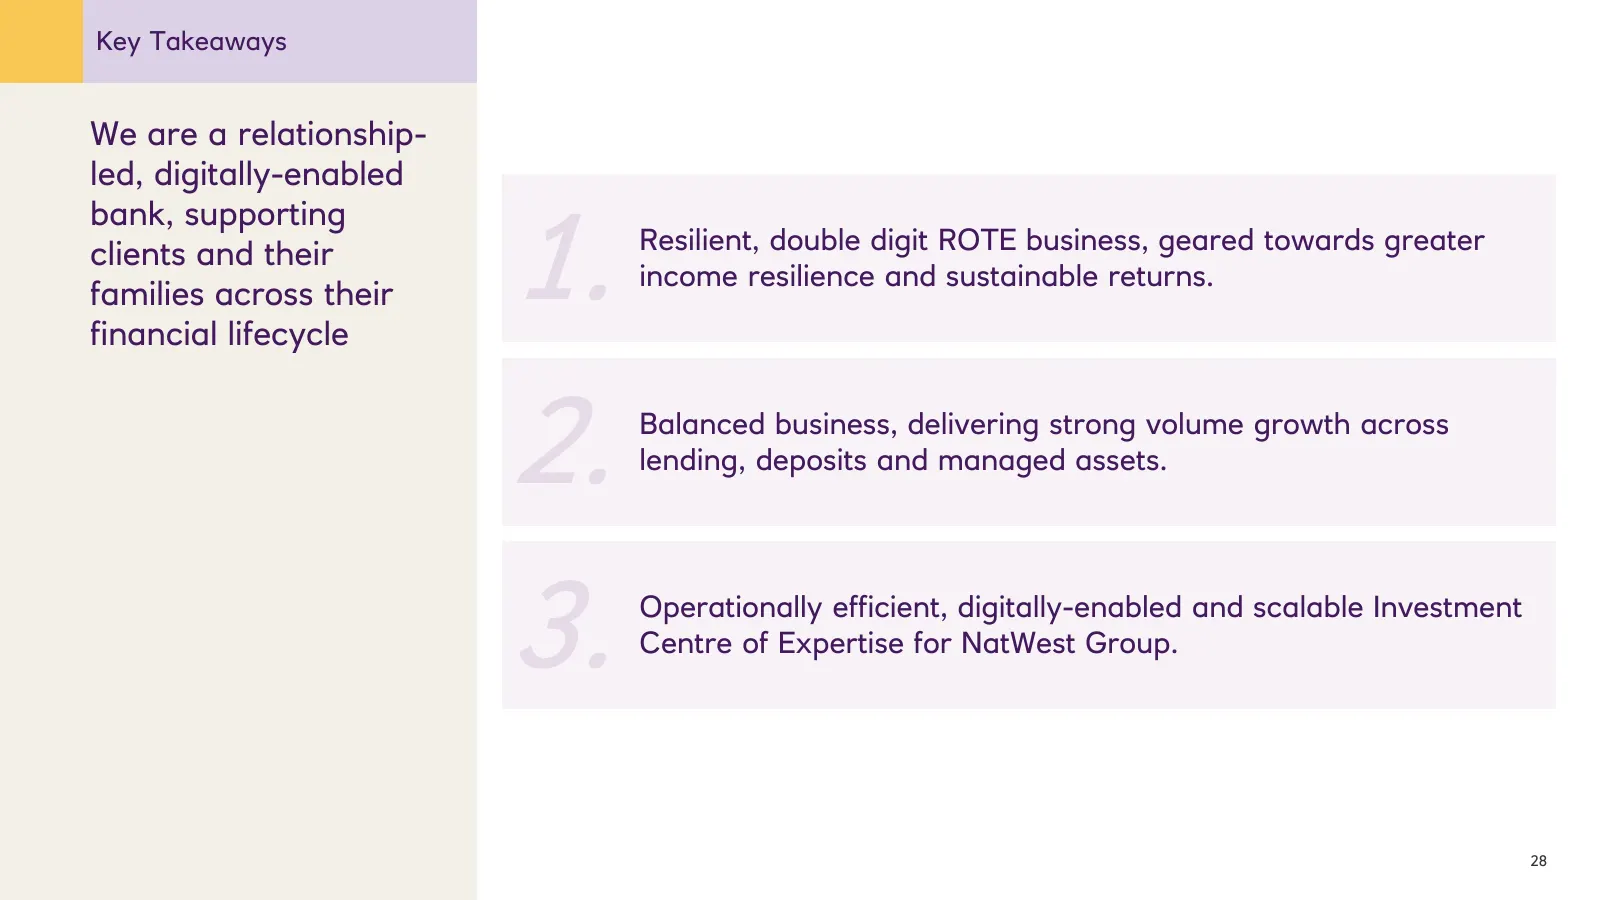
Slide 28: Key Takeaways
Key Takeaways We are a relationship- led, digitally-enabled 1. bank, supporting clients and their Resilient, double digit ROTE business, geared towards greater income resilience and sustainable returns. families across their financial lifecycle 2. Balanced business, delivering strong volume growth a
Slide 29: Simon McNamara, Chief Administrative Officer
Simon McNamara Chief Administrative Officer, Services 29
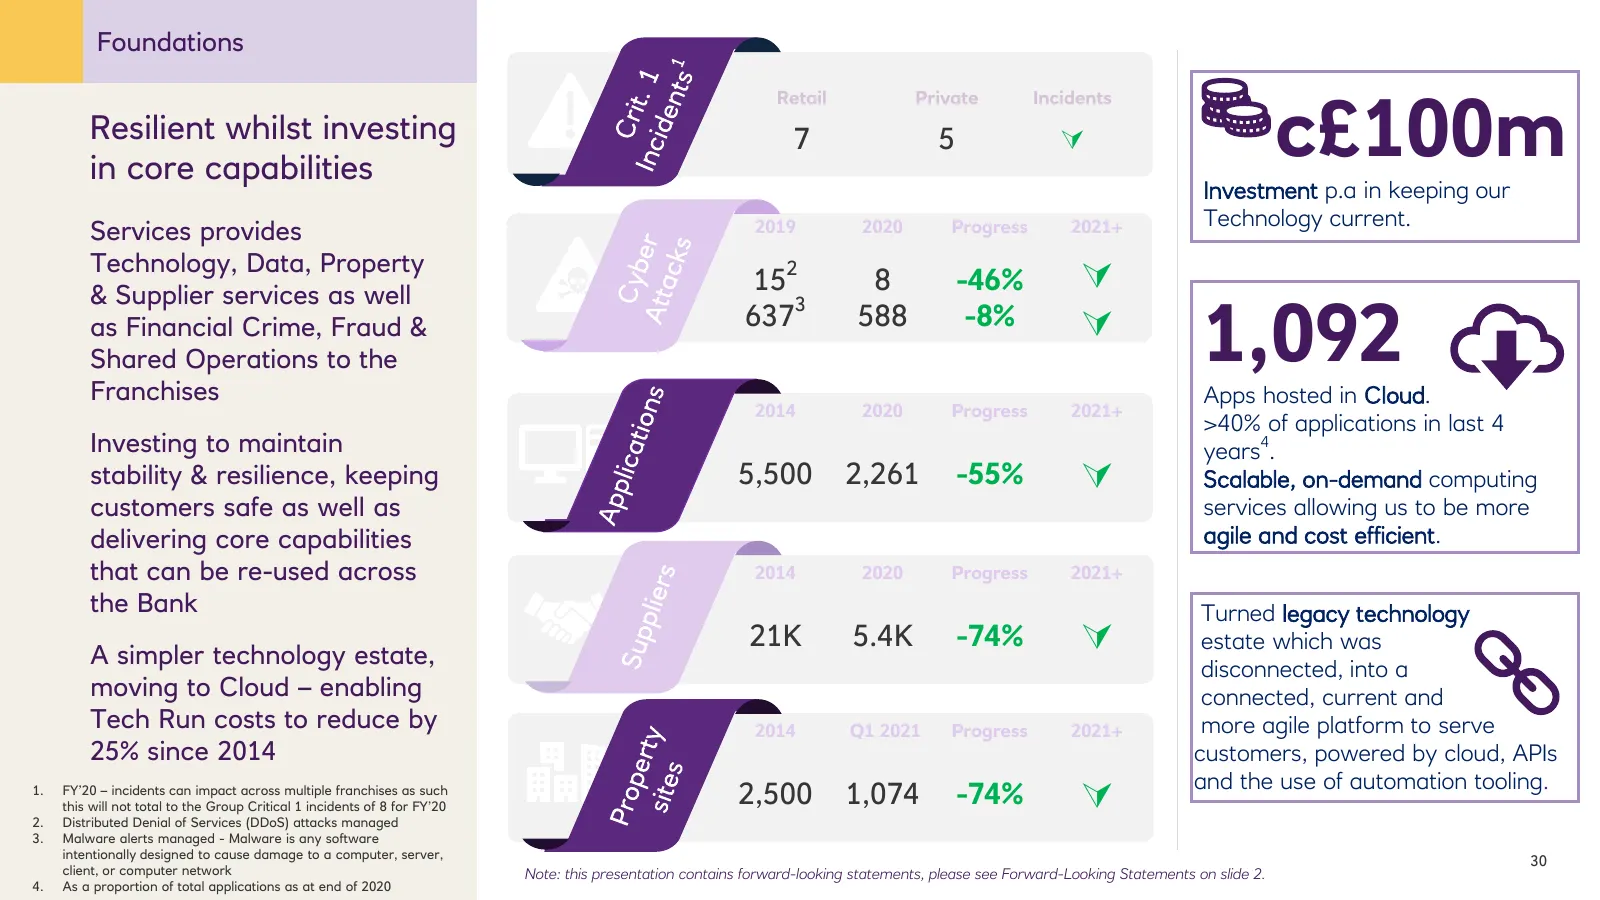
Slide 30: Resilient whilst investing in core capabilities
Foundations c£100m Retail Private Incidents Resilient whilst investing 7 5 in core capabilities Investment p.a in keeping our Technology current. Services provides 2019 2020 Progress 2021+ Technology, Data, Property & Supplier services as well 152 8 -46% as Financial Crime, Fraud & Shared Operat
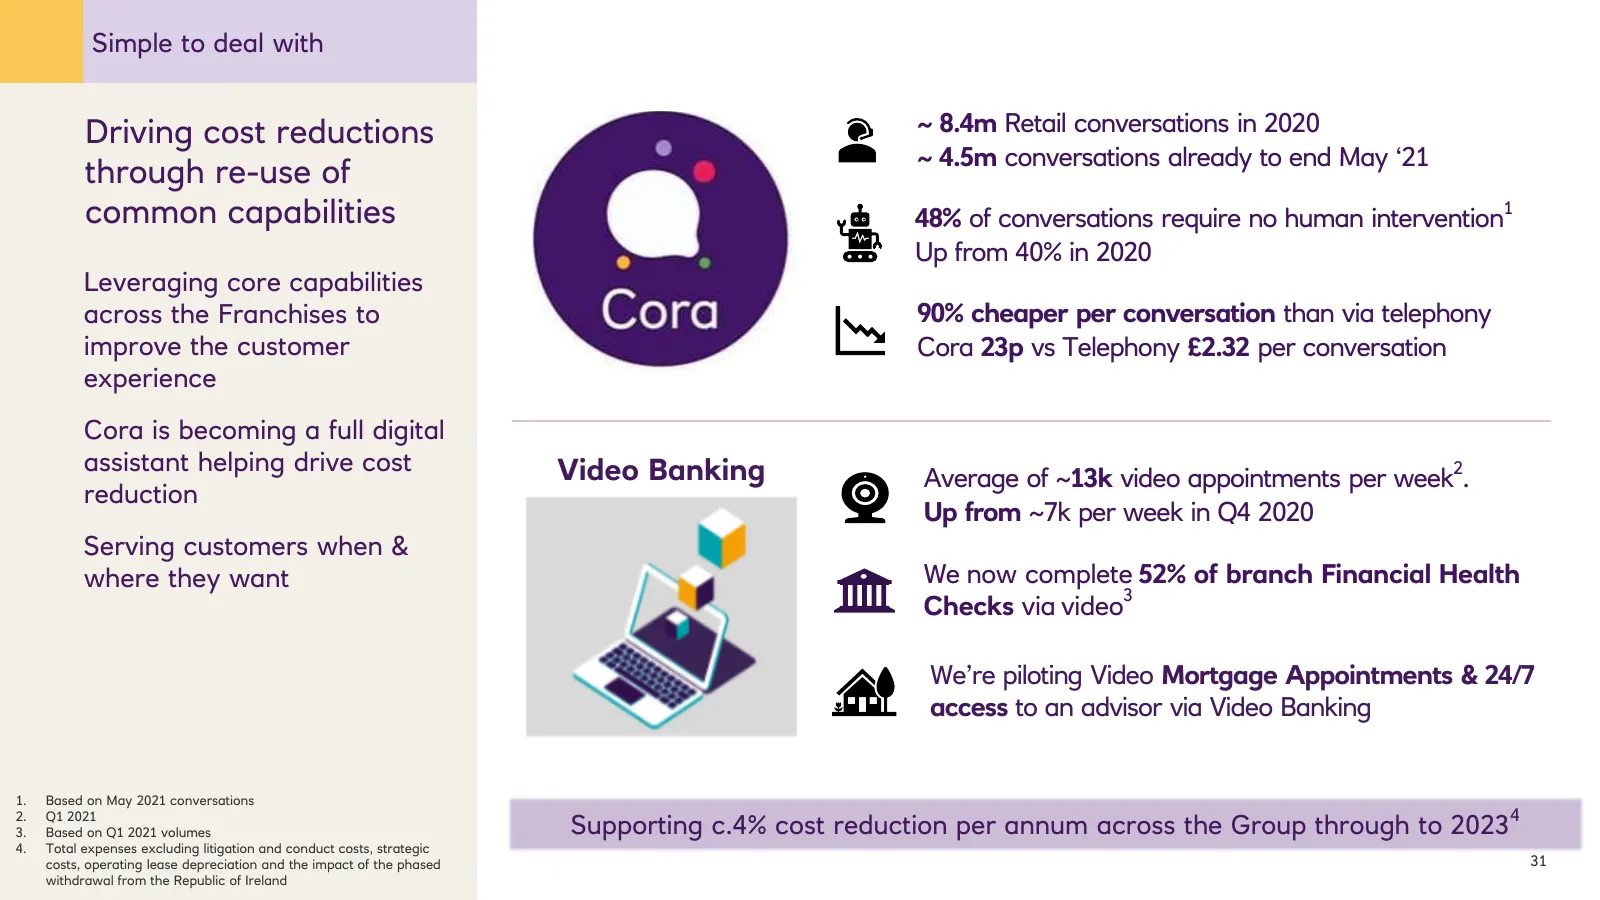
Slide 31: Driving cost reductions through re-use of common capabilities
Simple to deal with Driving cost reductions ~ 8.4m Retail conversations in 2020 ~ 4.5m conversations already to end May ‘21 through re-use of common capabilities 48% of conversations require no human intervention 1 Up from 40% in 2020 Leveraging core capabilities across the Franchises to 90% cheaper
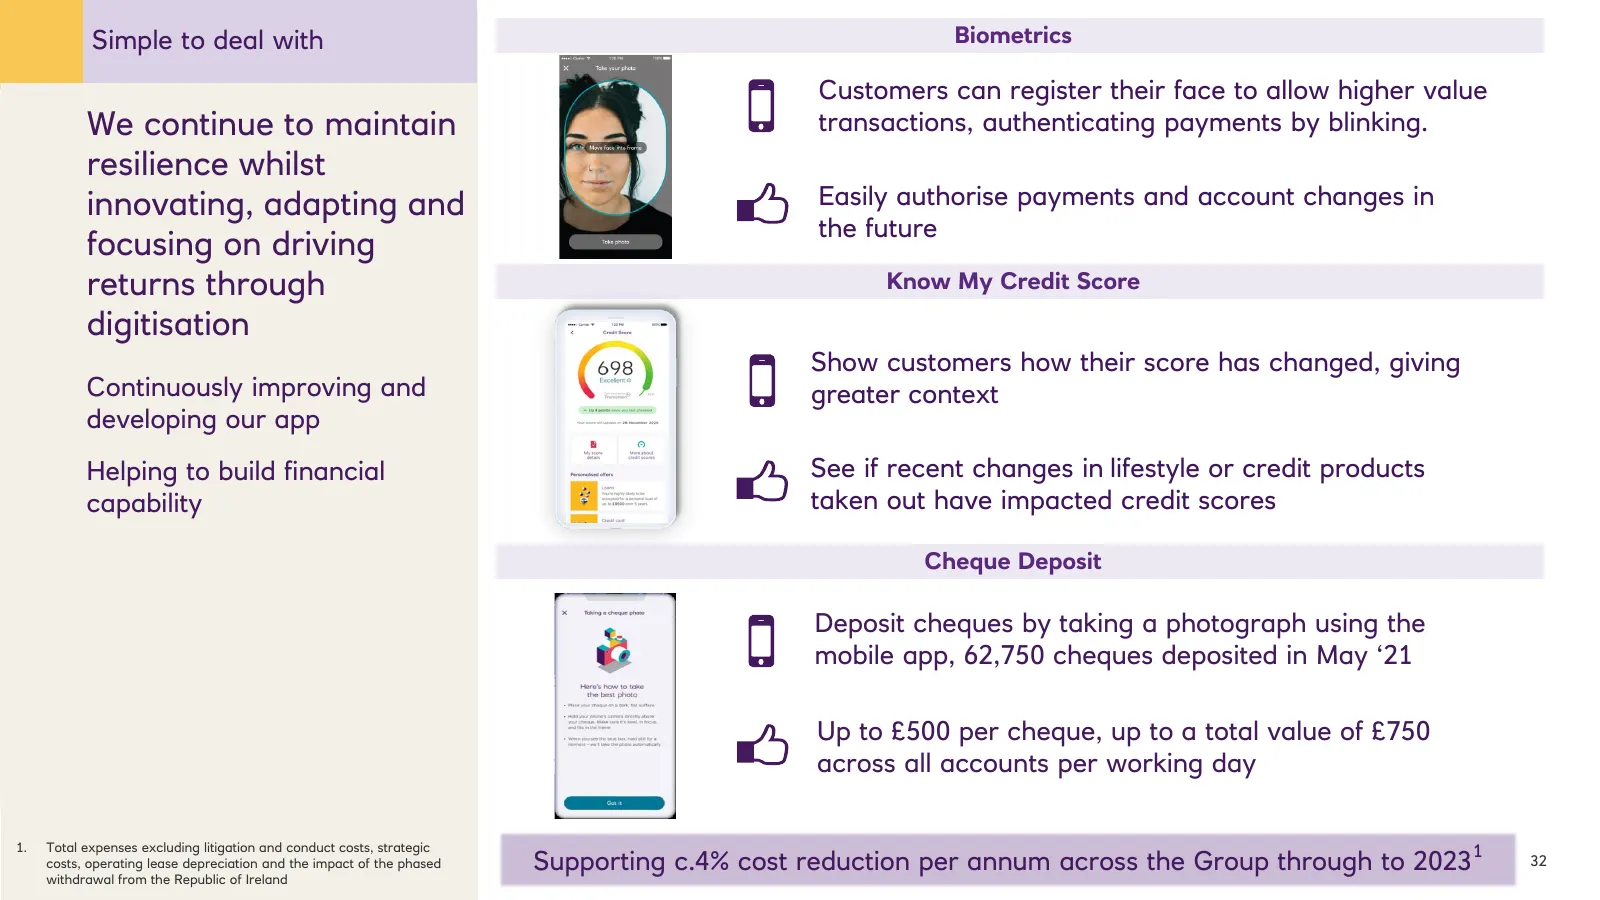
Slide 32: Maintaining resilience whilst innovating
Simple to deal with Biometrics Customers can register their face to allow higher value We continue to maintain transactions, authenticating payments by blinking. resilience whilst innovating, adapting and Easily authorise payments and account changes in the future focusing on driving returns through
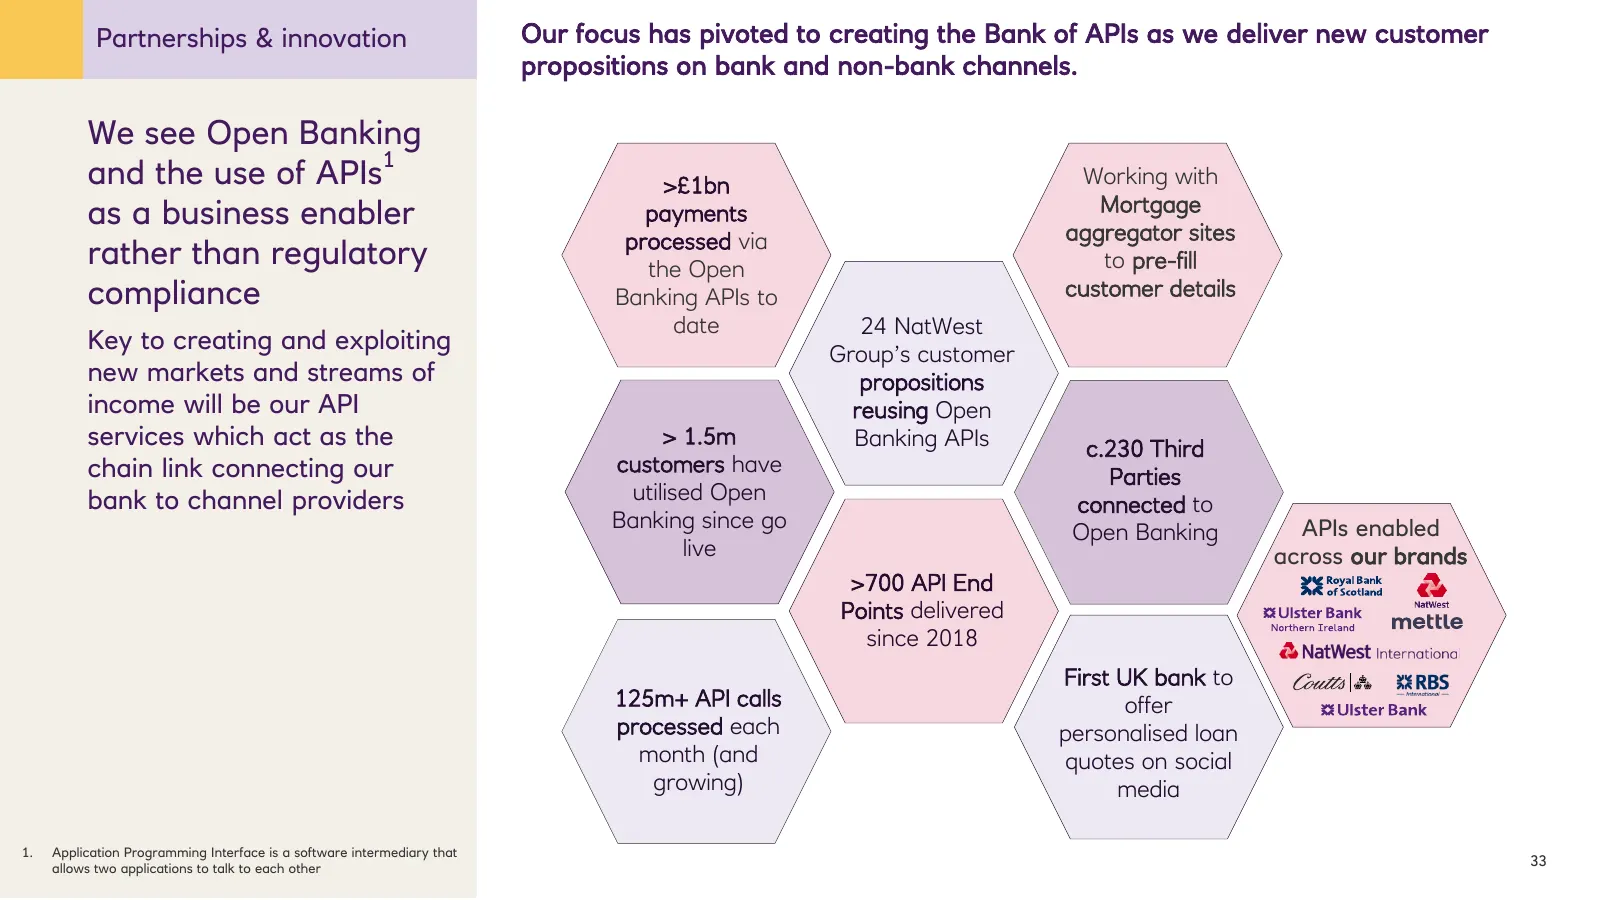
Slide 33: Open Banking and APIs as a business enabler
Partnerships & innovation Our focus has pivoted to creating the Bank of APIs as we deliver new customer propositions on bank and non-bank channels. We see Open Banking and the use of APIs1 >£1bn Working with Mortgage as a business enabler payments aggregator sites processed via rather than regulator
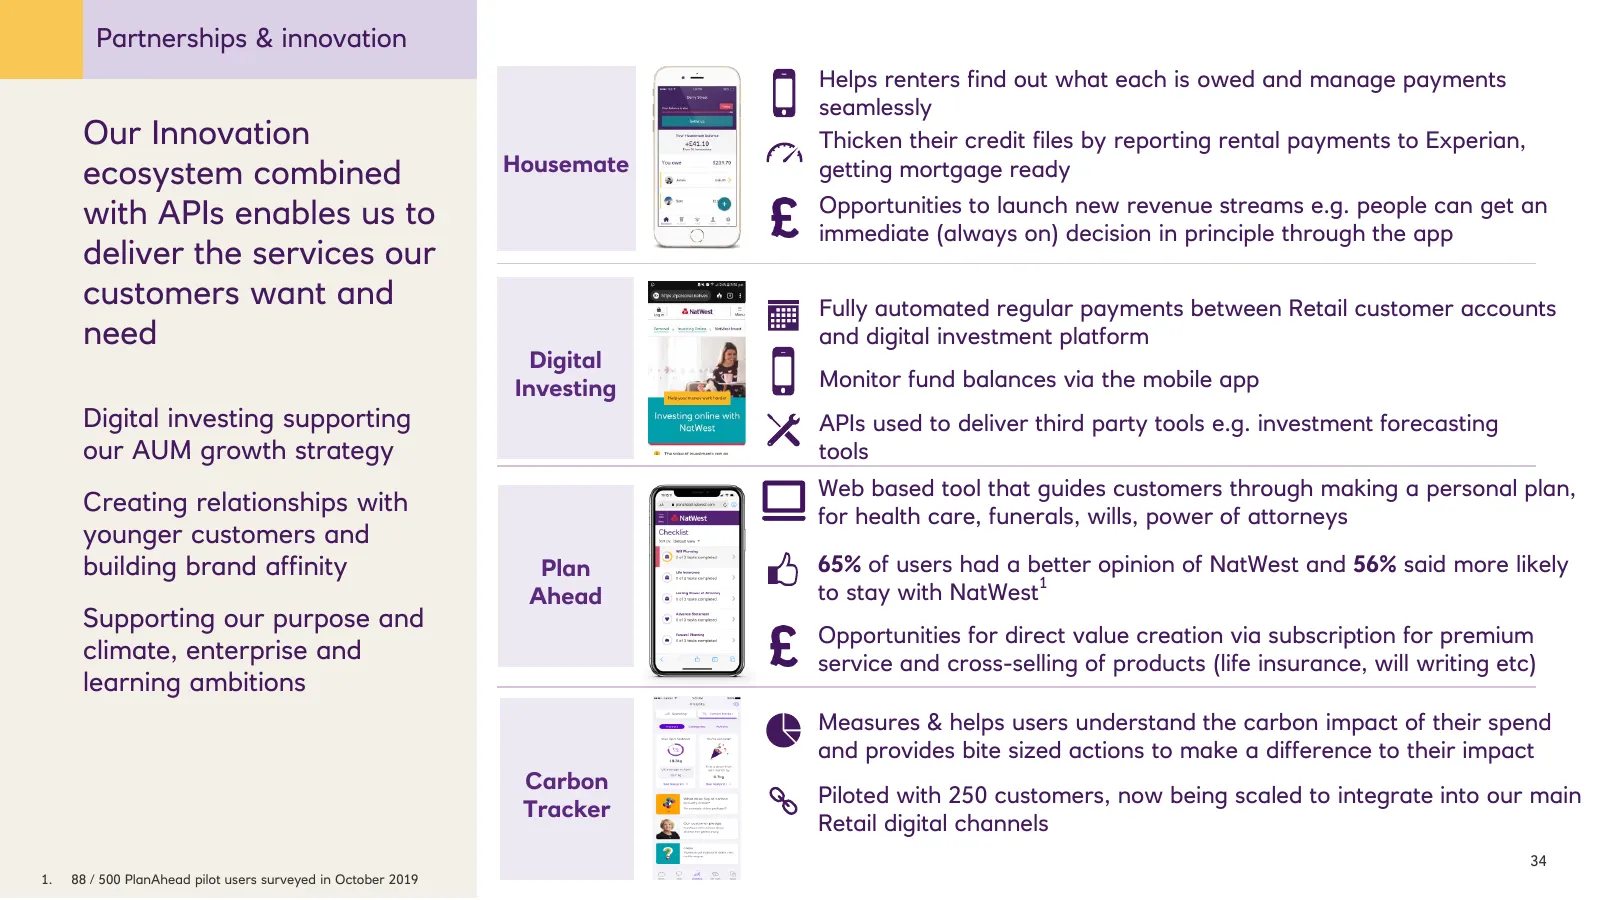
Slide 34: Innovation ecosystem combined with APIs
Partnerships & innovation Helps renters find out what each is owed and manage payments seamlessly Our Innovation Thicken their credit files by reporting rental payments to Experian, ecosystem combined Housemate getting mortgage ready with APIs enables us to Opportunities to launch new revenue stream
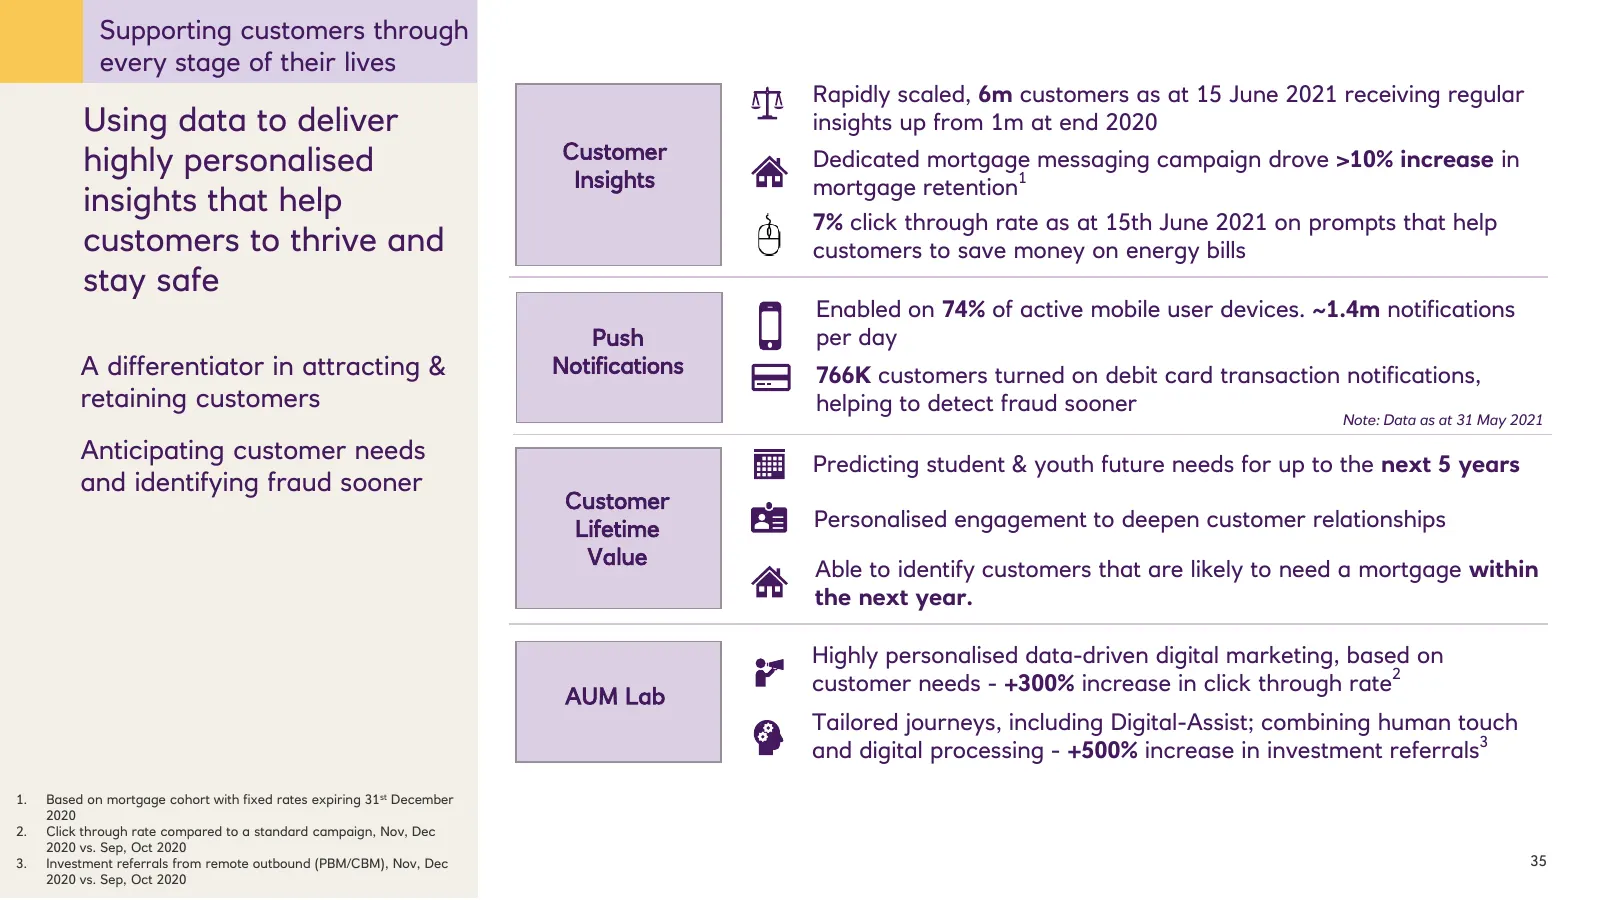
Slide 35: Using data to deliver personalised insights
Supporting customers through every stage of their lives Rapidly scaled, 6m customers as at 15 June 2021 receiving regular Using data to deliver insights up from 1m at end 2020 highly personalised Customer Dedicated mortgage messaging campaign drove >10% increase in Insights mortgage retention1 insig
Slide 36: Jen Tippin, Chief Transformation Officer
Jen Tippin Chief Transformation Officer 36
Slide 37: One Bank Transformation workstreams
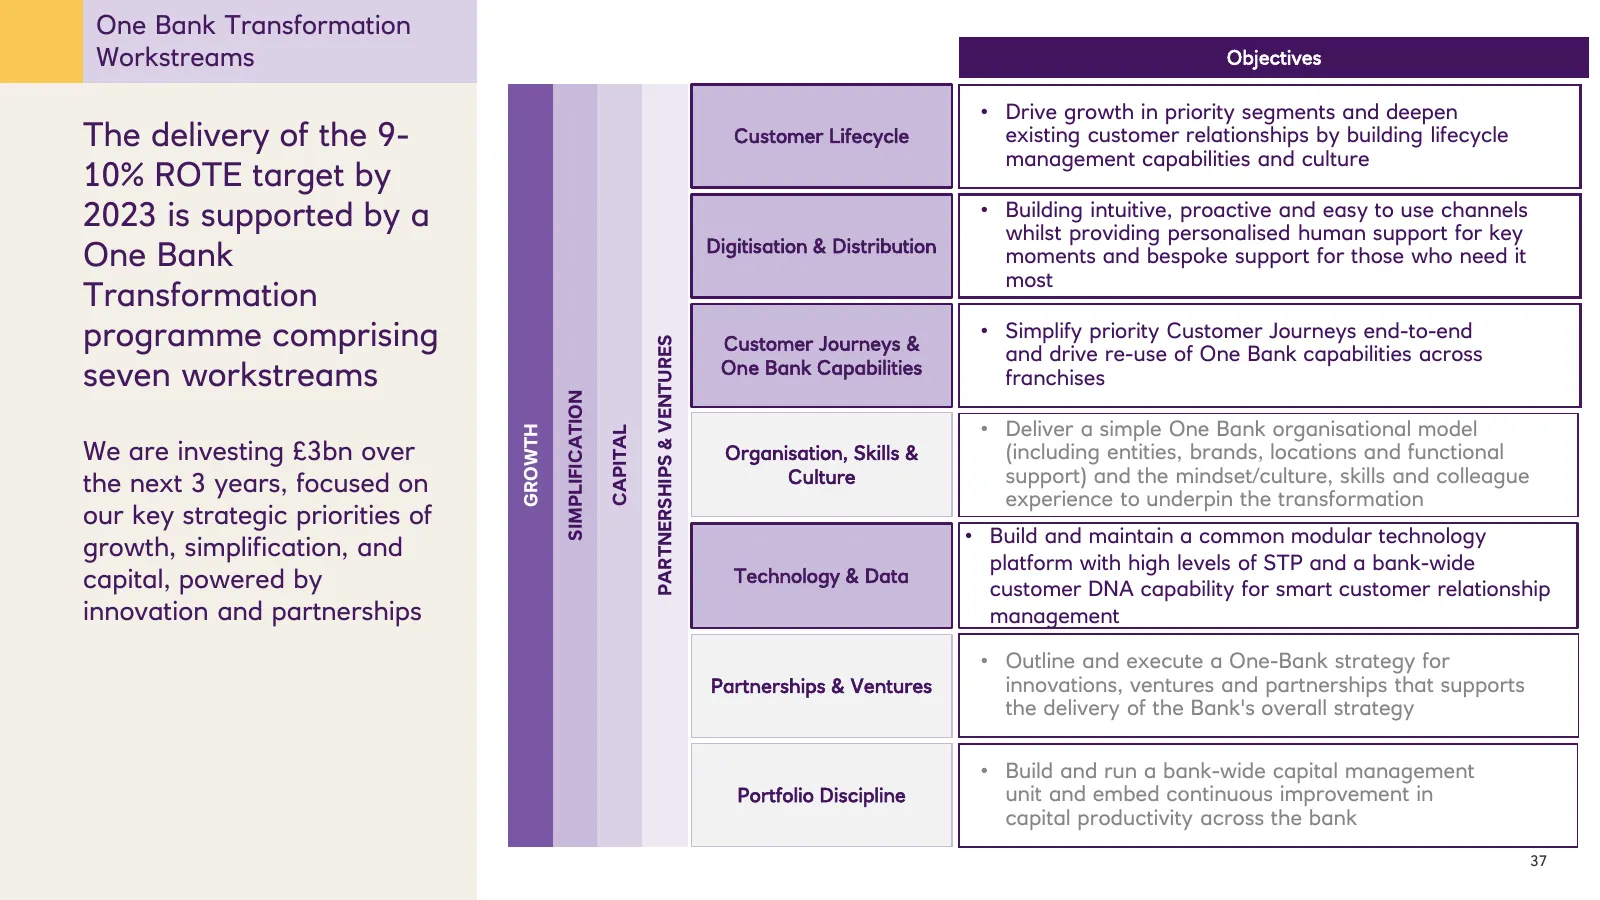
One Bank Transformation Workstreams Objectives • Drive growth in priority segments and deepen The delivery of the 9- Customer Lifecycle existing customer relationships by building lifecycle management capabilities and culture 10% ROTE target by 2023 is supported by a • Building intuitive, proactive
Slide 38: Customer Lifecycle
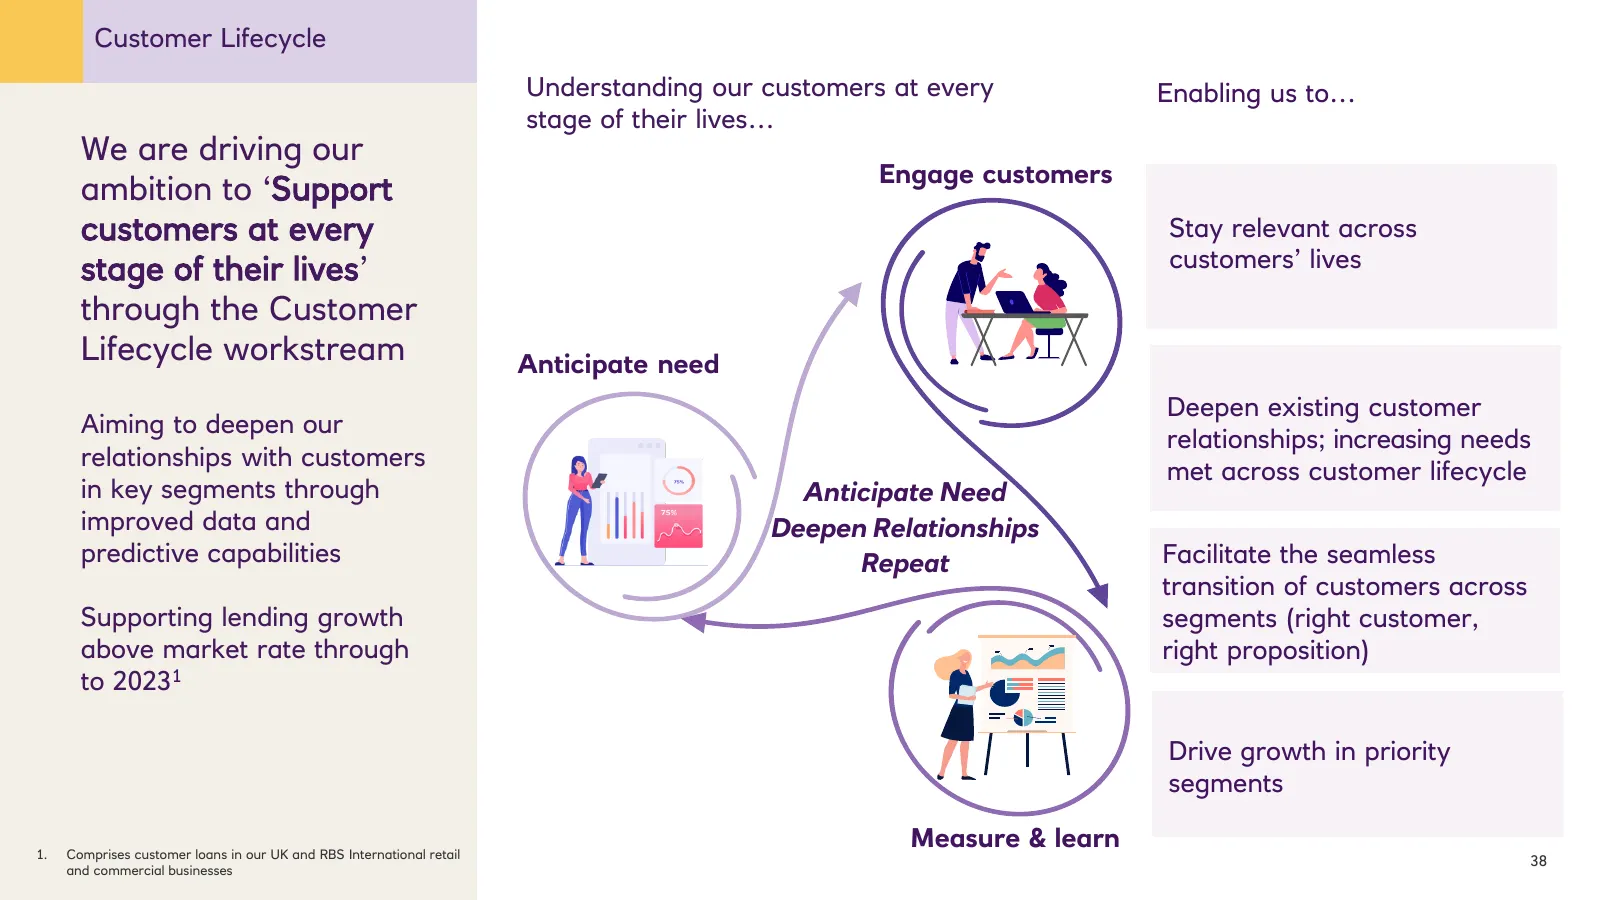
Customer Lifecycle Understanding our customers at every Enabling us to… stage of their lives… We are driving our Engage customers ambition to ‘Support customers at every Stay relevant across stage of their lives’ customers’ lives through the Customer Lifecycle workstream Anticipate need Deepen exist
Slide 39: Digitisation & Distribution
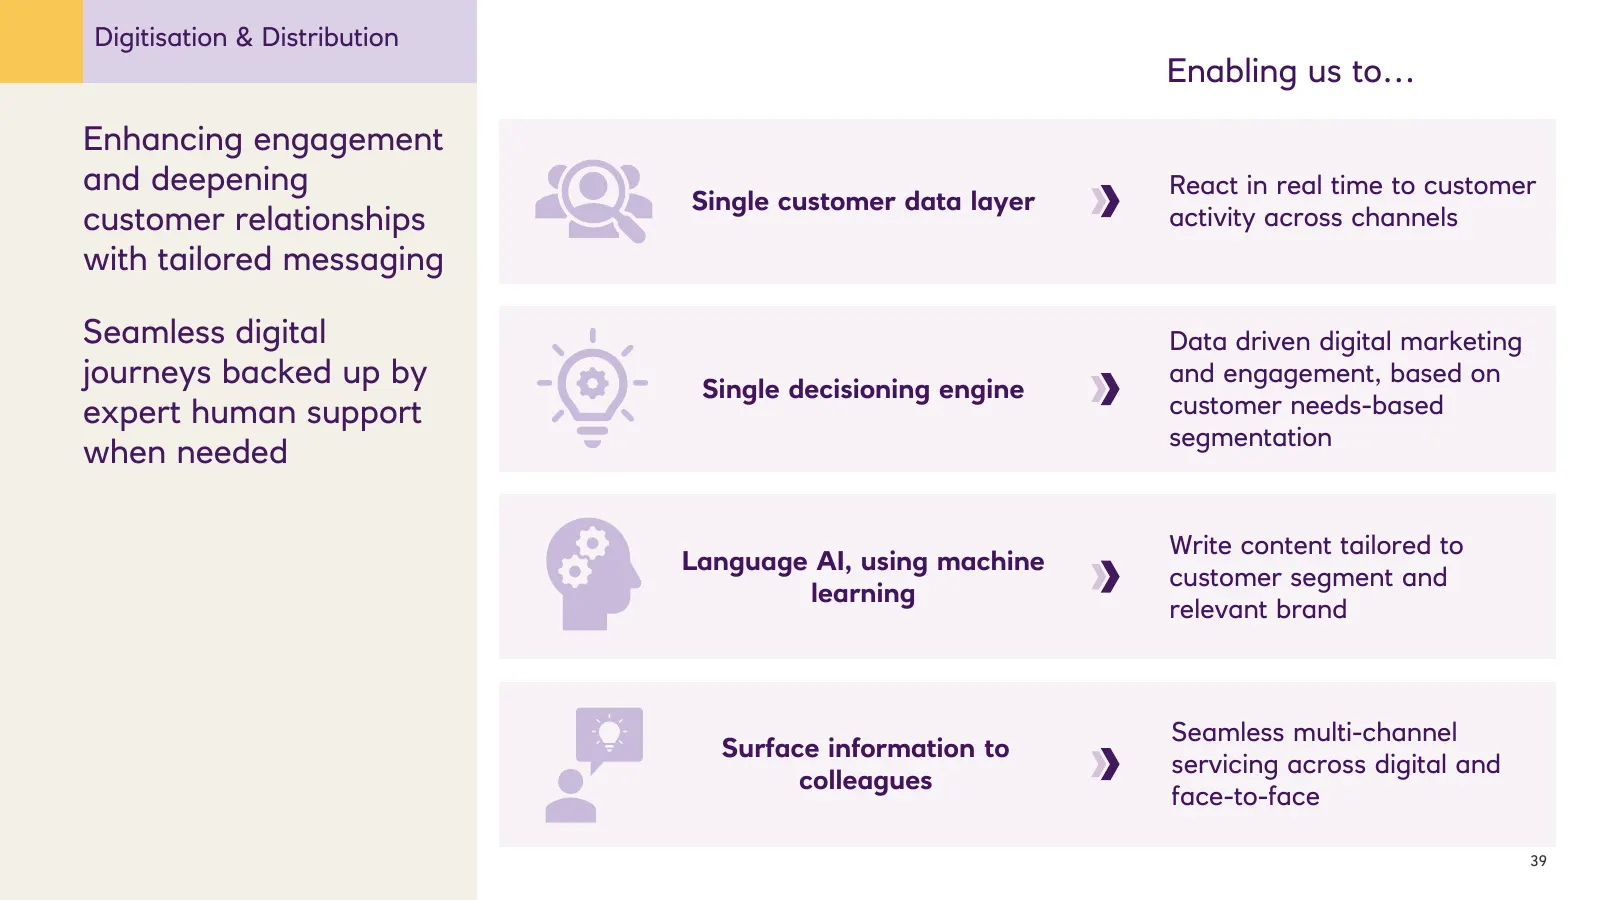
Digitisation & Distribution Enabling us to… Enhancing engagement and deepening React in real time to customer Single customer data layer customer relationships activity across channels with tailored messaging Seamless digital Data driven digital marketing journeys backed up by Single decisioning eng
Slide 40: Benefits of transformation in Customer Journey
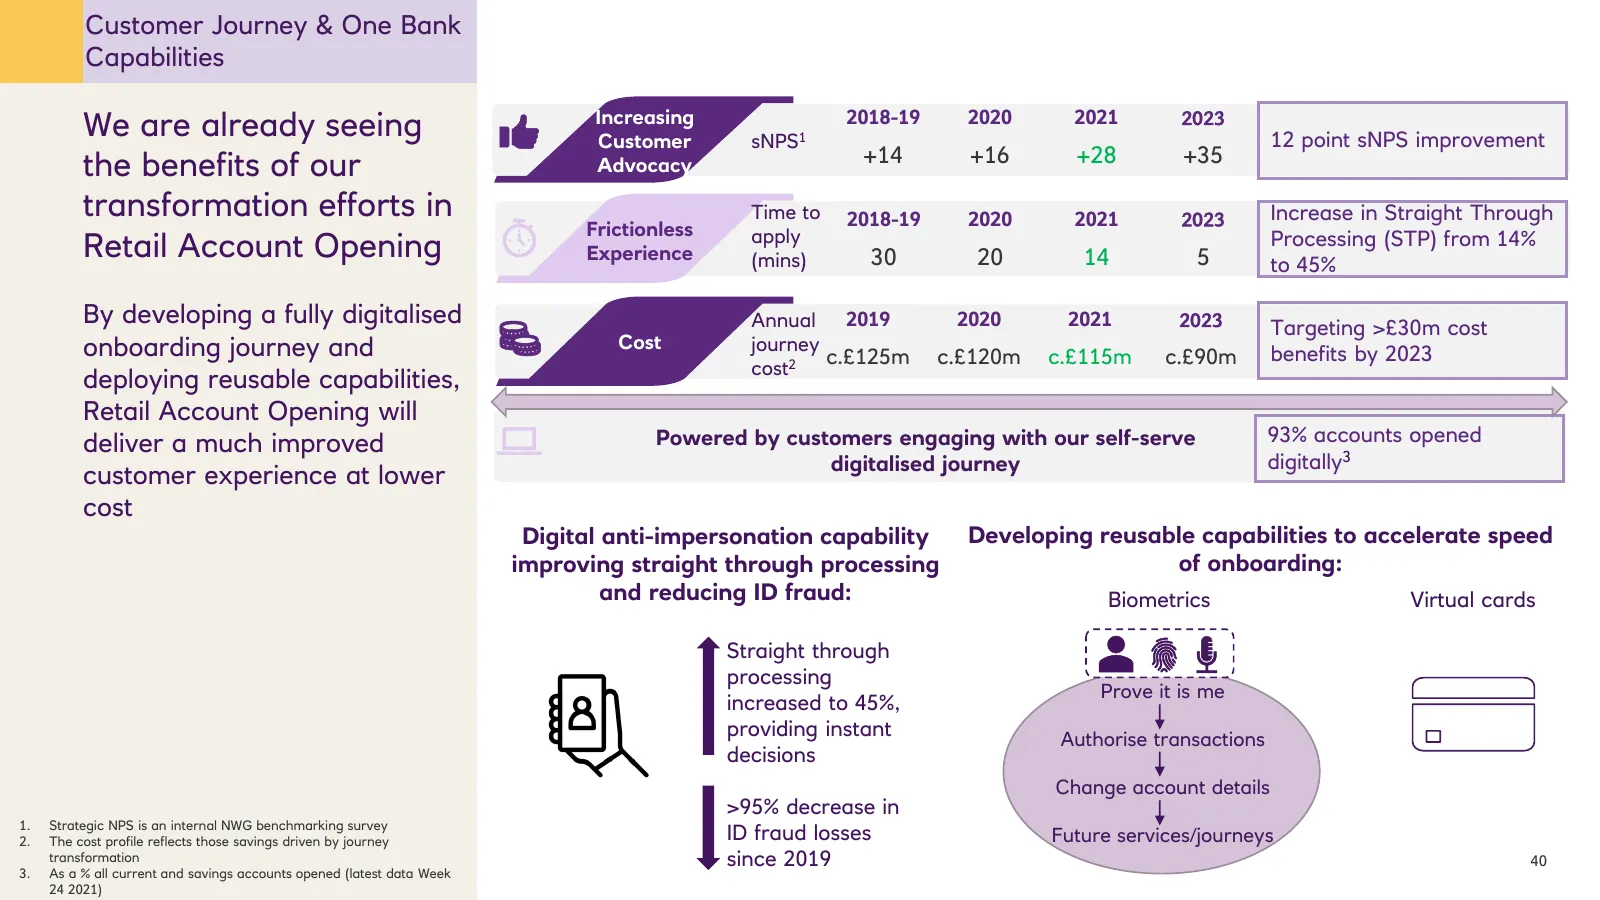
Customer Journey & One Bank Capabilities We are already seeing Increasing Customer sNPS1 2018-19 2020 2021 2023 12 point sNPS improvement +14 +16 +28 +35 the benefits of our Advocacy transformation efforts in Time to 2018-19 2020 2021 2023 Increase in Straight Through Frictionless apply Retail Accou
Slide 41: Transforming the payments journey
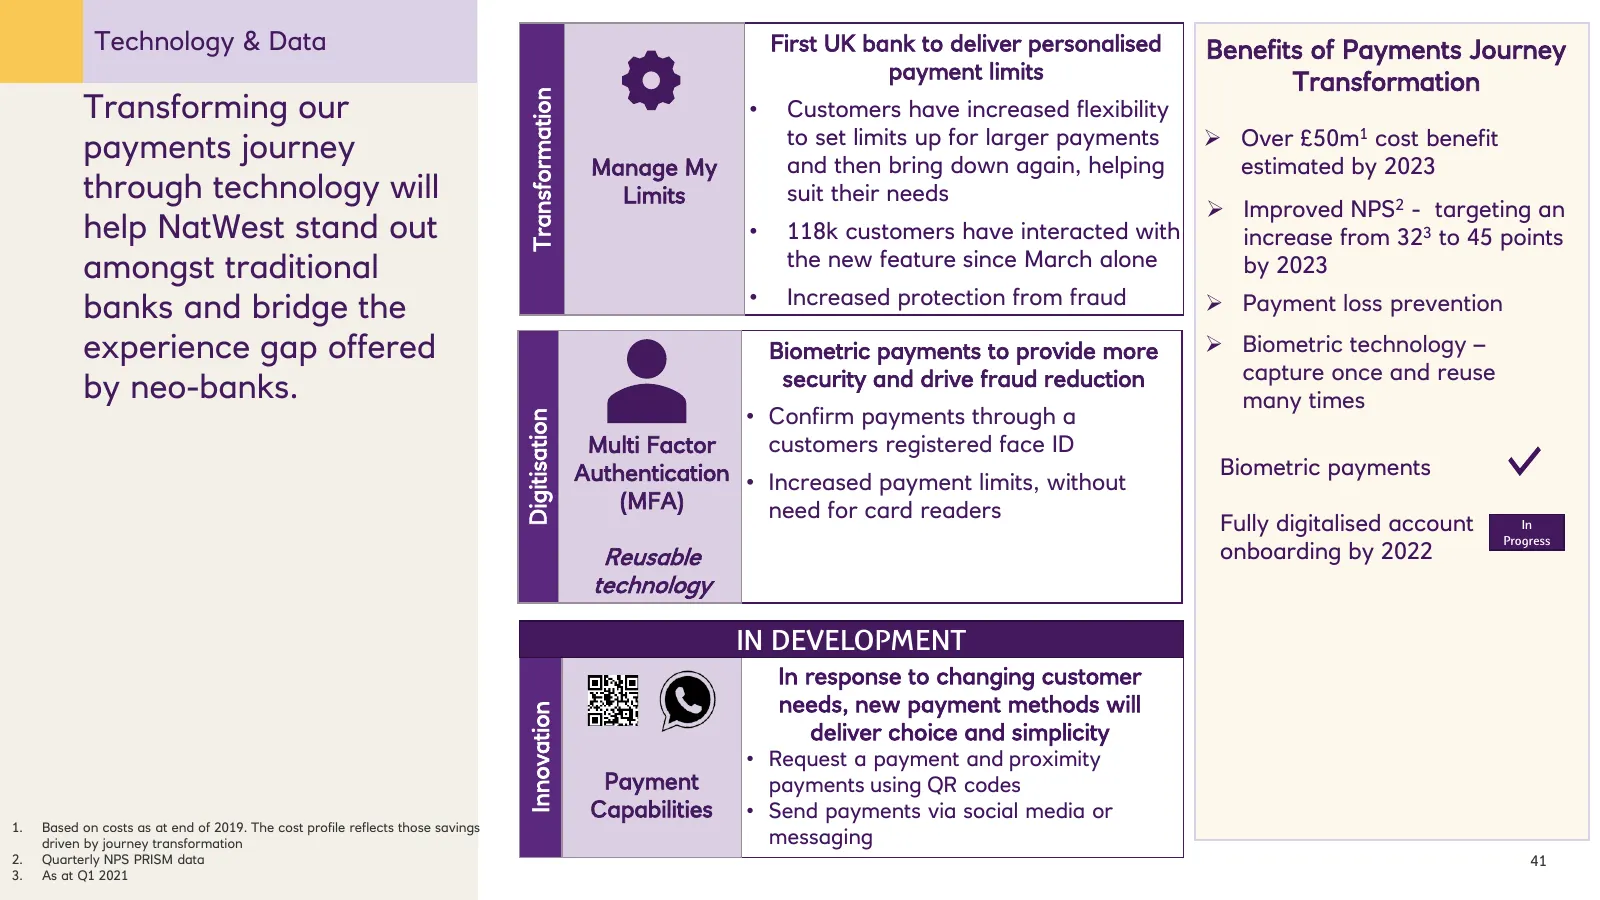
Technology & Data First UK bank to deliver personalised Benefits of Payments Journey payment limits Transformation Transforming our Transformation • Customers have increased flexibility to set limits up for larger payments ➢ Over £50m1 cost benefit payments journey Manage My and then bring down agai
Slide 42: Case Study - Simplification
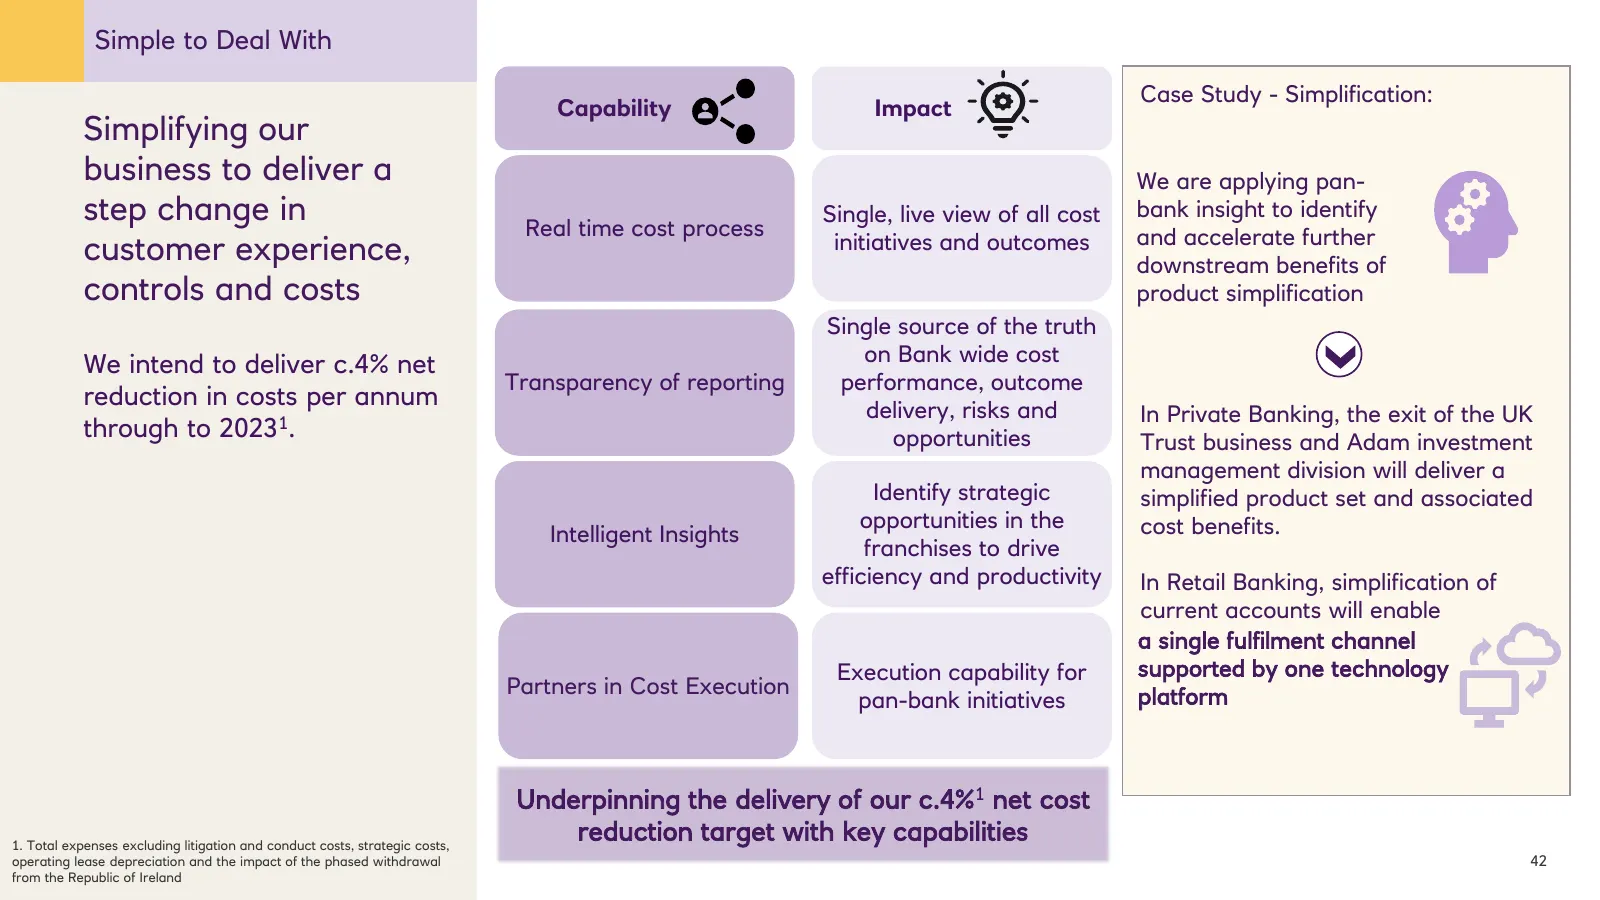
Simple to Deal With Case Study - Simplification: Capability Impact Simplifying our business to deliver a We are applying pan- step change in Real time cost process Single, live view of all cost bank insight to identify and accelerate further customer experience, initiatives and outcomes downstream b
Slide 43: A Relationship Bank for a digital world
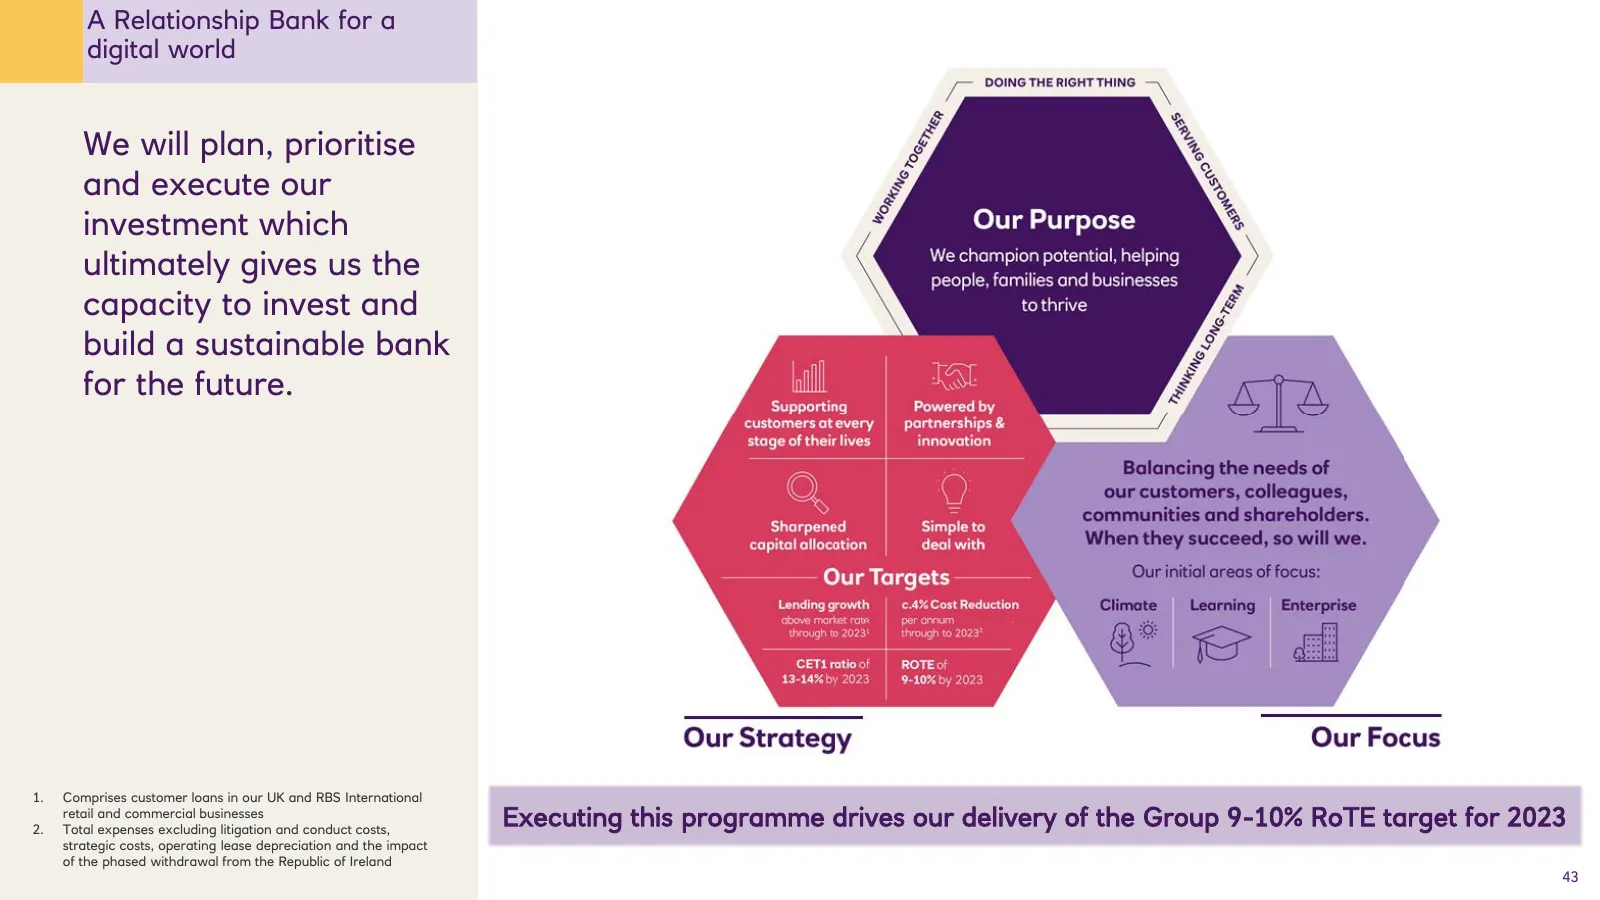
A Relationship Bank for a digital world We will plan, prioritise and execute our investment which ultimately gives us the capacity to invest and build a sustainable bank for the future. 1. Comprises customer loans in our UK and RBS International 2. retail and commercial businesses Total expenses exc
Slide 44: m f- ee :
ie m f- ee :
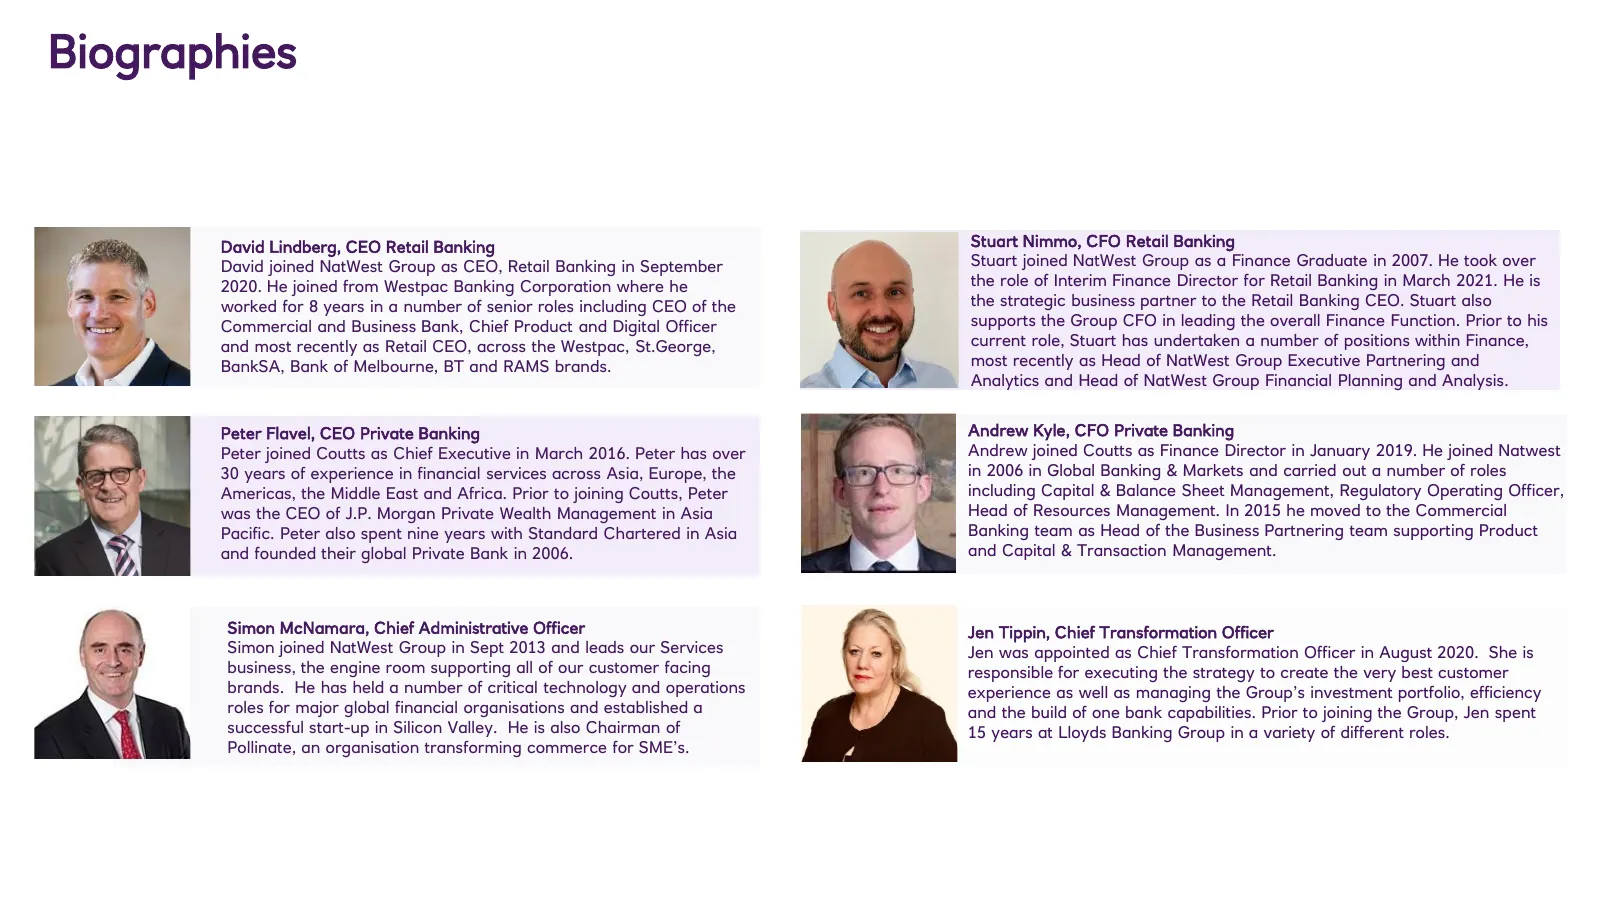
Slide 45: Biographies
Biographies David Lindberg, CEO Retail Banking Stuart Nimmo, CFO Retail Banking David joined NatWest Group as CEO, Retail Banking in September Stuart joined NatWest Group as a Finance Graduate in 2007. He took over 2020. He joined from Westpac Banking Corporation where he the role of Interim Finance
Source: company website
More decks from NatWest Group PLC
 Q3 2026 Earnings Presentation37 slides · Oct 30, 2026
 Debt Investor Presentation (July 2026)47 slides · Jul 31, 2026
 H1 2026 Earnings Presentation46 slides · Jul 31, 2026
 Q1 2026 Earnings Presentation41 slides · May 1, 2026
 FY2025 Earnings Presentation63 slides · Feb 13, 2026
 Debt Investor Presentation (February 2026)50 slides · Feb 13, 2026