Forterra PLC · LSE:FORT
Forterra — H1 2022 Earnings Presentation
38 slides from Forterra's earnings presentation, Jul 28, 2022
Slide 1: Forterra plc Interim Results Presentation
FORTERRA PLC INTERIM RESULTS PRESENTATION 28 JULY 2022 1
Slide 2: Disclaimer
DISCLAIMER This document has been prepared by Forterra plc (the “Company”) solely for use at a presentation in connection with the Company’s Results Announcement in respect of the financial period ended 30 June 2022 (the “Presentation”). For the purposes of this notice, “Presentation” shall mean and
Slide 3: Agenda
AGENDA 1. Highlights 2. Financial review 3. Our markets 4. Strategic update 5. Sustainability 6. Outlook 7. Q&A Stephen Harrison Ben Guyatt Chief Executive Officer Chief Financial Officer Keeping Britain Building 3
Slide 4: Operational and Trading Highlights
OPERATIONAL AND TRADING HIGHLIGHTS • Continued strong performance; full year expectations slightly increased • Strong trading continued throughout the period with results ahead of both the prior year and 2019 • Both housebuilding and RMI demand remains strong with London Brick volumes performing wel
Slide 5: Strategic Highlights
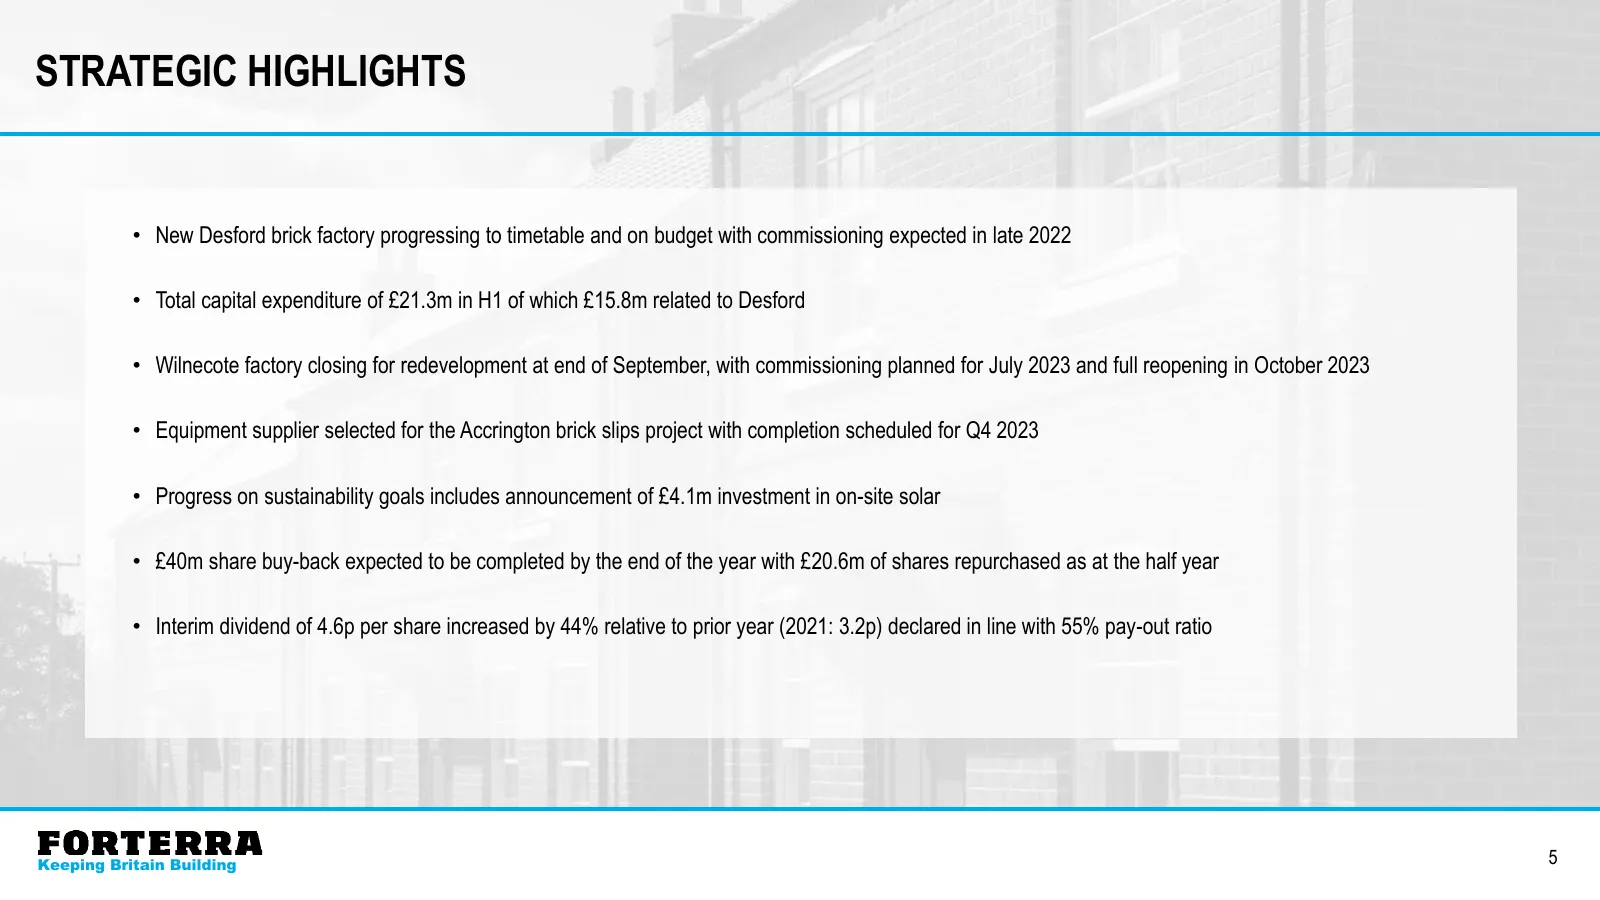
STRATEGIC HIGHLIGHTS • New Desford brick factory progressing to timetable and on budget with commissioning expected in late 2022 • Total capital expenditure of £21.3m in H1 of which £15.8m related to Desford • Wilnecote factory closing for redevelopment at end of September, with commissioning planne
Slide 6: Financial Review
Keeping Britain Building FINANCIAL REVIEW
Slide 7: Key Financials
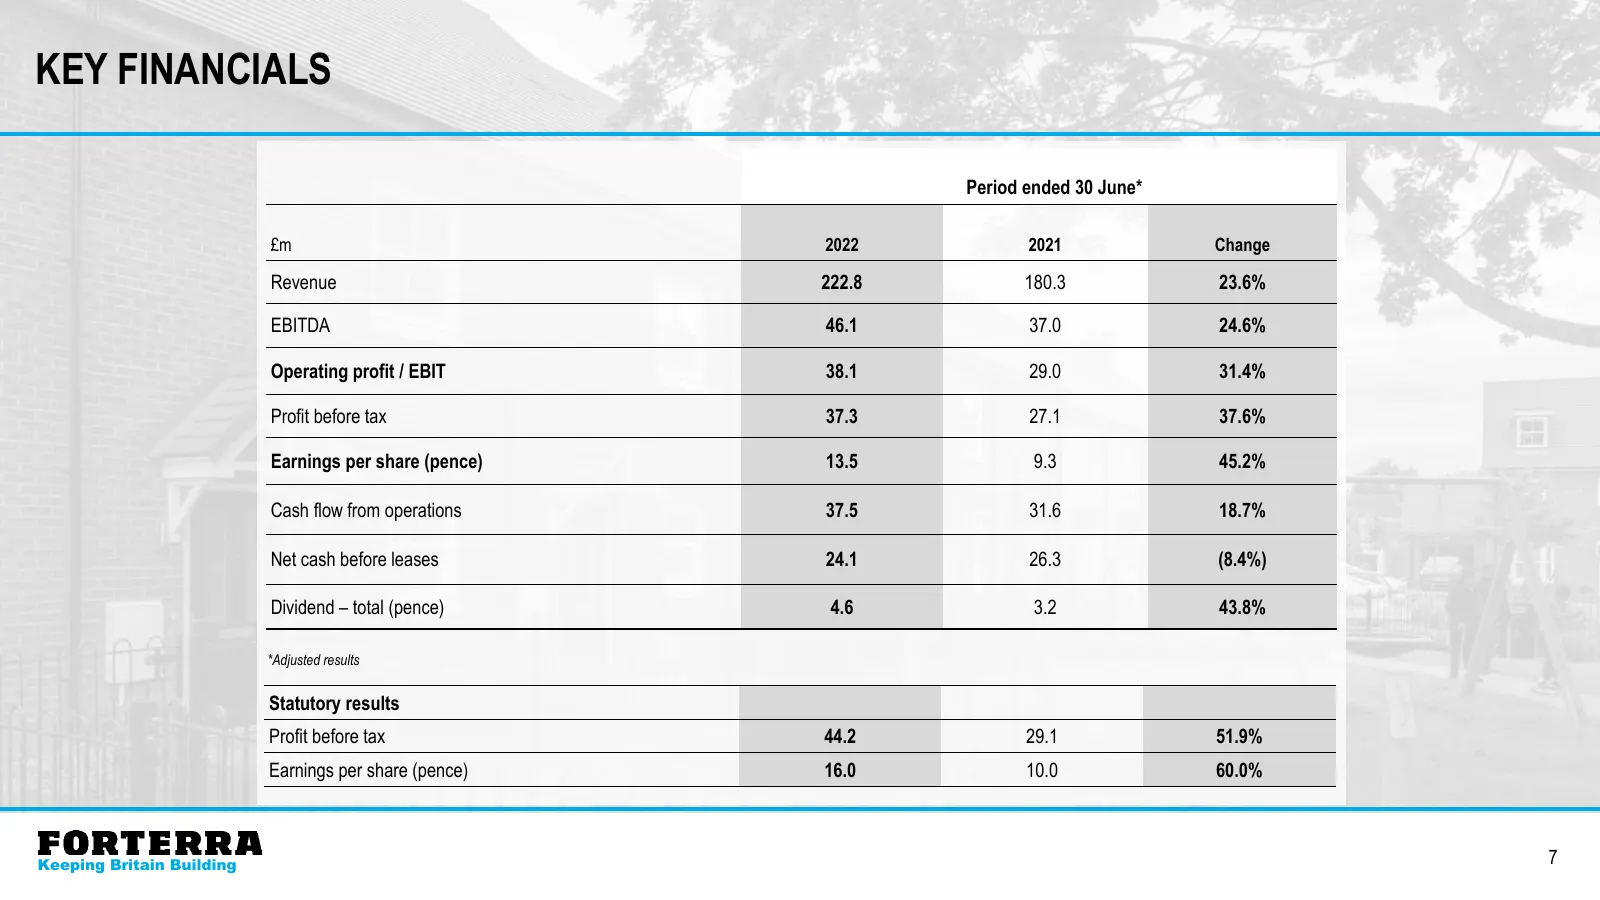
KEY FINANCIALS Period ended 30 June* £m 2022 2021 Change Revenue 222.8 180.3 23.6% EBITDA 46.1 37.0 24.6% Operating profit / EBIT 38.1 29.0 31.4% Profit before tax 37.3 27.1 37.6% Earnings per share (pence) 13.5 9.3 45.2% Cash flow from operations 37.5 31.6 18.7% Net cash before leases 24.1 26.3 (8.
Slide 8: Profit and Loss
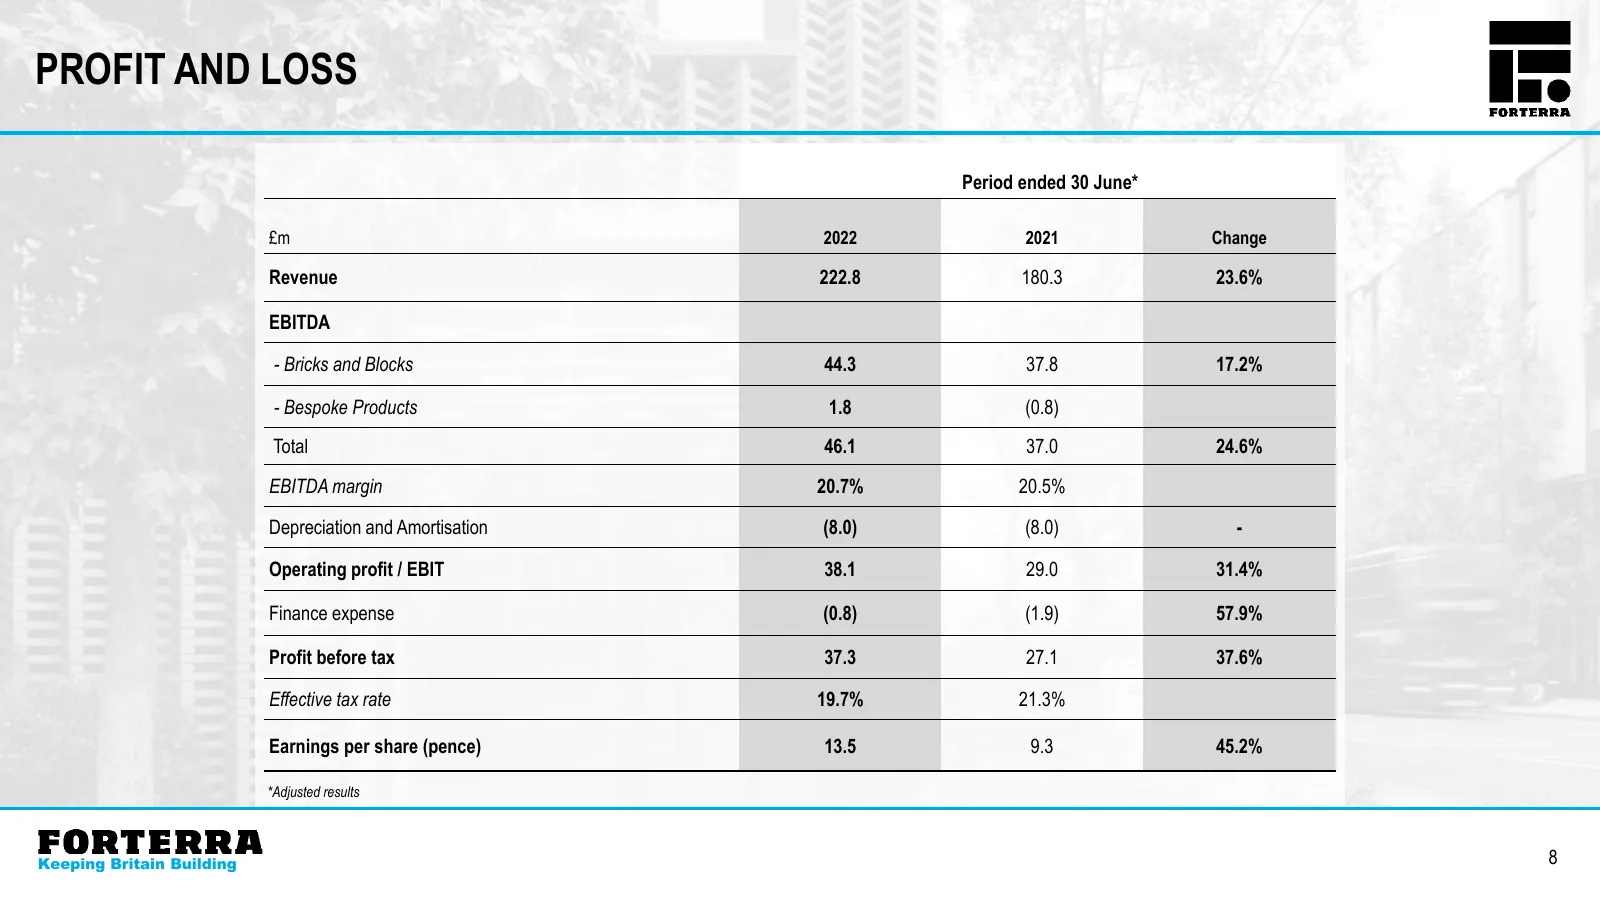
PROFIT AND LOSS Period ended 30 June* £m 2022 2021 Change Revenue 222.8 180.3 23.6% EBITDA - Bricks and Blocks 44.3 37.8 17.2% - Bespoke Products 1.8 (0.8) Total 46.1 37.0 24.6% EBITDA margin 20.7% 20.5% Depreciation and Amortisation (8.0) (8.0) - Operating profit / EBIT 38.1 29.0 31.4% Finance expe
Slide 9: Segmental Results: Bricks and Blocks
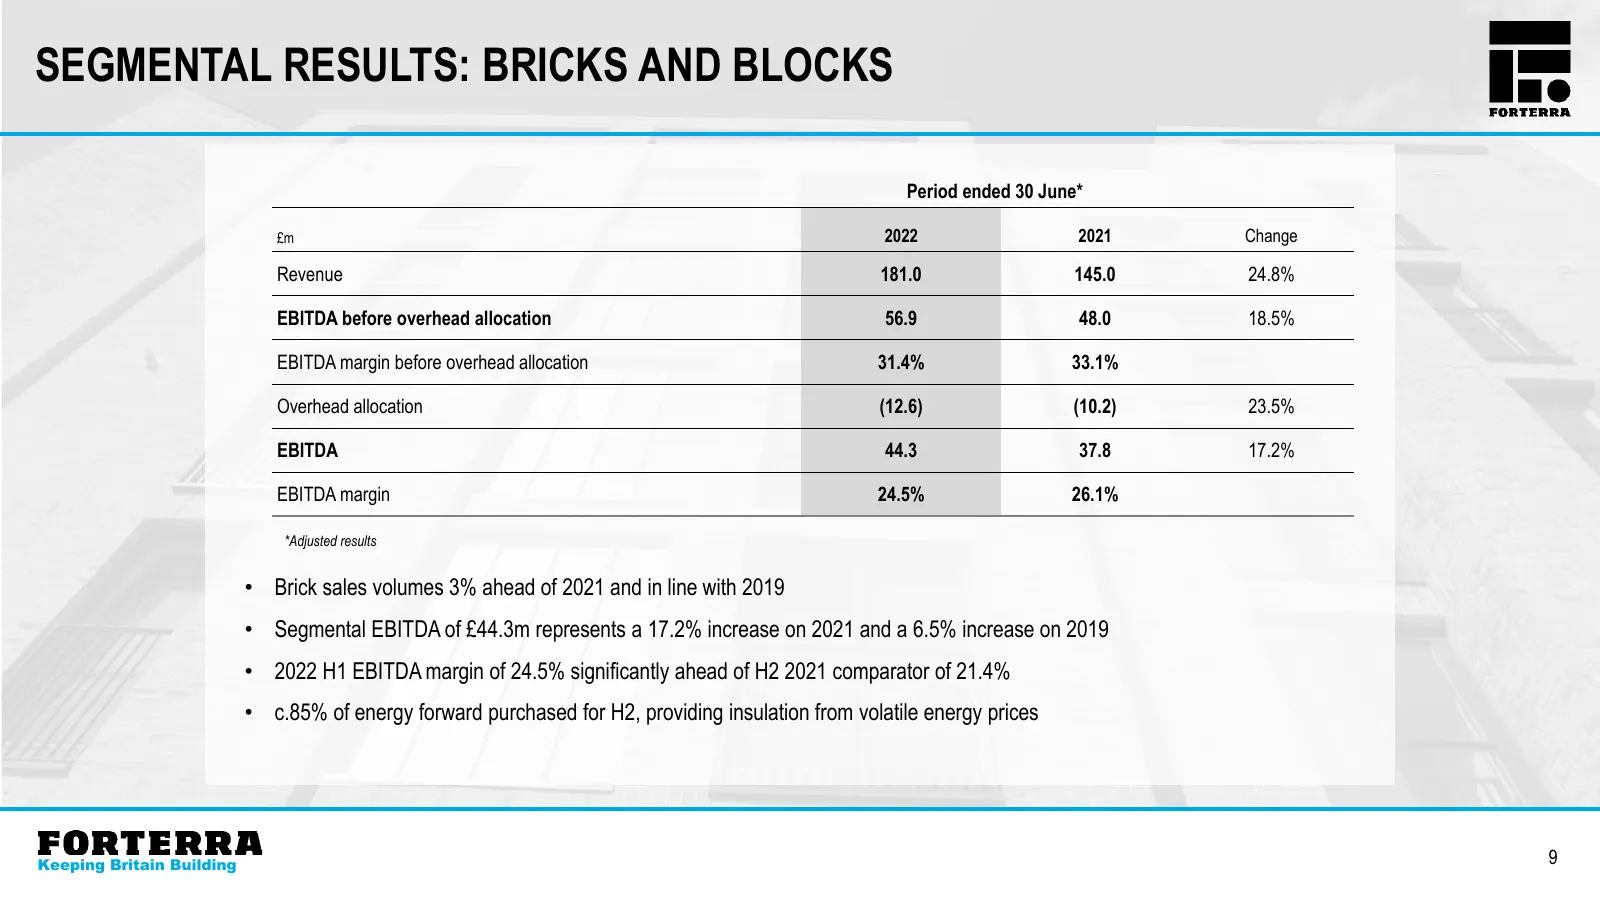
SEGMENTAL RESULTS: BRICKS AND BLOCKS Period ended 30 June* £m 2022 2021 Change Revenue 181.0 145.0 24.8% EBITDA before overhead allocation 56.9 48.0 18.5% EBITDA margin before overhead allocation 31.4% 33.1% Overhead allocation (12.6) (10.2) 23.5% EBITDA 44.3 37.8 17.2% EBITDA margin 24.5% 26.1% *Ad
Slide 10: Segmental Results: Bespoke Products
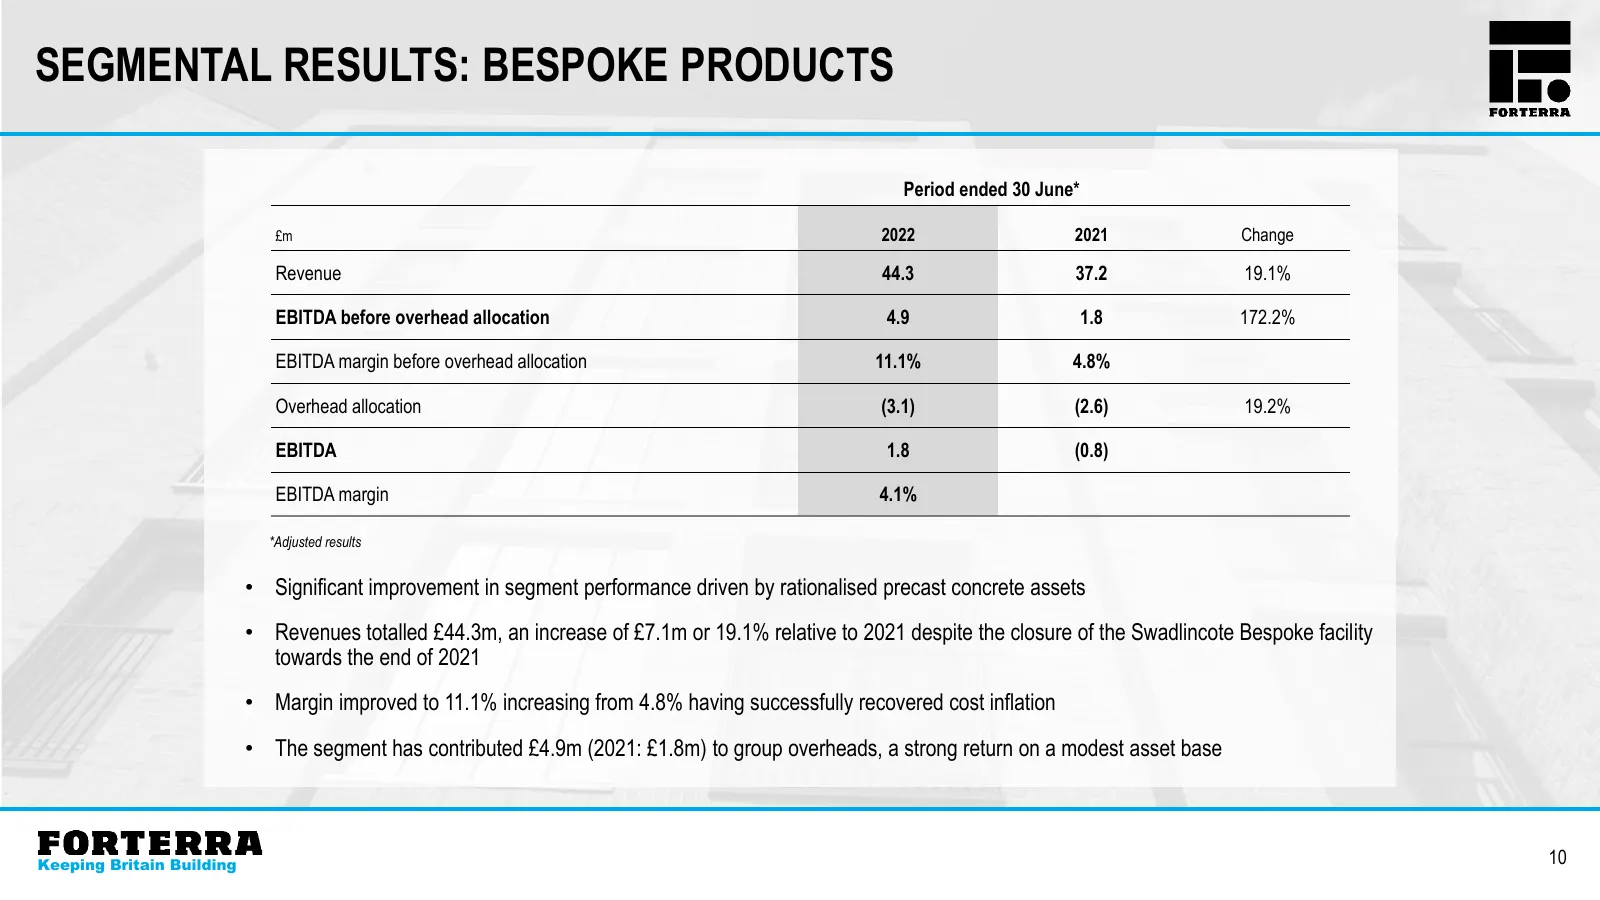
SEGMENTAL RESULTS: BESPOKE PRODUCTS Period ended 30 June* £m 2022 2021 Change Revenue 44.3 37.2 19.1% EBITDA before overhead allocation 4.9 1.8 172.2% EBITDA margin before overhead allocation 11.1% 4.8% Overhead allocation (3.1) (2.6) 19.2% EBITDA 1.8 (0.8) EBITDA margin 4.1% *Adjusted results • Sig
Slide 11: Cash Flow
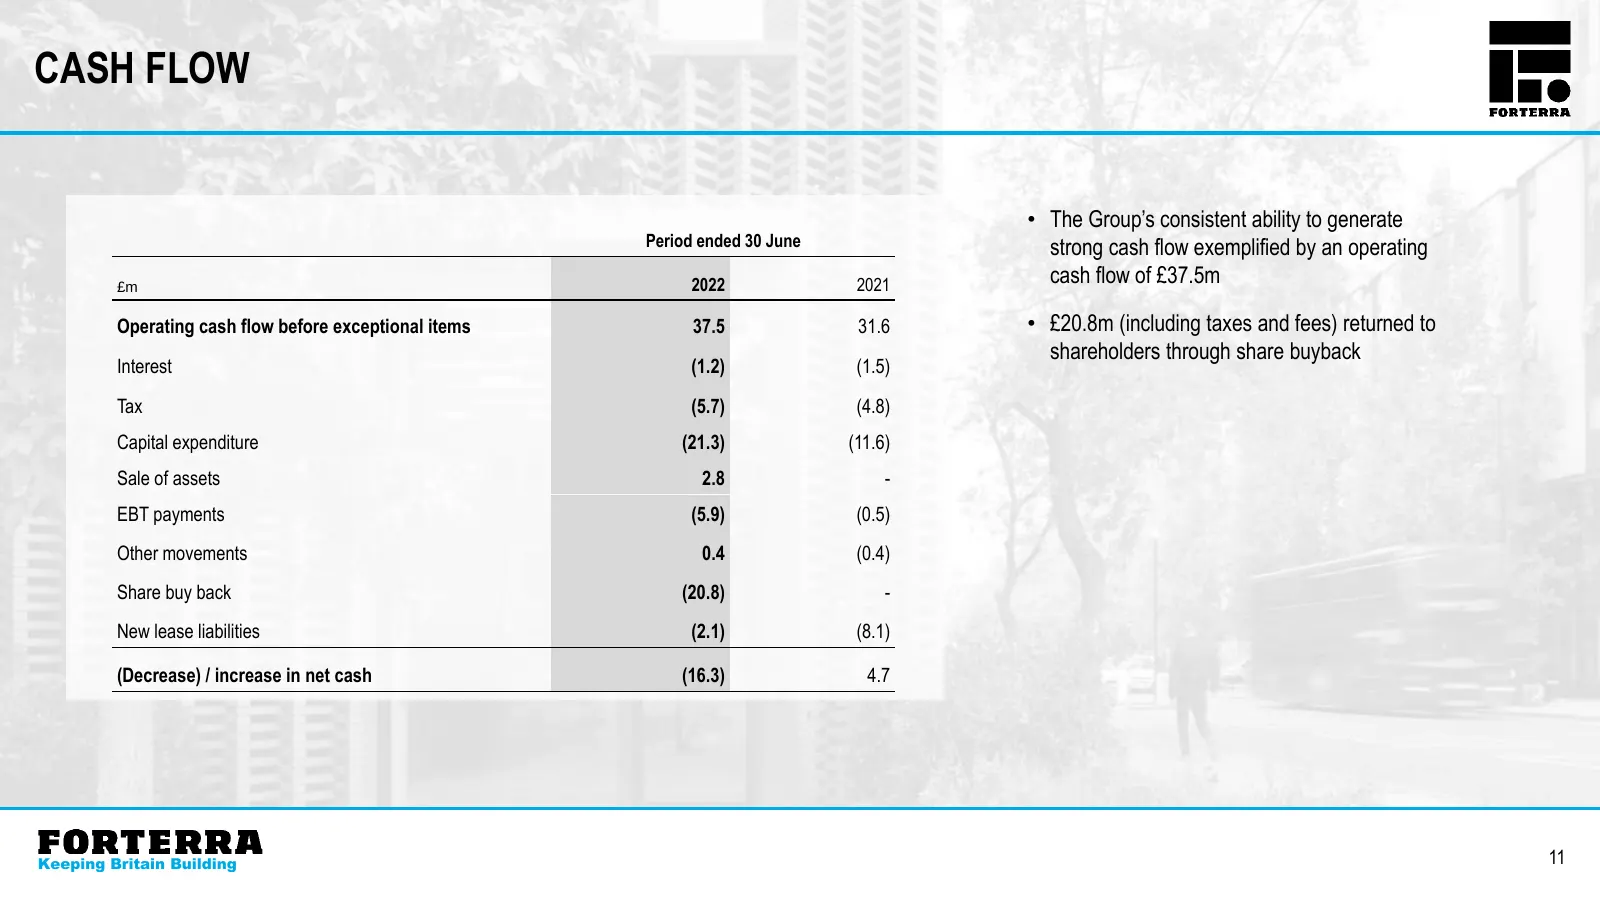
CASH FLOW • The Group’s consistent ability to generate Period ended 30 June strong cash flow exemplified by an operating £m 2022 2021 cash flow of £37.5m Operating cash flow before exceptional items 37.5 31.6 • £20.8m (including taxes and fees) returned to shareholders through share buyback Interest
Slide 12: Capex Guidance
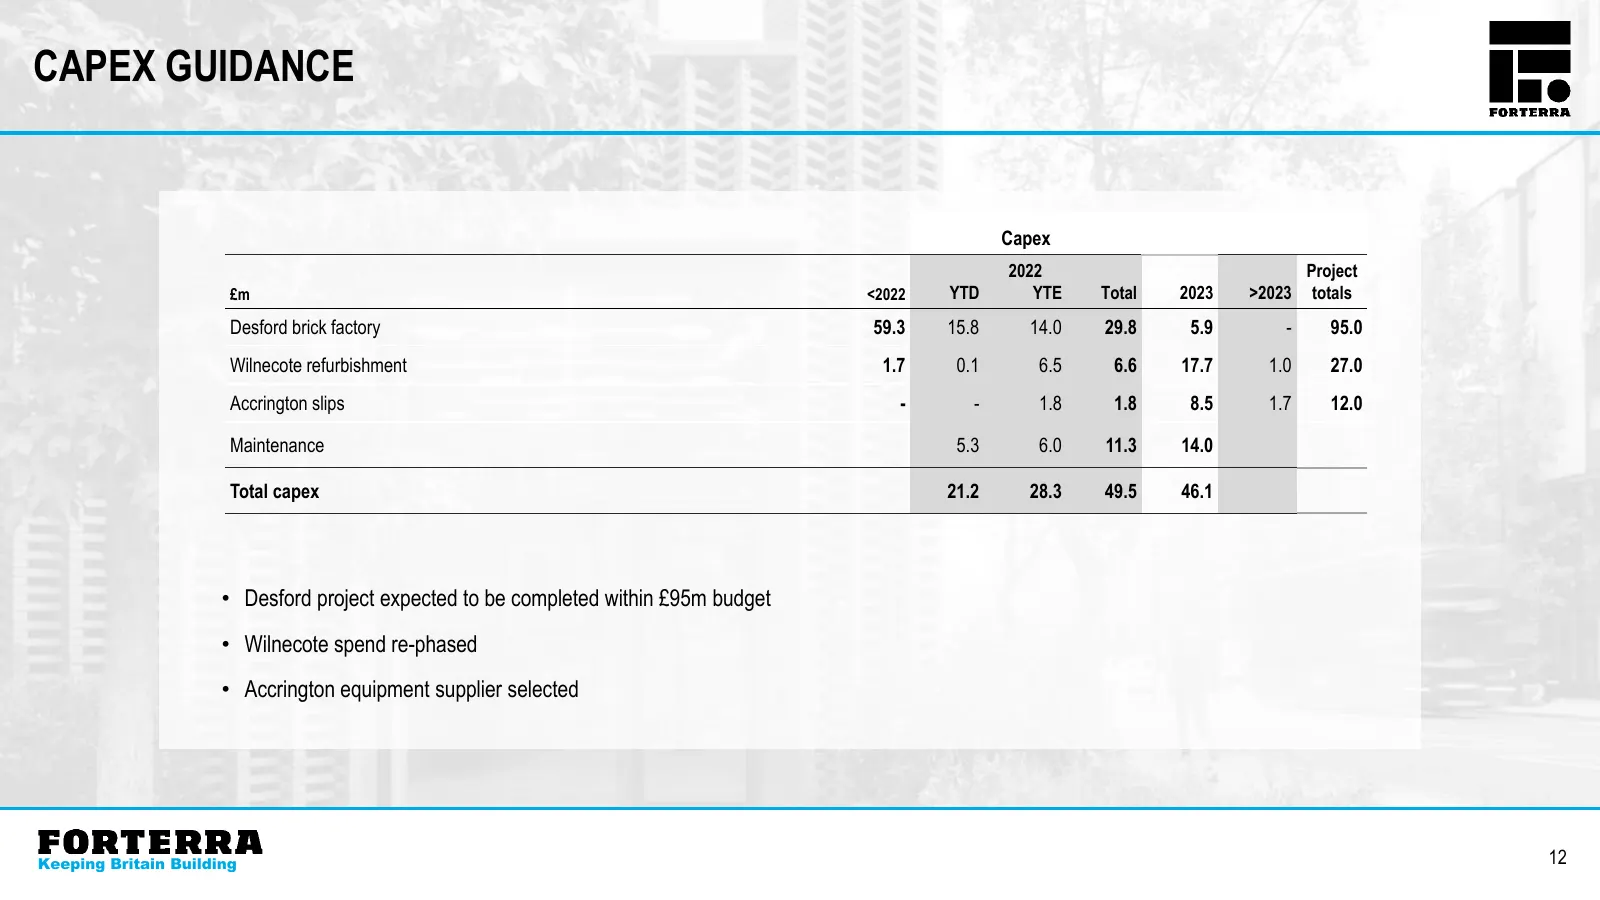
CAPEX GUIDANCE Capex 2022 Project £m <2022 YTD YTE Total 2023 >2023 totals Desford brick factory 59.3 15.8 14.0 29.8 5.9 - 95.0 Wilnecote refurbishment 1.7 0.1 6.5 6.6 17.7 1.0 27.0 Accrington slips - - 1.8 1.8 8.5 1.7 12.0 Maintenance 5.3 6.0 11.3 14.0 Total capex 21.2 28.3 49.5 46.1 • Desford proj
Slide 13: Working Capital
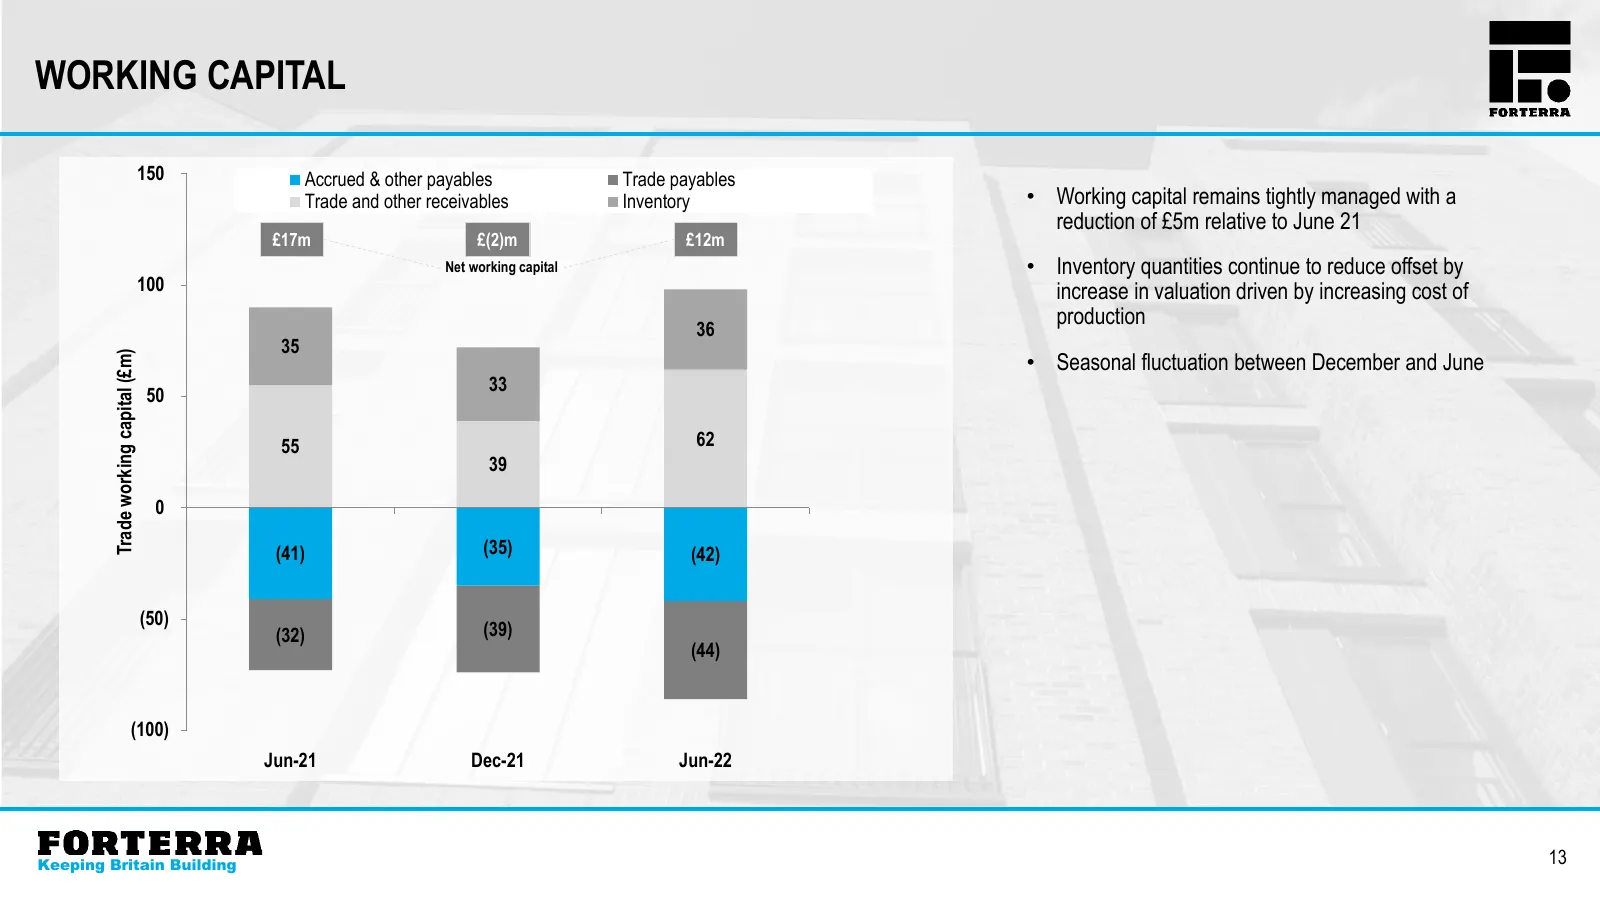
WORKING CAPITAL 150 Accrued & other payables Trade payables Trade and other receivables Inventory • Working capital remains tightly managed with a reduction of £5m relative to June 21 £17m £(2)m £12m Net working capital • Inventory quantities continue to reduce offset by 100 increase in valuation dr
Slide 14: Balance Sheet Position and Facilities
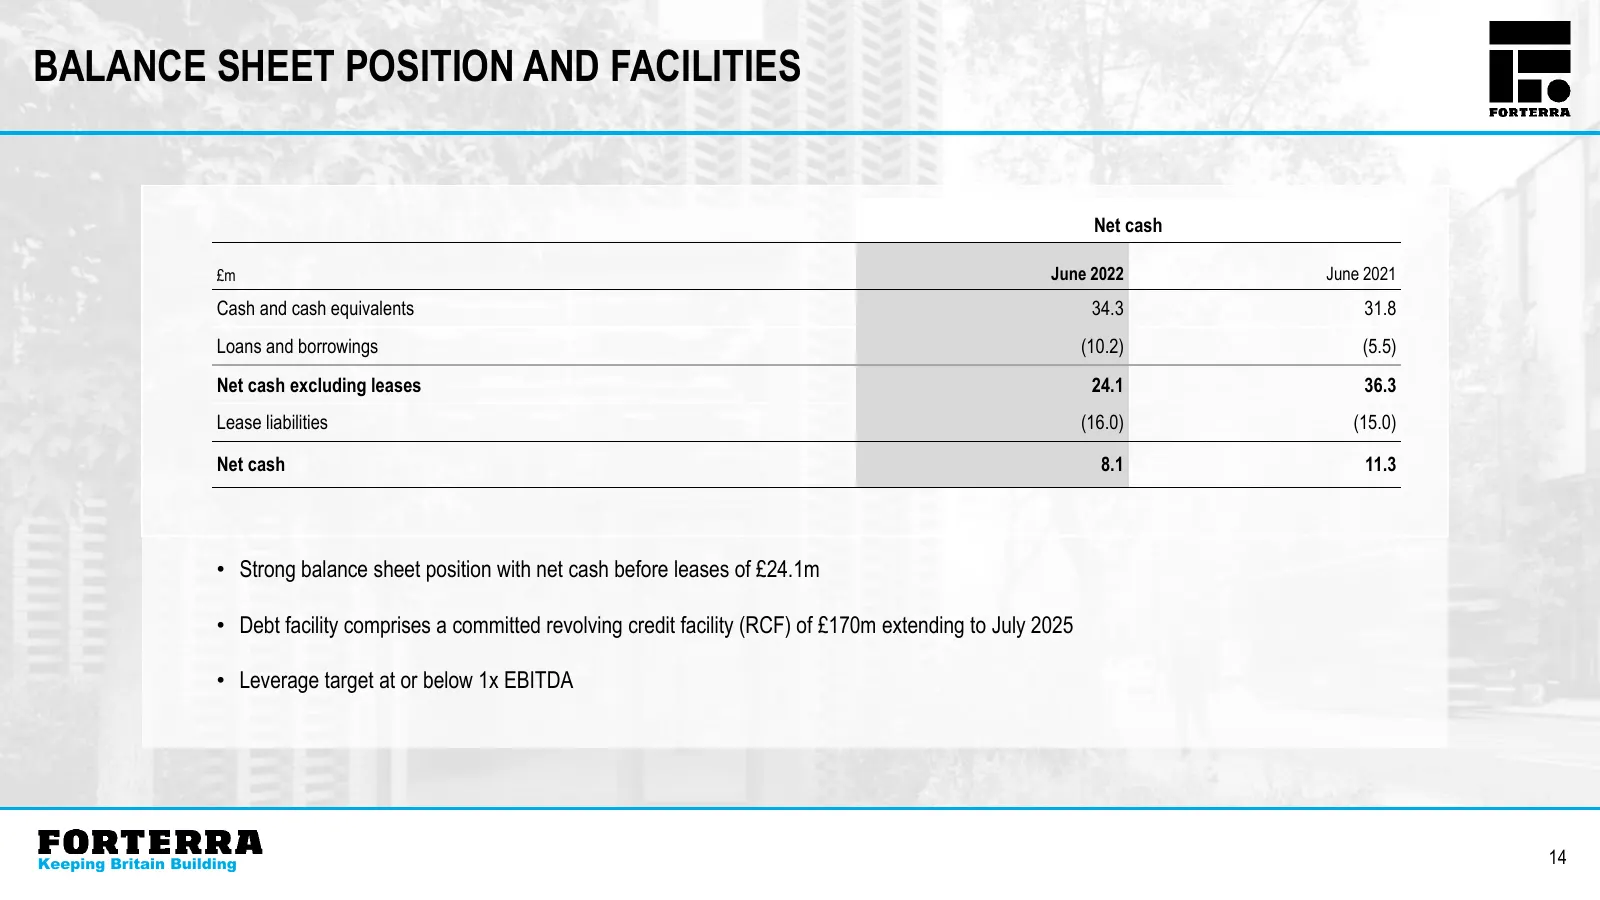
BALANCE SHEET POSITION AND FACILITIES Net cash £m June 2022 June 2021 Cash and cash equivalents 34.3 31.8 Loans and borrowings (10.2) (5.5) Net cash excluding leases 24.1 36.3 Lease liabilities (16.0) (15.0) Net cash 8.1 11.3 • Strong balance sheet position with net cash before leases of £24.1m • De
Slide 15: Our Markets
Keeping Britain Building OUR MARKETS
Slide 16: UK Housing Market
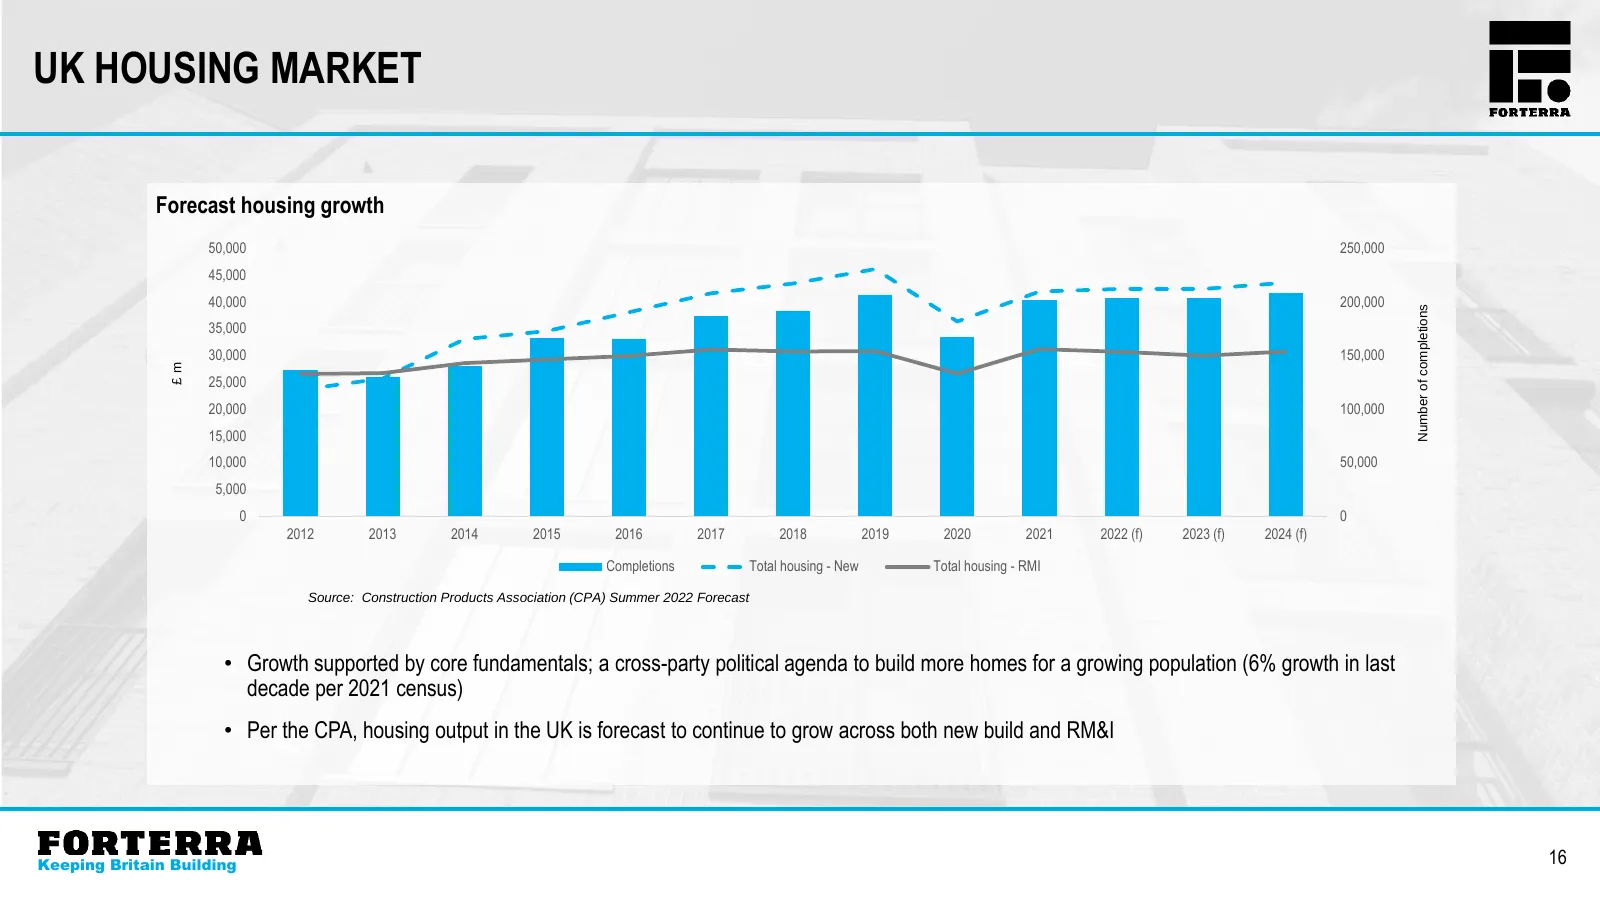
UK HOUSING MARKET Forecast housing growth 50,000 250,000 45,000 40,000 200,000 Number of completions 35,000 30,000 150,000 £m 25,000 20,000 100,000 15,000 10,000 50,000 5,000 0 0 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 (f) 2023 (f) 2024 (f) Completions Total housing - New Total housin
Slide 17: RMI Market – Planning Application Data
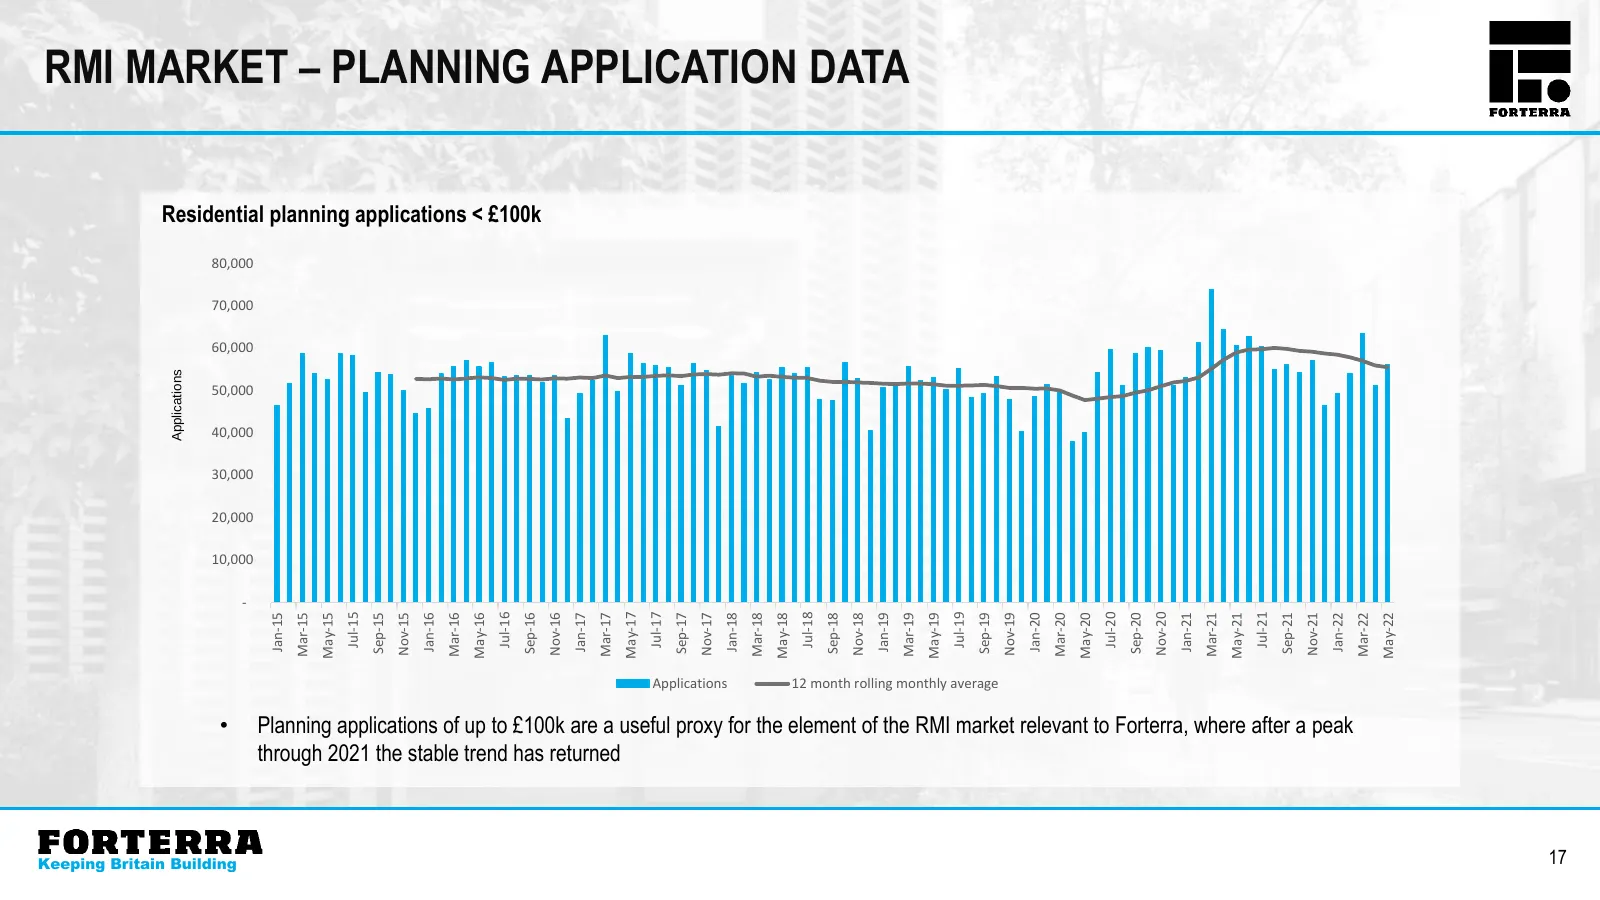
RMI MARKET – PLANNING APPLICATION DATA Residential planning applications < £100k 80,000 70,000 60,000 Applications 50,000 40,000 30,000 20,000 10,000 - Jul-15 Jul-16 May-17 Jul-17 Jul-18 Jul-19 Jul-20 Nov-20 Jul-21 May-15 Mar-20 Nov-15 May-16 Sep-16 Nov-16 Nov-17 May-18 Nov-18 May-19 Nov-19 May-20 M
Slide 18: UK Brick Market
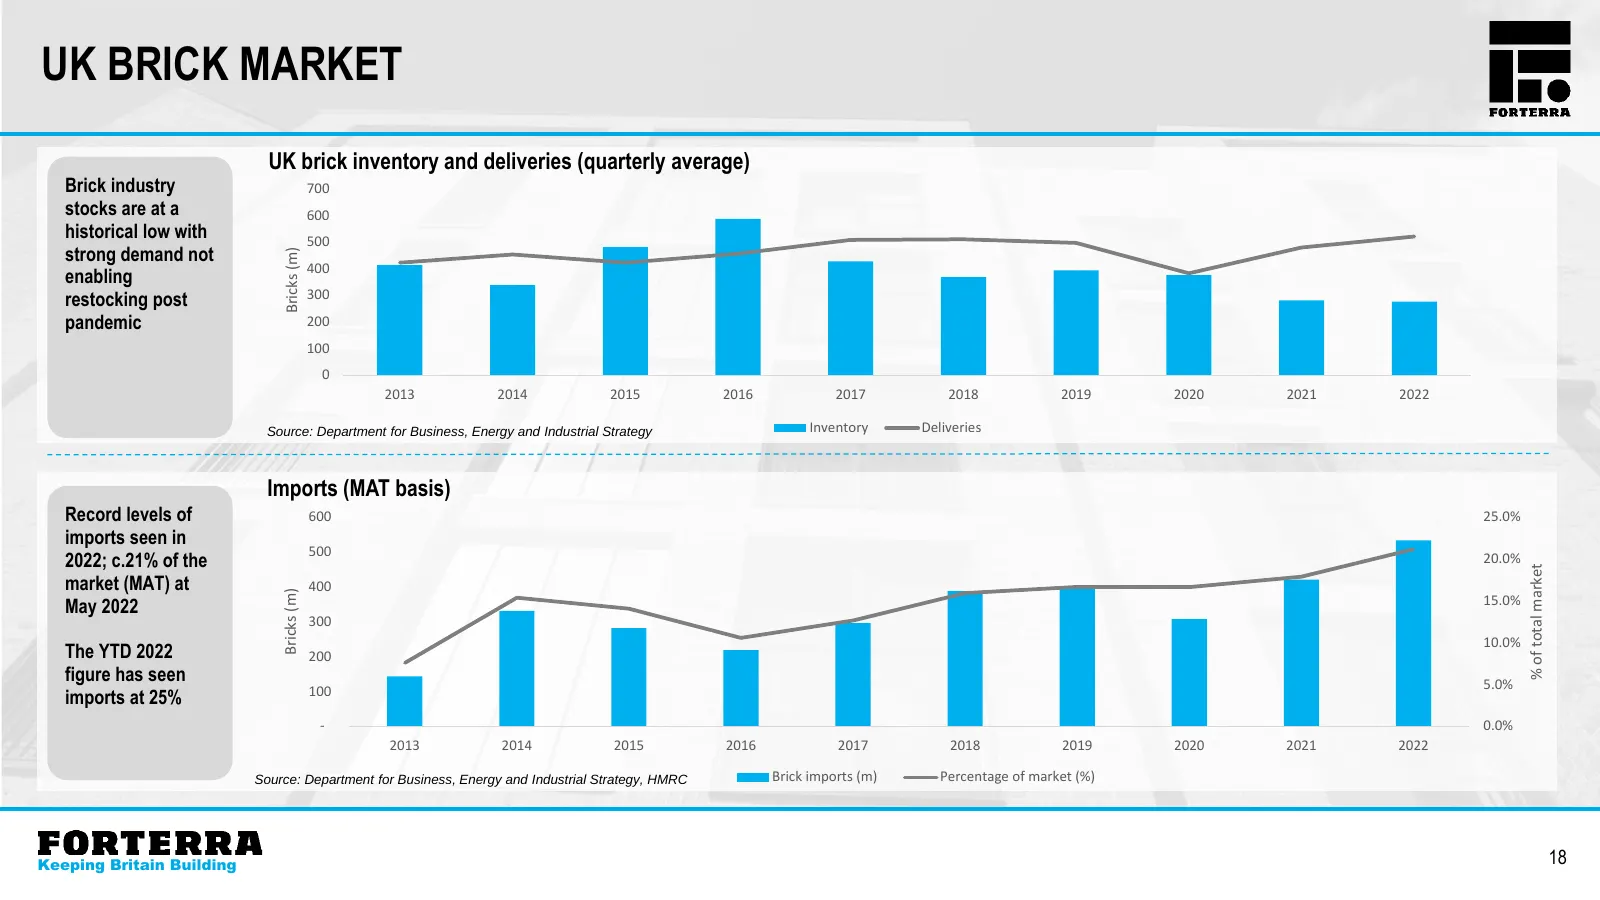
UK BRICK MARKET UK brick inventory and deliveries (quarterly average) Brick industry 700 stocks are at a 600 historical low with 500 strong demand not Bricks (m) 400 enabling restocking post 300 pandemic 200 100 0 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 Source: Department for Business, Ene
Slide 19: UK Brick Market Operating at Capacity
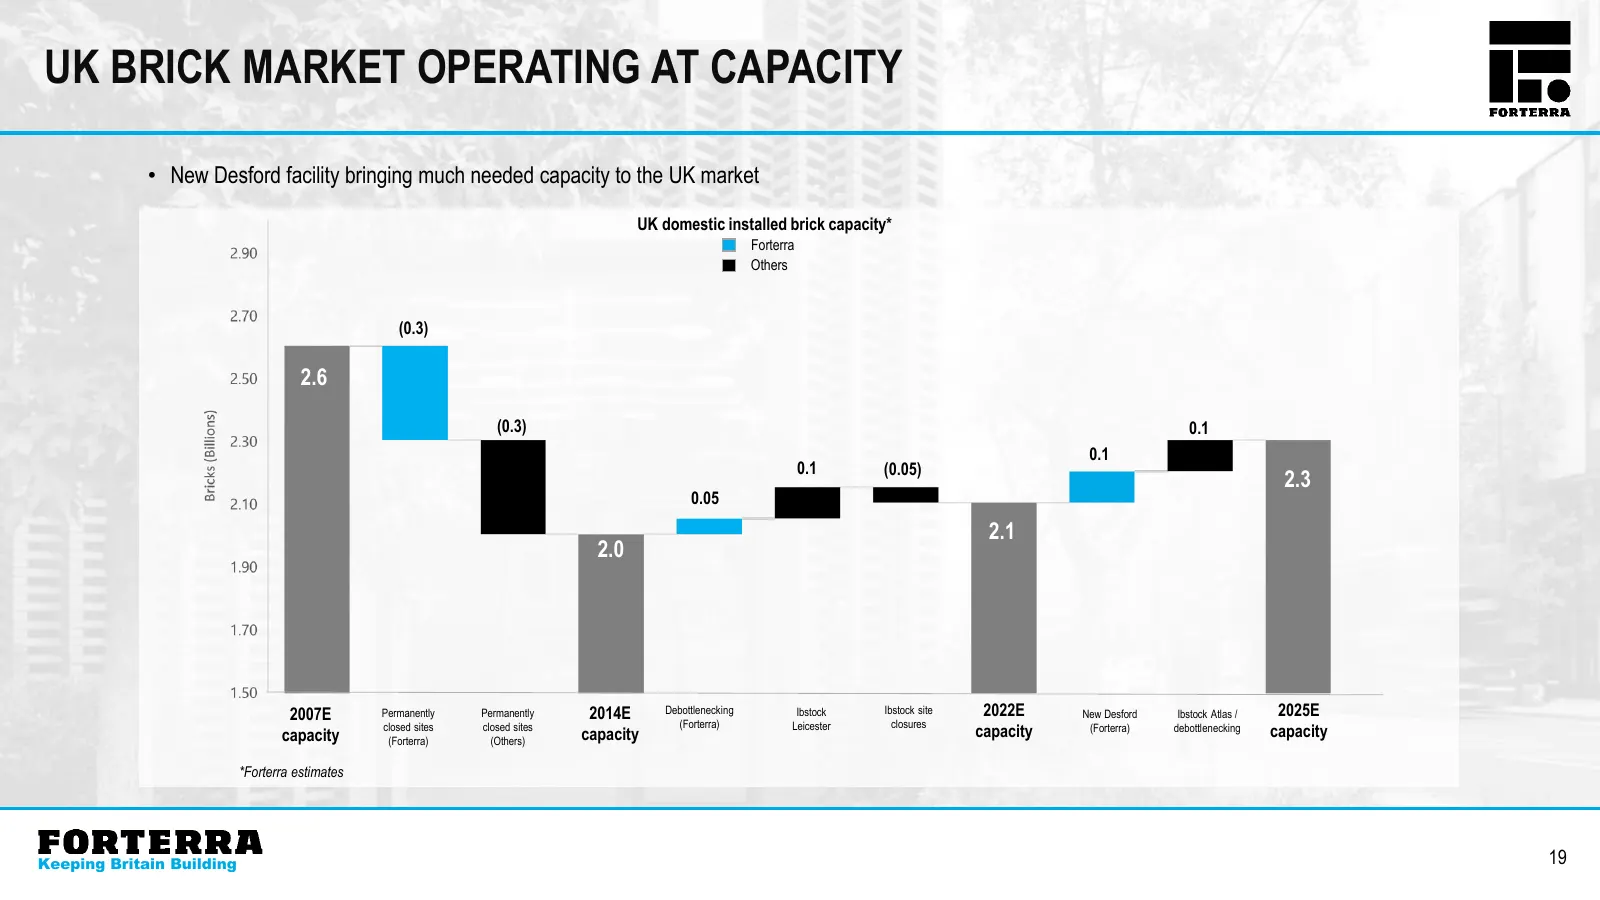
UK BRICK MARKET OPERATING AT CAPACITY • New Desford facility bringing much needed capacity to the UK market UK domestic installed brick capacity* Forterra Others (0.3) 2.6 (0.3) 0.1 0.1 0.1 (0.05) 2.3 0.05 2.1 2.0 2007E Permanently Permanently 2014E Debottlenecking Ibstock Ibstock site 2022E New Des
Slide 20: Strategic Update
Keeping Britain Building STRATEGIC UPDATE
Slide 21: A Clear and Focused Strategy
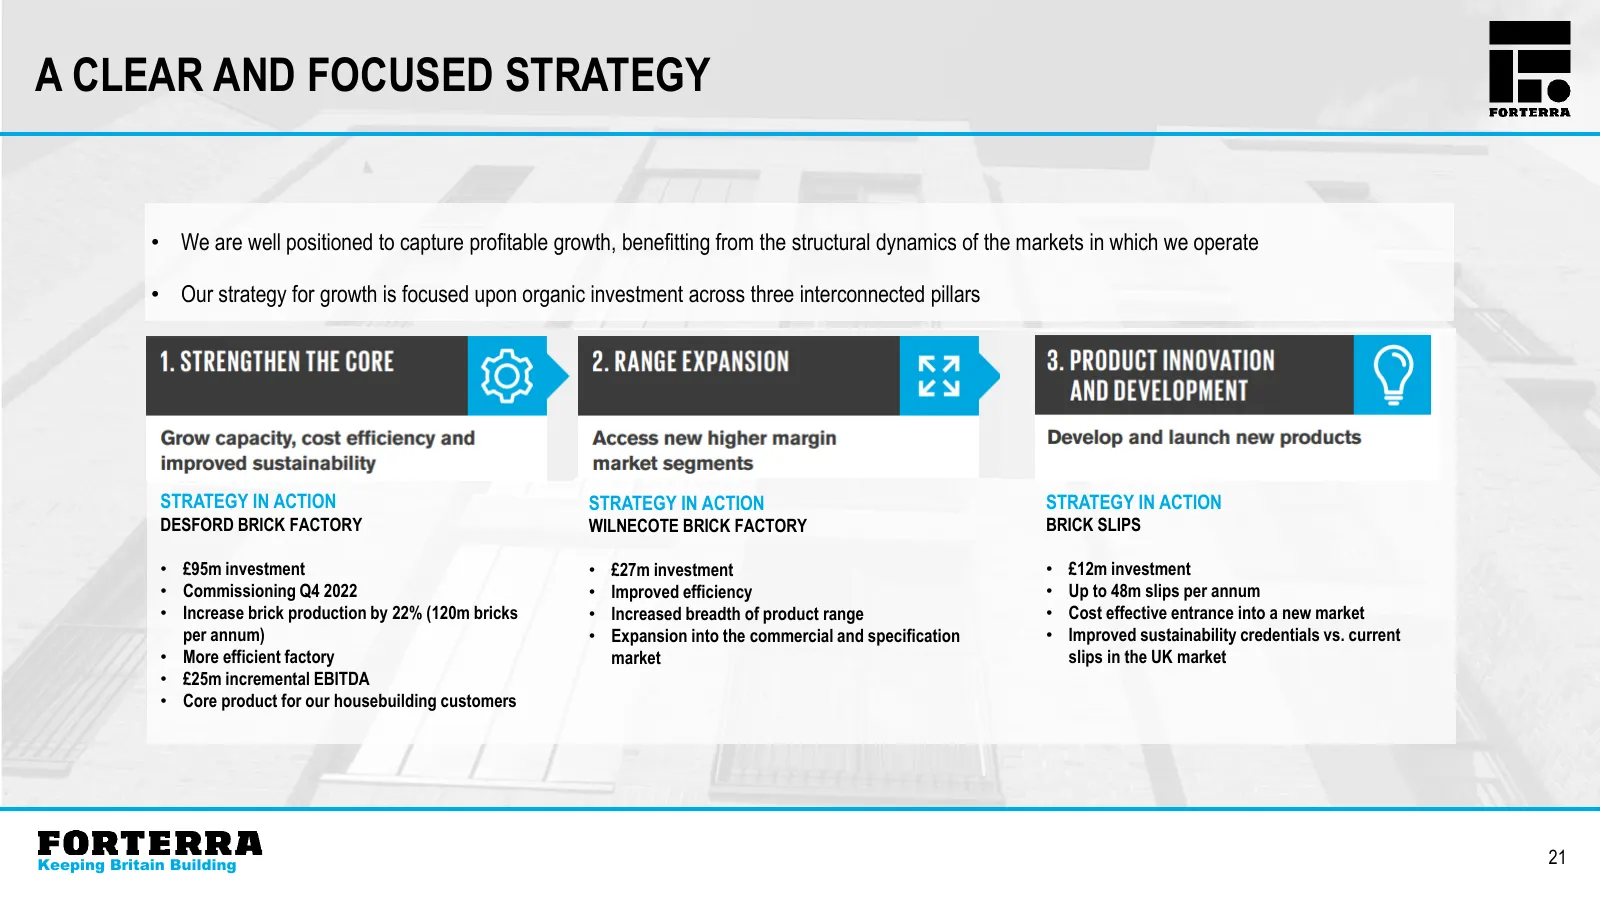
A CLEAR AND FOCUSED STRATEGY • We are well positioned to capture profitable growth, benefitting from the structural dynamics of the markets in which we operate • Our strategy for growth is focused upon organic investment across three interconnected pillars 1 STRATEGY IN ACTION STRATEGY IN ACTION STR
Slide 22: £25m Incremental EBITDA at New Desford Facility
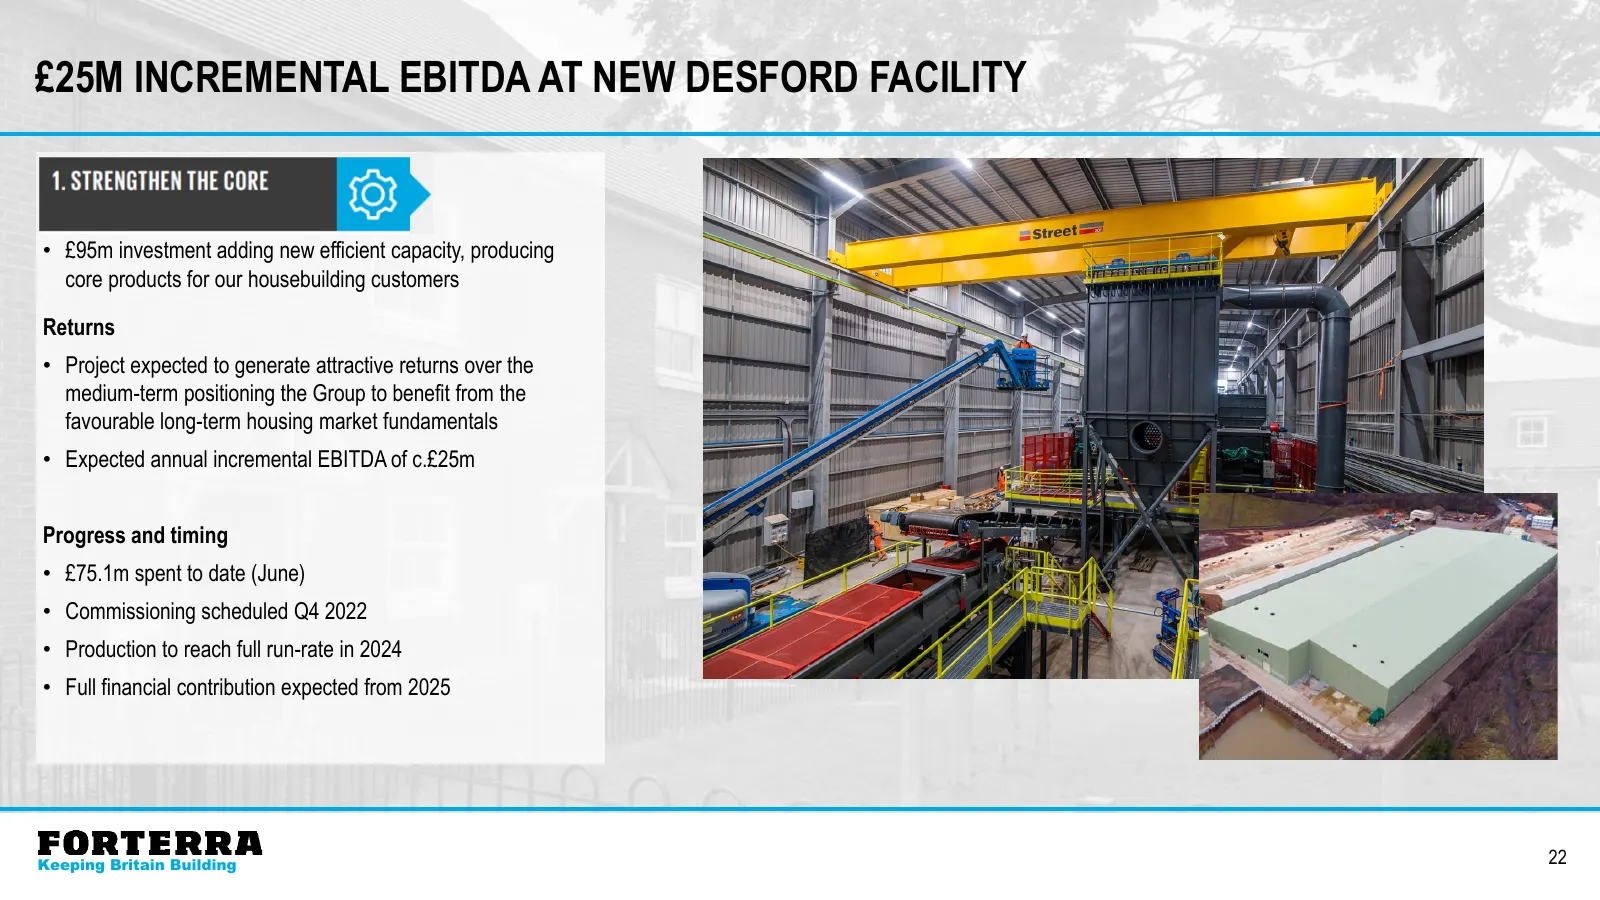
£25M INCREMENTAL EBITDA AT NEW DESFORD FACILITY • £95m investment adding new efficient capacity, producing core products for our housebuilding customers Returns • Project expected to generate attractive returns over the medium-term positioning the Group to benefit from the favourable long-term housi
Slide 23: Continued Strong Cash Generation
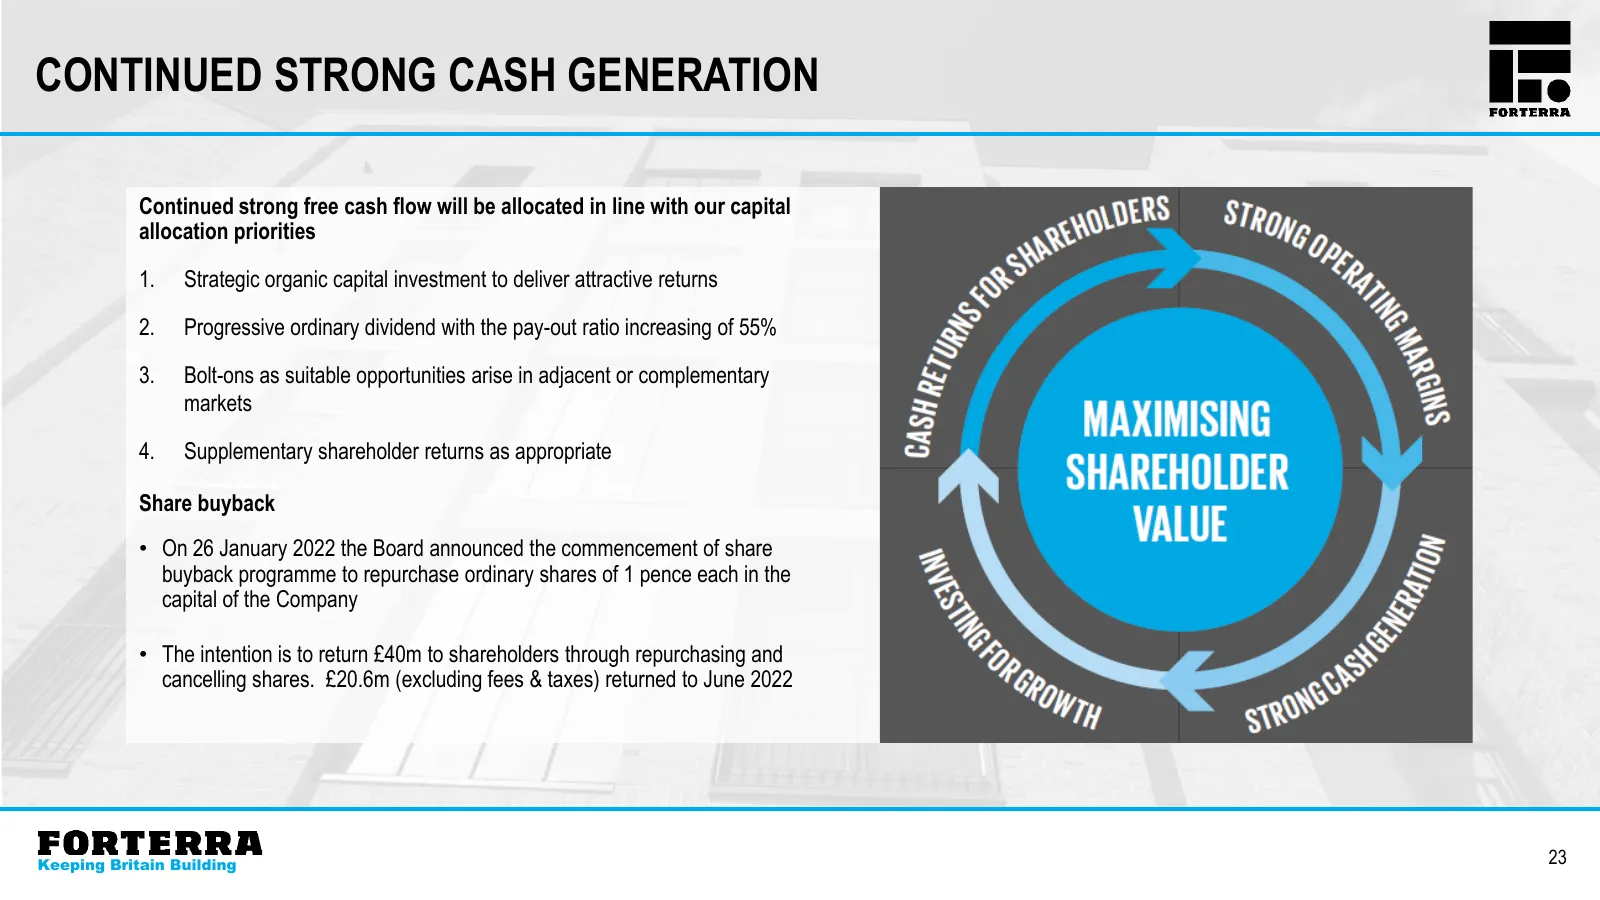
CONTINUED STRONG CASH GENERATION Continued strong free cash flow will be allocated in line with our capital allocation priorities 1. Strategic organic capital investment to deliver attractive returns 2. Progressive ordinary dividend with the pay-out ratio increasing of 55% 3. Bolt-ons as suitable op
Slide 24: Pipeline of Attractive Capex Projects
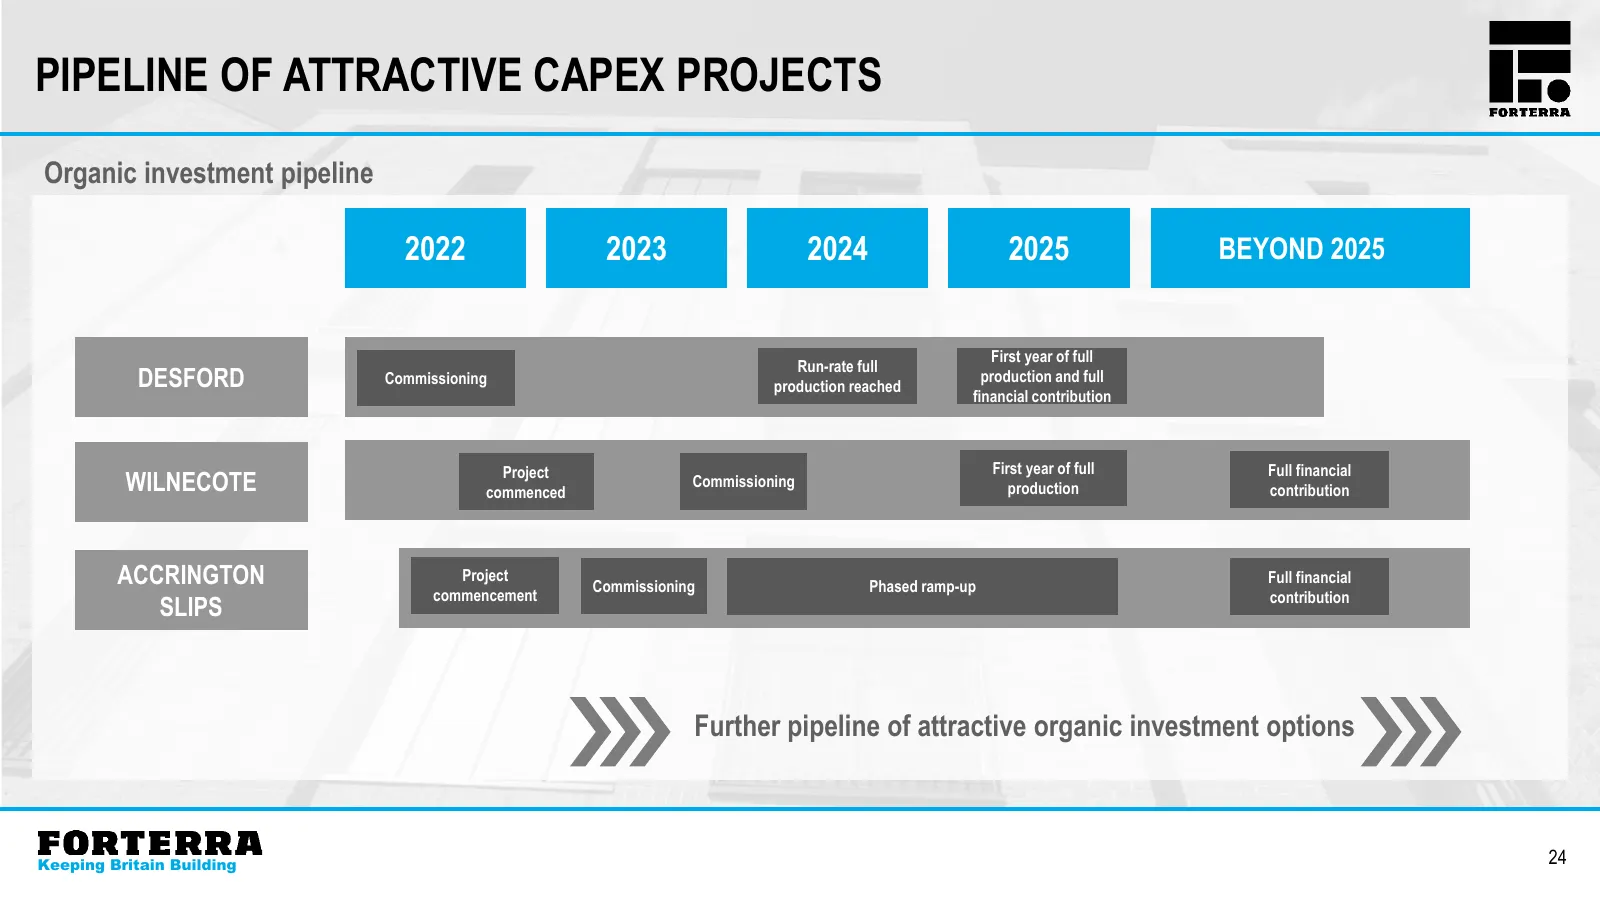
PIPELINE OF ATTRACTIVE CAPEX PROJECTS Organic investment pipeline 2022 2023 2024 2025 BEYOND 2025 First year of full Run-rate full DESFORD Commissioning production reached production and full financial contribution Project First year of full Full financial WILNECOTE commenced Commissioning productio
Slide 25: Sustainability
Keeping Britain Building SUSTAINABILITY
Slide 26: Commitment to Sustainability
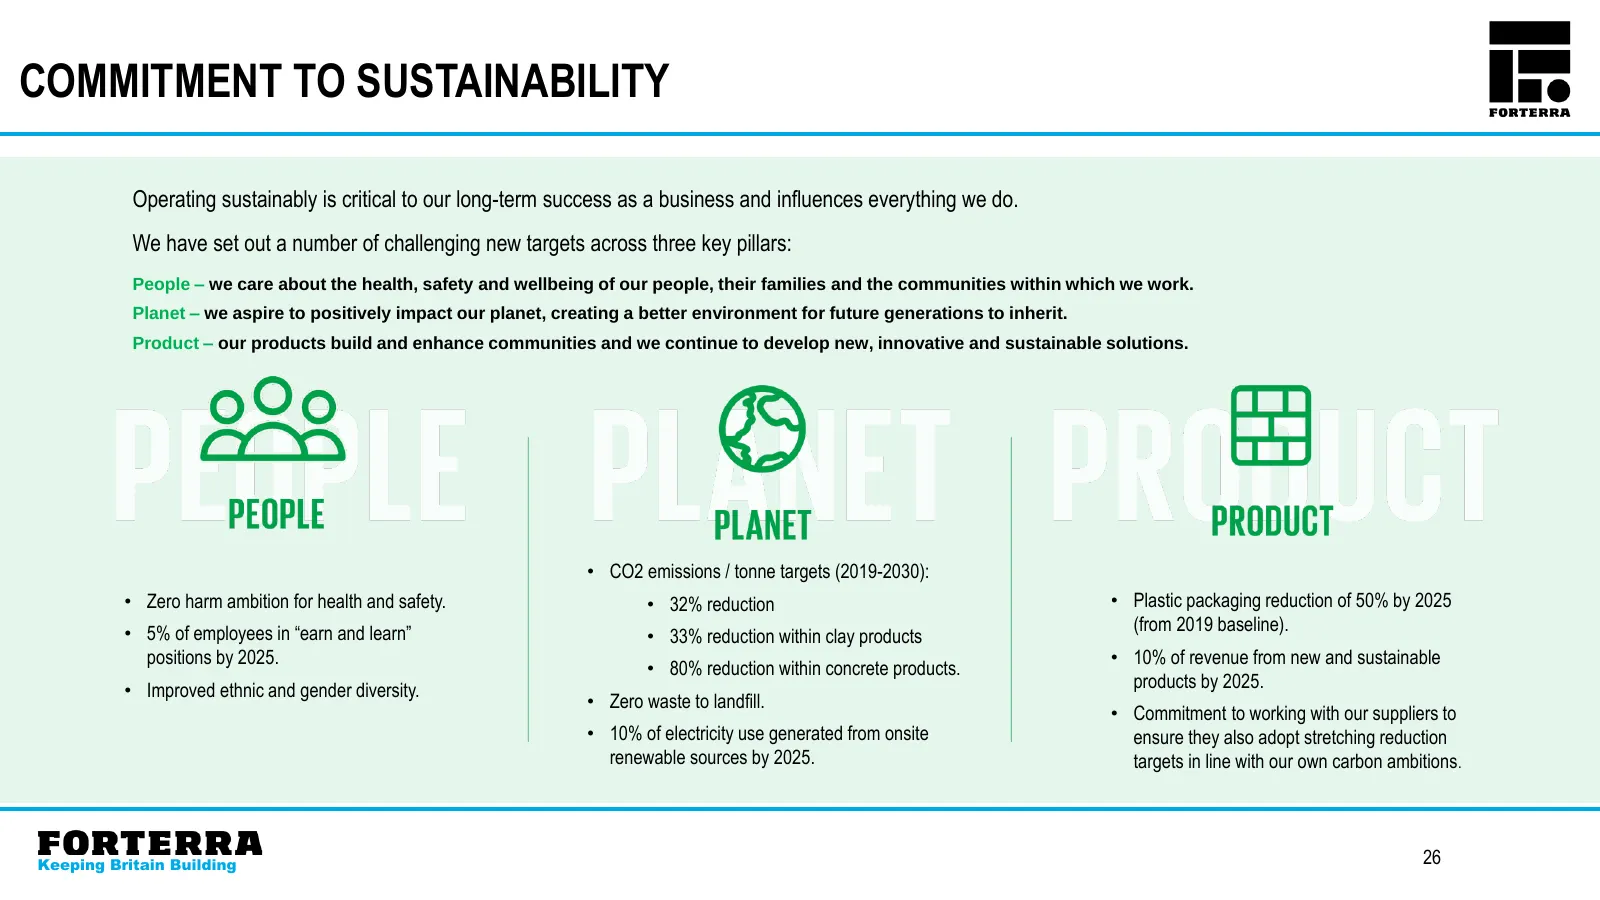
COMMITMENT TO SUSTAINABILITY Operating sustainably is critical to our long-term success as a business and influences everything we do. We have set out a number of challenging new targets across three key pillars: People – we care about the health, safety and wellbeing of our people, their families an
Slide 27: Continued Progress in 2022
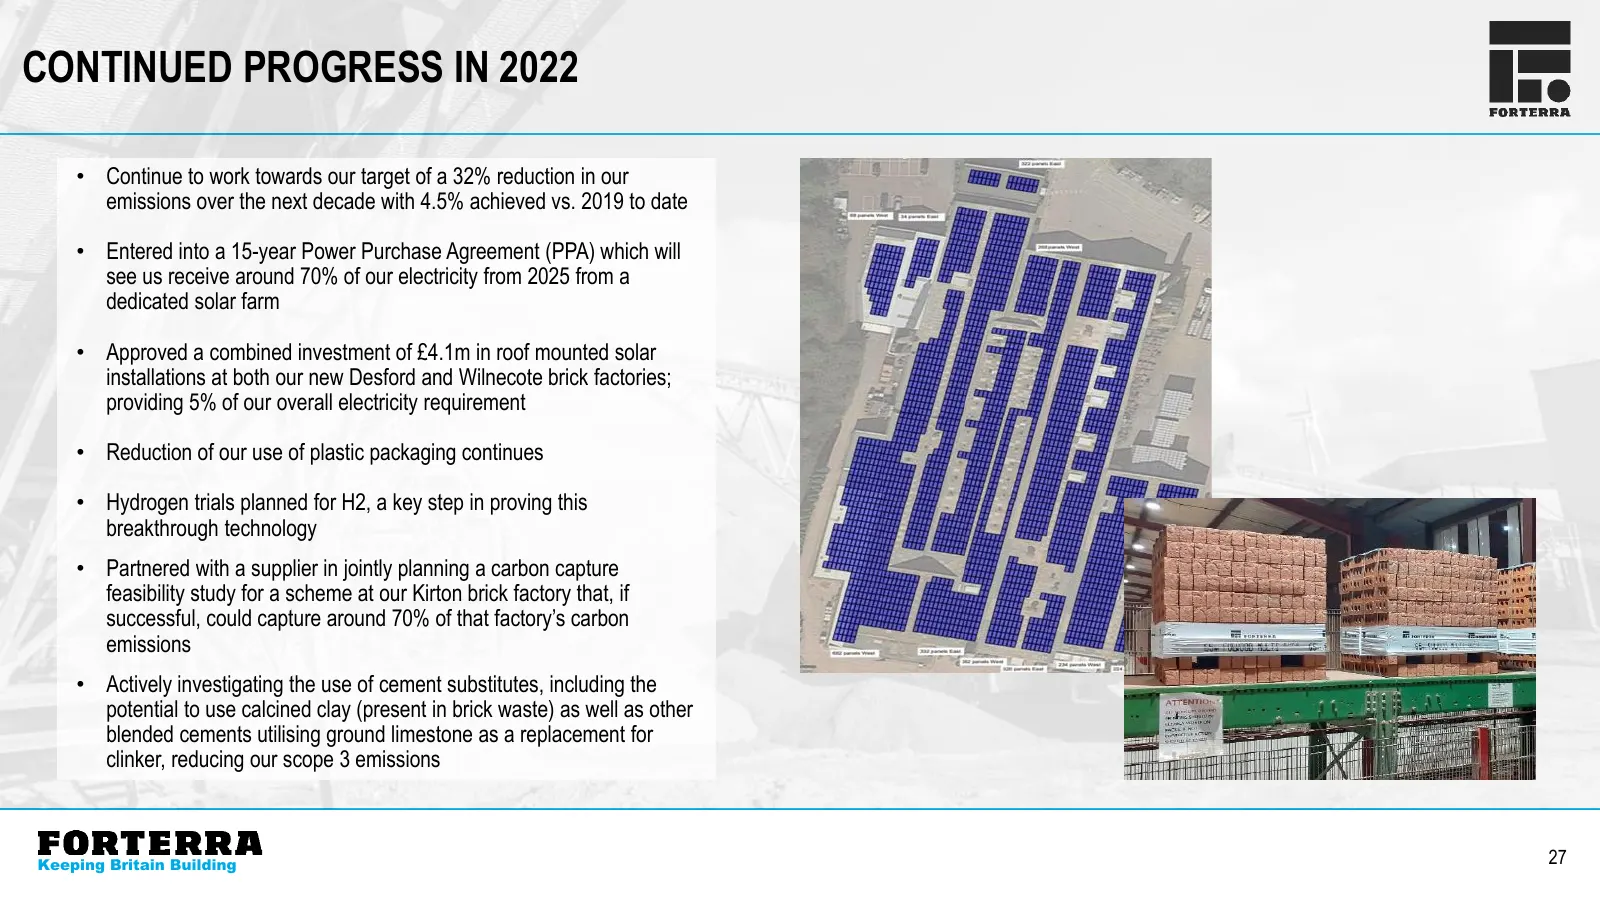
CONTINUED PROGRESS IN 2022 • Continue to work towards our target of a 32% reduction in our emissions over the next decade with 4.5% achieved vs. 2019 to date • Entered into a 15-year Power Purchase Agreement (PPA) which will see us receive around 70% of our electricity from 2025 from a dedicated sol
Slide 28: Outlook
Keeping Britain Building OUTLOOK
Slide 29: Outlook
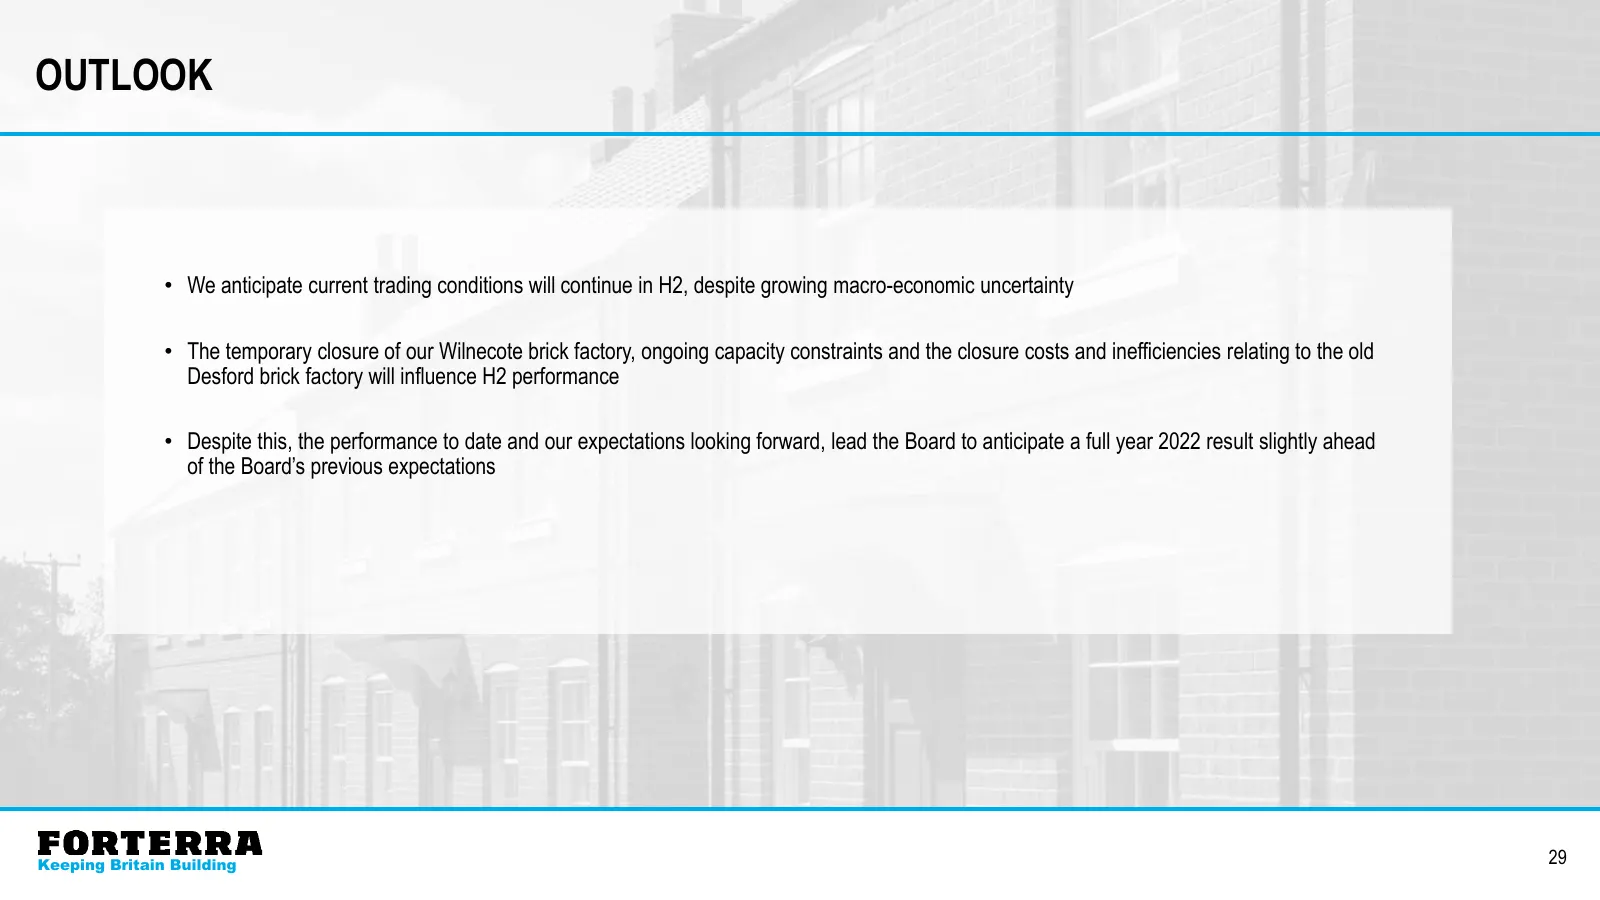
OUTLOOK • We anticipate current trading conditions will continue in H2, despite growing macro-economic uncertainty • The temporary closure of our Wilnecote brick factory, ongoing capacity constraints and the closure costs and inefficiencies relating to the old Desford brick factory will influence H2
Slide 30: Delivering Long-Term Shareholder Value
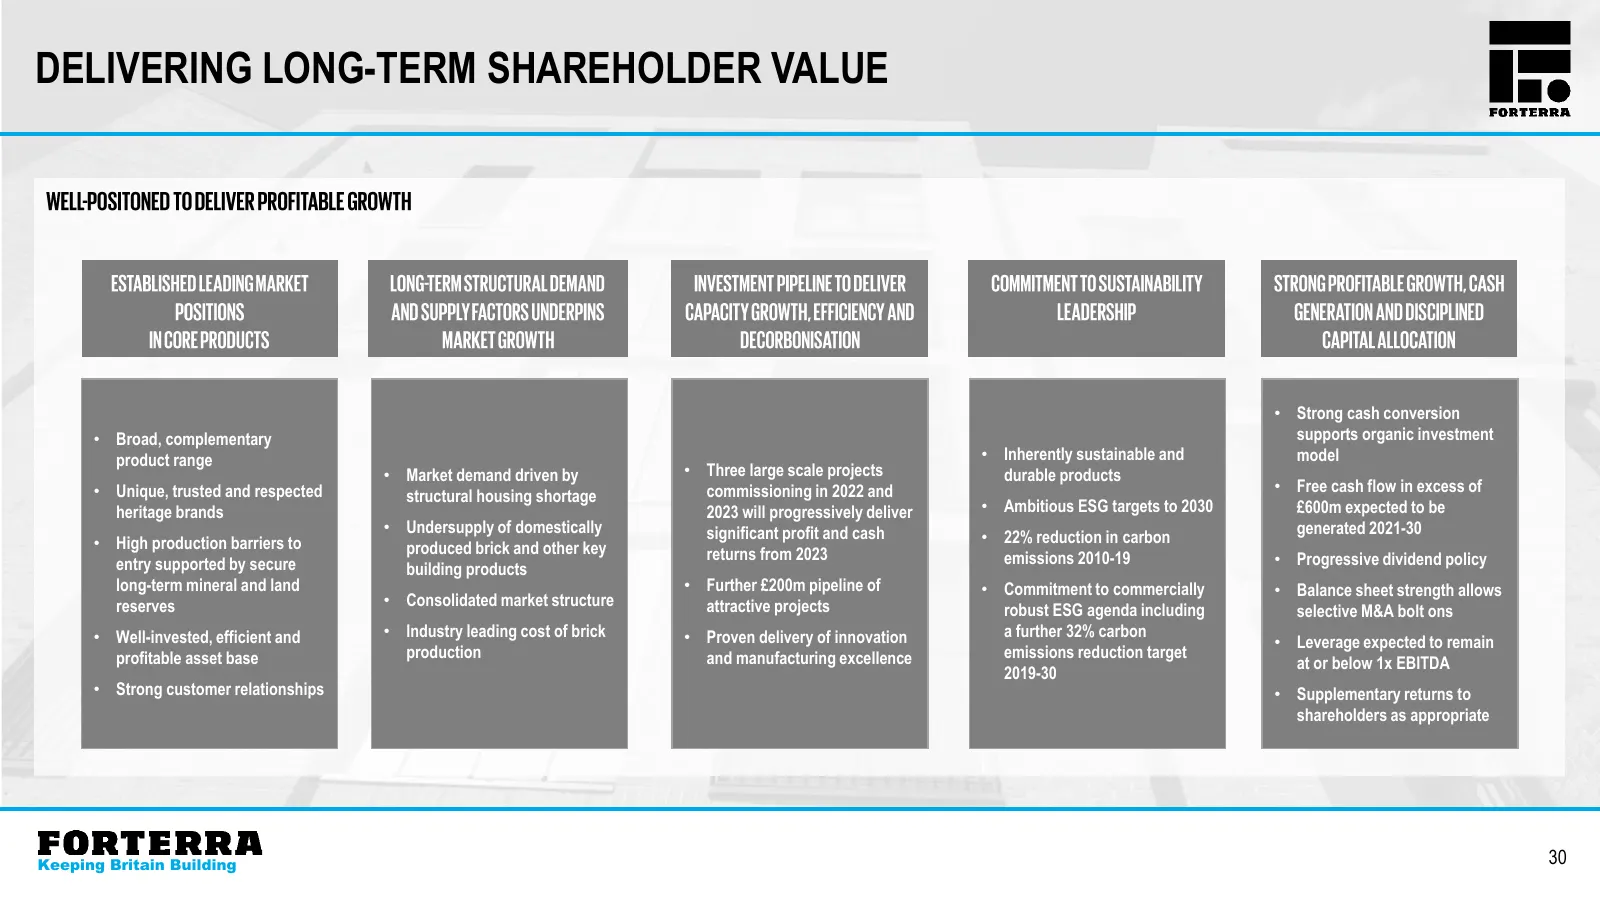
DELIVERING LONG-TERM SHAREHOLDER VALUE • Strong cash conversion • Broad, complementary supports organic investment product range • Inherently sustainable and model • Market demand driven by • Three large scale projects durable products • Unique, trusted and respected commissioning in 2022 and • Free
Slide 31: Appendices
Keeping Britain Building APPENDICES
Slide 32: Reconciliation of Alternative Measures to Statutory Results
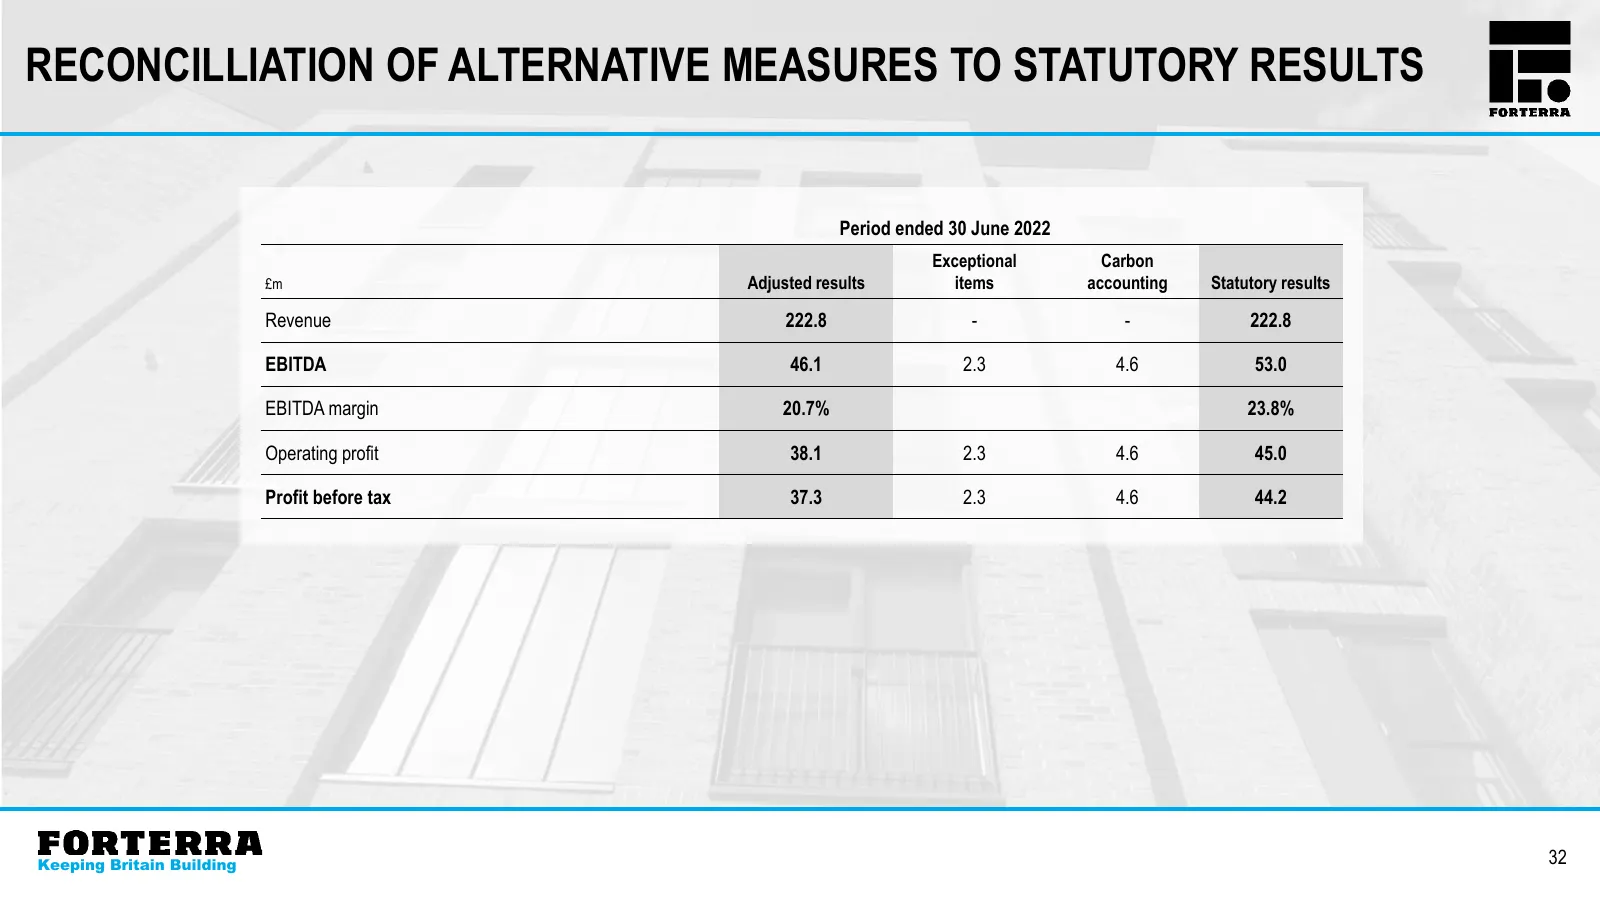
RECONCILLIATION OF ALTERNATIVE MEASURES TO STATUTORY RESULTS Period ended 30 June 2022 Exceptional Carbon £m Adjusted results items accounting Statutory results Revenue 222.8 - - 222.8 EBITDA 46.1 2.3 4.6 53.0 EBITDA margin 20.7% 23.8% Operating profit 38.1 2.3 4.6 45.0 Profit before tax 37.3 2.3 4.
Slide 33: Key Financials (vs. 2019)
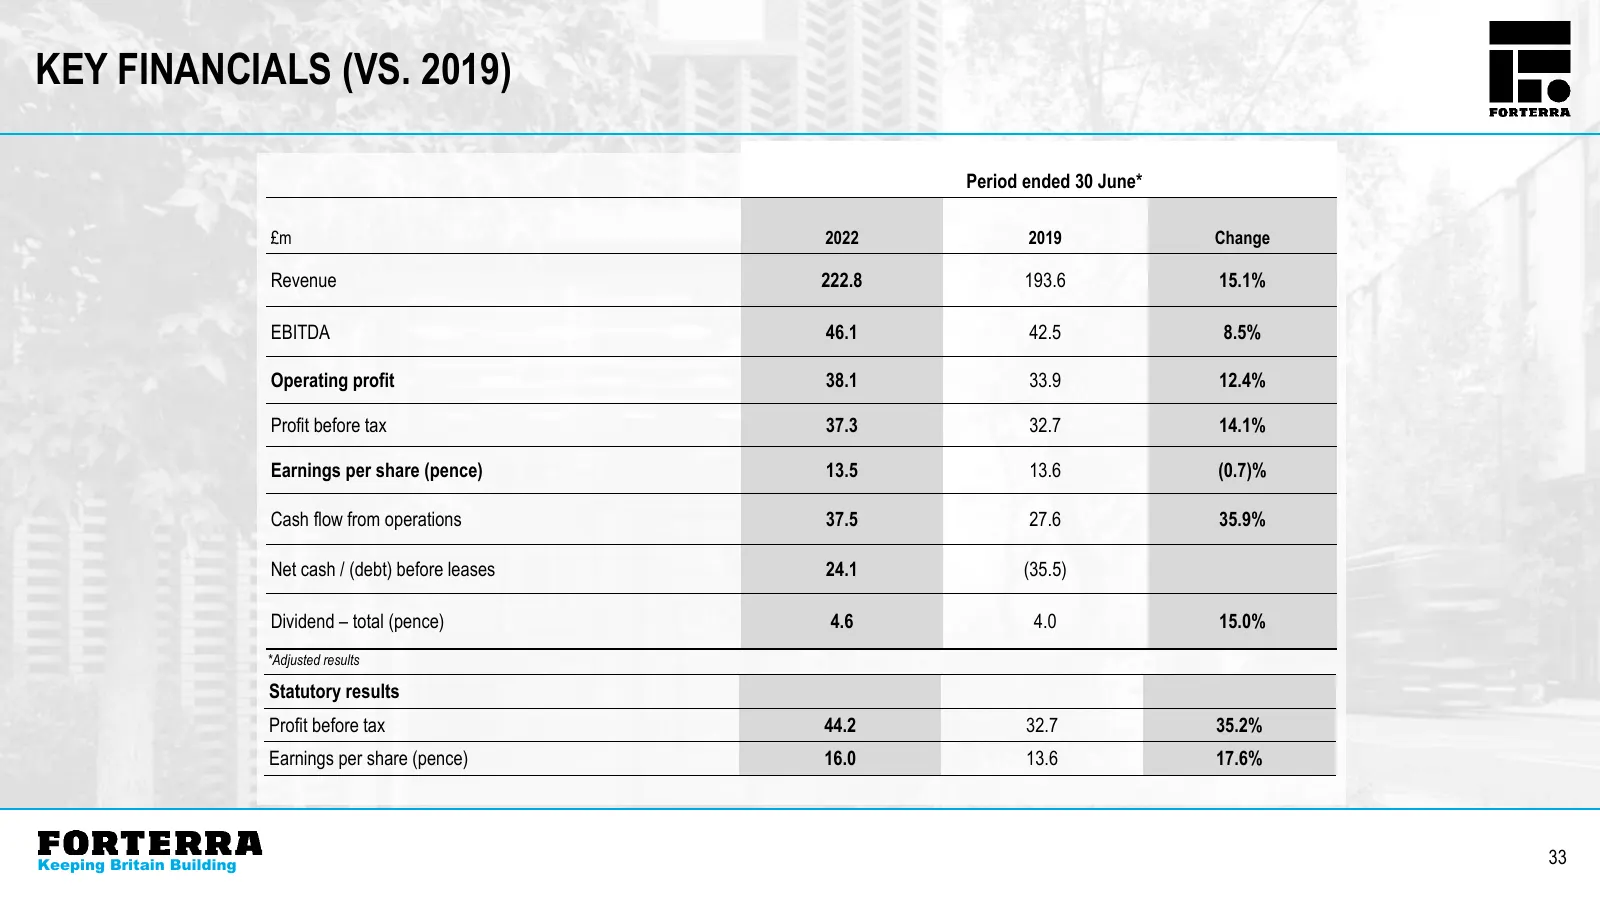
KEY FINANCIALS (VS. 2019) Period ended 30 June* £m 2022 2019 Change Revenue 222.8 193.6 15.1% EBITDA 46.1 42.5 8.5% Operating profit 38.1 33.9 12.4% Profit before tax 37.3 32.7 14.1% Earnings per share (pence) 13.5 13.6 (0.7)% Cash flow from operations 37.5 27.6 35.9% Net cash / (debt) before leases
Slide 34: Profit and Loss (vs. 2019)
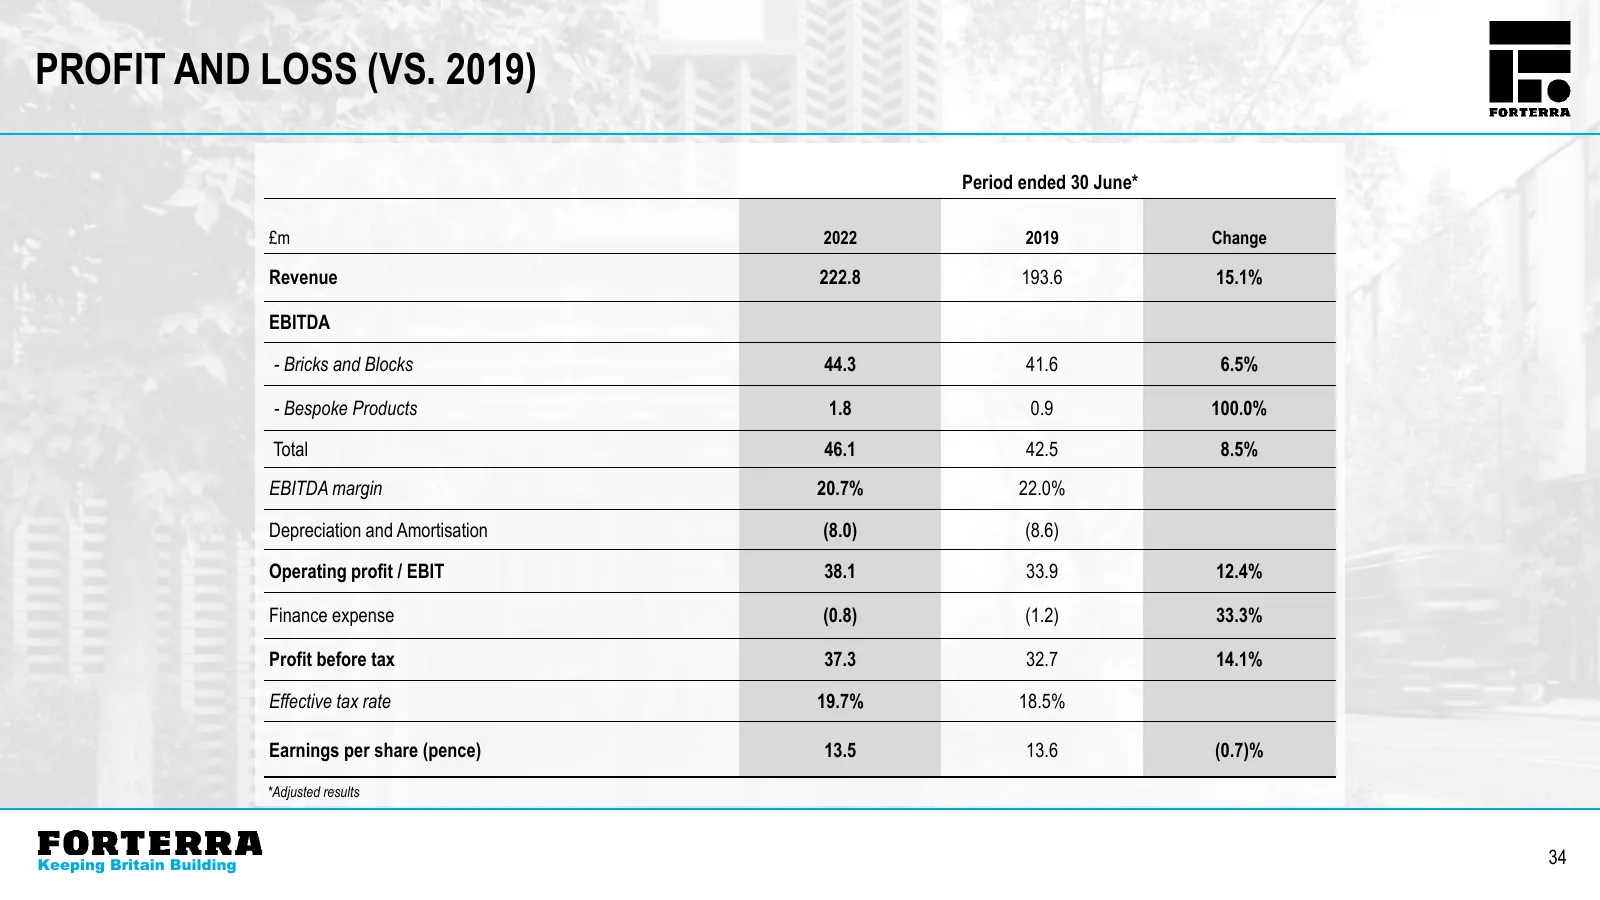
PROFIT AND LOSS (VS. 2019) Period ended 30 June* £m 2022 2019 Change Revenue 222.8 193.6 15.1% EBITDA - Bricks and Blocks 44.3 41.6 6.5% - Bespoke Products 1.8 0.9 100.0% Total 46.1 42.5 8.5% EBITDA margin 20.7% 22.0% Depreciation and Amortisation (8.0) (8.6) Operating profit / EBIT 38.1 33.9 12.4%
Slide 35: Segmental Results: Bricks and Blocks (vs. 2019)
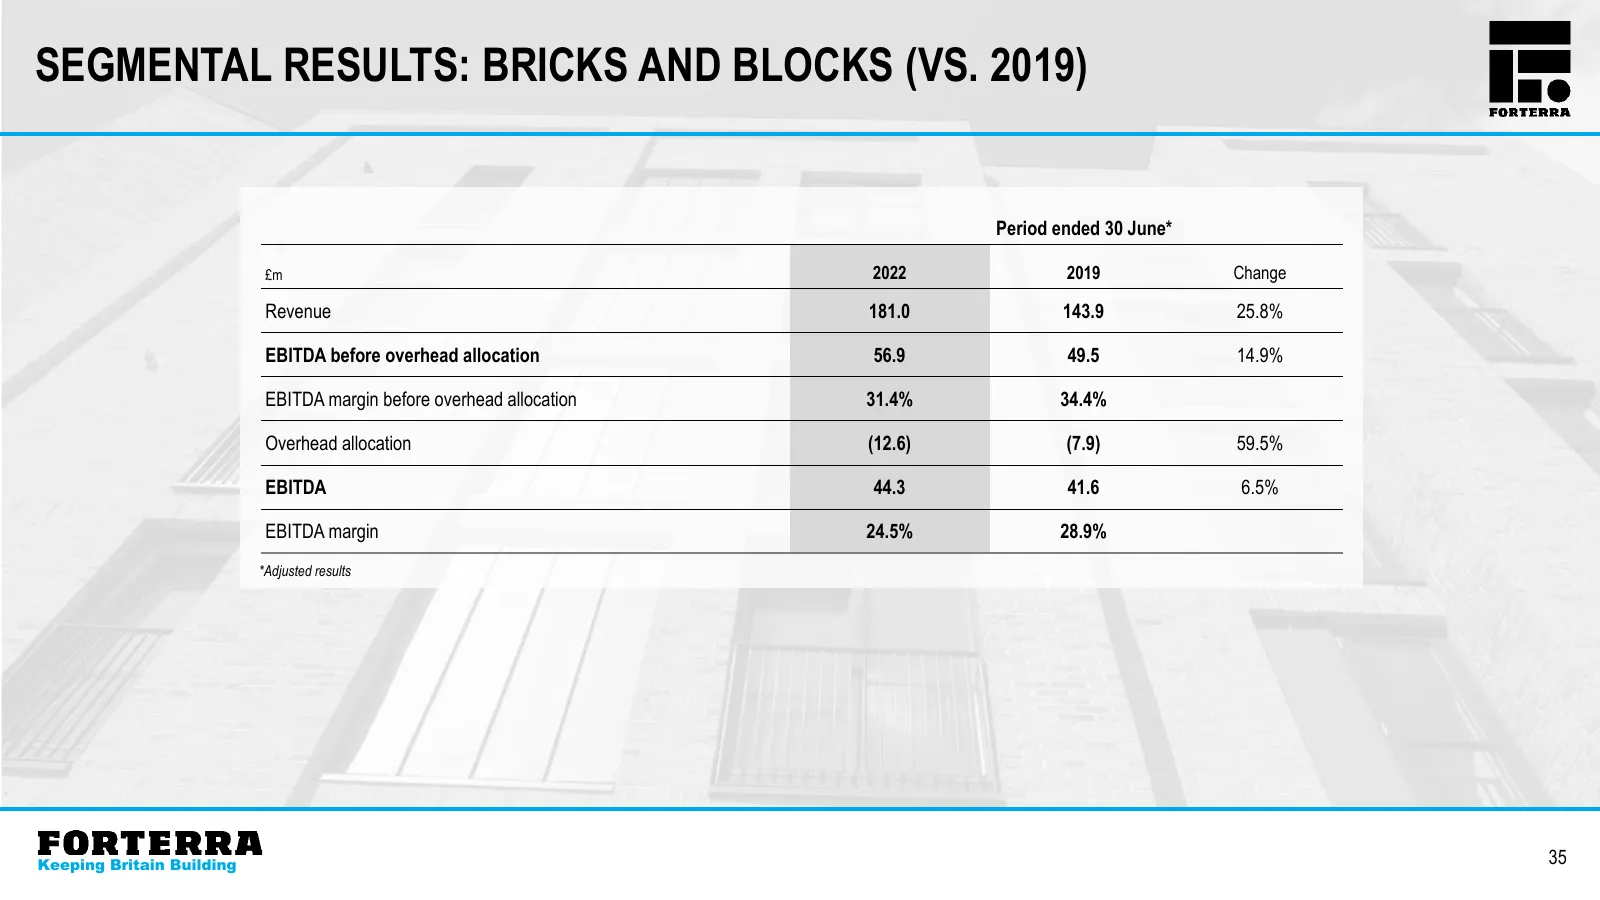
SEGMENTAL RESULTS: BRICKS AND BLOCKS (VS. 2019) Period ended 30 June* £m 2022 2019 Change Revenue 181.0 143.9 25.8% EBITDA before overhead allocation 56.9 49.5 14.9% EBITDA margin before overhead allocation 31.4% 34.4% Overhead allocation (12.6) (7.9) 59.5% EBITDA 44.3 41.6 6.5% EBITDA margin 24.5%
Slide 36: Segmental Results: Bespoke Products (vs. 2019)
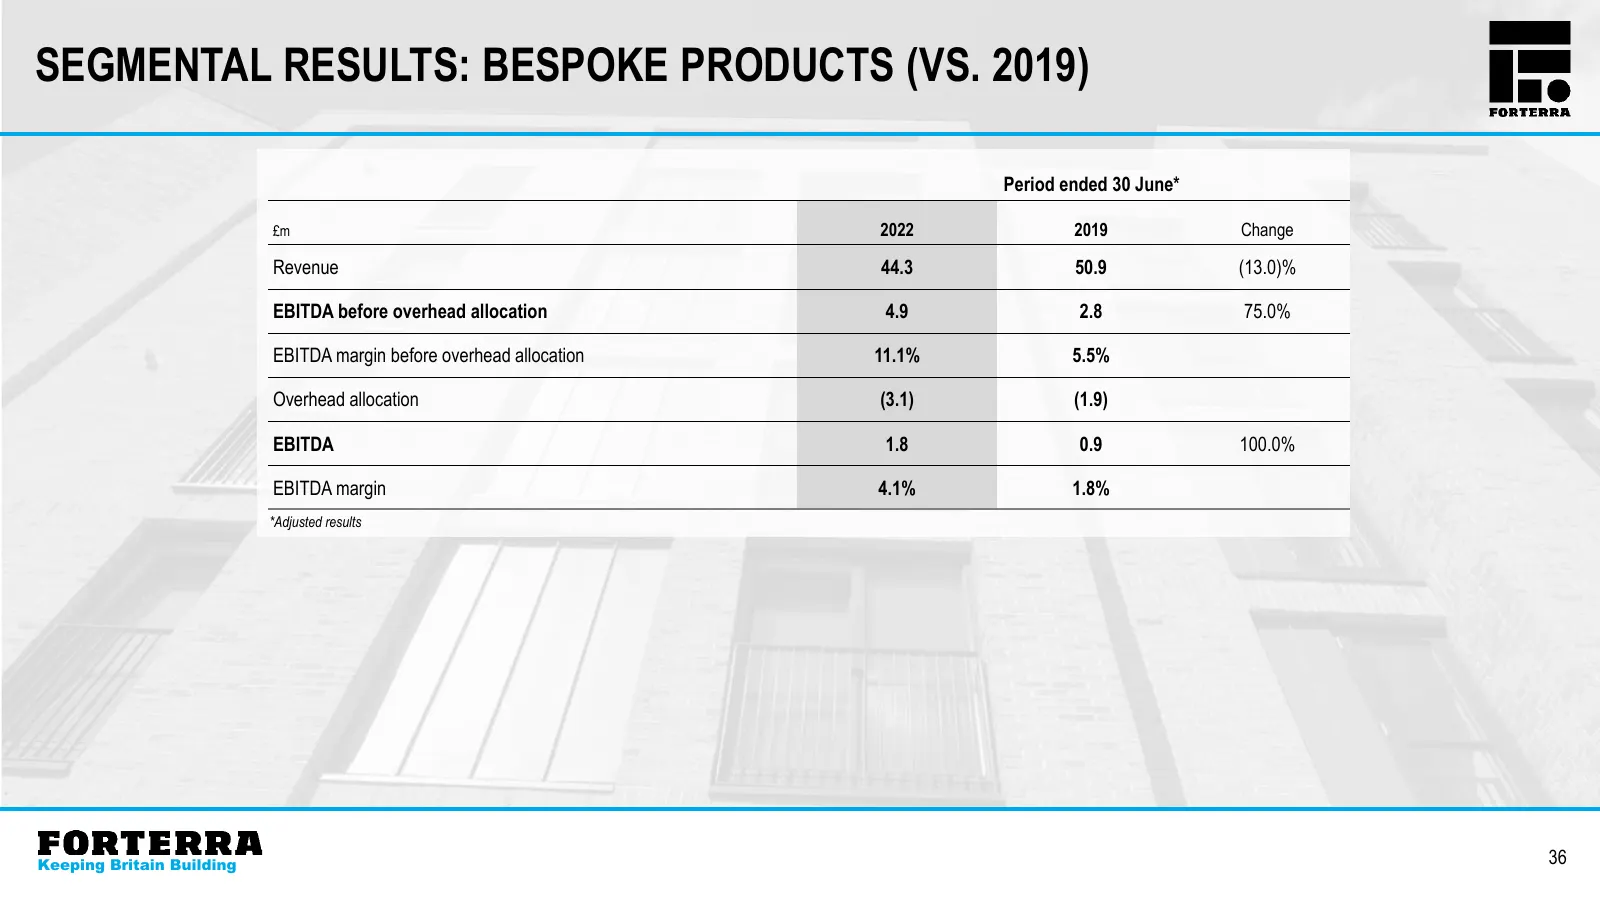
SEGMENTAL RESULTS: BESPOKE PRODUCTS (VS. 2019) Period ended 30 June* £m 2022 2019 Change Revenue 44.3 50.9 (13.0)% EBITDA before overhead allocation 4.9 2.8 75.0% EBITDA margin before overhead allocation 11.1% 5.5% Overhead allocation (3.1) (1.9) EBITDA 1.8 0.9 100.0% EBITDA margin 4.1% 1.8% *Adjust
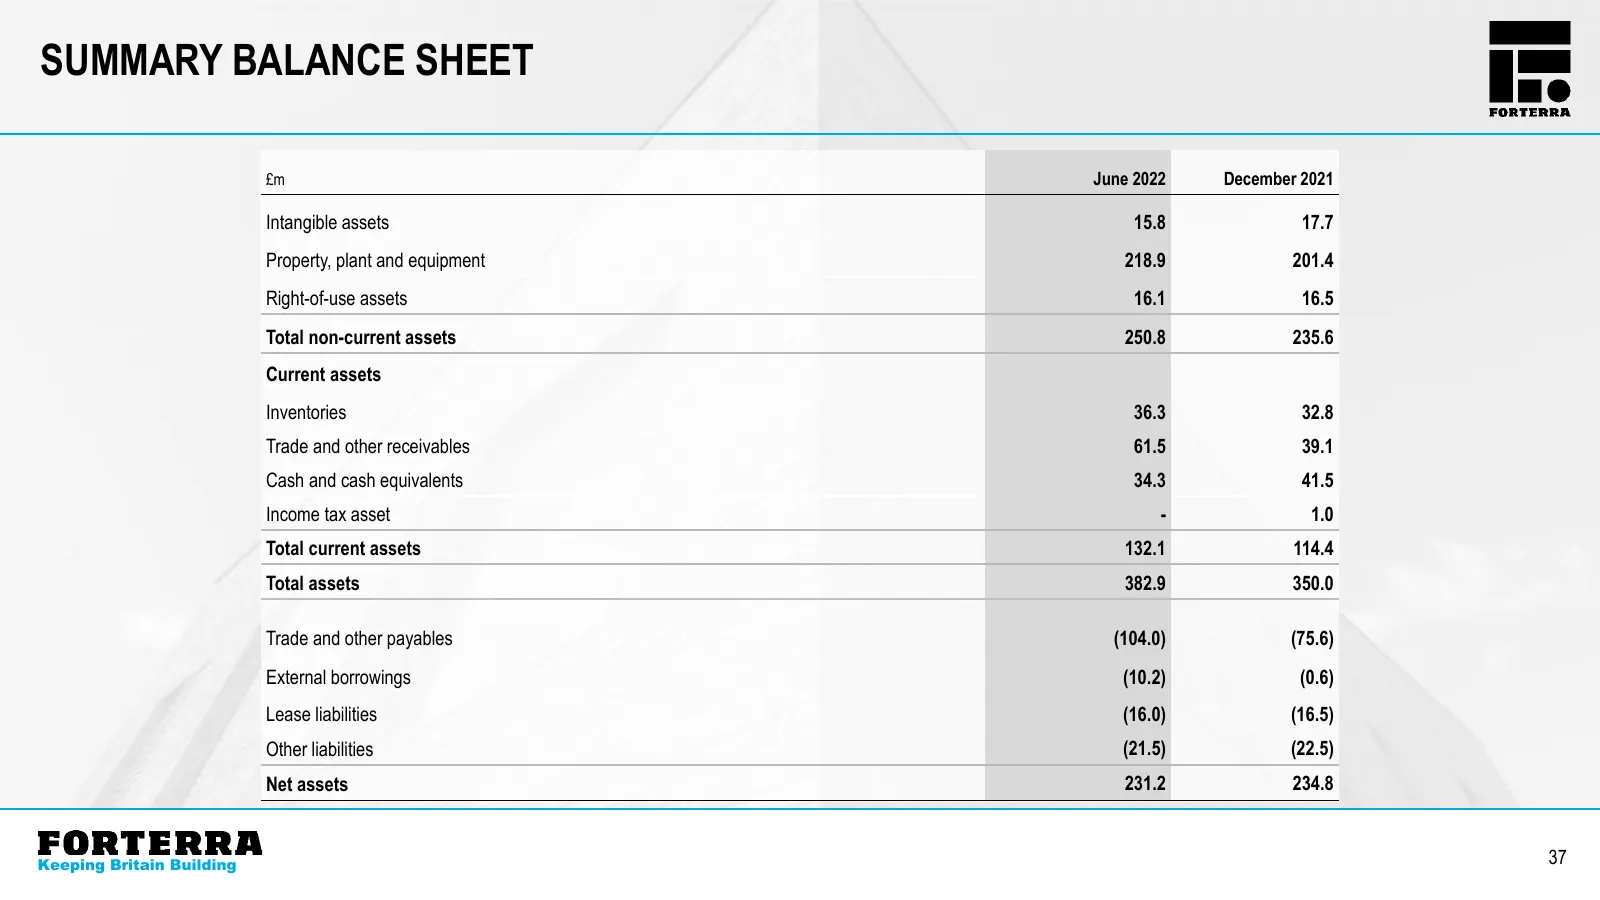
Slide 37: Summary Balance Sheet
SUMMARY BALANCE SHEET £m June 2022 December 2021 Intangible assets 15.8 17.7 Property, plant and equipment 218.9 201.4 Right-of-use assets 16.1 16.5 Total non-current assets 250.8 235.6 Current assets Inventories 36.3 32.8 Trade and other receivables 61.5 39.1 Cash and cash equivalents 34.3 41.5 Inc
Slide 38: Forterra contact details
Forterra 5 Grange Park Court Roman Way Northampton NN4 5EA 01604 707600 38
Source: company website
More decks from Forterra PLC
 H1 2026 Earnings Presentation28 slides · Jul 28, 2026
 FY2025 Earnings Presentation34 slides · Mar 11, 2026
 H1 2025 Earnings Presentation28 slides · Jul 29, 2025
 FY2024 Earnings Presentation33 slides · Mar 12, 2025
 H1 2024 Earnings Presentation34 slides · Jul 30, 2024
 FY2023 Earnings Presentation31 slides · Mar 26, 2024