Bravura Solutions Limited · ASX:BVS
Bravura Solutions — Shareholder Meeting (November 2009)
20 slides from Bravura Solutions's shareholder meeting presentation, Nov 20, 2009
Slide 1: AGM speech FY2009 - Iain Dunstan, Group CEO
AGM speech FY2009 Iain Dunstan - Group CEO & Managing Director Thank you Neil. Introduction General The 2009 financial year was certainly an eventful one for Bravura Solutions. The Recapitalisation Proposal and Rights Issue were a key focus this year, as was our success in winning a number of new an
Slide 2: Market conditions and financial overview
This current financial year, we also received a number 11 ranking in the Smart Company Smart50, and a ranking again in the Fintech 100. We are pleased to be seen in the market as an award winning innovator. Discussion of market conditions There is no doubt that deteriorating global economic conditio
Slide 3: Revenue by type and product
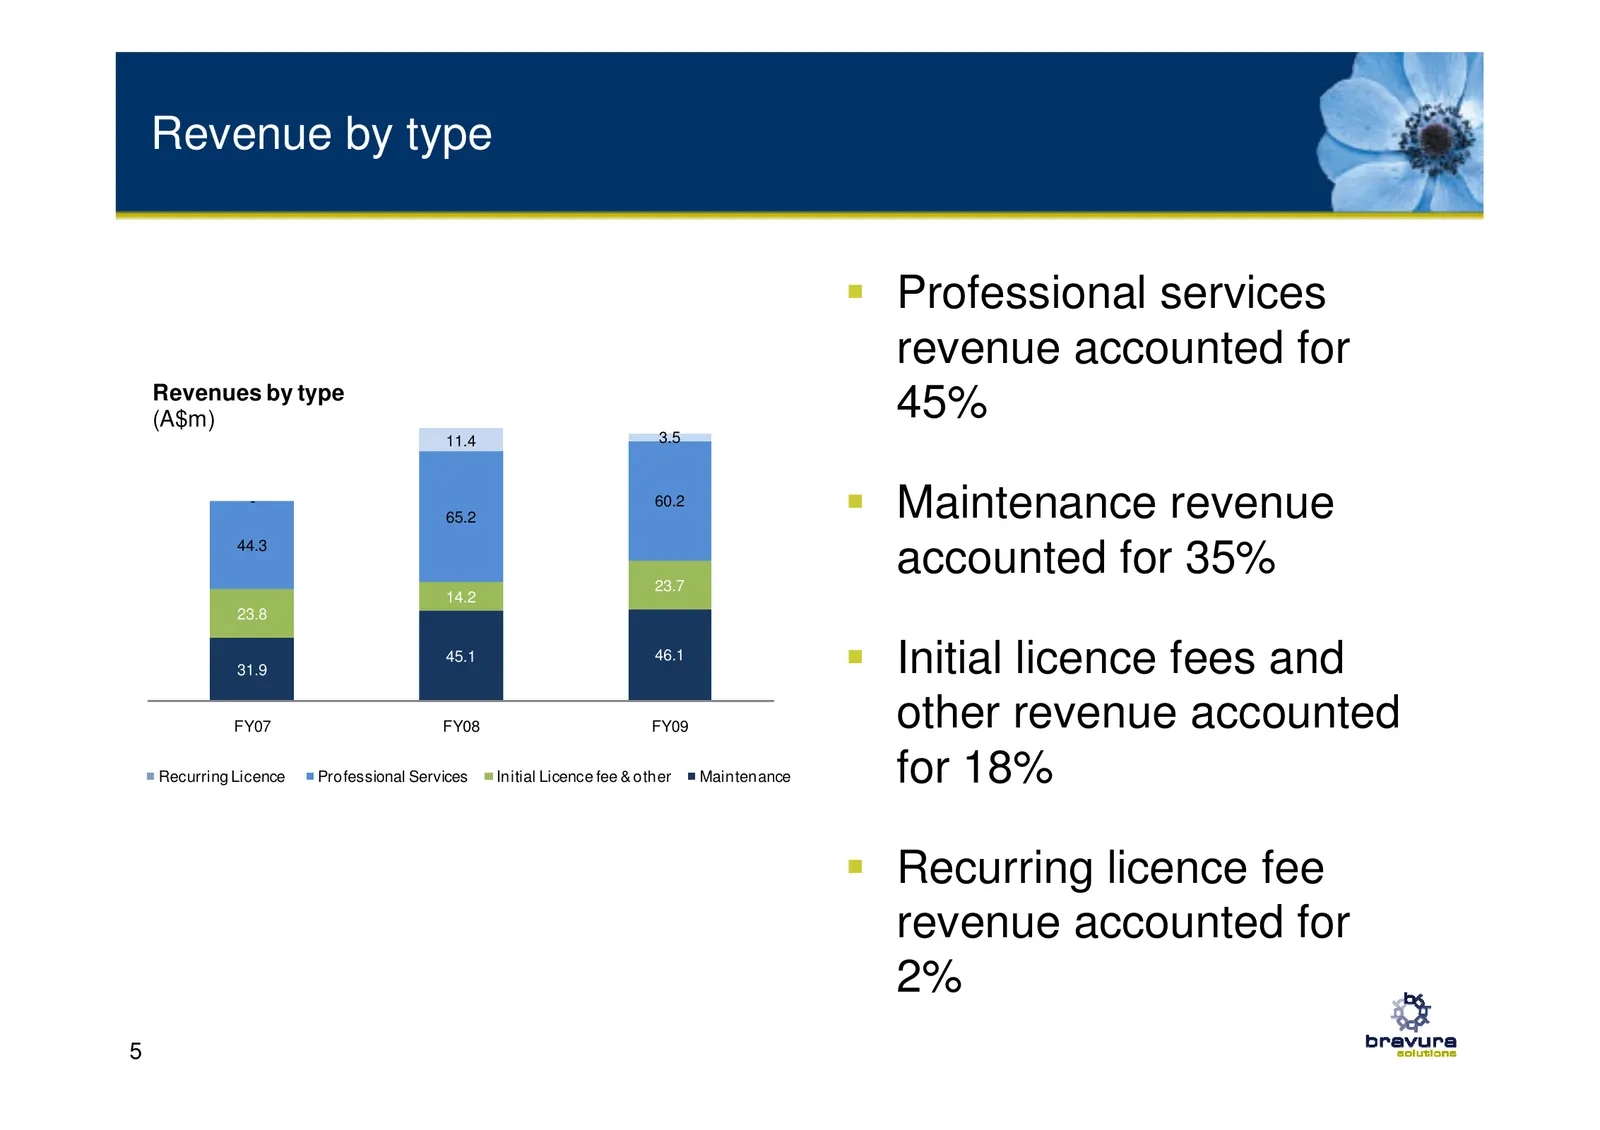
Maintenance revenue increased by two per cent to $46.1 million, due to completion of client implementations and CPI increases. Maintenance revenue accounted for 35 per cent of total revenue in the year ended 30 June 2009, compared with 33 per cent in the prior year. Initial licence fees and other re
Slide 4: ePASS, SuperB, cash flow, R&D and acquisitions
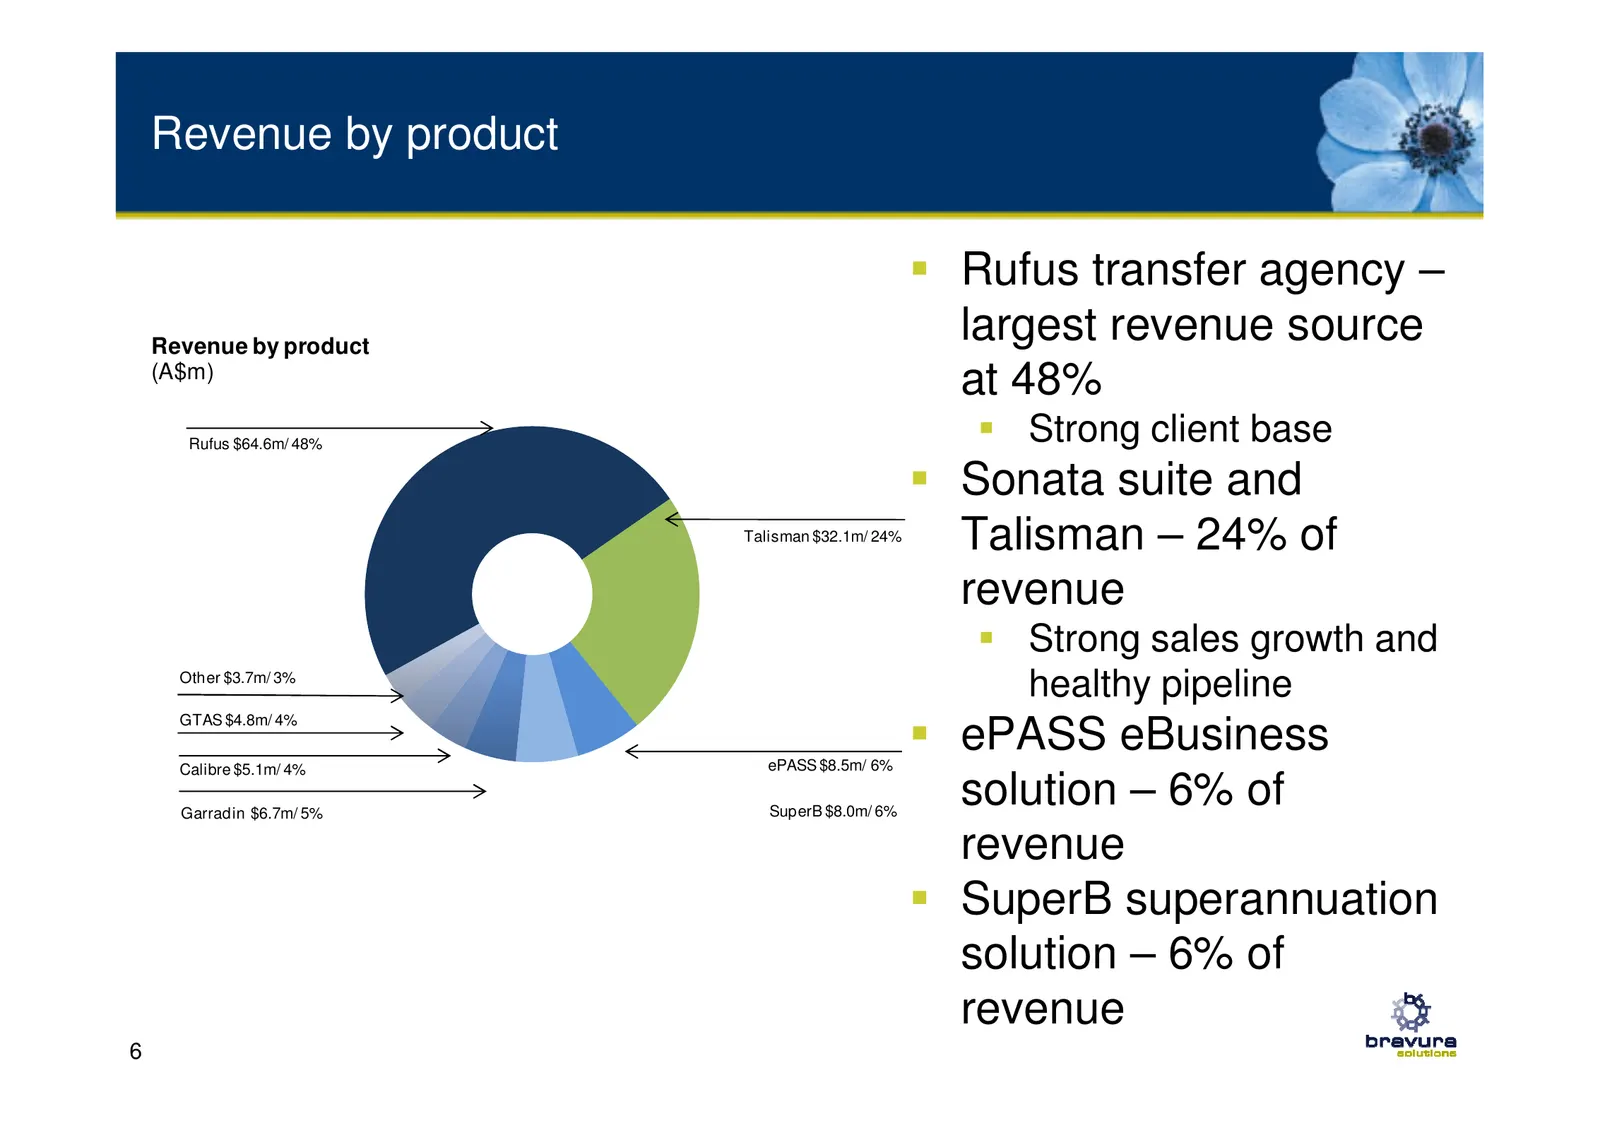
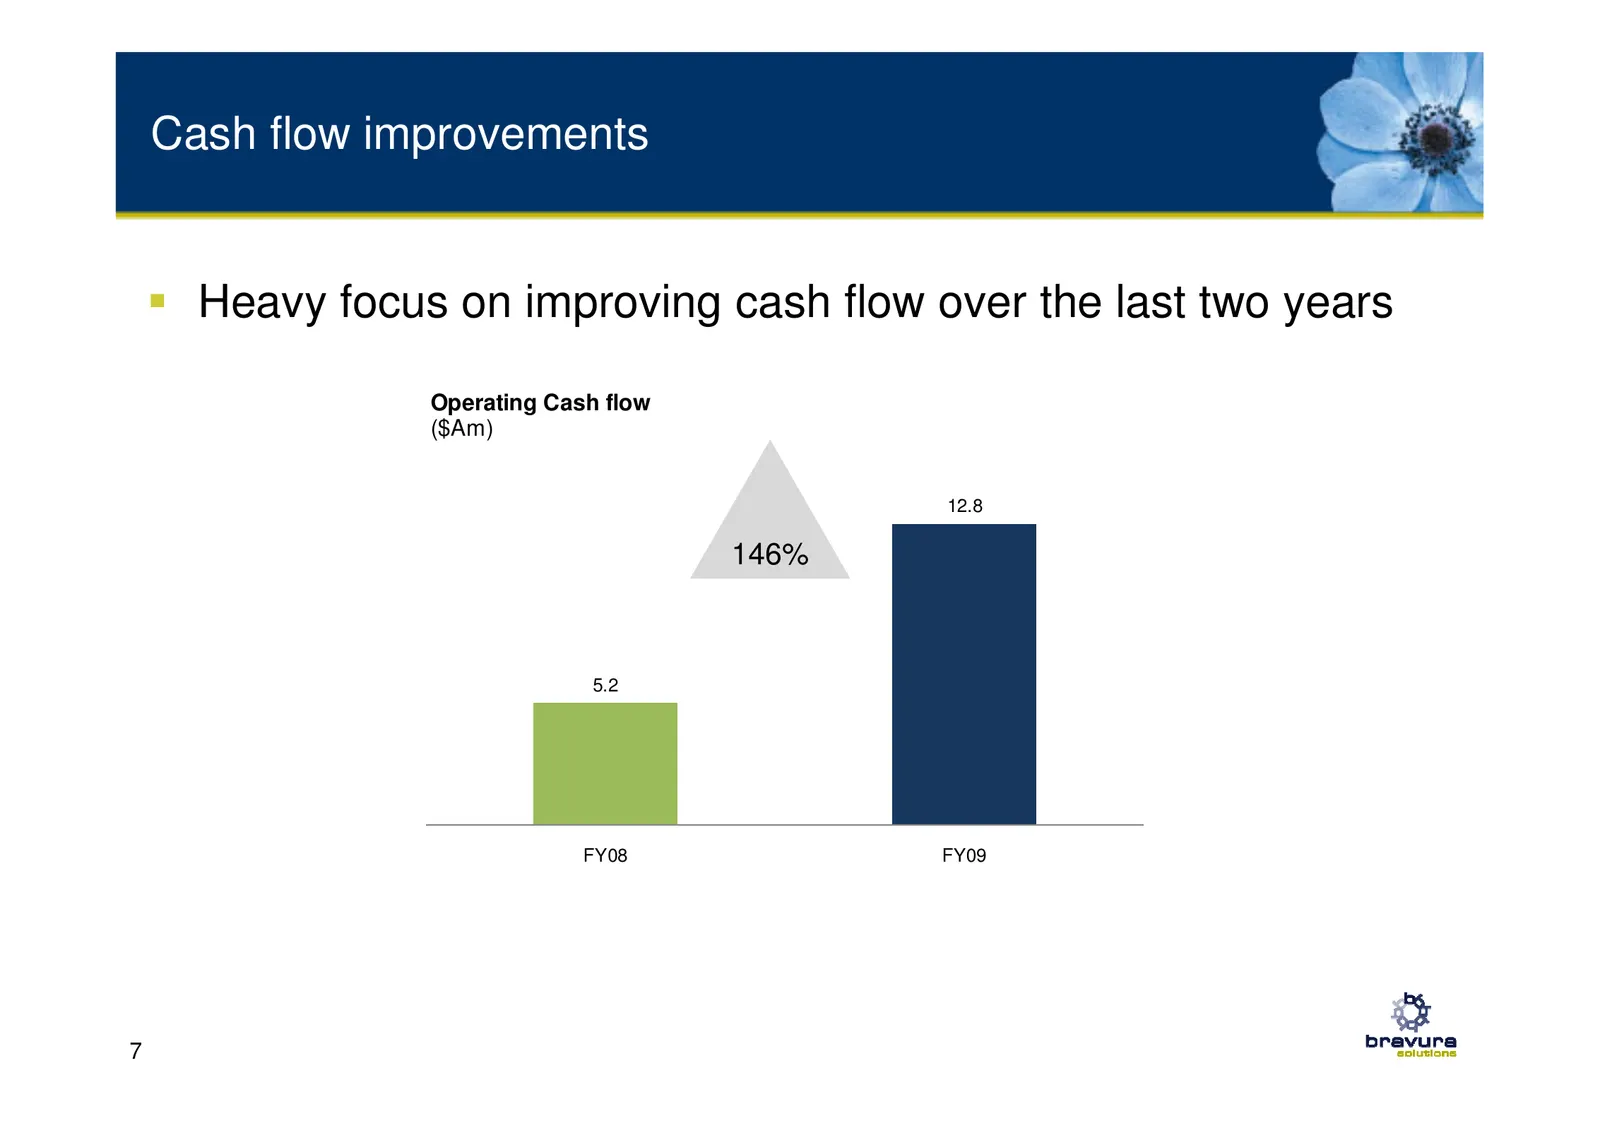
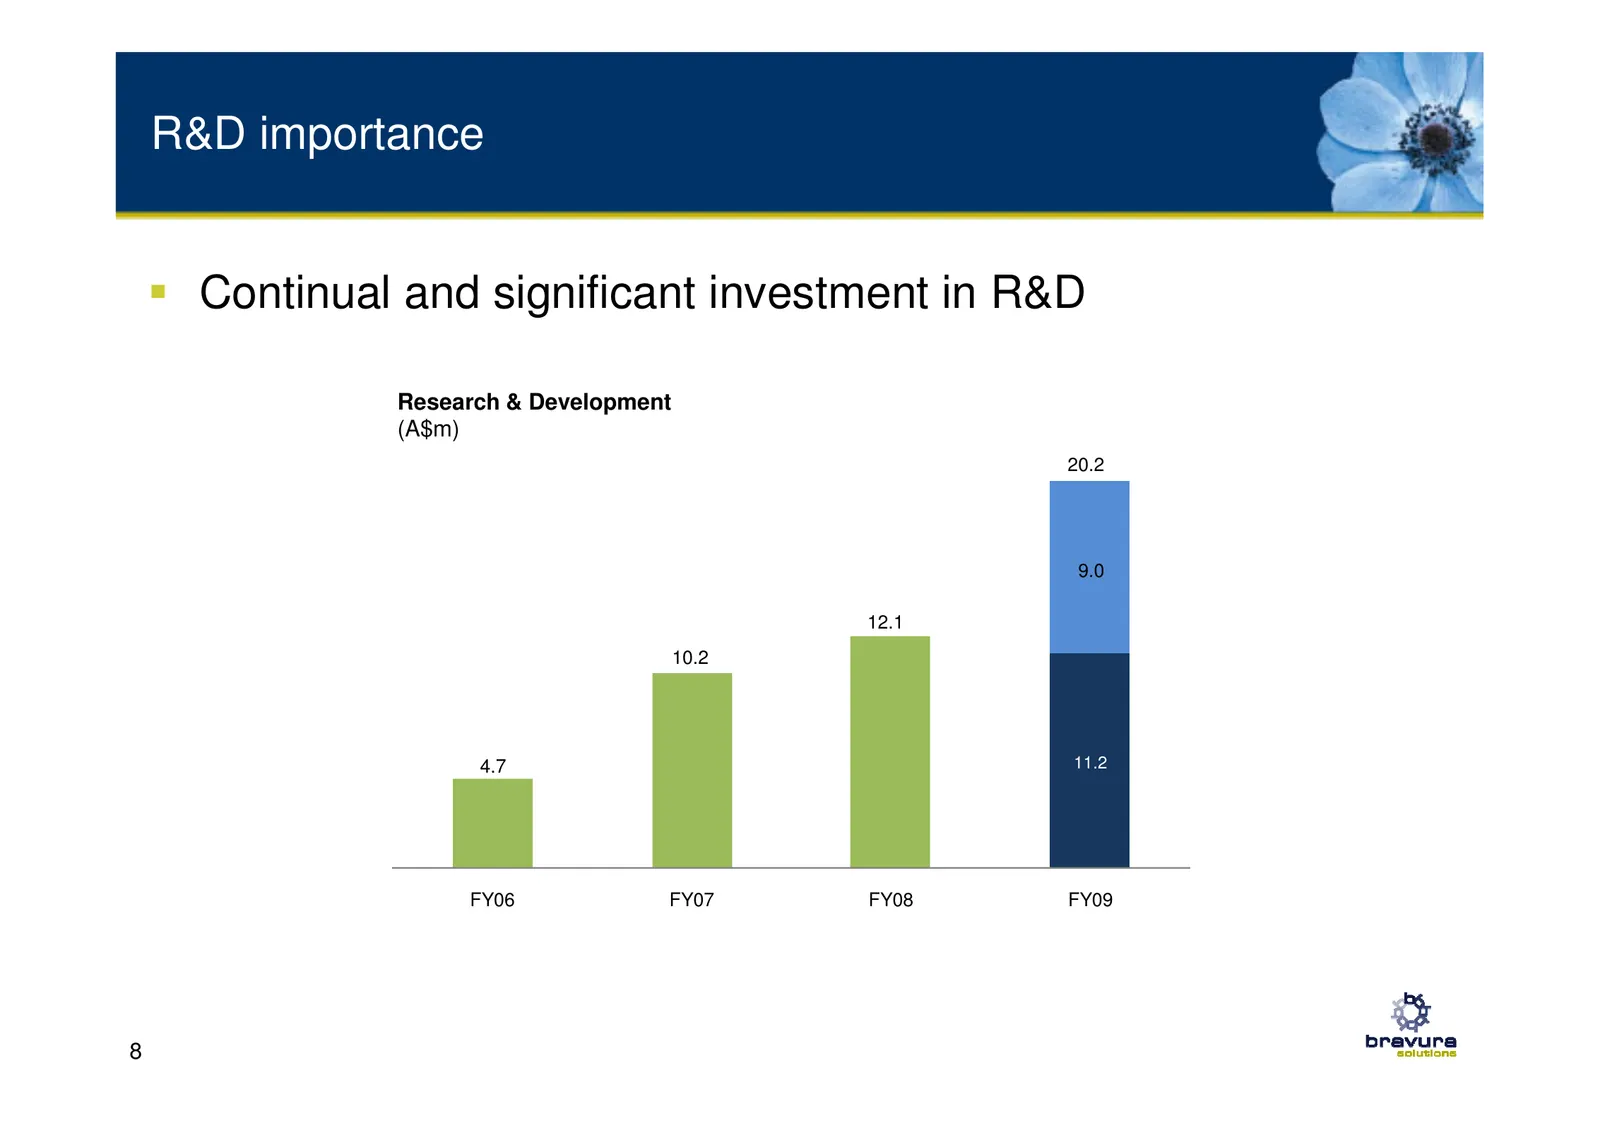
ePASS, our eBusiness application provides $8.5 million in revenue, or six per cent, and following closely behind is our superannuation application SuperB, also providing six per cent of revenue or $8.0 million. Cash flow Operating cash flow increased from $5.2 million in FY2008 to $12.8 million in F
Slide 5: Corporate Social Responsibility and outlook
contribute significantly to revenue, secure us new key strategic clients and encourage continuation of existing contracts and upgrades. Corporate Social Responsibility Bravura Solutions is strongly committed to operating as a sustainable enterprise and regards corporate social responsibility as bein
Slide 6: FY2010 EBITDA guidance
to an expected EBITDA of between $7.2 million to $8.2 million for the first half of this financial year. The expected EBITDA range provided above for the first half of this financial year is reliant upon the closure of certain contracts that are still under negotiation. These are all at advanced sta
Slide 7: Strategic priorities and conclusion
3. We will look to strengthen our foothold and deepen our strategic engagements with clients in the markets where we have an existing presence. We will also focus on further penetrating emerging markets such as South Africa and South East Asia. 4. We will continue to provide proven, world class soft
Slide 8: 2009 Annual General Meeting CEO review
2009 Annual General Meeting CEO review Presented by Iain Dunstan 20 November 2009
Slide 9: Internationally recognised achievements
Internationally recognised achievements 2
Slide 10: Challenging market conditions
Challenging market conditions Deteriorating conditions impacting financial services Client decision making and approval processes impeded Lengthier sales cycle Agreements delayed but not forgone 3
Slide 11: Solid EBITDA and revenue
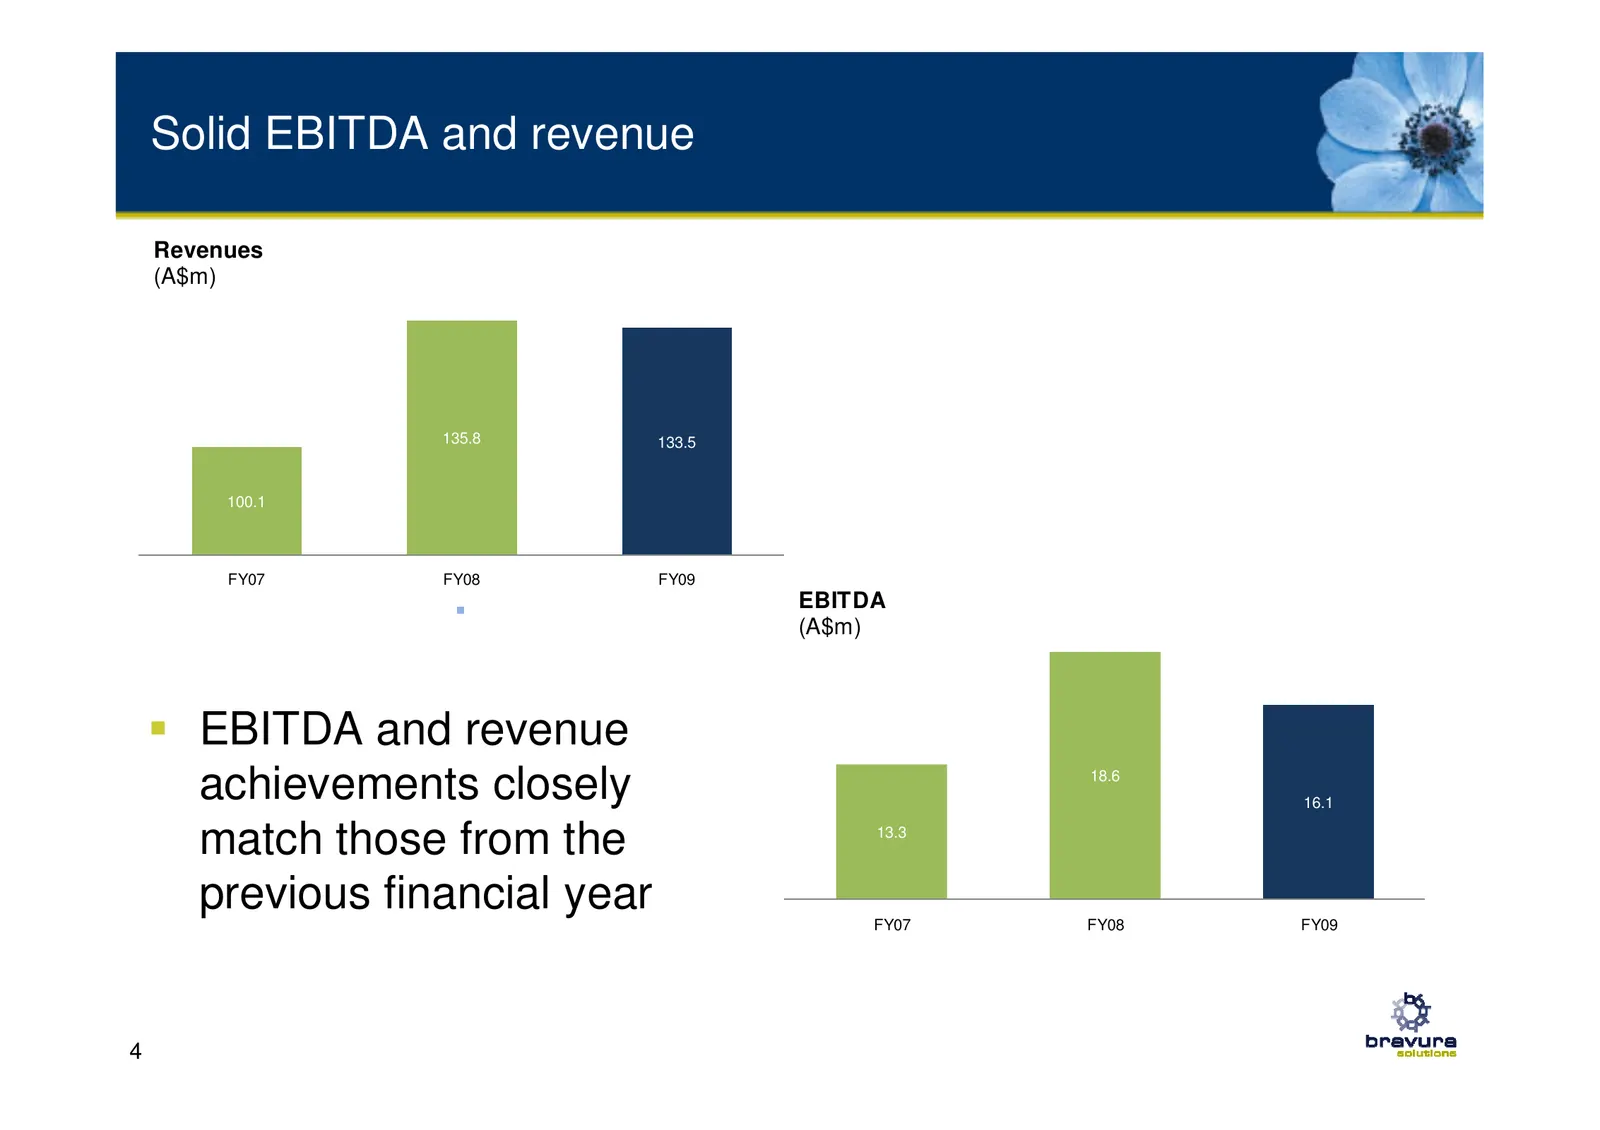
Solid EBITDA and revenue Revenues (A$m) 135.8 133.5 100.1 FY07 FY08 FY09 EBITDA (A$m) EBITDA and revenue achievements closely 18.6 16.1 match those from the 13.3 previous financial year FY07 FY08 FY09 4
Slide 12: Revenue by type
Revenue by type Professional services revenue accounted for Revenues by type (A$m) 45% 11.4 3.5 - 65.2 60.2 Maintenance revenue 44.3 23.7 accounted for 35% 14.2 23.8 31.9 45.1 46.1 Initial licence fees and FY07 FY08 FY09 other revenue accounted Recurring Licence Professional Services Initial Licence
Slide 13: Revenue by product
Revenue by product Rufus transfer agency – Revenue by product largest revenue source (A$m) at 48% Rufus $64.6m/ 48% Strong client base Sonata suite and Talisman $32.1m/ 24% Talisman – 24% of revenue Strong sales growth and Other $3.7m/ 3% healthy pipeline GTAS $4.8m/ 4% ePASS $8.5m/ 6% ePASS eBusine
Slide 14: Cash flow improvements
Cash flow improvements Heavy focus on improving cash flow over the last two years Operating Cash flow ($Am) 12.8 146% 5.2 FY08 FY09 7
Slide 15: R&D importance
R&D importance Continual and significant investment in R&D Research & Development (A$m) 20.2 9.0 12.1 10.2 4.7 11.2 FY06 FY07 FY08 FY09 8
Slide 16: Successful acquisitions
Successful acquisitions November 2008, acquisition of transfer agency division from Citi in Warsaw, Poland EPS accretive in FY2009 Generated significant recurring revenue Continues to outperform forecasts Three previous acquisitions all performing well 9
Slide 17: Commitment to Corporate Social Responsibility
Commitment to Corporate Social Responsibility Strongly committed to operating as a sustainable enterprise Objective to minimise environmental impact Efficient use of natural resources Engagement with charitable organisations to benefit communities Audit and monitor our carbon emissions through the C
Slide 18: FY2010 guidance
FY2010 guidance EBITDA for 1H FY2010 to be between $5.5m and $6.5m Had £ remained constant at average exchange rate of 2.16, would equate to EBITDA of between $7.2m and $8.2m EBITDA reliant upon closure of certain contracts EBITDA achieved from FY2009 was 60% in 1H and 40% in 2H Expect EBITDA achiev
Slide 19: Outlook
Outlook 1 Bravura has been re-established on sound financial footing – we intend to build upon this 2 Focus on margins and revenue 3 Strengthen our foothold in geographic markets 4 Continue to provide world class software solutions 5 Continue our R&D focus 6 Demonstrate solid and stable performance
Slide 20: Thank you
bravura solutions e: f
Source: Internet Archive copy of bravurasolutions.com
More decks from Bravura Solutions Limited
 FY2026 Earnings Presentation25 slides · Aug 12, 2026
 H1 2026 Earnings Presentation24 slides · Feb 11, 2026
 Shareholder Meeting (October 2025)13 slides · Oct 15, 2025
 FY2025 Earnings Presentation25 slides · Aug 13, 2025
 H1 2025 Earnings Presentation28 slides · Feb 12, 2025
 Shareholder Meeting (October 2024)18 slides · Oct 30, 2024