Cosi — First Albany Investment Conference (December 2004)
15 slides from Cosi's conference presentation, Dec 8, 2004
Slide 1: Cosi, Inc. First Albany Investment Conference
Cosi, Inc. (Nasdaq: COSI) First Albany Investment Conference William D. Forrest, Executive Chairman Kevin Armstrong, President & CEO December 7, 2004
Slide 2: Safe Harbor Concerning Forward Looking Statements
Safe Harbor Concerning Forward Looking Statements Matters discussed in this presentation that relate to events or developments which are expected to occur in the future, including any discussion, expressed or implied, of anticipated growth, new store openings, operating results or earnings constitut
Slide 3: Information About EBITDA and Adjusted EBITDA
Information About EBITDA and Adjusted EBITDA EBITDA, as included herein, is a non-GAAP financial measure that represents earnings before interest, taxes, depreciation and amortization. EBITDA is included in this release as it is a basis upon which we assess our financial performance. The Company use
Slide 4: Cosi – “Simply Good Taste”
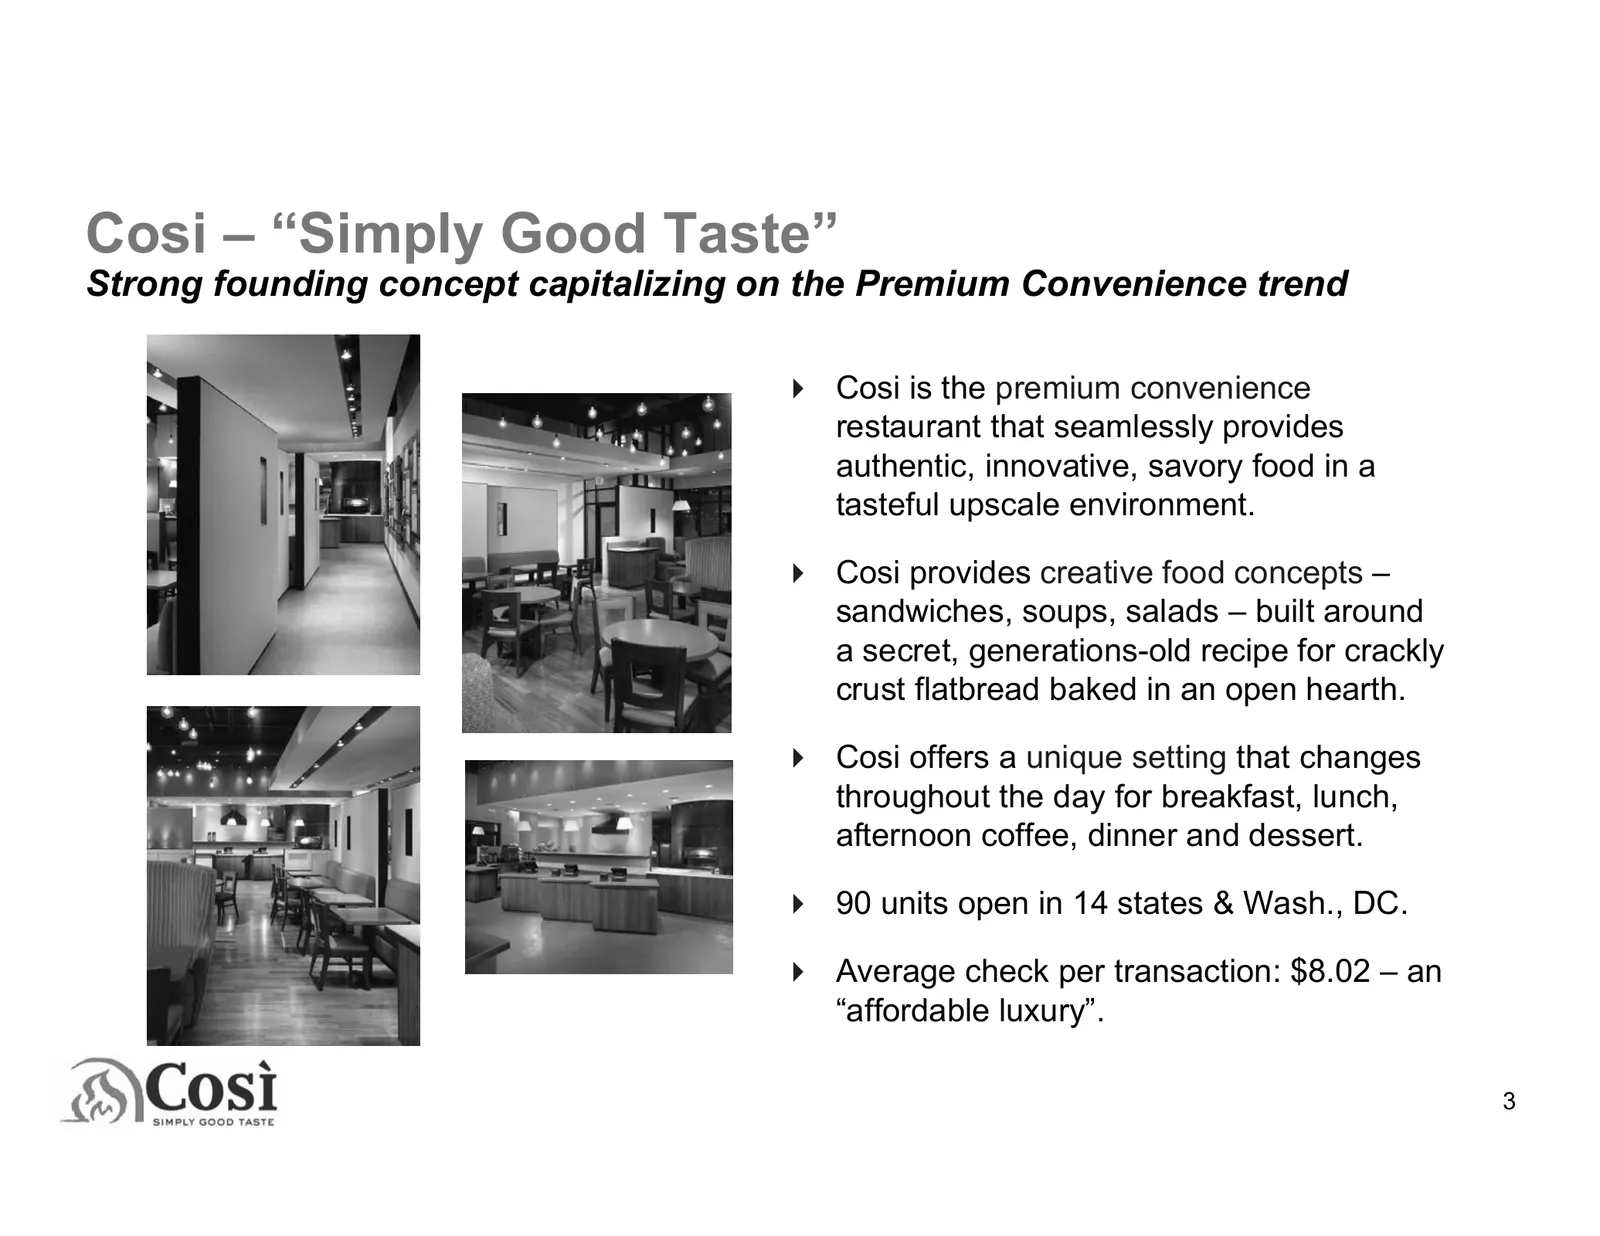
Cosi – “Simply Good Taste” Strong founding concept capitalizing on the Premium Convenience trend Cosi is the premium convenience restaurant that seamlessly provides authentic, innovative, savory food in a tasteful upscale environment. Cosi provides creative food concepts – sandwiches, soups, salads
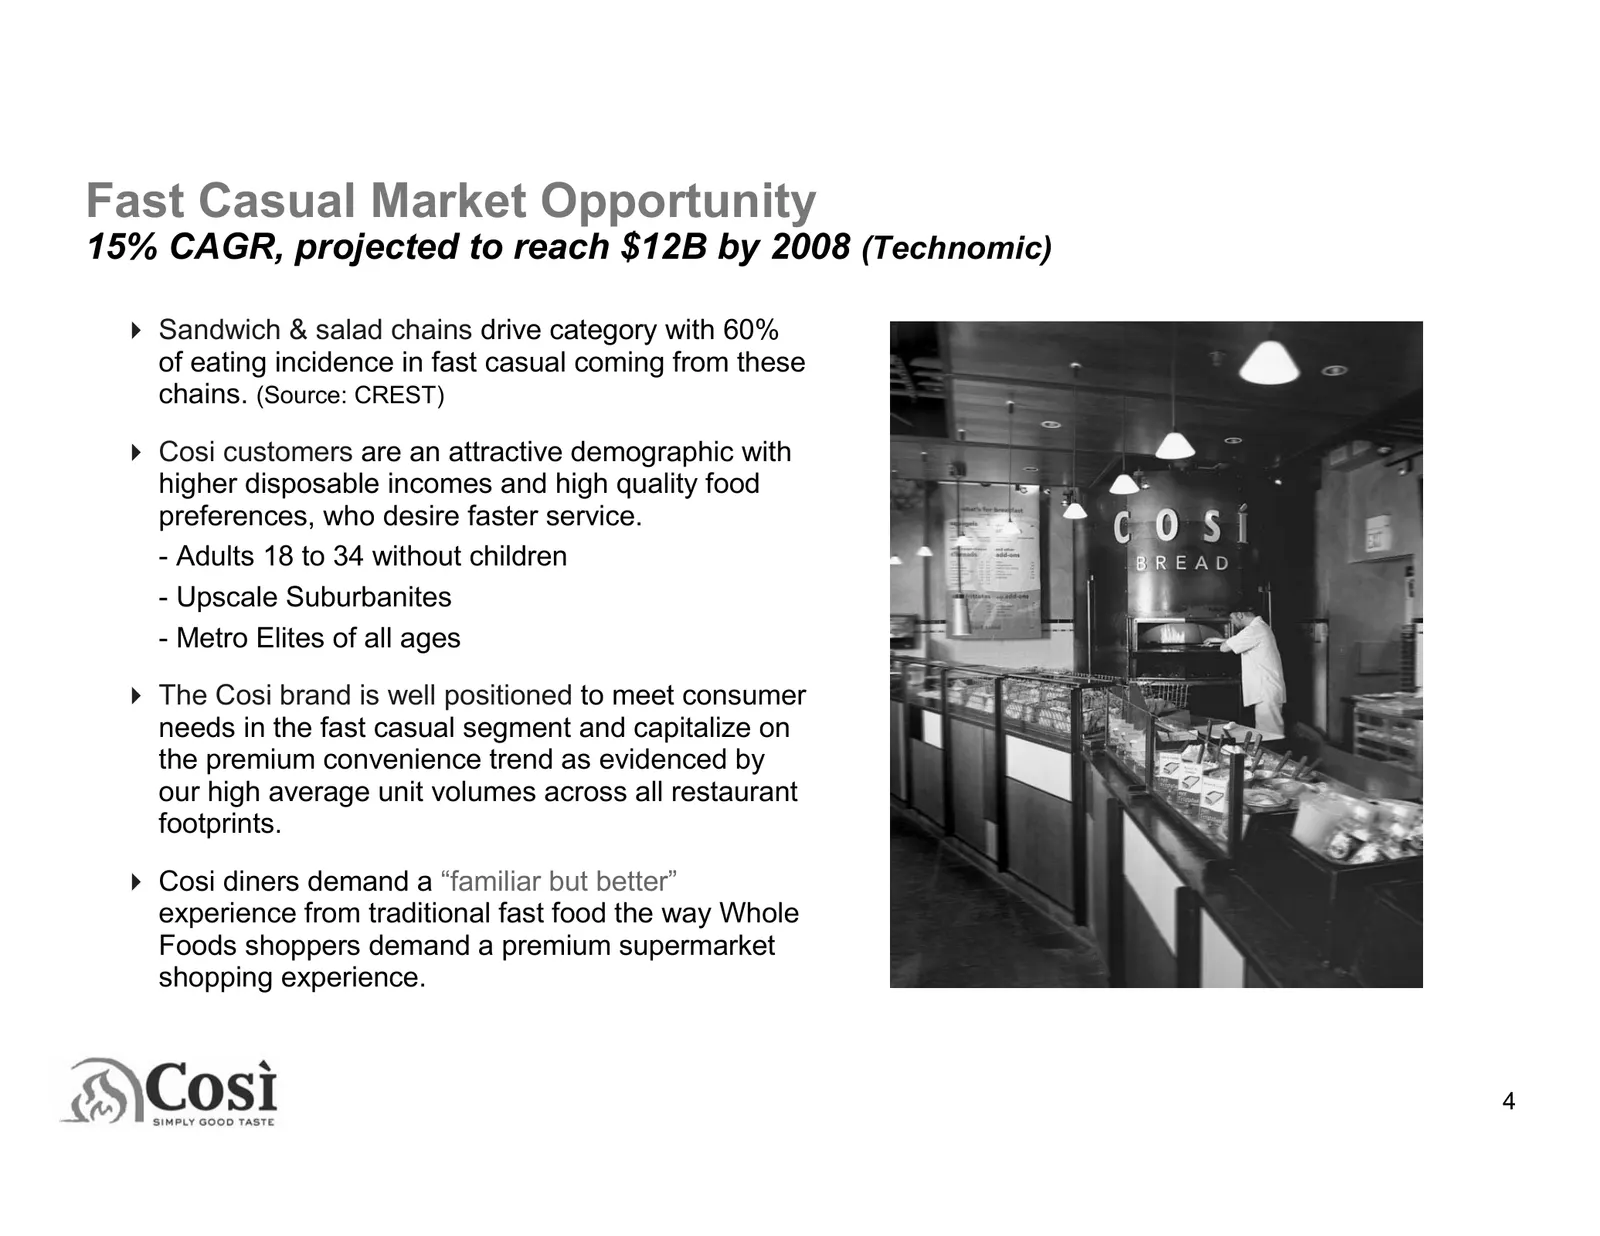
Slide 5: Fast Casual Market Opportunity
Fast Casual Market Opportunity 15% CAGR, projected to reach $12B by 2008 (Technomic) Sandwich & salad chains drive category with 60% of eating incidence in fast casual coming from these chains. (Source: CREST) Cosi customers are an attractive demographic with higher disposable incomes and high quali
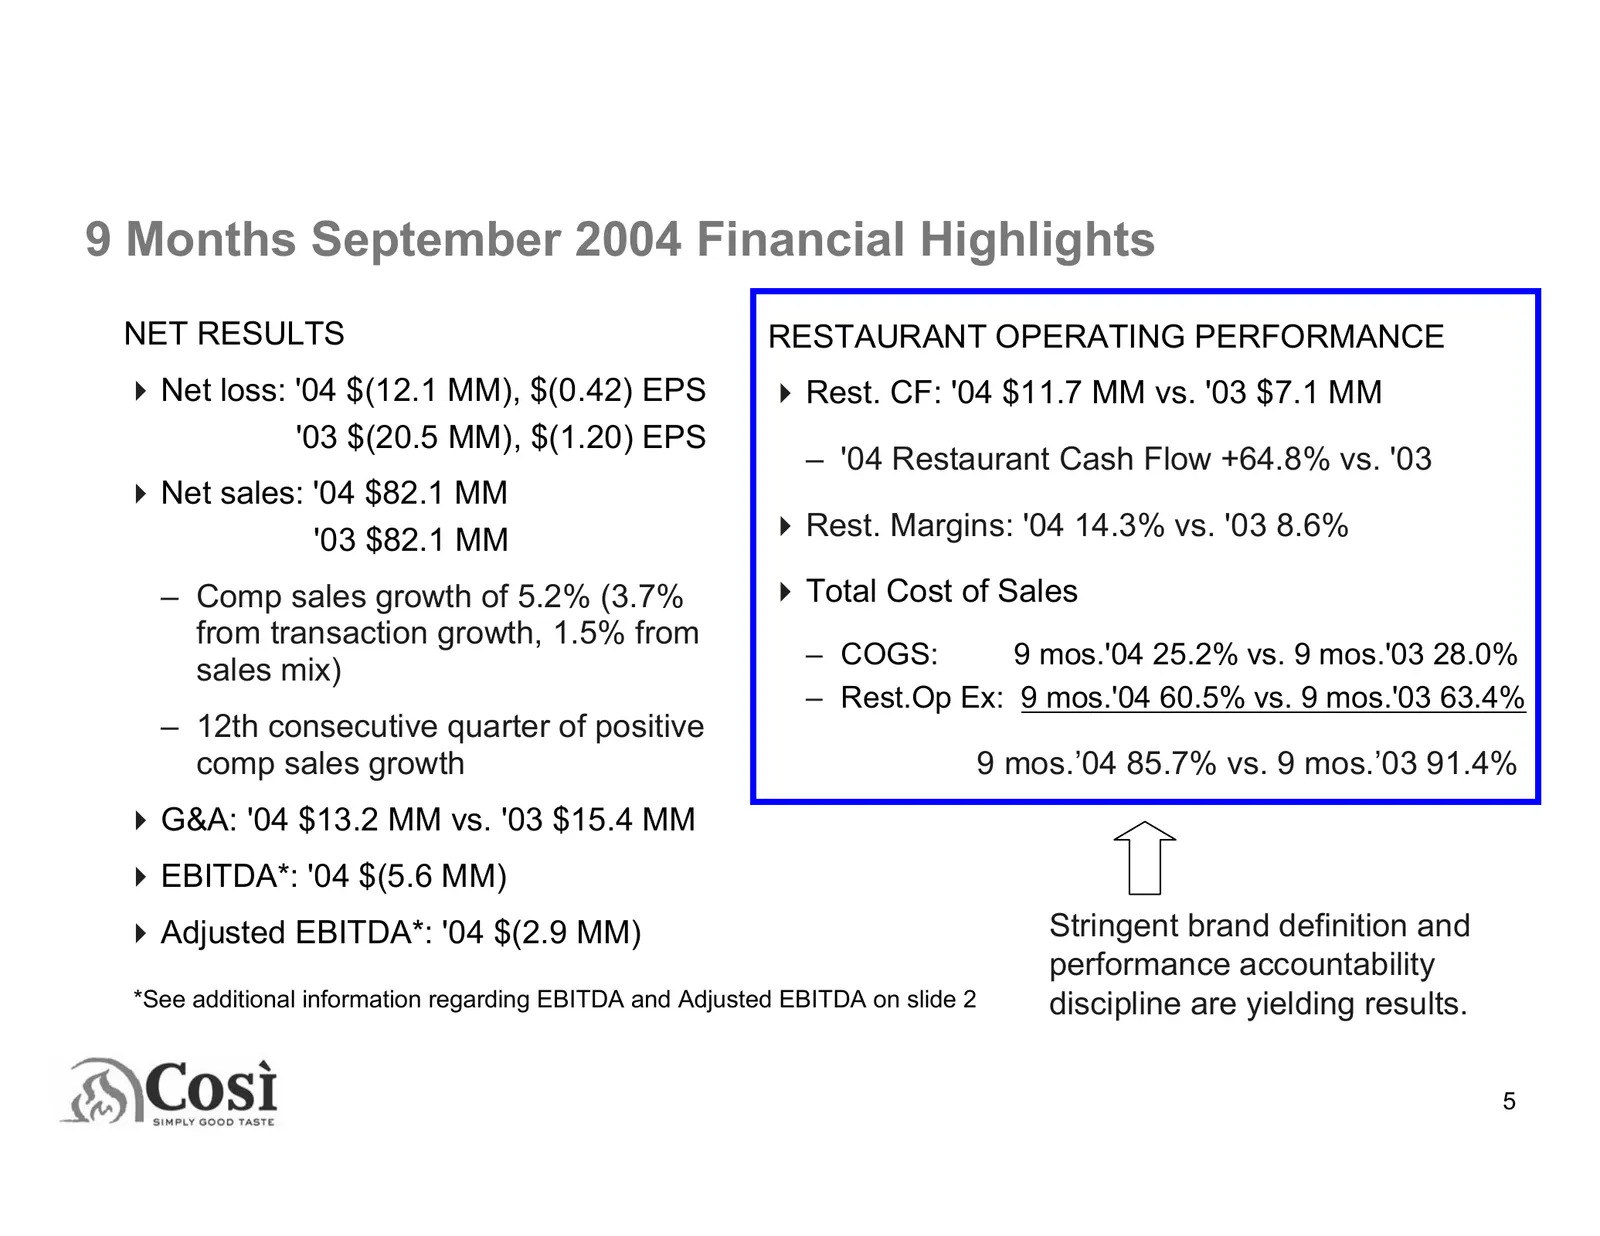
Slide 6: 9 Months September 2004 Financial Highlights
9 Months September 2004 Financial Highlights NET RESULTS RESTAURANT OPERATING PERFORMANCE Net loss: '04 $(12.1 MM), $(0.42) EPS Rest. CF: '04 $11.7 MM vs. '03 $7.1 MM '03 $(20.5 MM), $(1.20) EPS – '04 Restaurant Cash Flow +64.8% vs. '03 Net sales: '04 $82.1 MM '03 $82.1 MM Rest. Margins: '04 14.3% v
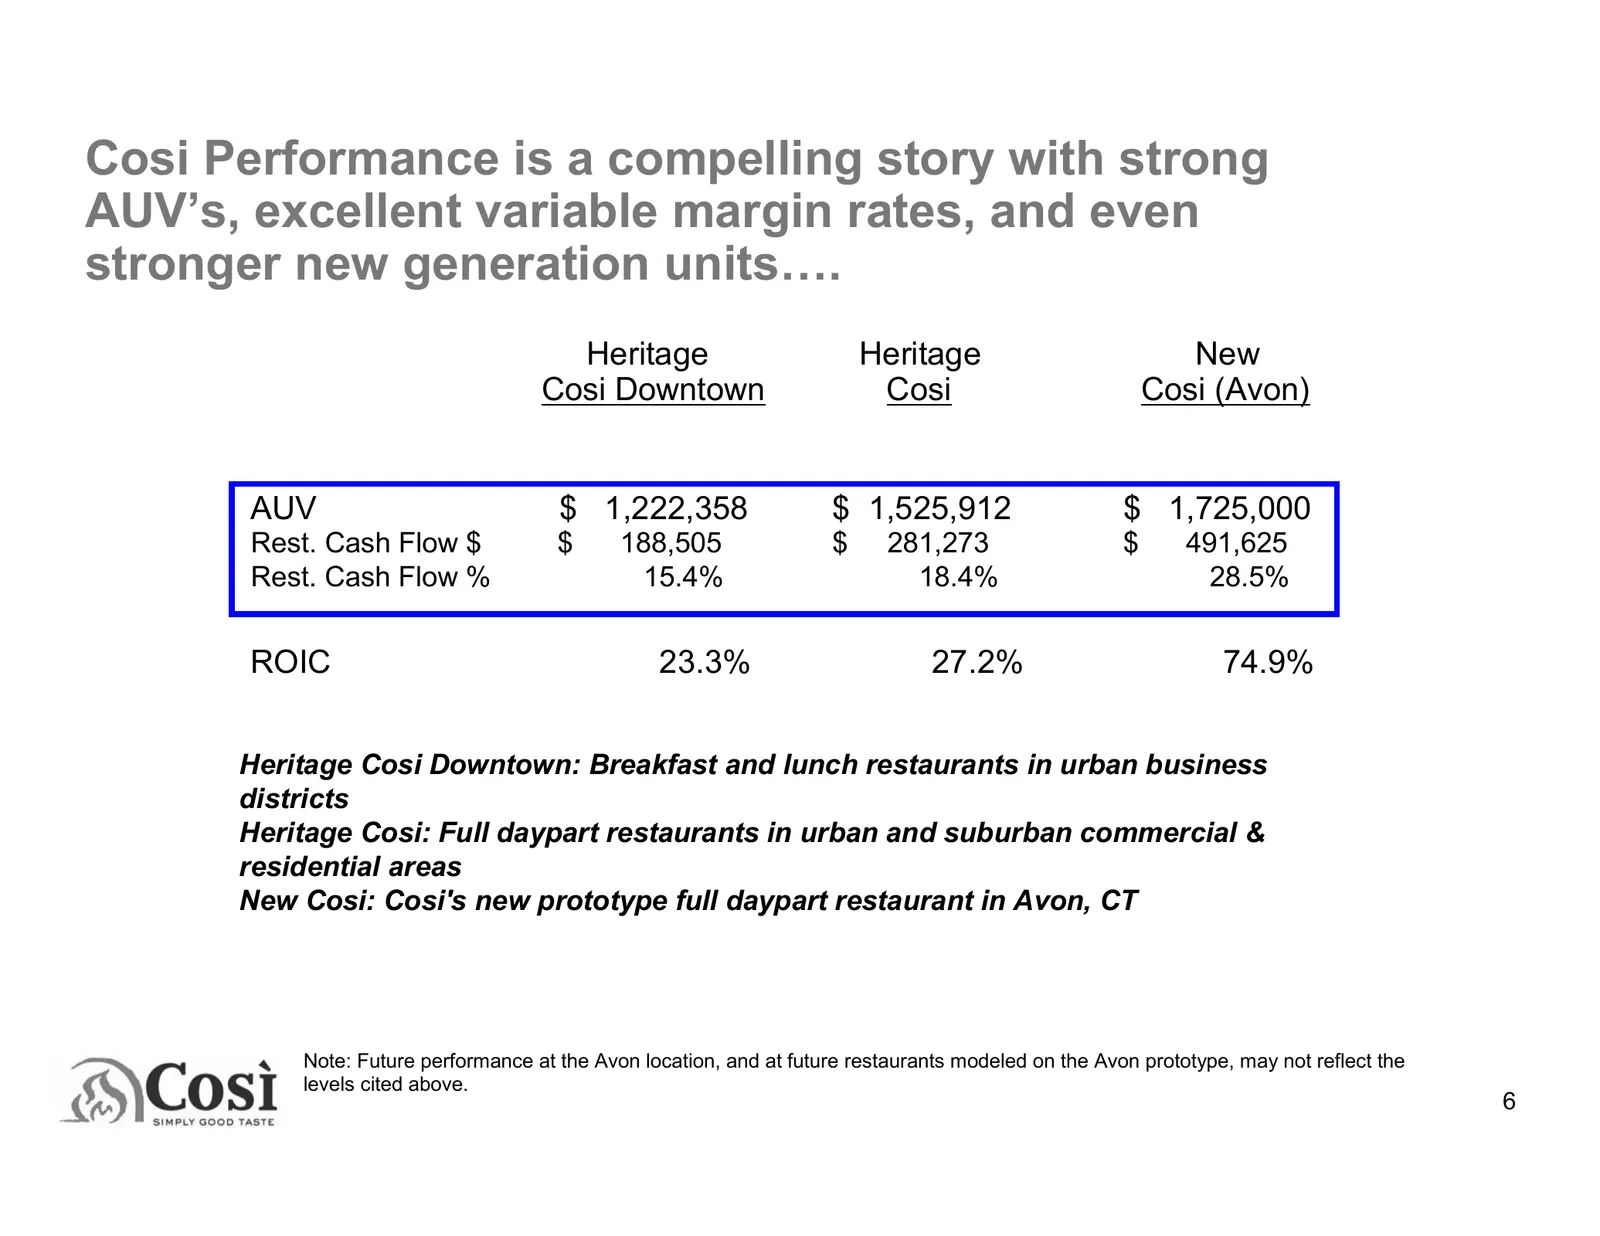
Slide 7: Cosi Performance: strong AUVs, excellent margins, stronger new units
Cosi Performance is a compelling story with strong AUV’s, excellent variable margin rates, and even stronger new generation units…. Heritage Heritage New Cosi Downtown Cosi Cosi (Avon) AUV $ 1,222,358 $ 1,525,912 $ 1,725,000 Rest. Cash Flow $ $ 188,505 $ 281,273 $ 491,625 Rest. Cash Flow % 15.4% 18.
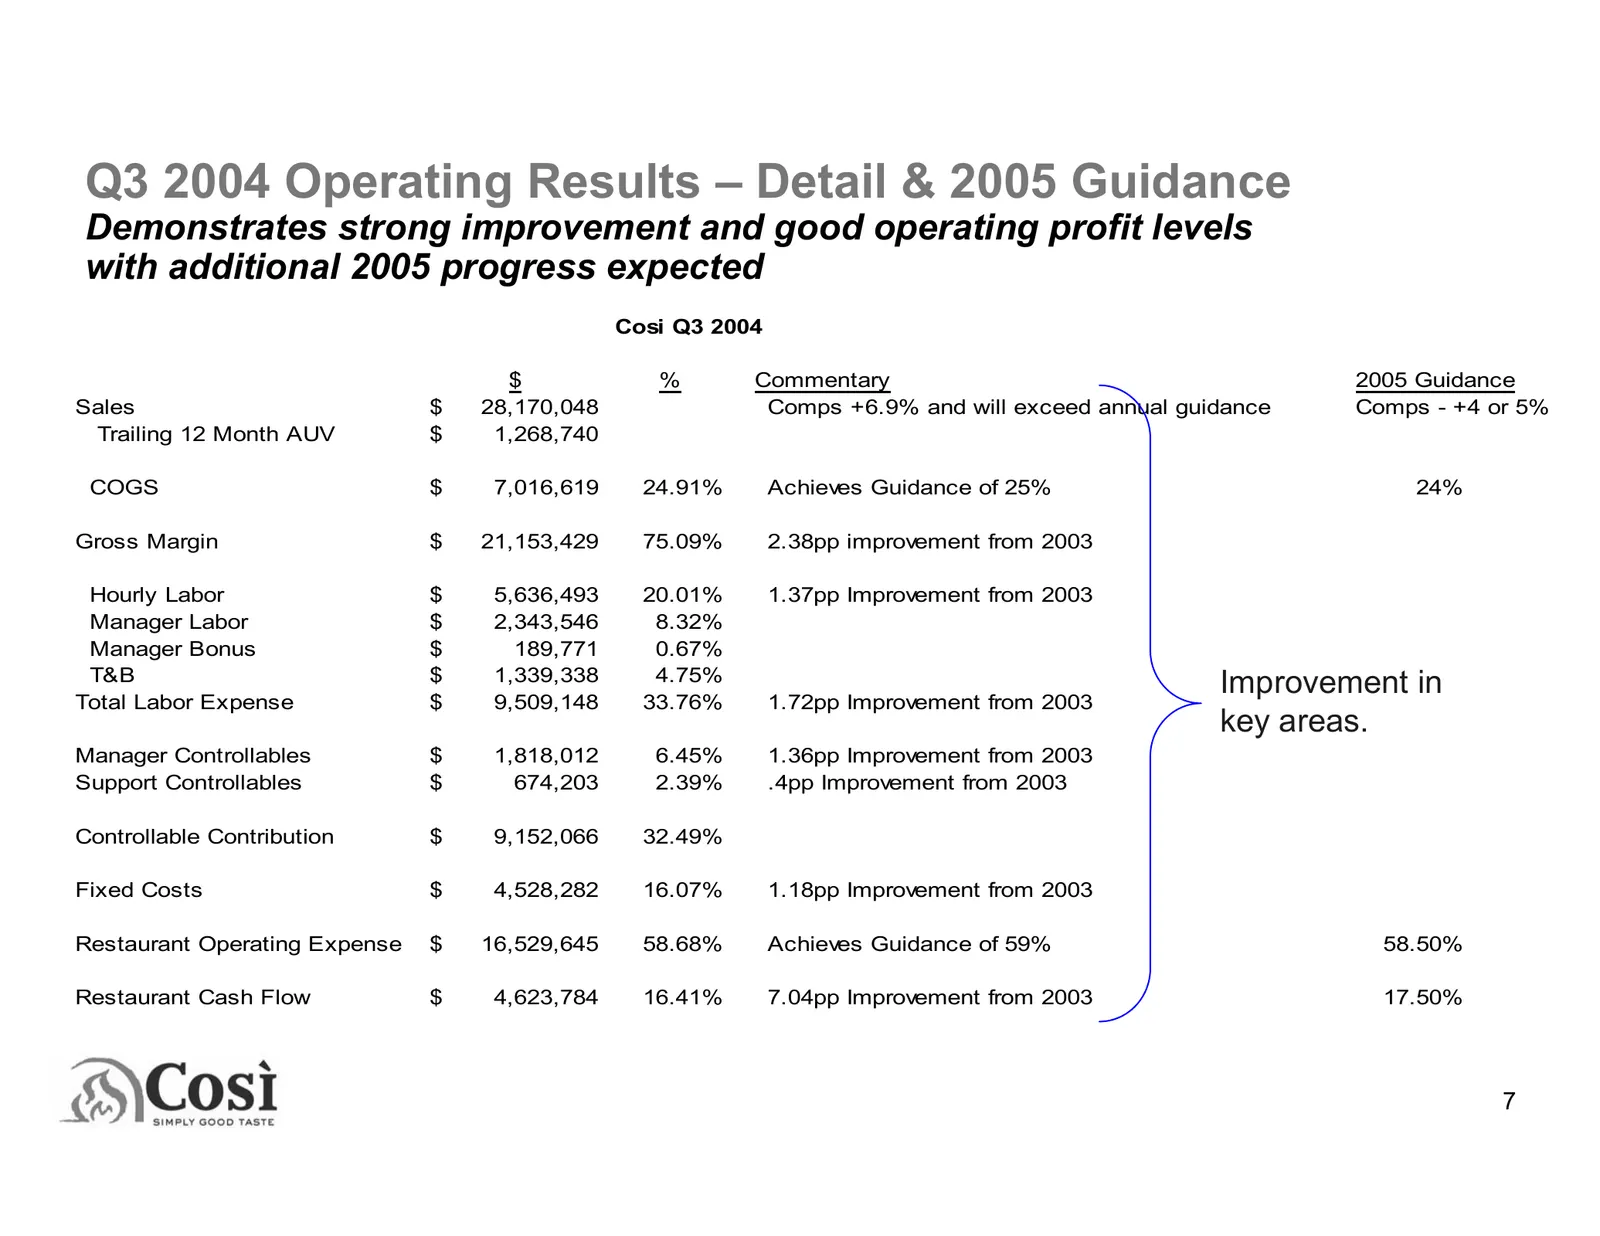
Slide 8: Q3 2004 Operating Results – Detail & 2005 Guidance
Q3 2004 Operating Results – Detail & 2005 Guidance Demonstrates strong improvement and good operating profit levels with additional 2005 progress expected Cosi Q3 2004 $ % Commentary 2005 Guidance Sales $ 28,170,048 Comps +6.9% and will exceed annual guidance Comps - +4 or 5% Trailing 12 Month AUV $
Slide 9: Cosi Balance Sheet
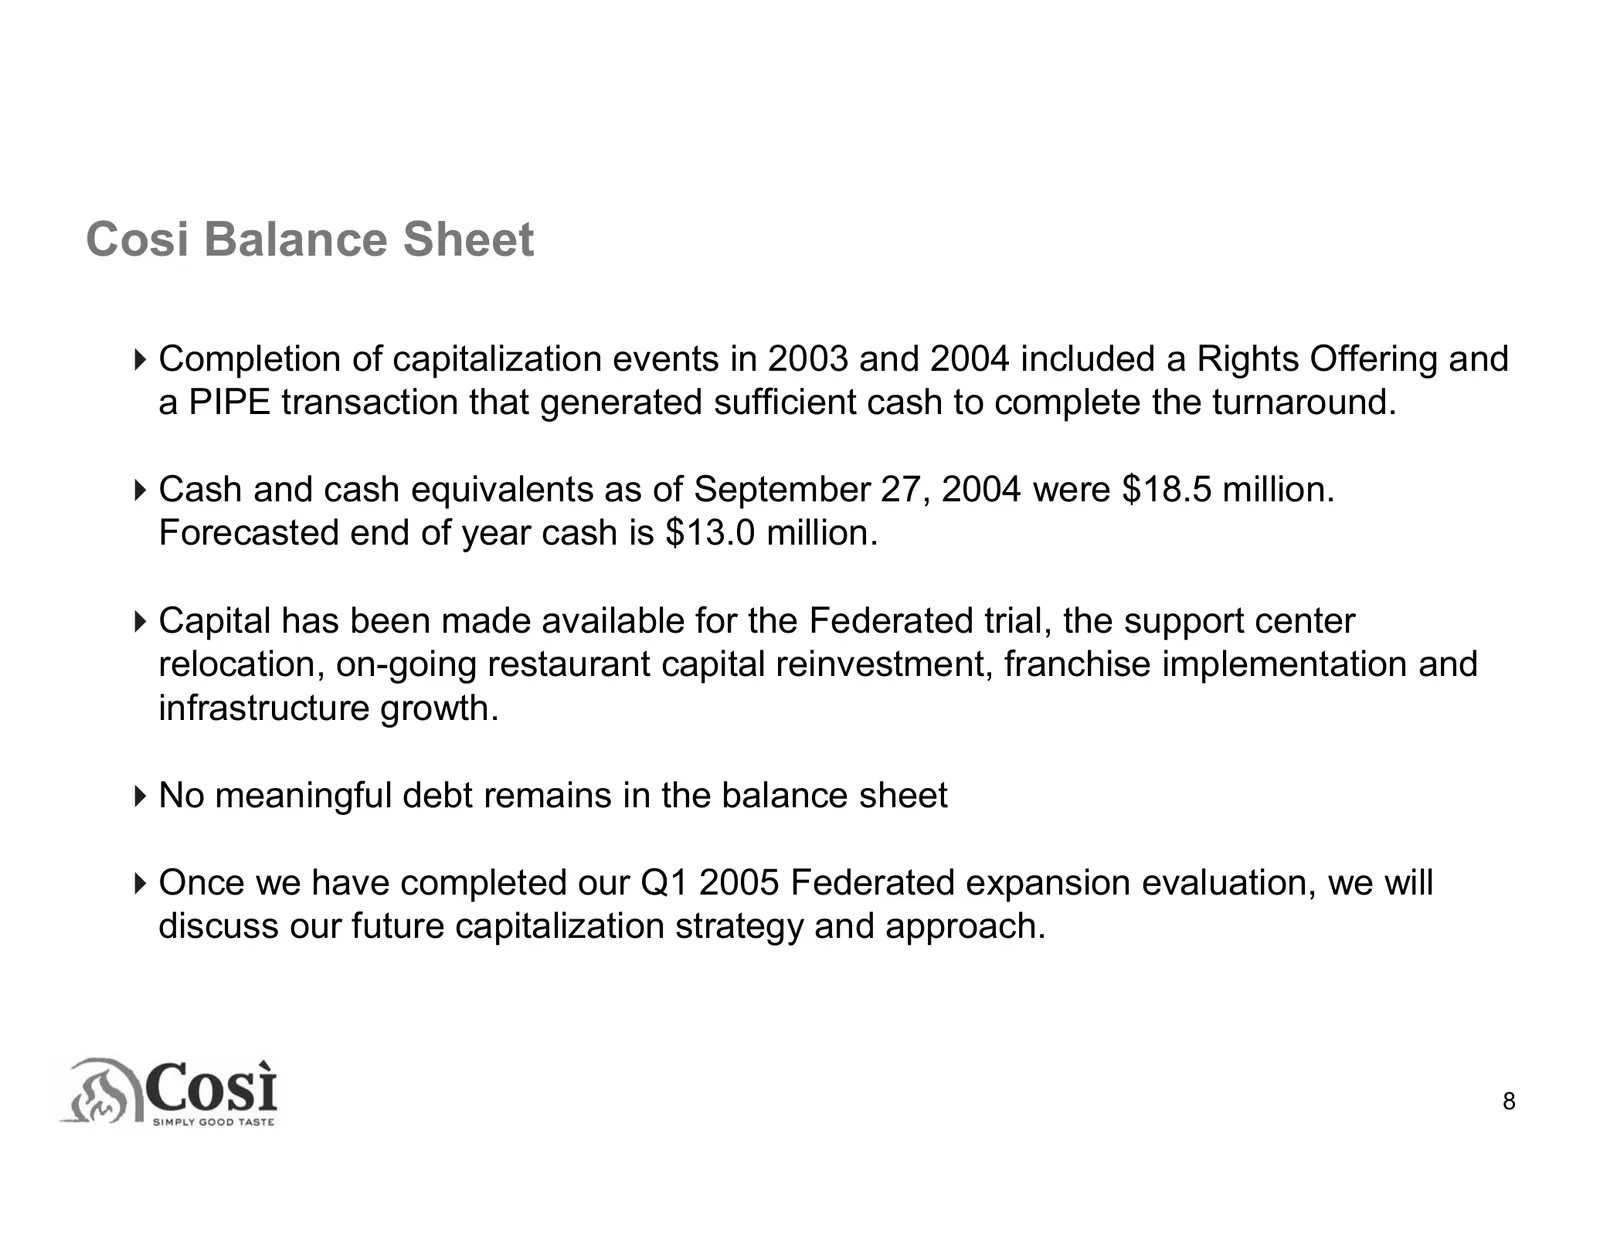
Cosi Balance Sheet Completion of capitalization events in 2003 and 2004 included a Rights Offering and a PIPE transaction that generated sufficient cash to complete the turnaround. Cash and cash equivalents as of September 27, 2004 were $18.5 million. Forecasted end of year cash is $13.0 million. Ca
Slide 10: Cosi, Inc. Management Team
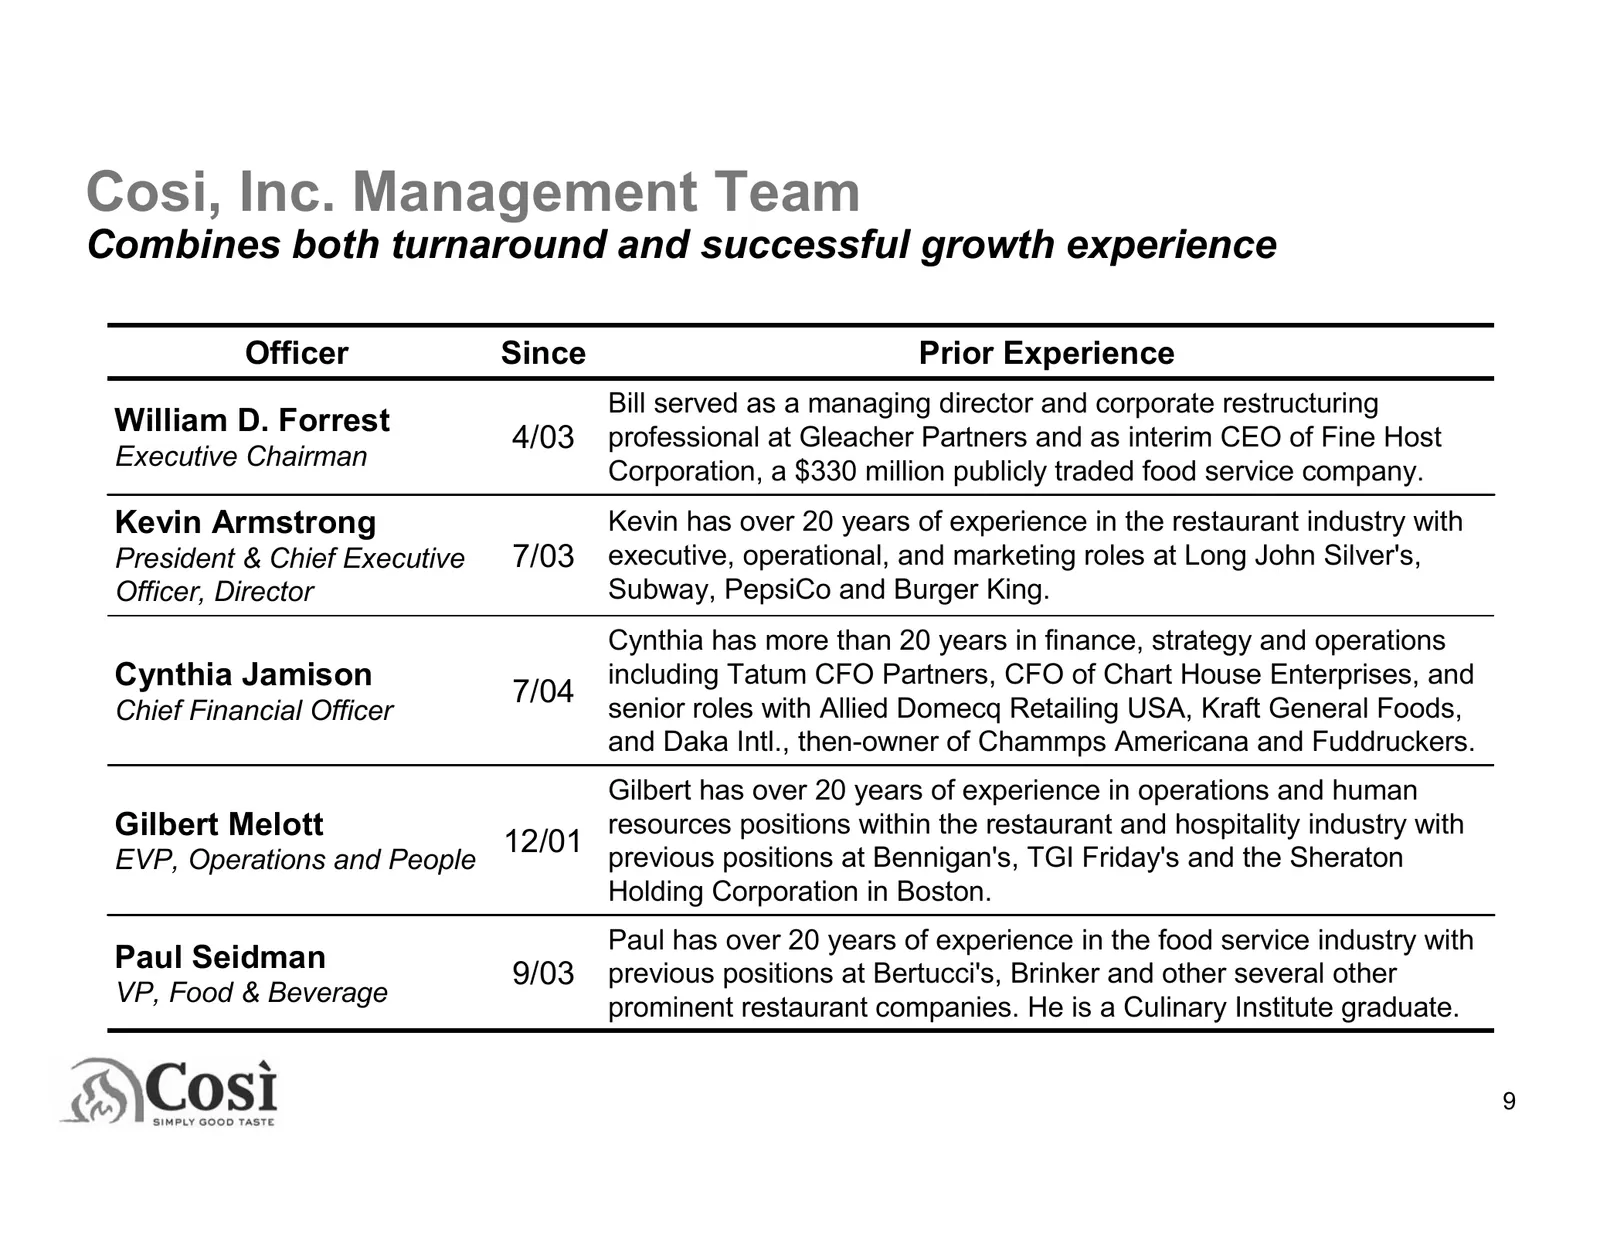
Cosi, Inc. Management Team Combines both turnaround and successful growth experience Officer Since Prior Experience Bill served as a managing director and corporate restructuring William D. Forrest 4/03 professional at Gleacher Partners and as interim CEO of Fine Host Executive Chairman Corporation,
Slide 11: Projected 5-Year Restaurant Development Goals
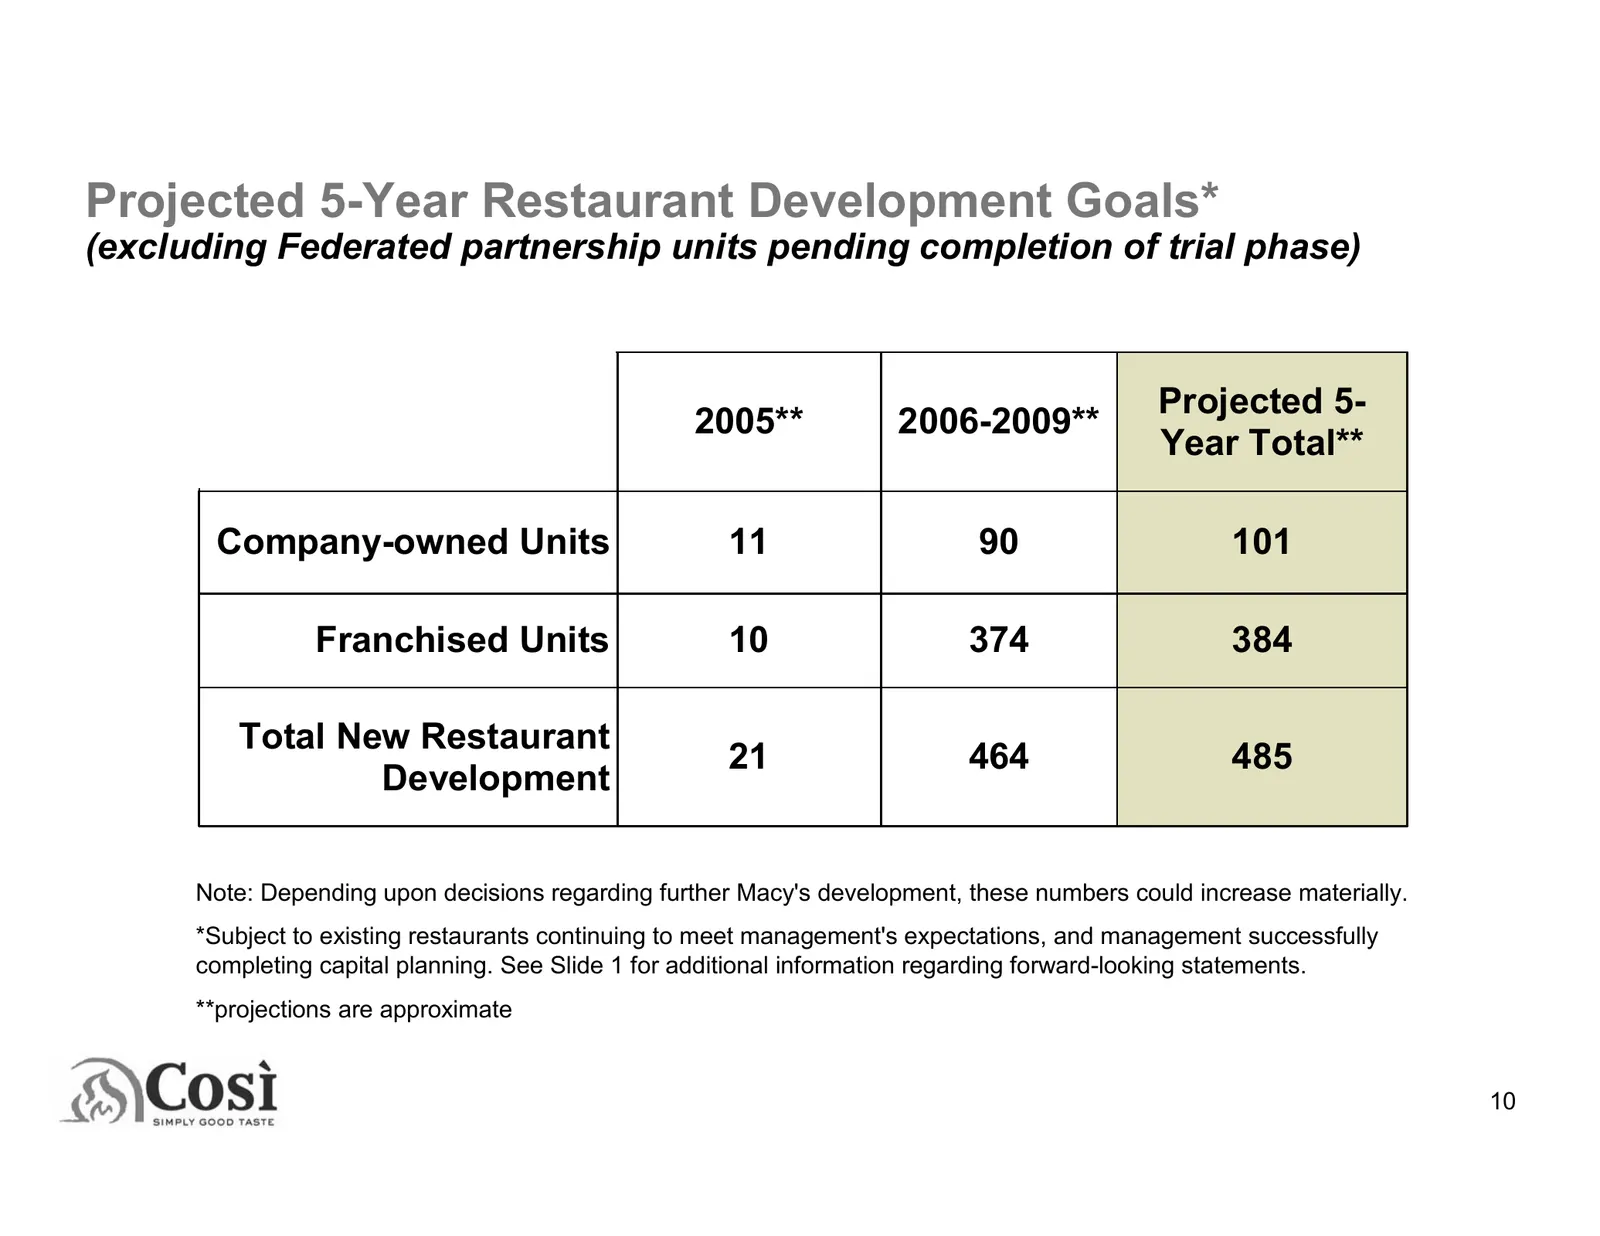
Projected 5-Year Restaurant Development Goals* (excluding Federated partnership units pending completion of trial phase) Projected 5- 2005** 2006-2009** Year Total** Company-owned Units 11 90 101 Franchised Units 10 374 384 Total New Restaurant 21 464 485 Development Note: Depending upon decisions r
Slide 12: Three-part Growth Strategy
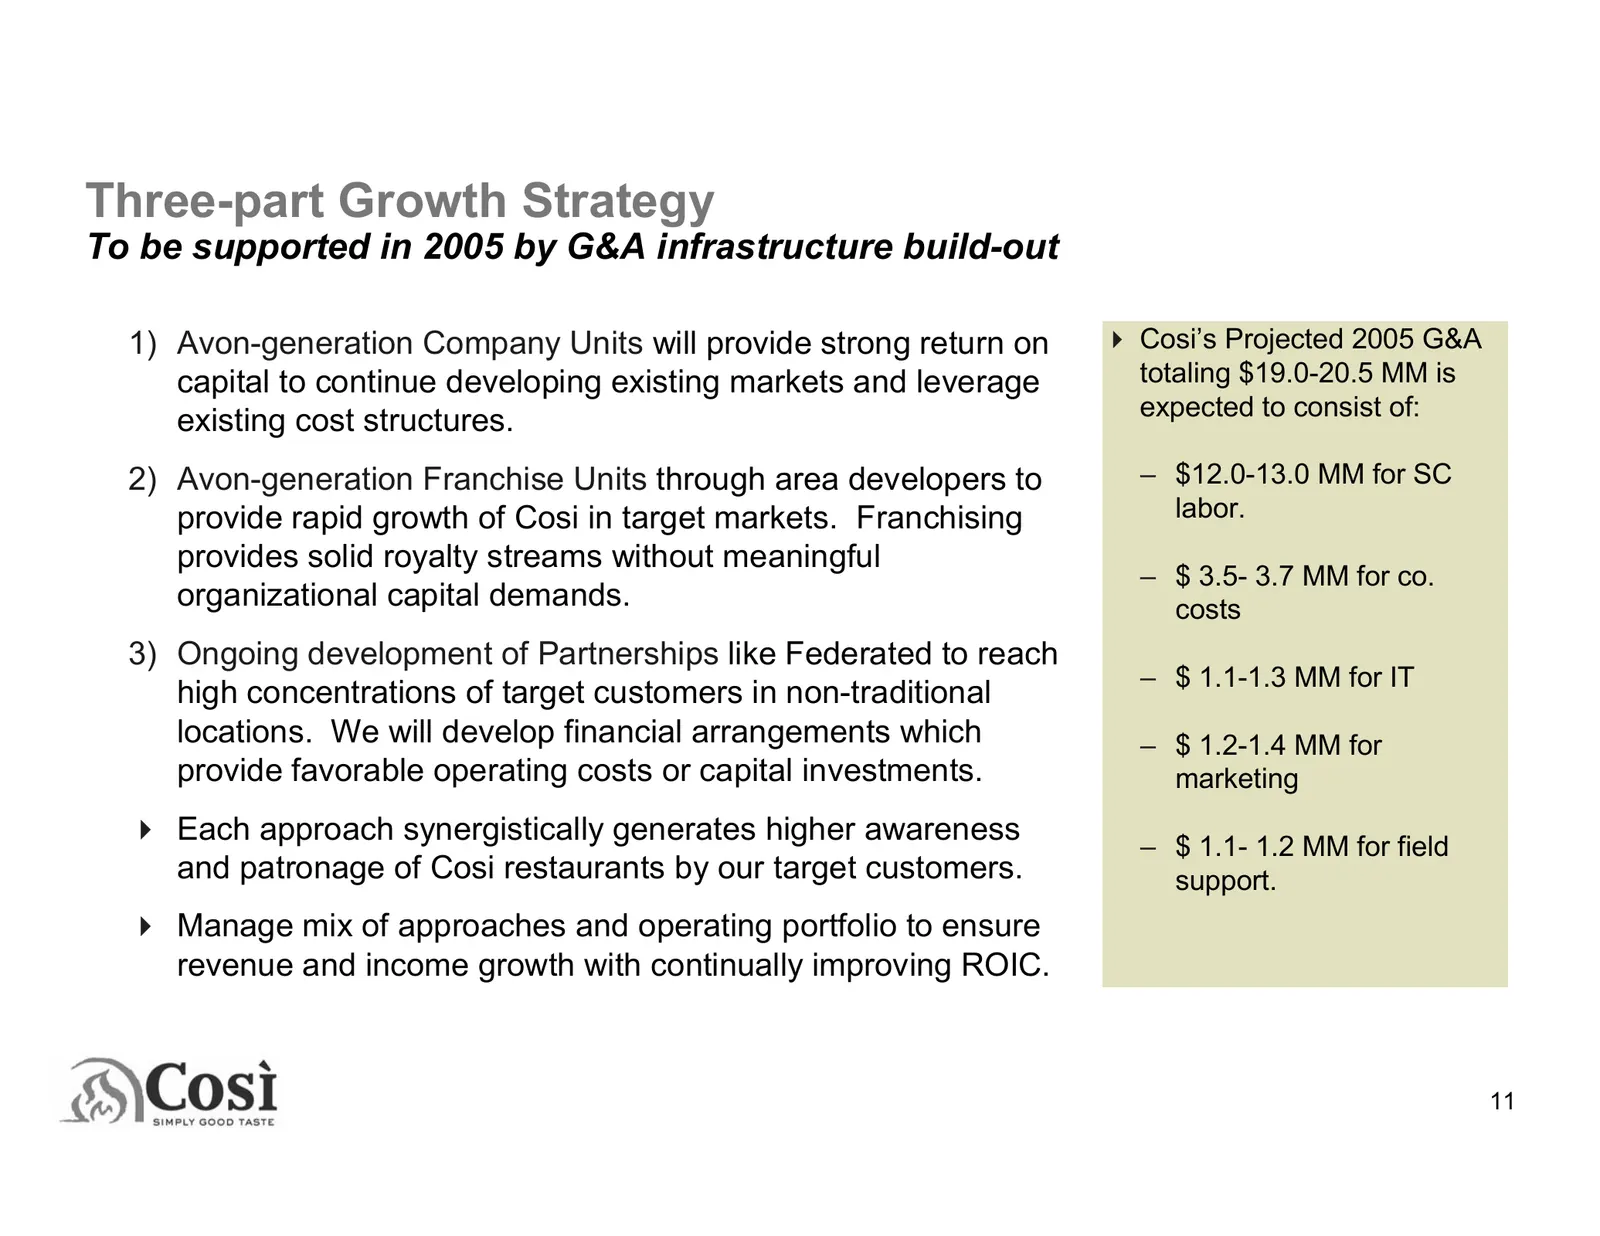
Three-part Growth Strategy To be supported in 2005 by G&A infrastructure build-out 1) Avon-generation Company Units will provide strong return on Cosi’s Projected 2005 G&A capital to continue developing existing markets and leverage totaling $19.0-20.5 MM is expected to consist of: existing cost str
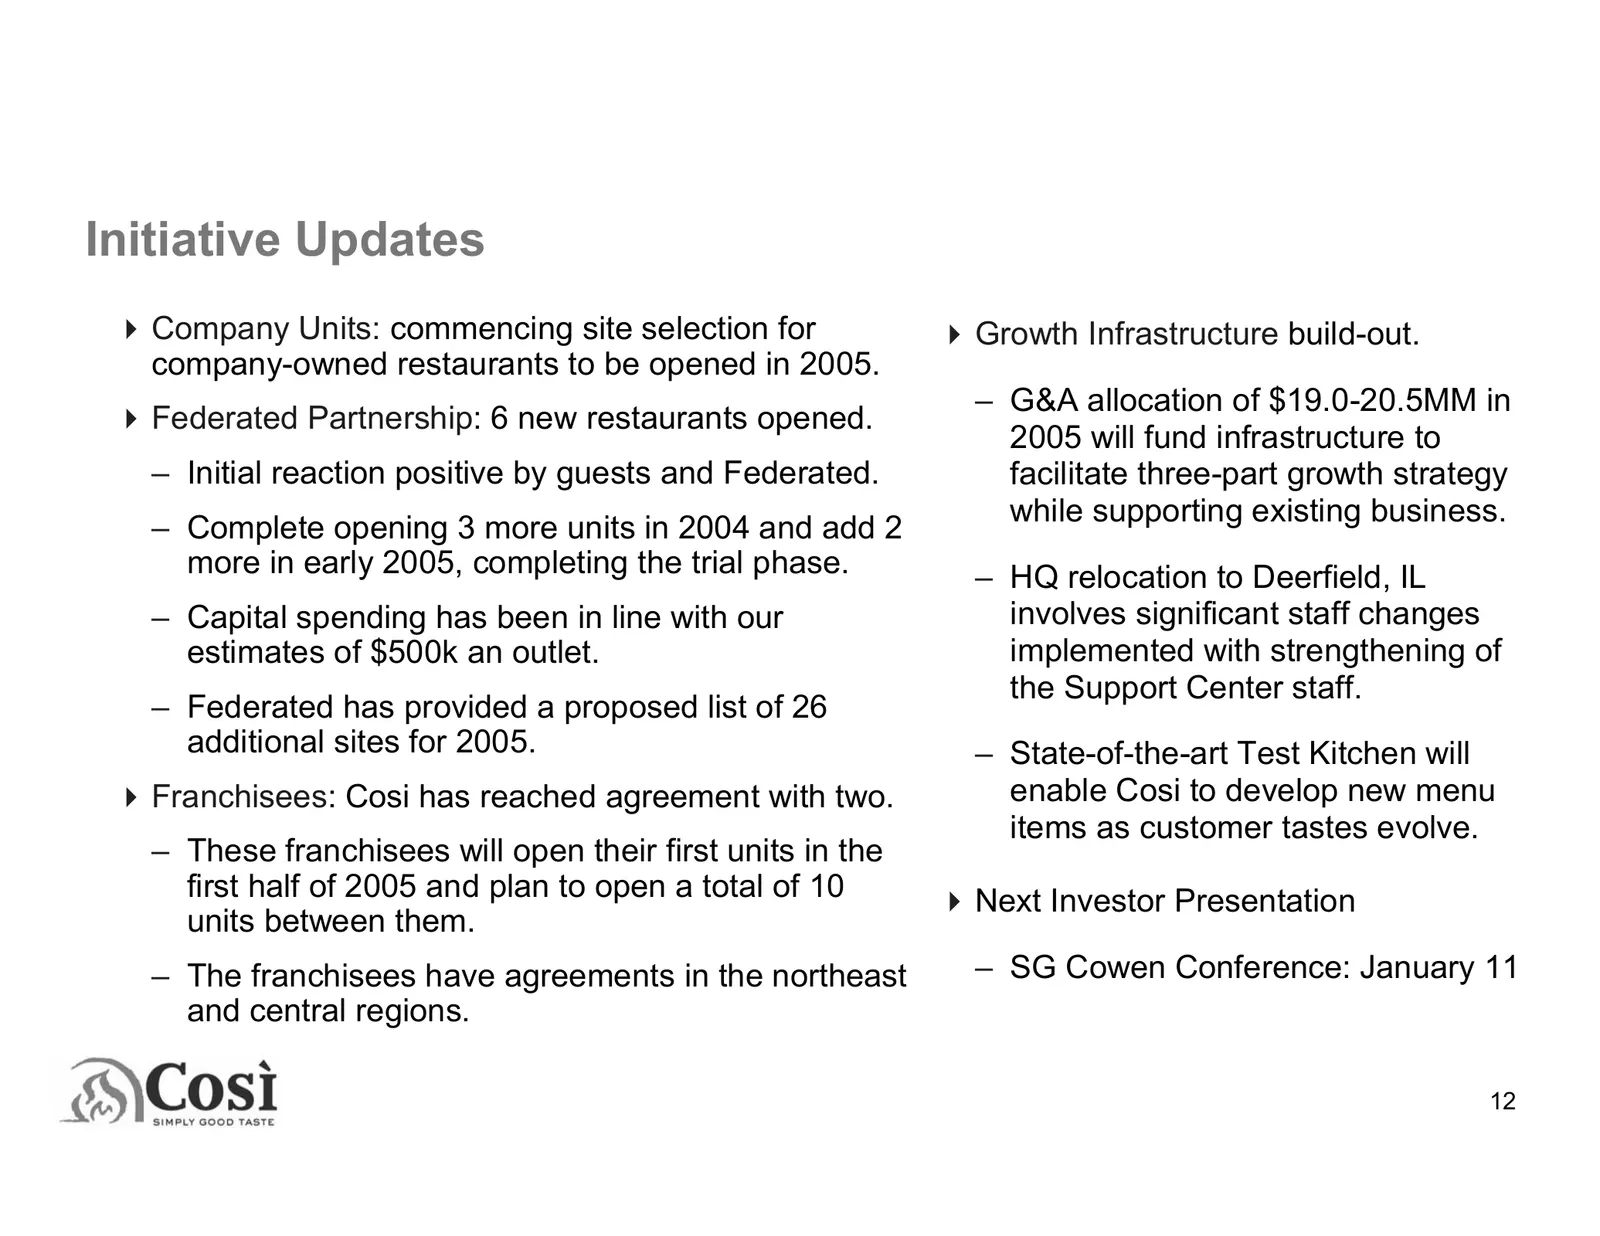
Slide 13: Initiative Updates
Initiative Updates Company Units: commencing site selection for Growth Infrastructure build-out. company-owned restaurants to be opened in 2005. – G&A allocation of $19.0-20.5MM in Federated Partnership: 6 new restaurants opened. 2005 will fund infrastructure to – Initial reaction positive by guests
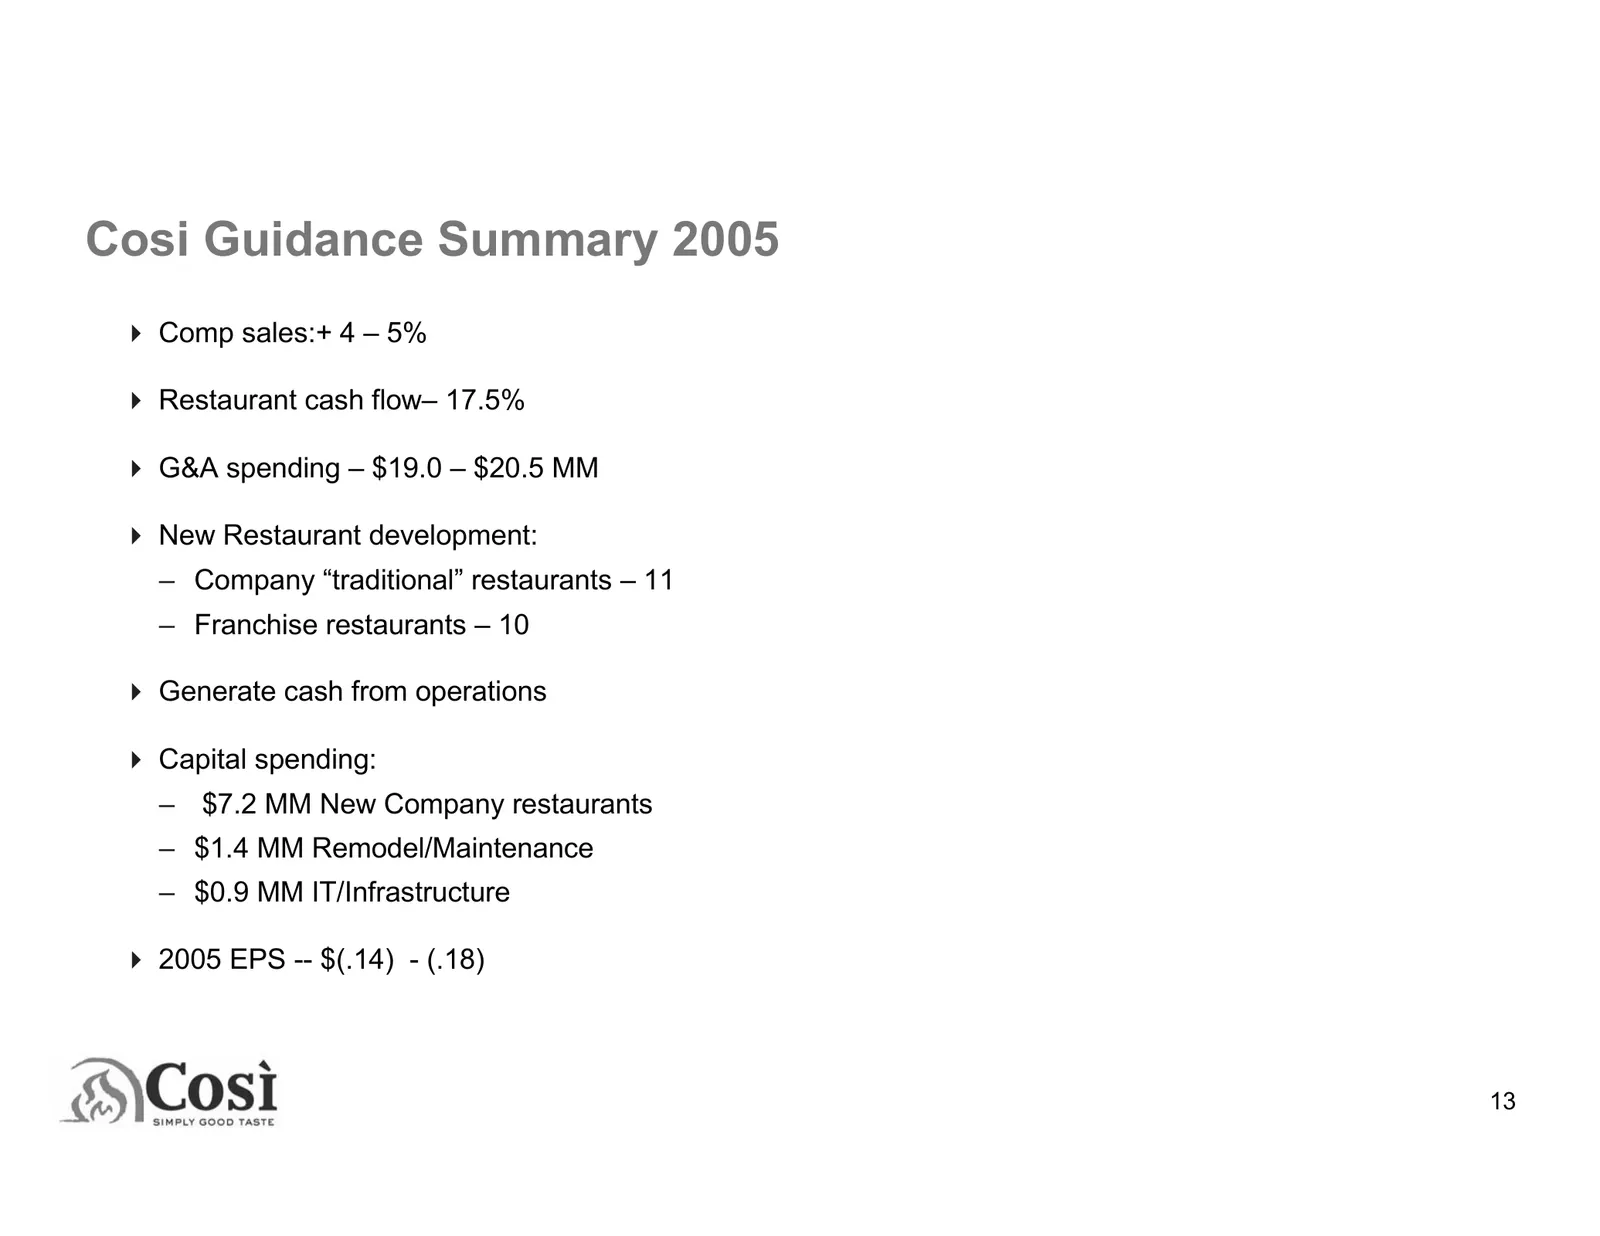
Slide 14: Cosi Guidance Summary 2005
Cosi Guidance Summary 2005 Comp sales:+ 4 – 5% Restaurant cash flow– 17.5% G&A spending – $19.0 – $20.5 MM New Restaurant development: – Company “traditional” restaurants – 11 – Franchise restaurants – 10 Generate cash from operations Capital spending: – $7.2 MM New Company restaurants – $1.4 MM Rem
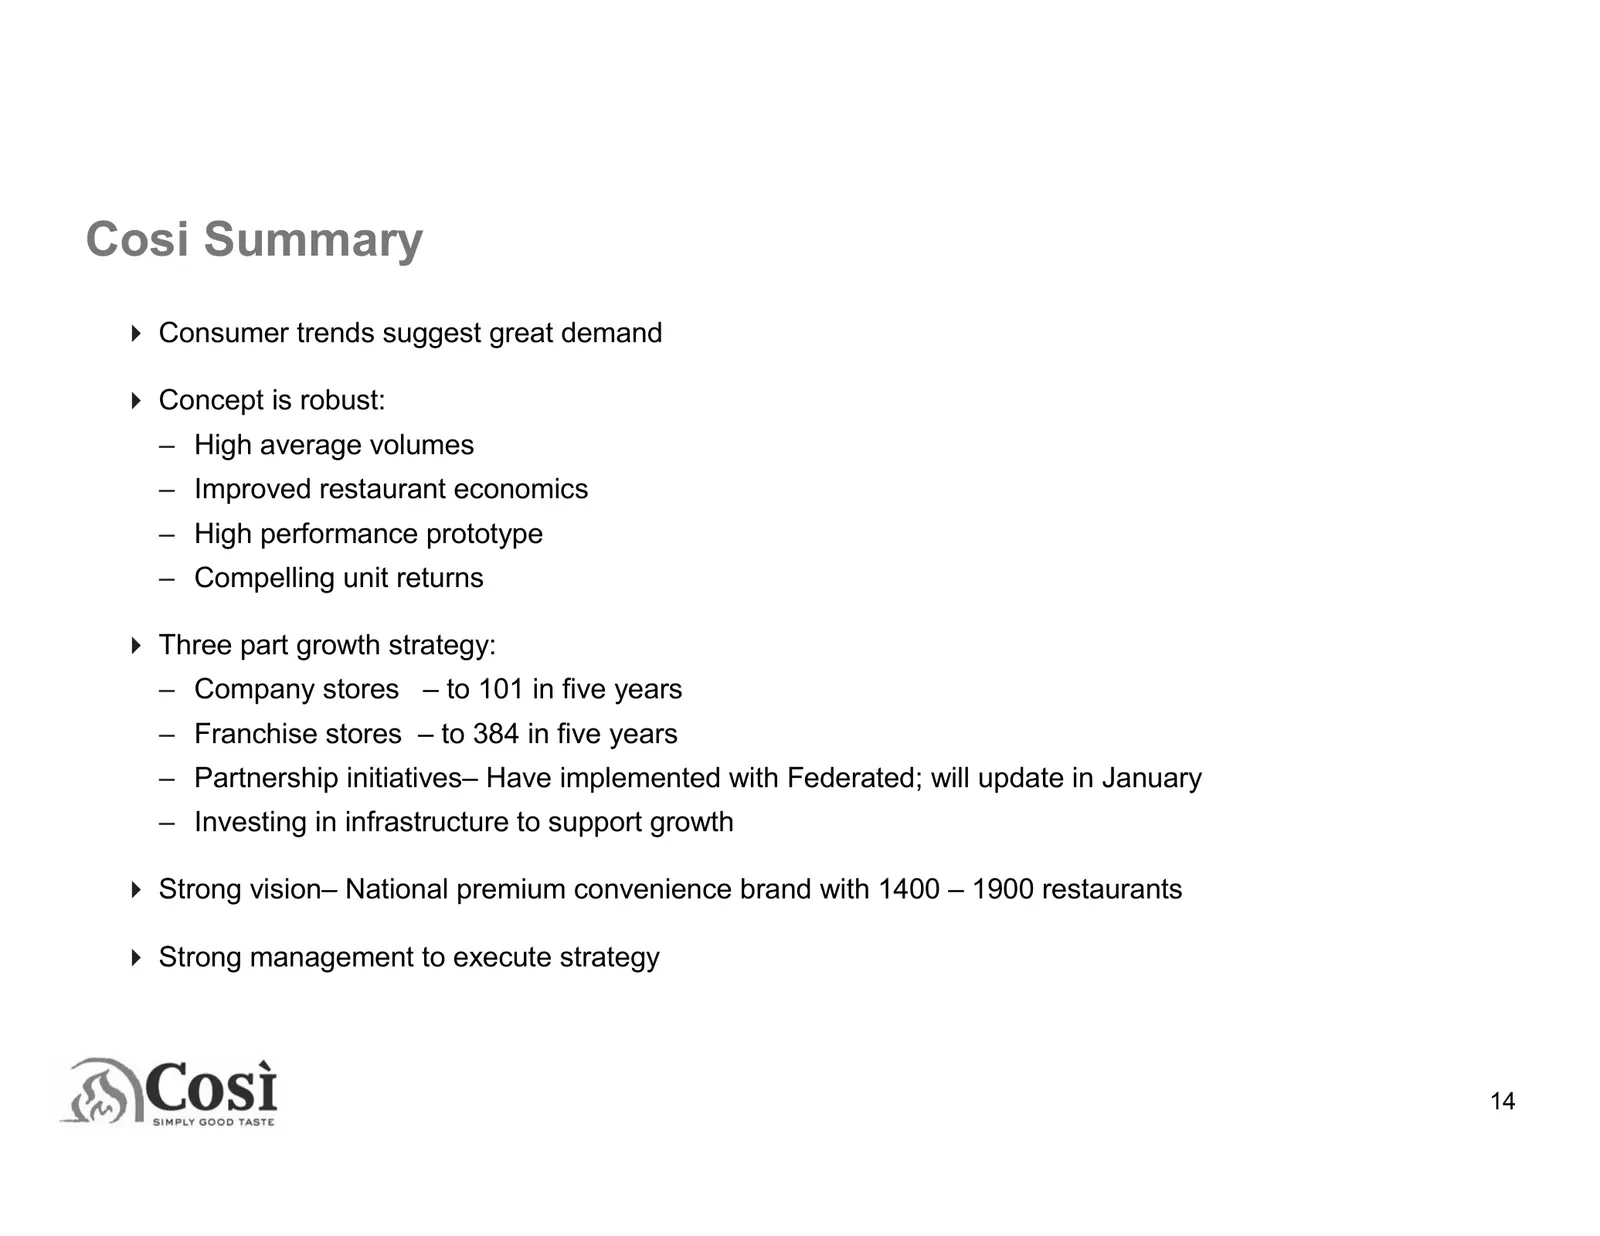
Slide 15: Cosi Summary
Cosi Summary Consumer trends suggest great demand Concept is robust: – High average volumes – Improved restaurant economics – High performance prototype – Compelling unit returns Three part growth strategy: – Company stores – to 101 in five years – Franchise stores – to 384 in five years – Partnersh
Source: SEC EDGAR · 8-K filed Dec 8, 2004
More decks from Cosi Inc
 Q2 2016 Earnings Presentation17 slides · Aug 12, 2016
 Q1 2016 Earnings Presentation19 slides · May 13, 2016
 Q4 2015 Earnings Presentation14 slides · Mar 25, 2016
 28th Annual Roth Conference (March 2016)15 slides · Mar 14, 2016
 4th Annual ROTH Utah Active & Healthy Lifestyle Corporate Access Event (December 2015)15 slides · Dec 10, 2015
 Southwest IDEAS Investor Conference 201517 slides · Nov 19, 2015