Tabcorp Holdings Limited · ASX:TAH
Tabcorp — Investor Presentation (November 2020)
31 slides from Tabcorp's investor presentation, November 2020
Slide 1: Tabcorp Limited
Tabcorp Limited November 2020 © Sandon Capital Pty Ltd 1
Slide 2: Important information
Important information This presentation has been prepared for use in conjunction with a verbal presentation and should be read in that context. It contains Sandon Capital Pty Limited’s (Sandon Capital’s) view on various matters and is based on publicly available information only. This presentation i
Slide 3: Contents
Contents ➢ Investment thesis ➢ Recent improvements yet to be reflected in share price i. Imminent departure of Chairman and Managing Director ii. Balance sheet has been repaired iii. Lotteries has demonstrated resilience iv. COVID-19 impact appears to be rapidly receding v. Unsustainable dividend po
Slide 4: Investment thesis
Investment thesis ➢ A recent media report1 has indicated that private equity firms are circling Tabcorp Ltd (TAH) and are interested in bidding for part or all of the company ➢ We view this as an unwelcome development given the longer-term improvements recently implemented at TAH are yet to be prope
Slide 5: Investment thesis
Investment thesis ➢ In our opinion, the Company should optimise its structure by demerging its world class Lotteries & Keno (Lotteries) business. This would enable: ⚫ Separate Boards and management teams the ability to focus on their respective core businesses ⚫ Increased transparency allowing each
Slide 6: Investment thesis: sum-of-the-parts valuation
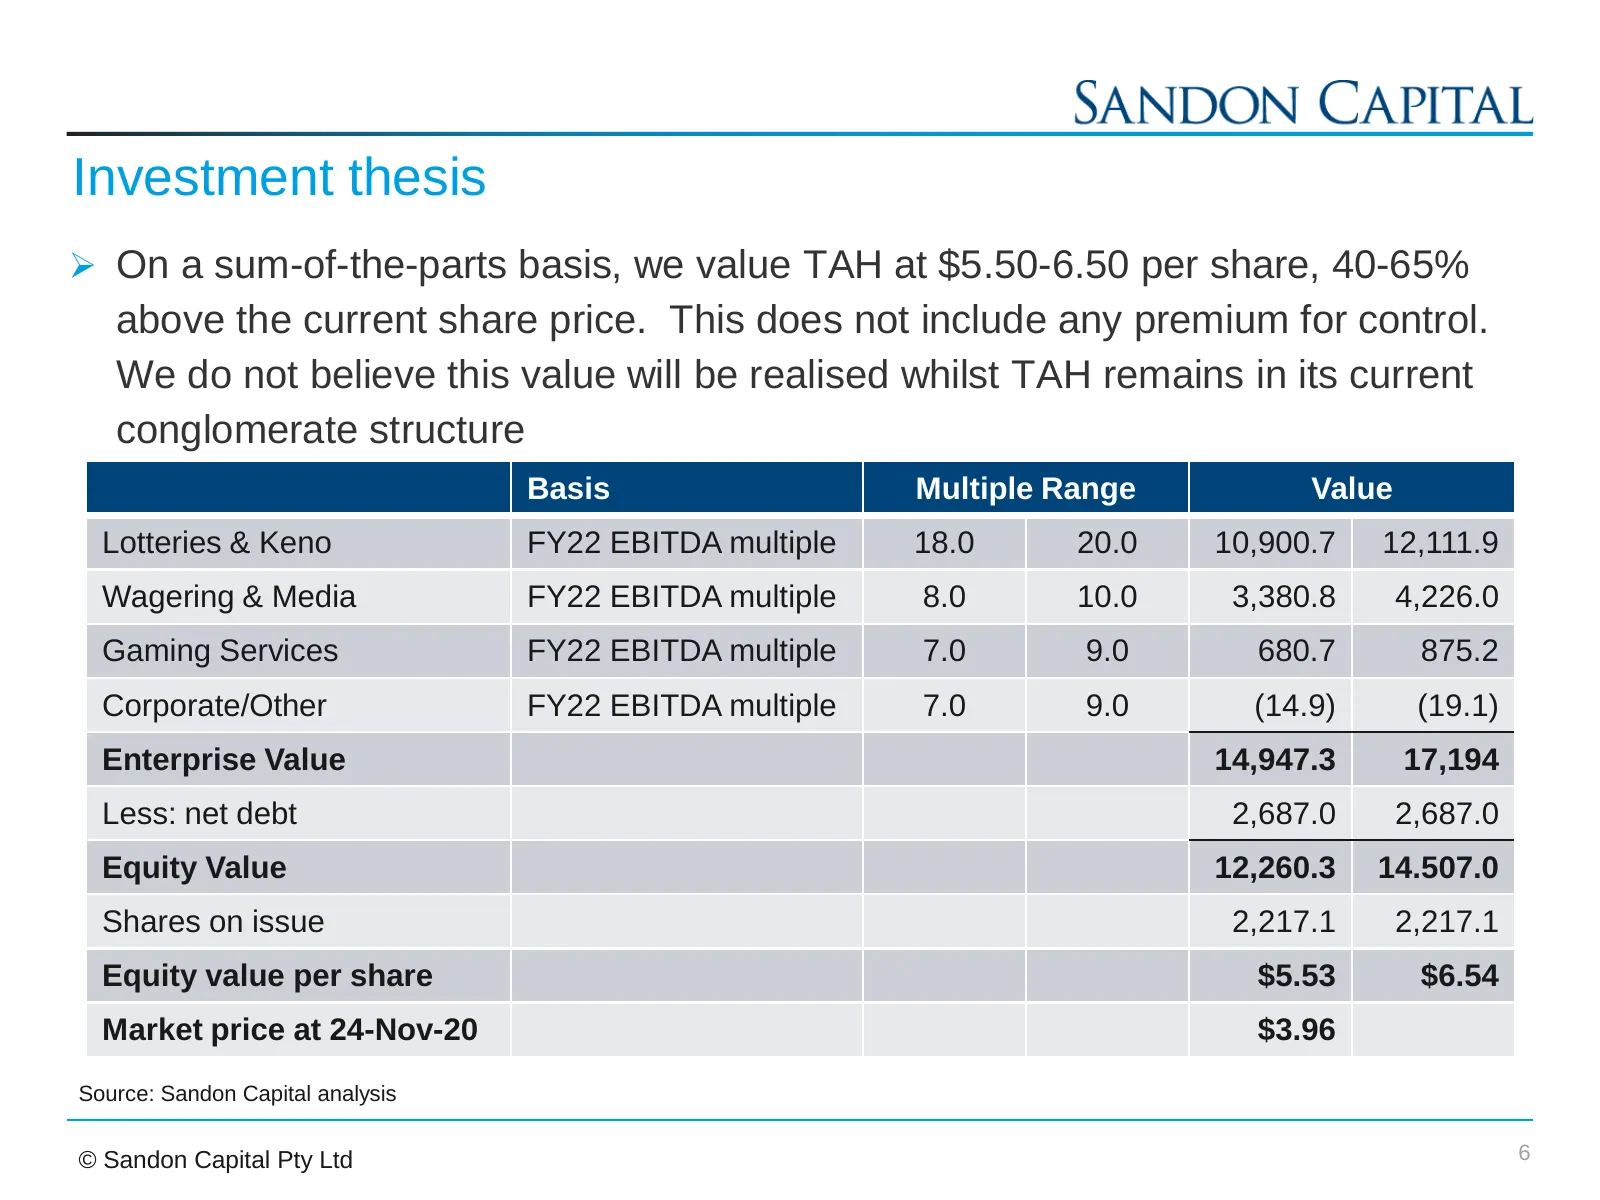
Investment thesis ➢ On a sum-of-the-parts basis, we value TAH at $5.50-6.50 per share, 40-65% above the current share price. This does not include any premium for control. We do not believe this value will be realised whilst TAH remains in its current conglomerate structure Basis Multiple Range Valu
Slide 7: Recent improvements yet to be reflected in share price
Recent improvements yet to be reflected in share price ➢ When the TAH and TTS nil premium merger was announced in October 2016, the Boards of both companies heralded a number of benefits of bringing the two companies together. These included: ⚫ Creating a leading, diversified portfolio of gambling b
Slide 8: Recent improvements yet to be reflected in share price
Recent improvements yet to be reflected in share price ➢ “Greater scale” may have resulted in higher compensation for management, however it has proven to be of no benefit to shareholders. In short, operational and financial performance of the combined entities has been poor ➢ A “strong balance shee
Slide 9: Imminent departure of Chairman and Managing Director
Recent improvements yet to be reflected in share price i. Imminent departure of Chairman and Managing Director ➢ After many years of poor operational and financial performance that have manifested themselves in an underperforming share price, events over the past 6 months point to a significantly im
Slide 10: Poor operational and financial performance
Recent improvements yet to be reflected in share price ➢ Poor operational and financial performance ⚫ In FY13, the first full year after the demerger of Echo Entertainment Group (now known as Star Entertainment Group) and the loss of the Victorian Tabaret gaming business1, TAH reported earnings per
Slide 11: TAH historical EPS profile
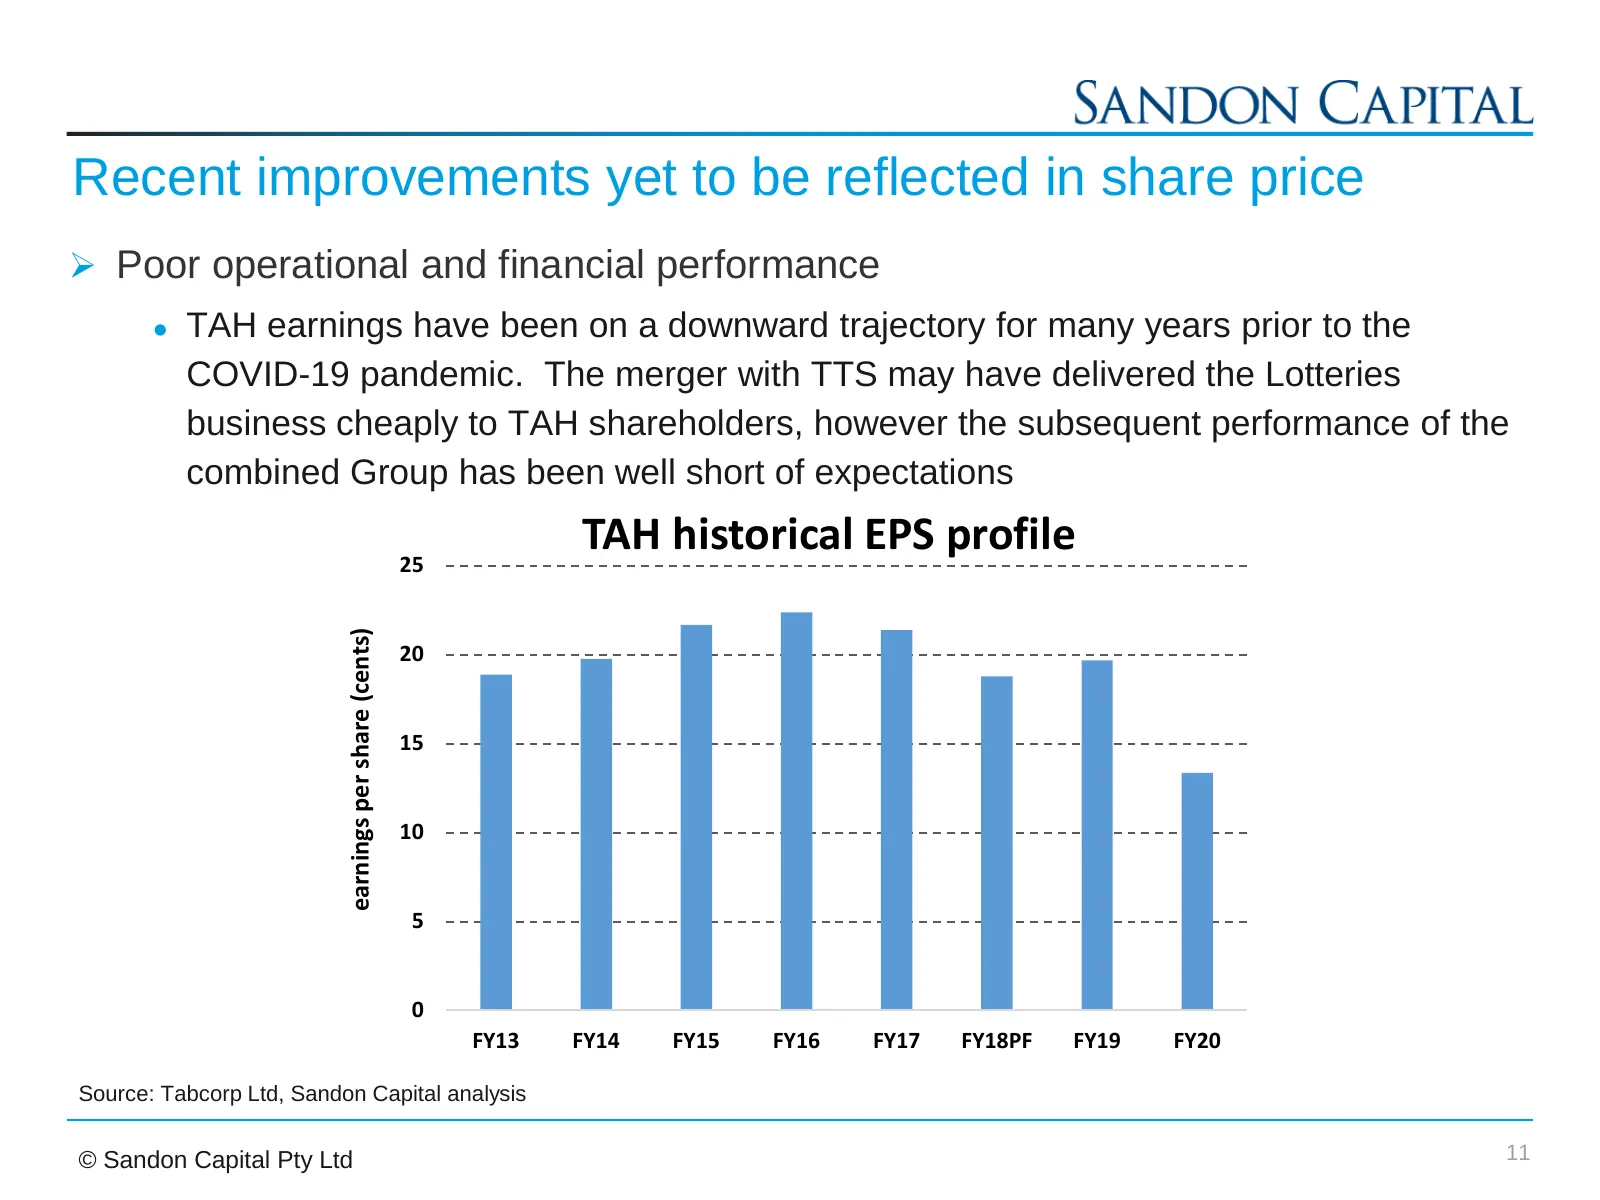
Recent improvements yet to be reflected in share price ➢ Poor operational and financial performance ⚫ TAH earnings have been on a downward trajectory for many years prior to the COVID-19 pandemic. The merger with TTS may have delivered the Lotteries business cheaply to TAH shareholders, however the
Slide 12: Share price underperformance versus ASX 200
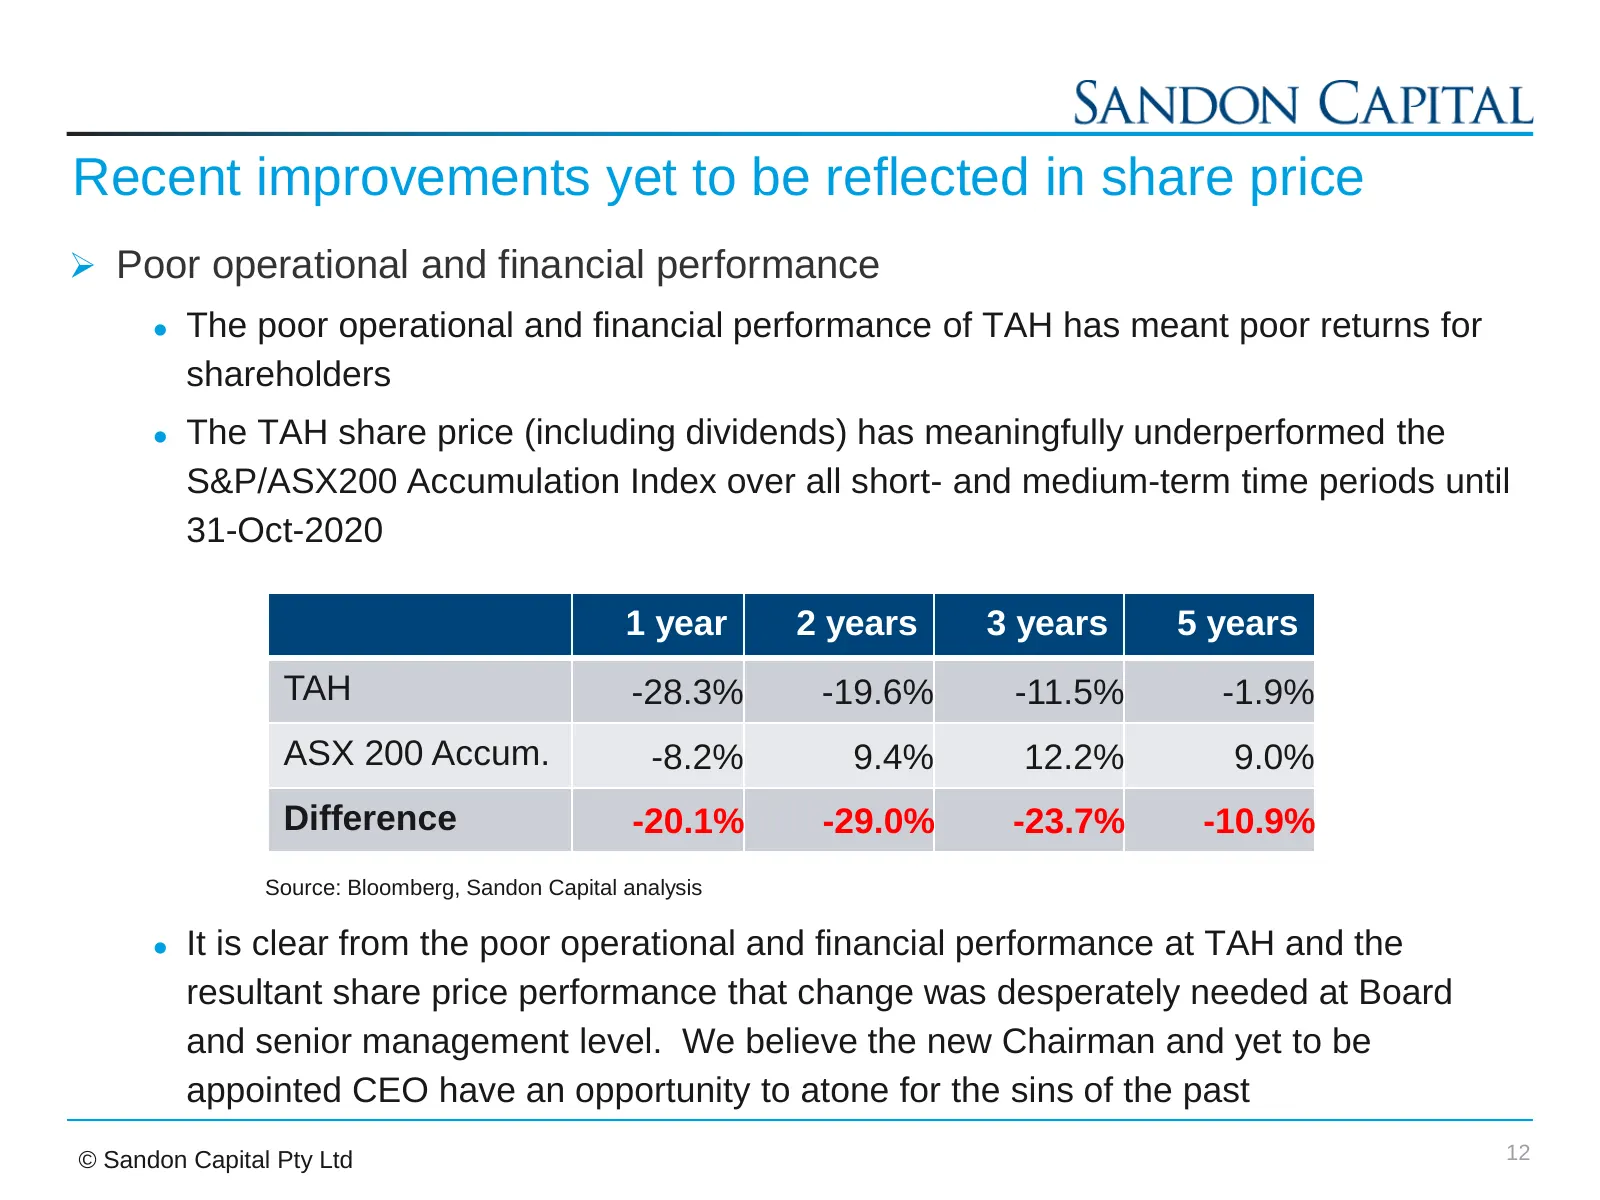
Recent improvements yet to be reflected in share price ➢ Poor operational and financial performance ⚫ The poor operational and financial performance of TAH has meant poor returns for shareholders ⚫ The TAH share price (including dividends) has meaningfully underperformed the S&P/ASX200 Accumulation
Slide 13: Balance sheet has been repaired
Recent improvements yet to be reflected in share price ii. Balance sheet has been repaired ➢ Following the $600m entitlement issue in August, TAH’s balance sheet is in a much-improved position. Concurrent with the entitlement issue, TAH announced a reduction in its target gearing range to 2.5-3.0x G
Slide 14: Lotteries has demonstrated resilience
Recent improvements yet to be reflected in share price iii. Lotteries has demonstrated resilience ➢ As previous shareholders of TTS prior to the merger with TAH, we highlighted the infrastructure like qualities of its Lotteries business ➢ The resilience and durability of Lotteries’ business model ha
Slide 15: COVID-19 impact appears to be rapidly receding
Recent improvements yet to be reflected in share price iv. COVID-19 impact appears to be rapidly receding ➢ TAH’s Wagering & Media, Keno and Gaming Services businesses were heavily impacted by COVID-19 pandemic lockdown measures in 2HFY20 ➢ Licenced venues (hotels and clubs), TAB agencies and on-cou
Slide 16: Unsustainable dividend policy has been reset
Recent improvements yet to be reflected in share price v. Unsustainable dividend policy has been reset ➢ As a result of its highly leveraged balance sheet and the negative earnings impact from COVID-19, TAH was forced to approach its banking syndicate for covenant relief in 2HFY20 ➢ As part of secur
Slide 17: Dividend policy and underinvestment in Wagering
Recent improvements yet to be reflected in share price ➢ In our opinion, the unsustainable dividend policy has been detrimental to the operating performance of the Company. We believe it has led to underinvestment in TAH’s Wagering business, resulting in an uncompetitive product and market share los
Slide 18: Separate Boards and management focused on core businesses
Lotteries should be demerged i. Separate Boards and management focused on their respective core businesses ➢ Whilst there are a number of successful gambling/gaming companies globally, we cannot identify one that is a sprawling conglomerate like TAH. We believe those that have been successful have f
Slide 19: Increased transparency allowing each business to be valued
Lotteries should be demerged ii. Increased transparency allowing each business to be appropriately valued ➢ In the ~14 years that Lotteries has been part of a conglomerate structure, an underperforming Wagering business has been the lowest common denominator that has driven the performance of the st
Slide 20: Lottery concessions as infrastructure-like monopolies
Lotteries should be demerged ➢ Lottery concessions in Australia are state-based monopolies, very similar in structure to infrastructure concessions ➢ They have significant barriers to entry and provide their owners with a dominant market position ➢ They allow the owner to profitably operate a monopo
Slide 21: Infrastructure versus Lotteries comparison
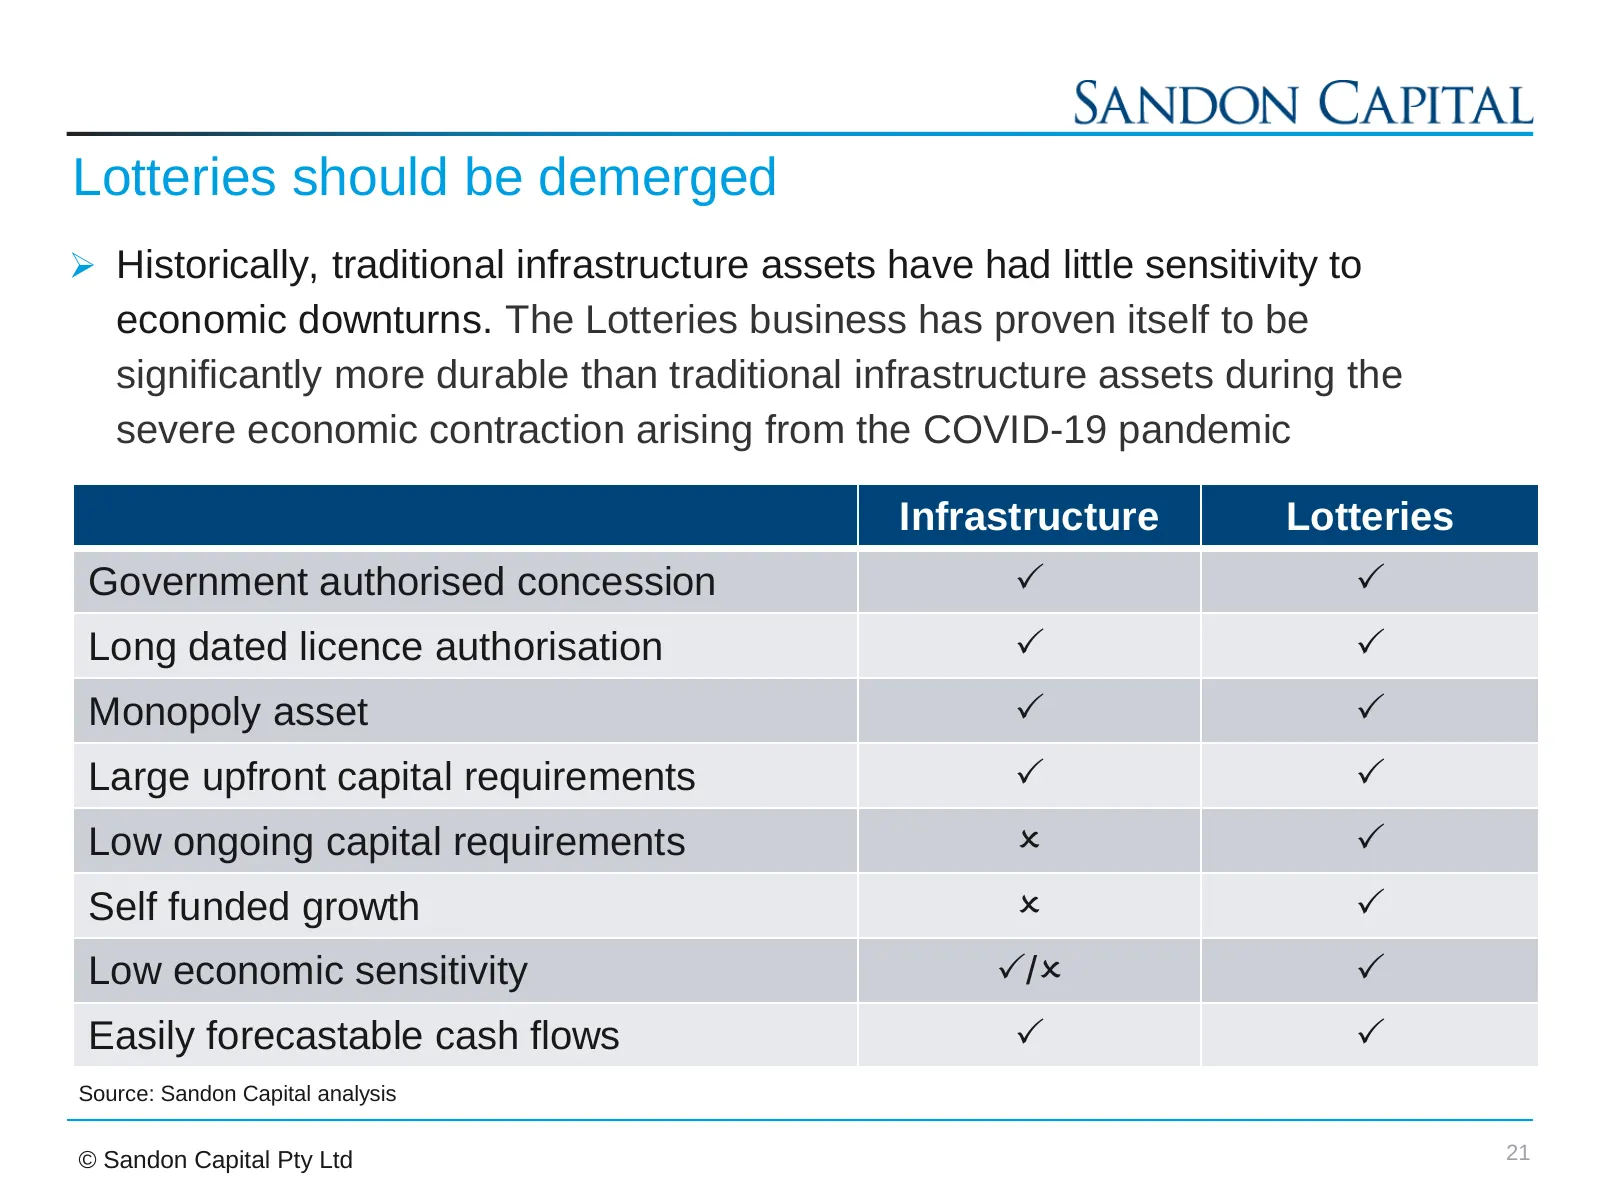
Lotteries should be demerged ➢ Historically, traditional infrastructure assets have had little sensitivity to economic downturns. The Lotteries business has proven itself to be significantly more durable than traditional infrastructure assets during the severe economic contraction arising from the C
Slide 22: Each business to pursue its own growth initiatives
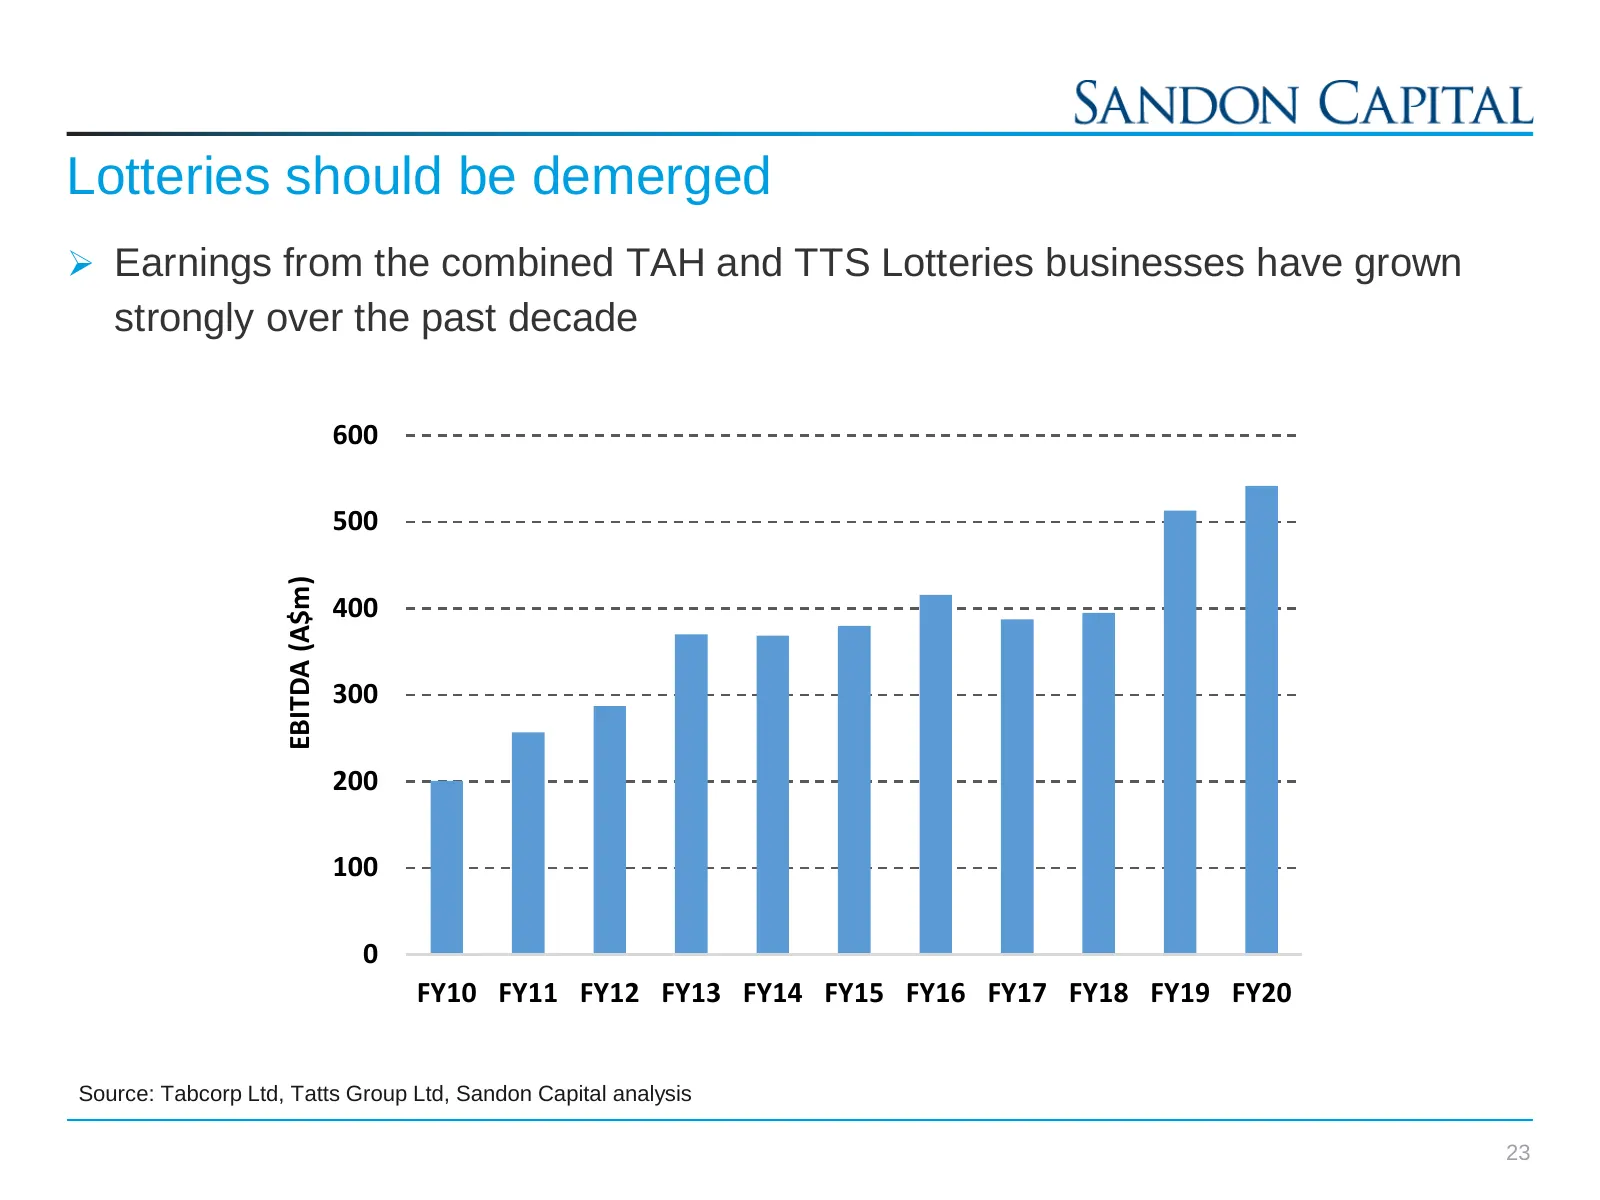
Lotteries should be demerged iii. Each business to pursue its own growth initiatives ➢ In our opinion, TAH’s Lotteries business has proven itself to be impervious to economic cycles and has generated sustainable long-term earnings growth with minimal ongoing capital expenditure ➢ As a business that
Slide 23: Lotteries EBITDA
Lotteries should be demerged ➢ Earnings from the combined TAH and TTS Lotteries businesses have grown strongly over the past decade 600 500 EBITDA (A$m) 400 300 200 100 0 FY10 FY11 FY12 FY13 FY14 FY15 FY16 FY17 FY18 FY19 FY20 Source: Tabcorp Ltd, Tatts Group Ltd, Sandon Capital analysis 23
Slide 24: Wagering earnings decline
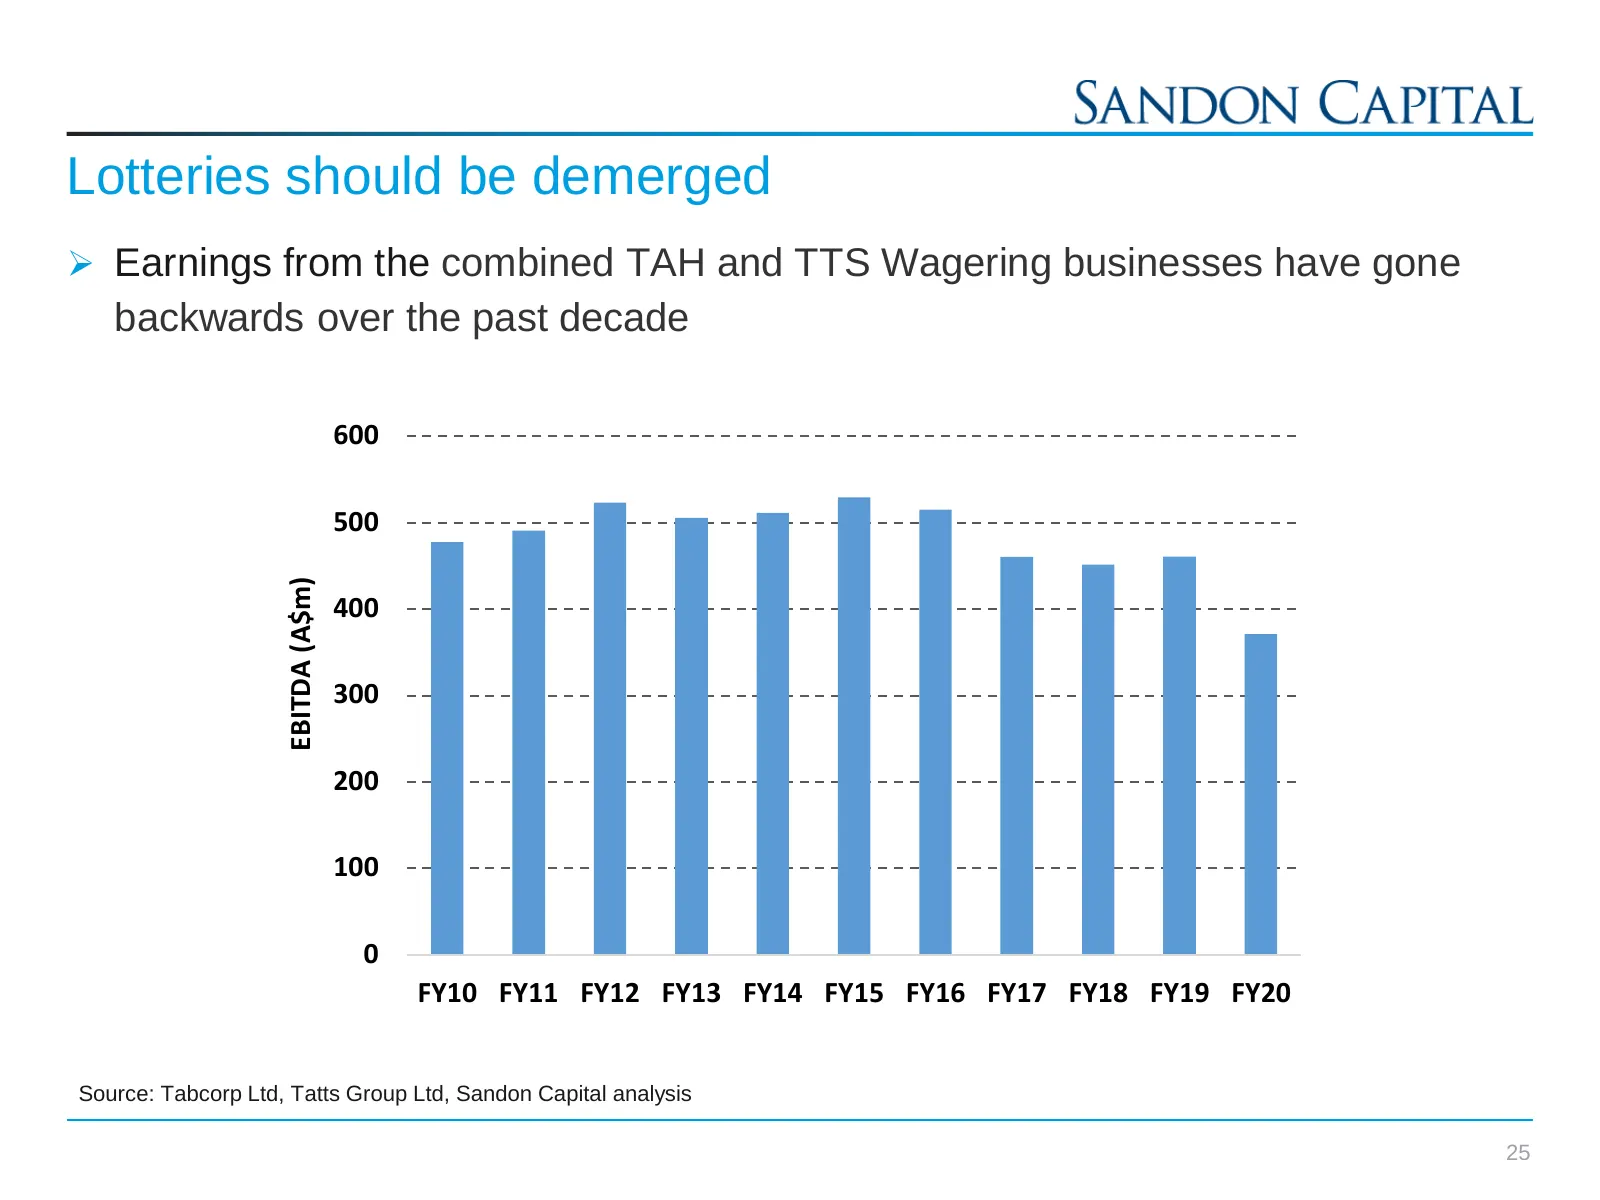
Lotteries should be demerged ➢ In contrast to the strong earnings growth seen in Lotteries, the combined Wagering businesses of TAH & TTS have seen earnings go backwards over the past decade ➢ In FY10, the TAH and TTS Wagering businesses reported combined EBITDA of $478m. A decade later, the combine
Slide 25: Wagering EBITDA
Lotteries should be demerged ➢ Earnings from the combined TAH and TTS Wagering businesses have gone backwards over the past decade 600 500 EBITDA (A$m) 400 300 200 100 0 FY10 FY11 FY12 FY13 FY14 FY15 FY16 FY17 FY18 FY19 FY20 Source: Tabcorp Ltd, Tatts Group Ltd, Sandon Capital analysis 25
Slide 26: Growth opportunities for Lotteries and Wagering turnaround
Lotteries should be demerged ➢ We believe there are a number of opportunities for the Lotteries business to further grow its earnings: ⚫ The purchase of the New South Wales (NSW) Lotteries tax stream should the NSW Government decide to sell it1 ⚫ Increased online penetration ⚫ A game refresh and pri
Slide 27: Better allocation of capital
Lotteries should be demerged iv. Better allocation of capital, tailored to needs and growth opportunities ➢ The capital requirements of the Lotteries and Wagering businesses are diametrically opposed ➢ Lotteries is a capital light business that self funds its own growth. Whilst TTS did not previousl
Slide 28: Wagering capital expenditure
Lotteries should be demerged ➢ Prior to the acquisition of TTS Wagering business, TAH was spending 3.5 – 4.5% of its Wagering net revenues on capital expenditure. That figure has risen to 6.5 – 7.0% since the acquisition of TTS Wagering ➢ The underperformance of the combined TAH and TTS Wagering bus
Slide 29: Separate entities appealing to different investors
Lotteries should be demerged v. Separate entities that will appeal to investors with different investment preferences ➢ The operating characteristics and financial policies of Lotteries and Wagering differ significantly and will likely appeal to different types of investors. Their combination within
Slide 30: Demerger conclusion
Lotteries should be demerged ➢ As outlined, we believe the obvious solution to the current situation of discordant businesses being housed under the same corporate roof is for TAH to demerge its strongly performing Lotteries business from its underperforming Wagering business ➢ This will unlock the
Slide 31: Sandon Capital team
Sandon Capital team ➢ Gabriel Radzyminski – Portfolio Manager Gabriel established Sandon Capital in 2008 after having devised and managed a number of successful investment funds for a leading high net worth wealth management firm. Sandon Capital has successfully invested its funds on behalf of whole
Source: Internet Archive copy of sandoncapital.com.au
More decks from Tabcorp Holdings Limited
 FY2026 Earnings Presentation40 slides · Aug 26, 2026
 FY2026 Earnings Presentation39 slides · Aug 25, 2026
 Investor Presentation (August 2026)16 slides · Aug 10, 2026
 Macquarie Australia Conference 202614 slides · May 5, 2026
 1H26 Earnings Presentation39 slides · Feb 25, 2026
 Shareholder Meeting (October 2025)17 slides · Oct 20, 2025