Symrise AG · XETR:SY1
Symrise — Deutsche Bank German Corporate Conference 2007
29 slides from Symrise's conference presentation, Jun 20, 2007
Slide 1: Always Inspiring More…
ALWAYS INSPIRING MORE… Deutsche Bank German Corporate Conference June 20/21, 2007 1
Slide 2: Agenda
AGENDA Company Overview Market Overview: Flavours & Fragrances Symrise Strategy Financials and Share Information Outlook 2
Slide 3: Company Overview
Company Overview 3
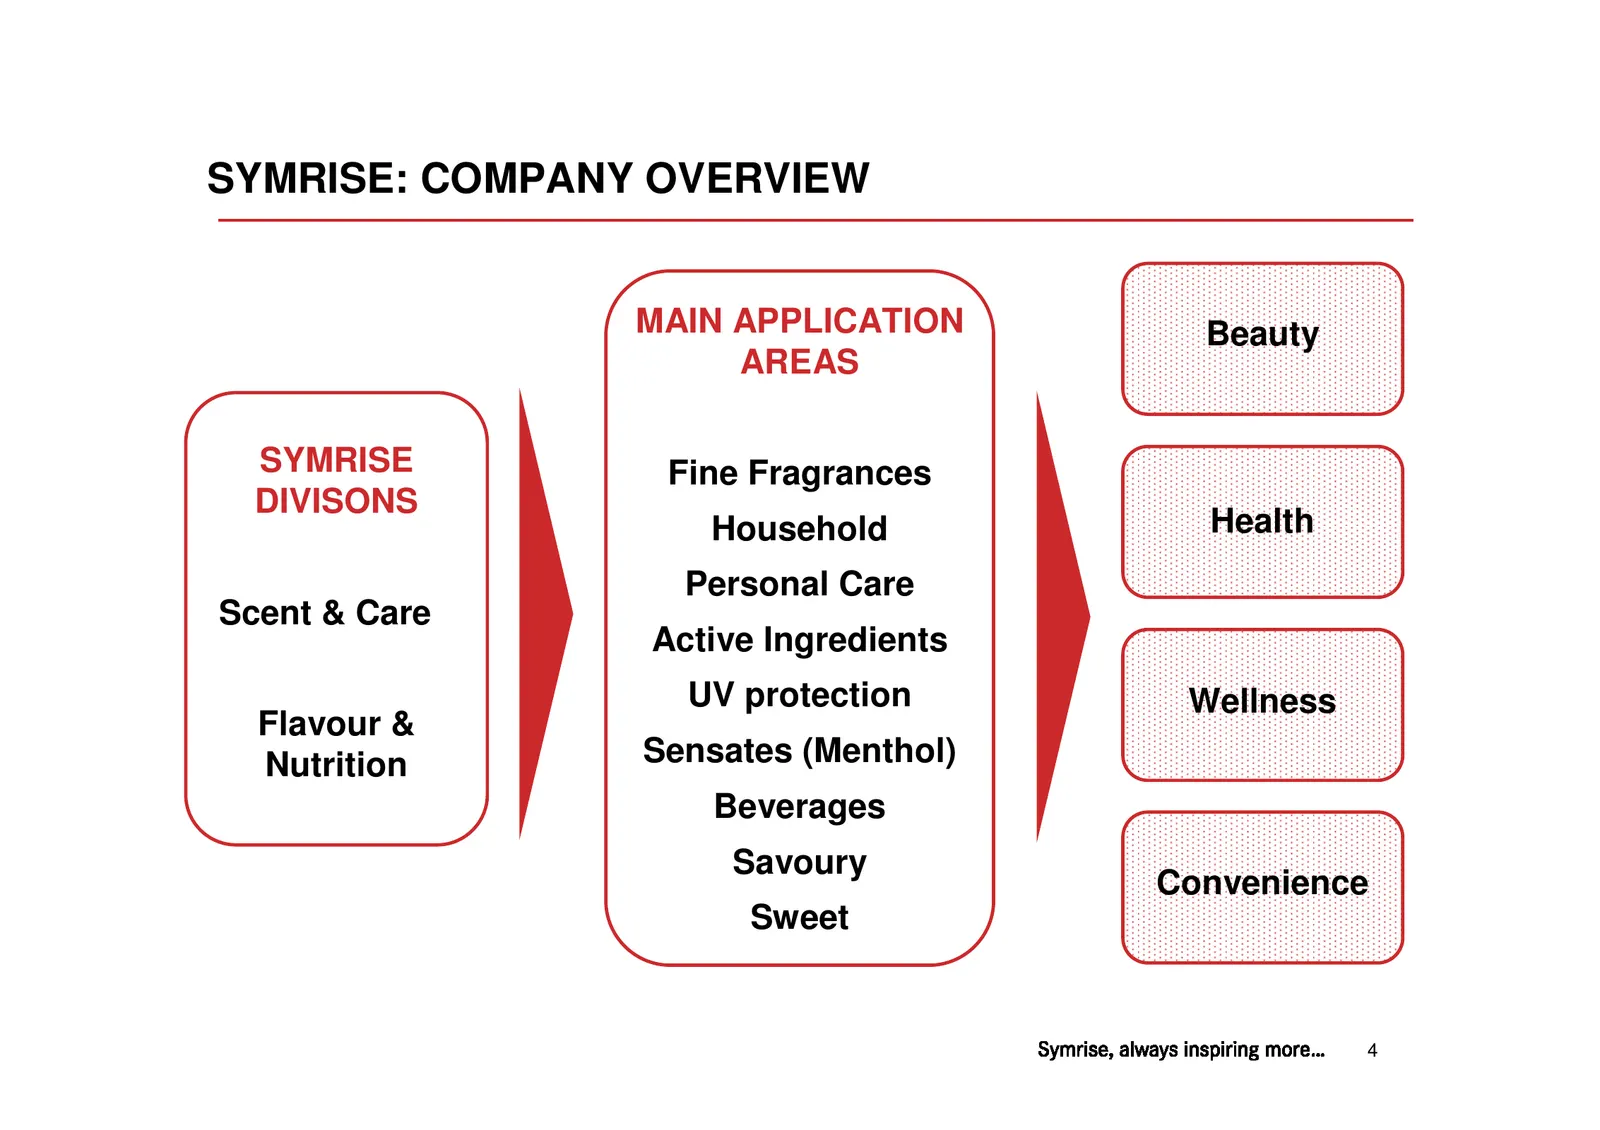
Slide 4: Symrise: Company Overview
SYMRISE: COMPANY OVERVIEW MAIN APPLICATION Beauty AREAS SYMRISE Fine Fragrances DIVISONS Household Health Personal Care Scent & Care Active Ingredients UV protection Wellness Flavour & Nutrition Sensates (Menthol) Beverages Savoury Convenience Sweet 4
Slide 5: Symrise: Fact Sheet
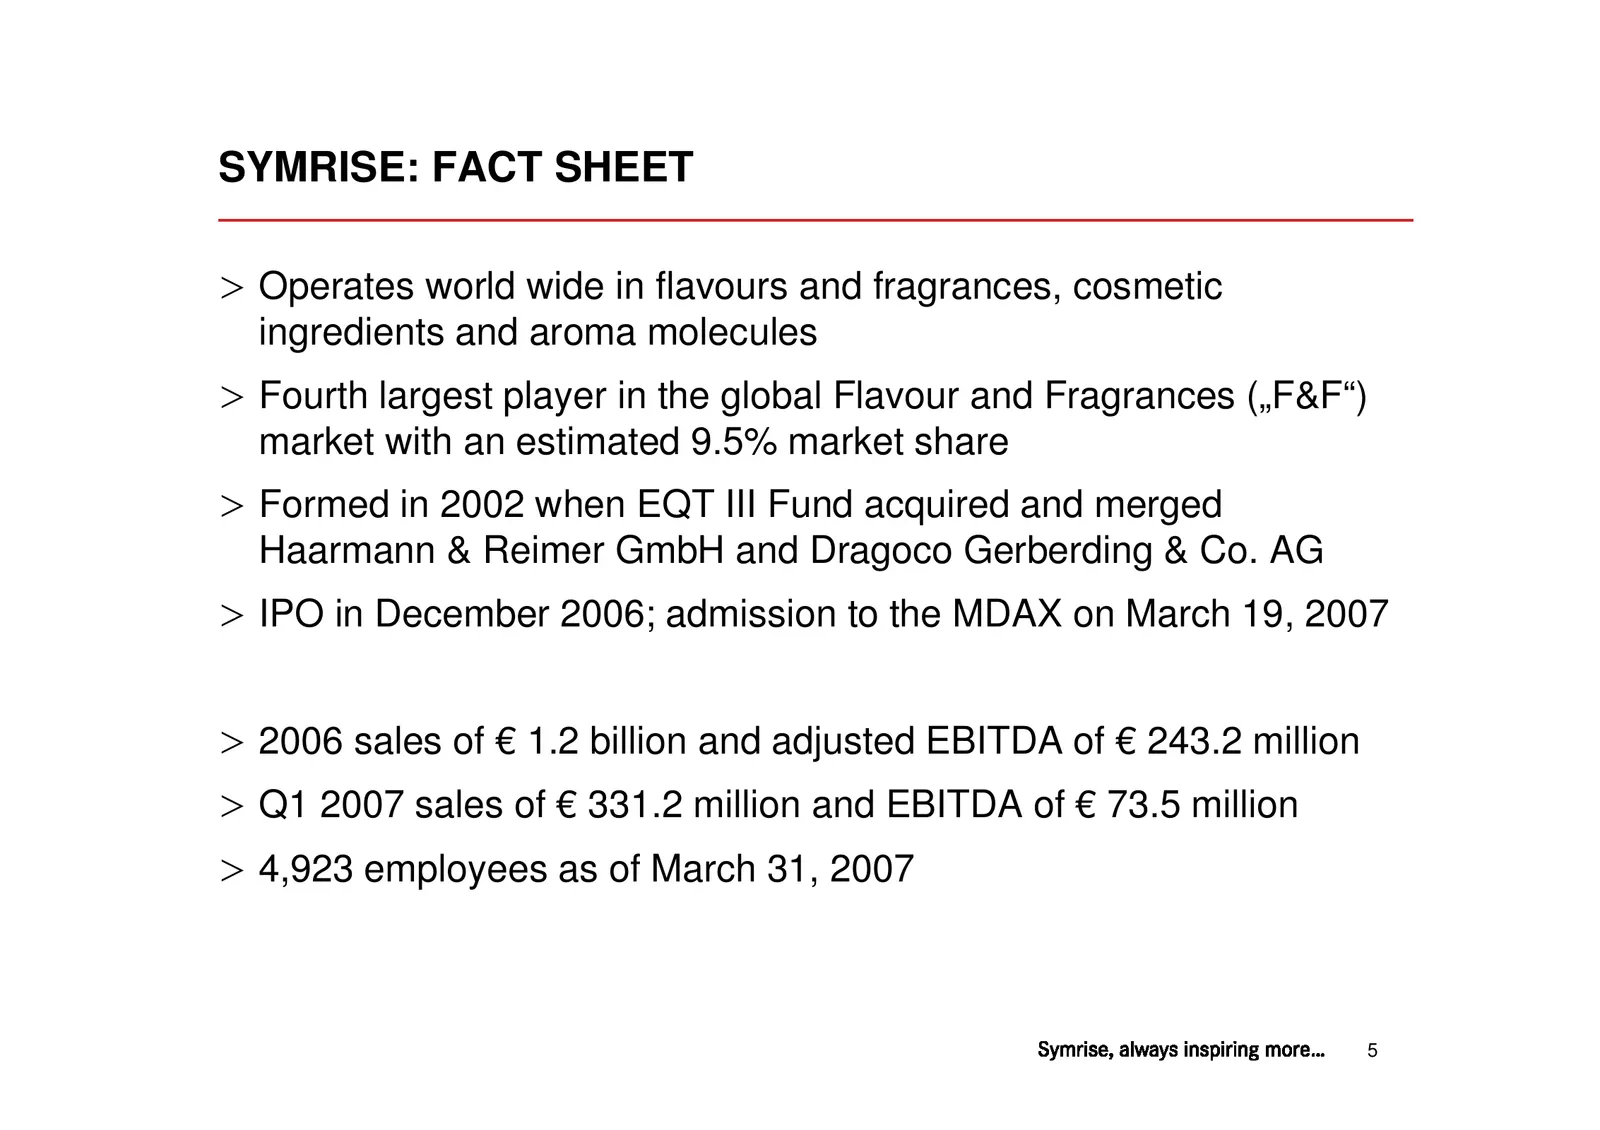
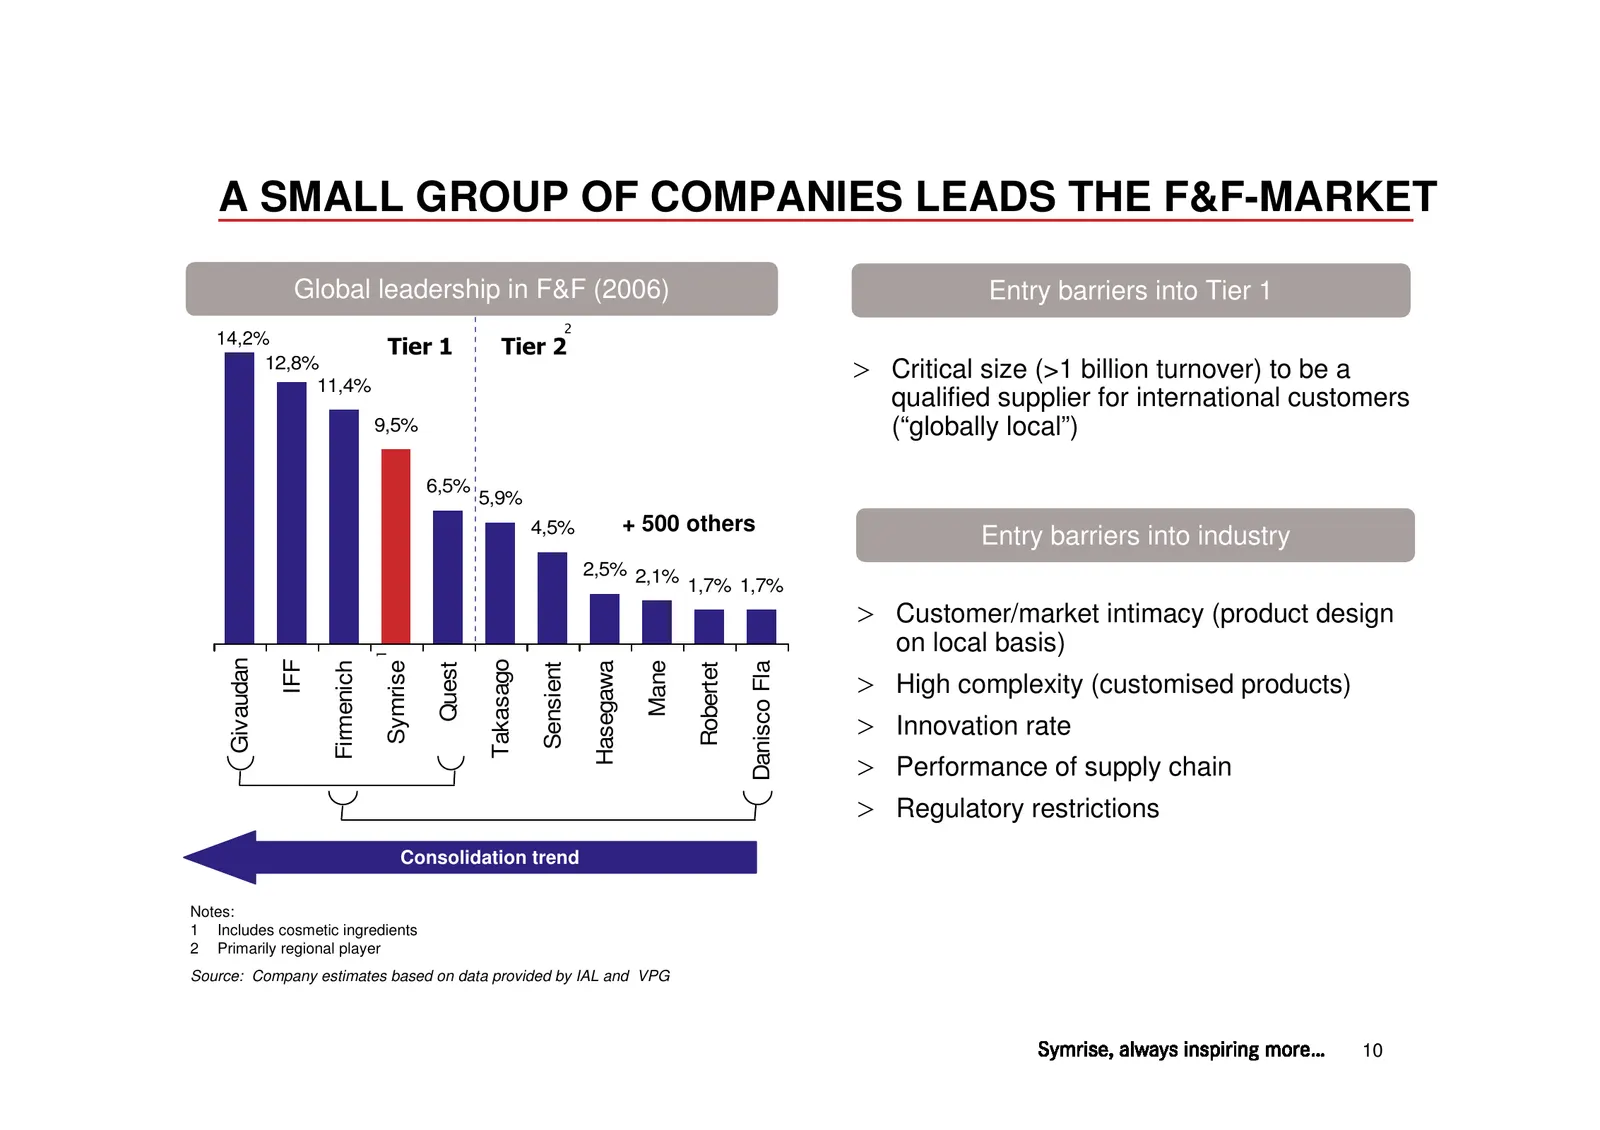
SYMRISE: FACT SHEET > Operates world wide in flavours and fragrances, cosmetic ingredients and aroma molecules > Fourth largest player in the global Flavour and Fragrances („F&F“) market with an estimated 9.5% market share > Formed in 2002 when EQT III Fund acquired and merged Haarmann & Reimer GmbH
Slide 6: We are globally present with two similar sized divisions
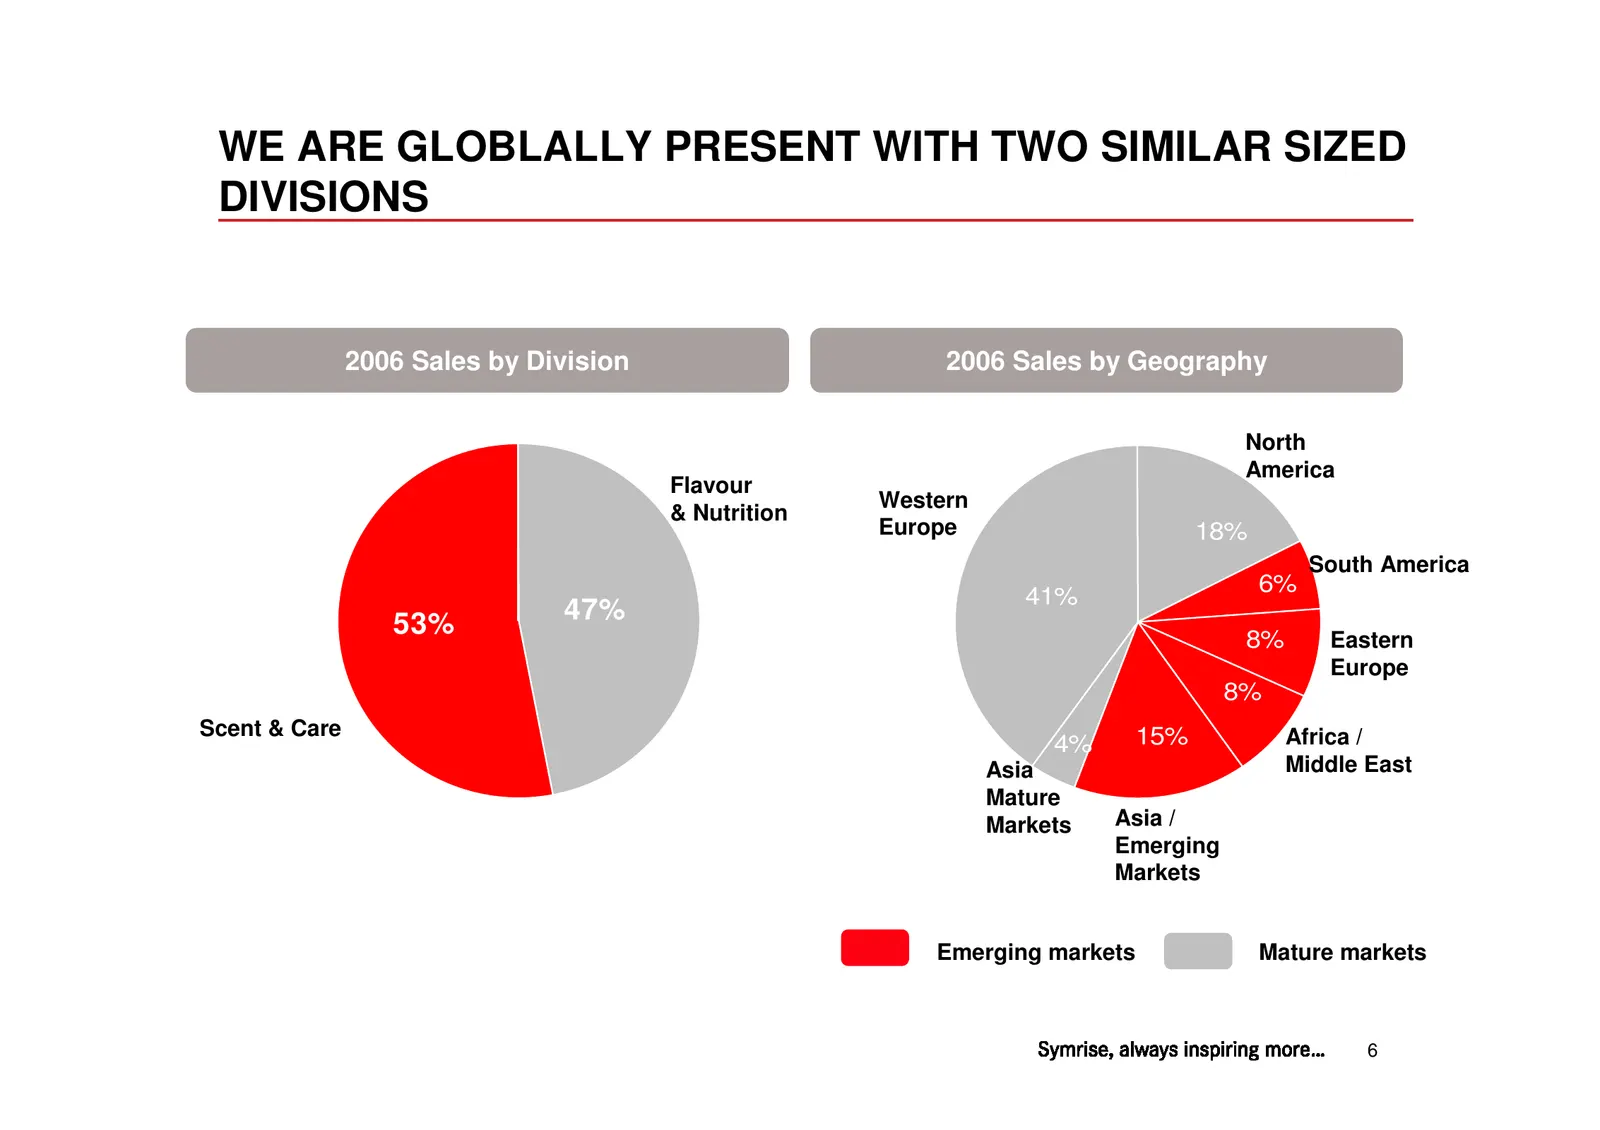
WE ARE GLOBLALLY PRESENT WITH TWO SIMILAR SIZED DIVISIONS 2006 Sales by Division 2006 Sales by Geography North America Flavour Western & Nutrition Europe 18% South America 41% 6% 53% 47% 8% Eastern Europe 8% Scent & Care 15% Africa / 4% Asia Middle East Mature Markets Asia / Emerging Markets Emergin
Slide 7: Division: Scent & Care
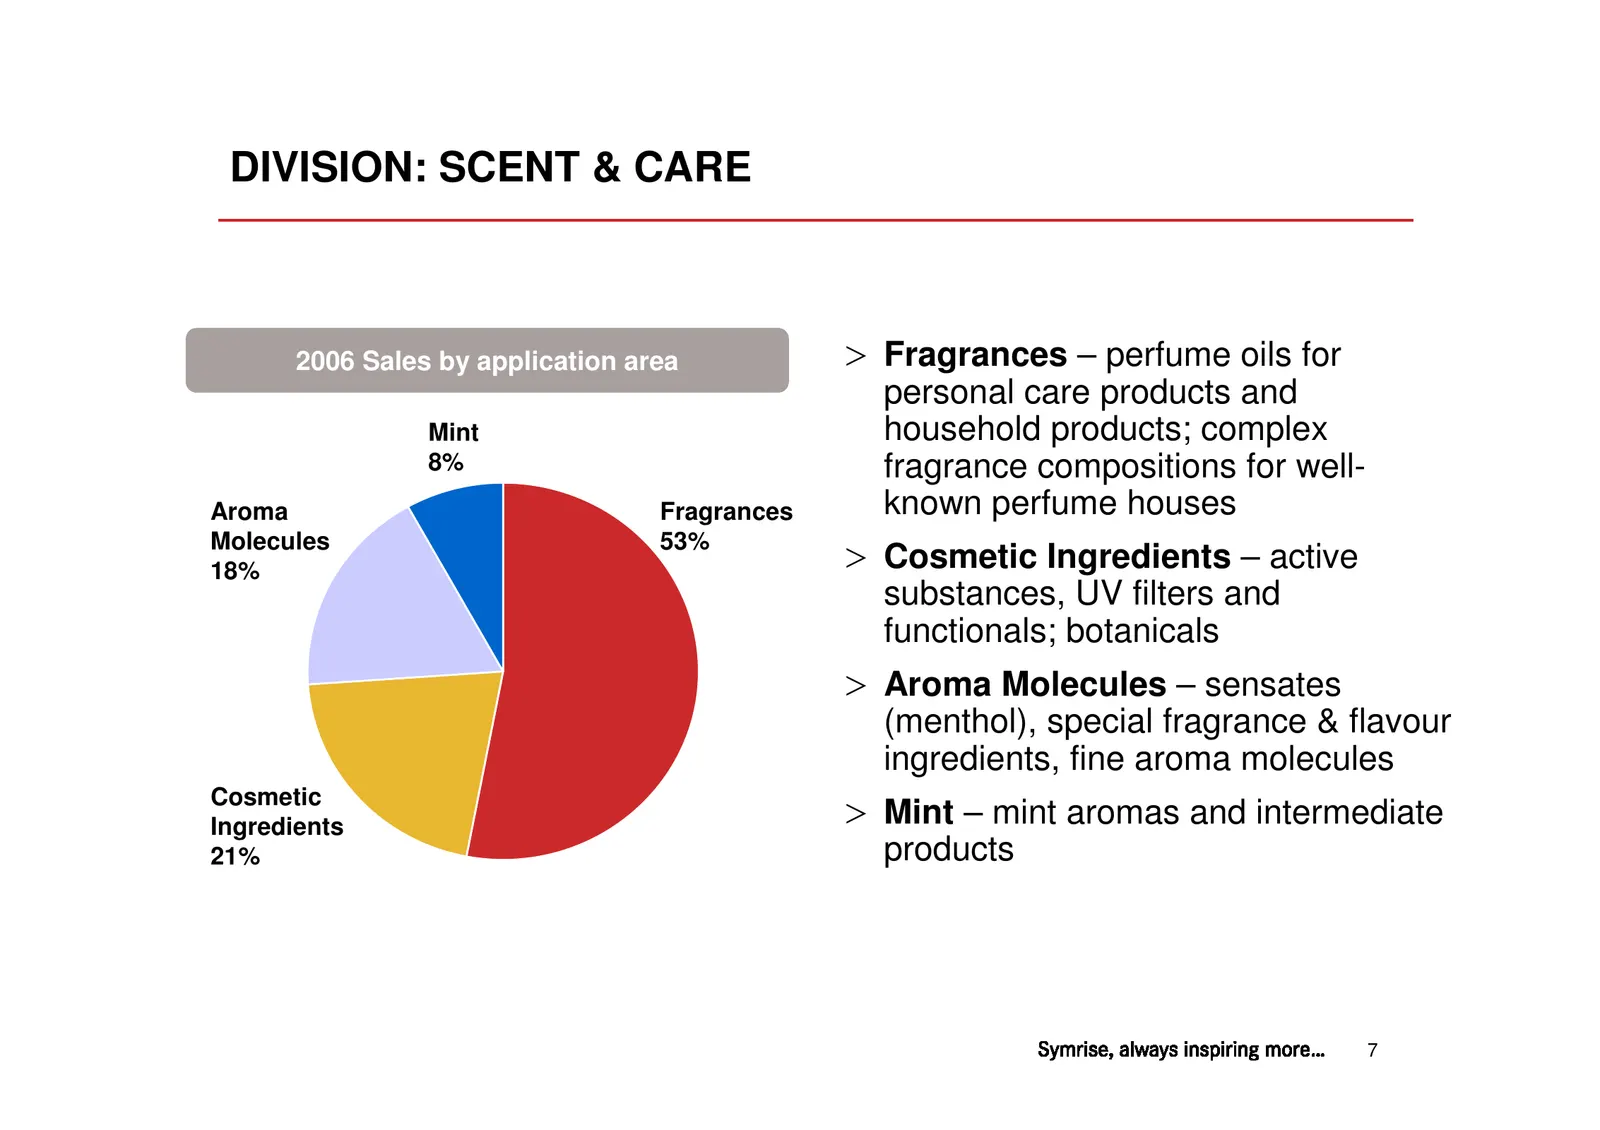
DIVISION: SCENT & CARE 2006 Sales by application area > Fragrances – perfume oils for personal care products and Mint household products; complex 8% fragrance compositions for well- Aroma Fragrances known perfume houses Molecules 53% 18% > Cosmetic Ingredients – active substances, UV filters and fun
Slide 8: Division: Flavour & Nutrition
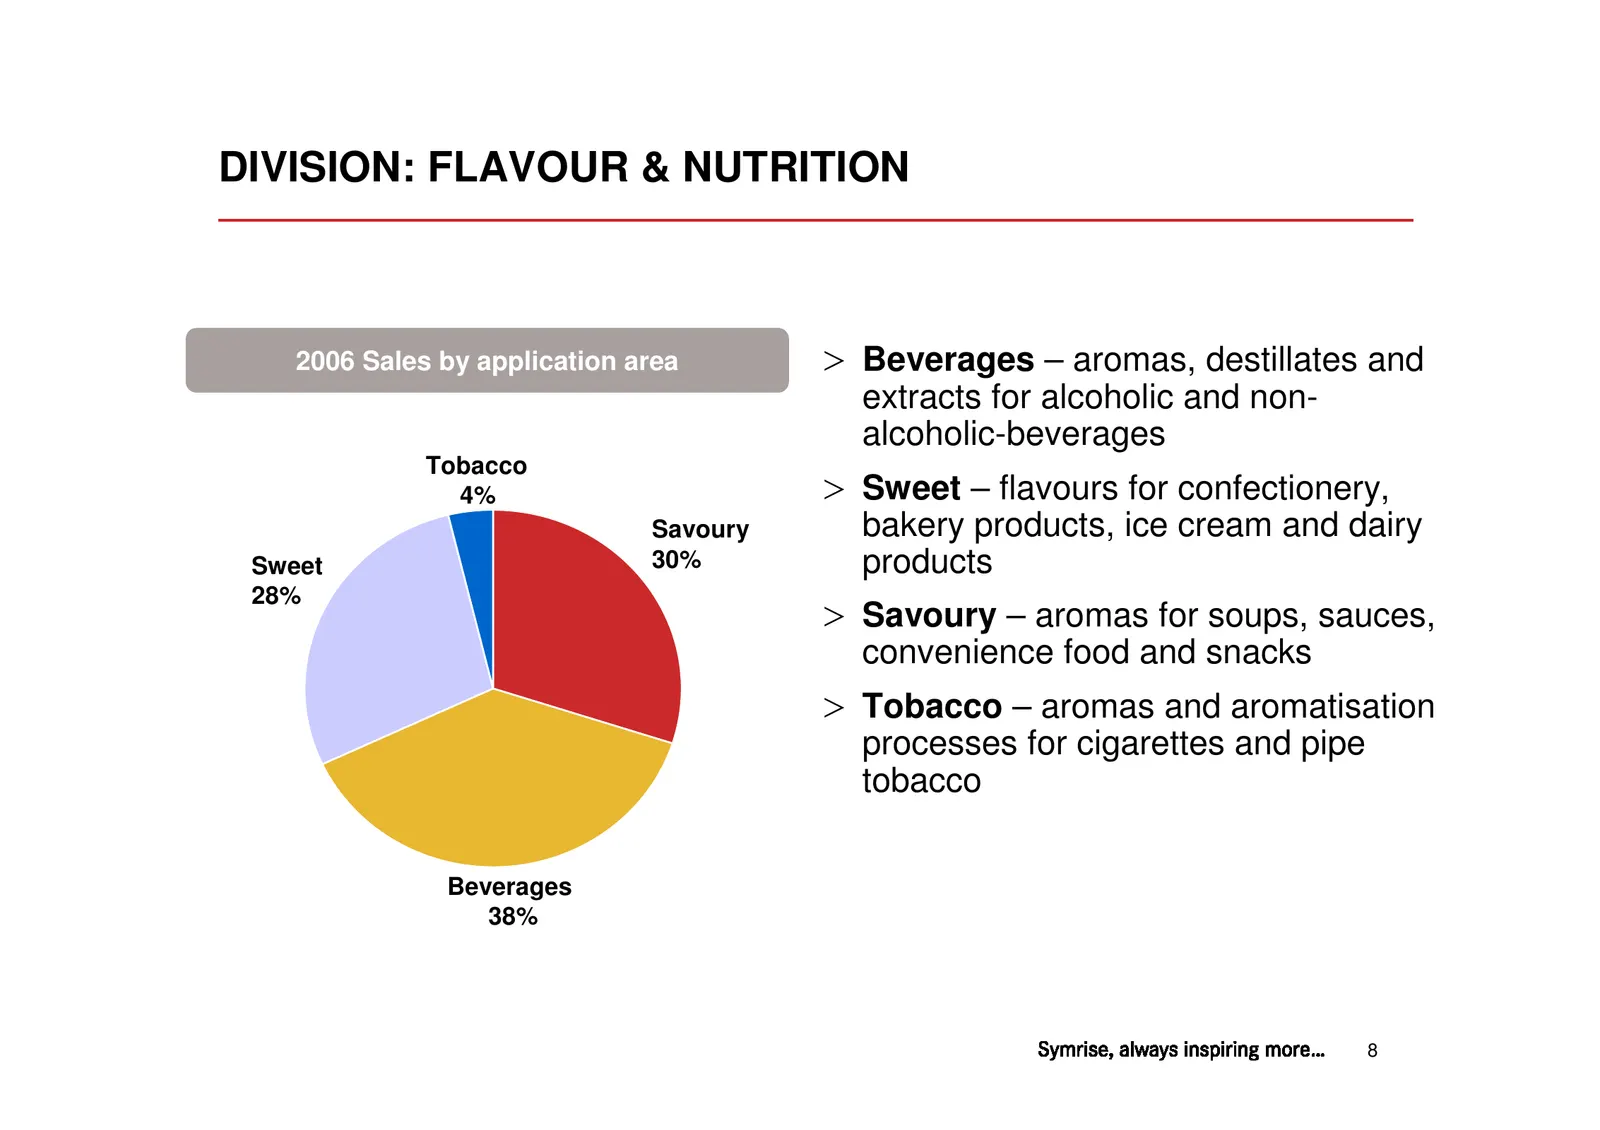
DIVISION: FLAVOUR & NUTRITION 2006 Sales by application area > Beverages – aromas, destillates and extracts for alcoholic and non- alcoholic-beverages Tobacco 4% > Sweet – flavours for confectionery, Savoury bakery products, ice cream and dairy Sweet 30% products 28% > Savoury – aromas for soups, sa
Slide 9: Market Overview: Flavours & Fragrances
Market Overview: Flavours & Fragrances 9
Slide 10: A small group of companies leads the F&F market
A SMALL GROUP OF COMPANIES LEADS THE F&F-MARKET Global leadership in F&F (2006) Entry barriers into Tier 1 2 14,2% Tier 1 Tier 2 12,8% > Critical size (>1 billion turnover) to be a 11,4% qualified supplier for international customers 9,5% (“globally local”) 6,5% 5,9% 4,5% + 500 others Entry barriers
Slide 11: It is a performance, not a price driven business
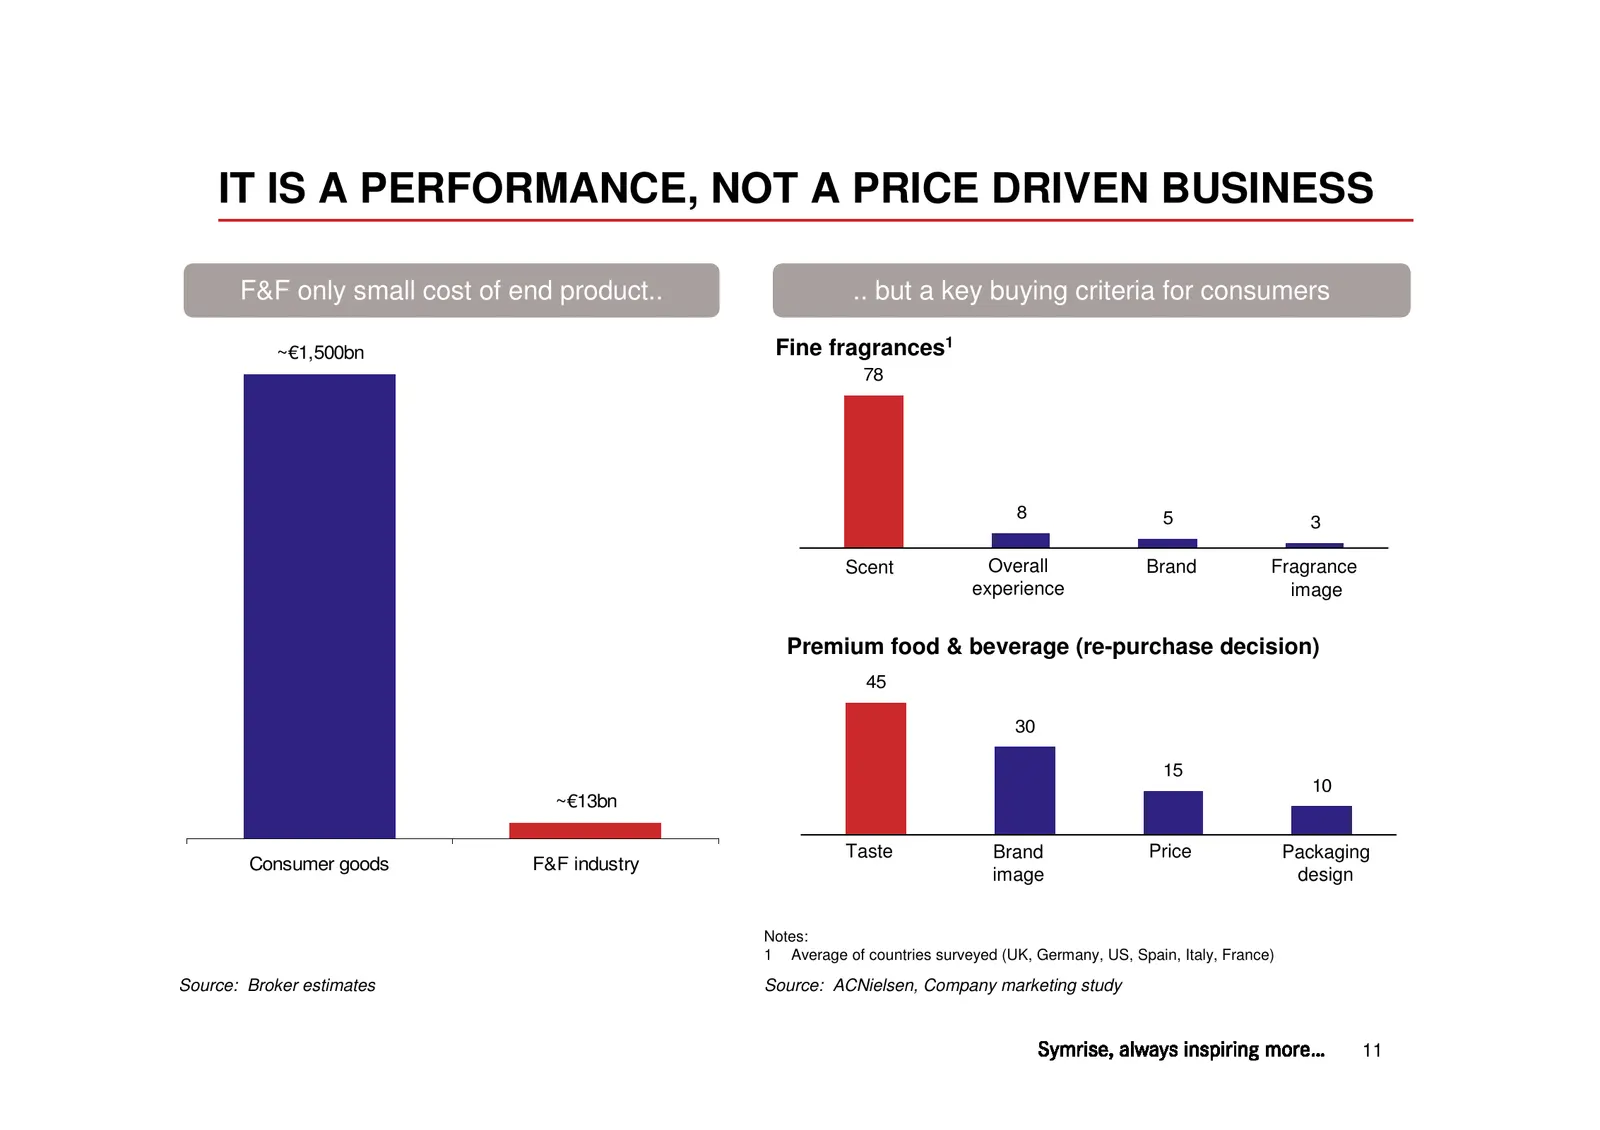
IT IS A PERFORMANCE, NOT A PRICE DRIVEN BUSINESS F&F only small cost of end product.. .. but a key buying criteria for consumers ~€1,500bn Fine fragrances1 78 8 5 3 Scent Overall Brand Fragrance experience image Premium food & beverage (re-purchase decision) 45 30 15 10 ~€13bn Taste Brand Price Pack
Slide 12: High and sustainable margins are achievable
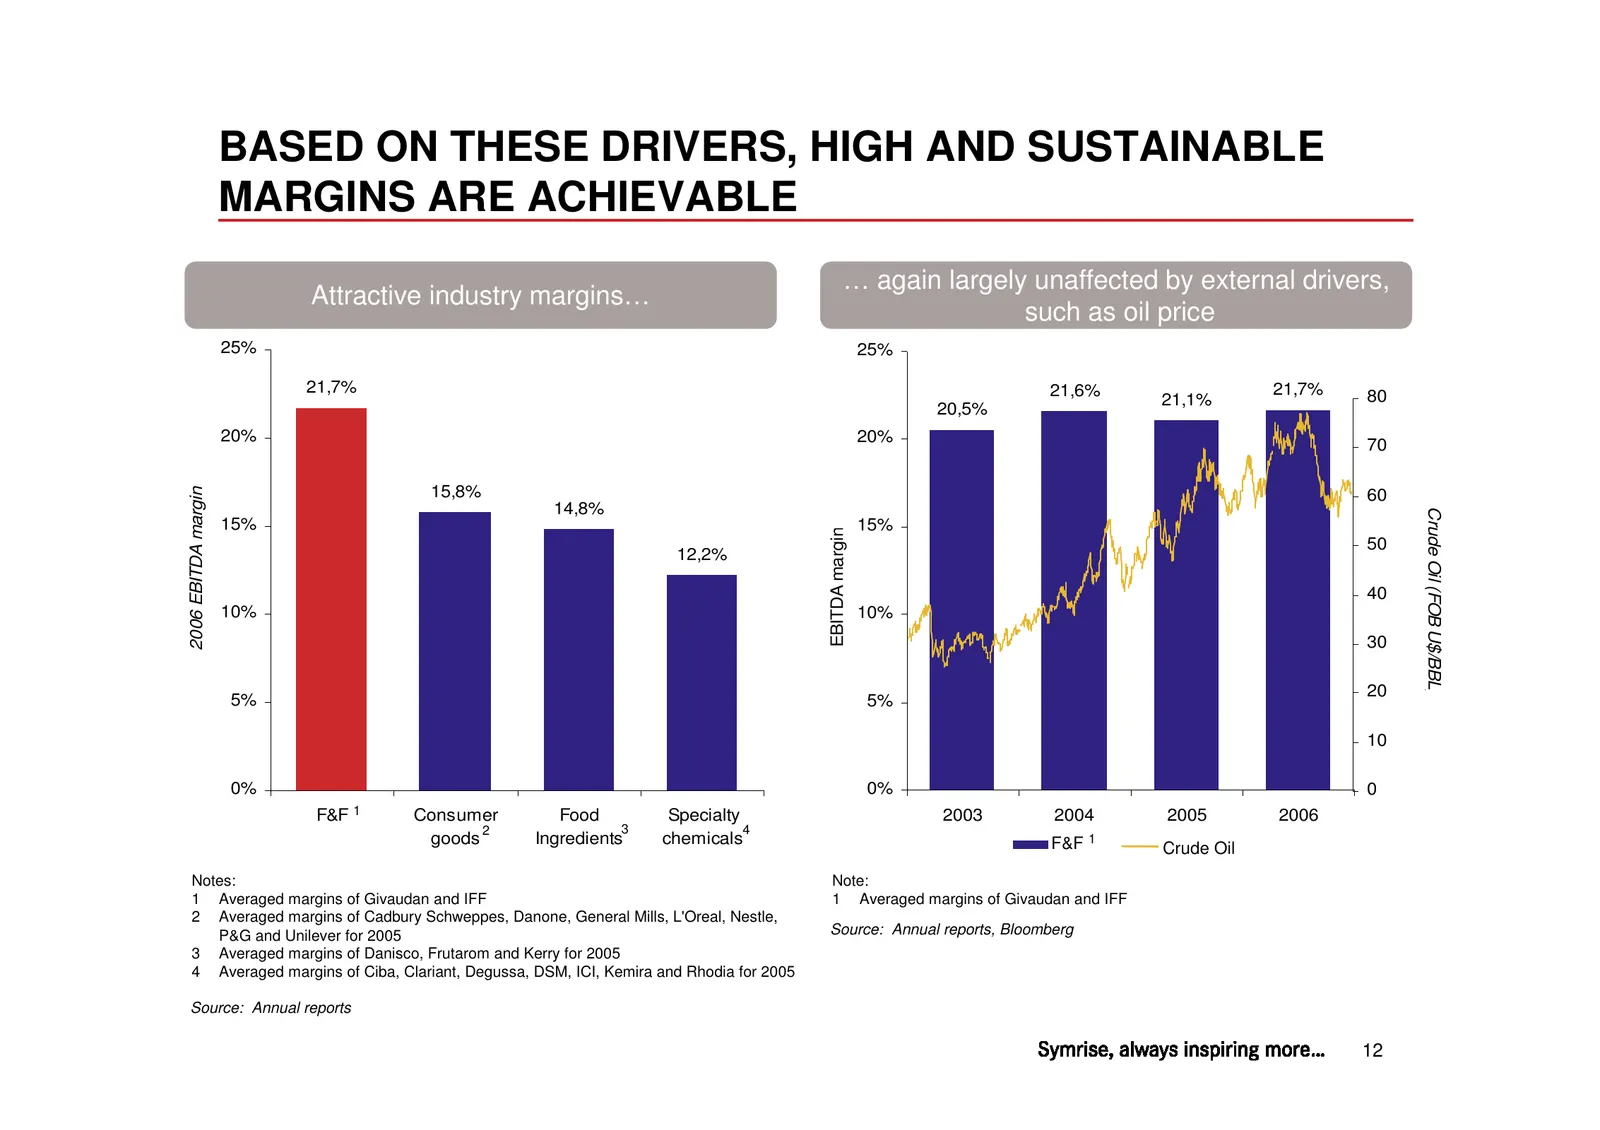
BASED ON THESE DRIVERS, HIGH AND SUSTAINABLE MARGINS ARE ACHIEVABLE … again largely unaffected by external drivers, Attractive industry margins… such as oil price 25% 25% 21,7% 21,6% 21,7% 21,1% 80 20,5% 20% 20% 70 15,8% 2006 EBITDA margin 60 14,8% Crude Oil (FOB U$/BBL) 15% 15% EBITDA margin 50 12,
Slide 13: Symrise Strategy
Symrise Strategy 13
Slide 14: Symrise strategy to outperform
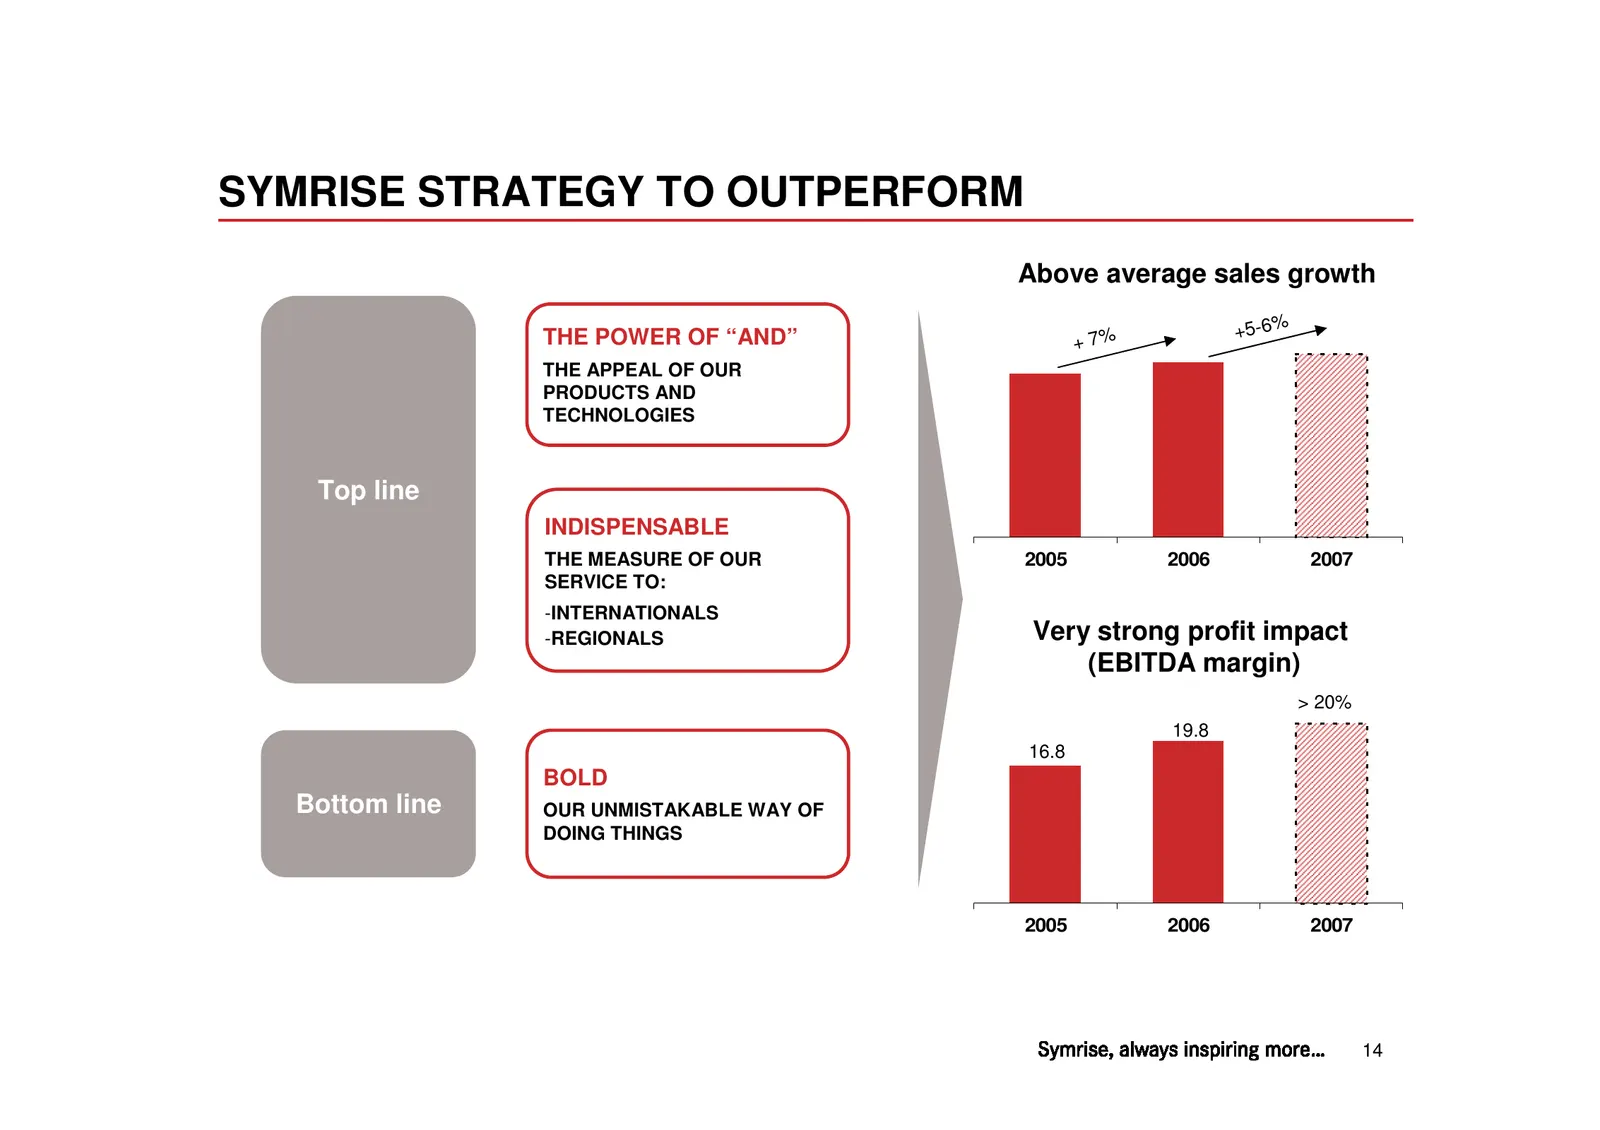
SYMRISE STRATEGY TO OUTPERFORM Above average sales growth THE POWER OF “AND” +5-6% + 7% THE APPEAL OF OUR PRODUCTS AND TECHNOLOGIES Top line INDISPENSABLE THE MEASURE OF OUR 2005 2006 2007 SERVICE TO: -INTERNATIONALS -REGIONALS Very strong profit impact (EBITDA margin) > 20% 19.8 16.8 BOLD Bottom li
Slide 15: Focus on fast growing markets, which require smart products
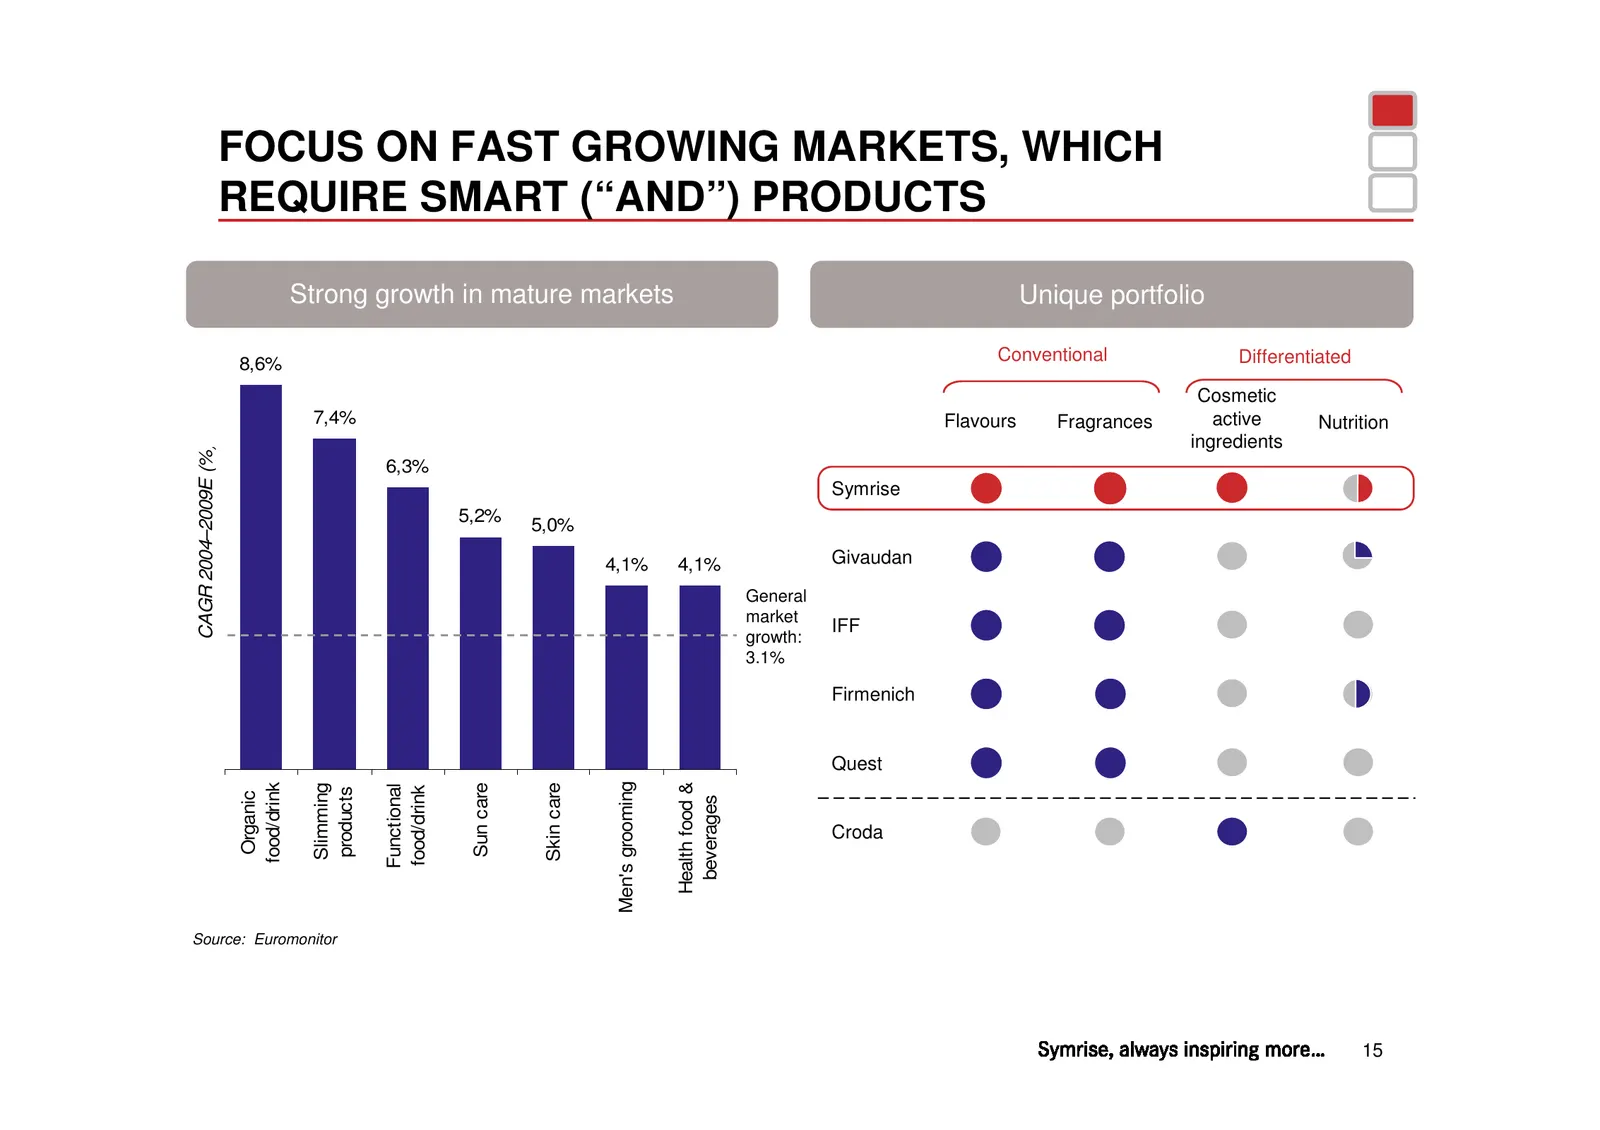
FOCUS ON FAST GROWING MARKETS, WHICH REQUIRE SMART (“AND”) PRODUCTS Strong growth in mature markets Unique portfolio 8,6% Conventional Differentiated Cosmetic 7,4% Flavours Fragrances active Nutrition ingredients CAGR 2004–2009E (%) 6,3% Symrise 5,2% 5,0% 4,1% 4,1% Givaudan General market IFF growth
Slide 16: We develop smart products with additional functionalities
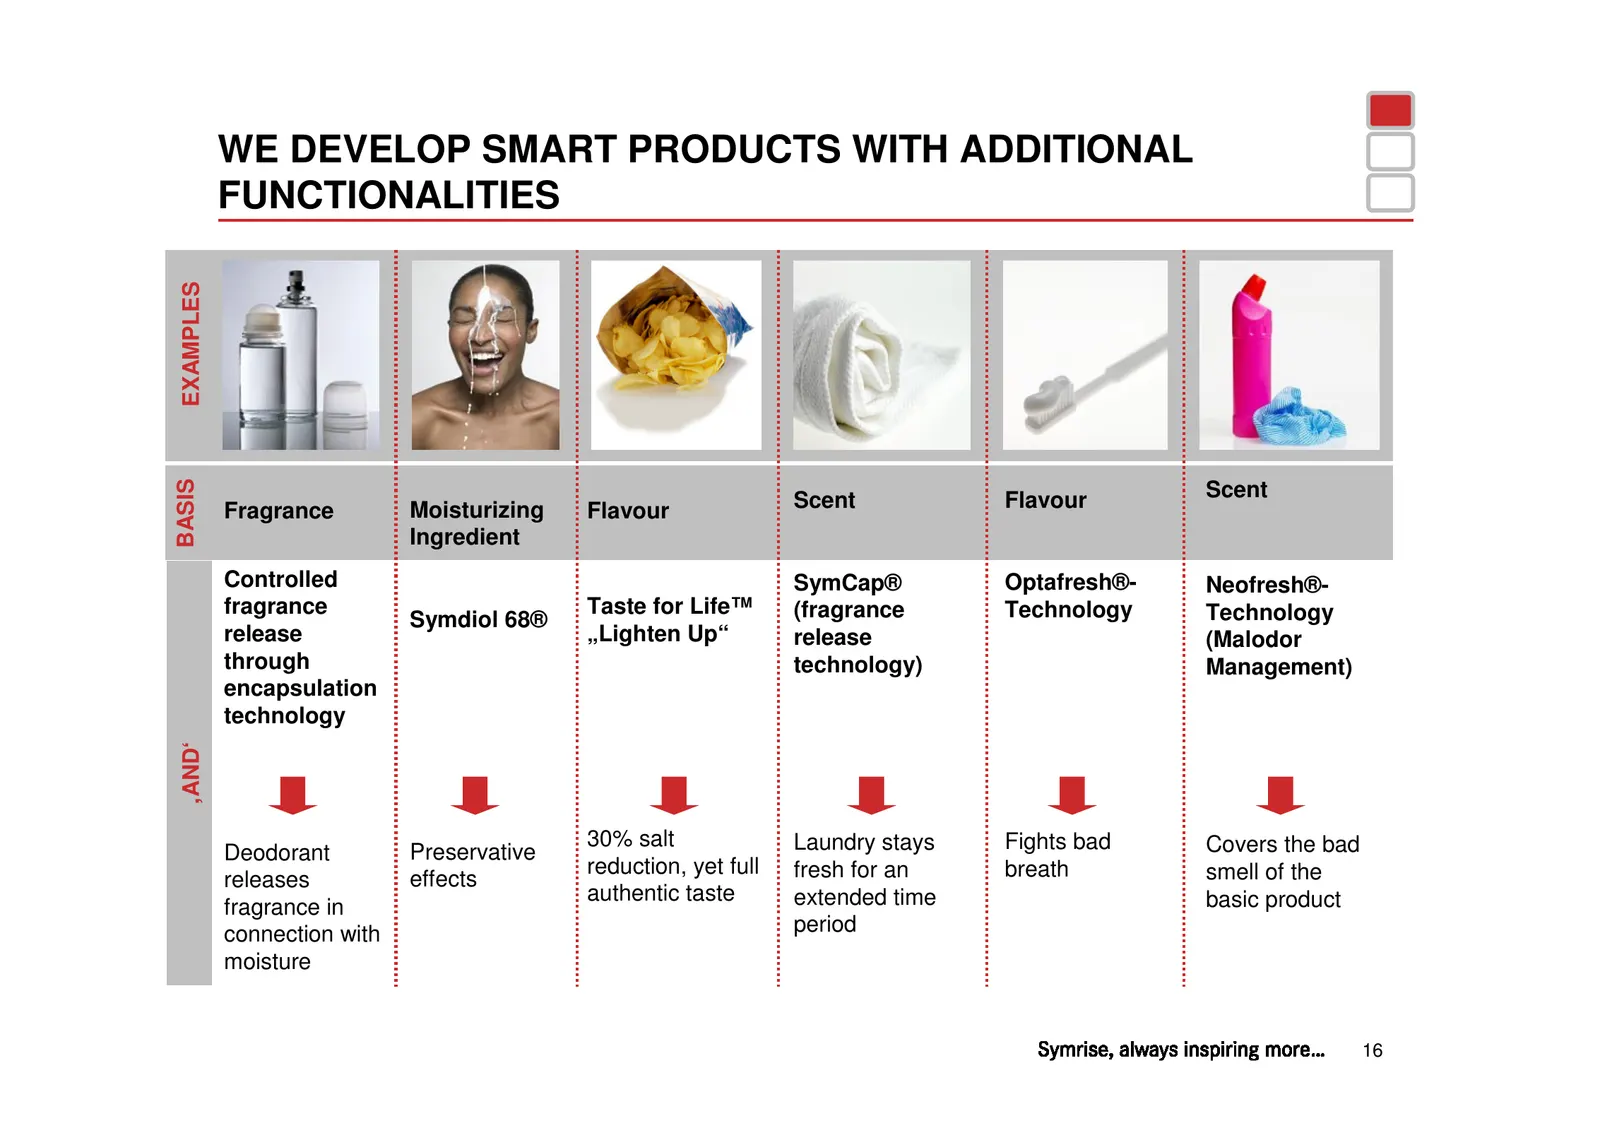
WE DEVELOP SMART PRODUCTS WITH ADDITIONAL EXAMPLES BASIS FUNCTIONALITIES Scent Flavour Scent Fragrance Moisturizing Flavour Ingredient Controlled SymCap® Optafresh®- Neofresh®- fragrance Taste for Life™ (fragrance Technology Technology Symdiol 68® release „Lighten Up“ release (Malodor through techno
Slide 17: Core list positions drive growth with multinationals
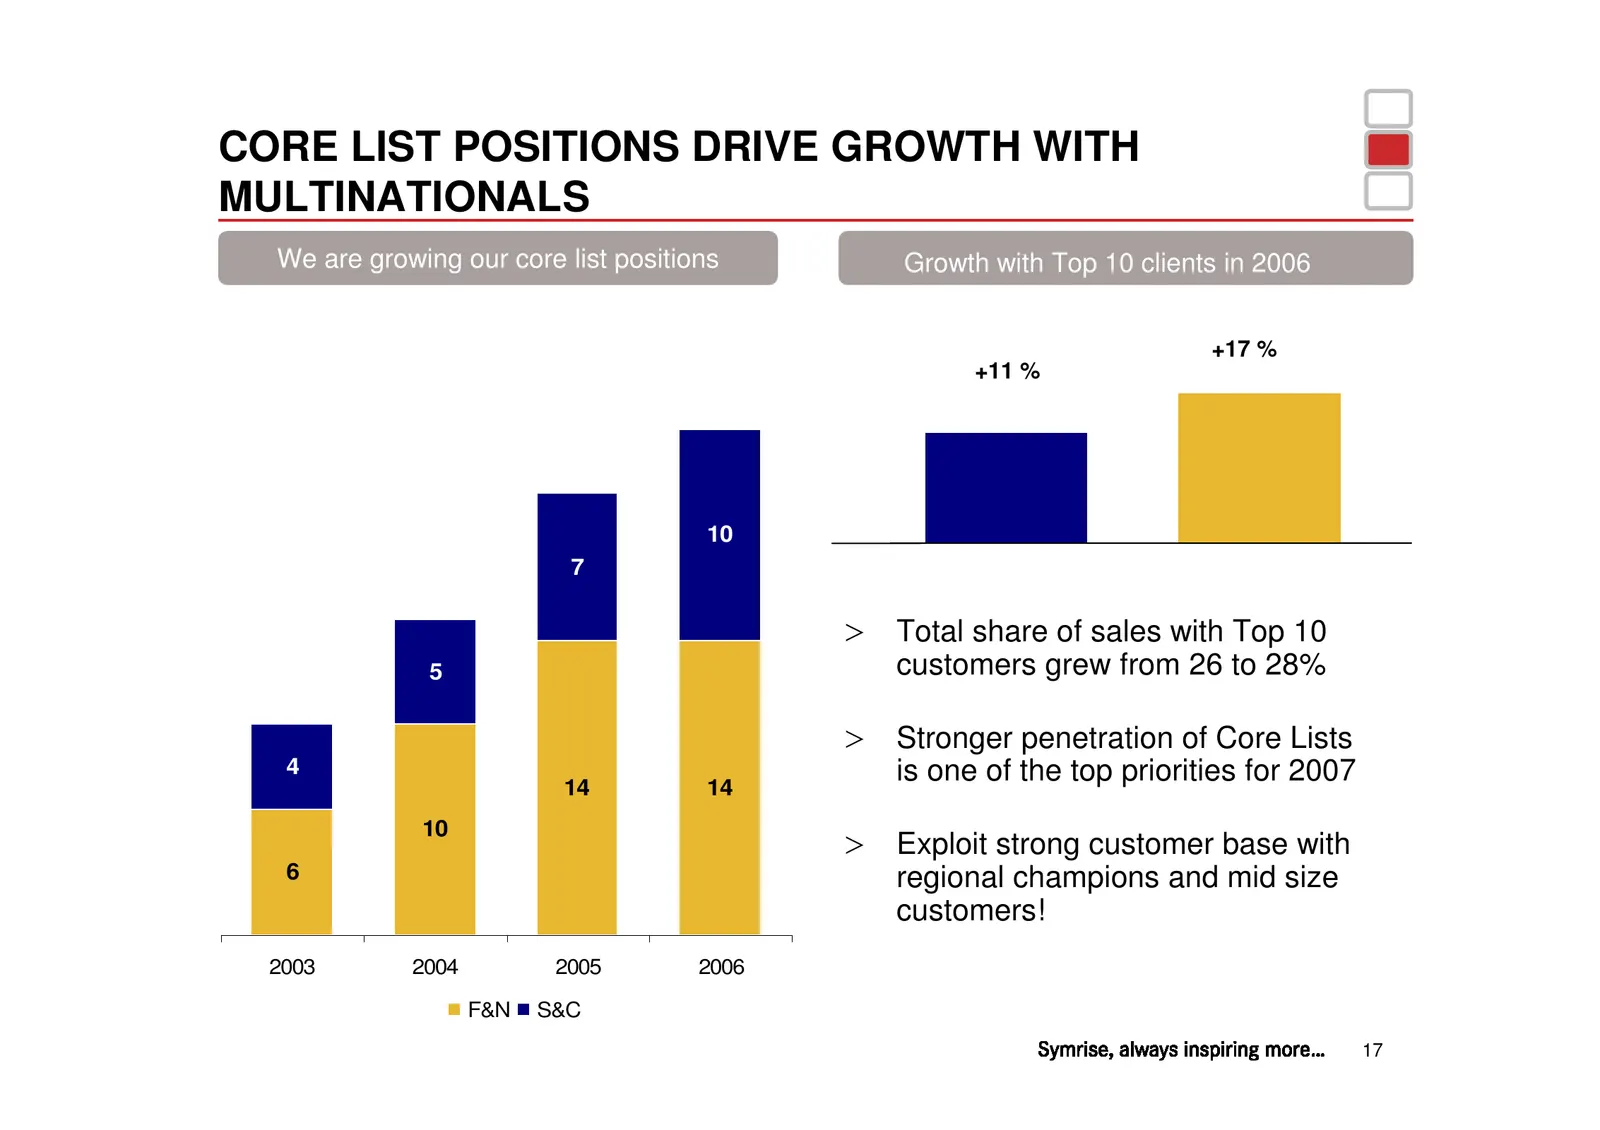
CORE LIST POSITIONS DRIVE GROWTH WITH MULTINATIONALS We are growing our core list positions Growth with Top 10 clients in 2006 +17 % +11 % 22% of 28% of sales sales 10 7 > Total share of sales with Top 10 5 customers grew from 26 to 28% > Stronger penetration of Core Lists 4 14 14 is one of the top
Slide 18: Even in fast growing emerging markets we outperformed GDP
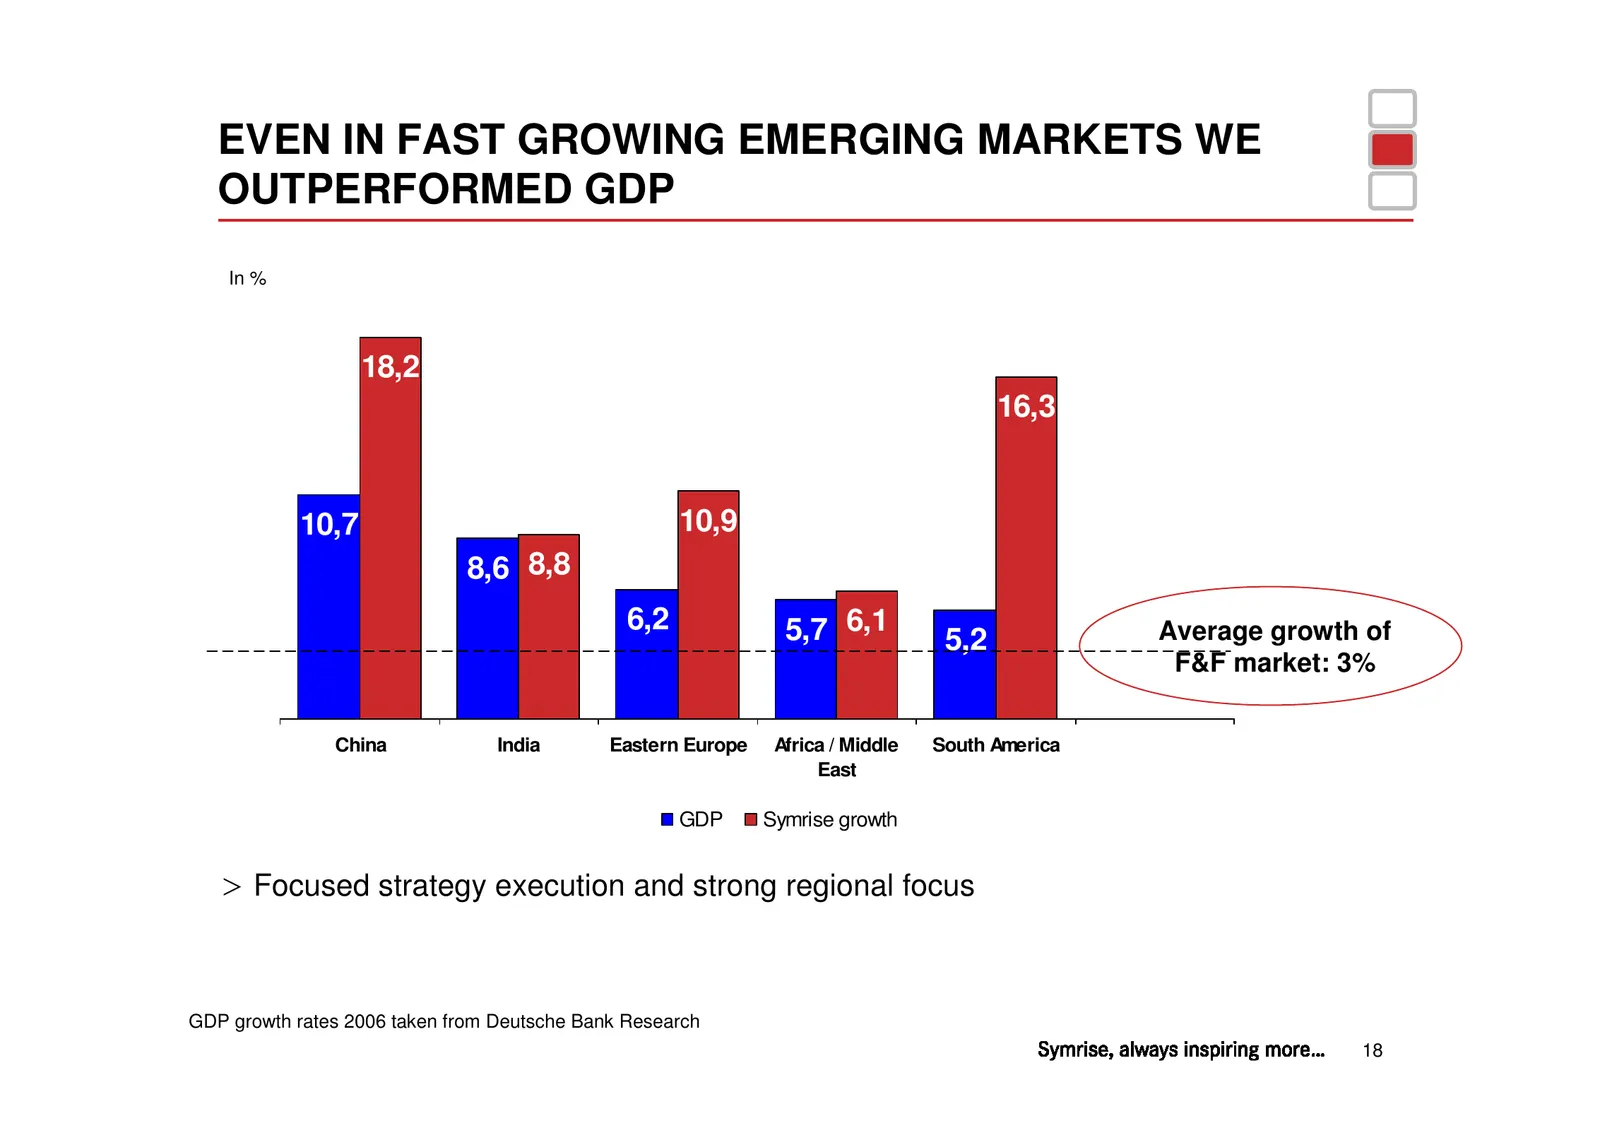
EVEN IN FAST GROWING EMERGING MARKETS WE OUTPERFORMED GDP In % 18,2 16,3 10,7 10,9 8,6 8,8 6,2 5,7 6,1 Average growth of 5,2 F&F market: 3% China India Eastern Europe Africa / Middle South America East GDP Symrise growth > Focused strategy execution and strong regional focus GDP growth rates 2006 ta
Slide 19: Profit-oriented corporate culture
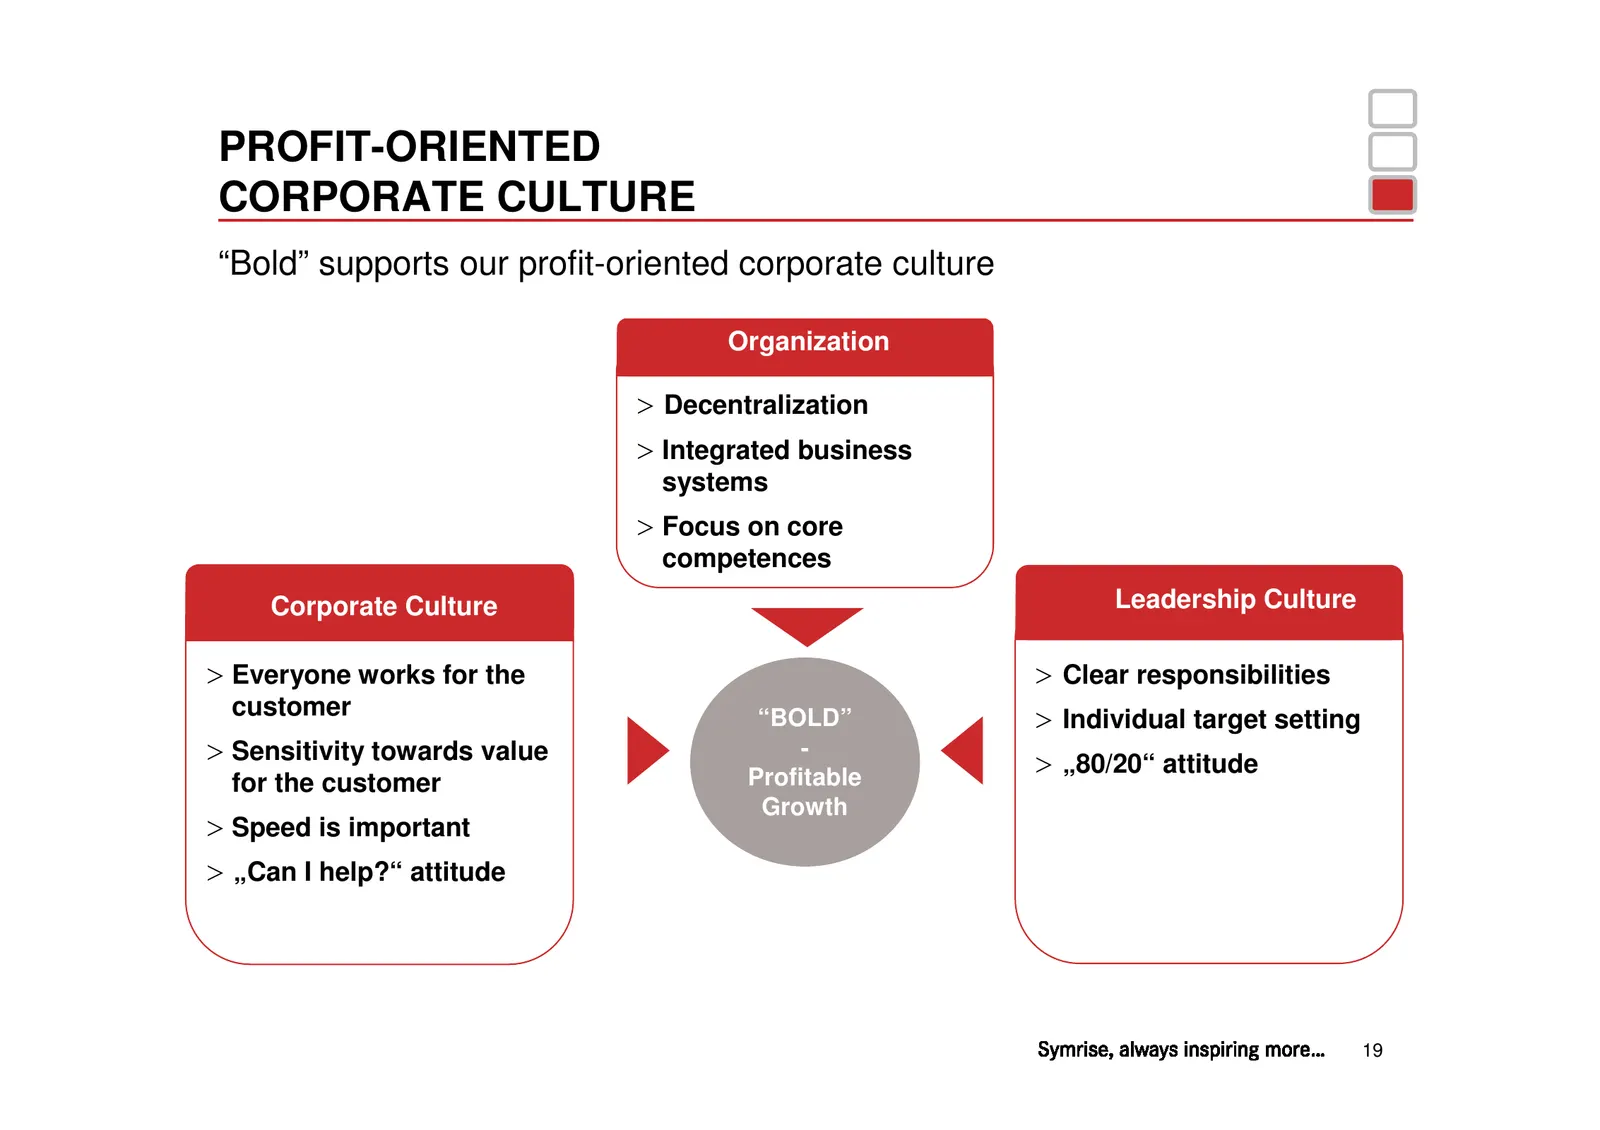
PROFIT-ORIENTED CORPORATE CULTURE “Bold” supports our profit-oriented corporate culture Organization > Decentralization > Integrated business systems > Focus on core competences Corporate Culture Leadership Culture > Everyone works for the > Clear responsibilities customer “BOLD” > Individual target
Slide 20: We boldly changed and simplified our organisation
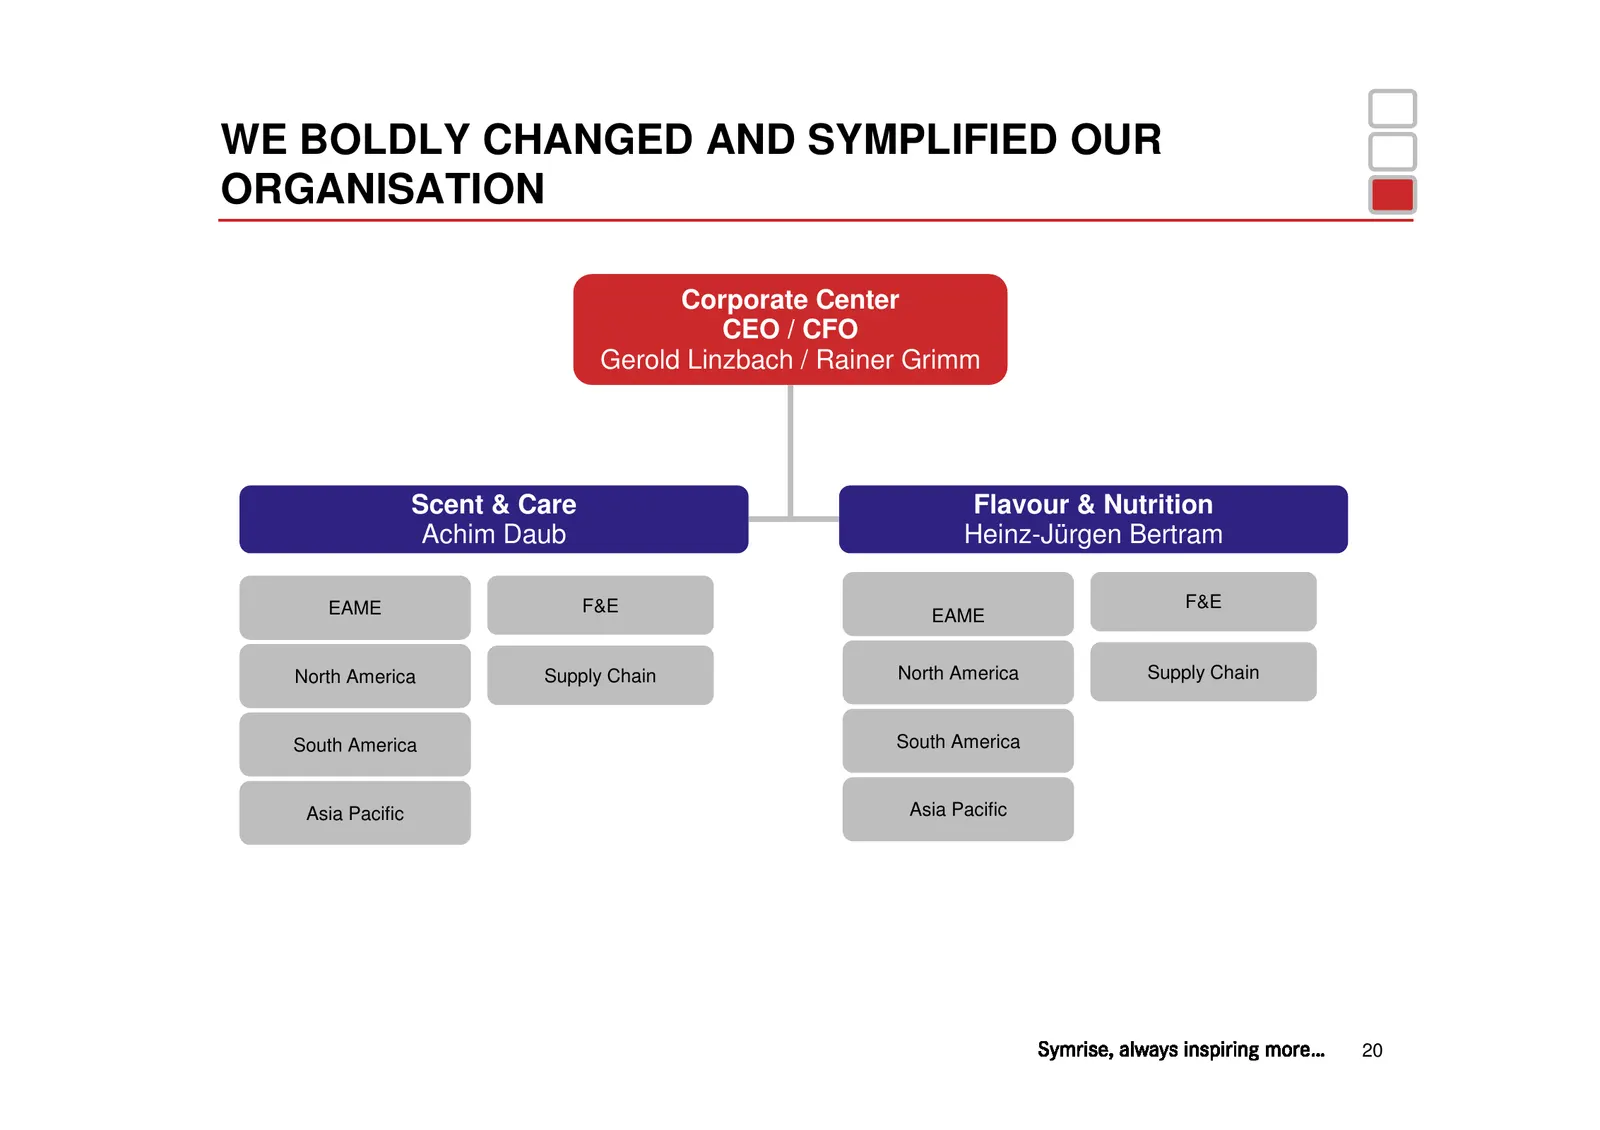
WE BOLDLY CHANGED AND SYMPLIFIED OUR ORGANISATION Corporate Center CEO / CFO Gerold Linzbach / Rainer Grimm Scent & Care Flavour & Nutrition Achim Daub Heinz-Jürgen Bertram EAME F&E F&E EAME North America Supply Chain North America Supply Chain South America South America Asia Pacific Asia Pacific 2
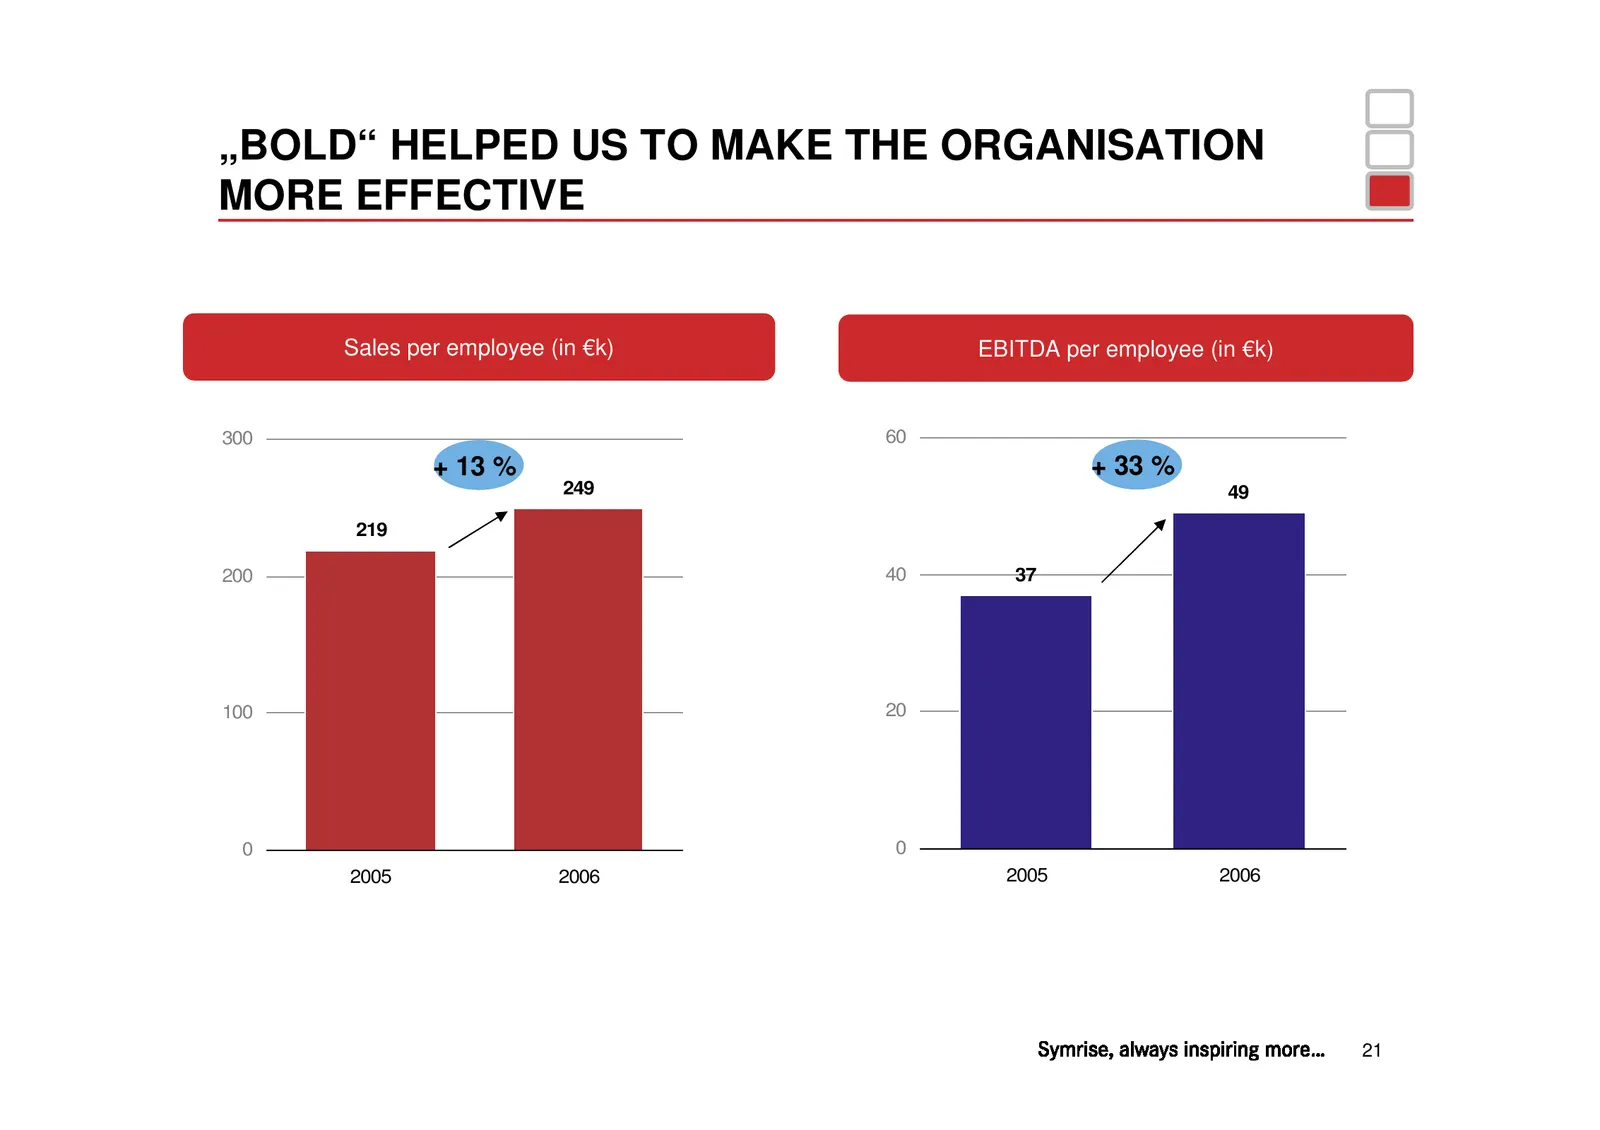
Slide 21: BOLD helped us to make the organisation more effective
„BOLD“ HELPED US TO MAKE THE ORGANISATION MORE EFFECTIVE Sales per employee (in €k) EBITDA per employee (in €k) 300 60 + 13 % + 33 % 249 49 219 200 40 37 100 20 0 0 2005 2006 2005 2006 21
Slide 22: Financials and Share Information
Financials and Share Information 22
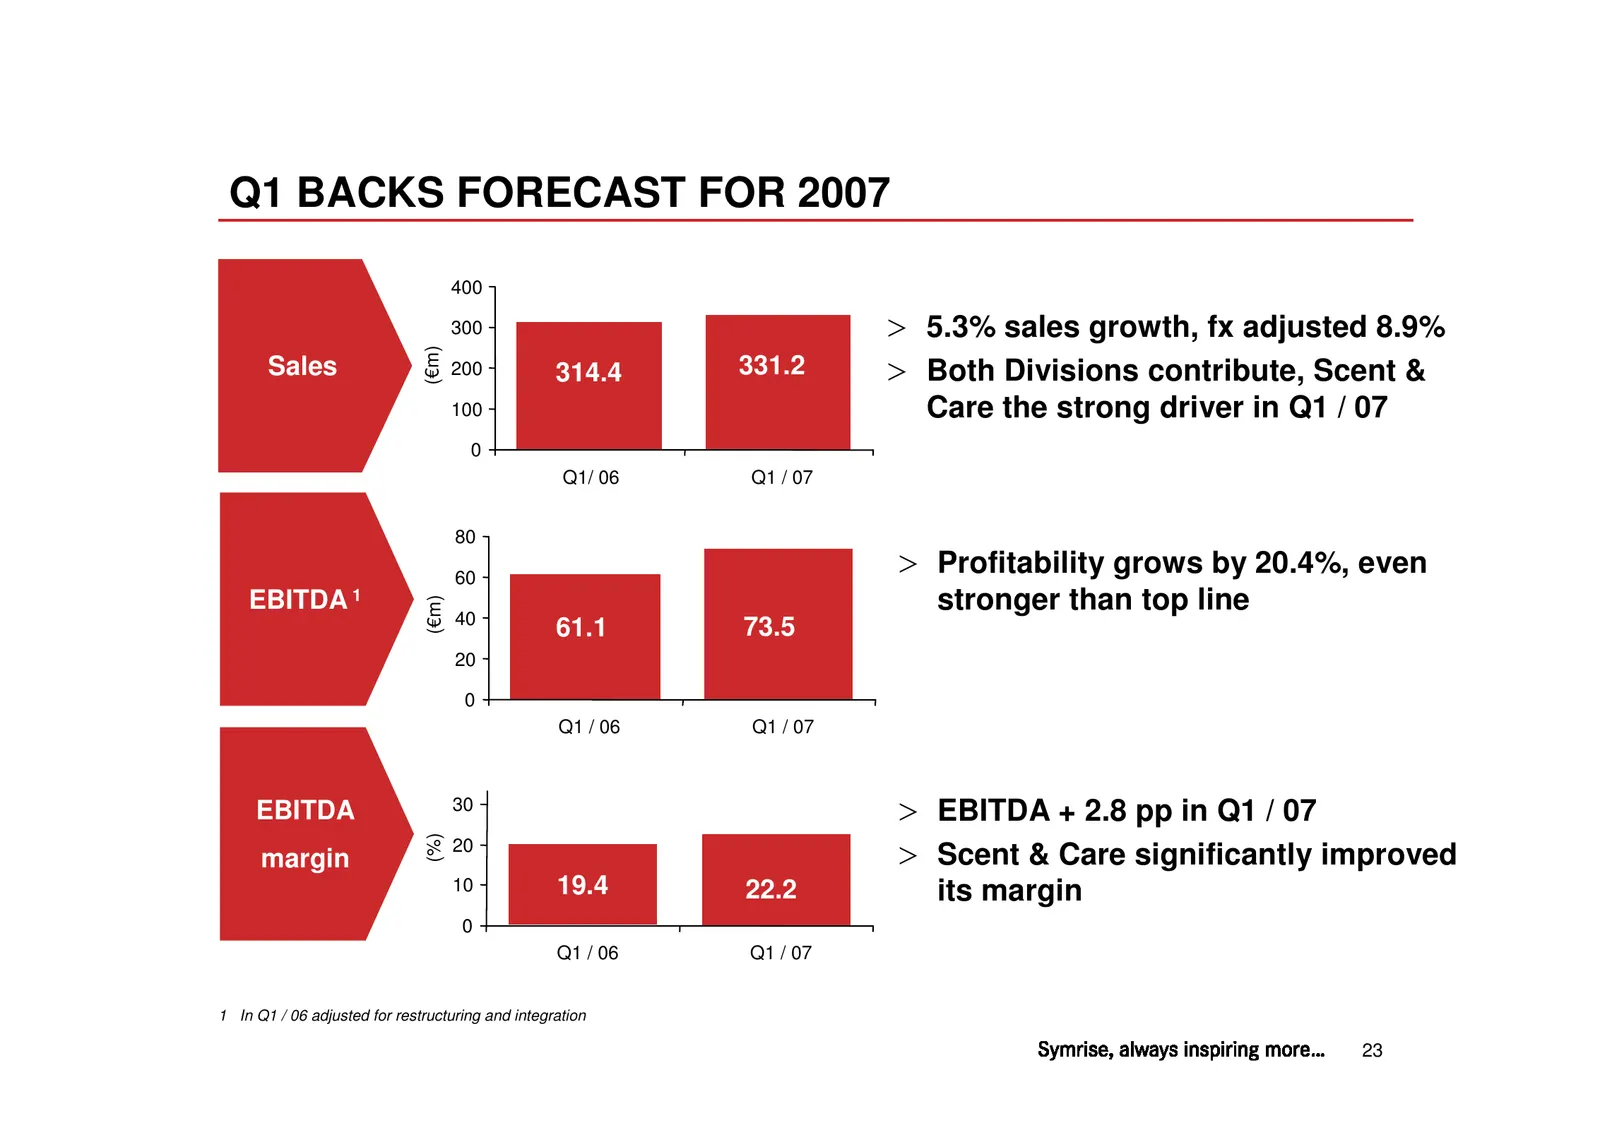
Slide 23: Q1 backs forecast for 2007
Q1 BACKS FORECAST FOR 2007 400 300 > 5.3% sales growth, fx adjusted 8.9% (€m) Sales 200 314.4 331.2 > Both Divisions contribute, Scent & 100 Care the strong driver in Q1 / 07 0 Q1/ 06 Q1 / 07 80 60 > Profitability grows by 20.4%, even EBITDA 1 stronger than top line (€m) 40 61.1 73.5 20 0 Q1 / 06 Q1
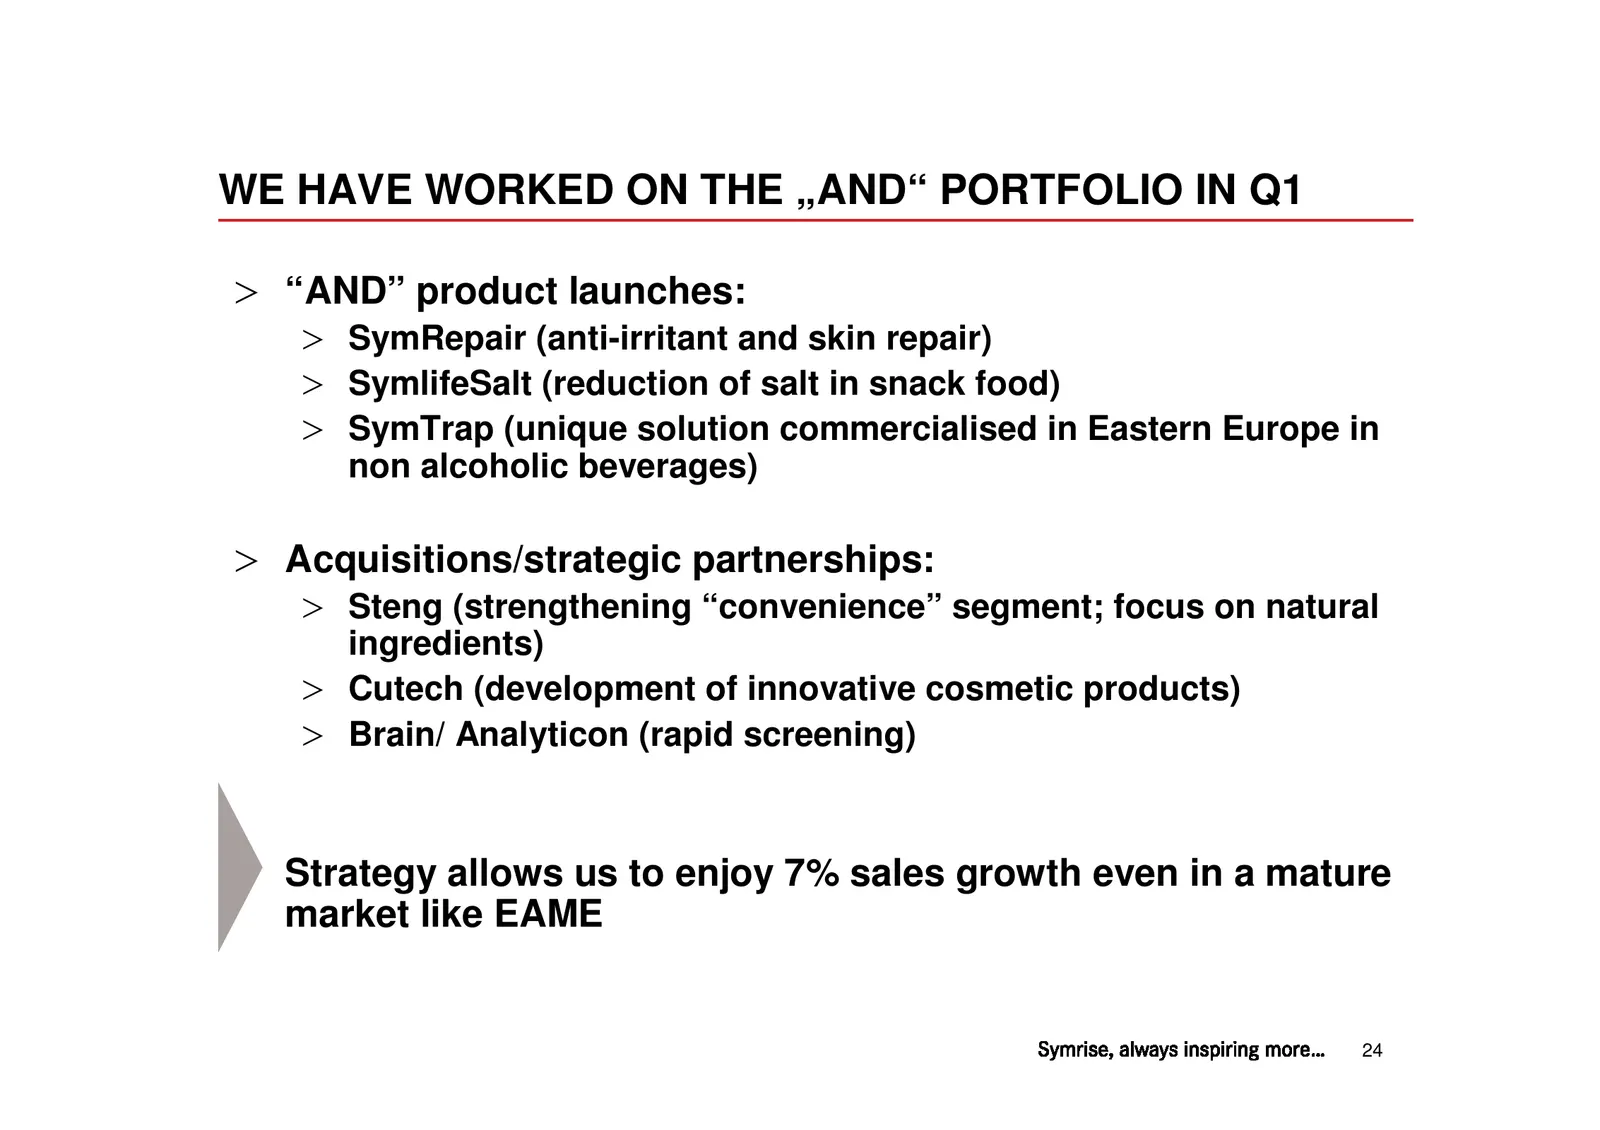
Slide 24: We have worked on the AND portfolio in Q1
WE HAVE WORKED ON THE „AND“ PORTFOLIO IN Q1 > “AND” product launches: > SymRepair (anti-irritant and skin repair) > SymlifeSalt (reduction of salt in snack food) > SymTrap (unique solution commercialised in Eastern Europe in non alcoholic beverages) > Acquisitions/strategic partnerships: > Steng (st
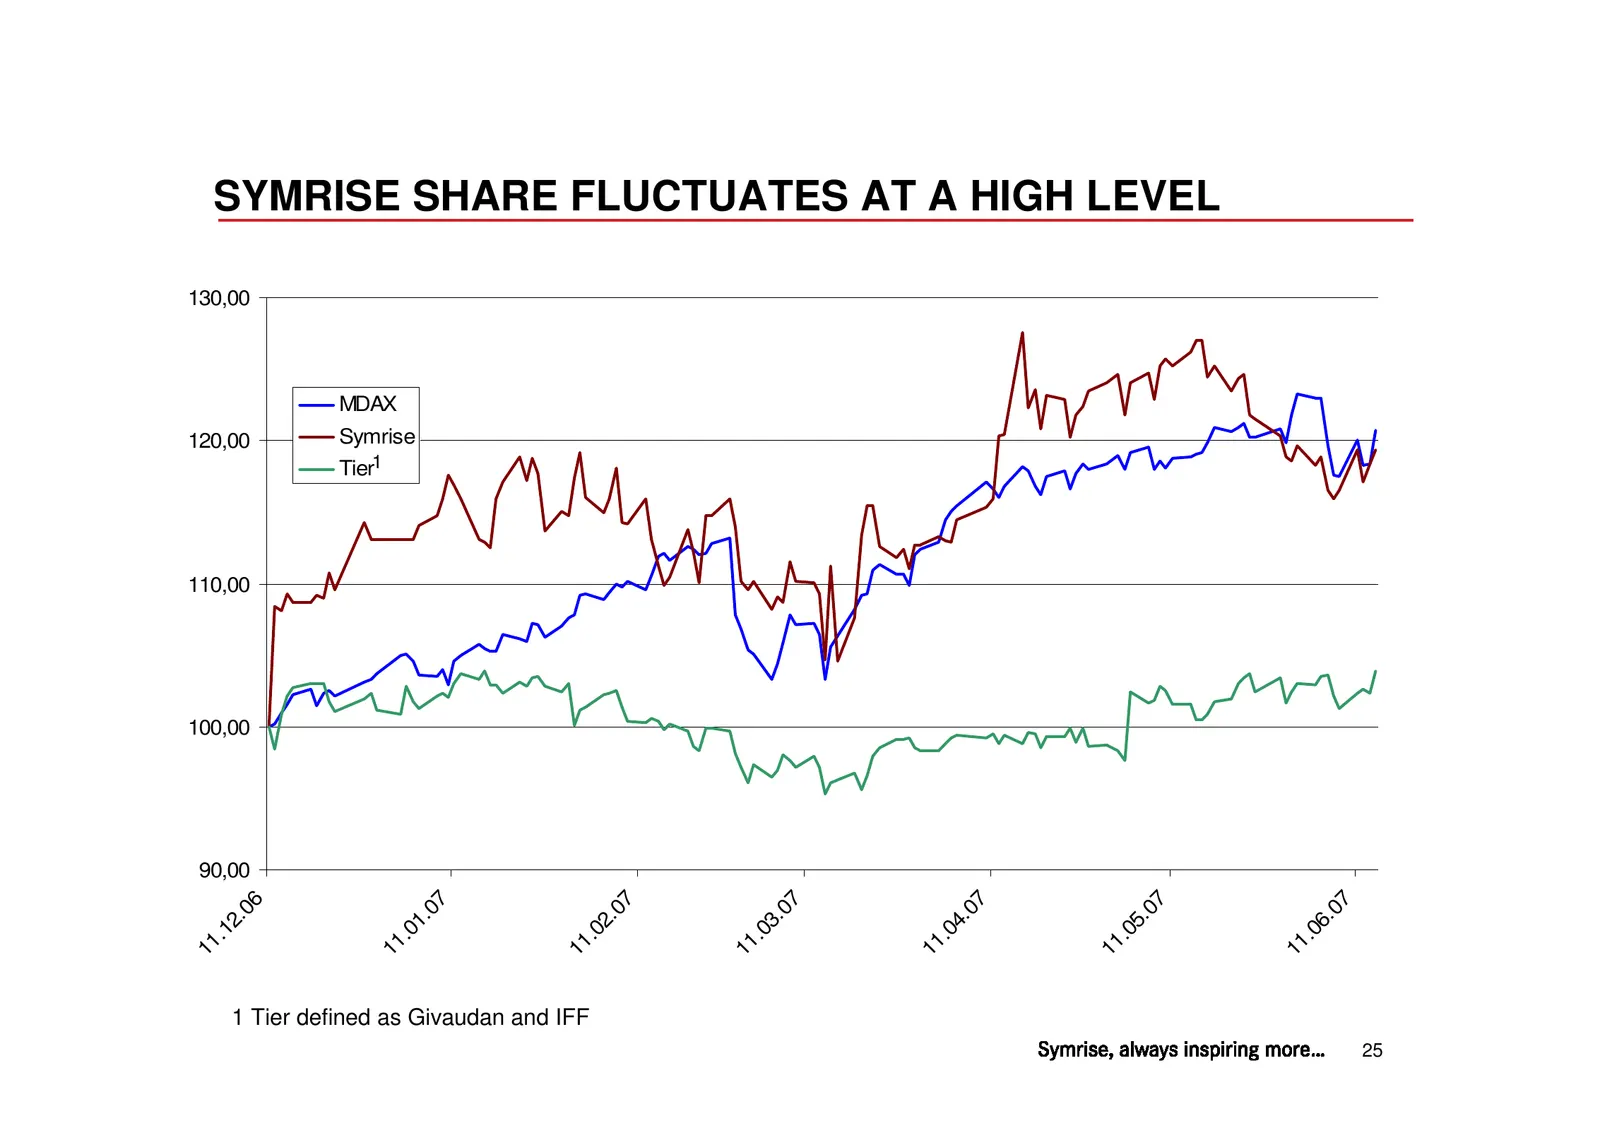
Slide 25: Symrise share fluctuates at a high level
SYMRISE SHARE FLUCTUATES AT A HIGH LEVEL 130,00 MDAX 120,00 Symrise Tier1 110,00 100,00 90,00 06 07 07 07 07 07 07 2. 1. 2. 3. 4. 5. 6. .1 .0 .0 .0 .0 .0 .0 11 11 11 11 11 11 11 1 Tier defined as Givaudan and IFF 25
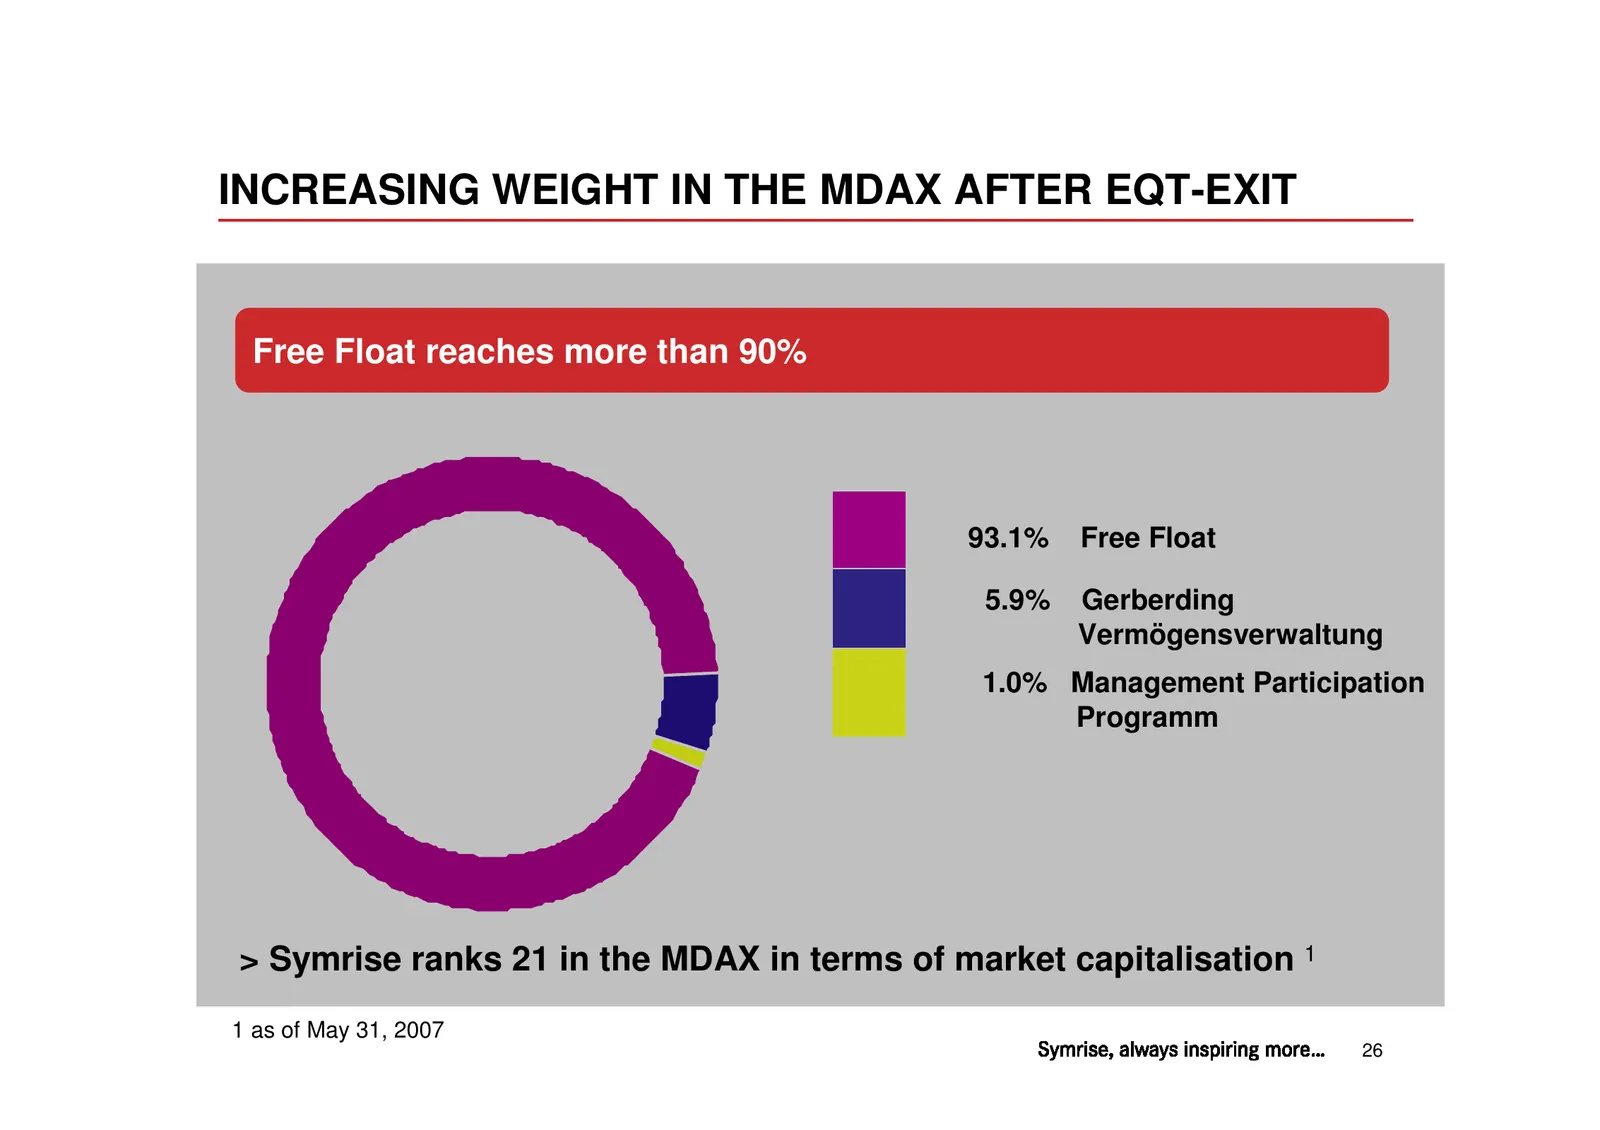
Slide 26: Increasing weight in the MDAX after EQT exit
INCREASING WEIGHT IN THE MDAX AFTER EQT-EXIT Free Float reaches more than 90% 93.1% Free Float 5.9% Gerberding Vermögensverwaltung 1.0% Management Participation Programm > Symrise ranks 21 in the MDAX in terms of market capitalisation 1 1 as of May 31, 2007 26
Slide 27: Outlook
Outlook 27
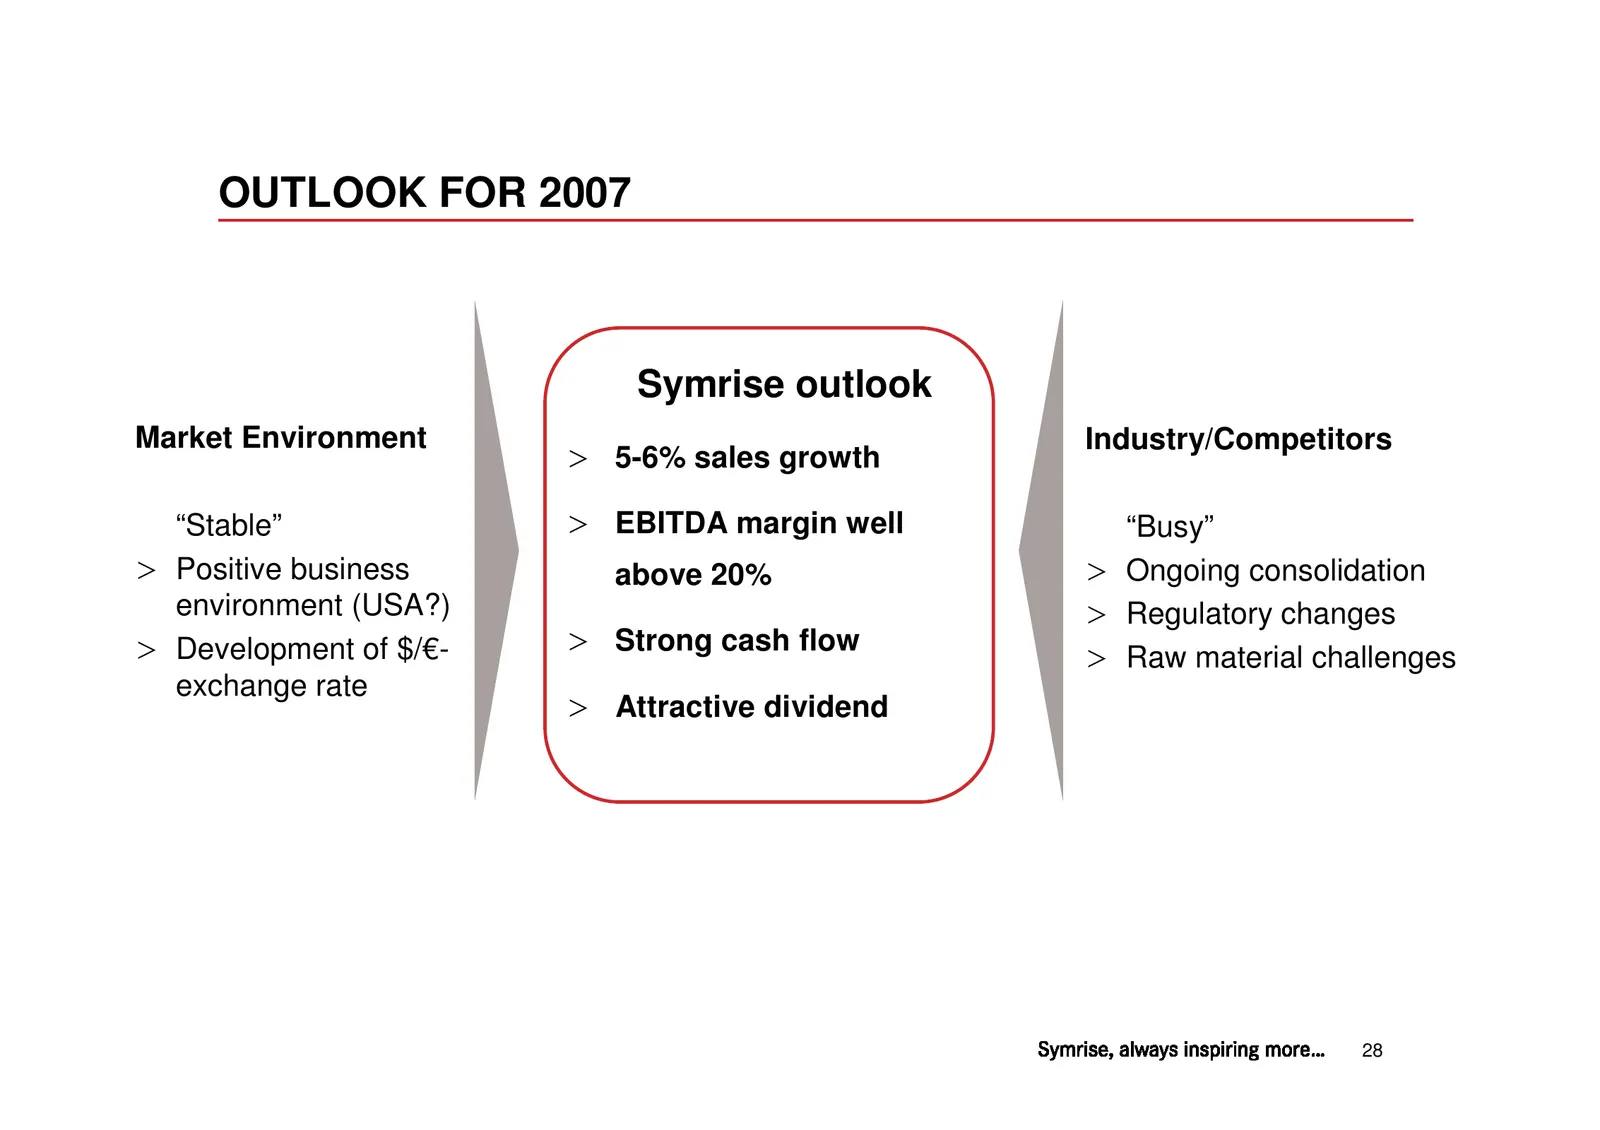
Slide 28: Outlook for 2007
OUTLOOK FOR 2007 Symrise outlook Market Environment Industry/Competitors > 5-6% sales growth “Stable” > EBITDA margin well “Busy” > Positive business above 20% > Ongoing consolidation environment (USA?) > Regulatory changes > Development of $/€- > Strong cash flow > Raw material challenges exchange
Slide 29: Q&A
Q&A Q&A ALWAYS INSPIRING 29 MORE …
Source: Internet Archive copy of investor.symrise.com
More decks from Symrise AG
 Q3 2026 Earnings Presentation22 slides · Oct 28, 2026
 Investor Presentation (October 2026)39 slides · October 2026
 H1 2026 Earnings Presentation25 slides · Jul 30, 2026
 Q2 2026 Earnings Presentation29 slides · Jul 30, 2026
 Shareholder Meeting (May 2026)19 slides · May 6, 2026
 Q1 2026 Earnings Presentation19 slides · Apr 29, 2026