INFICON Holding AG · SIX:IFCN
INFICON — Q2 2012 Earnings Presentation
29 slides from INFICON's earnings presentation, Aug 9, 2012
Slide 1
Slide 2: INFICON Q2 2012 Earnings Conference Call
INFICON Q2 2012 Earnings Conference Call August 9, 2012 Bad Ragaz, Switzerland
Slide 3: Safe Harbor Statement
Safe Harbor Statement This presentation contains forward-looking statements that reflect Management’s current views and estimates. The forward-looking statements involve certain risks and uncertainties that could cause actual results to differ materially from those contained in the forward-looking s
Slide 4: Speakers
Speakers Lukas Winkler, President and CEO Key figures Q2 2012 Target market business review 2012 Expectations Matthias Tröndle, Vice President and CFO Financials Q2 2012 Financials Half-Year 2012 Outlook 1 2008 Template - January 2008 4 9-August-2012 INFICON Q2 2012
Slide 5: Q2 2012 – Key Figures
Q2 2012 – Key Figures Solid but slightly weaker sales with growth in ER&S end-market • Consolidated sales decrease of 7.7% to USD 75.5 million compared with Q2 2011 • Sequential sales decrease over Q1 2012 of 6.4% • Book-to-bill ratio ~1 Operating result influenced by • Solid sales volume • Heal
Slide 6: Net Sales by End-Market
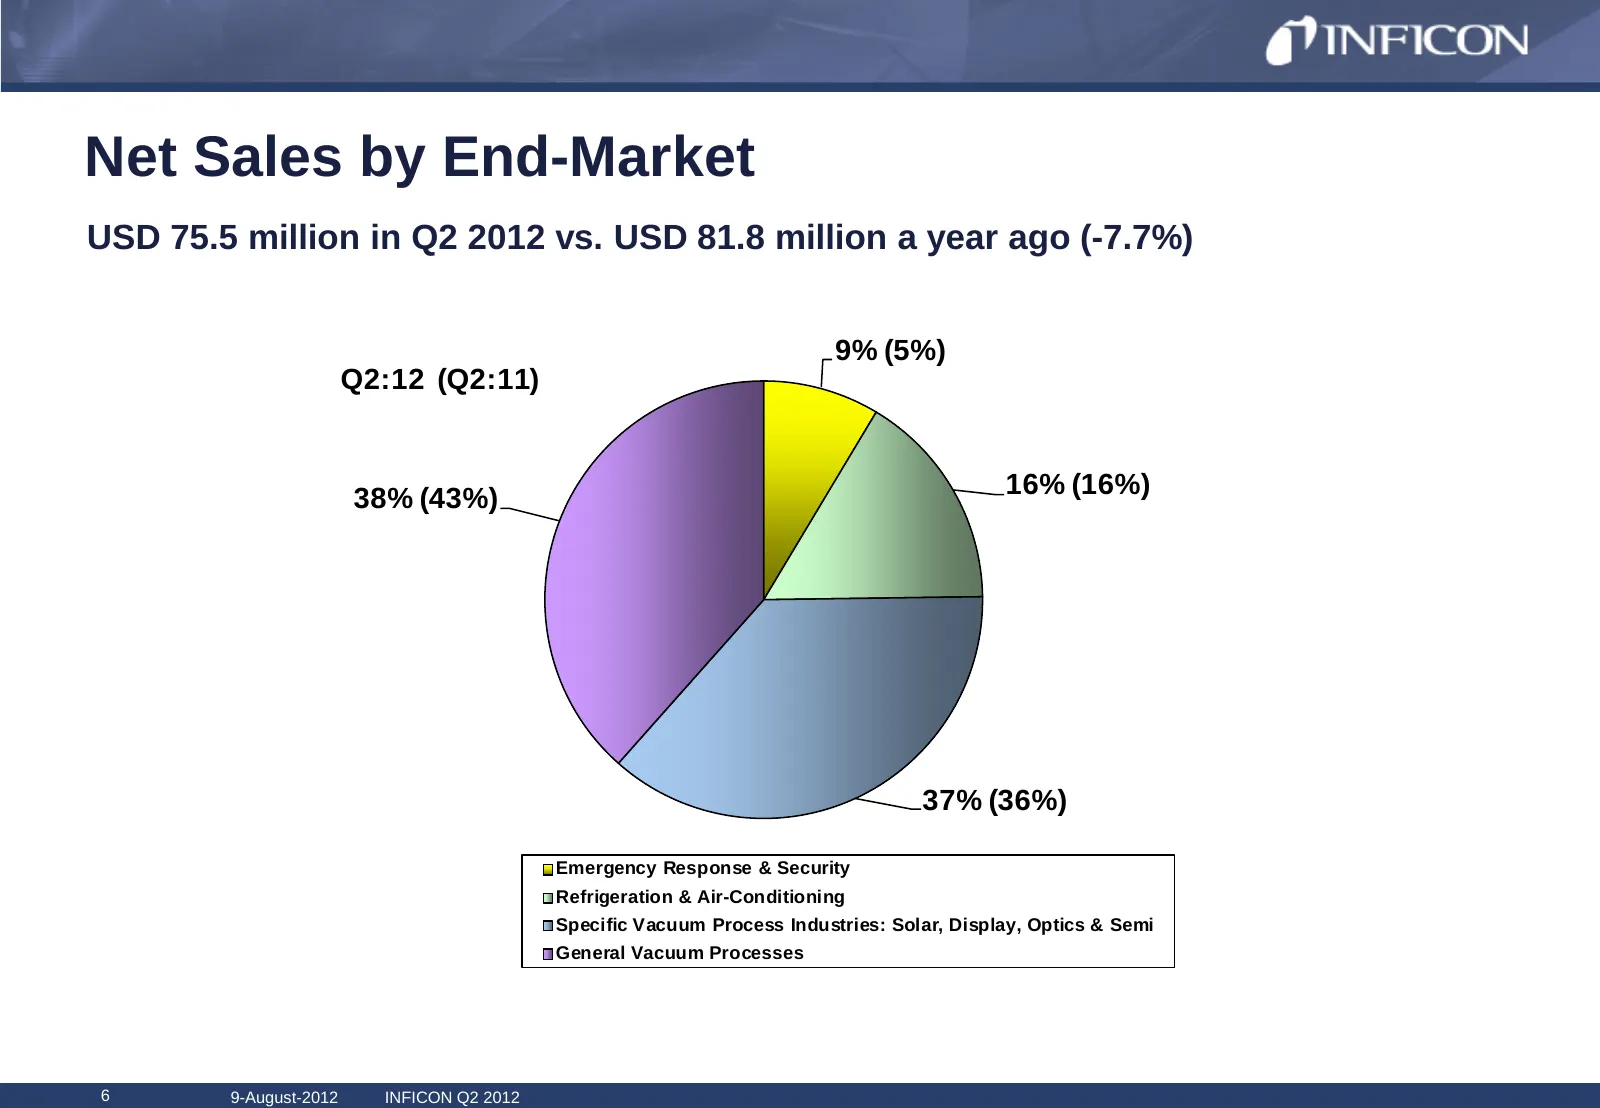
Net Sales by End-Market USD 75.5 million in Q2 2012 vs. USD 81.8 million a year ago (-7.7%) 9% (5%) Q2:12 (Q2:11) 38% (43%) 16% (16%) 37% (36%) Emergency Response & Security Refrigeration & Air-Conditioning Specific Vacuum Process Industries: Solar, Display, Optics & Semi 1 2008 Template - January 2
Slide 7: Emergency Response & Security
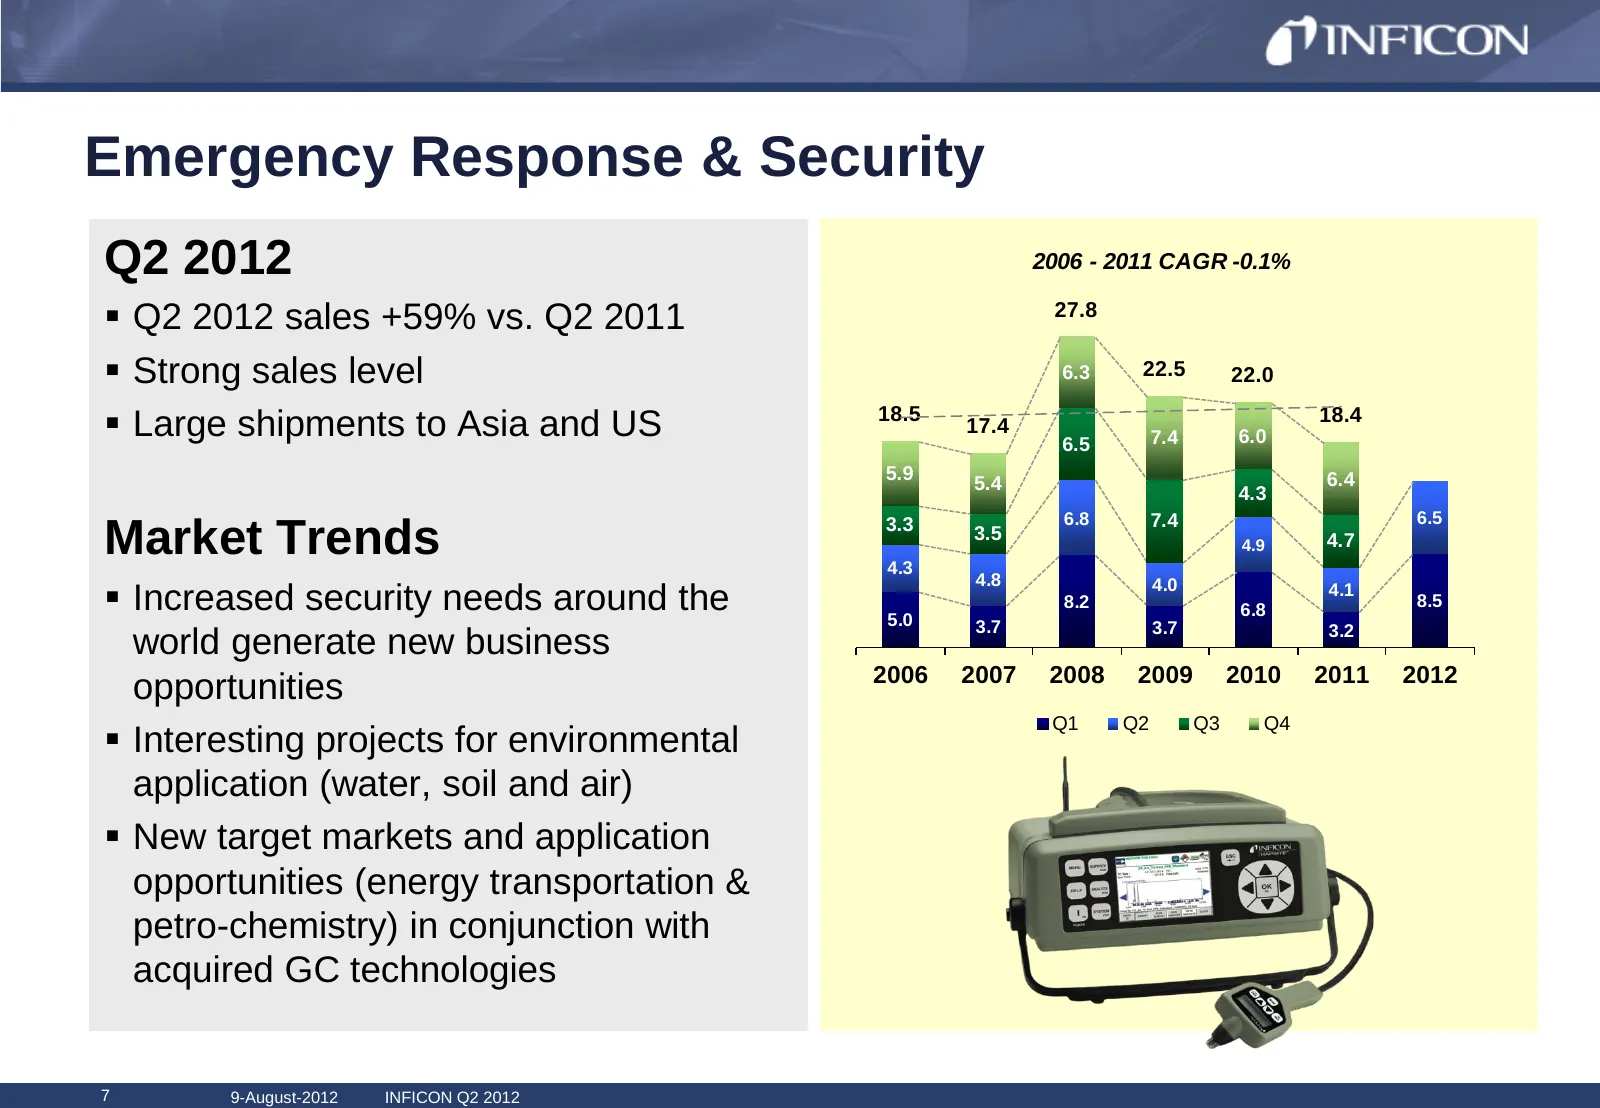
Emergency Response & Security Q2 2012 2006 - 2011 CAGR -0.1% Q2 2012 sales +59% vs. Q2 2011 27.8 Strong sales level 6.3 22.5 22.0 Large shipments to Asia and US 18.5 17.4 6.5 7.4 6.0 18.4 5.9 5.4 6.4 4.3 3.3 6.8 7.4 6.5 Market Trends 4.3 3.5 4.9 4.7 4.8 Increased security needs around the 4.
Slide 8: Refrigeration & Air Conditioning
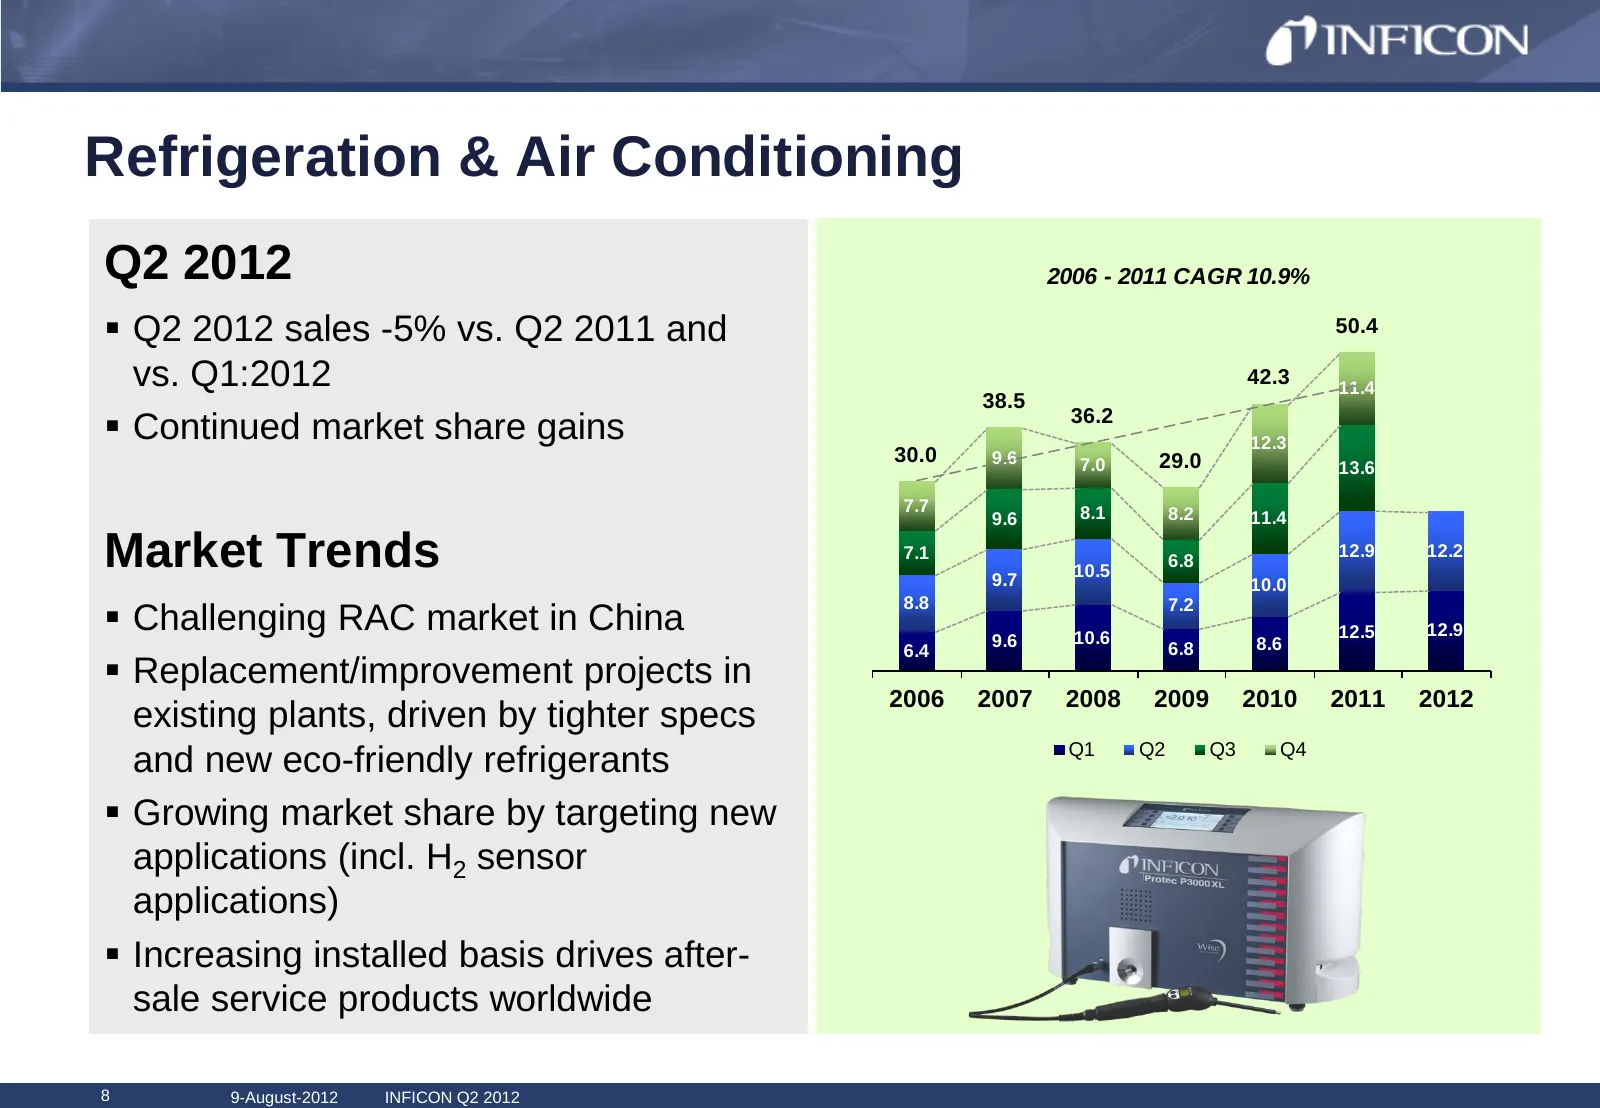
Refrigeration & Air Conditioning Q2 2012 2006 - 2011 CAGR 10.9% Q2 2012 sales -5% vs. Q2 2011 and 50.4 vs. Q1:2012 42.3 11.4 38.5 Continued market share gains 36.2 12.3 30.0 9.6 7.0 29.0 13.6 7.7 8.1 8.2 9.6 11.4 Market Trends 7.1 9.7 10.5 6.8 10.0 12.9 12.2 8.8 Challenging RAC market in China
Slide 9: Specific Vacuum Process Industries
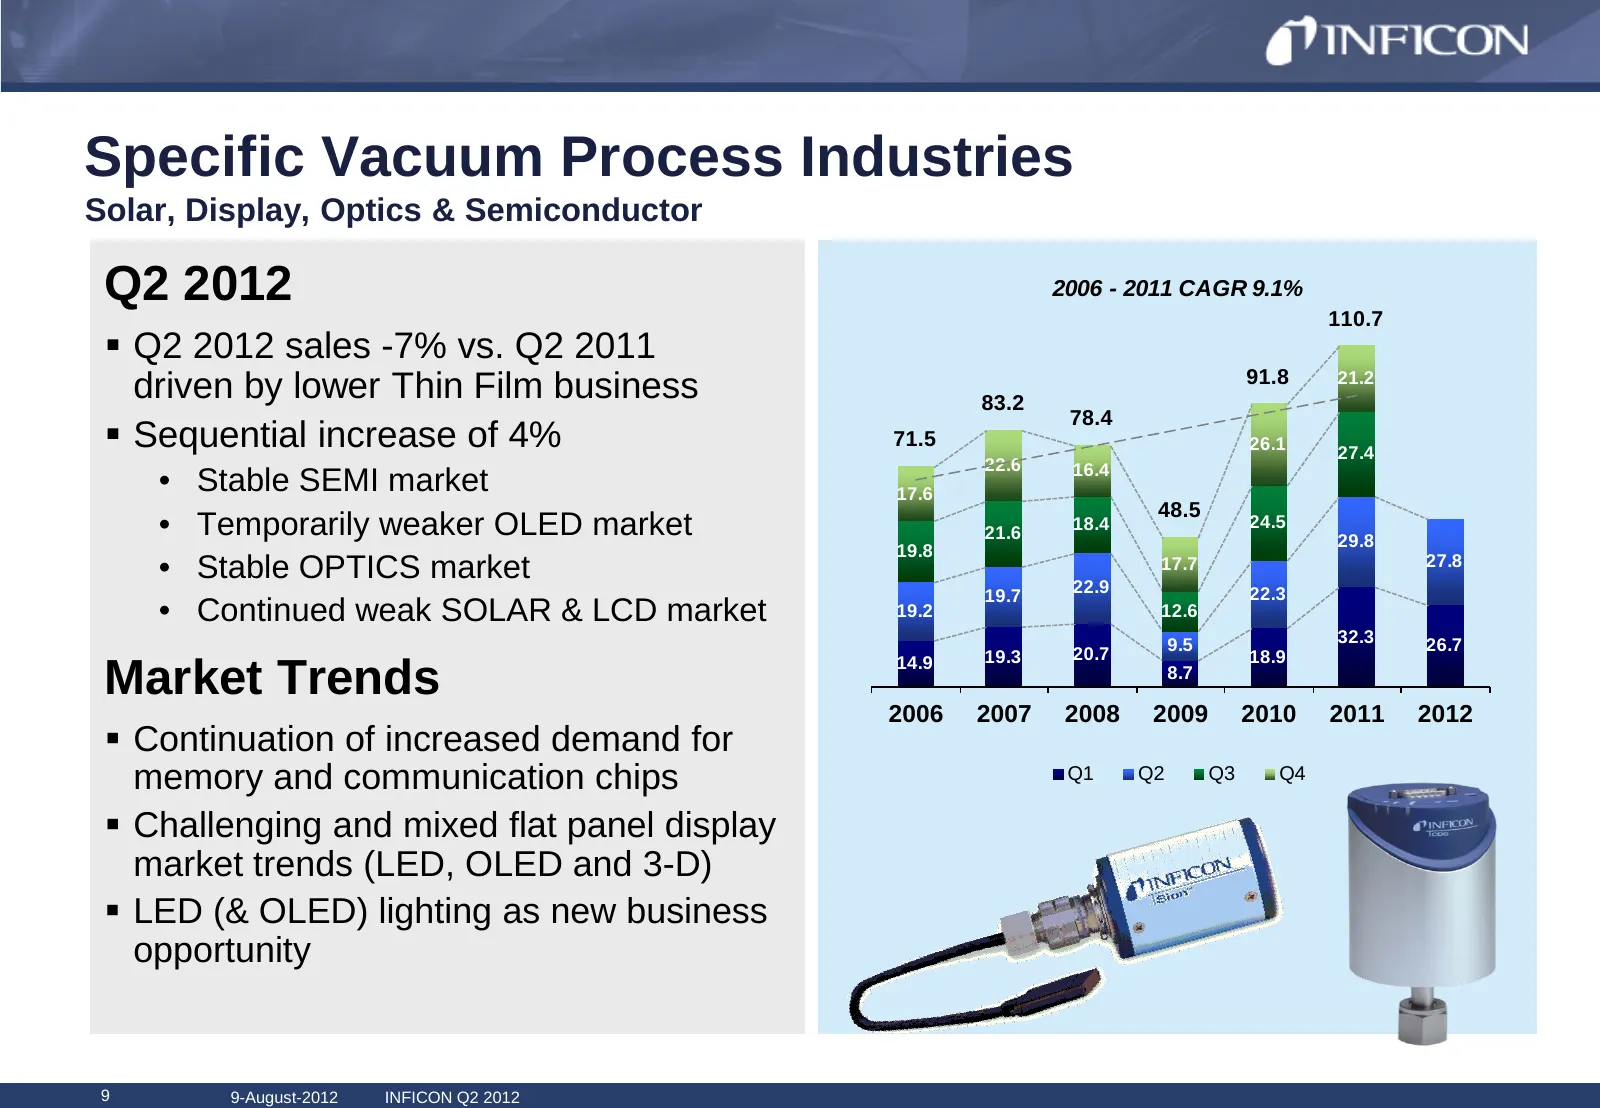
Specific Vacuum Process Industries Solar, Display, Optics & Semiconductor Q2 2012 2006 - 2011 CAGR 9.1% 110.7 Q2 2012 sales -7% vs. Q2 2011 91.8 21.2 driven by lower Thin Film business 83.2 78.4 Sequential increase of 4% 71.5 26.1 27.4 22.6 16.4 • Stable SEMI market 17.6 48.5 • Temporarily weake
Slide 10: General Vacuum Processes
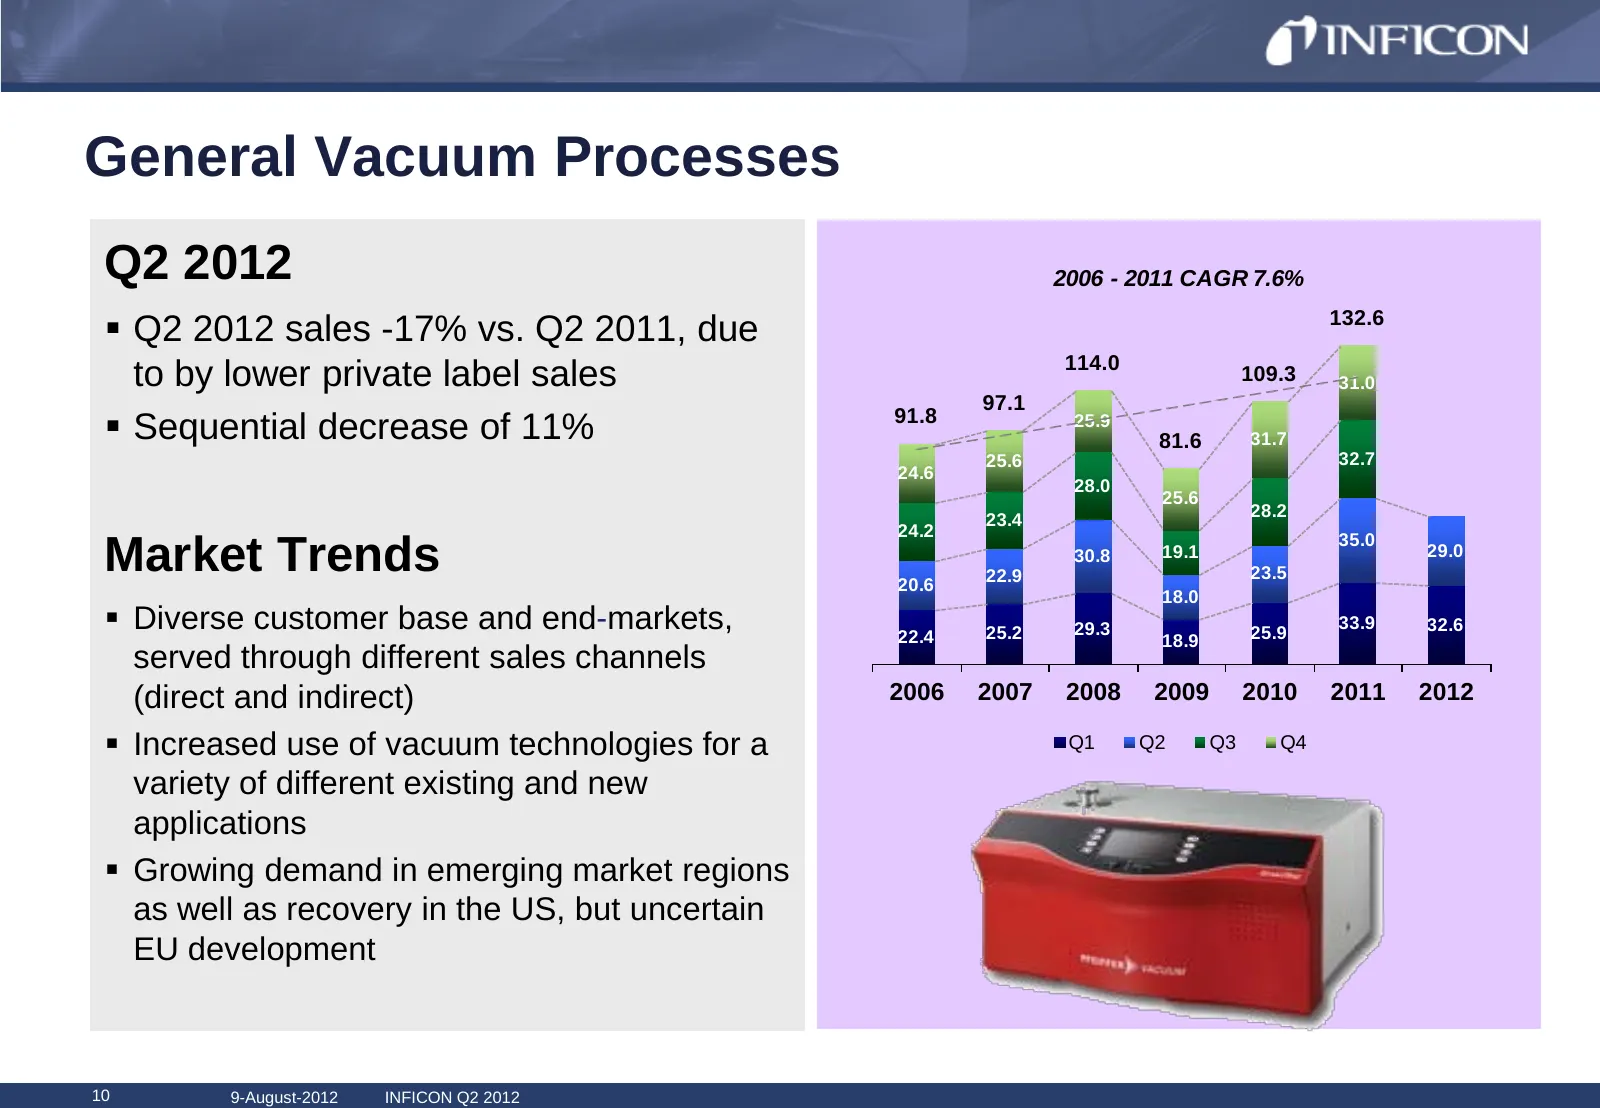
General Vacuum Processes Q2 2012 2006 - 2011 CAGR 7.6% Q2 2012 sales -17% vs. Q2 2011, due 132.6 114.0 to by lower private label sales 109.3 31.0 97.1 Sequential decrease of 11% 91.8 25.9 81.6 31.7 25.6 32.7 24.6 28.0 25.6 23.4 28.2 24.2 35.0 Market Trends 20.6 22.9 30.8 19.1 23.5 29.0 18.0 Di
Slide 11: Outlook 2012 and Beyond
Outlook 2012 and Beyond Mixed and sometimes challenging signals from different markets/regions Weaker demand in the Semiconductor market in Q3, but positive signals for Q4 • Investments in new equipment (OEM-business) low • Continued success with sensors and software (at end-users) to increase yie
Slide 12: Matthias Tröndle
Matthias Tröndle Vice President & Chief Financial Officer 9-August-2012 INFICON Q2 2012
Slide 13: Sales (in USD million)
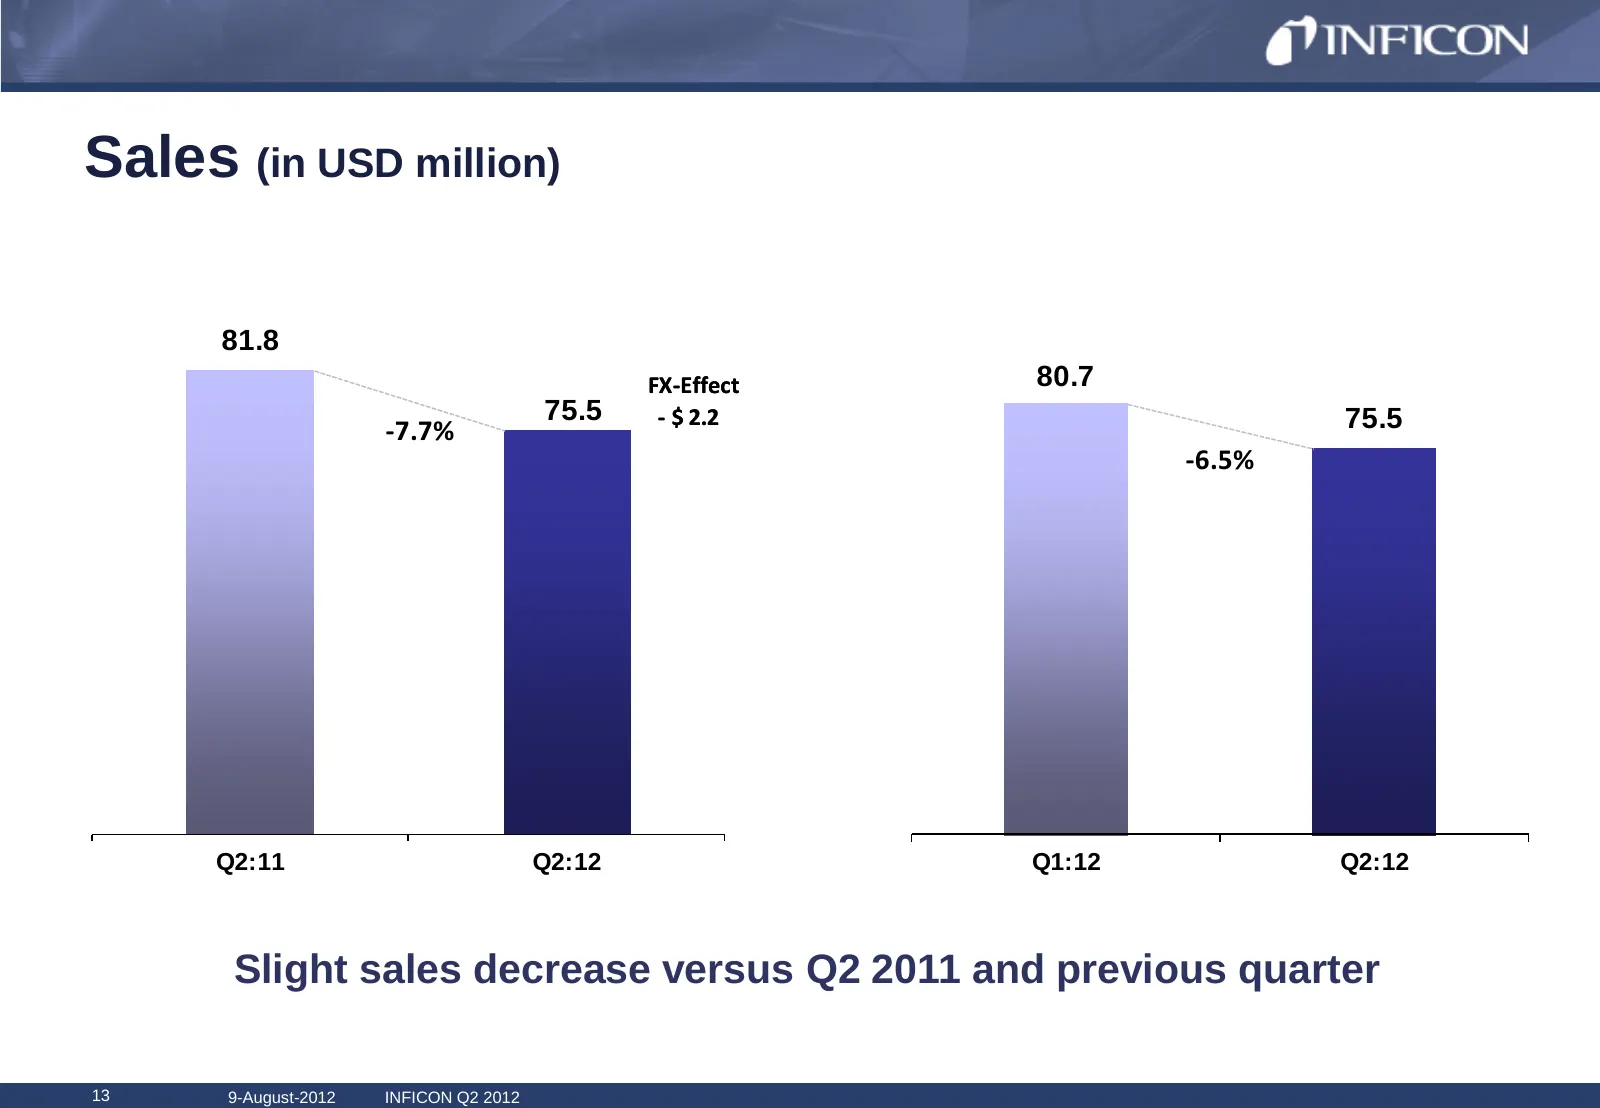
Sales (in USD million) 81.8 FX-Effect 80.7 75.5 - $ 2.2 75.5 -7.7% -6.5% Q2:11 Q2:12 Q1:12 Q2:12 1 Slight sales decrease versus Q2 2011 and previous quarter 2008 Template - January 2008 13 9-August-2012 INFICON Q2 2012
Slide 14: Geographic Revenue Breakdown – Second Quarter
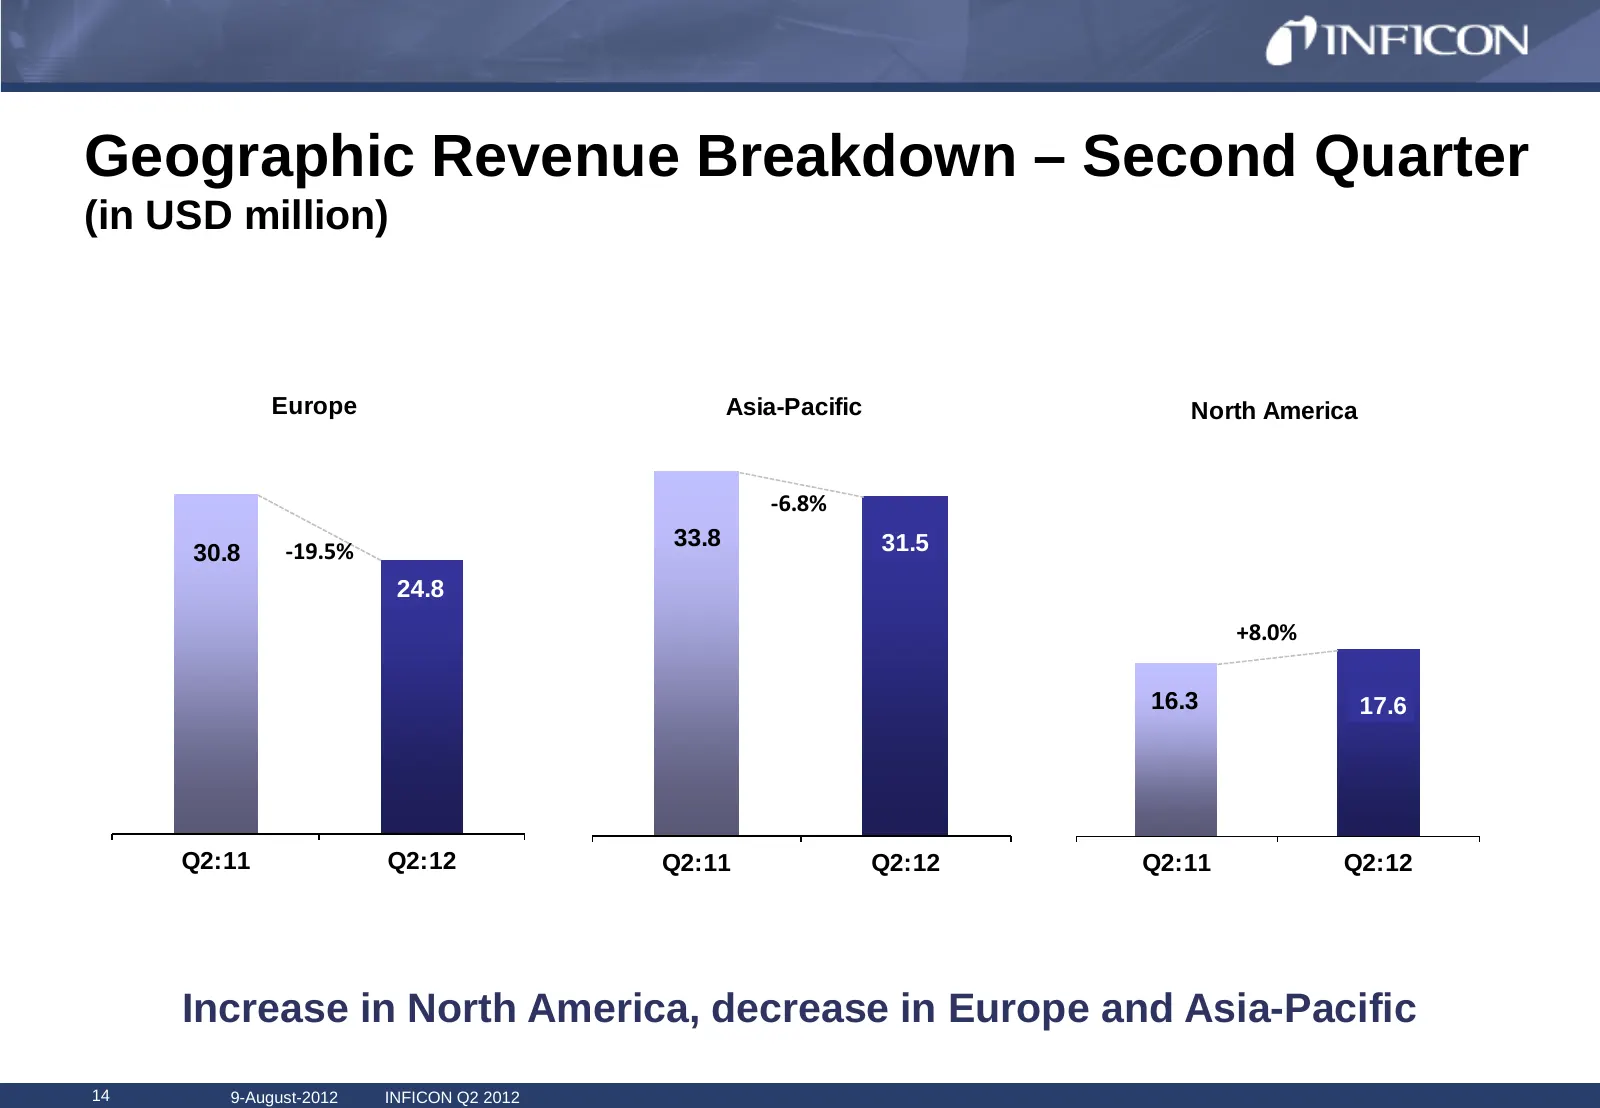
Geographic Revenue Breakdown – Second Quarter (in USD million) Europe Asia-Pacific North America -6.8% 33.8 31.5 30.8 -19.5% 24.8 +8.0% 16.3 17.6 Q2:11 Q2:12 Q2:11 Q2:12 Q2:11 Q2:12 1 2008 Template - January 2008 Increase in North America, decrease in Europe and Asia-Pacific 14 9-August-2012 INFICON
Slide 15: Sales (in USD million)
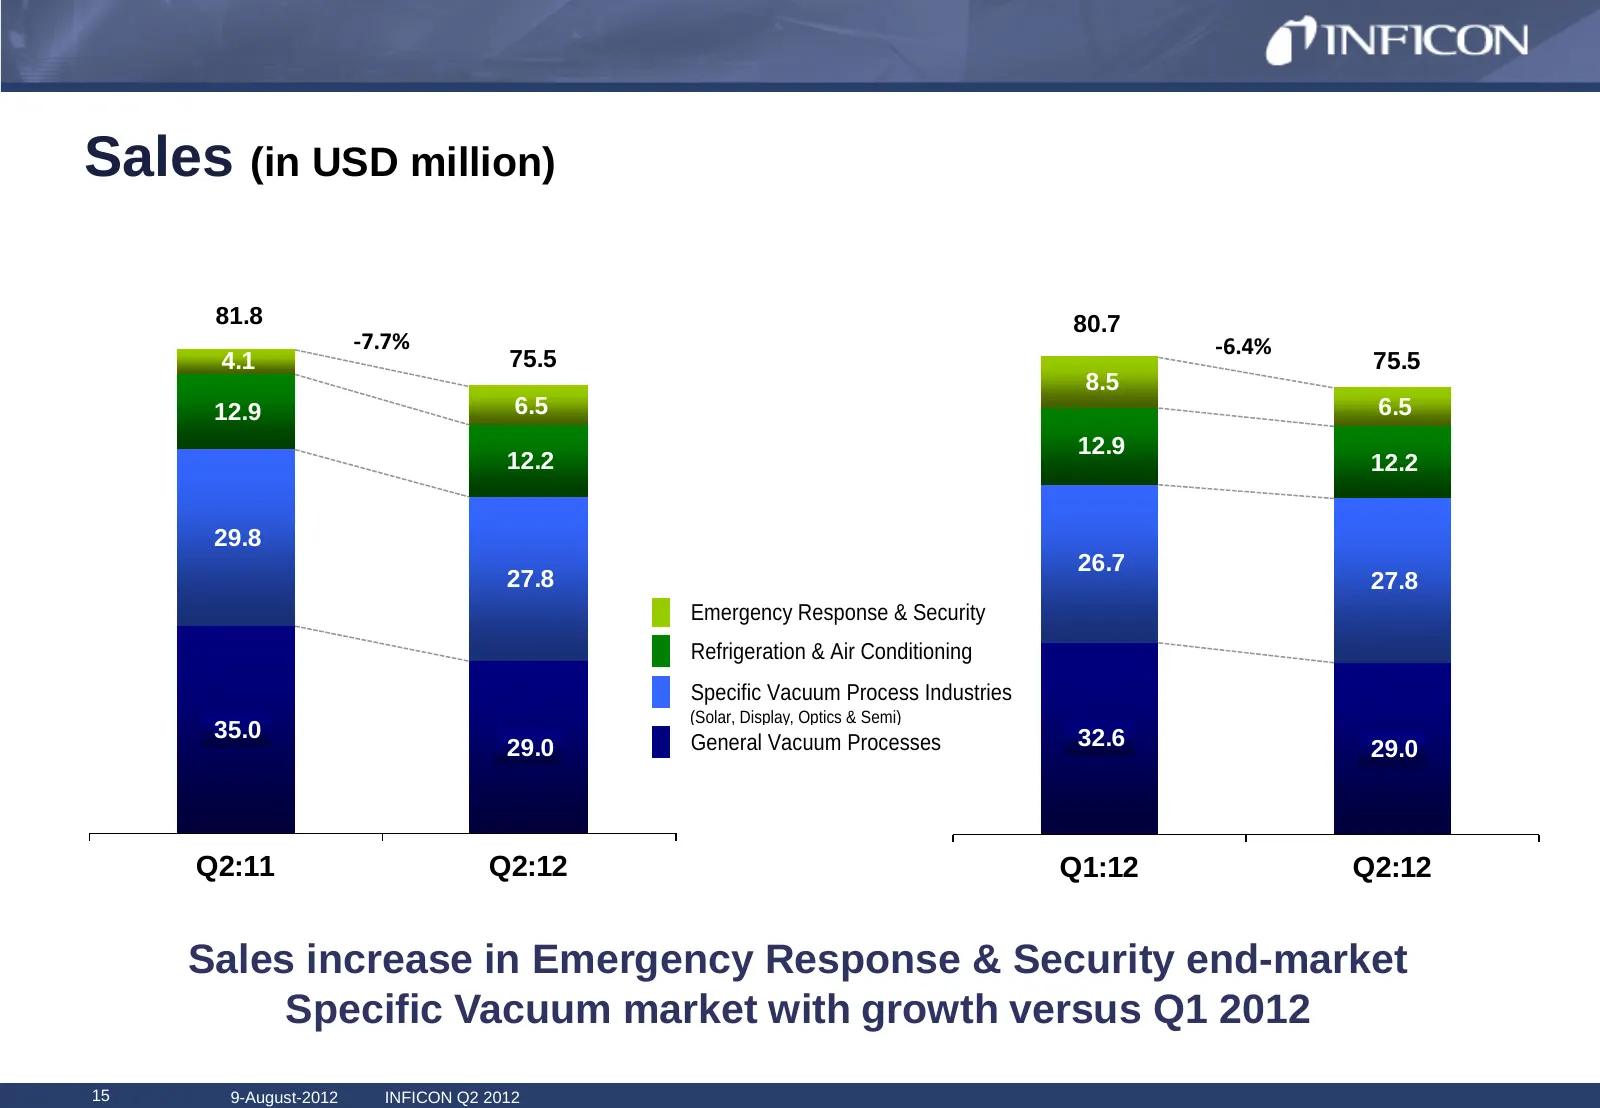
Sales (in USD million) 81.8 80.7 -7.7% -6.4% 4.1 75.5 75.5 8.5 12.9 6.5 6.5 12.9 12.2 12.2 29.8 26.7 27.8 27.8 Emergency Response & Security Refrigeration & Air Conditioning Specific Vacuum Process Industries (Solar, Display, Optics & Semi) 35.0 General Vacuum Processes 32.6 29.0 29.0 Q2:11 Q2:12 Q1
Slide 16: Gross Profit Margin (in %)
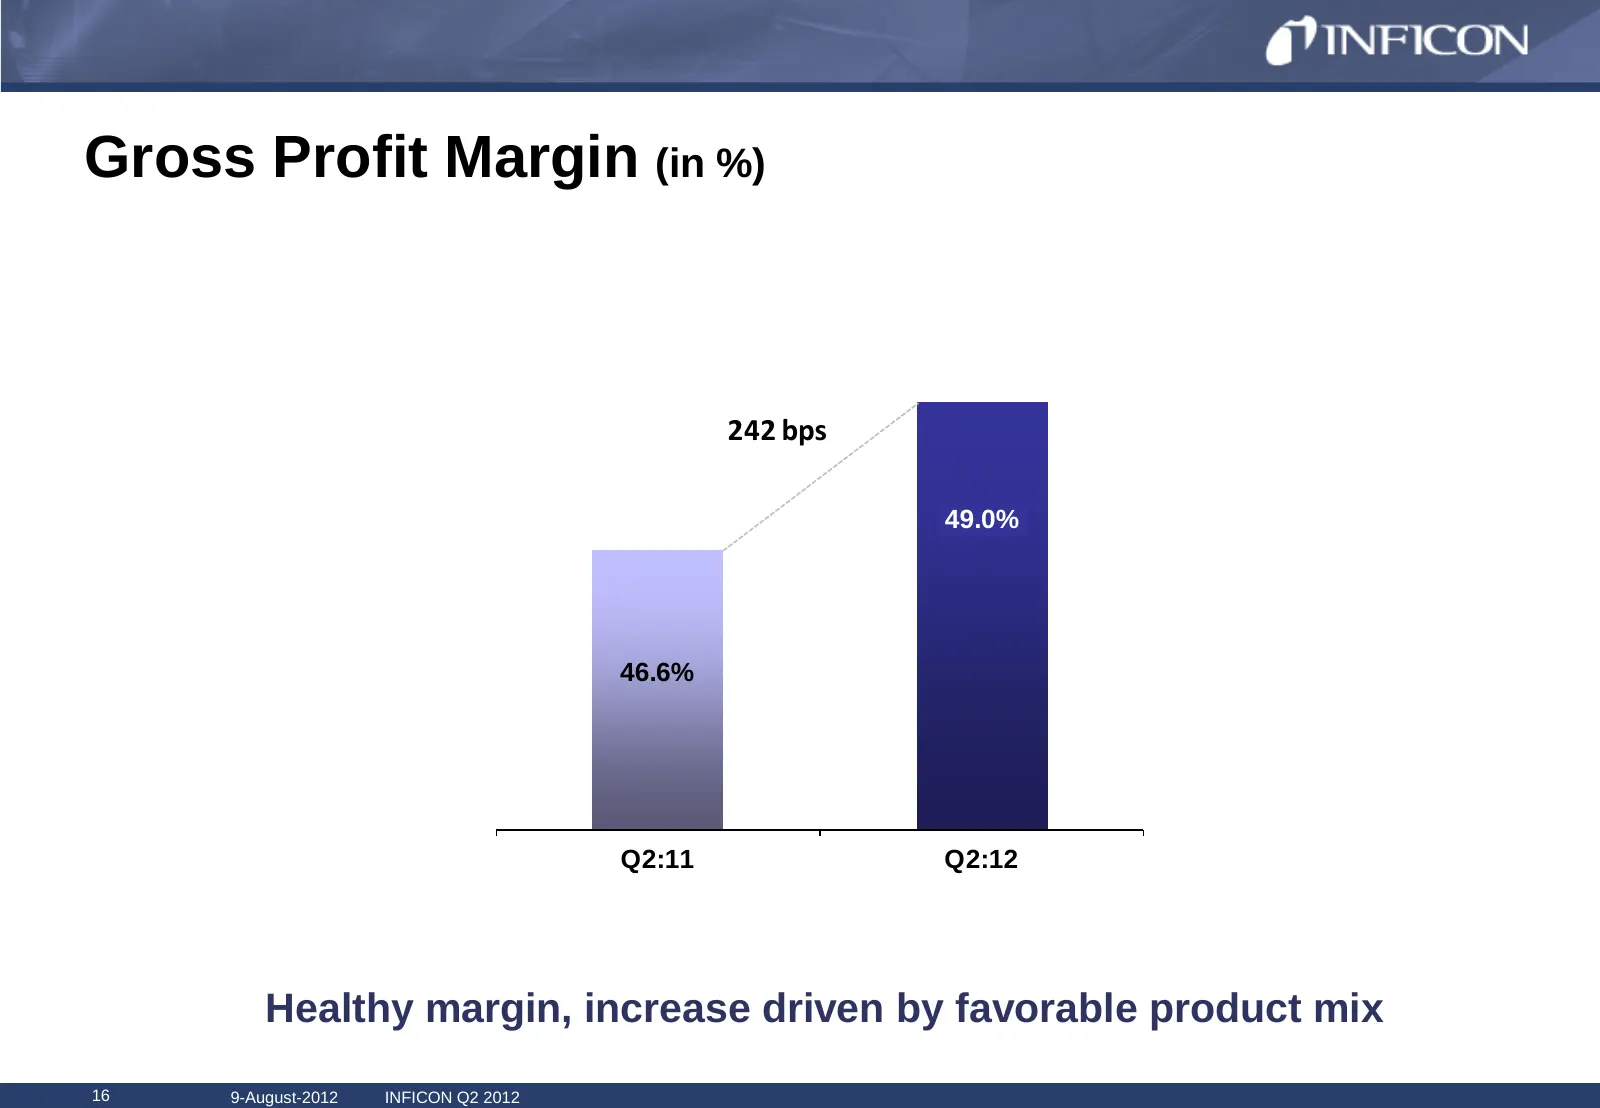
Gross Profit Margin (in %) 242 bps 49.0% 46.6% Q2:11 Q2:12 1 2008 Template - January 2008 Healthy margin, increase driven by favorable product mix 16 9-August-2012 INFICON Q2 2012
Slide 17: Research & Development; Selling, General & Administrative
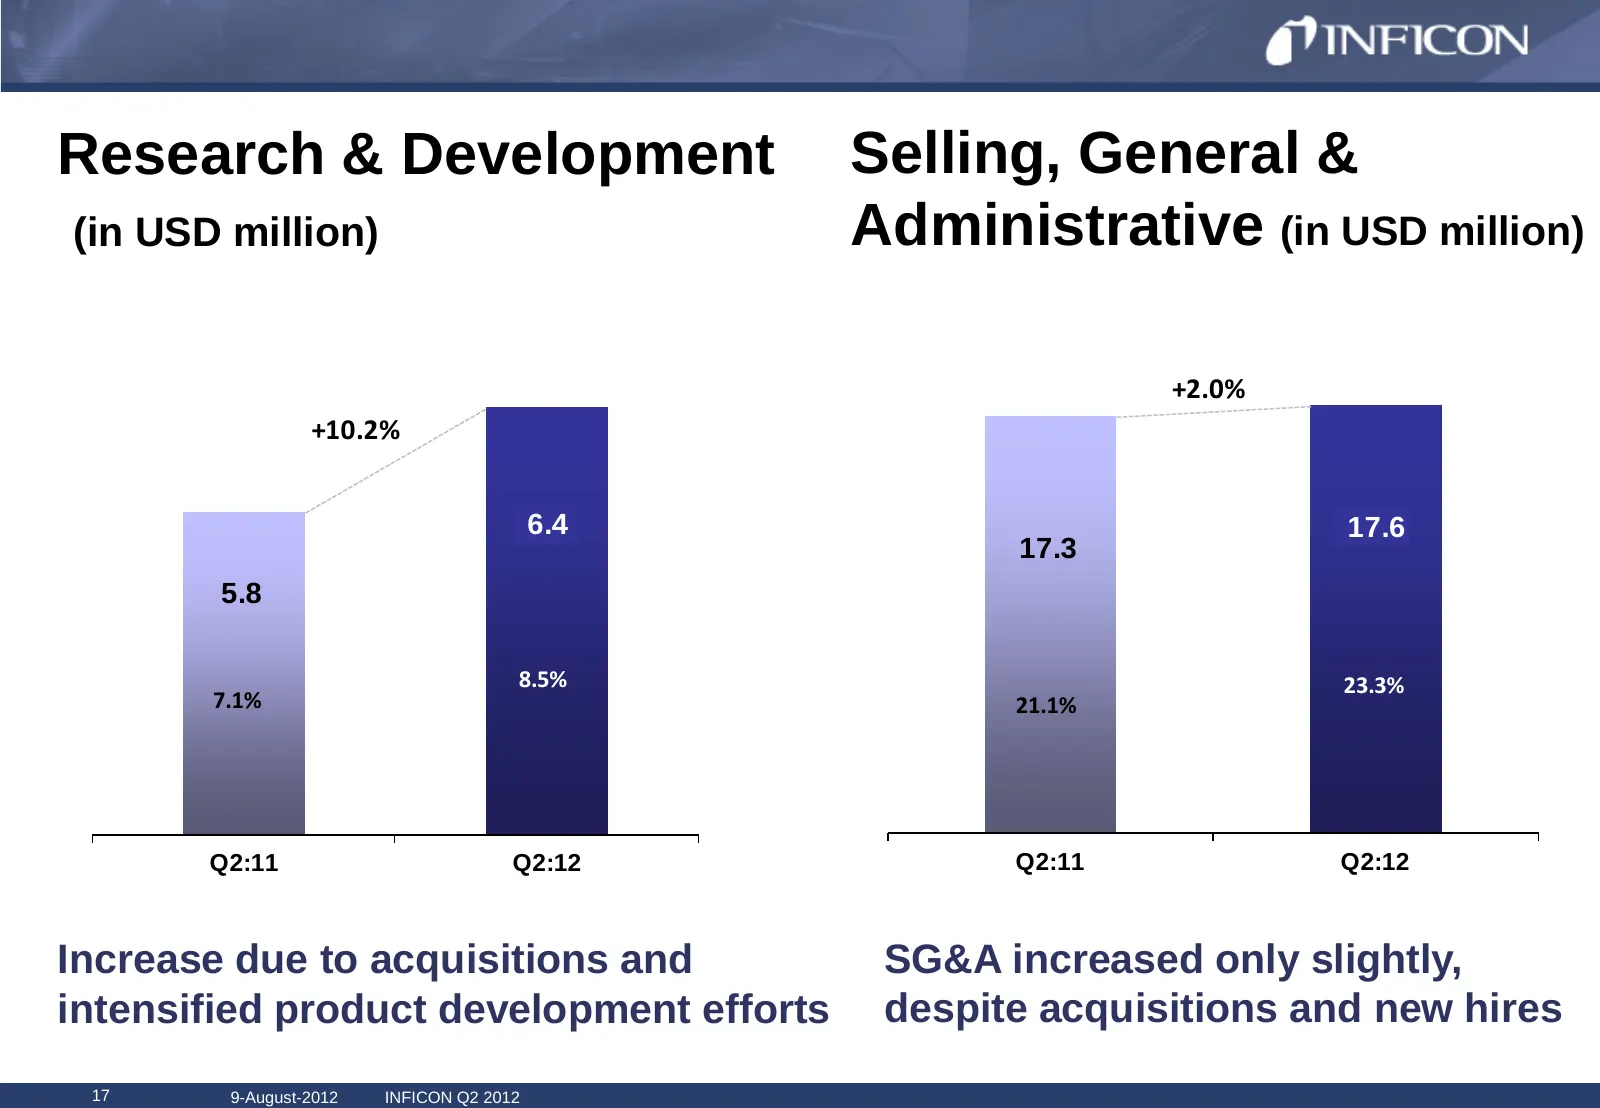
Research & Development Selling, General & (in USD million) Administrative (in USD million) +2.0% +10.2% 6.4 17.6 17.3 5.8 8.5% 23.3% 7.1% 21.1% Q2:11 Q2:12 Q2:11 Q2:12 Increase 1 due to- January 2008 Template acquisitions 2008 and SG&A increased only slightly, intensified product development efforts
Slide 18: Income from Operations (in USD million)
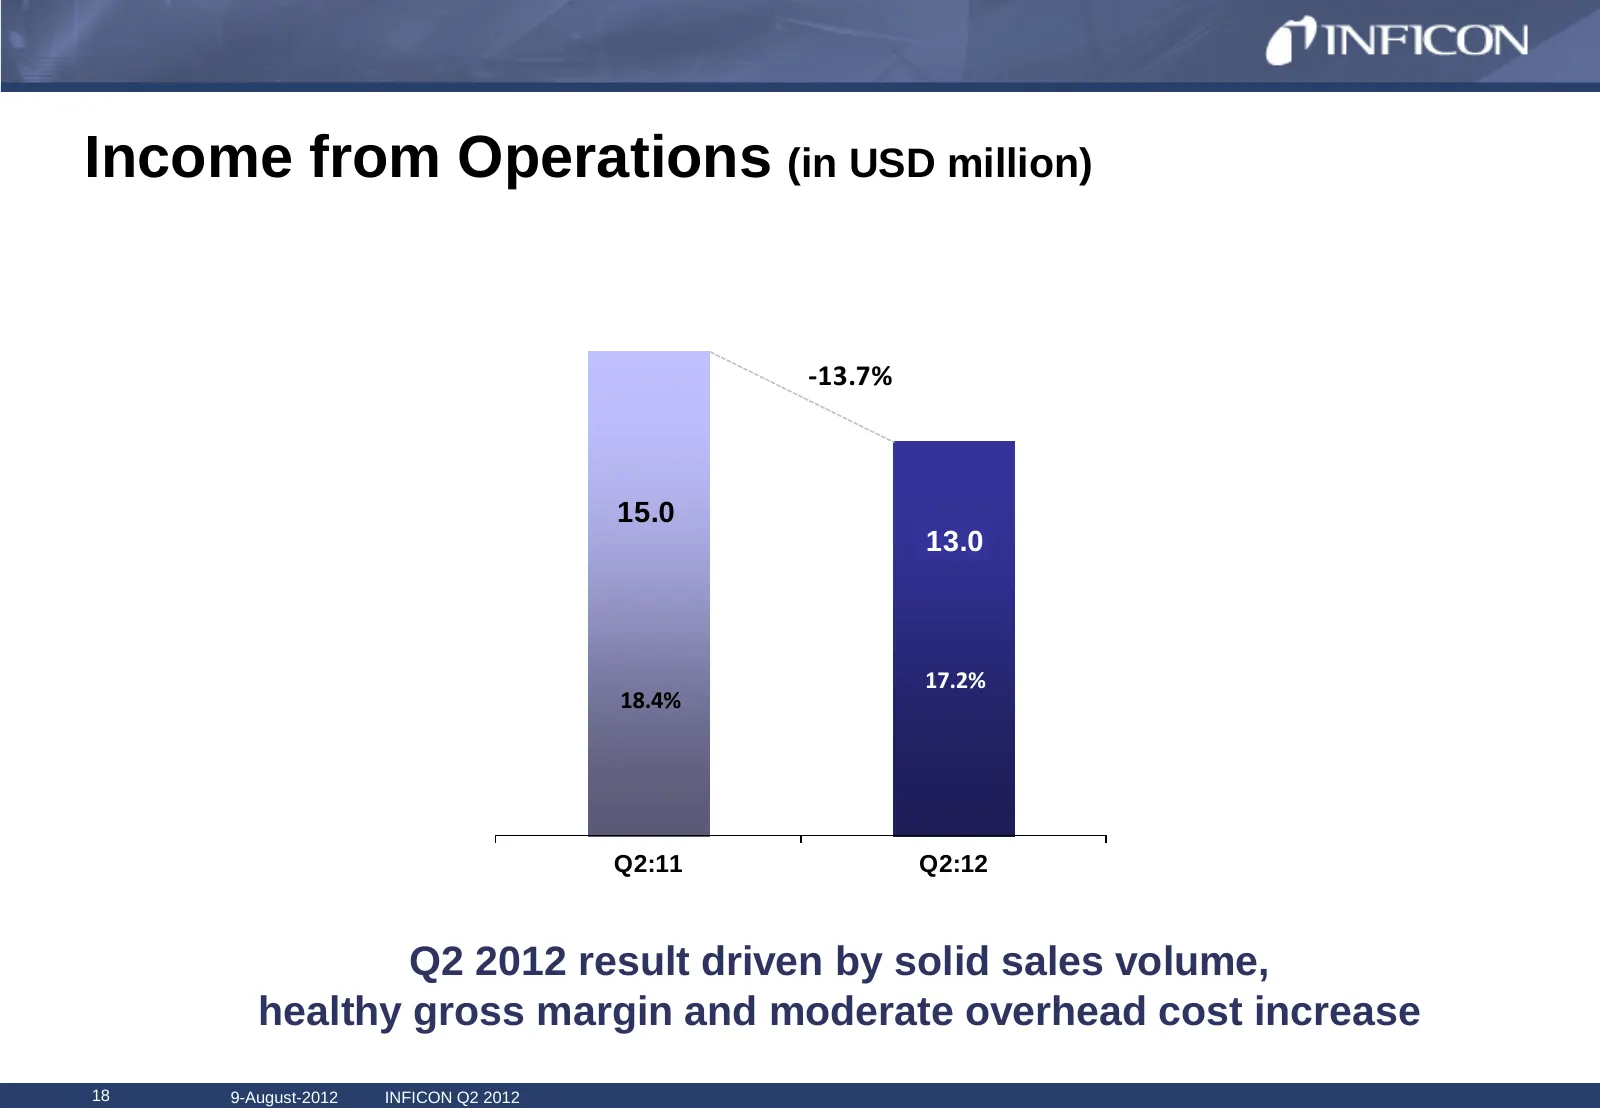
Income from Operations (in USD million) -13.7% 15.0 13.0 17.2% 18.4% Q2:11 Q2:12 1 Q2 2012 result driven by solid sales volume, 2008 Template - January 2008 healthy gross margin and moderate overhead cost increase 18 9-August-2012 INFICON Q2 2012
Slide 19: Net Income and EPS
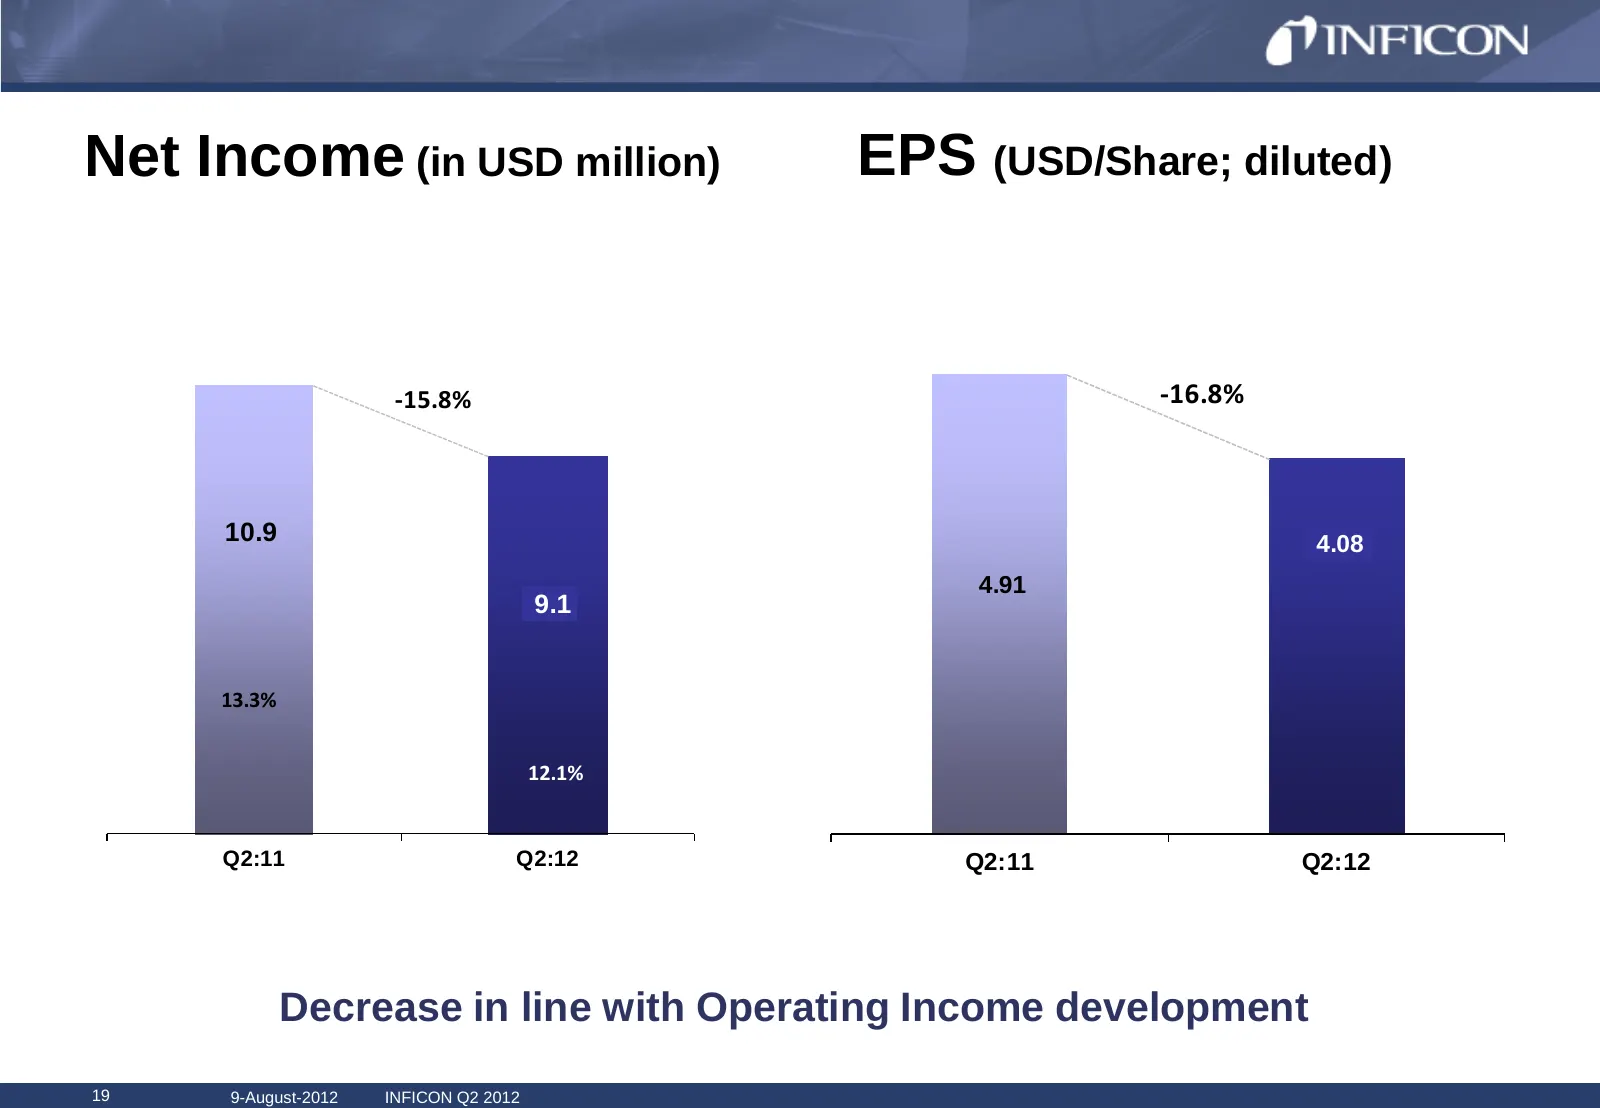
Net Income (in USD million) EPS (USD/Share; diluted) -15.8% -16.8% 10.9 4.08 4.91 9.1 13.3% 12.1% Q2:11 Q2:12 Q2:11 Q2:12 1 2008 Template - January 2008 Decrease in line with Operating Income development 19 9-August-2012 INFICON Q2 2012
Slide 20: Balance Sheet Highlights (in USD million)
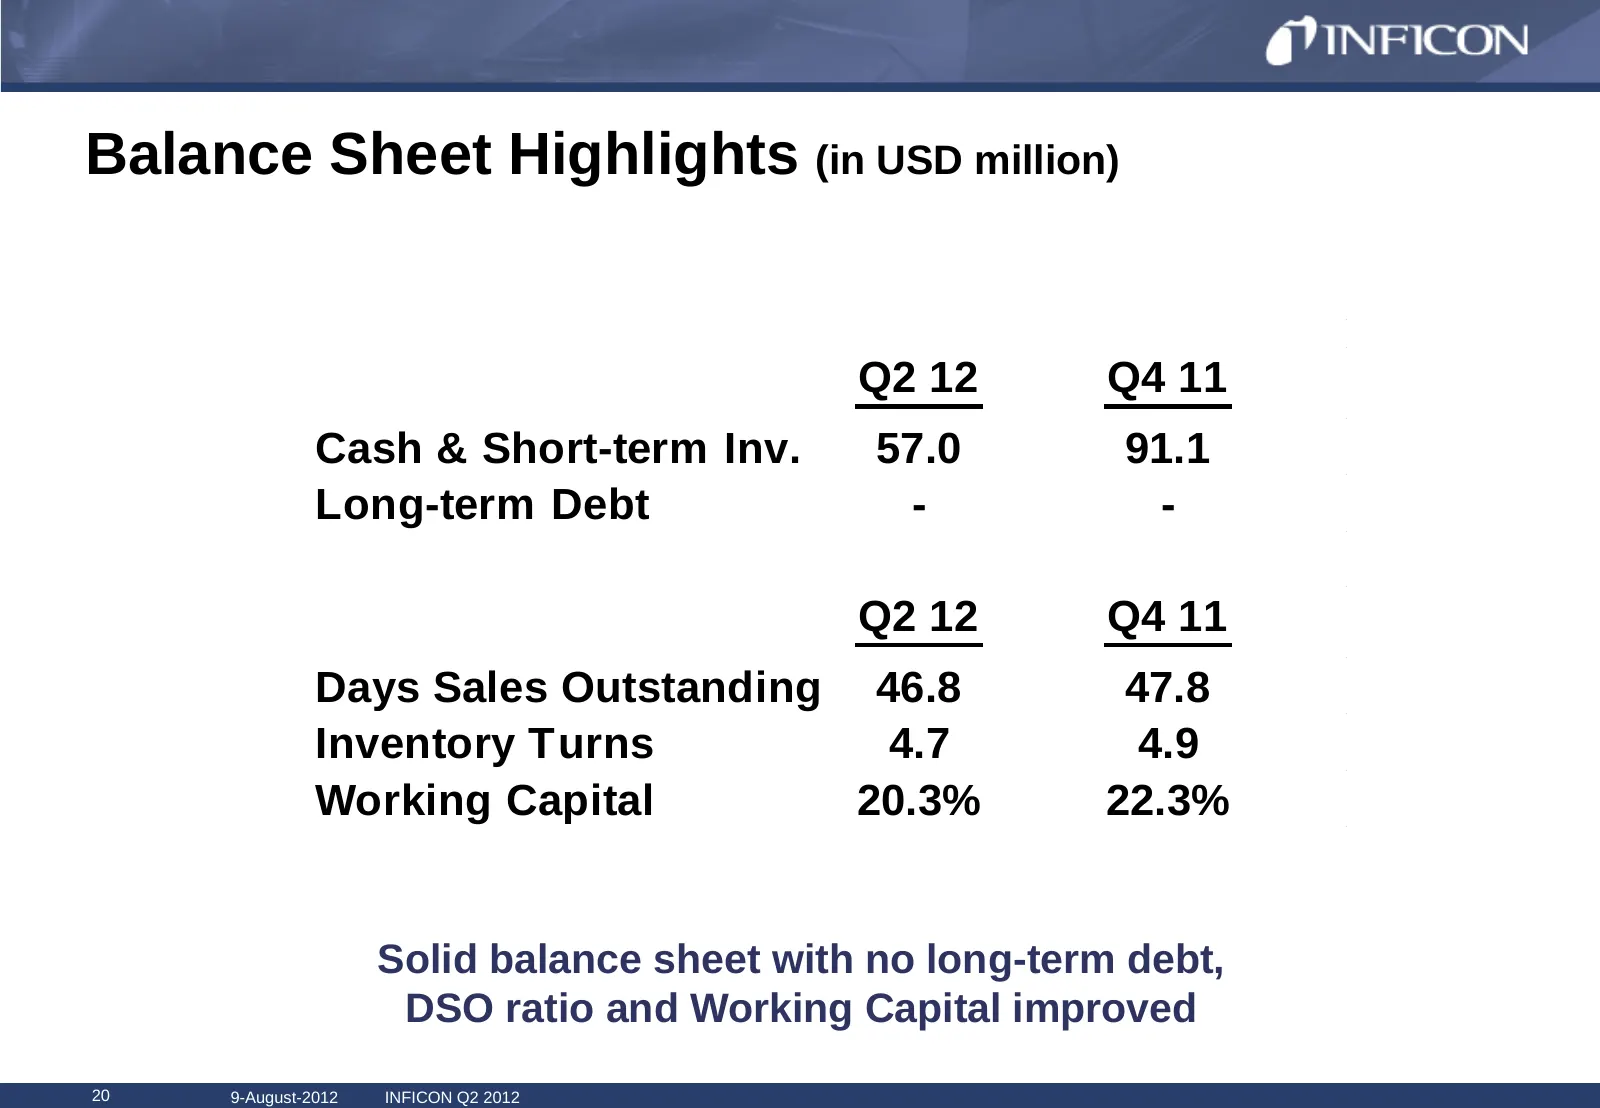
Balance Sheet Highlights (in USD million) Q2 12 Q4 11 Cash & Short-term Inv. 57.0 91.1 Long-term Debt - - Q2 12 Q4 11 Days Sales Outstanding 46.8 47.8 Inventory Turns 4.7 4.9 Working Capital 20.3% 22.3% 1 Solid balance sheet with no long-term debt, 2008 Template - January 2008 DSO ratio and Working
Slide 21: Operating Cash Flow (in USD million)
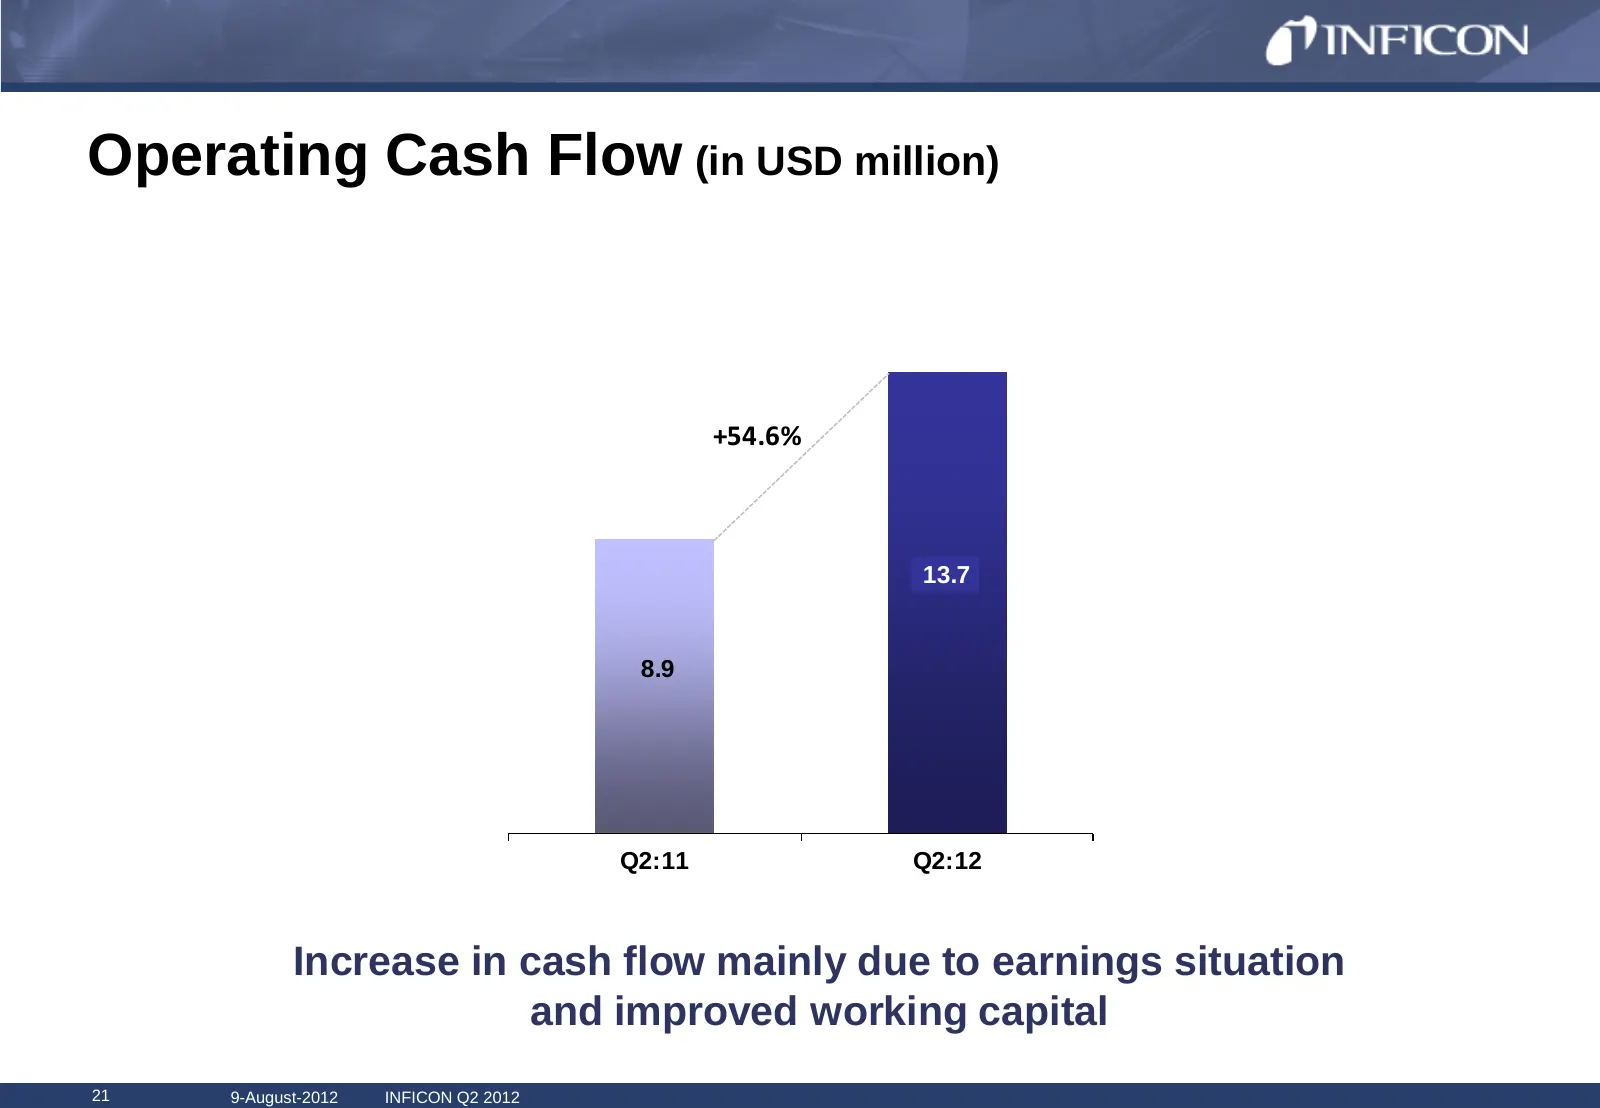
Operating Cash Flow (in USD million) +54.6% 13.7 8.9 Q2:11 Q2:12 1 Increase in cash flow mainly due to earnings situation 2008 Template - January 2008 and improved working capital 21 9-August-2012 INFICON Q2 2012
Slide 22: Equity Ratio (in %)
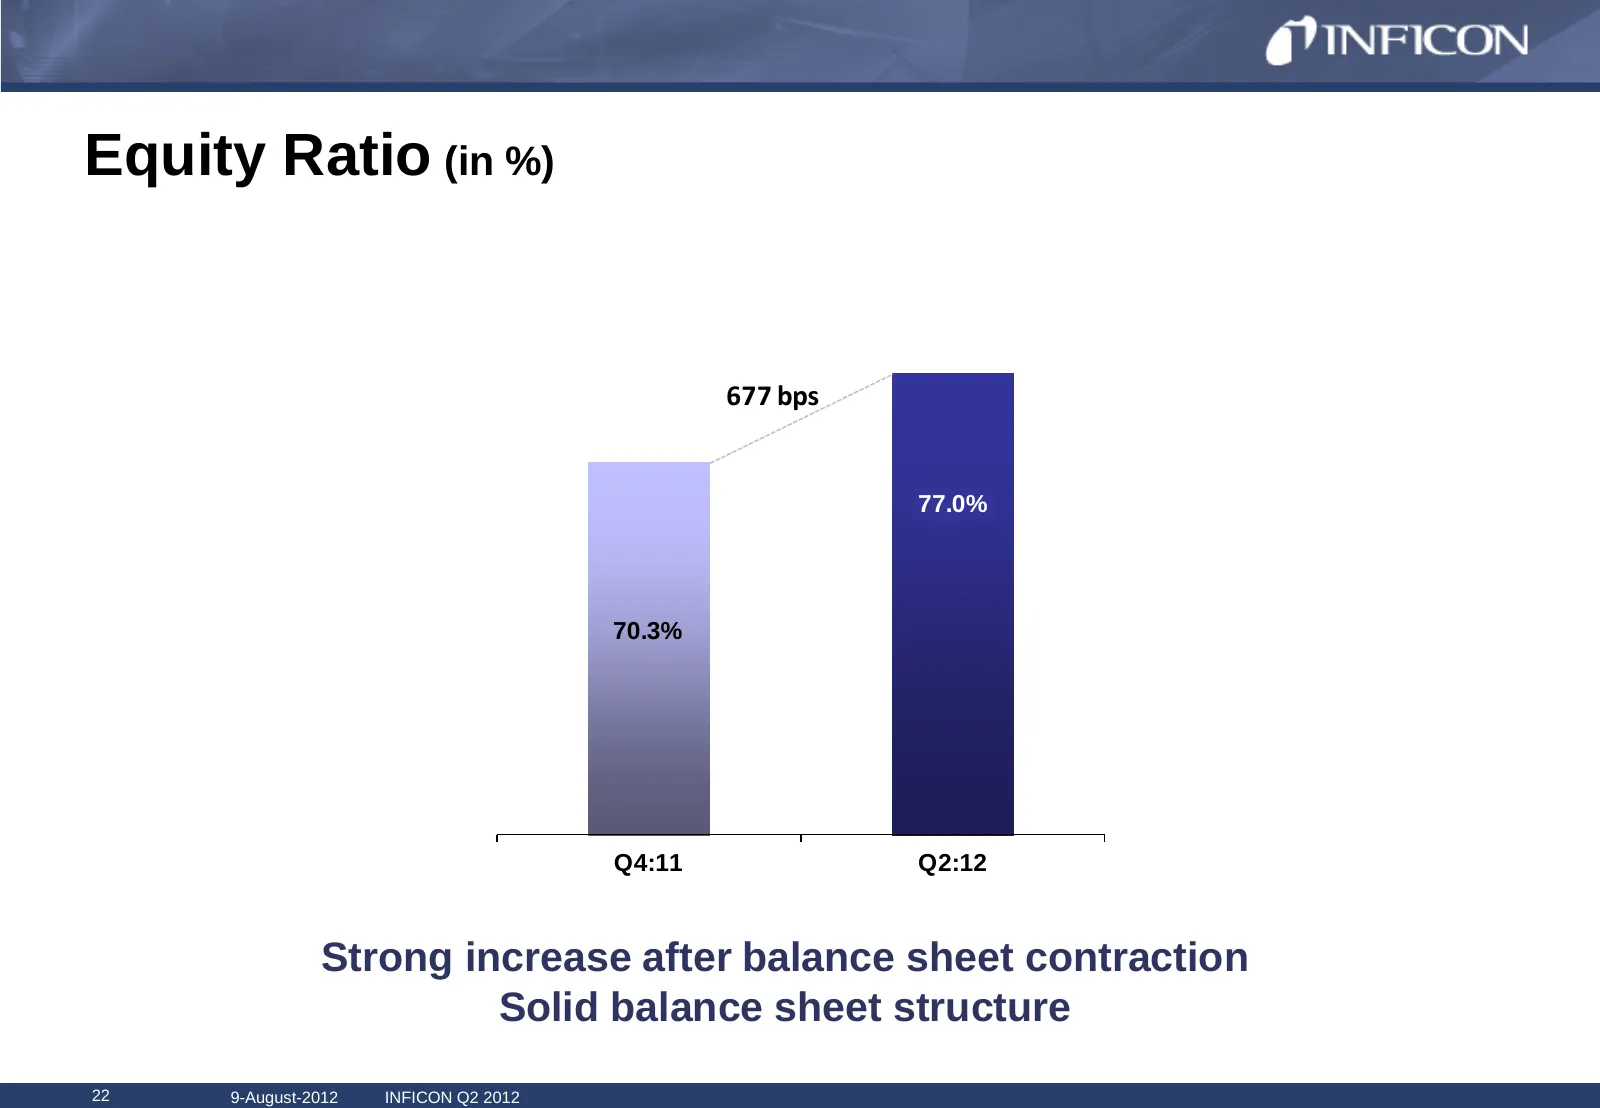
Equity Ratio (in %) 677 bps 77.0% 70.3% Q4:11 Q2:12 1 Strong increase after balance sheet contraction 2008 Template - January 2008 Solid balance sheet structure 22 9-August-2012 INFICON Q2 2012
Slide 23: Working Capital and Working Capital Ratio
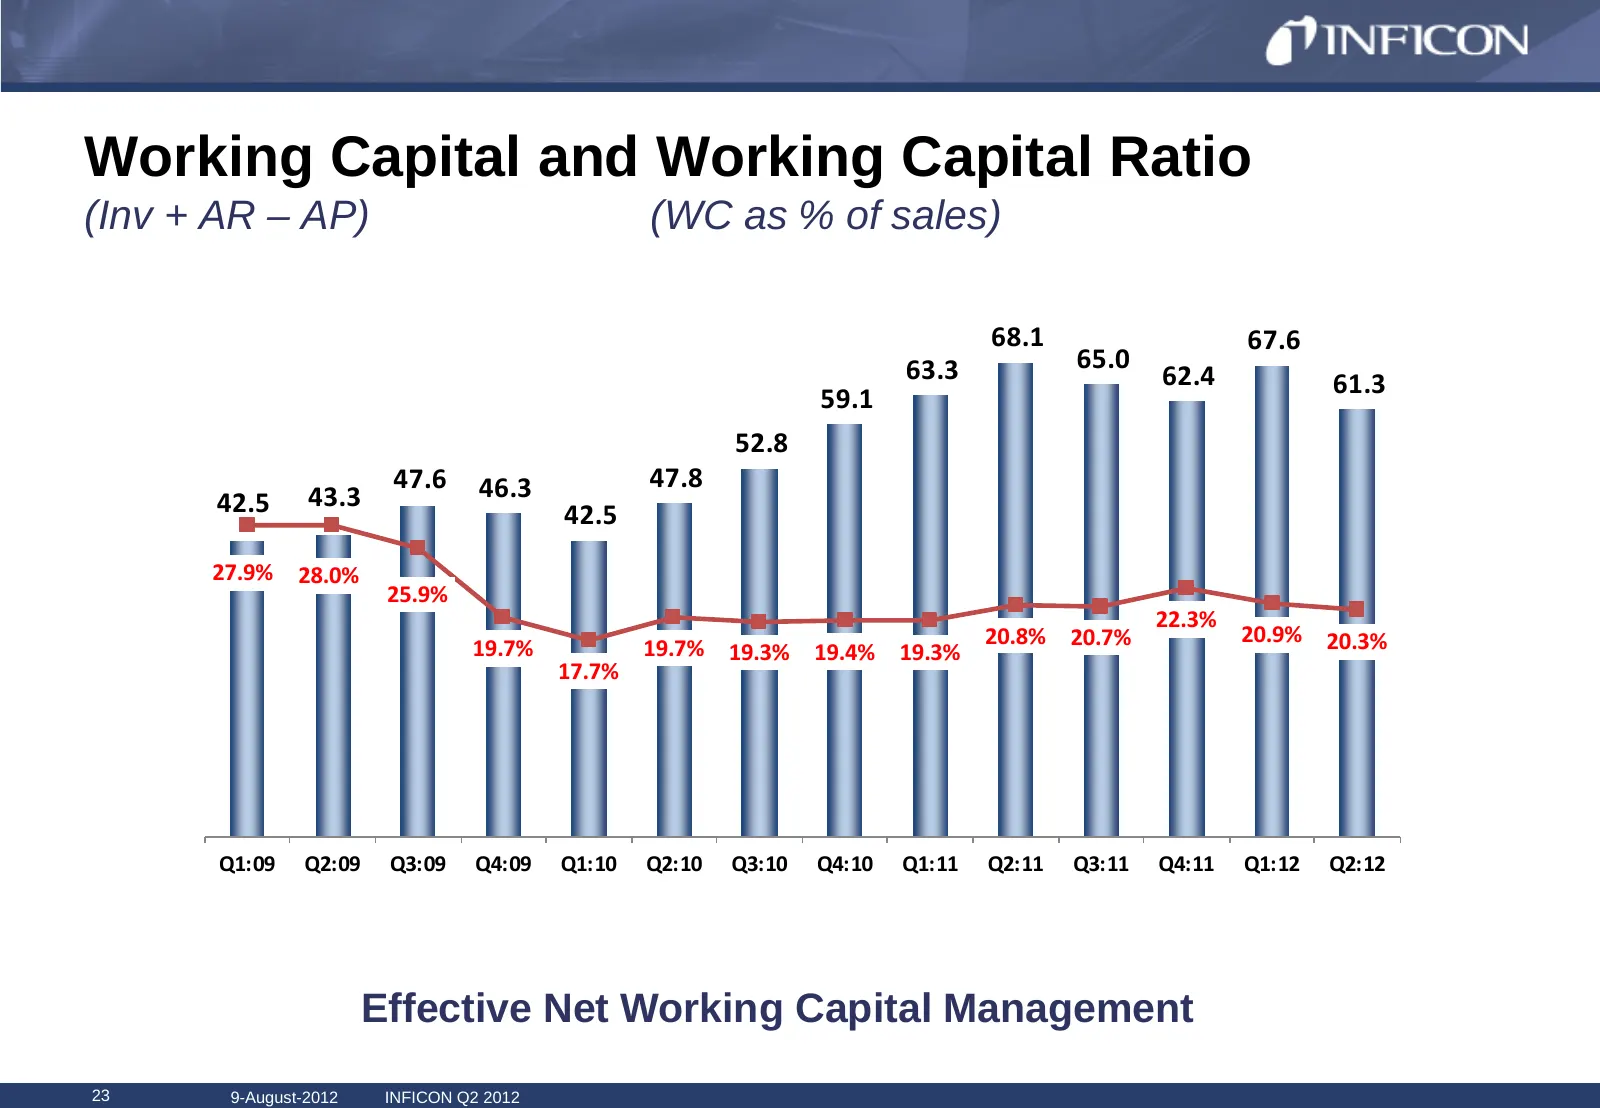
Working Capital and Working Capital Ratio (Inv + AR – AP) (WC as % of sales) 68.1 67.6 63.3 65.0 62.4 61.3 59.1 52.8 47.6 46.3 47.8 42.5 43.3 42.5 27.9% 28.0% 25.9% 22.3% 20.9% 20.3% 19.7% 19.7% 19.3% 19.4% 19.3% 20.8% 20.7% 17.7% Q1:09 Q2:09 Q3:09 Q4:09 Q1:10 Q2:10 Q3:10 Q4:10 Q1:11 Q2:11 Q3:11 Q4:
Slide 24: Capital Expenditures (in USD million, as % of sales)
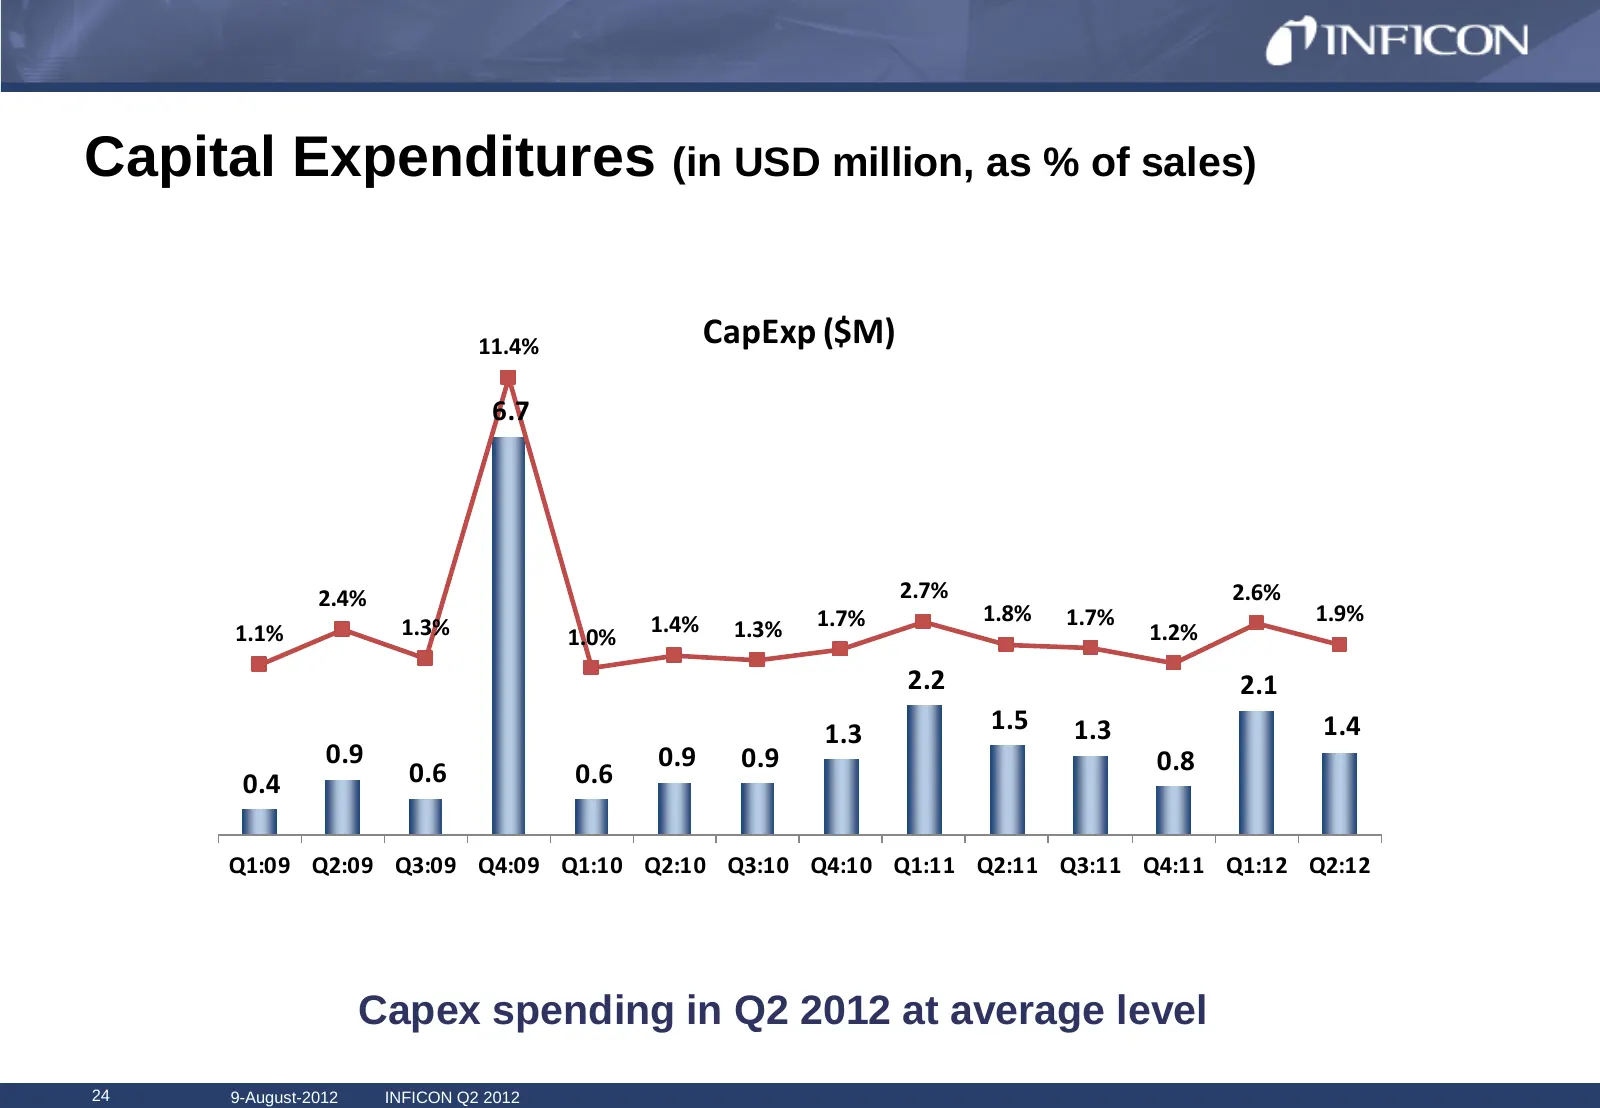
Capital Expenditures (in USD million, as % of sales) 11.4% CapExp ($M) 6.7 2.4% 2.7% 2.6% 1.4% 1.7% 1.8% 1.7% 1.9% 1.1% 1.3% 1.0% 1.3% 1.2% 2.2 2.1 1.3 1.5 1.3 1.4 0.9 0.9 0.9 0.8 0.4 0.6 0.6 Q1:09 Q2:09 Q3:09 Q4:09 Q1:10 Q2:10 Q3:10 Q4:10 Q1:11 Q2:11 Q3:11 Q4:11 Q1:12 Q2:12 1 2008 Template - Januar
Slide 25: Half-Year 2012 Performance
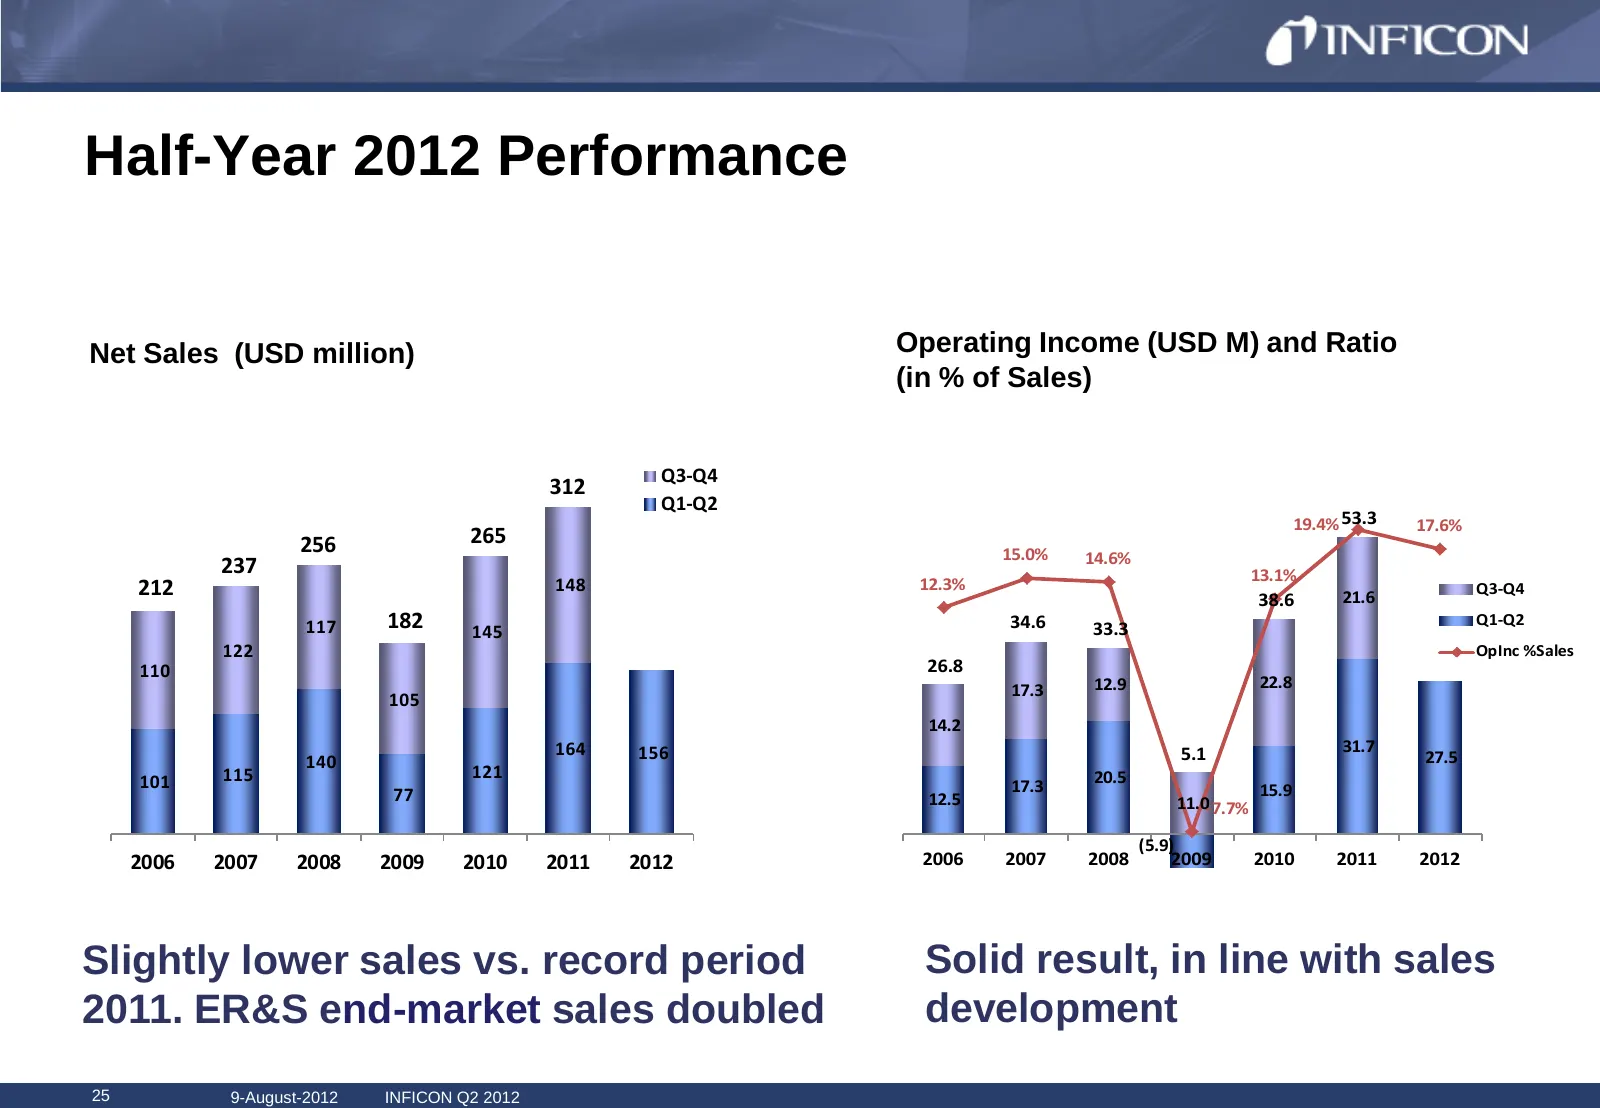
Half-Year 2012 Performance Net Sales (USD million) Operating Income (USD M) and Ratio (in % of Sales) Q3-Q4 312 Q1-Q2 19.4% 53.3 17.6% 256 265 15.0% 14.6% 237 13.1% 212 148 12.3% 38.6 21.6 Q3-Q4 117 182 145 34.6 33.3 Q1-Q2 122 OpInc %Sales 110 26.8 17.3 12.9 22.8 105 14.2 164 156 5.1 31.7 140 27.5 1
Slide 26: Half-Year 2012 Performance
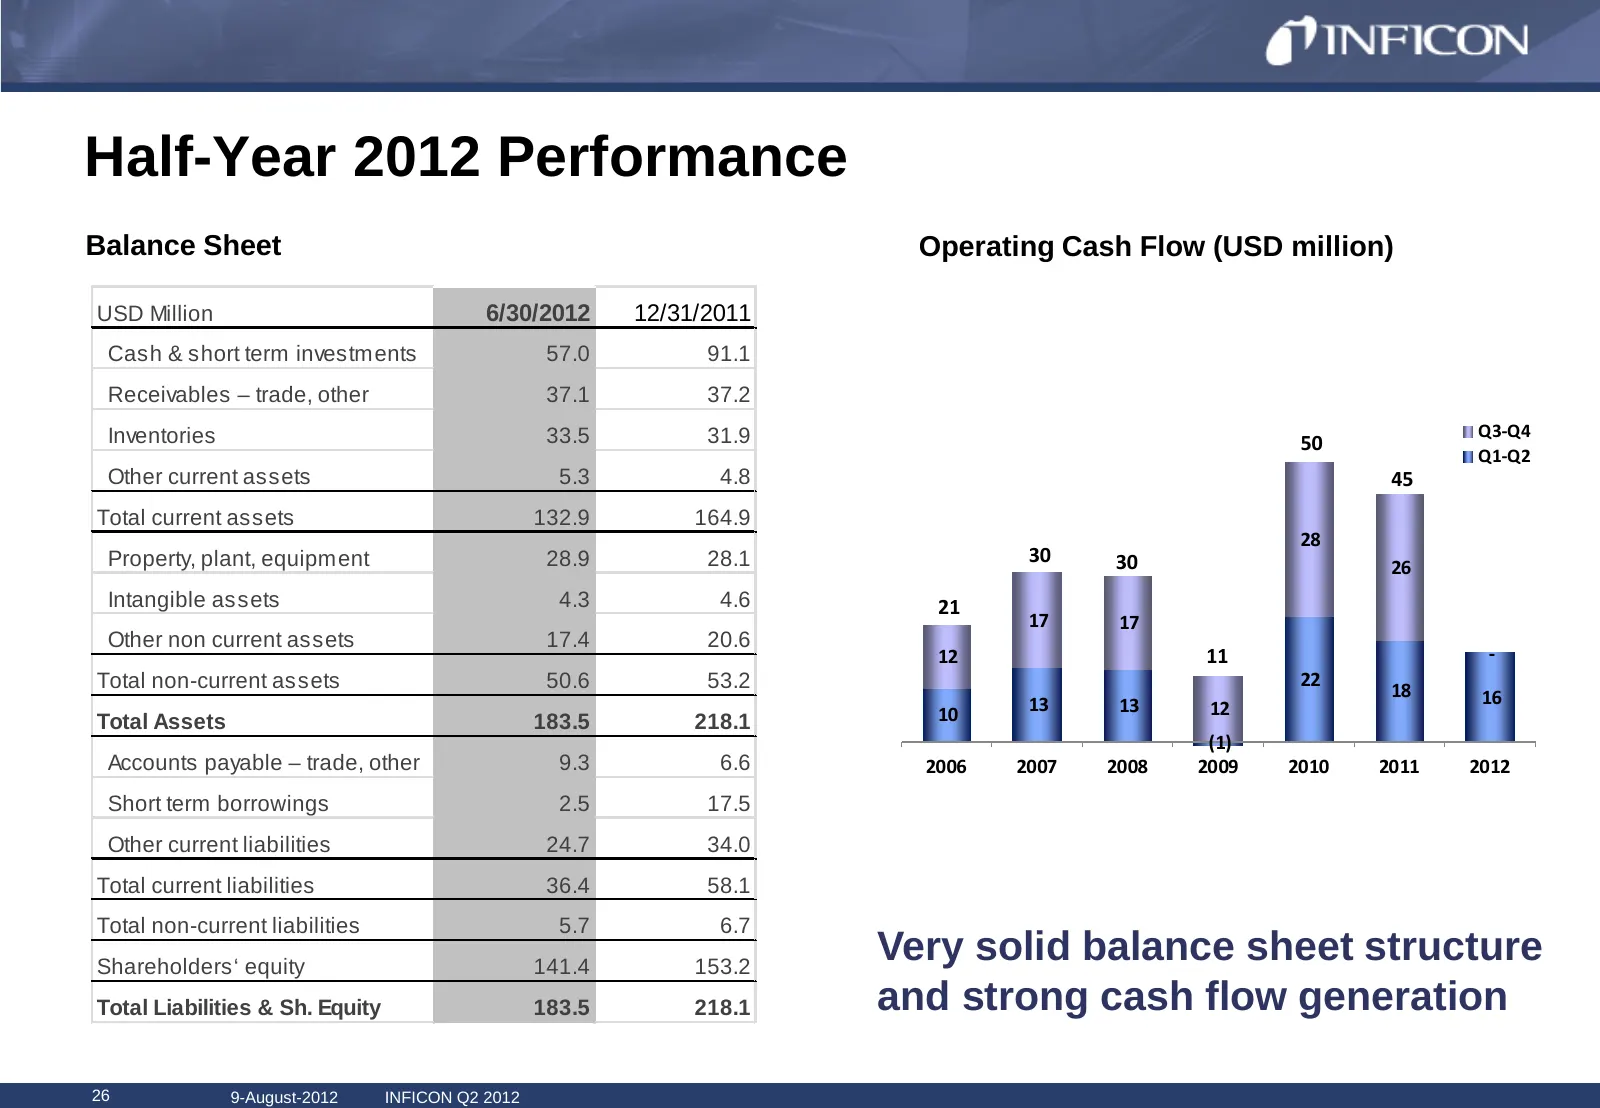
Half-Year 2012 Performance Balance Sheet Operating Cash Flow (USD million) USD Million 6/30/2012 12/31/2011 Cash & short term investments 57.0 91.1 Receivables – trade, other 37.1 37.2 Inventories 33.5 31.9 Q3-Q4 50 Q1-Q2 Other current assets 5.3 4.8 45 Total current assets 132.9 164.9 28 Property,
Slide 27: Full Year 2012 Guidance
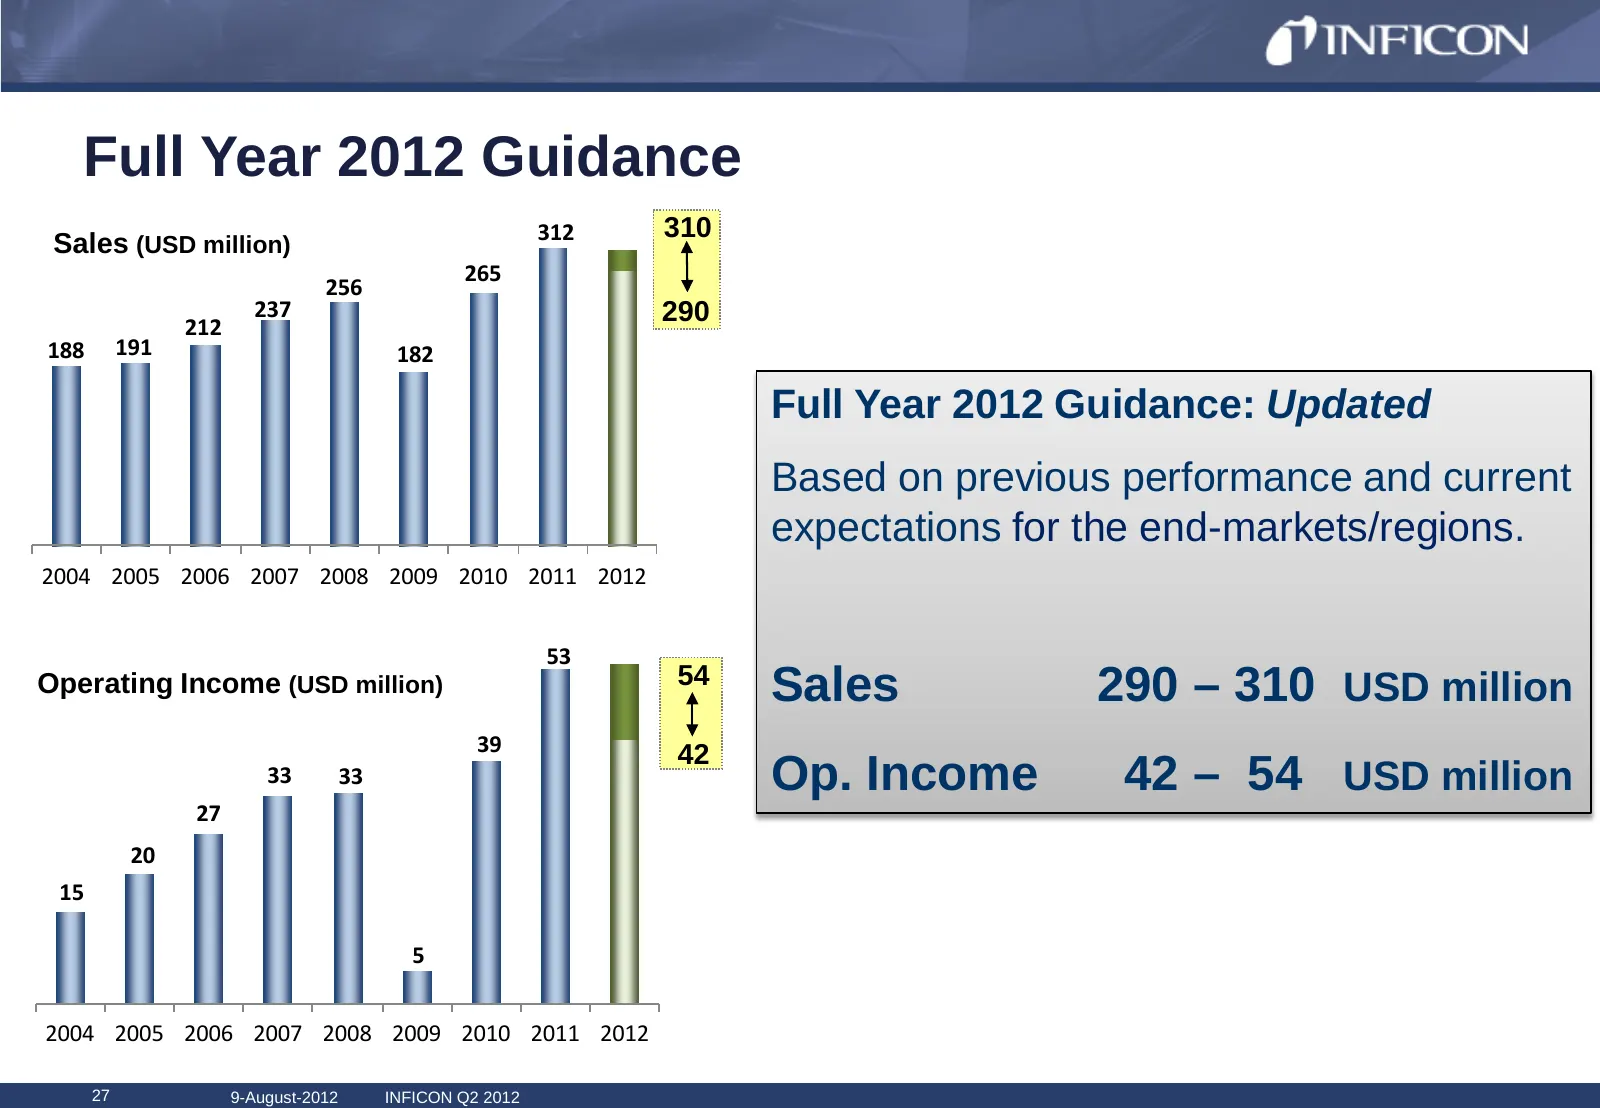
Full Year 2012 Guidance 312 310 Sales (USD million) 265 256 237 290 212 188 191 182 Full Year 2012 Guidance: Updated Based on previous performance and current expectations for the end-markets/regions. 2004 2005 2006 2007 2008 2009 2010 2011 2012 53 54 Operating Income (USD million) Sales 290 – 310 U
Slide 28: Thank You !
Thank You ! Q&A
Slide 29: INFICON
6) INFICON struments for Intelligent Control™
Source: Internet Archive copy of ir.inficon.com
More decks from INFICON Holding AG
 Q3 2026 Earnings Presentation18 slides · Oct 27, 2026
 Q2 2026 Earnings Presentation20 slides · Jul 30, 2026
 Q1 2026 Earnings Presentation20 slides · Apr 24, 2026
 Q4 2025 Earnings Presentation32 slides · Mar 24, 2026
 Q1 2025 Earnings Presentation20 slides · Apr 24, 2025
 Technical Presentation (September 2024)44 slides · September 2024