INFICON Holding AG · SIX:IFCN
INFICON — Q4 2013 Earnings Presentation
30 slides from INFICON's earnings presentation, Mar 13, 2014
Slide 1: Q4 2013 Earnings Conference Call
Q4 2013 EARNINGS CONFERENCE CALL March 13, 2014 Bad Ragaz, Switzerland
Slide 2: Speakers
Speakers Lukas Winkler, President and CEO Key figures Q4 2013 and FY 2013 Target market business review 2014 expectations Matthias Tröndle, Vice President and CFO Financials Q4 2013 and FY 2013 Distribution Guidance Q4 2013 Earnings Conference Call March 13, 2014 2
Slide 3: Lukas Winkler
Lukas Winkler INFICON President and Chief Executive Officer
Slide 4: Q4 2013 – Key Figures
Q4 2013 – Key Figures Sales increase driven by strong ER&S and Semiconductor market despite rather weak European General Vacuum market • Consolidated sales increase of 13.5% to USD 80.5 million compared with Q4 2012, organic increase of 15.5% • Sequential sales increase over Q3 2013 of 17.0% Ope
Slide 5: Net Sales by End Market
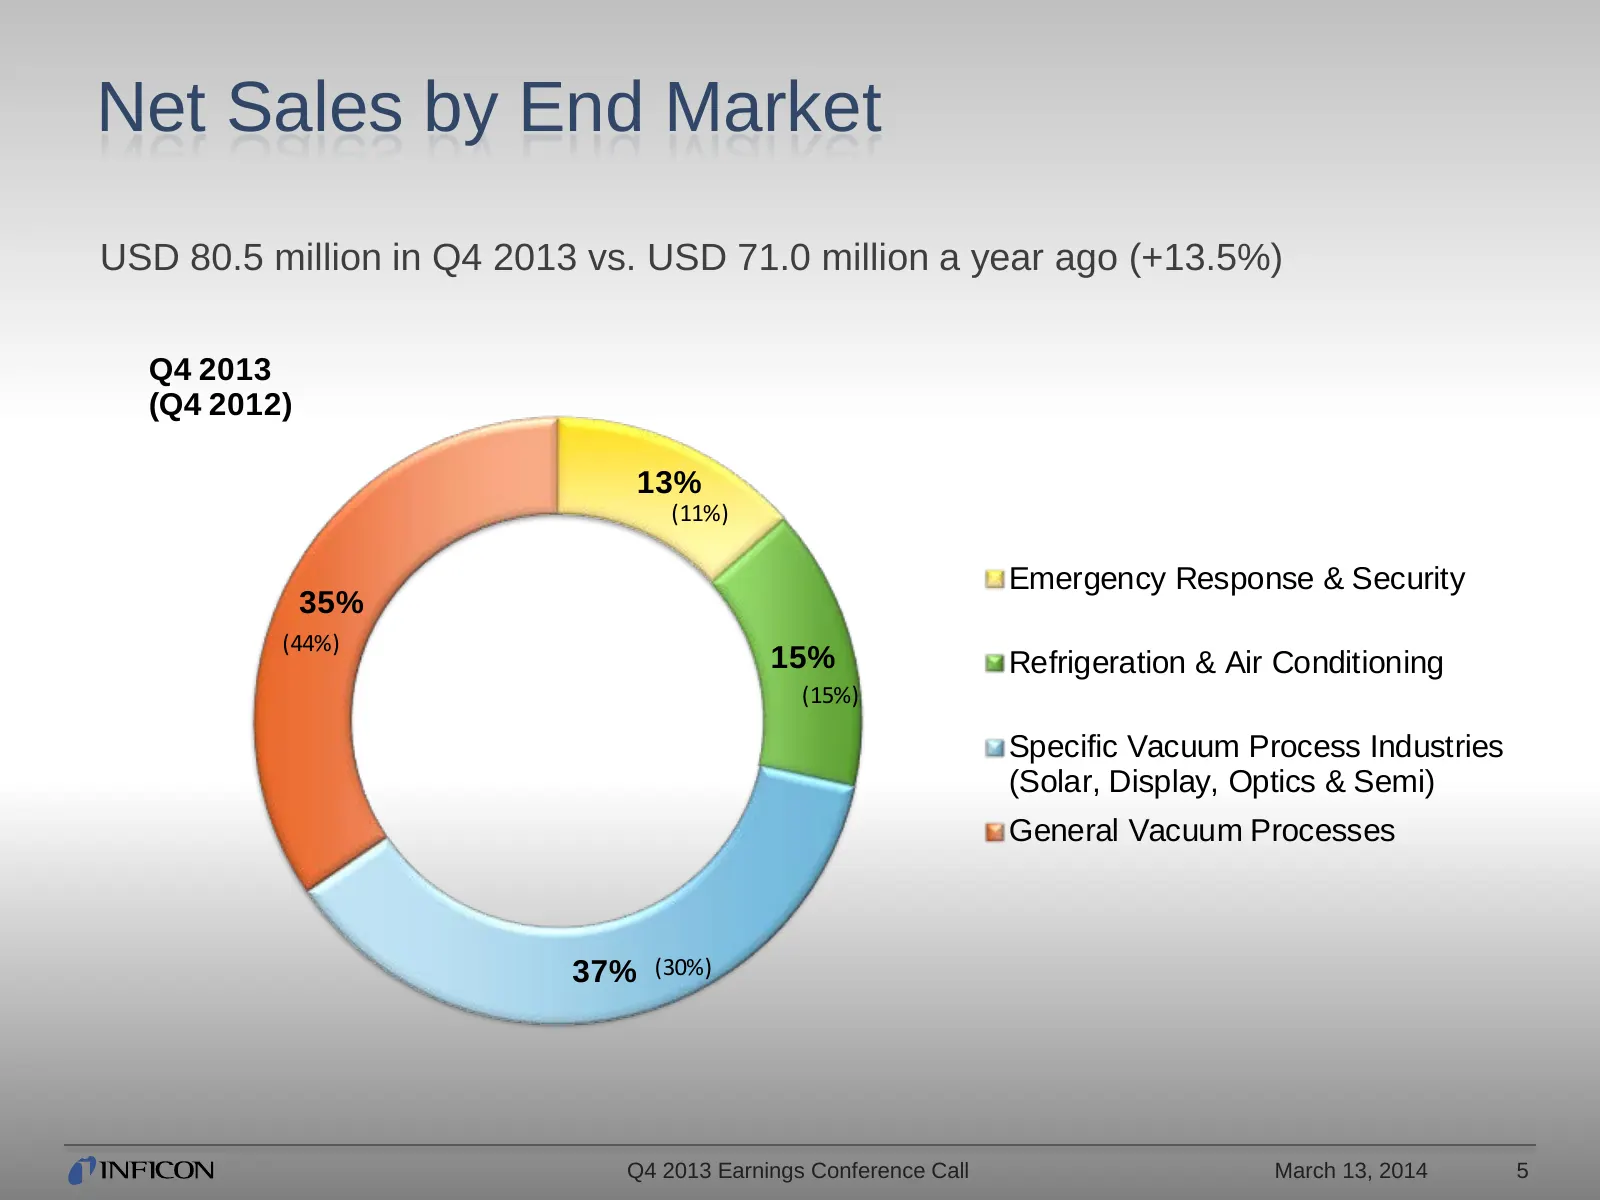
Net Sales by End Market USD 80.5 million in Q4 2013 vs. USD 71.0 million a year ago (+13.5%) Q4 2013 (Q4 2012) 13% (11%) Emergency Response & Security 35% (44%) 15% Refrigeration & Air Conditioning (15%) Specific Vacuum Process Industries (Solar, Display, Optics & Semi) General Vacuum Processes 37%
Slide 6: FY 2013 – Key Figures
FY 2013 – Key Figures Strong final Quarter drives sales increase and generates organic growth of +1.9% • Sales at USD 293 million – decrease of -1.4%, organic +1.9% • Sales increase in Semiconductor while GV and ER&S weakened • Book to Bill slightly > 1 Operating result influenced by • Solid sal
Slide 7: Specific Vacuum Process Industries
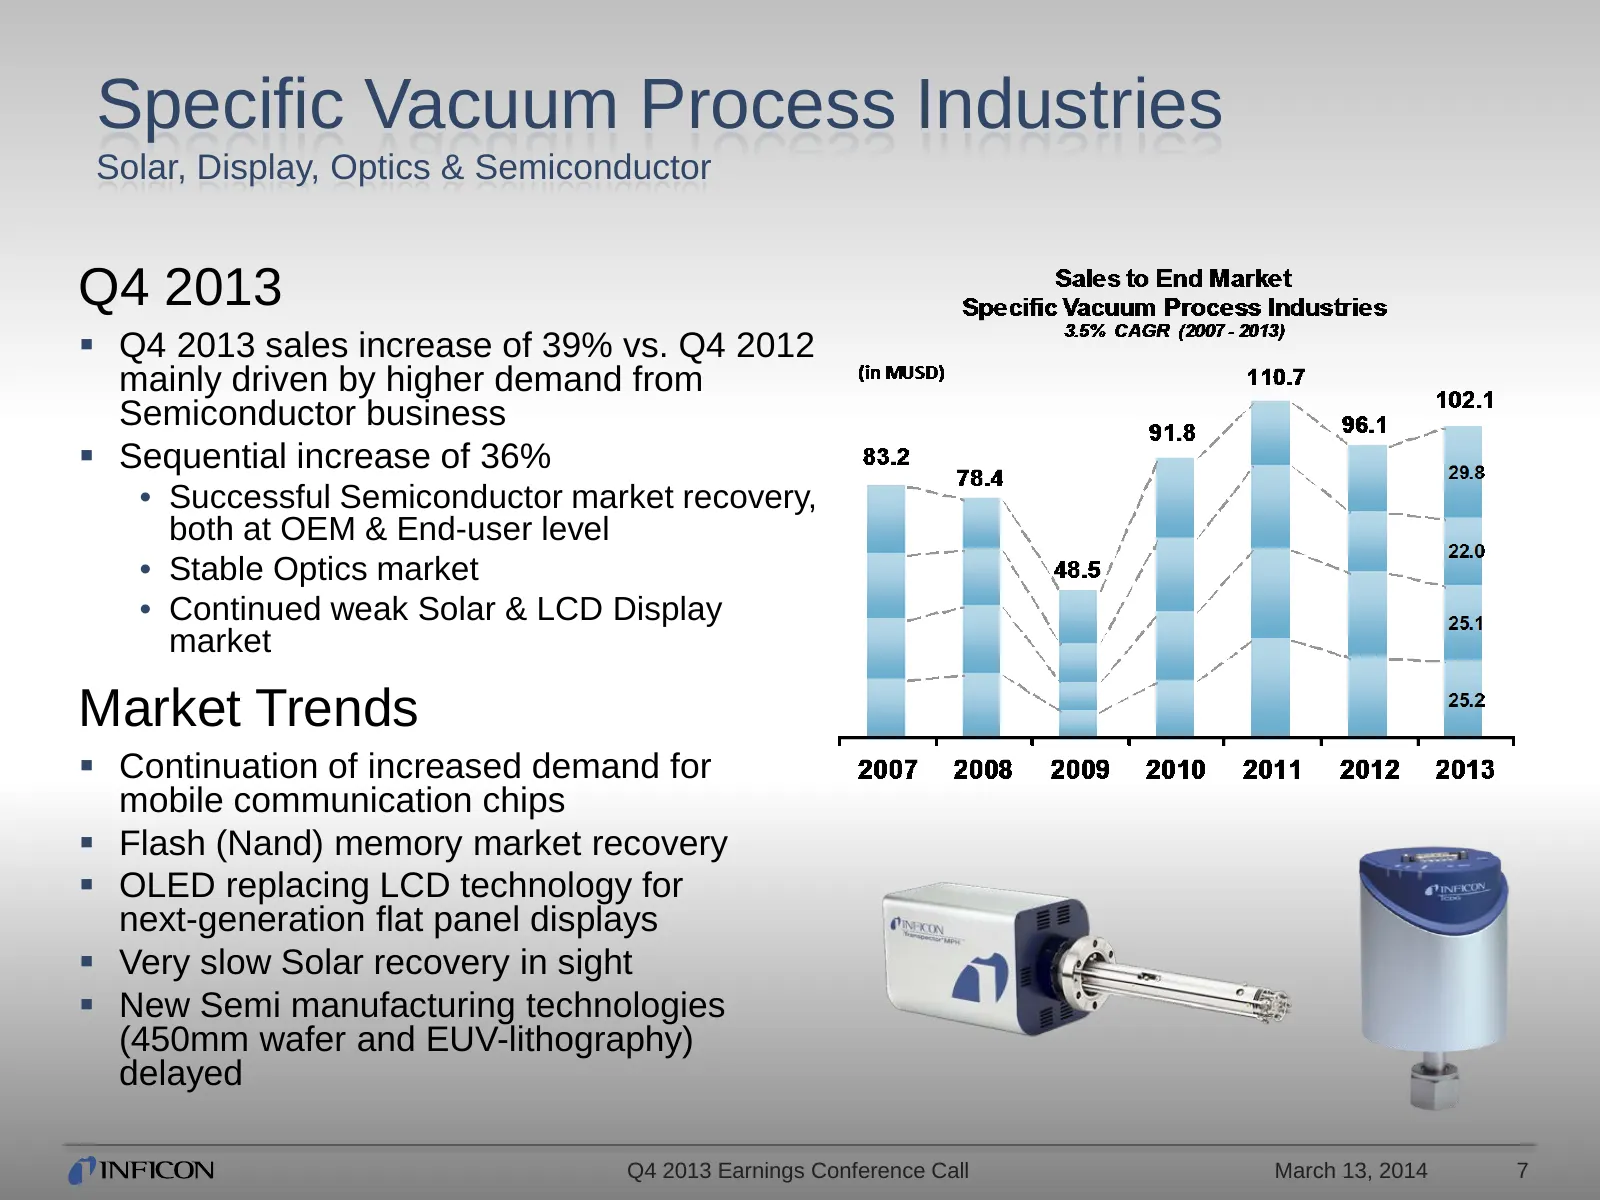
Specific Vacuum Process Industries Solar, Display, Optics & Semiconductor Q4 2013 Q4 2013 sales increase of 39% vs. Q4 2012 mainly driven by higher demand from Semiconductor business Sequential increase of 36% • Successful Semiconductor market recovery, both at OEM & End-user level • Stable Opti
Slide 8: Emergency Response & Security
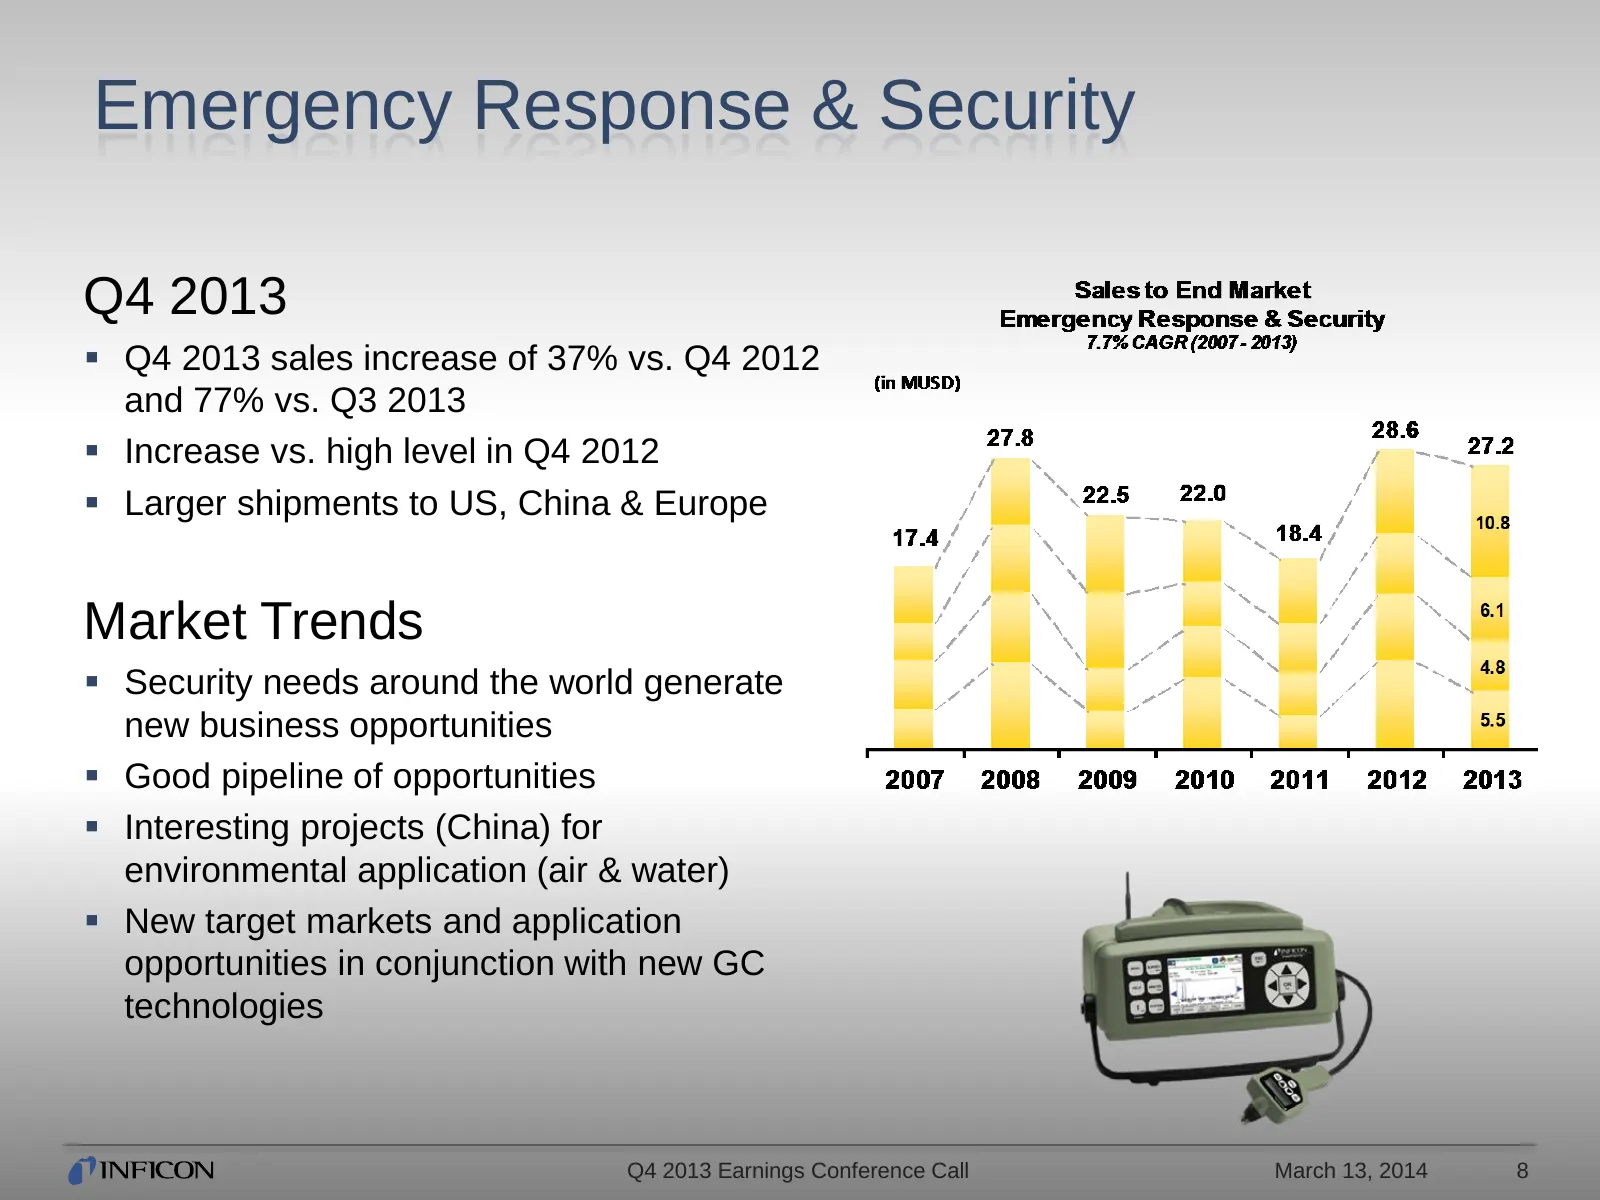
Emergency Response & Security Q4 2013 Q4 2013 sales increase of 37% vs. Q4 2012 and 77% vs. Q3 2013 Increase vs. high level in Q4 2012 Larger shipments to US, China & Europe Market Trends Security needs around the world generate new business opportunities Good pipeline of opportunities I
Slide 9: Refrigeration & Air Conditioning
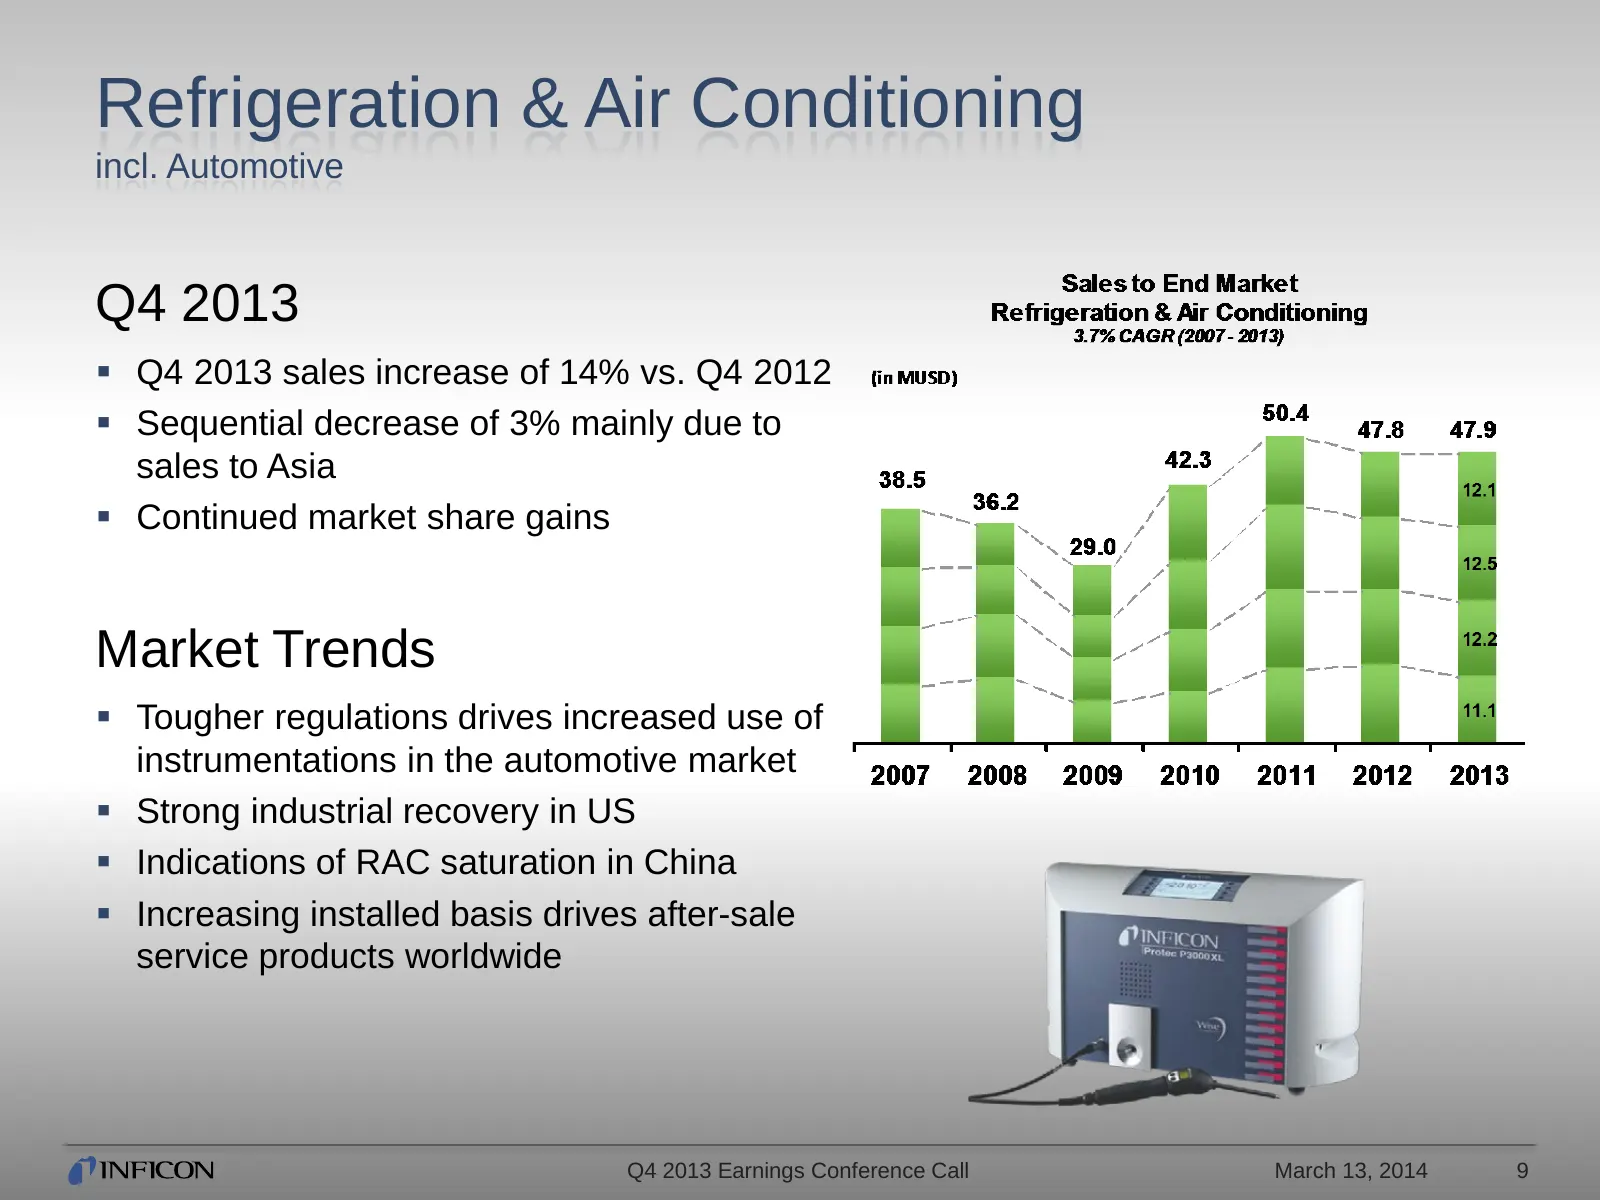
Refrigeration & Air Conditioning incl. Automotive Q4 2013 Q4 2013 sales increase of 14% vs. Q4 2012 Sequential decrease of 3% mainly due to sales to Asia Continued market share gains Market Trends Tougher regulations drives increased use of instrumentations in the automotive market Strong
Slide 10: General Vacuum Processes
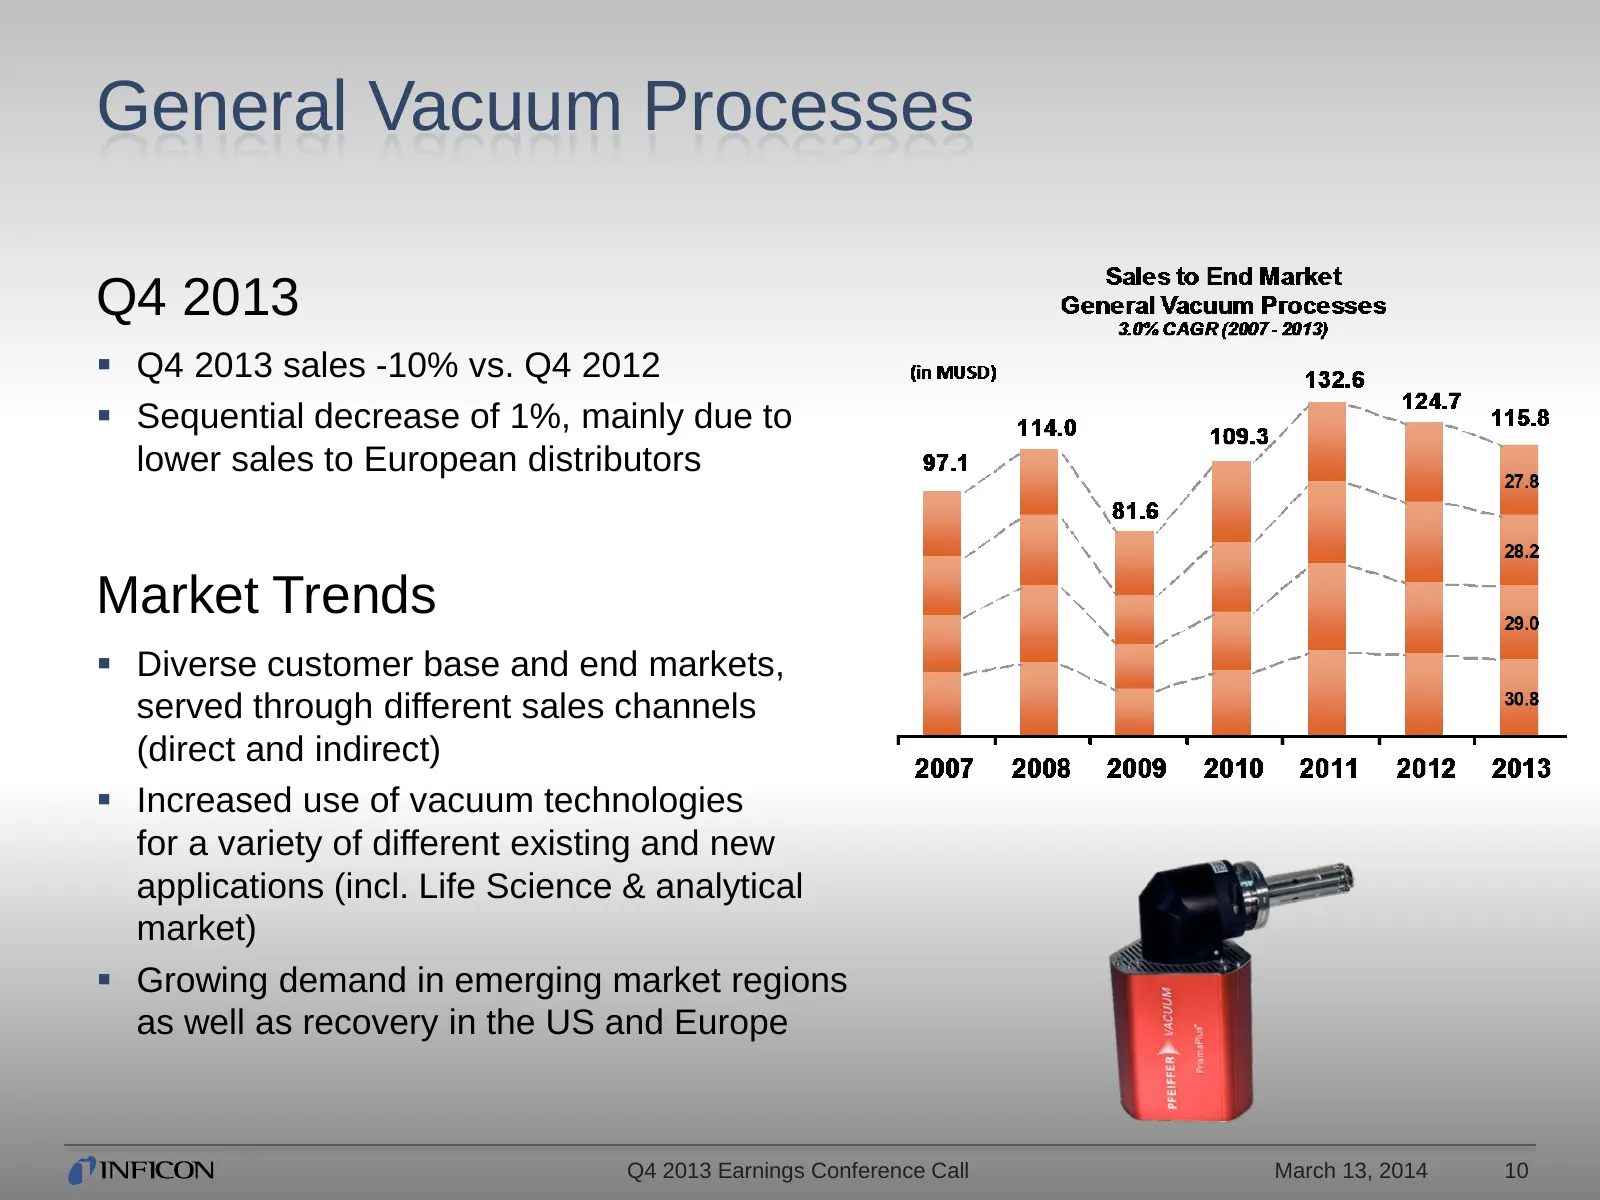
General Vacuum Processes Q4 2013 Q4 2013 sales -10% vs. Q4 2012 Sequential decrease of 1%, mainly due to lower sales to European distributors Market Trends Diverse customer base and end markets, served through different sales channels (direct and indirect) Increased use of vacuum technologie
Slide 11: Outlook 2014 and beyond
Outlook 2014 and beyond Challenging, but improving signals from different markets/regions Increased demand for mobile communication devices (Semiconductor market) • Investments in new equipment (OEM-business), driven by Foundries • Continued success with sensors and software (at end-users) to hand
Slide 12: Matthias Tröndle
Matthias Tröndle INFICON Vice President and Chief Financial Officer
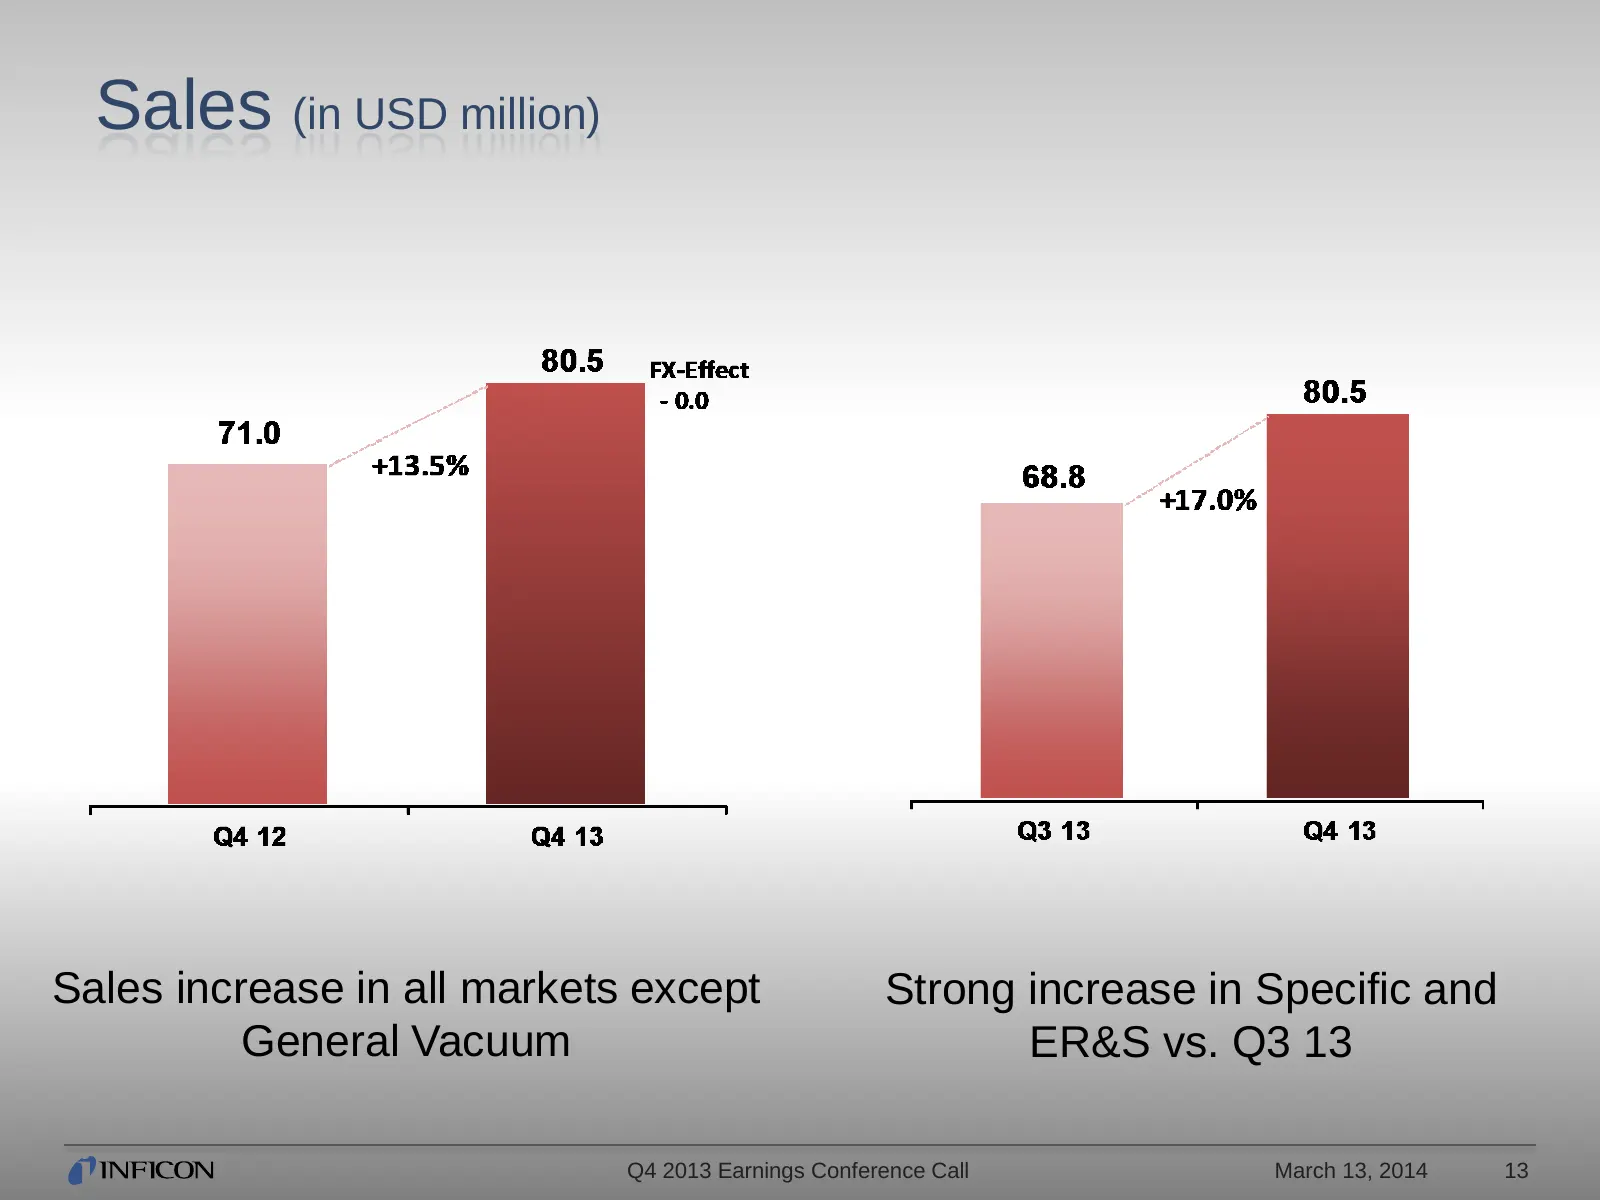
Slide 13: Sales (in USD million)
Sales (in USD million) Sales increase in all markets except Strong increase in Specific and General Vacuum ER&S vs. Q3 13 Q4 2013 Earnings Conference Call March 13, 2014 13
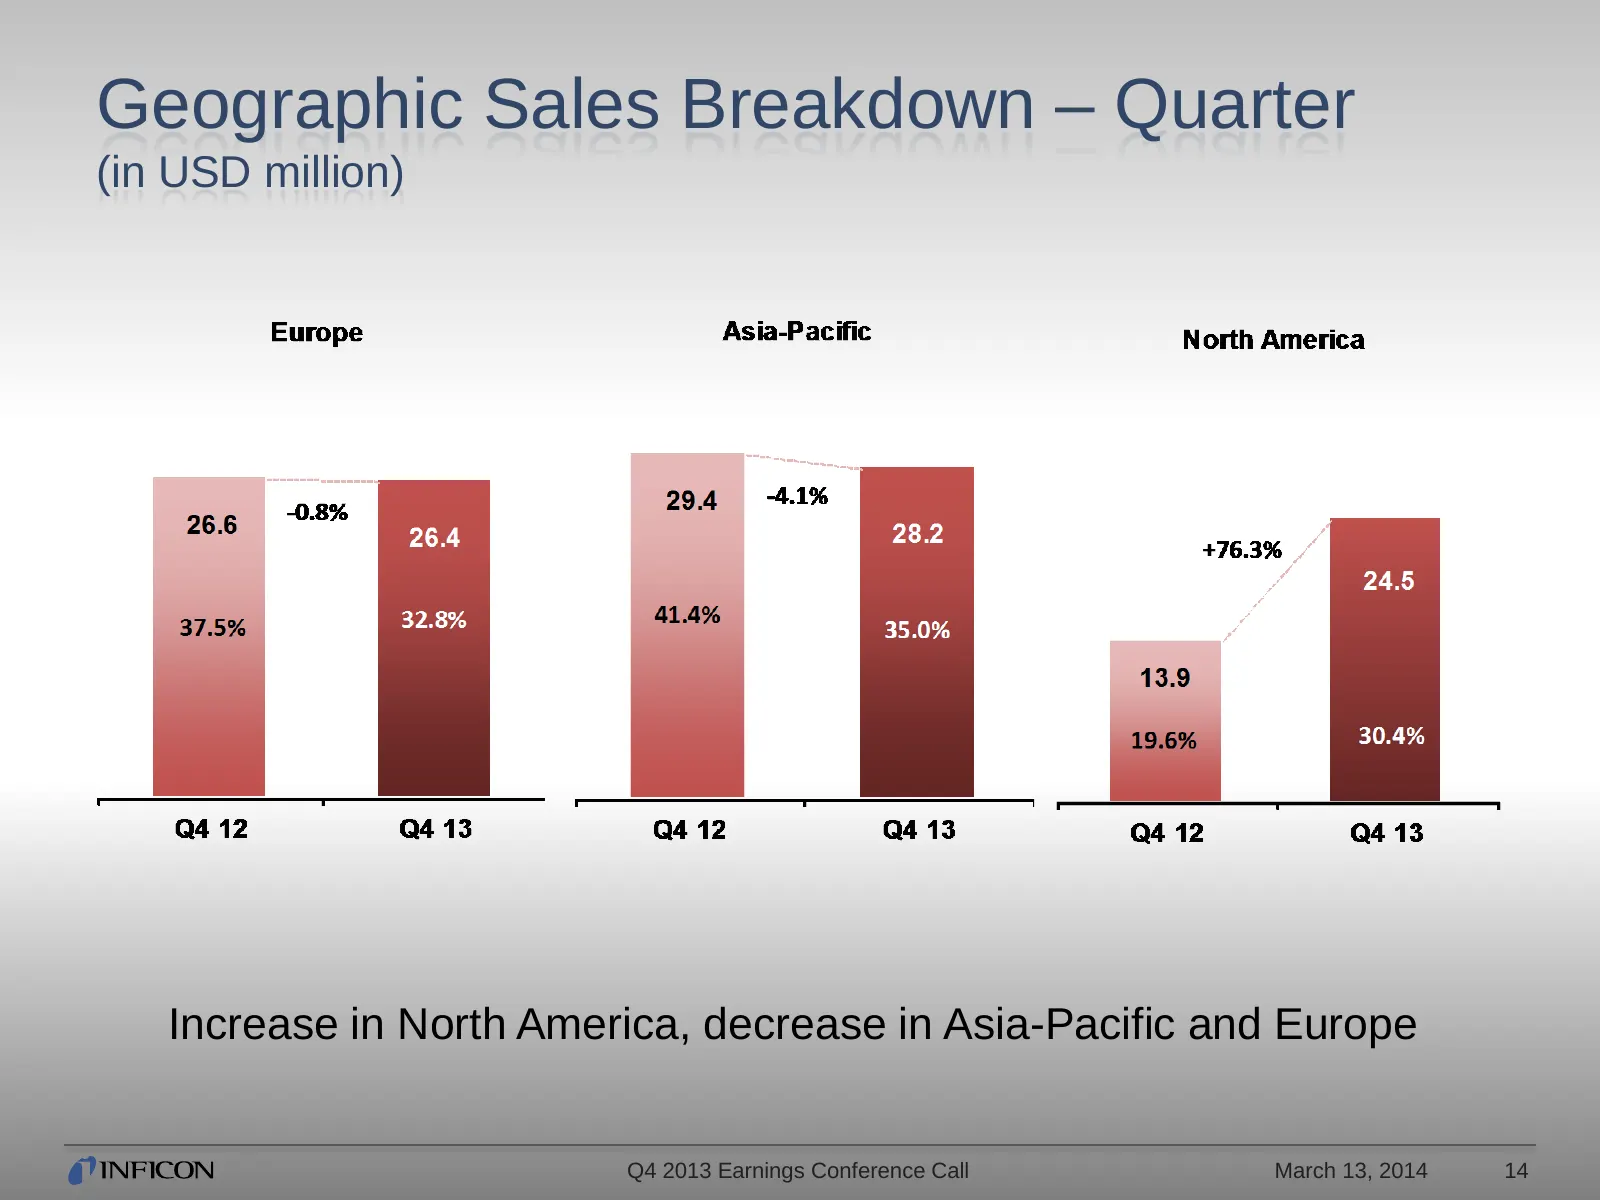
Slide 14: Geographic Sales Breakdown – Quarter
Geographic Sales Breakdown – Quarter (in USD million) Increase in North America, decrease in Asia-Pacific and Europe Q4 2013 Earnings Conference Call March 13, 2014 14
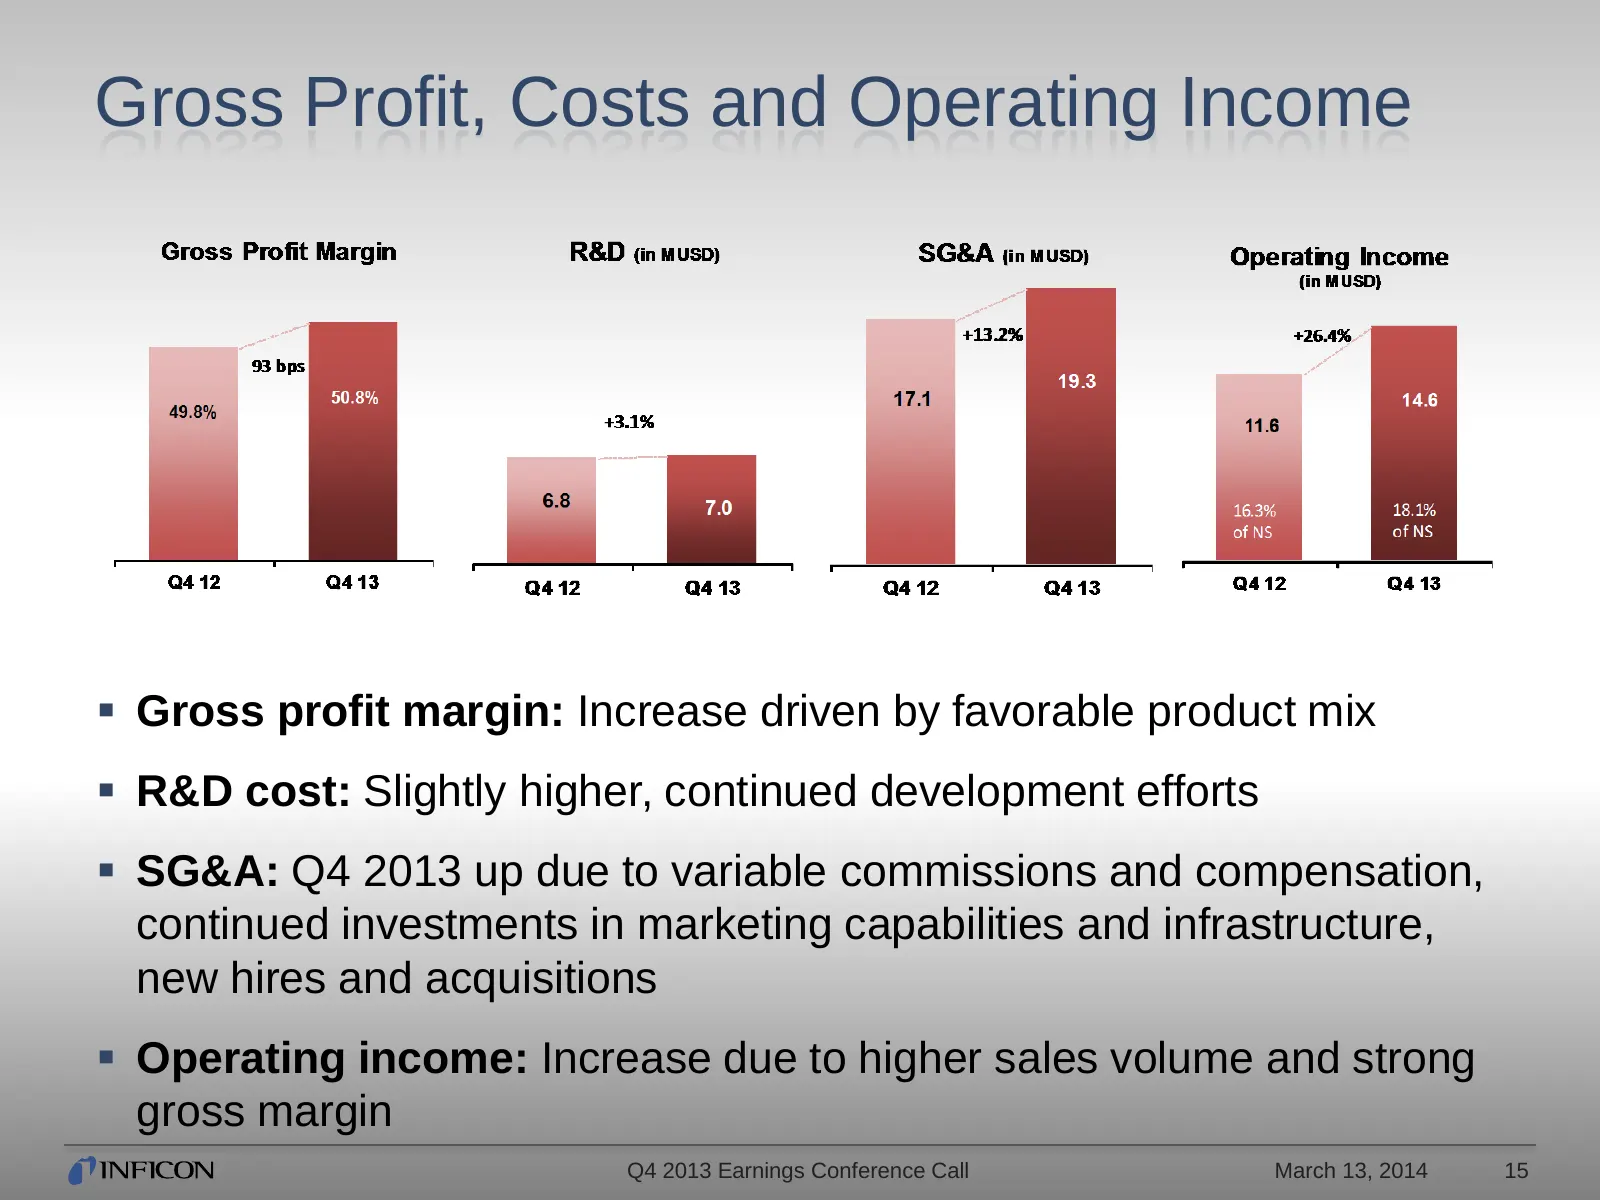
Slide 15: Gross Profit, Costs and Operating Income
Gross Profit, Costs and Operating Income Gross profit margin: Increase driven by favorable product mix R&D cost: Slightly higher, continued development efforts SG&A: Q4 2013 up due to variable commissions and compensation, continued investments in marketing capabilities and infrastructure, new
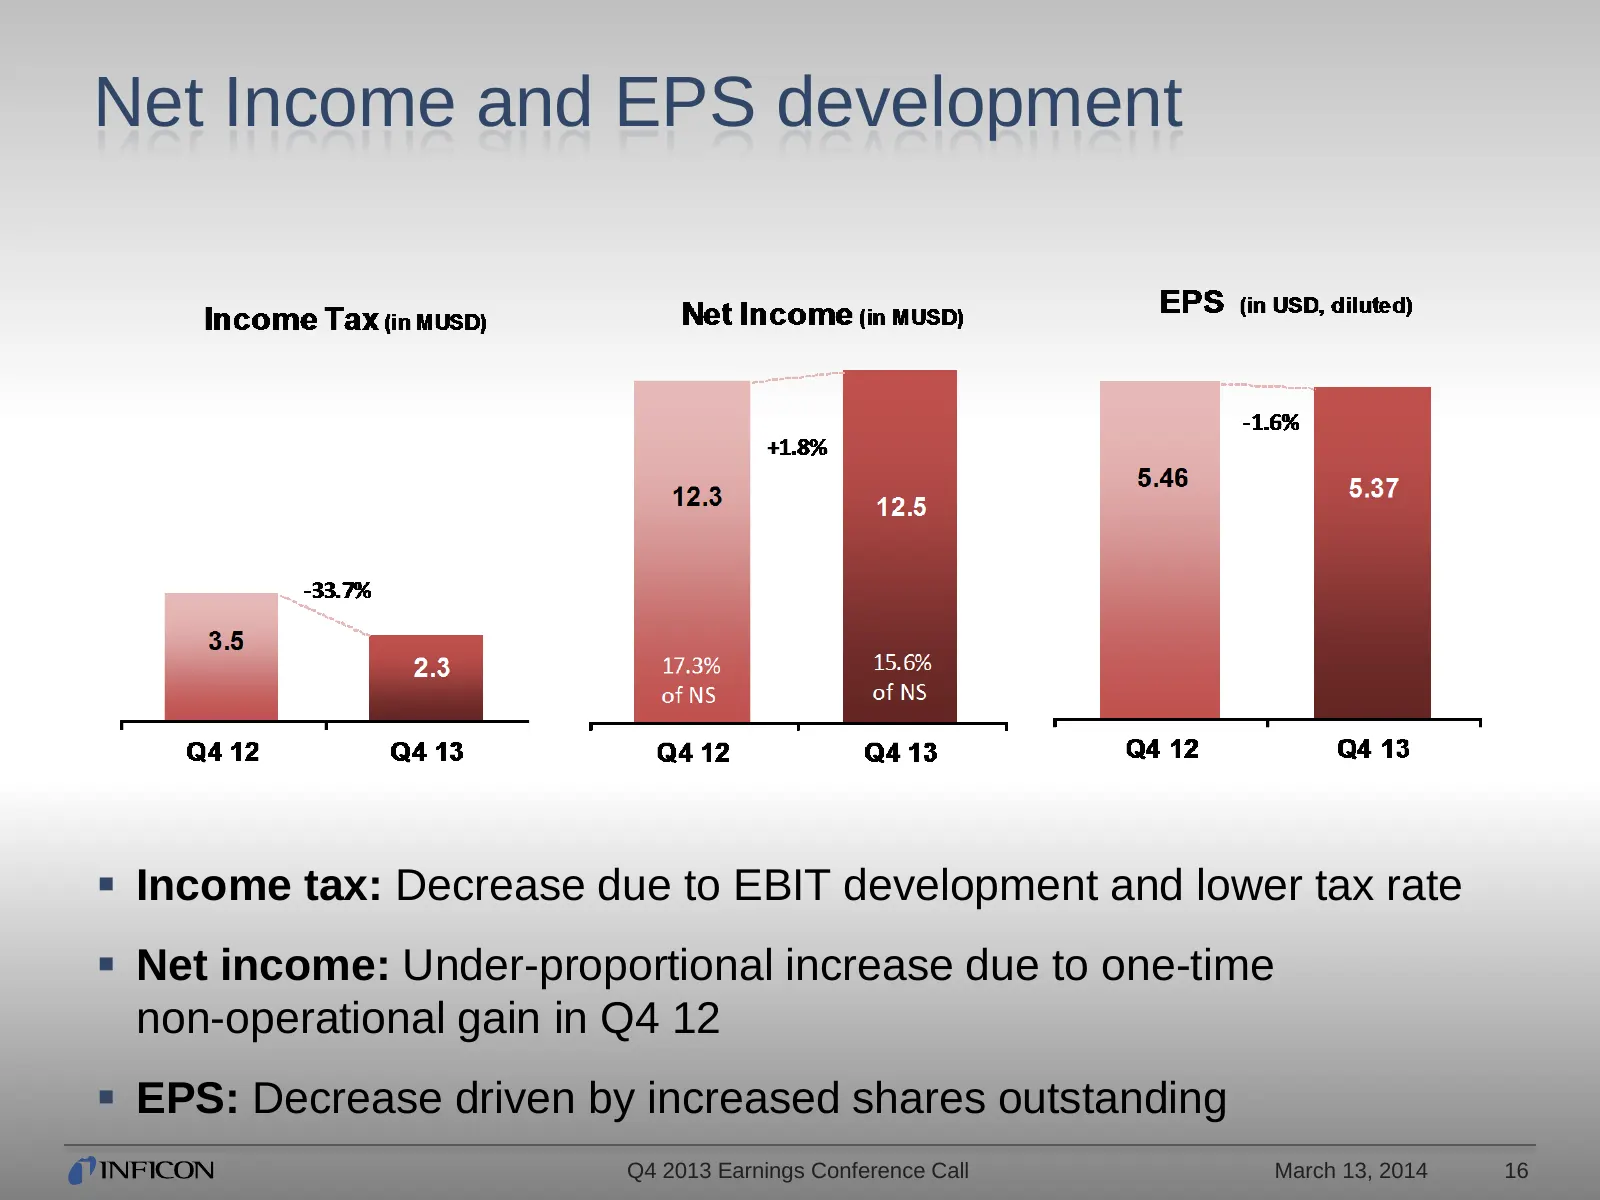
Slide 16: Net Income and EPS development
Net Income and EPS development Income tax: Decrease due to EBIT development and lower tax rate Net income: Under-proportional increase due to one-time non-operational gain in Q4 12 EPS: Decrease driven by increased shares outstanding Q4 2013 Earnings Conference Call March 13, 2014 16
Slide 17: Balance Sheet Highlights (in USD million)
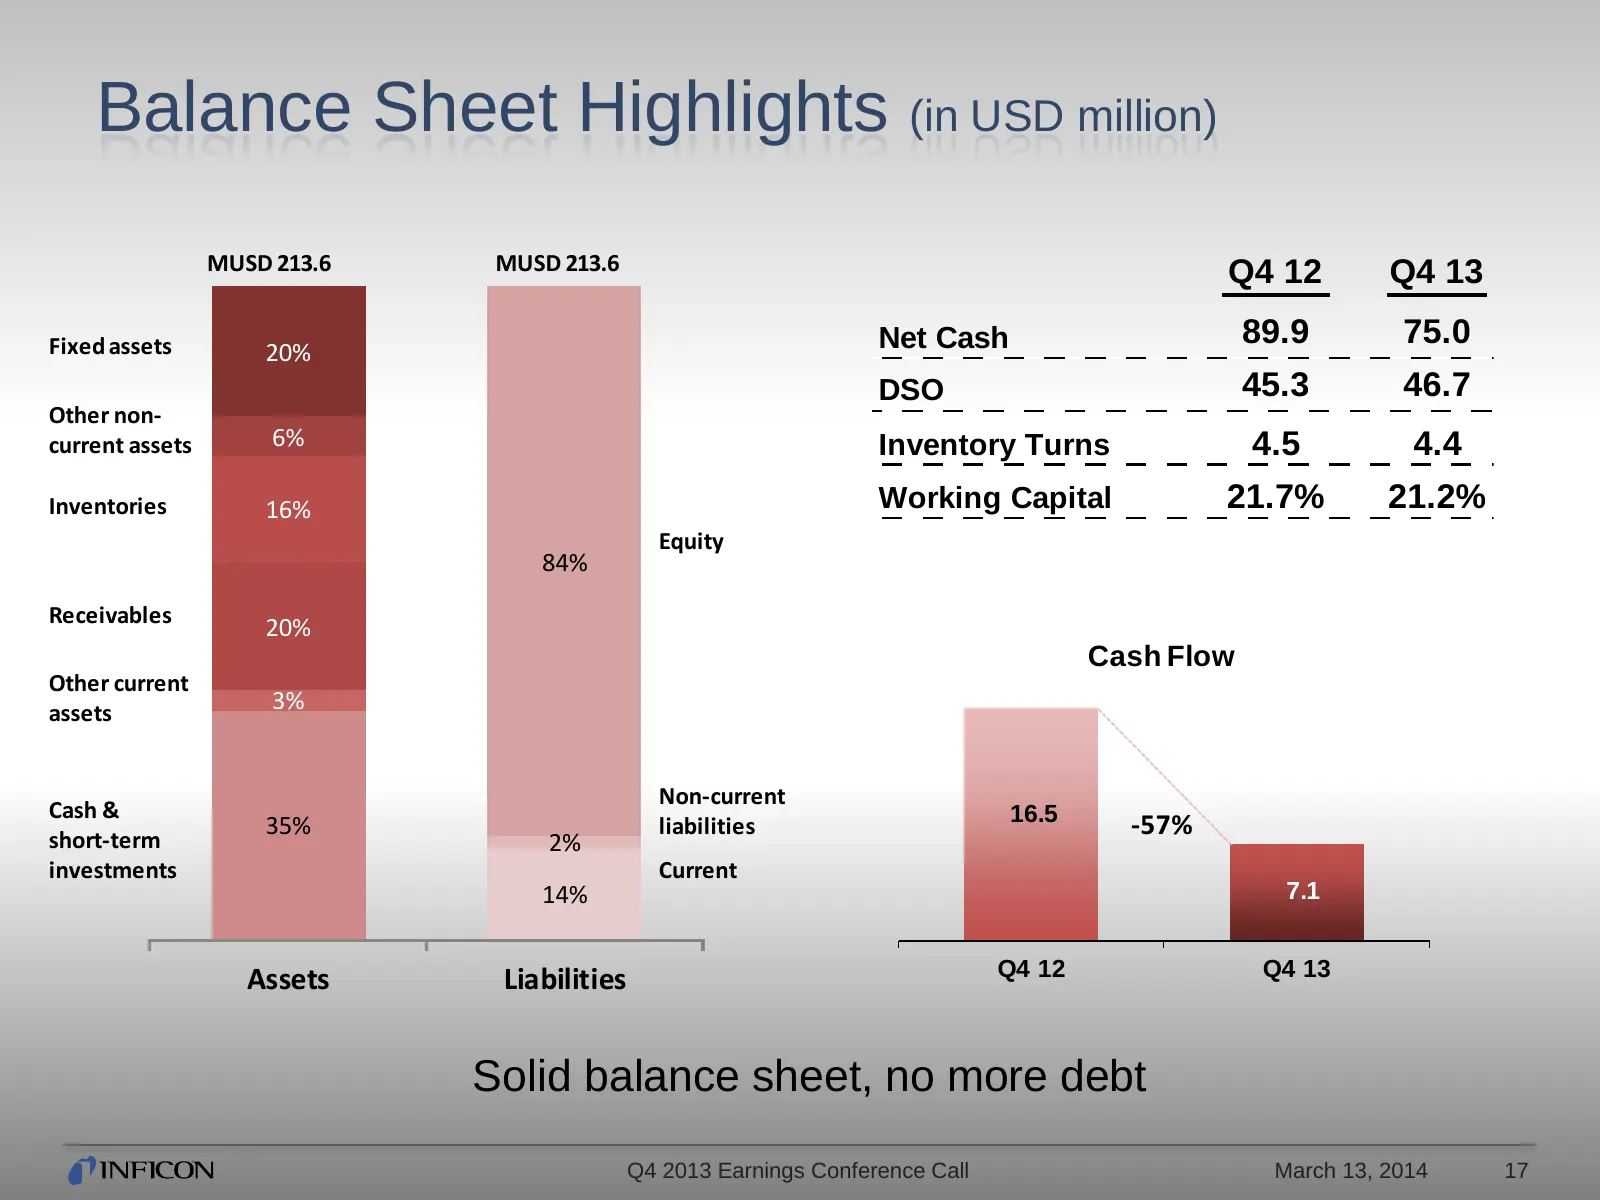
Balance Sheet Highlights (in USD million) MUSD 213.6 MUSD 213.6 Q4 12 Q4 13 Fixed assets Net Cash 89.9 75.0 20% DSO 45.3 46.7 Other non- current assets 6% Inventory Turns 4.5 4.4 Inventories 16% Working Capital 21.7% 21.2% Equity 84% Receivables 20% Cash Flow Other current assets 3% Non-current Cash
Slide 18: Fiscal Year 2013 Results
FISCAL YEAR 2013 RESULTS
Slide 19: Full Year Sales (in USD million)
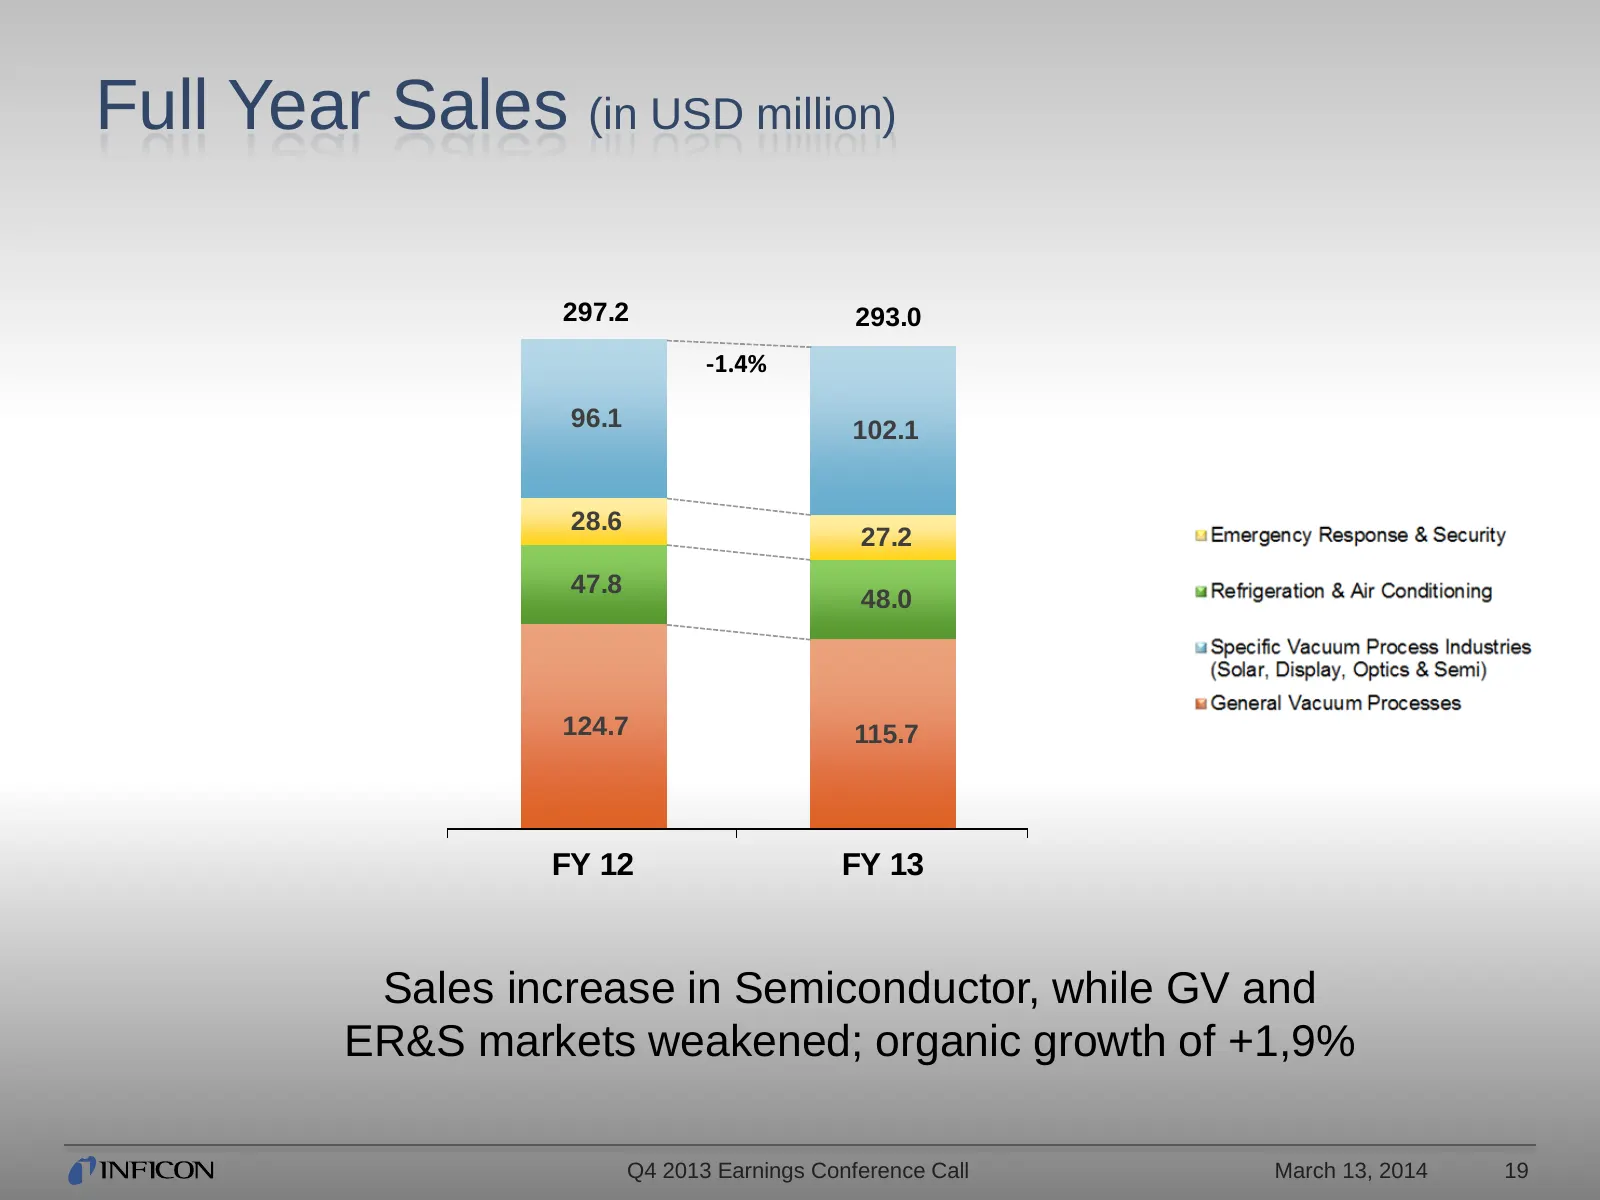
Full Year Sales (in USD million) 297.2 293.0 -1.4% 96.1 102.1 28.6 27.2 47.8 48.0 124.7 115.7 FY 12 FY 13 Sales increase in Semiconductor, while GV and ER&S markets weakened; organic growth of +1,9% Q4 2013 Earnings Conference Call March 13, 2014 19
Slide 20: Geographic Sales Breakdown – Full Year
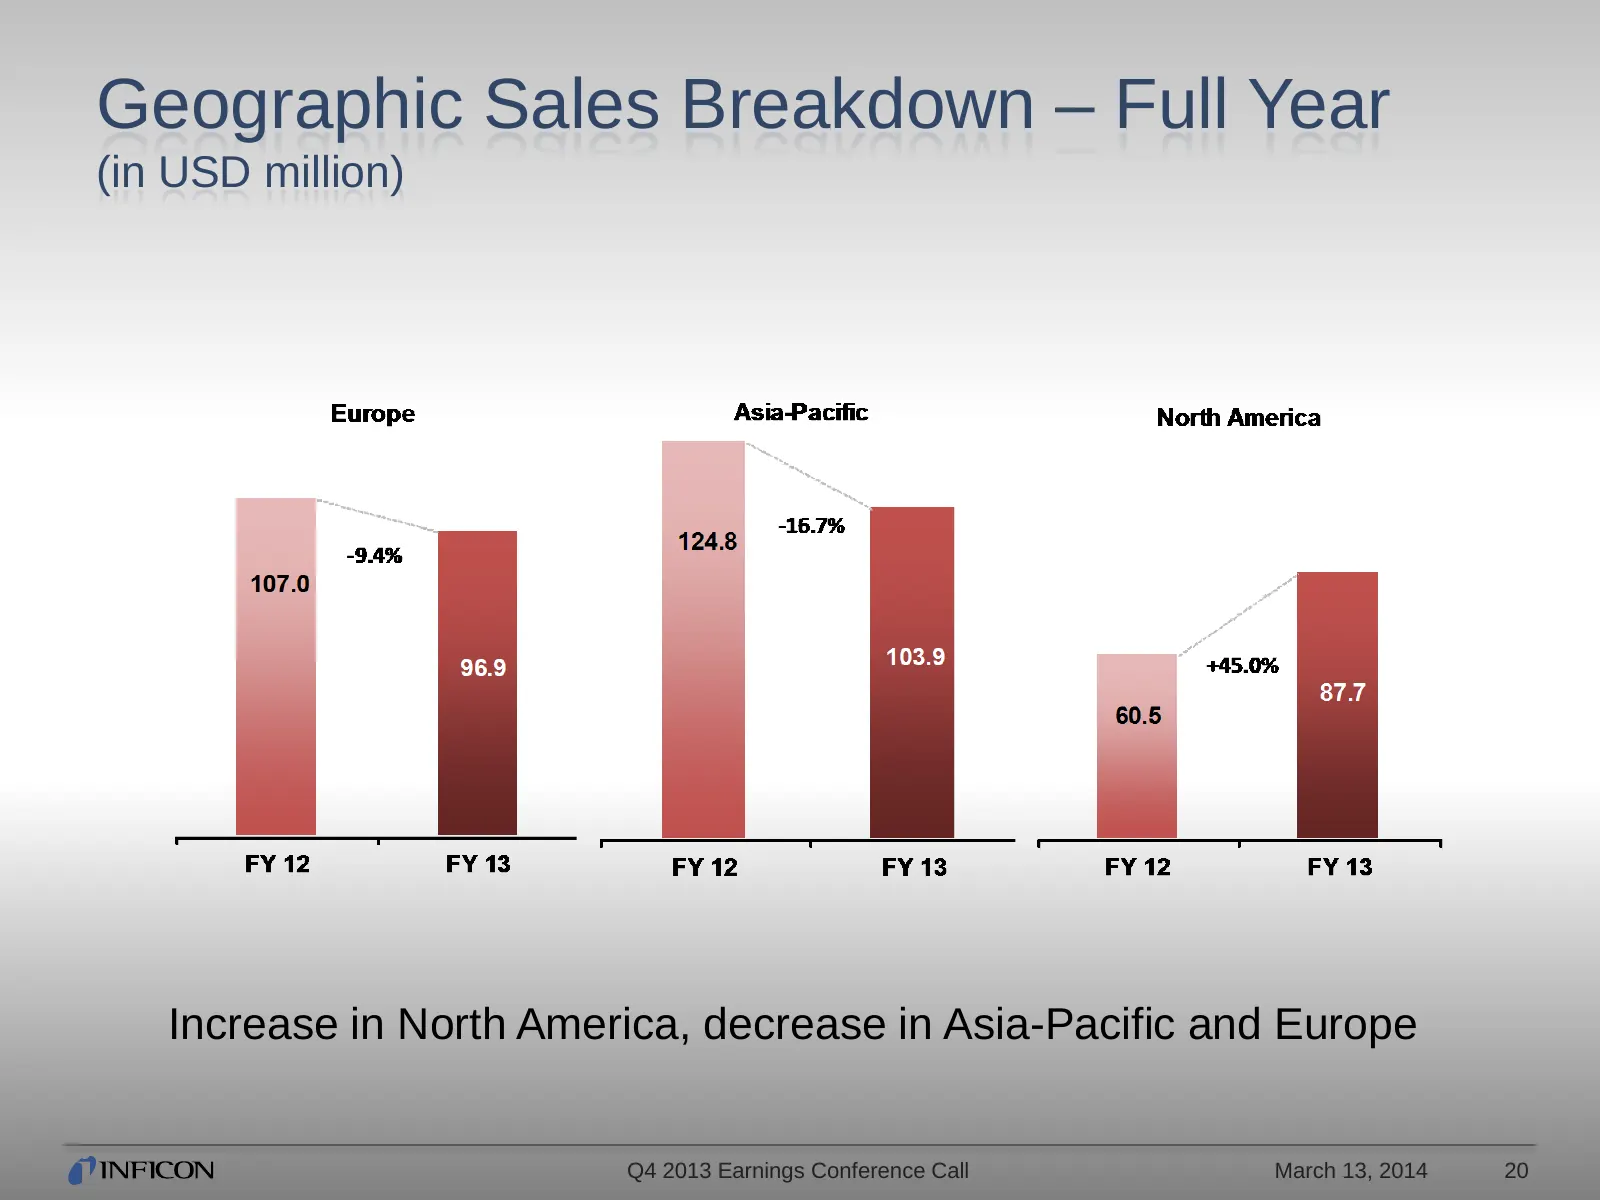
Geographic Sales Breakdown – Full Year (in USD million) Increase in North America, decrease in Asia-Pacific and Europe Q4 2013 Earnings Conference Call March 13, 2014 20
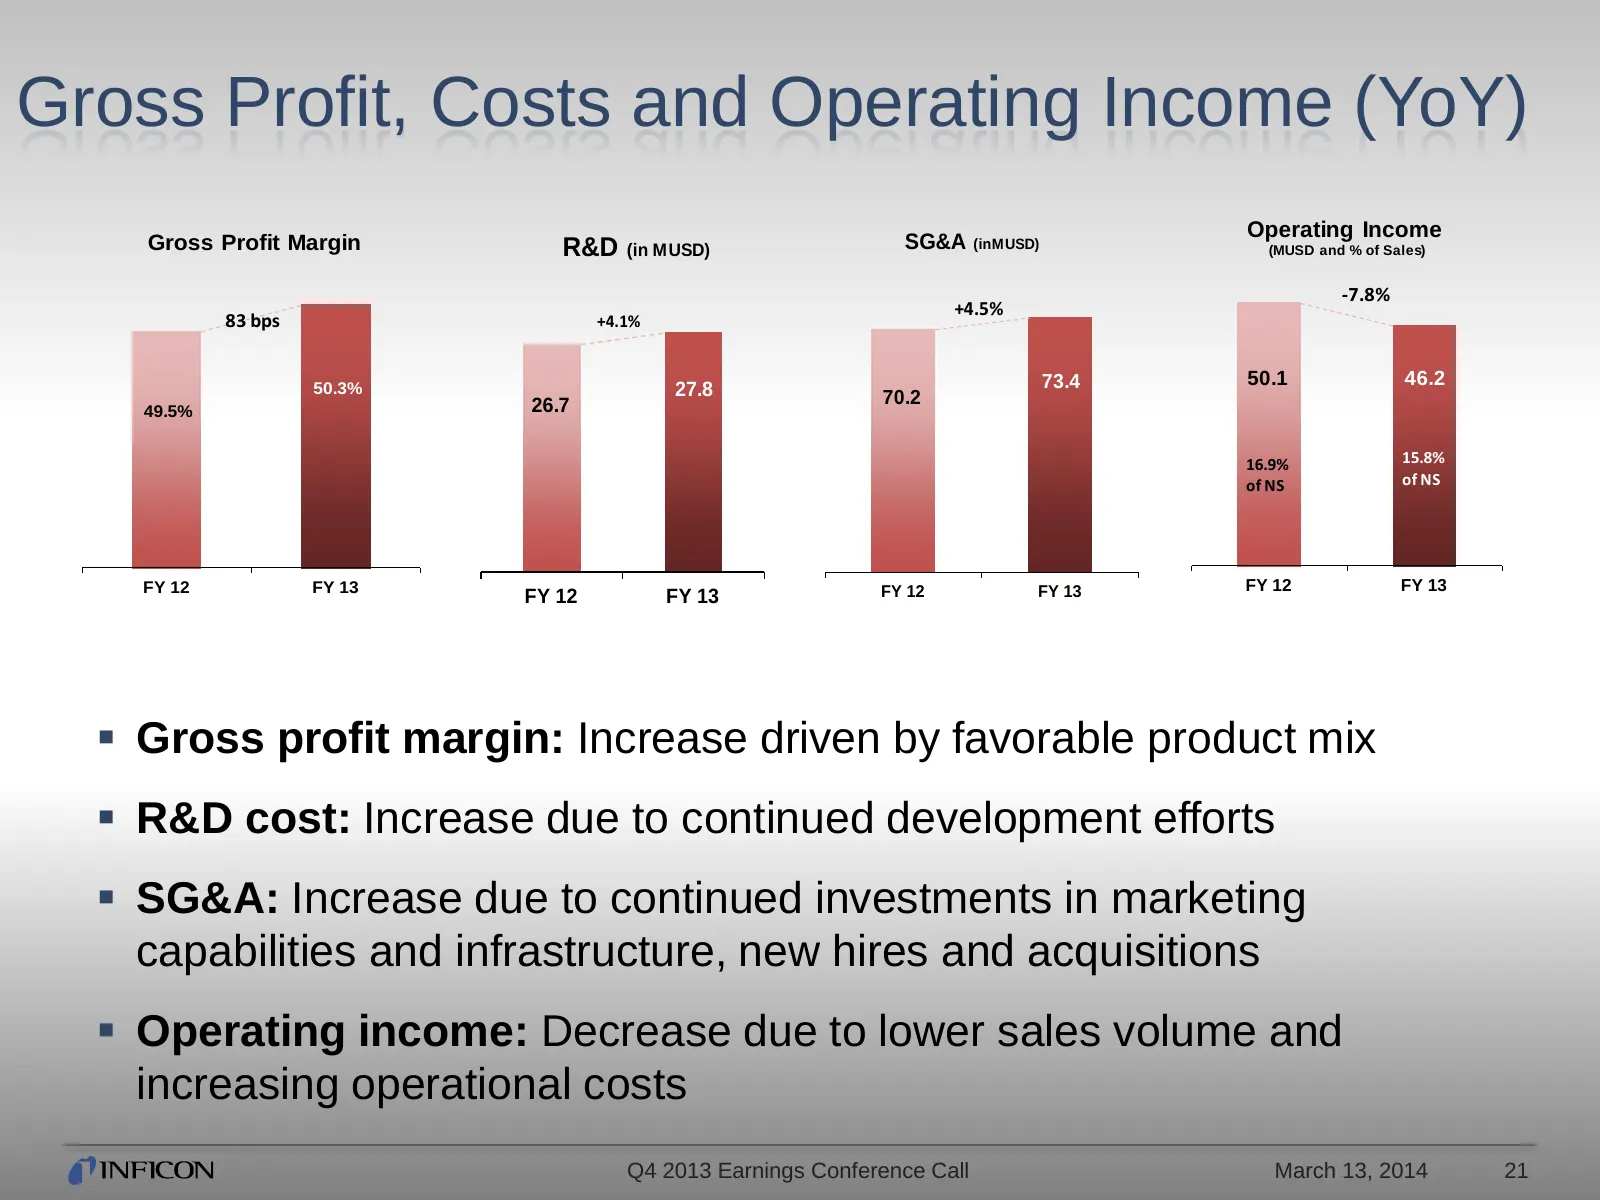
Slide 21: Gross Profit, Costs and Operating Income (YoY)
Gross Profit, Costs and Operating Income (YoY) Operating Income Gross Profit Margin R&D (in MUSD) SG&A (inMUSD) (MUSD and % of Sales) -7.8% +4.5% 83 bps +4.1% 73.4 50.1 46.2 50.3% 27.8 70.2 49.5% 26.7 16.9% 15.8% of NS of NS FY 12 FY 13 FY 12 FY 13 FY 12 FY 13 FY 12 FY 13 Gross profit margin: Incr
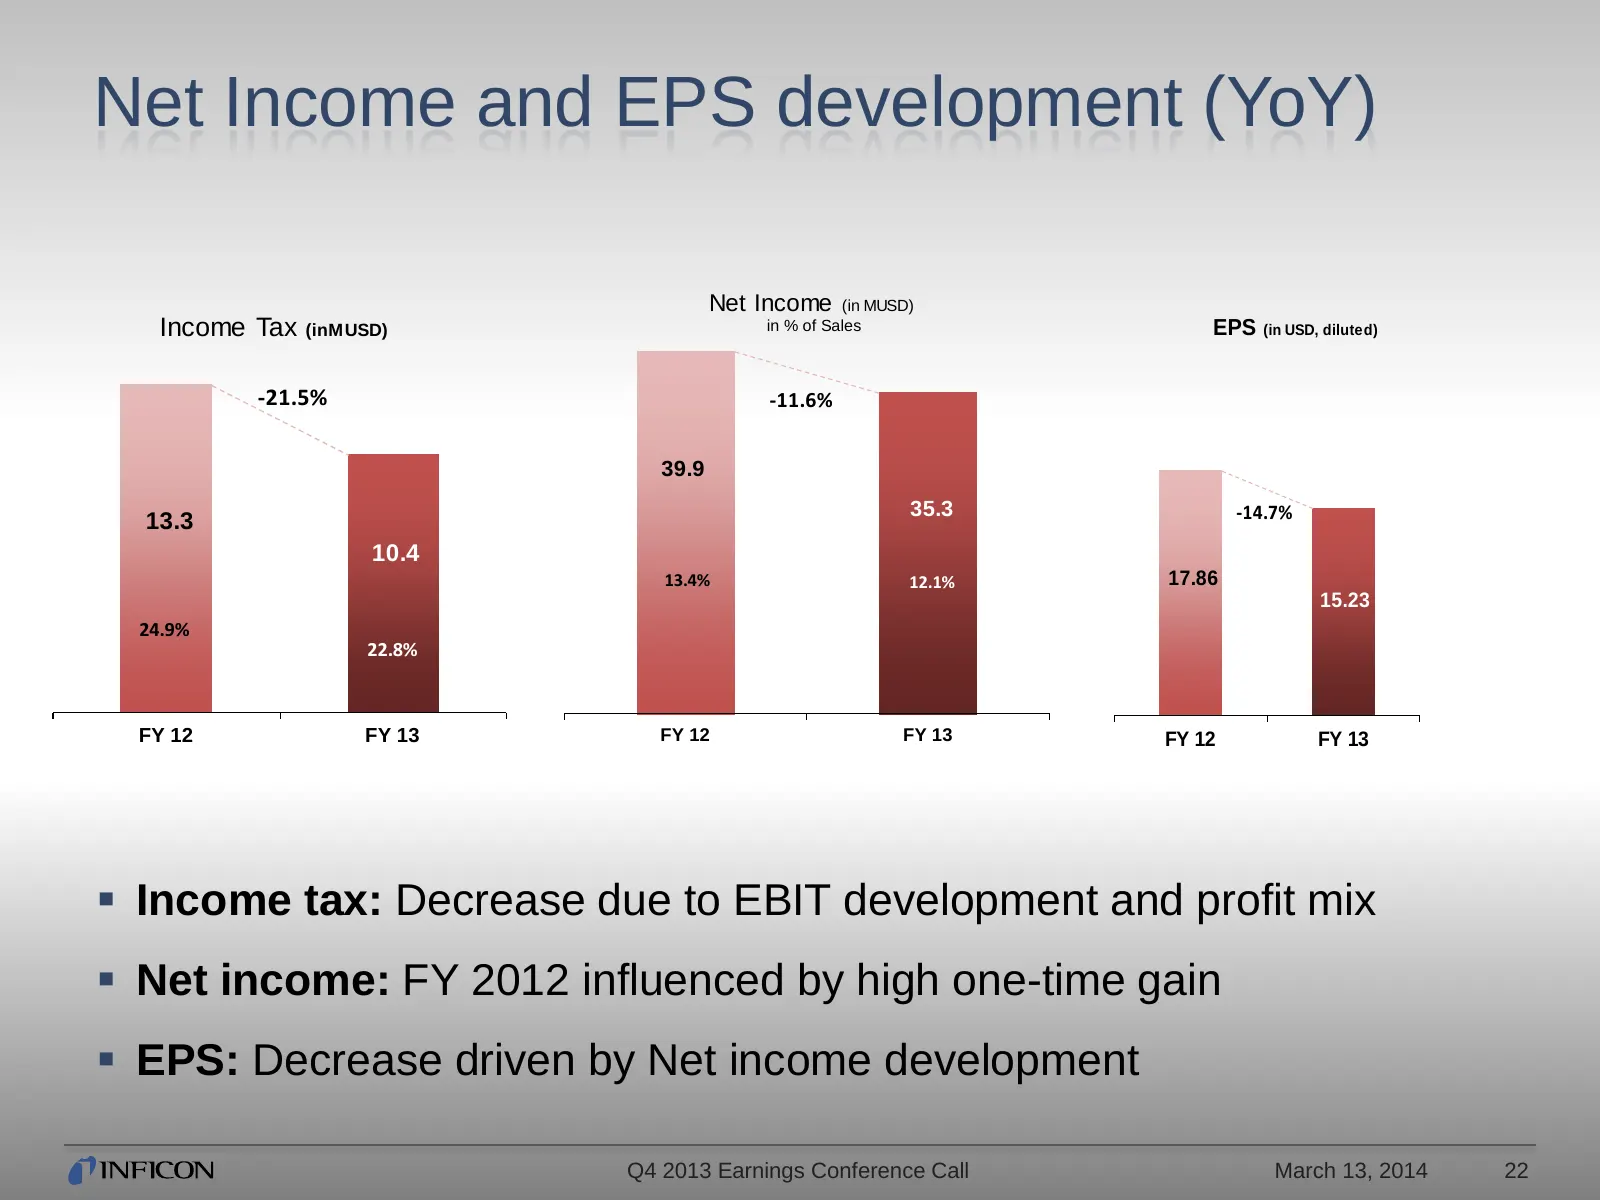
Slide 22: Net Income and EPS development (YoY)
Net Income and EPS development (YoY) Net Income (in MUSD) Income Tax (inMUSD) in % of Sales EPS (in USD, diluted) -21.5% -11.6% 39.9 13.3 35.3 -14.7% 10.4 13.4% 12.1% 17.86 15.23 24.9% 22.8% FY 12 FY 13 FY 12 FY 13 FY 12 FY 13 Income tax: Decrease due to EBIT development and profit mix Net incom
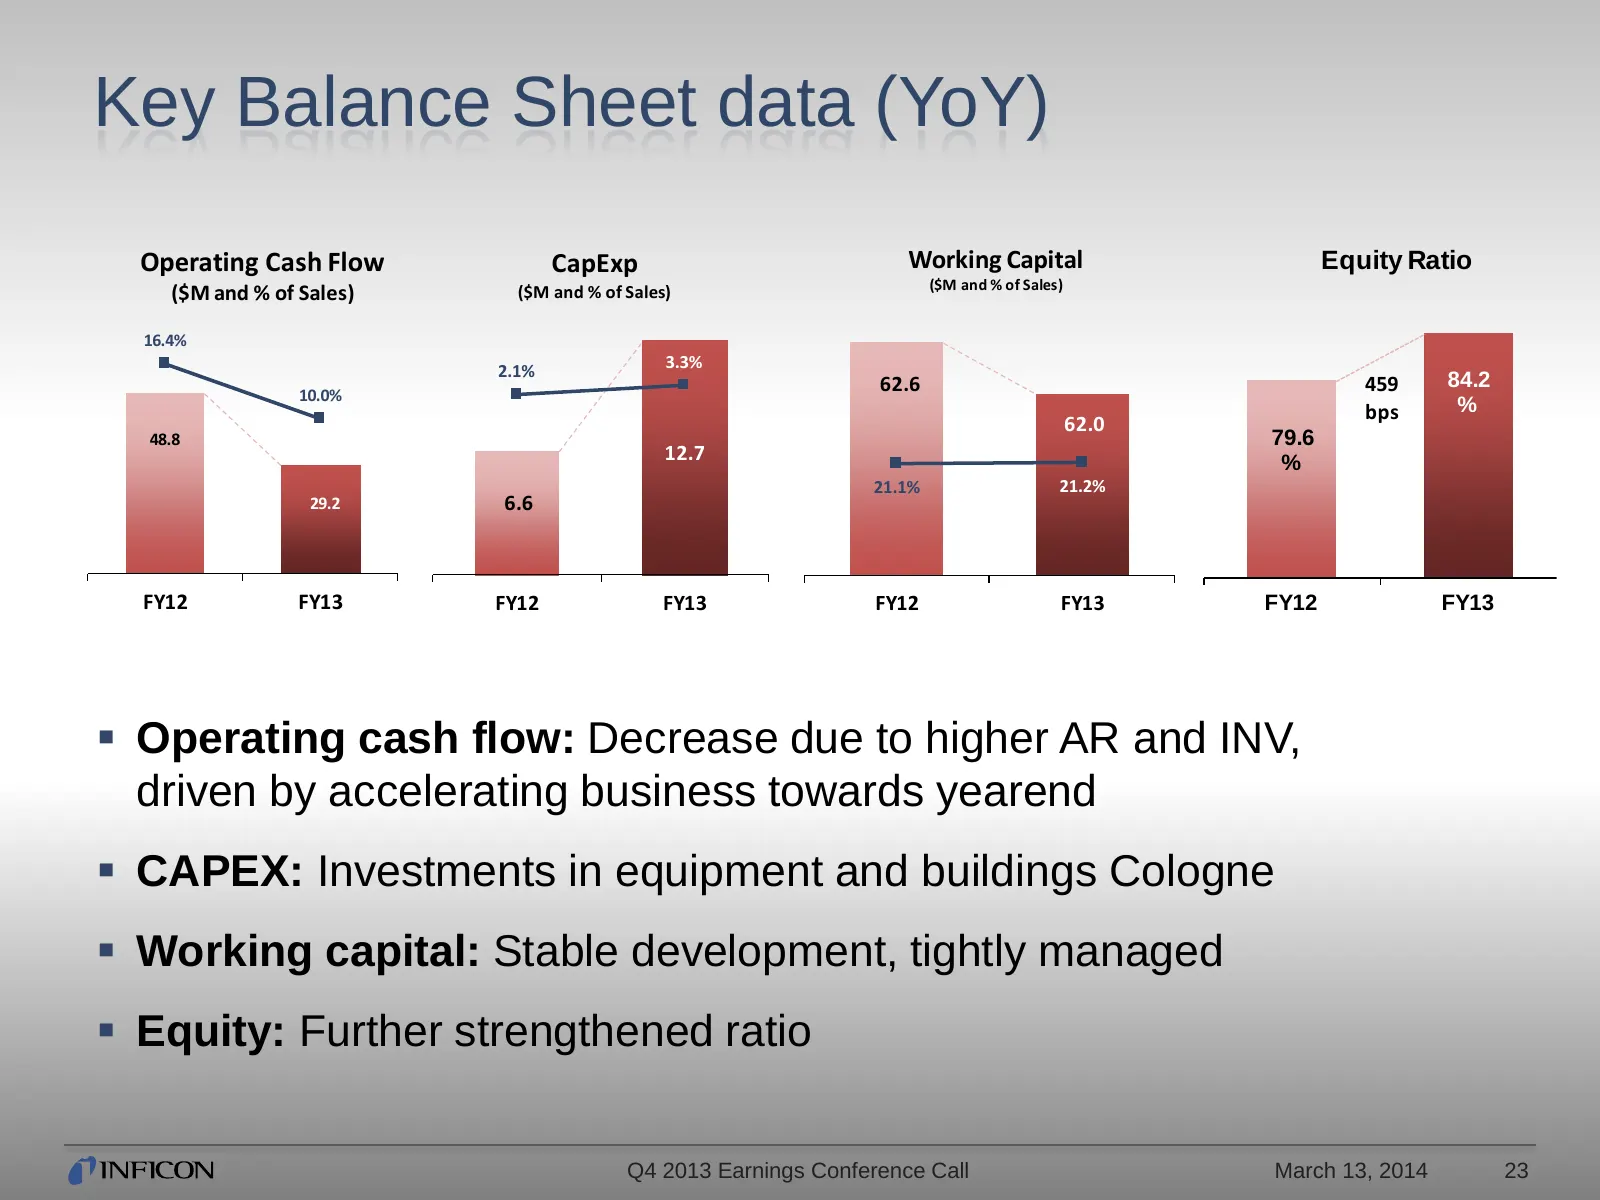
Slide 23: Key Balance Sheet data (YoY)
Key Balance Sheet data (YoY) Operating Cash Flow CapExp Working Capital Equity Ratio ($M and % of Sales) ($M and % of Sales) ($M and % of Sales) 16.4% 2.1% 3.3% 10.0% 62.6 459 84.2 bps % 62.0 48.8 79.6 12.7 % 21.1% 21.2% 29.2 6.6 FY12 FY13 FY12 FY13 FY12 FY13 FY12 FY13 Operating cash flow: Decreas
Slide 24: Distribution Proposal
DISTRIBUTION PROPOSAL
Slide 25: Distribution 2014
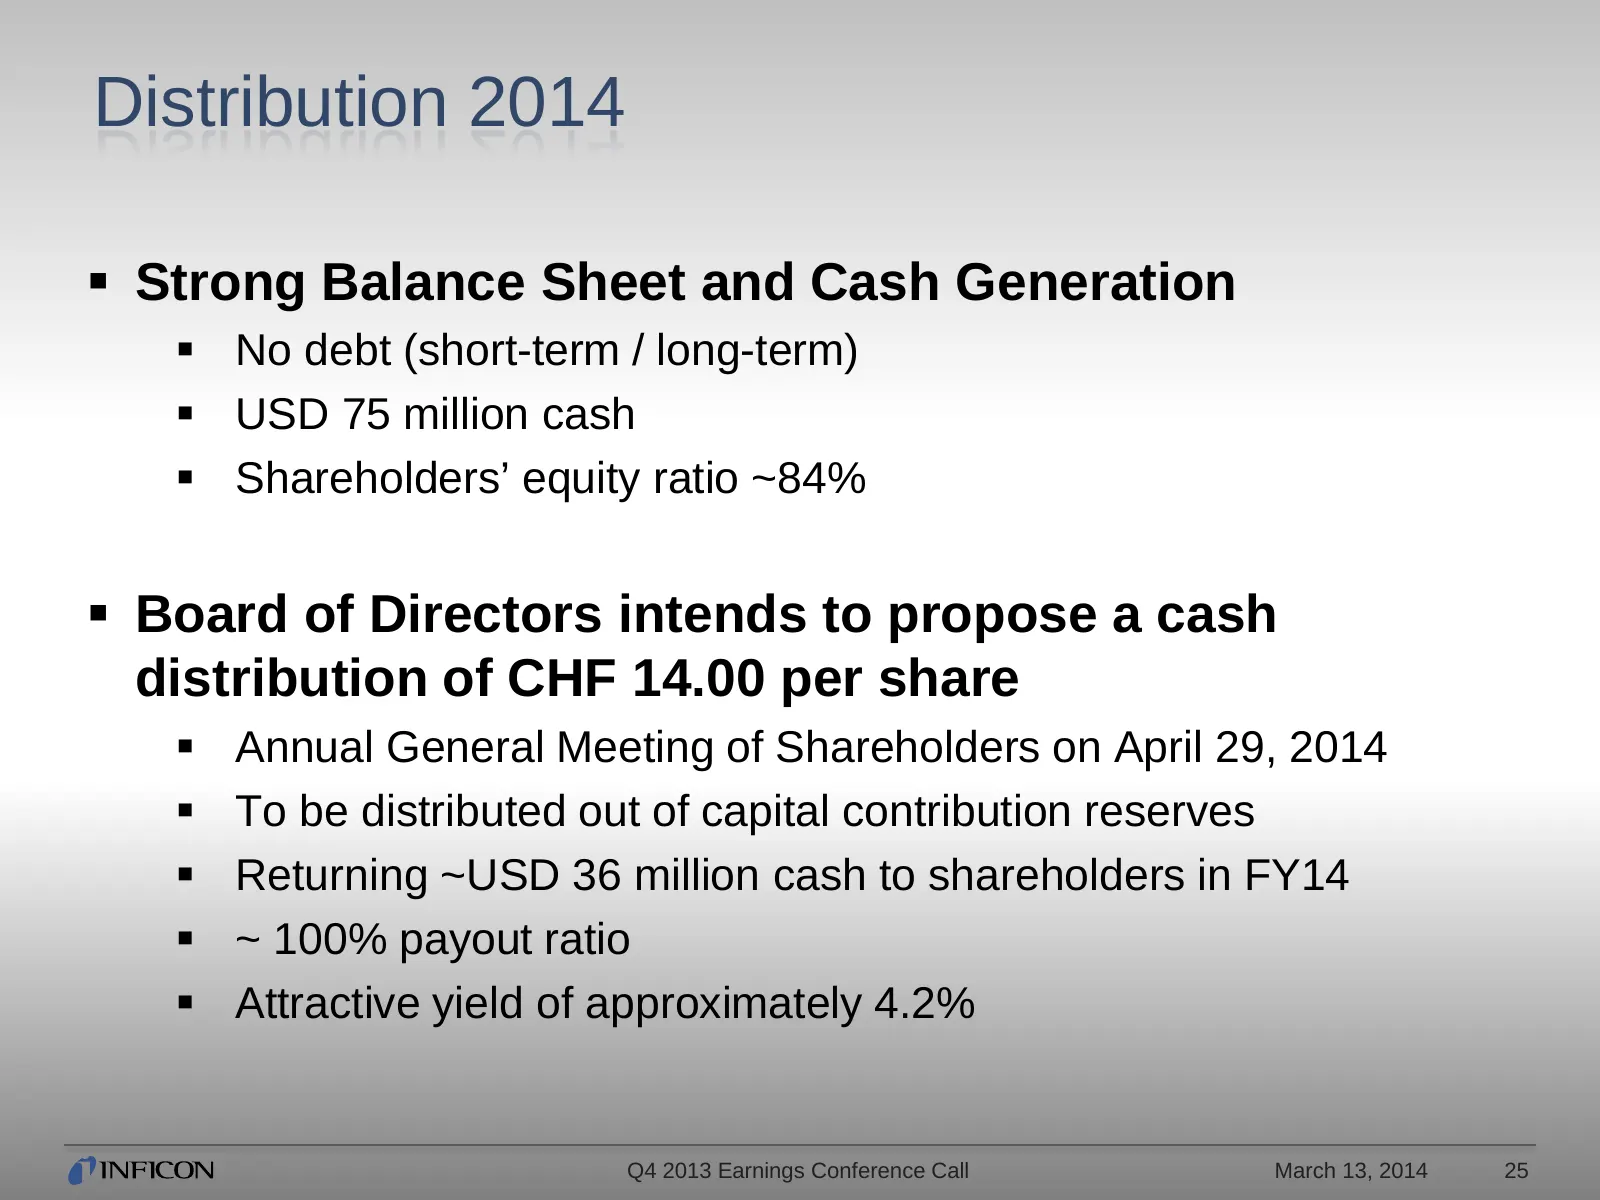
Distribution 2014 Strong Balance Sheet and Cash Generation No debt (short-term / long-term) USD 75 million cash Shareholders’ equity ratio ~84% Board of Directors intends to propose a cash distribution of CHF 14.00 per share Annual General Meeting of Shareholders on April 29, 2014 To b
Slide 26: Guidance FY 2014 and Calendar FY 2014
GUIDANCE FY 2014 AND CALENDAR FY 2014
Slide 27: Full Year 2014 Guidance
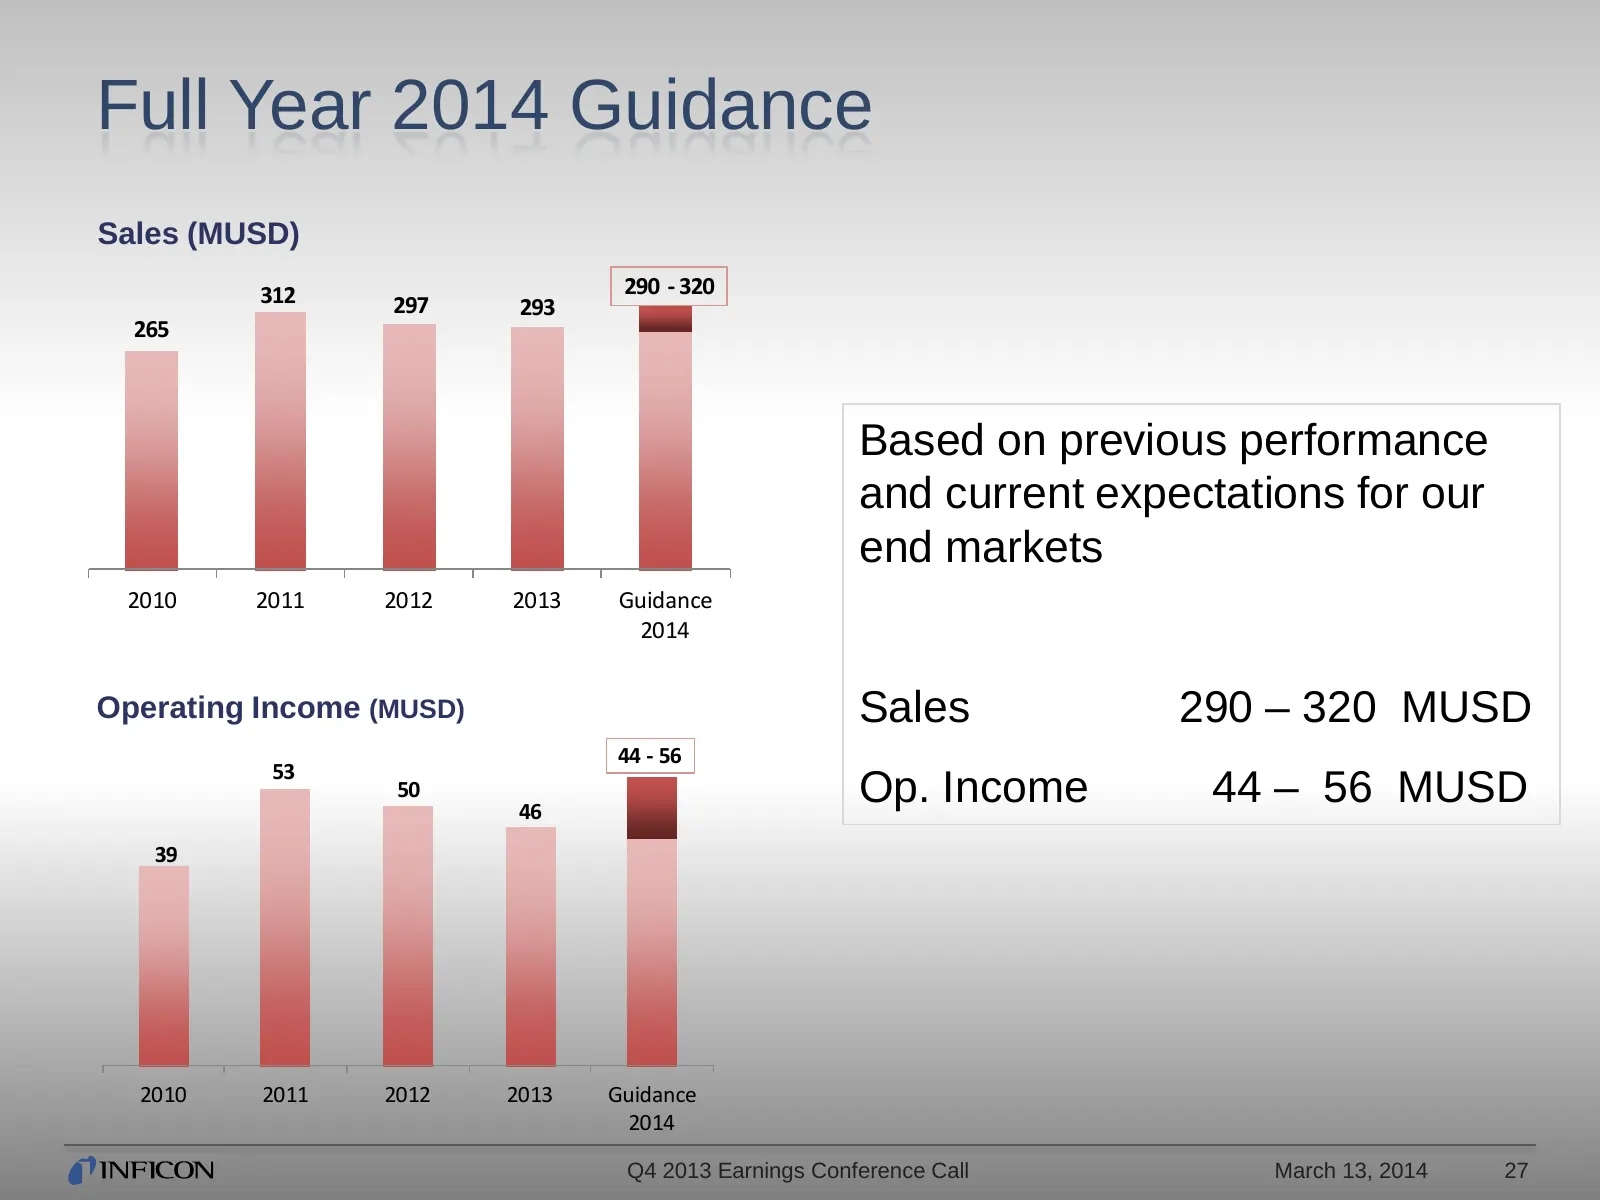
Full Year 2014 Guidance Sales (MUSD) 312 290 - 320 297 293 265 Based on previous performance and current expectations for our end markets 2010 2011 2012 2013 Guidance 2014 Operating Income (MUSD) Sales 290 – 320 MUSD 44 - 56 53 50 46 Op. Income 44 – 56 MUSD 39 2010 2011 2012 2013 Guidance 2014 Q4 20
Slide 28: Corporate Calendar FY 2014
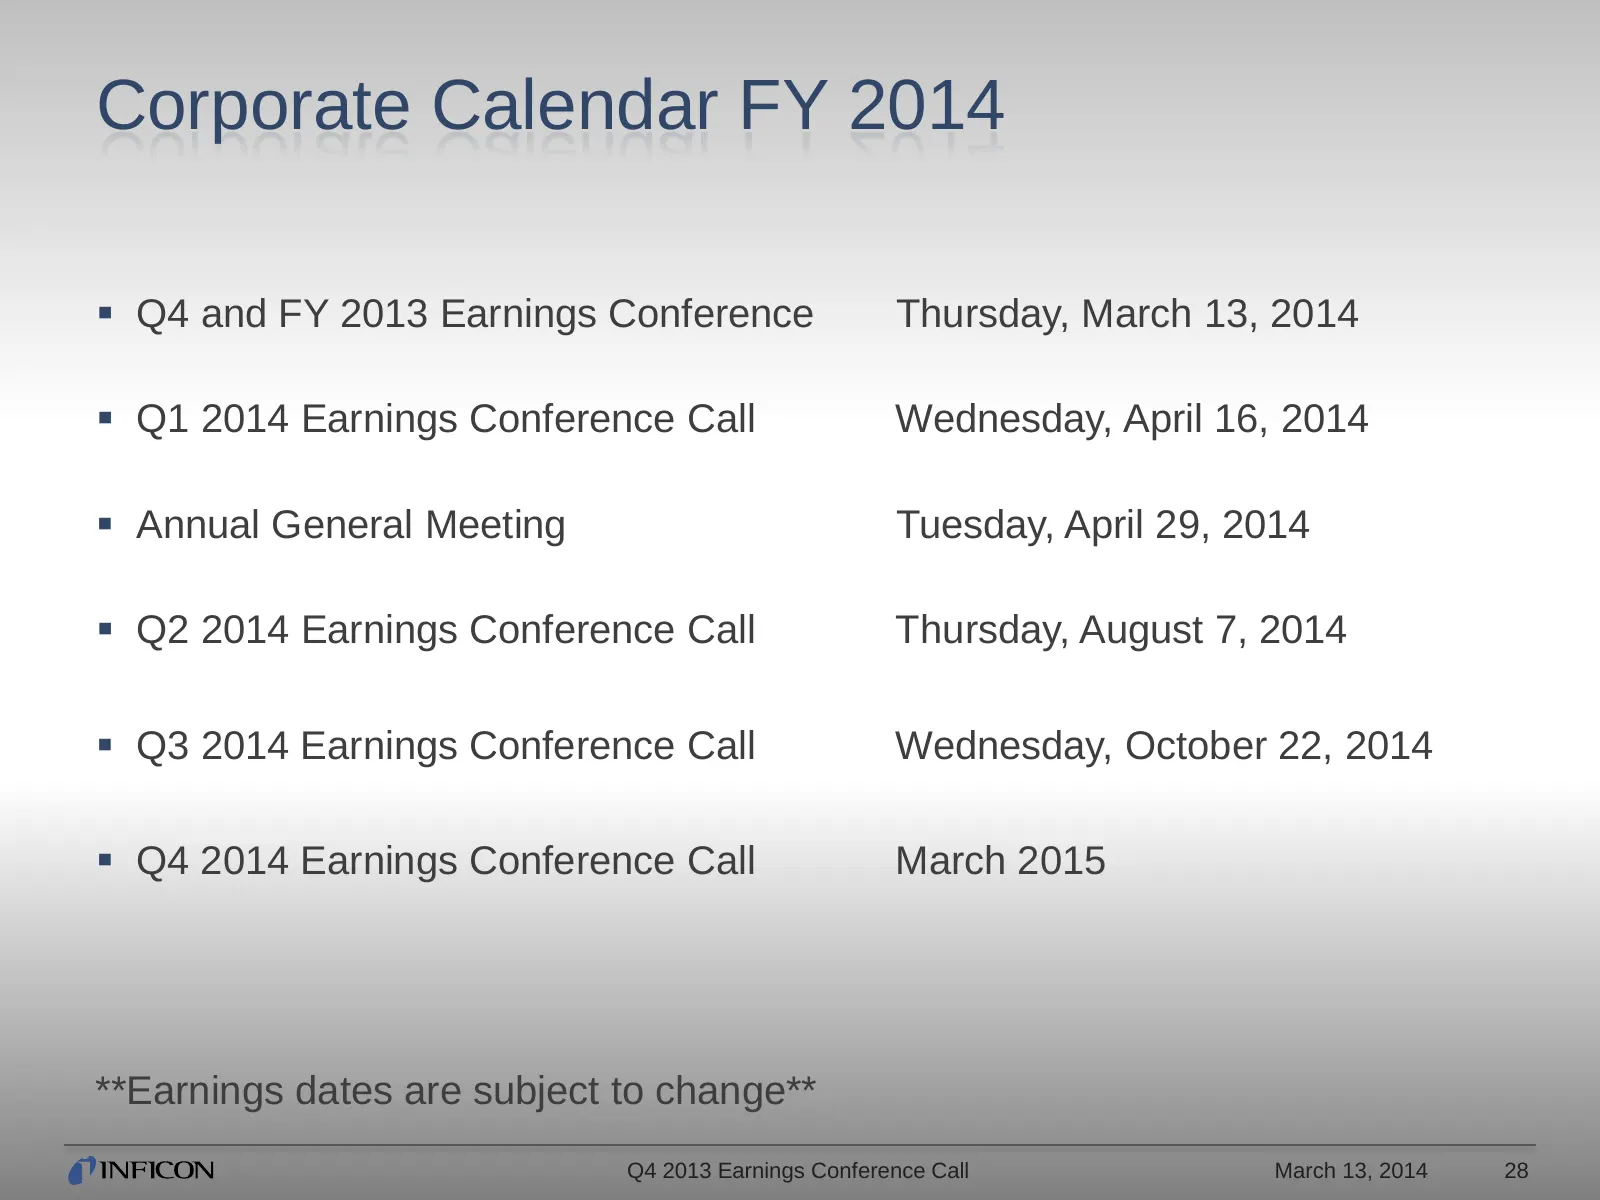
Corporate Calendar FY 2014 Q4 and FY 2013 Earnings Conference Thursday, March 13, 2014 Q1 2014 Earnings Conference Call Wednesday, April 16, 2014 Annual General Meeting Tuesday, April 29, 2014 Q2 2014 Earnings Conference Call Thursday, August 7, 2014 Q3 2014 Earnings Conference Call Wednes
Slide 29: Thank You! Q&A
THANK YOU ! Q&A Q4 2013 Earnings Conference Call March 13, 2014 29
Slide 30: INFICON
6) INFICON Instruments for Intelligent Control™
Source: Internet Archive copy of ir.inficon.com
More decks from INFICON Holding AG
 Q3 2026 Earnings Presentation18 slides · Oct 27, 2026
 Q2 2026 Earnings Presentation20 slides · Jul 30, 2026
 Q1 2026 Earnings Presentation20 slides · Apr 24, 2026
 Q4 2025 Earnings Presentation32 slides · Mar 24, 2026
 Q1 2025 Earnings Presentation20 slides · Apr 24, 2025
 Technical Presentation (September 2024)44 slides · September 2024