Firstcity Financial — Corporate Update (November 2005)
13 slides from Firstcity Financial's corporate update, Nov 29, 2005
Slide 1: American Pioneer Bank
AMERICAN PIONEER BANK PinstCiry November 28, 2005
Slide 2: Why a Bank?
Why a Bank? + Creates a predictable income stream from net interest margin + Establishes a diversification of income * Increases marketing effectiveness by pursuing quality performing loans; the Bank will not be a purchaser of sub-prime or non- performing credit + Fills an uncovered niche in FirstCi
Slide 3: Attributes of an Industrial Bank
Attributes of an Industrial Bank + State chartered institution with FDIC insured deposits * Regulated like a commercial bank, however the Bank Holding Company Act (BHCA) does not apply to parent + Permitted by federal law to export its home state's laws governing interest regardless of customer loca
Slide 4: U.S Industrial Banks with Total Assets of $500MM or more
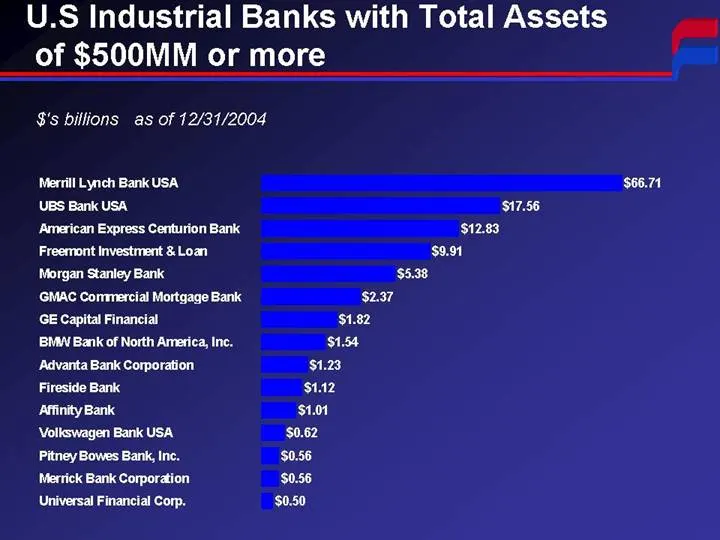
U.S Industrial Banks with Total Assets of $500MM or more = $'s billions as of 12/31/2004 Merrill Lynch Bank USA a UBS Bank USA aaa ES ‘American Express CenturionBank = $2.8. Freemont Investment & Loan 89,81 Morgan Stanley Bank $8.88 GMAC Commercial MortgageBank 82.37 GE Capital Financial $1.82. BMA
Slide 5: Why the Joint Venture with Cargill?
Why the Joint Venture with Cargill? Established Relationship FirstCity and Cargill Value Investment (CVI) have a fifteen year history of successful partnerships Expand Markets FirstCity and CVI have come together to establish the Bank for the purpose of expanding their established market and operati
Slide 6: American Pioneer Bank Business Model
American Pioneer Bank Business Model = + General Operating Structure — Single office in Salt Lake City, Utah + Sources of Funds — Deposits generated from wholesale sources _ including brokers and master CD programs with leading securities firms + Uses of Funds - Secondary market purchases of quality
Slide 7: Bank Structure and Organization
Bank Structure and Organization ae The ownership structure is designed to provide the Bank with the use of the FirstCity net operating loss carryforwards for federal income tax purposes Initial capitalization of $30 million with FirstCity contributing $19.2 million Bank will be a Utah Based “C” Corp
Slide 8: Relationship Between Bank and Parent
Relationship Between Bank and Parent ¢ The Bank will contract with FirstCity for certain general administrative, acquisition analysis and loan administration services in compliance with section “23B” of Federal Bank Regulations. ¢ FirstCity and Cargill Value Investment will present loans and portfol
Slide 9: Leveraging of Existing FirstCity Infrastructure
Leveraging of Existing FirstCily Infrastructure + Due diligence/underwriting concepts and staff in place « Systems familiarity * Credit Administration functionality ¢ Existing Marketing effort expanded to include quality performing loans * Existing management well-versed in banking and regulatory is
Slide 10: FirstCity Core Competencies
FirstCity Core Competencies Well experienced in business and legal matters relating to commerciall lending *«Management/resolution of purchased portfolios «Investor Reporting «Back room functionality to support business operations
Slide 11: Management
Management me Chairman of the Board of Directors: Frank Aelvoet Senior Vice President of FirstCity Servicing Corp. and Vice Chair of its Senior Loan Committee. Previous bank lending and board of directors experience. President: A. Hartie Spence Over 40 years of senior management bank experience incl
Slide 12: Business Plan Strengths
Business Plan Strengths + Recruited a seasoned Management team well versed and experienced in commercial banking + Assembled capable, knowledgeable and experienced independent Board members with commercial banking backgrounds + Proven business model * Owners long-term history of successful partnersh
Slide 13: Searchable text section of graphics shown above
Searchable text section of graphics shown above AMERICAN PIONEER BANK [LOGO] November 28, 2005 Wh y a Bank? • Creates a predictable income stream from net interest margin • Establishes a diversification of income • Increases marketing effectiveness by pursuing quality performing loans; the Bank will
Source: SEC EDGAR · 8-K filed Nov 29, 2005