IBERIABANK — Gulf South Banking Conference May 2012
51 slides from IBERIABANK's conference presentation, May 14, 2012
Slide 1: Gulf South Banking Conference May 2012
Gulf South Banking Conference May 2012 Gulf South Banking Conference May 2012
Slide 2: Safe Harbor Language
Safe Harbor Language Safe Harbor Language In connection with the proposed acquisition of Florida Gulf Bancorp, Inc., IBERIABANK Corporation will file a Registration Statement on Form S-4 that will contain a proxy statement/prospectus. INVESTORS ARE URGED TO CAREFULLY READ THE PROXY STATEMENT/PROSPEC
Slide 3: Company Overview
Company Company Overview Overview
Slide 4: IBERIABANK
IBERIABANK
Slide 5: Acquisitions, Conversions, Capital Activities and New Initiatives
Acquisitions Recent Conversions Capital Activities New Initiatives ANB (Bentonville, AR) - 2Q09 Pulaski Bank & Trust Becomes IBERIABANK fsb - 2Q09 Issued $7 Million in Trust Preferred - 1Q08 Added Teams in Mobile, New Orleans and Houston - 1Q09 CapitalSouth Bank (Birmingham, AL) - 3Q09 Converted Sys
Slide 6: Where We Lived & Worked
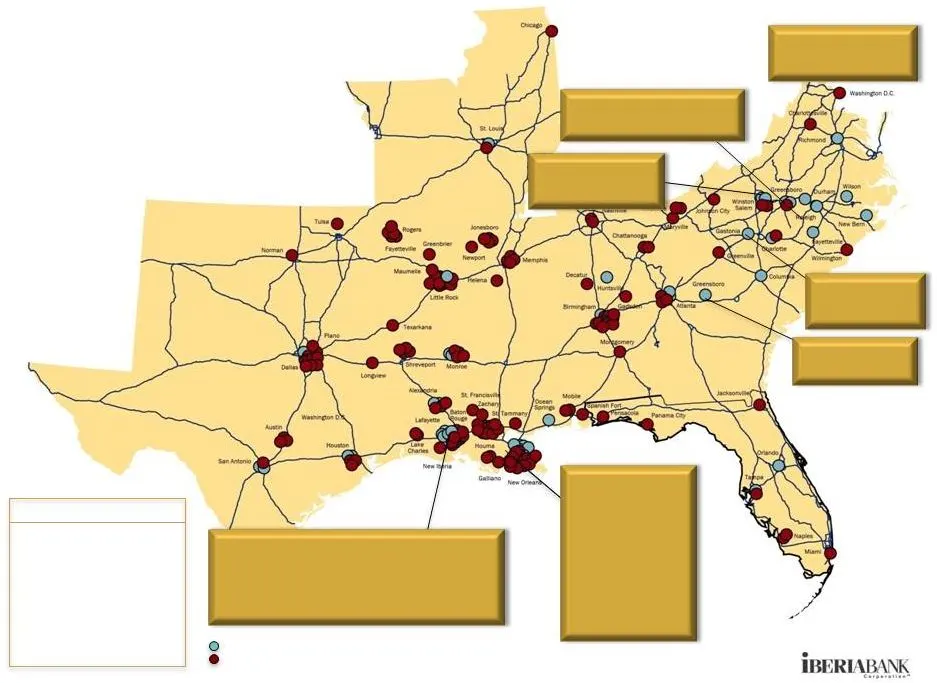
Indicates cities in which our members of Executive Management have resided/worked Indicates cities in which our members of Senior Management (Market Presidents, Executive Vice Presidents, etc.) have resided/worked. Albuquerque, NM Annapolis, MD Boston, MA Buffalo, NY Charlottetown, PE, Canada Chenna
Slide 7: Locations, Total Assets and Deposit Market Share
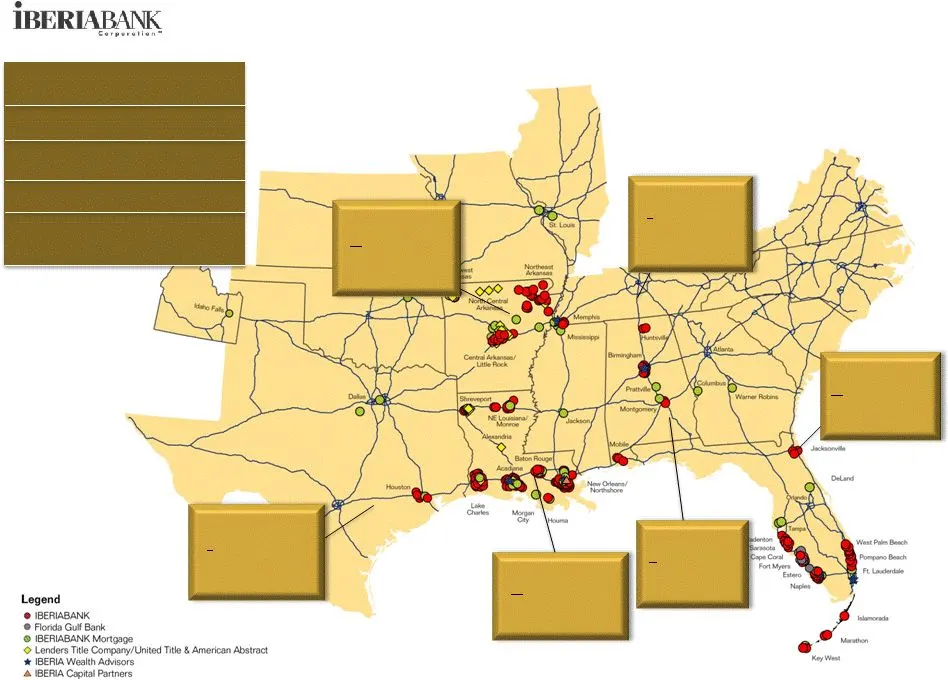
Locations 274 (Bank Branches 175) Total Assets $ 11.8 Billion Total Deposits $ 9.5 Billion Total Loans $ 7.5 Billion Market Capitalization $ 1.5 Billion Deposit Market Share as of June 30, 2011 Florida branch and deposit information reflects pro forma Florida Gulf Bank acquisition Source: SNL Financ
Slide 8: Unemployment Rate by MSA
IBKC Overview IBKC Overview Unemployment Rate by MSA Consistently Low Rates Of Unemployment In Our Legacy MSAs Many Of Our Legacy Markets Not Dependent On Housing For Growth Assets In FDIC- Assisted Acquisition Markets Are Protected Under Loss-Share Agreements * Markets entered via FDIC- assisted ac
Slide 9: Housing Market Trends
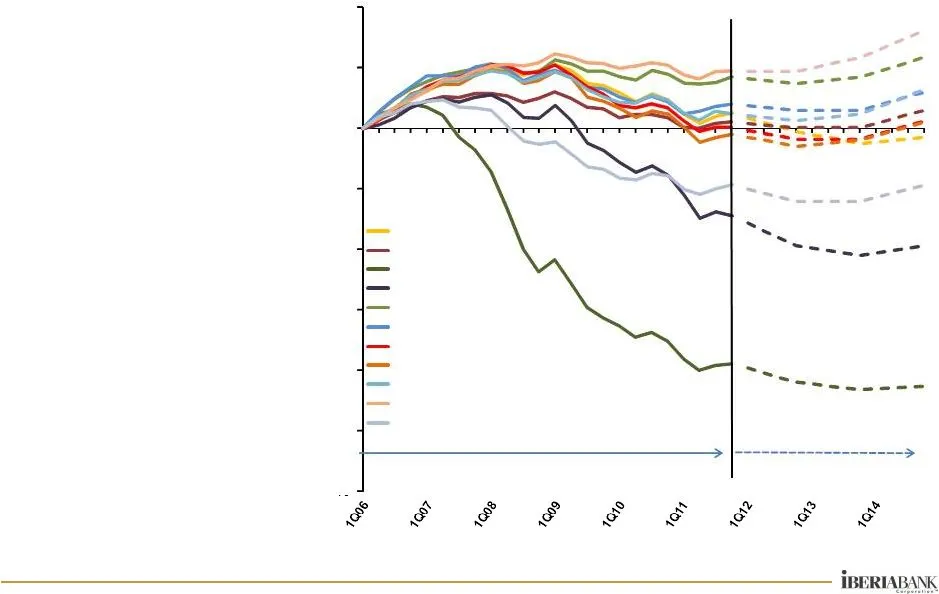
IBKC Overview IBKC Overview Housing Market Trends Impact Varies By State And Market Strength – TX & LA Weakness: FL, GA & VA Very Limited Rebound Florida - Decline Georgia - Decline Virginia – Flatten Large Embedded Losses Remain In Banks’ Balance Sheets Source: Local Market Monitor 4Q2011 14% 1% 2%
Slide 10: Loans & Deposits
Slide 11: Solid Organic Loan Growth
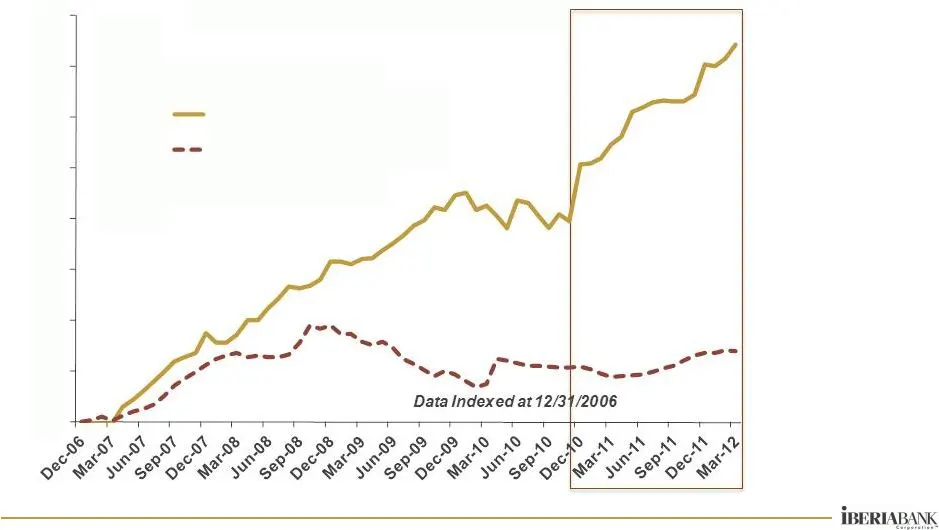
Solid Organic Loan Growth Loans Loans $164 Million Organic Loan Growth In YTD 2012 Counter To Industry Trends 0% 10% 20% 30% 40% 50% 60% 70% 80% Organic Loan Growth December 2006 - March 2012 IBKC data based on organic growth - excluding one-time impact of acquisitions IBERIABANK Corporation U.S. Co
Slide 12: Growth In Organic And Covered Loans
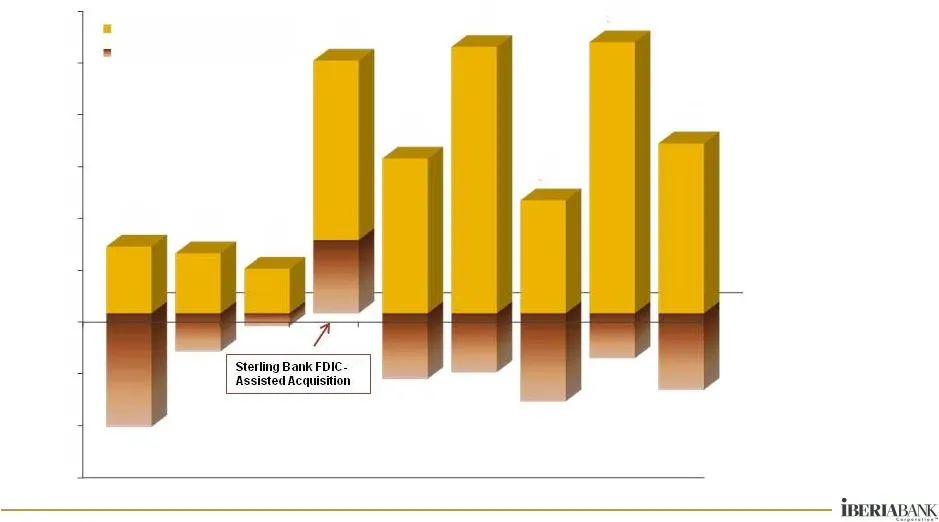
Growth In Organic And Covered Loans Loans Loans Organic Loan Growth of $1.3 Billion or 31% Since December 2009 (14% Annualized) FDIC Covered Loan Portfolio Declined $409 Million or -25% Since December 2009 (-11% Annualized) $ in millions -$150 -$100 -$50 $0 $50 $100 $150 $200 $250 $300 Mar-10 Jun-10
Slide 13: $7.5 Billion Loan Portfolio
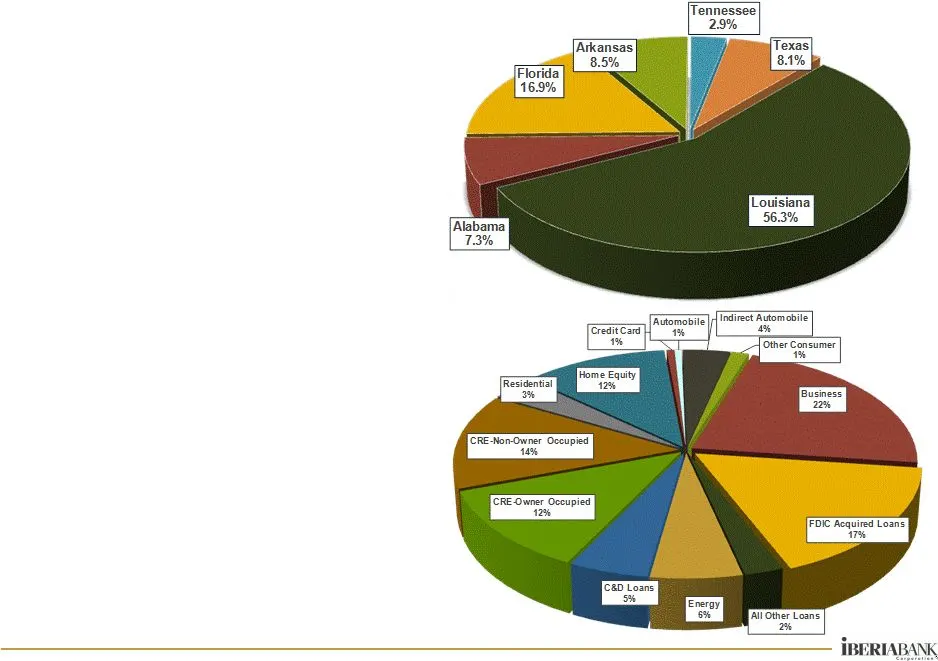
$7.5 Billion Loan Portfolio Acquired $3.2 Billion Of Gross Loans In FDIC-Assisted Acquisitions Covered Under Loss Share Agreements Includes $824 Million Of Fair Value Loans Acquired at Cameron and OMNI 1Q12 Net Loan Yield of 4.87% Note: Loans Net of Purchase Discounts at March 31, 2012 Loan Portfoli
Slide 14: Commercial Commitments Trend
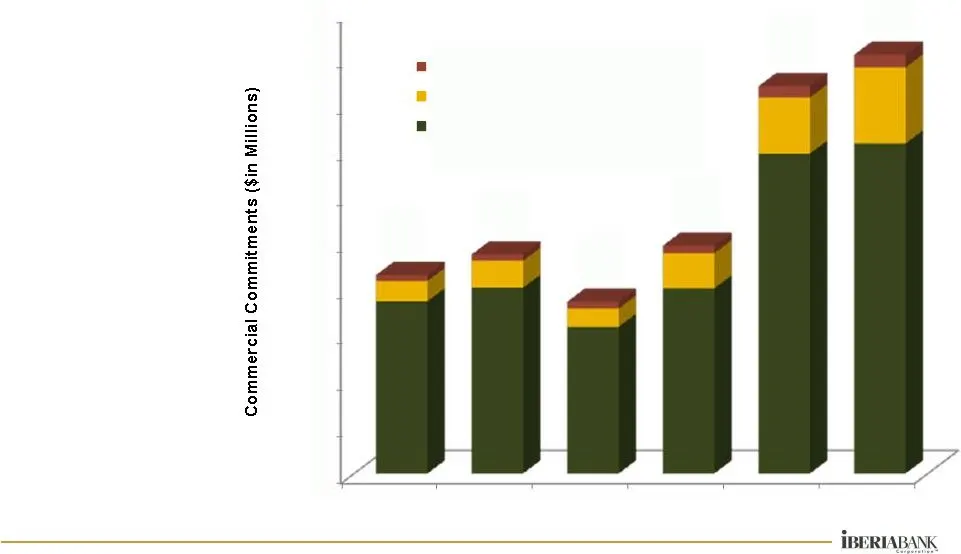
Commercial Commitments Trend Loans Loans Unfunded And Unused Commitments Nearly Doubled Over The Last 15 Months Strength In Houston, New Orleans, Baton Rouge And Birmingham Funding A Significant Portion Of These Commitments Would Expand Our Balance Sheet $863 $952 $747 $990 $1,683 $1,819 $- $200 $40
Slide 15: Growth In Organic Deposits
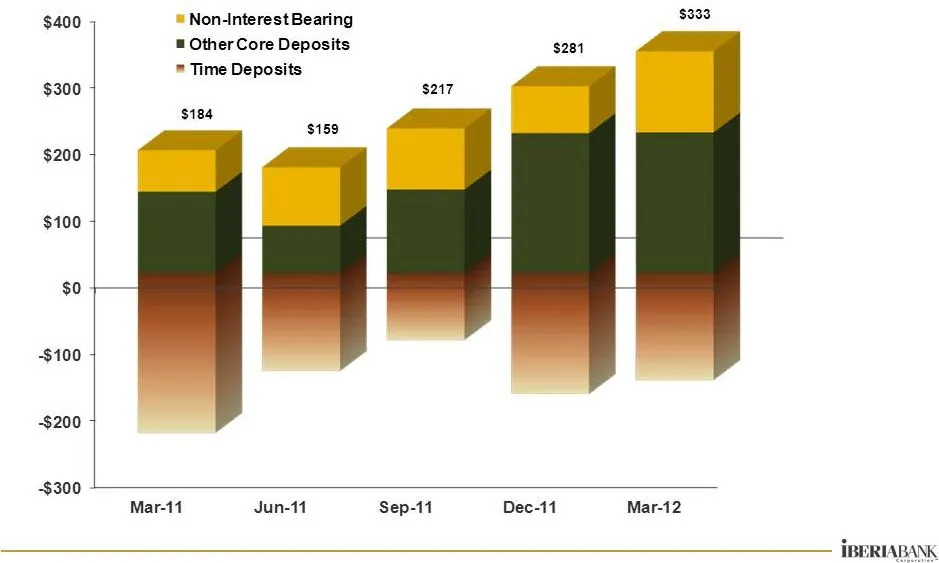
Deposits Deposits Growth In Organic Deposits Organic Core Deposit Growth Of $1.2 Billion Or 23% Since December 2010 (19% Annualized) Organic Non- Interest Bearing Deposit Growth of $435 Million or 50% Since December 2010 (40% Annualized) Cost of Core Deposits Has Fallen 34 bps To 0.47% Since Decembe
Slide 16: Deposit Summary
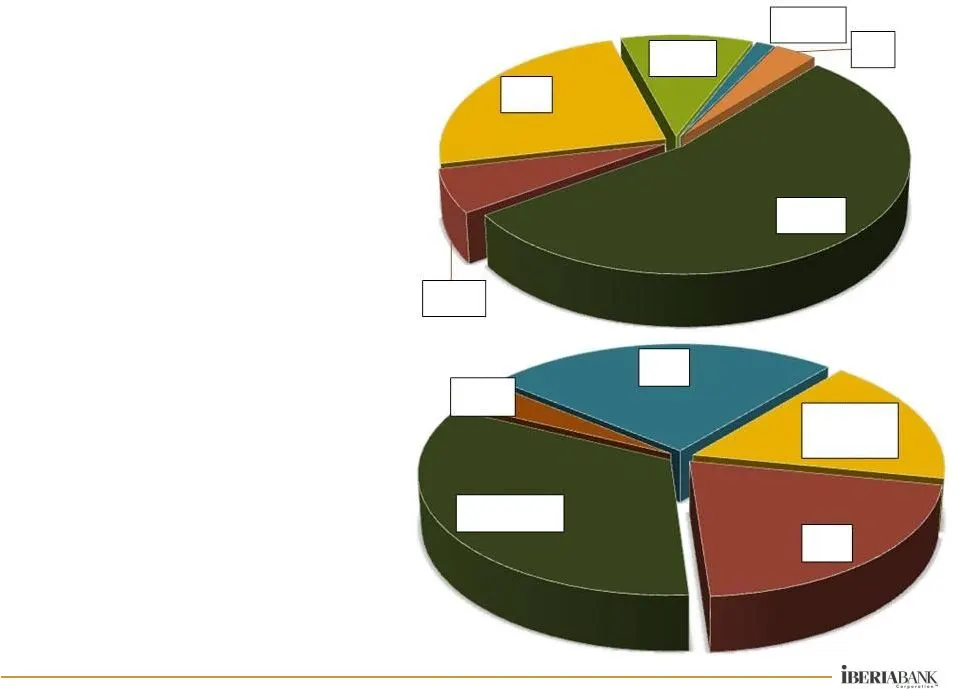
Deposit Summary Deposits Deposits Balanced And Diverse Deposit Portfolio Average Cost Of Interest Bearing Deposits Was 0.72% In 1Q12 Note: Deposits Net of Purchase Discounts at March 31 ,2012 Total Cost Of Deposits Was 0.60% In 1Q12 Non-Interest Bearing 17.0% NOW 20.8% Money Market 33.3% Savings 3.7
Slide 17: Asset Quality
Asset Asset Quality Quality
Slide 18: U.S. Nonperforming Assets
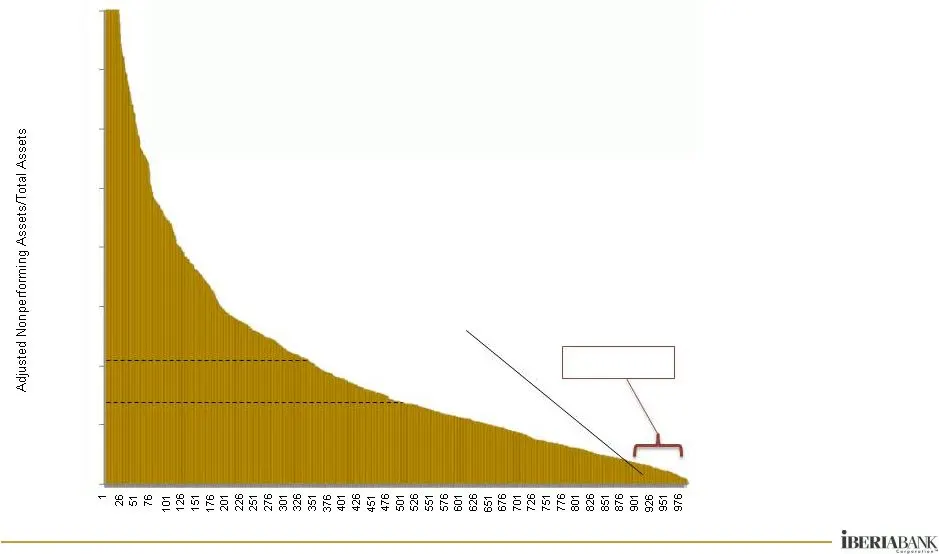
Asset Quality Asset Quality U.S. Nonperforming Assets Banks Invested In Real Estate At The Top Of The Cycle Industry NPA Ratios Improved; A Long Way To Recovery Historically, Typically Takes Many Years To Recover From Peak In NPAs Recovery Tied To: Borrower Health Property Values Sustained Low Inter
Slide 19: Peer Comparison Trends
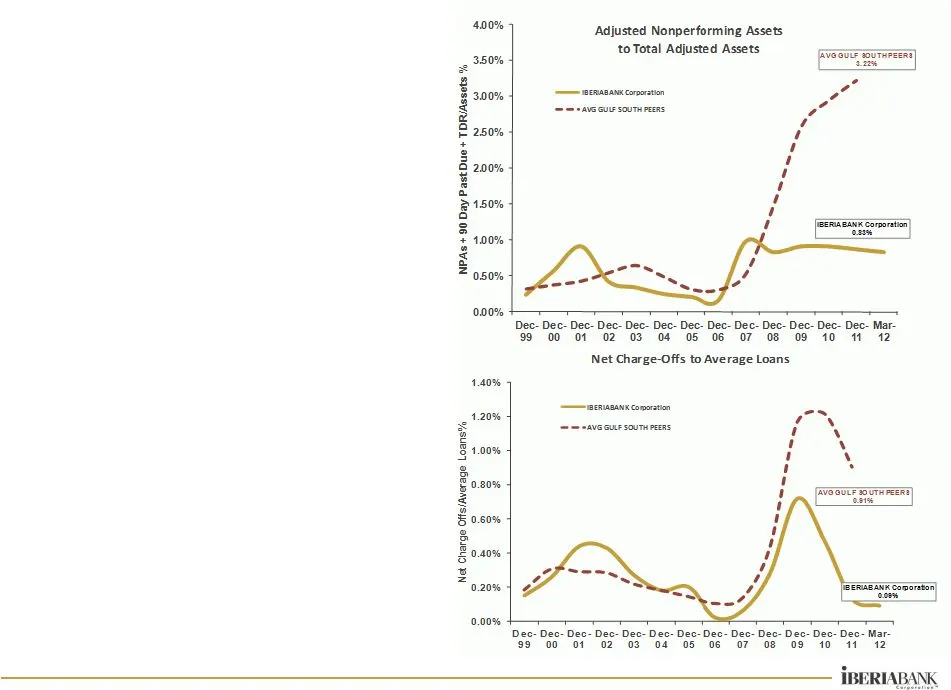
Peer Comparison Trends Asset Quality Asset Quality $812 Million in NPAs, But $729 Million Covered Under FDIC Loss Share Or Acquired Impaired Assets Legacy TDRs Total Only $27 Million * Excludes FDIC Covered Assets 17% Of Loans Are FDIC Covered Assets
Slide 20: Classified Assets
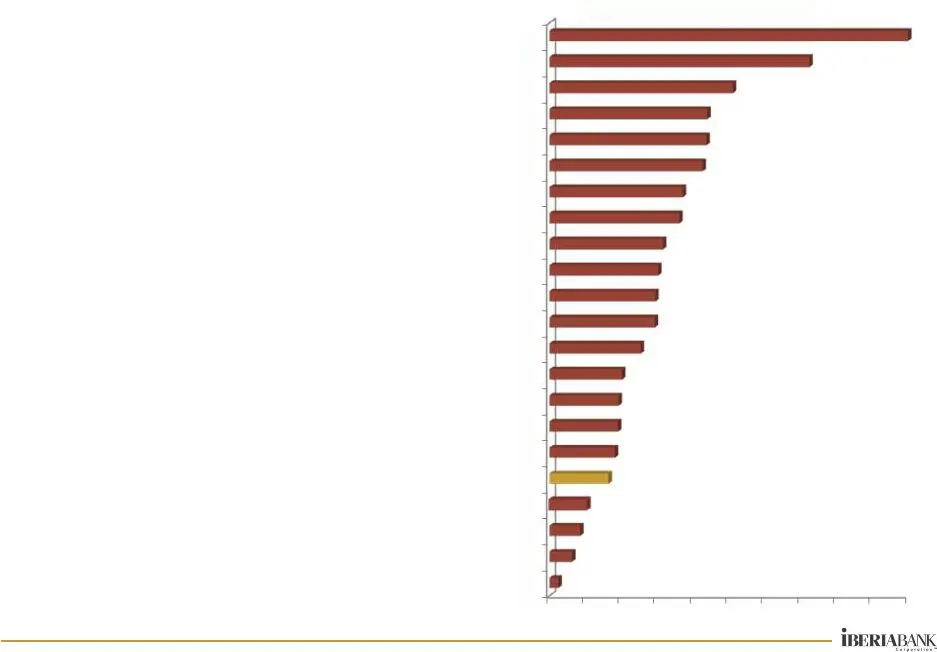
Asset Quality Asset Quality Classified Assets “Classified Assets” Are Loans That Exhibit Stress And Warrant Close Watching Classified Assets were $206 million at December 31, 2011 and $194 million at March 31, 2012 Our Classified Assets As A Percentage Of Total Assets Are Very Low, Particularly Comp
Slide 21: Financials
Financials
Slide 22: First Quarter 2012 vs. Fourth Quarter 2011
Financials Financials First Quarter 2012 vs. Fourth Quarter 2011 Revenues Up 1% Expenses Up Less Than 1% Margin Down 3 Bps. EPS Up 11% Stable Dividends Assets Up Less Than 1% Deposits Up 2% Market Cap Up 9% Book Value Per Share Up Less Than 1% Tangible Book Value Per Share Up 1% Share Price Up 8% St
Slide 23: Loan Yield Trends
Financials Financials Loan Yield Trends Net Covered Loan Yield In 2Q12 Yield Is Expected To Be Approximately 5.05% The Covered Portfolio Is Expected To Decline Approximately $75 Million Based On Current FDIC Loss Share Accounting Assumptions And Estimates 4.78% 5.14% 4.87% 4.00% 4.20% 4.40% 4.60% 4.
Slide 24: Time Deposits Repricing Over Next 12 Months
$1.8 Billion In Aggregate Time Deposits Repricing Over The Next 12 Months At A Weighted Average Rate Of 1.16% Financials Financials Repricing Schedule 2Q12 3Q12 4Q12 1Q13 2Q13 Cash Equivalents 450.7 $ - $ - $ - $ - $ 0.61% 0.00% 0.00% 0.00% 0.00% Investments 176.5 $ 142.2 $ 97.6 $ 84.6 $ 90.5 $ 3.15
Slide 25: Interest Rate Risk
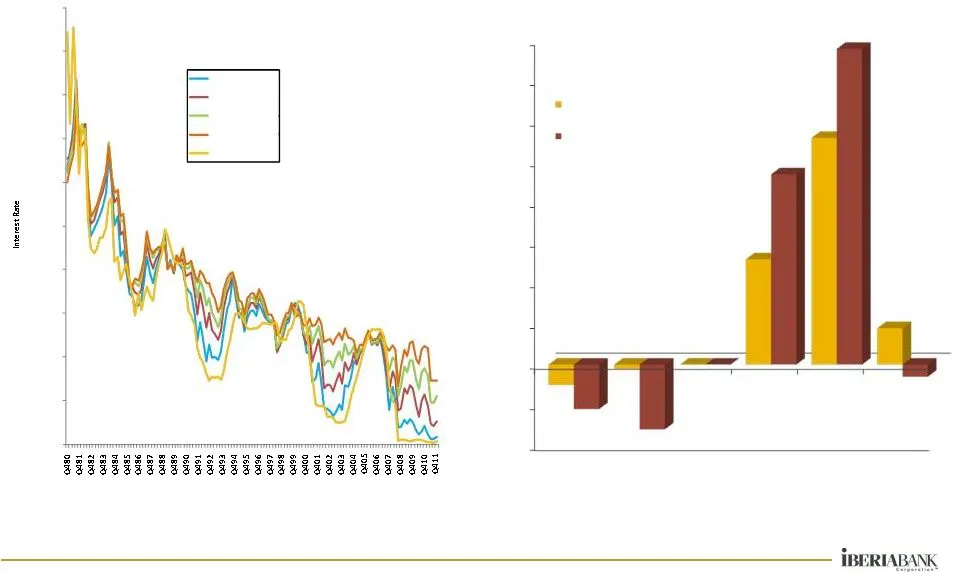
Financials Financials Interest Rate Risk IRR Simulation Results Source: Bancware March 31, 2012 Source: Bloomberg -2.00% -1.00% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 7.00% 8.00% -200 bps -100 bps Base Case +100 bps +200 bps Forward Curve Change in Net Interest Income Change in Economic Value of
Slide 26: Service Charges As A Percentage Of Revenues
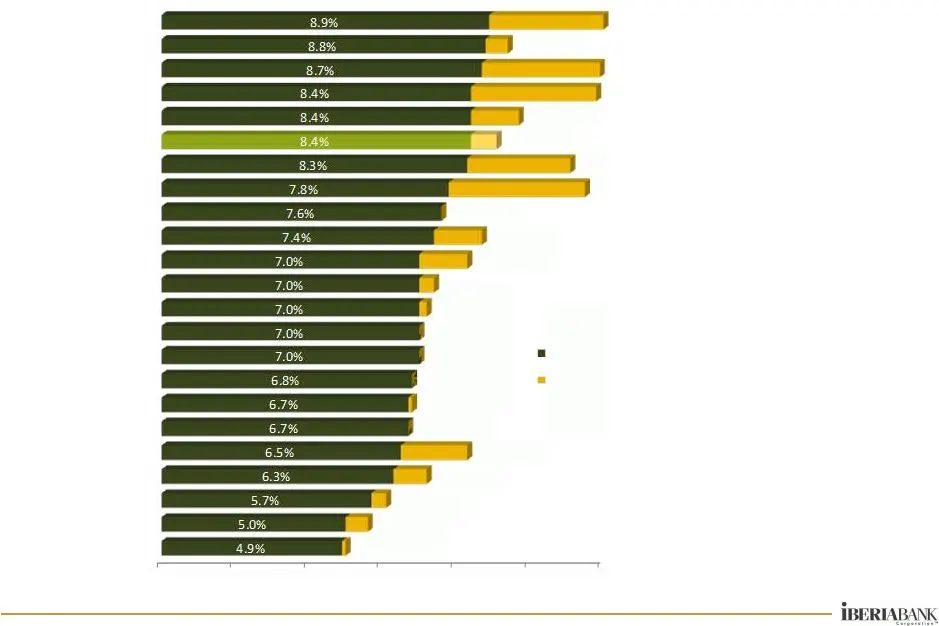
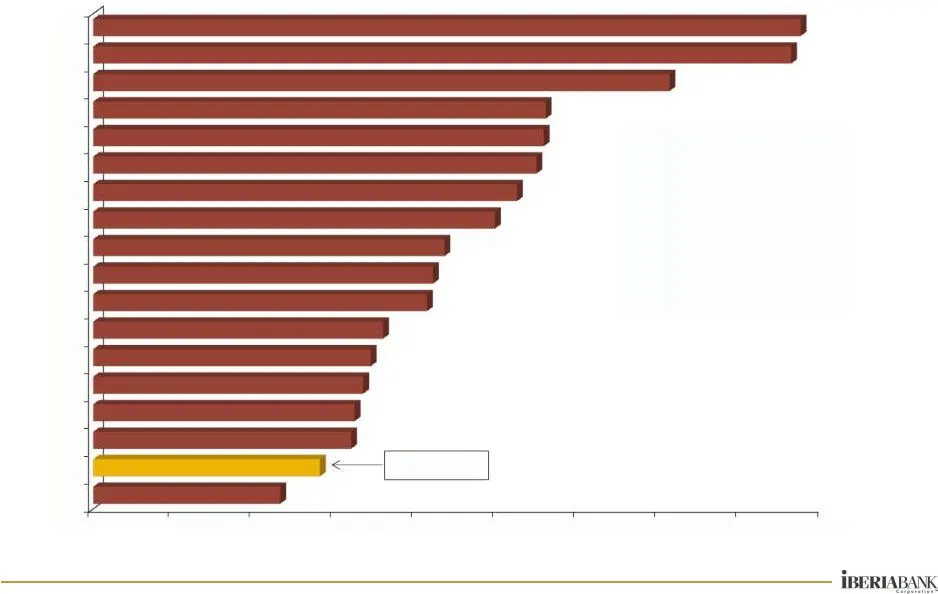
Financials Financials Service Charges As A Percentage Of Revenues 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% 18.0% PBIB IBKC CSFL SBCF HOMB UCBI OZRK PFBX HBHC FSGI RNST TRMK BXS SFNC FMFC SBSI CCBG MSL IBKC = 5% Less Reliance On Service Charge Income And Consumer Fees Than Peers Source: SNLDa
Slide 27: IBERIA Capital Partners And IBERIA Wealth Advisors Revenues
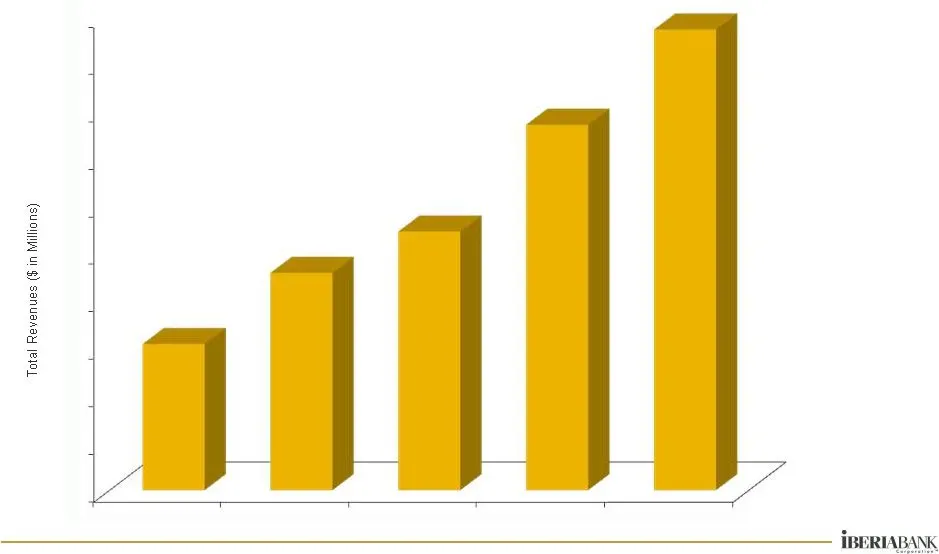
Financials Financials Quarterly Trend In Revenues IBERIA Capital Partners And IBERIA Wealth Advisors Steady Progress In Revenue Growth Since Launch In 4Q10 ICP/IWA Revenues Of $1.9 Million (+25% Vs. 4Q11) $0.0 $0.2 $0.4 $0.8 $1.0 $1.2 $1.4 $1.6 $1.8 $2.0 1Q11 2Q11 3Q11 4Q11 1Q12 $0.6
Slide 28: U.S. Tangible Efficiency Ratio
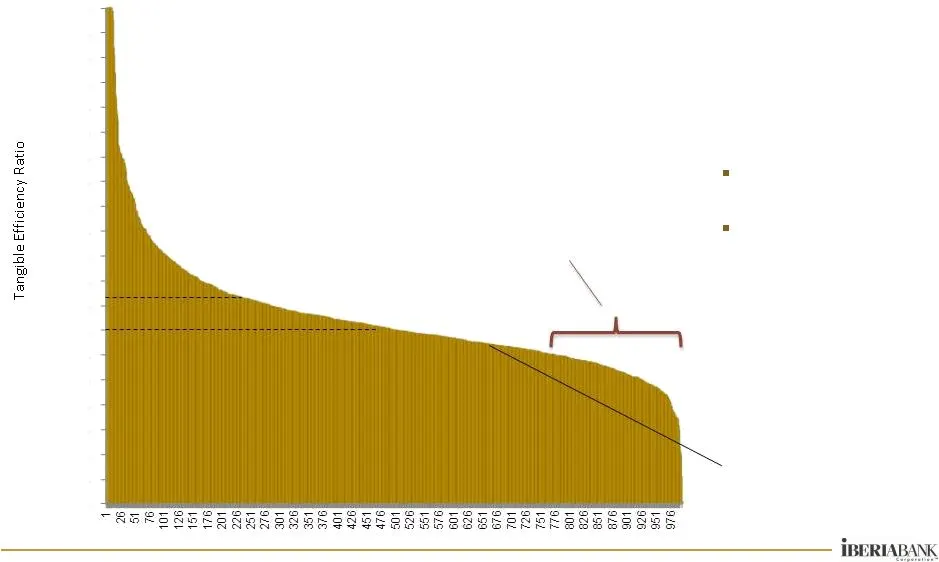
Financials Financials U.S. Tangible Efficiency Ratio Our Strategic Goal Is A Tangible Efficiency Ratio Of Less Than 60% Efficiency Gains Via: Revenue Improvements Expense Discipline Consolidation Within The Banking Industry May Improve Industry Efficiency Over Time Our Tangible Efficiency Ratio: 65%
Slide 29: Acquisitions
Acquisitions Acquisitions
Slide 30: Forces Accelerating Consolidation
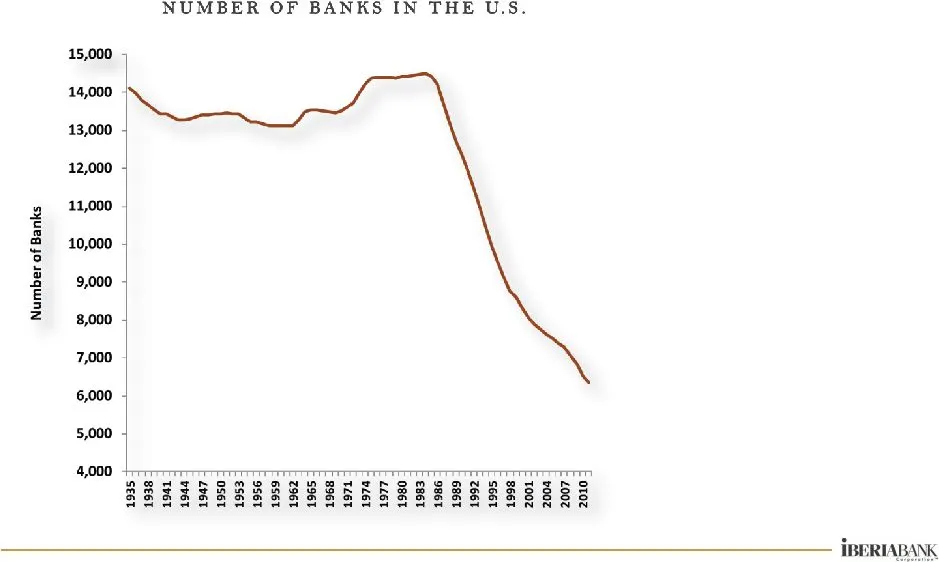
Acquisitions Acquisitions Forces Accelerating Consolidation Environmental Issues Credit Interest Rate Regulatory Legislative Real Estate Sector Client Issues Deleveraging Core Client Base Aging Technological Change Competitive Issues Shadow Banks Government Backing Government Life Support Future Dis
Slide 31: Completed Acquisitions Since 2003
Total Assets of $4.4 Billion Total Deposits of $3.5 Billion Net Loans of $1.9 Billion Loans Bought at a $515 Million Discount Loans Have FDIC Loss Share Protection Pre-Tax Gain of $243 Million 60 Offices in 10 MSAs in Alabama, Arkansas & Florida Average 121 Days To Convert Systems Total Assets of $3
Slide 32: Proposed Acquisition of Florida Gulf Bancorp, Inc.
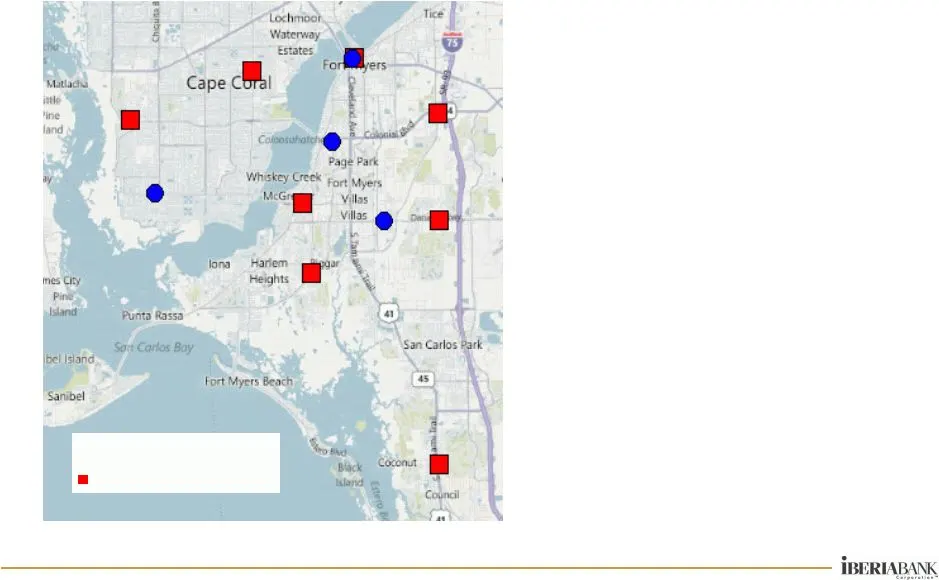
Source: SNL Financial Deposit Data as of June 2011 Announced March 19, 2012 Adds 8 branches in Fort Myers-Cape Coral, Florida MSA Attractive, established client base complements our existing client base Total Loans: $262 million Total Assets: $350 million Total Deposits: $279 million Total Equity: $
Slide 33: Summary
Summary Summary
Slide 34: Total Return Since August 2007
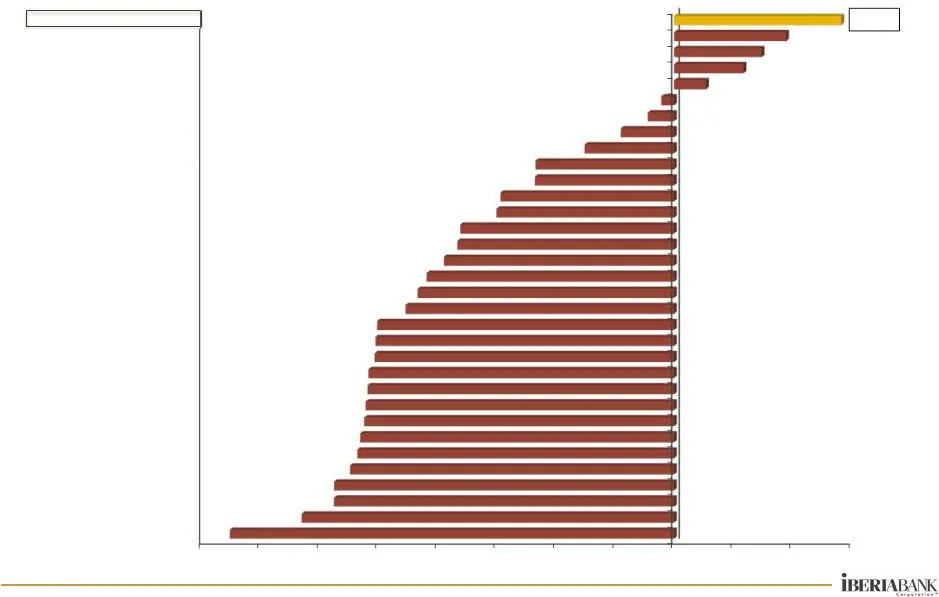
Total Return Since August 2007 Summary Summary * August 2007 - signifies the start of the financial crisis Source: SNL Through April 16, 2012 Outperformed During A Very Tumultuous Time Period Driven By Our Very Unique Position And Opportunities -80% -70% -60% -50% -40% -30% -20% -10% 0% 10% 20% 30%
Slide 35: Over The Past Four Years…
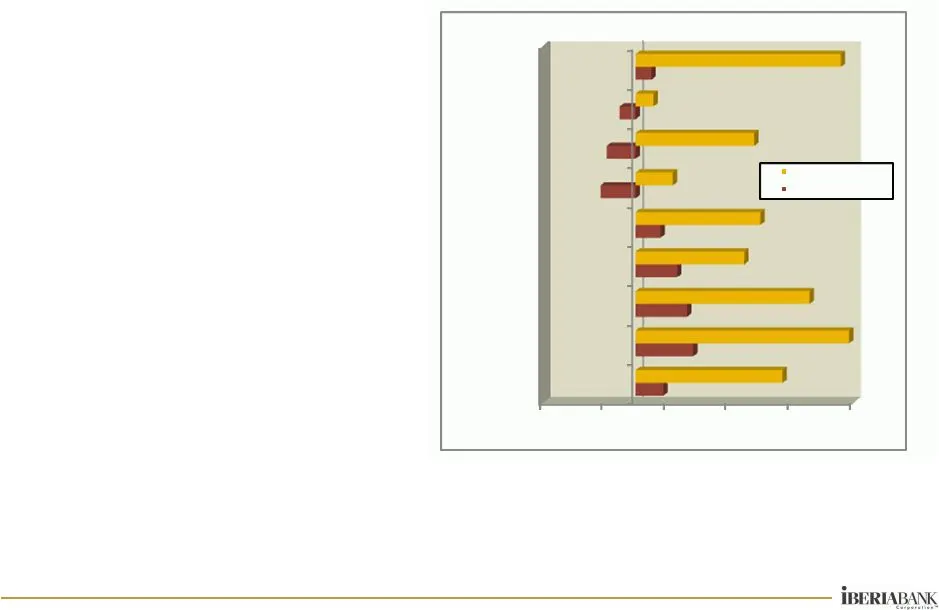
Over The Past Four Years… Summary Summary Total Revenues Of $1.8 Billion Earned $320 Million; $15.79 EPS Paid $125 Million In Dividends, Or $5.78 Per Share (39% Payout) Improved Asset Quality And Capital Strength Added: +$6.9 Billion Assets +124 New Locations +1,297 Associates +$18.17 In Tangible BV
Slide 36: Corporation
Corporation
Slide 37: Appendix
Appendix Appendix Other Other
Slide 38: MSA Home Price Trends: Louisiana
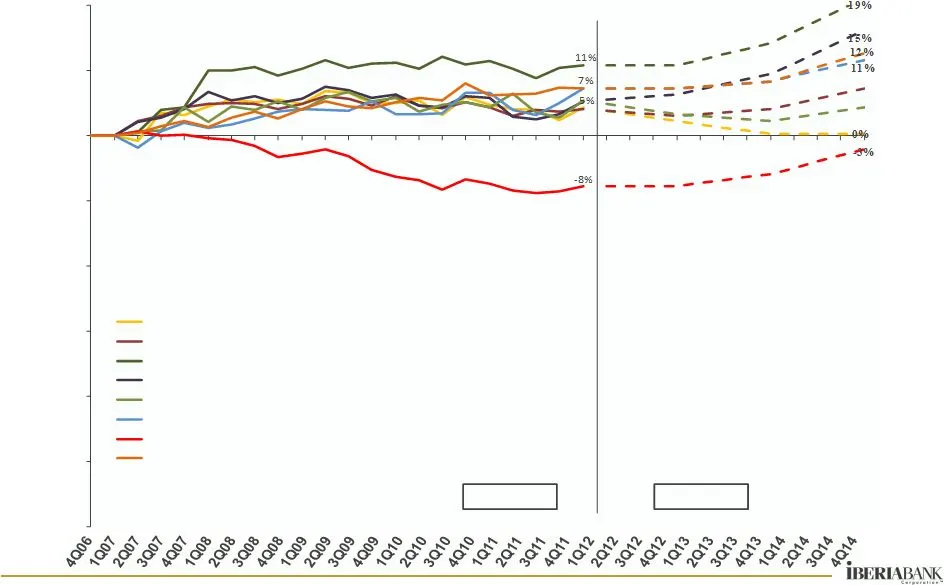
Appendix Appendix MSA Home Price Trends Source: Local Market Monitor 4Q2011 -60% -50% -40% -30% -20% -10% 0% 10% 20% Louisiana MSAs Alexandria, LA Baton Rouge, LA Houma-Bayou Cane-Thibodaux, LA Lafayette, LA Lake Charles, LA Monroe, LA New Orleans-Metairie-Kenner, LA Shreveport-Bossier City, LA Fore
Slide 39: MSA Home Price Trends: Arkansas
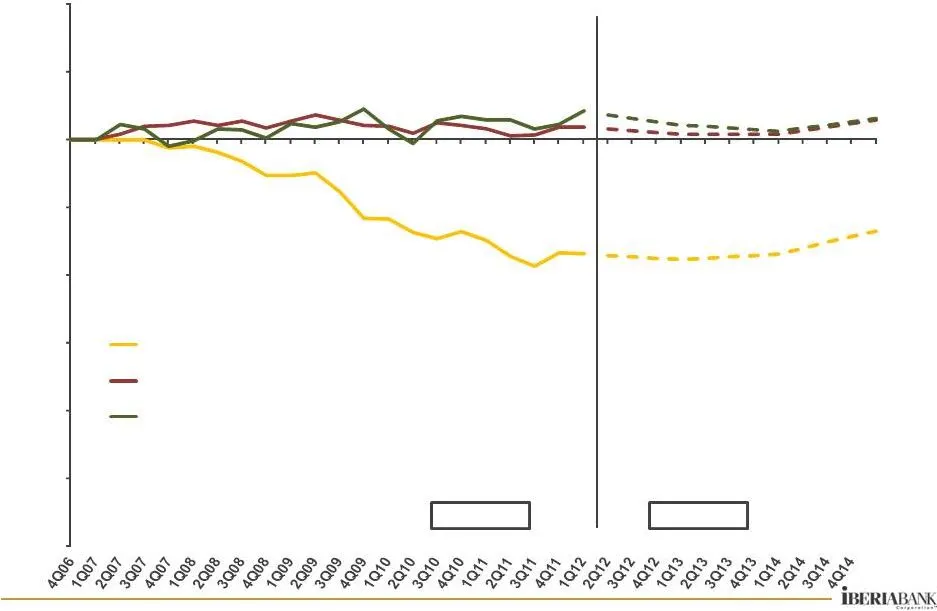
Appendix Appendix MSA Home Price Trends -17% 2% 4% -13% 3% -60% -50% -40% -30% -20% -10% 0% 10% 20% Fayetteville-Springdale-Rogers, AR-MO Little Rock-North Little Rock-Conway, AR Jonesboro, AR Actual Forecast Source: Local Market Monitor 4Q2011 Arkansas MSAs
Slide 40: MSA Home Price Trends: Florida
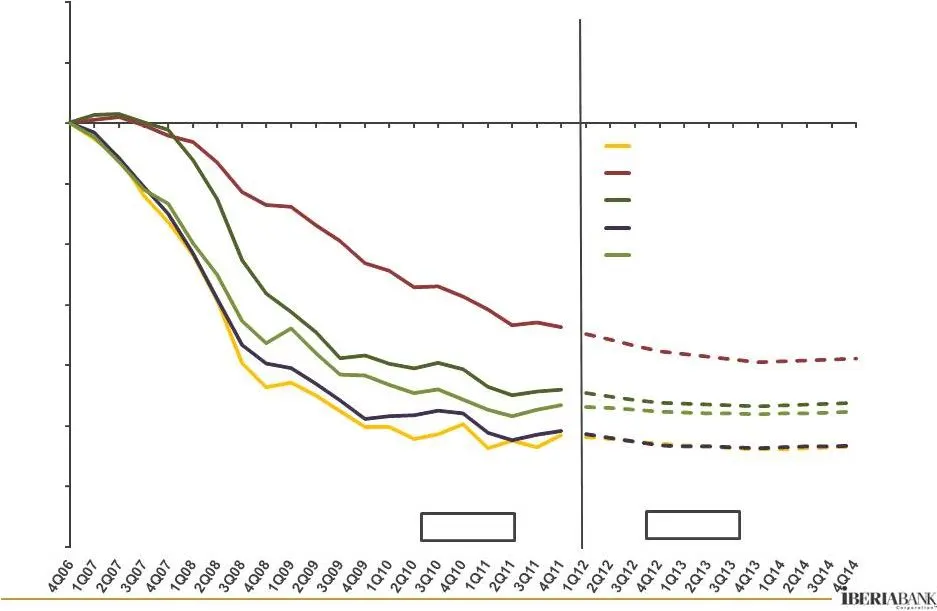
Appendix Appendix MSA Home Price Trends Source: Local Market Monitor 4Q2011 -34% -44% -51% -47% -54% -39% -46% -48% -70% -60% -50% -40% -30% -20% -10% 0% 10% 20% Cape Coral-Fort Myers, FL Jacksonville, FL Miami-Miami Beach-Kendall, FL (MSAD) Naples - Marco Island, FL North Port-Bradenton-Sarasota-Ve
Slide 41: MSA Home Price Trends: Other MSAs
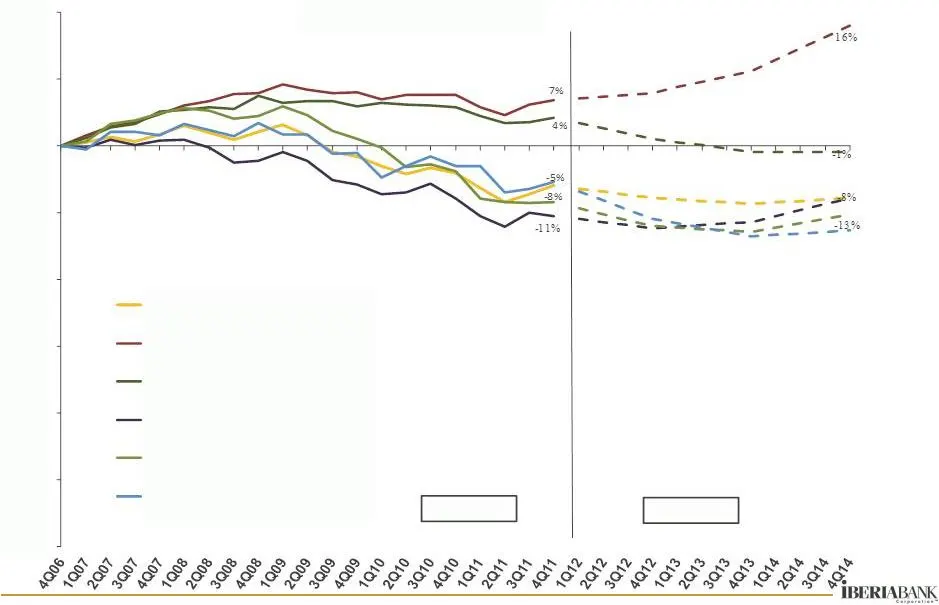
Appendix Appendix MSA Home Price Trends Source: Local Market Monitor 4Q2011 -60% -50% -40% -30% -20% -10% 0% 10% 20% Other MSAs Birmingham-Hoover, AL Houston-Sugar Land-Baytown, TX Huntsville, AL Memphis, TN-MS-AR Mobile, AL Montgomery, AL Actual Forecast
Slide 42: MSA Housing Price Declines – Last Year
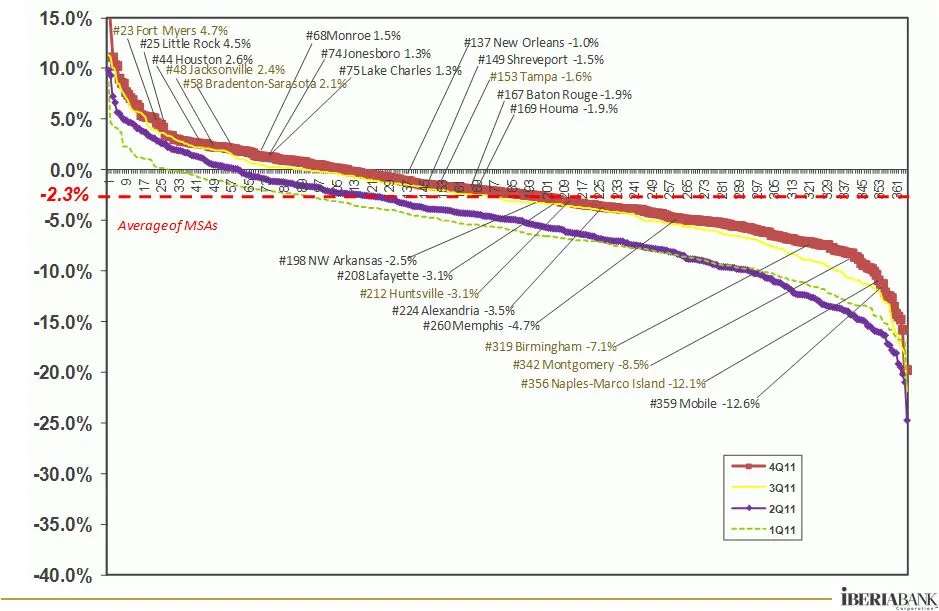
Appendix Appendix MSA Housing Price Declines – Last Year Source: Freddie Mac, FMHPI data series for 4Q2011
Slide 43: Housing Price Decline Probability
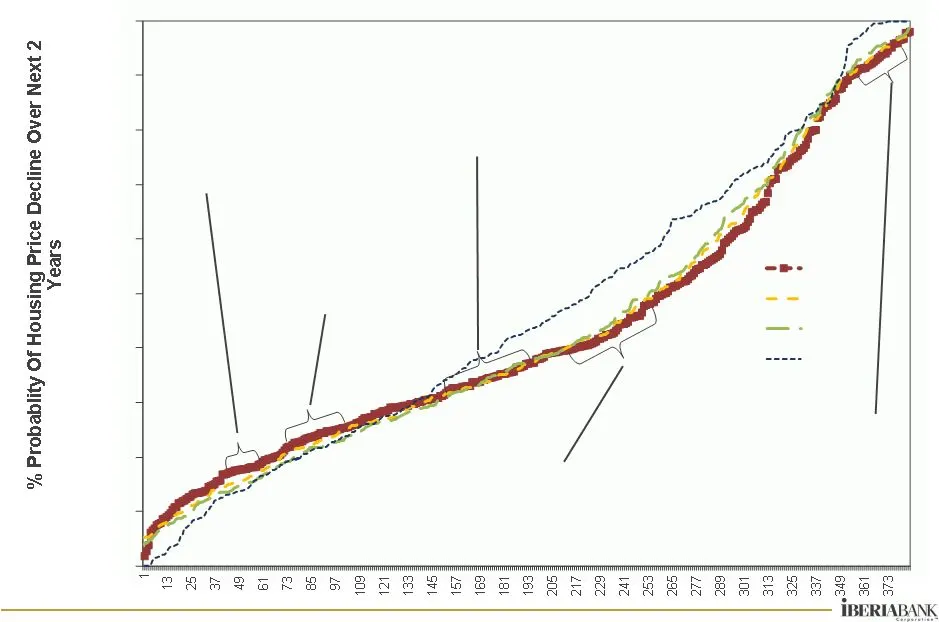
Appendix Appendix Housing Price Decline Probability – Next 2 Years Source: PMI Economic Real Estate Trends: 2Q11 data 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% 2Q11 1Q11 4Q10 2Q10 Shreveport, LA 17.6% Jonesboro, AR 17.7% Lafayette, LA 18.1% Mobile, AL 39.4% Baton Rouge, LA 40.9% New Orleans, LA 45
Slide 44: Energy Price Trends
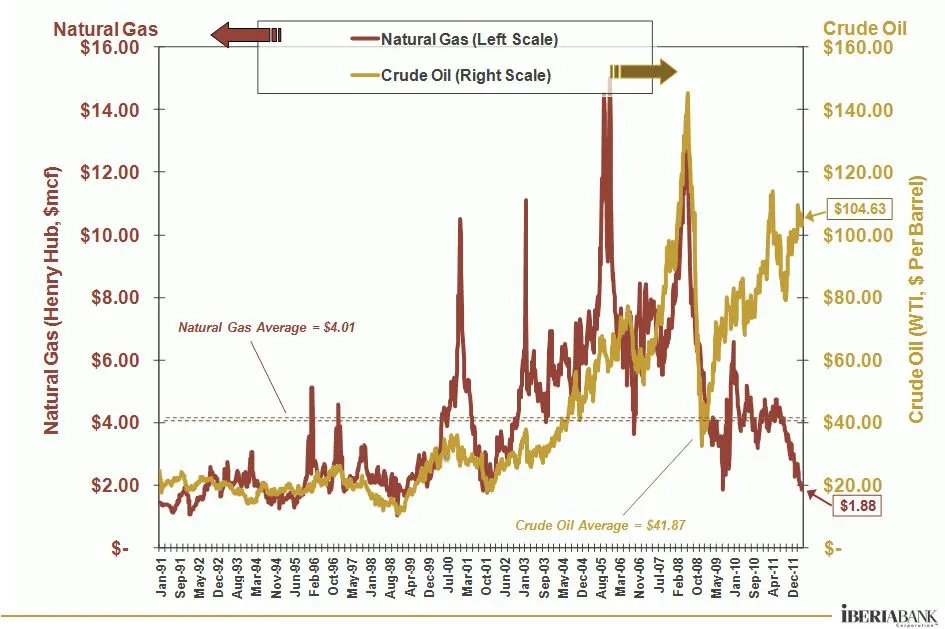
Appendix Appendix Energy Price Trends
Slide 45: Low Risk Balance Sheet At March 31, 2012
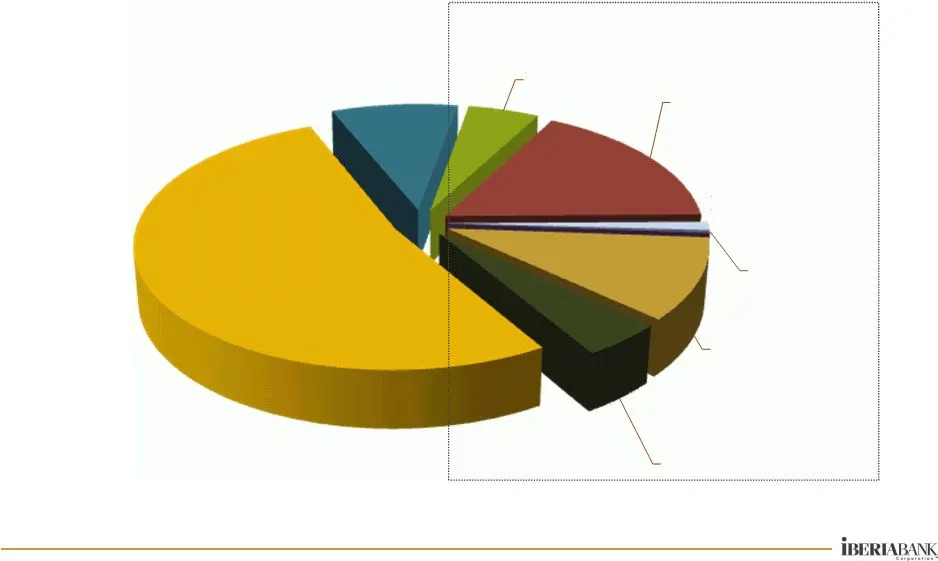
Appendix Appendix Low Risk Balance Sheet At March 31, 2012 Cash and Equivalents, 5% Investment Securities, 17% Mortgage Loans Held For Sale, 1% Acquired Loans - Fair Value, 0.3% Loans - FDIC Covered, 11% FDIC Loss Share Receivable, 5% Loans - Noncovered, 52% Other Assets, 9% 39% Of Balance Sheet In
Slide 46: FDIC Covered Loan Portfolio Roll Forward
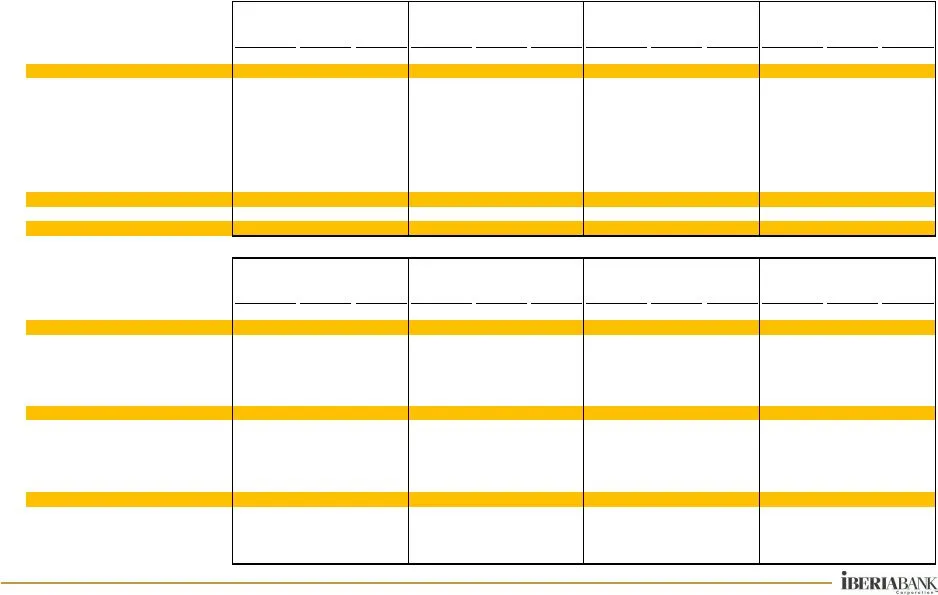
Appendix Appendix FDIC Covered Loan Portfolio Roll Forward ($ in thousands) Average Income / Expense Average Yield Average Income / Expense Average Yield Average Income / Expense Average Yield Average Income / Expense Average Yield Covered Loans 1,489,782 40,454 10.768% 1,421,784 28,201 7.819% 1,350
Slide 47: Industry Profitability Trends
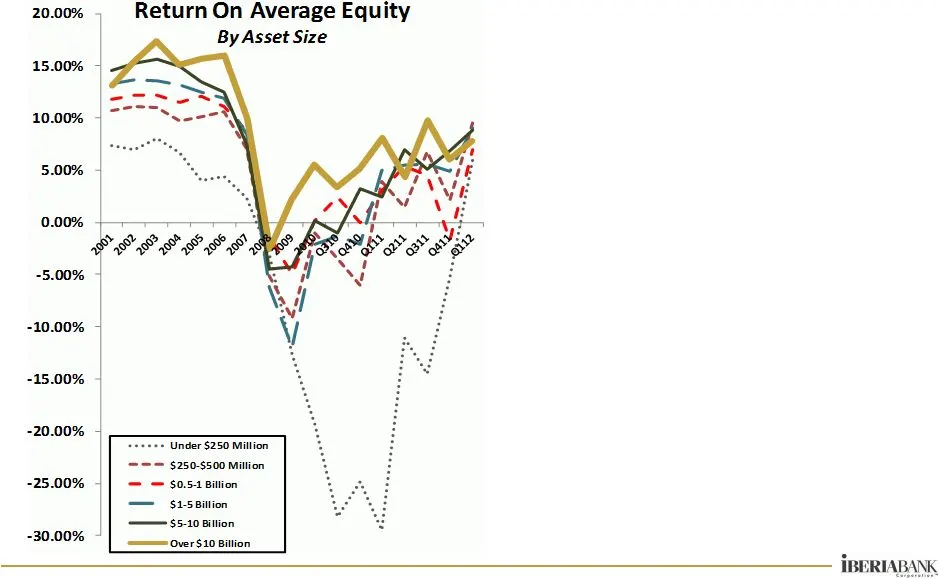
Appendix Appendix Industry Profitability Trends Industry Profitability Has Improved, But Structurally Well Below Historical Levels Highly Regulated Industry Industry Actions Needed: Favorable Asset Quality Watch Interest Rate Risk Offset Regulatory Costs Improve Efficiency Add Revenues Improve L/T E
Slide 48: New Charters, Acquisitions & Failures
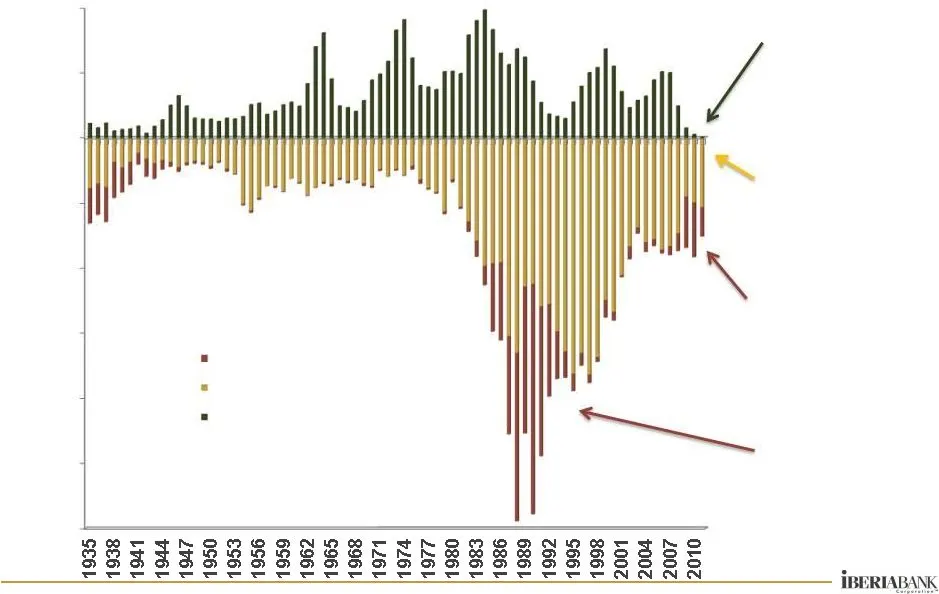
New Charters, Acquisitions & Failures Appendix Appendix Source: FDIC And OTS. – data through December 31, New Charters Have Gone Away The Number of Bank Mergers Has Declined The Number of Failures Has Increased…. …But Remain Well Below The Last Cycle (1,200) (1,000) (800) (600) (400) (200) - Failure
Slide 49: Florida Gulf Bancorp, Inc. Distribution
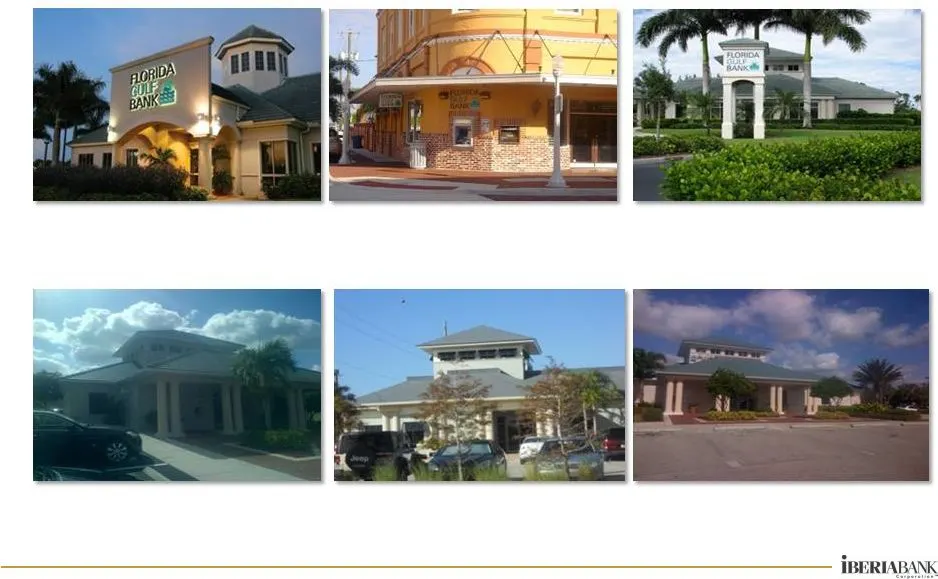
Florida Gulf Bancorp, Inc. Distribution Fort Myers - College Pointe Deposits: $92 million Fort Myers - First Street Deposits: $65 million Fort Myers - Daniels Parkway Deposits: $27 million Cape Coral - Del Prado Blvd Deposits: $21 million Fort Myers -Winkler Road Deposits: $30 million Fort Myers - D
Slide 50: Shareholder Return Over Last 10 Years
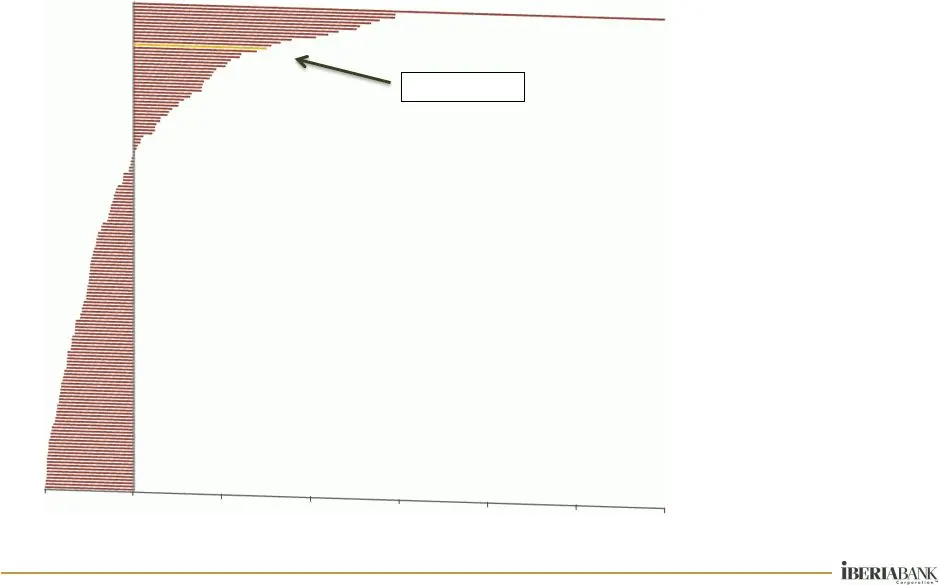
Shareholder Return Over Last 10 Years Appendix Appendix The Result Has Been A Dramatic Reduction In Bank Stock Prices In Contrast, Our Share Price Was Up 93% Over The Last 10 Years Many Banks Slashed Or Eliminated Dividends Over That Period To Conserve Capital Our Dividends Per Share Increased 136%
Slide 51: ember FDI QEQUAL HOUSING LENDER
ember FDI QEQUAL HOUSING LENDER
Source: SEC EDGAR · 425 filed May 14, 2012
More decks from IBERIABANK Corporation
 Q1 2020 Earnings Presentation39 slides · Apr 21, 2020
 Q4 2019 Earnings Presentation25 slides · Jan 17, 2020
 Goldman Sachs Financial Services Conference 201916 slides · Dec 11, 2019
 Merger or Acquisition (November 2019)30 slides · Nov 4, 2019
 Q3 2019 Earnings Presentation25 slides · Oct 18, 2019
 Q2 2019 Earnings Presentation24 slides · Jul 19, 2019