HCC Insurance — Q4 2009 Earnings Presentation
26 slides from HCC Insurance's earnings presentation, Mar 5, 2010
Slide 1: Fourth Quarter and Year End 2009 Investor Presentation
HCC INSURANCE HOLDINGS, INC. Fourth Quarter and Year End 2009 Investor Presentation
Slide 2: Notice About This Presentation
Notice About This Presentation ABOUT FORWARD-LOOKING STATEMENTS: This presentation contains certain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, which are intended to be covered by the safe harbor
Slide 3: HCC Overview
HCC Overview Specialty insurer since 1974 (NYSE: HCC) Diversified operations headquartered in Houston, Texas include: P&C, Surety, Aviation and Life, Accident & Health Domestic and International Rated AA (Very Strong) by Standard & Poor's, AA (Very Strong) by Fitch Ratings, A1 (Good Security) by Moo
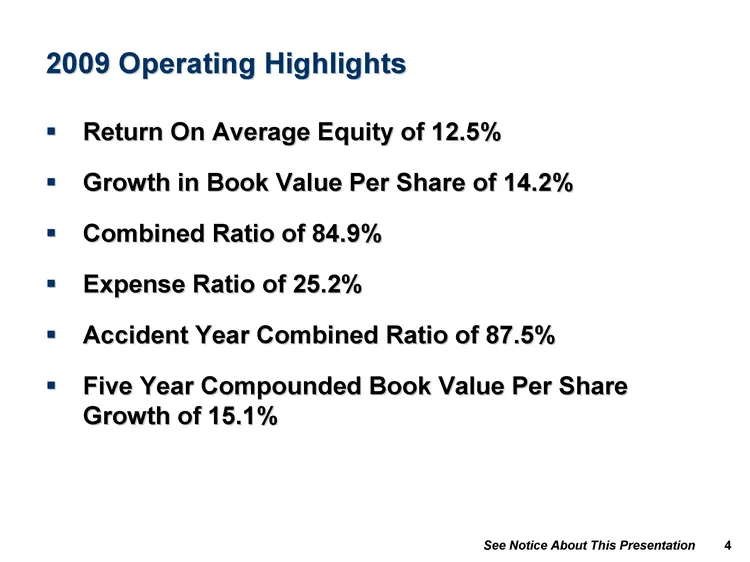
Slide 4: 2009 Operating Highlights
2009 Operating Highlights Return On Average Equity of 12.5% Growth in Book Value Per Share of 14.2% Combined Ratio of 84.9% Expense Ratio of 25.2% Accident Year Combined Ratio of 87.5% Five Year Compounded Book Value Per Share Growth of 15.1%
Slide 5: 2009 Financial Highlights
2009 Financial Highlights Stock Buyback Dividend Increase Term Debt OTTI Debt to Capital
Slide 6: Strategic Decisions
Strategic Decisions Merged Lloyd's Syndicates Sold Rattner Mackenzie to Guy Carpenter Exited Retail Business Sold Interest in SureTec Hired Teams of People
Slide 7: Lines of Business Overview
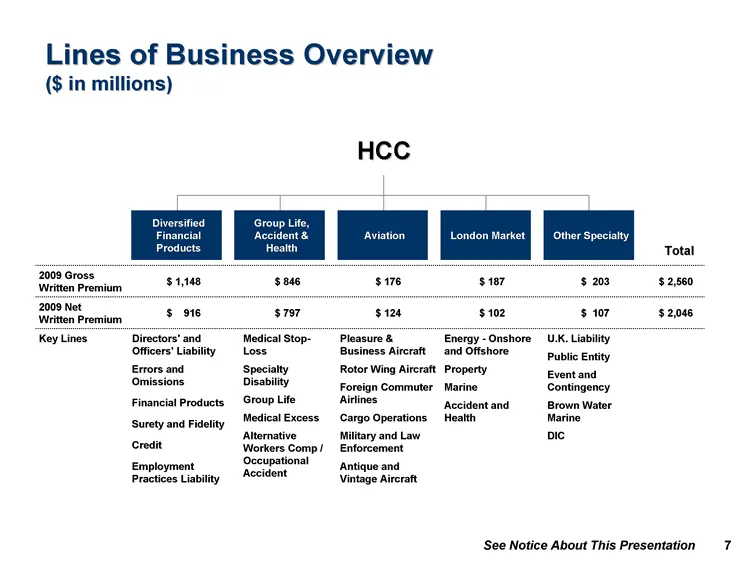
Lines of Business Overview ($ in millions) Total 2009 Gross Written Premium $ 1,148 $ 846 $ 176 $ 187 $ 203 $ 2,560 2009 Net Written Premium $ 916 $ 797 $ 124 $ 102 $ 107 $ 2,046 Key Lines Directors' and Officers' Liability Errors and Omissions Financial Products Surety and Fidelity Credit Employmen
Slide 8: Lines of Business Comparison
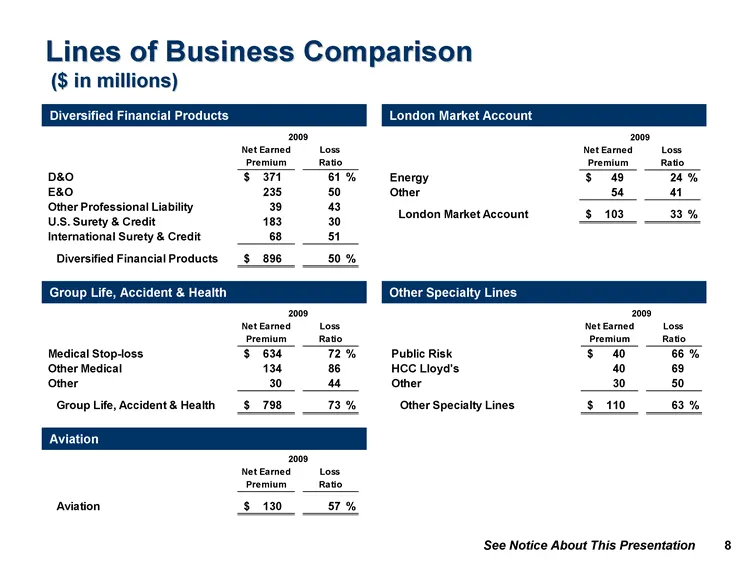
Lines of Business Comparison ($ in millions) Diversified Financial Products Group Life, Accident & Health Aviation London Market Account Other Specialty Lines
Slide 9: Historical Performance
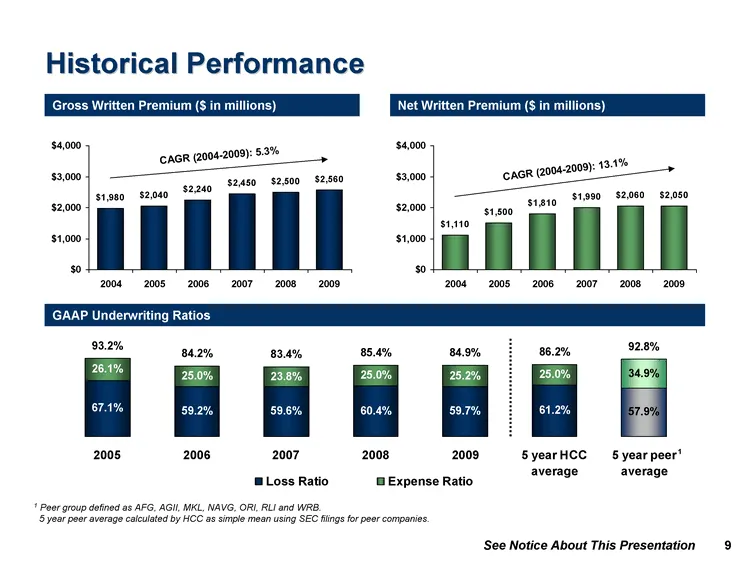
Historical Performance Gross Written Premium ($ in millions) 2004 2005 2006 2007 2008 2009 5 year HCC average 5 year peer average Loss Ratio 0.638 0.671 0.592 0.596 0.604 0.597 0.612 0.579 Expense Ratio 0.267 0.261 0.25 0.238 0.25 0.252 0.25 0.349 Total 0.905 0.932 0.842 0.834 0.854 0.849 0.862 0.92
Slide 10: 2009 Underwriting Performance
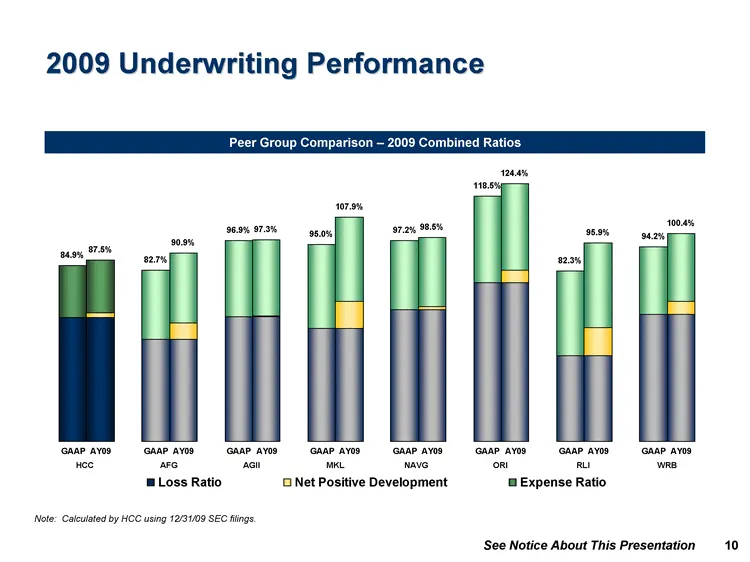
2009 Underwriting Performance GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 Loss Ratio 0.597 0.597 0.492 0.492 0.6029 0.6029 0.5468 0.5468 0.638 0.638 0.767 0.767 0.413 0.413 0.614 0.614 Net Positive Development 0.026 0.082 0.004 0.129 0.013 0.059 0.136 0.062 Expens
Slide 11: Strong, Predictable Return on Equity
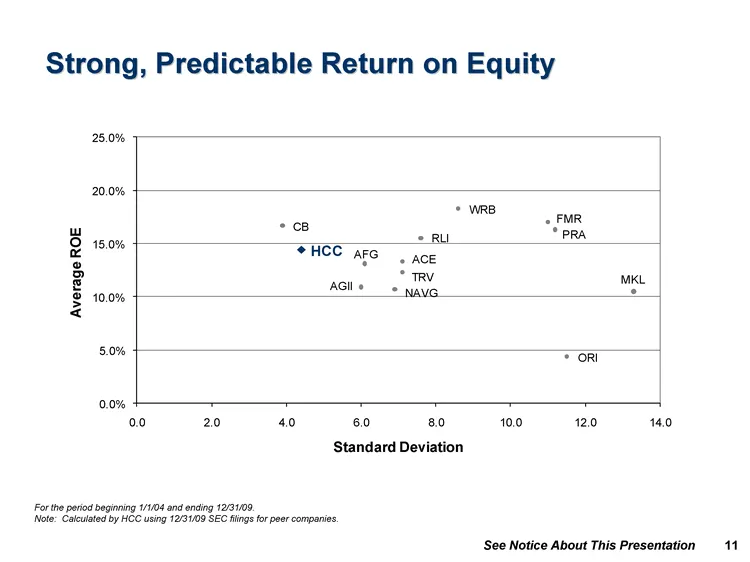
Strong, Predictable Return on Equity For the period beginning 1/1/04 and ending 12/31/09. Note: Calculated by HCC using 12/31/09 SEC filings for peer companies.
Slide 12: Strong BVPS Growth
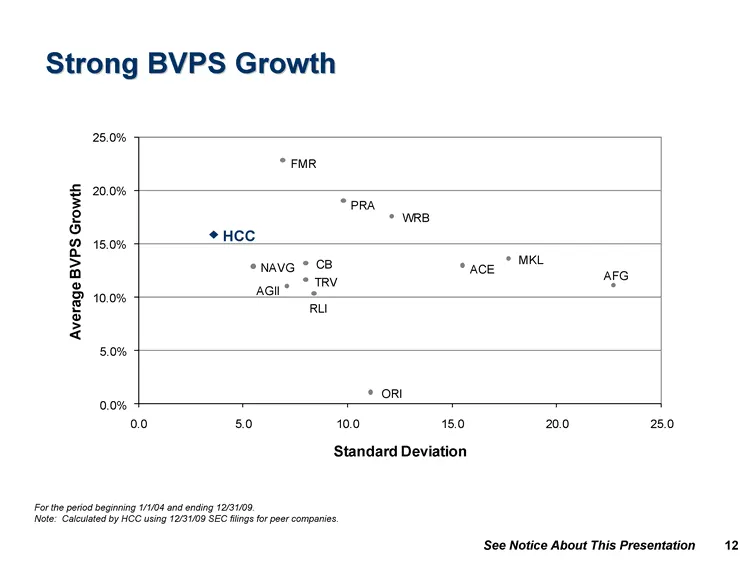
Strong BVPS Growth For the period beginning 1/1/04 and ending 12/31/09. Note: Calculated by HCC using 12/31/09 SEC filings for peer companies.
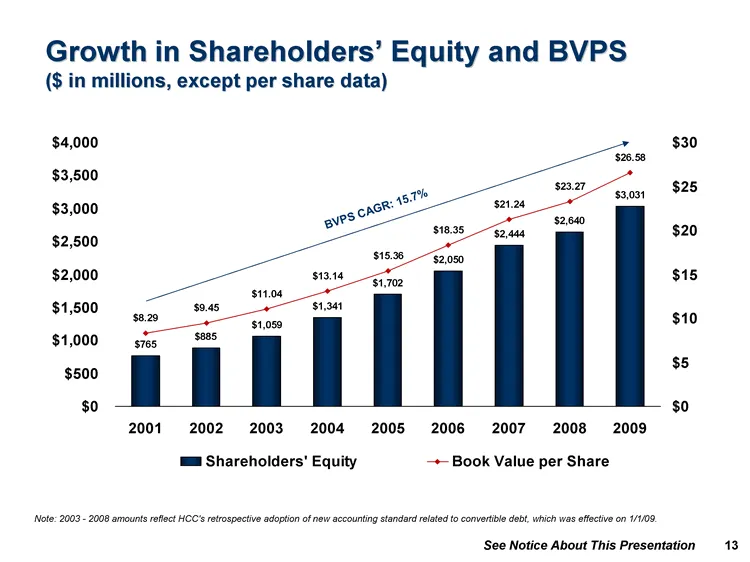
Slide 13: Growth in Shareholders' Equity and BVPS
1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 Shareholders' Equity 440430000 458439000 530930000 765.347 884.671 1059.135 1341.274 1702.015 2050.009 2443.695 2640.023 3031 Book Value per Share 8.29 9.45 11.04 13.14 15.36 18.35 21.24 23.27 26.58 Growth in Shareholders' Equity and BVPS (
Slide 14: Characteristics That Make HCC Unique
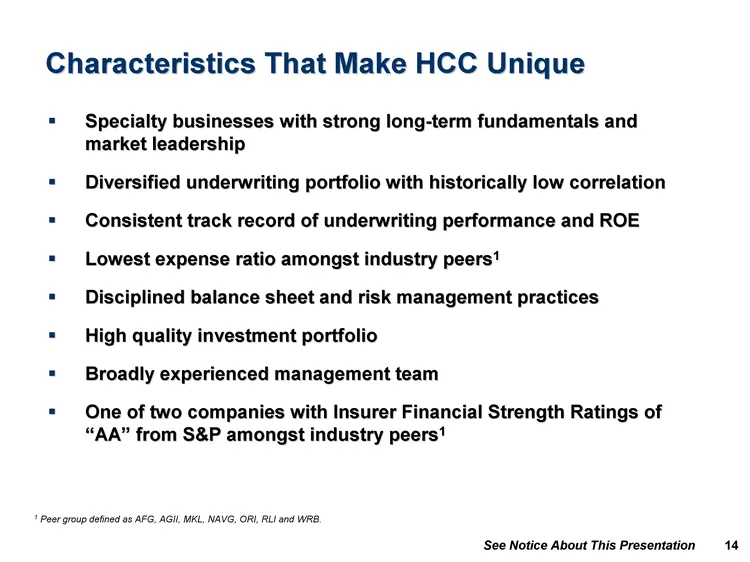
Characteristics That Make HCC Unique Specialty businesses with strong long-term fundamentals and market leadership Diversified underwriting portfolio with historically low correlation Consistent track record of underwriting performance and ROE Lowest expense ratio amongst industry peers1 Disciplined
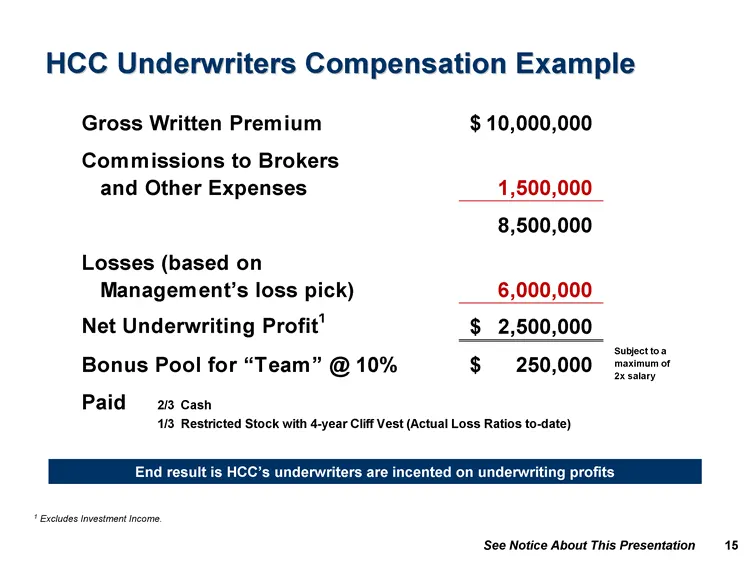
Slide 15: HCC Underwriters Compensation Example
HCC Underwriters Compensation Example 1 Excludes Investment Income. End result is HCC's underwriters are incented on underwriting profits
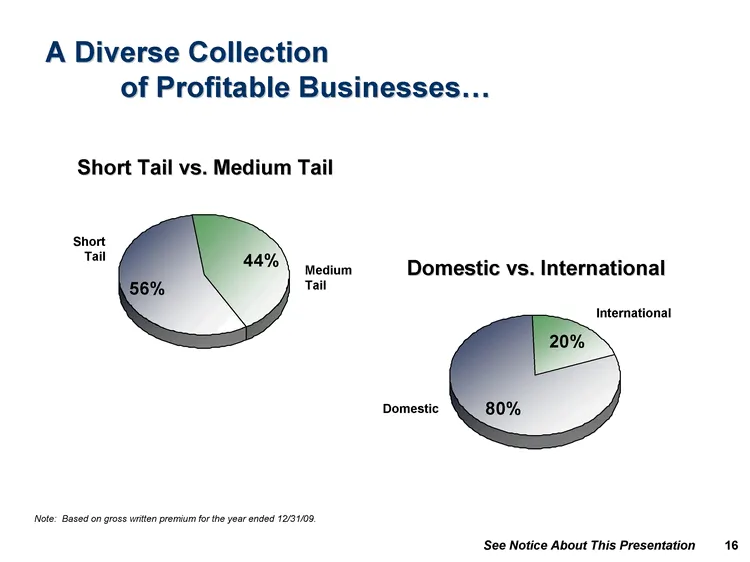
Slide 16: A Diverse Collection of Profitable Businesses
A Diverse Collection of Profitable Businesses... Short Medium 4th Qtr East 0.56 0.44 20.4 Short Tail vs. Medium Tail Short Tail Medium Tail Domestgic International East 0.8 0.2 Domestic vs. International International Domestic Note: Based on gross written premium for the year ended 12/31/09.
Slide 17: Effective Catastrophe Management
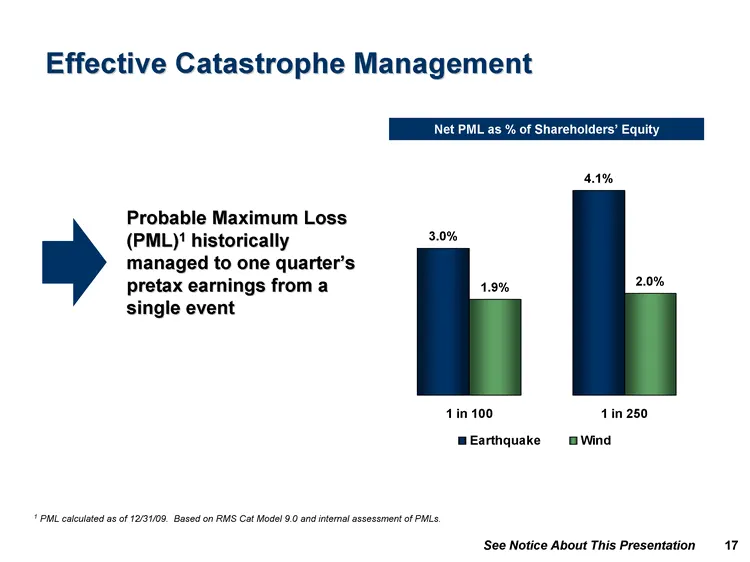
Effective Catastrophe Management 1 in 100 1 in 250 Earthquake 0.0296 0.0412 Wind 0.0192 0.0204 Probable Maximum Loss (PML)1 historically managed to one quarter's pretax earnings from a single event 1 PML calculated as of 12/31/09. Based on RMS Cat Model 9.0 and internal assessment of PMLs. Net PML a
Slide 18: Investment Portfolio December 31, 2009
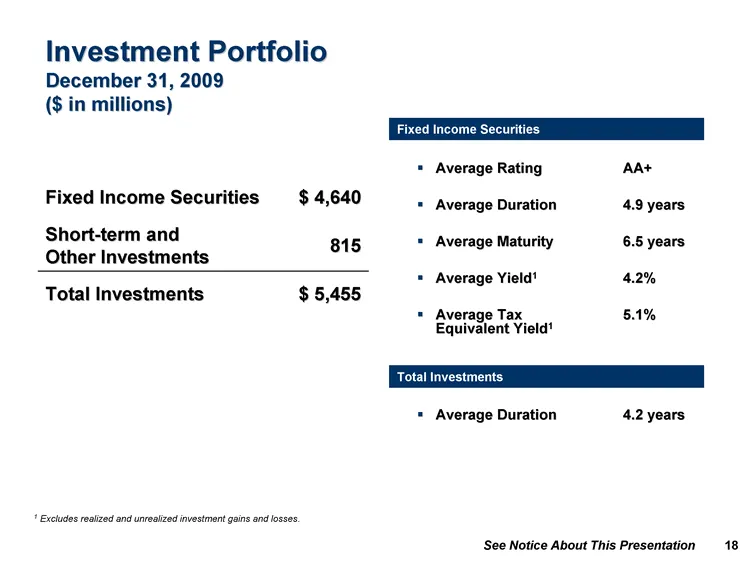
Average Rating AA+ Average Duration 4.9 years Average Maturity 6.5 years Average Yield1 4.2% Average Tax 5.1% Equivalent Yield1 Average Duration 4.2 years Fixed Income Securities $ 4,640 Short-term and Other Investments 815 Total Investments $ 5,455 Investment Portfolio December 31, 2009 ($ in milli
Slide 19: Investment Portfolio December 31, 2009
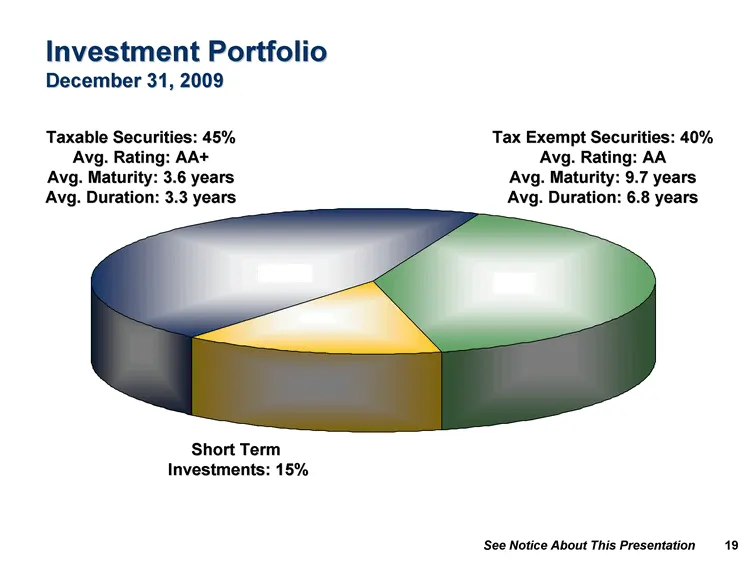
Taxable Securities Tax Exempt Securities Other Cash Short Term Investments 6/30/2007 45 40 0 1.1 15 Short Term Investments: 15% Tax Exempt Securities: 40% Avg. Rating: AA Avg. Maturity: 9.7 years Avg. Duration: 6.8 years Taxable Securities: 45% Avg. Rating: AA+ Avg. Maturity: 3.6 years Avg. Duration
Slide 20: Investment Analysis
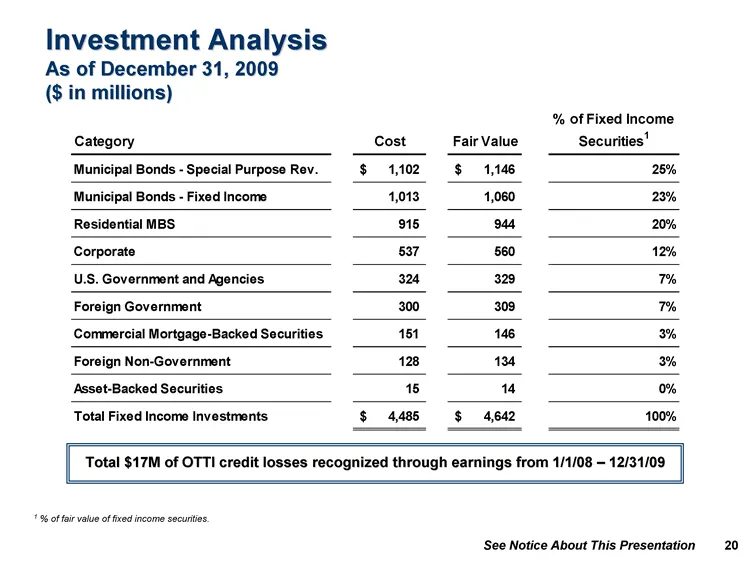
1 % of fair value of fixed income securities. Total $17M of OTTI credit losses recognized through earnings from 1/1/08 - 12/31/09 Investment Analysis As of December 31, 2009 ($ in millions)
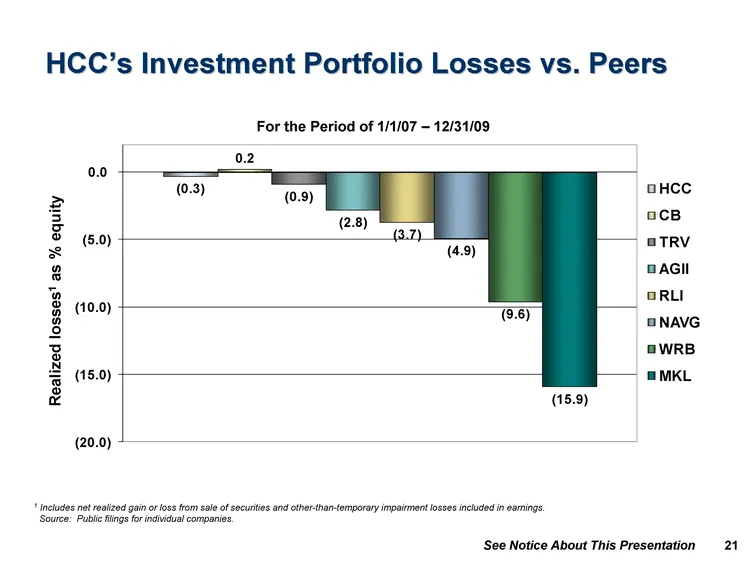
Slide 21: HCC's Investment Portfolio Losses vs. Peers
1 Includes net realized gain or loss from sale of securities and other-than-temporary impairment losses included in earnings. Source: Public filings for individual companies. HCC's Investment Portfolio Losses vs. Peers For the Period of 1/1/07 - 12/31/09
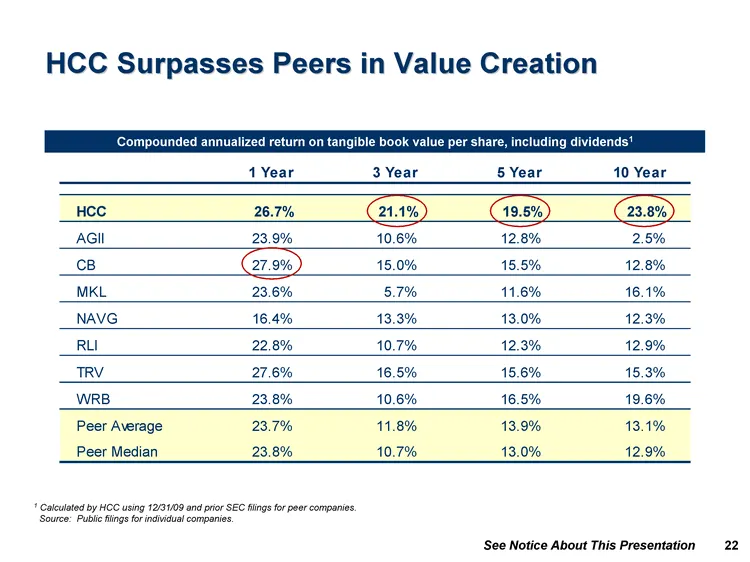
Slide 22: HCC Surpasses Peers in Value Creation
HCC Surpasses Peers in Value Creation 1 Calculated by HCC using 12/31/09 and prior SEC filings for peer companies. Source: Public filings for individual companies. Compounded annualized return on tangible book value per share, including dividends1
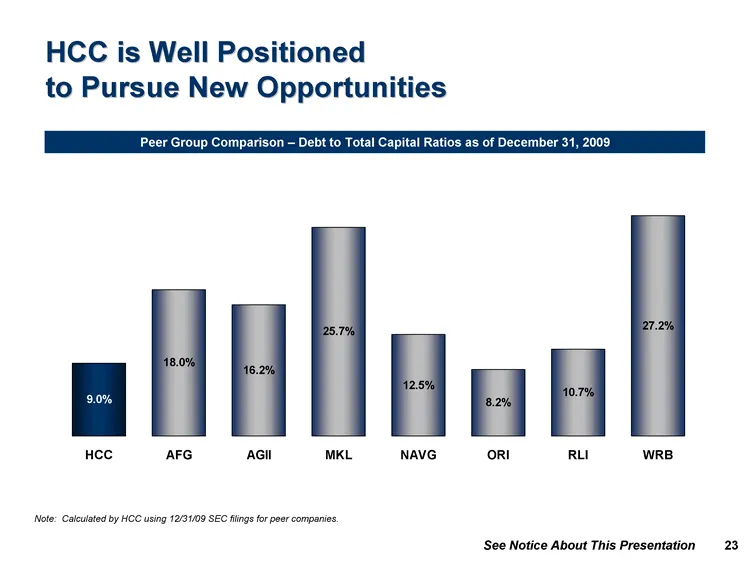
Slide 23: HCC is Well Positioned to Pursue New Opportunities
HCC AFG AGII MKL NAVG ORI RLI WRB Debt to Equity 0.09 0.18 0.162 0.257 0.125 0.082 0.107 0.272 HCC is Well Positioned to Pursue New Opportunities Peer Group Comparison - Debt to Total Capital Ratios as of December 31, 2009 Note: Calculated by HCC using 12/31/09 SEC filings for peer companies.
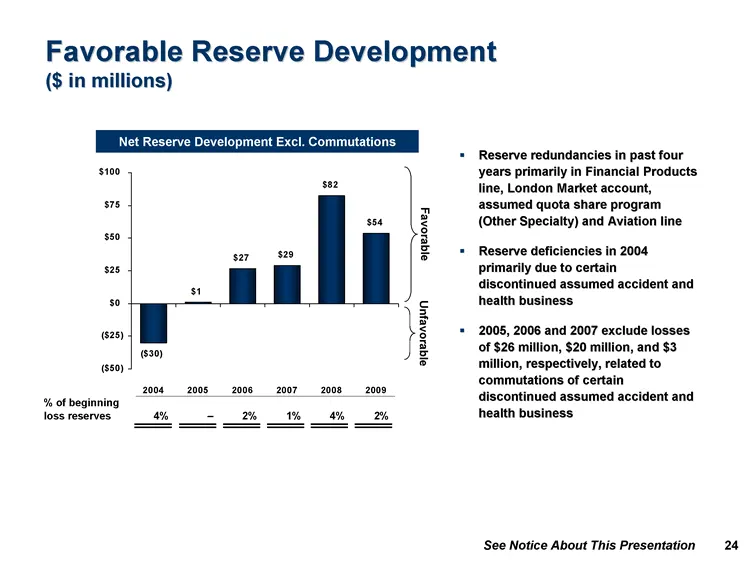
Slide 24: Favorable Reserve Development
Favorable Reserve Development ($ in millions) 2003 2004 2005 2006 2007 2008 2009 Cumulative redundancy (deficiency) -123.2 -30 1 27 29 82.4 54 Net Reserve Development Excl. Commutations Reserve redundancies in past four years primarily in Financial Products line, London Market account, assumed quota
Slide 25: Quality Reinsurance Security
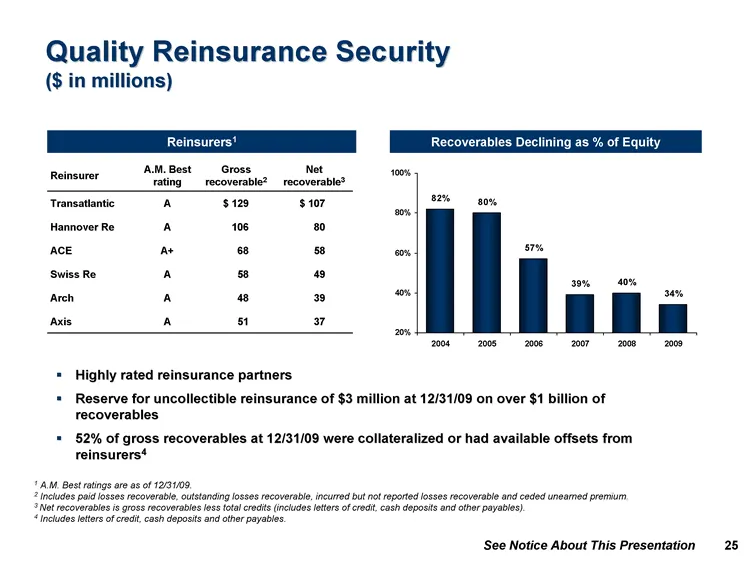
Quality Reinsurance Security ($ in millions) Reinsurers1 Reinsurer A.M. Best rating Gross recoverable2 Gross recoverable2 Net recoverable3 Net recoverable3 Transatlantic A $ 129 $ 107 $ 107 Hannover Re A 106 80 80 ACE A+ 68 58 58 Swiss Re A 58 49 49 Arch A 48 39 39 Axis A 51 37 37 1 A.M. Best rating
Slide 26: HCC's Value Proposition
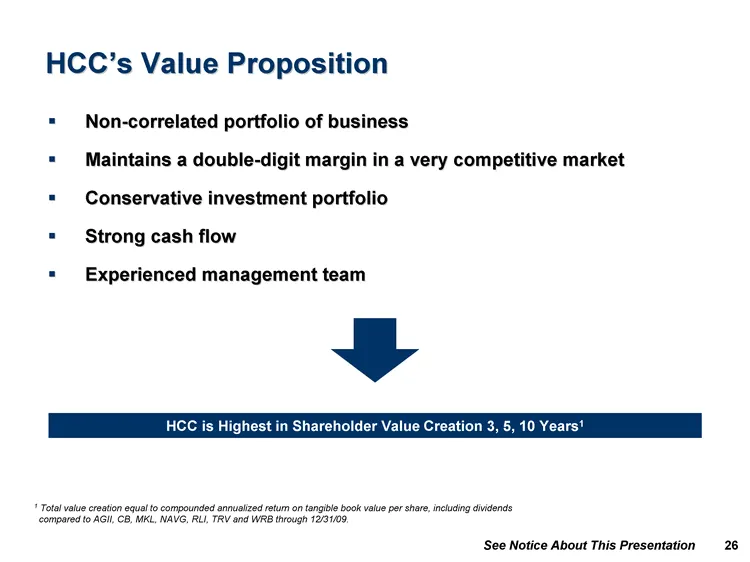
HCC's Value Proposition Non-correlated portfolio of business Maintains a double-digit margin in a very competitive market Conservative investment portfolio Strong cash flow Experienced management team 1 Total value creation equal to compounded annualized return on tangible book value per share, incl
Source: SEC EDGAR · 8-K filed Mar 5, 2010
More decks from HCC Insurance Holdings Inc
 Q2 2015 Earnings Presentation31 slides · Aug 14, 2015
 Merger or Acquisition (June 2015)22 slides · Jun 23, 2015
 Merger or Acquisition (June 2015)10 slides · Jun 10, 2015
 Merger or Acquisition (June 2015)30 slides · Jun 10, 2015
 Q1 2015 Earnings Presentation35 slides · May 21, 2015
 36th Annual Raymond James Institutional Investors Conference (February 2015)36 slides · Feb 27, 2015