KapStone Paper and Packaging Corporation
KapStone Paper and Packaging — Investor Presentation (January 2012)
29 slides from KapStone Paper and Packaging's investor presentation, Jan 11, 2012
Slide 1: Well Positioned to Prosper
January 2012 WELL POSITIONED TO PROSPER r Matt Kaplan President and Chief Operating Officer
Slide 2: Forward Looking Statements
2 FORWARD LOOKING STATEMENTS The information in this presentation and statements made during this presentation may contain certain forward-looking statements within the meaning of federal securities laws. These statements reflect management’s expectations regarding future events and operating perfor
Slide 3: Building of KapStone
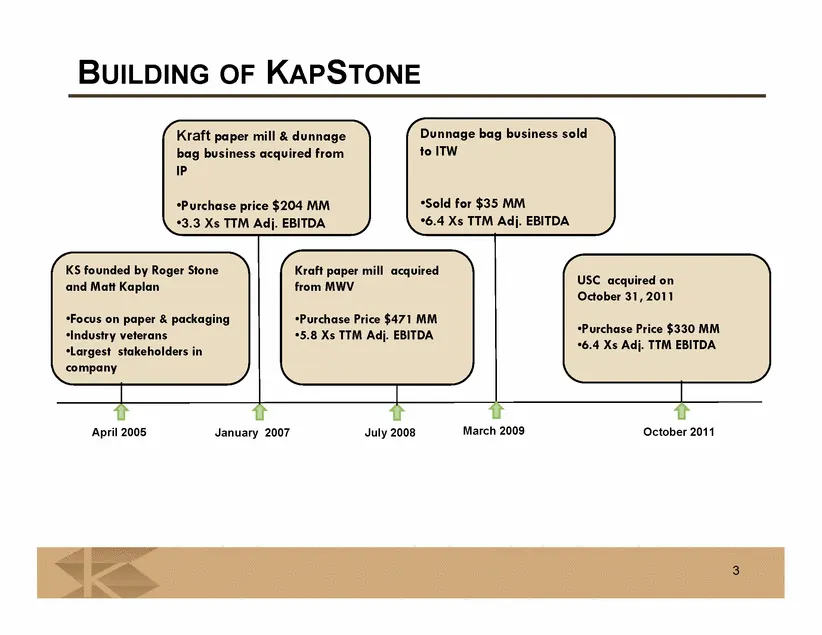
3 BUILDING OF KAPSTONE 3 KS founded by Roger Stone and Matt Kaplan Focus on paper & packaging Industry veterans Largest stakeholders in company April 2005 Kraft paper mill & dunnage bag business acquired from IP Purchase price $204 MM 3.3 Xs TTM Adj. EBITDA Kraft paper mill acquired from MWV Purchas
Slide 4: KapStone Today
4 KAPSTONE TODAY Three highly efficient and cost effective paper mills which produce linerboard, kraft paper, saturating, medium, and unbleached, folding carton board 2 virgin fiber mills 1 recycled fiber mill Capable of producing approximately 1.5 million tons of various kraft paper grades annually
Slide 5: KapStone Locations
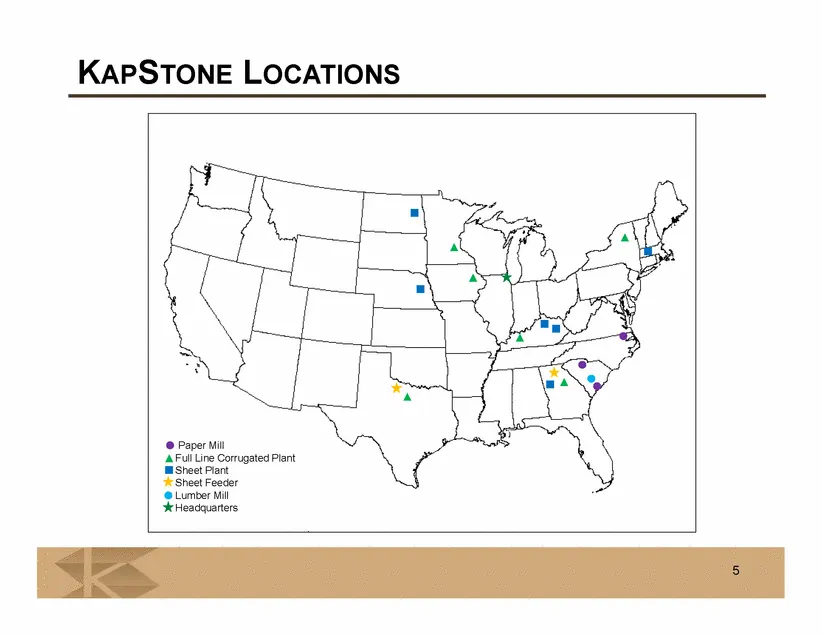
KAPSTONE LOCATIONS Paper Mill Full Line Corrugated Plant Sheet Plant Sheet Feeder Lumber Mill Headquarters 5
Slide 6: Our Industry: A Changing Industry
6 OUR INDUSTRY A CHANGING INDUSTRY Consolidation Sale of timber assets Behavioral changes in industry Capacity closures
Slide 7: Future Opportunities – Strong Fundamentals
Inventories are low Supply and demand are in balance Anticipate increased demand as worldwide economies improve Minimal growth in supply expected over next several years High industry-wide operating rates FUTURE OPPORTUNITIES – STRONG FUNDAMENTALS 7
Slide 8: KapStone – Compelling Growth Story
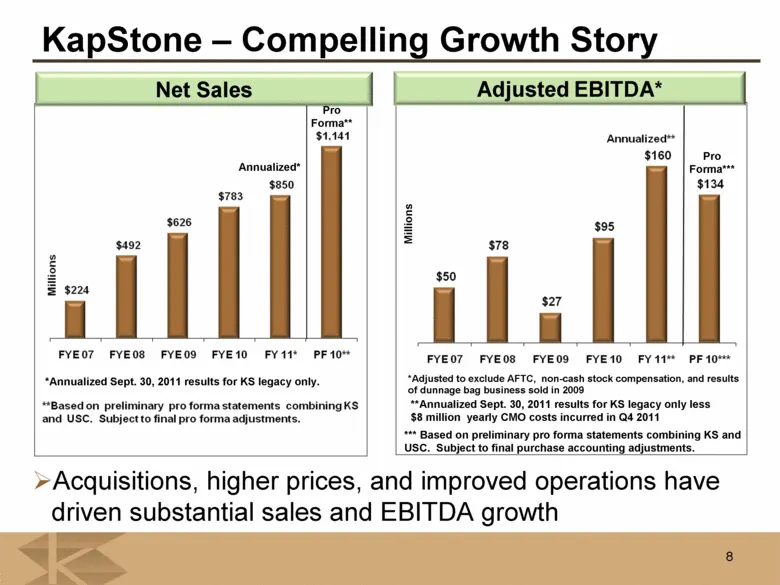
8 KapStone – Compelling Growth Story Adjusted EBITDA* Net Sales Millions Acquisitions, higher prices, and improved operations have driven substantial sales and EBITDA growth *Adjusted to exclude AFTC, non-cash stock compensation, and results of dunnage bag business sold in 2009 Pro Forma** Pro Forma
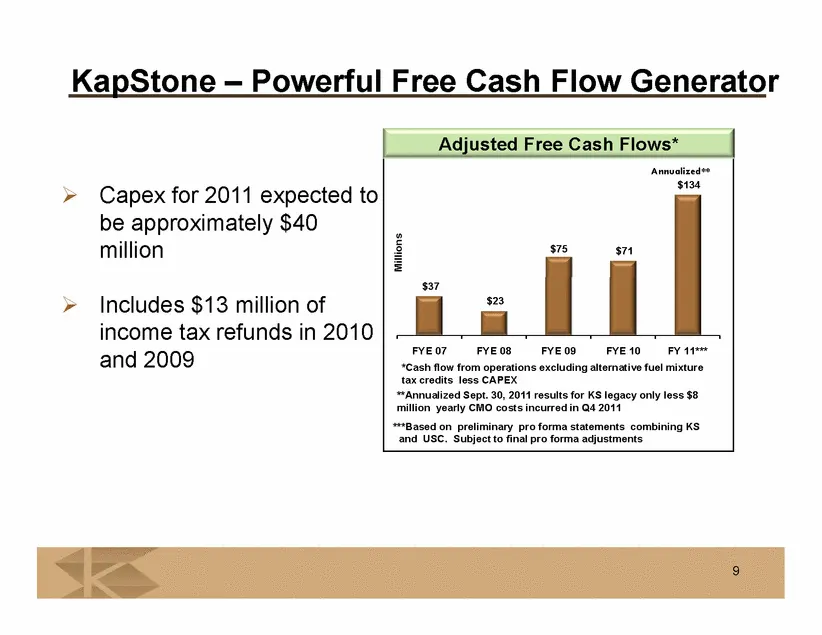
Slide 9: KapStone – Powerful Free Cash Flow Generator
Capex for 2011 expected to be approximately $40 million Includes $13 million of income tax refunds in 2010 and 2009 Adjusted Free Cash Flows* 9 KapStone – Powerful Free Cash Flow Generator *Cash flow from operations excluding alternative fuel mixture tax credits less CAPEX **Annualized Sept. 30, 201
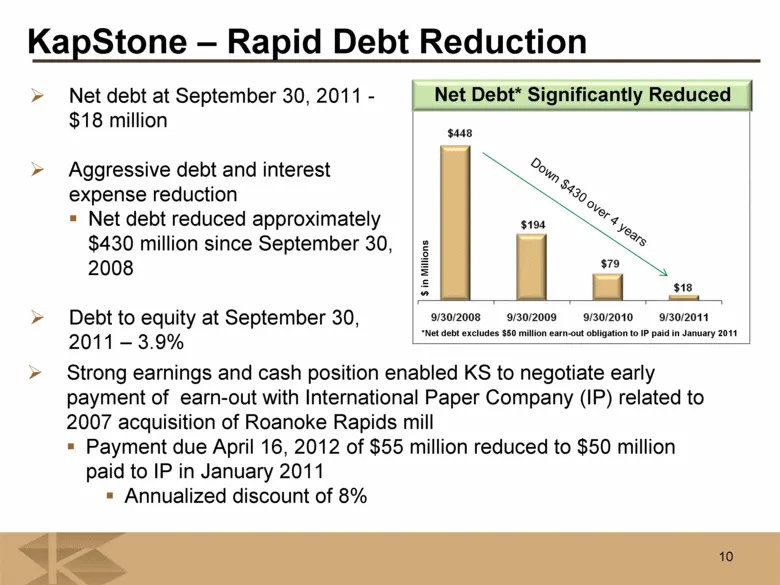
Slide 10: KapStone – Rapid Debt Reduction
10 Net Debt* Significantly Reduced $ in Millions Down $430 over 4 years *Net debt excludes $50 million earn-out obligation to IP paid in January 2011 KapStone – Rapid Debt Reduction Net debt at September 30, 2011 - $18 million Aggressive debt and interest expense reduction Net debt reduced approxima
Slide 11: KapStone's Most Recent Acquisition - USC
11 Unique opportunity No other similar system available in US Large, net buyer of containerboard Pro forma annual net sales of $358 million in 2010 195,000 ton net buyer of containerboard. These outside purchases will provide KS with enhanced flexibility Strong, long-term customer base resulting fro
Slide 12: Opportunities at Newly Acquired Plants
12 Substantially increase financial performance of under utilized converting facilities Elimination of corporate headquarters redundancies Day 1 cost elimination estimated to be $3 million Within 12 months, estimated total eliminated costs should exceed $8 million. Operational synergies estimated at
Slide 13: Purchase Price Summary
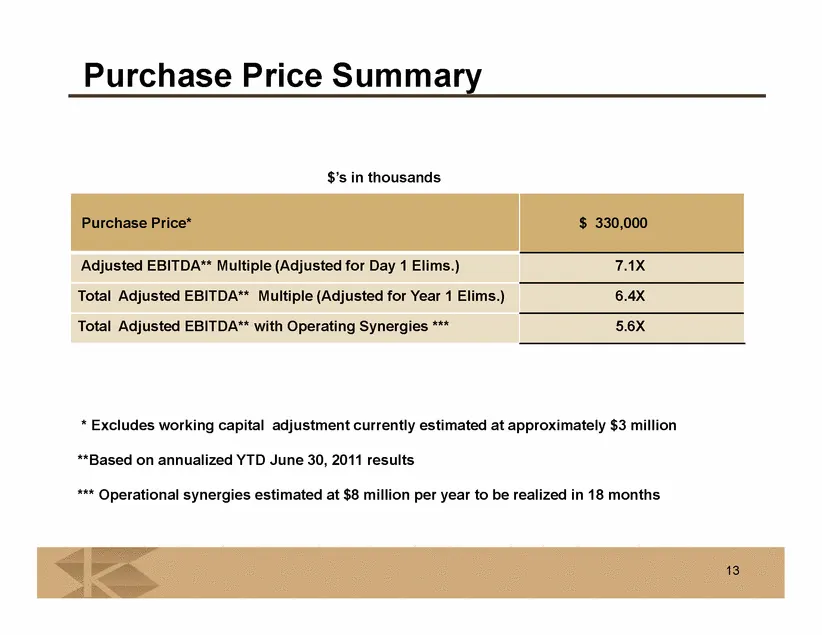
13 13 Purchase Price* $ 330,000 Adjusted EBITDA** Multiple (Adjusted for Day 1 Elims.) 7.1X Total Adjusted EBITDA** Multiple (Adjusted for Year 1 Elims.) 6.4X Total Adjusted EBITDA** with Operating Synergies *** 5.6X * Excludes working capital adjustment currently estimated at approximately $3 milli
Slide 14: Acquisition Rationale
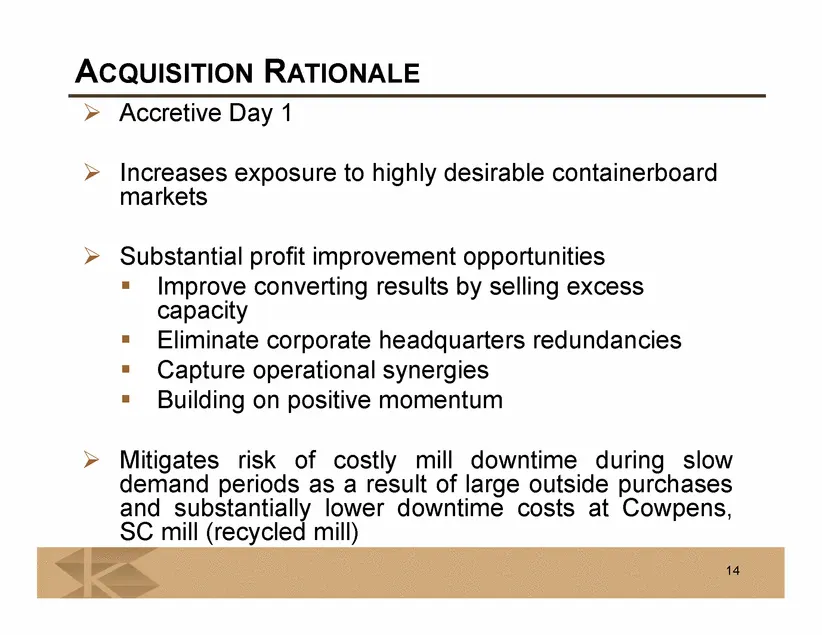
14 ACQUISITION RATIONALE Accretive Day 1 Increases exposure to highly desirable containerboard markets Substantial profit improvement opportunities Improve converting results by selling excess capacity Eliminate corporate headquarters redundancies Capture operational synergies Building on positive m
Slide 15: Acquisition Rationale
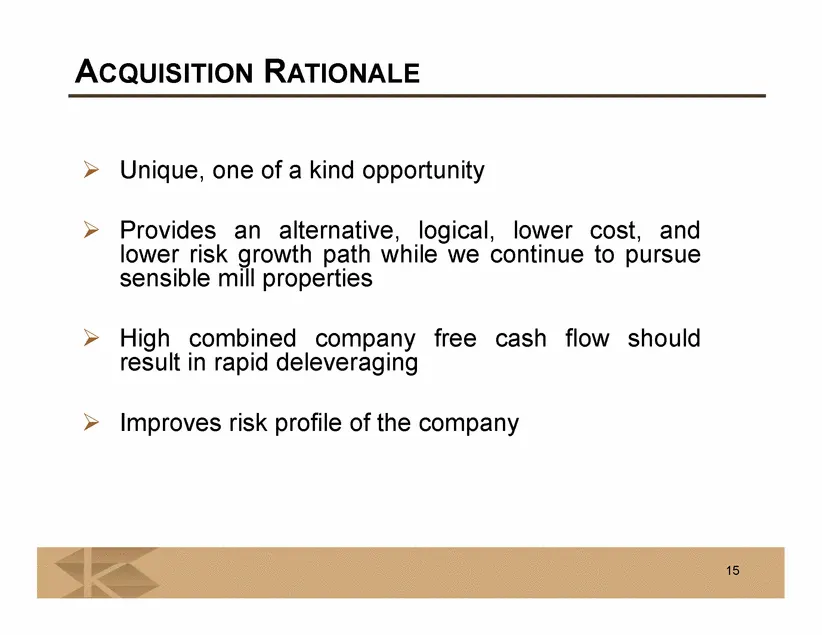
15 ACQUISITION RATIONALE Unique, one of a kind opportunity Provides an alternative, logical, lower cost, and lower risk growth path while we continue to pursue sensible mill properties High combined company free cash flow should result in rapid deleveraging Improves risk profile of the company 15
Slide 16: The "New, Transformed" KapStone
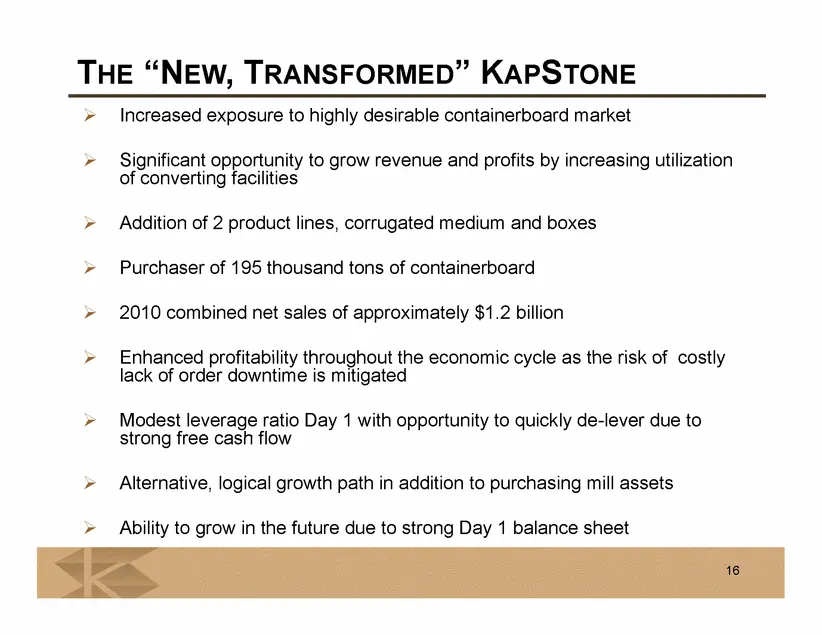
16 THE “NEW, TRANSFORMED” KAPSTONE 16 Increased exposure to highly desirable containerboard market Significant opportunity to grow revenue and profits by increasing utilization of converting facilities Addition of 2 product lines, corrugated medium and boxes Purchaser of 195 thousand tons of contain
Slide 17: Track Record of Providing Return to Our Shareholders
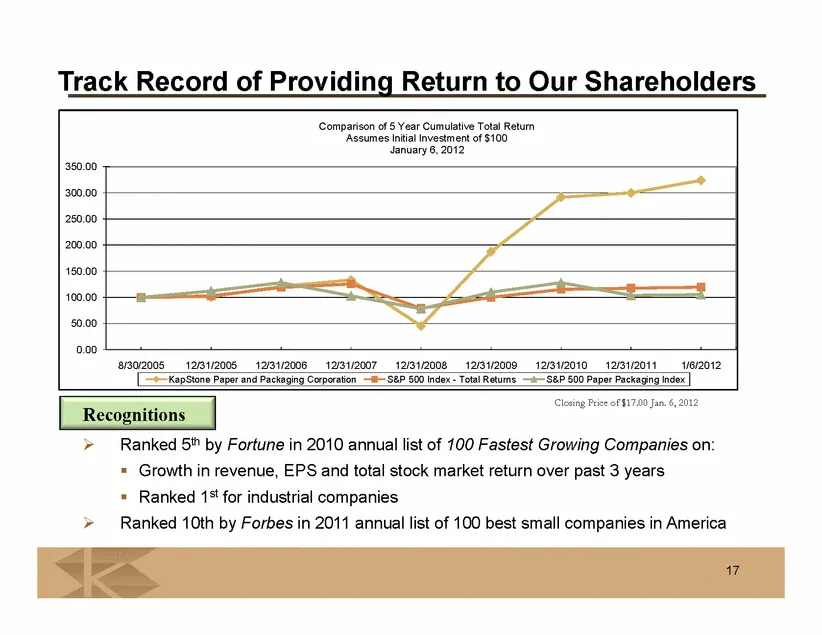
17 Track Record of Providing Return to Our Shareholders Closing Price of $17.00 Jan. 6, 2012 Ranked 5th by Fortune in 2010 annual list of 100 Fastest Growing Companies on: Growth in revenue, EPS and total stock market return over past 3 years Ranked 1st for industrial companies Ranked 10th by Forbes
Slide 18: Appendix
Appendix
Slide 19: USC Historical Financial Information
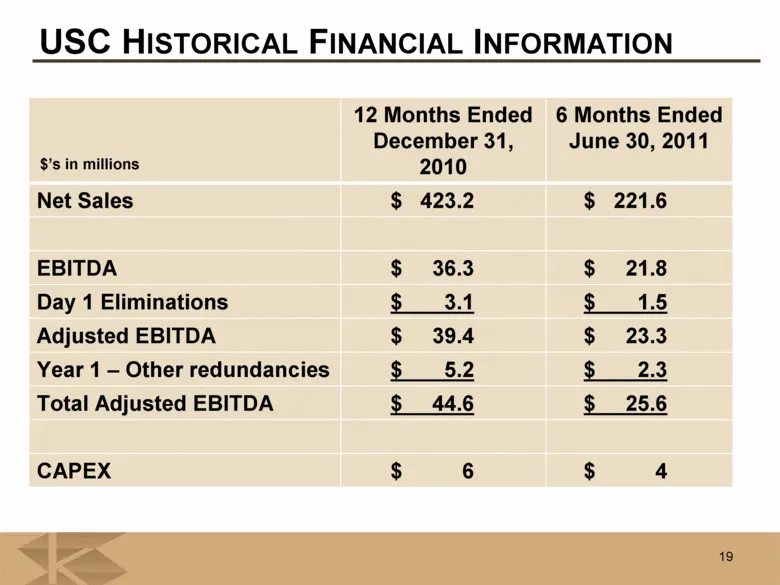
19 19 12 Months Ended December 31, 2010 6 Months Ended June 30, 2011 Net Sales $ 423.2 $ 221.6 EBITDA $ 36.3 $ 21.8 Day 1 Eliminations $ 3.1 $ 1.5 Adjusted EBITDA $ 39.4 $ 23.3 Year 1 – Other redundancies $ 5.2 $ 2.3 Total Adjusted EBITDA $ 44.6 $ 25.6 CAPEX $ 6 $ 4 $’s in millions USC HISTORICAL FI
Slide 20: Pro Forma Months Ended Sept. 30, 2011
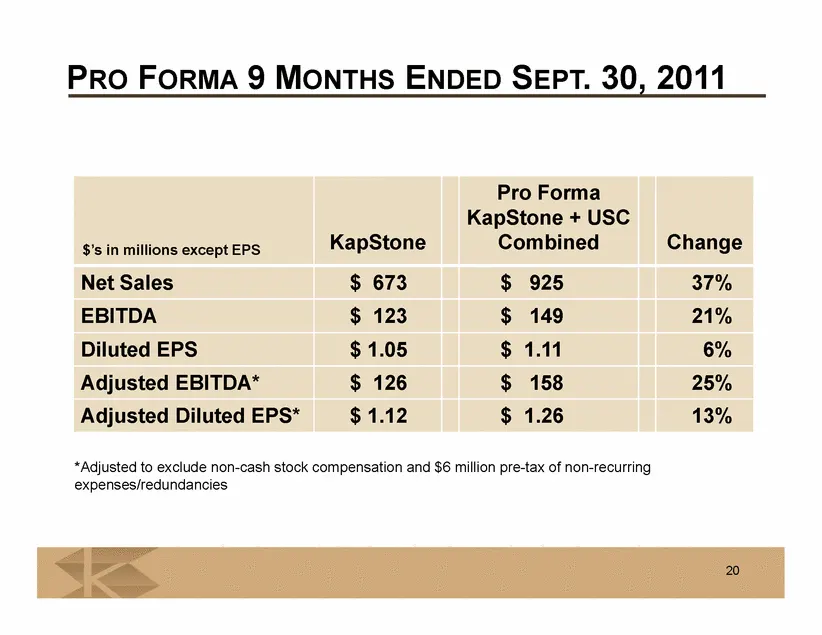
20 PRO FORMA 9 MONTHS ENDED SEPT. 30, 2011 20 KapStone Pro Forma KapStone + USC Combined Change Net Sales $ 673 $ 925 37% EBITDA $ 123 $ 149 21% Diluted EPS $ 1.05 $ 1.11 6% Adjusted EBITDA* $ 126 $ 158 25% Adjusted Diluted EPS* $ 1.12 $ 1.26 13% $’s in millions except EPS *Adjusted to exclude non-c
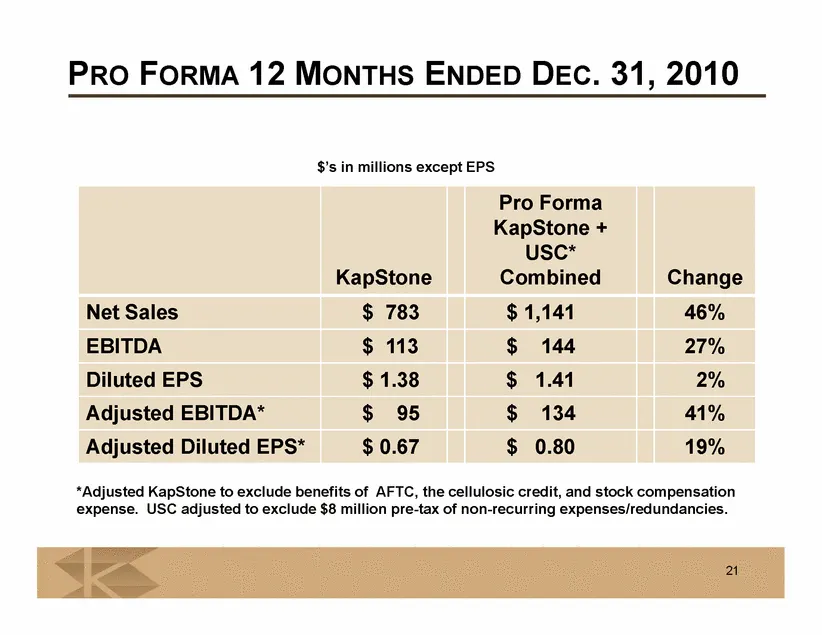
Slide 21: Pro Forma 12 Months Ended Dec. 31, 2010
21 21 KapStone Pro Forma KapStone + USC* Combined Change Net Sales $ 783 $ 1,141 46% EBITDA $ 113 $ 144 27% Diluted EPS $ 1.38 $ 1.41 2% Adjusted EBITDA* $ 95 $ 134 41% Adjusted Diluted EPS* $ 0.67 $ 0.80 19% $’s in millions except EPS *Adjusted KapStone to exclude benefits of AFTC, the cellulosic c
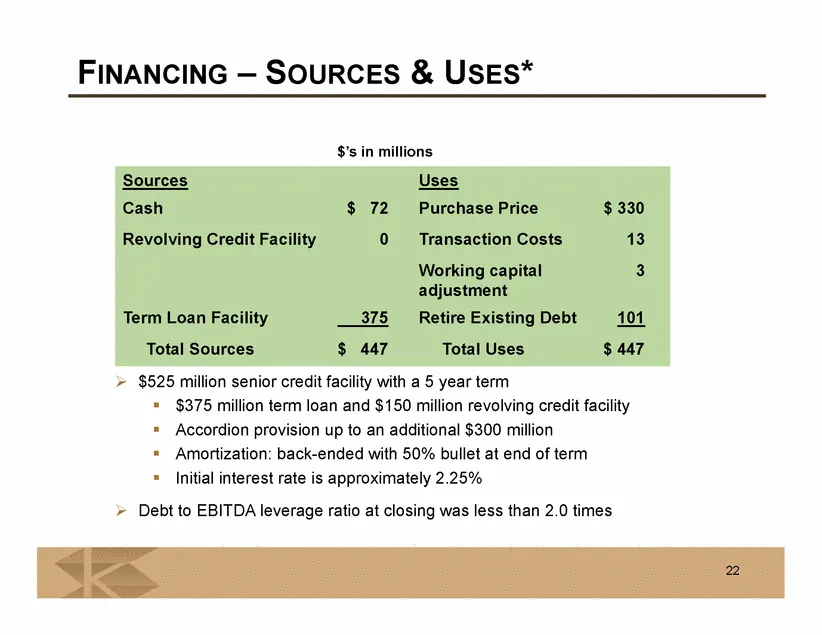
Slide 22: Financing – Sources & Uses
22 FINANCING – SOURCES & USES* 22 $525 million senior credit facility with a 5 year term $375 million term loan and $150 million revolving credit facility Accordion provision up to an additional $300 million Amortization: back-ended with 50% bullet at end of term Initial interest rate is approximate
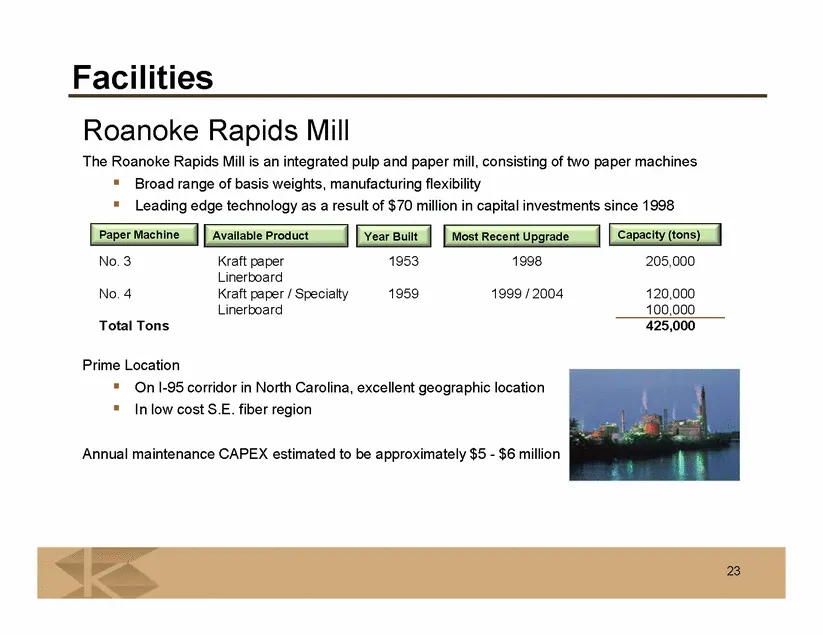
Slide 23: Roanoke Rapids Mill
Roanoke Rapids Mill The Roanoke Rapids Mill is an integrated pulp and paper mill, consisting of two paper machines Broad range of basis weights, manufacturing flexibility Leading edge technology as a result of $70 million in capital investments since 1998 Prime Location On I-95 corridor in North Car
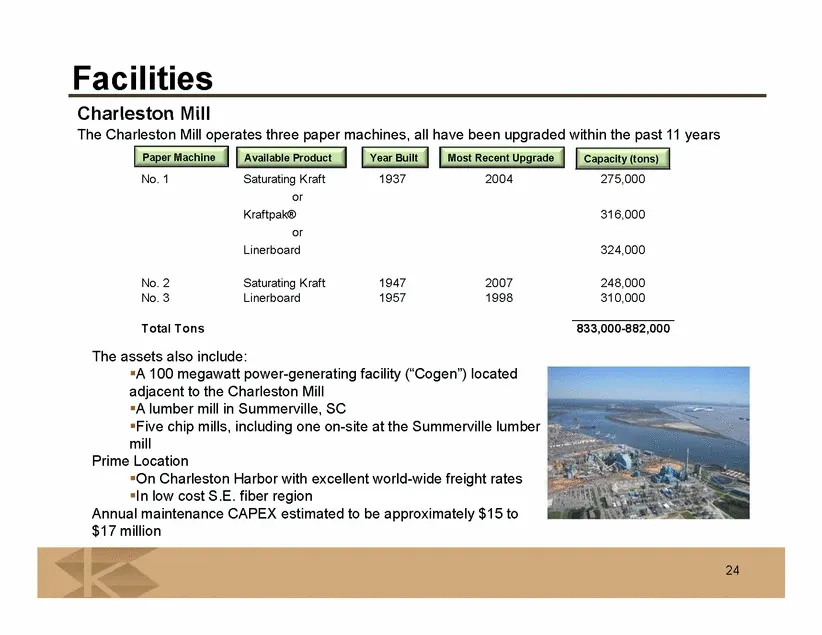
Slide 24: Charleston Mill
Charleston Mill The Charleston Mill operates three paper machines, all have been upgraded within the past 11 years 24 Facilities Paper Machine Available Product Year Built Most Recent Upgrade Capacity (tons) The assets also include: A 100 megawatt power-generating facility (“Cogen”) located adjacent
Slide 25: Cowpens Mill
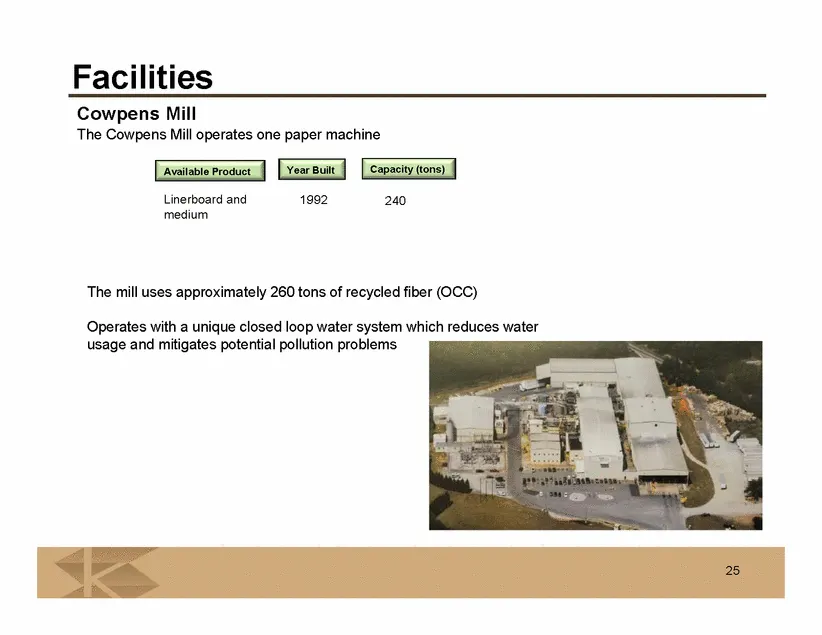
Cowpens Mill The Cowpens Mill operates one paper machine 25 Facilities Available Product Year Built Capacity (tons) The mill uses approximately 260 tons of recycled fiber (OCC) Operates with a unique closed loop water system which reduces water usage and mitigates potential pollution problems Linerb
Slide 26: Our Products
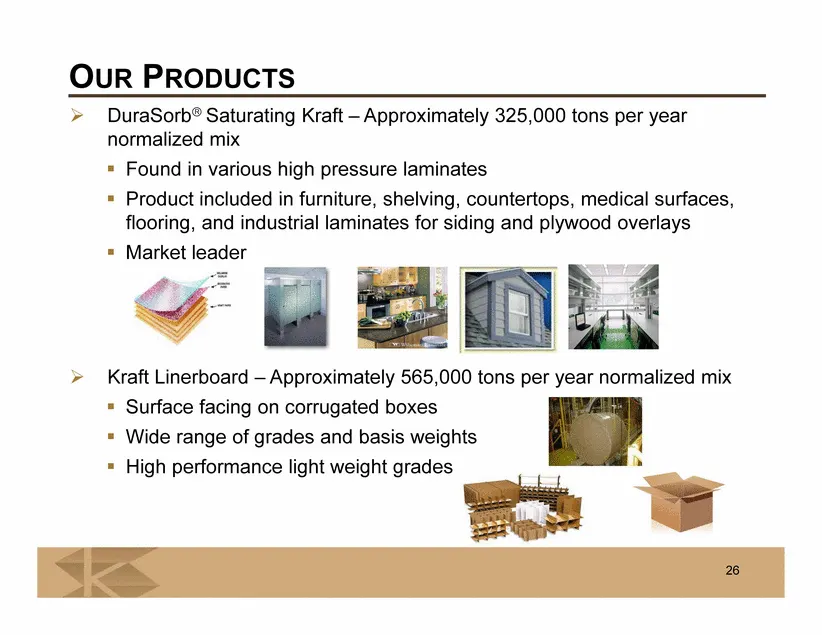
26 OUR PRODUCTS DuraSorb Saturating Kraft – Approximately 325,000 tons per year normalized mix Found in various high pressure laminates Product included in furniture, shelving, countertops, medical surfaces, flooring, and industrial laminates for siding and plywood overlays Market leader Kraft Liner
Slide 27: Our Products
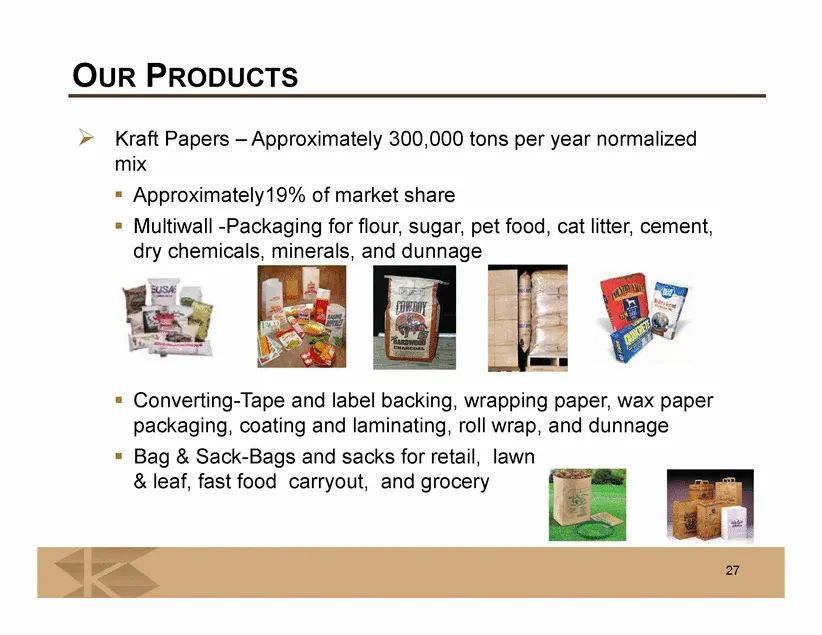
27 OUR PRODUCTS Kraft Papers – Approximately 300,000 tons per year normalized mix Approximately19% of market share Multiwall -Packaging for flour, sugar, pet food, cat litter, cement, dry chemicals, minerals, and dunnage Converting-Tape and label backing, wrapping paper, wax paper packaging, coating
Slide 28: Our Products
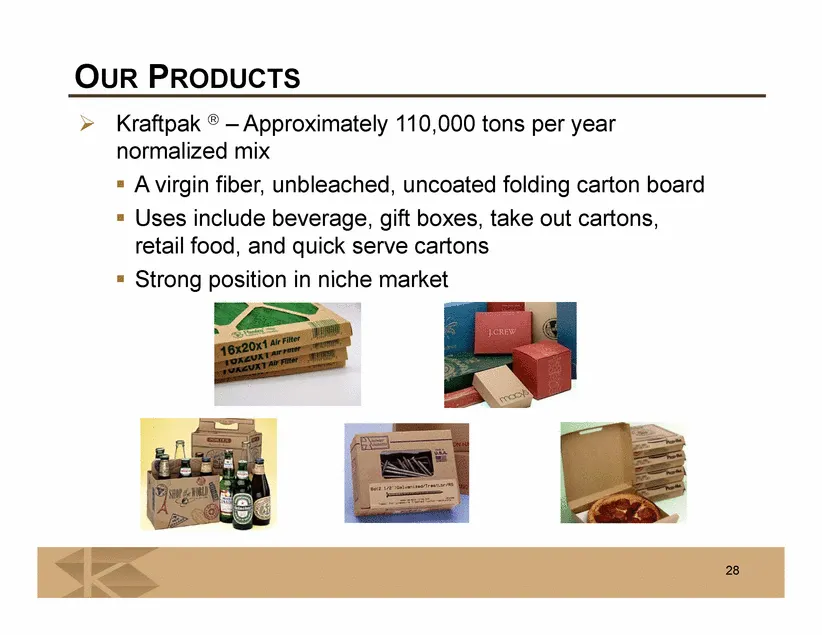
28 OUR PRODUCTS Kraftpak ® – Approximately 110,000 tons per year normalized mix A virgin fiber, unbleached, uncoated folding carton board Uses include beverage, gift boxes, take out cartons, retail food, and quick serve cartons Strong position in niche market
Slide 29: Our Products
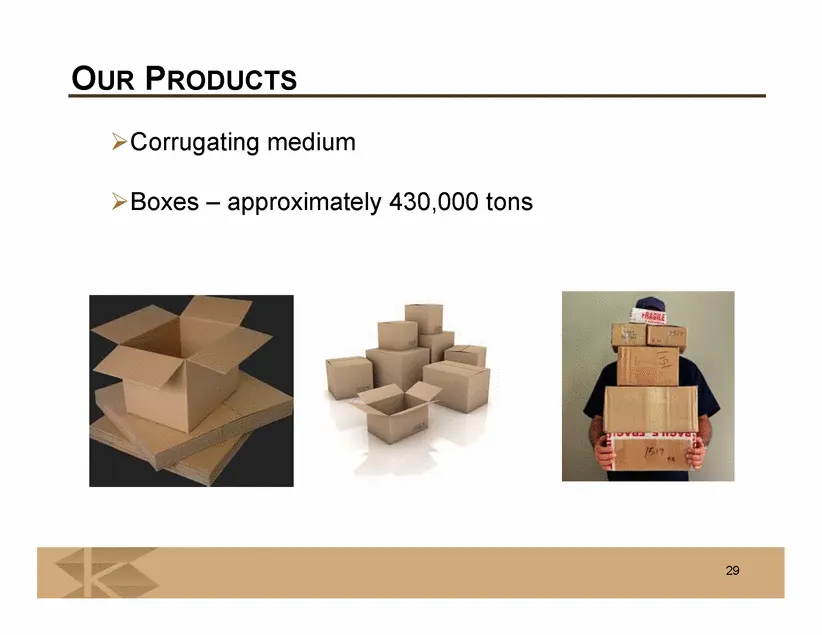
29 OUR PRODUCTS Corrugating medium Boxes – approximately 430,000 tons
Source: SEC EDGAR · 8-K filed Jan 11, 2012
More decks from KapStone Paper and Packaging Corporation
 Q3 2018 Earnings Presentation8 slides · Oct 23, 2018
 Q2 2018 Earnings Presentation8 slides · Jul 25, 2018
 Q1 2018 Earnings Presentation8 slides · Apr 18, 2018
 Citi Investor Meetings February 201828 slides · Feb 13, 2018
 Q1 FY18 Earnings Presentation37 slides · Jan 29, 2018
 Q3 2017 Earnings Presentation9 slides · Oct 25, 2017