McData — Merger or Acquisition (May 2005)
54 slides from McData's merger presentation, May 9, 2005
Slide 1: Driving Increased Value to Customers, Partners and Shareholders
@mepatTa MCDATA + CNT Driving Increased Value to Customers, Partners and Shareholders Conference Call and Road Show Presentation May 9 - May 12, 2005
Slide 2: Acquisition Update Conference Call Speakers
McDATA + CNT Acquisition Update Conference Call Speakers e@ John Kelley —Chairman, President and CEO, McDATA @ Tom Hudson - Chairman, President and CEO, CNT @ Ernest Sampias — Chief Financial Officer, McDATA Moderator e@ Renee Lyall — Sr. Director, Investor Relations, McCDATA Replay Information Tele
Slide 3: Securities Litigation Reform Act - Safe Harbor
Securities Litigation Reform Act — Safe Harbor This presentation includes forward looking statements regarding McDATA’s business outlook. These statements are only predictions and are subject to risks and uncertainties. McDATA’s actual results may differ materially. Any forward looking statements ma
Slide 4: Additional Information and Where To Find It
Additional Information and Where To Find It: McDATA has filed a registration Statement on SEC Form $4 and MeDATA and CNT have fd a Joint Proxy StztemandProcpectis with the SEC in connecton with the proposed merger. The Registration Statement was dedared effective bythe SEC on April 18,2005 and the J
Slide 5: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ PRELIMINARY FQ105 FINANCIAL RESULTS @ Strategic Overview @ Combined Product and Services Roadmap @ Go-To-Market Model @ Operational Plans @ Execution Imperatives @ Summary @ Q8A @mepata =cnT
Slide 6: Q1 FY2005 Preliminary Non-GAAP Operating Results
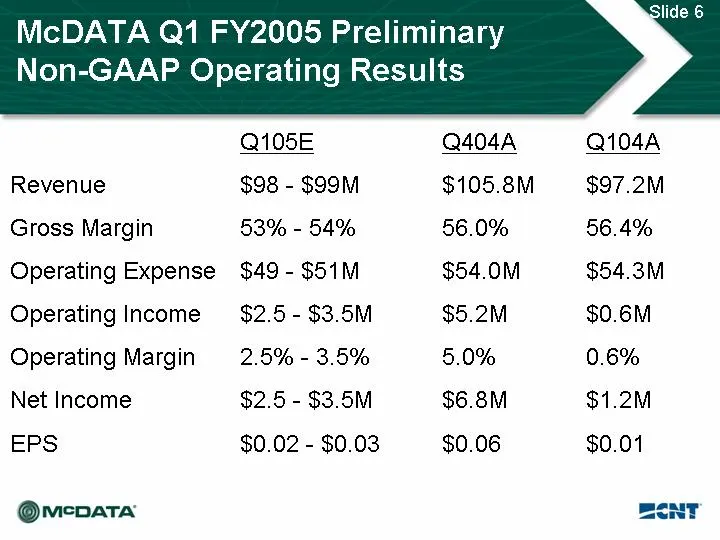
McDATA Q1 FY2005 Preliminary Non-GAAP Operating Results Revenue Gross Margin Operating Expense Operating Income Operating Margin Net Income EPS @mepata Q105E $98 - $99M 53% - 54% $49 - $51M $2.5 - $3.5M 2.5% - 3.5% $2.5 - $3.5M $0.02 - $0.03 Q404A $105.8M 56.0% $54.0M $5.2M 5.0% $6.8M $0.06 Q104A $9
Slide 7: Q1 FY2005 Preliminary Balance Sheet
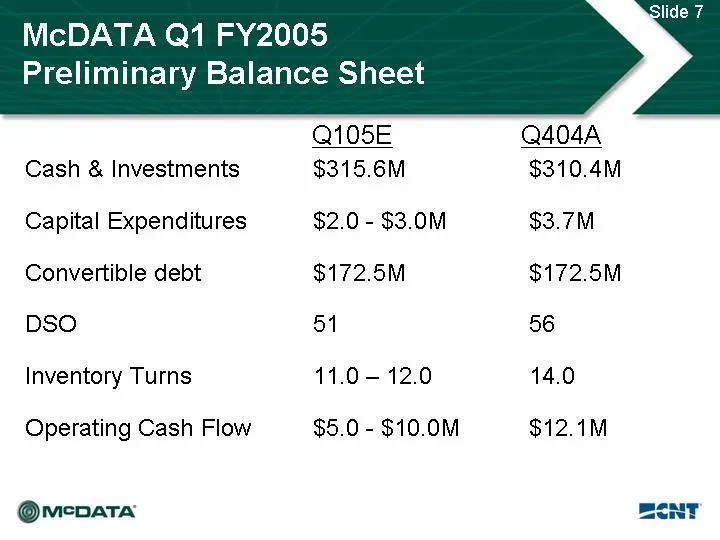
McDATA Q1 FY2005 Preliminary Balance Sheet Cash & Investments Capital Expenditures Convertible debt Dso Inventory Turns Operating Cash Flow @mepata Q105E $315.6M $2.0 - $3.0M $172.5M 51 11.0- 12.0 $5.0 - $10.0M Q404A $310.4M $3.7M $172.5M 56 14.0 $12.1M Ent
Slide 8: CNT Q1 FY2005 Preliminary Revenue Results
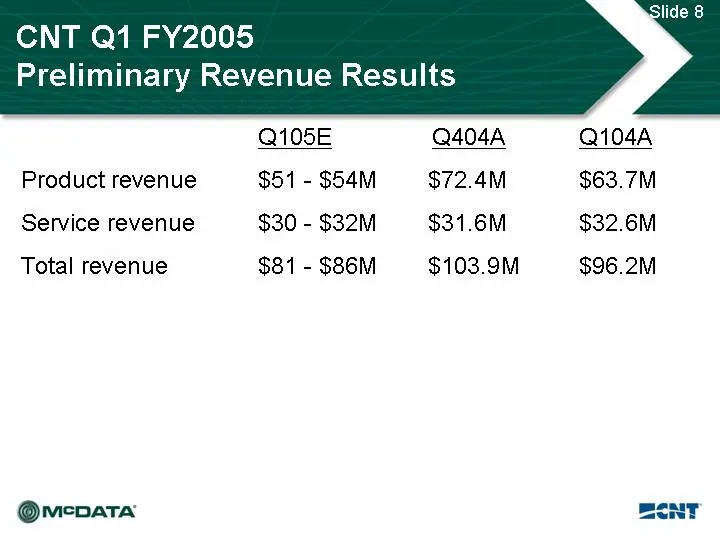
CNT Q1 FY2005 Preliminary Revenue Results Product revenue Service revenue Total revenue @mepata Q105E Q404A Q104A $51 - $54M $72.4M $63.7M $30 - $32M $31.6M $32.6M $81 - $86M $103.9M $96.2M Ent
Slide 9: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ Preliminary FQ105 Financial Results @ STRATEGIC OVERVIEW @ Combined Product and Services Roadmap @ Go-To-Market Model @ Operational Plans @ Execution Imperatives @ Summary @ Q8A @mepata =cnT
Slide 10: A Shared Vision
A Shared Vision Global Enterprise Data Infrastructure The GEDI is a vision shared by partners and end-user customers of the optimized data infrastructure characterized by: a switched, tiered network infrastructure delivering cost effective consolidation; integrated, centralized management and networ
Slide 11: A Common Goal
A Common Goal To become the most respected and reliable data infrastructure company, delivering data management solutions to the enterprise — Unifying diverse storage products — Bringing networking technologies together — Enabling any storage strategy — Connecting sites across the globe @mepata =cnT
Slide 12: Strategic Rationale
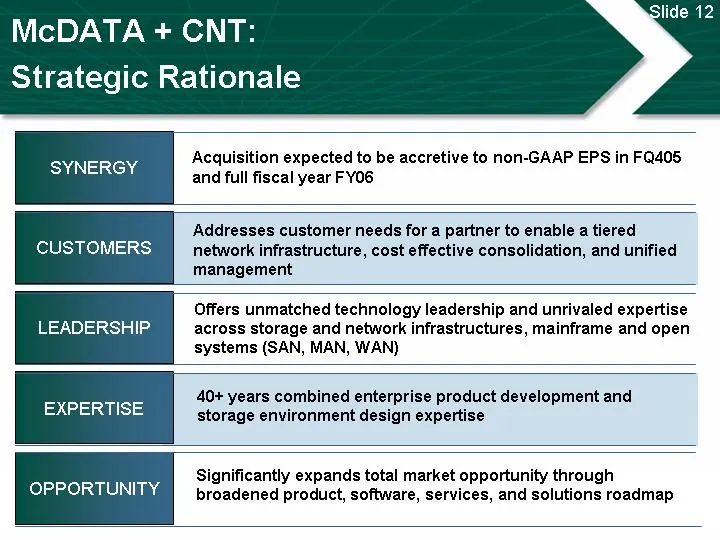
McDATA + CNT Strategic Rationale SYNERGY Acquisition expected to be accretive to non-GAAP EPS in FQ405 and full fiscal year FYO6 CUSTOMERS Addresses customer needs for a partner to enable a tiered network infrastructure, cost effective consolidation, and unified management LEADERSHIP. Offers unmatch
Slide 13: Straightforward Synergies
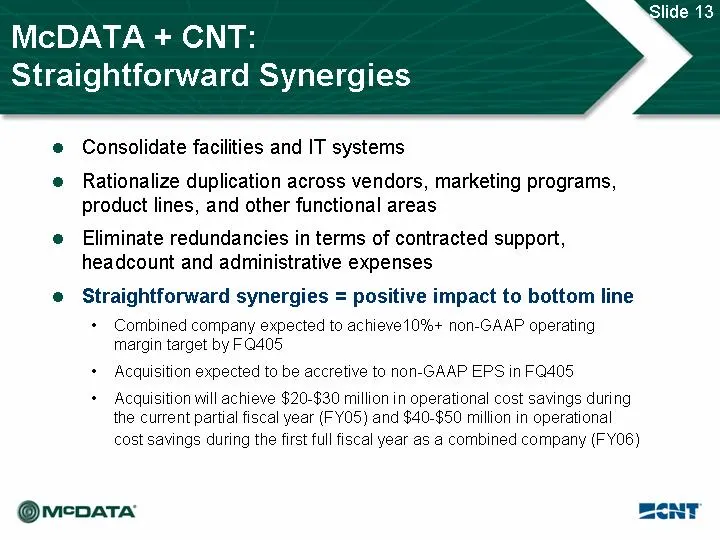
McDATA + CNT Straightforward Synergies @ Consolidate facilities and IT systems @ Rationalize duplication across vendors, marketing programs, product lines, and other functional areas @ Eliminate redundancies in terms of contracted support, headcount and administrative expenses e Straightforward syne
Slide 14: Expansive Customer Base
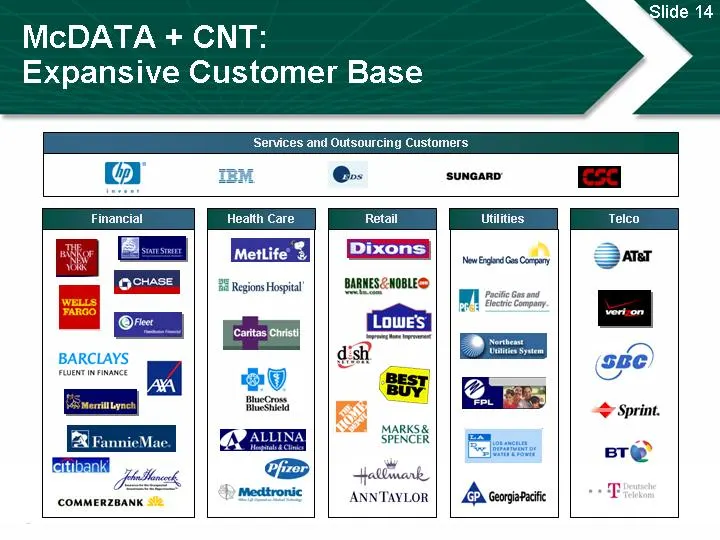
McDATA + CNT: Expansive Customer Base Services and Outsourcing Customers e. sunaano EE Health Care = ESE | | teresins tos BARCLAYS er ALUN) EXT ys GED) | hetiirark COMMERZBANK ANNTAYLOR
Slide 15: Comprehensive Leading Solution
McDATA + CNT: Comprehensive Leading Solution @ Fibre Channel and FICON storage networks (SAN) @ IP storage networking solutions (iSCSI SANs and gateways) @ Metro and wide area networking (MANAWVAN) @ SAN routing and storage services @ SAN security and management @ World-class professional and suppor
Slide 16: Complementary Strengths
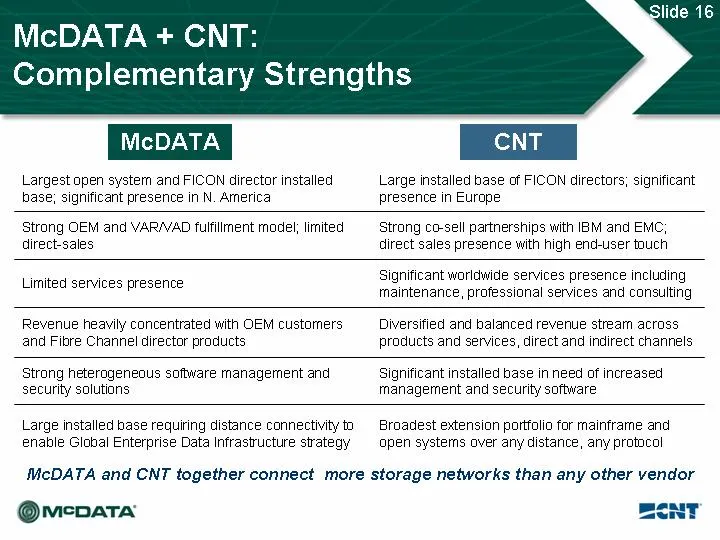
McDATA + CNT Complementary Strengths Largest open system and FICON director installed hase; significant presence in N. America Large installed base of FICON directors; significant presence in Europe Strong OEM and VAR/VAD fulfillment madel; limited direct-sales Strong co-sell partnerships with IBM a
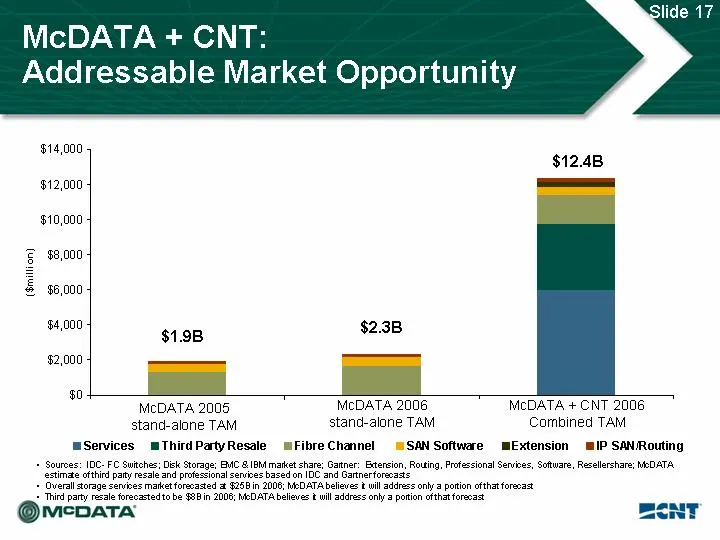
Slide 17: Addressable Market Opportunity
McDATA + CNT Addressable Market Opportunity $14,000 $12.4B $12,000 —<—i $10,000 $8,000 $6,000 $4,000 $198 $2.3B $2,000 = " sod McDATA 2005 McDATA 2006 MCDATA + CNT 2006 stand-alone TAM. Combined TAM stand-alone TAM Services mThirdPatyResale mFibreChannel =SANSoftware Extension IP SANRouting + Souree
Slide 18: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ Preliminary FQ105 Financial Results @ Strategic Overview e COMBINED PRODUCT AND SERVICES ROADMAP @ Go-To-Market Model @ Operational Plans @ Execution Imperatives @ Summary @ Q8A @mepata =cnT
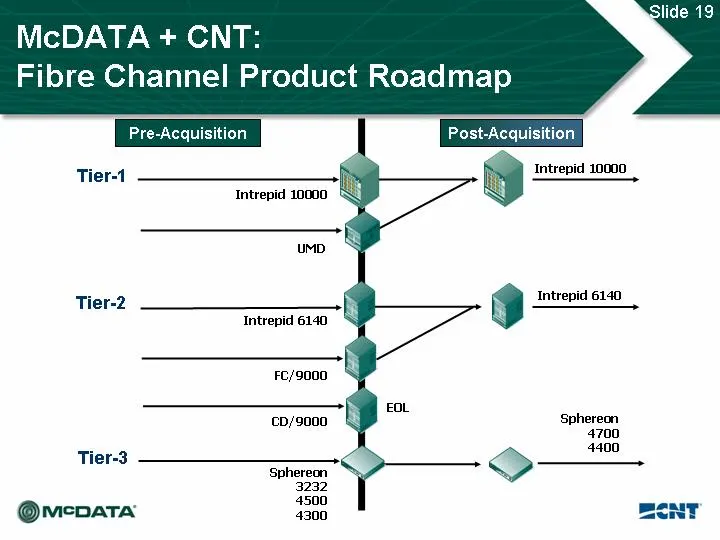
Slide 19: Fibre Channel Product Roadmap
McDATA + CNT: Fibre Channel Product Roadmap 9g Intrepid 6140 Intrepid 6140 Fc/9000 EOL cb/9000 Sphereon 4700 : 4400 Tier-3 o ‘Sphereon v 3232 . 4500 @mepatTa 4300 ZtNnT
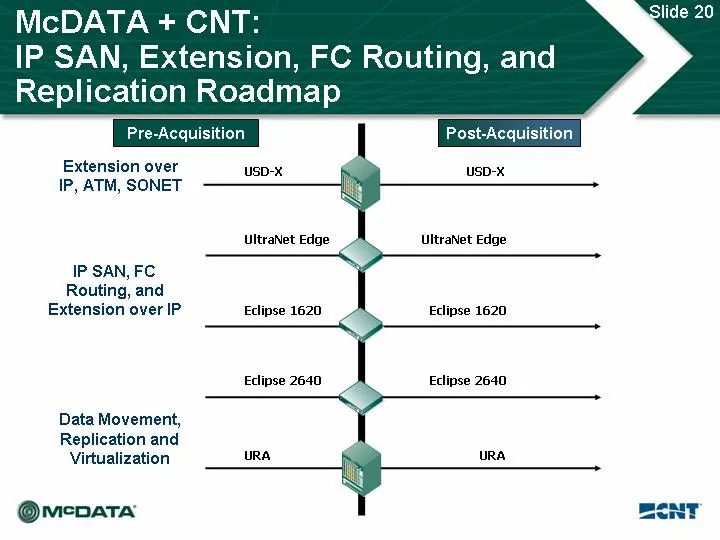
Slide 20: IP SAN, Extension, FC Routing, and Replication Roadmap
McDATA + CNT: IP SAN, Extension, FC Routing, and Replication Roadmap Pre-Acq Extension over IP, ATM, SONET UltraNet Edge IP SAN, FC Routing, and Extension over IP Eclipse 1620 Eclipse 2640 Data Movement, Replication and Virtualization URA URA @mepata =cnT
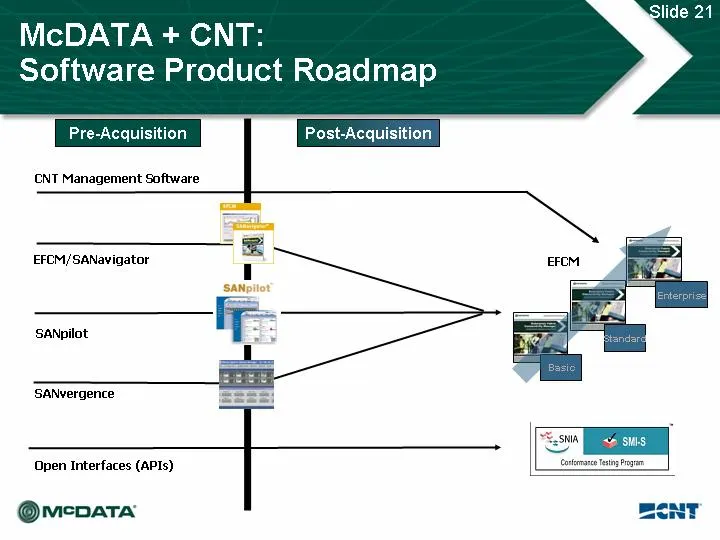
Slide 21: Software Product Roadmap
McDATA + CNT: Software Product Roadmap Pre-Acquisition | Post-Acquisition CNT Management Software EFCM/SANavigator SANpilot SANvergence Open Interfaces (APIs) @mepata =cnT
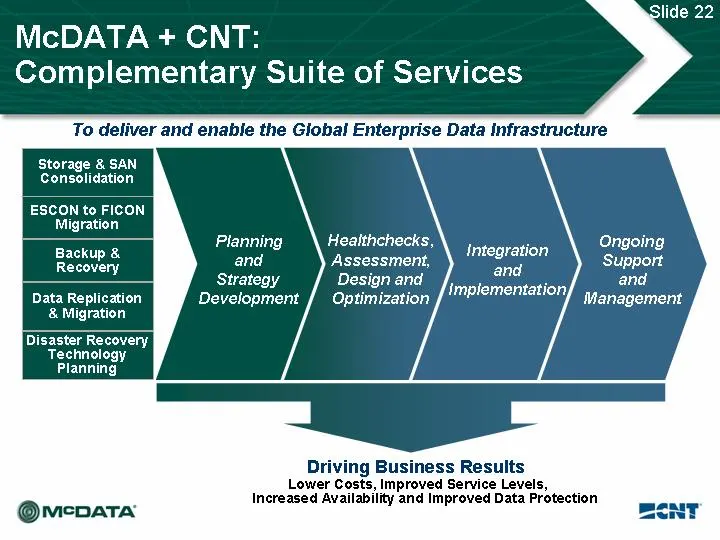
Slide 22: Complementary Suite of Services
lide 22 McDATA + CNT: Complementary Suite of Services "To deliver and enable the Global Enterprise Data Infrastructure Storage & SAN Consolidation ESCON to FICON Migration Planning \ Healthchecks, and Assessment, Support Strategy Design and and Data Replication Development Optimization Management &
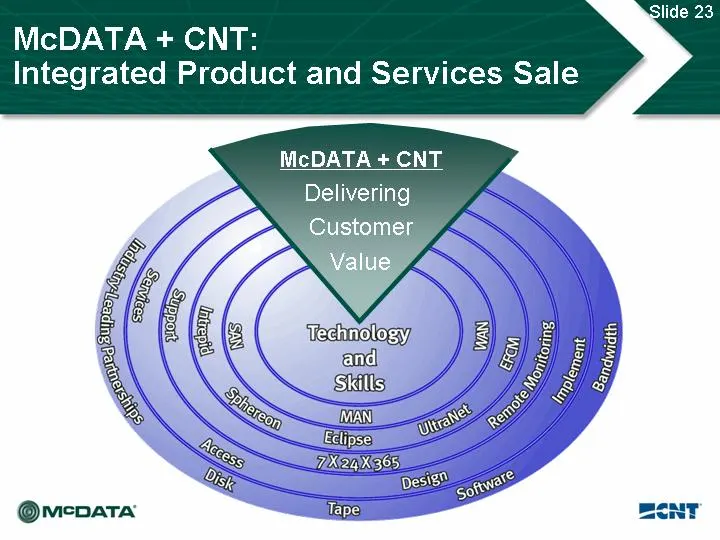
Slide 23: Integrated Product and Services Sale
McDATA + CNT Integrated Product and Services Sale McDATA + CNT Delivering @mepatTa ES =cnT
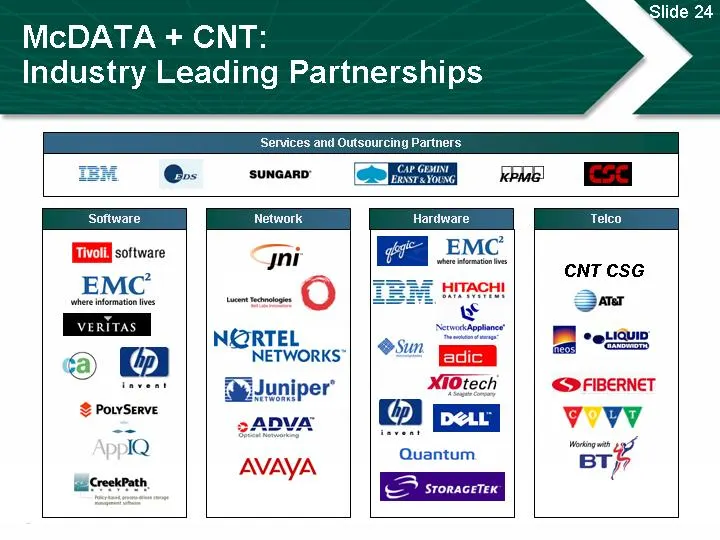
Slide 24: Industry Leading Partnerships
McDATA + CNT: Industry Leading Partnerships Services and Out ig Partners e@. SUNGARD software CNT CSG Saar ~ NTE aie an OHSS een wy 1Q aussi 4
Slide 25: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ Preliminary FQ105 Financial Results @ Strategic Overview @ Combined Product and Services Roadmap @ GO-TO-MARKET MODEL @ Operational Plans @ Execution Imperatives @ Summary @ Q8A @mepata =cnT
Slide 26: Drives Value to OEMs, VAR/VADs, and Customers
McDATA + CNT: Drives Value To OEMs, VAR/VADs, and Customers The broader products, services, and solutions offerings, combined with the larger installed base should: @ Enable the combined company to better meet the objectives and programs of all channel partners @ Provide channel partners the ability
Slide 27: OEM Partner Perspective
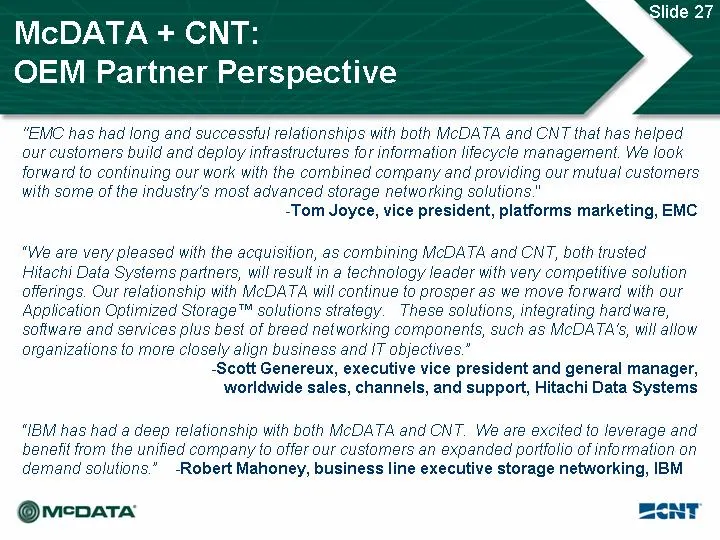
McDATA + CNT: OEM Partner Perspective “EMC has had long and successful relationships with both McDATA and CNT that has helped our customers build and deploy infrastructures for information lifecycle management. We look forward fo continuing our work with the combined company and providing our mutual
Slide 28: Diversified Routes to Market
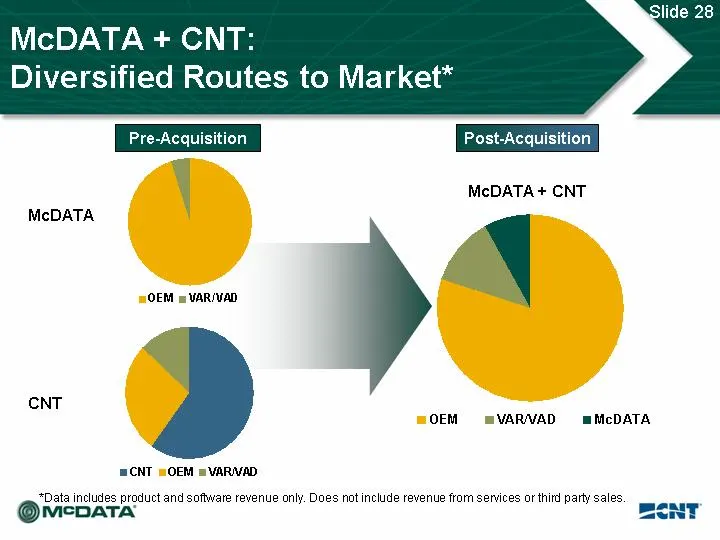
McDATA + CNT: Diversified Routes to Market* Pre-Acquisition Post-Acquisition McDATA + CNT McDATA CNT El M oo mVARVAD =m McDATA SCNT SOEM = VARVAD *Data includes product and software revenue only. Does not include revenue from services or third party sales. sai @mepata =Snt
Slide 29: Leveraging the Customer Opportunity
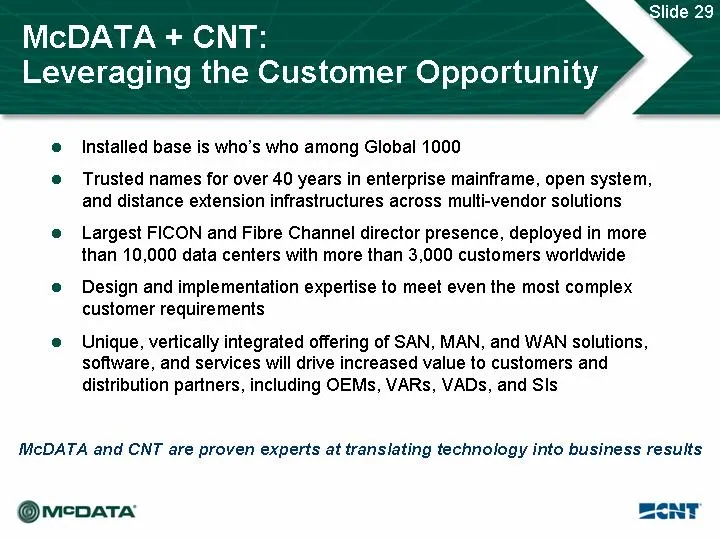
McDATA + CNT: Leveraging the Customer Opportunity @ Installed base is who’s who among Global 1000 @ Trusted names for over 40 years in enterprise mainframe, open system, and distance extension infrastructures across multi-vendor solutions e@ Largest FICON and Fibre Channel director presence, deploye
Slide 30: Customer Example: Large Financial Institution
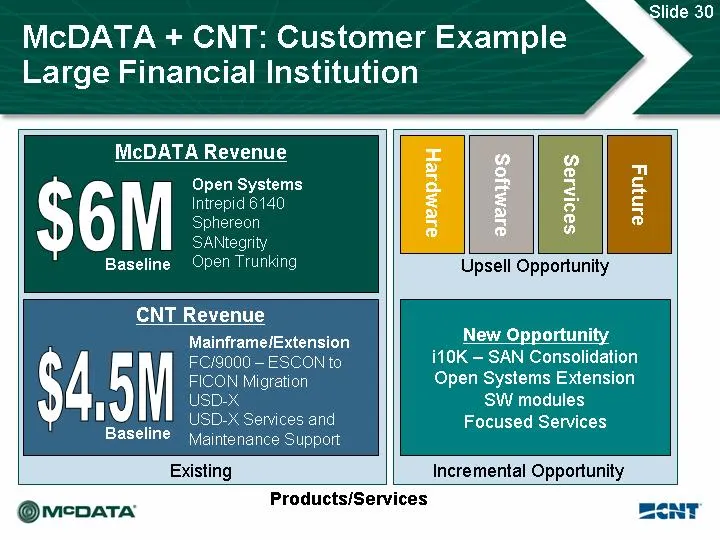
lide 30 McDATA + CNT: Customer Example Large Financial Institution McDATA Revenue Open Systems Intrepid 6140 Sphereon SANtegrity Baseline Open Trunking CNT Revenue Mainframe/Extension FC/9000 -ESCON to FICON Migration USD-X USD-X Services and Ness Maintenance Support Existing asempseyH Upsell Opport
Slide 31: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ Preliminary FQ105 Financial Results @ Strategic Overview @ Combined Product and Services Roadmap @ Go to Market Model e@ OPERATIONAL PLANS @ Execution Imperatives @ Summary @ Q8A @mepata =cnT
Slide 32: FY05 - FY06 Estimated Synergies
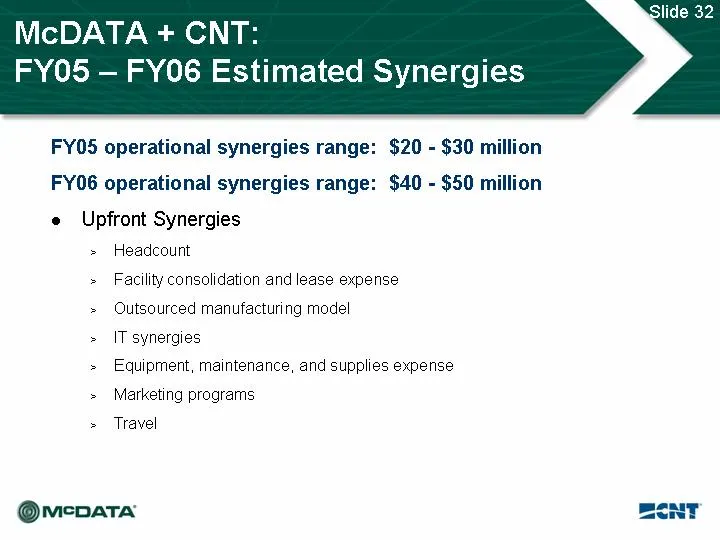
McDATA + CNT FY05 — FY06 Estimated Synergies FY05 operational synergies range: $20 - $30 million FY06 operational synergies range: $40 - $50 million e Upfront Synergies » Headcount » Facility consolidation and lease expense > Outsourced manufacturing model > IT synergies » Equipment, maintenance, an
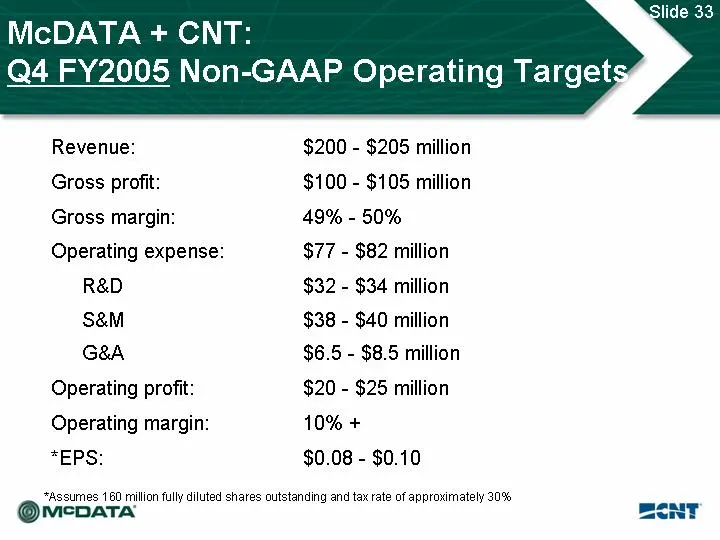
Slide 33: Q4 FY2005 Non-GAAP Operating Targets
McDATA + CNT: Q4 FY2005 Non-GAAP Operating Targets Revenue: 200 - $205 million Gross profit: 100 - $105 million Gross margin: 49% - 50% Operating expense: 77 - $82 million R&D 32 - $34 million S&M 38 - $40 million G&A 6.5 - $8.5 million Operating profit: 20 - $25 million Operating margin: 10% + *EPS
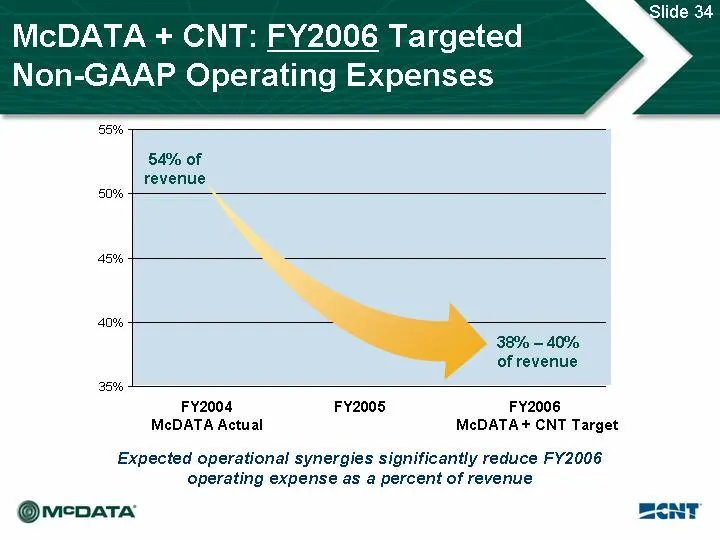
Slide 34: FY2006 Targeted Non-GAAP Operating Expenses
McDATA + CNT: FY2006 Targeted Non-GAAP Operating Expenses 58% 50% 45% 40% + 25% 54% of revenue 38% - 40% of revenue FY2004 FY2005 FY2006 McDATA Actual McDATA + CNT Target Expected operational synergies significantly reduce FY2006 operating expense as a percent of revenue @mepata =cnT
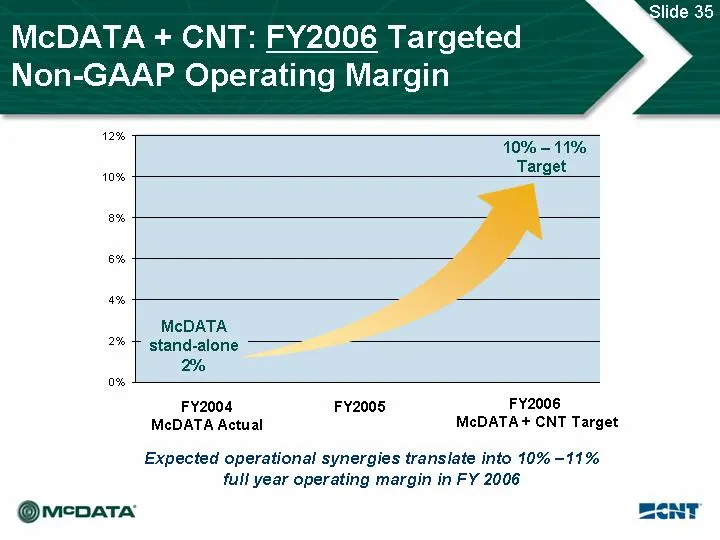
Slide 35: FY2006 Targeted Non-GAAP Operating Margin
McDATA + CNT: FY2006 Targeted Non-GAAP Operating Margin 12% 10% —11% Target 10% 8% 6% 4% McDATA 2% 7 stand-alone % 0% FY2004 FY2005 FY2006 McDATA Actual McDATA + CNT Target Expected operational synergies translate into 10% -11% full year operating margin in FY 2006 @mepata =cnT
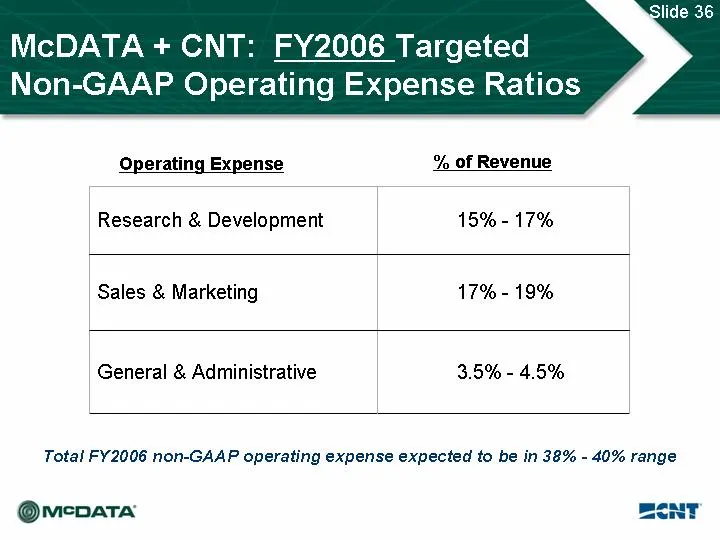
Slide 36: FY2006 Targeted Non-GAAP Operating Expense Ratios
McDATA + CNT: FY2006 Targeted Non-GAAP Operating Expense Ratios Operating Expense % of Revenue Research & Development 15% - 17% Sales & Marketing 17% - 19% General & Administrative 3.5% - 4.5% Total FY2006 non-GAAP operating expense expected to be in 38% - 40% range @mepata =cnT
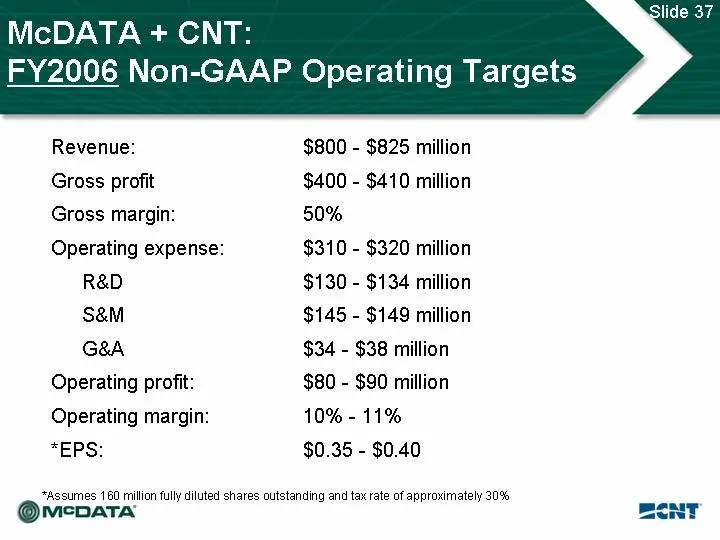
Slide 37: FY2006 Non-GAAP Operating Targets
FY2006 Non-GAAP Operating Targets Revenue: 800 - $825 million Gross profit 400 - $410 million Gross margin: 50% Operating expense: 310 - $320 million R&D 130 - $134 million S&M 145 - $149 million G&A 34 - $38 million Operating profit: 80 - $90 million Operating margin: 10% - 11% *EPS: 10.35 - $0.40
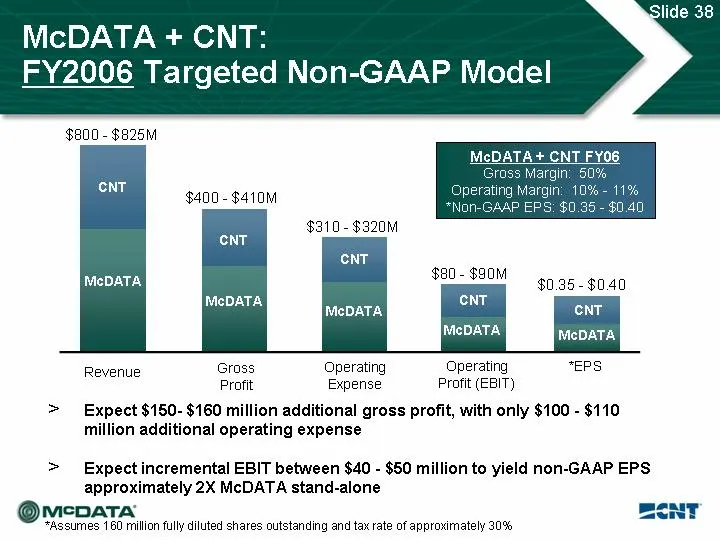
Slide 38: FY2006 Targeted Non-GAAP Model
McDATA + CNT: FY2006 Targeted Non-GAAP Model $800 - $825M McDATA+ CNT FY06 age NT $400 -$410M Be $310-$320M NT NT 80 - $20M Eve pee $0.35-$0.40 REESE MeDATA ses NT eee McDATA Revenue Gross Operating Operating “EPS Profit Expense Profit (EBIT) > Expect $150- $160 million additional gross profit, with
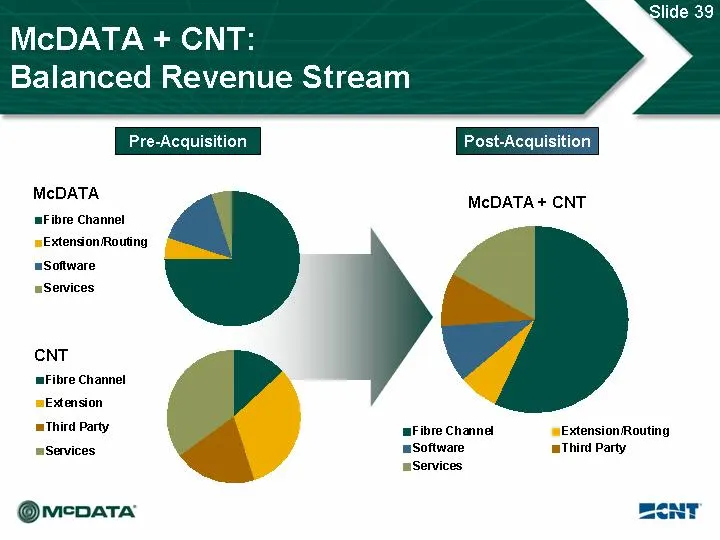
Slide 39: Balanced Revenue Stream
McDATA + CNT: Balanced Revenue Stream equi McDATA Fibre Channel Extenson/Routing McDATA + CNT Software Services CNT Fibre Channel Extension Third Party Fibre Channel Extension Routing oftware Third Party Services Services @mepata Ent
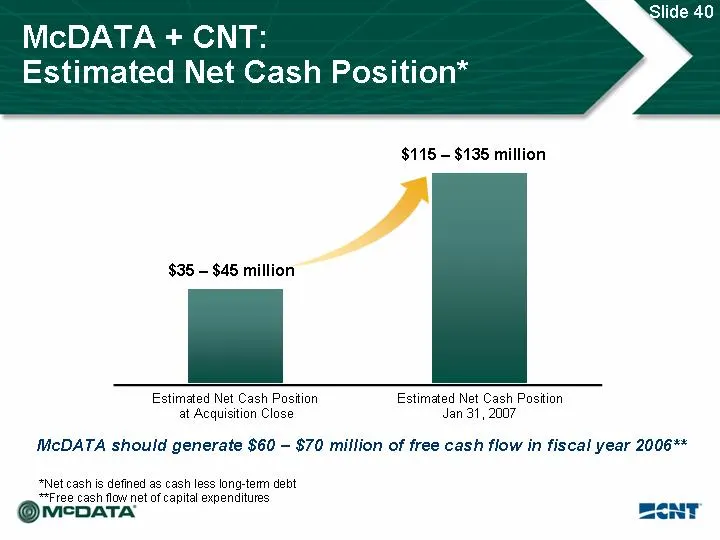
Slide 40: Estimated Net Cash Position
McDATA + CNT Estimated Net Cash Position $115 - $135 million $35 — $45 million Estimated Net Cash Position Estimated Net Cash Position at Acquisition Close Jan 31 , 2007 MCDATA should generate $60 — $70 million of free cash flow in fiscal year 2006** *Net cash is defined as cash less lange-term debt
Slide 41: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ Preliminary FQ105 Financial Results @ Strategic Overview @ Combined Product and Services Roadmap @ Go to Market Model @ Operational Plans e@ EXECUTION IMPERATIVES @ Summary @ Q8A @mepata =cnT
Slide 42: Execution Imperatives: Targeted Execution Timeline FY2005
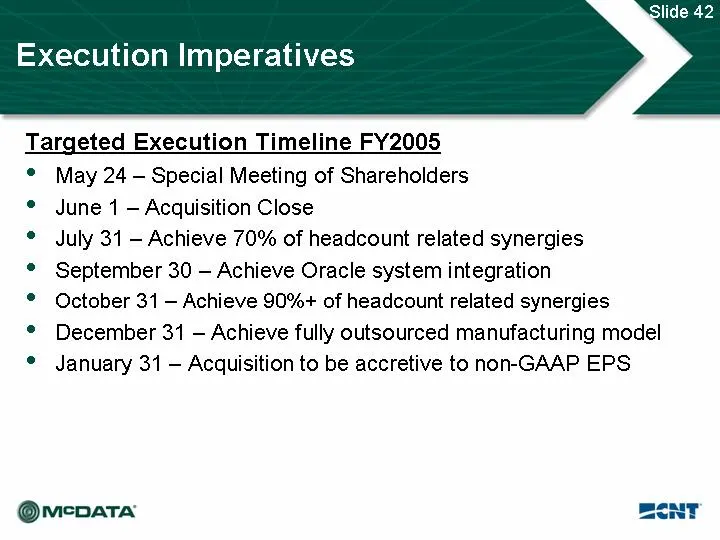
Execution Imperatives Targeted Execution Timeline FY2005 ° May 24 — Special Meeting of Shareholders e June 1 — Acquisition Close e July 31 - Achieve 70% of headcount related synergies *® September 30 — Achieve Oracle system integration * October 31 - Achieve 90%+ of headcount related synergies *® De
Slide 43: Link to searchable text of slide shown above
Link to searchable text of slide shown above
Slide 44: Execution Imperatives: Operational Cost Reduction and Integration
Execution Imperatives 1 Operational Cost Reduction and Efficiencies 2 Integration + The over-arching goal is for post-acquisition McDATA to improve its business model and processes @mepata Improve execution Ensure retention of key employees Leverage opportunity to build better processes throughout t
Slide 45: Execution Imperatives: Achieve Product Roadmap Deliverables
Execution Imperatives 1. Operational Cost Reduction and Efficiencies 2. Integration 3 «Achieve Product Roadmap Deliverables + Deliver 4 Gbps Sphereon 4400 and 4700 in second fiscal quarter 2005 + Deliver EFCM 9.0 before end of fiscal year 2005 + Bring virtualization solution to market 1HO6 + Execute
Slide 46: Execution Imperatives: Customer Focus
Execution Imperatives 1. Operational Cost Reduction and Efficiencies 2. Integration 3. Achieve Product Roadmap Deliverables 4 «Customer Focus + Strive to solve customer “pain points” + Aim to exceed customer and partner expectations + Deliver investment protection + Execute customer focused go-to-ma
Slide 47: Execution Imperatives: Innovate and Lead
Execution Imperatives = oS Be Operational Cost Reduction and Efficiencies Integration Achieve Product Roadmap Deliverables Customer Focus 5. Innovate and Lead @mepata = Pioneer new technology, products and services to retain strong competitive position Gain mindshare by leveraging the expanded resou
Slide 48: Execution Imperatives: Drive Shareholder Value
Execution Imperatives Operational Cost Reduction and Efficiencies Integration Achieve Product Roadmap Deliverables Customer Focus Innovate and Lead oe oe Bee 6. Drive Shareholder Value Drive profitable revenue growth + Exercise smart cost controls + Convey clear and consistent communications + Provi
Slide 49: Conference Call Agenda
McDATA + CNT: Acquisition Update Conference Call Agenda Agenda @ Preliminary FQ105 Financial Results @ Strategic Overview @ Combined Product and Services Roadmap @ Go to Market Model @ Operational Plans @ Execution Imperatives e SUMMARY @ Q8A @mepata =cnT
Slide 50: Transaction Summary
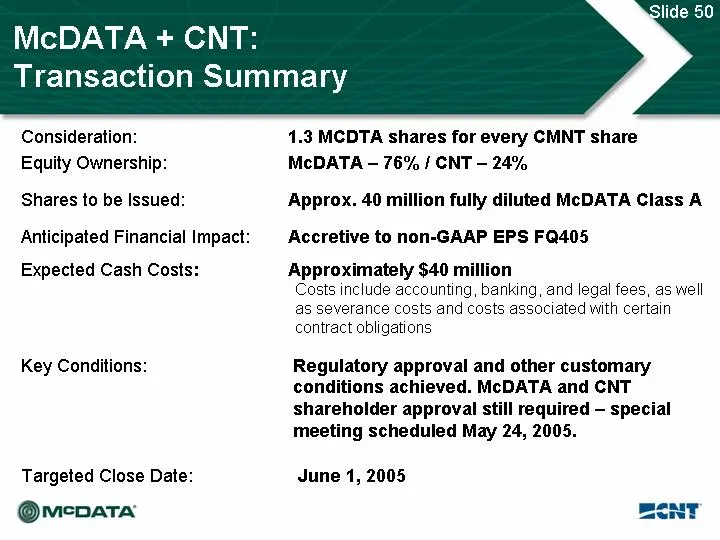
McDATA + CNT: Transaction Summary Consideration: Equity Ownership: Shares to be Issued: Anticipated Financial Impact: Expected Cash Costs: Key Conditions: Targeted Close Date: @mepata 1.3 MCDTA shares for every CMNT share McDATA — 76% / CNT — 24% Approx. 40 million fully diluted McDATA Class A Accre
Slide 51: Summary Financial Model Targets
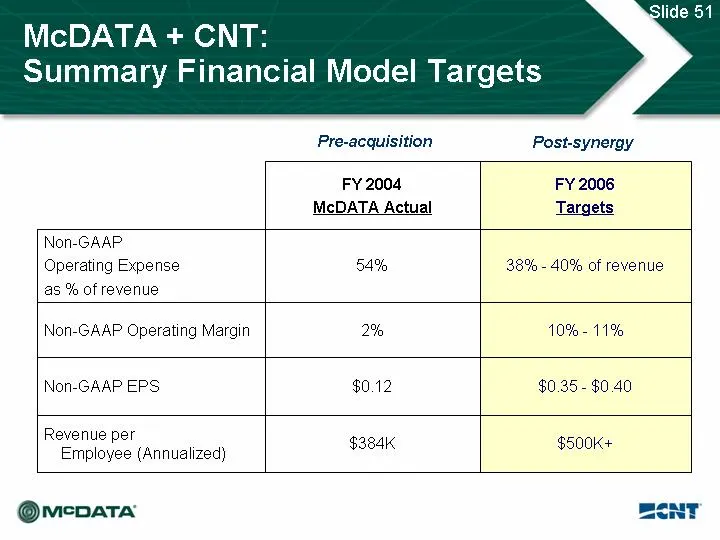
McDATA + CNT: Summary Financial Model Targets Pre-acquisition Post-synergy FY 2004 FY 2006 McDATA Actual Targets Non-GAAP Operating Expense 54% 38% - 40% of revenue as % of revenue Non-GAAP Operating Margin 2% 10% - 11% Non-GAAP EPS $0.12 $0.36 - $0.40 Revenue per Employee (Annualized) es Sadi @mepa
Slide 52: Executive Management & Board
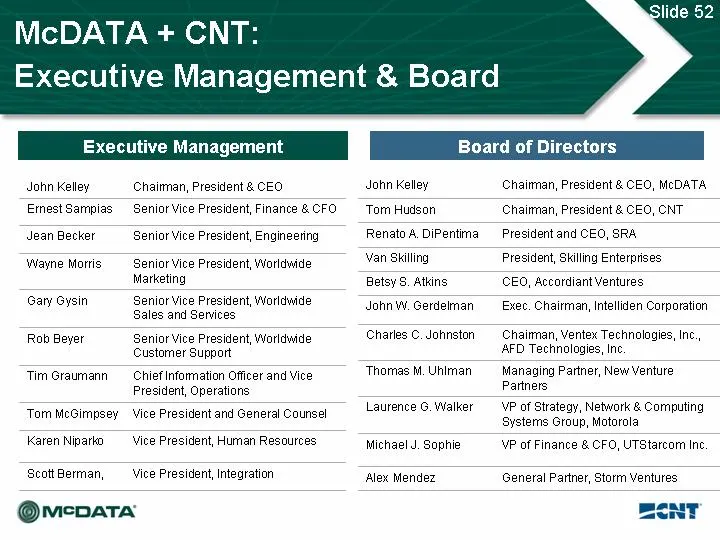
McDATA + CNT: Executive Management & Board Executive Management Board of Directors Chainman, President & CEO, McDATA John Kelley Emest Sampias Jean Becker Wayne Morris Gary Gysin Rob Beyer Timm Graumann Tom MeGimpsey Karen Niparko Scott Berman, Chaiman, President & CEO Senior Vice President, Finance
Slide 53: A Valuable Combination
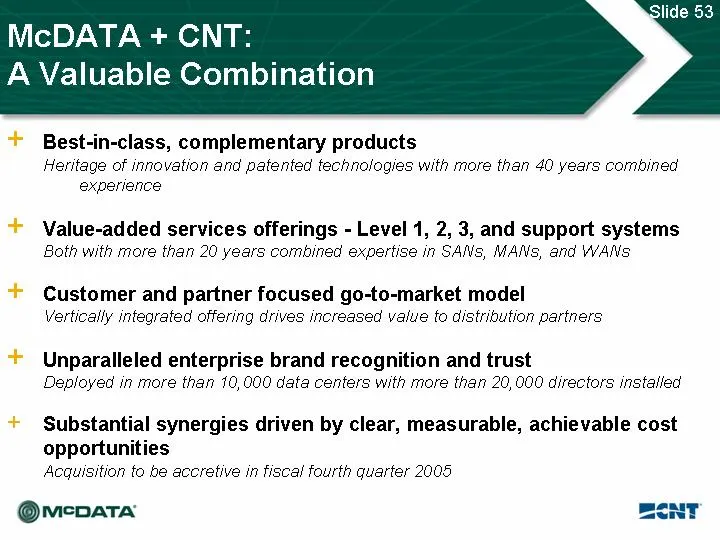
McDATA + CNT: A Valuable Combination ++ Best-in-class, complementary products Heritage of innovation and patented technologies with more than 40 years combined experience ‘+ Value-added services offerings - Level 1, 2, 3, and support systems Both with more than 20 years combined expertise in SANs, M
Slide 54: Searchable text section of graphics shown above
Searchable text section of graphics shown above [ LOG O] [LOGO] McDATA + CNT Driving Increased Value to Customers, Partners and Shareholders Conference Call and Road Show Presentation May 9 – May 12, 2005 McD ATA + CNT: Acquisition Update Conference Call Speakers • John Kelley –Chairman, President a
Source: SEC EDGAR · 8-K filed May 9, 2005
More decks from McData Corp
 Mcdata — Merger or Acquisition (September 2006)17 slides · Sep 12, 2006
 Q3 2006 Earnings Presentation27 slides · Aug 17, 2006
 Merger or Acquisition (August 2006)19 slides · Aug 8, 2006
 Mcdata — Merger or Acquisition (August 2006)17 slides · Aug 8, 2006
 Mcdata — Merger or Acquisition (August 2006)22 slides · Aug 8, 2006
 Computer Network Technology — Merger or Acquisition (May 2005)54 slides · May 10, 2005