DuPont Fabros Technology — Merger or Acquisition (June 2017)
18 slides from DuPont Fabros Technology's merger presentation, Jun 9, 2017
Slide 1: Home to the Cloud: Merger with DuPont Fabros Technology
EX99_2 HOME TO THE CLOUD MERGER WITH DUPONT FABROS TECHNOLOGY JUNE 2017
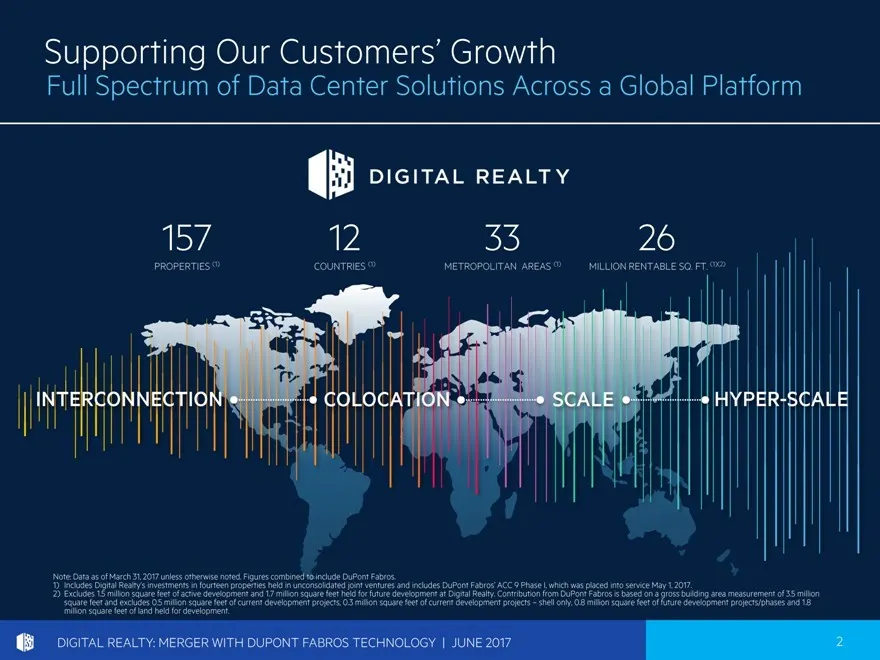
Slide 2: Full Spectrum of Data Center Solutions Across a Global Platform
Supporting Our Customers_ Growth Full Spectrum of Data Center Solutions Across a Global Platform 157 12 33 26 PROPERTIES (1) COUNTRIES (1) METROPOLITAN AREAS MILLION RENTABLE SQ. (1) FT. (1)(2) INTERCONNECTI COLOCATI SCAL HYPER- ON ON E SCALE Note: Data as of March 31, 2017 unless otherwise noted. F
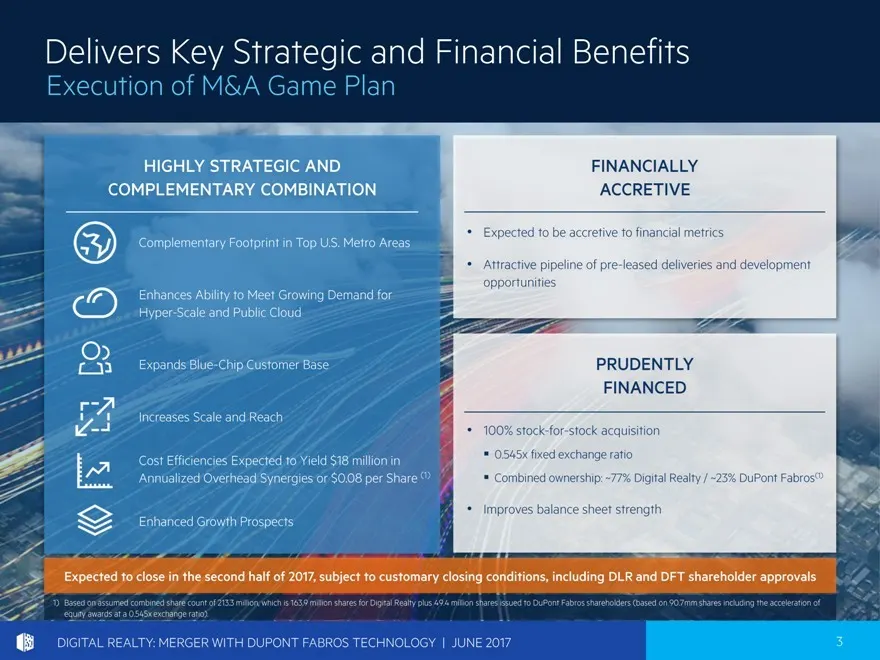
Slide 3: Delivers Key Strategic and Financial Benefits
Delivers Key Strategic and Financial Benefits Execution of M&A Game Plan HIGHLY STRATEGIC AND COMPLEMENTARY COMBINATION Complementary Footprint in Top U.S. Metro Areas Enhances Ability to Meet Growing Demand for Hyper-Scale and Public Cloud Expands Blue-Chip Customer Base Increases Scale and Reach C
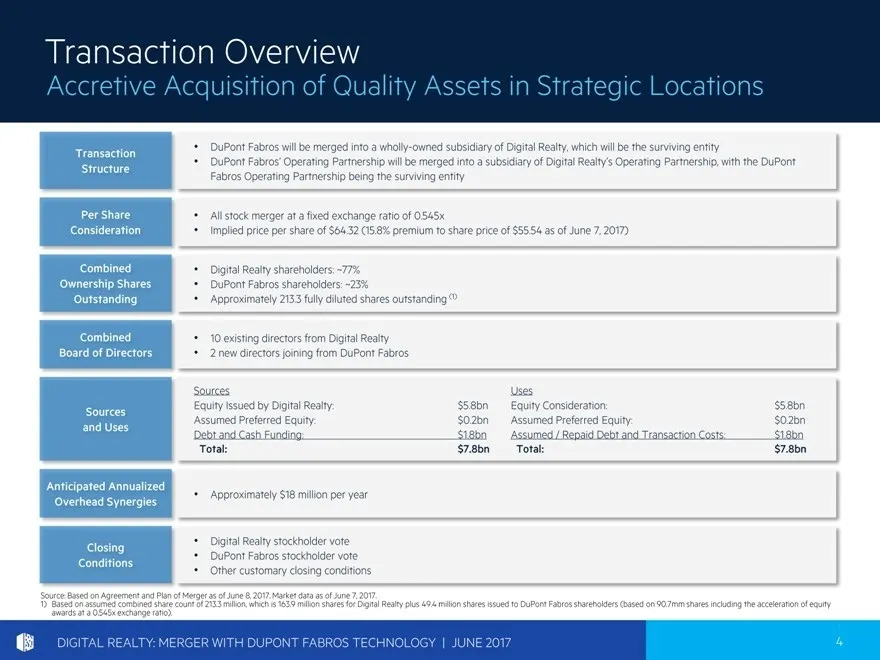
Slide 4: Transaction Overview
Transaction Overview Accretive Acquisition of Quality Assets in Strategic Locations Transaction Structure Per Share Consideration Combined Ownership Shares Outstanding Combined Board of Directors Sources and Uses Anticipated Annualized Overhead Synergies Closing Conditions DuPont Fabros will be merg
Slide 5: DuPont Fabros Technology At-a-Glance
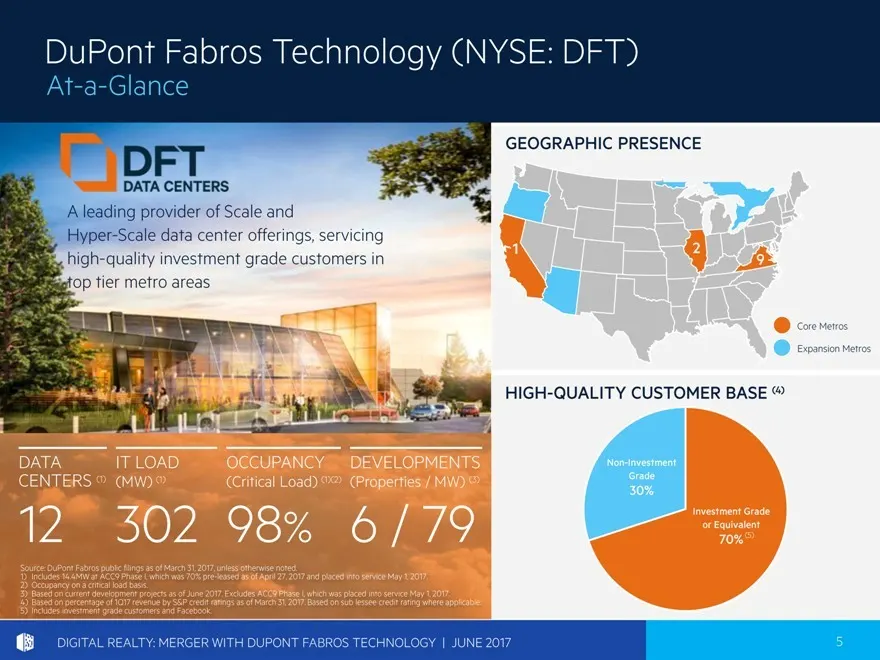
DuPont Fabros Technology (NYSE: DFT) At-a-Glance A leading provider of Scale and Hyper-Scale data center offerings, servicing high-quality investment grade customers in top tier metro areas DATA IT LOAD OCCUPANC DEVELOPME CENTER (MW) (1) Y NTS S (1) (Critical Load) (Properties/ 12 302 (1)(2) MW) (3)
Slide 6: Extends Footprint in Top U.S. Metro Areas
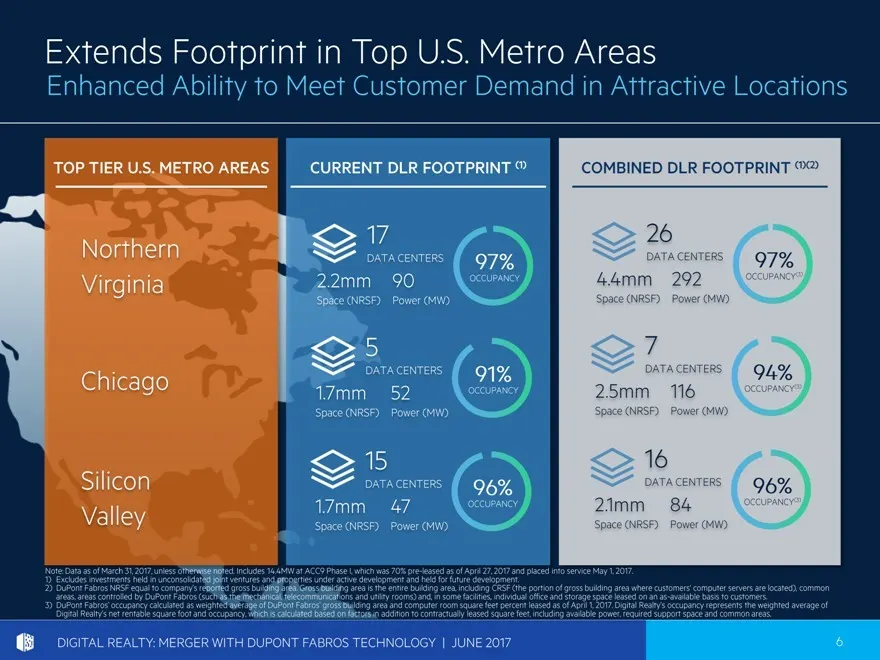
Extends Footprint in Top U.S. Metro Areas Enhanced Ability to Meet Customer Demand in Attractive Locations TOP TIER U.S. METRO CURRENT DLR FOOTPRINT COMBINED DLR FOOTPRINT (1)(2) AREAS (1) 17 26 Northern DATA DATA CENTERS 97% CENTERS 97% Virginia 2. OCCUPANCY 4.4 OCCUPANCY(3) Space Power Space Power
Slide 7: Complementary Campus Strategy
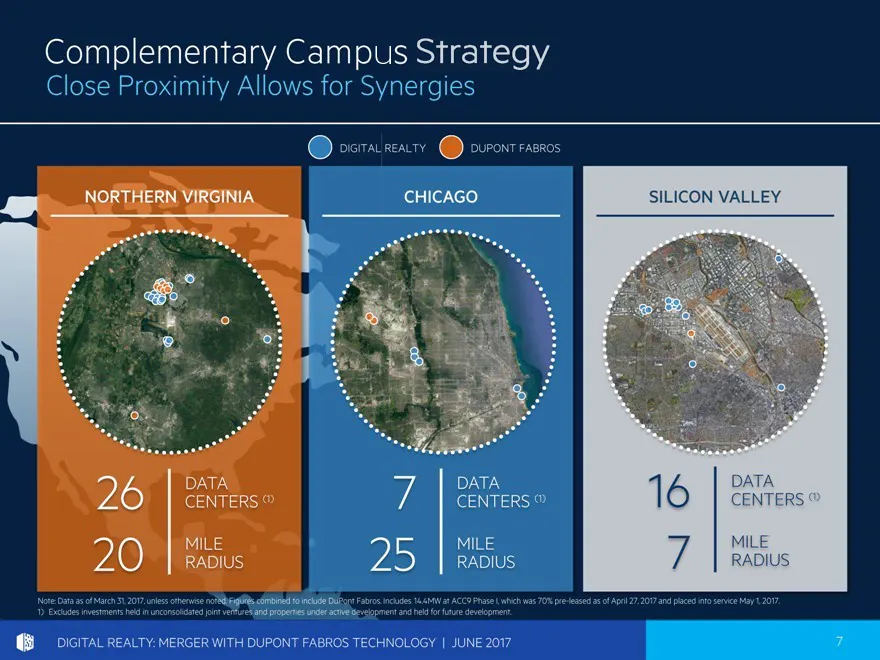
Complementary Campus Strategy Close Proximity Allows for Synergies DIGITAL DUPONT REALTY FABROS NORTHERN VIRGINIA CHICAGO SILICON VALLEY ATA 1 DATA 26 CENTERS DATA 2 CENTER CENTER ) (1) (1) MILE 20 RADIUS MILE 5 RADIUS 7 RADIUS MILE Note: Data as of March 31, 2017, unless otherwise noted. Figures co
Slide 8: Meeting Growing Demand for Hyper-Scale
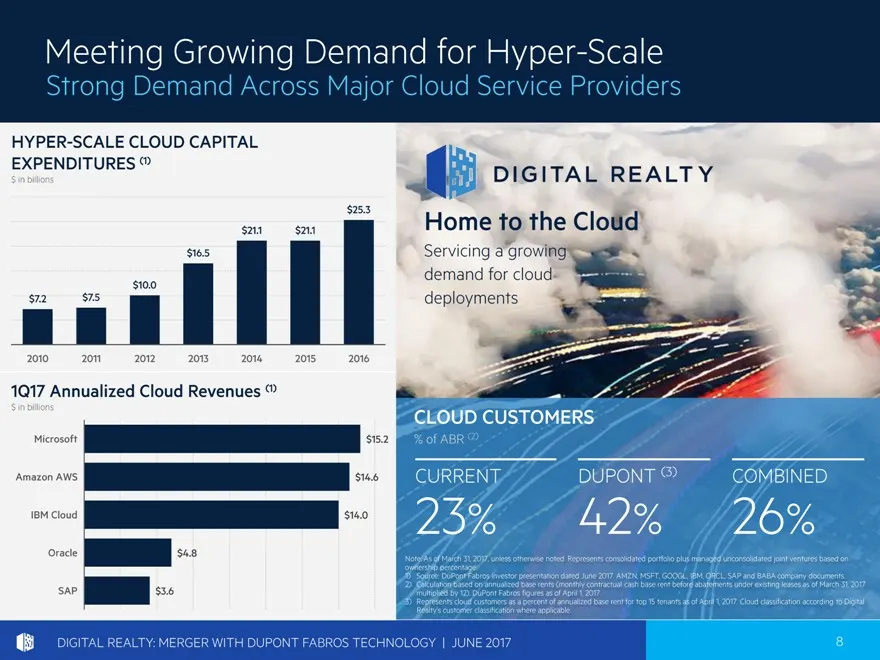
Meeting Growing Demand for Hyper-Scale Strong Demand Across Major Cloud Service Providers HYPER-SCALE CLOUD CAPITAL EXPENDITURES (1) $ in billions Home to the Cloud Servicing a growing demand for cloud deployments CLOUD CUSTOMERS % of ABR (2) CURRENT DUPONT (3) COMBINED 23% 42% 26% Note: As of March
Slide 9: Expands Blue-Chip Customer Base
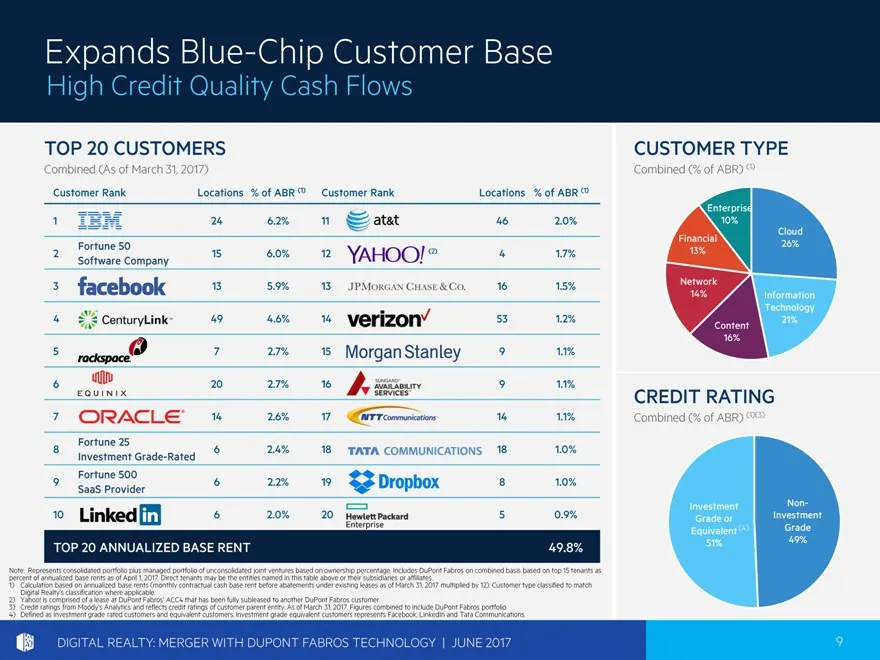
Expands Blue-Chip Customer Base High Credit Quality Cash Flows TOP 20 CUSTOMERS Combined (As of March 31, 2017) % of ABR Customer Rank Locations % of ABR (1) Customer Rank Locations (1) 1 24 6.2% 11 46 2.0% Fortune 50 2 Software Company 15 6.0% 12 (2) 4 1.7% 3 13 5.9% 13 16 1.5% 4 49 4.6% 14 53 1.2%
Slide 10: Leading Data Center REIT
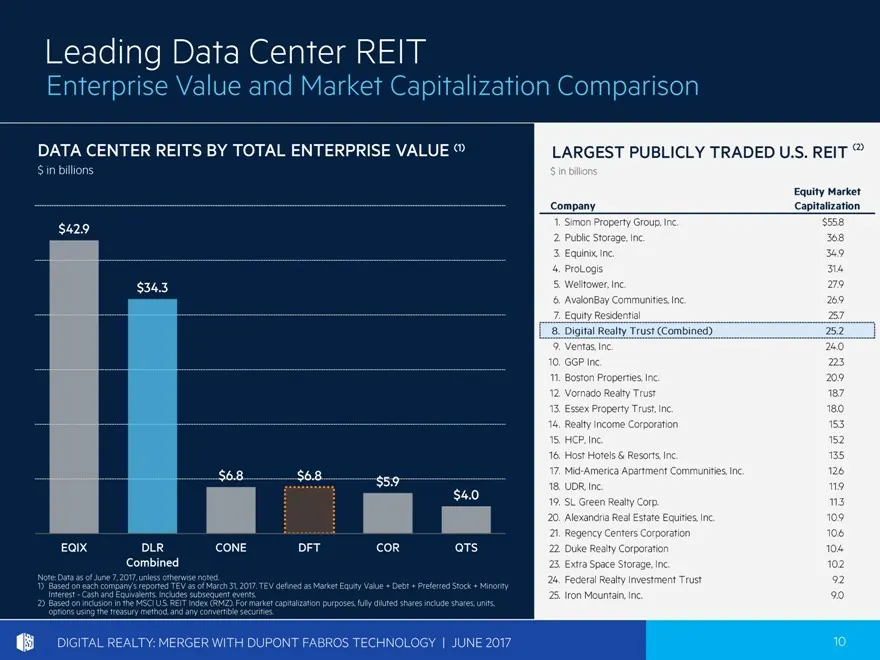
Leading Data Center REIT Enterprise Value and Market Capitalization Comparison DATA CENTER REITS BY TOTAL ENTERPRISE VALUE (1) $ in billions $42.9 $34.3 $6.8 $6.8 $5.9 $4.0 EQIX DLR CONE DFT COR QTS Combined Note: Data as of June 7, 2017, unless otherwise noted. Based on each company_s reported TEV
Slide 11: Benefits of Size and Scale on Display
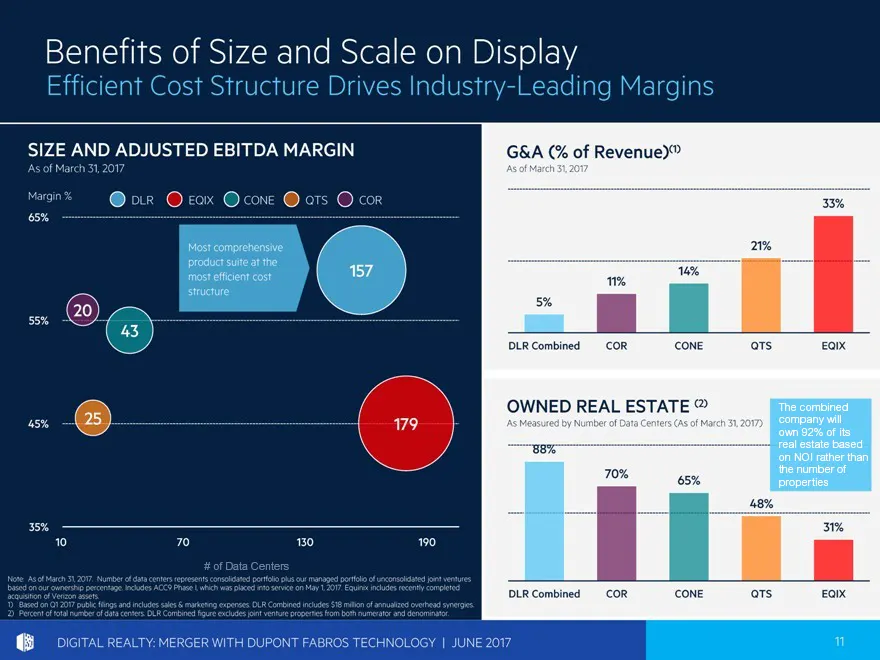
Benefits of Size and Scale on Display Efficient Cost Structure Drives Industry-Leading Margins SIZE AND ADJUSTED EBITDA MARGIN As of March 31, 2017 G&A (% of Revenue)(1) As of March 31, 2017 DLRCombined COR CONE QTS EQIX OWNED REAL ESTATE (2) The combined company will own 92% of its real estate base
Slide 12: Enhanced Growth Prospects
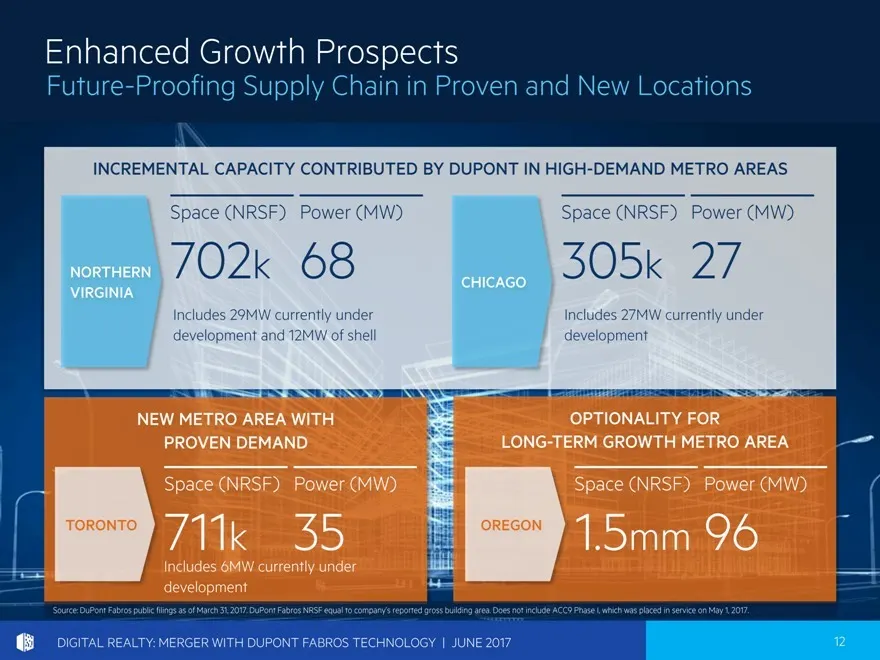
Enhanced Growth Prospects Future-Proofing Supply Chain in Proven and New Locations INCREMENTAL CAPACITY CONTRIBUTED BY DUPONT IN HIGH-DEMAND METRO Source: DuPont Fabros public filings as of March 31, 2017. DuPont Fabros NRSF equal to company_s reported gross building area. Does not include ACC9 Phas
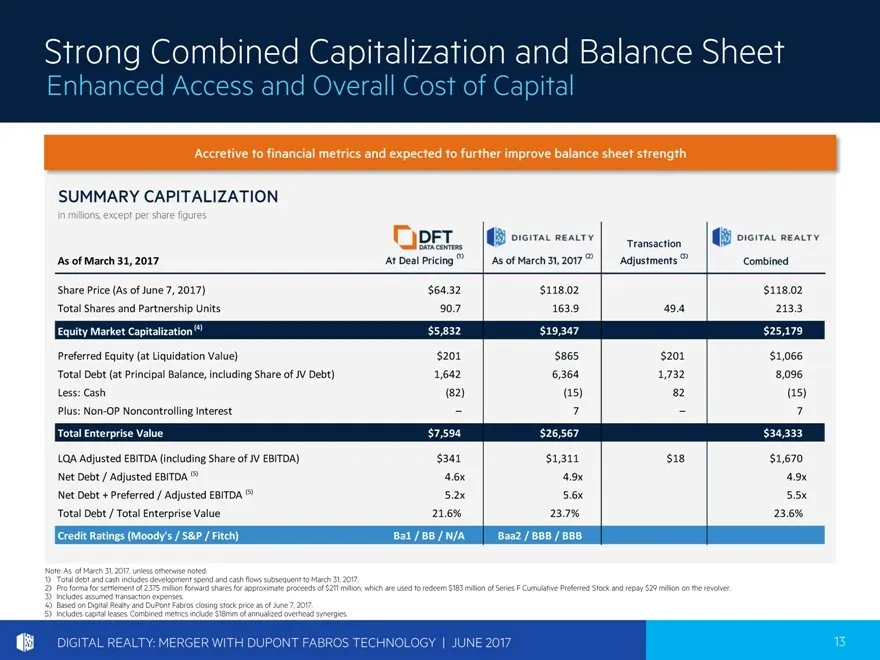
Slide 13: Strong Combined Capitalization and Balance Sheet
Strong Combined Capitalization and Balance Enhanced Access and Overall Cost of Capital Sheet Accretive to financial metrics and expected to further improve balance sheet strength SUMMARY CAPITALIZATION in millions, except per share figures Transaction As of March 31, 2017 (1) Adjustments(2) As of Ma
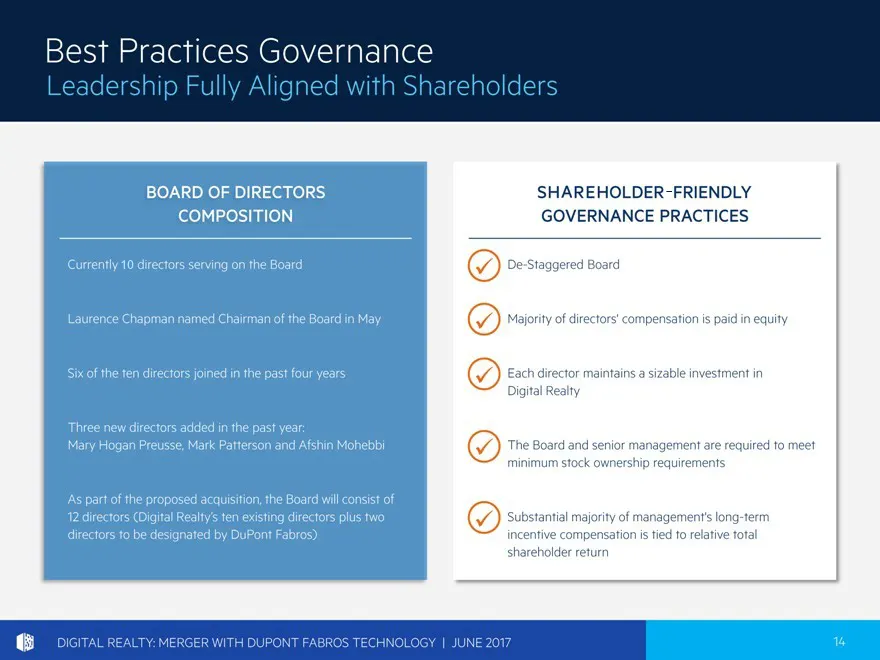
Slide 14: Best Practices Governance
Best Practices Governance Leadership Fully Aligned with Shareholders BOARD OF DIRECTORS SHAREHOLDER-FRIENDLY COMPOSITION GOVERNANCE PRACTICES Currently10 directors serving on the Board De-Staggered Board ü De-Staggered Board Laurence Chapman named Chairman of the Board Majority of directors’ compens
Slide 15: Leading Global Multi-Product Data Center Provider
Leading Global Multi-Product Data Center Extending Advantages for Our Customers Provider Unmatched Value Proposition Strengthens and Future Proofs Position in Strategic Metro Areas Improves Customer Base with Creditworthy Tenants Complementary Businesses with Significant Synergies Expected to be Acc
Slide 16: Appendix: Disclosures
Appendix Disclosures Digital Realty DIGITAL REALTY: MERGER WITH DUPONT FABROS TECHNOLOGY JUNE 2017 16
Slide 17: Additional Information and Where to Find It
Appendix Digital Realty Trust, Inc. (“Digital Realty”) and DuPont Fabros Technology, Inc. (“DuPont Fabros”) each intend to file a proxy statement/prospectus in connection with the merger. Investors are urged to read carefully the proxy statement/prospectus and other relevant materials because they c
Slide 18: Note Regarding Forward-Looking Statements
Appendix Note Regarding Forward-Looking Statements This document contains forward-looking statements that involve substantial risks and uncertainties. All statements, other than statements of historical facts, included in this presentation regarding our strategy, future operations, future financial
Source: SEC EDGAR · 425 filed Jun 9, 2017