Nedbank Group · JSE:NED
Nedbank — Investor Day (February 2012)
97 slides from Nedbank's investor day presentation, Feb 1, 2012
Slide 1: Retail & Business Banking strategy implementation update
Retail & Business Banking strategy implementation update Investor Day February 2012 Ingrid Johnson Group Managing Executive: Nedbank Retail & Business Banking 0 1 February, 2012
Slide 2: Disclaimer
Disclaimer ▪ Nedbank Group has acted in good faith and has made every reasonable effort to ensure the accuracy and completeness of the information contained in this document, including all information that may be defined as 'forward-looking statements' within the meaning of United States securities
Slide 3: Context for Investor Day
Context for Investor Day ▪ Retail & Business Banking are important contributors to the Nedbank Group ▪ Following a thorough strategic review of the retail business, an Investor Day was held in January 2011 to outline the charting of a new path to sustainable, profitable growth. At the time we undert
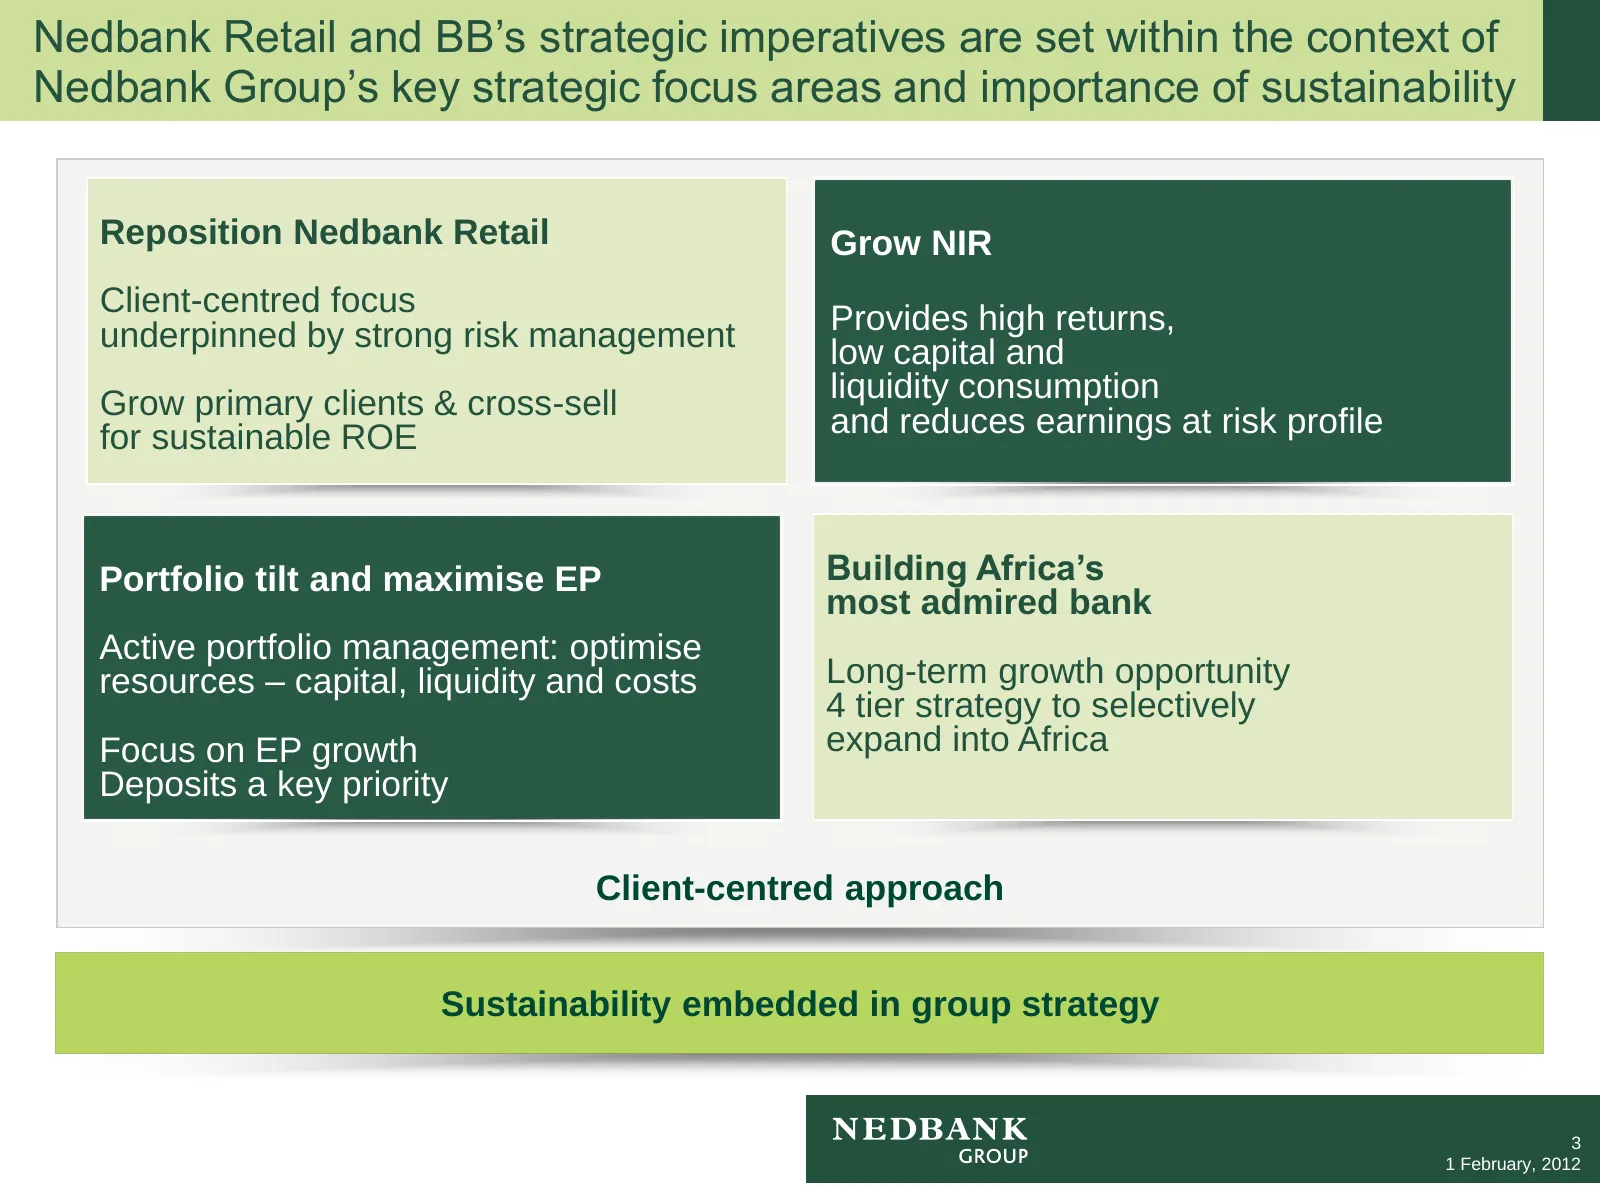
Slide 4: Strategic imperatives within Nedbank Group's key strategic focus areas
Nedbank Retail and BB’s strategic imperatives are set within the context of Nedbank Group’s key strategic focus areas and importance of sustainability Reposition Nedbank Retail Grow NIR Client-centred focus Provides high returns, underpinned by strong risk management low capital and Grow primary cli
Slide 5: Retail and Business Banking are important contributors to the Nedbank Group
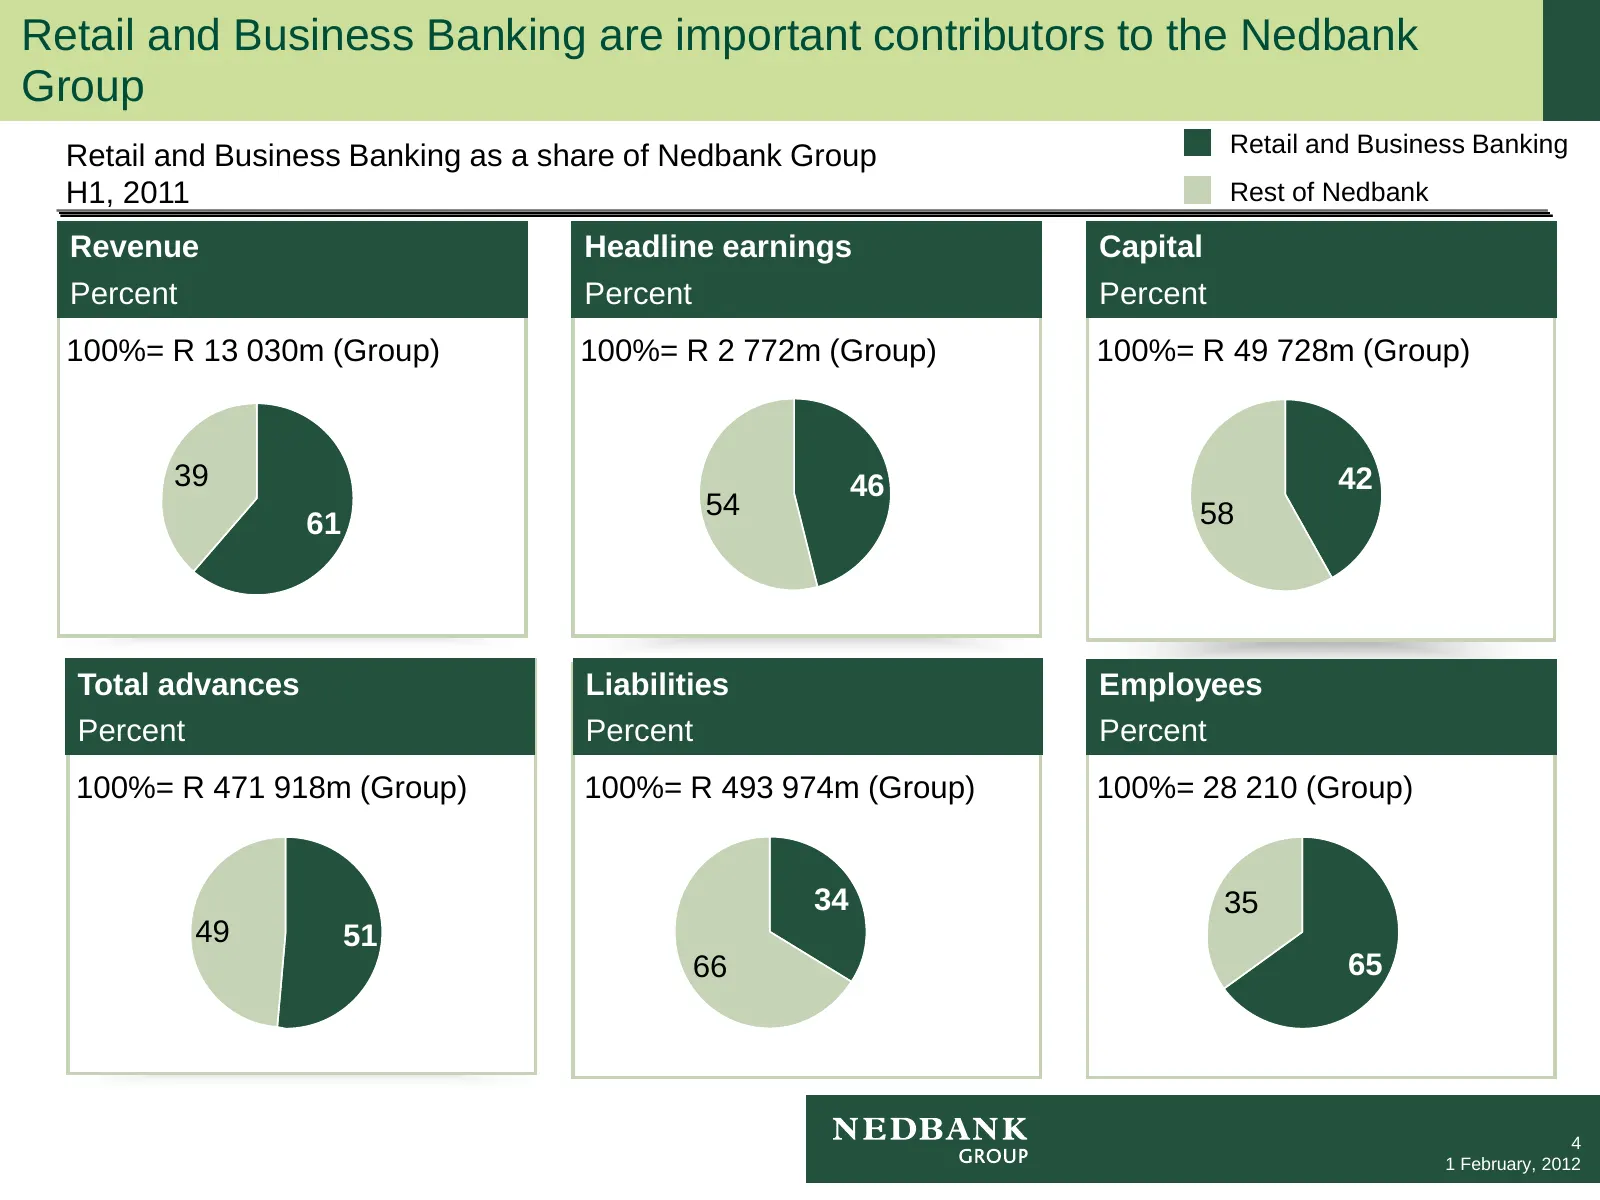
Retail and Business Banking are important contributors to the Nedbank Group Retail and Business Banking as a share of Nedbank Group Retail and Business Banking H1, 2011 Rest of Nedbank Revenue Headline earnings Capital Percent Percent Percent 100%= R 13 030m (Group) 100%= R 2 772m (Group) 100%= R 49
Slide 6: Target market & coverage model for Retail and Business Banking
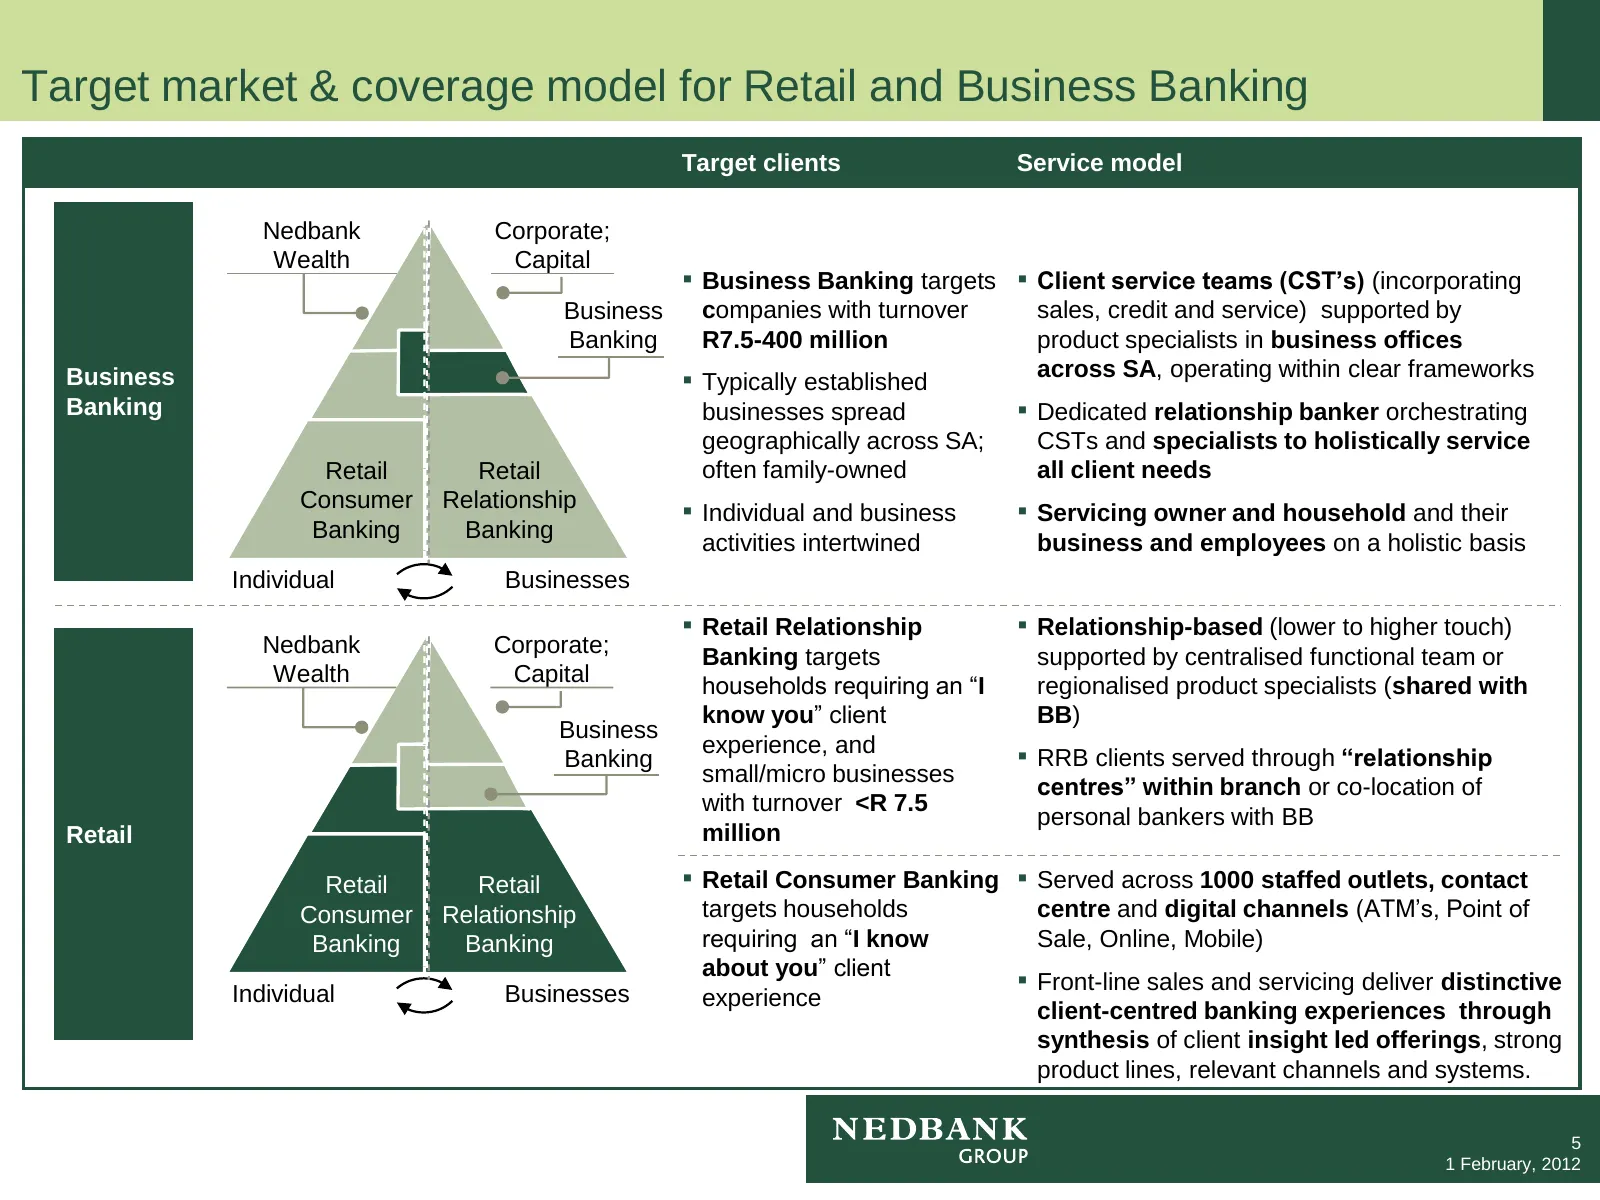
Target market & coverage model for Retail and Business Banking Target clients Service model Nedbank Corporate; Wealth Capital ▪ Business Banking targets ▪ Client service teams (CST’s) (incorporating Business companies with turnover sales, credit and service) supported by Banking R7.5-400 million pro
Slide 7: Uniquely positioned to generate shareholder value: key messages
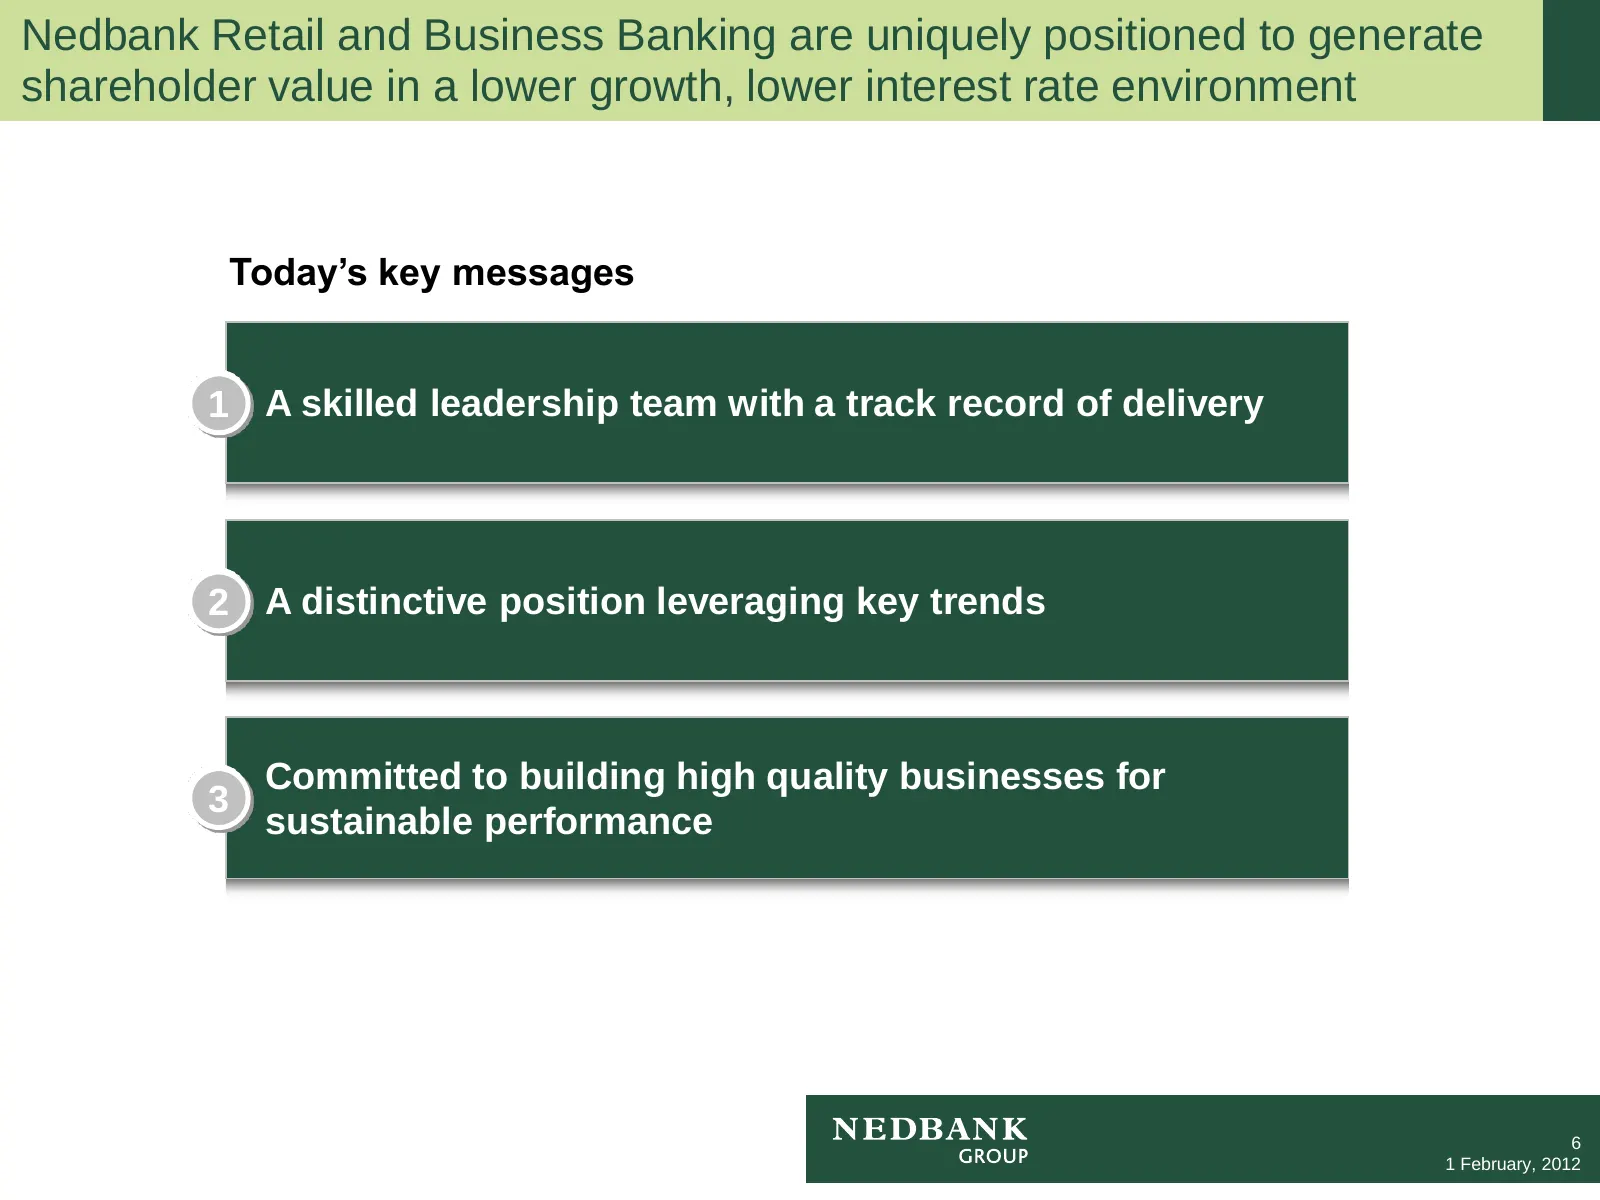
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment Today’s key messages 1 A skilled leadership team with a track record of delivery 2 A distinctive position leveraging key trends Committed to building high qual
Slide 8: A skilled leadership team with a track record of delivery
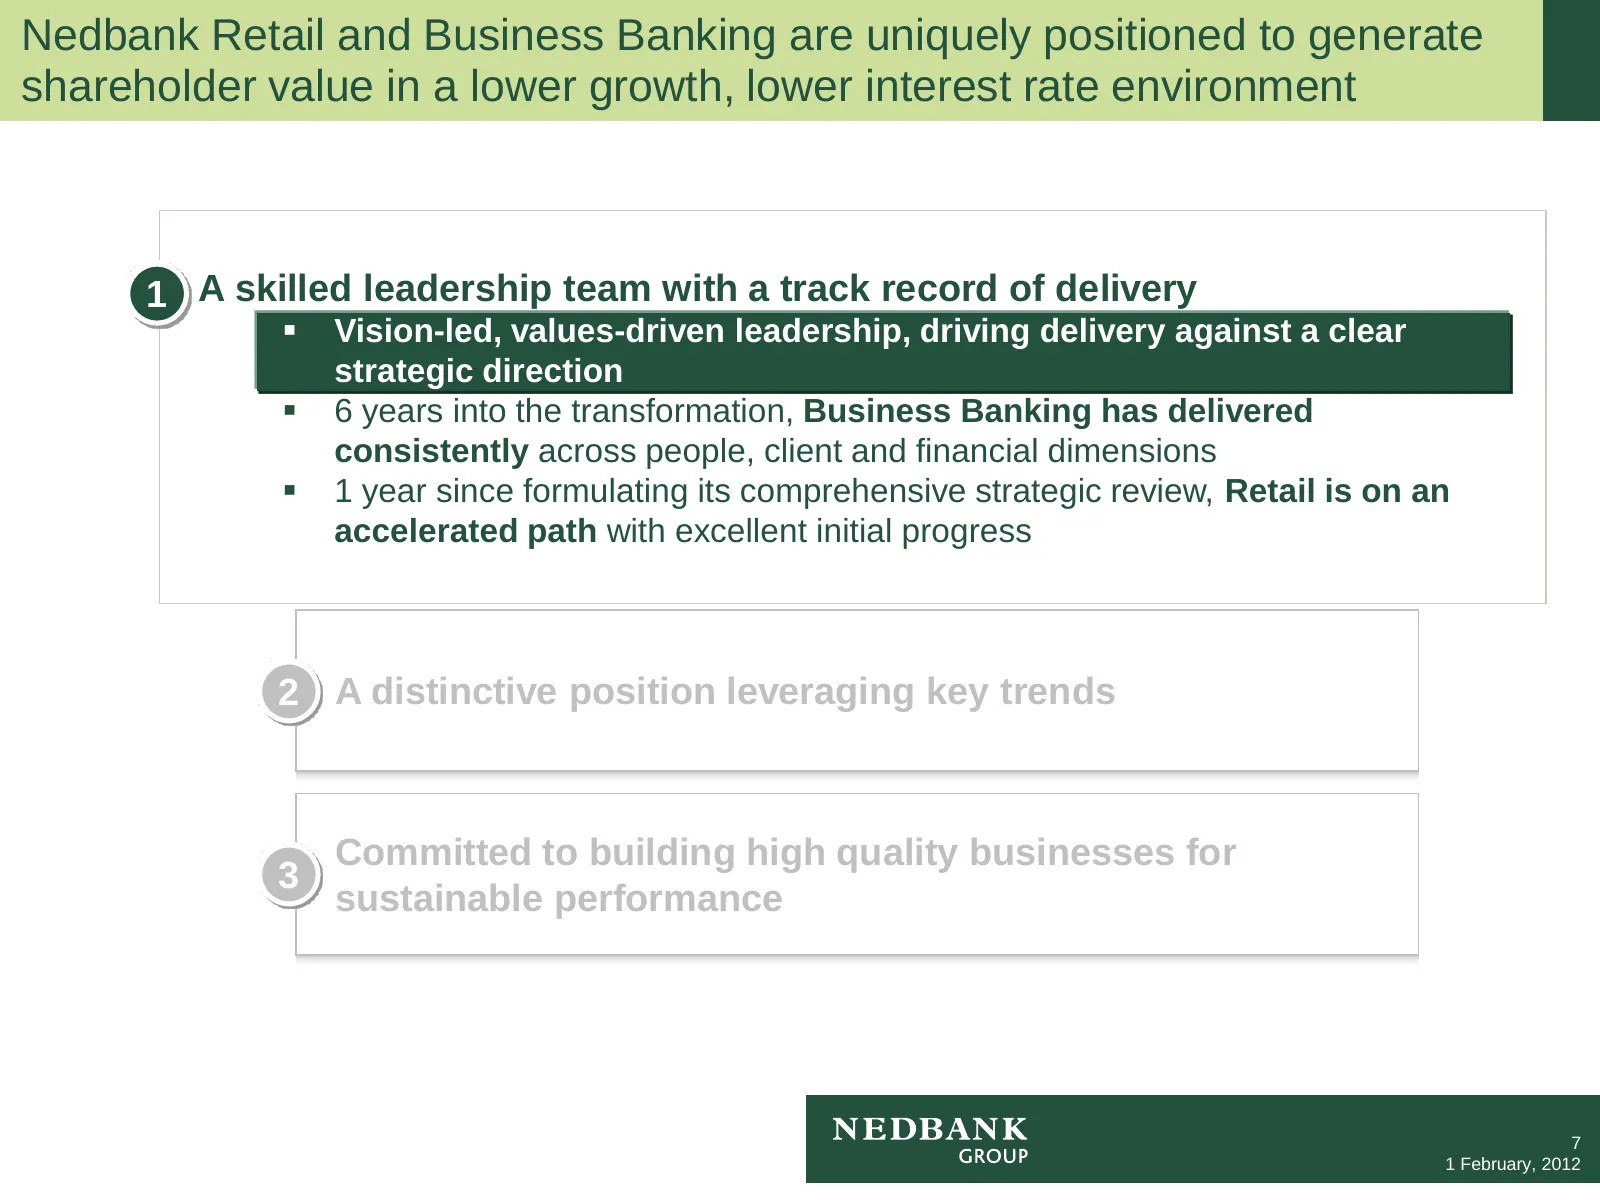
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment 1 A skilled leadership team with a track record of delivery Vision-led, values-driven leadership, driving delivery against a clear strategic direction 6 ye
Slide 9: Introducing the Retail and BB leadership team (1/2)
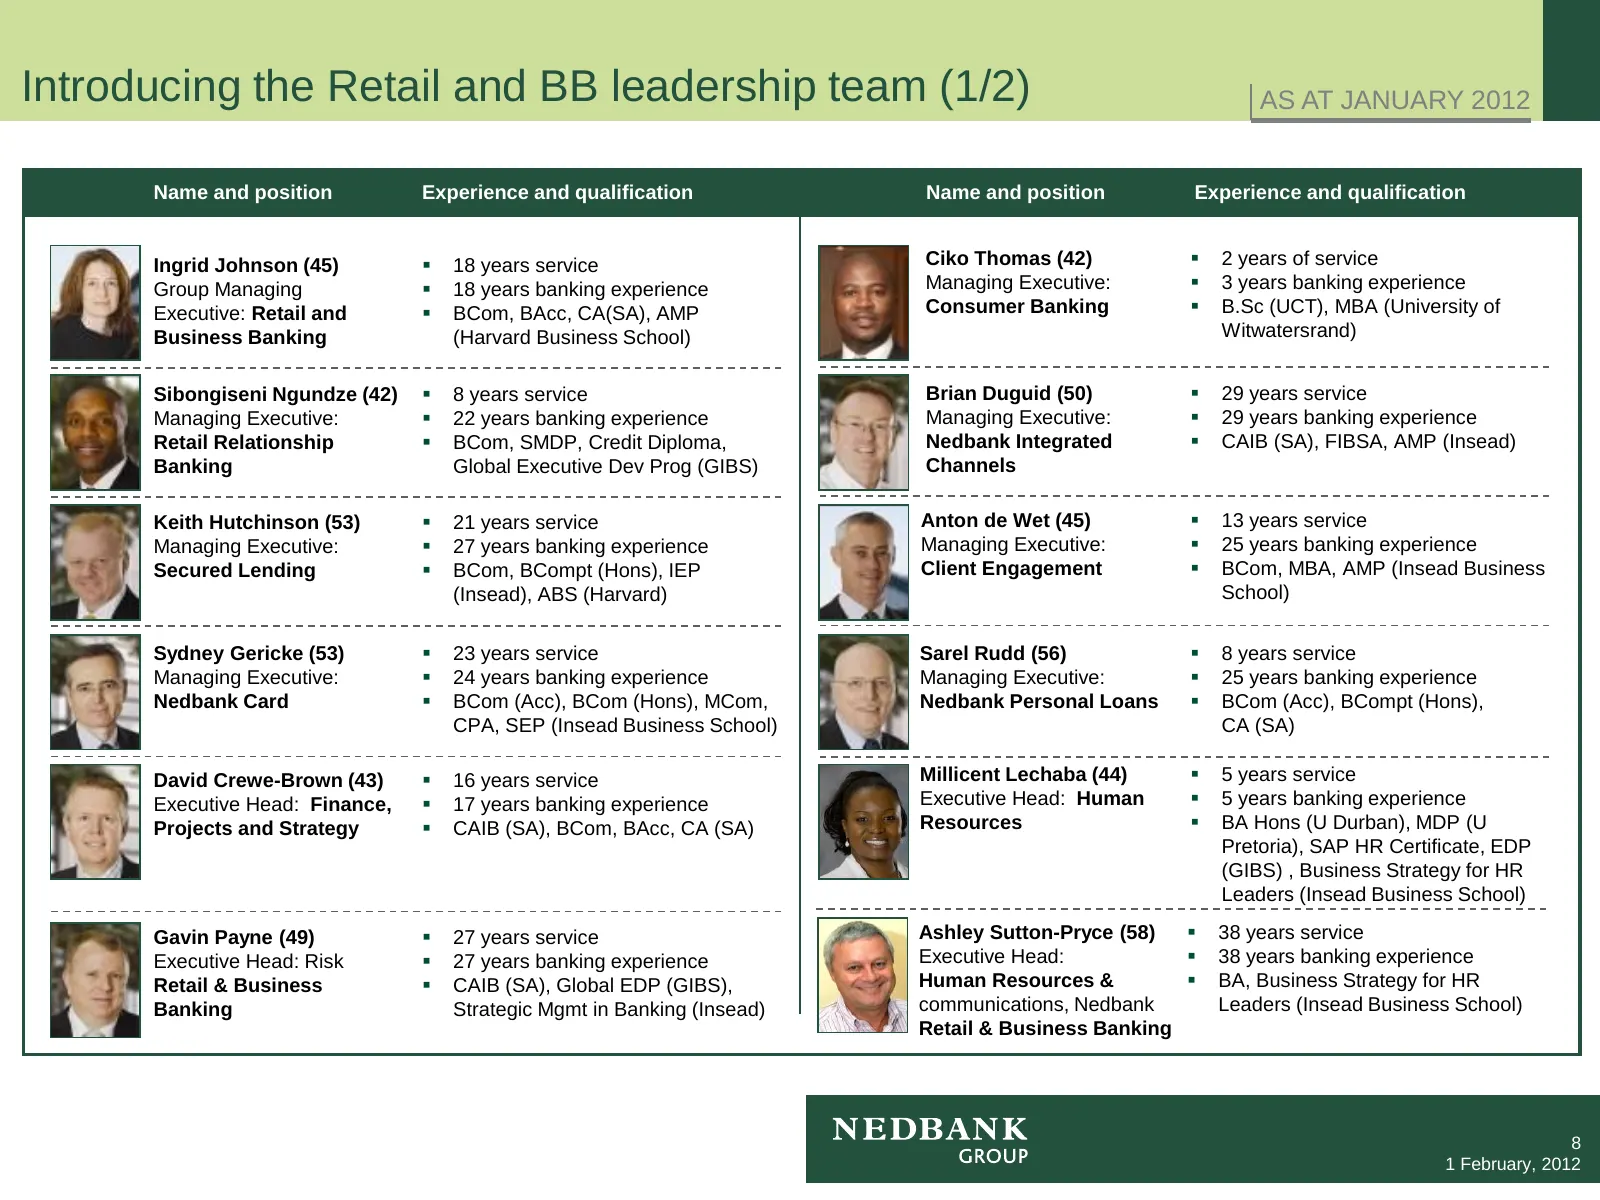
Introducing the Retail and BB leadership team (1/2) AS AT JANUARY 2012 Name and position Experience and qualification Name and position Experience and qualification Ingrid Johnson (45) 18 years service Ciko Thomas (42) 2 years of service Group Managing 18 years banking experience Managing Exec
Slide 10: Introducing the Retail and BB leadership team (2/2)
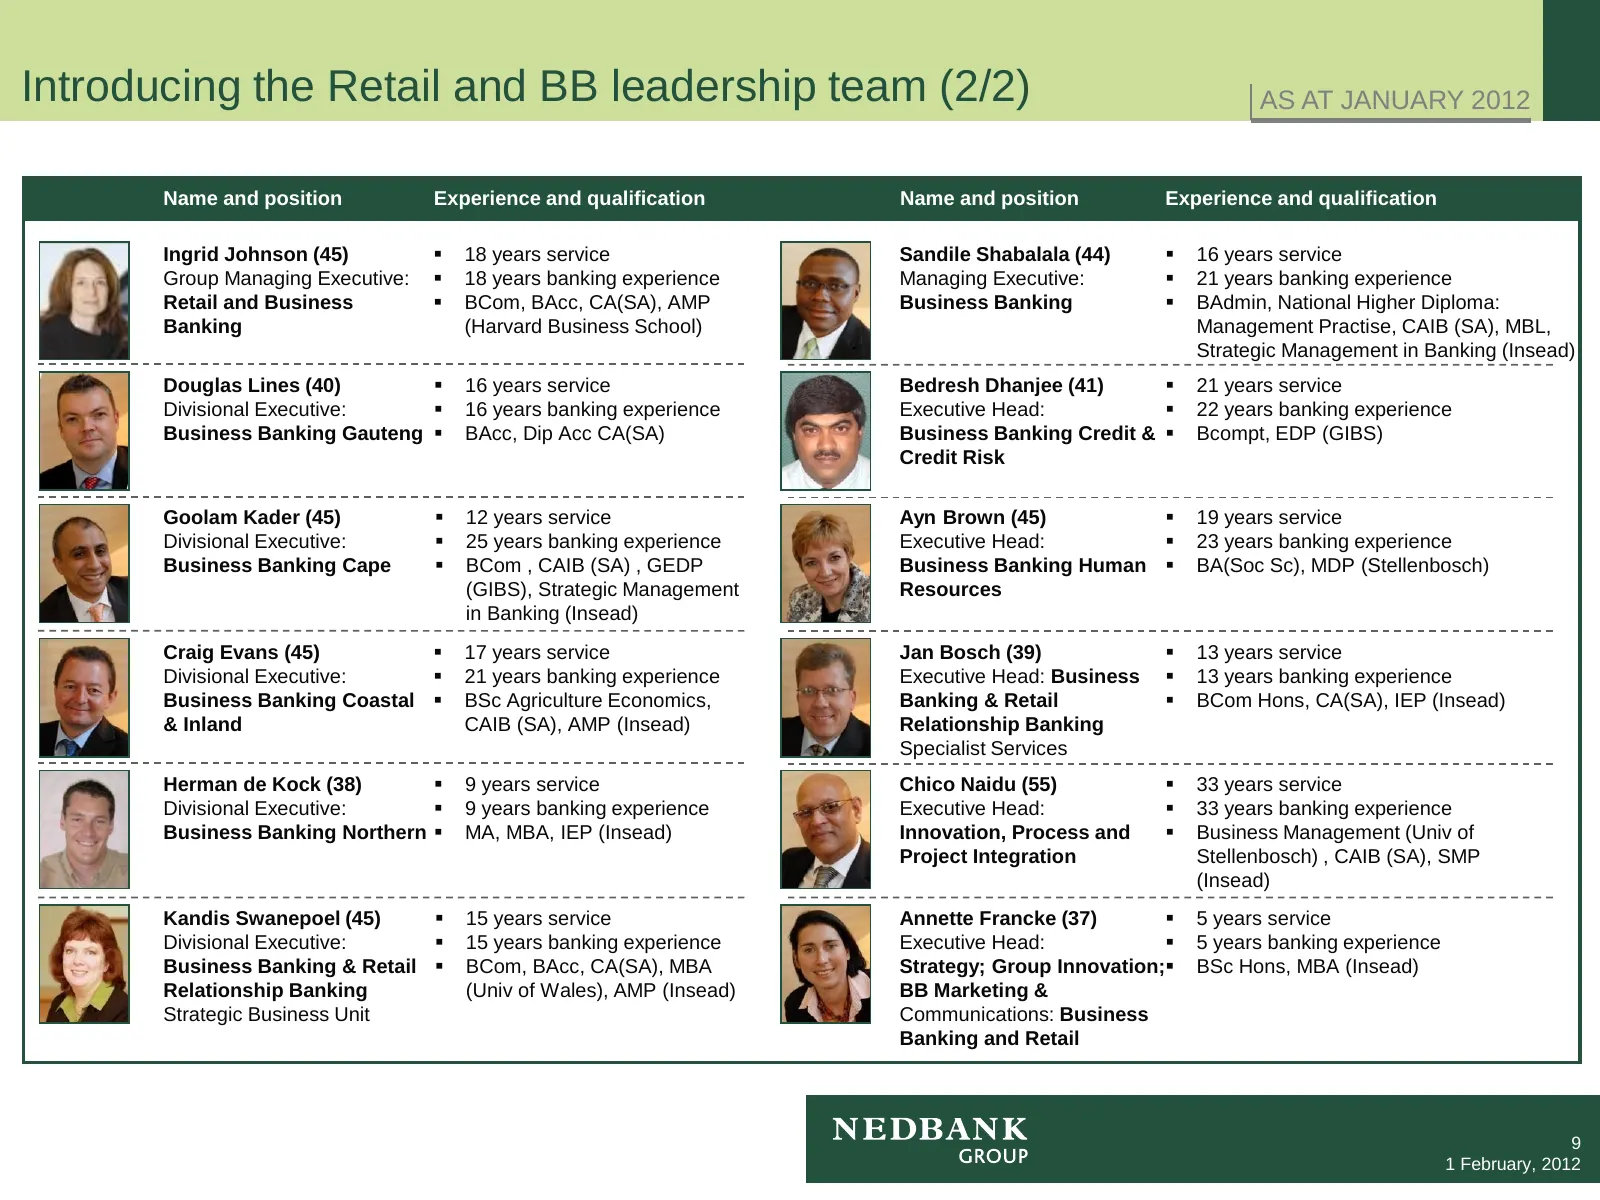
Introducing the Retail and BB leadership team (2/2) AS AT JANUARY 2012 Name and position Experience and qualification Name and position Experience and qualification Ingrid Johnson (45) 18 years service Sandile Shabalala (44) 16 years service Group Managing Executive: 18 years banking experienc
Slide 11: Strong functional lines
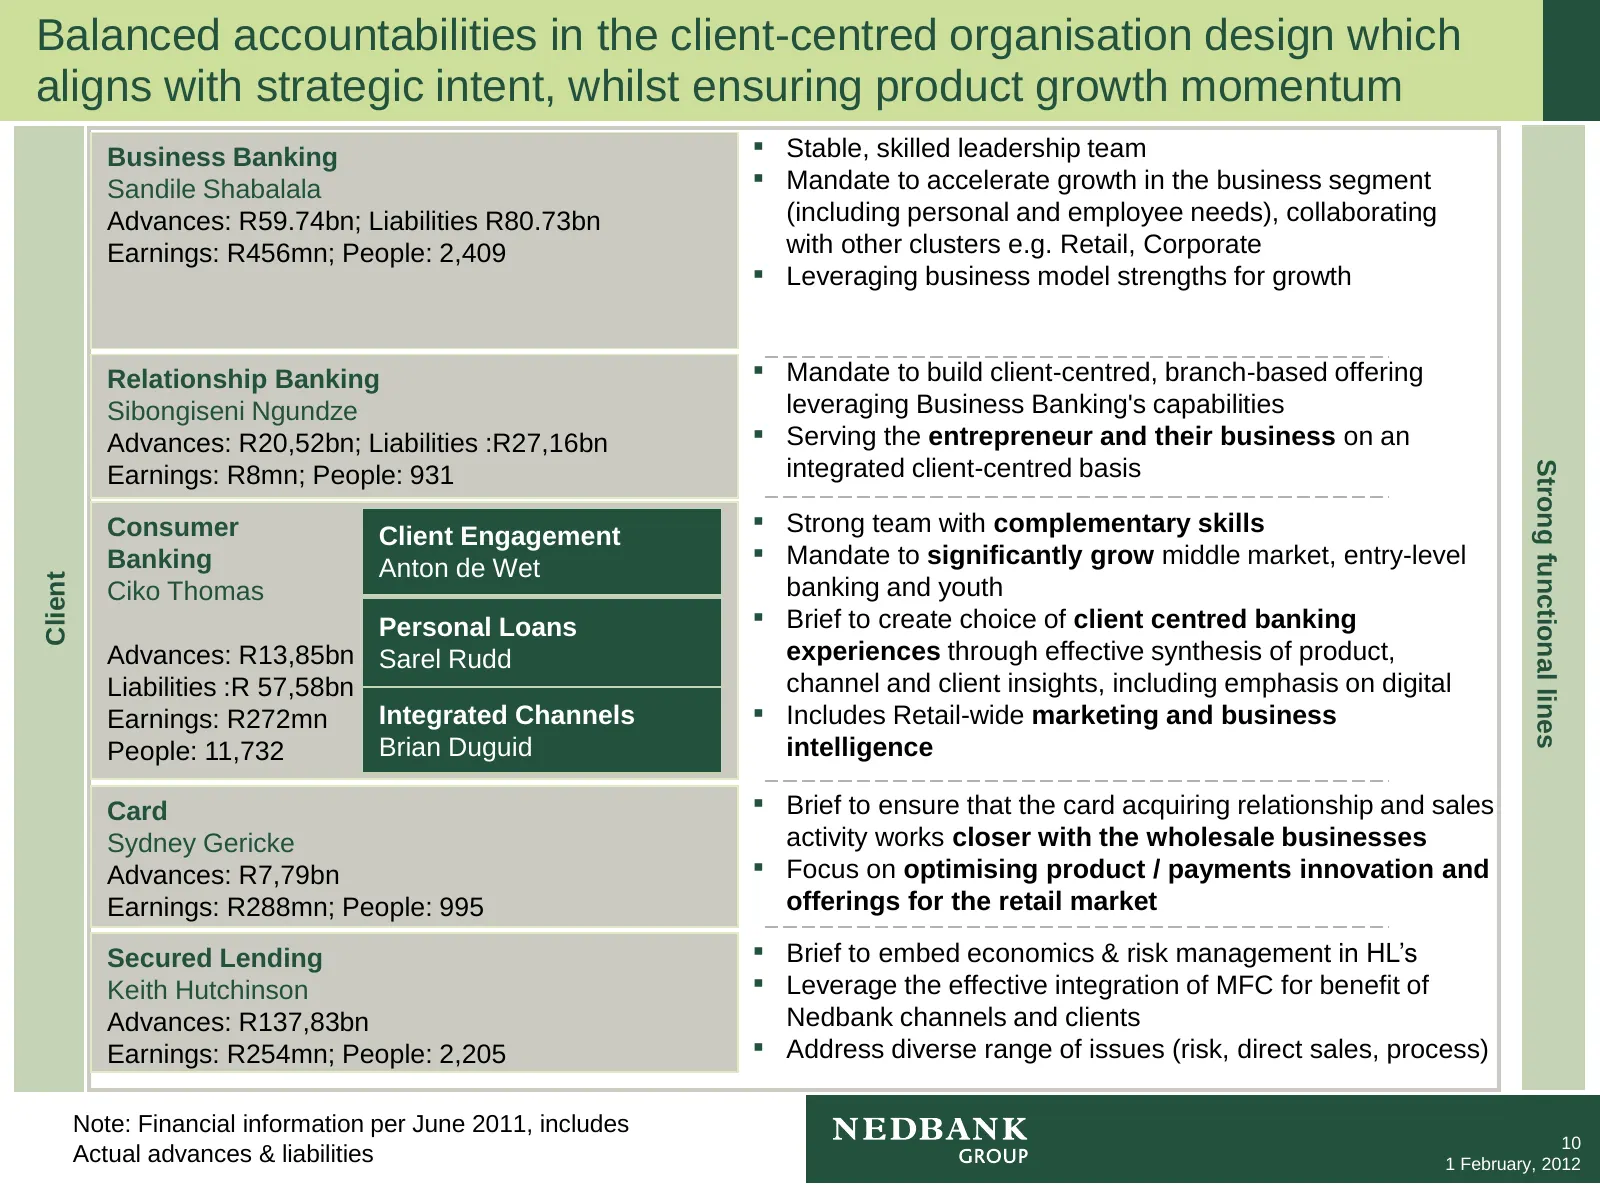
Balanced accountabilities in the client-centred organisation design which aligns with strategic intent, whilst ensuring product growth momentum Business Banking ▪ Stable, skilled leadership team Sandile Shabalala ▪ Mandate to accelerate growth in the business segment Advances: R59.74bn; Liabilities
Slide 12: Clear strategies while collaborating on common imperatives
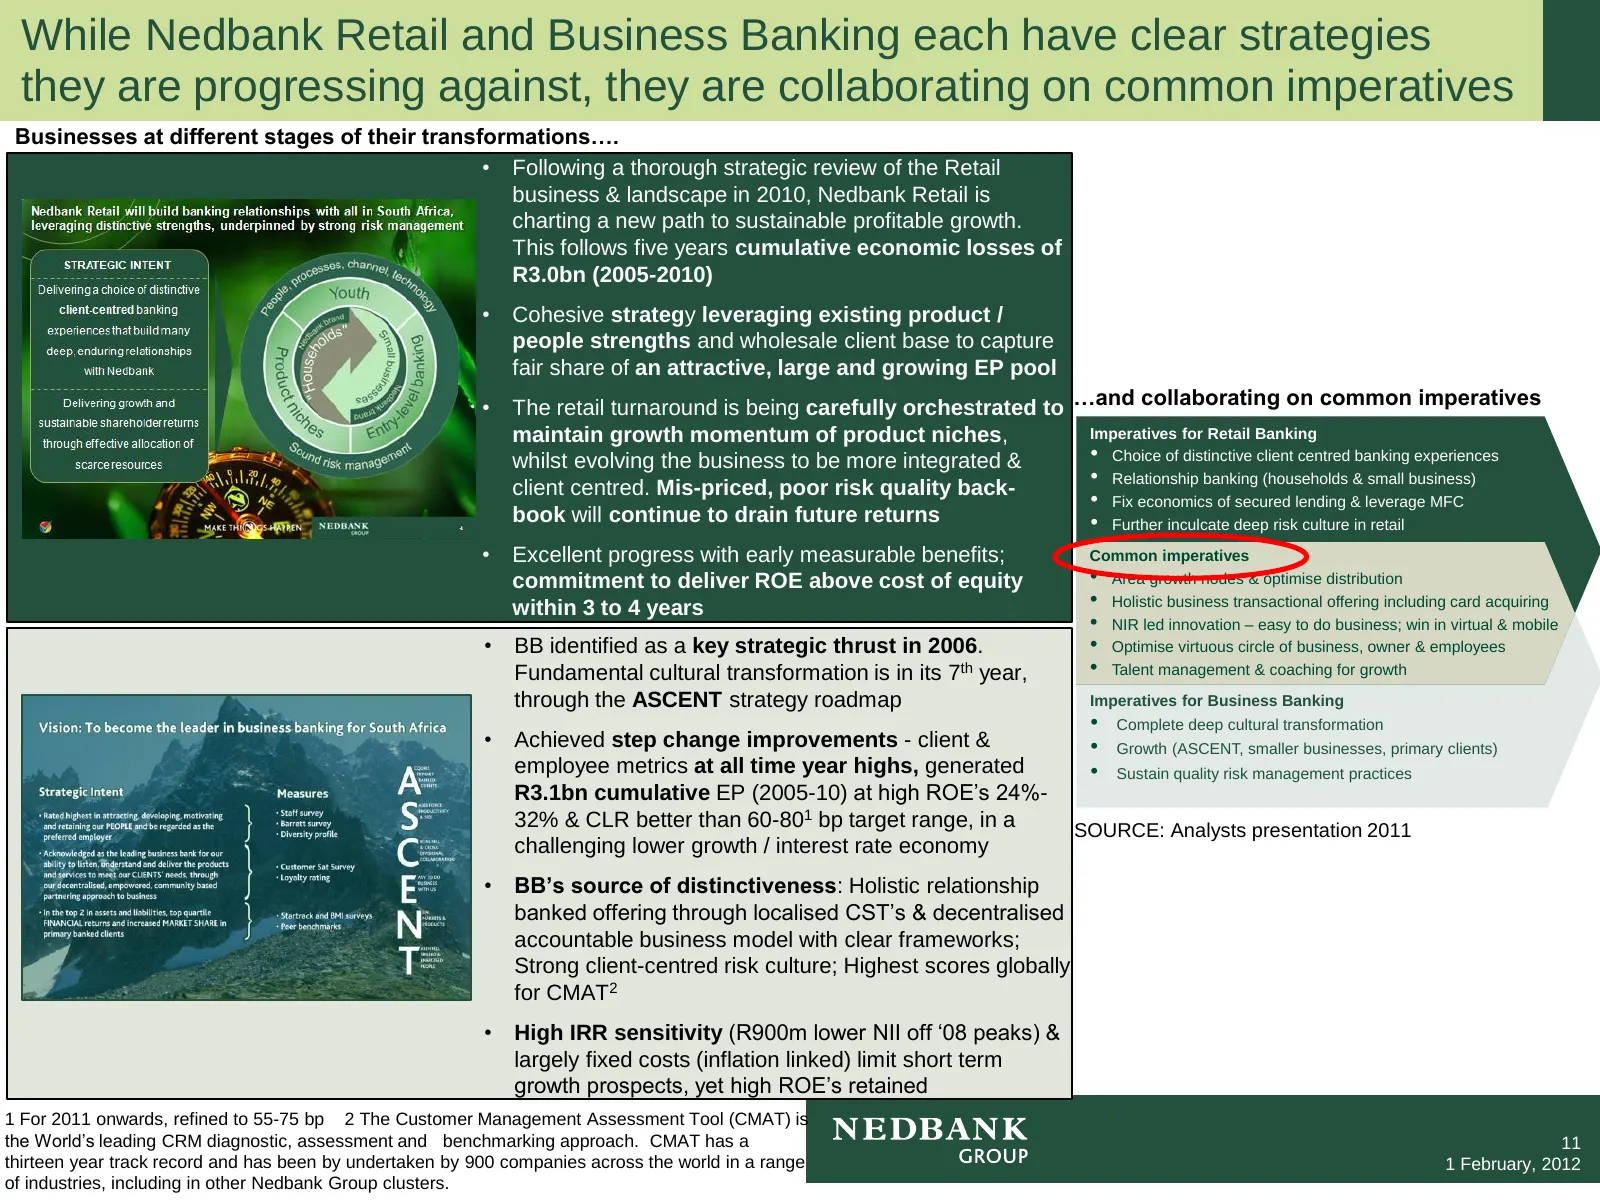
While Nedbank Retail and Business Banking each have clear strategies they are progressing against, they are collaborating on common imperatives Businesses at different stages of their transformations…. • Following a thorough strategic review of the Retail business & landscape in 2010, Nedbank Retail
Slide 13: Uniquely positioned to generate shareholder value: leadership team
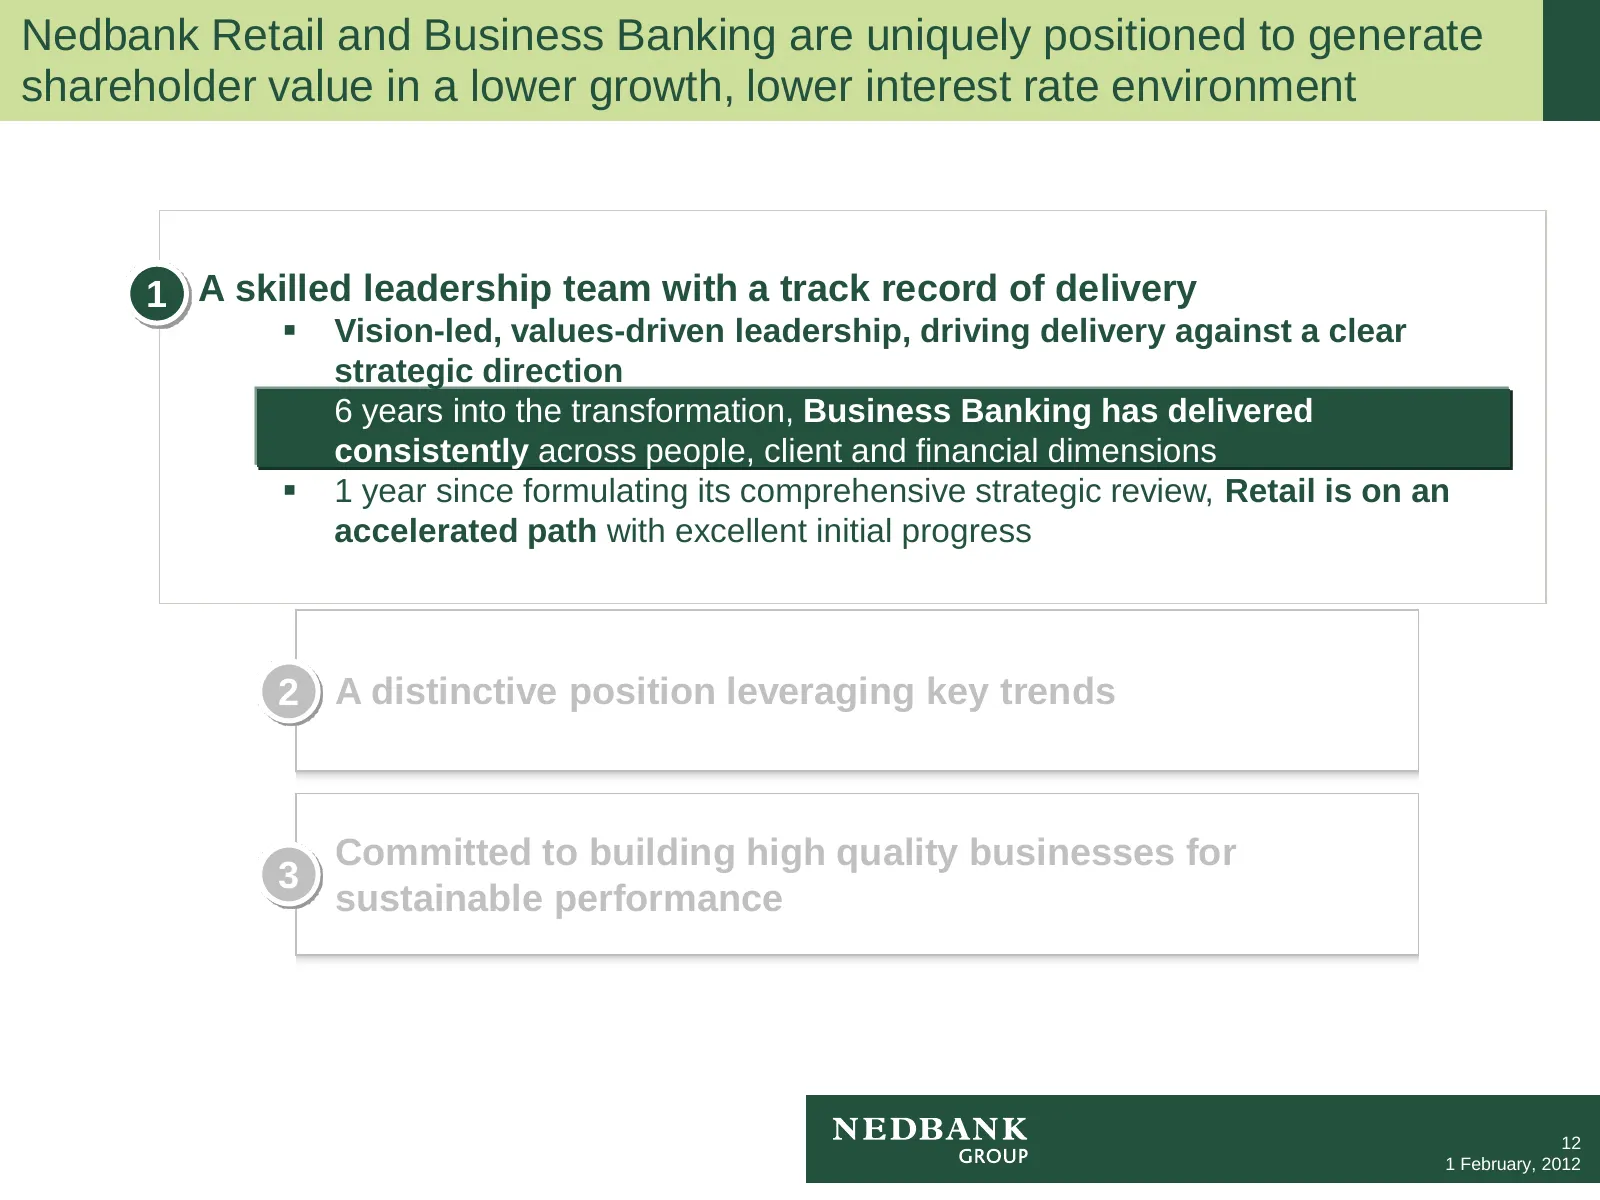
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment 1 A skilled leadership team with a track record of delivery Vision-led, values-driven leadership, driving delivery against a clear strategic direction 6 ye
Slide 14: Business Banking's vision and ASCENT strategy roadmap
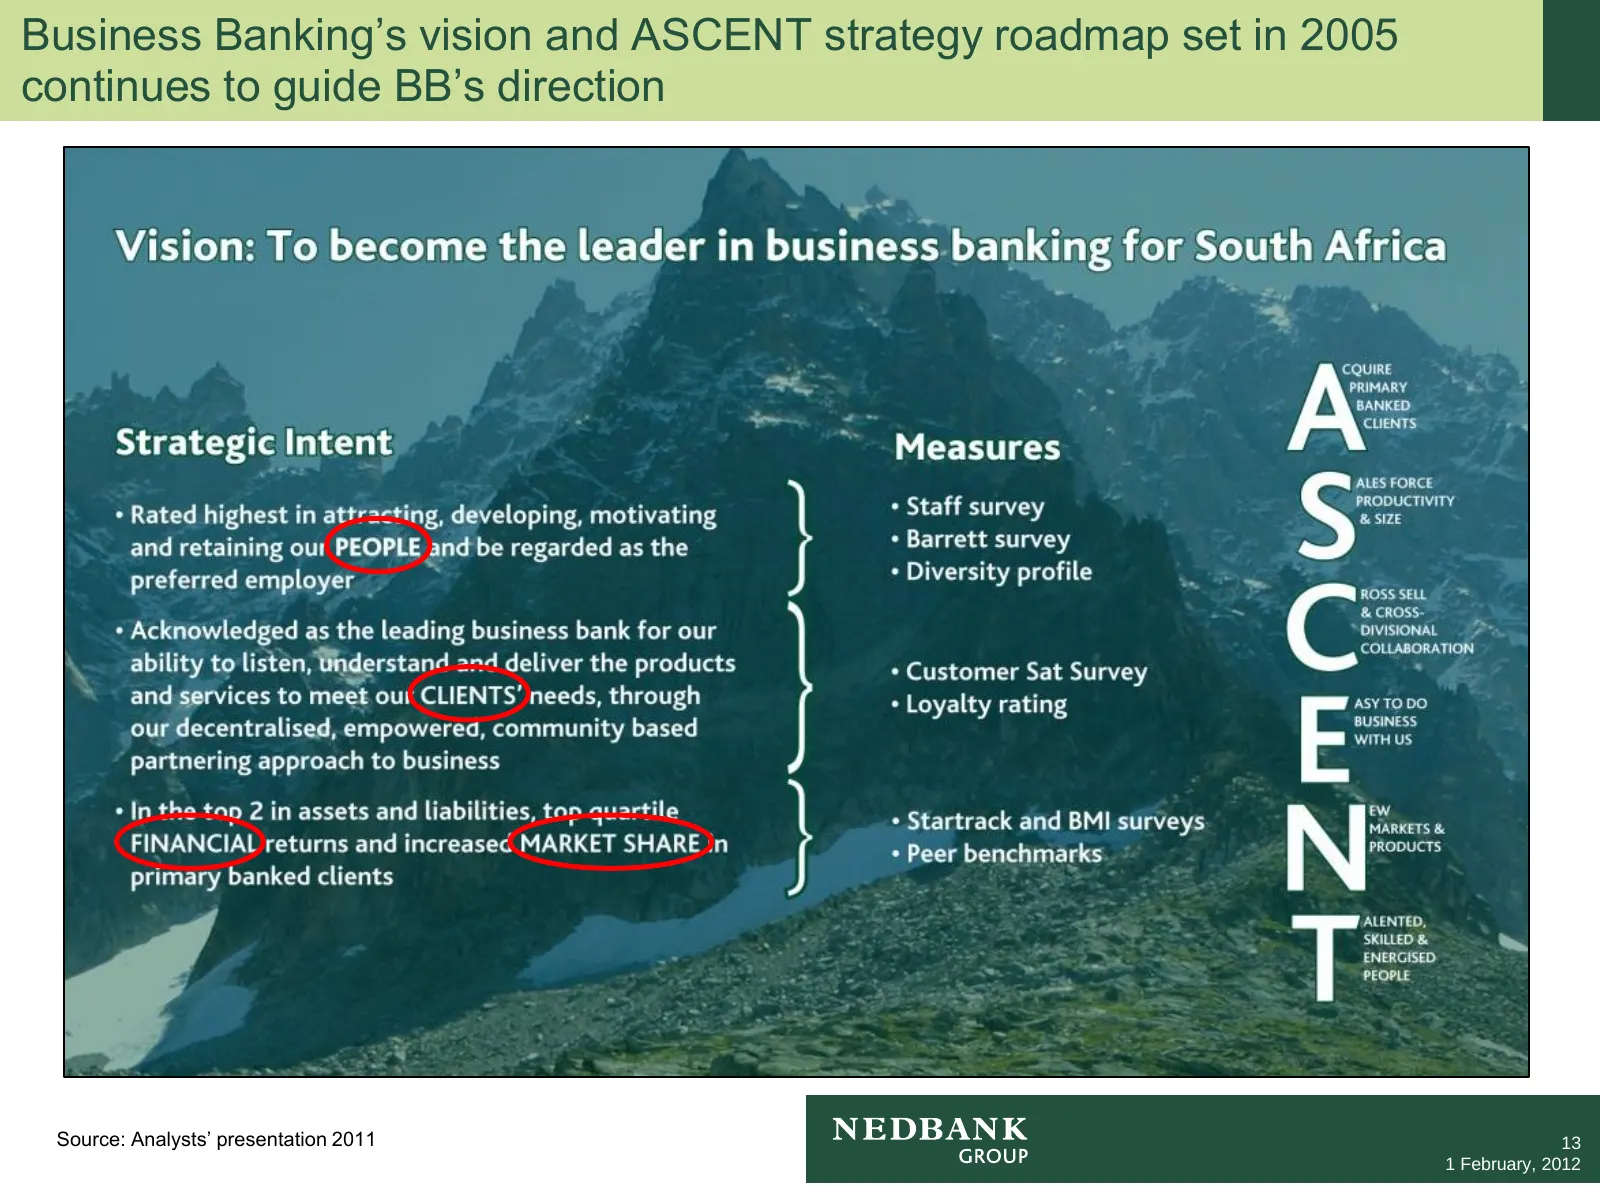
Business Banking’s vision and ASCENT strategy roadmap set in 2005 continues to guide BB’s direction Source: Analysts’ presentation 2011 13 1 February, 2012
Slide 15: Business Banking progress: PEOPLE dimension
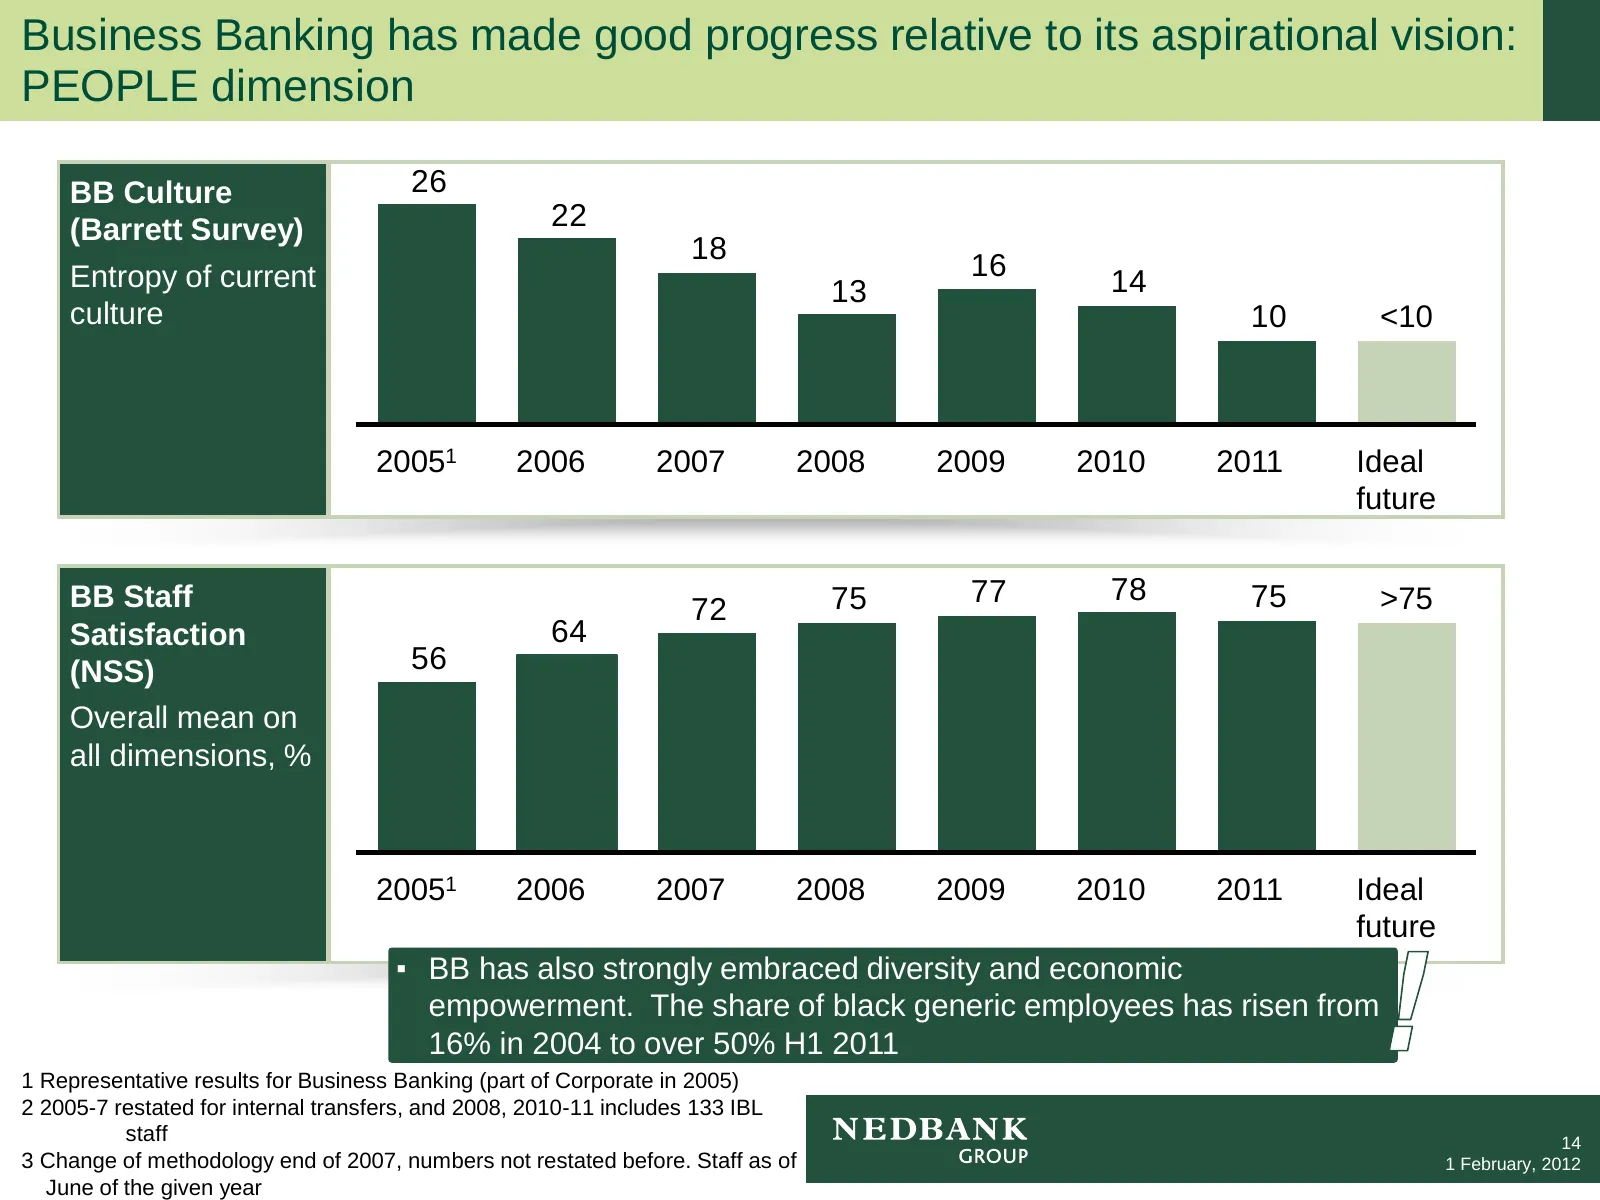
Business Banking has made good progress relative to its aspirational vision: PEOPLE dimension BB Culture 26 (Barrett Survey) 22 18 Entropy of current 16 13 14 culture 10 <10 20051 2006 2007 2008 2009 2010 2011 Ideal future BB Staff 75 77 78 75 >75 72 Satisfaction 64 (NSS) 56 Overall mean on all dime
Slide 16: Business Banking progress: CLIENT dimension
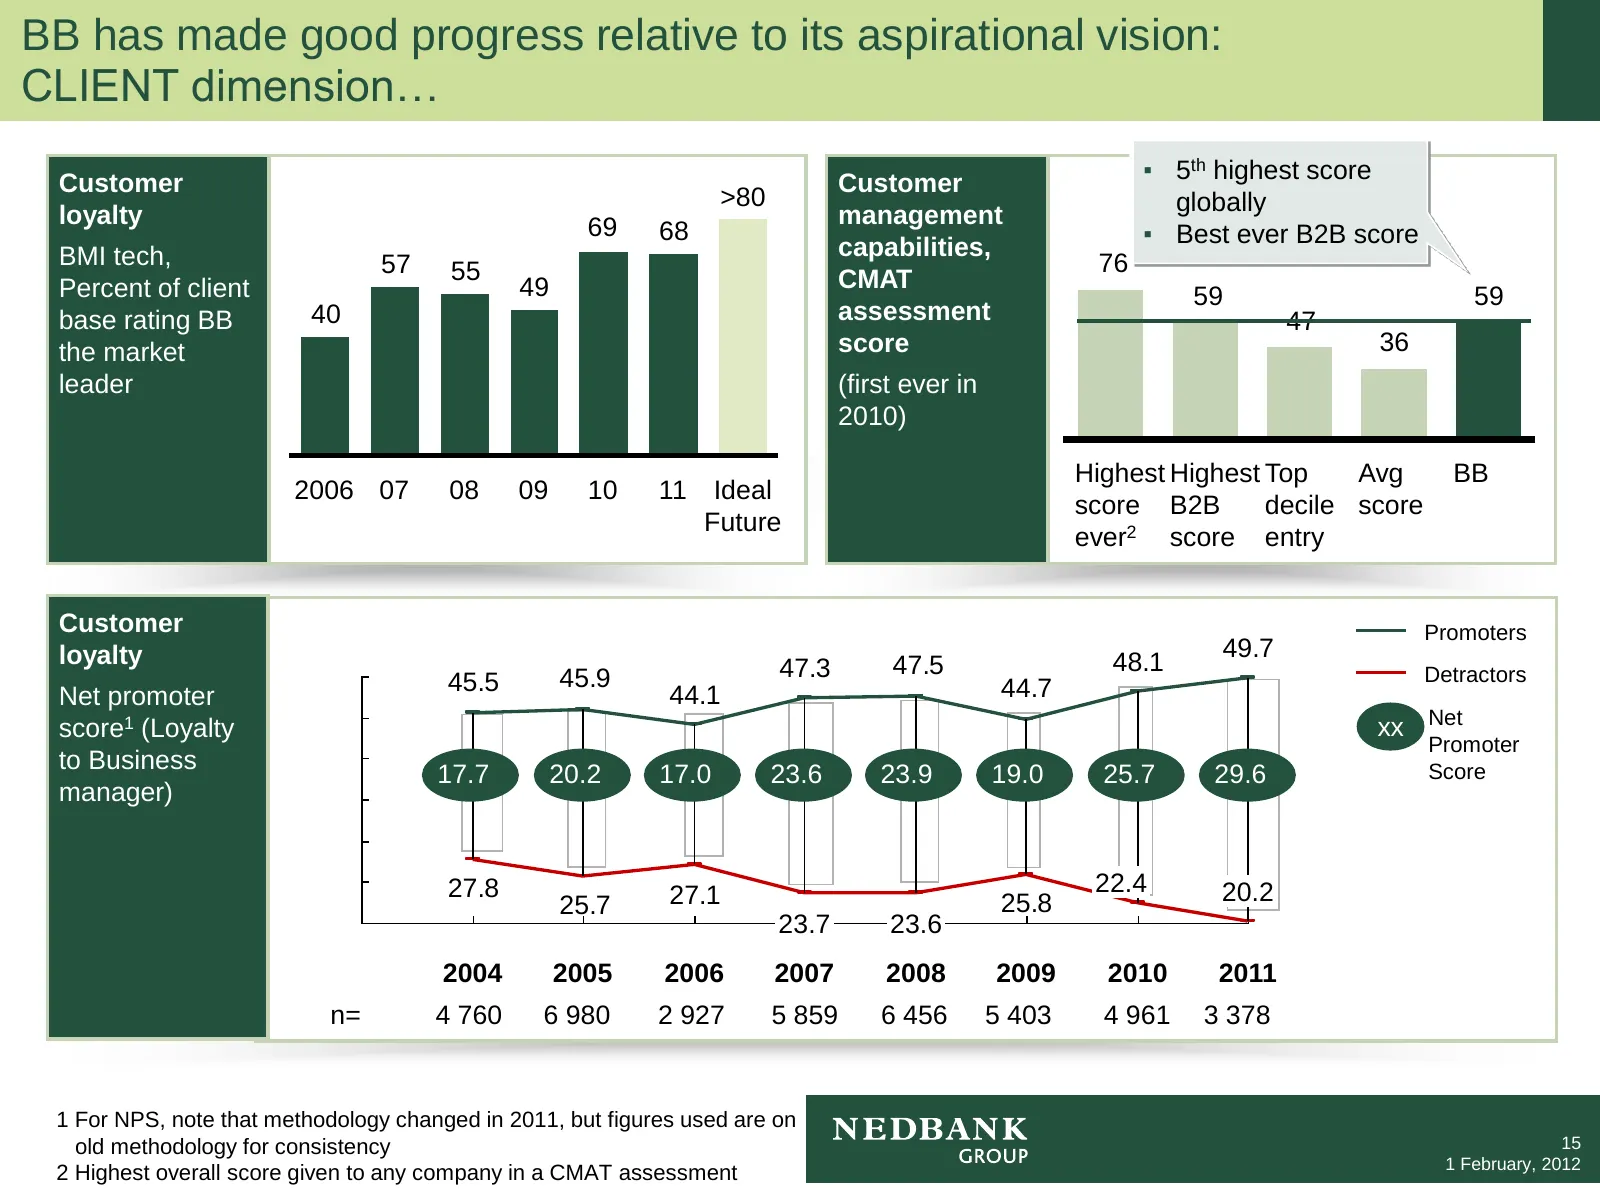
BB has made good progress relative to its aspirational vision: CLIENT dimension… Customer Customer ▪ 5th highest score >80 globally loyalty 69 management 68 capabilities, ▪ Best ever B2B score BMI tech, 57 76 55 CMAT Percent of client 49 59 59 base rating BB 40 assessment 47 the market score 36 lead
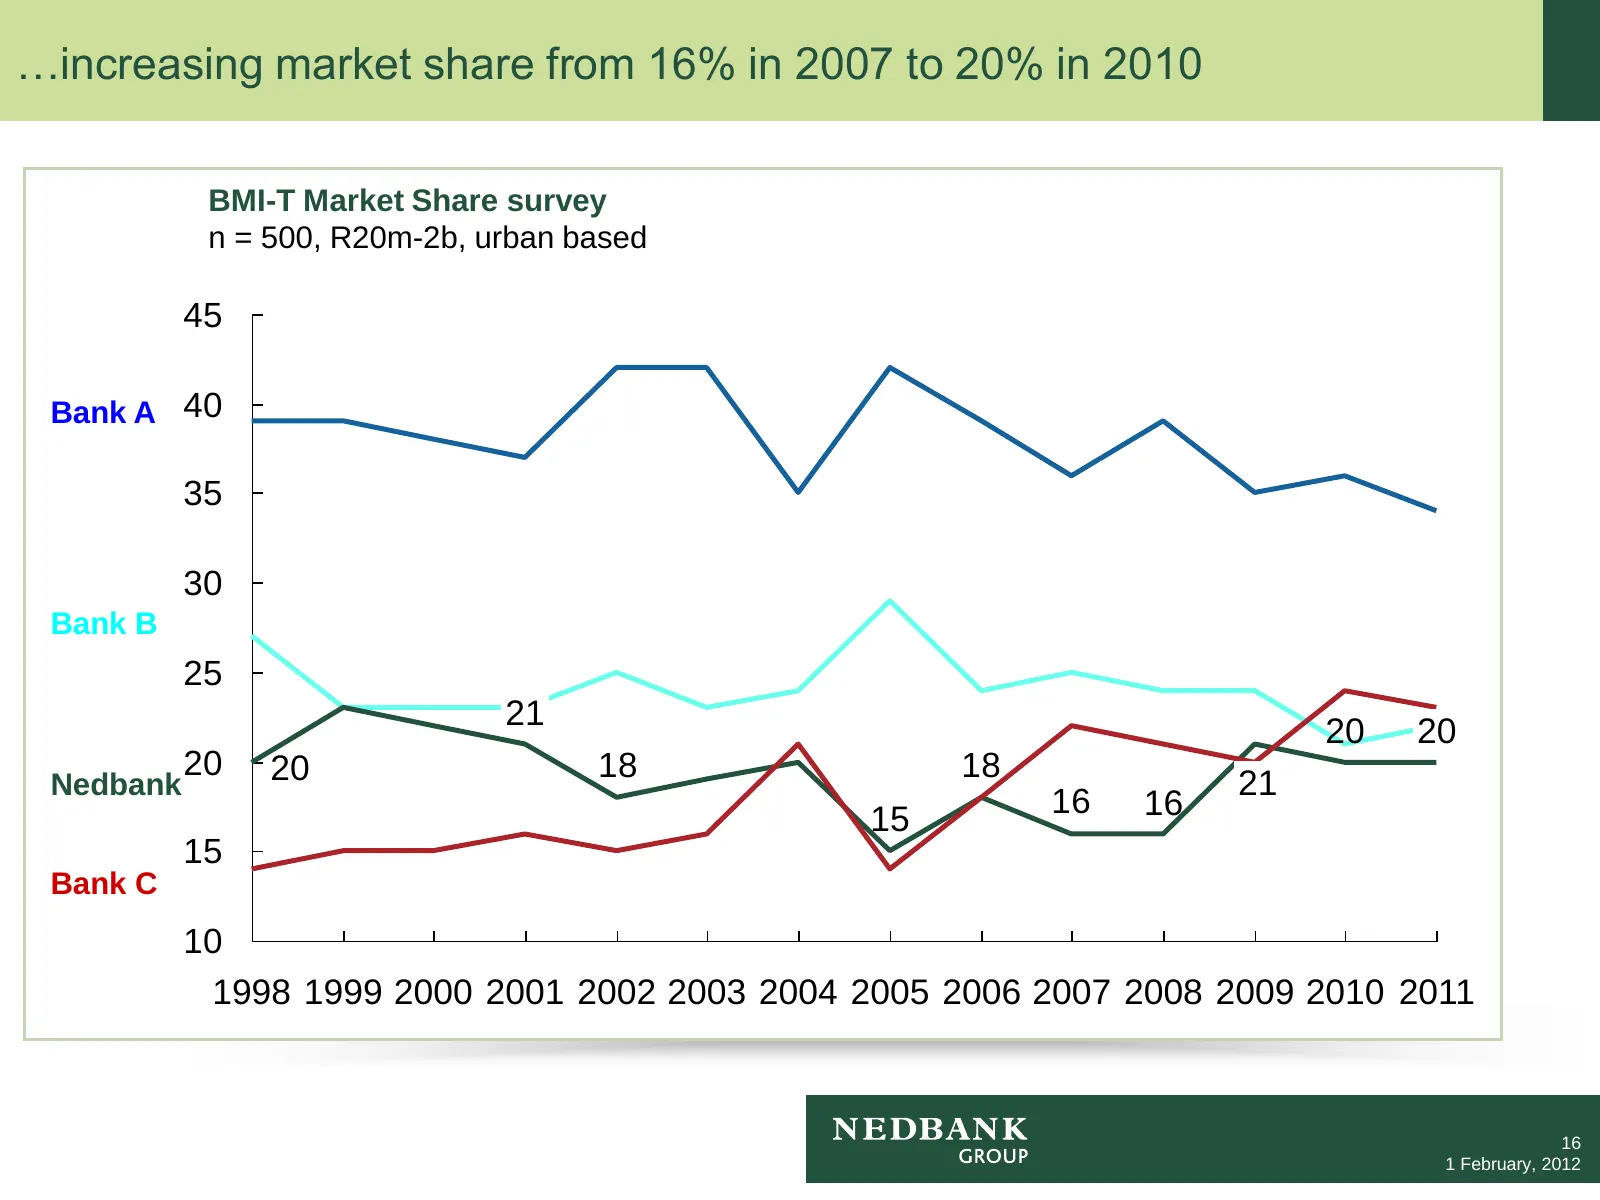
Slide 17: Increasing market share from 16% in 2007 to 20% in 2010
…increasing market share from 16% in 2007 to 20% in 2010 BMI-T Market Share survey n = 500, R20m-2b, urban based 45 Bank A 40 35 30 Bank B 25 21 20 20 20 20 18 18 Nedbank 21 16 16 15 15 Bank C 10 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 16 1 February, 2012
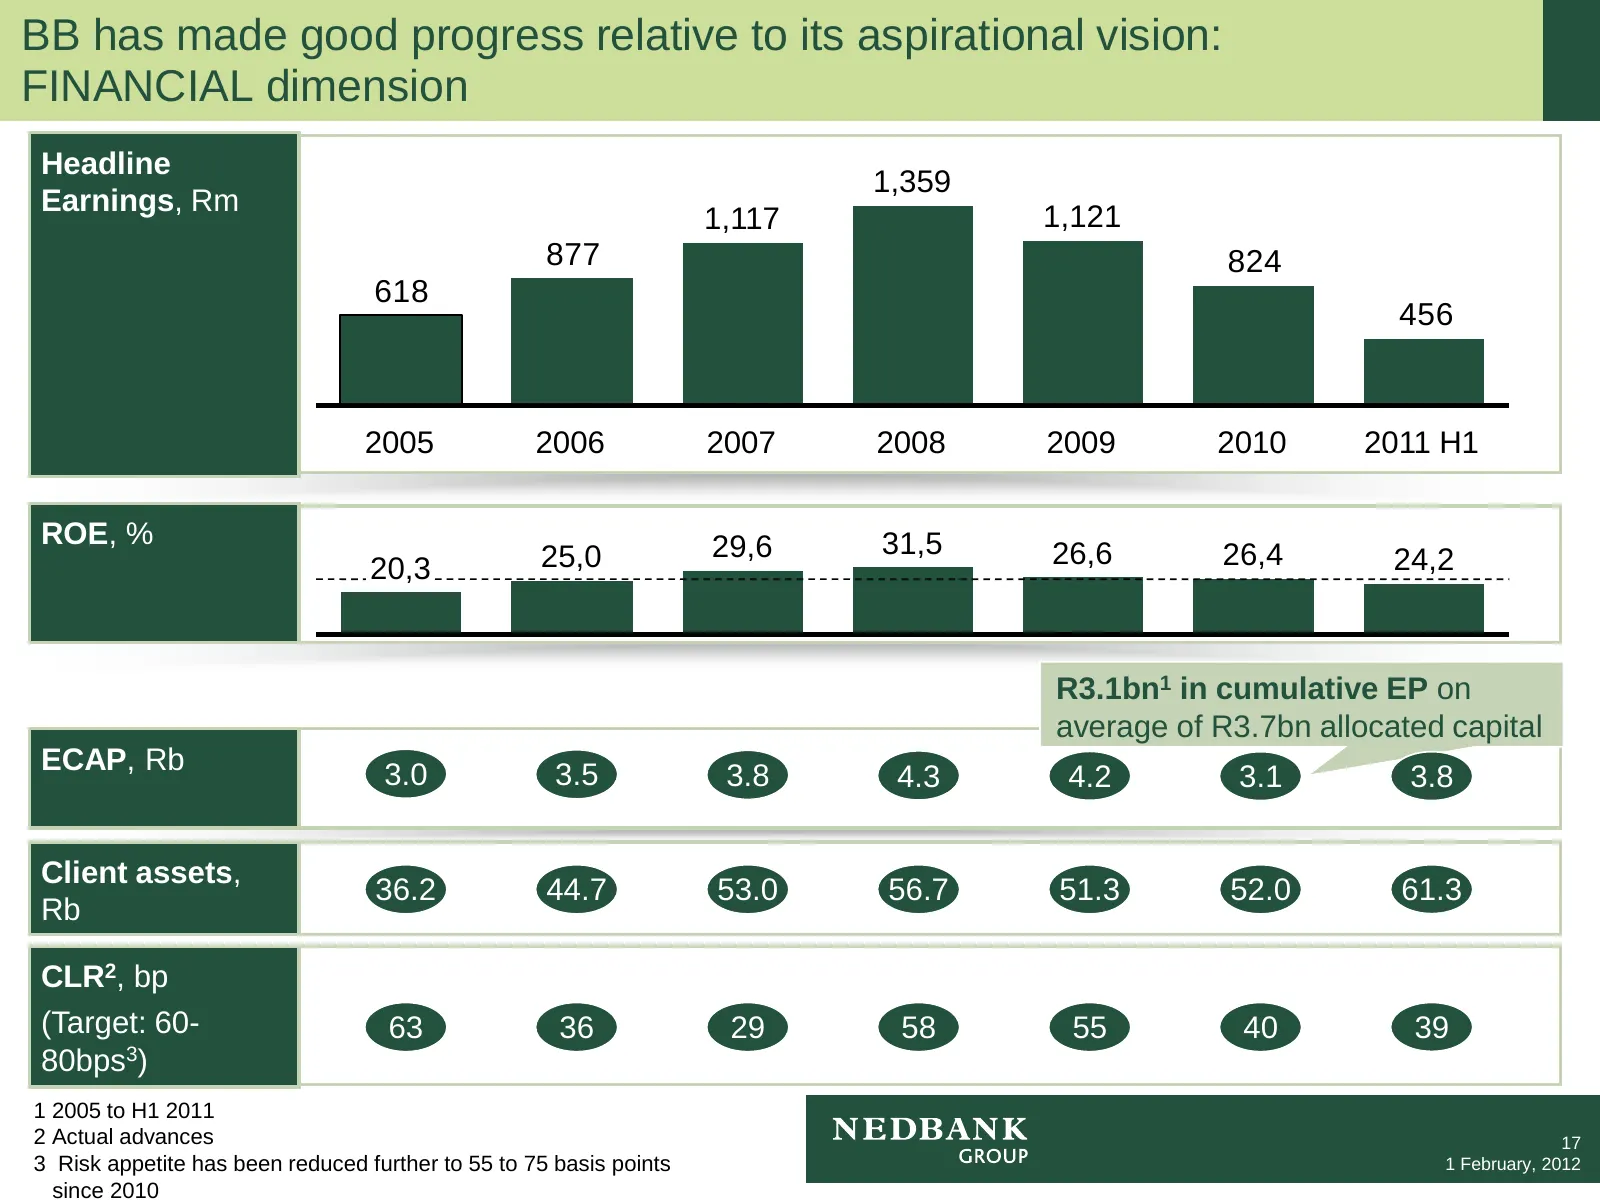
Slide 18: Business Banking progress: FINANCIAL dimension
BB has made good progress relative to its aspirational vision: FINANCIAL dimension Headline 1,359 Earnings, Rm 1,117 1,121 877 824 618 456 2005 2006 2007 2008 2009 2010 2011 H1 ROE, % 29,6 31,5 20,3 25,0 26,6 26,4 24,2 R3.1bn1 in cumulative EP on average of R3.7bn allocated capital ECAP, Rb 3.0 3.5
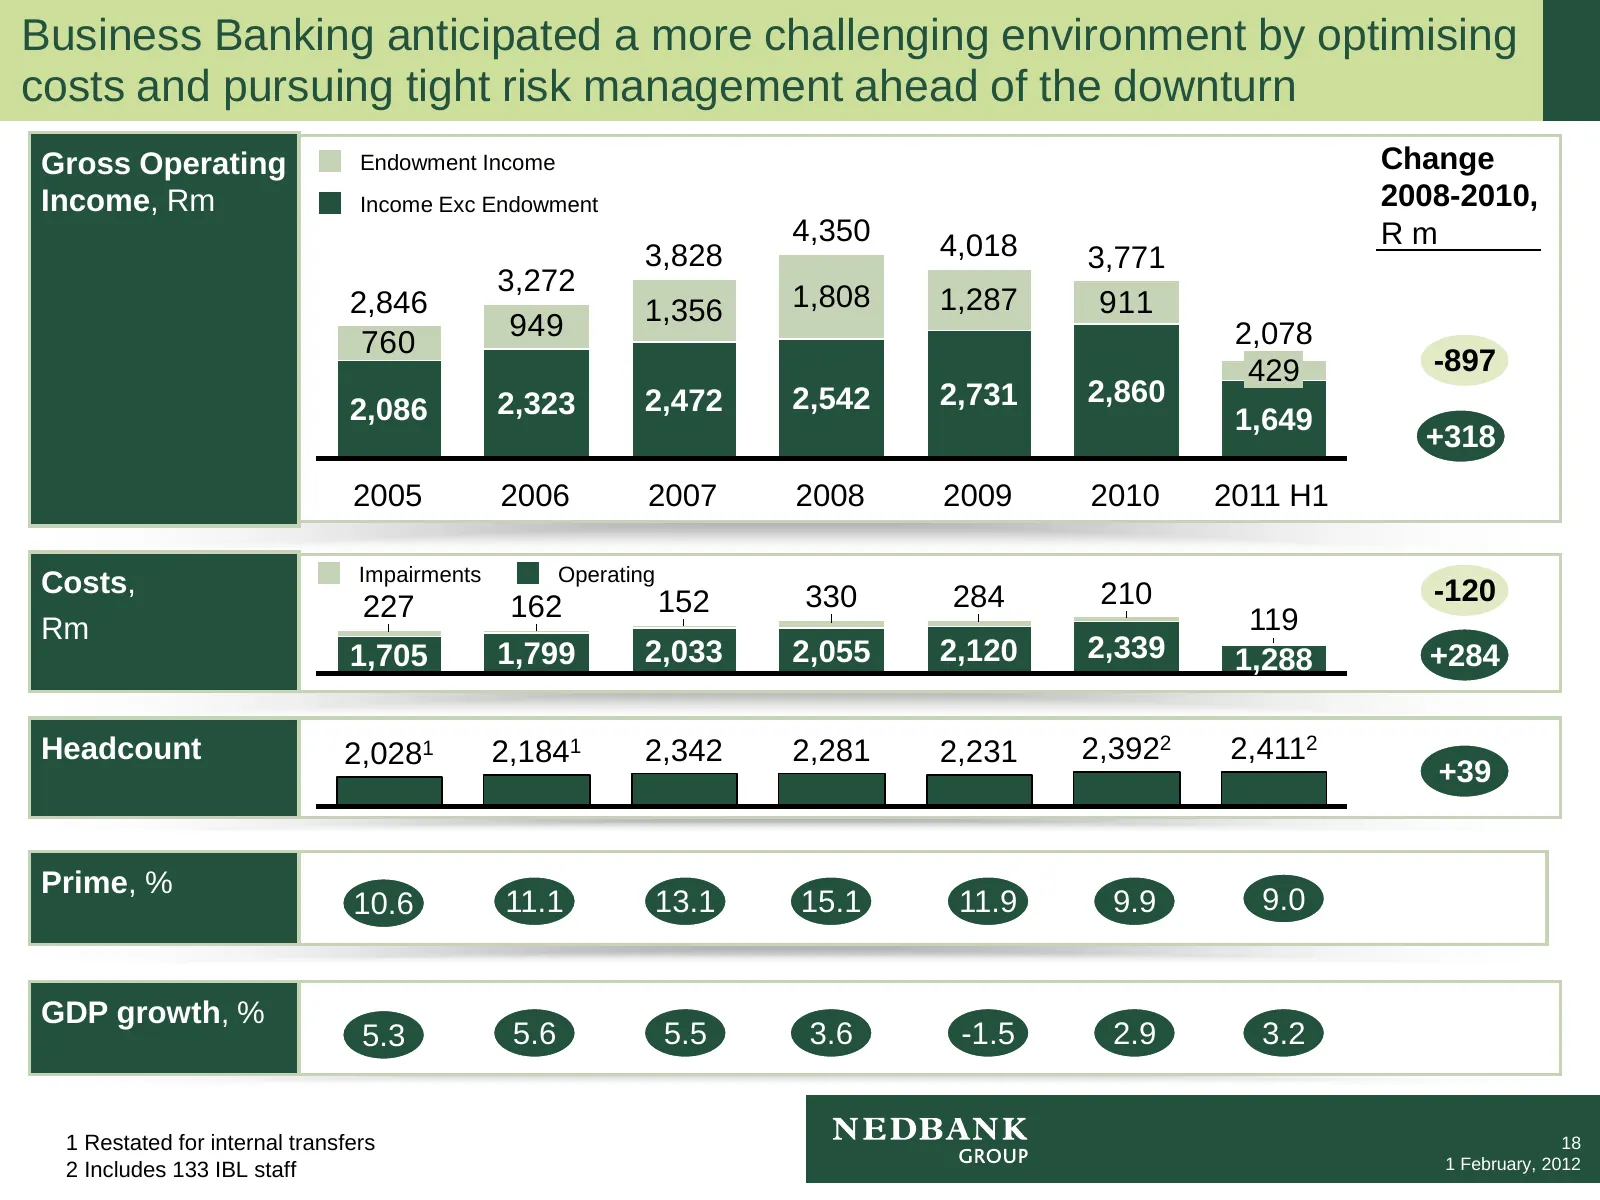
Slide 19: Business Banking optimising costs and tight risk management ahead of downturn
Business Banking anticipated a more challenging environment by optimising costs and pursuing tight risk management ahead of the downturn Gross Operating Endowment Income Change Income, Rm Income Exc Endowment 2008-2010, 4,350 4,018 Rm 3,828 3,771 3,272 2,846 1,356 1,808 1,287 911 949 2,078 760 429 -
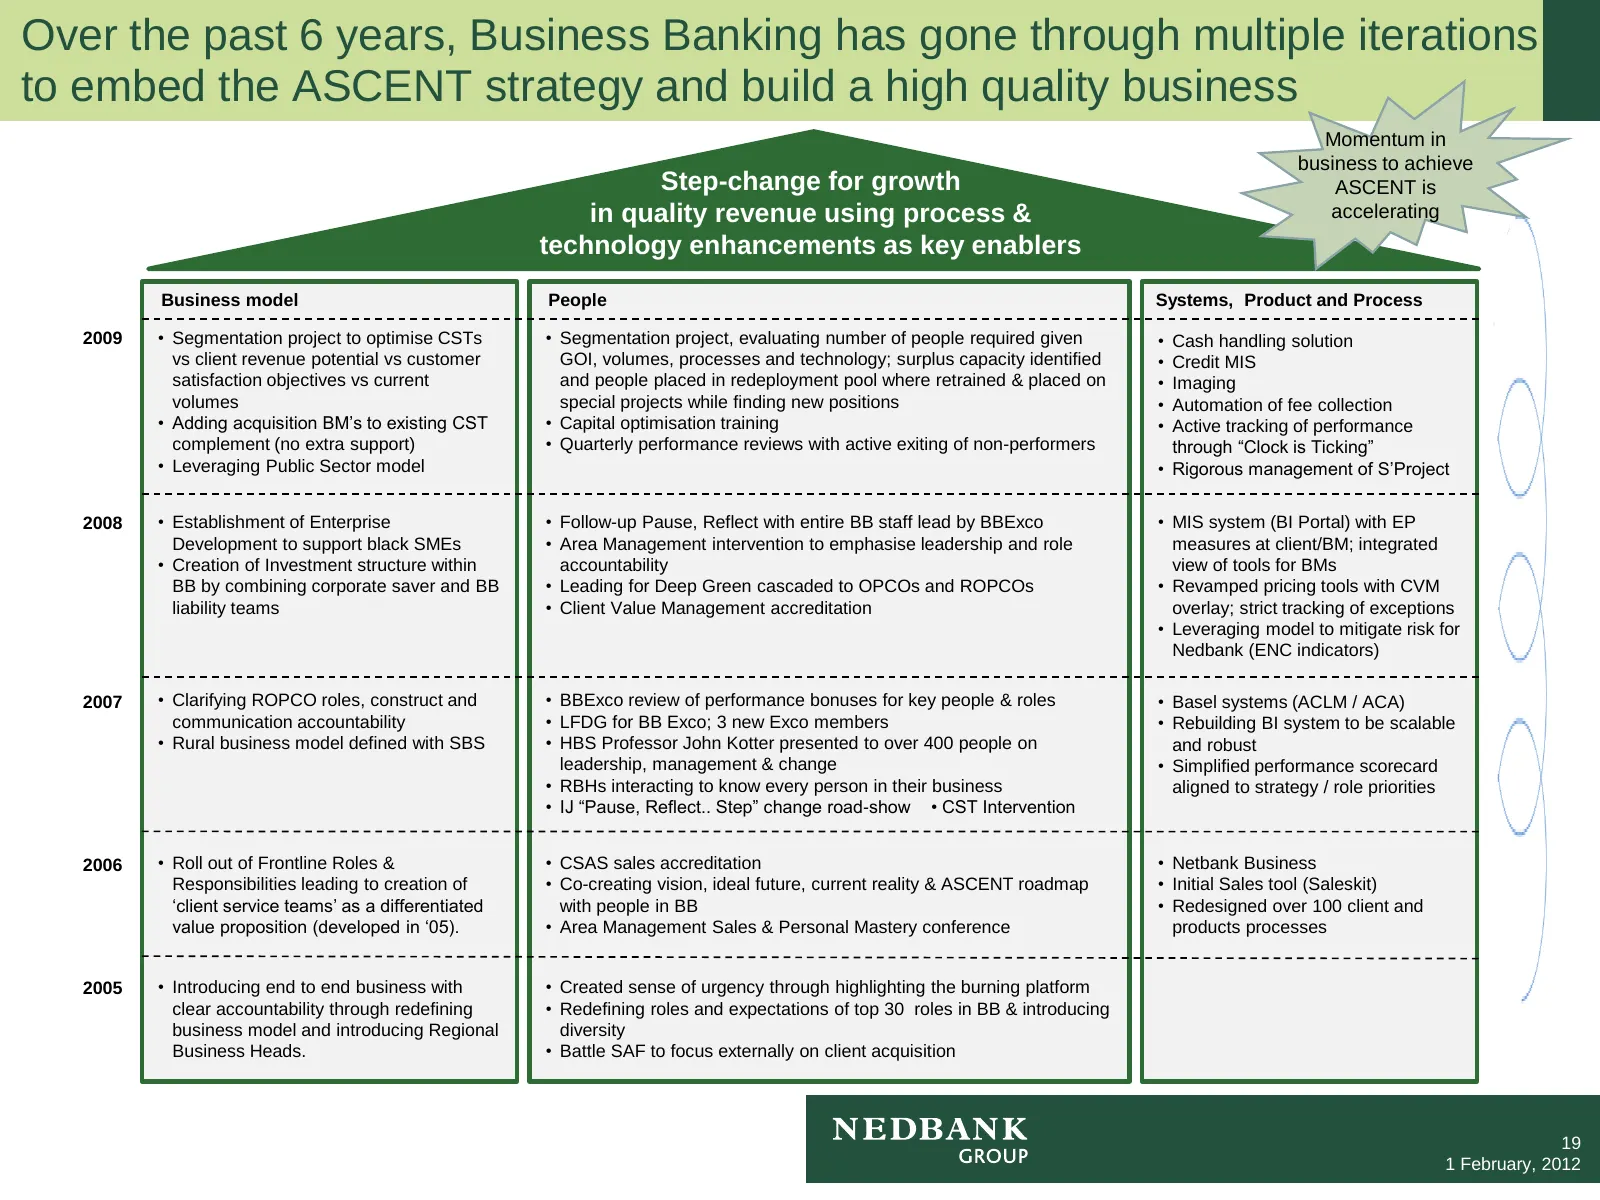
Slide 20: Business Banking iterations to embed the ASCENT strategy
Over the past 6 years, Business Banking has gone through multiple iterations to embed the ASCENT strategy and build a high quality business Momentum in business to achieve Step-change for growth ASCENT is in quality revenue using process & accelerating technology enhancements as key enablers Busines
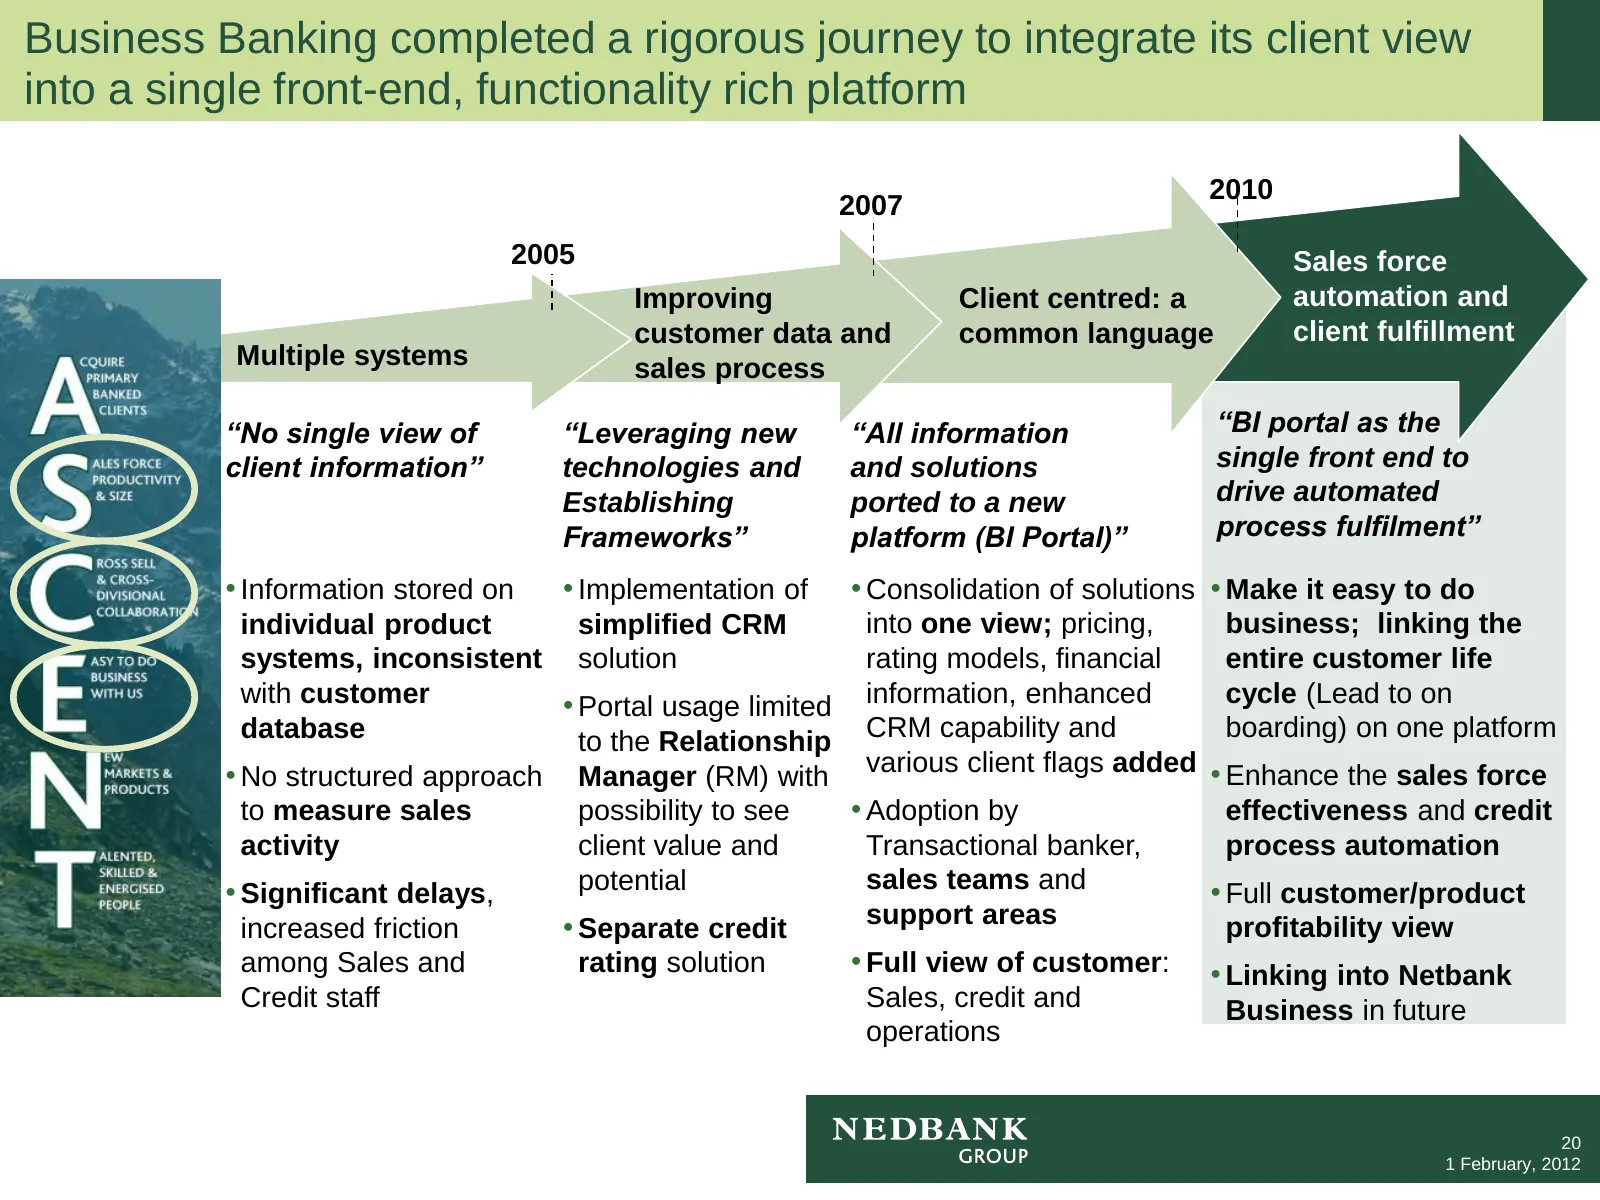
Slide 21: Integrating client view into a single front-end platform
Business Banking completed a rigorous journey to integrate its client view into a single front-end, functionality rich platform 2010 2007 2005 Sales force Improving Client centred: a automation and customer data and common language client fulfillment Multiple systems sales process “No single view of
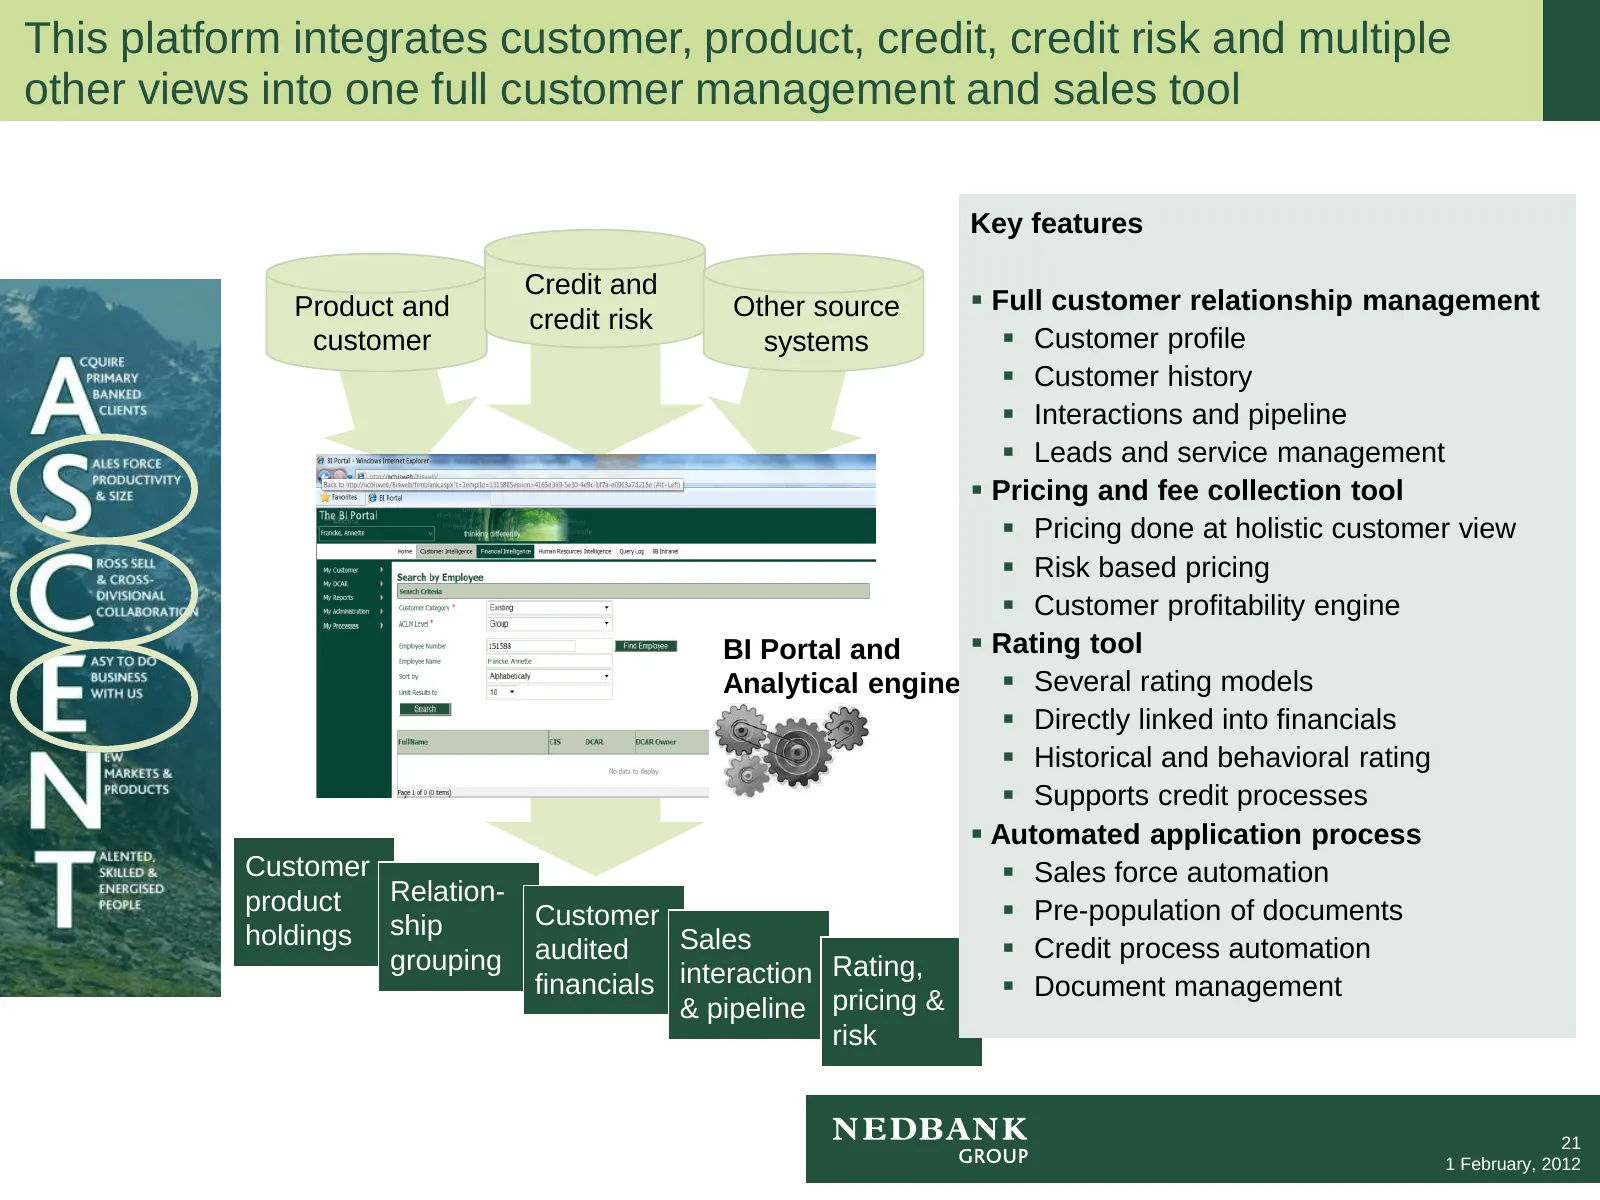
Slide 22: Platform integrating customer, product, credit and risk views
This platform integrates customer, product, credit, credit risk and multiple other views into one full customer management and sales tool Key features Credit and Product and Other source Full customer relationship management credit risk customer systems Customer profile Customer history Inte
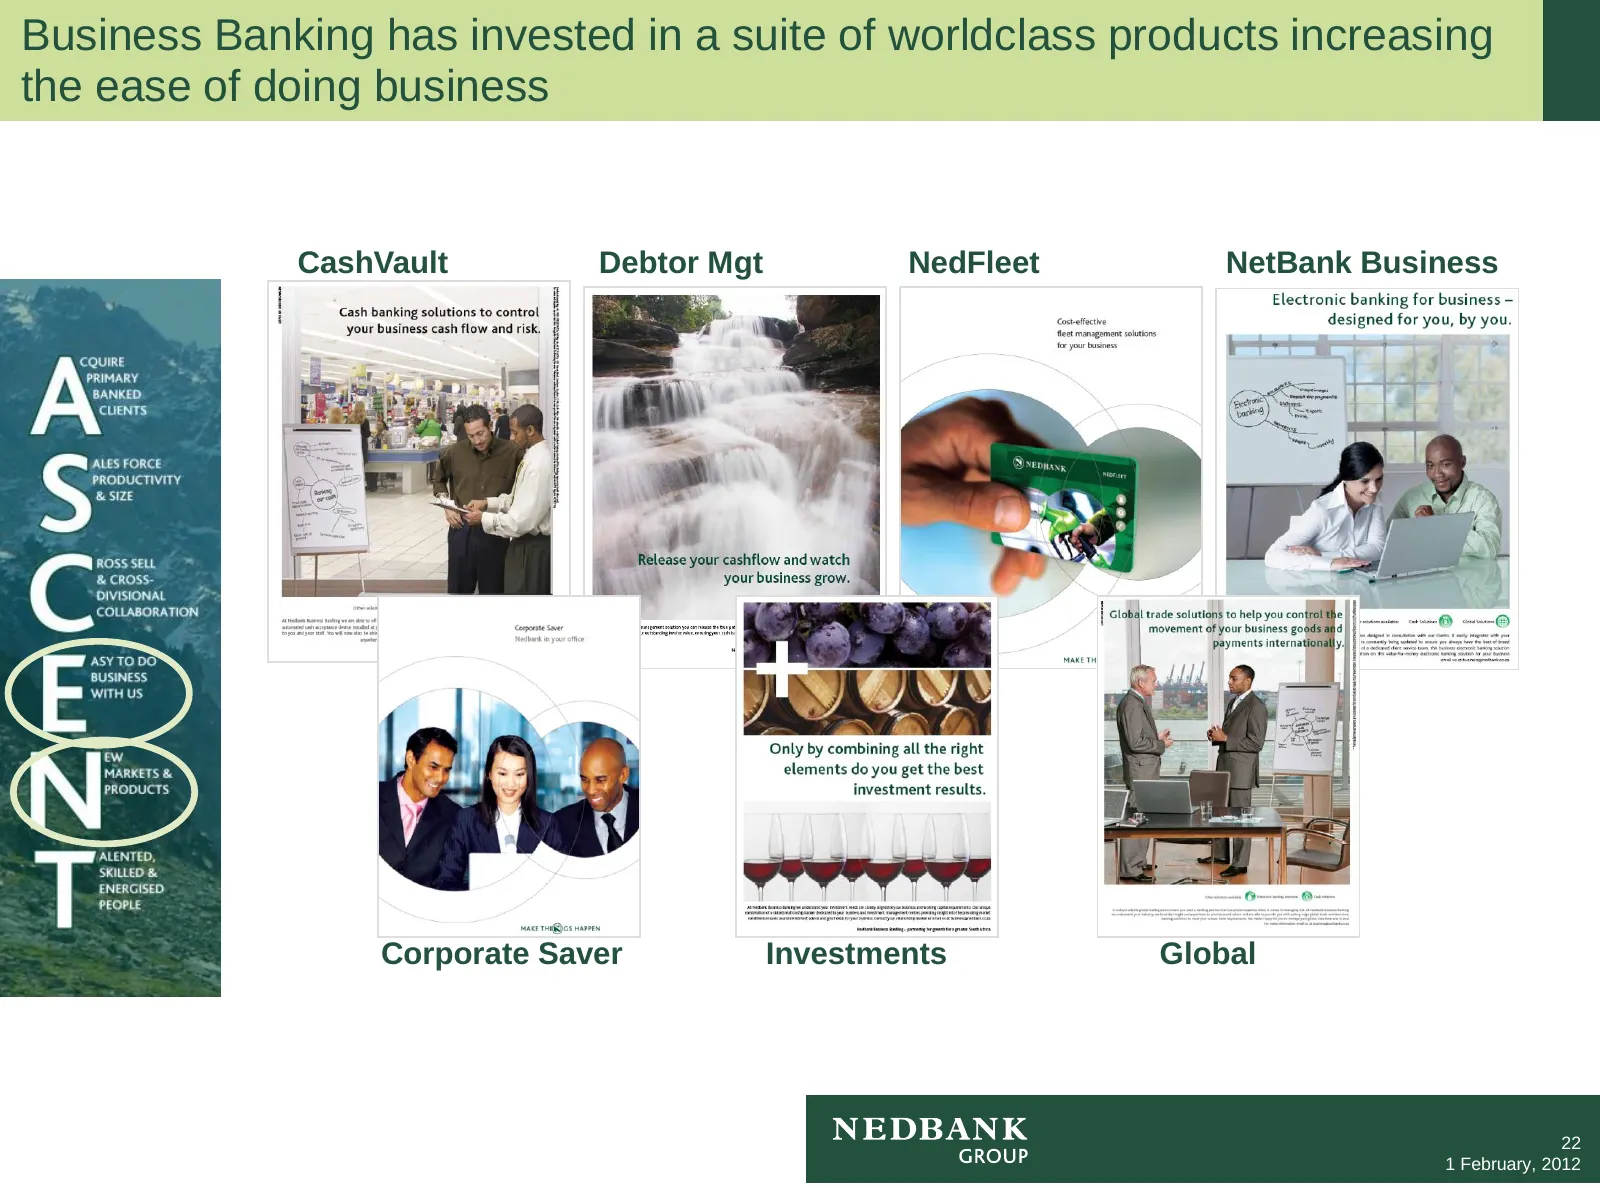
Slide 23: Suite of worldclass products increasing ease of doing business
Business Banking has invested in a suite of worldclass products increasing the ease of doing business CashVault Debtor Mgt NedFleet NetBank Business Corporate Saver Investments Global 22 1 February, 2012
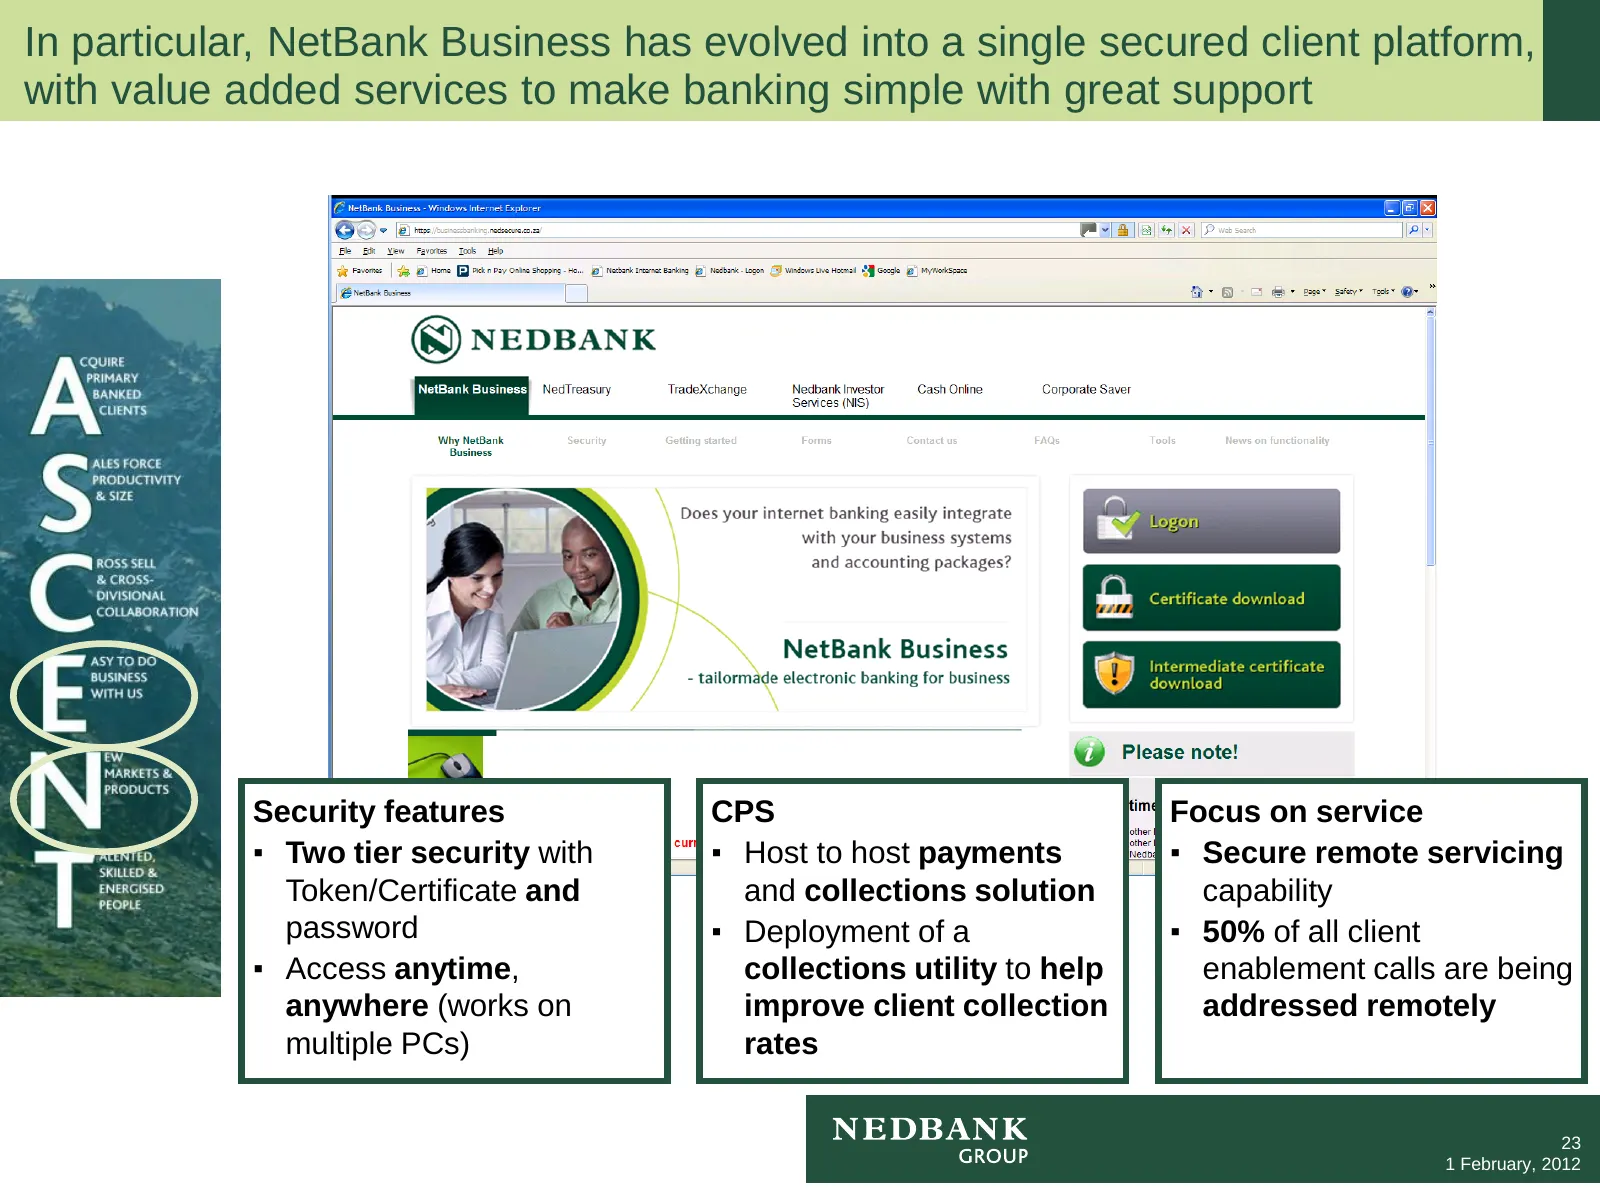
Slide 24: NetBank Business as a single secured client platform
In particular, NetBank Business has evolved into a single secured client platform, with value added services to make banking simple with great support Security features CPS Focus on service ▪ Two tier security with ▪ Host to host payments ▪ Secure remote servicing Token/Certificate and and collectio
Slide 25: Continual digital innovation improving client feedback
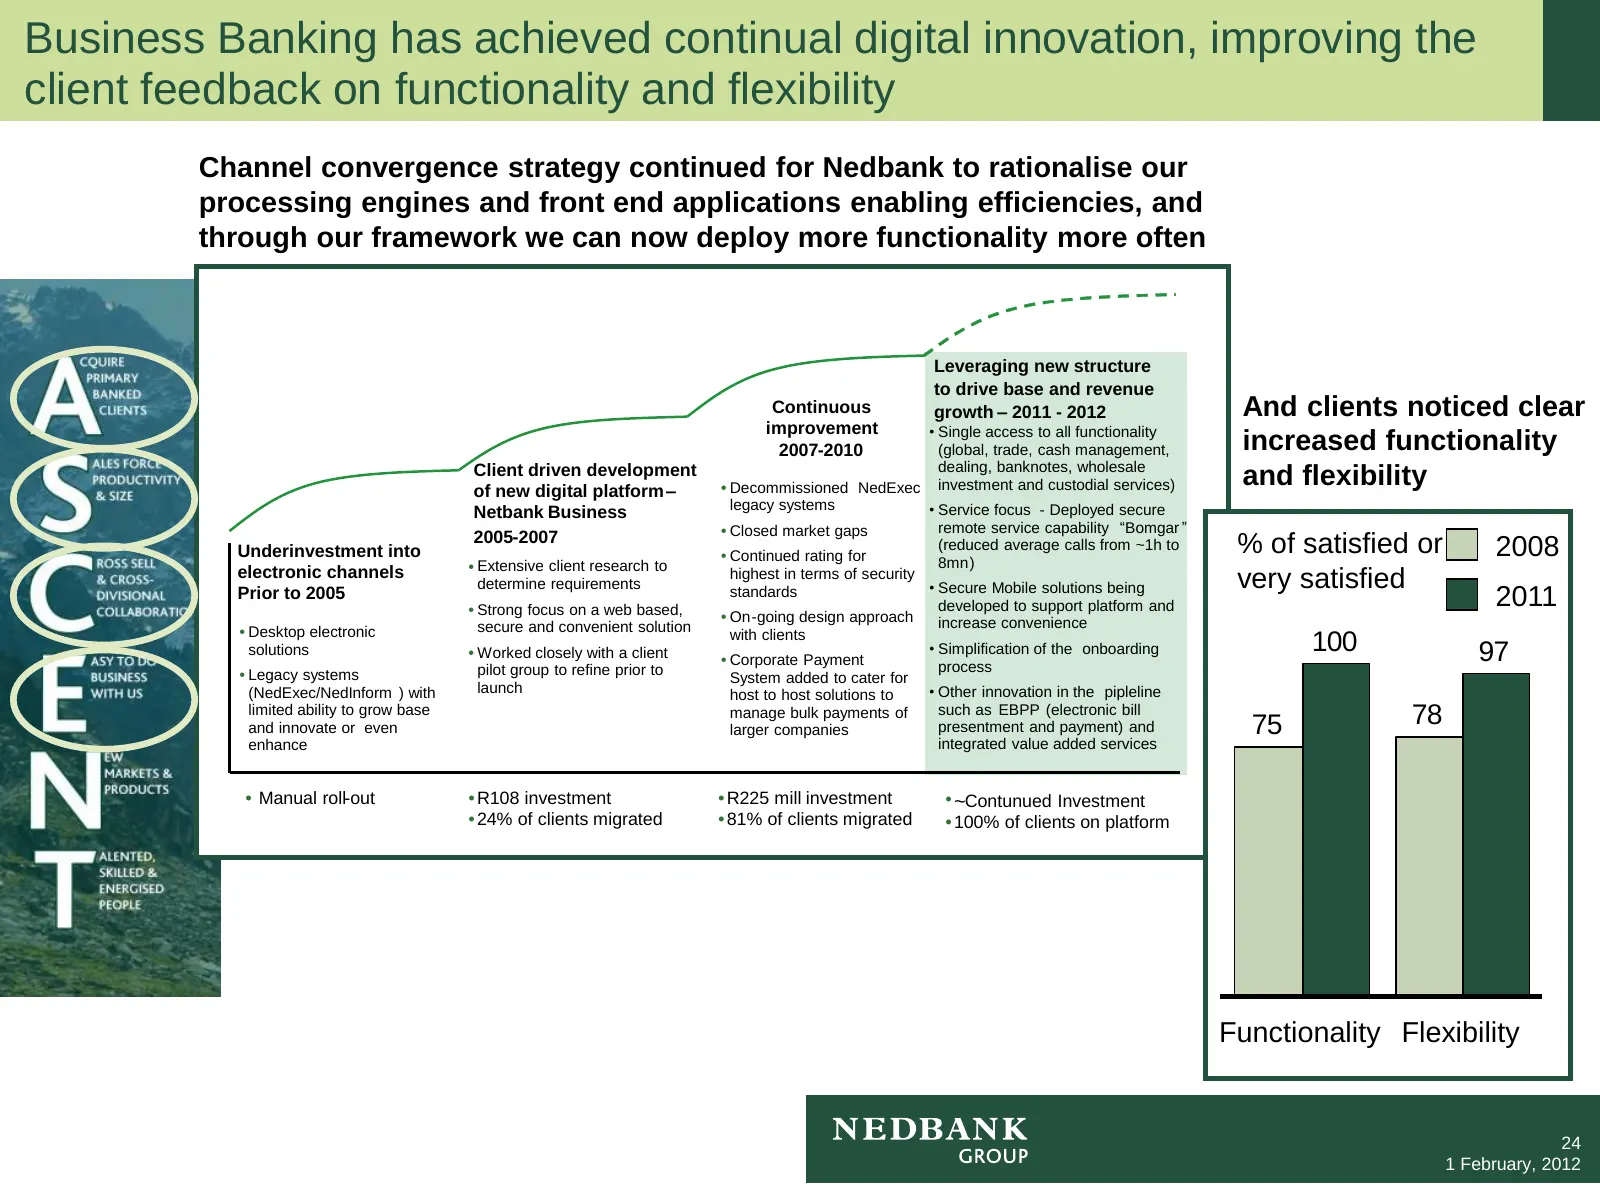
Business Banking has achieved continual digital innovation, improving the client feedback on functionality and flexibility Channel convergence strategy continued for Nedbank to rationalise our processing engines and front end applications enabling efficiencies, and through our framework we can now d
Slide 26: Driving towards the aspirational vision to lead BB in South Africa
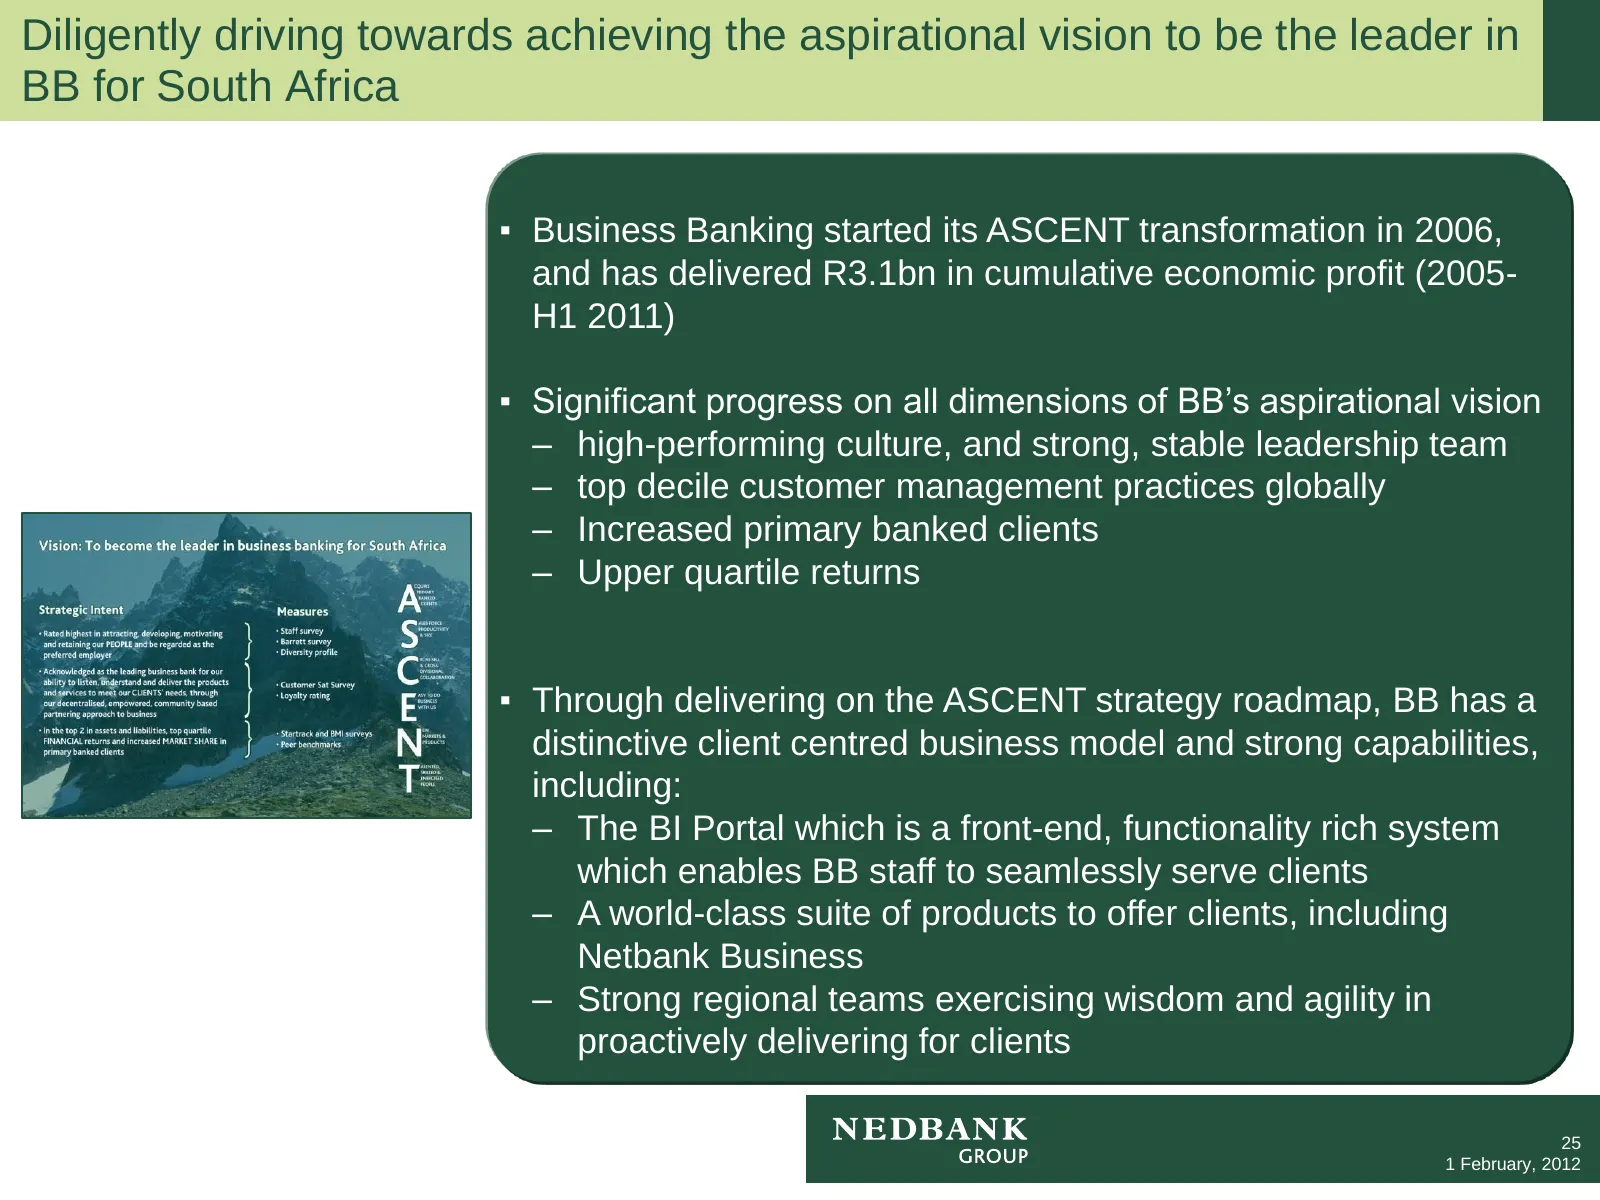
Diligently driving towards achieving the aspirational vision to be the leader in BB for South Africa ▪ Business Banking started its ASCENT transformation in 2006, and has delivered R3.1bn in cumulative economic profit (2005- H1 2011) ▪ Significant progress on all dimensions of BB’s aspirational visi
Slide 27: Uniquely positioned to generate shareholder value: Retail transformation
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment 1 A skilled leadership team with a track record of delivery Vision-led, values-driven leadership driving delivery on Retail and Business Banking 6 years in
Slide 28: Strategic journey in 2010 to turn around the retail business
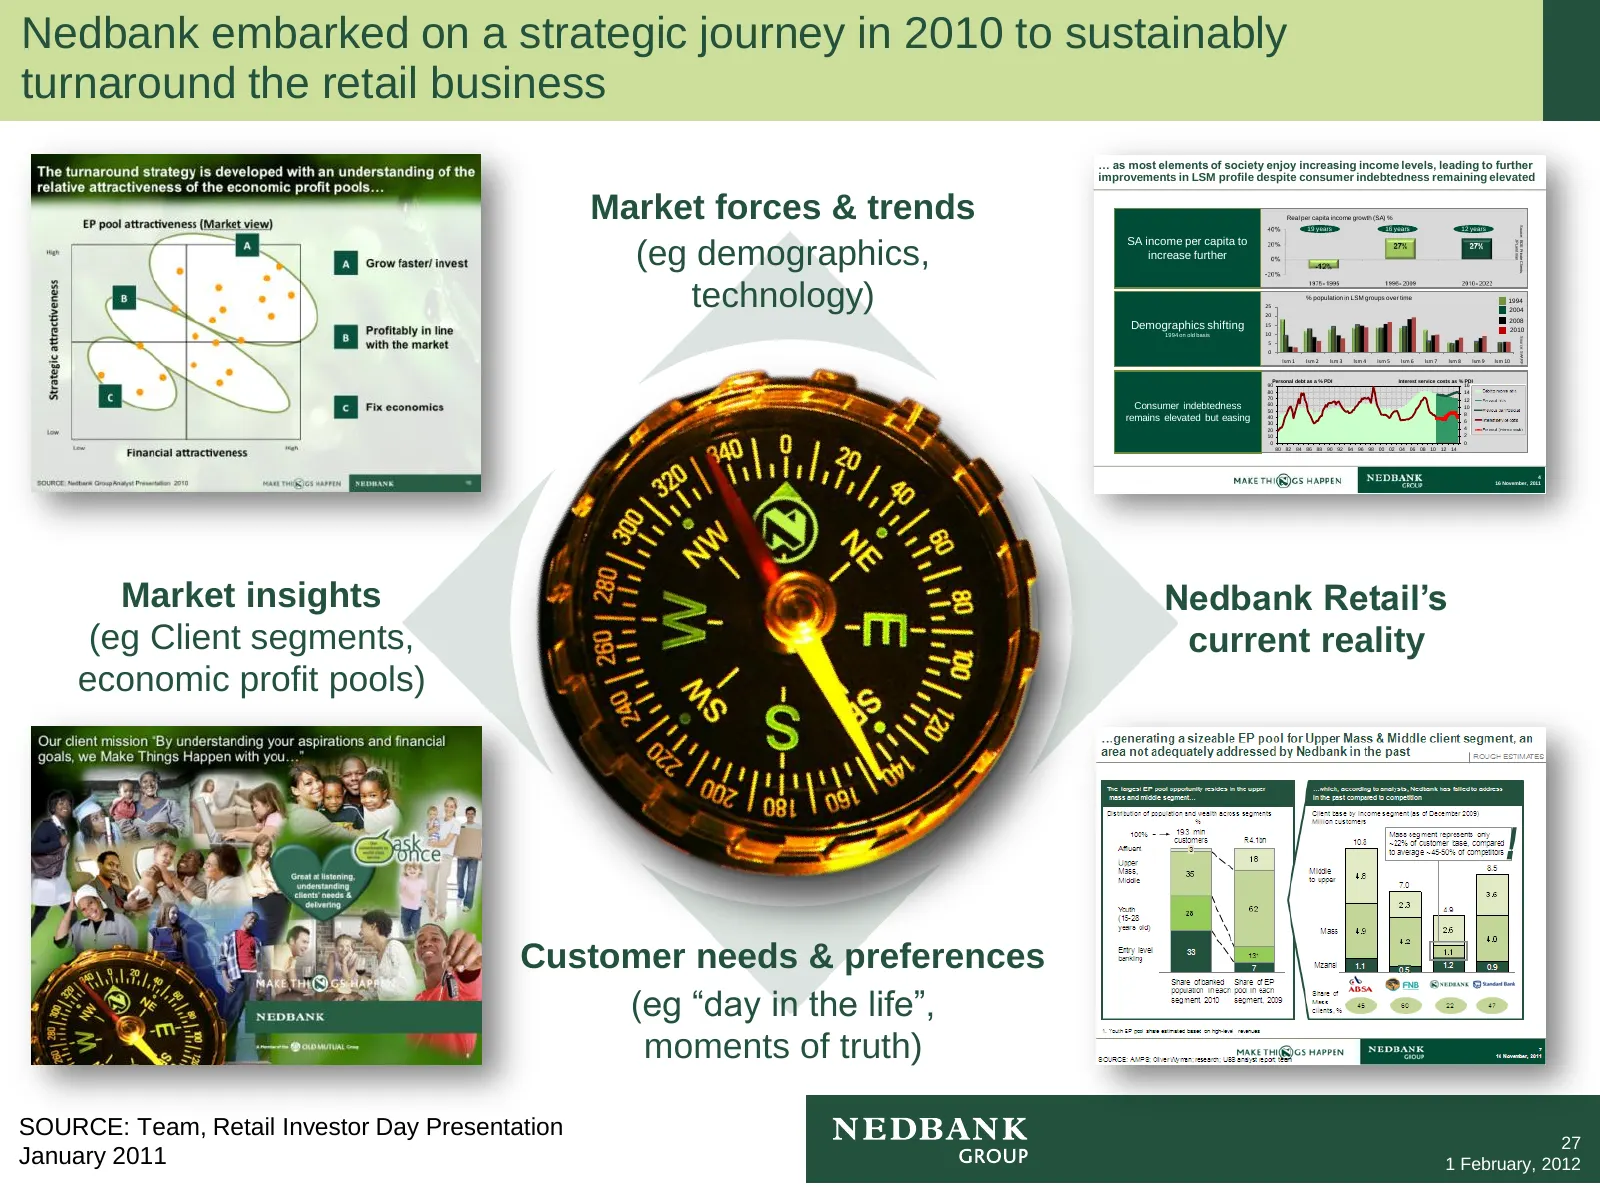
Nedbank embarked on a strategic journey in 2010 to sustainably turnaround the retail business Pg 66 … as most elements of society enjoy increasing income levels, leading to further improvements in LSM profile despite consumer indebtedness remaining elevated Market forces & trends Real per capita inc
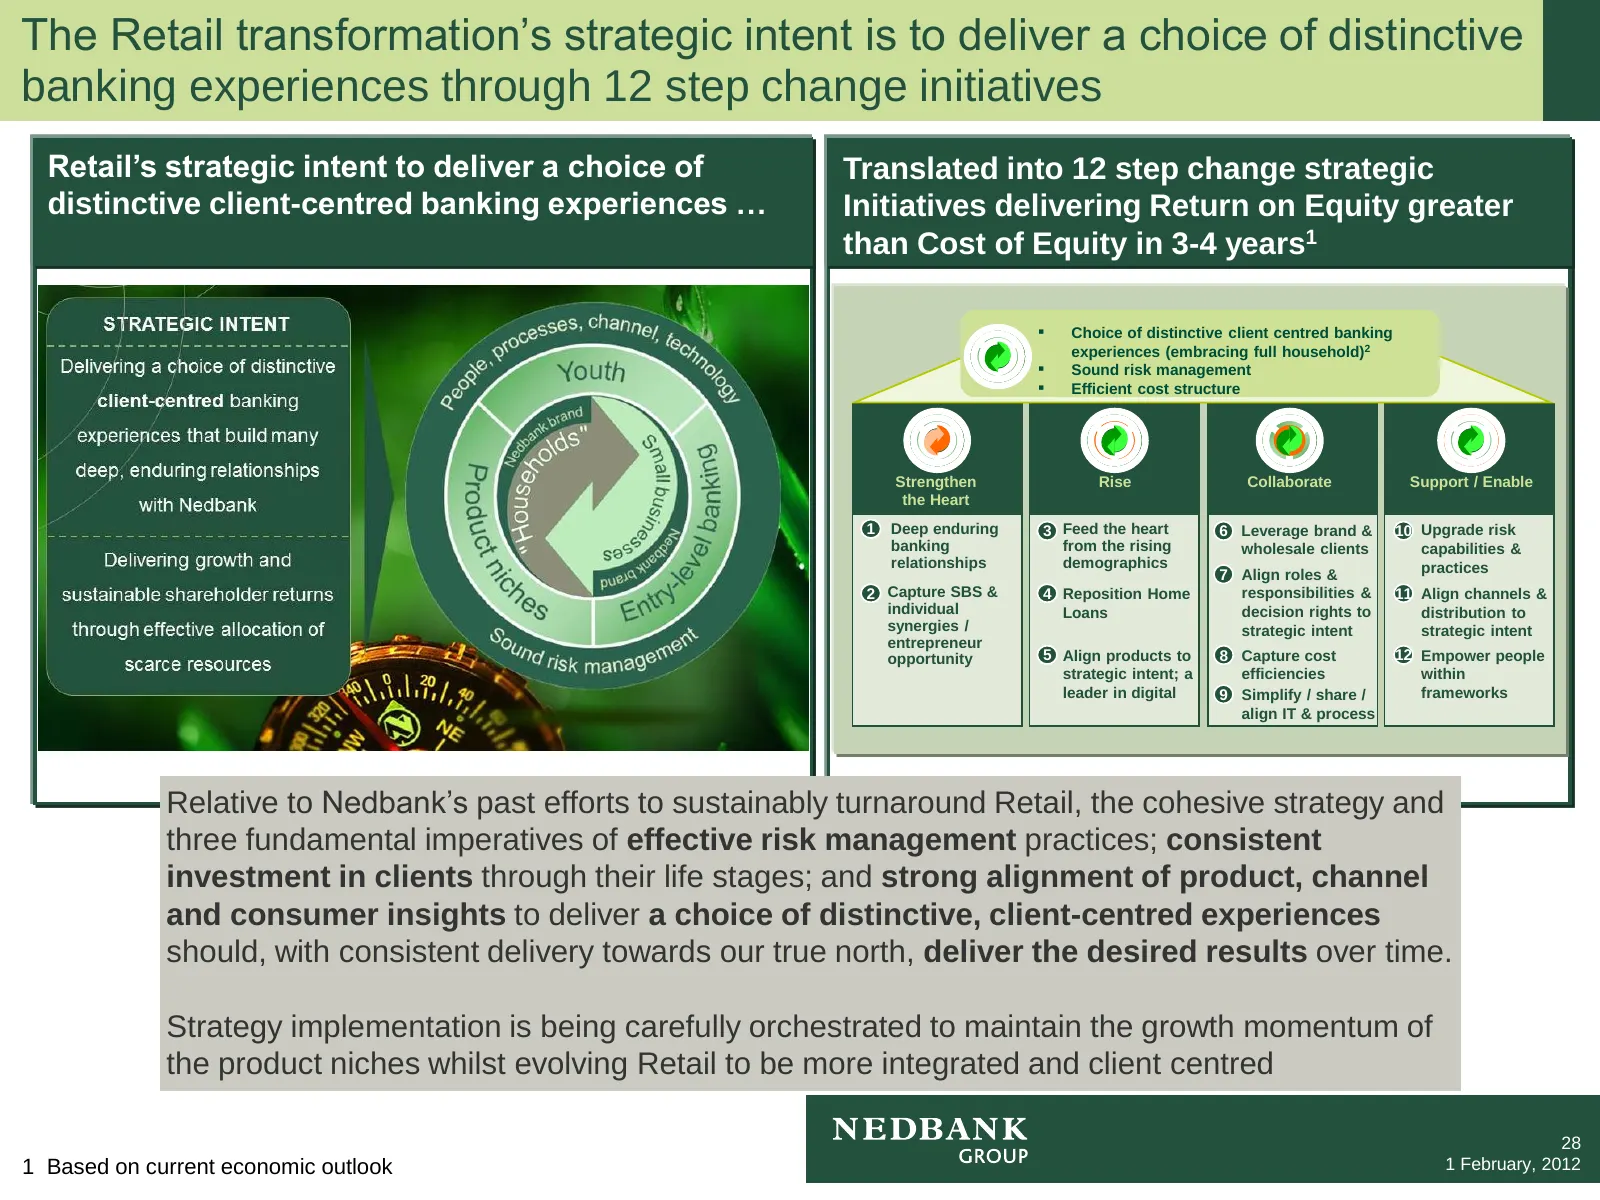
Slide 29: Retail strategic intent through 12 step change initiatives
The Retail transformation’s strategic intent is to deliver a choice of distinctive banking experiences through 12 step change initiatives Retail’s strategic intent to deliver a choice of Translated into 12 step change strategic distinctive client-centred banking experiences … Initiatives delivering
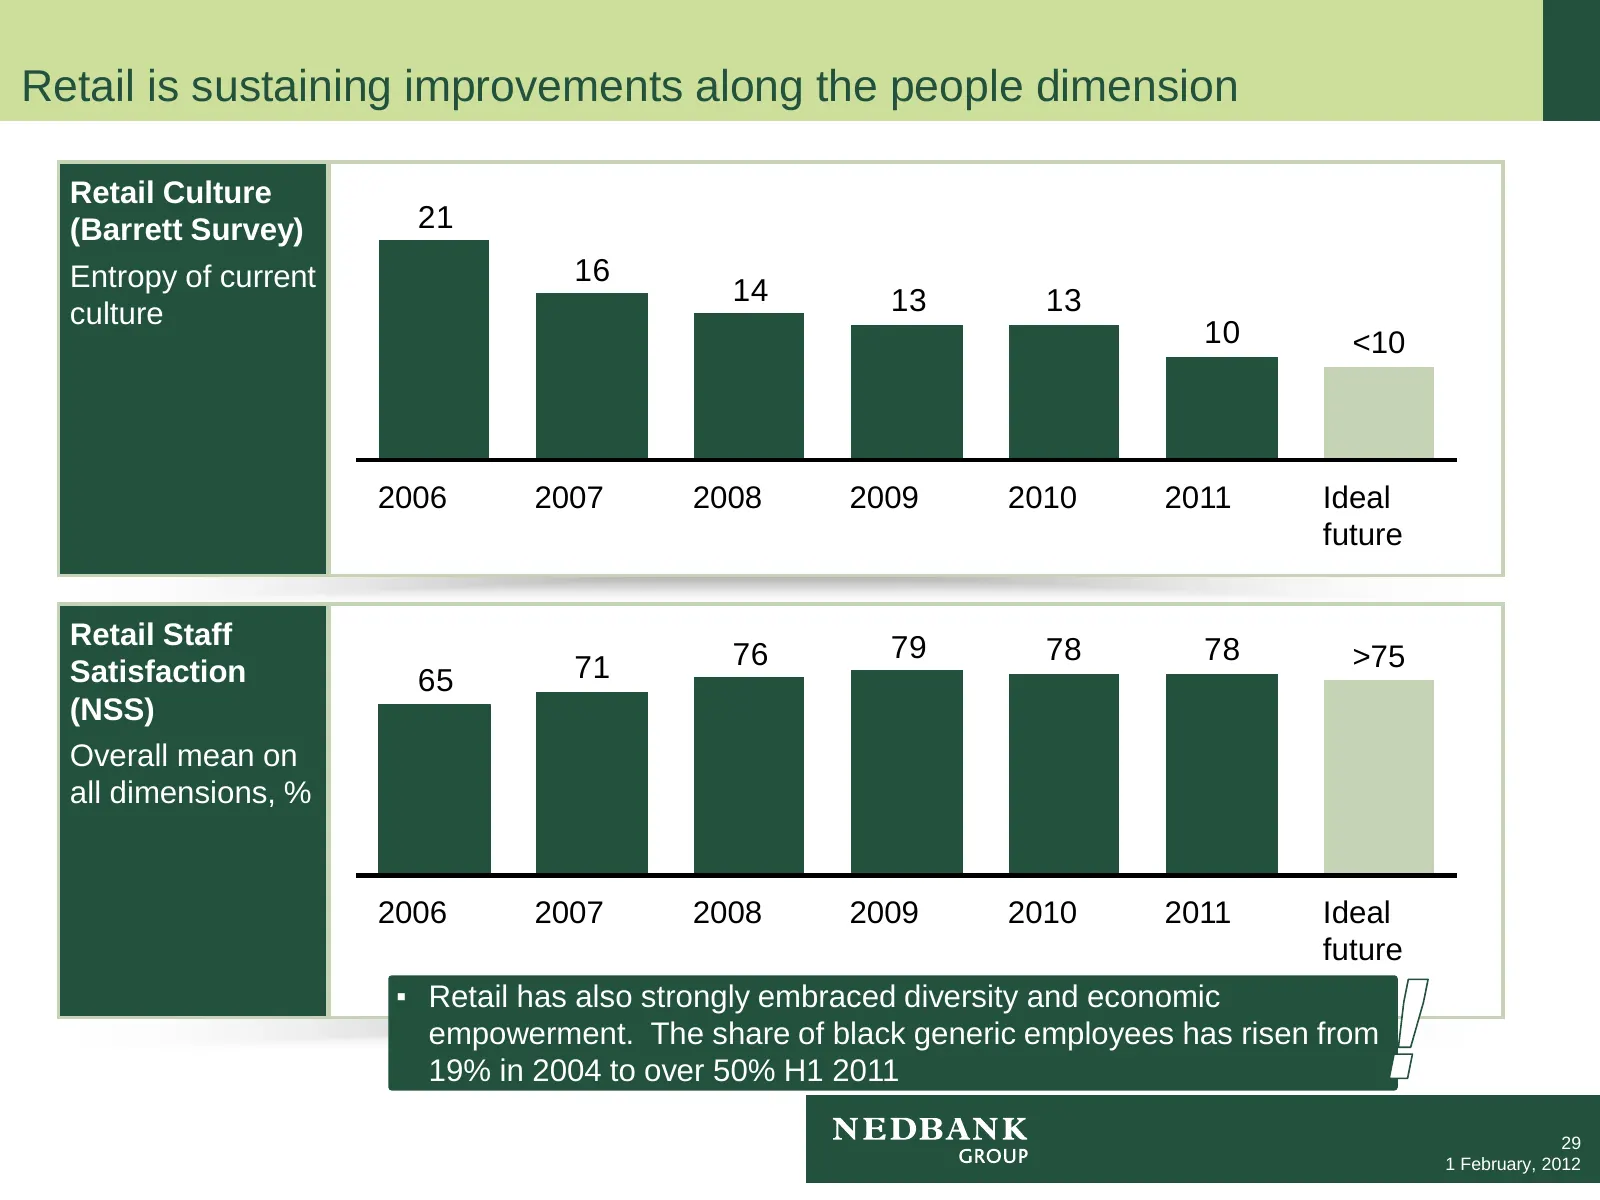
Slide 30: Retail sustaining improvements along the people dimension
Retail is sustaining improvements along the people dimension Retail Culture (Barrett Survey) 21 Entropy of current 16 14 13 13 culture 10 <10 2006 2007 2008 2009 2010 2011 Ideal future Retail Staff 79 78 78 71 76 >75 Satisfaction 65 (NSS) Overall mean on all dimensions, % 2006 2007 2008 2009 2010 20
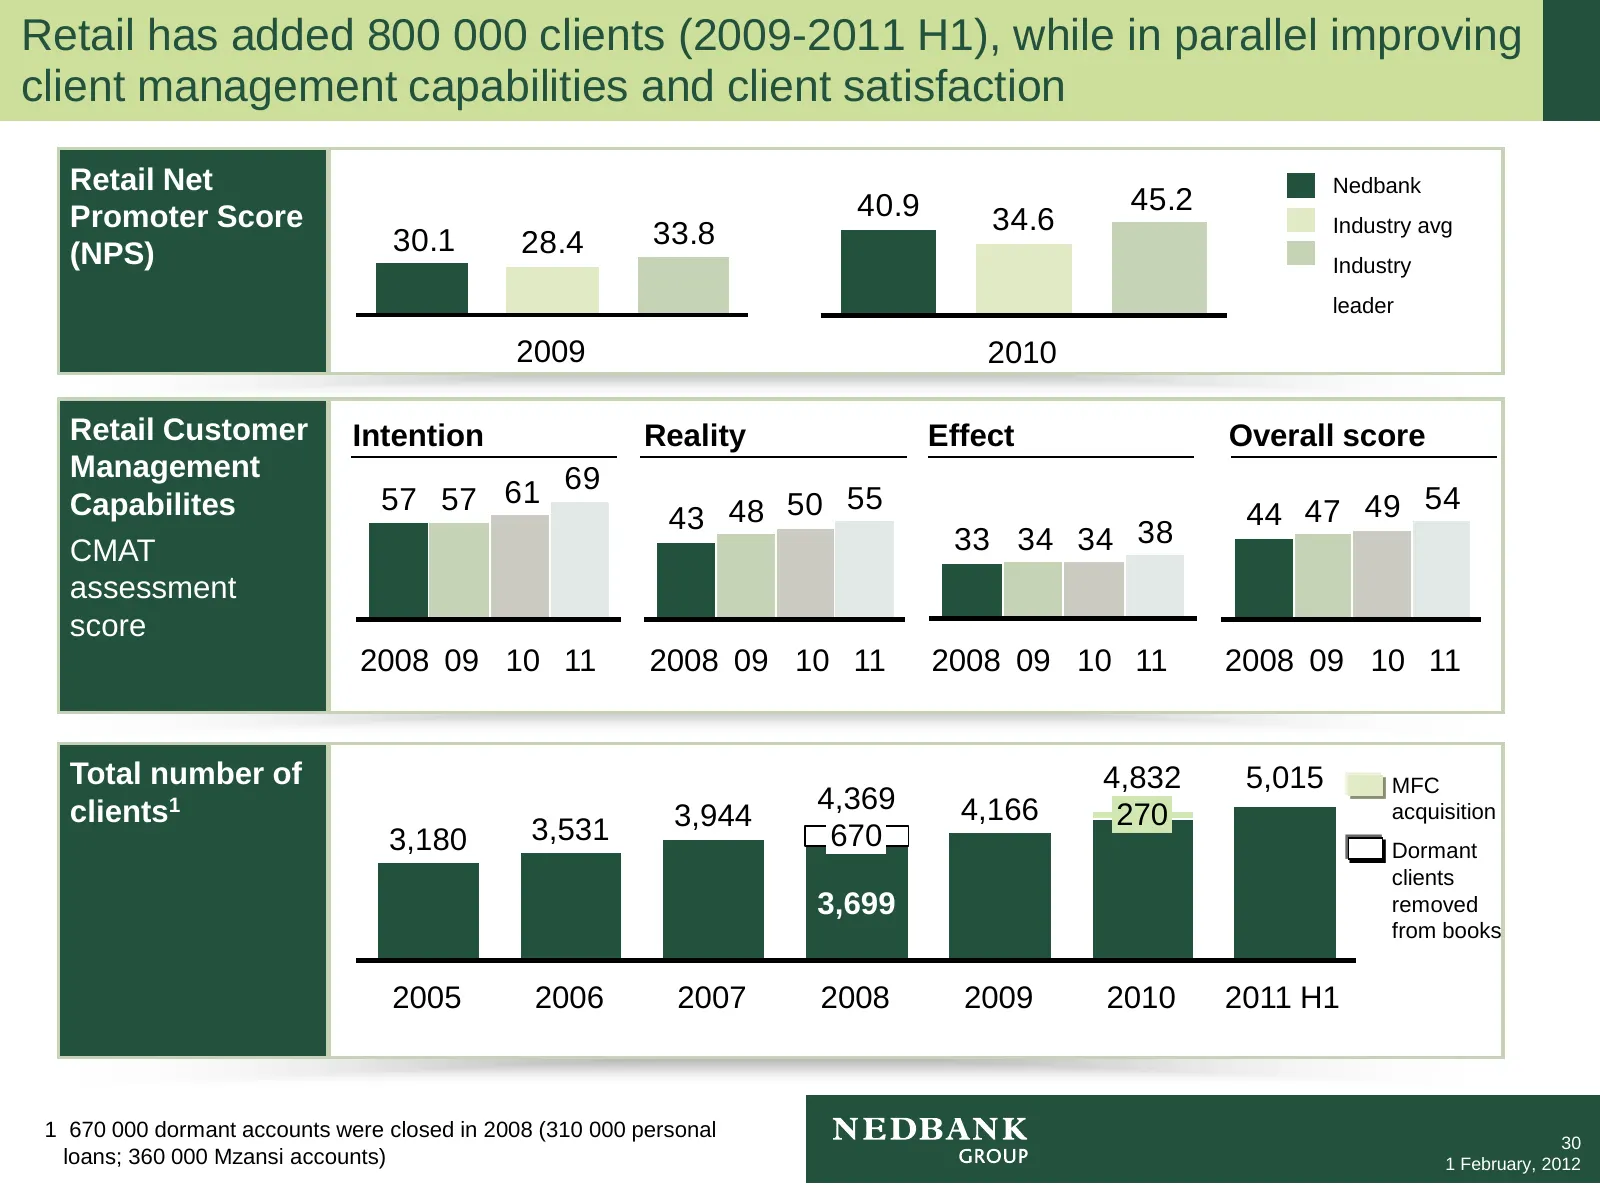
Slide 31: Retail added clients while improving client management and satisfaction
Retail has added 800 000 clients (2009-2011 H1), while in parallel improving client management capabilities and client satisfaction Retail Net Nedbank 40.9 45.2 Promoter Score 34.6 Industry avg 30.1 28.4 33.8 (NPS) Industry leader 2009 2010 Retail Customer Intention Reality Effect Overall score Mana
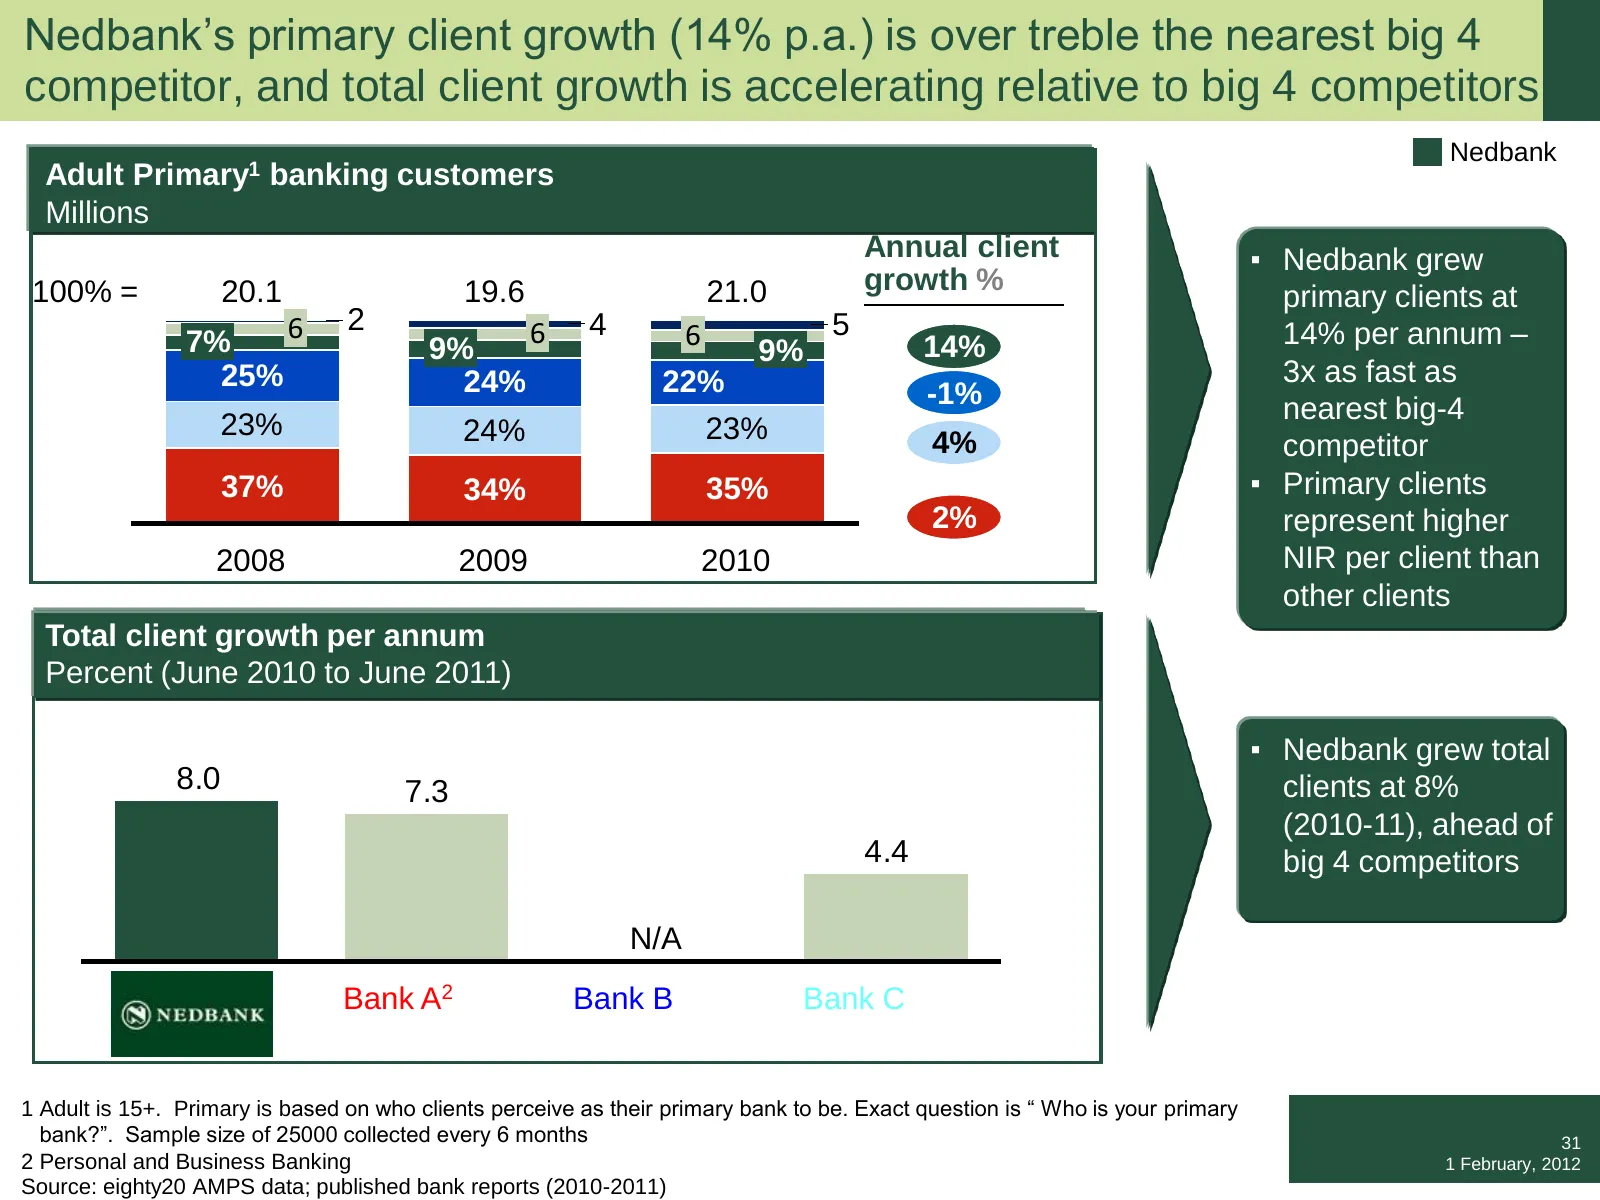
Slide 32: Primary client growth over treble the nearest big 4 competitor
Nedbank’s primary client growth (14% p.a.) is over treble the nearest big 4 competitor, and total client growth is accelerating relative to big 4 competitors Nedbank Adult Primary1 banking customers Millions Annual client ▪ Nedbank grew 100% = 20.1 19.6 21.0 growth % primary clients at 6 2 6 4 6 5 1
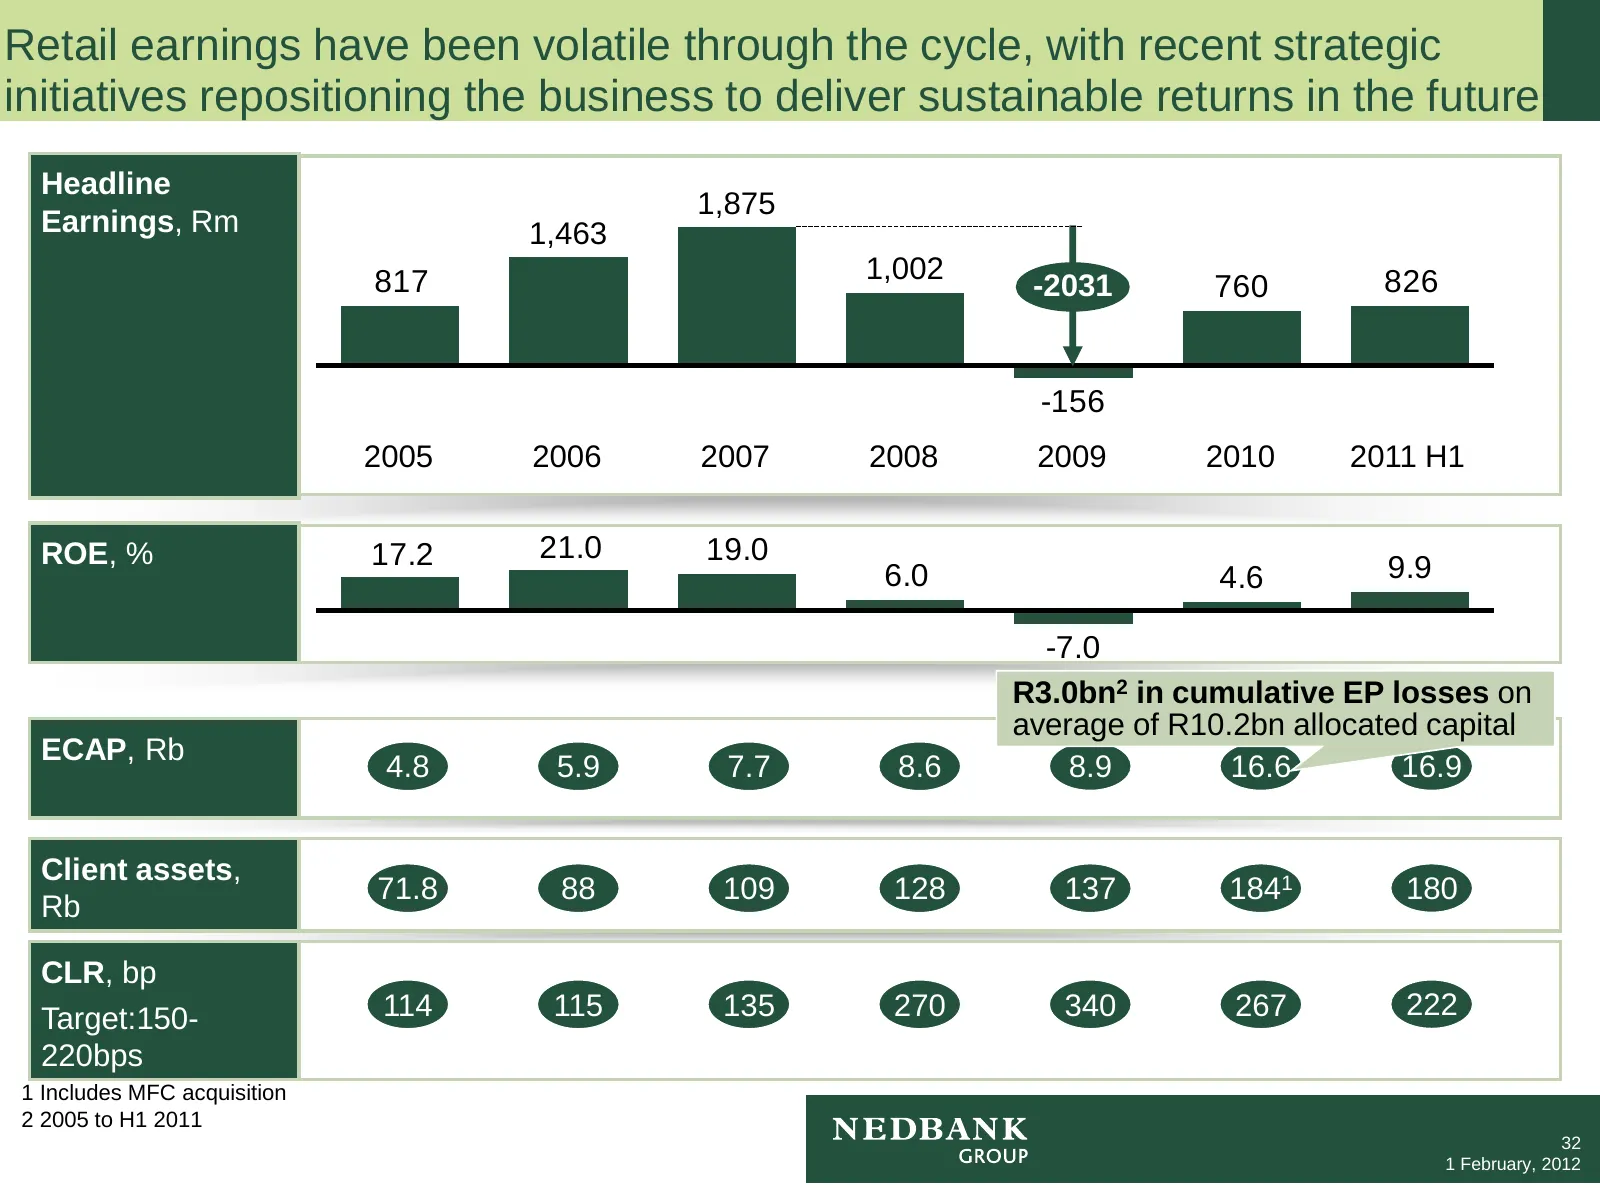
Slide 33: Retail earnings volatile through the cycle
Retail earnings have been volatile through the cycle, with recent strategic initiatives repositioning the business to deliver sustainable returns in the future Headline 1,875 Earnings, Rm 1,463 817 1,002 826 -2031 760 -156 2005 2006 2007 2008 2009 2010 2011 H1 ROE, % 17.2 21.0 19.0 6.0 4.6 9.9 -7.0
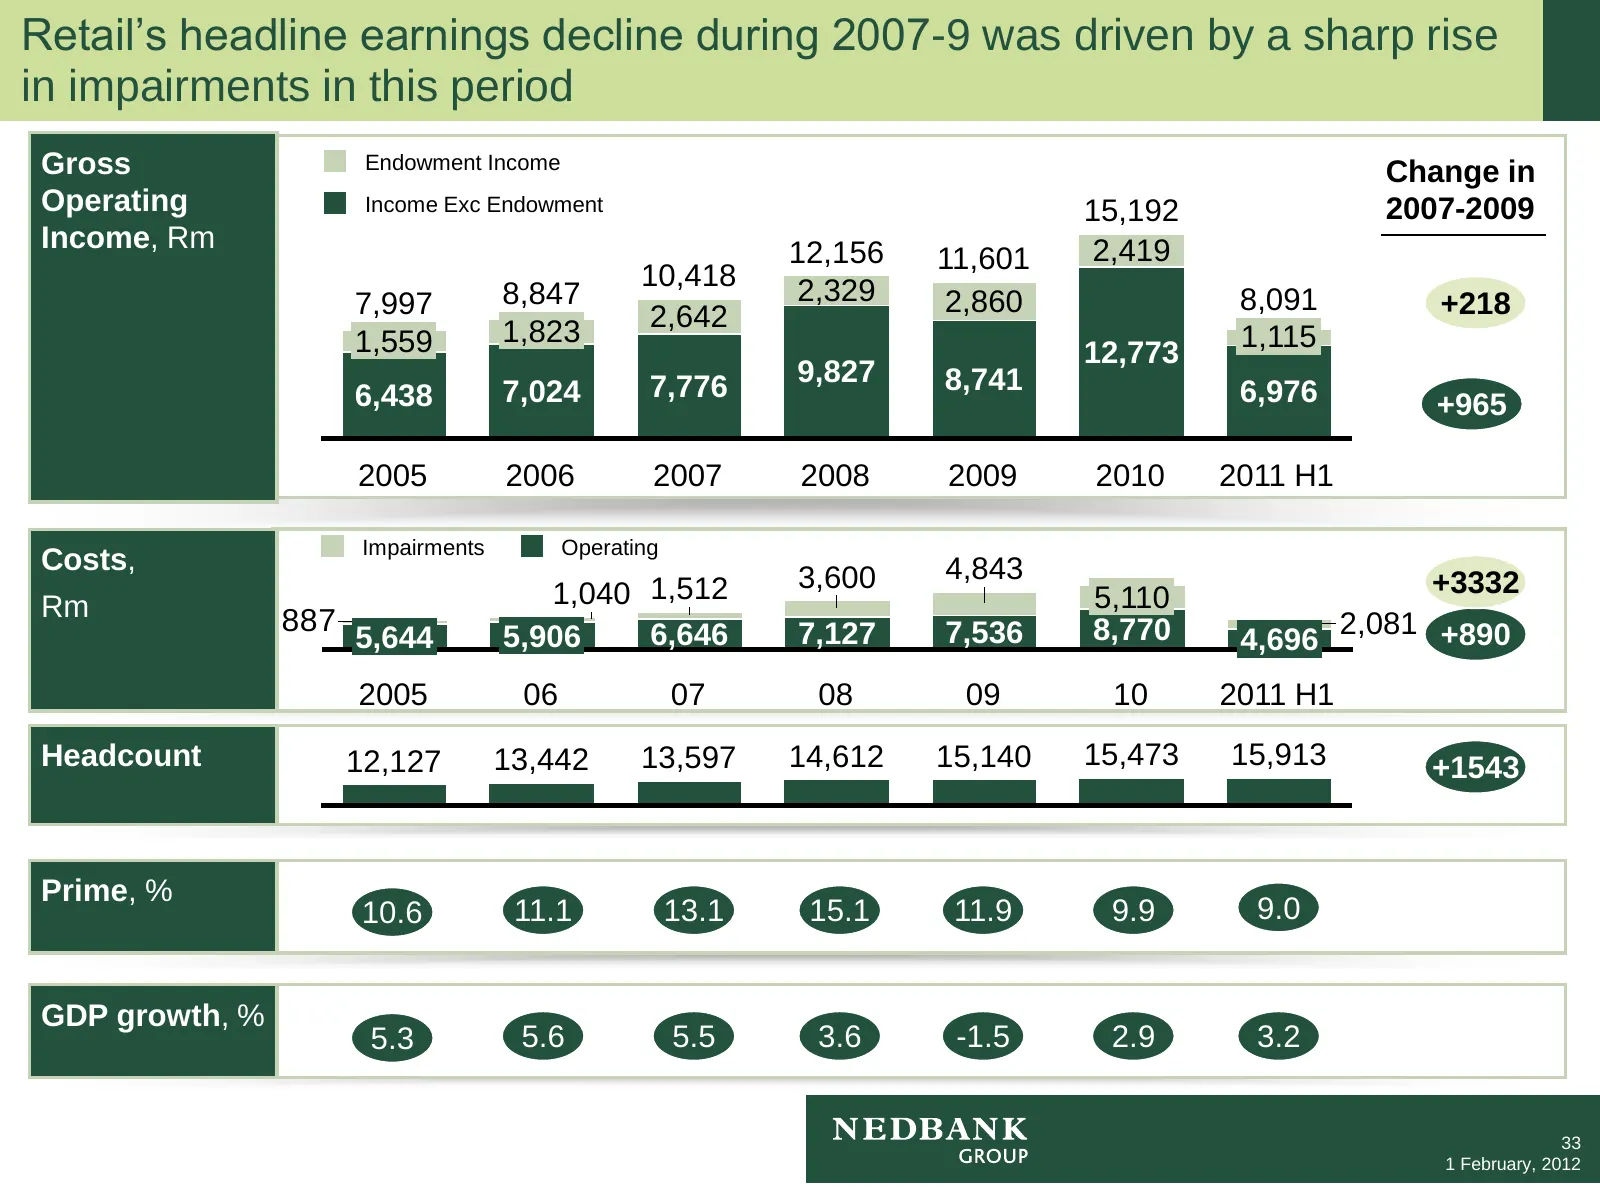
Slide 34: Retail earnings decline 2007-9 driven by rise in impairments
Retail’s headline earnings decline during 2007-9 was driven by a sharp rise in impairments in this period Gross Endowment Income Change in Operating Income Exc Endowment 15,192 2007-2009 Income, Rm 12,156 2,419 11,601 10,418 2,329 7,997 8,847 2,860 8,091 +218 1,823 2,642 1,559 1,115 12,773 7,776 9,8
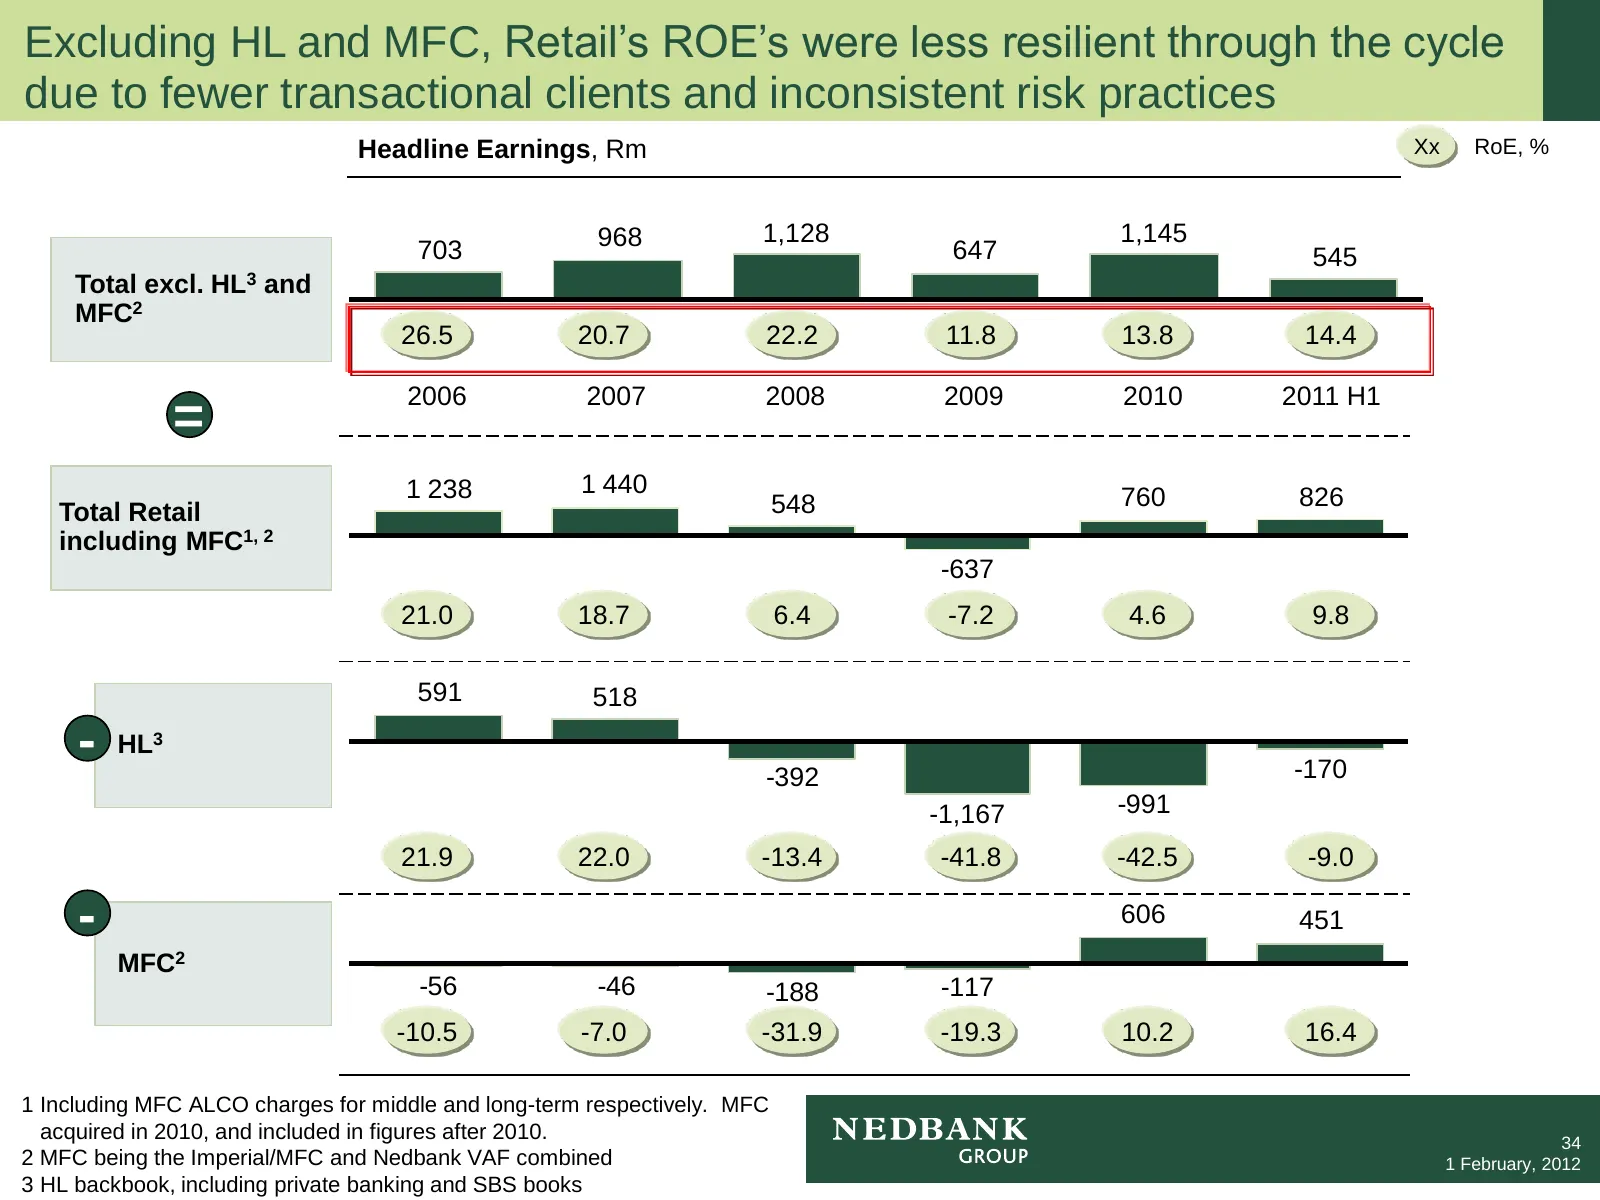
Slide 35: Excluding HL and MFC, Retail ROEs less resilient through the cycle
Excluding HL and MFC, Retail’s ROE’s were less resilient through the cycle due to fewer transactional clients and inconsistent risk practices Headline Earnings, Rm Xx RoE, % 968 1,128 1,145 703 647 545 Total excl. HL3 and MFC2 26.5 20.7 22.2 11.8 13.8 14.4 2006 2007 2008 2009 2010 2011 H1 = 1 238 1
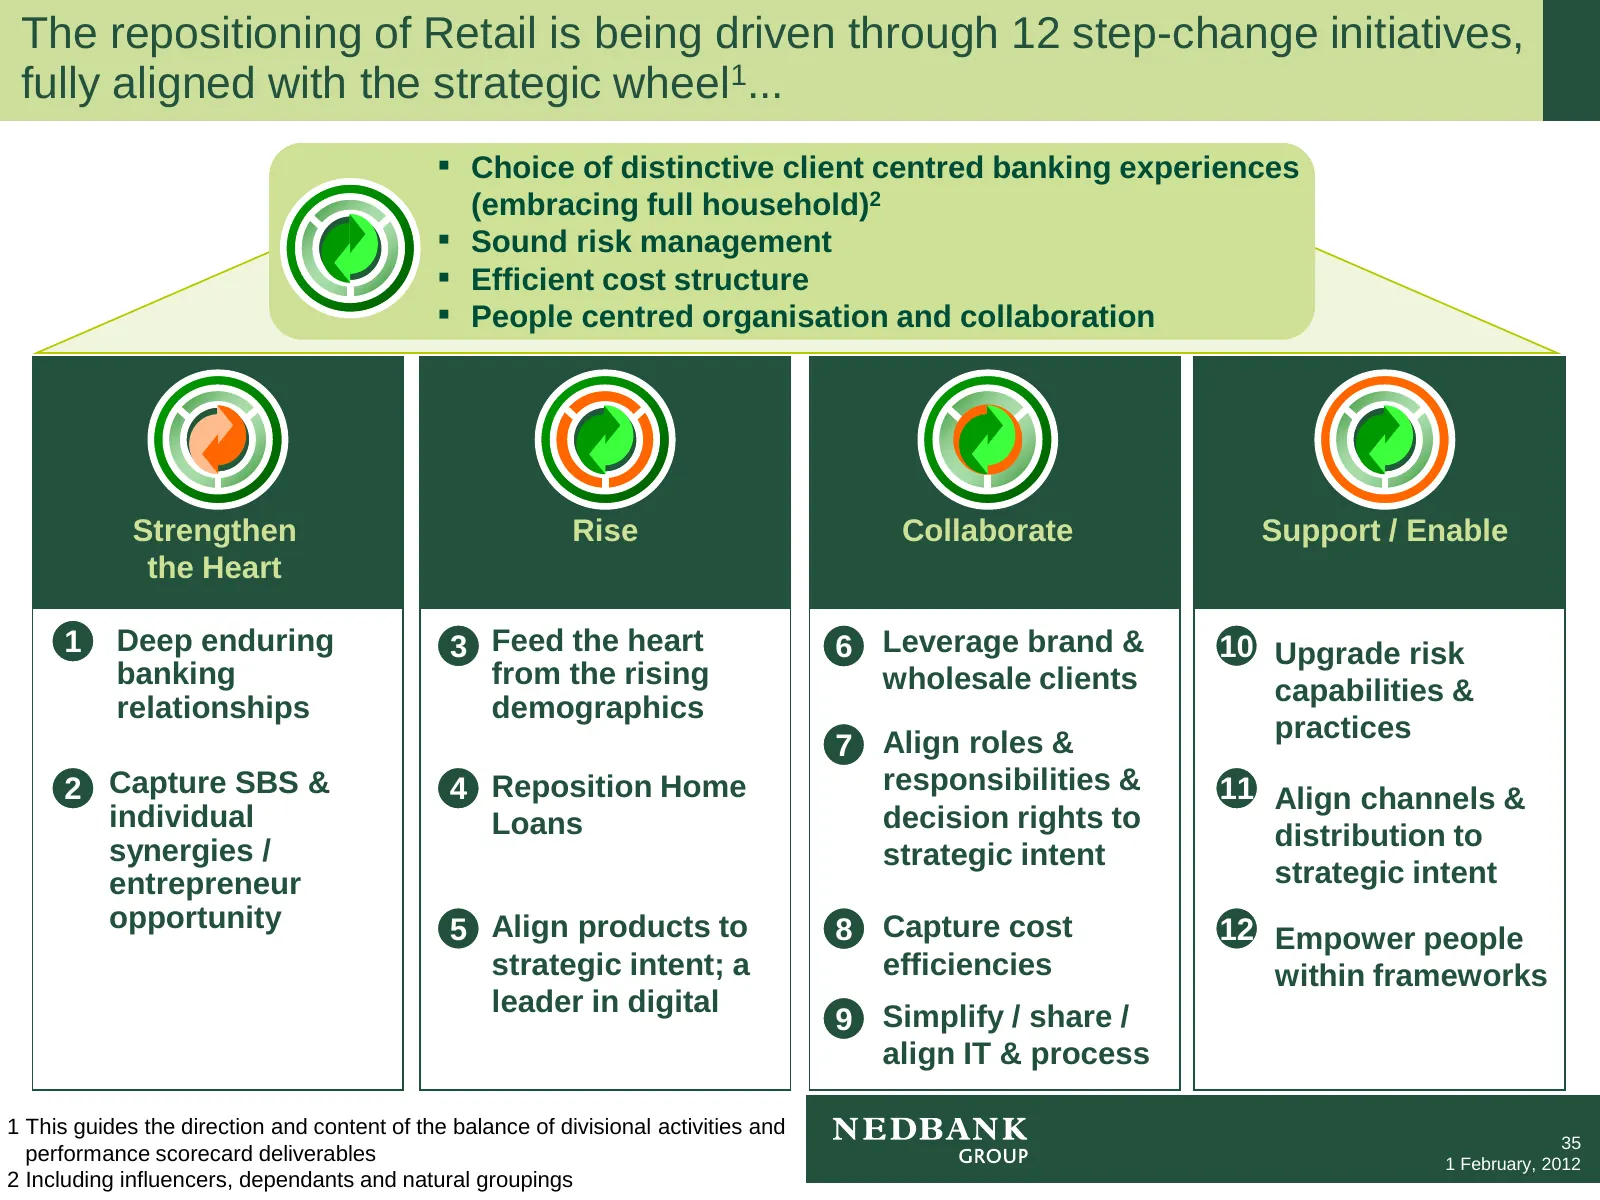
Slide 36: Repositioning of Retail driven through 12 step-change initiatives
The repositioning of Retail is being driven through 12 step-change initiatives, fully aligned with the strategic wheel1... ▪ Choice of distinctive client centred banking experiences (embracing full household)2 ▪ Sound risk management ▪ Efficient cost structure ▪ People centred organisation and colla
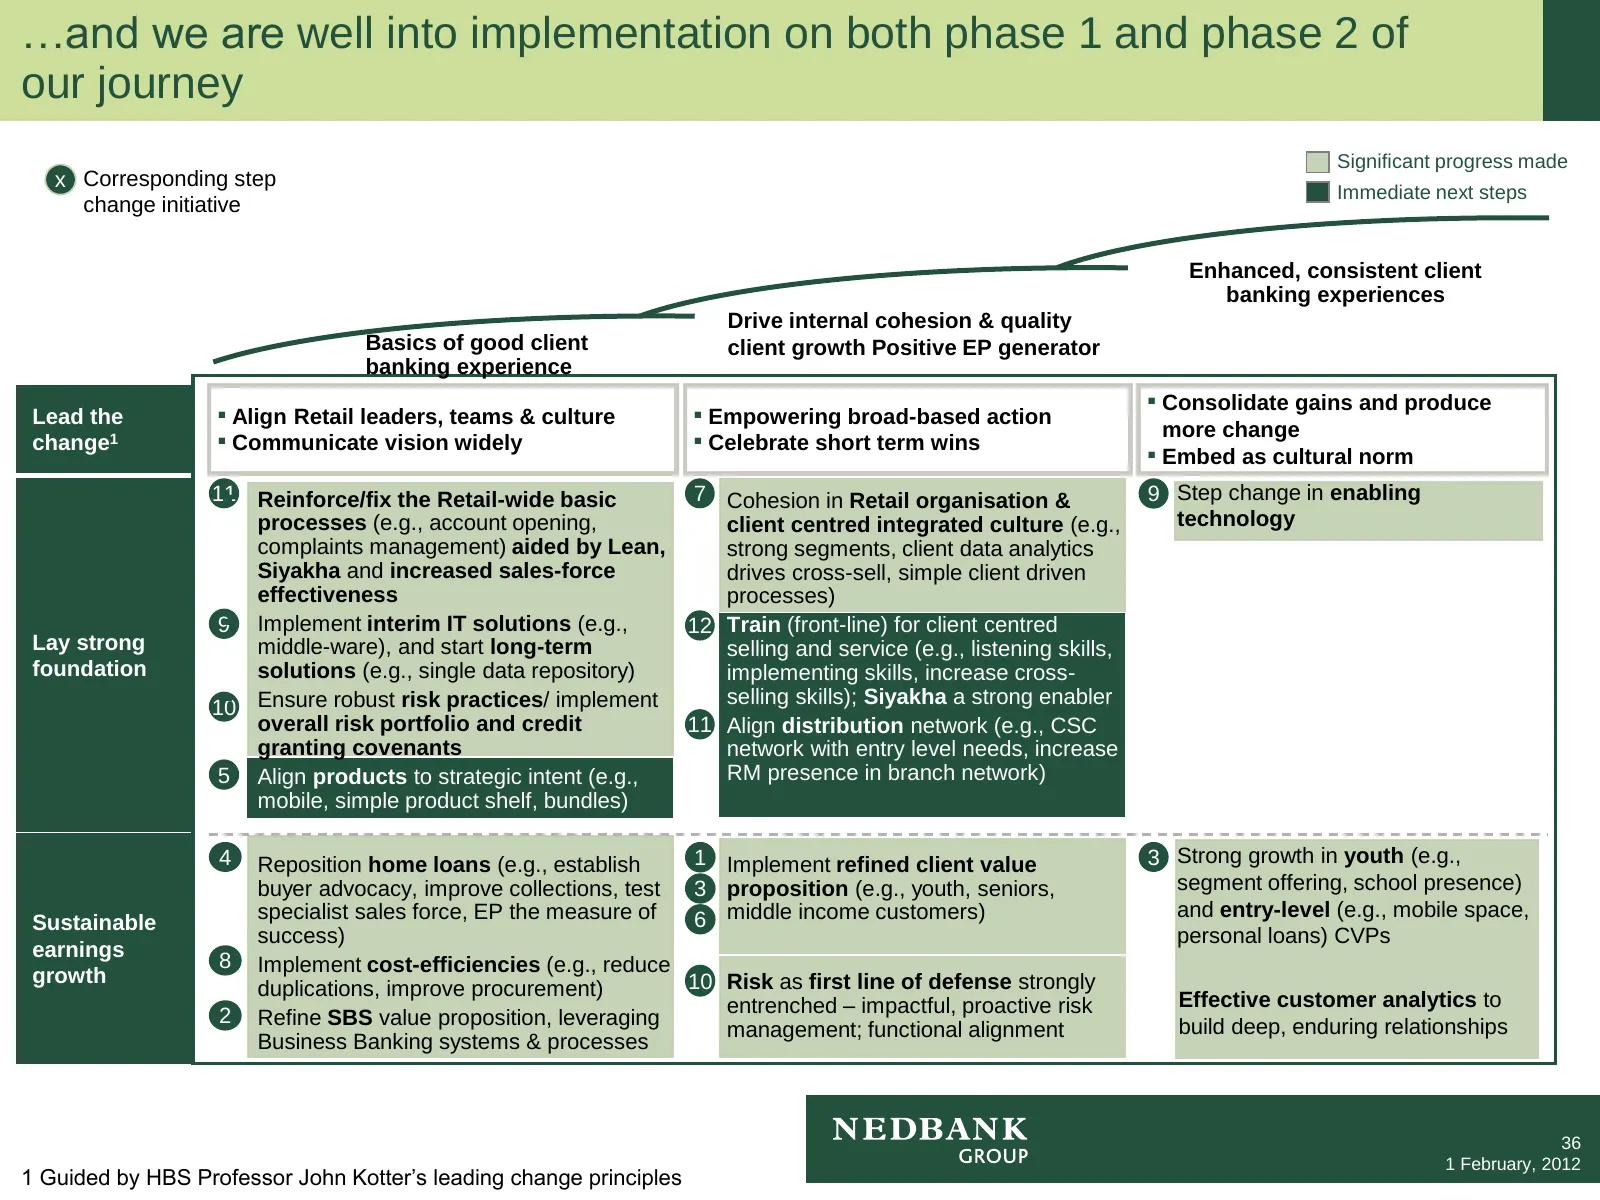
Slide 37: Well into implementation of phase 1 and phase 2
…and we are well into implementation on both phase 1 and phase 2 of our journey Significant progress made x Corresponding step Immediate next steps change initiative Enhanced, consistent client banking experiences Drive internal cohesion & quality Basics of good client client growth Positive EP gene
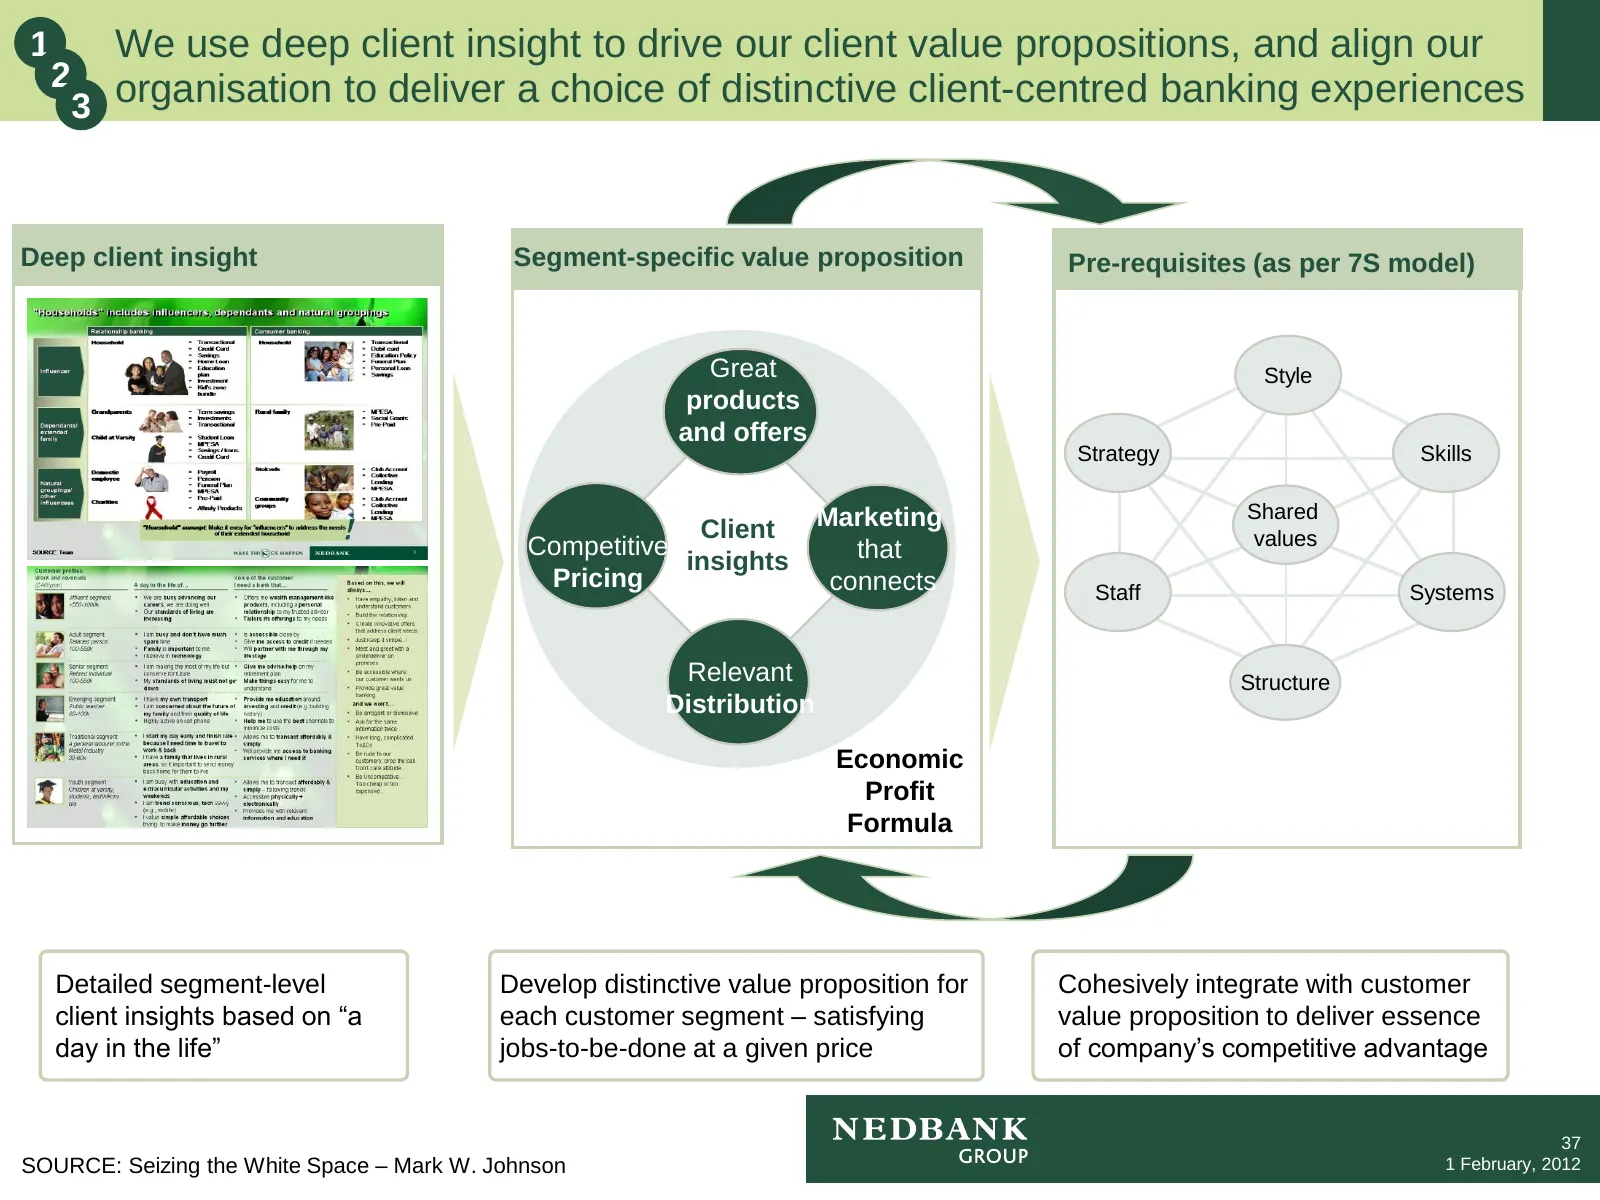
Slide 38: Deep client insight drives client value propositions
1 We use deep client insight to drive our client value propositions, and align our 2 3 organisation to deliver a choice of distinctive client-centred banking experiences Deep client insight Segment-specific value proposition Pre-requisites (as per 7S model) Great Style products and offers Strategy S
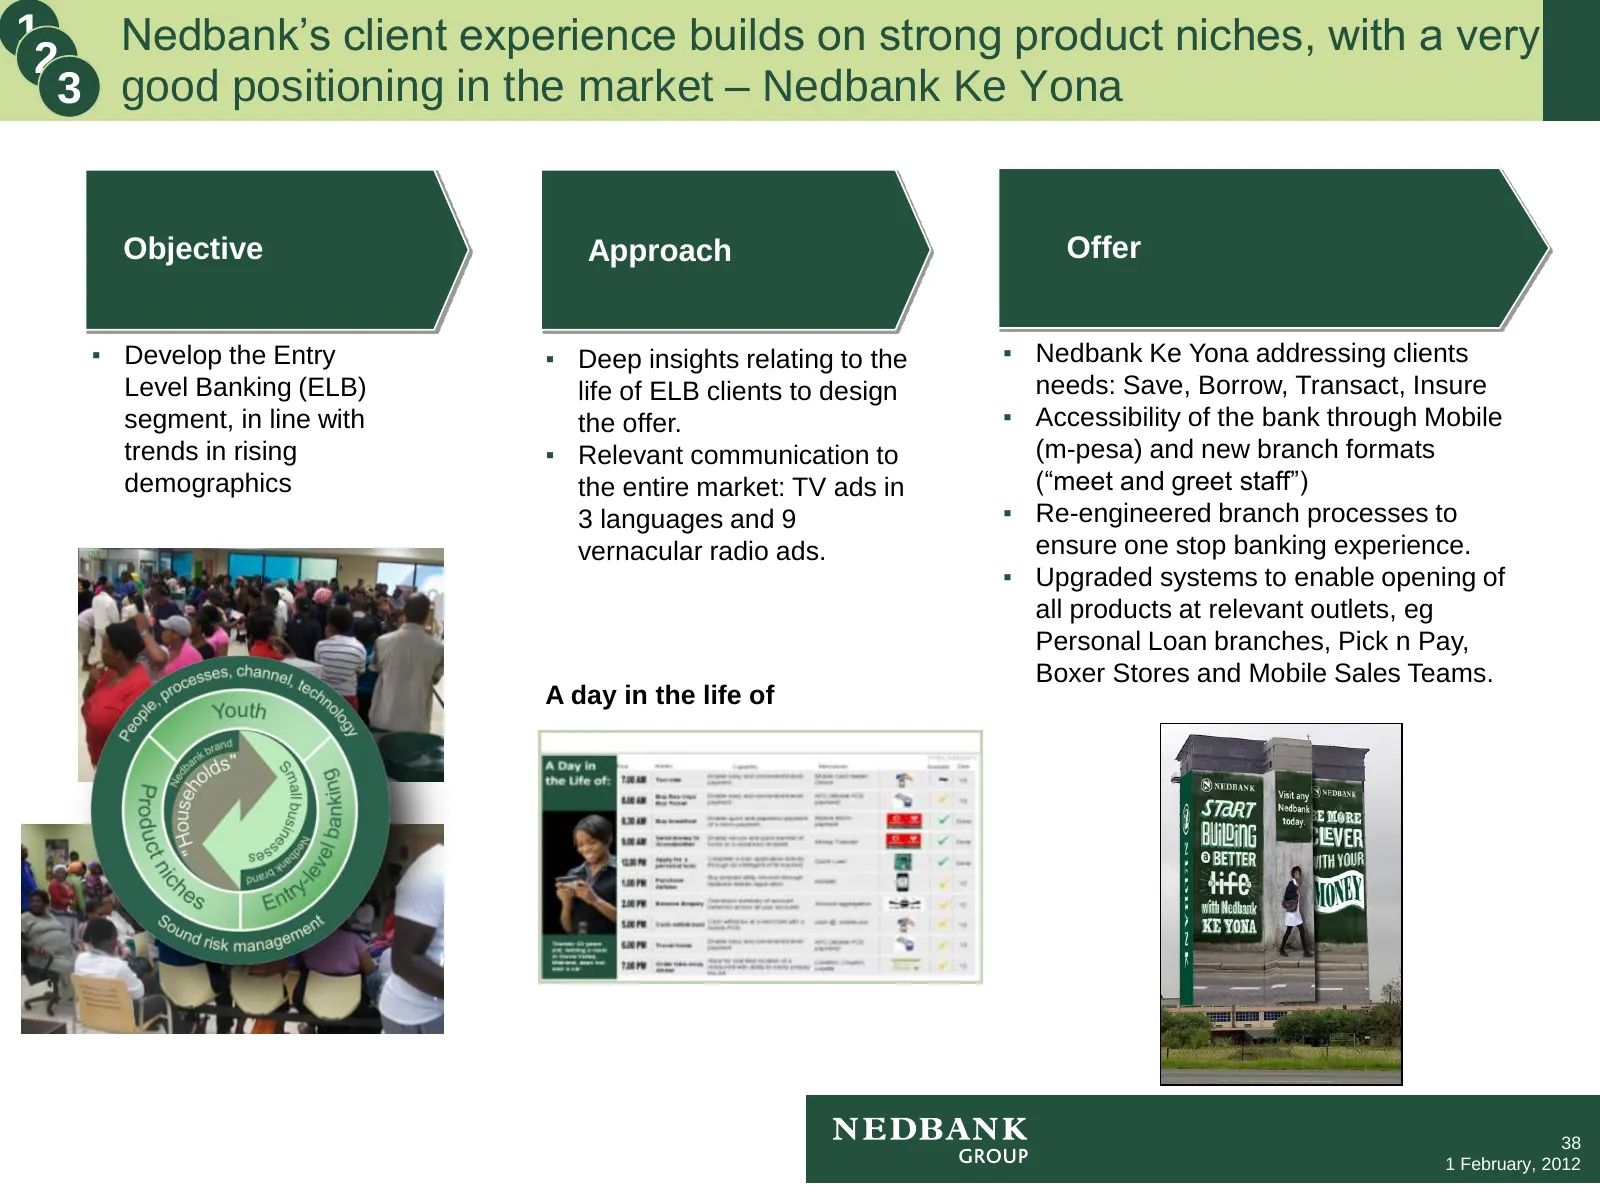
Slide 39: Nedbank Ke Yona entry-level banking offer
1 Nedbank’s client experience builds on strong product niches, with a very 2 3 good positioning in the market – Nedbank Ke Yona Objective Approach Approach Offer Results ▪ Develop the Entry ▪ Deep insights relating to the ▪ Nedbank Ke Yona addressing clients Level Banking (ELB) life of ELB clients t
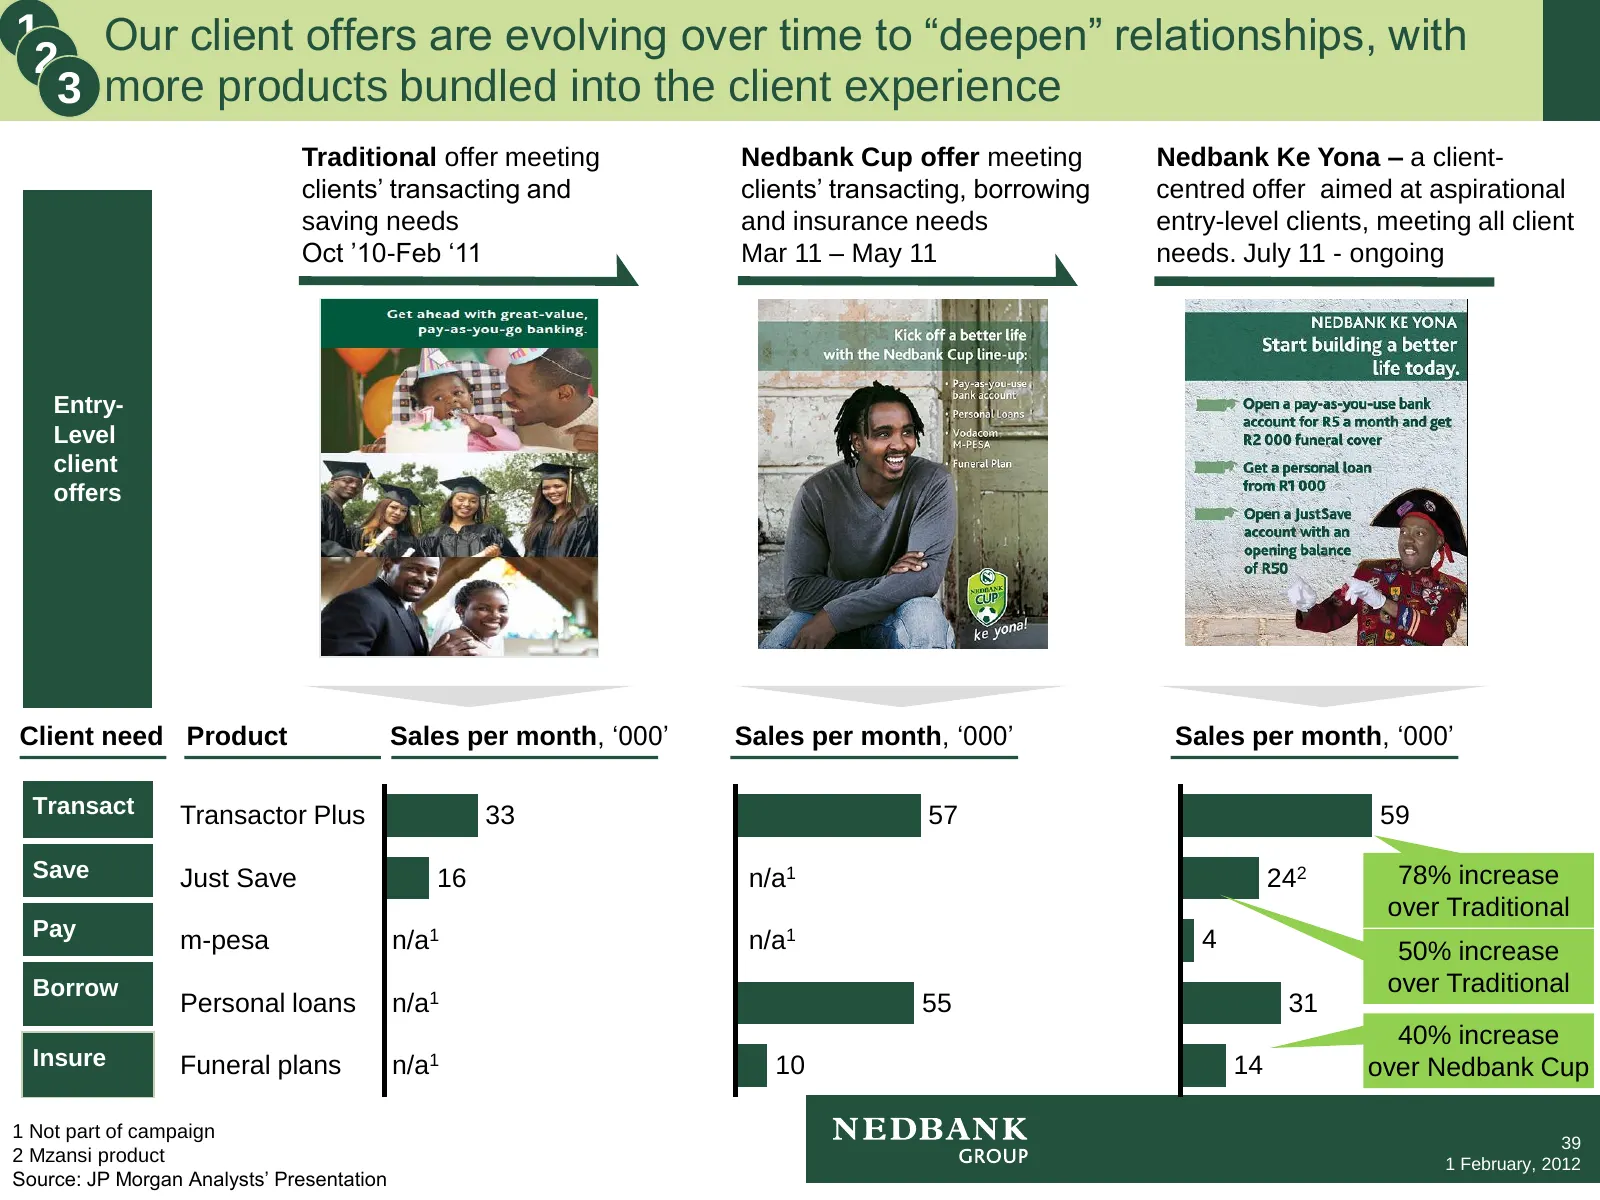
Slide 40: Client offers evolving to deepen relationships
1 Our client offers are evolving over time to “deepen” relationships, with 2 3 more products bundled into the client experience Traditional offer meeting Nedbank Cup offer meeting Nedbank Ke Yona – a client- clients’ transacting and clients’ transacting, borrowing centred offer aimed at aspirational
Slide 41: Savvy gaining momentum in the middle segment
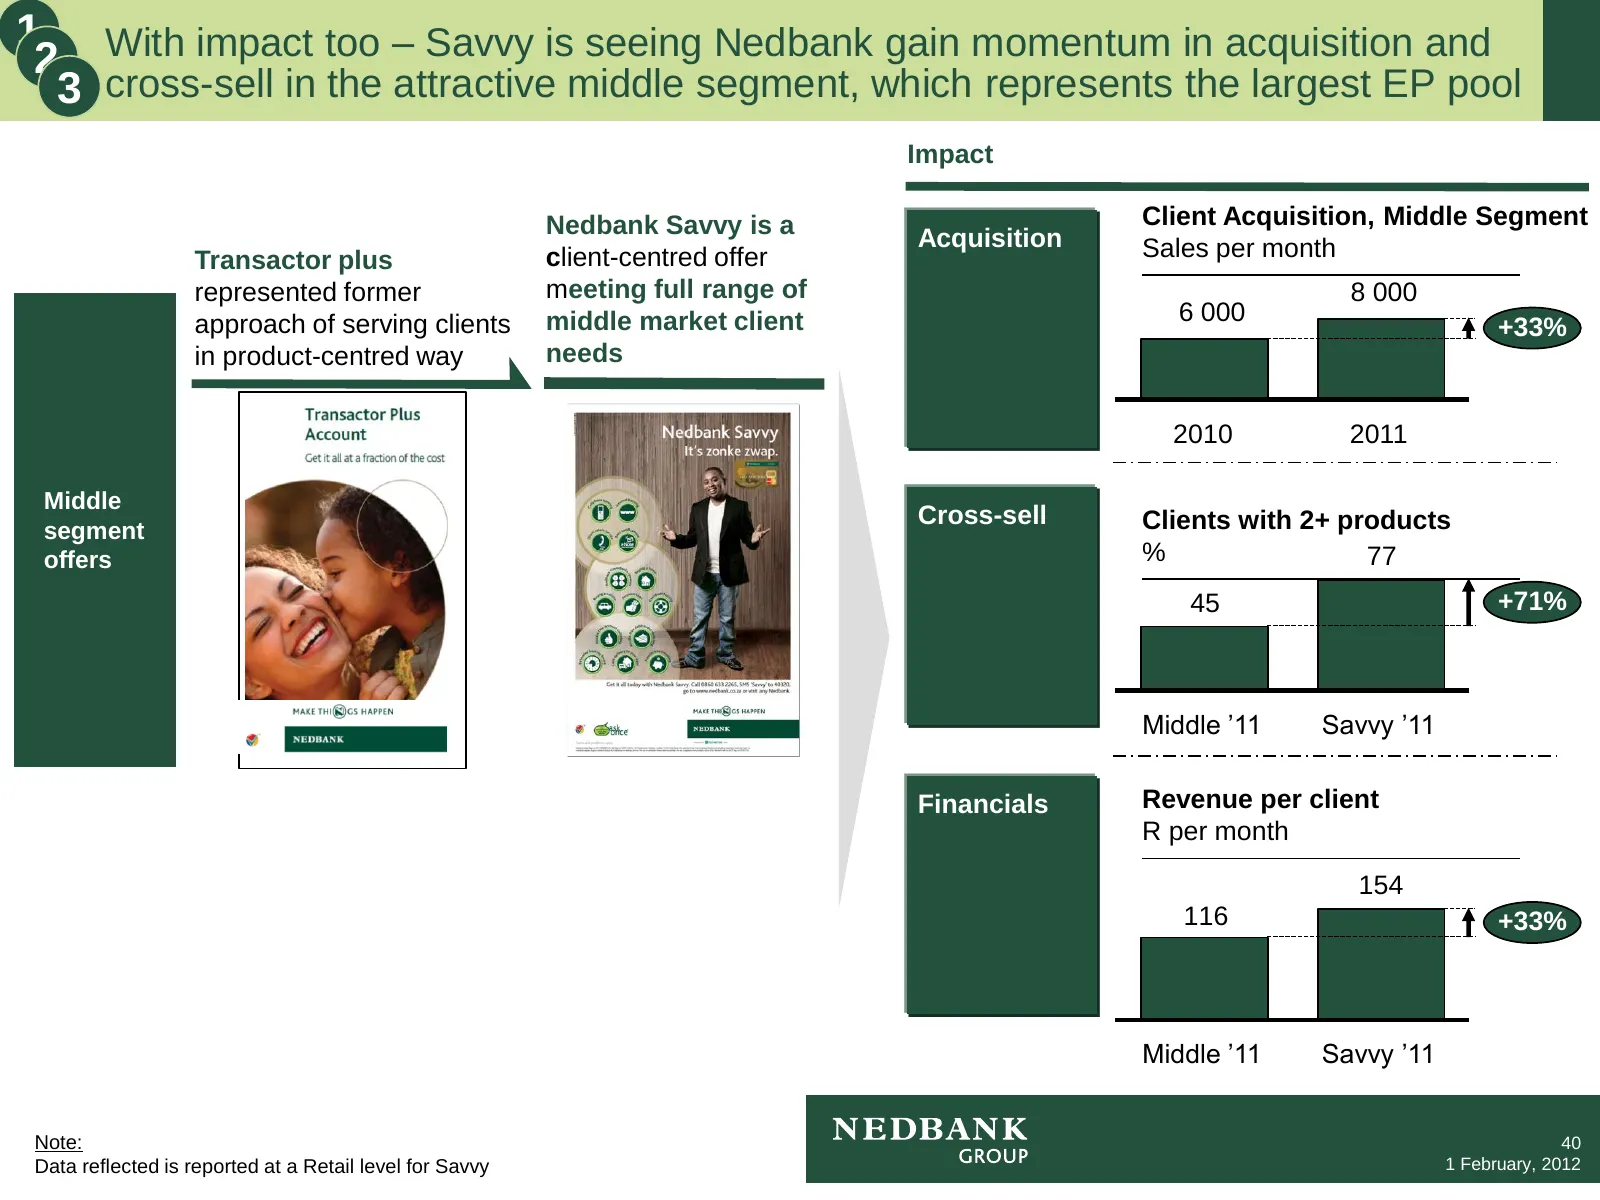
1 With impact too – Savvy is seeing Nedbank gain momentum in acquisition and 2 3 cross-sell in the attractive middle segment, which represents the largest EP pool Impact Nedbank Savvy is a Client Acquisition, Middle Segment Acquisition Sales per month Transactor plus client-centred offer represented
Slide 42: Improved mass market brand positioning
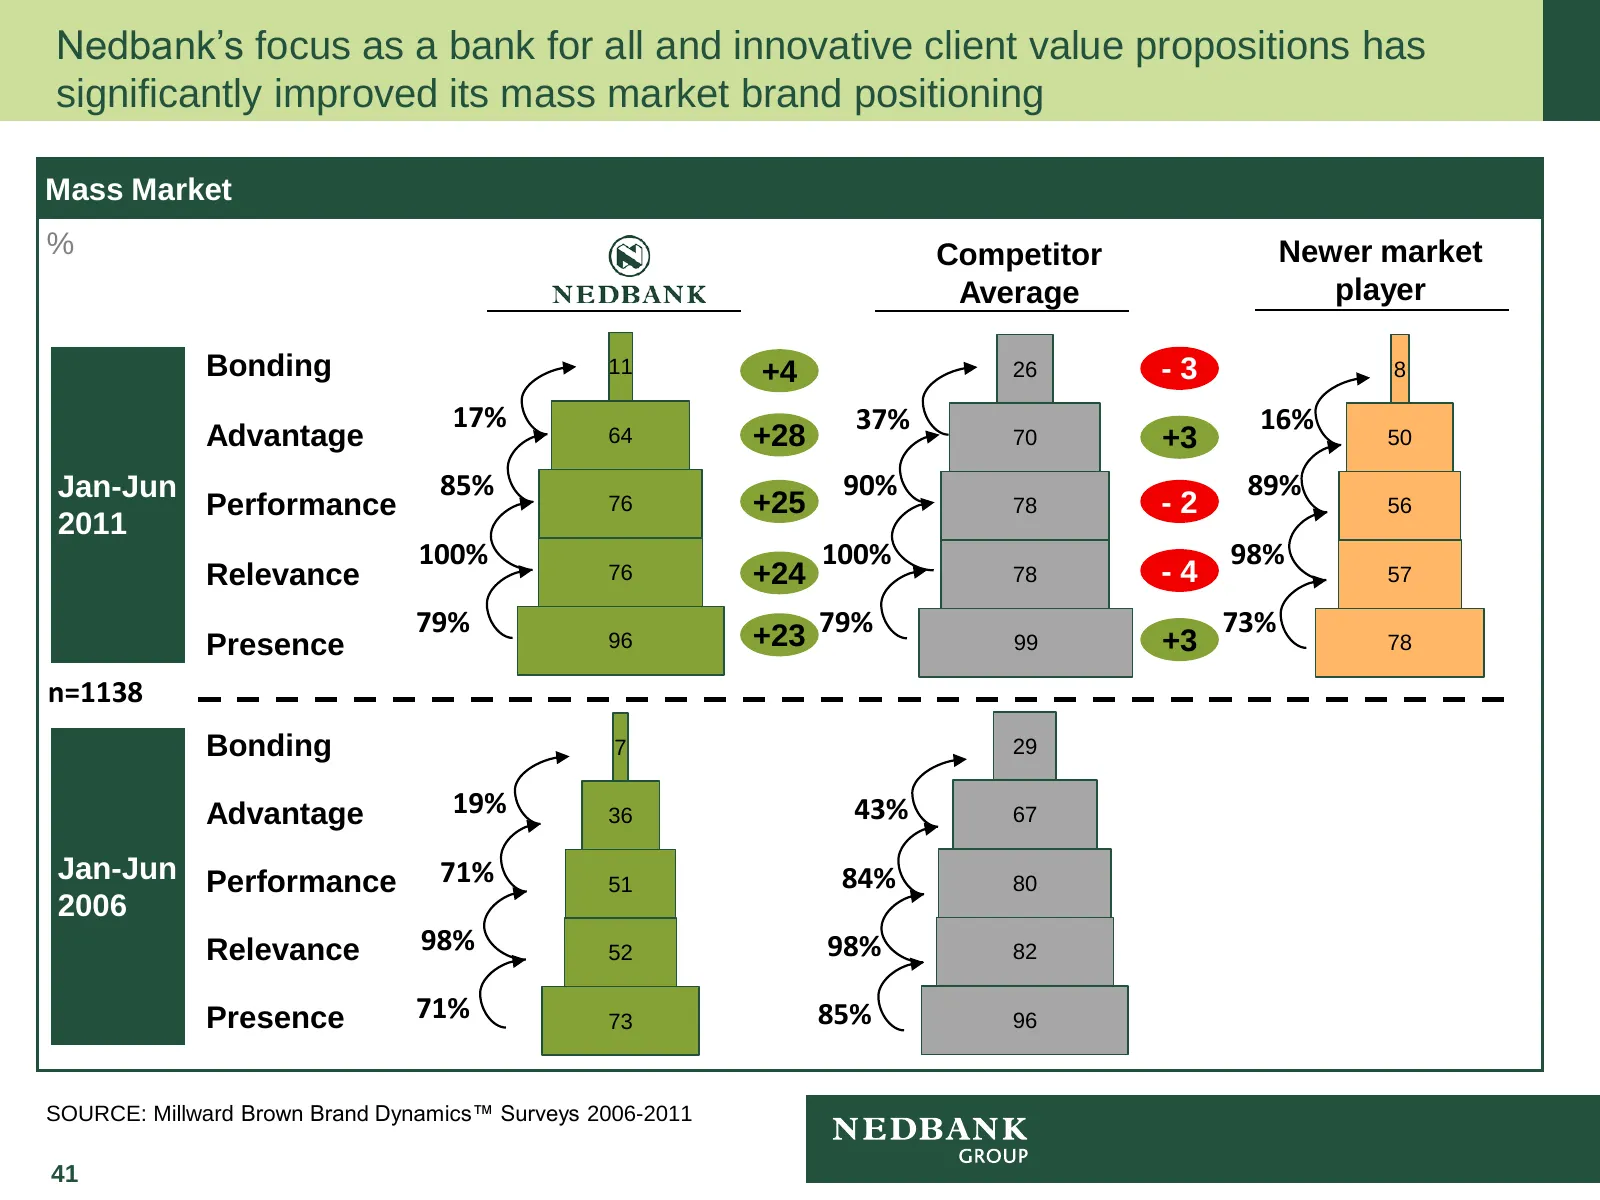
Nedbank’s focus as a bank for all and innovative client value propositions has significantly improved its mass market brand positioning Mass Market % Competitor Newer market Average player Bonding 11 +4 26 -3 8 17% 37% 16% Advantage 64 +28 70 +3 50 Jan-Jun 85% 90% 89% Performance 76 +25 78 -2 56 201
Slide 43: Repositioning Home Loans in an EP positive way
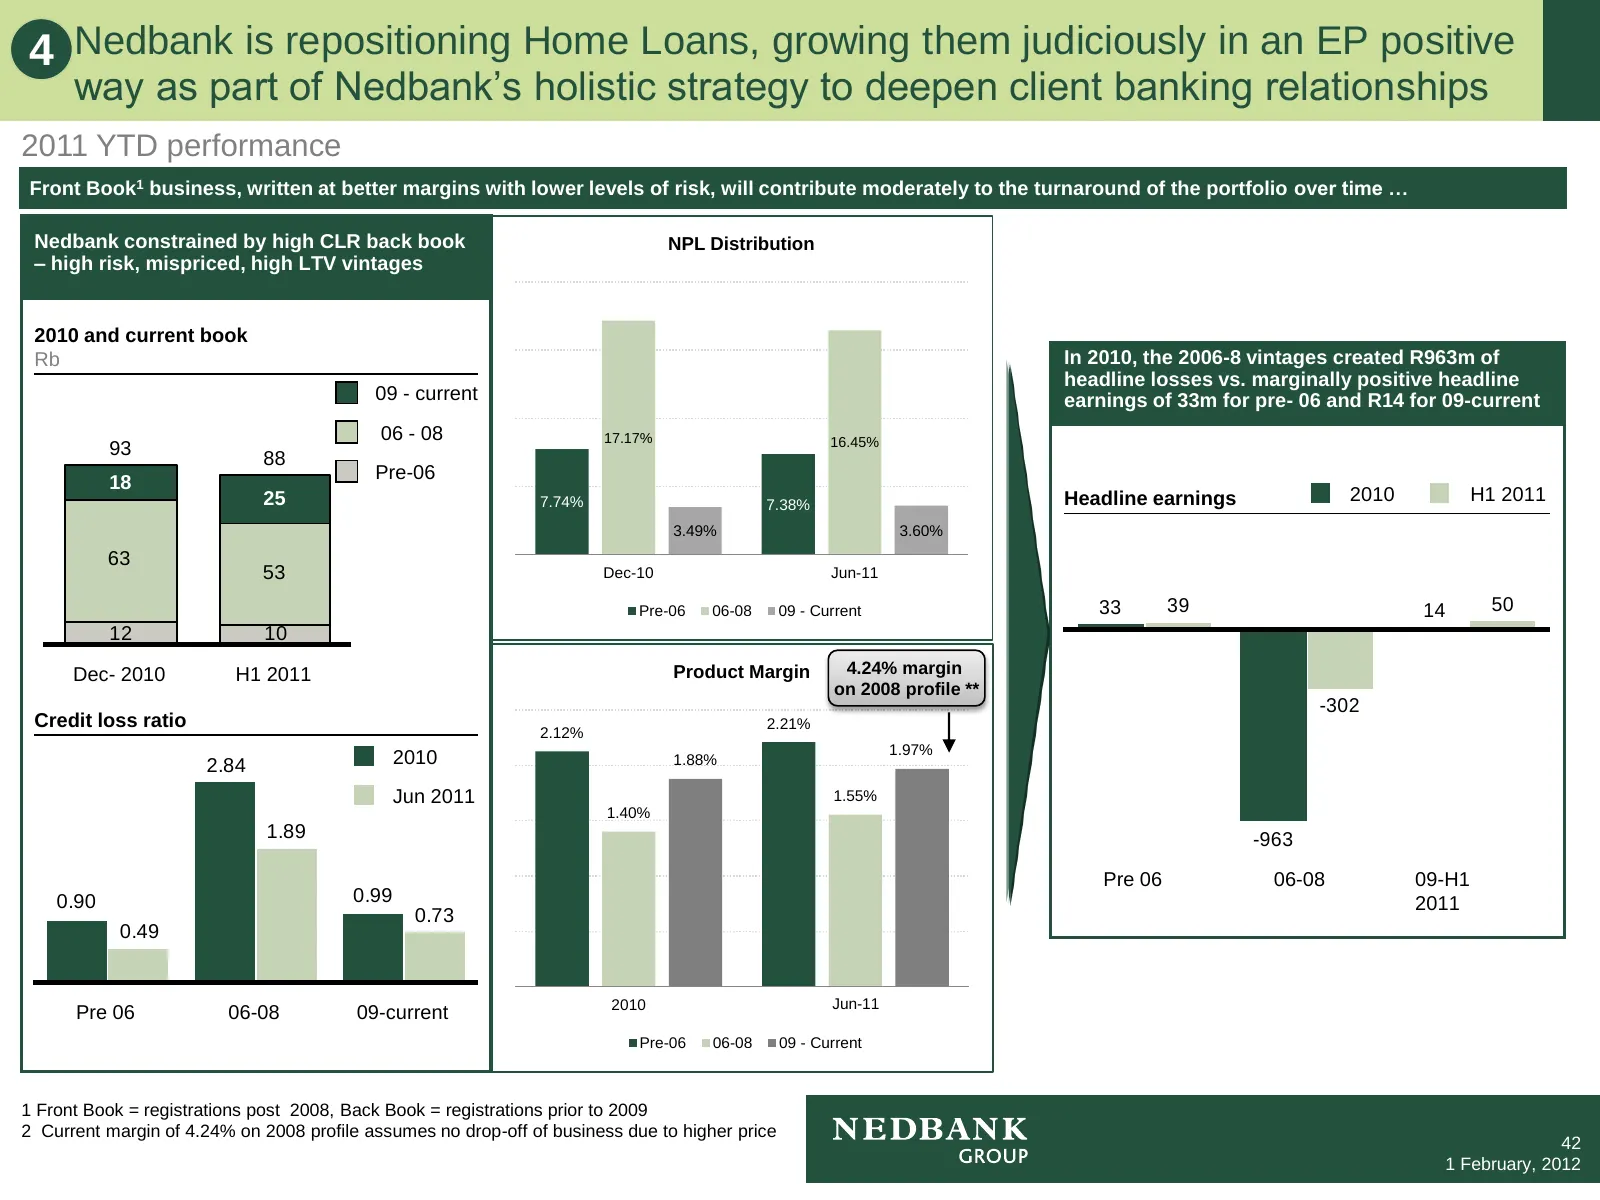
4 Nedbank is repositioning Home Loans, growing them judiciously in an EP positive way as part of Nedbank’s holistic strategy to deepen client banking relationships 2011 YTD performance Front Book1 business, written at better margins with lower levels of risk, will contribute moderately to the turnar
Slide 44: Leveraging product lines for transactional cross-sell
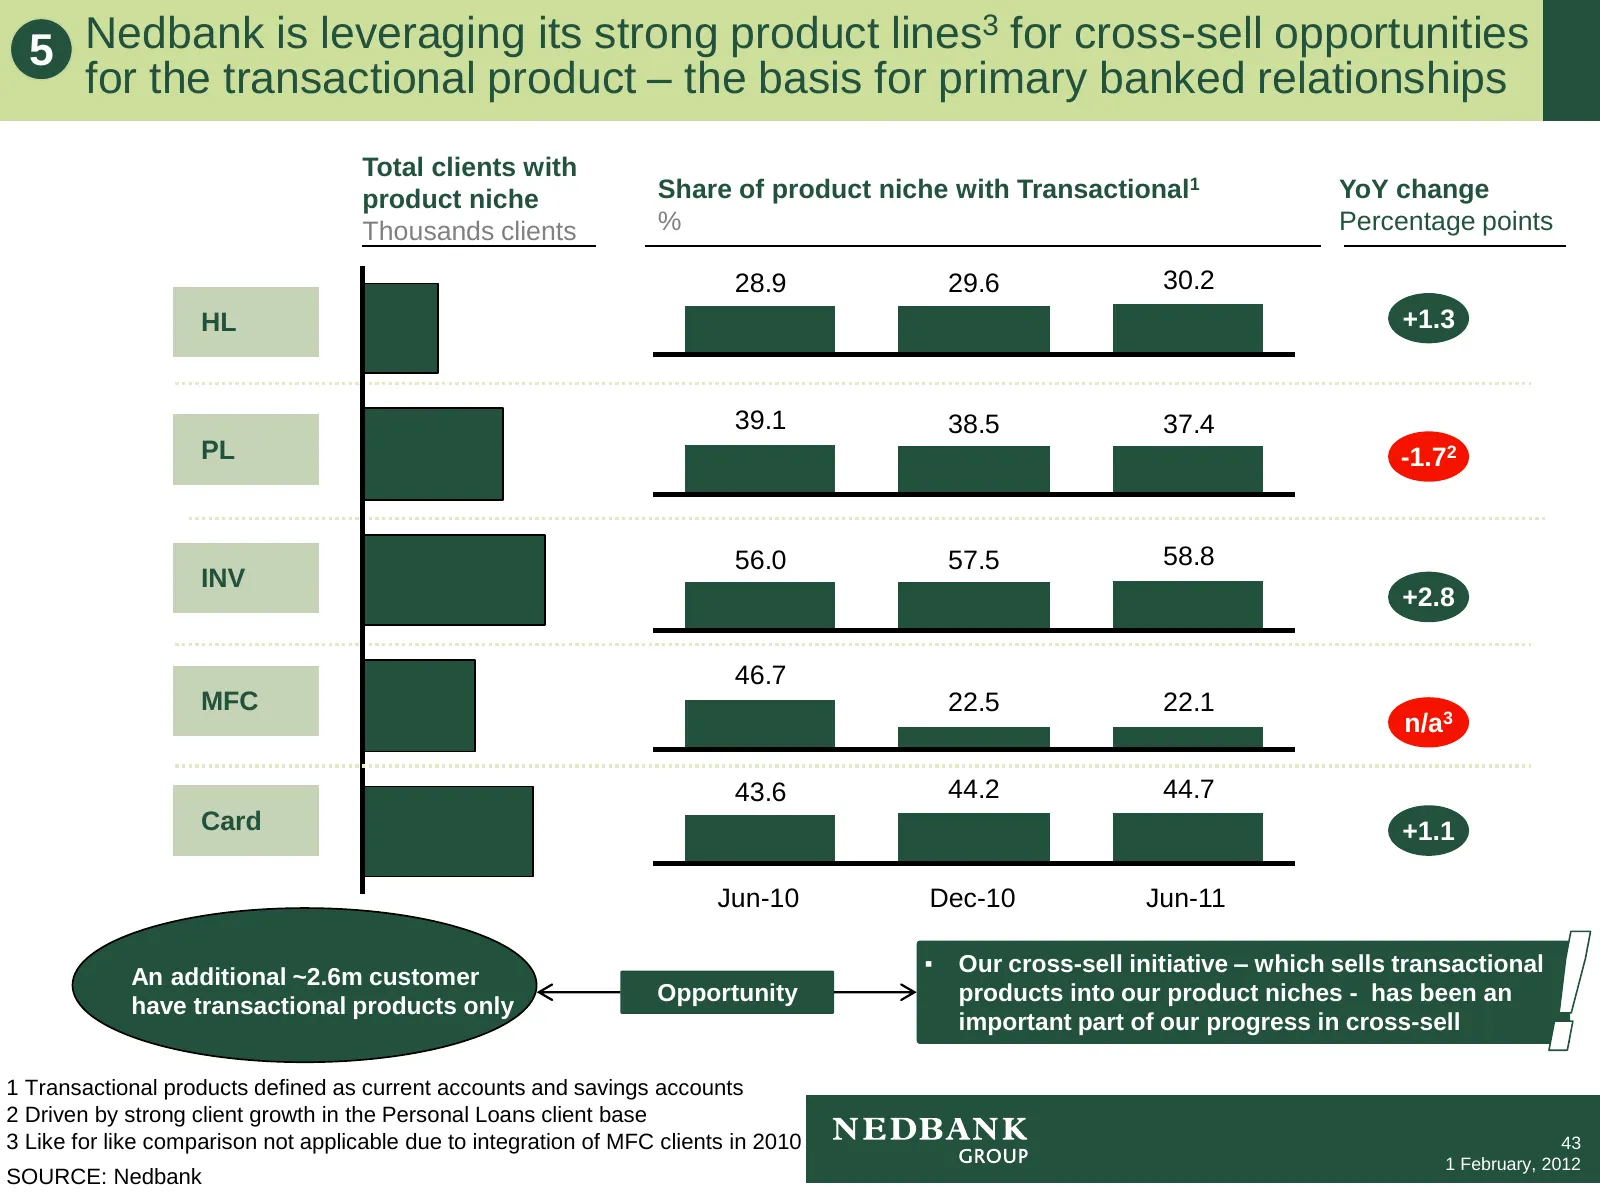
Nedbank is leveraging its strong product lines3 for cross-sell opportunities 5 for the transactional product – the basis for primary banked relationships Total clients with product niche Share of product niche with Transactional1 YoY change Thousands clients % Percentage points 28.9 29.6 30.2 HL +1.
Slide 45: Advancing on mobile: focus on largest opportunities with M-PESA
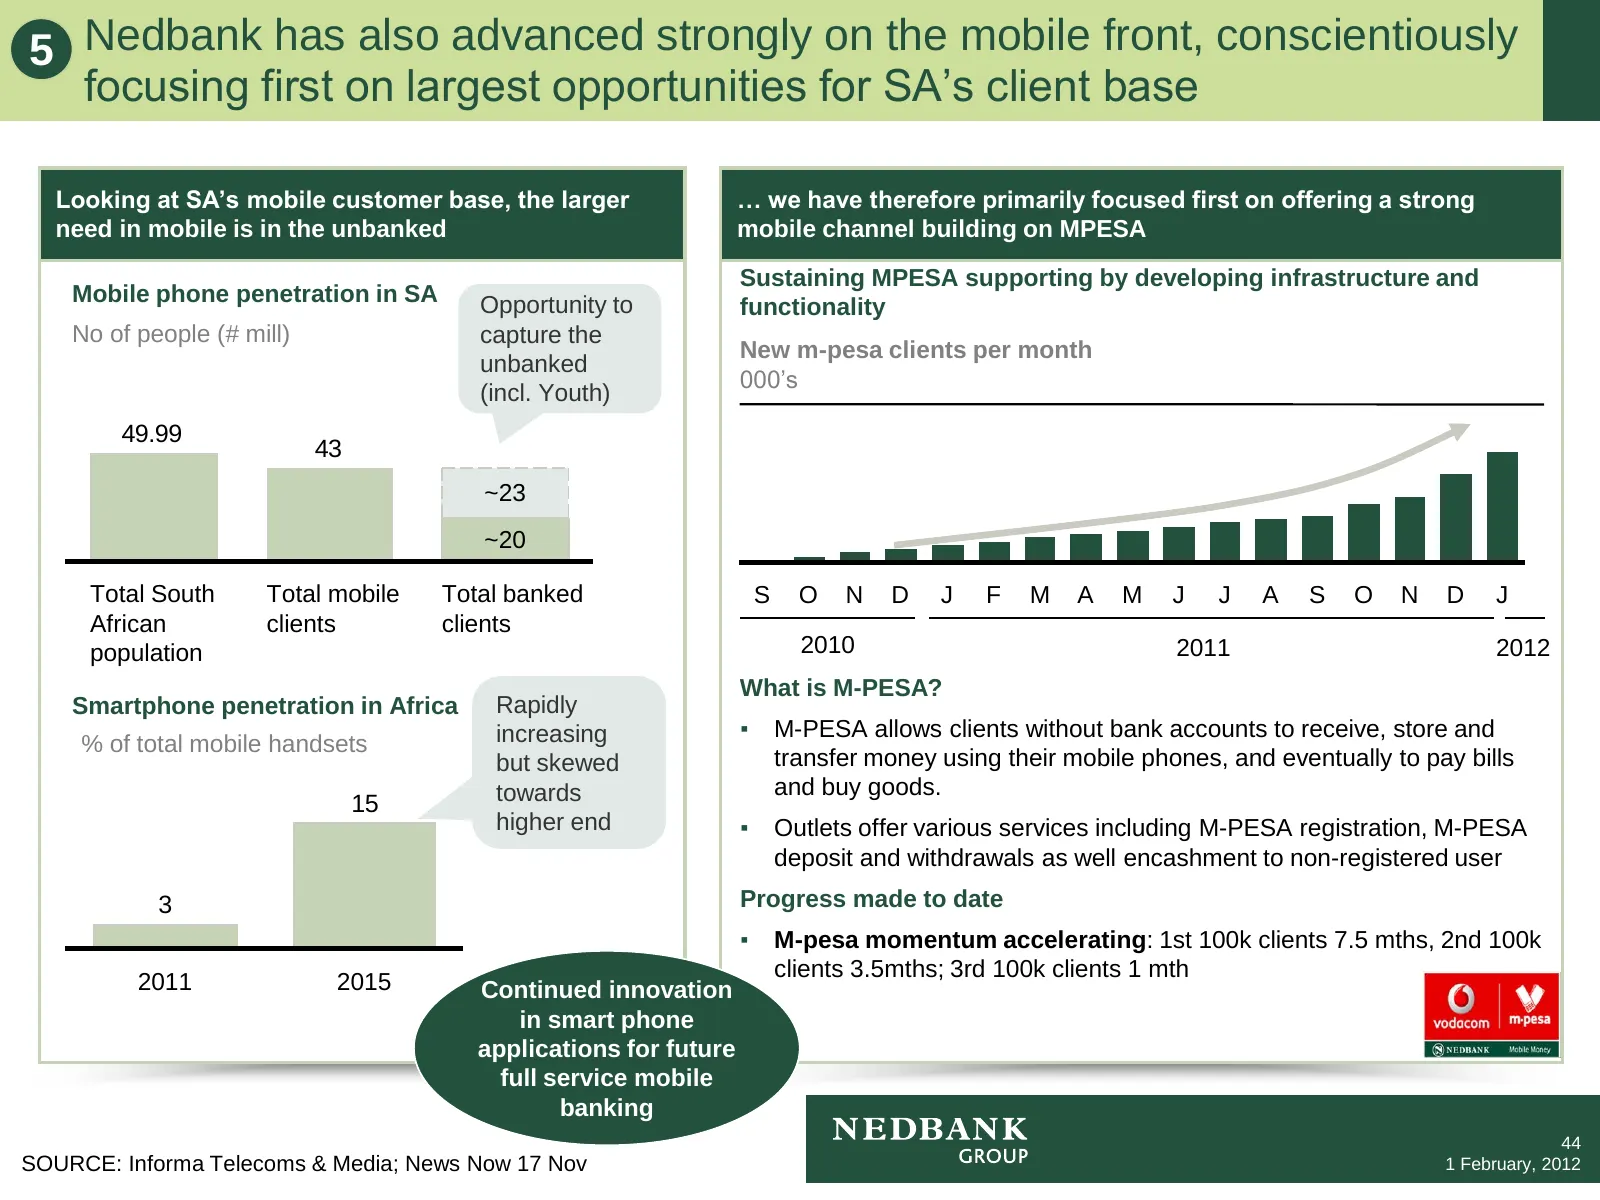
5 Nedbank has also advanced strongly on the mobile front, conscientiously focusing first on largest opportunities for SA’s client base Looking at SA’s mobile customer base, the larger … we have therefore primarily focused first on offering a strong need in mobile is in the unbanked mobile channel bu
Slide 46: MFC integration leveraging entrepreneurial distinctiveness
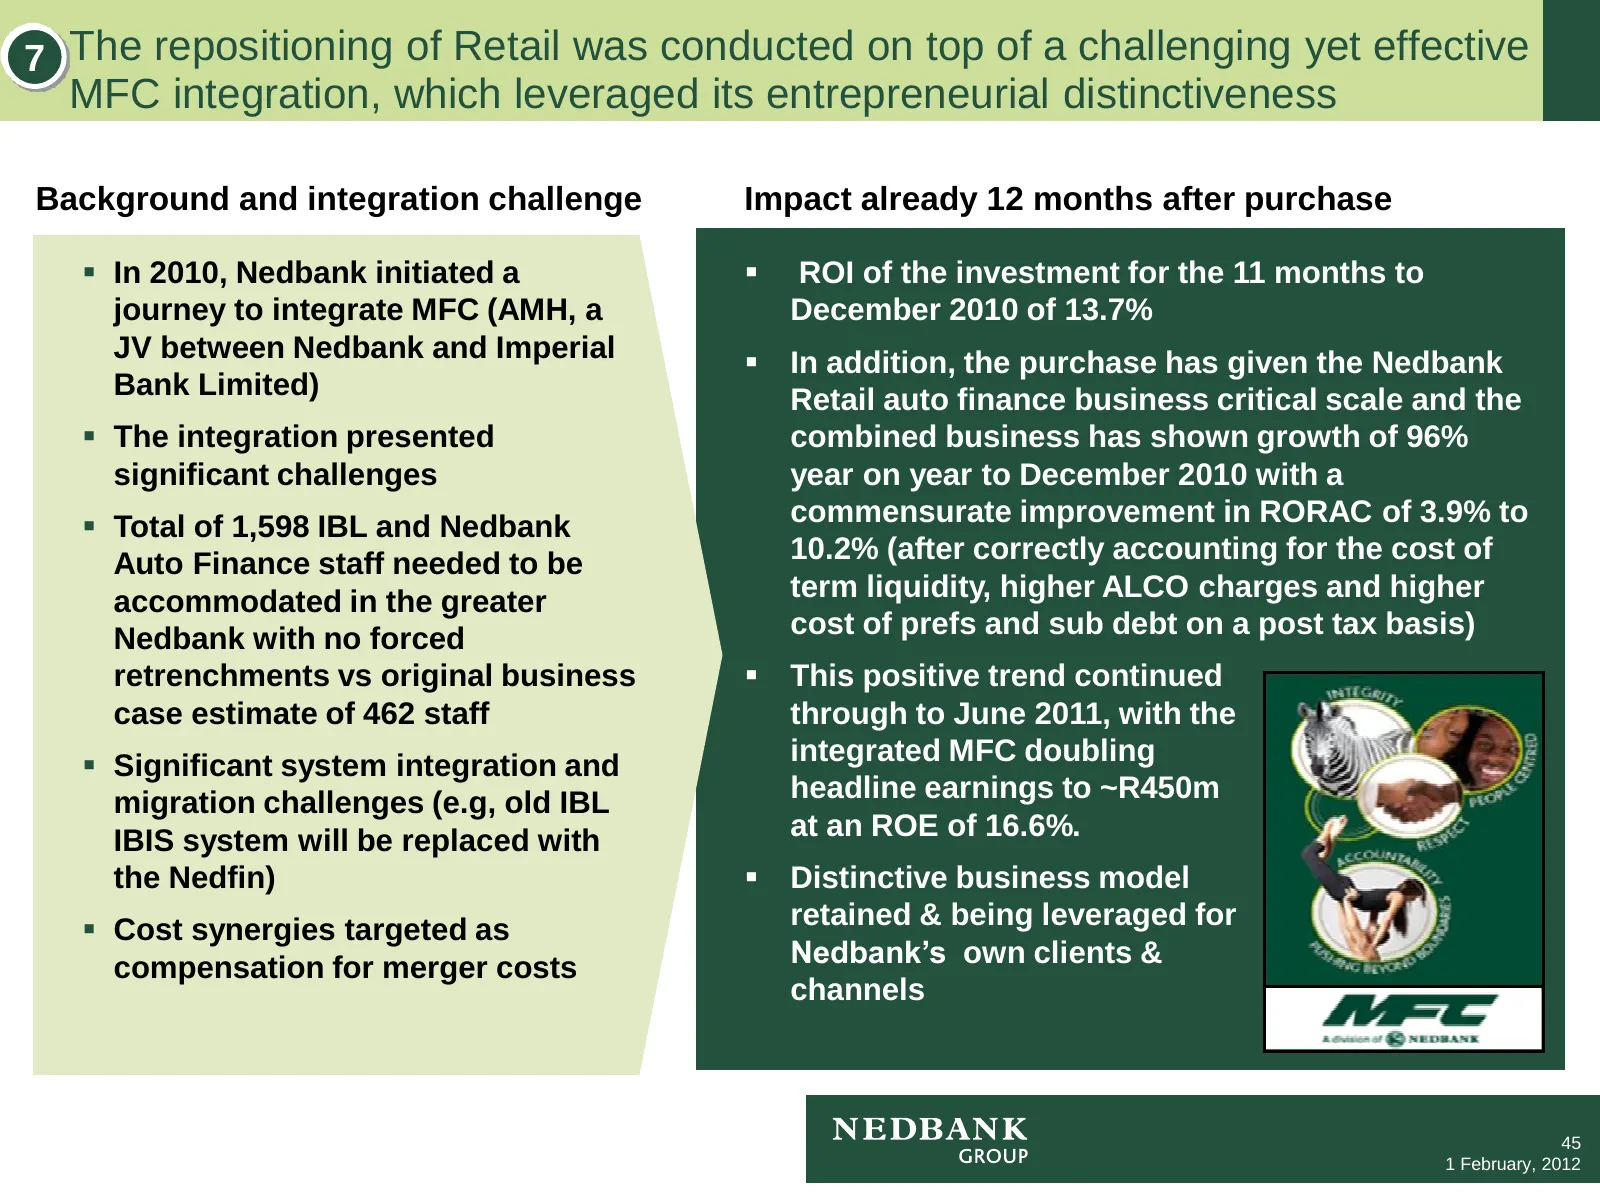
7 The repositioning of Retail was conducted on top of a challenging yet effective MFC integration, which leveraged its entrepreneurial distinctiveness Background and integration challenge Impact already 12 months after purchase In 2010, Nedbank initiated a ROI of the investment for the 11 months
Slide 47: New RRB structure unifying two sub-scale businesses
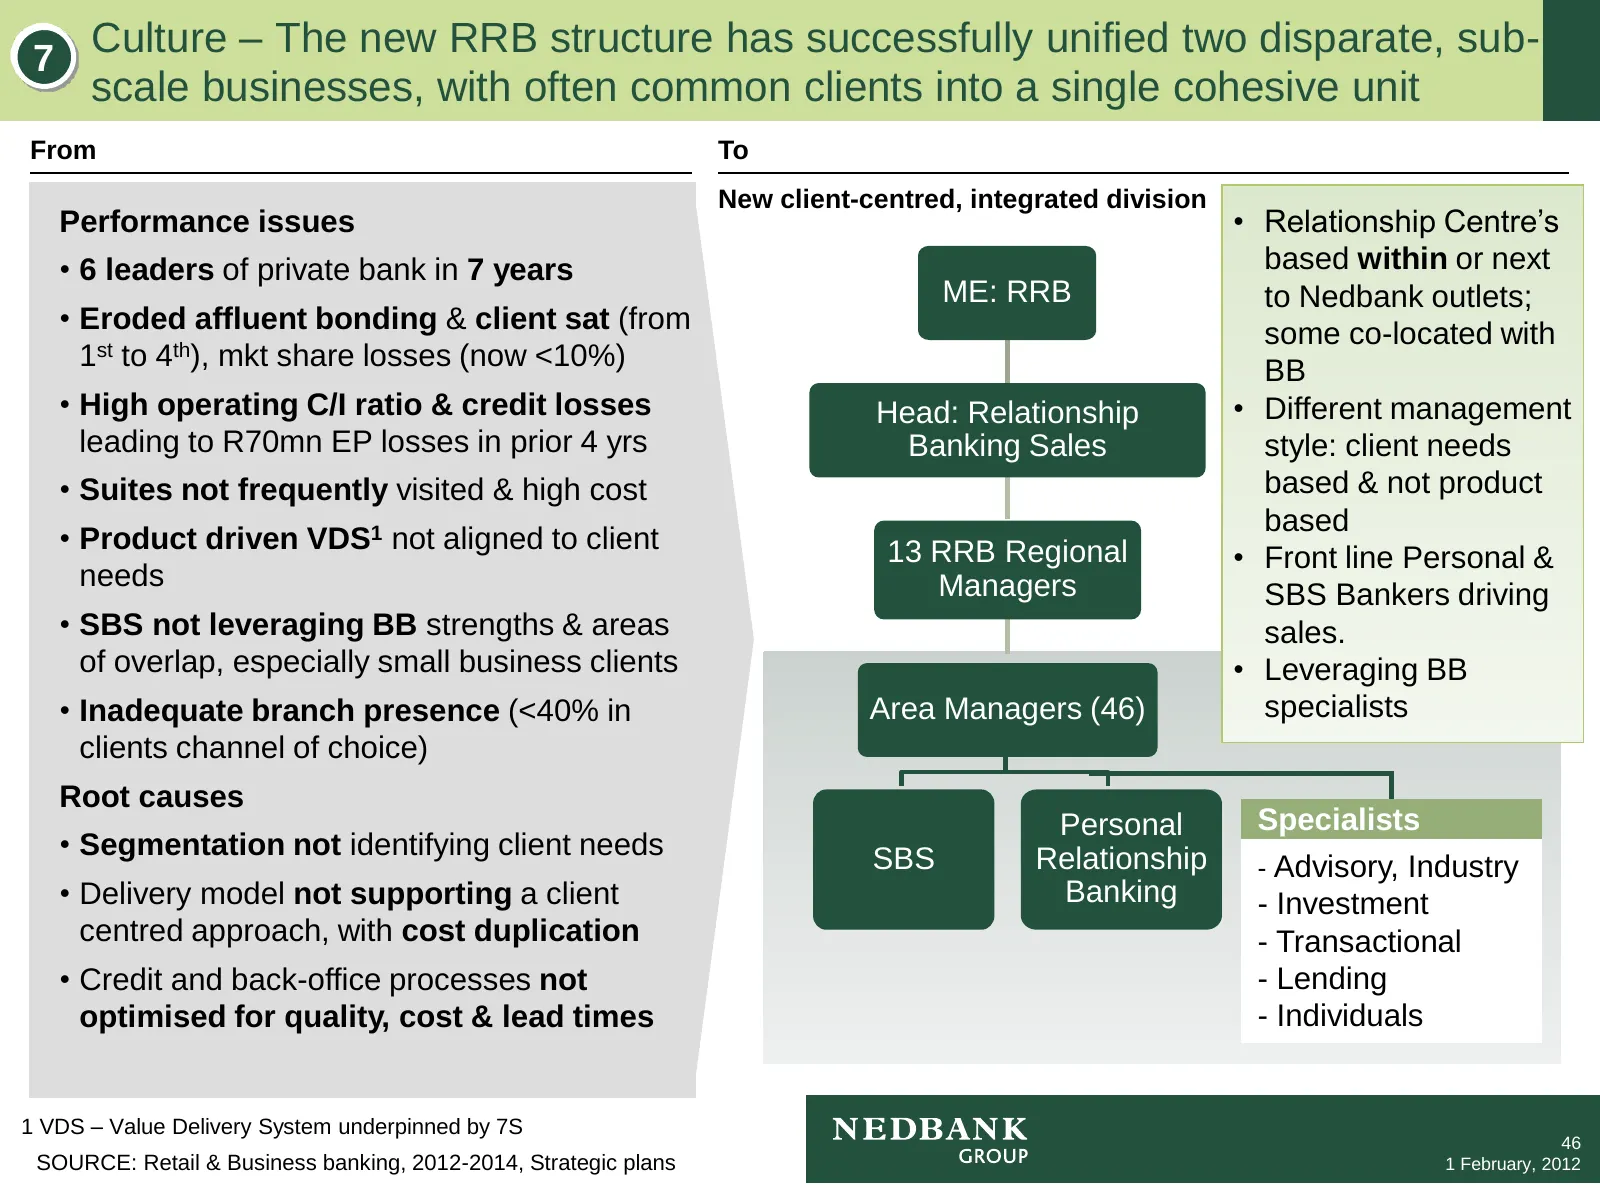
7 Culture – The new RRB structure has successfully unified two disparate, sub- scale businesses, with often common clients into a single cohesive unit From To New client-centred, integrated division Performance issues • Relationship Centre’s • 6 leaders of private bank in 7 years based within or nex
Slide 48: Migrating to an integrated client-driven platform
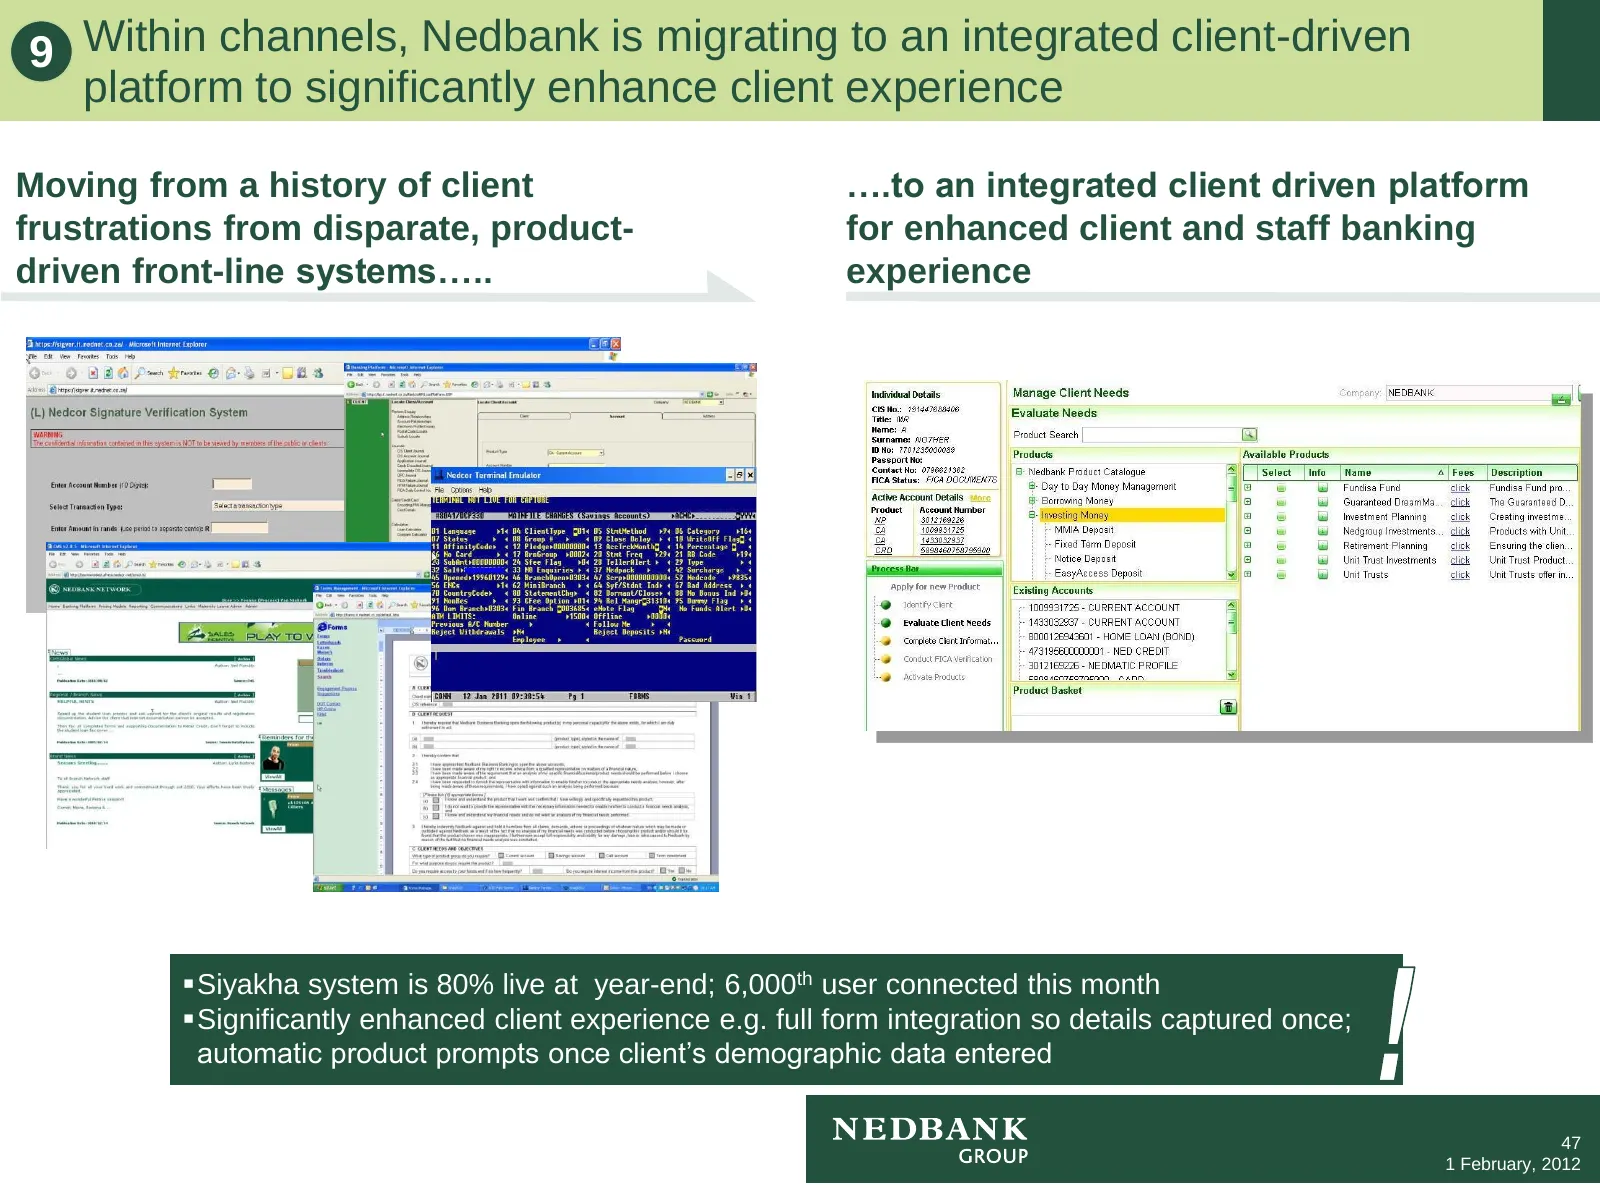
9 Within channels, Nedbank is migrating to an integrated client-driven platform to significantly enhance client experience Moving from a history of client ….to an integrated client driven platform frustrations from disparate, product- for enhanced client and staff banking driven front-line systems….
Slide 49: Rigorous credit risk management framework in Retail
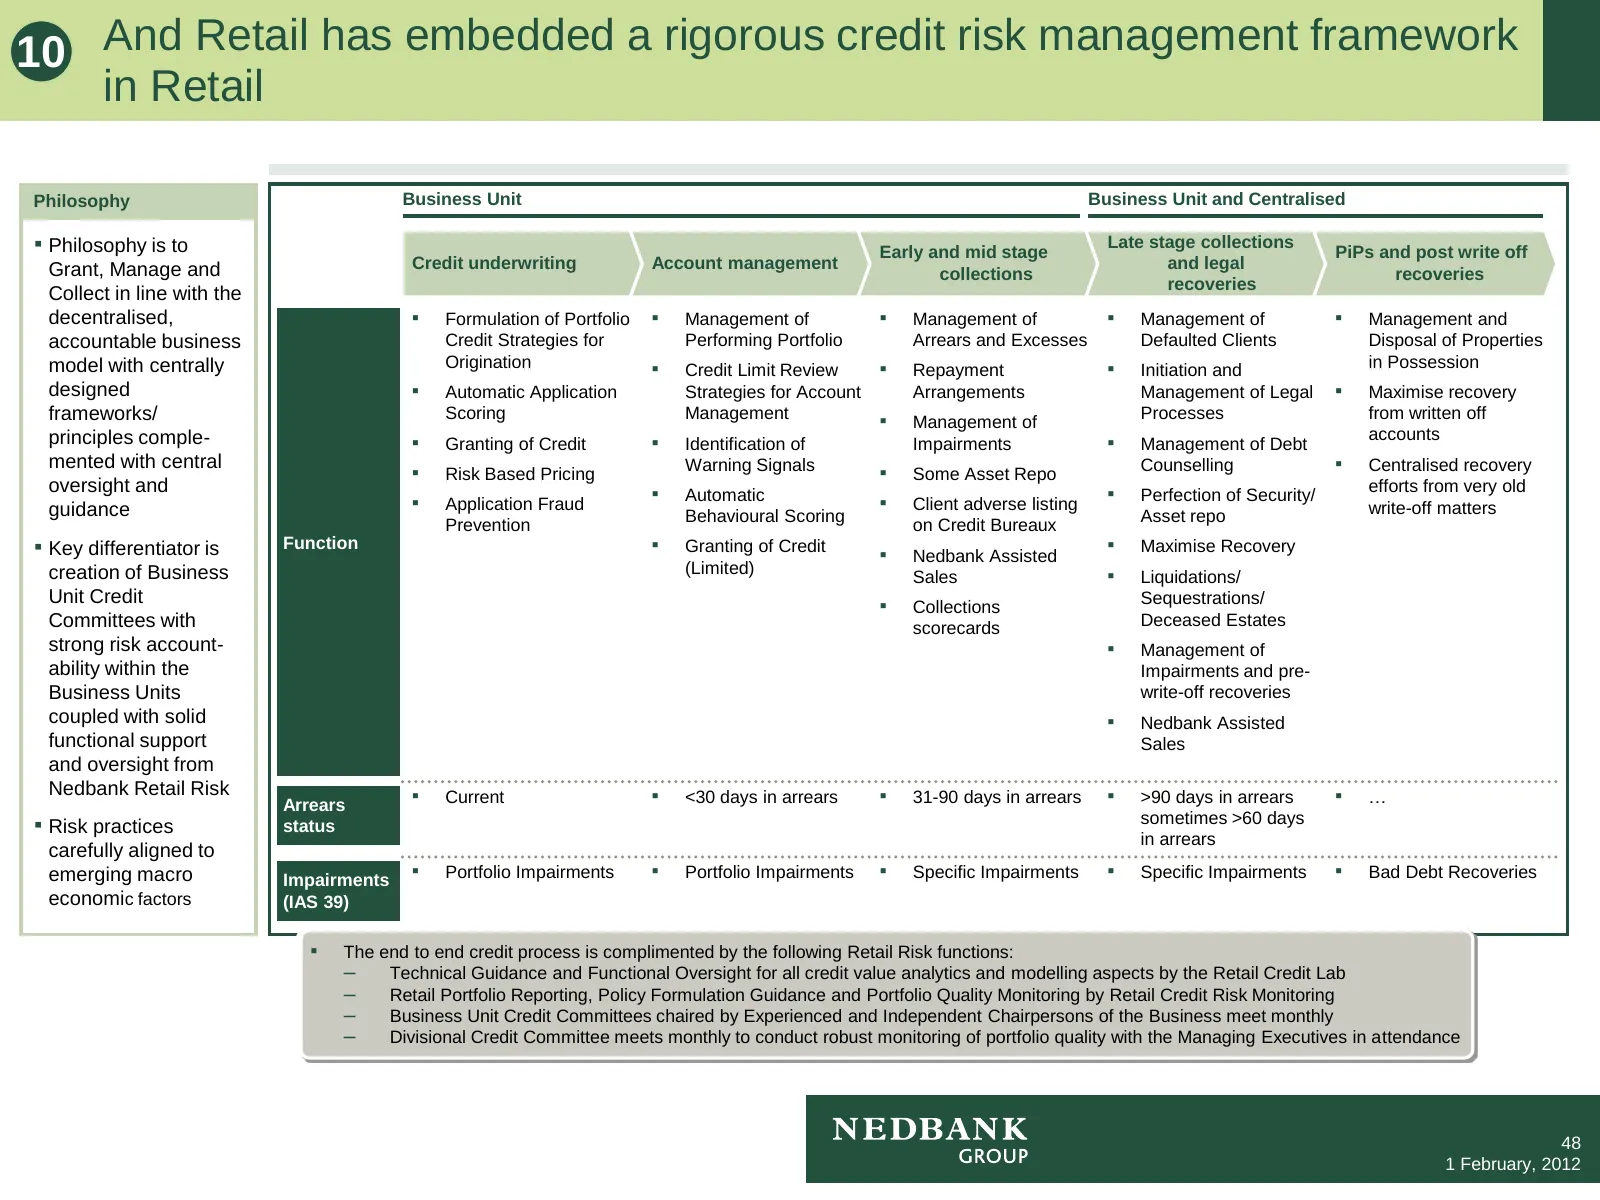
10 And Retail has embedded a rigorous credit risk management framework in Retail Philosophy Business Unit Business Unit and Centralised ▪ Philosophy is to Early and mid stage Late stage collections PiPs and post write off Grant, Manage and Credit underwriting Account management and legal collections
Slide 50: Retail distribution growing and more accessible
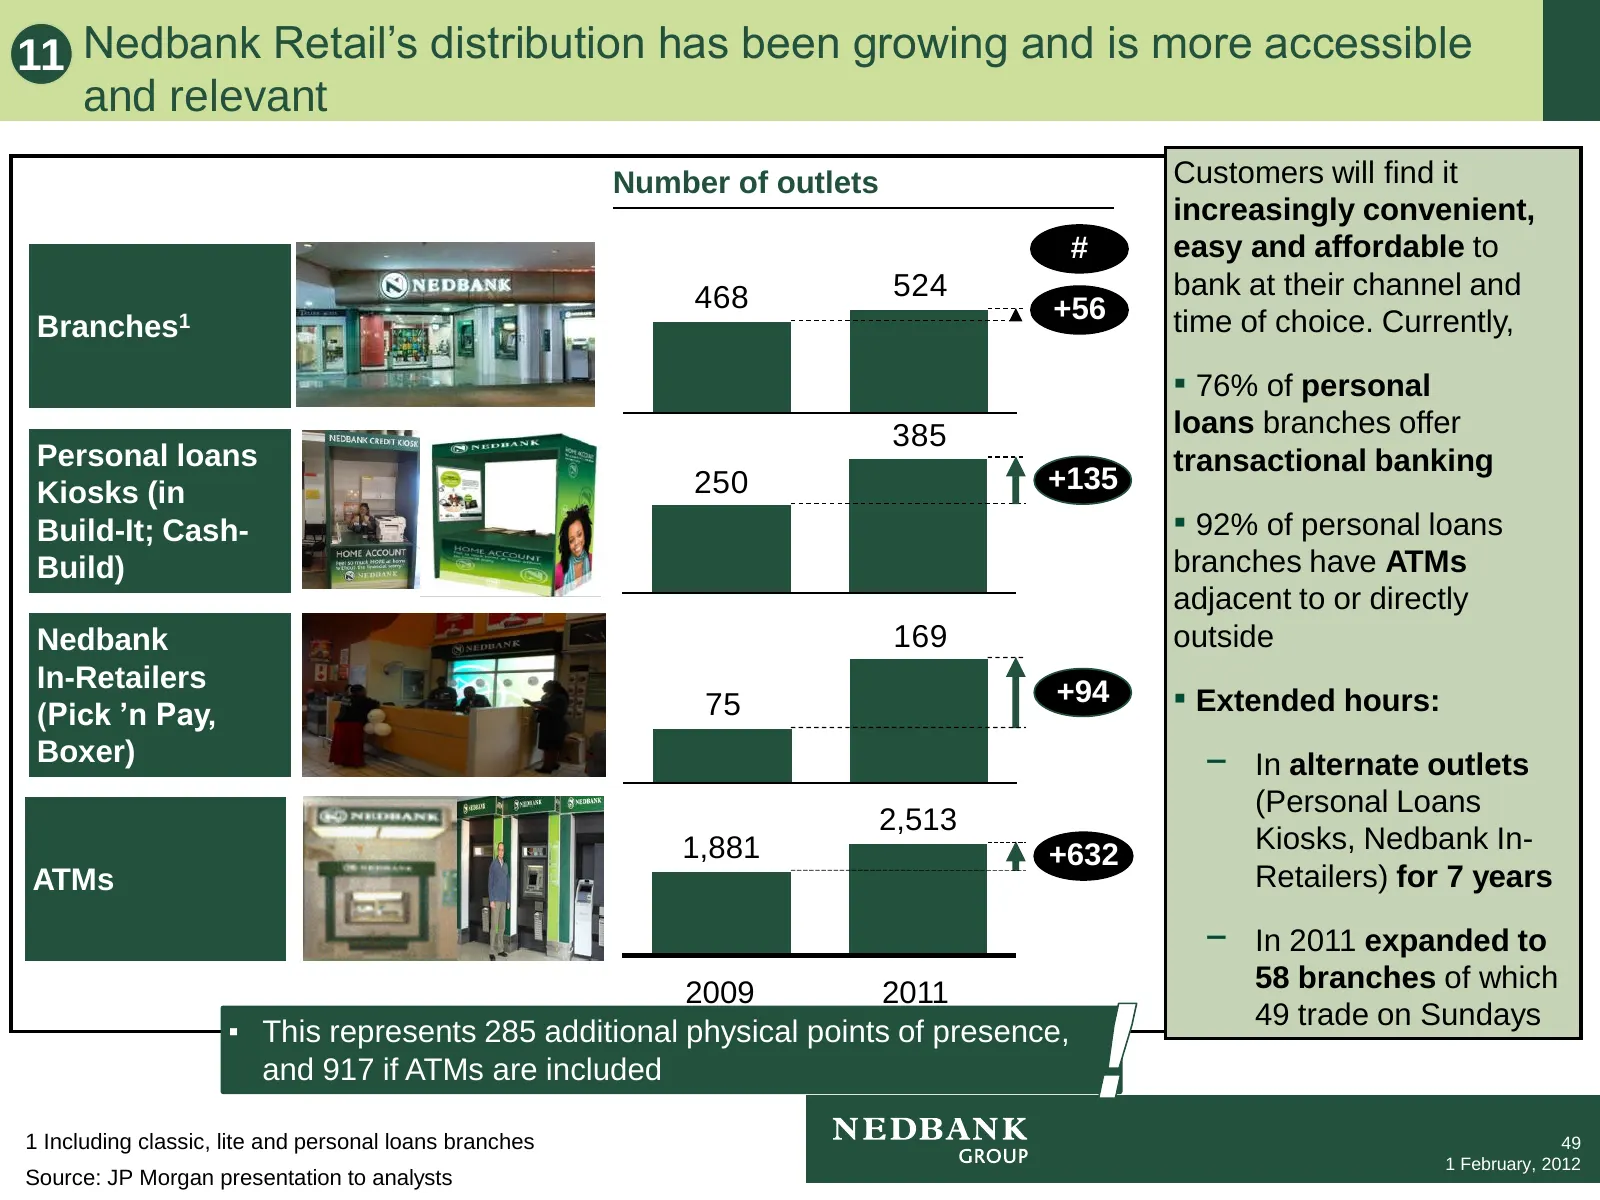
11 Nedbank Retail’s distribution has been growing and is more accessible and relevant Number of outlets Customers will find it increasingly convenient, # easy and affordable to 468 524 bank at their channel and +56 time of choice. Currently, Branches1 ▪ 76% of personal 385 loans branches offer Perso
Slide 51: Great client experience across channels
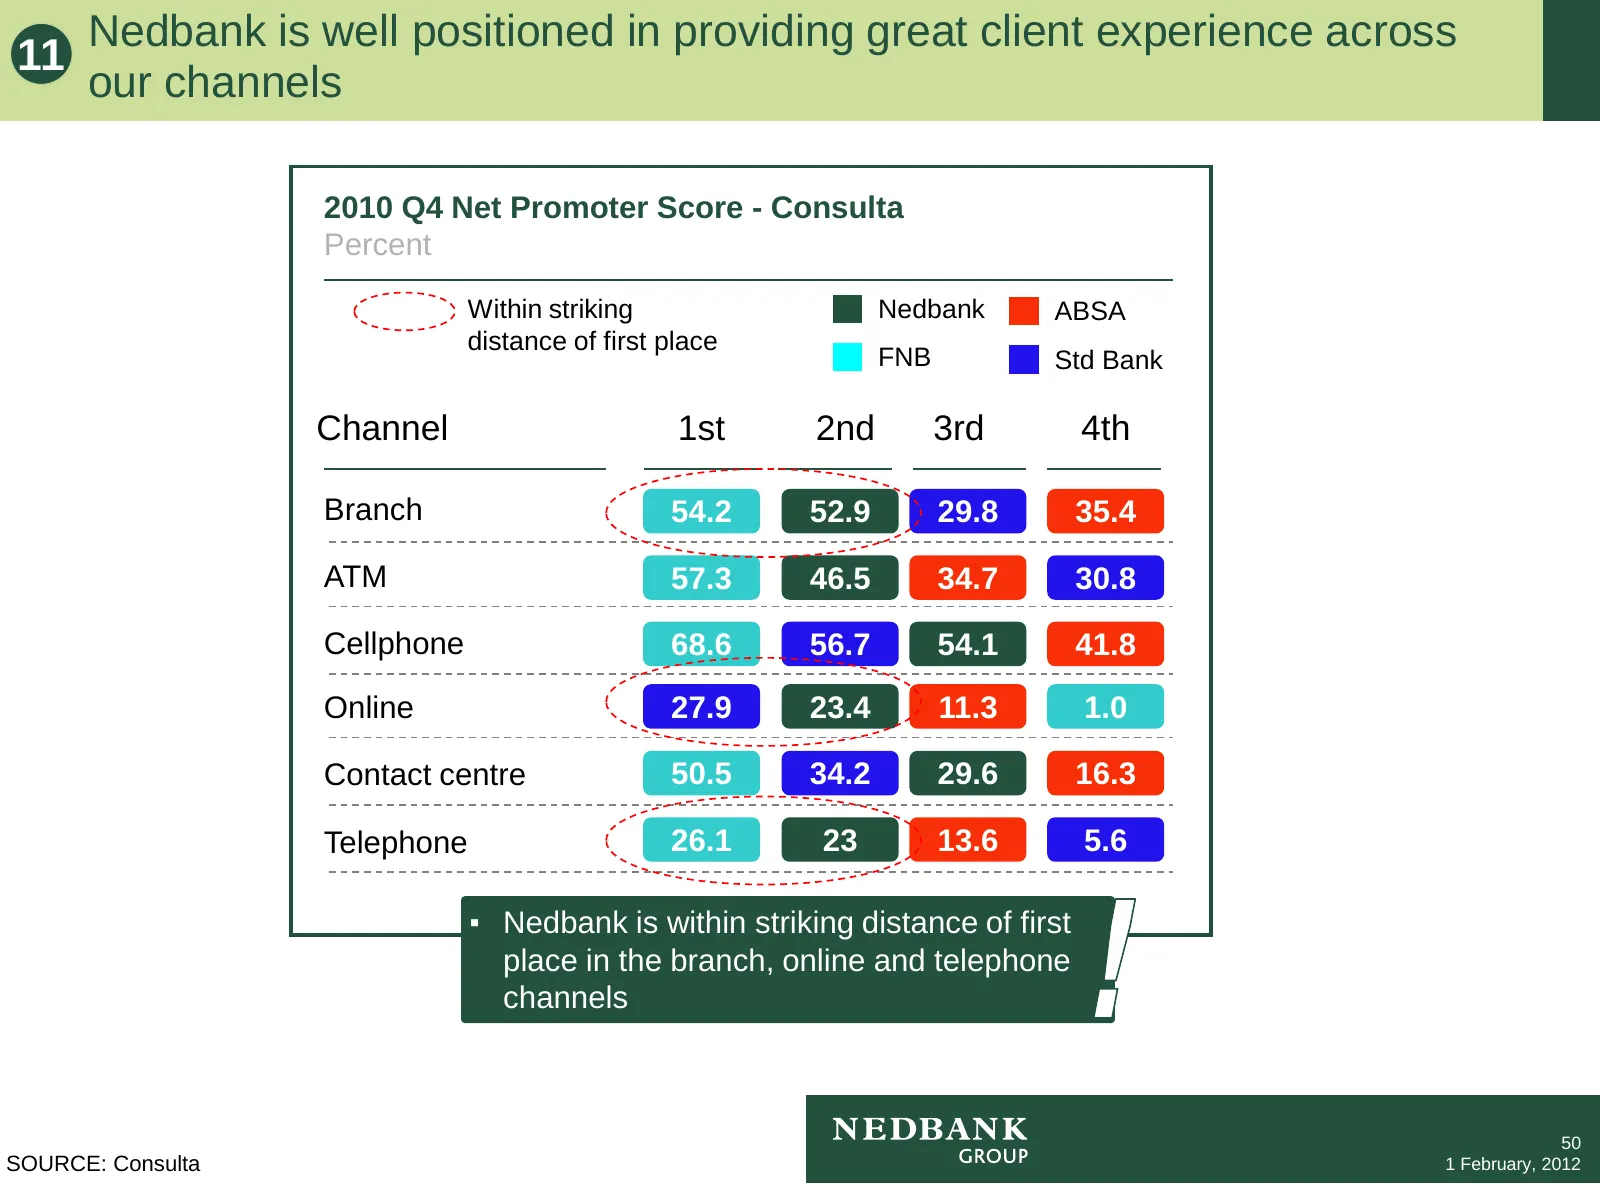
Nedbank is well positioned in providing great client experience across 11 our channels 2010 Q4 Net Promoter Score - Consulta Percent Within striking Nedbank ABSA distance of first place FNB Std Bank Channel 1st 2nd 3rd 4th Branch 54.2 52.9 29.8 35.4 ATM 57.3 46.5 34.7 30.8 Cellphone 68.6 56.7 54.1 4
Slide 52: Staff through facilitated change management process
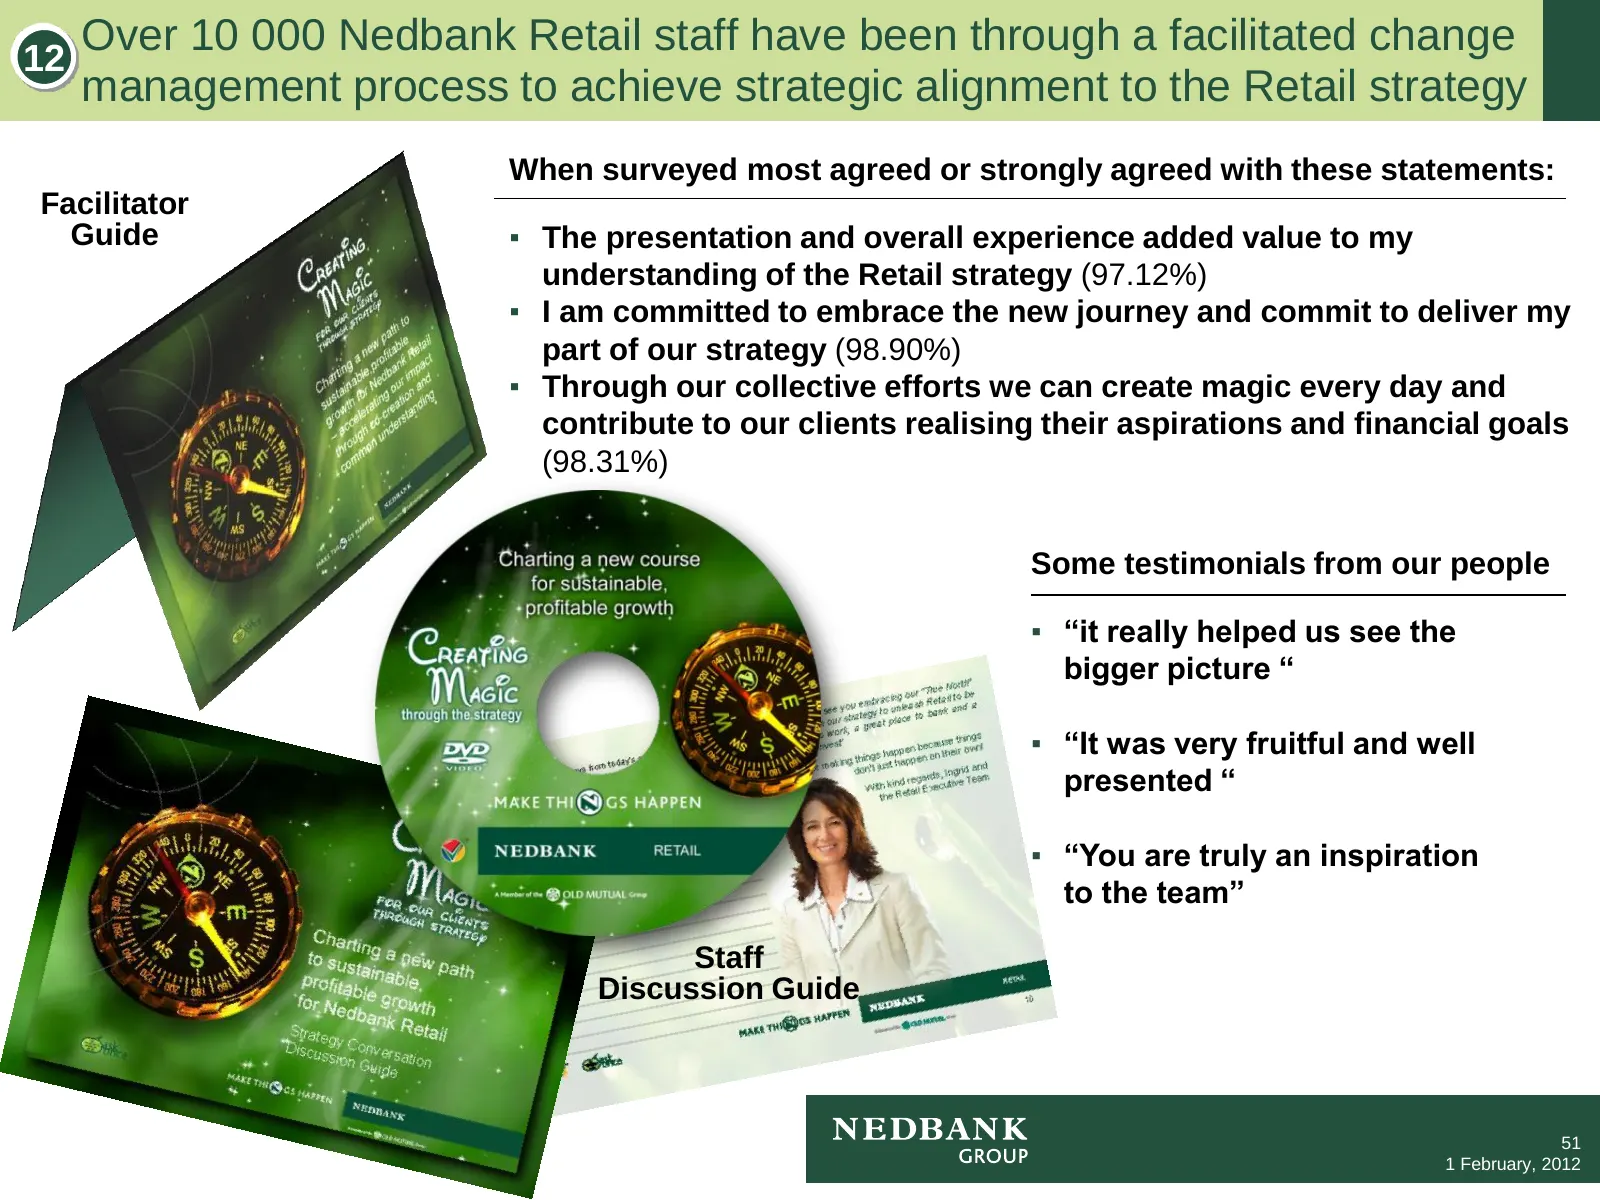
12 Over 10 000 Nedbank Retail staff have been through a facilitated change management process to achieve strategic alignment to the Retail strategy When surveyed most agreed or strongly agreed with these statements: Facilitator Guide ▪ The presentation and overall experience added value to my unders
Slide 53: Excellent implementation progress and speed of execution
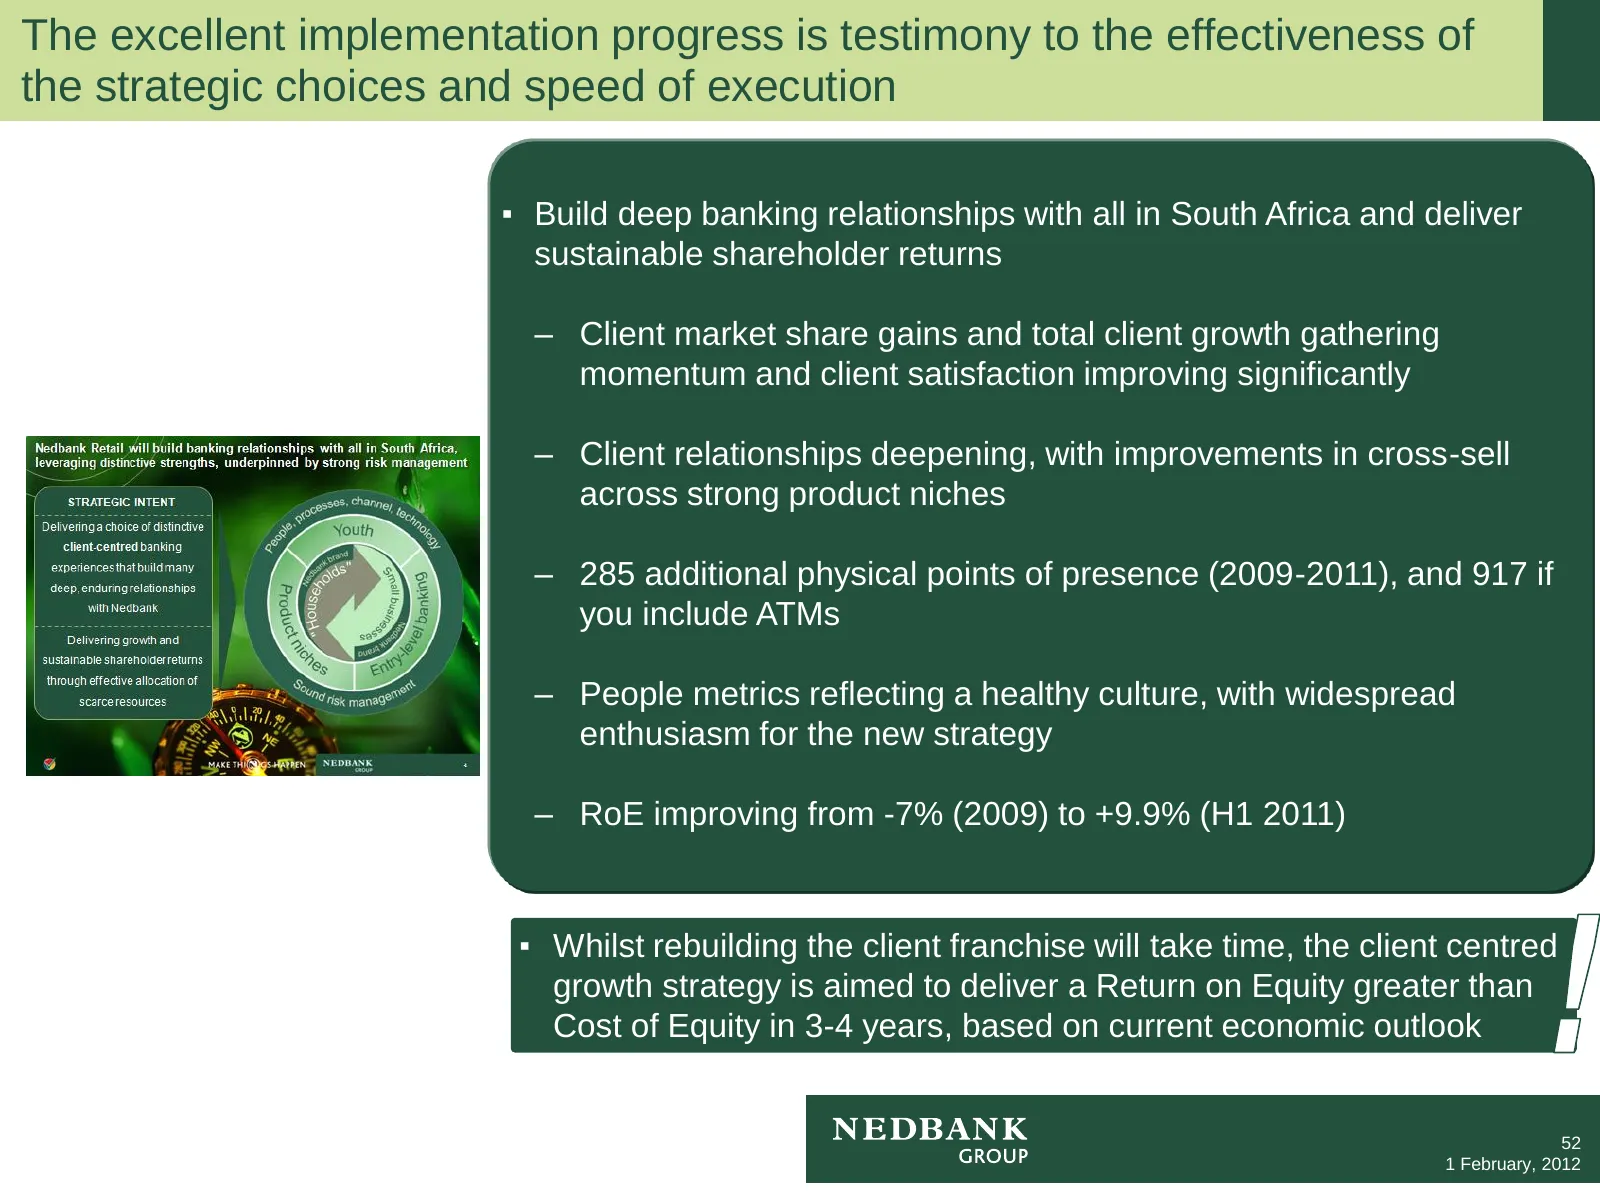
The excellent implementation progress is testimony to the effectiveness of the strategic choices and speed of execution ▪ Build deep banking relationships with all in South Africa and deliver sustainable shareholder returns – Client market share gains and total client growth gathering momentum and c
Slide 54: Area collaboration in the Kuruman micro-market
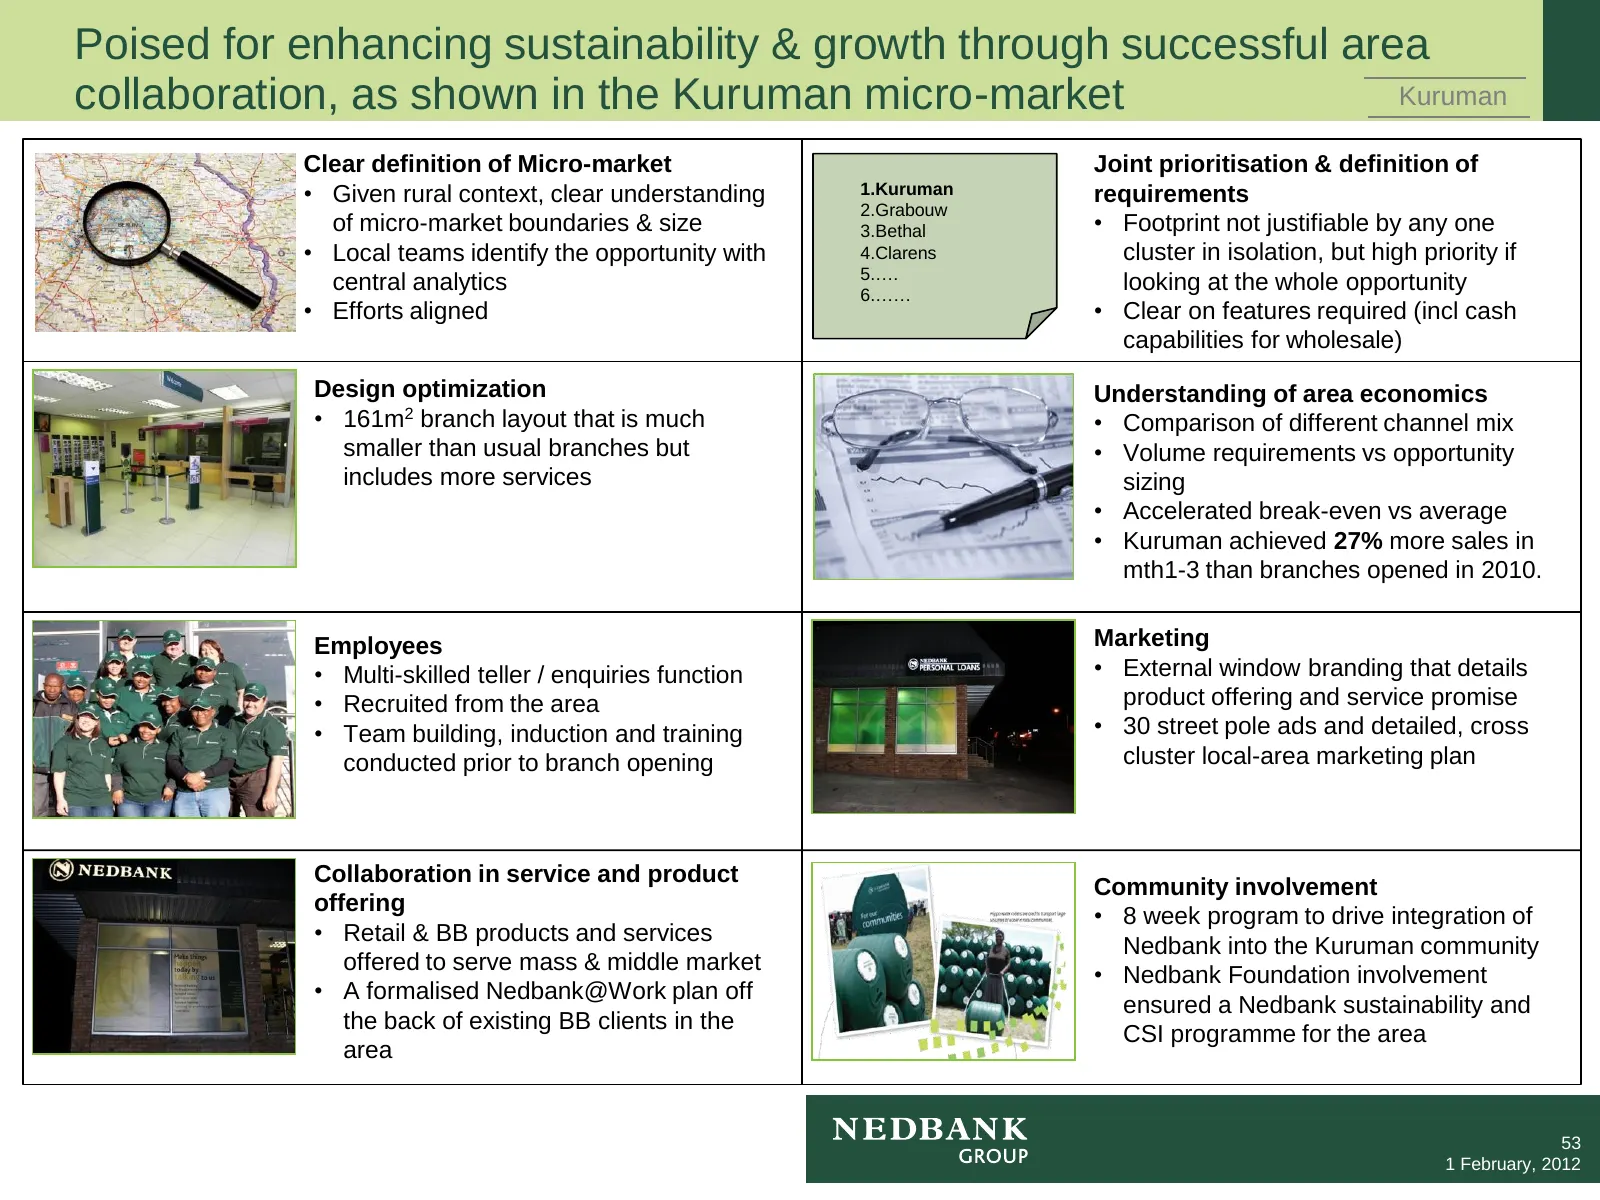
Poised for enhancing sustainability & growth through successful area collaboration, as shown in the Kuruman micro-market Kuruman Clear definition of Micro-market Joint prioritisation & definition of • Given rural context, clear understanding 1.Kuruman requirements 2.Grabouw of micro-market boundarie
Slide 55: Leadership team delivered on the 2011 imperatives
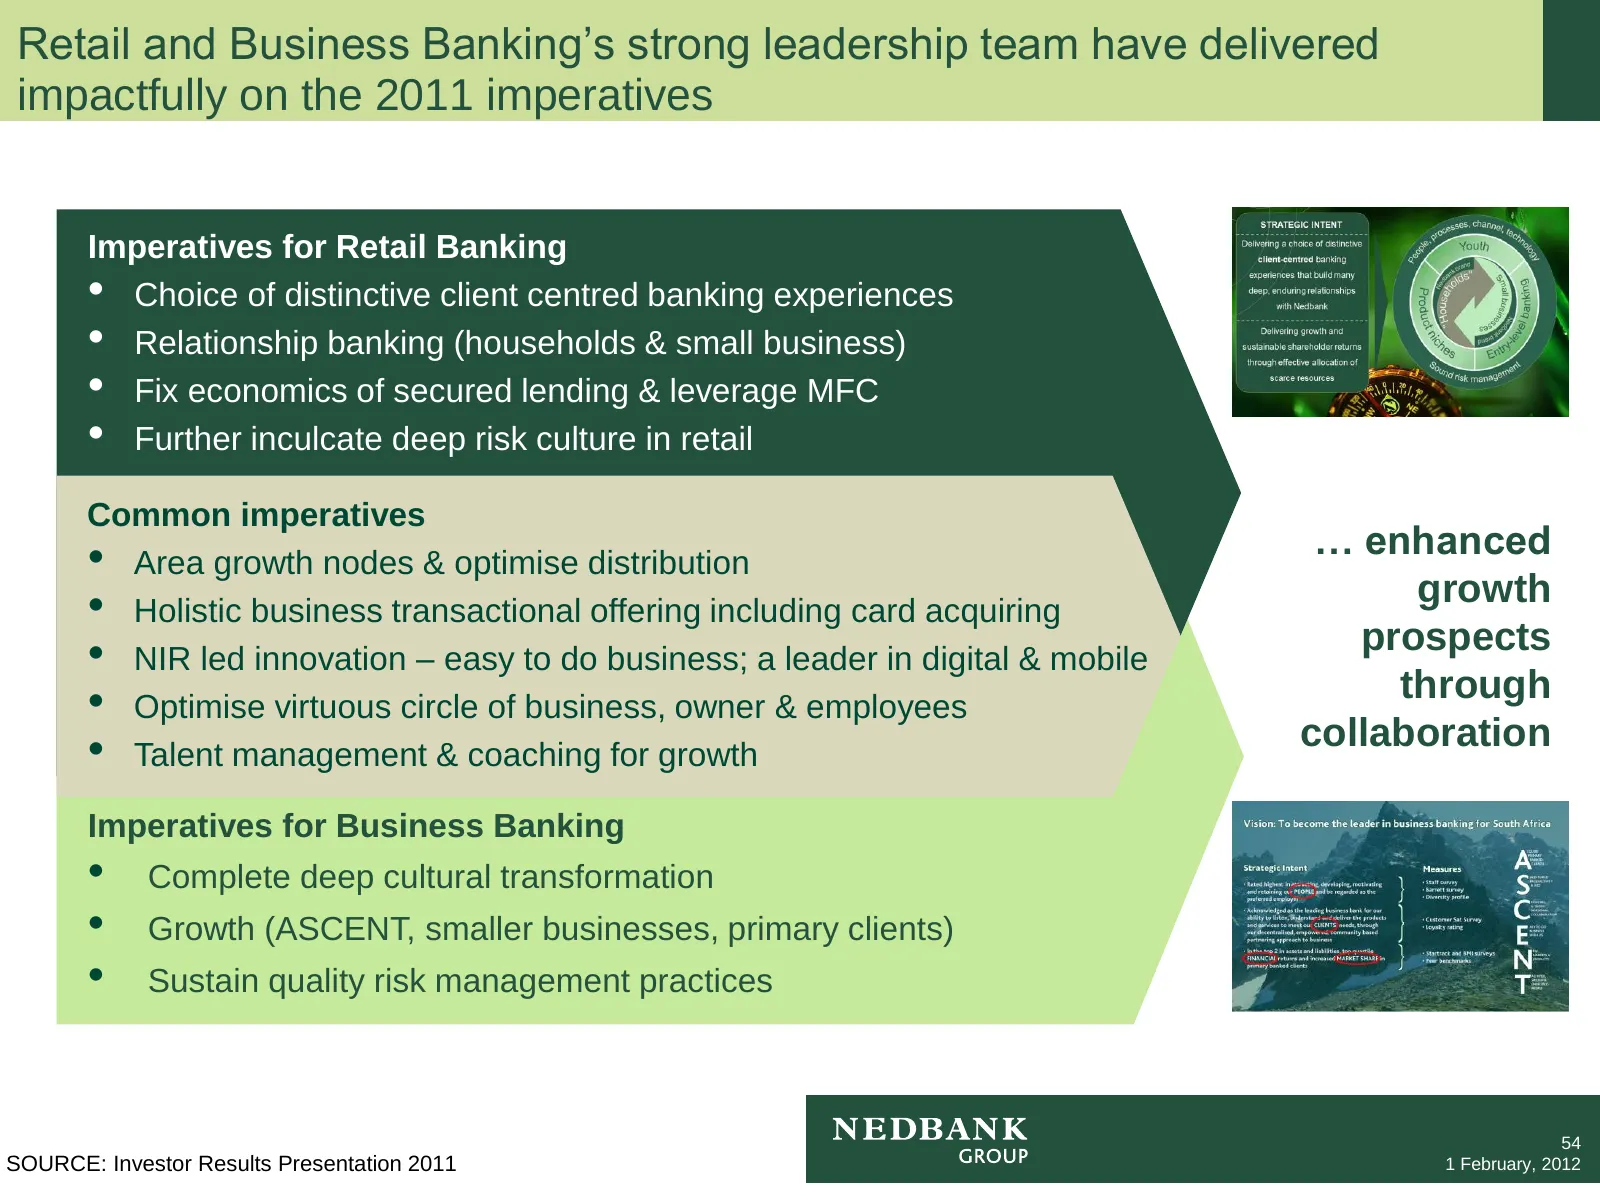
Retail and Business Banking’s strong leadership team have delivered impactfully on the 2011 imperatives Imperatives for Retail Banking • Choice of distinctive client centred banking experiences • Relationship banking (households & small business) • Fix economics of secured lending & leverage MFC • F
Slide 56: Uniquely positioned to generate shareholder value: distinctive position
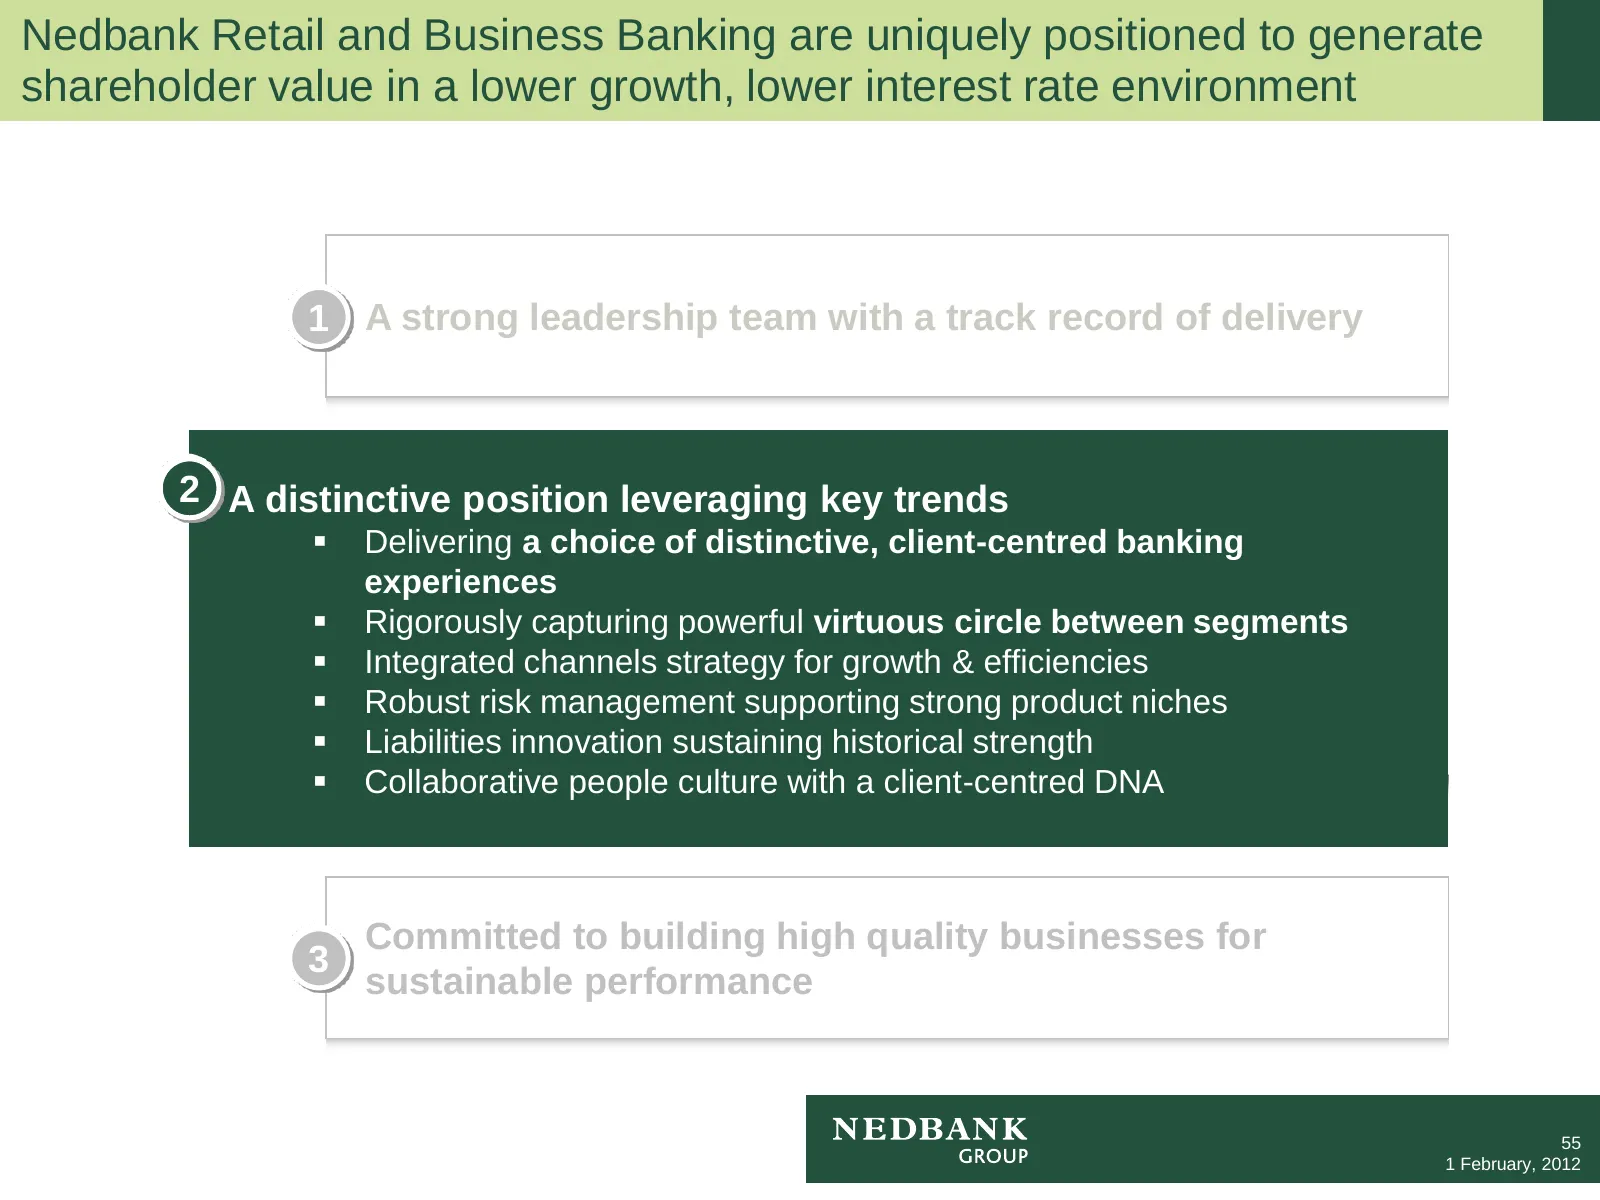
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment 1 A strong leadership team with a track record of delivery 2 A distinctive position leveraging key trends Delivering a choice of distinctive, client-centred
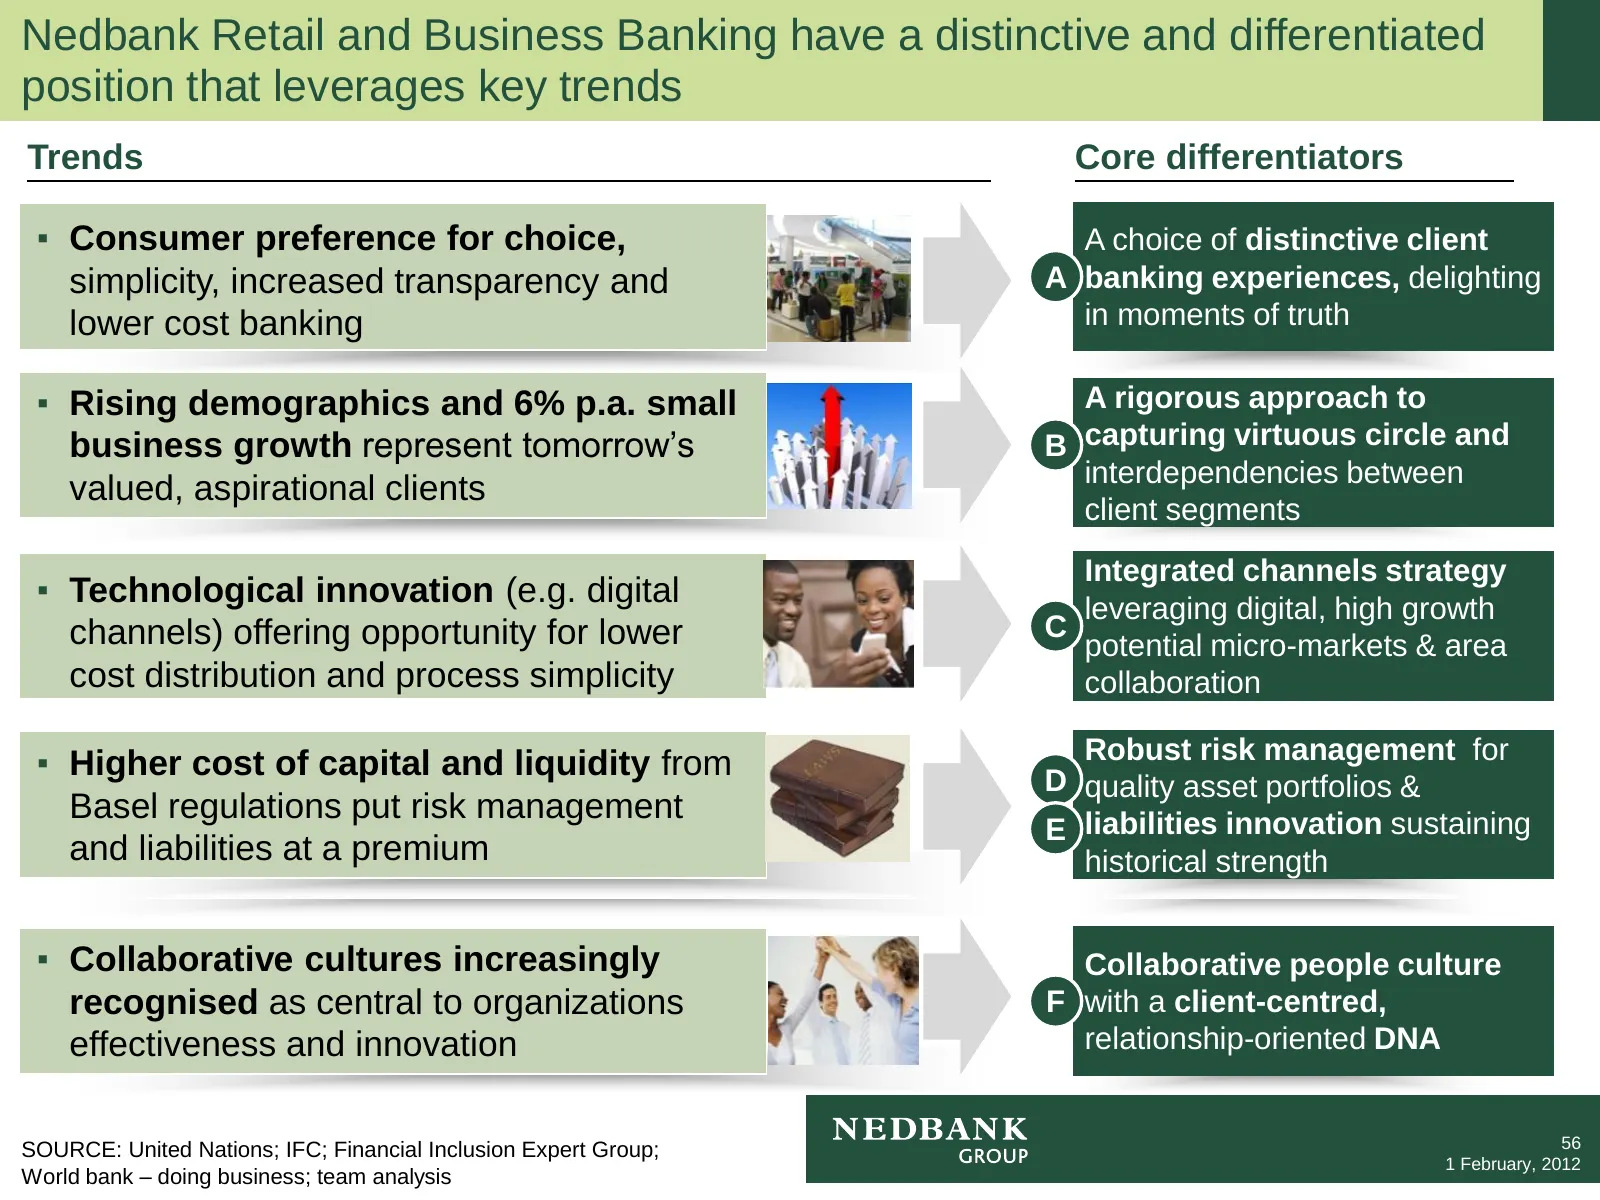
Slide 57: Distinctive position leveraging key trends
Nedbank Retail and Business Banking have a distinctive and differentiated position that leverages key trends Trends Core differentiators ▪ Consumer preference for choice, A choice of distinctive client simplicity, increased transparency and A banking experiences, delighting lower cost banking in mom
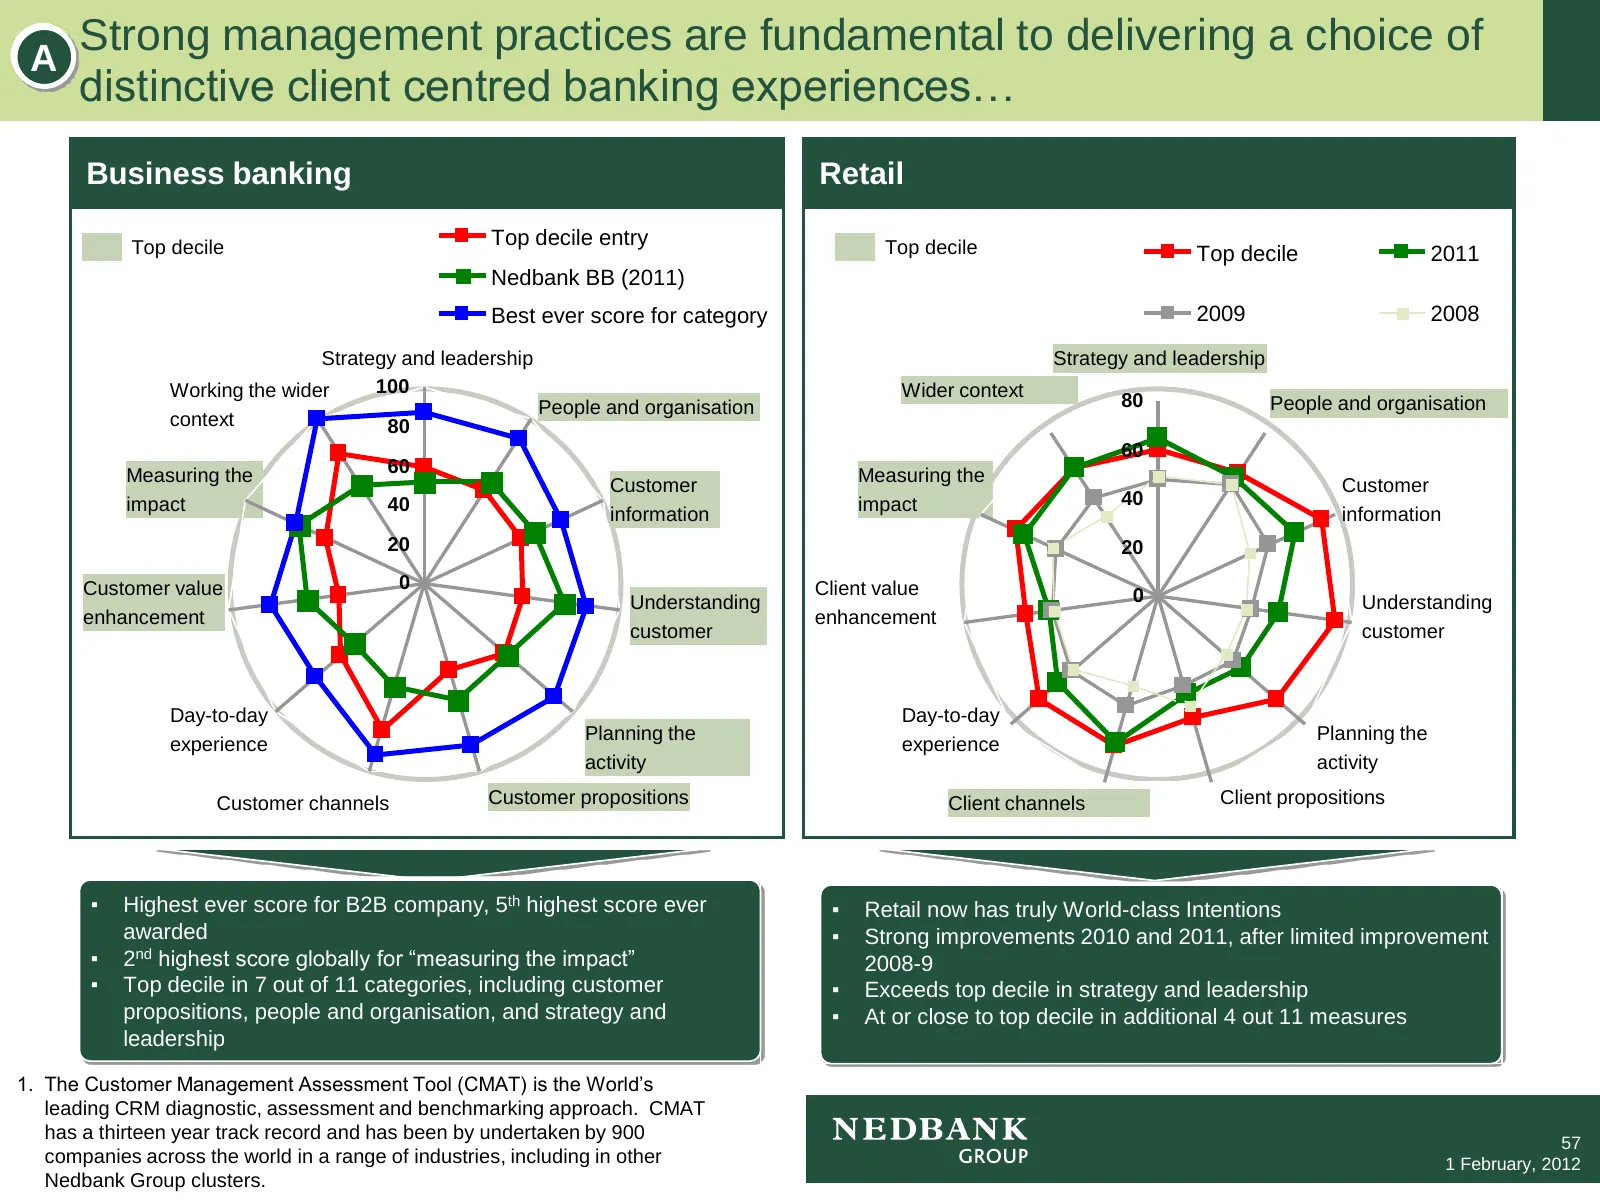
Slide 58: Strong management practices for distinctive client banking experiences
A Strong management practices are fundamental to delivering a choice of distinctive client centred banking experiences… Business banking Retail Top decile Top decile entry Top decile Top decile 2011 Nedbank BB (2011) Best ever score for category 2009 2008 Strategy and leadership Strategy and leaders
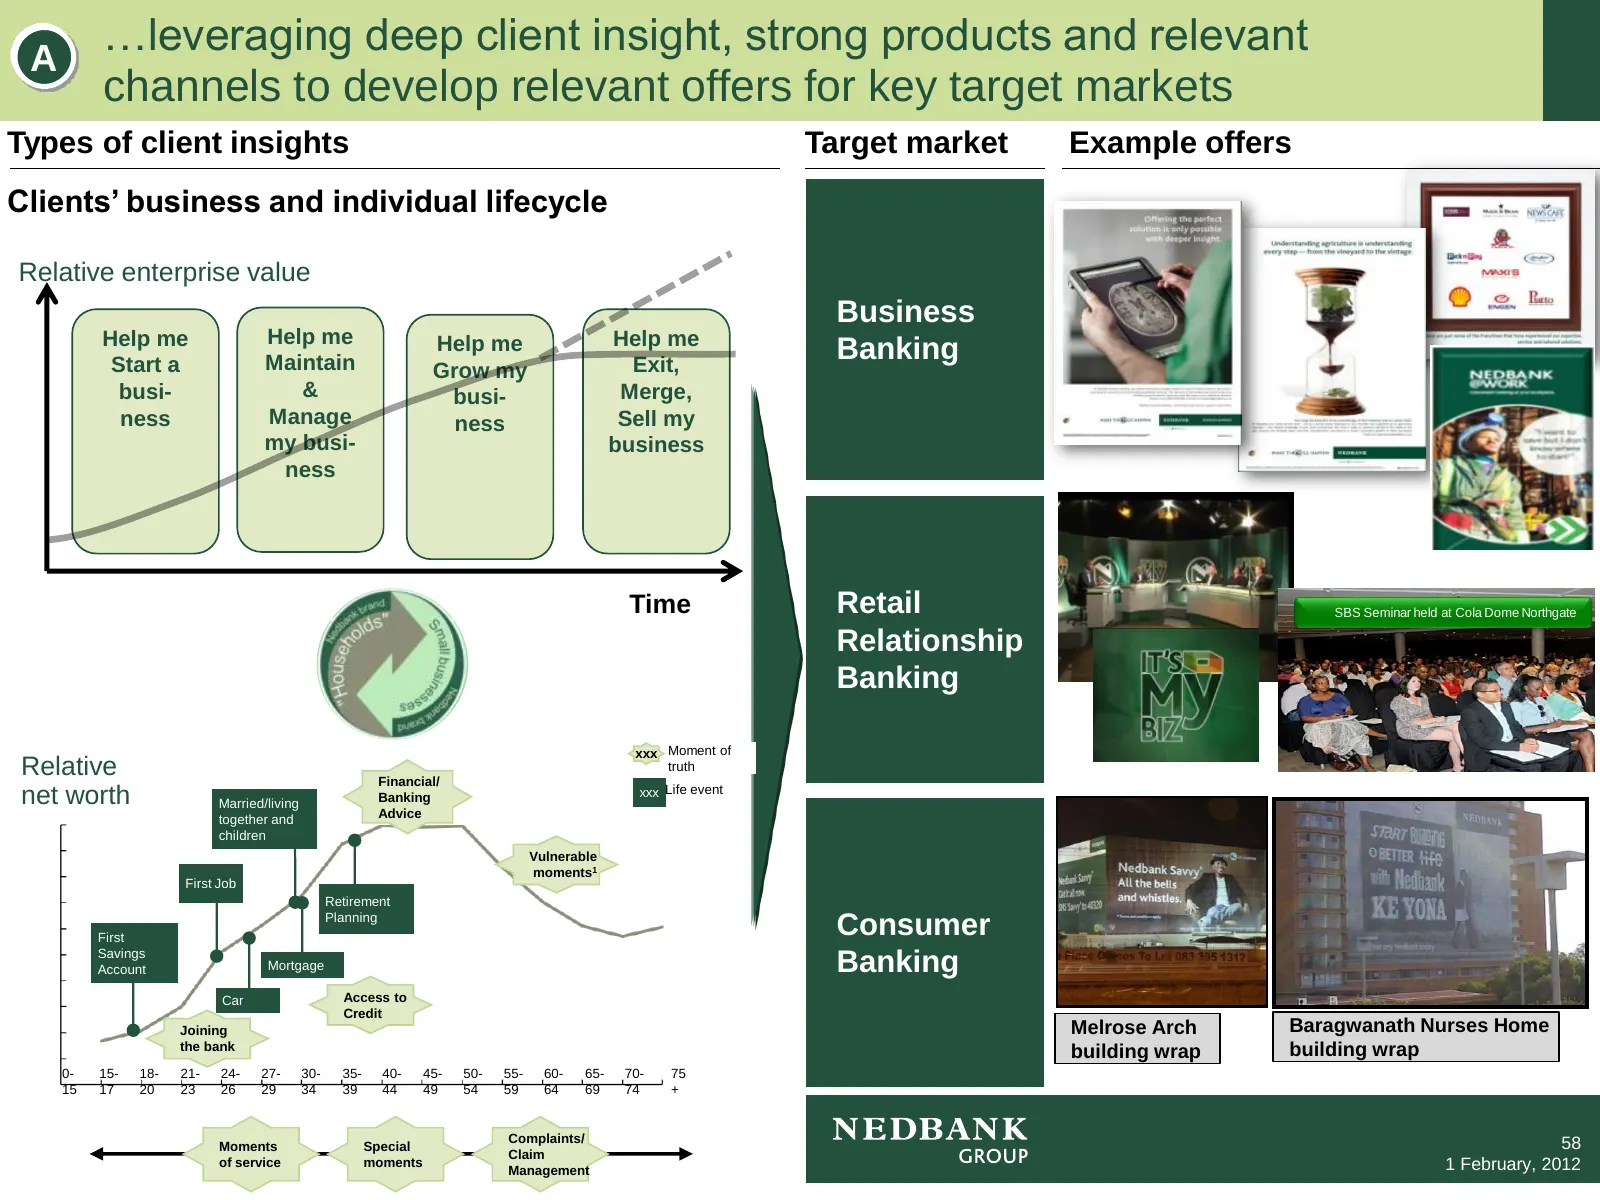
Slide 59: Leveraging client insight, products and channels for relevant offers
A …leveraging deep client insight, strong products and relevant channels to develop relevant offers for key target markets Types of client insights Target market Example offers Clients’ business and individual lifecycle Relative enterprise value Business Help me Help me Help me Help me Start a Maint
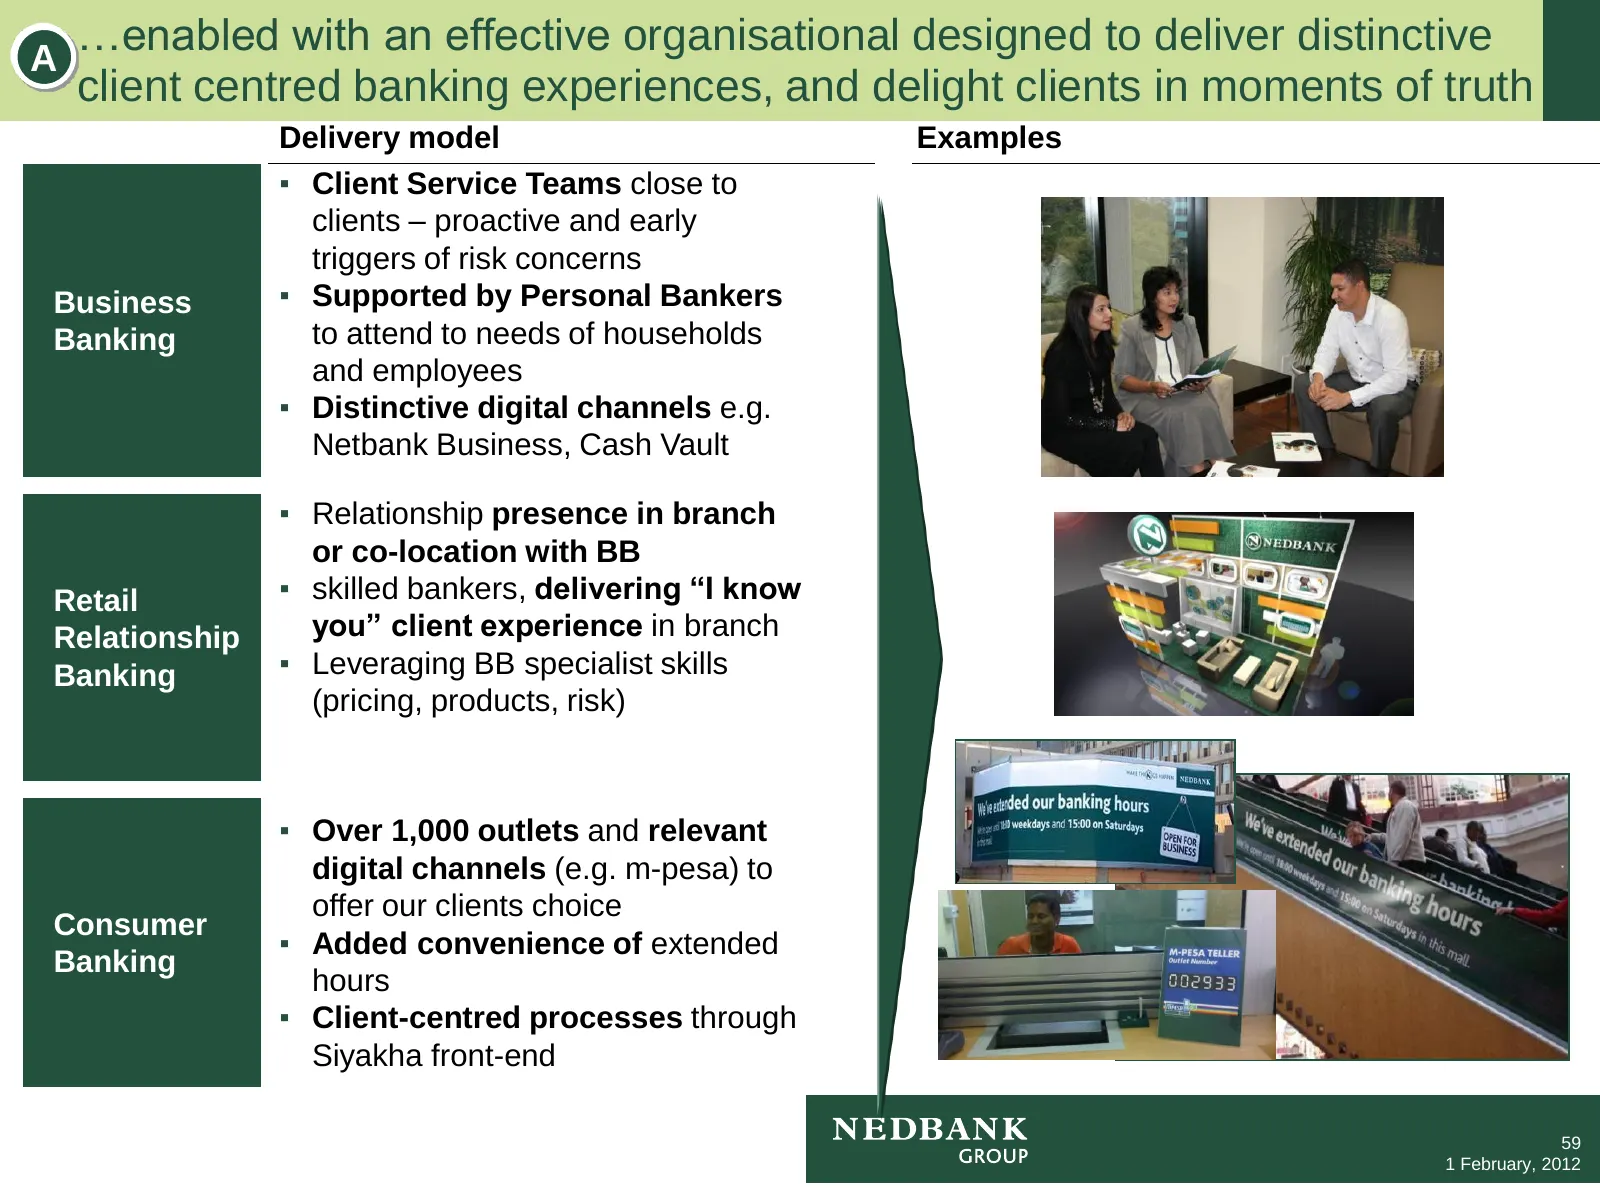
Slide 60: Organisational design to deliver distinctive client experiences
A …enabled with an effective organisational designed to deliver distinctive client centred banking experiences, and delight clients in moments of truth Delivery model Examples ▪ Client Service Teams close to clients – proactive and early triggers of risk concerns Business ▪ Supported by Personal Ban
Slide 61: Business Banking voice of client defines value propositions
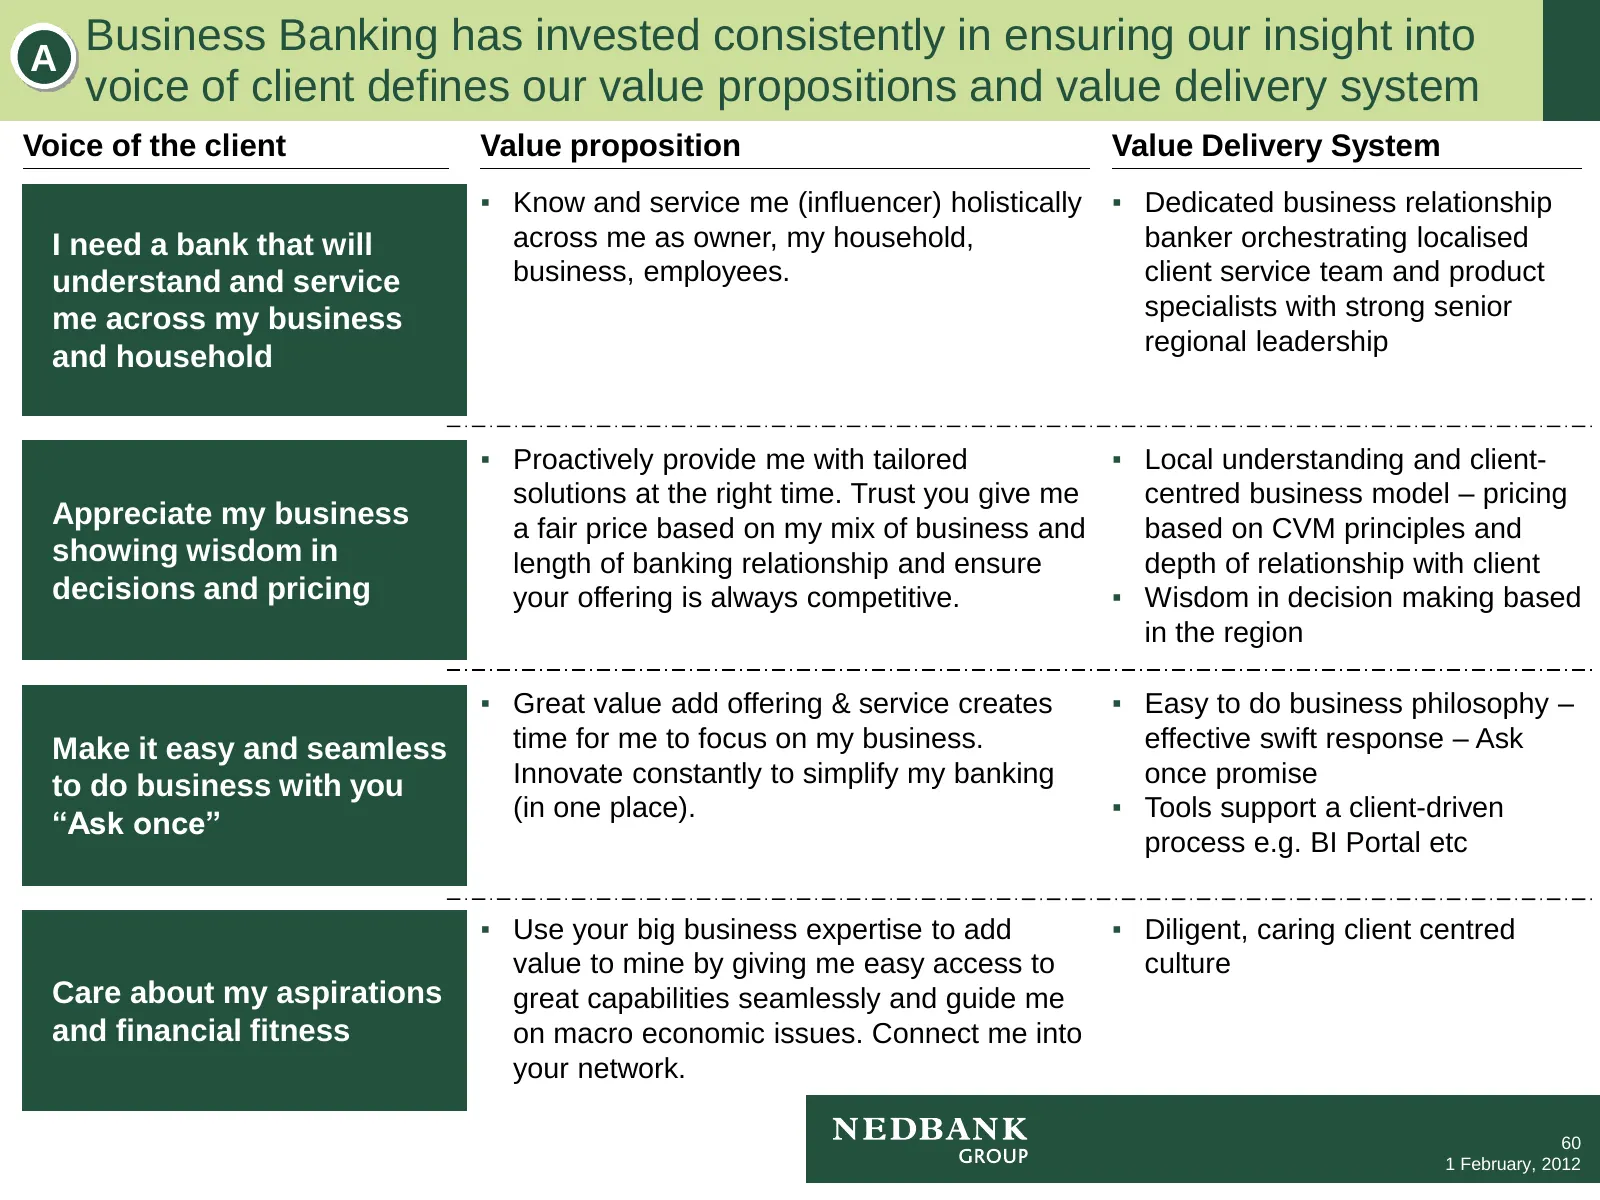
A Business Banking has invested consistently in ensuring our insight into voice of client defines our value propositions and value delivery system Voice of the client Value proposition Value Delivery System ▪ Know and service me (influencer) holistically ▪ Dedicated business relationship I need a ba
Slide 62: Business Banking delivery model unlocking the virtuous circle
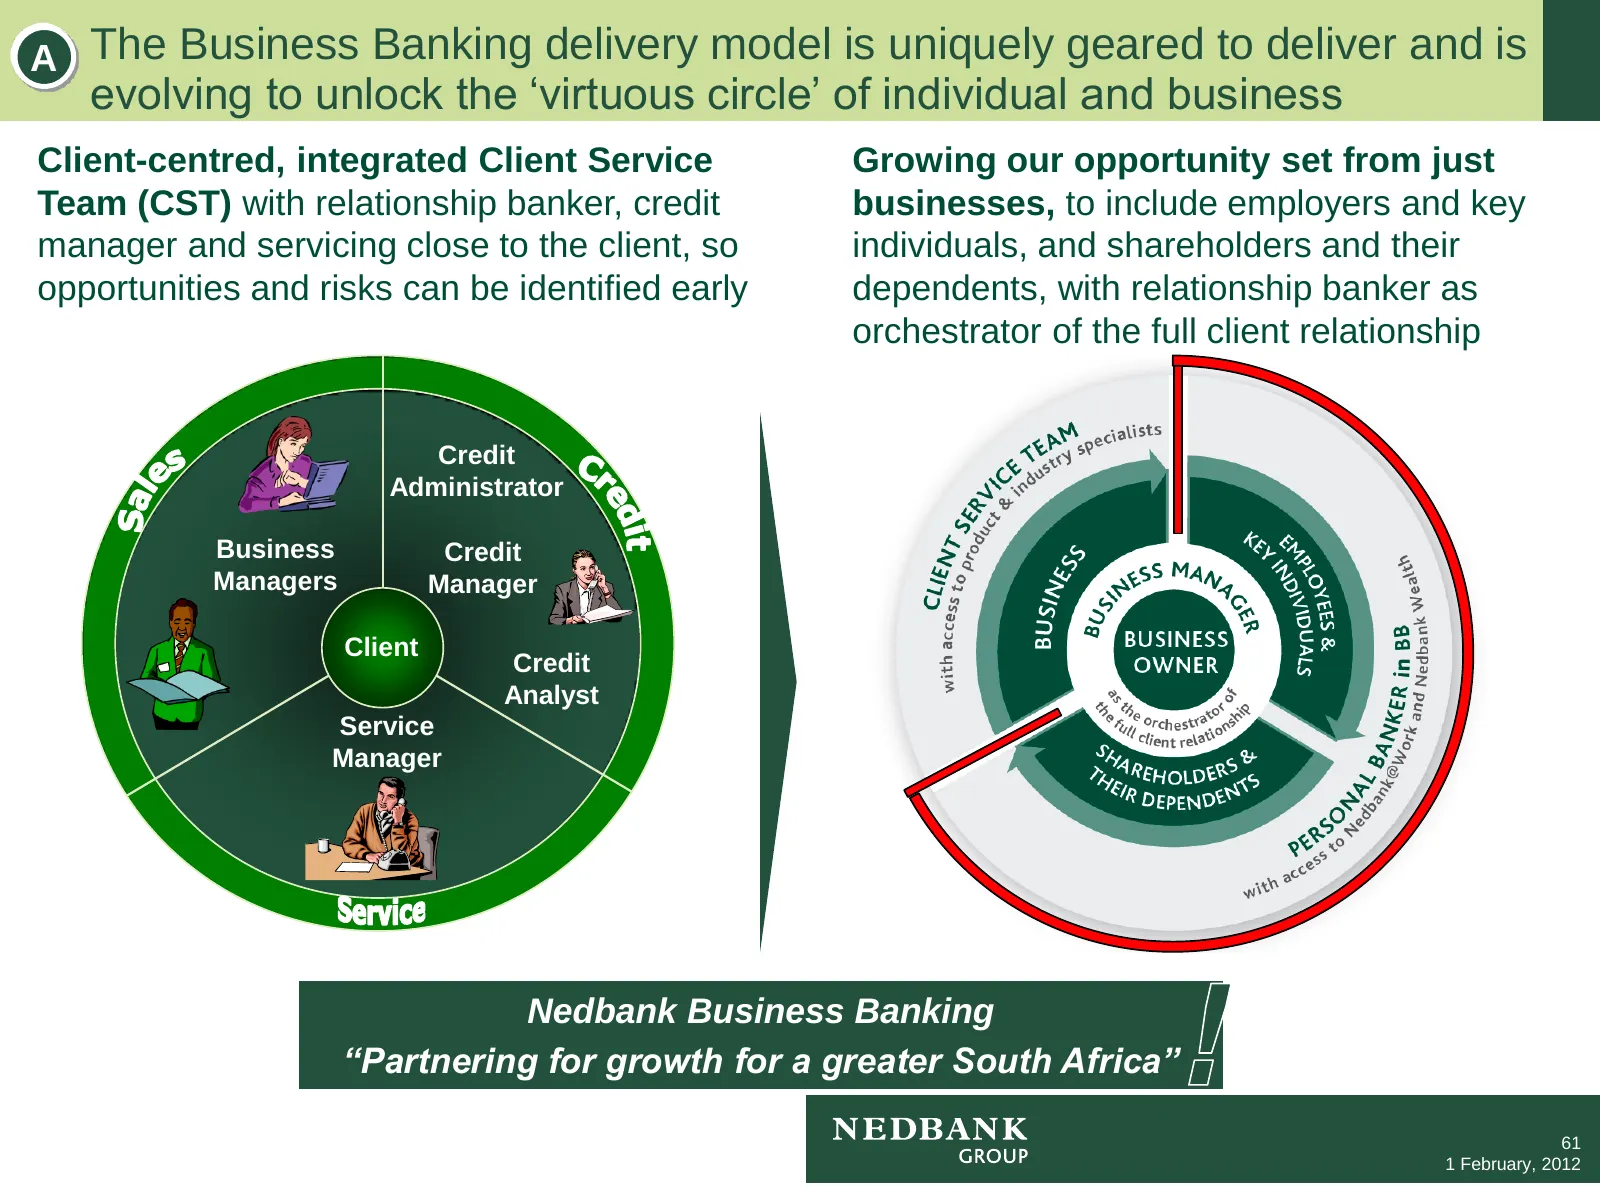
A The Business Banking delivery model is uniquely geared to deliver and is evolving to unlock the ‘virtuous circle’ of individual and business Client-centred, integrated Client Service Growing our opportunity set from just Team (CST) with relationship banker, credit businesses, to include employers
Slide 63: Excellent franchise in the business banking target market
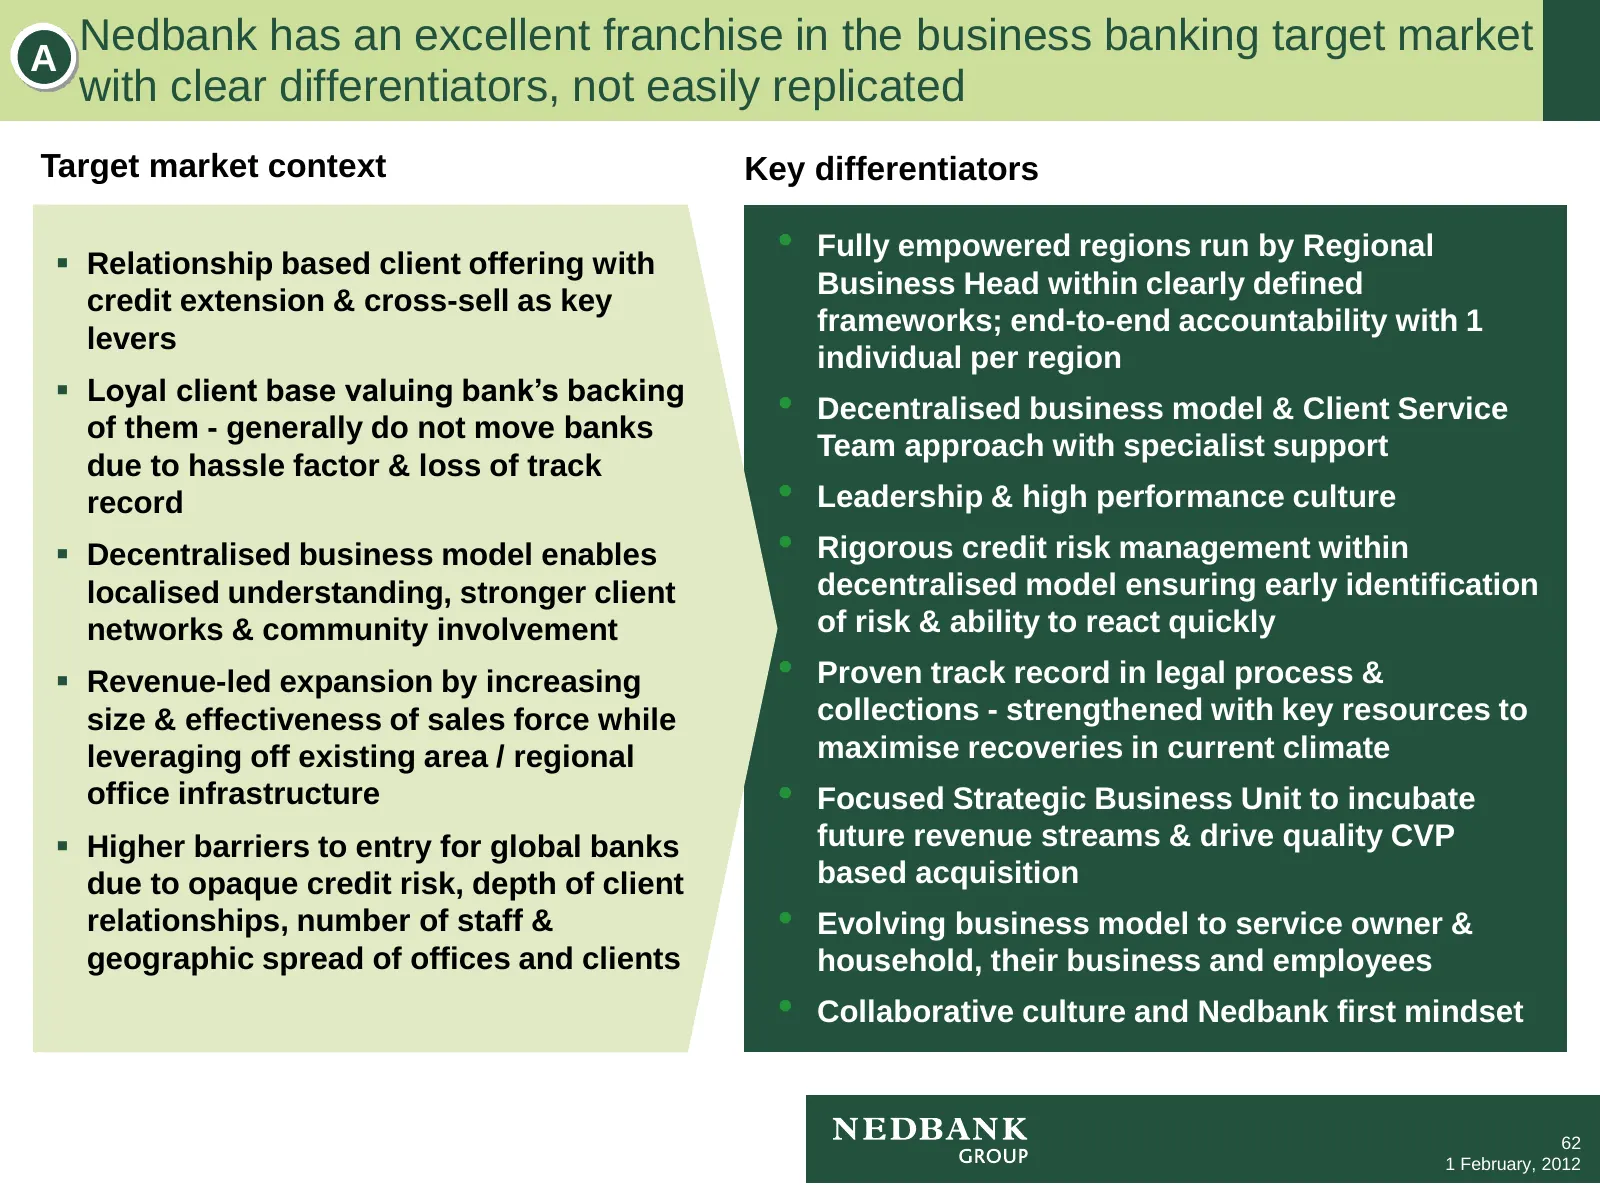
A Nedbank has an excellent franchise in the business banking target market with clear differentiators, not easily replicated Target market context Key differentiators Relationship based client offering with • Fully empowered regions run by Regional Business Head within clearly defined credit exten
Slide 64: Retail and BB collaborate to unlock the virtuous circle
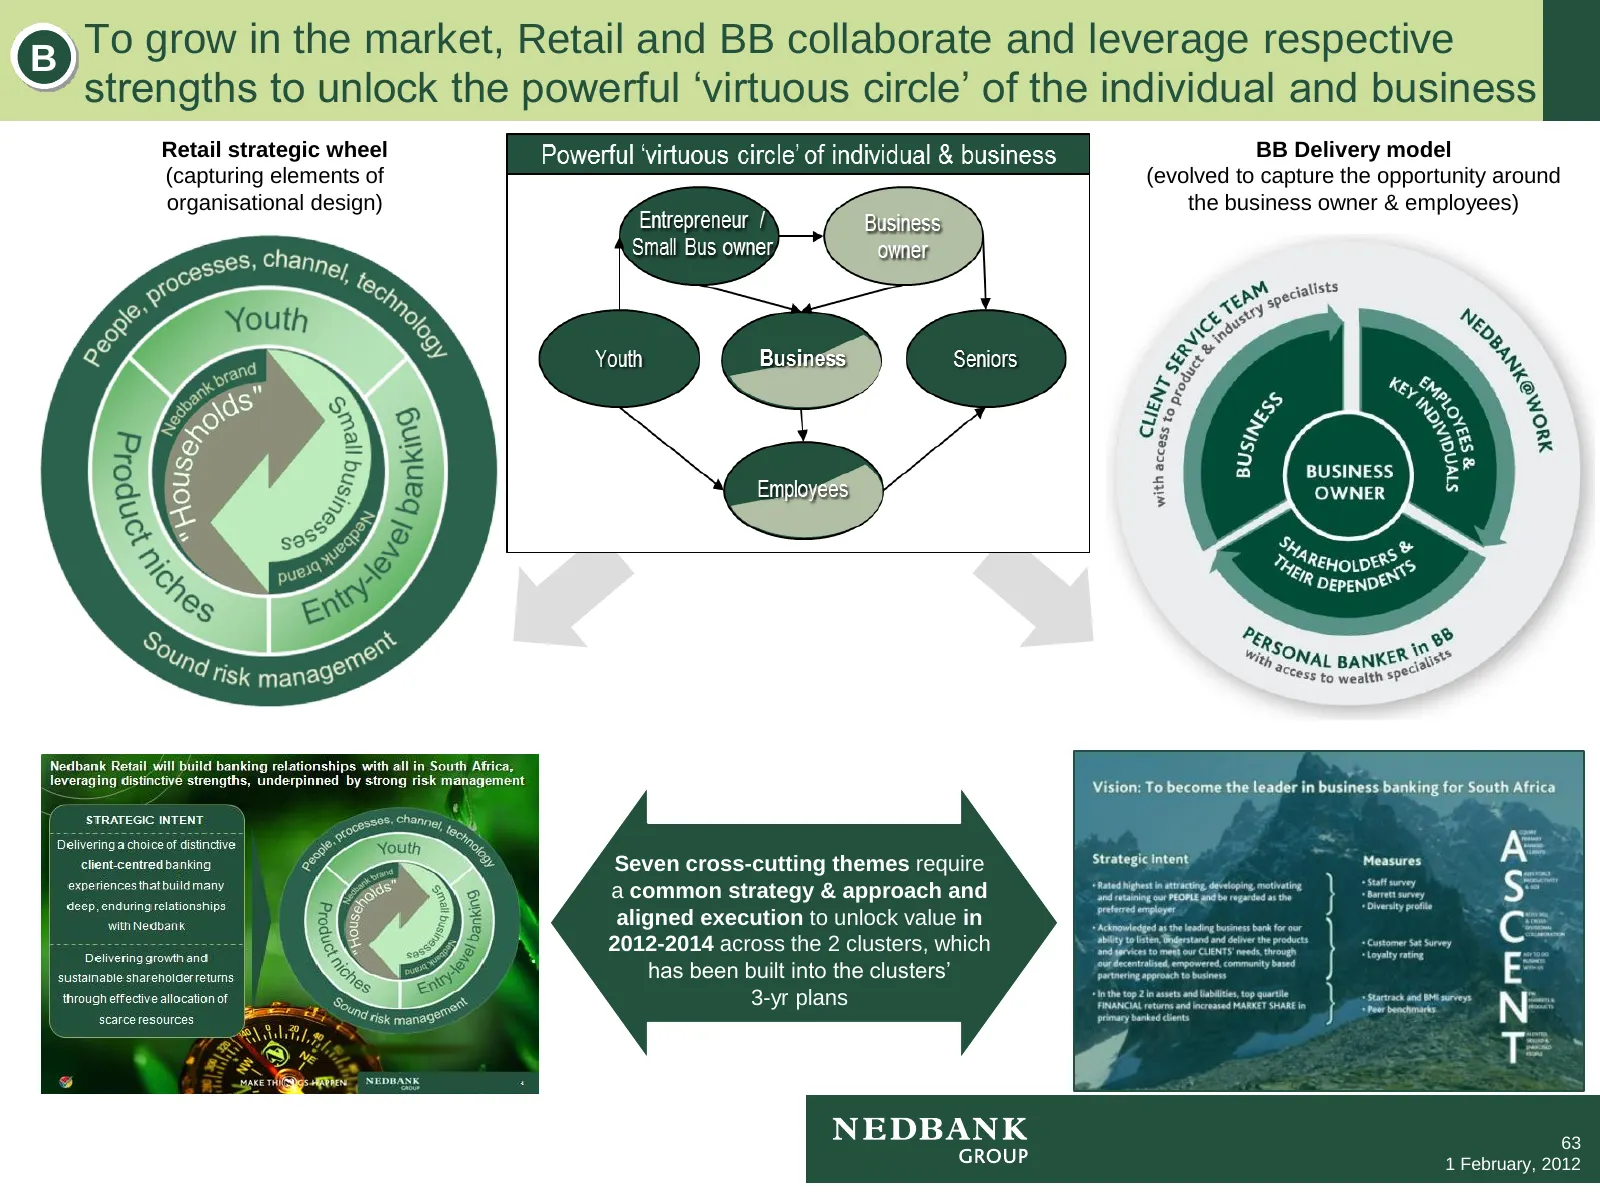
B To grow in the market, Retail and BB collaborate and leverage respective strengths to unlock the powerful ‘virtuous circle’ of the individual and business Retail strategic wheel BB Delivery model (capturing elements of (evolved to capture the opportunity around organisational design) the business
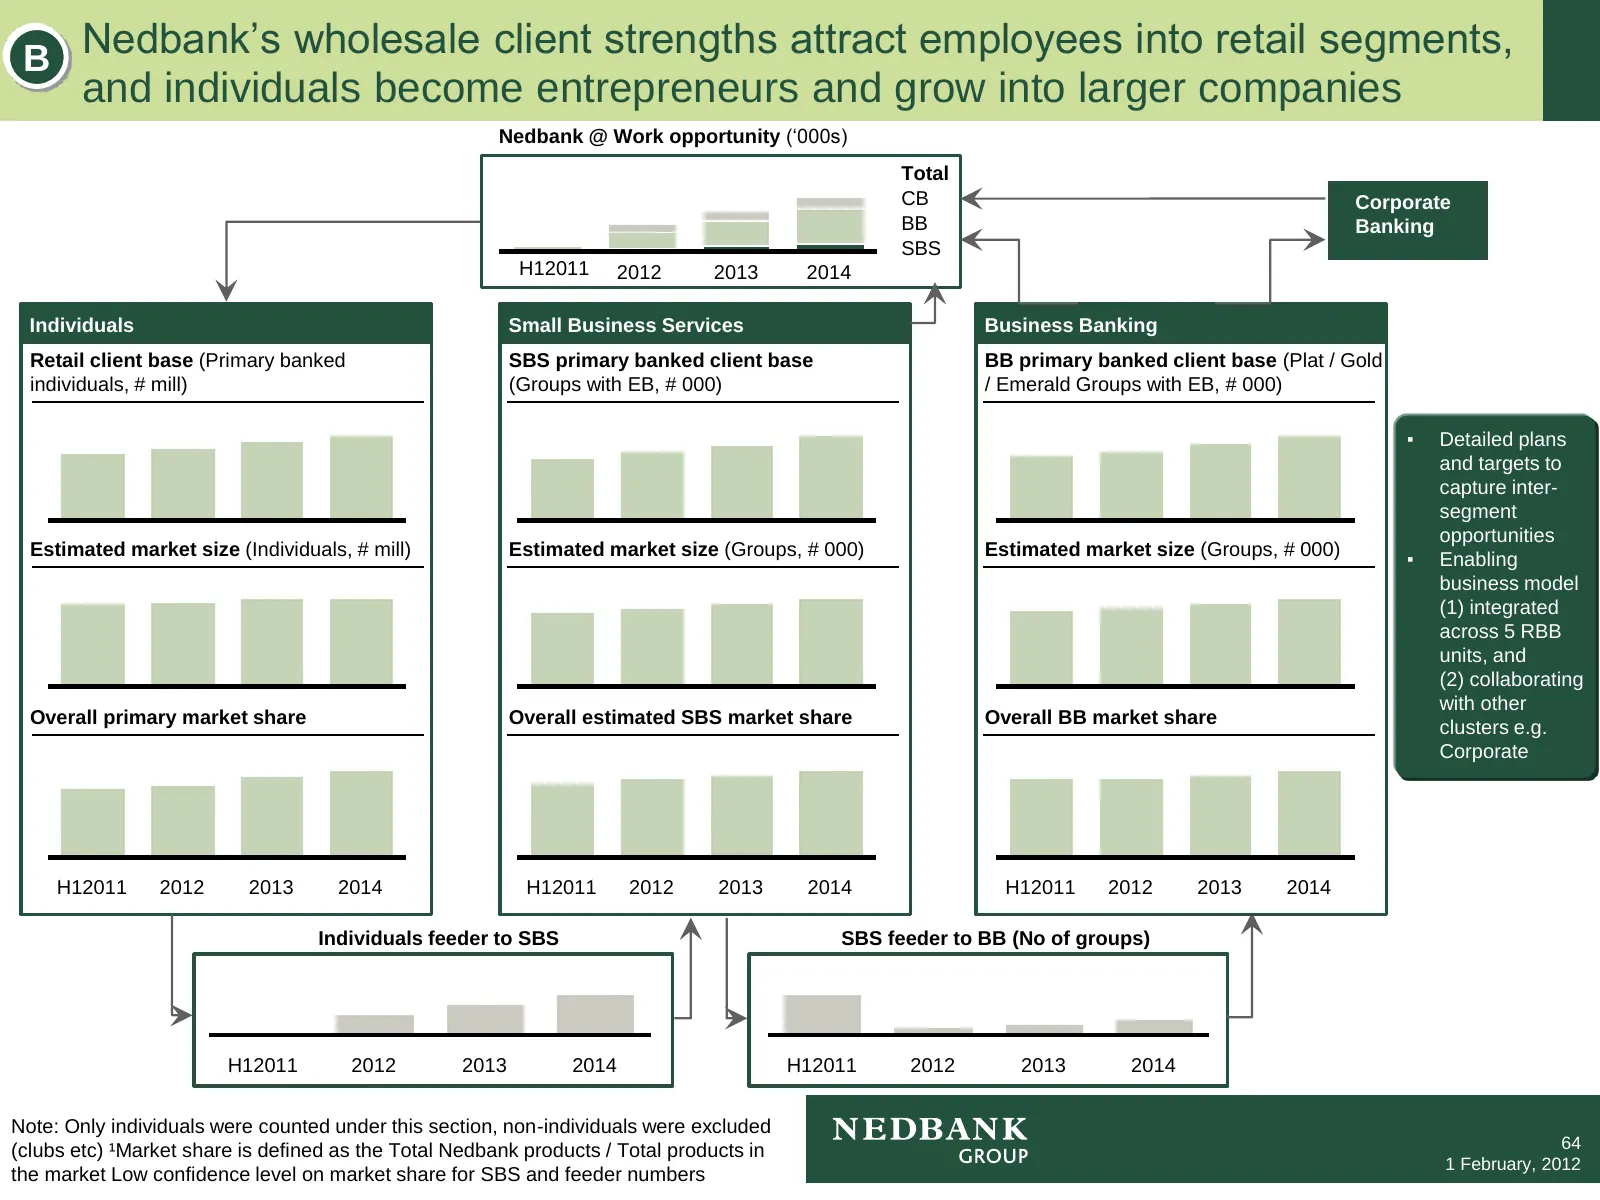
Slide 65: Wholesale client strengths attract employees into retail segments
B Nedbank’s wholesale client strengths attract employees into retail segments, and individuals become entrepreneurs and grow into larger companies Nedbank @ Work opportunity (‘000s) Total CB Corporate BB Banking SBS H12011 2012 2013 2014 Individuals Small Business Services Business Banking Retail cl
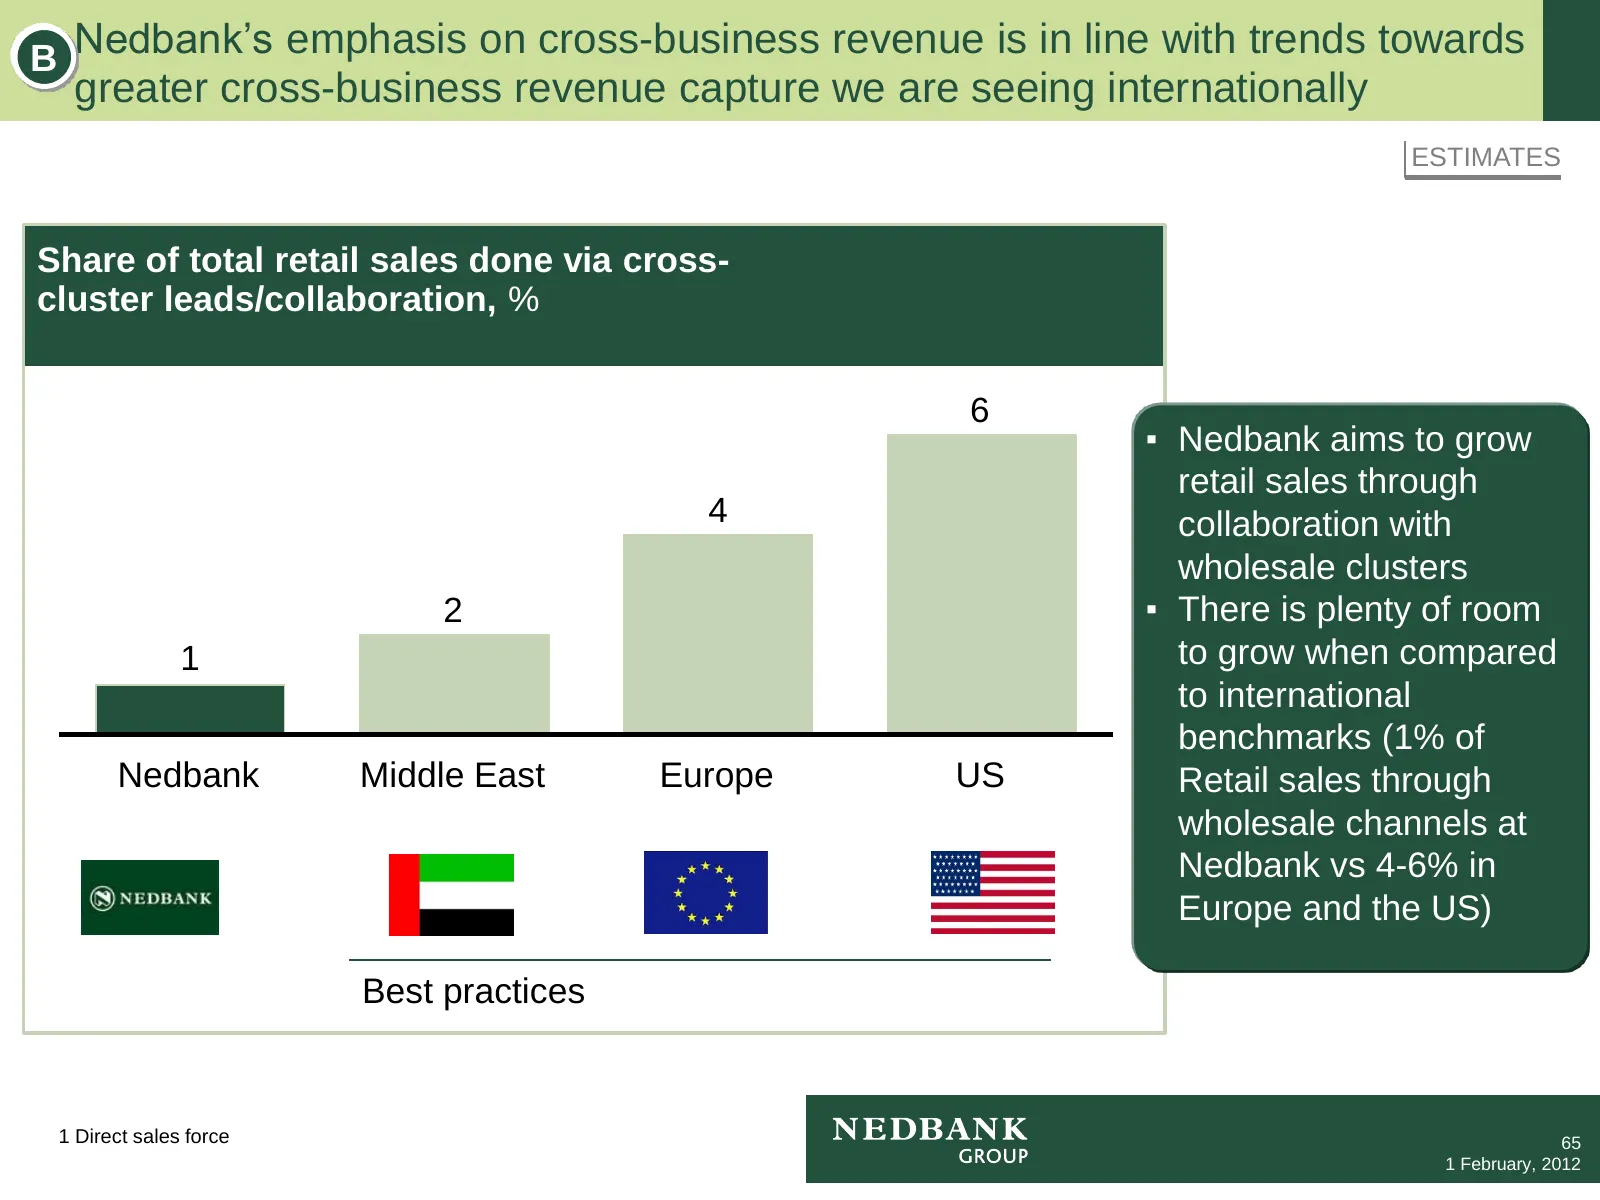
Slide 66: Cross-business revenue in line with international trends
B Nedbank’s emphasis on cross-business revenue is in line with trends towards greater cross-business revenue capture we are seeing internationally ESTIMATES Share of total retail sales done via cross- cluster leads/collaboration, % 6 ▪ Nedbank aims to grow retail sales through 4 collaboration with w
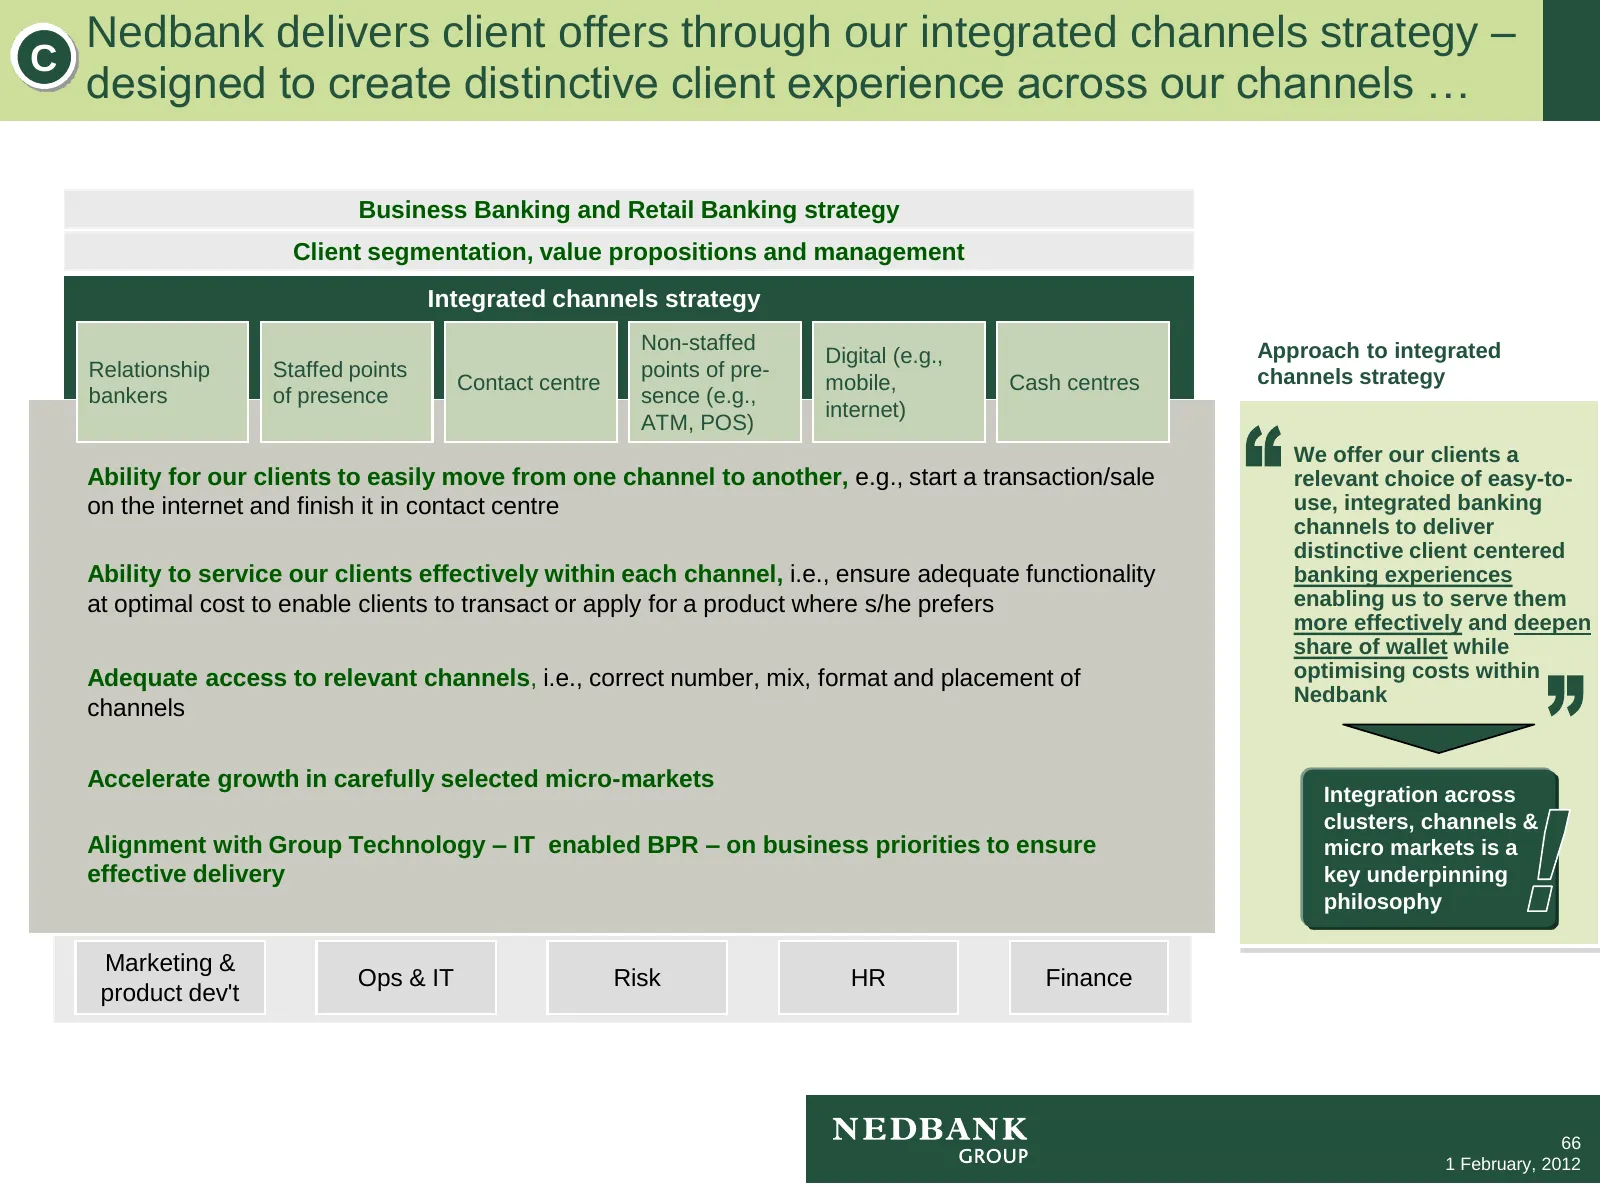
Slide 67: Integrated channels strategy for distinctive client experience
Nedbank delivers client offers through our integrated channels strategy – C designed to create distinctive client experience across our channels … Business Banking and Retail Banking strategy Client segmentation, value propositions and management Integrated channels strategy Non-staffed Approach to
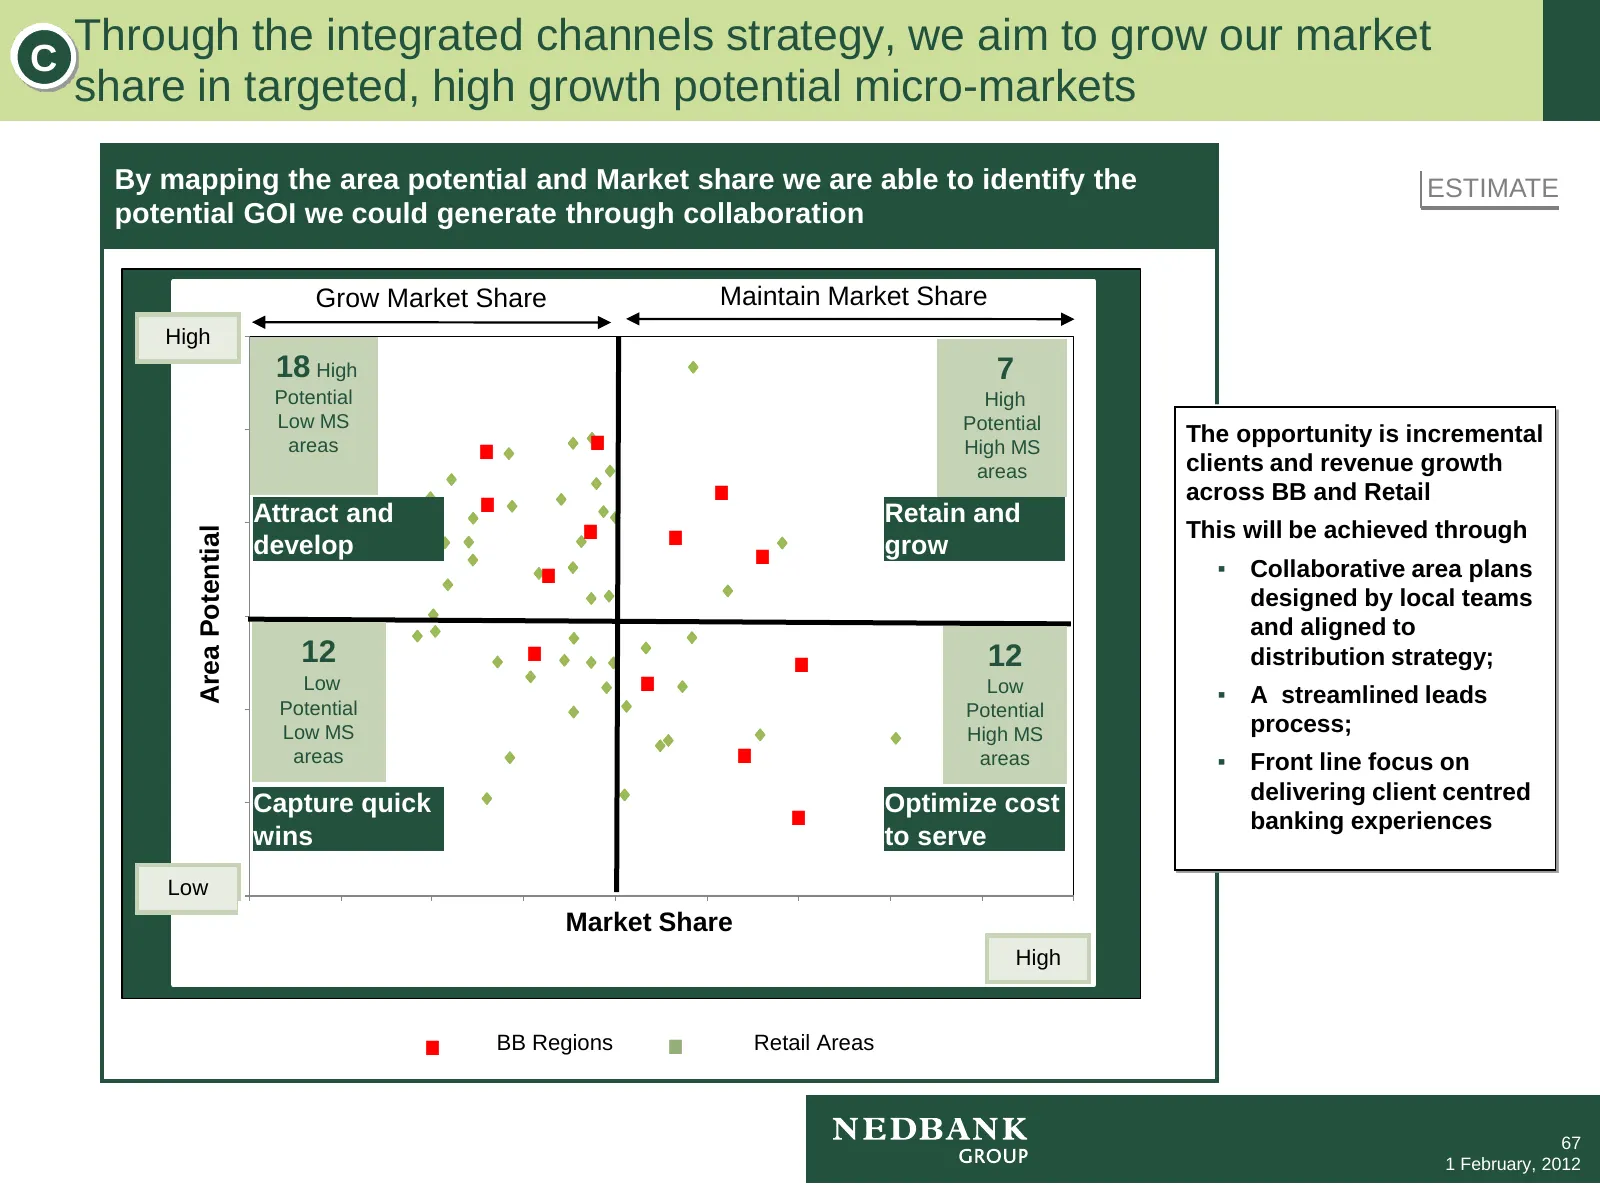
Slide 68: Growing market share in high growth potential micro-markets
C Through the integrated channels strategy, we aim to grow our market share in targeted, high growth potential micro-markets By mapping the area potential and Market share we are able to identify the ESTIMATE potential GOI we could generate through collaboration Grow Market Share Maintain Market Sha
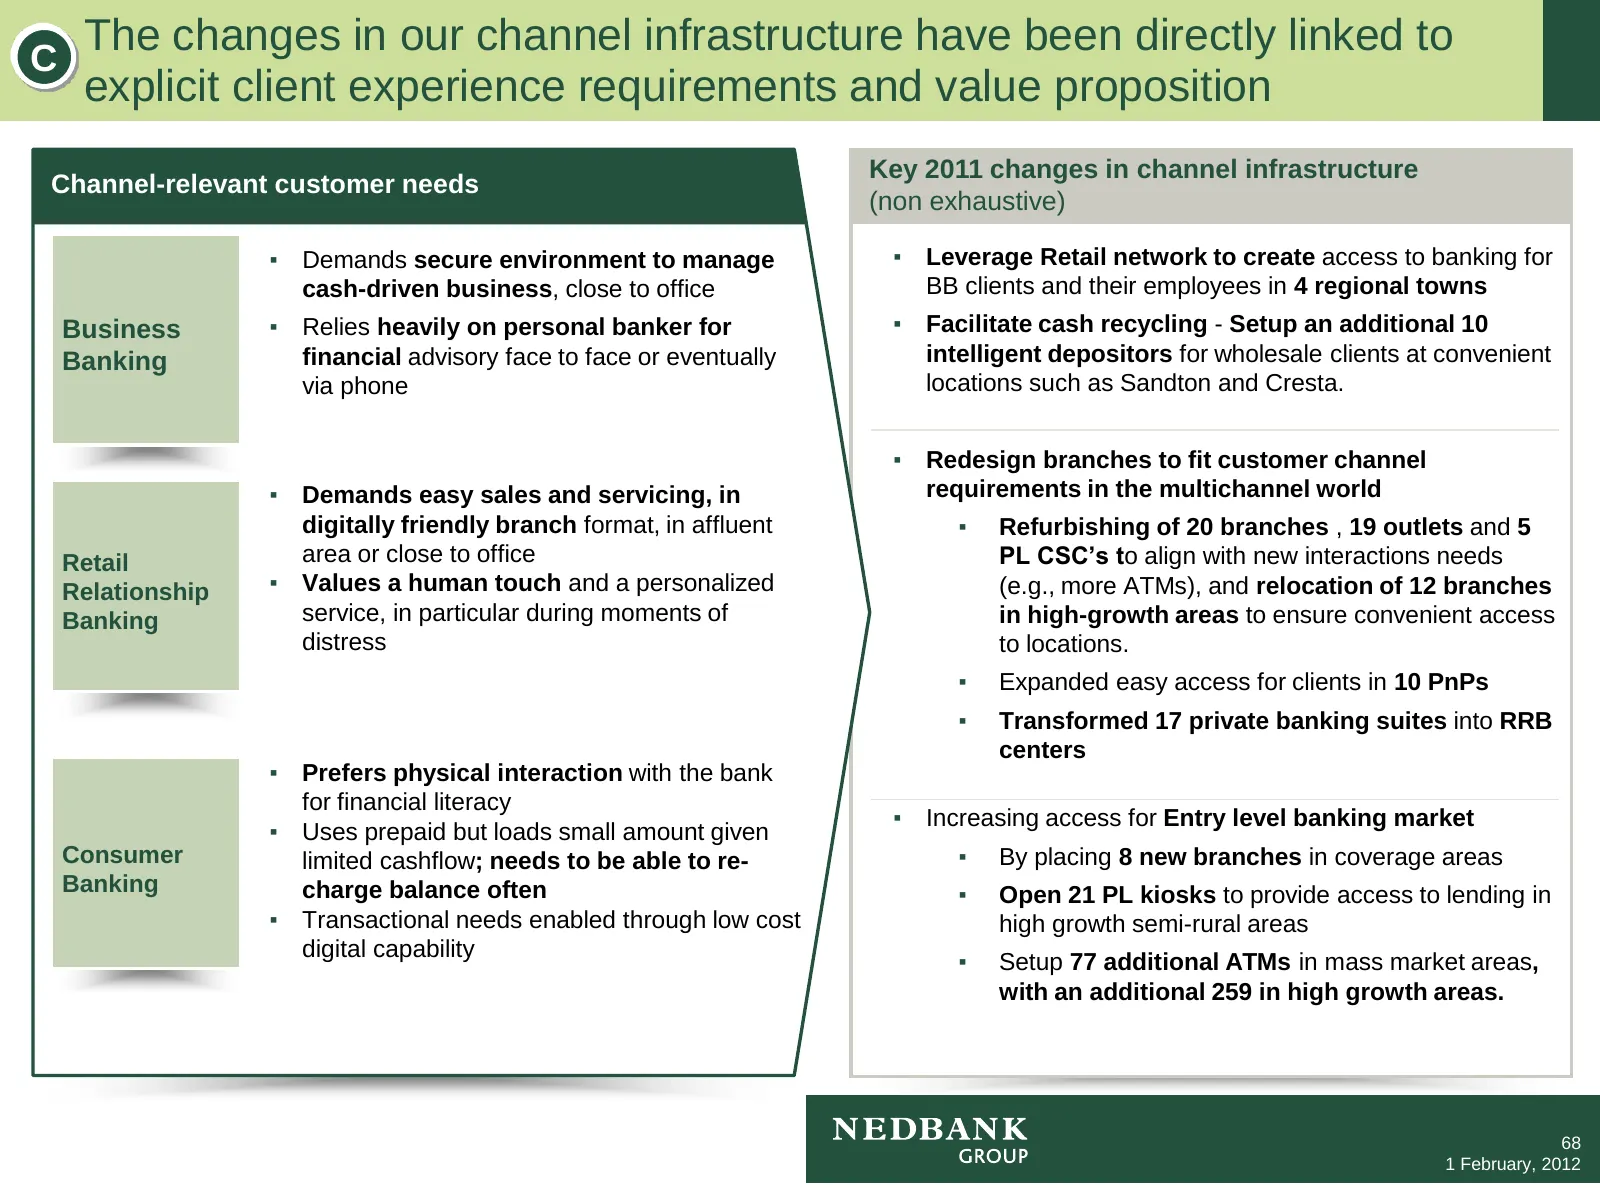
Slide 69: Channel infrastructure changes linked to client requirements
C The changes in our channel infrastructure have been directly linked to explicit client experience requirements and value proposition Key 2011 changes in channel infrastructure Channel-relevant customer needs (non exhaustive) ▪ Demands secure environment to manage ▪ Leverage Retail network to creat
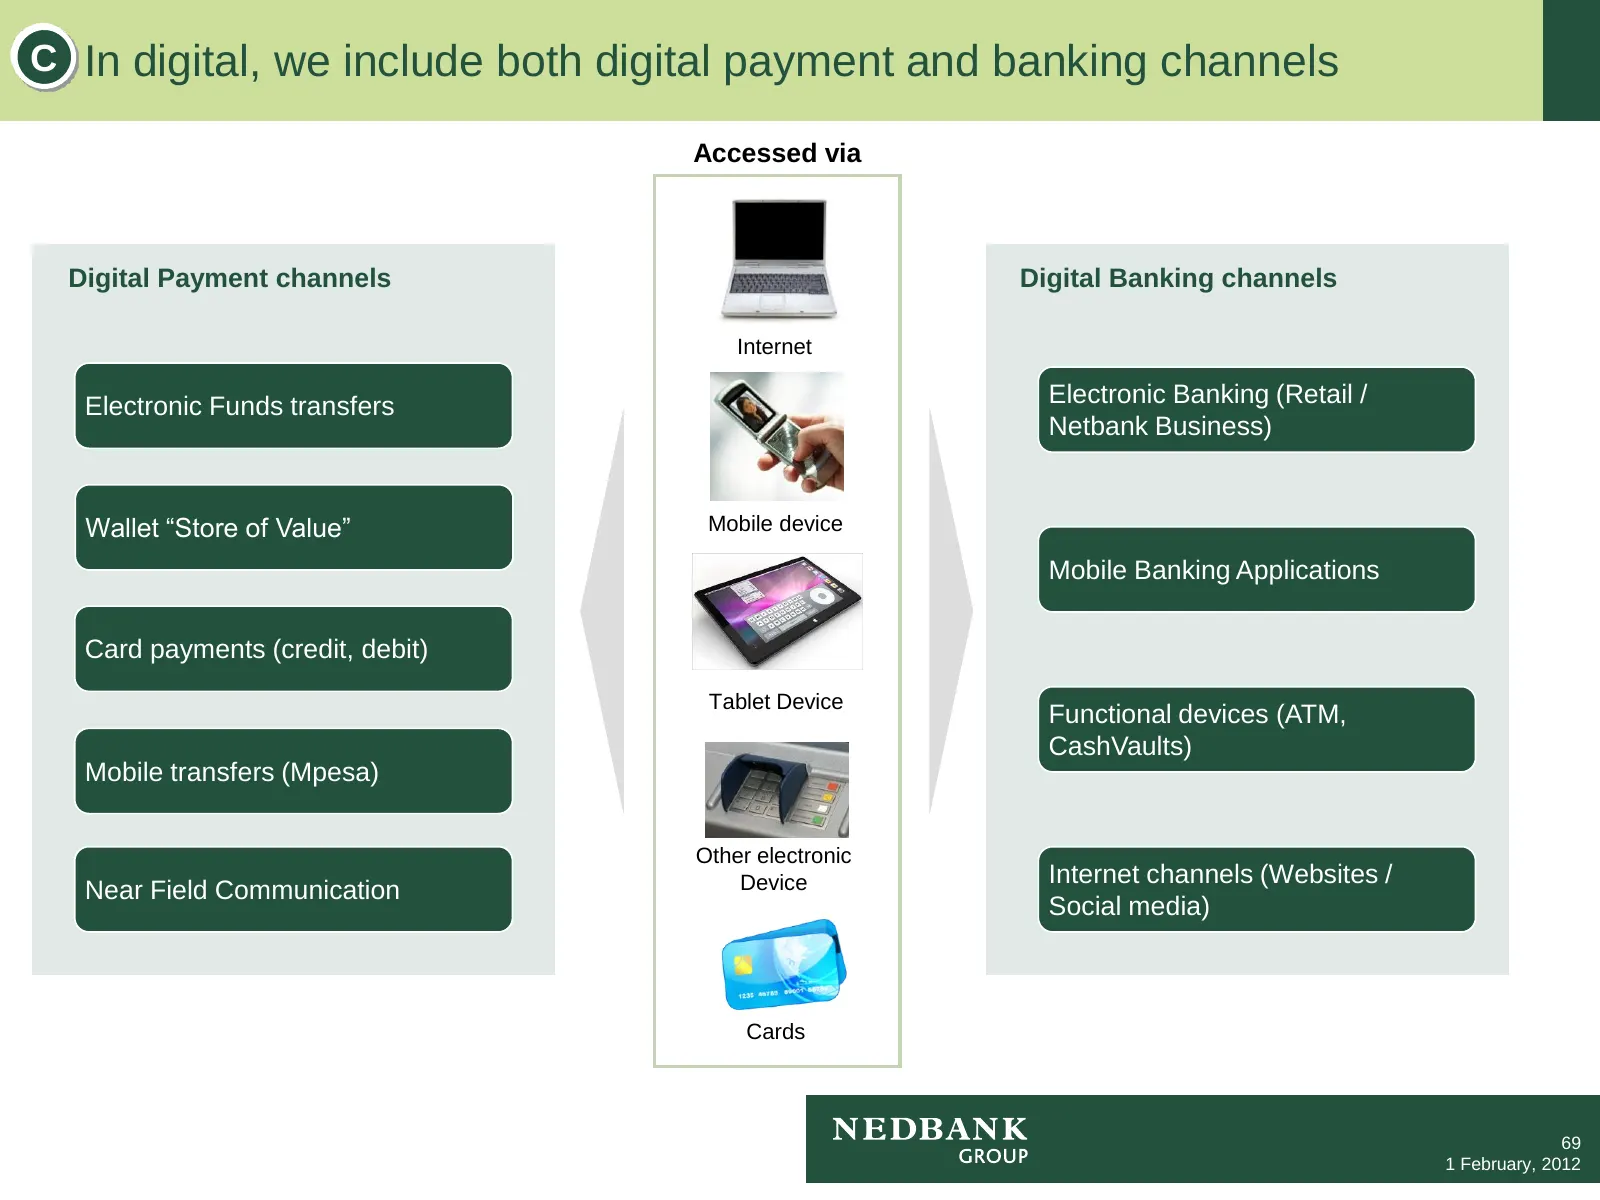
Slide 70: Digital payment and banking channels
C In digital, we include both digital payment and banking channels Accessed via Digital Payment channels Digital Banking channels Internet Electronic Funds transfers Electronic Banking (Retail / Netbank Business) Wallet “Store of Value” Mobile device Mobile Banking Applications Card payments (credit
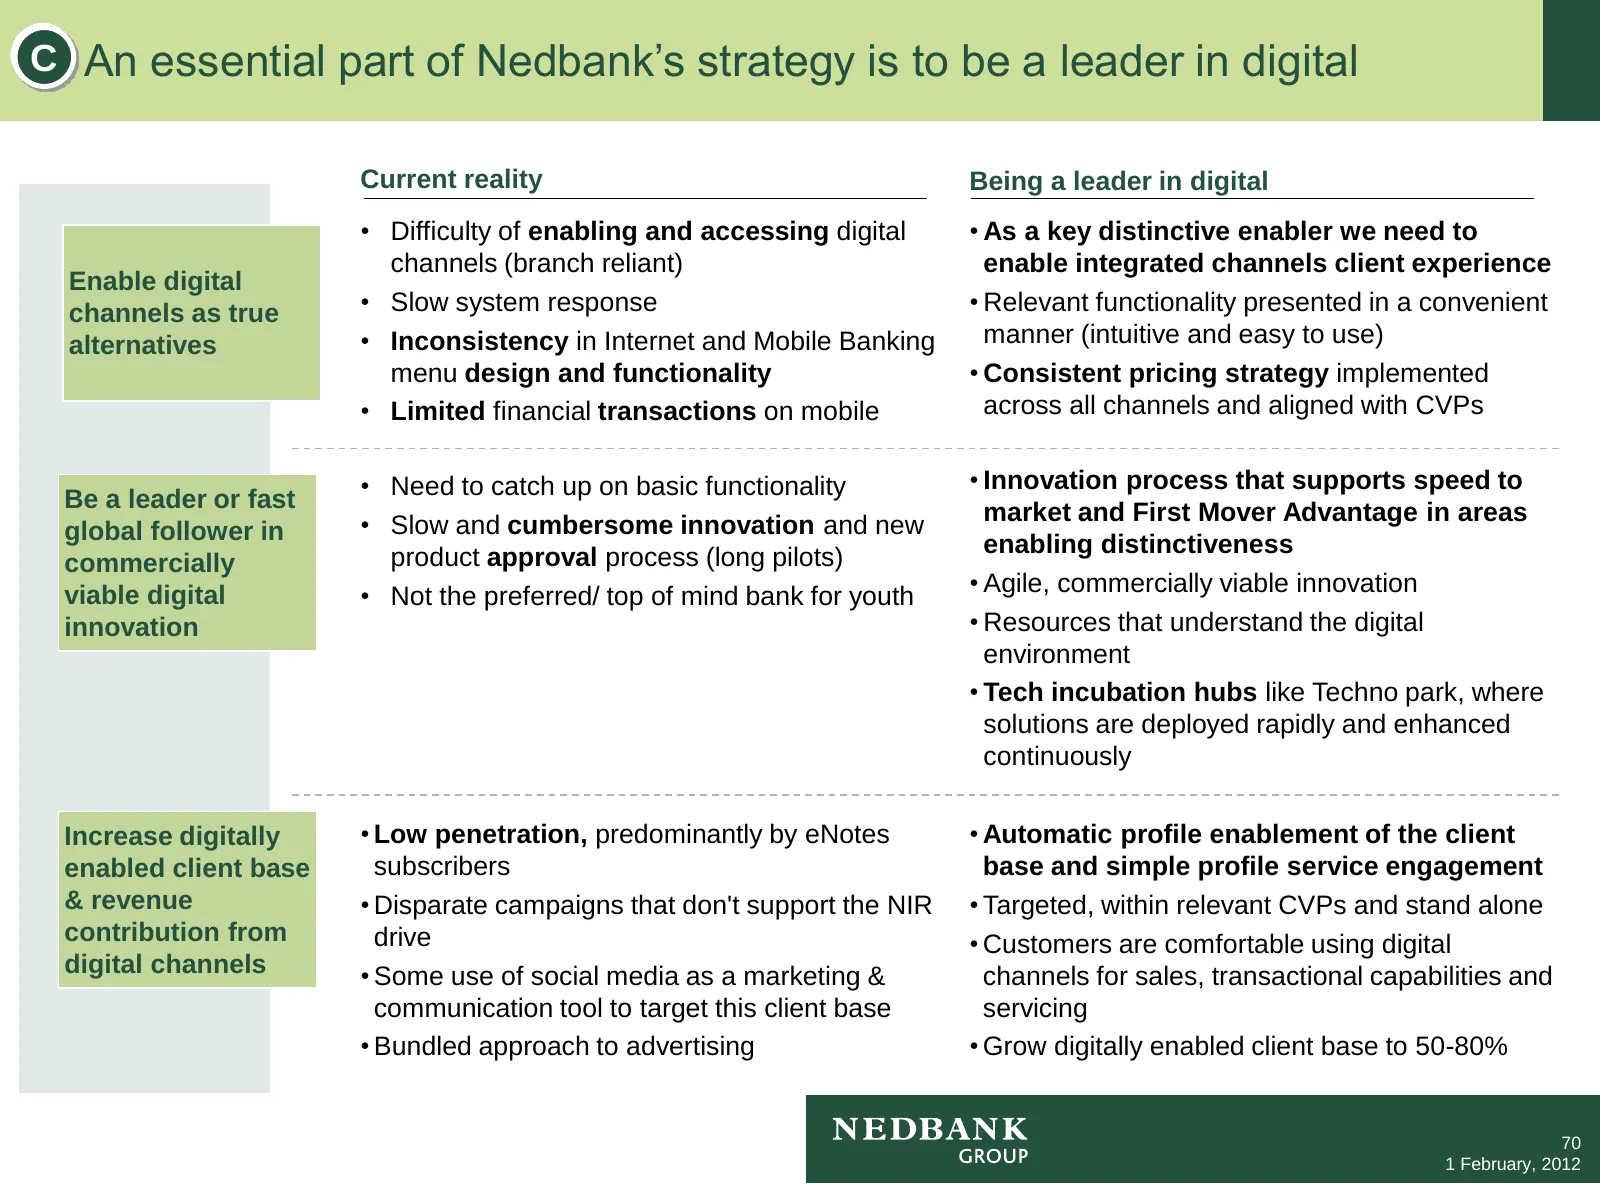
Slide 71: Being a leader in digital
C An essential part of Nedbank’s strategy is to be a leader in digital Current reality Being a leader in digital • Difficulty of enabling and accessing digital • As a key distinctive enabler we need to channels (branch reliant) enable integrated channels client experience Enable digital channels as
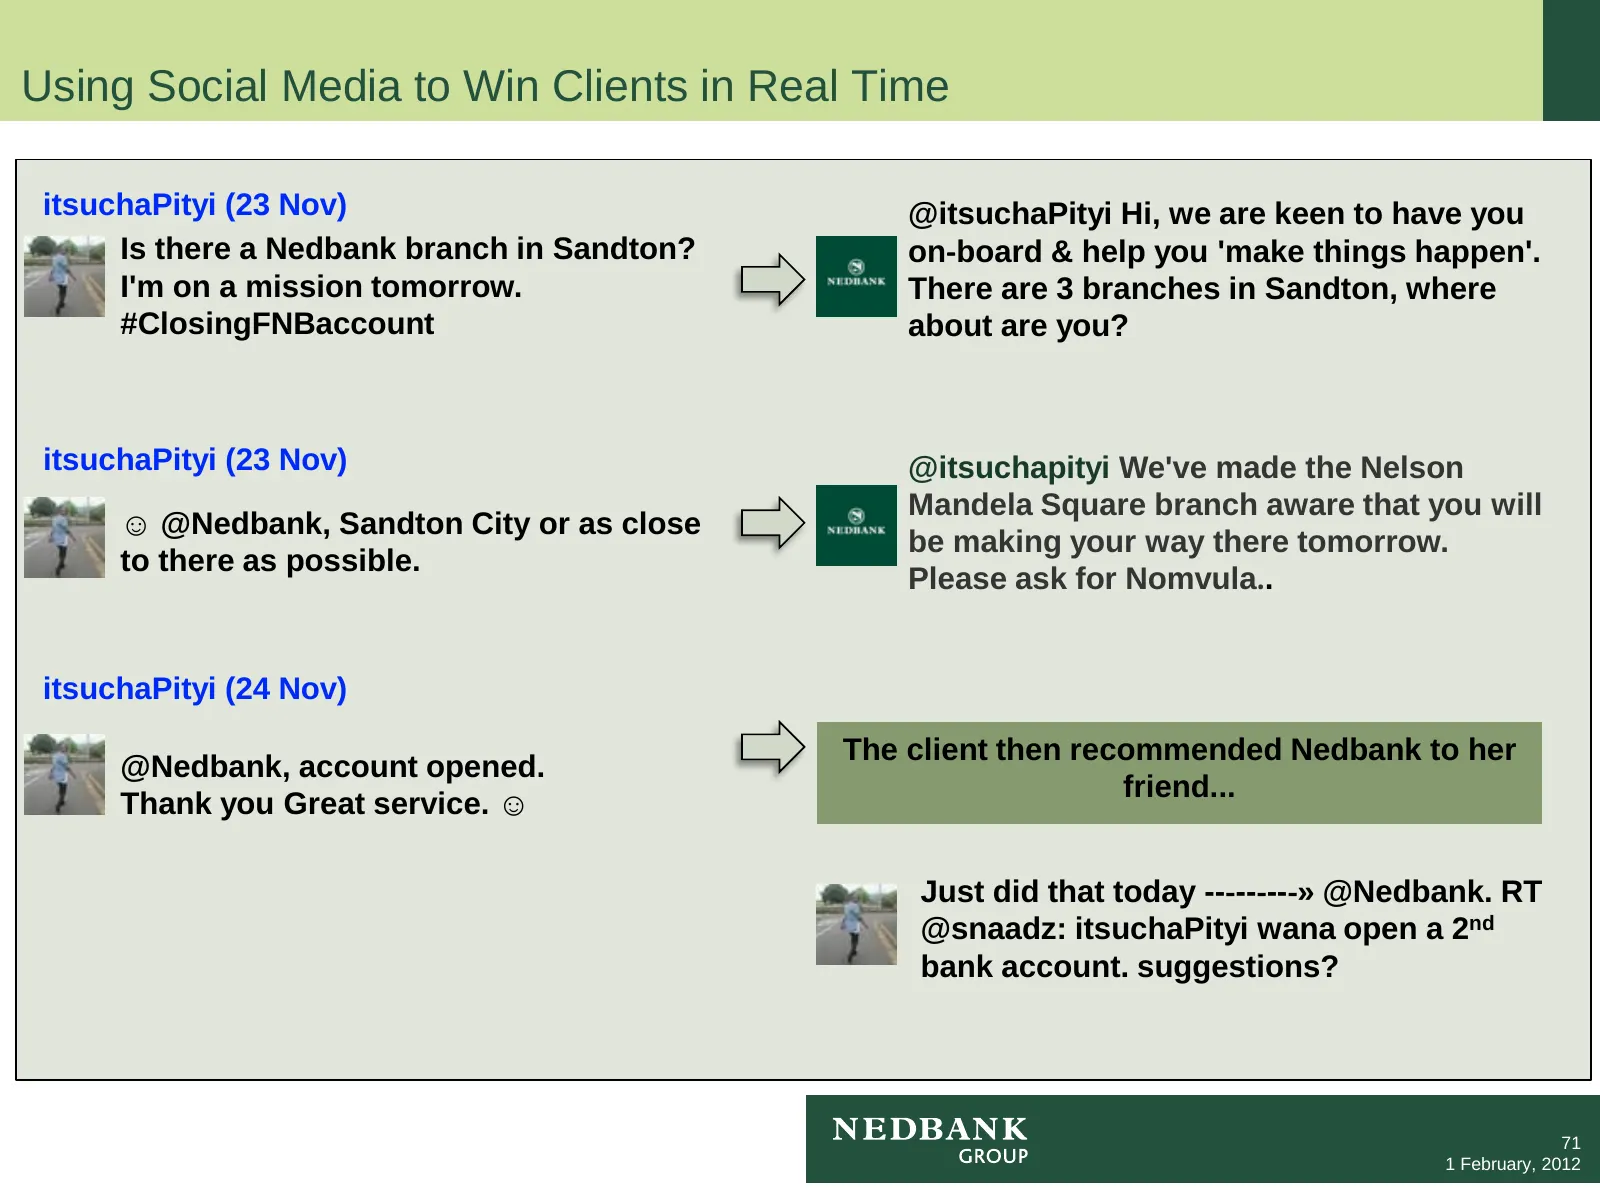
Slide 72: Using Social Media to Win Clients in Real Time
Using Social Media to Win Clients in Real Time itsuchaPityi (23 Nov) @itsuchaPityi Hi, we are keen to have you Is there a Nedbank branch in Sandton? on‐board & help you 'make things happen'. I'm on a mission tomorrow. There are 3 branches in Sandton, where #ClosingFNBaccount about are you? itsuchaPi
Slide 73: Leveraging risk management into Retail
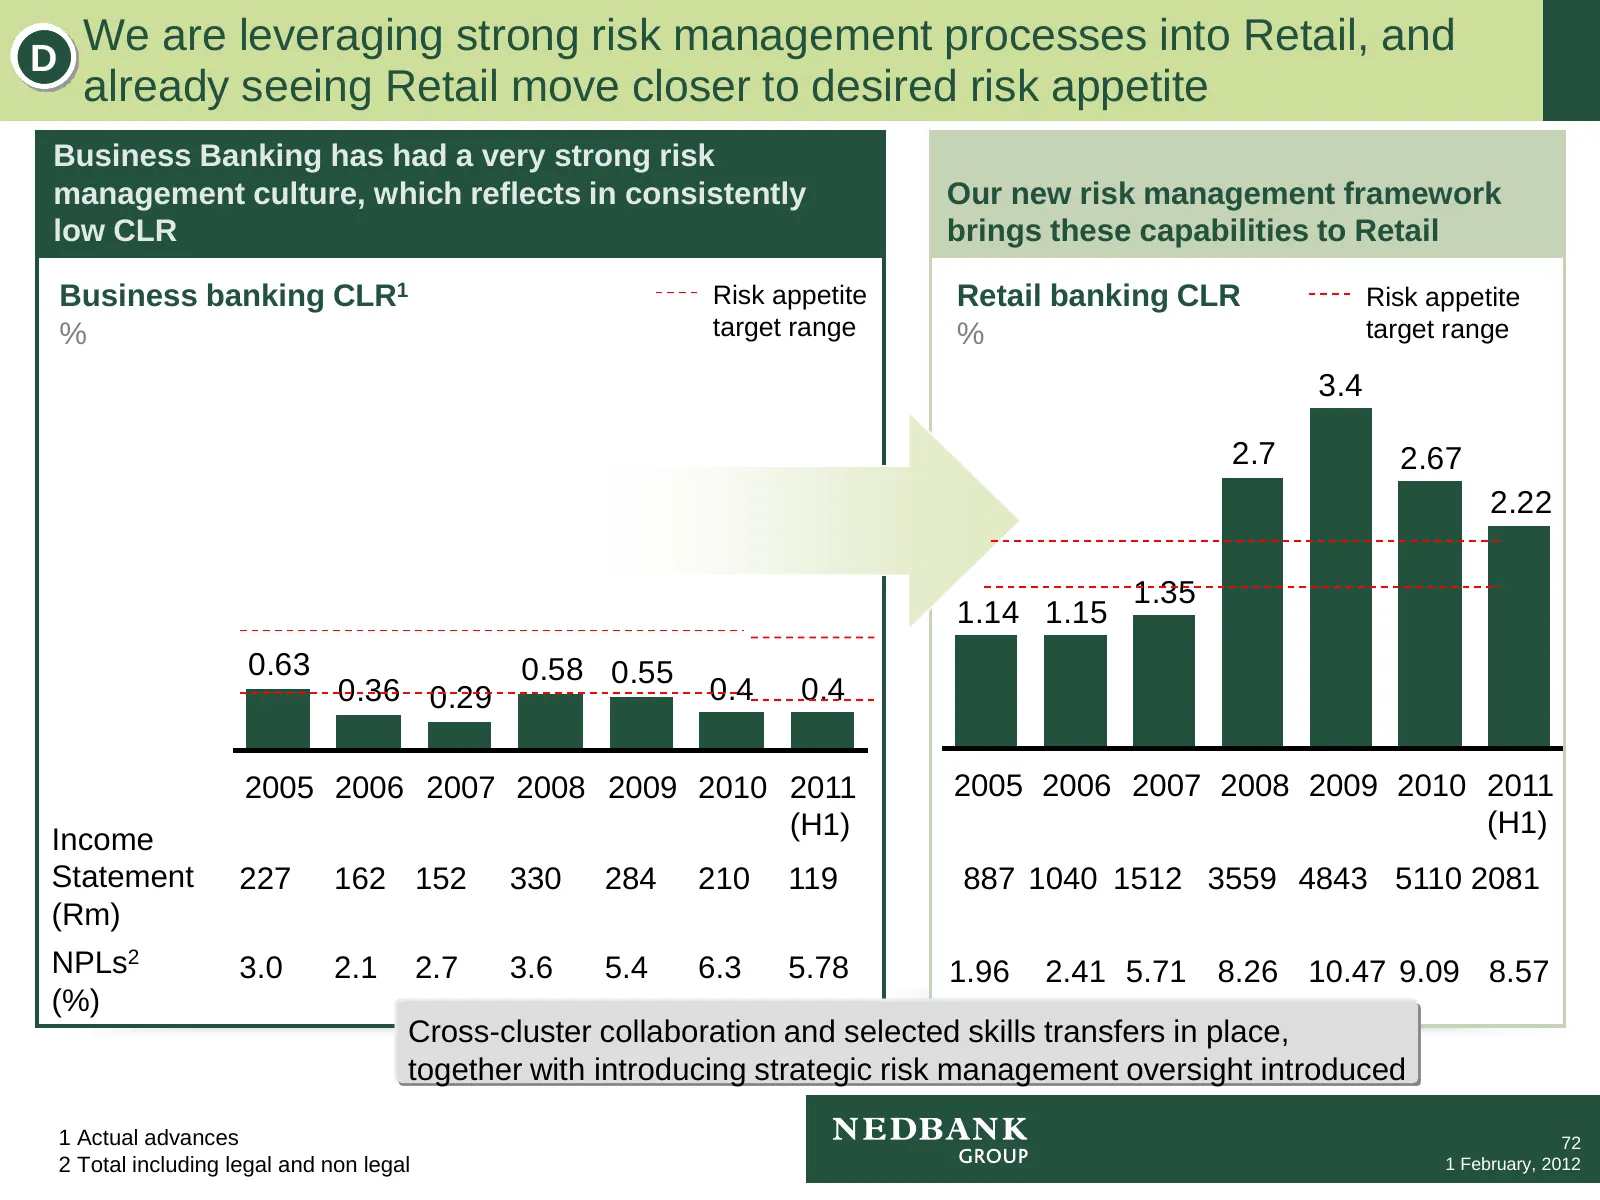
D We are leveraging strong risk management processes into Retail, and already seeing Retail move closer to desired risk appetite Business Banking has had a very strong risk management culture, which reflects in consistently Our new risk management framework low CLR brings these capabilities to Retai
Slide 74: Business Banking credit risk mechanisms to grant, manage and collect
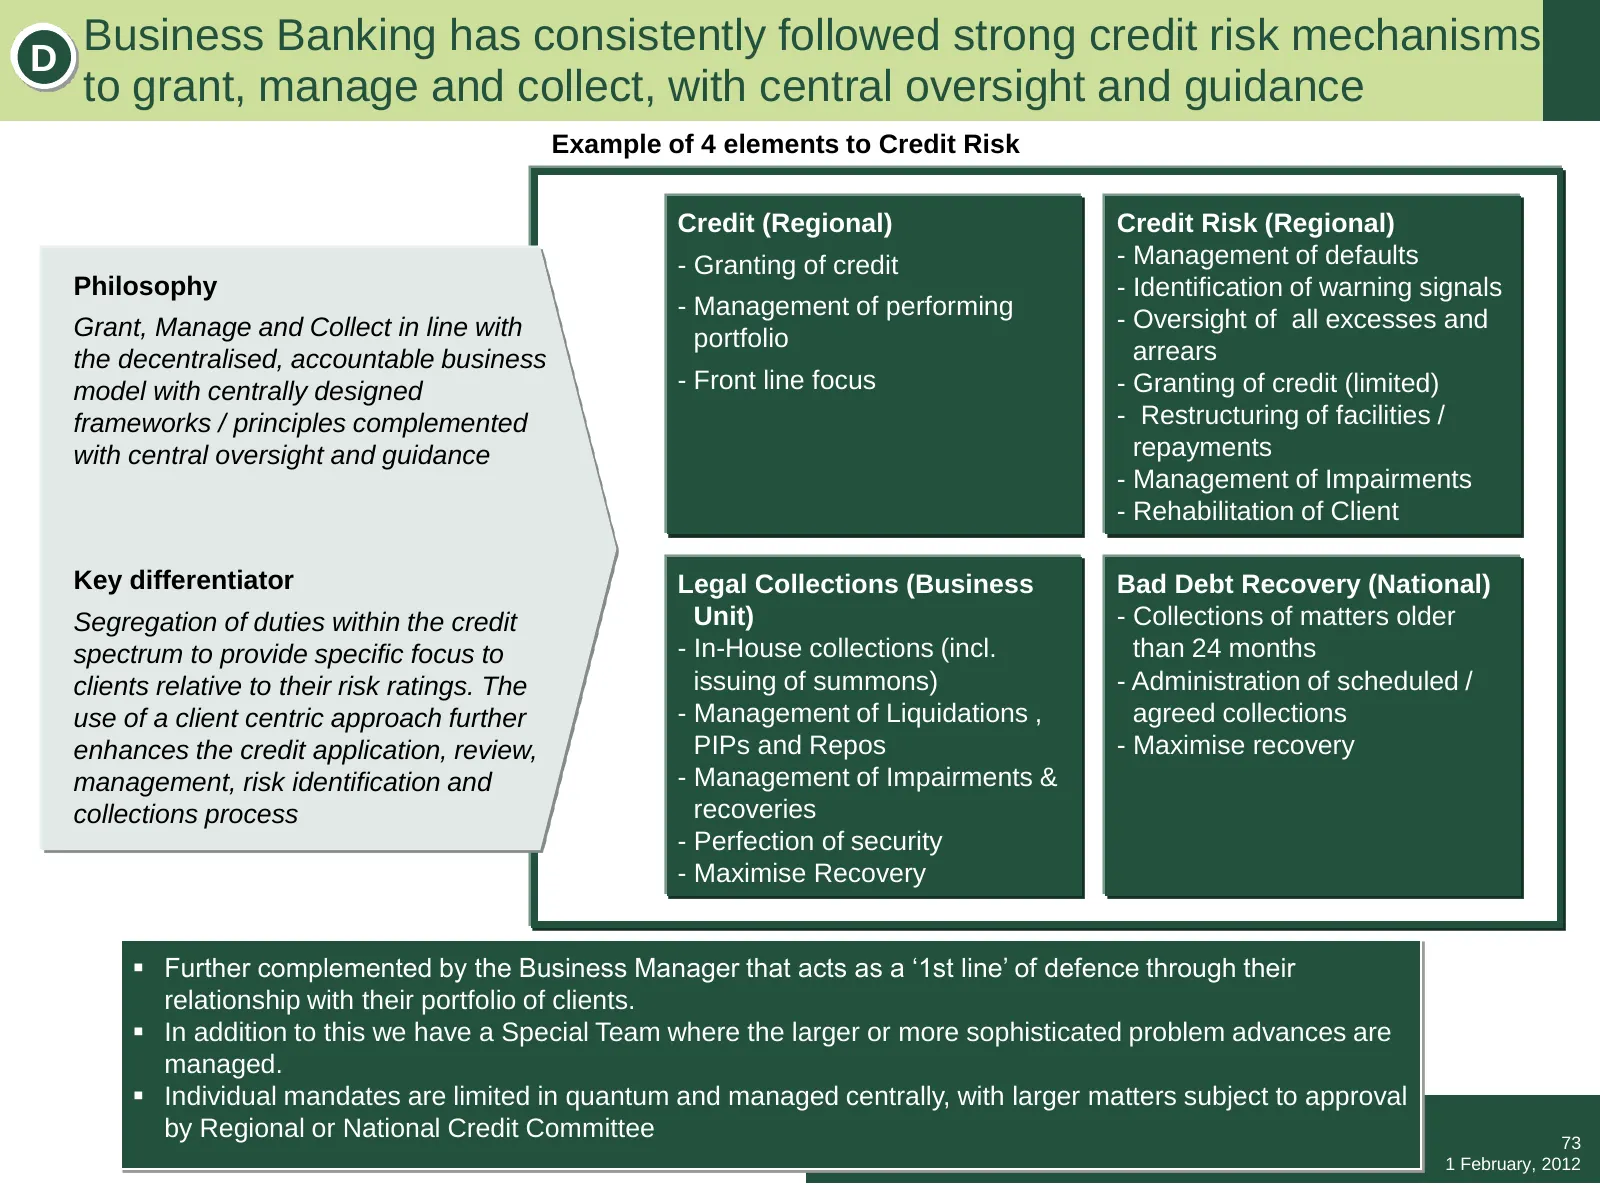
D Business Banking has consistently followed strong credit risk mechanisms to grant, manage and collect, with central oversight and guidance Example of 4 elements to Credit Risk Credit (Regional) Credit Risk (Regional) - Granting of credit - Management of defaults Philosophy - Identification of warn
Slide 75: Push across risk areas to address non-performing loans
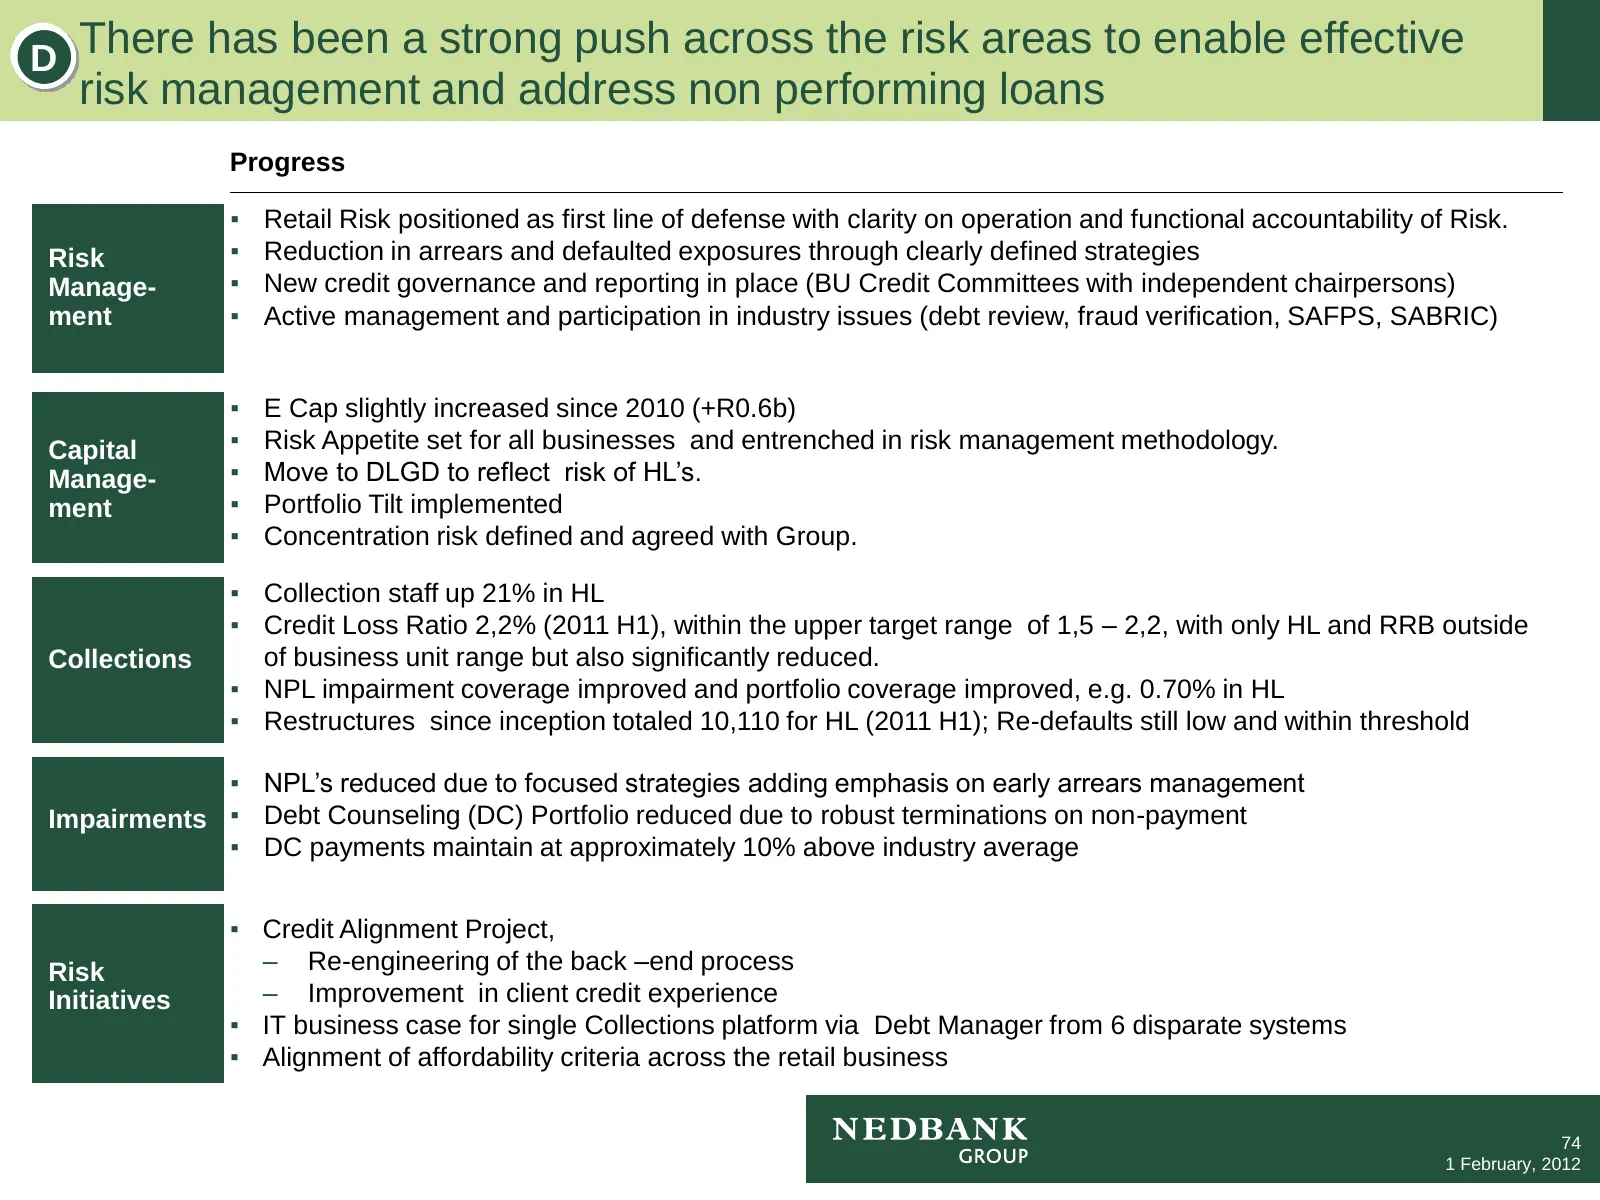
D There has been a strong push across the risk areas to enable effective risk management and address non performing loans Progress ▪ Retail Risk positioned as first line of defense with clarity on operation and functional accountability of Risk. Risk ▪ Reduction in arrears and defaulted exposures th
Slide 76: Discerning home loans strategy given industry dynamics
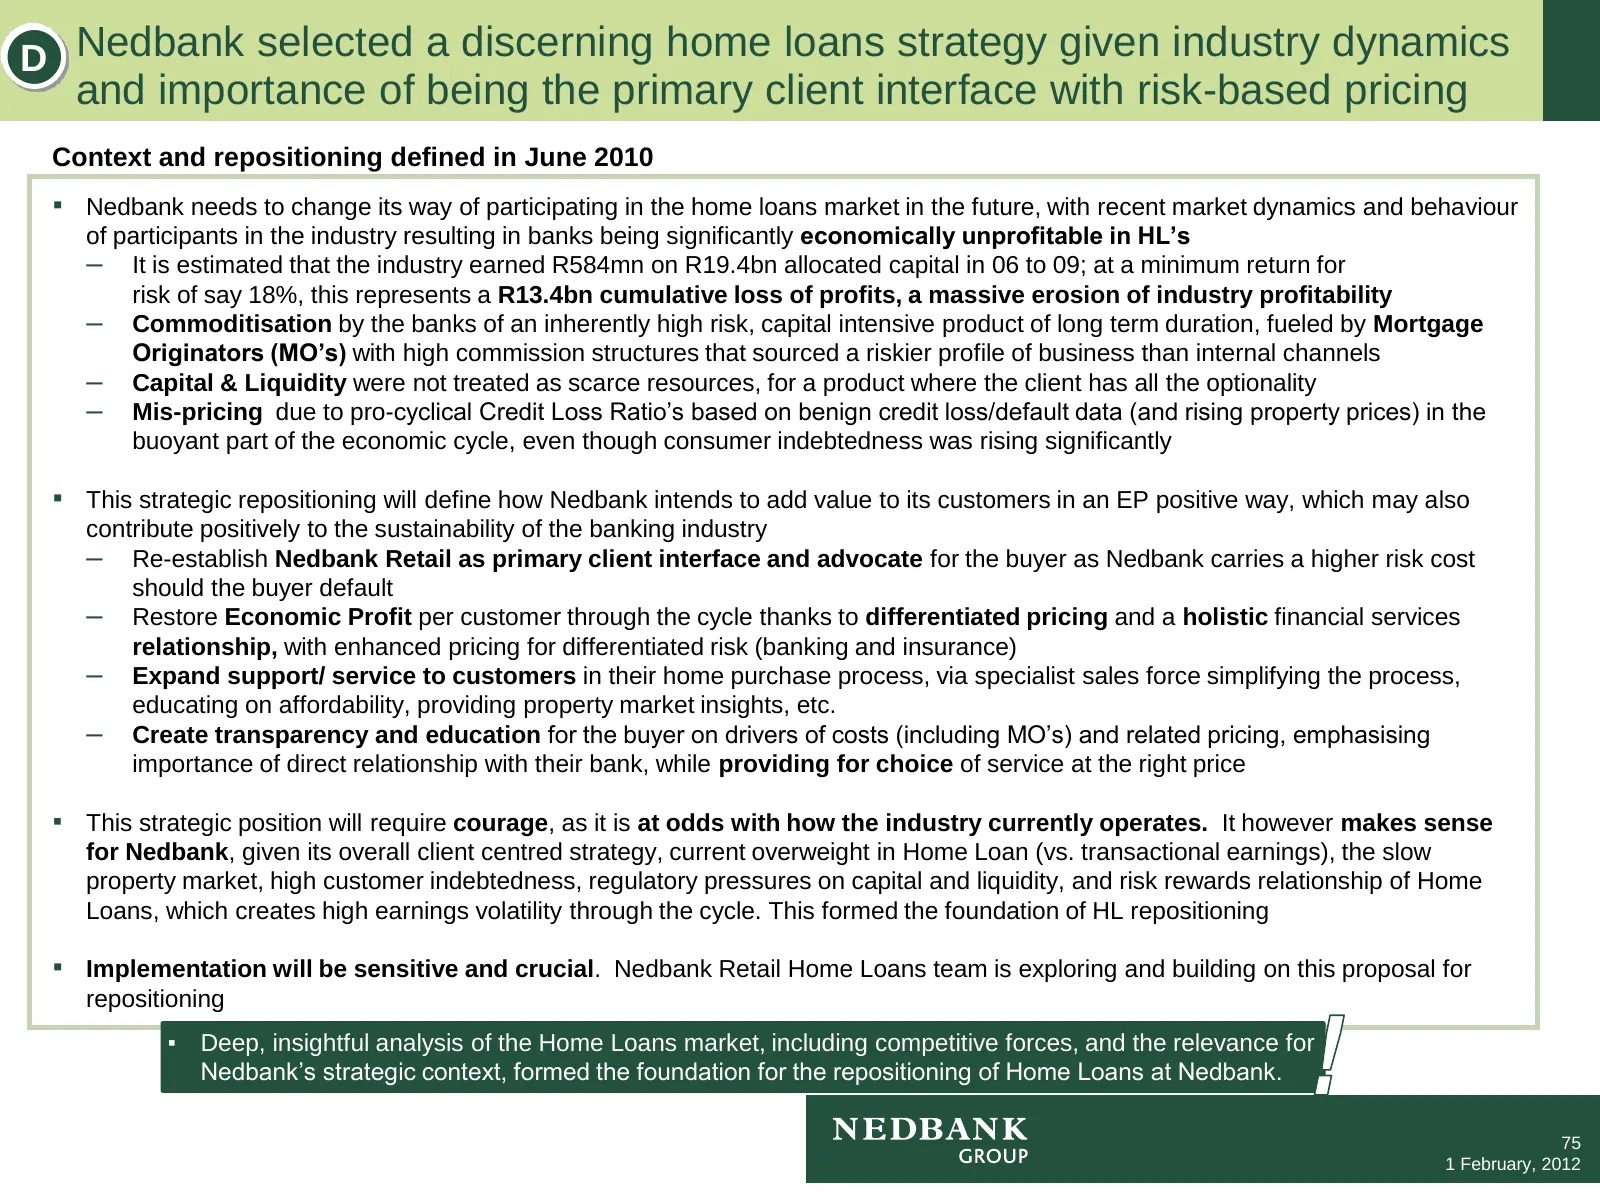
D Nedbank selected a discerning home loans strategy given industry dynamics and importance of being the primary client interface with risk-based pricing Context and repositioning defined in June 2010 ▪ Nedbank needs to change its way of participating in the home loans market in the future, with rece
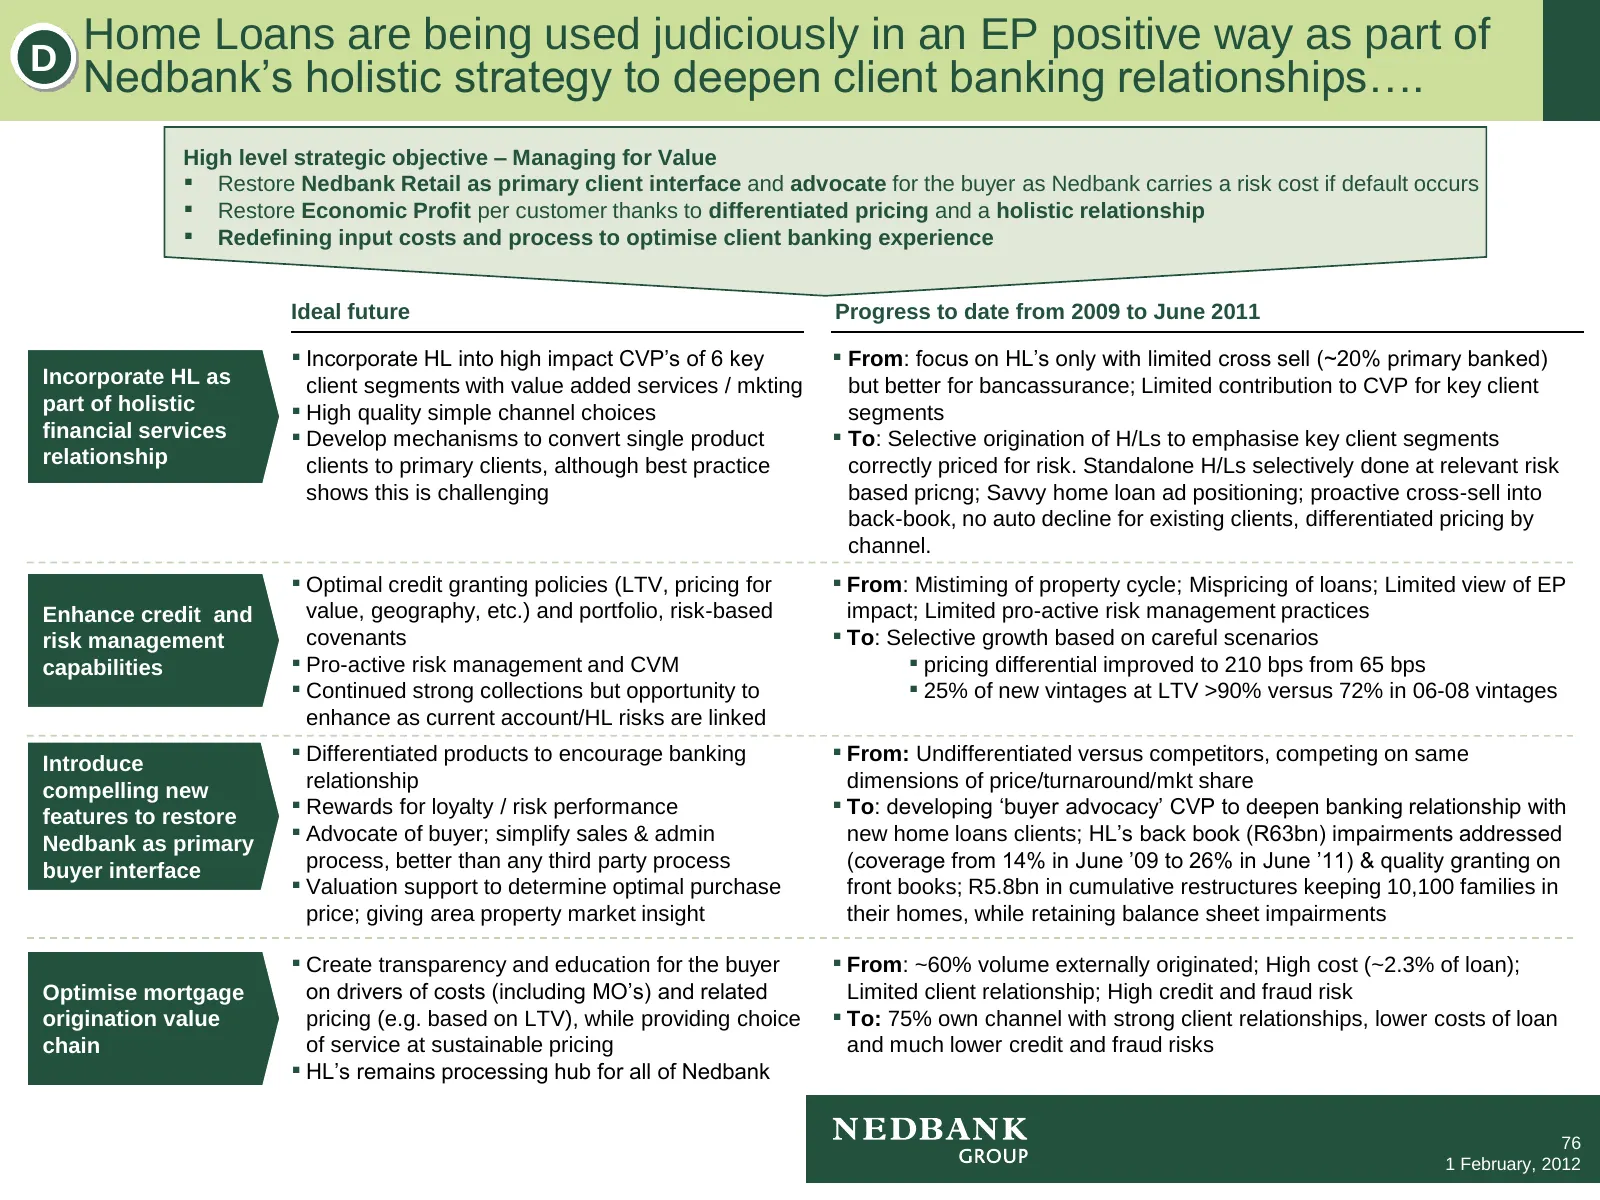
Slide 77: Home Loans used judiciously to deepen client relationships
D Home Loans are being used judiciously in an EP positive way as part of Nedbank’s holistic strategy to deepen client banking relationships…. High level strategic objective – Managing for Value ▪ Restore Nedbank Retail as primary client interface and advocate for the buyer as Nedbank carries a risk
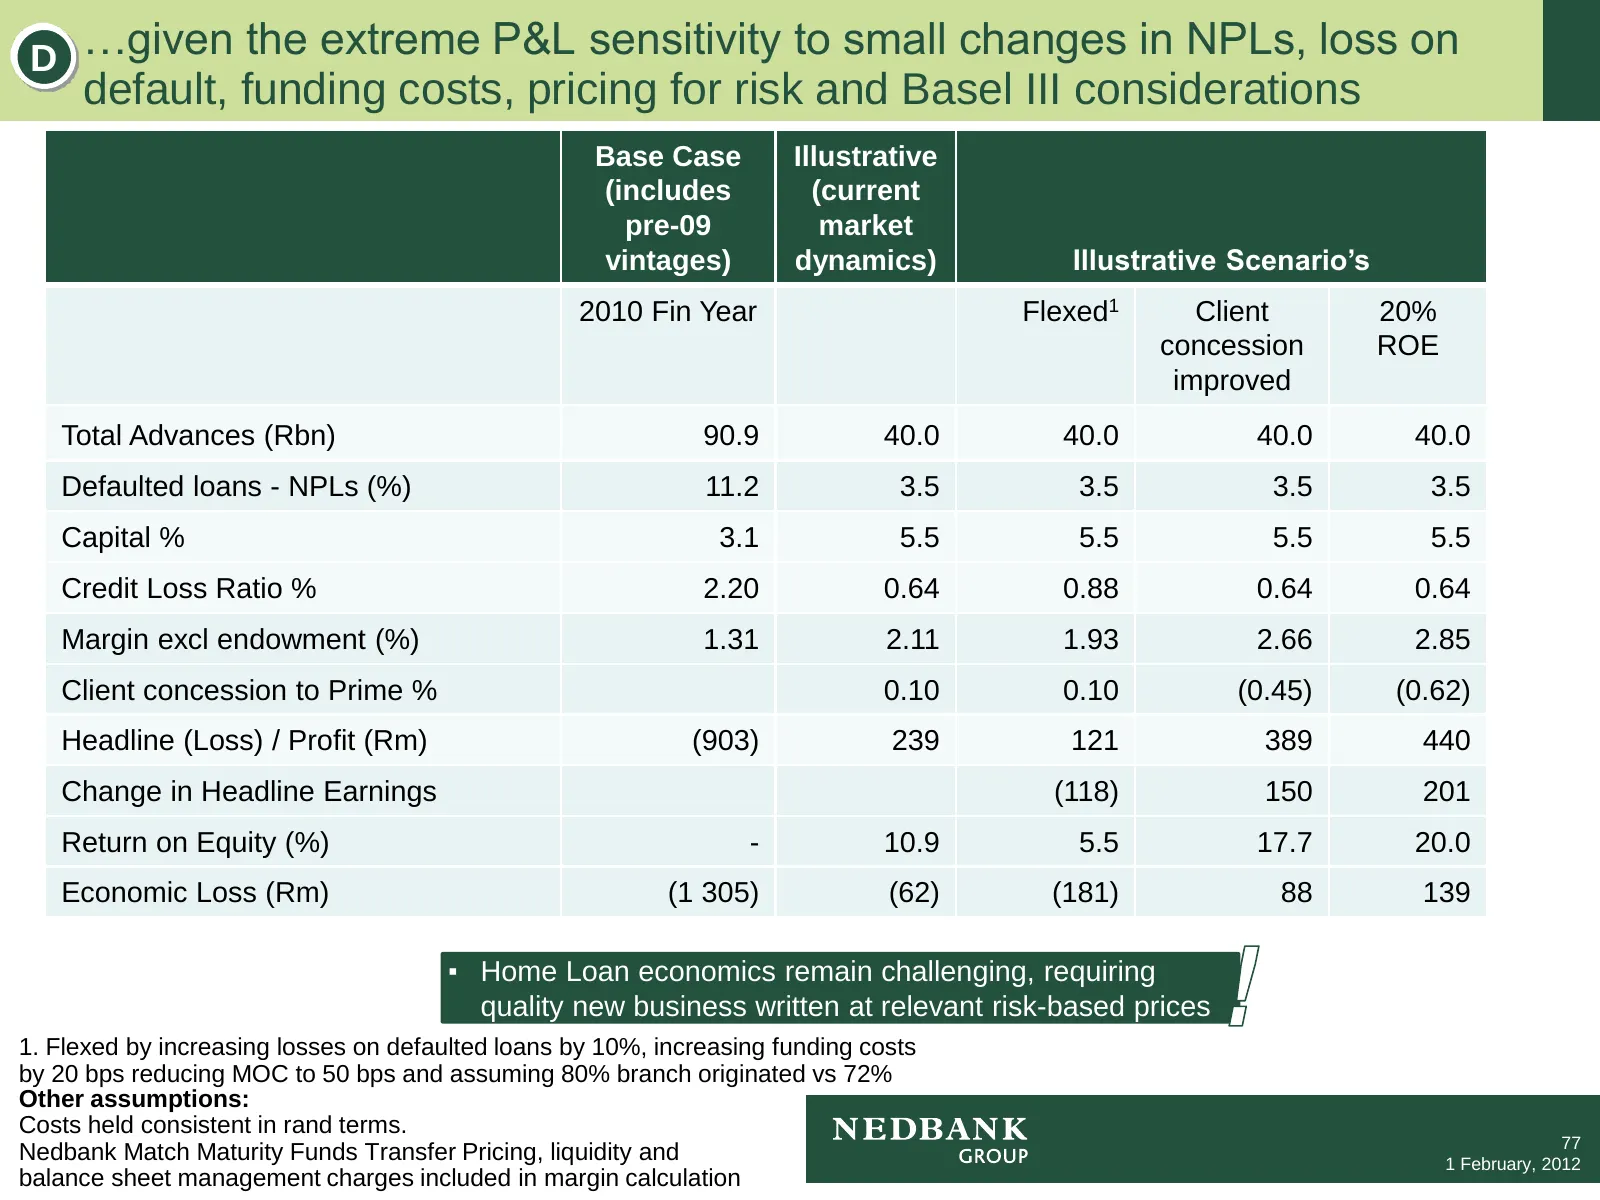
Slide 78: Home loan P&L sensitivity to NPLs, funding costs and pricing
D …given the extreme P&L sensitivity to small changes in NPLs, loss on default, funding costs, pricing for risk and Basel III considerations Base Case Illustrative (includes (current pre-09 market vintages) dynamics) Illustrative Scenario’s 2010 Fin Year Flexed1 Client 20% concession ROE improved To
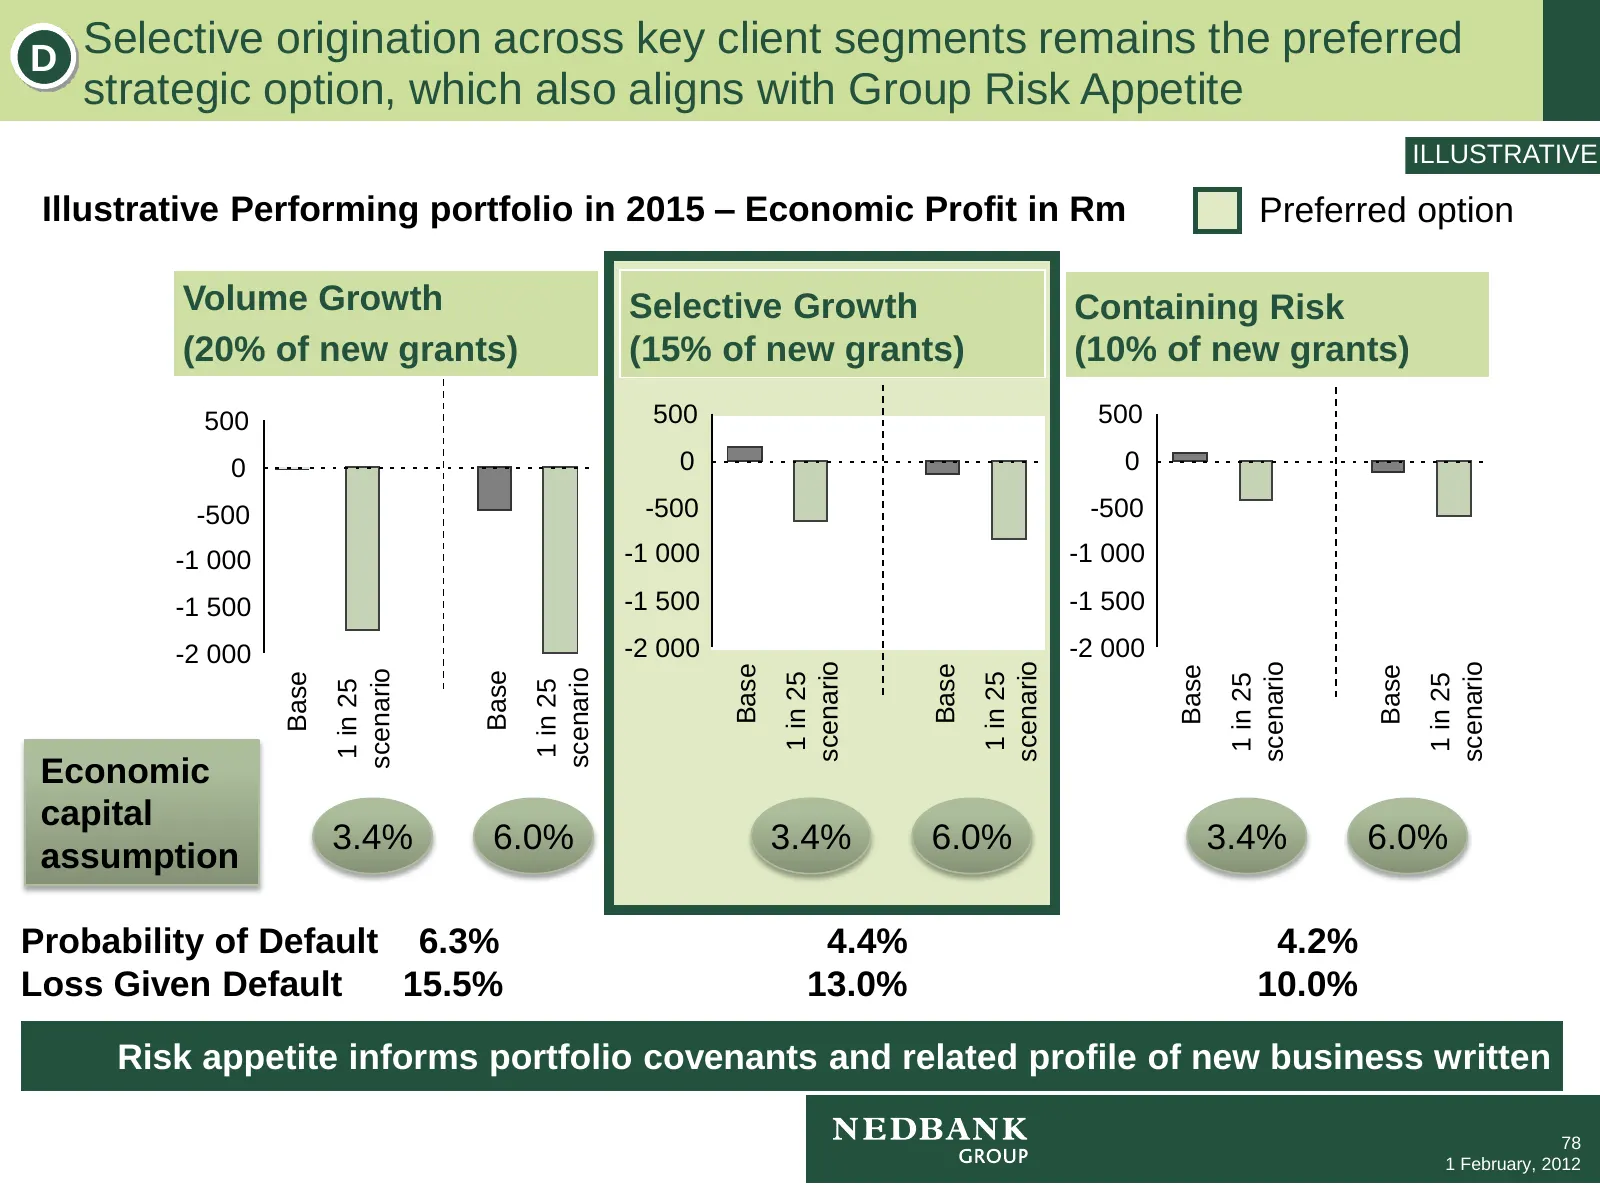
Slide 79: Selective origination across key client segments
D Selective origination across key client segments remains the preferred strategic option, which also aligns with Group Risk Appetite ILLUSTRATIVE Illustrative Performing portfolio in 2015 – Economic Profit in Rm Preferred option Volume Growth Selective Growth Containing Risk (20% of new grants) (15
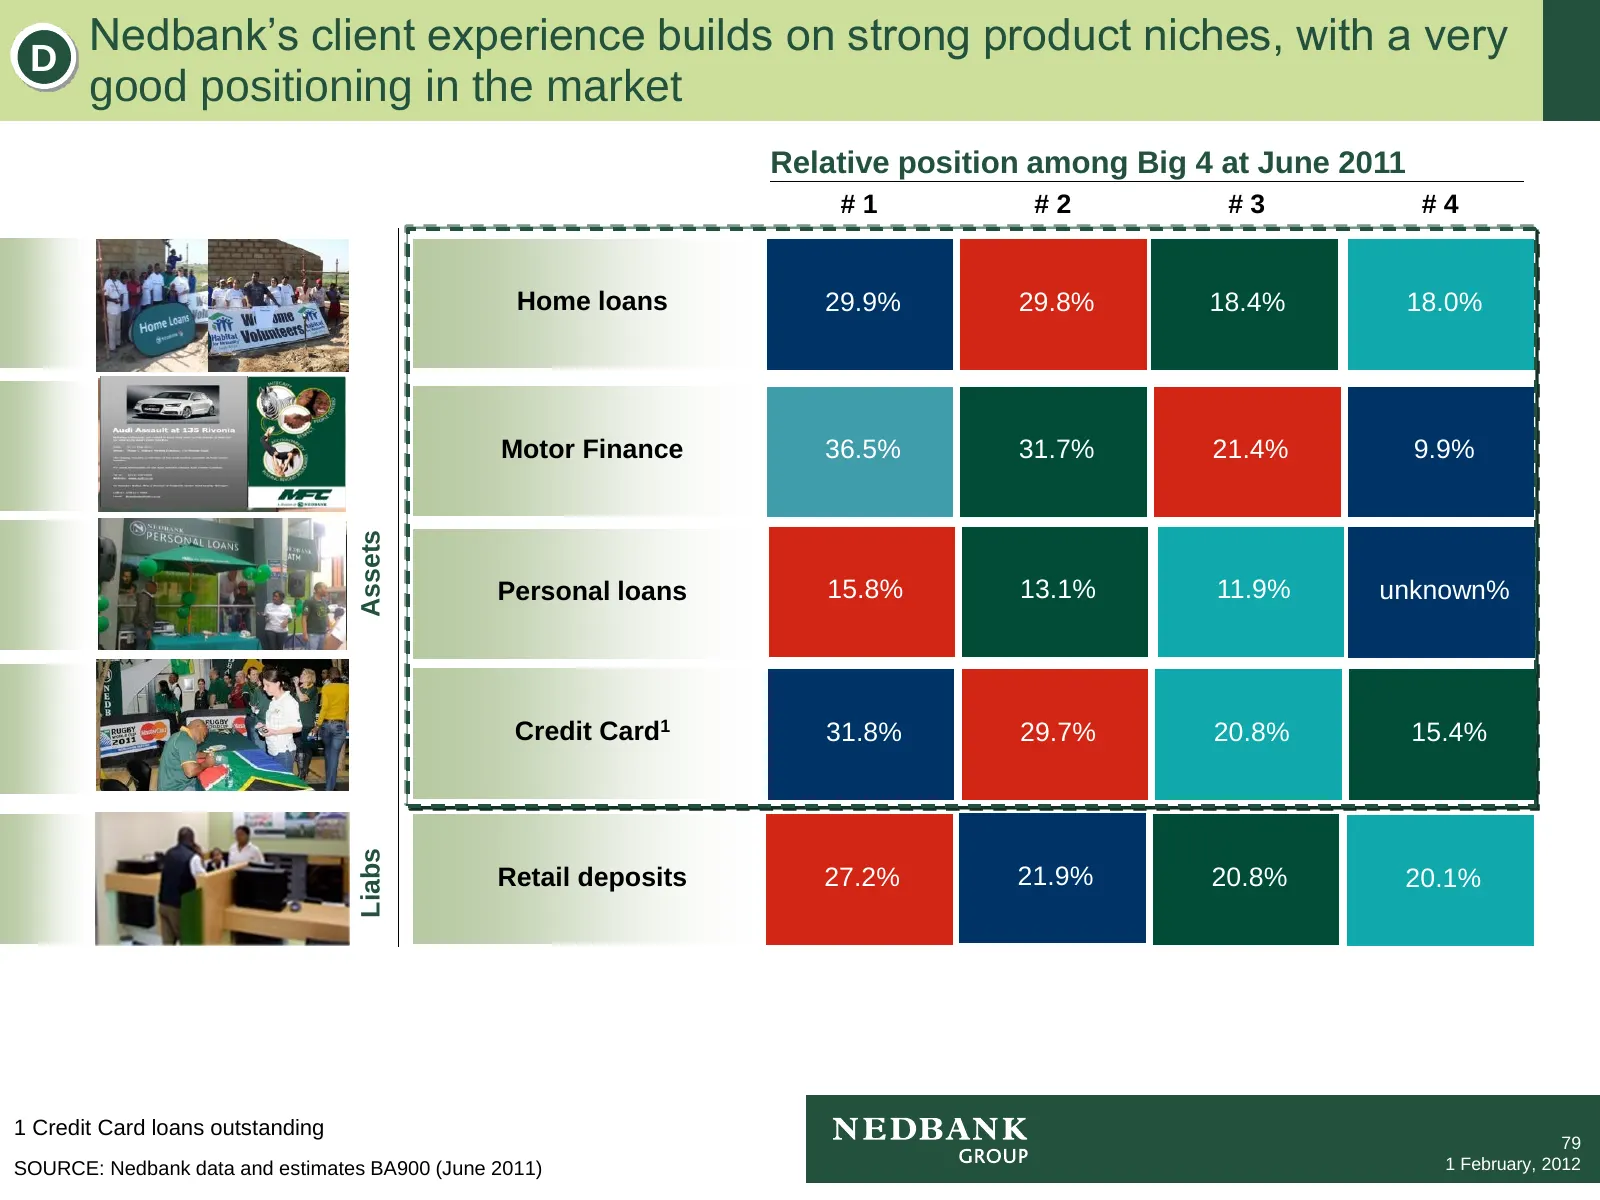
Slide 80: Strong product niches and market positioning among Big 4
D Nedbank’s client experience builds on strong product niches, with a very good positioning in the market Relative position among Big 4 at June 2011 #1 #2 #3 #4 Home loans 29.9% 29.8% 18.4% 18.0% Motor Finance 36.5% 31.7% 21.4% 9.9% Assets Personal loans 15.8% 13.1% 11.9% unknown% Credit Card1 31.8%
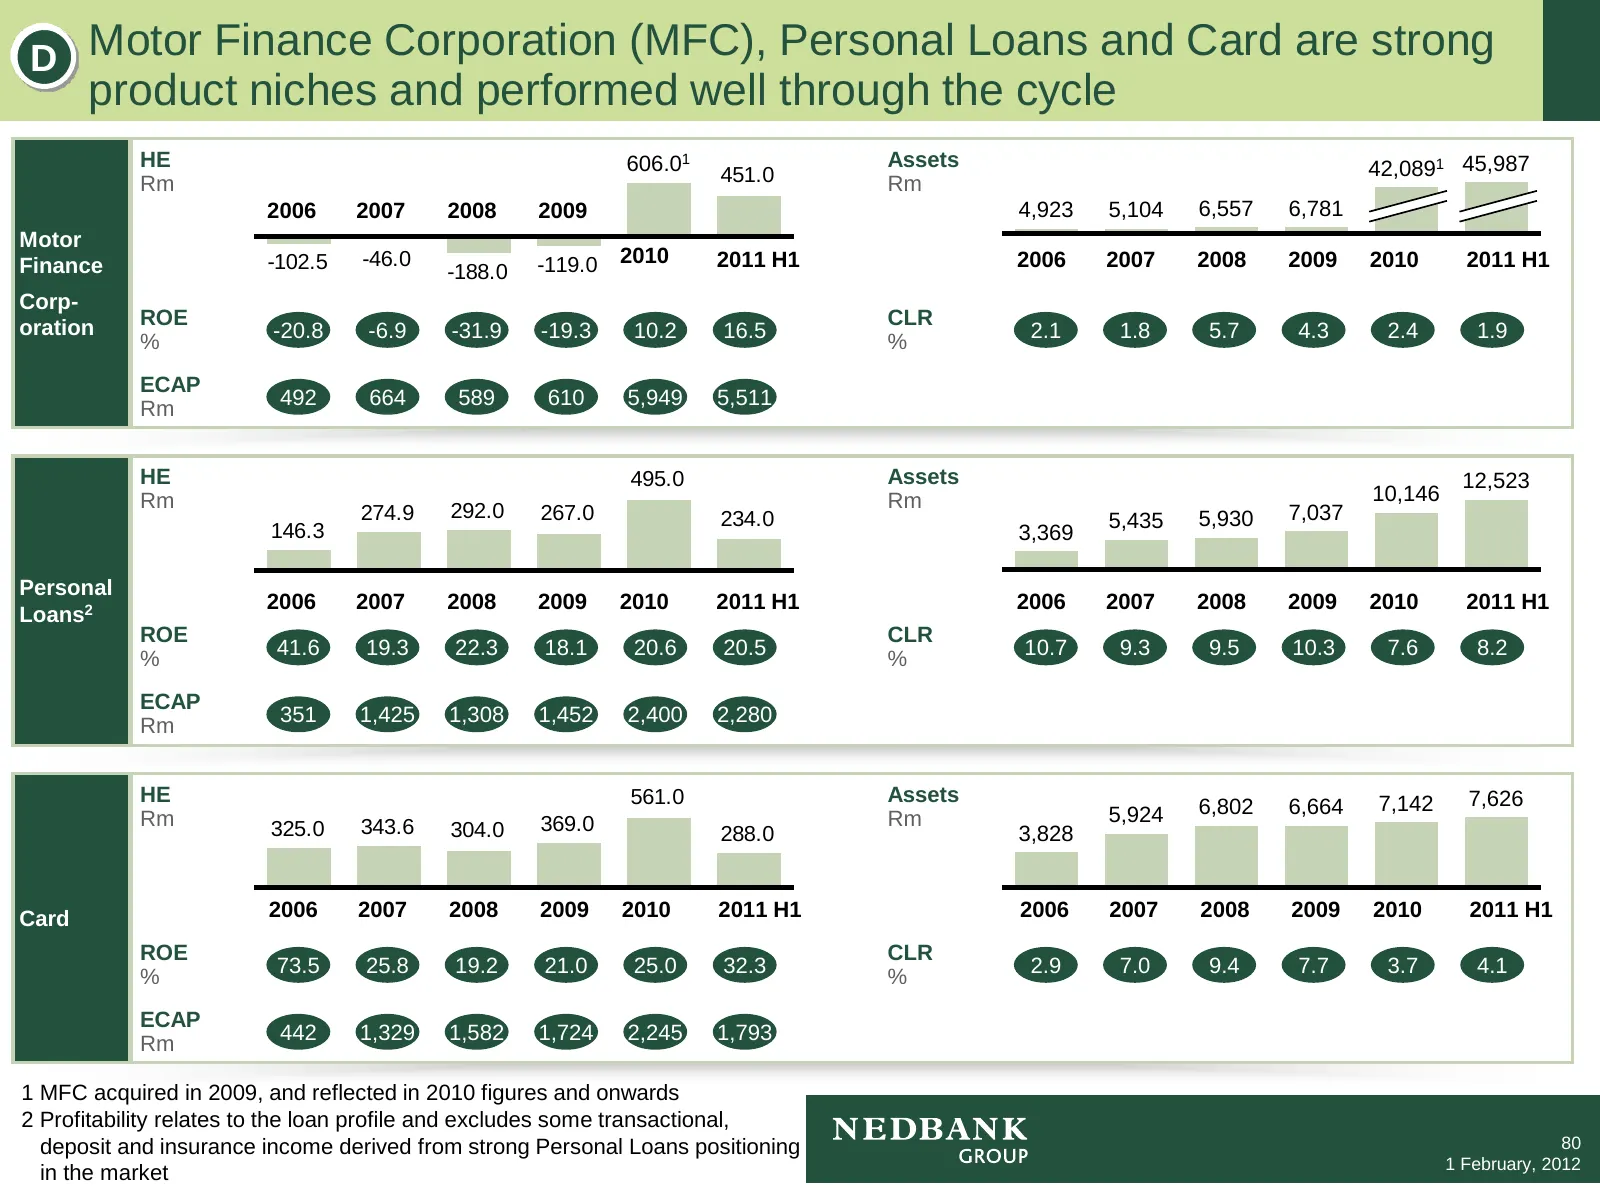
Slide 81: MFC, Personal Loans and Card strong product niches
D Motor Finance Corporation (MFC), Personal Loans and Card are strong product niches and performed well through the cycle HE 606.01 Assets 42,0891 45,987 Rm 451.0 Rm 2006 2007 2008 2009 4,923 5,104 6,557 6,781 Motor Finance -102.5 -46.0 -119.0 2010 2011 H1 2006 2007 2008 2009 2010 2011 H1 -188.0 Cor
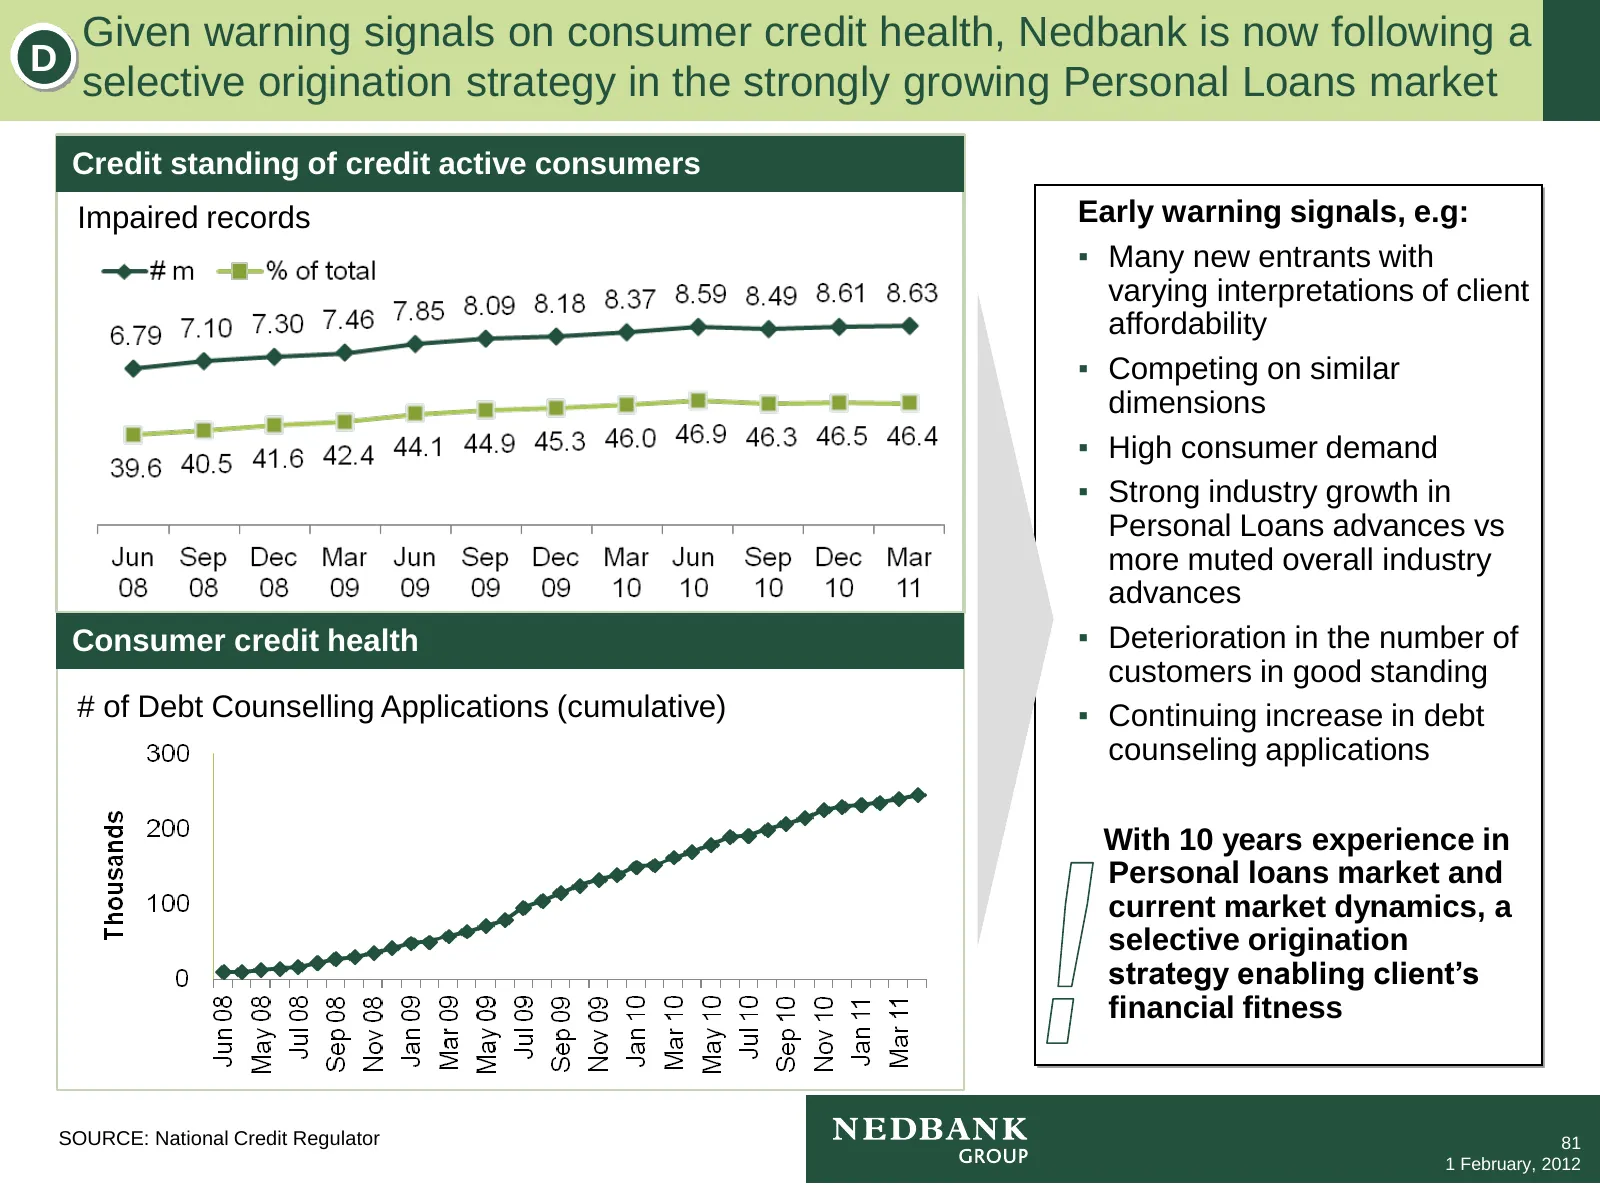
Slide 82: Selective origination in Personal Loans market
Given warning signals on consumer credit health, Nedbank is now following a D selective origination strategy in the strongly growing Personal Loans market Credit standing of credit active consumers Impaired records Early warning signals, e.g: ▪ Many new entrants with varying interpretations of clien
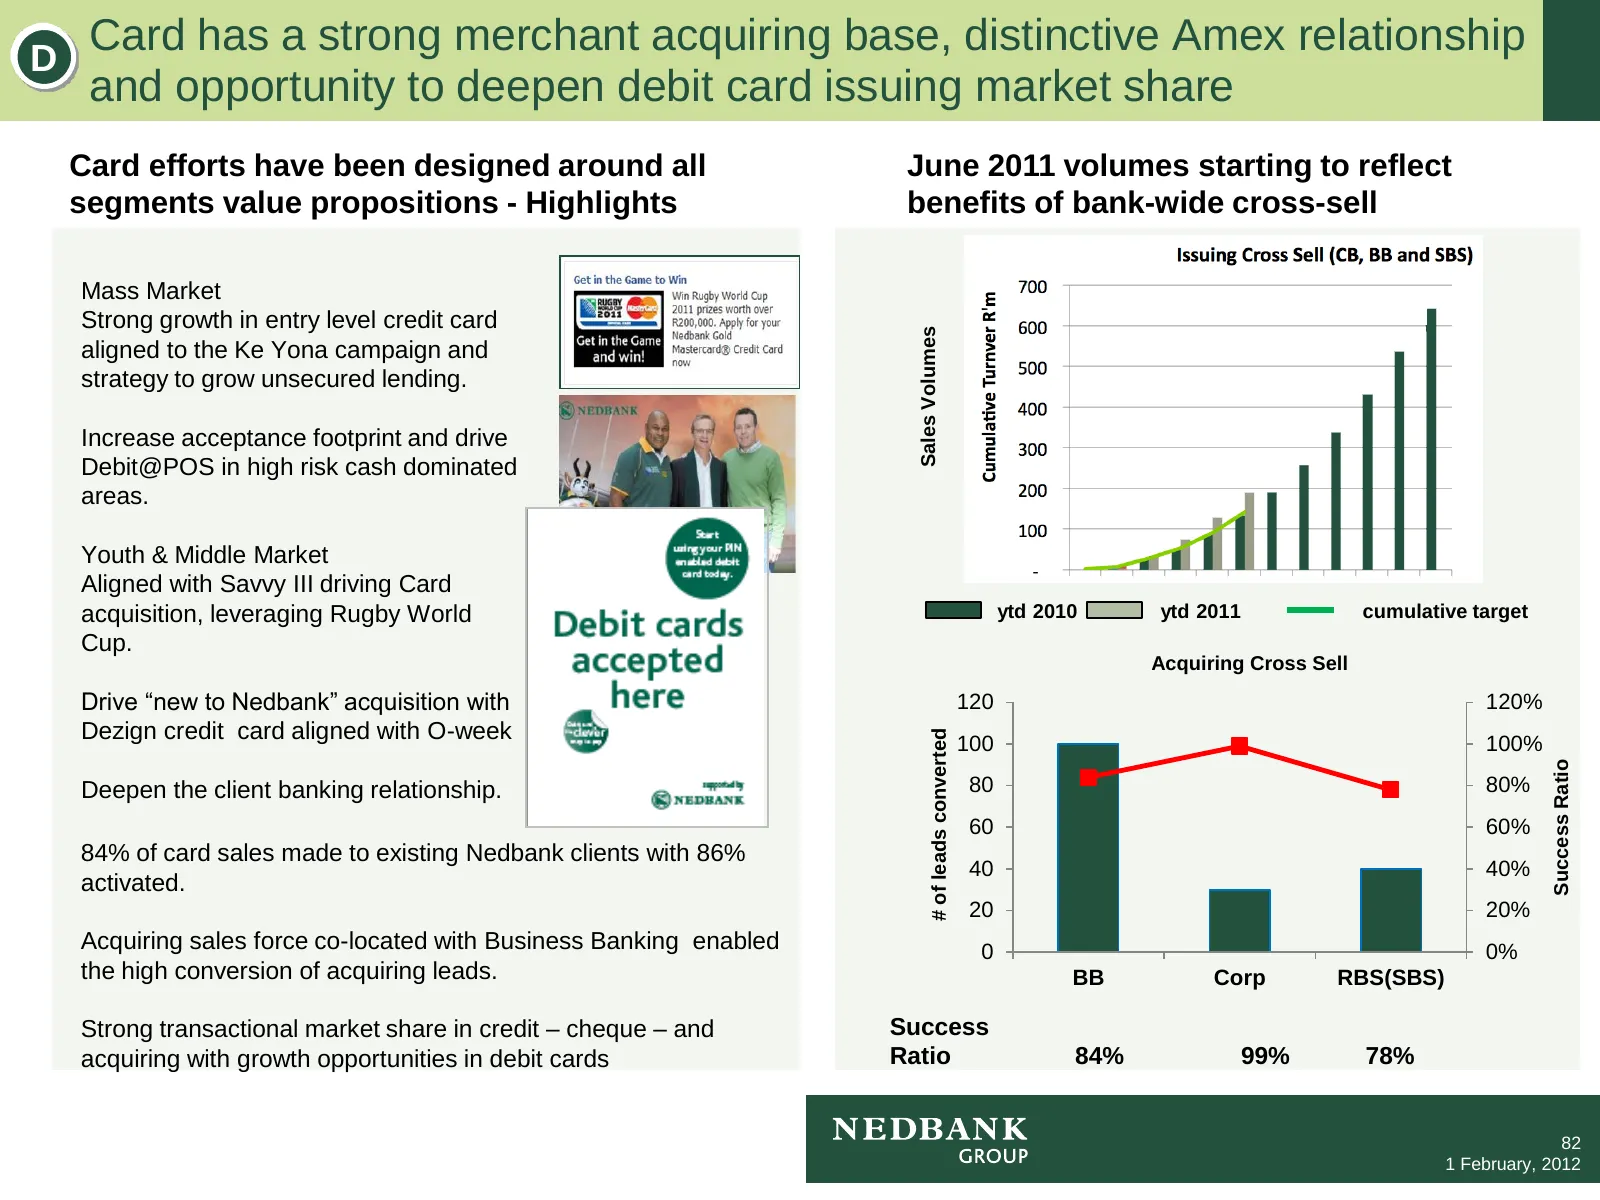
Slide 83: Card merchant acquiring base and Amex relationship
D Card has a strong merchant acquiring base, distinctive Amex relationship and opportunity to deepen debit card issuing market share Card efforts have been designed around all June 2011 volumes starting to reflect segments value propositions - Highlights benefits of bank-wide cross-sell Mass Market
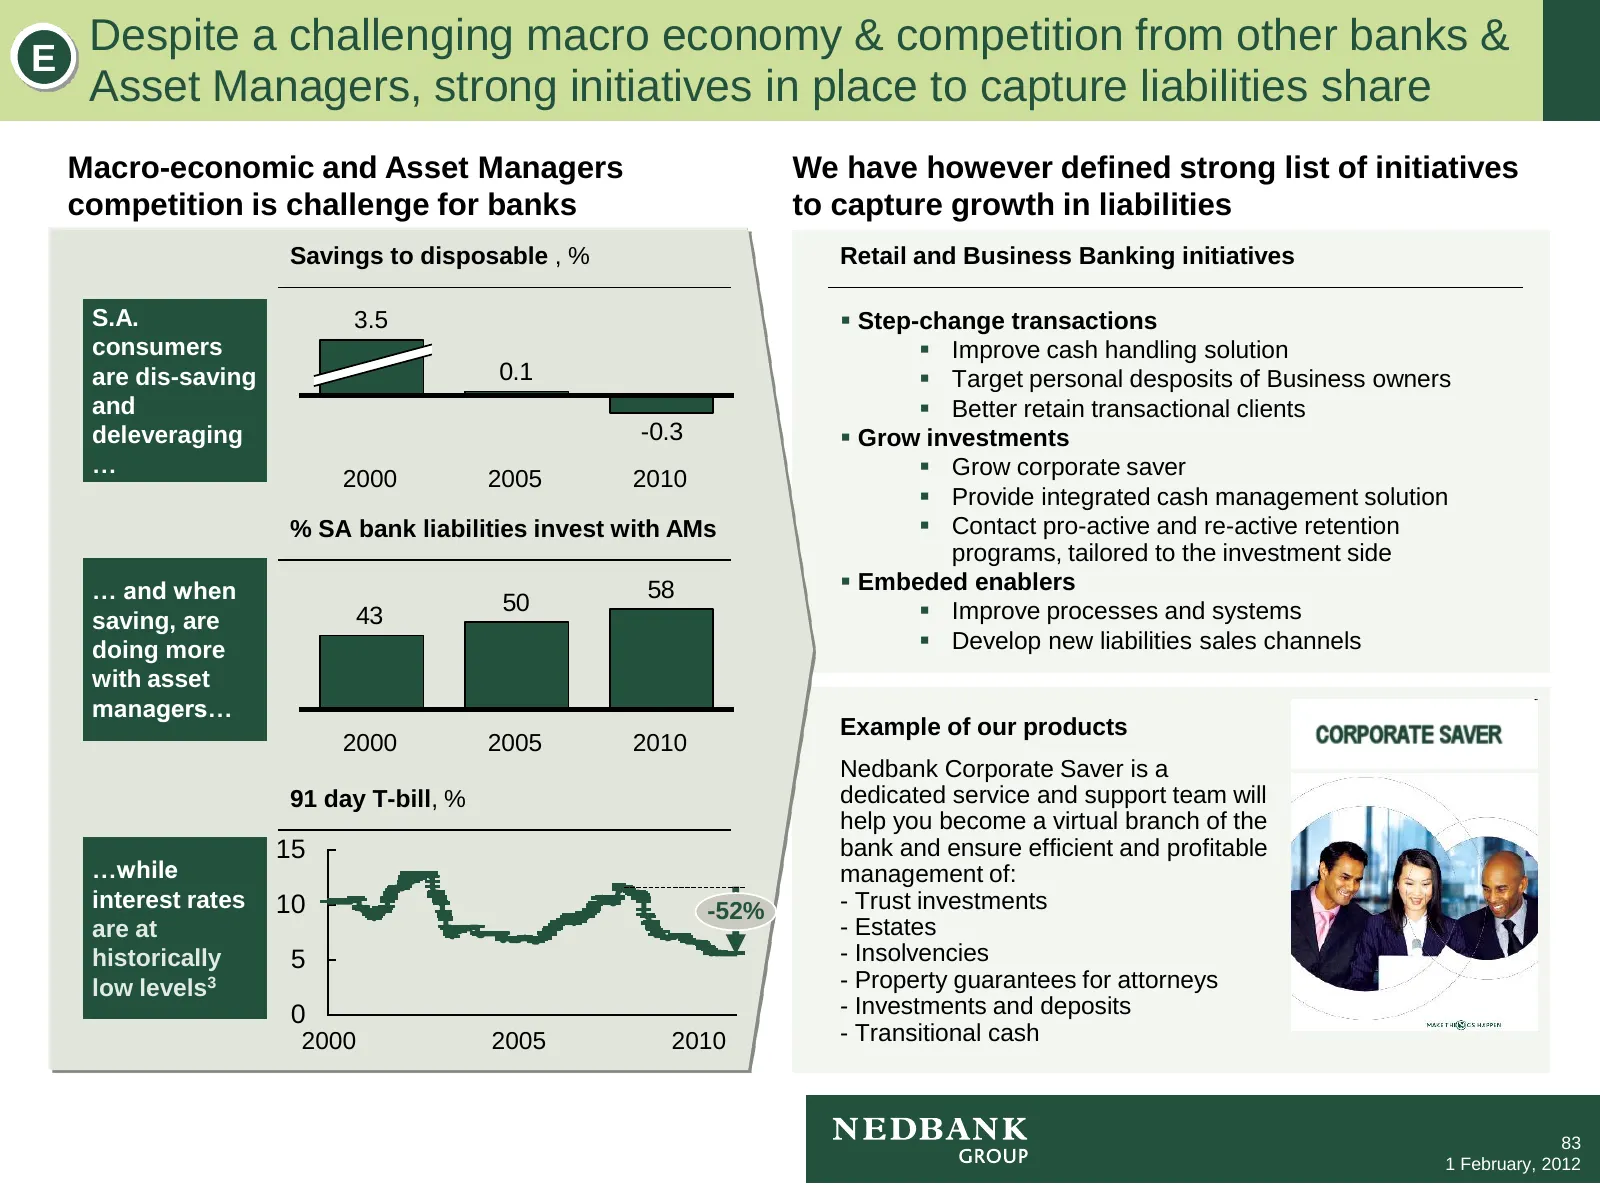
Slide 84: Initiatives to capture liabilities share
E Despite a challenging macro economy & competition from other banks & Asset Managers, strong initiatives in place to capture liabilities share Macro-economic and Asset Managers We have however defined strong list of initiatives competition is challenge for banks to capture growth in liabilities Sav
Slide 85: Strong products in the liabilities areas
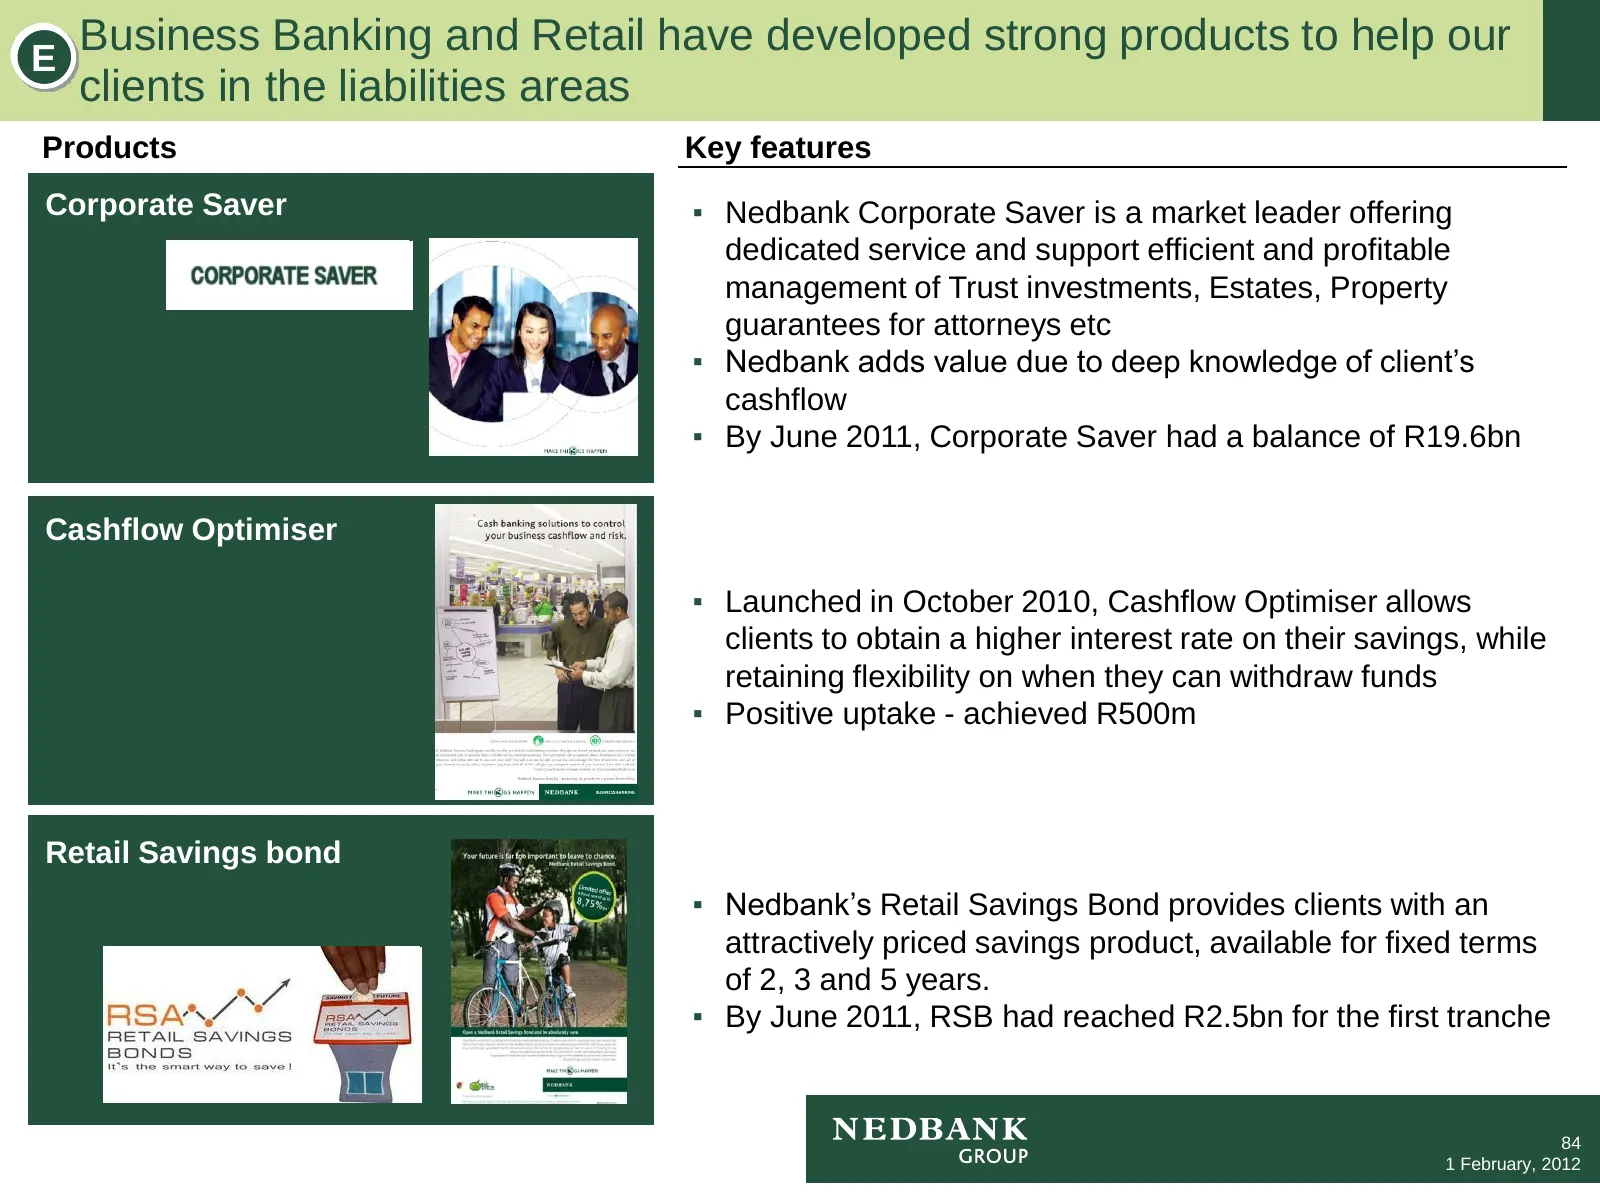
E Business Banking and Retail have developed strong products to help our clients in the liabilities areas Products Key features Corporate Saver ▪ Nedbank Corporate Saver is a market leader offering dedicated service and support efficient and profitable management of Trust investments, Estates, Prope
Slide 86: Unique organisational differentiators for the 21st century
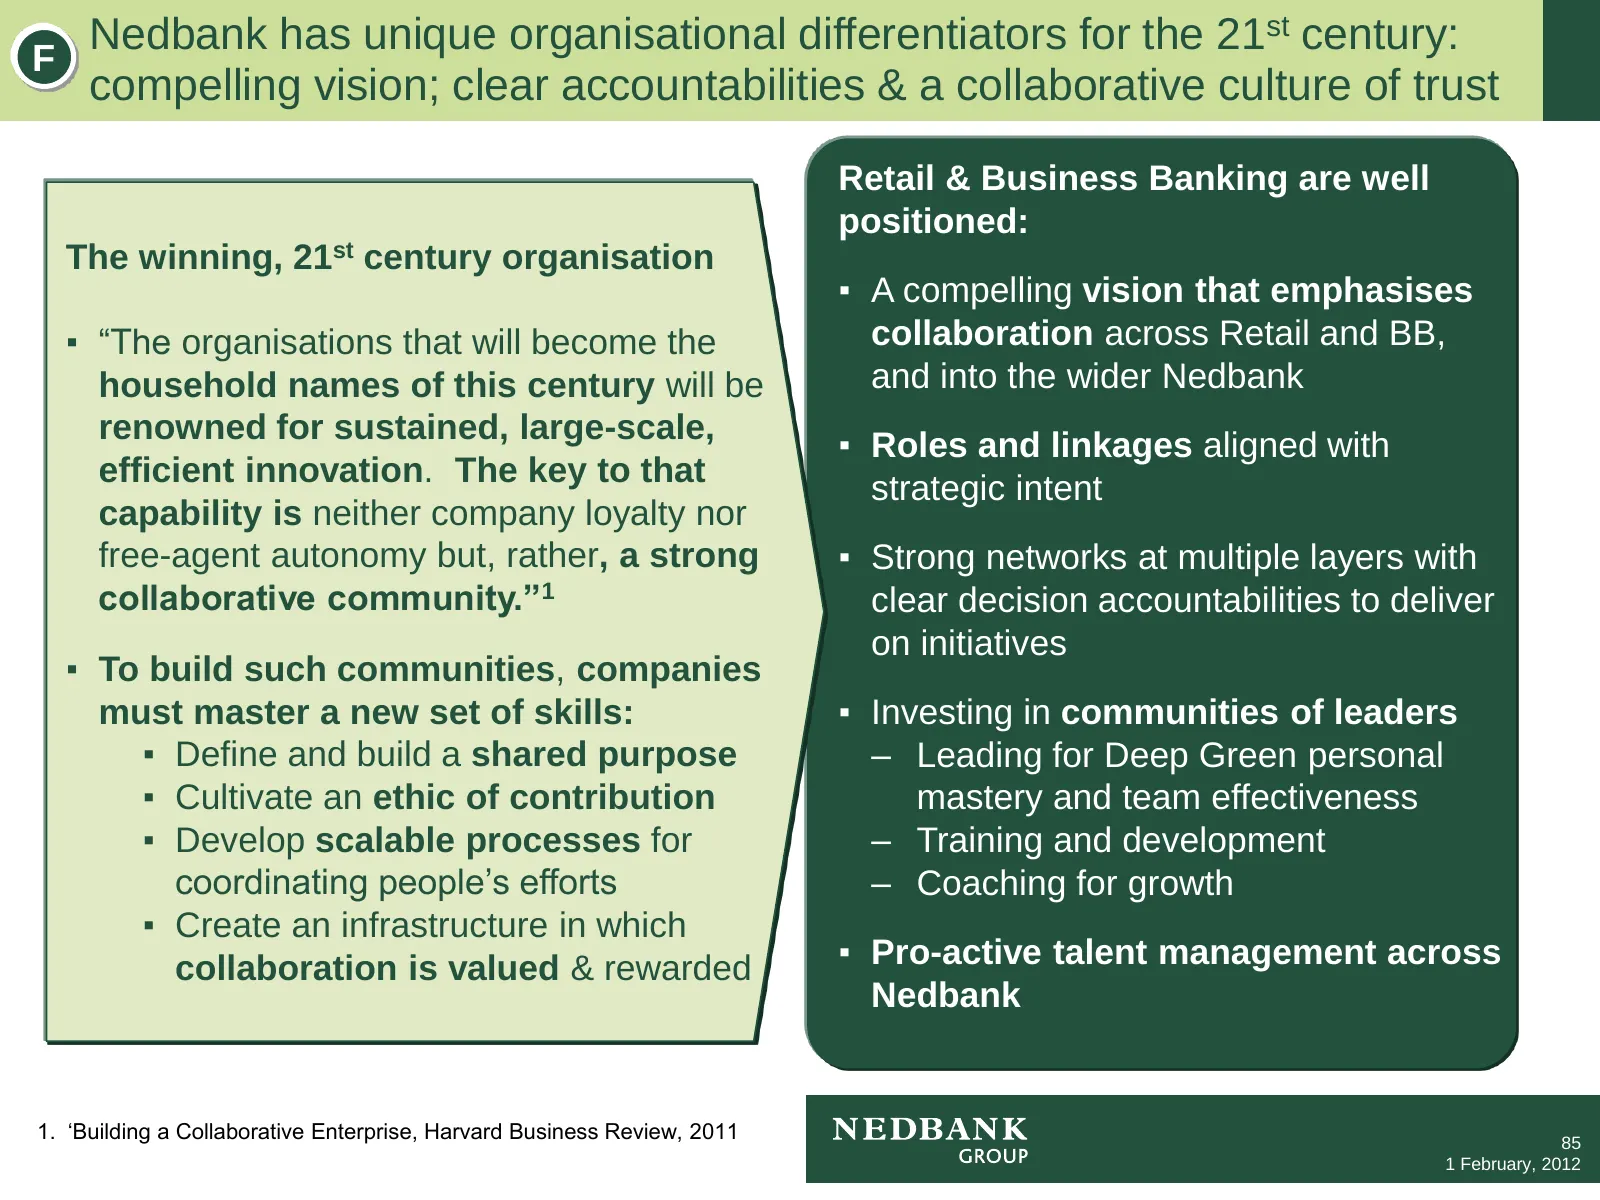
F Nedbank has unique organisational differentiators for the 21st century: compelling vision; clear accountabilities & a collaborative culture of trust Retail & Business Banking are well positioned: The winning, 21st century organisation ▪ A compelling vision that emphasises ▪ “The organisations that
Slide 87: Distinctive position leveraging key trends
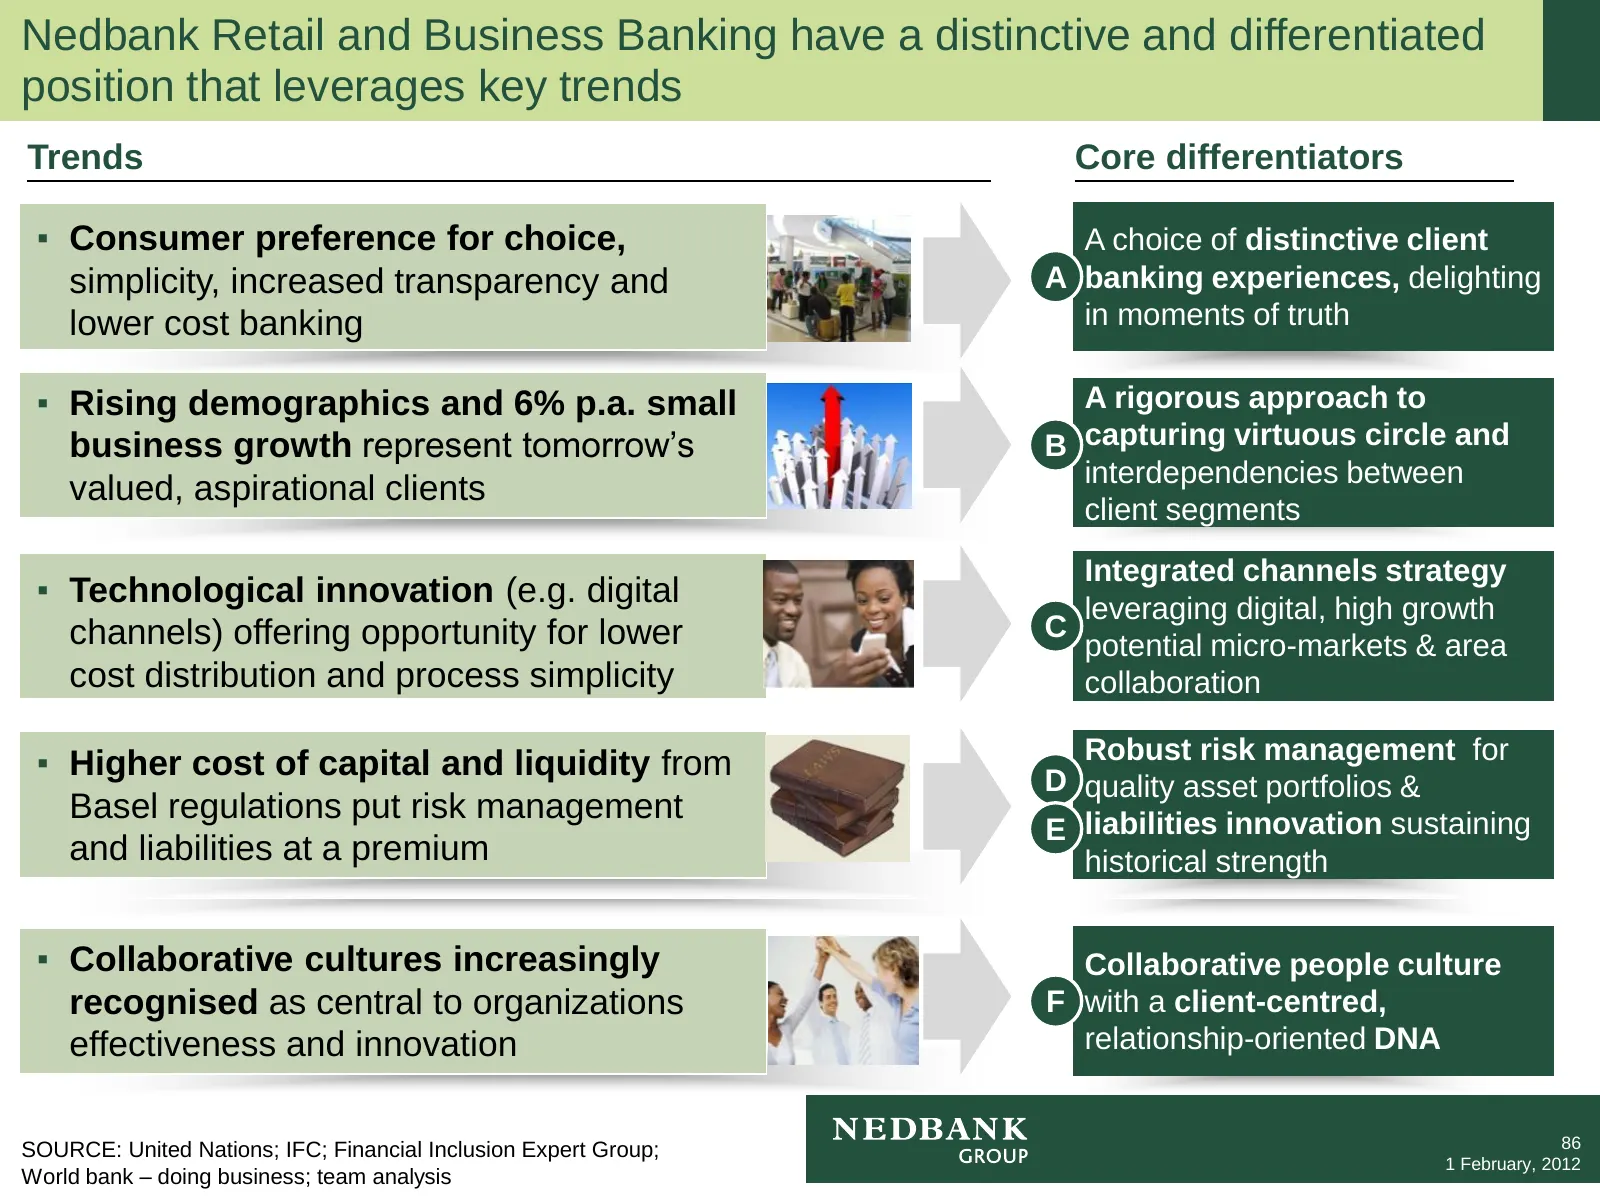
Nedbank Retail and Business Banking have a distinctive and differentiated position that leverages key trends Trends Core differentiators ▪ Consumer preference for choice, A choice of distinctive client simplicity, increased transparency and A banking experiences, delighting lower cost banking in mom
Slide 88: Uniquely positioned to generate shareholder value: sustainable performance
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment 1 A strong leadership team with a track record of delivery 2 A distinctive position leveraging key trends Committed to building high quality businesses for 3 s
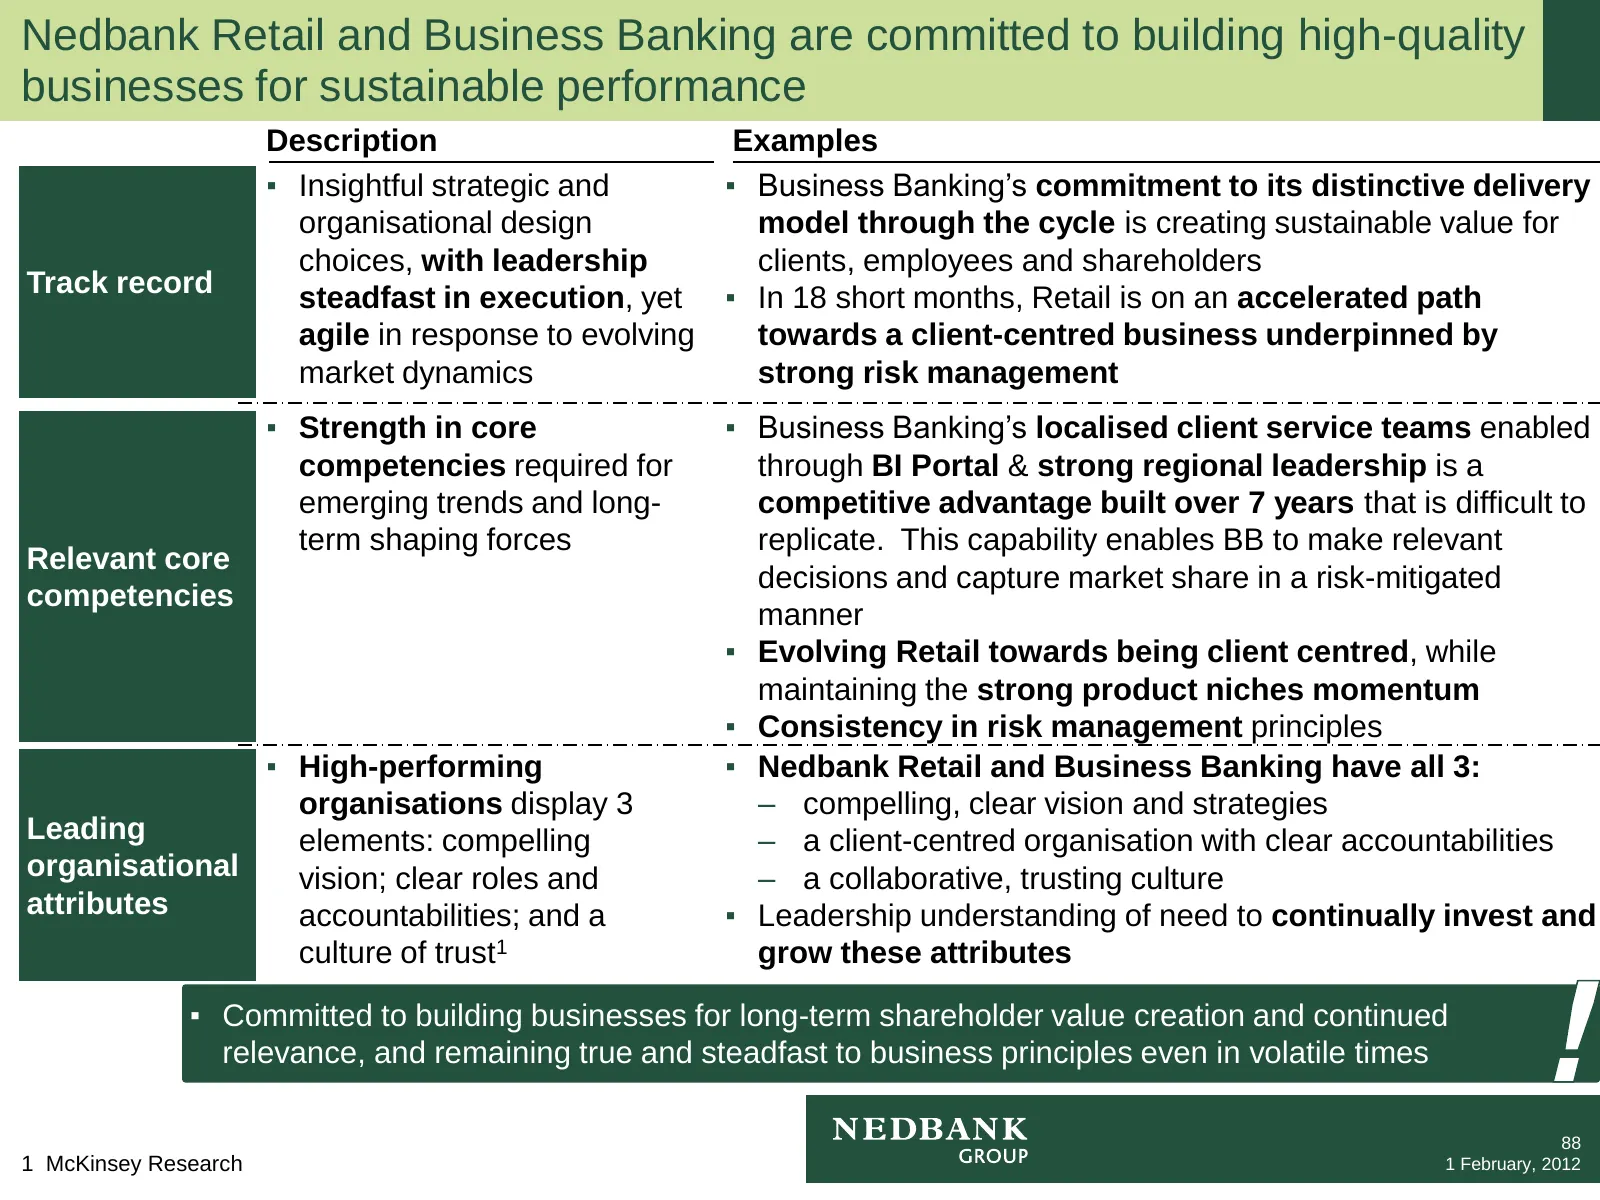
Slide 89: Committed to building high-quality businesses for sustainable performance
Nedbank Retail and Business Banking are committed to building high-quality businesses for sustainable performance Description Examples ▪ Insightful strategic and ▪ Business Banking’s commitment to its distinctive delivery organisational design model through the cycle is creating sustainable value fo
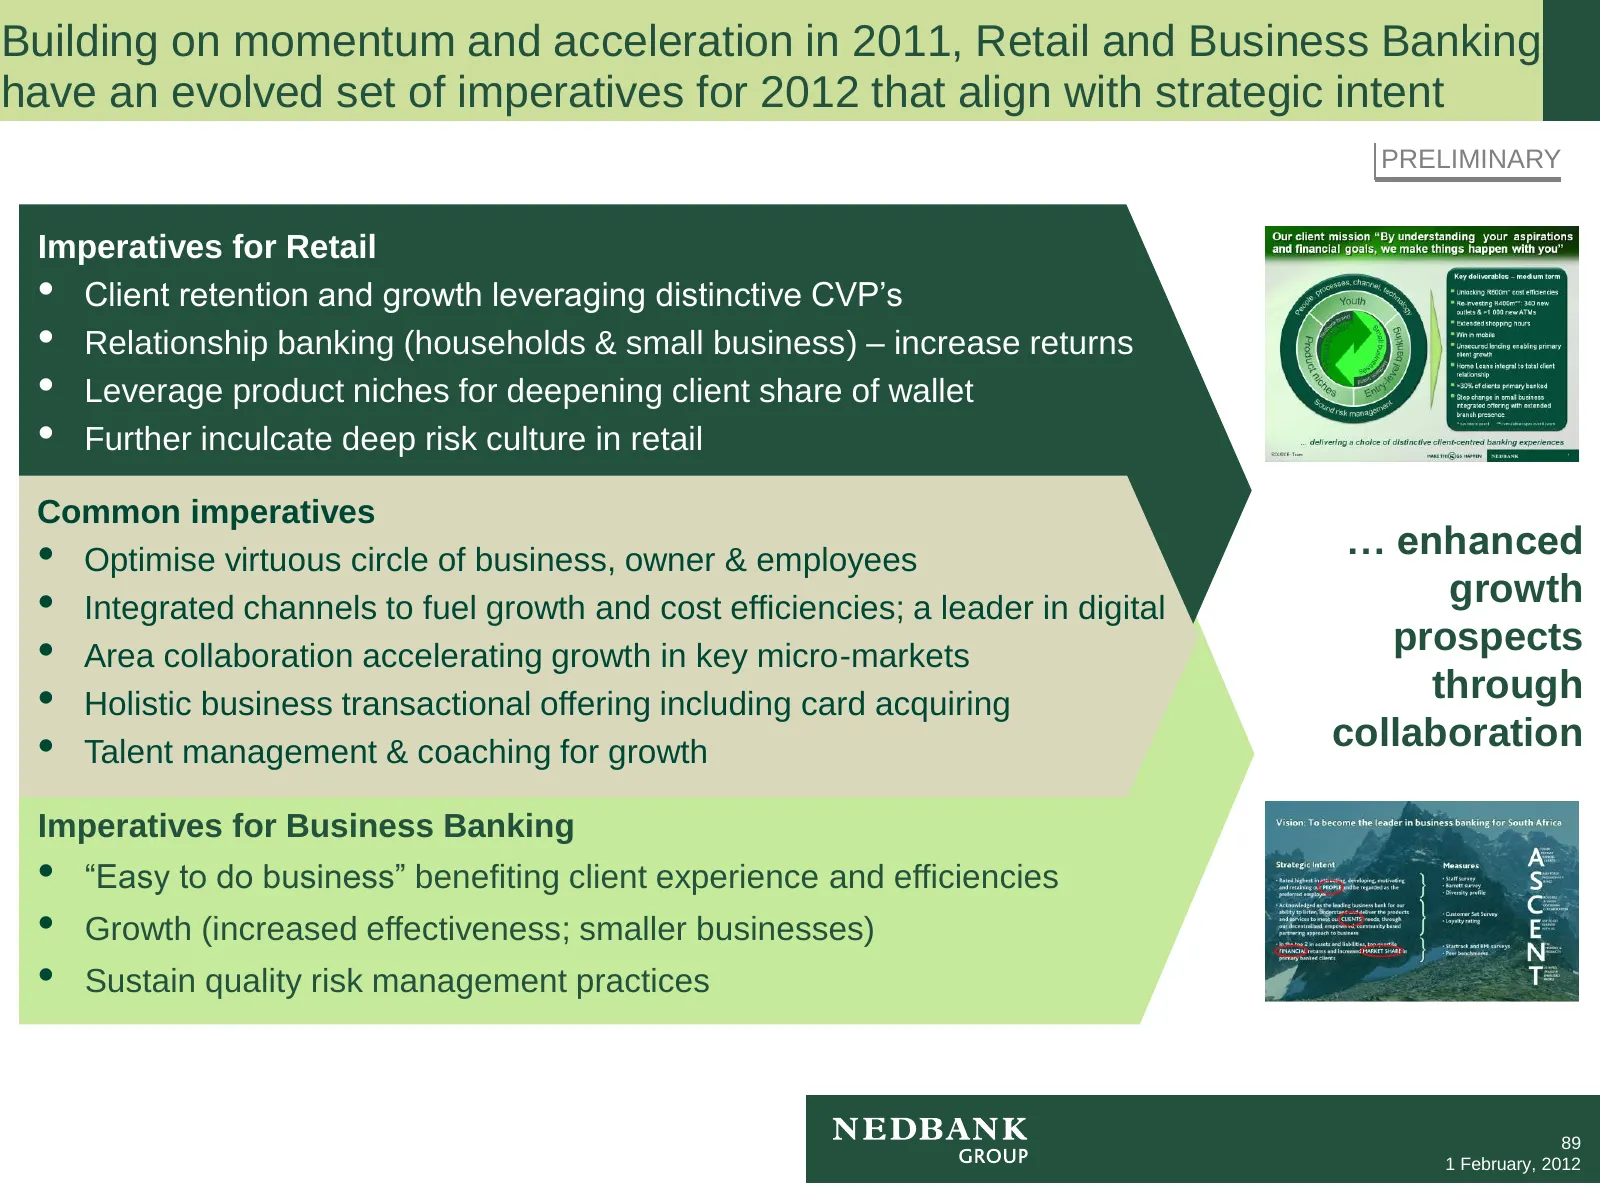
Slide 90: Evolved imperatives for 2012
Building on momentum and acceleration in 2011, Retail and Business Banking have an evolved set of imperatives for 2012 that align with strategic intent PRELIMINARY Imperatives for Retail • Client retention and growth leveraging distinctive CVP’s • Relationship banking (households & small business) –
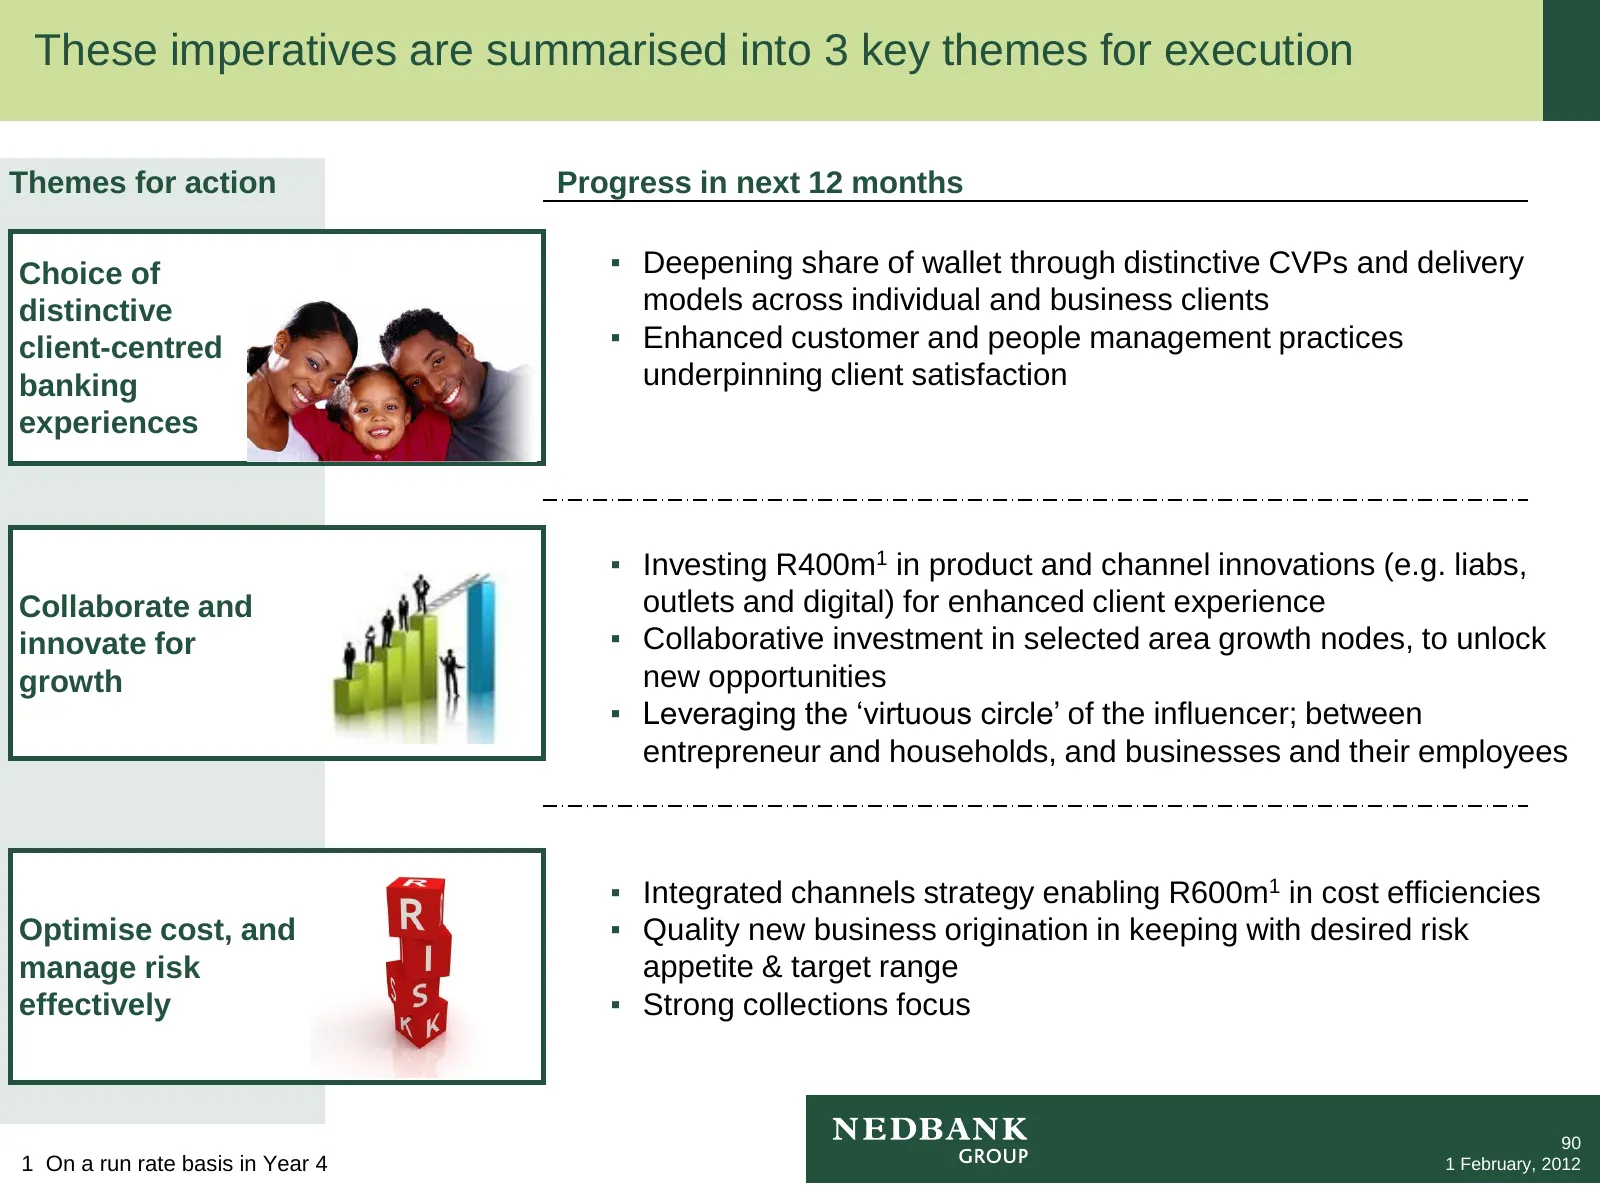
Slide 91: Imperatives summarised into key themes for execution
These imperatives are summarised into 3 key themes for execution Themes foraction Themes for action Progress in next 12 months Choice of ▪ Deepening share of wallet through distinctive CVPs and delivery distinctive models across individual and business clients client-centred ▪ Enhanced customer and
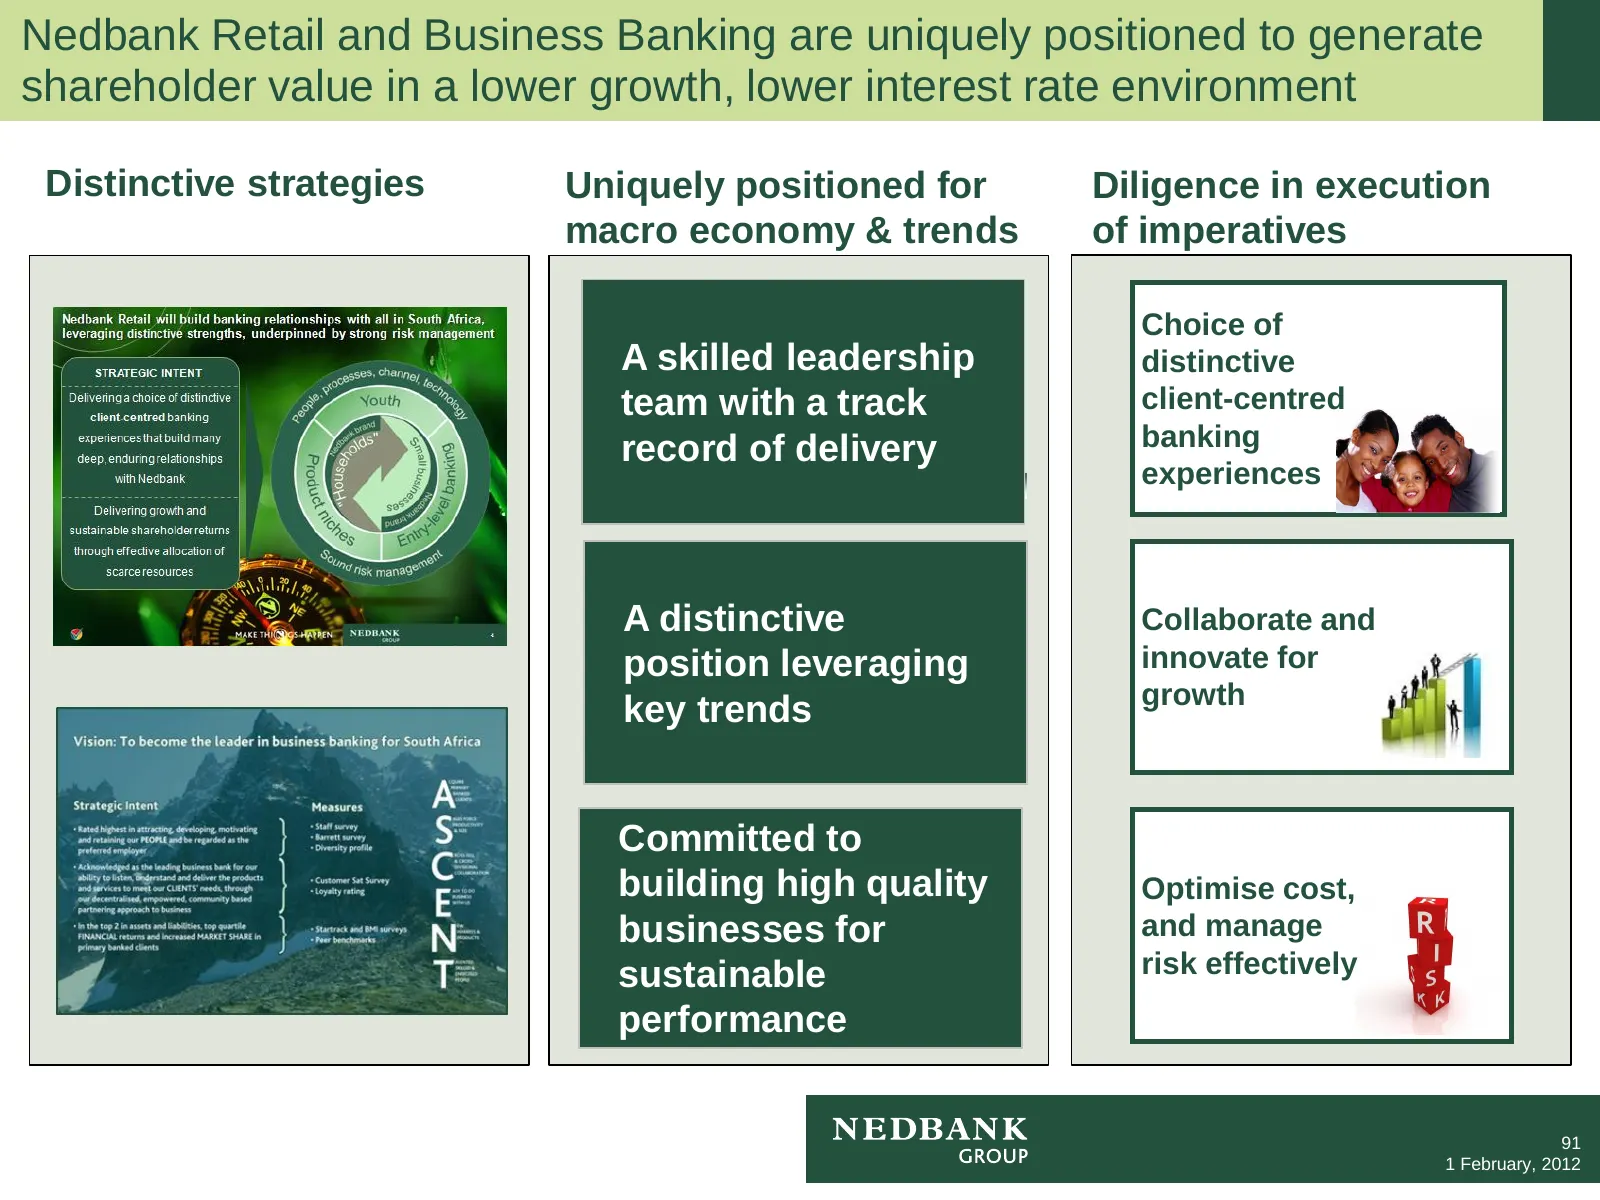
Slide 92: Uniquely positioned to generate shareholder value: summary
Nedbank Retail and Business Banking are uniquely positioned to generate shareholder value in a lower growth, lower interest rate environment Distinctive strategies Uniquely positioned for Diligence in execution macro economy & trends of imperatives Choice of A skilled leadership distinctive team wit
Slide 93: Delivery for our stakeholders will be achieved through diligence
Delivery for our stakeholders will be achieved through diligence 92 1 February, 2012
Slide 94: Executive summary
Executive summary • Clearly defined Retail & Business Banking (BB) strategy in place to contribute to Group delivering its medium term targets, specifically: − Sustaining the consistent strong financial performance and accelerating the momentum in BB to become the leader in business banking for Sout
Slide 95: Drivers of financial performance going forward (1/2) - BB
As synthesis, we believe that both Business Banking and Retail banking have strong drivers of financial performance going forward (1/2) - BB Income statement Key drivers of financial performance – Business Banking ▪ Successfully widened asset margin, maintaining prior years’ gains in a competitive m
Slide 96: Drivers of financial performance going forward (2/2) - Retail
As synthesis, we believe that both Business Banking and Retail banking have strong drivers of financial performance going forward (2/2) - Retail Income statement Key drivers of financial performance – Retail Banking ▪ Unsecured lending to grow faster than secured lending; selective origination in ho
Slide 97: About this booklet
About this booklet This report is printed on Sappi Triple Green – a paper grade manufactured according to three environmental pillars: a minimum of 60% of the pulp used in the production of this paper is sugar cane fibre, which is the material remaining after raw sugar has been extracted from sugar
Source: Internet Archive copy of nedbank.co.za
More decks from Nedbank Group
 FY2025 Earnings Presentation50 slides · February 2026
 FY2024 Earnings Presentation63 slides · March 2025
 27th UBS SA Financial Services Conference 202424 slides · October 2024
 Investor Presentation (October 2024)20 slides · October 2024
 Emerge — Nedbank Investment Conference (2024)22 slides · Sep 10, 2024
 H1 2024 Earnings Presentation85 slides · Aug 6, 2024