TUI AG · XETR:TUI1
TUI — TUI Travel — H1 2013 Earnings Presentation
42 slides from TUI's earnings presentation, May 10, 2013
Slide 1: TUI Travel PLC Interim Results
TUI Travel PLC Interim Results 10th May 2013 Thomson Couples - Atlantica Kalliston Resort & Spa, Crete
Slide 2: Agenda
Agenda H1 Overview – Peter Long Financial Performance – Will Waggott Current Trading – Peter Long Strategic Highlights – Peter Long Summary & Outlook – Peter Long Q&A Interim Results – 10th May 2013 2
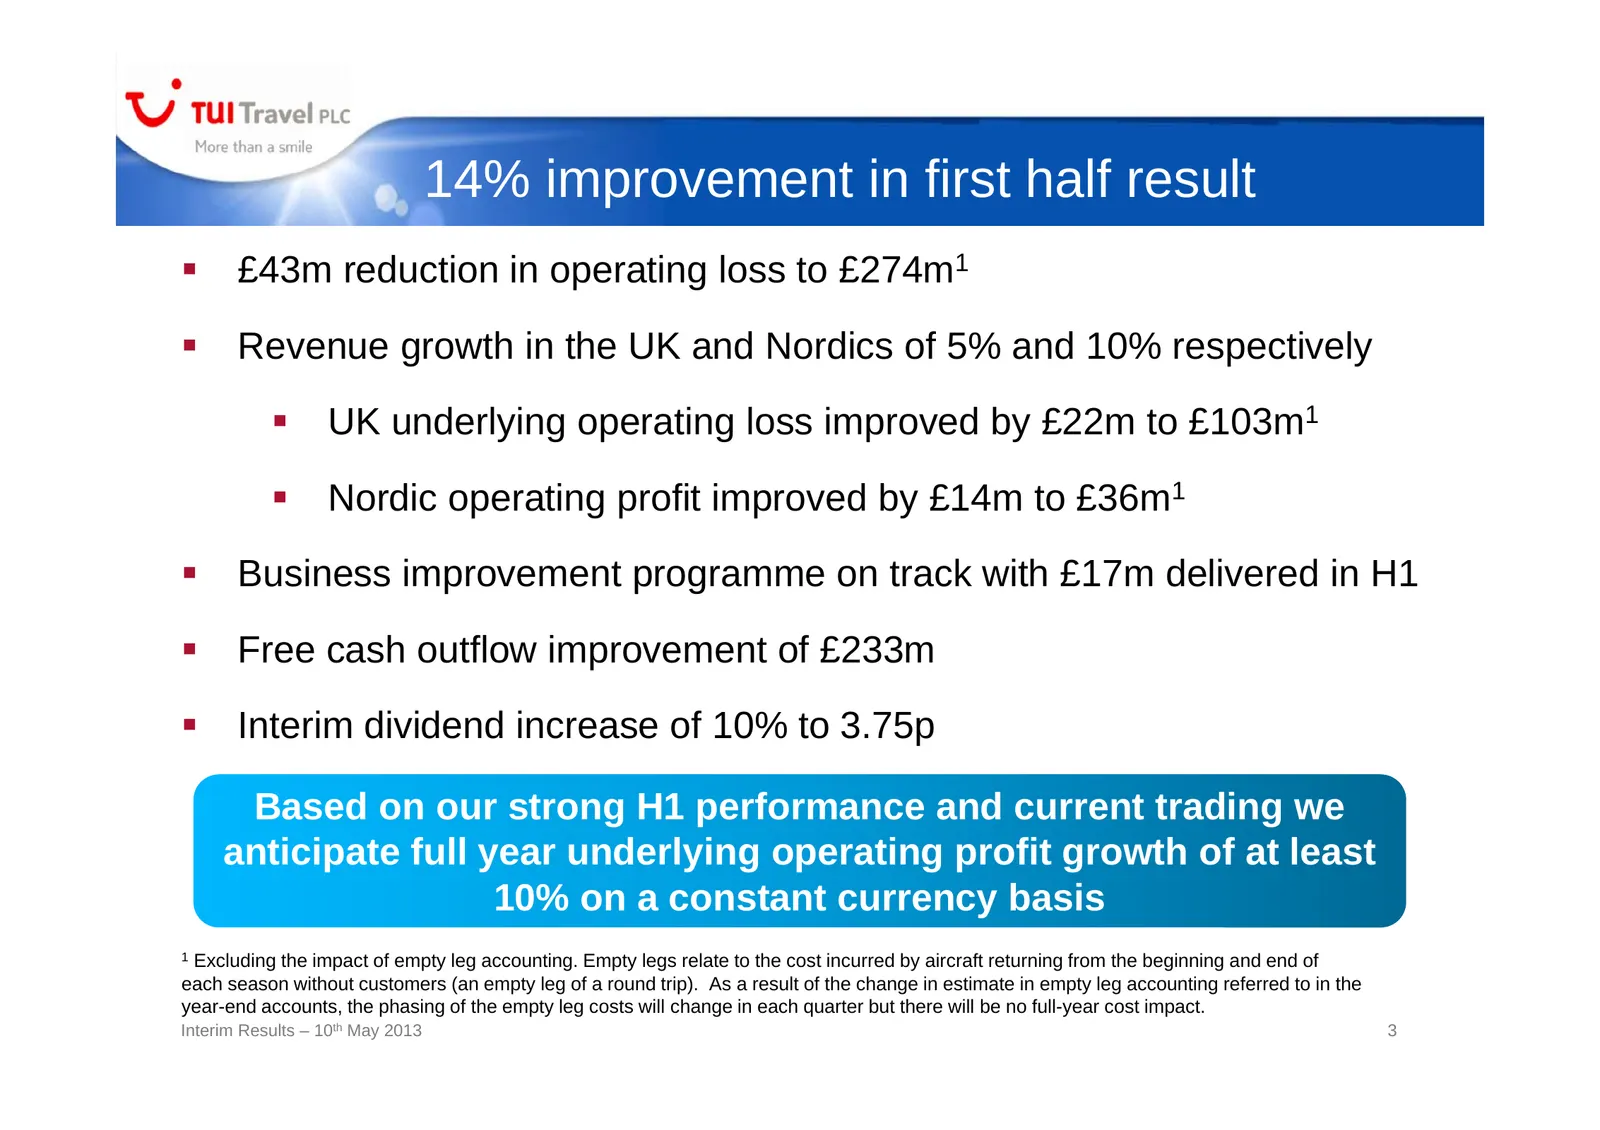
Slide 3: 14% improvement in first half result
14% improvement in first half result £43m reduction in operating loss to £274m1 Revenue growth in the UK and Nordics of 5% and 10% respectively UK underlying operating loss improved by £22m to £103m1 Nordic operating profit improved by £14m to £36m1 Business improvement programme on track
Slide 4: Financial Performance
Financial Performance Will Waggott Thomson Couples - Atlantica Kalliston Resort & Spa, Crete
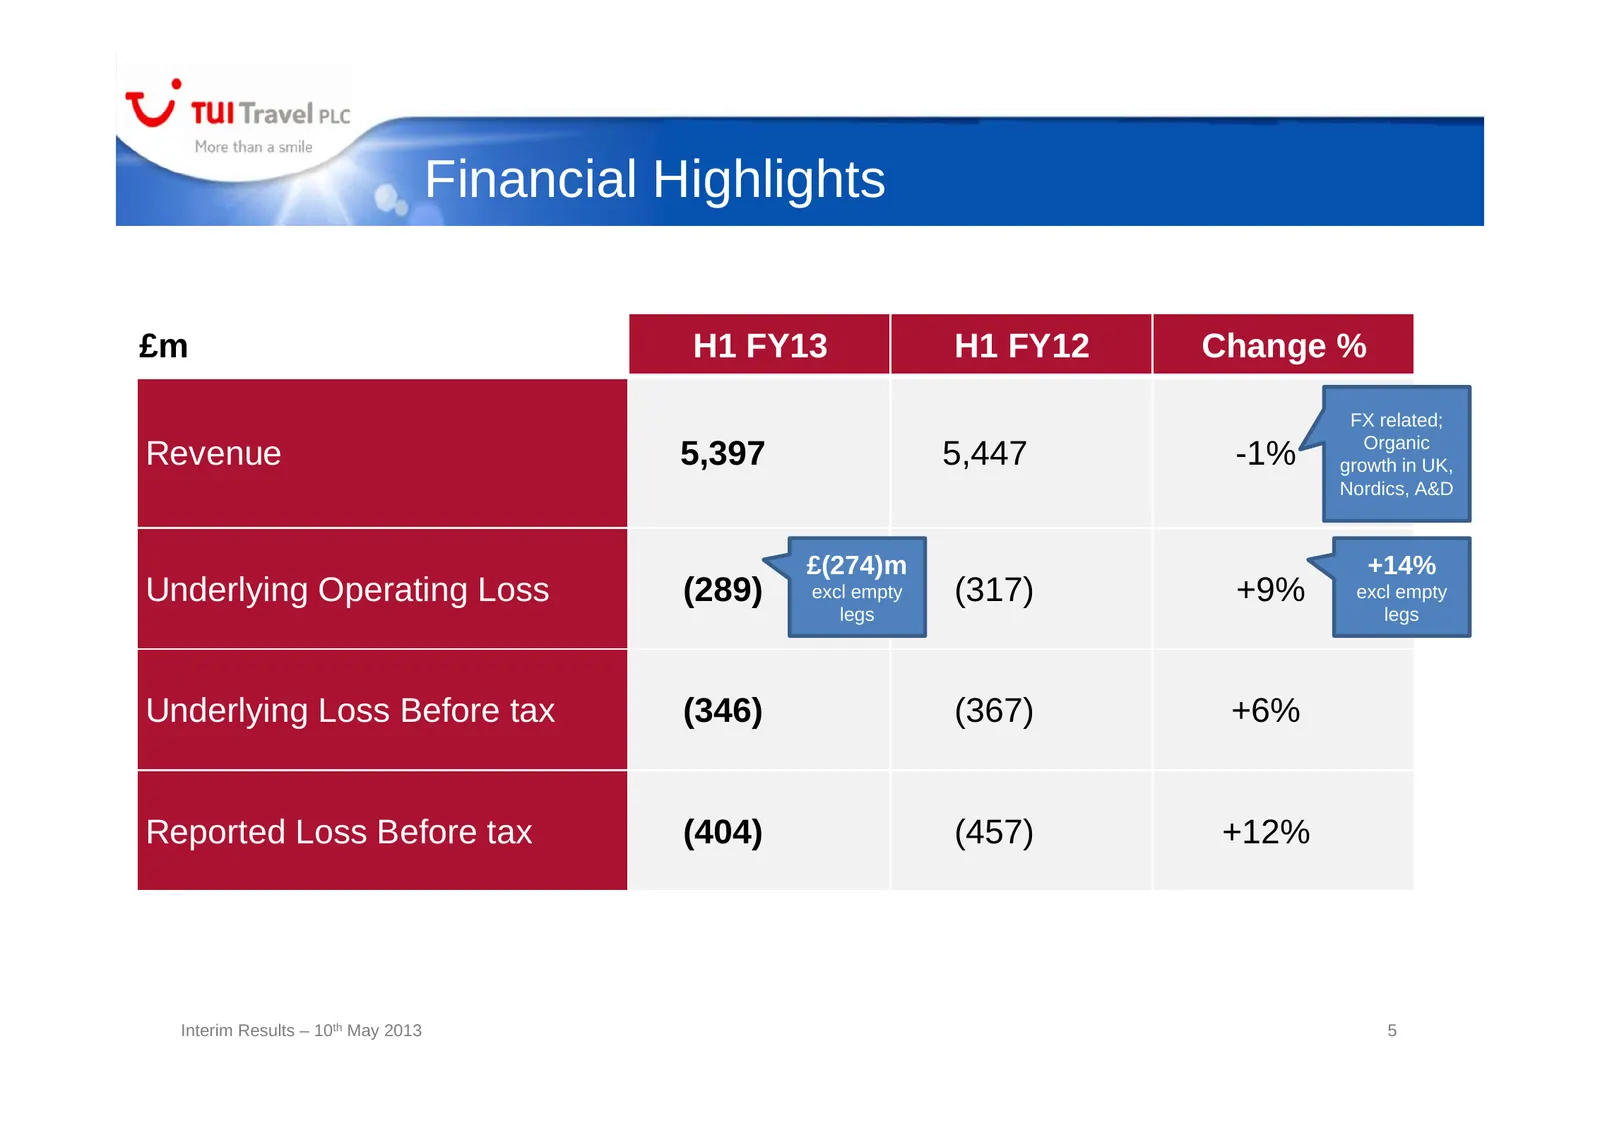
Slide 5: Financial Highlights
Financial Highlights £m H1 FY13 H1 FY12 Change % FX related; Organic Revenue 5,397 5,447 -1% growth in UK, Nordics, A&D £(274)m +14% Underlying Operating Loss (289) excl empty (317) +9% excl empty legs legs Underlying Loss Before tax (346) (367) +6% Reported Loss Before tax (404) (457) +12% Interim
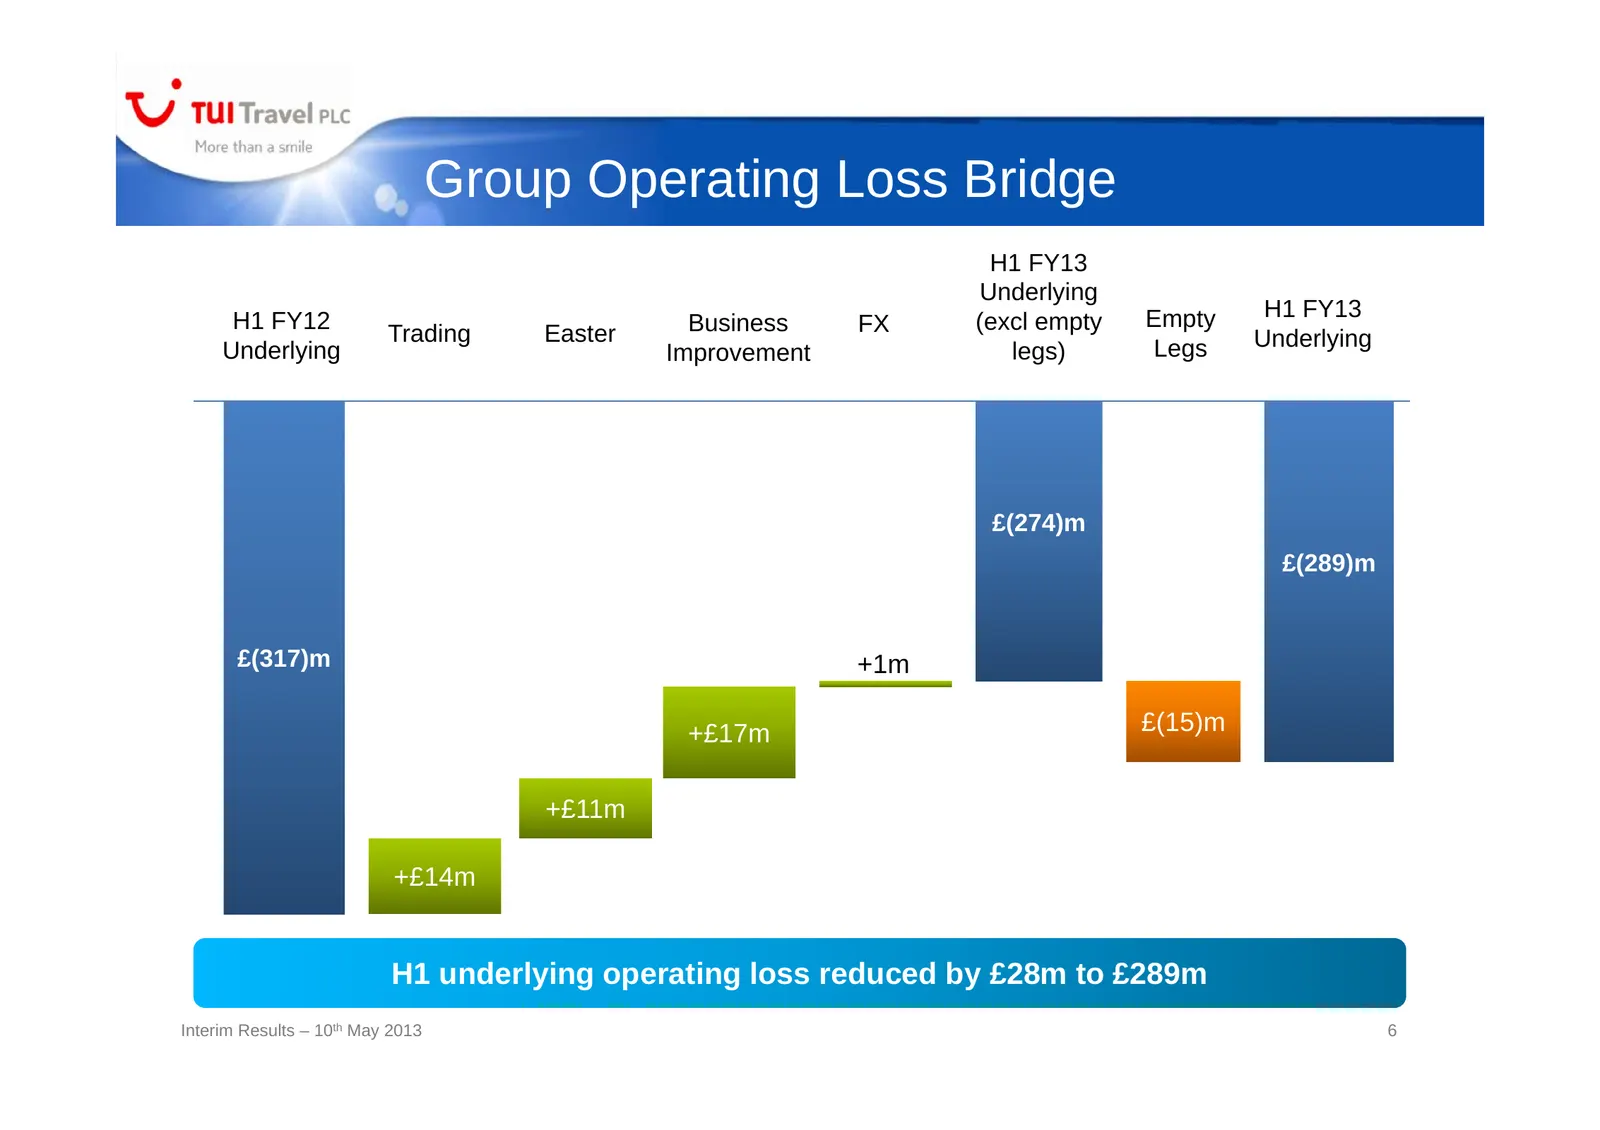
Slide 6: Group Operating Loss Bridge
Group Operating Loss Bridge H1 FY13 Underlying H1 FY12 Empty H1 FY13 Trading Easter Business FX (excl empty Underlying Legs Underlying Improvement legs) £(274)m £(289)m £(317)m +1m +£17m £(15)m +£11m +£14m H1 underlying operating loss reduced by £28m to £289m Interim Results – 10th May 2013 6
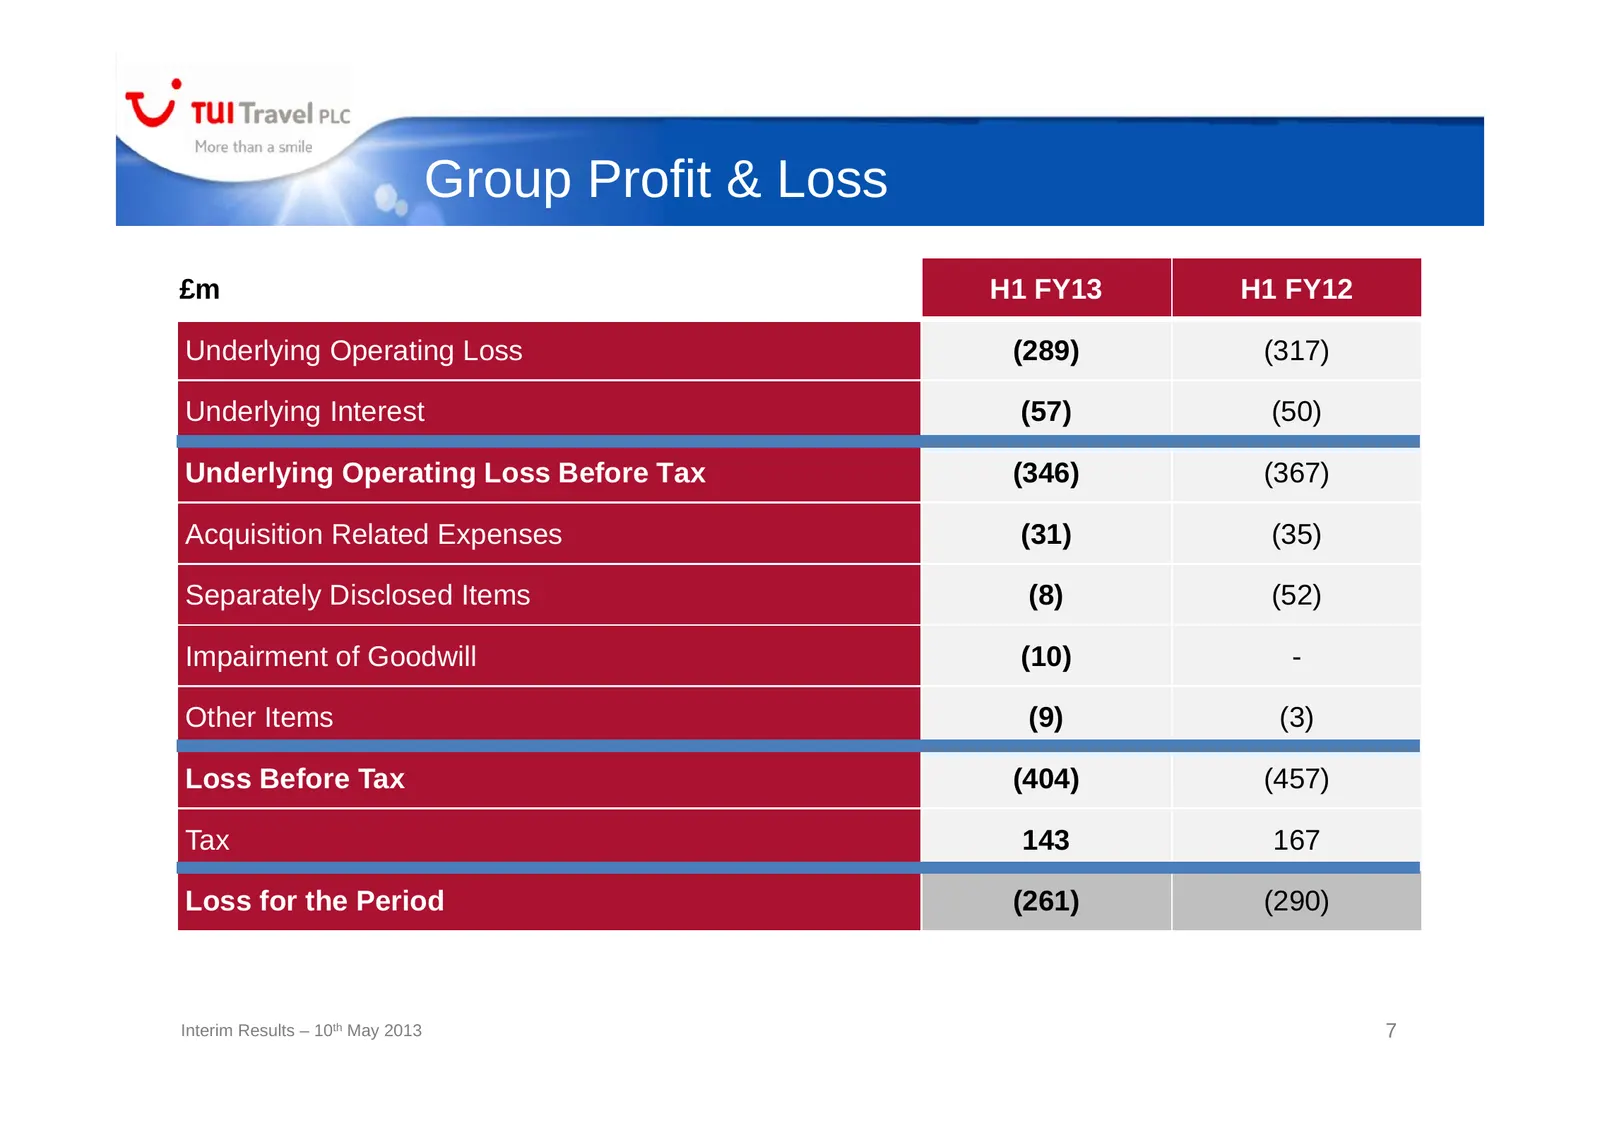
Slide 7: Group Profit & Loss
Group Profit & Loss £m H1 FY13 H1 FY12 Underlying Operating Loss (289) (317) Underlying Interest (57) (50) Underlying Operating Loss Before Tax (346) (367) Acquisition Related Expenses (31) (35) Separately Disclosed Items (8) (52) Impairment of Goodwill (10) - Other Items (9) (3) Loss Before Tax (40
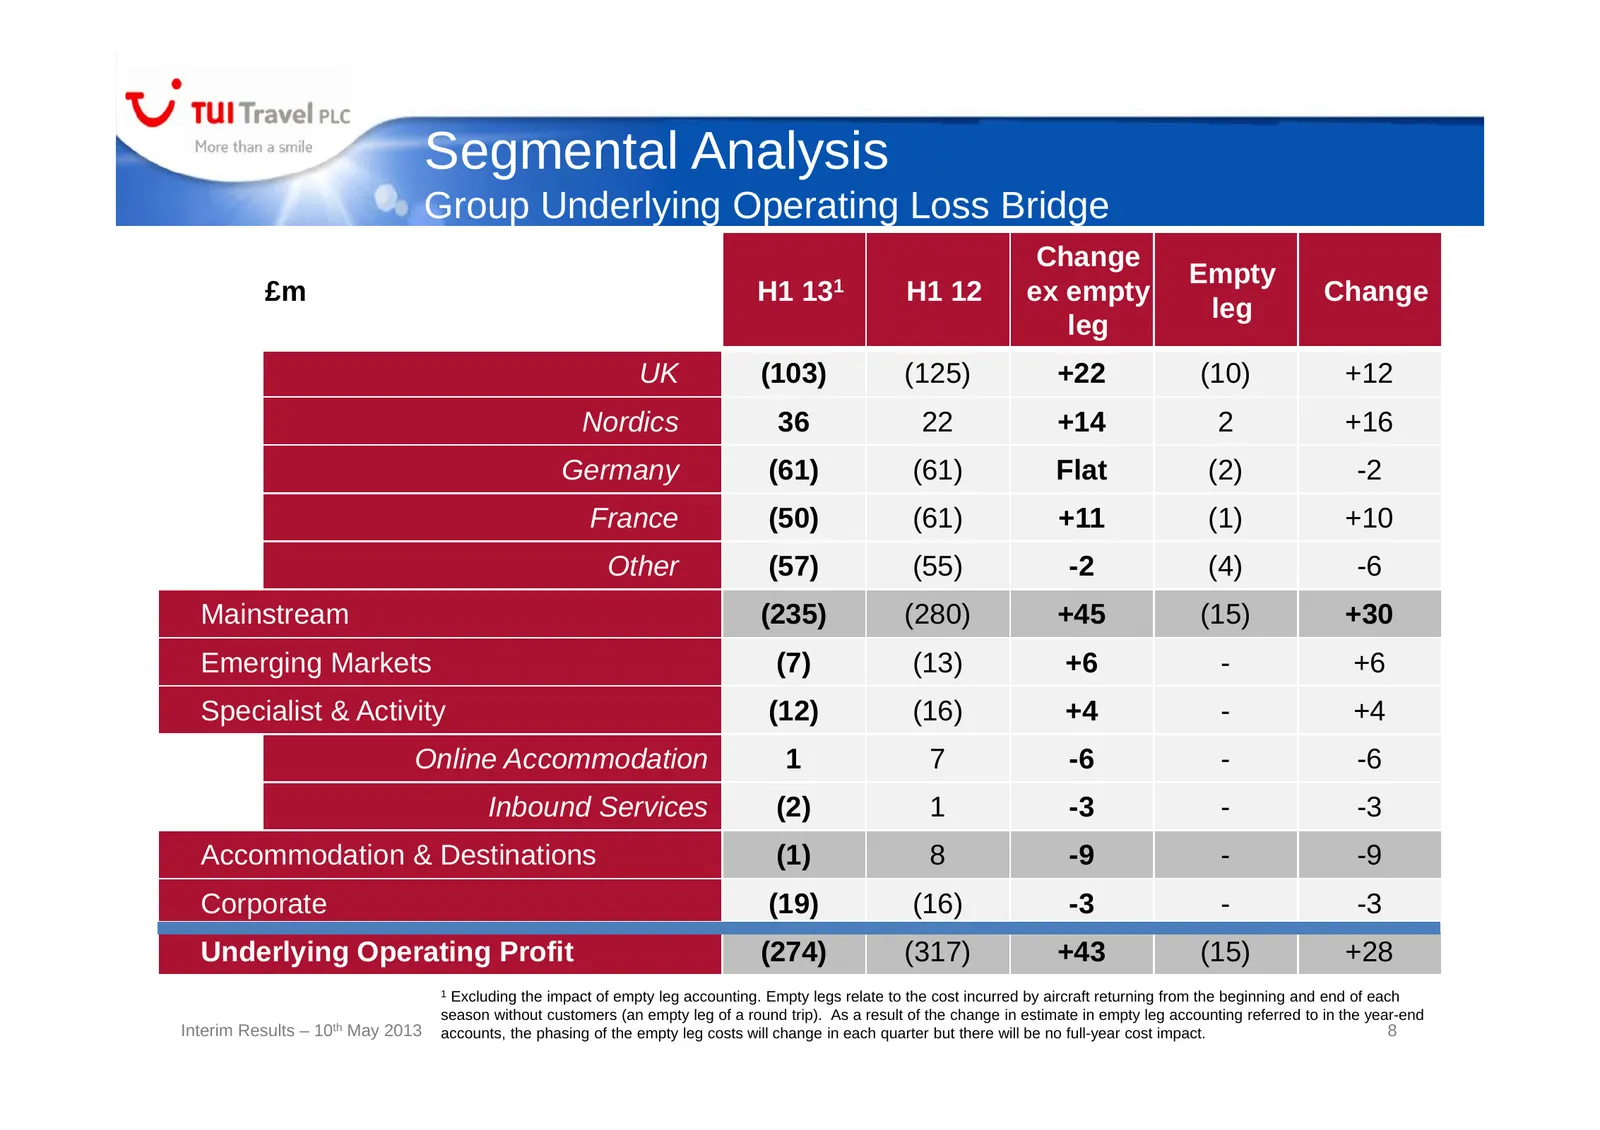
Slide 8: Segmental Analysis
Segmental Analysis Group Underlying Operating Loss Bridge Change Empty £m H1 131 H1 12 ex empty Change leg leg UK (103) (125) +22 (10) +12 Nordics 36 22 +14 2 +16 Germany (61) (61) Flat (2) -2 France (50) (61) +11 (1) +10 Other (57) (55) -2 (4) -6 Mainstream (235) (280) +45 (15) +30 Emerging Markets
Slide 9: Business Improvement Programme
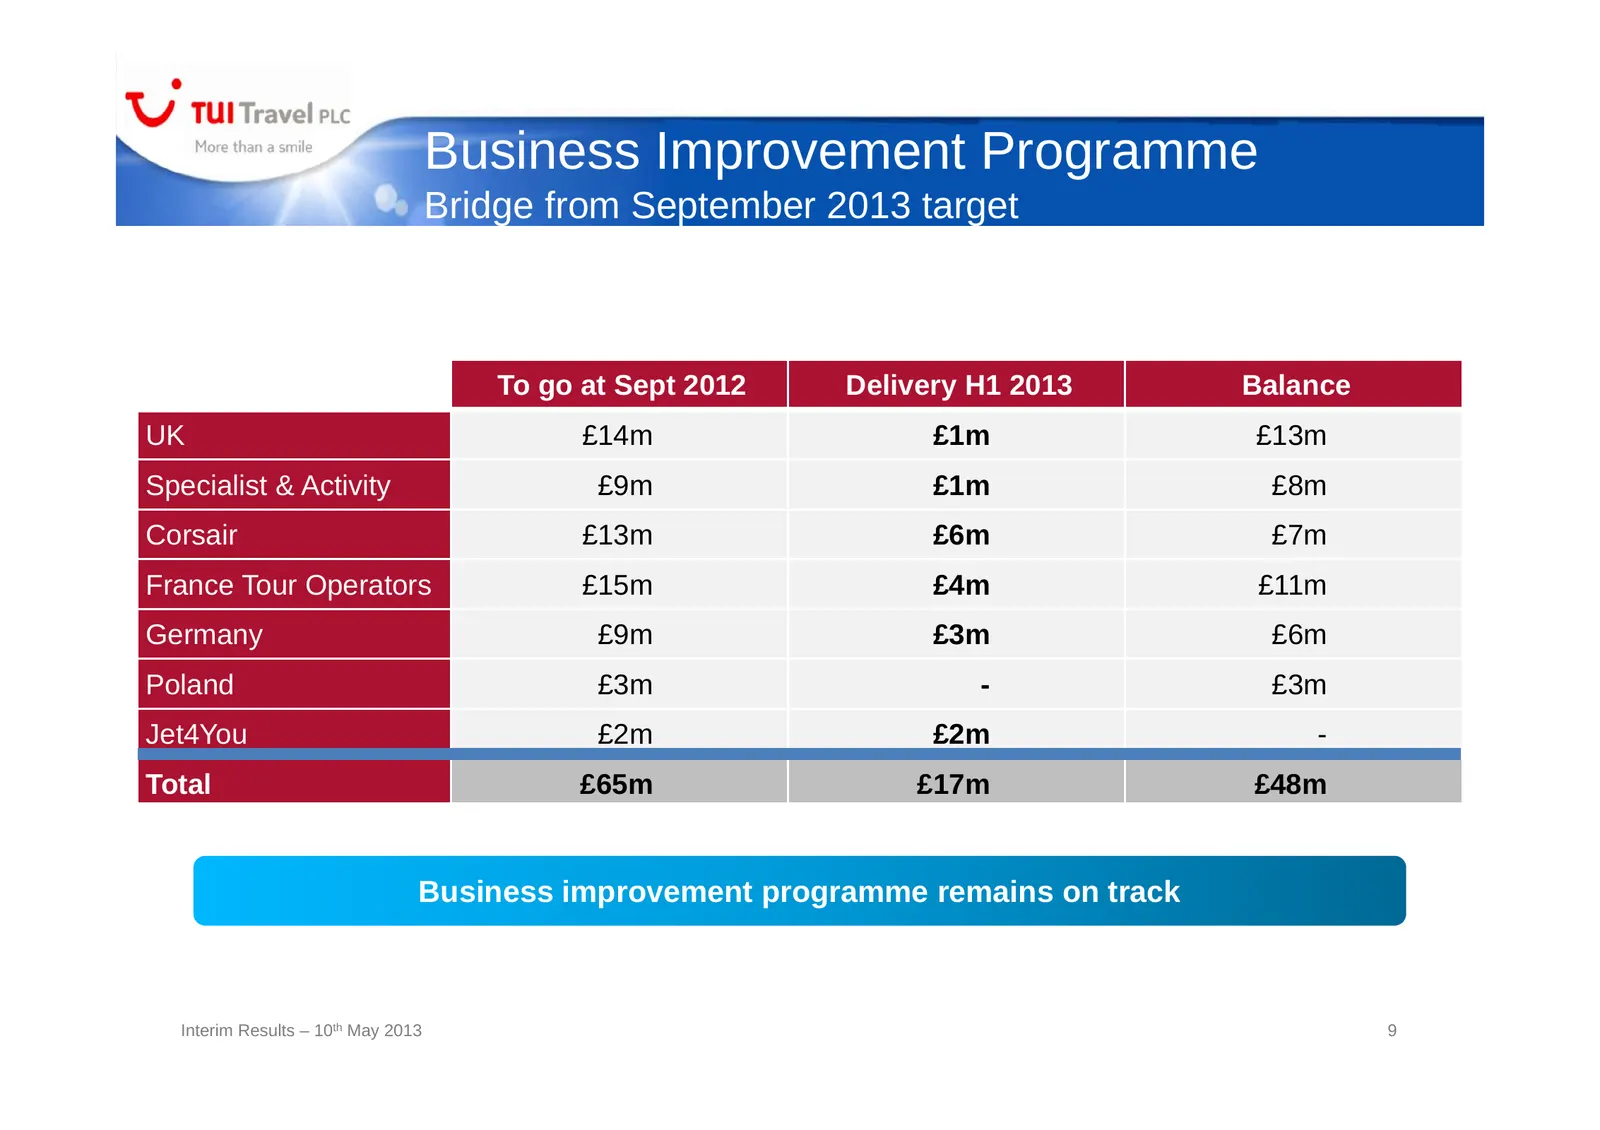
Business Improvement Programme Bridge from September 2013 target To go at Sept 2012 Delivery H1 2013 Balance UK £14m £1m £13m Specialist & Activity £9m £1m £8m Corsair £13m £6m £7m France Tour Operators £15m £4m £11m Germany £9m £3m £6m Poland £3m - £3m Jet4You £2m £2m - Total £65m £17m £48m Busines
Slide 10: Group Cashflow
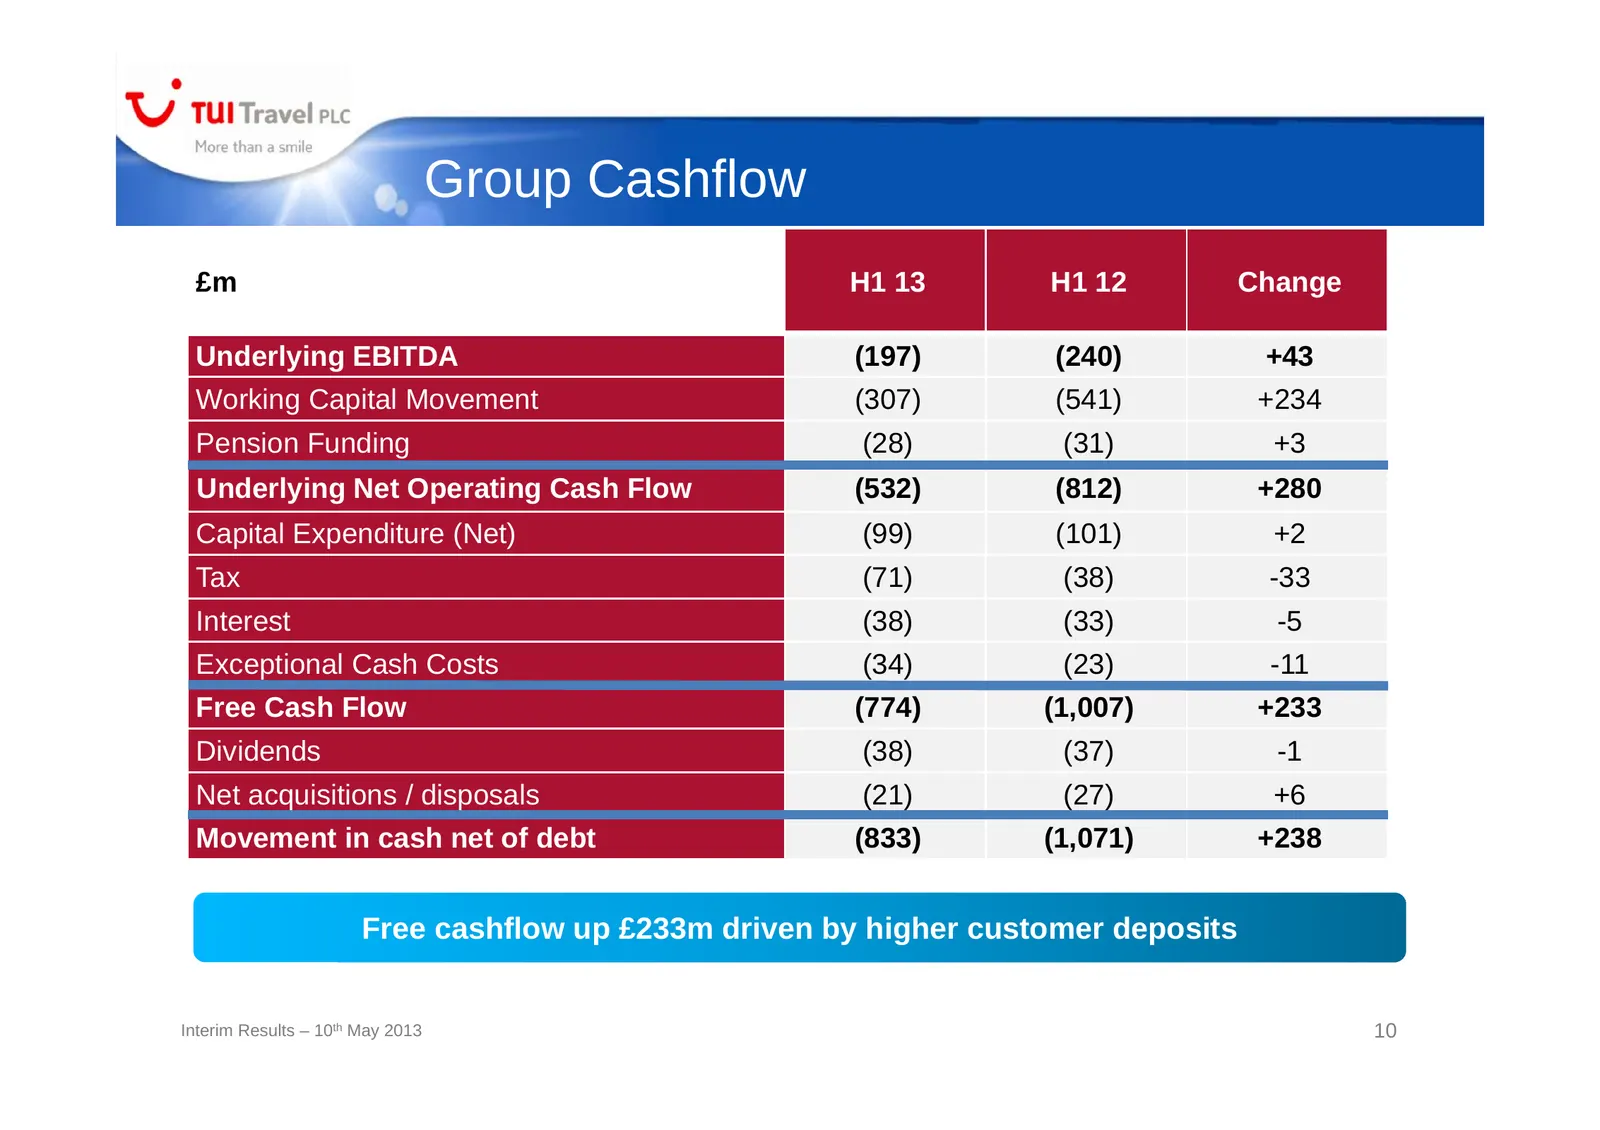
Group Cashflow £m H1 13 H1 12 Change Underlying EBITDA (197) (240) +43 Working Capital Movement (307) (541) +234 Pension Funding (28) (31) +3 Underlying Net Operating Cash Flow (532) (812) +280 Capital Expenditure (Net) (99) (101) +2 Tax (71) (38) -33 Interest (38) (33) -5 Exceptional Cash Costs (34
Slide 11: Net Debt Movement
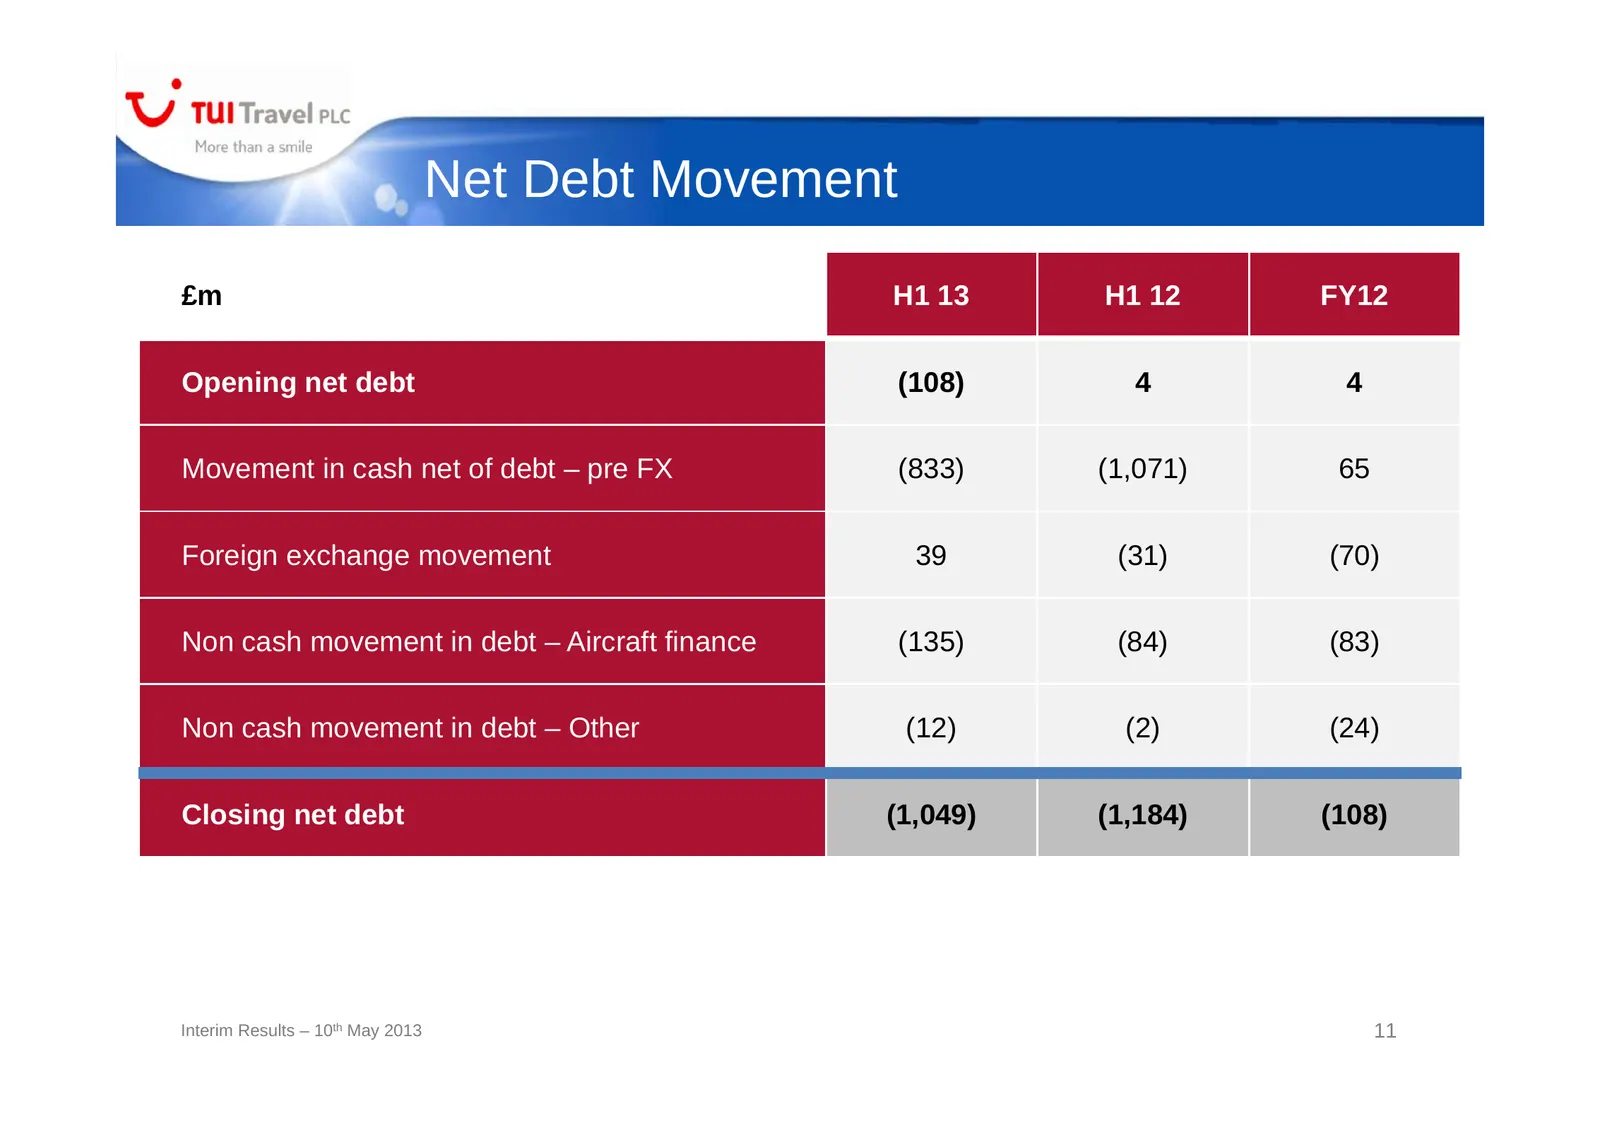
Net Debt Movement £m H1 13 H1 12 FY12 Opening net debt (108) 4 4 Movement in cash net of debt – pre FX (833) (1,071) 65 Foreign exchange movement 39 (31) (70) Non cash movement in debt – Aircraft finance (135) (84) (83) Non cash movement in debt – Other (12) (2) (24) Closing net debt (1,049) (1,184)
Slide 12: Net Debt Analysis
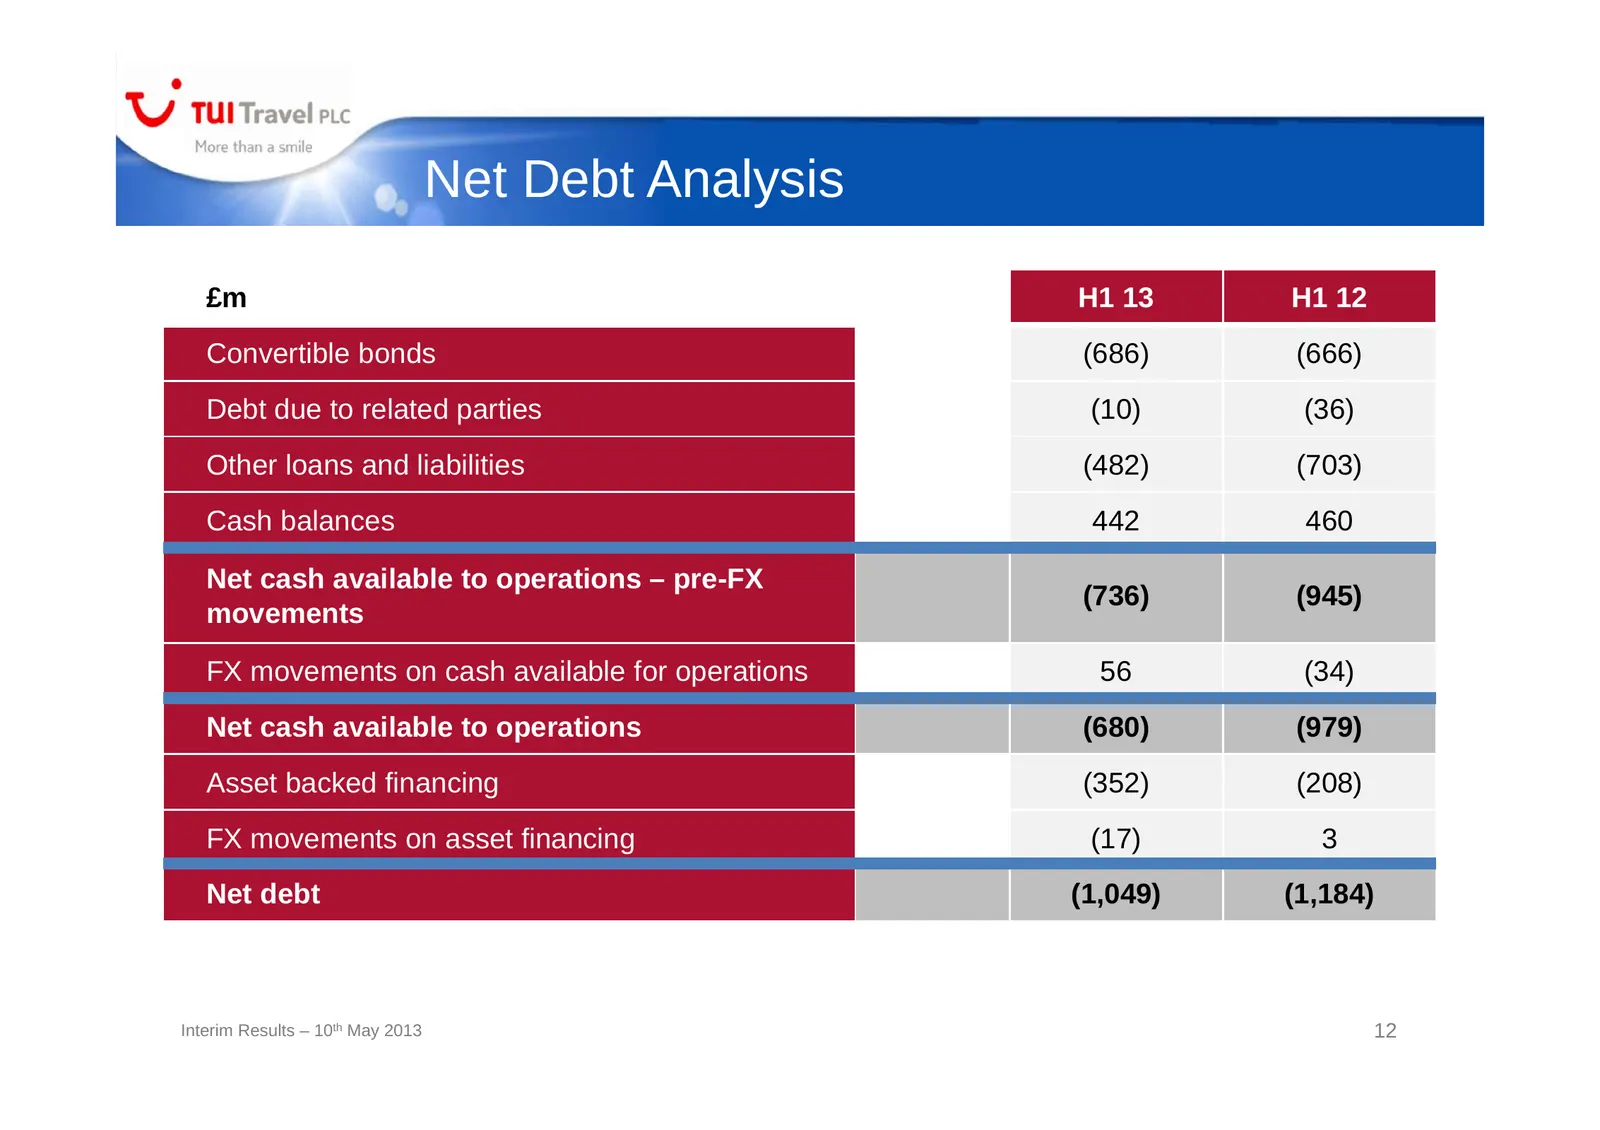
Net Debt Analysis £m H1 13 H1 12 Convertible bonds (686) (666) Debt due to related parties (10) (36) Other loans and liabilities (482) (703) Cash balances 442 460 Net cash available to operations – pre-FX (736) (945) movements FX movements on cash available for operations 56 (34) Net cash available
Slide 13: Current Trading
Current Trading Peter Long Thomson Couples - Atlantica Kalliston Resort & Spa, Crete
Slide 14: Current Trading – Summer 2013
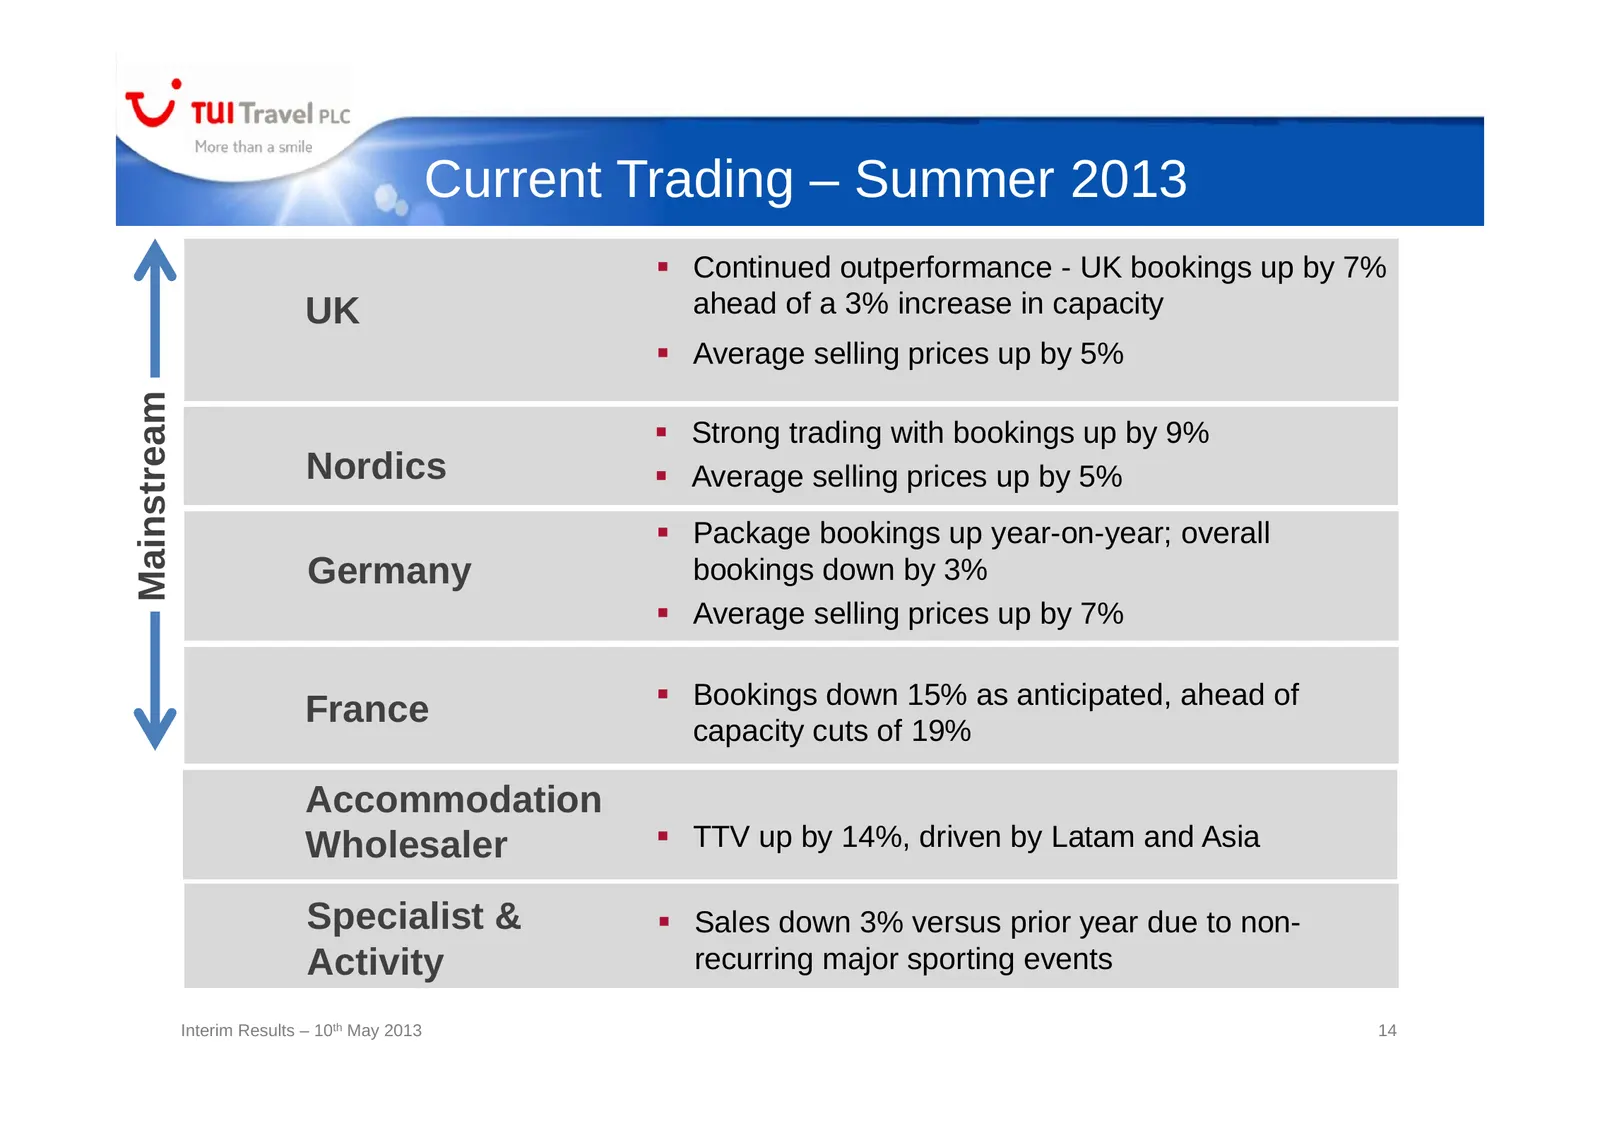
Current Trading – Summer 2013 Continued outperformance - UK bookings up by 7% UK ahead of a 3% increase in capacity Average selling prices up by 5% Mainstream Strong trading with bookings up by 9% Nordics Average selling prices up by 5% Package bookings up year-on-year; overall Germany boo
Slide 15: Strategic Highlights
Strategic Highlights Peter Long Thomson Couples - Atlantica Kalliston, Crete
Slide 16: Strategic Highlights
Strategic Highlights Mainstream Online Accommodation Specialist & Activity Interim Results – 10th May 2013 16
Slide 17: Strategic Highlights
Strategic Highlights Mainstream Online Accommodation Specialist & Activity Interim Results – 10th May 2013 17
Slide 18: Mainstream
Mainstream Mainstream Sector simplified Mainstream Board responsible for delivery of Sector’s growth Clearly defined goals and accountability across all source markets and functions Working to maximise identified opportunities This is delivering and has a clear link to our continued outperfo
Slide 19: Mainstream: Delivering the Strategy
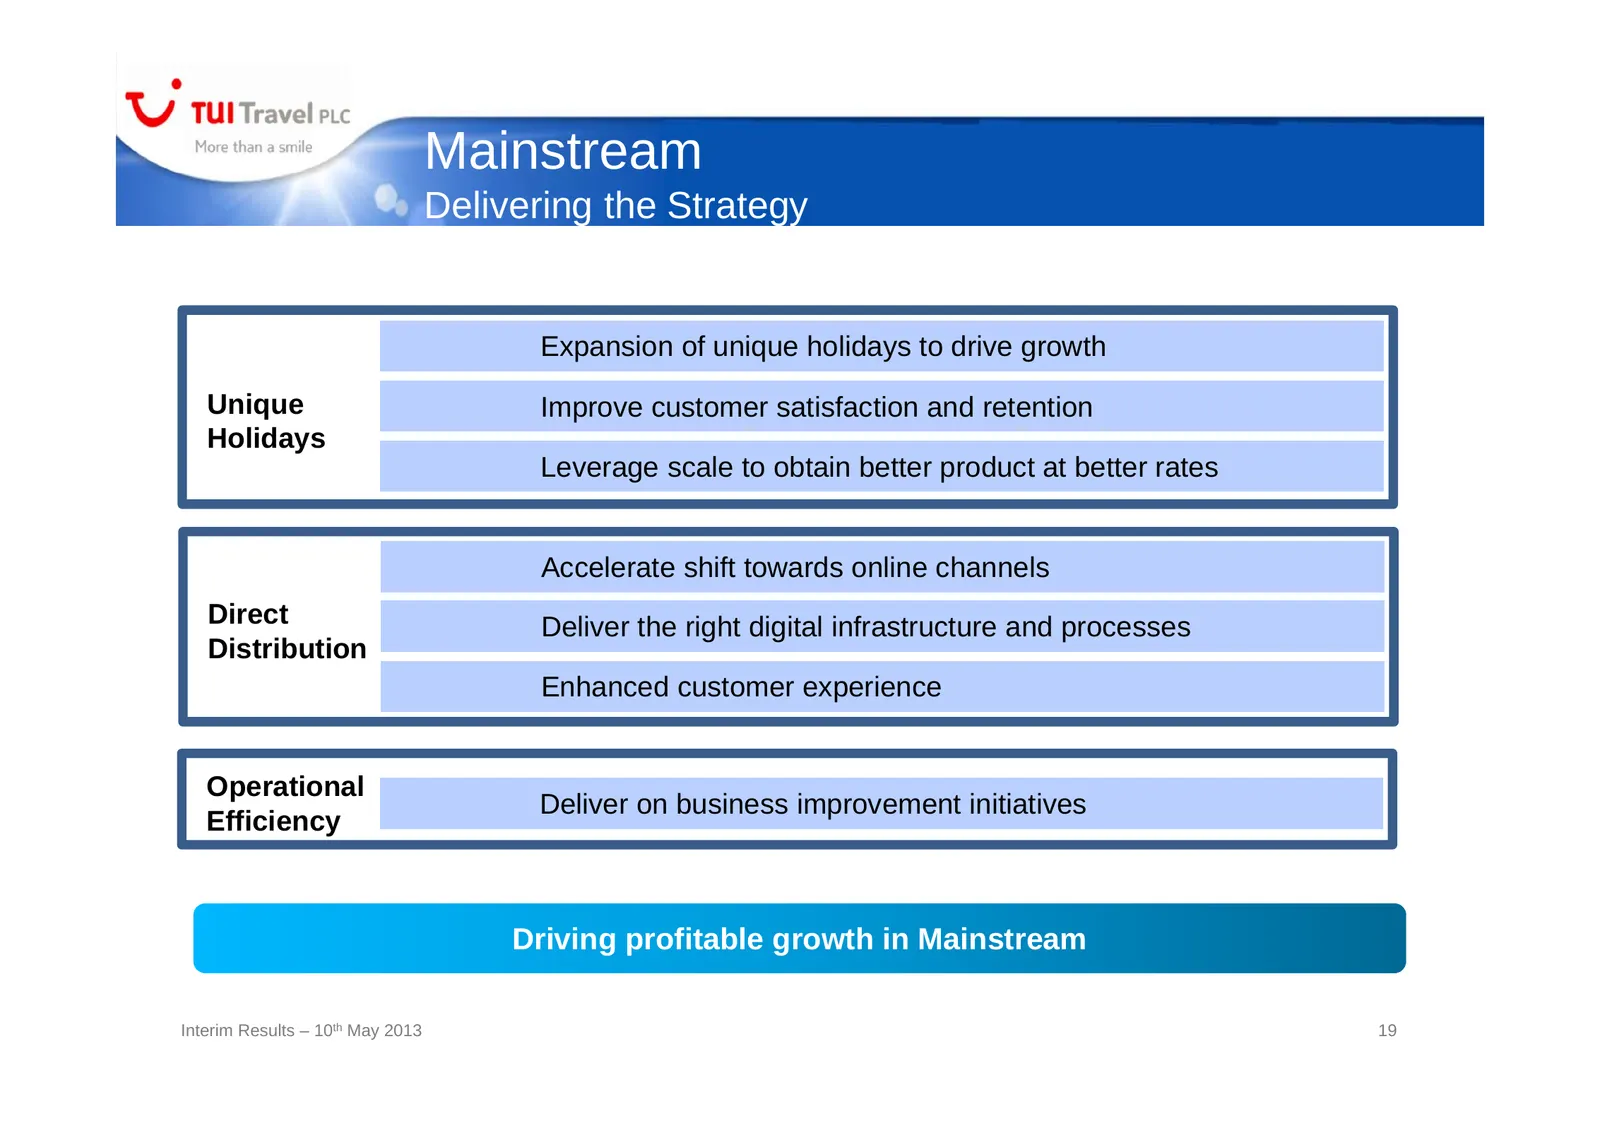
Mainstream Delivering the Strategy Expansion of unique holidays to drive growth Unique Improve customer satisfaction and retention Holidays Leverage scale to obtain better product at better rates Accelerate shift towards online channels Direct Deliver the right digital infrastructure and processes D
Slide 20: Mainstream: Delivering the Strategy
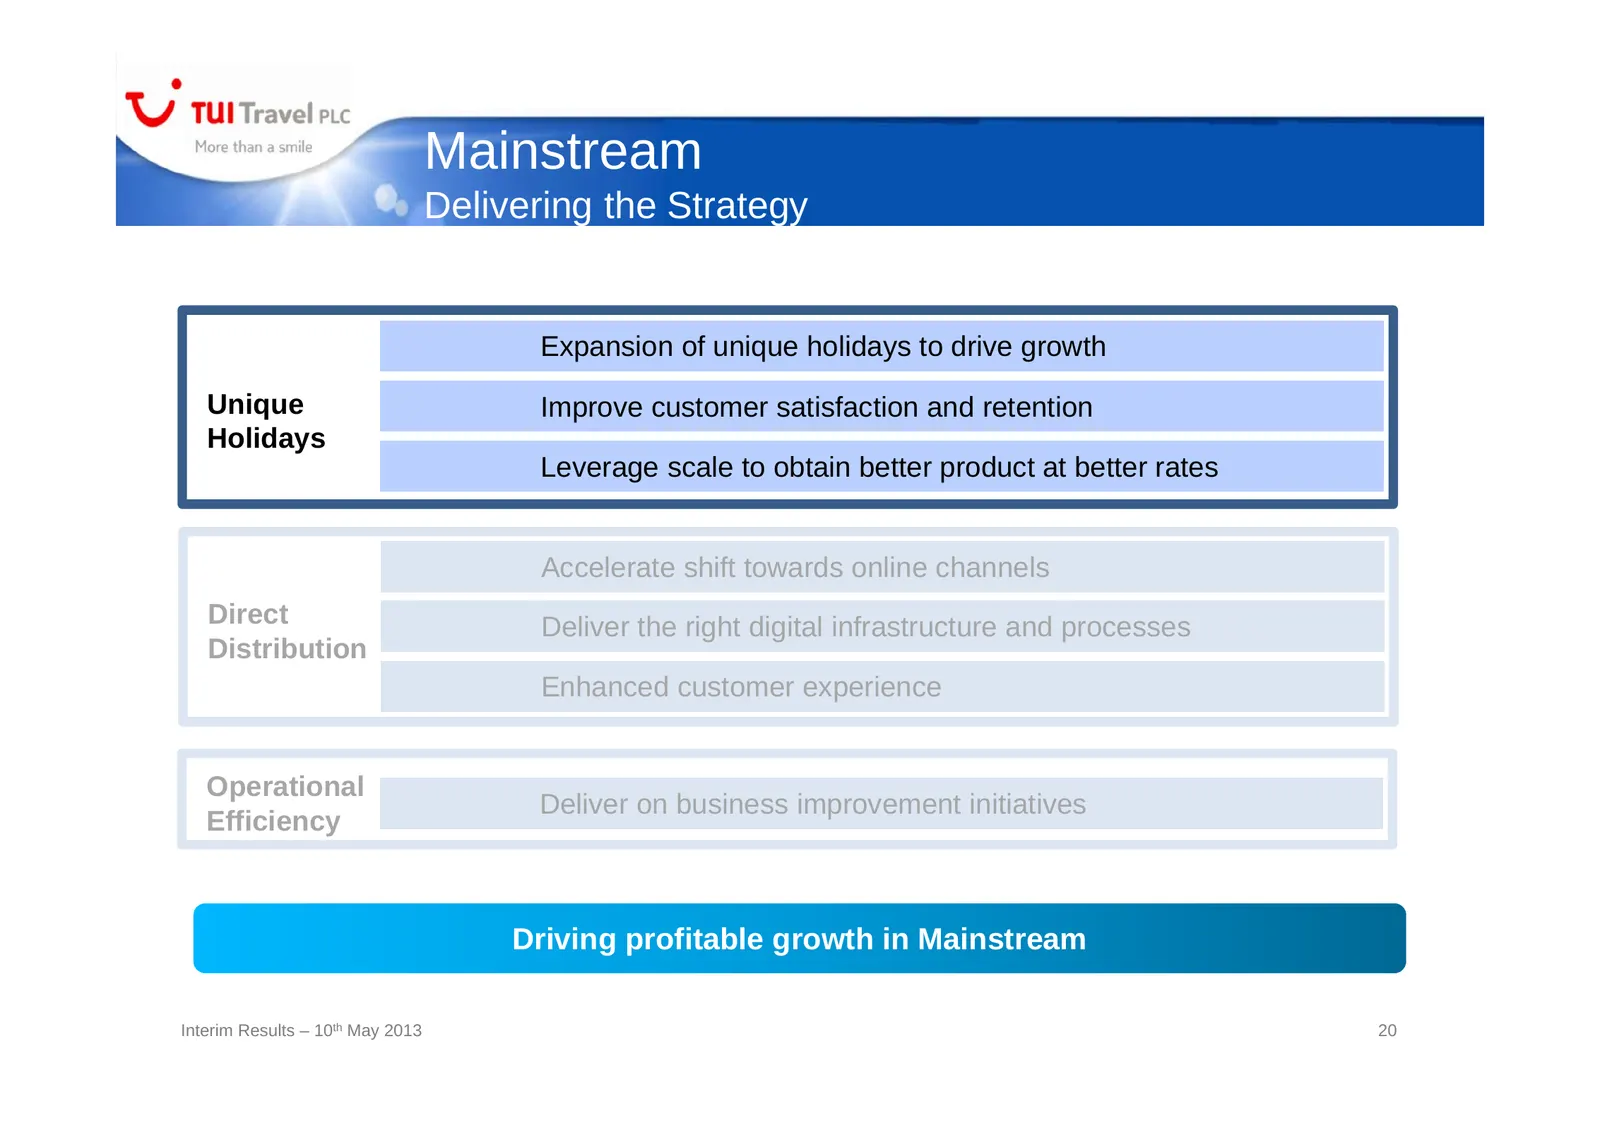
Mainstream Delivering the Strategy Expansion of unique holidays to drive growth Unique Improve customer satisfaction and retention Holidays Leverage scale to obtain better product at better rates Accelerate shift towards online channels Direct Deliver the right digital infrastructure and processes D
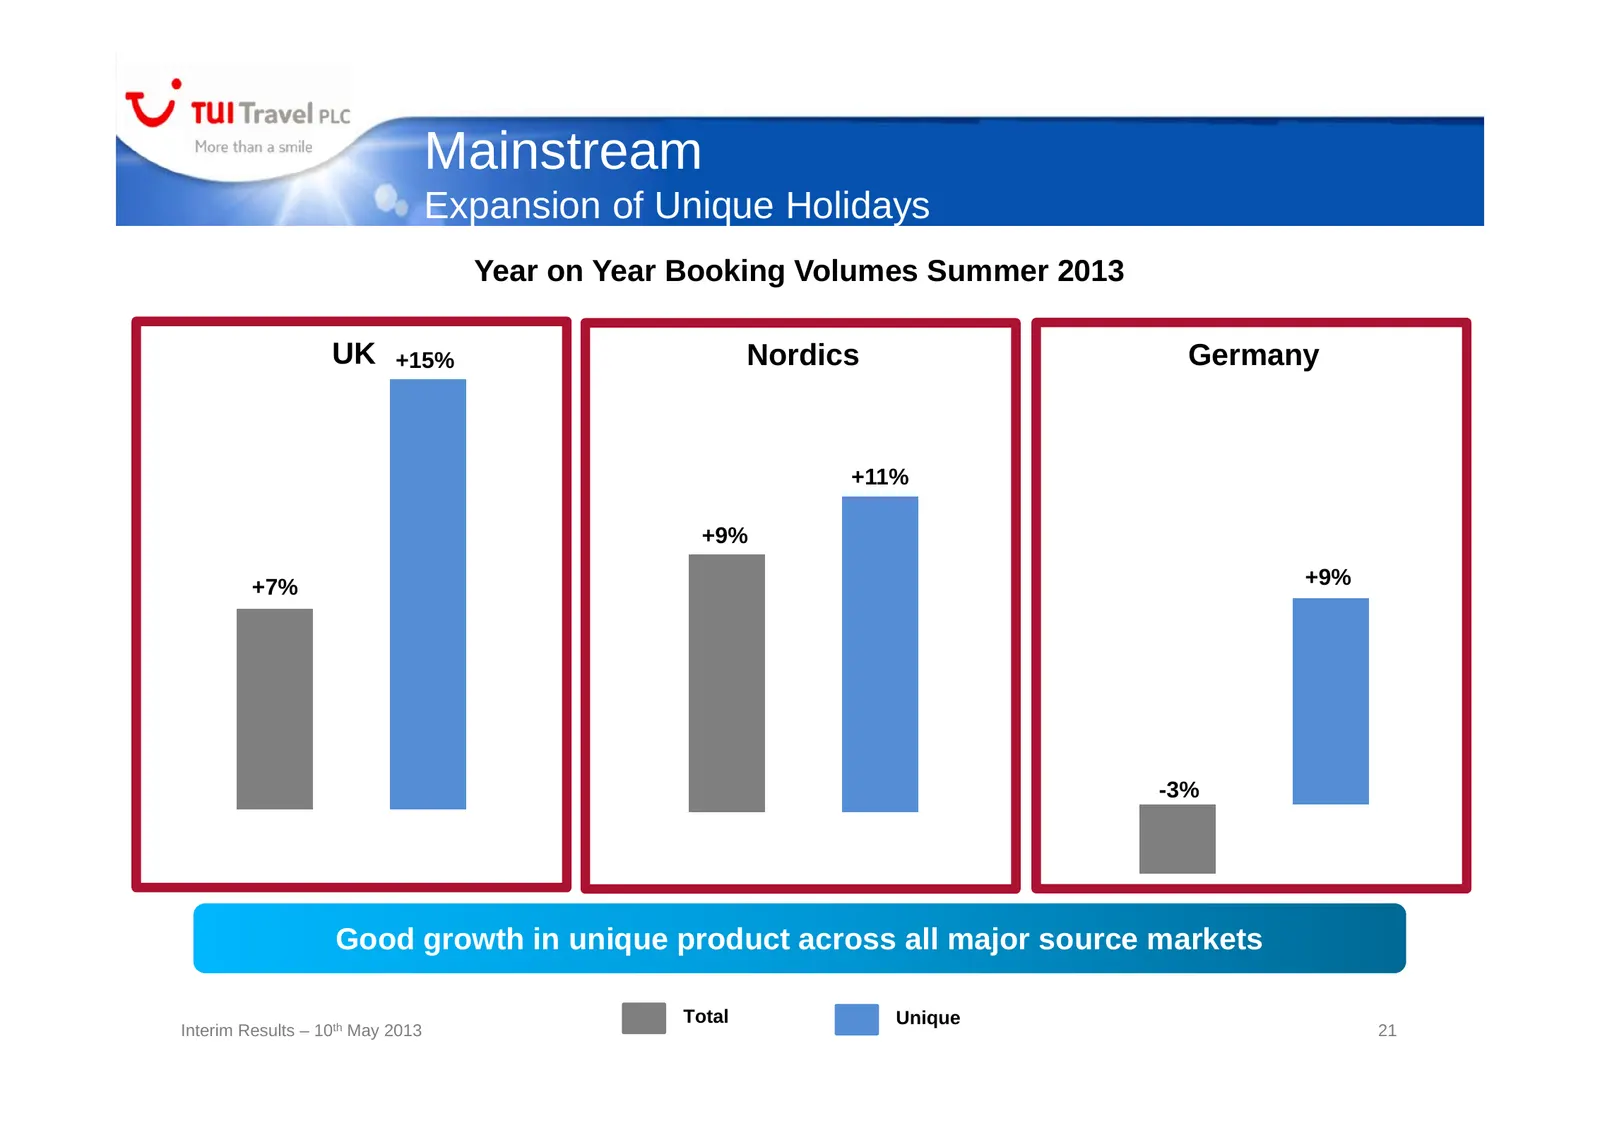
Slide 21: Expansion of Unique Holidays
Mainstream Expansion of Unique Holidays Year on Year Booking Volumes Summer 2013 UK +15% Nordics Germany +11% +9% +7% +9% -3% Good growth in unique product across all major source markets Total Unique Interim Results – 10th May 2013 21
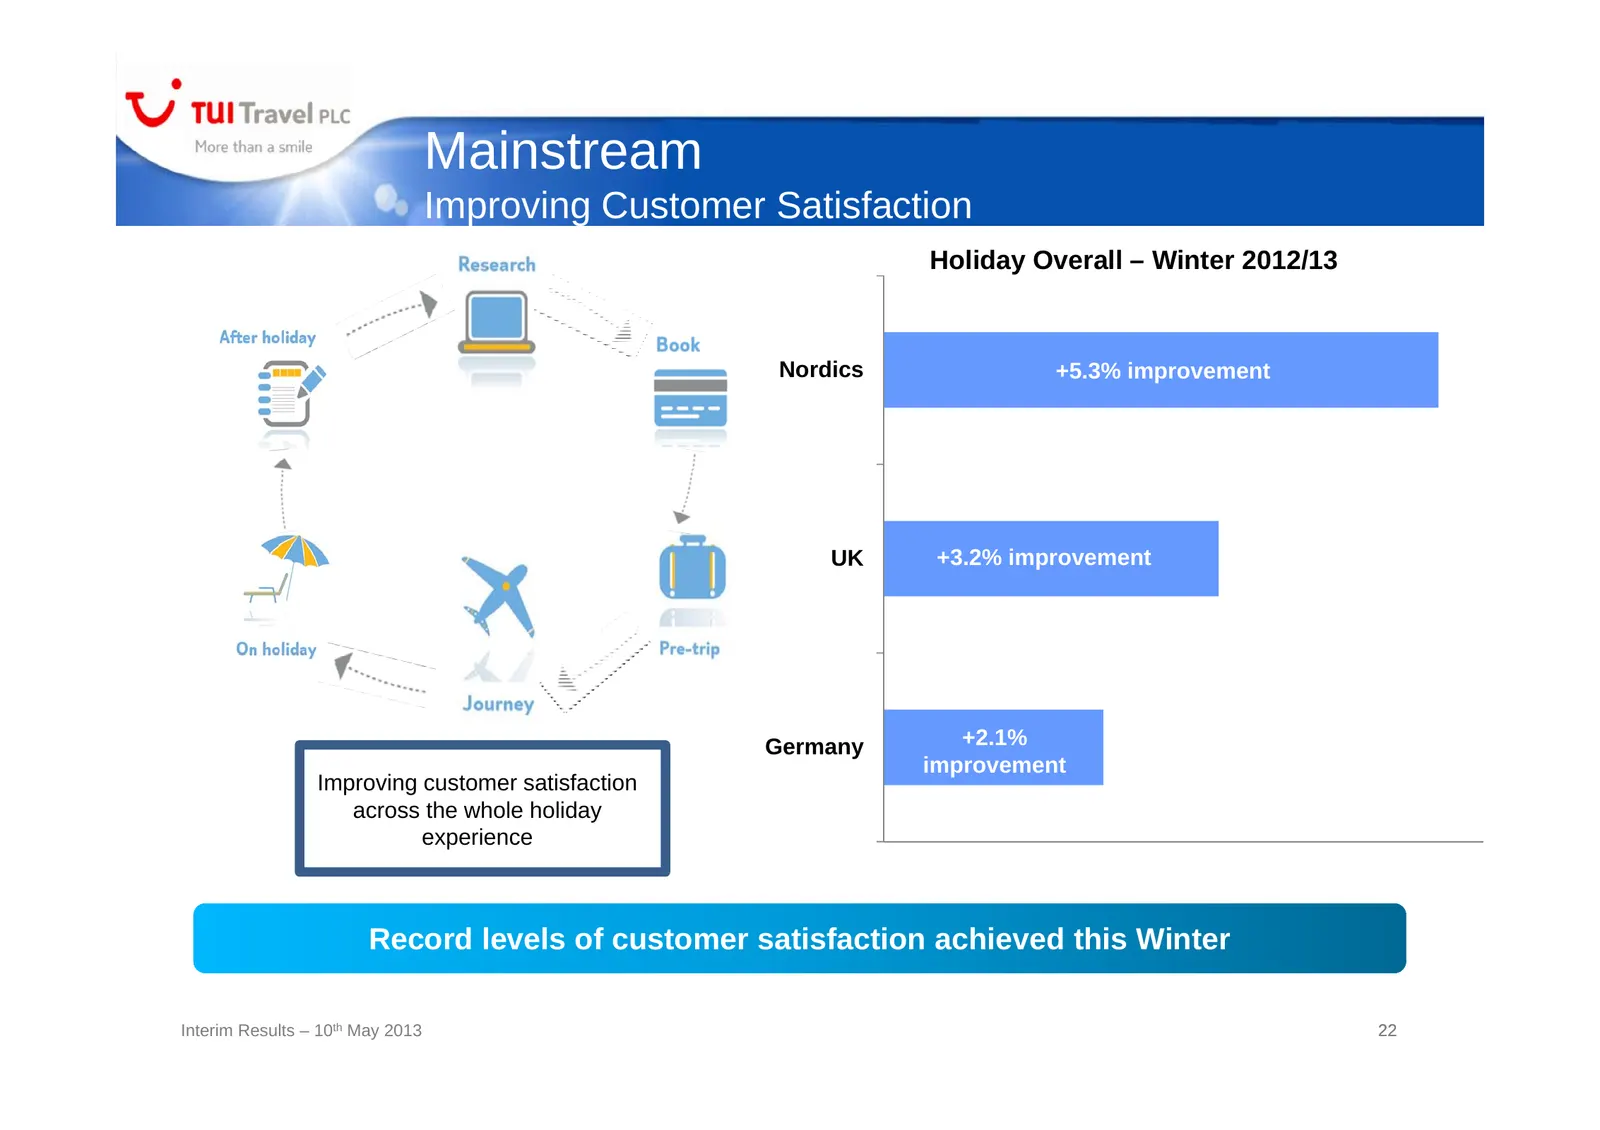
Slide 22: Improving Customer Satisfaction
Mainstream Improving Customer Satisfaction Holiday Overall – Winter 2012/13 Nordics +5.3% improvement UK +3.2% improvement Germany +2.1% improvement Improving customer satisfaction across the whole holiday experience WeRecord are achieving levels of record customer CSQ satisfaction scores in ourachi
Slide 23: UK - Social Media Customer Service
Mainstream UK - Social Media Customer Service Since January, the UK Social Media Customer Service Team has been operating 24/7 March rankings for ‘socially devoted’ Facebook brands1: Thomson Holidays ranked fourth in the UK Ranked number one for customer service response rate Putting the cus
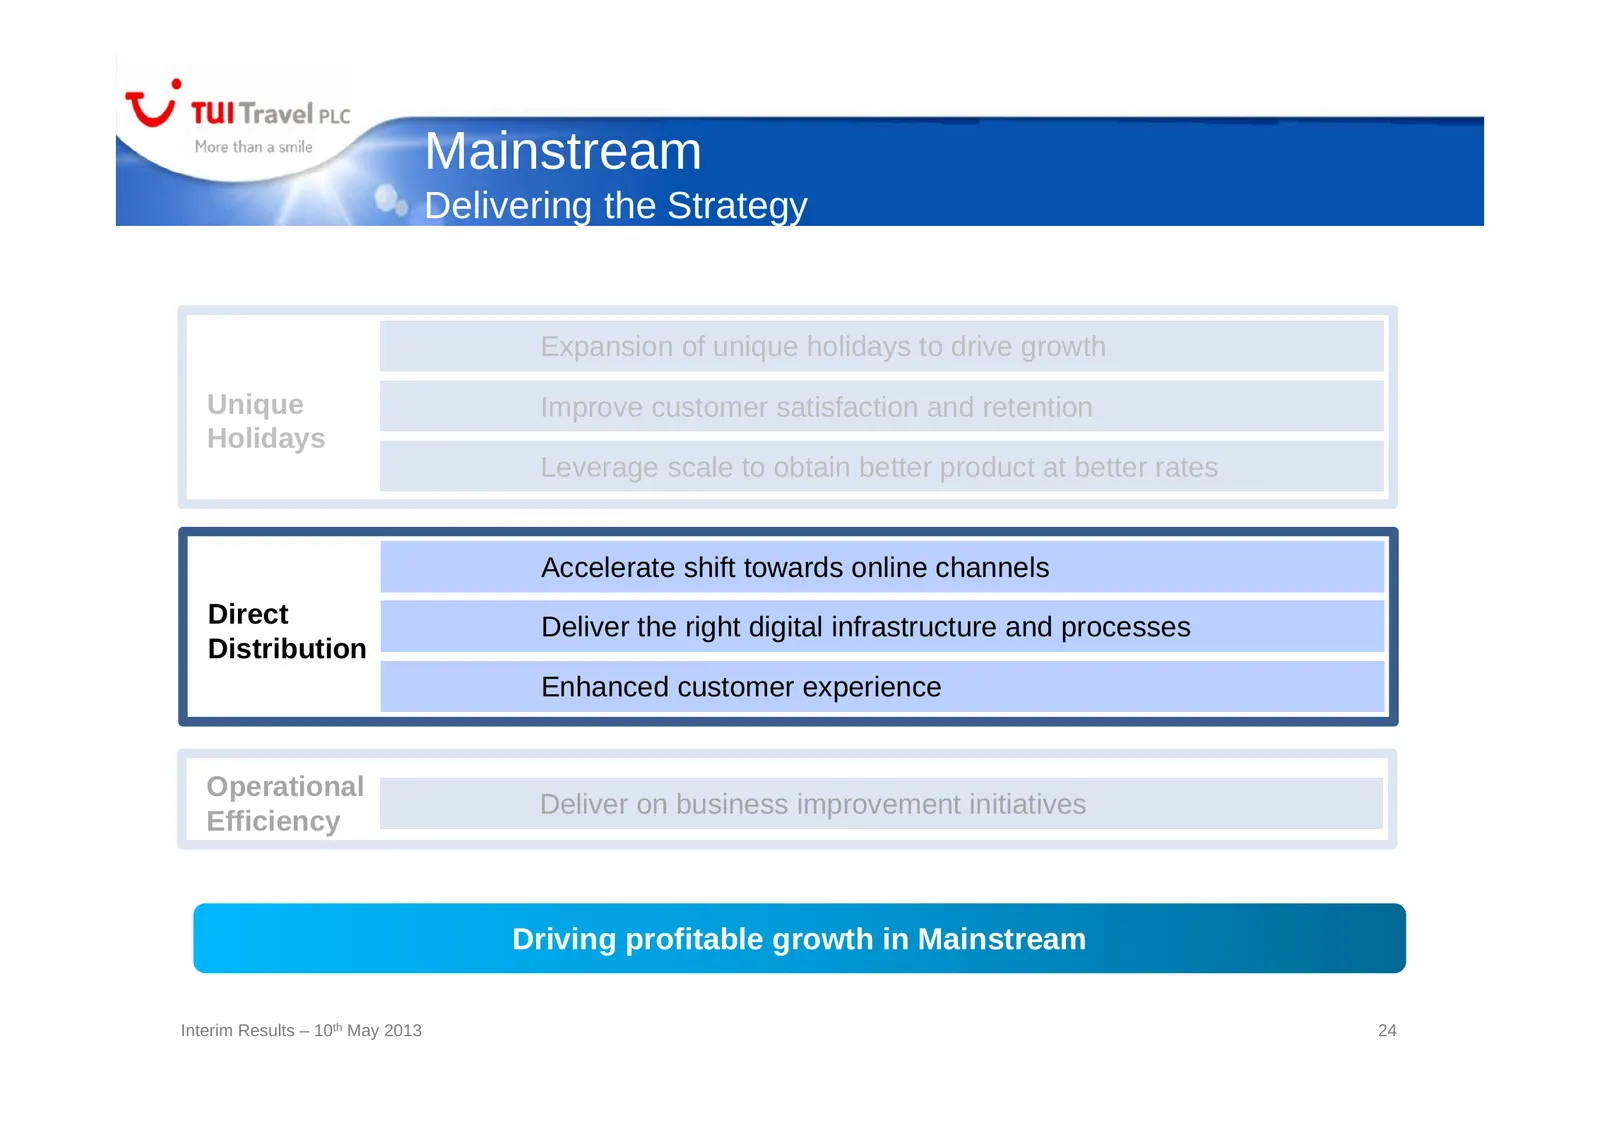
Slide 24: Mainstream: Delivering the Strategy
Mainstream Delivering the Strategy Expansion of unique holidays to drive growth Unique Improve customer satisfaction and retention Holidays Leverage scale to obtain better product at better rates Accelerate shift towards online channels Direct Deliver the right digital infrastructure and processes D
Slide 25: Distribution - Multiple Customer Touchpoints
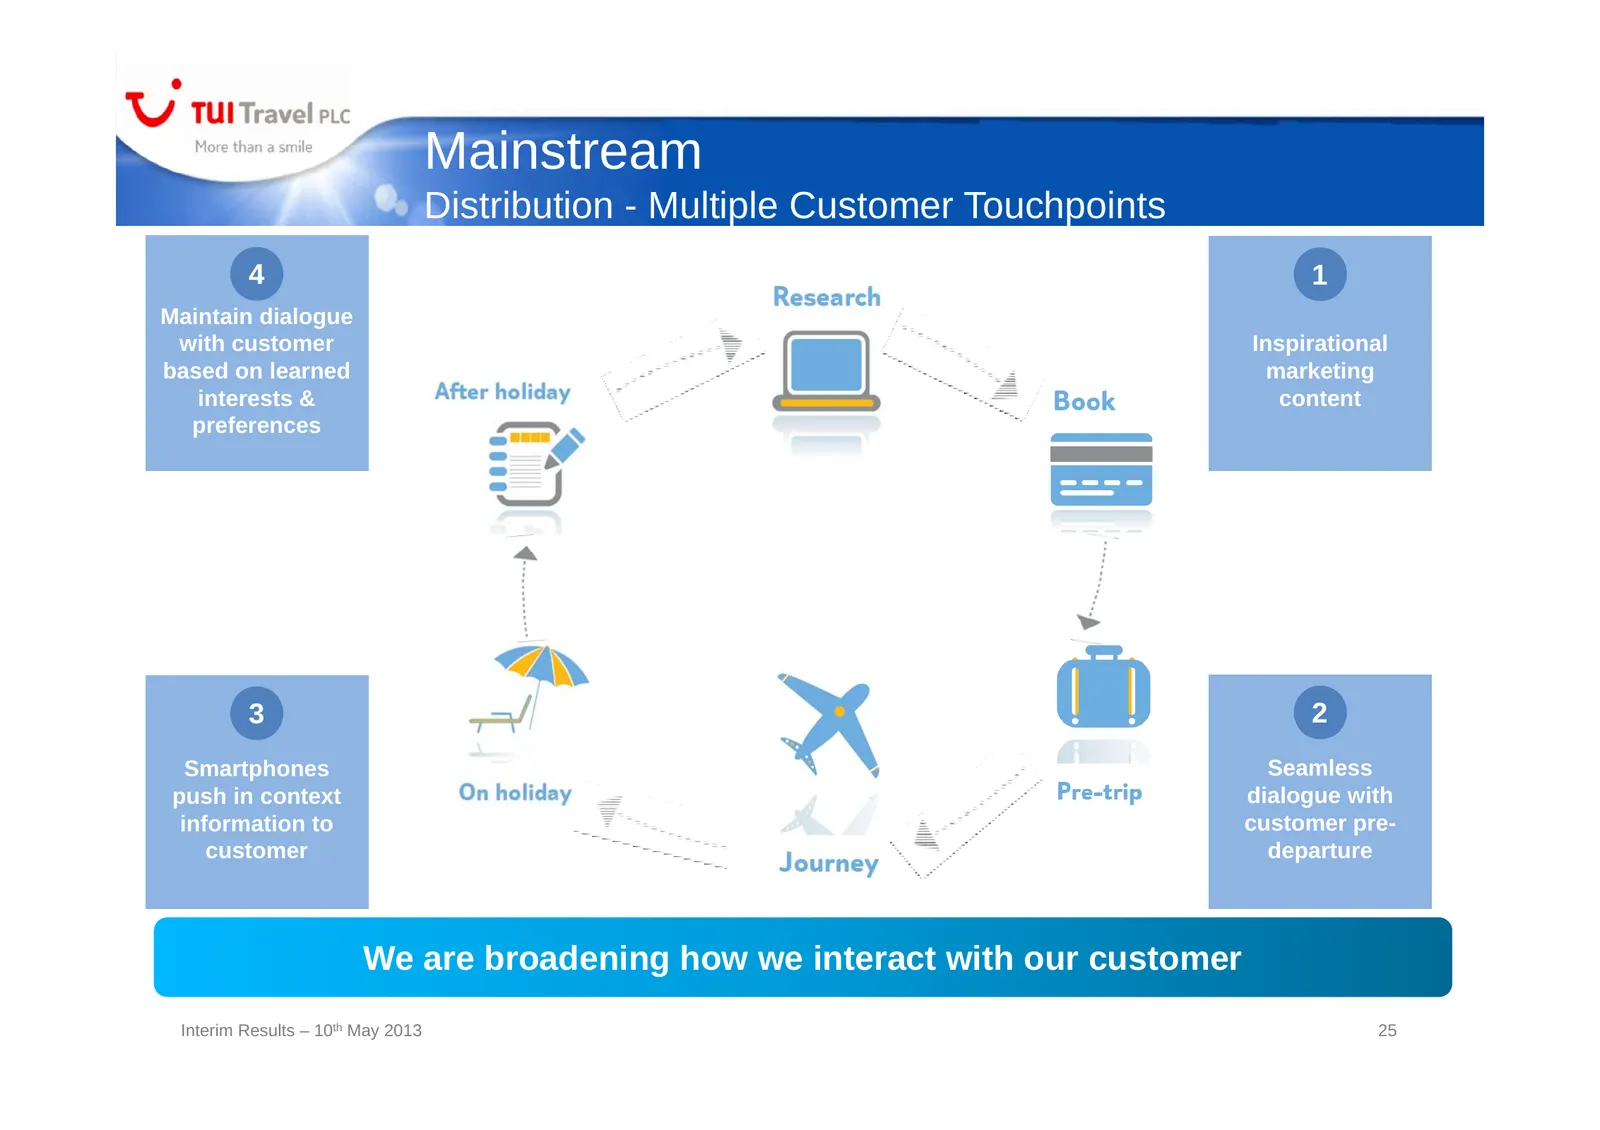
Mainstream Distribution - Multiple Customer Touchpoints 4 1 Maintain dialogue with customer Inspirational based on learned marketing interests & content preferences 3 2 Smartphones Seamless push in context dialogue with information to customer pre- customer departure We are broadening how we interac
Slide 26: Multi Channel Approach
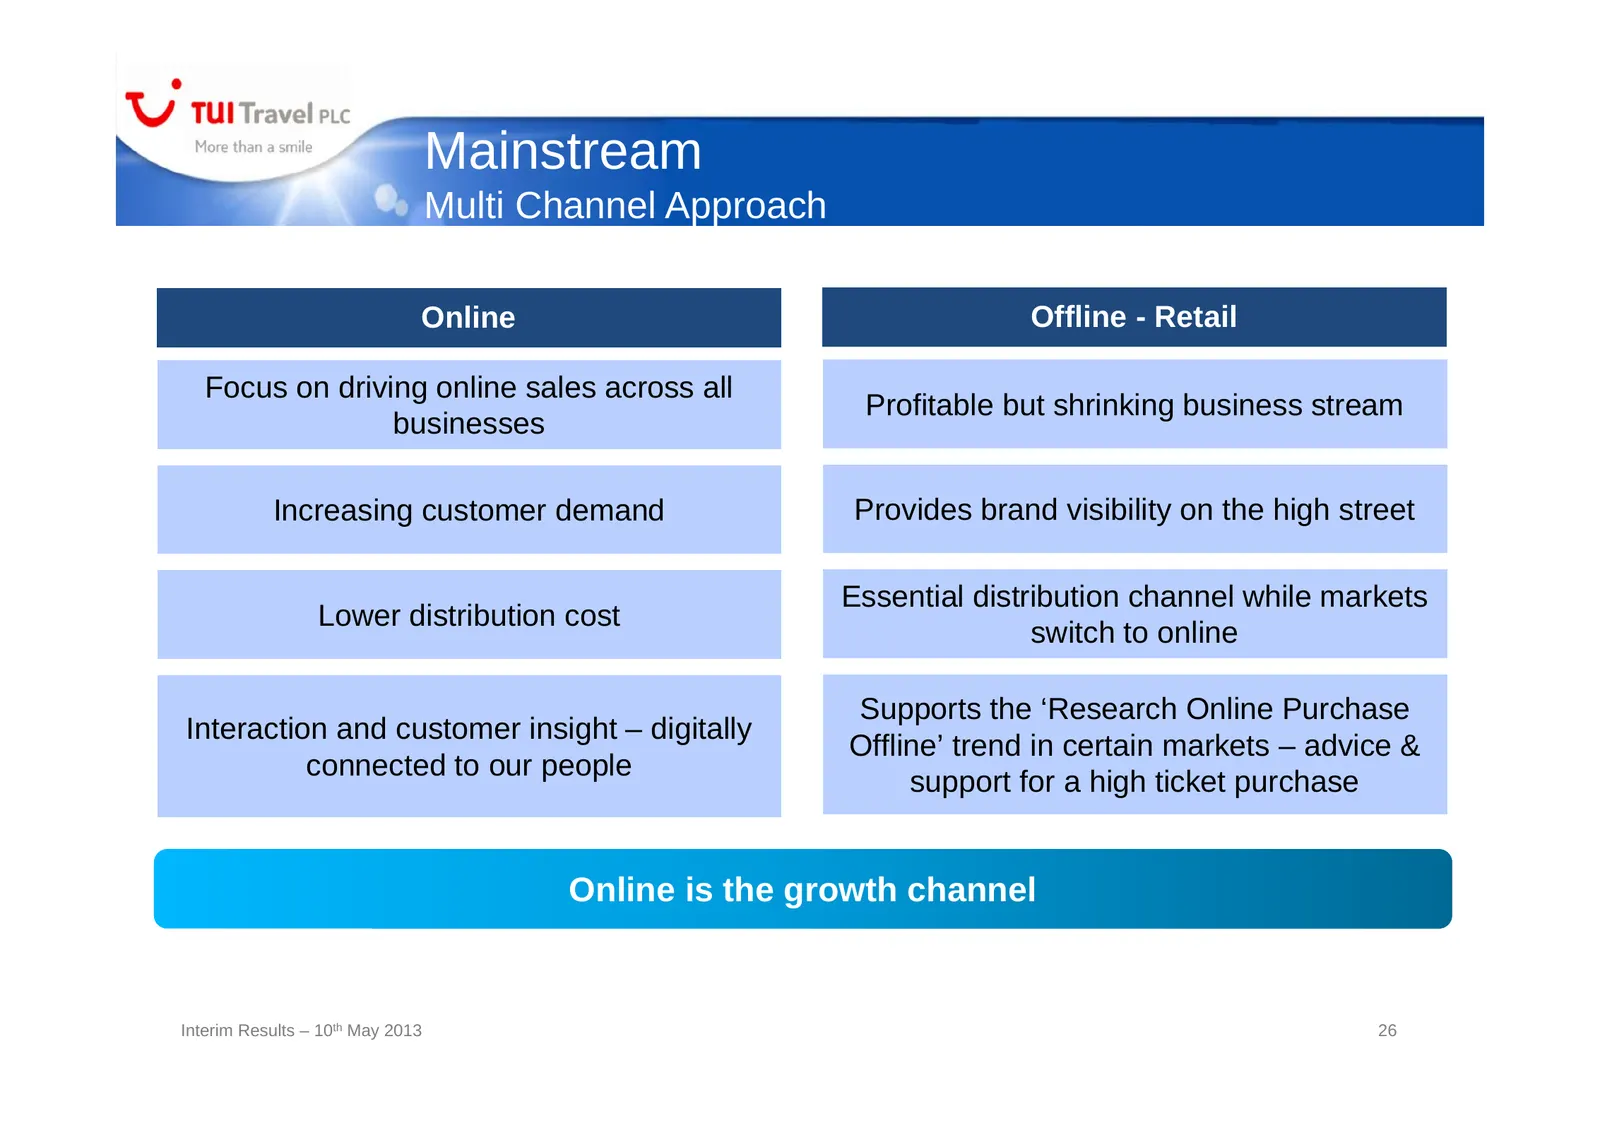
Mainstream Multi Channel Approach Online Offline - Retail Focus on driving online sales across all Profitable but shrinking business stream businesses Increasing customer demand Provides brand visibility on the high street Essential distribution channel while markets Lower distribution cost switch t
Slide 27: Mobile – Anytime, Anywhere, Anyway
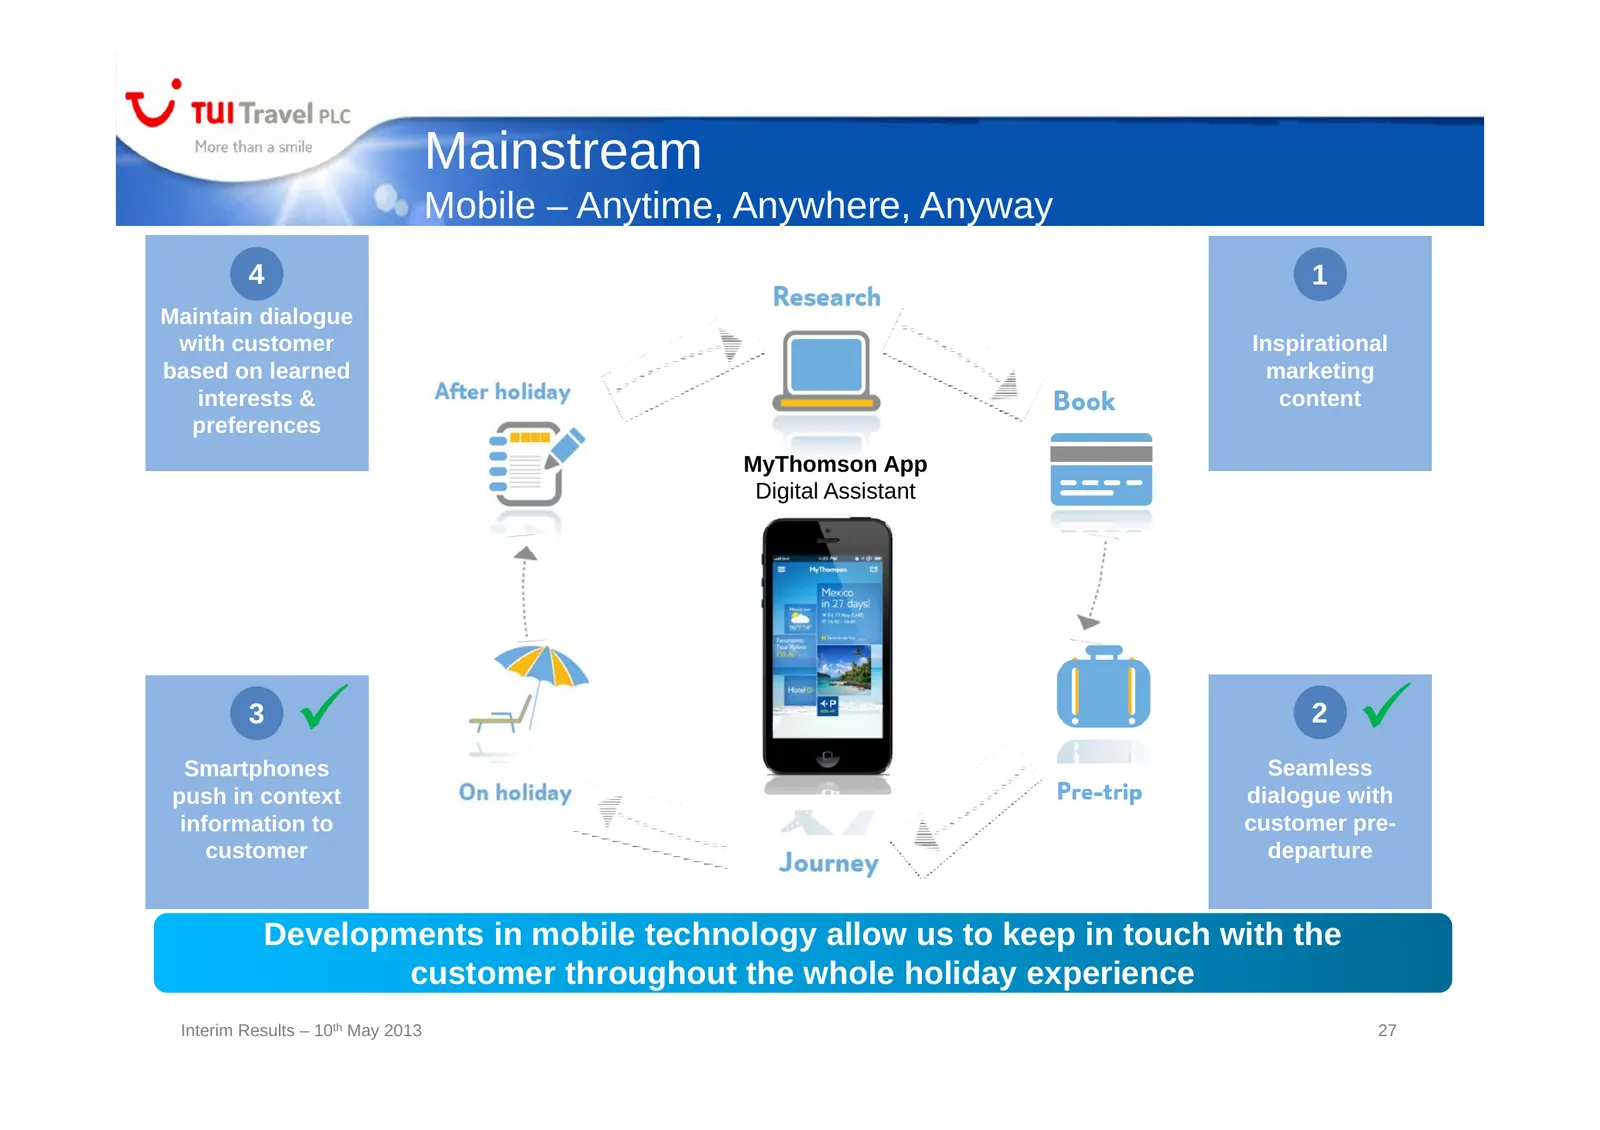
Mainstream Mobile – Anytime, Anywhere, Anyway 4 1 Maintain dialogue with customer Inspirational based on learned marketing interests & content preferences MyThomson App Digital Assistant 3 2 Smartphones Seamless push in context dialogue with information to customer pre- customer departure Develo
Slide 28: Next Generation Thomson Store
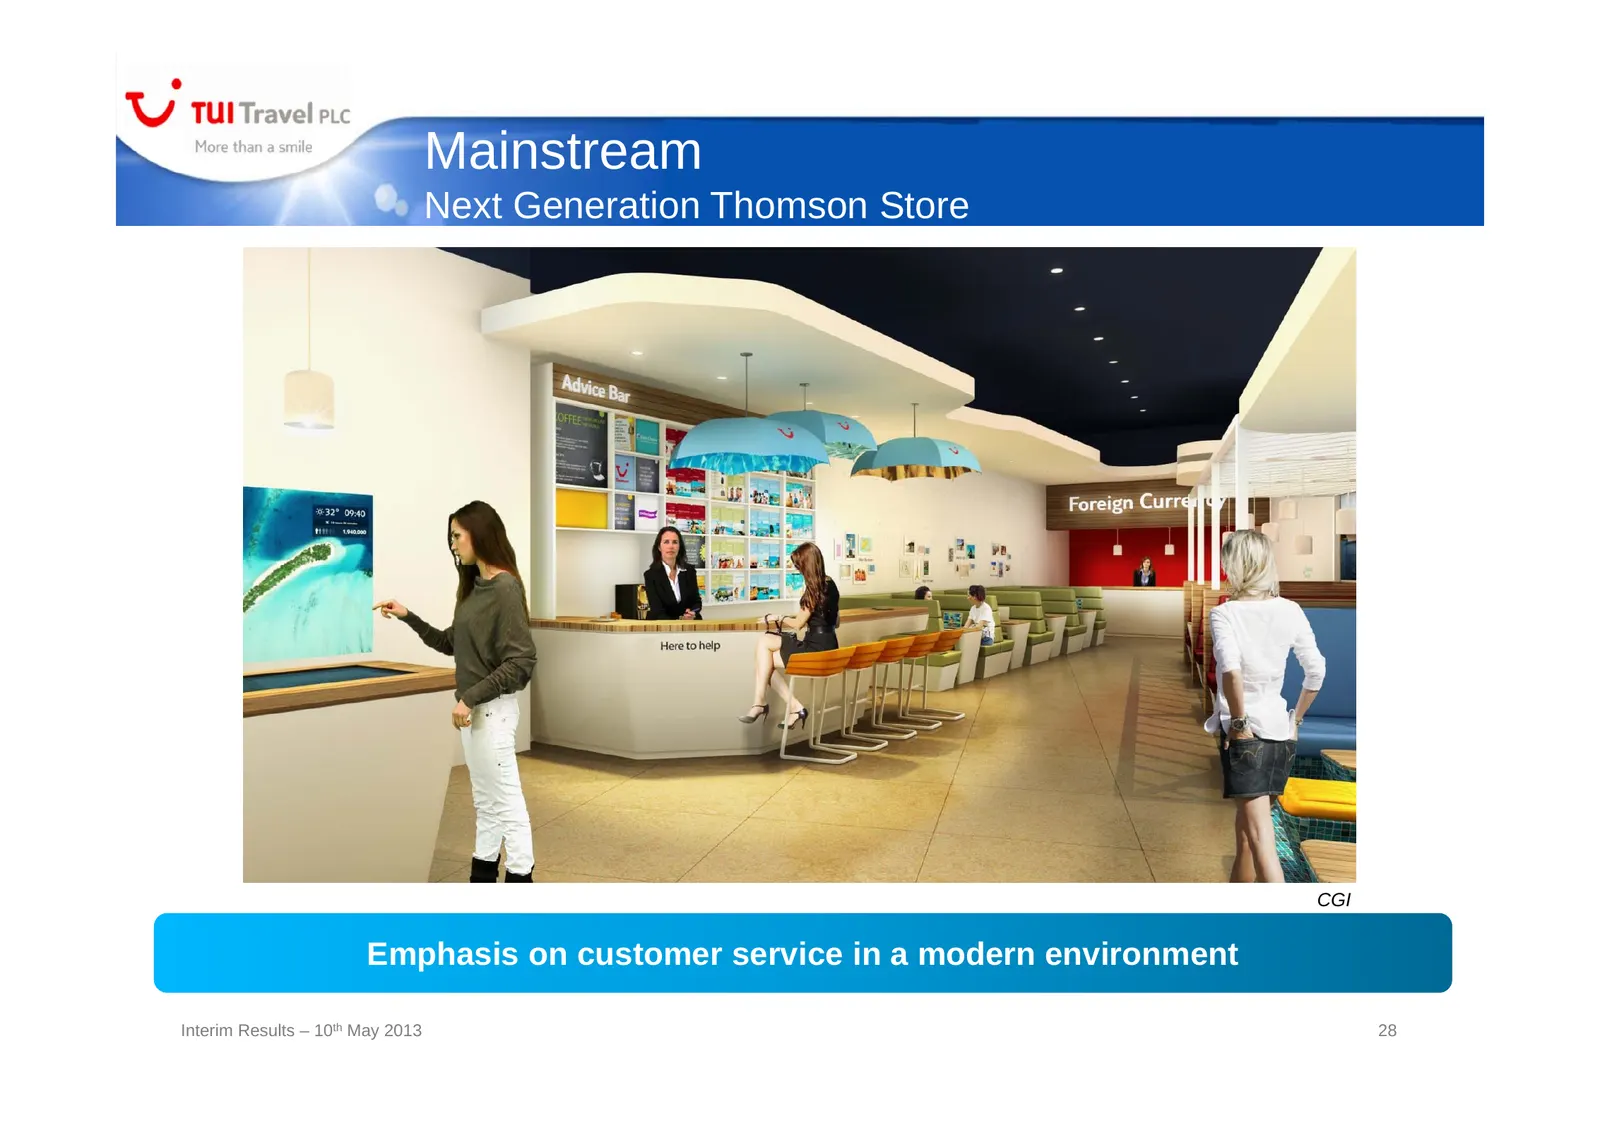
Mainstream Next Generation Thomson Store CGI Emphasis on customer service in a modern environment Interim Results – 10th May 2013 28
Slide 29: Strategic Highlights
Strategic Highlights Mainstream Online Accommodation Specialist & Activity Interim Results – 10th May 2013 29
Slide 30: Online Accommodation
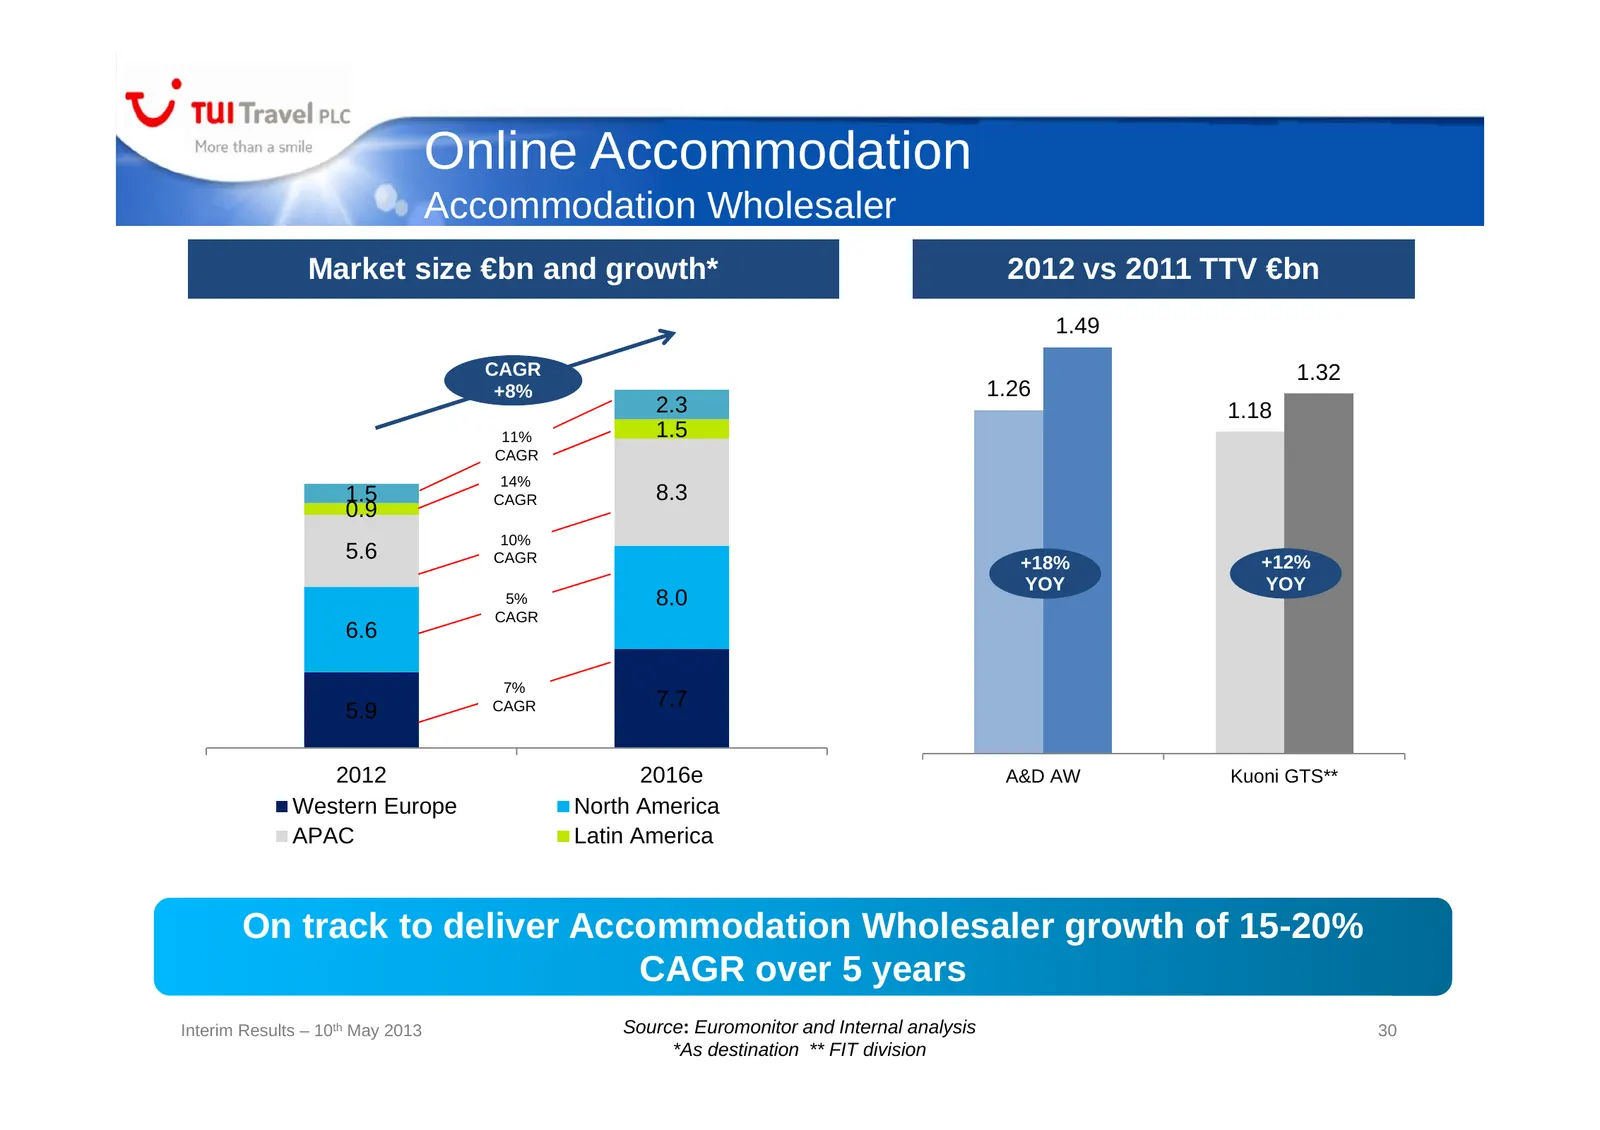
Online Accommodation Accommodation Wholesaler Market size €bn and growth* 2012 vs 2011 TTV €bn 1.49 CAGR 1.32 +8% 1.26 2.3 1.18 11% 1.5 CAGR 14% 1.5 CAGR 8.3 0.9 10% 5.6 CAGR +18% +12% YOY YOY 5% 8.0 CAGR 6.6 7% CAGR 7.7 5.9 2012 2016e A&D AW Kuoni GTS** Western Europe North America APAC Latin Ameri
Slide 31: Strategic Highlights
Strategic Highlights Mainstream Online Accommodation Specialist & Activity Interim Results – 10th May 2013 31
Slide 32: Specialist & Activity
Specialist & Activity Sector restructured and simplified Clear management accountability Strategic review undertaken Detailed plans being developed to improve profitability Further update to be provided in Preliminary results announcement Interim Results – 10th May 2013 32
Slide 33: Summary & Outlook
Summary & Outlook Peter Long Thomson Couples - Atlantica Kalliston Resort & Spa, Crete
Slide 34: Summary & Outlook
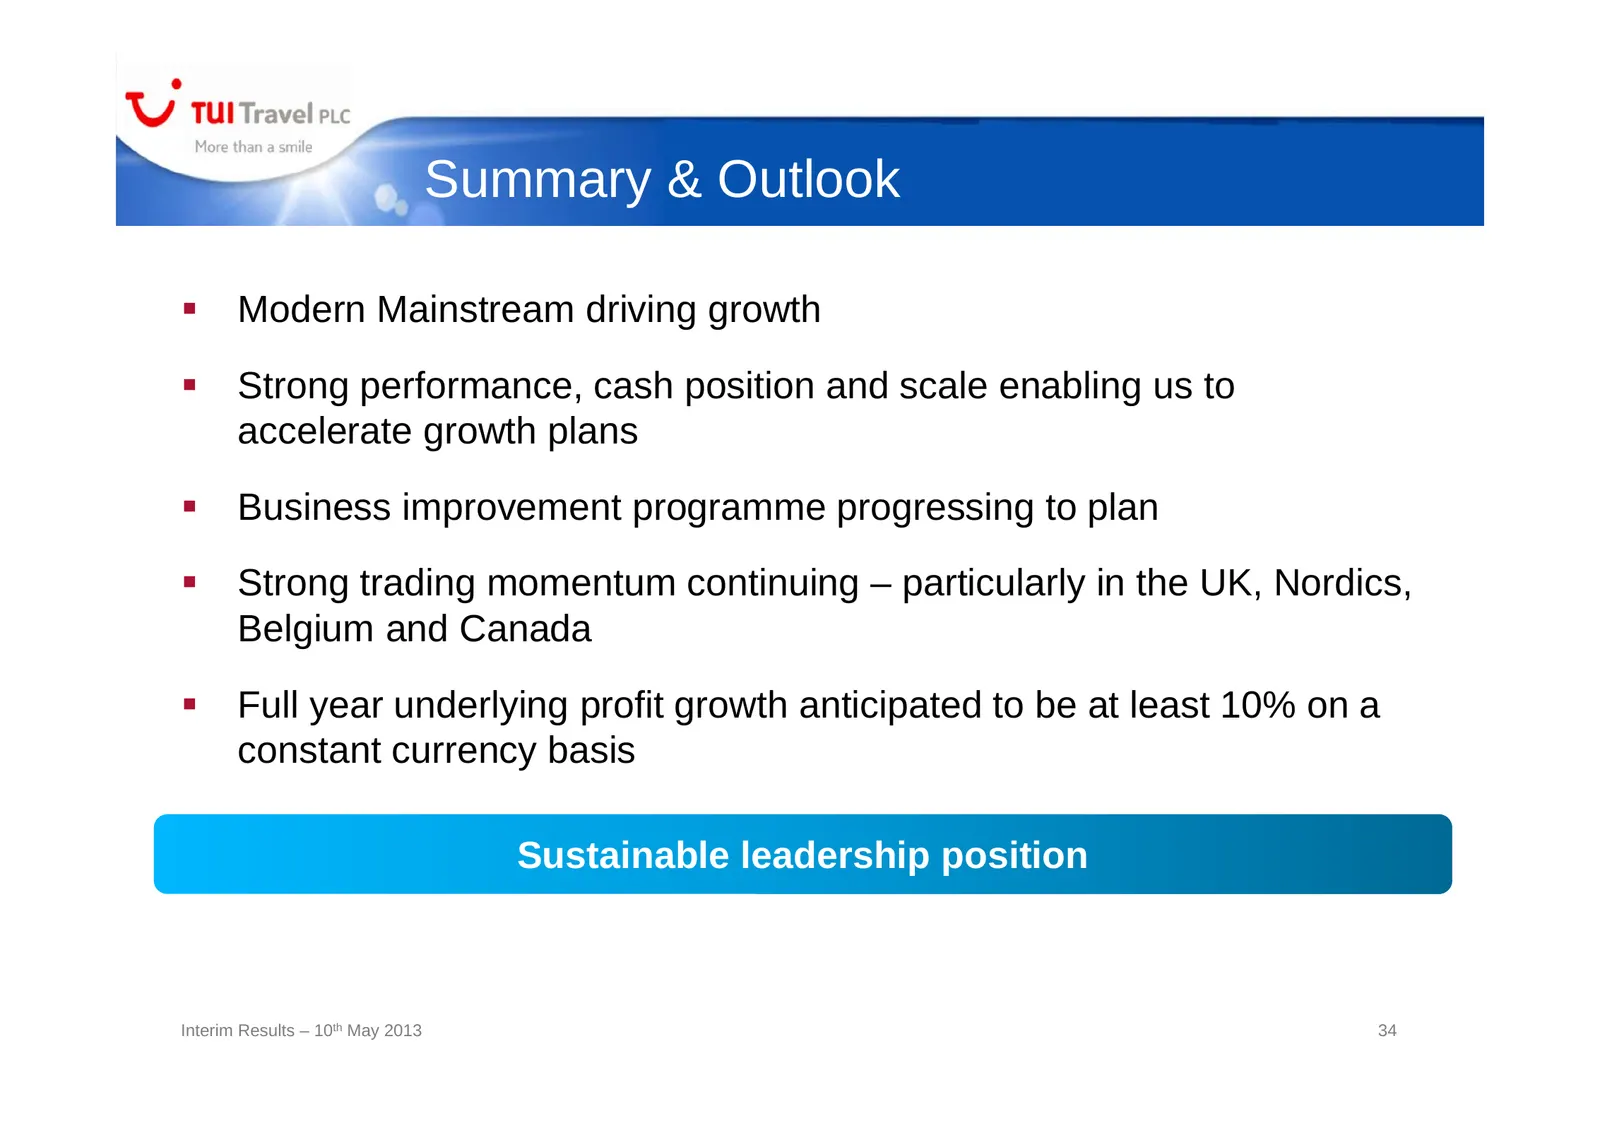
Summary & Outlook Modern Mainstream driving growth Strong performance, cash position and scale enabling us to accelerate growth plans Business improvement programme progressing to plan Strong trading momentum continuing – particularly in the UK, Nordics, Belgium and Canada Full year underl
Slide 35: TUI Travel plc - More than a smile
e YU TUI Travel pic More than a smile
Slide 36: Appendix
Appendix Thomson Couples - Atlantica Kalliston Resort & Spa, Crete
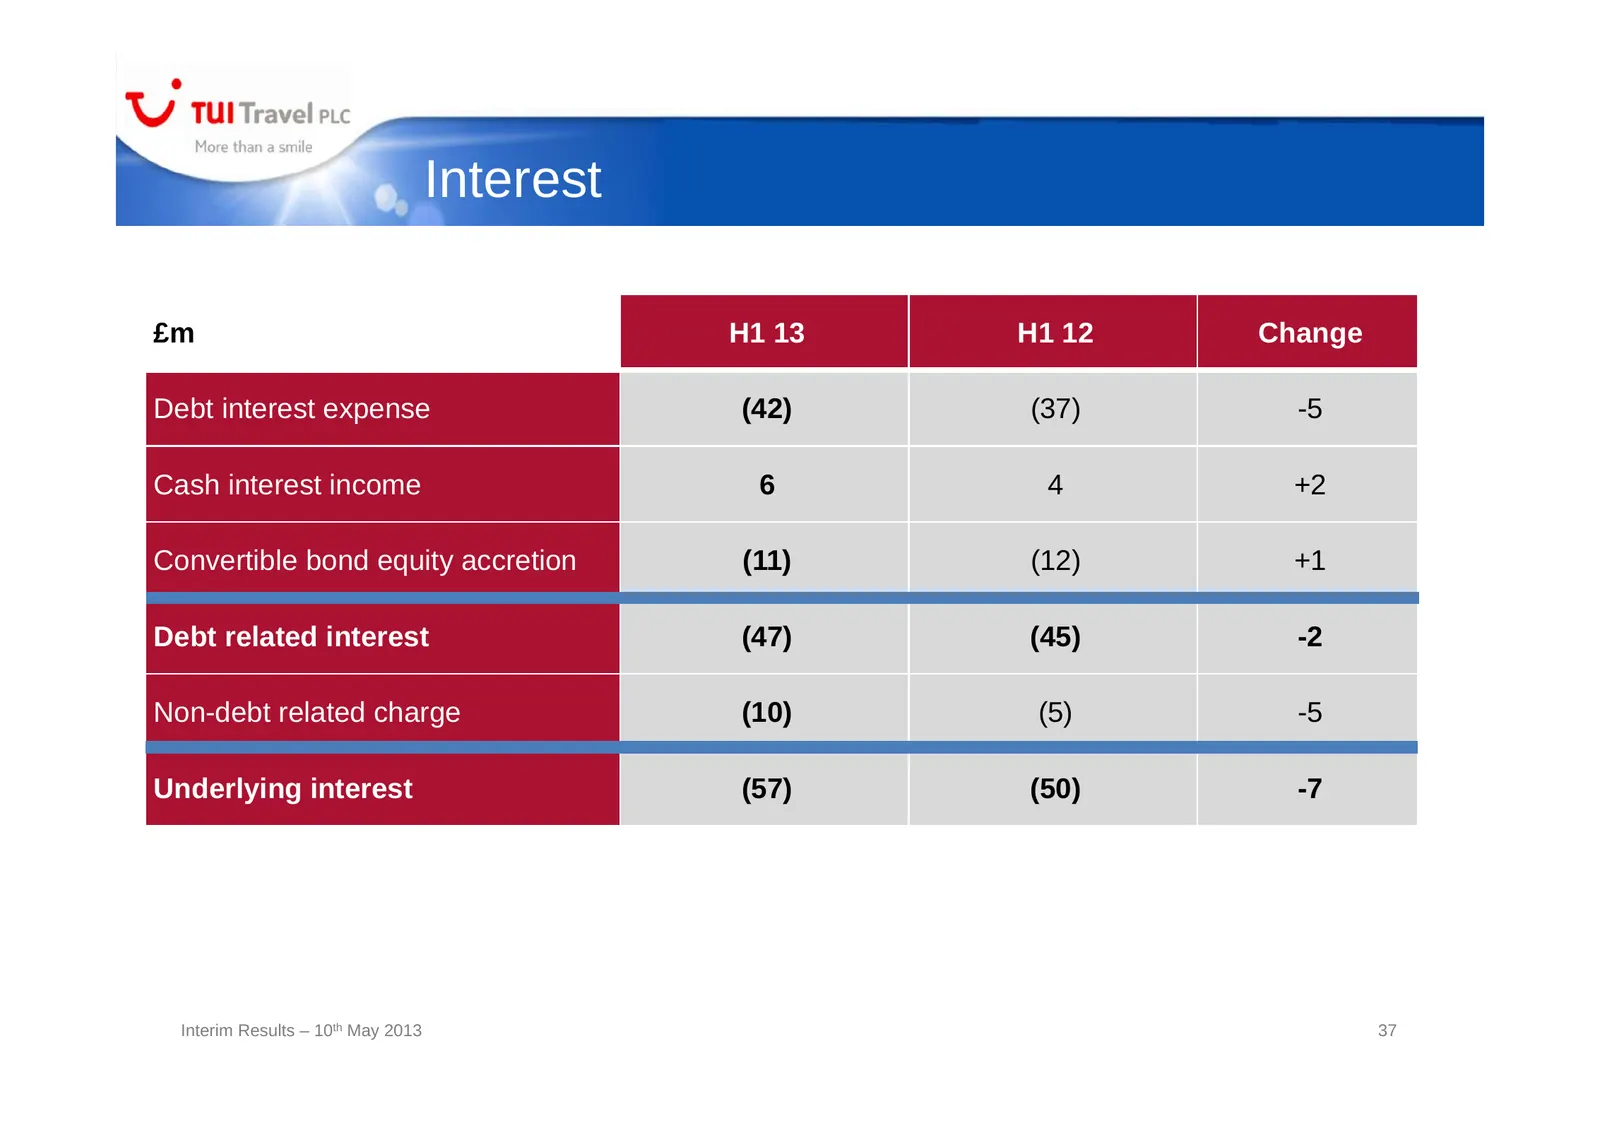
Slide 37: Interest
Interest £m H1 13 H1 12 Change Debt interest expense (42) (37) -5 Cash interest income 6 4 +2 Convertible bond equity accretion (11) (12) +1 Debt related interest (47) (45) -2 Non-debt related charge (10) (5) -5 Underlying interest (57) (50) -7 Interim Results – 10th May 2013 37
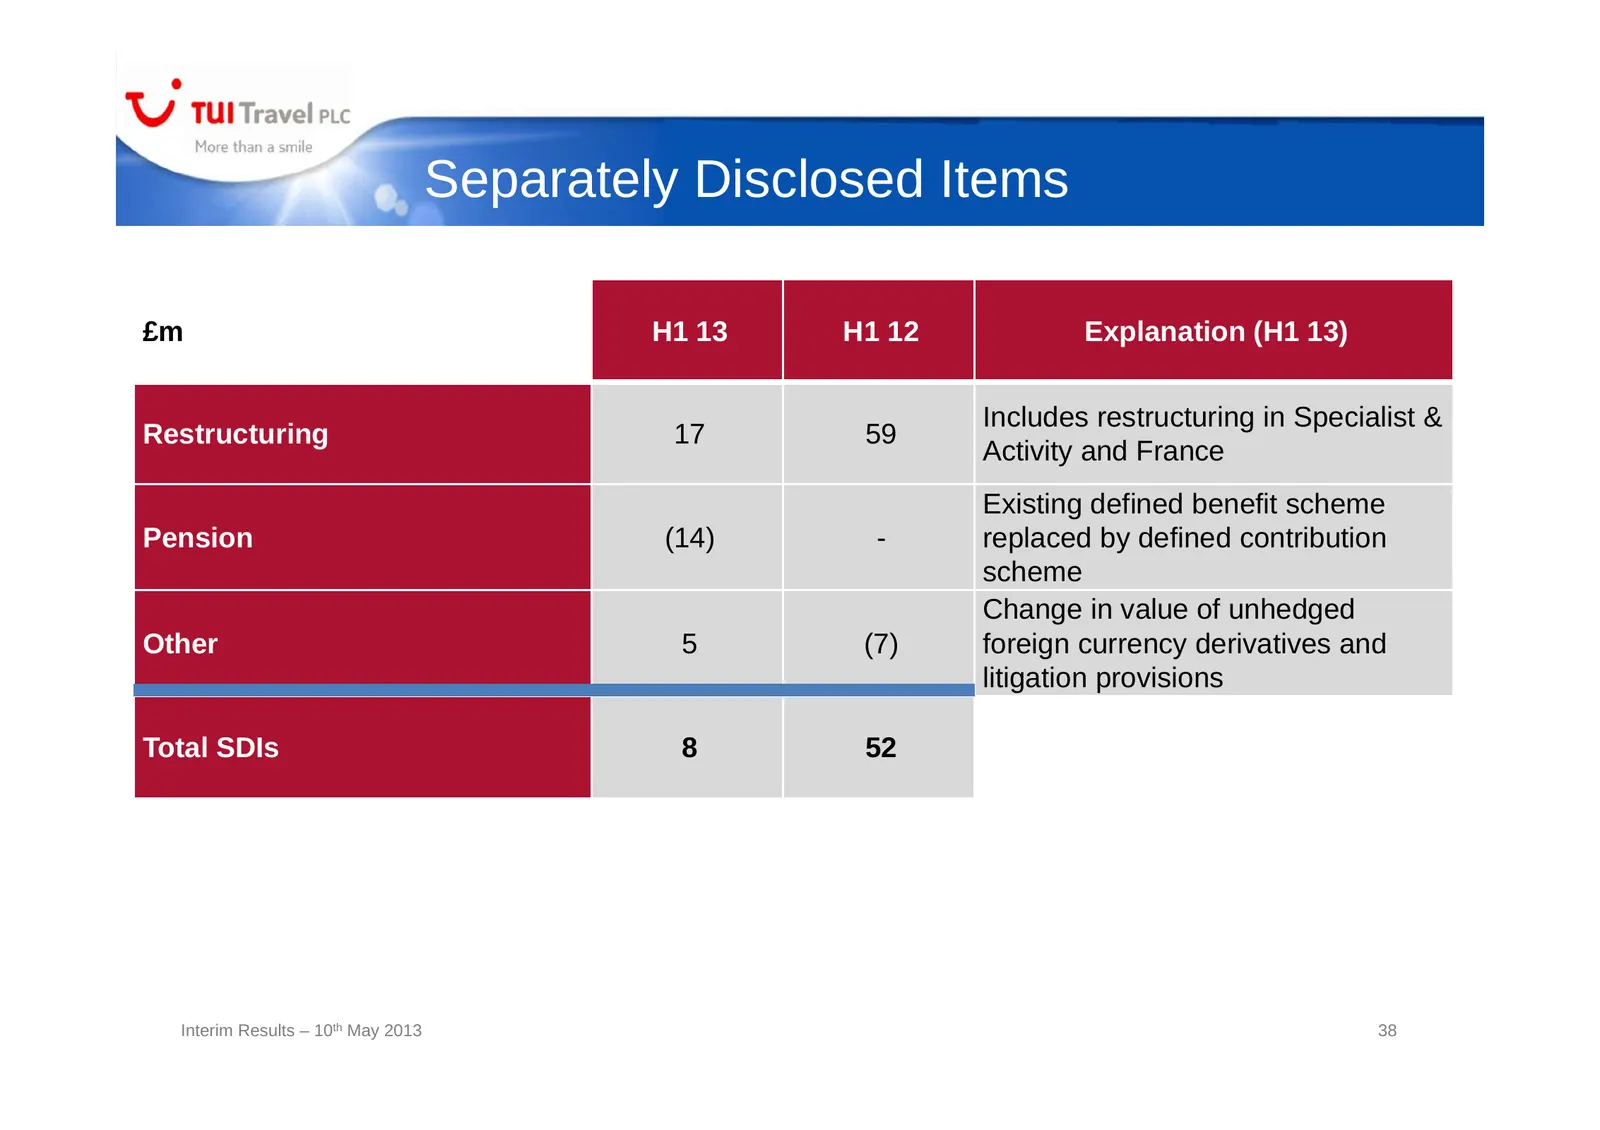
Slide 38: Separately Disclosed Items
Separately Disclosed Items £m H1 13 H1 12 Explanation (H1 13) Includes restructuring in Specialist & Restructuring 17 59 Activity and France Existing defined benefit scheme Pension (14) - replaced by defined contribution scheme Change in value of unhedged Other 5 (7) foreign currency derivatives and
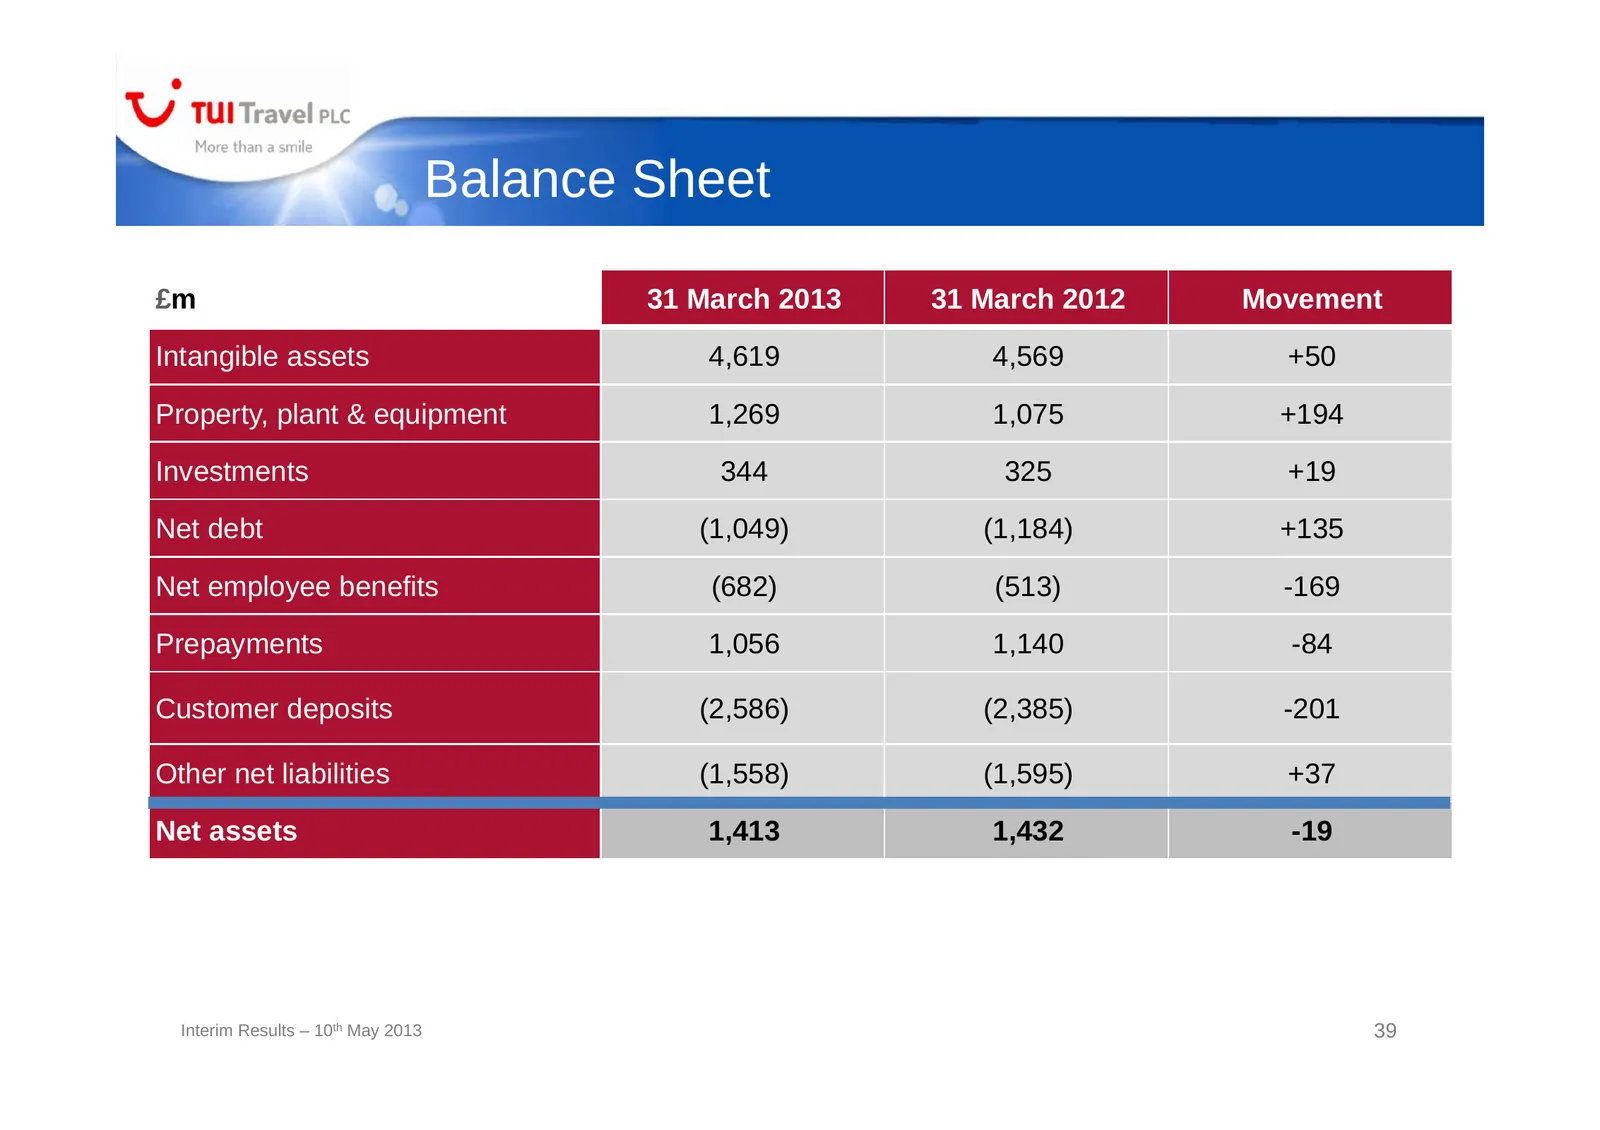
Slide 39: Balance Sheet
Balance Sheet £m 31 March 2013 31 March 2012 Movement Intangible assets 4,619 4,569 +50 Property, plant & equipment 1,269 1,075 +194 Investments 344 325 +19 Net debt (1,049) (1,184) +135 Net employee benefits (682) (513) -169 Prepayments 1,056 1,140 -84 Customer deposits (2,586) (2,385) -201 Other n
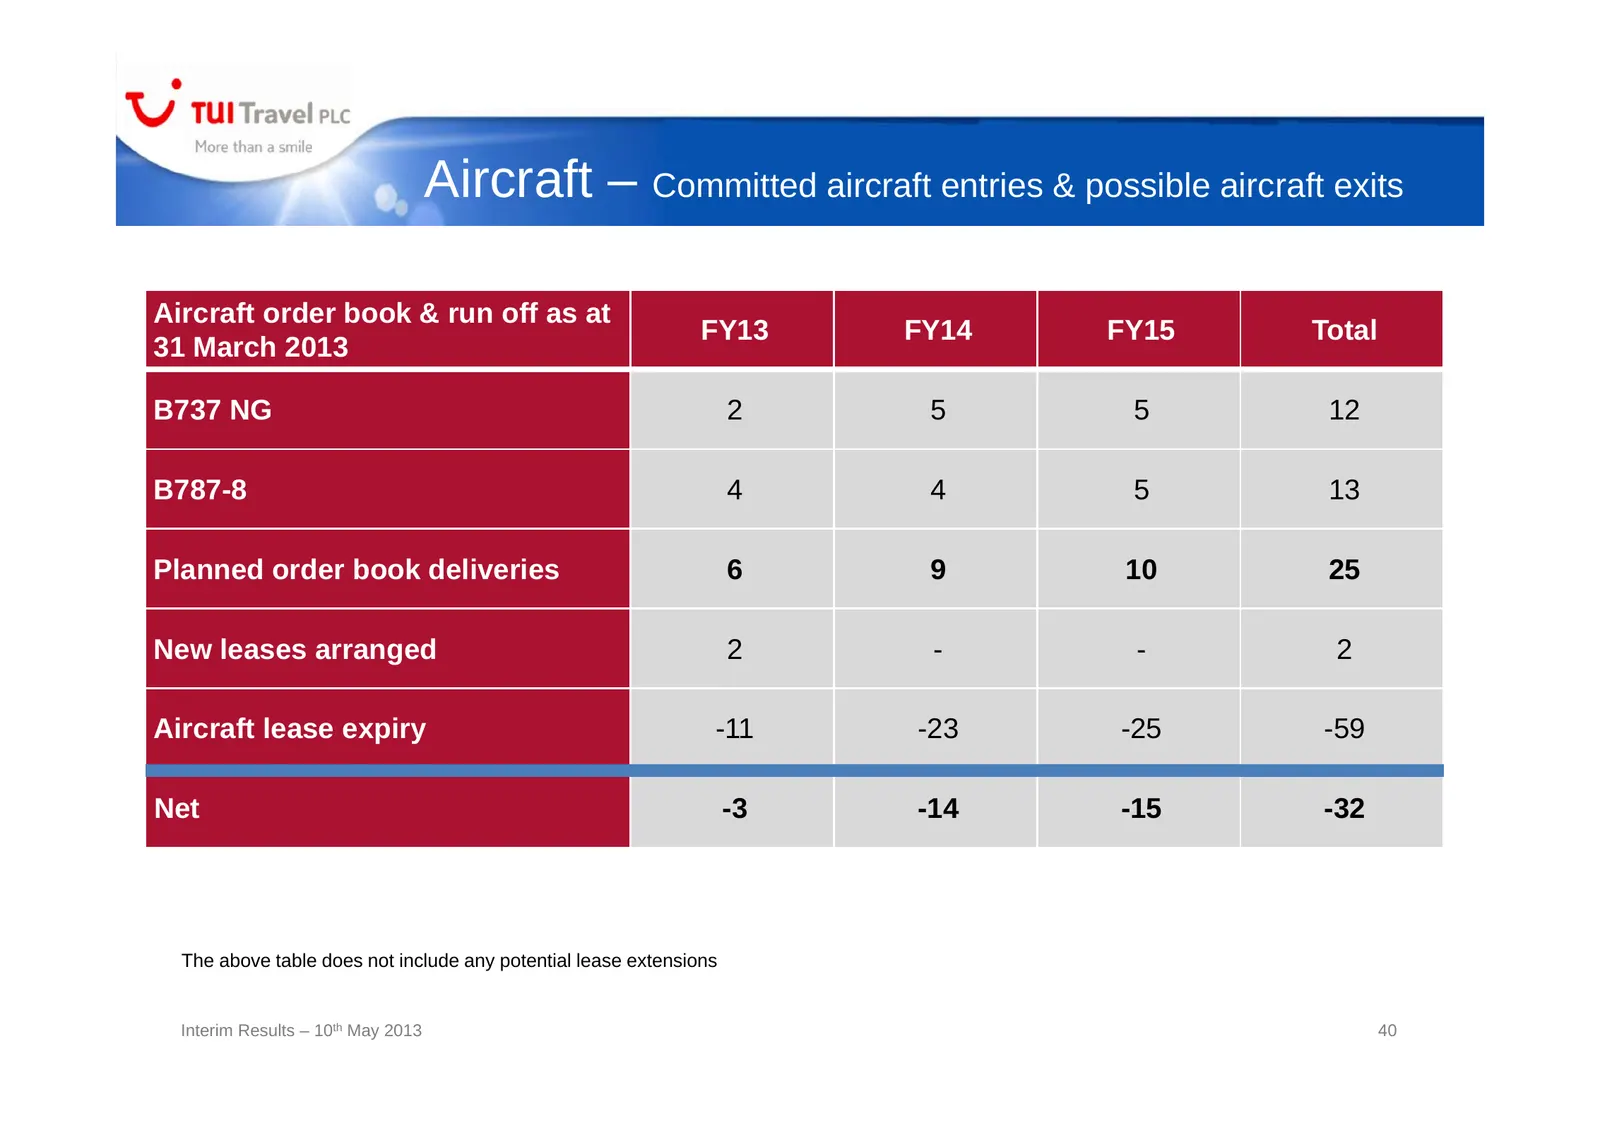
Slide 40: Aircraft – Committed aircraft entries & possible aircraft exits
Aircraft – Committed aircraft entries & possible aircraft exits Aircraft order book & run off as at FY13 FY14 FY15 Total 31 March 2013 B737 NG 2 5 5 12 B787-8 4 4 5 13 Planned order book deliveries 6 9 10 25 New leases arranged 2 - - 2 Aircraft lease expiry -11 -23 -25 -59 Net -3 -14 -15 -32 The abo
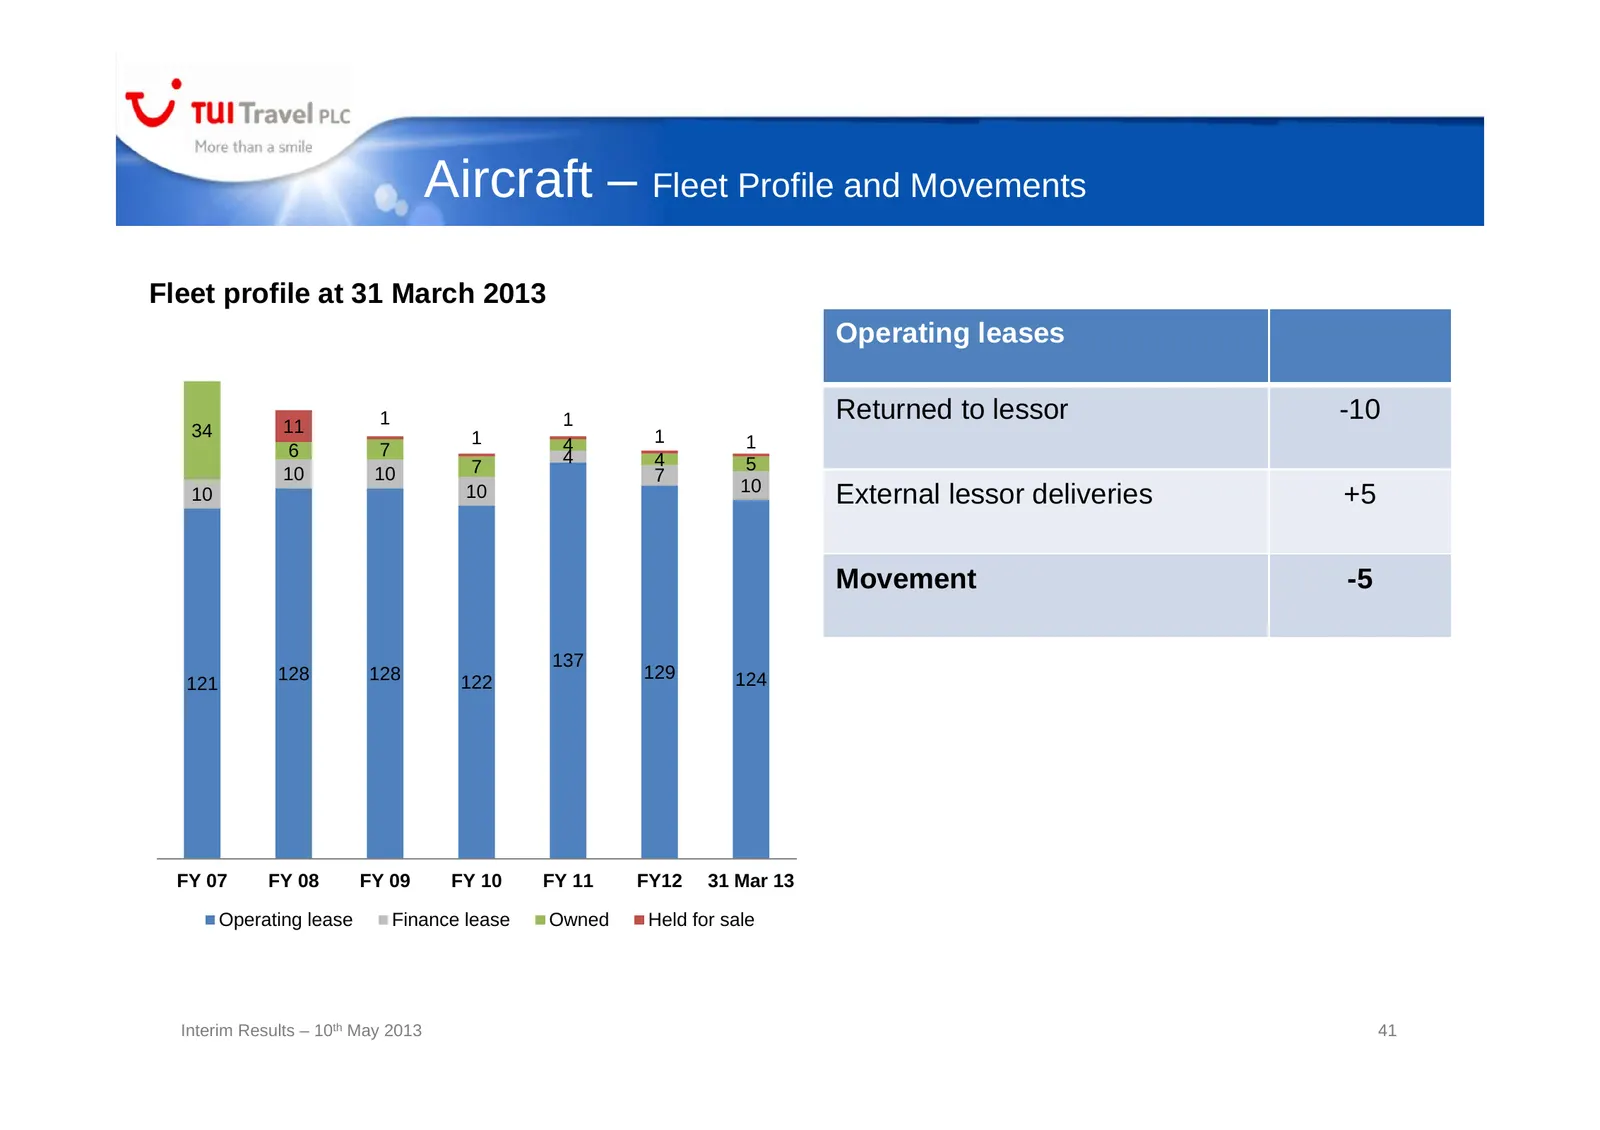
Slide 41: Aircraft – Fleet Profile and Movements
Aircraft – Fleet Profile and Movements Fleet profile at 31 March 2013 Operating leases 11 1 1 Returned to lessor -10 34 1 1 6 7 4 1 4 4 5 10 10 7 7 10 10 10 External lessor deliveries +5 Movement -5 137 128 128 129 124 121 122 FY 07 FY 08 FY 09 FY 10 FY 11 FY12 31 Mar 13 Operating lease Finance leas
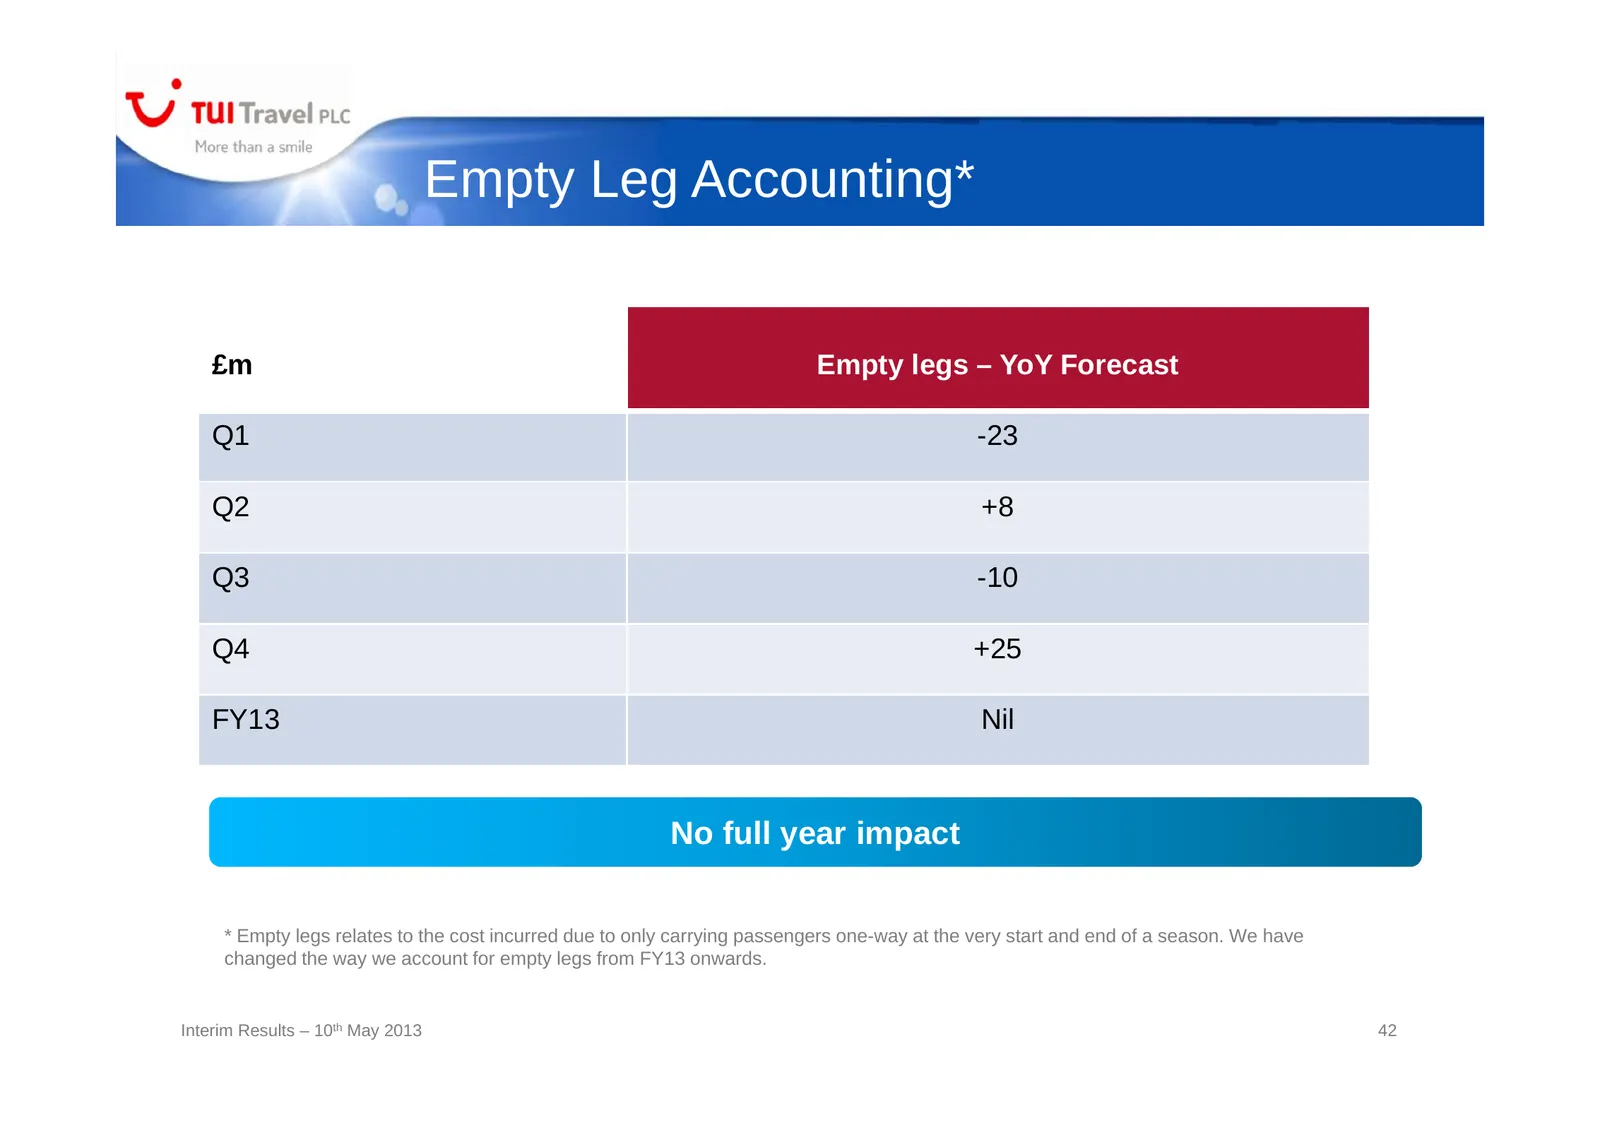
Slide 42: Empty Leg Accounting
Empty Leg Accounting* £m Empty legs – YoY Forecast Q1 -23 Q2 +8 Q3 -10 Q4 +25 FY13 Nil No full year impact * Empty legs relates to the cost incurred due to only carrying passengers one-way at the very start and end of a season. We have changed the way we account for empty legs from FY13 onwards. Int
Source: Internet Archive copy of tuigroup.com
More decks from TUI AG
 Q3 2026 Earnings Presentation38 slides · Aug 12, 2026
 Q2 2026 Earnings Presentation41 slides · May 13, 2026
 Q1 2026 Earnings Presentation33 slides · Feb 10, 2026
 FY2025 Earnings Presentation58 slides · Dec 10, 2025
 Q1 2025 Earnings Presentation23 slides · Feb 11, 2025
 FY2024 Earnings Presentation54 slides · Dec 11, 2024