Bertrandt AG · XETR:BDT
Bertrandt — FY2013/2014 Earnings Presentation
32 slides from Bertrandt's earnings presentation, Dec 11, 2014
Slide 1: Analyst Conference FY 2013/2014 Bertrandt AG
Analyst Conference FY 2013/2014 Bertrandt AG Dietmar Bichler, CEO Markus Ruf, CFO Frankfurt am Main, December 11th, 2014 Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 0
Slide 2: Welcome to the analyst conference 2014 of Bertrandt AG
Welcome to the analyst conference 2014 of Bertrandt AG CHANGE. KNOWLEDGE. GROWTH. Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 1
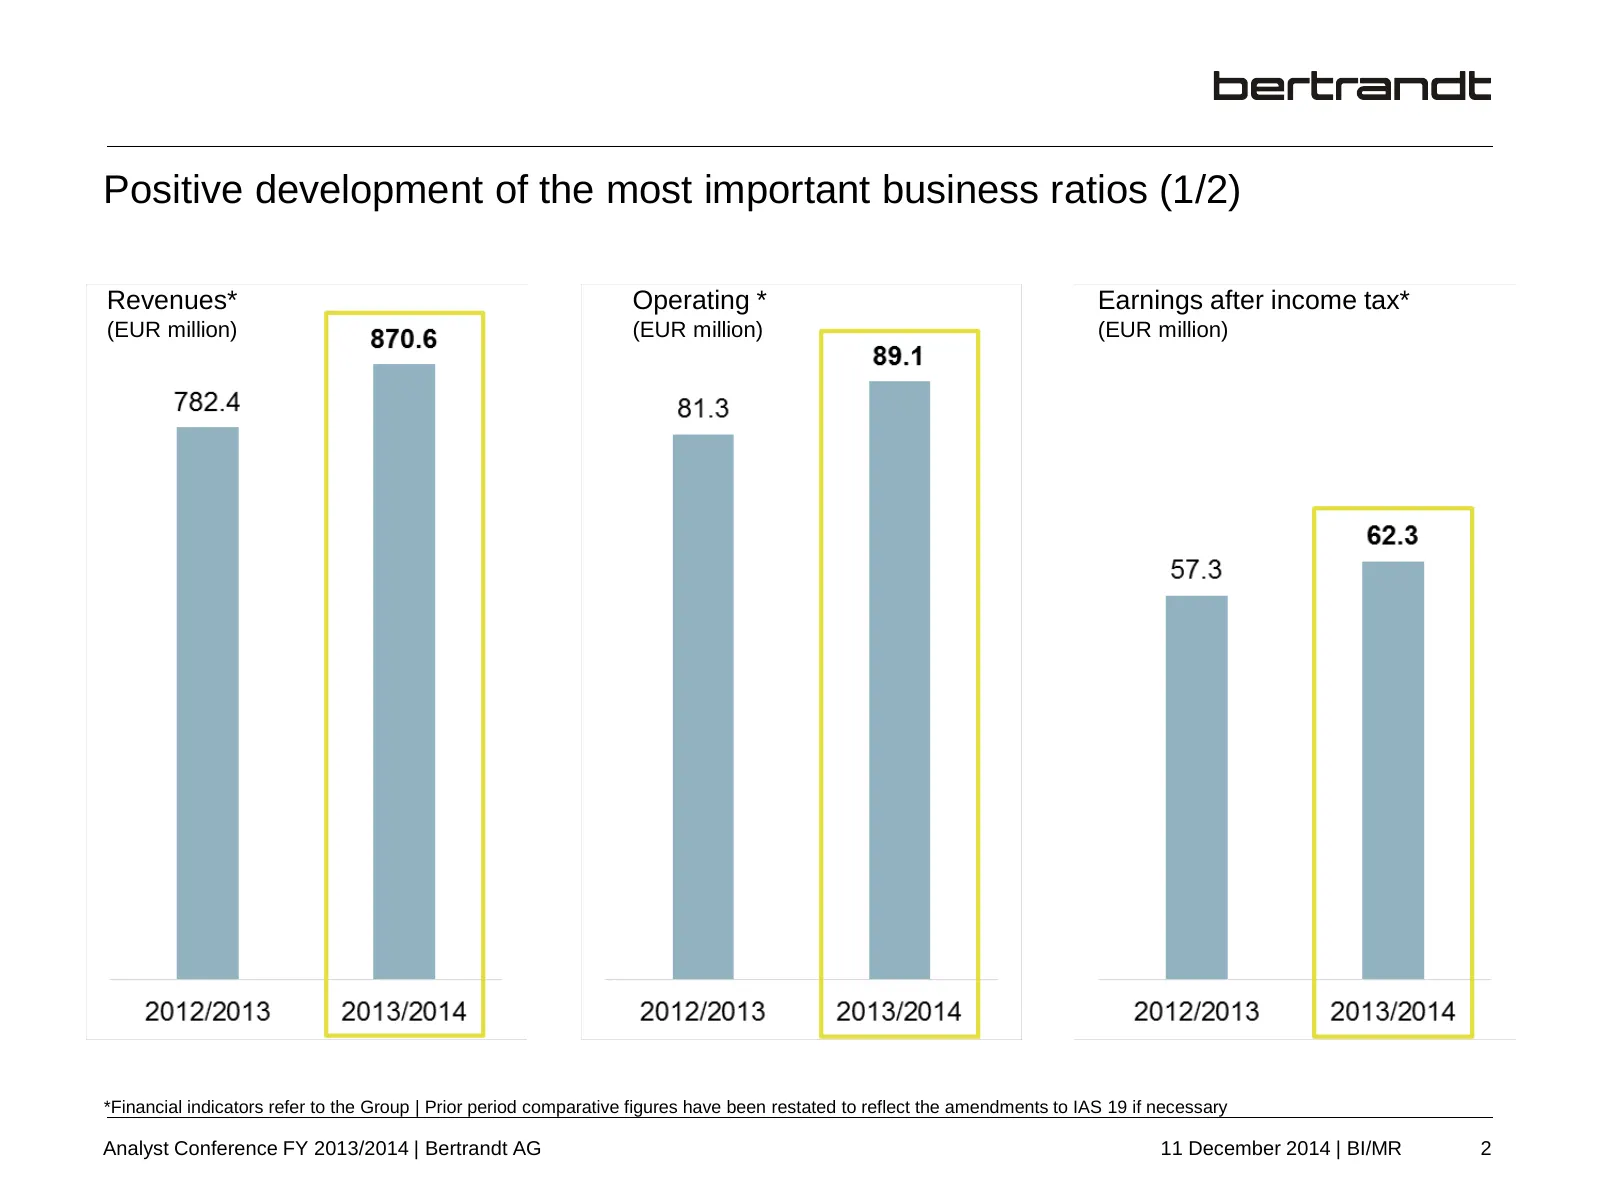
Slide 3: Positive development of the most important business ratios (1/2)
Positive development of the most important business ratios (1/2) Revenues* Operating * Earnings after income tax* (EUR million) (EUR million) (EUR million) *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amendments to IAS 19 if necessary
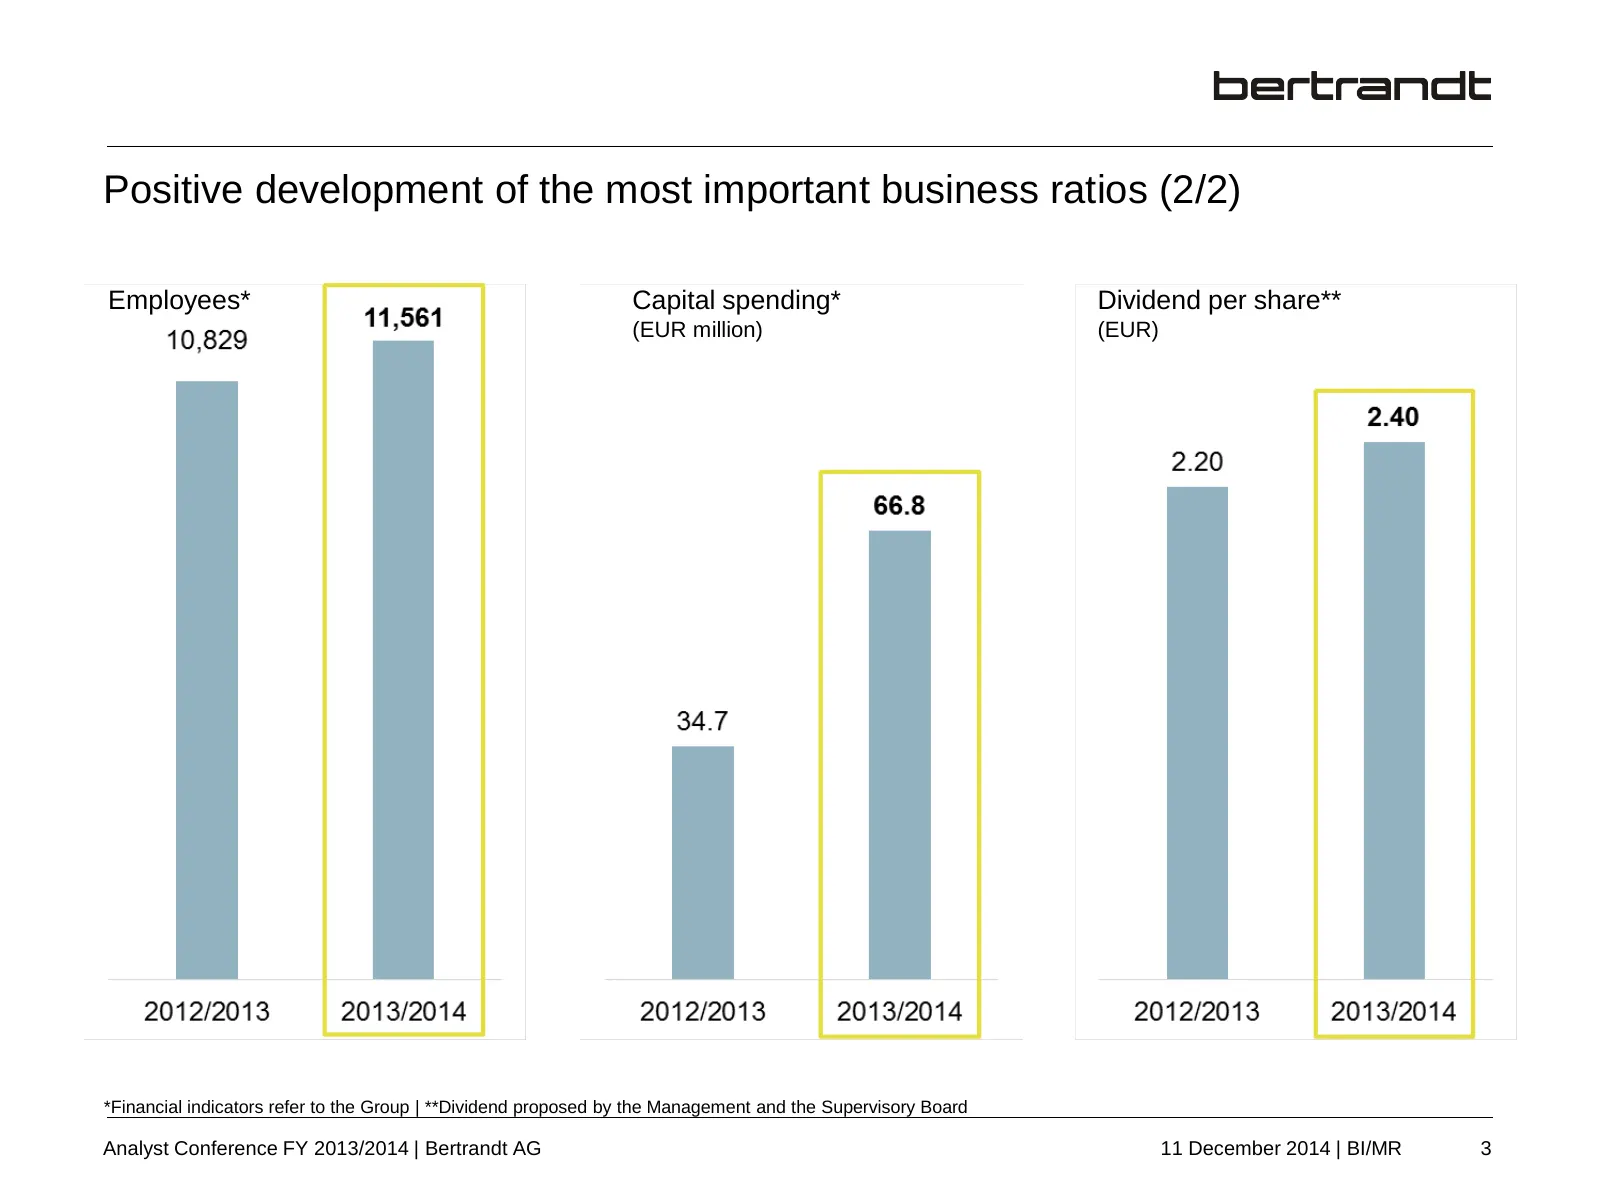
Slide 4: Positive development of the most important business ratios (2/2)
Positive development of the most important business ratios (2/2) Employees* Capital spending* Dividend per share** (EUR million) (EUR) *Financial indicators refer to the Group | **Dividend proposed by the Management and the Supervisory Board Analyst Conference FY 2013/2014 | Bertrandt AG 11 December
Slide 5: Agenda
Agenda 1. Fiscal year 2013/2014 – General framework 2. Fiscal year 2013/2014 – Figures 3. Fiscal year 2014/2015 – Outlook Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 4
Slide 6: Automotive industry with a successful year 2013/2014
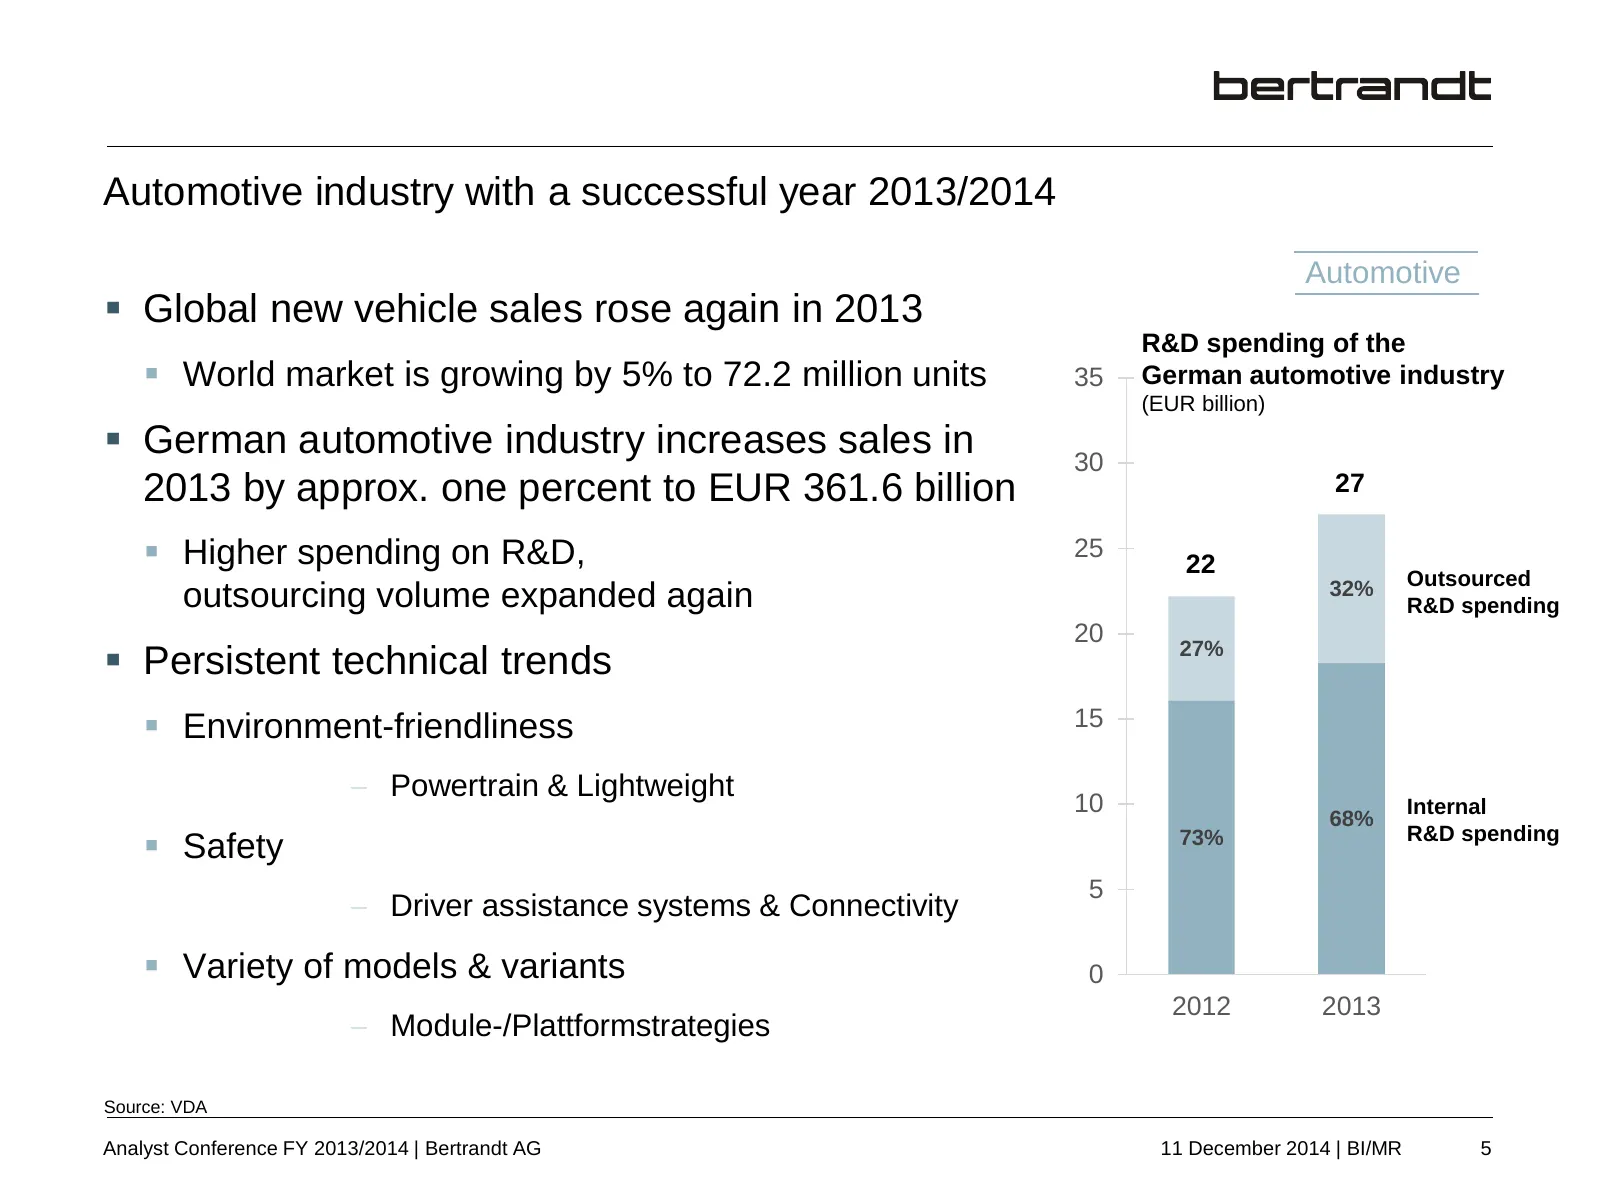
Automotive industry with a successful year 2013/2014 Automotive Global new vehicle sales rose again in 2013 R&D spending of the World market is growing by 5% to 72.2 million units 35 German automotive industry (EUR billion) German automotive industry increases sales in 30 2013 by approx. one p
Slide 7: German aerospace industry with continued growth in 2013
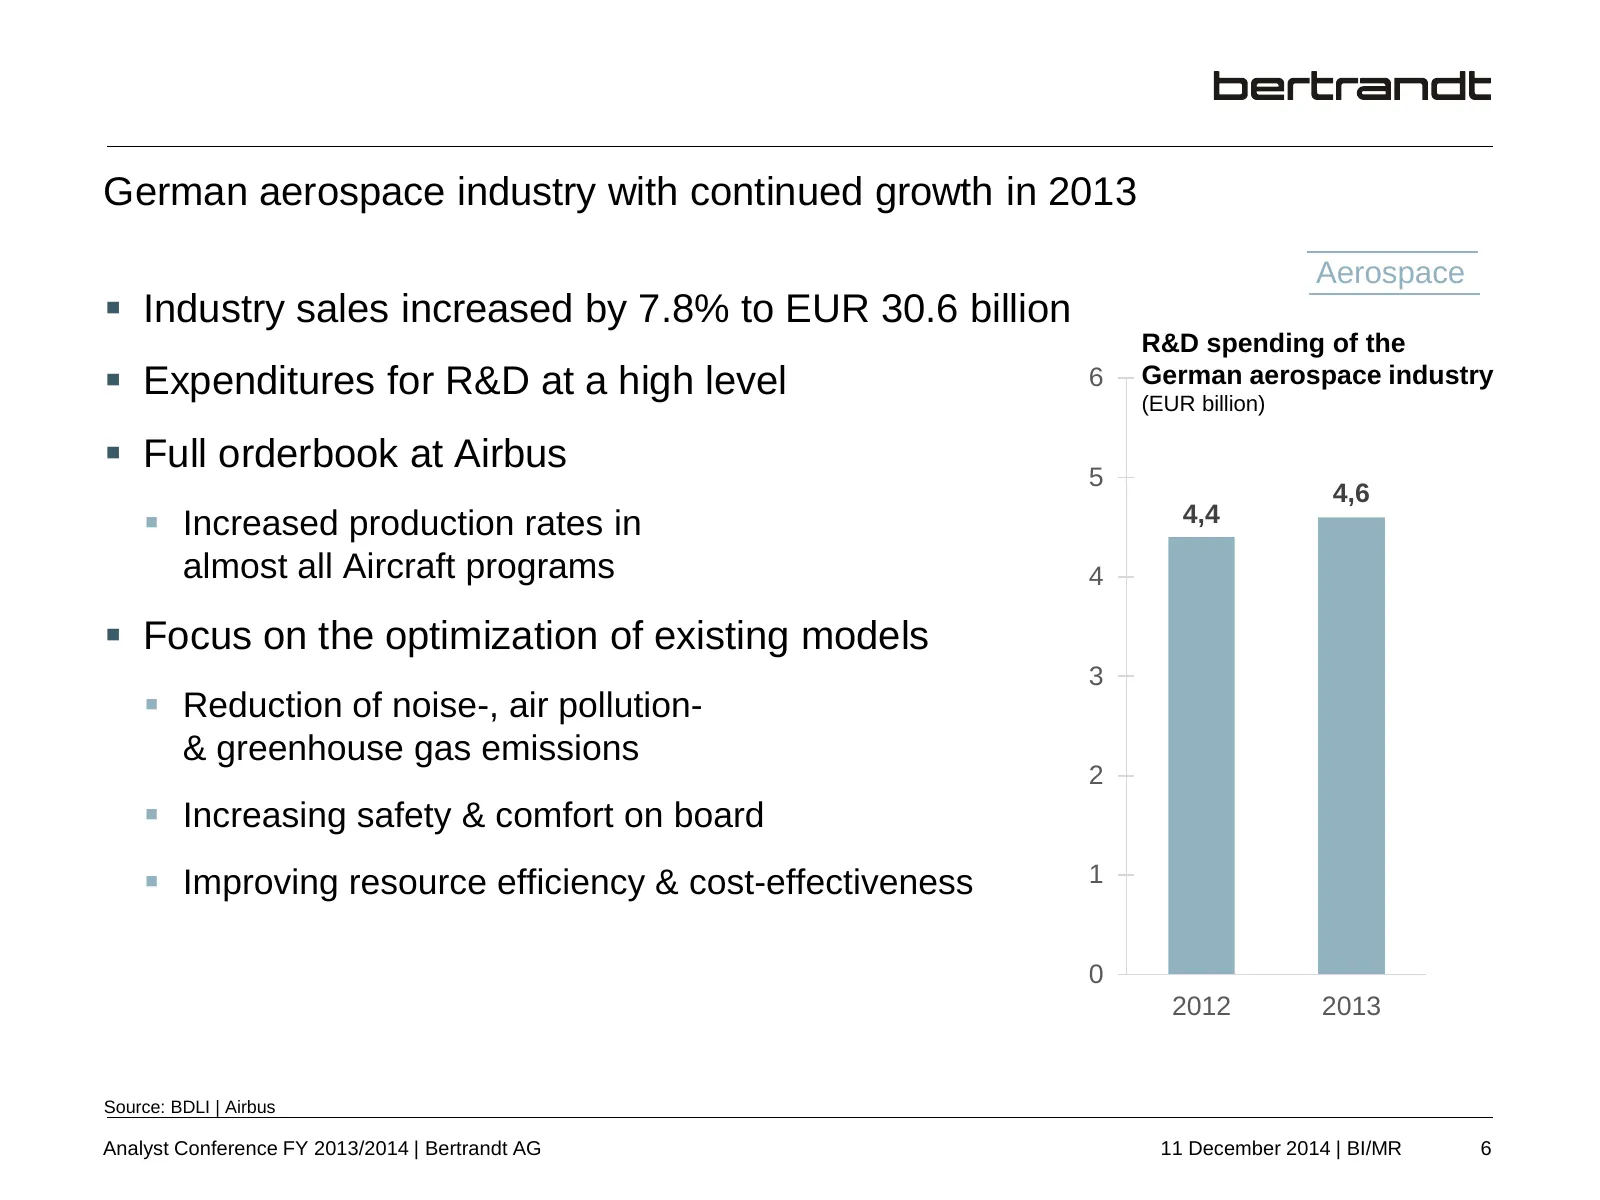
German aerospace industry with continued growth in 2013 Aerospace Industry sales increased by 7.8% to EUR 30.6 billion R&D spending of the Expenditures for R&D at a high level 6 German aerospace industry (EUR billion) Full orderbook at Airbus 5 4,6 Increased production rates in 4,4 almost al
Slide 8: Challenging conditions for technological key sectors
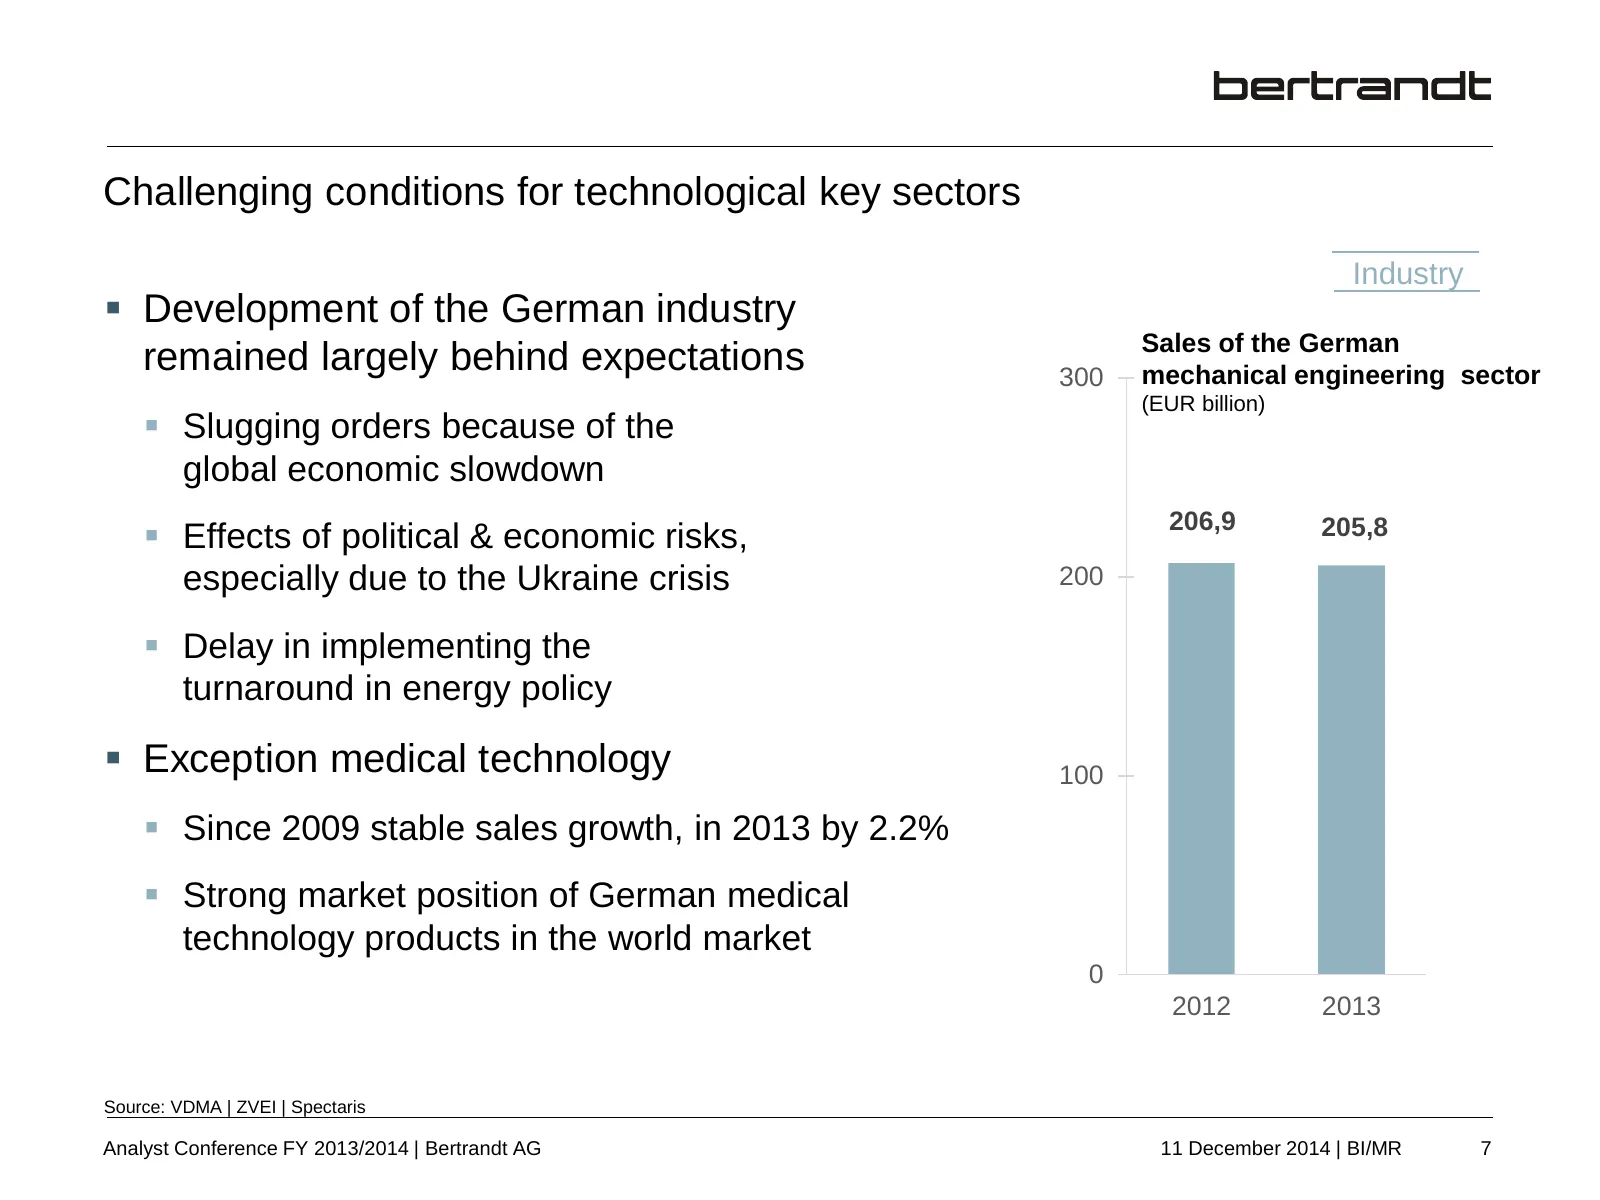
Challenging conditions for technological key sectors Industry Development of the German industry Sales of the German remained largely behind expectations 300 mechanical engineering sector (EUR billion) Slugging orders because of the global economic slowdown 206,9 Effects of political & economi
Slide 9: Bertrandt improved market position in FY 2013/2014 successfully
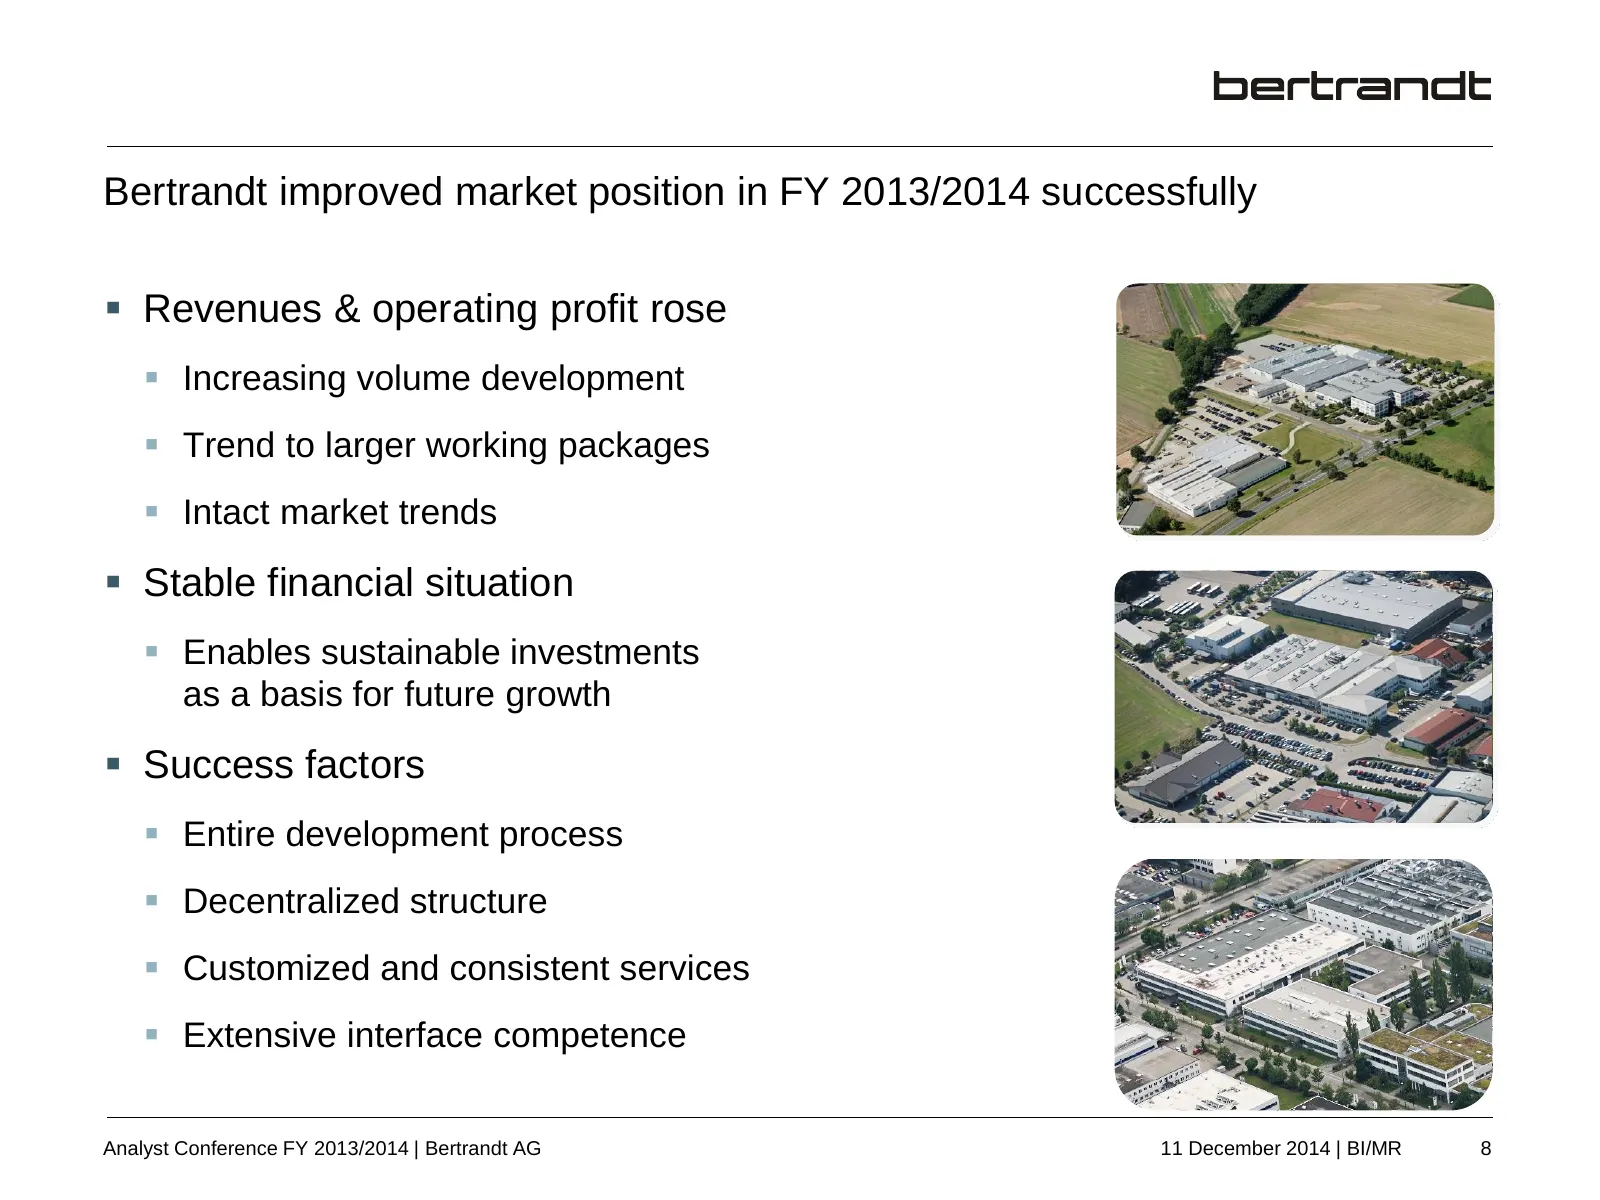
Bertrandt improved market position in FY 2013/2014 successfully Revenues & operating profit rose Increasing volume development Trend to larger working packages Intact market trends Stable financial situation Enables sustainable investments as a basis for future growth Success factors
Slide 10: Agenda
Agenda 1. Fiscal year 2013/2014 – General framework 2. Fiscal year 2013/2014 – Figures 3. Fiscal year 2014/2015 – Outlook Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 9
Slide 11: Revenues increased repeatedly
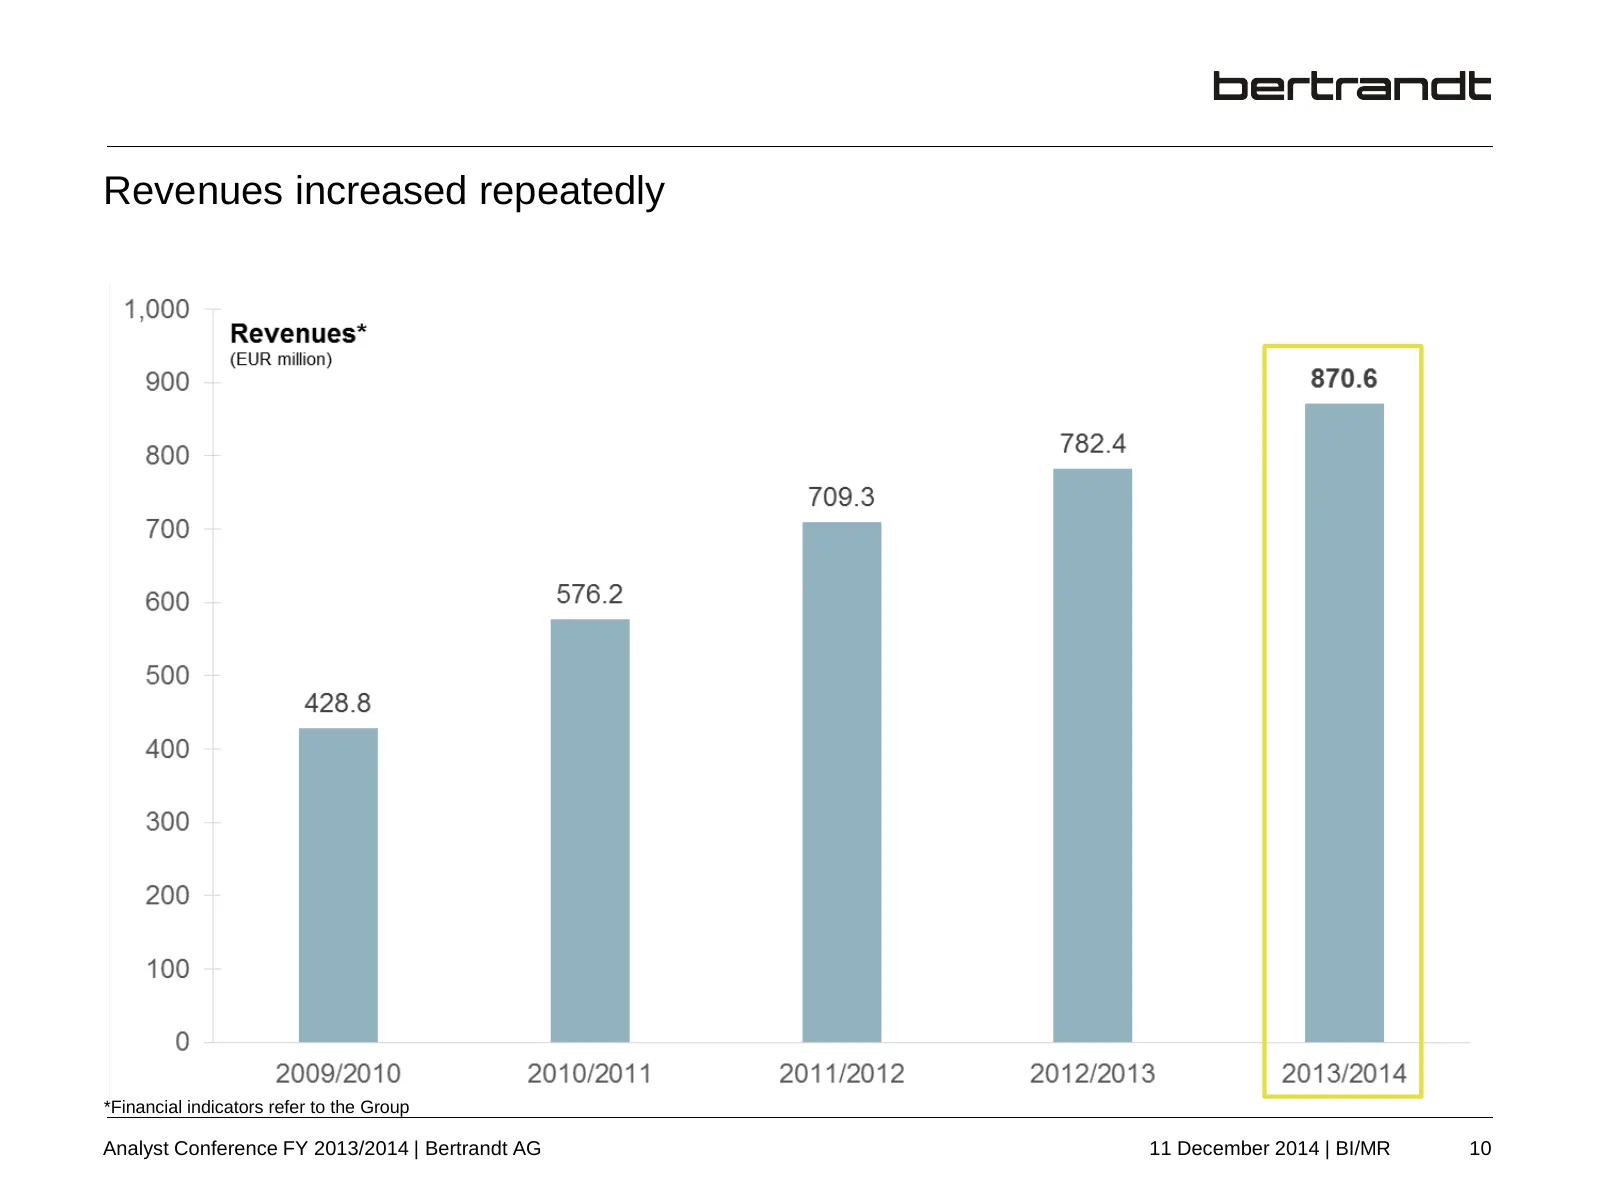
Revenues increased repeatedly *Financial indicators refer to the Group Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 10
Slide 12: Operating profit stays on a high level
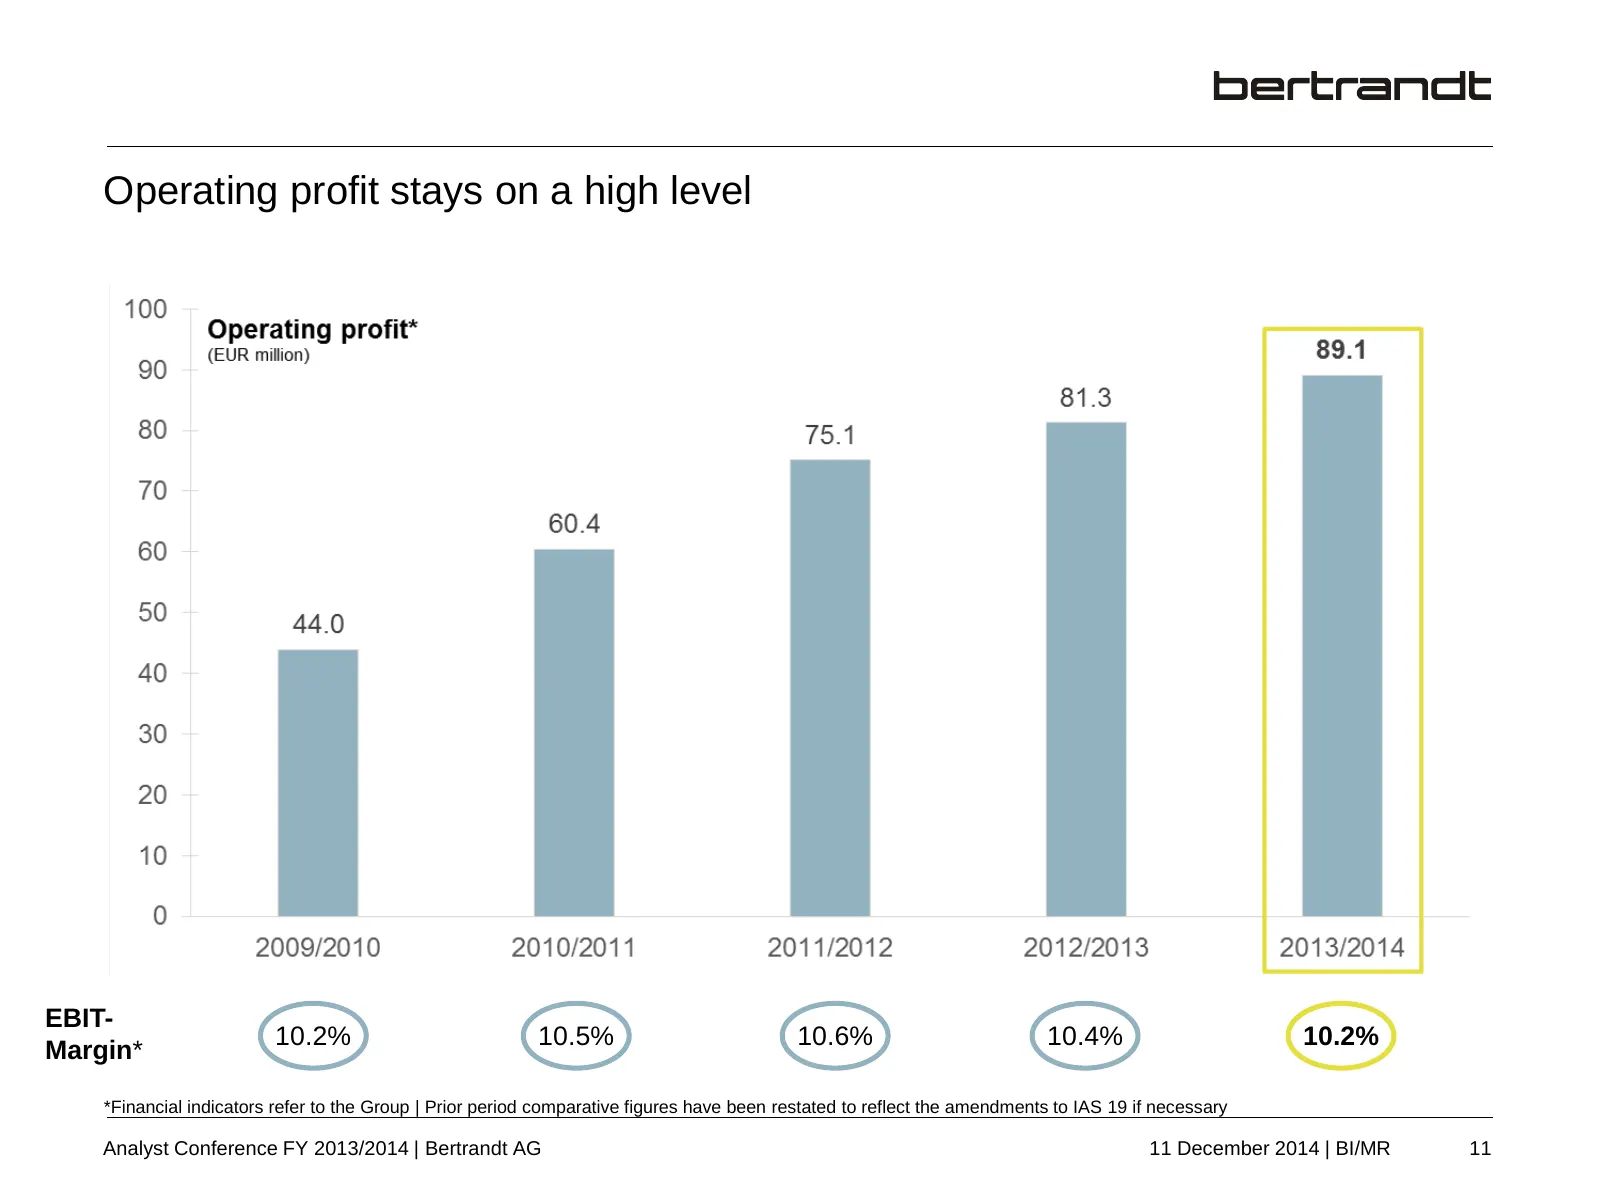
Operating profit stays on a high level EBIT- 10.2% 10.5% 10.6% 10.4% 10.2% Margin* *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amendments to IAS 19 if necessary Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 1
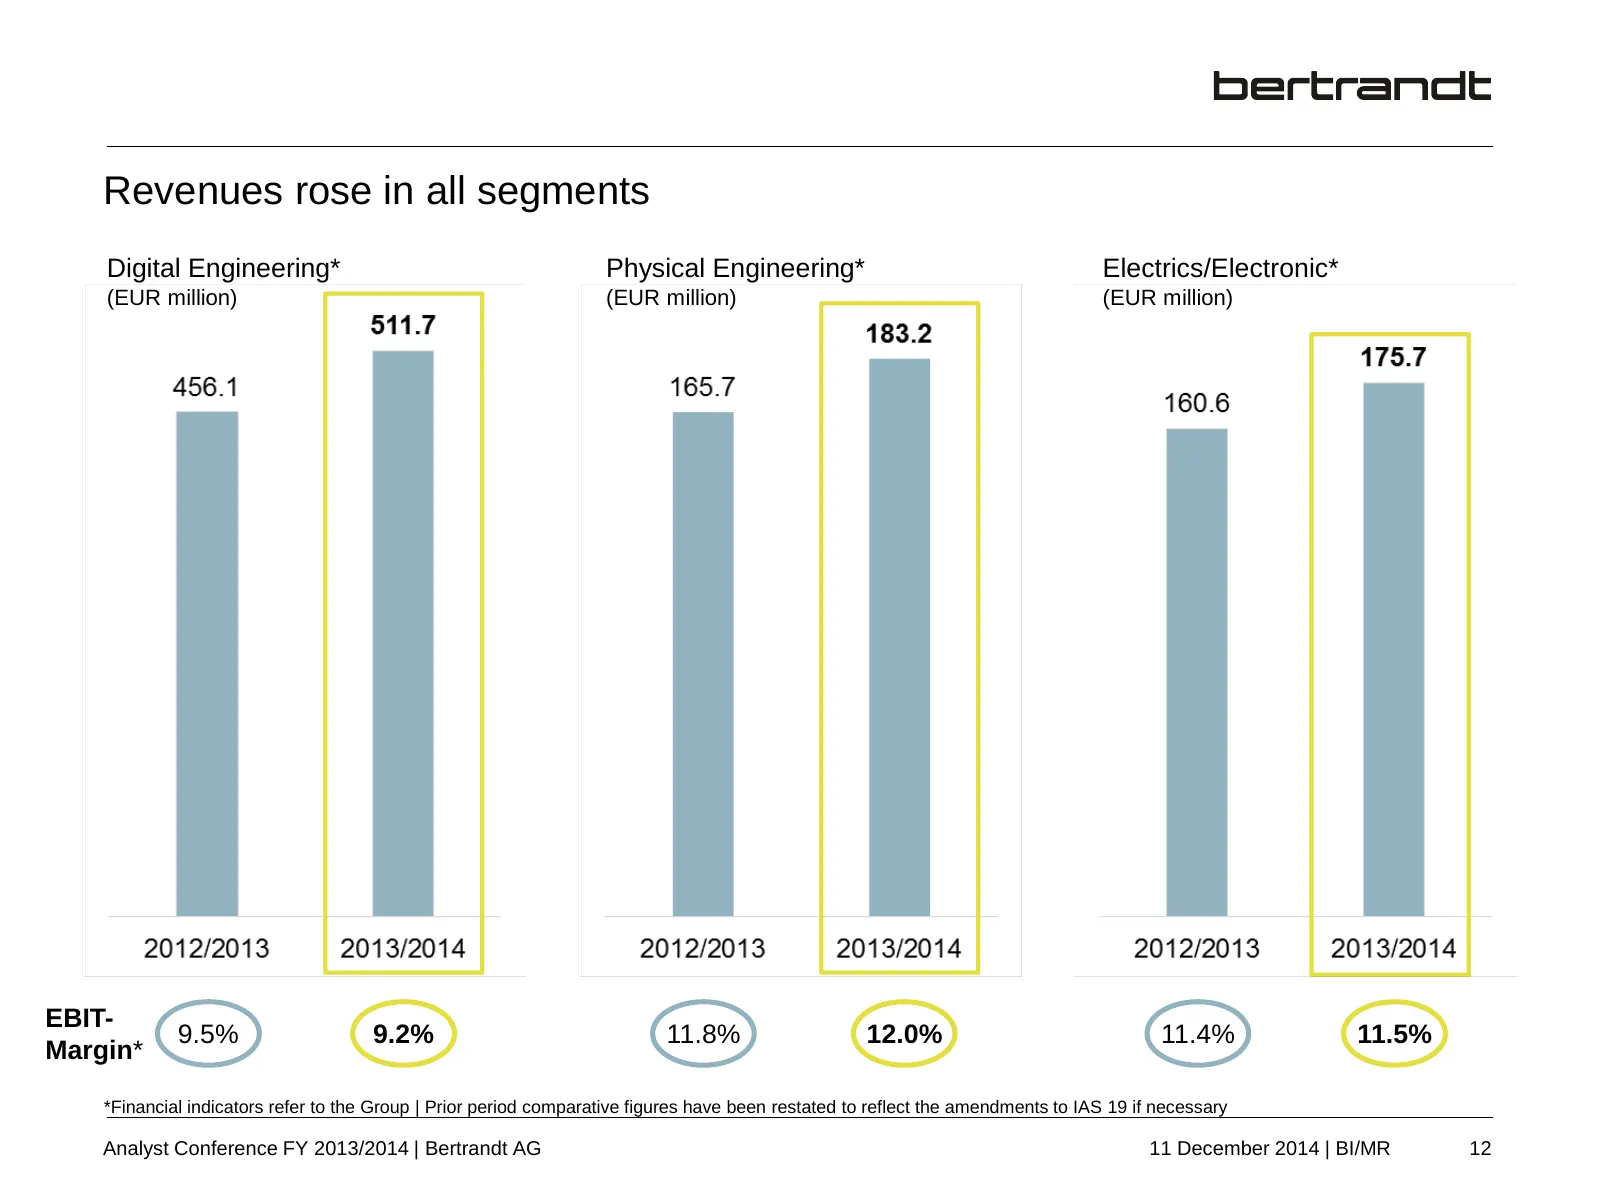
Slide 13: Revenues rose in all segments
Revenues rose in all segments Digital Engineering* Physical Engineering* Electrics/Electronic* (EUR million) (EUR million) (EUR million) EBIT- 9.5% 9.2% 11.8% 12.0% 11.4% 11.5% Margin* *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amend
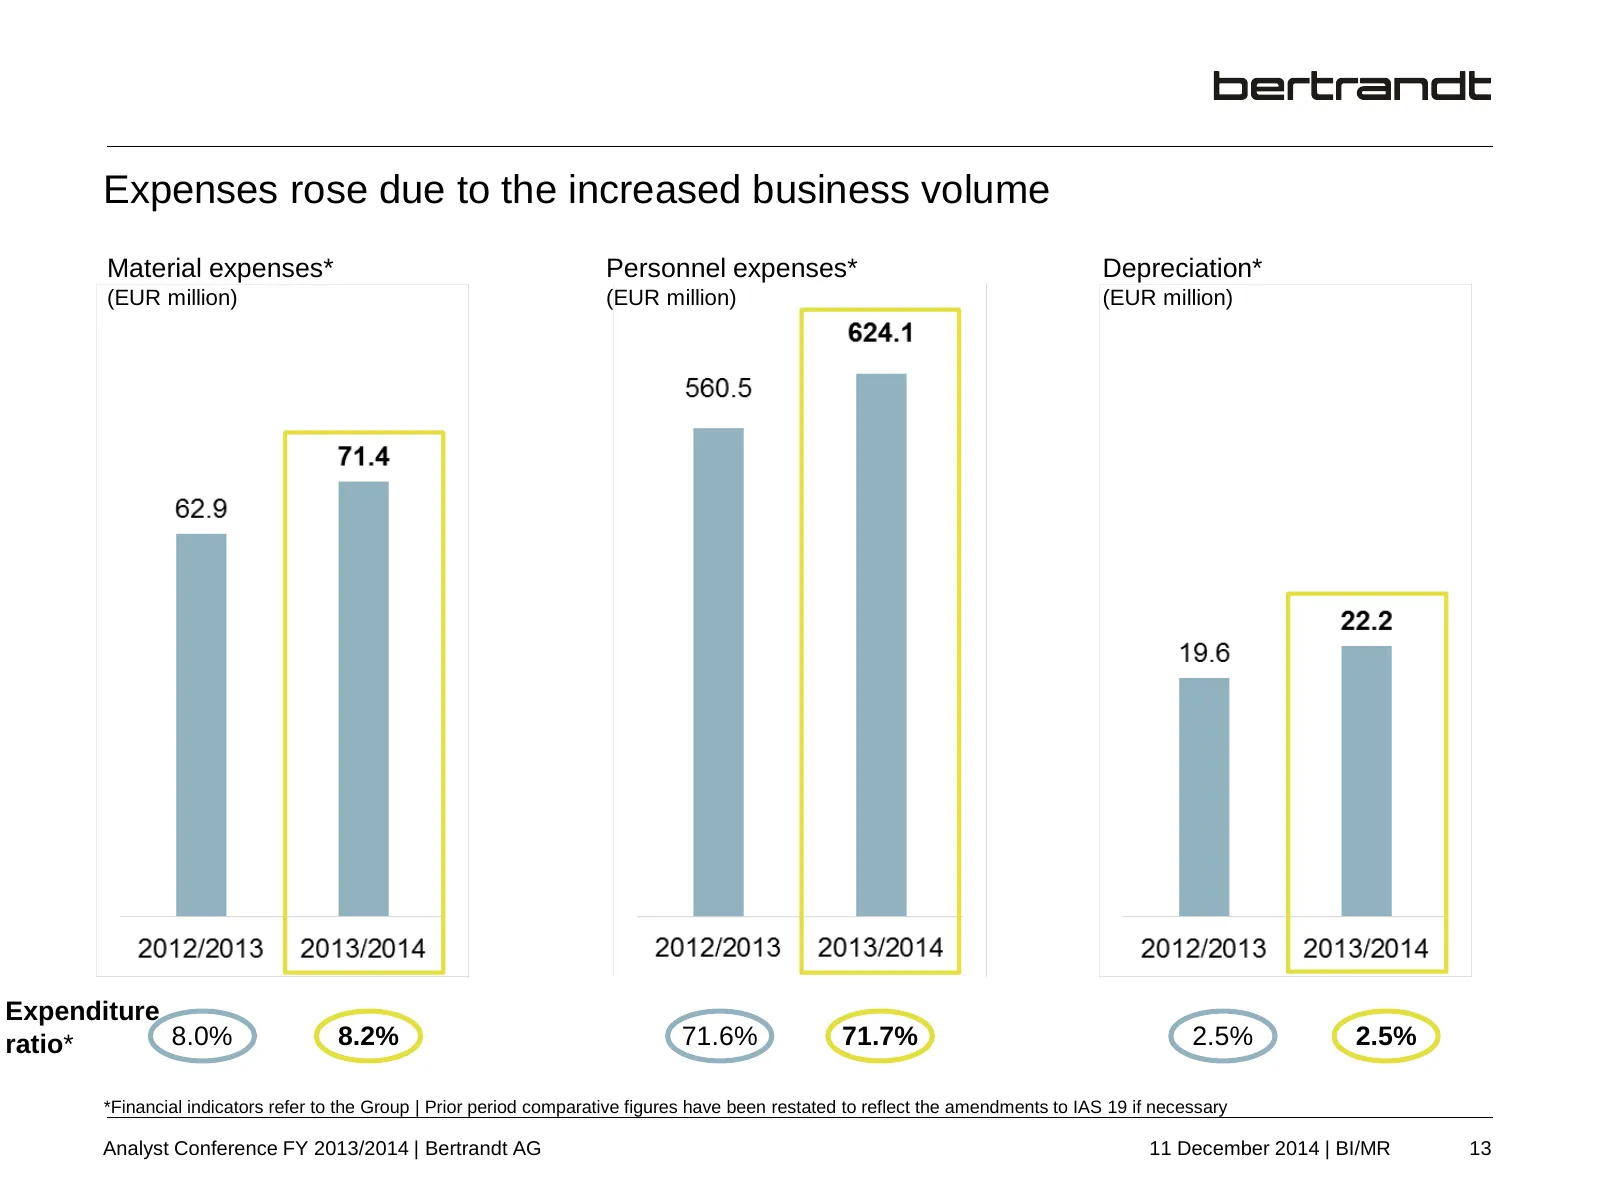
Slide 14: Expenses rose due to the increased business volume
Expenses rose due to the increased business volume Material expenses* Personnel expenses* Depreciation* (EUR million) (EUR million) (EUR million) Expenditure ratio* 8.0% 8.2% 71.6% 71.7% 2.5% 2.5% *Financial indicators refer to the Group | Prior period comparative figures have been restated to refle
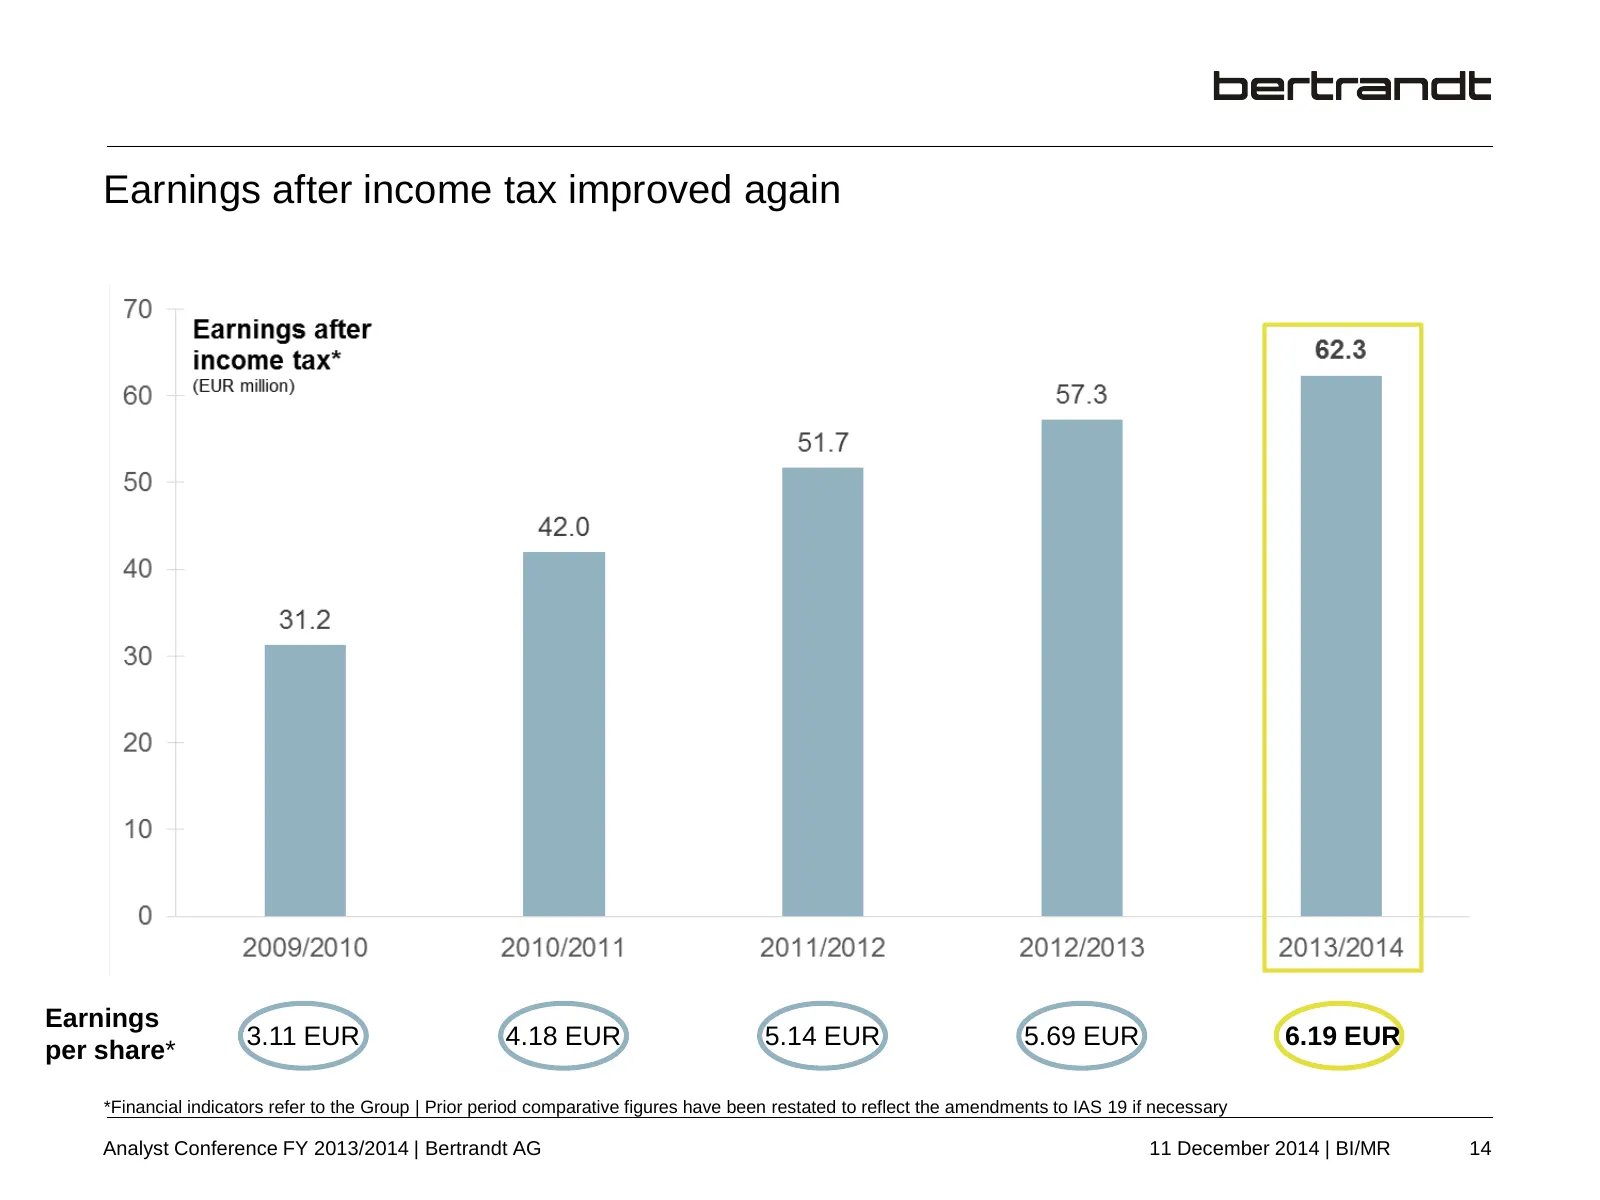
Slide 15: Earnings after income tax improved again
Earnings after income tax improved again Earnings 3.11 EUR 4.18 EUR 5.14 EUR 5.69 EUR 6.19 EUR per share* *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amendments to IAS 19 if necessary Analyst Conference FY 2013/2014 | Bertrandt AG 11
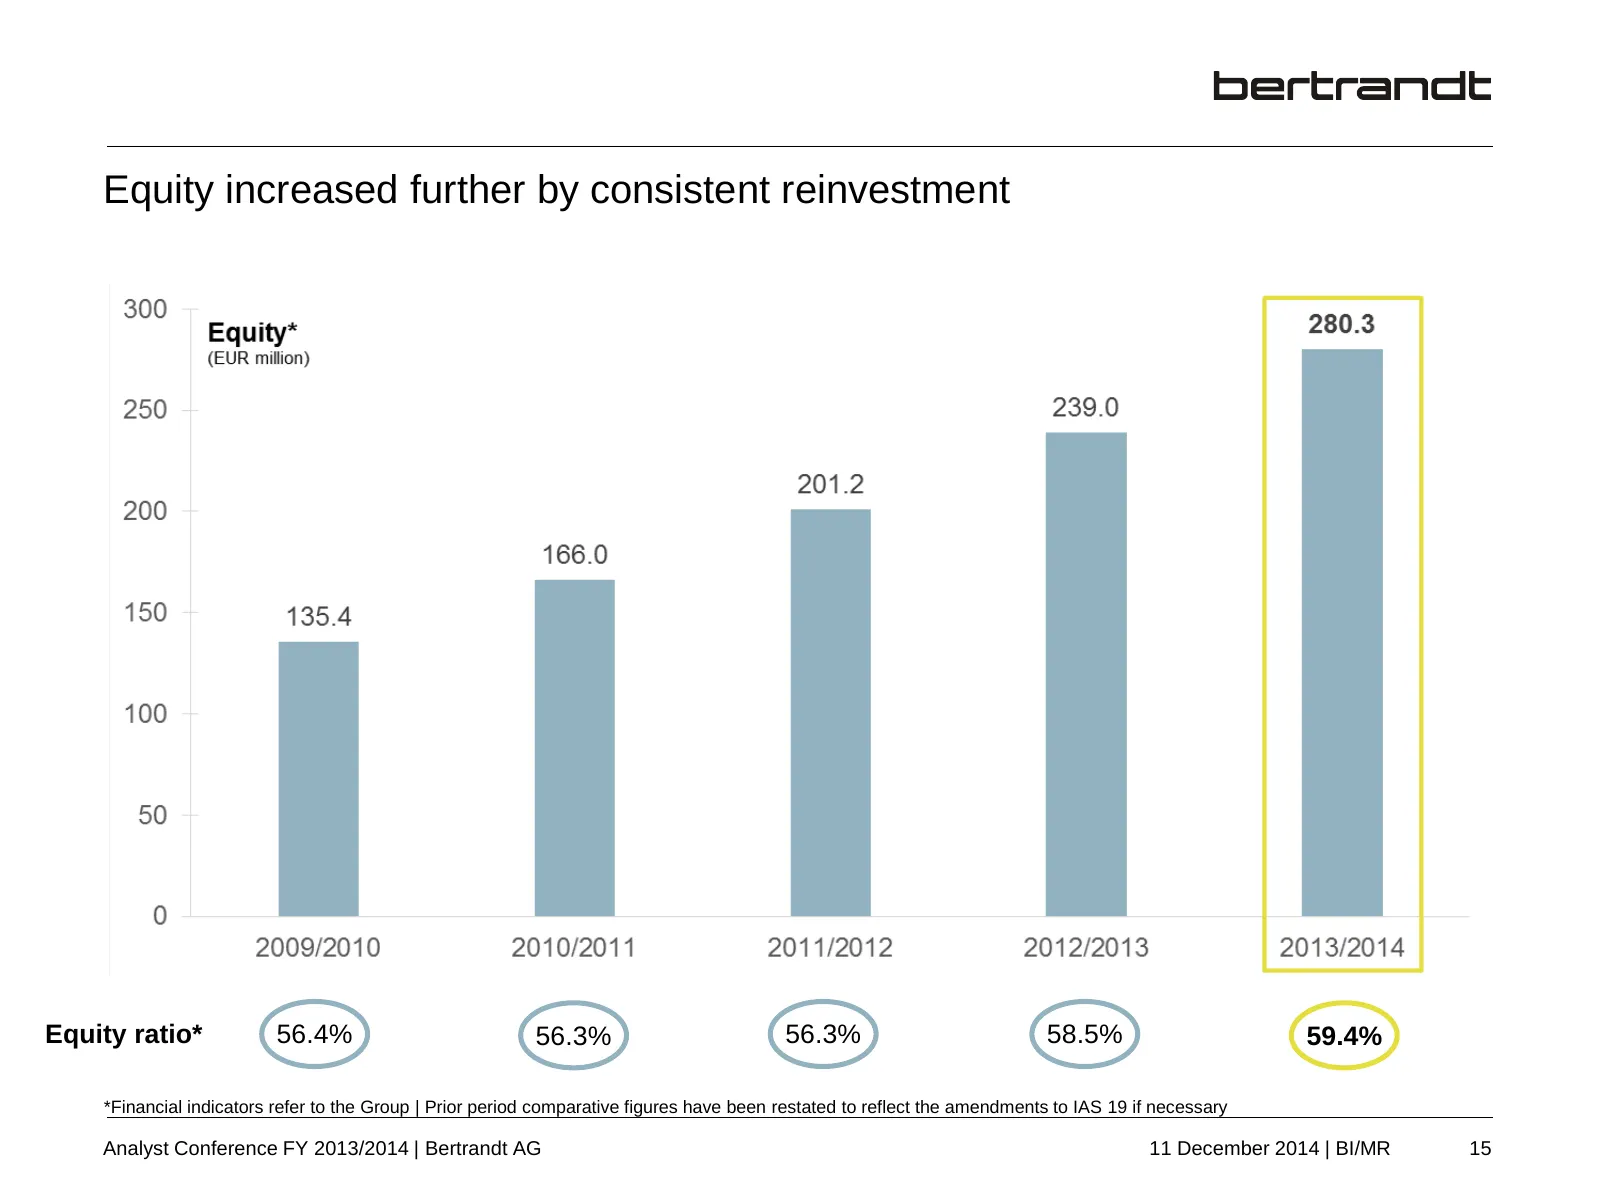
Slide 16: Equity increased further by consistent reinvestment
Equity increased further by consistent reinvestment Equity ratio* 56.4% 56.3% 56.3% 58.5% 59.4% *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amendments to IAS 19 if necessary Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2
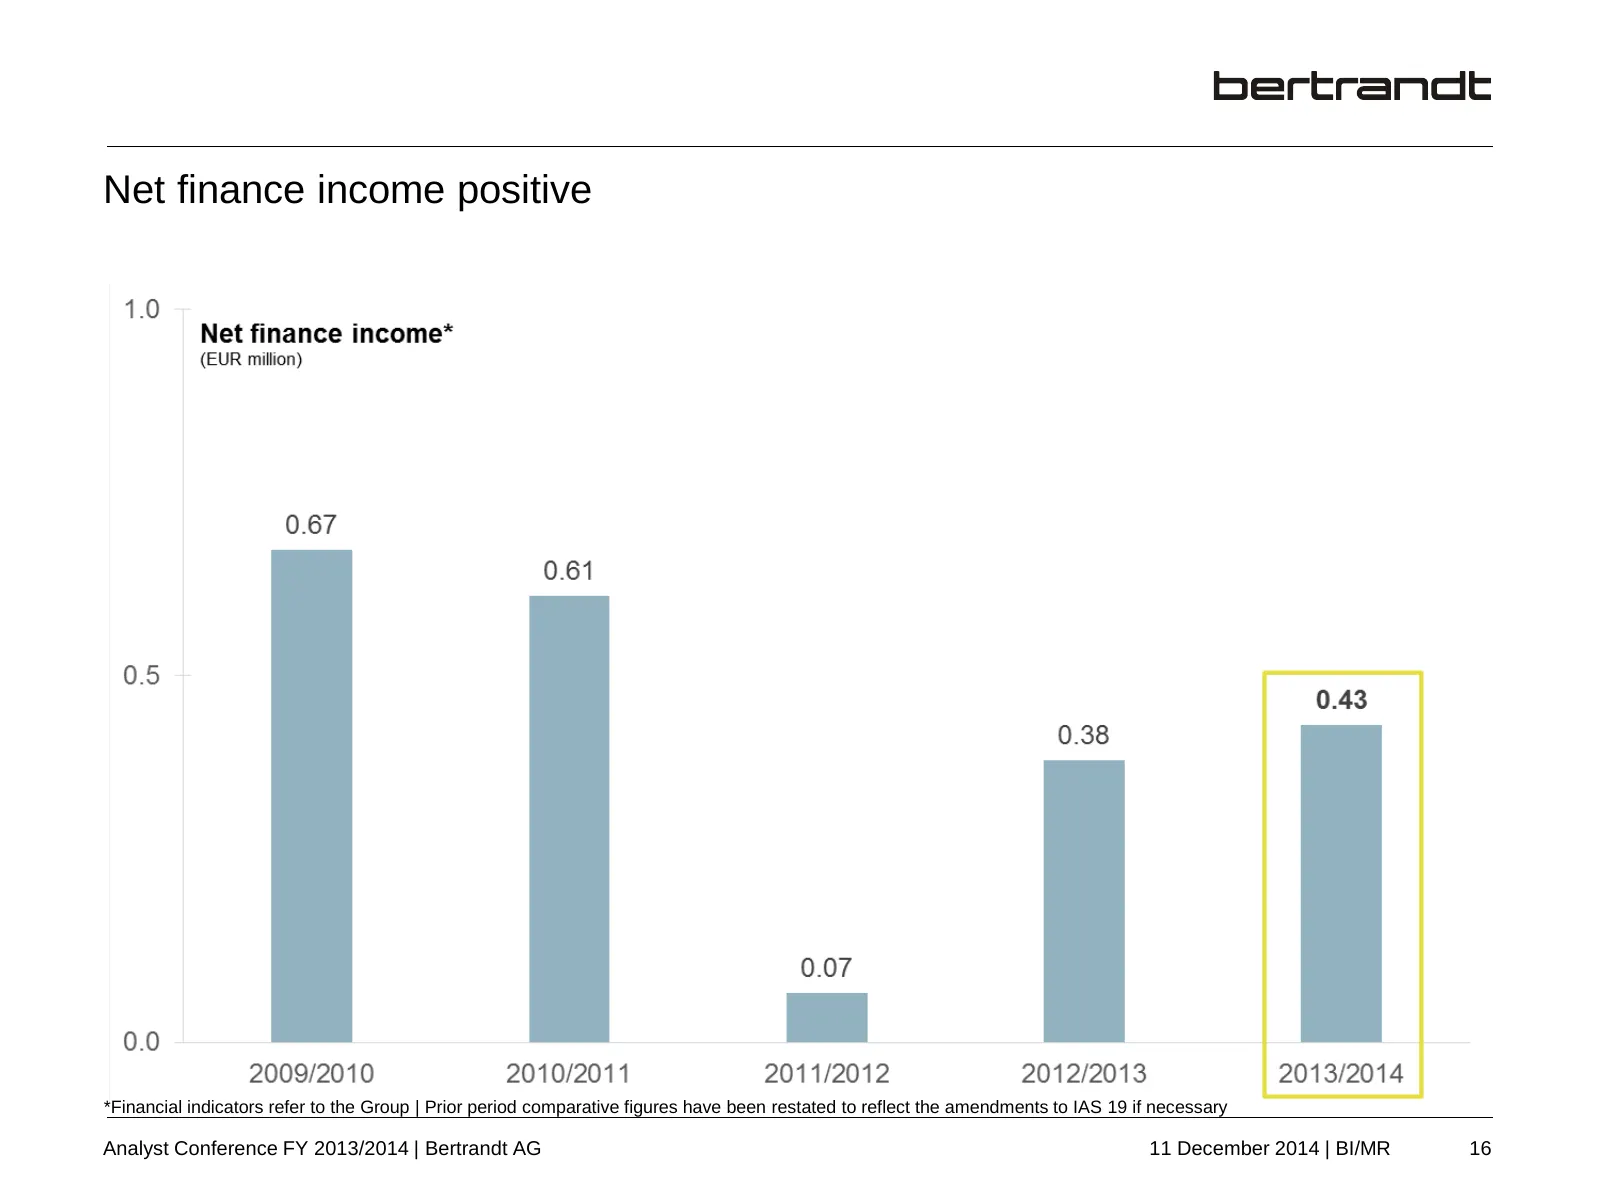
Slide 17: Net finance income positive
Net finance income positive *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amendments to IAS 19 if necessary Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 16
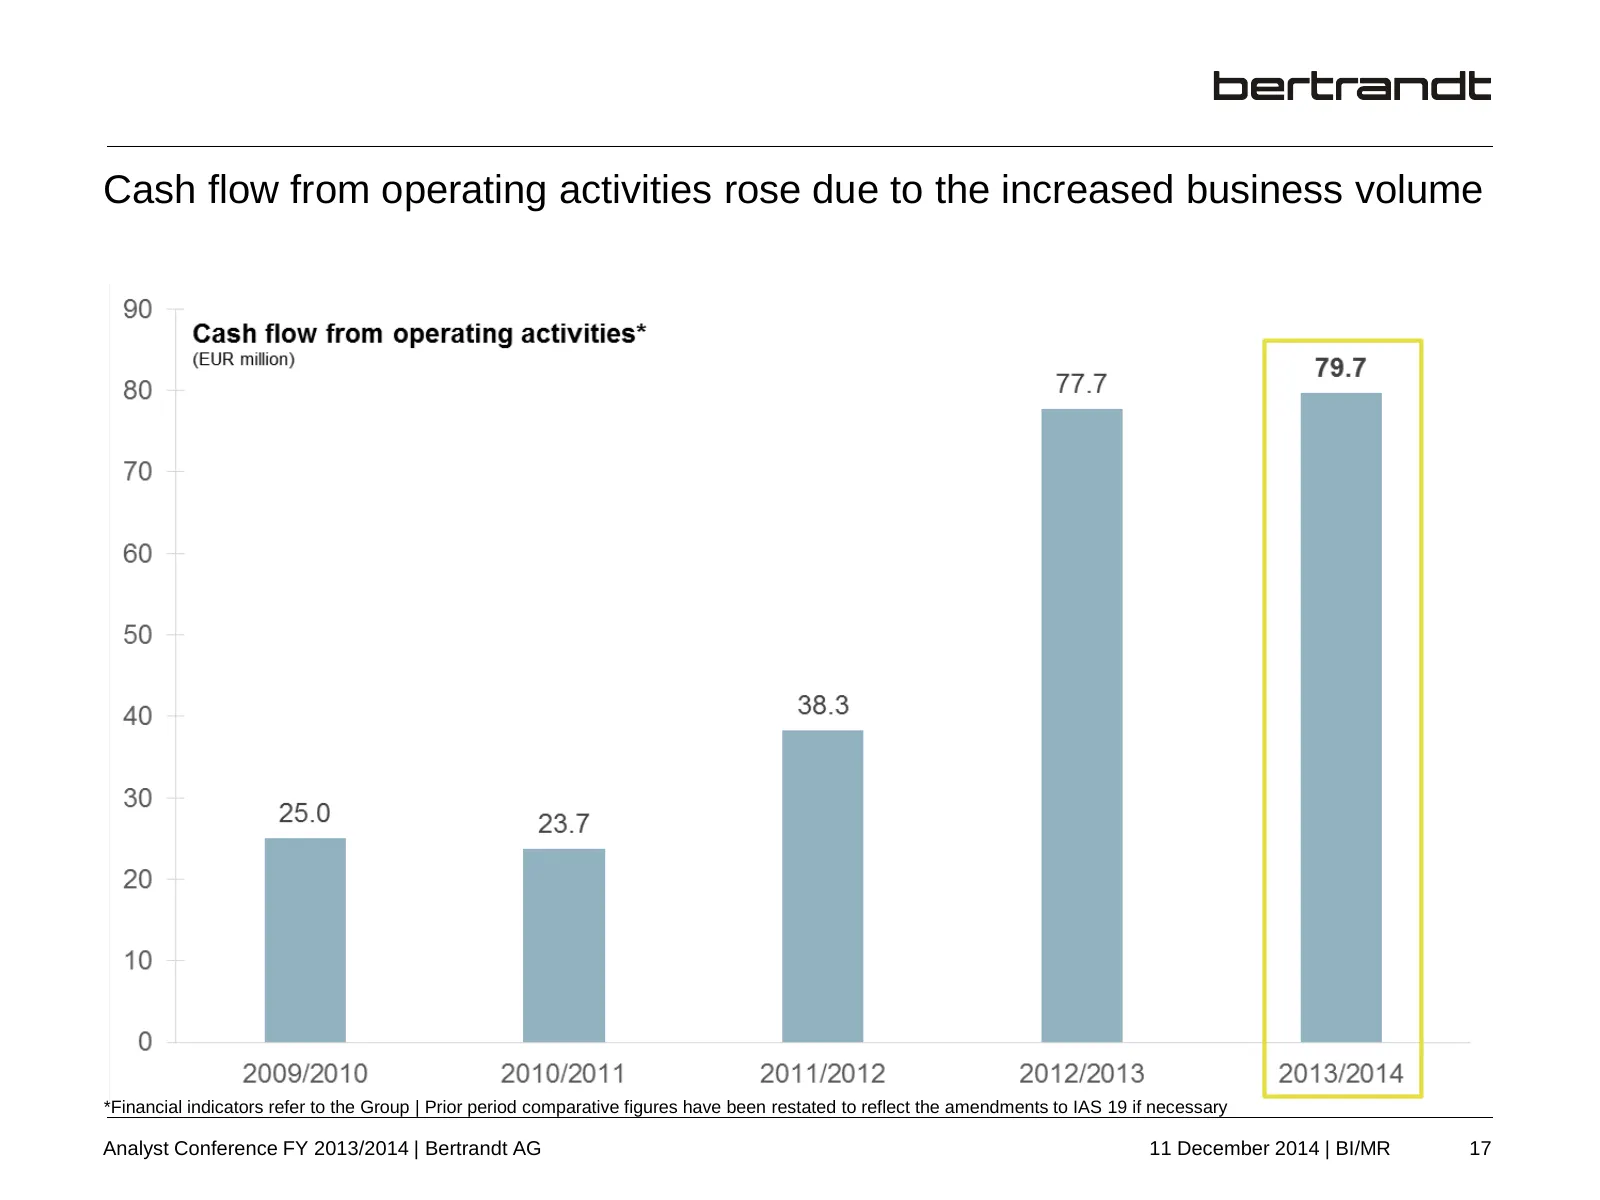
Slide 18: Cash flow from operating activities rose due to the increased business volume
Cash flow from operating activities rose due to the increased business volume *Financial indicators refer to the Group | Prior period comparative figures have been restated to reflect the amendments to IAS 19 if necessary Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 17
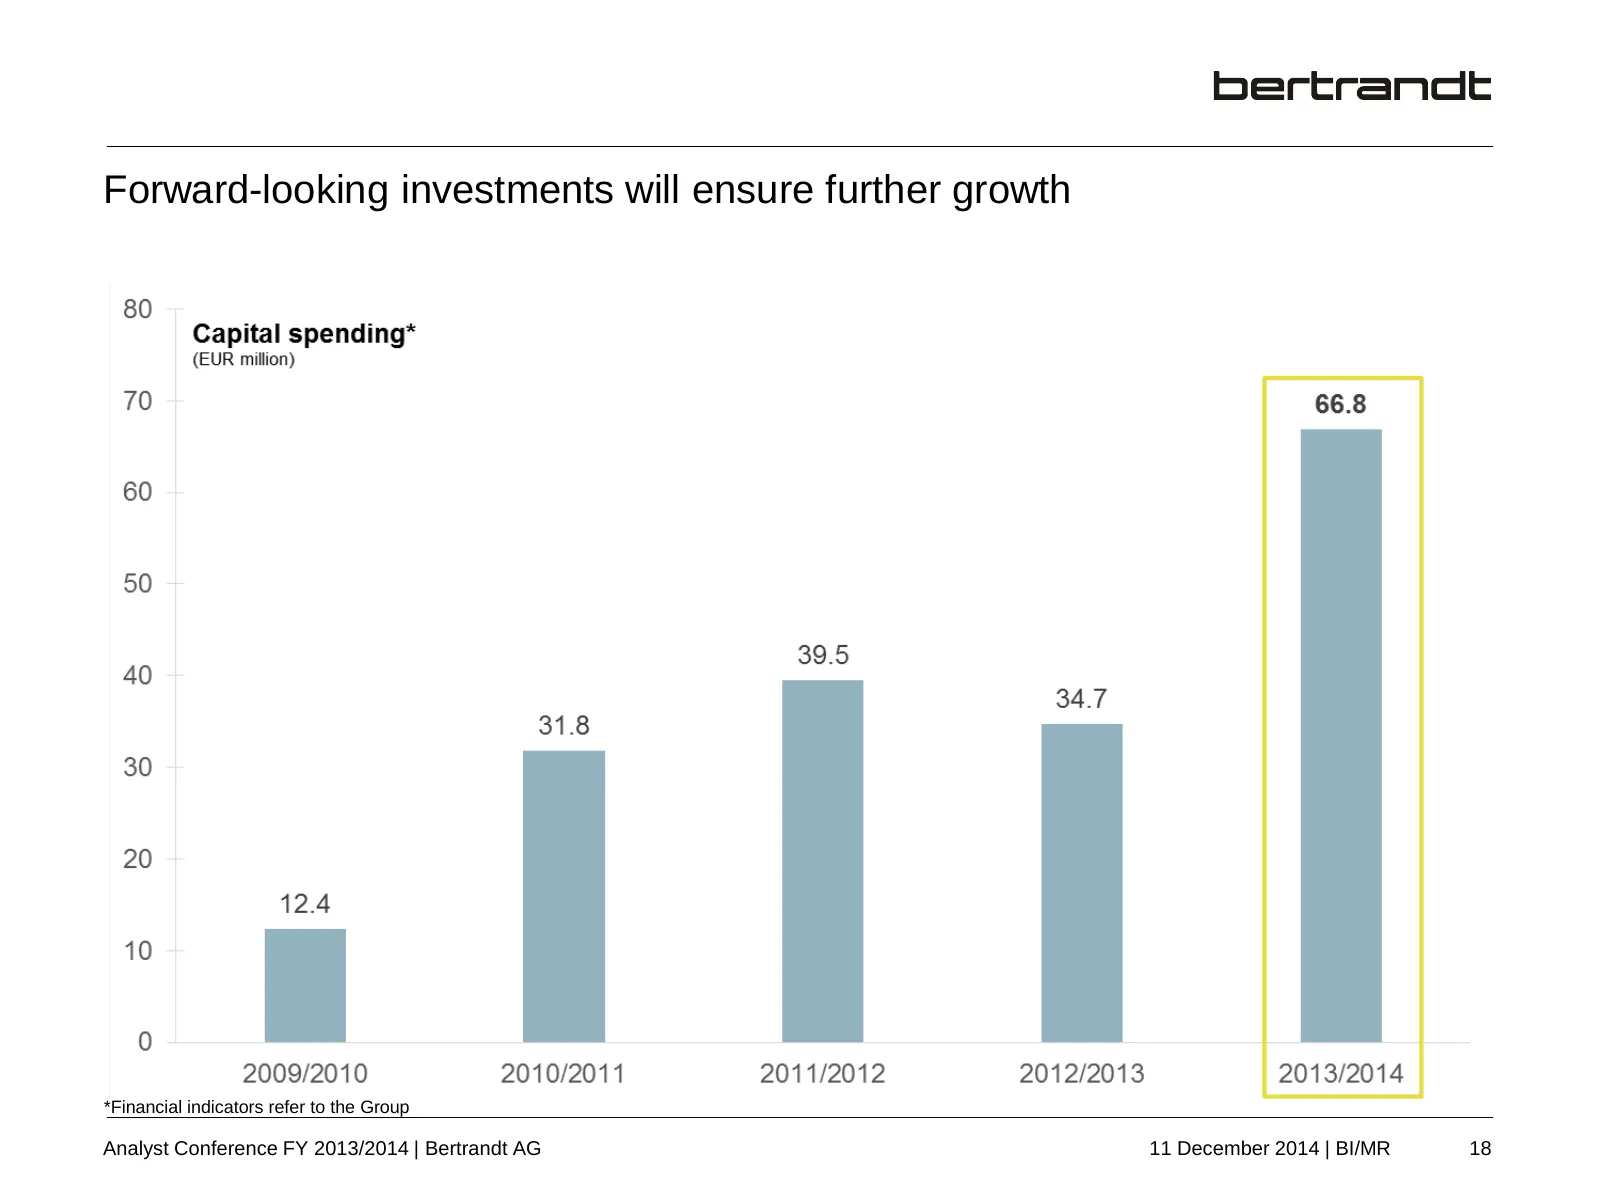
Slide 19: Forward-looking investments will ensure further growth
Forward-looking investments will ensure further growth *Financial indicators refer to the Group Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 18
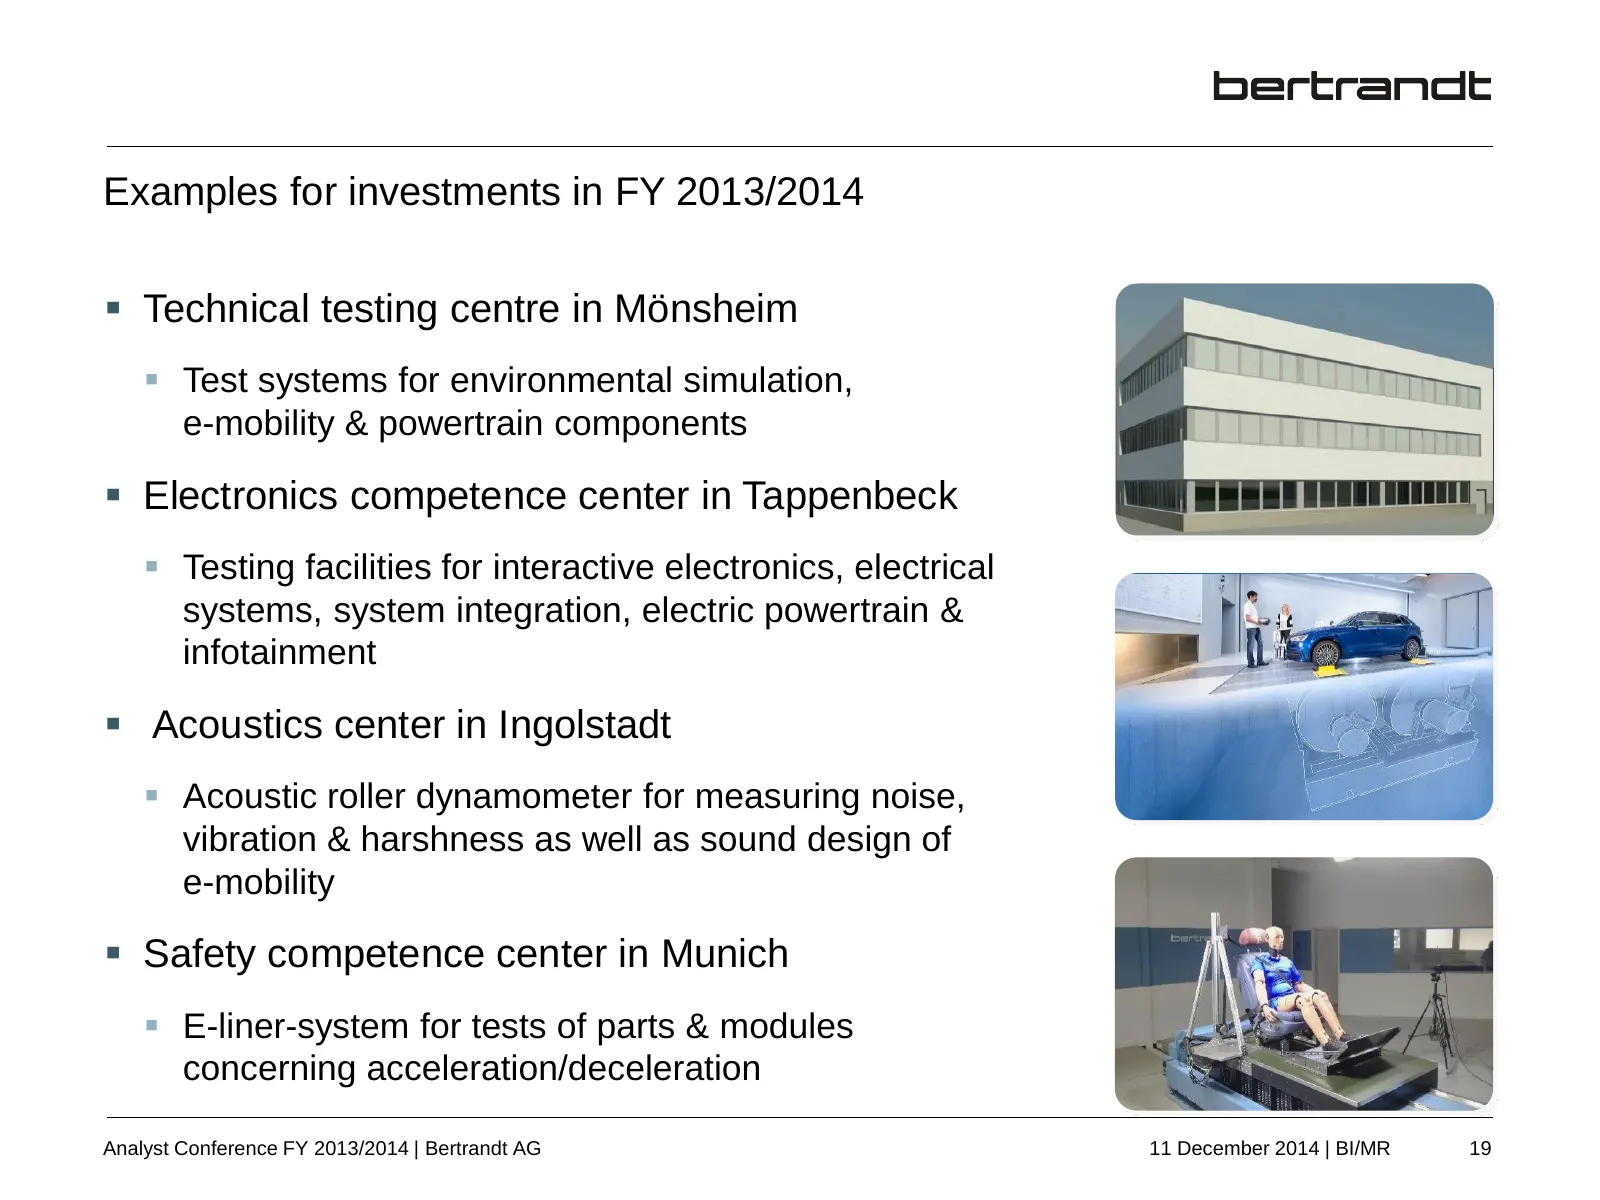
Slide 20: Examples for investments in FY 2013/2014
Examples for investments in FY 2013/2014 Technical testing centre in Mönsheim Test systems for environmental simulation, e-mobility & powertrain components Electronics competence center in Tappenbeck Testing facilities for interactive electronics, electrical systems, system integration, elec
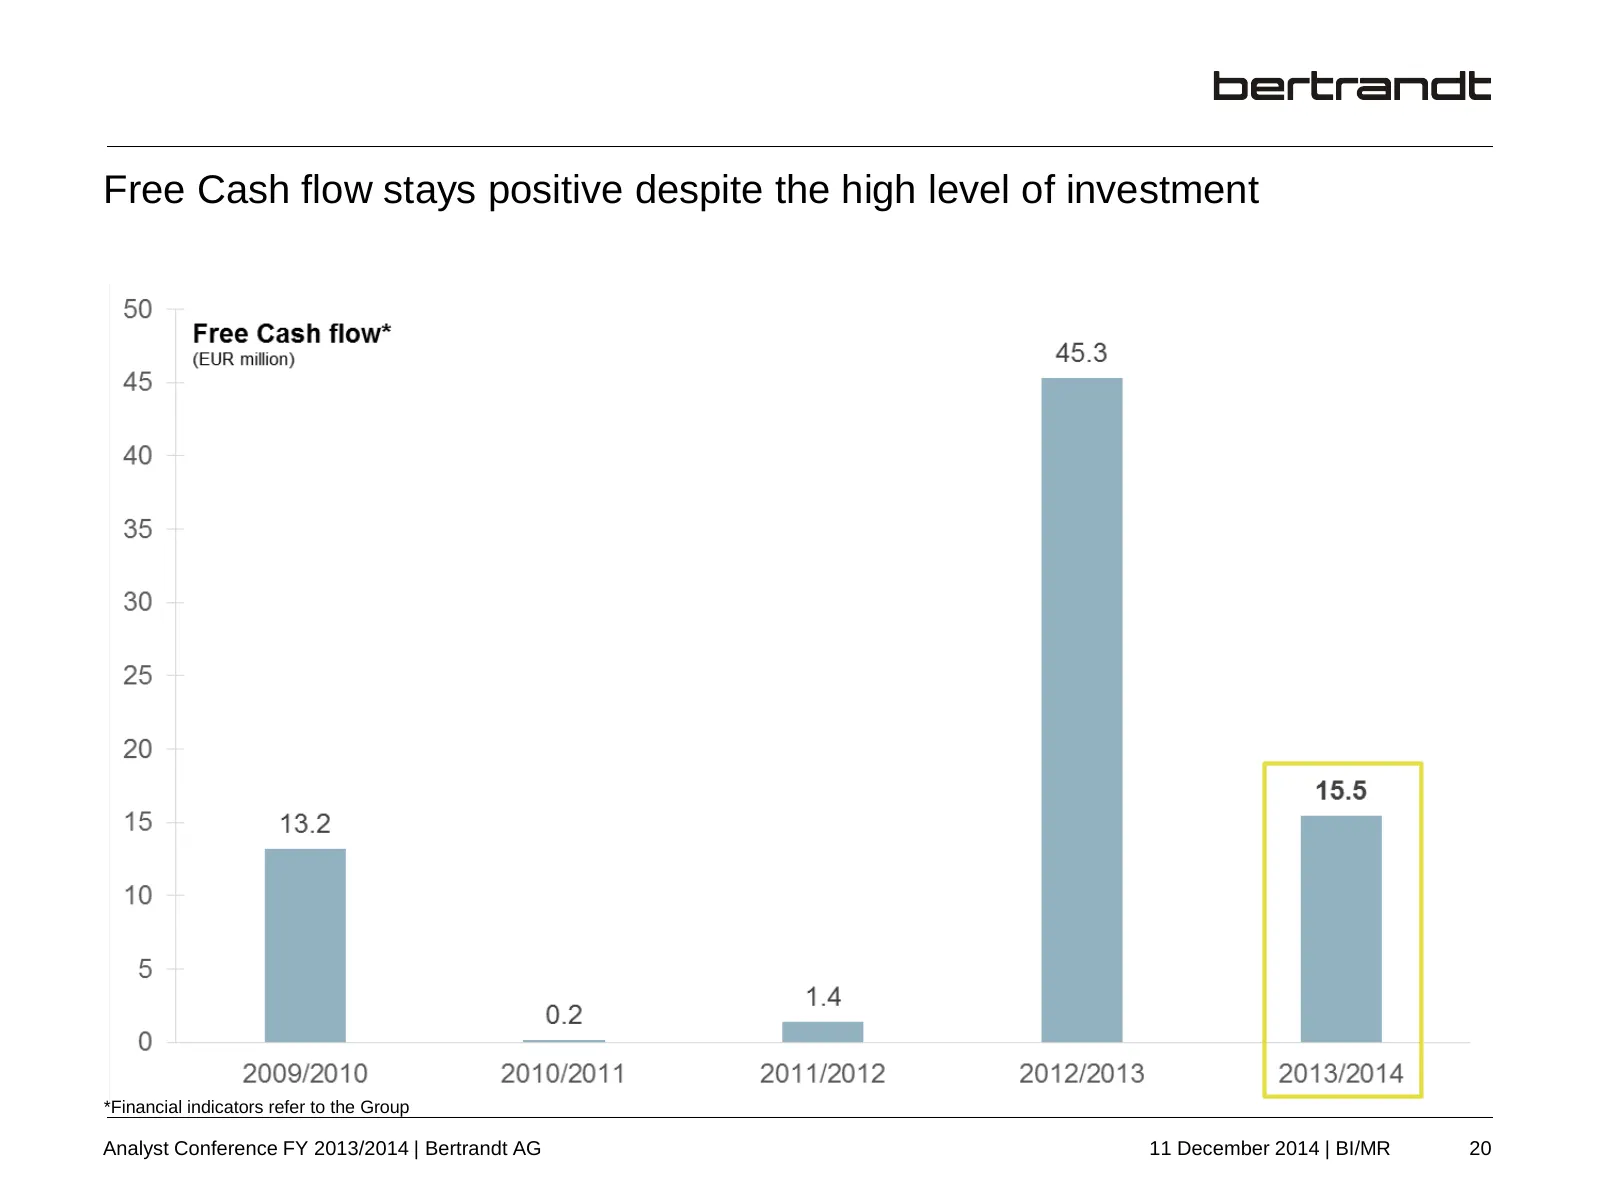
Slide 21: Free Cash flow stays positive despite the high level of investment
Free Cash flow stays positive despite the high level of investment *Financial indicators refer to the Group Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 20
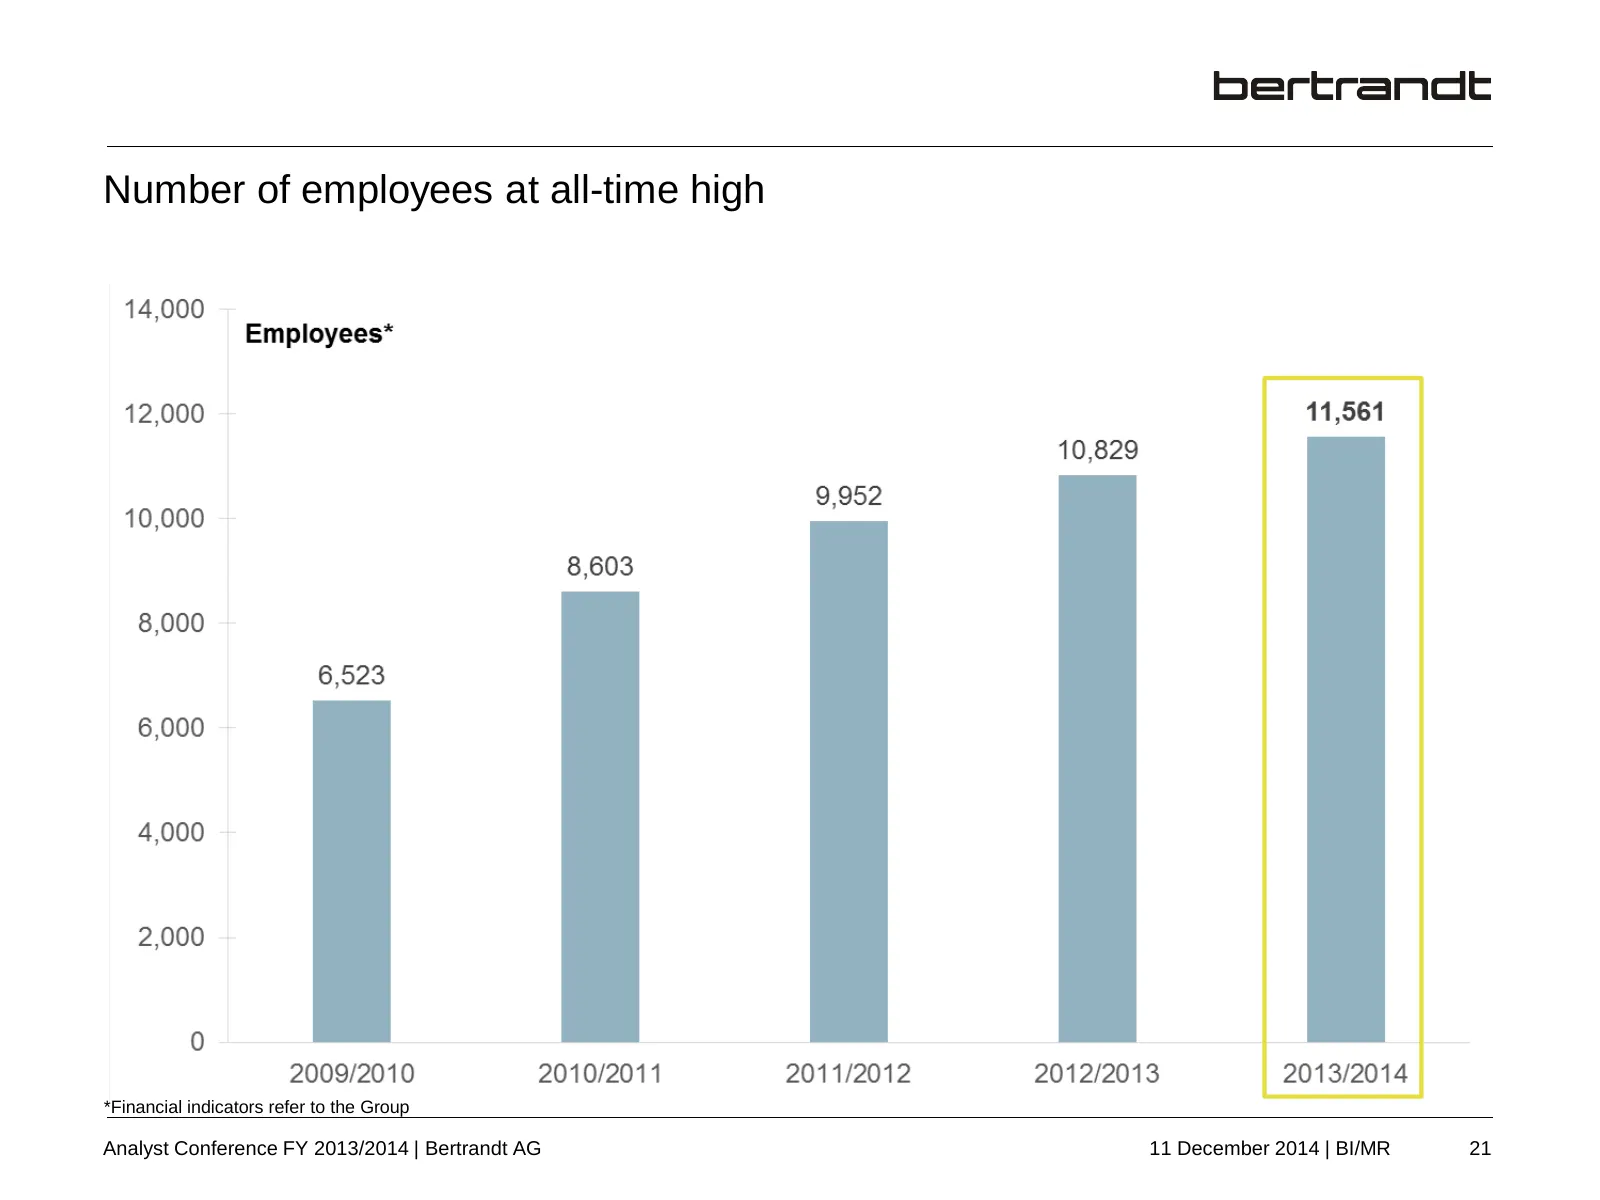
Slide 22: Number of employees at all-time high
Number of employees at all-time high *Financial indicators refer to the Group Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 21
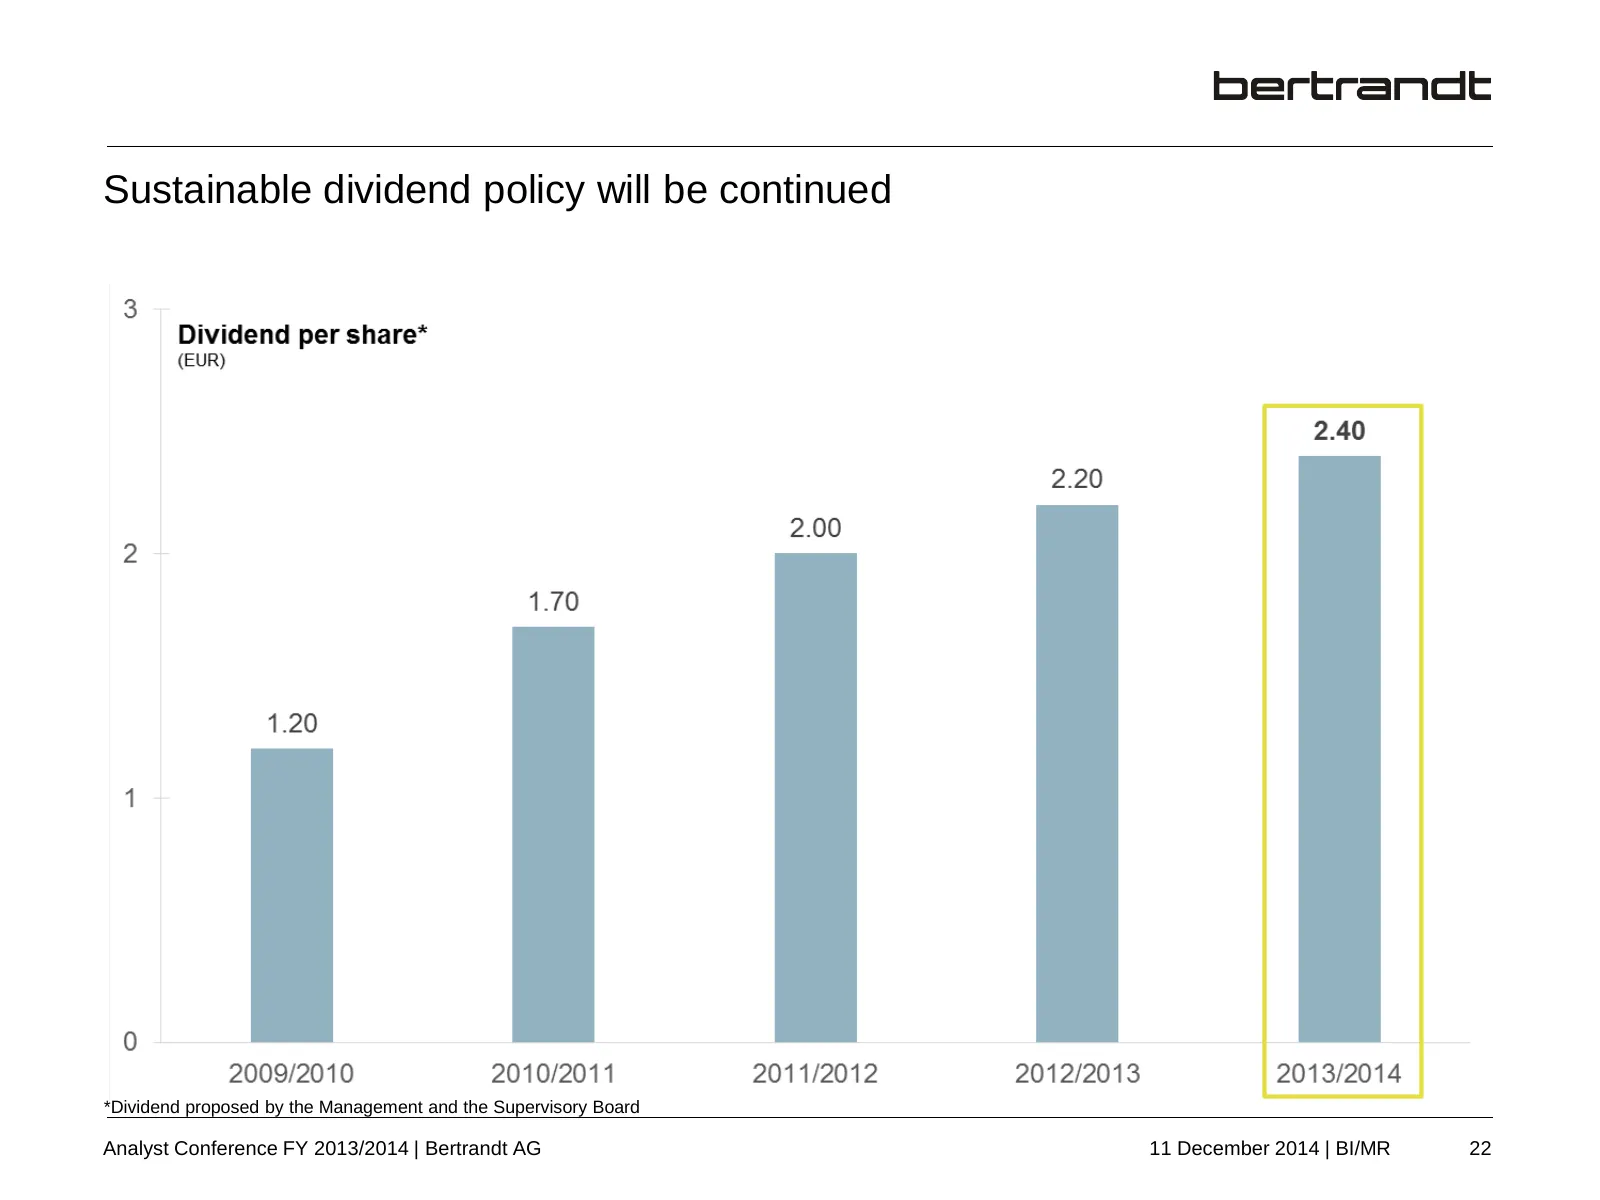
Slide 23: Sustainable dividend policy will be continued
Sustainable dividend policy will be continued *Dividend proposed by the Management and the Supervisory Board Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 22
Slide 24: Agenda
Agenda 1. Fiscal year 2013/2014 – General framework 2. Fiscal year 2013/2014 – Figures 3. Fiscal year 2014/2015 – Outlook Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 23
Slide 25: Economic outlook for 2015 entails uncertainty
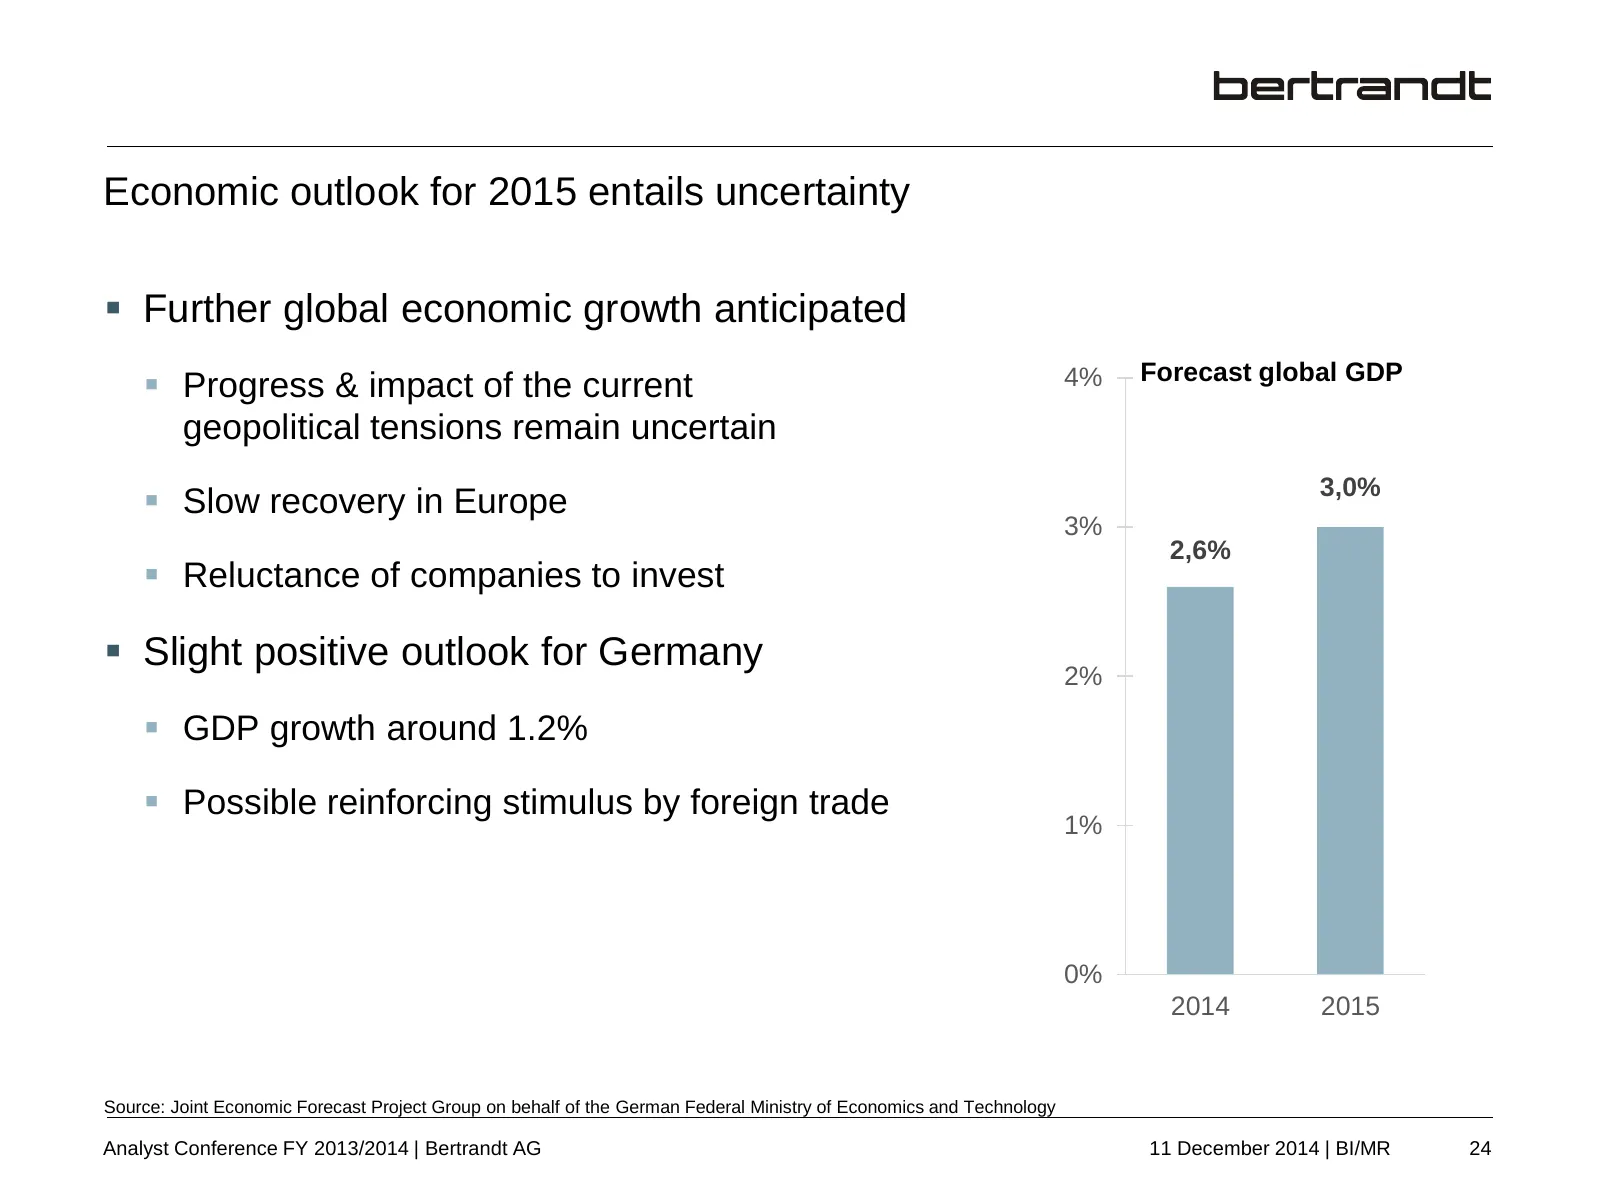
Economic outlook for 2015 entails uncertainty Further global economic growth anticipated Forecast global GDP Progress & impact of the current 4% geopolitical tensions remain uncertain 3,0% Slow recovery in Europe 3% 2,6% Reluctance of companies to invest Slight positive outlook for Germany
Slide 26: Core business automotive industry with potential for further growth
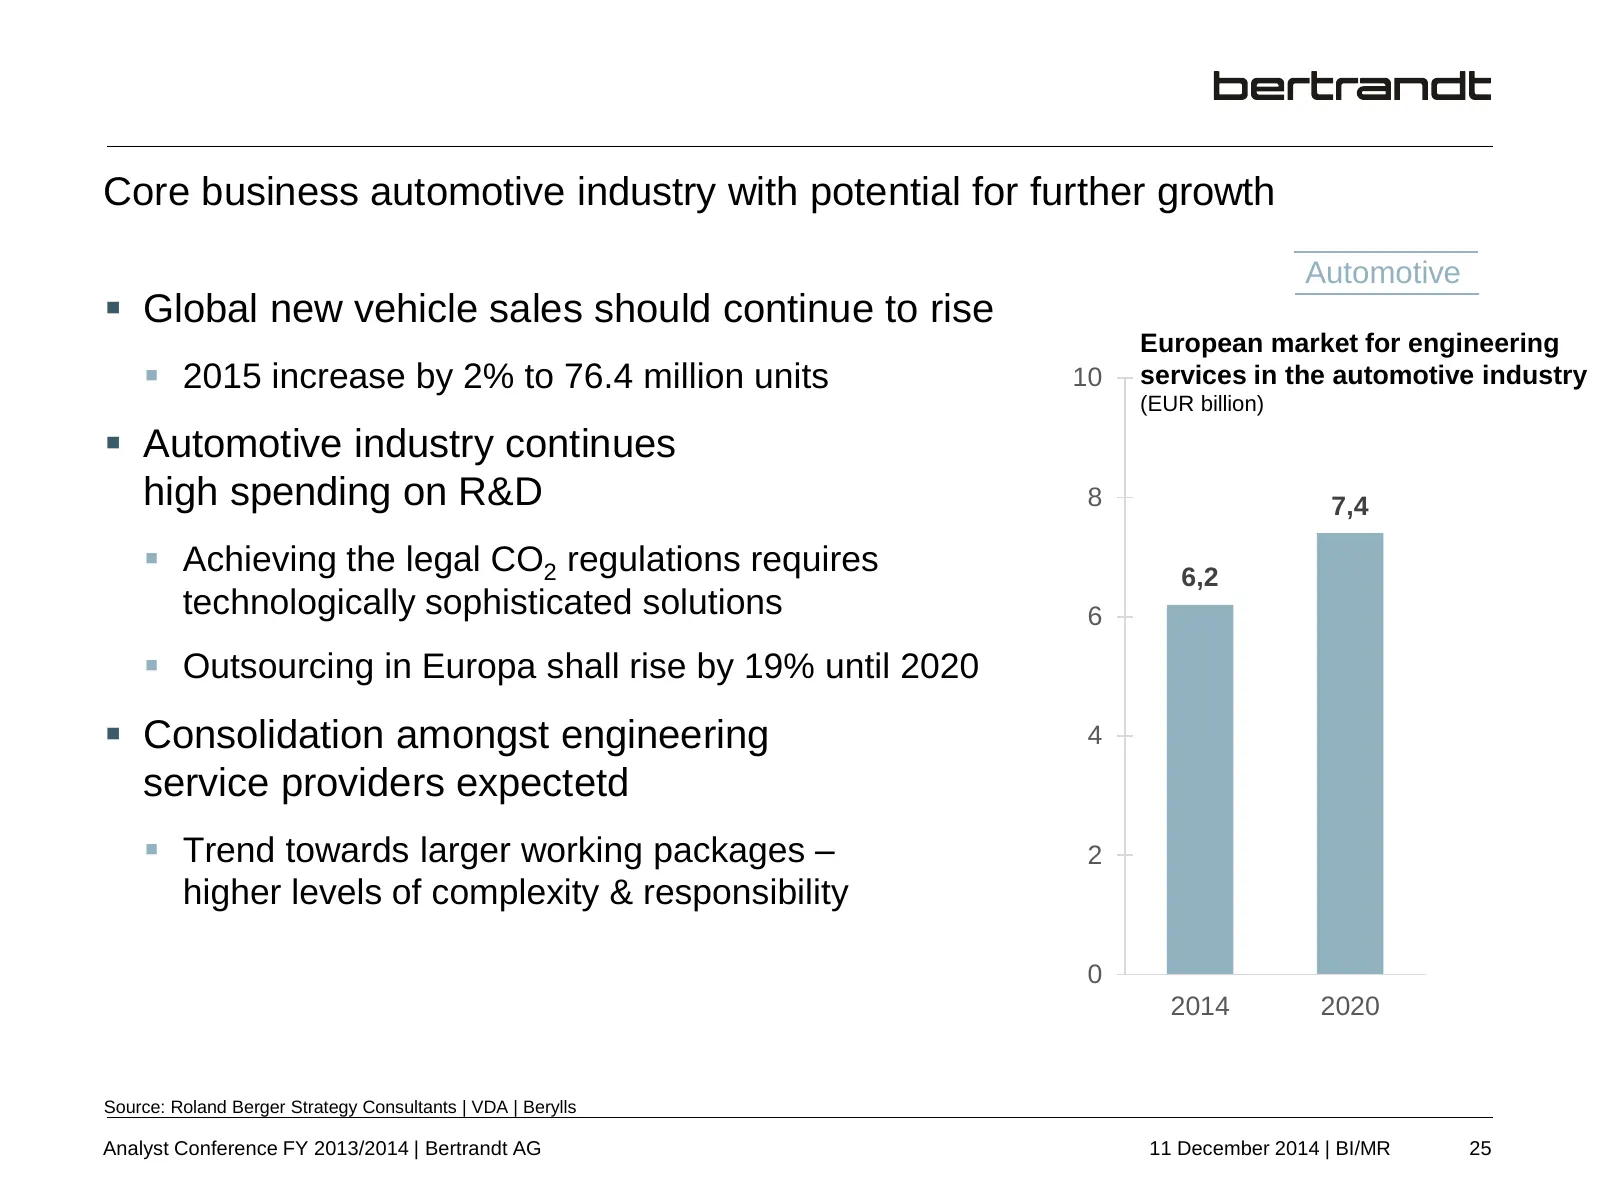
Core business automotive industry with potential for further growth Automotive Global new vehicle sales should continue to rise European market for engineering 2015 increase by 2% to 76.4 million units 10 services in the automotive industry (EUR billion) Automotive industry continues high spen
Slide 27: Fleet growth and modernization requirements in civil aviation continue
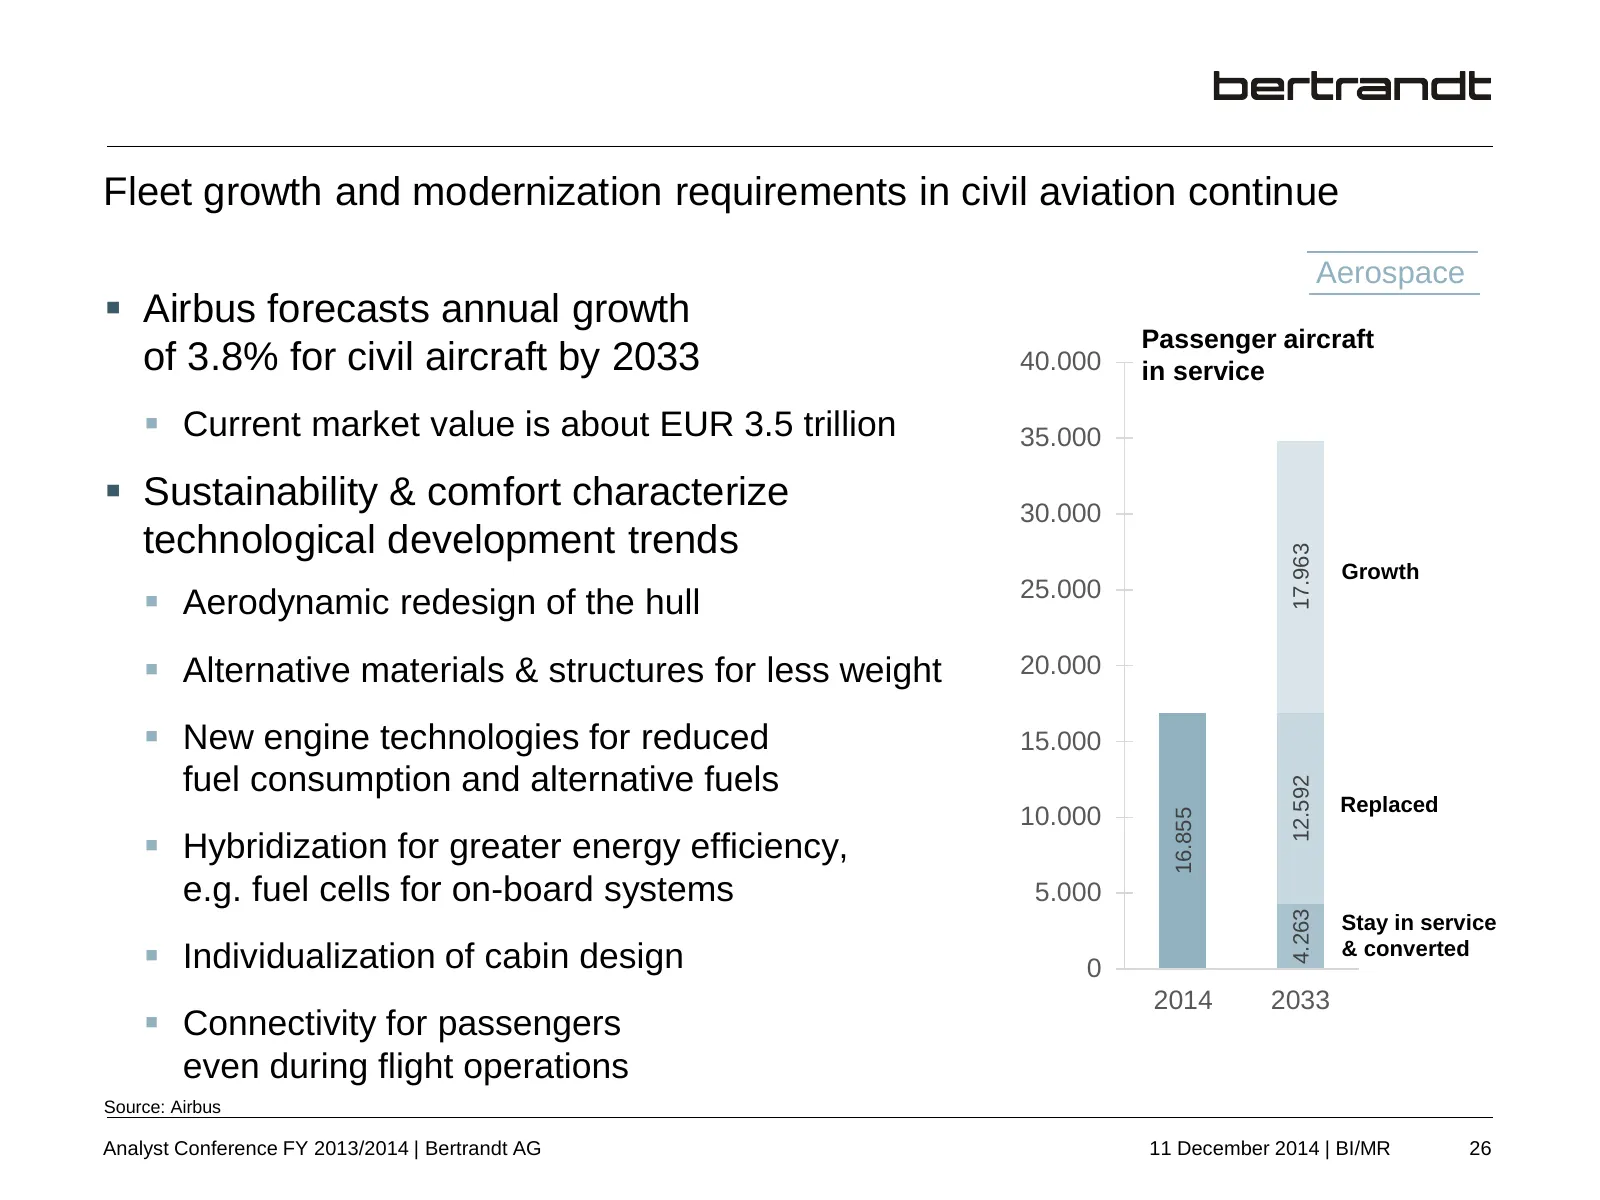
Fleet growth and modernization requirements in civil aviation continue Aerospace Airbus forecasts annual growth Passenger aircraft of 3.8% for civil aircraft by 2033 40.000 in service Current market value is about EUR 3.5 trillion 35.000 Sustainability & comfort characterize 30.000 technologic
Slide 28: Industry 4.0 − Huge potential for value creation waiting to be tapped
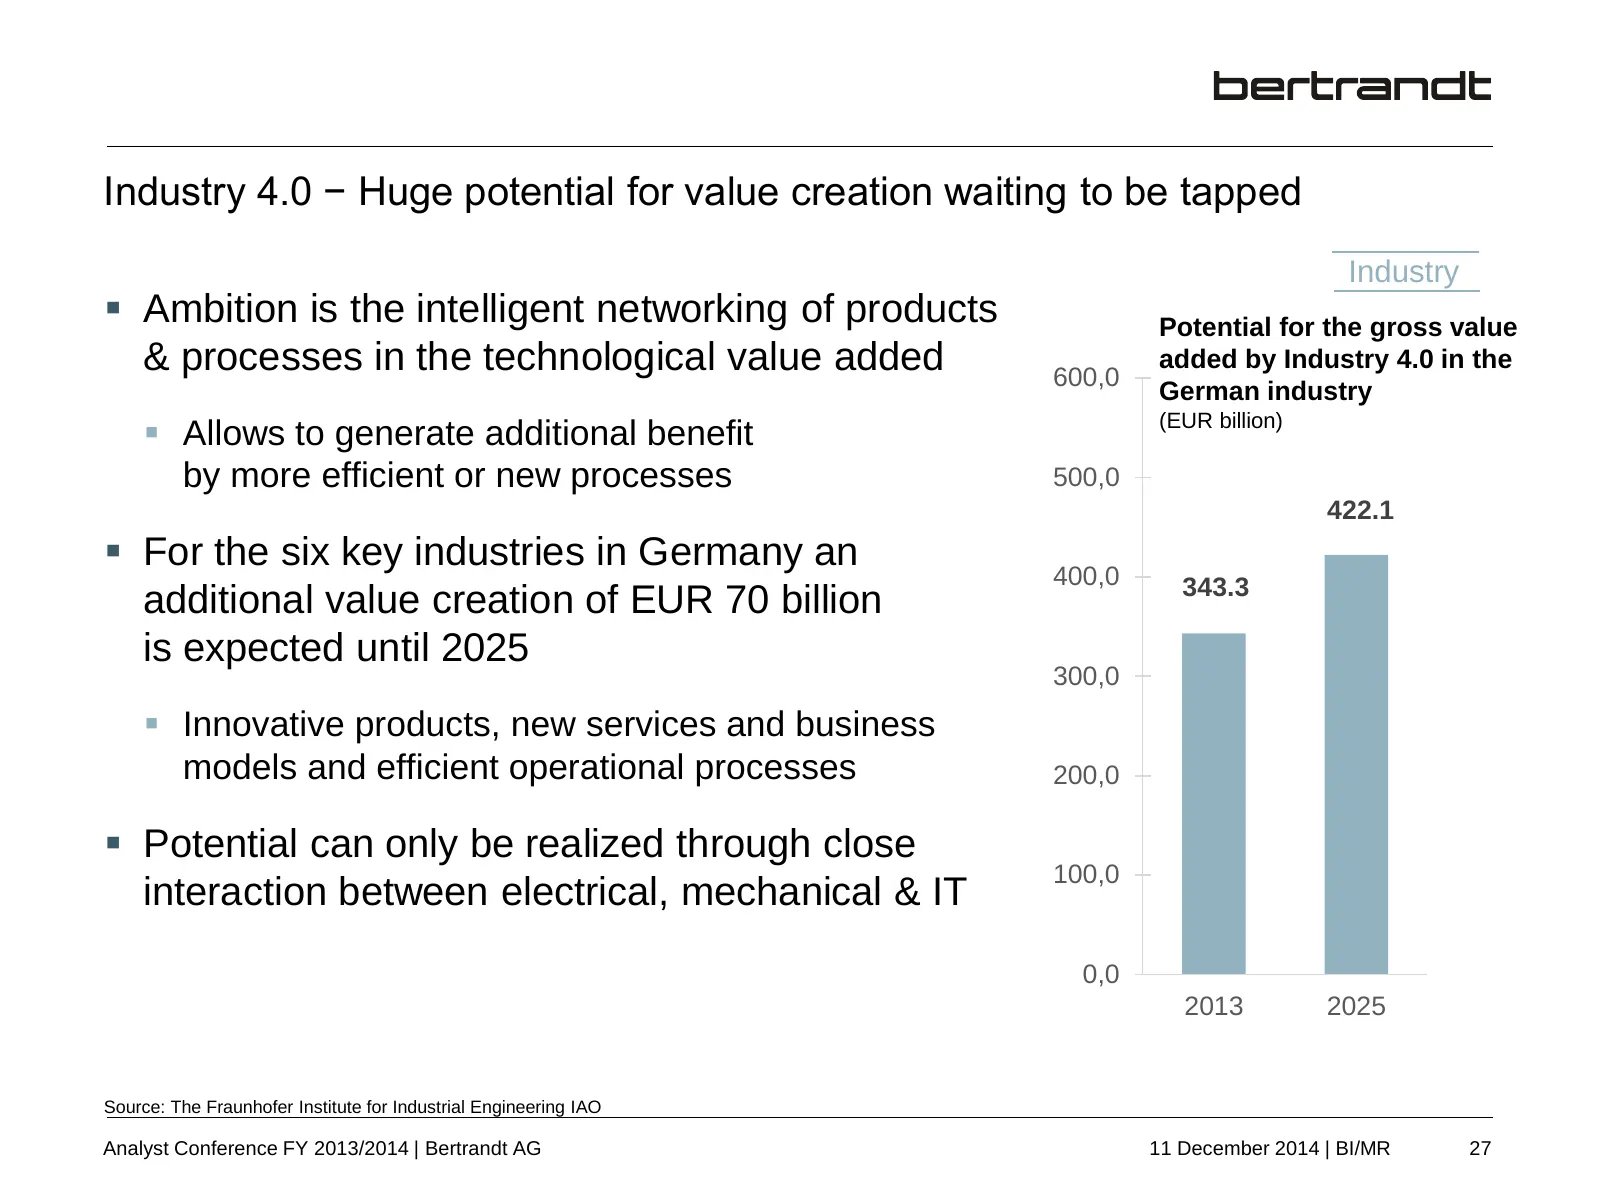
Industry 4.0 − Huge potential for value creation waiting to be tapped Industry Ambition is the intelligent networking of products Potential for the gross value & processes in the technological value added 600,0 added by Industry 4.0 in the German industry (EUR billion) Allows to generate additio
Slide 29: FY2014/2015 with more business opportunities for Bertrandt
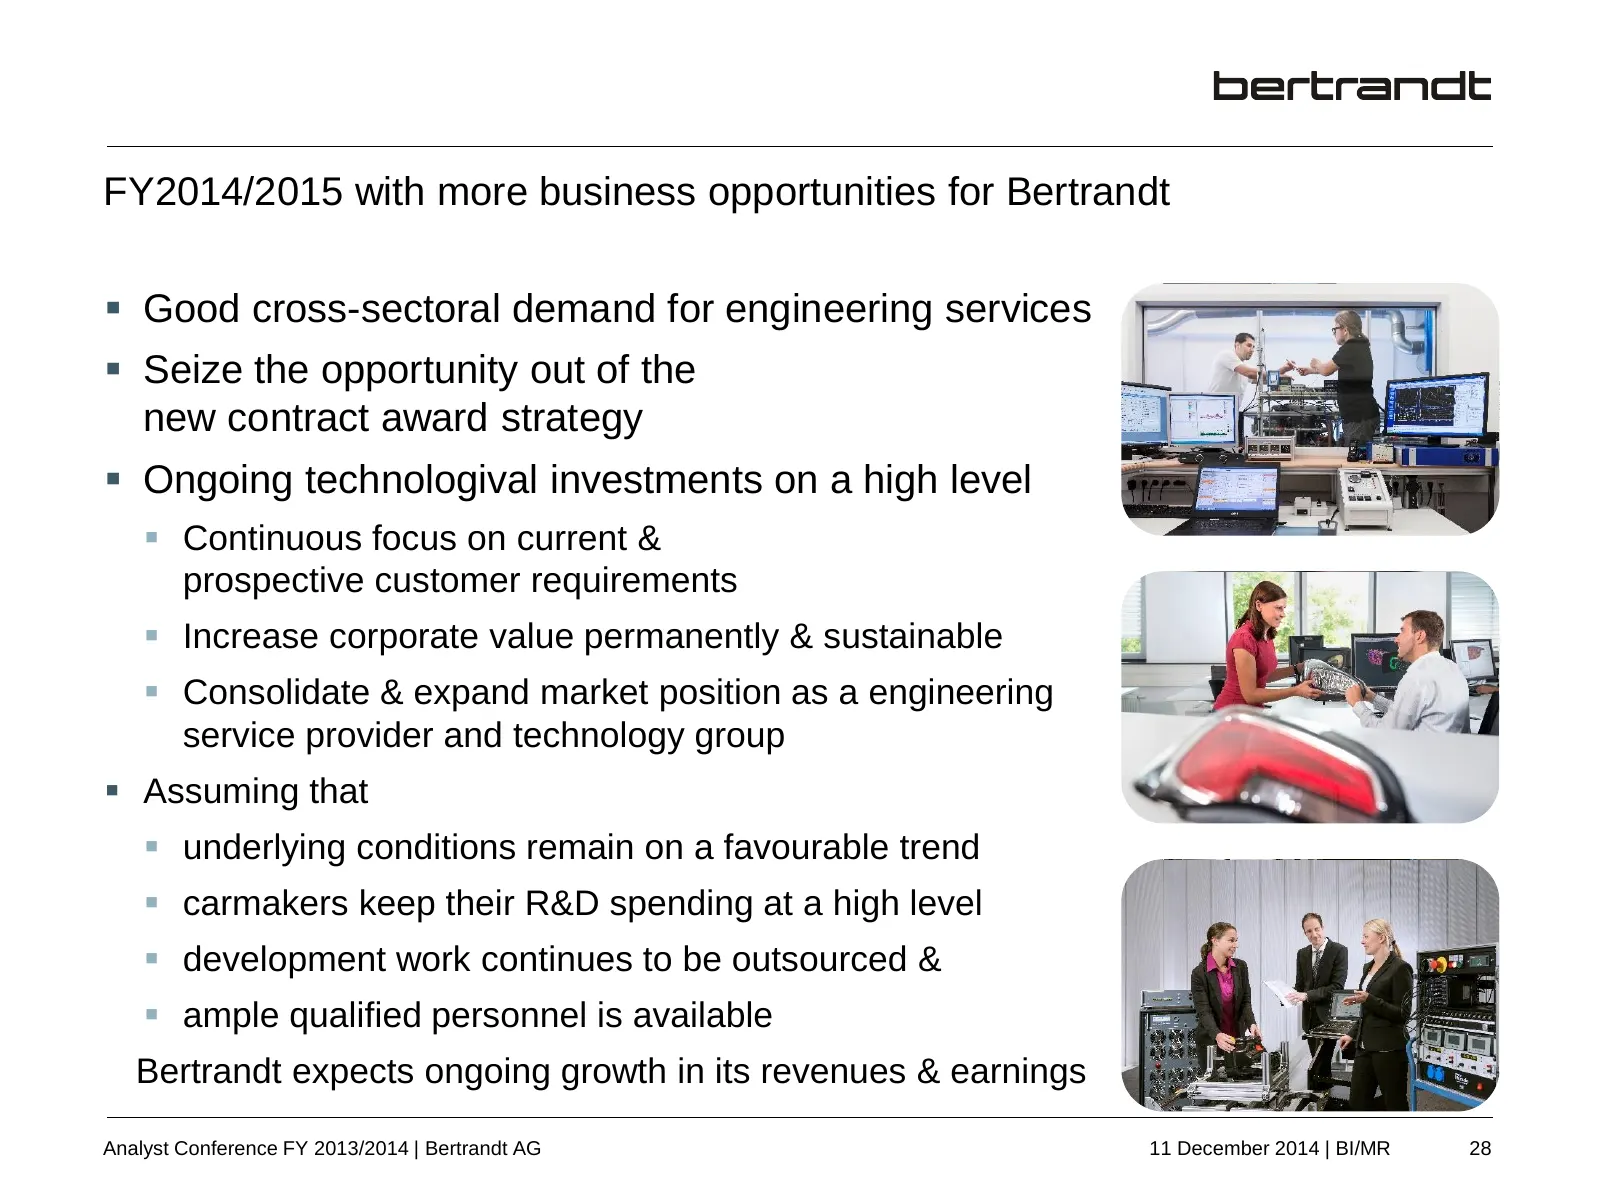
FY2014/2015 with more business opportunities for Bertrandt Good cross-sectoral demand for engineering services Seize the opportunity out of the new contract award strategy Ongoing technologival investments on a high level Continuous focus on current & prospective customer requirements Incr
Slide 30: Overview – Our financial calendar in FY 2014/2015
Overview – Our financial calendar in FY 2014/2015 16.02.2015 Report on the 1st quarter FY 2014/2015 18.02.2015 General meeting in Sindelfingen 20.05.2015 10th Capital Market Day in Ehningen & Report on the 2nd quarter FY 2014/2015 12.08.2015 Report on the 3th quarter FY 2014/2015 10.12.201
Slide 31: Thank you for you attention!
Thank you for you attention! Analyst Conference FY 2013/2014 | Bertrandt AG 11 December 2014 | BI/MR 30
Slide 32: Legal notice
Legal notice This presentation contains inter alia certain foresighted statements about future developments, which are based on current estimates of management. Such statements are subjected to certain risks and uncertainties. If one of these factors of uncertainty or other imponderables should oc
Source: Internet Archive copy of bertrandt.com
More decks from Bertrandt AG
 9M 2025/2026 Earnings Presentation20 slides · Aug 3, 2026
 Investor Day (May 2026)82 slides · May 13, 2026
 H1 2025/2026 Earnings Presentation19 slides · May 13, 2026
 Q1 2025/2026 Earnings Presentation15 slides · Feb 12, 2026
 Investor Presentation (January 2026)61 slides · Jan 12, 2026
 FY2024/2025 Earnings Presentation41 slides · Dec 18, 2025