Old Mutual Ltd. · JSE:OMU
Old Mutual — Q3 2015 Earnings Presentation
22 slides from Old Mutual's earnings presentation, Nov 4, 2015
Slide 1: Q3 2015 Investor Update
Q3 2015 INVESTOR UPDATE November 2015 INVESTMENT | SAVINGS | INSURANCE | BANKING
Slide 2: Disclaimer
DISCLAIMER This presentation may contain certain forward-looking statements with respect to certain of Old Mutual plc’s plans and its current goals and expectations relating to its future financial condition, performance and results. By their nature, all forward-looking statements involve risk and u
Slide 3: Strong sales growth reflects focus on operational execution
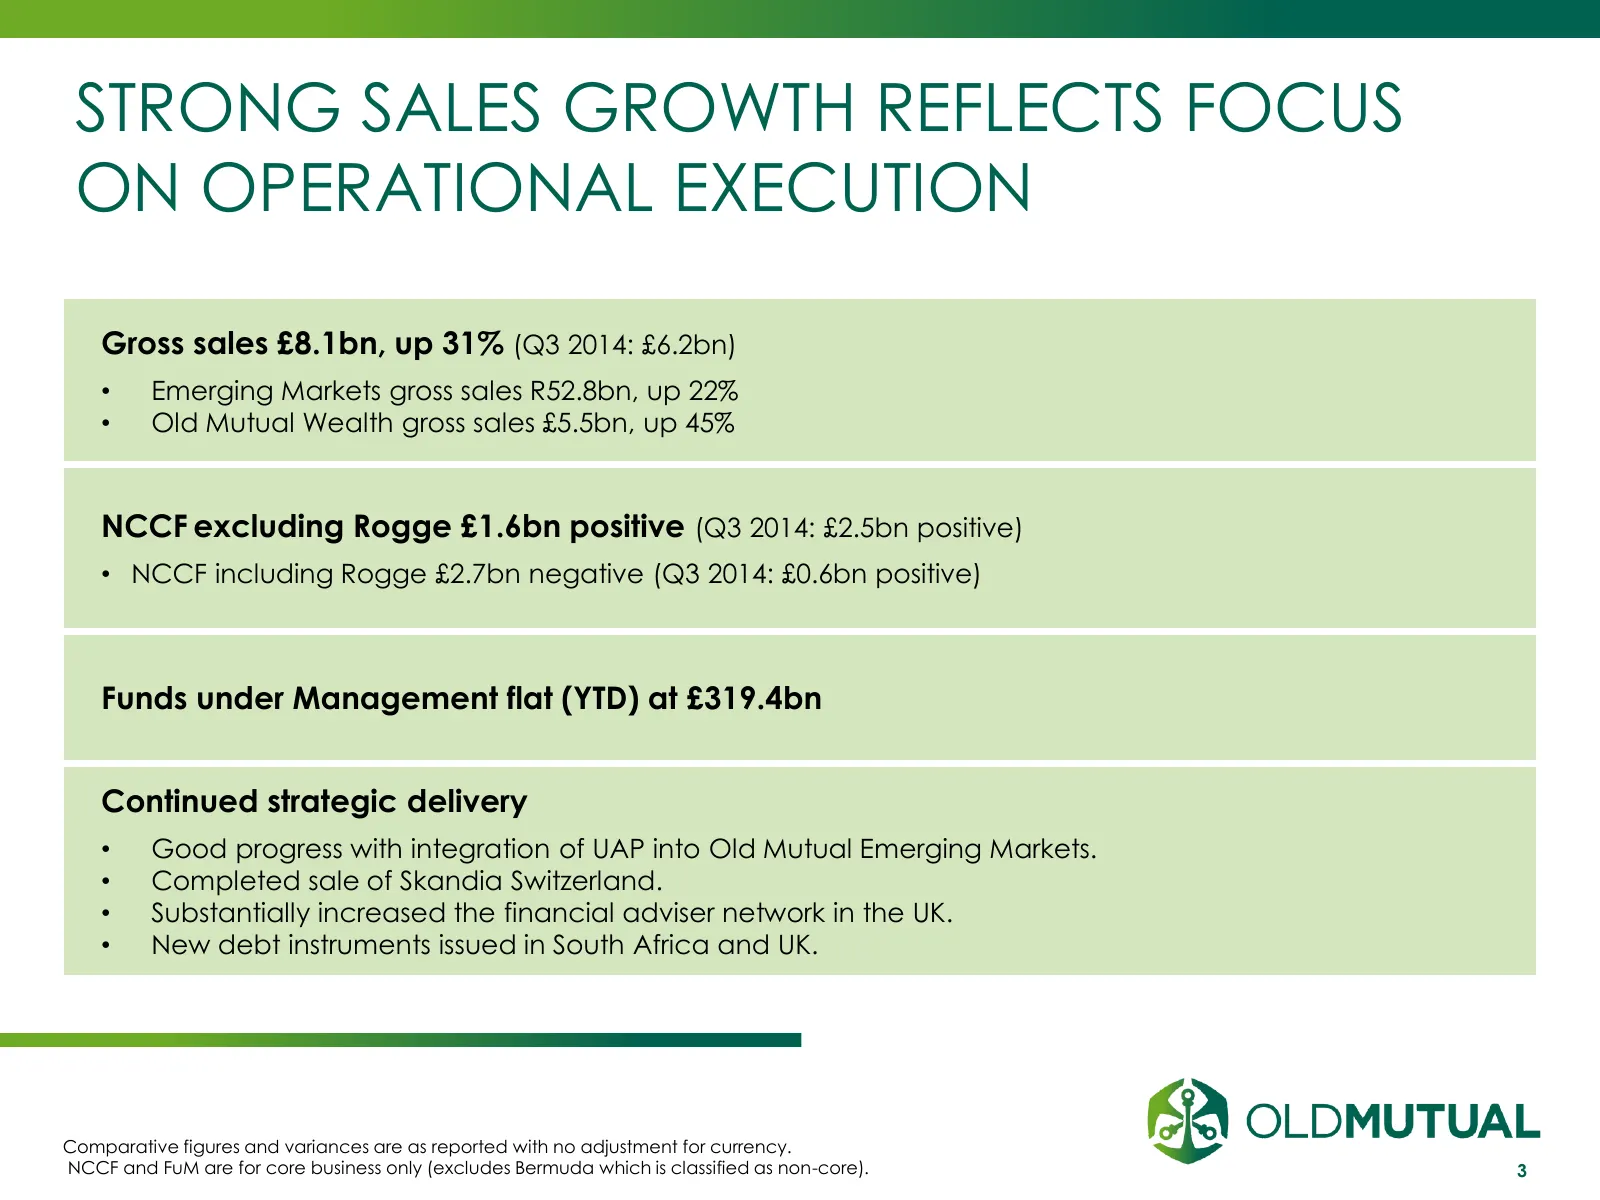
STRONG SALES GROWTH REFLECTS FOCUS ON OPERATIONAL EXECUTION Gross sales £8.1bn, up 31% (Q3 2014: £6.2bn) • Emerging Markets gross sales R52.8bn, up 22% • Old Mutual Wealth gross sales £5.5bn, up 45% NCCF excluding Rogge £1.6bn positive (Q3 2014: £2.5bn positive) • NCCF including Rogge £2.7bn negativ
Slide 4: Group overview: Sales & NCCF
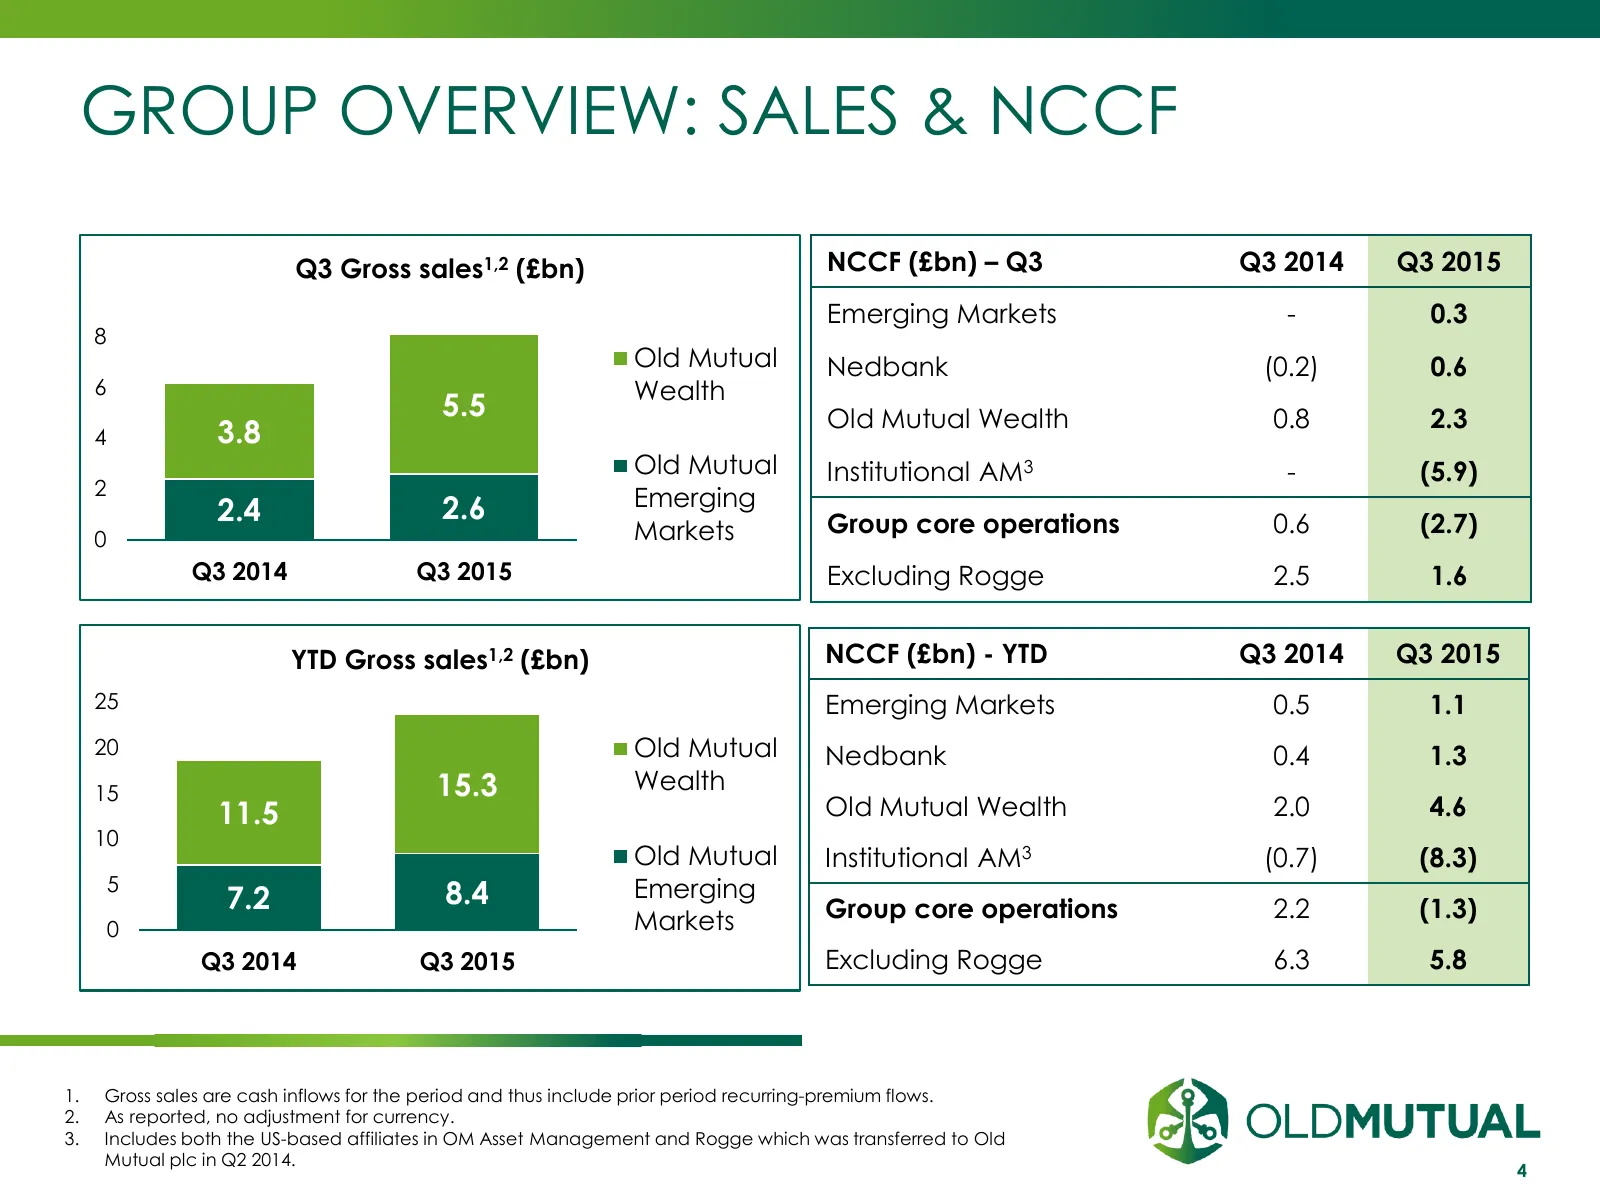
GROUP OVERVIEW: SALES & NCCF Q3 Gross sales1,2 (£bn) NCCF (£bn) – Q3 Q3 2014 Q3 2015 Emerging Markets - 0.3 8 Old Mutual Nedbank (0.2) 0.6 6 Wealth 5.5 Old Mutual Wealth 0.8 2.3 4 3.8 Old Mutual Institutional AM3 - (5.9) 2 2.6 Emerging 2.4 Group core operations 0.6 (2.7) 0 Markets Q3 2014 Q3 2015 Ex
Slide 5: Group overview: FuM
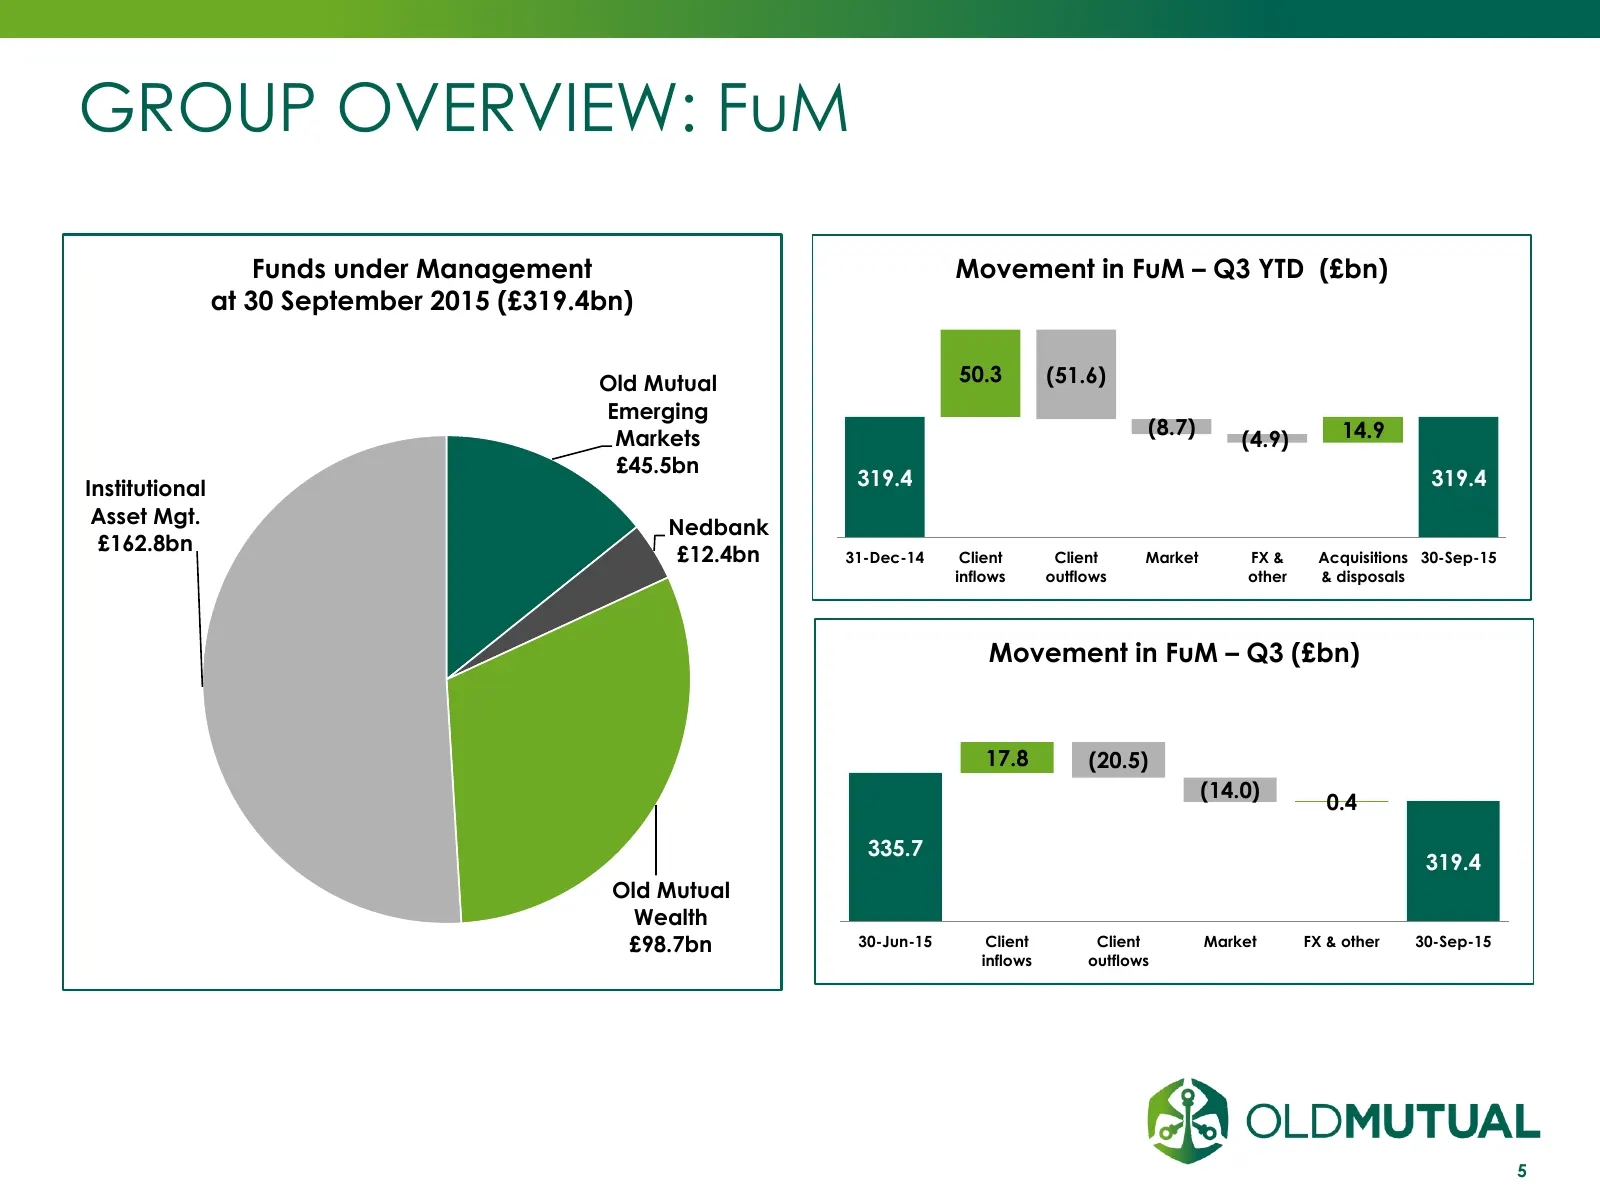
GROUP OVERVIEW: FuM Funds under Management Movement in FuM – Q3 YTD (£bn) at 30 September 2015 (£319.4bn) Old Mutual 50.3 (51.6) Emerging Markets (8.7) 14.9 (4.9) £45.5bn Institutional 319.4 319.4 Asset Mgt. Nedbank £162.8bn £12.4bn 31-Dec-14 Client Client Market FX & Acquisitions 30-Sep-15 inflows
Slide 6: Old Mutual Emerging Markets
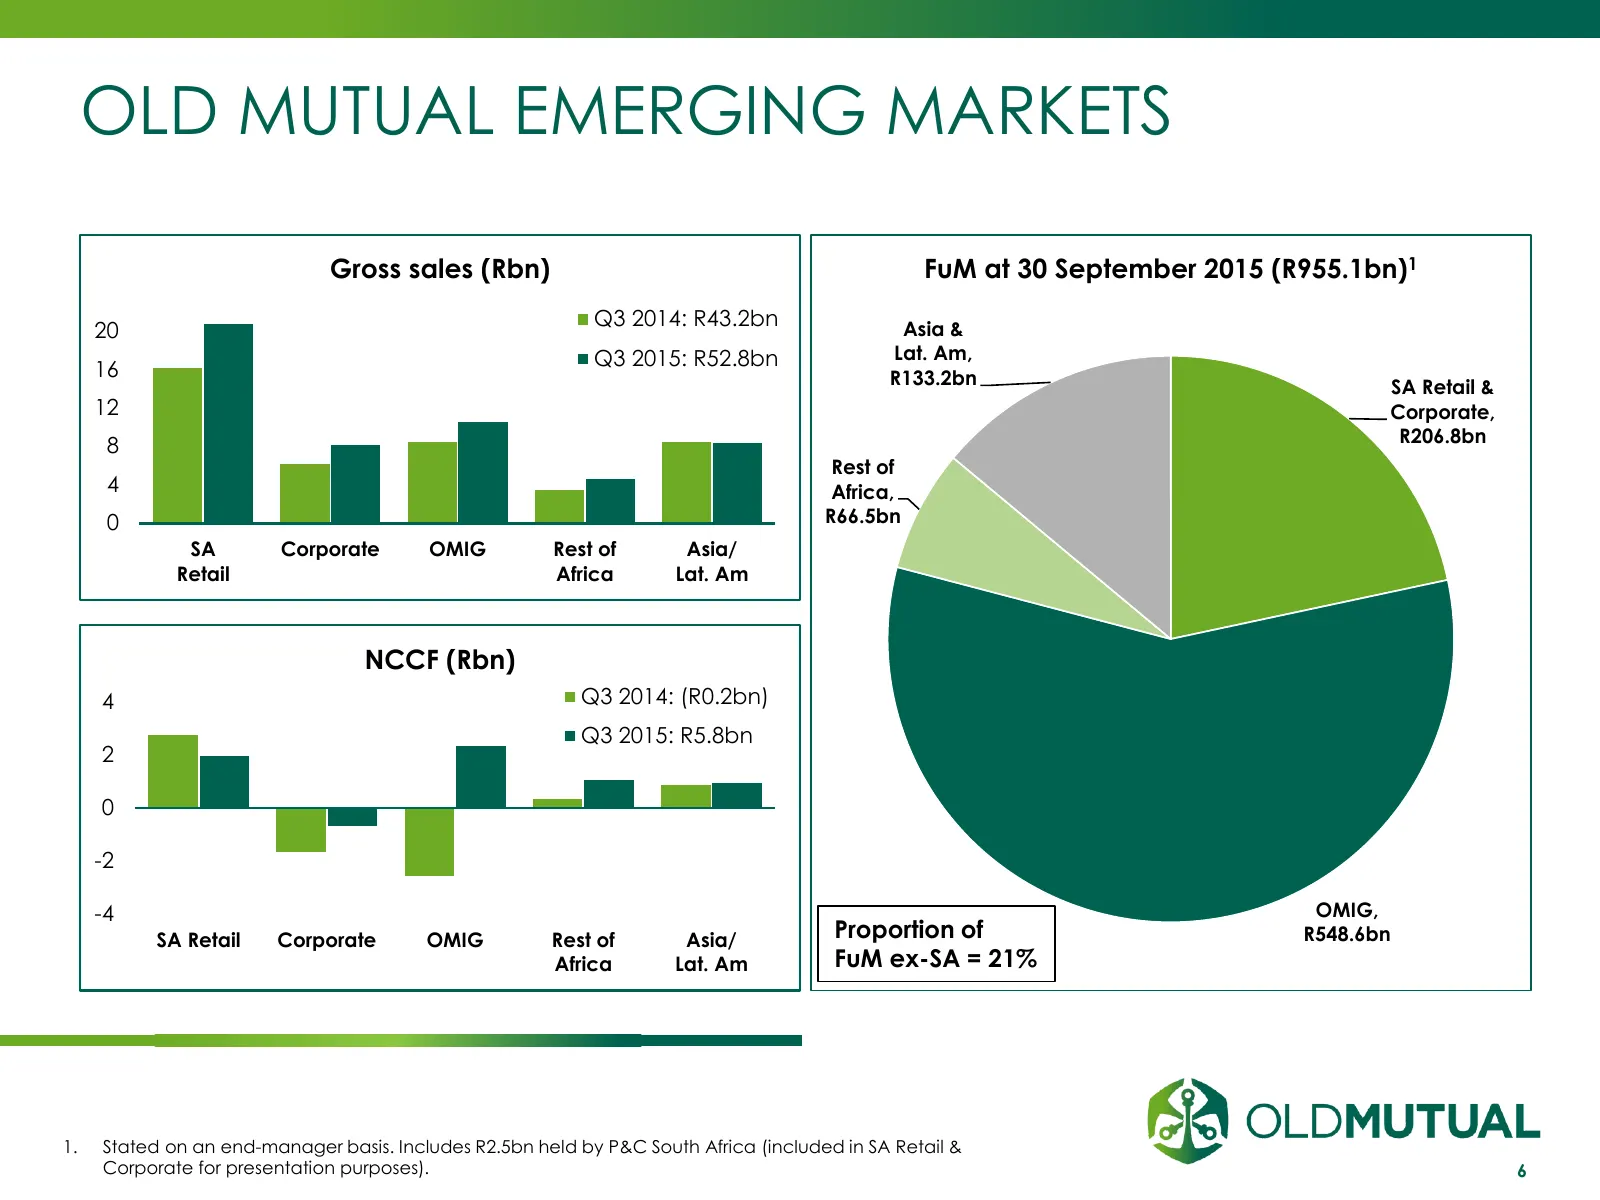
OLD MUTUAL EMERGING MARKETS Gross sales (Rbn) FuM at 30 September 2015 (R955.1bn)1 Q3 2014: R43.2bn Asia & 20 Q3 2015: R52.8bn Lat. Am, 16 R133.2bn SA Retail & 12 Corporate, R206.8bn 8 Rest of 4 Africa, 0 R66.5bn SA Corporate OMIG Rest of Asia/ Retail Africa Lat. Am NCCF (Rbn) 4 Q3 2014: (R0.2bn) Q3
Slide 7: Emerging Markets
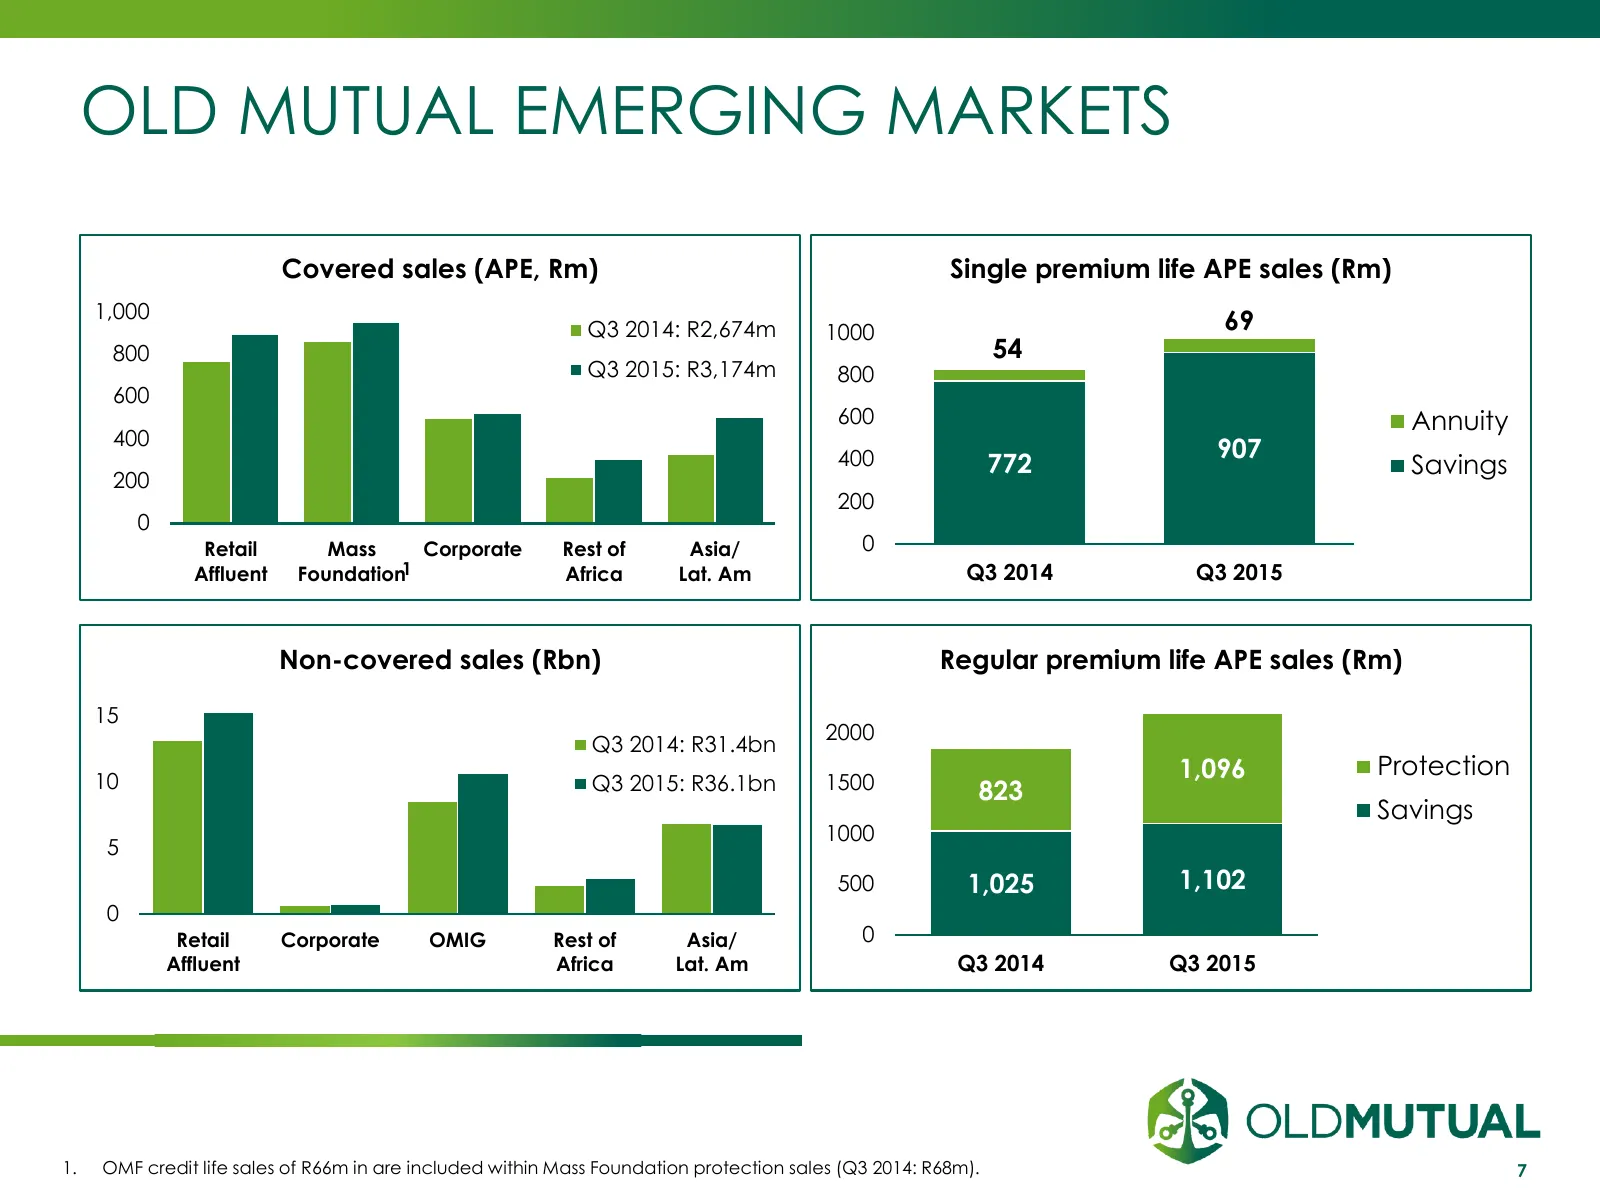
OLD MUTUAL EMERGING MARKETS Covered sales (APE, Rm) Single premium life APE sales (Rm) 1,000 Q3 2014: R2,674m 1000 69 800 54 Q3 2015: R3,174m 800 600 600 Annuity 400 400 907 772 Savings 200 200 0 Retail Mass Corporate Rest of Asia/ 0 Affluent Foundation1 Africa Lat. Am Q3 2014 Q3 2015 Non-covered sa
Slide 8: Nedbank
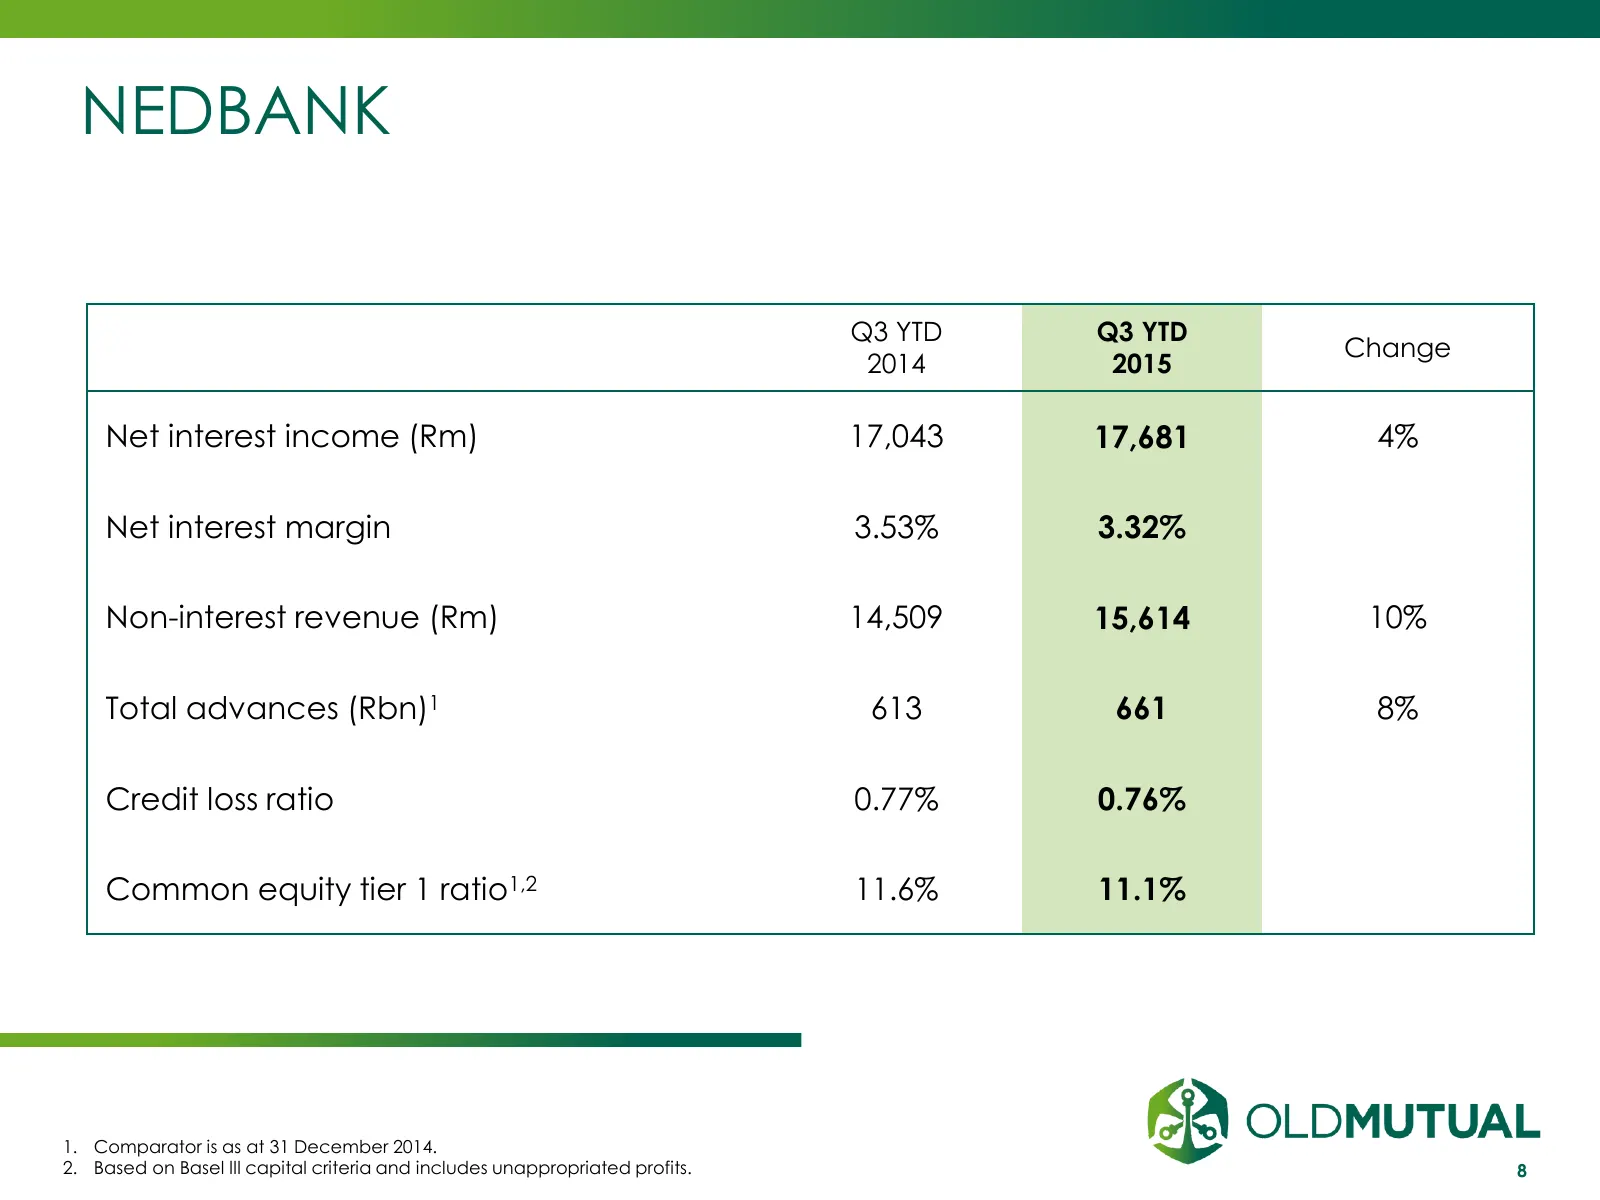
NEDBANK Q3 YTD Q3 YTD Change 2014 2015 Net interest income (Rm) 17,043 17,681 4% Net interest margin 3.53% 3.32% Non-interest revenue (Rm) 14,509 15,614 10% Total advances (Rbn)1 613 661 8% Credit loss ratio 0.77% 0.76% Common equity tier 1 ratio1,2 11.6% 11.1% 1. Comparator is as at 31 December 201
Slide 9: Old Mutual Wealth
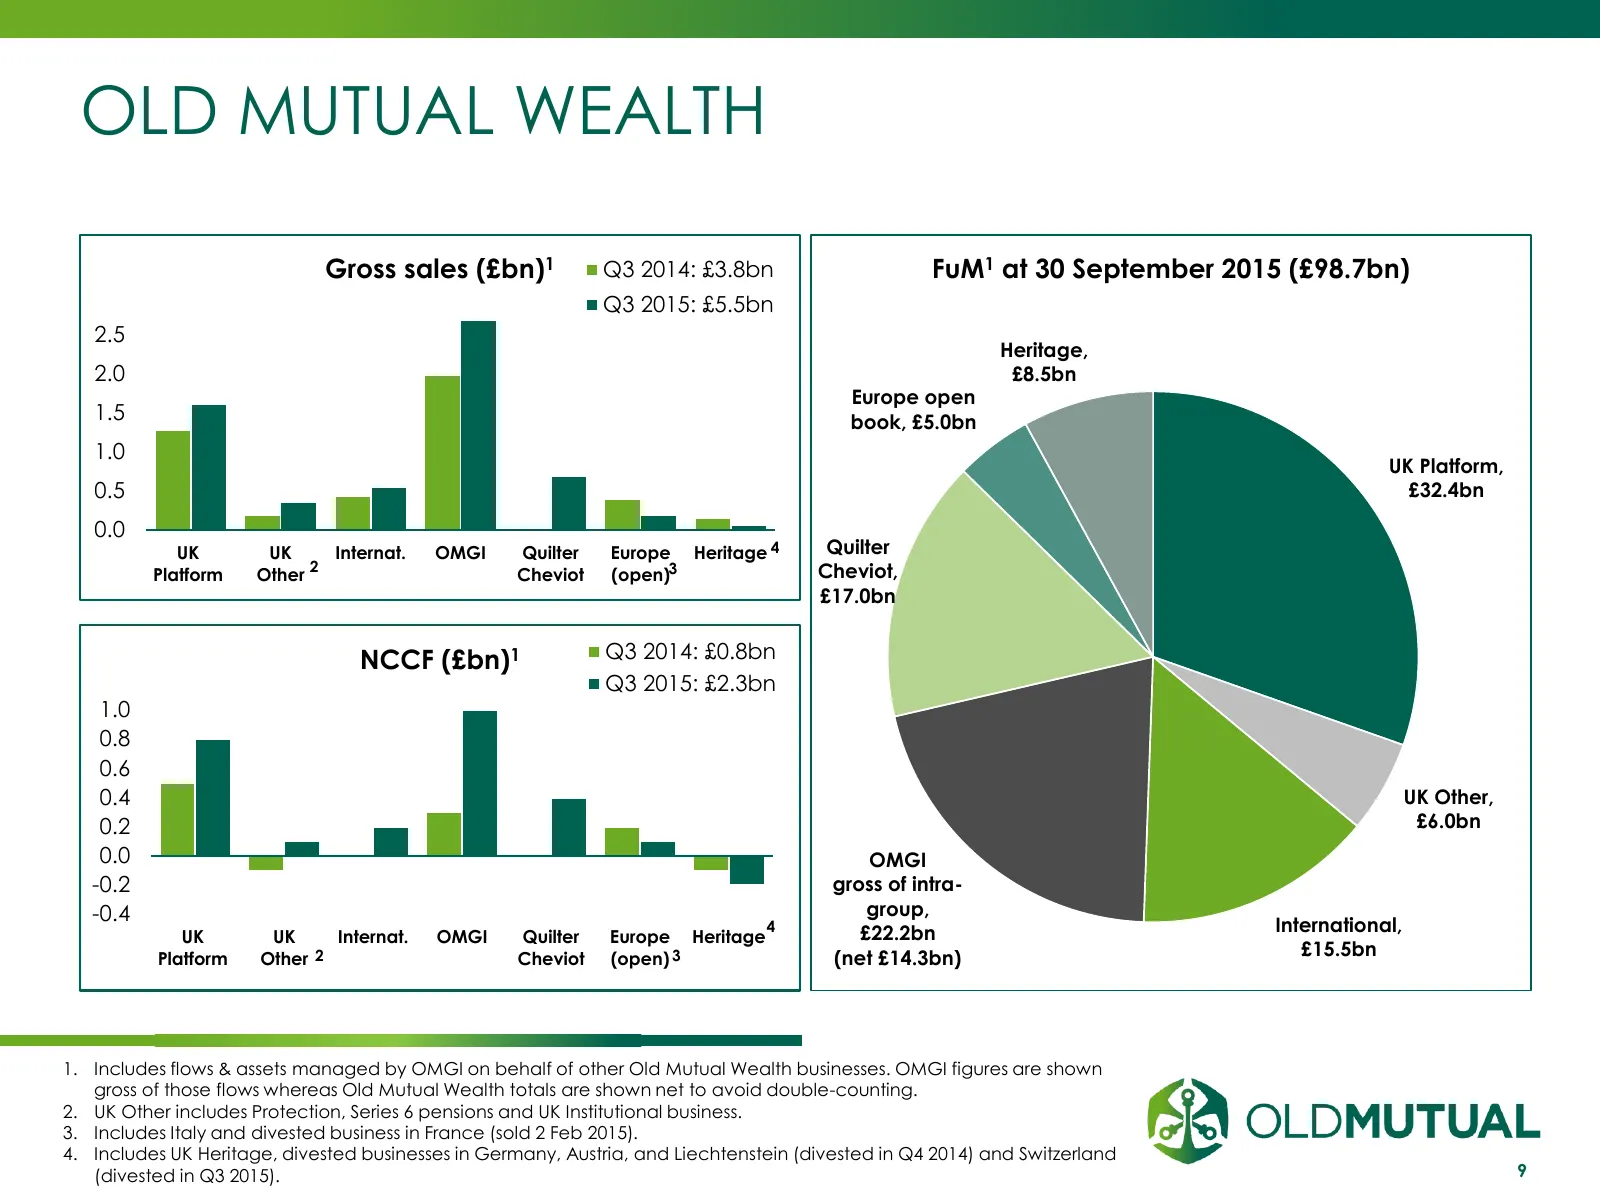
OLD MUTUAL WEALTH Gross sales (£bn)1 Q3 2014: £3.8bn FuM1 at 30 September 2015 (£98.7bn) Q3 2015: £5.5bn 2.5 Heritage, 2.0 £8.5bn Europe open 1.5 book, £5.0bn 1.0 UK Platform, 0.5 £32.4bn 0.0 UK UK Internat. OMGI Quilter Europe Heritage 4 Quilter Platform Other 2 Cheviot (open)3 Cheviot, £17.0bn NCC
Slide 10: Institutional Asset Management
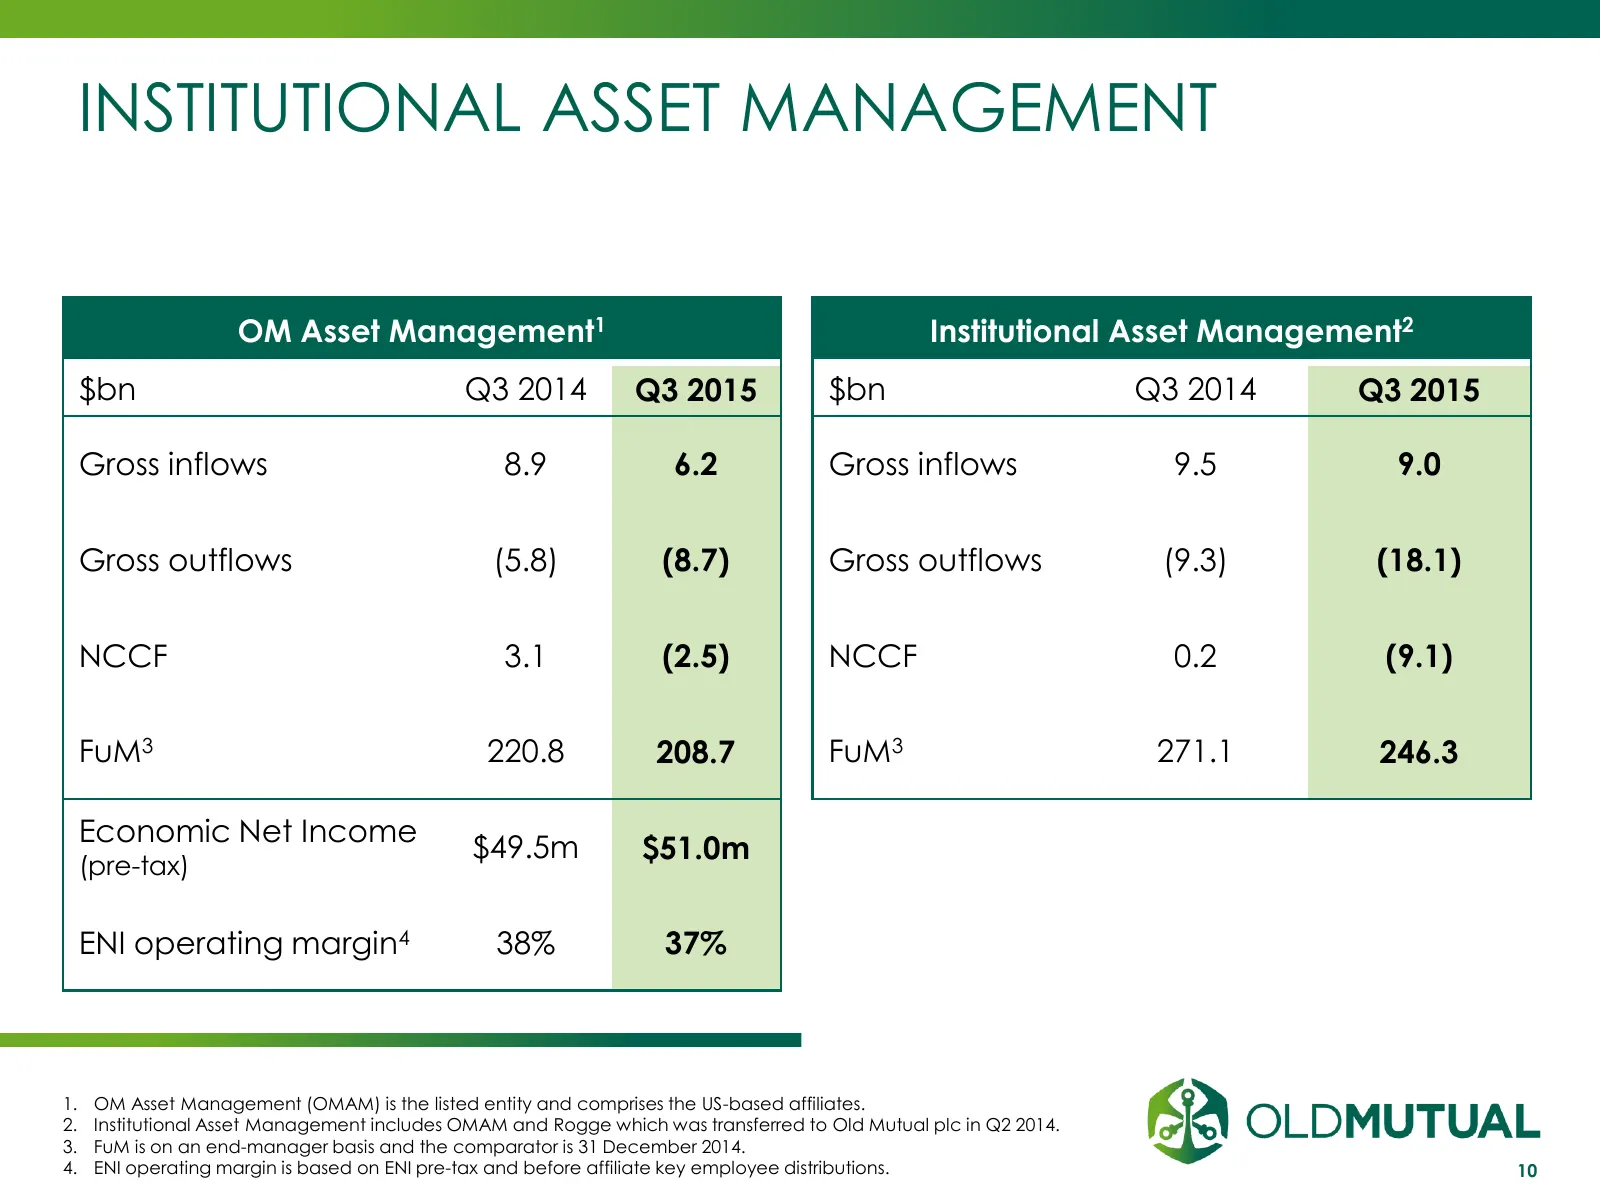
INSTITUTIONAL ASSET MANAGEMENT OM Asset Management1 Institutional Asset Management2 $bn Q3 2014 Q3 2015 $bn Q3 2014 Q3 2015 Gross inflows 8.9 6.2 Gross inflows 9.5 9.0 Gross outflows (5.8) (8.7) Gross outflows (9.3) (18.1) NCCF 3.1 (2.5) NCCF 0.2 (9.1) FuM3 220.8 208.7 FuM3 271.1 246.3 Economic Net
Slide 11: Our strategy for growth
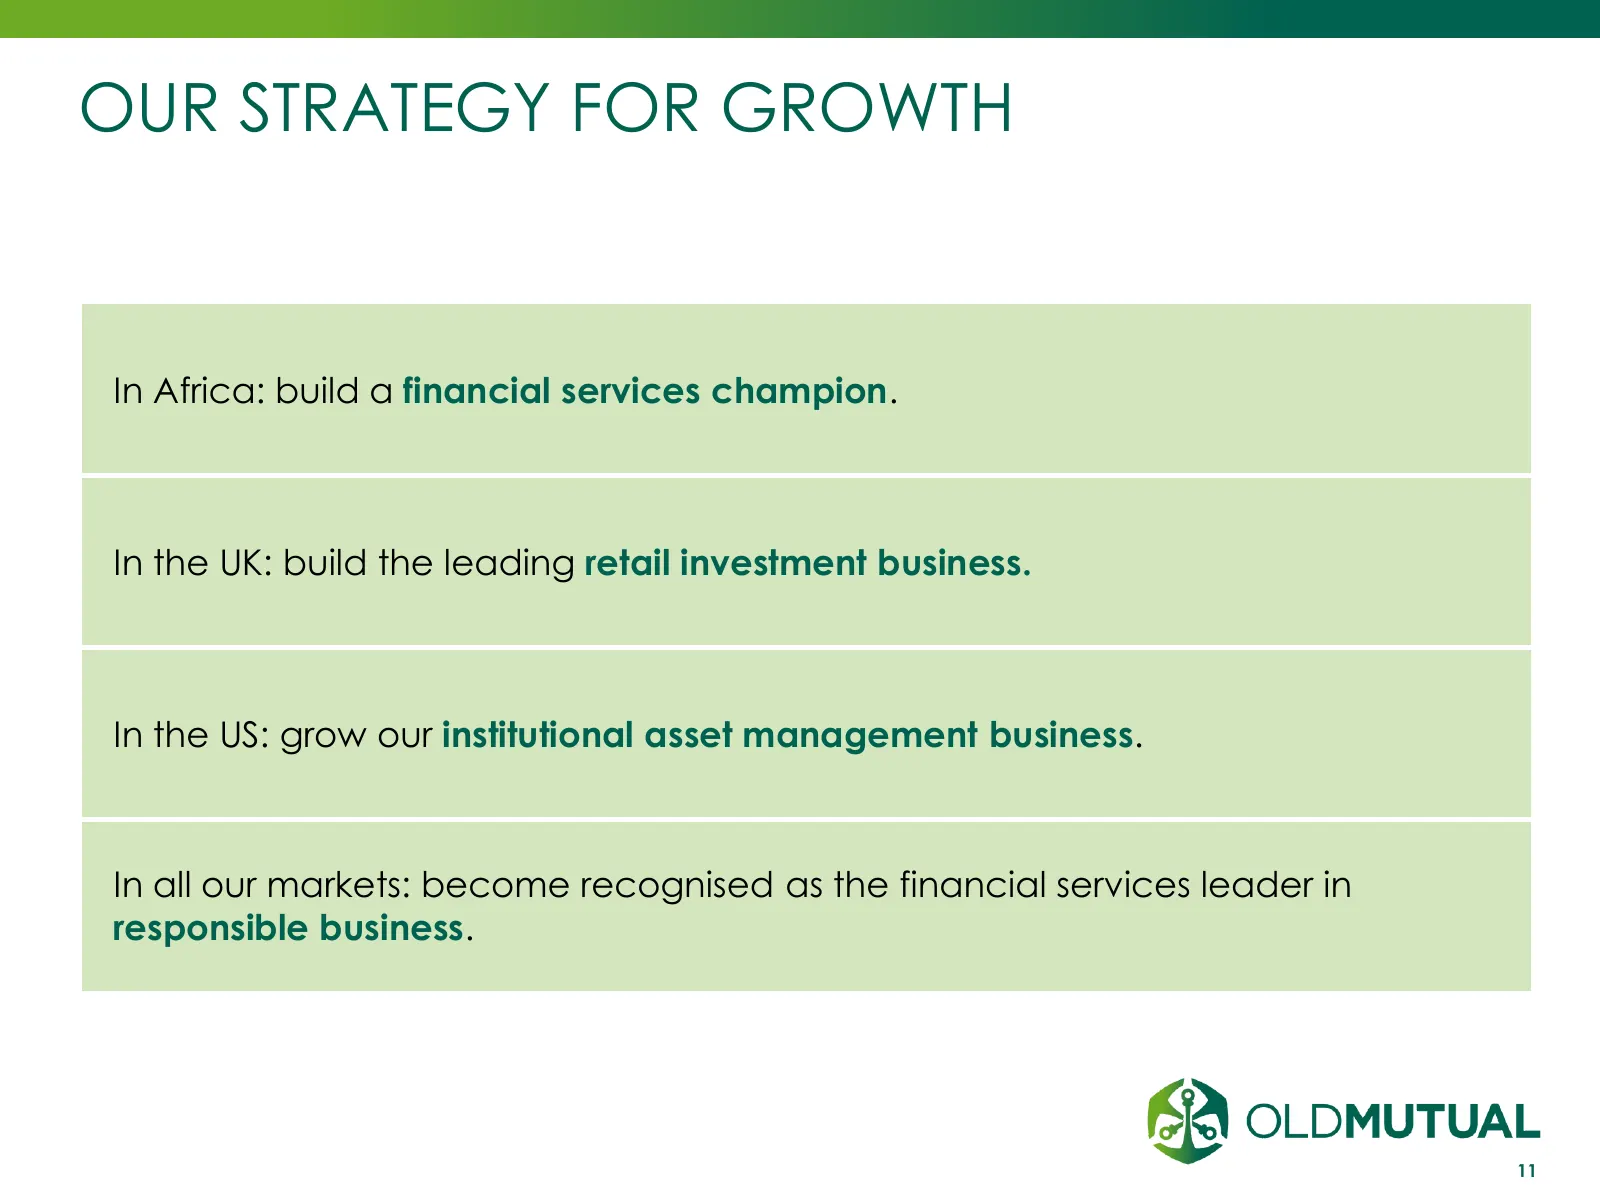
OUR STRATEGY FOR GROWTH In Africa: build a financial services champion. In the UK: build the leading retail investment business. In the US: grow our institutional asset management business. In all our markets: become recognised as the financial services leader in responsible business. 11
Slide 12: Appendix
APPENDIX INVESTMENT | SAVINGS | INSURANCE | BANKING
Slide 13: Macro environment
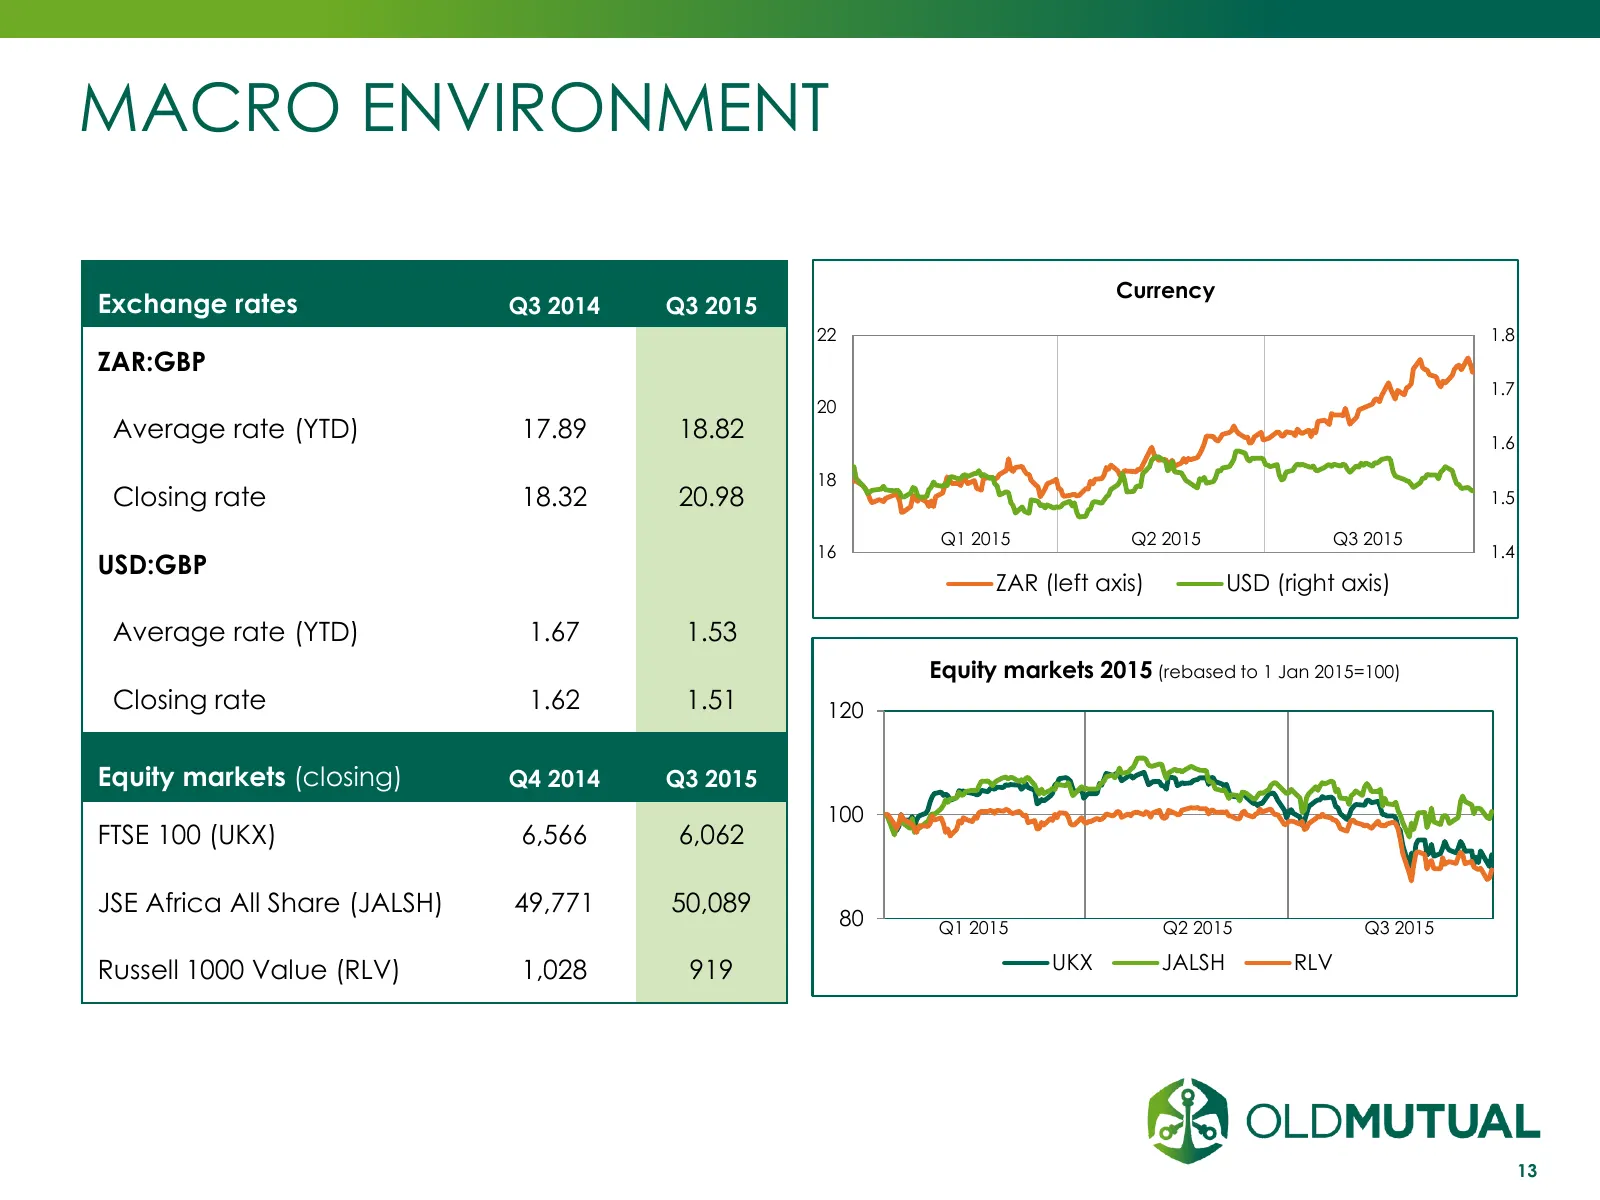
MACRO ENVIRONMENT Currency Exchange rates Q3 2014 Q3 2015 22 1.8 ZAR:GBP 1.7 20 Average rate (YTD) 17.89 18.82 1.6 18 Closing rate 18.32 20.98 1.5 Q1 2015 Q2 2015 Q3 2015 16 1.4 USD:GBP ZAR (left axis) USD (right axis) Average rate (YTD) 1.67 1.53 Equity markets 2015 (rebased to 1 Jan 2015=100) Clos
Slide 14: Emerging Markets: Retail Affluent
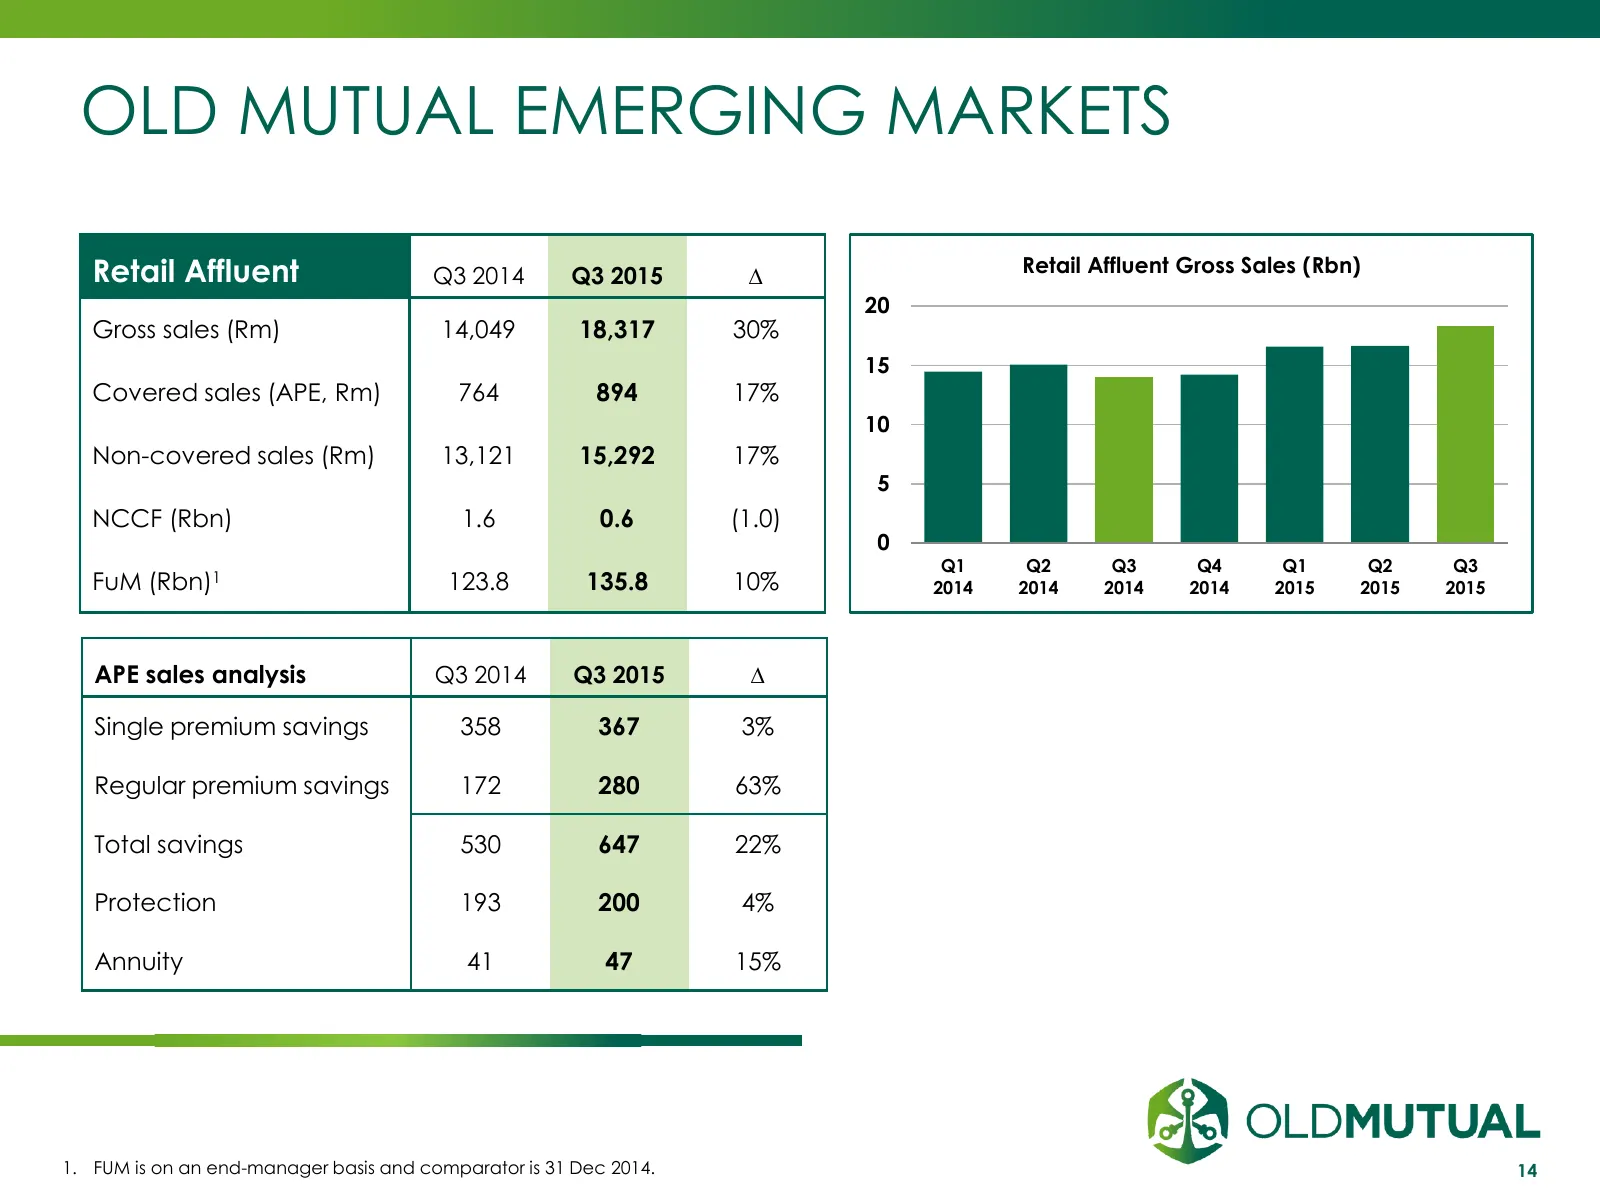
OLD MUTUAL EMERGING MARKETS Retail Affluent Q3 2014 Q3 2015 ∆ Retail Affluent Gross Sales (Rbn) 20 Gross sales (Rm) 14,049 18,317 30% 15 Covered sales (APE, Rm) 764 894 17% 10 Non-covered sales (Rm) 13,121 15,292 17% 5 NCCF (Rbn) 1.6 0.6 (1.0) 0 Q1 Q2 Q3 Q4 Q1 Q2 Q3 FuM (Rbn)1 123.8 135.8 10% 2014 2
Slide 15: Emerging Markets: Mass Foundation
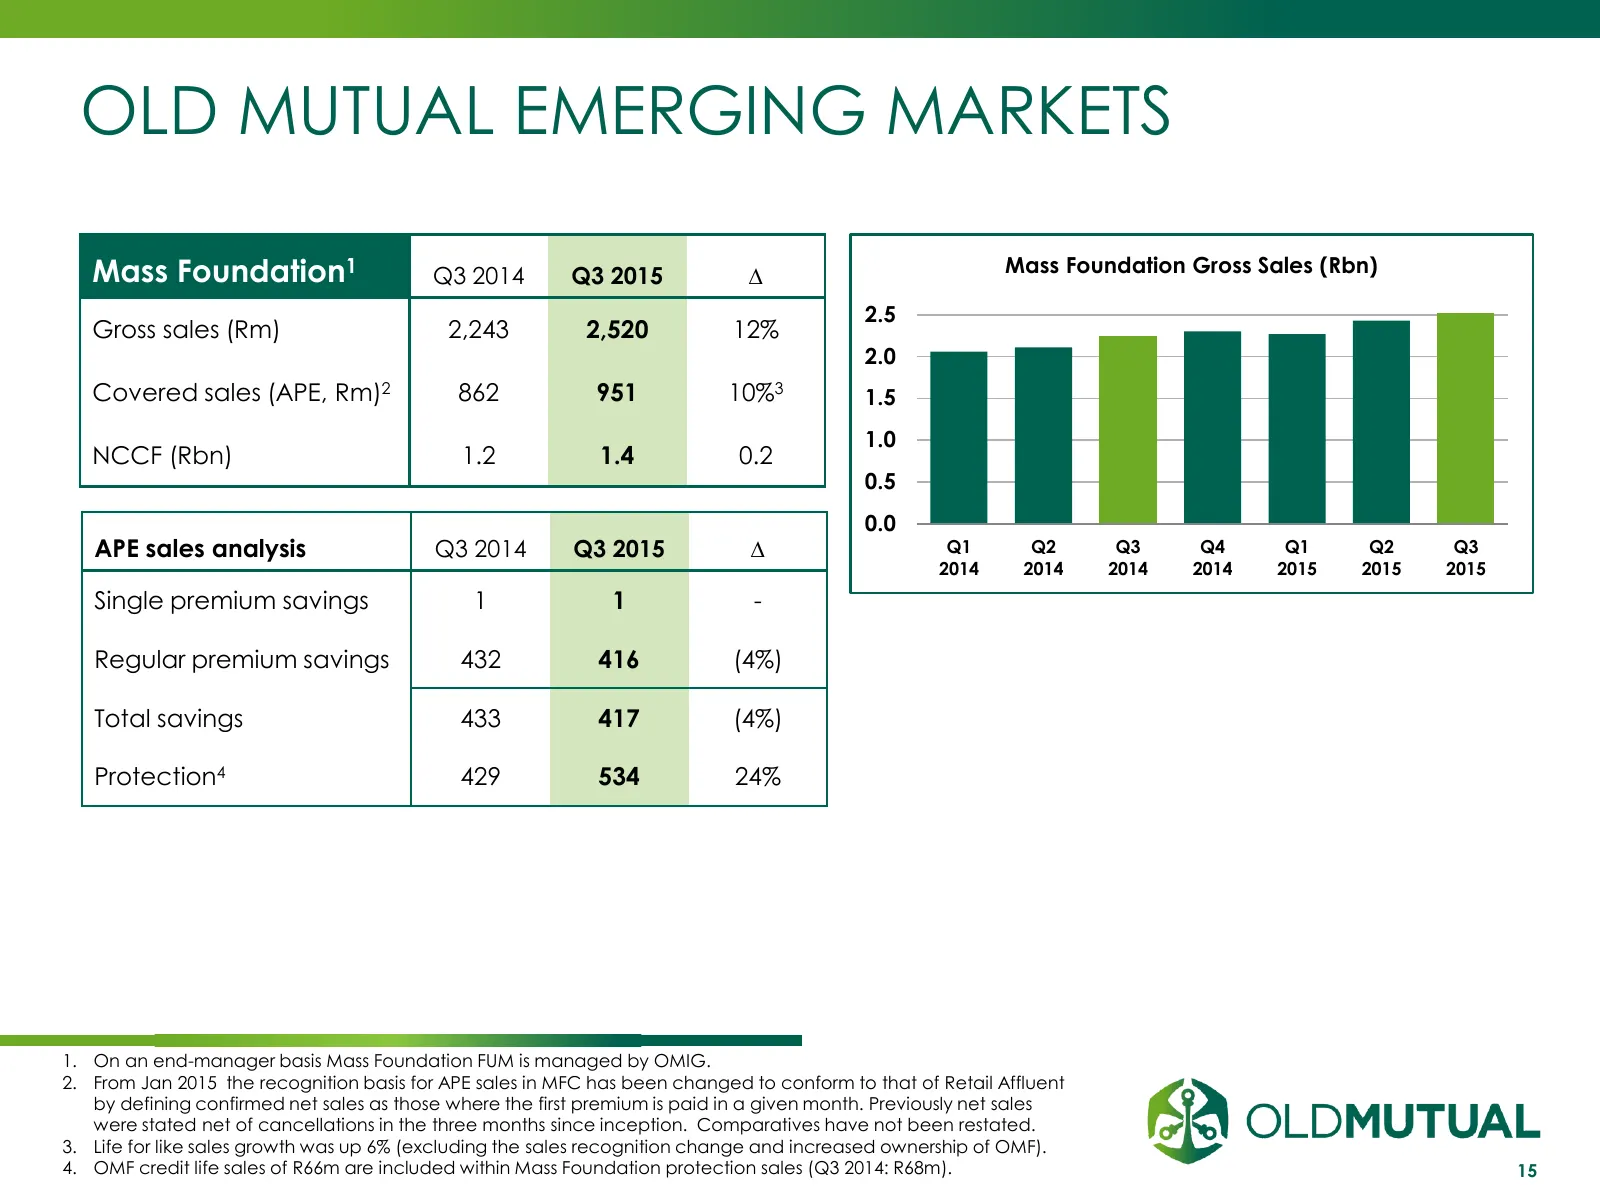
OLD MUTUAL EMERGING MARKETS Mass Foundation1 Q3 2014 Q3 2015 ∆ Mass Foundation Gross Sales (Rbn) 2.5 Gross sales (Rm) 2,243 2,520 12% 2.0 Covered sales (APE, Rm)2 862 951 10%3 1.5 1.0 NCCF (Rbn) 1.2 1.4 0.2 0.5 0.0 APE sales analysis Q3 2014 Q3 2015 ∆ Q1 Q2 Q3 Q4 Q1 Q2 Q3 2014 2014 2014 2014 2015 20
Slide 16: Emerging Markets: Corporate and OMIG
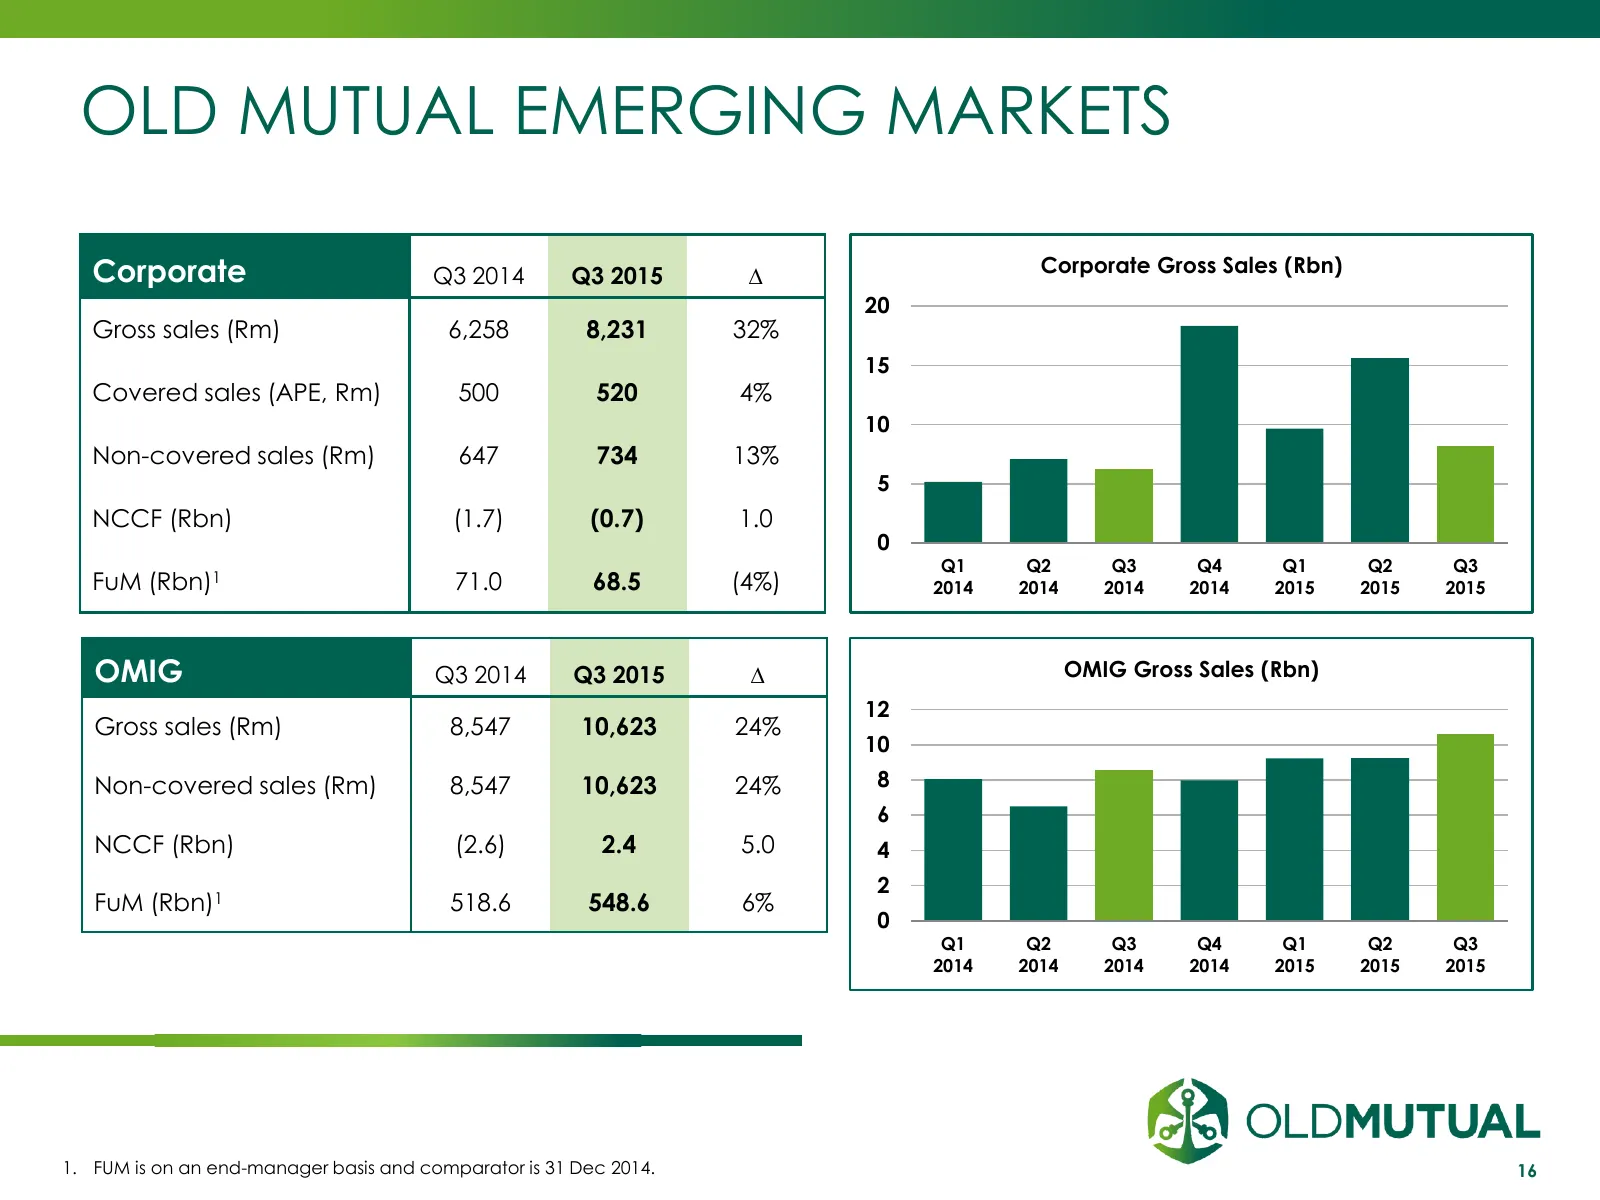
OLD MUTUAL EMERGING MARKETS Corporate Q3 2014 Q3 2015 ∆ Corporate Gross Sales (Rbn) 20 Gross sales (Rm) 6,258 8,231 32% 15 Covered sales (APE, Rm) 500 520 4% 10 Non-covered sales (Rm) 647 734 13% 5 NCCF (Rbn) (1.7) (0.7) 1.0 0 Q1 Q2 Q3 Q4 Q1 Q2 Q3 FuM (Rbn)1 71.0 68.5 (4%) 2014 2014 2014 2014 2015 2
Slide 17: Emerging Markets: Rest of Africa, Asia & Latin America
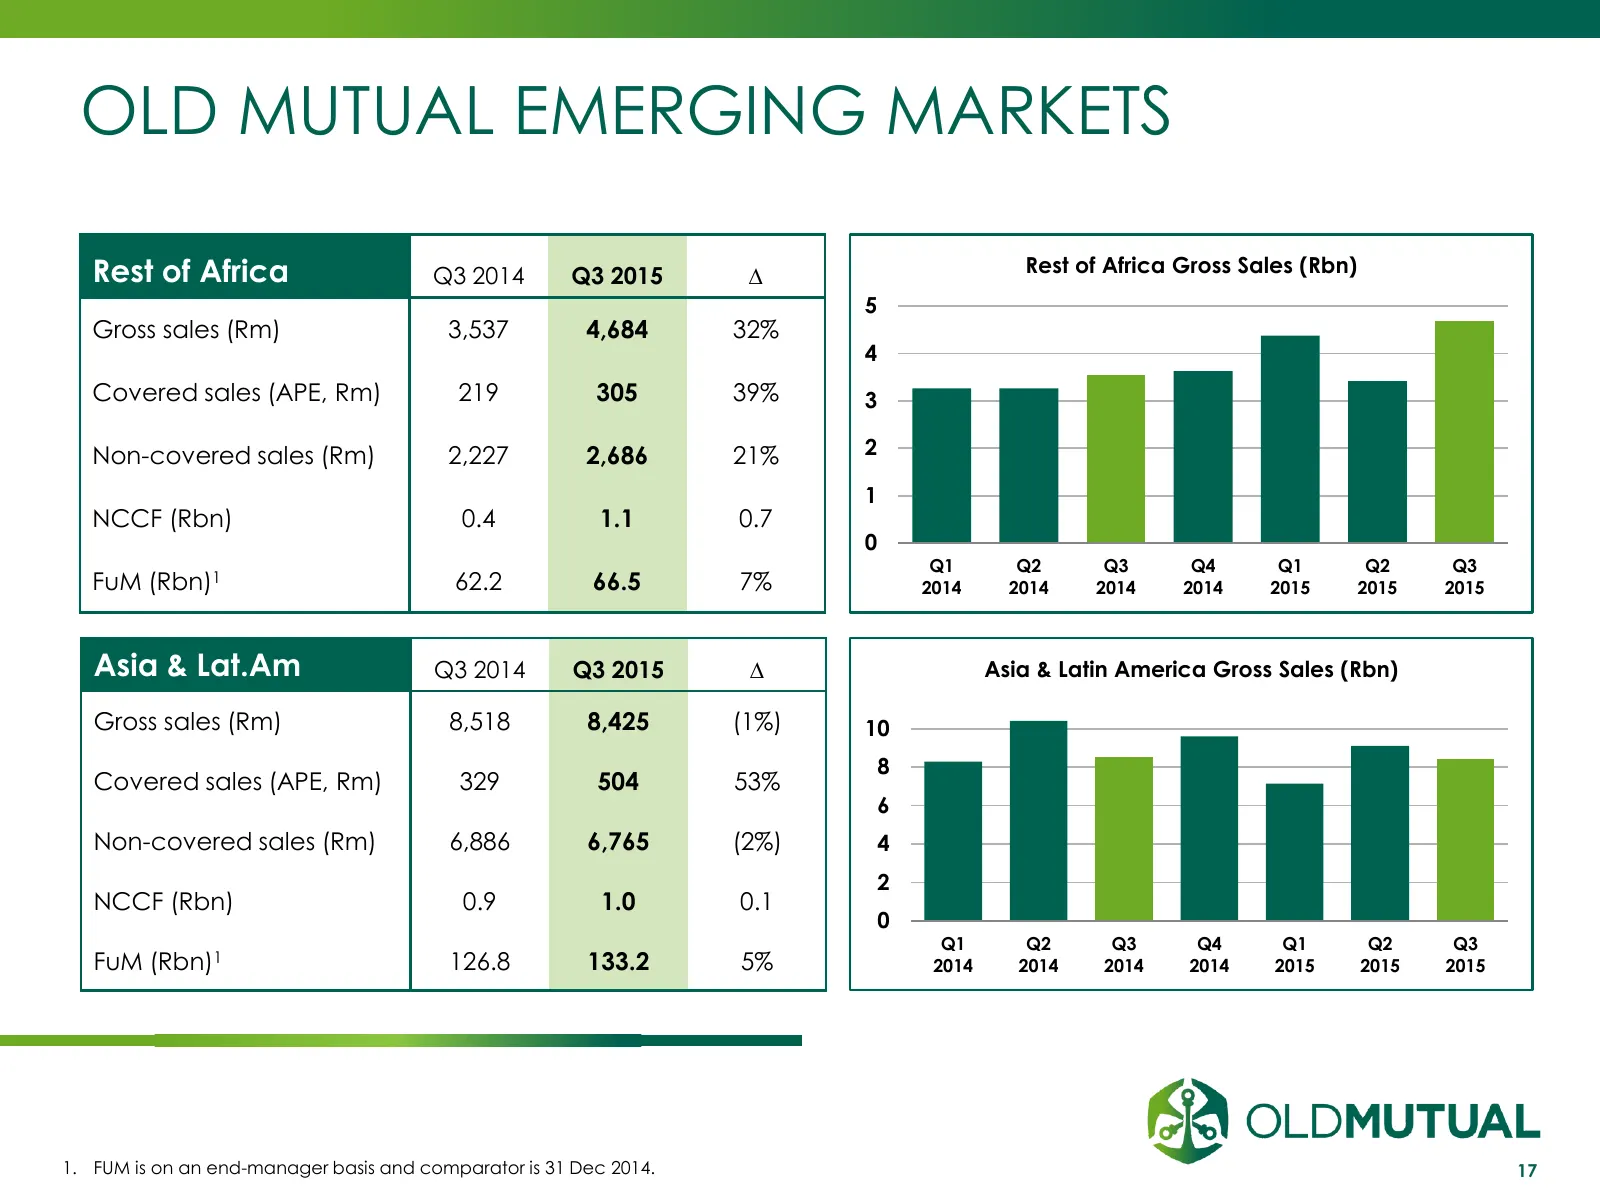
OLD MUTUAL EMERGING MARKETS Rest of Africa Q3 2014 Q3 2015 ∆ Rest of Africa Gross Sales (Rbn) 5 Gross sales (Rm) 3,537 4,684 32% 4 Covered sales (APE, Rm) 219 305 39% 3 Non-covered sales (Rm) 2,227 2,686 21% 2 1 NCCF (Rbn) 0.4 1.1 0.7 0 Q1 Q2 Q3 Q4 Q1 Q2 Q3 FuM (Rbn)1 62.2 66.5 7% 2014 2014 2014 201
Slide 18: Wealth: UK Platform and OMGI
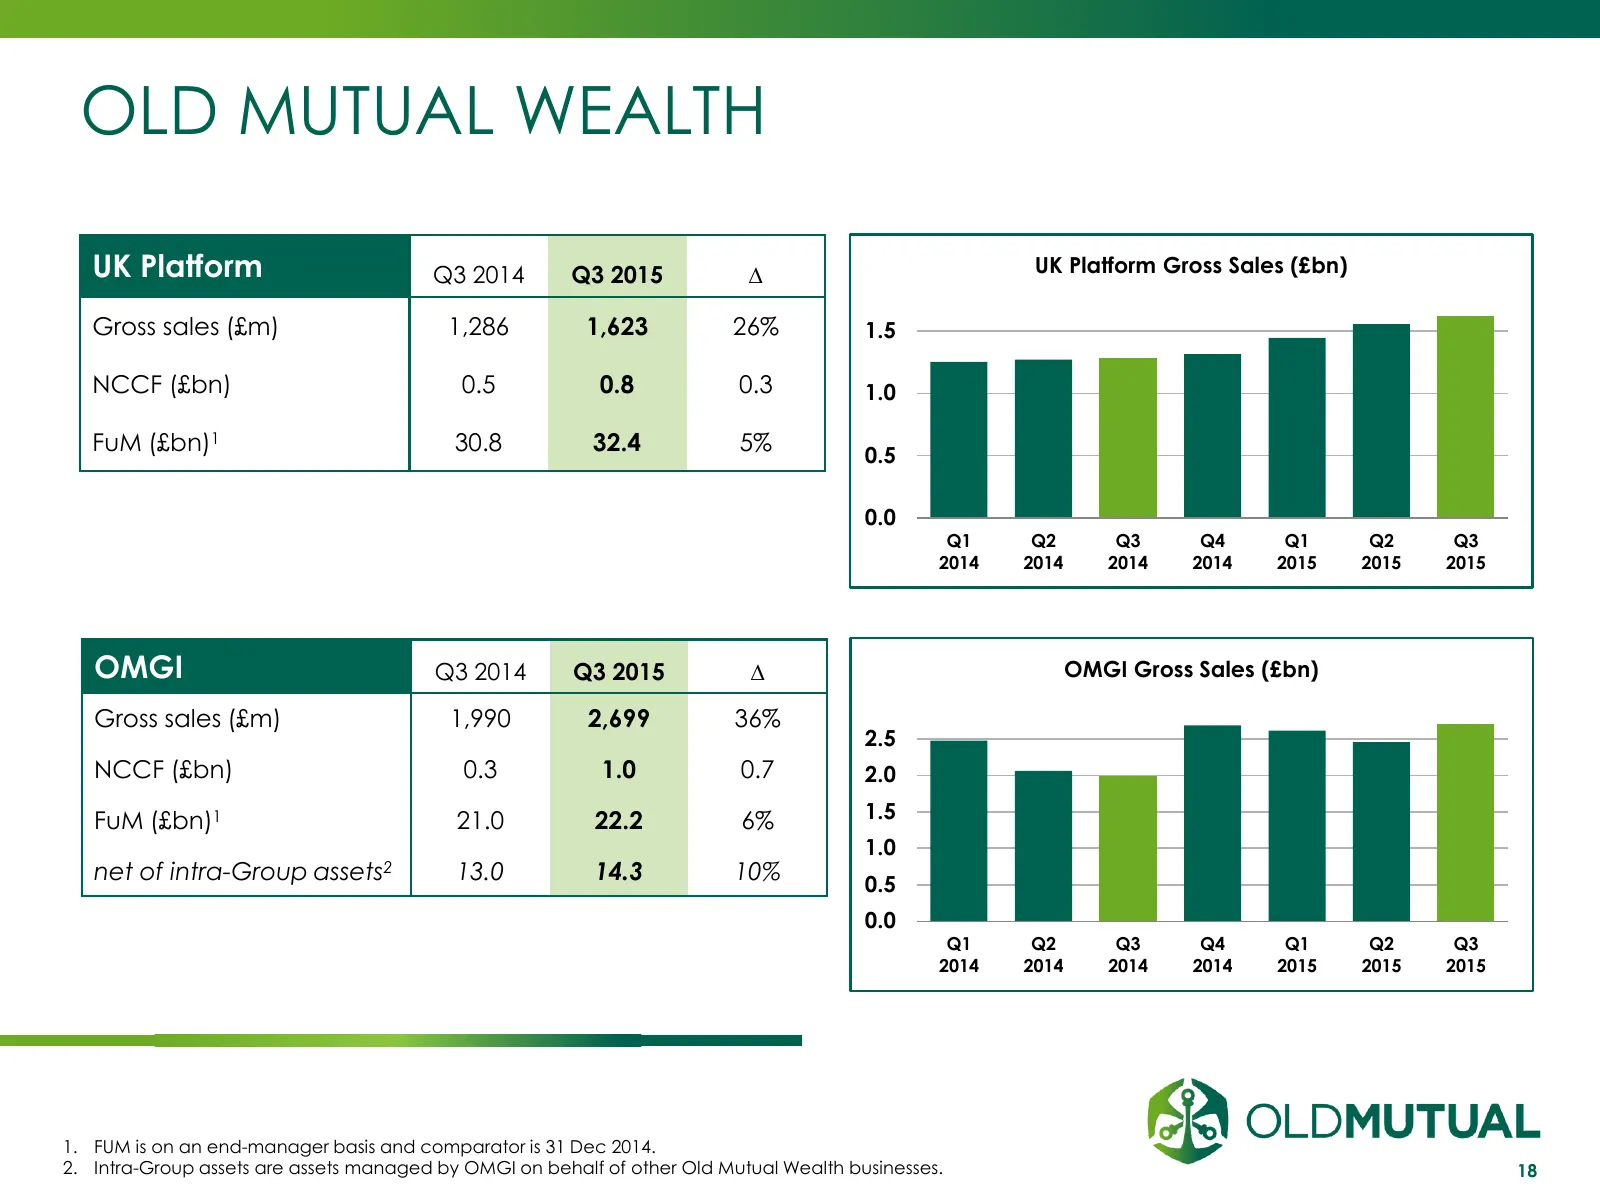
OLD MUTUAL WEALTH UK Platform Q3 2014 Q3 2015 ∆ UK Platform Gross Sales (£bn) Gross sales (£m) 1,286 1,623 26% 1.5 NCCF (£bn) 0.5 0.8 0.3 1.0 FuM (£bn)1 30.8 32.4 5% 0.5 0.0 Q1 Q2 Q3 Q4 Q1 Q2 Q3 2014 2014 2014 2014 2015 2015 2015 OMGI Q3 2014 Q3 2015 ∆ OMGI Gross Sales (£bn) Gross sales (£m) 1,990 2
Slide 19: Wealth: International and other businesses
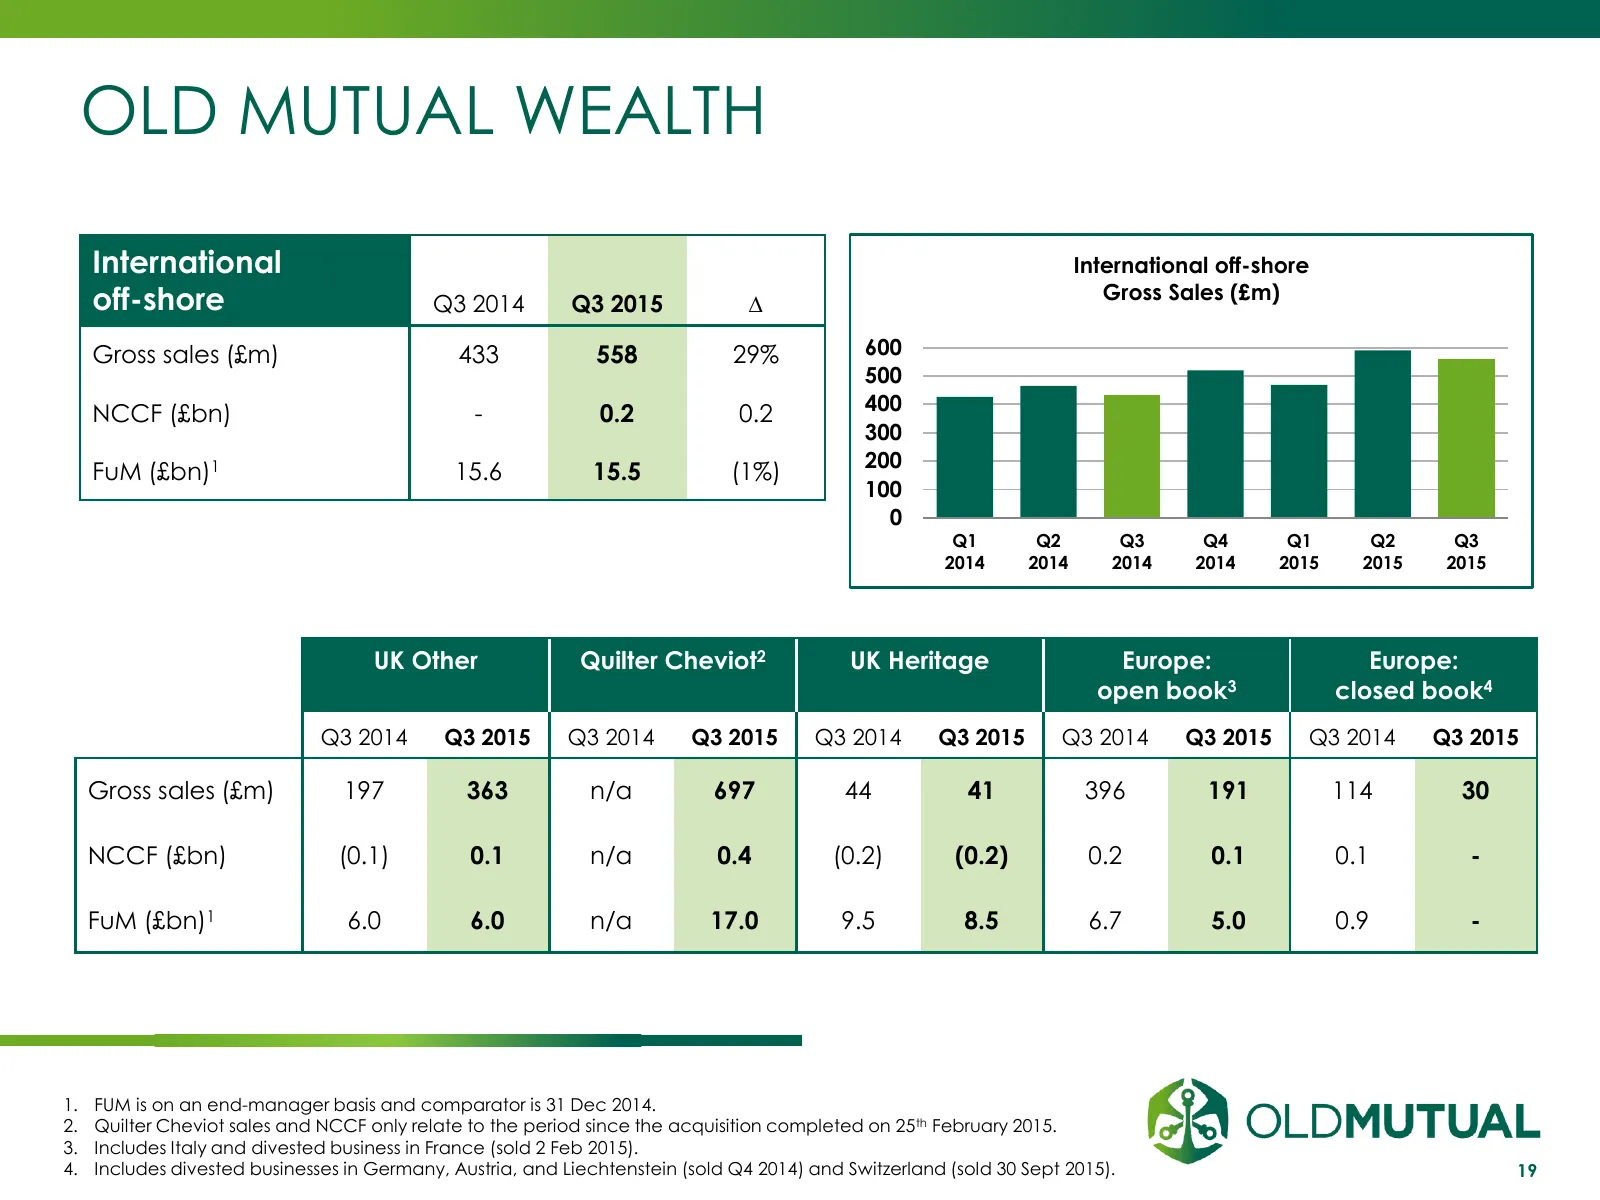
OLD MUTUAL WEALTH International International off-shore off-shore Gross Sales (£m) Q3 2014 Q3 2015 ∆ Gross sales (£m) 433 558 29% 600 500 NCCF (£bn) - 0.2 0.2 400 300 200 FuM (£bn)1 15.6 15.5 (1%) 100 0 Q1 Q2 Q3 Q4 Q1 Q2 Q3 2014 2014 2014 2014 2015 2015 2015 UK Other Quilter Cheviot2 UK Heritage Eur
Slide 20: Fund profile by investment type
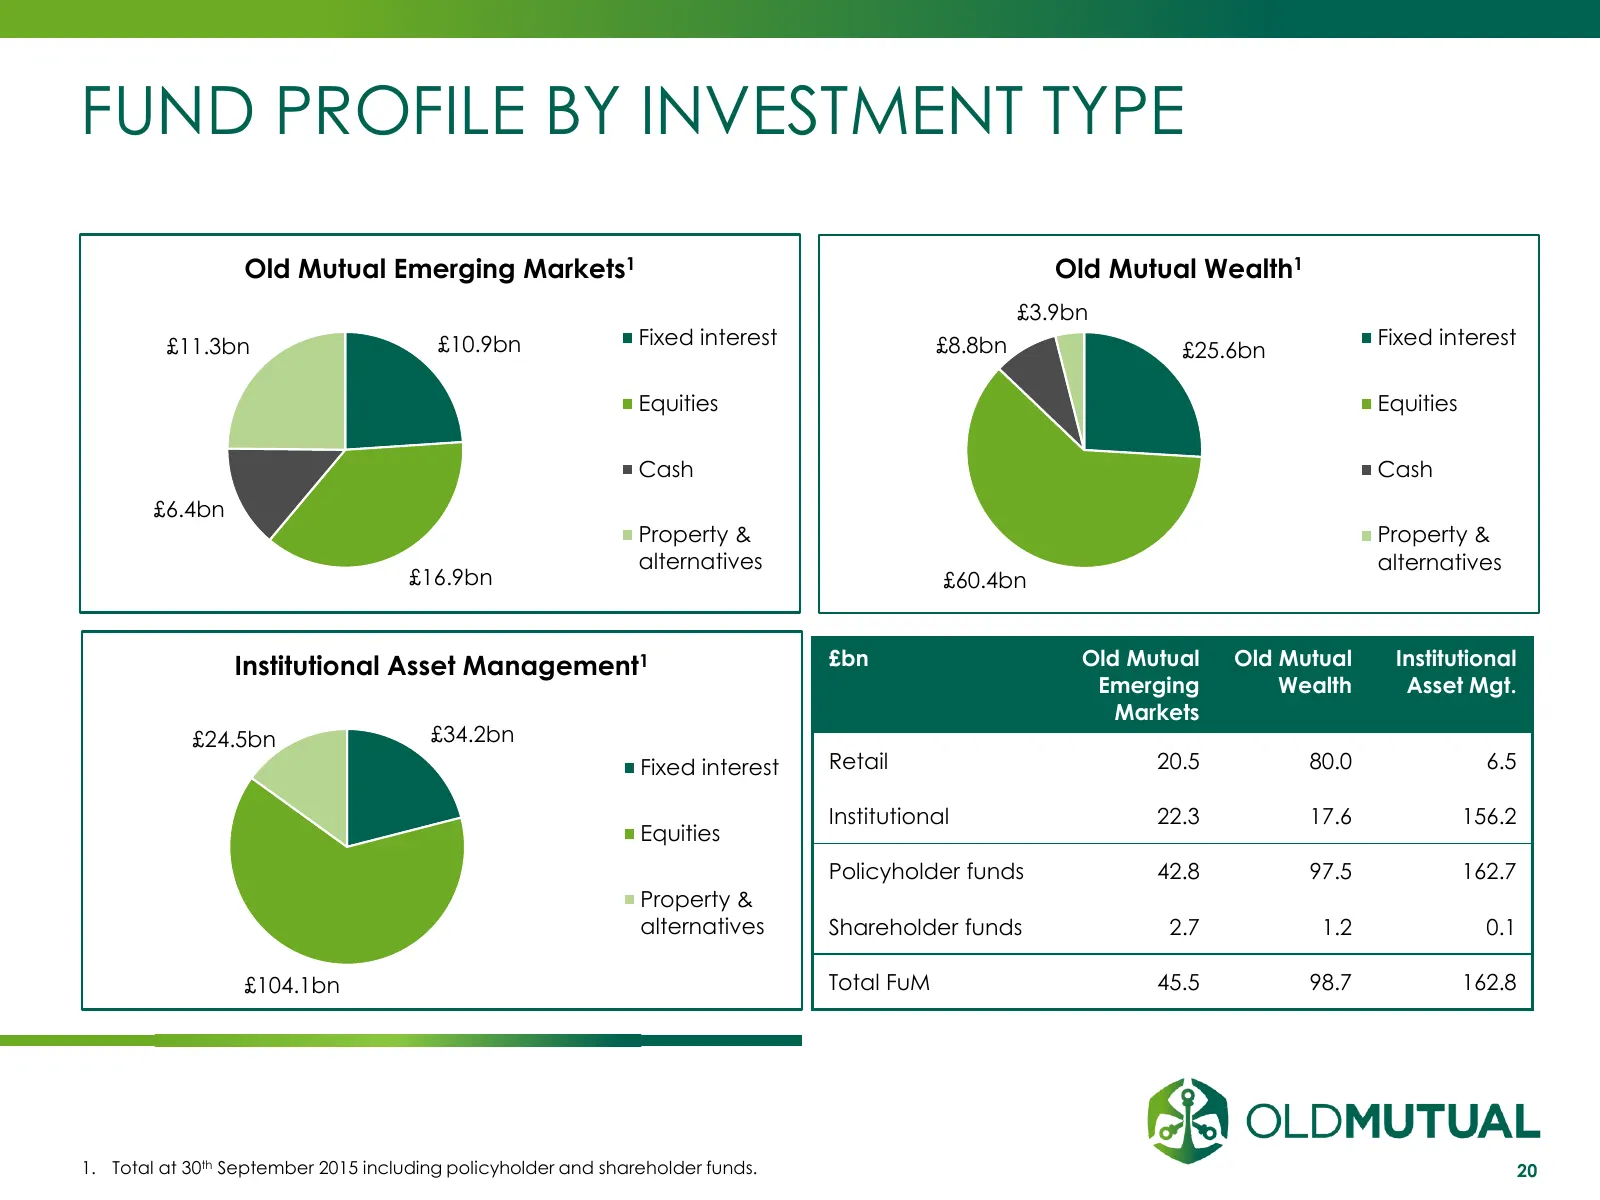
FUND PROFILE BY INVESTMENT TYPE Old Mutual Emerging Markets1 Old Mutual Wealth1 £3.9bn £11.3bn £10.9bn Fixed interest £8.8bn Fixed interest £25.6bn Equities Equities Cash Cash £6.4bn Property & Property & alternatives alternatives £16.9bn £60.4bn Institutional Asset Management1 £bn Old Mutual Old Mu
Slide 21: Investment performance
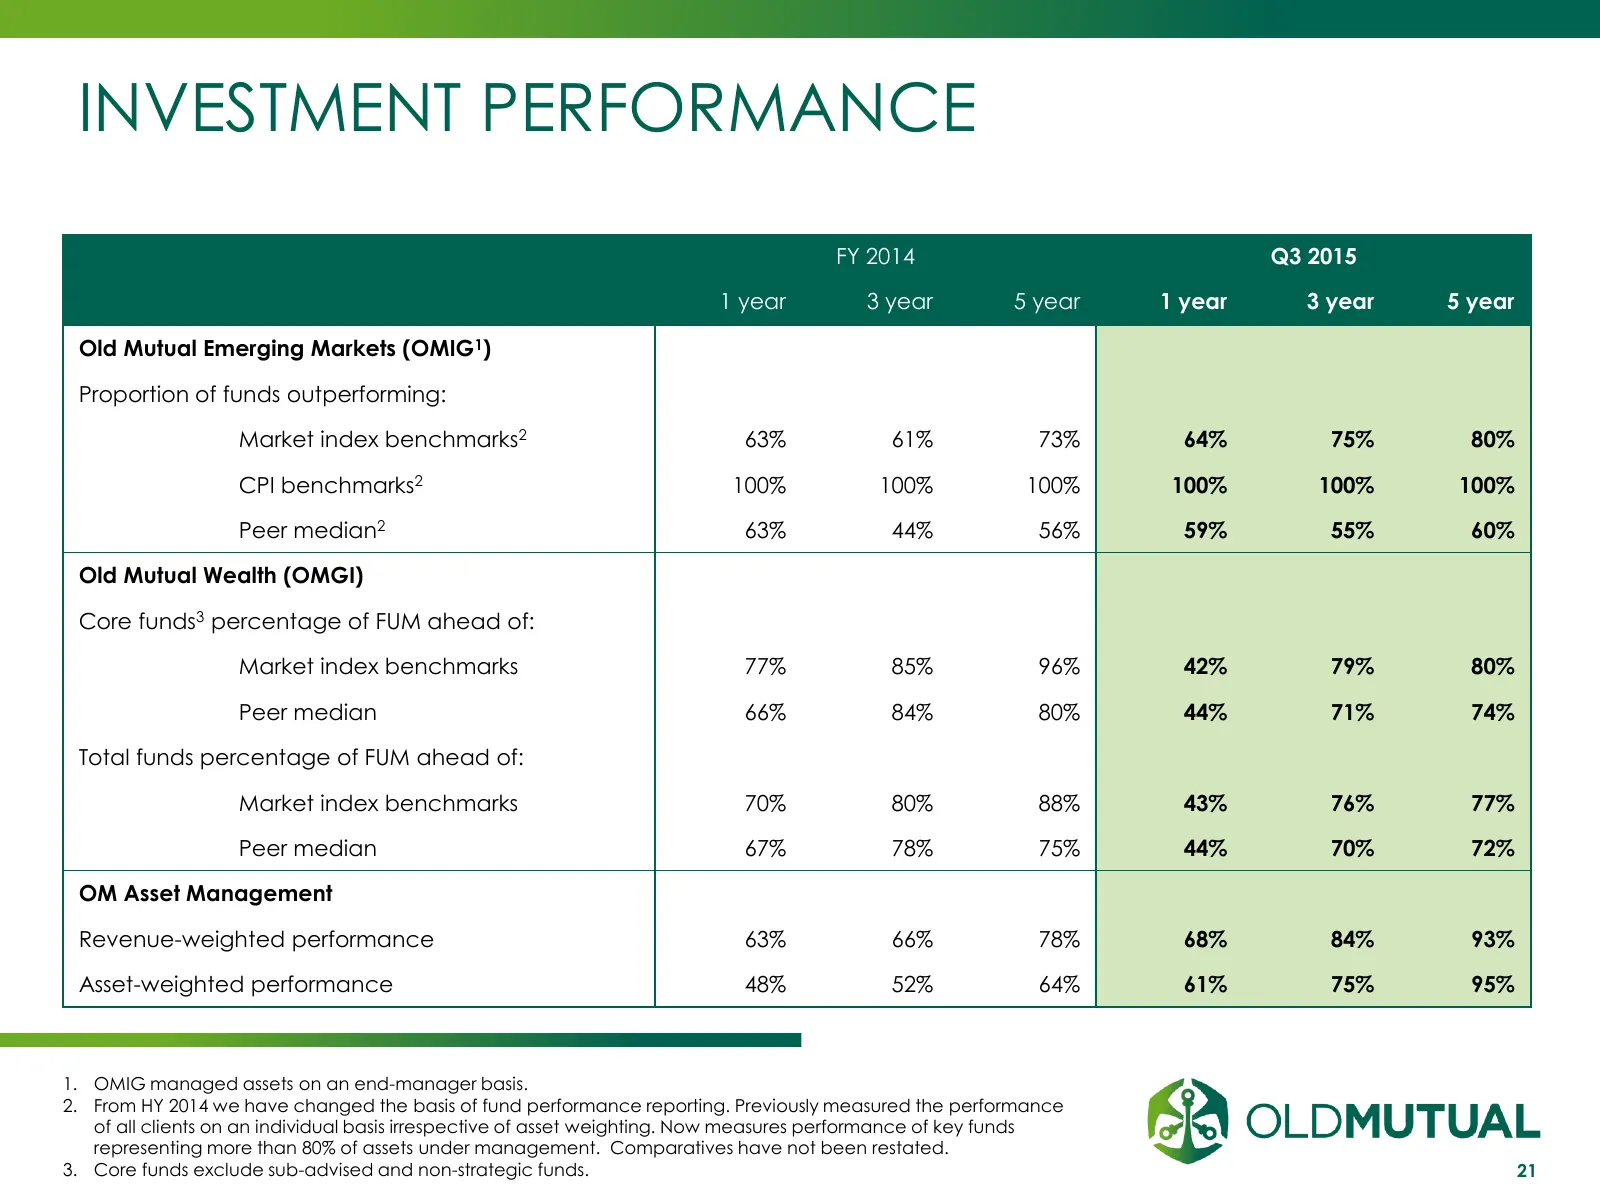
INVESTMENT PERFORMANCE FY 2014 Q3 2015 1 year 3 year 5 year 1 year 3 year 5 year Old Mutual Emerging Markets (OMIG1) Proportion of funds outperforming: Market index benchmarks2 63% 61% 73% 64% 75% 80% CPI benchmarks2 100% 100% 100% 100% 100% 100% Peer median2 63% 44% 56% 59% 55% 60% Old Mutual Wealt
Slide 22: Contacts
CONTACTS For further information please visit the Old Mutual website at: www.oldmutual.com/ir The Investor Relations team can be contacted on: +44 (0)20 7002 7367 Or by email at: omg-ir@omg.co.uk 22
Source: Internet Archive copy of oldmutual.com
More decks from Old Mutual Ltd.
 FY2025 Earnings Presentation46 slides · Oct 12, 2026
 Q2 2026 Earnings Presentation48 slides · Sep 8, 2026
 H1 2025 Earnings Presentation45 slides · Sep 10, 2025
 FY2024 Earnings Presentation40 slides · Mar 18, 2025
 FY2023 Earnings Presentation39 slides · Mar 27, 2024
 H1 2024 Earnings Presentation33 slides · 2024