Kingfisher PLC · LSE:KGF
Kingfisher — Investor Day (October 2014)
47 slides from Kingfisher's investor day presentation, Oct 21, 2014
Slide 1: B&Q UK & Ireland Investor Event
B&Q UK & Ireland Investor Event st 21 October 2014 1
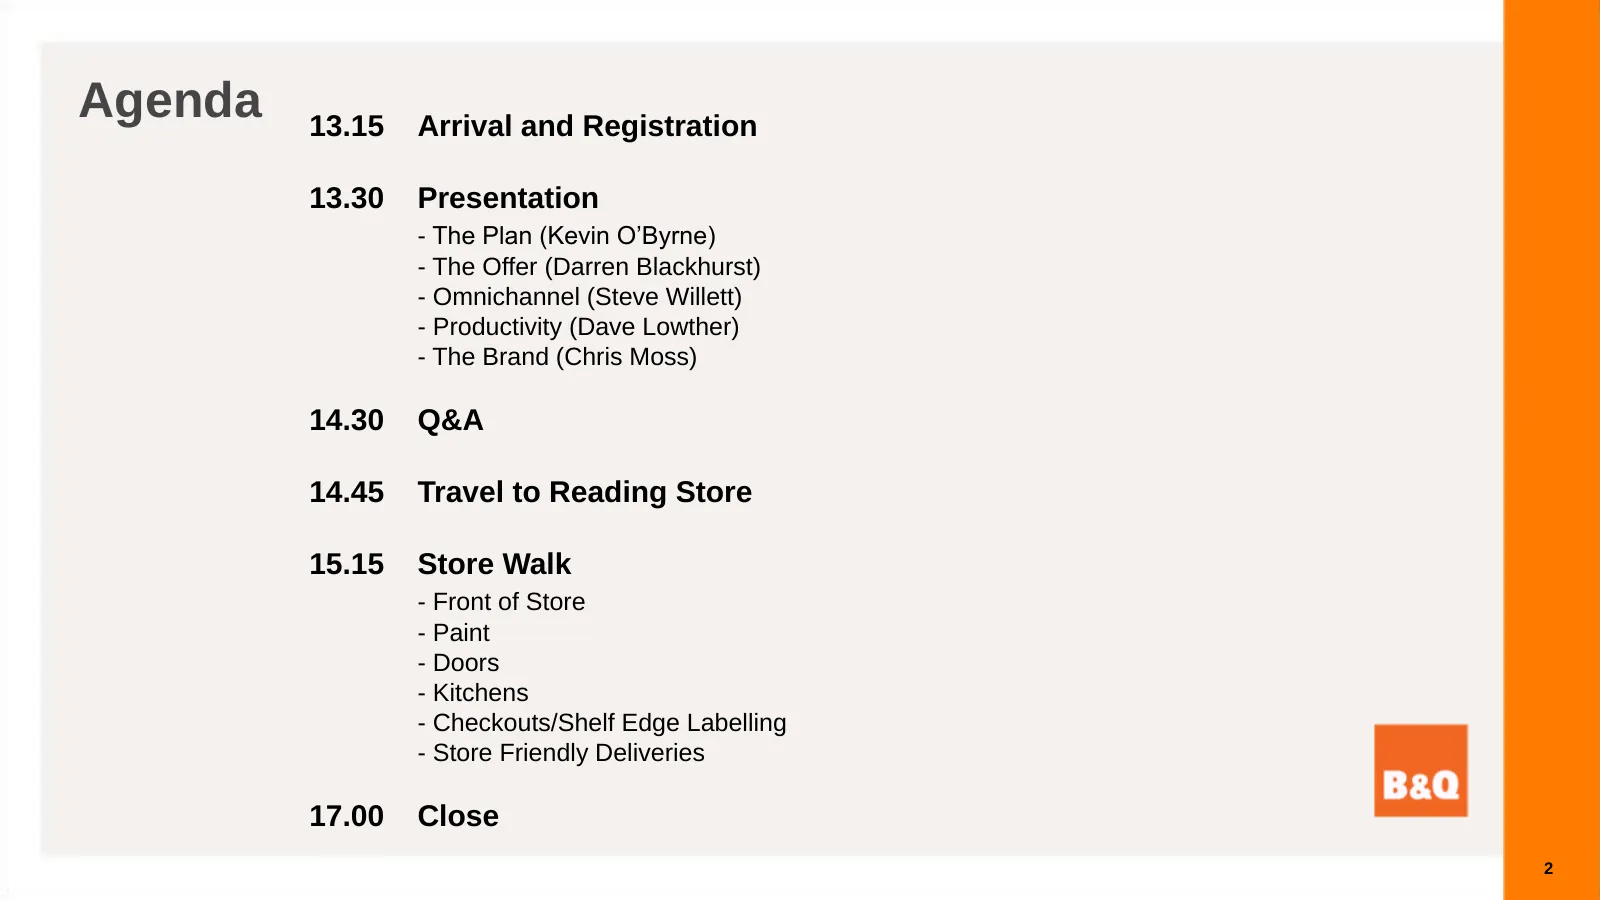
Slide 2: Agenda
Agenda 13.15 Arrival and Registration 13.30 Presentation - The Plan (Kevin O’Byrne) - The Offer (Darren Blackhurst) - Omnichannel (Steve Willett) - Productivity (Dave Lowther) - The Brand (Chris Moss) 14.30 Q&A 14.45 Travel to Reading Store 15.15 Store Walk - Front of Store - Paint - Doors - Kitchen
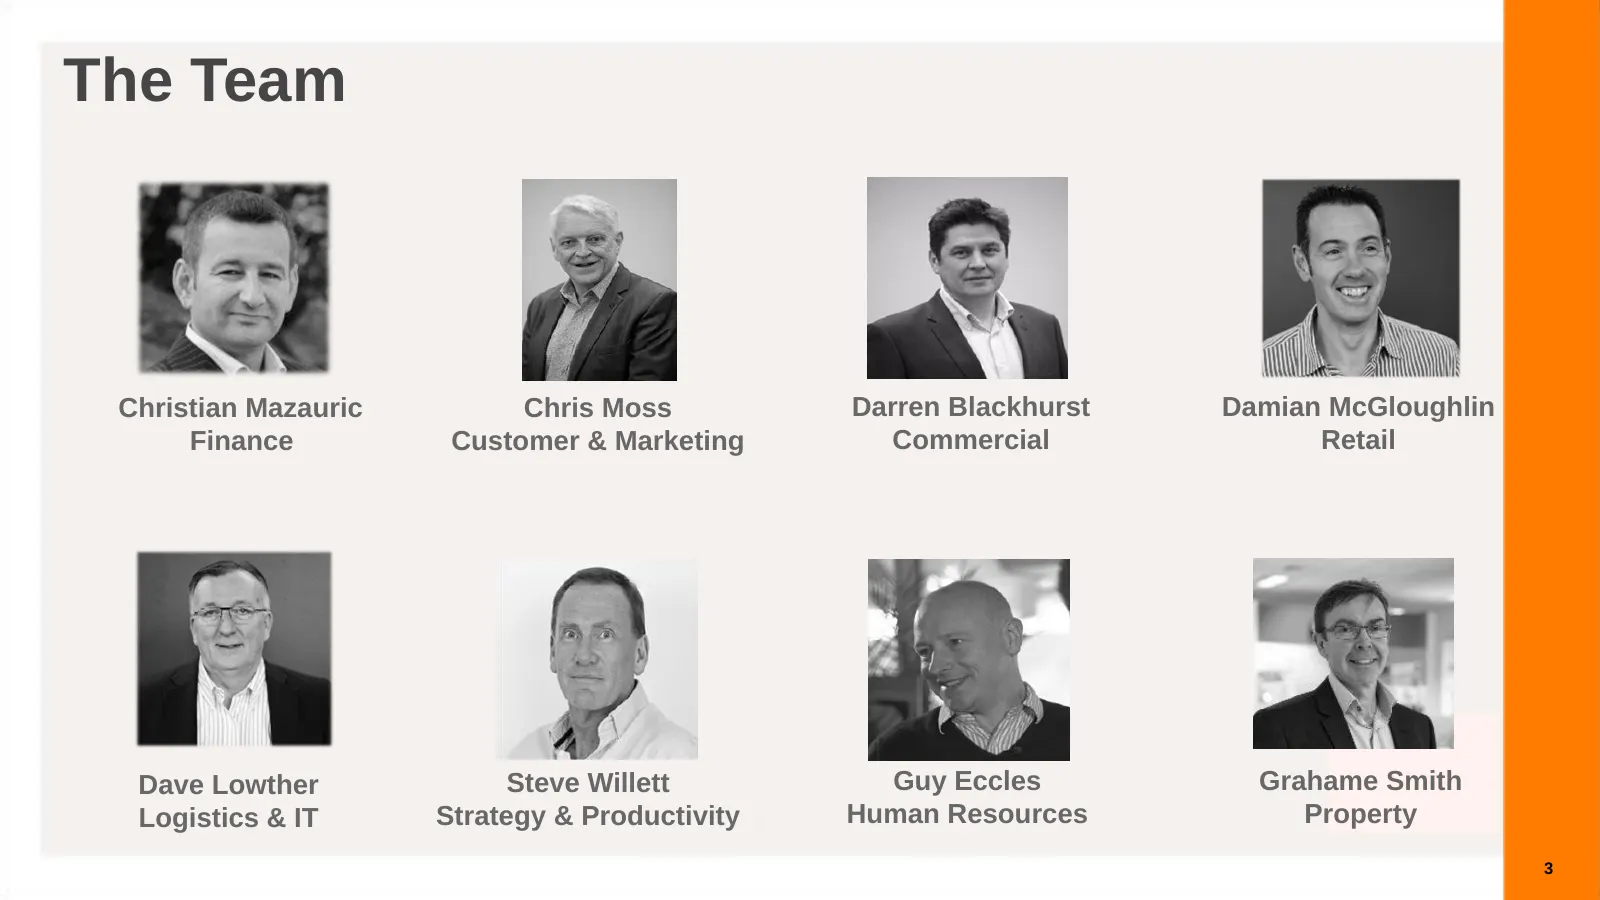
Slide 3: The Team
The Team Christian Mazauric Chris Moss Darren Blackhurst Damian McGloughlin Finance Customer & Marketing Commercial Retail Dave Lowther Steve Willett Guy Eccles Grahame Smith Logistics & IT Strategy & Productivity Human Resources Property 3
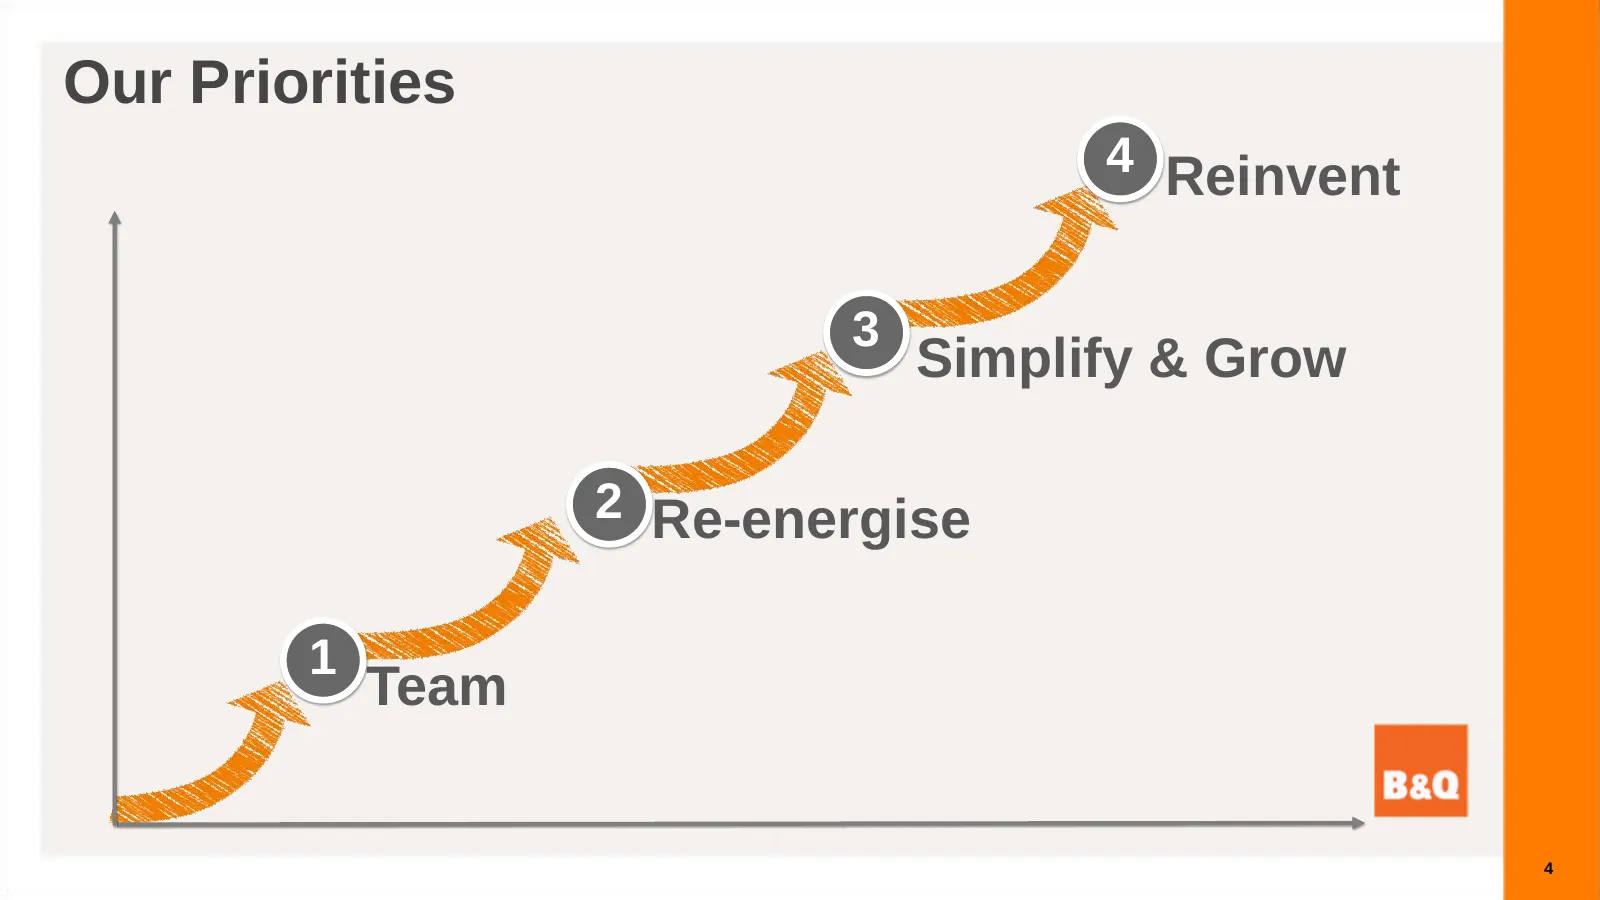
Slide 4: Our Priorities
Our Priorities 4 Reinvent 3 Simplify & Grow 2 Re-energise 1 Team 4
Slide 5: Our ambition is to Reinvent home improvement retailing for the digital age
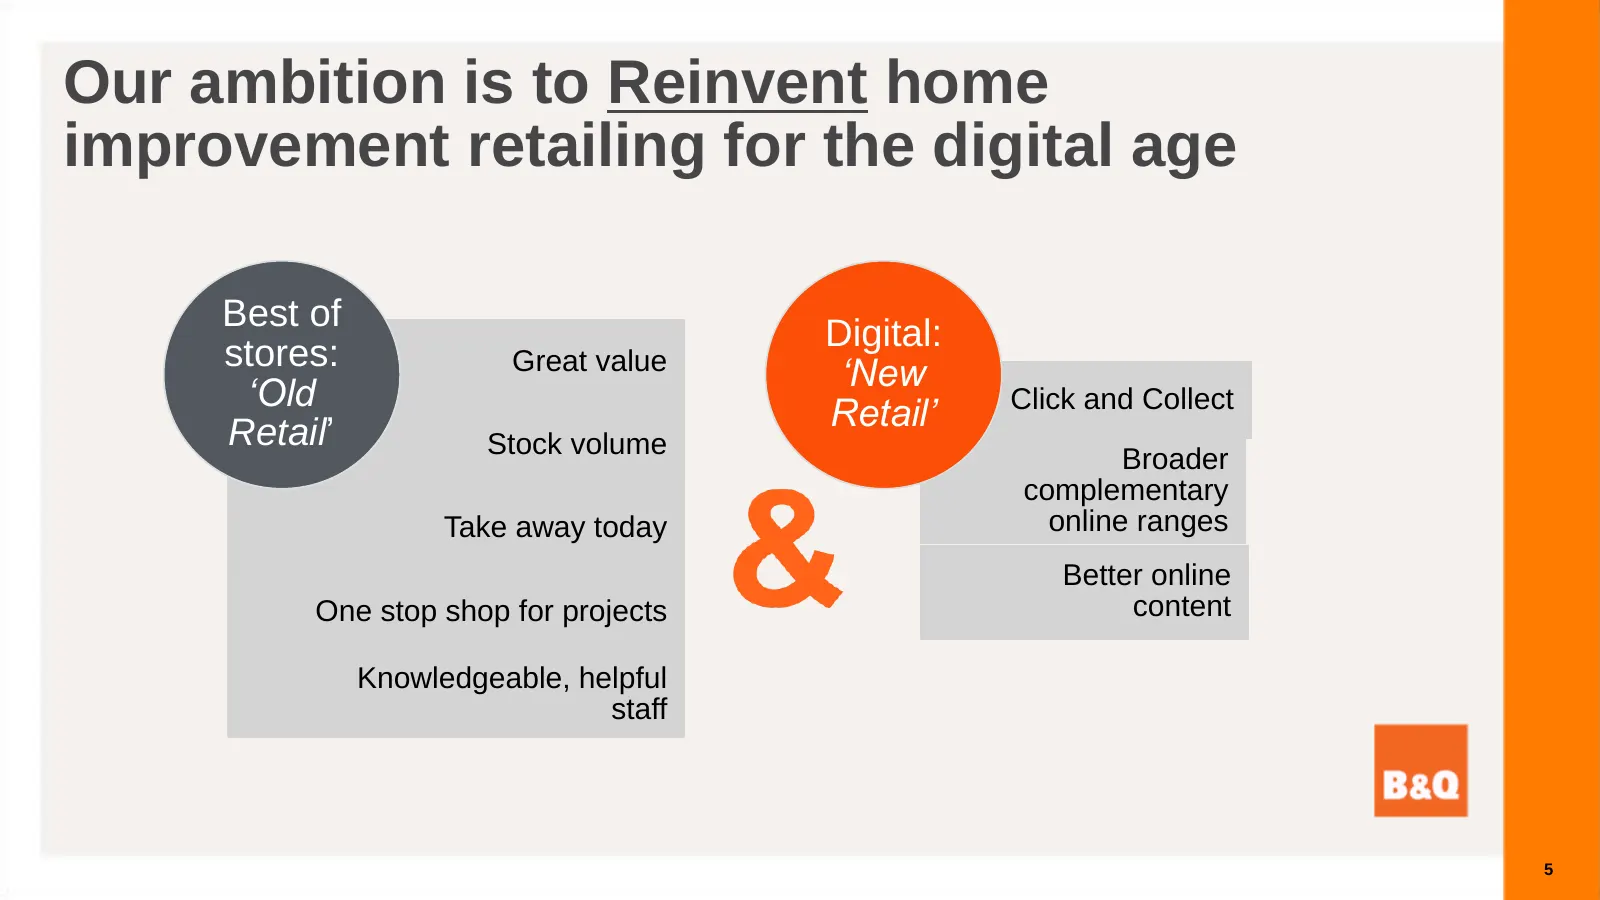
Our ambition is to Reinvent home improvement retailing for the digital age Best of Digital: stores: Great value ‘New ‘Old Click and Collect Retail’ Retail’ Stock volume Broader complementary Take away today online ranges Better online One stop shop for projects content Knowledgeable, helpful staff 5
Slide 6: We have detailed plans to Simplify & Grow B&Q over the medium term
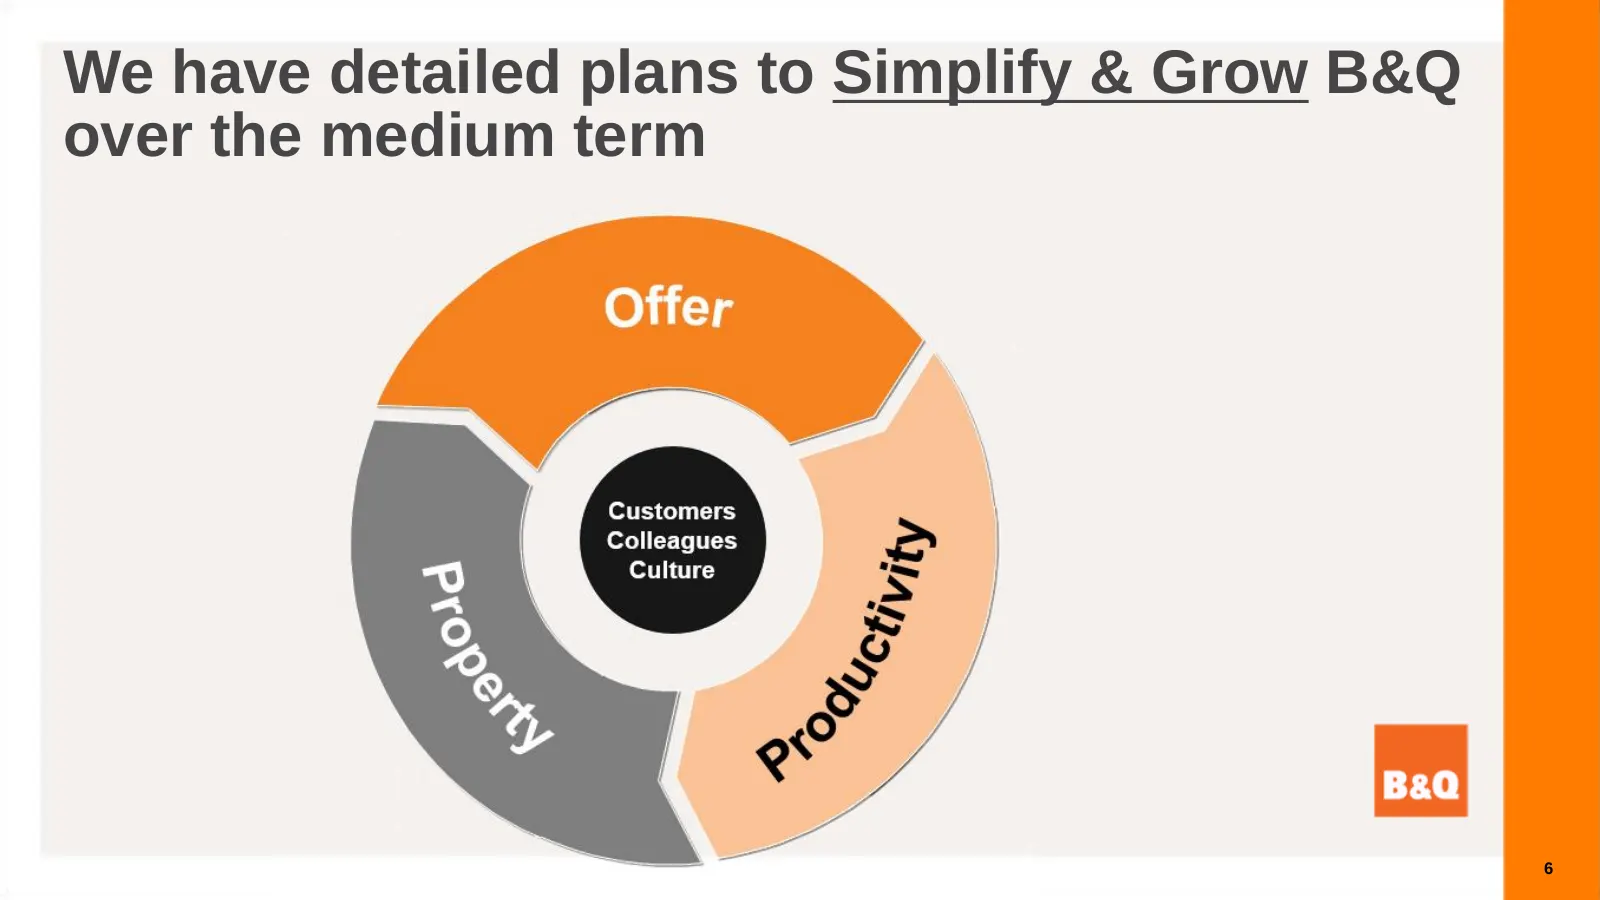
We have detailed plans to Simplify & Grow B&Q over the medium term 6
Slide 7: Our culture is built around the customer
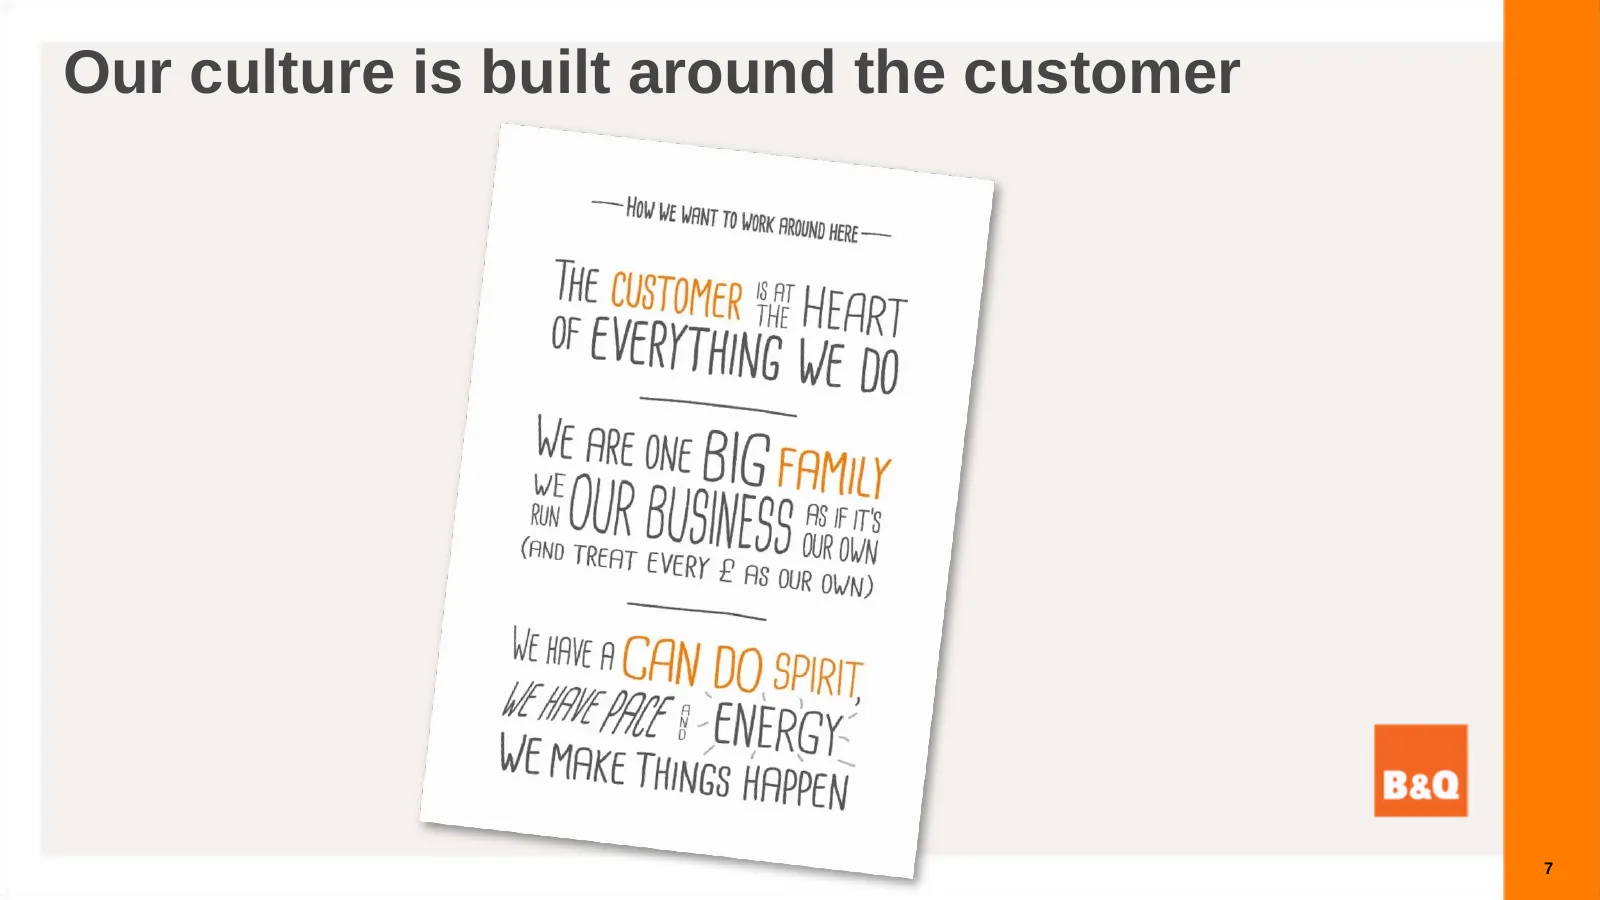
Our culture is built around the customer 7
Slide 8: Offer
Baa Offer Darren Blackhurst
Slide 9: Everyday Great Value is key to our offer
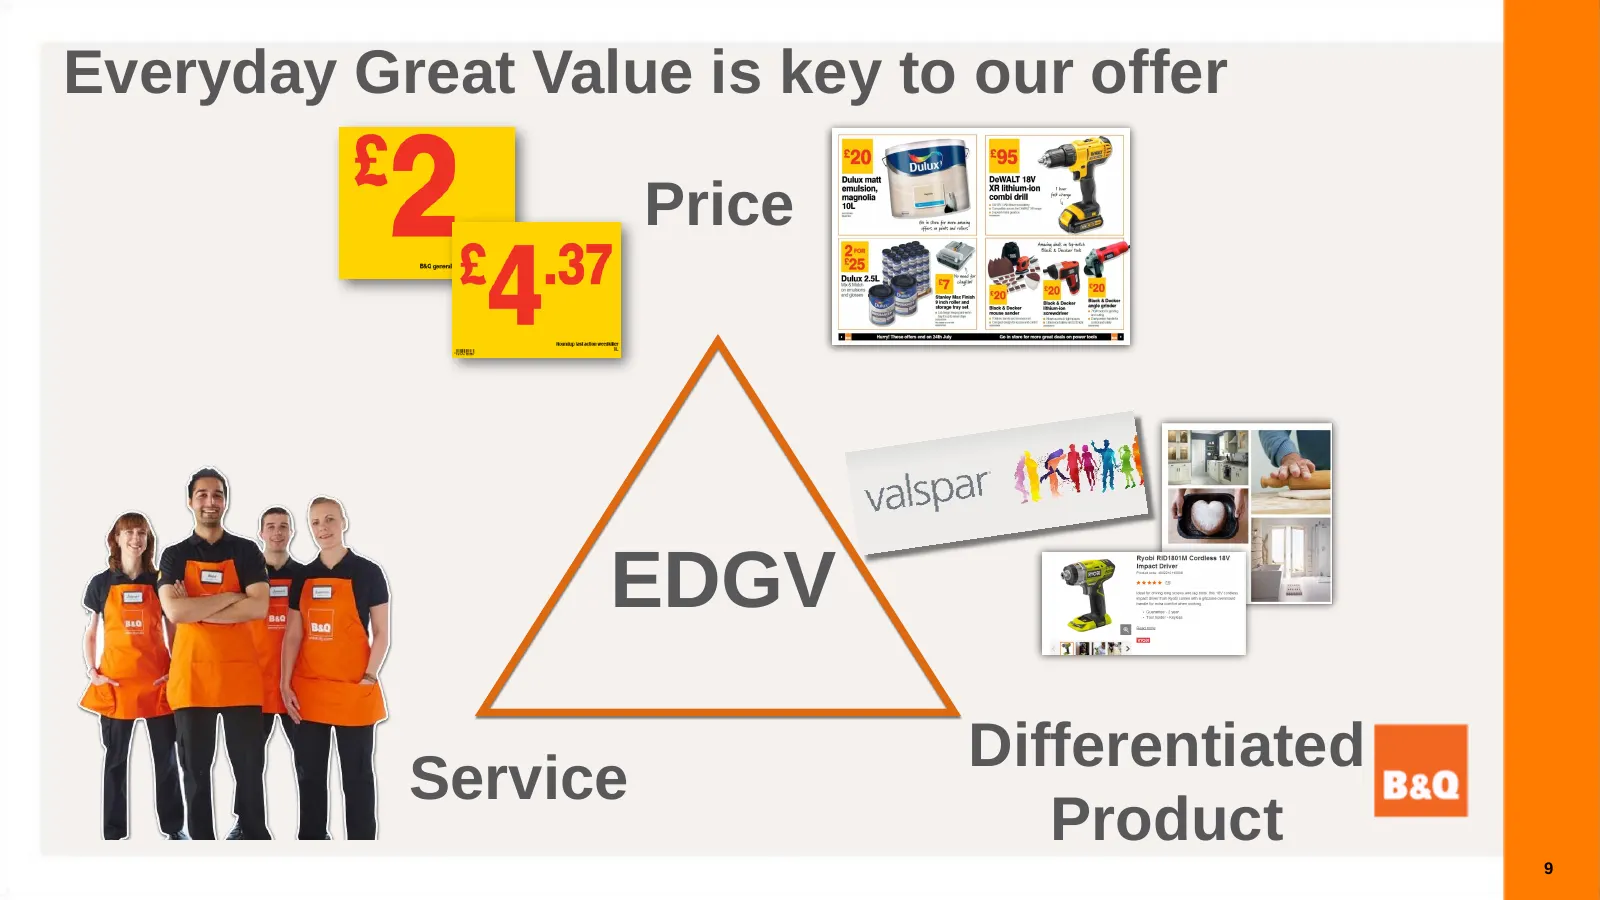
Everyday Great Value is key to our offer Price EDGV Differentiated Service Product 9
Slide 10: Price: Where we were…
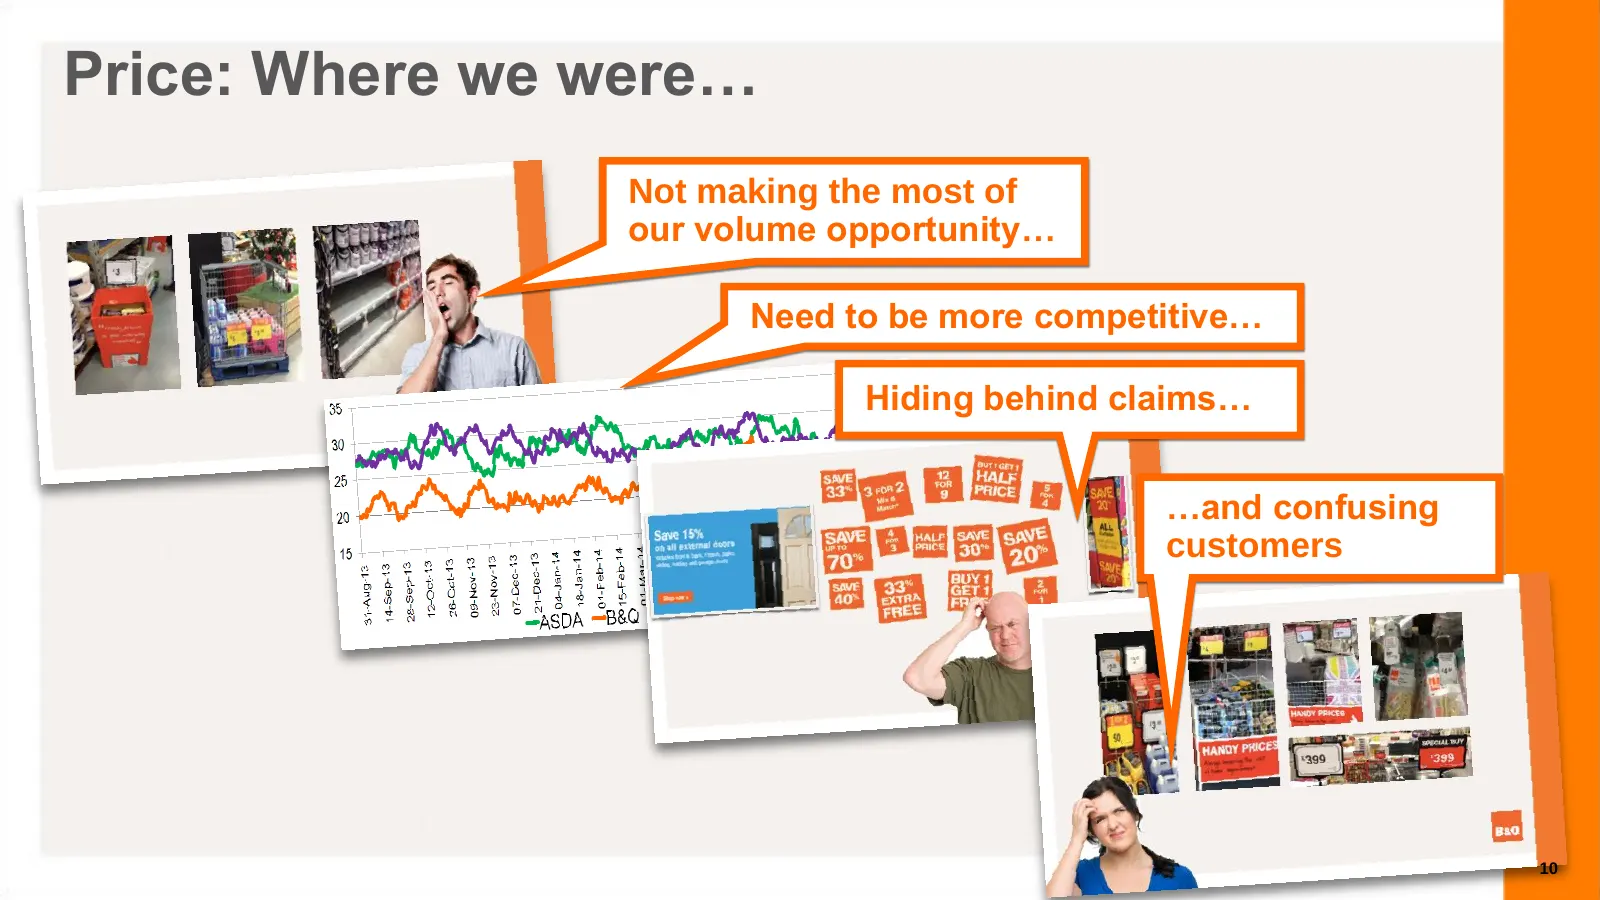
Price: Where we were… Not making the most of our volume opportunity… Need to be more competitive… Hiding behind claims… …and confusing customers 10
Slide 11: We're OUT of claims...
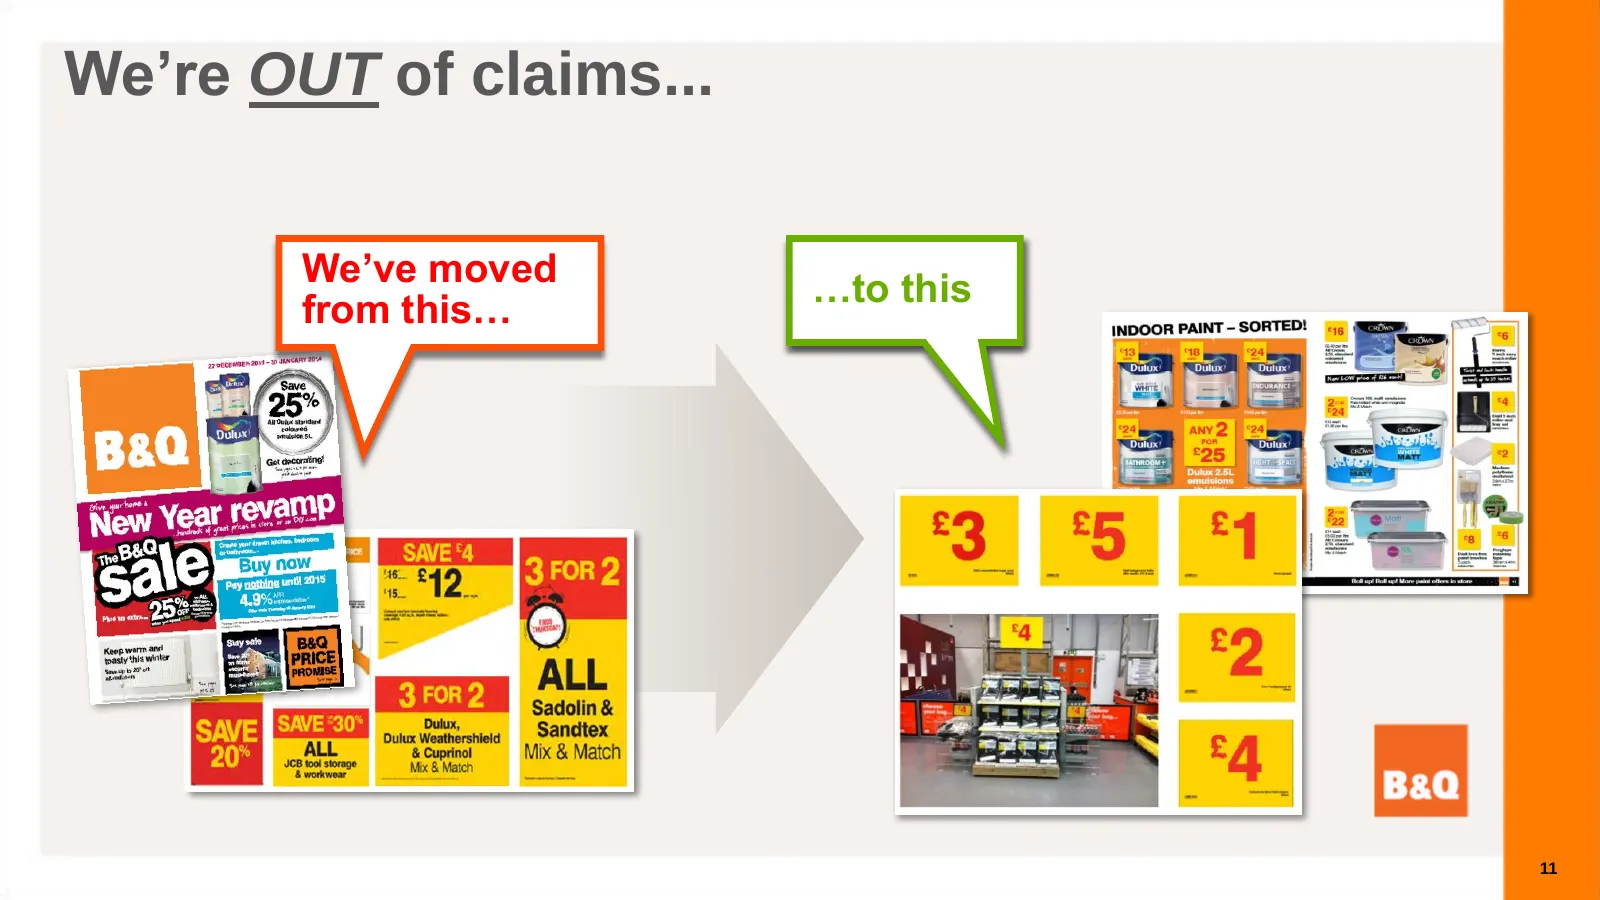
We’re OUT of claims... We’ve moved …to this from this… 11
Slide 12: We're investing in price…
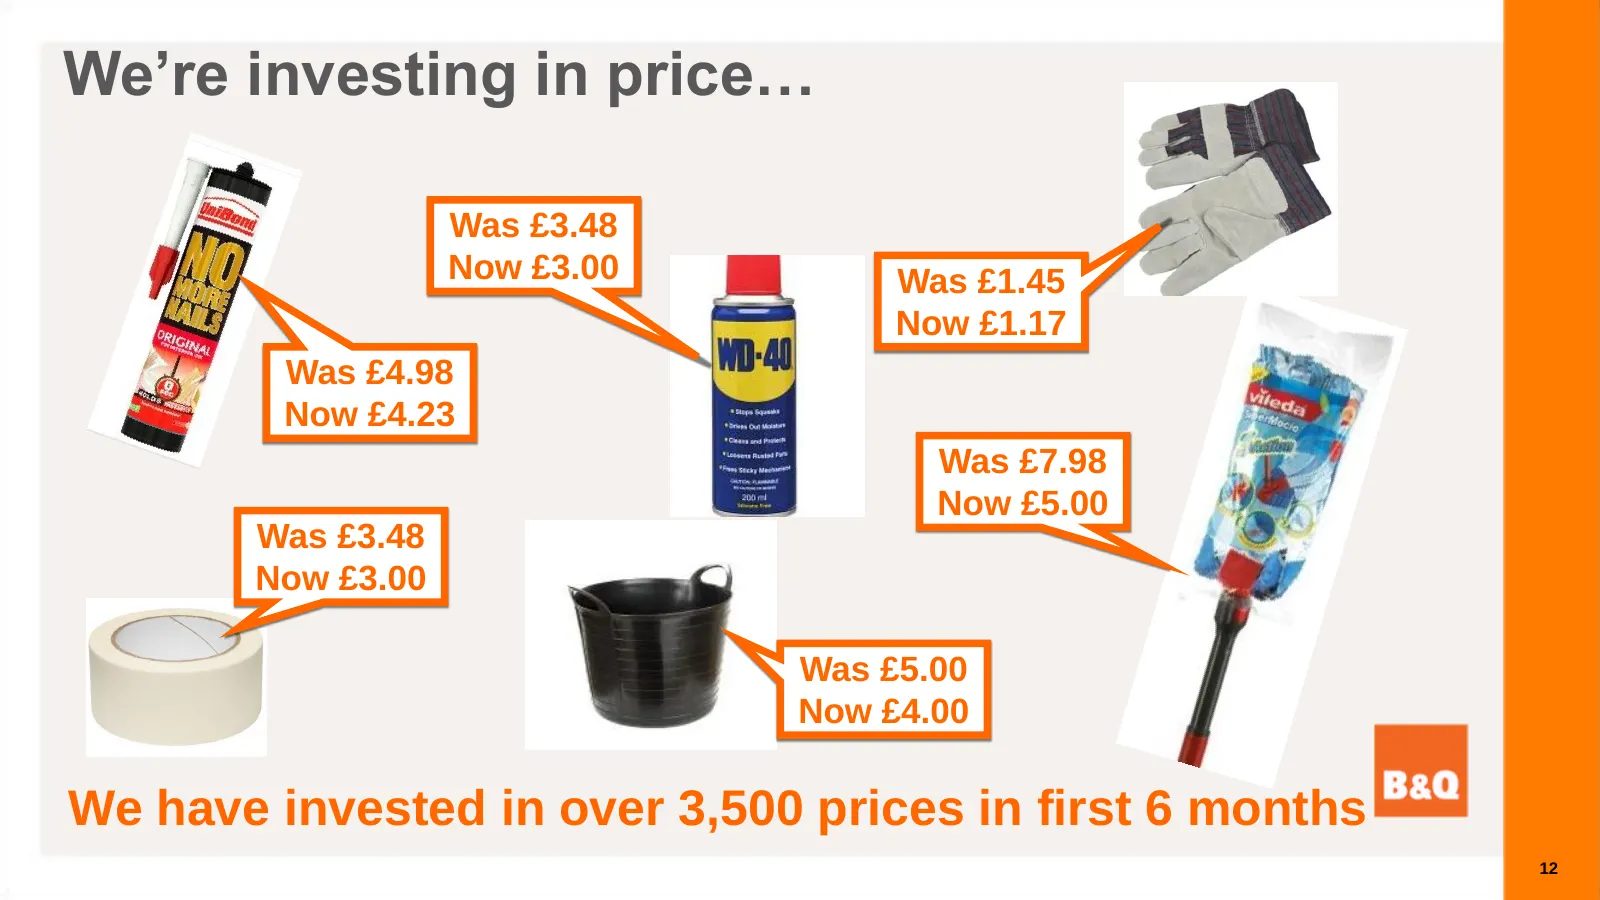
We’re investing in price… Was £3.48 Now £3.00 Was £1.45 Now £1.17 Was £4.98 Now £4.23 Was £7.98 Now £5.00 Was £3.48 Now £3.00 Was £5.00 Now £4.00 We have invested in over 3,500 prices in first 6 months 12
Slide 13: The Top and Doorbusters have been a success…
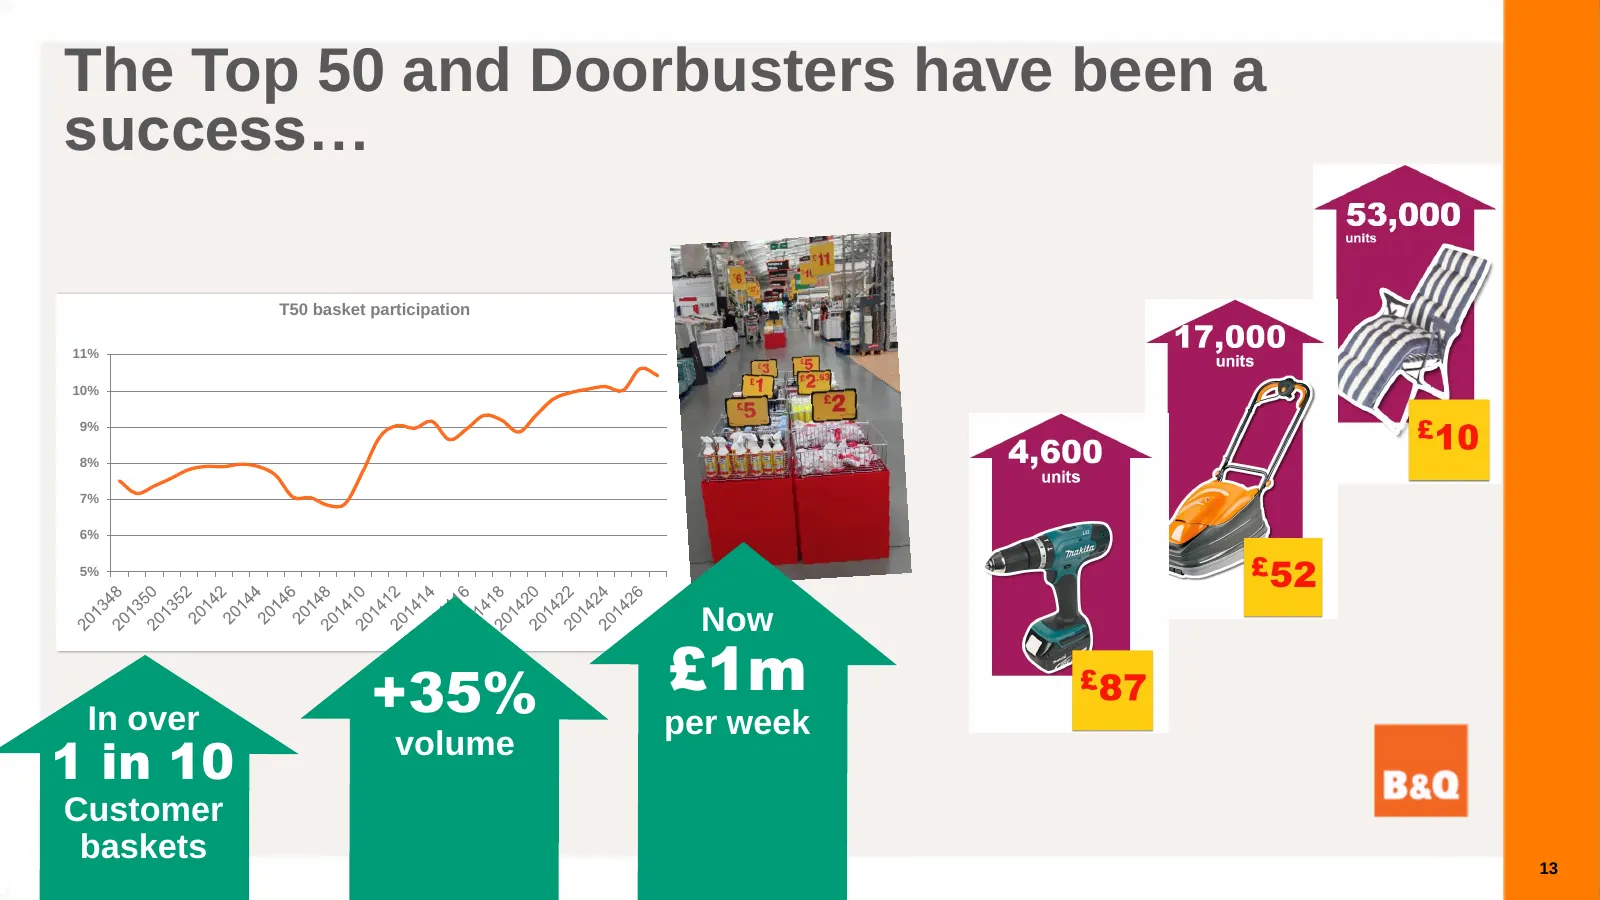
The Top 50 and Doorbusters have been a success… T50 basket participation 11% 10% 9% 8% 7% 6% 5% Now +35% £1m In over per week 1 in 10 volume Customer baskets 13
Slide 14: Perception data shows we're closing the gap to discounters
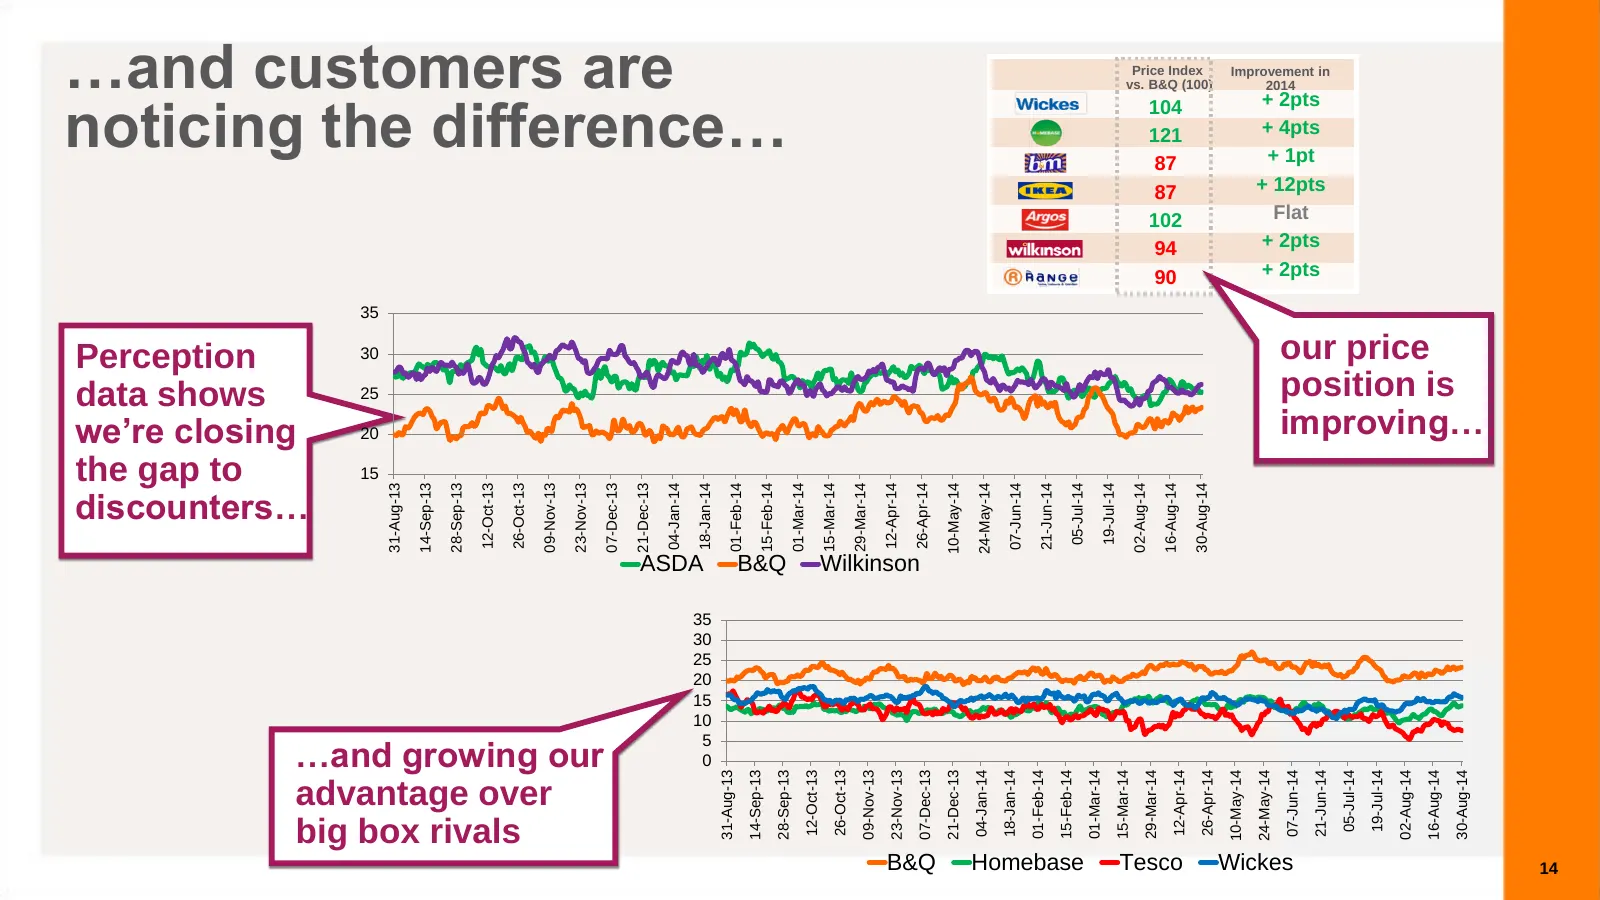
the gap to Perception data shows we’re closing discounters… 15 20 25 30 35 31-Aug-13 14-Sep-13 28-Sep-13 12-Oct-13 big box rivals 26-Oct-13 advantage over 09-Nov-13 23-Nov-13 …and growing our 07-Dec-13 21-Dec-13 …and customers are 04-Jan-14 ASDA 0 5 10 15 20 25 30 35 18-Jan-14 31-Aug-13 01-Feb-14 14
Slide 15: Differentiated Product: The need for change
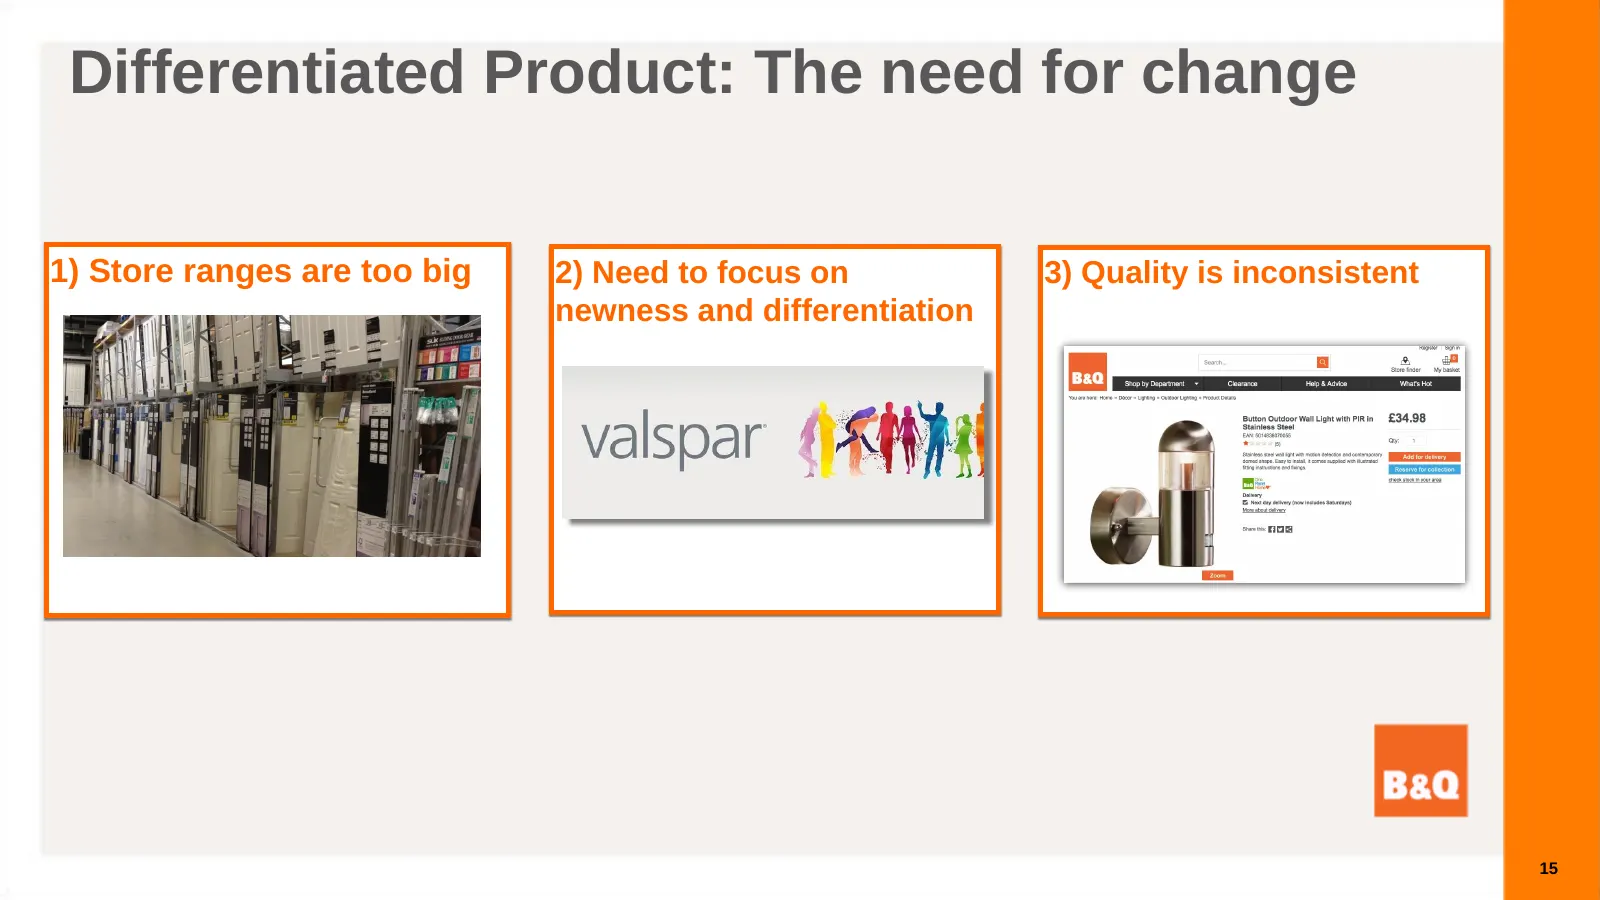
Differentiated Product: The need for change 1) Store ranges are too big 2) Need to focus on 3) Quality is inconsistent newness and differentiation 15
Slide 16: We've created a clear plan to drive growth
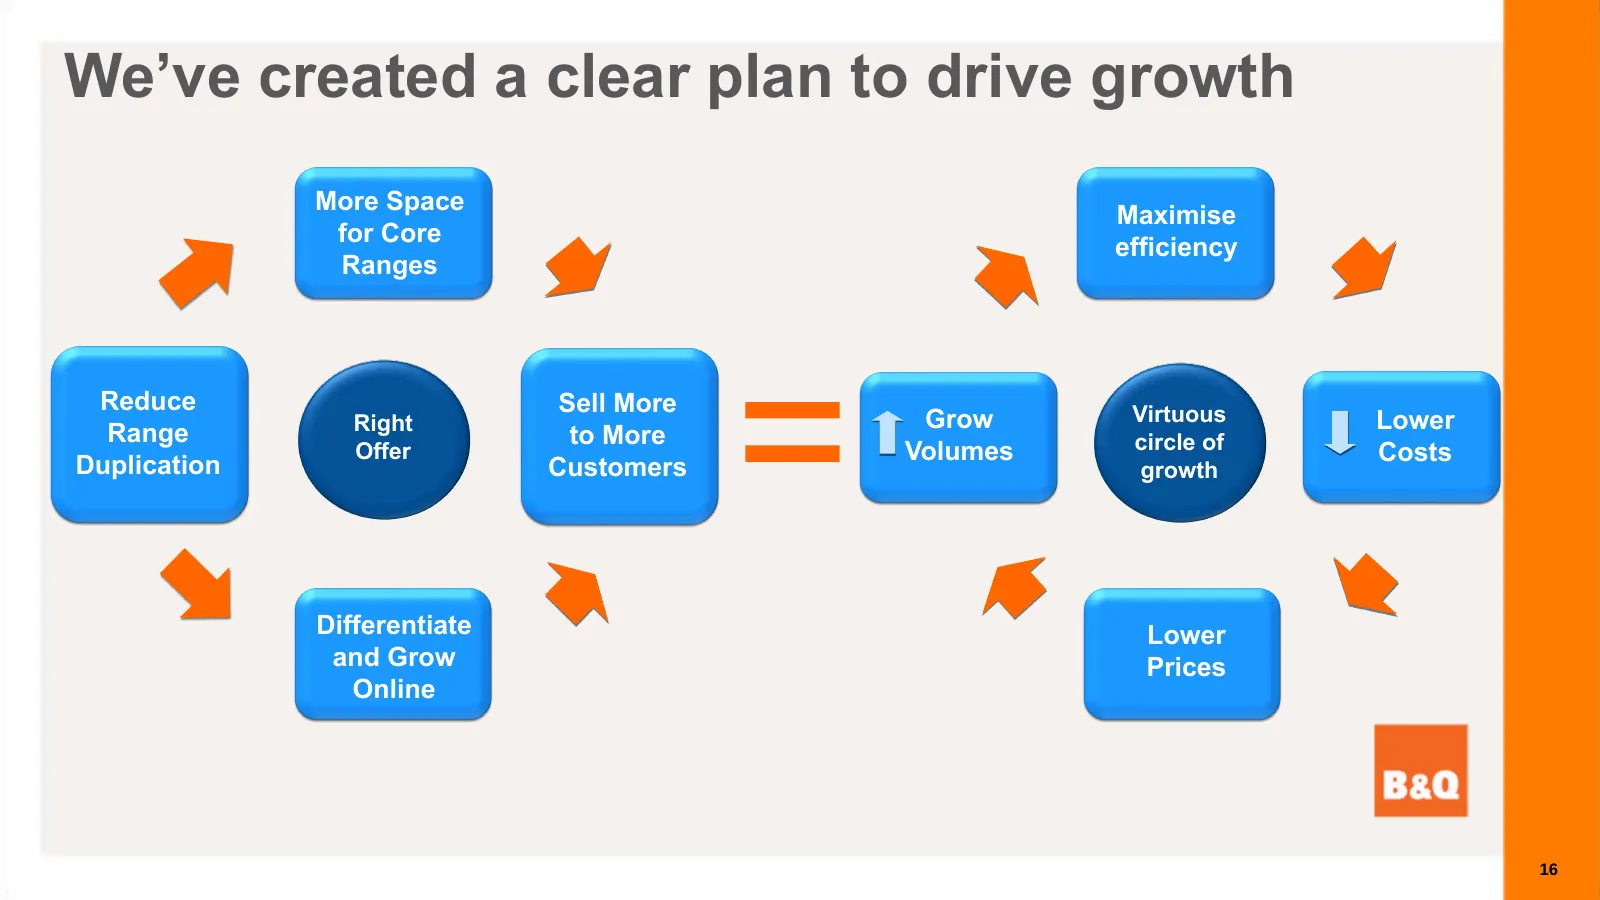
We’ve created a clear plan to drive growth More Space Maximise for Core efficiency Ranges Reduce Sell More Virtuous Right Grow Lower Range to More circle of Offer Volumes Costs Duplication Customers growth Differentiate Lower and Grow Prices Online 16
Slide 17: What we've done so far…
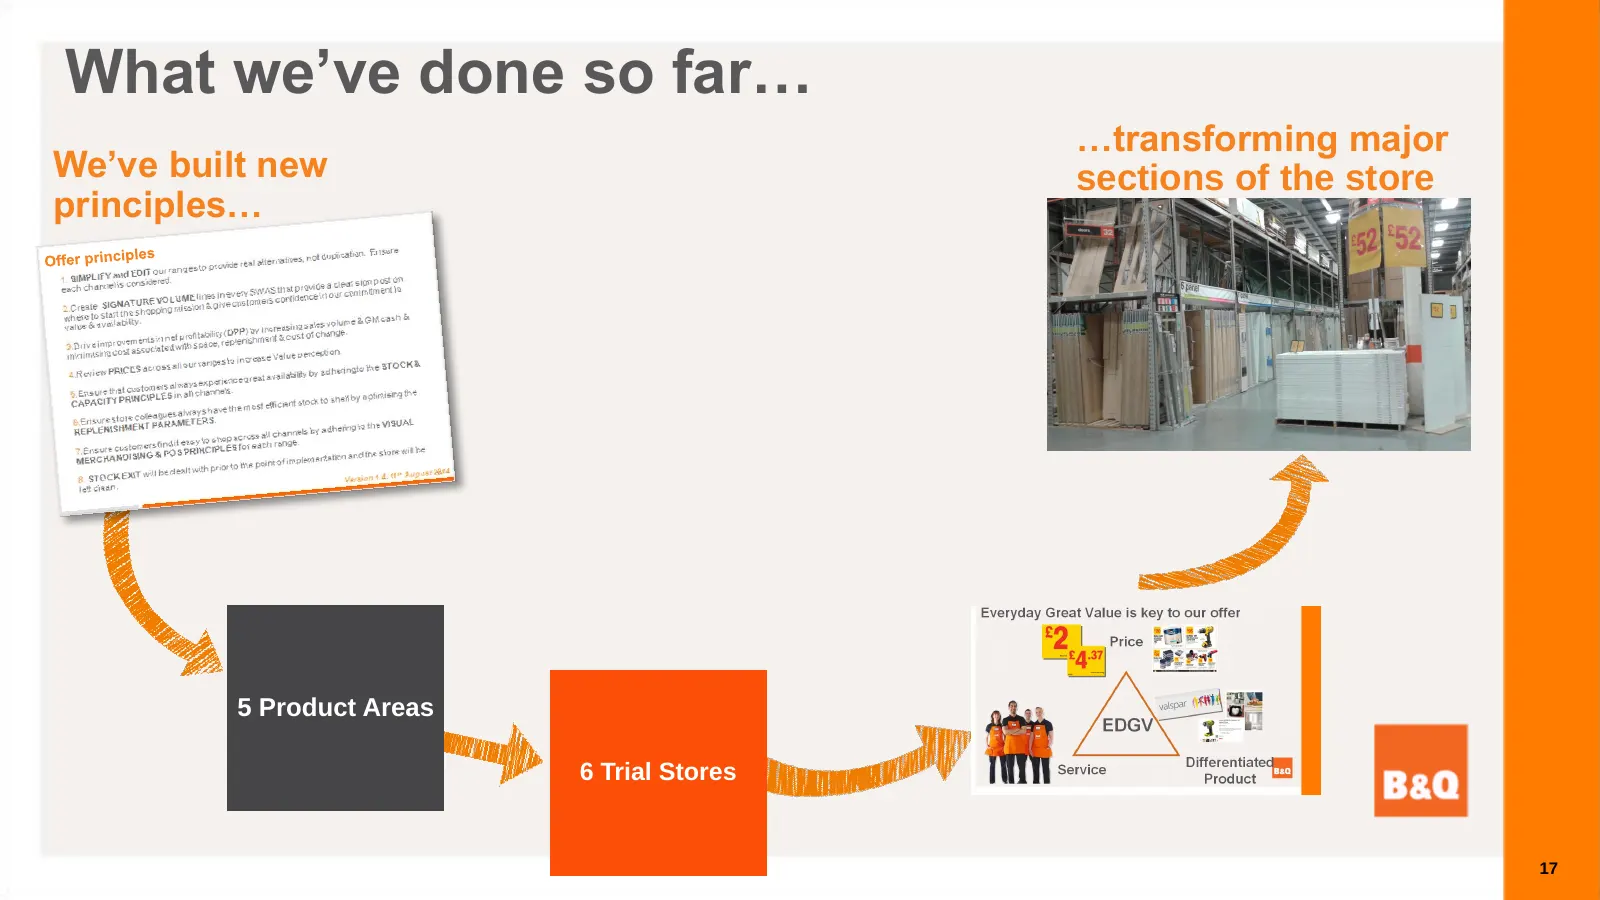
What we’ve done so far… …transforming major We’ve built new sections of the store principles… 5 Product Areas 6 Trial Stores 17
Slide 18: We have a 3 year roll out plan in place
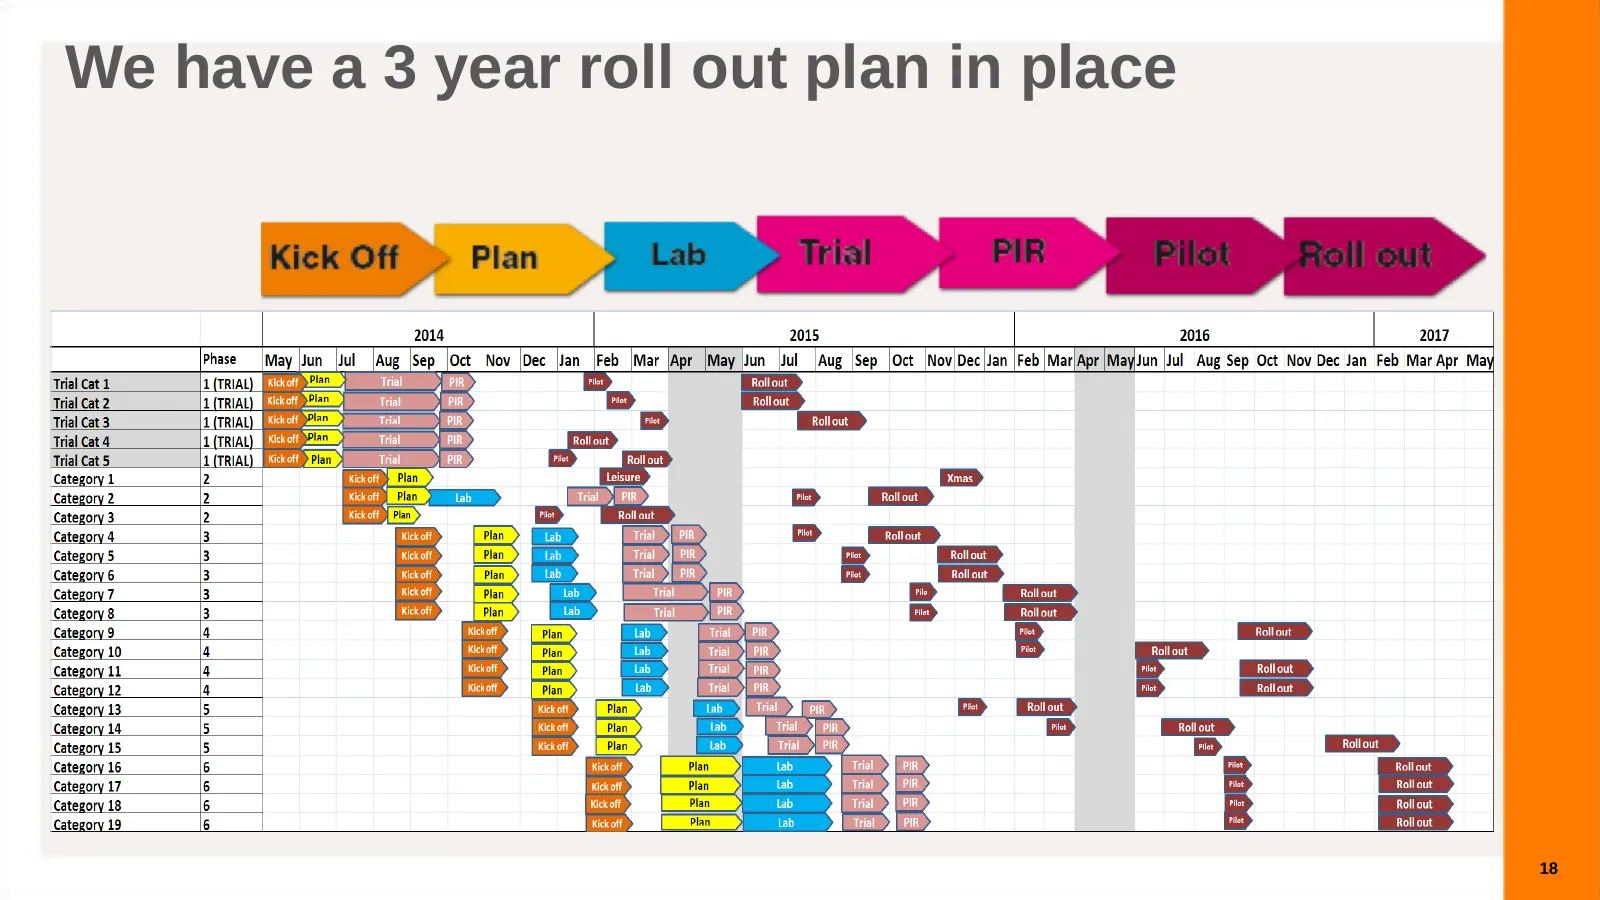
We have a 3 year roll out plan in place 18
Slide 19: Omnichannel
Omnichannel Steve Willett 19
Slide 20: Our online business is growing at pace
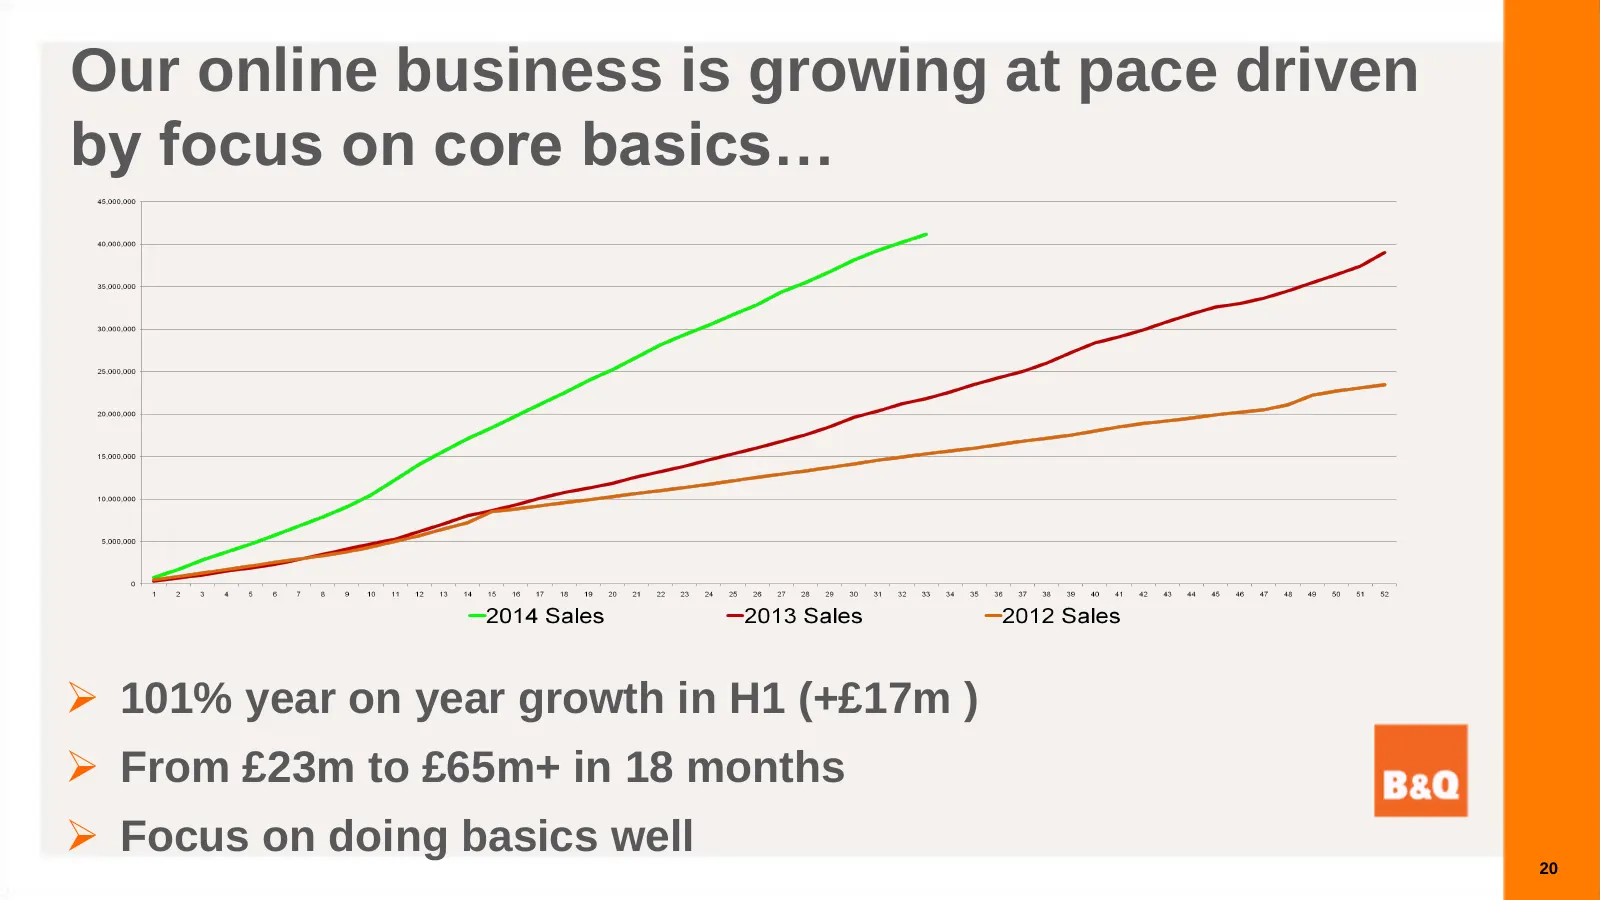
Our online business is growing at pace driven by focus on core basics… 101% year on year growth in H1 (+£17m ) From £23m to £65m+ in 18 months Focus on doing basics well 20
Slide 21: Massive opportunity in future by focusing on 3 key areas
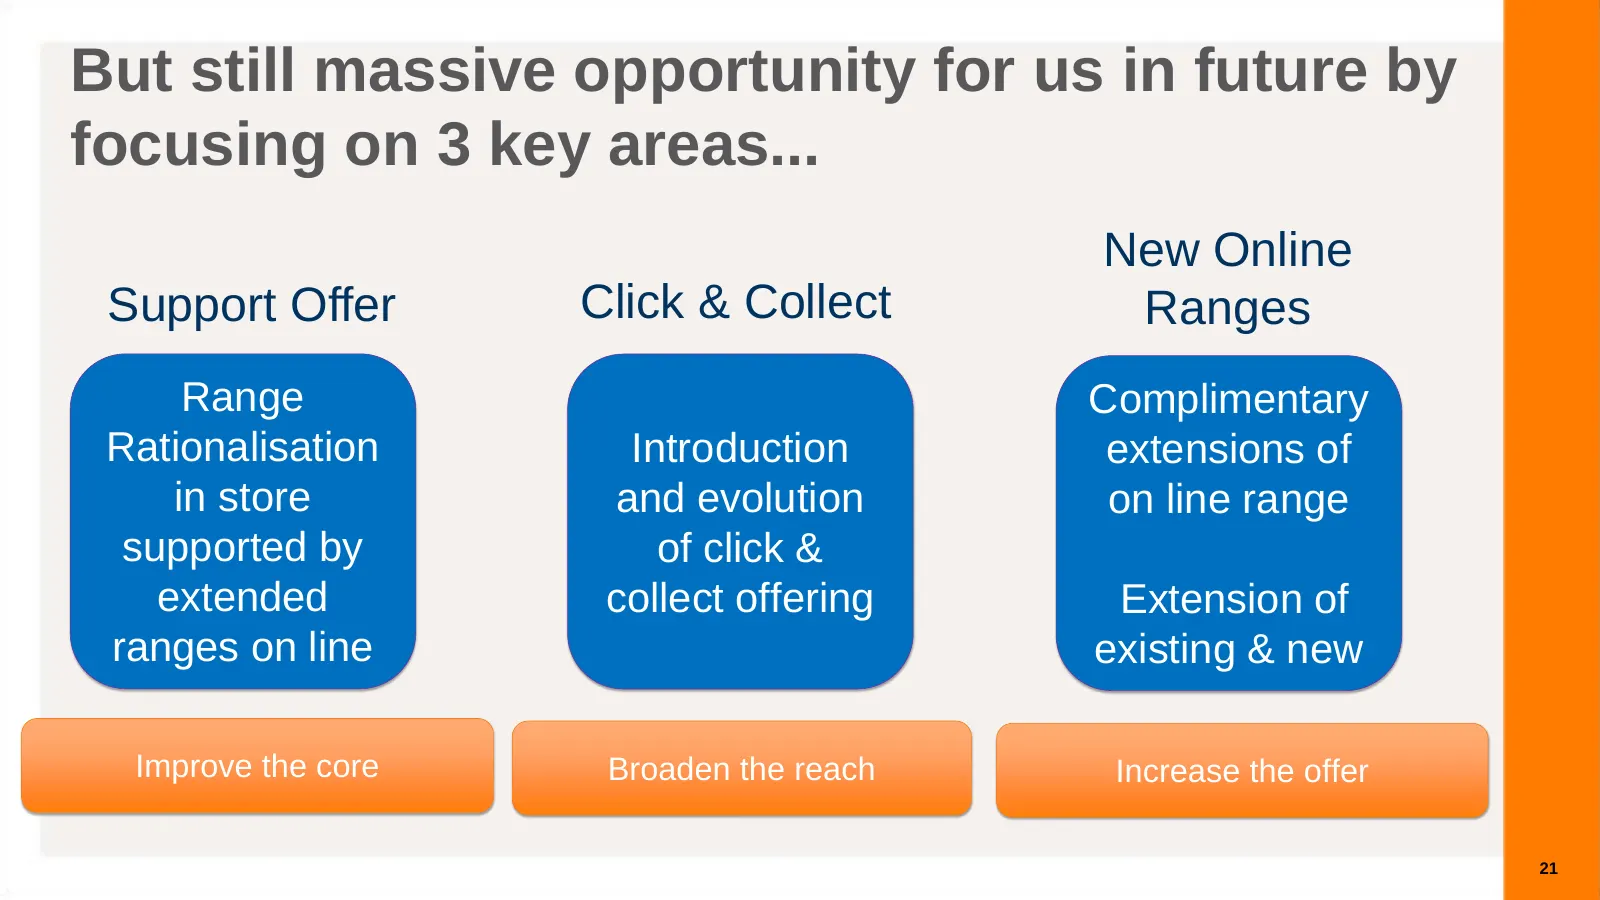
But still massive opportunity for us in future by focusing on 3 key areas... New Online Support Offer Click & Collect Ranges Range Complimentary Rationalisation Introduction extensions of in store and evolution on line range supported by of click & extended collect offering Extension of ranges on li
Slide 22: New web site live on new group platform…
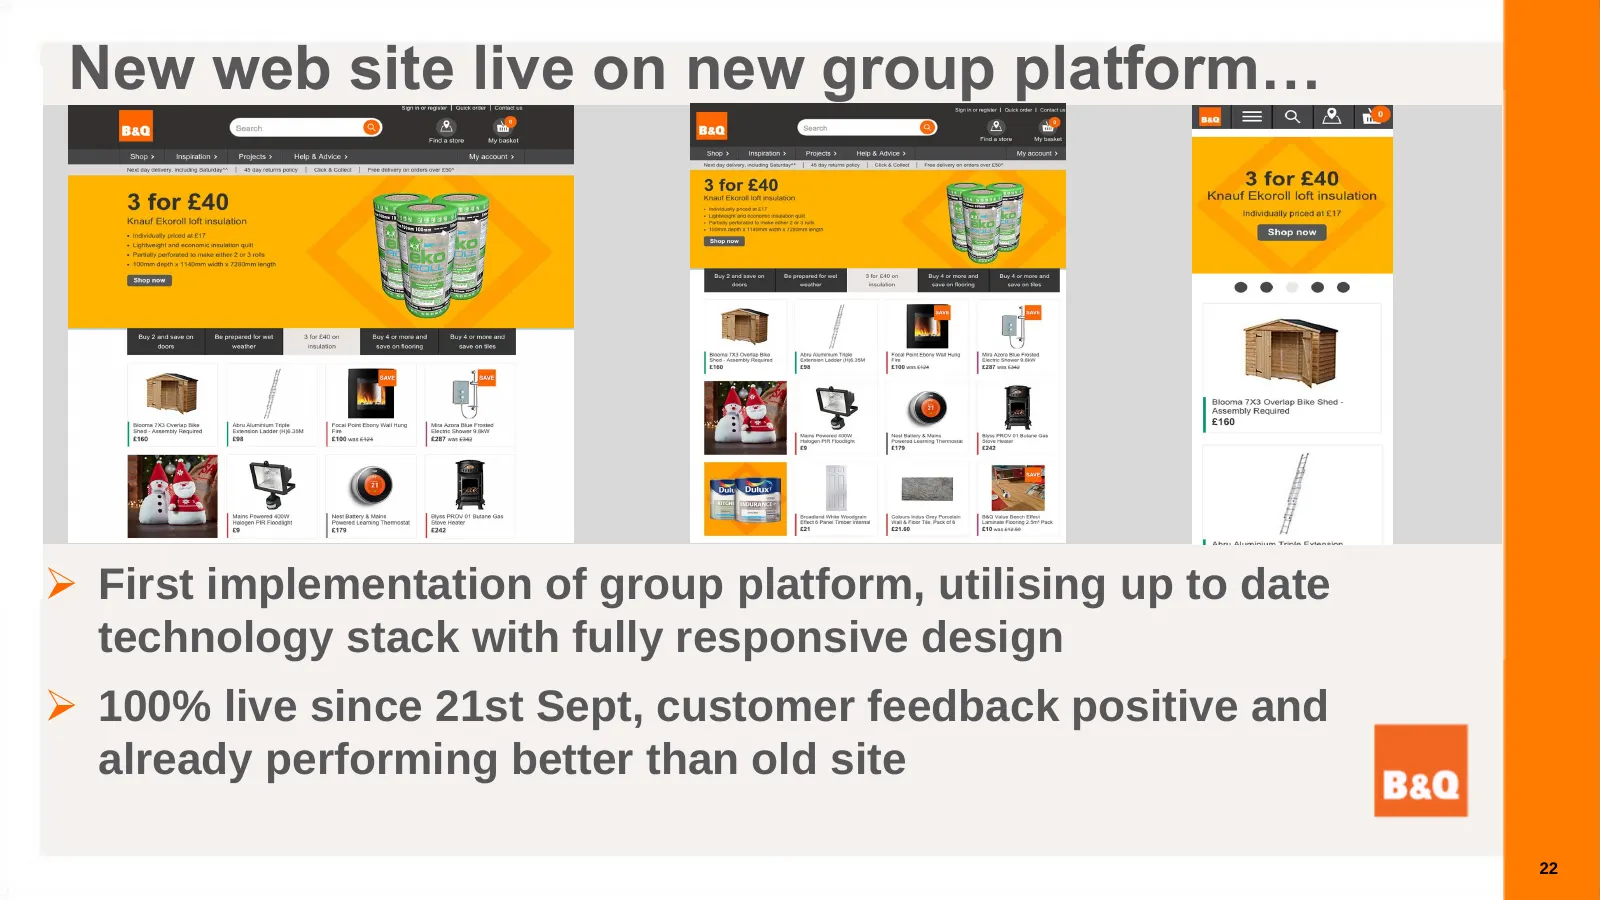
New web site live on new group platform… First implementation of group platform, utilising up to date technology stack with fully responsive design 100% live since 21st Sept, customer feedback positive and already performing better than old site 22
Slide 23: First key priority supporting the offer programme…
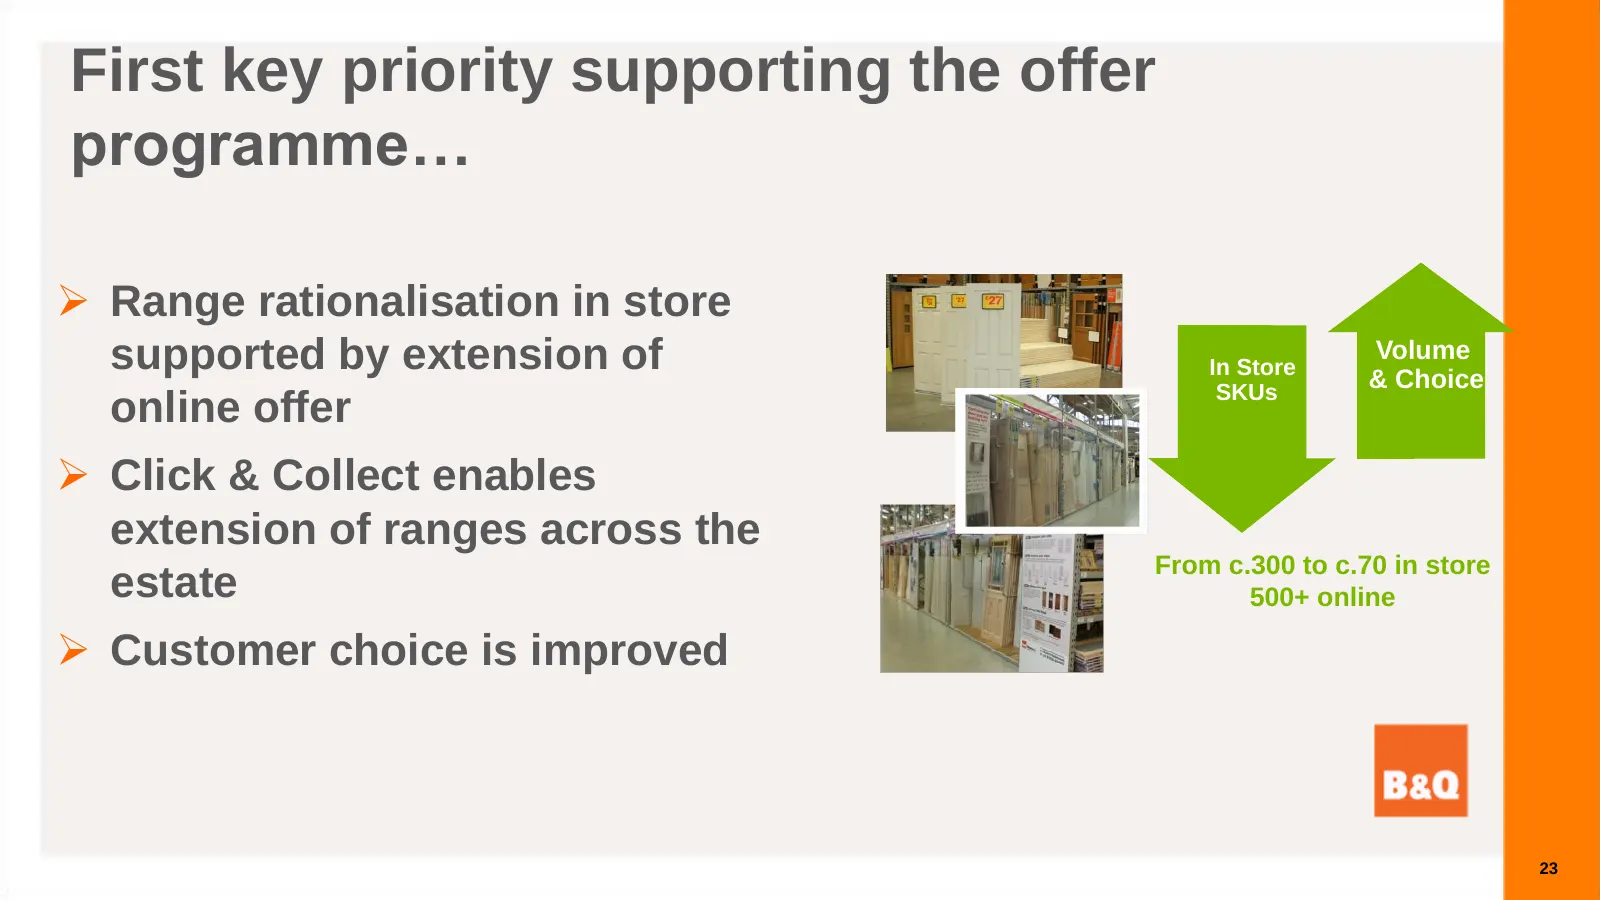
First key priority supporting the offer programme… Range rationalisation in store supported by extension of In Store Volume & Choice SKUs online offer Click & Collect enables extension of ranges across the From c.300 to c.70 in store estate 500+ online Customer choice is improved 23
Slide 24: We have launched new Click & Collect
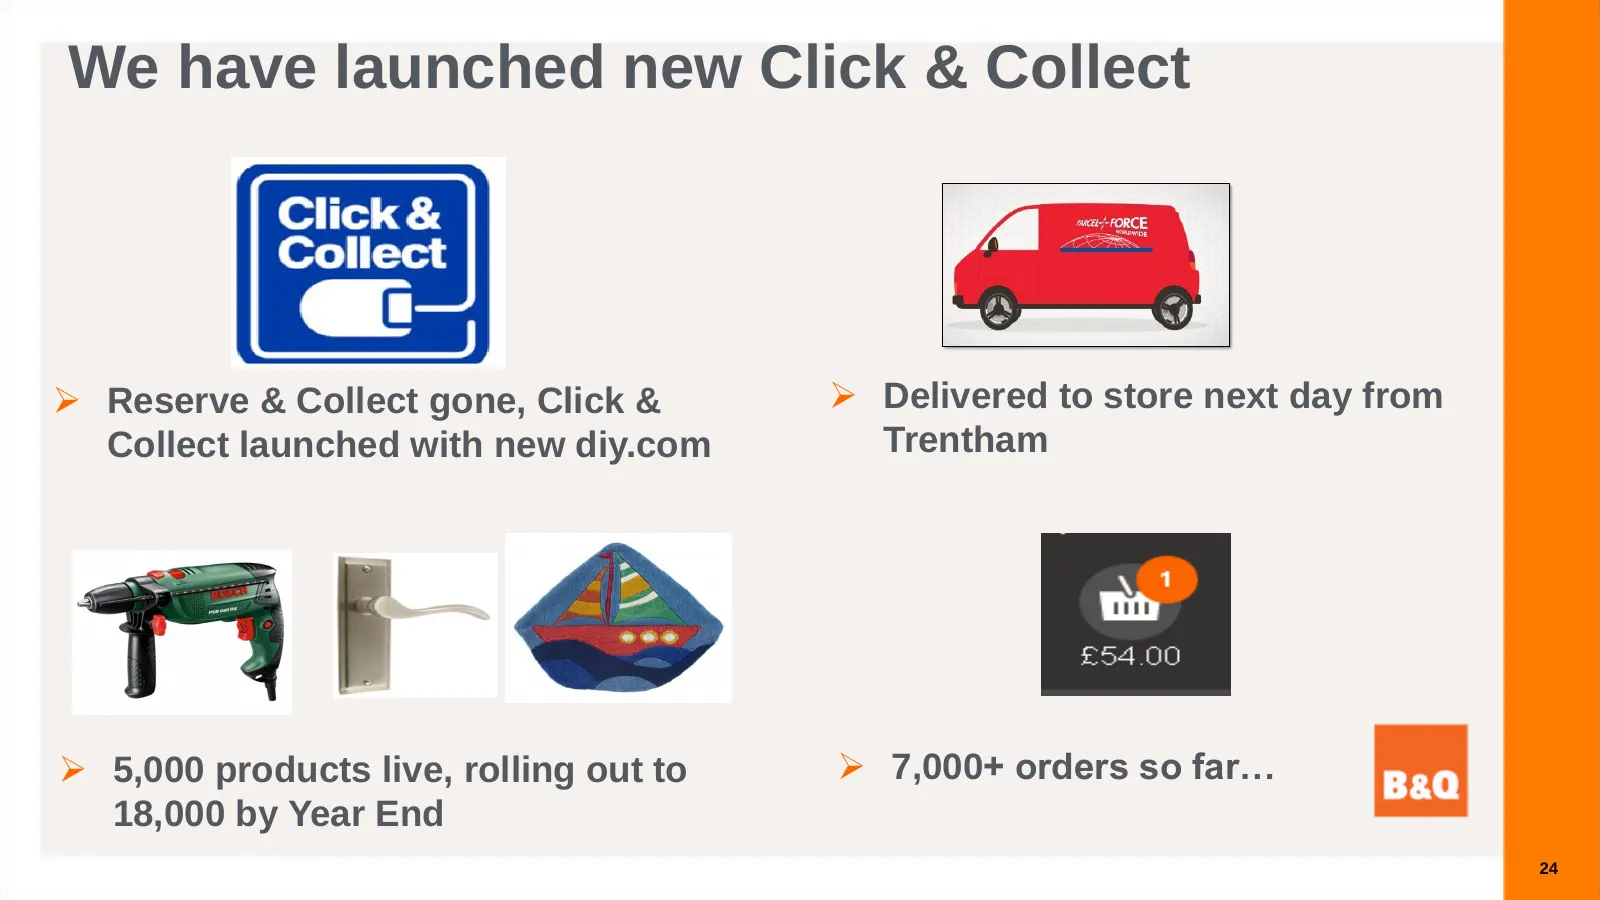
We have launched new Click & Collect Reserve & Collect gone, Click & Delivered to store next day from Collect launched with new diy.com Trentham 5,000 products live, rolling out to 7,000+ orders so far… 18,000 by Year End 24
Slide 25: Click & Collect will evolve over next 2 years…
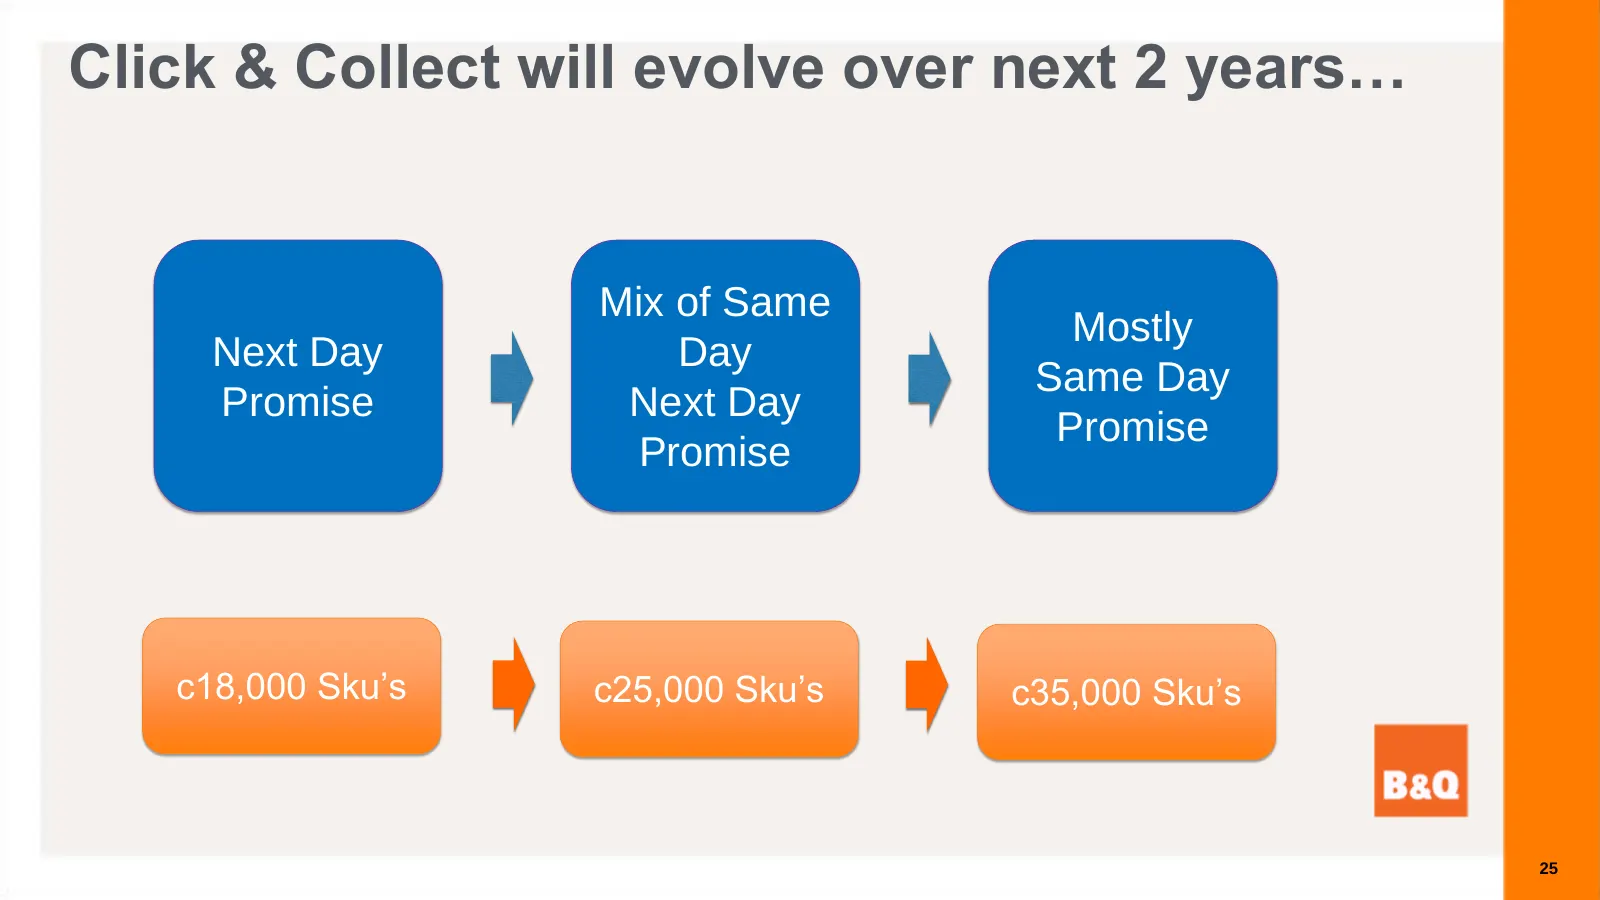
Click & Collect will evolve over next 2 years… Mix of Same Mostly Next Day Day Same Day Promise Next Day Promise Promise c18,000 Sku’s c25,000 Sku’s c35,000 Sku’s 25
Slide 26: Next priority delivering complementary extensions of online range…
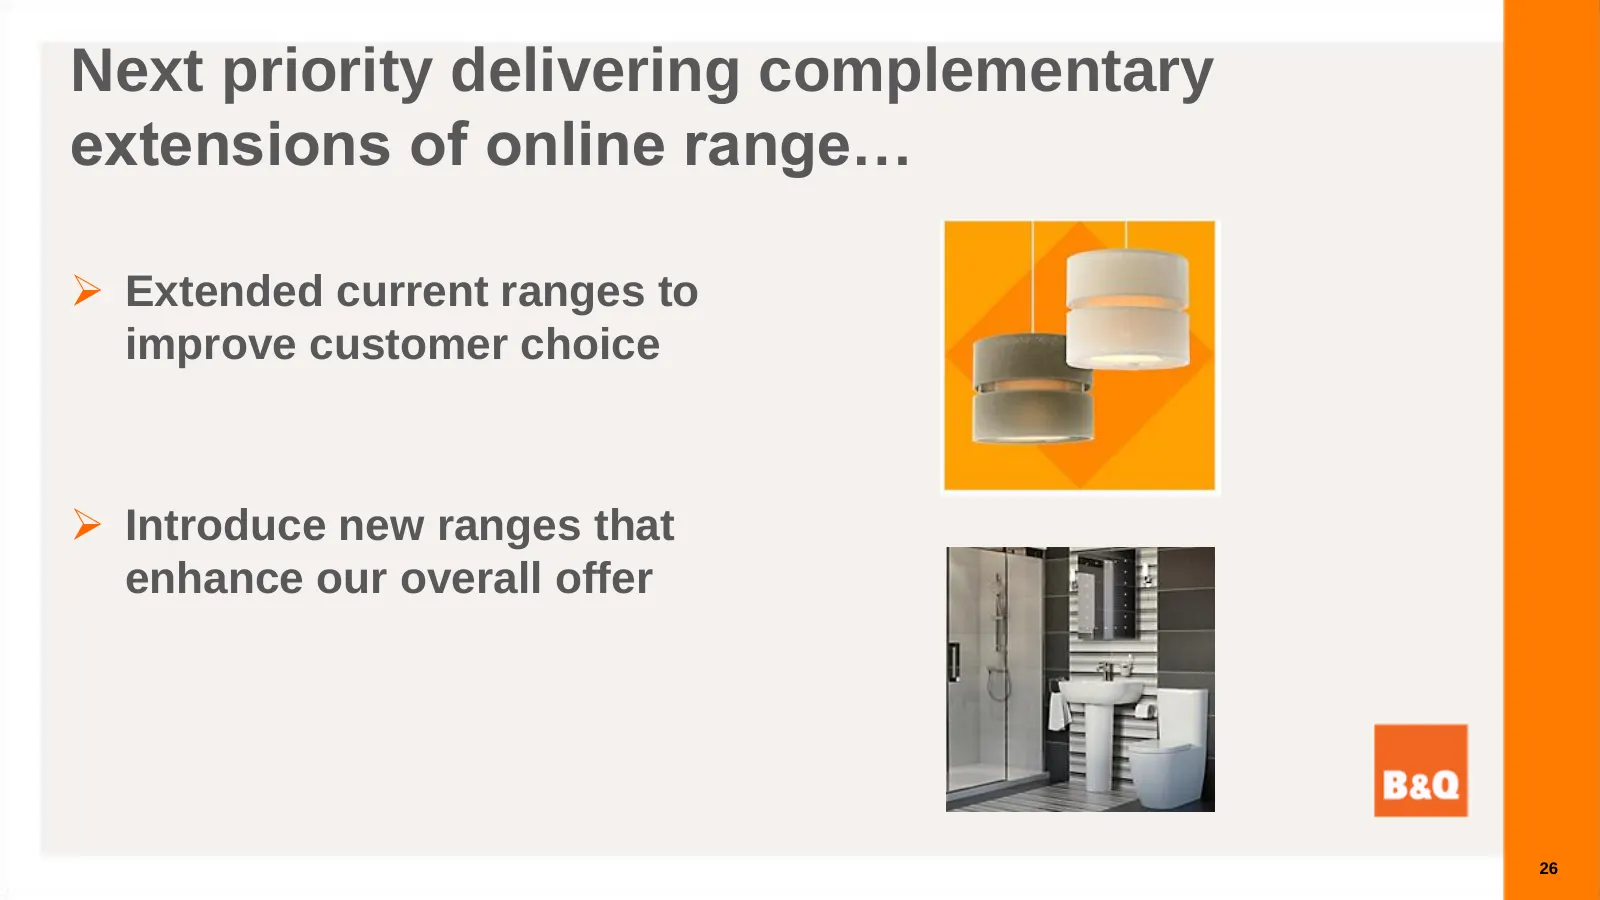
Next priority delivering complementary extensions of online range… Extended current ranges to improve customer choice Introduce new ranges that enhance our overall offer 26
Slide 27: Productivity
Productivity Dave Lowther 27
Slide 28: The productivity programme is cross functional and end to end
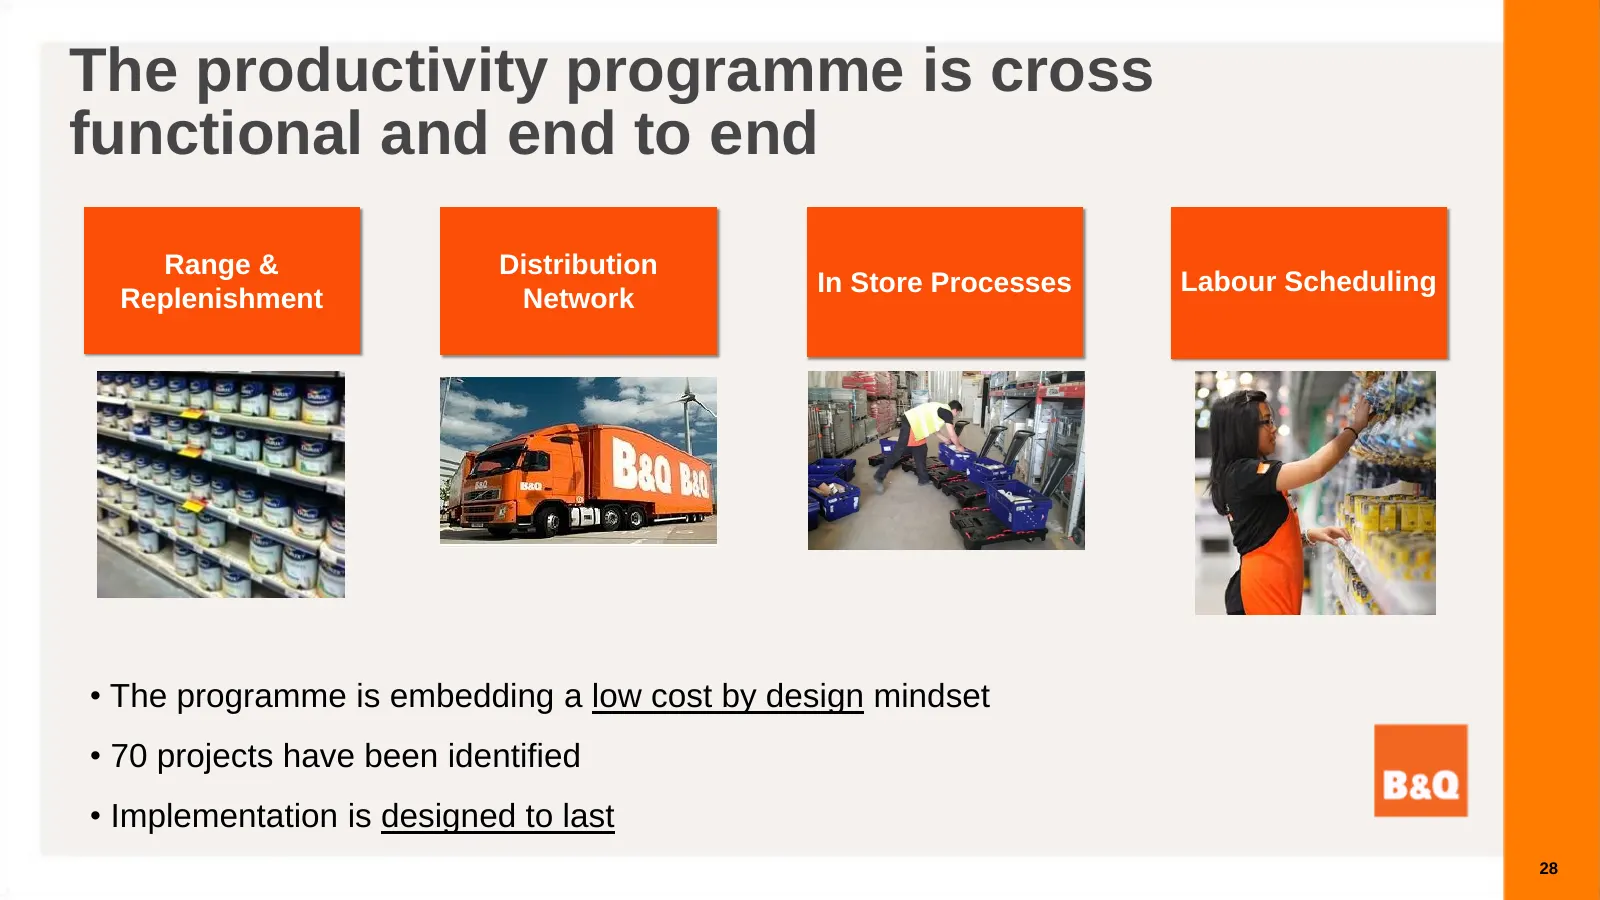
The productivity programme is cross functional and end to end Range & Distribution In Store Processes Labour Scheduling Replenishment Network • The programme is embedding a low cost by design mindset • 70 projects have been identified • Implementation is designed to last 28
Slide 29: We've already made good progress
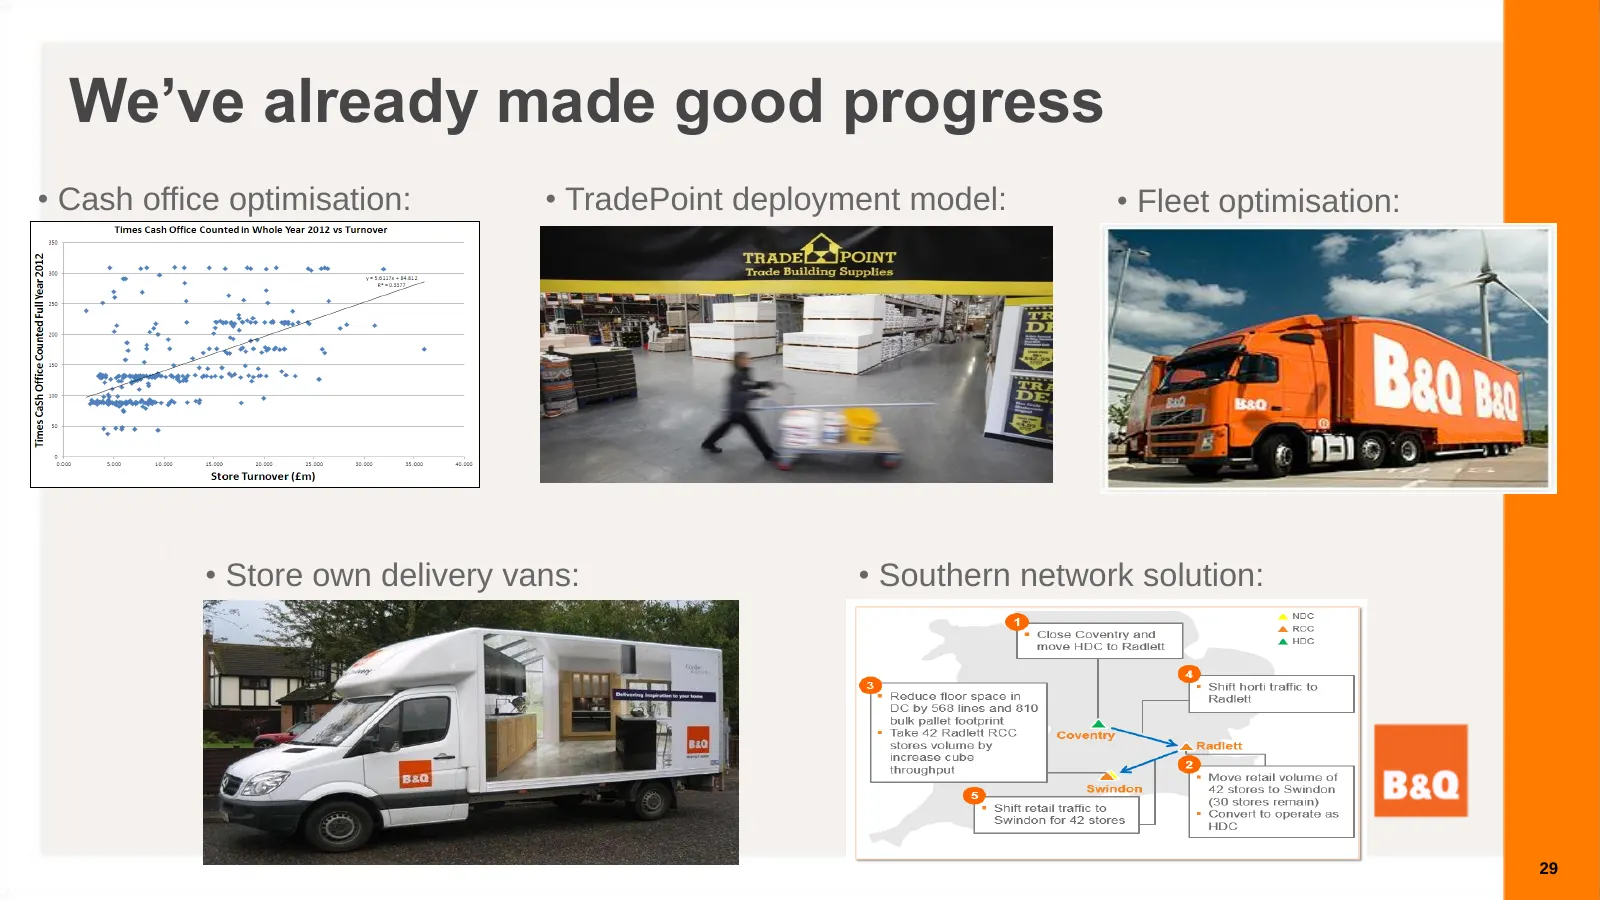
We’ve already made good progress • Cash office optimisation: • TradePoint deployment model: • Fleet optimisation: • Store own delivery vans: • Southern network solution: 29
Slide 30: There's more to come…
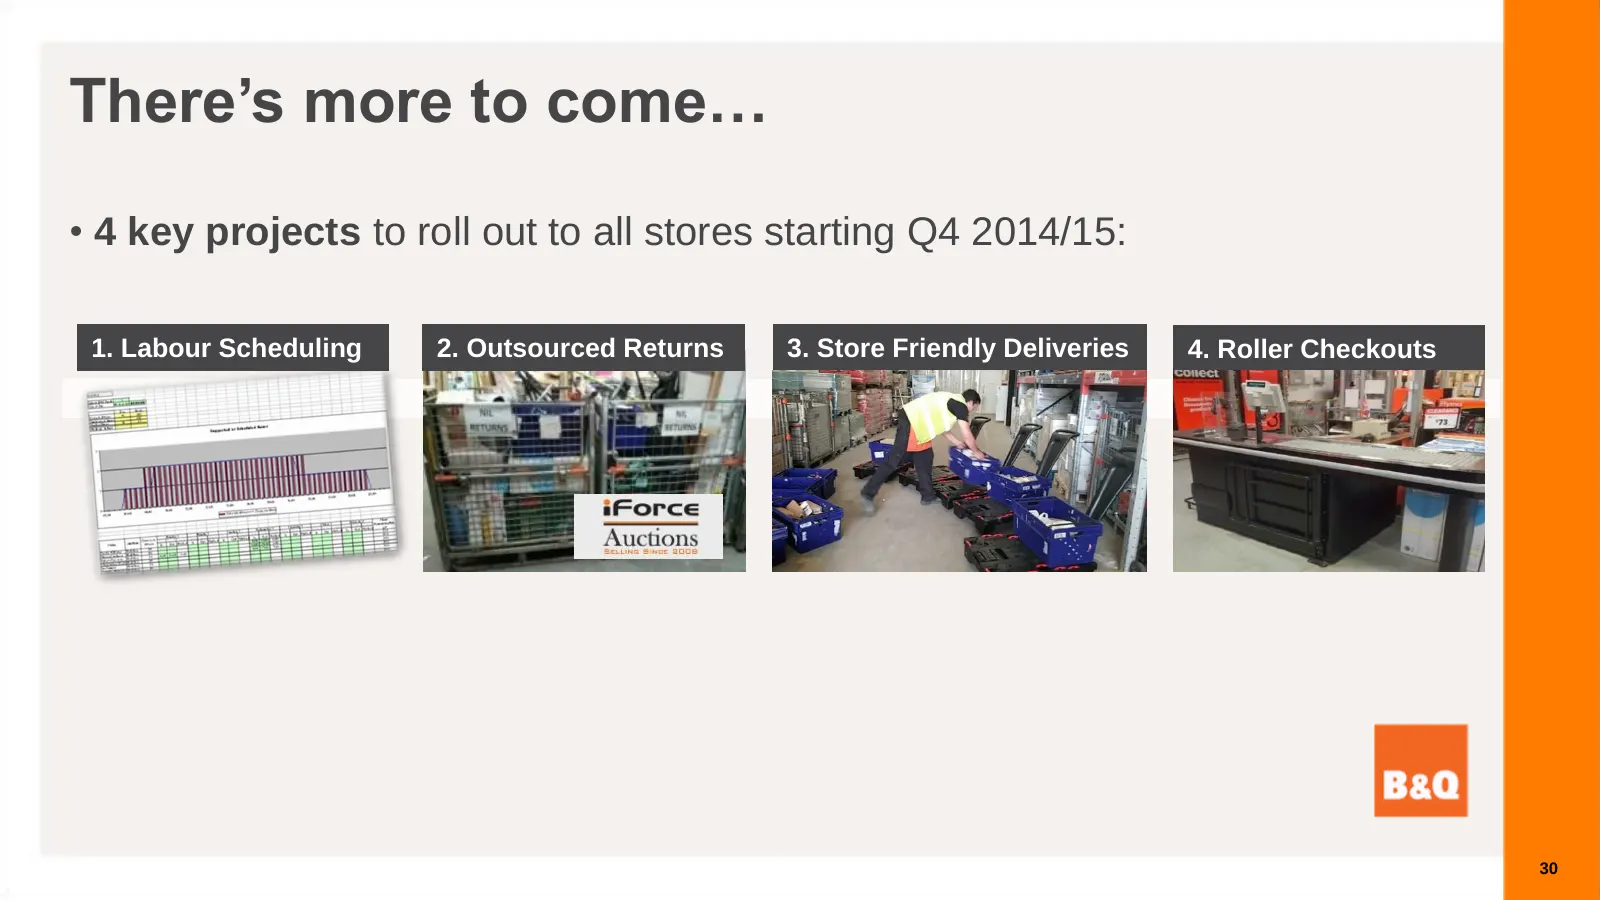
There’s more to come… • 4 key projects to roll out to all stores starting Q4 2014/15: 1. Labour Scheduling 2. Outsourced Returns 3. Store Friendly Deliveries 4. Roller Checkouts 30
Slide 31: Customer and Marketing
Customer and Marketing Chris Moss 31
Slide 32: The customer is at the core of our business
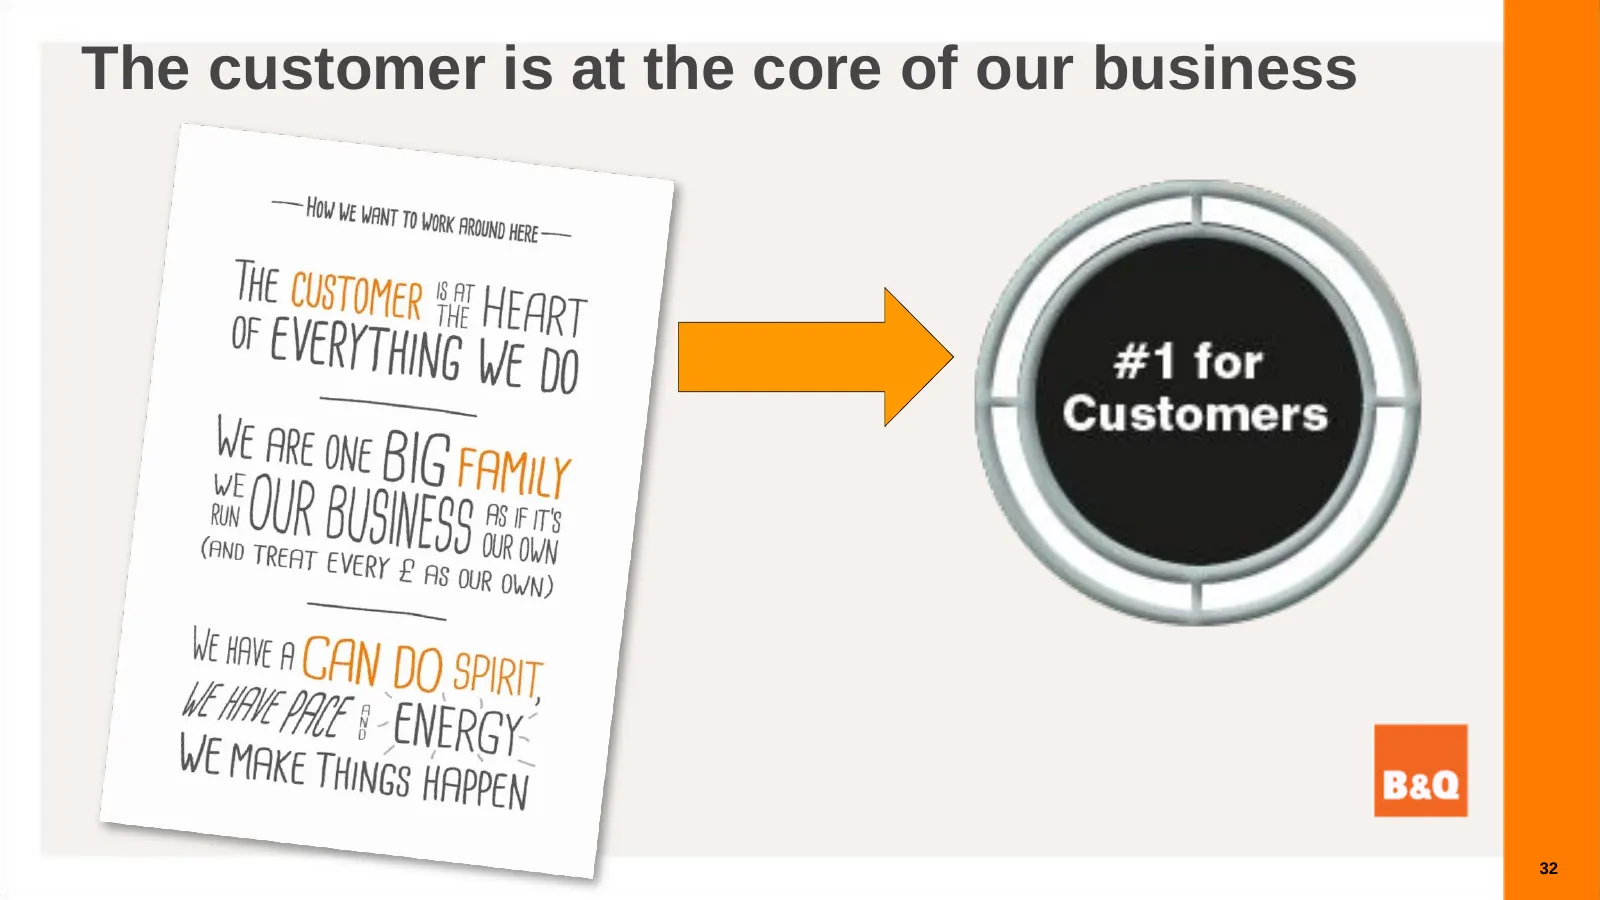
The customer is at the core of our business 32
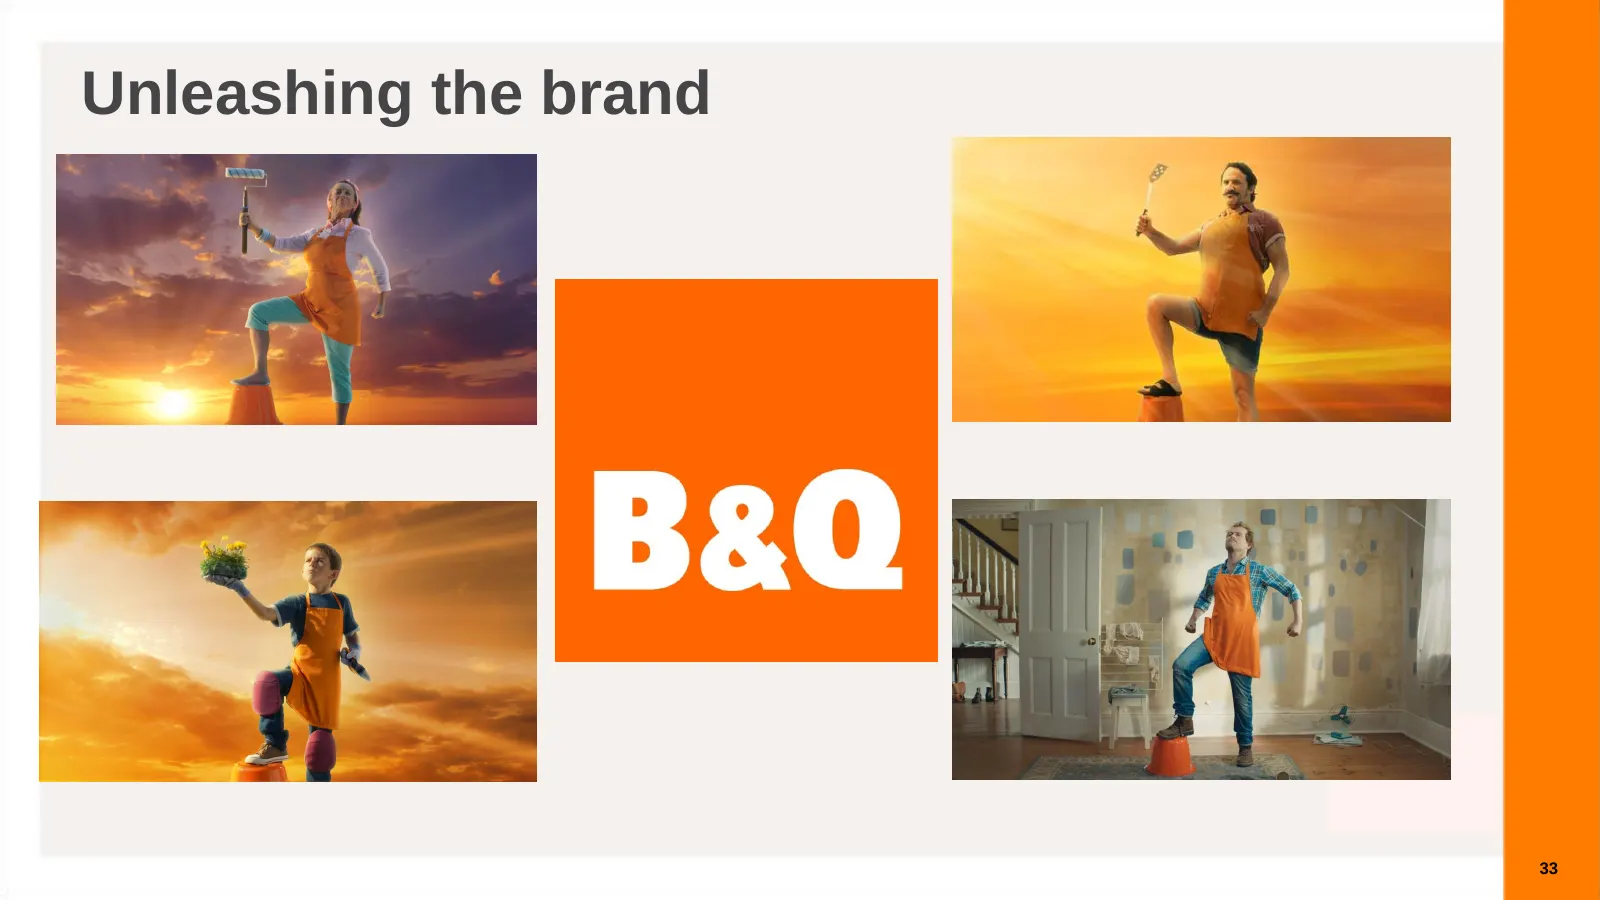
Slide 33: Unleashing the brand
Unleashing the brand ae a ee
Slide 34: The Home Improvement Warehouse for the Digital Age
“The Home Improvement Warehouse for the Digital Age” 34
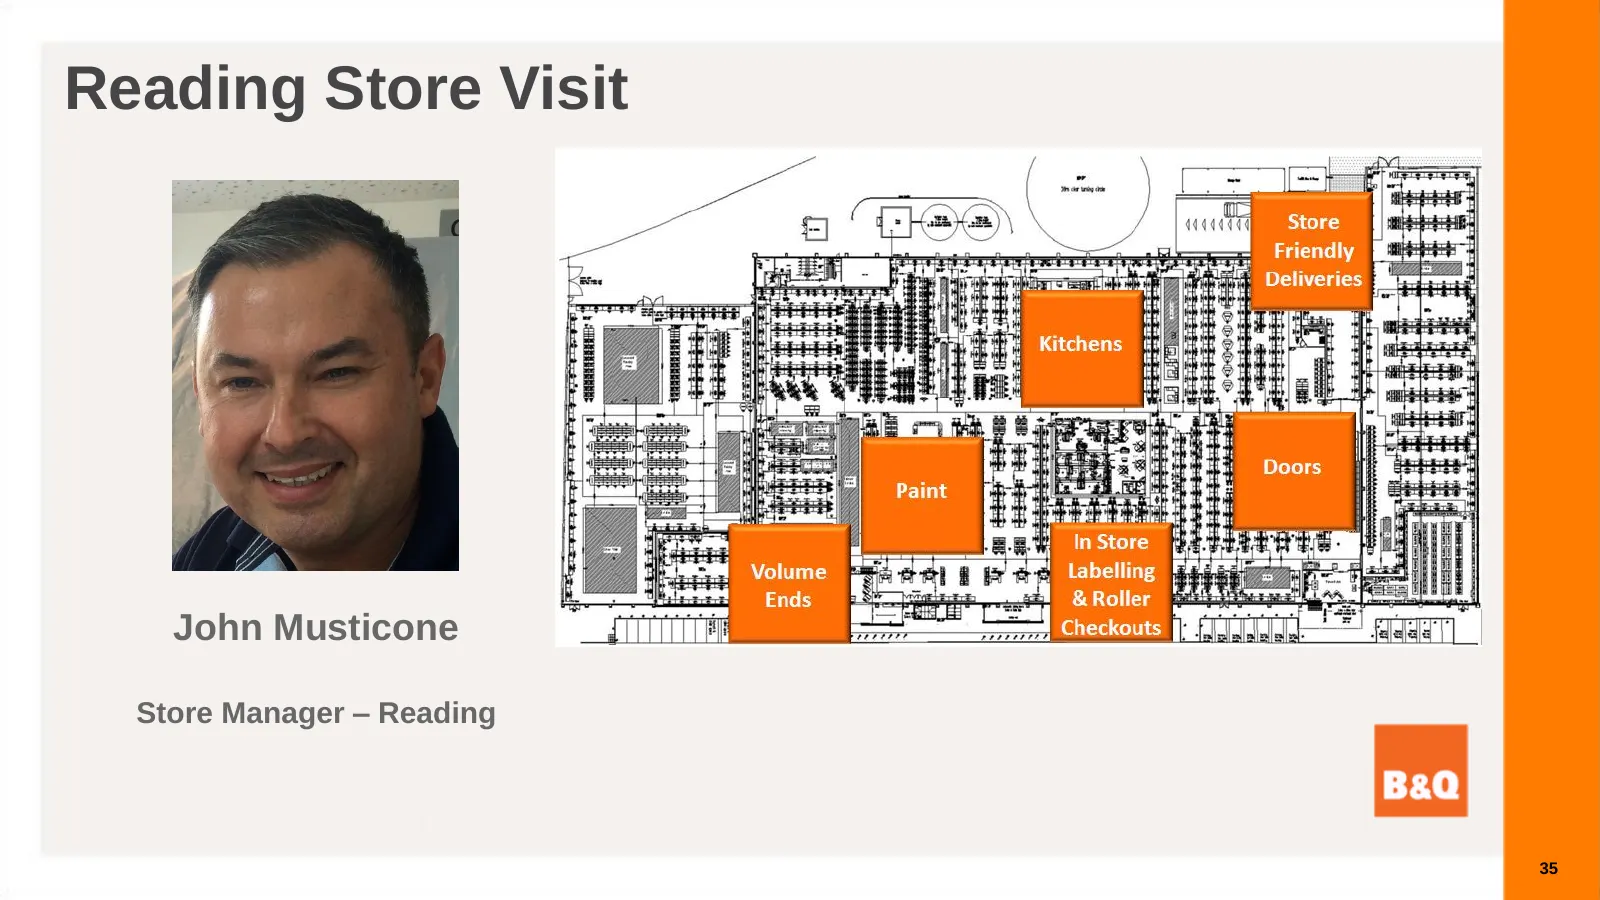
Slide 35: Reading Store Visit
Reading Store Visit John Musticone Store Manager – Reading 35
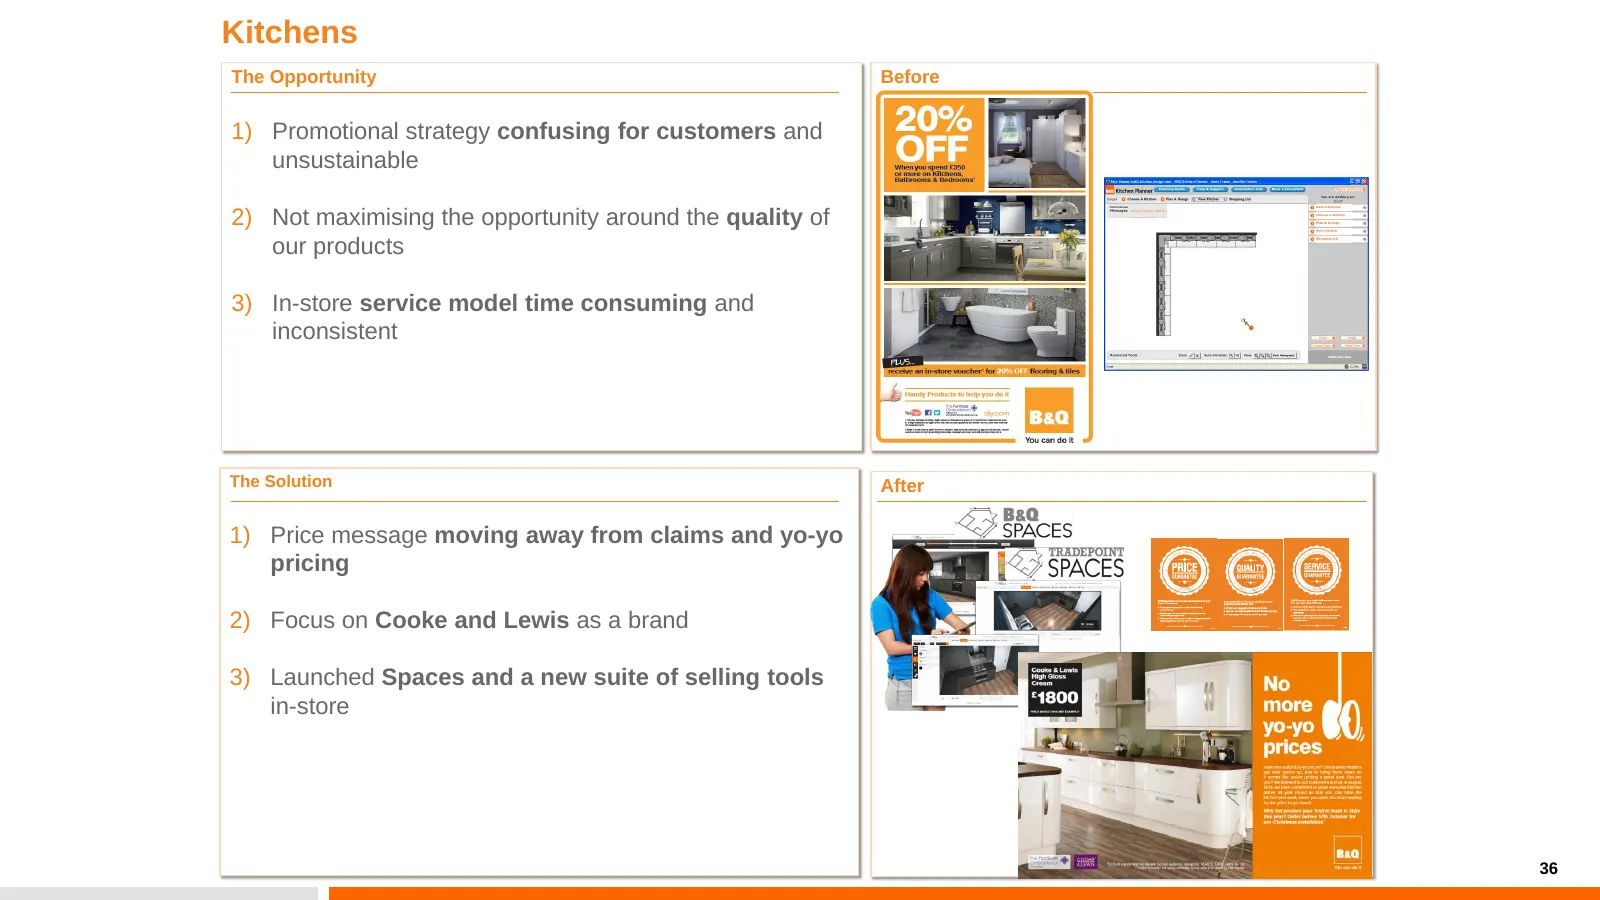
Slide 36: Kitchens
Kitchens The Opportunity Before 1) Promotional strategy confusing for customers and unsustainable 2) Not maximising the opportunity around the quality of our products 3) In-store service model time consuming and inconsistent The Solution After 1) Price message moving away from claims and yo-yo prici
Slide 37: Store Friendly Deliveries
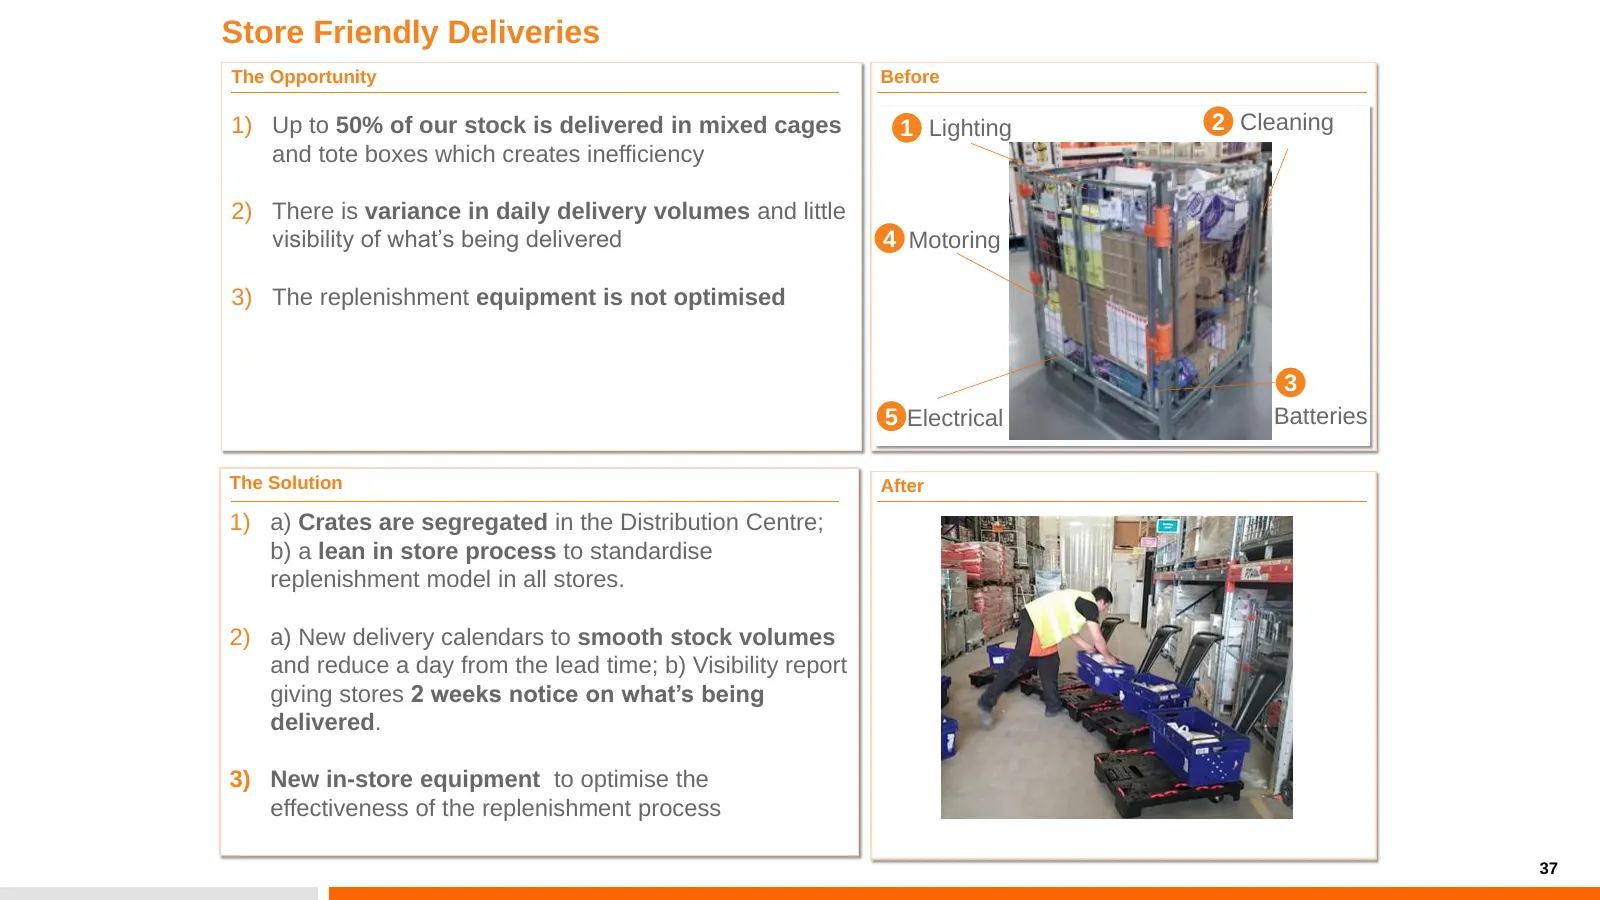
Store Friendly Deliveries The Opportunity Before 1) Up to 50% of our stock is delivered in mixed cages 1 Lighting 2 Cleaning and tote boxes which creates inefficiency 2) There is variance in daily delivery volumes and little visibility of what’s being delivered 4 Motoring 3) The replenishment equipm
Slide 38: Internal Doors
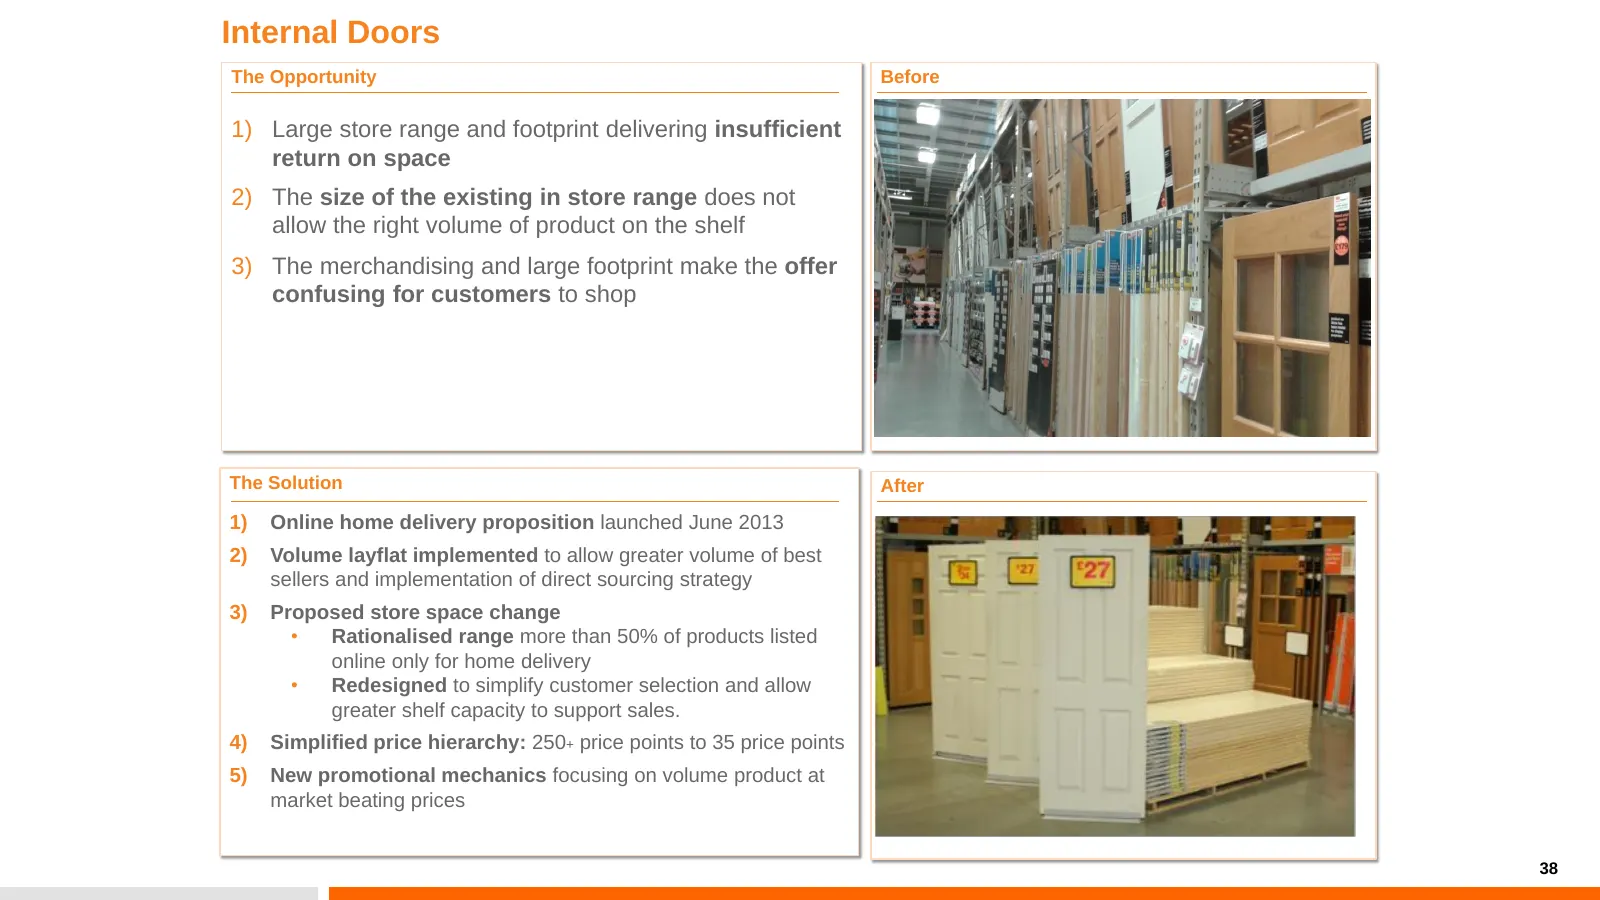
Internal Doors The Opportunity Before 1) Large store range and footprint delivering insufficient return on space 2) The size of the existing in store range does not allow the right volume of product on the shelf 3) The merchandising and large footprint make the offer confusing for customers to shop
Slide 39: In-Store Labelling and Roller Checkouts
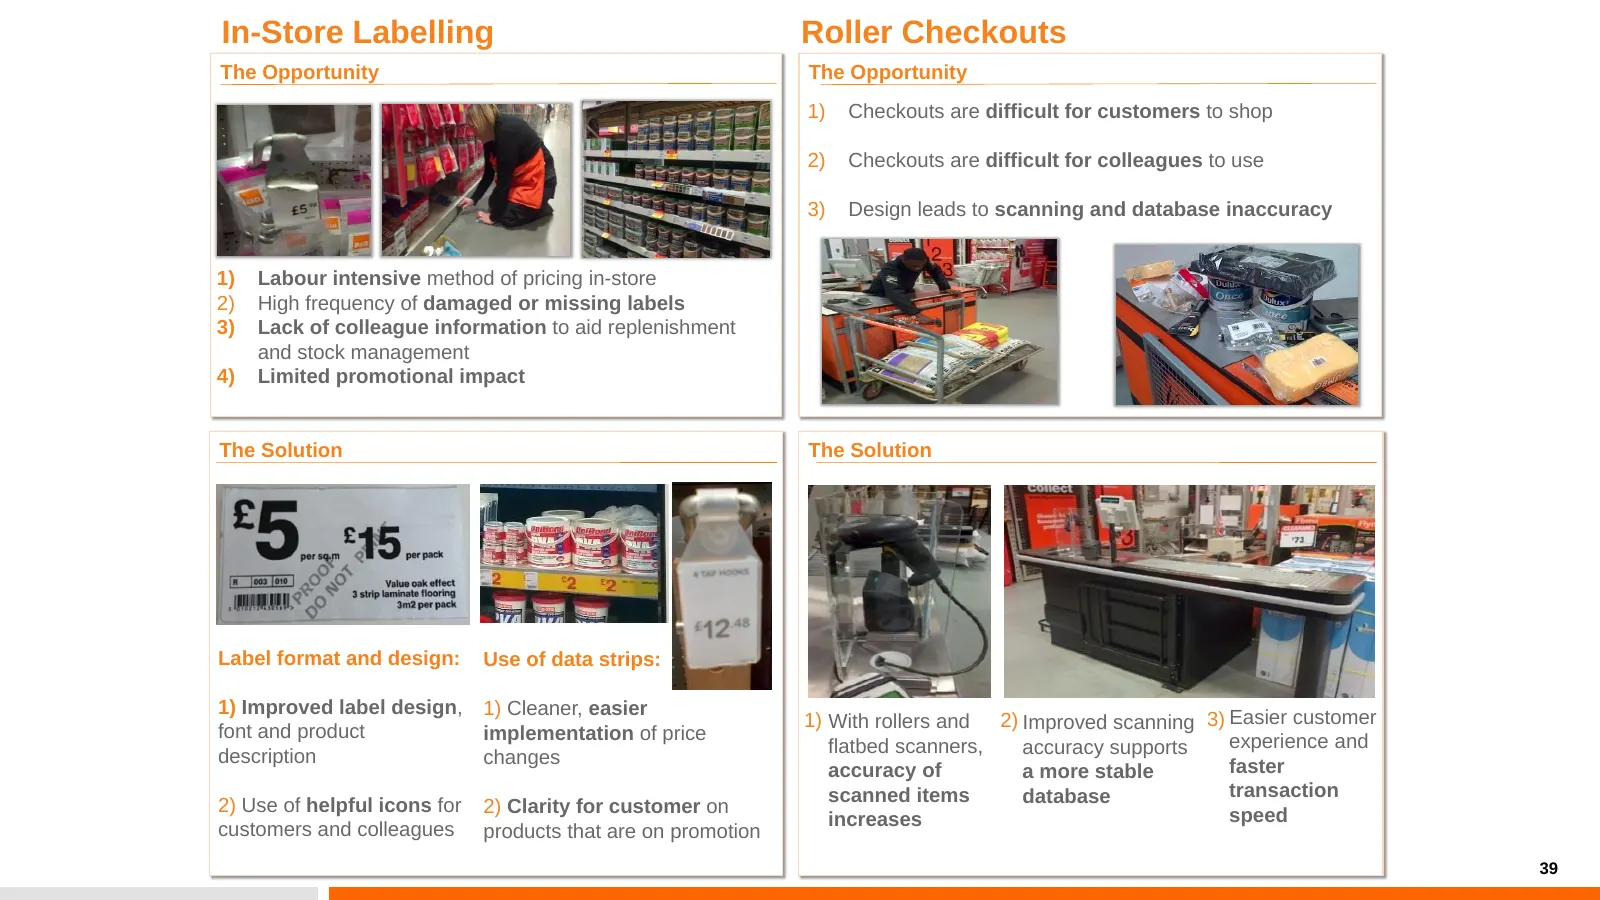
In-Store Labelling Roller Checkouts The Opportunity The Opportunity 1) Checkouts are difficult for customers to shop 2) Checkouts are difficult for colleagues to use 3) Design leads to scanning and database inaccuracy 1) Labour intensive method of pricing in-store 2) High frequency of damaged or mis
Slide 40: Volume Ends
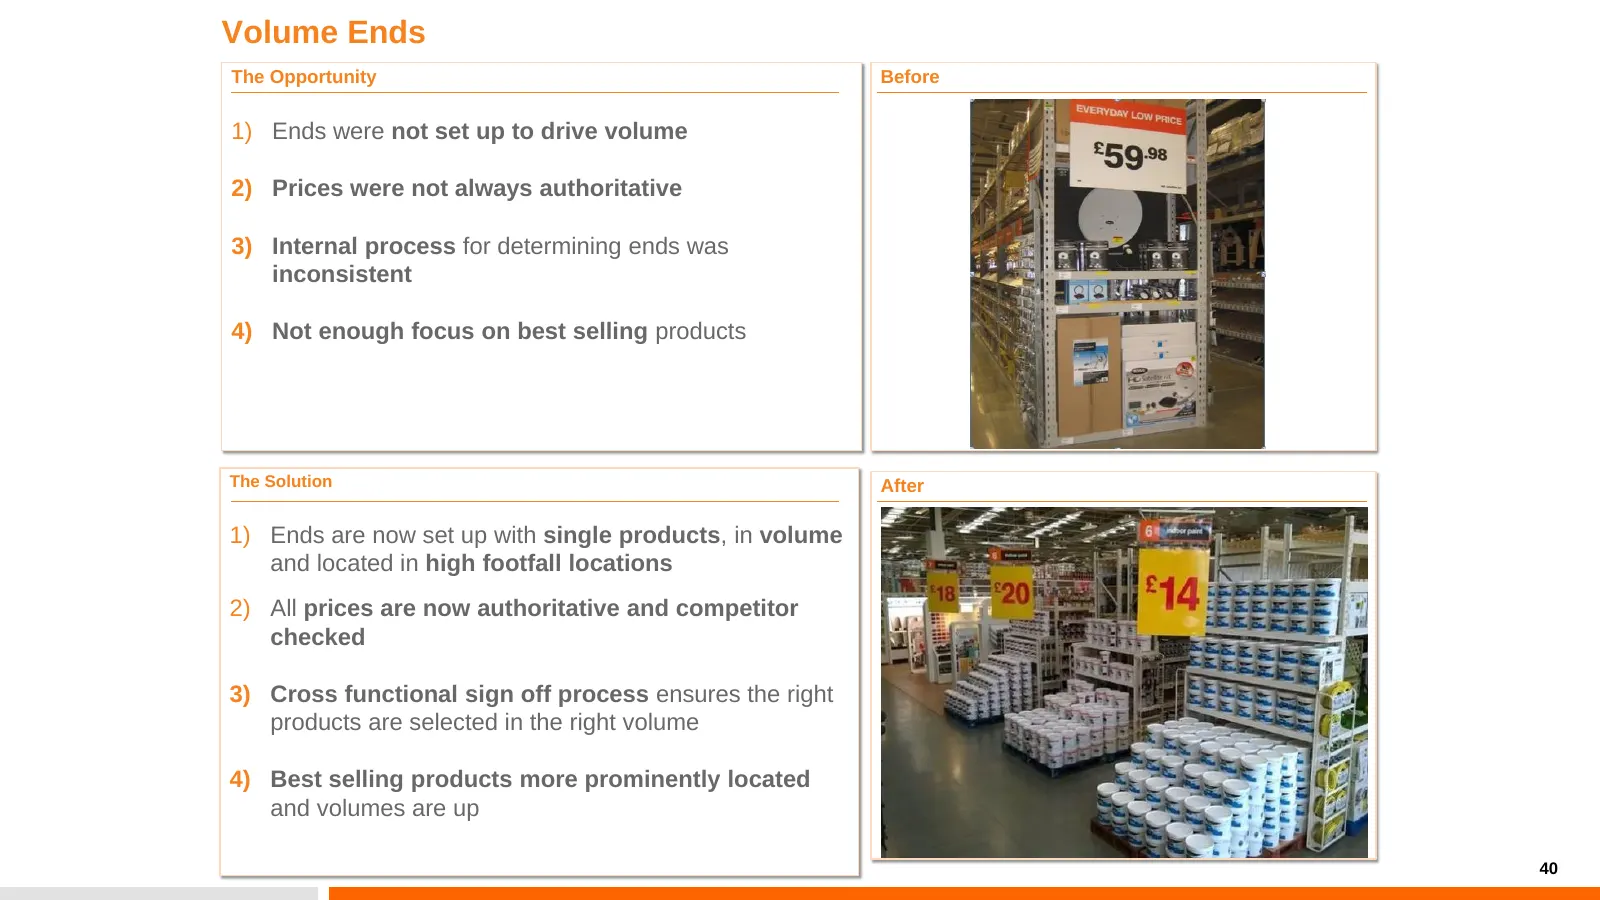
Volume Ends The Opportunity Before 1) Ends were not set up to drive volume 2) Prices were not always authoritative 3) Internal process for determining ends was inconsistent 4) Not enough focus on best selling products The Solution After 1) Ends are now set up with single products, in volume and loca
Slide 41: Paint
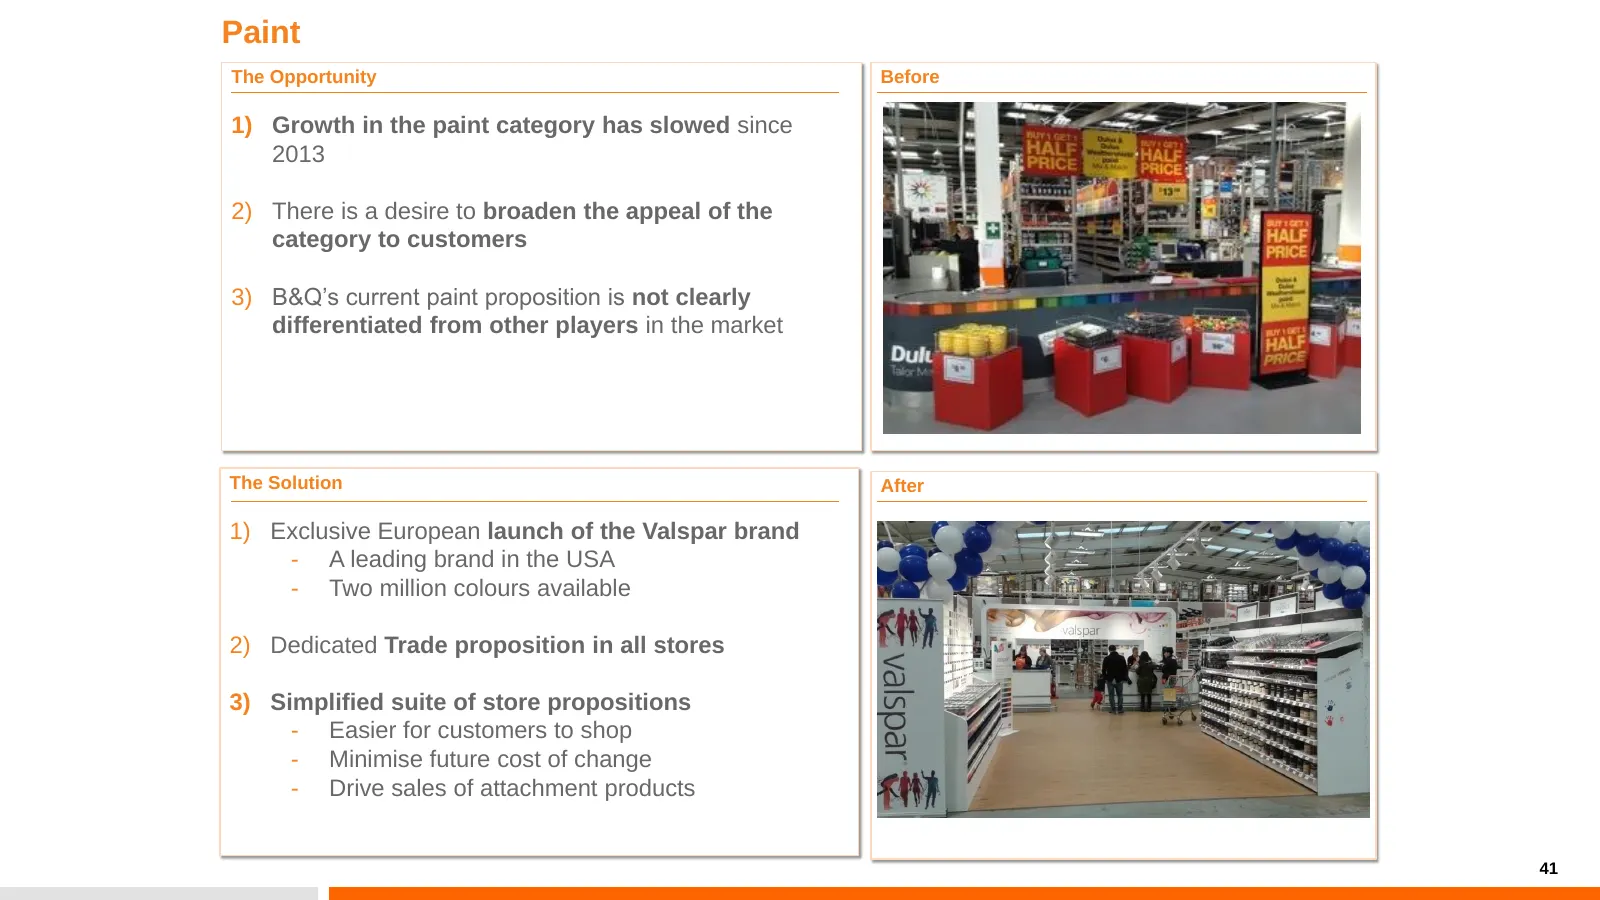
Paint The Opportunity Before 1) Growth in the paint category has slowed since 2013 2) There is a desire to broaden the appeal of the category to customers 3) B&Q’s current paint proposition is not clearly differentiated from other players in the market The Solution After 1) Exclusive European launch
Slide 42: Appendix
Baa Appendix Baa
Slide 43: B&Q UK & Ireland Board
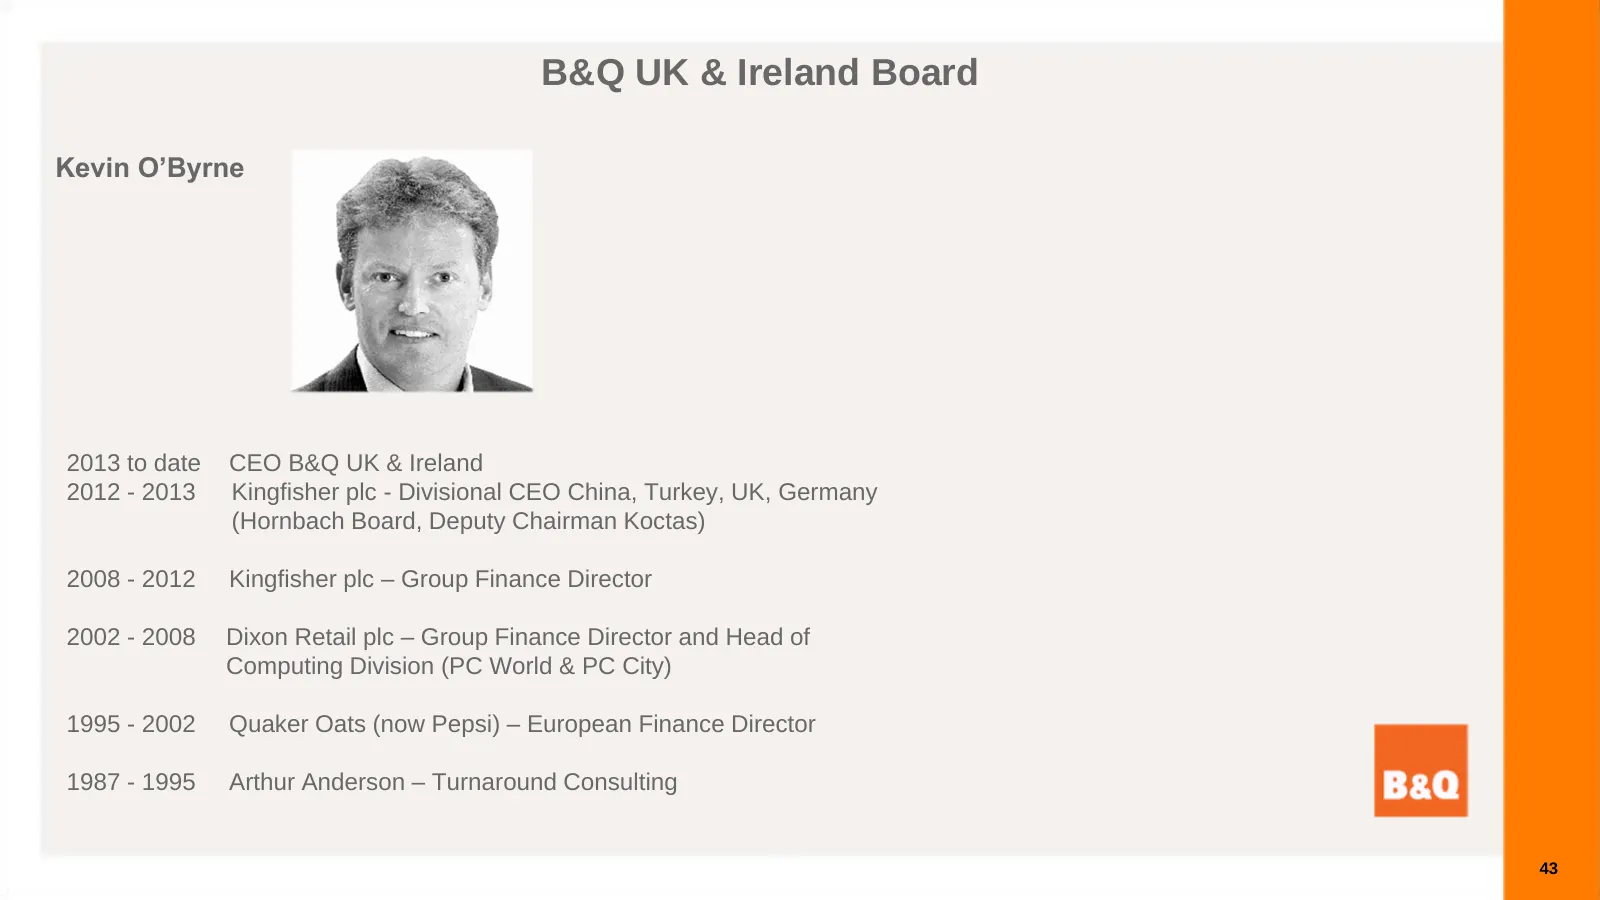
B&Q UK & Ireland Board Kevin O’Byrne 2013 to date CEO B&Q UK & Ireland 2012 - 2013 Kingfisher plc - Divisional CEO China, Turkey, UK, Germany (Hornbach Board, Deputy Chairman Koctas) 2008 - 2012 Kingfisher plc – Group Finance Director 2002 - 2008 Dixon Retail plc – Group Finance Director and Head of
Slide 44: B&Q UK & Ireland Board
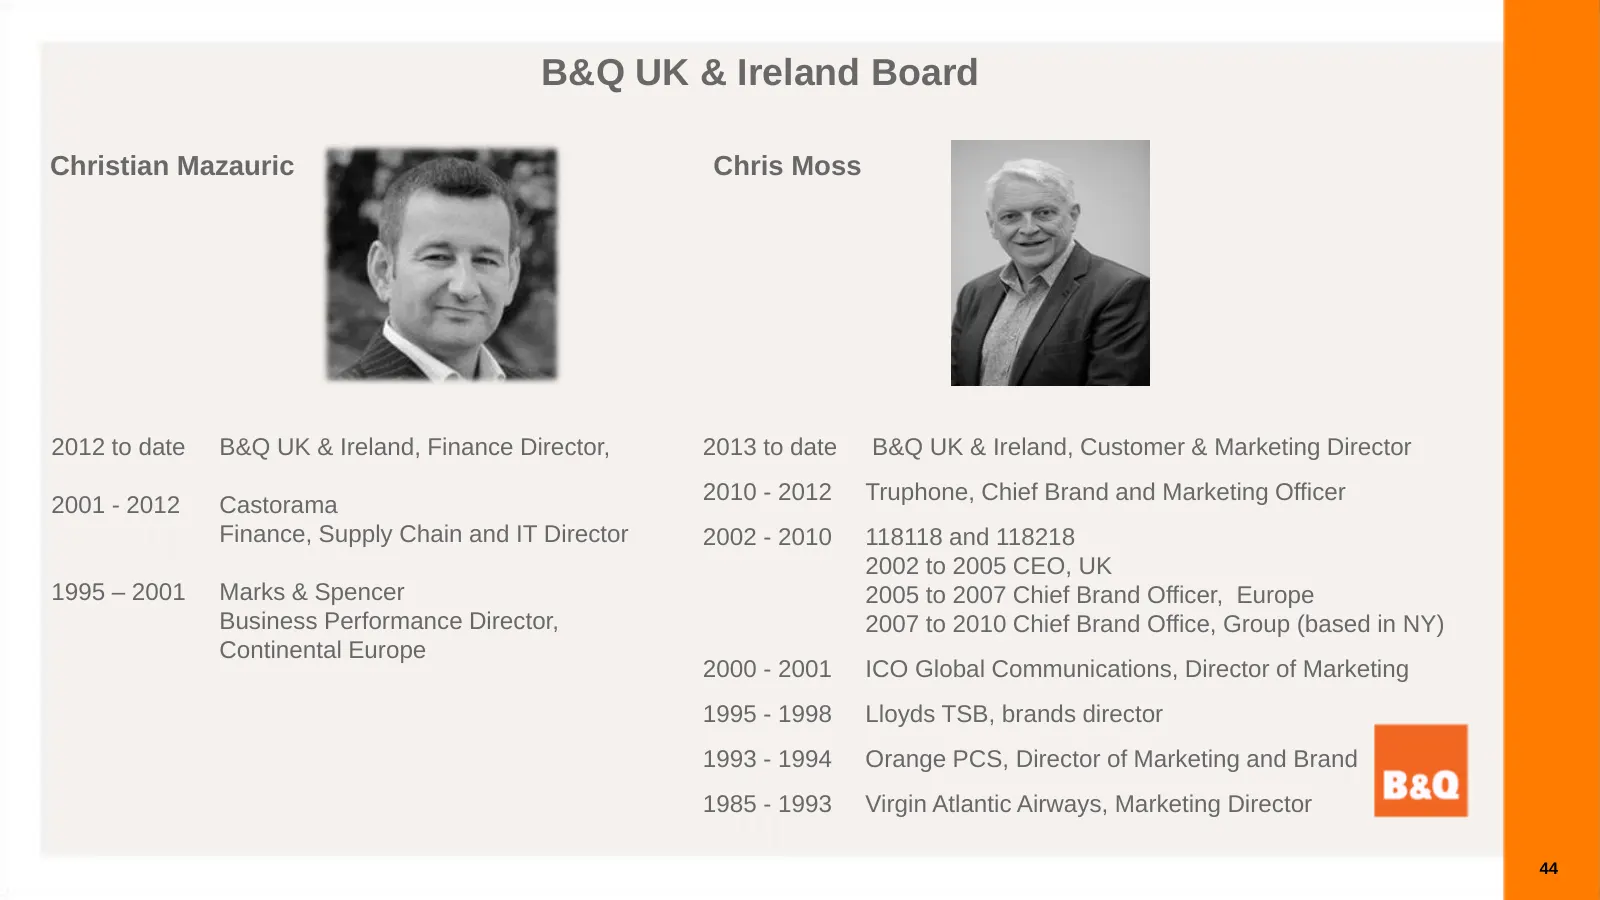
B&Q UK & Ireland Board Christian Mazauric Chris Moss 2012 to date B&Q UK & Ireland, Finance Director, 2013 to date B&Q UK & Ireland, Customer & Marketing Director 2010 - 2012 Truphone, Chief Brand and Marketing Officer 2001 - 2012 Castorama Finance, Supply Chain and IT Director 2002 - 2010 118118 an
Slide 45: B&Q UK & Ireland Board
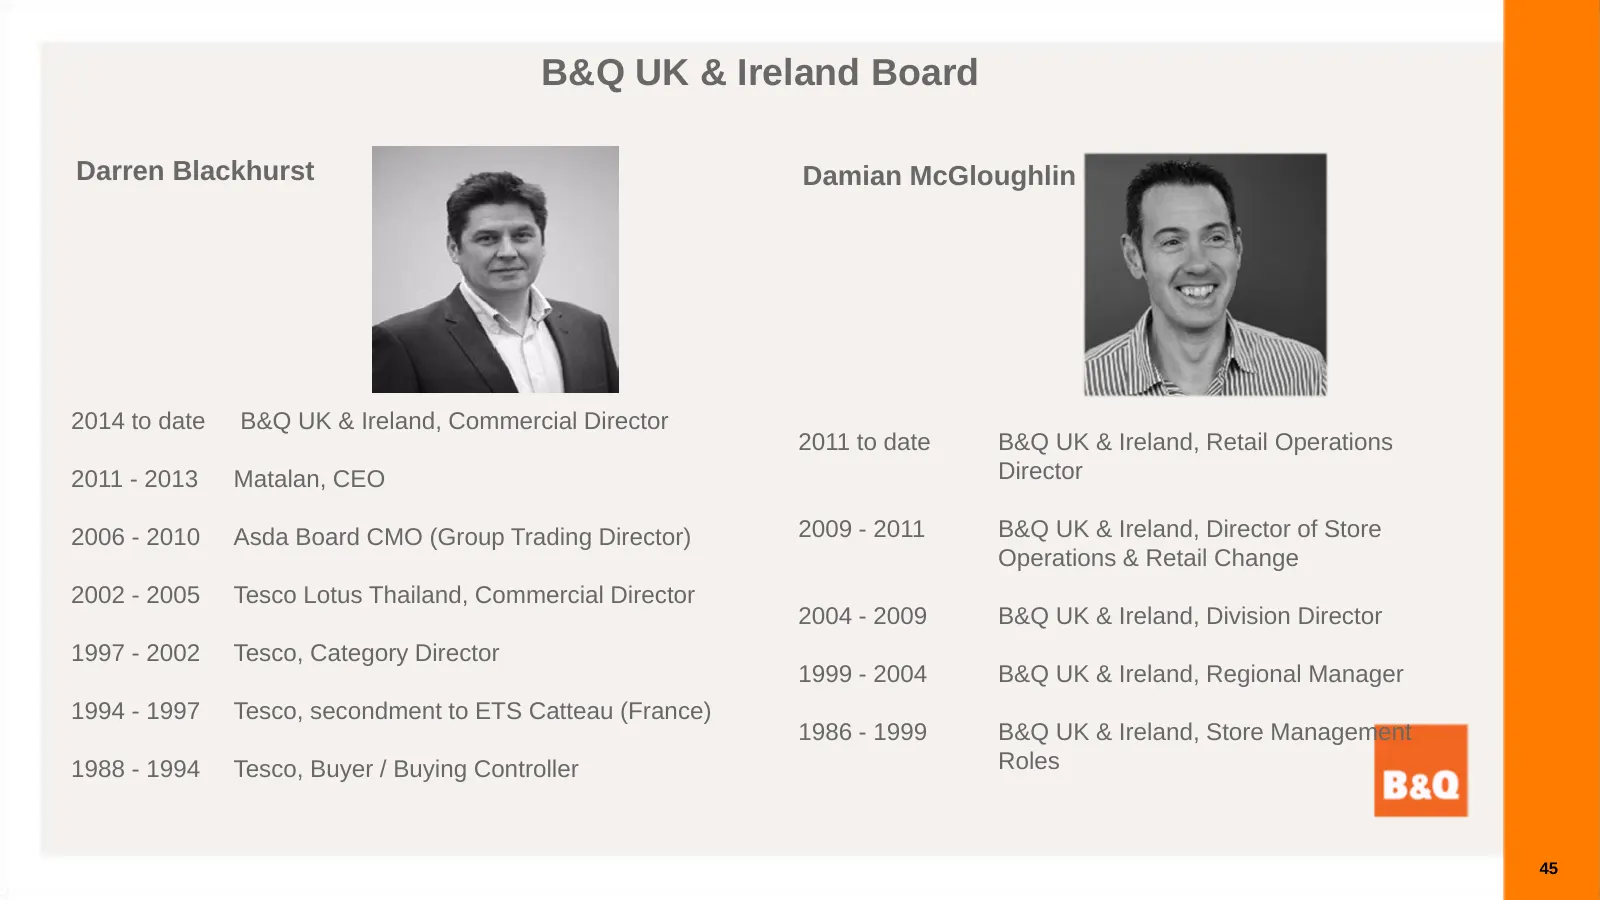
B&Q UK & Ireland Board Darren Blackhurst Damian McGloughlin 2014 to date B&Q UK & Ireland, Commercial Director 2011 to date B&Q UK & Ireland, Retail Operations 2011 - 2013 Matalan, CEO Director 2006 - 2010 Asda Board CMO (Group Trading Director) 2009 - 2011 B&Q UK & Ireland, Director of Store Operat
Slide 46: B&Q UK & Ireland Board
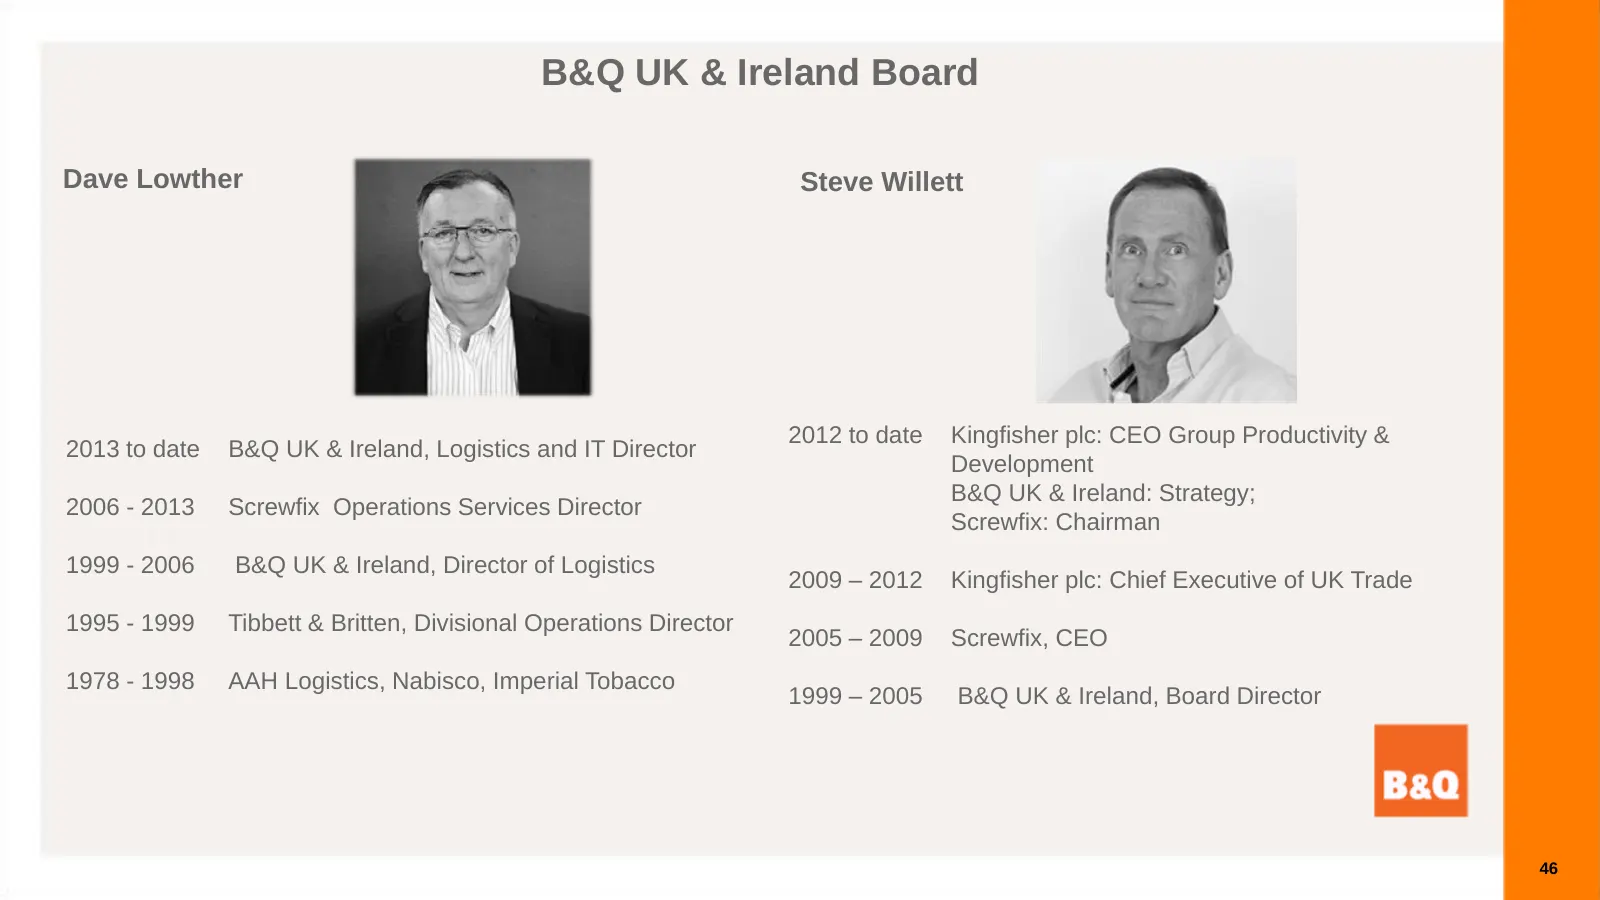
B&Q UK & Ireland Board Dave Lowther Steve Willett 2012 to date Kingfisher plc: CEO Group Productivity & 2013 to date B&Q UK & Ireland, Logistics and IT Director Development B&Q UK & Ireland: Strategy; 2006 - 2013 Screwfix Operations Services Director Screwfix: Chairman 1999 - 2006 B&Q UK & Ireland,
Slide 47: B&Q UK & Ireland Board
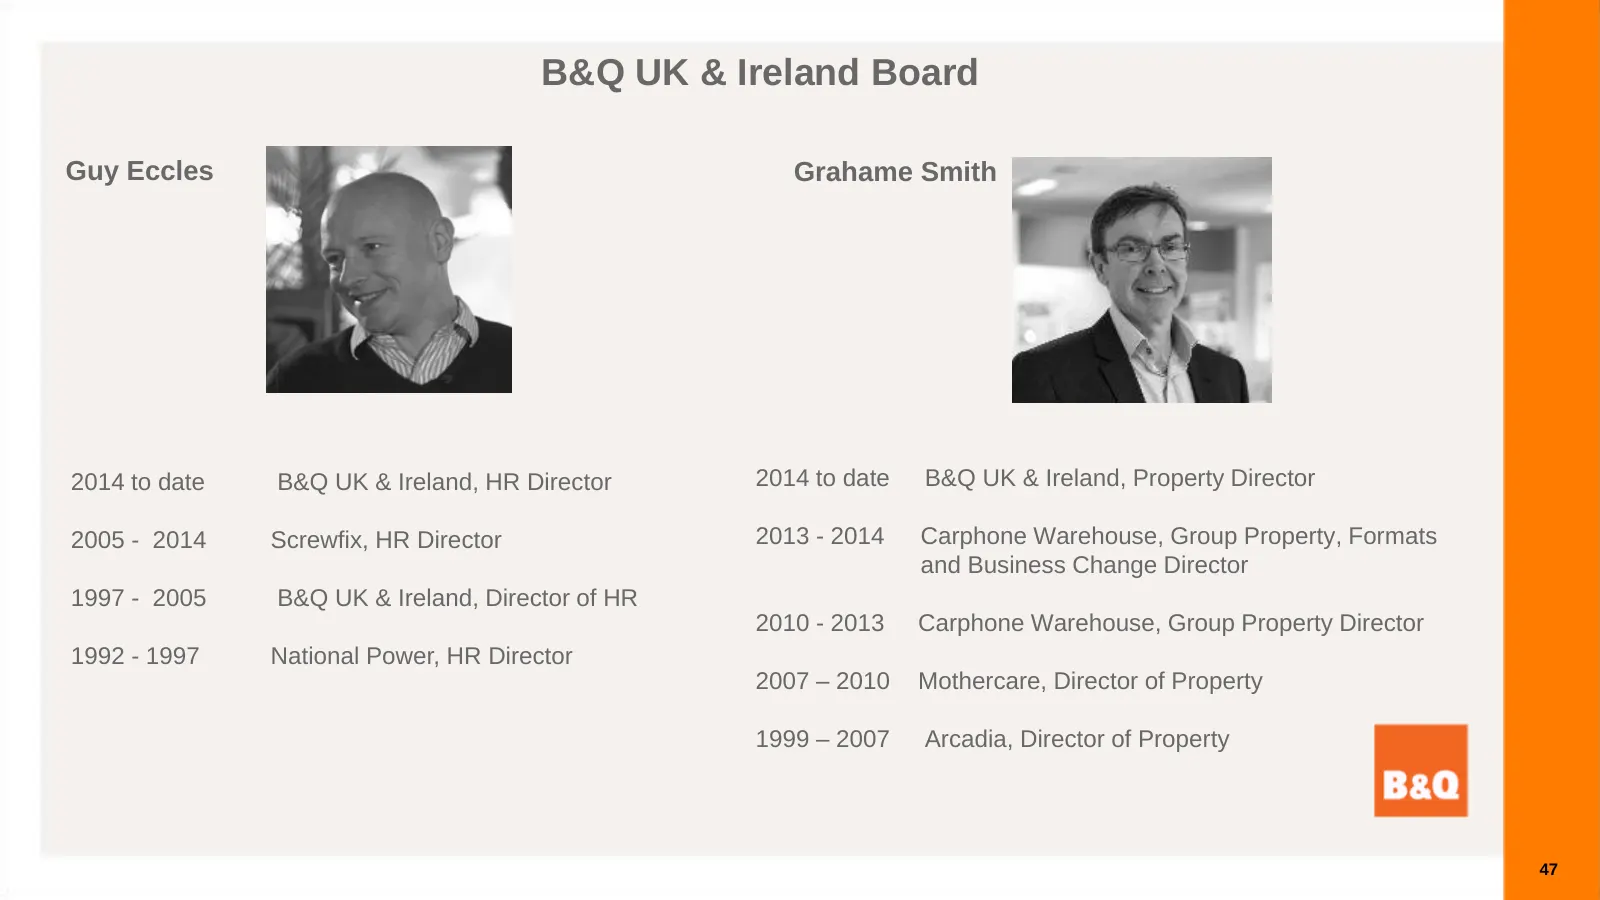
B&Q UK & Ireland Board Guy Eccles Grahame Smith 2014 to date B&Q UK & Ireland, HR Director 2014 to date B&Q UK & Ireland, Property Director 2005 - 2014 Screwfix, HR Director 2013 - 2014 Carphone Warehouse, Group Property, Formats and Business Change Director 1997 - 2005 B&Q UK & Ireland, Director of
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
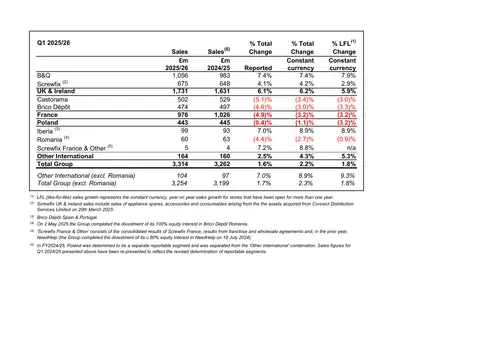 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025