Daktronics, Inc. · NASDAQ:DAKT
Daktronics — Q3 FY2010 Earnings Presentation
30 slides from Daktronics's earnings presentation, Mar 24, 2010
Slide 1: Investor Presentation FY2010 Third Quarter
Investor Presentation FY2010 Third Quarter
Slide 2: Safe Harbor Statement
Safe Harbor Statement In addition to statements of fact, this presentation contains forward- looking within the meaning of the Private Securities Litigation Reform Act of 1995 and is intended to enjoy the protection of that Act. These forward looking statements reflect the company’s expectations or
Slide 3: Why we are No. 1 in our industry
Why we are No. 1 in our industry - Executing against our mission to be the world leader at informing people through large dynamic audio-visual communications systems • Over 40 years of proven track record in the industry • Unparalleled sales and service coverage • Depth and breadth of product offeri
Slide 4: Daktronics
DAKTRONICS DAKTRONICS
Slide 5: Financial History
(Dollars in thousands except per share data) FY2005 FY2006 FY2007 FY2008 FY2009 5-Yr CAGR Sales $230,346 $309,370 $433,201 $499,677 $581,931 Operating Income $19,436 $31,815 $36,915 $38,243 $42,617 9.1% Earnings Per Share $0.39 $0.52 $0.59 $0.63 $0.64 Dividend Per Share - 0.05 0.06 0.07 0.09 (Dollar
Slide 6: FY 2010 Third Quarter YTD Results
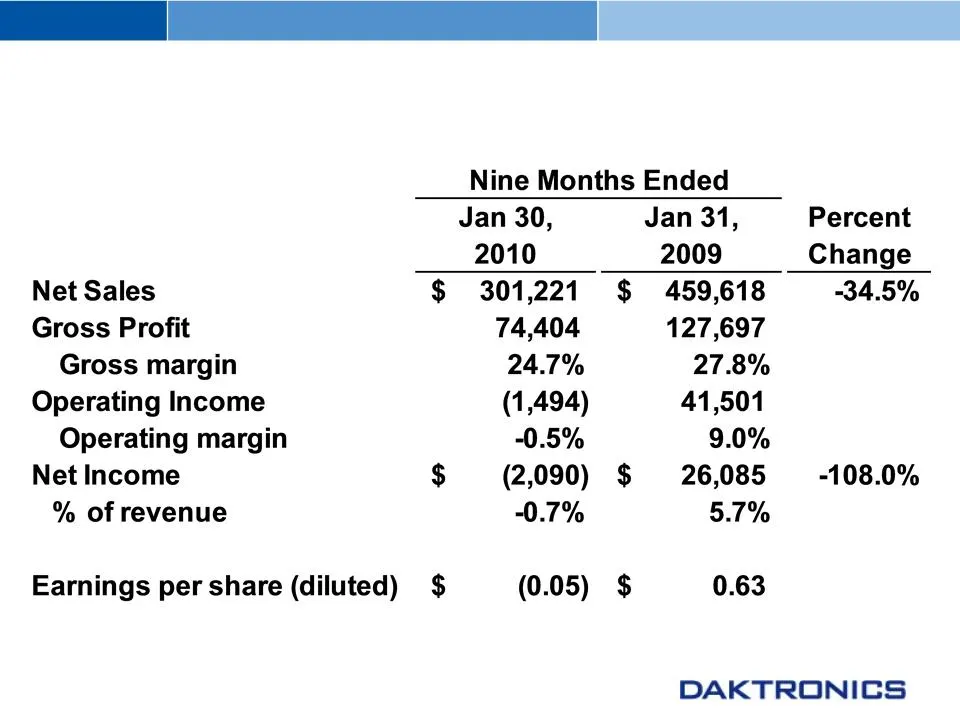
FY 2010 Third Quarter YTD Results* *($ in thousands, except per share data)
Slide 7: Historical Perspective FY2005 through FY2008
Historical Perspective FY2005 through FY2008 During this timeframe: • Revenue more than doubled- 30% CAGR • Capacity was the primary constraint • Added two manufacturing plants, Sioux Falls, and Redwood Falls and reorganized existing plants to a product focus • Initiated major “lean manufacturing” i
Slide 8: Overview FY09 through Q3 of FY10
Overview FY09 through Q3 of FY10 Revenues • First half of FY09 revenues were $330 million, a $660 million run rate (10.5% operating margin) • Second half of FY09 revenues were $250 million, or a $500 million run rate (3.2% operating margin) • Billboard business declined from a $100 million to less t
Slide 9: Overview FY09 through Q3 of FY10 (cont.)
Overview FY09 through Q3 of FY10 (cont.) Costs • Significant excess capacity in FY10 • Decreased operating expenses by more than 19% from Q1 of FY09 • Decreased manufacturing conversion costs by more than 28% from Q1 of FY09 Cash • Increased cash from $6 million in Q1 of FY09 to $58 million in Q3 of
Slide 10: Business is Organized in Business Units
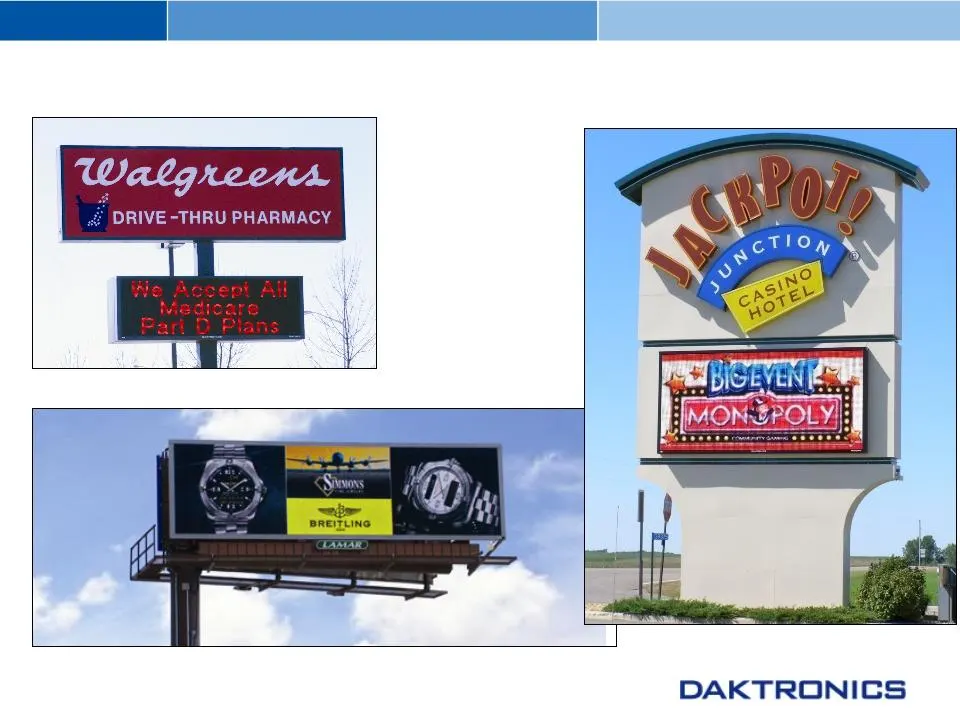
Business is Organized in 5 Business Units (“BU”) • Domestic (includes Canada) • Commercial • Live Events • Schools and Theaters • Transportation • International • BUs provide focus, but key strategy is to leverage resources across the company
Slide 11: = S) < = F- < = a a = = ie w z
= S) < = F- < = a a = = ie w 2 z DAKTRONICS
Slide 12: Commercial
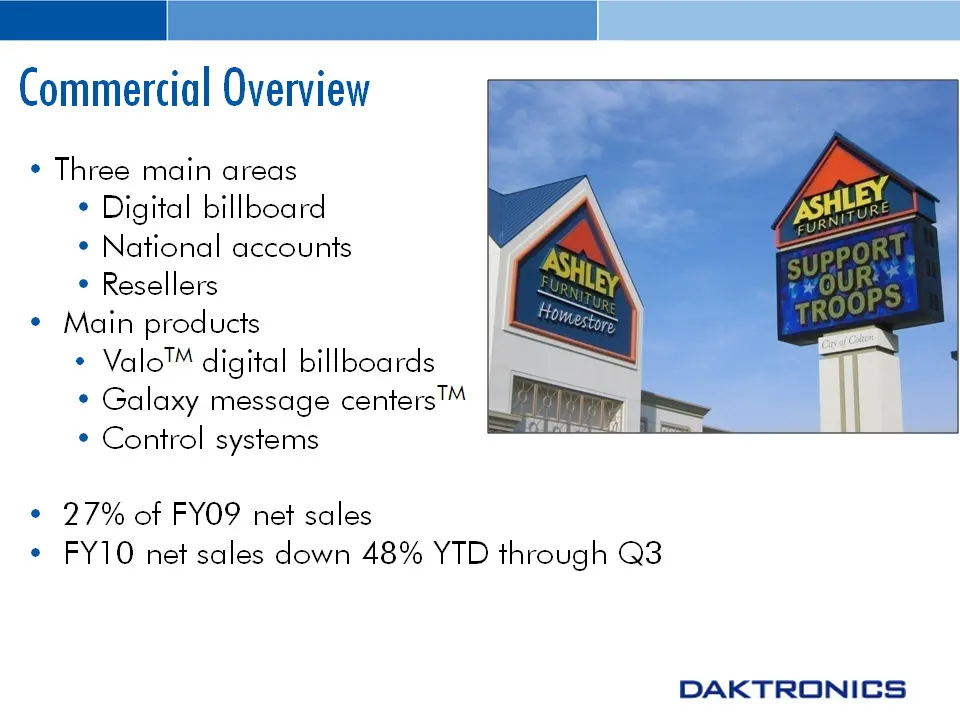
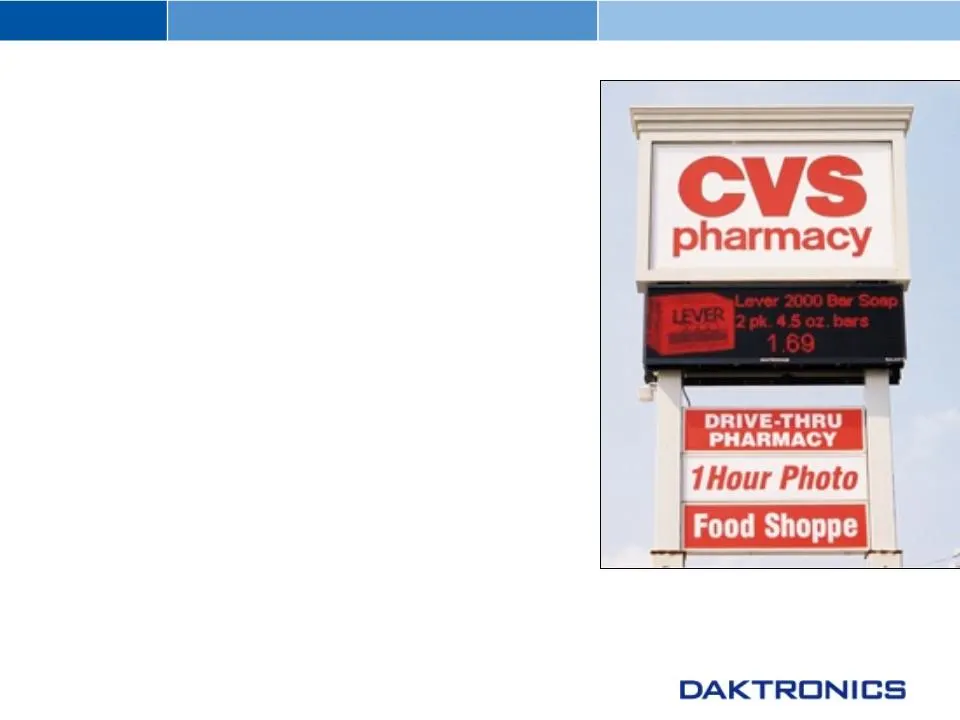
ymmerc ¢ Three main areas * Digital billboard ¢ National accounts * Resellers ¢ Main products * Valo™ digital billboards * Galaxy message centers™ * Control systems 6 | el ° 27% of FYO9 net sales > FY10 net sales down 48% YTD through Q3 DAKTRONICS
Slide 13: Commercial Overview
Commercial Overview • Long-term Growth Drivers • Greater acceptance & increasing use • Effective advertising medium • Competitors • Resellers, National accounts - Optec Watchfire, EDS • Digital Billboards - Yesco, Optotec, Watchfire
Slide 14: Current Outlook for Commercial
Current Outlook for Commercial • Some indications of upward trend in billboard orders for Q1 and Q2 of FY10 • Increasing interest from outdoor companies • Recent public announcements regarding positive performance of digital, intent to buy • Introducing enhanced billboard product in Q1of FY11 - redu
Slide 15: Daktronics
DAKTRONICS
Slide 16: Live Events Overview
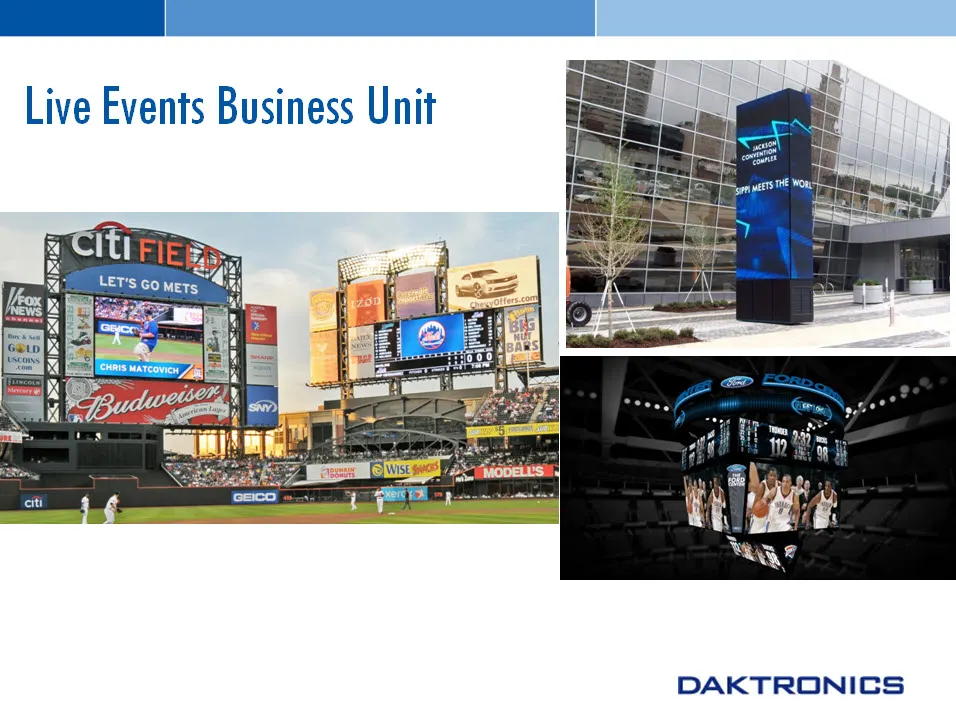
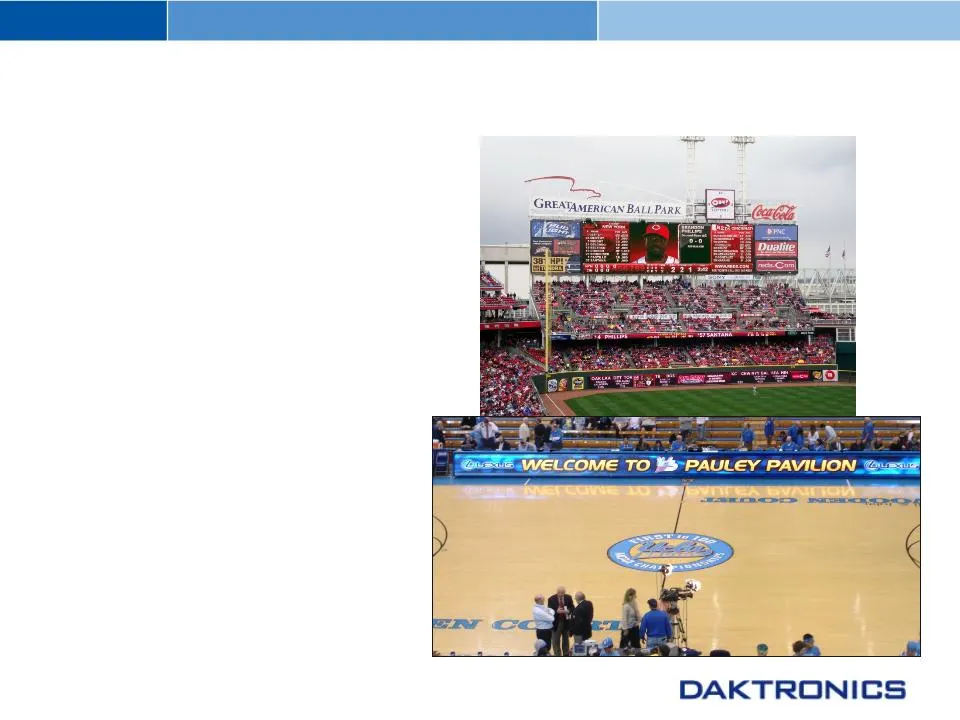
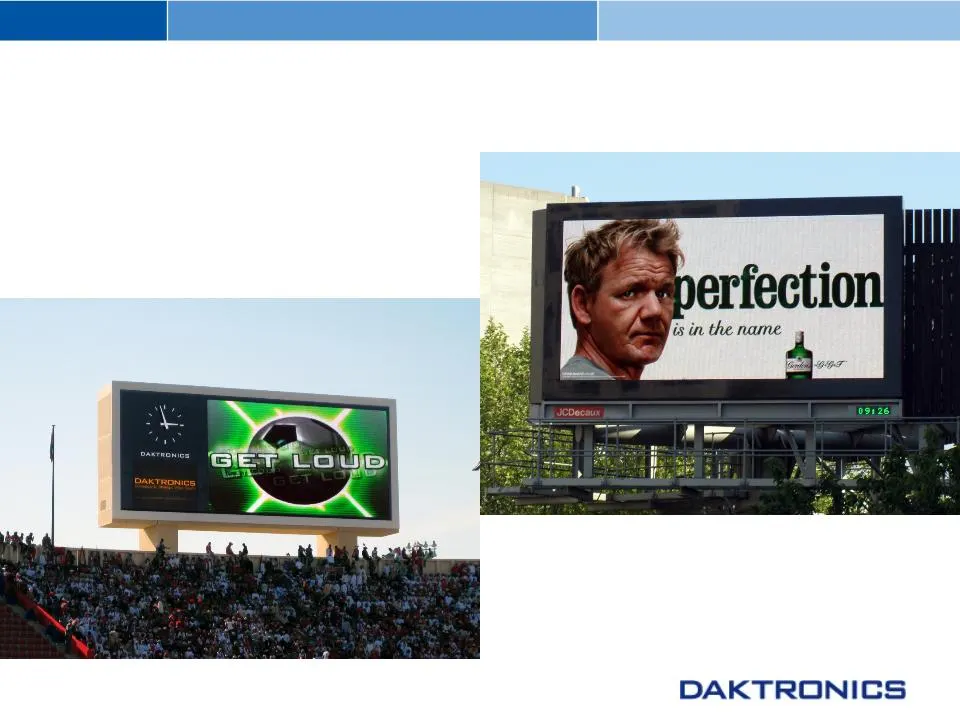
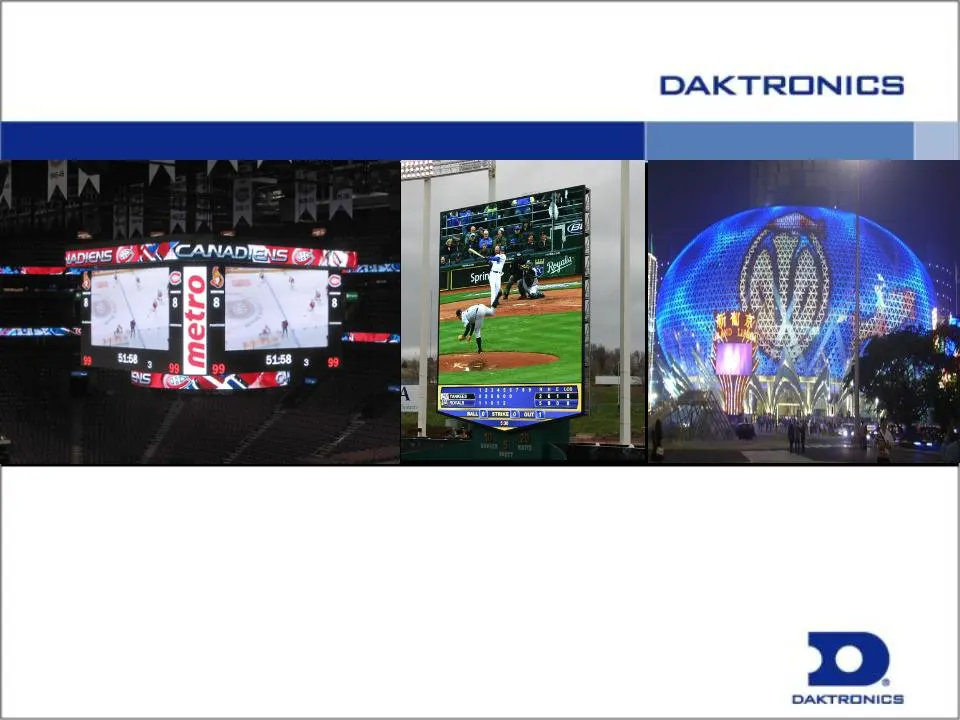
Live Events Overview • Large sports venues • Professional sports facilities • College and university facilities • Mobile and modular: • Rental and staging • Touring companies • Pari-mutuel • 46% of net sales in FY09 • FY09 net sales up 60% over FY08 • FY10 net sales down 39% YTD through Q3
Slide 17: Live Events Long-term Growth Drivers
Live Events Long-term Growth Drivers • Fan experience must exceed living room experience • High definition (HD) • Competition between venues • Improving price/ performance of LED technology • Revenue generation
Slide 18: Live Events Outlook
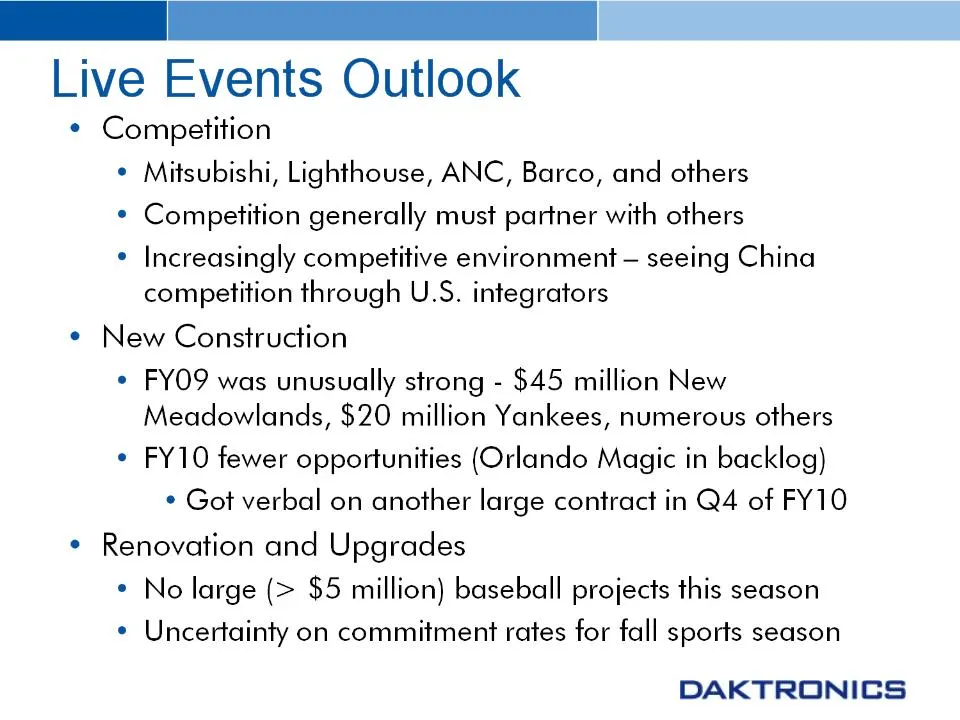
aaaaaaee—‘“‘“‘<‘<i<its Live Events Outlook * Competition * Mitsubishi, Lighthouse, ANC, Barco, and others * Competition generally must partner with others * Increasingly competitive environment — seeing China competition through U.S. integrators ¢ New Construction * FYO9 was unusually strong - $45 m
Slide 19: Schools & Theatres Business Unit
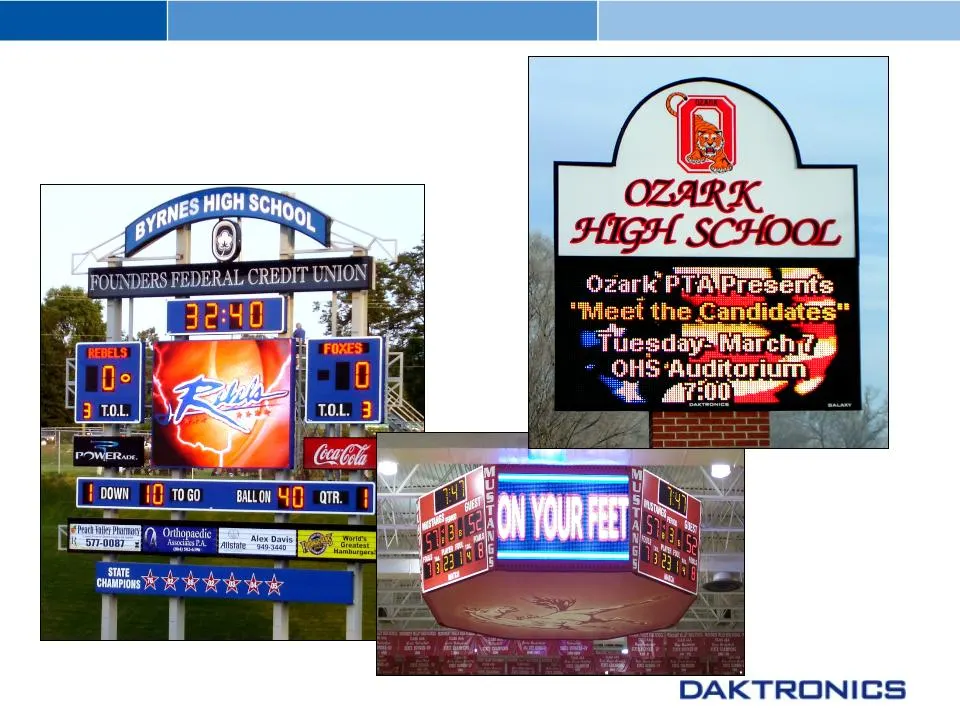
Schools & Theatres Business Unit
Slide 20: Schools & Theatres Overview
Schools & Theatres Overview • Customers • Elementary and high schools, junior colleges • Park and recreation departments • Theatres • Main Products • Scoring Systems • Galaxy® displays • Vortek® hoist systems • Sound systems (Sportsound®) • 11% of net sales in FY09 • Primary funding is through local
Slide 21: International Business Unit
International Business Unit
Slide 22: International
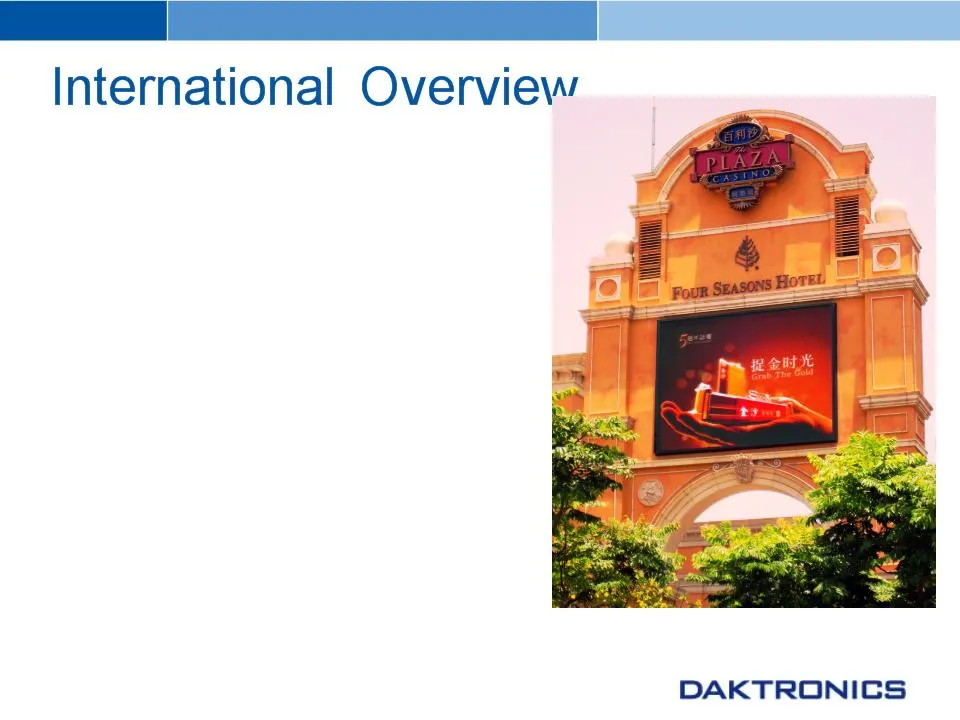
• Sales and service offices in Canada, Europe, China, Middle East, and Australia • Limited manufacturing in China • 10% of net sales in FY09 • Large project driven - -commercial and sports • Expecting lower sales in FY10 due to economic and competitive factors • FY10 net sales down 46% YTD through Q
Slide 23: Transportation Business Unit
Transportation Business Unit
Slide 24: Transportation Overview
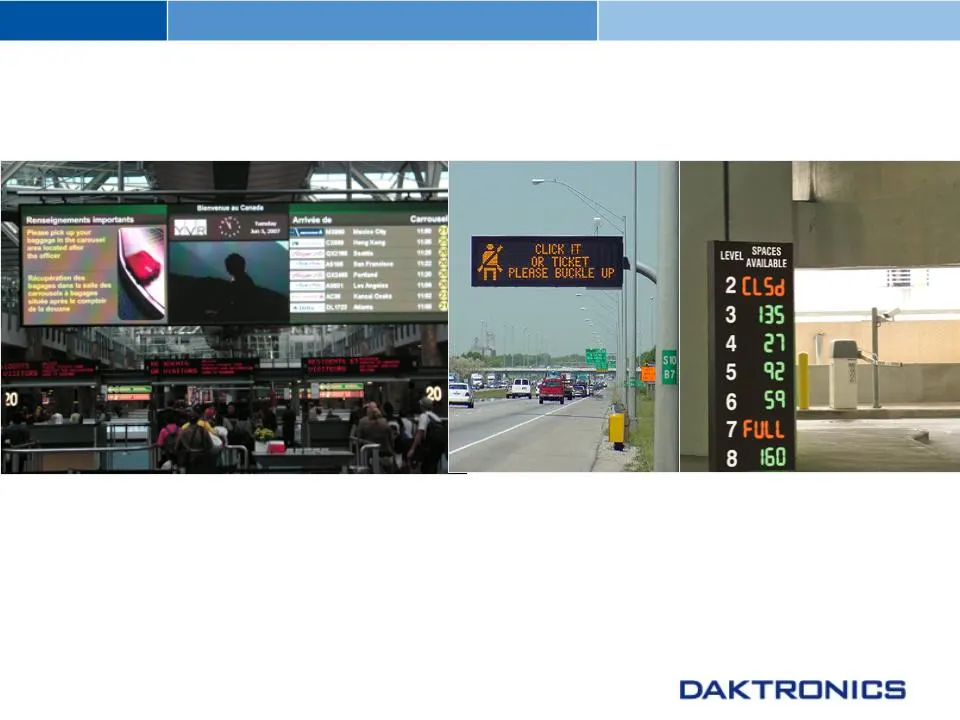
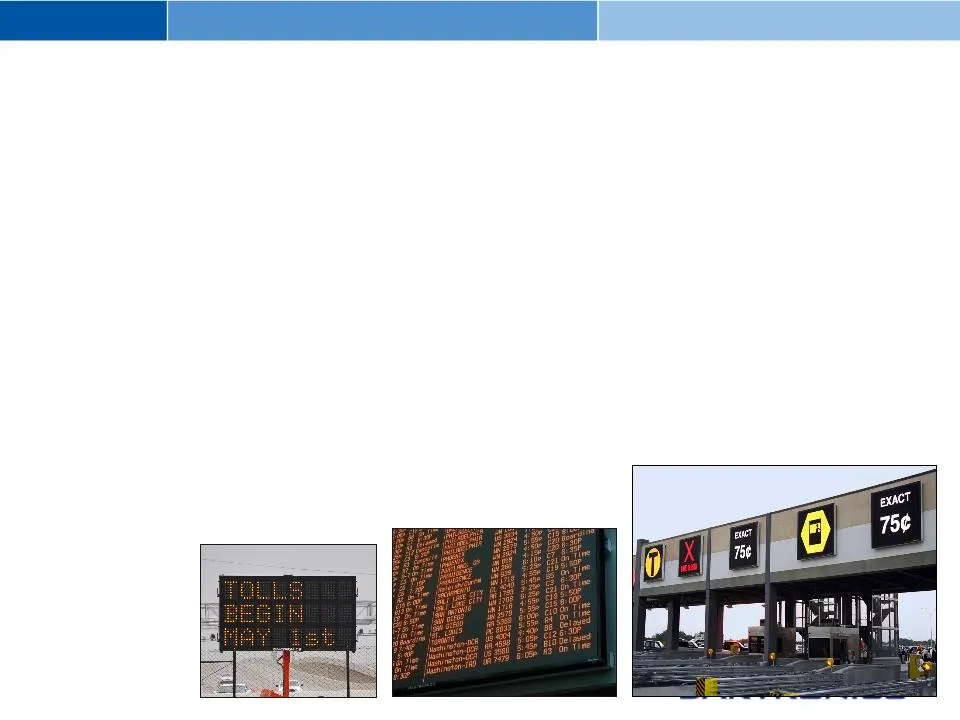
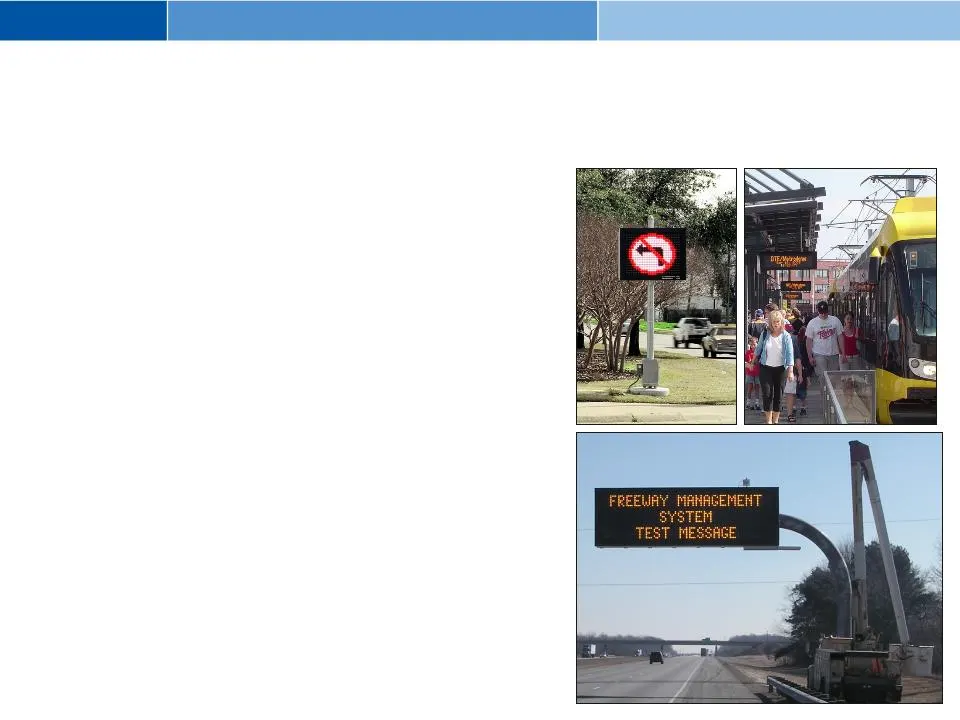
Transportation Overview • Three main areas • Intelligent transportation systems (ITS) • Aviation, including airports and airlines • Mass Transit • 6% of FY09 net sales • Strong backlog going into FY2010 • FY10 net sales up 34% YTD through Q3 • Competitors • Skyline, Ledstar, others
Slide 25: Transportation Overview: Long-term Growth Drivers
Transportation Overview • Long-term Growth Drivers • Government spending • Capacity constraints on highways, public transit, airports and parking systems • Limited ability to build and expand new roads • Recent developments • $25 million NJ Turnpike order • Departure of disruptive competitor • New V
Slide 26: Daktronics
DAKTRONICS DAKTRONICS
Slide 27: Revenue Outlook
Revenue Outlook • Lighter ($100 million) backlog going into Q4 • Competitive price pressure in all markets • Orders continue to be relatively slow -difficult to project orders in today’s environment • Slower order flow for Q4 of FY10 limiting revenue opportunities for Q4, may impact Q1 • Will know m
Slide 28: Returning to Long-Term Profitable Growth
Returning to Long-Term Profitable Growth • Focus on orders, cost reduction, customer service, quality and reliability. • Ongoing product development - historically 4% of net sales (higher in FY2010) • Enhance existing products while reducing costs • New DVX video display product began shipping in Q4
Slide 29: Cost Reduction Is Ongoing Process
Cost Reduction Is Ongoing Process • Continued emphasis on reducing costs and improving quality through lean initiatives • Improve asset turns (inventory alignment, process improvement) • Focus on operating margin and free cash flow • Leverage service (process improvement) • More aggressive cost redu
Slide 30: Daktronics
DAKTRONICS DAKTRONICS
Source: SEC EDGAR · 8-K filed Mar 24, 2010
More decks from Daktronics, Inc.
 Q1 2027 Earnings Presentation19 slides · Sep 2, 2026
 Investor Presentation (August 2026)23 slides · August 2026
 Q4 2026 Earnings Presentation20 slides · Jun 24, 2026
 Investor Presentation (May 2026)22 slides · May 28, 2026
 Investor Day (April 2026)161 slides · Apr 9, 2026
 Investor Day (April 2026)178 slides · Apr 9, 2026