Provident Bankshares — Investor Presentation (March 2006)
66 slides from Provident Bankshares's investor presentation, Mar 1, 2006
Slide 1: Provident Bankshares Corporation, February 2006
PROVIDENT BANKSHARES C O R P O R A T I O N February 2006 Exhibit 99.1 PROVIDENT BANKSHARES C O R P O R A T I O N
Slide 2: Forward-Looking Statements and Risk Factors
FORWARD-LOOKING STATEMENTS AND RISK FACTORS This presentation, as well as other written communications made from time to time by Provident Bankshares Corporation and its subsidiaries (the “Corporation”) (including, without limitation, the Corporation’s 2004 Annual Report to Stockholders) and oral co
Slide 3: Agenda
• Introduction and Overview • Key Strategies • Financial Performance Agenda Agenda
Slide 4: Introduction and Overview
– Headquartered in Baltimore, Maryland – Total assets of $6.4 billion (as of 12/31/05) – Serves individuals, families, small businesses and larger companies in Baltimore, Washington and Richmond areas – Over 2,000 employees Introduction and Overview Introduction and Overview
Slide 5: Provident Bank History
Provident Bank History • 1886 Founded as a Mutual Thrift • 1987 Converted to Commercial Bank • 1993 Retail Banking Expansion • 1997 Citizen’s Savings Bank Merger • 2004 Southern Financial Merger Introduction Introduction
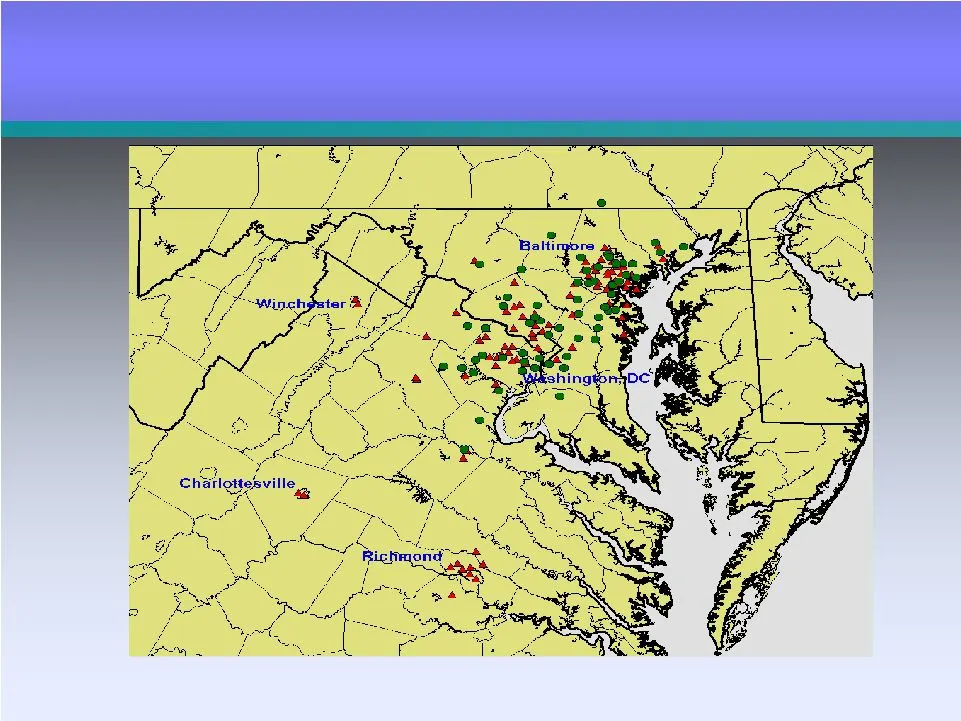
Slide 6: Banking Office Network 2006
Banking Office Network 2006 Banking Office Network 2006 152 Branches 152 Branches Green dots are in-store, red triangles are traditional locations.
Slide 7: Provident Bank Mission
Provident Bank’s mission is to exceed customer expectations by delivering superior service, products and banking convenience. Every employee’s commitment to serve our customers in this fashion will establish Provident Bank as the primary bank of choice of individuals, families, small businesses and
Slide 8: Provident Bank Vision
Provident Bank’s vision is to be chosen as our customers’ primary bank because we consistently execute our business as The Right Size Bank. Introduction Introduction Provident Bank Vision Provident Bank Vision
Slide 9: Provident Bank Core Values
Integrity Excellence Caring Partnership Results Driven Introduction Introduction Provident Bank Core Values Provident Bank Core Values
Slide 10: Provident Bank Key Strategies
– Maximize Provident’s Position as the “Right Size” Bank in the Marketplace – Grow and Deepen Commercial and Real Estate Relationships in Maryland and Virginia – Grow and Deepen Consumer and Small Business Relationships in Maryland and Virginia – Move from a Product Driven Organization to a Customer
Slide 11: Positioning Strategy
We will continue to provide the products and services of our largest competitors, while delivering the level of service found in only the best community banks. Provident Bank Provident Bank Positioning Strategy Positioning Strategy
Slide 12: Key Strategy #2: Commercial and Real Estate Relationships
– Maximize Provident’s Position as the “Right Size” Bank in the Marketplace – Grow and Deepen Consumer and Small Business Relationships in Maryland and Virginia – Move from a Product Driven Organization to a Customer Relationship Focused Sales Culture – Create a High Performance Culture that Focuses
Slide 13: Commercial Loan and Deposit/Repo Average Balances
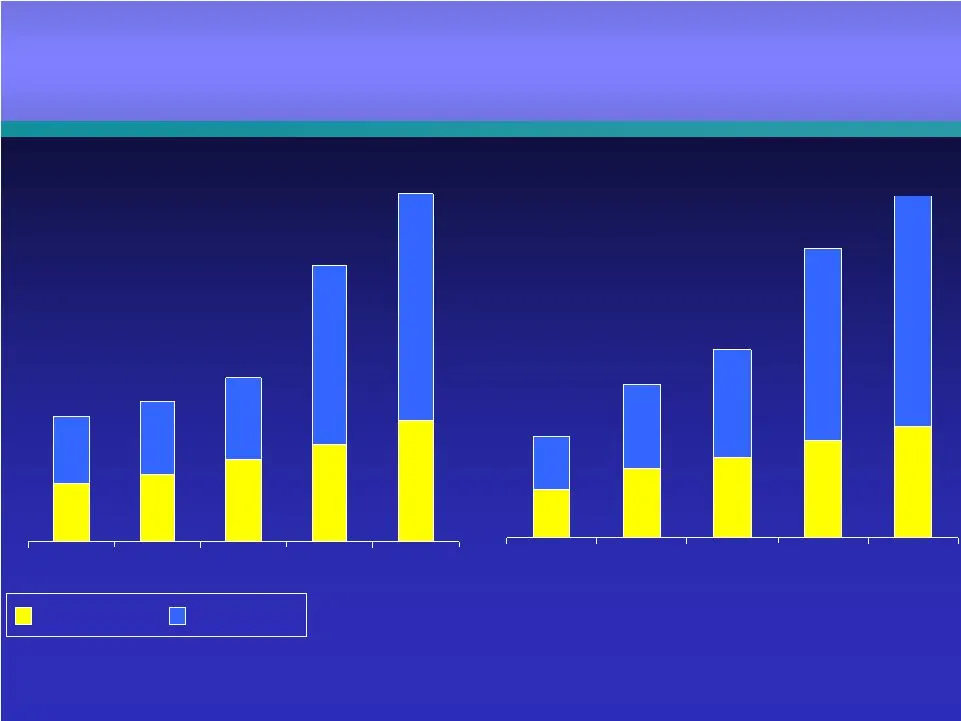
2001 2002 2003 2004 2005 Baltimore VA/Wash $791 $856 $961 2001 2002 2003 2004 2005 $426 $579 $680 $982 $1,444 $1,754 $1,143 Commercial Loan Commercial Loan and Deposit/Repo and Deposit/Repo Average Balances (millions) Loans exclude acquired loans LOANS DEPOSIT/REPO CAGR 2001-2005* Loans 22.0% CAGR 2
Slide 14: Commercial Loans
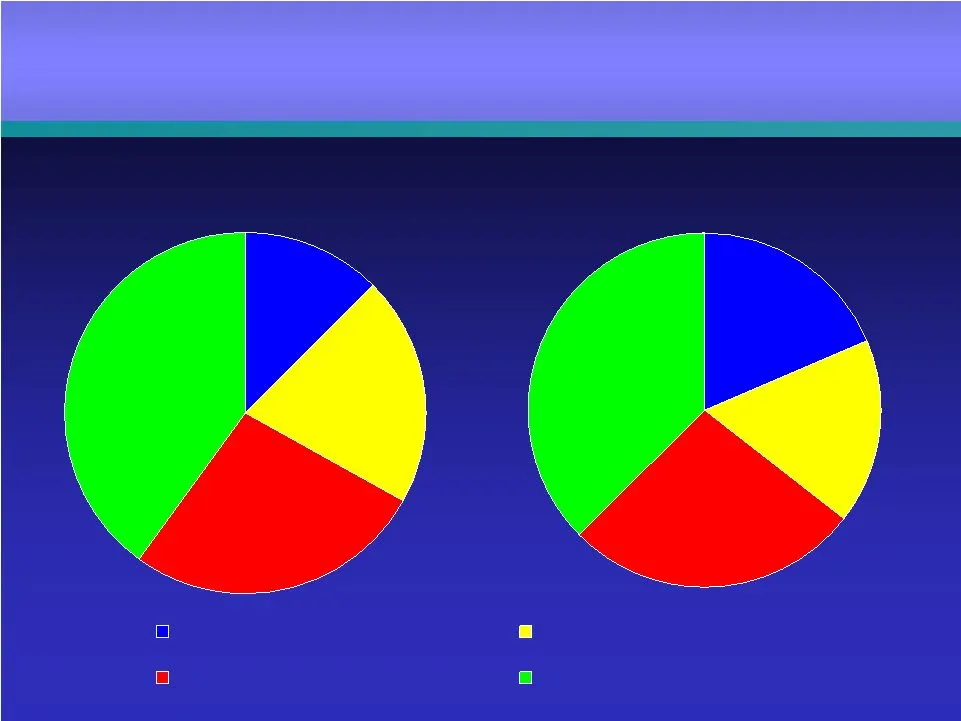
2005 Total $1.8 B Residential Construction Commercial Construction Commercial Mortgage Commercial Business 2001 Total $875 MM Commercial Loans Commercial Loans 37% 27% 17% 19% Average Balances 12% 27% 21% 40%
Slide 15: Key Strategy #3: Consumer and Small Business Relationships
– Maximize Provident’s Position as the “Right Size” Bank in the Marketplace – Grow and Deepen Commercial and Real Estate Relationships in Maryland and Virginia – Move from a Product Driven Organization to a Customer Relationship Focused Sales Culture – Create a High Performance Culture that Focuses
Slide 16: Consumer Loan and Deposit Growth
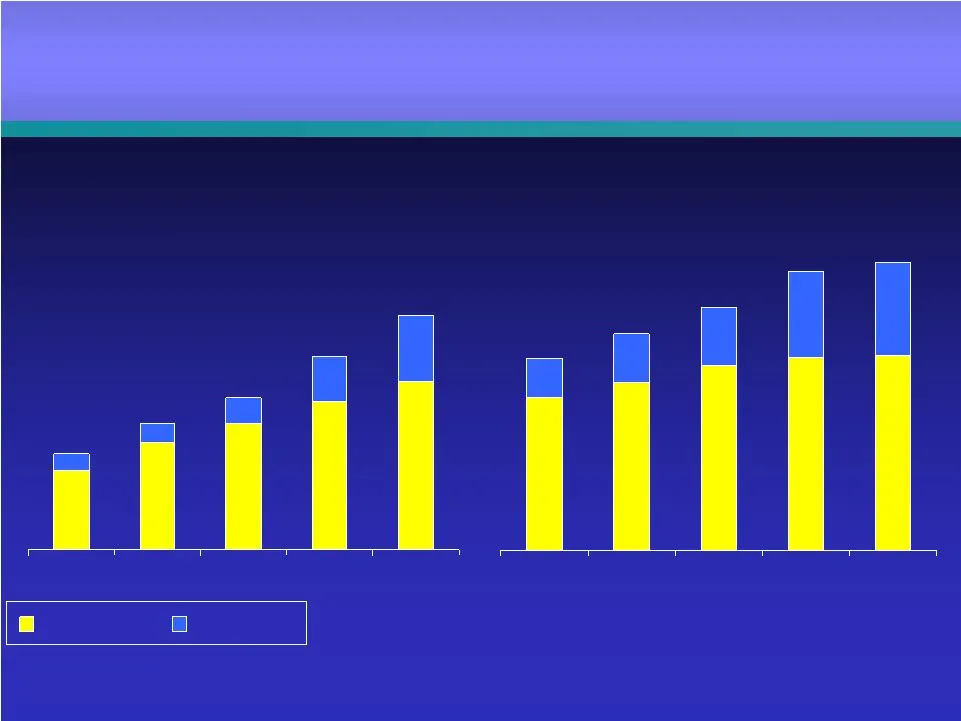
2001 2002 2003 2004 2005 Baltimore VA/Wash $663 $797 $906 LOANS 2001 2002 2003 2004 2005 $1,394 $1,536 $1,682 DEPOSITS (E xcluding CD/IRA ) $1,891 $1,089 $1,264 $1,940 Consumer Loan and Consumer Loan and Deposit Growth Deposit Growth Average Balances (millions) Loans exclude acquired residential CAG
Slide 17: Retail DDA Fees
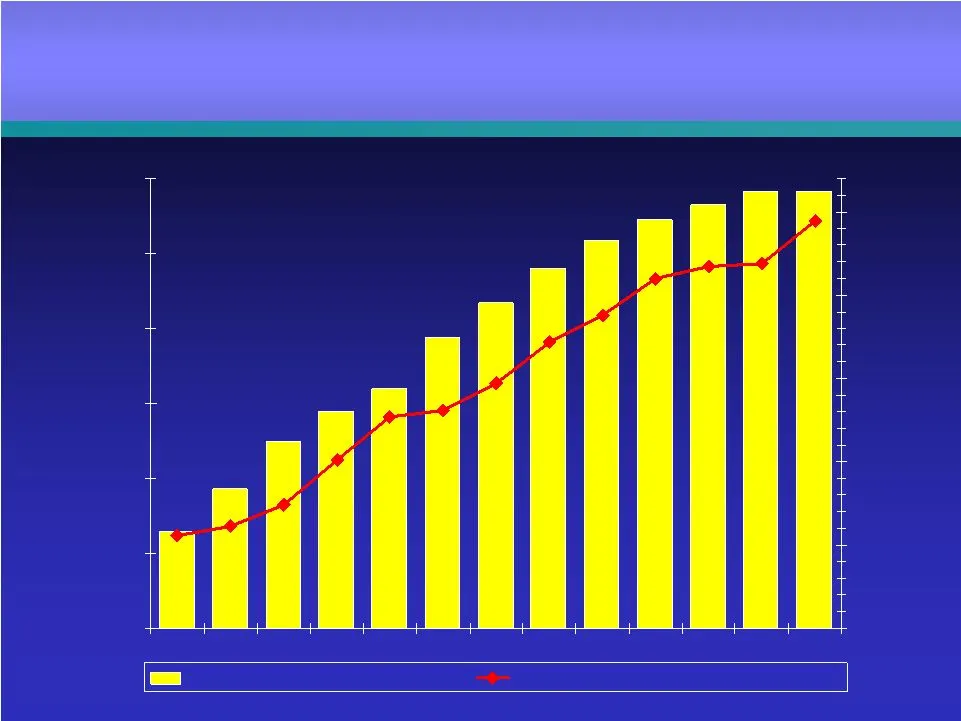
0 50,000 100,000 150,000 200,000 250,000 300,000 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 $0 $50 $100 $150 $200 $250 Accounts on Hand Average Fee Income Per Consumer DDA CAGR (Acounts) = 13.46% CAGR (Fee Inc.) = 13.26% Retail DDA Fees Retail DDA Fees Annual Fees Per Account A
Slide 18: Consumer Loans
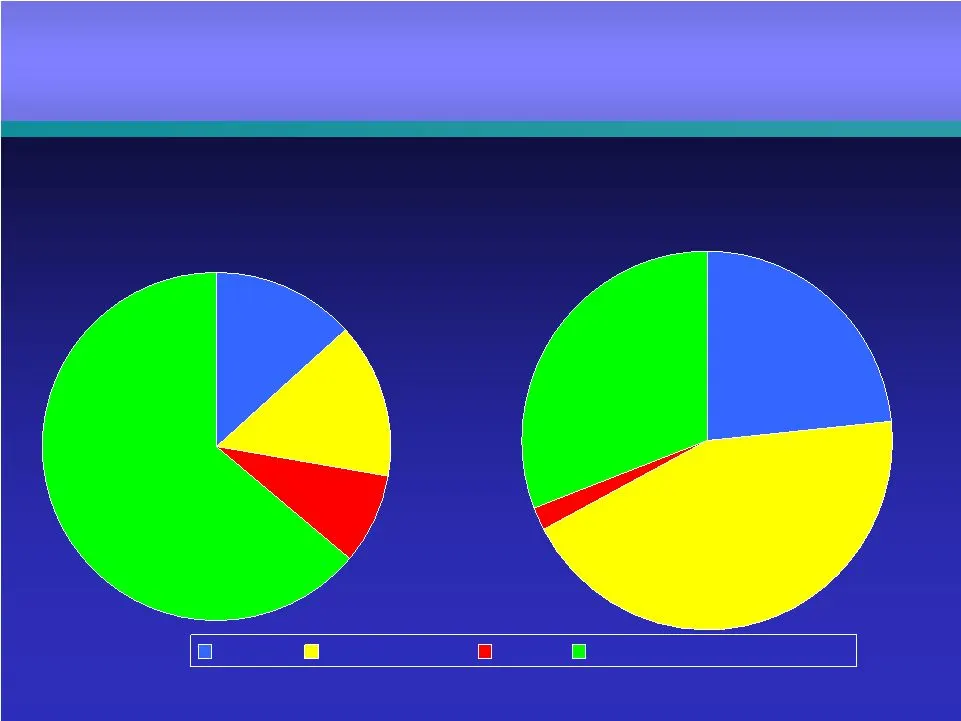
2005 Total $1.8 B Marine Home Equity Other Residential & Acquired 2001 Total $2.2 B Consumer Loans Consumer Loans 31% 2% 44% 23% Average Balances 13% 15% 8% 64%
Slide 19: Home Equity Quarterly Comparison
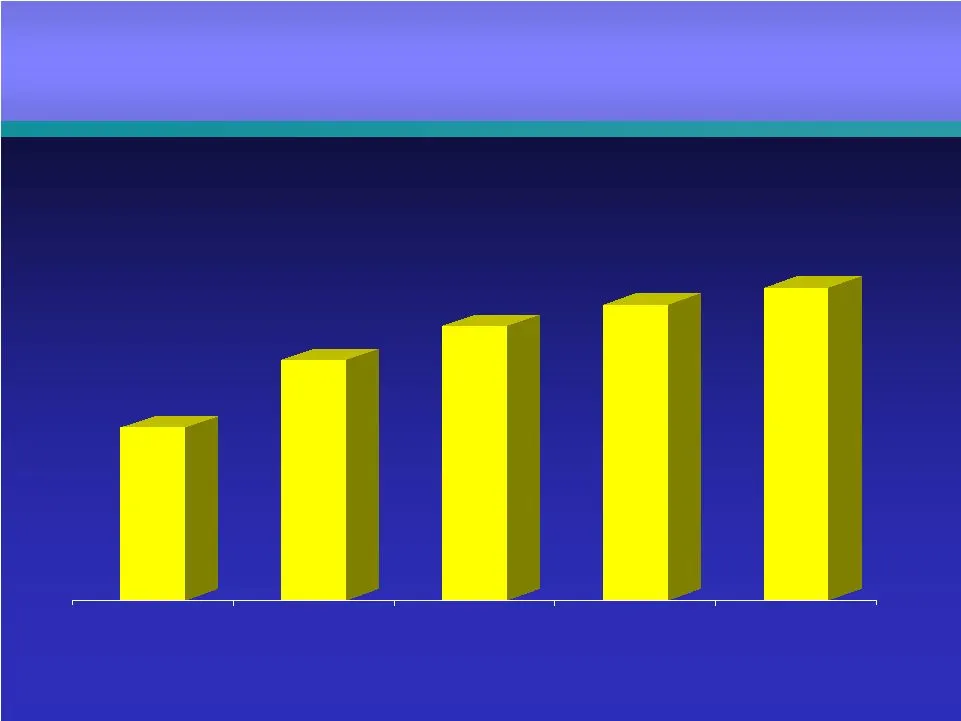
$485,931 $676,169 $772,558 $831,987 $879,598 4Q 03 4Q 04 2Q 05 3Q 05 4Q 05 34.5% CAGR Home Equity Home Equity Quarterly Comparison Quarterly Comparison
Slide 20: Provident Bank Branches
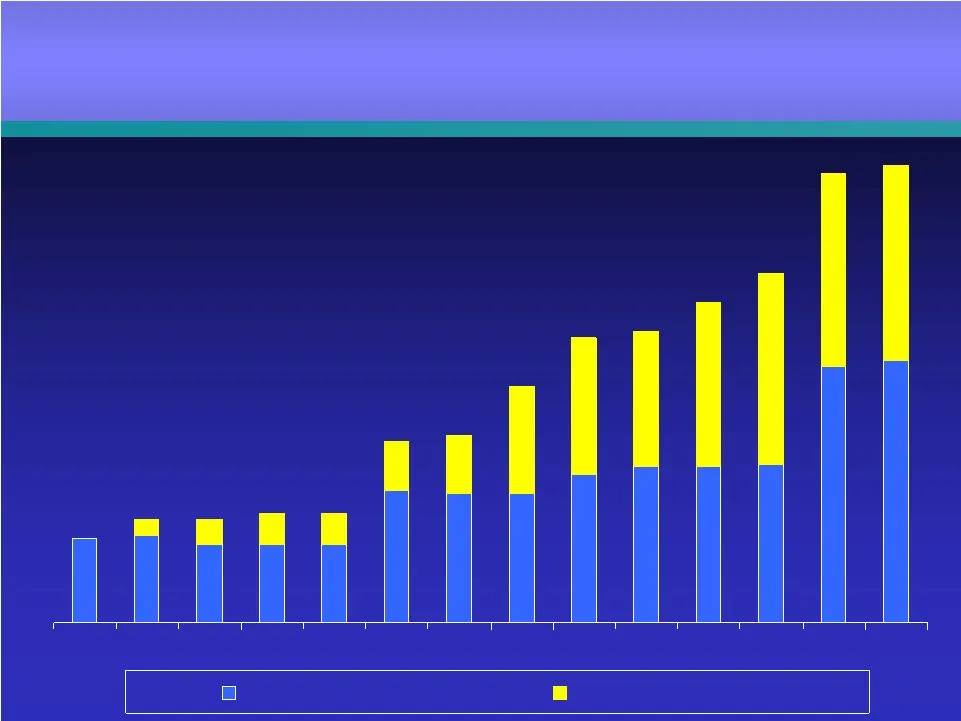
91 58 58 89 59 56 36 34 34 51 50 50 37 34 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 Traditional In-Store/ATM Plus Provident Bank Branches Provident Bank Branches TRADITIONAL/IN-STORE
Slide 21: Virginia and Washington Metro Expansion
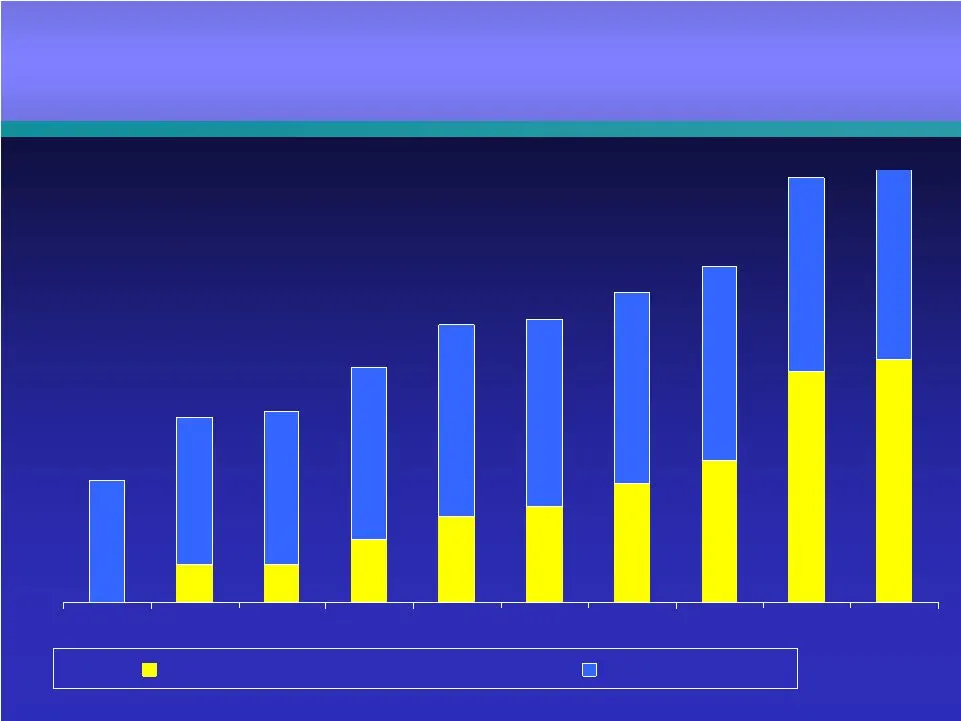
66 44 67 67 66 65 66 59 53 51 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 Washington Metro/VA Baltimore BRANCH NETWORK Virginia And Washington Virginia And Washington Metro Expansion Metro Expansion
Slide 22: Opportunities
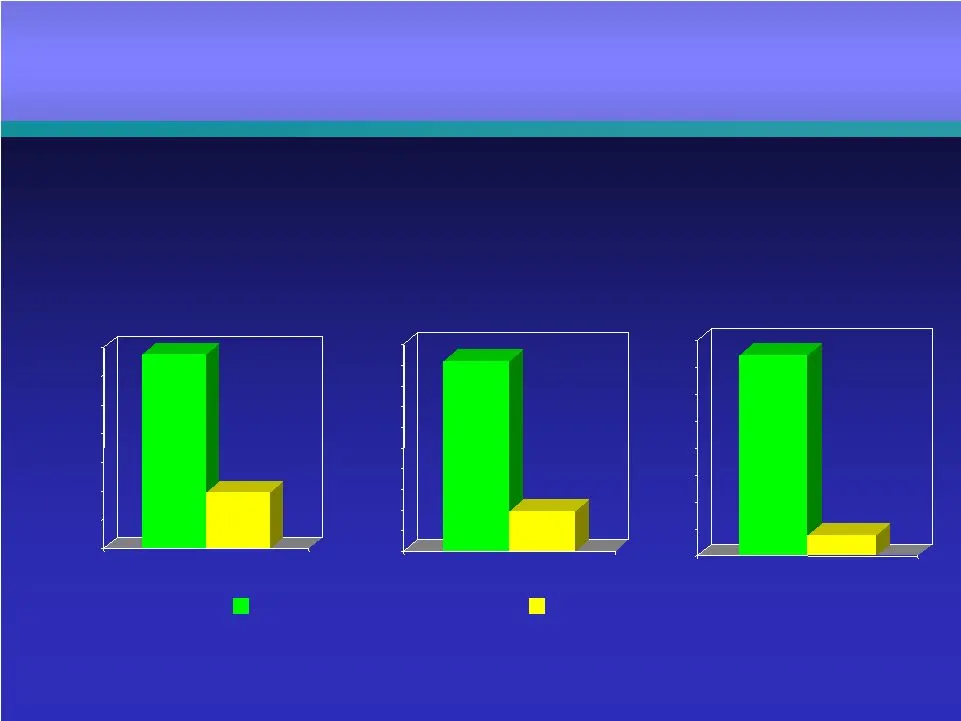
• Build relationships with existing customers • We have 53 “new” branches in Virginia “New VA” Branches MD Branches $33,682,000 $9,783,020 $0 $5,000,000 $10,000,000 $15,000,000 $20,000,000 $25,000,000 $30,000,000 $35,000,000 Deposits $4,595,000 $969,323 $0 $500,000 $1,000,000 $1,500,000 $2,000,000 $
Slide 23: Small Business Growth
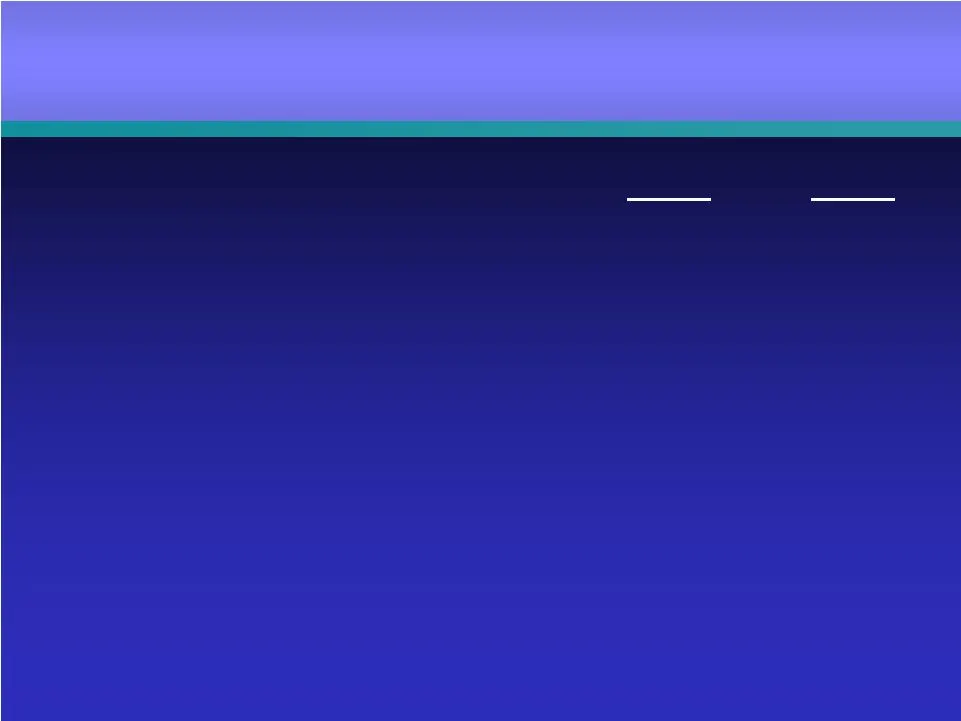
Average Balances ($ millions) Total Loans $ 82 $253 Total Deposits $138 $408 Customer Relationships 18,368 30,000 2001 2005 Small Business Growth Small Business Growth
Slide 24: Key Strategy #4: Customer Relationship Focused Sales Culture
– Maximize Provident’s Position as the “Right Size” Bank in the Marketplace – Grow and Deepen Commercial and Real Estate Relationships in Maryland and Virginia – Grow and Deepen Consumer and Small Business Relationships in Maryland and Virginia – Create a High Performance Culture that Focuses on Emp
Slide 25: Customer Relationship Strategy
Customer Relationship Customer Relationship Strategy Strategy
Slide 26: Provident Bank Vision
Provident Bank’s vision is to be chosen as our customers’ primary bank because we consistently execute our business as The Right Size Bank. Provident Bank Vision Provident Bank Vision
Slide 27: Customer Relationship Strategy: Executing our Vision
Executing our Vision • Acquire • Enhance • Retain Customer Relationship Strategy Customer Relationship Strategy
Slide 28: Customer Acquisition Strategy
• 1993 Introduction –High Performance Checking –In-Store Banking –Exception Decisioning Customer Acquisition Strategy Customer Acquisition Strategy
Slide 29: Acquire Customer Relationships
Acquire different customers and acquire customers differently Success Factors: • Right size bank positioning • Unparalleled convenience • Value-oriented product line • Reputation for superior service Success Metric: Growth in Primary Bank Relationships Acquire Customer Relationships Acquire Customer
Slide 30: Enhance Customer Relationships: The Opportunity
2.91 312 Real Estate 2.73 912 Commercial 2.22 30,000 Small Business 2.79 263,661 Retail Enhance Customer Relationships Enhance Customer Relationships The Opportunity The Opportunity Provident Cross Sell Households Data is as of Q3 2005
Slide 31: Enhance Customer Relationships
• Leverage customer segmentation methodology • Build a relationship sales culture • Roll-out sales and leadership training • Achieve CSBI relationship Success Metric: 1 More to 400,000 Enhance Customer Relationships Enhance Customer Relationships
Slide 32: Retain Customer Relationships
One additional product to a household with one product increases their retention from 83% to 92% • Utilize on-boarding program for all customers • Survey customers’ satisfaction quarterly • Build specific retention plans based on customer segmentation data Success Metric: Level of Customer Engagemen
Slide 33: Key Strategy #5: High Performance Culture
– Maximize Provident’s Position as the “Right Size” Bank in the Marketplace – Grow and Deepen Commercial and Real Estate Relationships in Maryland and Virginia – Grow and Deepen Consumer and Small Business Relationships in Maryland and Virginia – Move from a Product Driven Organization to a Customer
Slide 34: Employee Development and Retention
• Succession planning for key positions • Compensation awards based upon results • Expanded training curriculum with additional online development offerings • Disciplined performance management system Employee Development Employee Development and Retention and Retention
Slide 35: Key Strategy #6: Improve Financial Fundamentals
– Maximize Provident’s Position as the “Right Size” Bank in the Marketplace – Grow and Deepen Commercial and Real Estate Relationships in Maryland and Virginia – Grow and Deepen Consumer and Small Business Relationships in Maryland and Virginia – Move from a Product Driven Organization to a Customer
Slide 36: 2005 Financial Performance
II. Strong growth in core loans and deposits III. Solid fee income growth IV. Growth in earnings with improved quality of earnings V. Higher capital levels VI. Improved asset quality 2005 Financial Performance 2005 Financial Performance I. Continued transformation of the balance sheet
Slide 37: Components of Earning Assets
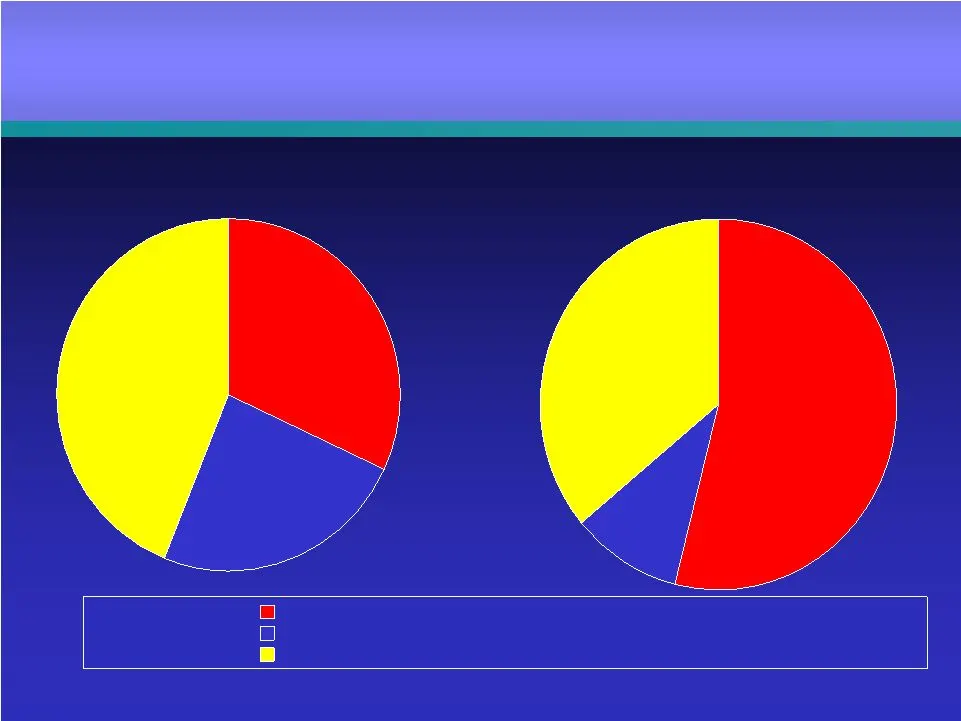
Commercial & Consumer Loans (Core) Residential & Acquired Loans (Non-core) Investment Securities 2005 1995 Components of Earning Assets Components of Earning Assets 44% 24% 32% 10% 54% 36% $2,851,766 $5,664,773
Slide 38: Components of Liabilities
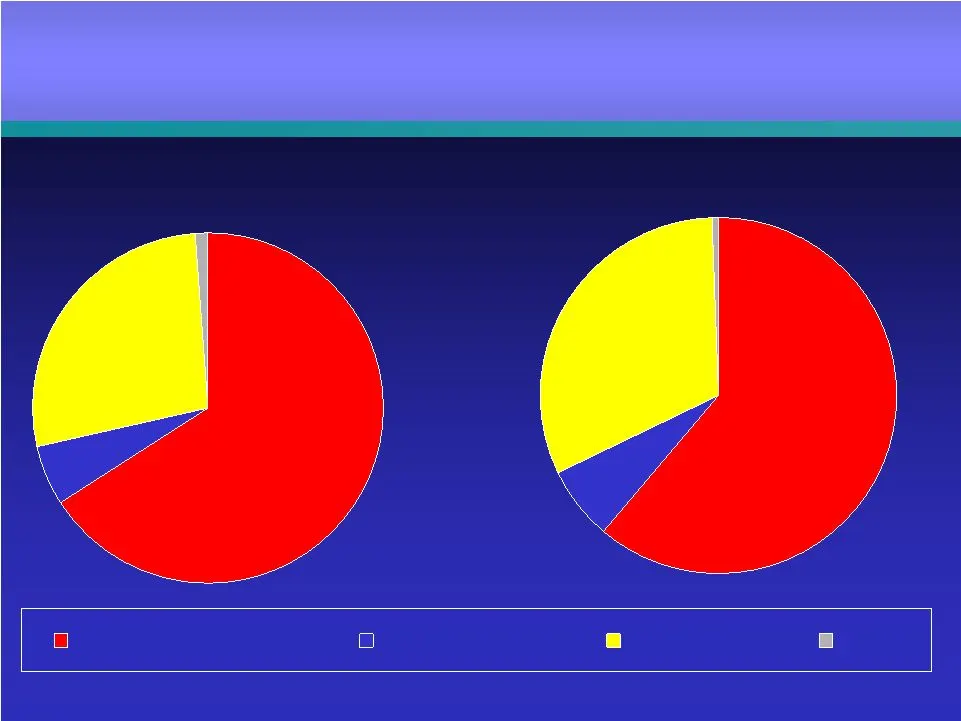
Customer Deposits Brokered CD's Borrowings Other 2005 1995 Components of Liabilities Components of Liabilities 1% 27% 6% 66% 7% 60% 32% 1% $2,764,701 $5,752,044
Slide 39: Operating Earnings Per Share
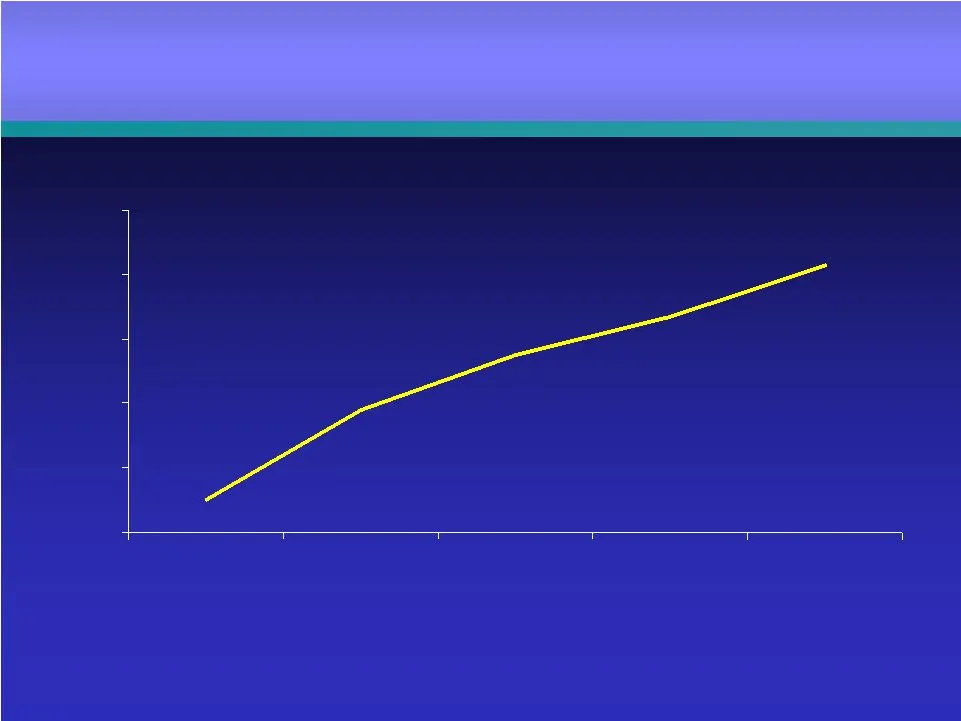
1.50 1.70 1.90 2.10 2.30 2.50 2001 2002 2003 2004 2005 Operating Earnings Per Share Operating Earnings Per Share 1.88 2.05 2.17 2.33 1.60
Slide 40: Investments / Assets
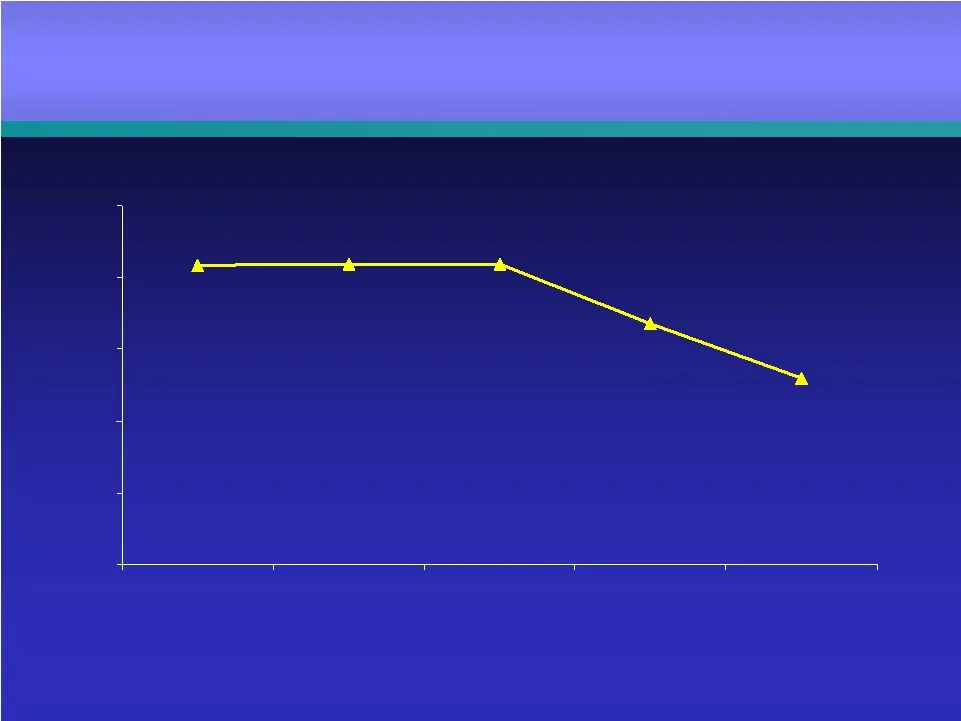
10% 20% 30% 40% 50% 60% 2001 2002 2003 2004 2005 Note: investments include acquired loans Investments / Assets Investments / Assets 51.7% 51.9% 51.8% 43.5% 36.0%
Slide 41: Loans / Assets
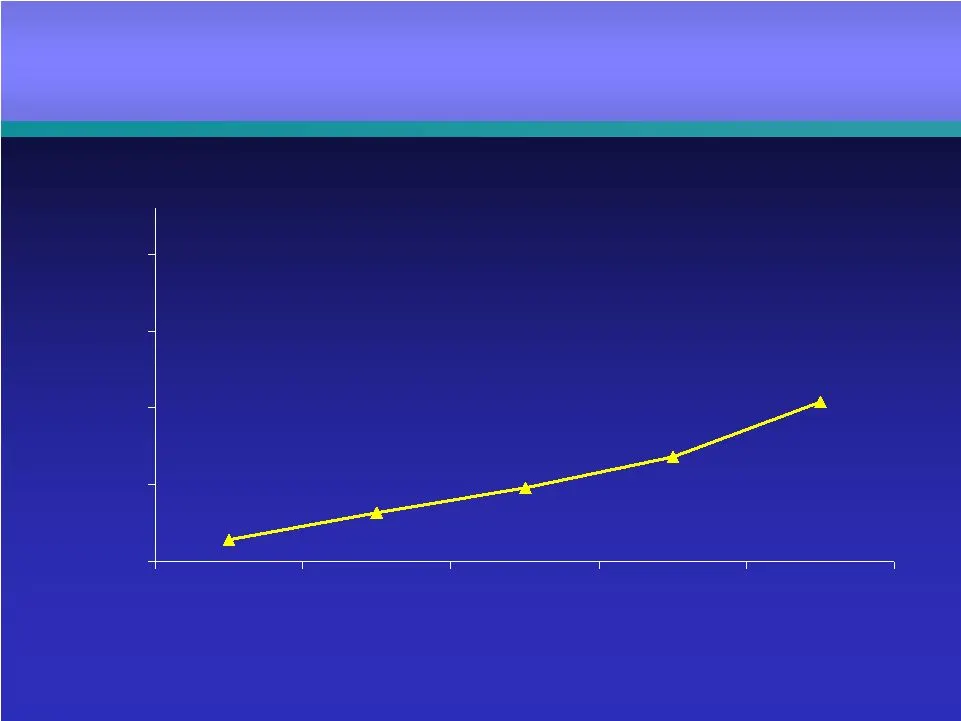
30.0% 40.0% 50.0% 60.0% 70.0% 2001 2002 2003 2004 2005 Note: Ratio is represented by core loans to assets Loans / Assets Loans / Assets 32.9% 36.4% 39.6% 43.6% 50.8%
Slide 42: Free Funding / Avg Earning Assets
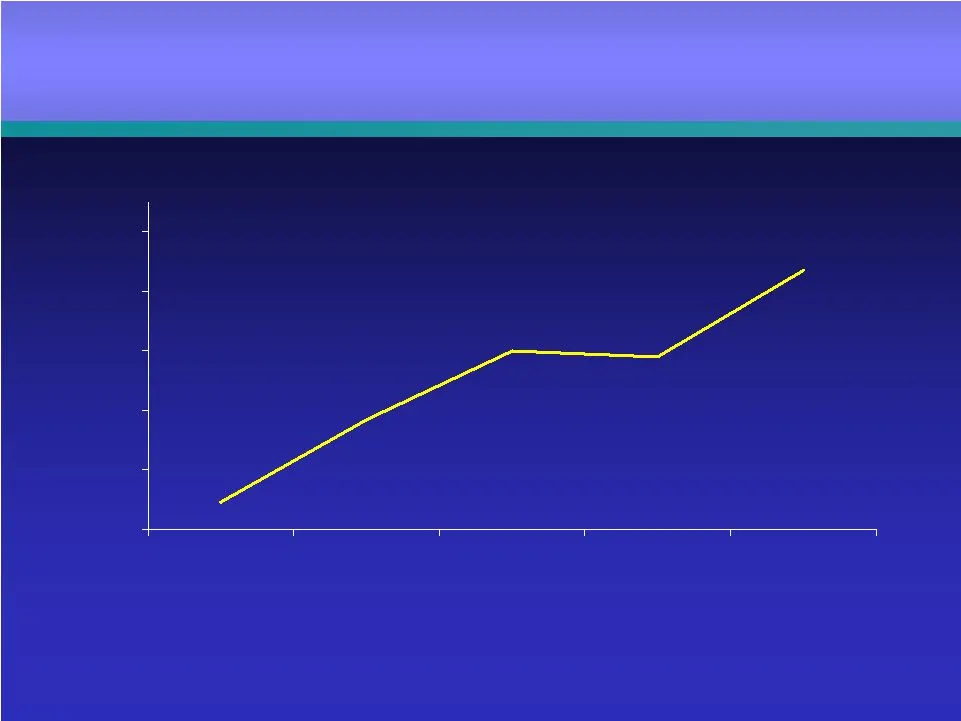
12.0% 14.0% 16.0% 18.0% 20.0% 22.0% 2001 2002 2003 2004 2005 Free Funding / Avg Earning Assets Free Funding / Avg Earning Assets 12.9% 15.7% 18.0% 17.8% 20.7%
Slide 43: 2005 Financial Performance: Core Loans and Deposits
I. Continued transformation of the balance sheet III. Solid fee income growth IV. Growth in earnings with improved quality of earnings V. Higher capital levels VI. Improved asset quality 2005 Financial Performance 2005 Financial Performance II. Strong growth in core loans and deposits
Slide 44: Core Loan Growth
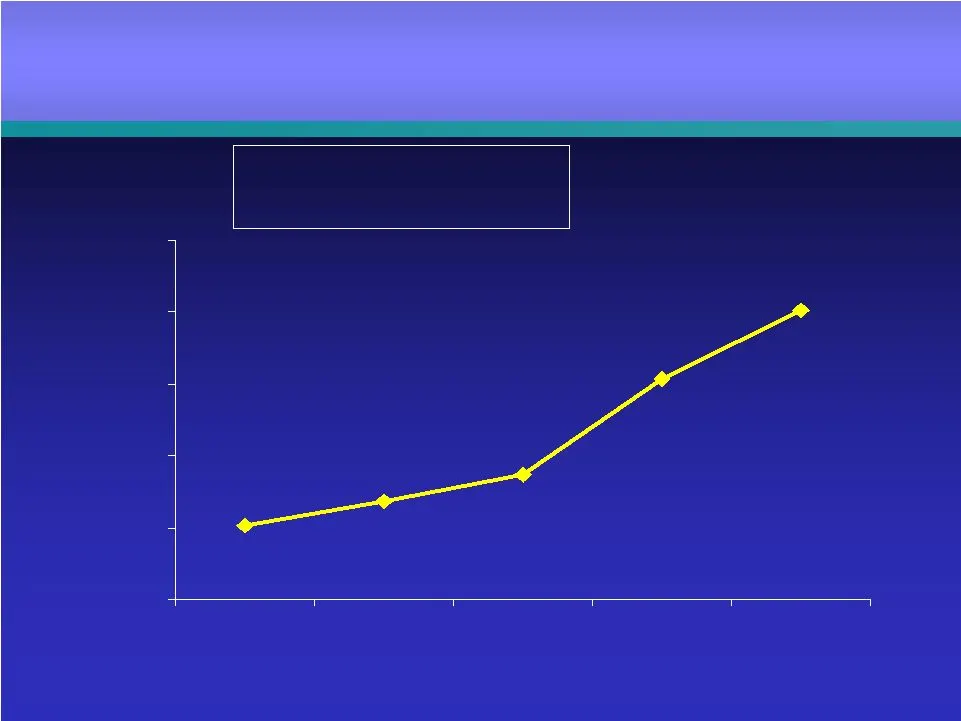
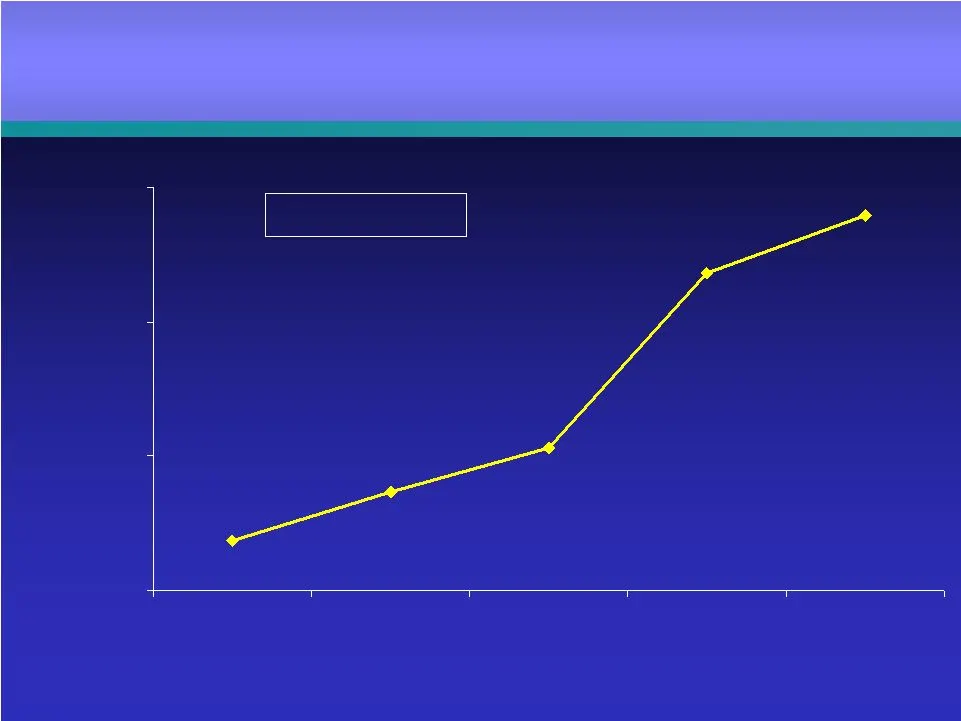
$1,000,000 $1,500,000 $2,000,000 $2,500,000 $3,000,000 $3,500,000 2001 2002 2003 2004 2005 CAGR (Core Loans) = 18.84% CAGR (Total Assets) = 6.72% Average balances Core Loan Growth Core Loan Growth $1,512,021 $1,686,343 $1,867,002 $2,533,458 $3,015,984
Slide 45: Core Deposit Growth
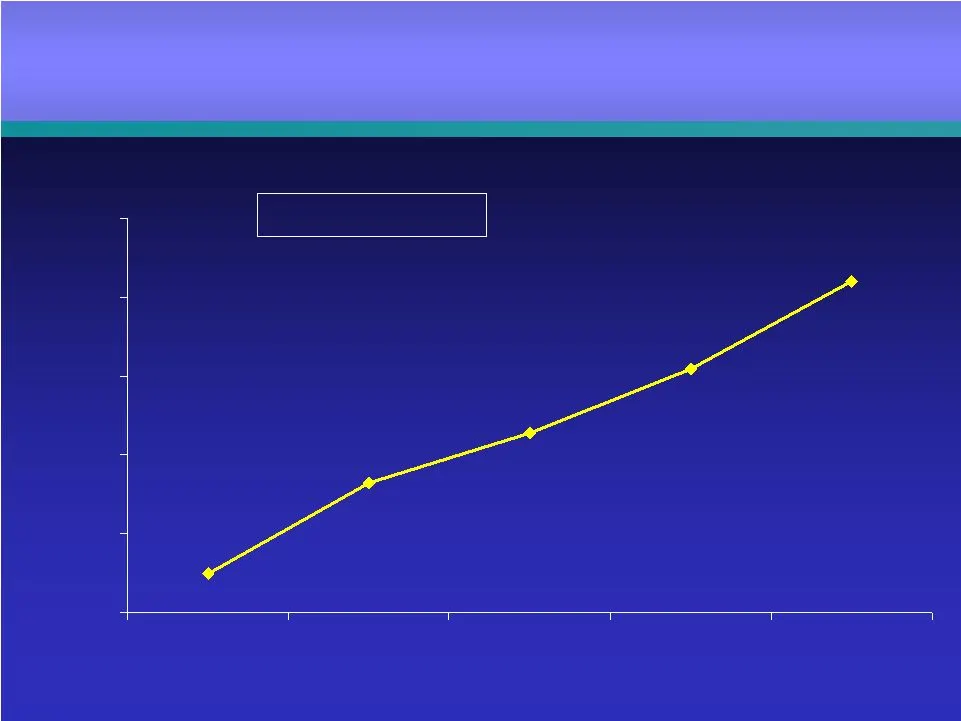
$2,400,000 $2,800,000 $3,200,000 $3,600,000 2001 2002 2003 2004 2005 CAGR = 8.40% Average balances Core Deposit Growth Core Deposit Growth $2,692,617 $3,517,648 $3,344,660 $2,825,412 $2,547,804
Slide 46: 2005 Financial Performance: Fee Income Growth
I. Continued transformation of the balance sheet II. Strong growth in core loans and deposits IV. Growth in earnings with improved quality of earnings V. Higher capital levels VI. Improved asset quality 2005 Financial Performance 2005 Financial Performance III. Solid fee income growth
Slide 47: Fee Income
$70,000 $80,000 $90,000 $100,000 $110,000 $120,000 2001 2002 2003 2004 2005 CAGR = 10.58% Fee Income Fee Income $112,072 $100,840 $92,752 $86,394 $74,955
Slide 48: 2005 Financial Performance: Earnings Growth
I. Continued transformation of the balance sheet II. Strong growth in core loans and deposits III. Solid fee income growth V. Higher capital levels VI. Improved asset quality 2005 Financial Performance 2005 Financial Performance IV. Growth in earnings with improved quality of earnings
Slide 49: Return on Assets
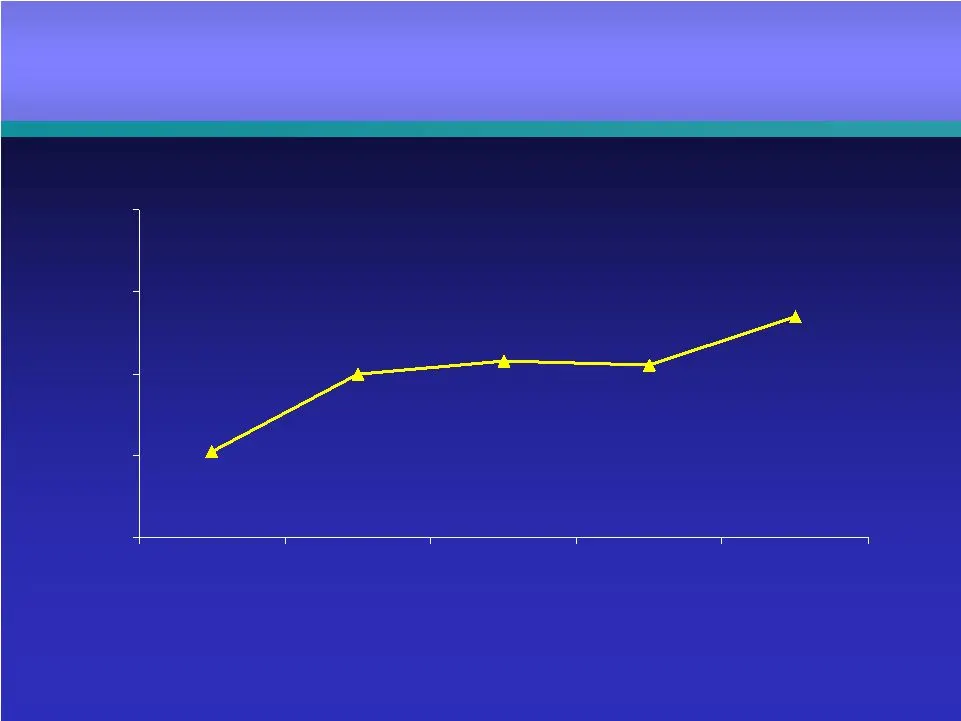
0.60% 0.80% 1.00% 1.20% 1.40% 2001 2002 2003 2004 2005 Return on Assets Return on Assets 1.14% 1.02% 1.03% 1.00% 0.81%
Slide 50: Net Interest Margin
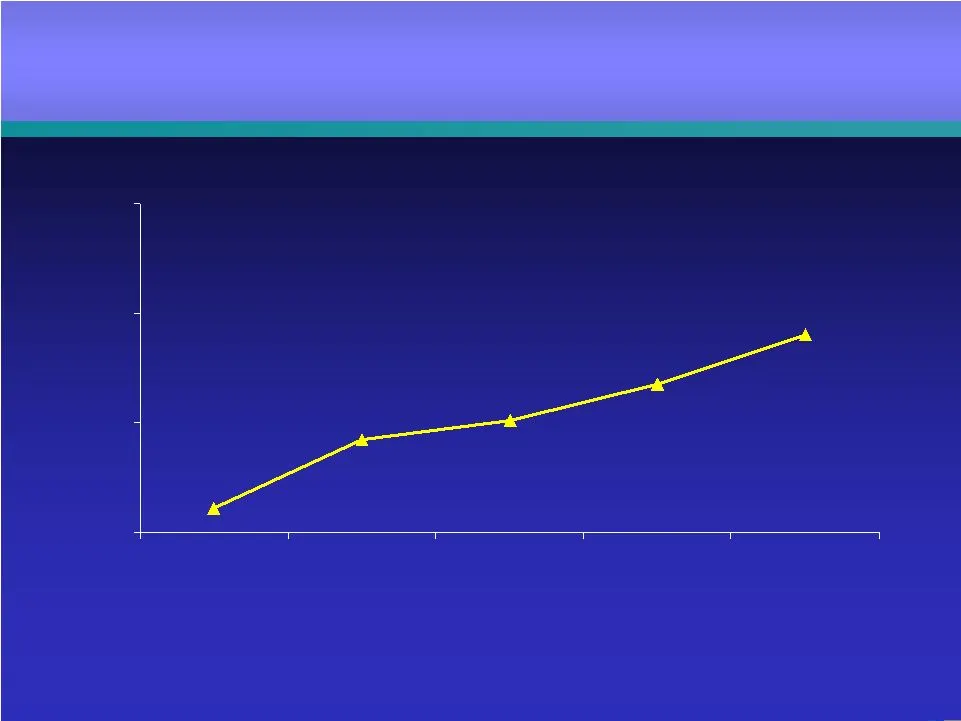
2.8% 3.2% 3.6% 4.0% 2001 2002 2003 2004 2005 Net Interest Margin Net Interest Margin 3.14% 3.21% 3.34% 2.89% 3.52%
Slide 51: Earnings Per Share
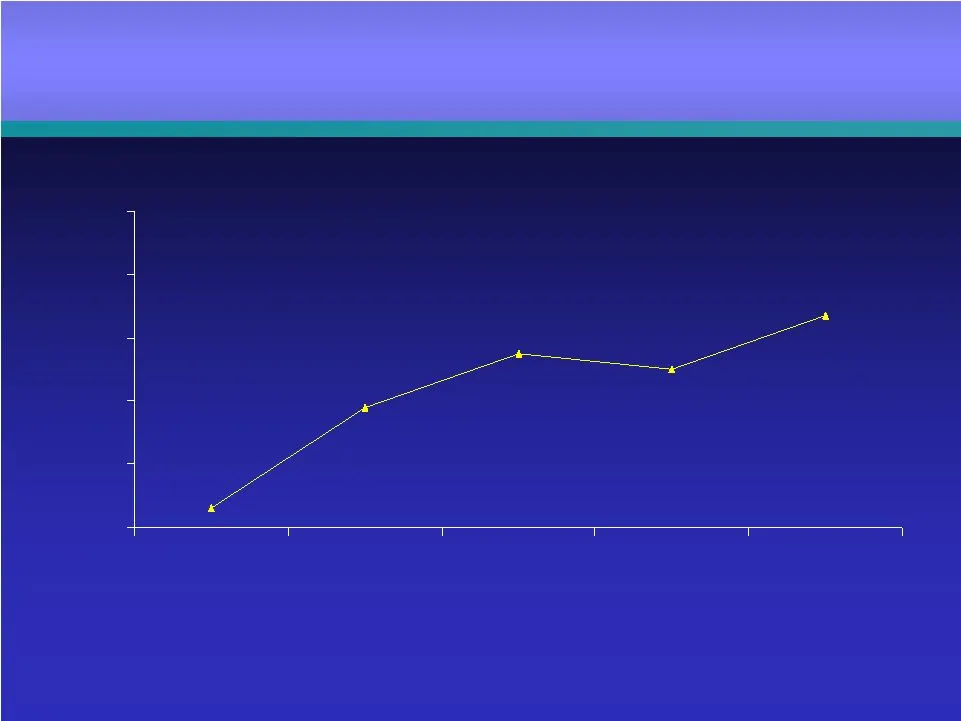
1.50 1.70 1.90 2.10 2.30 2.50 2001 2002 2003 2004 2005 Earnings Per Share Earnings Per Share 1.56 1.88 2.05 2.00 2.17
Slide 52: Customer Deposits
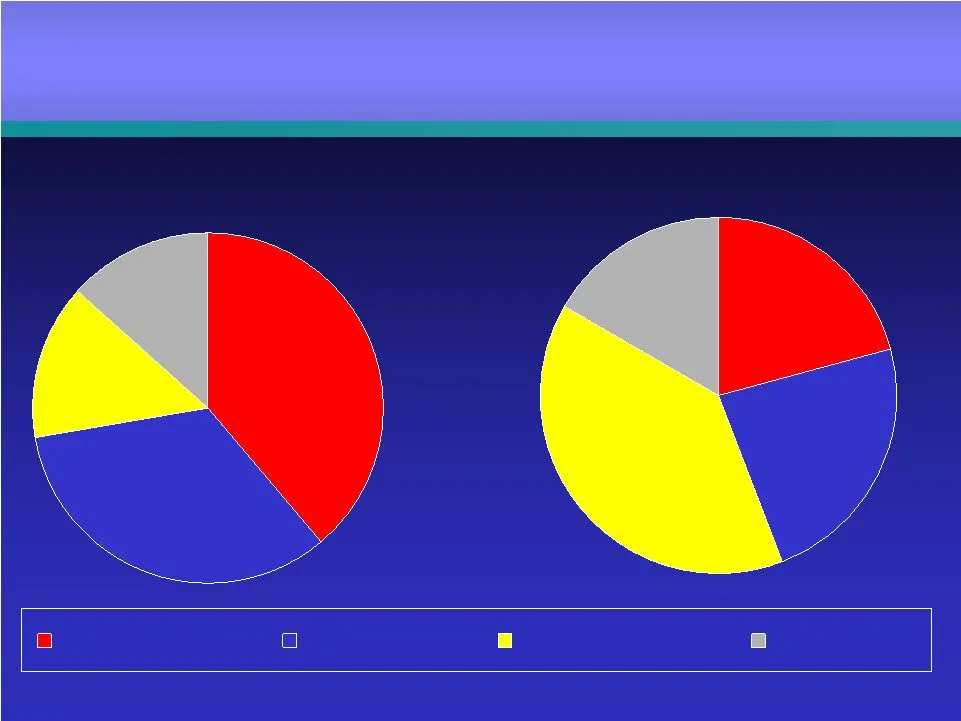
Savings Deposits Time Deposits Demand Deposits MM Deposits 2005 1995 Customer Deposits Customer Deposits 13% 14% 33% 40% 23% 21% 39% 17% $1,632, 544 $3,517,648
Slide 53: 2005 Financial Performance: Higher Capital Levels
I. Continued transformation of the balance sheet II. Strong growth in core loans and deposits III. Solid fee income growth IV. Growth in earnings with improved quality of earnings VI. Improved asset quality 2005 Financial Performance 2005 Financial Performance V. Higher capital levels
Slide 54: Tangible Common Equity Ratio
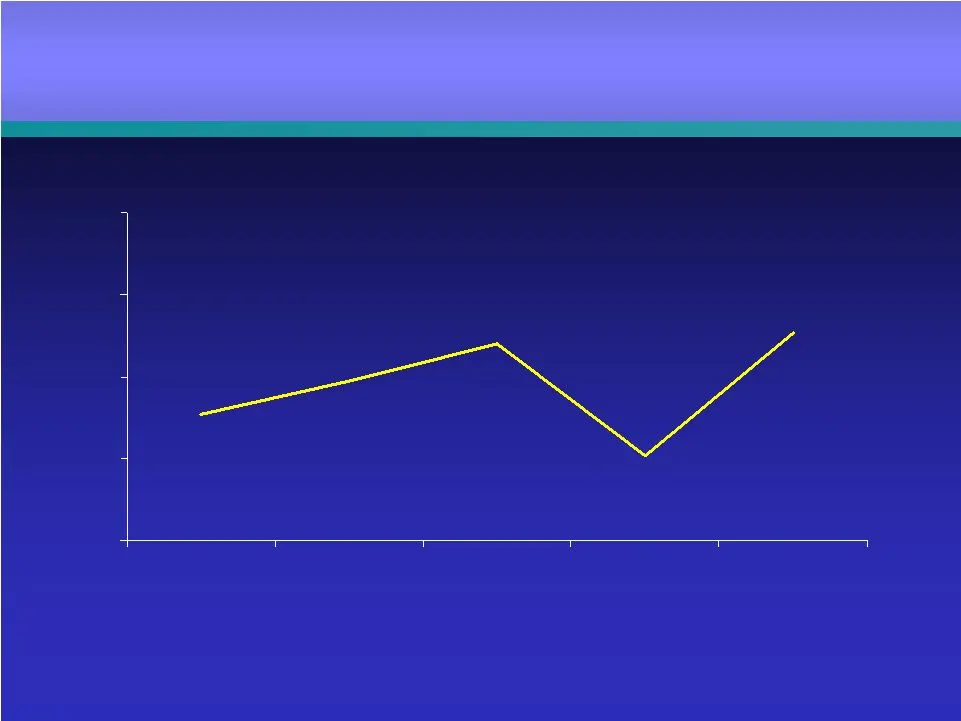
5.0% 5.5% 6.0% 6.5% 7.0% 2001 2002 2003 2004 2005 Tangible Common Equity Ratio Tangible Common Equity Ratio 6.27% 5.52% 6.20% 5.97% 5.77%
Slide 55: 2005 Financial Performance: Improved Asset Quality
I. Continued transformation of the balance sheet II. Strong growth in core loans and deposits III. Solid fee income growth IV. Growth in earnings with improved quality of earnings V. Higher capital levels 2005 Financial Performance 2005 Financial Performance VI. Improved asset quality
Slide 56: Net Charge-Offs / Average Loans
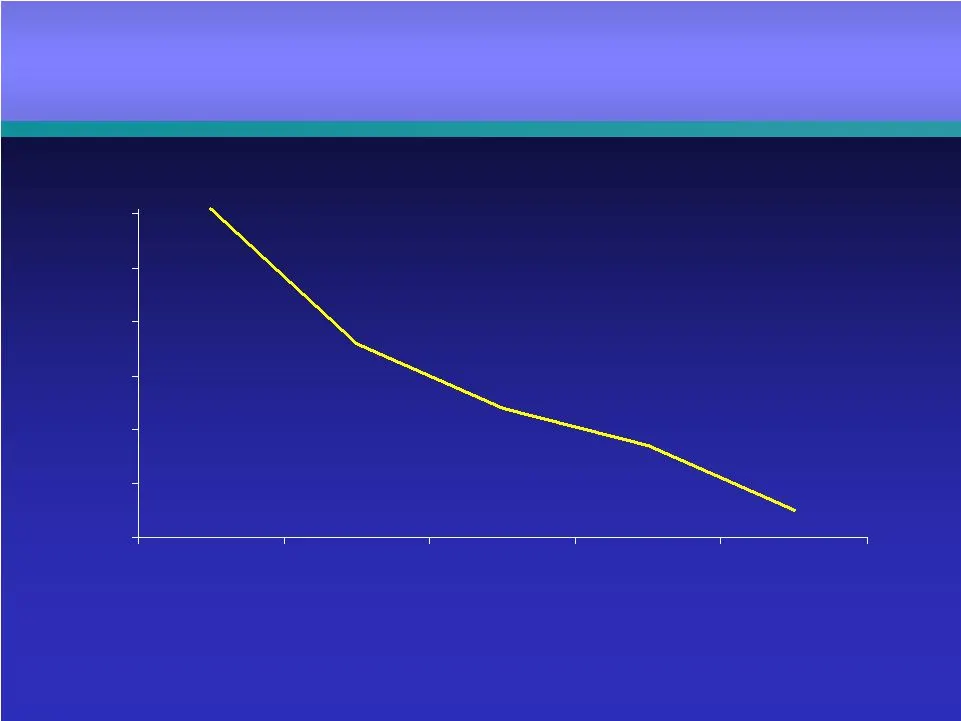
0.10% 0.20% 0.30% 0.40% 0.50% 0.60% 0.70% 2001 2002 2003 2004 2005 Net Charge-Offs / Average Loans Net Charge-Offs / Average Loans 0.15% 0.27% 0.34% 0.46% 0.71%
Slide 57: Reserves / Loans
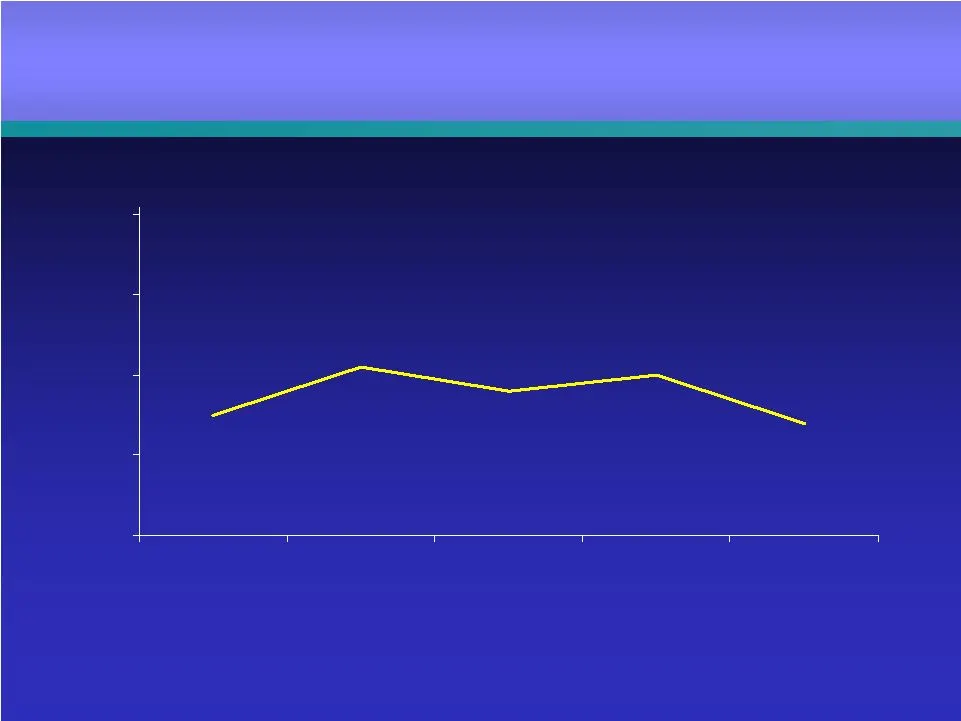
1.1% 1.2% 1.3% 1.4% 1.5% 2001 2002 2003 2004 2005 Reserves / Loans Reserves / Loans 1.24% 1.30% 1.27% 1.23% 1.29%
Slide 58: Equity Summary 2005
Current yield: 3.23% Shares repurchased: 684,962 P/E ratio: 15.6 x Market Capitalization: $ 1.2 billion (As of 12/30/05) Equity Summary Equity Summary 2005 2005 • • • •
Slide 59: Equity Summary 2003-2005: Total Return Comparison
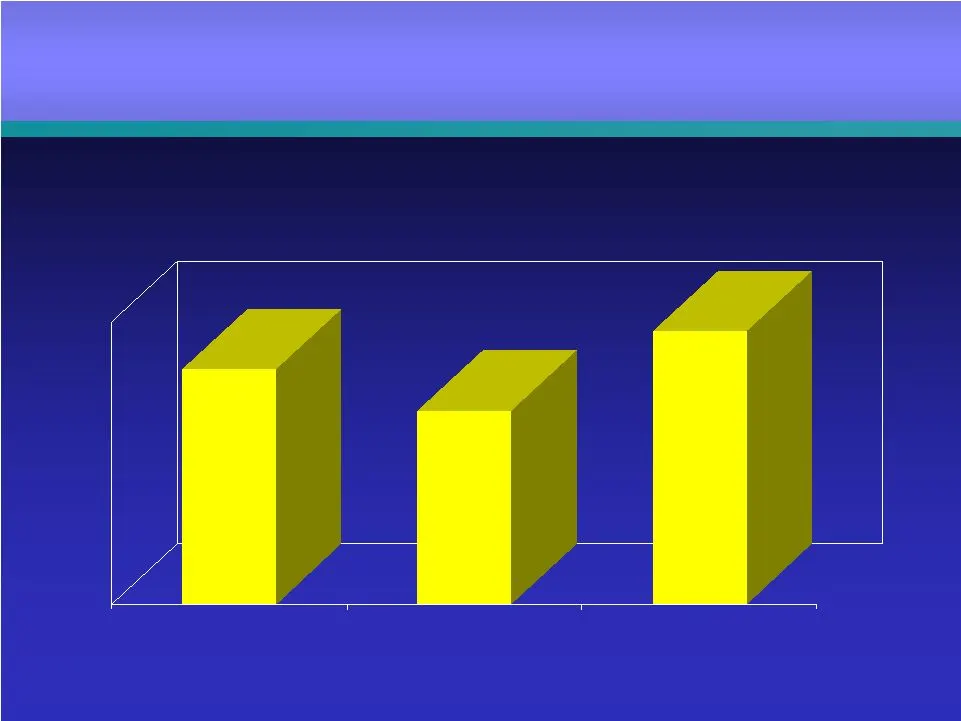
53.23% 43.79% 61.74% SNL Bank Index Peer Group Provident Equity Summary 2003 - Equity Summary 2003 - 2005 2005 Total Return Comparison Total Return Comparison
Slide 60: Appendix
Following pages provide regional economic data for Provident Bank’s market. Appendix Appendix
Slide 61: Office Vacancy
National 14.4% Baltimore Metro 14.7% Wash DC Metro 12.1% Richmond Metro 10.1% Data is as of Q3 2005 Office Vacancy Office Vacancy
Slide 62: Regional Employment: Unemployment Rate
Unemployment Rate National 5% Baltimore Metro 4.5% Wash DC Metro 3.4% Richmond Metro 3.7% Data is as of Q3 2005 Regional Employment Regional Employment
Slide 63: Regional Employment: Employment Growth
Employment Growth Baltimore 29,200 Washington DC 97,800 Richmond 24,300 N. VA 61,800 Data is as of August 2005, Year over Year Regional Employment Regional Employment
Slide 64: Market Demographics: Change in Population
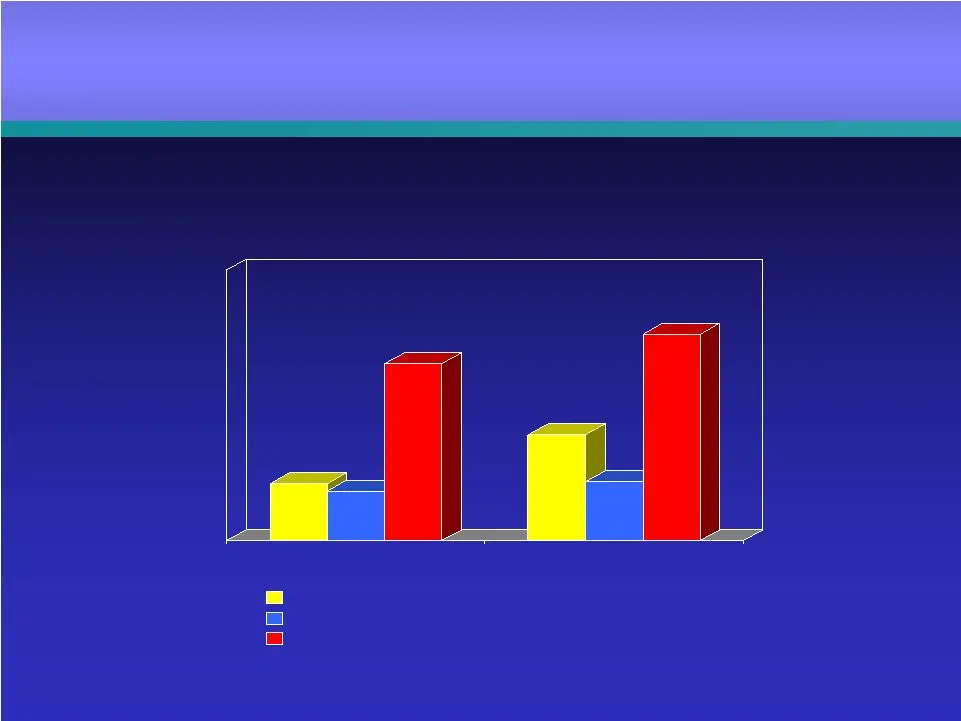
3.3% 3.0% 8.2% 5.3% 3.4% 9.4% 2000-2004 2004-2009 US Baltimore-Towson,MD Washington-Arlington-Alexandria Change in Population Market Demographics Market Demographics Market Demographics
Slide 65: Market Demographics: Median Household Income
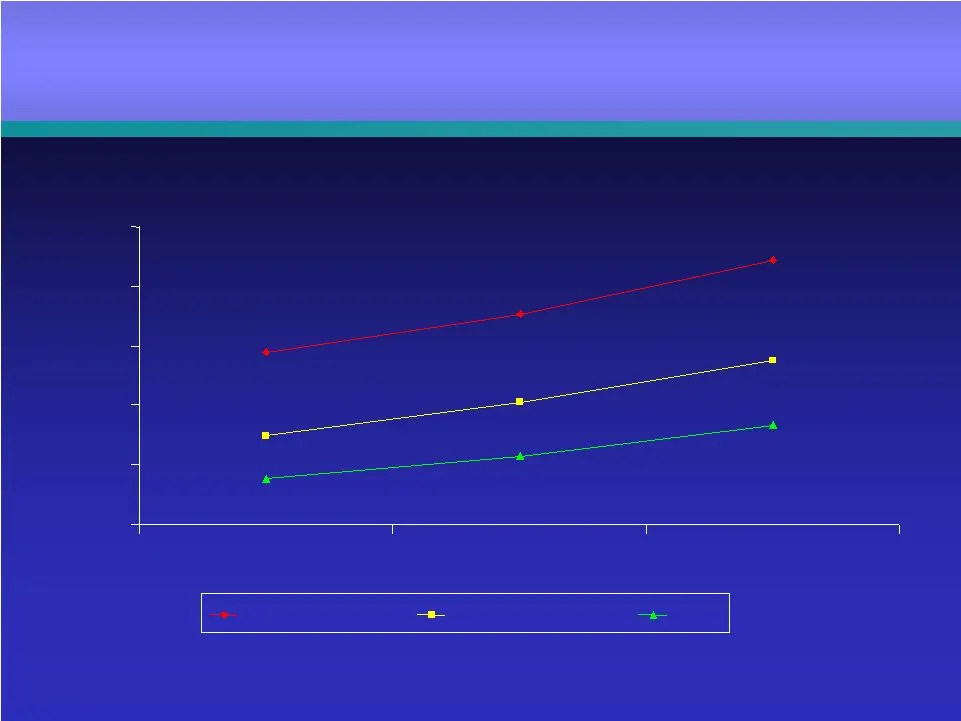
Median Household Income $63,992 $70,274 $79,287 $49,949 $55,412 $62,571 $42,600 $46,475 $51,597 $35,000 $45,000 $55,000 $65,000 $75,000 $85,000 2000 2004 2009 Wash Metro Balto/Towson U.S. Market Demographics Market Demographics
Slide 66: Provident Bankshares Corporation Contacts
PROVIDENT BANKSHARES C O R P O R A T I O N www.provbank.com Contact Media : Lillian Kilroy (410) 277-2833 Investment Community : Melissa Kelly (410) 277-2080 PROVIDENT BANKSHARES C O R P O R A T I O N
Source: SEC EDGAR · 8-K filed Mar 1, 2006
More decks from Provident Bankshares Corp
 Merger or Acquisition (December 2008)32 slides · Dec 19, 2008
 2007 Stifel Nicolaus Financial Institutions Investor Conference52 slides · Dec 6, 2007
 Investor Presentation (November 2007)49 slides · Nov 8, 2007
 FTN Midwest Small and Mid Cap Bank Conference 200757 slides · Sep 6, 2007
 Investor Presentation (May 2007)51 slides · May 8, 2007
 KBW Regional Bank Conference 200751 slides · Feb 28, 2007