Scatec ASA · OSL:SCATC
Scatec ASA — Scatec Solar — Investor Presentation (February 2016)
23 slides from Scatec ASA's investor presentation, February 2016
Slide 1: Investor presentation
Investor presentation February 2016 Our values • Predictable • Driving results • Changemakers • Working together
Slide 2: Disclaimer
Disclaimer The following presentation is being made only to, and is only directed at, persons to whom such presentation may lawfully be communicated (’relevant persons’). Any person who is not a relevant person should not rely, act or make assessment on the basis of this presentation or anything inc
Slide 3: Introduction to Scatec Solar ASA
Introduction to Scatec Solar ASA
Slide 4: An independent solar power producer
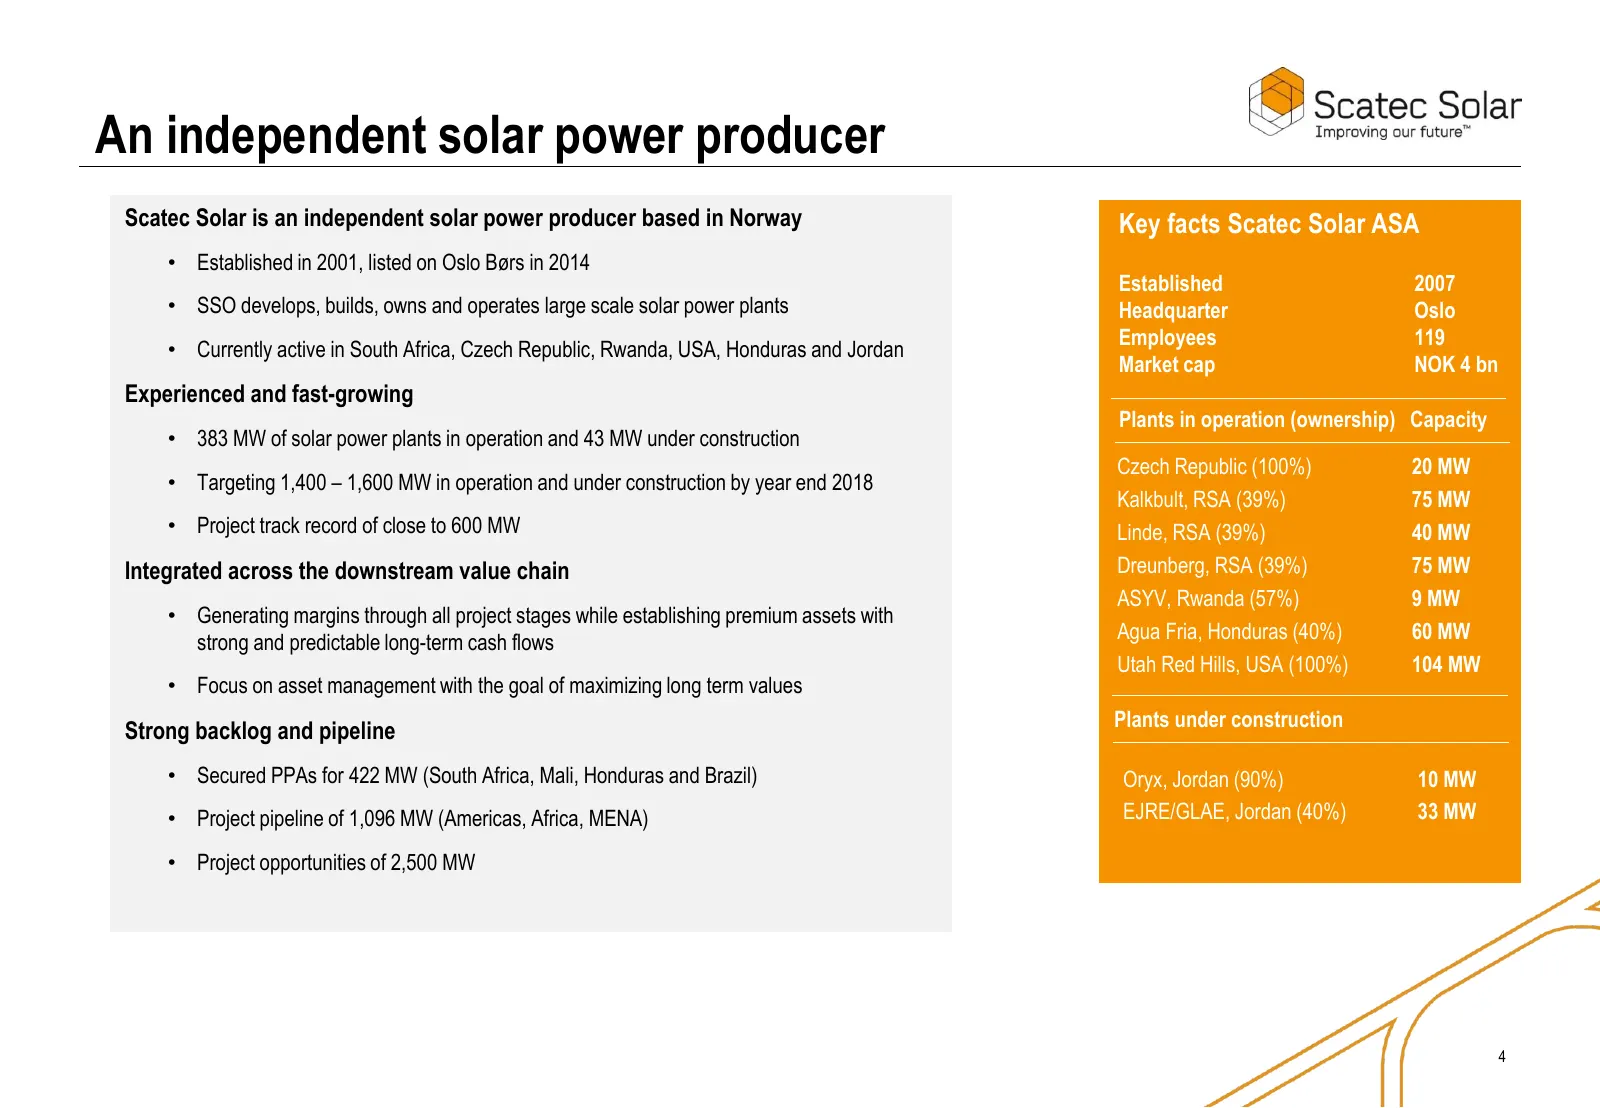
An independent solar power producer Scatec Solar is an independent solar power producer based in Norway Key facts Scatec Solar ASA • Established in 2001, listed on Oslo Børs in 2014 Established 2007 • SSO develops, builds, owns and operates large scale solar power plants Headquarter Oslo Employees 1
Slide 5: Integrated approach captures the full project value
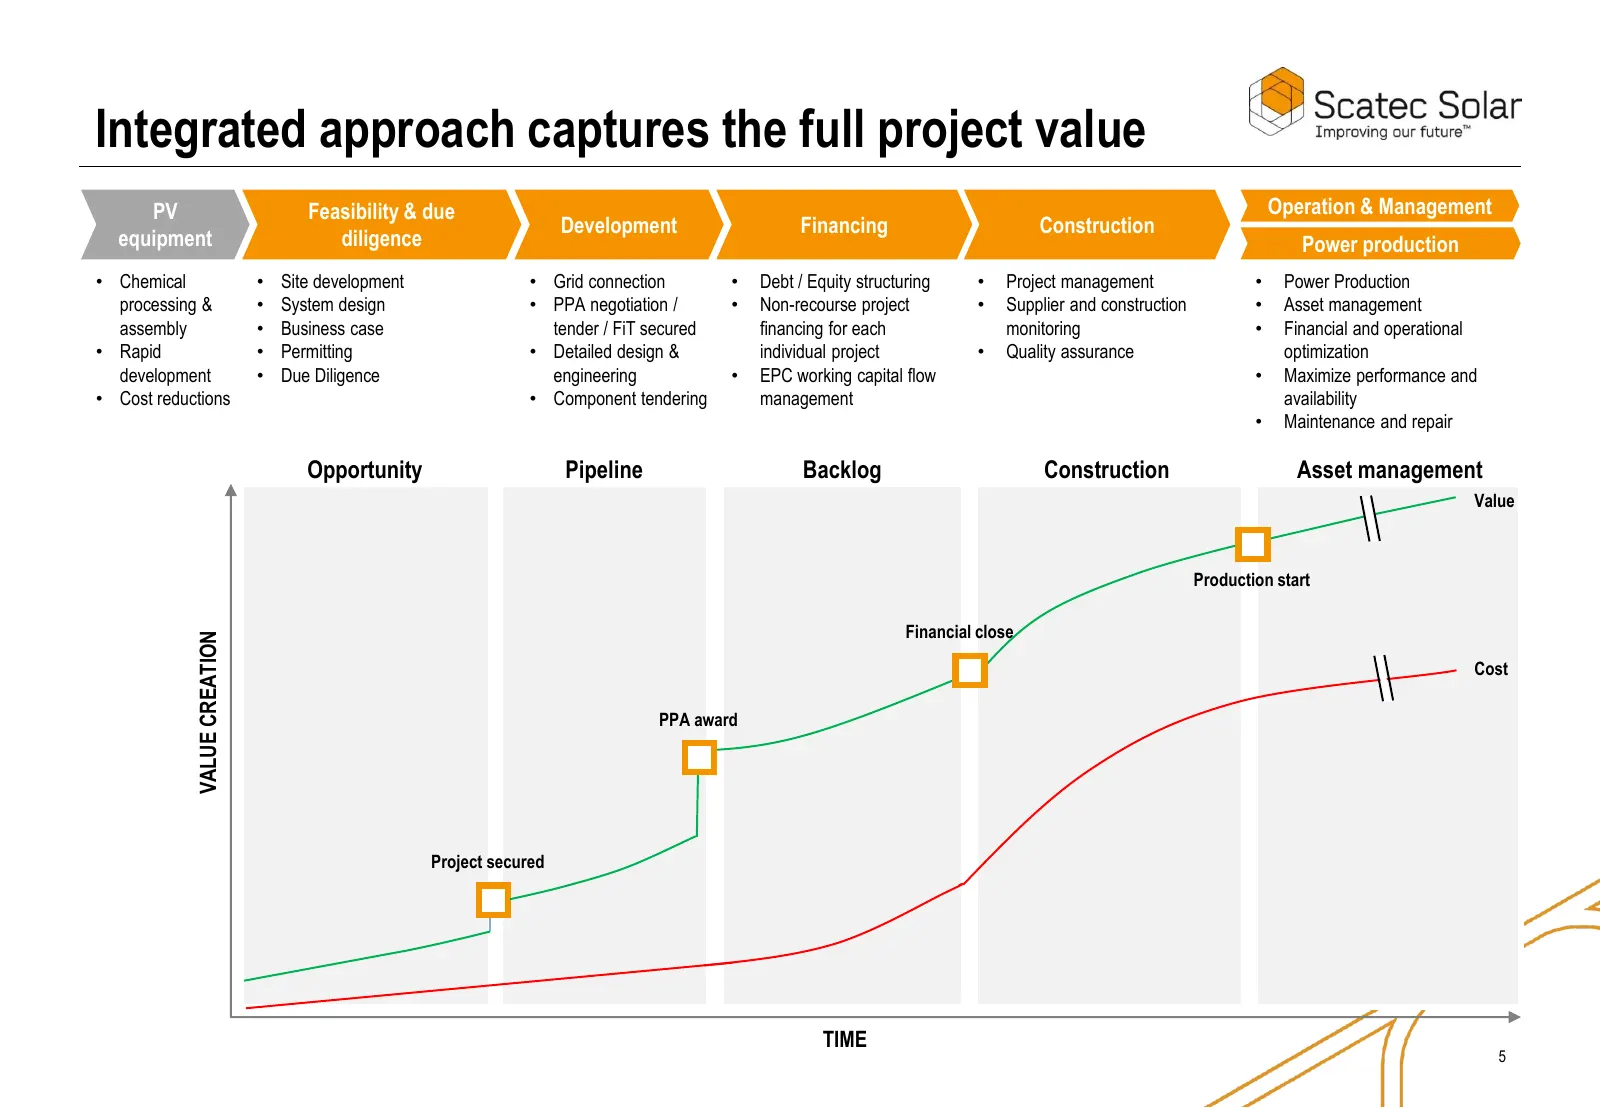
Integrated approach captures the full project value PV Feasibility & due Operation & Management Development Financing Construction equipment diligence Power production • Chemical • Site development • Grid connection • Debt / Equity structuring • Project management • Power Production processing & • S
Slide 6: Scatec Solar asset portfolio – 848 MW
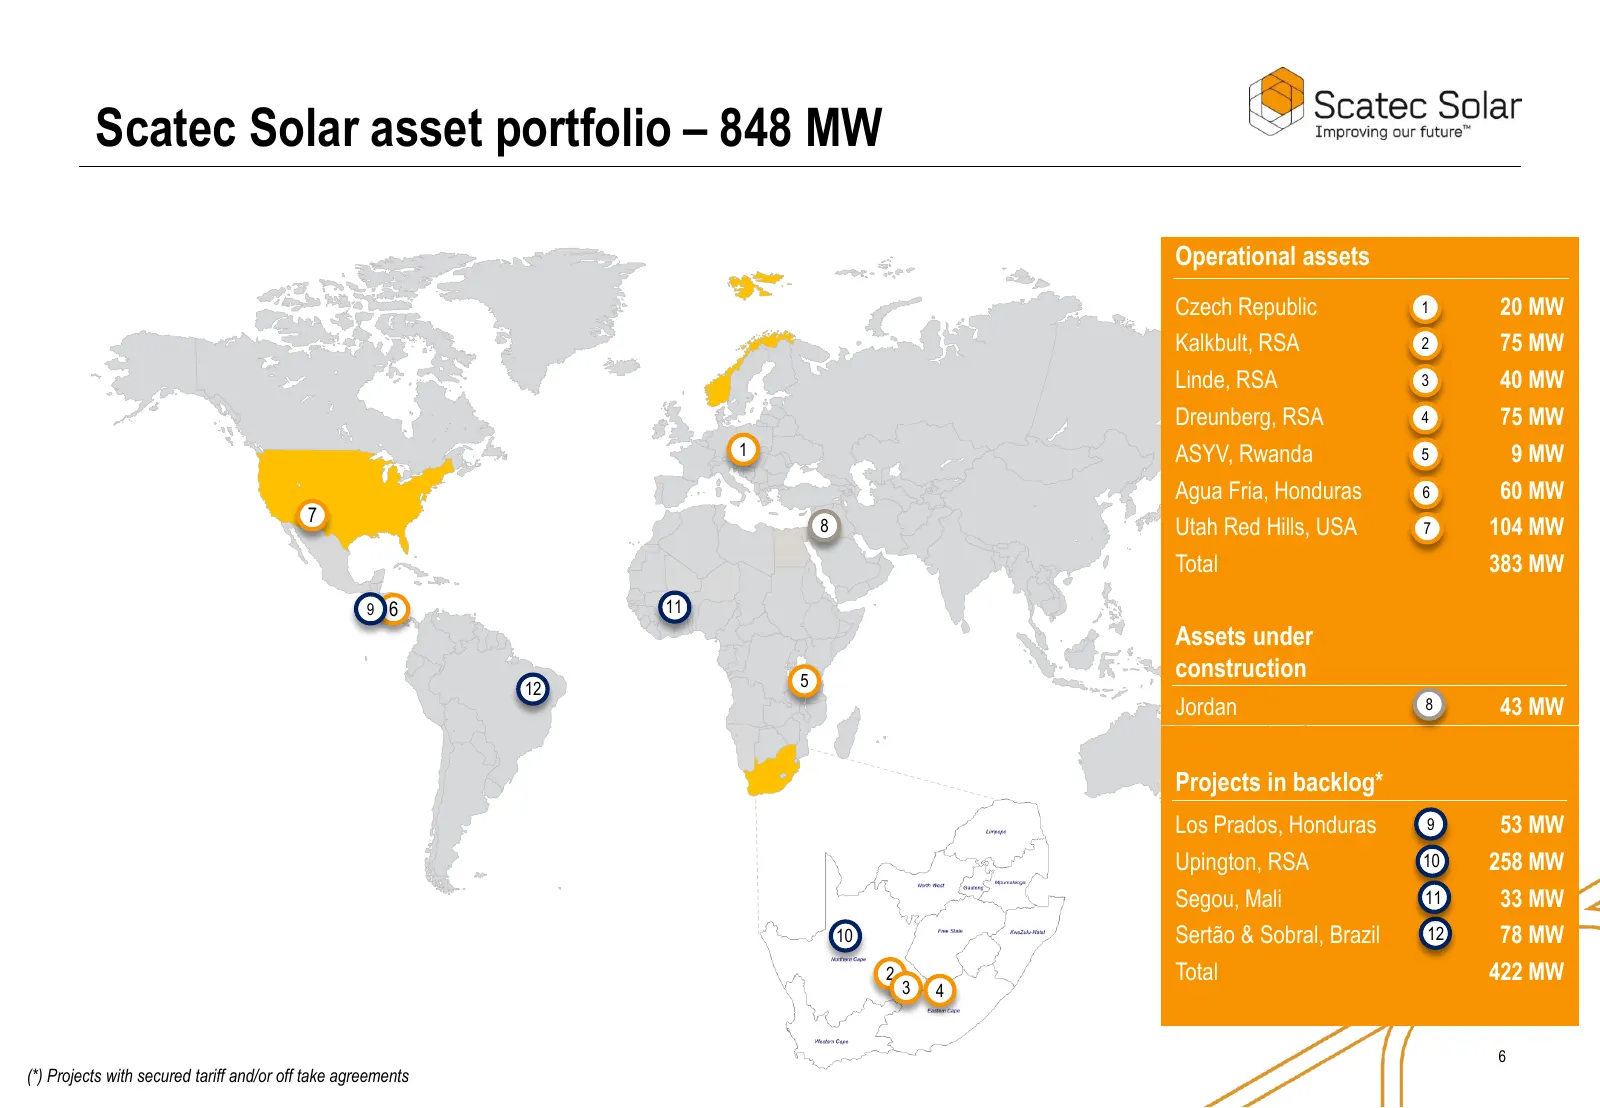
Scatec Solar asset portfolio – 848 MW Operational assets Czech Republic 1 20 MW Kalkbult, RSA 2 75 MW Linde, RSA 3 40 MW Dreunberg, RSA 4 75 MW 1 ASYV, Rwanda 5 9 MW Agua Fria, Honduras 6 60 MW 7 8 Utah Red Hills, USA 7 104 MW Total 383 MW 9 6 11 Assets under 5 construction 12 Jordan 8 43 MW Project
Slide 7: A solid project funnel – basis for further growth
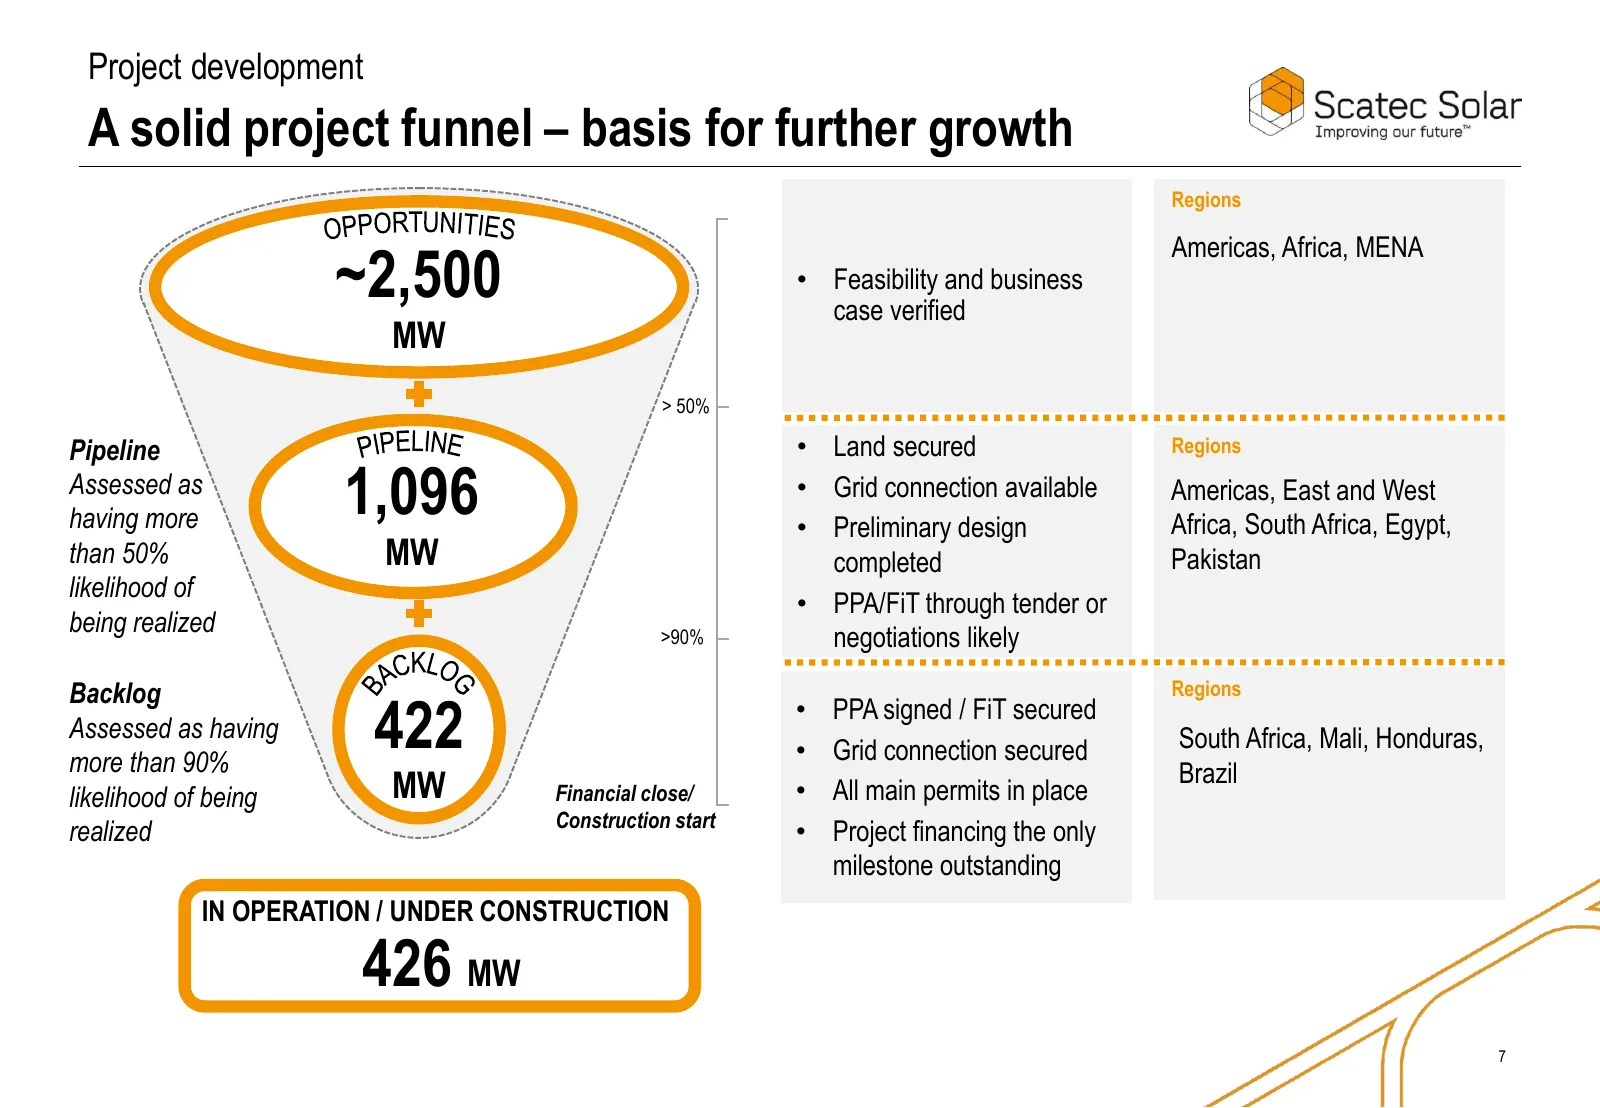
Project development A solid project funnel – basis for further growth Regions Americas, Africa, MENA ~2,500 • Feasibility and business case verified MW > 50% Pipeline • Land secured Regions Assessed as having more 1,096 • Grid connection available • Preliminary design Americas, East and West Africa,
Slide 8: A comprehensive project structuring phase
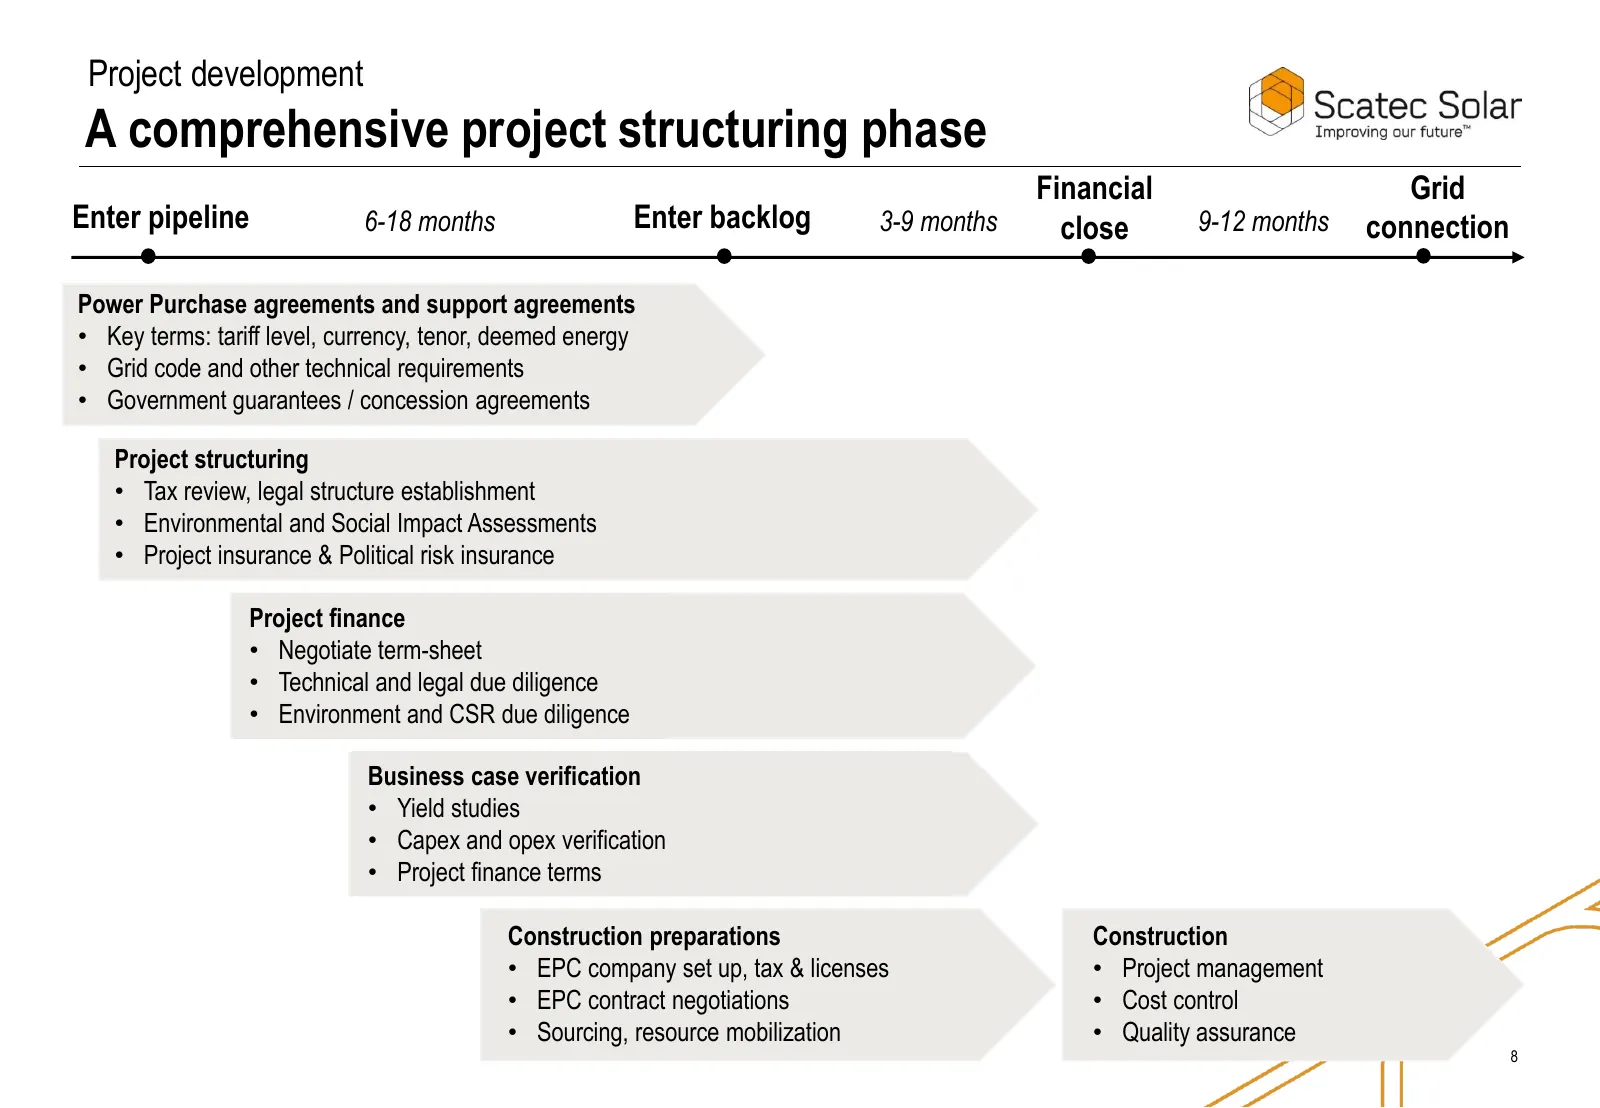
Project development A comprehensive project structuring phase Financial Grid Enter pipeline 6-18 months Enter backlog 3-9 months close 9-12 months connection Power Purchase agreements and support agreements • Key terms: tariff level, currency, tenor, deemed energy • Grid code and other technical req
Slide 9: Preparing to execute backlog
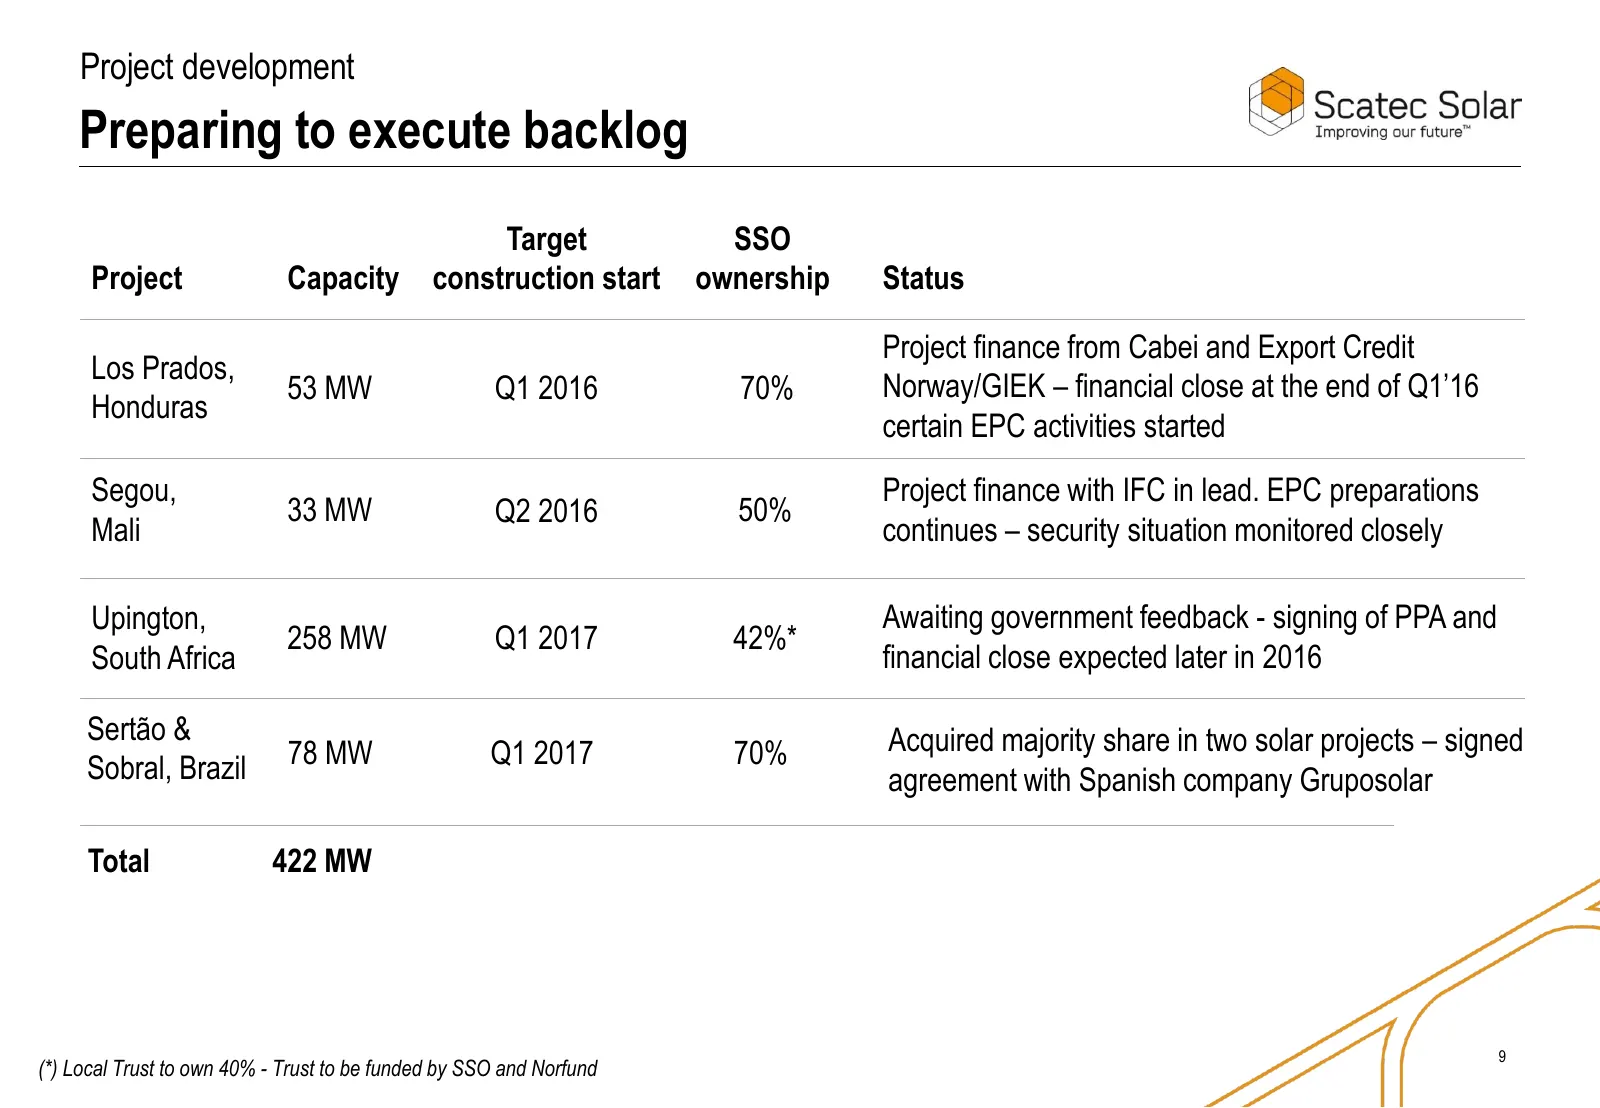
Project development Preparing to execute backlog Target SSO Project Capacity construction start ownership Status Project finance from Cabei and Export Credit Los Prados, 53 MW Q1 2016 70% Norway/GIEK – financial close at the end of Q1’16 Honduras certain EPC activities started Segou, Project finance
Slide 10: Pipeline continues to mature
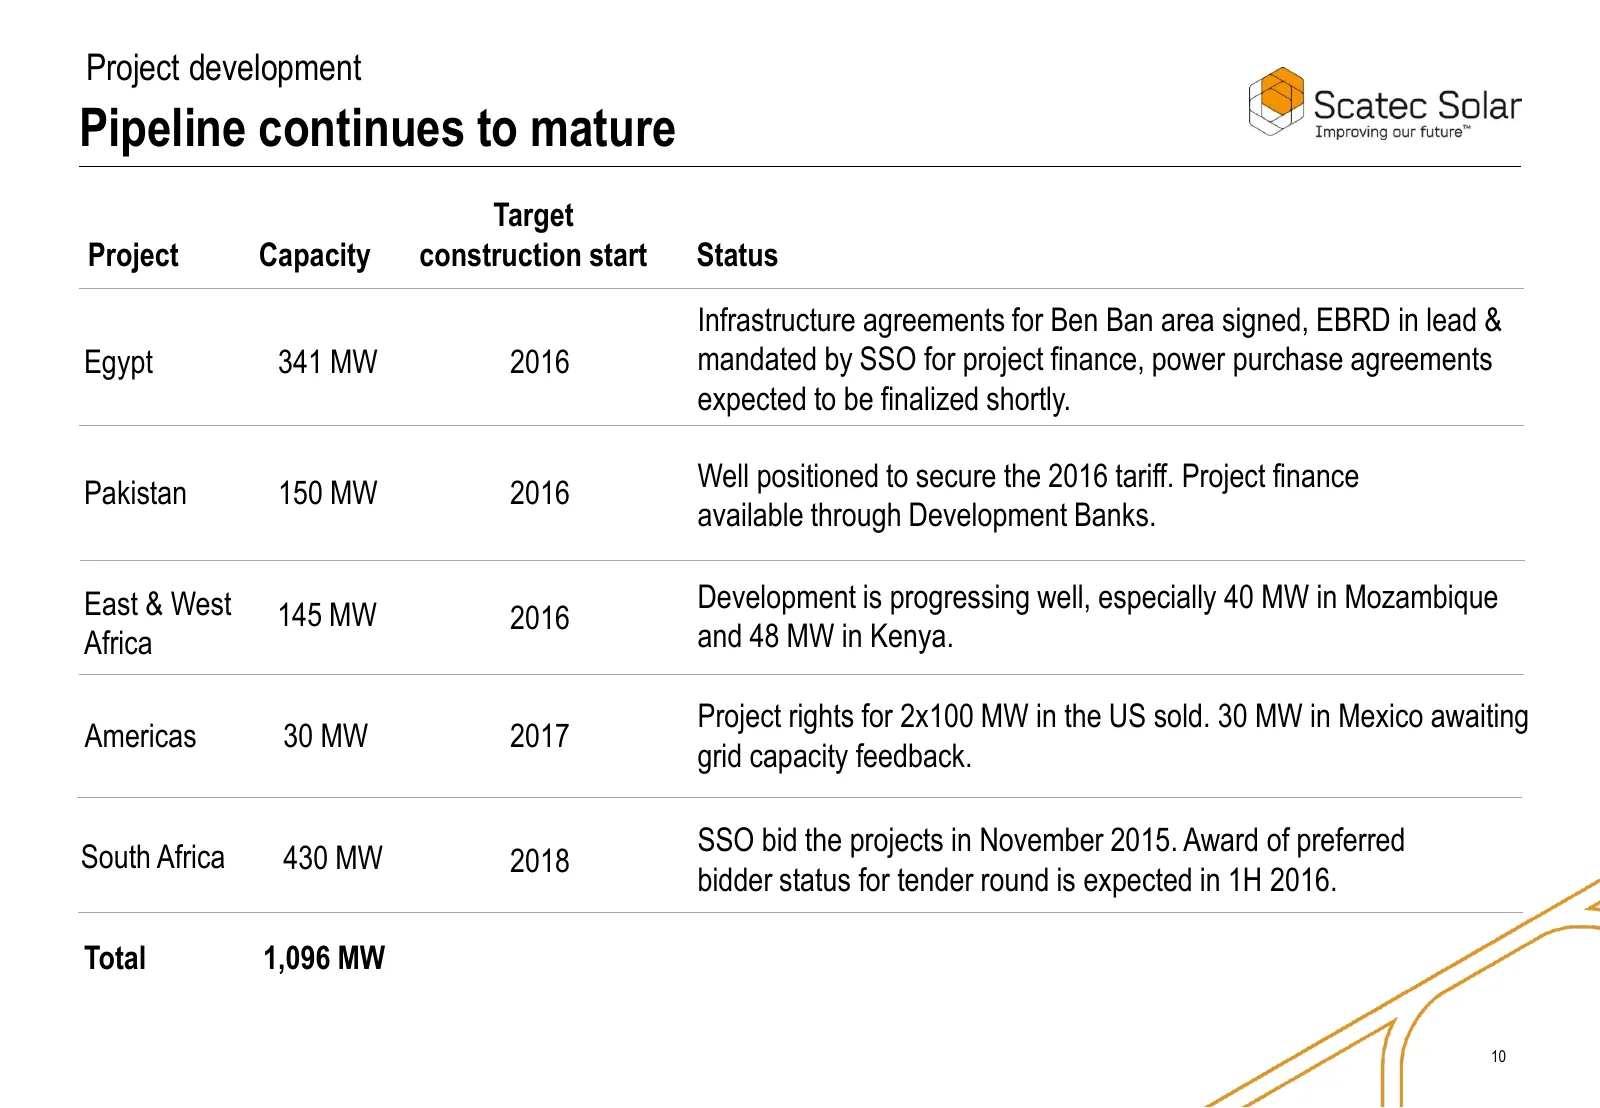
Project development Pipeline continues to mature Target Project Capacity construction start Status Infrastructure agreements for Ben Ban area signed, EBRD in lead & Egypt 341 MW 2016 mandated by SSO for project finance, power purchase agreements expected to be finalized shortly. Well positioned to s
Slide 11: Norfund, IFC and other partnerships
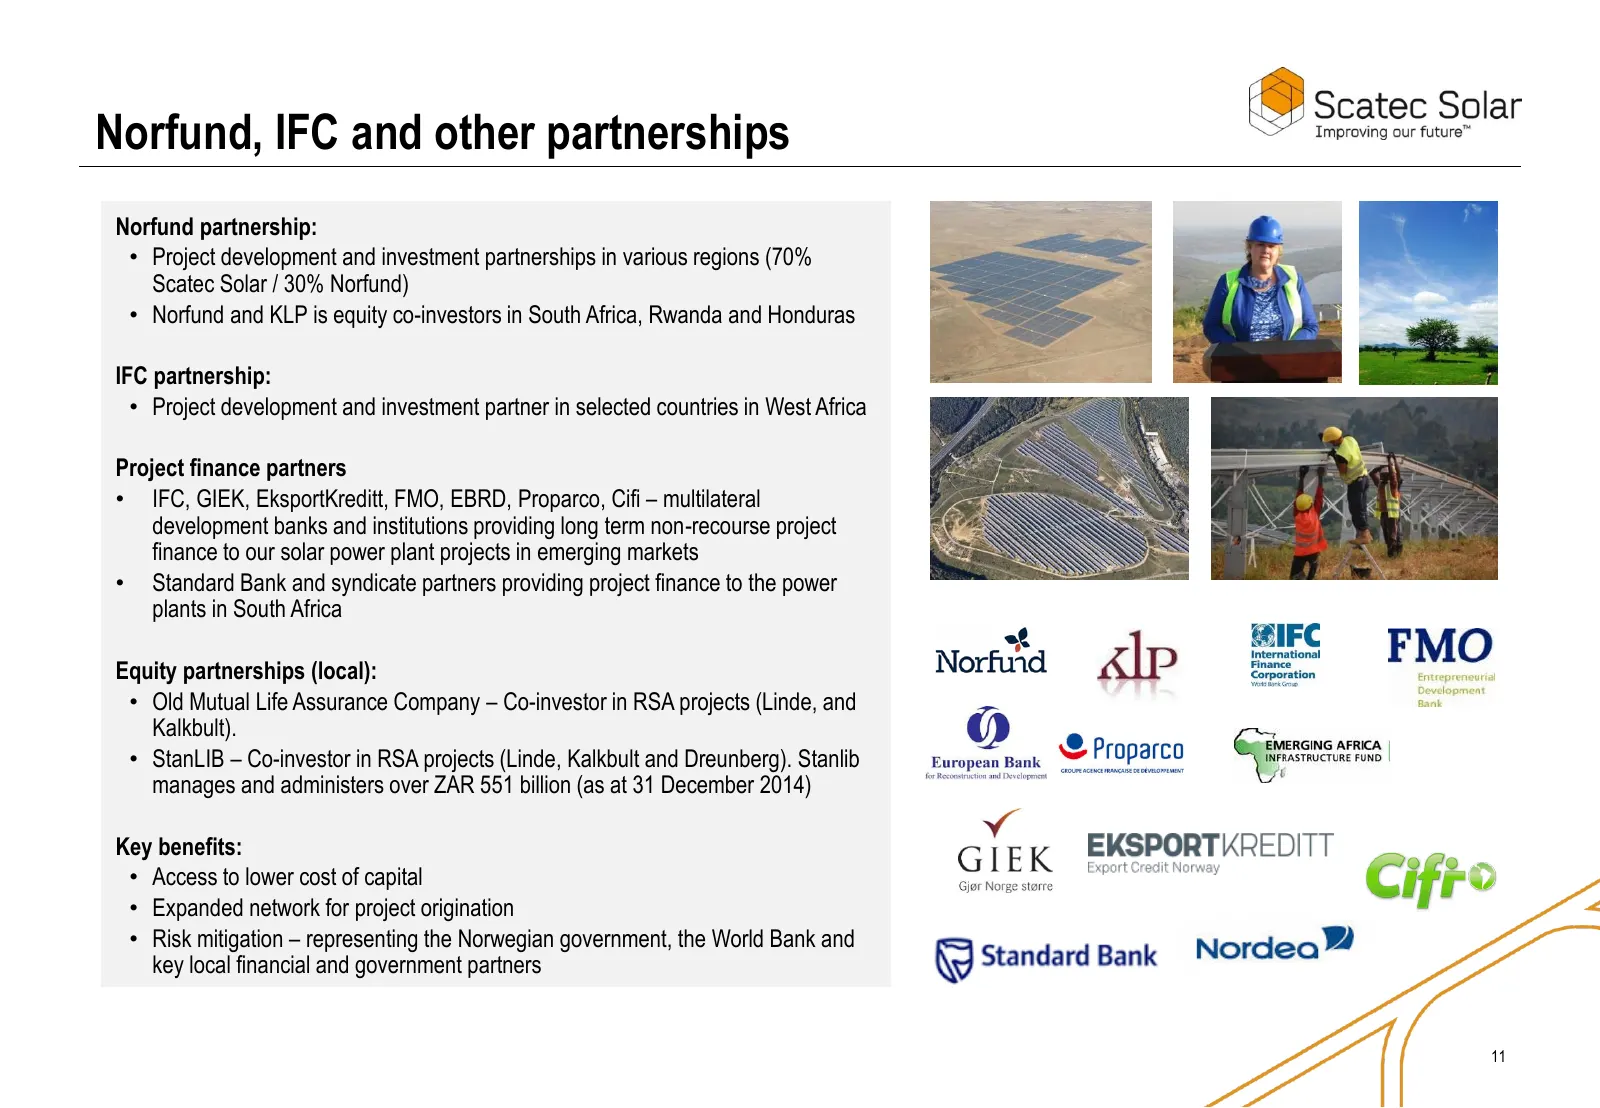
Norfund, IFC and other partnerships Norfund partnership: • Project development and investment partnerships in various regions (70% Scatec Solar / 30% Norfund) • Norfund and KLP is equity co-investors in South Africa, Rwanda and Honduras IFC partnership: • Project development and investment partner i
Slide 12: Positive market outlook
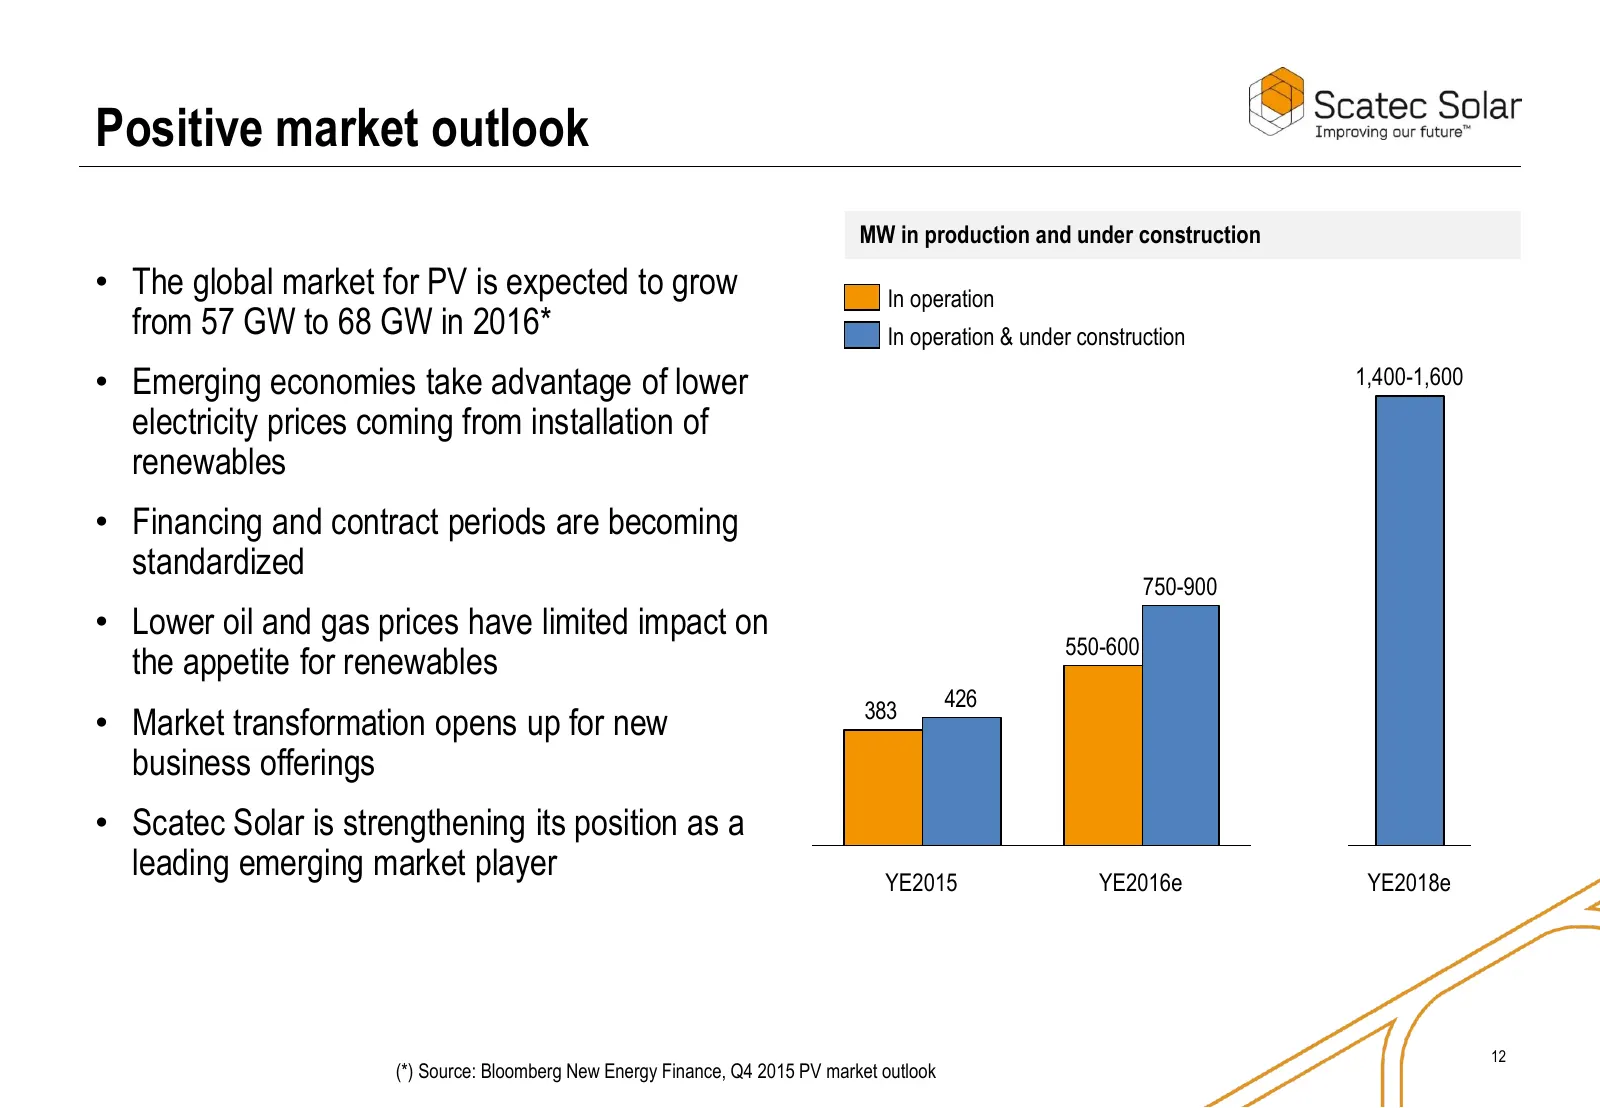
Positive market outlook MW in production and under construction • The global market for PV is expected to grow In operation from 57 GW to 68 GW in 2016* In operation & under construction • Emerging economies take advantage of lower 1,400-1,600 electricity prices coming from installation of renewable
Slide 13: Financials
o Scatec Solar Improving our future™ Financials
Slide 14: Continued strong growth
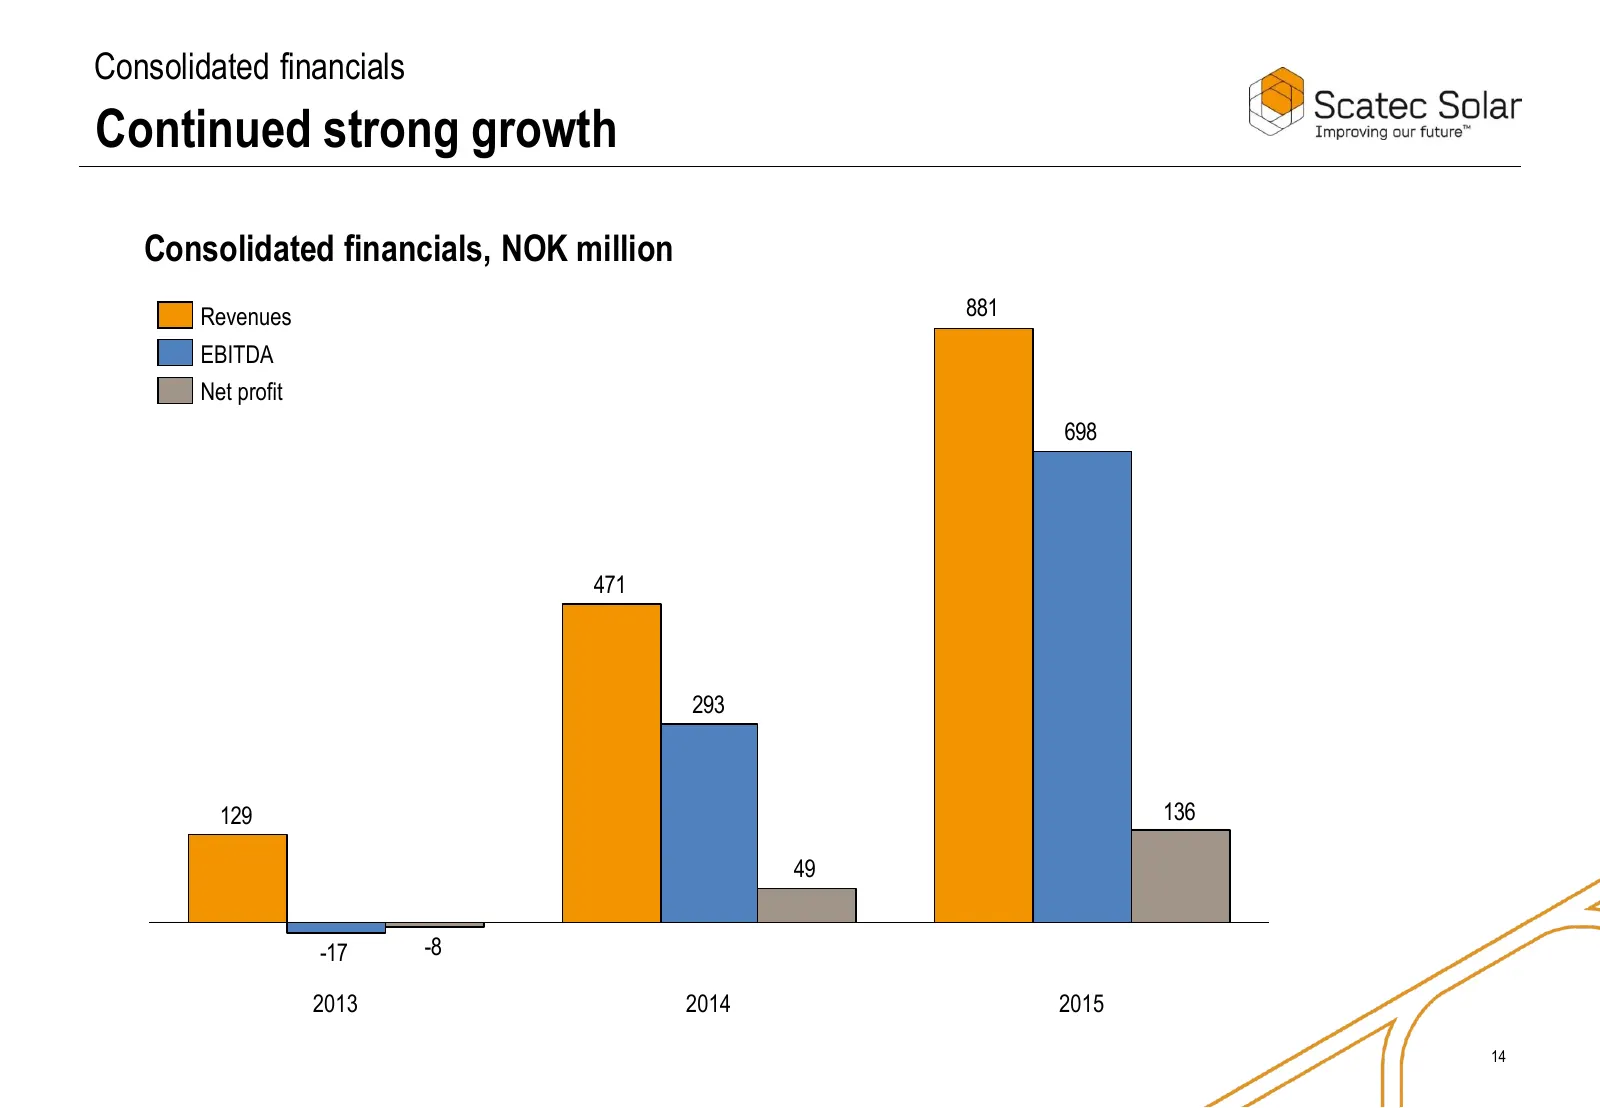
Consolidated financials Continued strong growth Consolidated financials, NOK million Revenues 881 EBITDA Net profit 698 471 293 129 136 49 -17 -8 2013 2014 2015 14
Slide 15: Strong growth in net profit
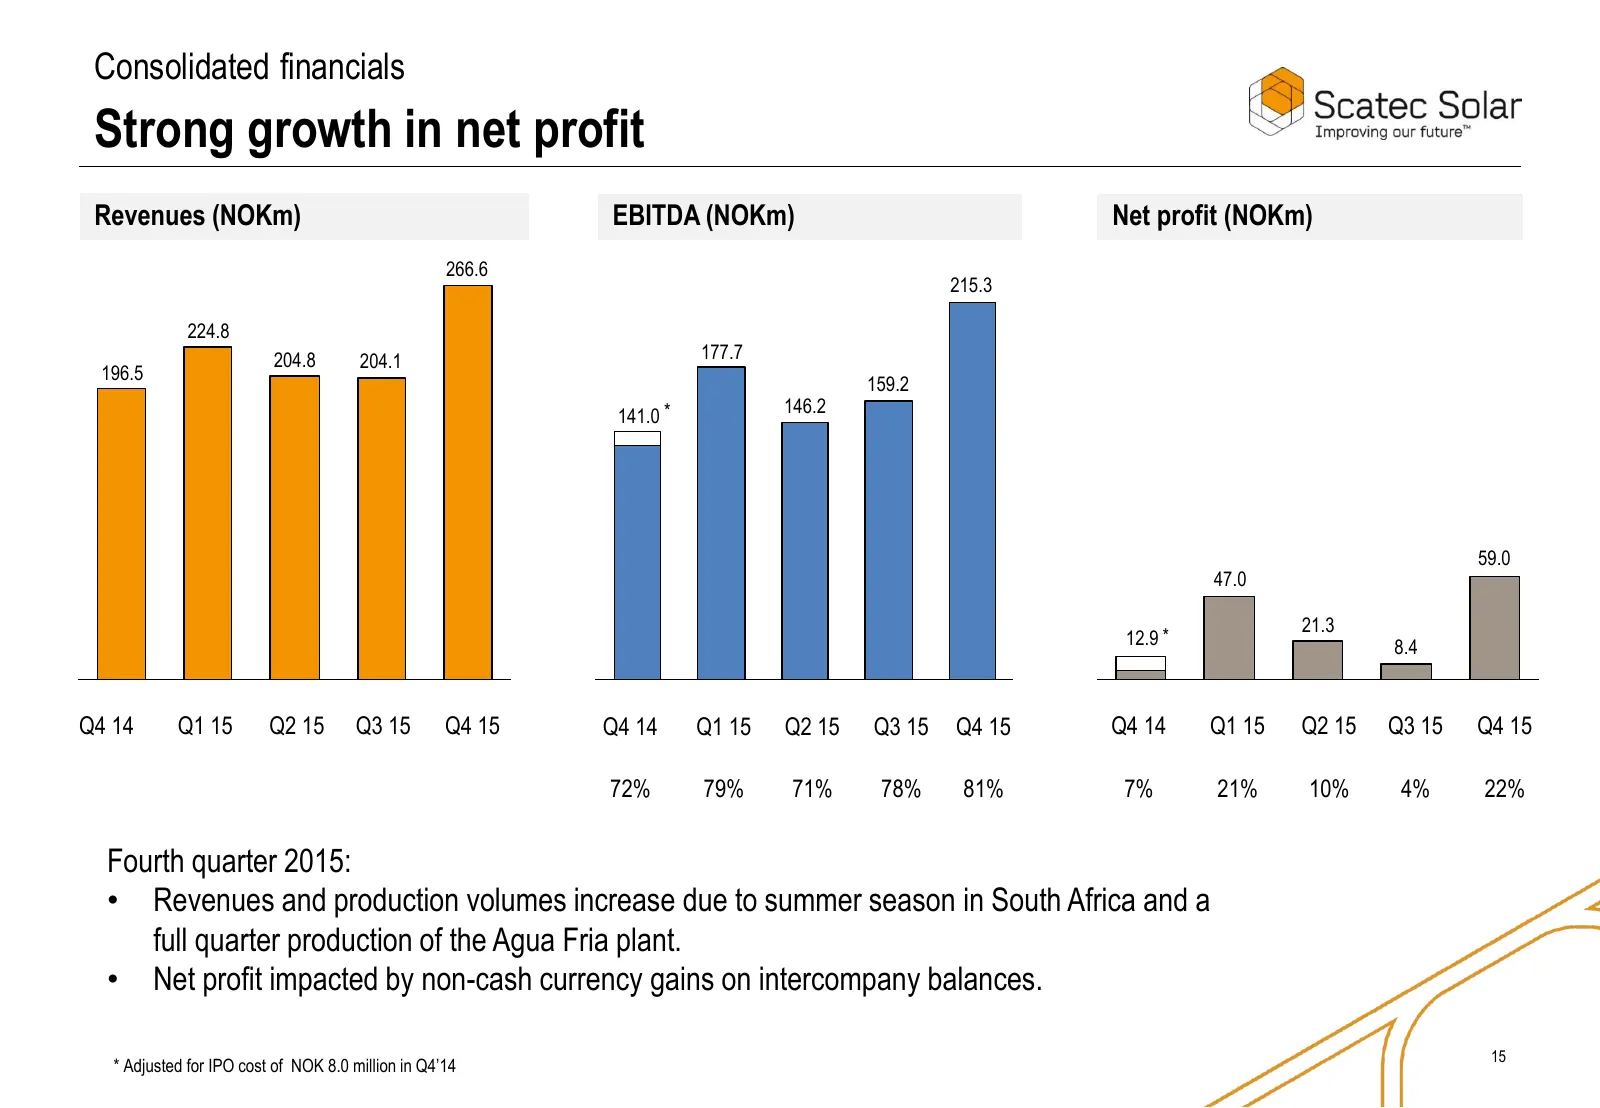
Consolidated financials Strong growth in net profit Revenues (NOKm) EBITDA (NOKm) Net profit (NOKm) 266.6 215.3 224.8 204.8 204.1 177.7 196.5 159.2 141.0 * 146.2 59.0 47.0 21.3 12.9 * 8.4 Q4 14 Q1 15 Q2 15 Q3 15 Q4 15 Q4 14 Q1 15 Q2 15 Q3 15 Q4 15 Q4 14 Q1 15 Q2 15 Q3 15 Q4 15 72% 79% 71% 78% 81% 7%
Slide 16: Summer in South Africa and Agua Fria in full production
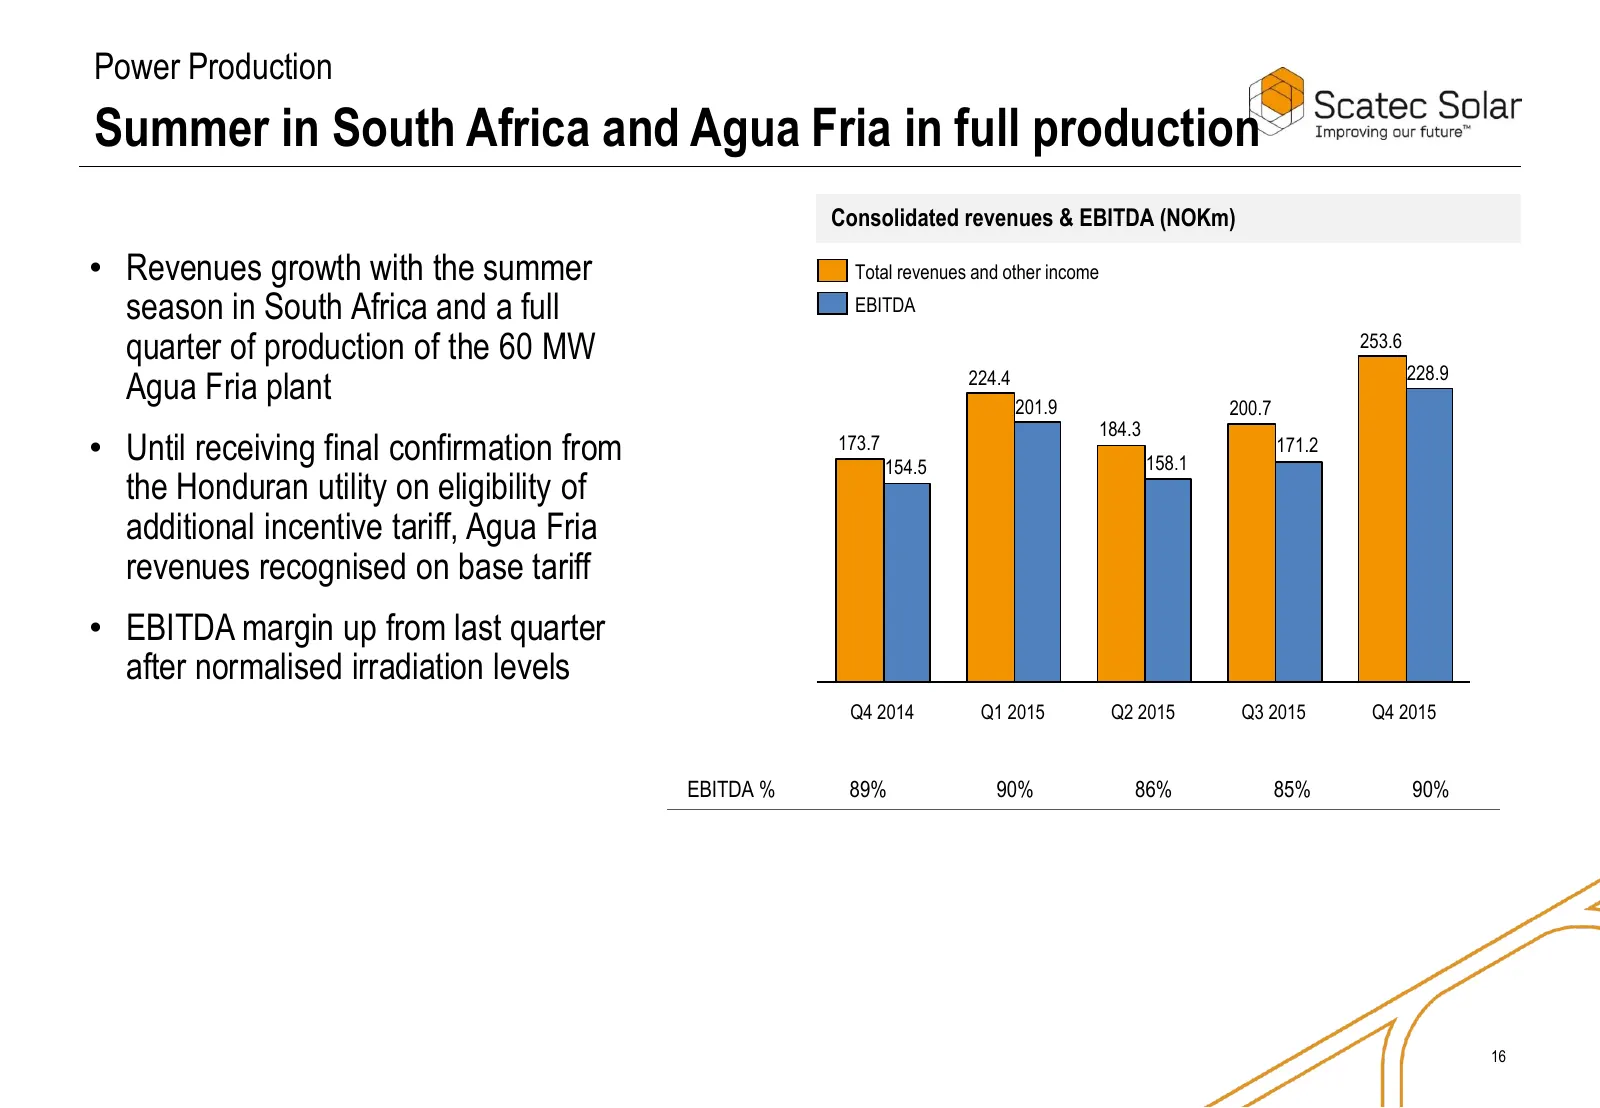
Power Production Summer in South Africa and Agua Fria in full production Consolidated revenues & EBITDA (NOKm) • Revenues growth with the summer Total revenues and other income season in South Africa and a full EBITDA quarter of production of the 60 MW 253.6 228.9 Agua Fria plant 224.4 201.9 200.7 1
Slide 17: Lower revenues due to reduced performance bonus
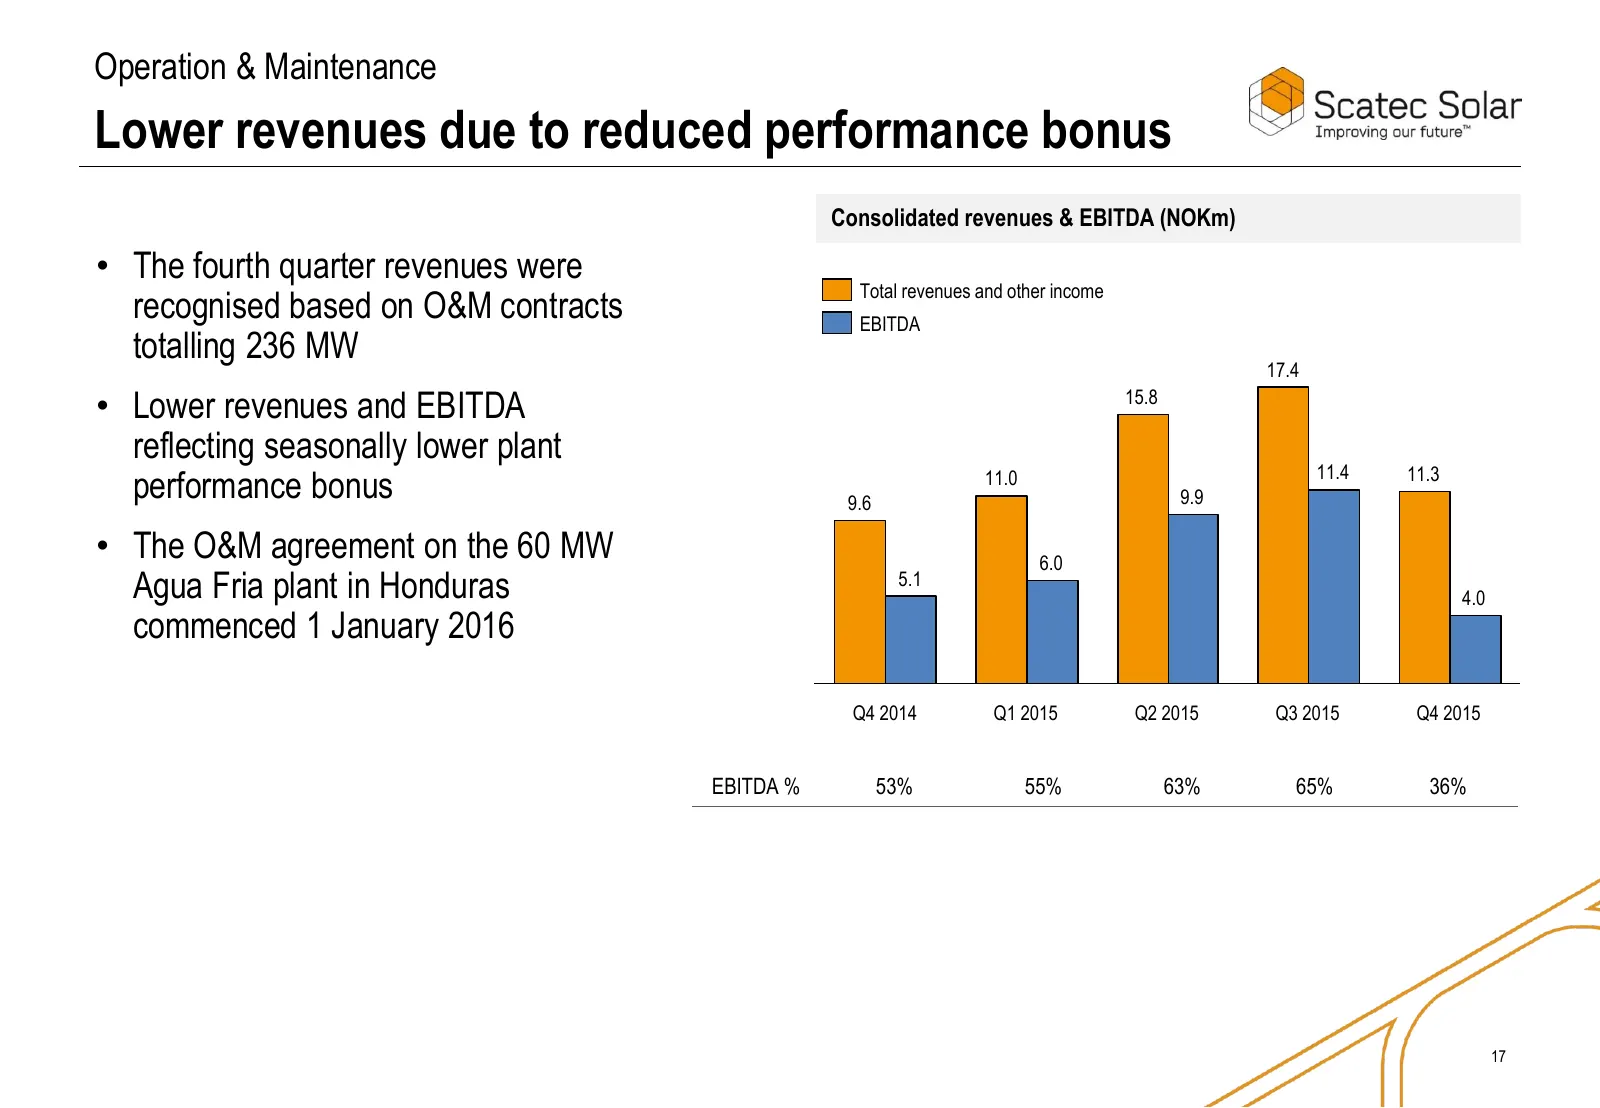
Operation & Maintenance Lower revenues due to reduced performance bonus Consolidated revenues & EBITDA (NOKm) • The fourth quarter revenues were Total revenues and other income recognised based on O&M contracts EBITDA totalling 236 MW 17.4 • Lower revenues and EBITDA 15.8 reflecting seasonally lower
Slide 18: Construction in Jordan moving forward
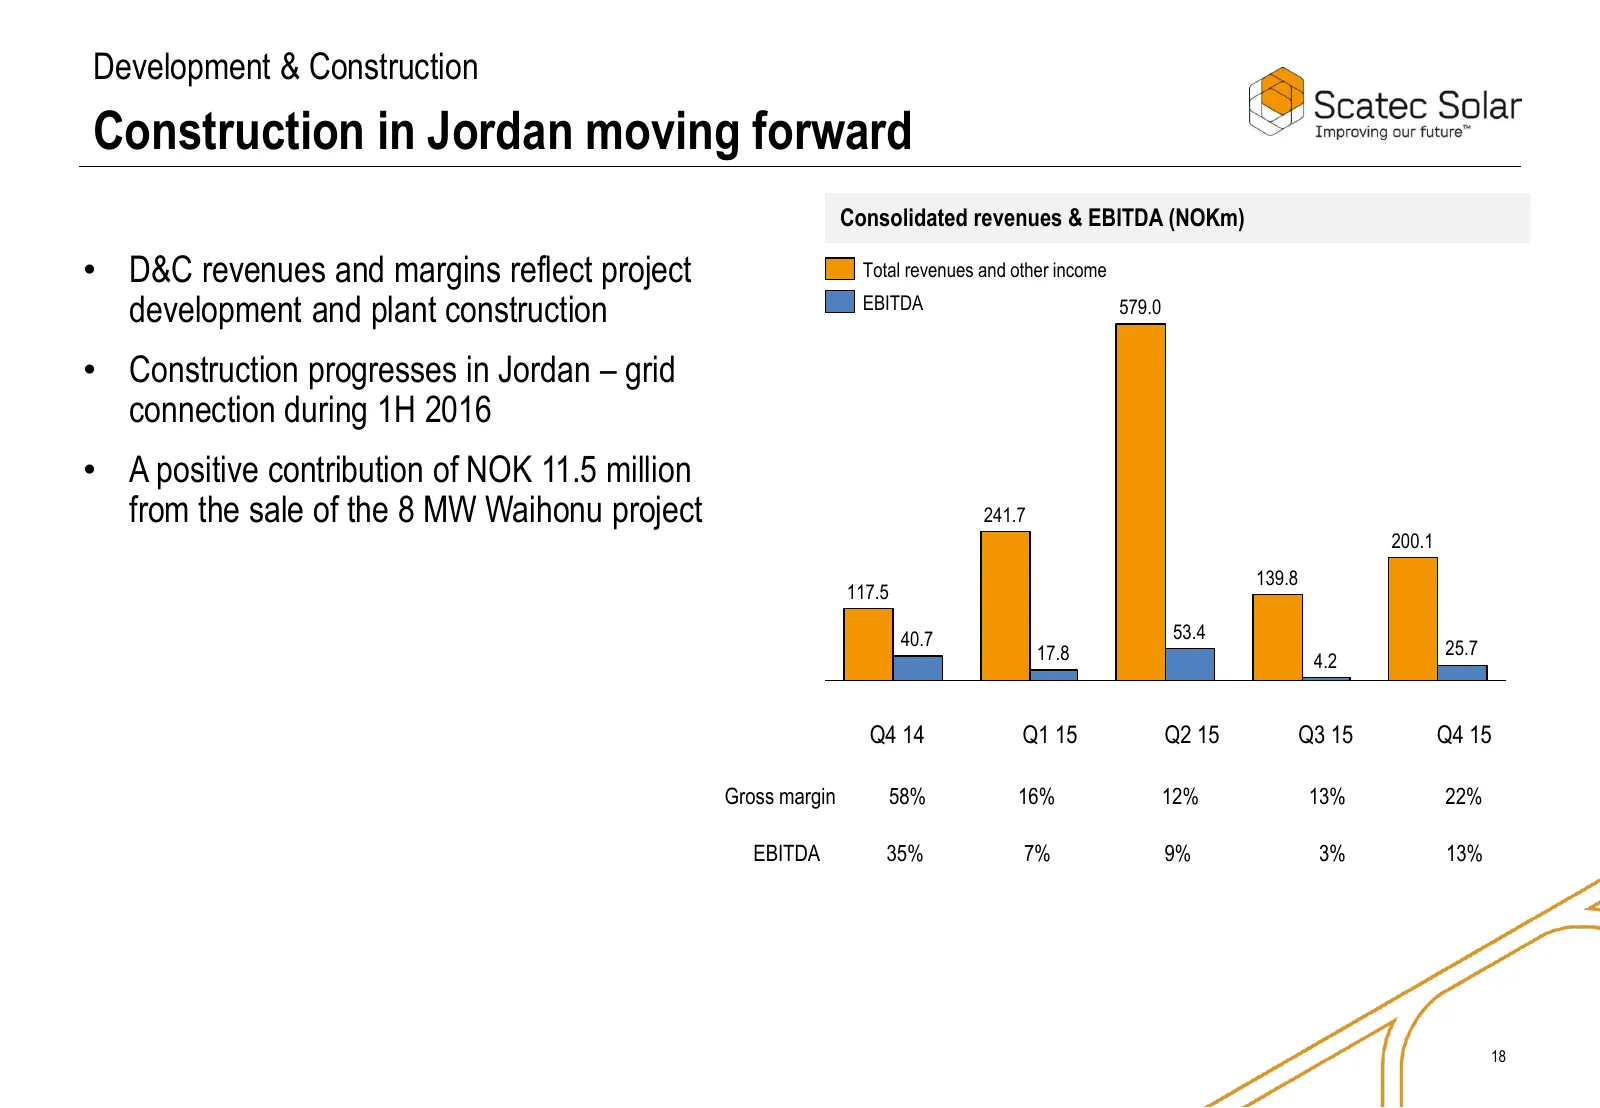
Development & Construction Construction in Jordan moving forward Consolidated revenues & EBITDA (NOKm) • D&C revenues and margins reflect project Total revenues and other income development and plant construction EBITDA 579.0 • Construction progresses in Jordan – grid connection during 1H 2016 • A p
Slide 19: Cash generation to Scatec Solar
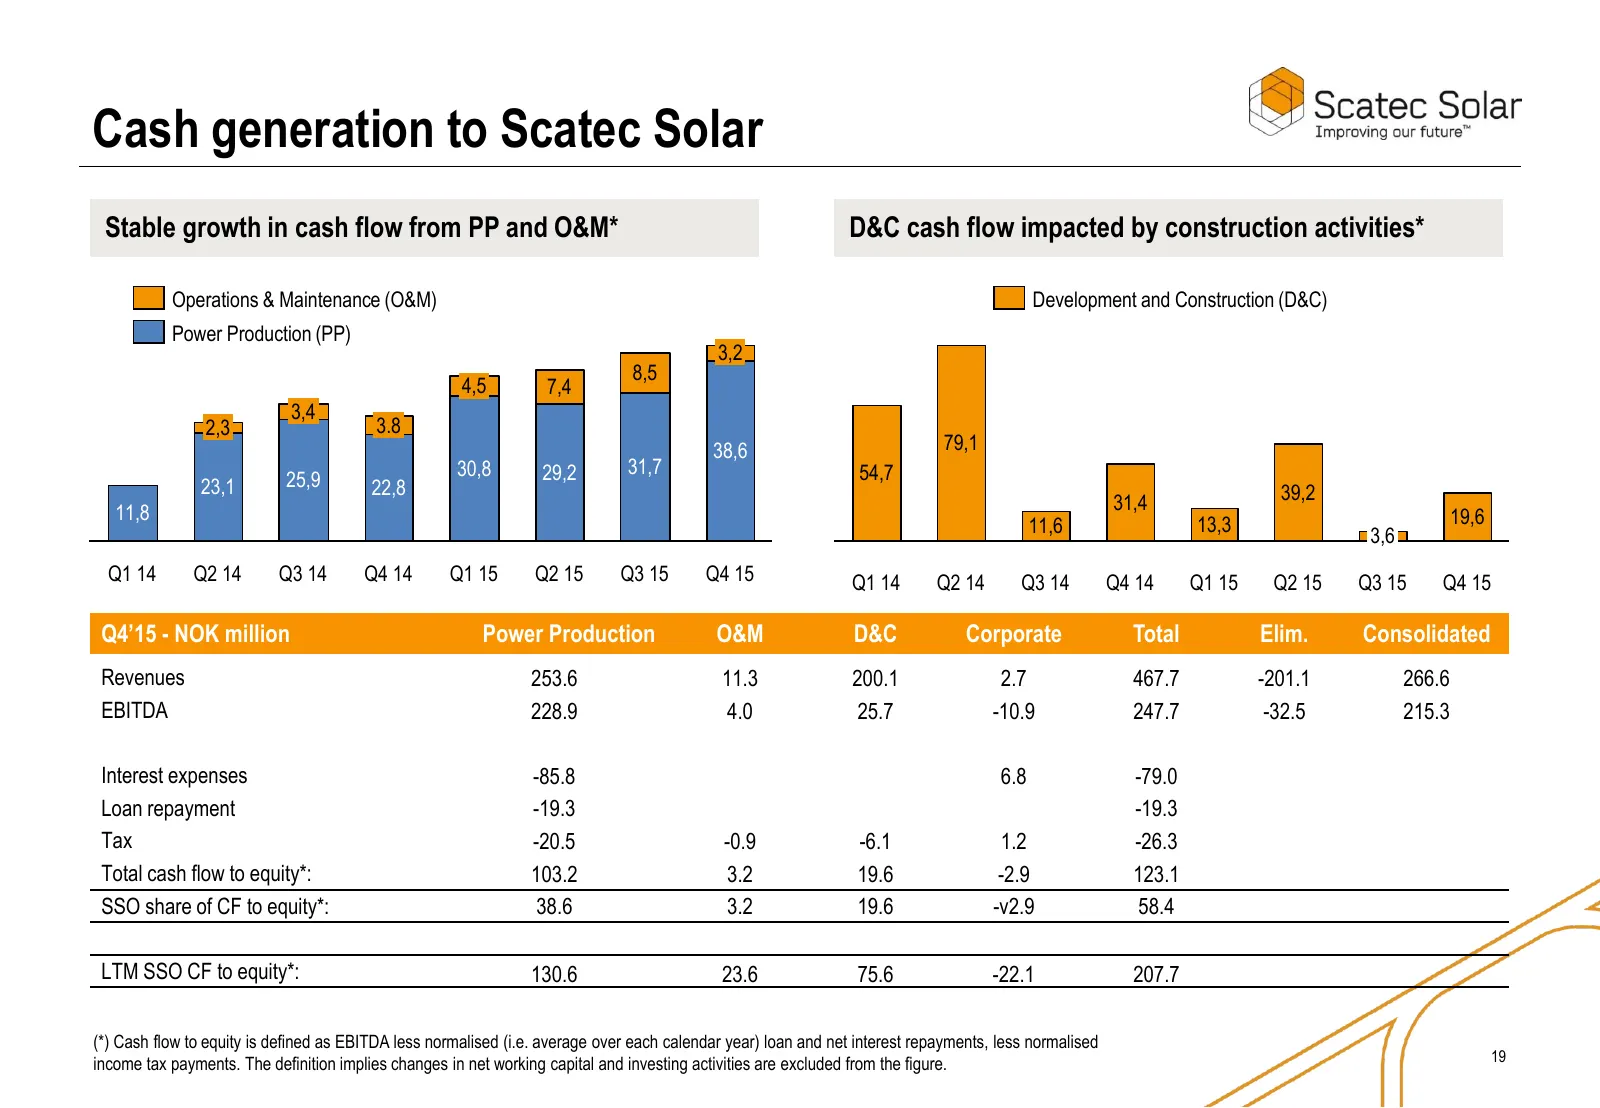
Cash generation to Scatec Solar Stable growth in cash flow from PP and O&M* D&C cash flow impacted by construction activities* Operations & Maintenance (O&M) Development and Construction (D&C) Power Production (PP) 3,2 8,5 4,5 7,4 3,4 2,3 3.8 38,6 79,1 30,8 29,2 31,7 54,7 23,1 25,9 22,8 31,4 39,2 11
Slide 20: A solid financial position
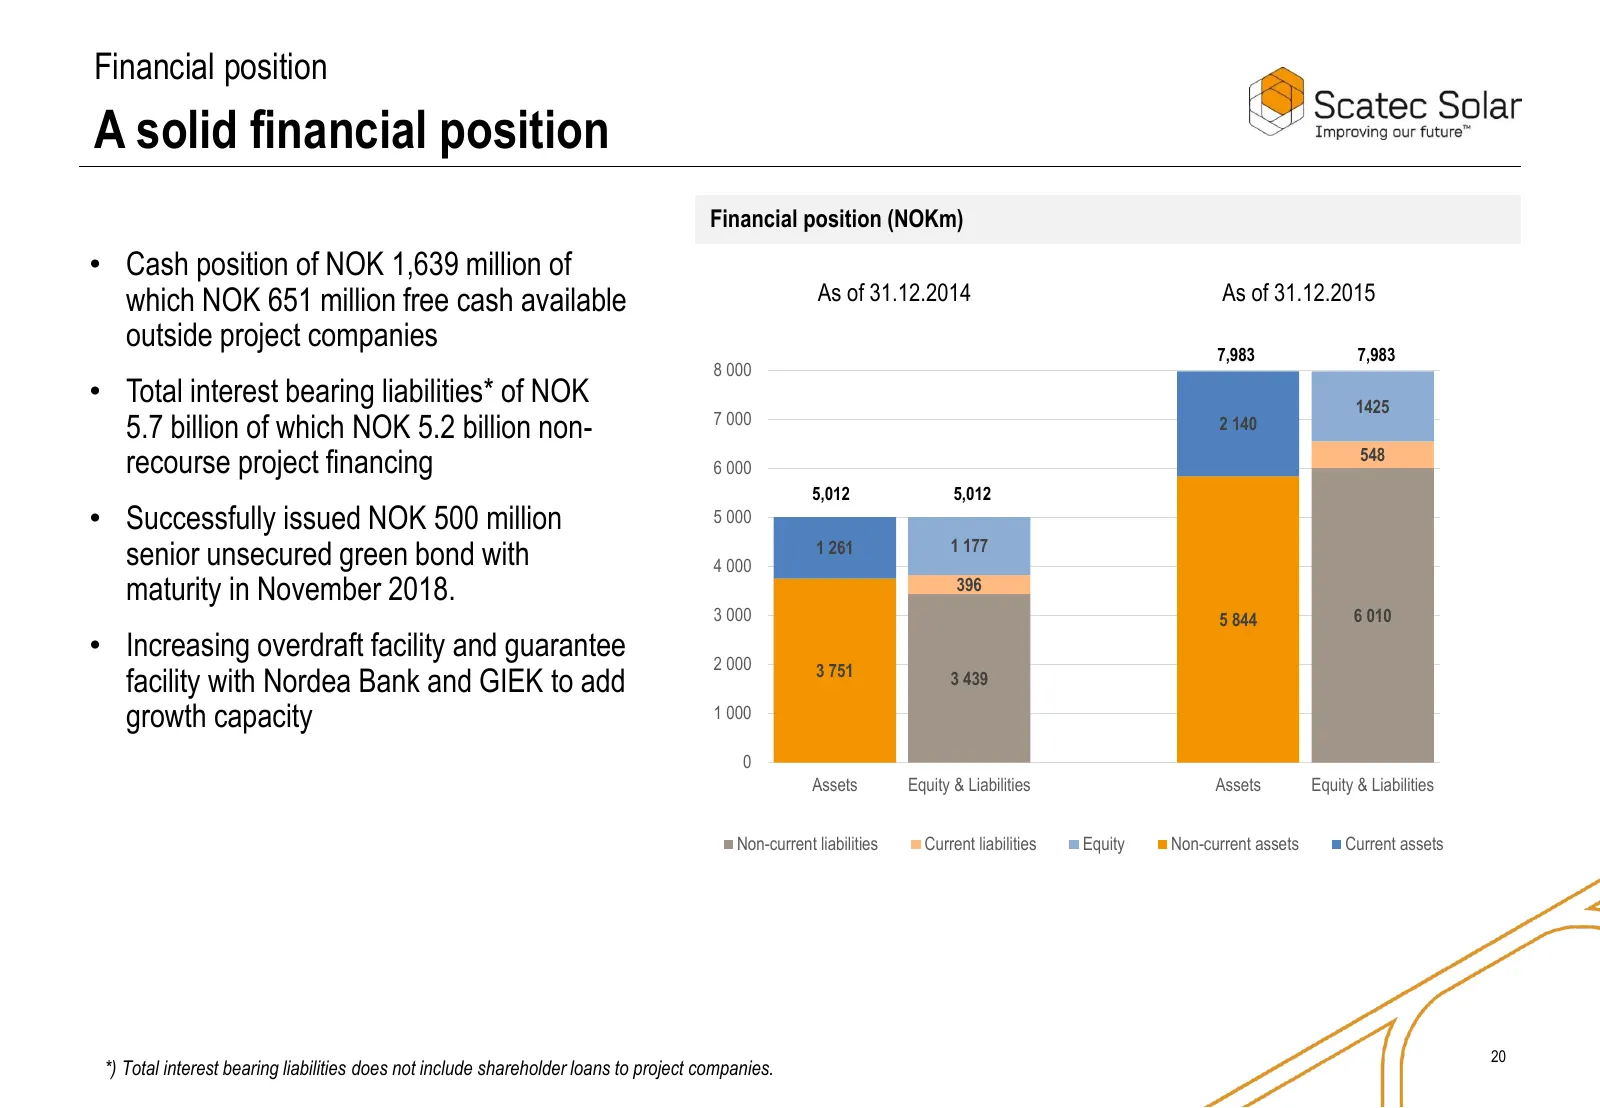
Financial position A solid financial position Financial position (NOKm) • Cash position of NOK 1,639 million of which NOK 651 million free cash available As of 31.12.2014 As of 31.12.2015 outside project companies 7,983 7,983 8 000 • Total interest bearing liabilities* of NOK 1425 5.7 billion of whi
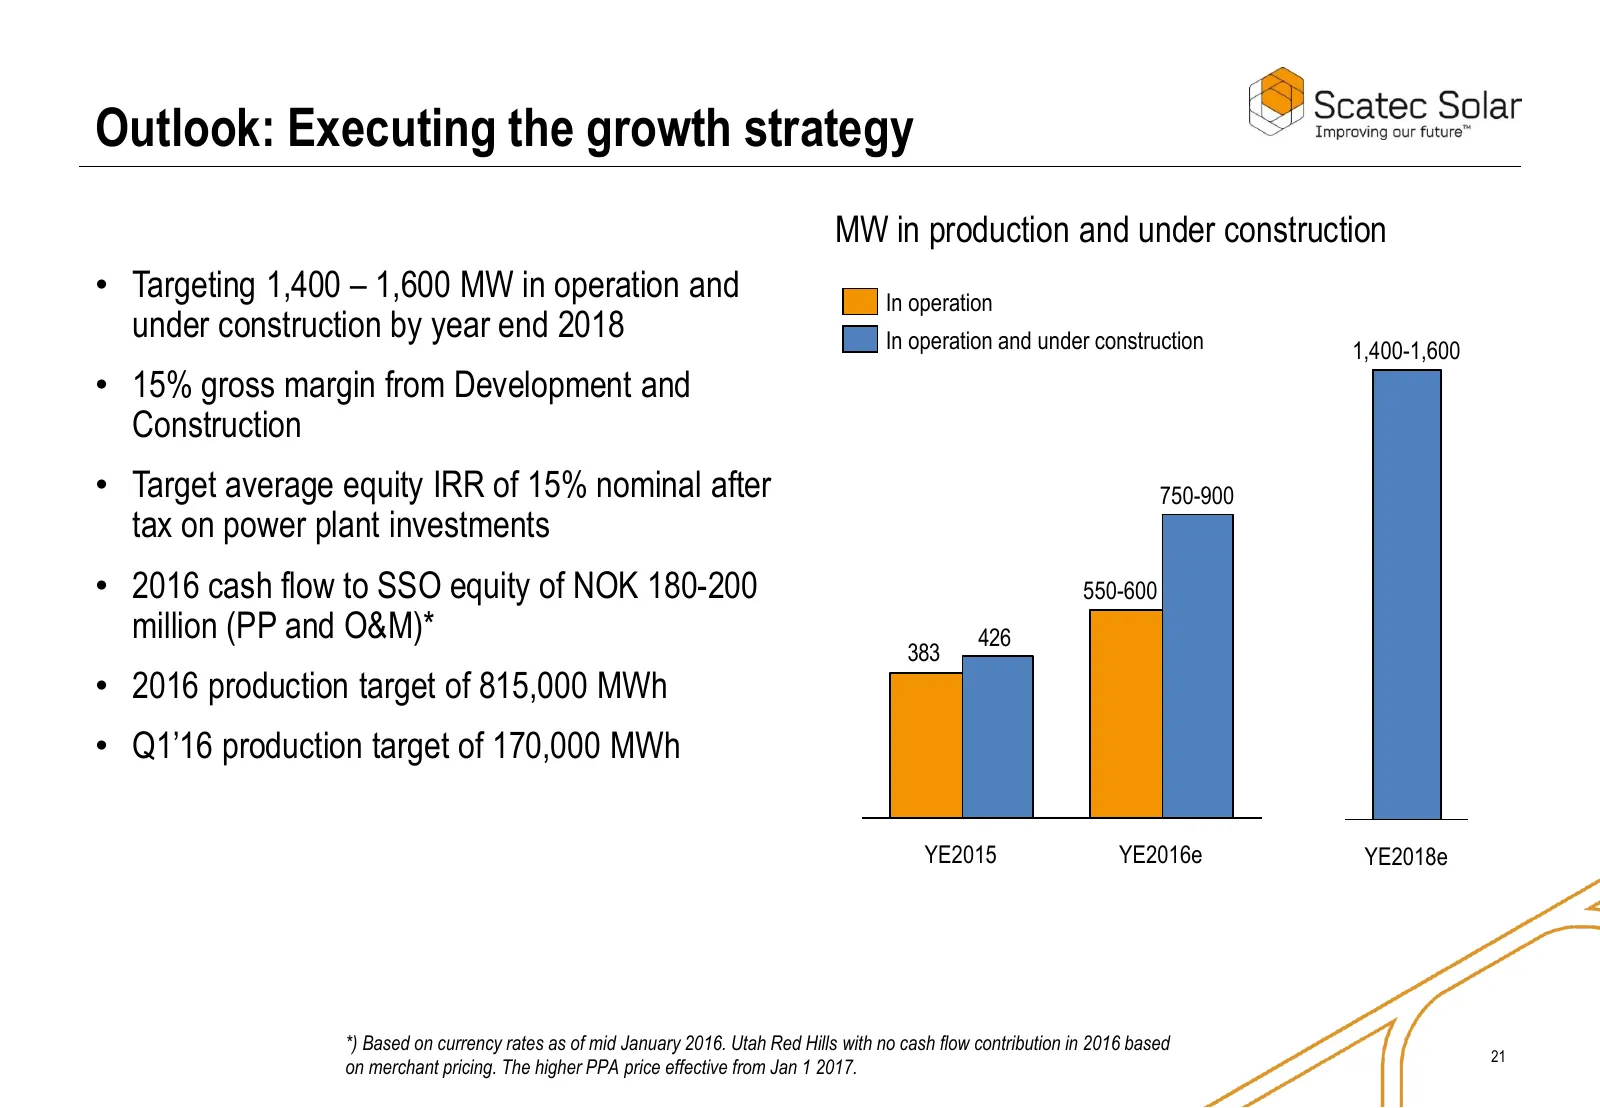
Slide 21: Outlook: Executing the growth strategy
Outlook: Executing the growth strategy MW in production and under construction • Targeting 1,400 – 1,600 MW in operation and In operation under construction by year end 2018 In operation and under construction 1,400-1,600 • 15% gross margin from Development and Construction • Target average equity I
Slide 22: Thank you
Thank you Our values • Predictable • Driving results • Changemakers • Working together
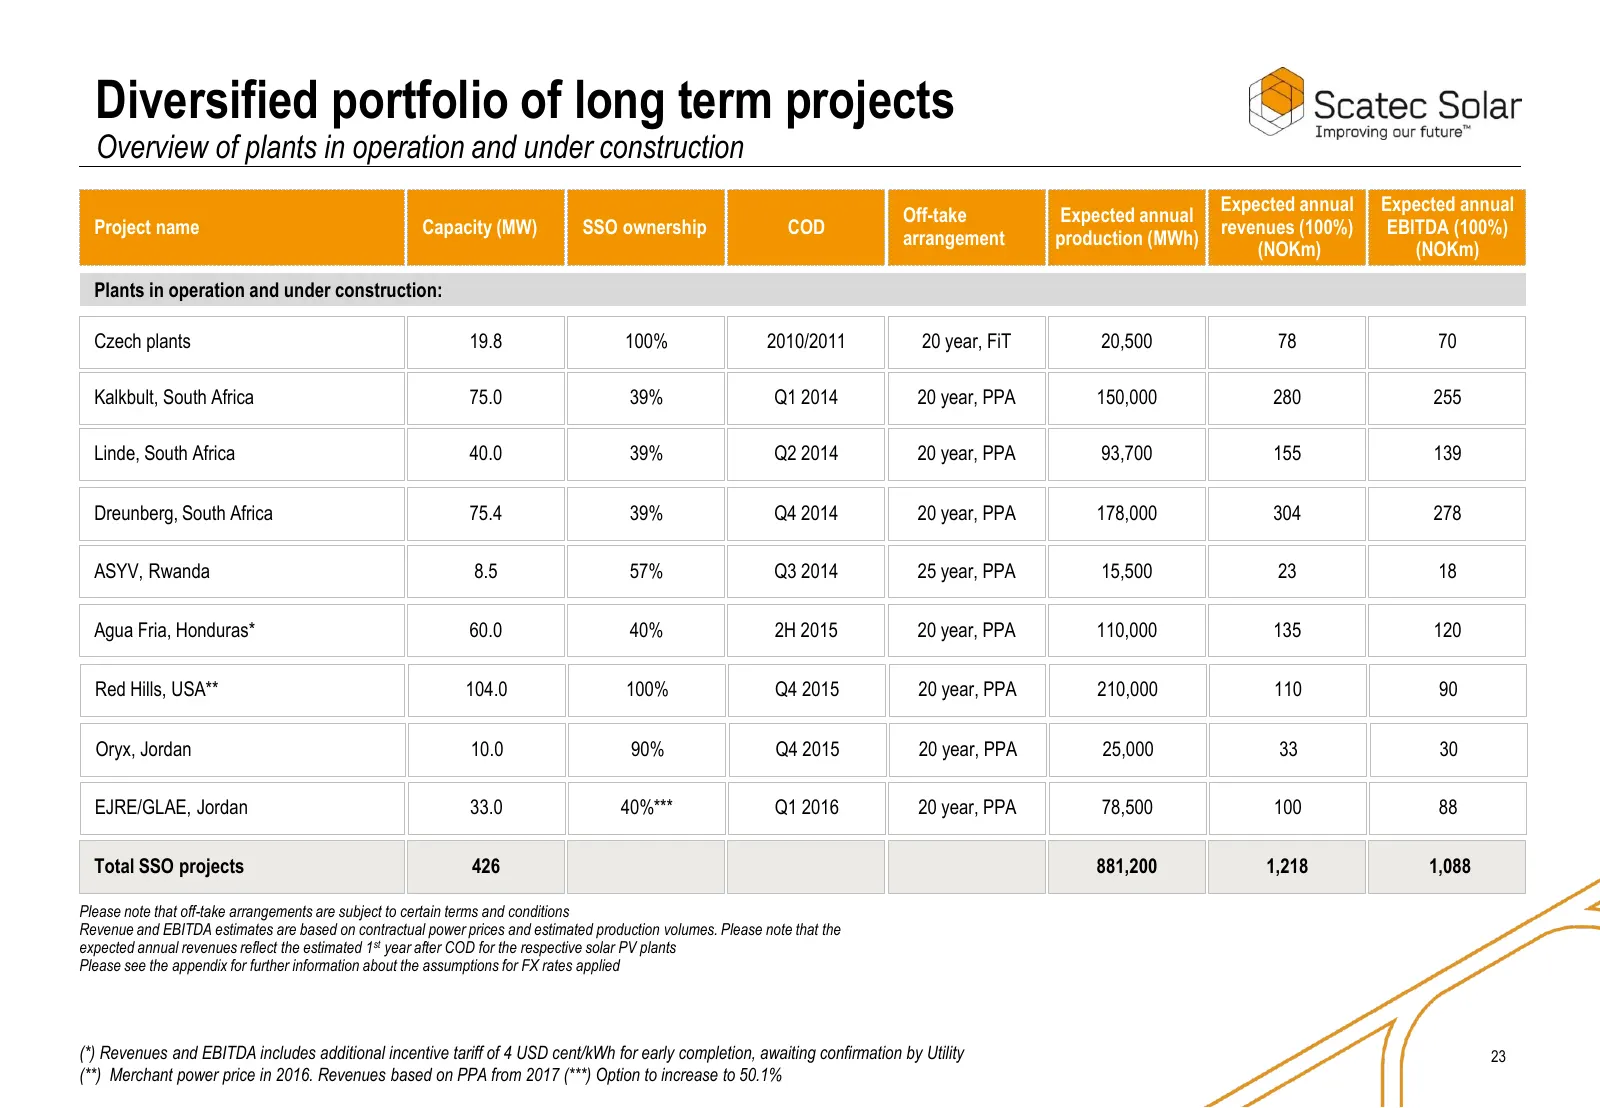
Slide 23: Diversified portfolio of long term projects
Diversified portfolio of long term projects Overview of plants in operation and under construction Expected annual Expected annual Off-take Expected annual Project name Capacity (MW) SSO ownership COD revenues (100%) EBITDA (100%) arrangement production (MWh) (NOKm) (NOKm) Plants in operation and un
Source: Internet Archive copy of scatecsolar.com
More decks from Scatec ASA
 Q3 2026 Earnings Presentation32 slides · Oct 30, 2026
 Q2 2026 Earnings Presentation23 slides · Aug 21, 2026
 Investor Presentation (August 2026)22 slides · August 2026
 Q1 2026 Earnings Presentation23 slides · May 6, 2026
 Investor Presentation (March 2026)22 slides · March 2026
 Q4 2025 Earnings Presentation24 slides · Jan 30, 2026