Vodafone Idea Ltd · NSE:IDEA
Vodafone Idea — Idea Cellular — Investor Presentation (2016)
31 slides from Vodafone Idea's investor presentation, 2016
Slide 1: Idea Cellular Limited Investor Presentation
IDEA CELLULAR LIMITED INVESTOR PRESENTATION Internal
Slide 2: Idea Cellular – An Overview
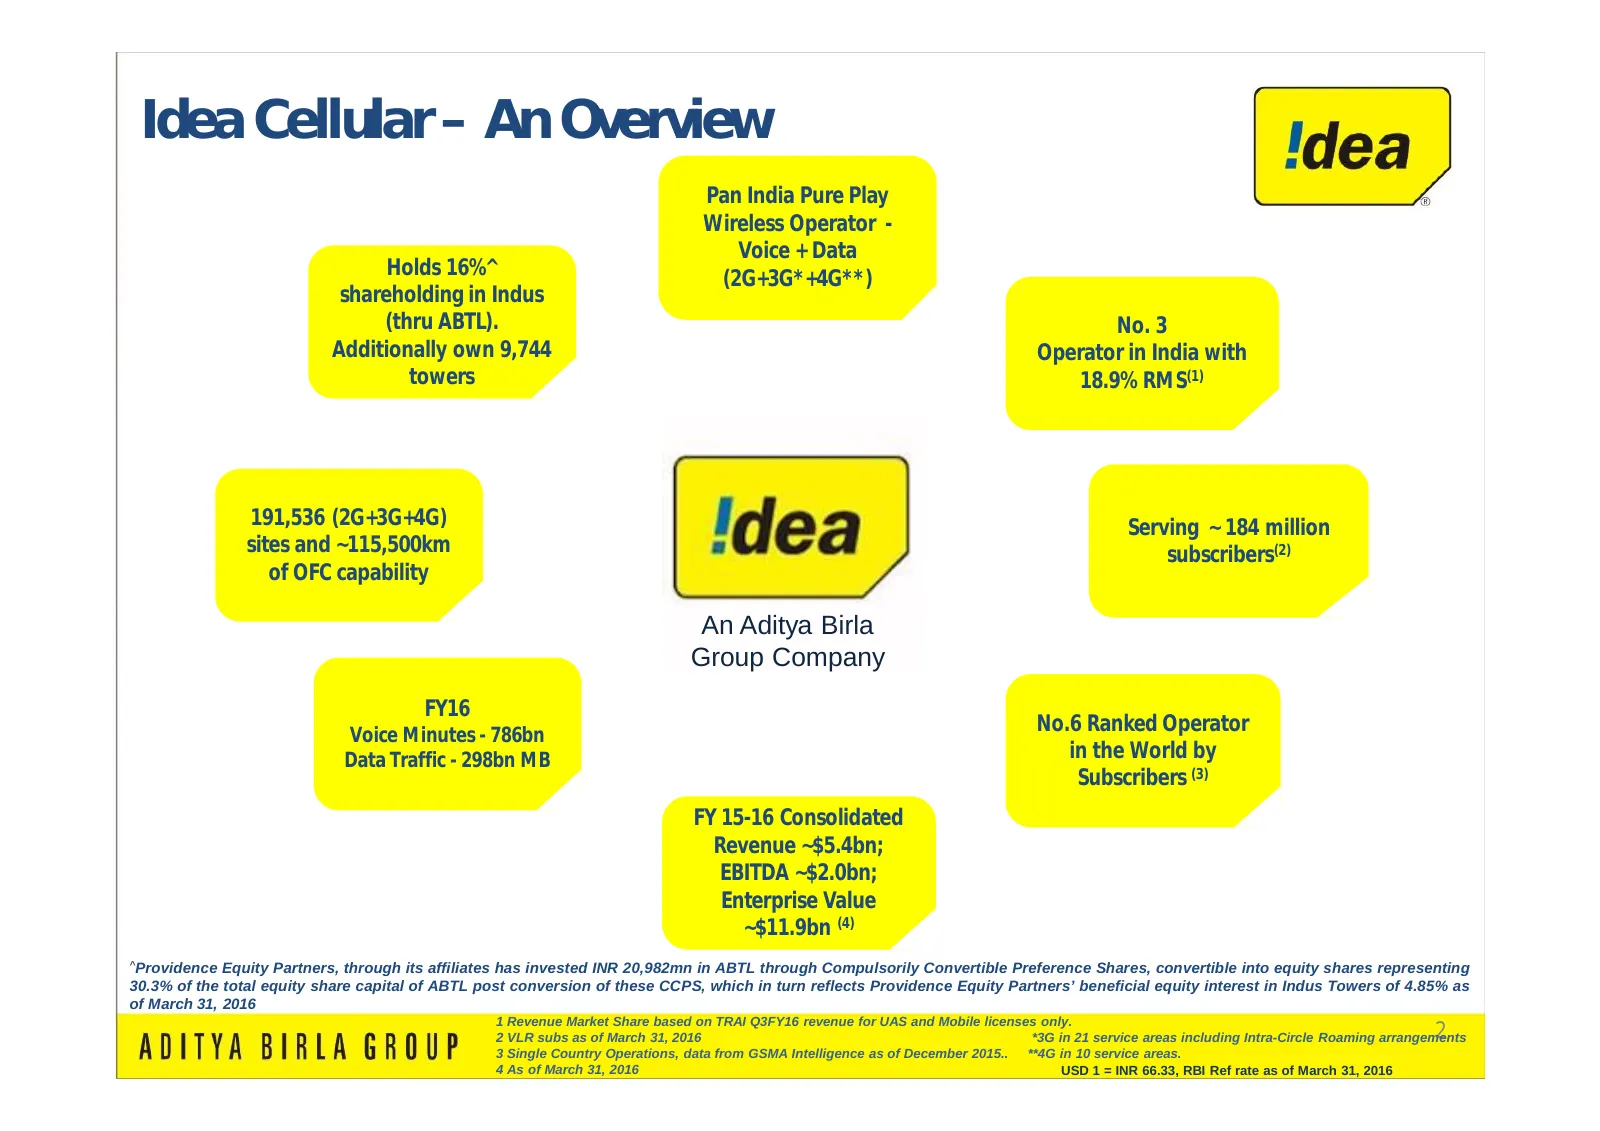
Internal Idea Cellular – An Overview Pan India Pure Play Wireless Operator - Voice + Data Holds 16%^ (2G+3G*+4G**) shareholding in Indus (thru ABTL). No. 3 Additionally own 9,744 Operator in India with towers 18.9% RMS(1) 191,536 (2G+3G+4G) Serving ~ 184 million sites and ~115,500km subscribers(2) o
Slide 3: Since Inception, as Idea Grew & Evolved
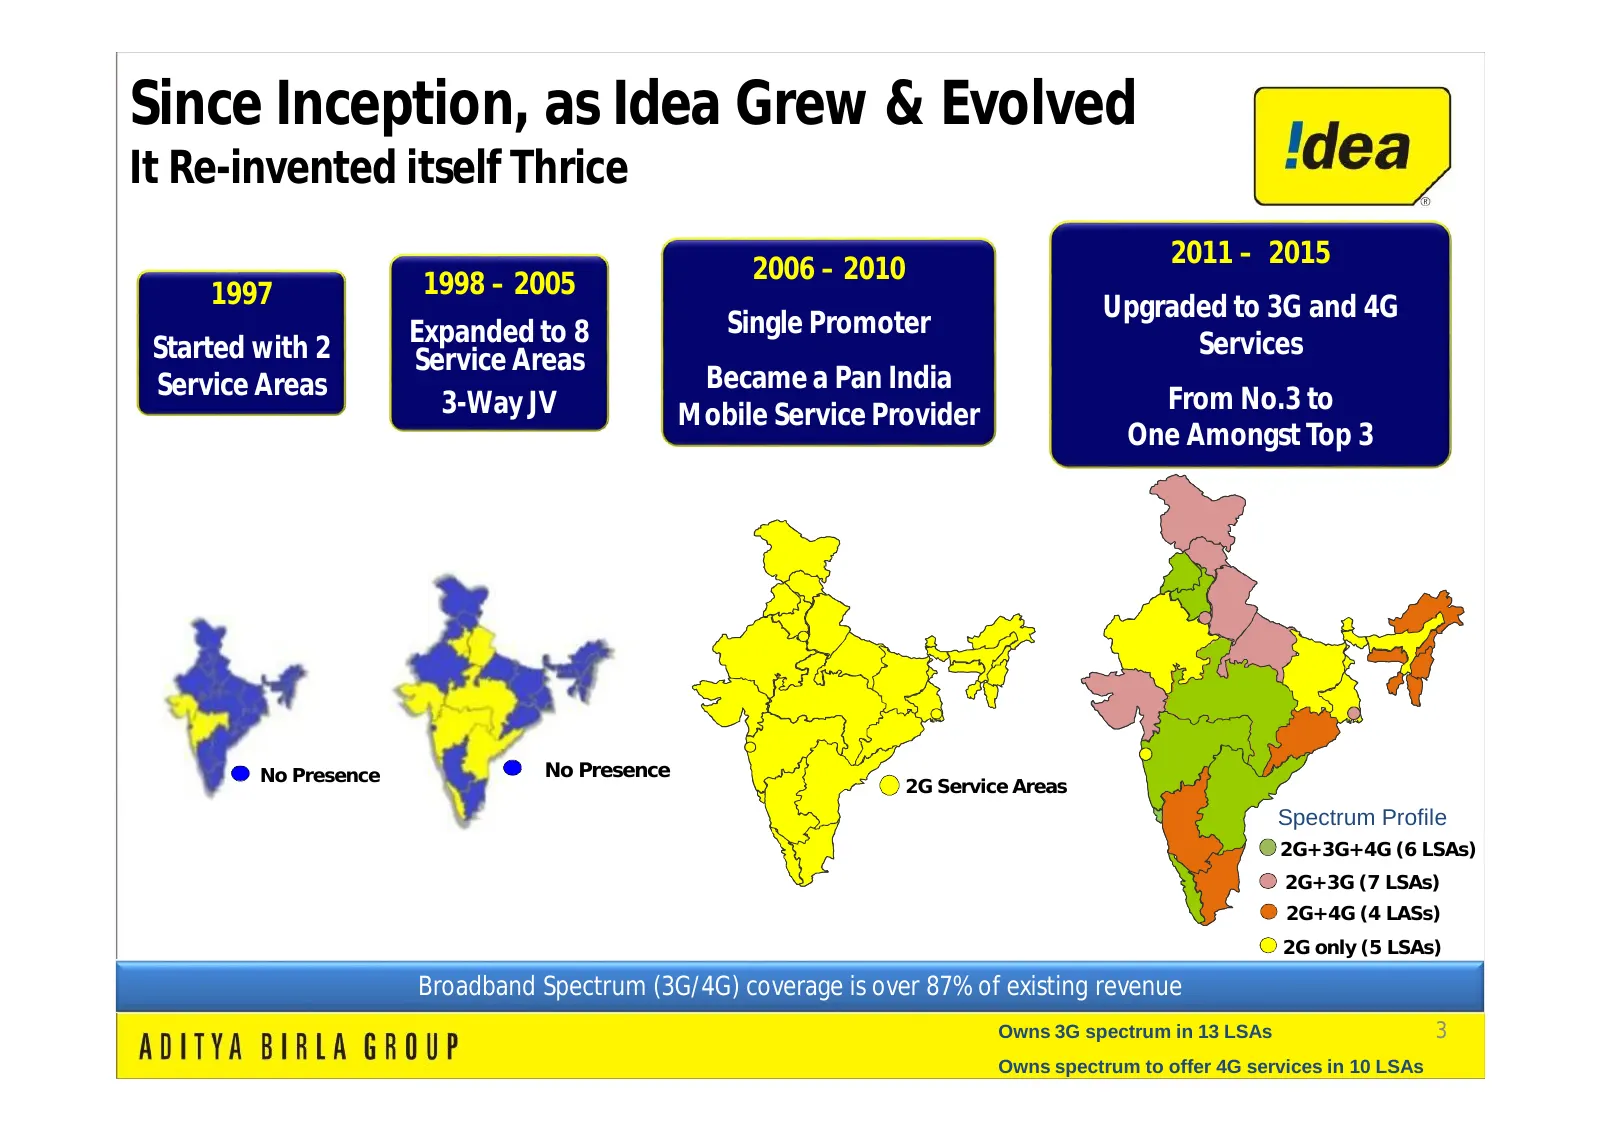
Internal Since Inception, as Idea Grew & Evolved It Re-invented itself Thrice 2011 – 2015 2006 – 2010 1997 1998 – 2005 Upgraded to 3G and 4G Expanded to 8 Single Promoter Started with 2 Services Service Areas Service Areas Became a Pan India 3-Way JV From No.3 to Mobile Service Provider One Amongst
Slide 4: India Telecom Sector Backdrop
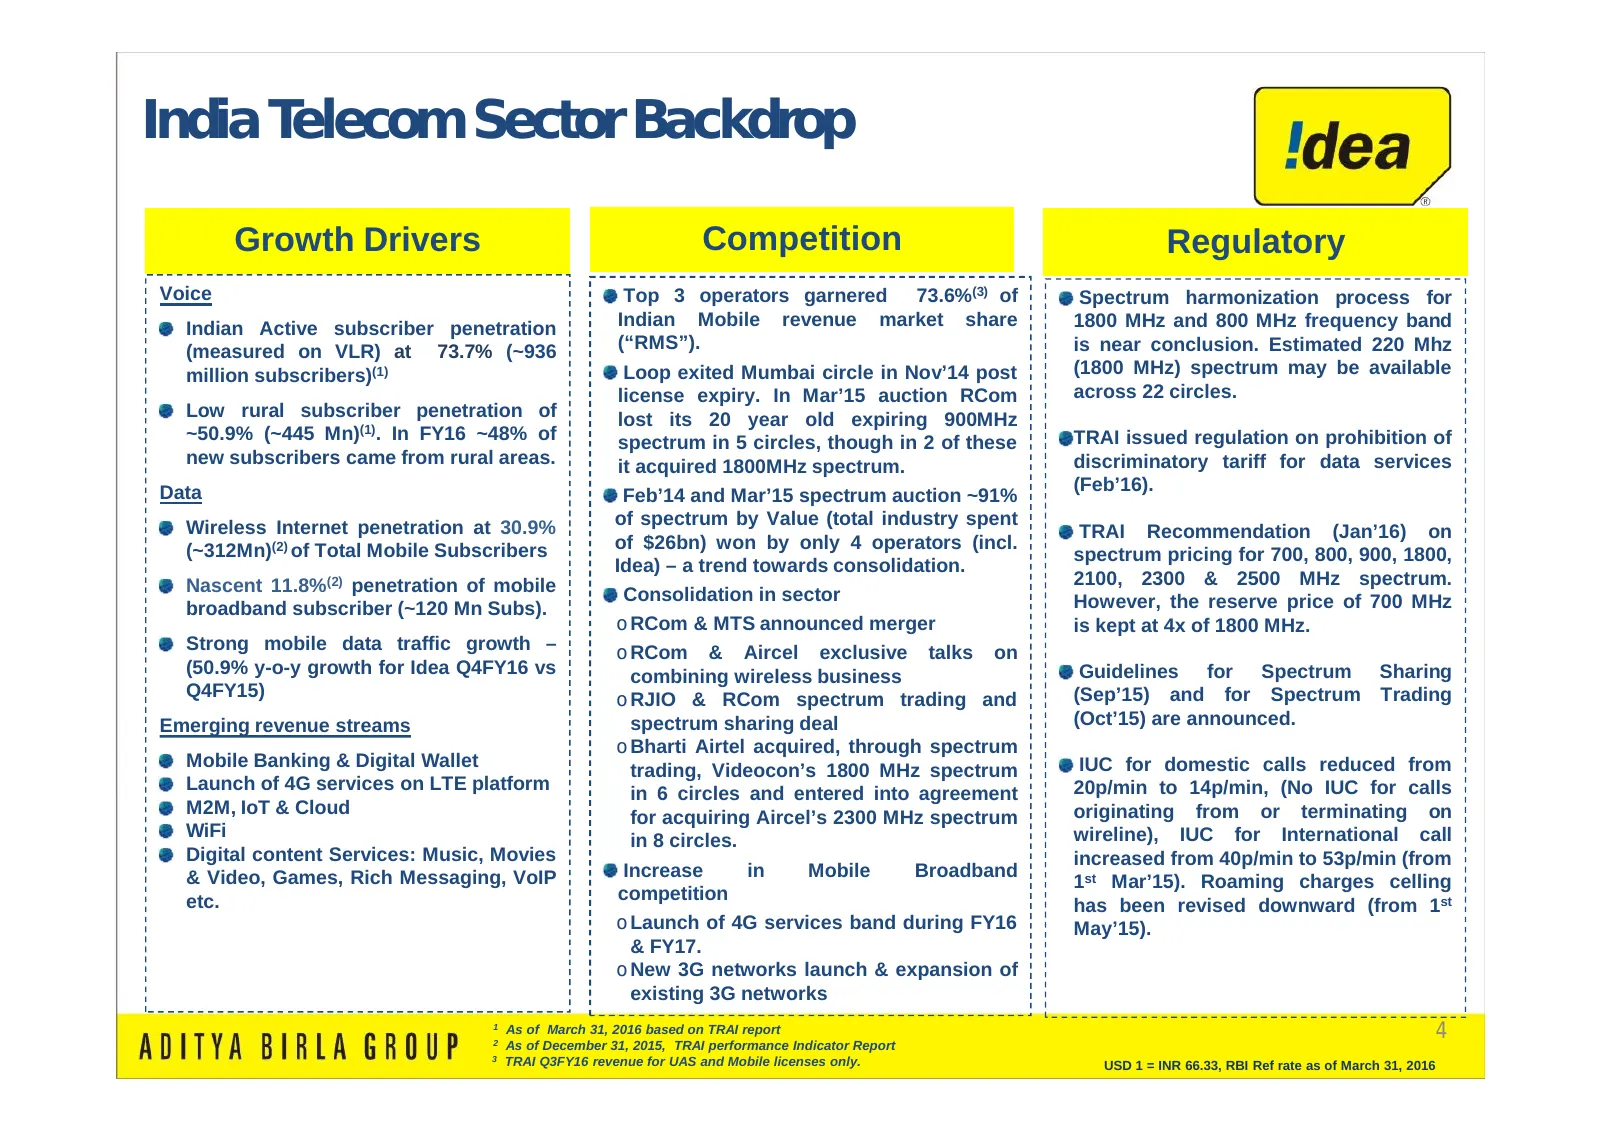
Internal India Telecom Sector Backdrop Growth Drivers Competition Regulatory Voice Top 3 operators garnered 73.6%(3) of Spectrum harmonization process for Indian Active subscriber penetration Indian Mobile revenue market share 1800 MHz and 800 MHz frequency band (measured on VLR) at 73.7% (~936 (“RM
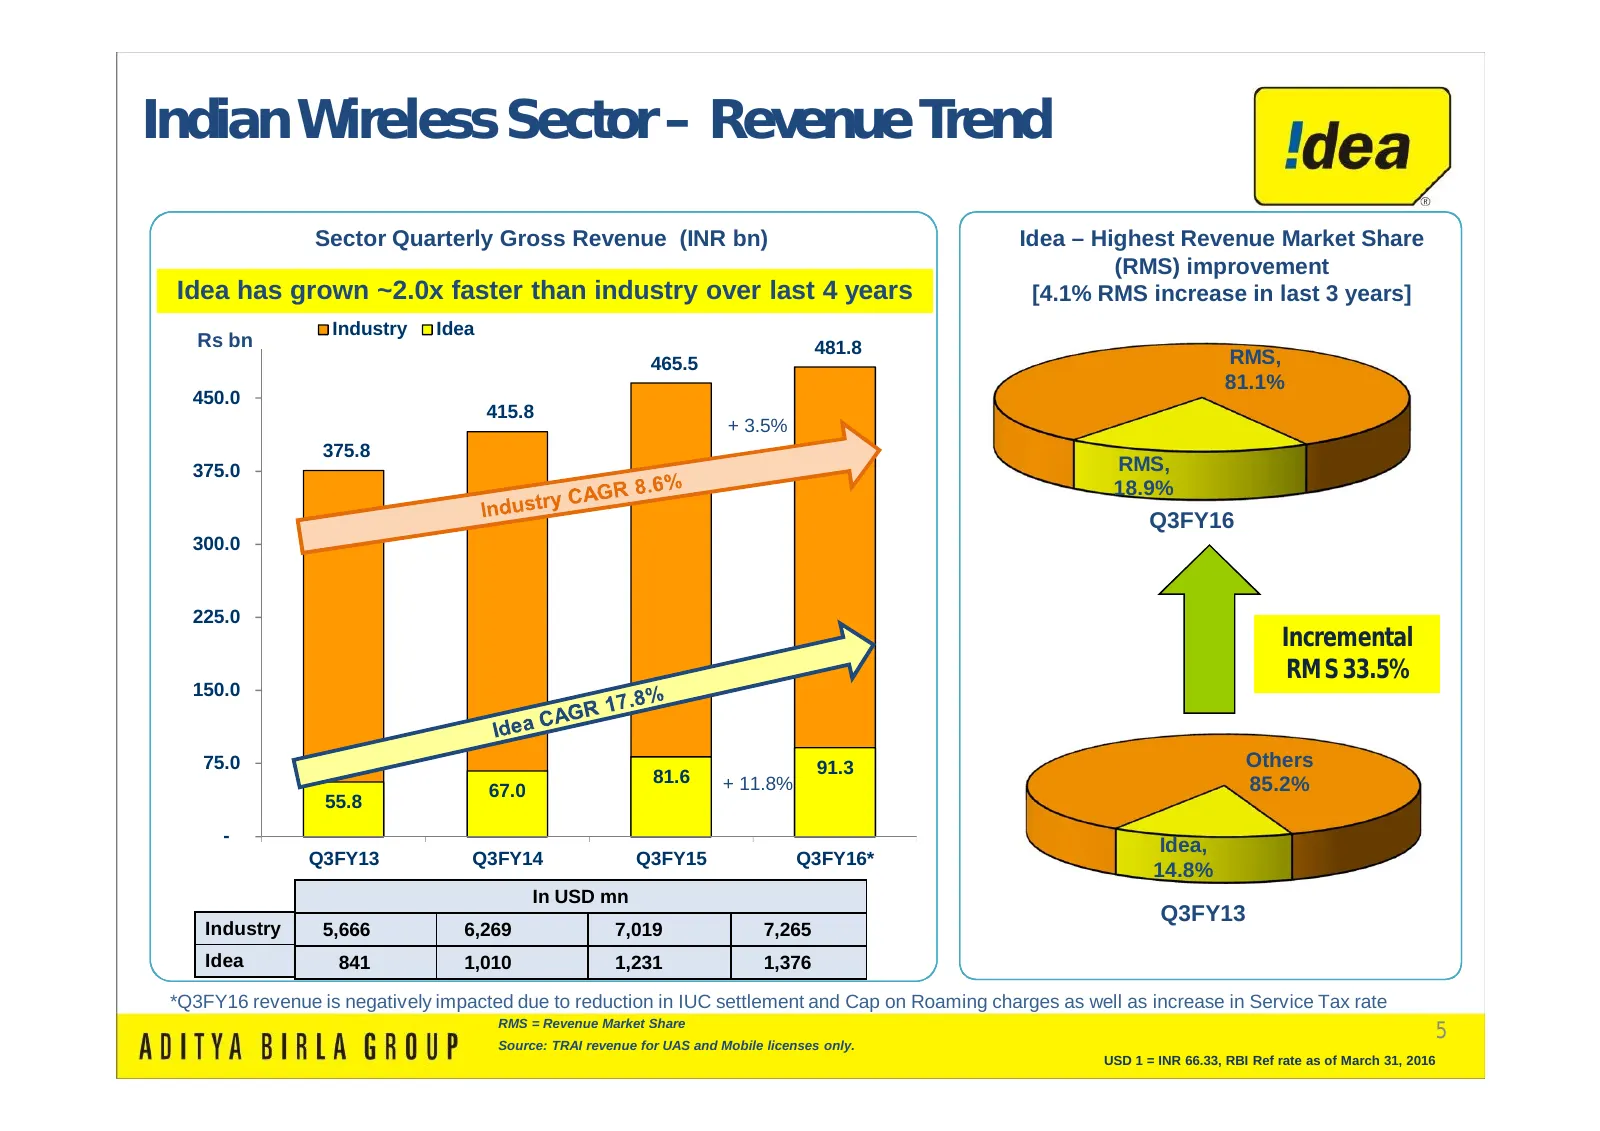
Slide 5: Indian Wireless Sector – Revenue Trend
Internal Indian Wireless Sector – Revenue Trend Sector Quarterly Gross Revenue (INR bn) Idea – Highest Revenue Market Share (RMS) improvement Idea has grown ~2.0x faster than industry over last 4 years [4.1% RMS increase in last 3 years] Industry Idea Rs bn 481.8 465.5 RMS, 81.1% 450.0 415.8 + 3.5%
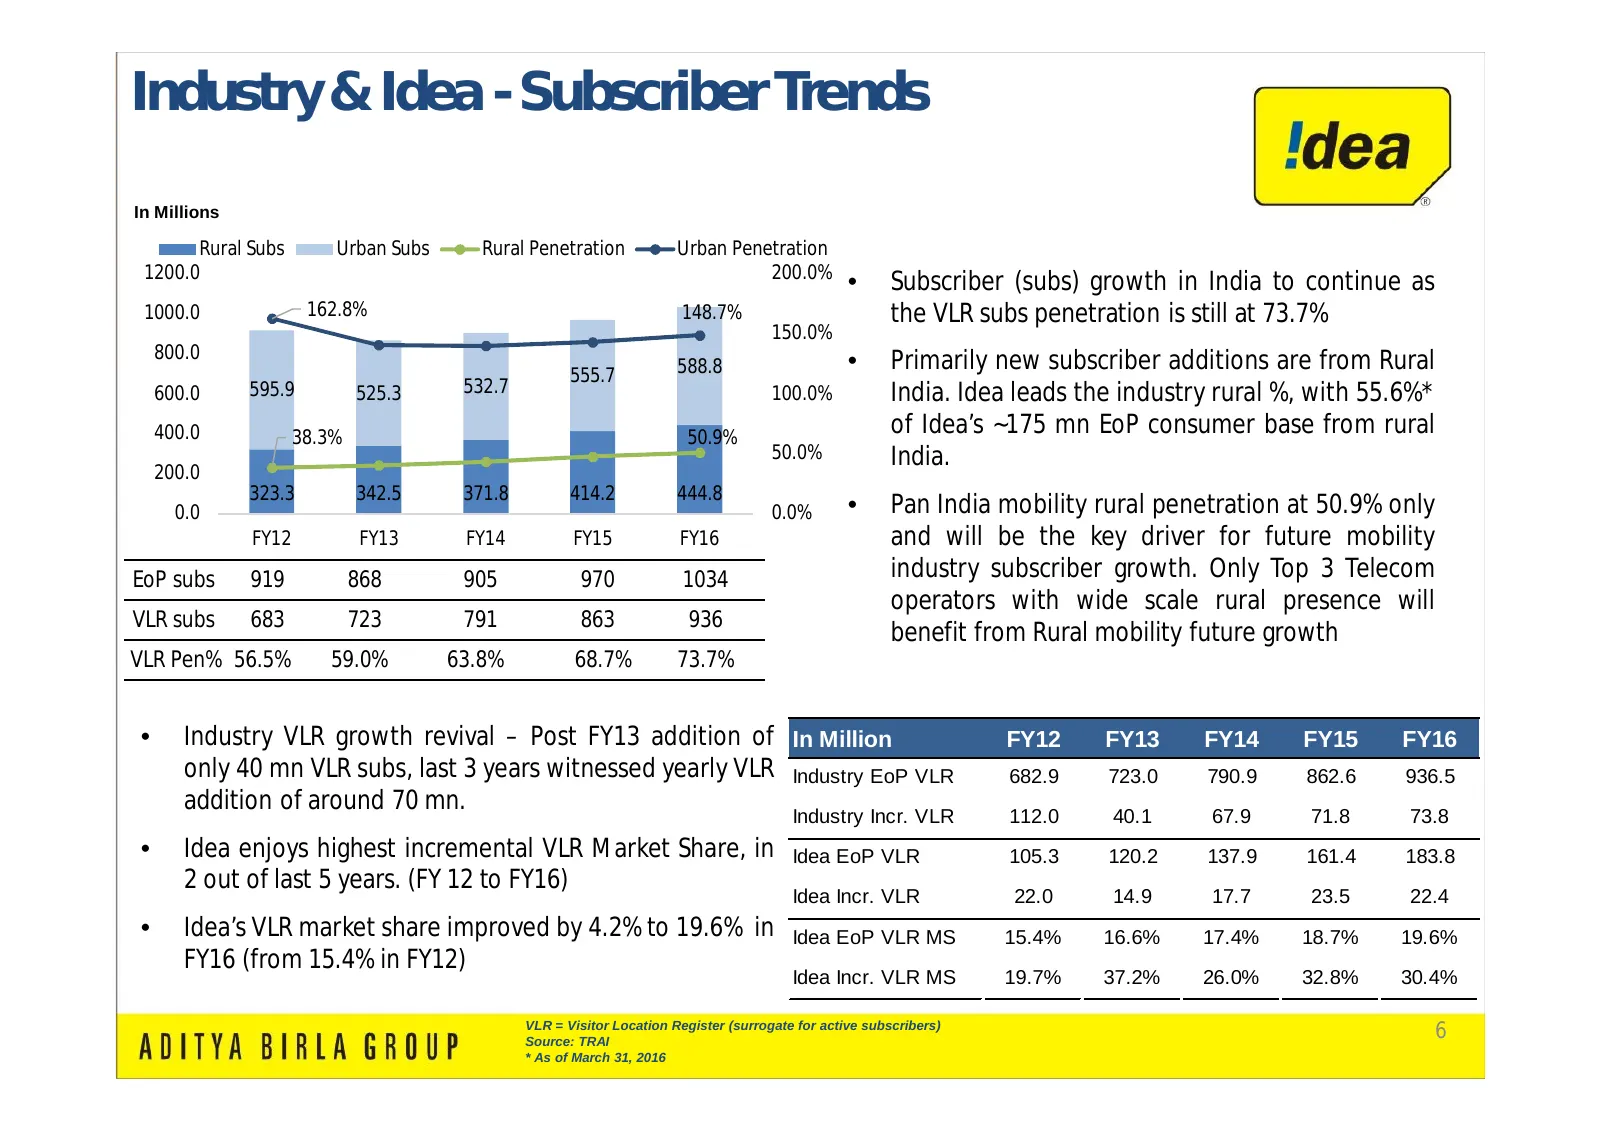
Slide 6: Industry & Idea - Subscriber Trends
Internal Industry & Idea - Subscriber Trends In Millions Rural Subs Urban Subs Rural Penetration Urban Penetration 1200.0 200.0% • Subscriber (subs) growth in India to continue as 1000.0 162.8% 148.7% the VLR subs penetration is still at 73.7% 150.0% 800.0 555.7 588.8 • Primarily new subscriber addi
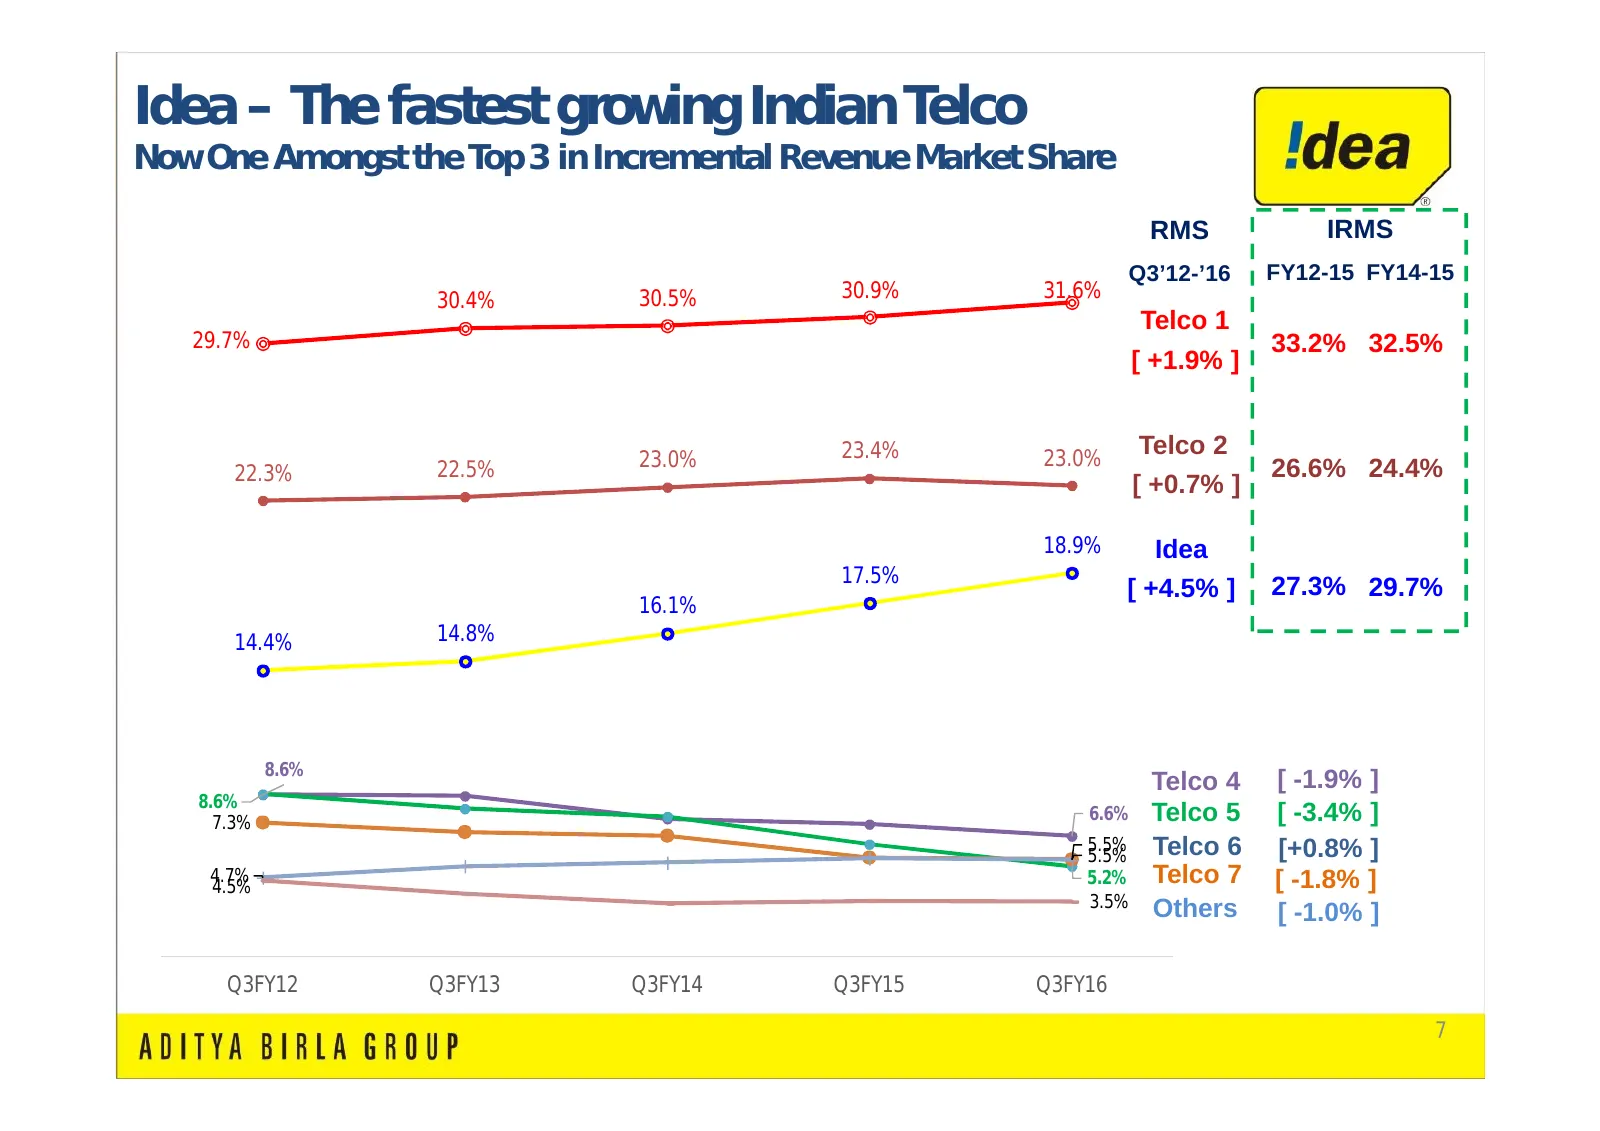
Slide 7: Idea – The fastest growing Indian Telco
Internal Idea – The fastest growing Indian Telco Now One Amongst the Top 3 in Incremental Revenue Market Share RMS IRMS Q3’12-’16 FY12-15 FY14-15 30.4% 30.5% 30.9% 31.6% Telco 1 29.7% 33.2% 32.5% [ +1.9% ] 23.4% 23.0% Telco 2 22.5% 23.0% 26.6% 24.4% 22.3% [ +0.7% ] 18.9% Idea 17.5% [ +4.5% ] 27.3% 2
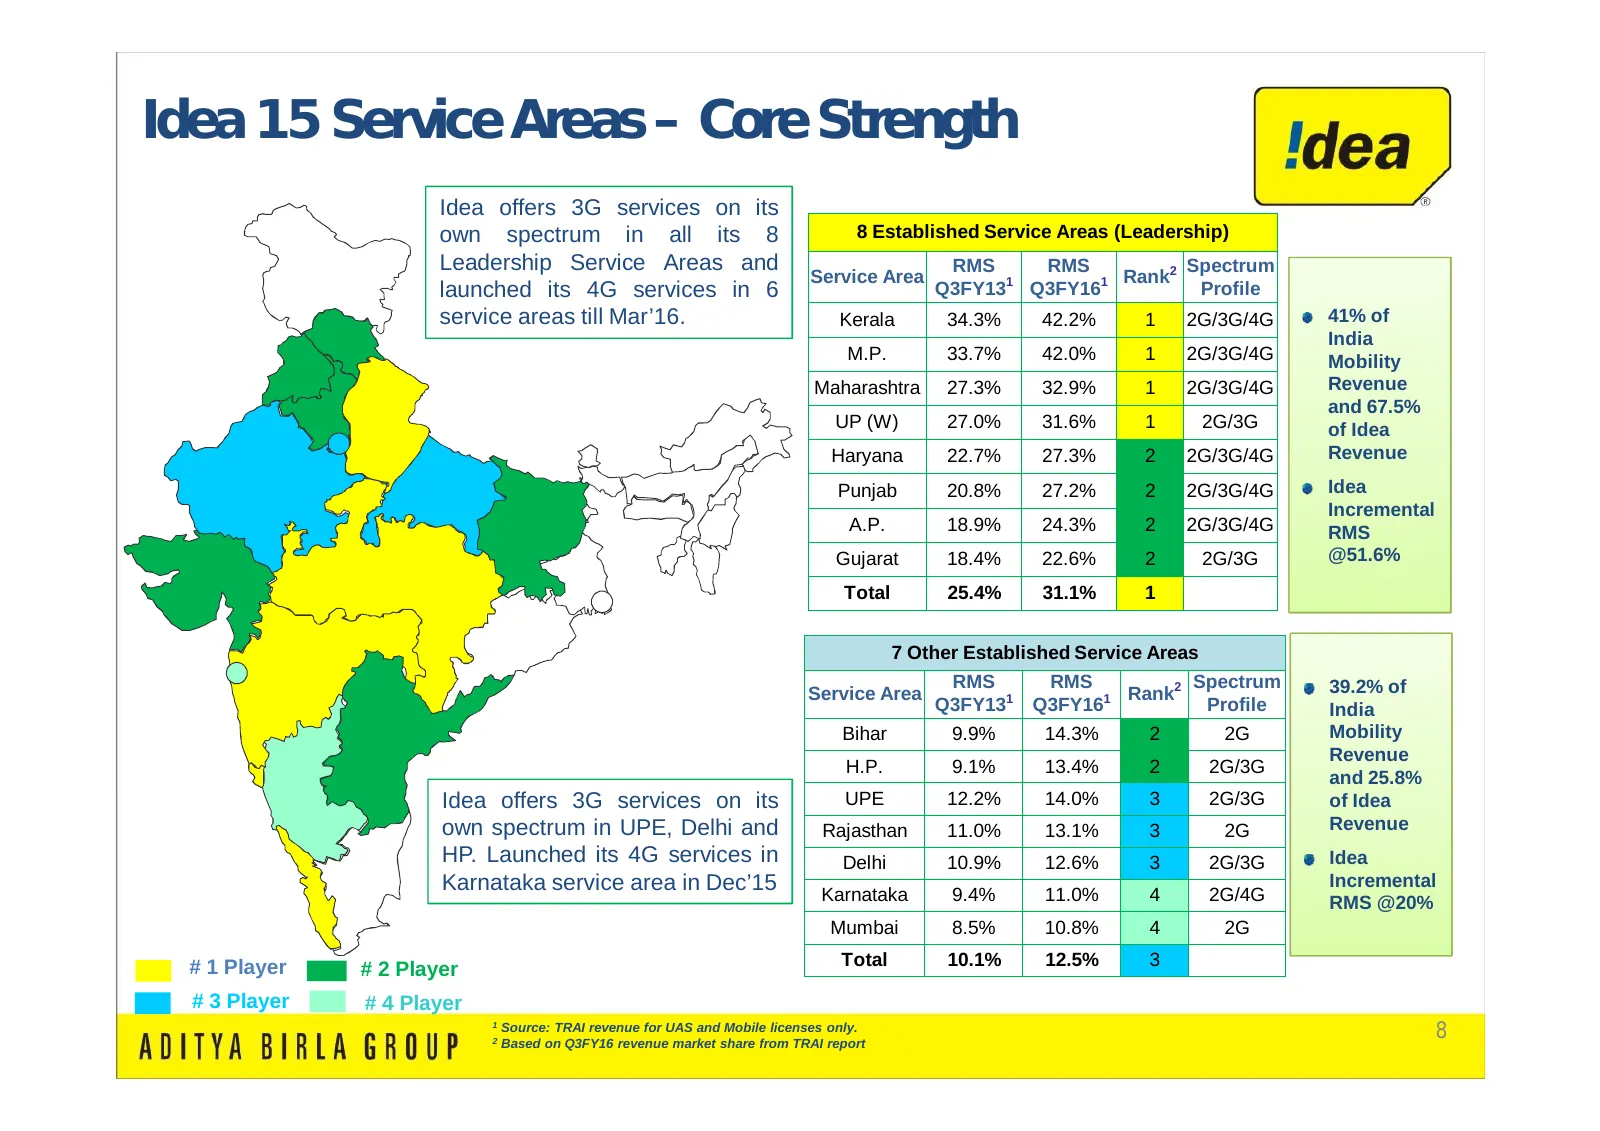
Slide 8: Idea 15 Service Areas – Core Strength
Internal Idea 15 Service Areas – Core Strength Idea offers 3G services on its own spectrum in all its 8 8 Established Service Areas (Leadership) Leadership Service Areas and RMS RMS Spectrum Service Area Rank2 launched its 4G services in 6 Q3FY131 Q3FY161 Profile service areas till Mar’16. Kerala 34
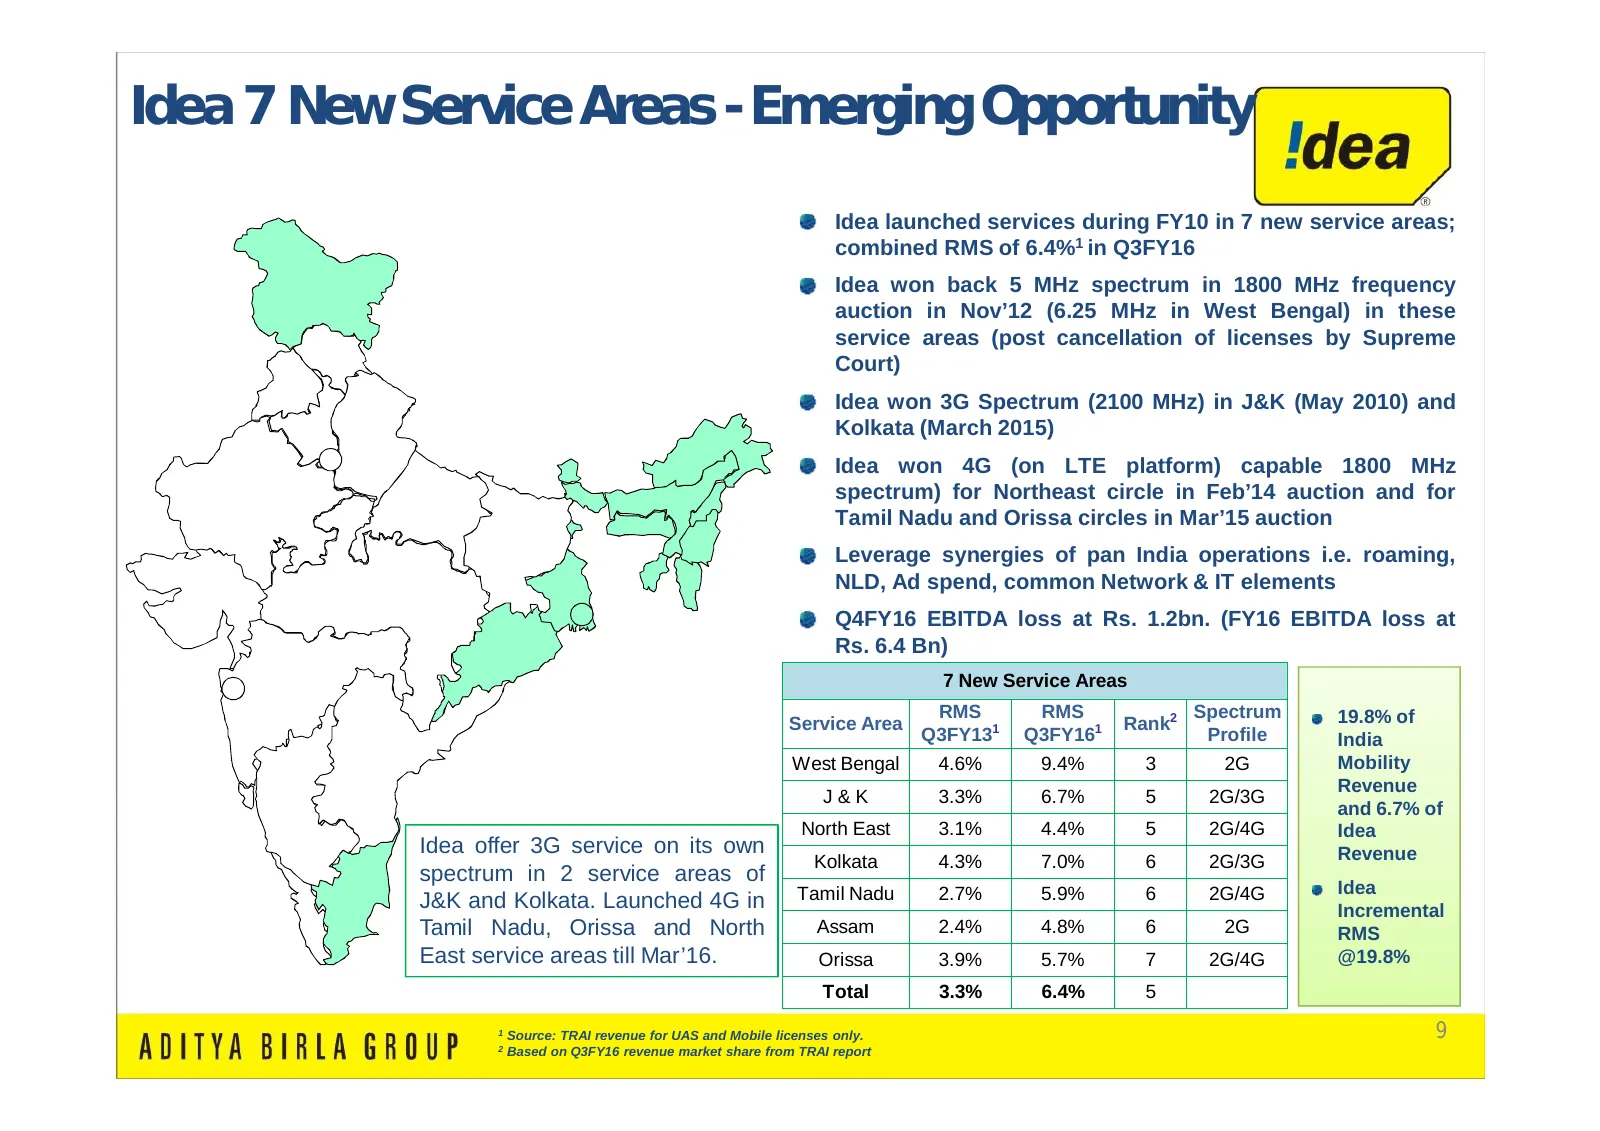
Slide 9: Idea 7 New Service Areas - Emerging Opportunity
Internal Idea 7 New Service Areas - Emerging Opportunity Idea launched services during FY10 in 7 new service areas; combined RMS of 6.4%1 in Q3FY16 Idea won back 5 MHz spectrum in 1800 MHz frequency auction in Nov’12 (6.25 MHz in West Bengal) in these service areas (post cancellation of licenses by
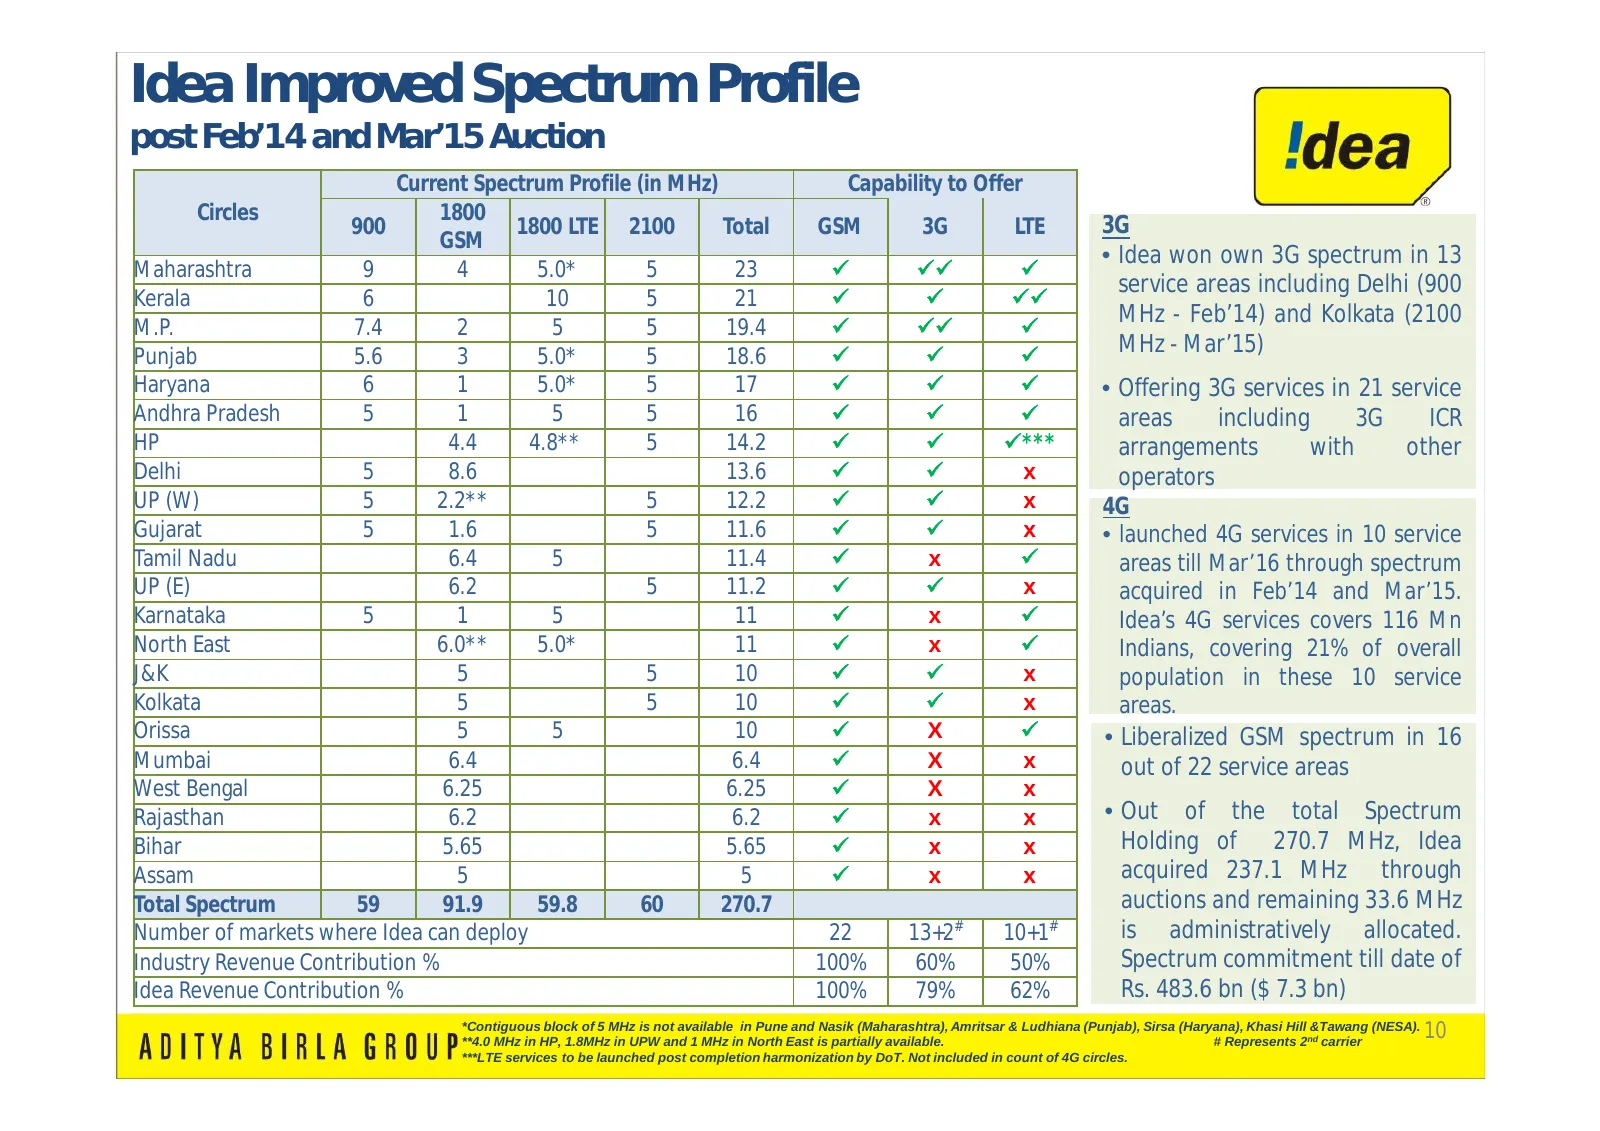
Slide 10: Idea Improved Spectrum Profile
Internal Idea Improved Spectrum Profile post Feb’14 and Mar’15 Auction Current Spectrum Profile (in MHz) Capability to Offer Circles 1800 900 1800 LTE 2100 Total GSM 3G LTE 3G GSM • Idea won own 3G spectrum in 13 Maharashtra 9 4 5.0* 5 23 service areas including Delhi (900 Kerala 6 10 5 21
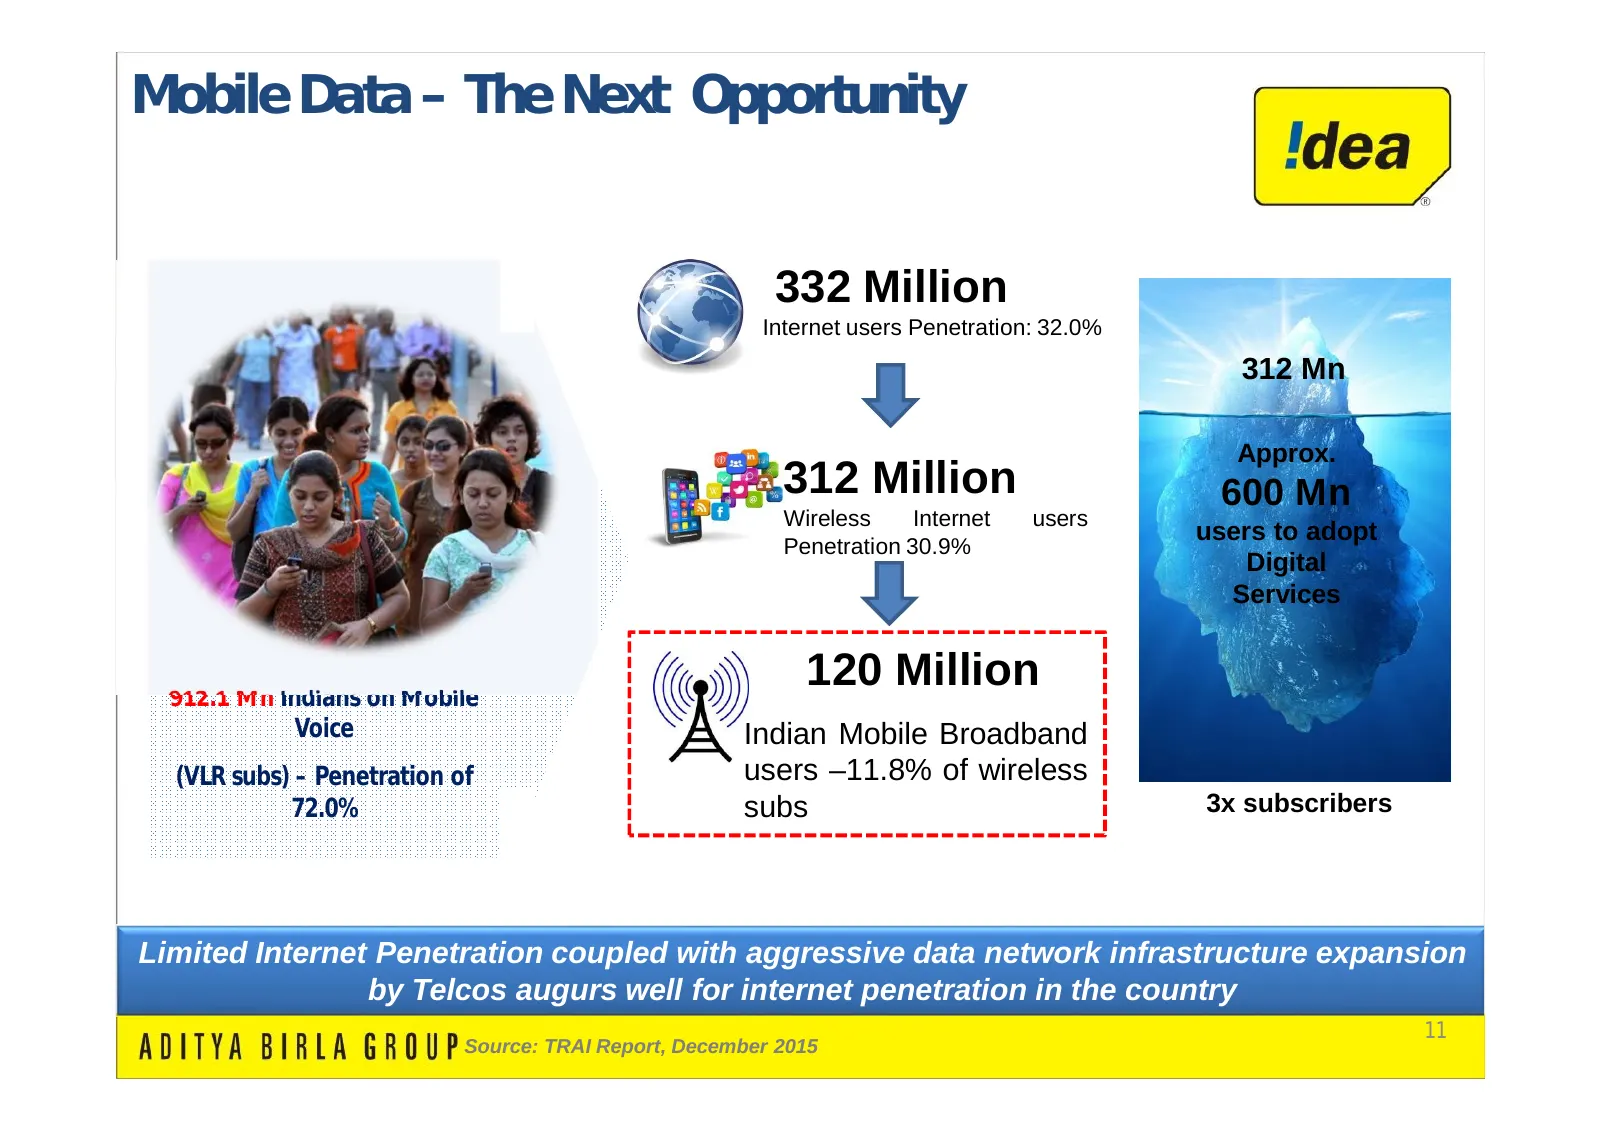
Slide 11: Mobile Data – The Next Opportunity
Internal Mobile Data – The Next Opportunity 332 Million Internet users Penetration: 32.0% 312 Mn Approx. 312 Million 600 Mn Wireless Internet users users to adopt Penetration 30.9% Digital Services 912.1 Mn Indians on Mobile 120 Million Voice Indian Mobile Broadband (VLR subs) – Penetration of users
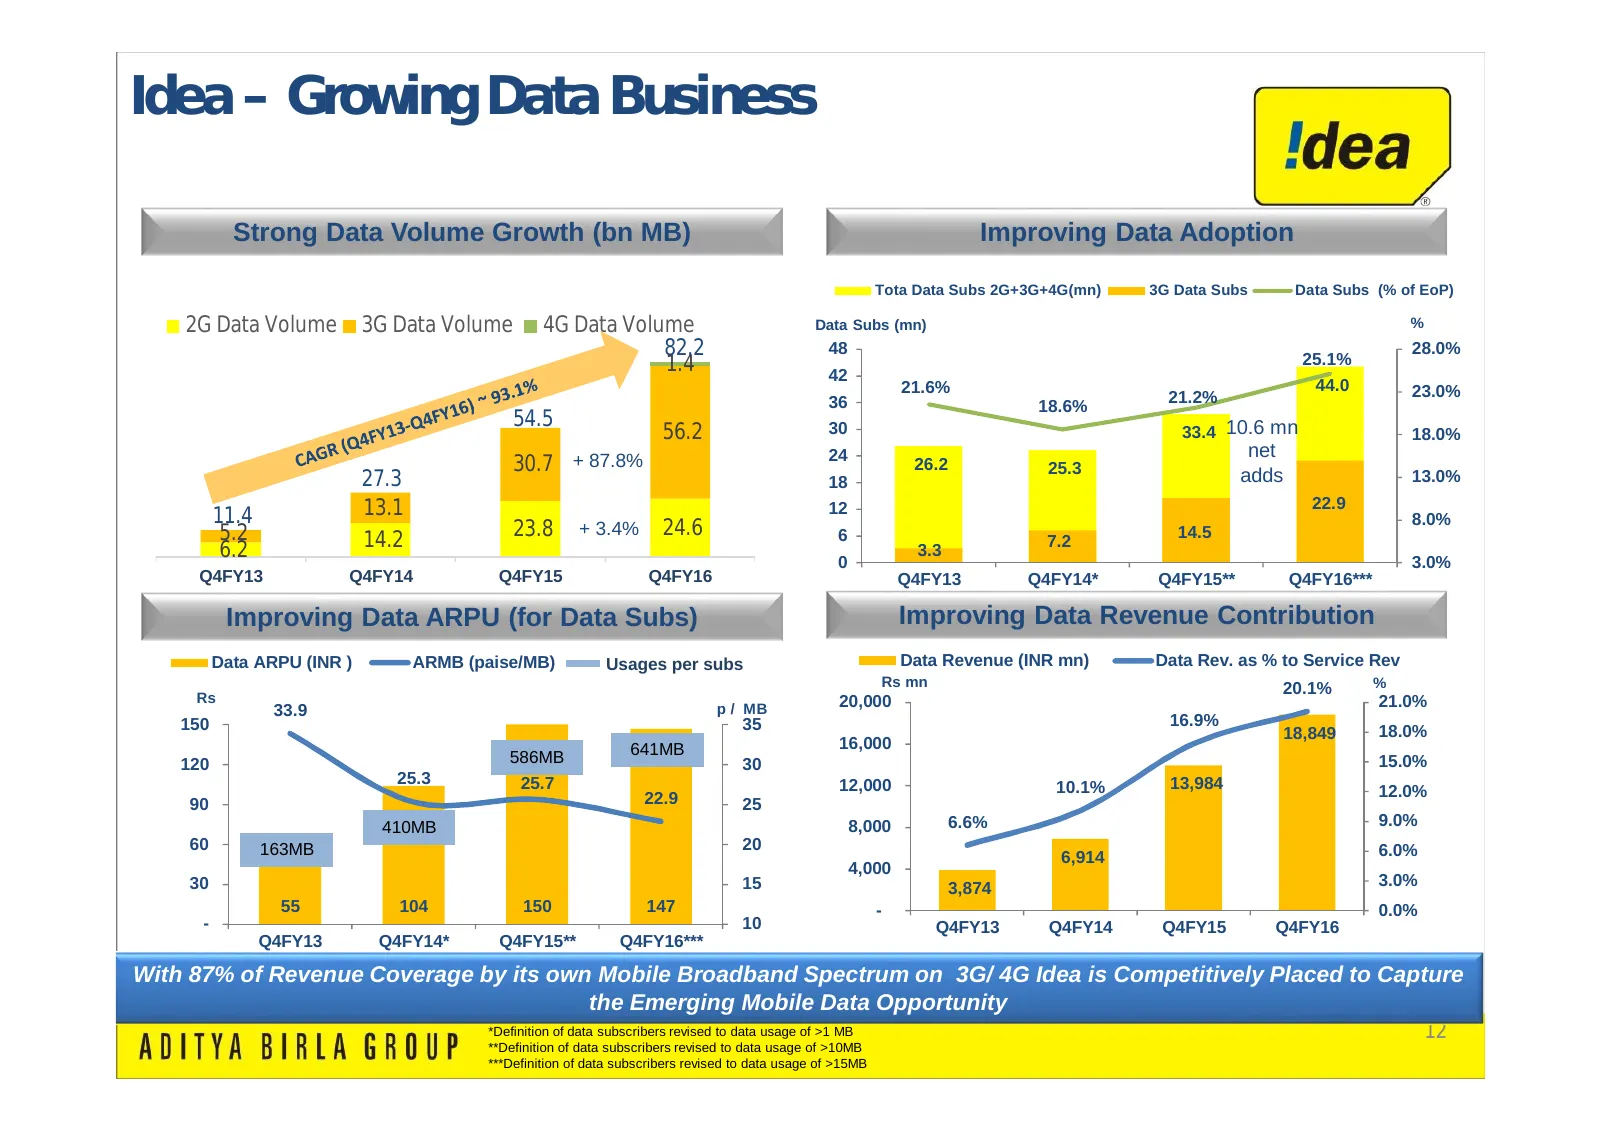
Slide 12: Idea – Growing Data Business
Internal Idea – Growing Data Business Strong Data Volume Growth (bn MB) Improving Data Adoption Tota Data Subs 2G+3G+4G(mn) 3G Data Subs Data Subs (% of EoP) 2G Data Volume 3G Data Volume 4G Data Volume Data Subs (mn) % 82.2 48 25.1% 28.0% 1.4 42 21.6% 44.0 23.0% 36 21.2% 18.6% 54.5 56.2 30 33.4 10.
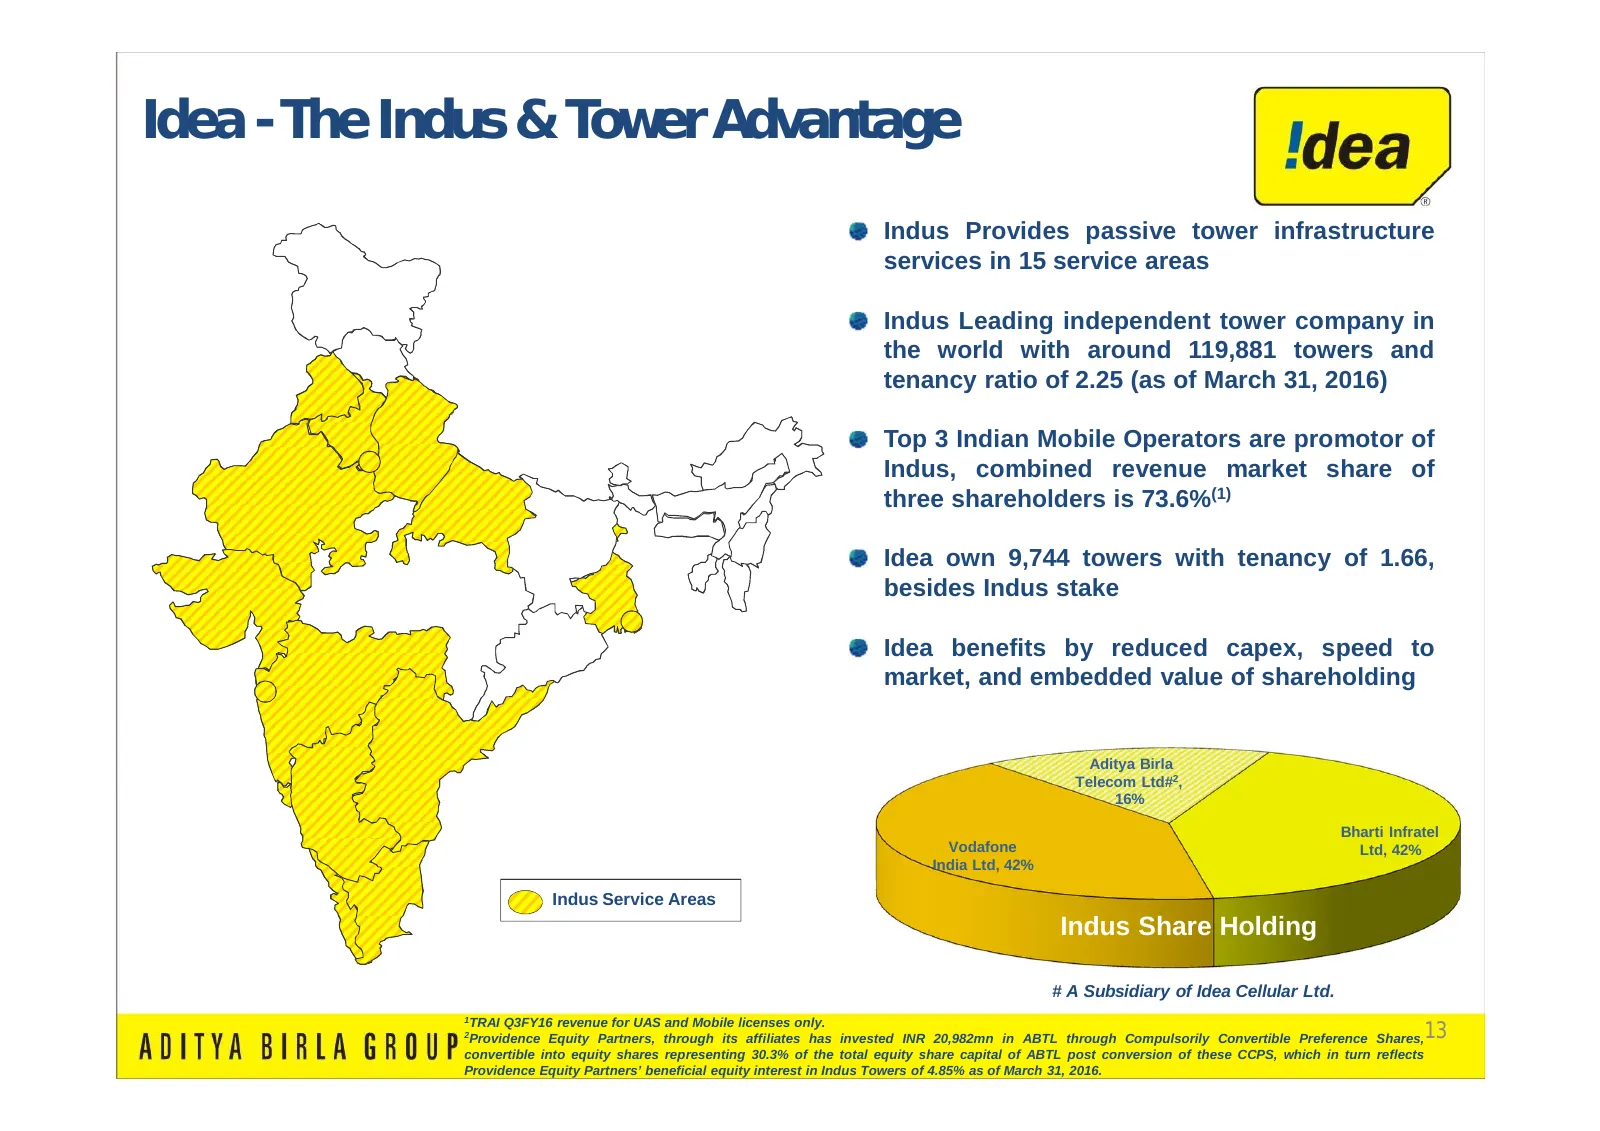
Slide 13: Idea - The Indus & Tower Advantage
Internal Idea - The Indus & Tower Advantage Indus Provides passive tower infrastructure services in 15 service areas Indus Leading independent tower company in the world with around 119,881 towers and tenancy ratio of 2.25 (as of March 31, 2016) Top 3 Indian Mobile Operators are promotor of Indus, c
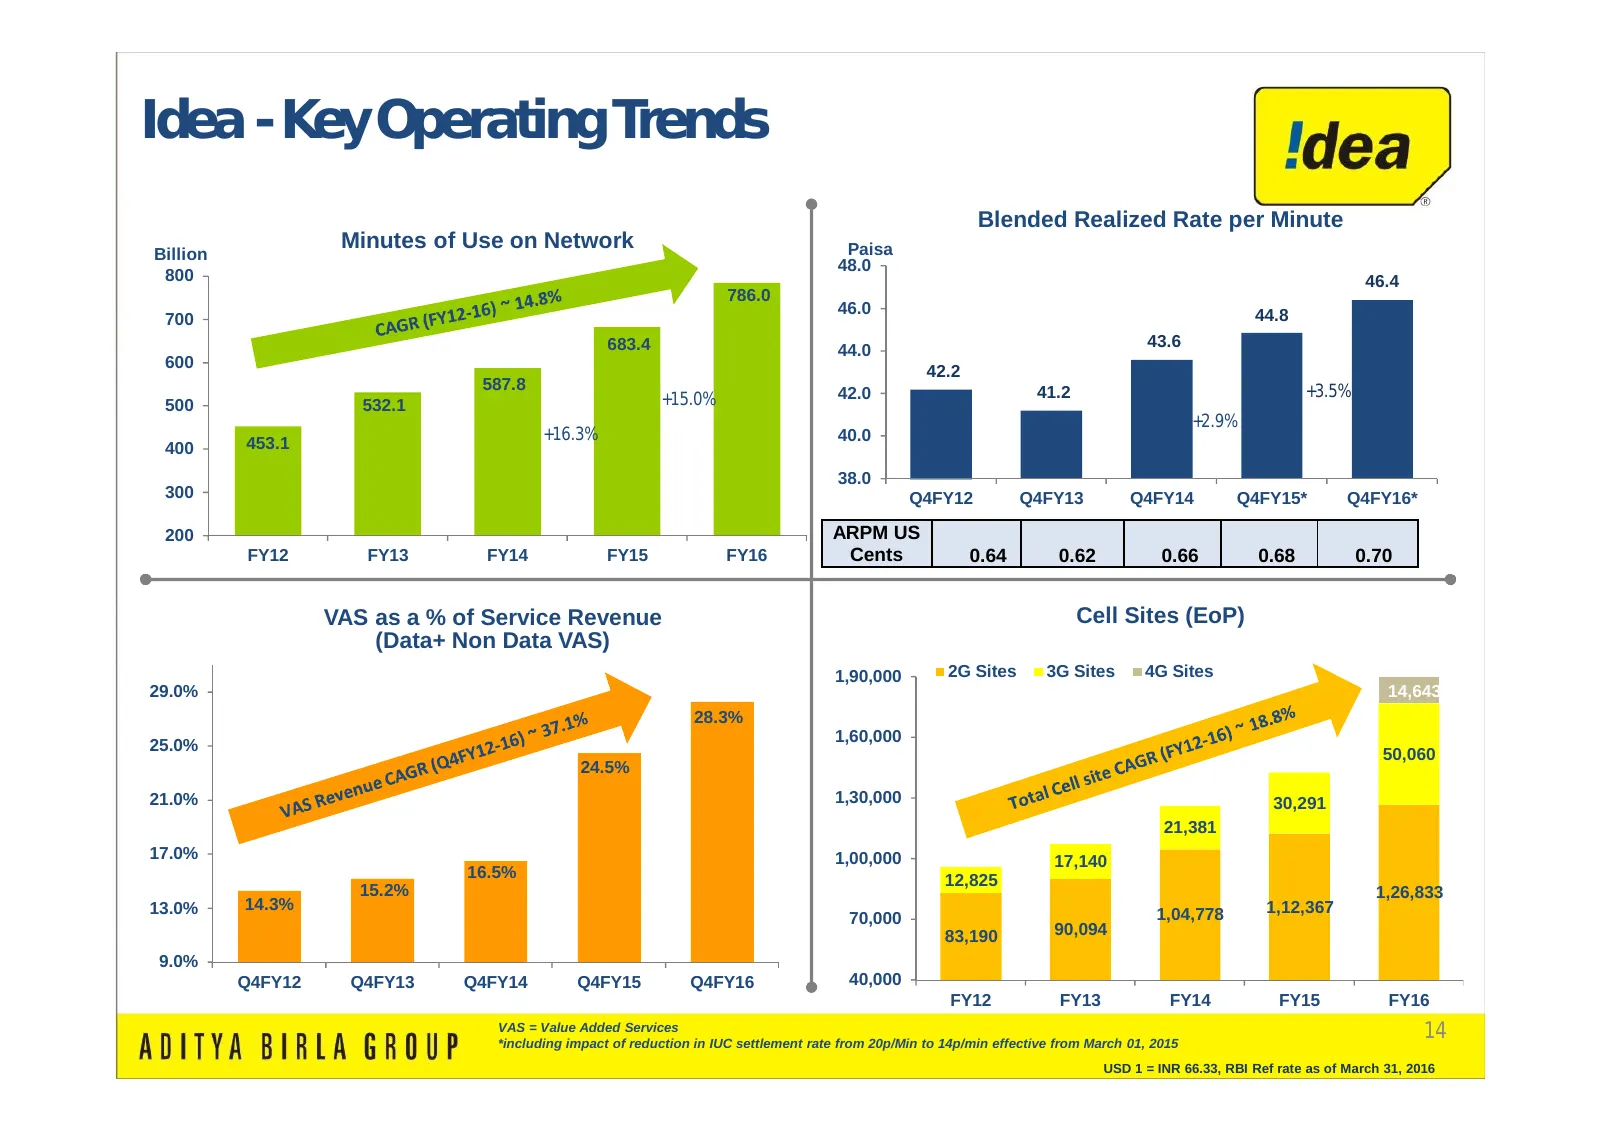
Slide 14: Idea - Key Operating Trends
Internal Idea - Key Operating Trends Blended Realized Rate per Minute Minutes of Use on Network Paisa Billion 48.0 800 46.4 786.0 46.0 44.8 700 683.4 43.6 44.0 600 42.2 587.8 42.0 41.2 +3.5% 500 532.1 +15.0% +2.9% +16.3% 40.0 400 453.1 38.0 300 Q4FY12 Q4FY13 Q4FY14 Q4FY15* Q4FY16* 200 ARPM US FY12 F
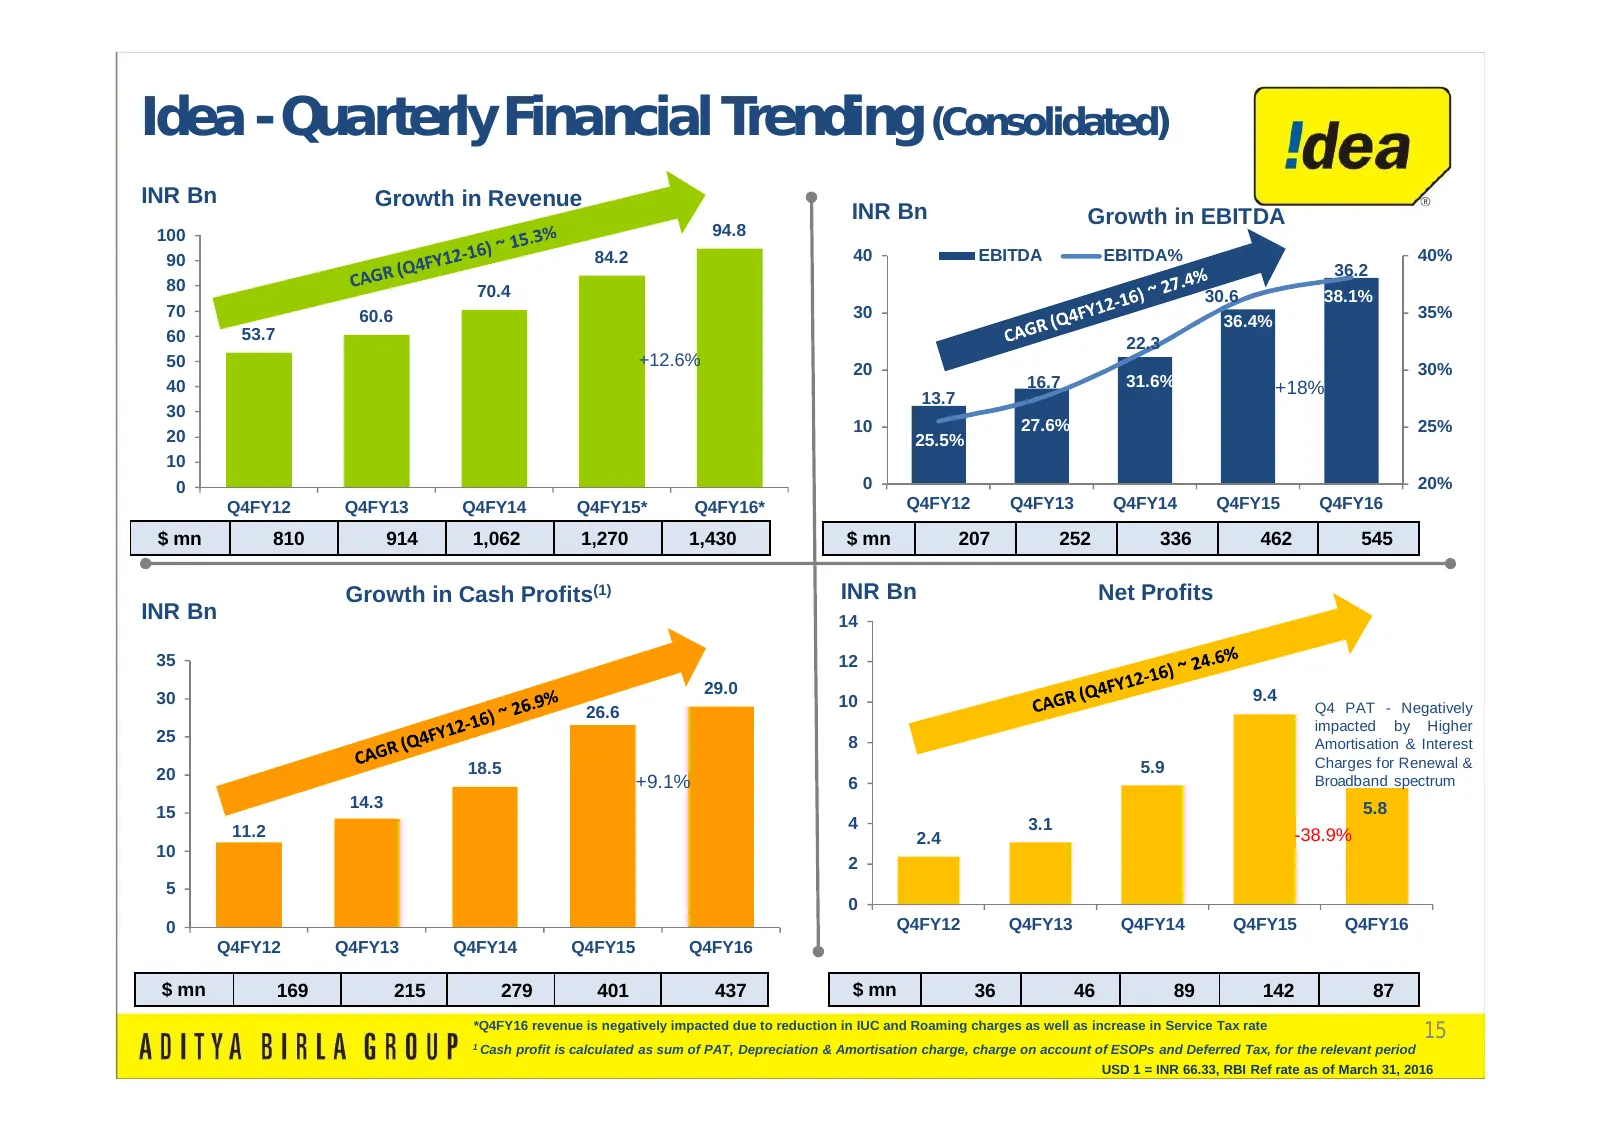
Slide 15: Idea - Quarterly Financial Trending (Consolidated)
Internal Idea - Quarterly Financial Trending (Consolidated) INR Bn Growth in Revenue INR Bn Growth in EBITDA 100 94.8 90 84.2 40 EBITDA EBITDA% 40% 36.2 80 70.4 30.6 38.1% 70 60.6 30 35% 36.4% 60 53.7 22.3 50 +12.6% 20 30% 40 16.7 31.6% +18% 13.7 30 10 27.6% 25% 20 25.5% 10 0 0 20% Q4FY12 Q4FY13 Q4F
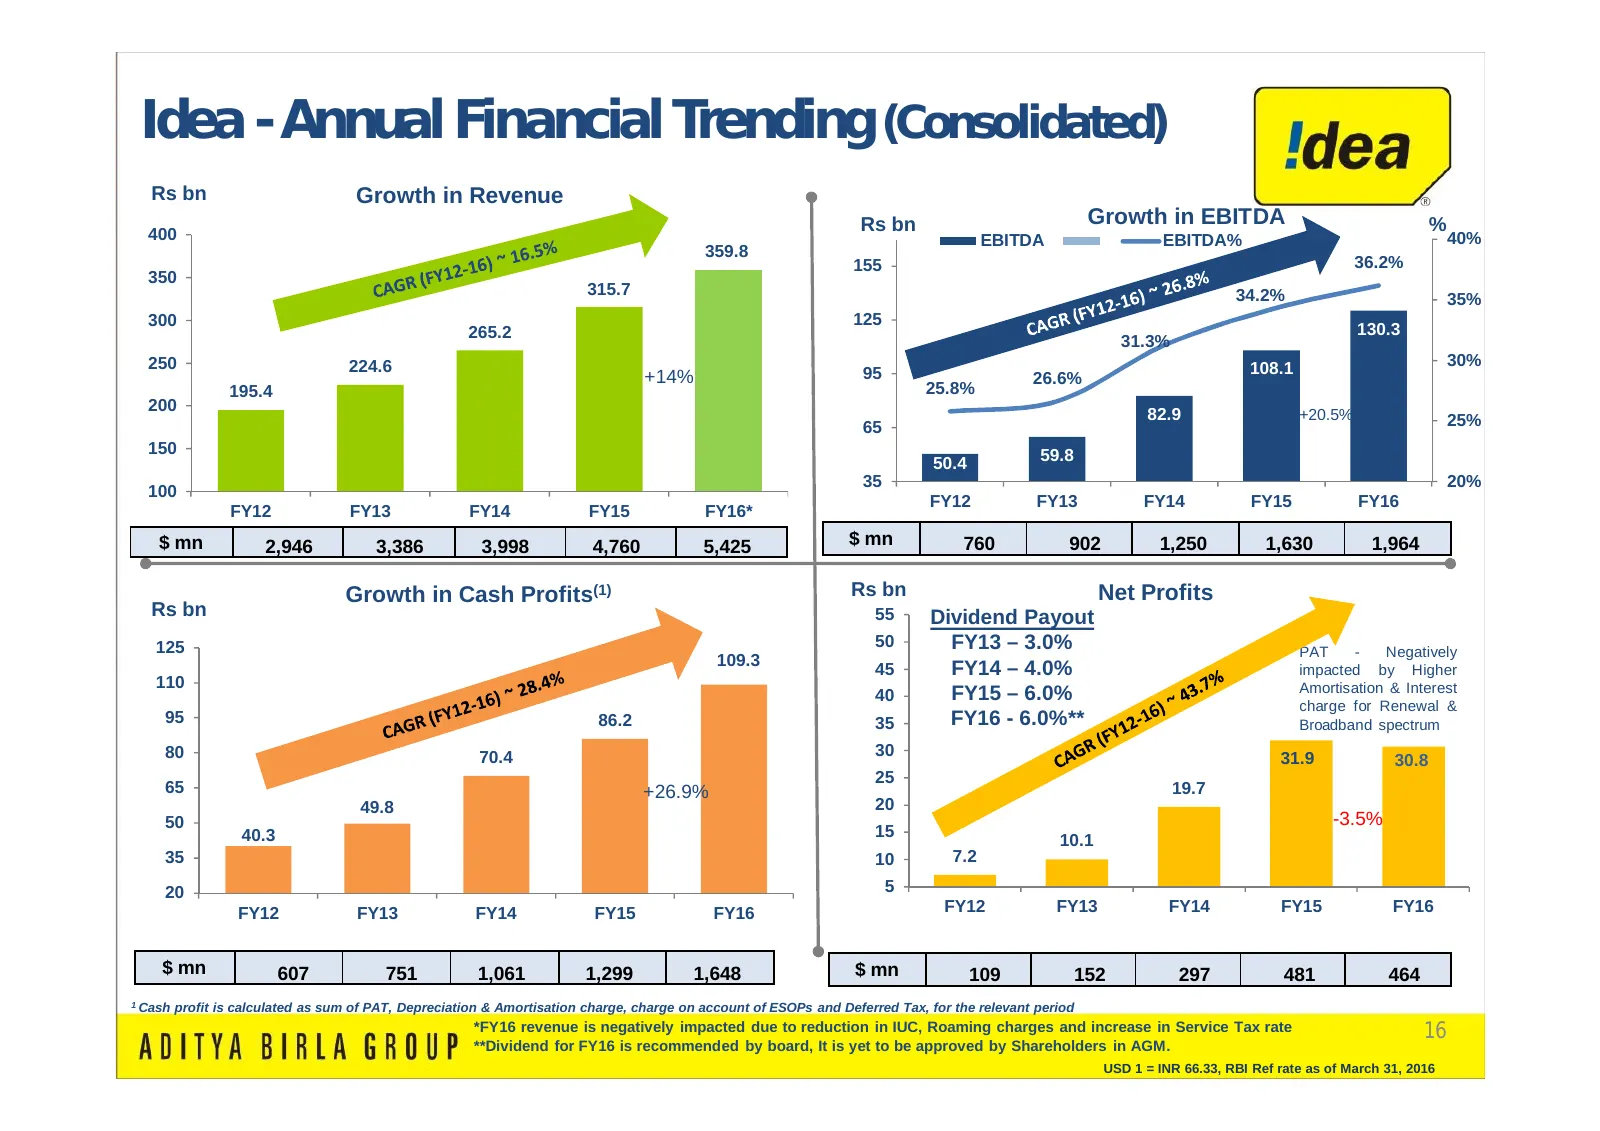
Slide 16: Idea - Annual Financial Trending (Consolidated)
Internal Idea - Annual Financial Trending (Consolidated) Rs bn Growth in Revenue Rs bn Growth in EBITDA % 400 EBITDA EBITDA% 40% 359.8 155 36.2% 350 315.7 34.2% 35% 300 125 265.2 130.3 31.3% 250 224.6 30% 95 108.1 +14% 26.6% 195.4 25.8% 200 82.9 +20.5% 25% 65 150 59.8 50.4 35 20% 100 FY12 FY13 FY14
Slide 17: Key Financial Ratios
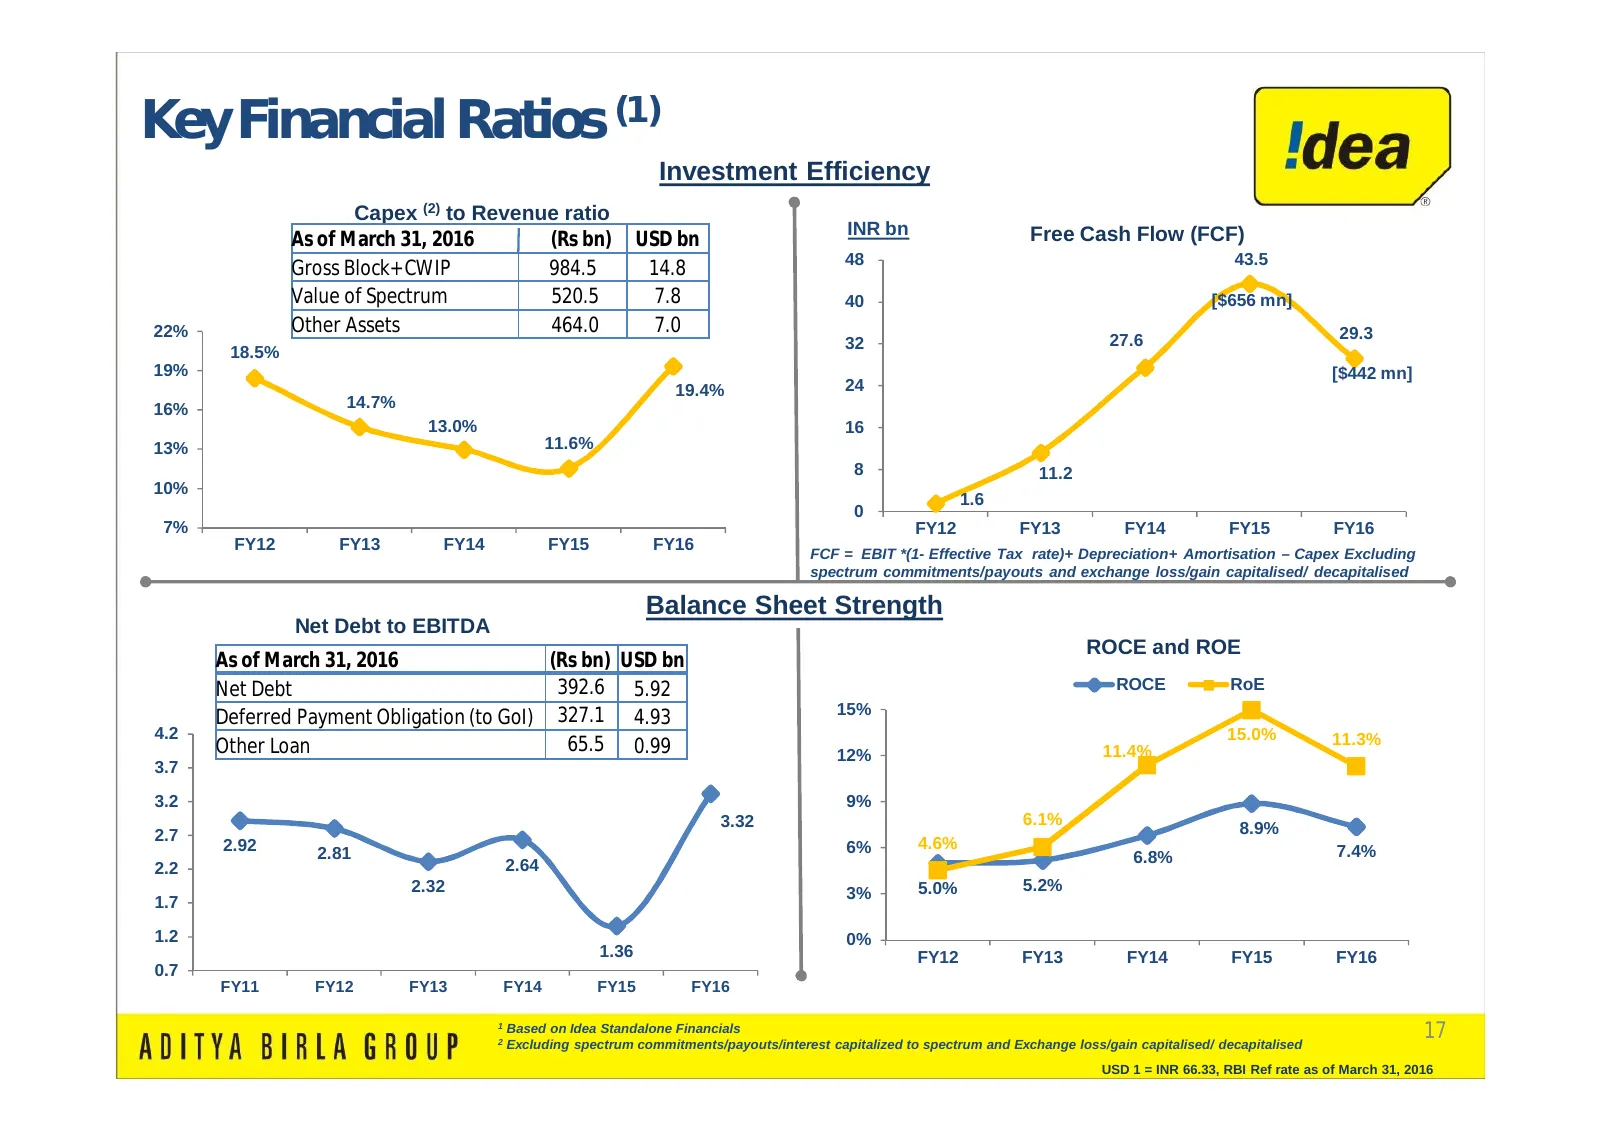
Internal Key Financial Ratios (1) Investment Efficiency Capex (2) to Revenue ratio INR bn Free Cash Flow (FCF) As of March 31, 2016 (Rs bn) USD bn 48 43.5 Gross Block+ CWIP 984.5 14.8 Value of Spectrum 520.5 7.8 40 [$656 mn] 22% Other Assets 464.0 7.0 29.3 32 27.6 18.5% 19% [$442 mn] 19.4% 24 16% 14
Slide 18: Appendix
Internal Appendix 18
Slide 19: Recent Financial Trends
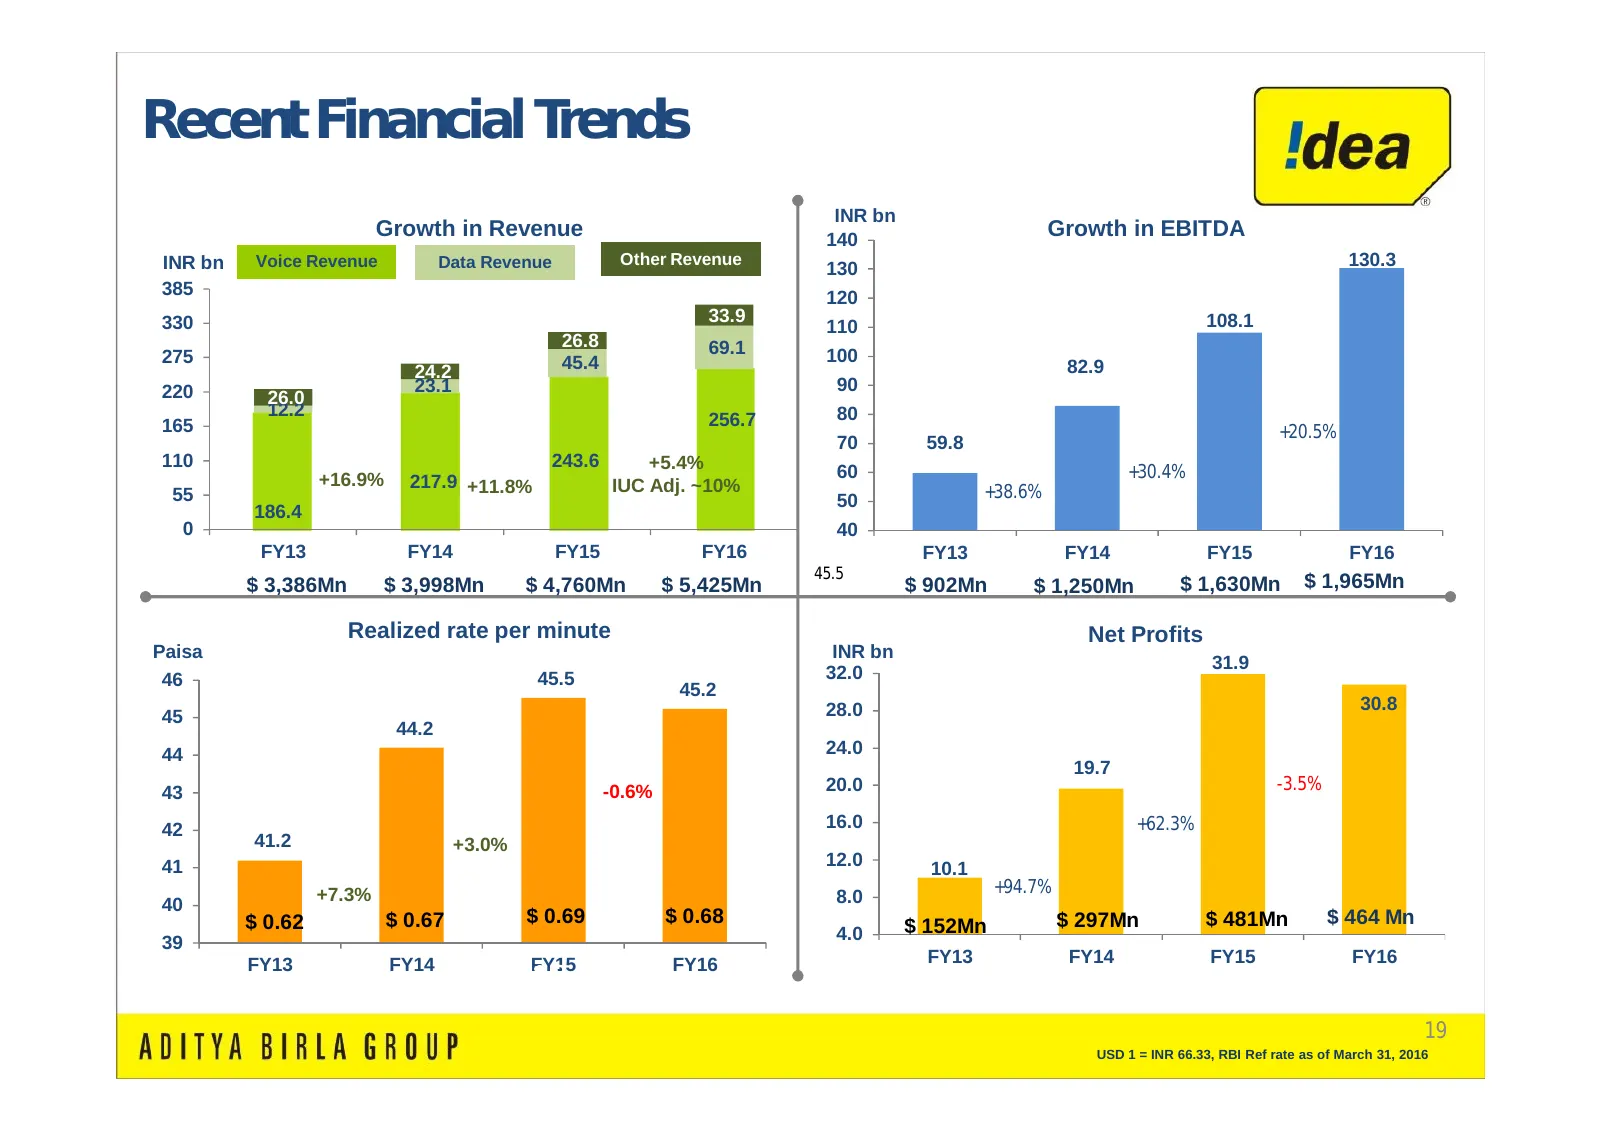
Internal Recent Financial Trends INR bn Growth in Revenue 140 Growth in EBITDA INR bn Voice Revenue Data Revenue Other Revenue 130.3 130 385 120 330 33.9 108.1 110 26.8 69.1 275 45.4 100 24.2 82.9 220 23.1 90 26.0 12.2 80 165 256.7 +20.5% 70 59.8 110 243.6 +5.4% +16.9% 217.9 +11.8% 60 +30.4% 55 IUC
Slide 20: Idea – Key Capabilities & Strengths
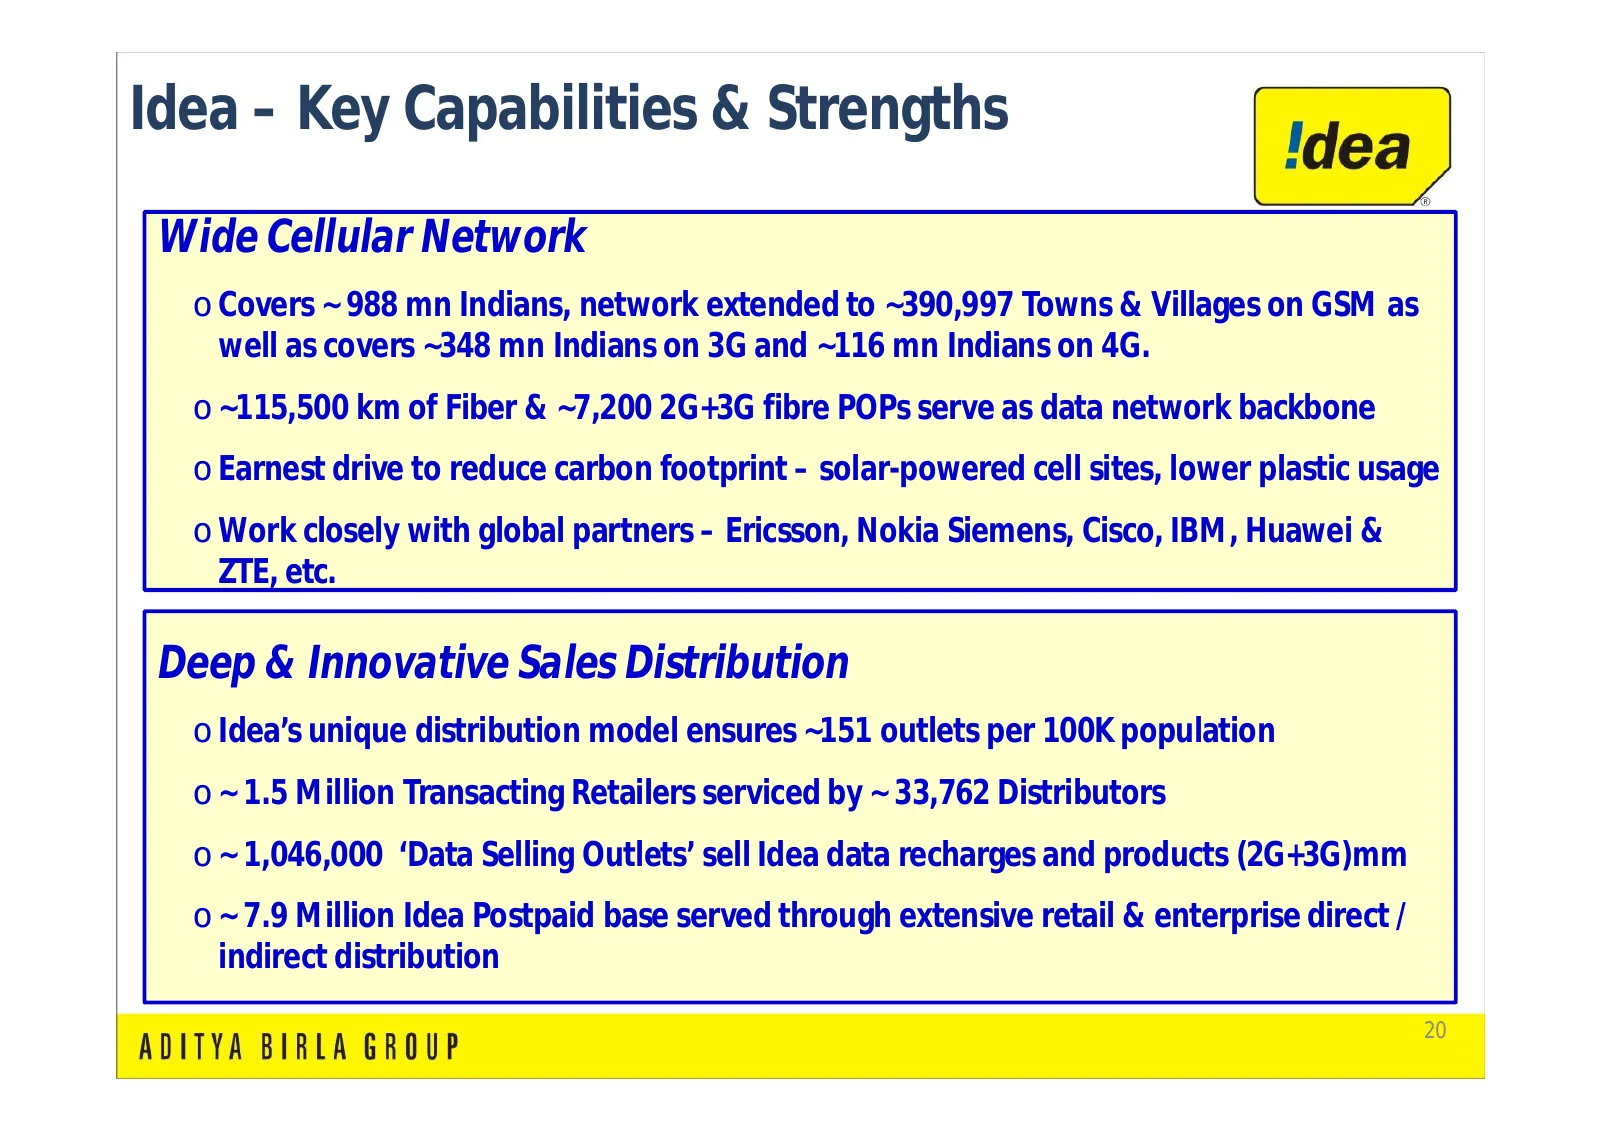
Internal Idea – Key Capabilities & Strengths Wide Cellular Network o Covers ~ 988 mn Indians, network extended to ~390,997 Towns & Villages on GSM as well as covers ~348 mn Indians on 3G and ~116 mn Indians on 4G. o ~115,500 km of Fiber & ~7,200 2G+3G fibre POPs serve as data network backbone o Earn
Slide 21: Idea – Key Capabilities & Strengths
Internal Idea – Key Capabilities & Strengths Growing Data Business o ~ 44 Million data users on 2G EDGE, 3G HSPA and 4G LTE services o ~22.9 Million subscribers use 3G mobile data out of ~175.1 Million total subscriber base o ~60.4Mn Idea subscribers own 3G devices but only 30.5 mn use 3G platform (
Slide 22: Idea – Key Capabilities & Strengths
Internal Idea – Key Capabilities & Strengths Strong IT Processes & Support o Modern Prepaid Vtop-Up system & Pan-India Postpaid billing system BSCS IX o Large Siebel based pan-India Prepaid and Postpaid CRM deployment o High emphasis on sales automation through advanced Dealer Sales Mgmt. applicatio
Slide 23: Idea – Some Recent Awards & Recognitions
Internal Idea – Some Recent Awards & Recognitions Corporate Awards oIdea Cellular awarded as the winner of the prestigious India Business Leader Awards (IBLA) by CNBC, for the category ‘Outstanding Company of the Year’ oAmity Corporate Excellence Award 2015 for “Customer Connect and Engagement in Te
Slide 24: Idea Brand Philosophy
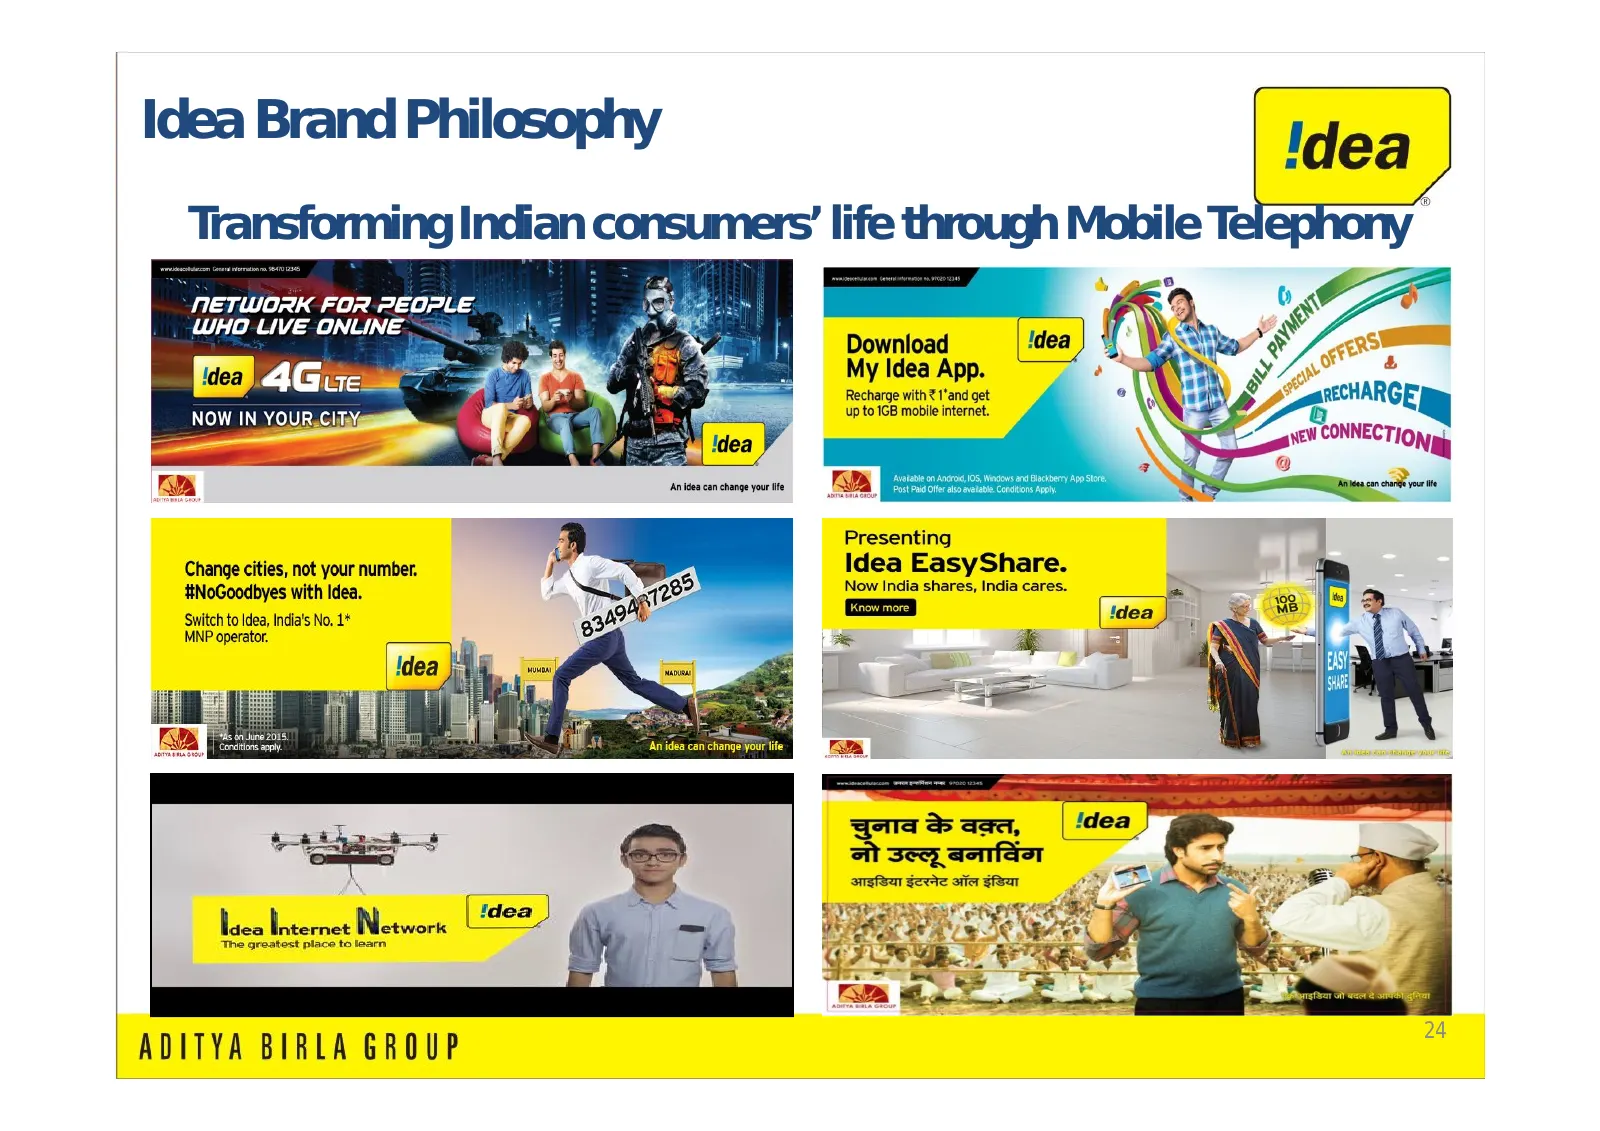
Internal Idea Brand Philosophy Transforming Indian consumers’ life through Mobile Telephony 24
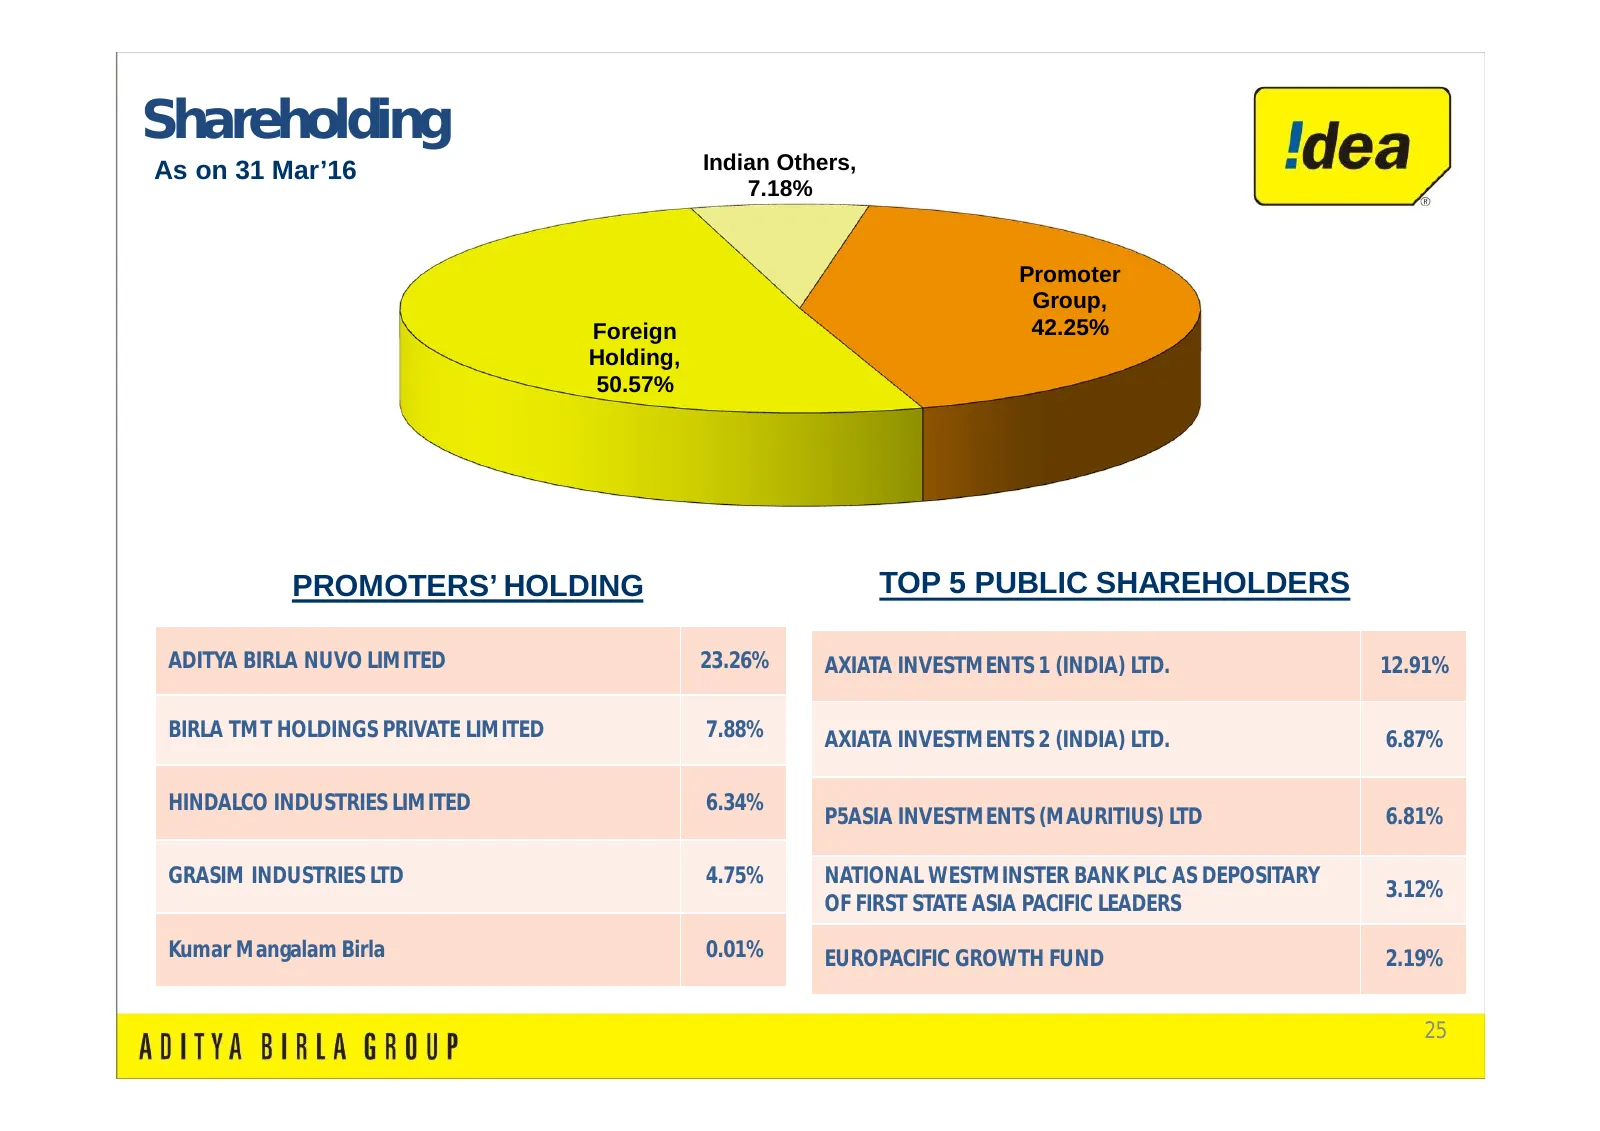
Slide 25: Shareholding
Internal Shareholding As on 31 Mar’16 Indian Others, 7.18% Promoter Group, Foreign 42.25% Holding, 50.57% PROMOTERS’ HOLDING TOP 5 PUBLIC SHAREHOLDERS ADITYA BIRLA NUVO LIMITED 23.26% AXIATA INVESTMENTS 1 (INDIA) LTD. 12.91% BIRLA TMT HOLDINGS PRIVATE LIMITED 7.88% AXIATA INVESTMENTS 2 (INDIA) LTD.
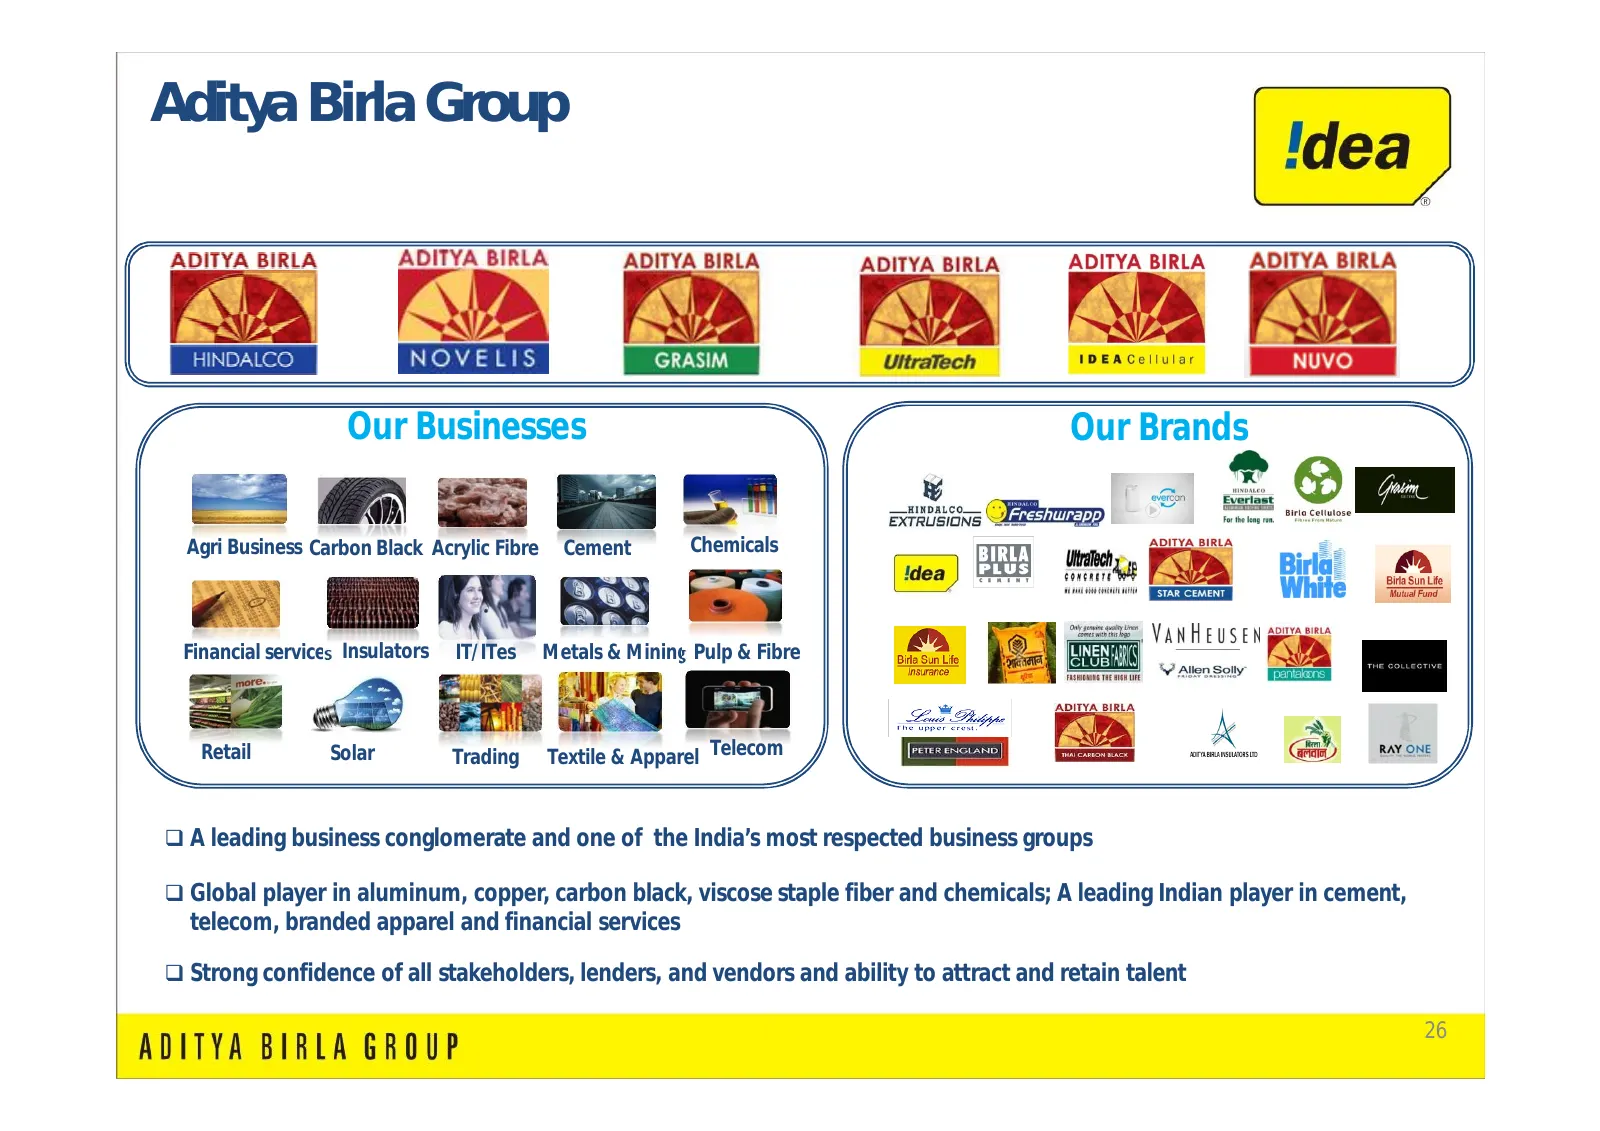
Slide 26: Aditya Birla Group
Internal Aditya Birla Group Our Businesses Our Brands Agri Business Carbon Black Acrylic Fibre Cement Chemicals Financial services Insulators IT/ITes Metals & Mining Pulp & Fibre Retail Solar Trading Textile & Apparel Telecom A leading business conglomerate and one of the India’s most respected bu
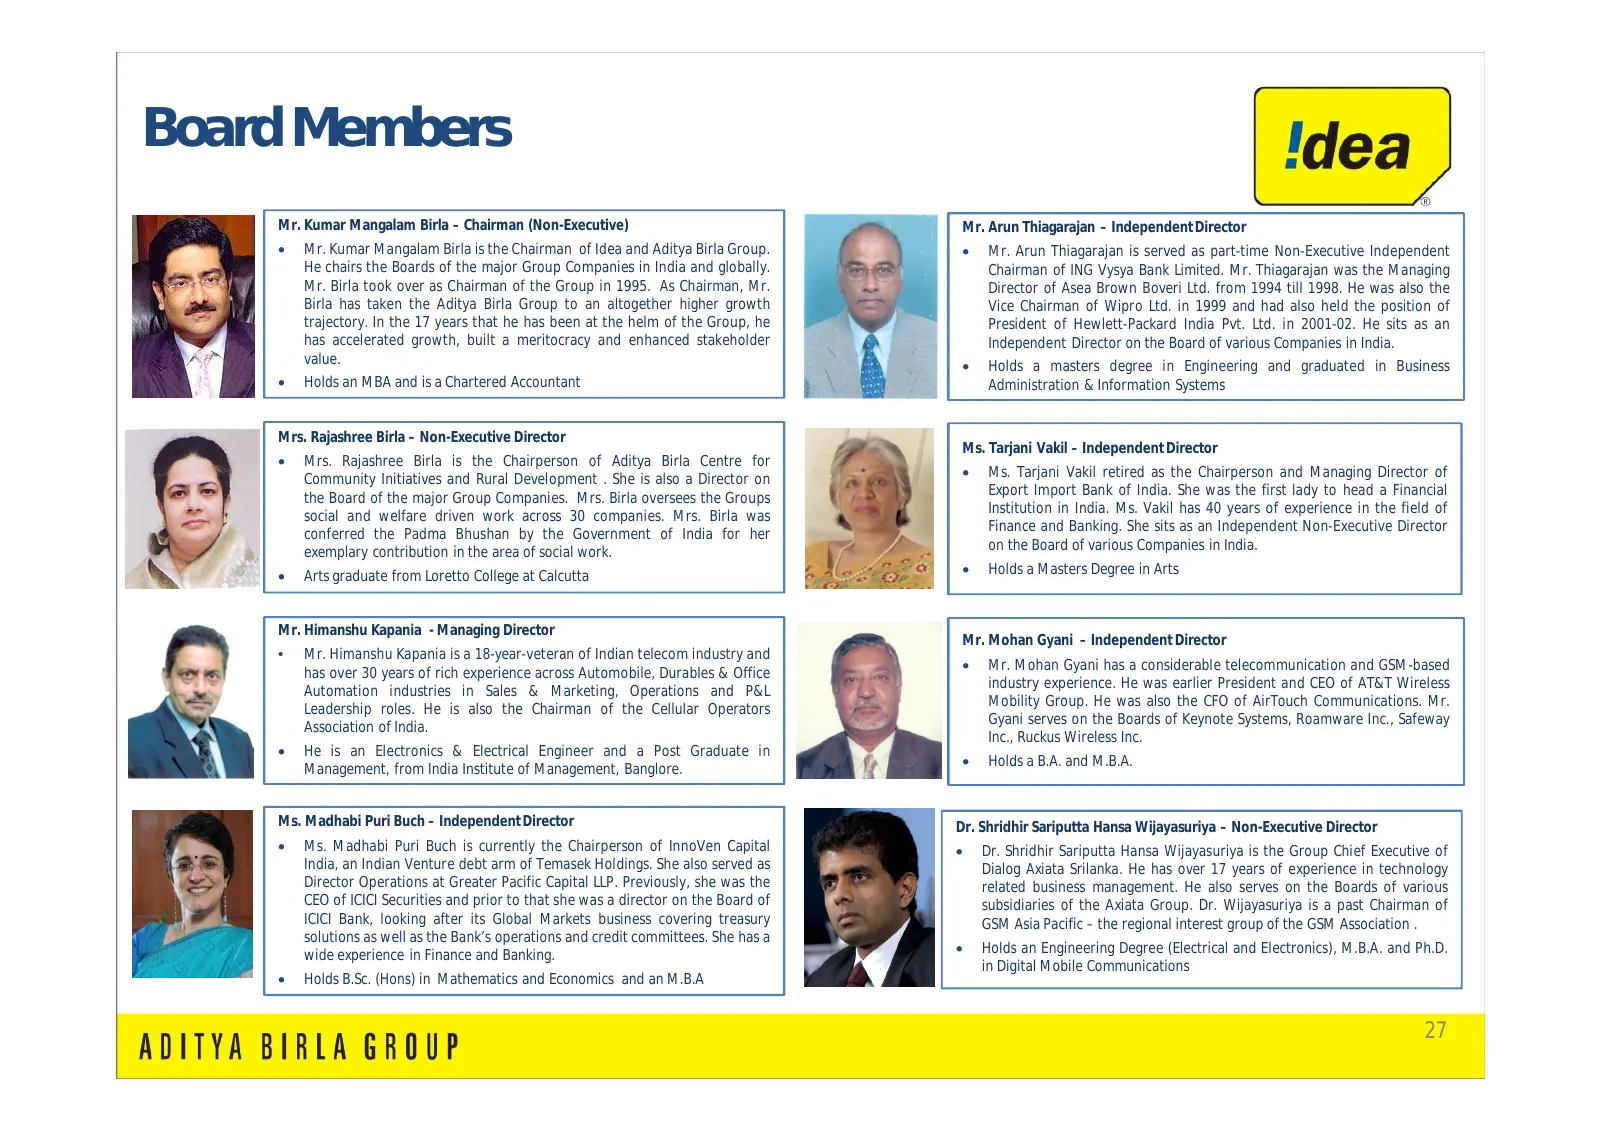
Slide 27: Board Members
Internal Board Members Mr. Kumar Mangalam Birla – Chairman (Non-Executive) Mr. Arun Thiagarajan – Independent Director Mr. Kumar Mangalam Birla is the Chairman of Idea and Aditya Birla Group. Mr. Arun Thiagarajan is served as part-time Non-Executive Independent He chairs the Boards of the major
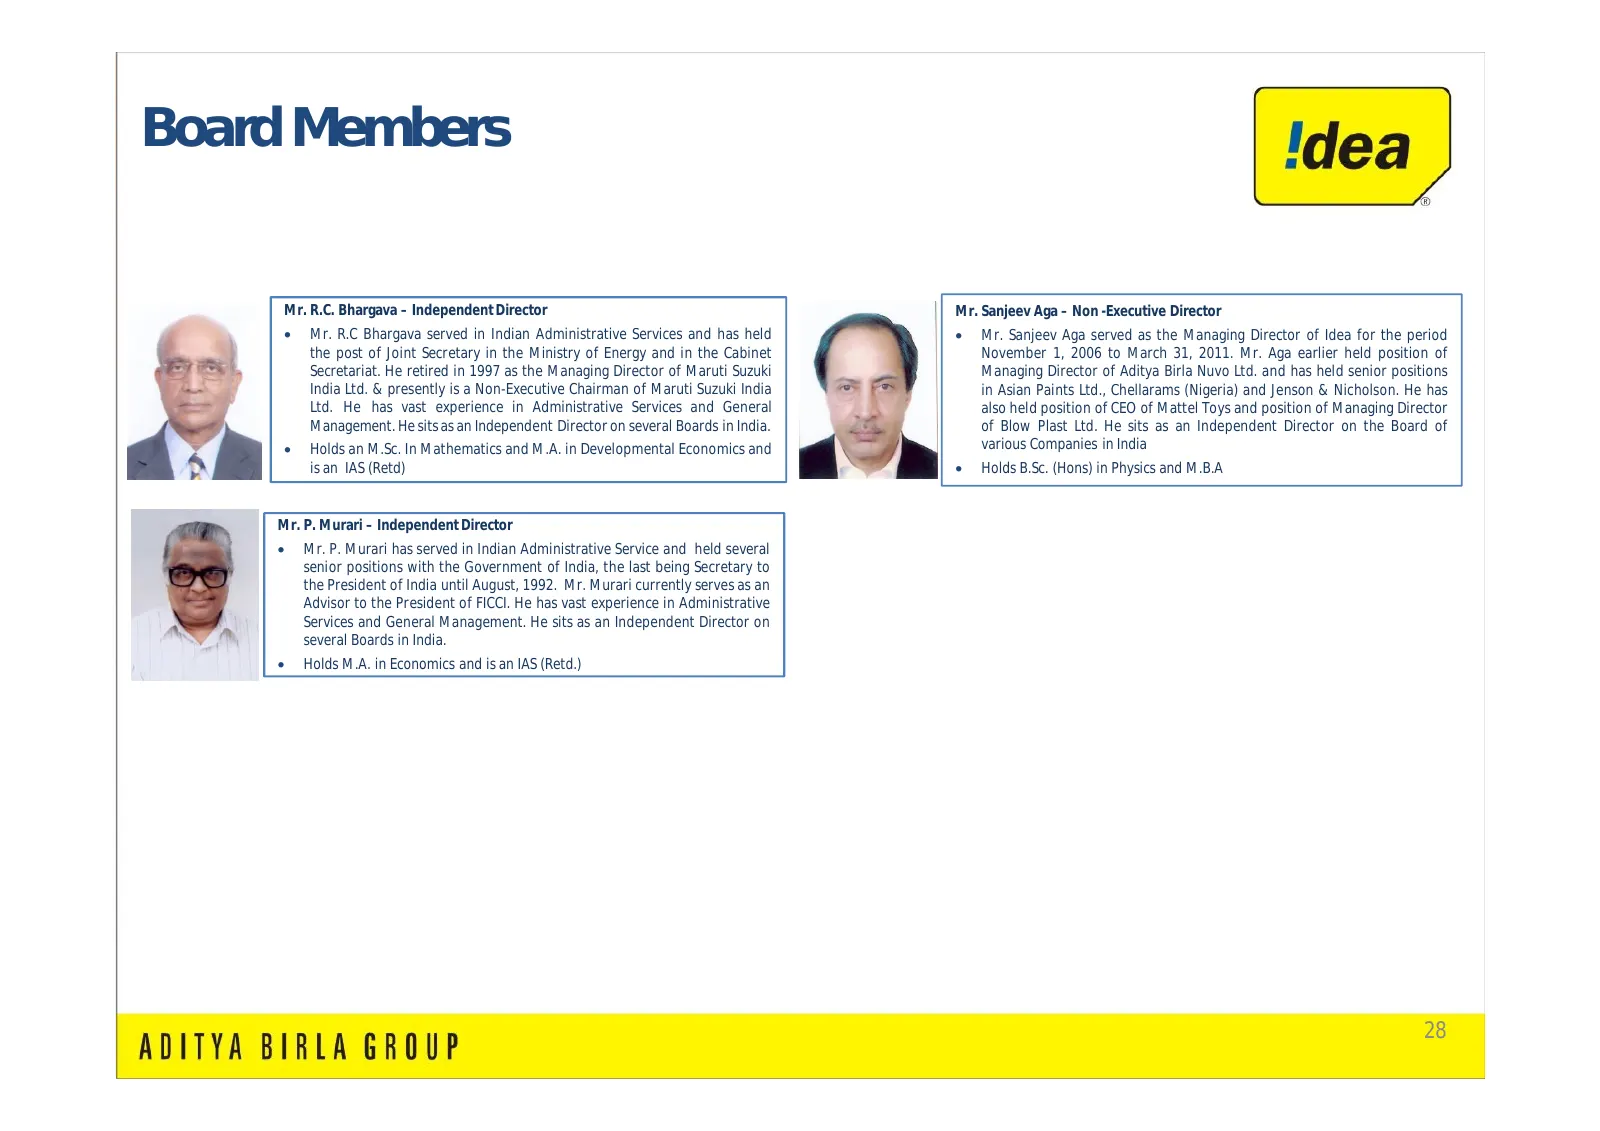
Slide 28: Board Members
Internal Board Members Mr. R.C. Bhargava – Independent Director Mr. Sanjeev Aga – Non -Executive Director Mr. R.C Bhargava served in Indian Administrative Services and has held Mr. Sanjeev Aga served as the Managing Director of Idea for the period the post of Joint Secretary in the Ministry of E
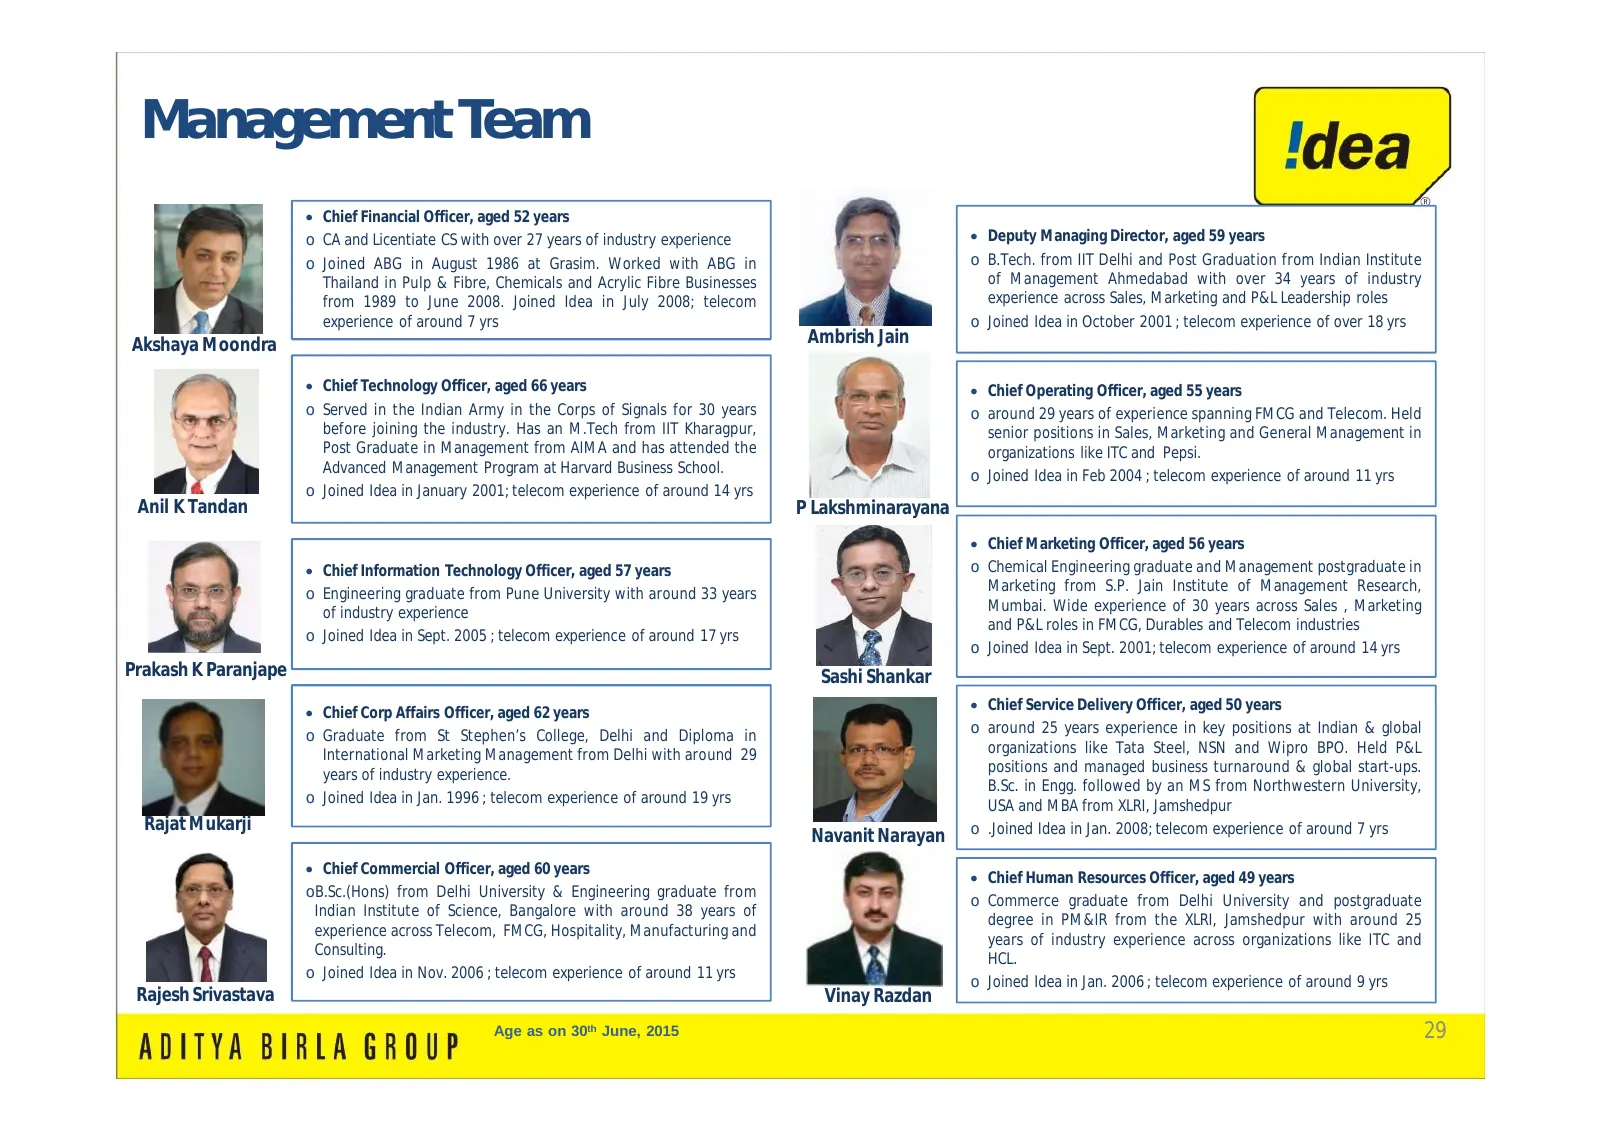
Slide 29: Management Team
Internal Management Team Chief Financial Officer, aged 52 years o CA and Licentiate CS with over 27 years of industry experience Deputy Managing Director, aged 59 years o Joined ABG in August 1986 at Grasim. Worked with ABG in o B.Tech. from IIT Delhi and Post Graduation from Indian Institute Th
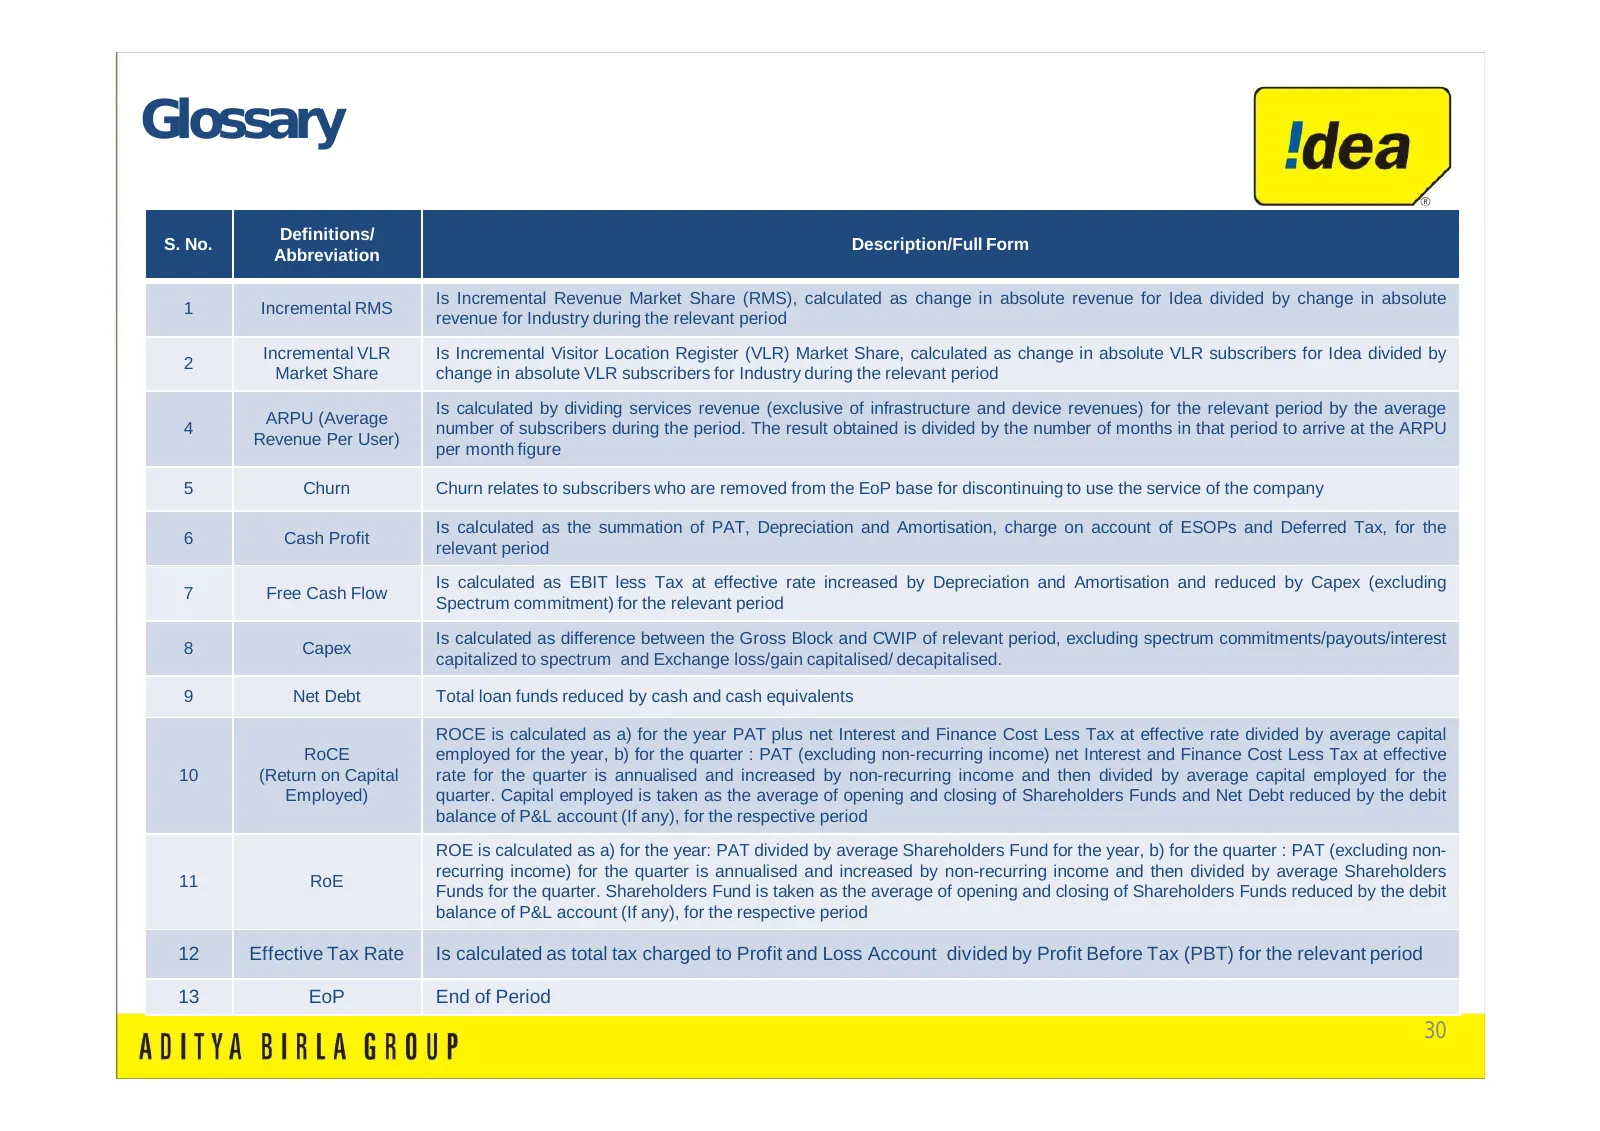
Slide 30: Glossary
Internal Glossary Definitions/ S. No. Description/Full Form Abbreviation Is Incremental Revenue Market Share (RMS), calculated as change in absolute revenue for Idea divided by change in absolute 1 Incremental RMS revenue for Industry during the relevant period Incremental VLR Is Incremental Visitor
Slide 31: Thank You
Thank You ADITYA BIRLA GROUP
Source: Internet Archive copy of myvi.in
More decks from Vodafone Idea Ltd
 Investor Presentation (November 2026)25 slides · Nov 12, 2026
 Investor Presentation (September 2026)21 slides · Sep 15, 2026
 Investor Presentation (June 2026)20 slides · Jun 30, 2026
 Investor Presentation (June 2026)19 slides · June 2026
 Investor Presentation (January 2026)31 slides · Jan 28, 2026
 Investor Presentation (January 2026)32 slides · Jan 28, 2026