VEREIT — American Realty Capital Properties — IPO Roadshow (July 2013)
27 slides from VEREIT's IPO roadshow presentation, Jul 23, 2013
Slide 1: $300,000,000 Convertible Senior Notes Offering due 2018
July 2013 $300,000,000 Convertible Senior Notes Offering due 2018
Slide 2: Additional Information about the Proposed Transaction and Where to Find It
Additional Information about the Proposed Transaction and Where to Find It This communication does not constitute an offer to sell or the solicitation of an offer to buy any securities. In connection with the proposed transaction, American Realty Capital Properties, Inc. (“ARCP”) has filed a registr
Slide 3: Forward-Looking Statements
Forward-Looking Statements Information set forth herein contains “forward-looking statements” (as defined in Section 21E of the Securities Exchange Act of 1934, as amended), which reflect ARCP’s expectations regarding future events. The forward-looking statements involve a number of risks, uncertain
Slide 4: Agenda
Agenda Transaction Summary 5 ARCP Overview 7 ARCT IV Acquisition Overview 20 Page Appendix 26 4
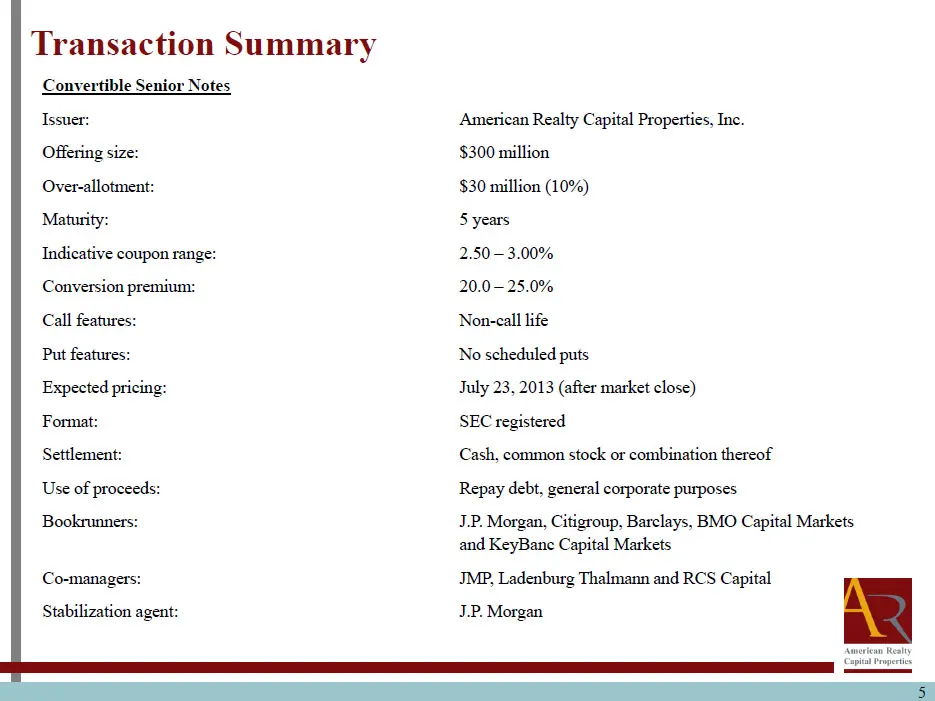
Slide 5: Transaction Summary
Transaction Summary Convertible Senior Notes Issuer: American Realty Capital Properties, Inc. Offering size: $300 million Over-allotment: $30 million (10%) Maturity: 5 years Indicative coupon range: 2.50 – 3.00% Conversion premium: 20.0 – 25.0% Call features: Non-call life Put features: No scheduled
Slide 6: Agenda
Agenda Transaction Summary 5 ARCP Overview 7 ARCT IV Acquisition Overview 20 Page Appendix 26 6
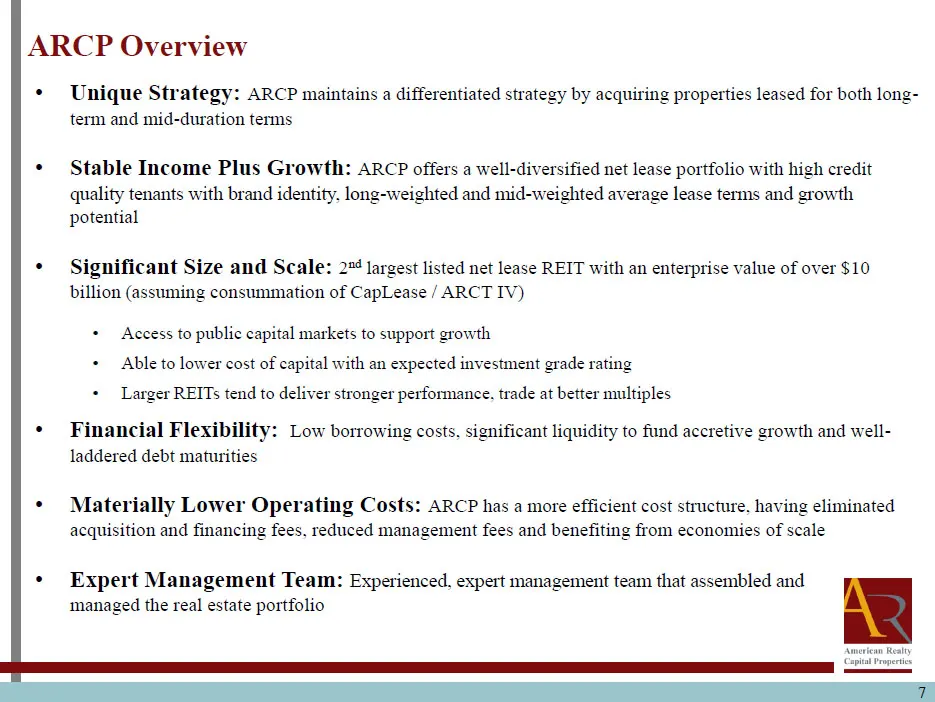
Slide 7: ARCP Overview
ARCP Overview Unique Strategy: ARCP maintains a differentiated strategy by acquiring properties leased for both long-term and mid-duration terms •Stable Income Plus Growth: ARCP offers a well-diversified net lease portfolio with high credit quality tenants with brand identity, long-weighted and mid-
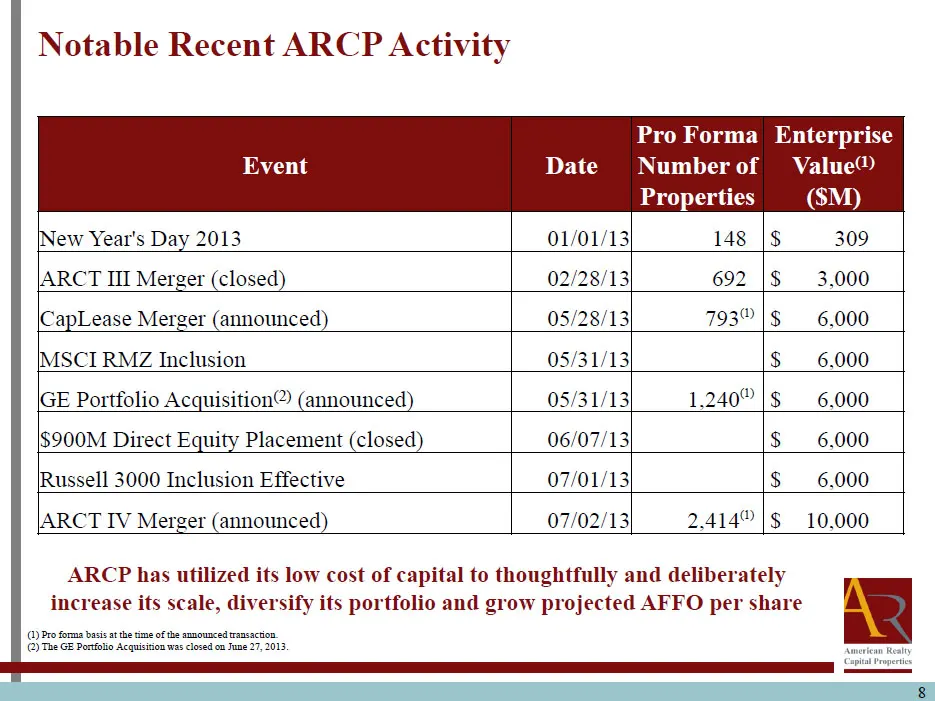
Slide 8: Notable Recent ARCP Activity
Notable Recent ARCP Activity ARCP has utilized its low cost of capital to thoughtfully and deliberately increase its scale, diversify its portfolio and grow projected AFFO per share Event Date Pro Forma Number of Properties Enterprise Value(1) ($M) New Year's Day 2013 01/01/13 148 $ 309 ARCT III Mer
Slide 9: ARCP Shareholder Benefits of ARCT IV Merger
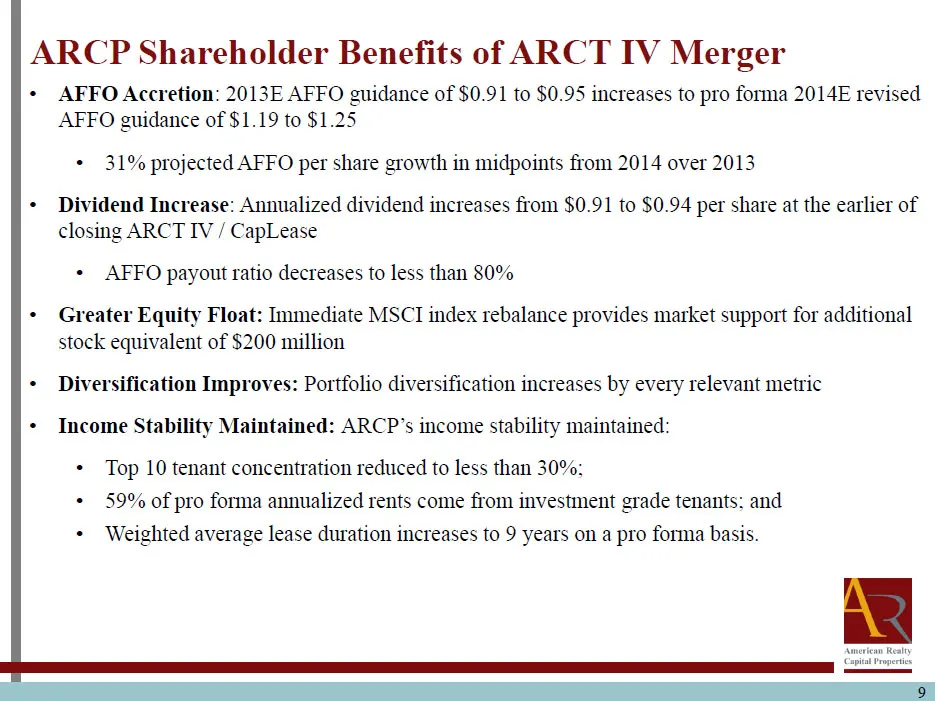
ARCP Shareholder Benefits of ARCT IV Merger •AFFO Accretion: 2013E AFFO guidance of $0.91 to $0.95 increases to pro forma 2014E revised AFFO guidance of $1.19 to $1.25 •31% projected AFFO per share growth in midpoints from 2014 over 2013 •Dividend Increase: Annualized dividend increases from $0.91 t
Slide 10: AFFO per share is projected to grow significantly from 2013 to 2014
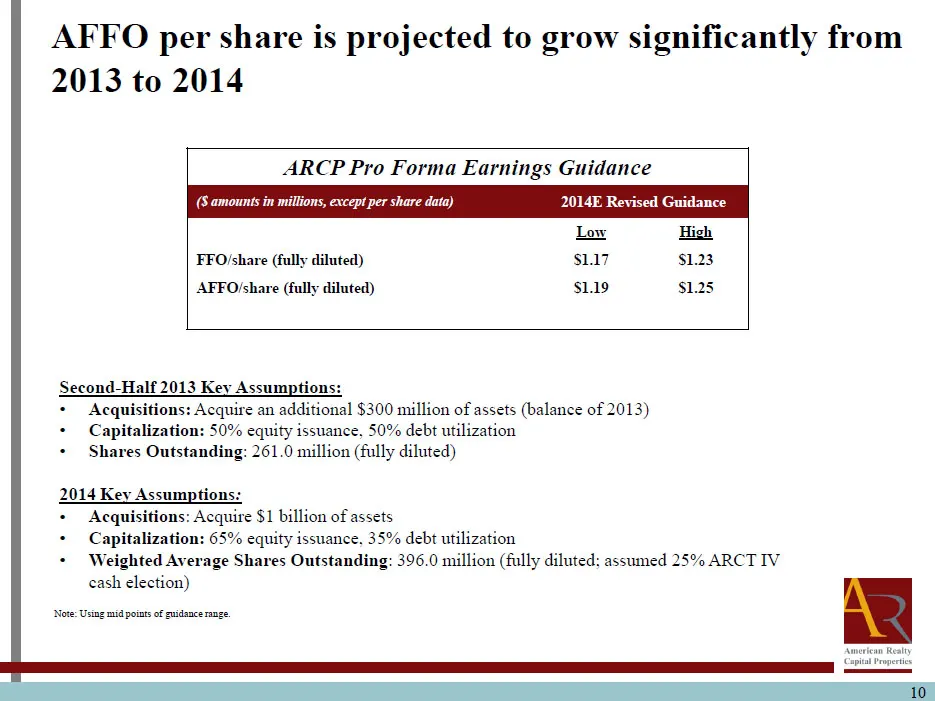
AFFO per share is projected to grow significantly from 2013 to 2014 ARCP Pro Forma Earnings Guidance ($ amounts in millions, except per share data) 2014E Revised Guidance Low High FFO/share (fully diluted) $1.17 $1.23 AFFO/share (fully diluted) $1.19 $1.25 Second-Half 2013 Key Assumptions: •Acquisit
Slide 11: ARCP's Annualized Dividend will Increase for the 7th Consecutive Quarter
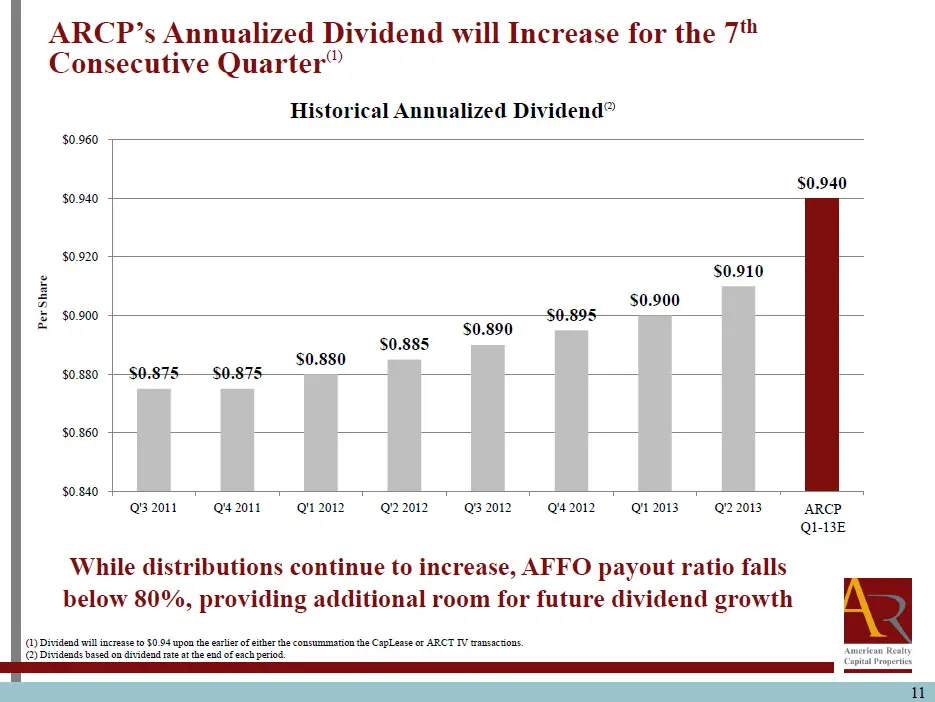
ARCP’s Annualized Dividend will Increase for the 7th Consecutive Quarter(1) (1) Dividend will increase to $0.94 upon the earlier of either the consummation the CapLease or ARCT IV transactions. (2) Dividends based on dividend rate at the end of each period. $0.875 $0.875 $0.880 $0.885 $0.890 $0.895
Slide 12: Only 7.6% of Leases Mature in the Next Years
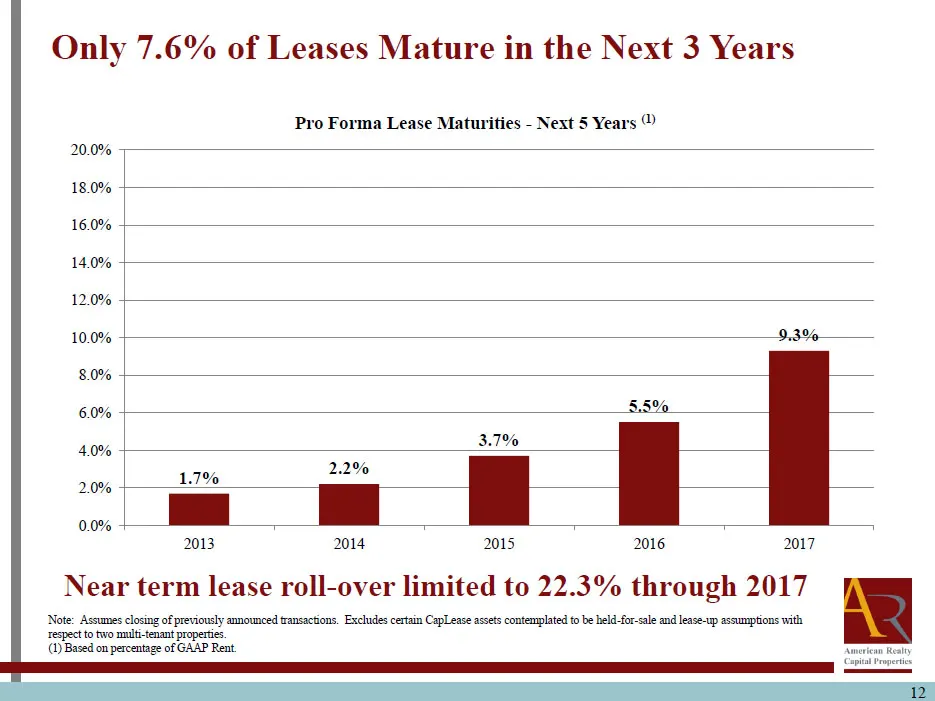
Only 7.6% of Leases Mature in the Next 3 Years Near term lease roll-over limited to 22.3% through 2017 1.7% 2.2% 3.7% 5.5% 9.3% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% 18.0% 20.0% 2013 2014 2015 2016 2017 Pro Forma Lease Maturities - Next 5 Years (1) Note: Assumes closing of previously anno
Slide 13: ARCP's Proven Management Team
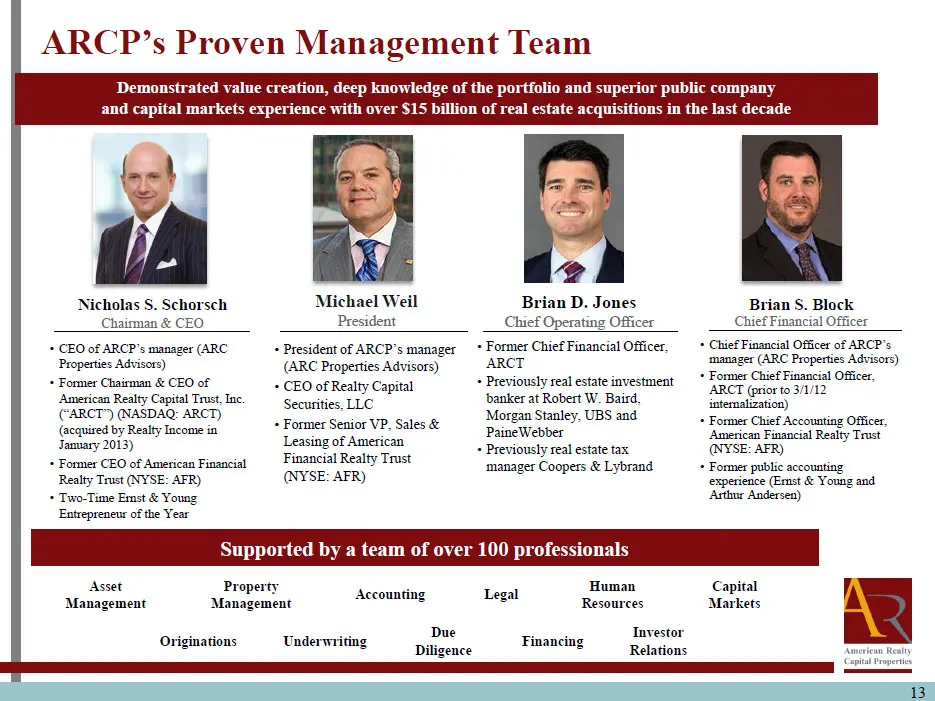
ARCP’s Proven Management Team Demonstrated value creation, deep knowledge of the portfolio and superior public company and capital markets experience with over $15 billion of real estate acquisitions in the last decade Nicholas S. Schorsch Chairman & CEO •CEO of ARCP’s manager (ARC Properties Adviso
Slide 14: ARCP's Management Structure Brings Significant Benefits to Shareholders
ARCP’s Management Structure Brings Significant Benefits to Shareholders Scale and expertise generate better execution at lower costs, resulting in higher shareholder values •Largest, most experienced U.S. buyer of net lease real estate •Strong, consistent track record in net lease space •Performance
Slide 15: ARCP Acquisition Capabilities Span the Deal Landscape
ARCP Acquisition Capabilities Span the Deal Landscape Single Asset Acquisitions •ARCP’s 100+ investment professionals source, underwrite, negotiate and close granular, single asset acquisitions with great precision •$367 million of acquisitions year-to-date, comprised of 81 properties •Proprietary c
Slide 16: Among the Lowest G&A Expenses in the REIT Industry
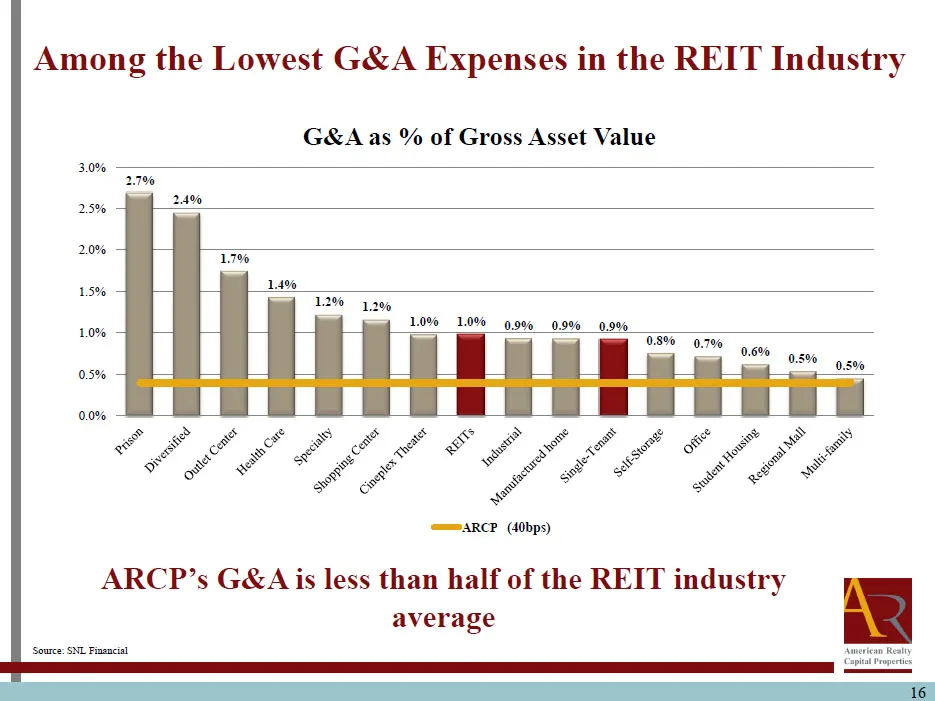
Among the Lowest G&A Expenses in the REIT Industry Source: SNL Financial 2.7% 2.4% 1.7% 1.4% 1.2% 1.2% 1.0% 1.0% 0.9% 0.9% 0.9% 0.8% 0.7% 0.6% 0.5% 0.5% 0.0% 0.5% 1.0% 1.5% 2.0% 2.5% 3.0% G&A as % of Gross Asset Value ARCP (3bp) (40bps) ARCP’s G&A is less than half of the REIT industry average 16
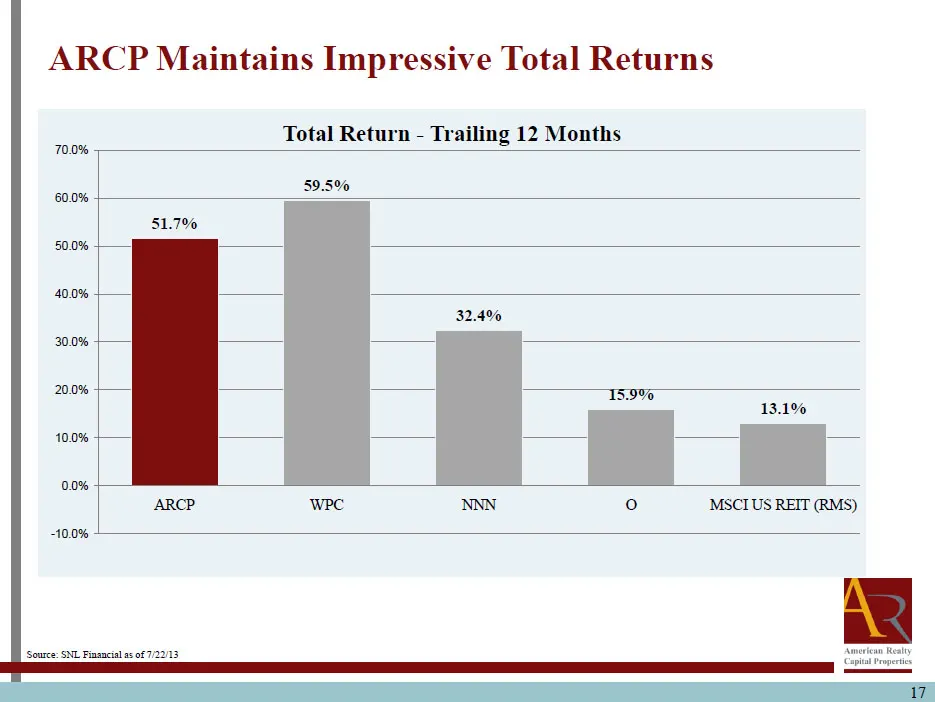
Slide 17: ARCP Maintains Impressive Total Returns
ARCP Maintains Impressive Total Returns Source: SNL Financial as of 7/22/13 51.7% 59.5% 32.4% 15.9% 13.1% -10.0% 0.0% 10.0% 20.0% 30.0% 40.0% 50.0% 60.0% 70.0% ARCP WPC NNN O MSCI US REIT (RMS) Total Return - Trailing 12 Months 17
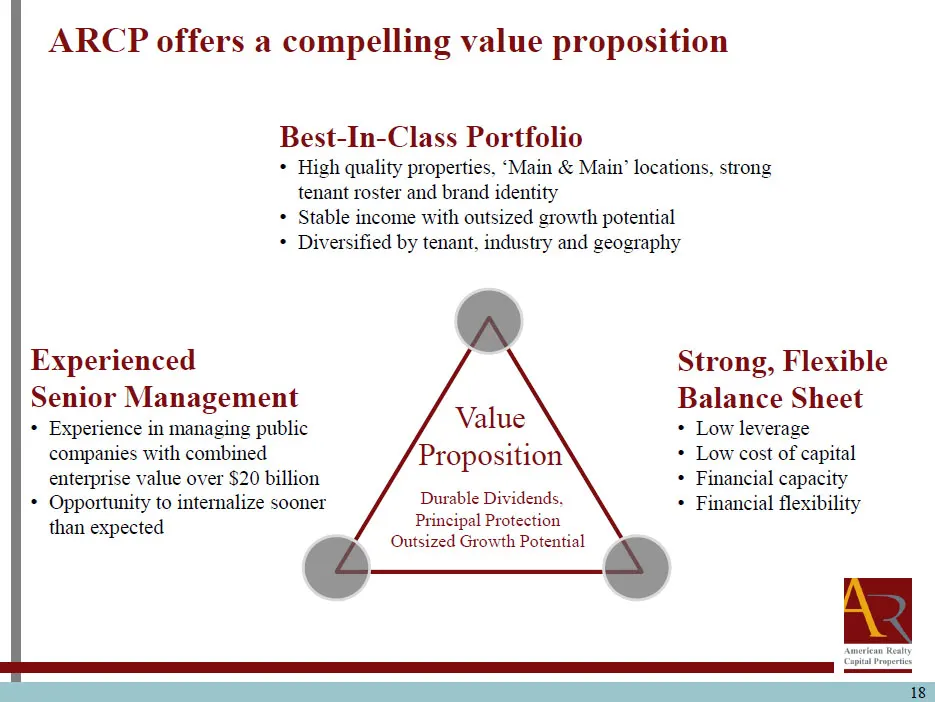
Slide 18: ARCP offers a compelling value proposition
ARCP offers a compelling value proposition Best-In-Class Portfolio •High quality properties, ‘Main & Main’ locations, strong tenant roster and brand identity •Stable income with outsized growth potential •Diversified by tenant, industry and geography Experienced Senior Management •Experience in mana
Slide 19: Agenda
Agenda Transaction Summary 5 ARCP Overview 7 ARCT IV Acquisition Overview 20 Page Appendix 26 19
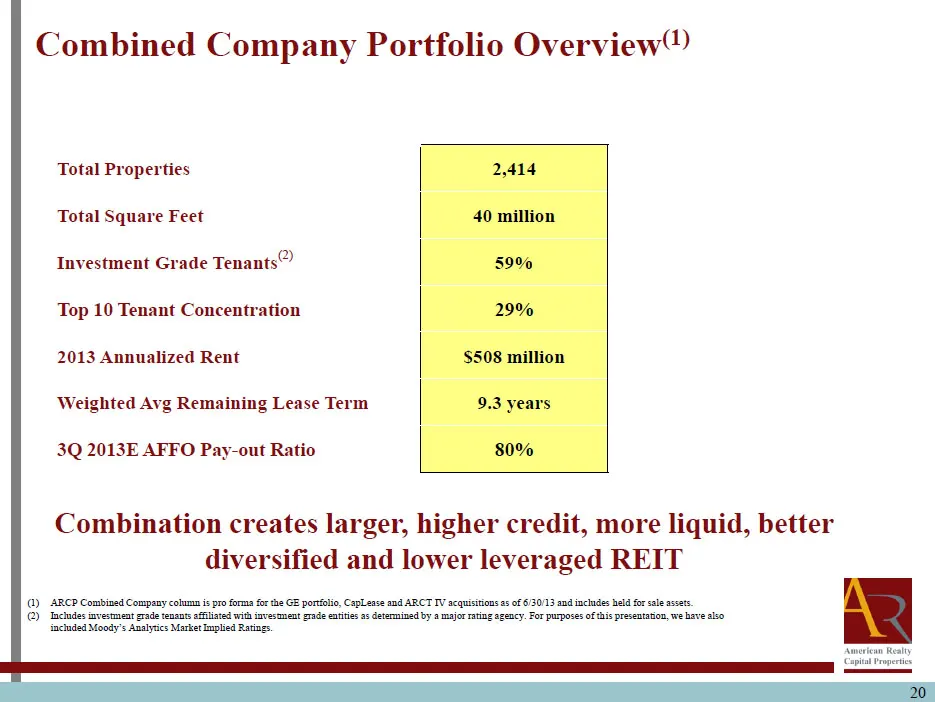
Slide 20: Combined Company Portfolio Overview
Combined Company Portfolio Overview(1) Combination creates larger, higher credit, more liquid, better diversified and lower leveraged REIT Total Properties 2,414 Total Square Feet 40 million Investment Grade Tenants(2) 59% Top 10 Tenant Concentration 29% 2013 Annualized Rent $508 million Weighted Av
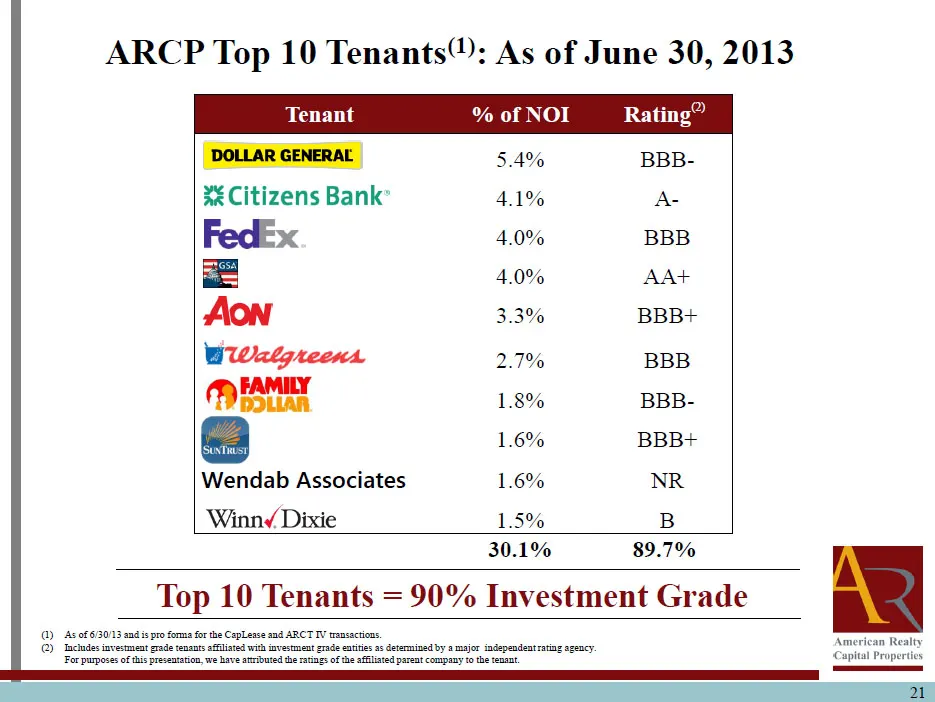
Slide 21: ARCP Top Tenants
ARCP Top 10 Tenants(1): As of June 30, 2013 Tenant % of NOI Rating(2) 5.4% BBB- 4.1% A- 4.0% BBB 4.0% AA+ 3.3% BBB+ 2.7% BBB 1.8% BBB- 1.6% BBB+ Wendab Associates 1.6% NR 1.5% B 30.1% 89.7% Top 10 Tenants = 90% Investment Grade (1)As of 6/30/13 and is pro forma for the CapLease and ARCT IV transacti
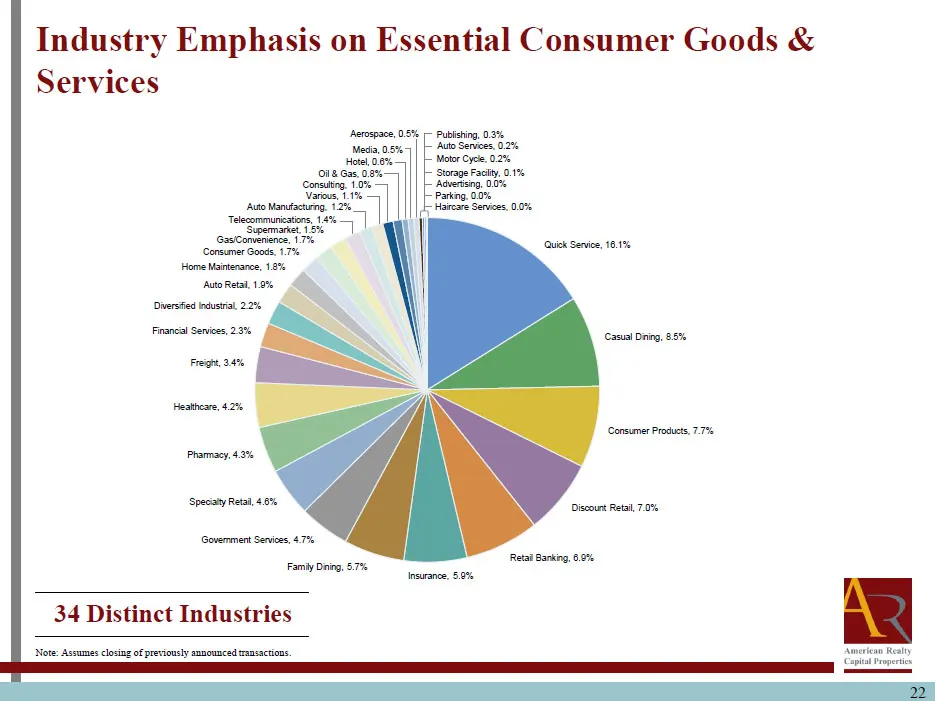
Slide 22: Industry Emphasis on Essential Consumer Goods & Services
Industry Emphasis on Essential Consumer Goods & Services 34 Distinct Industries Note: Assumes closing of previously announced transactions. Quick Service, 16.1%Casual Dining, 8.5%Consumer Products, 7.7%Discount Retail, 7.0%Retail Banking, 6.9%Insurance, 5.9%Family Dining, 5.7%Government Services, 4.
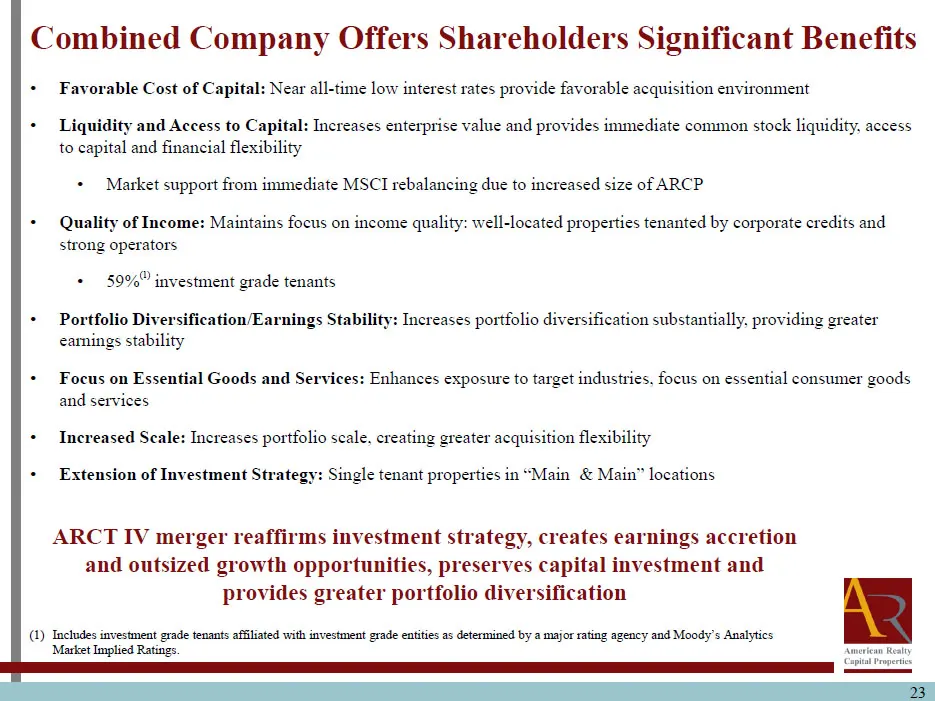
Slide 23: Combined Company Offers Shareholders Significant Benefits
Combined Company Offers Shareholders Significant Benefits •Favorable Cost of Capital: Near all-time low interest rates provide favorable acquisition environment •Liquidity and Access to Capital: Increases enterprise value and provides immediate common stock liquidity, access to capital and financial
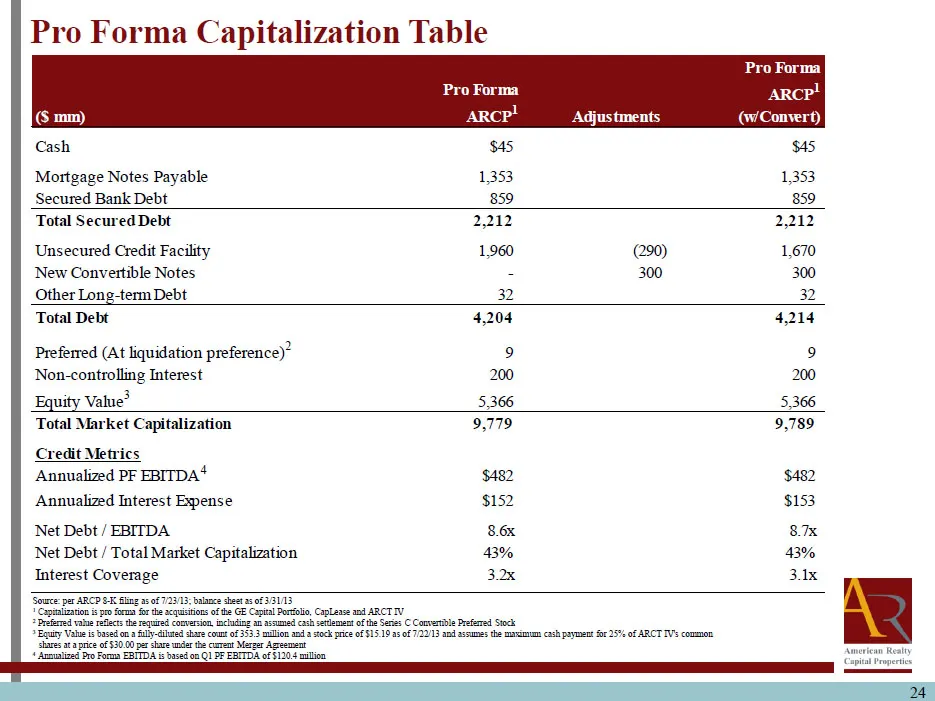
Slide 24: Pro Forma Capitalization Table
Pro Forma Capitalization Table Source: per ARCP 8-K filing as of 7/23/13; balance sheet as of 3/31/13 1 Capitalization is pro forma for the acquisitions of the GE Capital Portfolio, CapLease and ARCT IV 2 Preferred value reflects the required conversion, including an assumed cash settlement of the S
Slide 25: Agenda
Agenda Transaction Summary 5 ARCP Overview 7 ARCT IV Acquisition Overview 20 Page Appendix 26 25
Slide 26: Non-GAAP – FFO/AFFO Reconciliation
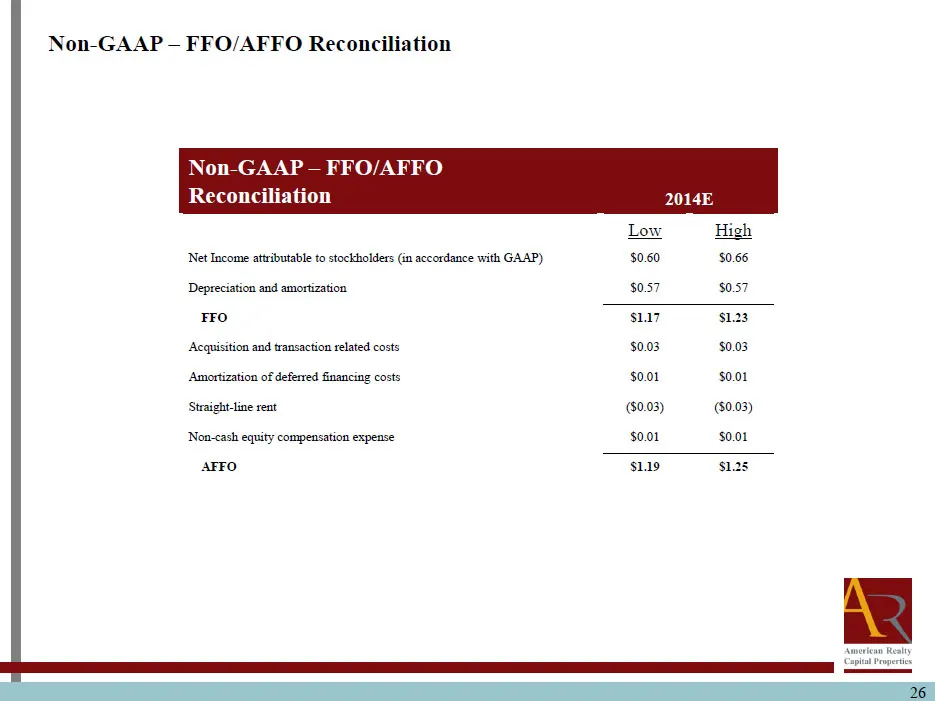
Non-GAAP – FFO/AFFO Reconciliation Non-GAAP – FFO/AFFO Reconciliation 2014E Low High Net Income attributable to stockholders (in accordance with GAAP) $0.60 $0.66 Depreciation and amortization $0.57 $0.57 FFO $1.17 $1.23 Acquisition and transaction related costs $0.03 $0.03 Amortization of deferred
Slide 27: Funds from Operations and Adjusted Funds from Operations
Funds from Operations and Adjusted Funds from Operations ARCP considers funds from operations (“FFO”) and AFFO, which is FFO as adjusted to exclude acquisition-related fees and expenses, amortization of above-market lease assets and liabilities, amortization of deferred financing costs, straight-lin
Source: SEC EDGAR · FWP filed Jul 23, 2013
More decks from VEREIT Inc
 Q3 2021 Earnings Presentation35 slides · Oct 29, 2021
 Q2 2021 Earnings Presentation35 slides · Aug 5, 2021
 Q1 2021 Earnings Presentation35 slides · May 6, 2021
 Merger or Acquisition (April 2021)16 slides · Apr 29, 2021
 Q4 2020 Earnings Presentation44 slides · Feb 24, 2021
 Q1 2021 Earnings Presentation39 slides · 2021