E*TRADE Financial — 2010 Citi Financial Services Conference
40 slides from E*TRADE Financial's conference presentation, Mar 10, 2010
Slide 1: 2010 Citi Financial Services Conference
2010 Citi Financial Services Conference Bruce Nolop Chief Financial Officer March 10, 2010 © 2010 E*TRADE FINANCIAL Corp. All rights reserved. This presentation contains confidential information and may not be disclosed without E*TRADE FINANCIAL Corporation’s written permission. EXHIBIT 99.1
Slide 2: Safe Harbor Statement
Safe Harbor Statement This presentation contains certain projections or other forward- looking statements regarding future events or the future performance of the Company. Various factors, including risks and uncertainties referred to in the 10Ks, 10Qs and other reports E*TRADE FINANCIAL Corporation
Slide 3: Overview
Overview Thriving Online Brokerage Business Improving Loan Performance Trends Strengthened Financial Condition
Slide 4: Thriving Online Brokerage Business
Thriving Online Brokerage Business
Slide 5: Achieved record levels in 2009 for DARTs, brokerage accounts
Thriving Online Brokerage Business Achieved record levels in 2009 for DARTs, brokerage accounts, and consistent growth in brokerage cash Gained market share versus traditional brokers and remained competitive versus online brokers Introduced new products and enhancements for both active traders and
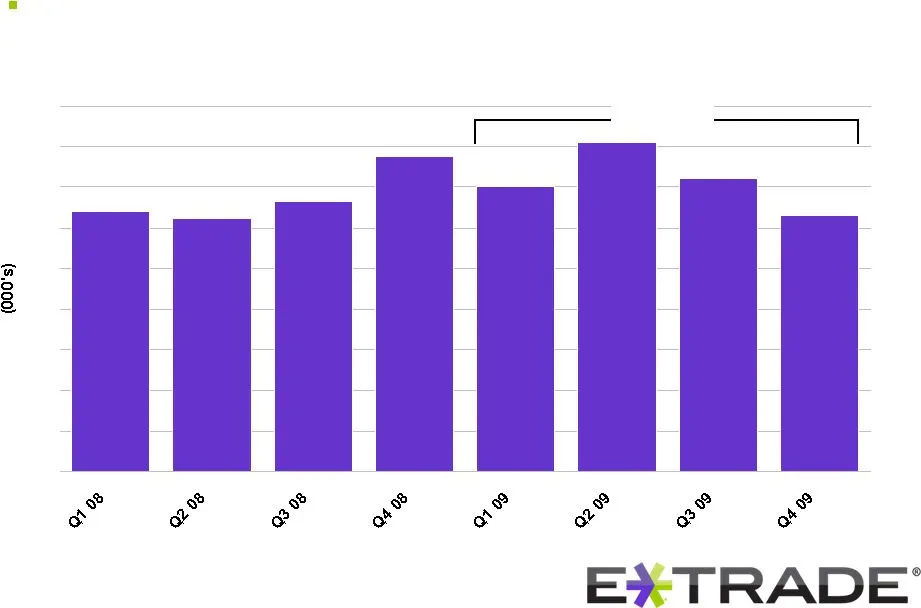
Slide 6: Strength in DARTs
161 156 166 194 175 203 180 158 Thriving Online Brokerage Business Strength in DARTs (1)
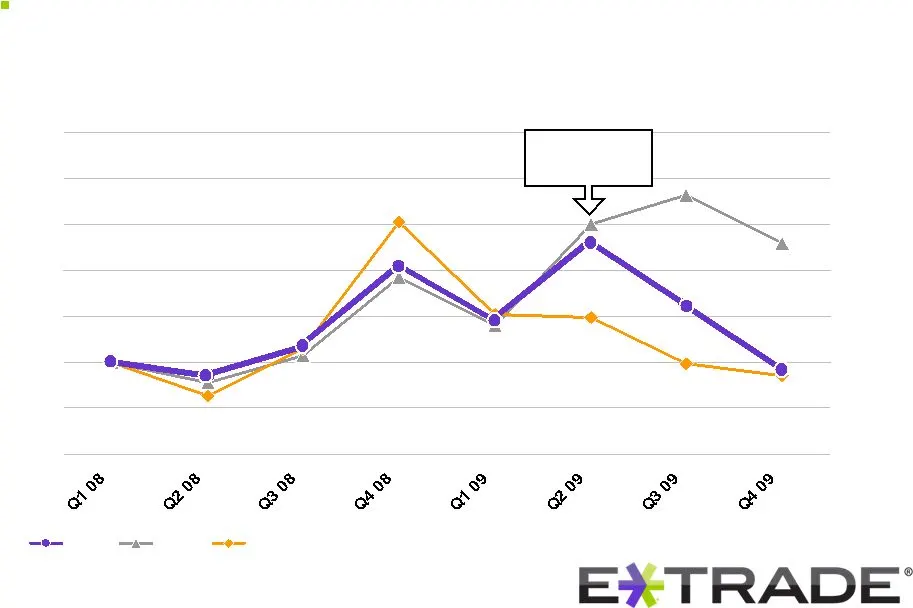
Slide 7: Competitive versus largest online brokers
ETFC AMTD SCHW Thriving Online Brokerage Business Competitive versus largest online brokers DARTs indexed to Q1 2008 Ameritrade acquires thinkorswim
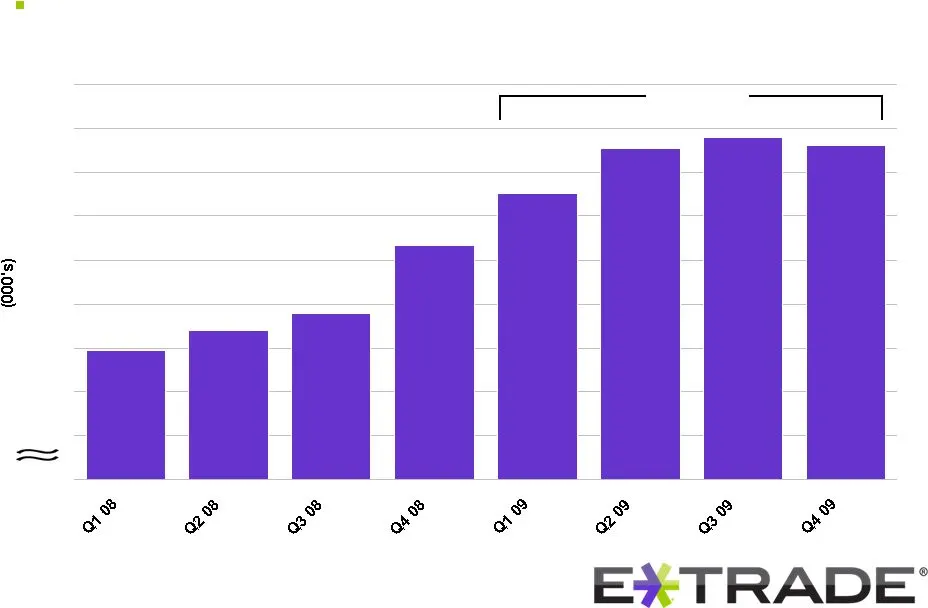
Slide 8: Growth in brokerage accounts
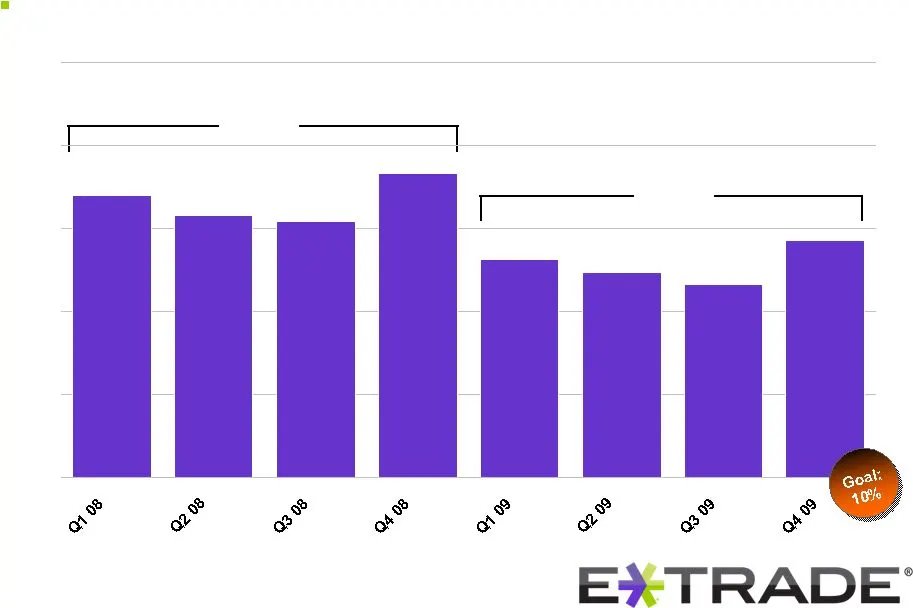
2,397 2,420 2,440 2,516 2,575 2,627 2,639 2,630 Thriving Online Brokerage Business Growth in brokerage accounts (2) 114K net new 2,300 2,350 2,400 2,450 2,500 2,550 2,600 2,650 2,700
Slide 9
Slide 10: Net new brokerage assets
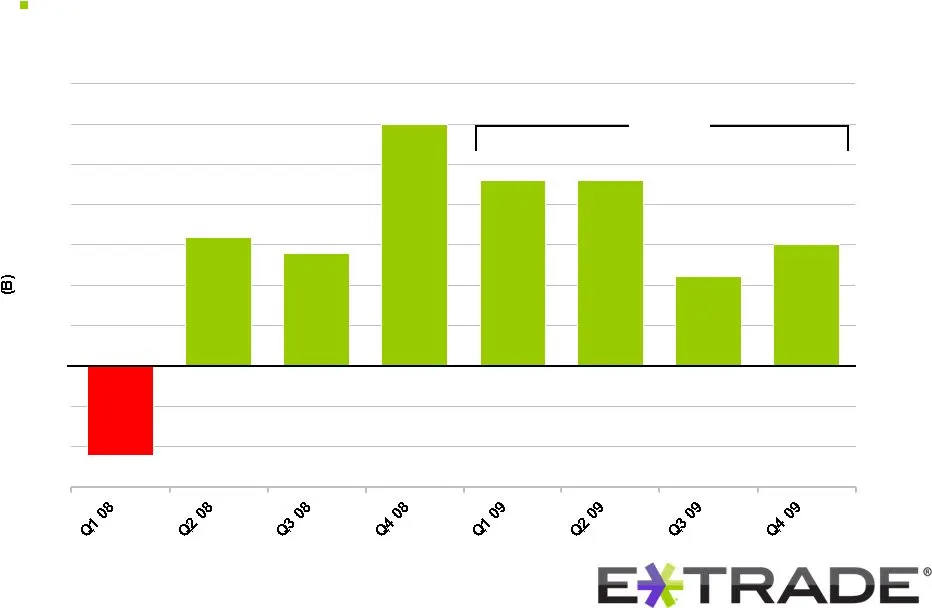
-$1.5 -$1.0 -$0.5 $0.0 $0.5 $1.0 $1.5 $2.0 $2.5 $3.0 $3.5 Thriving Online Brokerage Business Net new brokerage assets (4) $7.2B
Slide 11: Growth in brokerage-related cash
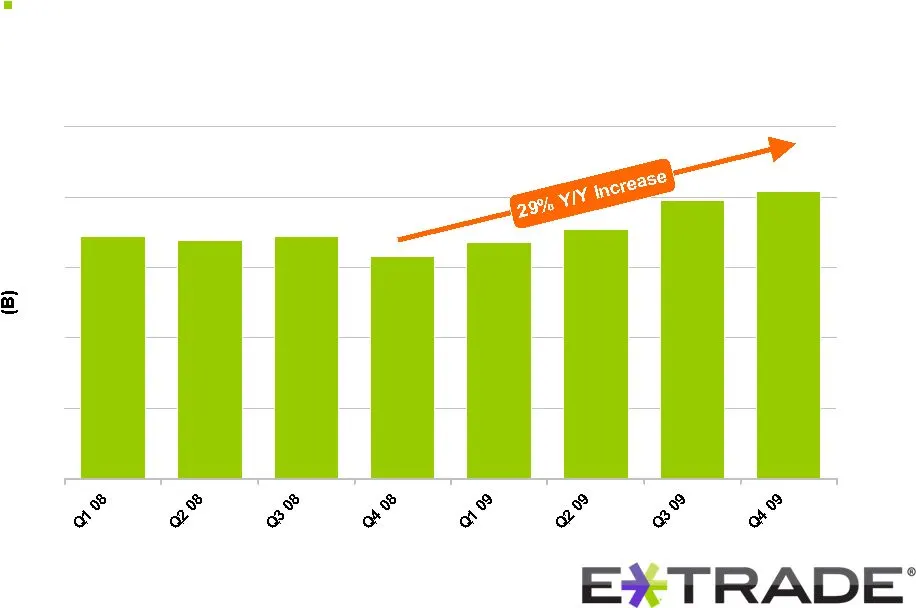
$0 $5 $10 $15 $20 $25 Thriving Online Brokera g e Business Growth in brokerage-related cash
Slide 12: Planned decline in bank-related cash
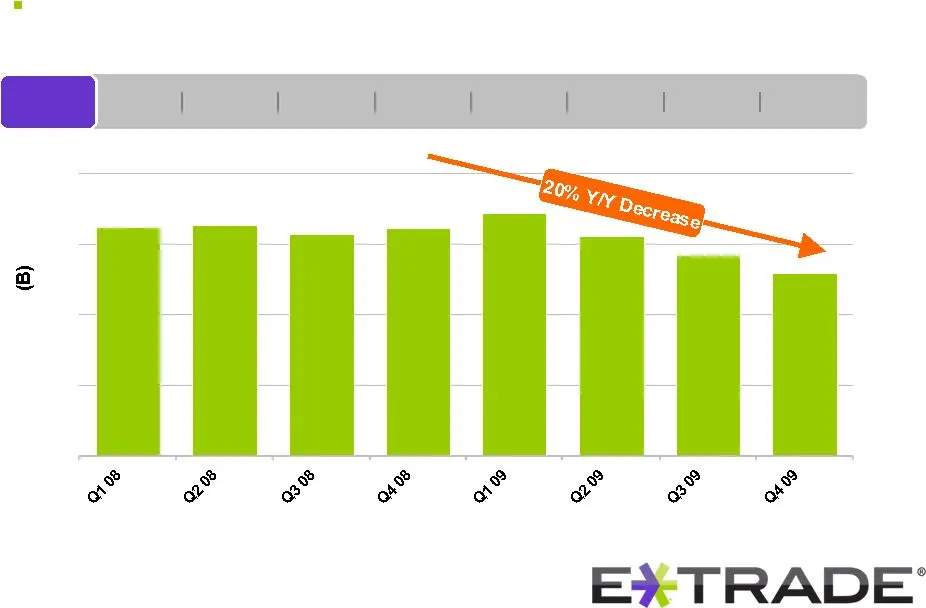
CSA* Thrivin g Online Brokera g e Business Planned decline in bank-related cash * APY for E*TRADE Complete Savings Account 3.45% 3.15% 3.30% 3.01% 1.45% 0.95% 0.60% 0.50% Balances are not adjusted for the sale of approximately $1B of deposits to Discover Financial Services, completed in Q1 2010 $0 $
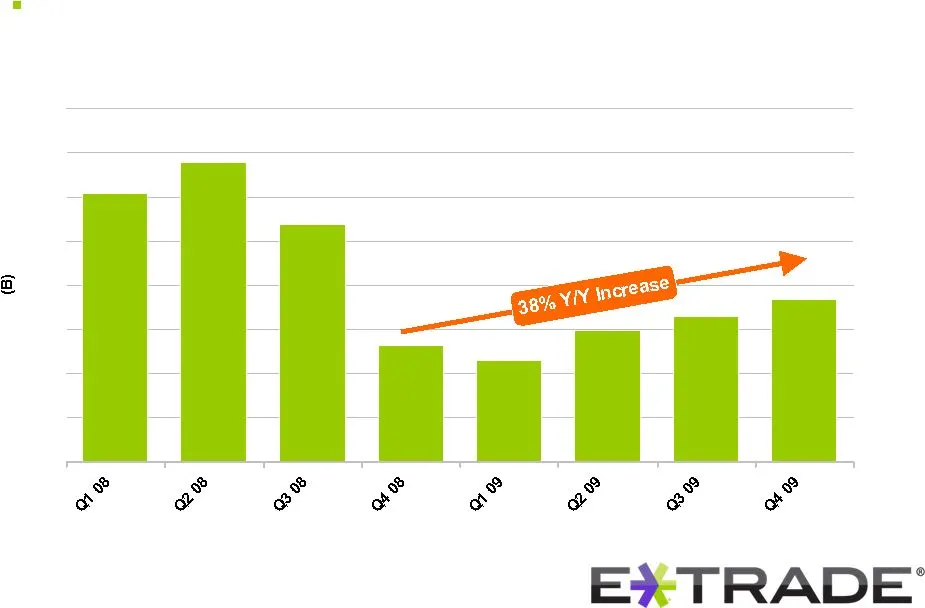
Slide 13: Recovery of customer margin receivables
$0.0 $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 $7.0 $8.0 Thrivin g Online Brokera g e Business Recovery of customer margin receivables
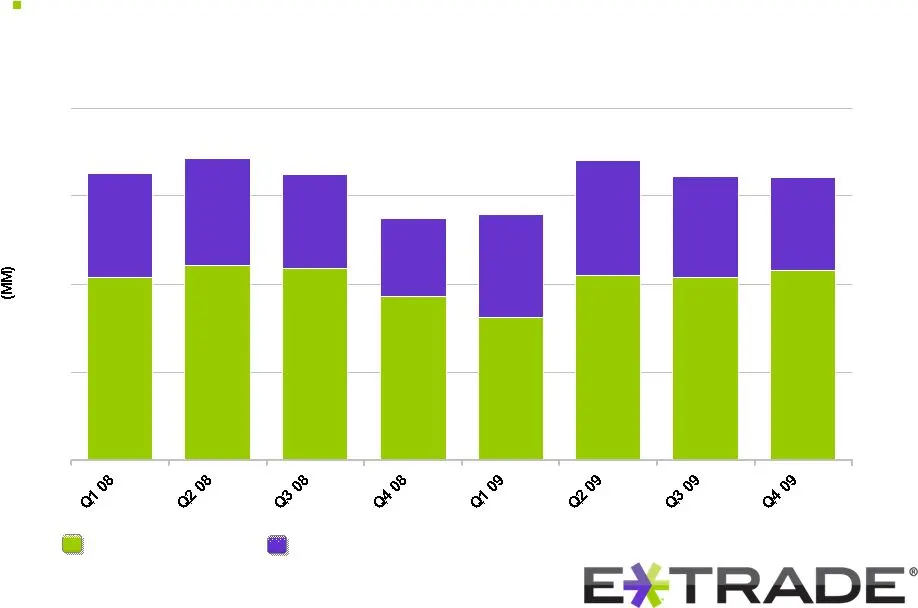
Slide 14: Consistent net operating interest income
$0 $100 $200 $300 $400 Thriving Online Brokera g e Business Consistent net operating interest income Trading and Investing Balance Sheet Management
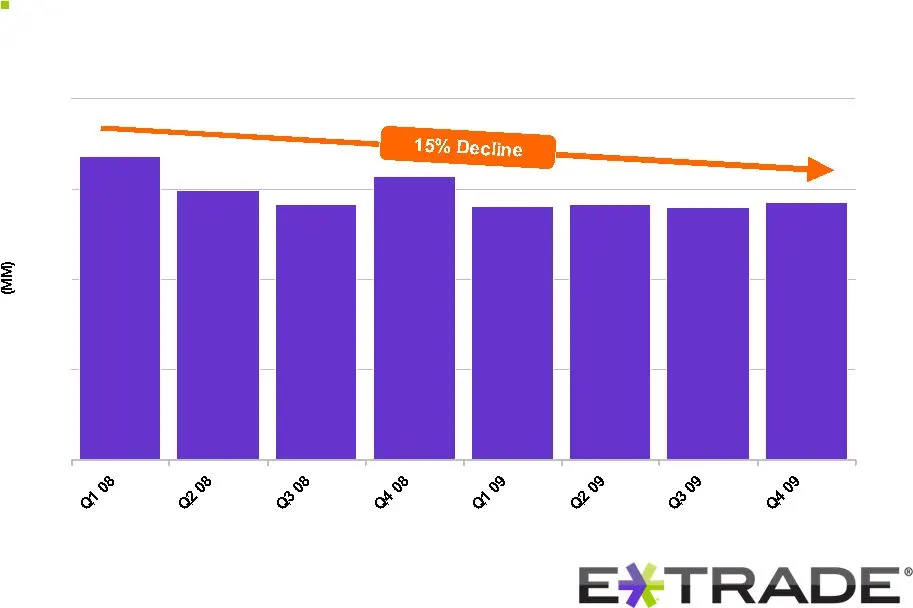
Slide 15: Disciplined expense management
$285 $279 $283 $281 $313 $283 $299 $335 $0 $100 $200 $300 $400 Thriving Online Brokerage Business Disciplined expense management Adjusted Total Operating Expense (5)
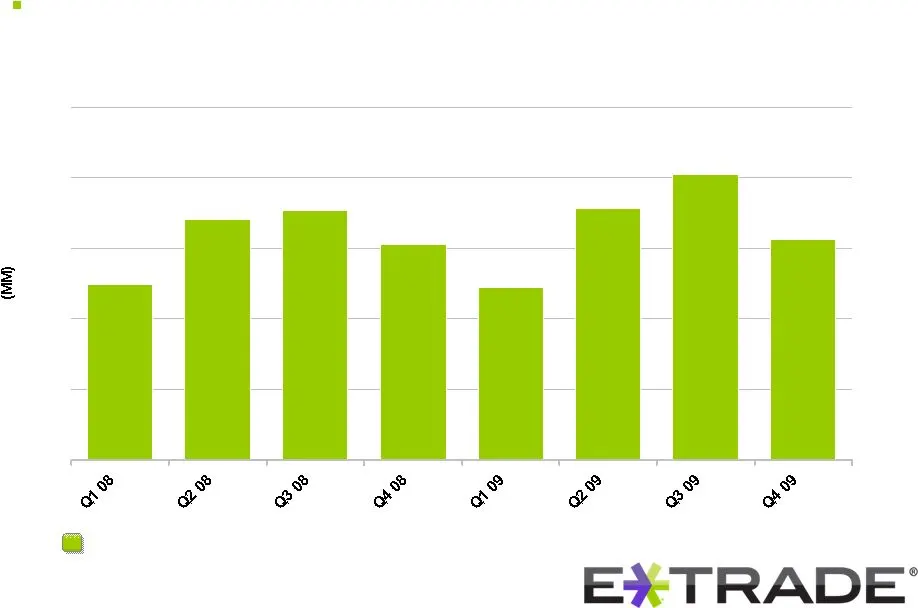
Slide 16: Profitable trading and investing segment
$0 $50 $100 $150 $200 $250 Thriving Online Brokerage Business Profitable trading and investing segment Segment income
Slide 17: Simplified and transparent pricing
Thriving Online Brokerage Business Simplified and transparent pricing Eliminated $12.99 commission tier Eliminated per share charges (6) Eliminated account inactivity fees (7) Estimated revenue impact: $50 million 150+ trades per quarter 0-149 trades per quarter Stock trades (8) $7.99 $9.99 Options
Slide 18: New products and enhancements for active traders
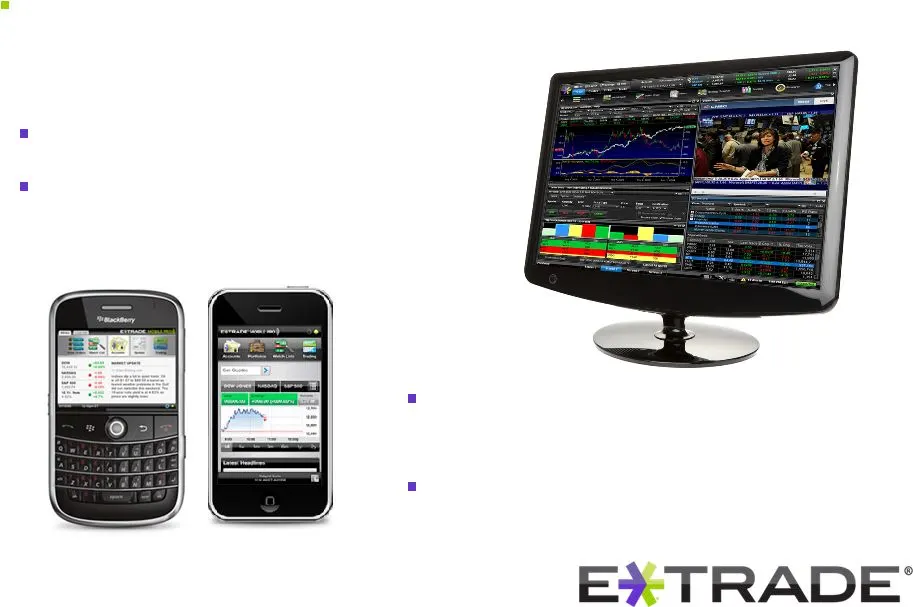
Thriving Online Brokerage Business New products and enhancements for active traders Updated Power E*TRADE Pro Upgrades for mobile devices Back-testing and advanced screeners Portfolio margining
Slide 19: New products and enhancements for long-term investors
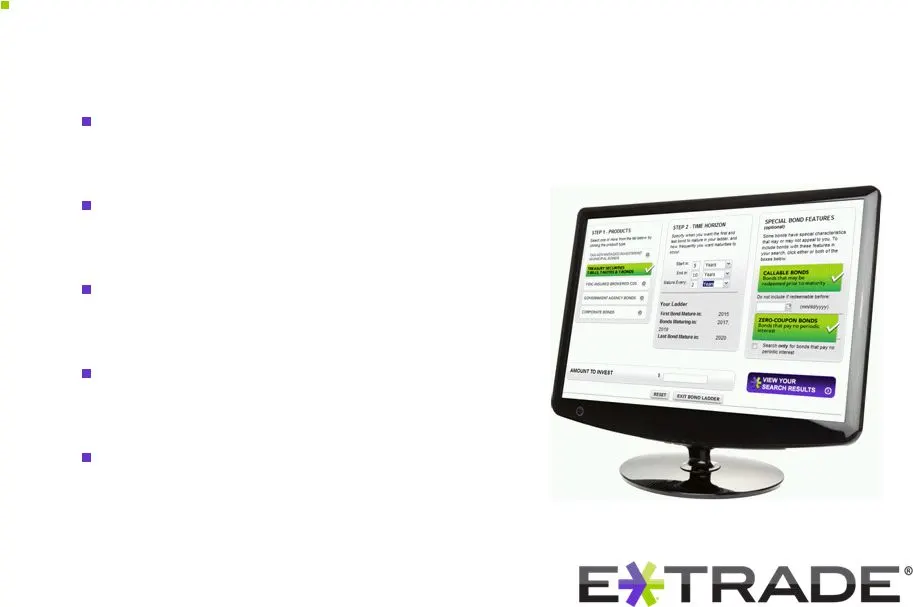
Thriving Online Brokerage Business New products and enhancements for long-term investors Managed Investment Portfolio Retirement QuickPlan Investor Resource Center Bond Investor Tools Online Advisor
Slide 20: Brand expansion
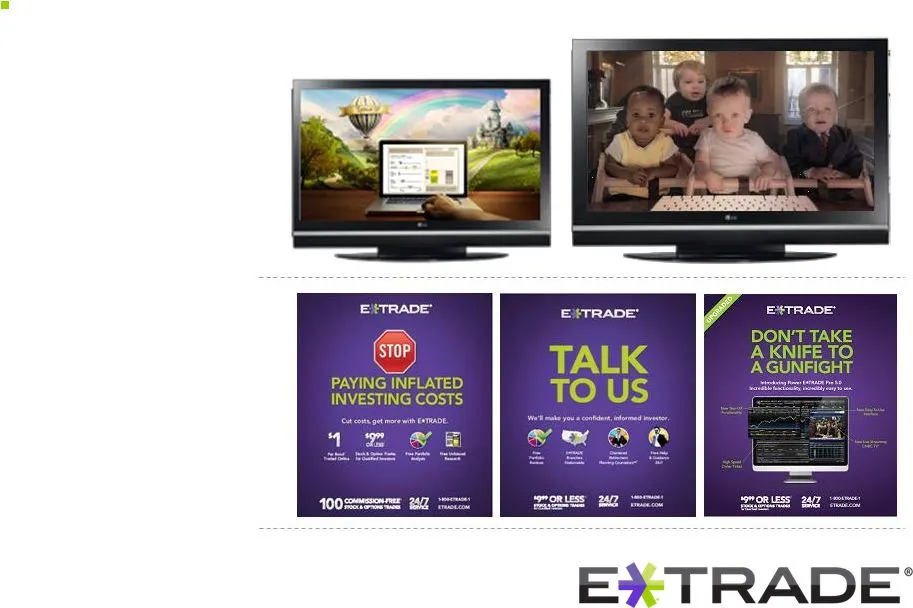
Brand expansion Value propositions Thriving Online Brokerage Business Highly effective marketing program
Slide 21: Focusing on profitable growth
Thriving Online Brokerage Business Grow active trader franchise Deepen penetration of long-term investor segment Increase the quality of customer accounts Reduce brokerage account attrition Restructure international operations to improve profitability Focusing on profitable growth
Slide 22: Improving Loan Performance Trends
Improving Loan Performance Trends
Slide 23: Loan portfolio in full run-off mode
Loan portfolio in full run-off mode Proactively managing to reduce charge-offs Meaningful improvement in delinquencies Provision has crossed below the level of charge-offs Expect loan loss provision and internally-generated Bank capital to breakeven in 2010 Improving Loan Performance Trends
Slide 24: Improving Loan Performance Trends
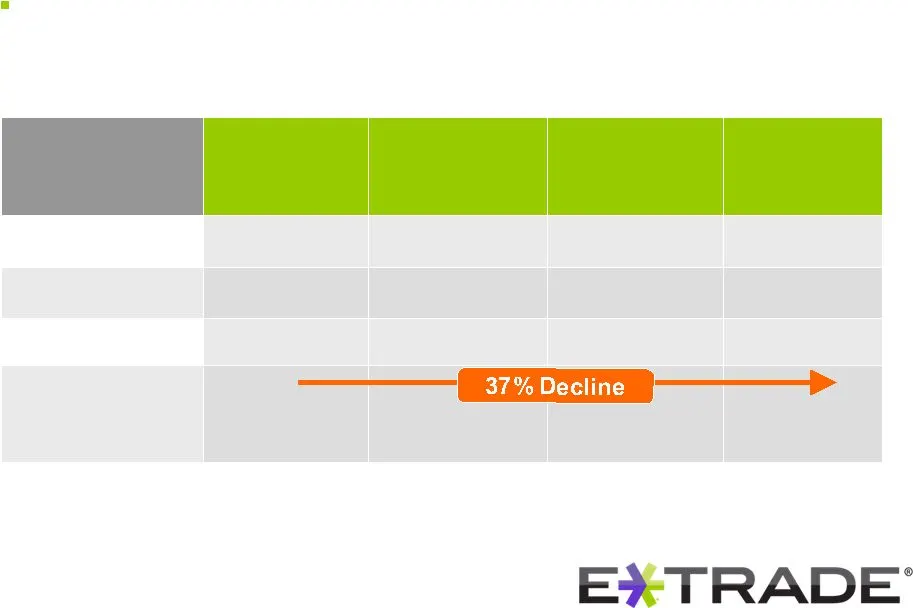
Improving Loan Performance Trends ($ in billions) Loan Balance 9/30/07 (9) Paydowns (10) Charge-offs Loan Balance 12/31/09 (9) 1-4 Family loans $16.9 ($5.8) ($0.5) $10.6 Home equity $12.4 ($2.7) ($1.9) $7.8 Consumer $3.0 ($1.0) ($0.2) $1.8 TOTAL $32.3 ($9.5) ($2.6) $20.2 Loan portfolio in full run-o
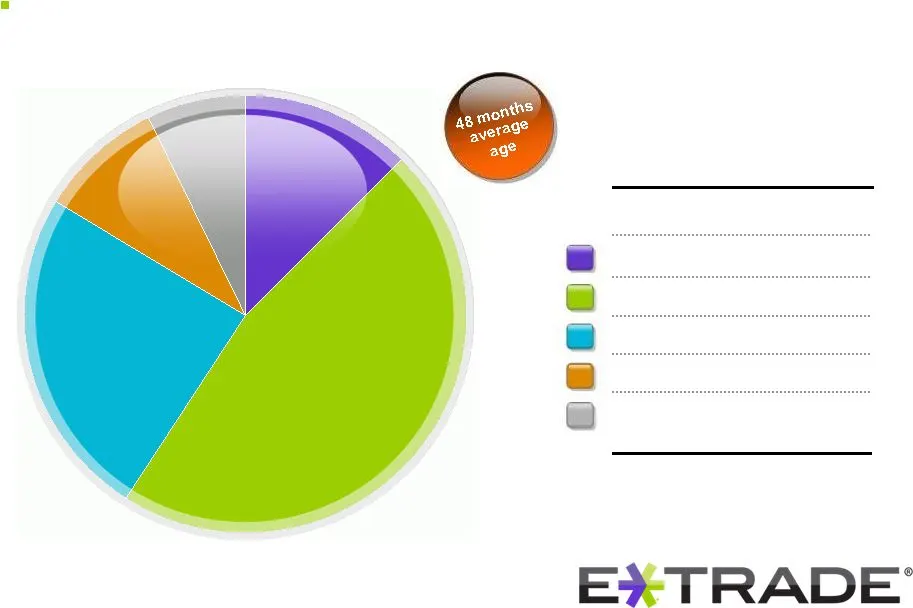
Slide 25: Seasoning of the home equity portfolio
$0.0B 0% $1.0B 12% $3.6B 47% $1.9B 24% $0.7B 9% and older $0.6B 7% Total $7.8B 100% Unpaid Balances by Origination Vintage and older Improving Loan Performance Trends Seasoning of the home equity portfolio
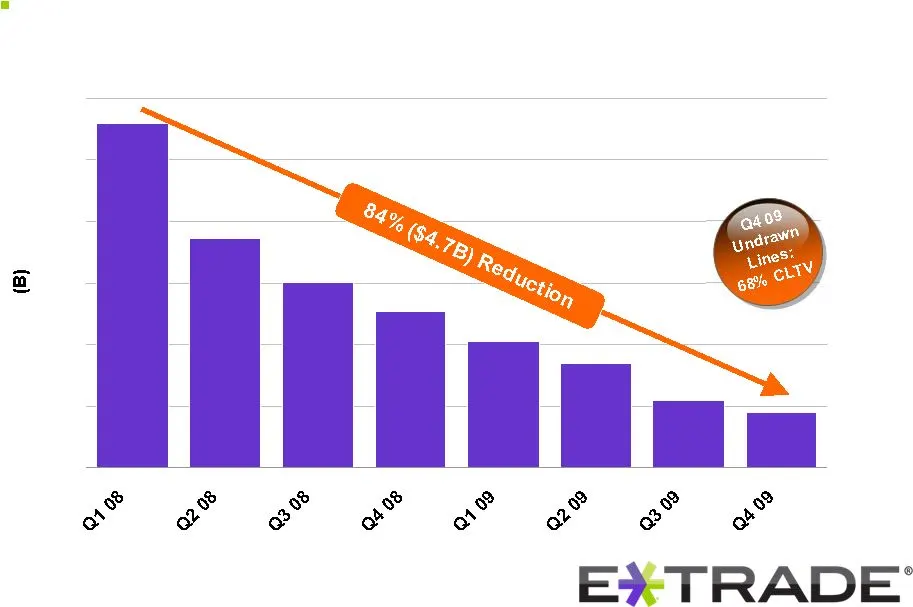
Slide 26: Proactively managing to reduce exposure
$0.9 $1.1 $1.7 $2.0 $2.5 $3.0 $3.7 $5.6 $0.0 $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 Undrawn Home Equity Lines Improving Loan Performance Trends Proactively managing to reduce exposure
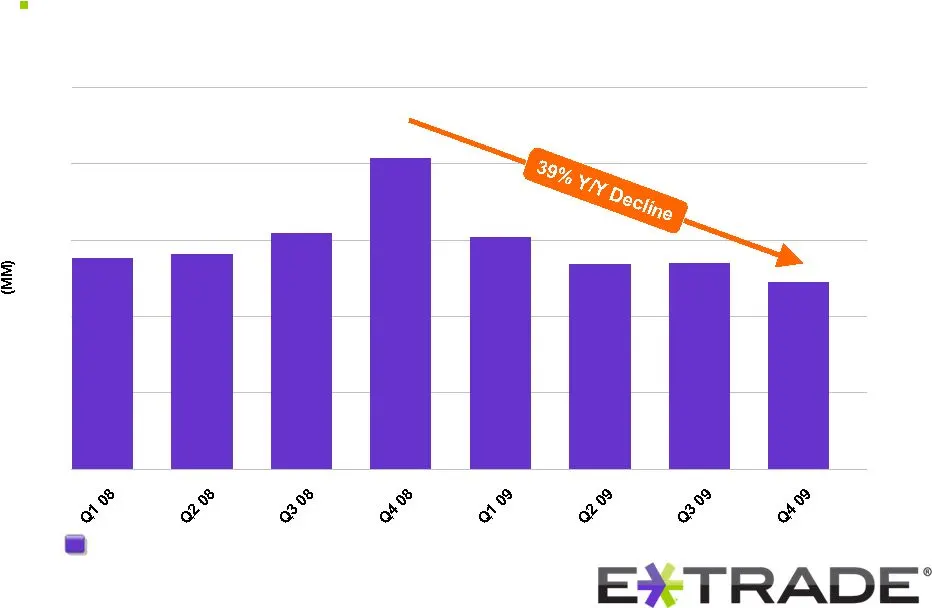
Slide 27: Significantly lower home equity delinquencies in 2009
$0 $100 $200 $300 $400 $500 Improving Loan Performance Trends Significantly lower home equity delinquencies in 2009 30-89 Days Delinquent
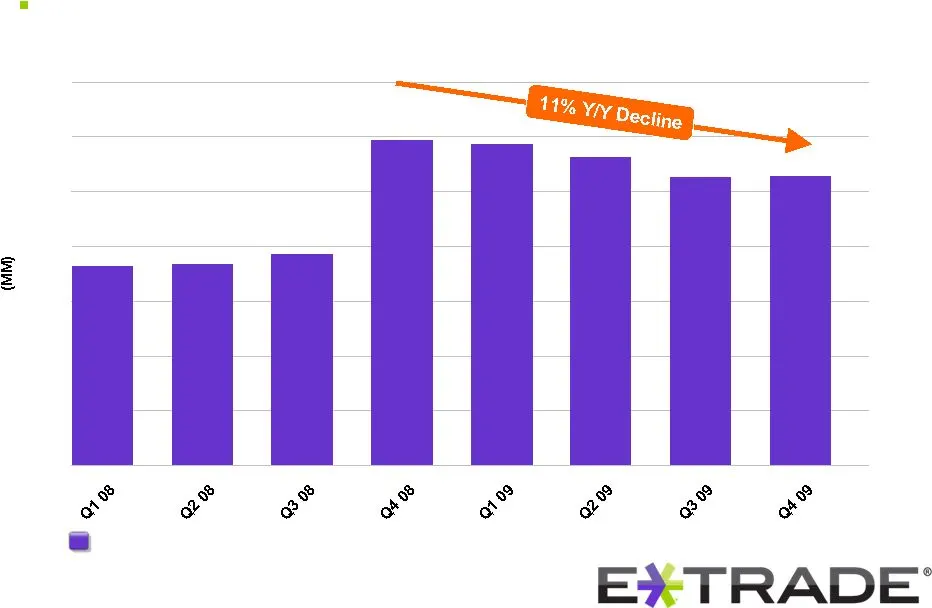
Slide 28: Gradually declining 1-4 Family delinquencies in 2009
$0 $100 $200 $300 $400 $500 $600 $700 Improving Loan Performance Trends Gradually declining 1-4 Family delinquencies in 2009 30-89 Days Delinquent
Slide 29: Declining provisions below charge-offs
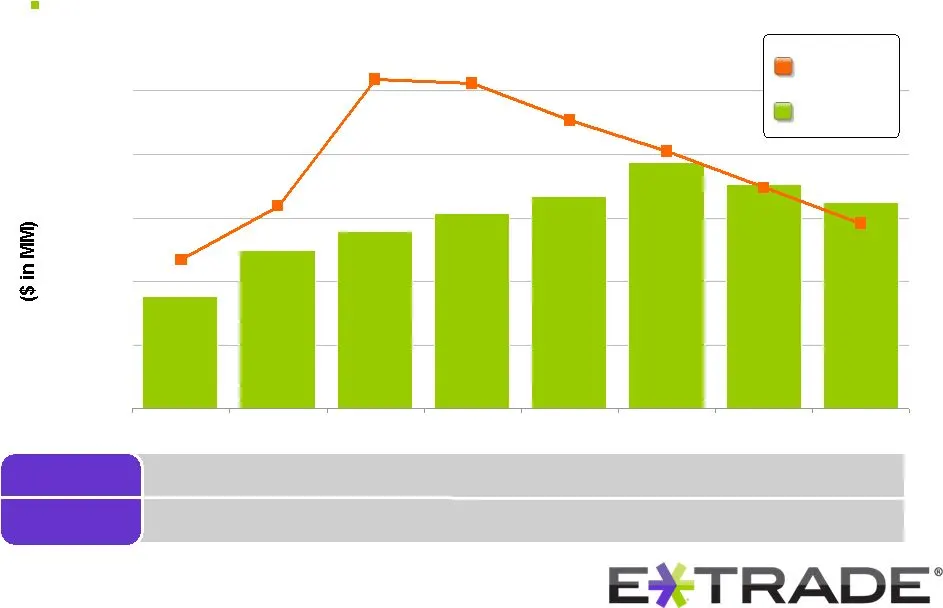
Allowance % of total gross loans 1.95% Improving Loan Performance Trends 5.27% 4.91% 4.23% 3.31% 2.30% 5.66% 5.81% $566 $1,219 $1,201 $1,081 $874 $636 $1,215 $1,183 Provision for loan losses Charge-offs Declining provisions below charge-offs $0 $100 $200 $300 $400 $500 Q1 08 Q2 08 Q3 08 Q4 08 Q1 09
Slide 30: Generating regulatory capital to absorb loan loss provision
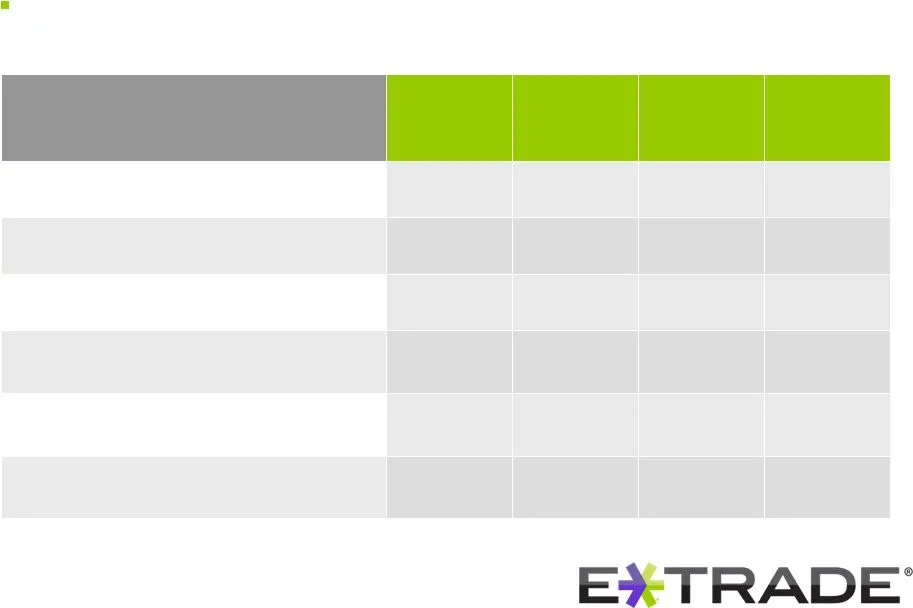
Improving Loan Performance Trends Generating regulatory capital to absorb loan loss provision ($ in millions) Q1 2009 Q2 2009 Q3 2009 Q4 2009 Bank earnings (11) $181 $232 $243 $247 Dividend to parent -- -- -- ($28) Loan run-off (12) $84 $101 $131 $81 Portfolio changes and other (12) ($82) $39 ($53)
Slide 31: Strengthened Financial Condition
Strengthened Financial Condition
Slide 32: Strengthened Financial Condition
Reduced parent debt burden Bolstered Bank capital ratios Improved consolidated capital structure Retained value of the deferred tax asset Eliminated uncertainty about long-term viability Strengthened Financial Condition
Slide 33: Benefits from 2009 recapitalization
Strengthened Financial Condition Benefits from 2009 recapitalization as of 12/31/09 ($ in millions) Ratio Excess to well-capitalized Total capital to risk-weighted assets 14.1% $899 Tier I Capital to risk-weighted assets 12.8% $1,496 Tier I Capital to total adjusted assets 6.7% $724 2009 Recapitaliz
Slide 34: Improved consolidated capital structure
(in millions) 7 3/8% Due 2013 7 7/8% Due 2015 12 1/2% Due 2017 (15) Total Outstanding (14) $415 $243 $930 $1,591 Annual interest payments $31 $19 $116 $166 Strengthened Financial Condition Improved consolidated capital structure Interest-bearing debt (in billions) Shares Book value Common stock 1.89
Slide 35: Substantial value in deferred tax asset
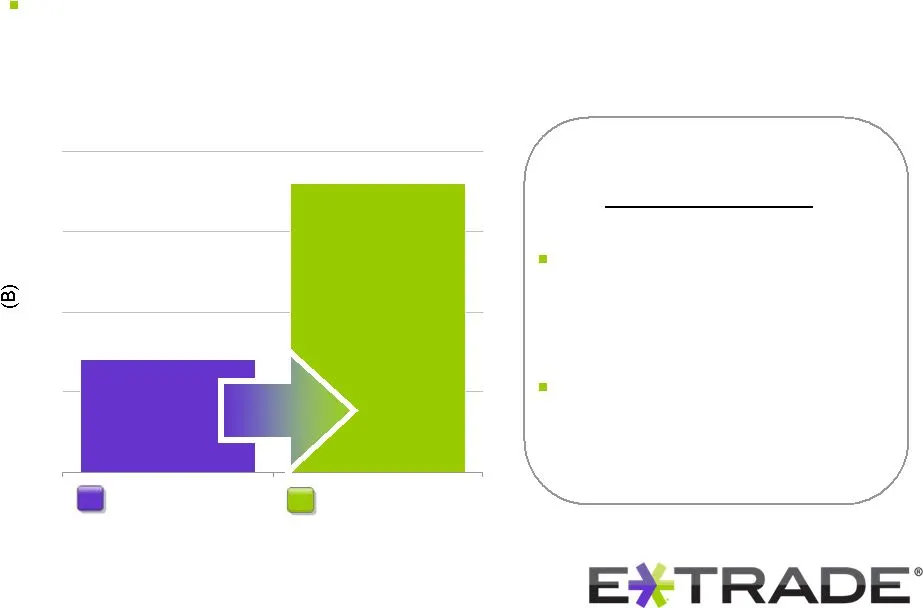
$1.4 $3.6 $0.0 $1.0 $2.0 $3.0 $4.0 DTA Pre-tax Income Strengthened Financial Condition Substantial value in deferred tax asset Shelters approximately $3.6 billion of income from tax in future periods Approximately 19 years to utilize Approximately $1.4B Deferred Tax Asset
Slide 36: Substantial value in deferred tax asset
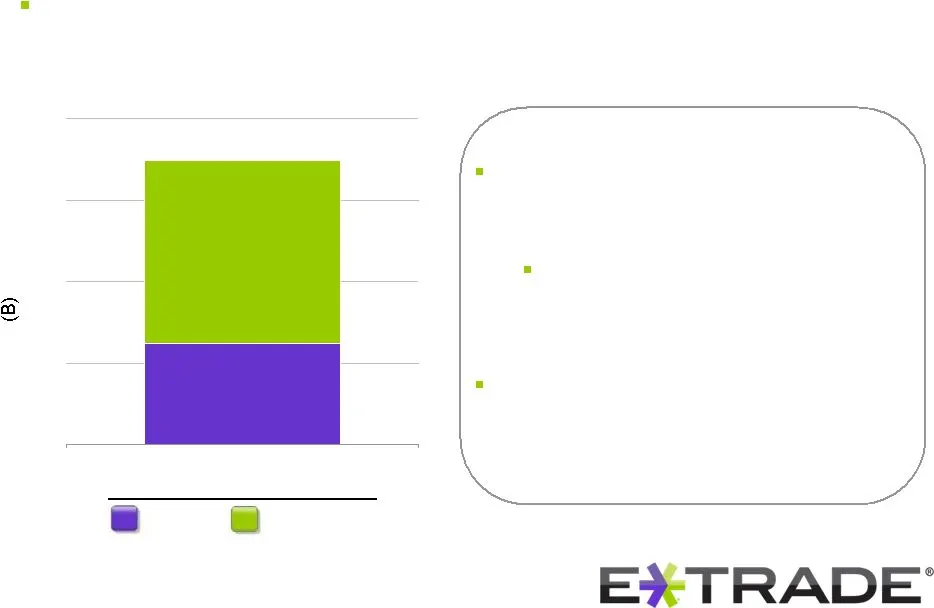
$0.9 $0.5 $0.0 $0.4 $0.8 $1.2 $1.6 Limited Not limited Strengthened Financial Condition Substantial value in deferred tax asset Total DTA: $1.4B Tax code 382 Limitation 382 Tax ownership change imposes an annual limitation on a portion of the Company’s DTA Limited to using $60 million per year, shel
Slide 37: Conclusion
Conclusion Thriving Online Brokerage Business Improving Loan Performance Trends Strengthened Financial Condition
Slide 38: E*TRADE
E-t¢TRADE’
Slide 39: Appendix
($ in thousands) Appendix Q1 08 Q2 08 Q3 08 Q4 08 Q1 09 Q2 09 Q3 09 Q4 09 Operating expense 354,333 $ 318,543 $ 295,890 $ 321,449 $ 293,984 $ 329,226 $ 301,714 $ 318,405 $ Less: FDIC insurance premiums 8,859 7,592 7,721 7,086 12,712 42,129 19,993 19,424 Less: Facility restructuring and other exit ac
Slide 40: Appendix
Appendix (a) The capital release from loan portfolio run-off includes the decrease in risk-based capital required for our one- to four-family, home equity and consumer loan portfolios. (b) Represents cash flows to and from the parent company. (c) Represents the capital impact related to changes in o
Source: SEC EDGAR · 8-K filed Mar 10, 2010
More decks from E*TRADE Financial LLC
 Merger or Acquisition (February 2020)23 slides · Feb 20, 2020
 Corporate Update (April 2019)13 slides · Apr 16, 2019
 Raymond James 34th Annual Institutional Investors Conference (March 2013)29 slides · Mar 5, 2013
 KBW Securities Brokerage & Market Structure Conference (November 2012)24 slides · Nov 28, 2012
 Barclays Global Financial Services Conference 201222 slides · Sep 11, 2012
 Sandler O'Neill Global Exchange & Brokerage Conference (June 2012)21 slides · Jun 7, 2012