Versum Materials — Barclays Electronic Chemical Conference 2018
28 slides from Versum Materials's conference presentation, May 14, 2018
Slide 1: Enabling the Golden Age of Semiconductors
ENABLING THE GOLDEN AGE OF SEMICONDUCTORS GUILLERMO NOVO PRESIDENT AND CEO VERSUM MATERIALS, INC. Barclays Electronic Chemical Conference May 14, 2018 © Versum Materials 2018
Slide 2: Forward-Looking Information
FORWARD-LOOKING INFORMATION This presentation contains, and management may make, certain “forward-looking statements” within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933 and Section 21E of the Securi
Slide 3: Semiconductor Materials Today's Discussion
SEMICONDUCTOR MATERIALS TODAYS DISCUSSION • Semiconductor Materials vs. Electronic Materials • How Semiconductors are Changing the World • Semiconductor Industry from a Materials Supplier Perspective • Versum Materials © Versum Materials 2018 3
Slide 4: Why Semiconductor Materials Differ from Electronic Materials?
WHY SEMICONDUCTOR MATERIALS DIFFER FROM ELECTRONIC MATERIALS? © Versum Materials 2018 4
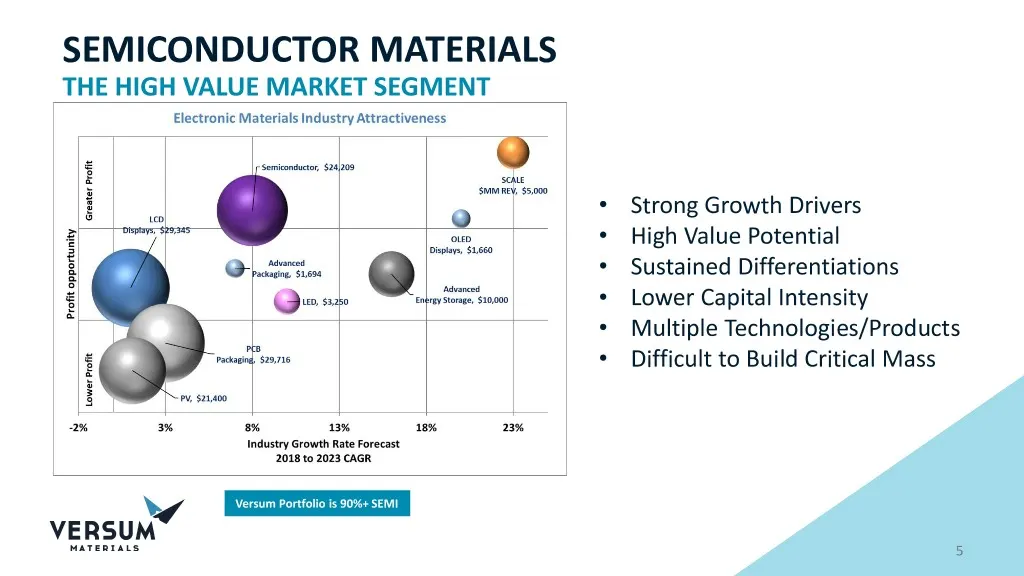
Slide 5: Semiconductor Materials: The High Value Market Segment
SEMICONDUCTOR MATERIALS THE HIGH VALUE MARKET SEGMENT • Strong Growth Drivers • High Value Potential • Sustained Differentiations • Lower Capital Intensity • Multiple Technologies/Products • Difficult to Build Critical Mass Versum Portfolio is 90%+ SEMI 5
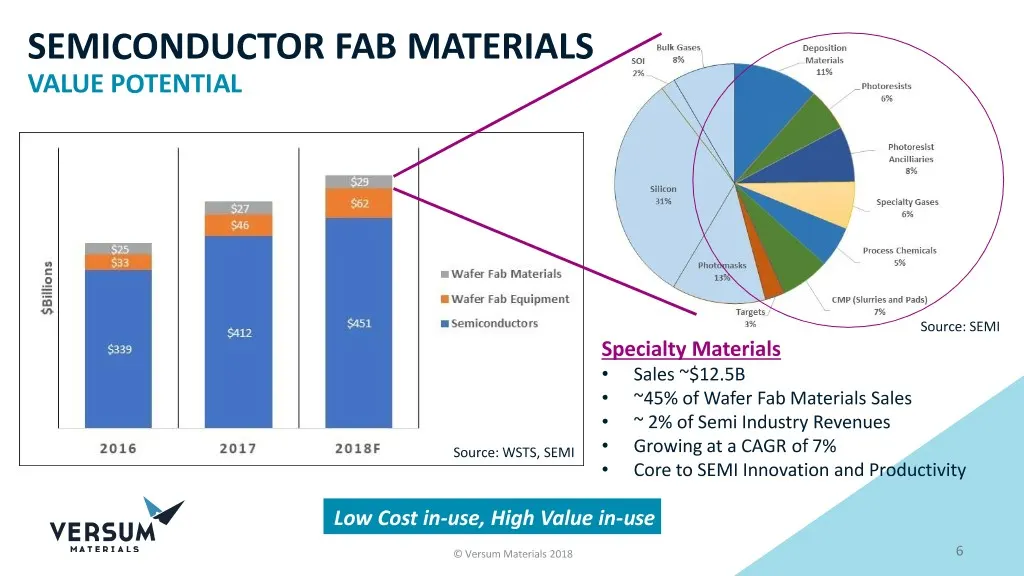
Slide 6: Semiconductor Fab Materials Value Potential
SEMICONDUCTOR FAB MATERIALS VALUE POTENTIAL Source: SEMI Specialty Materials • Sales ~$12.5B • ~45% of Wafer Fab Materials Sales • ~ 2% of Semi Industry Revenues Source: WSTS, SEMI • Growing at a CAGR of 7% • Core to SEMI Innovation and Productivity Low Cost in-use, High Value in-use © Versum Materi
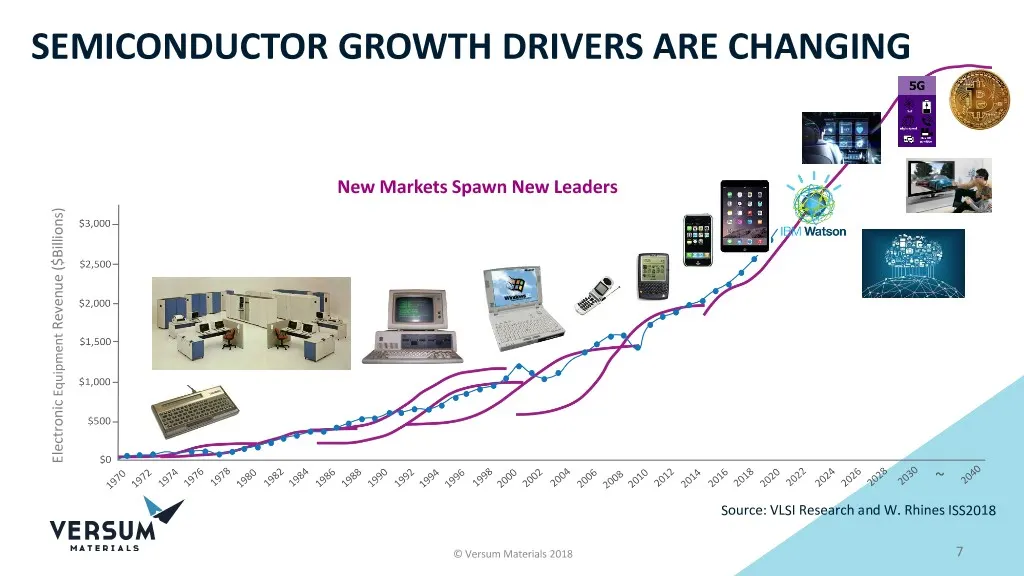
Slide 7: Semiconductor Growth Drivers Are Changing
SEMICONDUCTOR GROWTH DRIVERS ARE CHANGING New Markets Spawn New Leaders Revenue ($Billions) Revenue Equipment Electronic Source: VLSI Research and W. Rhines ISS2018 © Versum Materials 2018 7
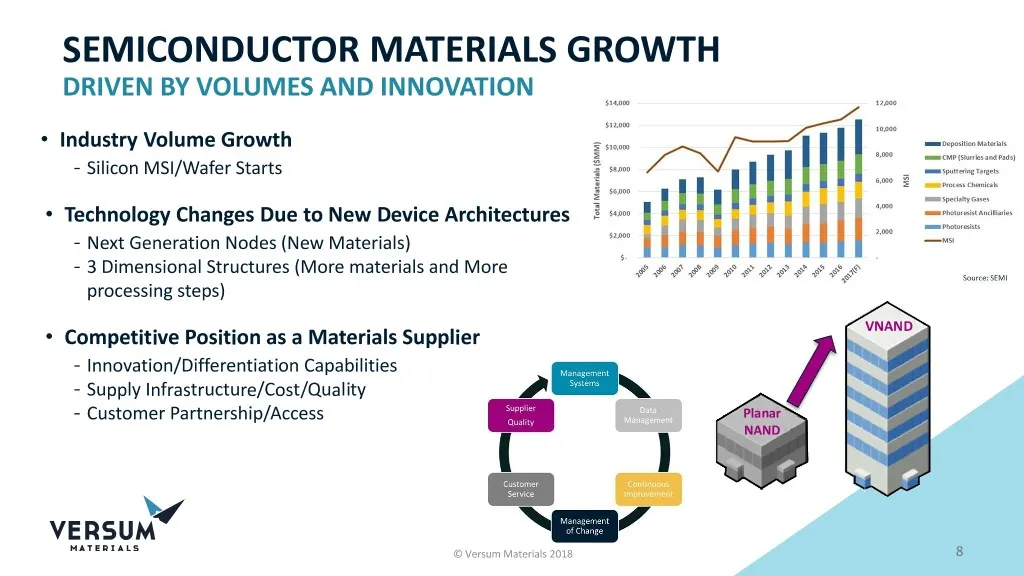
Slide 8: Semiconductor Materials Growth Driven by Volumes and Innovation
SEMICONDUCTOR MATERIALS GROWTH DRIVEN BY VOLUMES AND INNOVATION • Industry Volume Growth - Silicon MSI/Wafer Starts • Technology Changes Due to New Device Architectures - Next Generation Nodes (New Materials) - 3 Dimensional Structures (More materials and More processing steps) • Competitive Positio
Slide 9: Why the Increased Excitement? Future Growth Potential!
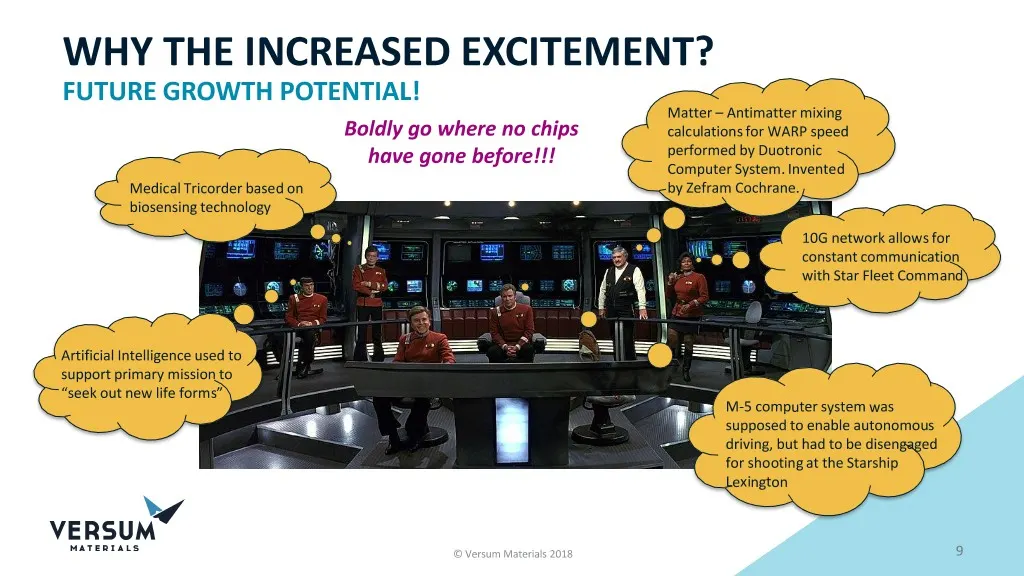
WHY THE INCREASED EXCITEMENT? FUTURE GROWTH POTENTIAL! Matter – Antimatter mixing Boldly go where no chips calculations for WARP speed have gone before!!! performed by Duotronic Computer System. Invented Medical Tricorder based on by Zefram Cochrane. biosensing technology 10G network allows for cons
Slide 10: We Are in the Early Stages of the Digital Revolution
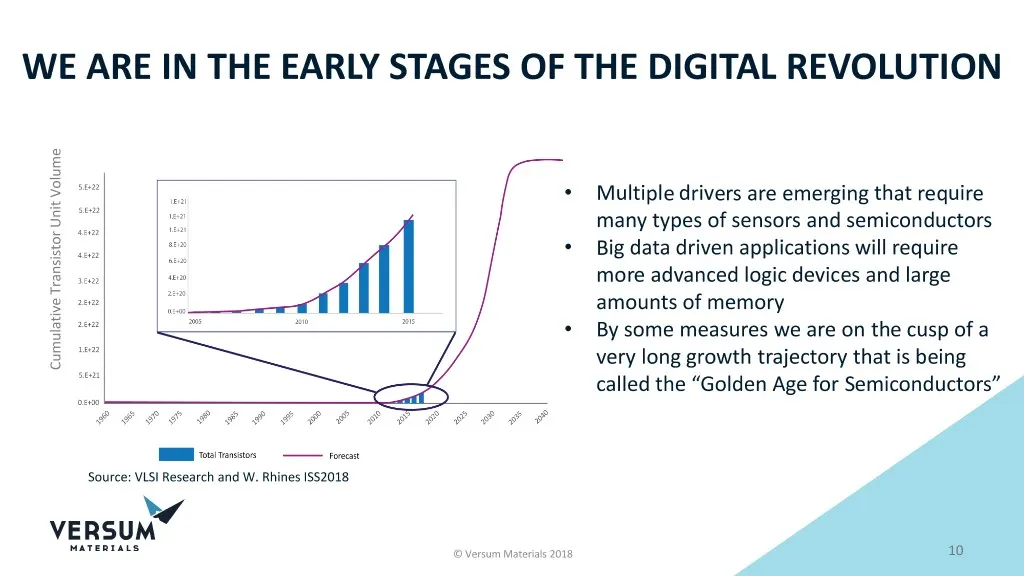
WE ARE IN THE EARLY STAGES OF THE DIGITAL REVOLUTION • Multiple drivers are emerging that require many types of sensors and semiconductors • Big data driven applications will require more advanced logic devices and large amounts of memory • By some measures we are on the cusp of a very long growth t
Slide 11: So, What Is Changing?
SO, WHAT IS CHANGING? © Versum Materials 2018 11
Slide 12: There Are New Forces Acting on Material Suppliers
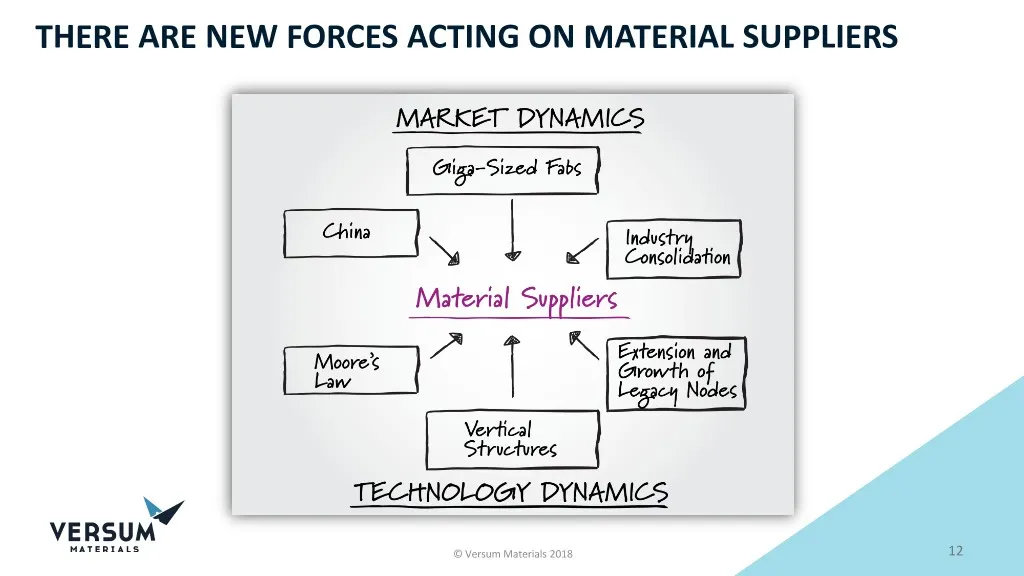
THERE ARE NEW FORCES ACTING ON MATERIAL SUPPLIERS © Versum Materials 2018 12
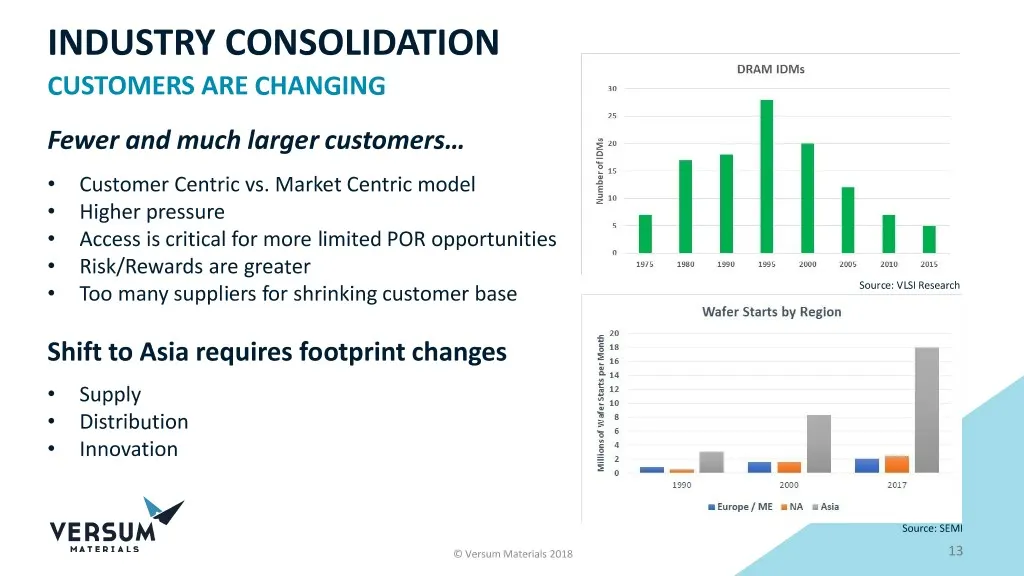
Slide 13: Industry Consolidation: Customers Are Changing
INDUSTRY CONSOLIDATION CUSTOMERS ARE CHANGING Fewer and much larger customers… • Customer Centric vs. Market Centric model • Higher pressure • Access is critical for more limited POR opportunities • Risk/Rewards are greater • Too many suppliers for shrinking customer base Source: VLSI Research Shift
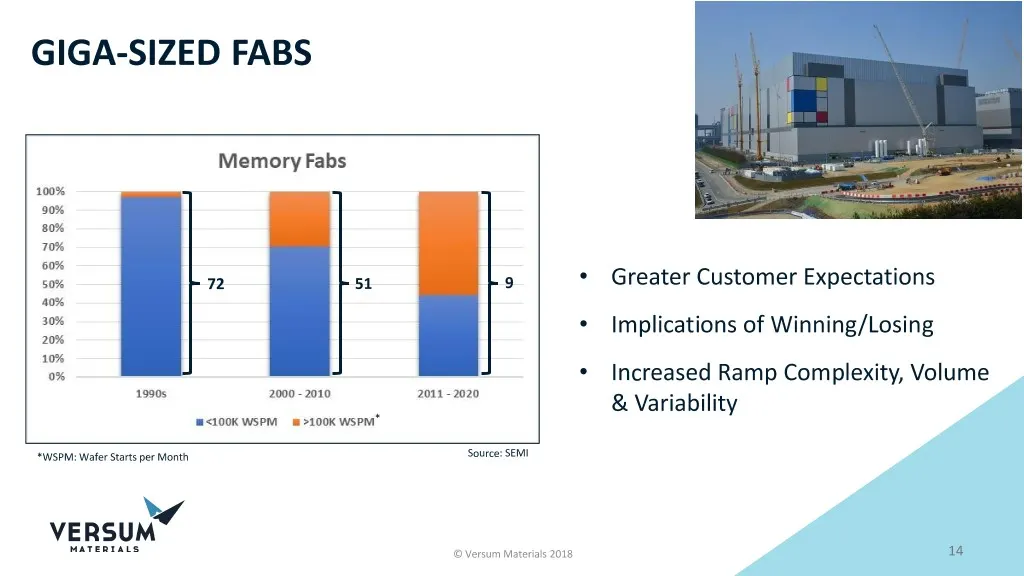
Slide 14: Giga-Sized Fabs
GIGA-SIZED FABS 72 51 9 • Greater Customer Expectations • Implications of Winning/Losing • Increased Ramp Complexity, Volume & Variability * *WSPM: Wafer Starts per Month Source: SEMI © Versum Materials 2018 14
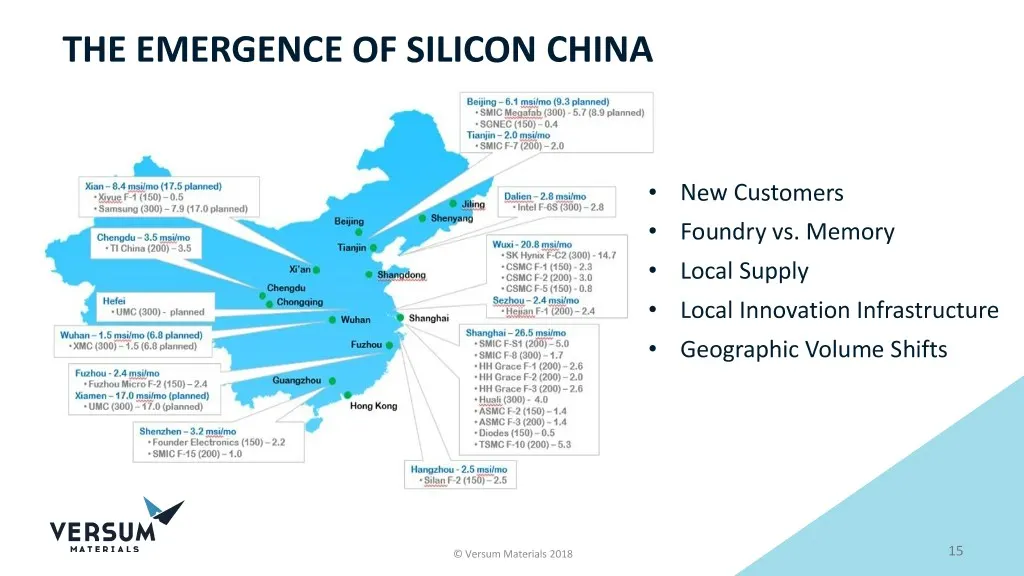
Slide 15: The Emergence of Silicon China
THE EMERGENCE OF SILICON CHINA • New Customers • Foundry vs. Memory • Local Supply • Local Innovation Infrastructure • Geographic Volume Shifts © Versum Materials 2018 15
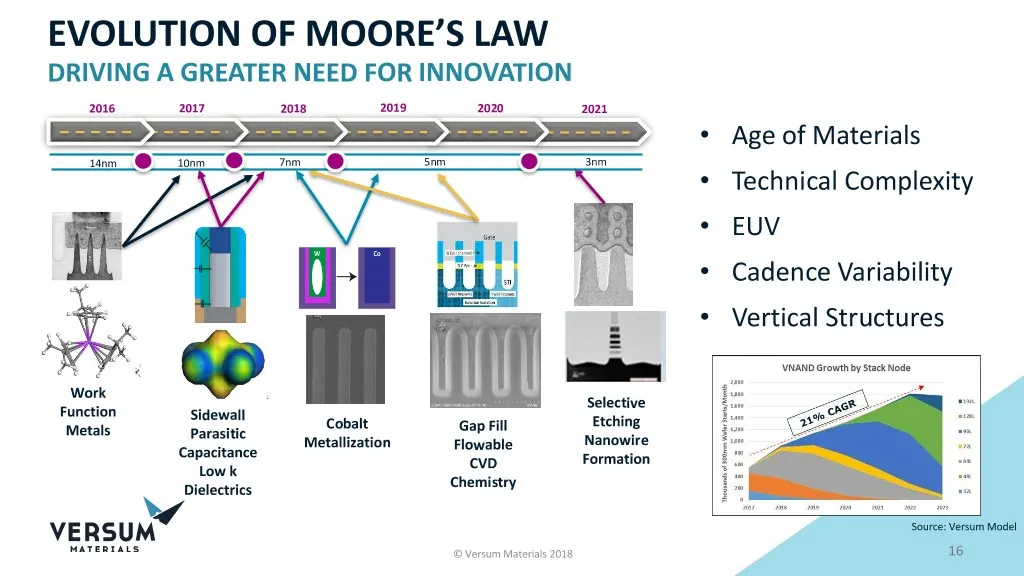
Slide 16: Evolution of Moore's Law Driving a Greater Need for Innovation
EVOLUTION OF MOORE’S LAW DRIVING A GREATER NEED FOR INNOVATION 2016 2017 2018 2019 2020 2021 • Age of Materials 14nm 10nm 7nm 5nm 3nm • Technical Complexity • EUV • Cadence Variability • Vertical Structures Work Selective Function Sidewall Cobalt Etching Metals Parasitic Gap Fill Metallization Flowa
Slide 17: IoT, Industry and Auto Driving Demand for Legacy Nodes
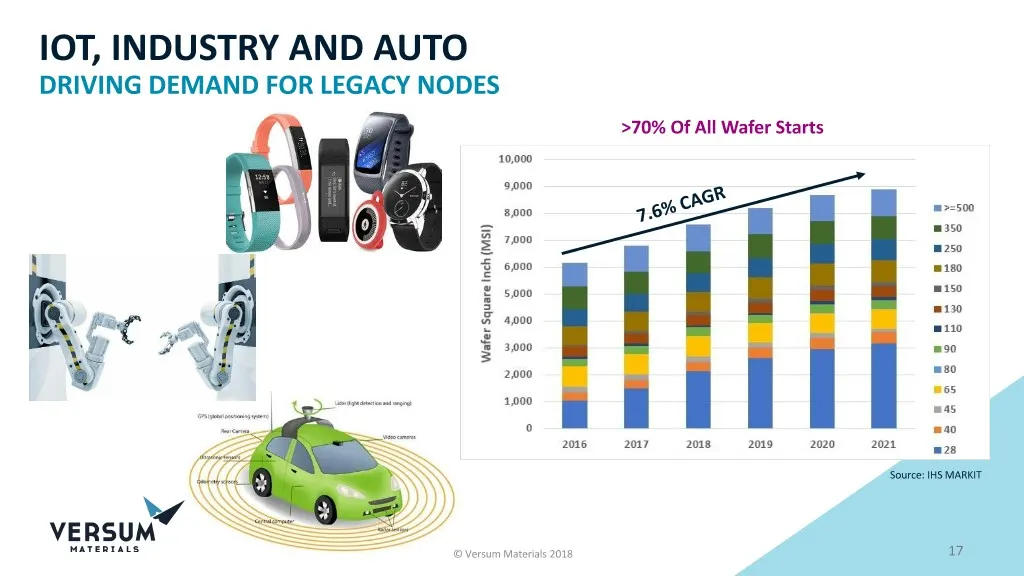
IOT, INDUSTRY AND AUTO DRIVING DEMAND FOR LEGACY NODES >70% Of All Wafer Starts Source: IHS MARKIT © Versum Materials 2018 17
Slide 18: Criteria for Success Going into the 2020s
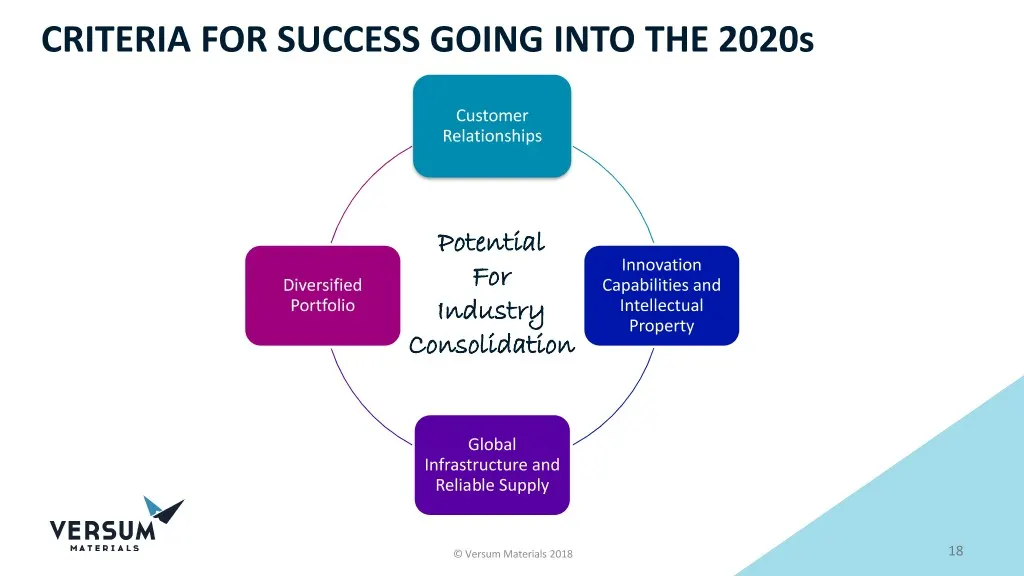
CRITERIA FOR SUCCESS GOING INTO THE 2020s Customer Relationships Potential Innovation Diversified For Capabilities and Portfolio Industry Intellectual Property Consolidation Global Infrastructure and Reliable Supply © Versum Materials 2018 18
Slide 19: Versum Materials
VERSUM MATERIALS © Versum Materials 2018 19
Slide 20: Versum Materials at a Glance
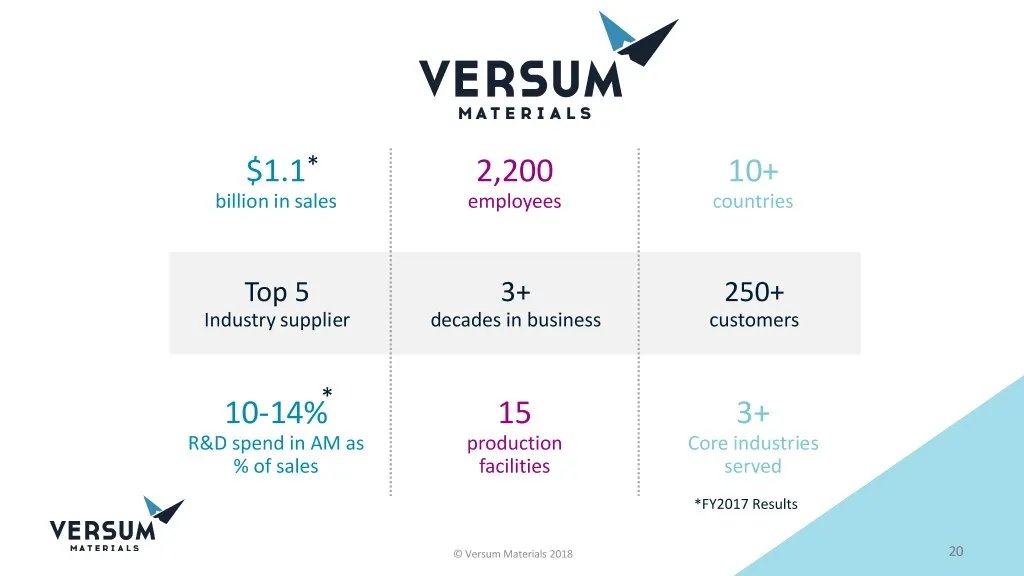
$1.1* 2,200 10+ billion in sales employees countries Top 5 3+ 250+ Industry supplier decades in business customers 10-14%* 15 3+ R&D spend in AM as production Core industries % of sales facilities served *FY2017 Results © Versum Materials 2018 20
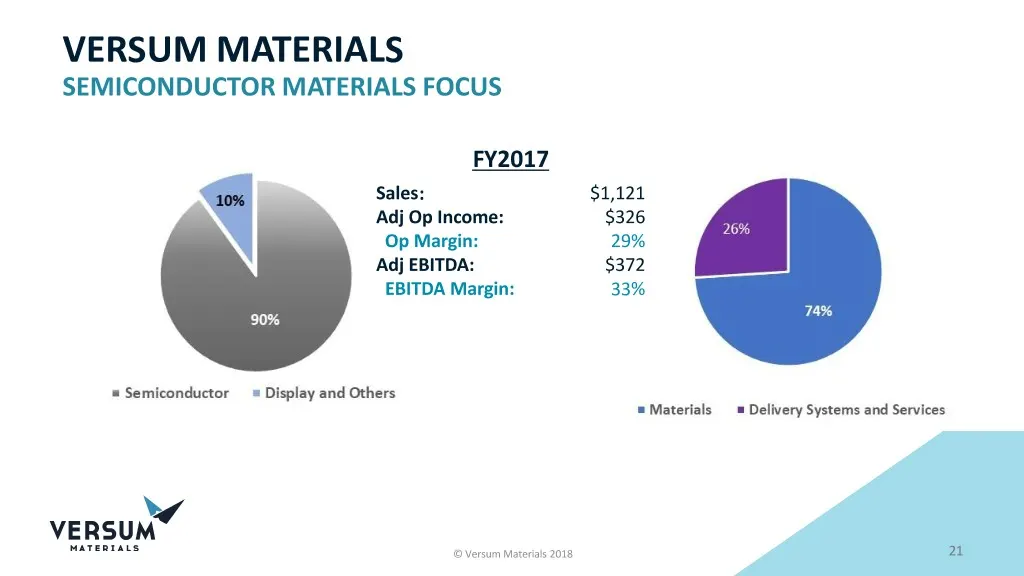
Slide 21: Versum Materials: Semiconductor Materials Focus
VERSUM MATERIALS SEMICONDUCTOR MATERIALS FOCUS FY2017 Sales: $1,121 Adj Op Income: $326 Op Margin: 29% Adj EBITDA: $372 EBITDA Margin: 33% © Versum Materials 2018 21
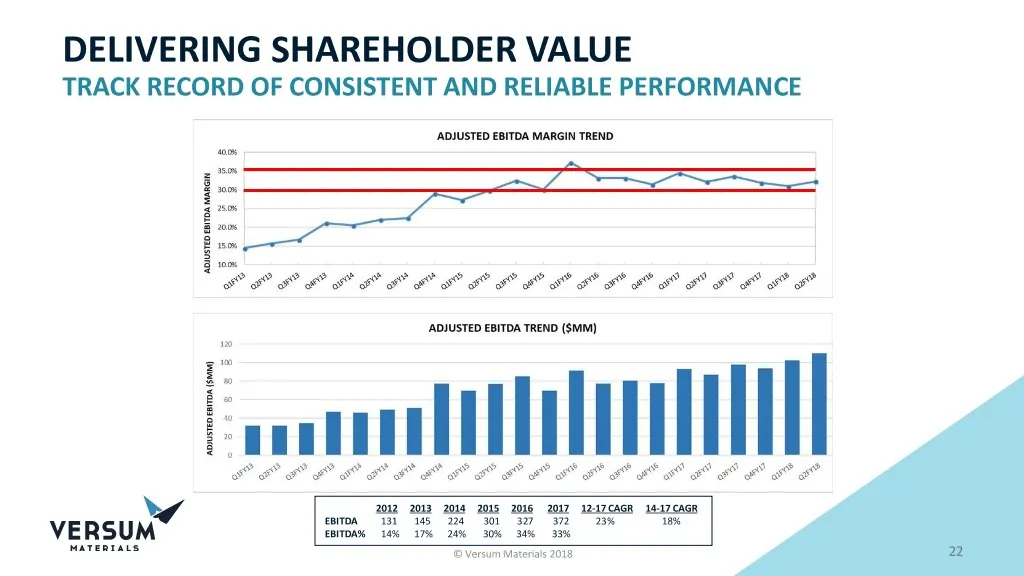
Slide 22: Delivering Shareholder Value: Track Record of Consistent and Reliable Performance
DELIVERING SHAREHOLDER VALUE TRACK RECORD OF CONSISTENT AND RELIABLE PERFORMANCE 2012 2013 2014 2015 2016 2017 12-17 CAGR 14-17 CAGR EBITDA 131 145 224 301 327 372 23% 18% EBITDA% 14% 17% 24% 30% 34% 33% © Versum Materials 2018 22
Slide 23: Versum Materials: Focused on Organic Growth
VERSUM MATERIALS FOCUSED ON ORGANIC GROWTH • Finalizing Standalone Infrastructure and Capabilities • Focused on creating value for our Customers • Strengthening competitive position and Technical Capabilities • Increasing investment driving Organic Growth - Prioritizing growth of our Advance Materia
Slide 24: Versum Materials: An Exciting Future Ahead
VERSUM MATERIALS AN EXCITING FUTURE AHEAD ➢ Top Line Growth at 1.5-3x MSI ➢ Investing in organic growth accelerators Solid growth ➢ Margin improvement from productivity, mix from High margins greater AM growth and SARD leverage Low capital intensity ➢ Asset light profile will deliver strong Free Cas
Slide 25: VE —F
VE —F Z n 2 Qo a = Oo 2 je) oO lu cw
Slide 26: Reconciliations
RECONCILIATIONS Non-GAAP Financial Measures This presentation and the accompanying earnings press release includes “non-GAAP financial measures,” including Adjusted Net Income, Adjusted Net Income Margin, Adjusted Diluted Earnings Per Share, Adjusted EBITDA, Segment Adjusted EBITDA, Adjusted EBITDA
Slide 27: Reconciliation of NI to Adj EBITDA, NI to Adj NI, Diluted EPS to Adj Diluted EPS
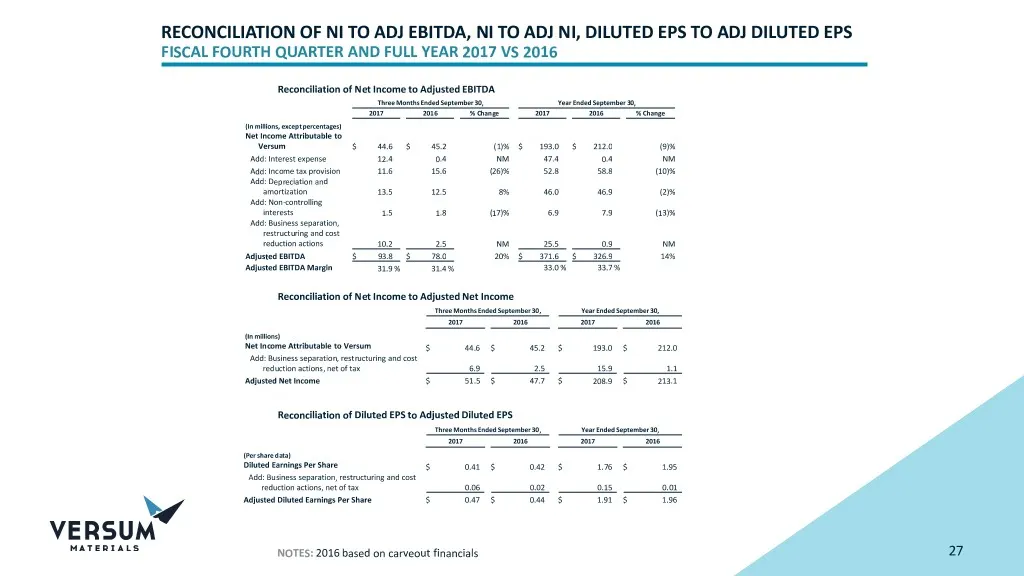
RECONCILIATION OF NI TO ADJ EBITDA, NI TO ADJ NI, DILUTED EPS TO ADJ DILUTED EPS FISCAL FOURTH QUARTER AND FULL YEAR 2017 VS 2016 Reconciliation of Net Income to Adjusted EBITDA Three Months Ended September 30, Year Ended September 30, 2017 2016 % Change 2017 2016 % Change (In millions, except perce
Slide 28: Thank You
THANK YOU © Versum Materials 2018 28
Source: SEC EDGAR · 8-K filed May 14, 2018
More decks from Versum Materials Inc
 Merger or Acquisition (April 2019)20 slides · Apr 12, 2019
 Merger or Acquisition (April 2019)20 slides · Apr 12, 2019
 Proxy Contest (April 2019)37 slides · Apr 2, 2019
 Merger or Acquisition (April 2019)17 slides · Apr 1, 2019
 Proxy Contest (March 2019)26 slides · Mar 14, 2019
 Merger or Acquisition (February 2019)46 slides · Feb 27, 2019