Capita plc · LSE:CPI
Capita — Investor Presentation (September 2017)
62 slides from Capita's investor presentation, Sep 7, 2017
Slide 1: IFRS 15 teach-in
IFRS 15 teach–in 7 September 2017
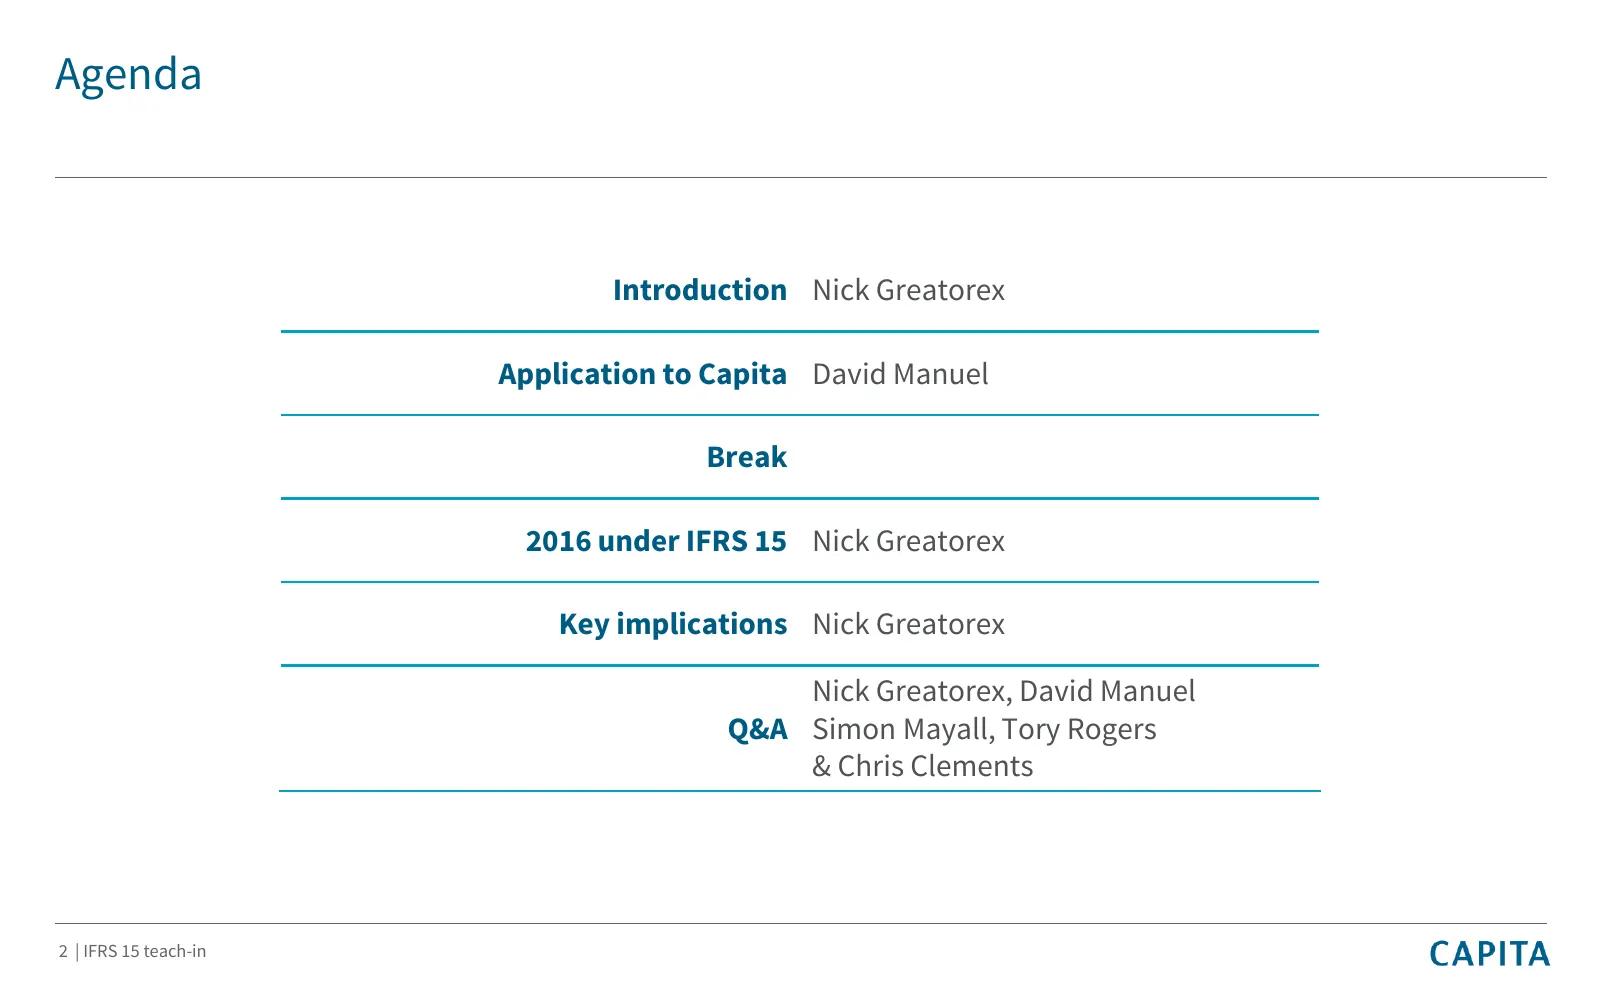
Slide 2: Agenda
Agenda Introduction Nick Greatorex Application to Capita David Manuel Break 2016 under IFRS 15 Nick Greatorex Key implications Nick Greatorex Nick Greatorex, David Manuel Q&A Simon Mayall, Tory Rogers & Chris Clements 2 | IFRS 15 teach-in
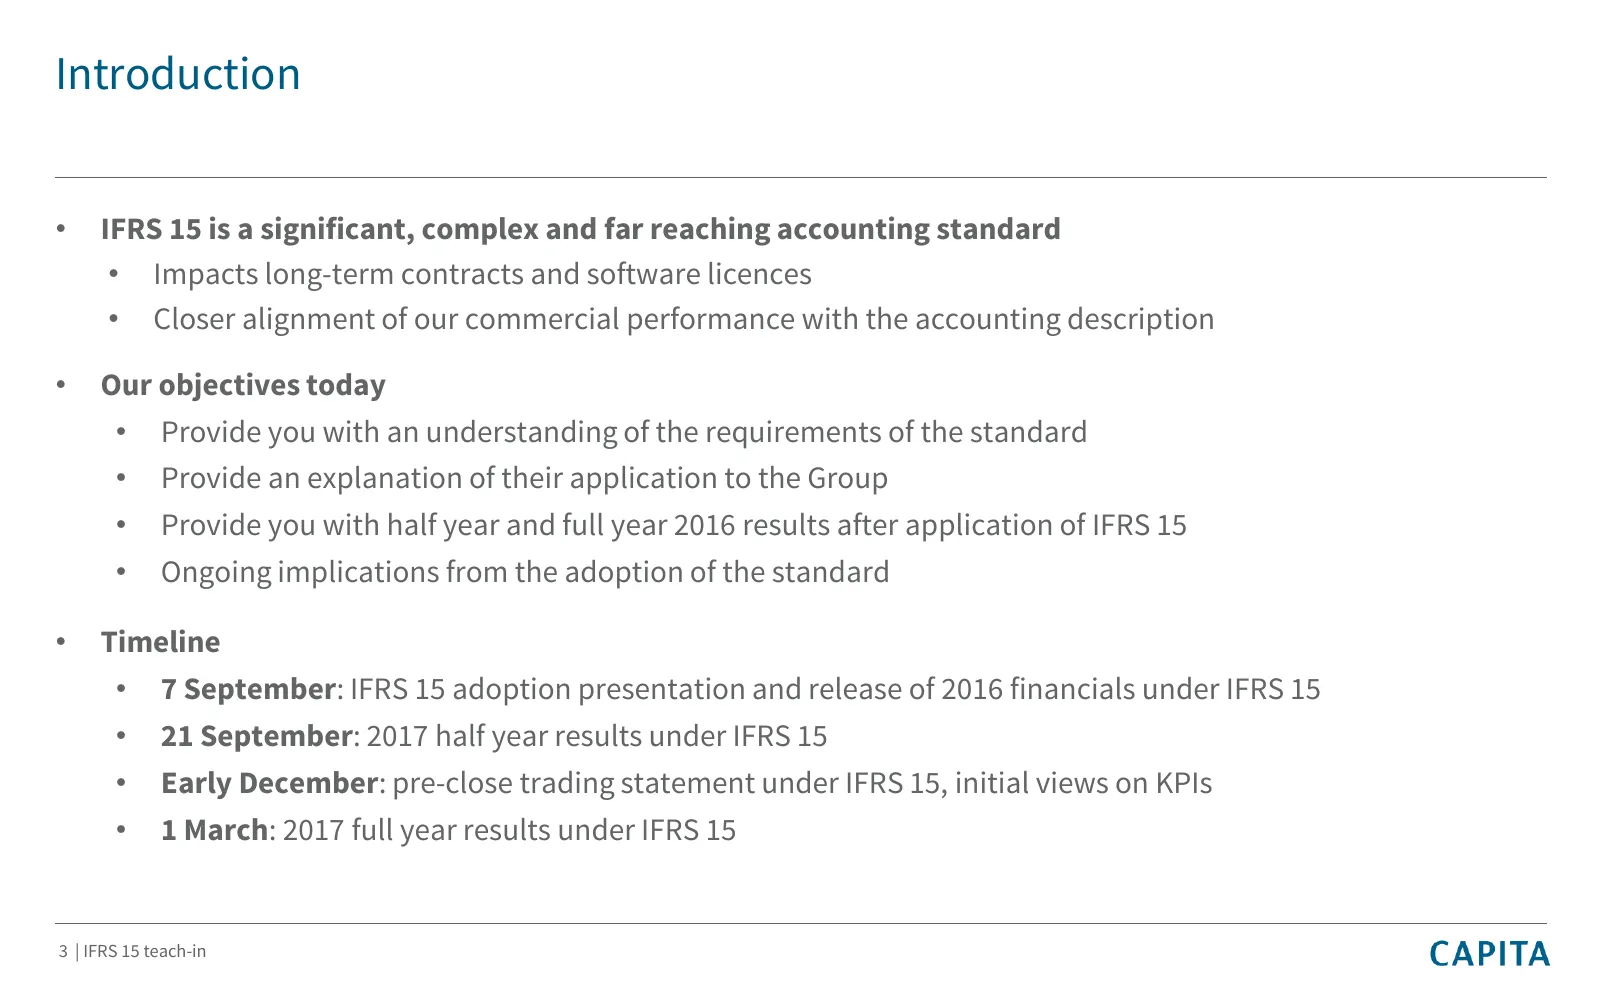
Slide 3: Introduction
Introduction • IFRS 15 is a significant, complex and far reaching accounting standard • Impacts long-term contracts and software licences • Closer alignment of our commercial performance with the accounting description • Our objectives today • Provide you with an understanding of the requirements of
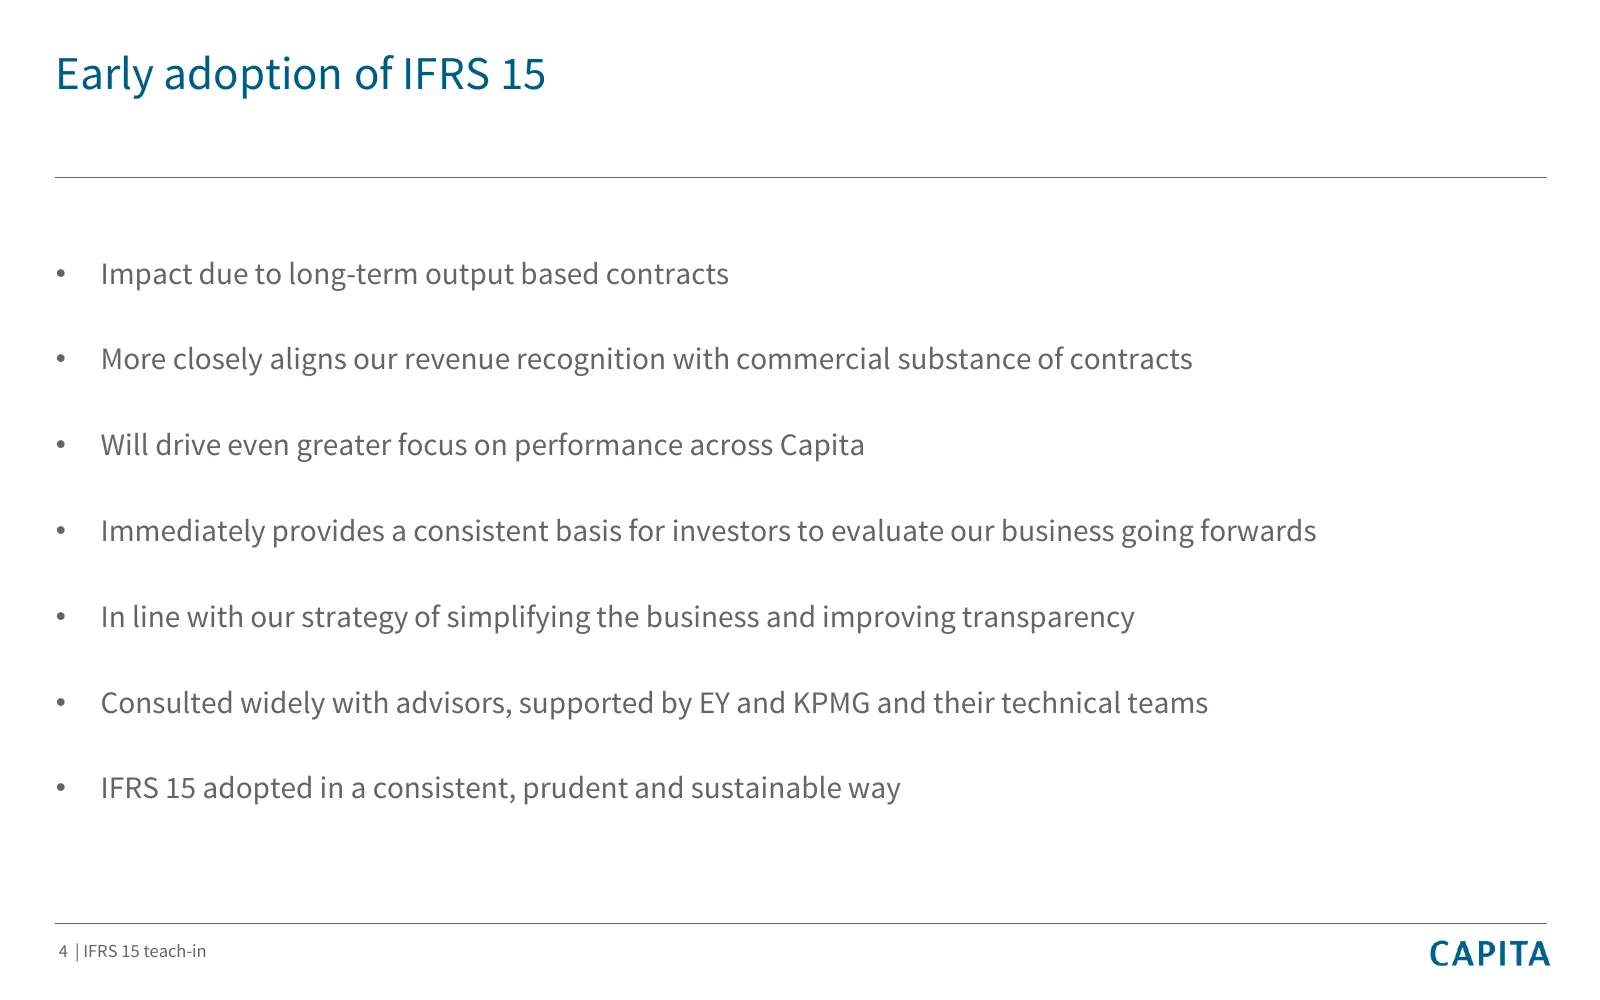
Slide 4: Early adoption of IFRS 15
Early adoption of IFRS 15 • Impact due to long-term output based contracts • More closely aligns our revenue recognition with commercial substance of contracts • Will drive even greater focus on performance across Capita • Immediately provides a consistent basis for investors to evaluate our busines
Slide 5: Key judgements
Key judgements • Presents a number of judgements on adoption • Transformation packaged with the service as an integrated solution - Capita’s clients value the ‘what’ we do for them (the delivery of outcomes) rather than the ‘how’ we do it • Software products require regular updates, making them a se
Slide 6: Other important points to note
Other important points to note • No impact on Capita’s cash flow • Changes the way revenue is recognised – a matter of timing • Does not change lifetime revenue or profits of contracts • New contracts may give rise to losses in early years • Profitable long-term contract portfolio continues to drive
Slide 7: IFRS 15 – key points
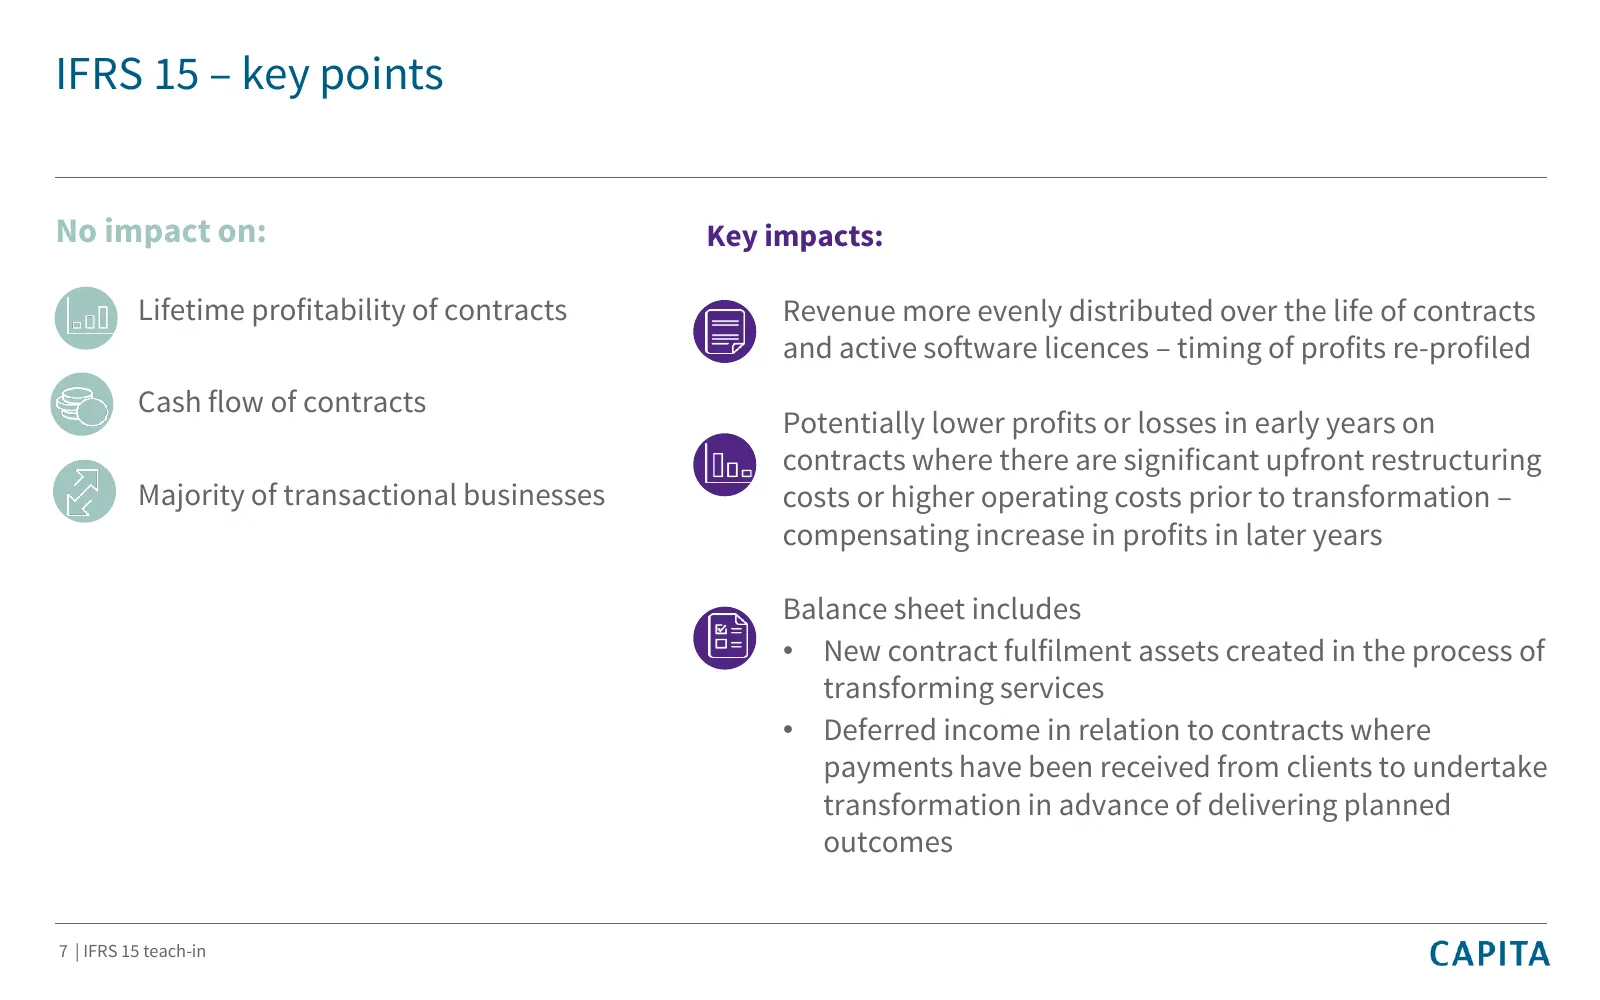
IFRS 15 – key points No impact on: Key impacts: Lifetime profitability of contracts Revenue more evenly distributed over the life of contracts and active software licences – timing of profits re-profiled Cash flow of contracts Potentially lower profits or losses in early years on contracts where the
Slide 8: IFRS 15 – key points (cont.)
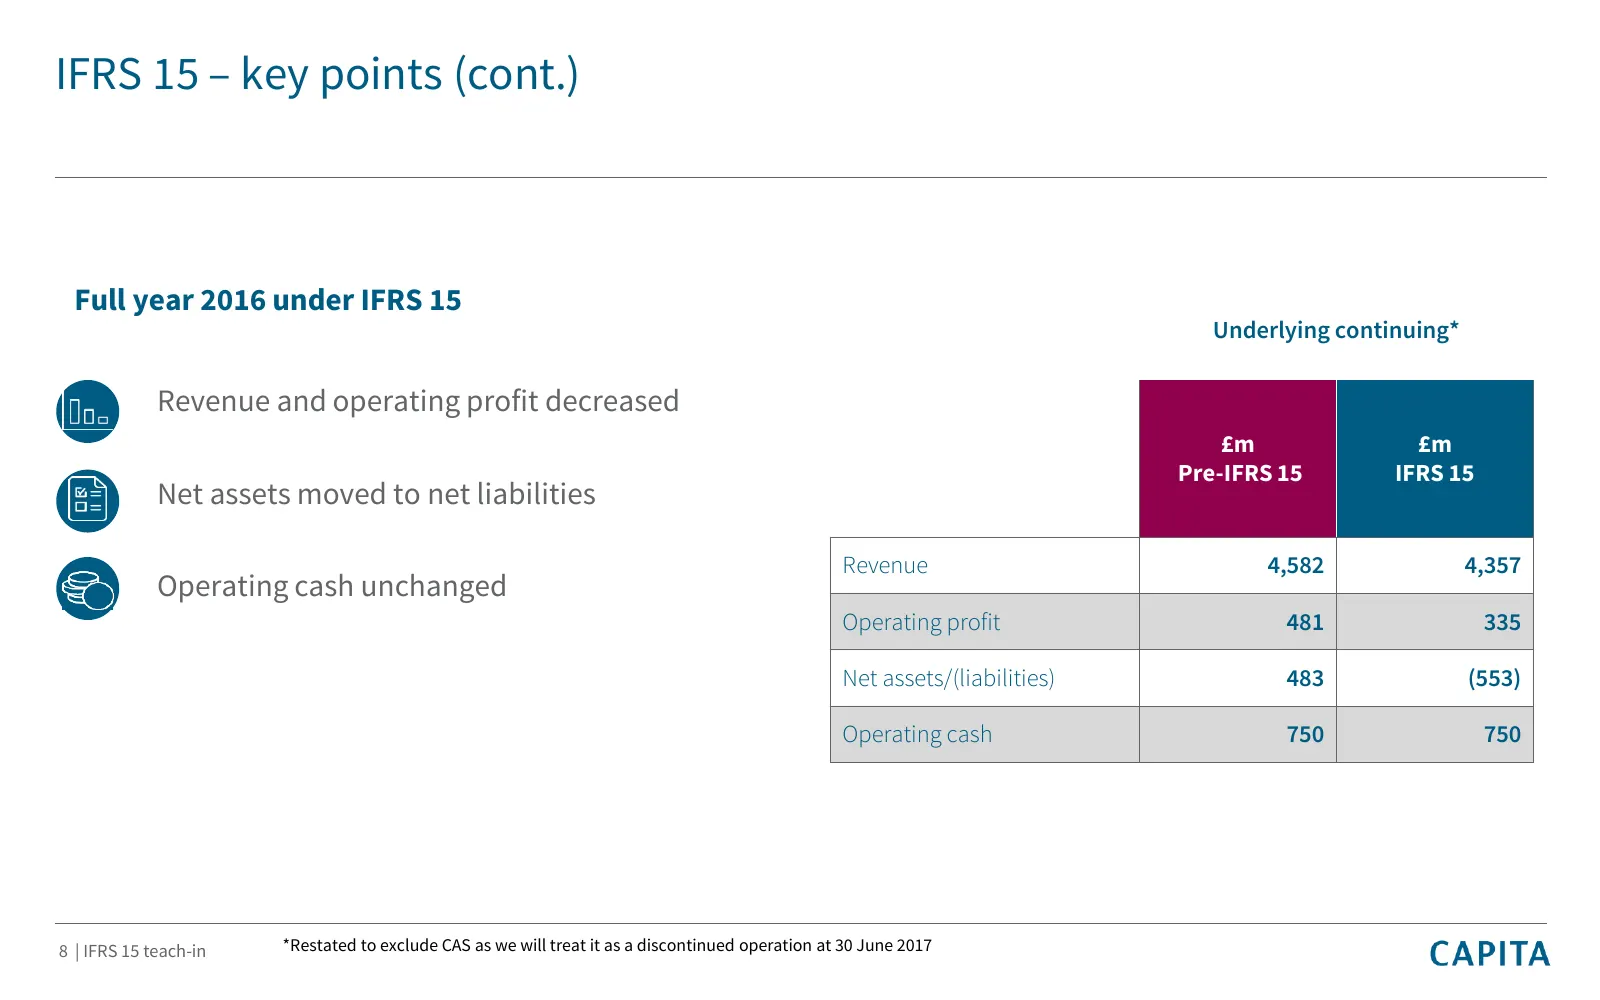
IFRS 15 – key points (cont.) Full year 2016 under IFRS 15 Underlying continuing* Revenue and operating profit decreased £m £m Pre-IFRS 15 IFRS 15 Net assets moved to net liabilities Revenue 4,582 4,357 Operating cash unchanged Operating profit 481 335 Net assets/(liabilities) 483 (553) Operating cas
Slide 9: Application to Capita
Application to Capita David Manuel Director, Group Finance 9 | IFRS 15 teach-in
Slide 10: Overview
Overview • Commercial model • Previous accounting policy • Example outsourcing contract pre-IFRS 15 • The IFRS 15 five step revenue model and application to Capita • main impacts • areas of no impact • Example outsourcing contract post-IFRS 15 • Software licence revenue • Working capital • Presentat
Slide 11: Commercial model – key points
Commercial model – key points Large contracts: • We take an inefficient process being run by our client, and transform this into a more efficient and effective solution • The outcome we strive for is a high quality, efficient solution that addresses our client’s needs, delivered consistently over th
Slide 12: Previous accounting policy
Previous accounting policy • Matching revenue and costs • Recognise revenue separately for restructure, transformation and BAU • Percentage of completion, common across the sector • Higher profits in early years 12 | IFRS 15 teach-in
Slide 13: Illustrative example - Capita's outsourcing proposition
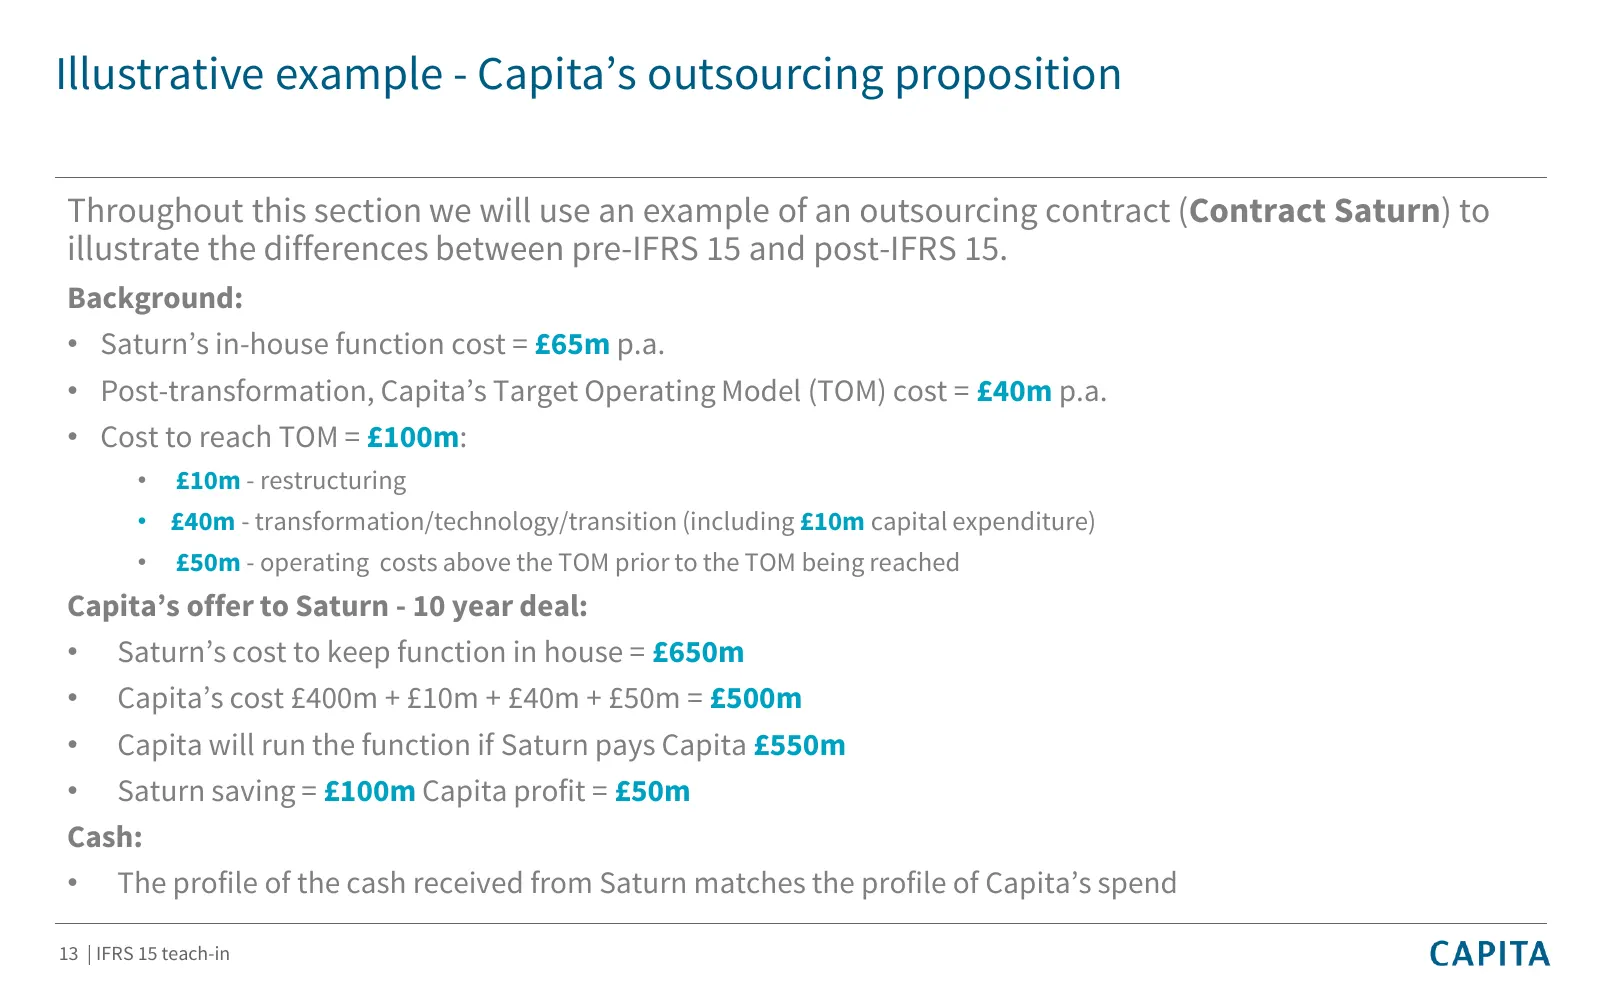
Illustrative example - Capita’s outsourcing proposition Throughout this section we will use an example of an outsourcing contract (Contract Saturn) to illustrate the differences between pre-IFRS 15 and post-IFRS 15. Background: • Saturn’s in-house function cost = £65m p.a. • Post-transformation, Cap
Slide 14: Contract Saturn - pre-IFRS 15
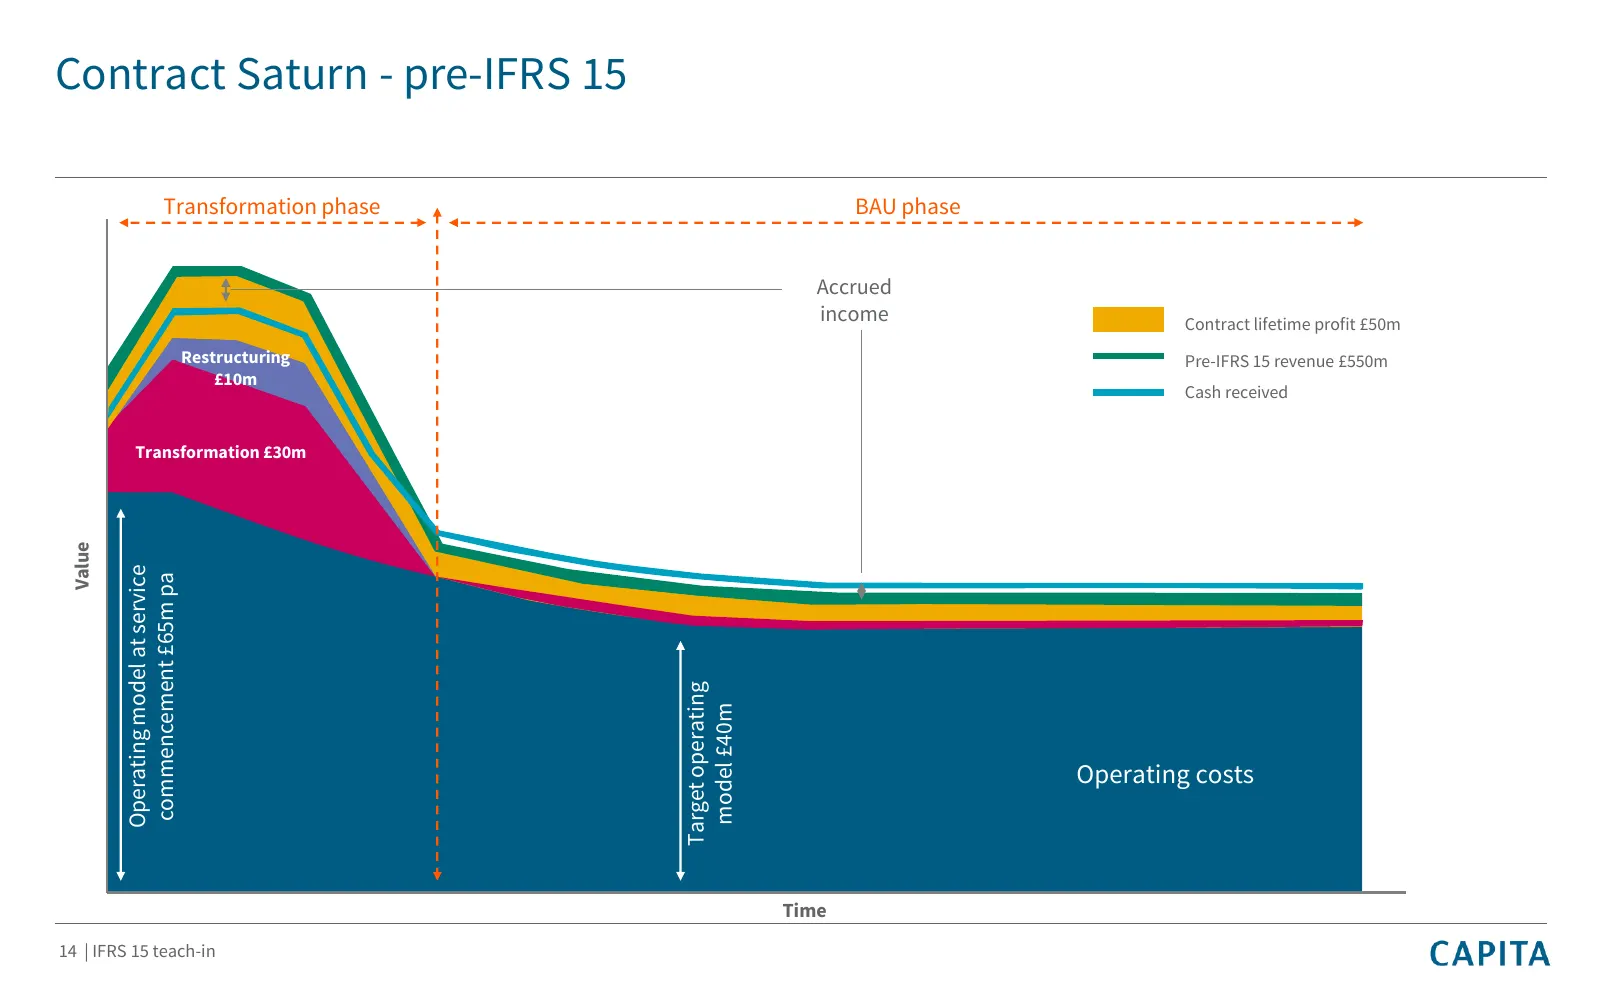
Contract Saturn - pre-IFRS 15 Transformation phase BAU phase Accrued income Contract lifetime profit £50m Restructuring Pre-IFRS 15 revenue £550m £10m Cash received Transformation £30m Value Operating model at service commencement £65m pa Target operating model £40m Operating costs Time 14 | IFRS 15
Slide 15: Contract Saturn - pre-IFRS 15 (cont.)
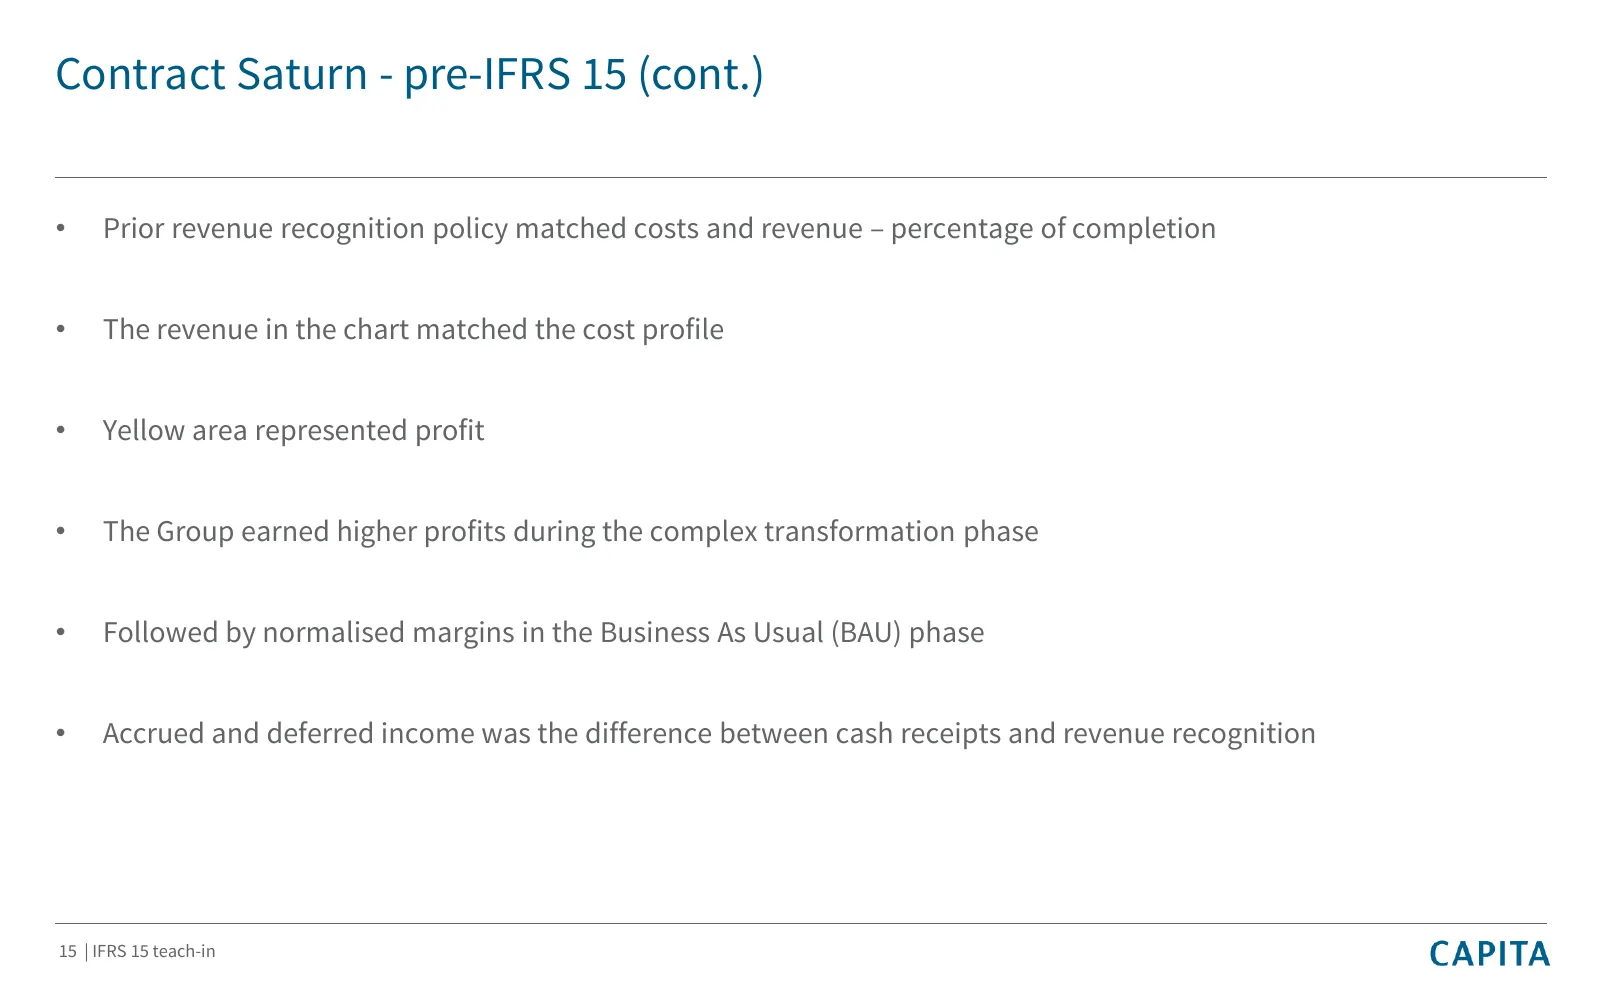
Contract Saturn - pre-IFRS 15 (cont.) • Prior revenue recognition policy matched costs and revenue – percentage of completion • The revenue in the chart matched the cost profile • Yellow area represented profit • The Group earned higher profits during the complex transformation phase • Followed by n
Slide 16: Contract Saturn - IFRS 15
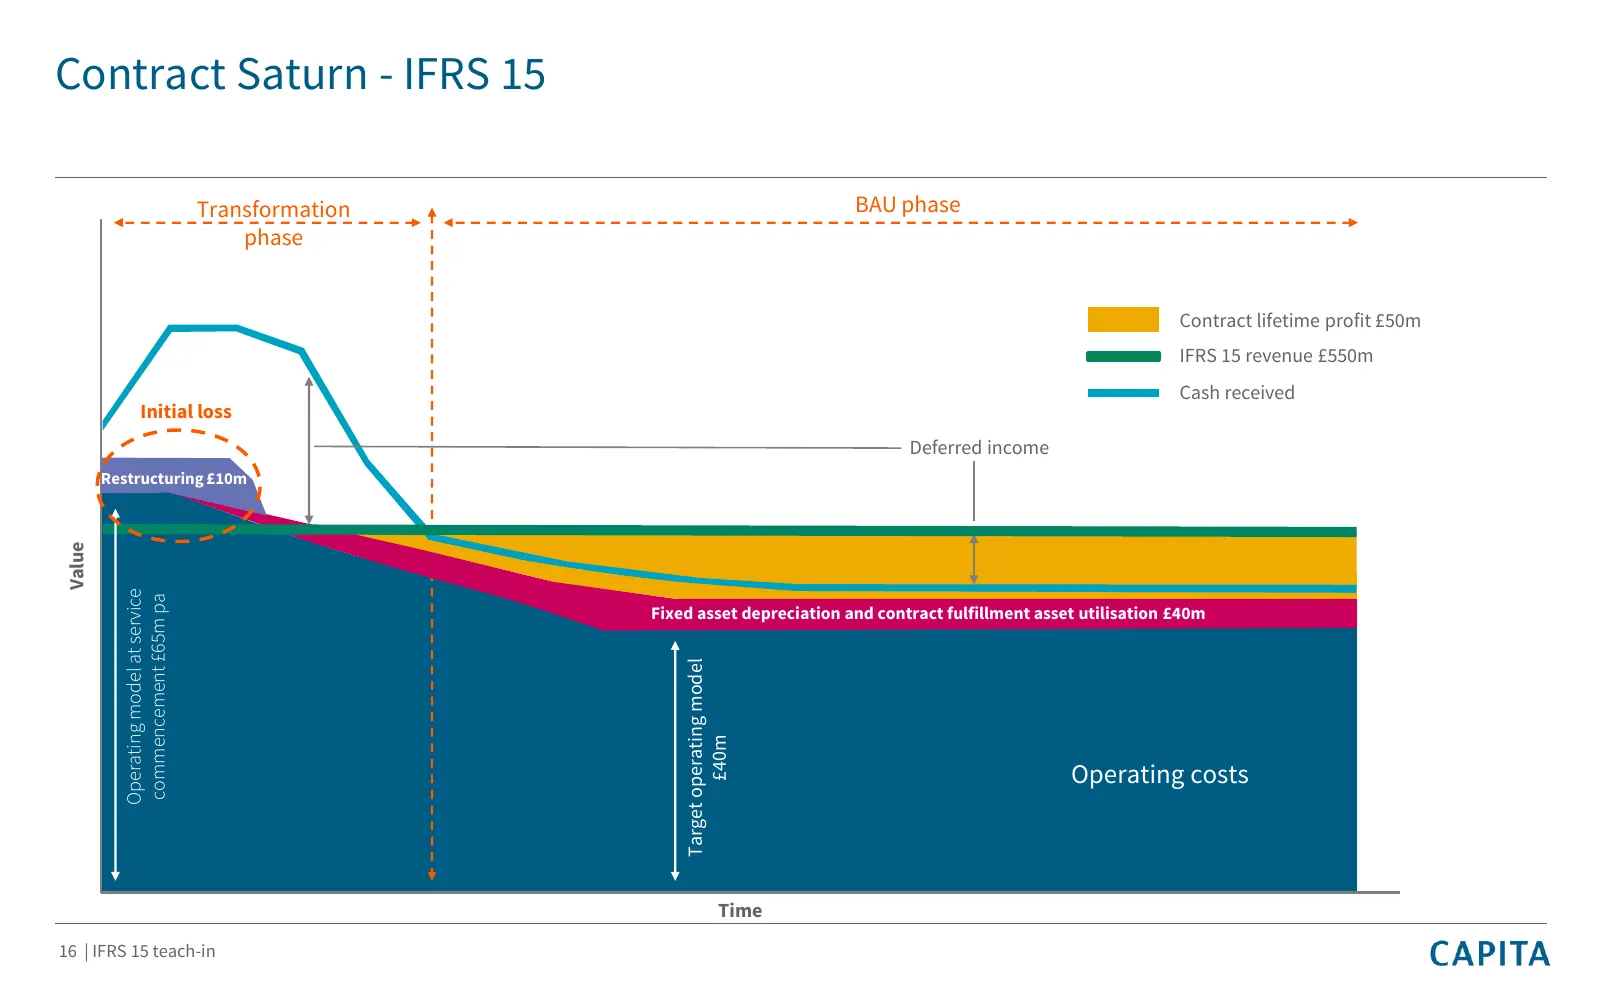
Contract Saturn - IFRS 15 Transformation BAU phase phase Contract lifetime profit £50m IFRS 15 revenue £550m Cash received Initial loss Deferred income Restructuring £10m Value Operating model at service commencement £65m pa Fixed asset depreciation and contract fulfillment asset utilisation £40m Ta
Slide 17: IFRS 15 - main impacts for Capita
IFRS 15 - main impacts for Capita • Revenue: recognition of revenue over the life of major contracts and active software licences spread more evenly • Costs: certain transformation spend, previously expensed, now capitalised as contract fulfilment assets and released over the contract life. Redundan
Slide 18: IFRS 15 – a five step revenue model
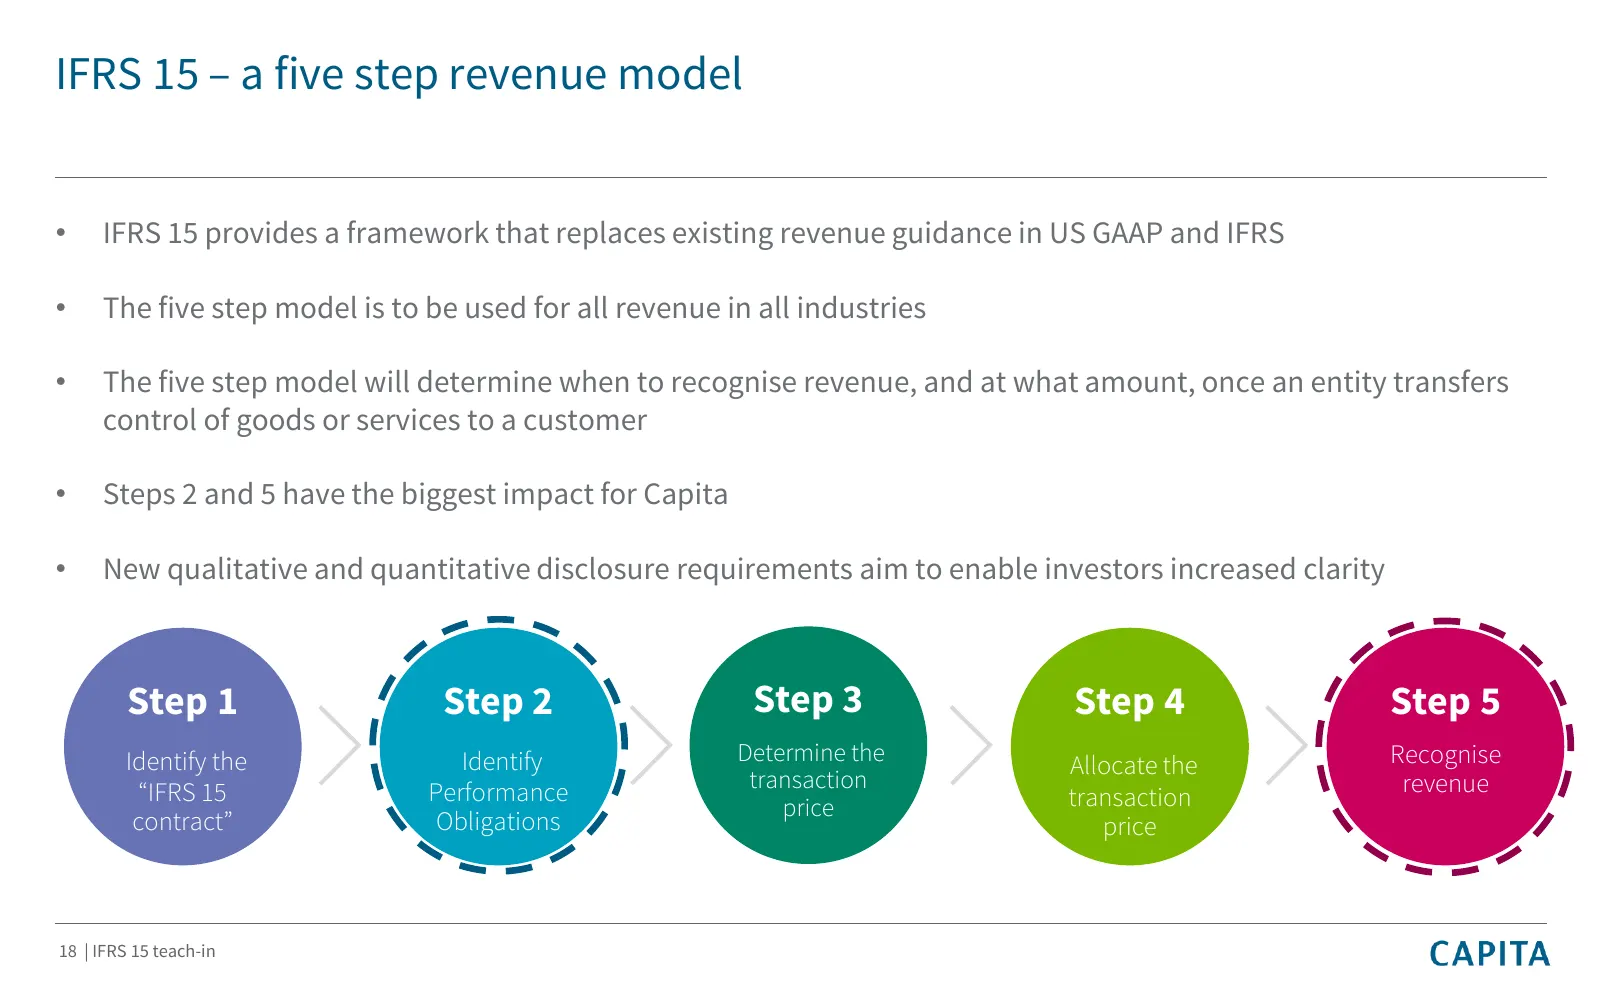
IFRS 15 – a five step revenue model • IFRS 15 provides a framework that replaces existing revenue guidance in US GAAP and IFRS • The five step model is to be used for all revenue in all industries • The five step model will determine when to recognise revenue, and at what amount, once an entity tran
Slide 19: Step 1 – Identify the IFRS 15 contract
Step 1 – Identify the “IFRS 15 contract” An “IFRS 15 contract” broader than just legal Application to Capita: agreements such as frameworks, contracts and side letters so that the combined agreement meets the following criteria: Trading businesses – no difference as each standalone transaction meets
Slide 20: Step 2 – Identify performance obligations
Step 2 – Identify performance obligations Identify the promises Application to Capita: A promise is an implicit or explicit commitment made by Requirement to consider what the distinct performance you to your customer within the “IFRS 15 contract” obligations are for each contract identified in Step
Slide 21: Step 2 – Identify performance obligations (cont.)
Step 2 – Identify performance obligations (cont.) Contract fulfilment asset Application to Capita: Costs of fulfilling a contract that cannot be The Group will capitalise investment in the IP of the capitalised under another standard are capitalised if business solution that achieves the target oper
Slide 22: Step 3 & 4 – Determine and allocate the transaction price
Step 3 & 4 – Determine and allocate the transaction price Allocation of the transaction price This step has two goals: 1. ensure appropriate revenue allocation between performance Determine transaction price obligations IFRS 15 introduces the concept of transaction price 2. allow revenue to be alloc
Slide 23: Step 5 – Recognise revenue
Step 5 – Recognise revenue Over time vs point in time To be over time a service must meet one of the following conditions: • Entity creates or enhances an asset that the customer controls as it is created or enhanced • Entity’s performance does not create an asset with alternative use and the entity
Slide 24: Step 5 – Recognise revenue (cont.)
Step 5 – Recognise revenue (cont.) Application to Capita: As the client benefits from the more efficient Capita service throughout the contract Capita’s revenue will be recognised over time The value to Capita’s clients is not based on how Capita delivers the service, but on what service Capita deli
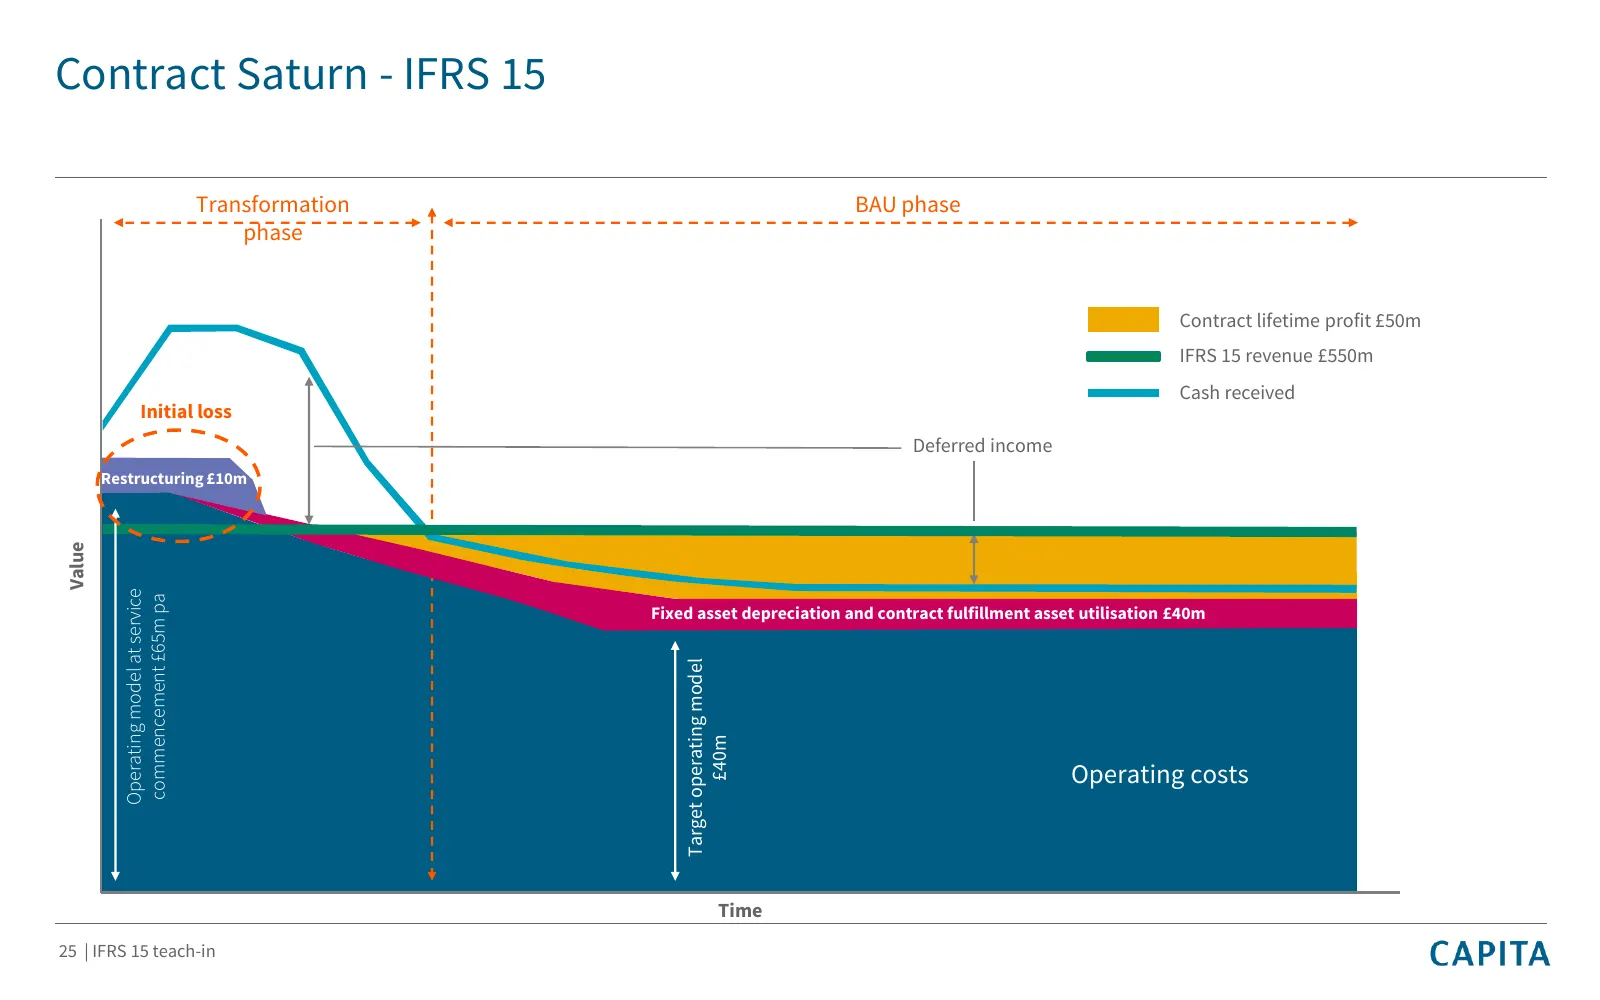
Slide 25: Contract Saturn - IFRS 15
Contract Saturn - IFRS 15 Transformation BAU phase phase Contract lifetime profit £50m IFRS 15 revenue £550m Cash received Initial loss Deferred income Restructuring £10m Value Operating model at service commencement £65m pa Fixed asset depreciation and contract fulfillment asset utilisation £40m Ta
Slide 26: Contract Saturn - IFRS 15 (cont.)
Contract Saturn - IFRS 15 (cont.) • IFRS 15 revenue more evenly spread following the IFRS 15 series guidance and output method of recognition with a single performance obligation (green line) • Operating costs unchanged (dark blue) • Fixed asset depreciation and contract fulfilment cost utilisation
Slide 27: Software licences
Software licences Pre IFRS 15: Perpetual licences: the revenue is recognised as a point in time when the licence legally transfers to the customer; or Term licences: the revenue is spread over the term of the licence. IFRS 15: Active licences – a right to access: licences which require continuous up
Slide 28: Illustrative example - Capita's software proposition
Illustrative example - Capita’s software proposition Throughout this section we will use an example of a software licence (Neptune) to illustrate the differences between pre-IFRS 15 and post-IFRS 15. Background: • Neptune is a B2B sale of a perpetual software licence for operationally critical syste
Slide 29: Software - contract level analysis
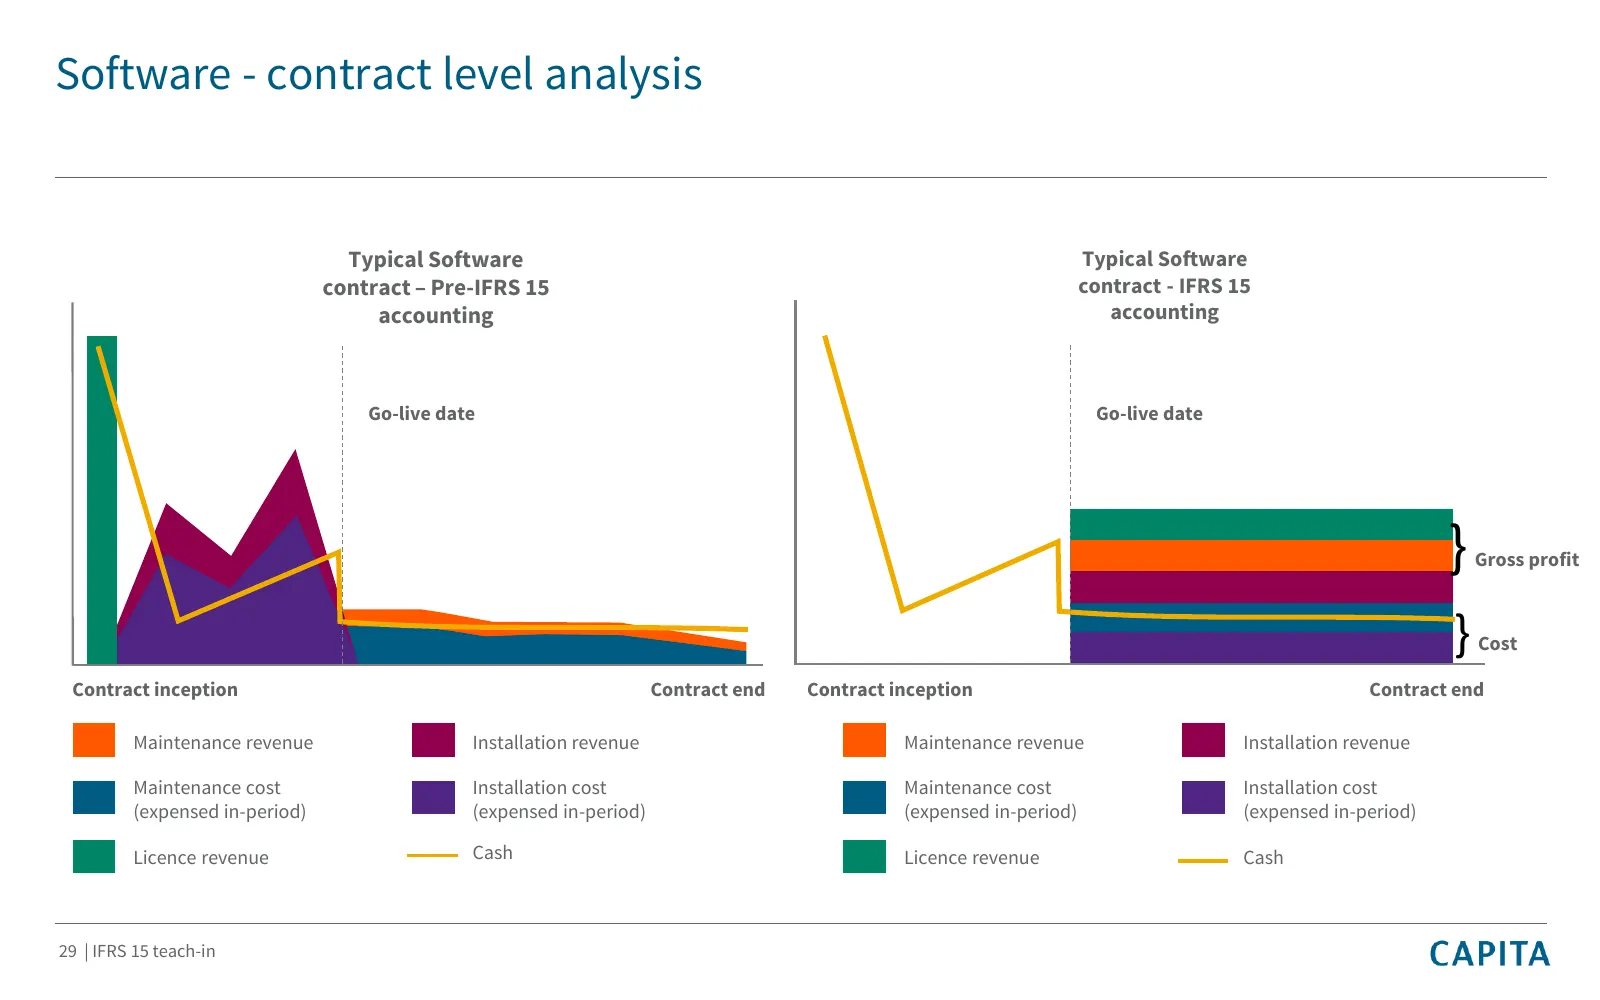
Software - contract level analysis Typical Software Typical Software contract – Pre-IFRS 15 contract - IFRS 15 accounting accounting Go-live date Go-live date } Gross profit } Cost Contract inception Contract end Contract inception Contract end Maintenance revenue Installation revenue Maintenance re
Slide 30: Illustrative working capital cycle
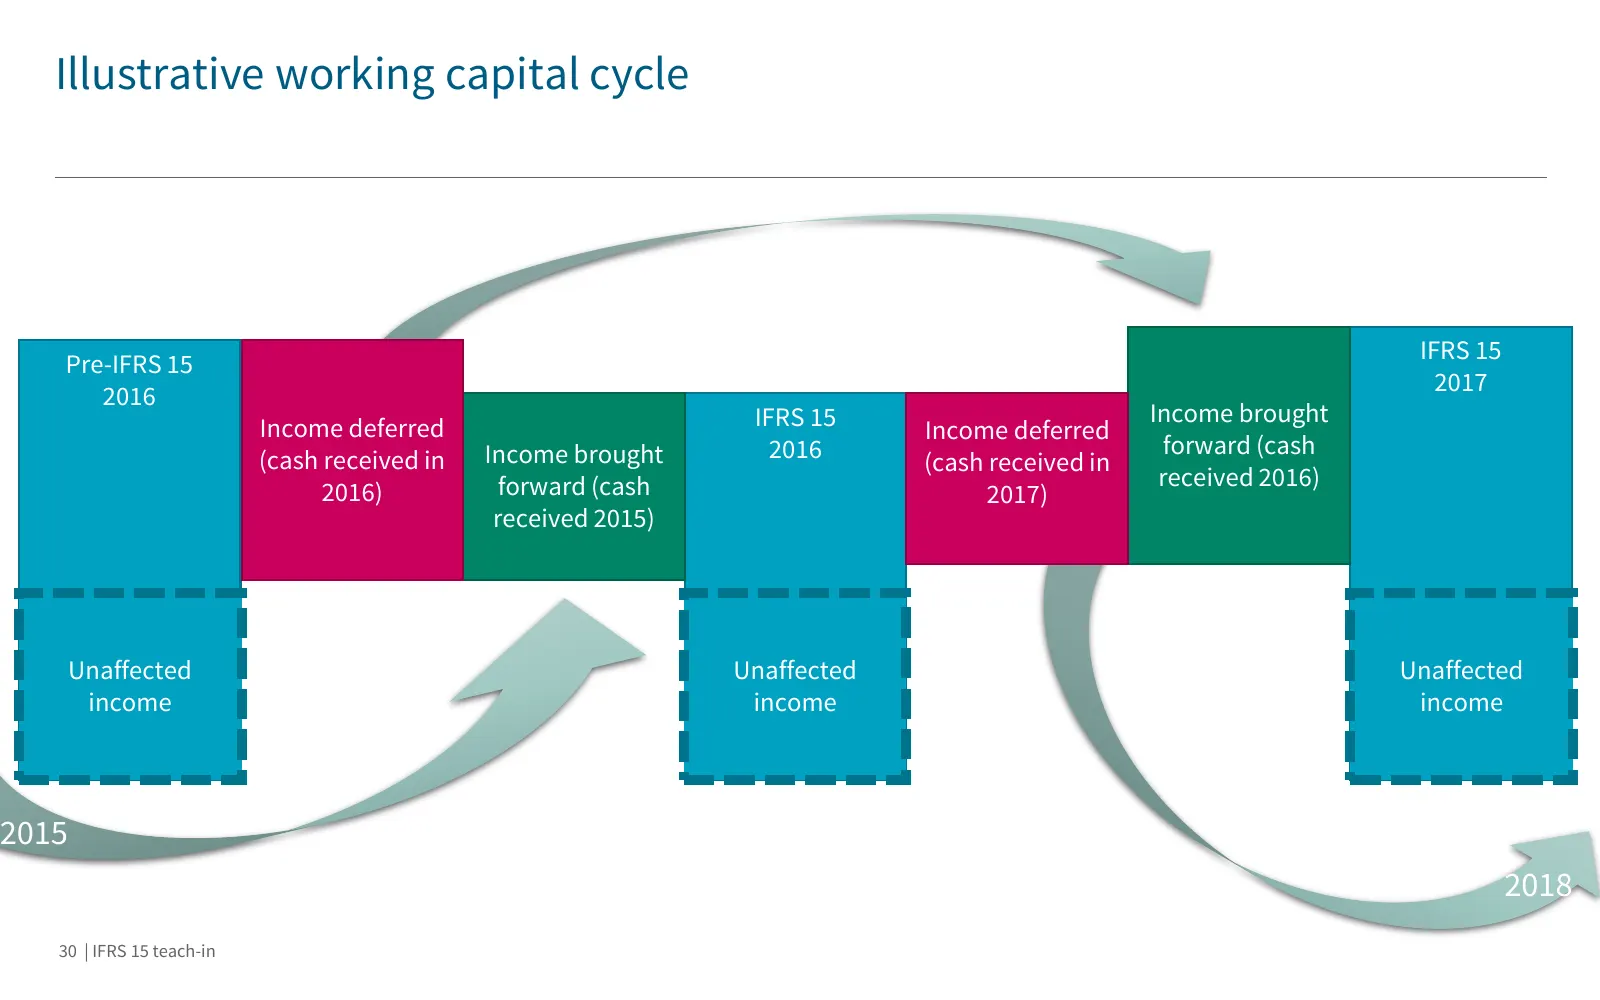
Illustrative working capital cycle IFRS 15 Pre-IFRS 15 2017 2016 IFRS 15 Income brought Income deferred Income deferred Income brought 2016 forward (cash (cash received in (cash received in forward (cash received 2016) 2016) 2017) received 2015) Unaffected Unaffected Unaffected income income income
Slide 31: Presentation of underlying operating profit
Presentation of underlying operating profit • New presentation of the in year profits/losses from significant new contract wins and related, or significant, restructuring. Provides greater transparency of performance • Underlying operating profit reported at the half year and full year to be analyse
Slide 32: IFRS 15 – re-cap of main impacts for Capita
IFRS 15 – re-cap of main impacts for Capita • Revenue: recognition of revenue over the life of major contracts and active software licences spread more evenly • Costs: certain transformation spend, previously expensed, now capitalised as contract fulfilment assets and released over the contract life
Slide 33: 2016 Results under IFRS 15
2016 Results under IFRS 15 Nick Greatorex Group Finance Director 33 | IFRS 15 teach-in
Slide 34: Underlying results excluding discontinued operations
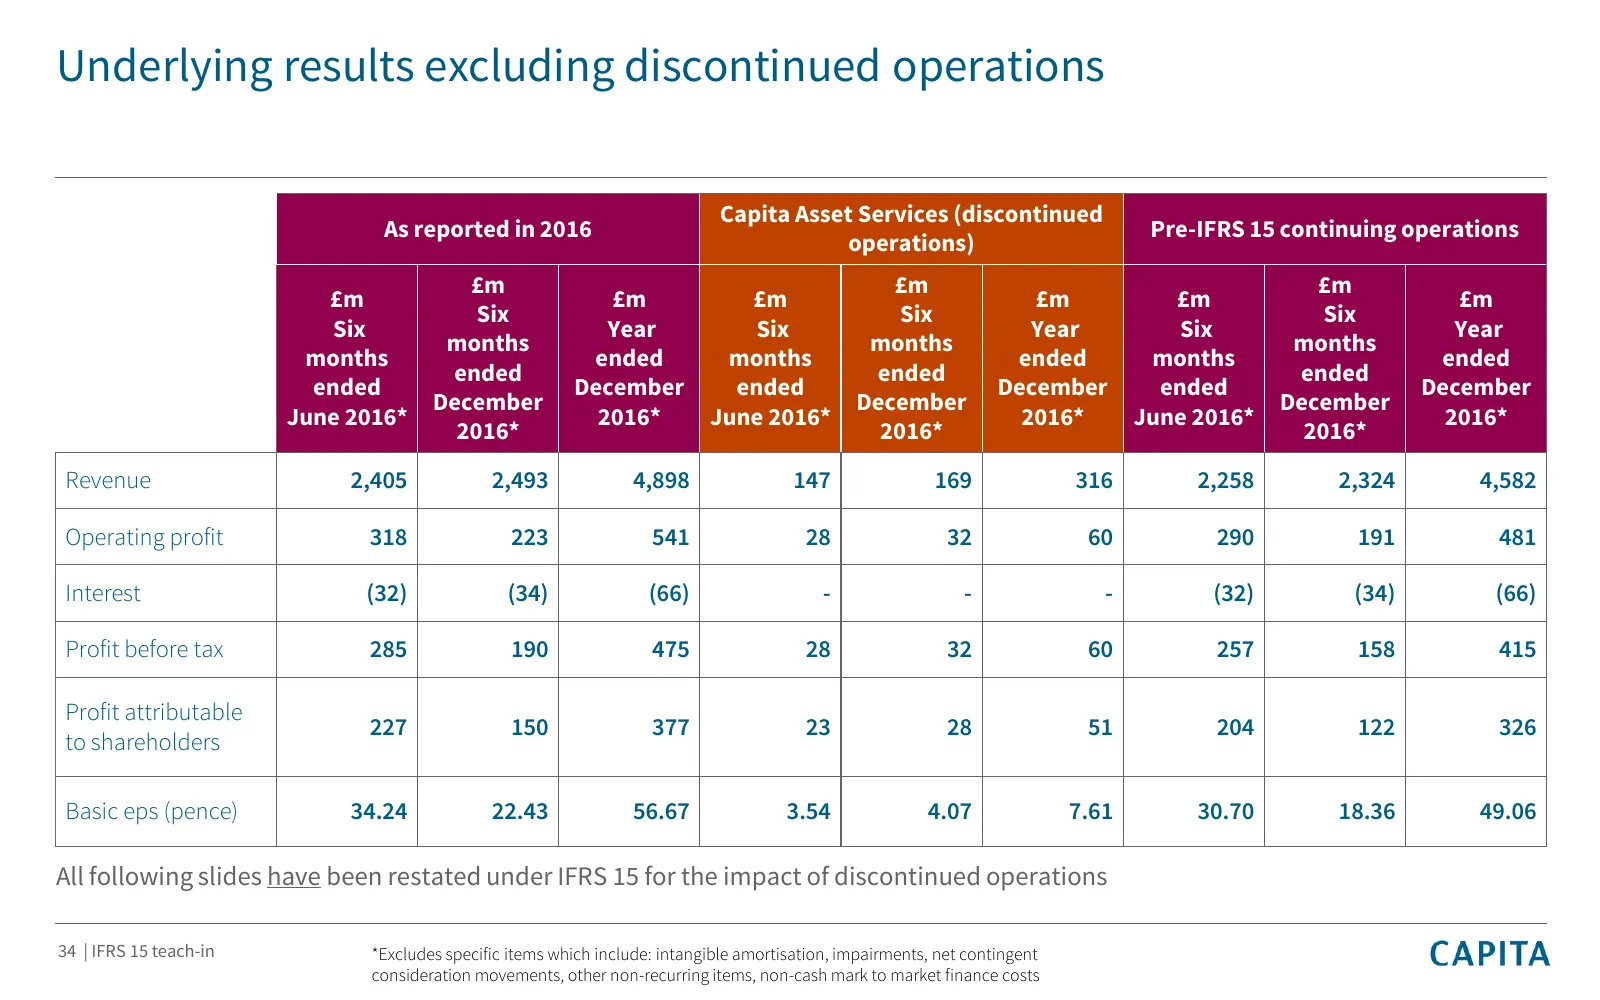
Underlying results excluding discontinued operations Capita Asset Services (discontinued As reported in 2016 Pre-IFRS 15 continuing operations operations) £m £m £m £m £m £m £m £m £m Six Six Six Six Year Six Year Six Year months months months months ended months ended months ended ended ended ended e
Slide 35: Underlying income statement
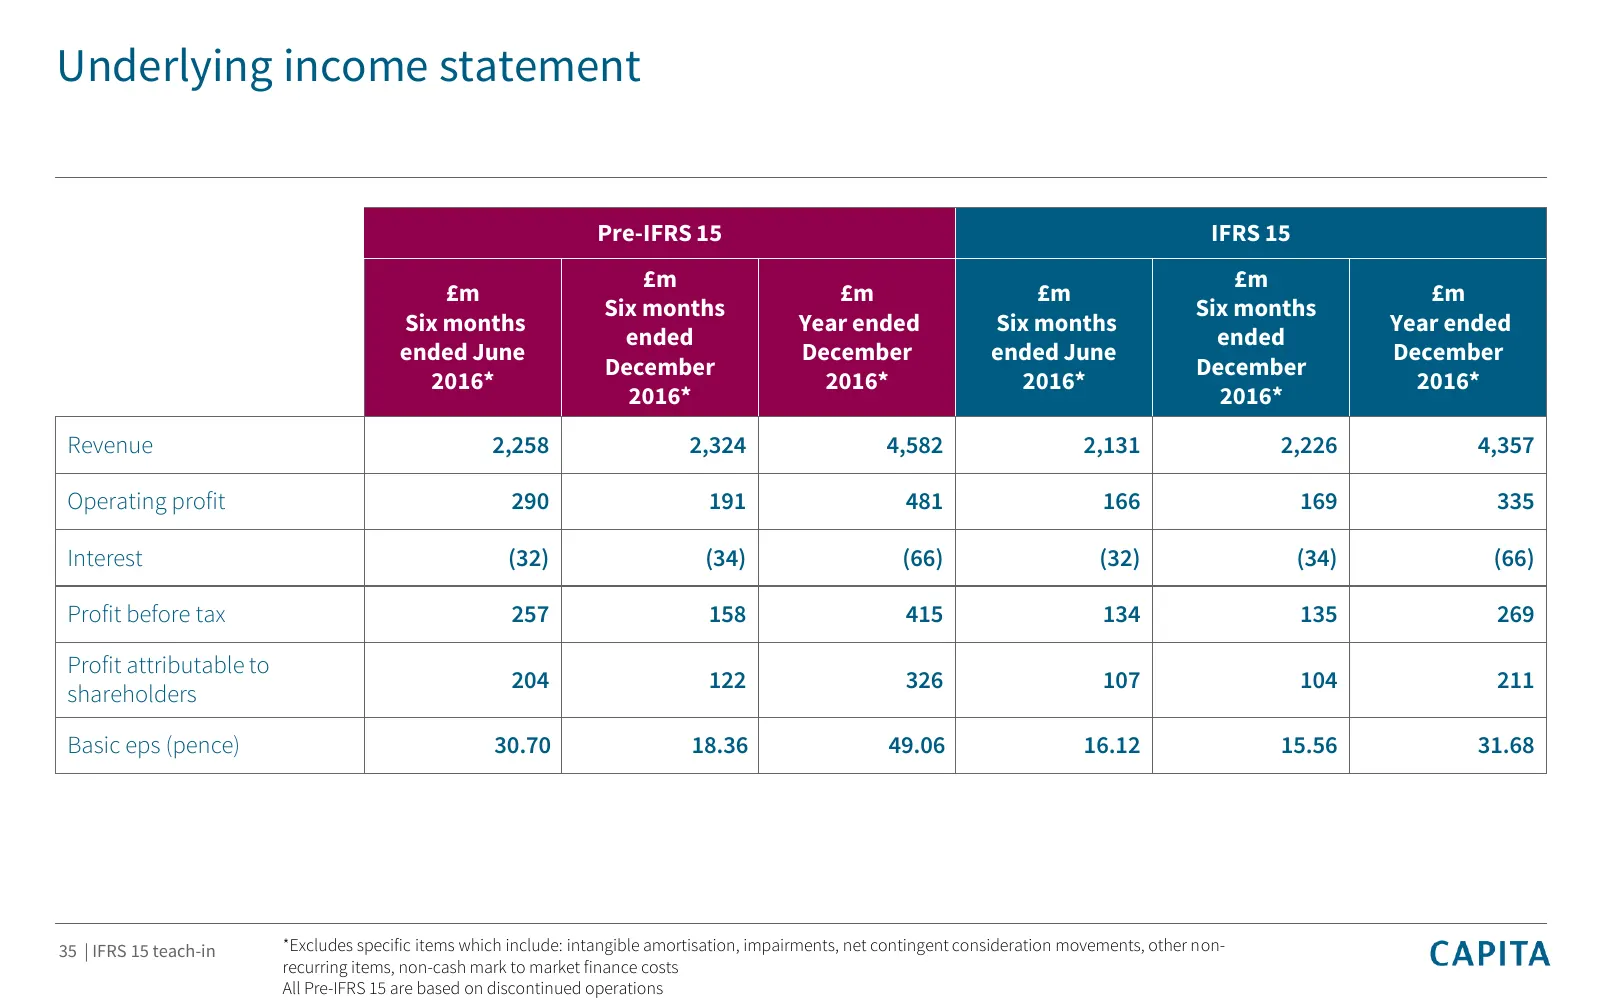
Underlying income statement Pre-IFRS 15 IFRS 15 £m £m £m £m £m £m Six months Six months Six months Year ended Six months Year ended ended ended ended June December ended June December December December 2016* 2016* 2016* 2016* 2016* 2016* Revenue 2,258 2,324 4,582 2,131 2,226 4,357 Operating profit 2
Slide 36: Underlying revenue
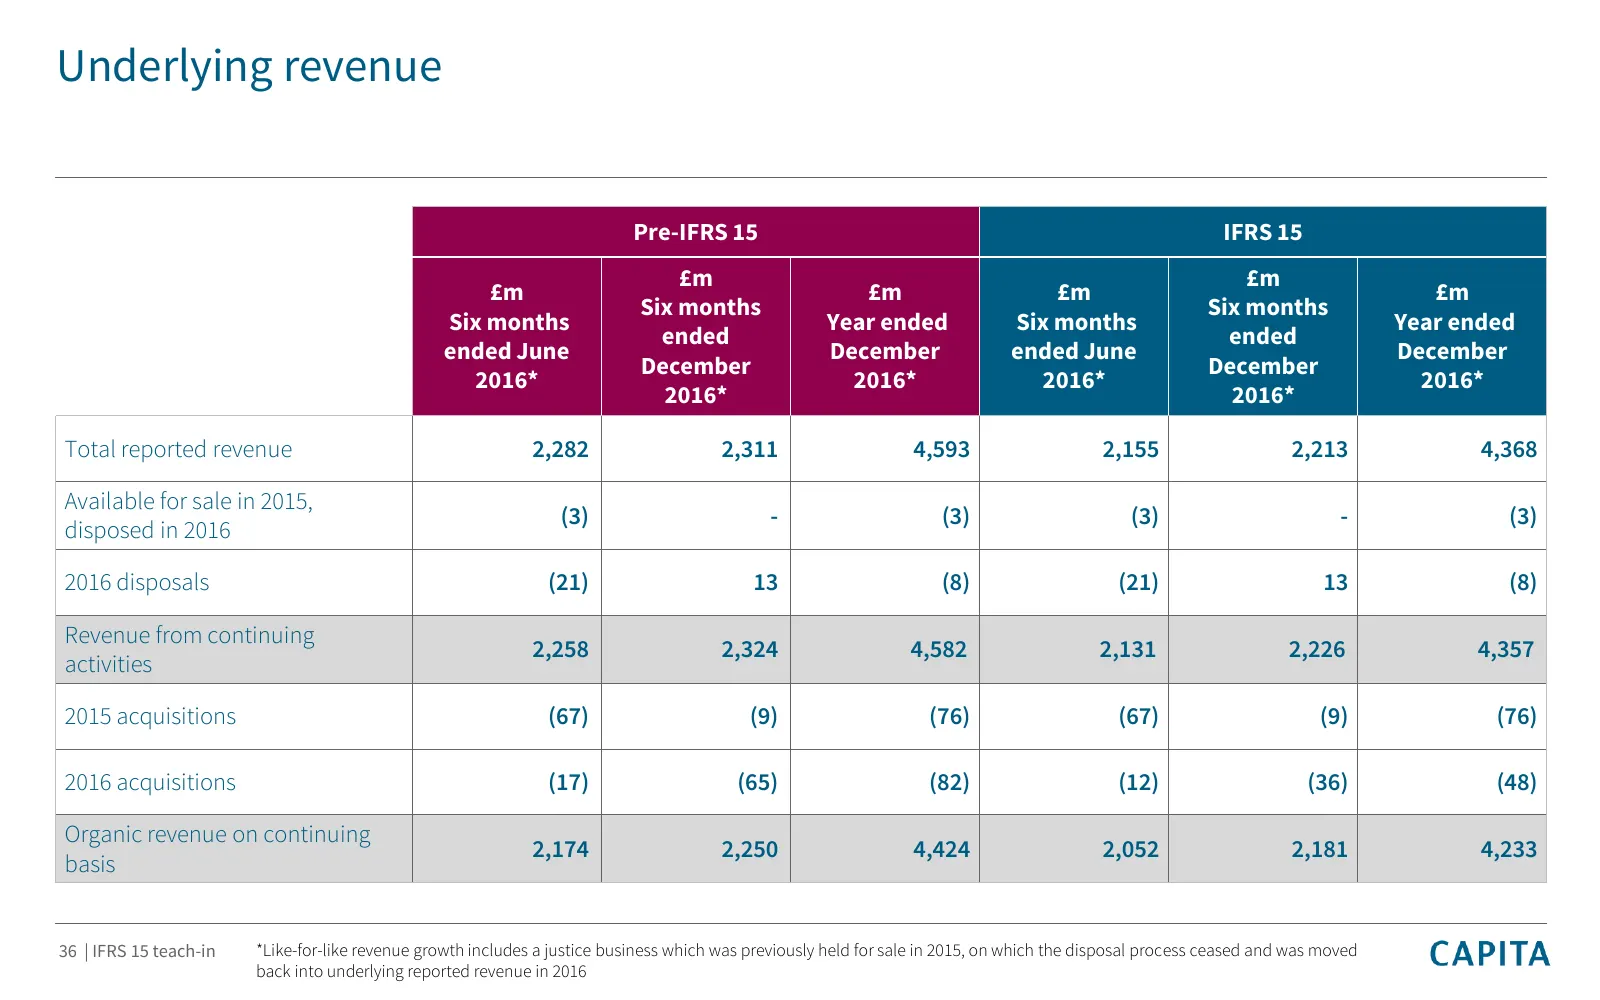
Underlying revenue Pre-IFRS 15 IFRS 15 £m £m £m £m £m £m Six months Six months Six months Year ended Six months Year ended ended ended ended June December ended June December December December 2016* 2016* 2016* 2016* 2016* 2016* Total reported revenue 2,282 2,311 4,593 2,155 2,213 4,368 Available fo
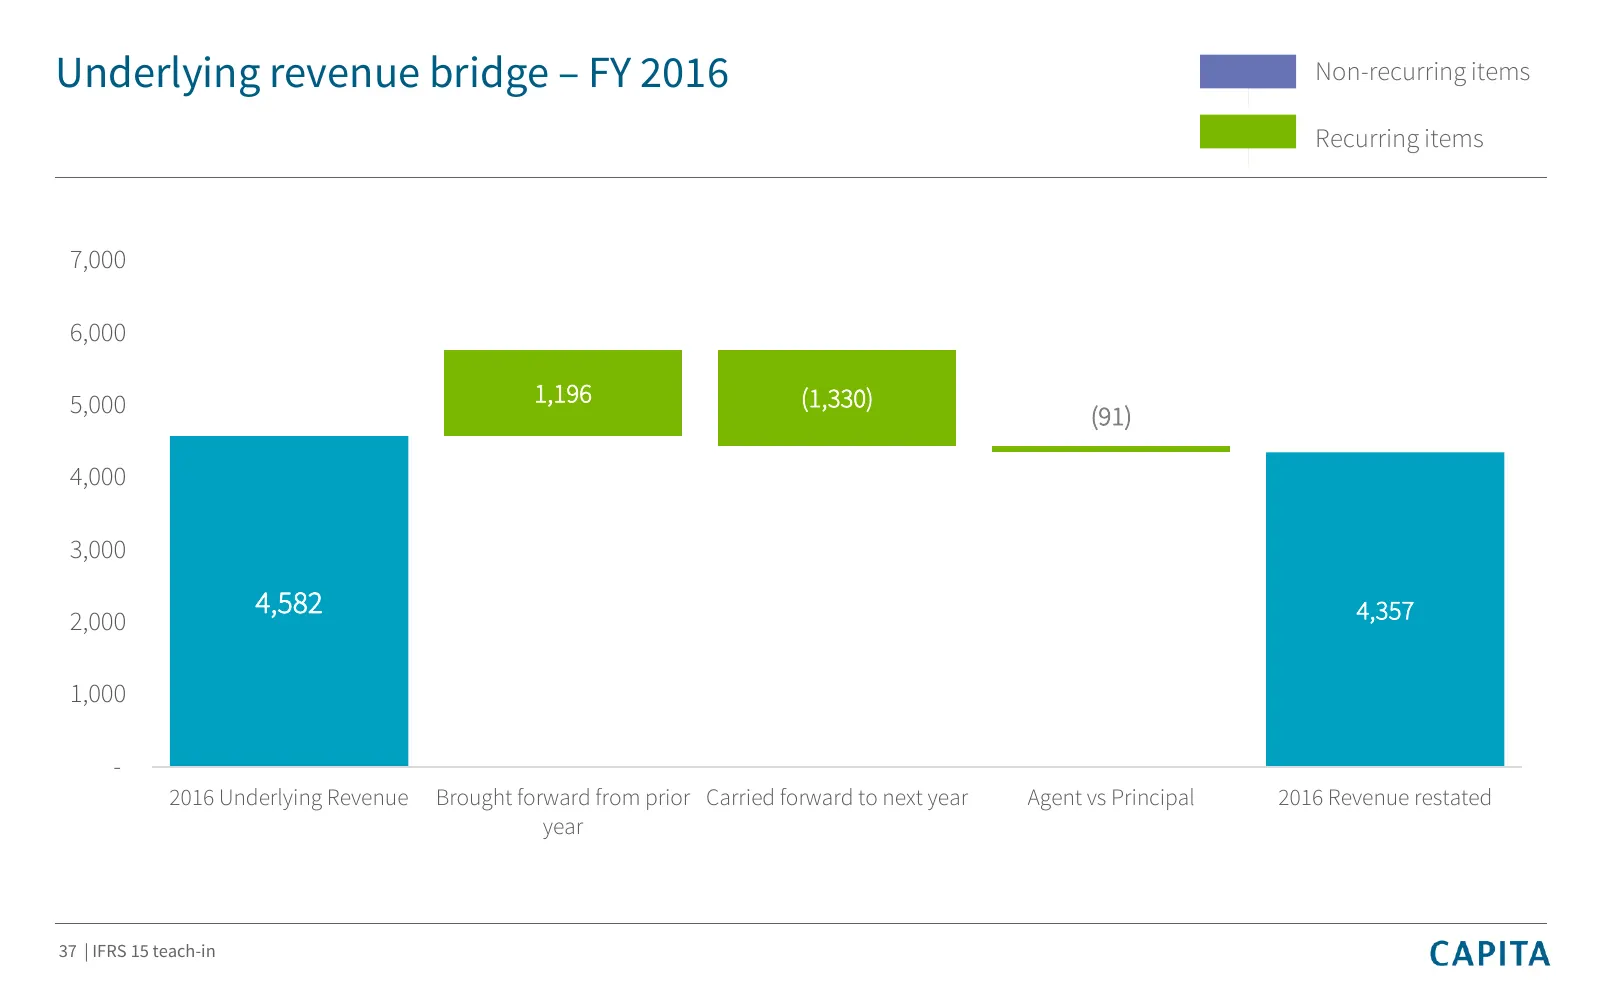
Slide 37: Underlying revenue bridge – FY 2016
Underlying revenue bridge – FY 2016 Non-recurring items Recurring items 7,000 6,000 5,000 1,196 (1,330) (91) 4,000 3,000 4,582 4,357 2,000 1,000 - 2016 Underlying Revenue Brought forward from prior Carried forward to next year Agent vs Principal 2016 Revenue restated year 37 | IFRS 15 teach-in
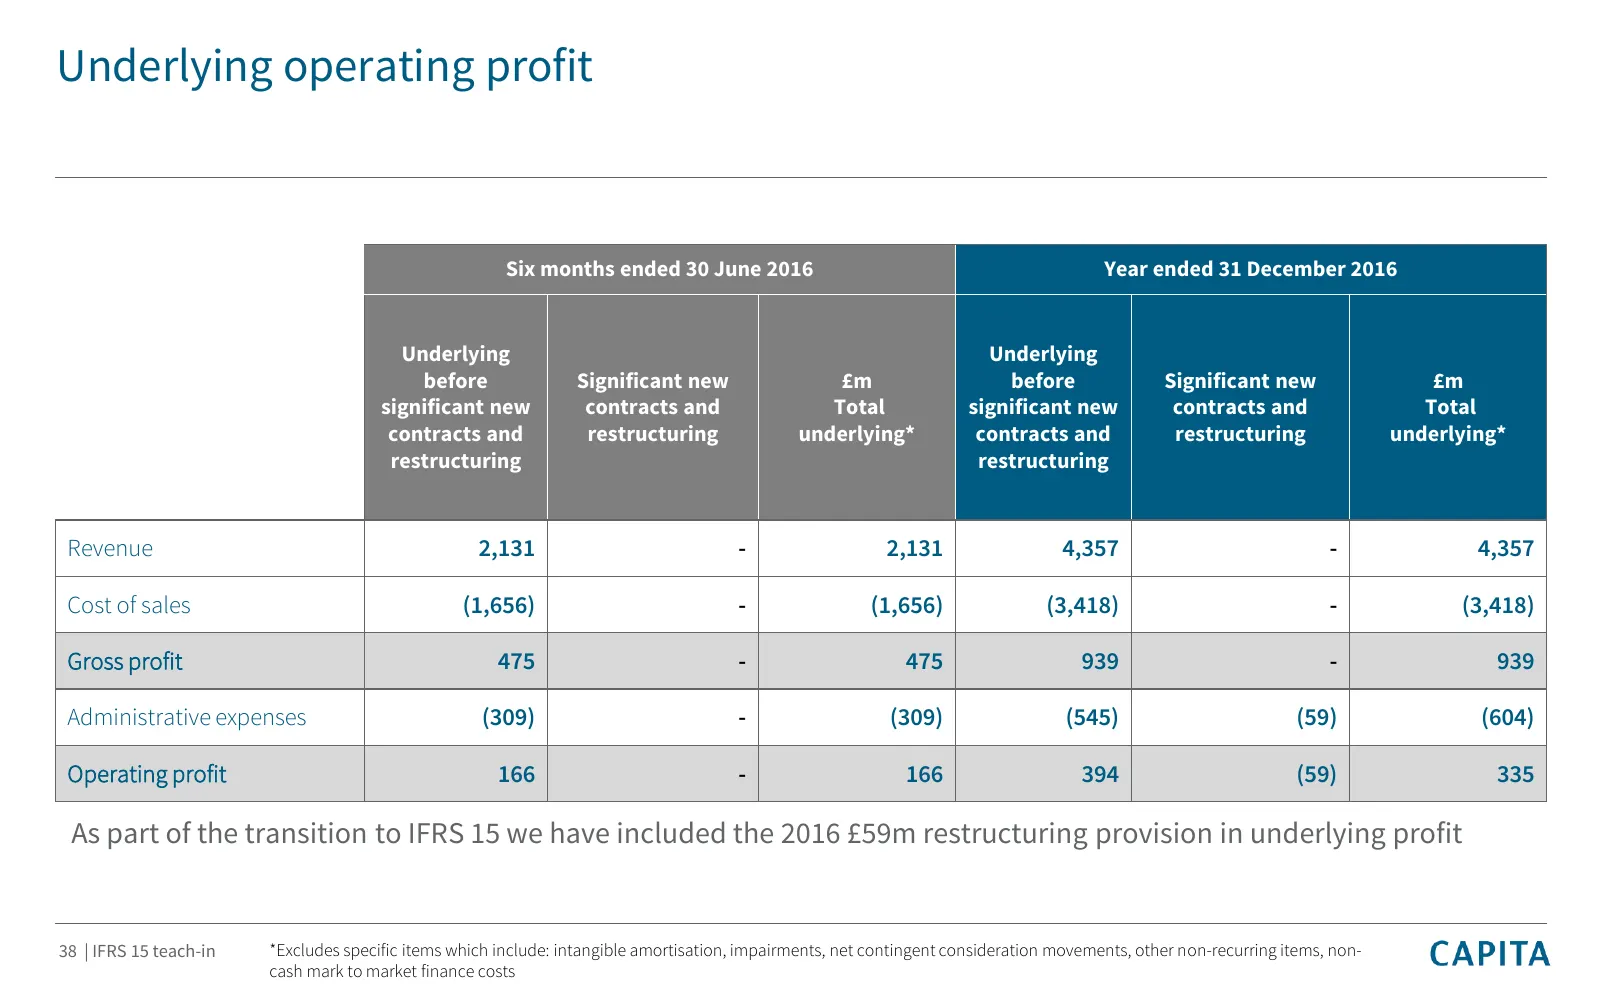
Slide 38: Underlying operating profit
Underlying operating profit Six months ended 30 June 2016 Year ended 31 December 2016 Underlying Underlying before Significant new £m before Significant new £m significant new contracts and Total significant new contracts and Total contracts and restructuring underlying* contracts and restructuring
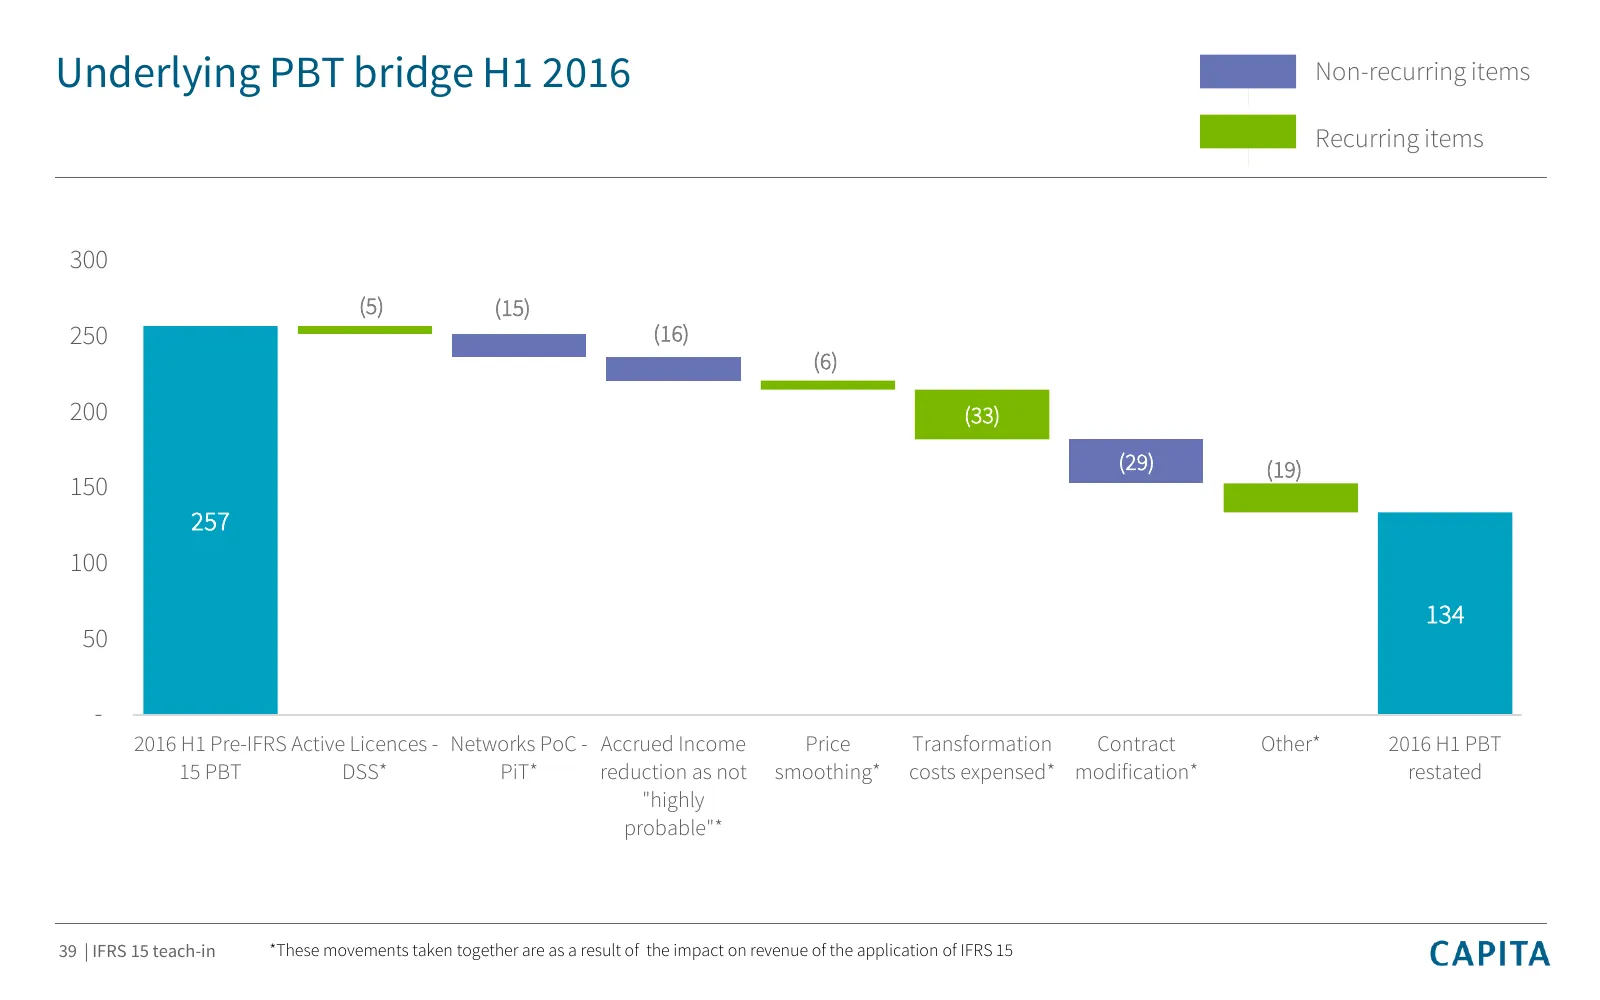
Slide 39: Underlying PBT bridge H1 2016
Underlying PBT bridge H1 2016 Non-recurring items Recurring items 300 (5) (15) 250 (16) (6) 200 (33) (29) (19) 150 257 100 134 50 - 2016 H1 Pre-IFRS Active Licences - Networks PoC - Accrued Income Price Transformation Contract Other* 2016 H1 PBT 15 PBT DSS* PiT* reduction as not smoothing* costs exp
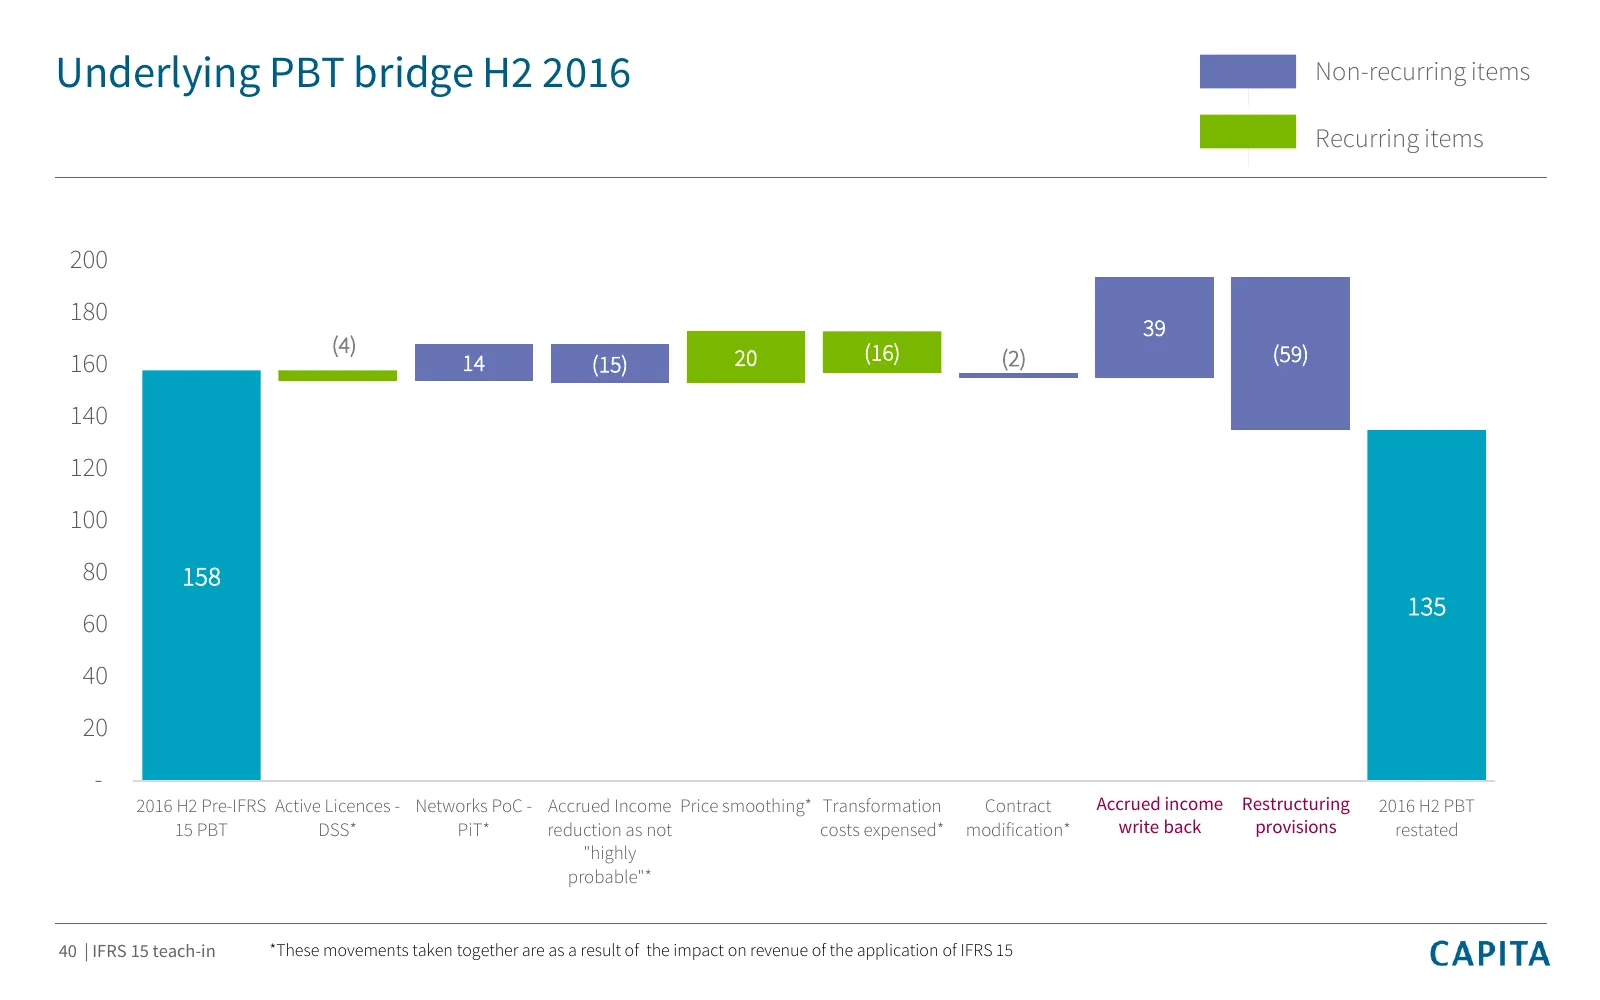
Slide 40: Underlying PBT bridge H2 2016
Underlying PBT bridge H2 2016 Non-recurring items Recurring items 200 180 39 (4) (16) (59) 160 14 (15) 20 (2) 140 120 100 80 158 135 60 40 20 - 2016 H2 Pre-IFRS Active Licences - Networks PoC - Accrued Income Price smoothing* Transformation Contract Accrued income Restructuring 2016 H2 PBT 15 PBT DS
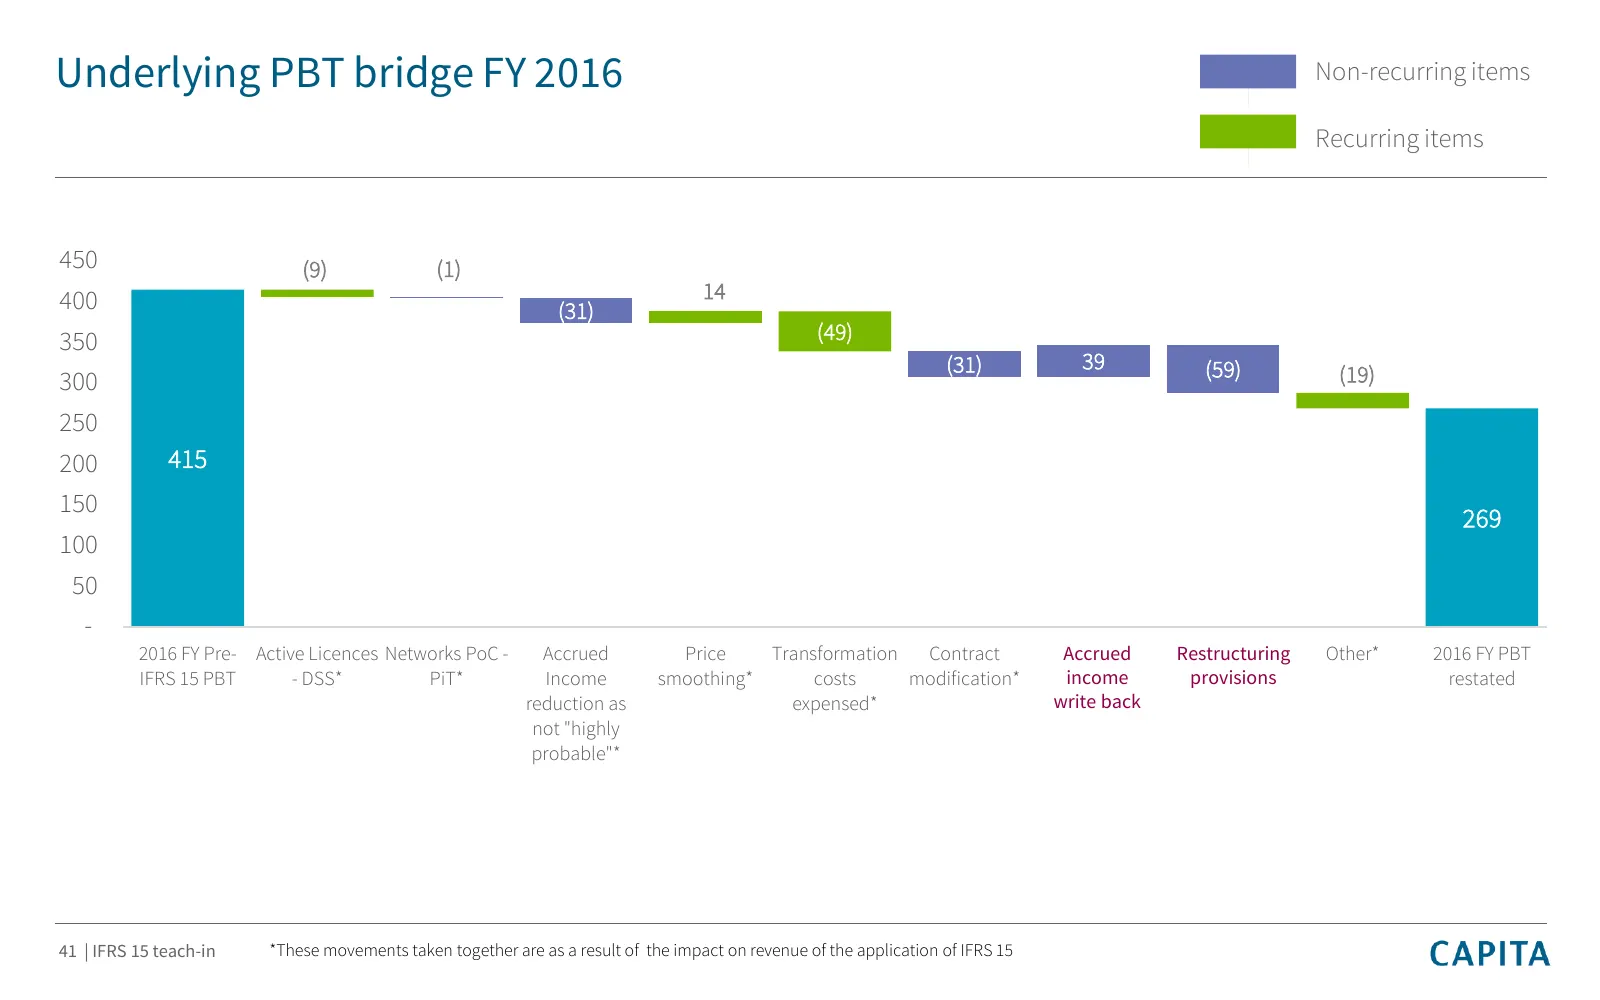
Slide 41: Underlying PBT bridge FY 2016
Underlying PBT bridge FY 2016 Non-recurring items Recurring items 450 (9) (1) 400 14 (31) 350 (49) (31) 39 (59) 300 (19) 250 200 415 150 269 100 50 - 2016 FY Pre- Active Licences Networks PoC - Accrued Price Transformation Contract Accrued Restructuring Other* 2016 FY PBT IFRS 15 PBT - DSS* PiT* Inc
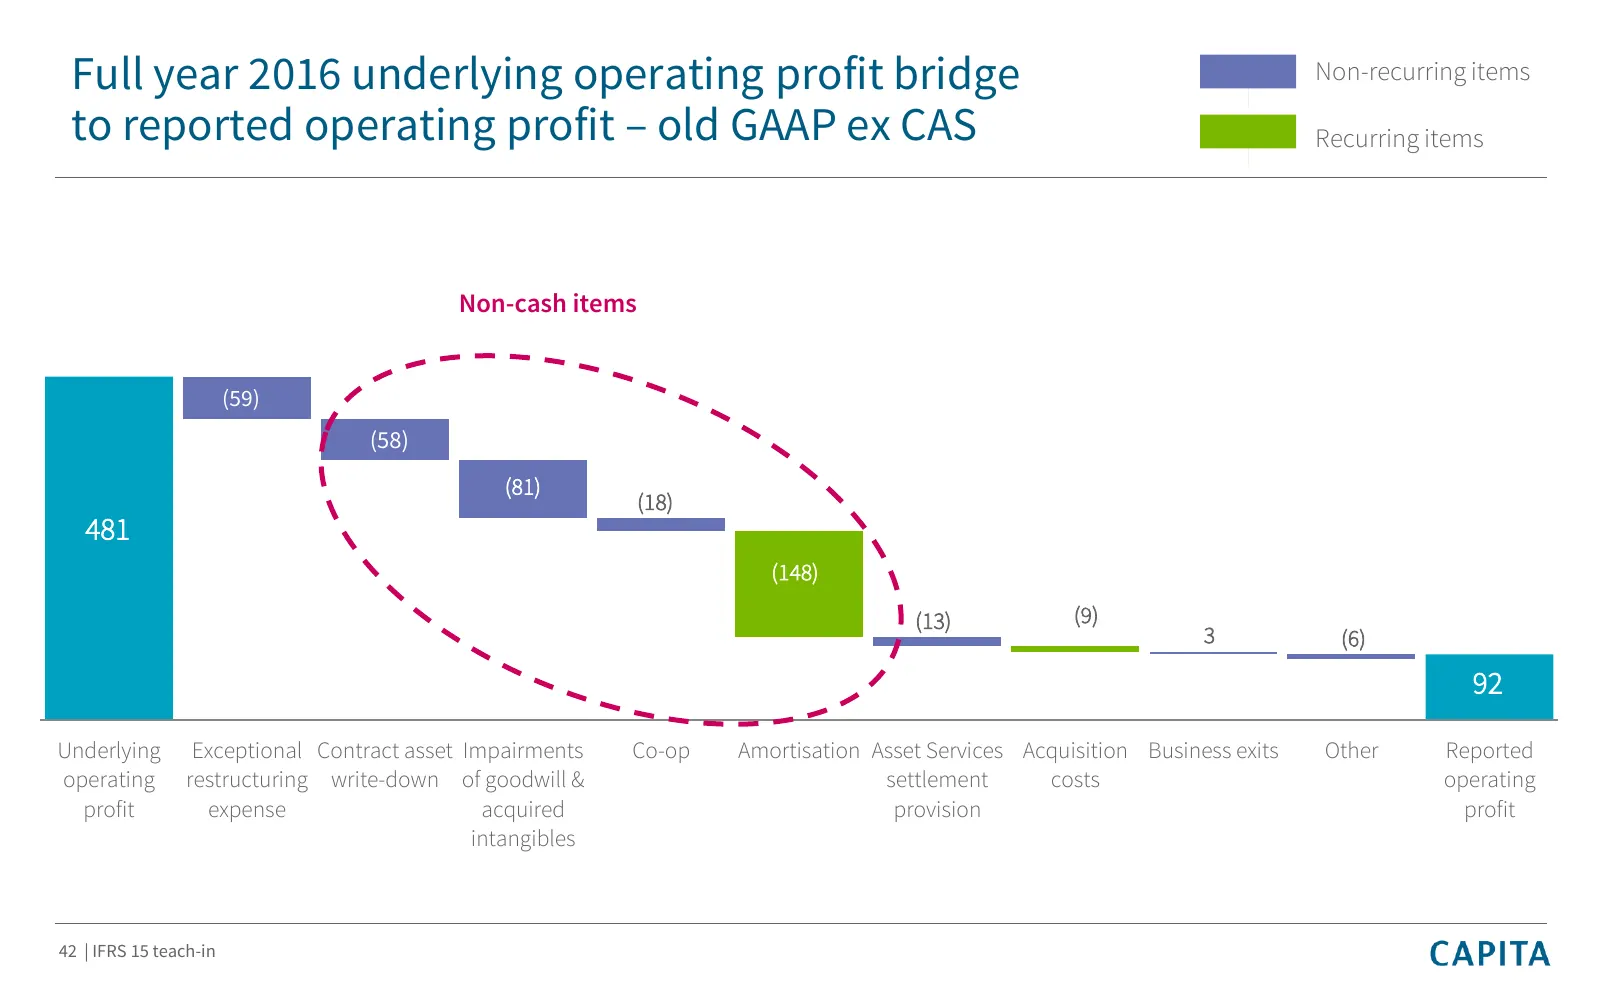
Slide 42: FY2016 underlying to reported operating profit bridge – old GAAP
Full year 2016 underlying operating profit bridge Non-recurring items to reported operating profit – old GAAP ex CAS Recurring items Non-cash items (59) (58) (81) (18) 481 (148) (13) (9) 3 (6) 92 Underlying Exceptional Contract asset Impairments Co-op Amortisation Asset Services Acquisition Business
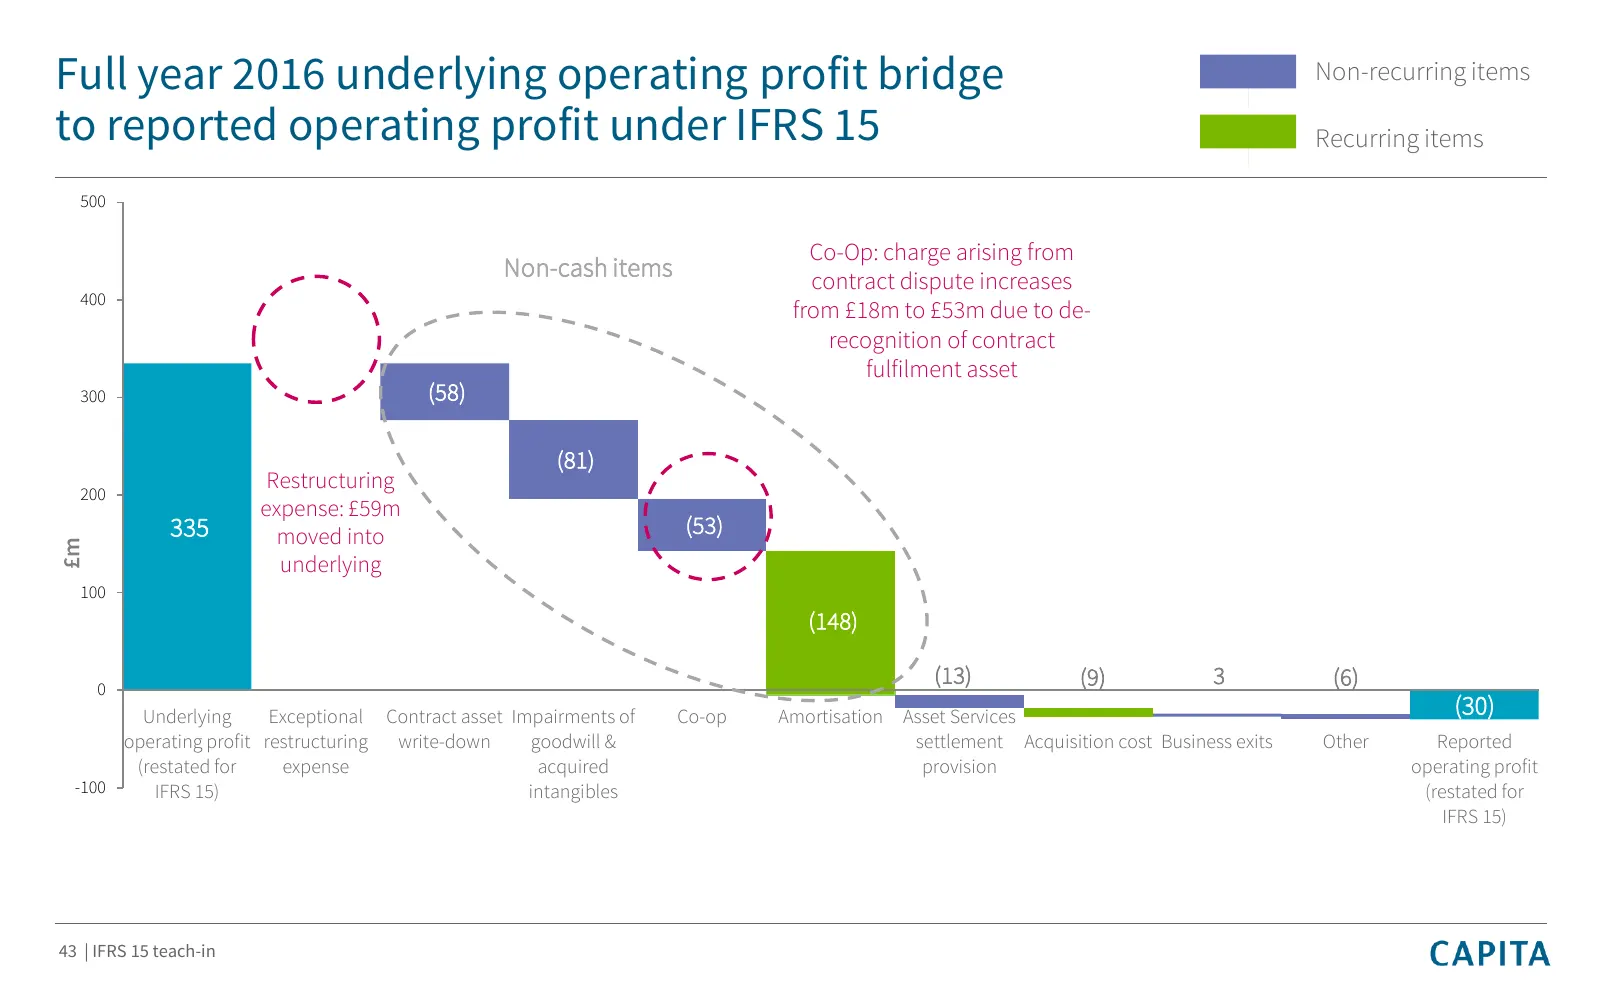
Slide 43: FY2016 underlying to reported operating profit bridge under IFRS 15
Full year 2016 underlying operating profit bridge Non-recurring items to reported operating profit under IFRS 15 Recurring items 500 Co-Op: charge arising from Non-cash items contract dispute increases 400 from £18m to £53m due to de- recognition of contract fulfilment asset 300 (58) (81) Restructur
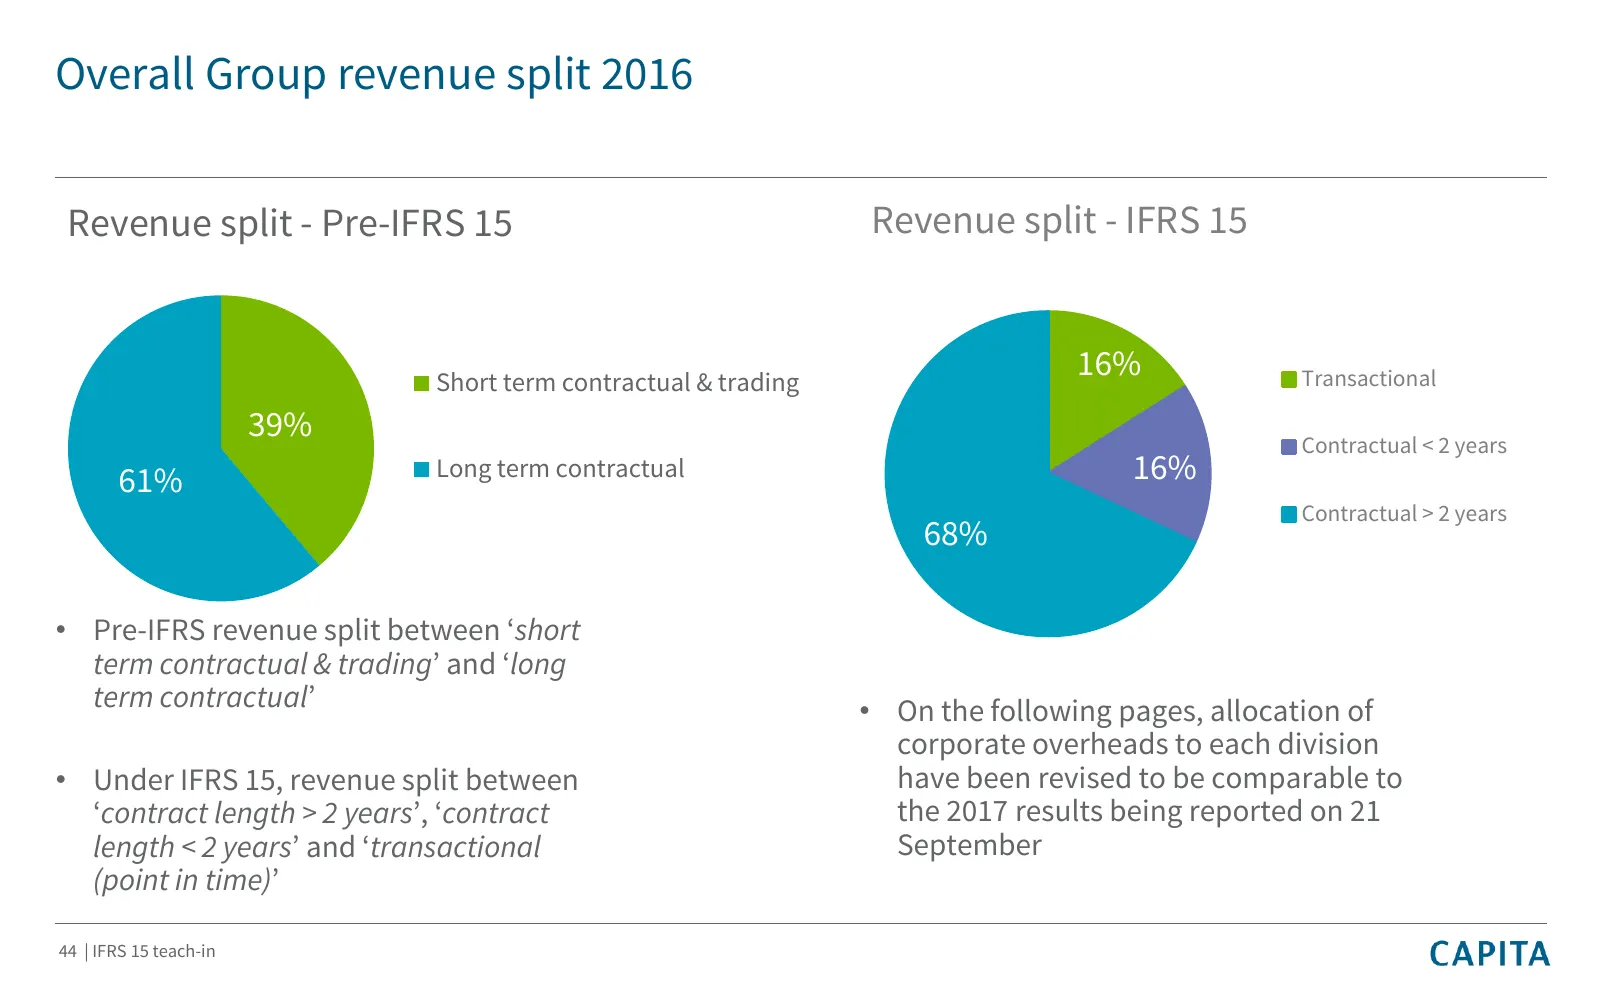
Slide 44: Overall Group revenue split 2016
Overall Group revenue split 2016 Revenue split - Pre-IFRS 15 Revenue split - IFRS 15 Short term contractual & trading 16% Transactional 39% Contractual < 2 years 61% Long term contractual 16% Contractual > 2 years 68% • Pre-IFRS revenue split between ‘short term contractual & trading’ and ‘long term
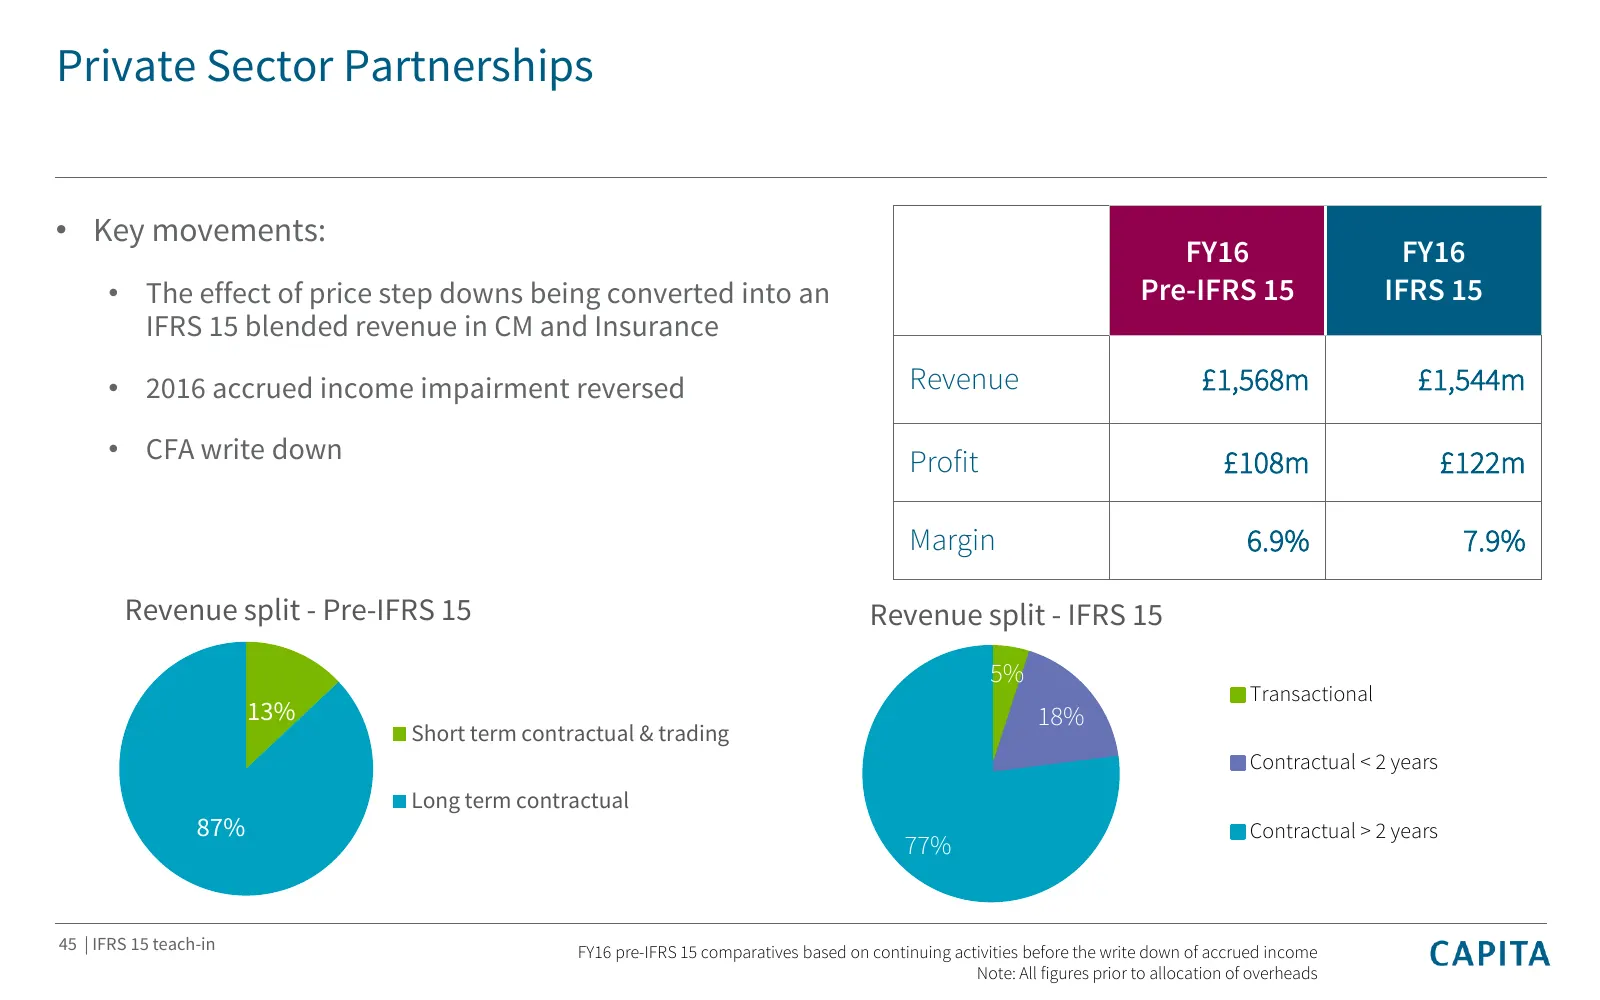
Slide 45: Private Sector Partnerships
Private Sector Partnerships • Key movements: FY16 FY16 • The effect of price step downs being converted into an Pre-IFRS 15 IFRS 15 IFRS 15 blended revenue in CM and Insurance • 2016 accrued income impairment reversed Revenue £1,568m £1,544m • CFA write down Profit £108m £122m Margin 6.9% 7.9% Reven
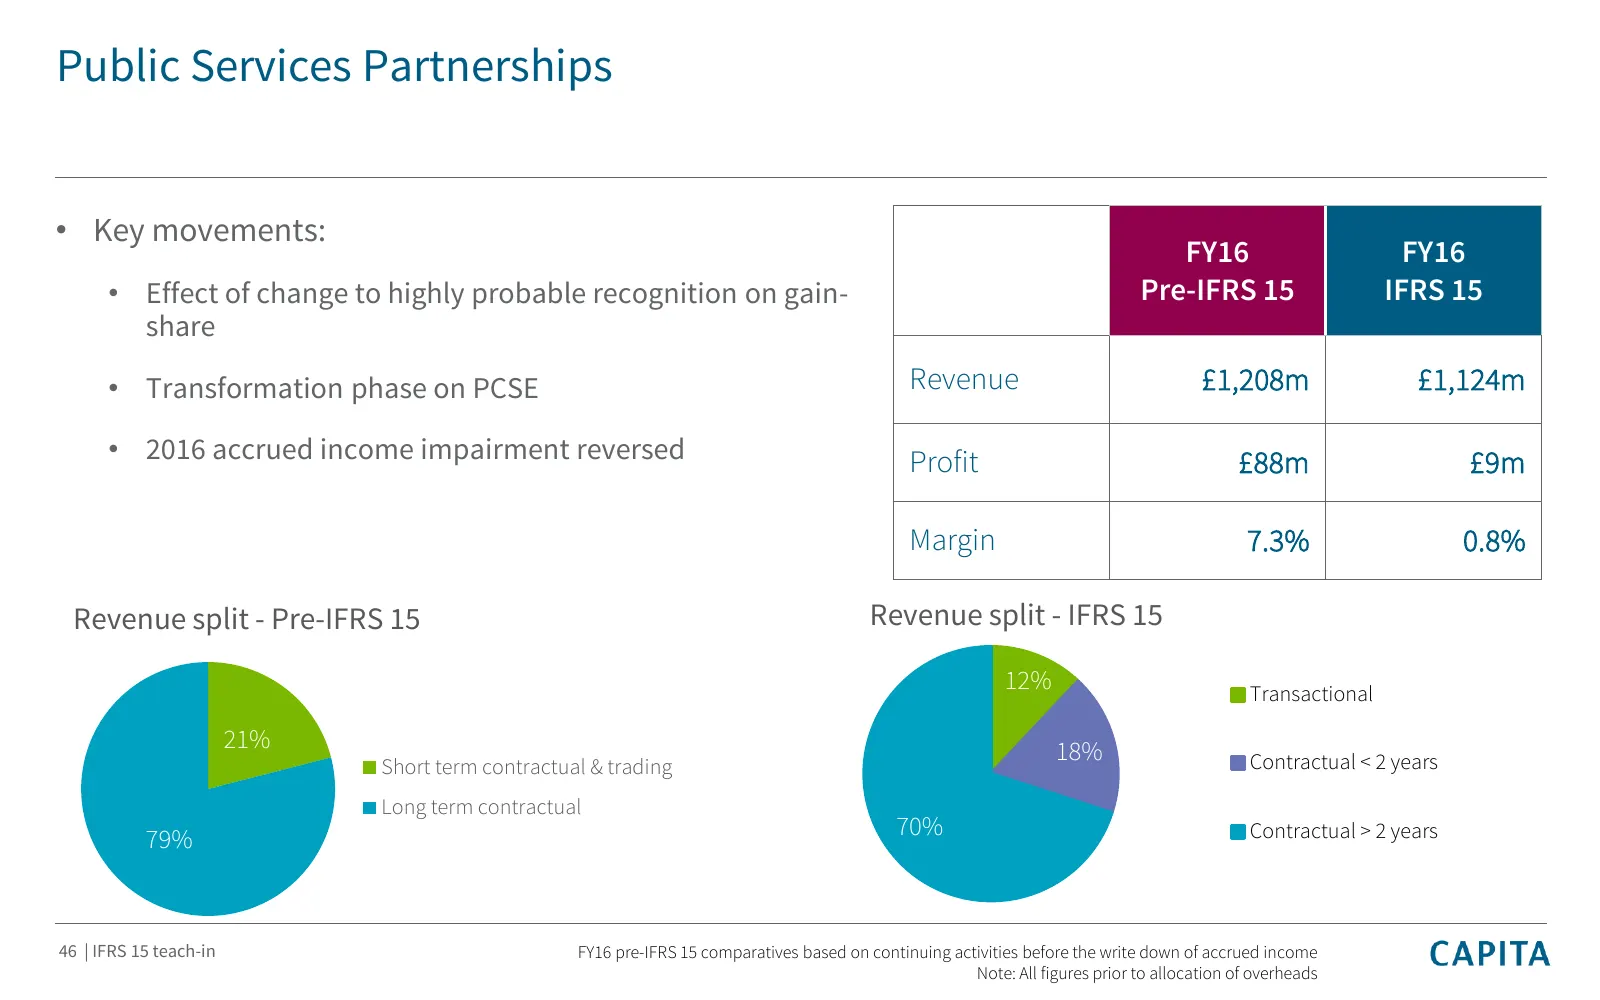
Slide 46: Public Services Partnerships
Public Services Partnerships • Key movements: FY16 FY16 • Effect of change to highly probable recognition on gain- Pre-IFRS 15 IFRS 15 share • Transformation phase on PCSE Revenue £1,208m £1,124m • 2016 accrued income impairment reversed Profit £88m £9m Margin 7.3% 0.8% Revenue split - Pre-IFRS 15 R
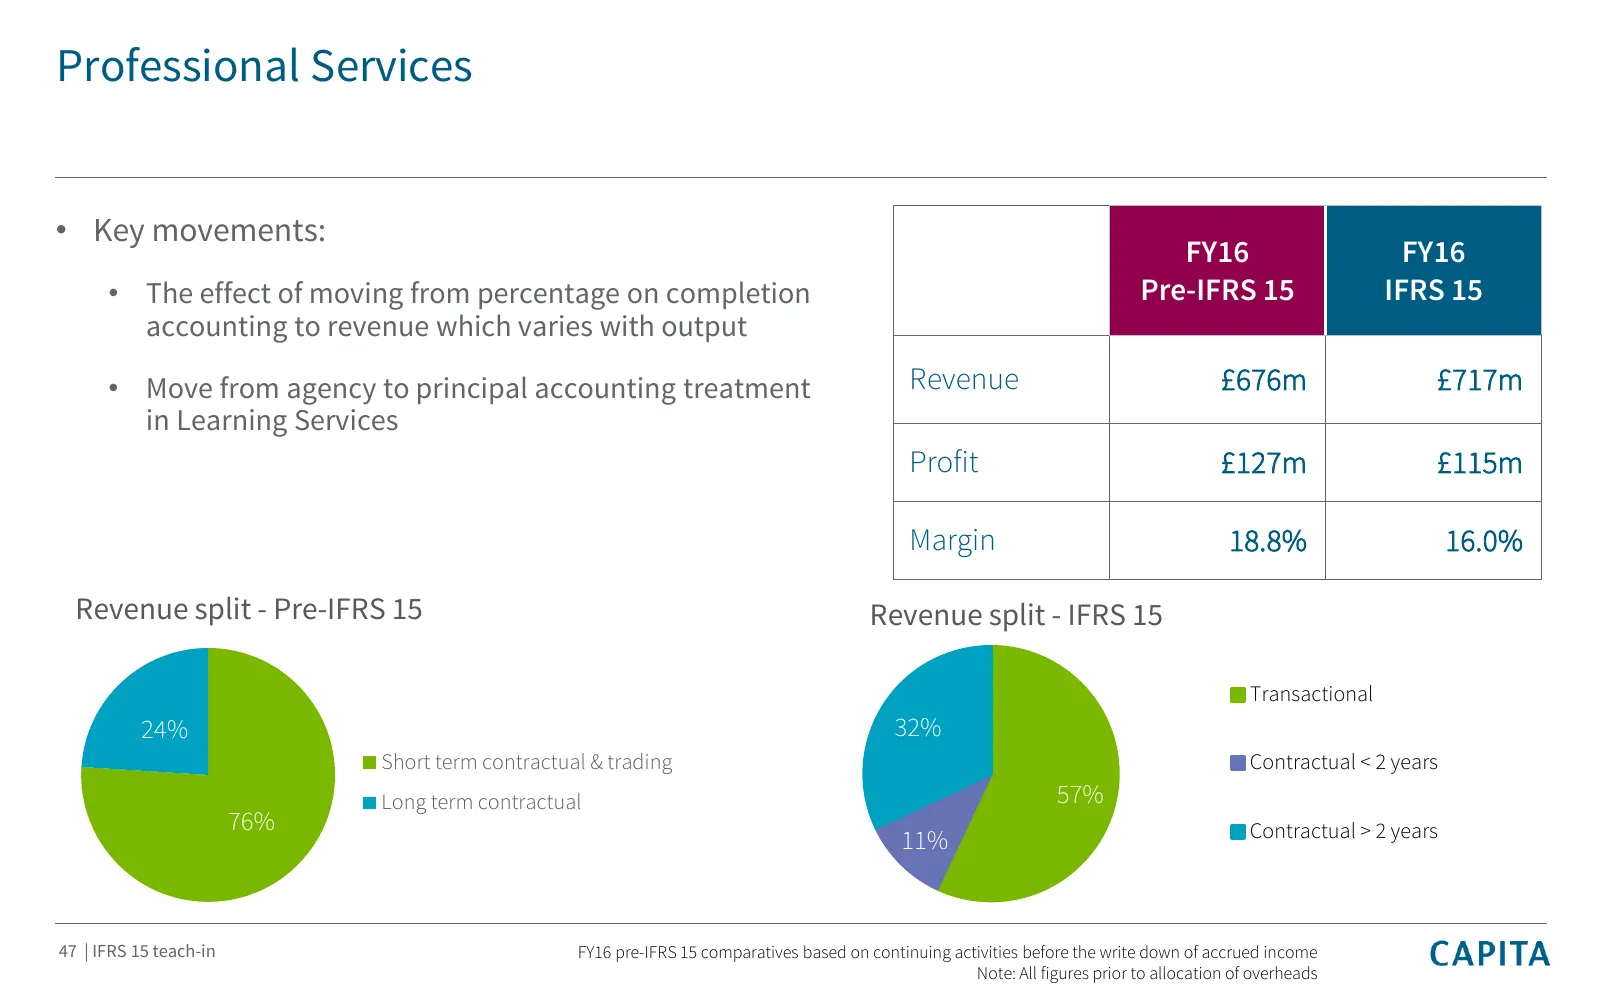
Slide 47: Professional Services
Professional Services • Key movements: FY16 FY16 • The effect of moving from percentage on completion Pre-IFRS 15 IFRS 15 accounting to revenue which varies with output • Move from agency to principal accounting treatment Revenue £676m £717m in Learning Services Profit £127m £115m Margin 18.8% 16.0%
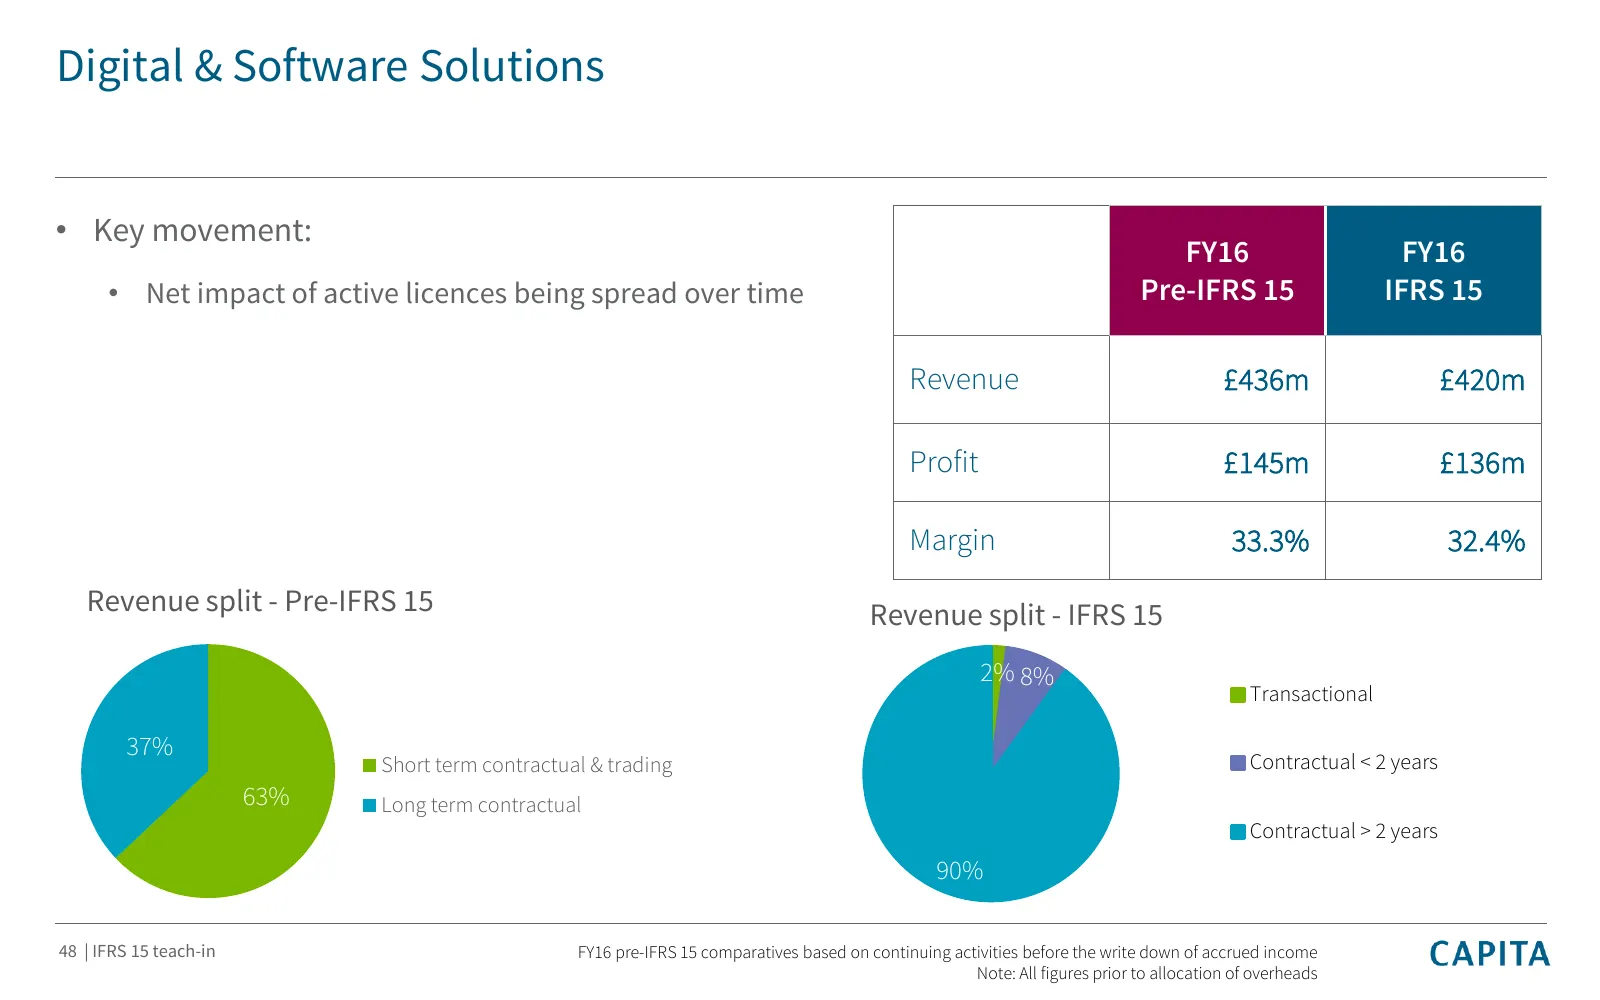
Slide 48: Digital & Software Solutions
Digital & Software Solutions • Key movement: FY16 FY16 • Net impact of active licences being spread over time Pre-IFRS 15 IFRS 15 Revenue £436m £420m Profit £145m £136m Margin 33.3% 32.4% Revenue split - Pre-IFRS 15 Revenue split - IFRS 15 2% 8% Transactional 37% Short term contractual & trading Con
Slide 49: IT Services
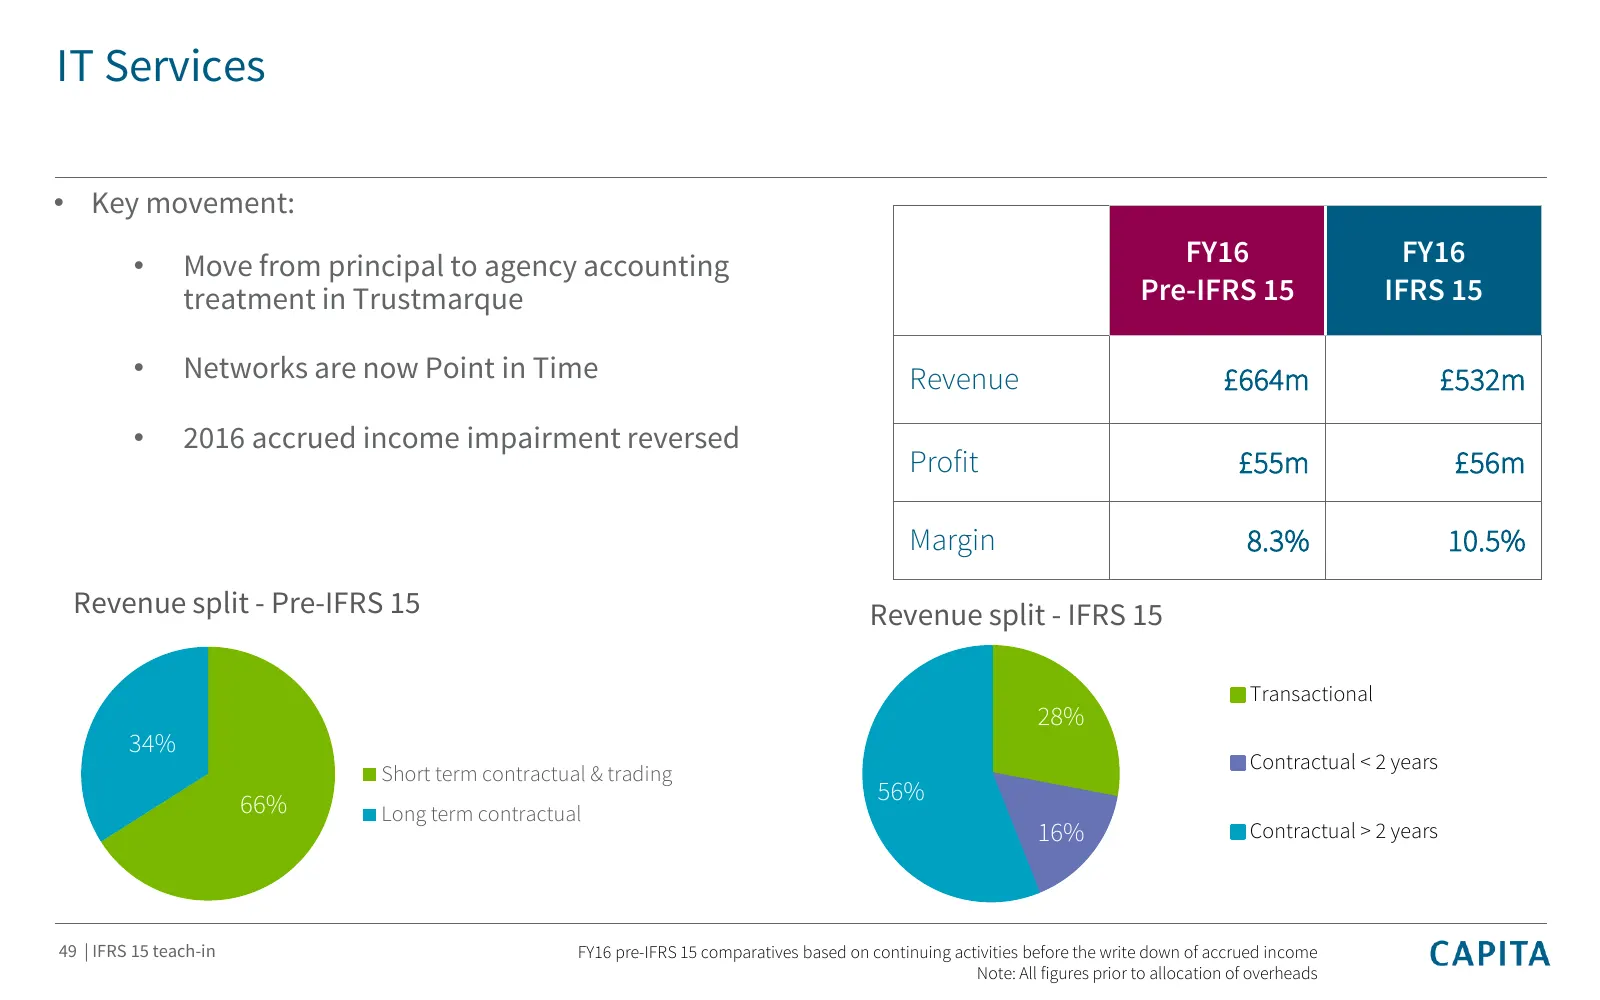
IT Services • Key movement: • Move from principal to agency accounting FY16 FY16 treatment in Trustmarque Pre-IFRS 15 IFRS 15 • Networks are now Point in Time Revenue £664m £532m • 2016 accrued income impairment reversed Profit £55m £56m Margin 8.3% 10.5% Revenue split - Pre-IFRS 15 Revenue split -
Slide 50: Underlying free funds from operations and free cash flows
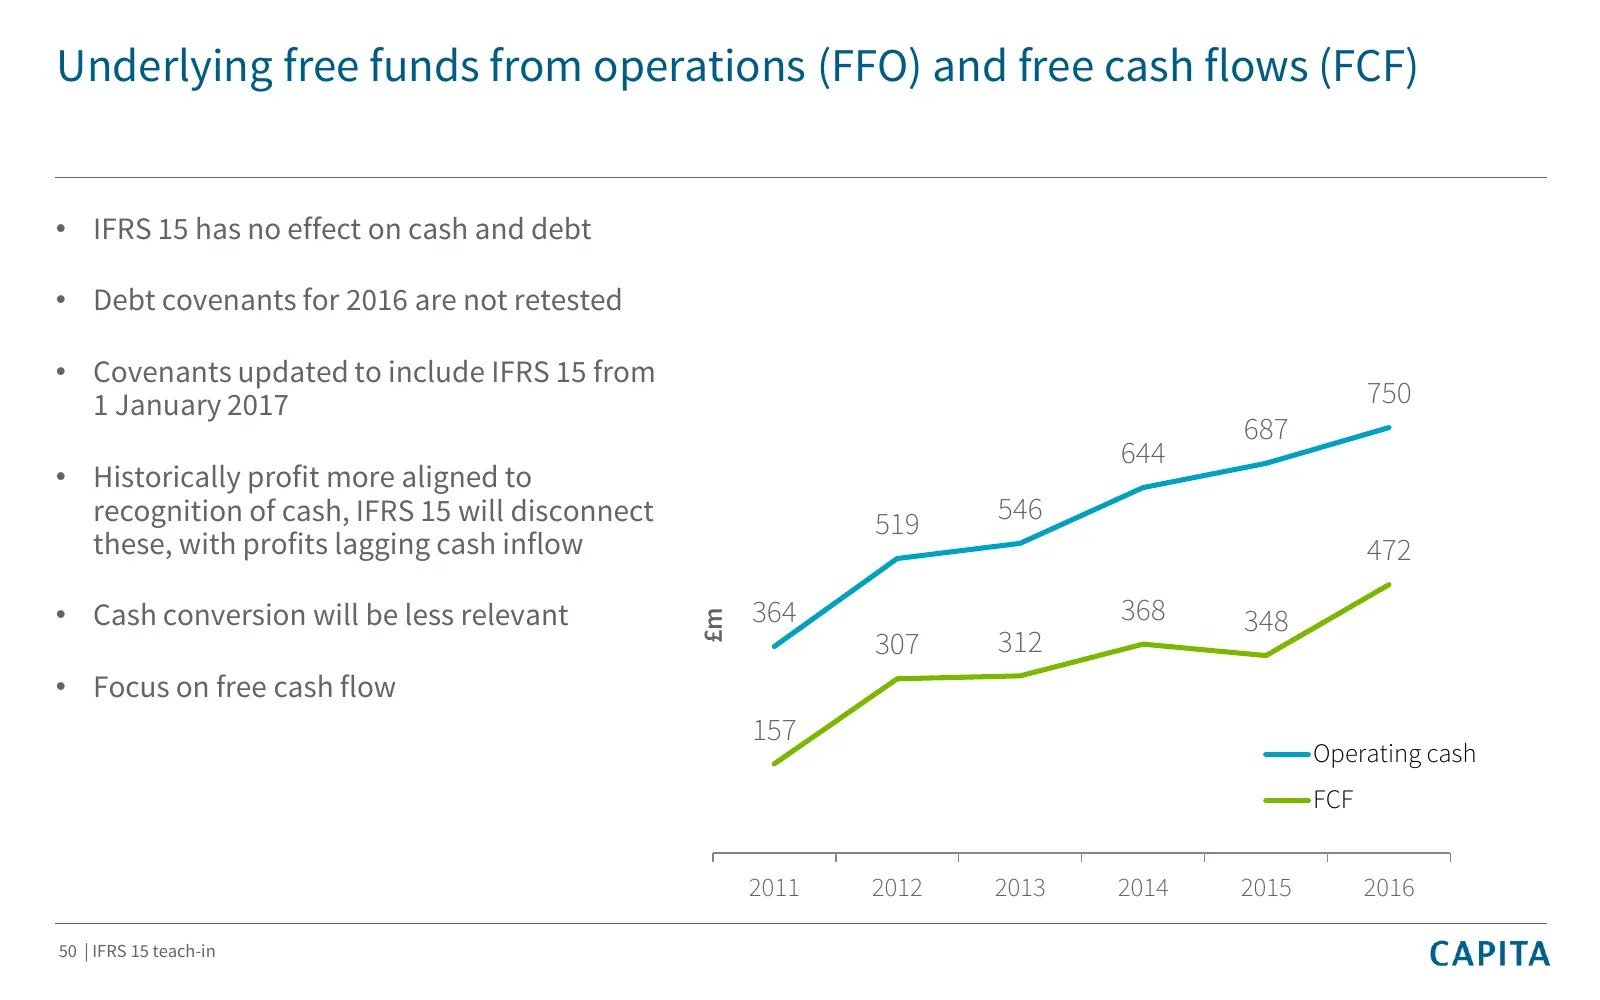
Underlying free funds from operations (FFO) and free cash flows (FCF) • IFRS 15 has no effect on cash and debt • Debt covenants for 2016 are not retested • Covenants updated to include IFRS 15 from 1 January 2017 750 687 644 • Historically profit more aligned to recognition of cash, IFRS 15 will dis
Slide 51: Balance sheet 2015
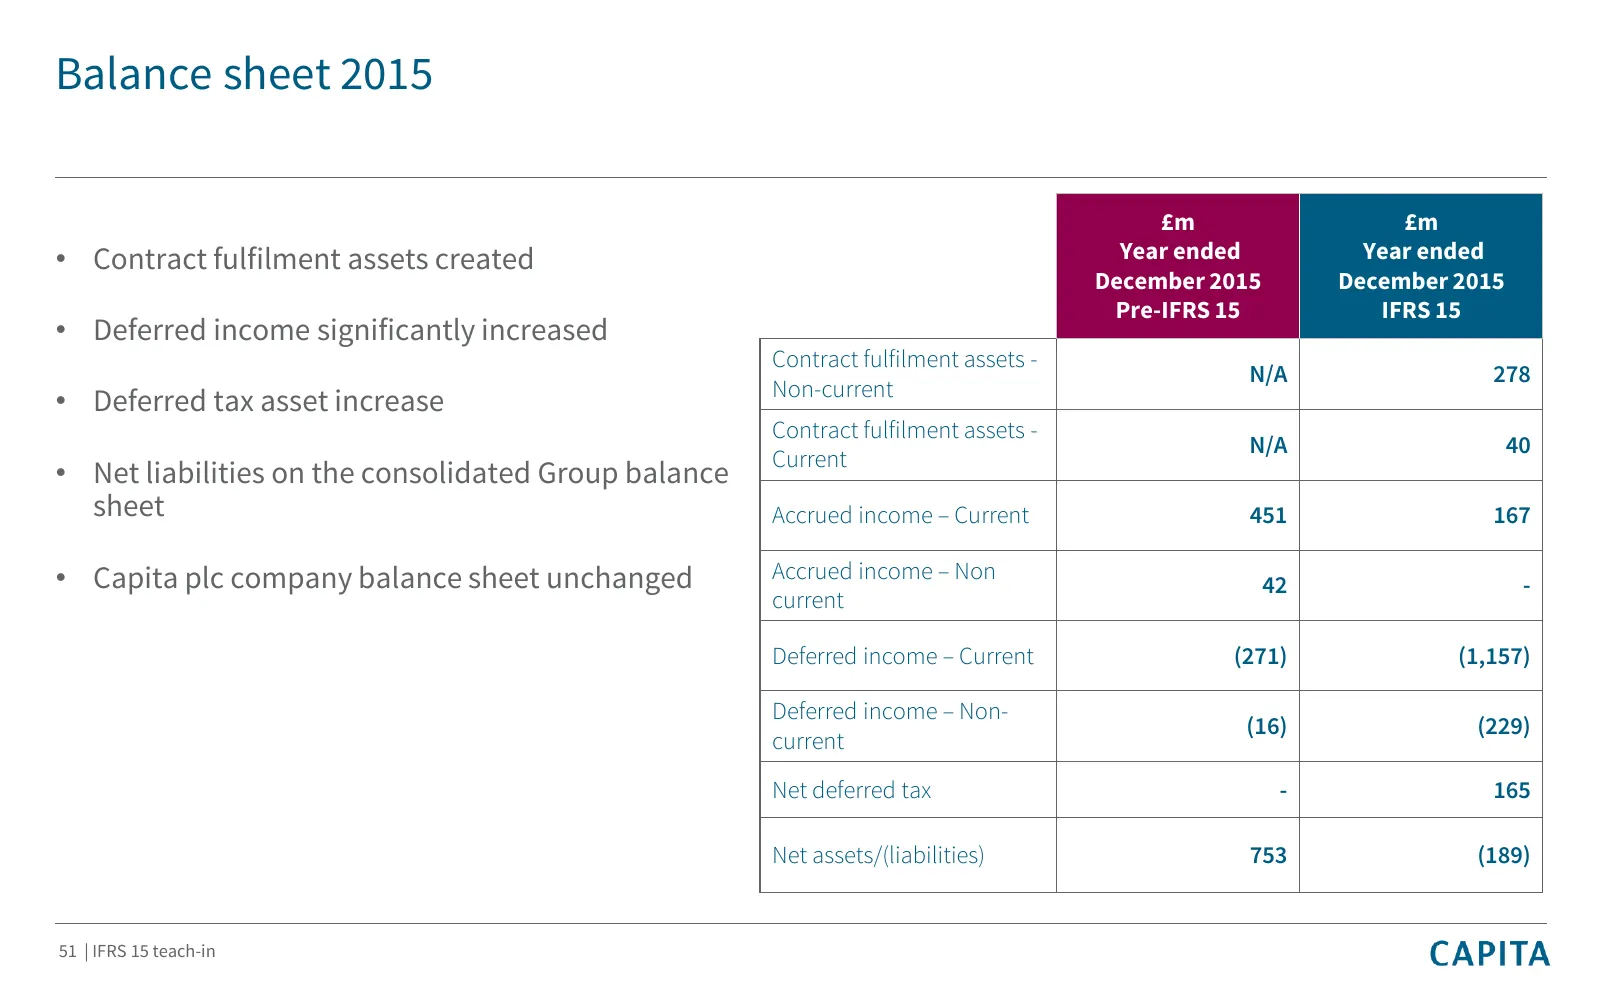
Balance sheet 2015 £m £m • Contract fulfilment assets created Year ended Year ended December 2015 December 2015 Pre-IFRS 15 IFRS 15 • Deferred income significantly increased Contract fulfilment assets - N/A 278 Non-current • Deferred tax asset increase Contract fulfilment assets - N/A 40 Current • N
Slide 52: IFRS 15 balance sheet bridge 2015-2016 – significant items
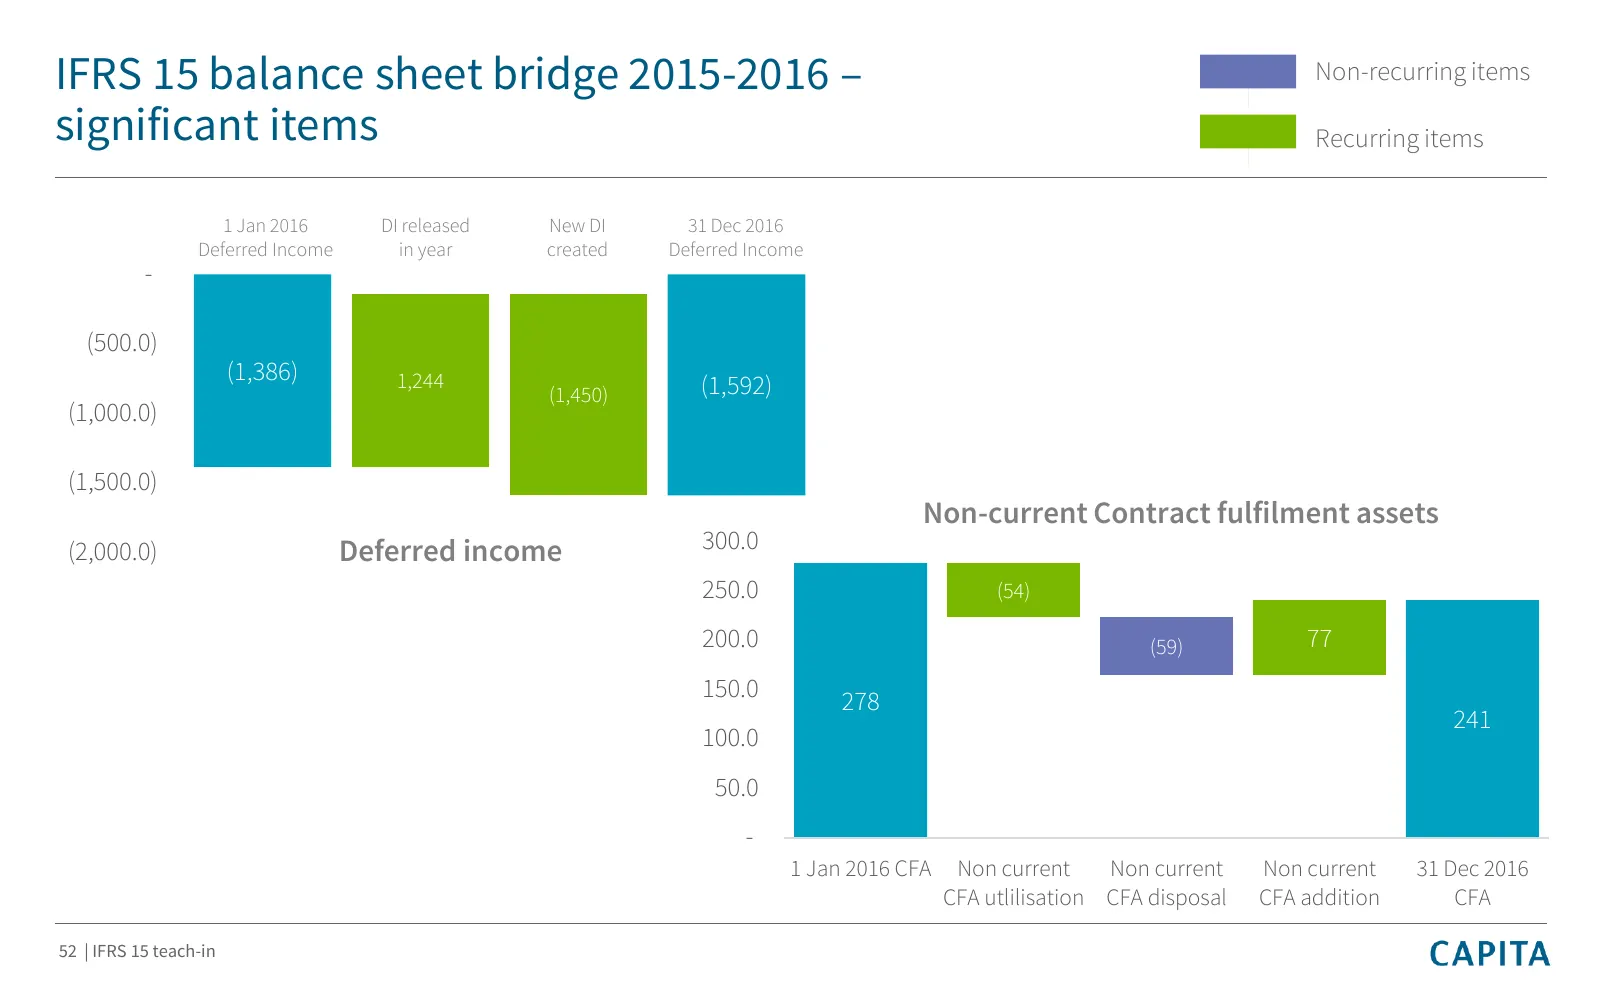
IFRS 15 balance sheet bridge 2015-2016 – Non-recurring items significant items Recurring items 1 Jan 2016 DI released New DI 31 Dec 2016 Deferred Income in year created Deferred Income - (500.0) (1,386) 1,244 (1,450) (1,592) (1,000.0) (1,500.0) Non-current Contract fulfilment assets (2,000.0) Deferr
Slide 53: Balance sheet 2016
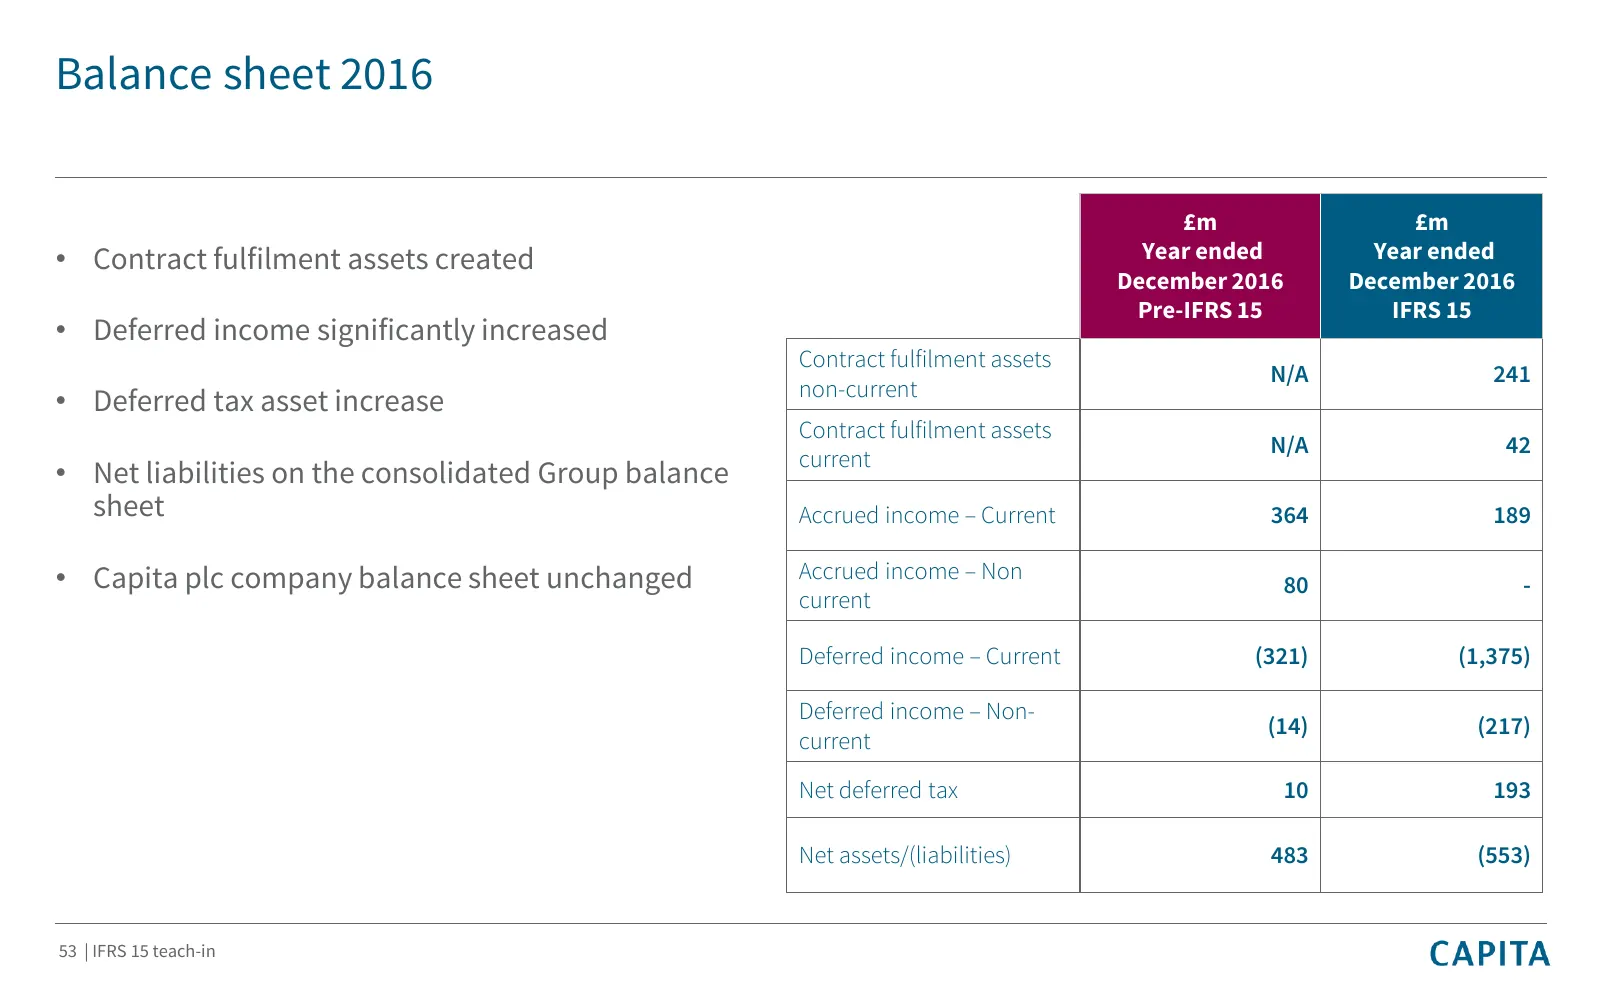
Balance sheet 2016 £m £m • Contract fulfilment assets created Year ended Year ended December 2016 December 2016 Pre-IFRS 15 IFRS 15 • Deferred income significantly increased Contract fulfilment assets N/A 241 non-current • Deferred tax asset increase Contract fulfilment assets N/A 42 current • Net l
Slide 54: Working capital
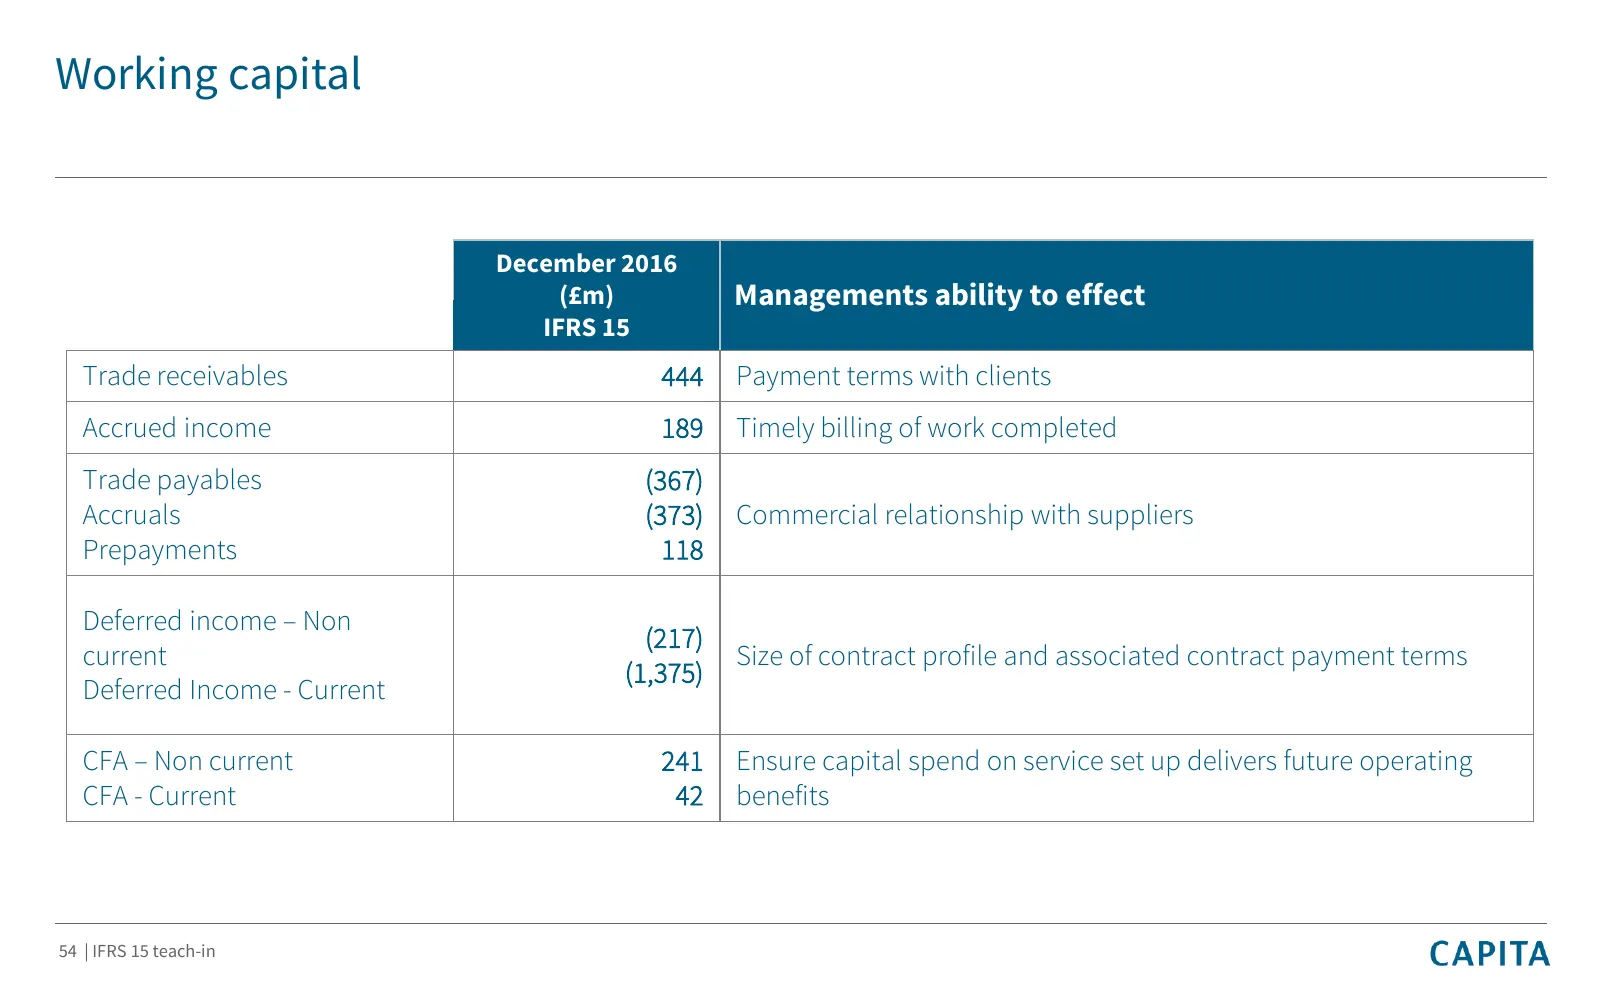
Working capital December 2016 (£m) Managements ability to effect IFRS 15 Trade receivables 444 Payment terms with clients Accrued income 189 Timely billing of work completed Trade payables (367) Accruals (373) Commercial relationship with suppliers Prepayments 118 Deferred income – Non (217) current
Slide 55: Ongoing implications
Ongoing implications 55 | IFRS 15 teach-in
Slide 56: Commercial implications
Commercial implications • IFRS 15 better aligns the commercial substance of our contracts to the financial accounting – we are more profitable once we have transformed the service and are running it in an efficient way • We are looking at how metrics and incentives need to change as part of this tra
Slide 57: Change management
Change management • Dedicated change management team • Group and divisional expertise • Staff training sessions and manual • Sales teams continue to negotiate best possible commercial terms • Bid models updated to align to IFRS 15 • Review of incentive schemes for management and business development
Slide 58: IFRS 15 – key points
IFRS 15 – key points No impact on: Key impacts: Lifetime profitability of contracts Revenue more evenly distributed over the life of contracts and active software licences – timing of Cash flow of contracts profits re-profiled Potentially lower profits or losses in early years on Majority of transac
Slide 59: Summary
Summary • IFRS 15 is a significant, complex and far reaching accounting standard • It will have a material impact on the way that long term contracts and software licences are accounted for • We welcome the adoption of IFRS 15 as it better aligns our revenue recognition with the commercial substance
Slide 60: Notes
Notes: 60 | IFRS 15 teach-in CAPITA
Slide 61: Appendices
Appendices 61 | IFRS 15 teach-in
Slide 62: Contract fulfilment asset - examples
Contract fulfilment asset - examples A contract fulfilment asset is a directly attributable cost for a contract that is not a fixed asset, not redundancies/training or recruitment but does create or enhance a resource that is used to deliver a service, such as: • Designing a target operating model •
Source: Internet Archive copy of capita.com
More decks from Capita plc
 H1 2026 Earnings Presentation44 slides · Aug 4, 2026
 FY2025 Earnings Presentation46 slides · March 2026
 Merger or Acquisition (March 2026)10 slides · March 2026
 H1 2025 Earnings Presentation51 slides · August 2025
 FY2024 Earnings Presentation44 slides · March 2025
 H1 2024 Earnings Presentation33 slides · Aug 1, 2024