Citizens Republic Bancorp — Citi 2009 Financial Services Conference
39 slides from Citizens Republic Bancorp's conference presentation, Jan 27, 2009
Slide 1: Citi 2009 Financial Services Conference
Citi 2009 Financial Services Conference January 27, 2009
Slide 2: Safe Harbor Statement
Safe Harbor Statement Discussions in this presentation that are not statements of historical fact (including statements that include terms such as "will," "may," "should," "believe," "expect," "anticipate," "estimate," "project","intend," and "plan") are forward-looking statements that involve risks
Slide 3: Who We Are
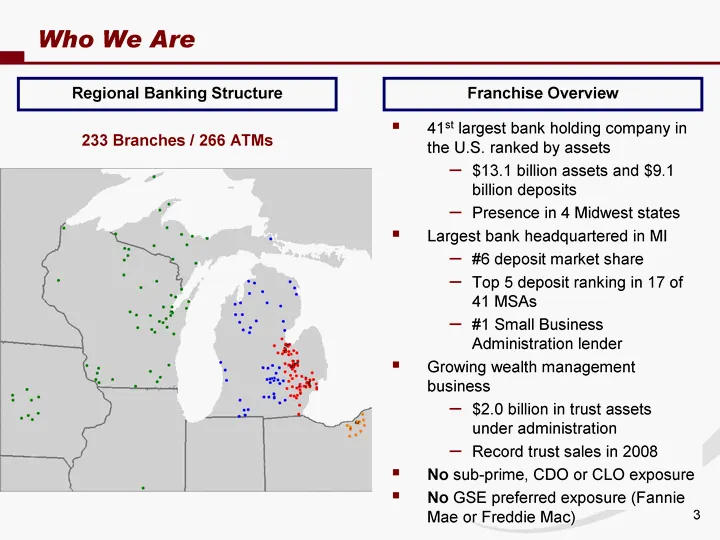
Who We Are 41st largest bank holding company in the U.S. ranked by assets $13.1 billion assets and $9.1 billion deposits Presence in 4 Midwest states Largest bank headquartered in MI #6 deposit market share Top 5 deposit ranking in 17 of 41 MSAs #1 Small Business Administration lender Growing wealth
Slide 4: Key Strengths: Management, Credit Culture, Capital
Key Strengths Strong Management Team Management team with broad big bank experience Strong track record of managing turnaround/workout situations in difficult operating environments Great bench strength Prudent Credit Culture Significant Excess Capital Hallmark conservative credit culture Diversifie
Slide 5: Key Strengths: Liquidity, Growth, Valuation
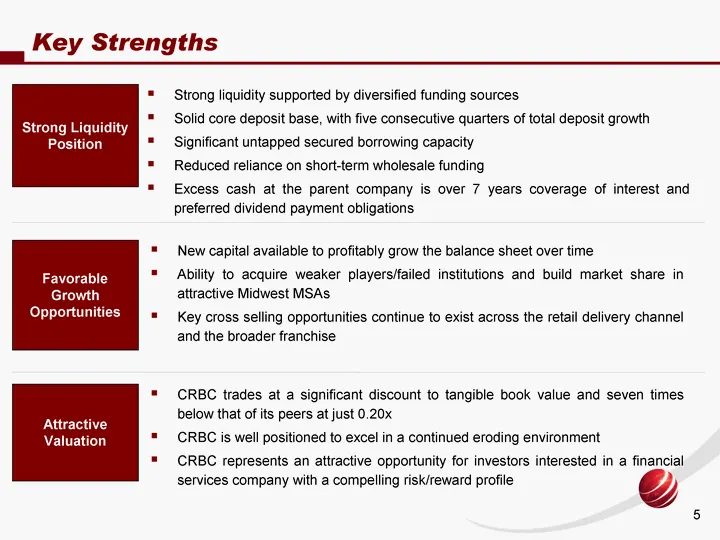
Key Strengths Strong Liquidity Position Strong liquidity supported by diversified funding sources Solid core deposit base, with five consecutive quarters of total deposit growth Significant untapped secured borrowing capacity Reduced reliance on short-term wholesale funding Excess cash at the parent
Slide 6: Diversified Loan Portfolio
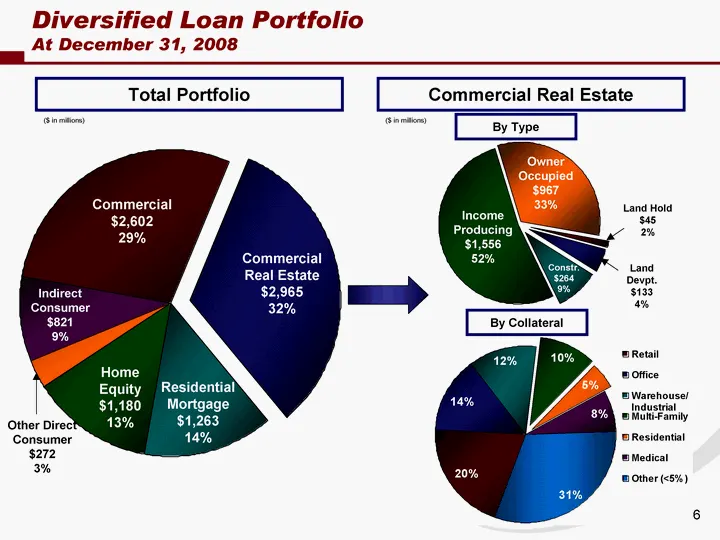
Diversified Loan Portfolio At December 31, 2008 Commercial Commercial Real Estate Residential Mortgage Home Equity Other Direct Consumer Indirect Consumer East 2602.334 2964.721 1262.841 1180.101 272.065 820.536 Land Hold Land Development Construction Income Producing Owner Occupied East 45 132.7 26
Slide 7: Commercial Loan Concentration and Auto Related Exposure Are Small
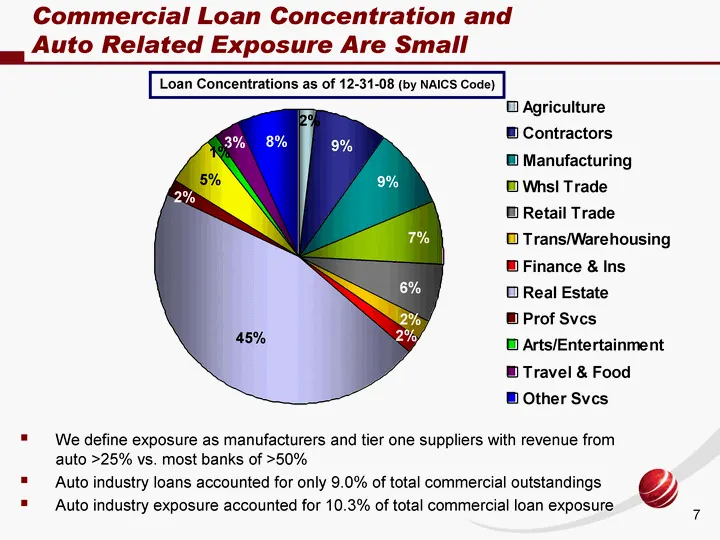
Commercial Loan Concentration and Auto Related Exposure Are Small Agriculture Contractors Manufacturing Whsl Trade Retail Trade Trans/Warehousing Finance & Ins Real Estate Prof Svcs Health Svcs Arts/Entertainment Travel & Food Other Svcs Commercial Loan Concentrations 107035.774 456794.45 496335.147
Slide 8: Majority of Stress from Smallest Portfolio
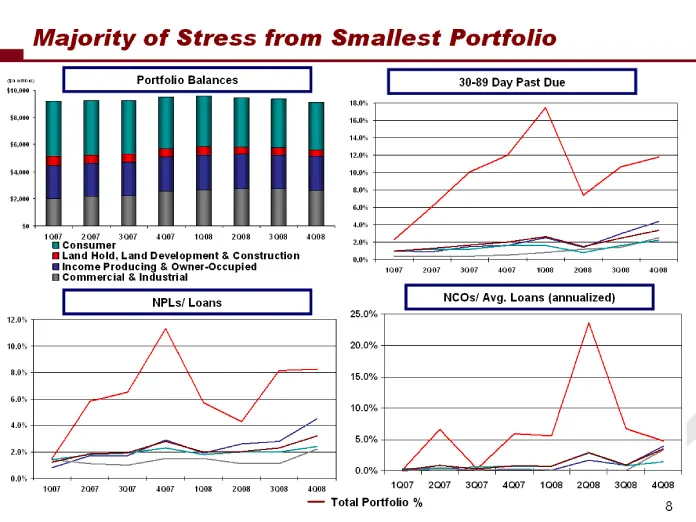
1Q07 2Q07 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 Land Hold, Development & Construction 0.0016 0.0665 0.0032 0.0592 0.0561 0.2367 0.0677 0.0478 Income Producing & Owner-Occupied 0 0.0052 0.0011 0.003 0.0012 0.0172 0.009 0.0393 Commercial & Industrial 0 0.003 0.001 0.002 0.0014 0.0009 0.0006 0.0337 Consumer 0.
Slide 9: Large Portion of CRE - Manageable Stress
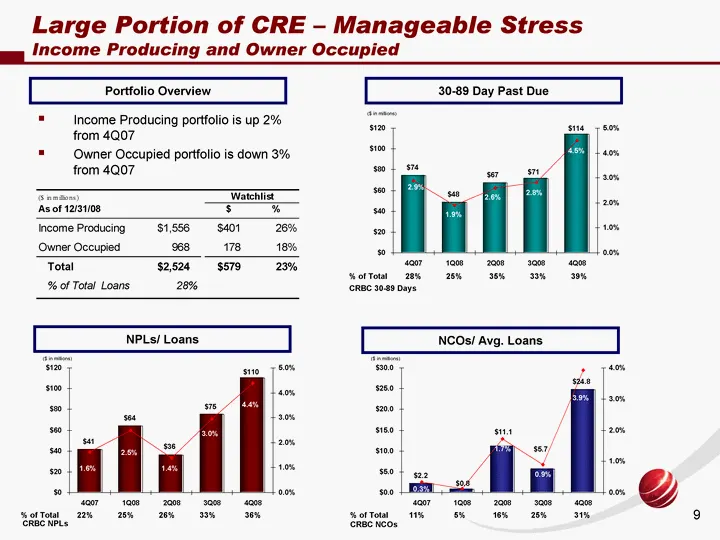
Large Portion of CRE - Manageable Stress Income Producing and Owner Occupied 30-89 Day Past Due Portfolio Overview 1Q07 2Q07 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 $ 19 41 42 74.3 48.3 67.1 71.4 114.2 % 0.008 0.017 0.017 0.029 0.019 0.0259 0.0282 0.045 % of Total 28% 25% 35% 33% 39% NPLs/ Loans 1Q07 2Q07 3Q0
Slide 10: Stressed Portion of CRE Portfolio
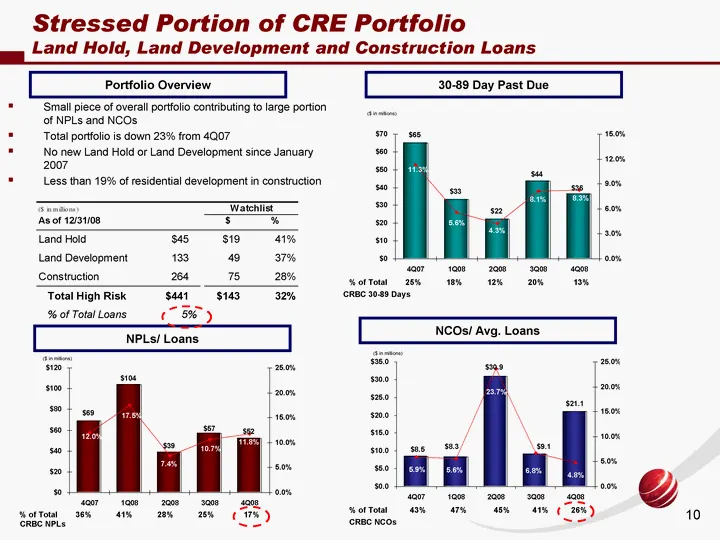
Stressed Portion of CRE Portfolio Land Hold, Land Development and Construction Loans 30-89 Day Past Due 1Q07 2Q07 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 $ 11 37 40 65 33.4 22.3 43.7 36.4 % 0.015 0.0581 0.0652 0.1132 0.056 0.0427 0.0813 0.0825 NPLs/ Loans NCOs/ Avg. Loans Portfolio Overview Small piece of ove
Slide 11: Solid Commercial Loan Performance
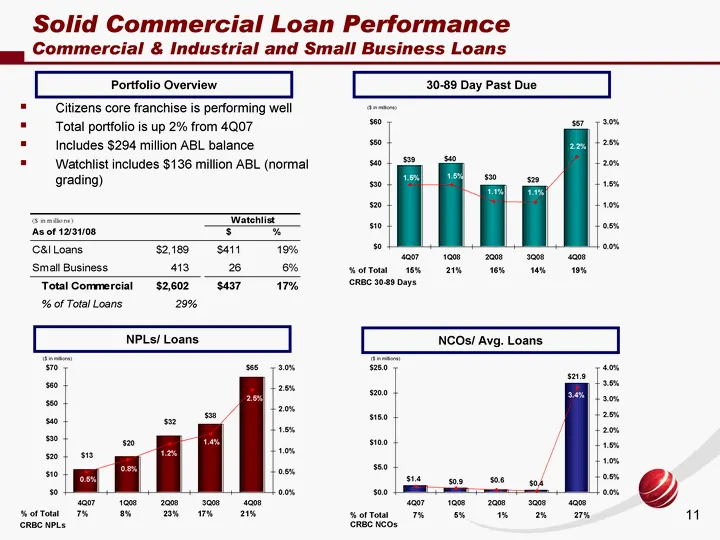
Solid Commercial Loan Performance Commercial & Industrial and Small Business Loans 30-89 Day Past Due Portfolio Overview 1Q07 2Q07 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 $ 27 23 22 39 40 29.5 29.1 56.5 % 0.014 0.011 0.01 0.015 0.015 0.01094 0.0108 0.0217 % of Total 15% 21% 16% 14% 19% NPLs/ Loans 1Q07 2Q07 3
Slide 12: Disciplined Underwriting Showing Strong Results
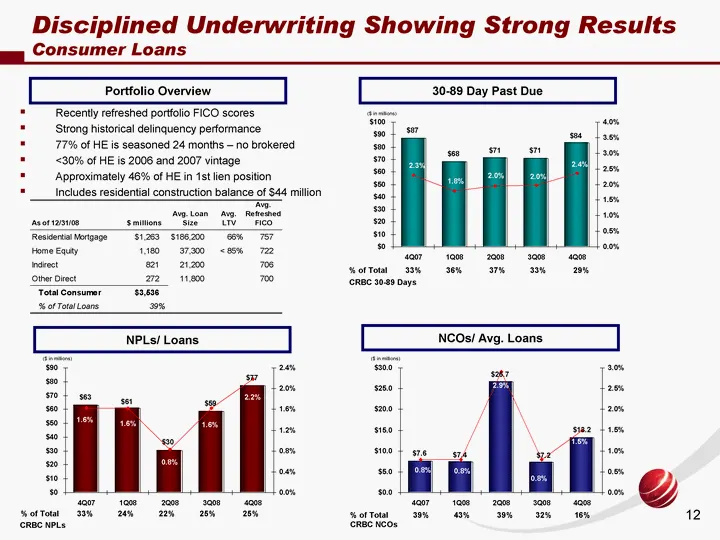
30-89 Day Past Due Portfolio Overview Recently refreshed portfolio FICO scores Strong historical delinquency performance 77% of HE is seasoned 24 months - no brokered <30% of HE is 2006 and 2007 vintage Approximately 46% of HE in 1st lien position Includes residential construction balance of $44 mil
Slide 13: Proven Success in Loan Work Out
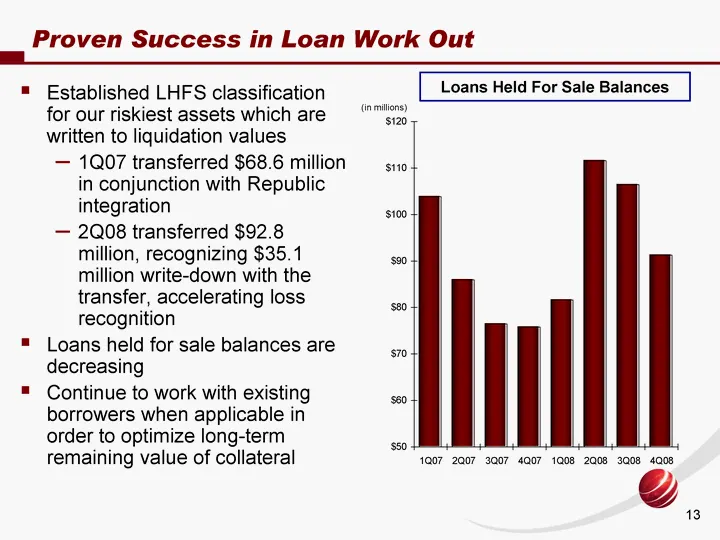
Proven Success in Loan Work Out Established LHFS classification for our riskiest assets which are written to liquidation values 1Q07 transferred $68.6 million in conjunction with Republic integration 2Q08 transferred $92.8 million, recognizing $35.1 million write-down with the transfer, accelerating
Slide 14: Diligently Addressing Credit Issues
Diligently Addressing Credit Issues Proactively accelerate the recognition of losses and continue to boost loan loss reserves Transitioned mortgage servicing and collection to PHH Mortgage Tightened underwriting criteria Commercial loans - revised approval levels to provide greater oversight Residen
Slide 15: Prudently Building Reserve in Uncertain Economy
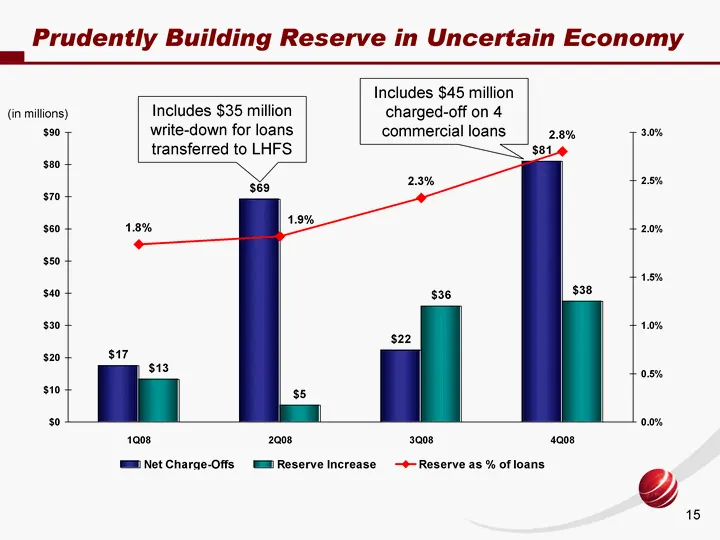
Prudently Building Reserve in Uncertain Economy 1Q08 2Q08 3Q08 4Q08 Net Charge-Offs 17.444 69.29 22.381 80.971 Reserve as % of loans 0.0184 0.0192 0.0232 0.028 Reserve Increase 13.175 5.19 36.009 37.594 (in millions) Includes $35 million write-down for loans transferred to LHFS Includes $45 million
Slide 16: Citizens Continues to Carry Higher LLR Levels
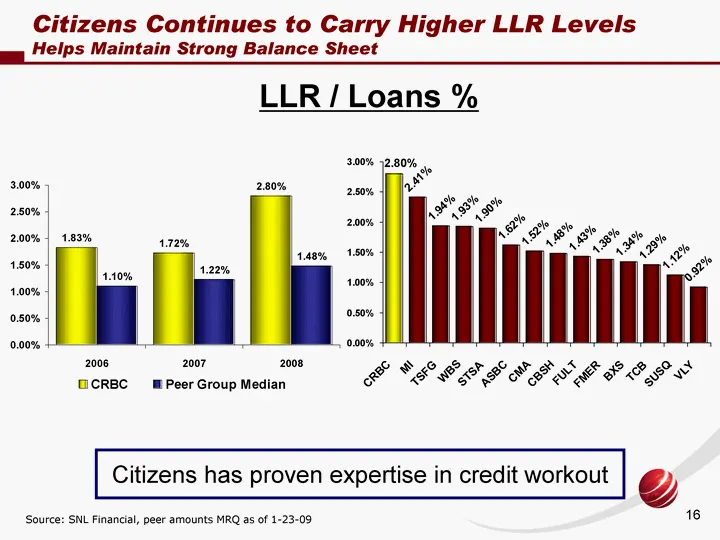
LLR / Loans % Source: SNL Financial, peer amounts MRQ as of 1-23-09 Citizens Continues to Carry Higher LLR Levels Helps Maintain Strong Balance Sheet 2006 2007 2008 CRBC 0.0183 0.0172 0.028 Peer Group Median 0.011 0.0122 0.0148 Citizens has proven expertise in credit workout CRBC MI TSFG WBS STSA AS
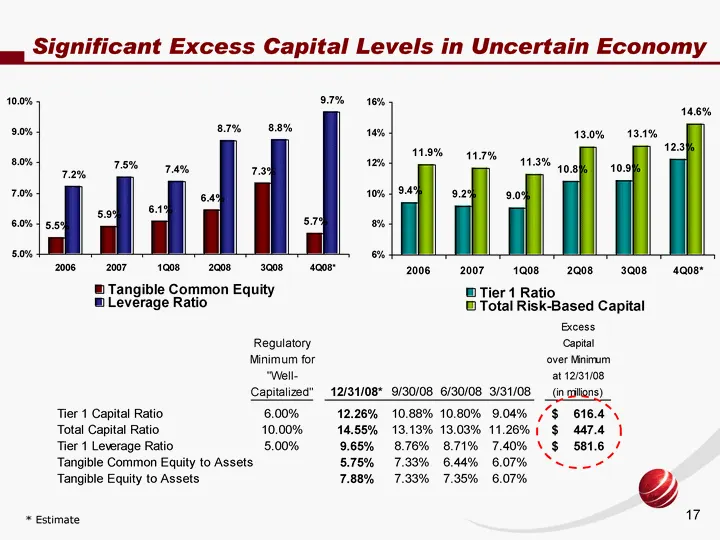
Slide 17: Significant Excess Capital Levels in Uncertain Economy
2002 2003 2004 2005 2006 2007 1Q08 2Q08 3Q08 4Q08* Tangible Common Equity 0.0773 0.0738 0.0767 0.0769 0.0554 0.059 0.0607 0.0644 0.0733 0.0569 Leverage Ratio 0.0718 0.0745 0.0784 0.0798 0.0722 0.0753 0.074 0.0871 0.0876 0.0965 2002 2003 2004 2005 2006 2007 1Q08 2Q08 3Q08 4Q08* Tier 1 Ratio 0.0918 0.
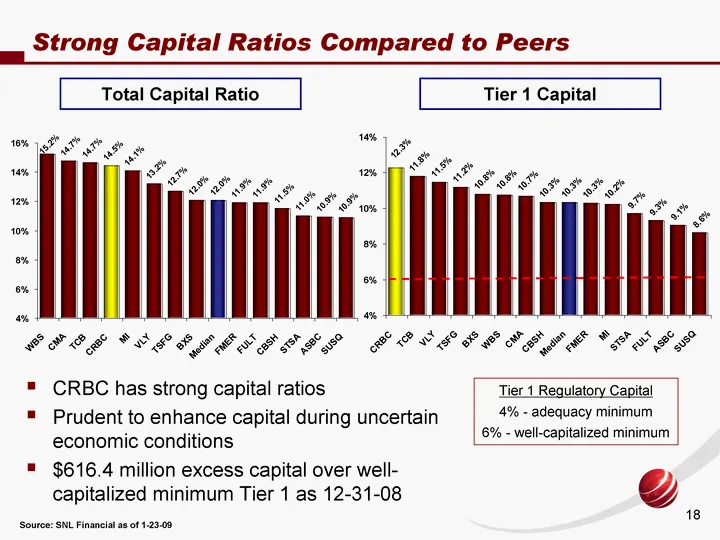
Slide 18: Strong Capital Ratios Compared to Peers
Strong Capital Ratios Compared to Peers Source: SNL Financial as of 1-23-09 WBS CMA TCB CRBC MI VLY TSFG BXS Median FMER FULT CBSH STSA ASBC SUSQ East 0.152 0.1473 0.1465 0.1445 0.1407 0.1319 0.1268 0.1204 0.1204 0.119 0.119 0.1149 0.1098 0.1092 0.1086 CRBC TCB VLY TSFG BXS WBS CMA CBSH Median FMER
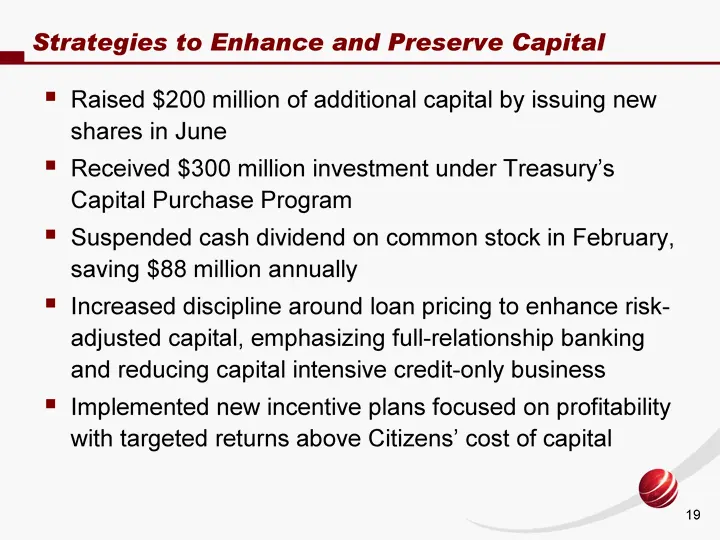
Slide 19: Strategies to Enhance and Preserve Capital
Strategies to Enhance and Preserve Capital Raised $200 million of additional capital by issuing new shares in June Received $300 million investment under Treasury's Capital Purchase Program Suspended cash dividend on common stock in February, saving $88 million annually Increased discipline around l
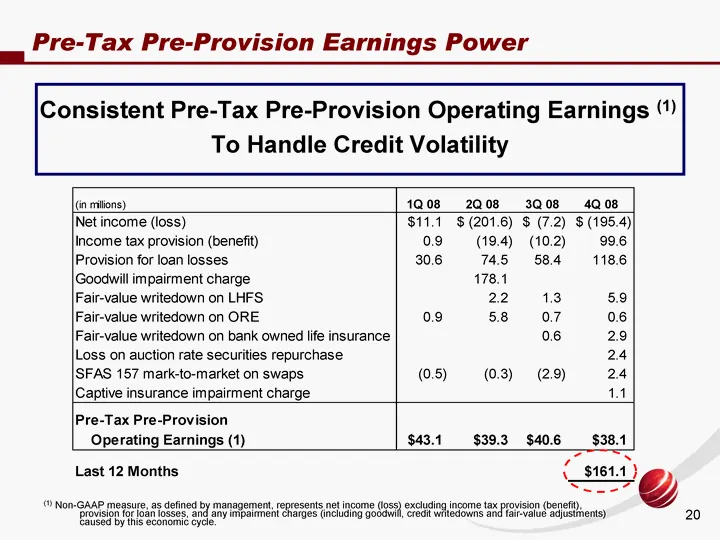
Slide 20: Pre-Tax Pre-Provision Earnings Power
Pre-Tax Pre-Provision Earnings Power Consistent Pre-Tax Pre-Provision Operating Earnings (1) To Handle Credit Volatility (1) Non-GAAP measure, as defined by management, represents net income (loss) excluding income tax provision (benefit), provision for loan losses, and any impairment charges (inclu
Slide 21: Capital Stress Test
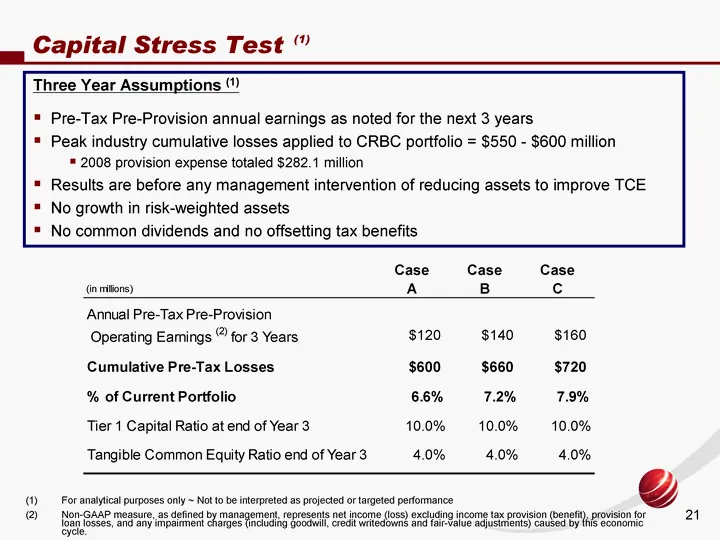
Capital Stress Test (1) Three Year Assumptions (1) Pre-Tax Pre-Provision annual earnings as noted for the next 3 years Peak industry cumulative losses applied to CRBC portfolio = $550 - $600 million 2008 provision expense totaled $282.1 million Results are before any management intervention of reduc
Slide 22: Diversified Funding Sources
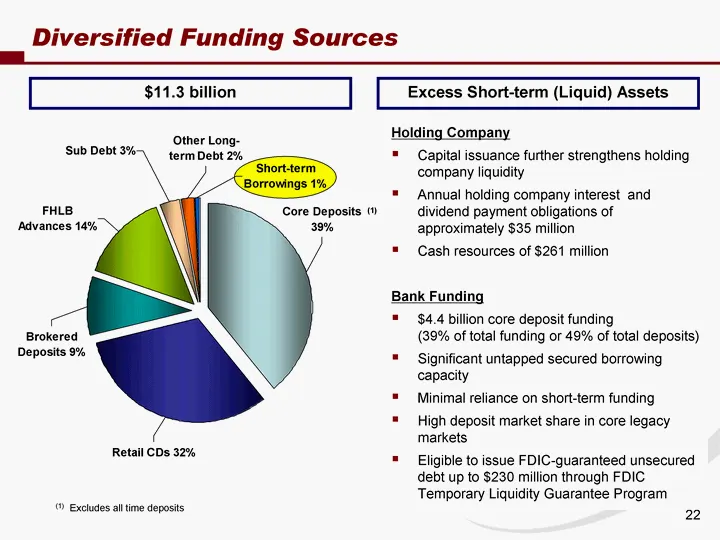
Diversified Funding Sources Core Deposits 0.39 Retail CDs 0.32 Brokered Deposits 0.09 FHLB Advances 0.14 Sub Debt 0.03 Other Long-term Debt 0.02 Short-term Borrowings 0.007 $11.3 billion Holding Company Capital issuance further strengthens holding company liquidity Annual holding company interest an
Slide 23: Strong Retail Deposit Growth
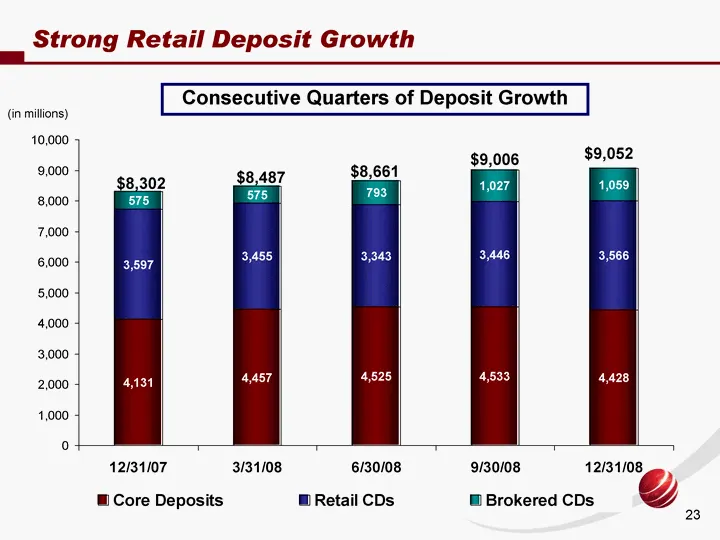
9/30/2007 12/31/2007 3/31/2008 6/30/2008 9/30/2008 12/31/2008 Core Deposits 4037.024 4130.668 4457.117 4524.843 4532.859 4427.79 Retail CDs 3604.675 3596.754 3454.811 3343.226 3445.801 3565.922 Brokered CDs 300.04 574.503 575.049 793.069 1027.415 1058.694 (in millions) Strong Retail Deposit Growth $
Slide 24: Improving Profitability of Relationships
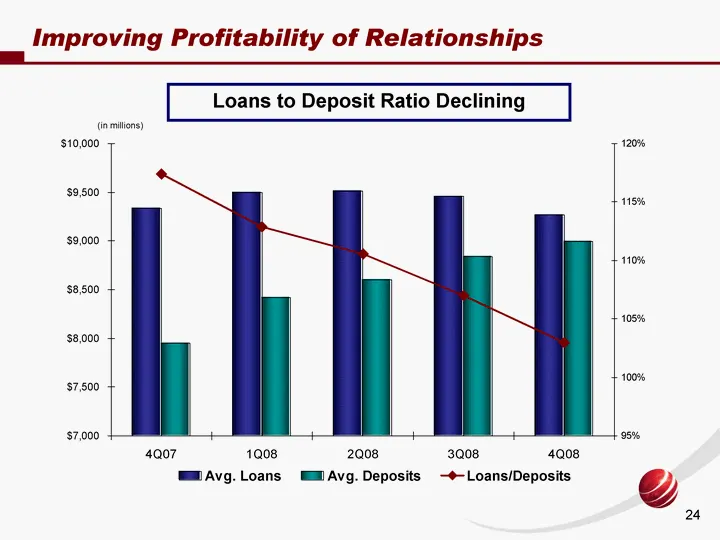
Improving Profitability of Relationships 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 Avg. Loans 9163 9335 9499 9514 9456 9267 Loans/Deposits 1.1384 1.1741 1.1285 1.10576 1.07005 1.02991 Avg. Deposits 8049 7951 8417 8604 8837 8998 (in millions) Loans to Deposit Ratio Declining
Slide 25: Strong Liquidity Position
Strong Liquidity Position Added longer-term brokered CDs Increased focus on cross-sales through retail delivery channel Conducted targeted marketing campaigns for deposits Increased available collateral for FHLB funding Increased discipline around loan funding and pricing to better align changes in
Slide 26: Cathy Nash - President & CEO
Cathy Nash - President & CEO Joined Citizens in 2006 as EVP, Regional & Consumer Banking 13 years at Sun Trust: SVP, Director of Branch Banking - oversaw sales strategy of 1,700 branch locations EVP, Director of Retail Banking, Florida - over 425 branch locations, including small business & private
Slide 27: Other Key Priorities
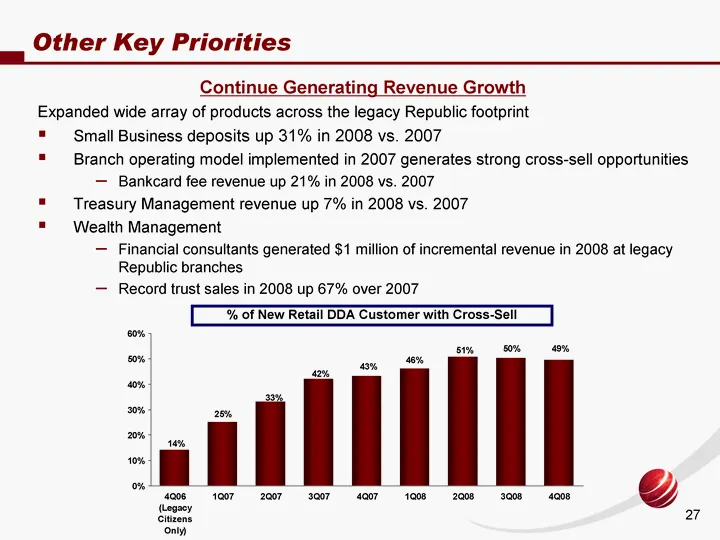
Other Key Priorities Continue Generating Revenue Growth Expanded wide array of products across the legacy Republic footprint Small Business deposits up 31% in 2008 vs. 2007 Branch operating model implemented in 2007 generates strong cross-sell opportunities Bankcard fee revenue up 21% in 2008 vs. 20
Slide 28: Favorable Growth Opportunities
Favorable Growth Opportunities New capital to prudently grow the balance sheet over time Key cross selling opportunities across the retail delivery channel and the broader franchise Ability to acquire weaker players / failed institutions inexpensively and build market share in attractive Midwest MSA
Slide 29: Focus on Expense Management
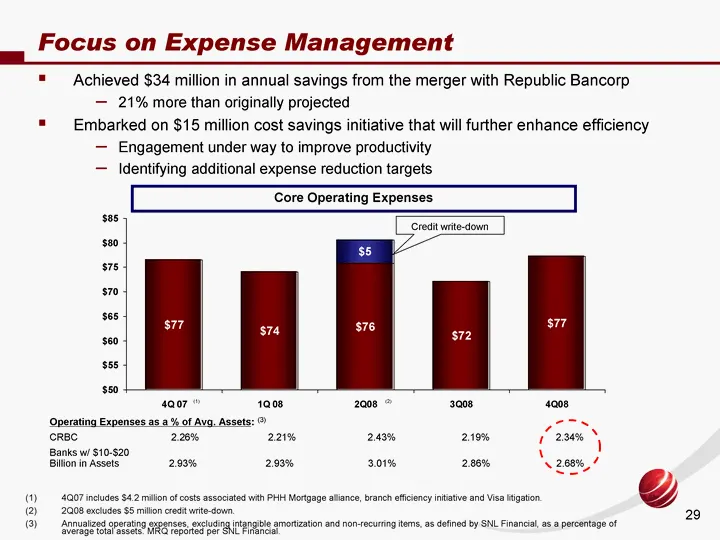
Focus on Expense Management 2Q 07 3Q 07 4Q 07 1Q 08 2Q08 3Q08 4Q08 Core Operating Expenses 81.128 73.531 76.577 74.115 75.806 72.075 77.229 0 0 0 0 4.8 0 0 4Q07 includes $4.2 million of costs associated with PHH Mortgage alliance, branch efficiency initiative and Visa litigation. 2Q08 excludes $5 mi
Slide 30: CRBC - Trading at a Discount to Peers
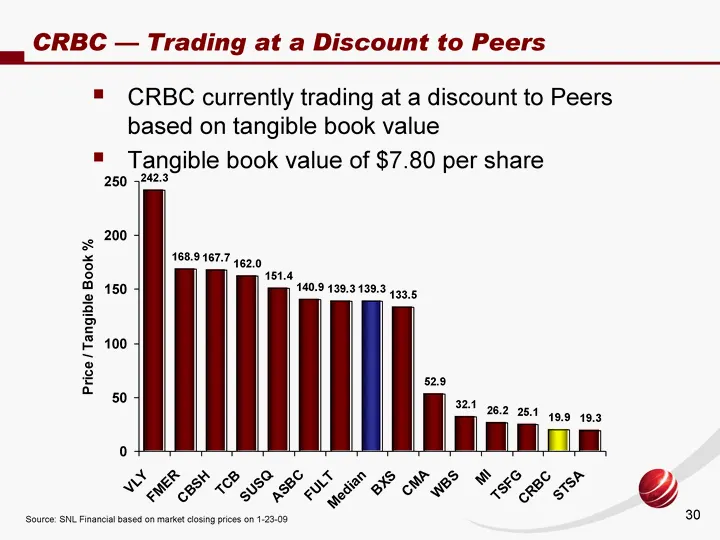
CRBC - Trading at a Discount to Peers CRBC currently trading at a discount to Peers based on tangible book value Tangible book value of $7.80 per share Source: SNL Financial based on market closing prices on 1-23-09 VLY FMER CBSH TCB SUSQ ASBC FULT Median BXS CMA WBS MI TSFG CRBC STSA East 242.3 168
Slide 31: Investor Takeaways
Investor Takeaways Revenue synergy opportunities continue to exist within the Citizens franchise Focused on delivering results and creating long-term value for shareholders Talented team with significant expertise in managing credit Strong balance sheet to withstand a stressed credit cycle More than
Slide 32: Appendix
Appendix 32
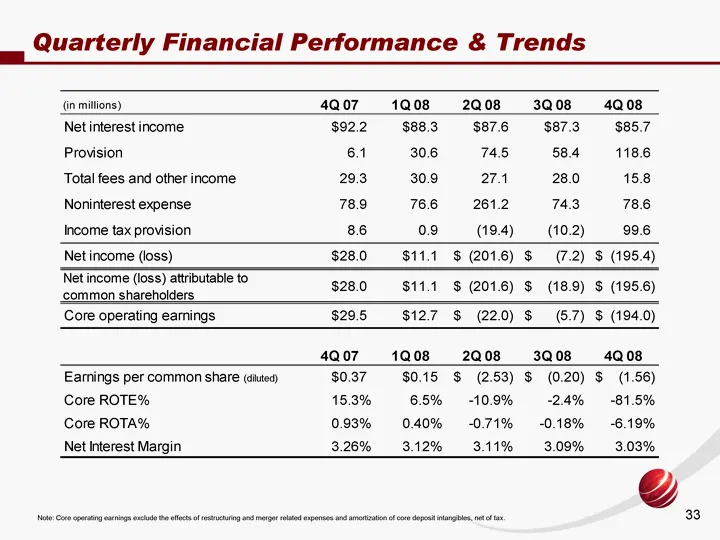
Slide 33: Quarterly Financial Performance & Trends
Quarterly Financial Performance & Trends Note: Core operating earnings exclude the effects of restructuring and merger related expenses and amortization of core deposit intangibles, net of tax.
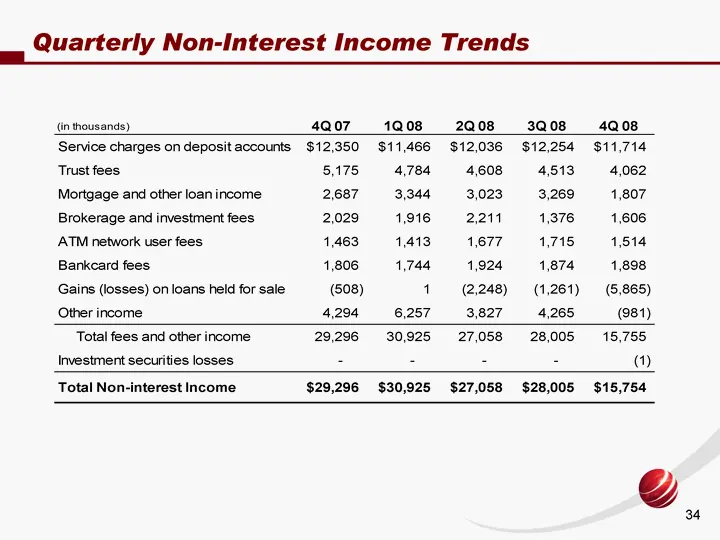
Slide 34: Quarterly Non-Interest Income Trends
Quarterly Non-Interest Income Trends
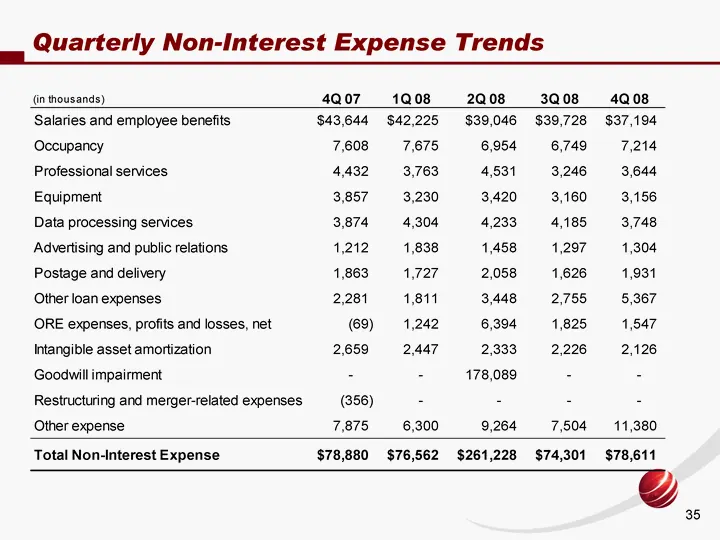
Slide 35: Quarterly Non-Interest Expense Trends
Quarterly Non-Interest Expense Trends
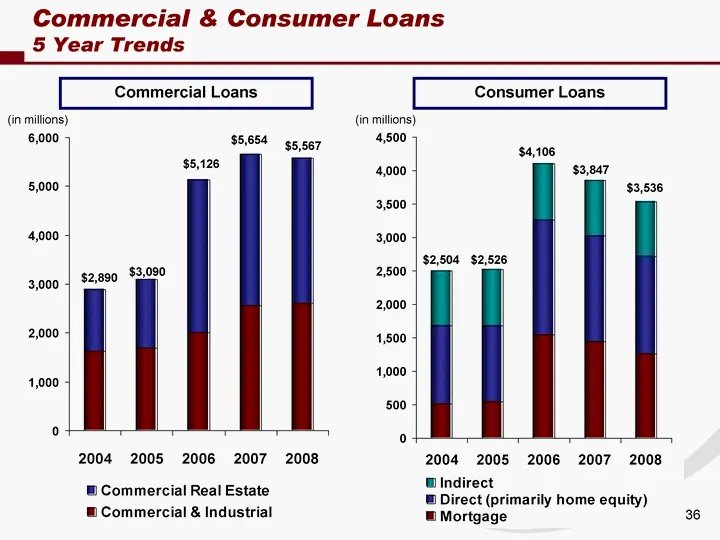
Slide 36: Commercial & Consumer Loans Year Trends
Commercial & Consumer Loans 5 Year Trends 2004 2005 2006 2007 2008 Commercial & Industrial 1633.8 1688.1 2004.9 2557.1 2602.3 Commercial Real Estate 1255.9 1402.1 3120.6 3097.2 2964.7 $5,567 $5,654 $5,126 $3,090 $2,890 (in millions) Commercial Loans 2004 2005 2006 2007 2008 Mortgage 508.2 539.8 1543
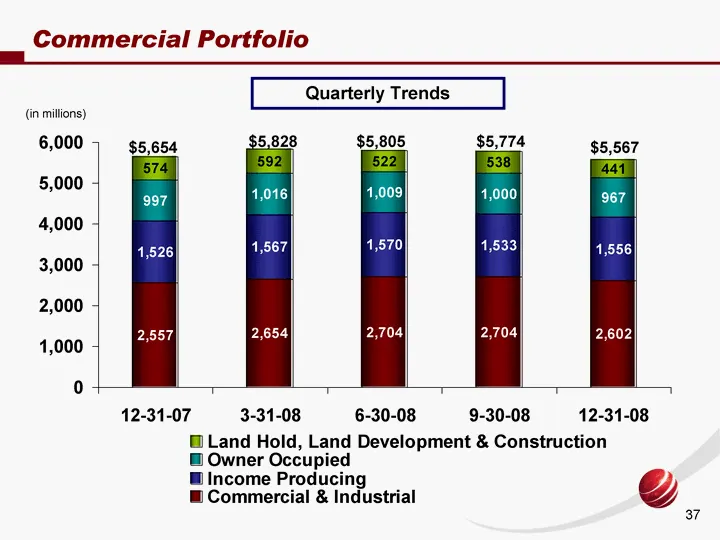
Slide 37: Commercial Portfolio Quarterly Trends
12-31-06 3-31-07 6-30-07 9-30-07 12-31-07 3-31-08 6-30-08 9-30-08 12-31-08 Commercial & Industrial 2004.9 1993.7 2153.2 2236.2 2557.1 2653.8 2703.8 2703.7 2602.334 Income Producing 1237.1 1351.7 1338.9 1338.8 1526 1567.3 1569.9 1533.2 1556.2 Owner Occupied 1132 1077.7 1115.6 1113.5 997 1015.6 1009.3
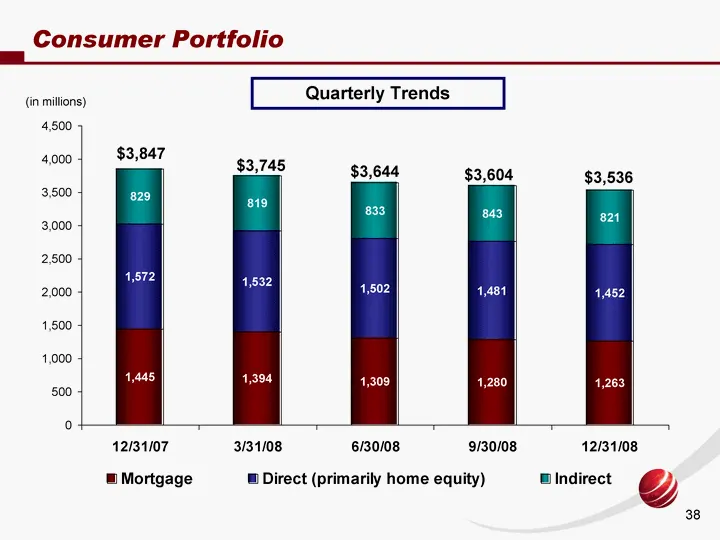
Slide 38: Consumer Portfolio Quarterly Trends
2003 2004 2005 2006 3/31/2007 6/30/2007 9/30/2007 12/31/2007 3/31/2008 6/30/2008 9/30/2008 12/31/2008 Mortgage 492.7 508.2 539.8 1543.5 1518.198 1494.45 1460.993 1445.2 1393.801 1308.729 1279.696 1262.841 Direct (primarily home equity) 998.3 1169.6 1142 1721.4 1677.842 1636.026 1602.126 1572.3 1531.
Slide 39: Citizens Republic Bancorp
CITIZENS REPUBLIC BANCORP
Source: SEC EDGAR · 8-K filed Jan 27, 2009
More decks from Citizens Republic Bancorp Inc
 Debt Investor Presentation (January 2013)30 slides · Jan 23, 2013
 Q4 2012 Earnings Presentation47 slides · Jan 22, 2013
 Q3 2012 Earnings Presentation47 slides · Oct 26, 2012
 Merger or Acquisition (September 2012)28 slides · Sep 13, 2012
 Q2 2012 Earnings Presentation47 slides · Jul 30, 2012
 Q1 2012 Earnings Presentation49 slides · Apr 27, 2012