NCC Limited · NSE:NCC
NCC — Investor Presentation (November 2012)
34 slides from NCC's investor presentation, Nov 8, 2012
Slide 1: NCC Limited Investor Presentation
NCC LIMITED INVESTOR PRESENTATION Date Calibri 16pt 8th November 2012
Slide 2: Disclaimer
DISCLAIMER No representation or warranty, express or implied, is made as to, and no reliance should be placed on, the fairness, accuracy, completeness or correctness of the information or opinions contained in this presentation. Such information and opinions are in all events not current after the d
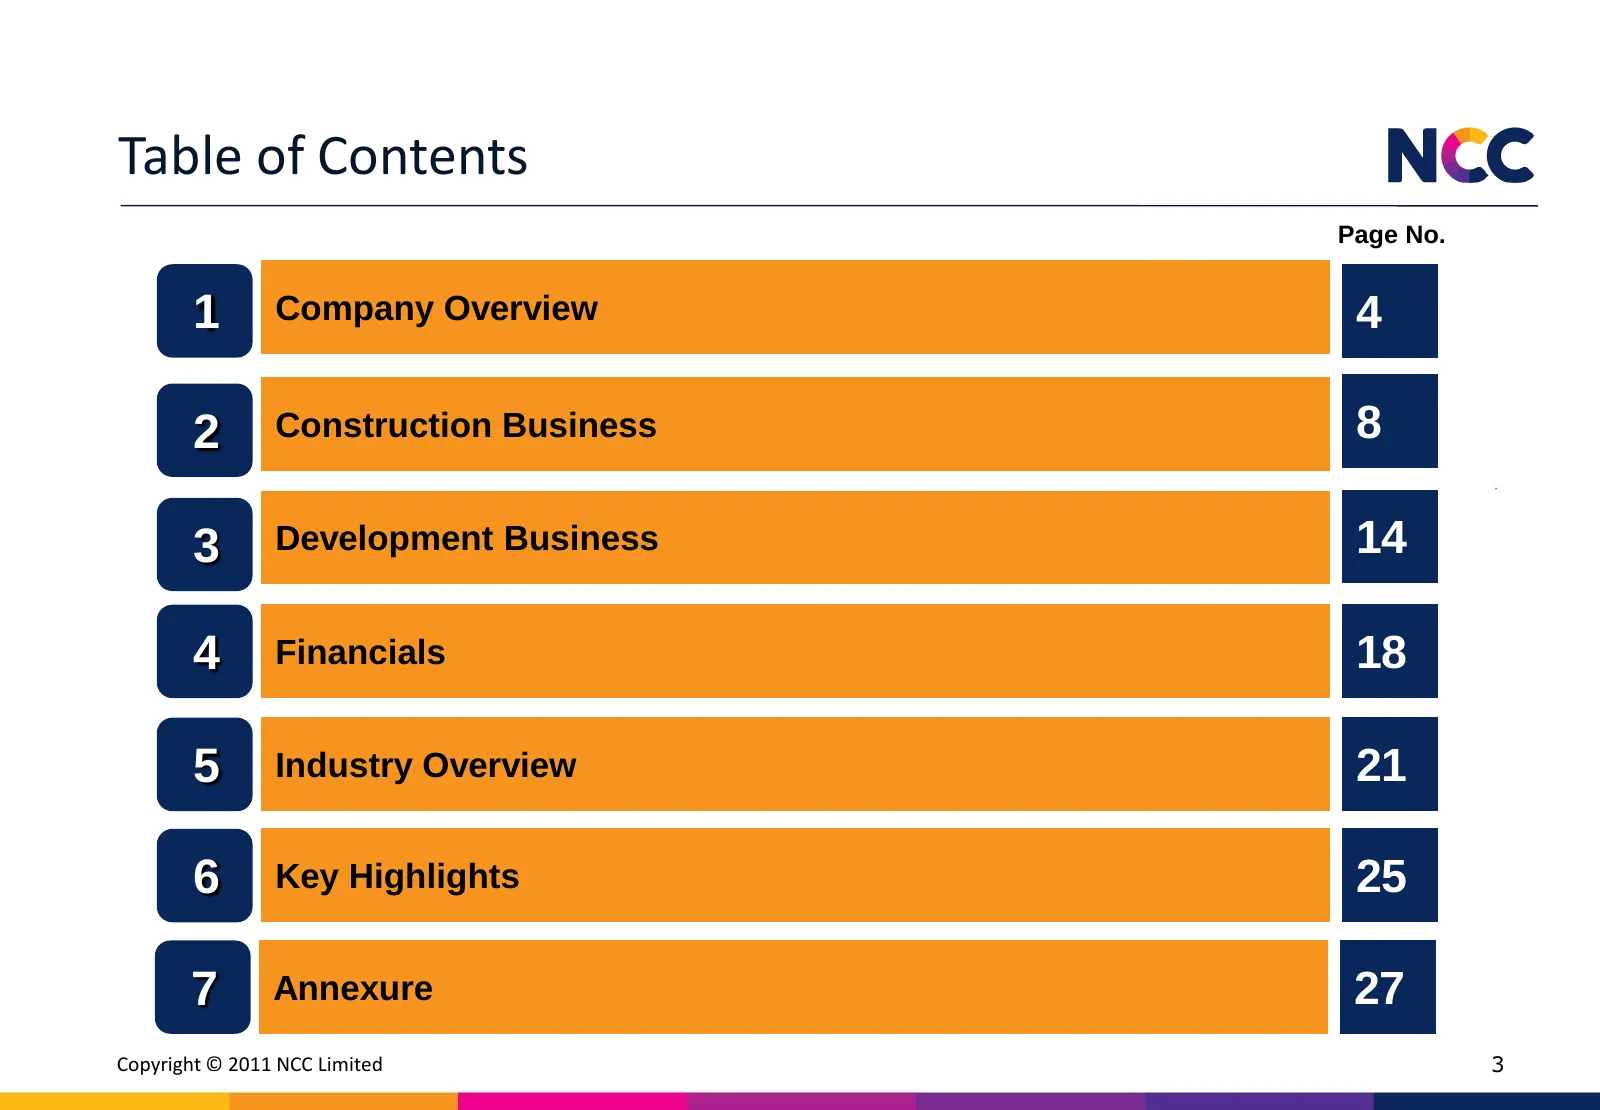
Slide 3: Table of Contents
Table of Contents Page No. 1 Company Overview 4 2 Construction Business 8 3 Development Business 14 4 Financials 18 5 Industry Overview 21 6 Key Highlights 25 7 Annexure 27 Copyright © 2011 NCC Limited 3
Slide 4: Company Overview
COMPANY OVERVIEW
Slide 5: Company Snapshot
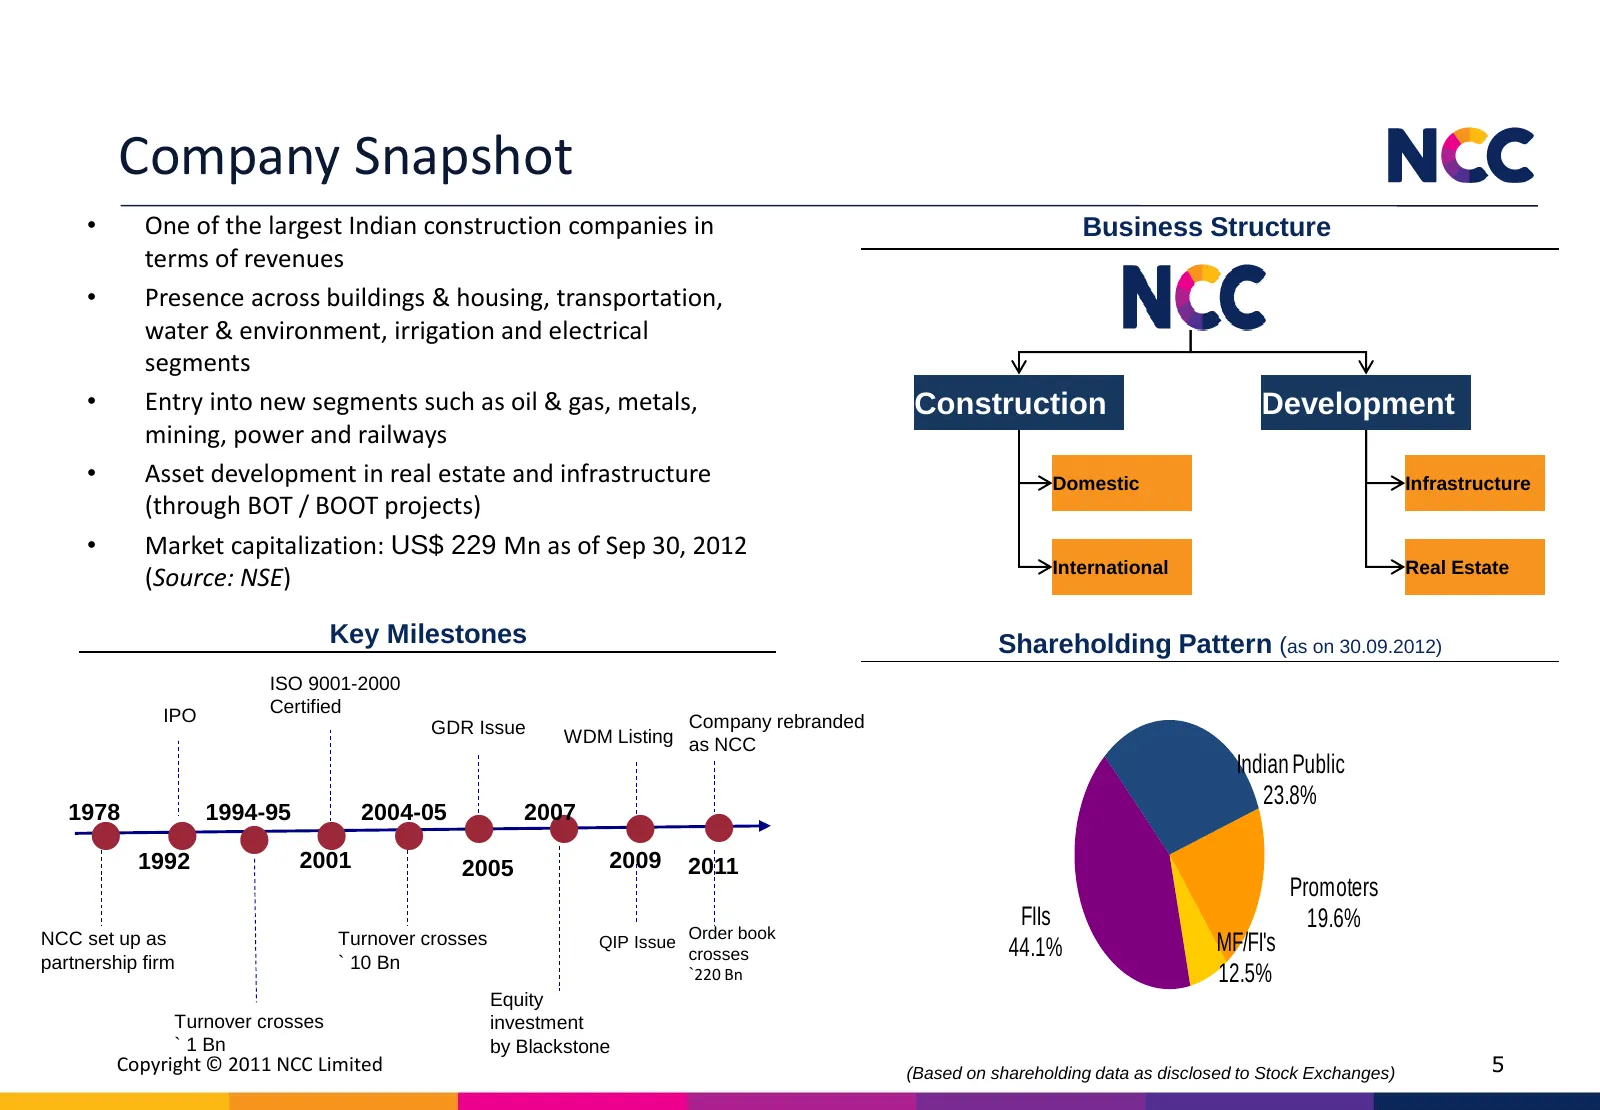
Company Snapshot • One of the largest Indian construction companies in Business Structure terms of revenues • Presence across buildings & housing, transportation, water & environment, irrigation and electrical segments • Entry into new segments such as oil & gas, metals, Construction Development min
Slide 6: Business Strategy
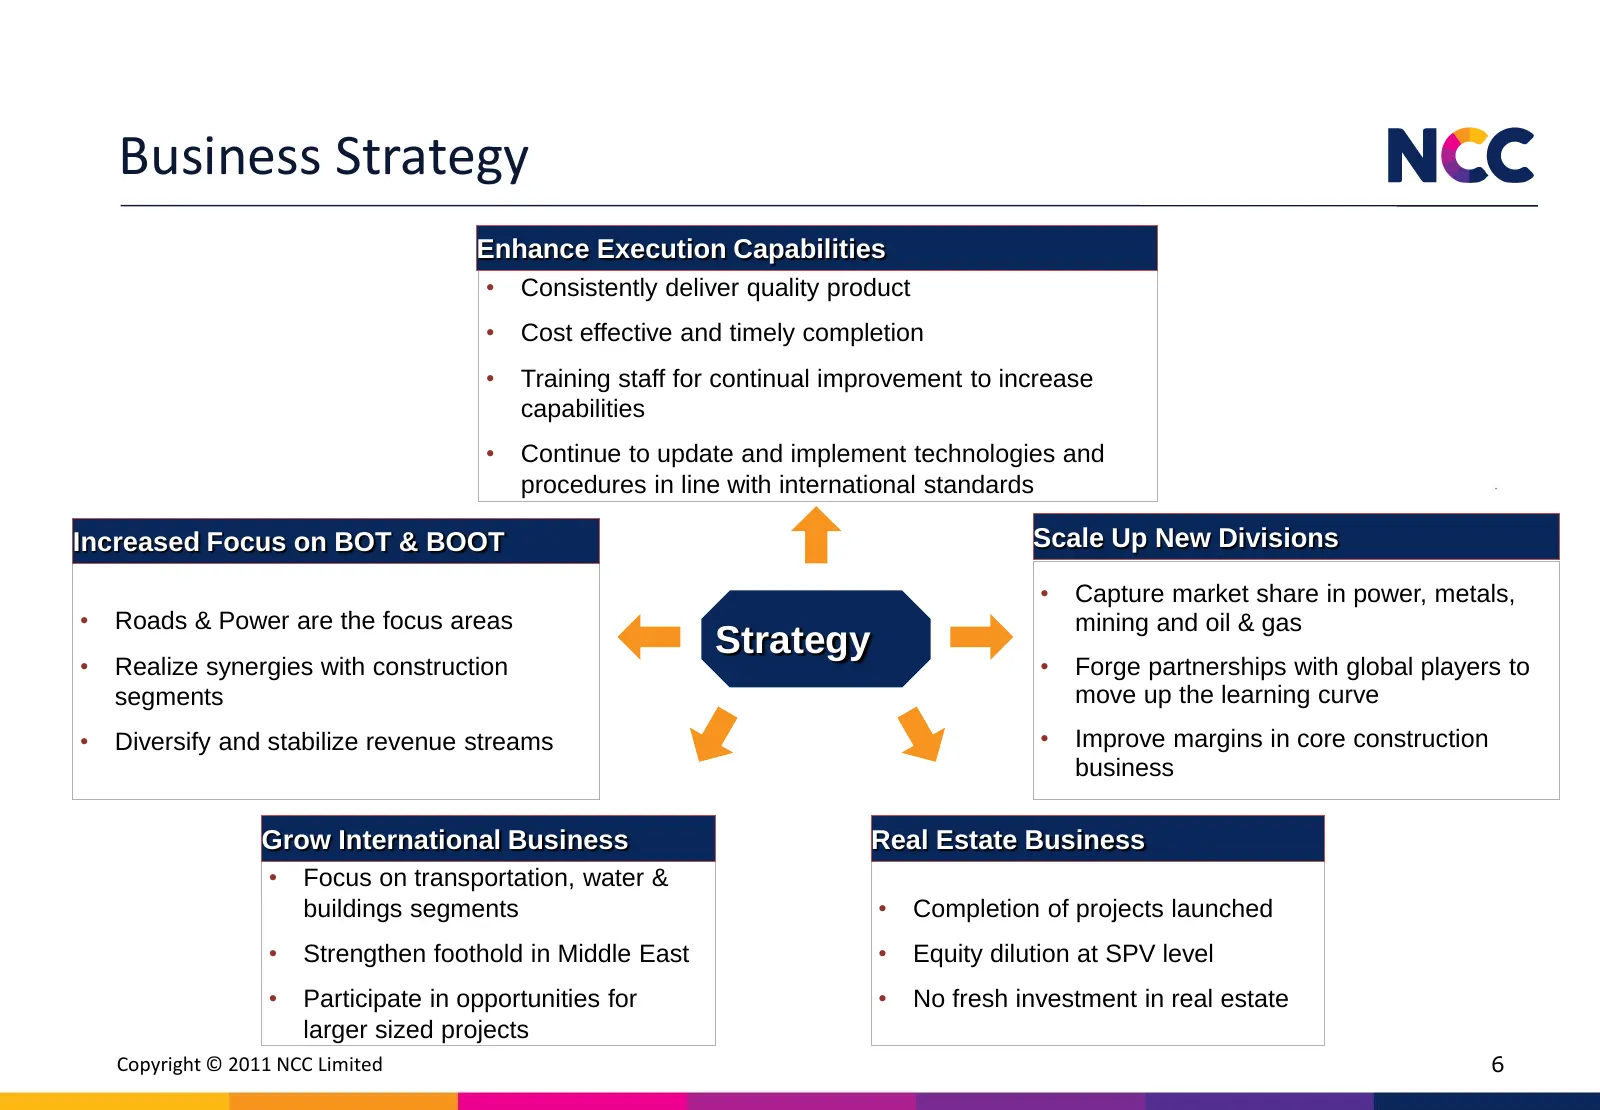
Business Strategy Enhance Execution Capabilities • Consistently deliver quality product • Cost effective and timely completion • Training staff for continual improvement to increase capabilities • Continue to update and implement technologies and procedures in line with international standards Incre
Slide 7: Experienced and Professional Management
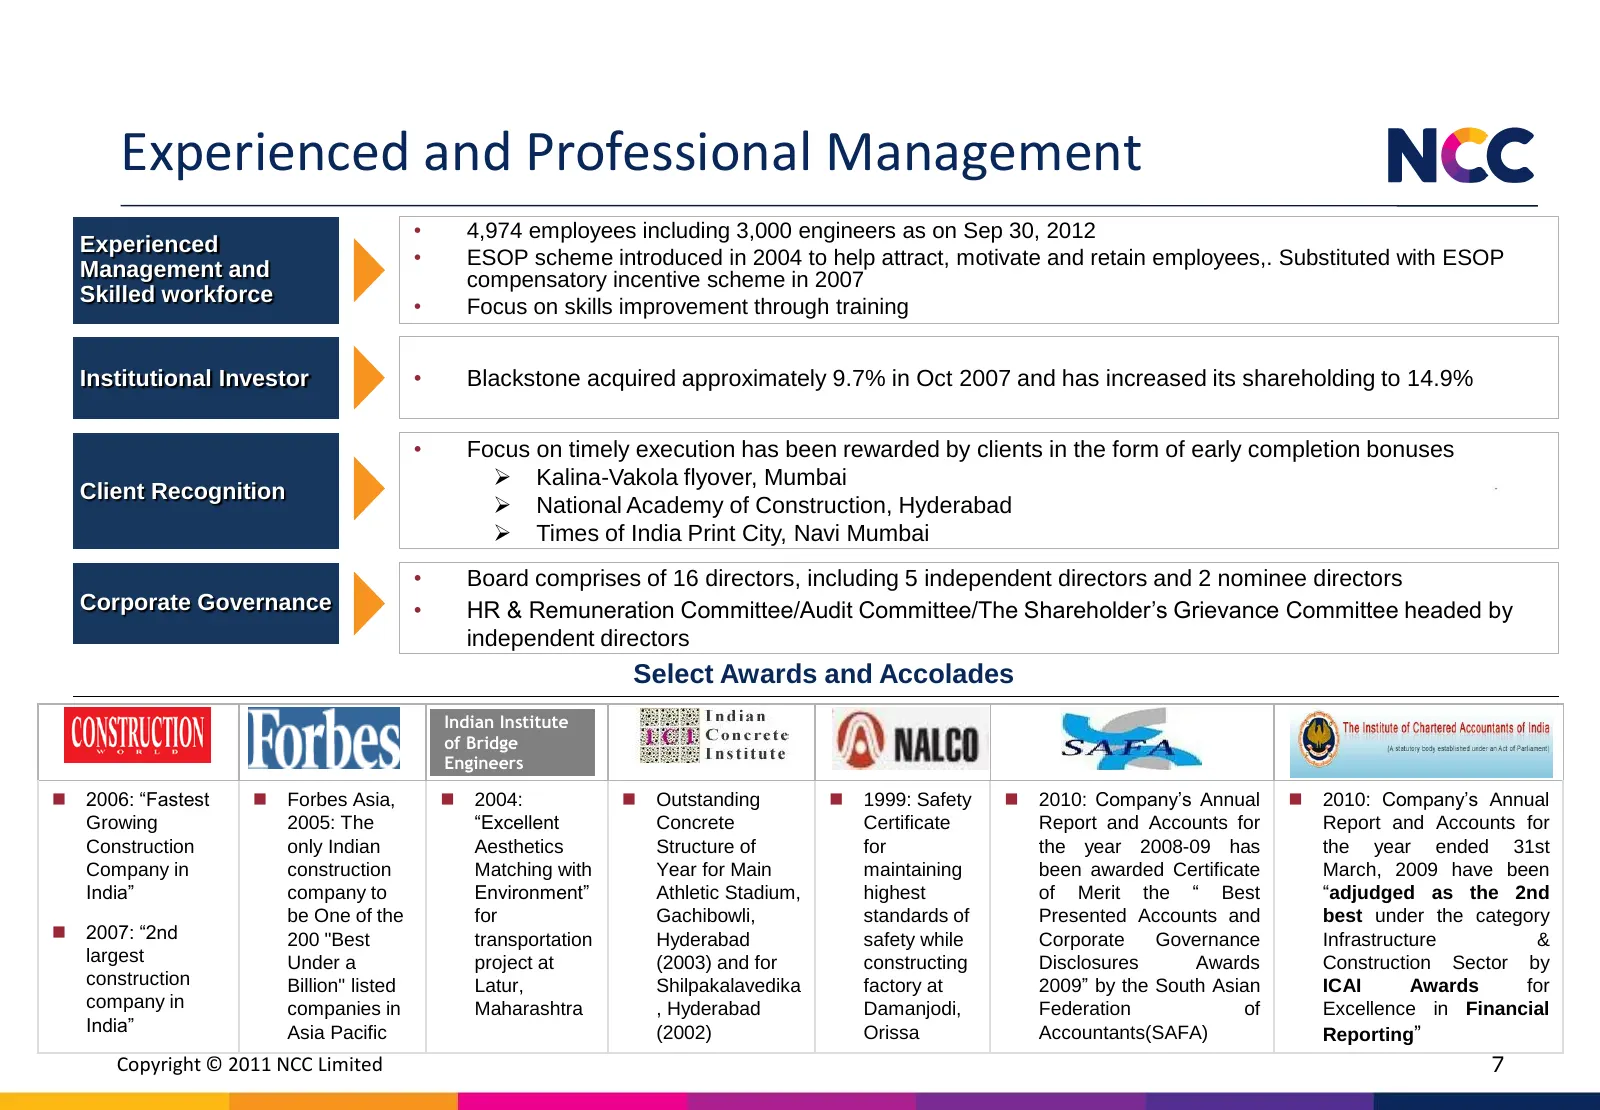
Experienced and Professional Management • 4,974 employees including 3,000 engineers as on Sep 30, 2012 Experienced • ESOP scheme introduced in 2004 to help attract, motivate and retain employees,. Substituted with ESOP Management and compensatory incentive scheme in 2007 Skilled workforce • Focus on
Slide 8: Construction Business
CONSTRUCTION BUSINESS
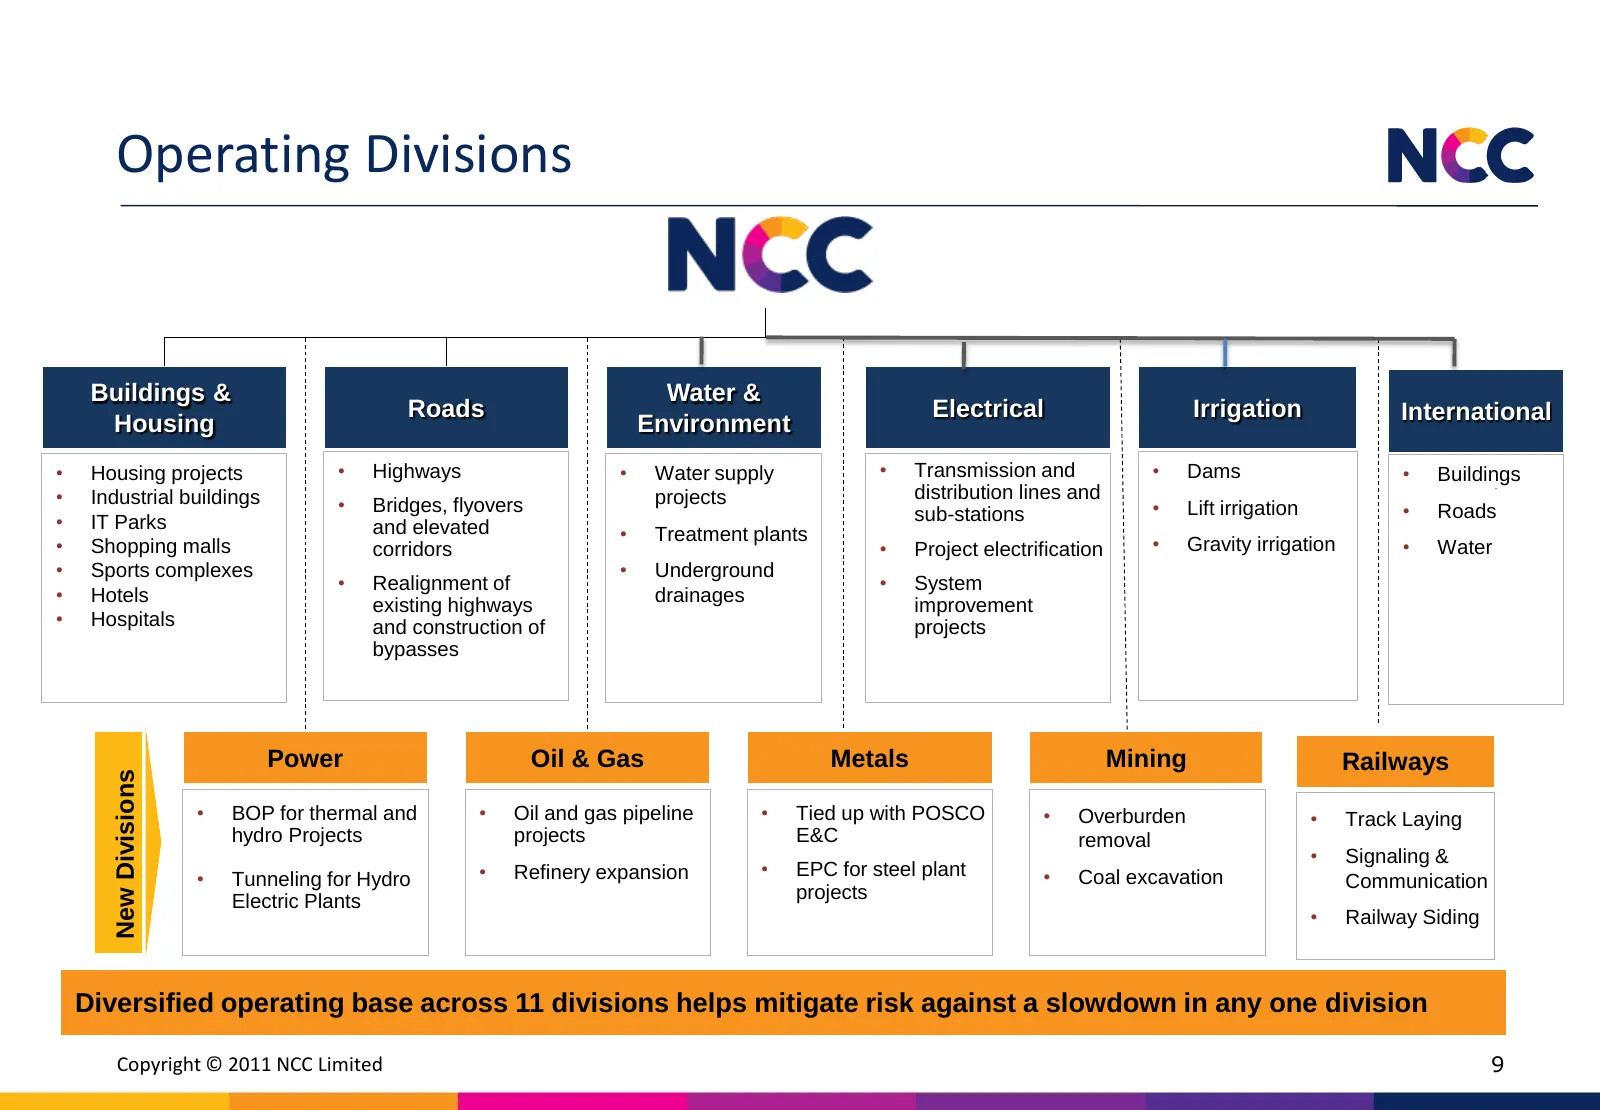
Slide 9: Operating Divisions and New Divisions
Operating Divisions Buildings & Water & Roads Electrical Irrigation International Housing Environment • Housing projects • Highways • Water supply • Transmission and • Dams • Buildings • Industrial buildings projects distribution lines and • Bridges, flyovers sub-stations • Lift irrigation • Roads •
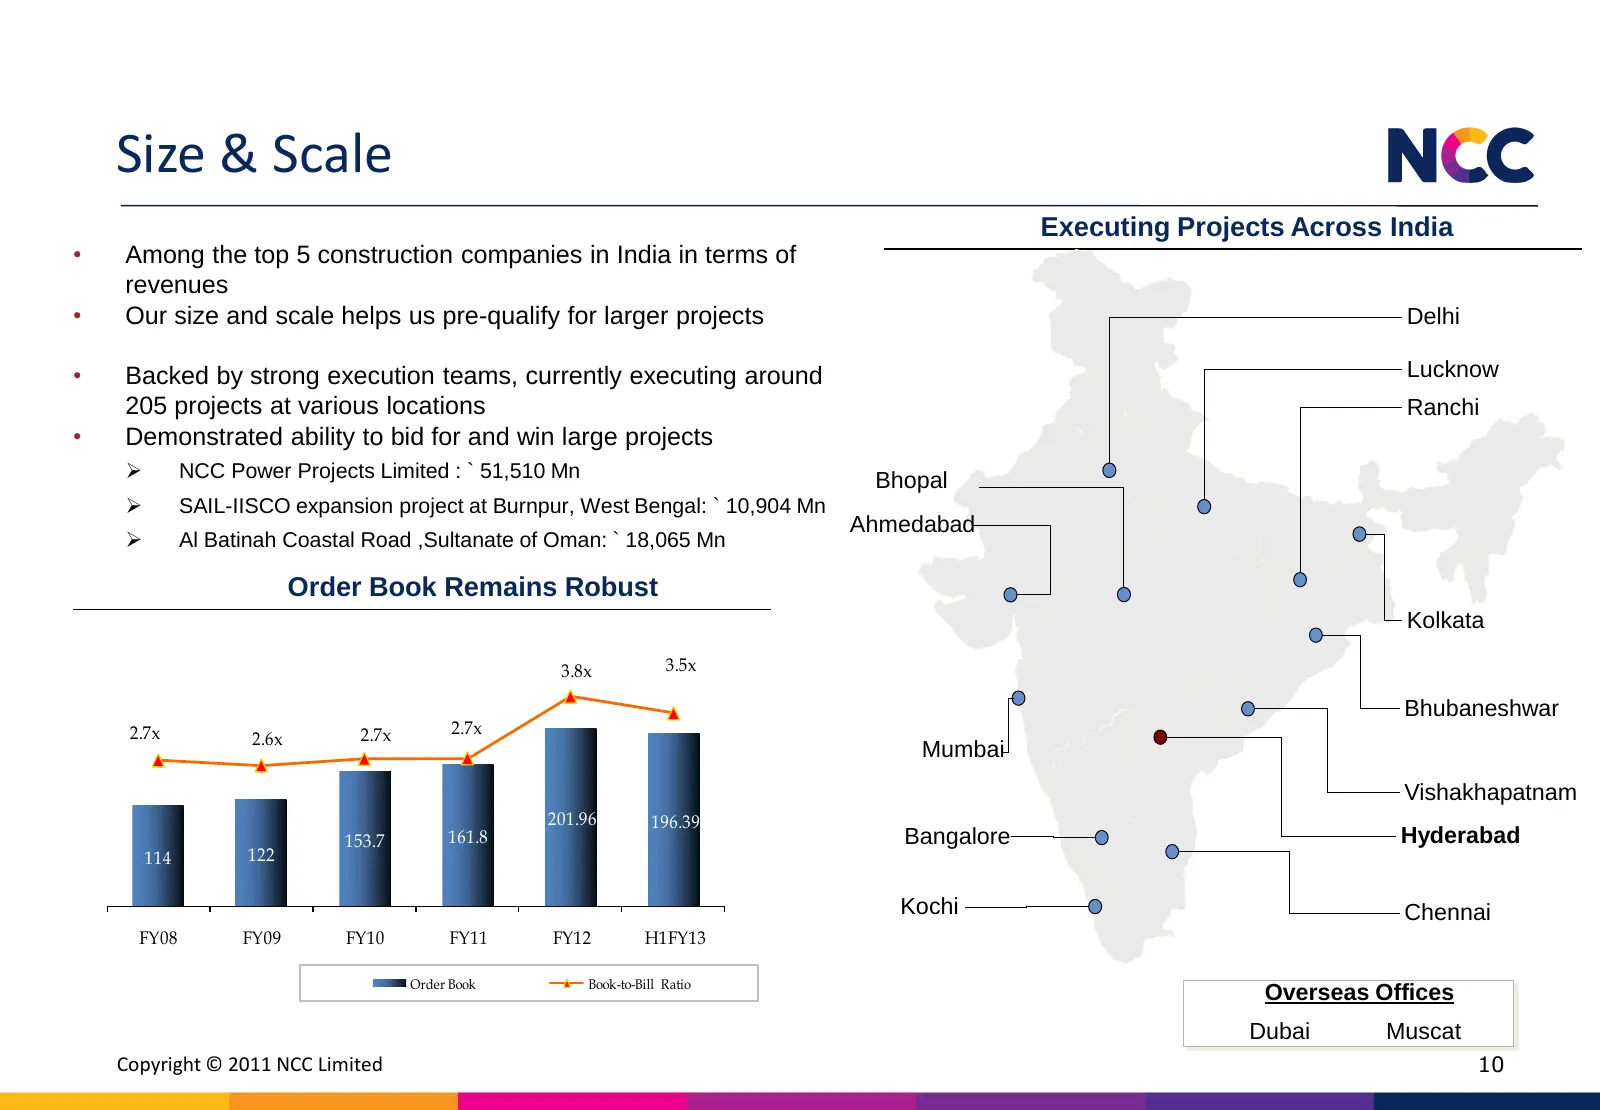
Slide 10: Size & Scale
Size & Scale Executing Projects Across India • Among the top 5 construction companies in India in terms of revenues • Our size and scale helps us pre-qualify for larger projects Delhi • Backed by strong execution teams, currently executing around Lucknow 205 projects at various locations Ranchi • De
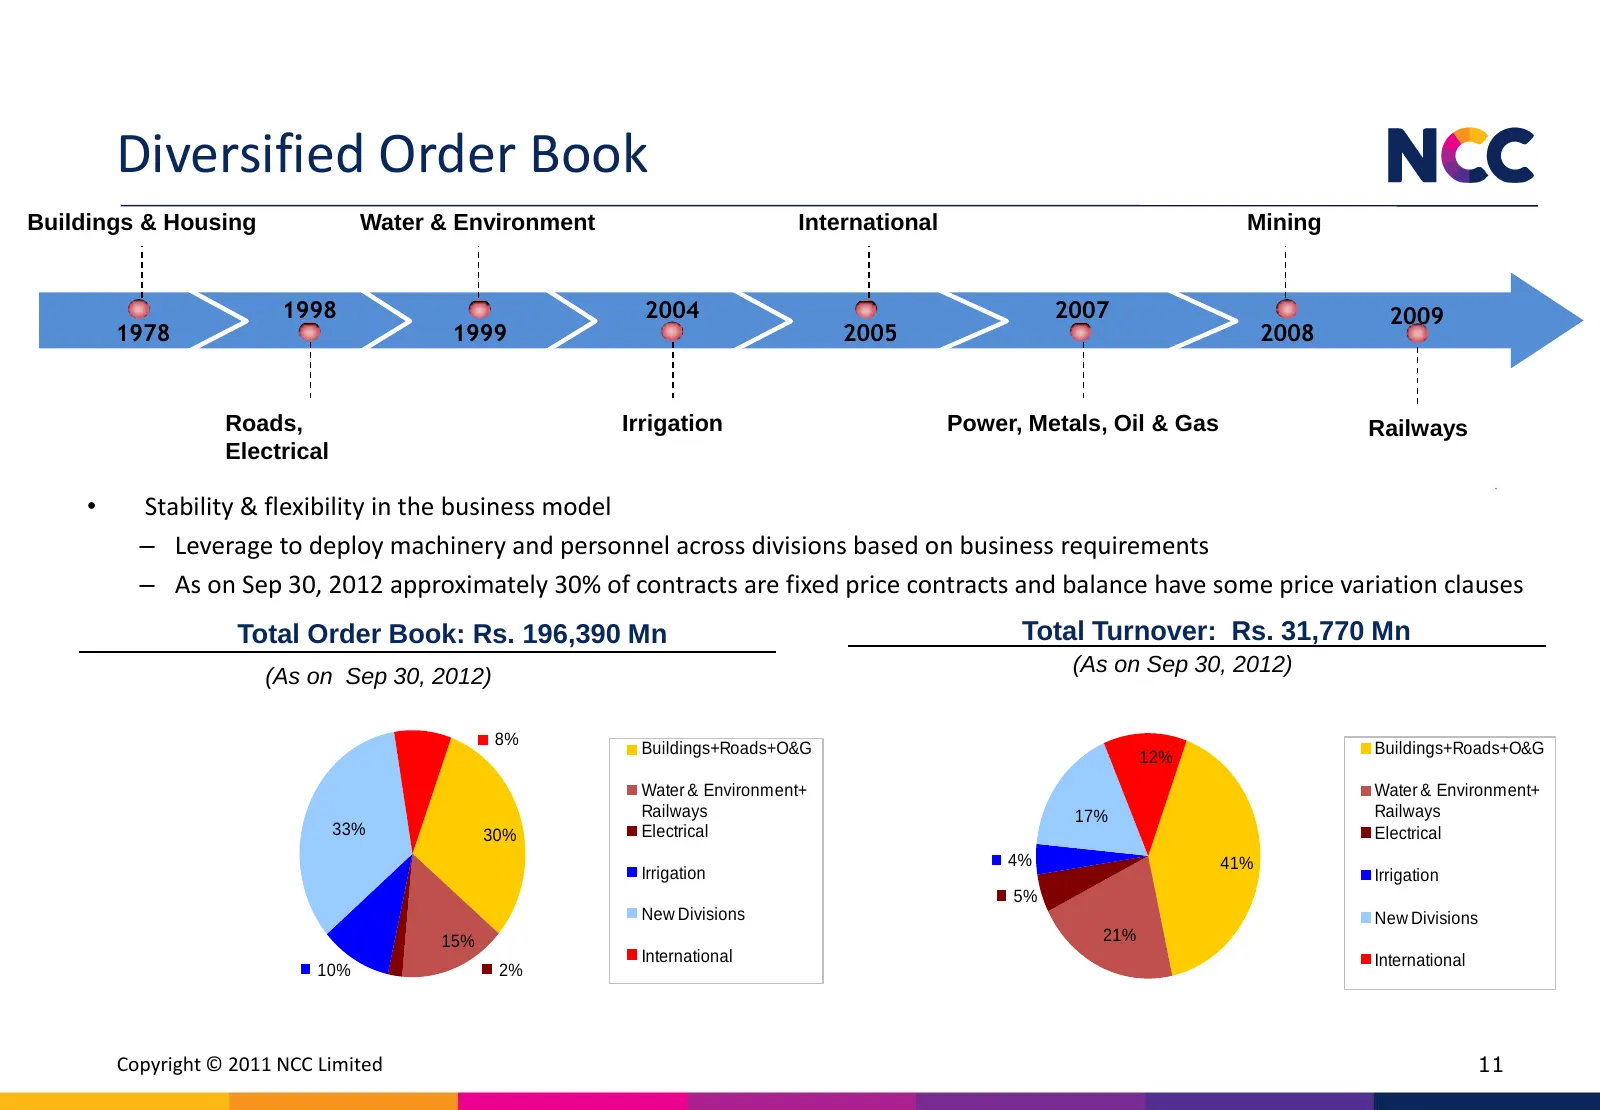
Slide 11: Diversified Order Book
Diversified Order Book Buildings & Housing Water & Environment International Mining 1998 2004 2007 2009 1978 1999 2005 2008 Roads, Irrigation Power, Metals, Oil & Gas Railways Electrical • Stability & flexibility in the business model – Leverage to deploy machinery and personnel across divisions bas
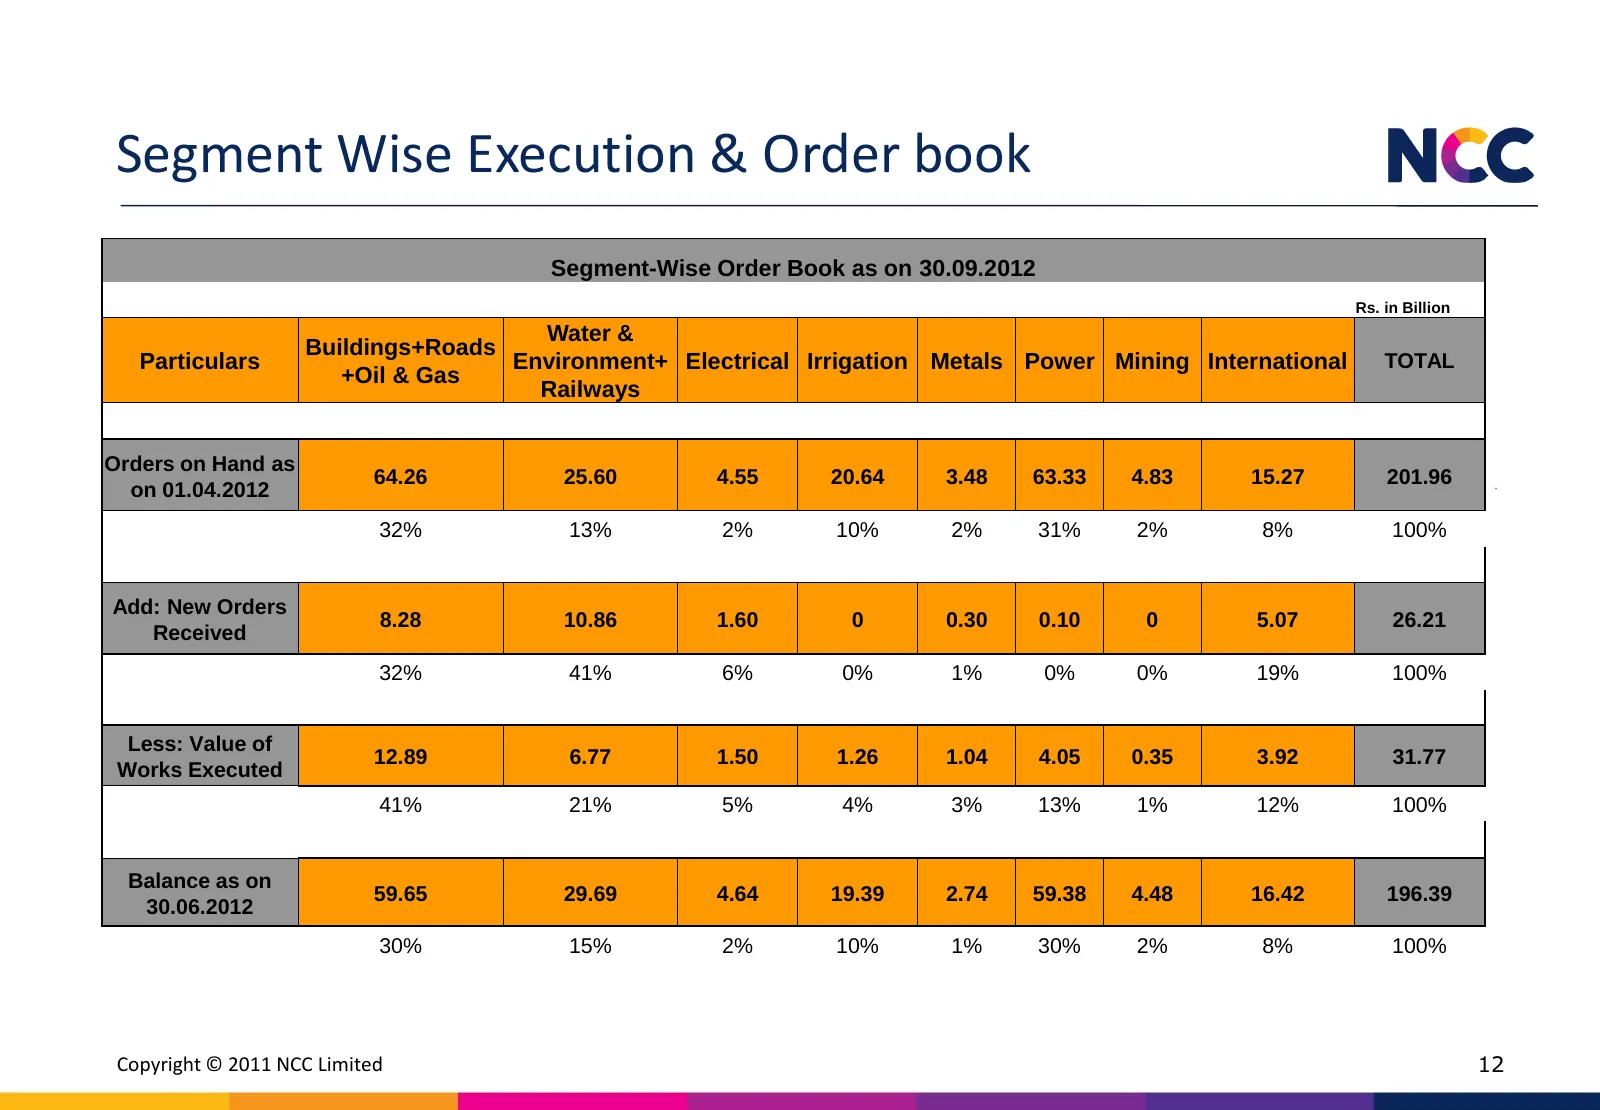
Slide 12: Segment Wise Execution & Order book
Segment Wise Execution & Order book Segment-Wise Order Book as on 30.09.2012 Rs. in Billion Water & Buildings+Roads Particulars Environment+ Electrical Irrigation Metals Power Mining International TOTAL +Oil & Gas Railways Orders on Hand as 64.26 25.60 4.55 20.64 3.48 63.33 4.83 15.27 201.96 on 01.0
Slide 13: Moving Up the Value Chain
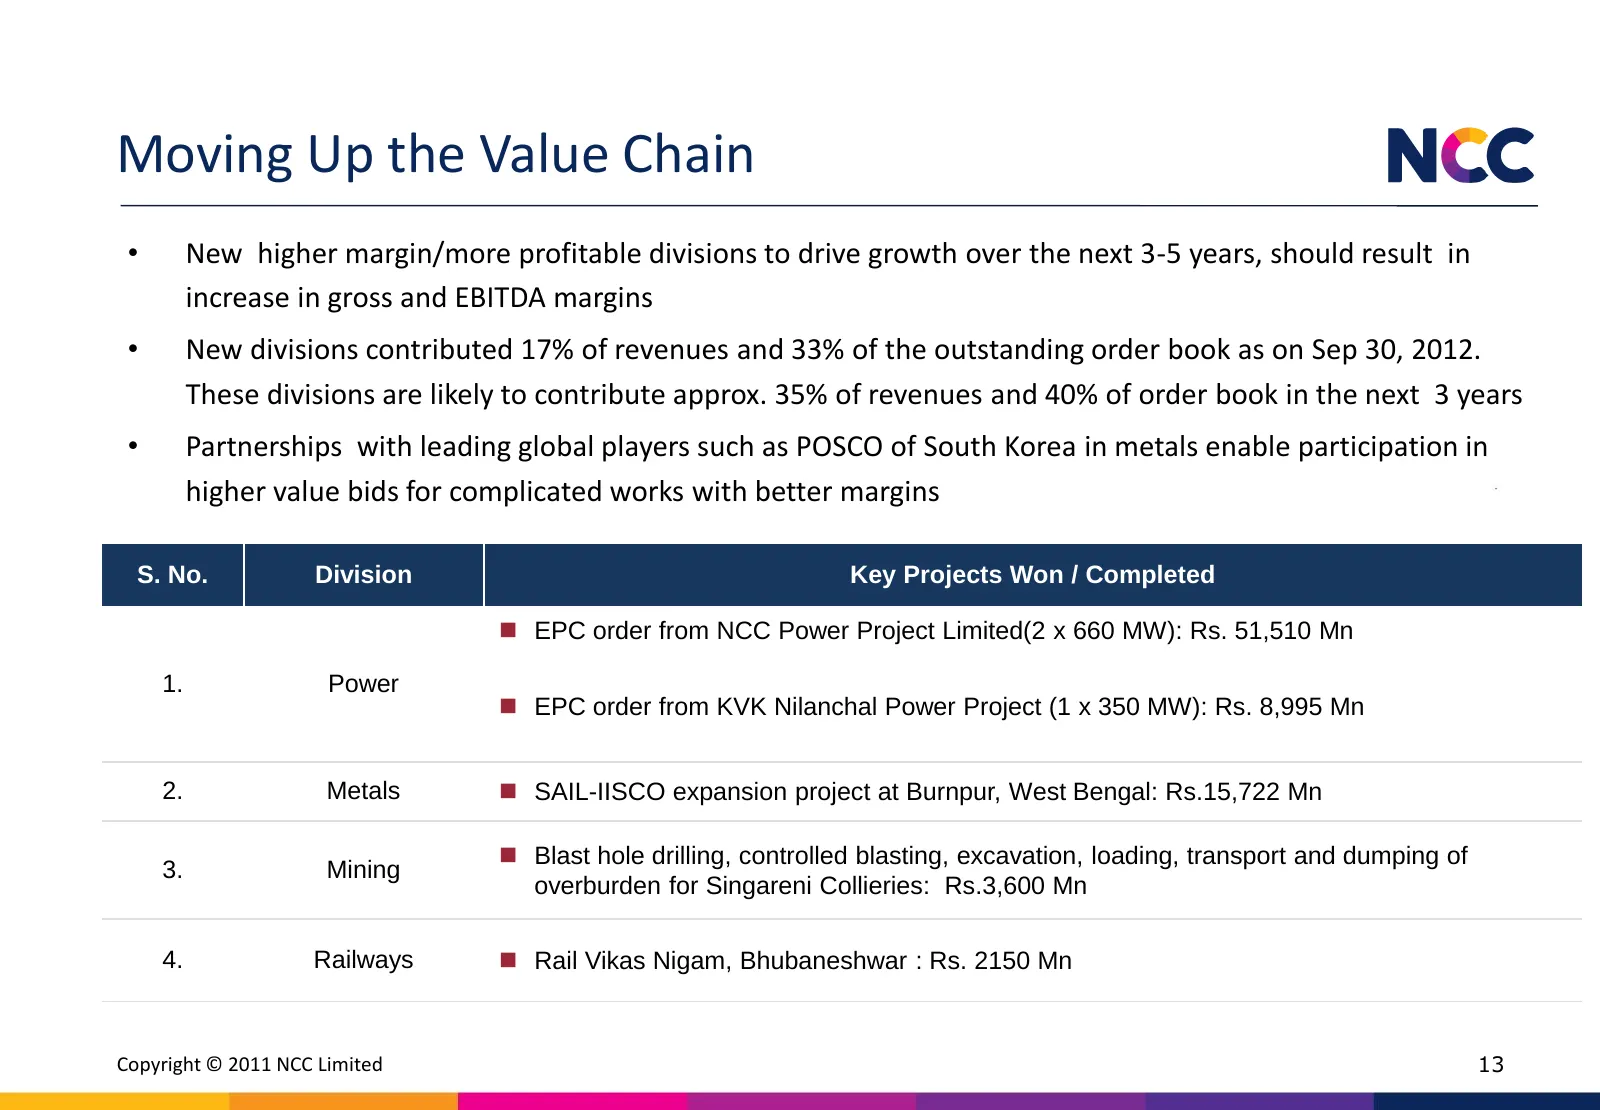
Moving Up the Value Chain • New higher margin/more profitable divisions to drive growth over the next 3-5 years, should result in increase in gross and EBITDA margins • New divisions contributed 17% of revenues and 33% of the outstanding order book as on Sep 30, 2012. These divisions are likely to c
Slide 14: International Presence
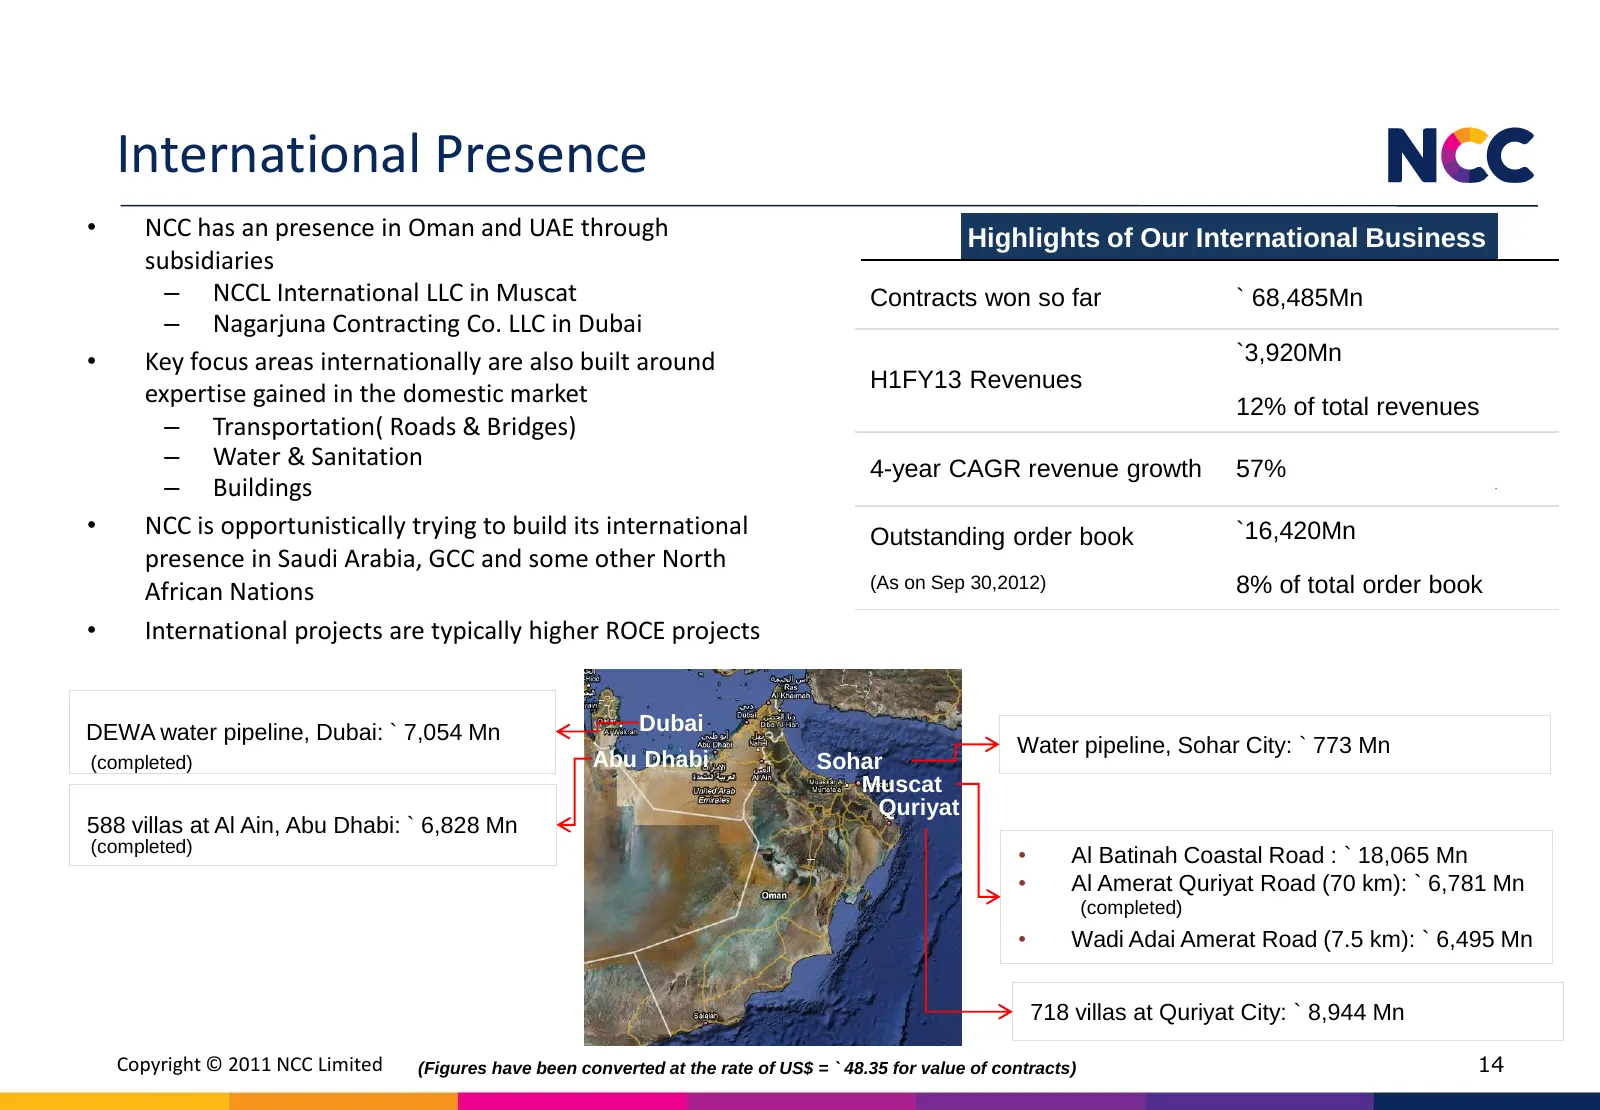
International Presence • NCC has an presence in Oman and UAE through Highlights of Our International Business subsidiaries – NCCL International LLC in Muscat Contracts won so far ` 68,485Mn – Nagarjuna Contracting Co. LLC in Dubai • Key focus areas internationally are also built around `3,920Mn H1FY
Slide 15: Development Business
DEVELOPMENT BUSINESS
Slide 16: Current BOT Portfolio
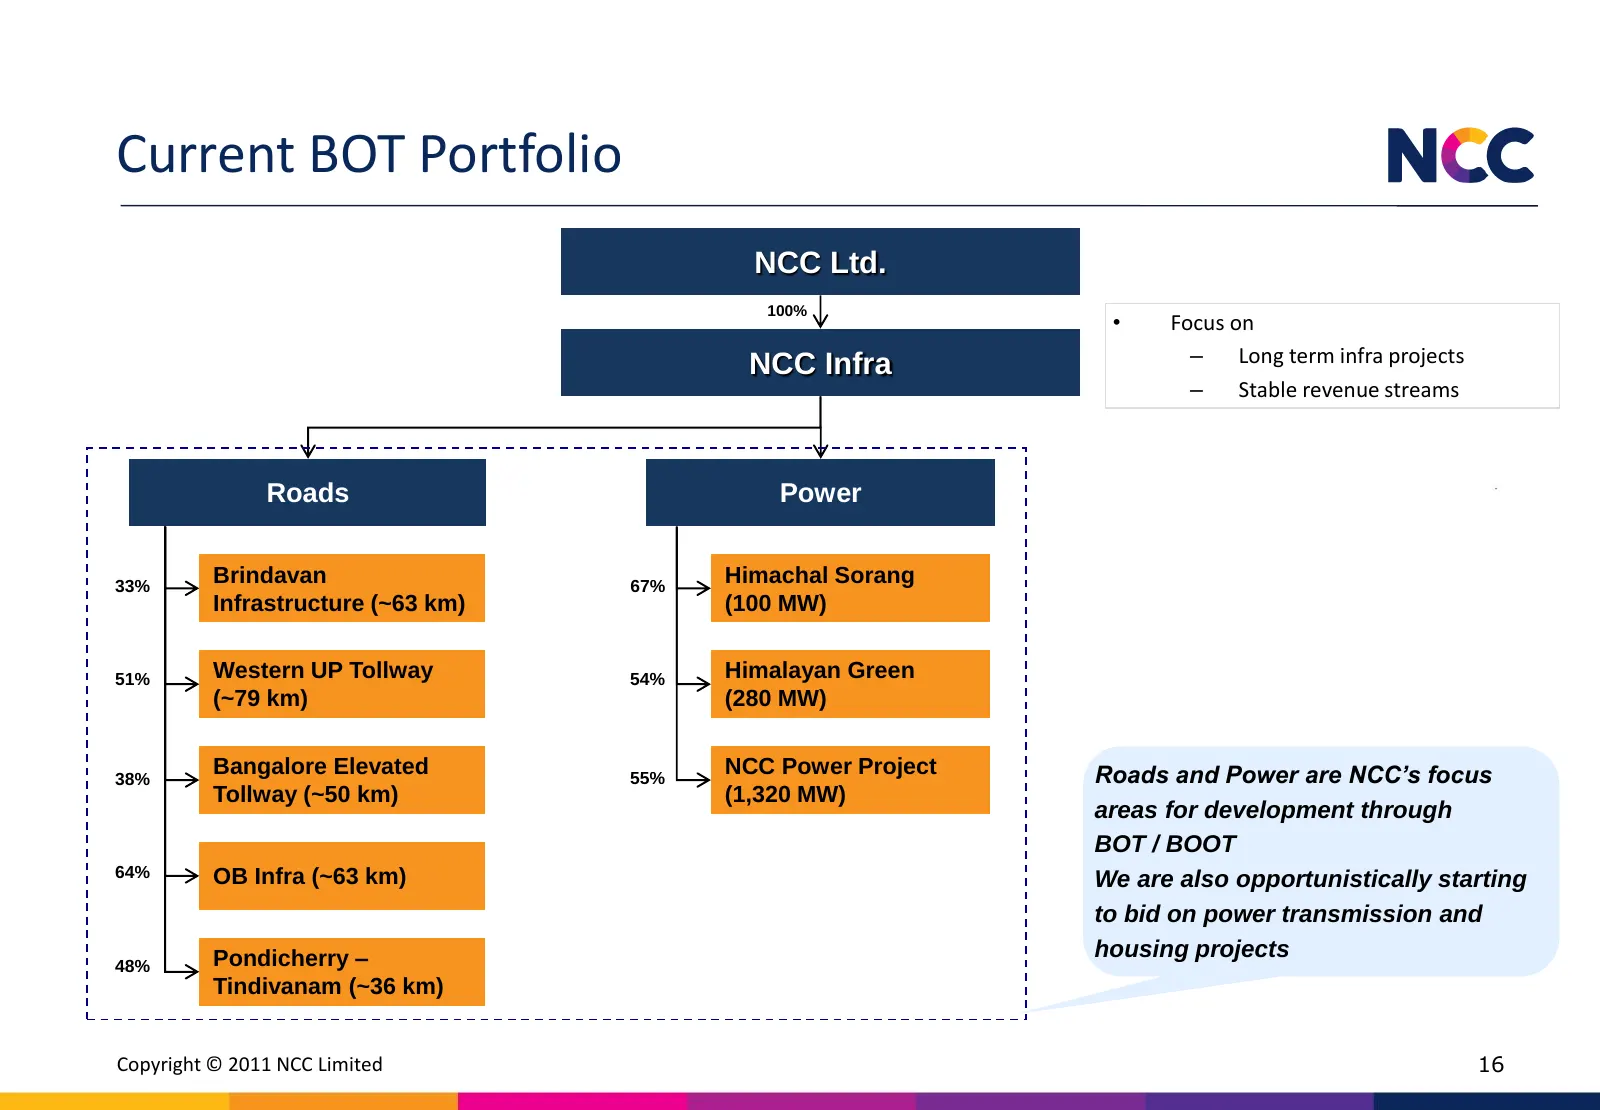
Current BOT Portfolio NCC Ltd. 100% • Focus on NCC Infra – Long term infra projects – Stable revenue streams Roads Power 33% Brindavan 67% Himachal Sorang Infrastructure (~63 km) (100 MW) 51% Western UP Tollway 54% Himalayan Green (~79 km) (280 MW) 38% Bangalore Elevated 55% NCC Power Project Roads
Slide 17: Execution on Track
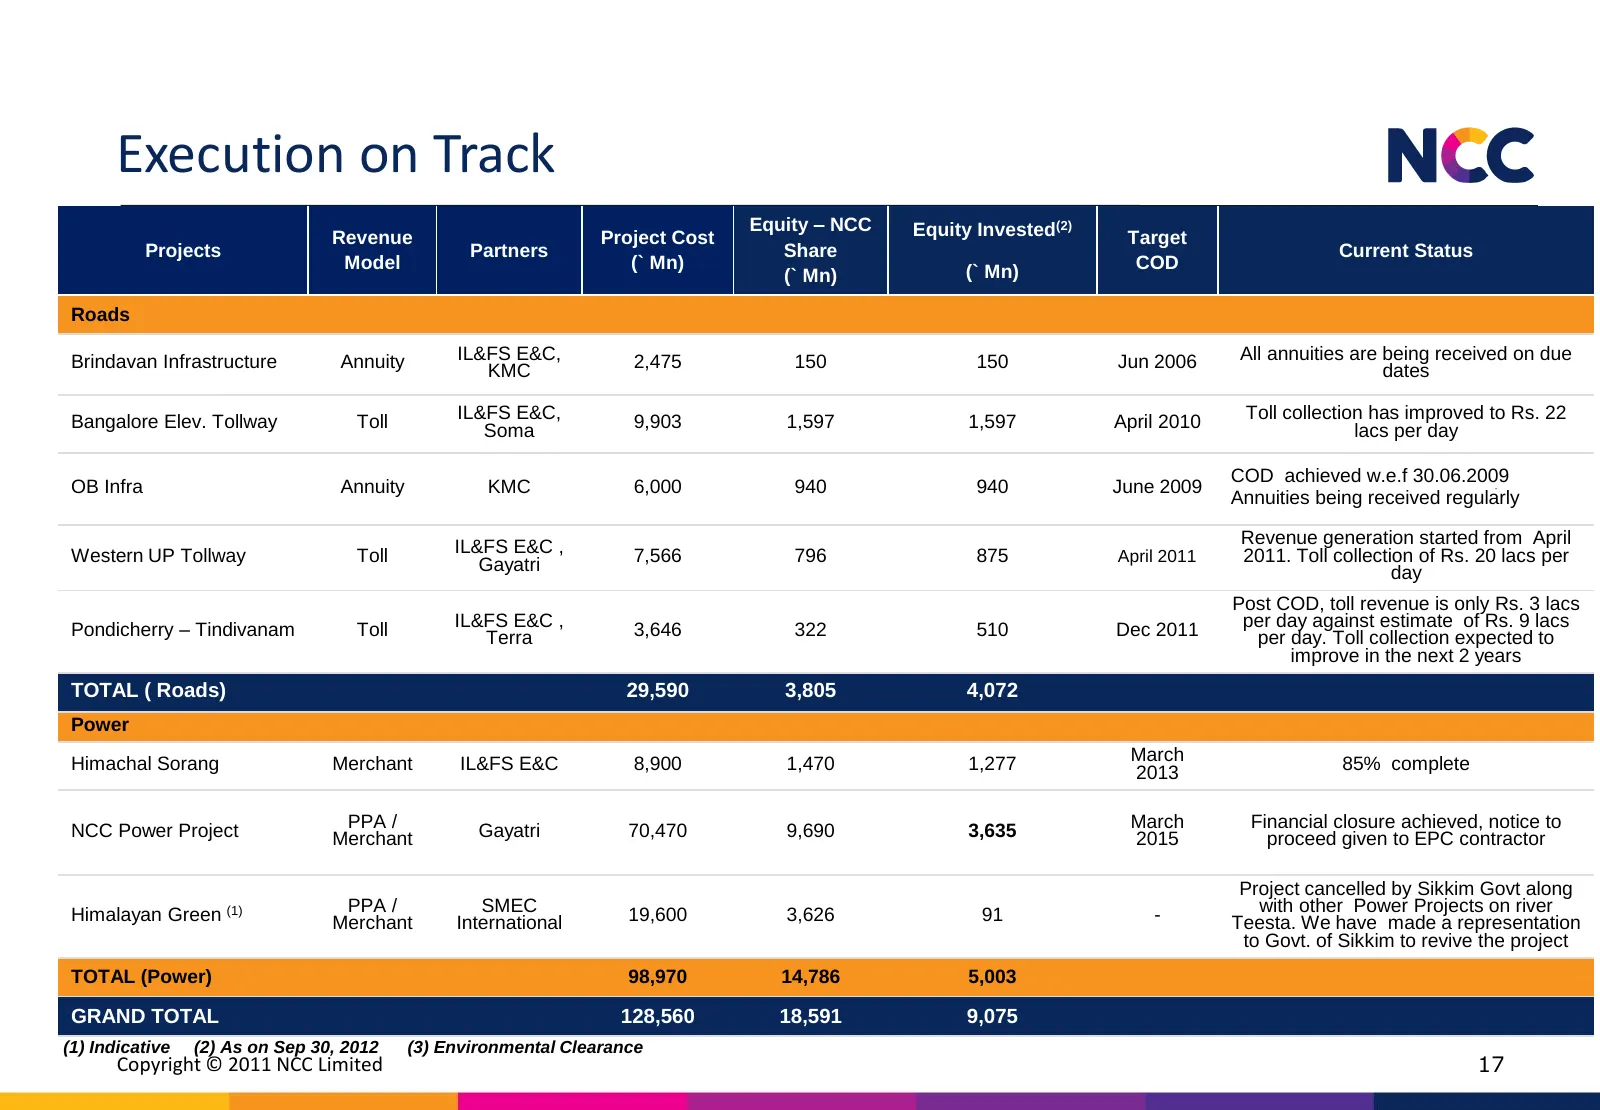
Execution on Track Equity – NCC Equity Invested(2) Revenue Project Cost Target Projects Partners Share Current Status Model (` Mn) (` Mn) COD (` Mn) Roads Brindavan Infrastructure Annuity IL&FS E&C, 2,475 150 150 Jun 2006 All annuities are being received on due KMC dates Bangalore Elev. Tollway Toll
Slide 18: Real Estate Projects
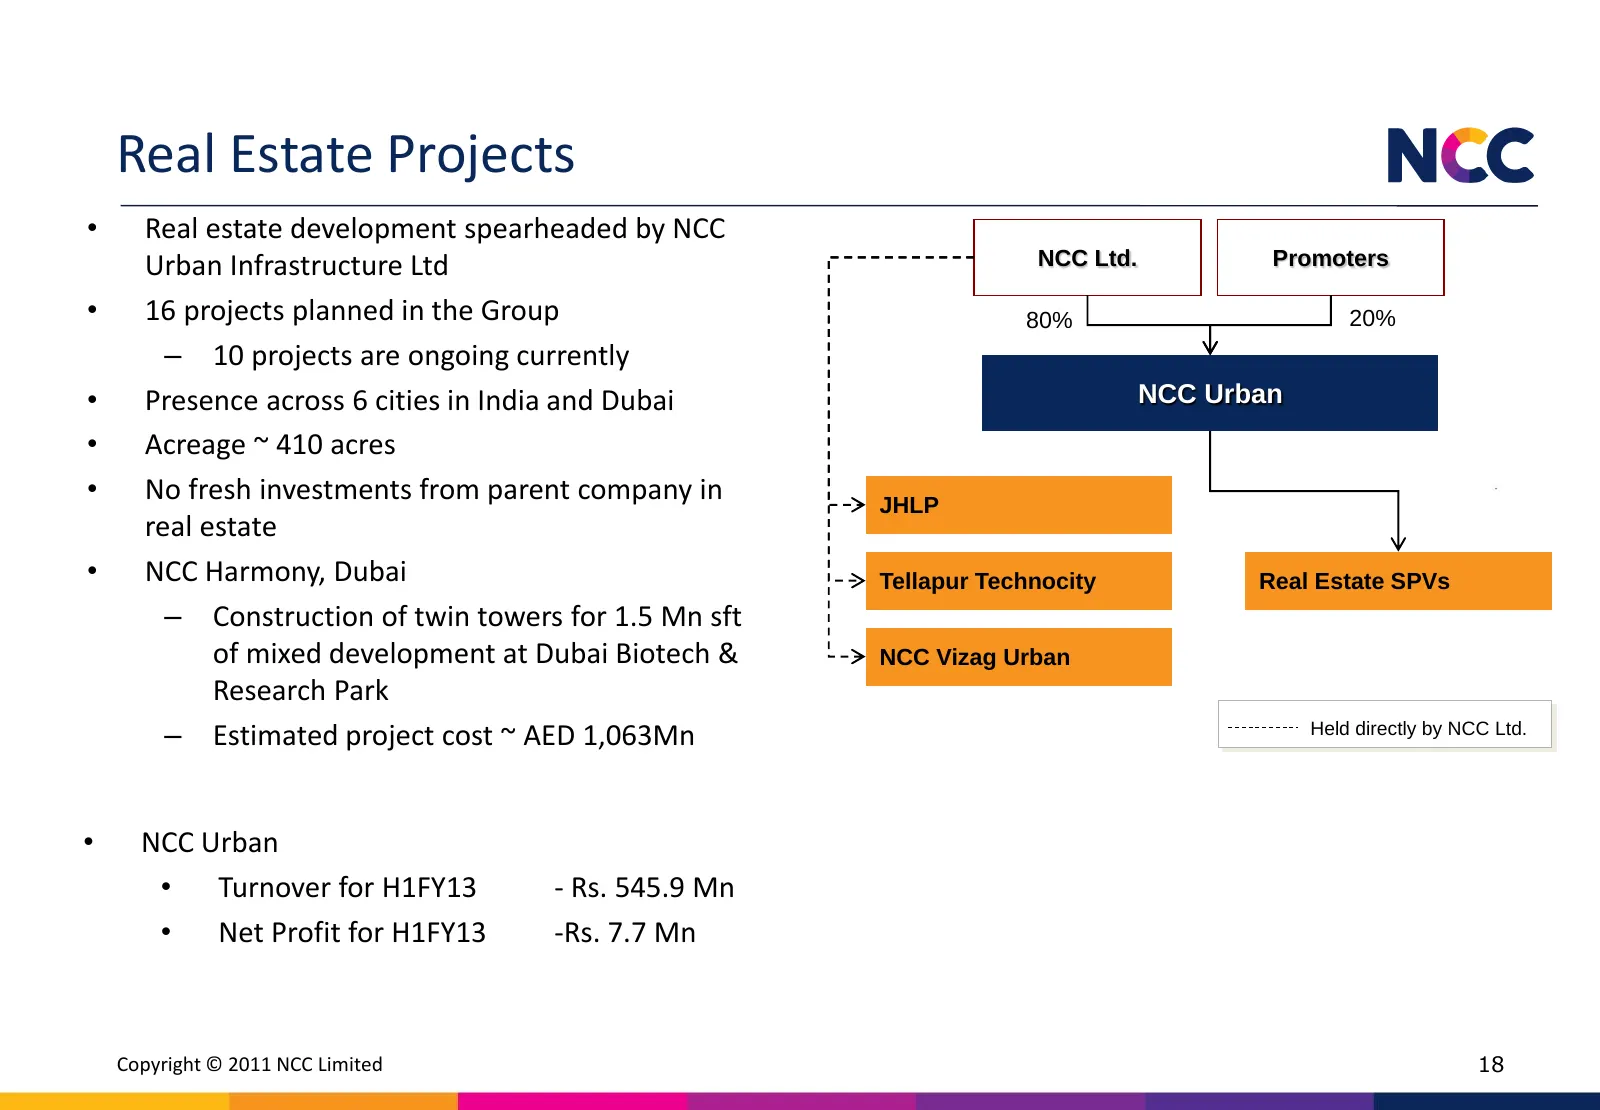
Real Estate Projects • Real estate development spearheaded by NCC Urban Infrastructure Ltd NCC Ltd. Promoters • 16 projects planned in the Group 80% 20% – 10 projects are ongoing currently • Presence across 6 cities in India and Dubai NCC Urban • Acreage ~ 410 acres • No fresh investments from paren
Slide 19: Financials
FINANCIALS
Slide 20: Stand alone Financials
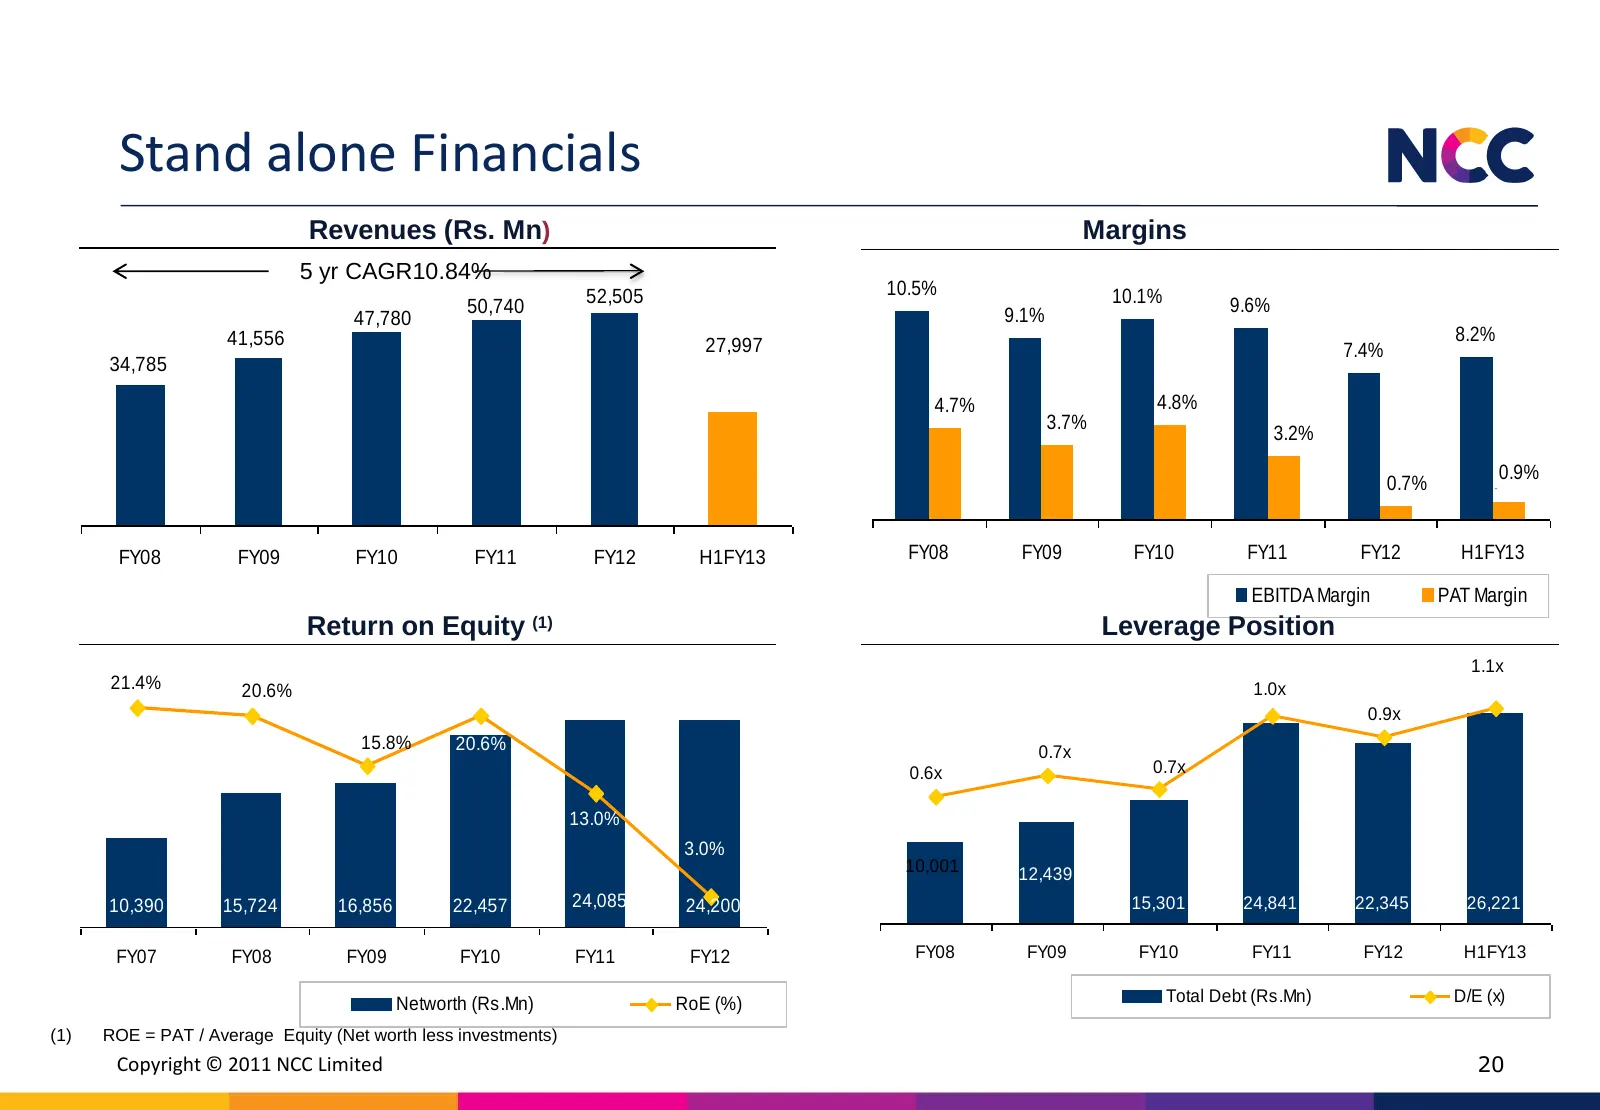
Stand alone Financials Revenues (Rs. Mn) Margins 5 yr CAGR10.84% 52,505 10.5% 10.1% 50,740 9.6% 47,780 9.1% 41,556 8.2% 27,997 7.4% 34,785 4.7% 4.8% 3.7% 3.2% 0.7% 0.9% FY08 FY09 FY10 FY11 FY12 H1FY13 FY08 FY09 FY10 FY11 FY12 H1FY13 EBITDA Margin PAT Margin Return on Equity (1) Leverage Position 30,
Slide 21: Consolidated Financials
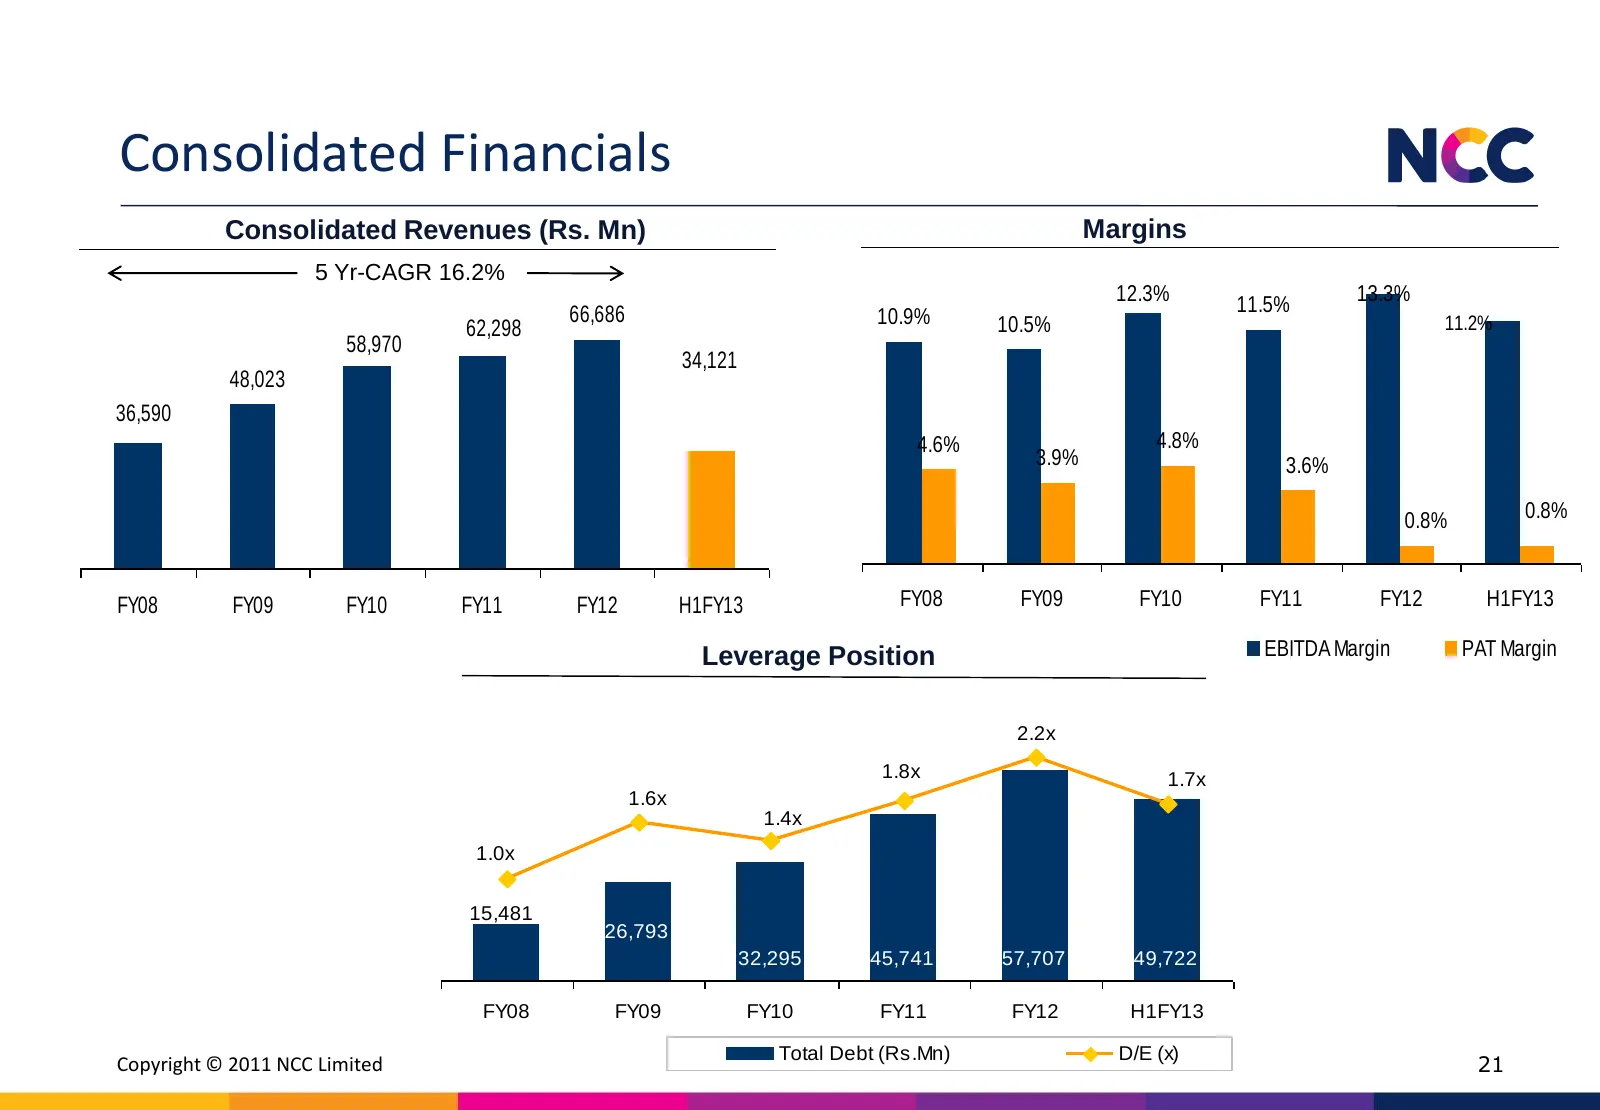
Consolidated Financials Consolidated Revenues (Rs. Mn) Margins 5 Yr-CAGR 16.2% 12.3% 13.3% 66,686 10.9% 11.5% 62,298 10.5% 11.2% 58,970 34,121 48,023 36,590 4.6% 4.8% 3.9% 3.6% 0.8% 0.8% FY08 FY09 FY10 FY11 FY12 H1FY13 FY08 FY09 FY10 FY11 FY12 H1FY13 Leverage Position EBITDA Margin PAT Margin 70000
Slide 22: Industry Overview
INDUSTRY OVERVIEW
Slide 23: Indian Economy
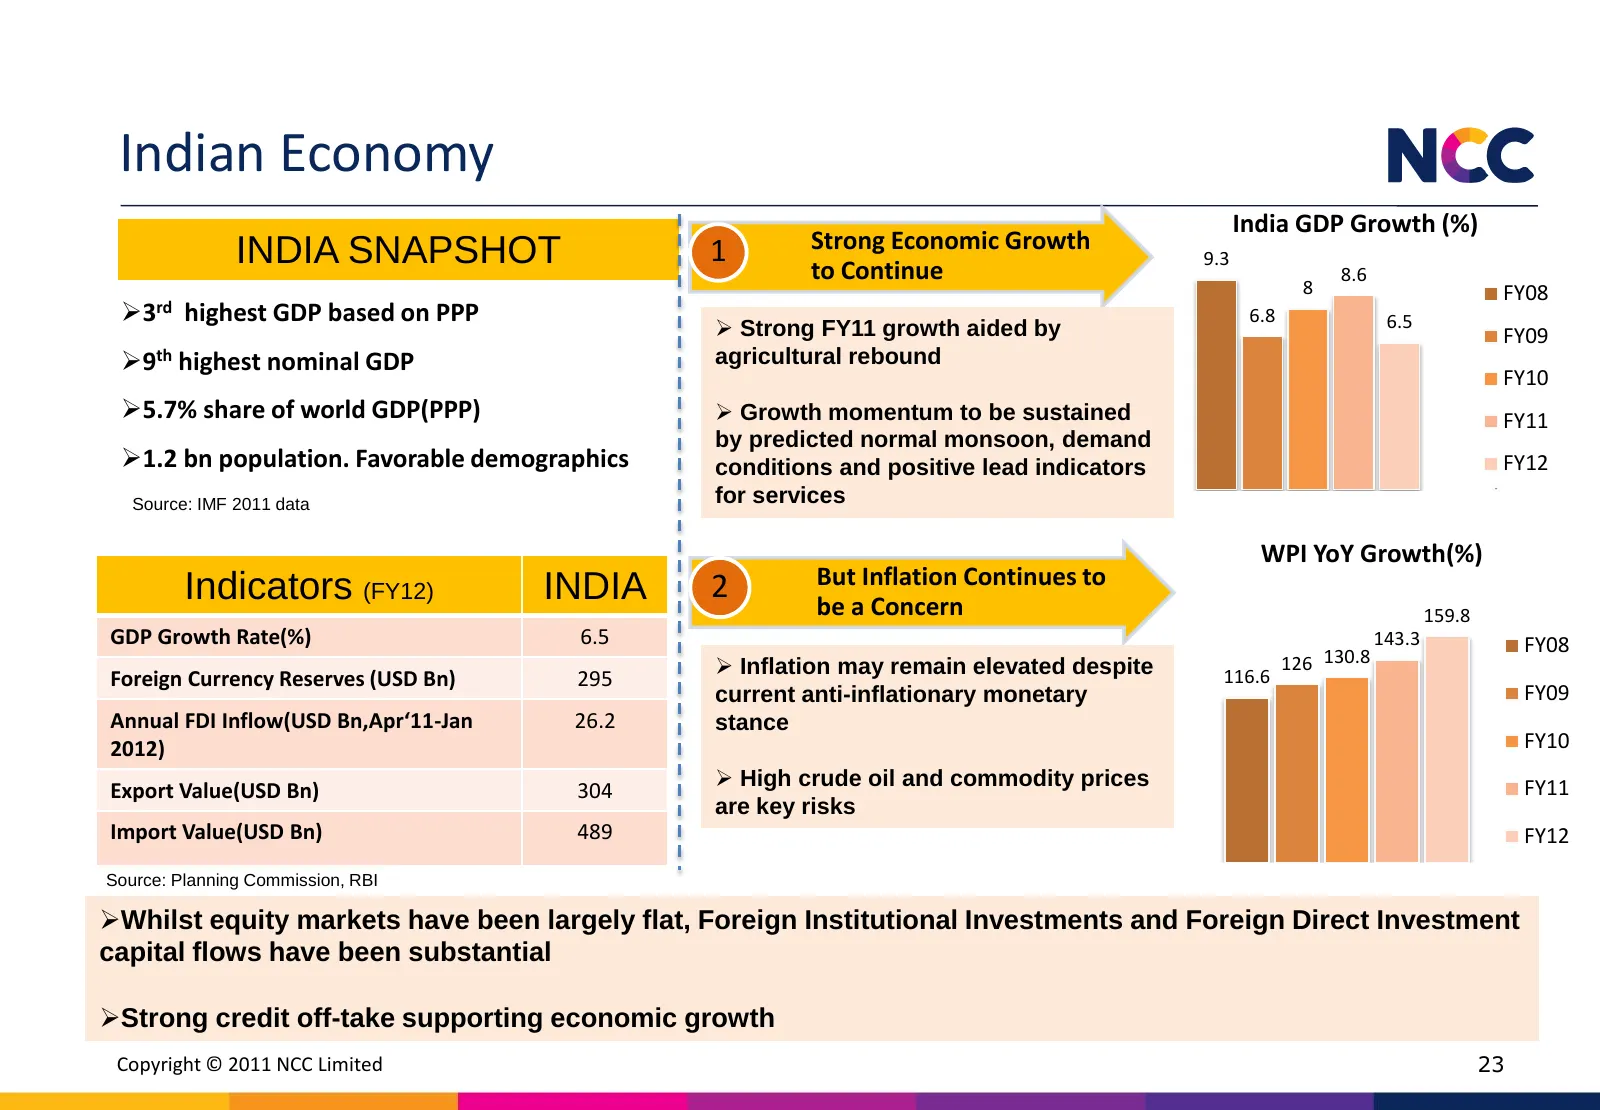
Indian Economy India GDP Growth (%) Strong Economic Growth INDIA SNAPSHOT 1 to Continue 9.3 8.6 8 FY08 3rd highest GDP based on PPP 6.8 6.5 Strong FY11 growth aided by FY09 9th highest nominal GDP agricultural rebound FY10 5.7% share of world GDP(PPP) Growth momentum to be sustained FY11 by p
Slide 24: Growth Potential of Construction Industry
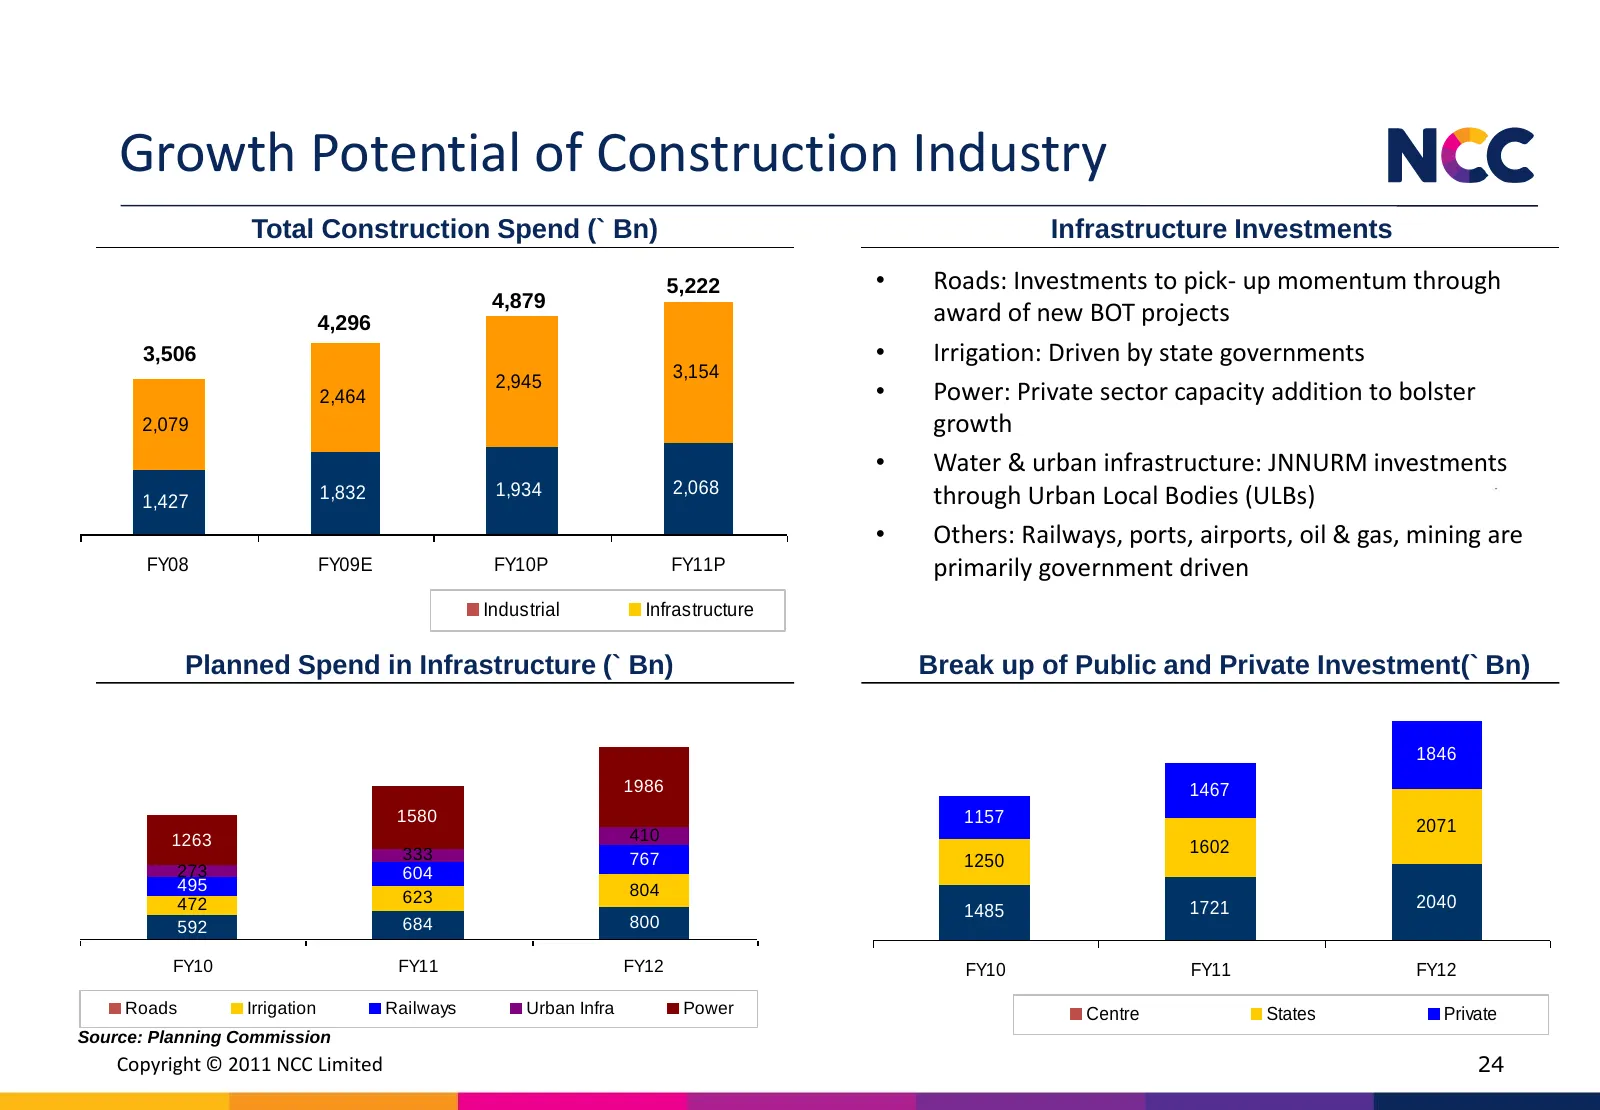
Growth Potential of Construction Industry Total Construction Spend (` Bn) Infrastructure Investments 5,222 • Roads: Investments to pick- up momentum through 4,879 4,296 award of new BOT projects 3,506 • Irrigation: Driven by state governments 2,945 3,154 2,464 • Power: Private sector capacity additi
Slide 25: Next Wave of Growth in Infrastructure BOT
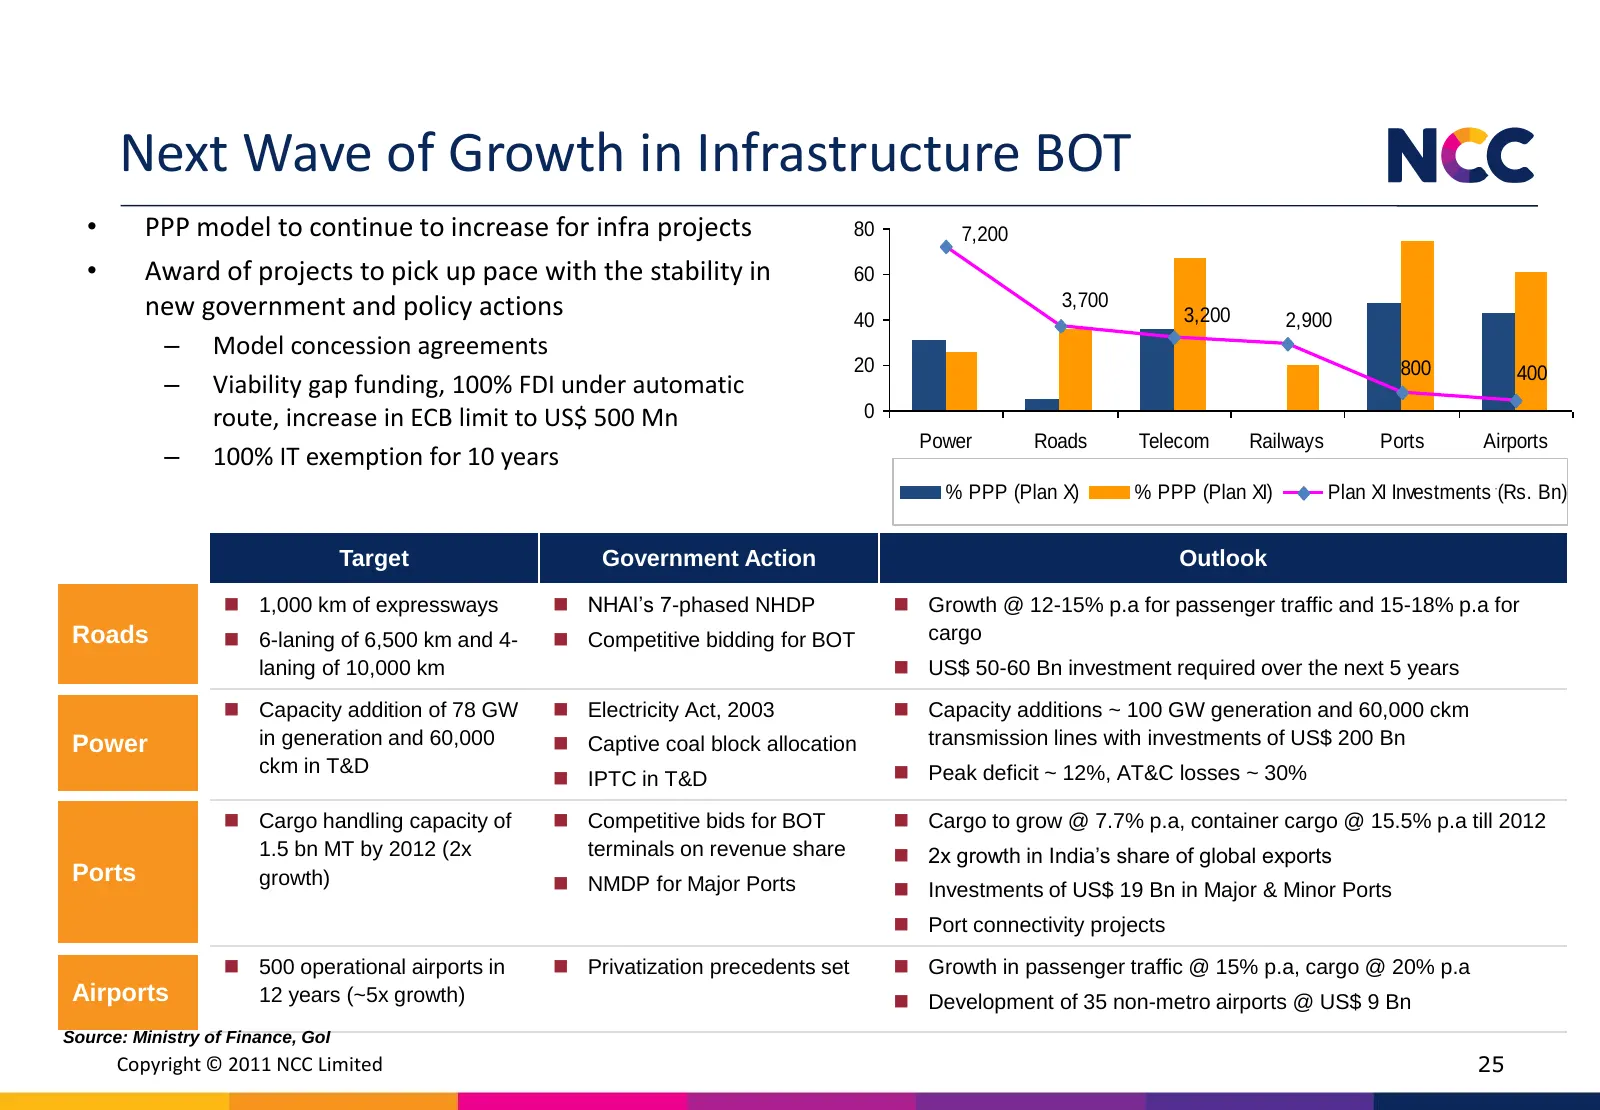
Next Wave of Growth in Infrastructure BOT • PPP model to continue to increase for infra projects 80 7,200 • Award of projects to pick up pace with the stability in 60 new government and policy actions 3,700 40 3,200 2,900 – Model concession agreements 20 800 400 – Viability gap funding, 100% FDI und
Slide 26: Key Highlights
KEY HIGHLIGHTS
Slide 27: NCC: Major Player in an Attractive Industry
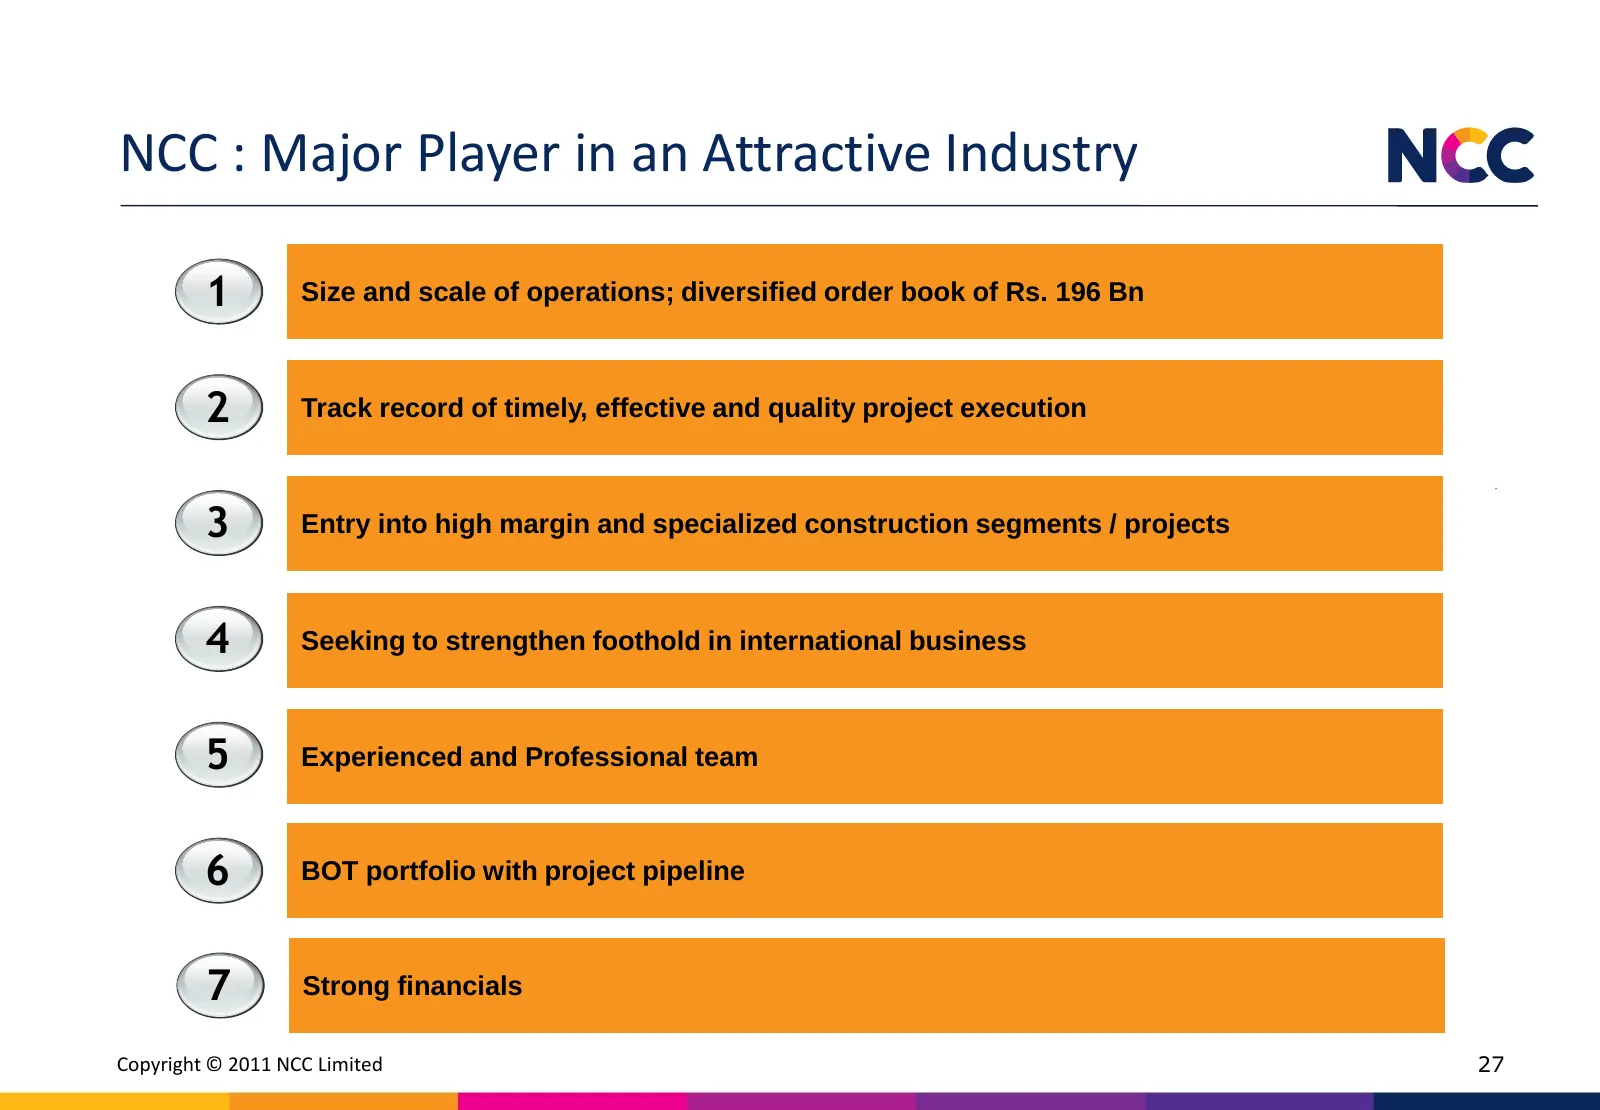
NCC : Major Player in an Attractive Industry 1 Size and scale of operations; diversified order book of Rs. 196 Bn 2 Track record of timely, effective and quality project execution 3 Entry into high margin and specialized construction segments / projects 4 Seeking to strengthen foothold in internatio
Slide 28: Annexure
ANNEXURE
Slide 29: Divisional Performance
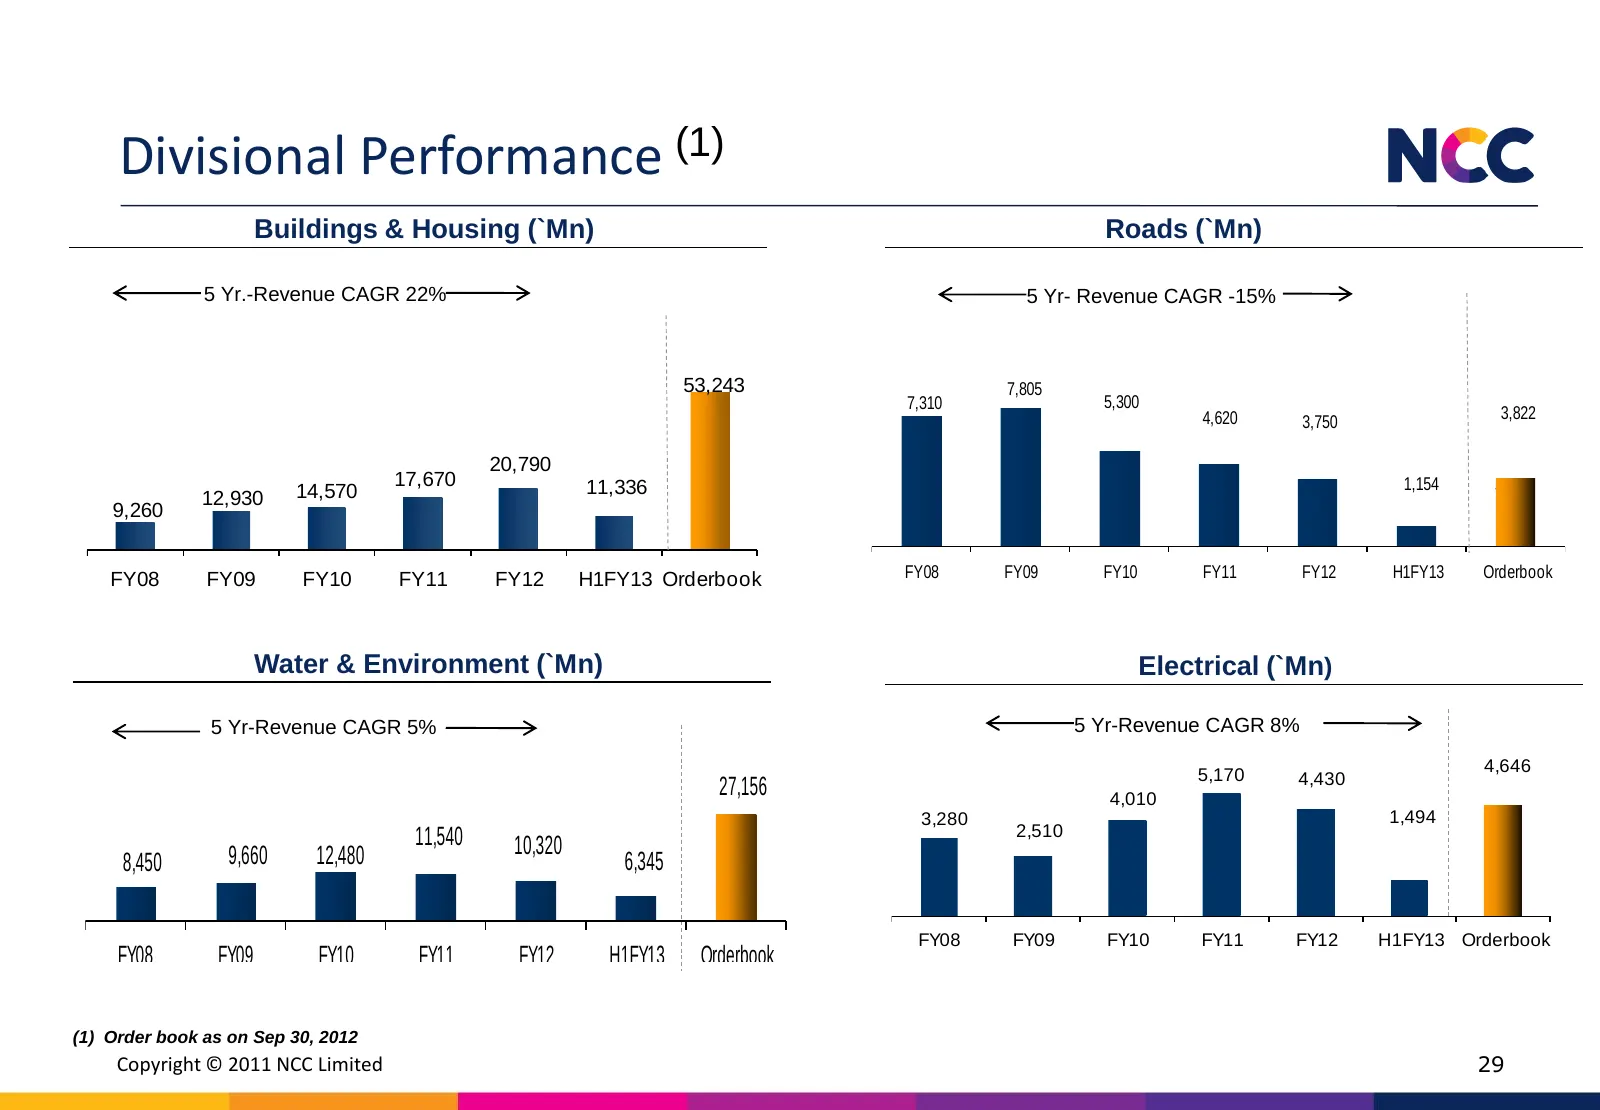
Divisional Performance (1) Buildings & Housing (`Mn) Roads (`Mn) 5 Yr.-Revenue CAGR 22% 5 Yr- Revenue CAGR -15% 53,243 7,805 7,310 5,300 4,620 3,750 3,822 20,790 17,670 11,336 1,154 12,930 14,570 9,260 FY08 FY09 FY10 FY11 FY12 H1FY13 Orderbook FY08 FY09 FY10 FY11 FY12 H1FY13 Orderbook Water & Enviro
Slide 30: Divisional Performance
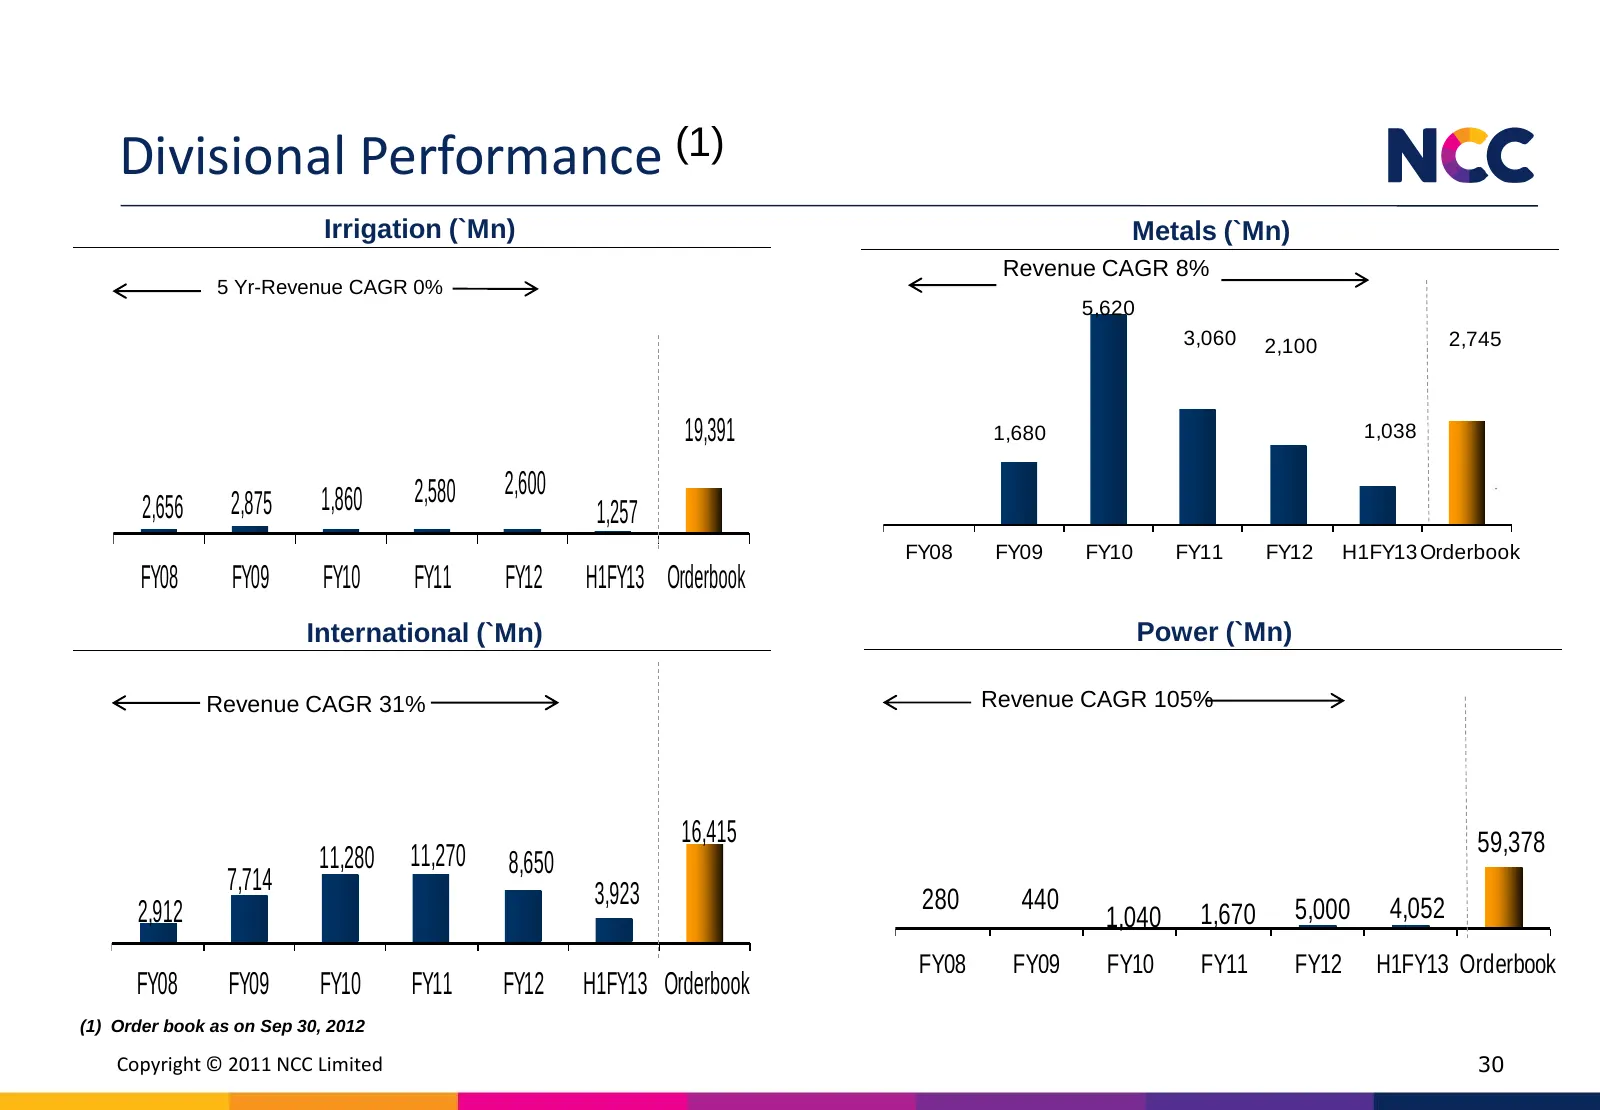
Divisional Performance (1) Irrigation (`Mn) Metals (`Mn) Revenue CAGR 8% 5 Yr-Revenue CAGR 0% 5,620 3,060 2,100 2,745 19,391 1,680 1,038 1,860 2,580 2,600 2,656 2,875 1,257 FY08 FY09 FY10 FY11 FY12 H1FY13 Orderbook FY08 FY09 FY10 FY11 FY12 H1FY13 Orderbook International (`Mn) Power (`Mn) Revenue CAG
Slide 31: Divisional Performance
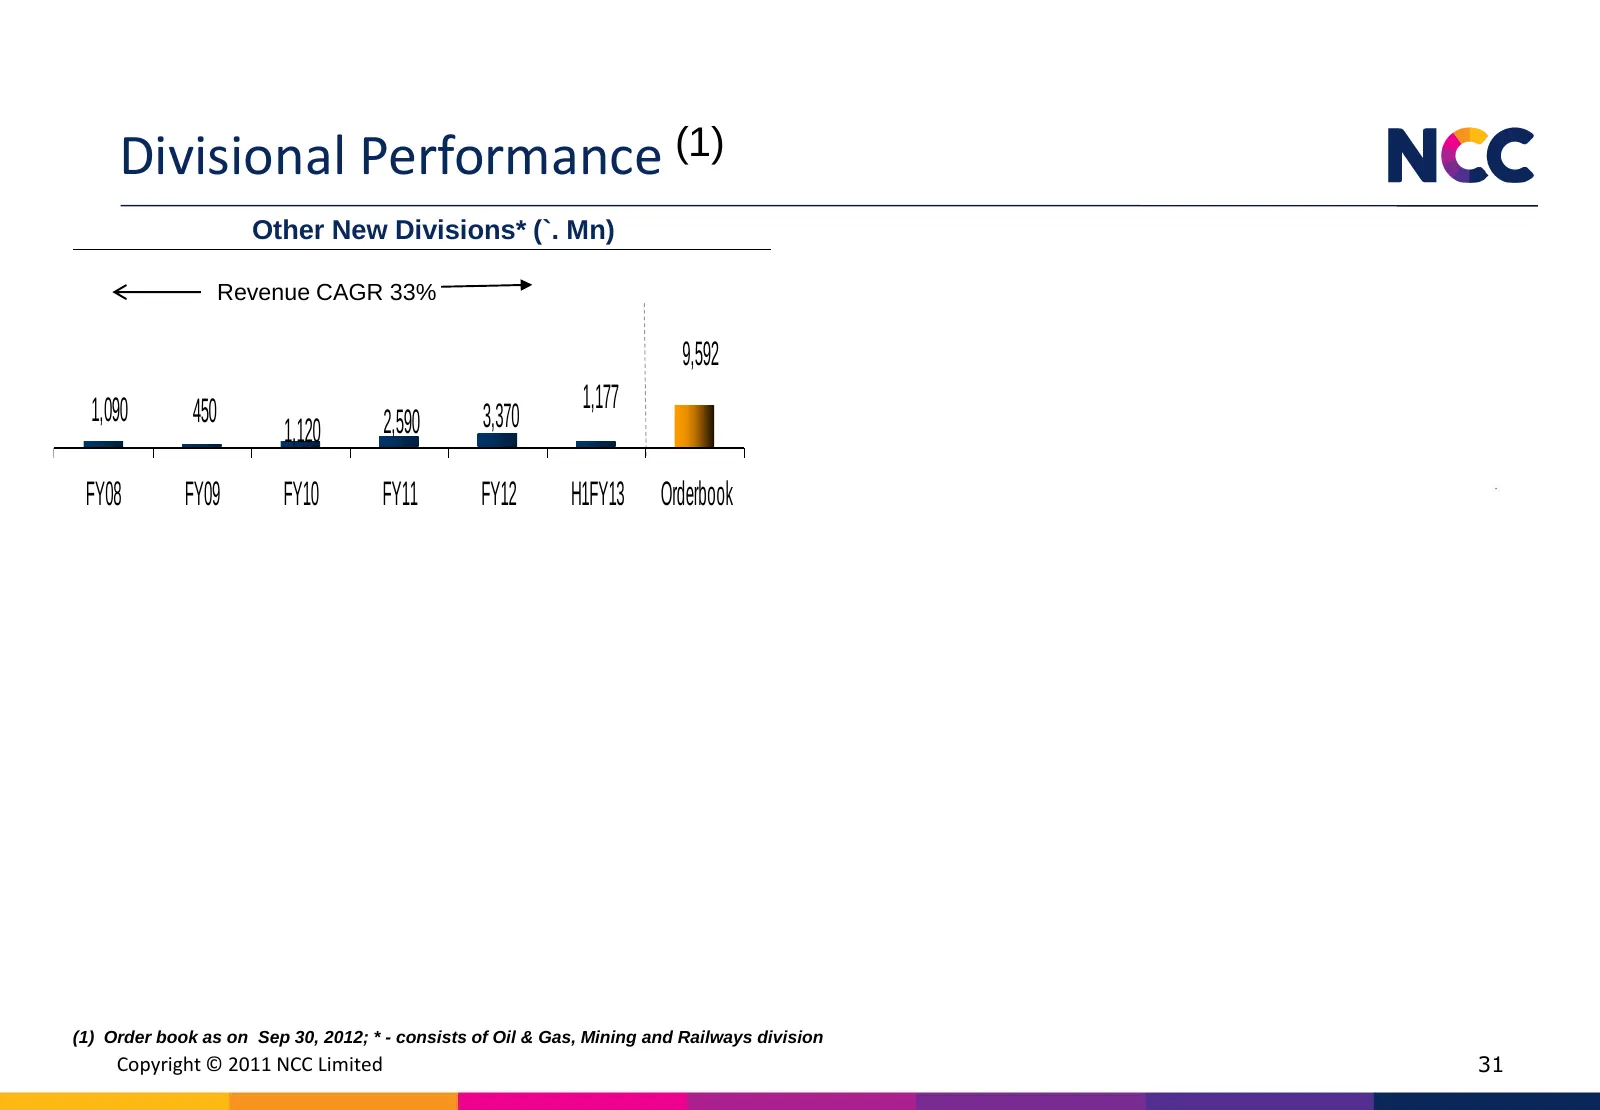
Divisional Performance (1) Other New Divisions* (`. Mn) Revenue CAGR 33% 9,592 1,090 450 1,177 1,120 2,590 3,370 FY08 FY09 FY10 FY11 FY12 H1FY13 Orderbook (1) Order book as on Sep 30, 2012; * - consists of Oil & Gas, Mining and Railways division Copyright © 2011 NCC Limited 31
Slide 32: Real Estate Portfolio
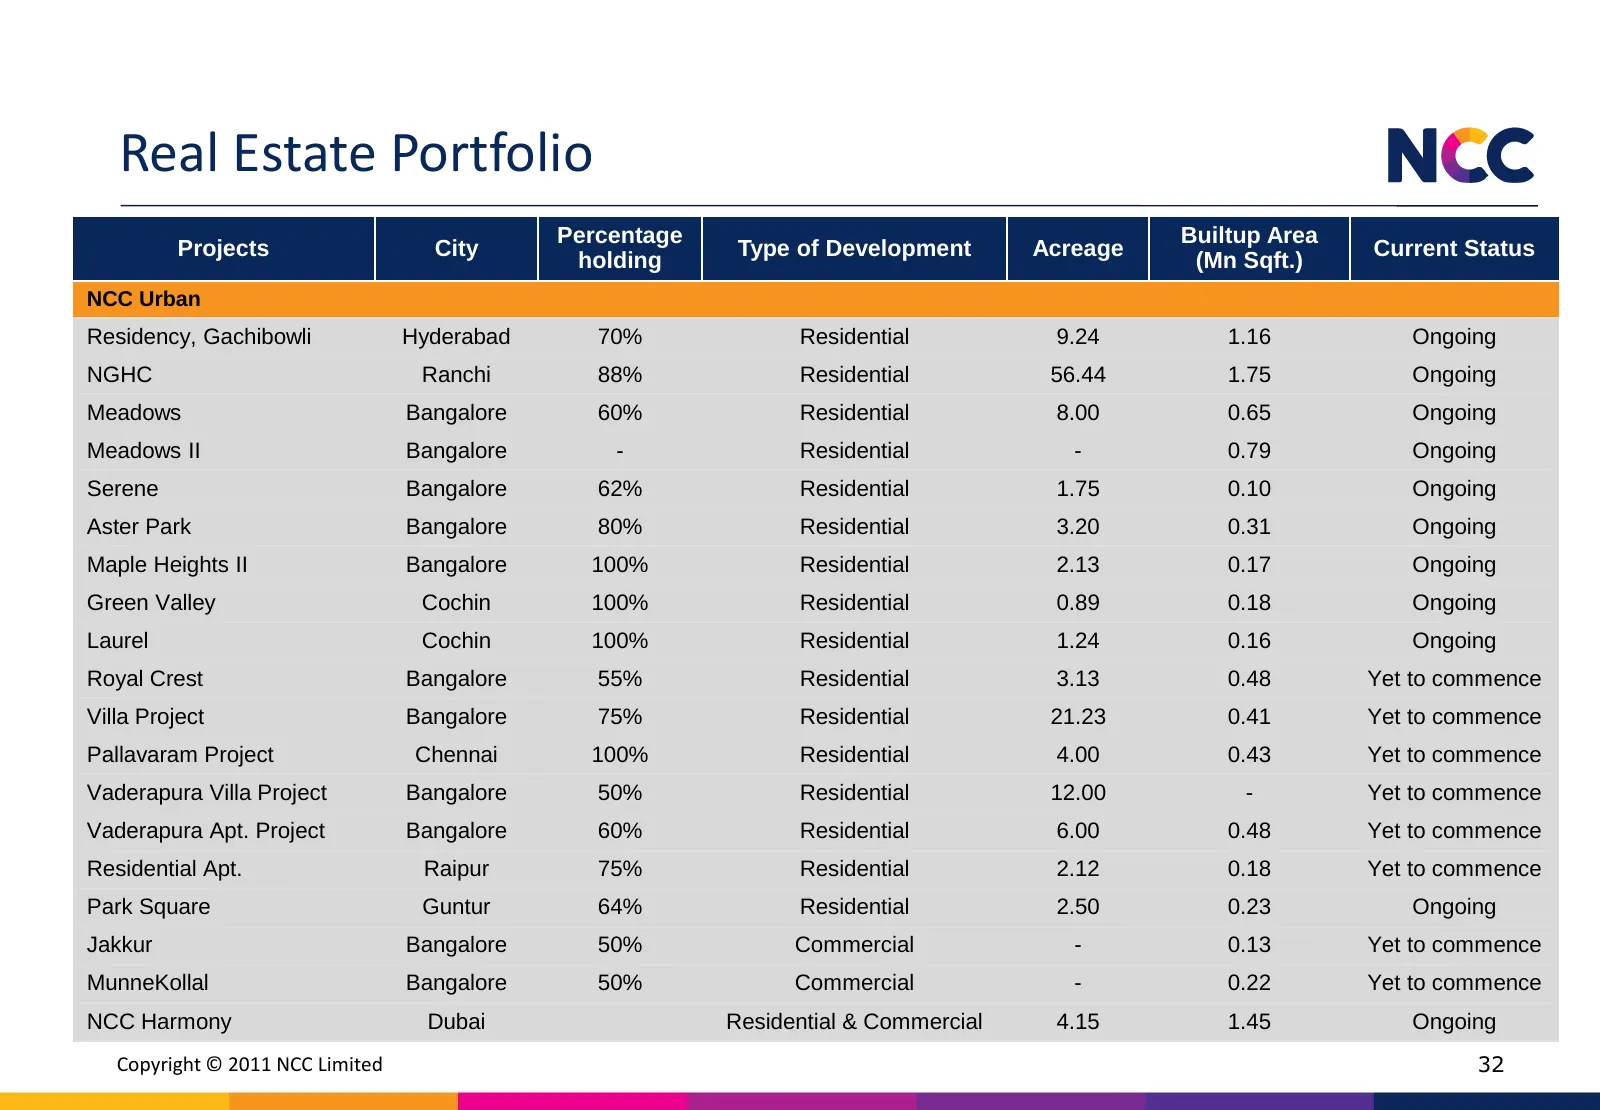
Real Estate Portfolio Percentage Builtup Area Projects City Type of Development Acreage Current Status holding (Mn Sqft.) NCC Urban Residency, Gachibowli Hyderabad 70% Residential 9.24 1.16 Ongoing NGHC Ranchi 88% Residential 56.44 1.75 Ongoing Meadows Bangalore 60% Residential 8.00 0.65 Ongoing Mea
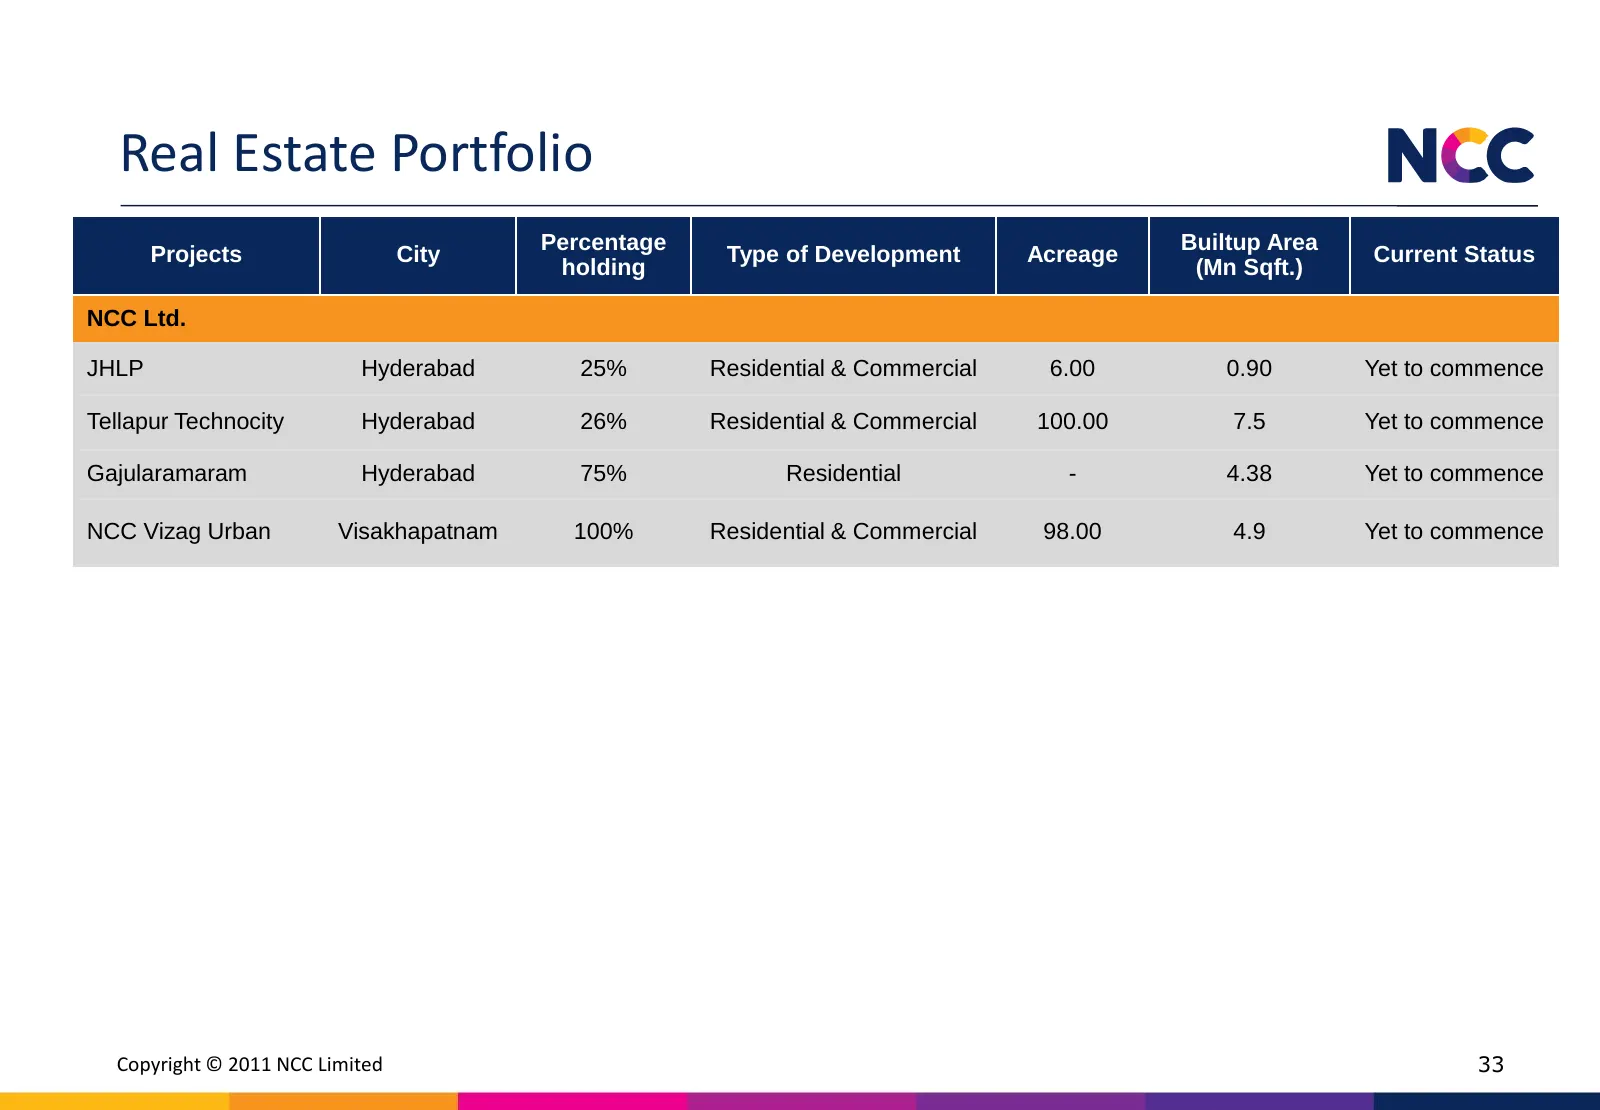
Slide 33: Real Estate Portfolio
Real Estate Portfolio Percentage Builtup Area Projects City Type of Development Acreage Current Status holding (Mn Sqft.) NCC Ltd. JHLP Hyderabad 25% Residential & Commercial 6.00 0.90 Yet to commence Tellapur Technocity Hyderabad 26% Residential & Commercial 100.00 7.5 Yet to commence Gajularamaram
Slide 34: Thank you
Thank you
Source: Internet Archive copy of ncclimited.com
More decks from NCC Limited
 Q2 FY2027 Earnings Presentation34 slides · Nov 5, 2026
 Q1 FY2027 Earnings Presentation35 slides · Aug 6, 2026
 Q4 FY2026 Earnings Presentation37 slides · May 15, 2026
 Q3 FY26 Earnings Presentation32 slides · Feb 5, 2026
 Q2 & H1 FY26 Earnings Presentation34 slides · Nov 6, 2025
 Q1 FY26 Earnings Presentation20 slides · Aug 5, 2025