Texas Industries — Longbow Research San Francisco Client Roadshow (May 2010)
46 slides from Texas Industries's conference presentation, May 19, 2010
Slide 1: Texas Industries, Inc. Investor Presentation
1 TEXAS INDUSTRIES, INC. INVESTOR PRESENTATION LONGBOW RESEARCH SAN FRANCISCO CLIENT ROADSHOW MAY 19, 2010
Slide 2: Forward-Looking Statement
FORWARD-LOOKING STATEMENT 2 Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are subject to risks, uncertainties and other factors, which could cause actual results to differ
Slide 3: A Building Materials Company
A BUILDING MATERIALS COMPANY ¨ Cement, Aggregate and Concrete ¨ Used in all types of construction ¨ Cement accounts for approximately 75% of operating earnings over time 3
Slide 4: Primary Earnings Drivers
4 PRIMARY EARNINGS DRIVERS ¨ Cement Capacity Expansion Projects (millions of tons) FY07 Total Capacity 5.0 California expansion 1.0 Central Texas expansion 1.4 North Texas incremental production 0.5 Targeted Capacity 7.9 ¨ Margin Expansion ◊ Efficiency improvements ◊ All operations ¨ The timing for
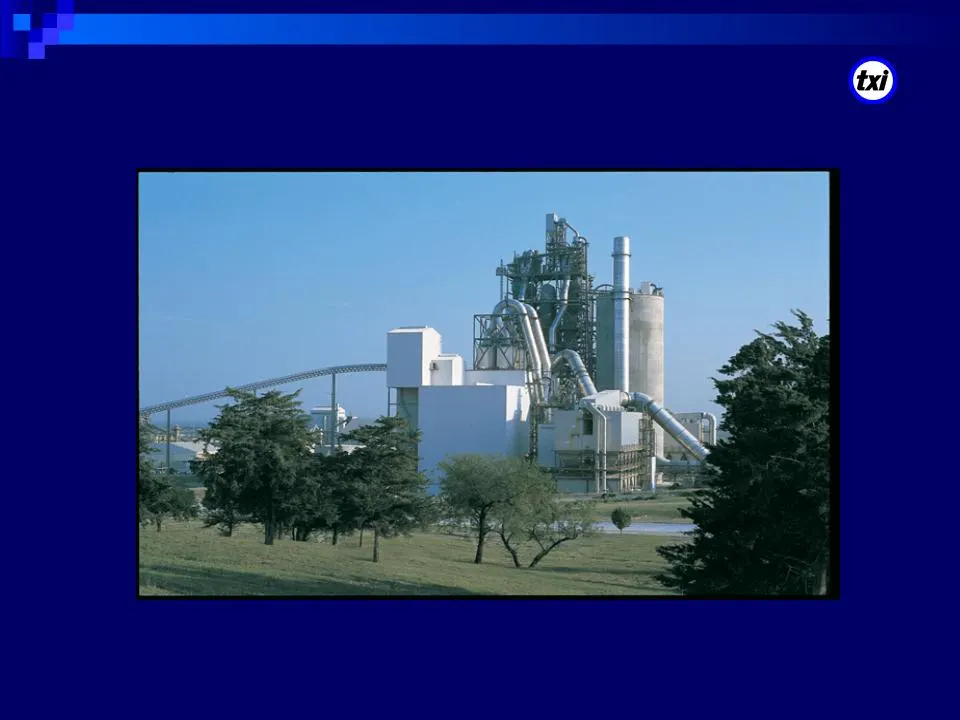
Slide 5: North Texas Cement Plant
NORTH TEXAS CEMENT PLANT 5
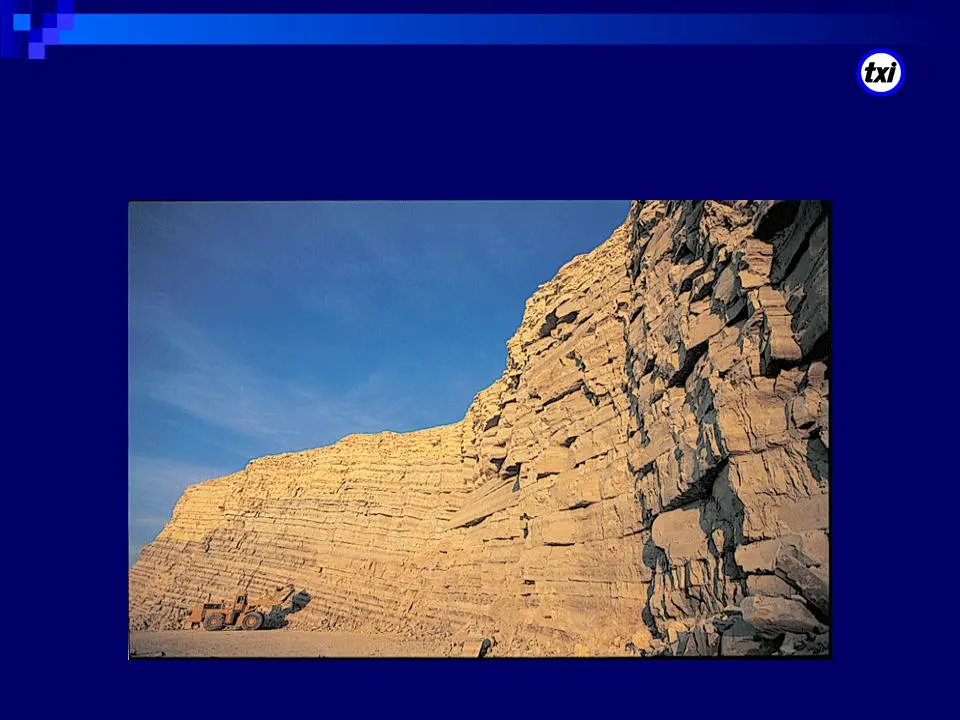
Slide 6: Quarry
QUARRY 6
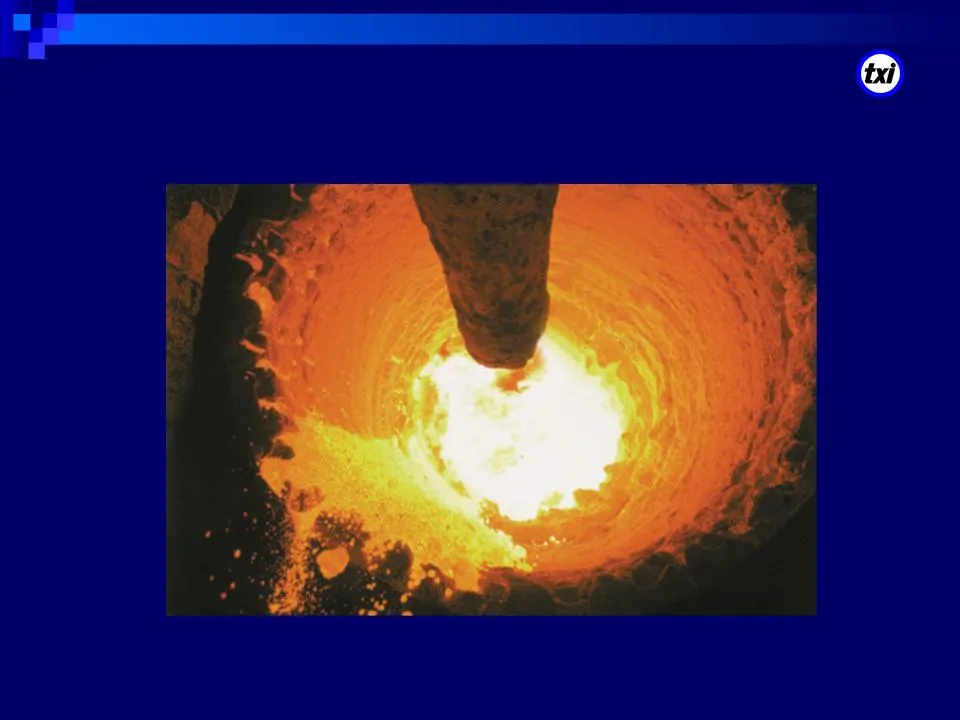
Slide 7: Cement Plant Kiln
CEMENT PLANT KILN 7
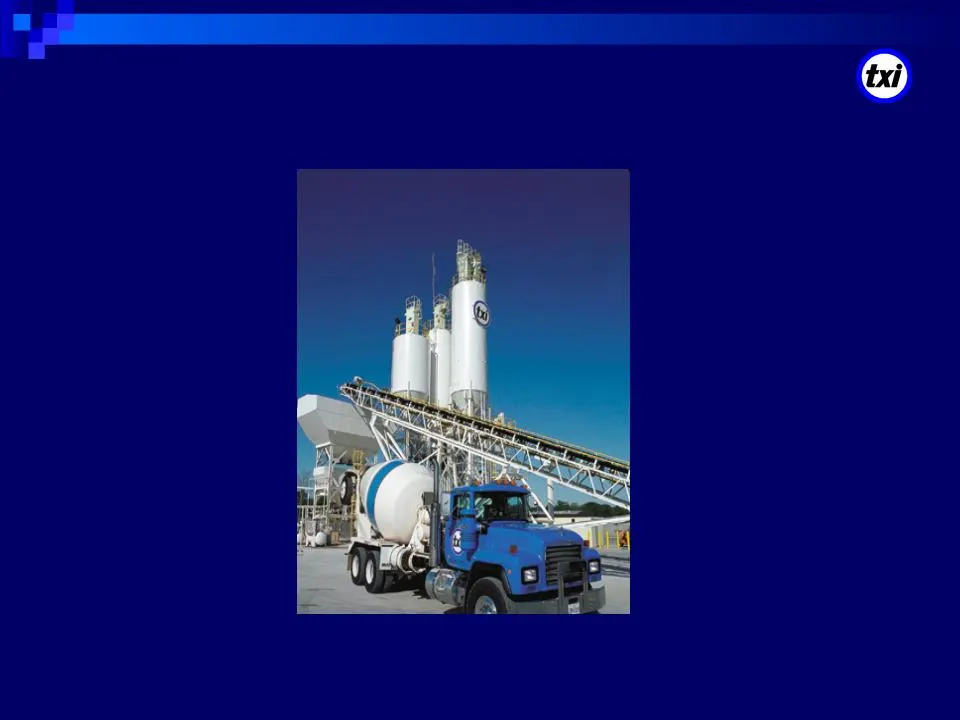
Slide 8: Ready-Mix Concrete
READY-MIX CONCRETE 8
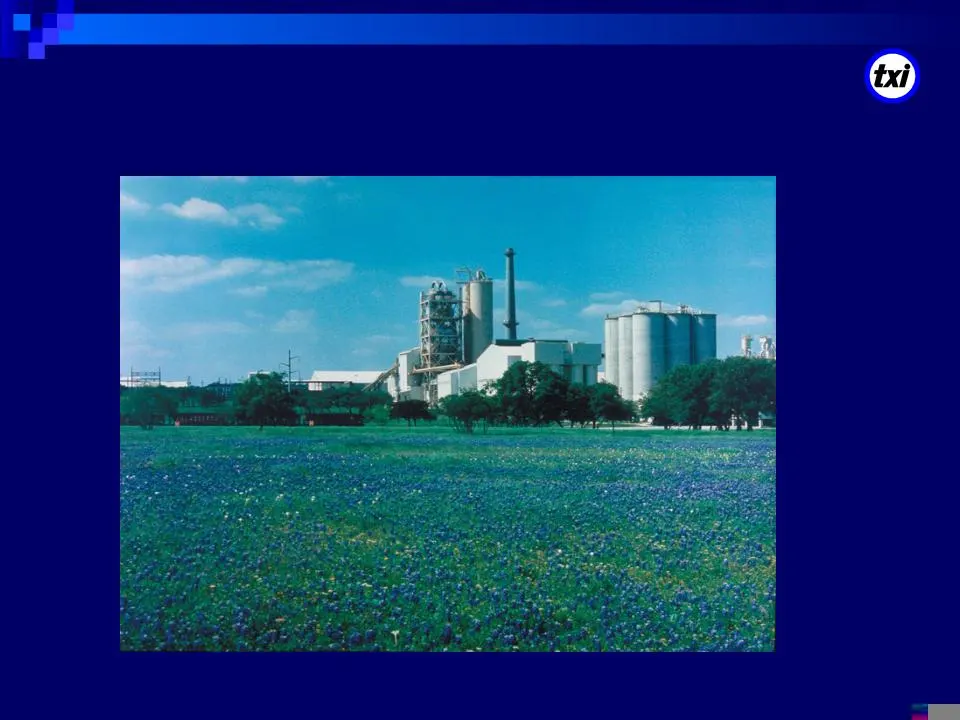
Slide 9: Central Texas Cement Plant
CENTRAL TEXAS CEMENT PLANT 9
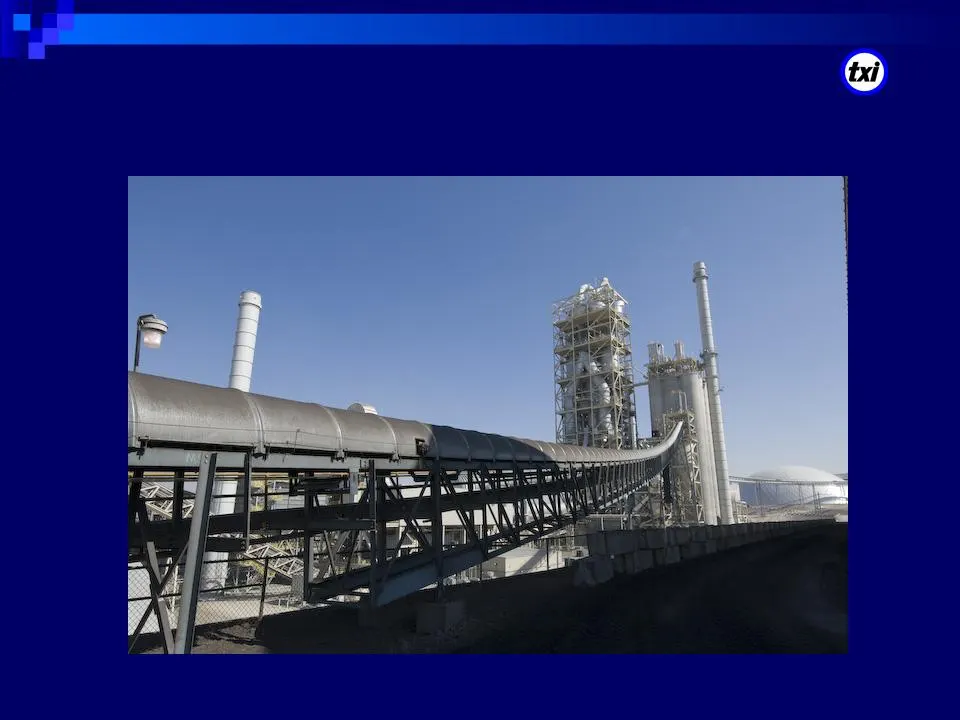
Slide 10: New California Cement Plant
NEW CALIFORNIA CEMENT PLANT 10
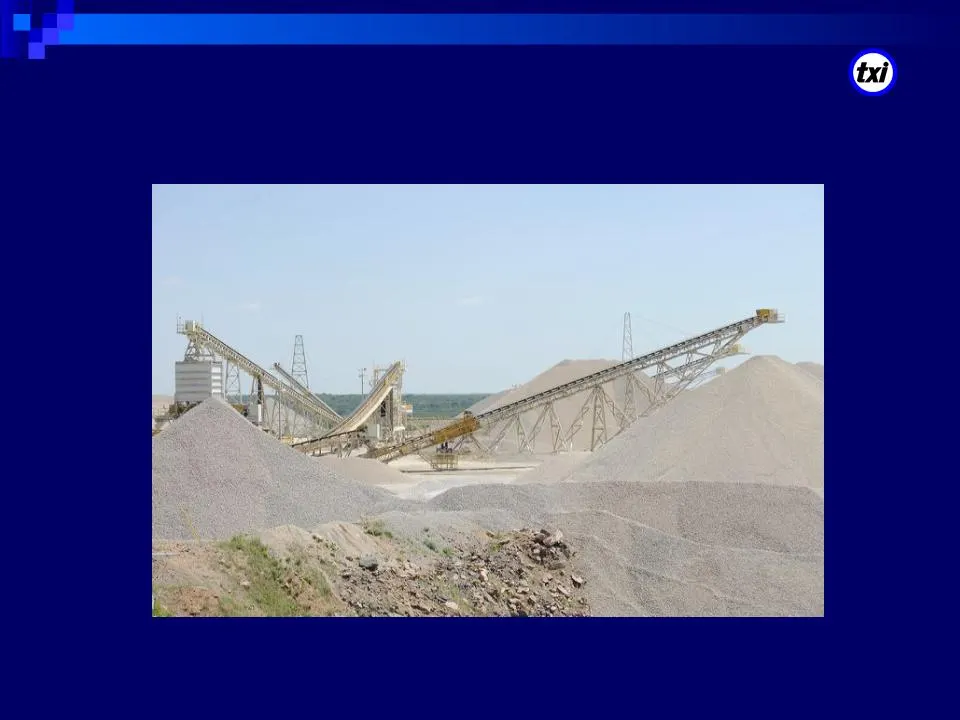
Slide 11: Stone Plant in Oklahoma
STONE PLANT IN OKLAHOMA 11
Slide 12: Long Term Drivers of Cement Demand
12 LONG TERM DRIVERS OF CEMENT DEMAND
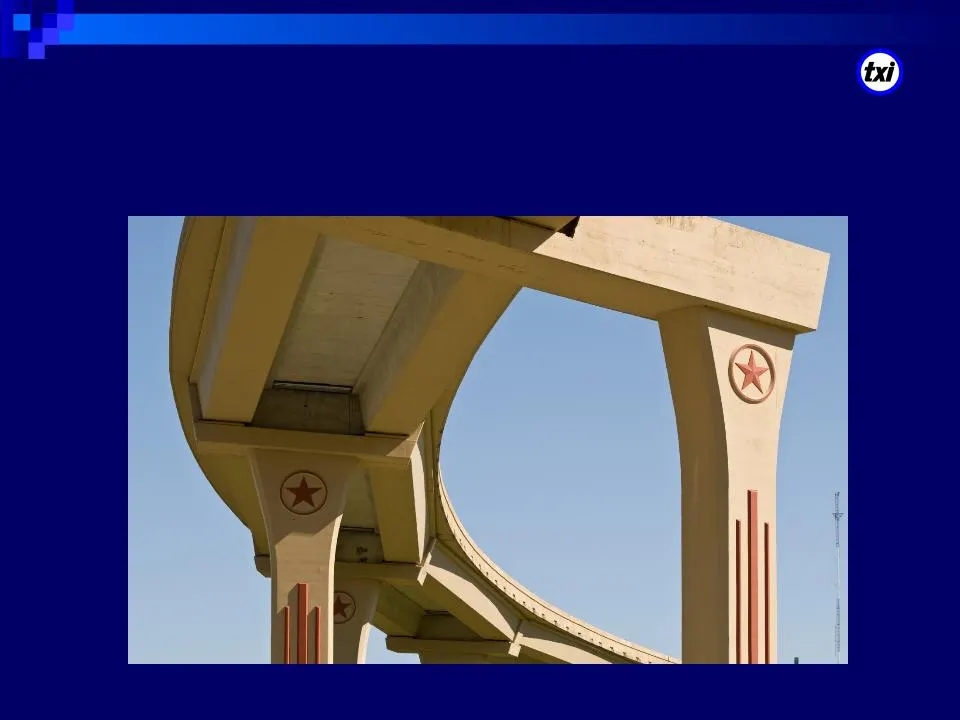
Slide 13: Public Works - 50%
PUBLIC WORKS - 50% 13
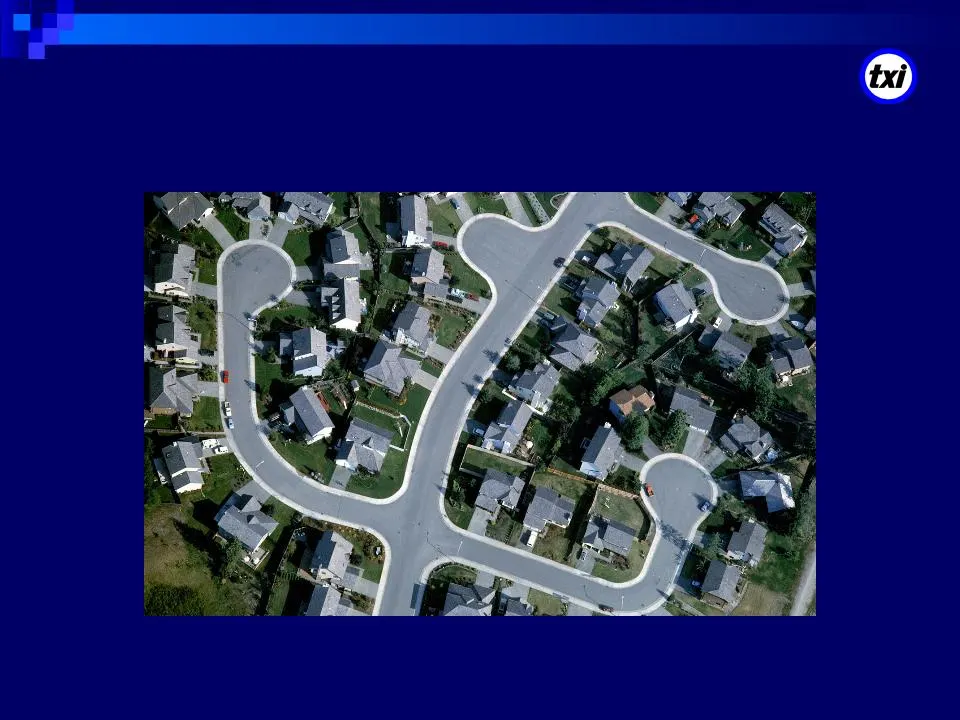
Slide 14: Residential - 25%
RESIDENTIAL - 25% 14
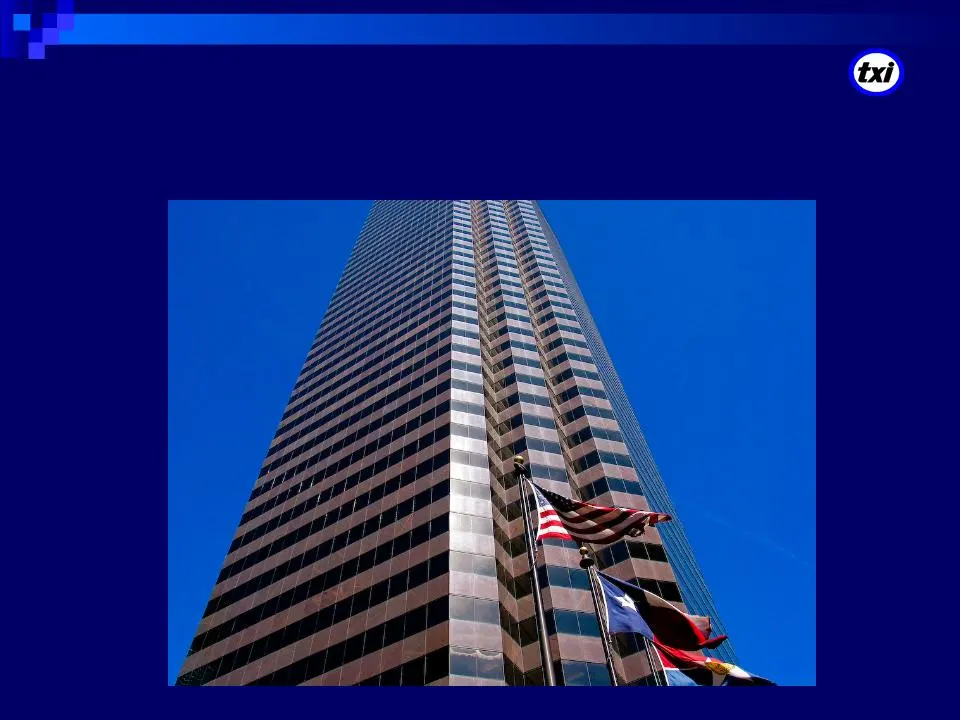
Slide 15: Non-Residential - 25%
15 NON-RESIDENTIAL - 25%
Slide 16: Favorable Industry Structure
16 FAVORABLE INDUSTRY STRUCTURE
Slide 17: Favorable Industry Structure
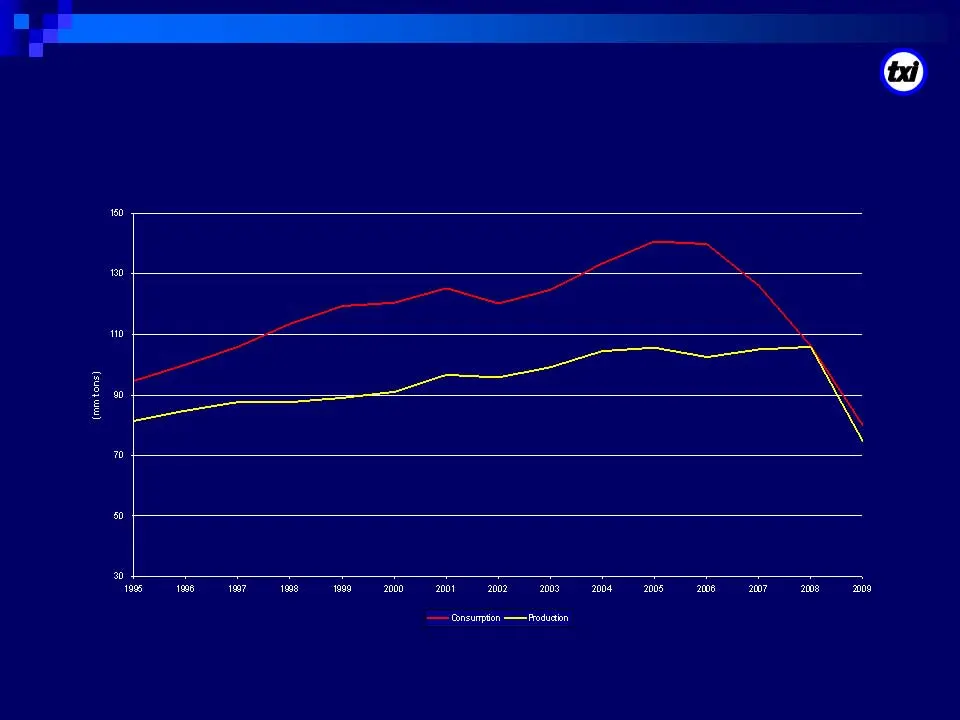
FAVORABLE INDUSTRY STRUCTURE 17 ¨ U. S. cement consumption has historically exceeded domestic production capacity
Slide 18: U.S. Cement Consumption and Production 1995-2009
U.S. CEMENT CONSUMPTION AND PRODUCTION 1995 - 2009 18 Source: U.S. Geological Survey 2009 Estimated
Slide 19: Favorable Industry Structure
FAVORABLE INDUSTRY STRUCTURE 19 ¨ U. S. cement consumption has historically exceeded domestic production capacity ¨ U.S. cement capacity and import terminals are largely owned or controlled by international producers ¨ Significant barriers to entry exist for new cement capacity ¨ Significant transpo
Slide 20: Texas and California Attractive Long-Term Markets
20 TEXAS AND CALIFORNIA ATTRACTIVE LONG-TERM MARKETS
Slide 21: Texas and California Attractive Long-Term Markets
TEXAS AND CALIFORNIA ATTRACTIVE LONG-TERM MARKETS ¨ The two largest cement markets in the U.S. ¨ Account for almost 25% of cement consumption ¨ Receive the largest shares of federal transportation funding ¨ Favorable demographics ◊ Large populations ◊ Above average population growth rates 21
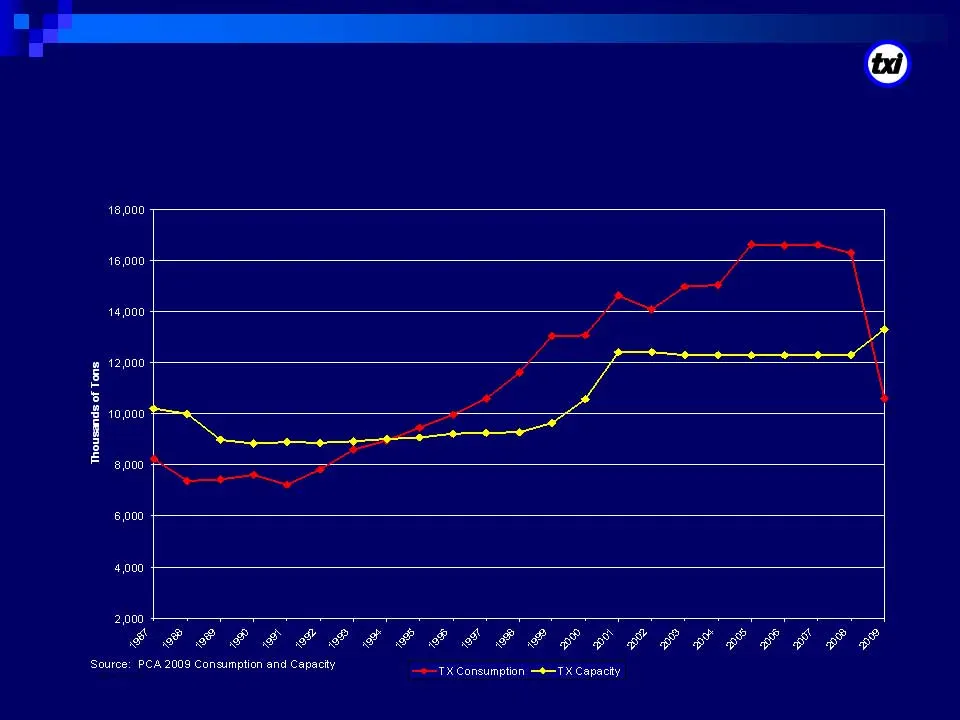
Slide 22: Texas Cement Consumption and Capacity
TEXAS CEMENT CONSUMPTION AND CAPACITY 22
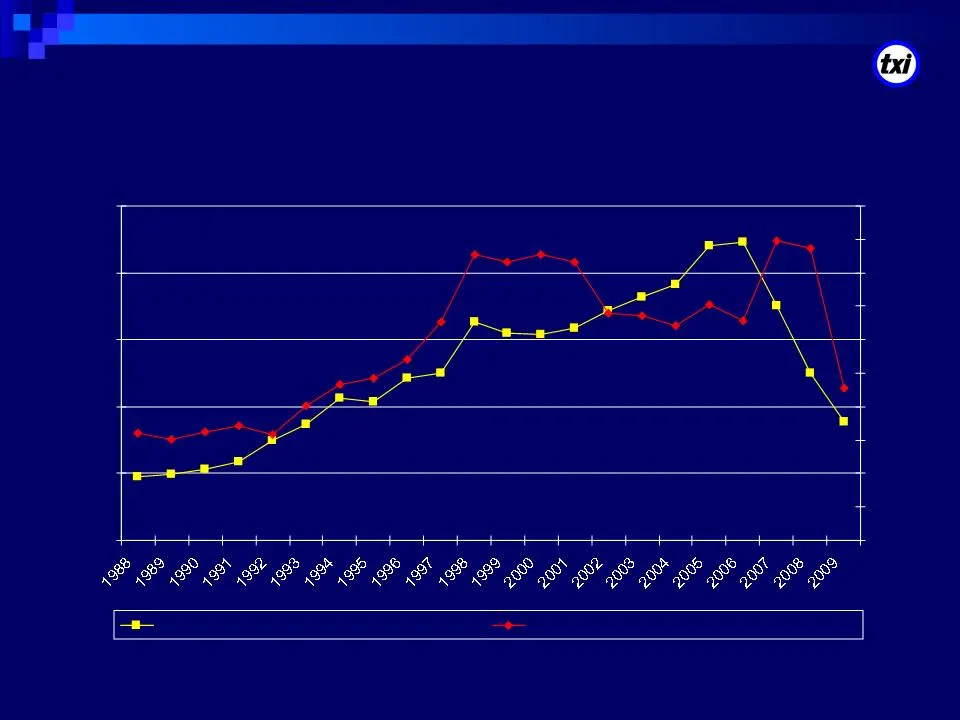
Slide 23: Texas Construction Residential and Non-Residential
TEXAS CONSTRUCTION RESIDENTIAL AND NON-RESIDENTIAL 23 Source: Dodge 0 50 100 150 200 250 0 20 40 60 80 100 120 140 160 180 200 Residential Construction M Starts Rt. Axis Non-Residential Awards MM Sq. Ft. Lt. Axis
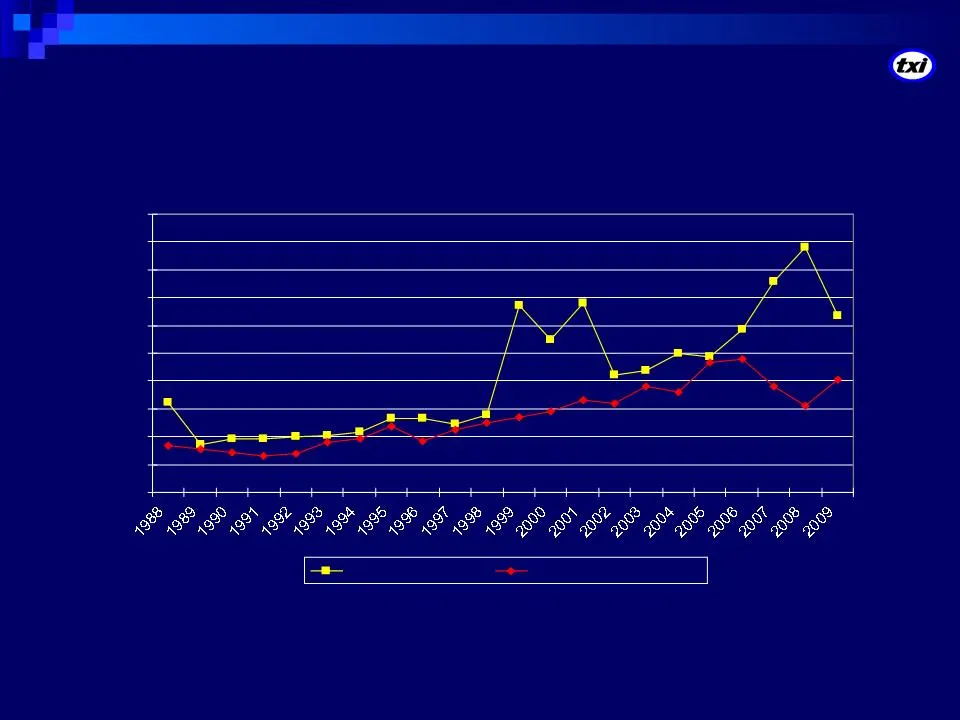
Slide 24: Texas Construction Non-Building and Highway Contract Awards
TEXAS CONSTRUCTION NON-BUILDING AND HIGHWAY CONTRACT AWARDS 24 Source: Dodge - 1 2 3 4 5 6 7 8 9 10 Non-Building ($Bn) Street & Highway ($Bn)
Slide 25: California Cement Consumption and Capacity
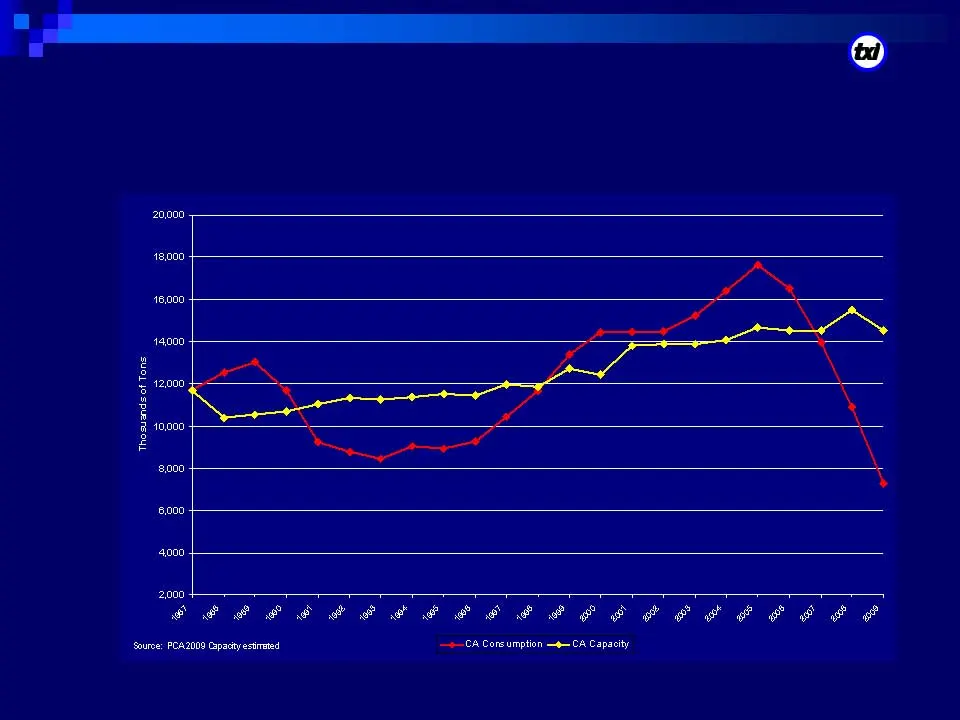
CALIFORNIA CEMENT CONSUMPTION AND CAPACITY 25
Slide 26: California Construction Residential and Non-Residential
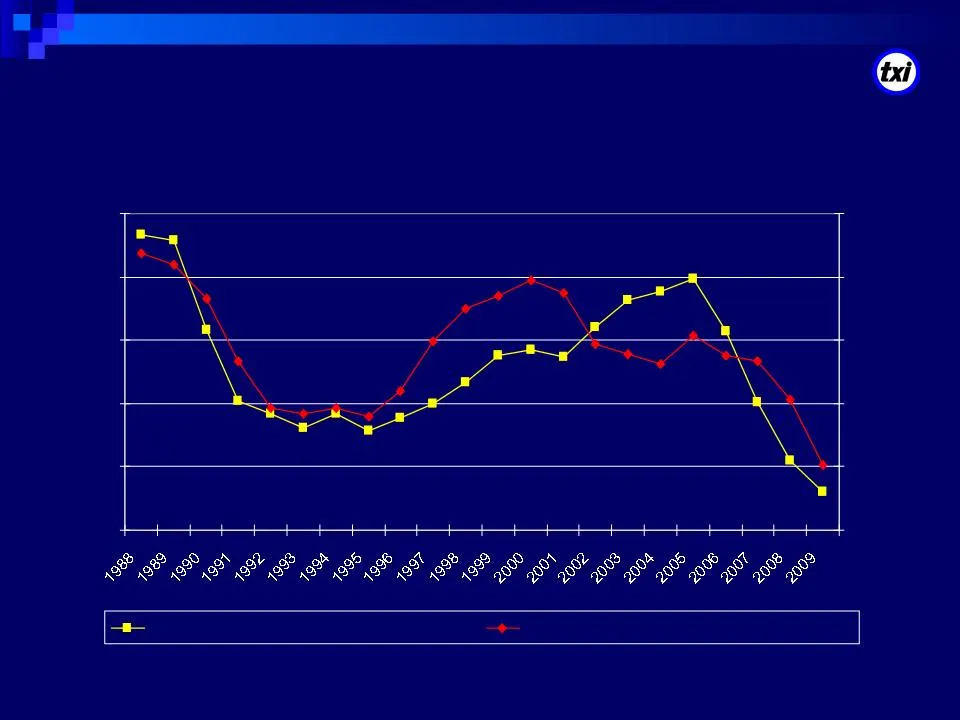
CALIFORNIA CONSTRUCTION RESIDENTIAL AND NON-RESIDENTIAL 26 Source: Dodge 0 50 100 150 200 250 0 50 100 150 200 250 Residential Construction M Starts Rt. Axis Non-Residential Awards MM Sq. Ft. Lt. Axis
Slide 27: California Construction Non-Building and Highway Contract Awards
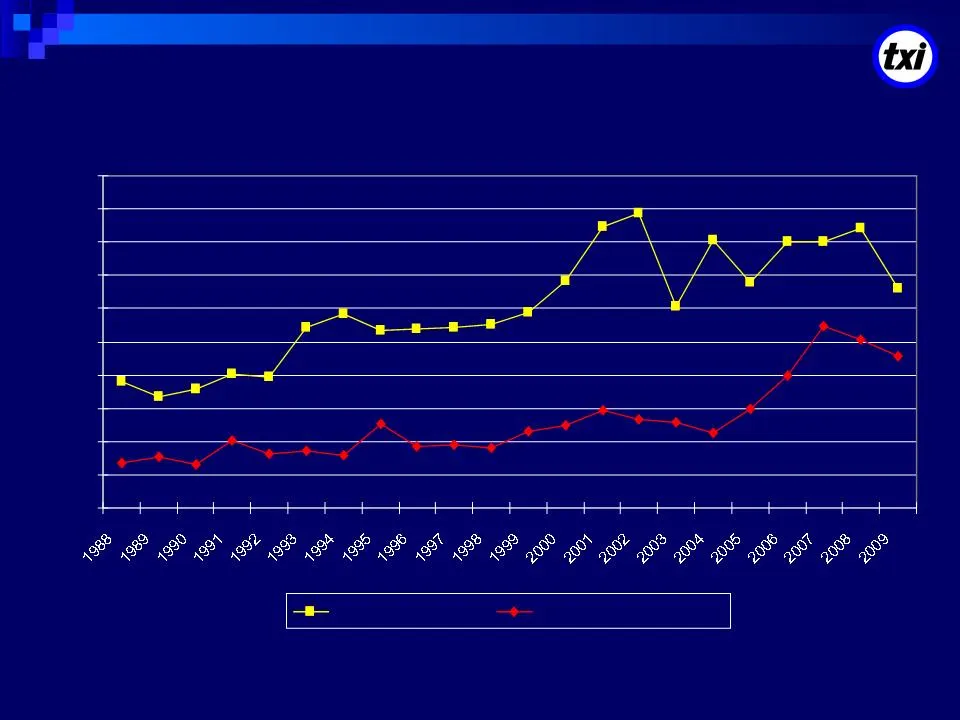
27 CALIFORNIA CONSTRUCTION NON-BUILDING AND HIGHWAY CONTRACT AWARDS Source: Dodge 0 1 2 3 4 5 6 7 8 9 10 Non-Building ($Bn) Street & Highway ($Bn)
Slide 28: Texas Market - 1980, 2000 and 2020
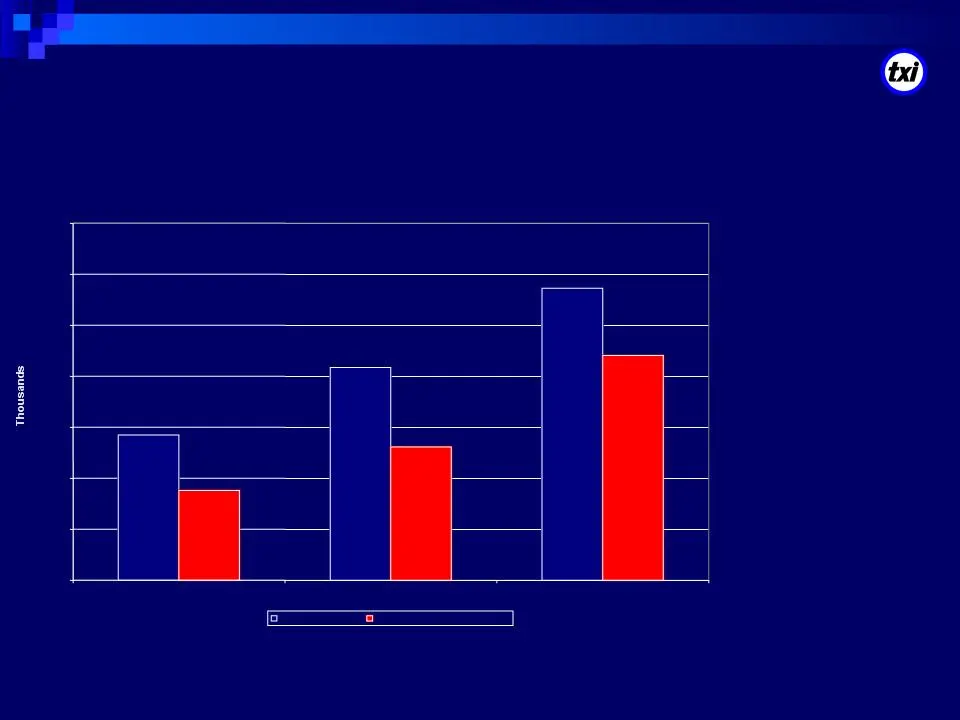
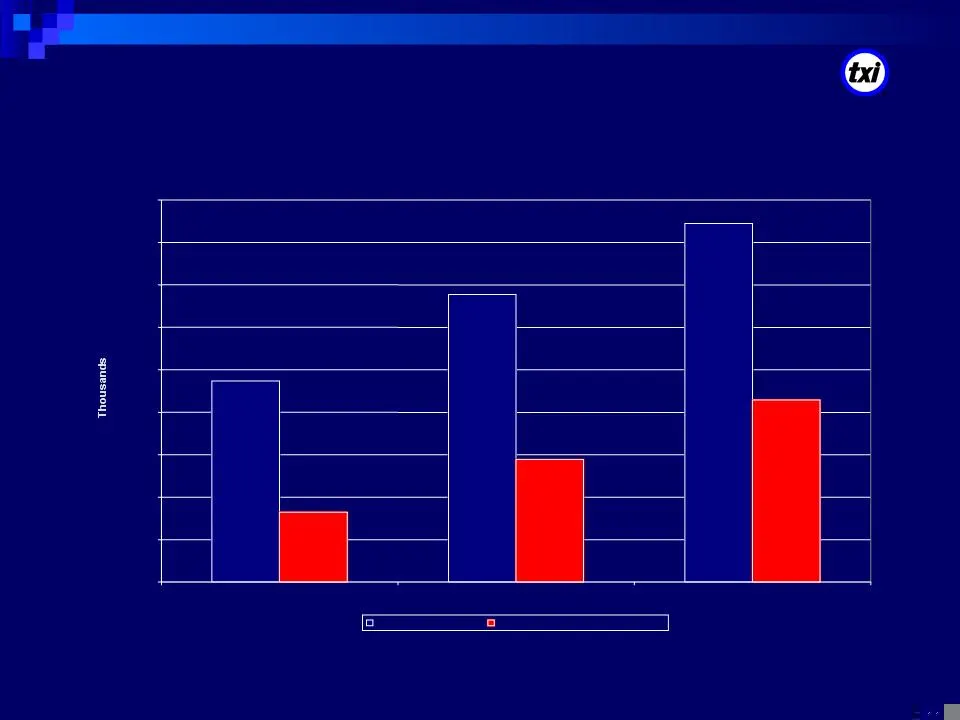
TEXAS MARKET - 1980, 2000 AND 2020 28 Sources: U. S. Census Bureau, Portland Cement Association (PCA), USGS (projected) Texas Population and Cement Consumption 0 5,000 10,000 15,000 20,000 25,000 30,000 35,000 1980 2000 2020 Texas Population Texas Cement Consumption
Slide 29: California Market - 1980, 2000 and 2020
CALIFORNIA MARKET - 1980, 2000 AND 2020 29 Sources: U.S. Census Bureau, Portland Cement Association (PCA), USGS (projected) California Population and Cement Consumption 0 5,000 10,000 15,000 20,000 25,000 30,000 35,000 40,000 45,000 1980 2000 2020 California Populaton California Cement Consumption
Slide 30: Strong Competitive Position
30 STRONG COMPETITIVE POSITION
Slide 31: Strong Competitive Positions
STRONG COMPETITIVE POSITIONS ¨ Texas ◊ Accounts for approximately 80% of TXI sales ◊ TXI is the largest cement supplier in the state ◊ TXI is a low cost cement supplier ◊ Aggregate and ready mix operations are concentrated in Texas ◊ Largest expanded shale and clay supplier in Texas ¨ California ◊ C
Slide 32: Low Cost Operations Are Key
32 LOW COST OPERATIONS ARE KEY Notes: 1 North Texas productivity from the dry kiln for the twelve months ended May 31, 2008 2 Old California productivity for the twelve months ended May 31, 2007 3 Expected California productivity for the new kiln at full capacity 4 Current Central Texas productivity
Slide 33: Cement Plant Expansions
33 CEMENT PLANT EXPANSIONS
Slide 34: California Cement Plant Modernization and Expansion
CALIFORNIA CEMENT PLANT MODERNIZATION AND EXPANSION ¨ Commissioned May 2008 ¨ Added 2.3 million tons of state-of-the-art annual cement capacity ¨ Replaced 1.3 million tons of 50 year old production capacity ¨ Combined benefit of more capacity and significantly increased production efficiencies ◊ Com
Slide 35: Central Texas Cement Plant Expansion
CENTRAL TEXAS CEMENT PLANT EXPANSION ¨ Enhances TXI’s market-leading position in Texas ¨ Adds 1.4 million tons of state-of-the-art cement capacity ¨ Existing .9 million ton cement facility will remain in operation ¨ Required permits and permissions are in place ¨ Completion of the project has been d
Slide 36: North Texas Cement Plant Incremental Production
NORTH TEXAS CEMENT PLANT INCREMENTAL PRODUCTION ¨ The plant’s current annual production capacity is 2.8 million tons ¨ We plan to increase production capacity on the dry kiln, built in 2001, by .5 million tons annually ¨ The increased production will come from a series of projects to improve the kil
Slide 37: Current Market Conditions
37 CURRENT MARKET CONDITIONS
Slide 38: Current Economic Conditions
CURRENT ECONOMIC CONDITIONS ¨ The Texas economy continues to be one of the better economies in the nation ¨ California economic activity continues to be weak ¨ Energy costs have been volatile in recent years ¨ Credit markets have begun to heal 38
Slide 39: Infrastructure Development
INFRASTRUCTURE DEVELOPMENT ¨ The current federal stimulus program calls for approximately $27 - 30 billion to be invested in highways and bridges ¨ Total recent annual U.S. investment (all sources) in highways and bridges has approximated $75 billion ¨ Roadbuilding: ◊ Creates jobs ◊ Creates a founda
Slide 40: Focus on Liquidity
FOCUS ON LIQUIDITY ¨ CASH BALANCE OF $75 MILLION AT FEBRUARY 28, 2010 ¨ $200 MILLION BANK CREDIT LINE ◊ Matures August 2012 ◊ Utilization at February 28, 2010 - $28 million of letters of credit ¨ $550 MILLION 7.25% NOTES ◊ Mature July 2013 ◊ $300 million add-on financing was completed in August 2008
Slide 41: Earnings Potential and Strategy
41 EARNINGS POTENTIAL AND STRATEGY
Slide 42: Earnings Potential
EARNINGS POTENTIAL Shipments Sales Normalized Margin Potential Operating Profit (Mill) ($Mill) ($Mill) Cement (tons) 7.9 751 30% 225 Aggregates (tons) 25.0 200 20% 40 Ready-mix (yards) 4.5 405 9% 37 Other 130 20% 26 Combined Operating Profit 328 Corporate Expenses, Net (30) Depreciation 85 EBITDA 38
Slide 43: TXI's Strategy Remains Intact
TXI’S STRATEGY REMAINS INTACT ¨ Expand TXI’s most important business line - Cement ◊ All projects are at existing sites s They utilize infrastructure already in place s Growth is organic rather than through acquisitions ◊ All projects are in attractive long-term markets ◊ All projects should improve
Slide 44: Addendum - Reconciliation EBITDA to Net Income
44 ADDENDUM - RECONCILIATION EBITDA TO NET INCOME
Slide 45: Reconciliation of EBITDA to Net Income
RECONCILIATION OF EBITDA TO NET INCOME IN $ MILLIONS FY 2009 EBITDA Reconciled Net Income from Continuing Operations 17 Plus (minus): Interest 33 Income Taxes (13) Depreciation, Depletion & Amortization 68 Plus Goodwill Impairment (59) EBITDA 130 EBITDA represents income from continuing operations b
Slide 46: Texas Industries, Inc. Investor Presentation
46 TEXAS INDUSTRIES, INC. INVESTOR PRESENTATION LONGBOW RESEARCH SAN FRANCISCO CLIENT ROADSHOW MAY 19, 2010
Source: SEC EDGAR · 8-K filed May 19, 2010
More decks from Texas Industries Inc
 BB&T 8th Annual Commercial & Industrial Investor Conference (March 2014)26 slides · Mar 26, 2014
 Merger or Acquisition (January 2014)16 slides · Jan 28, 2014
 Stephens Conference 201337 slides · Nov 12, 2013
 Investor Presentation (March 2013)39 slides · Mar 5, 2013
 Investor Presentation (September 2012)33 slides · Sep 11, 2012
 Bank of America Merrill Lynch Leveraged Finance Conference 201133 slides · Dec 1, 2011