Kingfisher PLC · LSE:KGF
Kingfisher — FY2010/11 Earnings Presentation
24 slides from Kingfisher's earnings presentation, Mar 24, 2011
Slide 1: Full year results 2010/11 & 'Delivering Value'
Full year results 2010/11 & ‘Delivering Value’ Media Presentation 24th March 2011 1
Slide 2: 2010/11: Strong Financial Performance
2010/11: Strong g Financial Performance • Self-help driving strong results in challenging markets – Sales broadly flat at £10,450m – Adjusted pre-tax profit £670m, +22.5% – Adjusted basic EPS at 2020.5p, 5p +25 +25.0% 0% – Reported net cash £14m (2009/10: financial net debt £250m) – Dividend 7.07p +
Slide 3: Strong profit growth across all geographies
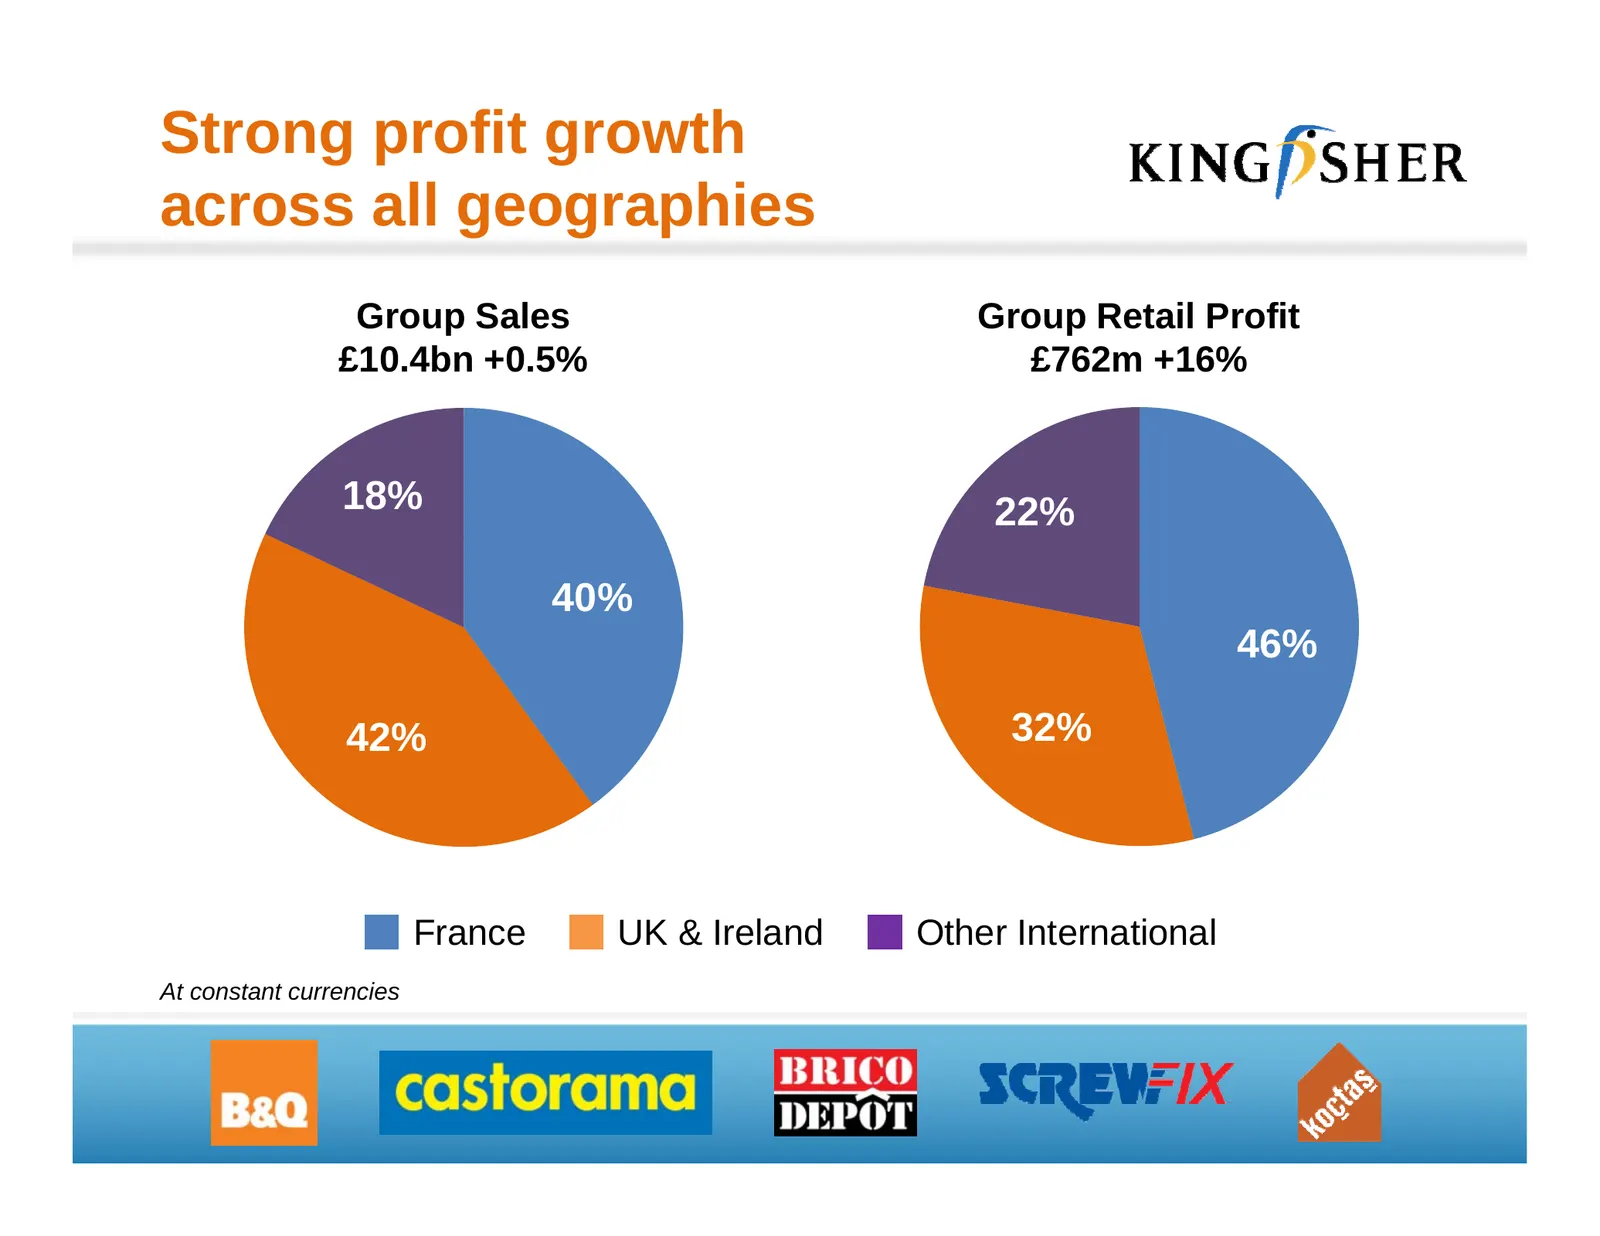
Strong profit growth across all geographies g g p Group Sales Group Retail Profit £10.4bn +0.5% £762m +16% 18% 22% 40% 46% 42% 32% France UK & Ireland Other International At constant currencies
Slide 4: 2011/12 – 'stepping up a gear'
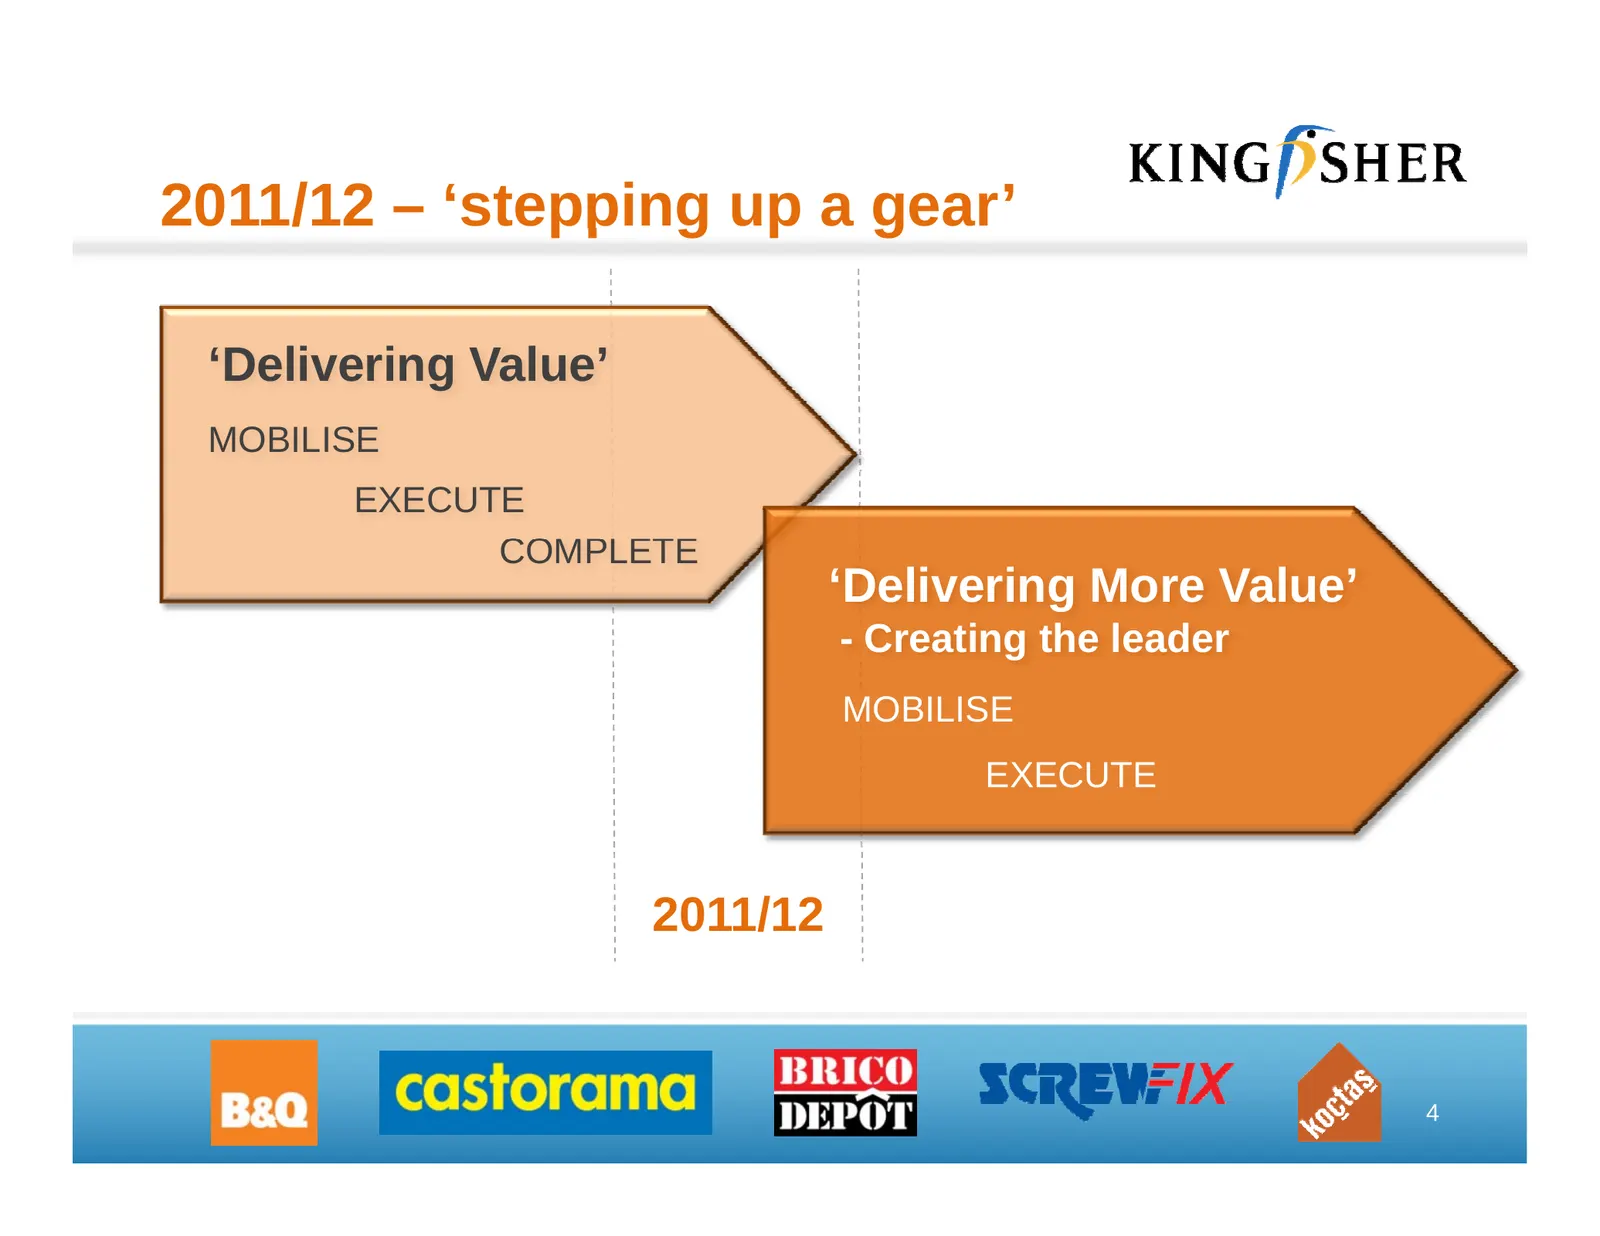
2011/12 – ‘stepping pp g up p a gear’ g ‘Delivering g Value’ MOBILISE EXECUTE COMPLETE ‘Delivering More Value’ - Creating the leader MOBILISE EXECUTE 2011/12 4
Slide 5: Agenda
Agenda g Delivering g Value - a success powerful base for growth Attractive markets more growth to unlock Delivering More Value creating ti the th lleader d 5
Slide 6: Delivering in the business 2008 – 2011
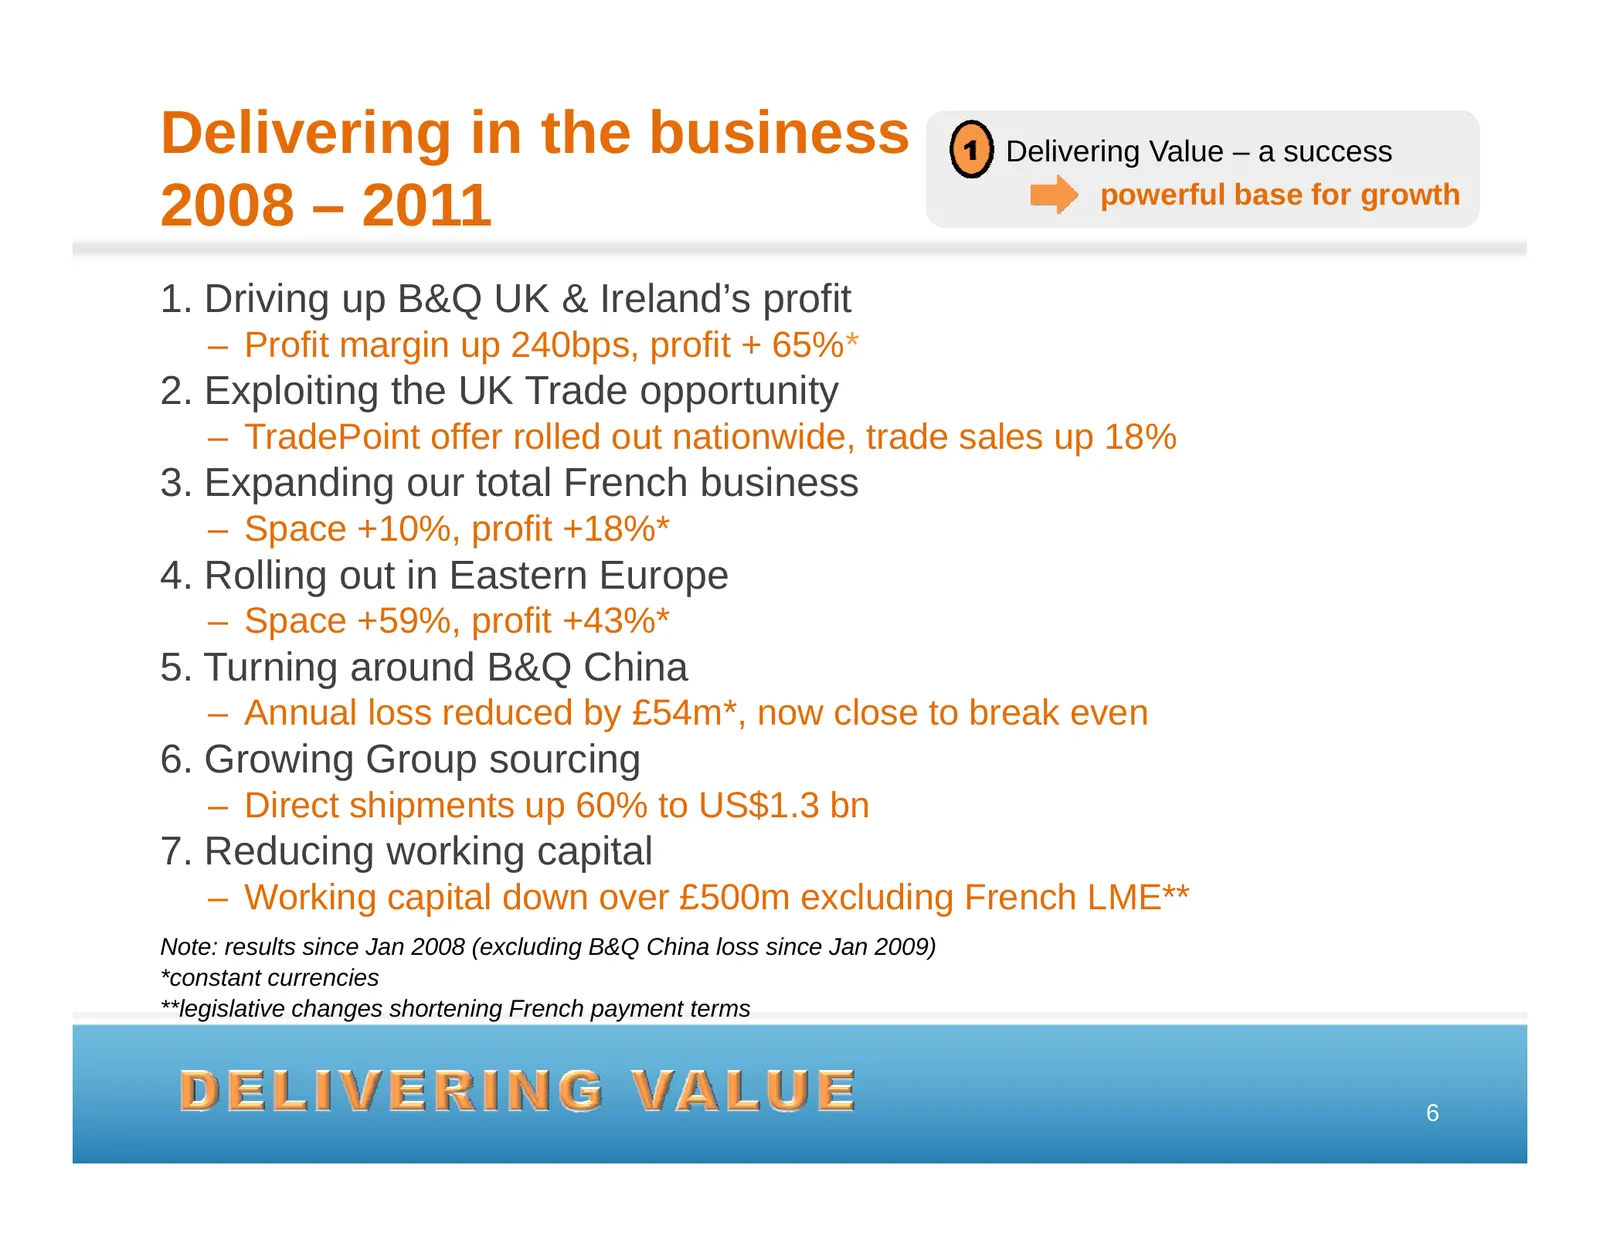
Delivering in the business Delivering Value – a success 2008 – 2011 powerful base for growth 1. Driving up B&Q UK & Ireland’s profit – Profit margin up 240bps, profit + 65%* 2 Exploiting the UK Trade opportunity 2. – TradePoint offer rolled out nationwide, trade sales up 18% 3. Expanding our total F
Slide 7: Delivering for shareholders 2008 – 2011
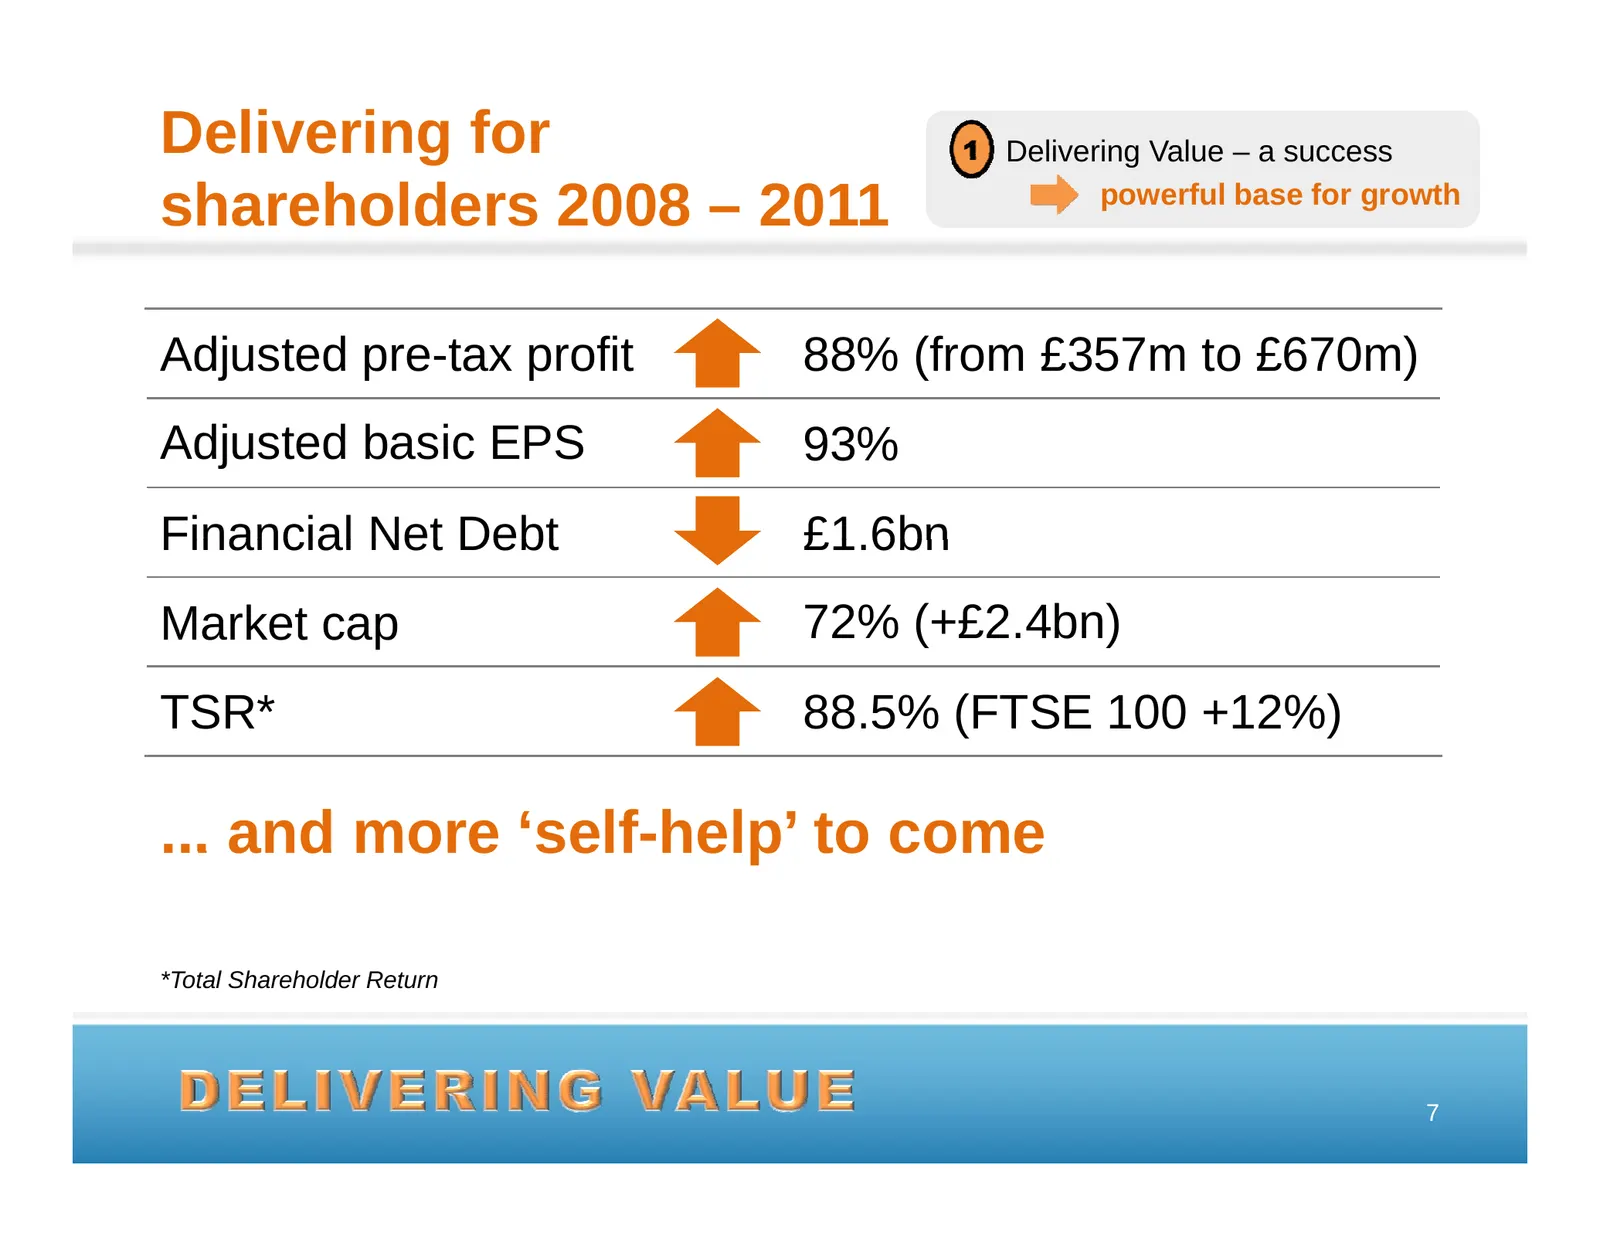
Delivering for Delivering Value – a success shareholders 2008 – 2011 powerful base for growth Adjusted pre-tax profit 88% (from £357m to £670m) Adjusted basic EPS 93% Financial Net Debt £1 6bn £1.6bn Market cap 72% (+£2.4bn) TSR* 88 5% (FTSE 100 +12%) 88.5% 12%) ... and more ‘self-help’ self help to
Slide 8: A stronger business
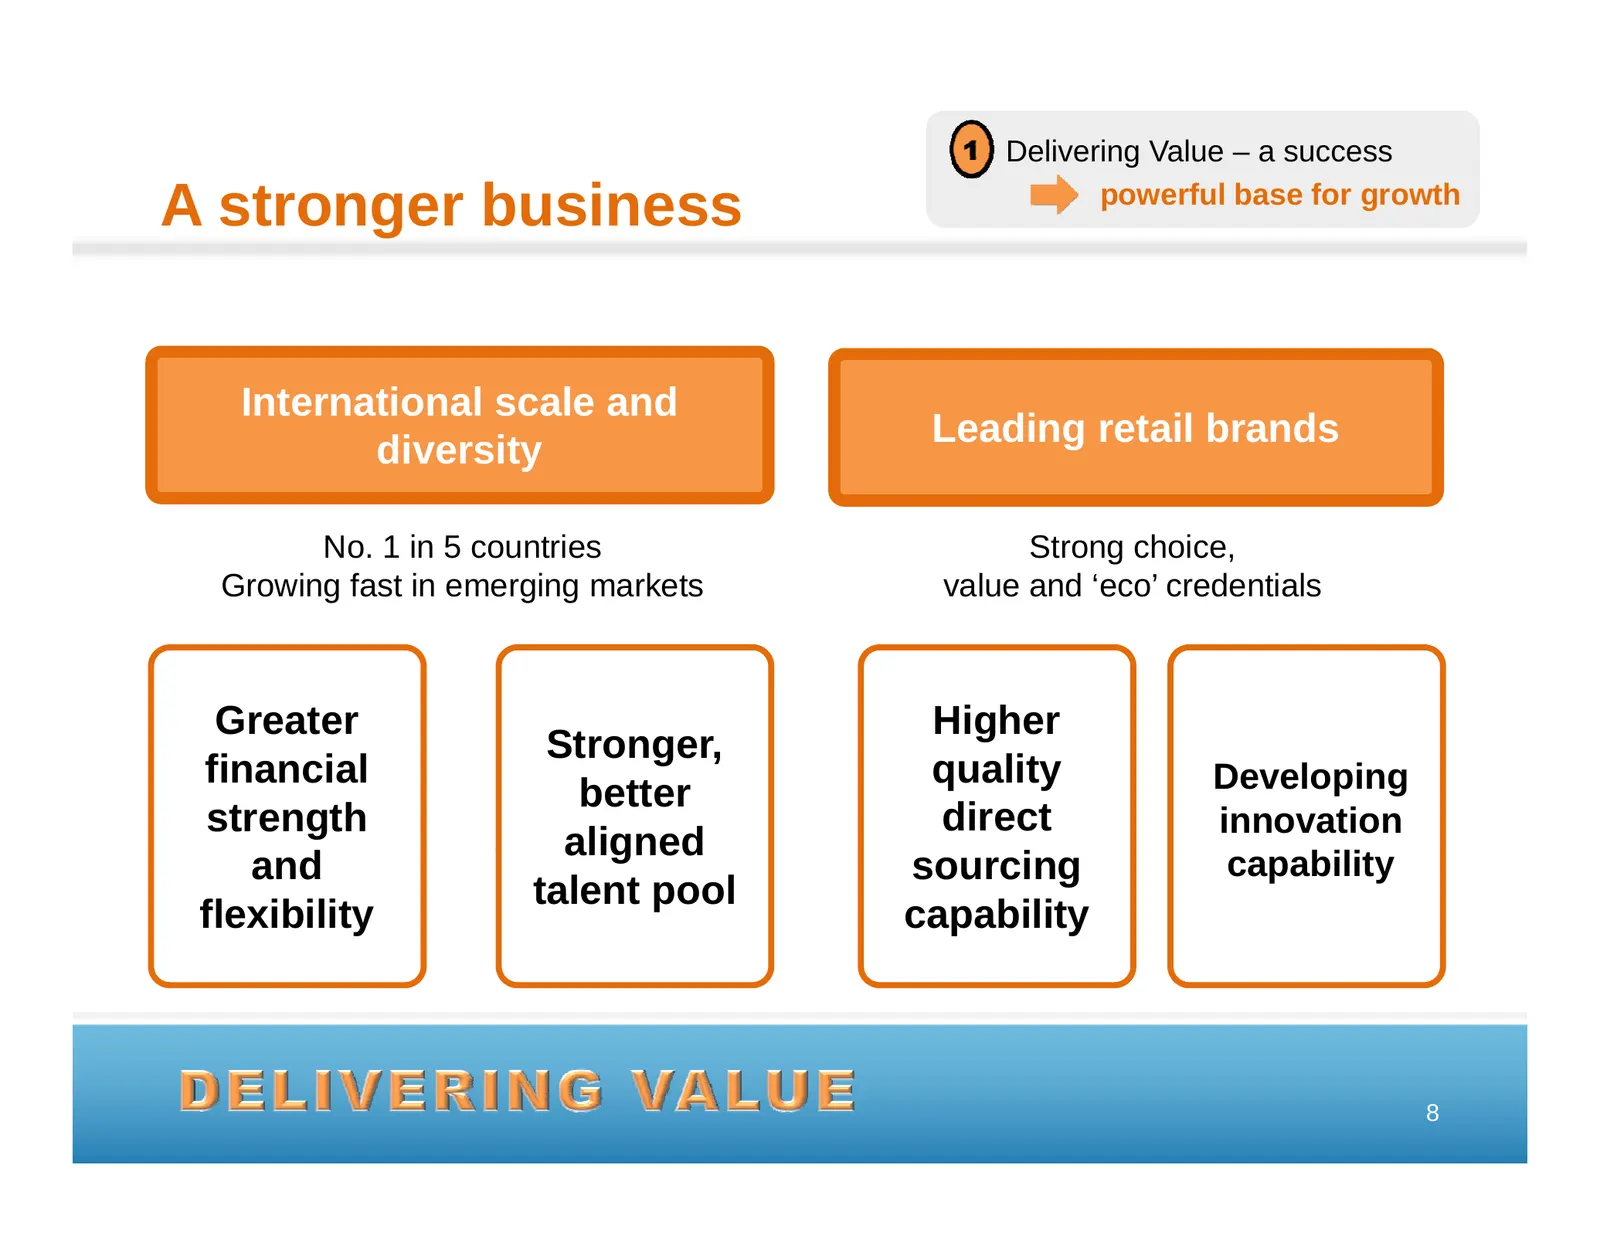
Delivering Value – a success A stronger g business powerful base for growth International scale and Leading retail brands diversity No. 1 iin 5 countries N ti Strong choice, St h i Growing fast in emerging markets value and ‘eco’ credentials Greater Higher Stronger, financial quality Developing bett
Slide 9: Attractive markets
Attractive markets Attractive market more growth to unlock • Big and growing – Over 500 million homes, £120 billion market* • Scale advantage – Customer tastes converging across markets – Few known manufacturer brands – International core common range and own brands • Defensible – Customers demand c
Slide 10: Developed markets - growth opportunity
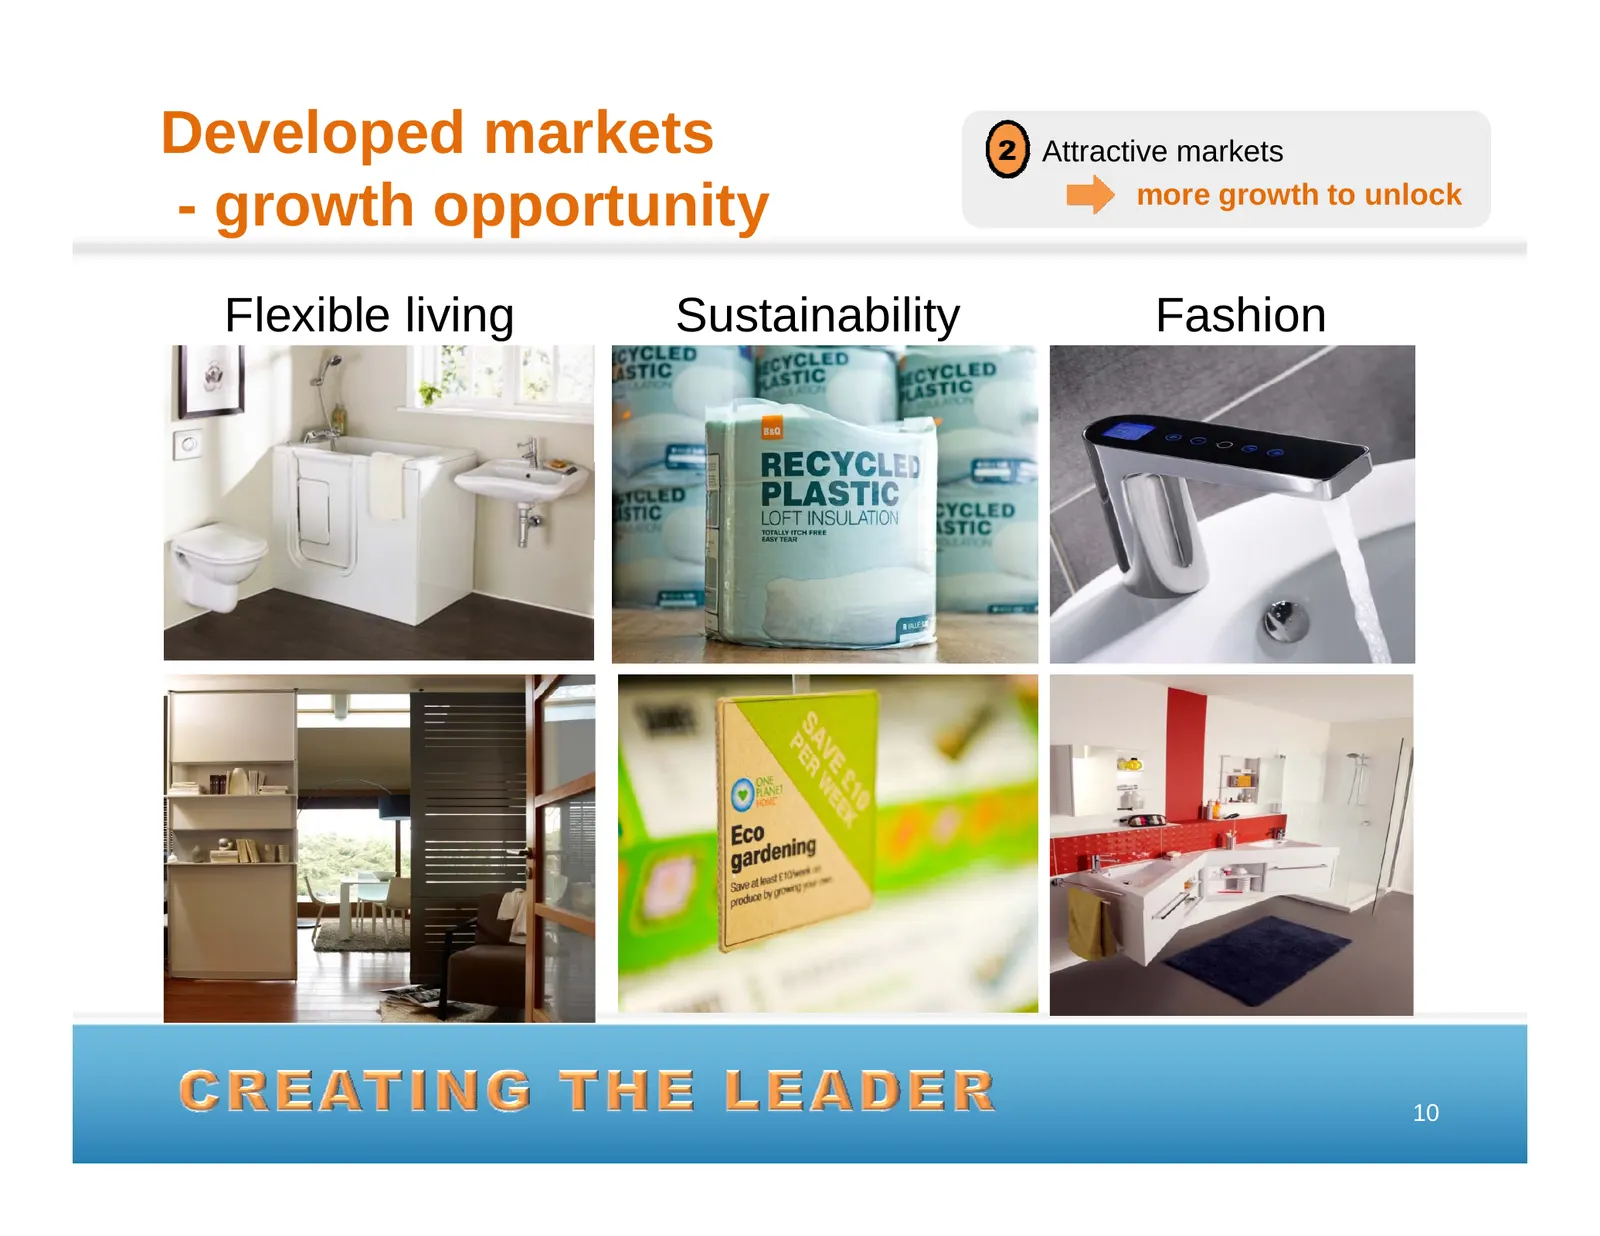
Developed markets Attractive markets -g growth opportunity pp y more growth to unlock Flexible living Sustainability Fashion 10
Slide 11: Developed markets – more growth to unlock
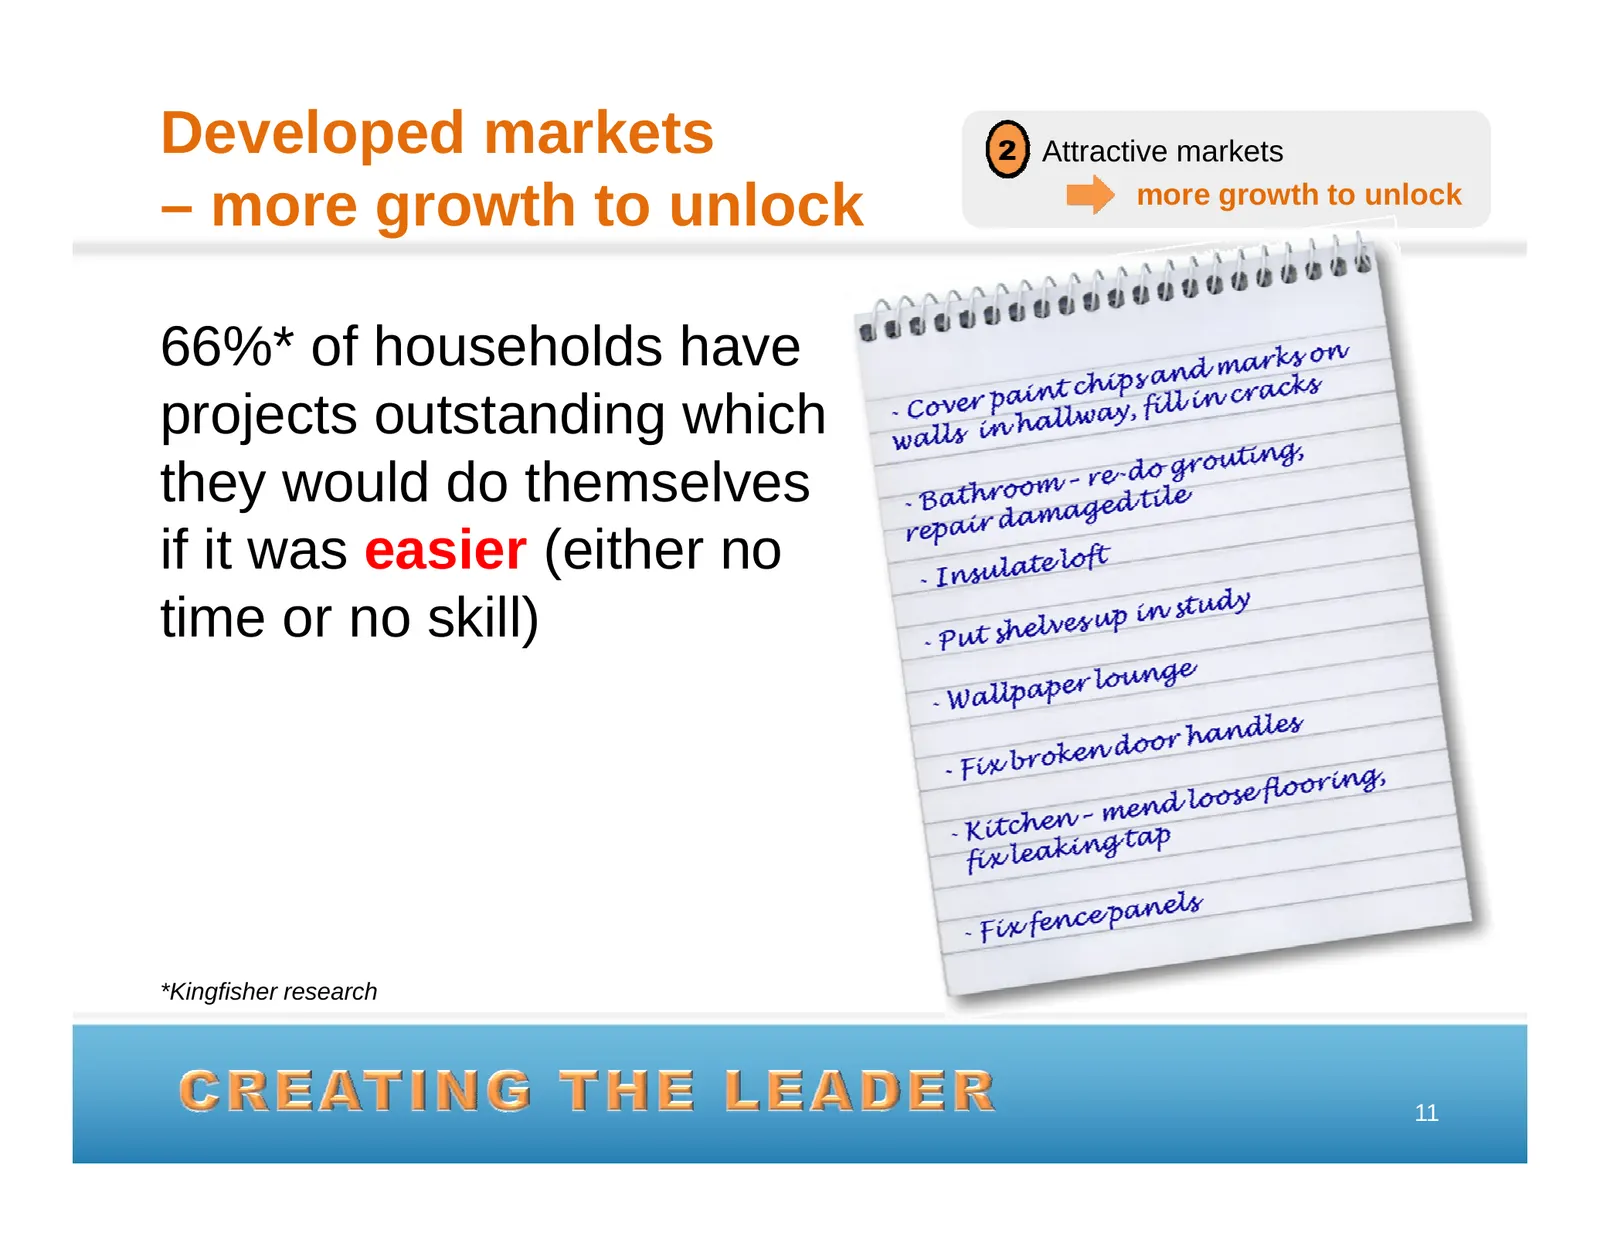
Developed markets Attractive markets – more g growth to unlock more growth to unlock 66%* of households have projects outstanding which they would do themselves if it was as easier (either no time or no skill) *Kingfisher research 11
Slide 12: Emerging markets – ongoing strong demand
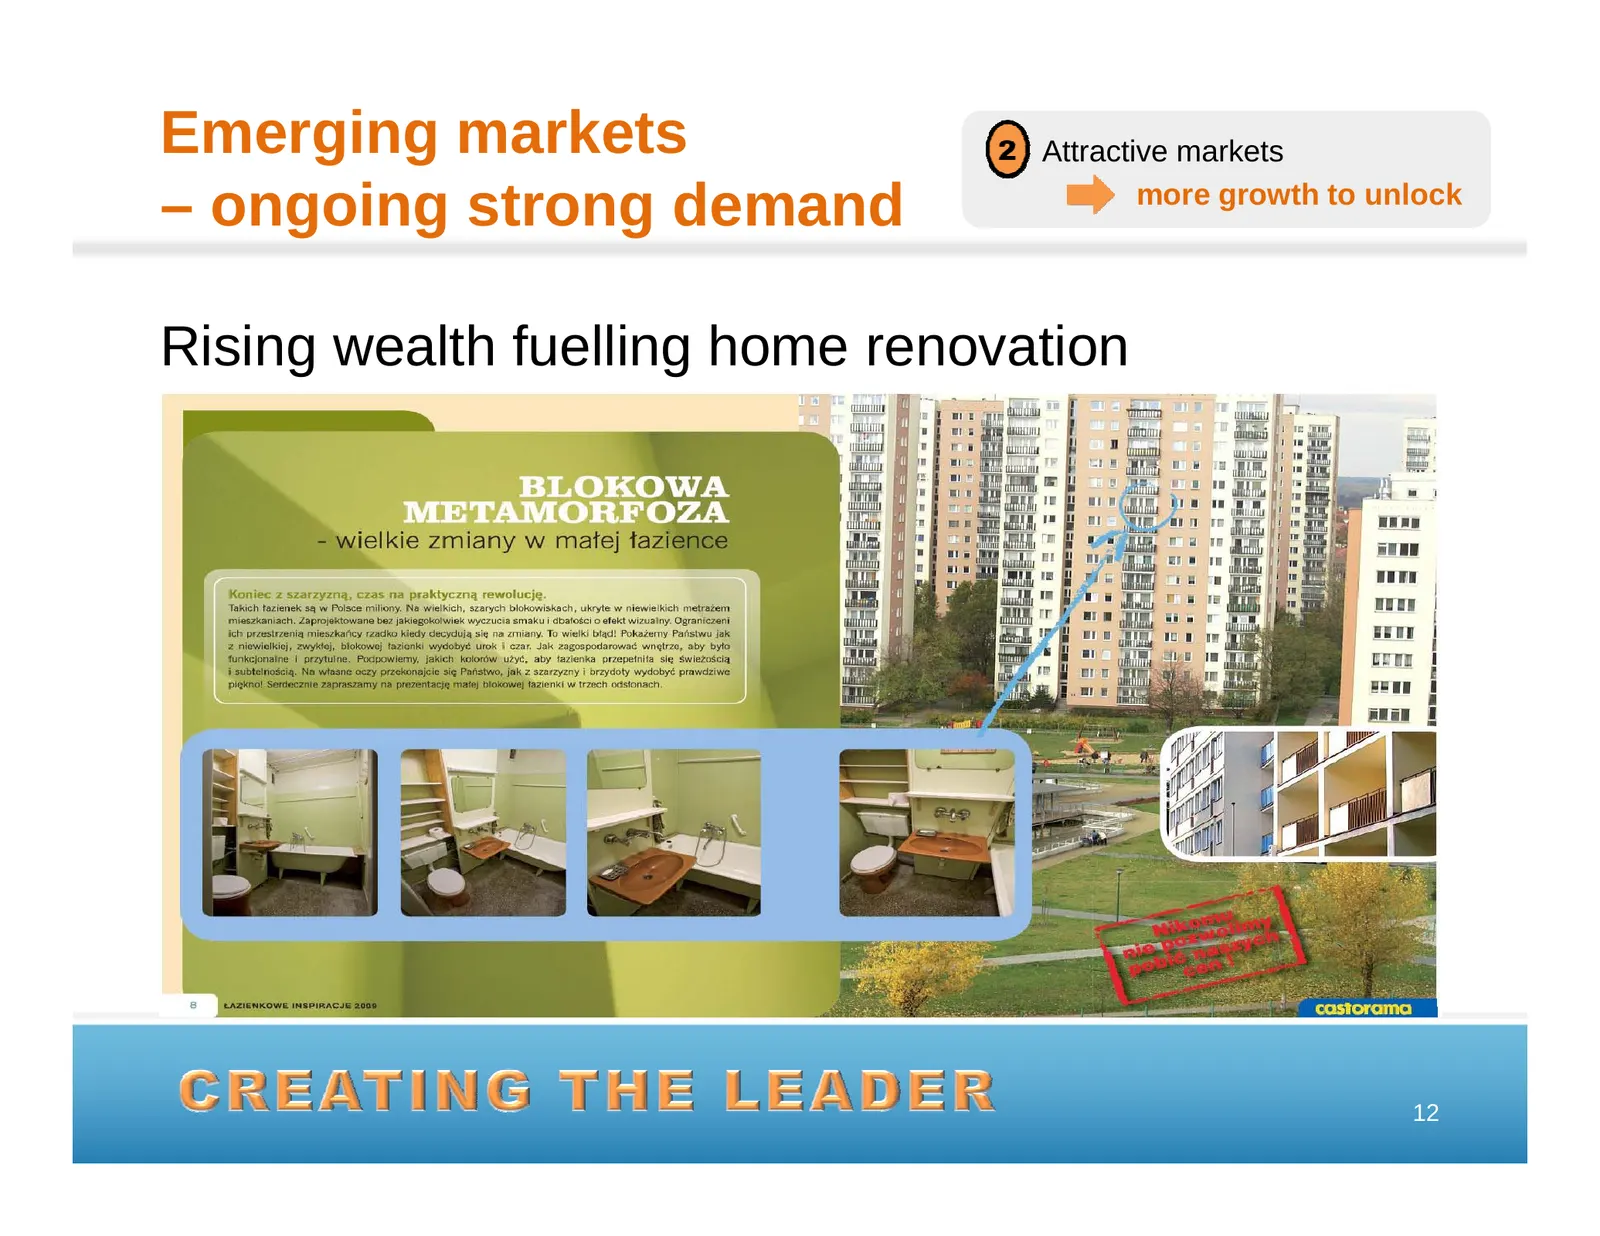
Emerging markets Attractive markets – ongoing g g strong g demand more growth to unlock Rising wealth fuelling home renovation 12
Slide 13: A new ambition for the next 10 years
A new ambition Attractive markets for the next 10 years y more growth to unlock ‘To deliver faster g growth and higher g returns by y working together to become the world’s expert at making home improvement easier for customers’ 13
Slide 14: Faster growth & higher returns
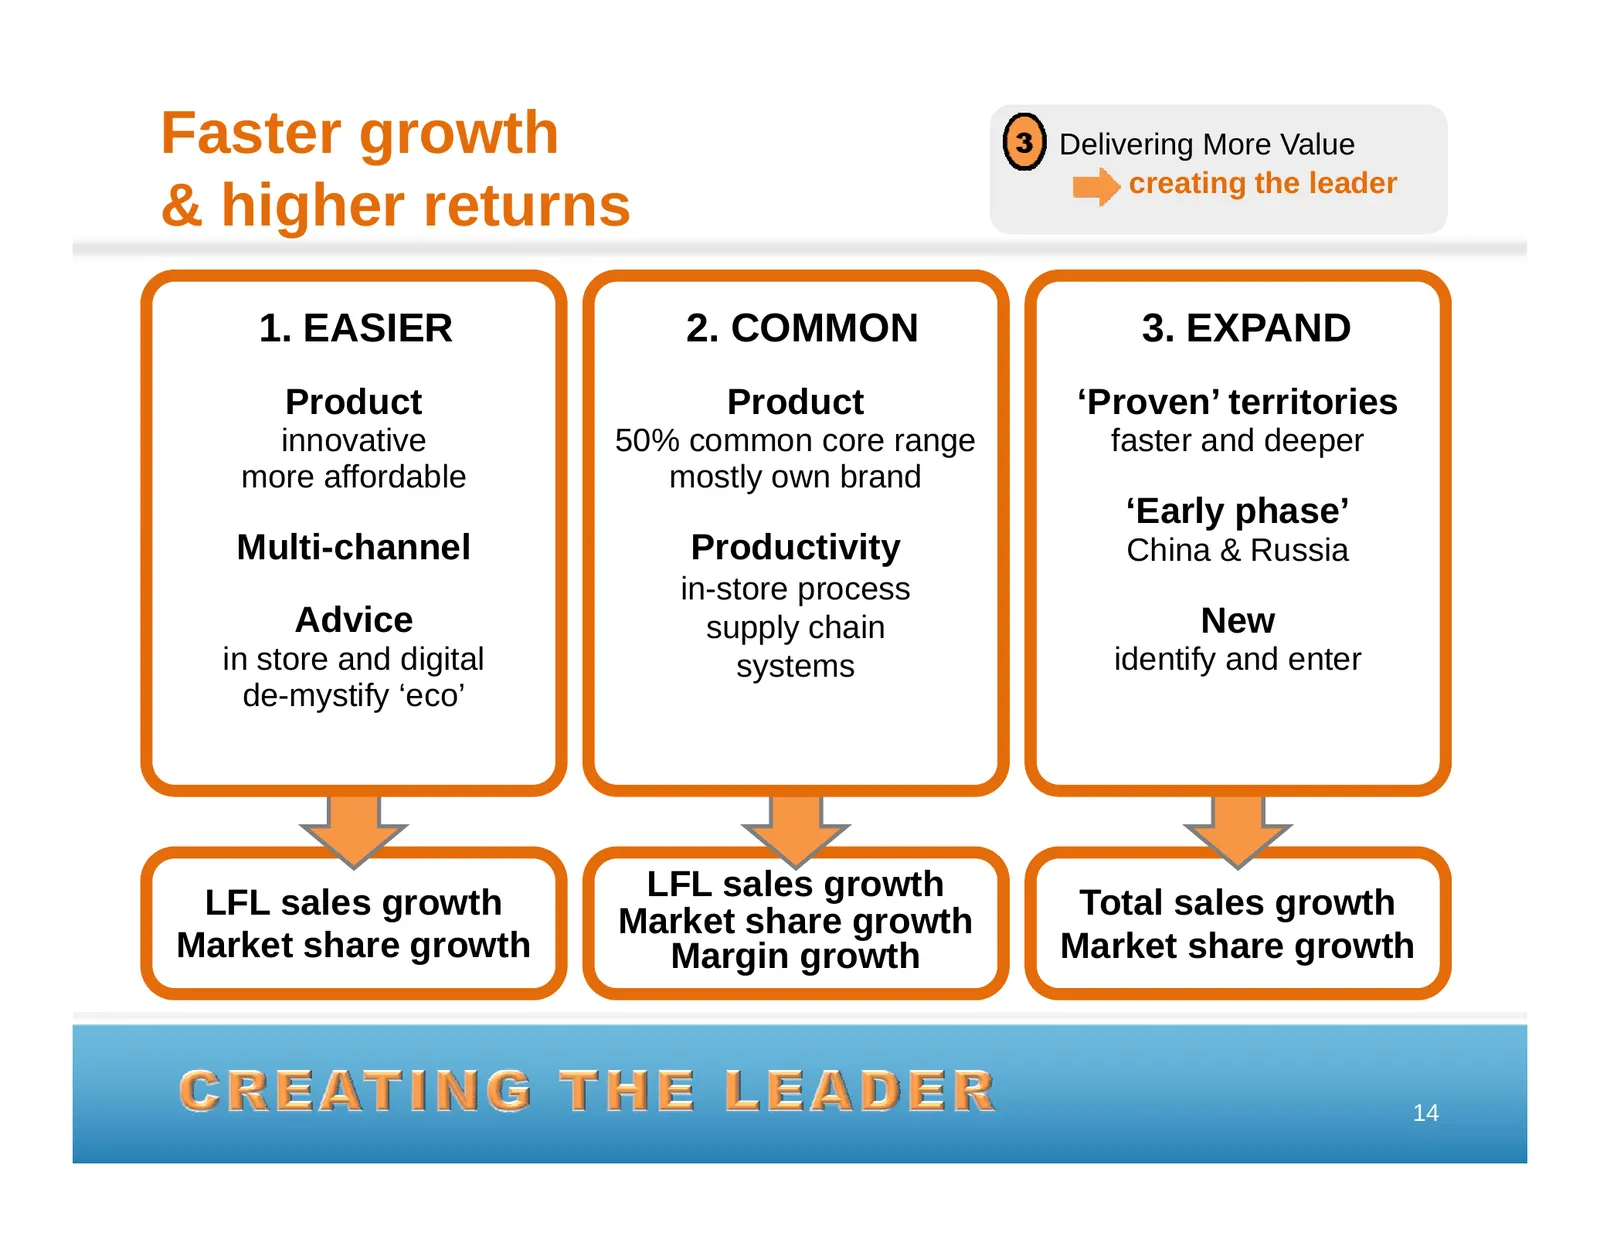
Faster growth Delivering More Value creating the leader & higher g returns 1. EASIER 2. COMMON 3. EXPAND Product Product ‘Proven’ territories innovative 50% common core range faster and deeper more affordable mostly own brand ‘Early phase’ M lti h Multi-channel l P d ti it Productivity Chi & R China
Slide 15: 1. Easier
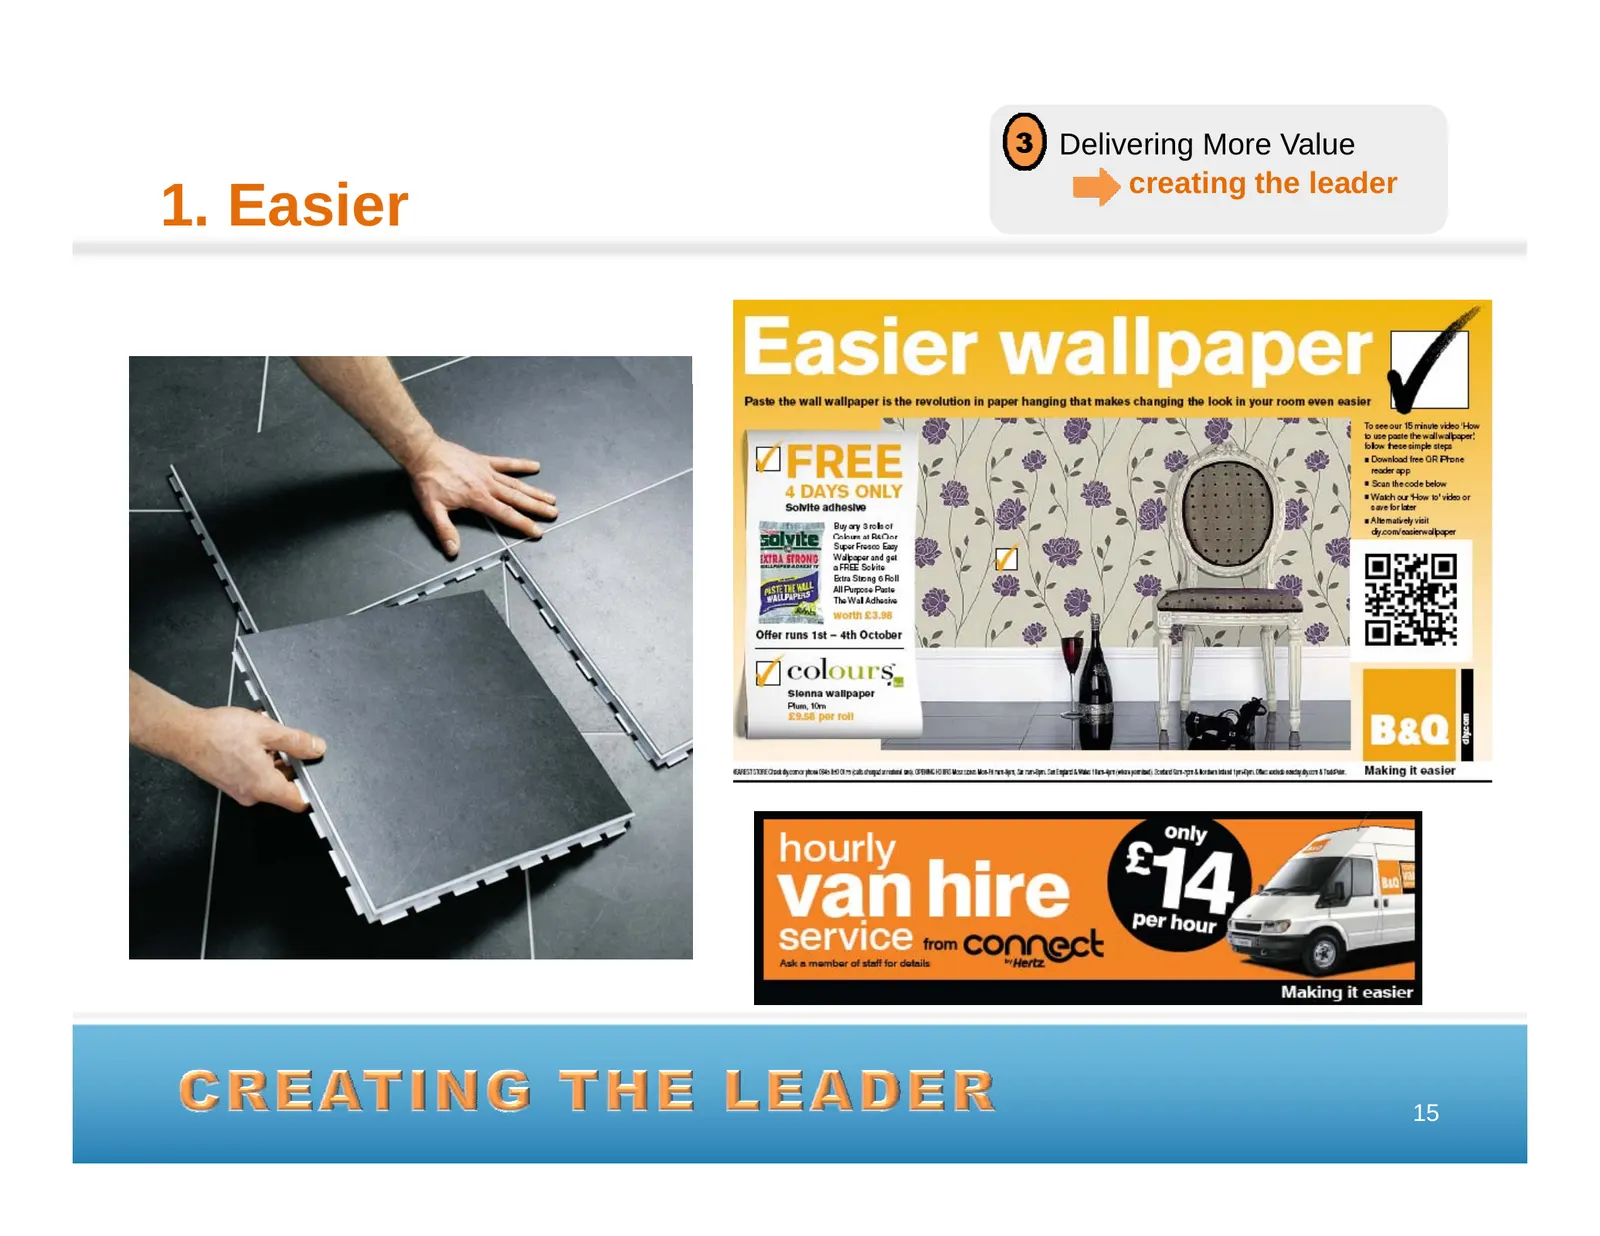
Delivering More Value creating the leader 1. Easier 15
Slide 16: 2. Common
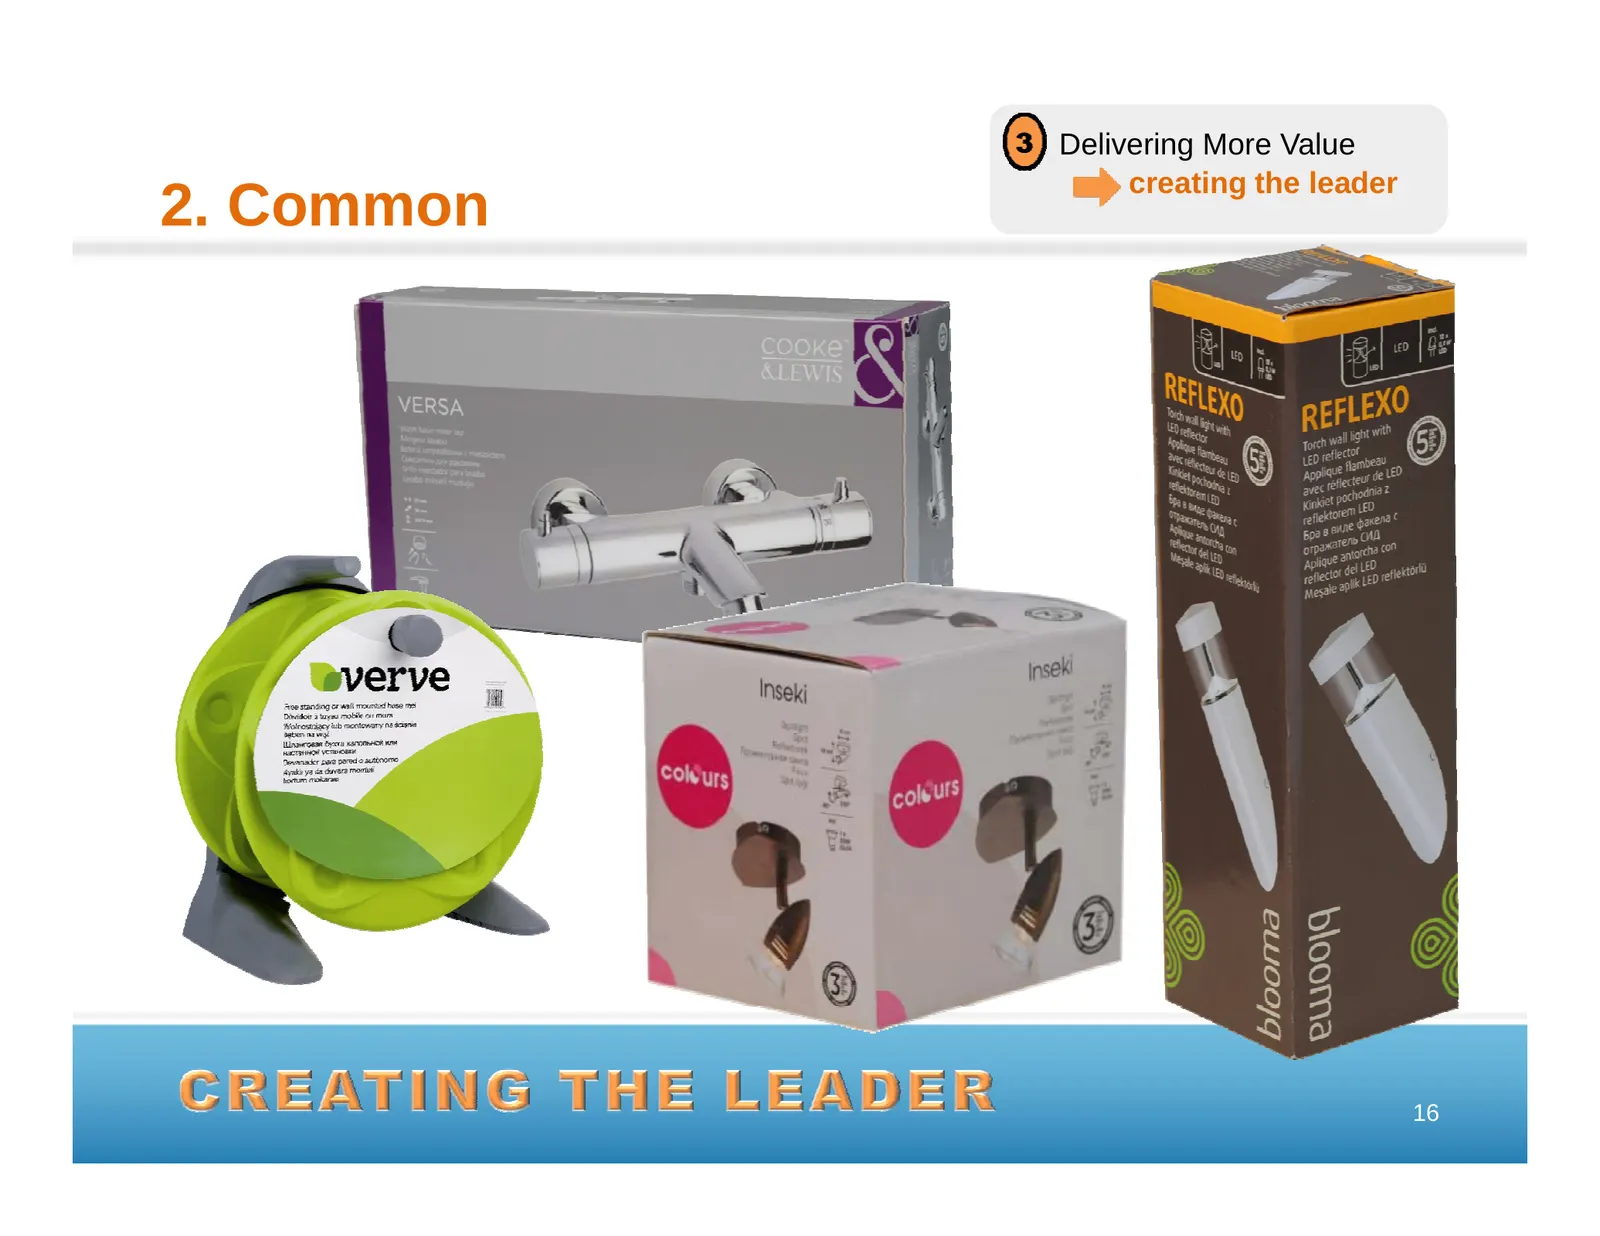
Delivering More Value creating the leader 2. Common 16
Slide 17: 3. Expand
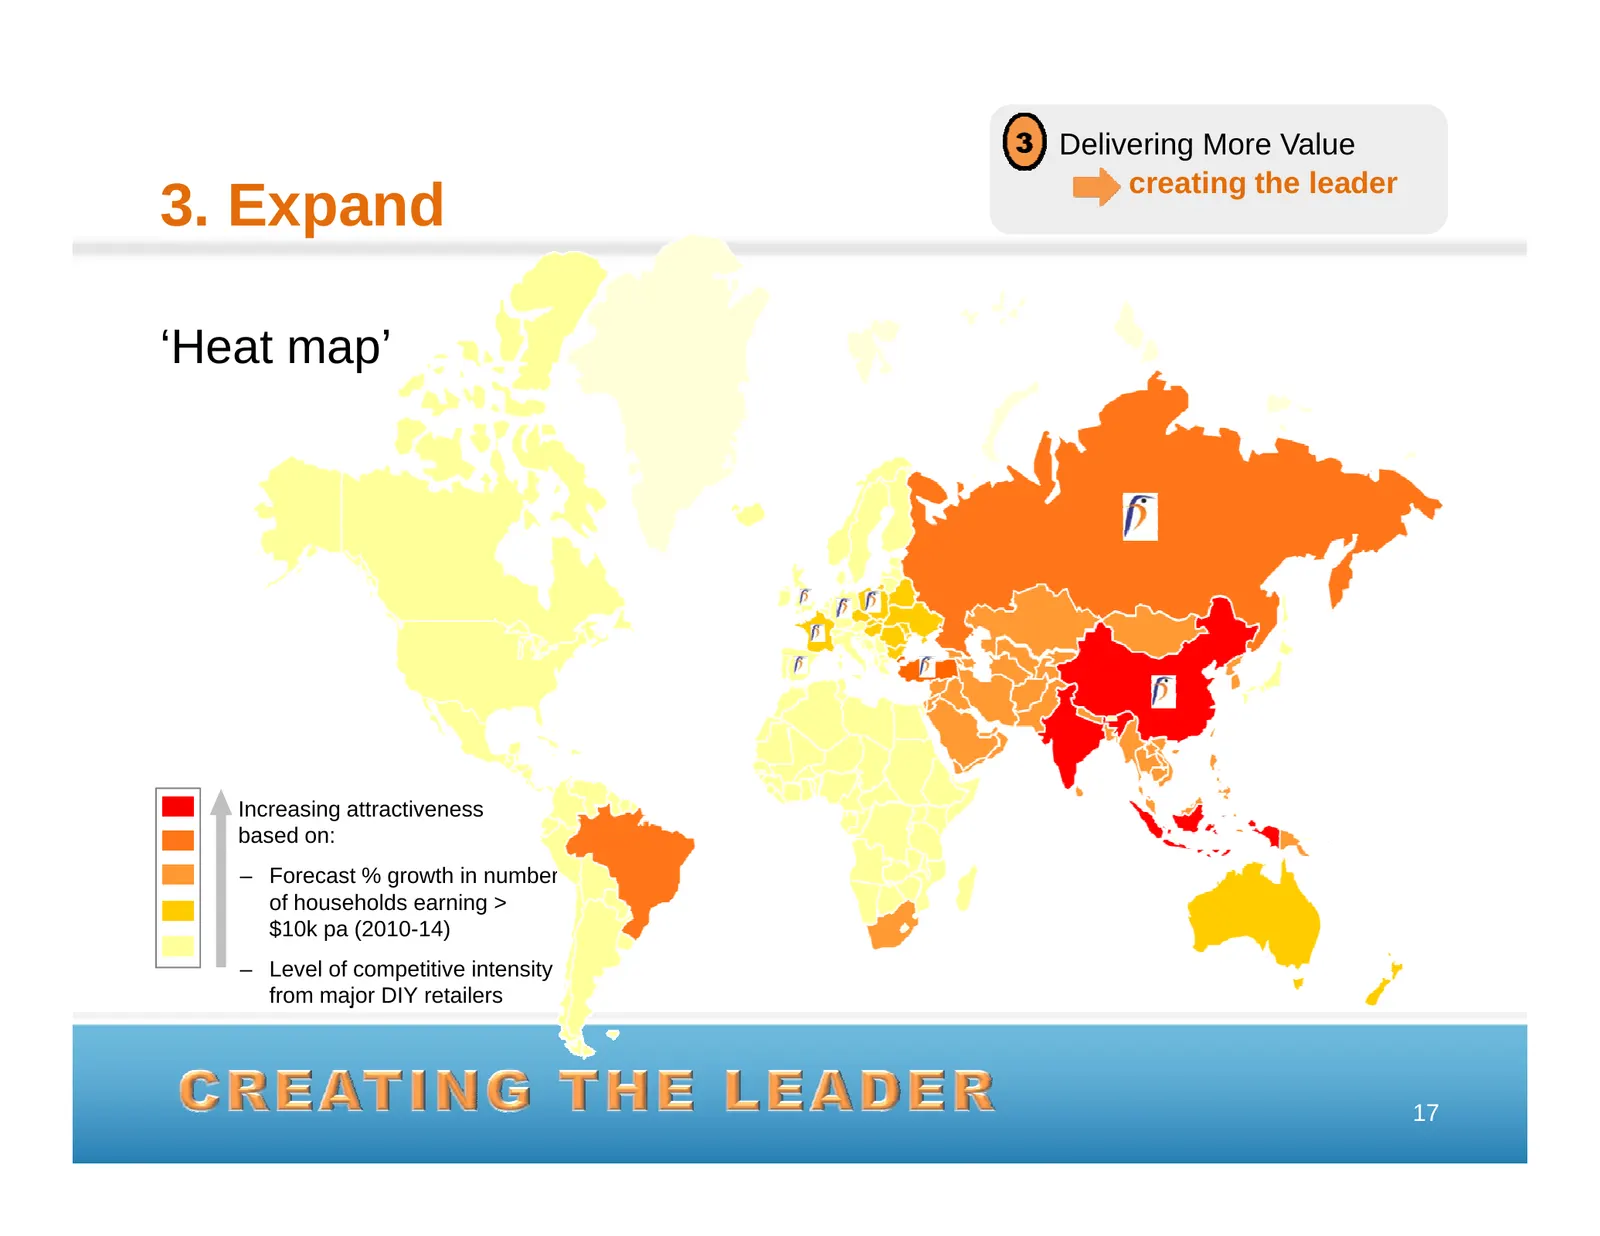
Delivering More Value creating the leader 3. Expand p ‘Heat map’ Increasing attractiveness based on: – Forecast % growth in number of households earning > $10k pa (2010-14) – Level of competitive intensity from major j DIY retailers 17
Slide 18: 3. Expand
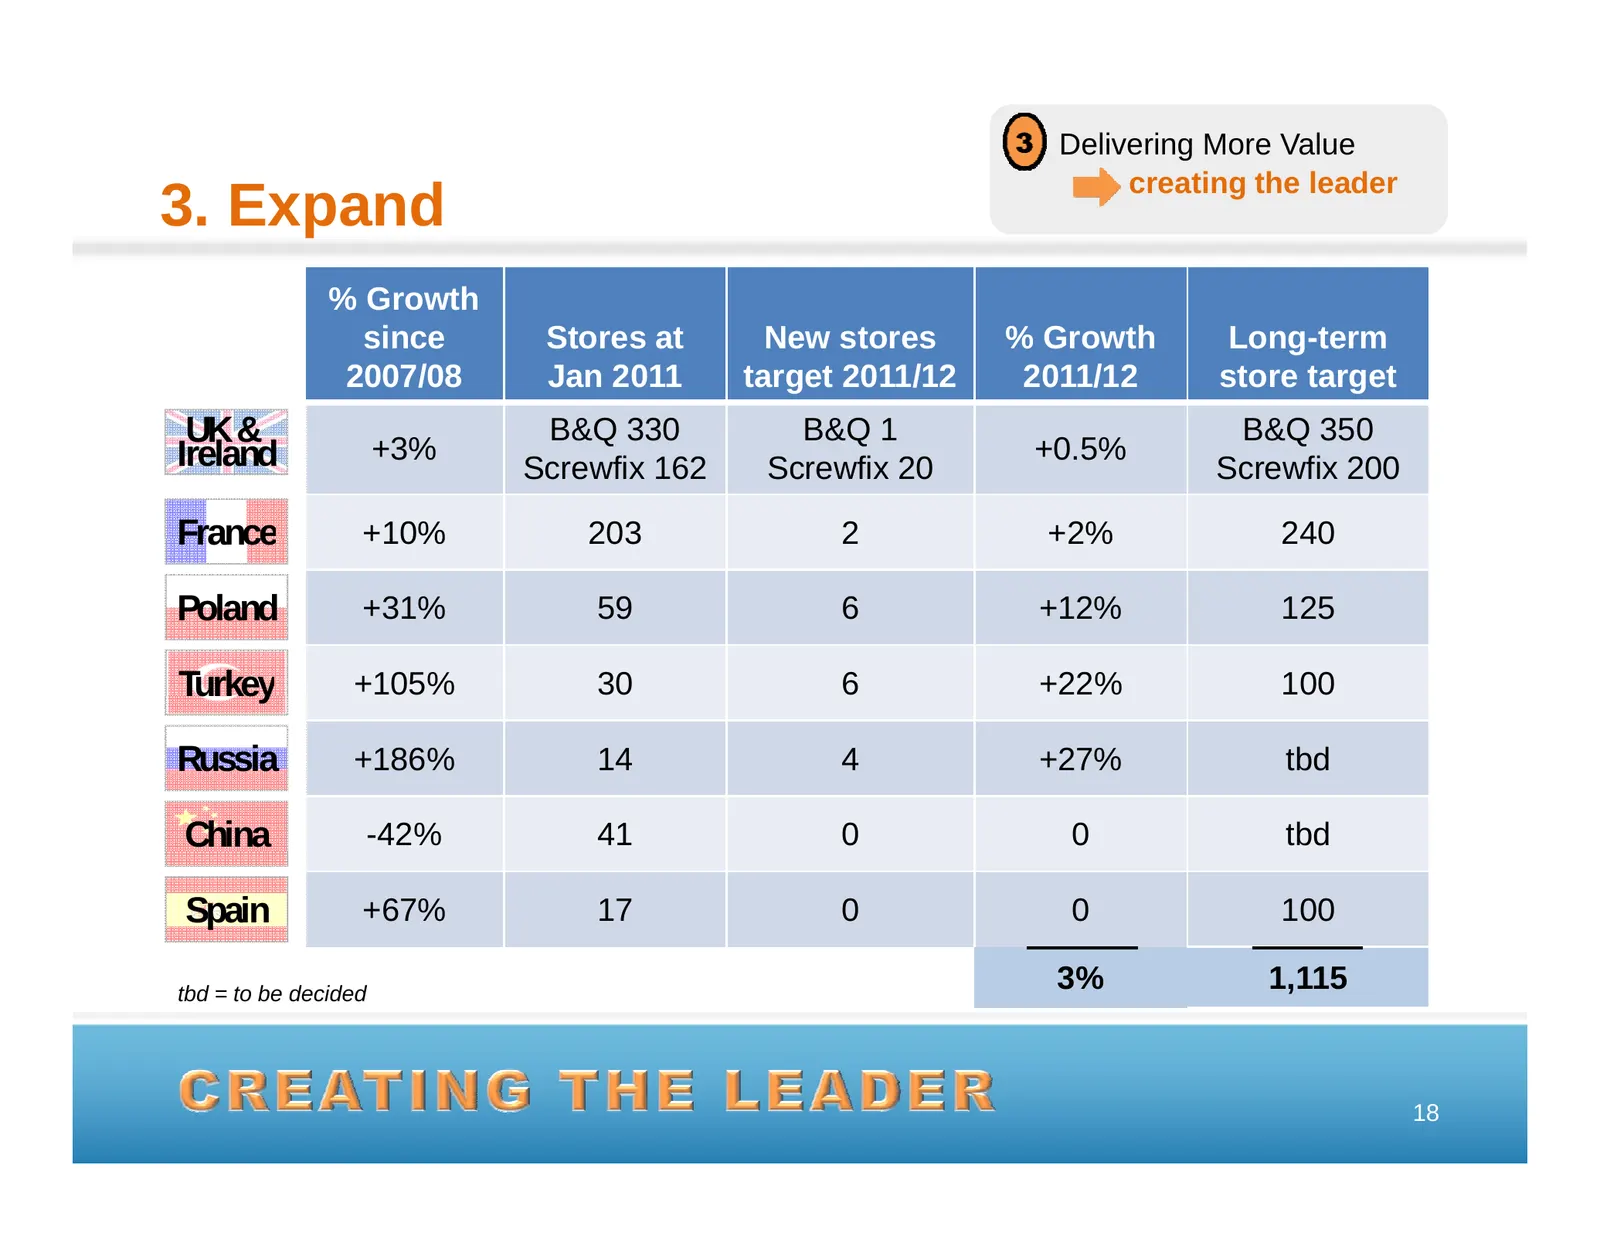
Delivering More Value creating the leader 3. Expand p % Growth since Stores at New stores % Growth Long-term 2007/08 Jan 2011 target 2011/12 2011/12 store target UK & B&Q 330 B&Q 1 B&Q 350 Ireland +3% Screwfix 162 Screwfix 20 +0.5% Screwfix 200 France +10% 203 2 +2% 240 Poland +31% 59 6 +12% 125 Tur
Slide 19: Completing our journey…
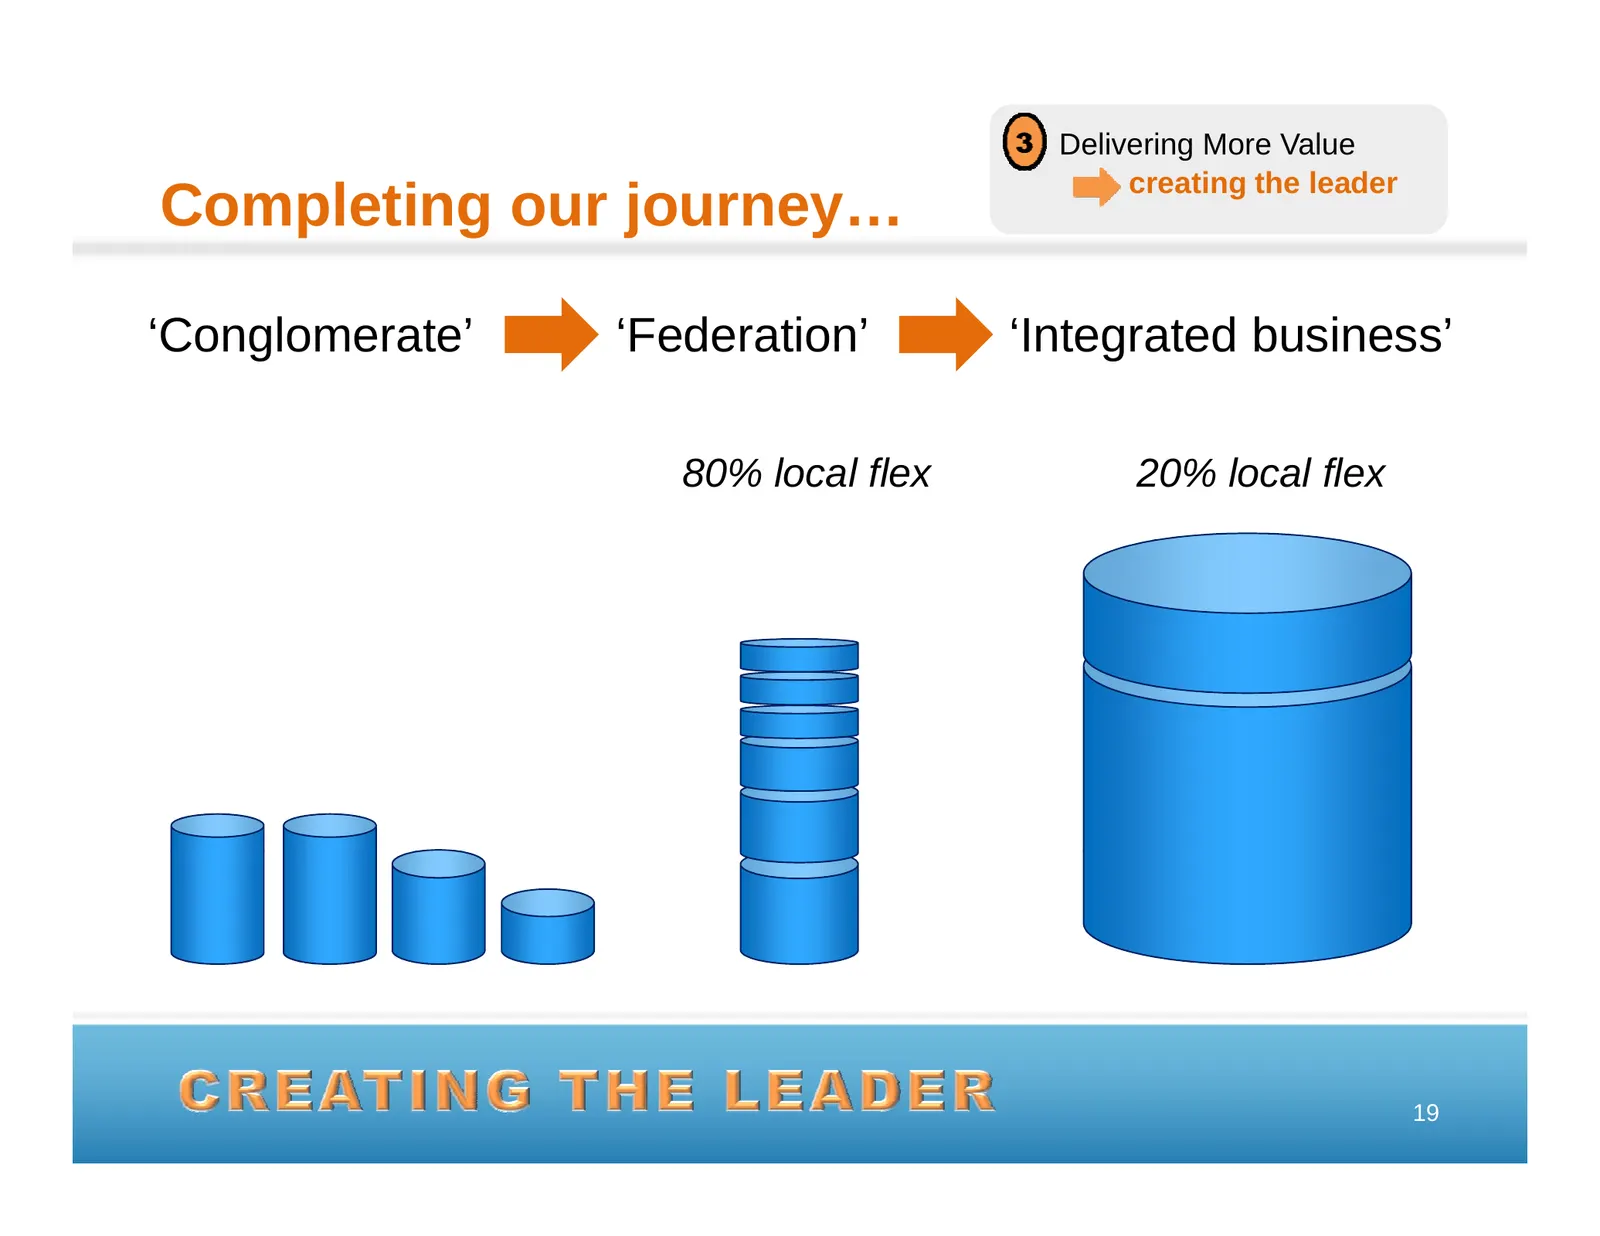
Delivering More Value creating the leader Completing p g our journey… j y ‘Conglomerate’ ‘Federation’ ‘Integrated business’ 80% local flex 20% local flex 19
Slide 20: …to unlock our strength
Delivering More Value creating the leader …to unlock our strength g ‘Centralised v decentralised’ an out-dated debate ‘Intelligent Intelligent network’ network 20
Slide 21: New commercial board
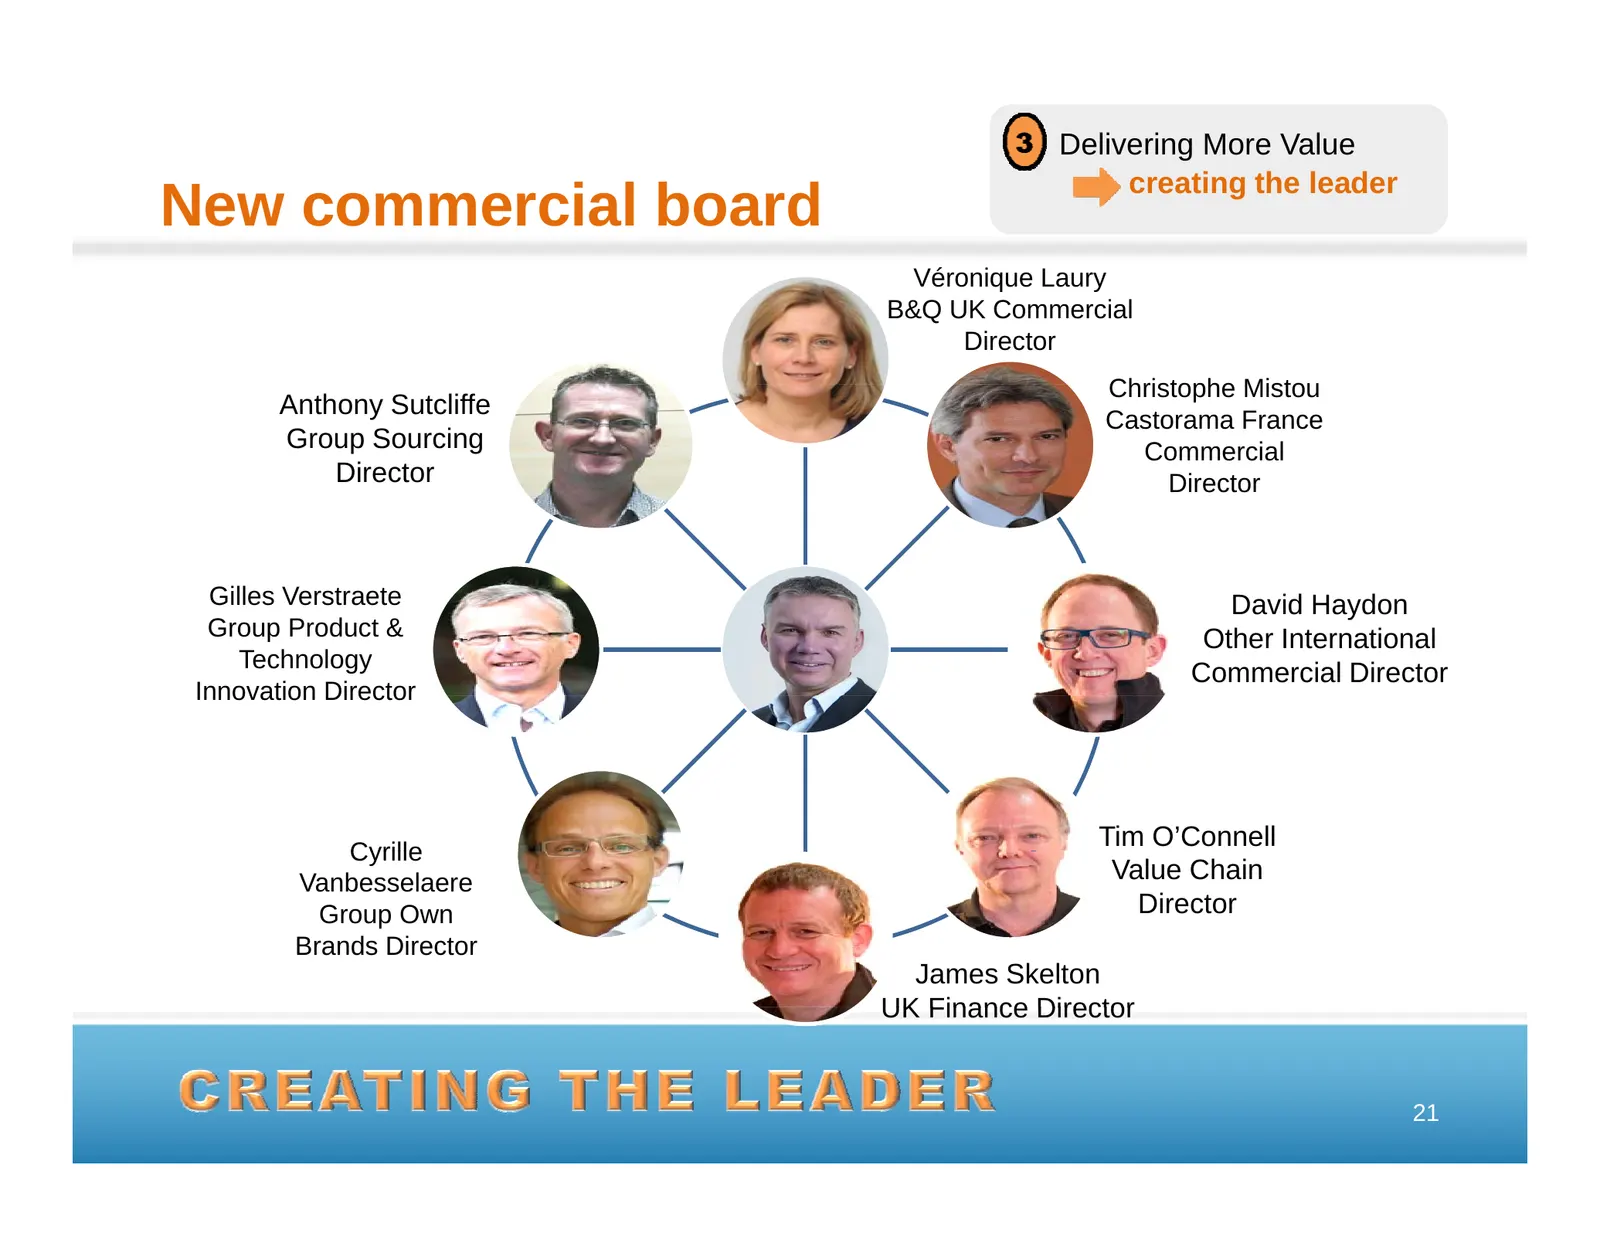
Delivering More Value creating the leader New commercial board Véronique Laury B&Q UK Commercial Director Christophe Mistou Anthony Sutcliffe Castorama France Group Sourcing Commercial Director Director Gilles Verstraete David Haydon Group Product & Other International Technology Commercial Director
Slide 22: Kingfisher 2020: Will be the leader
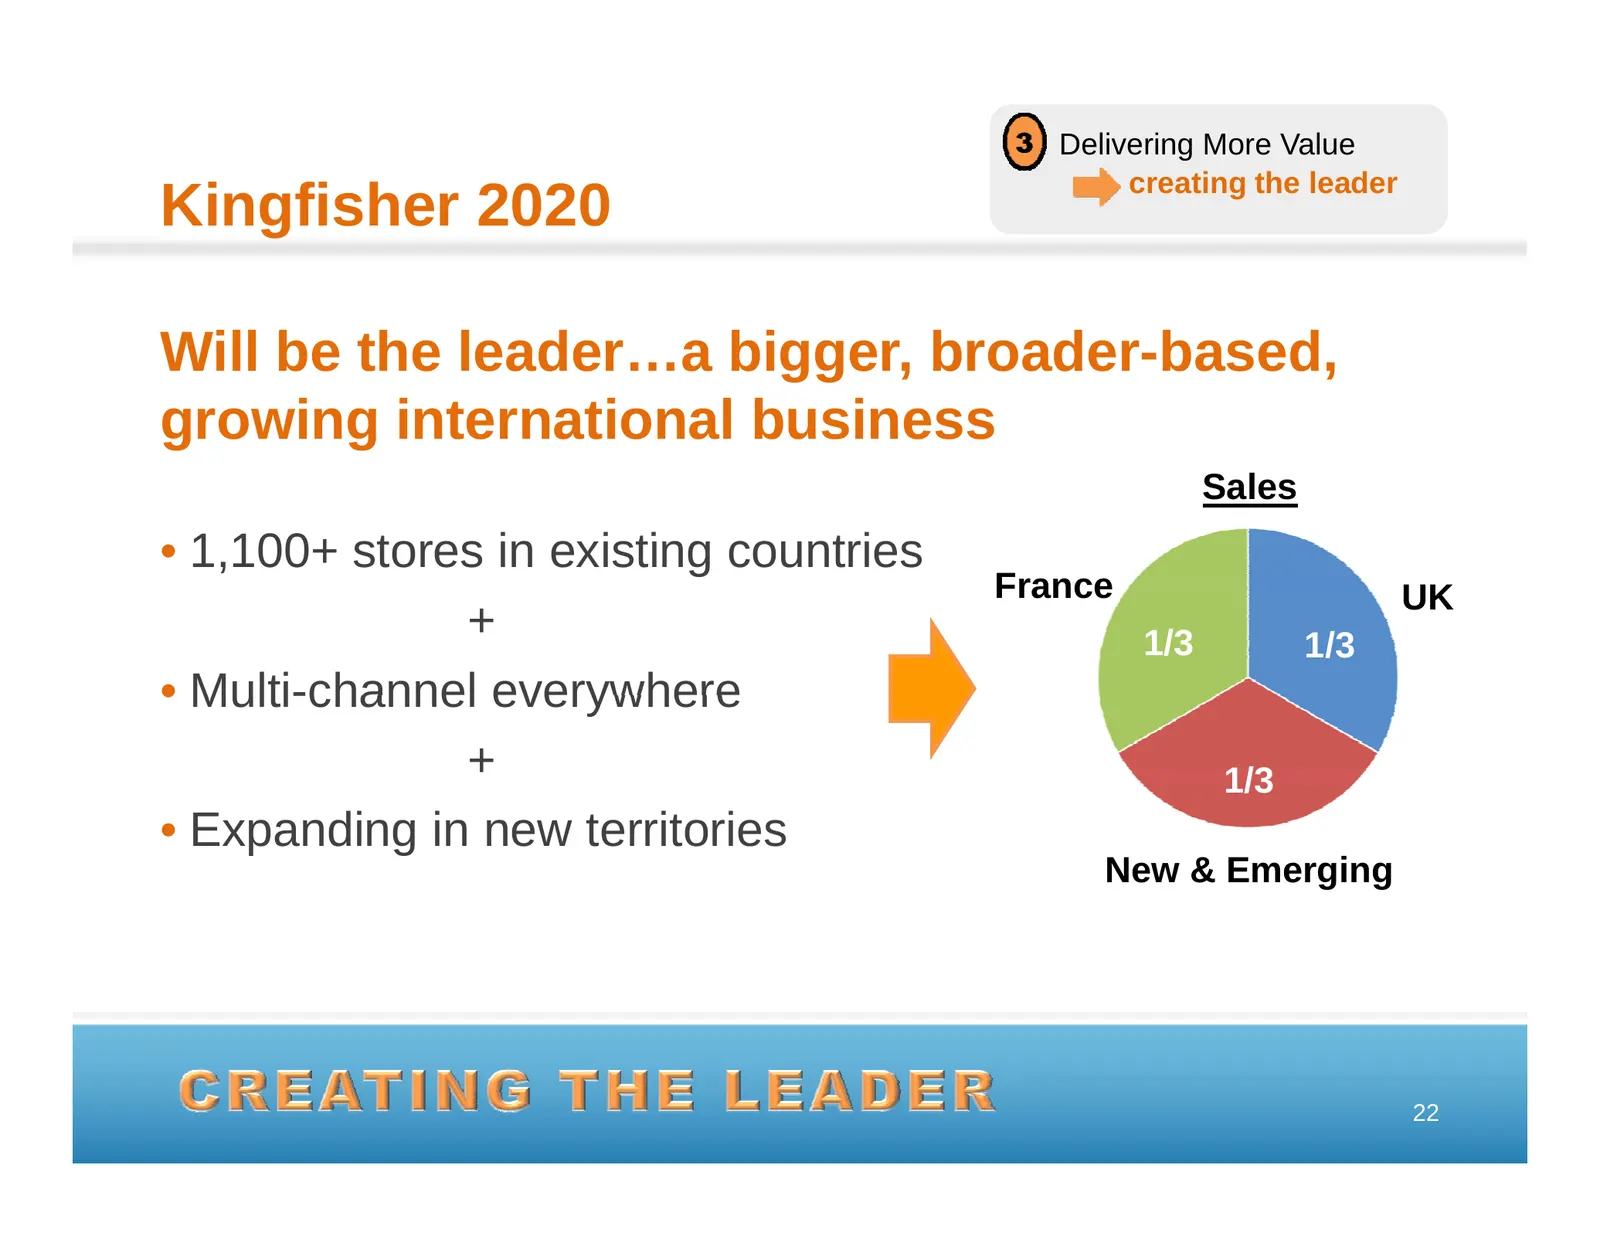
Delivering More Value creating the leader Kingfisher g 2020 Will be the leader…a bigger, broader-based, growing international business Sales • 1,100+ 1 100+ stores t iin existing i ti countries ti France UK + 1/3 1/3 • Multi-channel everywhere + 1/3 p • Expanding g in new territories New & Emerging
Slide 23: Kingfisher 2020: Will be the leader for customers, colleagues, communities
Delivering More Value creating the leader Kingfisher g 2020 Will be the leader…for customers, colleagues, communities and shareholders • 50% core common ranges • High quality, unique and affordable ff own brands • The industry’s innovator • Expert global sourcing • Envied for our people • Sustainabl
Slide 24: Kingfisher – strong growth prospects
Kingfisher g – strong g growth g prospects p p Delivering g Value - a success powerful base for growth Attractive markets more growth to unlock Delivering More Value creating ti the th lleader d 24
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025