Doral Financial — Investor Presentation (February 2005)
34 slides from Doral Financial's investor presentation, Feb 1, 2005
Slide 1: Doral Financial Corporation Investors Presentation
~ @ &» Doral FINANCIAL CORPORATION Investors Presentation
Slide 2: A diversified financial services company
A diversified financial services company with mortgage banking, commercial banking, insurance and investment banking operations in Puerto Rico and a depository institution in New York. Since it was founded, Doral has been continuously profitable (1972-2004) through all economic and interest rate cyc
Slide 3: Puerto Rico's largest residential mortgage company
Puerto Rico's largest residential mortgage company: 45% market share in highly competitive market (55% in New Housing) Servicing Portfolio of $14.3 billion Low credit-risk lending profile: conservative underwriting standards low LTV on non-agency guaranteed loans 98% of our loans are secured by real
Slide 4: Successful and profitable branch banking operations
Successful and profitable branch banking operations: fastest-growing commercial bank in Puerto Rico (4th largest) serving attractive niche markets in New York City Increased fee-based revenues and commissions from Doral Insurance Agency, investment banking and asset management operations.
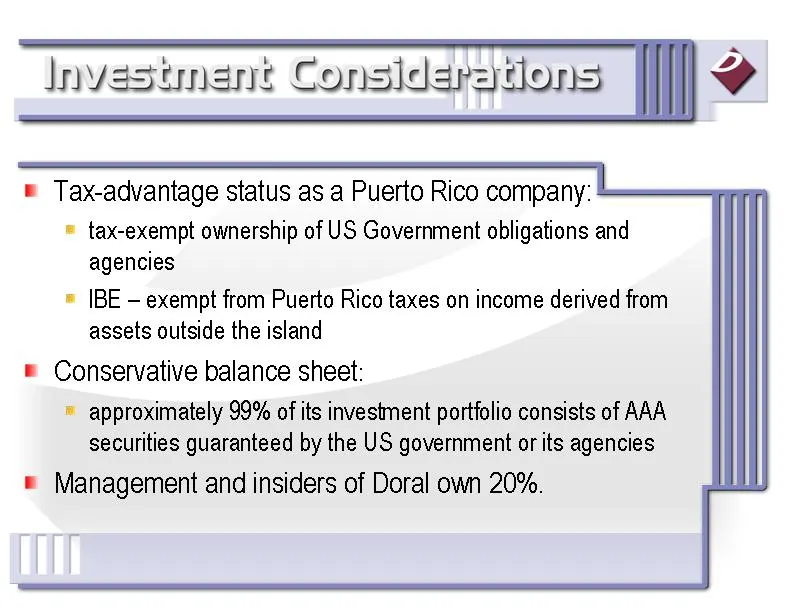
Slide 5: Tax-advantage status as a Puerto Rico company
Tax-advantage status as a Puerto Rico company: tax-exempt ownership of US Government obligations and agencies IBE - exempt from Puerto Rico taxes on income derived from assets outside the island Conservative balance sheet: approximately 99% of its investment portfolio consists of AAA securities guar
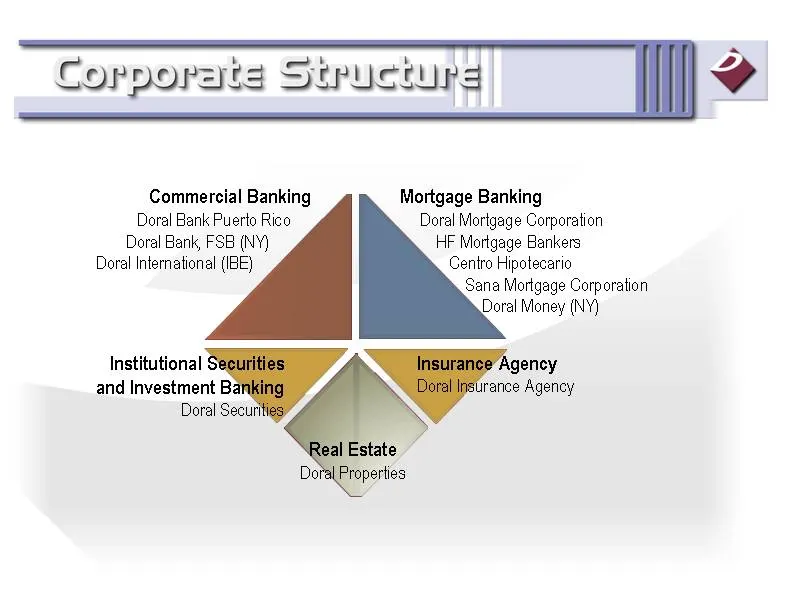
Slide 6: Doral Financial business units and subsidiaries
Commercial Banking Doral Bank Puerto Rico Doral Bank, FSB (NY) Doral International (IBE) Mortgage Banking Doral Mortgage Corporation HF Mortgage Bankers Centro Hipotecario Sana Mortgage Corporation Doral Money (NY) Institutional Securities and Investment Banking Doral Securities Insurance Agency Dor
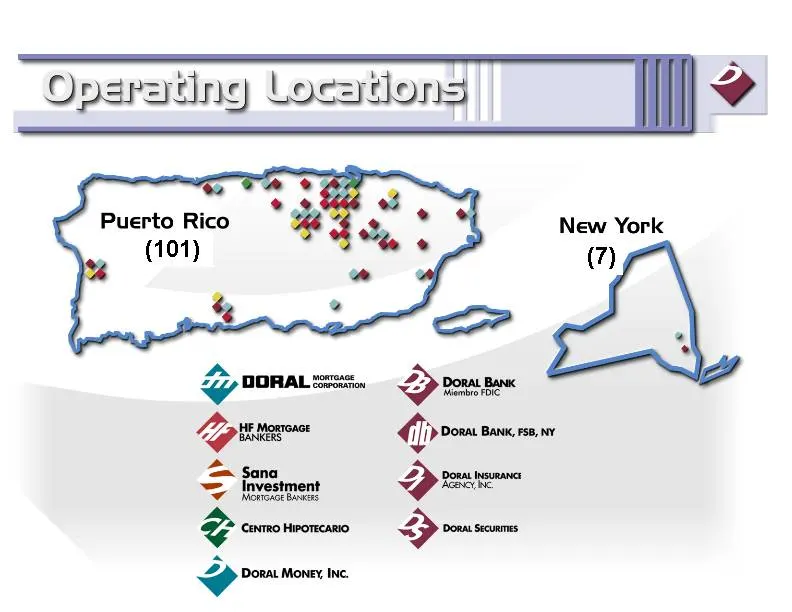
Slide 7: New York and Puerto Rico operations
New York (7) Gy MORAL sn 2 Doral Bani Donn Ba (27> WF Monroxcs prom sucro > === Sana 4 >» Dorat Insuranct ~= Investment “AGENCY, INC. "7% Morrcace Banners: ZB comoroncseo Lp vowns secures
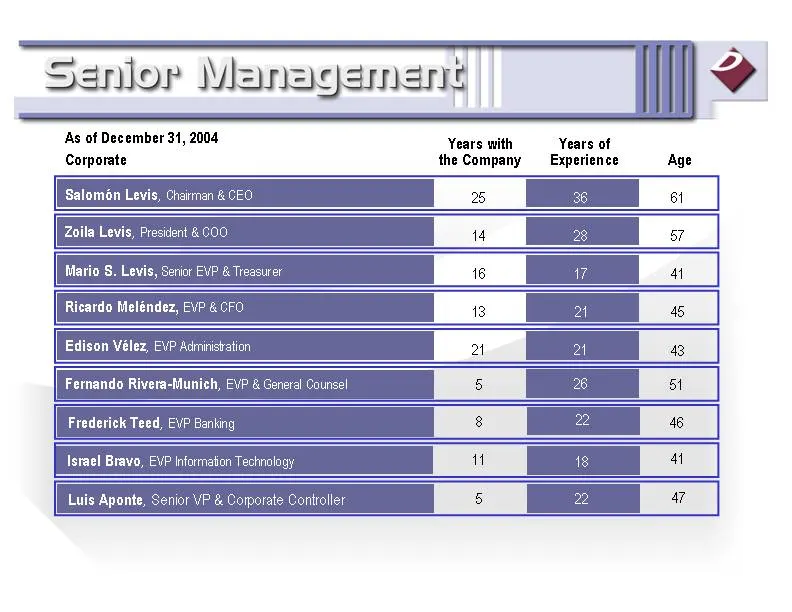
Slide 8: Corporate management
Salomon Levis, Chairman & CEO 25 36 61 Zoila Levis, President & COO 14 28 57 Mario S. Levis, Senior EVP & Treasurer 16 17 41 Ricardo Melendez, EVP & CFO 13 21 45 Edison Velez, EVP Administration 21 21 43 Fernando Rivera-Munich, EVP & General Counsel 5 26 51 Israel Bravo, EVP Information Technology 1
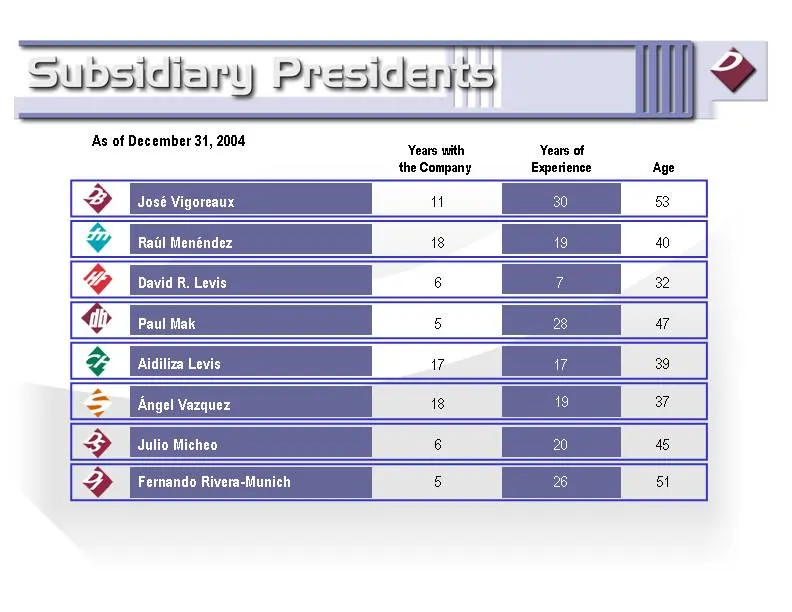
Slide 9: Subsidiary management
Years with the Company Years of Experience Age Jose Vigoreaux 11 30 53 Raul Menendez 18 19 40 David R. Levis 6 7 32 Paul Mak 5 28 47 Aidiliza Levis 17 17 39 Angel Vazquez Julio Micheo 6 20 45 5 26 51 Fernando Rivera-Munich 37 19 18 As of December 31, 2004
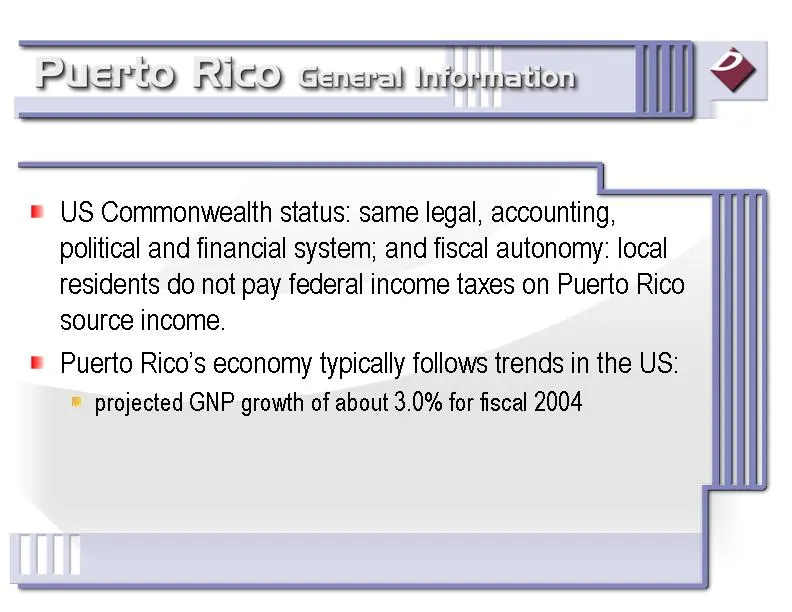
Slide 10: US Commonwealth status and Puerto Rico economy
US Commonwealth status: same legal, accounting, political and financial system; and fiscal autonomy: local residents do not pay federal income taxes on Puerto Rico source income. Puerto Rico's economy typically follows trends in the US: projected GNP growth of about 3.0% for fiscal 2004
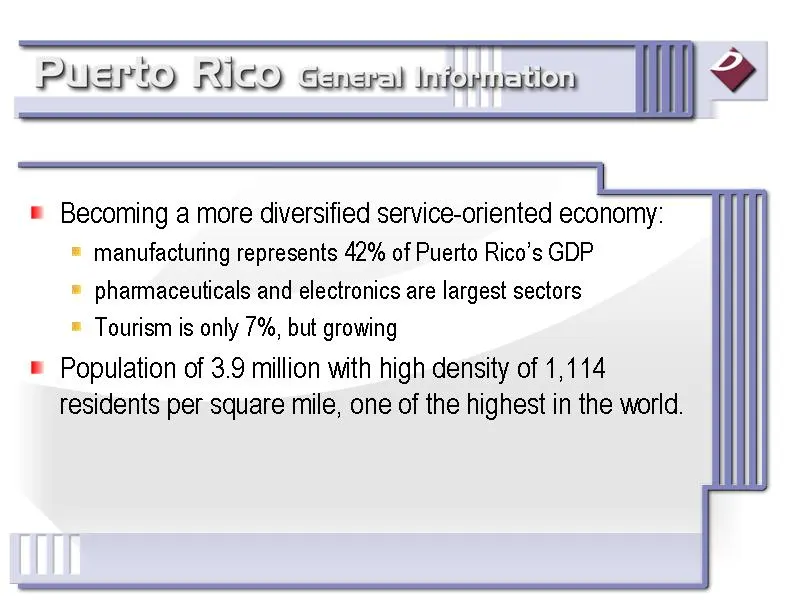
Slide 11: Diversifying Puerto Rico economy
Becoming a more diversified service-oriented economy: manufacturing represents 42% of Puerto Rico's GDP pharmaceuticals and electronics are largest sectors Tourism is only 7%, but growing Population of 3.9 million with high density of 1,114 residents per square mile, one of the highest in the world.
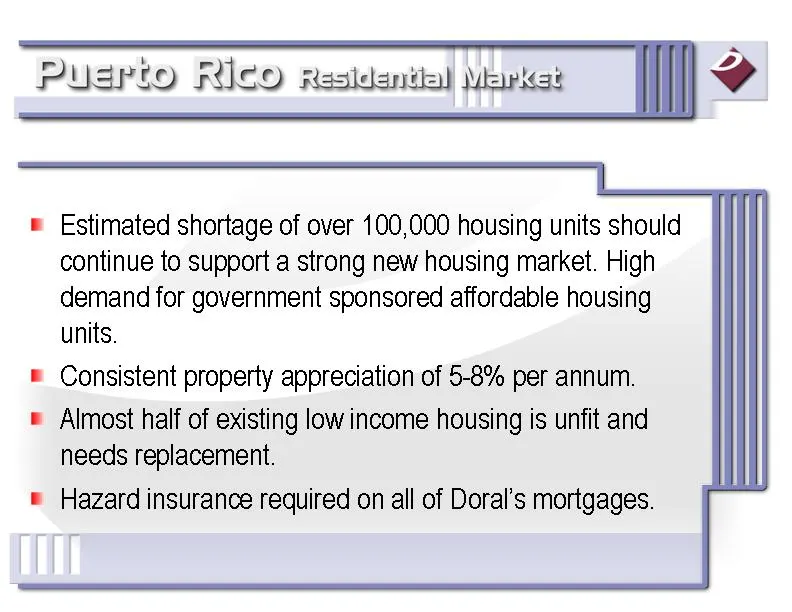
Slide 12: Housing unit shortage supports new housing market
Estimated shortage of over 100,000 housing units should continue to support a strong new housing market. High demand for government sponsored affordable housing units. Consistent property appreciation of 5-8% per annum. Almost half of existing low income housing is unfit and needs replacement. Hazar
Slide 13: Government-sponsored affordable housing programs
Government-sponsored affordable housing programs: tax incentives to developers mortgage subsidies to buyers interest tax-exemption on FHA / VA loans for new housing down payment subsidies ("The Key to your Home" program)
Slide 14: High home ownership and refinancing
73% home ownership (vs 66% in the US) and reliance on home equity for debt consolidation refinancing. Average loan charge-off rates below those in the US. Refinancings have historically represented a higher proportion of mortgage loan volume than in the US mostly for debt consolidation purposes.
Slide 15: Business Overview
Businass Ovarvisw {il °¢
Slide 16: Expand mortgage lending and grow Doral Bank
Continue to expand our mortgage lending business and further increase our market share of approximately 45%. Grow Doral Bank by opening new branches throughout Puerto Rico (40 branches, and 6 to 8 in 2005). Further increase our bank deposits market share of 7%. Emphasize greater cross-selling betwee
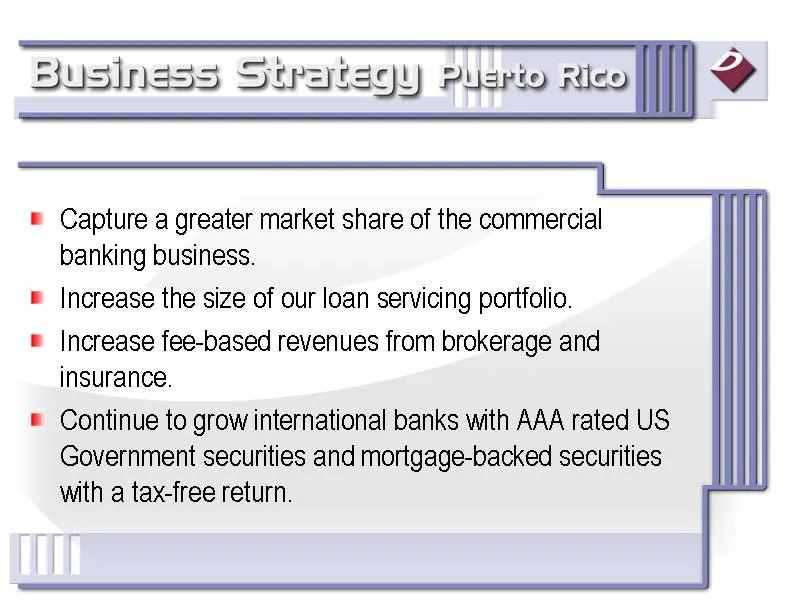
Slide 17: Capture greater commercial banking share
Capture a greater market share of the commercial banking business. Increase the size of our loan servicing portfolio. Increase fee-based revenues from brokerage and insurance. Continue to grow international banks with AAA rated US Government securities and mortgage-backed securities with a tax-free
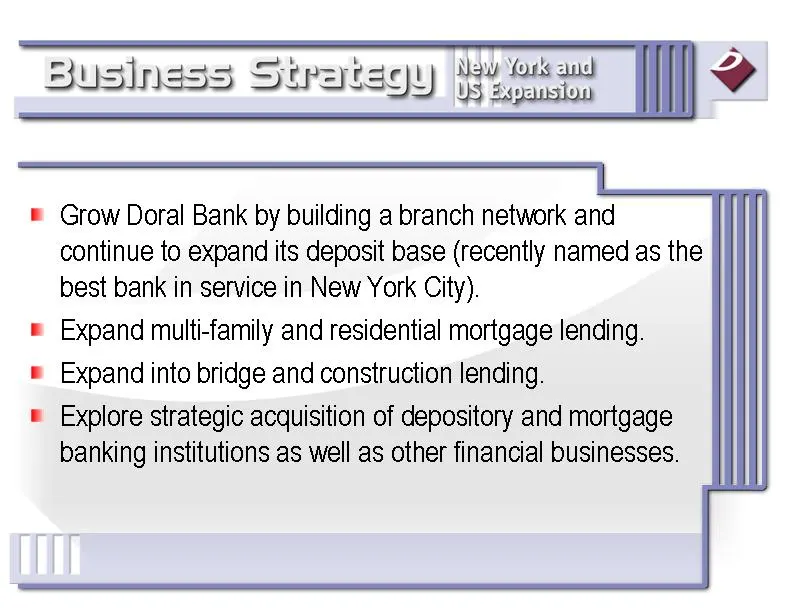
Slide 18: Grow Doral Bank branch network and deposits
Grow Doral Bank by building a branch network and continue to expand its deposit base (recently named as the best bank in service in New York City). Expand multi-family and residential mortgage lending. Expand into bridge and construction lending. Explore strategic acquisition of depository and mortg
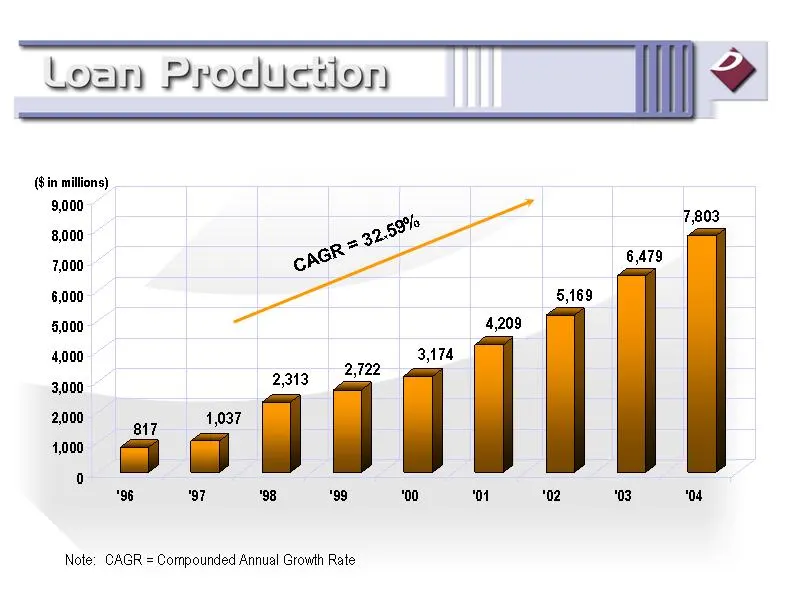
Slide 19: Loan Production
'96 '97 '98 '99 '00 '01 '02 '03 '04 Loan Production 817 1037 2313 2722 3174 4209 5169 6479 7803 Note: CAGR = Compounded Annual Growth Rate CAGR = 32.59% ($ in millions)
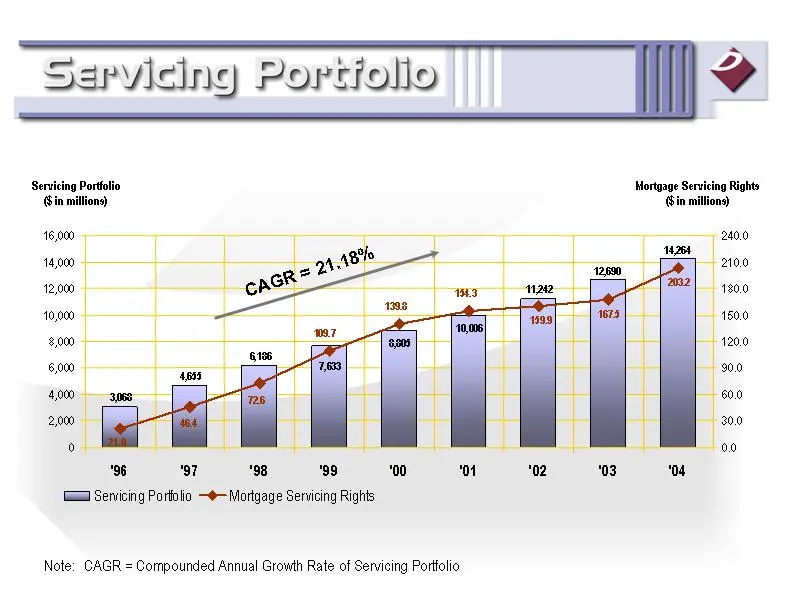
Slide 20: Servicing Portfolio and Mortgage Servicing Rights
'96 '97 '98 '99 '00 '01 '02 '03 '04 Servicing Portfolio 3068 4655 6186 7633 8805 10006 11242 12690 14264 Mortgage Servicing Rights 21 46.4 72.6 109.7 139.8 154.3 159.9 167.5 203.2 Note: CAGR = Compounded Annual Growth Rate of Servicing Portfolio CAGR = 21.18% Mortgage Servicing Rights ($ in millions
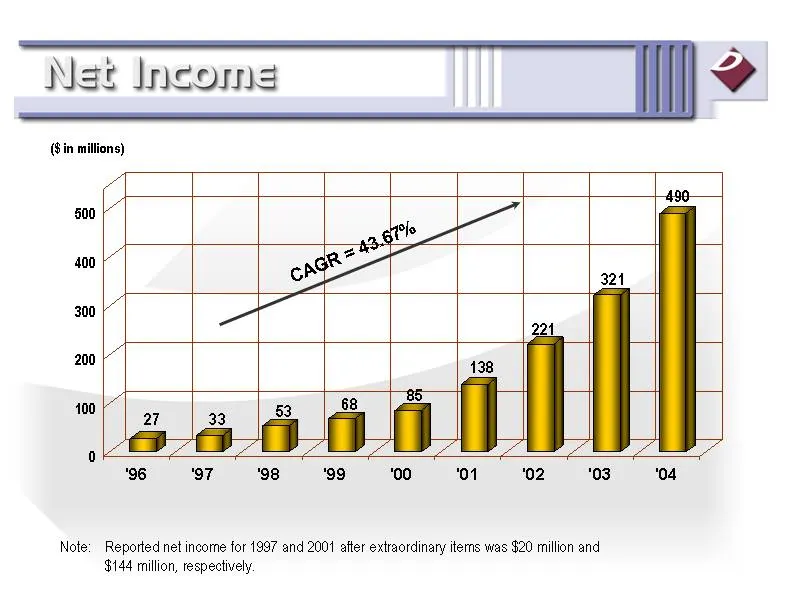
Slide 21: Net Income
'96 '97 '98 '99 '00 '01 '02 '03 '04 27 33 53 68 85 138 221 321 490 Note: Reported net income for 1997 and 2001 after extraordinary items was $20 million and $144 million, respectively. CAGR = 43.67% ($ in millions)
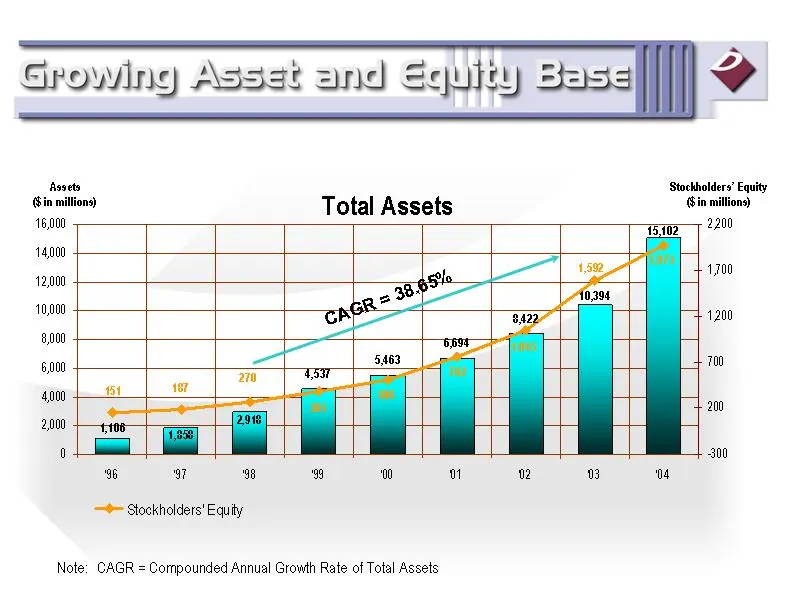
Slide 22: Total Assets and Stockholders' Equity
'96 '97 '98 '99 '00 '01 '02 '03 '04 1106 1858 2918 4537 5463 6694 8422 10394 15102 Stockholders' Equity 151 187 270 385 506 762 1045 1592 1973 Note: CAGR = Compounded Annual Growth Rate of Total Assets CAGR = 38.65% Stockholders' Equity ($ in millions) Assets ($ in millions) Total Assets
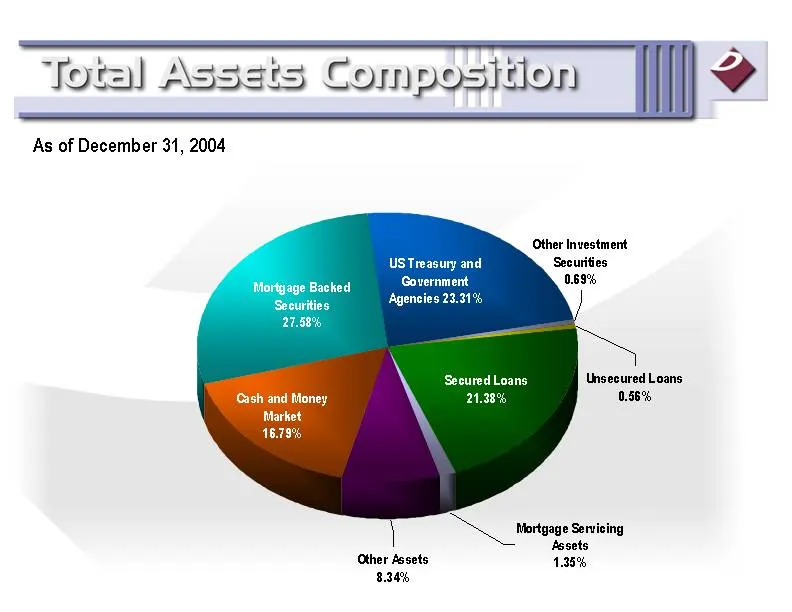
Slide 23: Asset composition as of December 31, 2004
Unsecured Loans Secured Loans Mortgage Servicing Assets Other Assets Cash and Money Market Mortgage Backed Securities US Treasury and Government Agencies Other Investment Securities 0.0056 0.2141 0.0135 0.0834 0.1679 0.2758 0.2331 0.0069 As of December 31, 2004
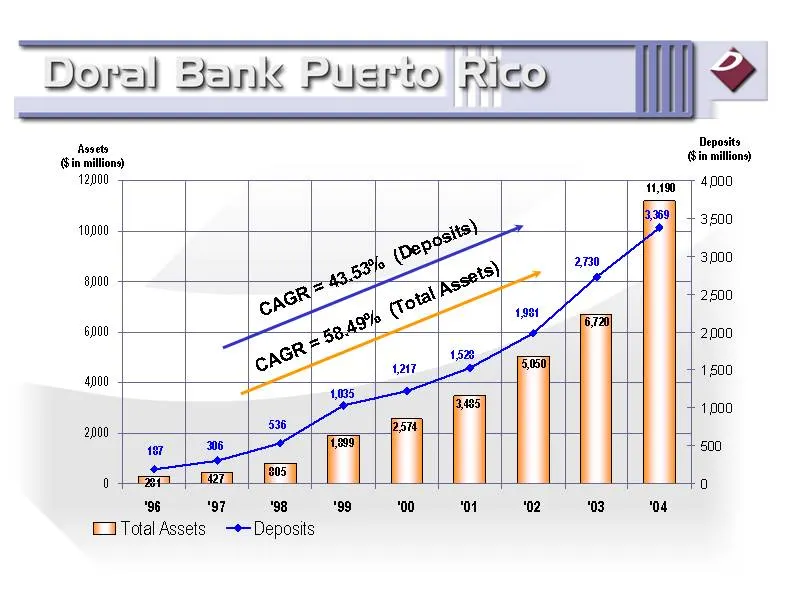
Slide 24: Doral Bank Total Assets and Deposits
'96 '97 '98 '99 '00 '01 '02 '03 '04 Total Assets 281 427 805 1899 2574 3485 5050 6720 11190 Deposits 187 306 536 1035 1217 1528 1981 2730 3369 Assets ($ in millions) Deposits ($ in millions) CAGR = 43.53% (Deposits) CAGR = 58.49% (Total Assets)
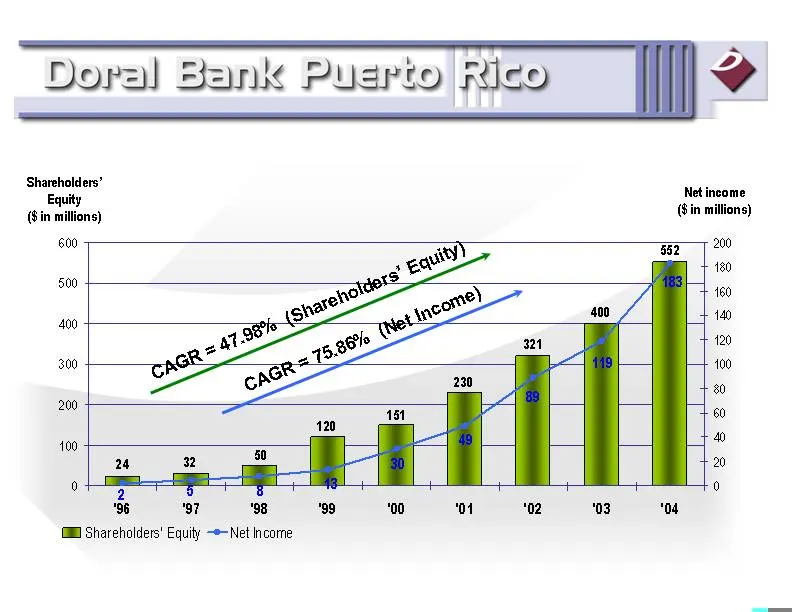
Slide 25: Shareholders' Equity and Net Income
'96 '97 '98 '99 '00 '01 '02 '03 '04 Shareholders' Equity 24 32 50 120 151 230 321 400 552 Net Income 2 5 8 13 30 49 89 119 183 Shareholders' Equity ($ in millions) Net income ($ in millions) CAGR = 47.98% (Shareholders' Equity) CAGR = 75.86% (Net Income)
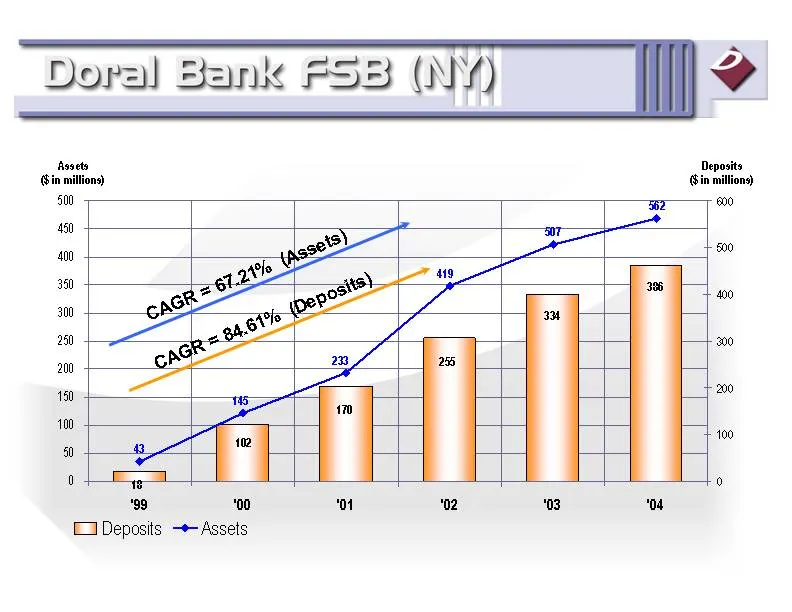
Slide 26: Doral Bank NY Assets and Deposits
'99 '00 '01 '02 '03 '04 Deposits 18 102 170 255 334 386 Assets 43 145 233 419 507 562 Assets ($ in millions) Deposits ($ in millions) CAGR = 67.21% (Assets) CAGR = 84.61% (Deposits)
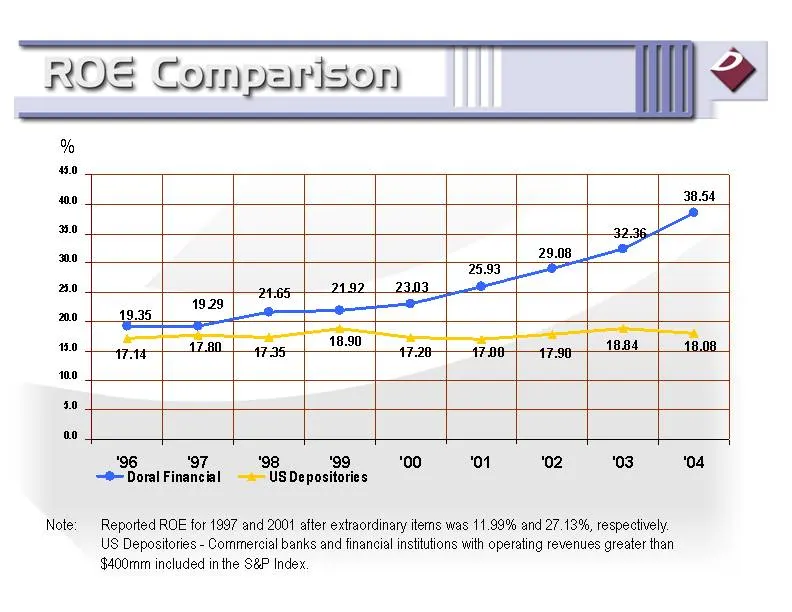
Slide 27: Return on Equity vs US Depositories
Note: Reported ROE for 1997 and 2001 after extraordinary items was 11.99% and 27.13%, respectively. US Depositories - Commercial banks and financial institutions with operating revenues greater than $400mm included in the S&P Index. '96 '97 '98 '99 '00 '01 '02 '03 '04 Doral Financial 19.35 19.29 21.
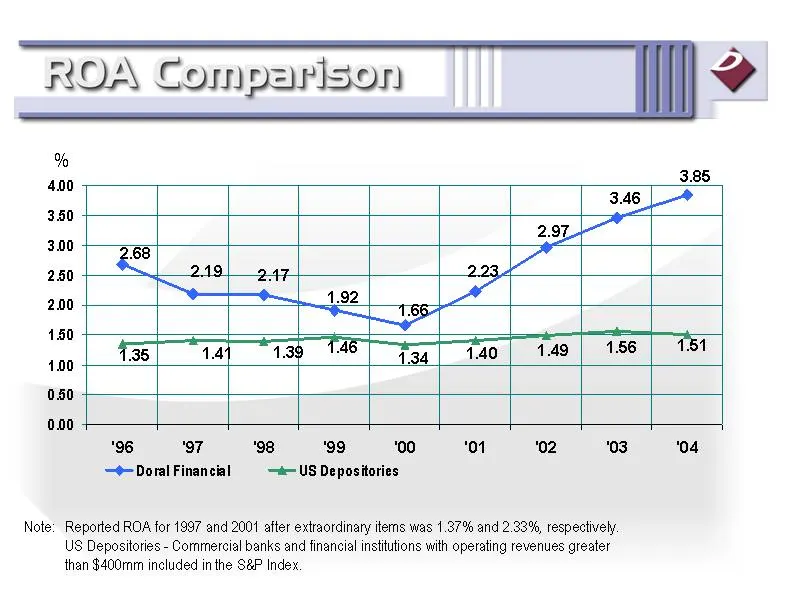
Slide 28: Return on Assets vs US Depositories
'96 '97 '98 '99 '00 '01 '02 '03 '04 Doral Financial 2.68 2.19 2.17 1.92 1.66 2.23 2.97 3.46 3.85 US Depositories 1.35 1.41 1.39 1.46 1.34 1.4 1.49 1.56 1.51 Note: Reported ROA for 1997 and 2001 after extraordinary items was 1.37% and 2.33%, respectively. US Depositories - Commercial banks and financ
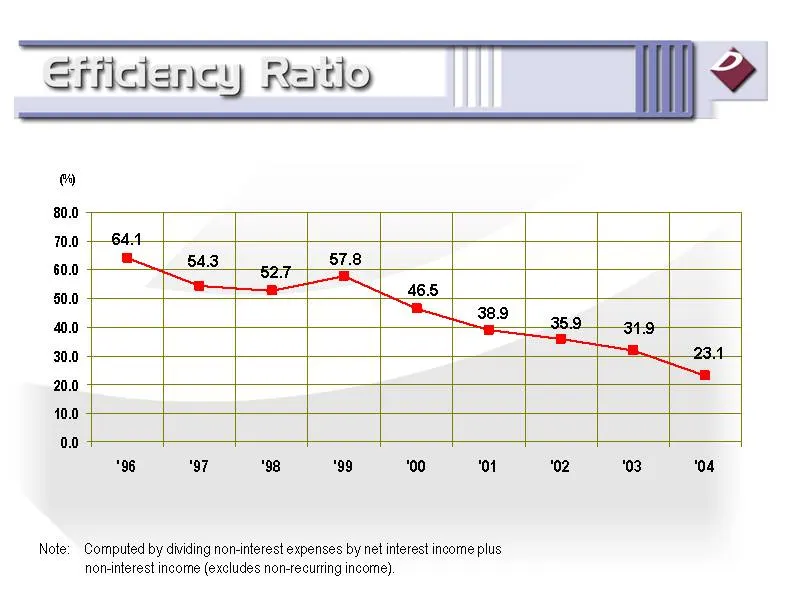
Slide 29: Efficiency Ratio
'96 '97 '98 '99 '00 '01 '02 '03 '04 Efficiency Ratio 64.1 54.3 52.7 57.8 46.5 38.91 35.91 31.9 23.1 Note: Computed by dividing non-interest expenses by net interest income plus non-interest income (excludes non-recurring income).
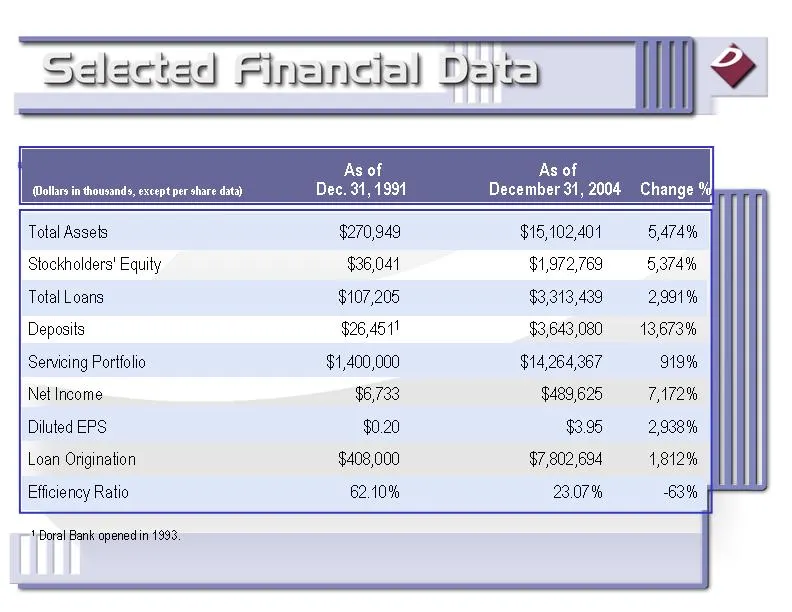
Slide 30: Growth since 1991
Total Assets $270,949 $15,102,401 5,474% Stockholders' Equity $36,041 $1,972,769 5,374% Total Loans $107,205 $3,313,439 2,991% Deposits $26,4511 $3,643,080 13,673% Servicing Portfolio $1,400,000 $14,264,367 919% Net Income $6,733 $489,625 7,172% Diluted EPS $0.20 $3.95 2,938% Loan Origination $408,0
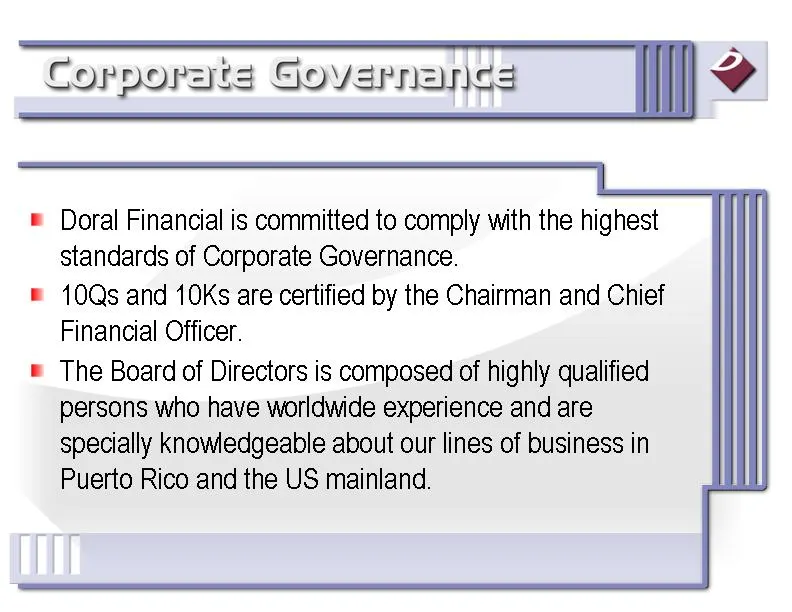
Slide 31: Corporate governance
Doral Financial is committed to comply with the highest standards of Corporate Governance. 10Qs and 10Ks are certified by the Chairman and Chief Financial Officer. The Board of Directors is composed of highly qualified persons who have worldwide experience and are specially knowledgeable about our l
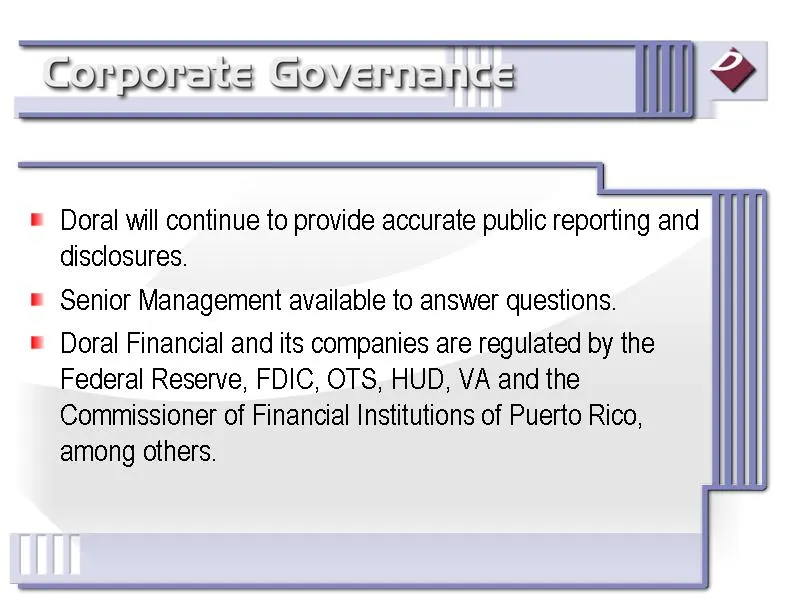
Slide 32: Public reporting and regulation
Doral will continue to provide accurate public reporting and disclosures. Senior Management available to answer questions. Doral Financial and its companies are regulated by the Federal Reserve, FDIC, OTS, HUD, VA and the Commissioner of Financial Institutions of Puerto Rico, among others.
Slide 33: Continued expansion and growth outlook
Continued expansion of mortgage banking operations in Puerto Rico. Continued expansion of retail banking operations in Puerto Rico and New York. Continued expansion of new residential business in Puerto Rico. Continued growth on the US mainland. Increase fee-based revenues from brokerage services an
Slide 34: Cautionary Language
CAUTIONARY LANGUAGE The forward looking statements presented today including, among other things, projections with respect to revenue and earnings growth and the Company's plans and objectives are subject to risks and uncertainties. Various factors, including regional and national economic condition
Source: SEC EDGAR · 8-K filed Feb 1, 2005
More decks from Doral Financial Corp
 Q4 2013 Earnings Presentation13 slides · Mar 21, 2014
 Q3 2013 Earnings Presentation14 slides · Nov 5, 2013
 Q2 2013 Earnings Presentation14 slides · Aug 16, 2013
 Q1 2013 Earnings Presentation13 slides · May 9, 2013
 Q4 2012 Earnings Presentation4 slides · Mar 13, 2013
 Q3 2012 Earnings Presentation12 slides · Nov 9, 2012