Human Genome Sciences — JPMorgan Healthcare Conference 2011
29 slides from Human Genome Sciences's conference presentation, Jan 10, 2011
Slide 1: BENLYSTA and Beyond
BENLYSTA(r) AND BEYOND H. Thomas Watkins President and Chief Executive Officer JP Morgan Healthcare Conference January 10, 2011
Slide 2: Note Regarding Forward-Looking Statements
NOTE REGARDING FORWARD-LOOKING STATEMENTS 2 JPMorgan Healthcare Conference | January 10, 2011 This presentation contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The for
Slide 3: Broad Potential Beyond Initial Market Entry in SLE
BROAD POTENTIAL BEYOND INITIAL MARKET ENTRY IN SLE 3 JPMorgan Healthcare Conference | January 10, 2011 Drivers of Near-Term Growth Drivers of Long-Term Growth
Slide 4: Drivers of Near-Term Growth
Drivers of Near-Term Growth BENLYSTA: potentially improves standard of care for SLE First Phase 3 trials to achieve primary endpoint in SLE Positive FDA Ad Comm vote for approval (13-2); New PDUFA target March 10, 2011 Initial U.S. market-200,000 patients with moderate-to-severe systemic lupus Speci
Slide 5: A Formula for Sustained Growth: Drivers of Long-Term Growth
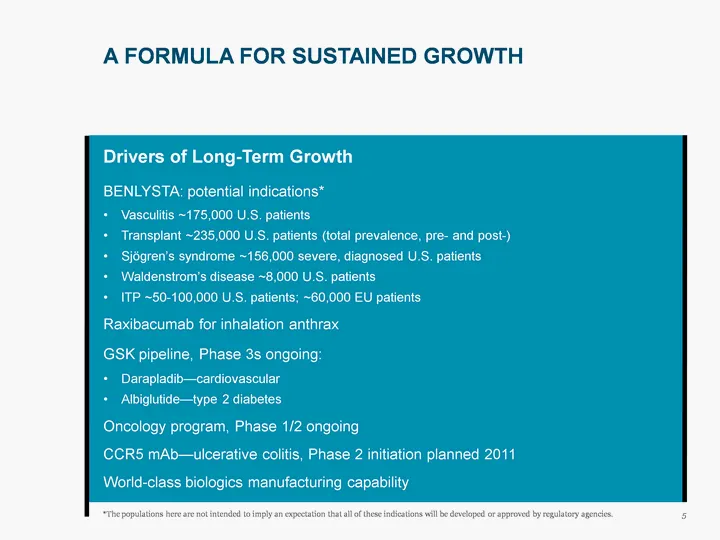
A FORMULA FOR SUSTAINED GROWTH 5 Drivers of Long-Term Growth BENLYSTA: potential indications* Vasculitis ~175,000 U.S. patients Transplant ~235,000 U.S. patients (total prevalence, pre- and post-) Sjogren's syndrome ~156,000 severe, diagnosed U.S. patients Waldenstrom's disease ~8,000 U.S. patients
Slide 6: Potentially Improves Standard of Care for SLE
6 JPMorgan Healthcare Conference | January 10, 2011 POTENTIALLY IMPROVES STANDARD OF CARE FOR SLE
Slide 7: BENLYSTA Near Term Opportunity
Potential to be the first drug approved for SLE in 50 years High unmet need Global alliance with GSK Targeted commercial strategy BENLYSTA(r) NEAR TERM OPPORTUNITY SLE THE MEANINGFUL DRIVER 7 JPMorgan Healthcare Conference | January 10, 2011
Slide 8: SLE Is a Systemic Disease Affecting Multiple Organs
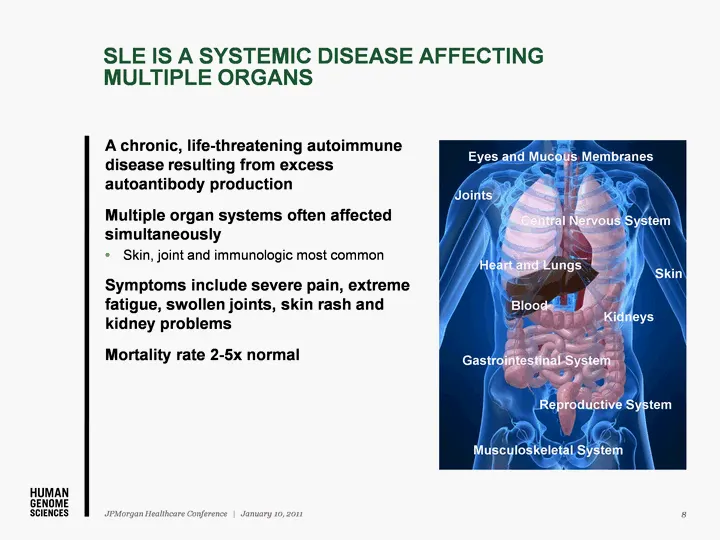
SLE IS A SYSTEMIC DISEASE AFFECTING MULTIPLE ORGANS 8 JPMorgan Healthcare Conference | January 10, 2011 A chronic, life-threatening autoimmune disease resulting from excess autoantibody production Multiple organ systems often affected simultaneously Skin, joint and immunologic most common Symptoms i
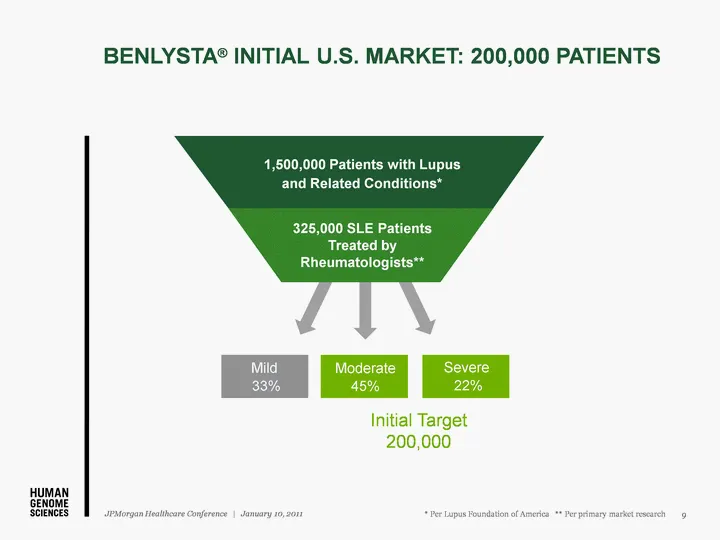
Slide 9: BENLYSTA Initial U.S. Market: 200,000 Patients
Mild 33% Severe 22% Moderate 45% Initial Target 200,000 1,500,000 Patients with Lupus and Related Conditions* 325,000 SLE Patients Treated by Rheumatologists** * Per Lupus Foundation of America ** Per primary market research BENLYSTA(r) INITIAL U.S. MARKET: 200,000 PATIENTS 9 JPMorgan Healthcare Con
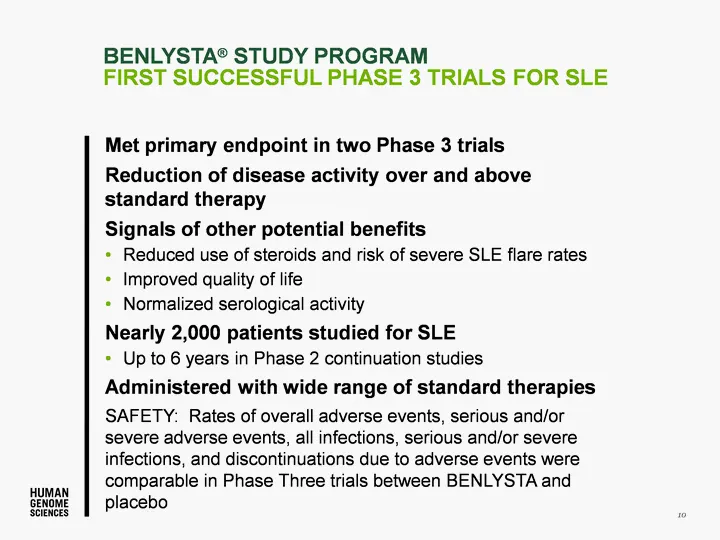
Slide 10: BENLYSTA Study Program: First Successful Phase 3 Trials for SLE
Met primary endpoint in two Phase 3 trials Reduction of disease activity over and above standard therapy Signals of other potential benefits Reduced use of steroids and risk of severe SLE flare rates Improved quality of life Normalized serological activity Nearly 2,000 patients studied for SLE Up to
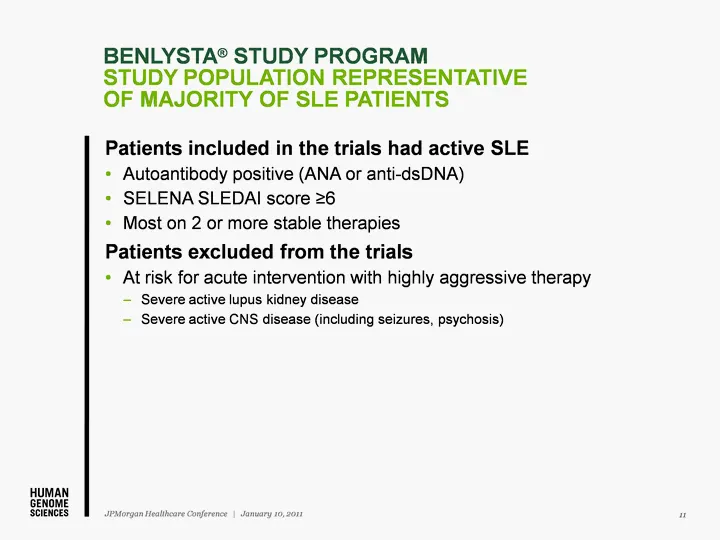
Slide 11: Study Population Representative of Majority of SLE Patients
BENLYSTA(r) STUDY PROGRAM STUDY POPULATION REPRESENTATIVE OF MAJORITY OF SLE PATIENTS 11 JPMorgan Healthcare Conference | January 10, 2011 Patients included in the trials had active SLE Autoantibody positive (ANA or anti-dsDNA) SELENA SLEDAI score ^6 Most on 2 or more stable therapies Patients exclu
Slide 12: Bringing BENLYSTA to Patients
Bringing BENLYSTA(r) to Patients 12 JPMorgan Healthcare Conference | January 10, 2011
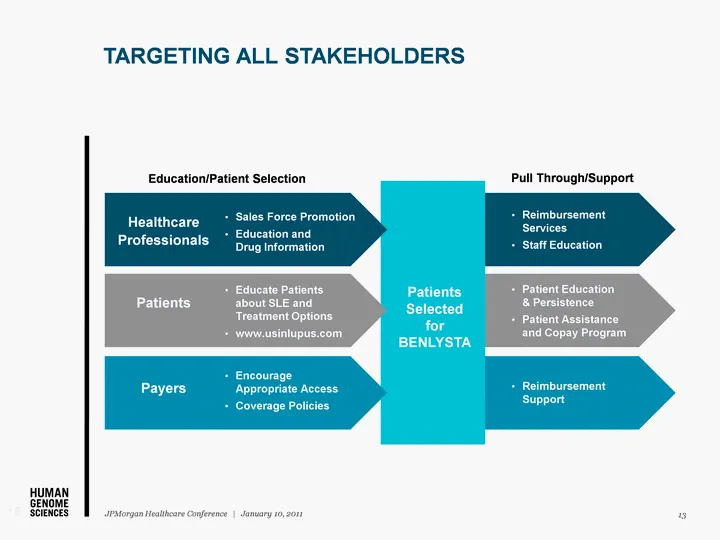
Slide 13: Targeting All Stakeholders
Patients Selected for BENLYSTA TARGETING ALL STAKEHOLDERS 13 JPMorgan Healthcare Conference | January 10, 2011 13 Education/Patient Selection Pull Through/Support Healthcare Professionals Sales Force Promotion Education and Drug Information Reimbursement Services Staff Education Patient Education &
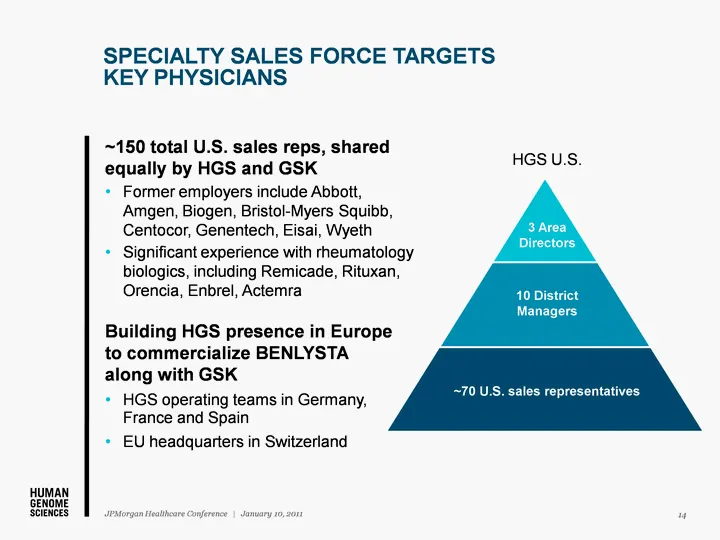
Slide 14: Specialty Sales Force Targets Key Physicians
SPECIALTY SALES FORCE TARGETS KEY PHYSICIANS ~150 total U.S. sales reps, shared equally by HGS and GSK Former employers include Abbott, Amgen, Biogen, Bristol-Myers Squibb, Centocor, Genentech, Eisai, Wyeth Significant experience with rheumatology biologics, including Remicade, Rituxan, Orencia, Enb
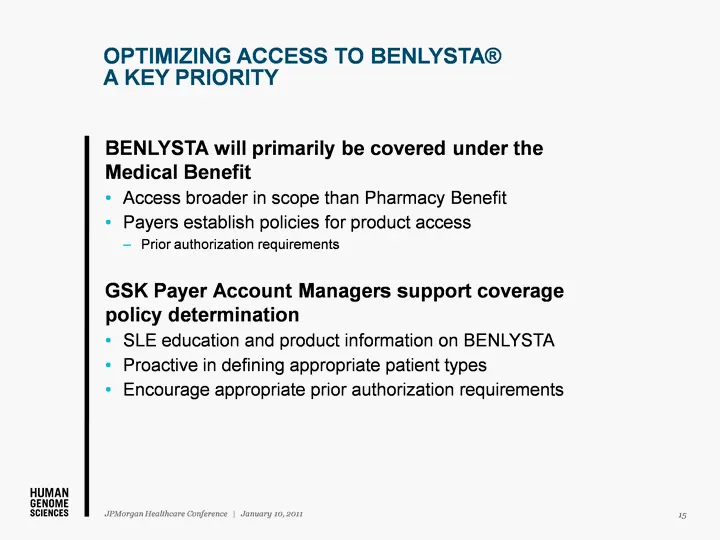
Slide 15: Optimizing Access to BENLYSTA a Key Priority
OPTIMIZING ACCESS TO BENLYSTA(r) A KEY PRIORITY BENLYSTA will primarily be covered under the Medical Benefit Access broader in scope than Pharmacy Benefit Payers establish policies for product access Prior authorization requirements GSK Payer Account Managers support coverage policy determination SL
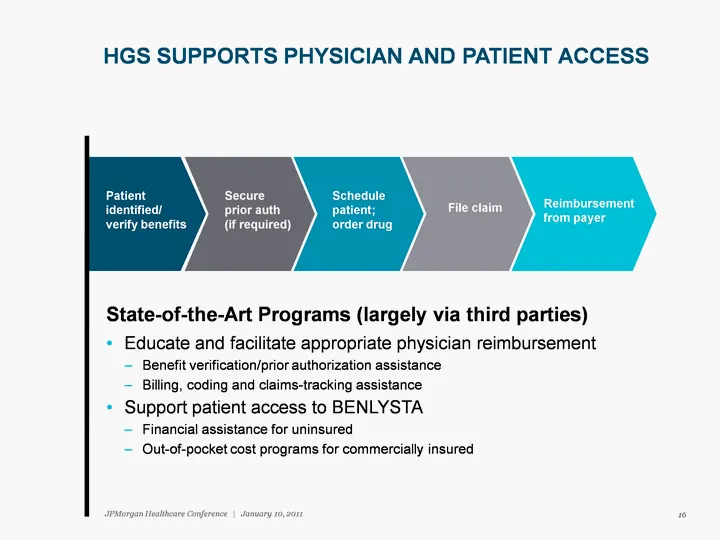
Slide 16: HGS Supports Physician and Patient Access
Patient identified/ verify benefits Secure prior auth (if required) Schedule patient; order drug File claim Reimbursement from payer HGS SUPPORTS PHYSICIAN AND PATIENT ACCESS State-of-the-Art Programs (largely via third parties) Educate and facilitate appropriate physician reimbursement Benefit veri
Slide 17: Pricing BENLYSTA Right for the Market
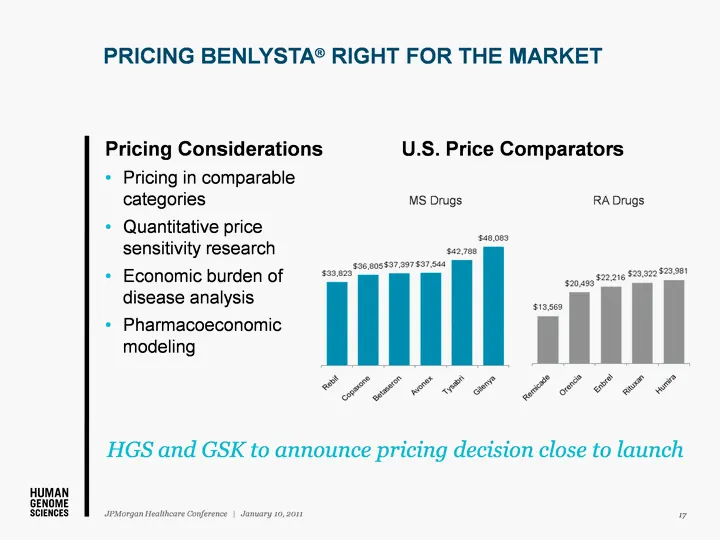
PRICING BENLYSTA(r) RIGHT FOR THE MARKET Pricing Considerations Pricing in comparable categories Quantitative price sensitivity research Economic burden of disease analysis Pharmacoeconomic modeling U.S. Price Comparators HGS and GSK to announce pricing decision close to launch MS Drugs RA Drugs 17
Slide 18: Manufacturing Supply to Meet Demand
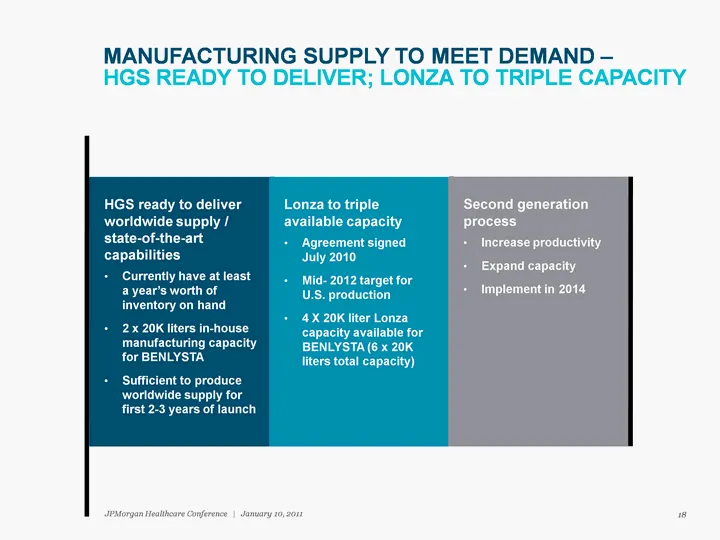
MANUFACTURING SUPPLY TO MEET DEMAND - HGS READY TO DELIVER; LONZA TO TRIPLE CAPACITY 18 JPMorgan Healthcare Conference | January 10, 2011
Slide 19: BENLYSTA Long Term Opportunity
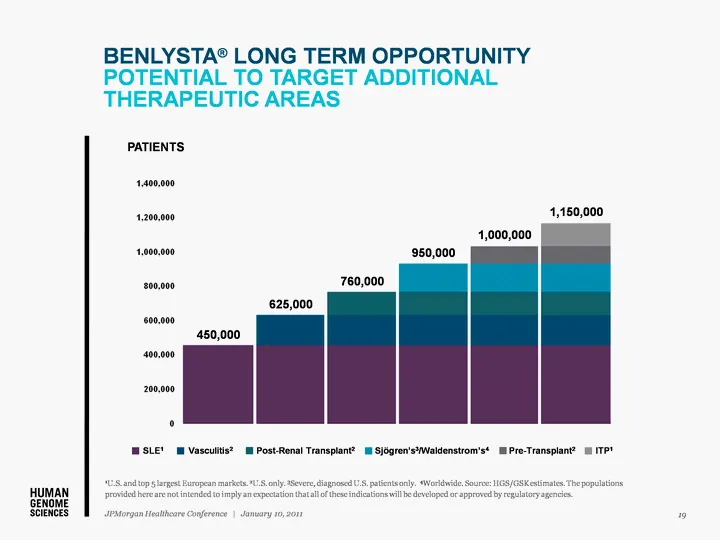
BENLYSTA(r) LONG TERM OPPORTUNITY POTENTIAL TO TARGET ADDITIONAL THERAPEUTIC AREAS 19 JPMorgan Healthcare Conference | January 10, 2011 1U.S. and top 5 largest European markets. 2U.S. only. 3Severe, diagnosed U.S. patients only. 4Worldwide. Source: HGS/GSK estimates. The populations provided here ar
Slide 20: Broad Potential Beyond Initial Market Entry in SLE
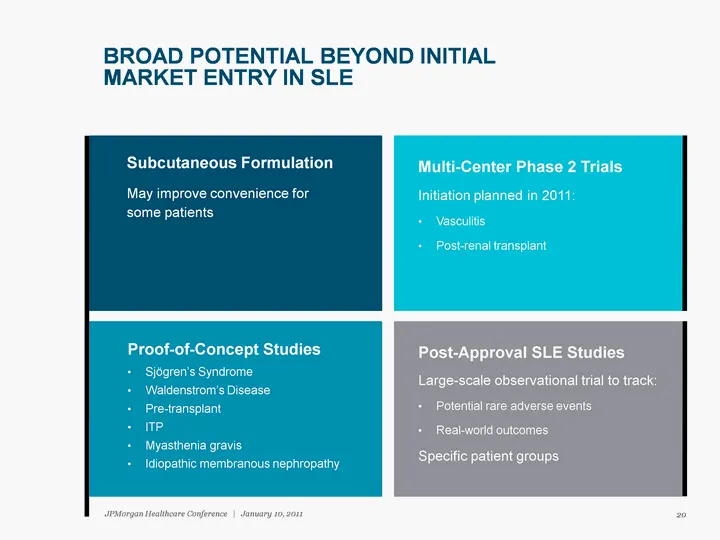
Proof-of-Concept Studies Sjogren's Syndrome Waldenstrom's Disease Pre-transplant ITP Myasthenia gravis Idiopathic membranous nephropathy BROAD POTENTIAL BEYOND INITIAL MARKET ENTRY IN SLE Subcutaneous Formulation May improve convenience for some patients Multi-Center Phase 2 Trials Initiation planne
Slide 21: Beyond
Beyond 21 JPMorgan Healthcare Conference | January 10, 2011
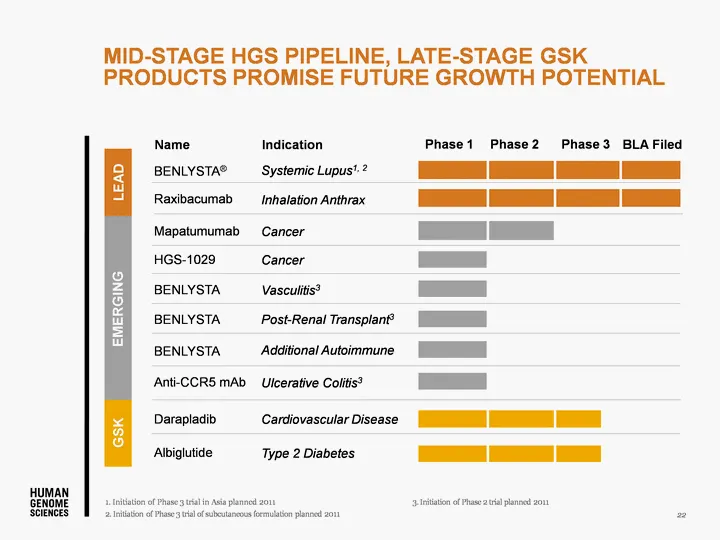
Slide 22: Mid-Stage HGS Pipeline, Late-Stage GSK Products
MID-STAGE HGS PIPELINE, LATE-STAGE GSK PRODUCTS PROMISE FUTURE GROWTH POTENTIAL 22 BENLYSTA(r) Anti-CCR5 mAb HGS-1029 BENLYSTA BENLYSTA BENLYSTA Raxibacumab Mapatumumab Darapladib Systemic Lupus1, 2 Ulcerative Colitis3 Cancer Additional Autoimmune Vasculitis3 Post-Renal Transplant3 Inhalation Anthra
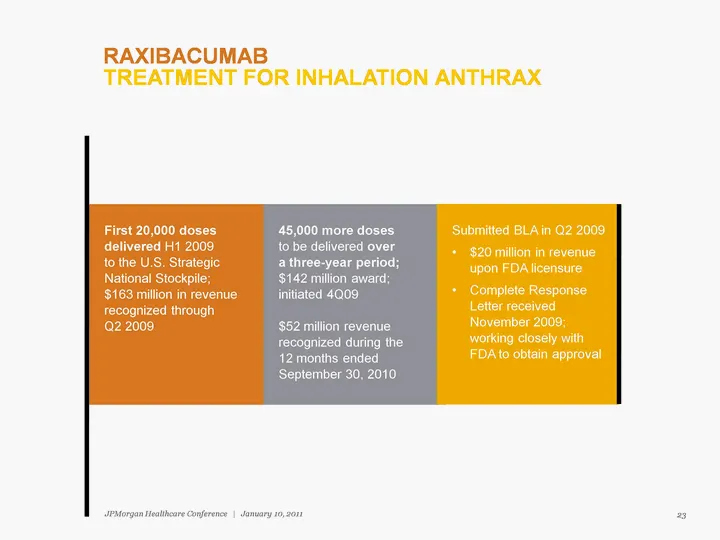
Slide 23: Raxibacumab Treatment for Inhalation Anthrax
First 20,000 doses delivered H1 2009 to the U.S. Strategic National Stockpile; $163 million in revenue recognized through Q2 2009 45,000 more doses to be delivered over a three-year period; $142 million award; initiated 4Q09 $52 million revenue recognized during the 12 months ended September 30, 201
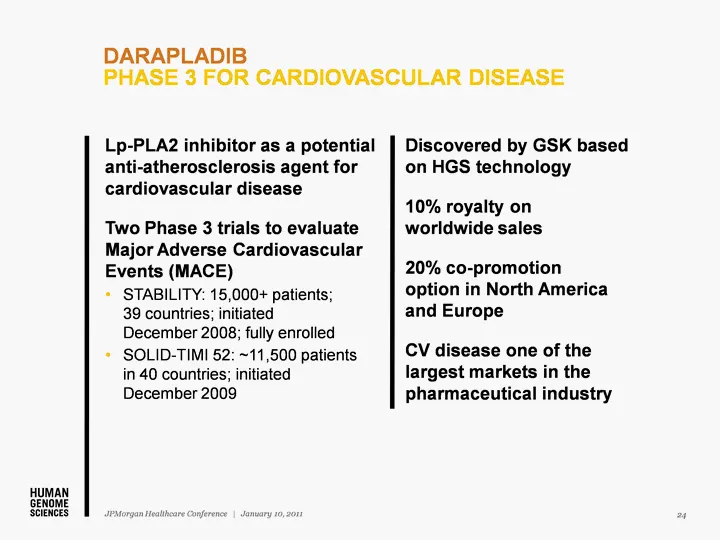
Slide 24: Darapladib Phase 3 for Cardiovascular Disease
Discovered by GSK based on HGS technology 10% royalty on worldwide sales 20% co-promotion option in North America and Europe CV disease one of the largest markets in the pharmaceutical industry DARAPLADIB PHASE 3 FOR CARDIOVASCULAR DISEASE 24 JPMorgan Healthcare Conference | January 10, 2011 Lp-PLA2
Slide 25: Albiglutide Phase 3 for Type 2 Diabetes
Licensed to GSK Fees and milestone payments up to $183 million; up to $150 million still to be received Single-digit net royalties on worldwide sales Approximately 17.9 million diagnosed type 2 diabetes patients in the U.S.1 ALBIGLUTIDE PHASE 3 FOR TYPE 2 DIABETES 25 JPMorgan Healthcare Conference |
Slide 26: TRAIL Pathway Offers Therapeutic Opportunities Across Cancers
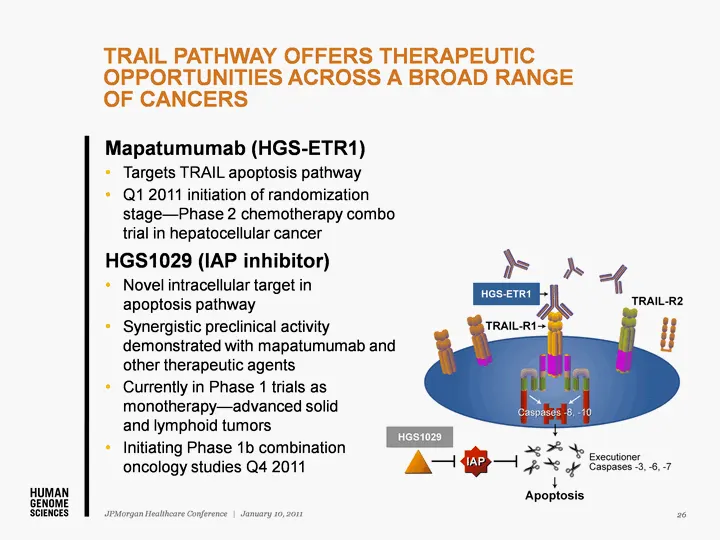
TRAIL PATHWAY OFFERS THERAPEUTIC OPPORTUNITIES ACROSS A BROAD RANGE OF CANCERS 26 JPMorgan Healthcare Conference | January 10, 2011 Mapatumumab (HGS-ETR1) Targets TRAIL apoptosis pathway Q1 2011 initiation of randomization stage-Phase 2 chemotherapy combo trial in hepatocellular cancer HGS1029 (IAP
Slide 27: Strong Financial Position to Fuel Product Launches
Cash and investments at Sept 30, 2010: $1.0 billion Expected net cash burn 2010: $300-$350 million Expected cash and investments at year-end 2010: $900-950 million Products Nearing Commercialization High-Potential Pipeline STRONG FINANCIAL POSITION TO FUEL PRODUCT LAUNCHES, PIPELINE ADVANCEMENT 27 J
Slide 28: A Formula for Sustainable Growth
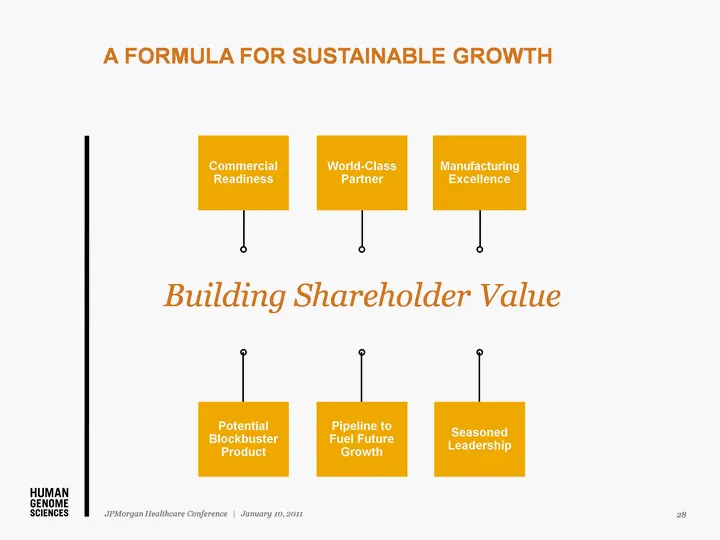
Potential Blockbuster Product Pipeline to Fuel Future Growth Manufacturing Excellence Commercial Readiness World-Class Partner Seasoned Leadership A FORMULA FOR SUSTAINABLE GROWTH 28 JPMorgan Healthcare Conference | January 10, 2011 Building Shareholder Value
Slide 29: The End
The End 29
Source: SEC EDGAR · 8-K filed Jan 10, 2011
More decks from Human Genome Sciences Inc
 Corporate Update (April 2012)15 slides · Apr 24, 2012
 JP Morgan Healthcare Conference 201229 slides · Jan 9, 2012
 Investor Presentation (November 2011)26 slides · Nov 10, 2011
 Investor Presentation (September 2011)25 slides · Sep 8, 2011
 Investor Day (April 2011)59 slides · Apr 14, 2011
 American College of Rheumatology (ACR) 74th Annual Scientific Meeting 201010 slides · Nov 8, 2010