Genomma Lab Internacional SAB de CV Class B · BMV:LAB/B
Genomma Lab Internacional SAB de CV Class B — Investor Day (September 2015)
58 slides from Genomma Lab Internacional SAB de CV Class B's investor day presentation, Sep 29, 2015
Slide 1: Genomma Lab Day
GENOMMA LAB DAY September 29, 2015
Slide 2: Agenda
AGENDA 1 Company’s Strategy and Core Competences 2 Changes in Corporate Structure 3 Track Record – Results in International Operations 4 Diversification 5 U.S.A. 6 Mexico 7 LATAM 8 Valuation, Core Brands and Learning from the Past 9 Guidance
Slide 3: Company's Strategy and Core Competences
COMPANY’S STRATEGY AND CORE COMPETENCES 3
Slide 4: Strategy: Core Competences
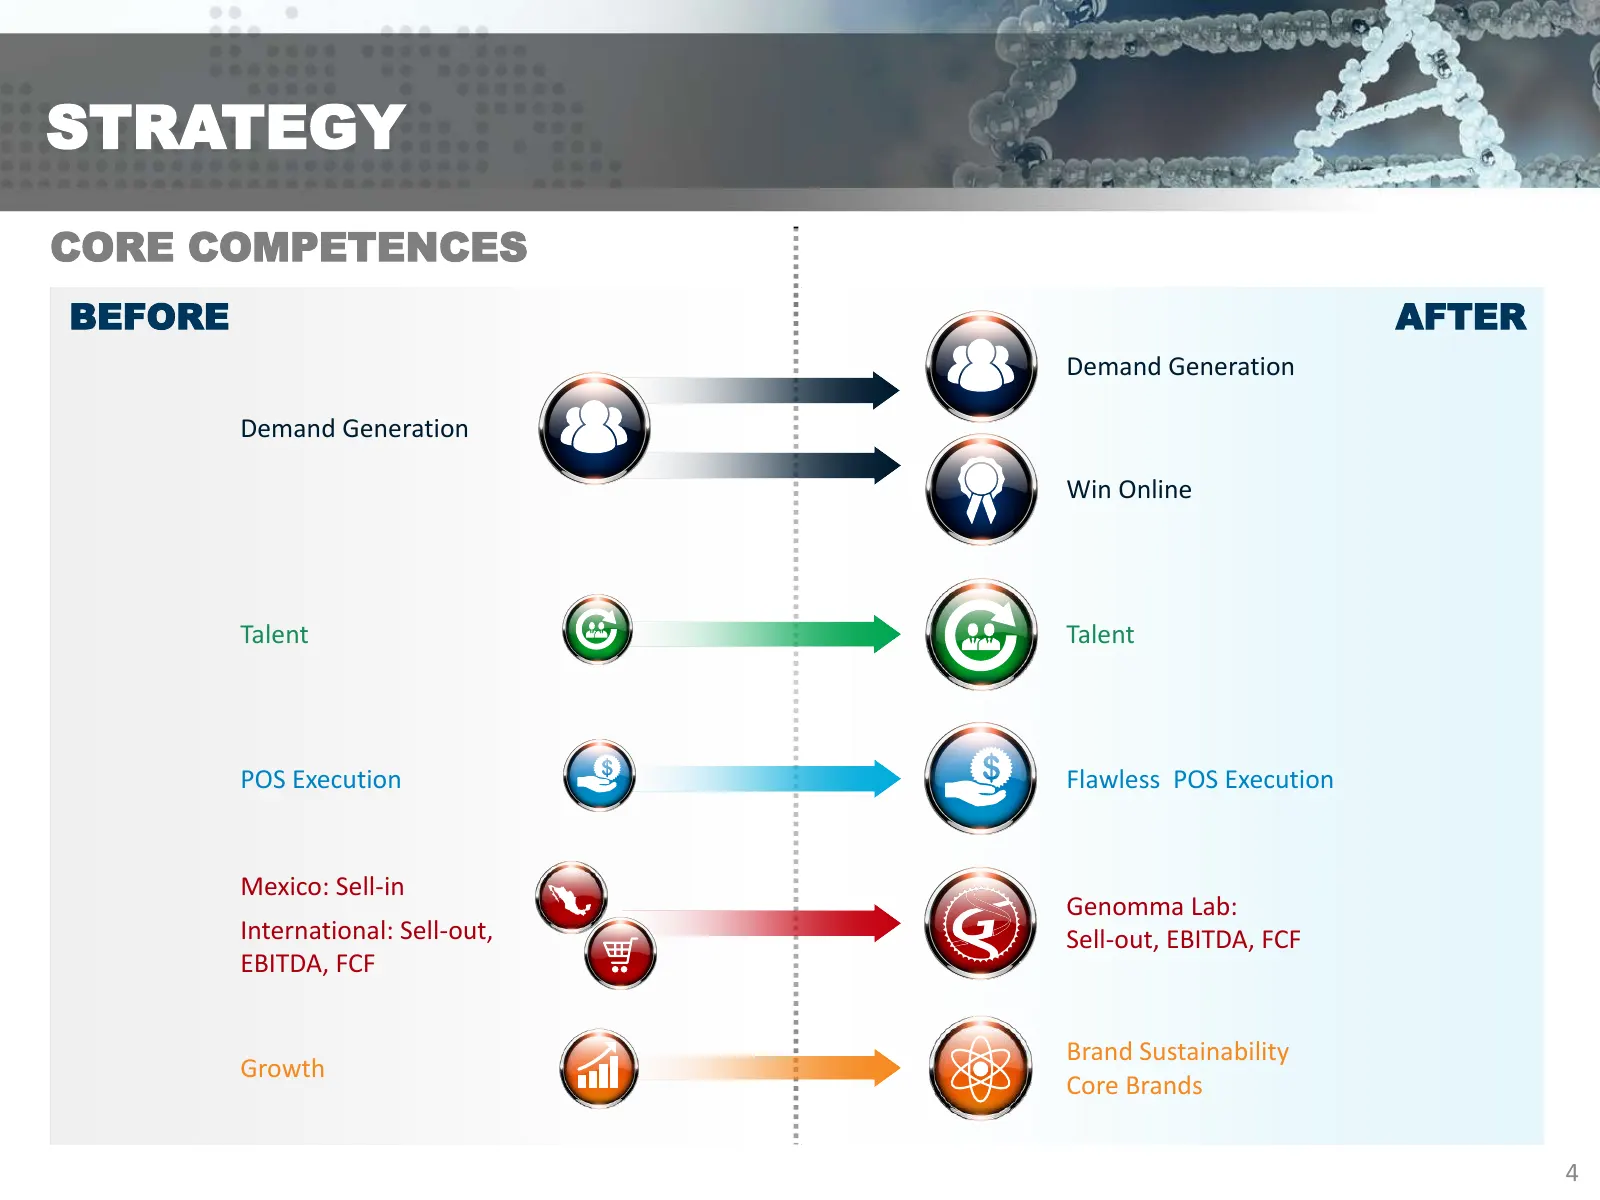
STRATEGY CORE COMPETENCES BEFORE AFTER Demand Generation Demand Generation Win Online Talent Talent POS Execution Flawless POS Execution Mexico: Sell-in Genomma Lab: International: Sell-out, Sell-out, EBITDA, FCF EBITDA, FCF Brand Sustainability Growth Core Brands 4
Slide 5: Changes in Corporate Structure
CHANGES IN CORPORATE STRUCTURE 5
Slide 6: New Corporate Structure
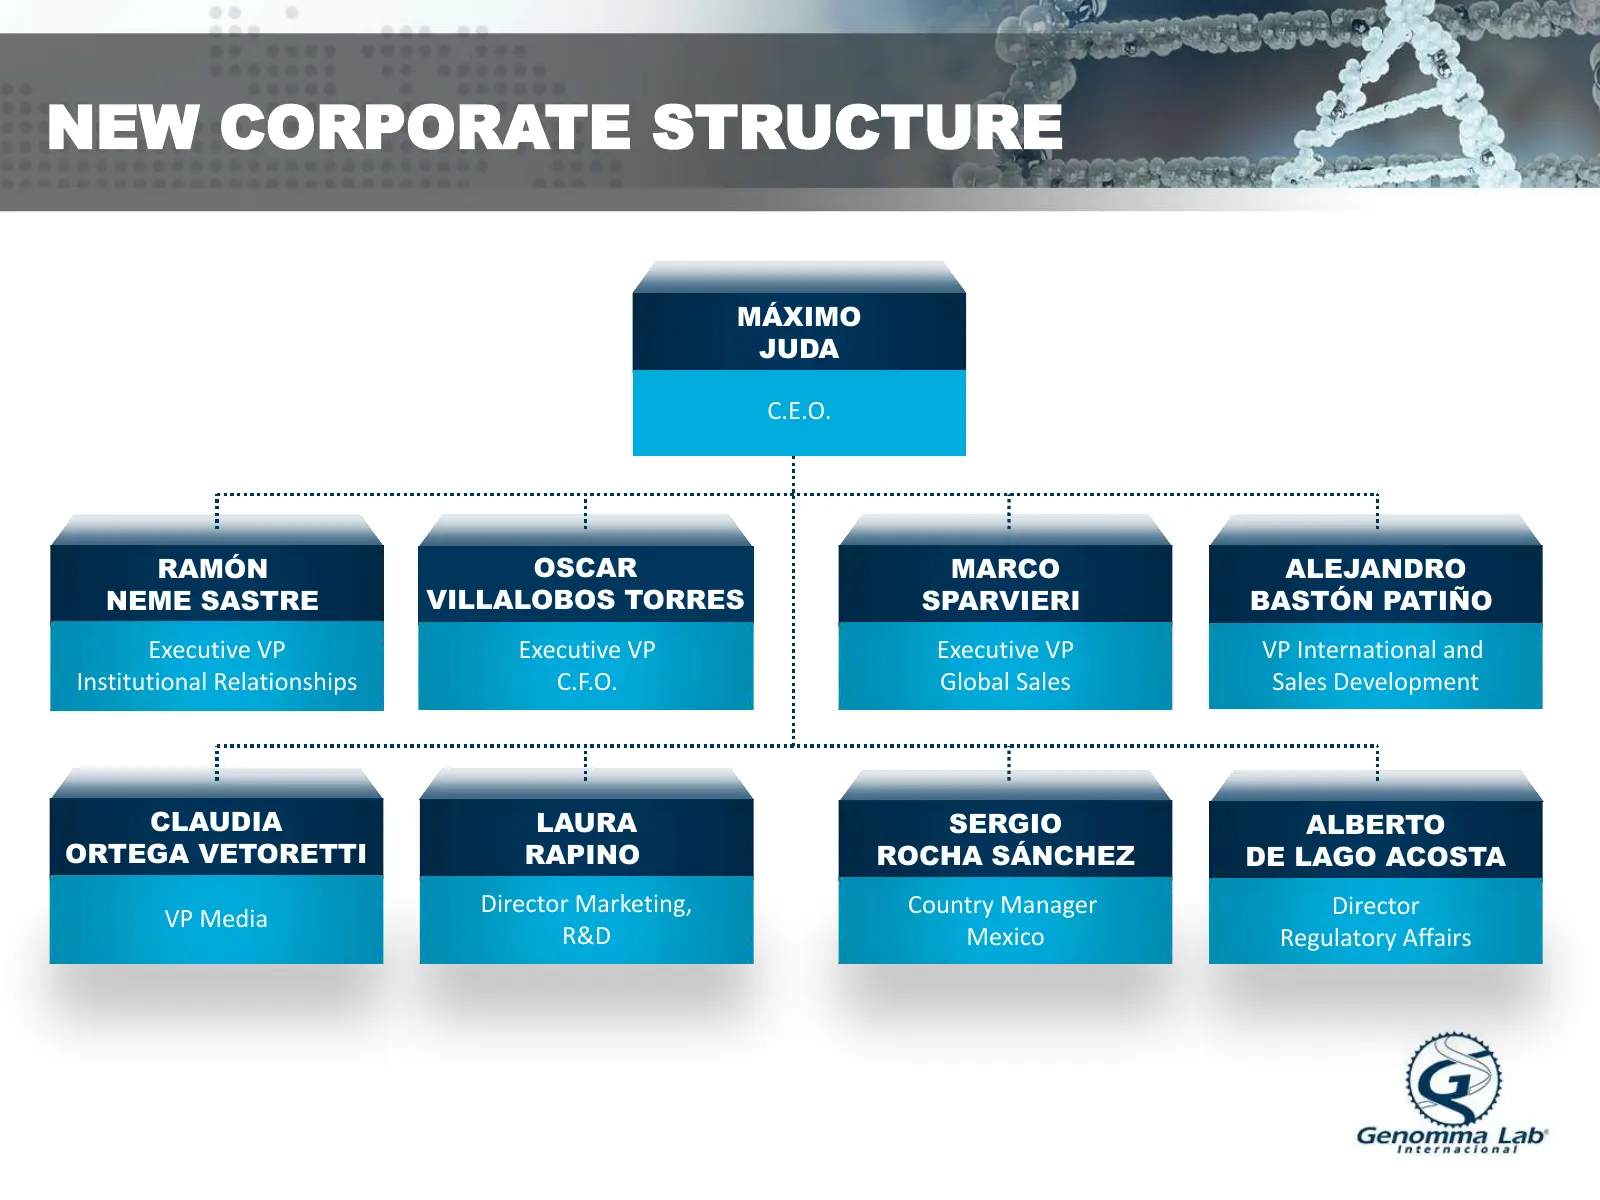
NEW CORPORATE STRUCTURE MÁXIMO JUDA C.E.O. RAMÓN OSCAR MARCO ALEJANDRO NEME SASTRE VILLALOBOS TORRES SPARVIERI BASTÓN PATIÑO Executive VP Executive VP Executive VP VP International and Institutional Relationships C.F.O. Global Sales Sales Development CLAUDIA LAURA SERGIO ALBERTO ORTEGA VETORETTI RAP
Slide 7: Recent Changes in Key Management Positions
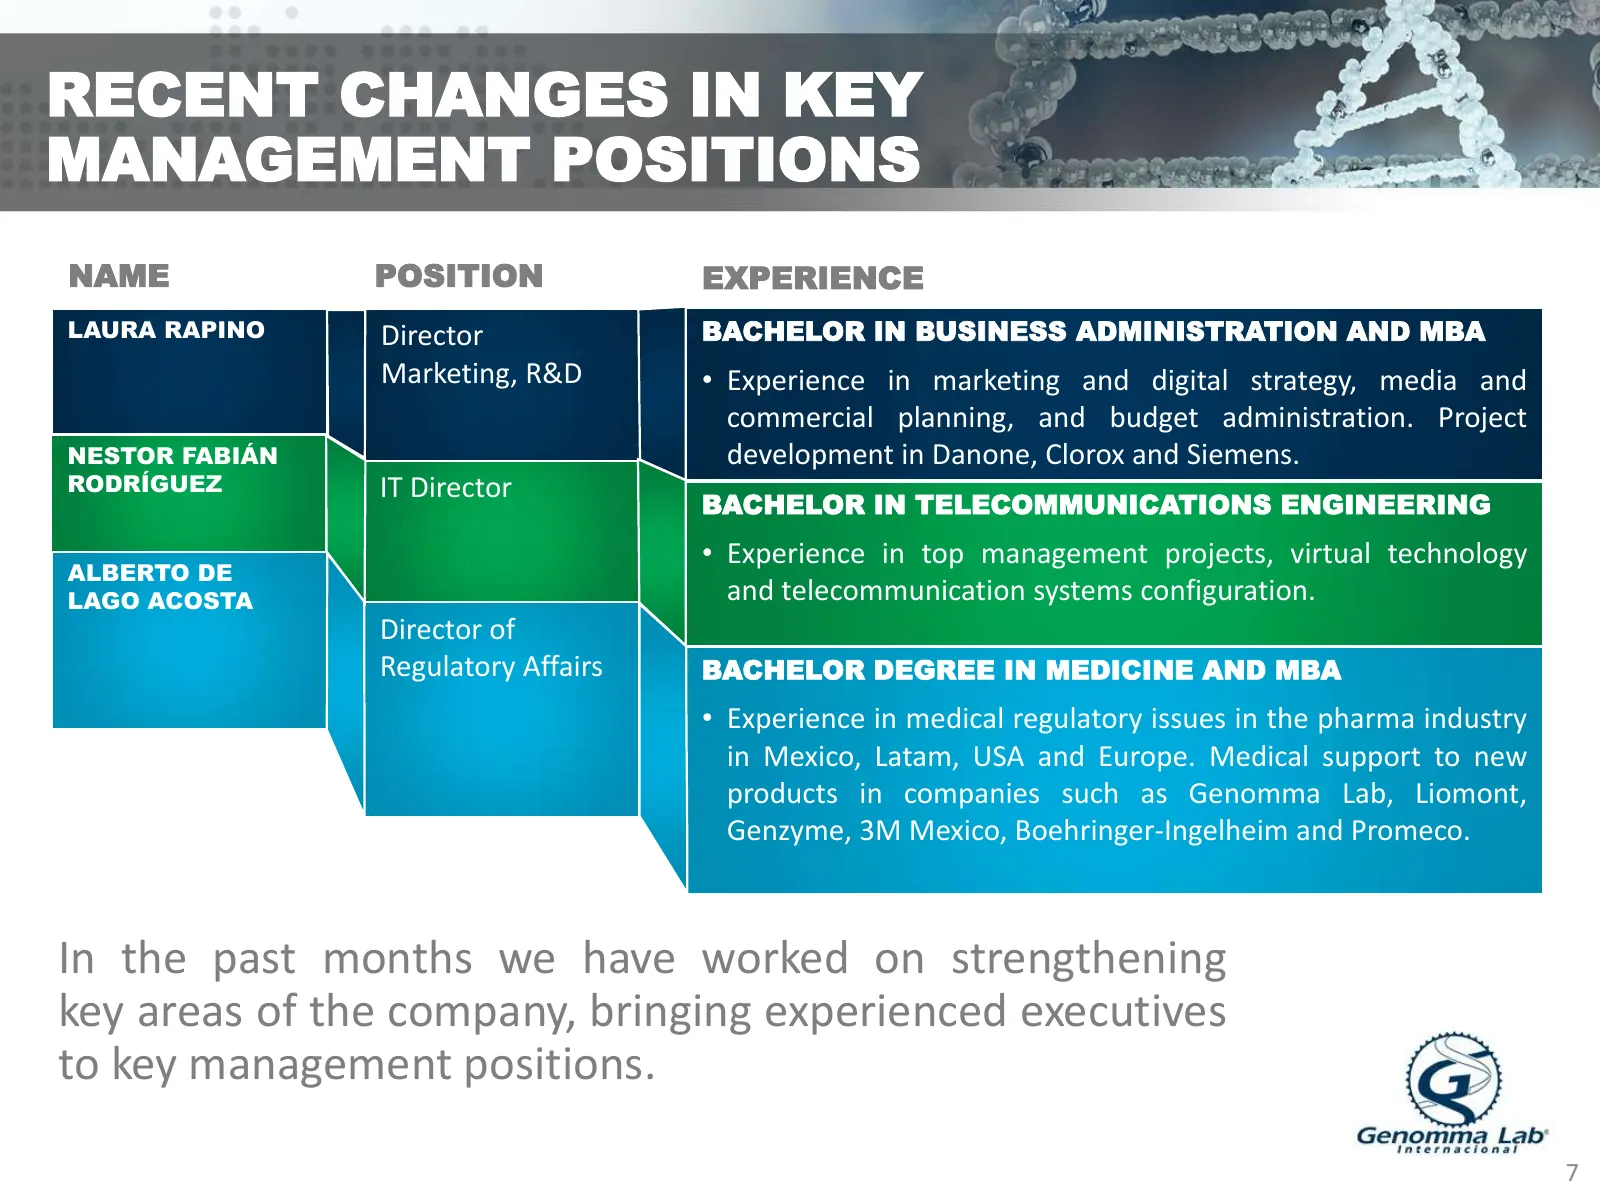
RECENT CHANGES IN KEY MANAGEMENT POSITIONS NAME POSITION EXPERIENCE LAURA RAPINO Director BACHELOR IN BUSINESS ADMINISTRATION AND MBA Marketing, R&D • Experience in marketing and digital strategy, media and commercial planning, and budget administration. Project NESTOR FABIÁN development in Danone,
Slide 8: Recent Changes in Key Management Positions
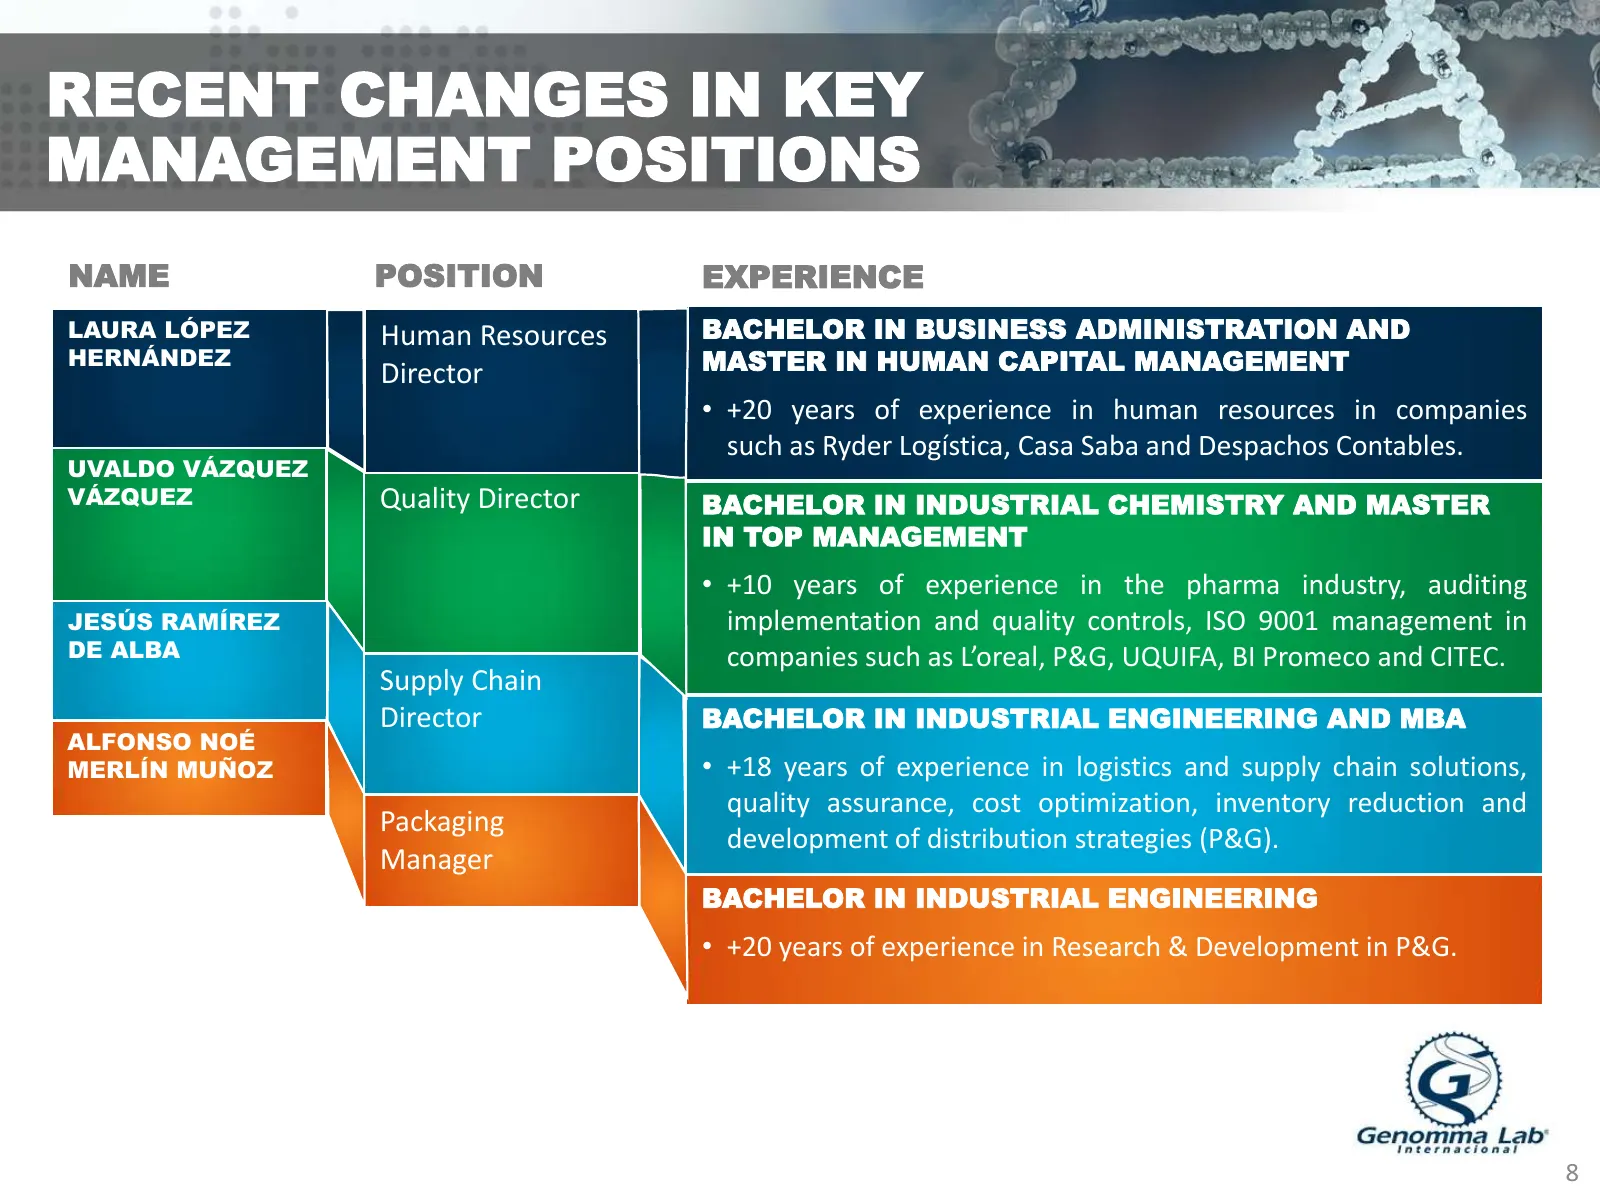
RECENT CHANGES IN KEY MANAGEMENT POSITIONS NAME POSITION EXPERIENCE LAURA LÓPEZ Human Resources BACHELOR IN BUSINESS ADMINISTRATION AND HERNÁNDEZ MASTER IN HUMAN CAPITAL MANAGEMENT Director • +20 years of experience in human resources in companies such as Ryder Logística, Casa Saba and Despachos Con
Slide 9: Rodrigo Herrera's Role
RODRIGO HERRERA’S ROLE MR. RODRIGO HERRERA ASPRA FOUNDER OF THE COMPANY AND CEO UNTIL JULY 23RD, 2015, IS CURRENTLY: • PRESIDENT of the Board • INCREASED his share of Genomma Lab from 25.9% to 29.9% in 1Q15 • PRESIDENT of the Operations Committee, meets quarterly • ADVISOR in Research & Development
Slide 10: Track Record - Results in International Operations
TRACK RECORD - RESULTS IN INTERNATIONAL OPERATIONS 10
Slide 11: Track Record: Colombia
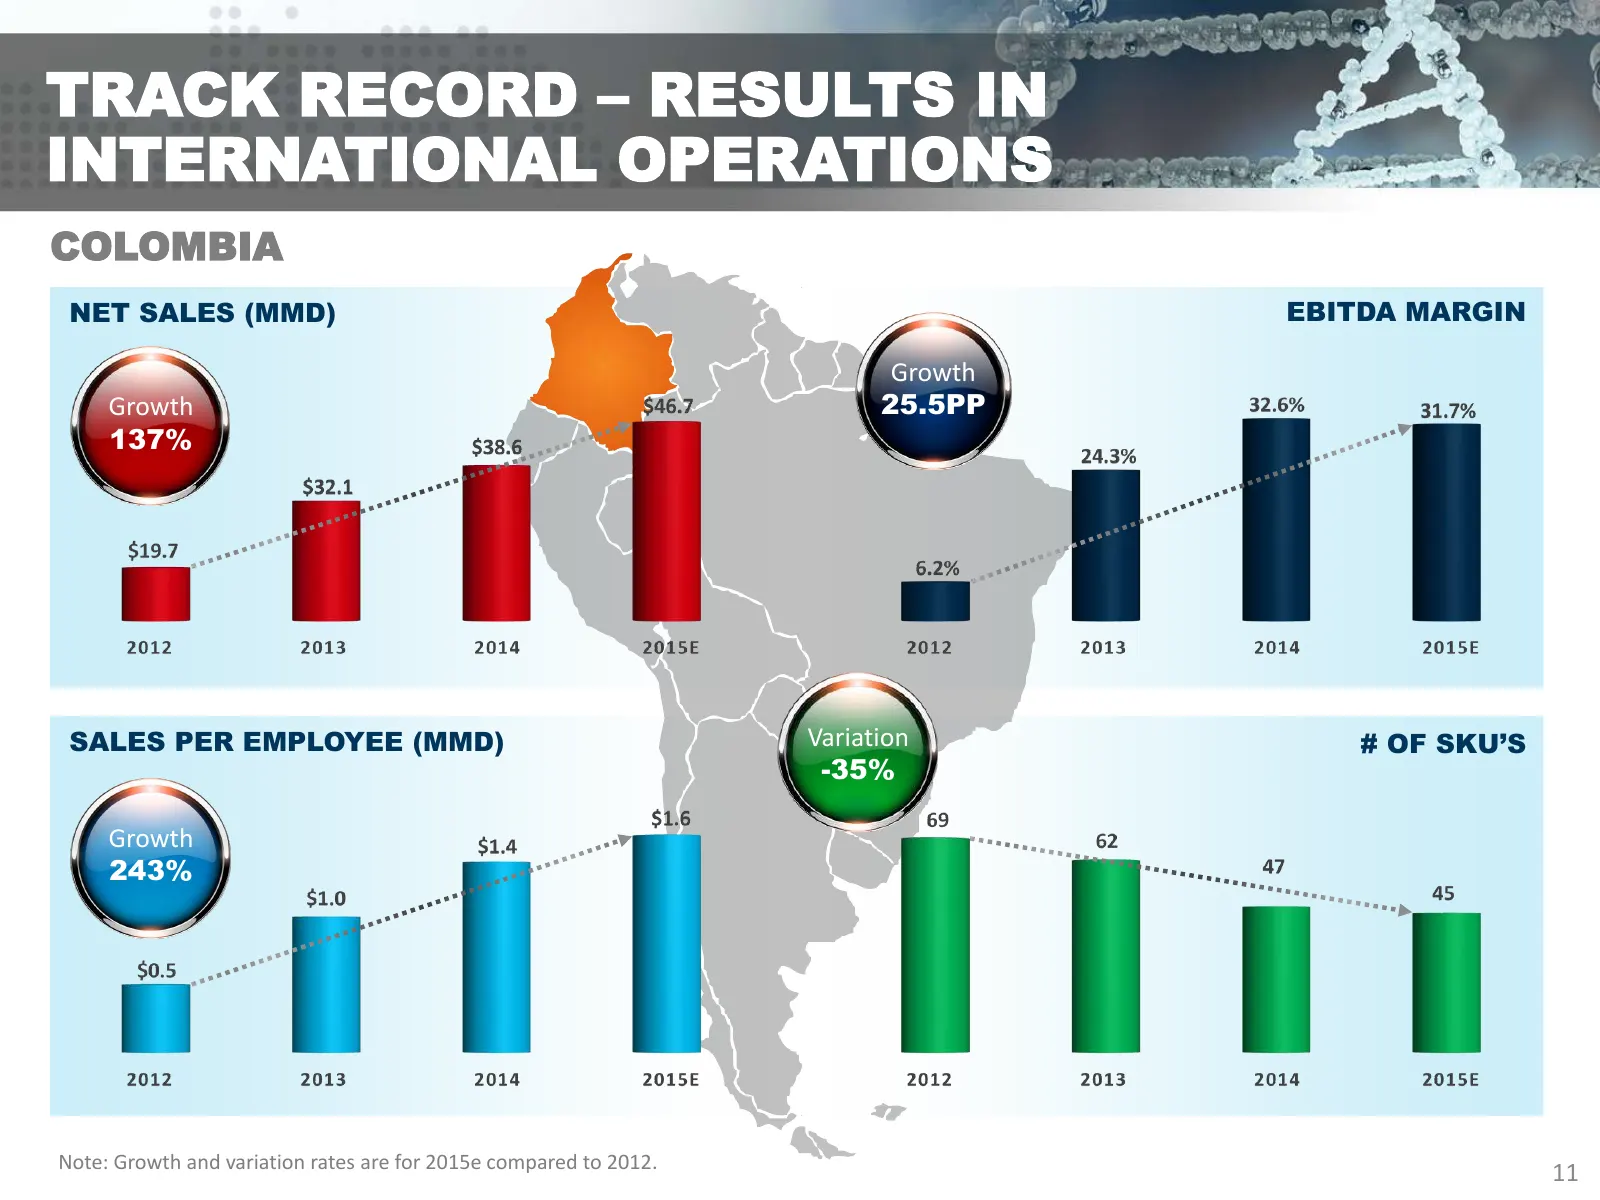
TRACK RECORD – RESULTS IN INTERNATIONAL OPERATIONS COLOMBIA NET SALES (MMD) EBITDA MARGIN Growth Growth 25.5PP 137% SALES PER EMPLOYEE (MMD) Variation # OF SKU’S -35% Growth 243% Note: Growth and variation rates are for 2015e compared to 2012. 11
Slide 12: Track Record: Peru
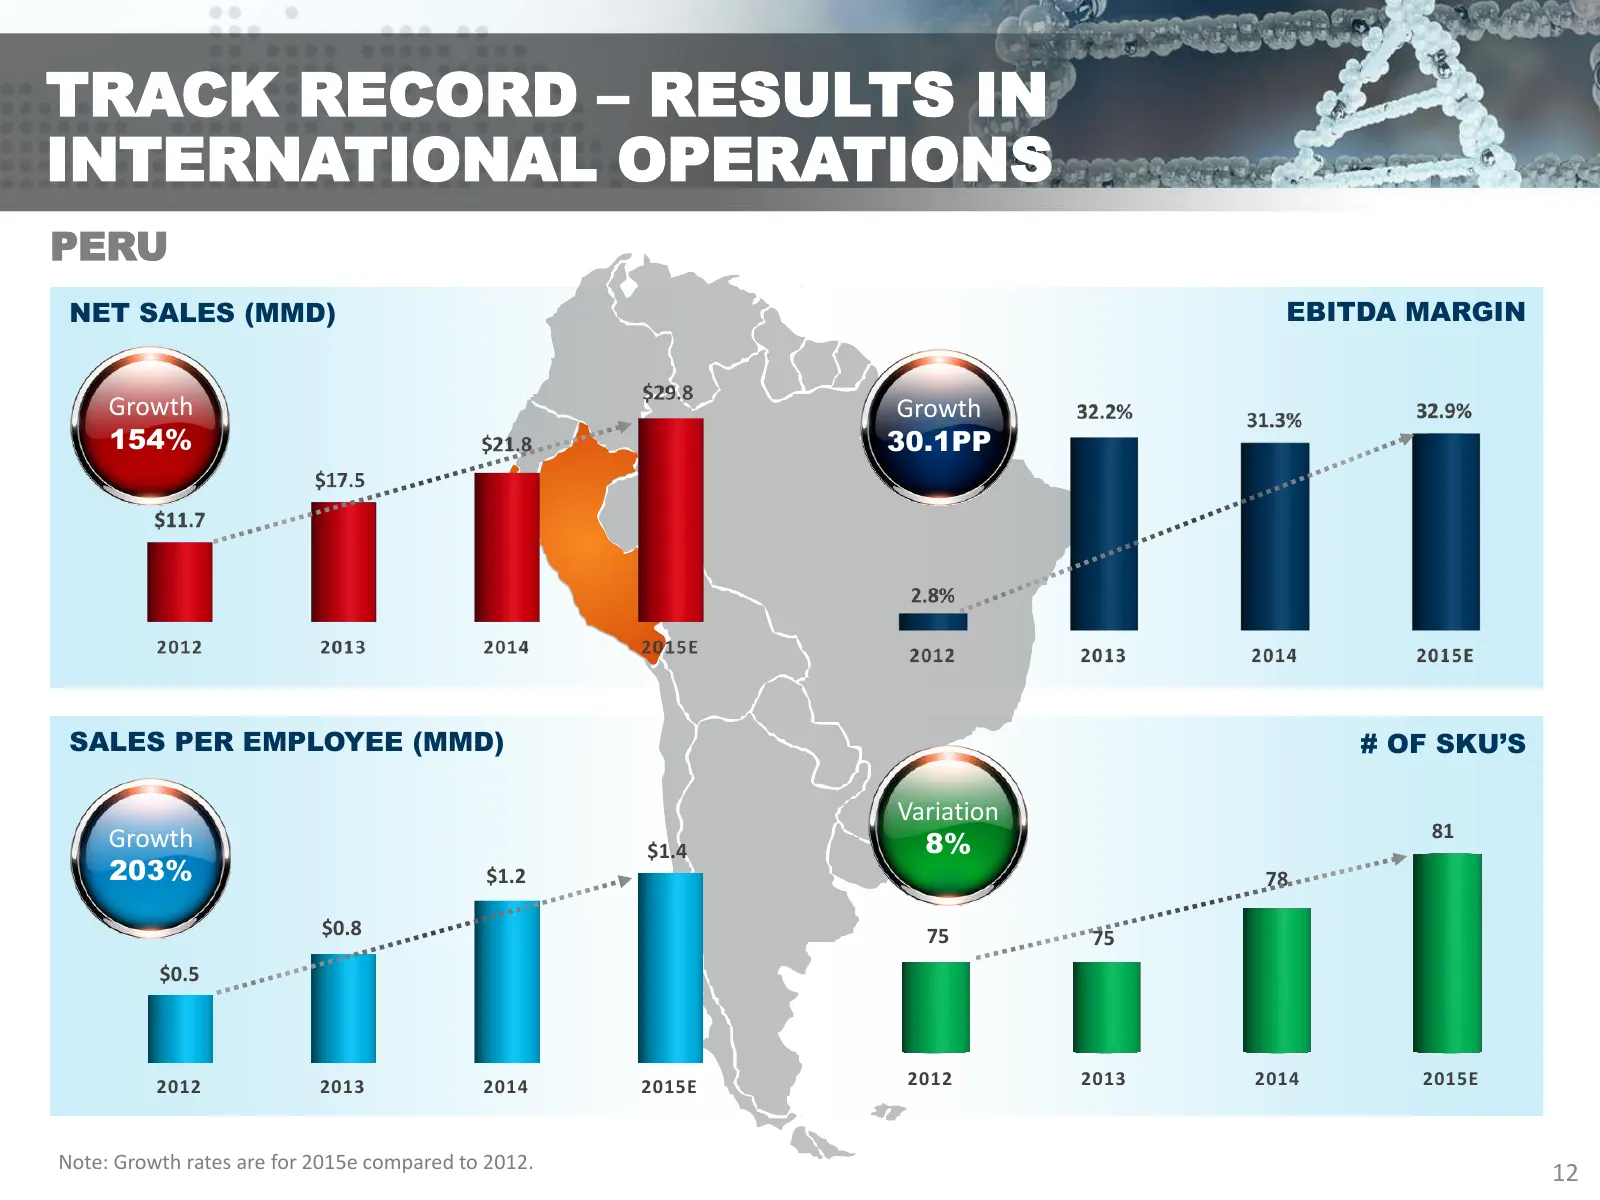
TRACK RECORD – RESULTS IN INTERNATIONAL OPERATIONS PERU NET SALES (MMD) EBITDA MARGIN Growth Growth 154% 30.1PP SALES PER EMPLOYEE (MMD) # OF SKU’S Variation 81 Growth $1.4 8% 203% $1.2 78 $0.8 75 75 $0.5 2012 2013 2014 2015E 2012 2013 2014 2015E Note: Growth rates are for 2015e compared to 2012. 12
Slide 13: Track Record: Chile
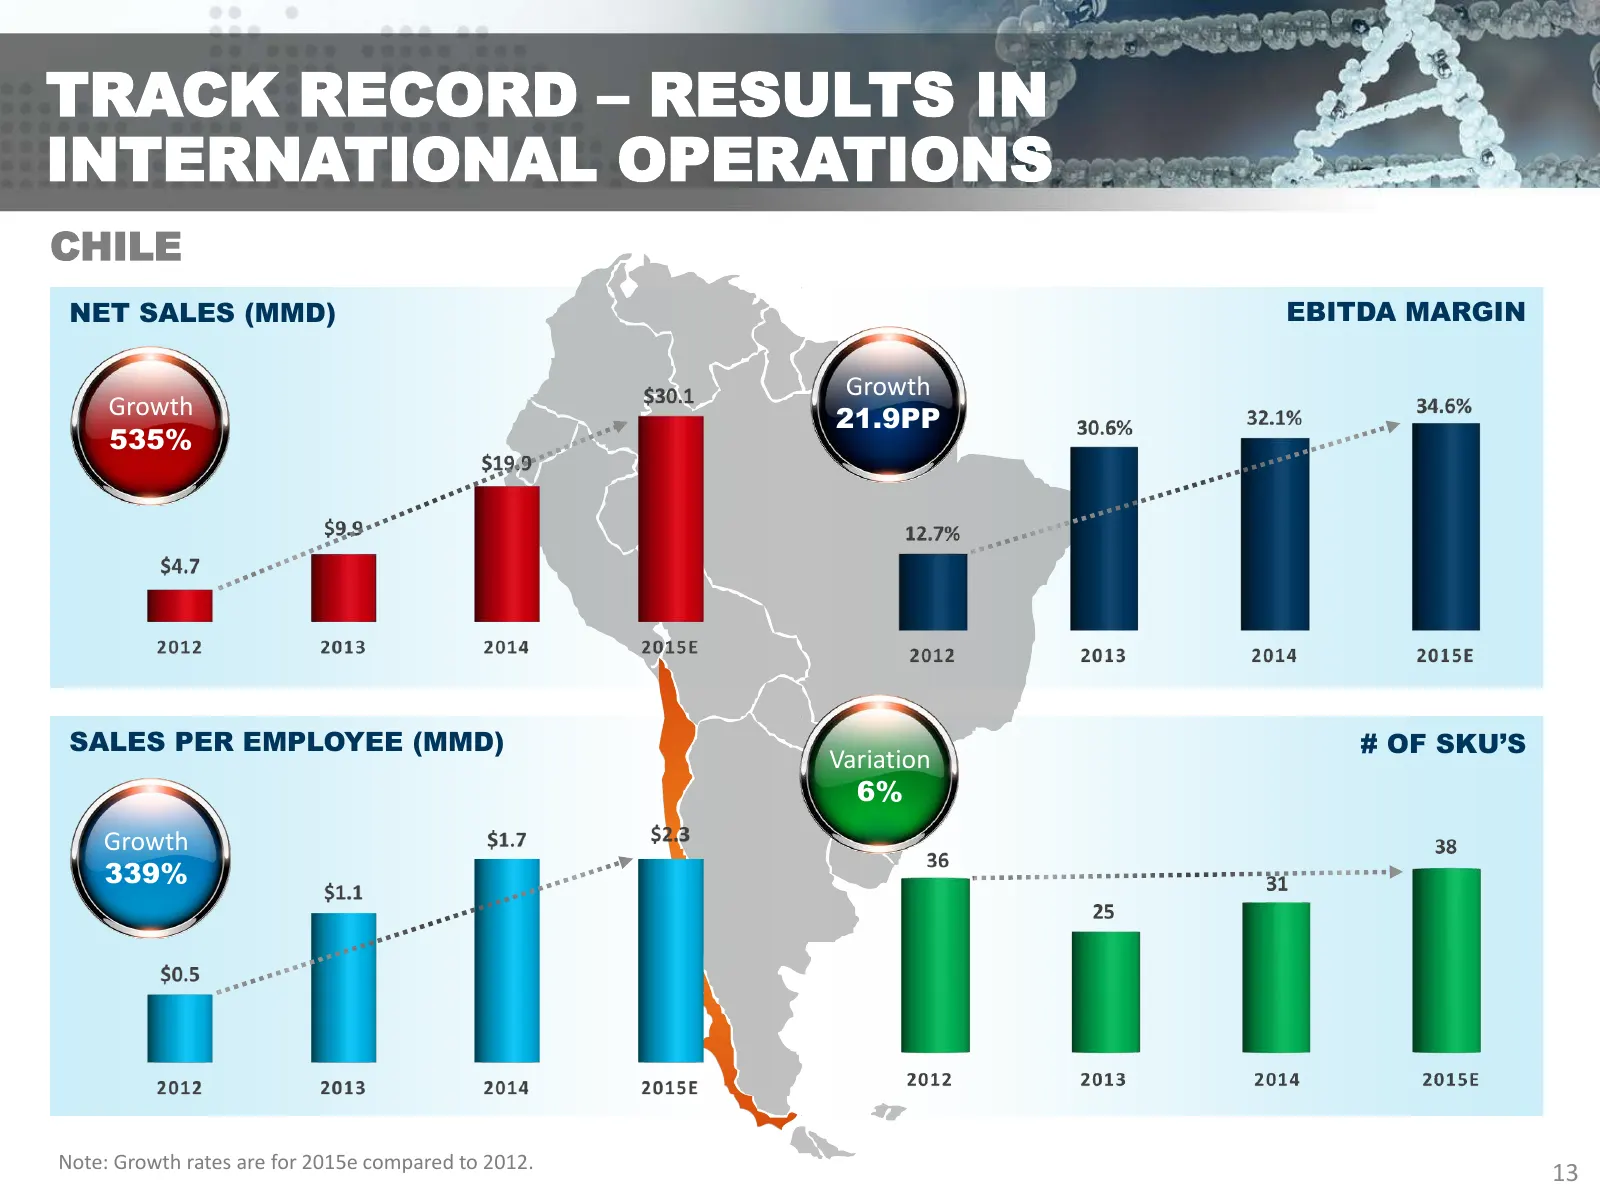
TRACK RECORD – RESULTS IN INTERNATIONAL OPERATIONS CHILE NET SALES (MMD) EBITDA MARGIN Growth Growth 21.9PP 535% SALES PER EMPLOYEE (MMD) # OF SKU’S Variation 6% Growth Growth 203% 339% Note: Growth rates are for 2015e compared to 2012. 13
Slide 14: Track Record: U.S.A.
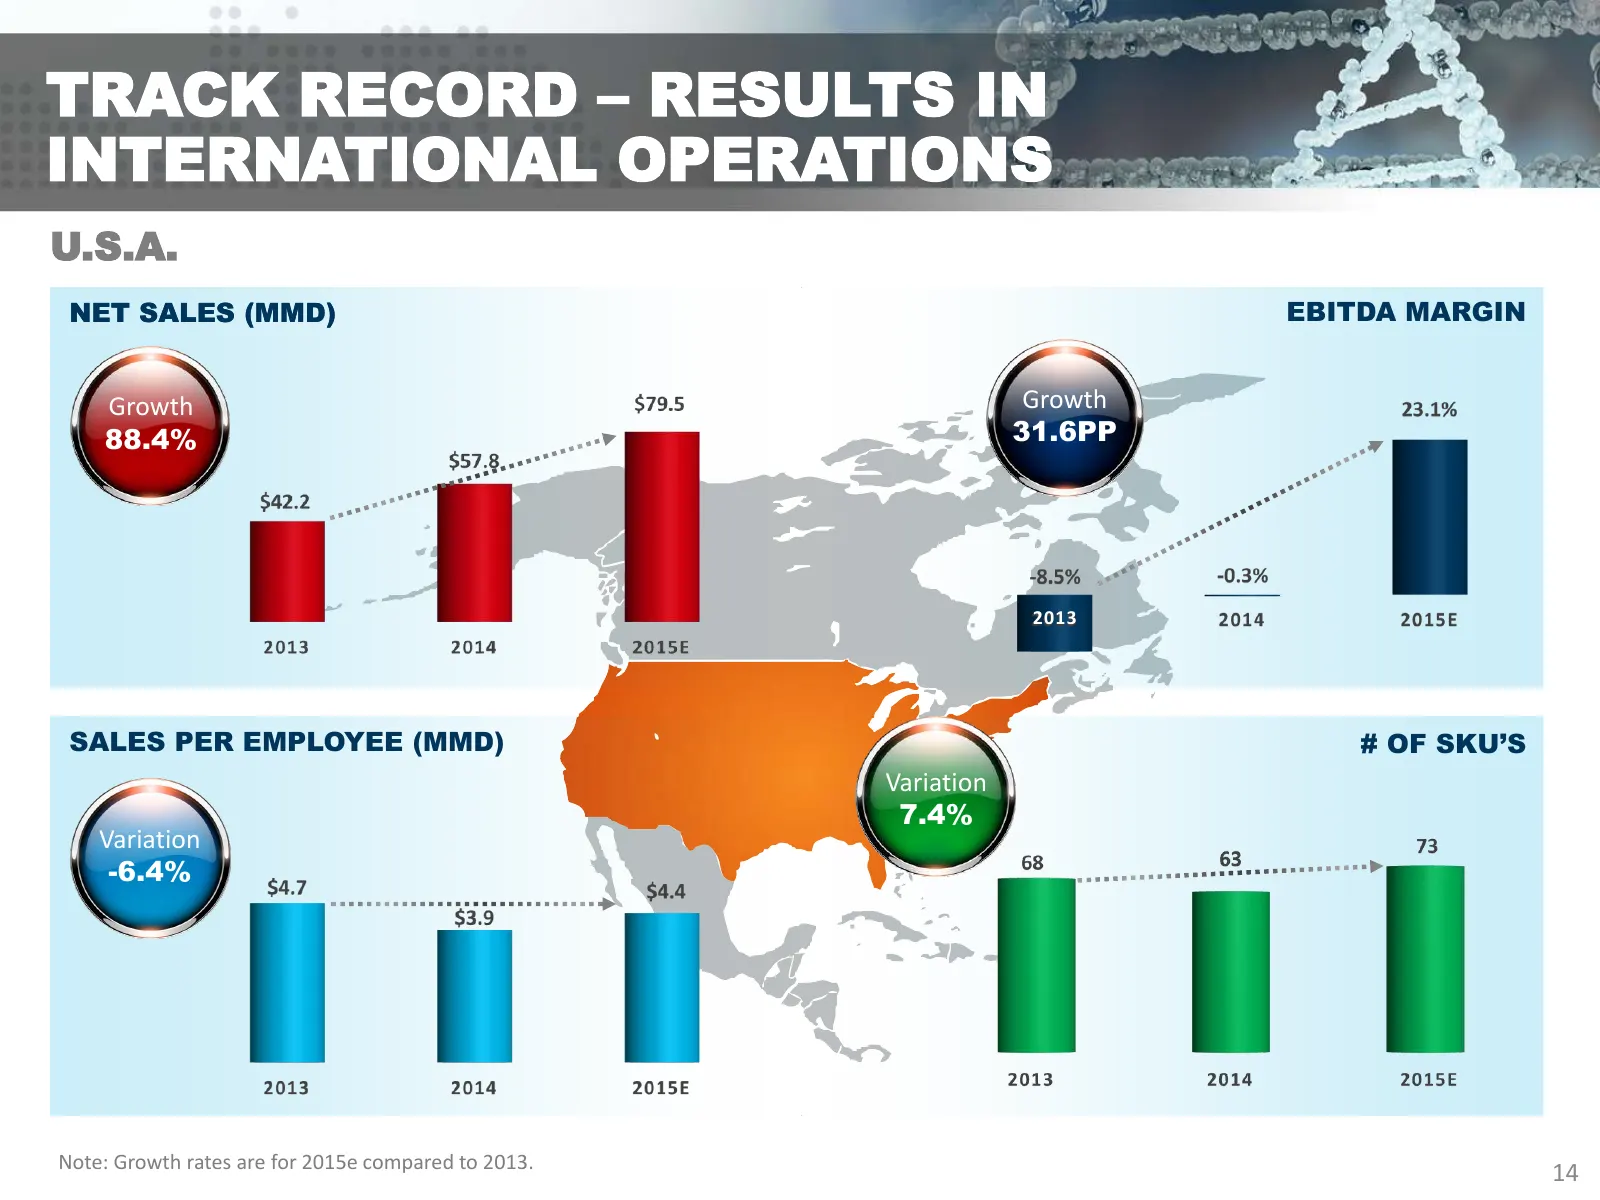
TRACK RECORD – RESULTS IN INTERNATIONAL OPERATIONS U.S.A. NET SALES (MMD) EBITDA MARGIN Growth Growth 88.4% 31.6PP 2013 SALES PER EMPLOYEE (MMD) # OF SKU’S Variation 7.4% Growth Variation 203% -6.4% Note: Growth rates are for 2015e compared to 2013. 14
Slide 15: Diversification
Genomma Lab‘ Internacional
Slide 16: Diversification
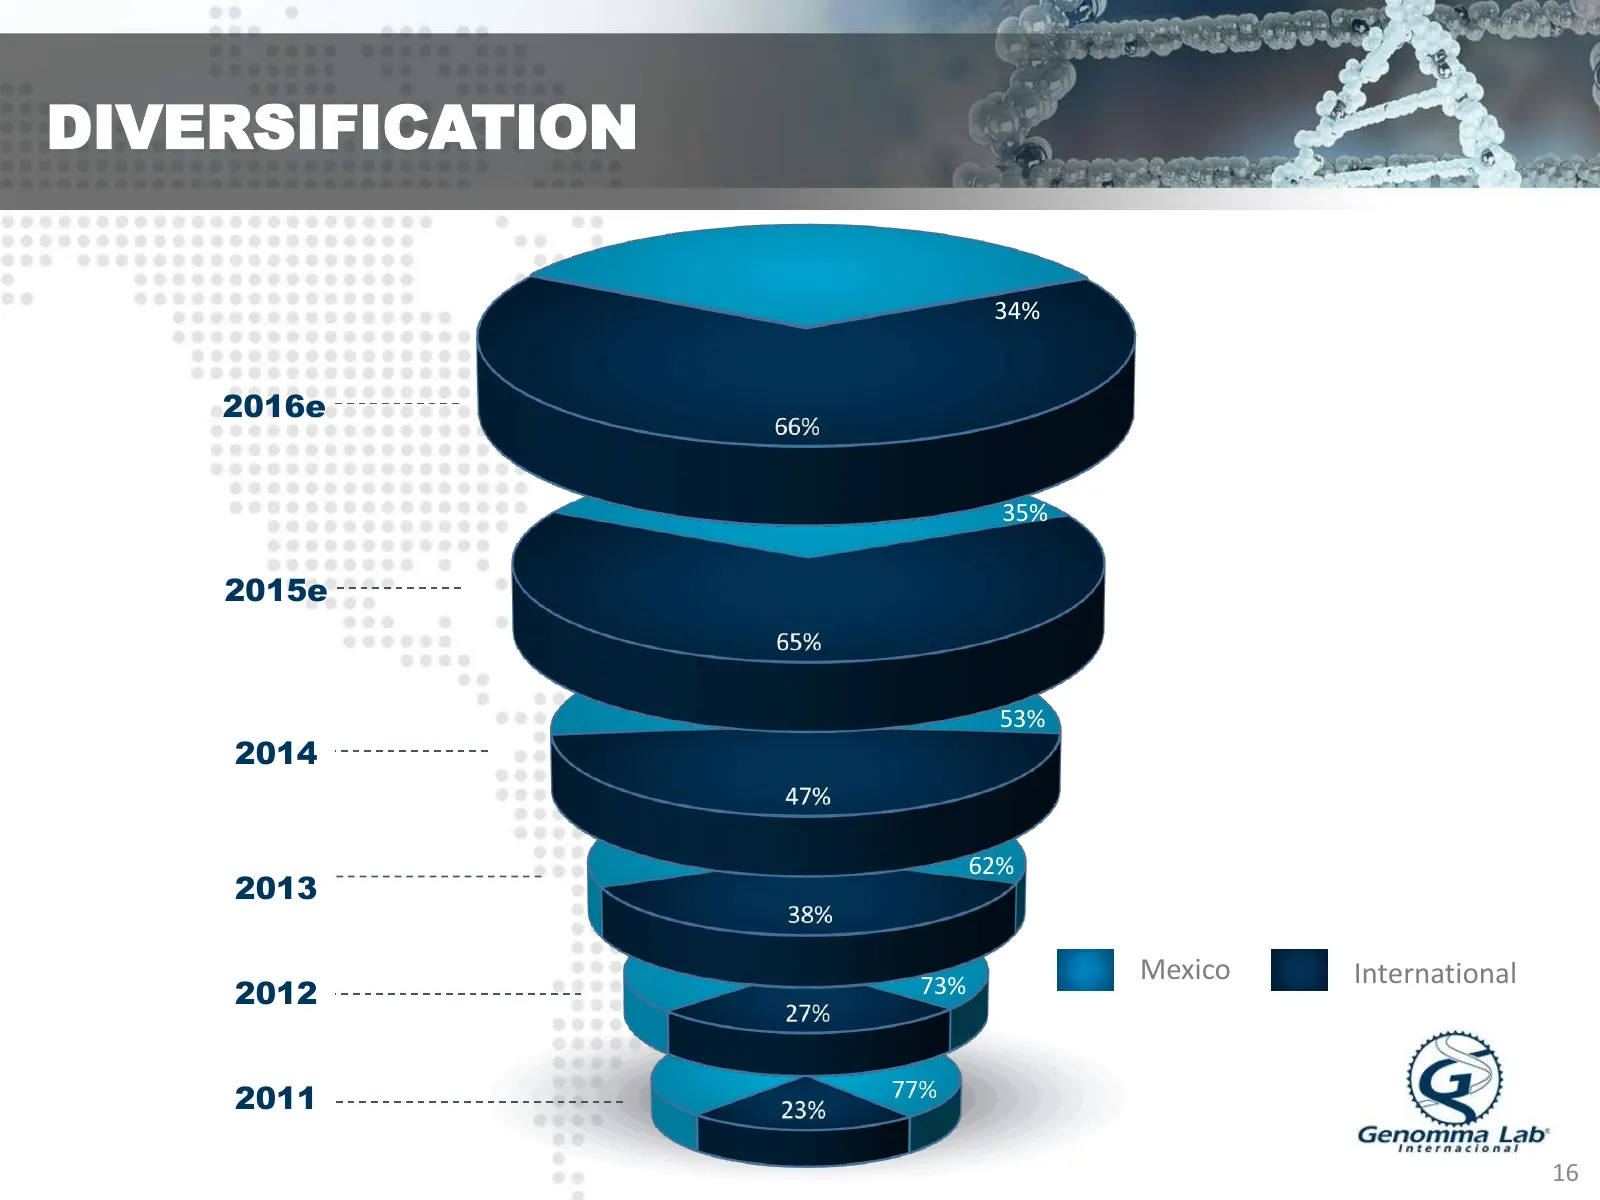
DIVERSIFICATION 34% 2016e 35% 2015e 53% 2014 62% 2013 Mexico International 2012 73% 2011 16
Slide 17: International Presence
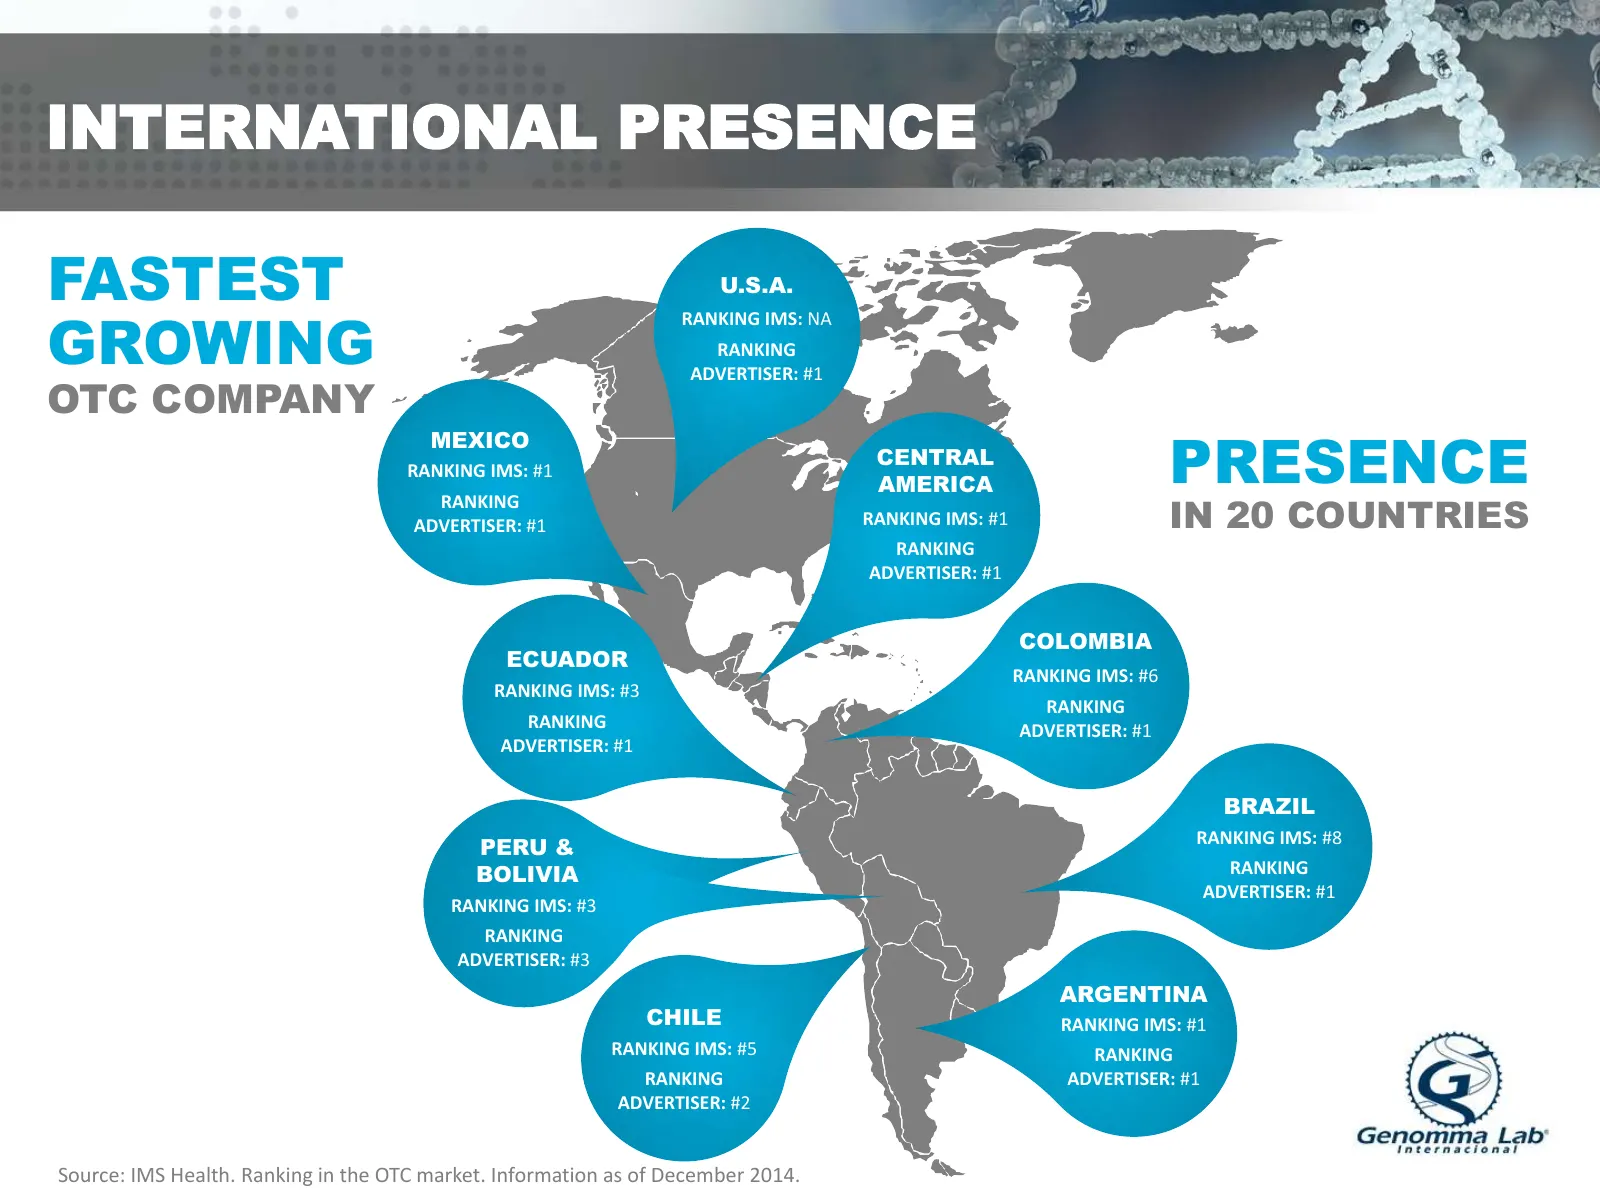
INTERNATIONAL PRESENCE FASTEST U.S.A. GROWING RANKING IMS: NA RANKING ADVERTISER: #1 OTC COMPANY PRESENCE MEXICO CENTRAL RANKING IMS: #1 AMERICA IN 20 COUNTRIES RANKING ADVERTISER: #1 RANKING IMS: #1 RANKING ADVERTISER: #1 COLOMBIA ECUADOR RANKING IMS: #6 RANKING IMS: #3 RANKING RANKING ADVERTISER:
Slide 18: Diversification Going Forward
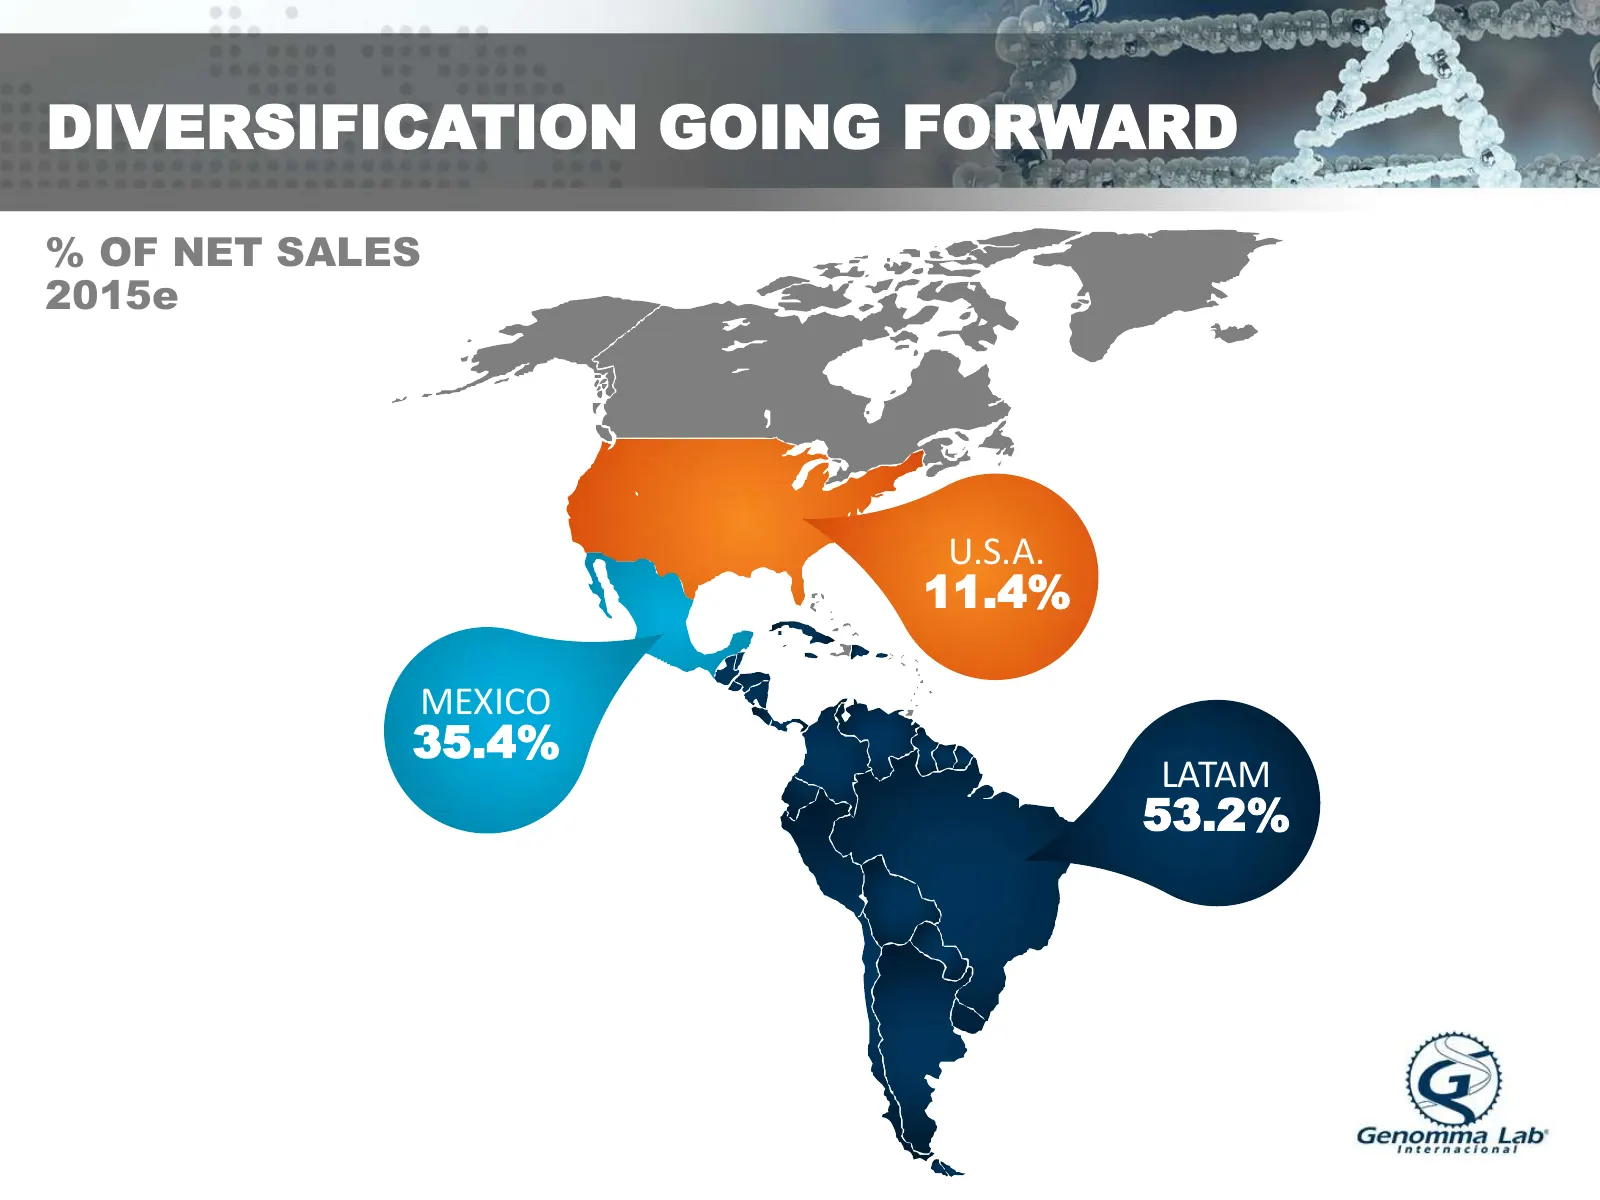
DIVERSIFICATION GOING FORWARD % OF NET SALES 2015e U.S.A. 11.4% MEXICO 35.4% LATAM 53.2%
Slide 19: Diversification vs. Other Companies
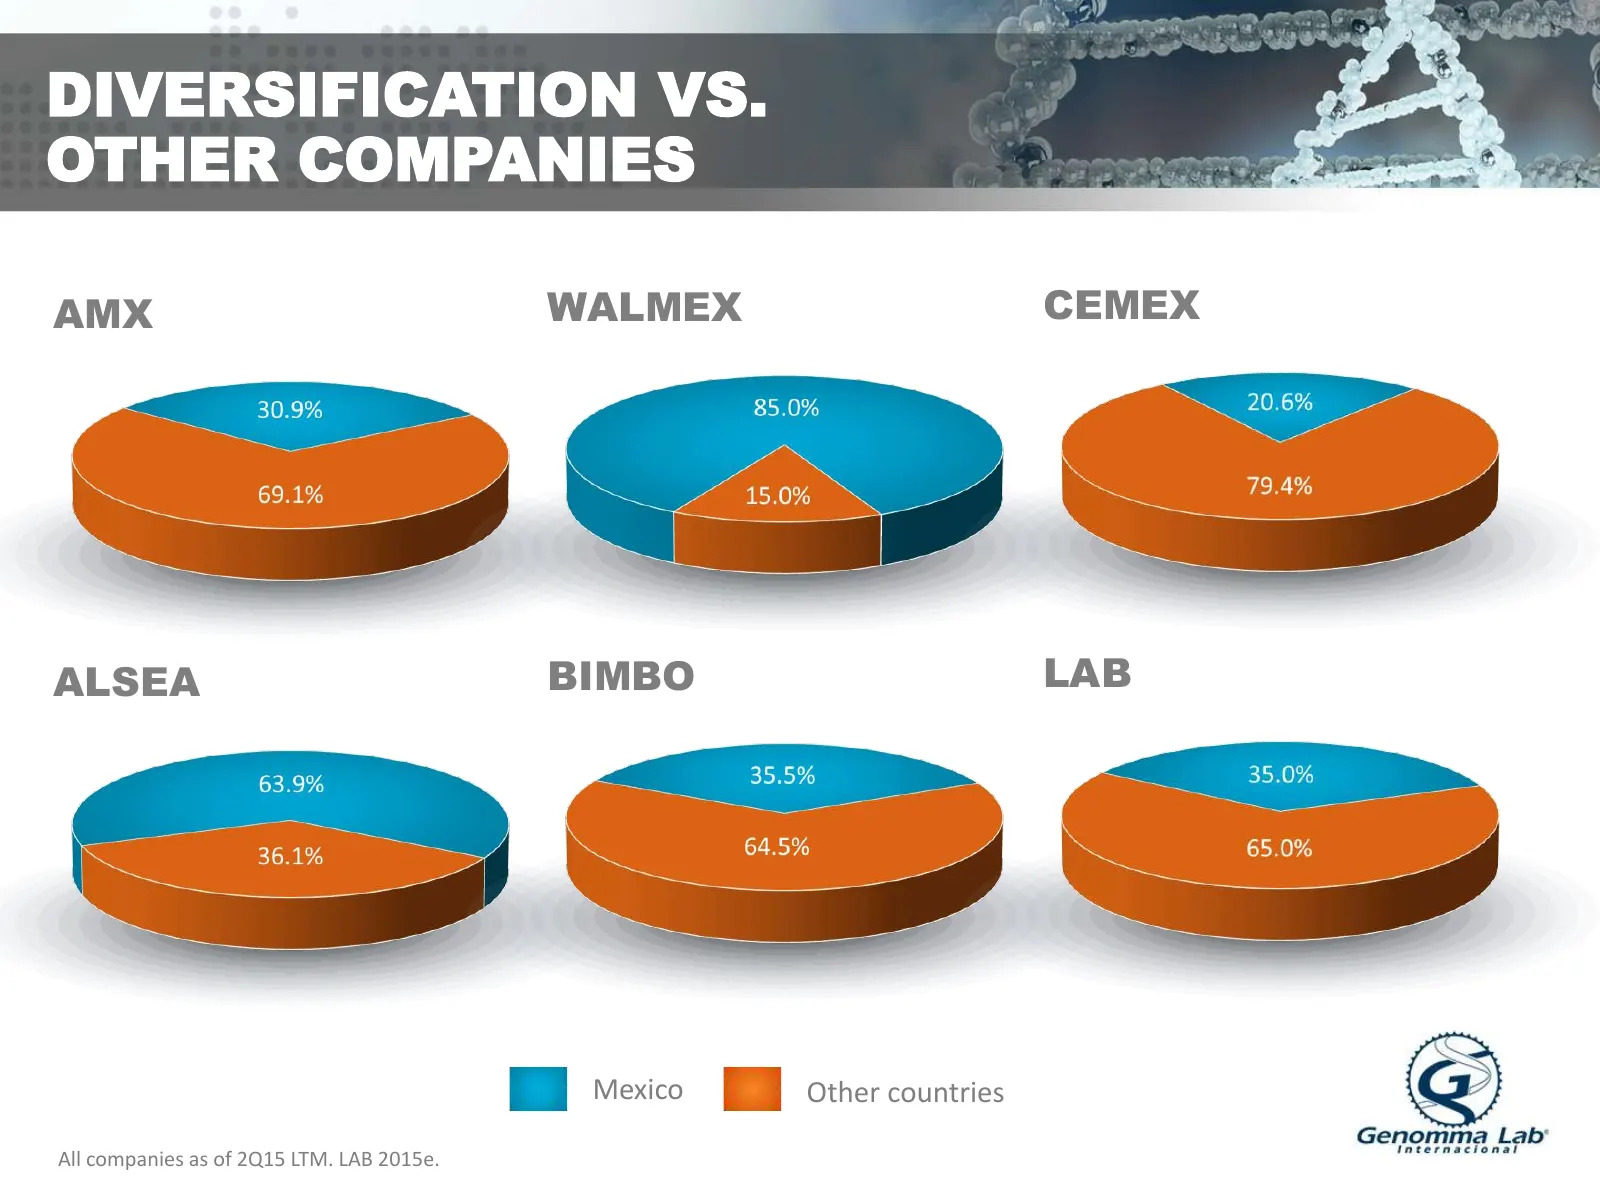
DIVERSIFICATION VS. OTHER COMPANIES AMX WALMEX CEMEX ALSEA BIMBO LAB Mexico Other countries All companies as of 2Q15 LTM. LAB 2015e.
Slide 20: Diversification vs. Other Companies
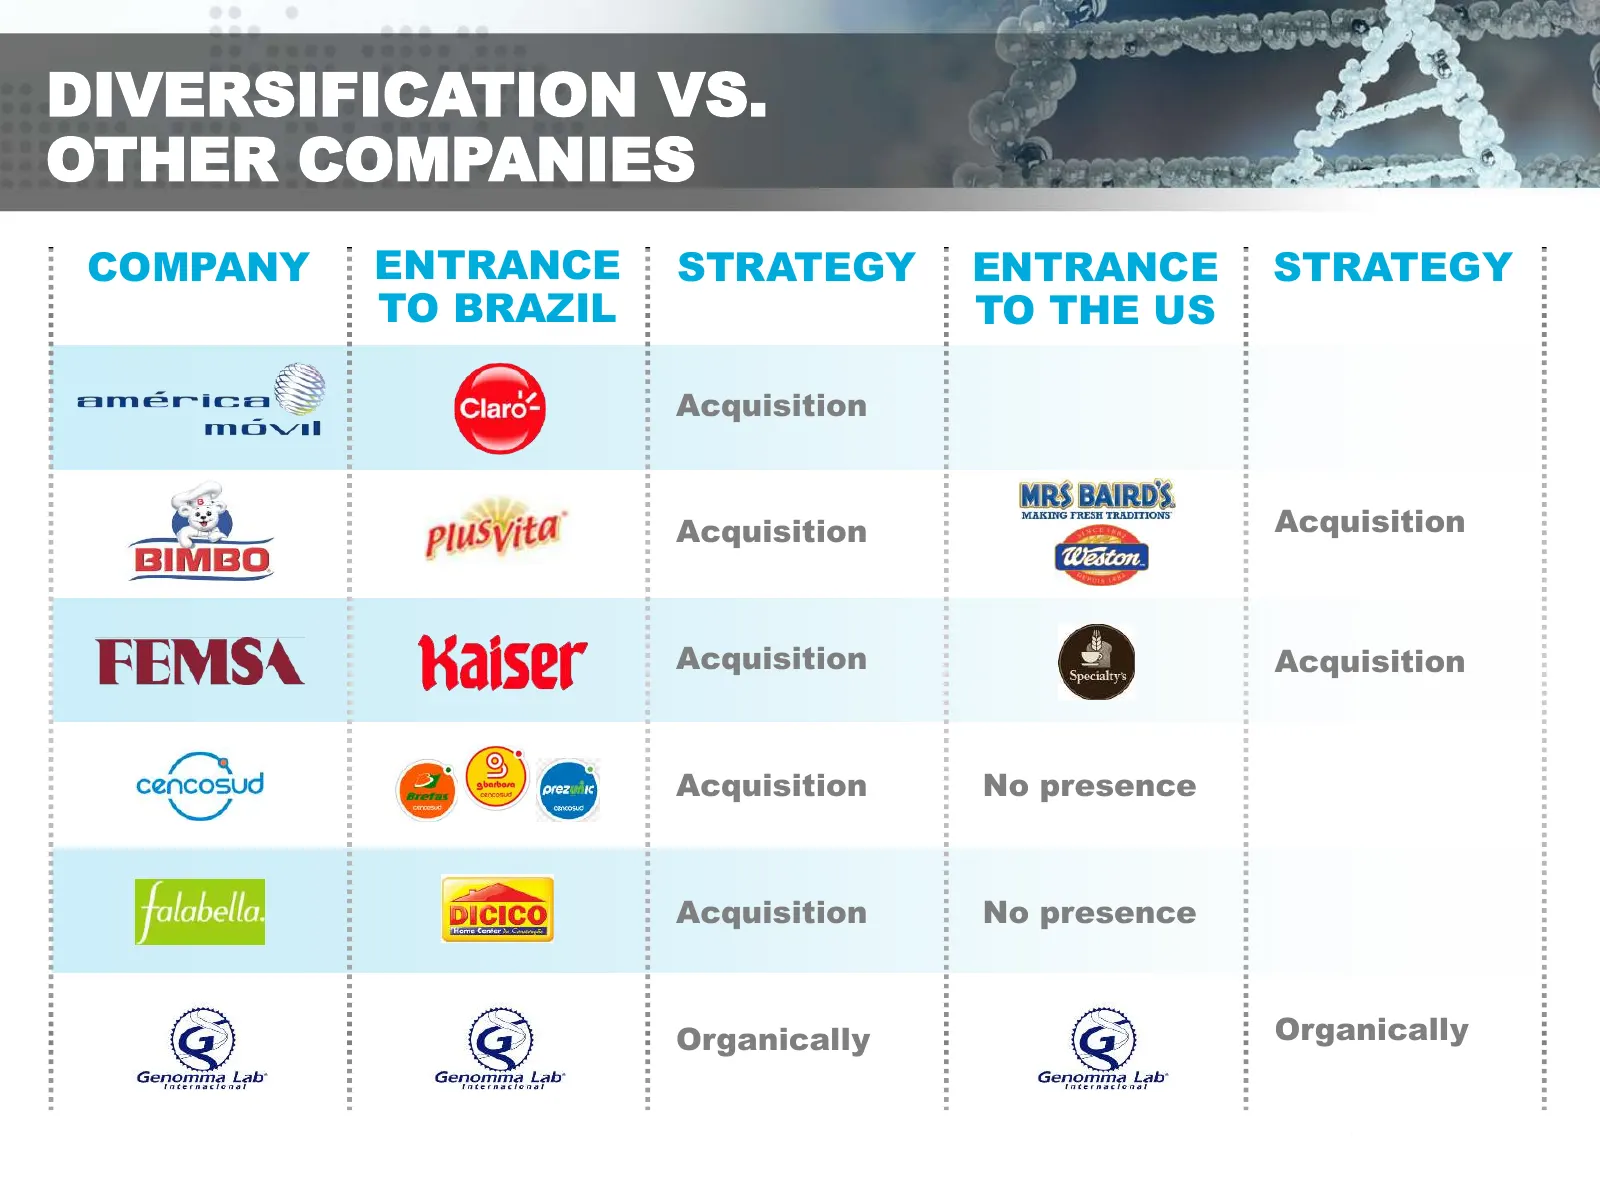
DIVERSIFICATION VS. OTHER COMPANIES COMPANY ENTRANCE STRATEGY ENTRANCE STRATEGY TO BRAZIL TO THE US Acquisition Acquisition Acquisition Acquisition Acquisition Acquisition No presence Acquisition No presence Organically Organically
Slide 21: U.S.A.
Genomma Lab‘ Internacional
Slide 22: Brand Sustainability
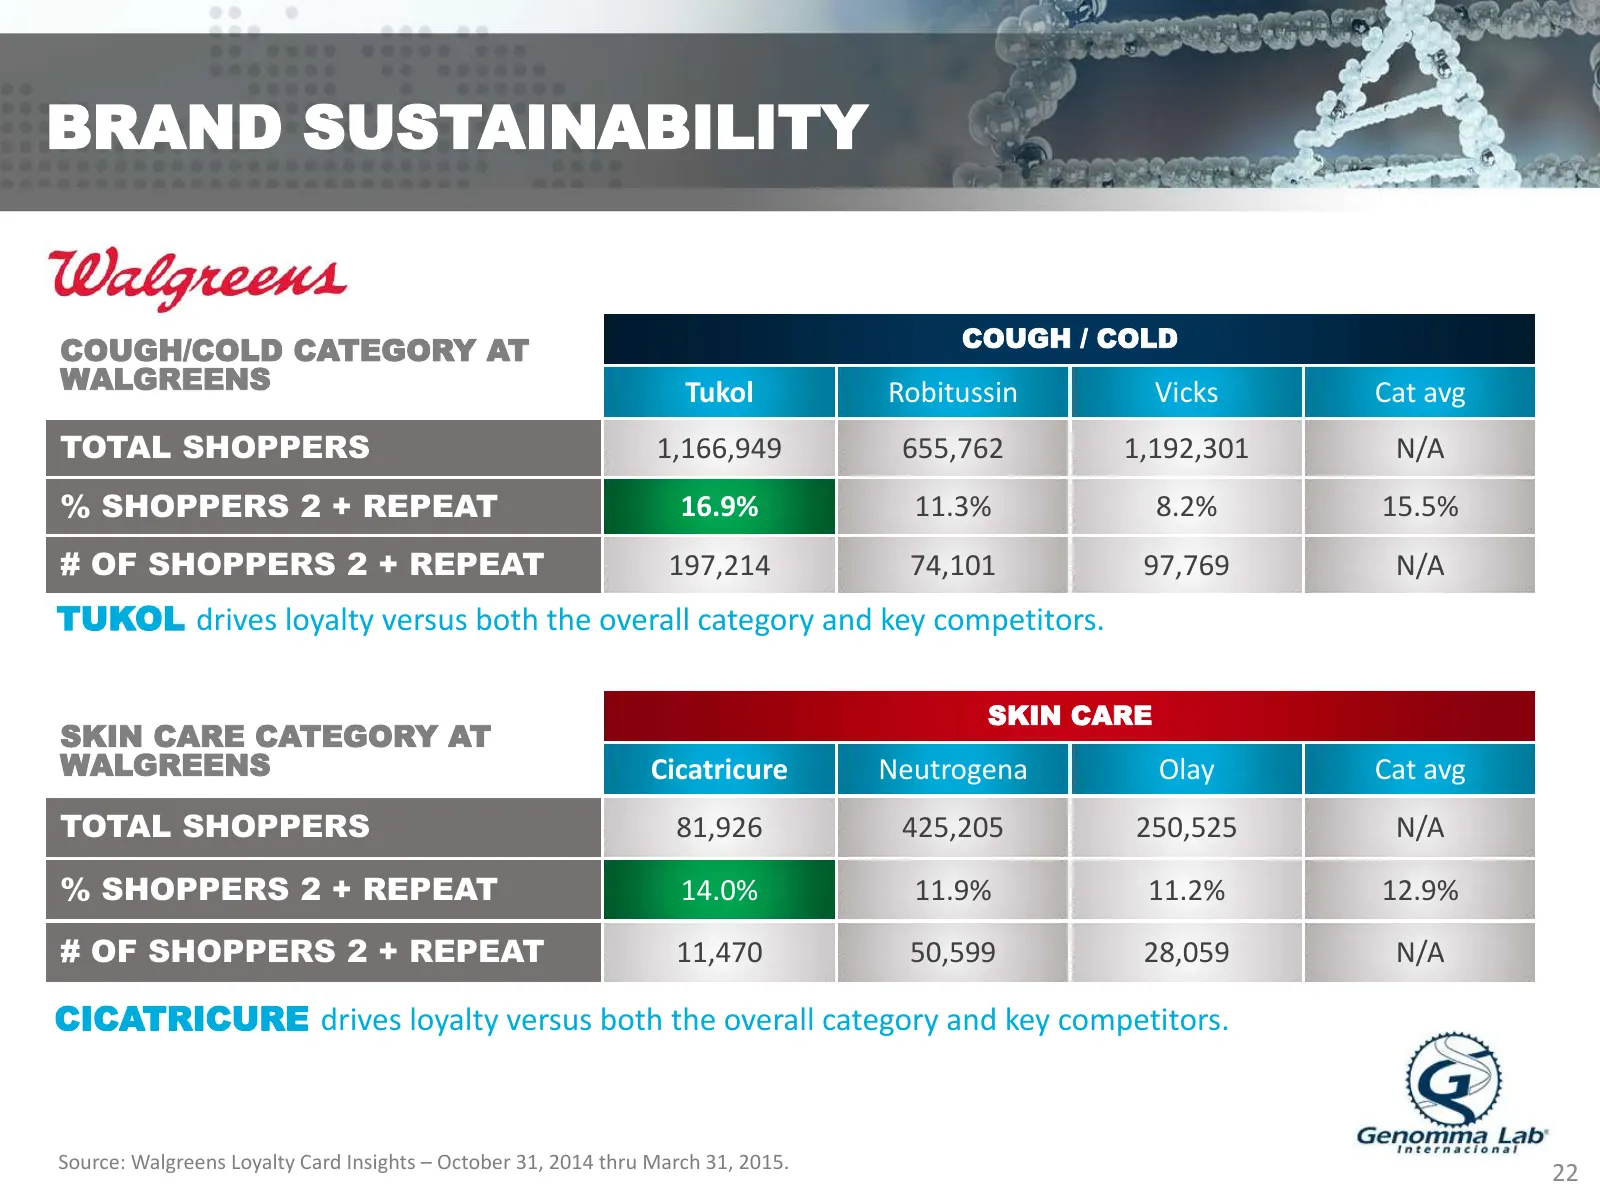
BRAND SUSTAINABILITY COUGH/COLD CATEGORY AT COUGH / COLD WALGREENS Tukol Robitussin Vicks Cat avg TOTAL SHOPPERS 1,166,949 655,762 1,192,301 N/A % SHOPPERS 2 + REPEAT 16.9% 11.3% 8.2% 15.5% # OF SHOPPERS 2 + REPEAT 197,214 74,101 97,769 N/A TUKOL drives loyalty versus both the overall category and k
Slide 23: Brand Sustainability
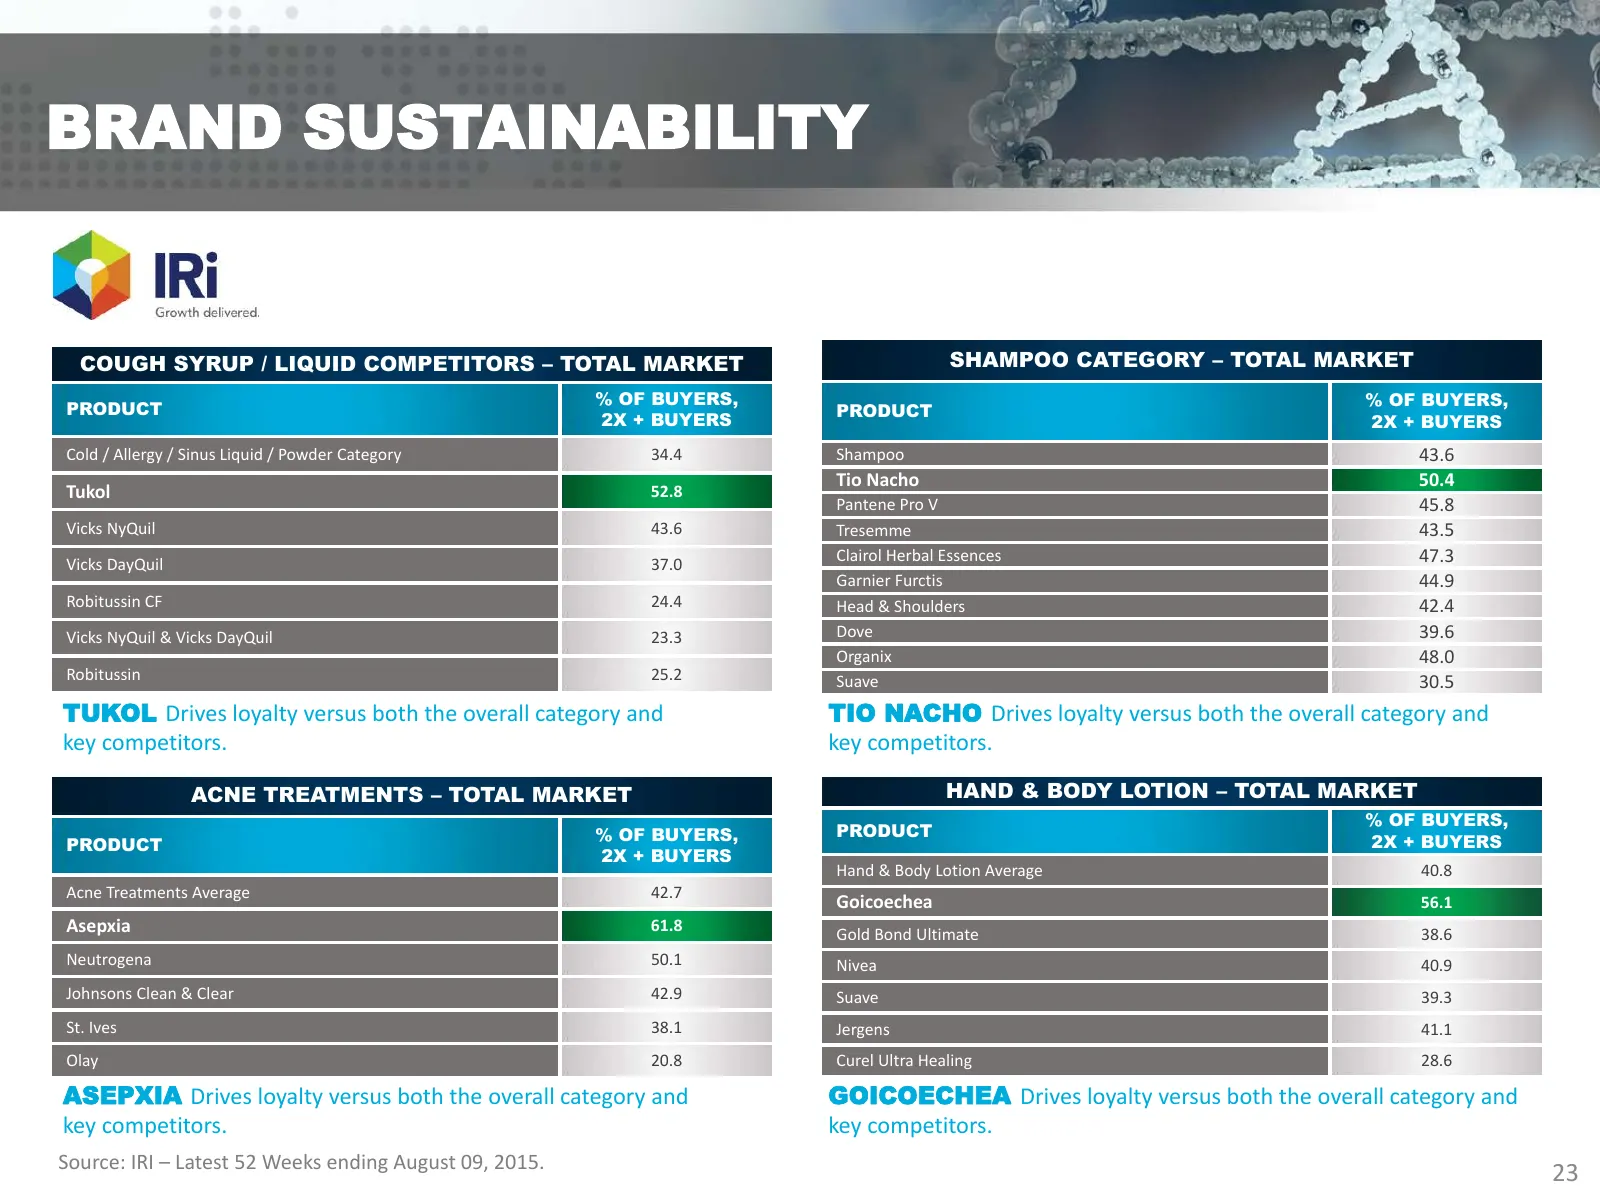
BRAND SUSTAINABILITY COUGH SYRUP / LIQUID COMPETITORS – TOTAL MARKET SHAMPOO CATEGORY – TOTAL MARKET % OF BUYERS, % OF BUYERS, PRODUCT PRODUCT 2X + BUYERS 2X + BUYERS Cold / Allergy / Sinus Liquid / Powder Category 34.4 Shampoo 43.6 Tio Nacho 50.4 Tukol 52.8 Pantene Pro V 45.8 Vicks NyQuil 43.6 Tres
Slide 24: Brand Sustainability
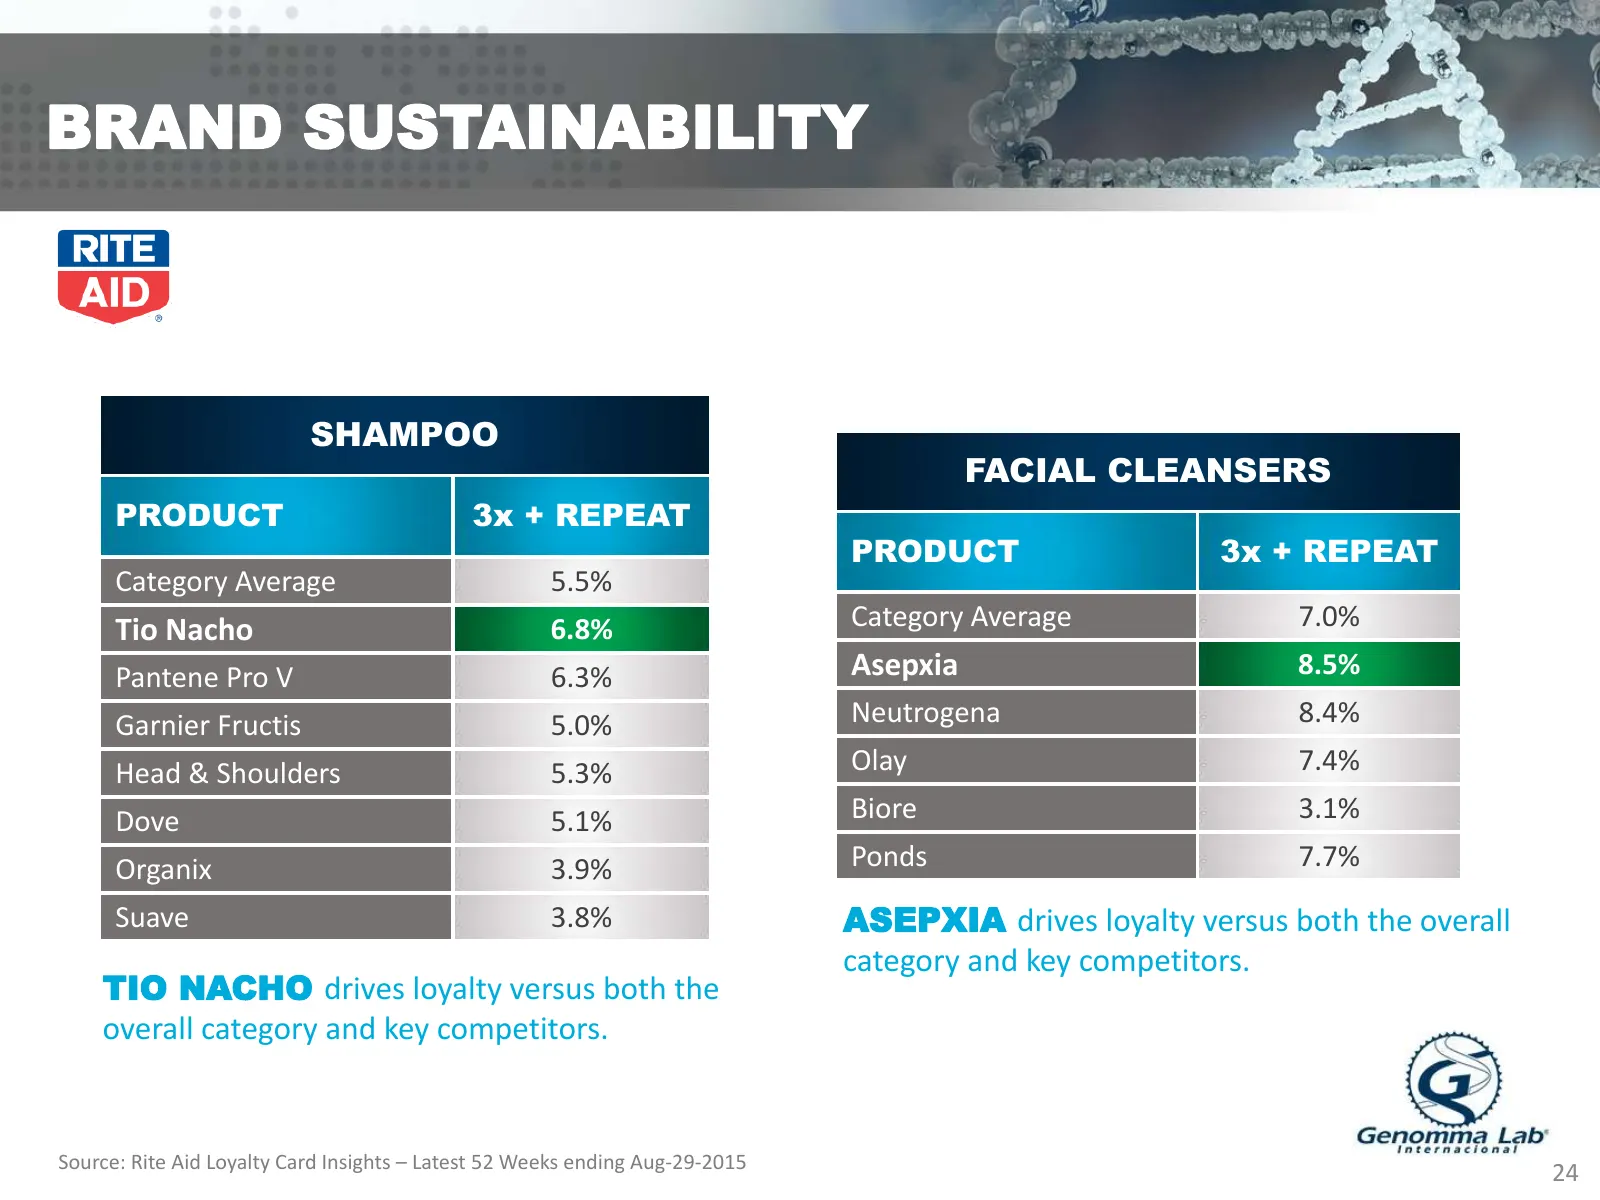
BRAND SUSTAINABILITY SHAMPOO FACIAL CLEANSERS PRODUCT 3x + REPEAT PRODUCT 3x + REPEAT Category Average 5.5% Tio Nacho 6.8% Category Average 7.0% Pantene Pro V 6.3% Asepxia 8.5% Garnier Fructis 5.0% Neutrogena 8.4% Head & Shoulders 5.3% Olay 7.4% Dove 5.1% Biore 3.1% Organix 3.9% Ponds 7.7% Suave 3.8
Slide 25: Success Cases in POS
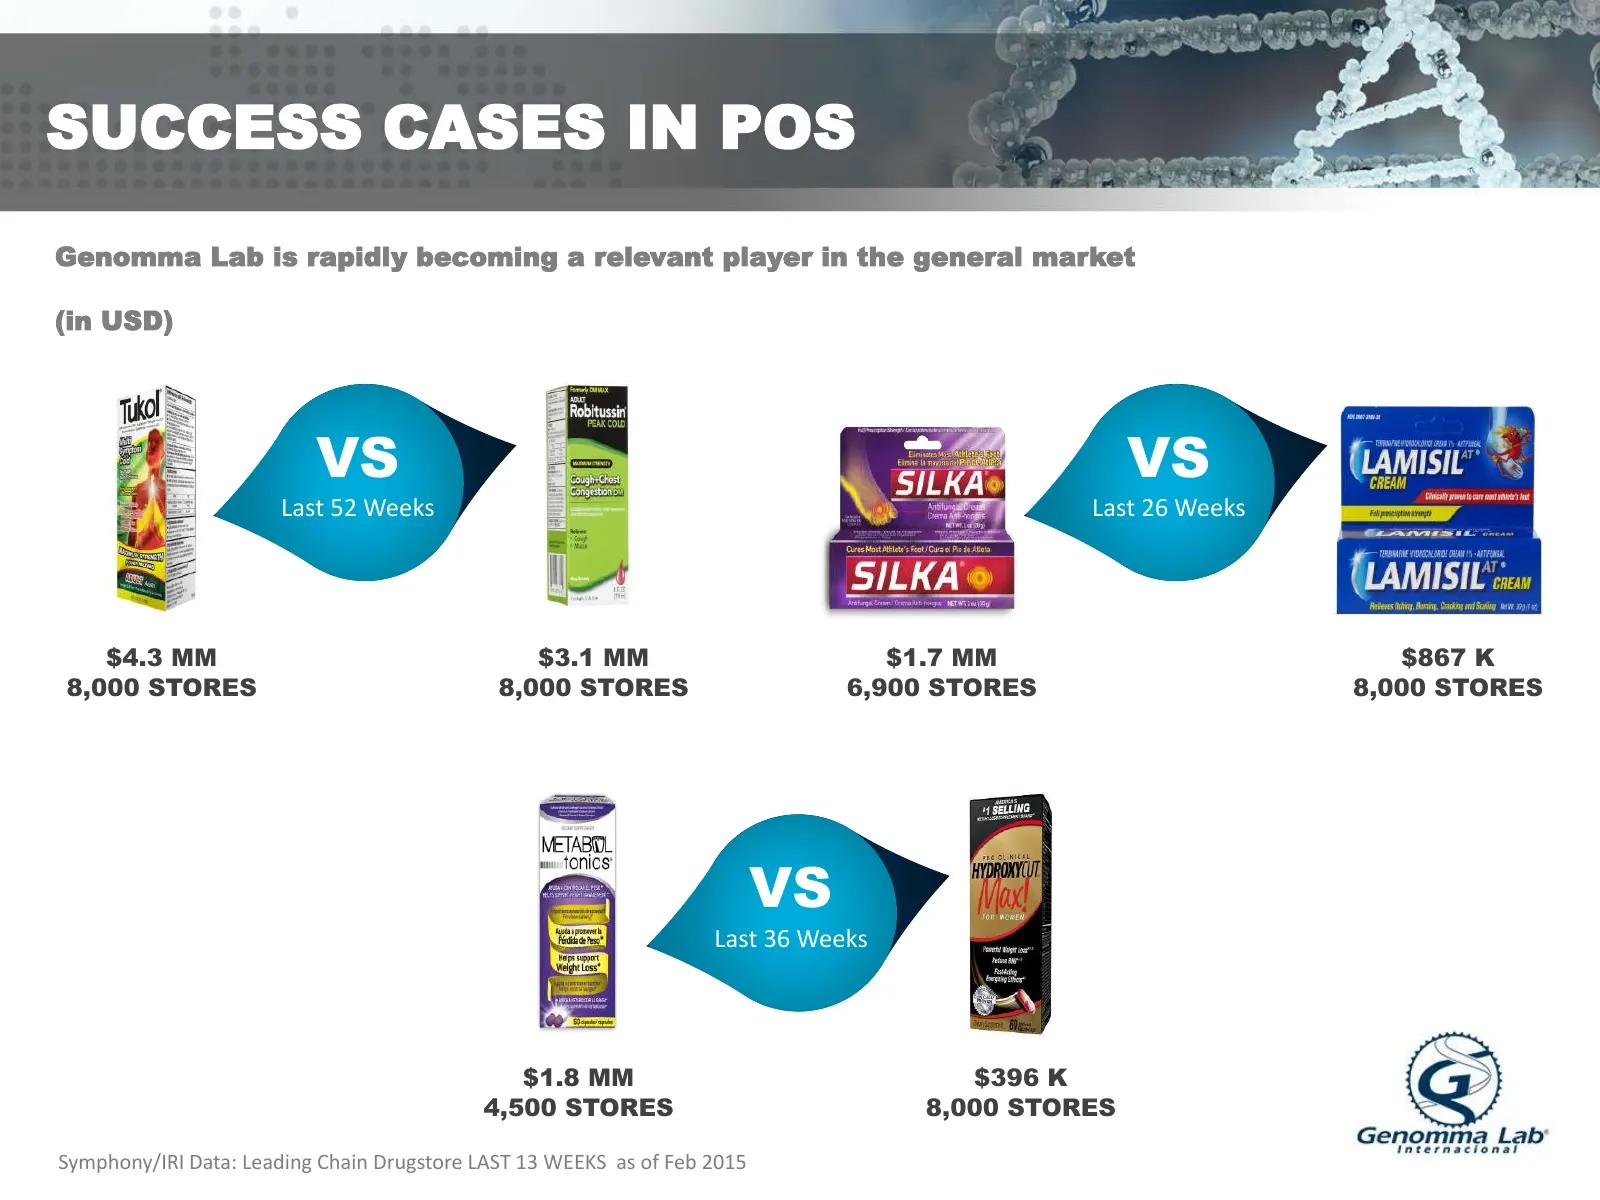
SUCCESS CASES IN POS Genomma Lab is rapidly becoming a relevant player in the general market (in USD) VS VS Last 52 Weeks Last 26 Weeks $4.3 MM $3.1 MM $1.7 MM $867 K 8,000 STORES 8,000 STORES 6,900 STORES 8,000 STORES VS Last 36 Weeks $1.8 MM $396 K 4,500 STORES 8,000 STORES Symphony/IRI Data: Lead
Slide 26: GL Increases Walgreens Hispanic Market Share
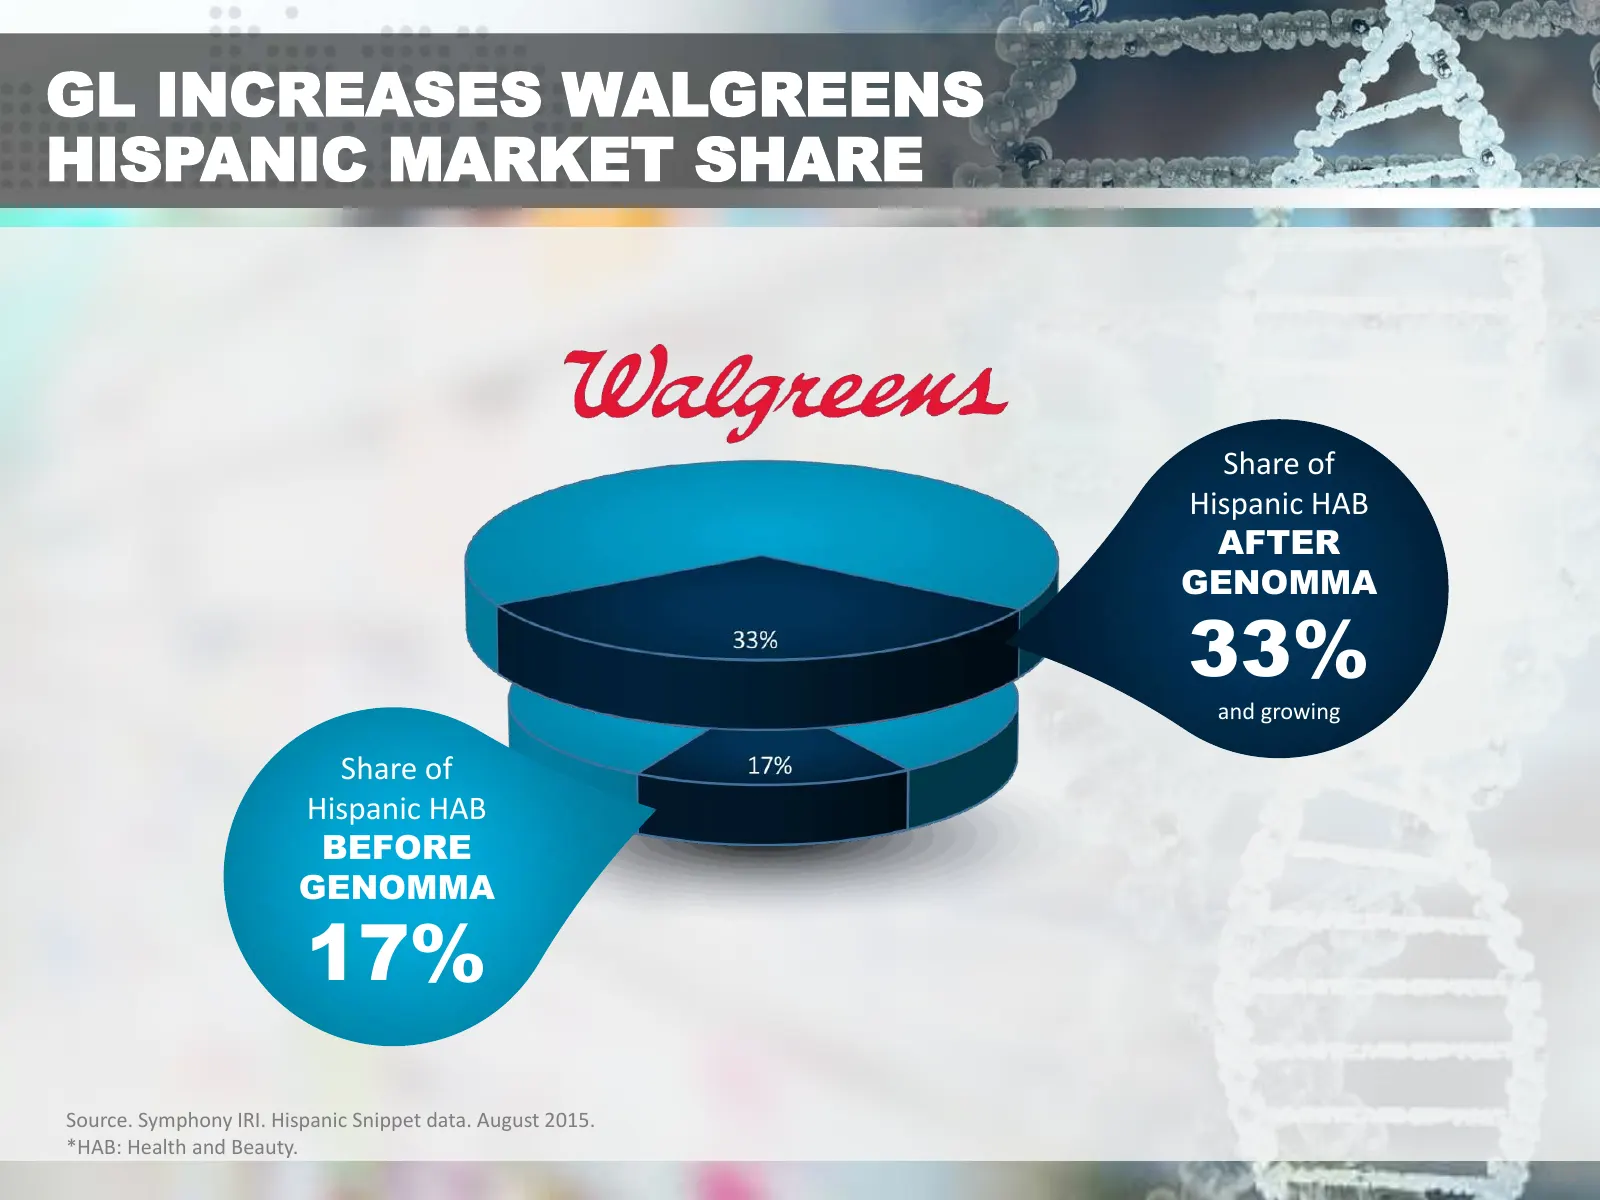
GL INCREASES WALGREENS HISPANIC MARKET SHARE Share of Hispanic HAB AFTER GENOMMA 33% and growing Share of Hispanic HAB BEFORE GENOMMA 17% Source. Symphony IRI. Hispanic Snippet data. August 2015. *HAB: Health and Beauty. 26
Slide 27: Genomma's Sales in Walgreens
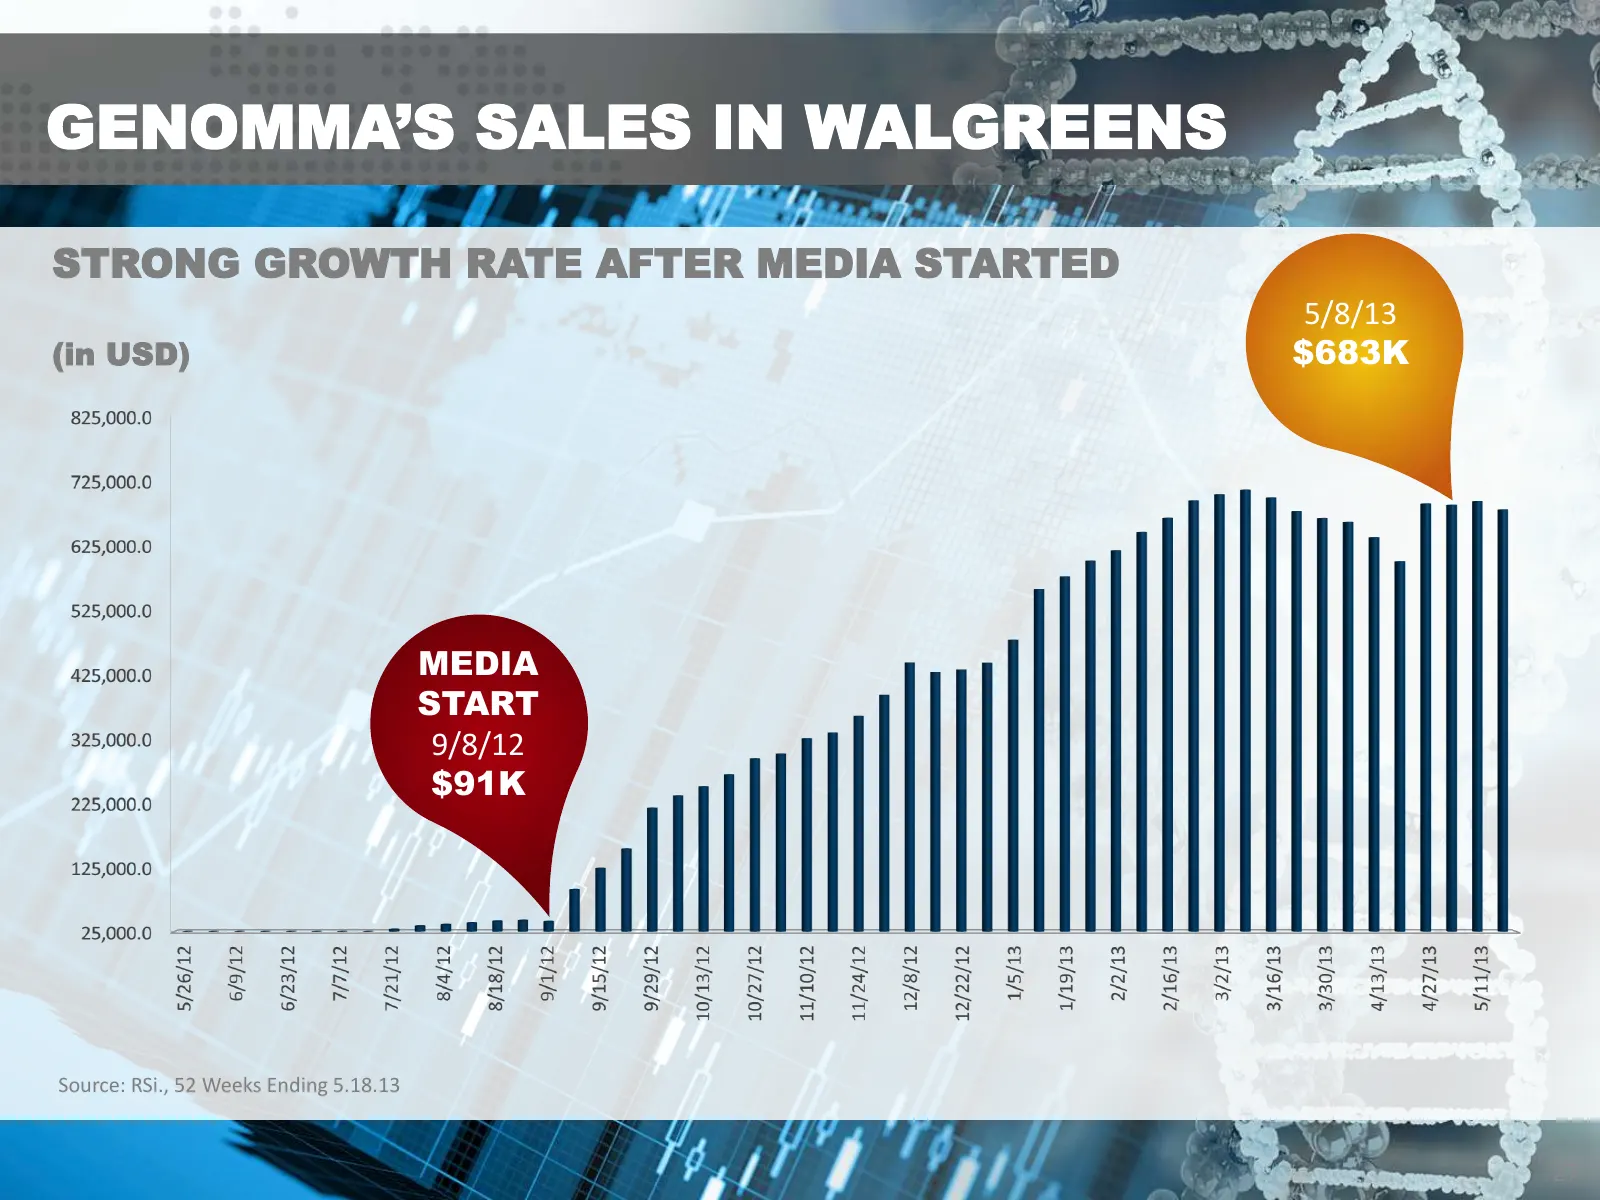
GENOMMA’S SALES IN WALGREENS STRONG GROWTH RATE AFTER MEDIA STARTED 5/8/13 (in USD) $683K MEDIA START 9/8/12 $91K Source: RSi., 52 Weeks Ending 5.18.13 27
Slide 28: Presence in POS - Walgreens
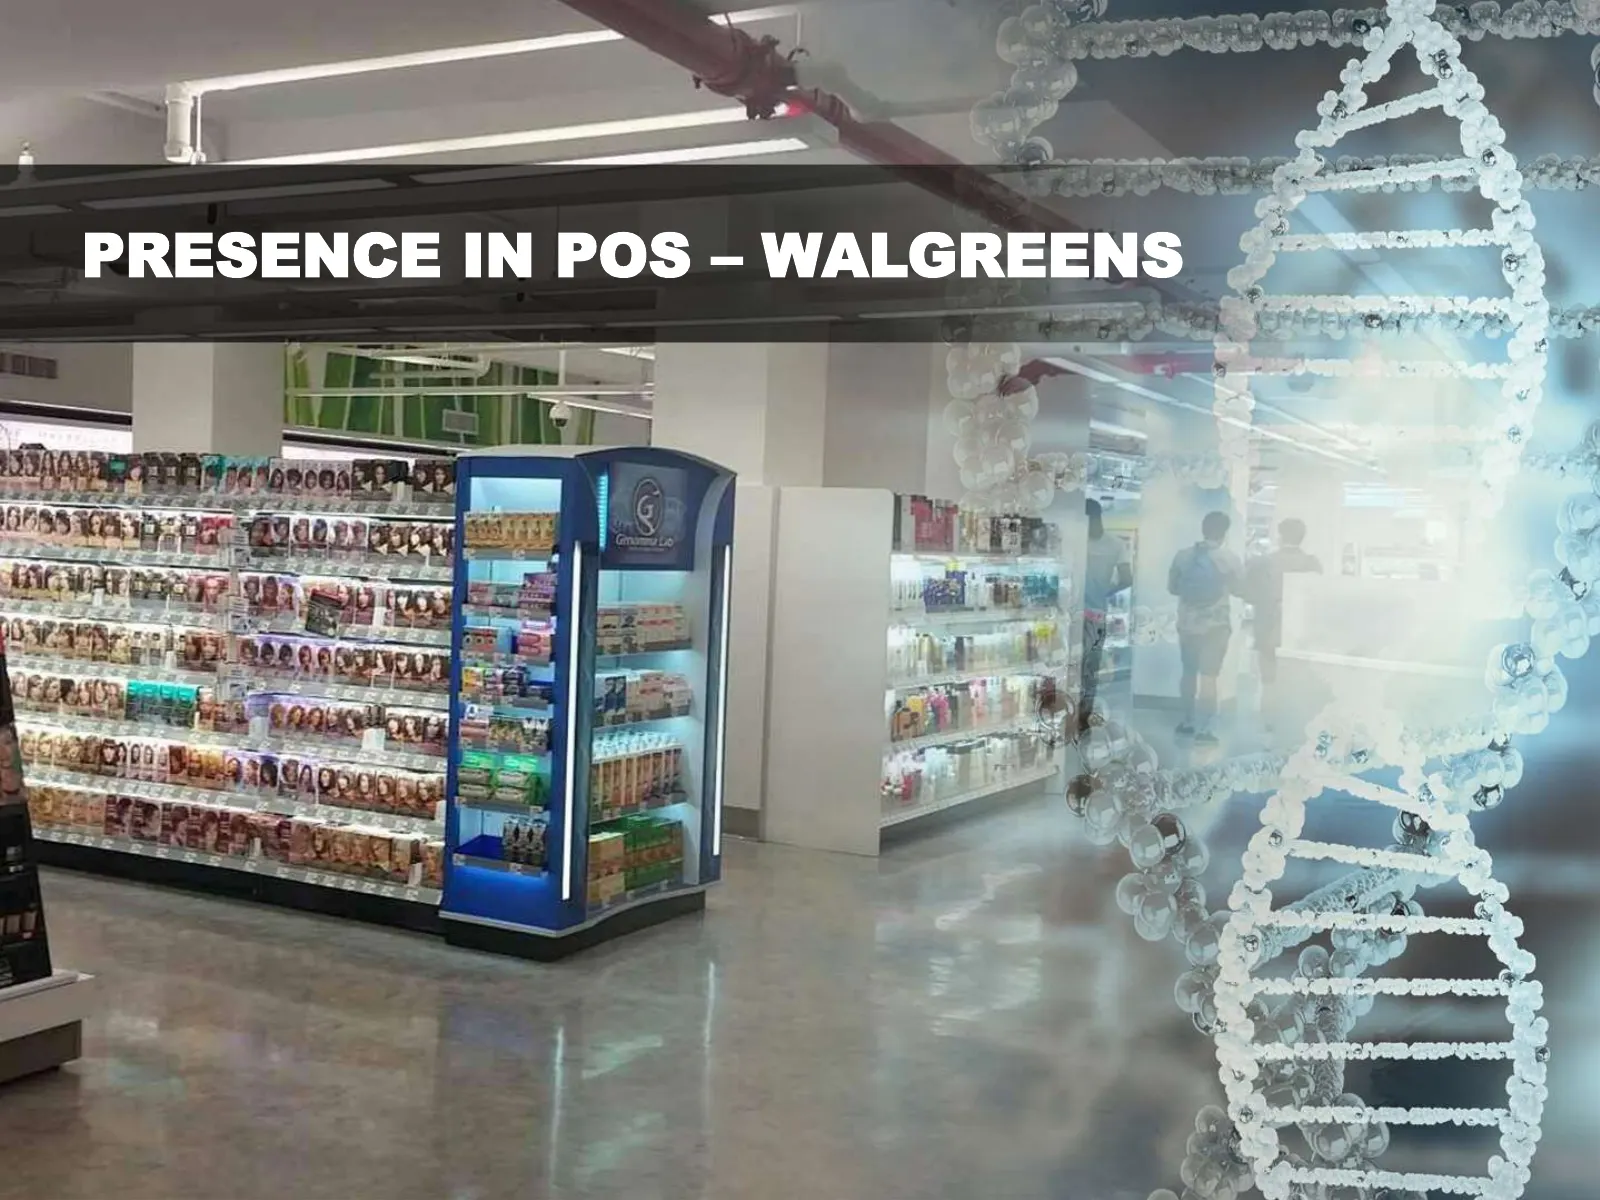
PRESENCE IN POS – WALGREENS 28
Slide 29: Results in the U.S.A.
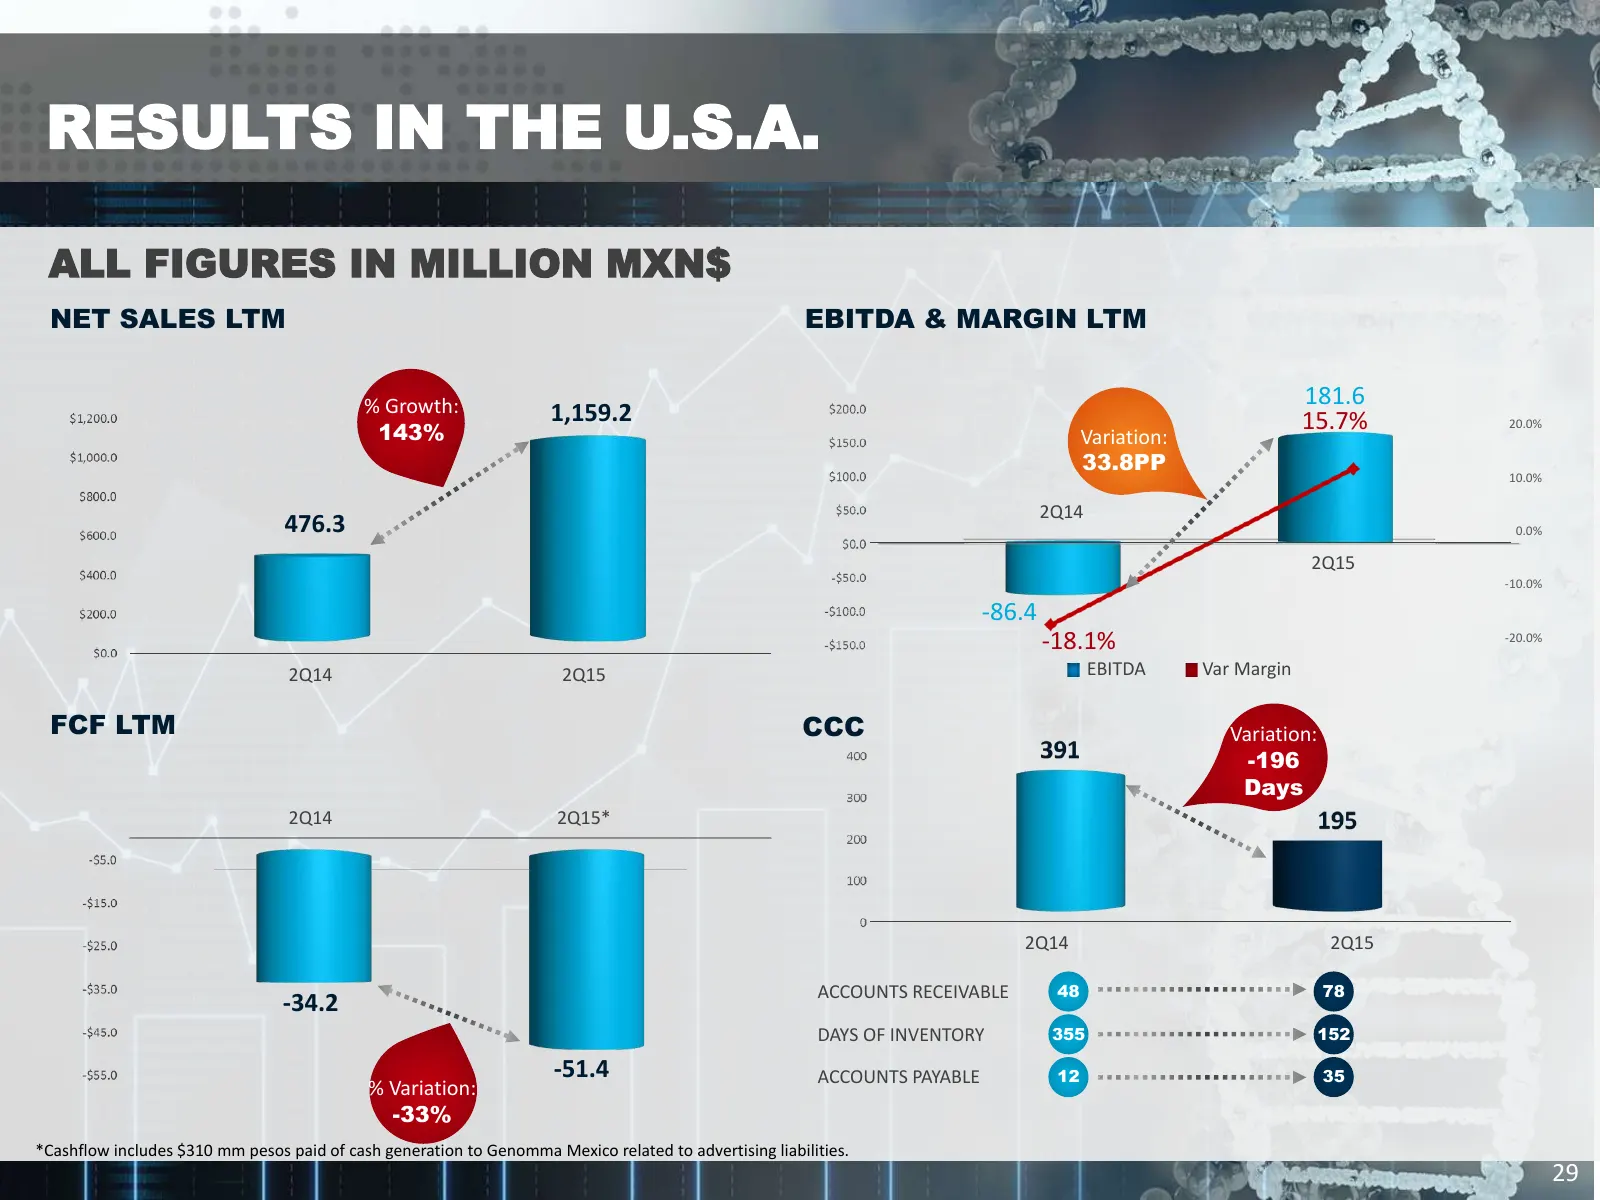
RESULTS IN THE U.S.A. ALL FIGURES IN MILLION MXN$ NET SALES LTM EBITDA & MARGIN LTM % Growth: 181.6 1,159.2 15.7% 143% 20.0% Variation: 33.8PP 10.0% 2Q14 476.3 0.0% 2Q15 -10.0% -86.4 -18.1% -20.0% 2Q14 2Q15 EBITDA Var Margin FCF LTM CCC Variation: -196 Days 2Q14 2Q15* 2Q14 2Q15 ACCOUNTS RECEIVABLE 4
Slide 30: U.S.A. - Potential for Growth
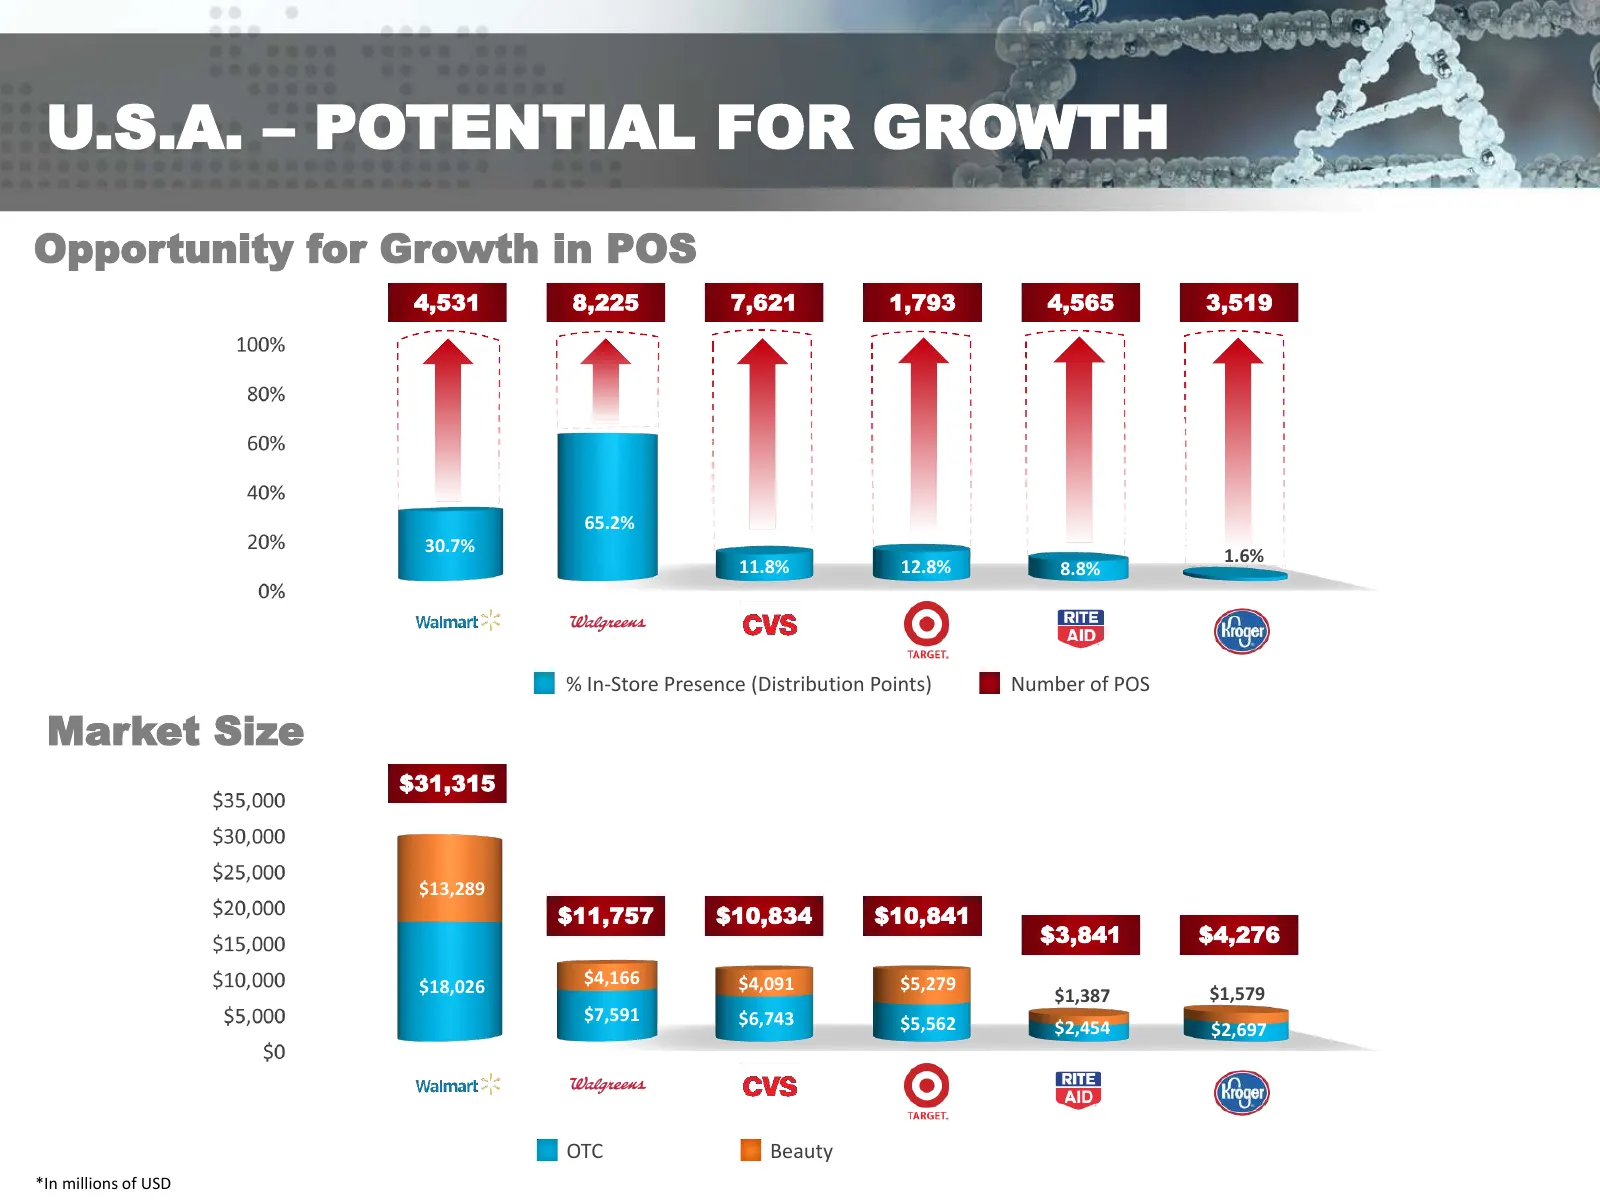
U.S.A. – POTENTIAL FOR GROWTH Opportunity for Growth in POS 4,531 8,225 7,621 1,793 4,565 3,519 65.2% 65.2% 30.7% 30.7% 11.8% 12.8% 1.6% 11.8% 12.8% 8.8% 8.8% % In-Store Presence (Distribution Points) Number of POS Market Size $31,315 $13,289 $11,757 $10,834 $10,841 $3,841 $4,276 $18,026 $4,166 $4,0
Slide 31: Mexico
Genomma Lab‘ Internacional MEXICO
Slide 32: Turnaround in Mexico
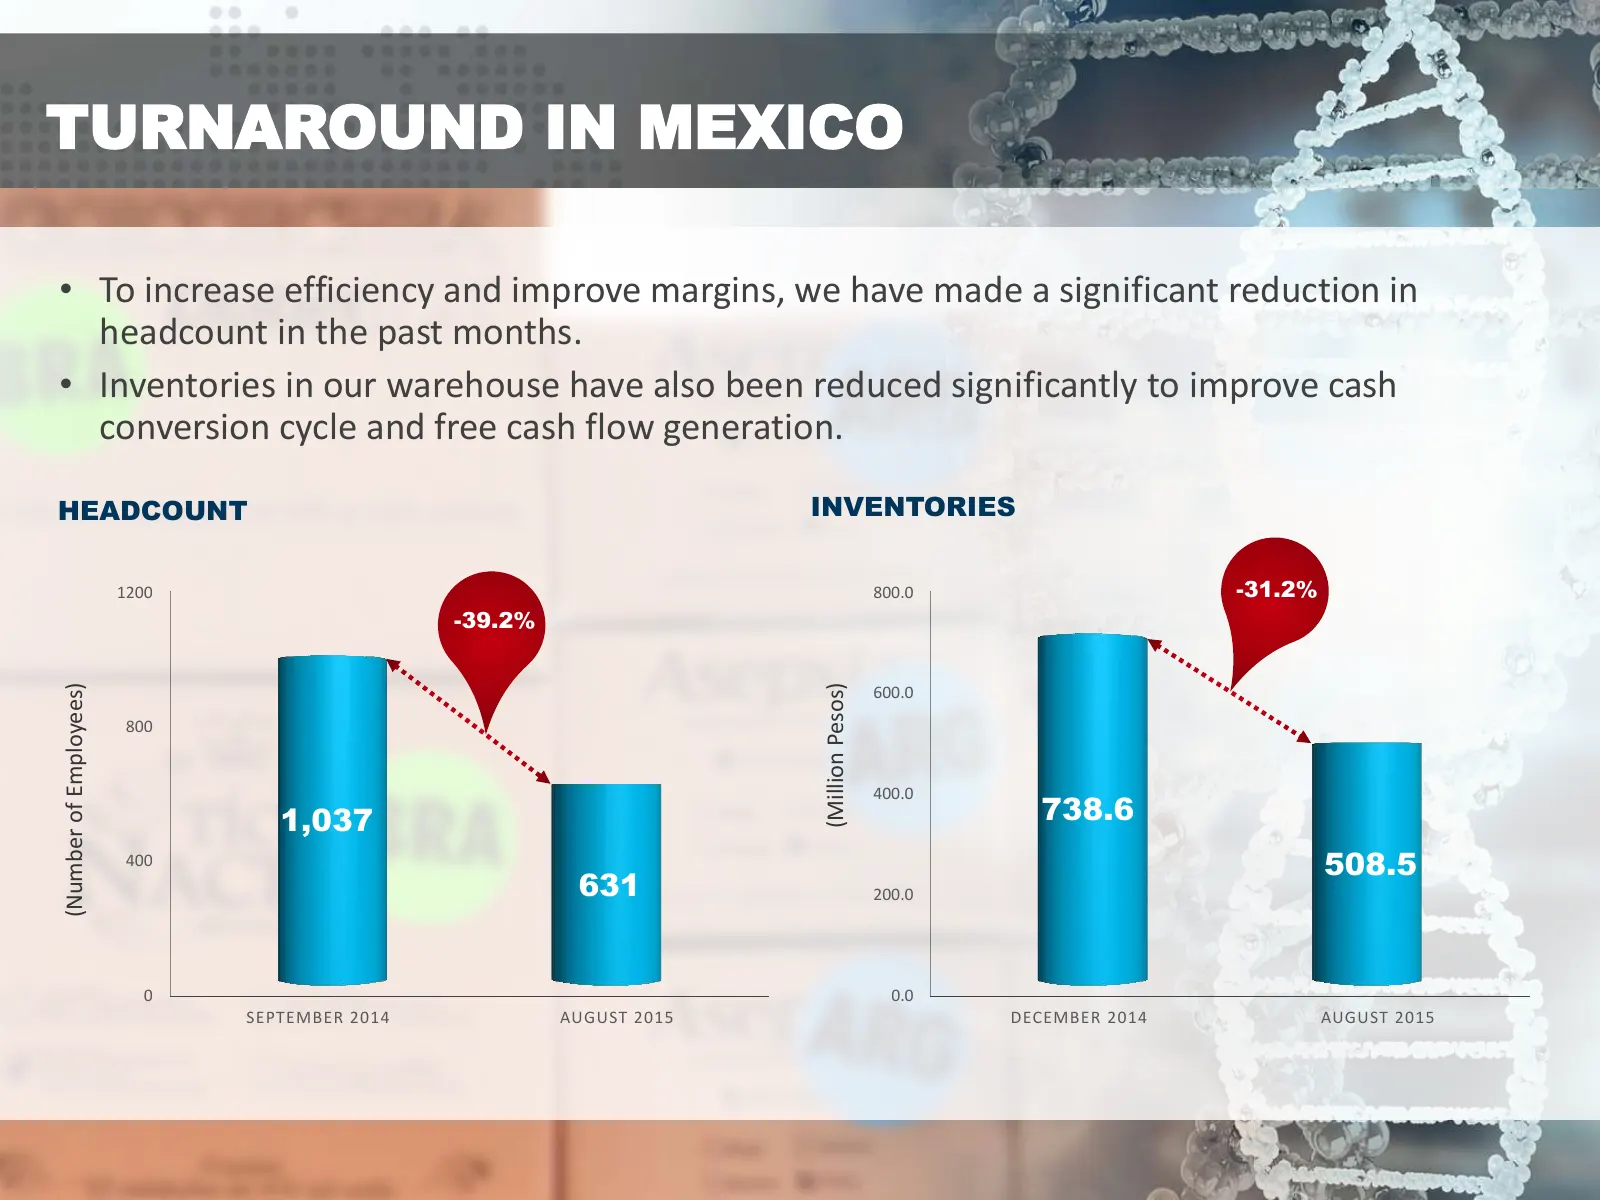
TURNAROUND IN MEXICO • To increase efficiency and improve margins, we have made a significant reduction in headcount in the past months. • Inventories in our warehouse have also been reduced significantly to improve cash conversion cycle and free cash flow generation. HEADCOUNT INVENTORIES 1200 800.
Slide 33: Turnaround in Mexico
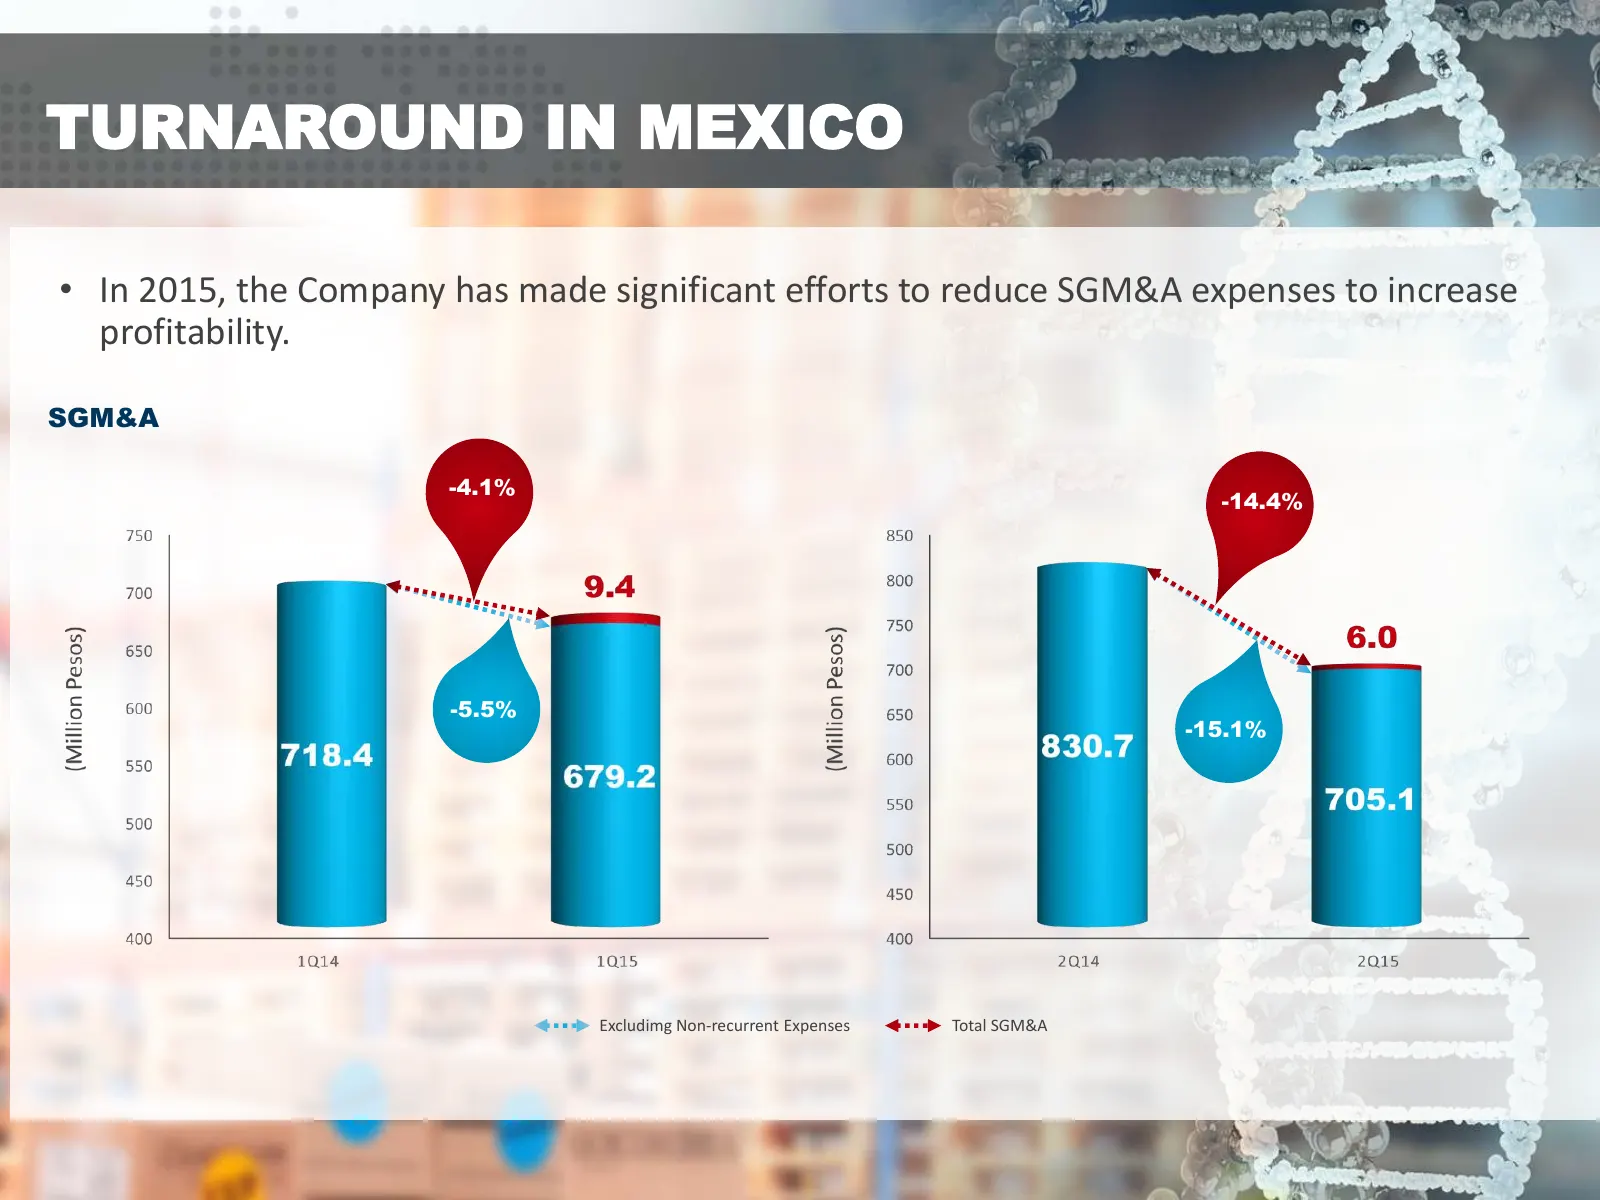
TURNAROUND IN MEXICO • In 2015, the Company has made significant efforts to reduce SGM&A expenses to increase profitability. SGM&A -4.1% -14.4% -5.5% -15.1% Excludimg Non-recurrent Expenses Total SGM&A
Slide 34: Turnaround in Mexico
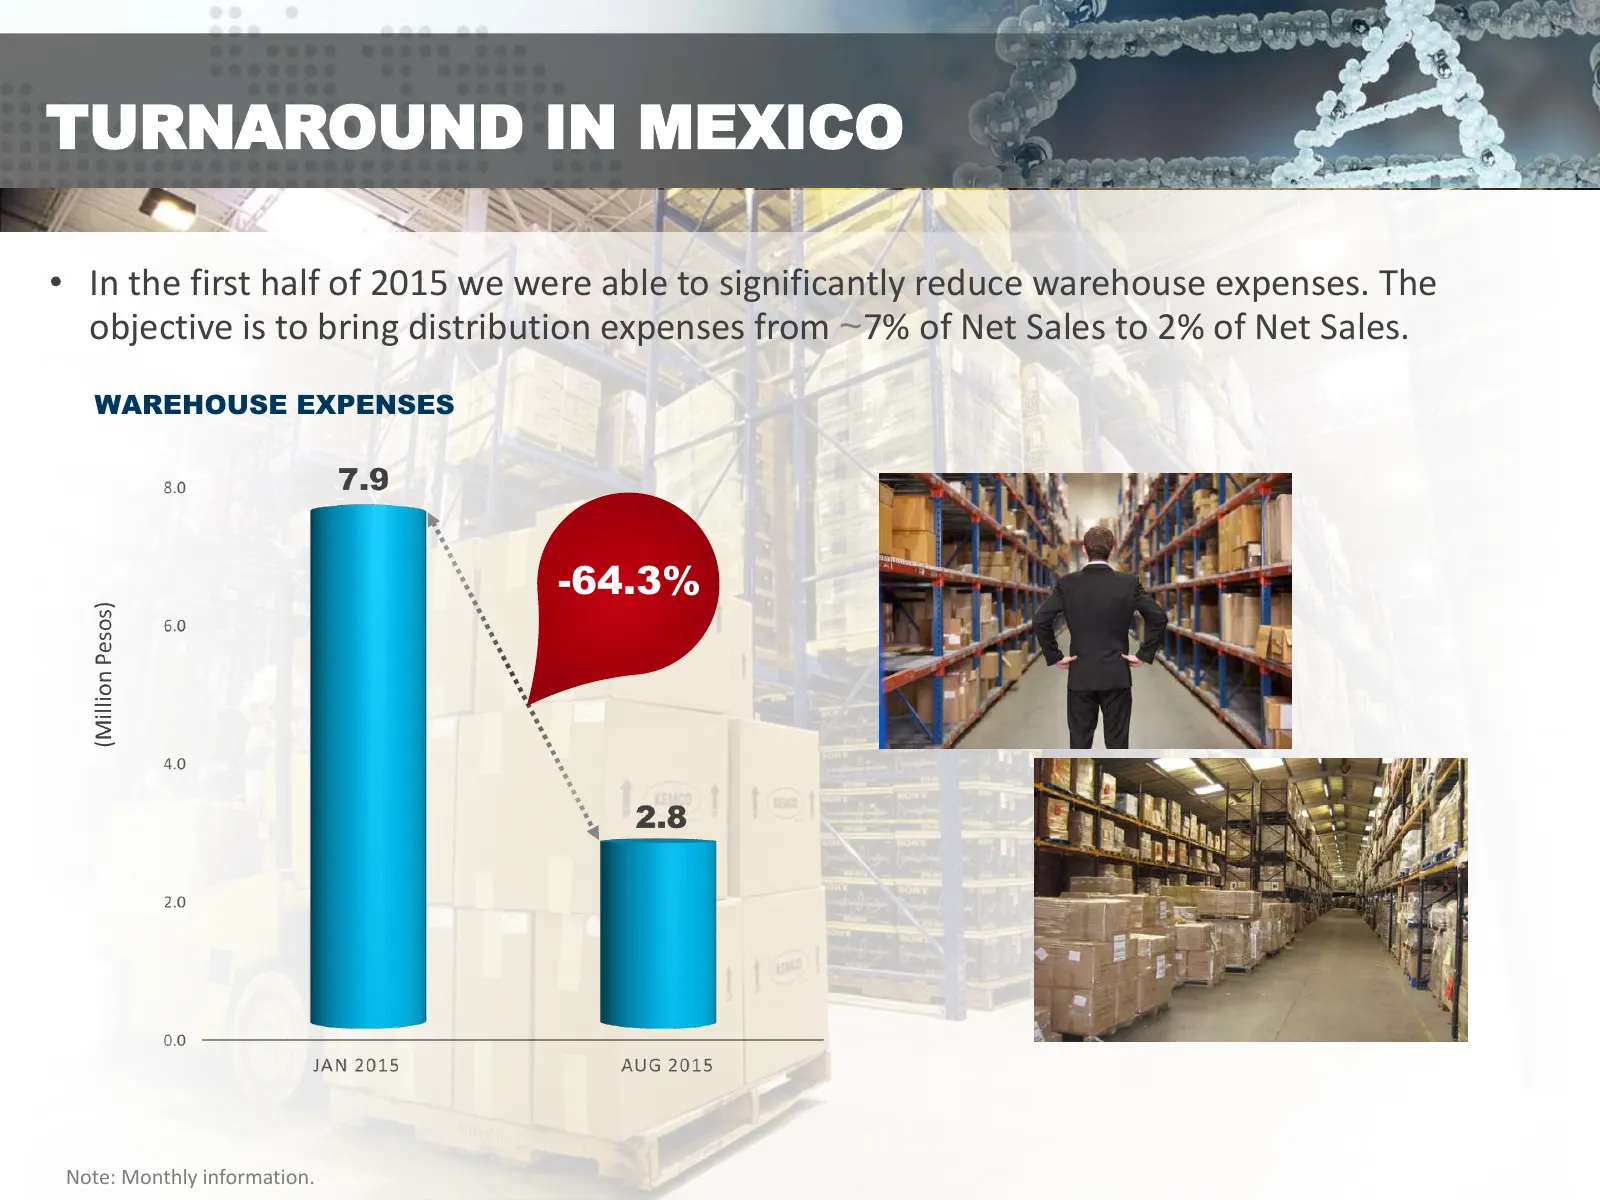
TURNAROUND IN MEXICO • In the first half of 2015 we were able to significantly reduce warehouse expenses. The objective is to bring distribution expenses from ~7% of Net Sales to 2% of Net Sales. WAREHOUSE EXPENSES -64.3% Note: Monthly information. 34
Slide 35: Turnaround in Mexico: Sell-out
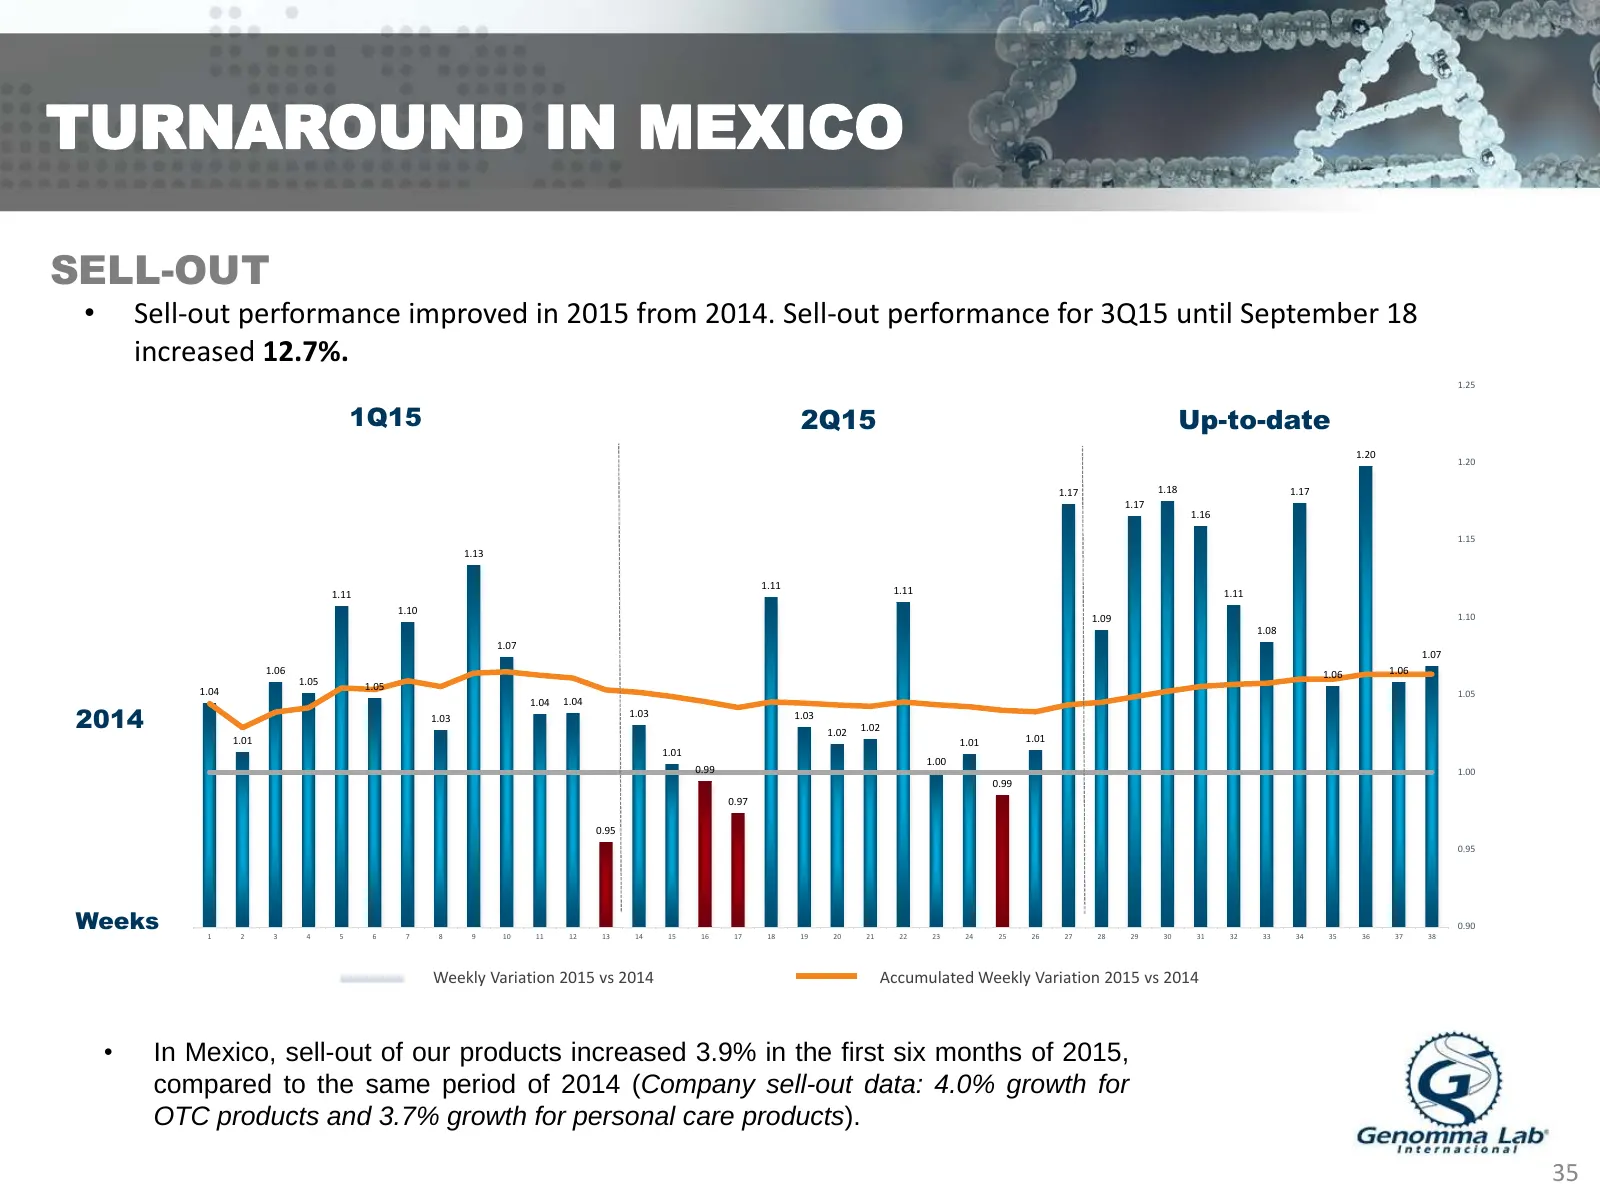
TURNAROUND IN MEXICO SELL-OUT • Sell-out performance improved in 2015 from 2014. Sell-out performance for 3Q15 until September 18 increased 12.7%. 1.25 1Q15 2Q15 Up-to-date 1.20 1.20 1.17 1.18 1.17 1.17 1.16 1.15 1.13 1.11 1.11 1.11 1.11 1.10 1.09 1.10 1.08 1.07 1.0687 1.07 1.06 1.06 1.06 1.05 1.05
Slide 36: Results in Mexico
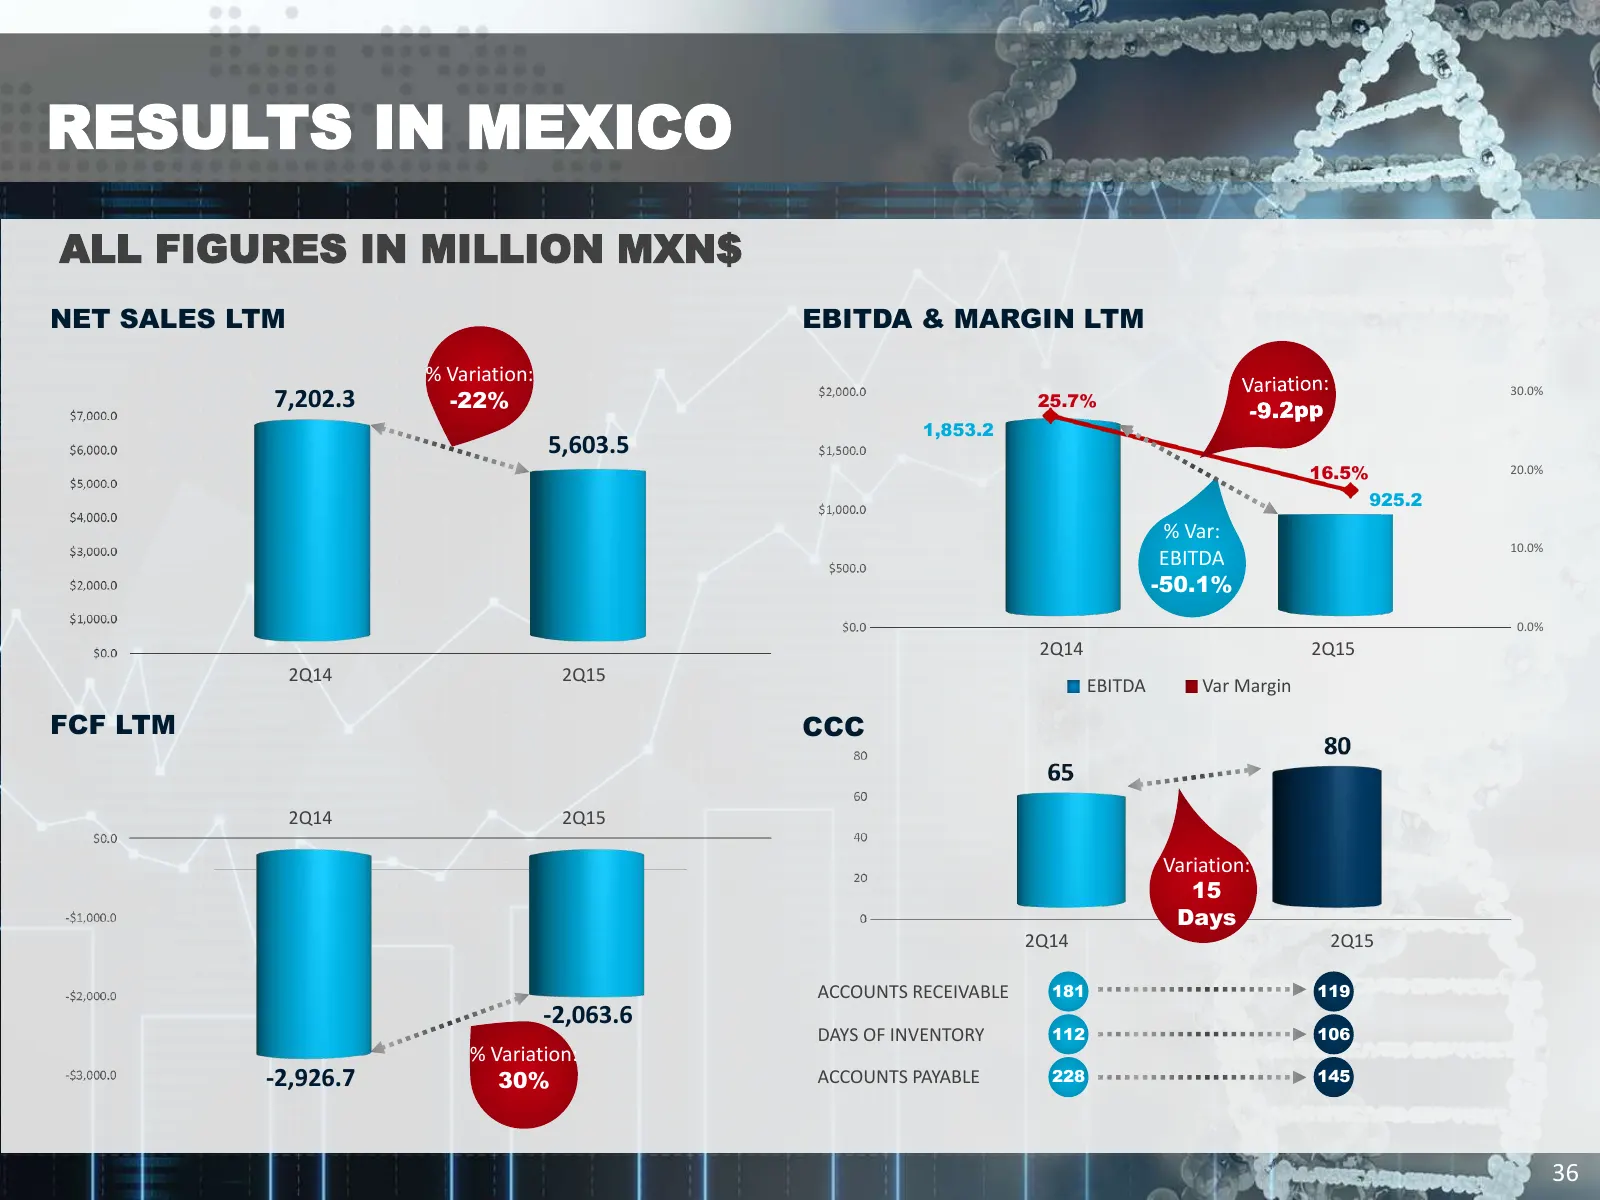
RESULTS IN MEXICO ALL FIGURES IN MILLION MXN$ NET SALES LTM EBITDA & MARGIN LTM % Variation: -22% 30.0% 7,202.3 25.7% 1,853.2 5,603.5 16.5% 20.0% 925.2 % Var: 10.0% EBITDA -50.1% 0.0% 2Q14 2Q15 2Q14 2Q15 EBITDA Var Margin FCF LTM CCC 2Q14 2Q15 Variation: 15 Days 2Q14 2Q15 ACCOUNTS RECEIVABLE 181 119
Slide 37: Commercial Strategy - Update
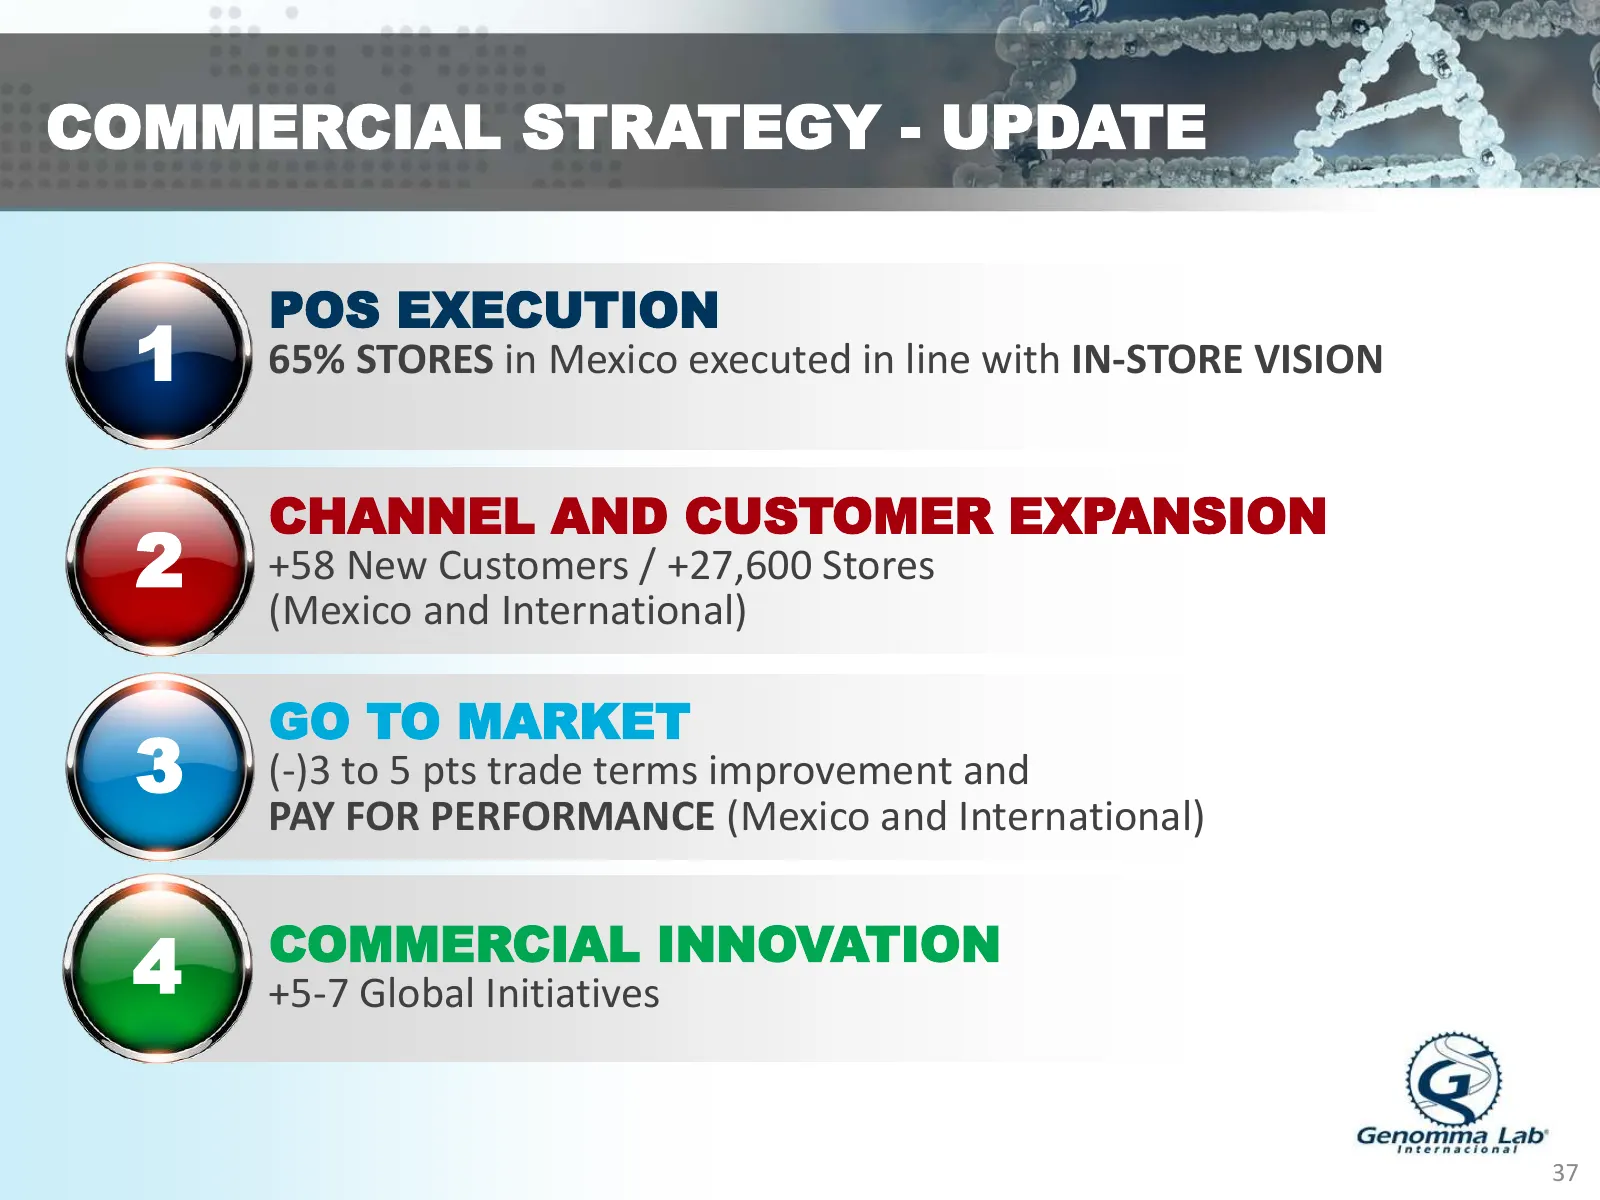
COMMERCIAL STRATEGY - UPDATE POS EXECUTION 1 65% STORES in Mexico executed in line with IN-STORE VISION CHANNEL AND CUSTOMER EXPANSION 2 +58 New Customers / +27,600 Stores (Mexico and International) GO TO MARKET 3 (-)3 to 5 pts trade terms improvement and PAY FOR PERFORMANCE (Mexico and Internationa
Slide 38: POS Execution
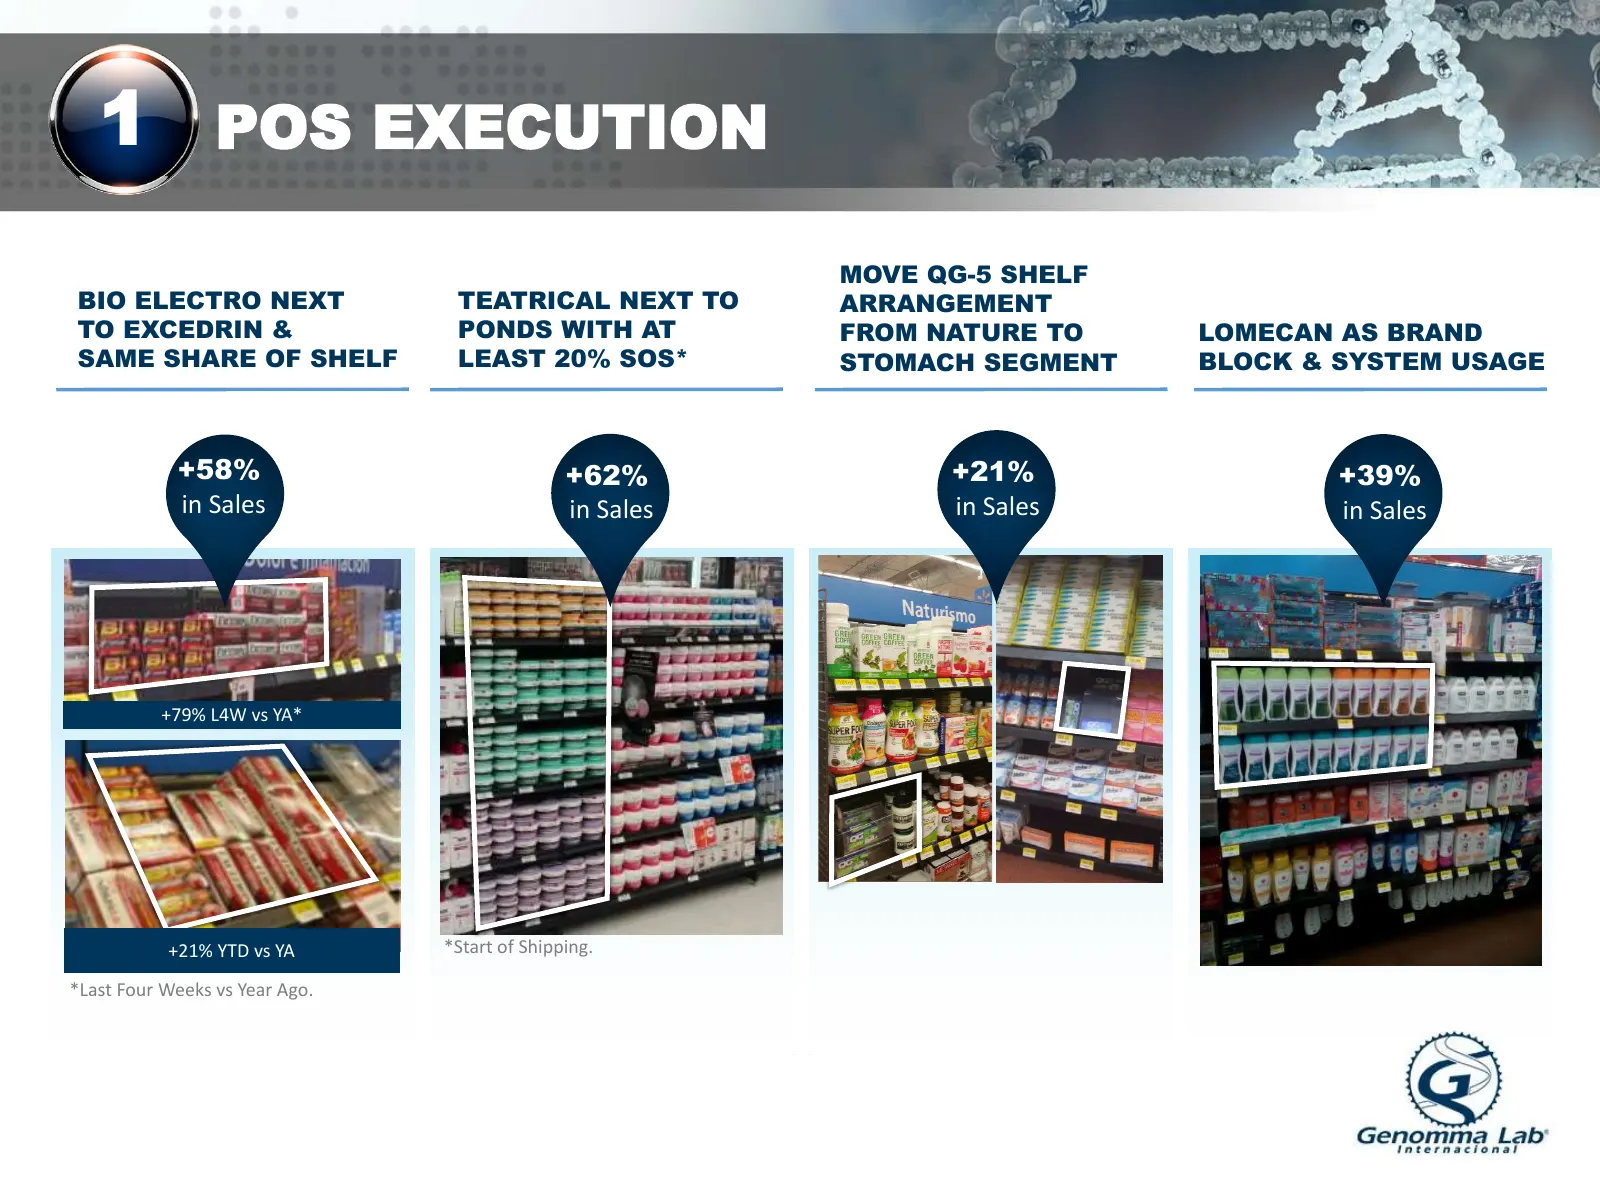
1 POS EXECUTION MOVE QG-5 SHELF BIO ELECTRO NEXT TEATRICAL NEXT TO ARRANGEMENT TO EXCEDRIN & PONDS WITH AT FROM NATURE TO LOMECAN AS BRAND SAME SHARE OF SHELF LEAST 20% SOS* STOMACH SEGMENT BLOCK & SYSTEM USAGE +58% +62% +21% +39% in Sales in Sales in Sales in Sales +79% L4W vs YA* +21% YTD vs YA *S
Slide 39: Customer & Channel Expansion
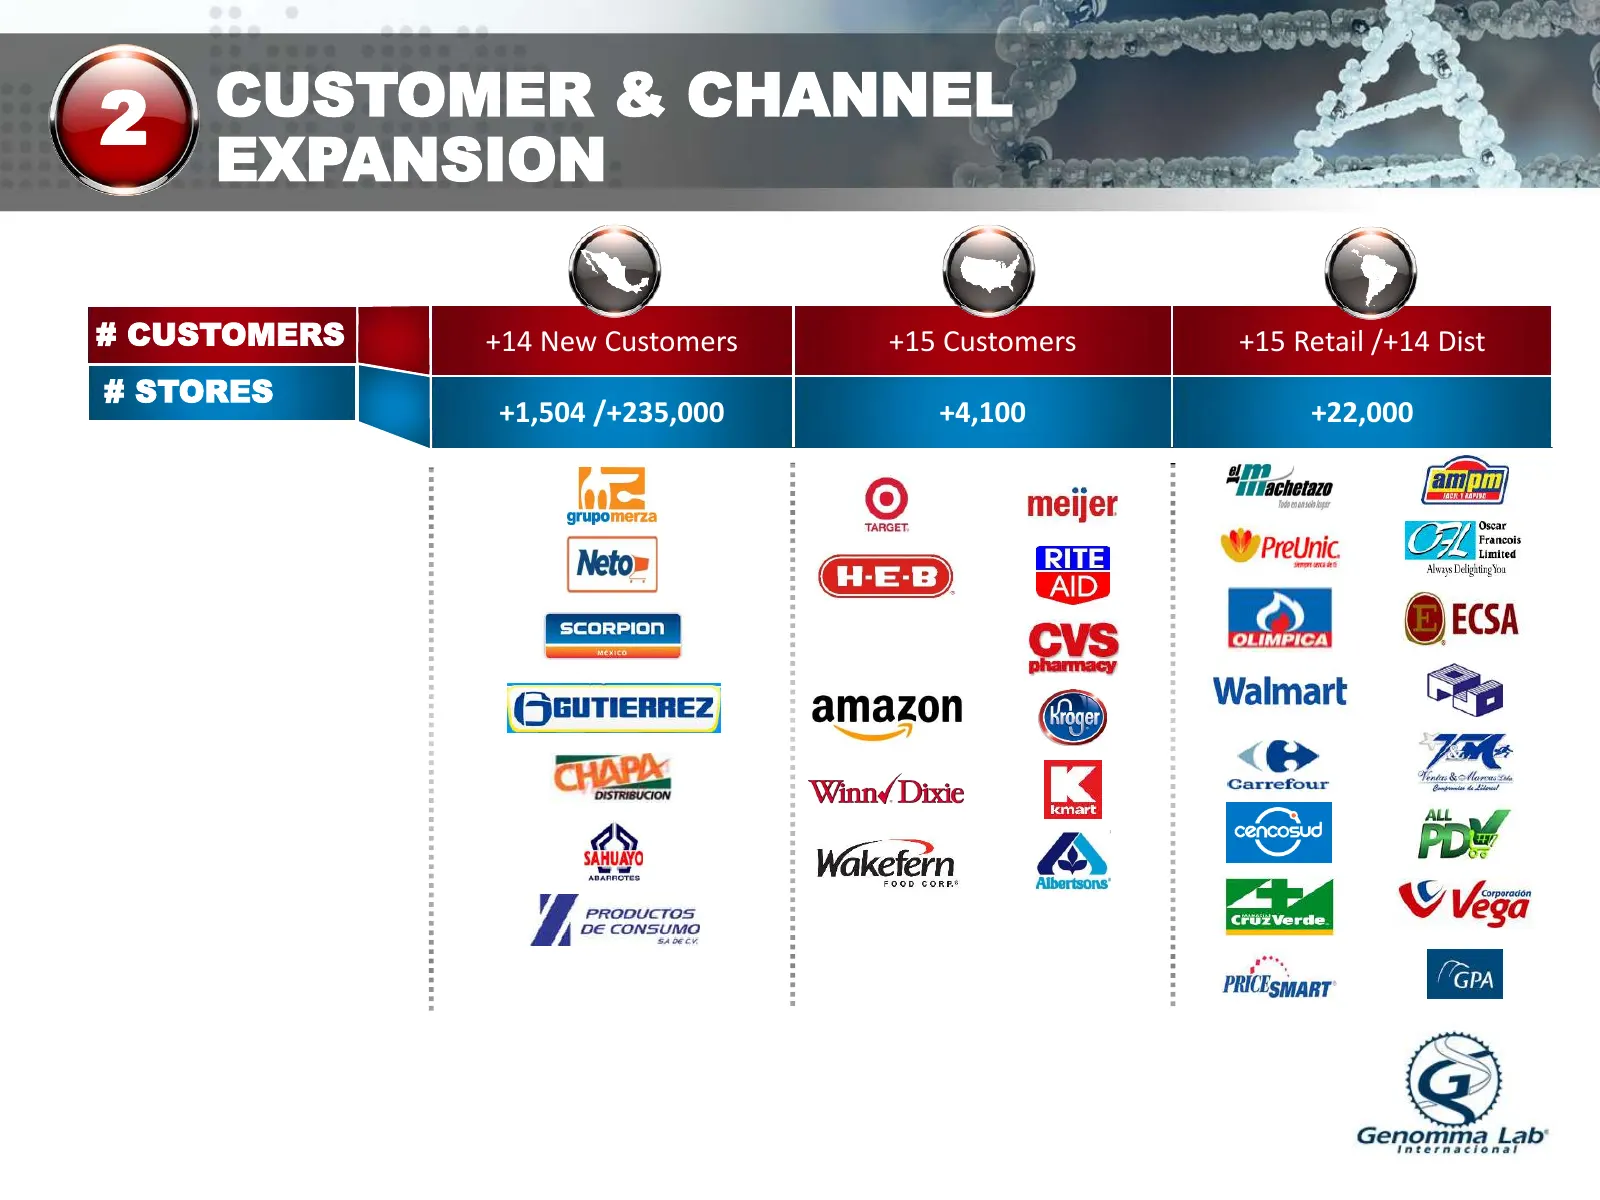
2 CUSTOMER & CHANNEL EXPANSION # CUSTOMERS +14 New Customers +15 Customers +15 Retail /+14 Dist # STORES +1,504 /+235,000 +4,100 +22,000
Slide 40: Go to Market (Pay for Performance)
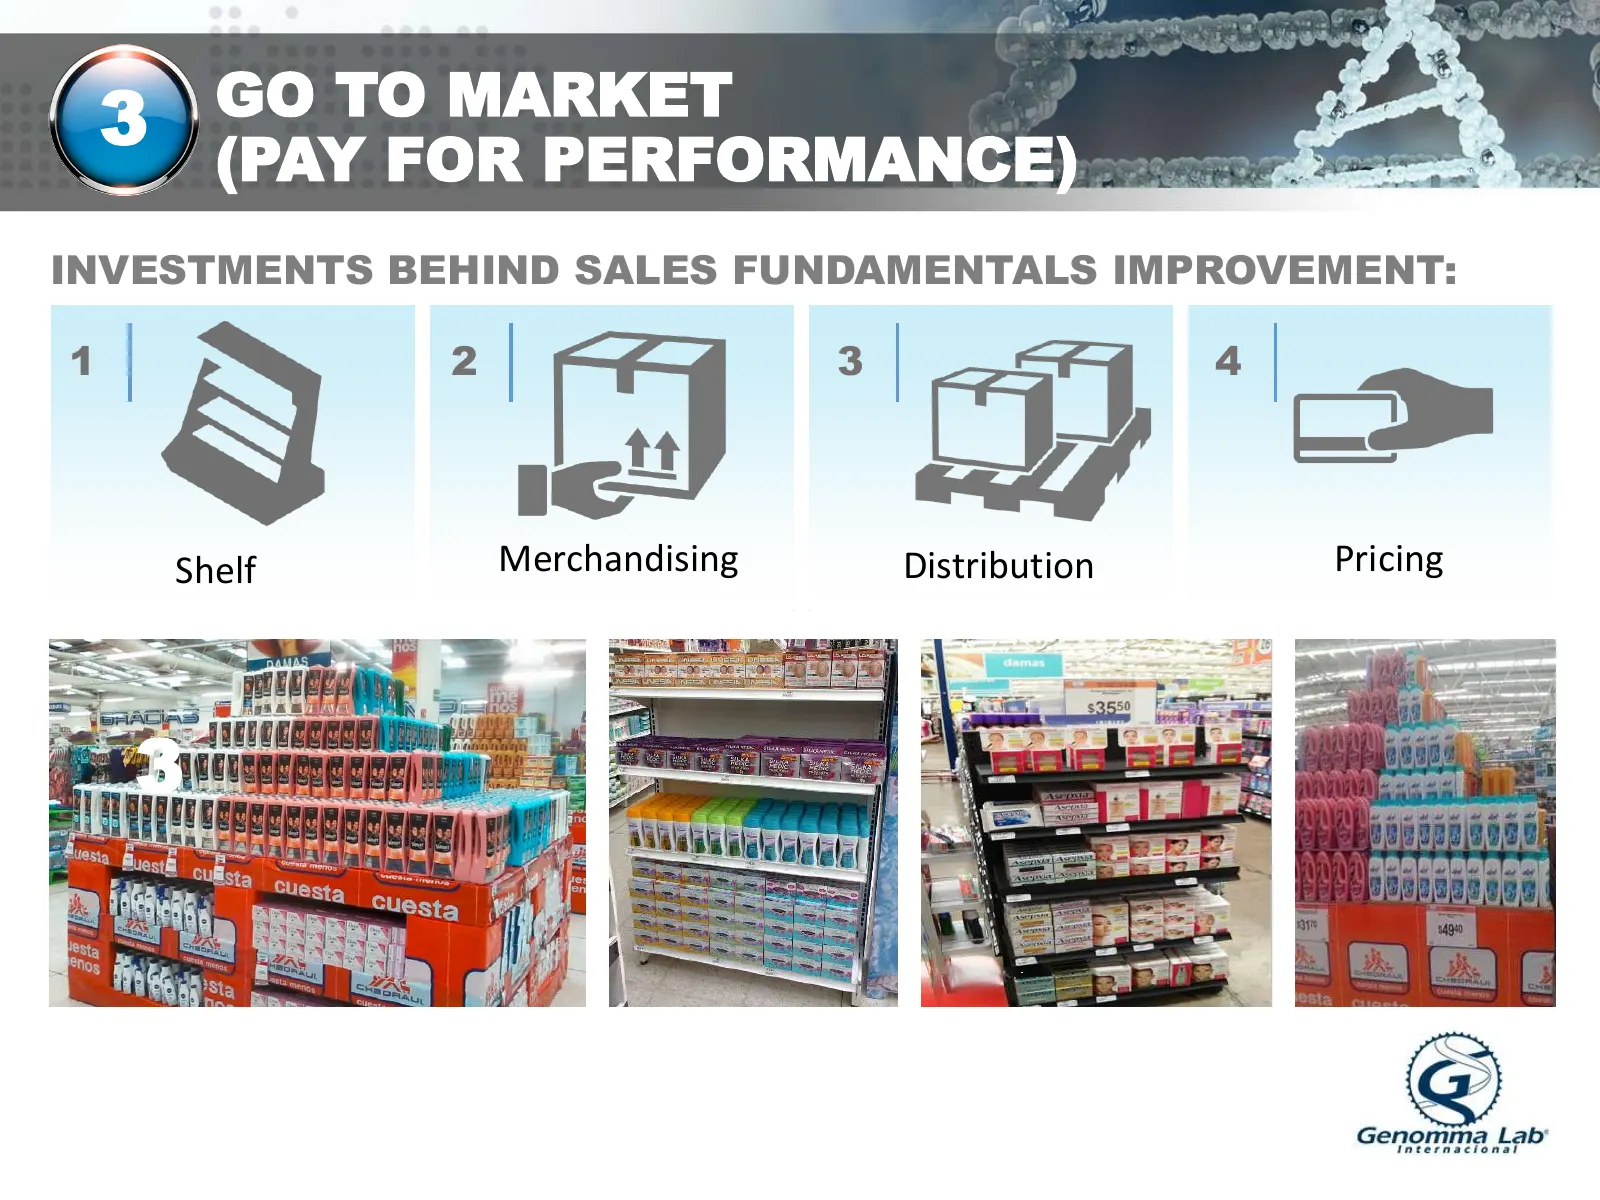
3 GO TO MARKET (PAY FOR PERFORMANCE) INVESTMENTS BEHIND SALES FUNDAMENTALS IMPROVEMENT: 1 2 3 4 Shelf Merchandising Distribution Pricing 3
Slide 41: Commercial Innovation
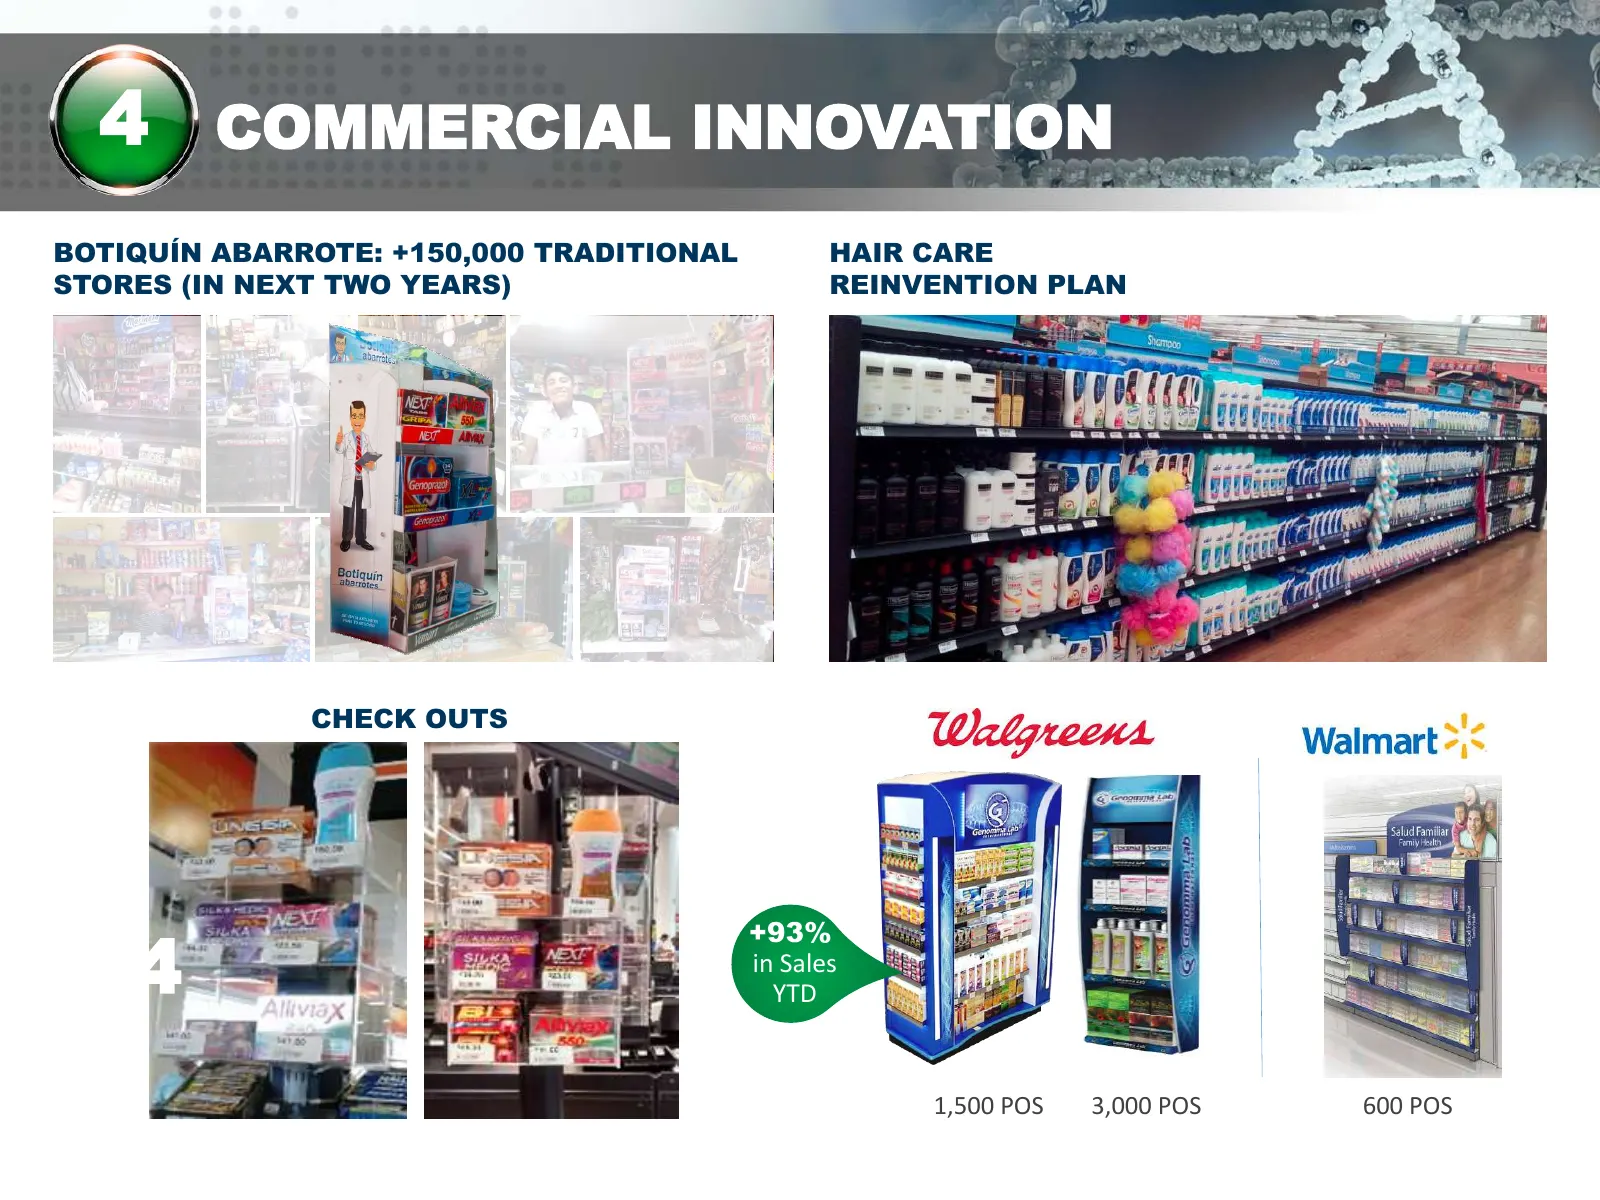
4 COMMERCIAL INNOVATION BOTIQUÍN ABARROTE: +150,000 TRADITIONAL HAIR CARE STORES (IN NEXT TWO YEARS) REINVENTION PLAN CHECK OUTS 4 +93% in Sales YTD 1,500 POS 3,000 POS 600 POS
Slide 42: Marzam
MARZAM • On August 25th, 2015 the Comisión Federal de Competencia Economica (COFECE) approved the sale of 50% plus one share of Grupo Comercial e Industrial Marzam S.A.P.I. de C.V. • According to previously negotiated contracts, the closing of the transaction took place on September 25th. In such da
Slide 43: Marzam: Impact on Financial Statements
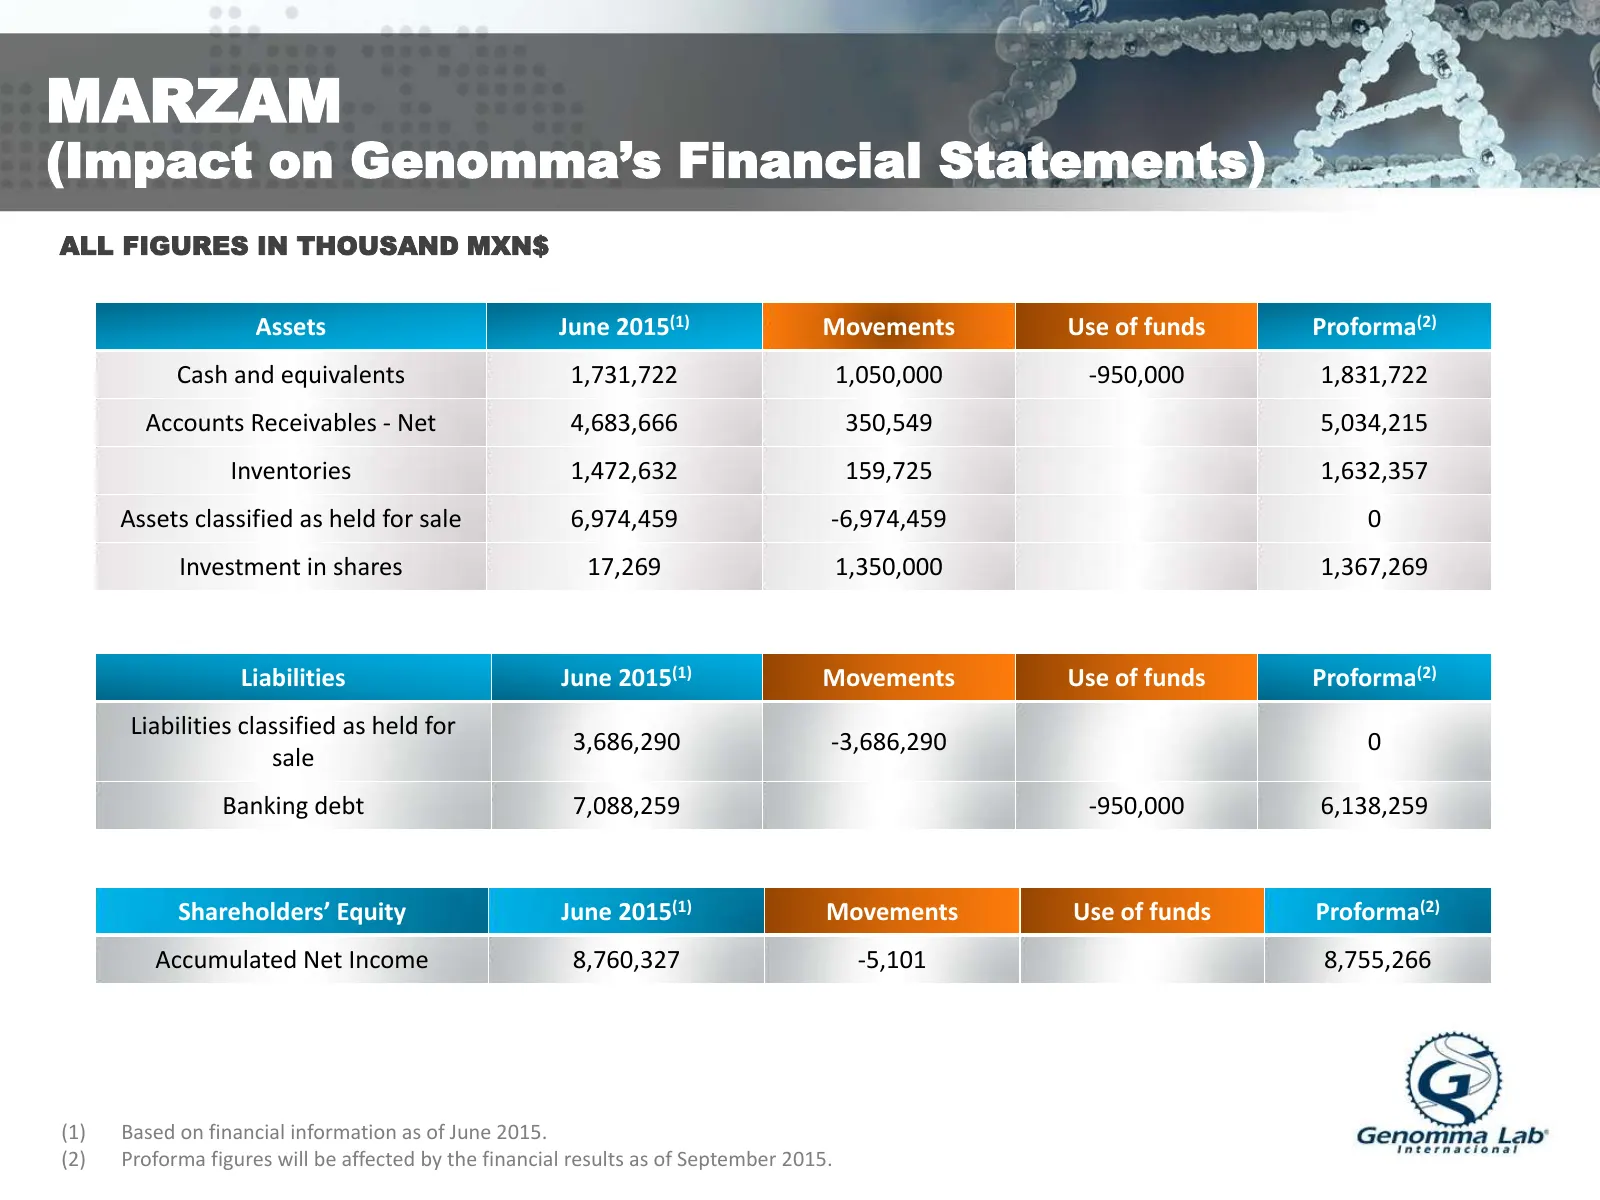
MARZAM (Impact on Genomma’s Financial Statements) ALL FIGURES IN THOUSAND MXN$ Assets June 2015(1) Movements Use of funds Proforma(2) Cash and equivalents 1,731,722 1,050,000 -950,000 1,831,722 Accounts Receivables - Net 4,683,666 350,549 5,034,215 Inventories 1,472,632 159,725 1,632,357 Assets clas
Slide 44: Marzam: Proforma Financial Statements
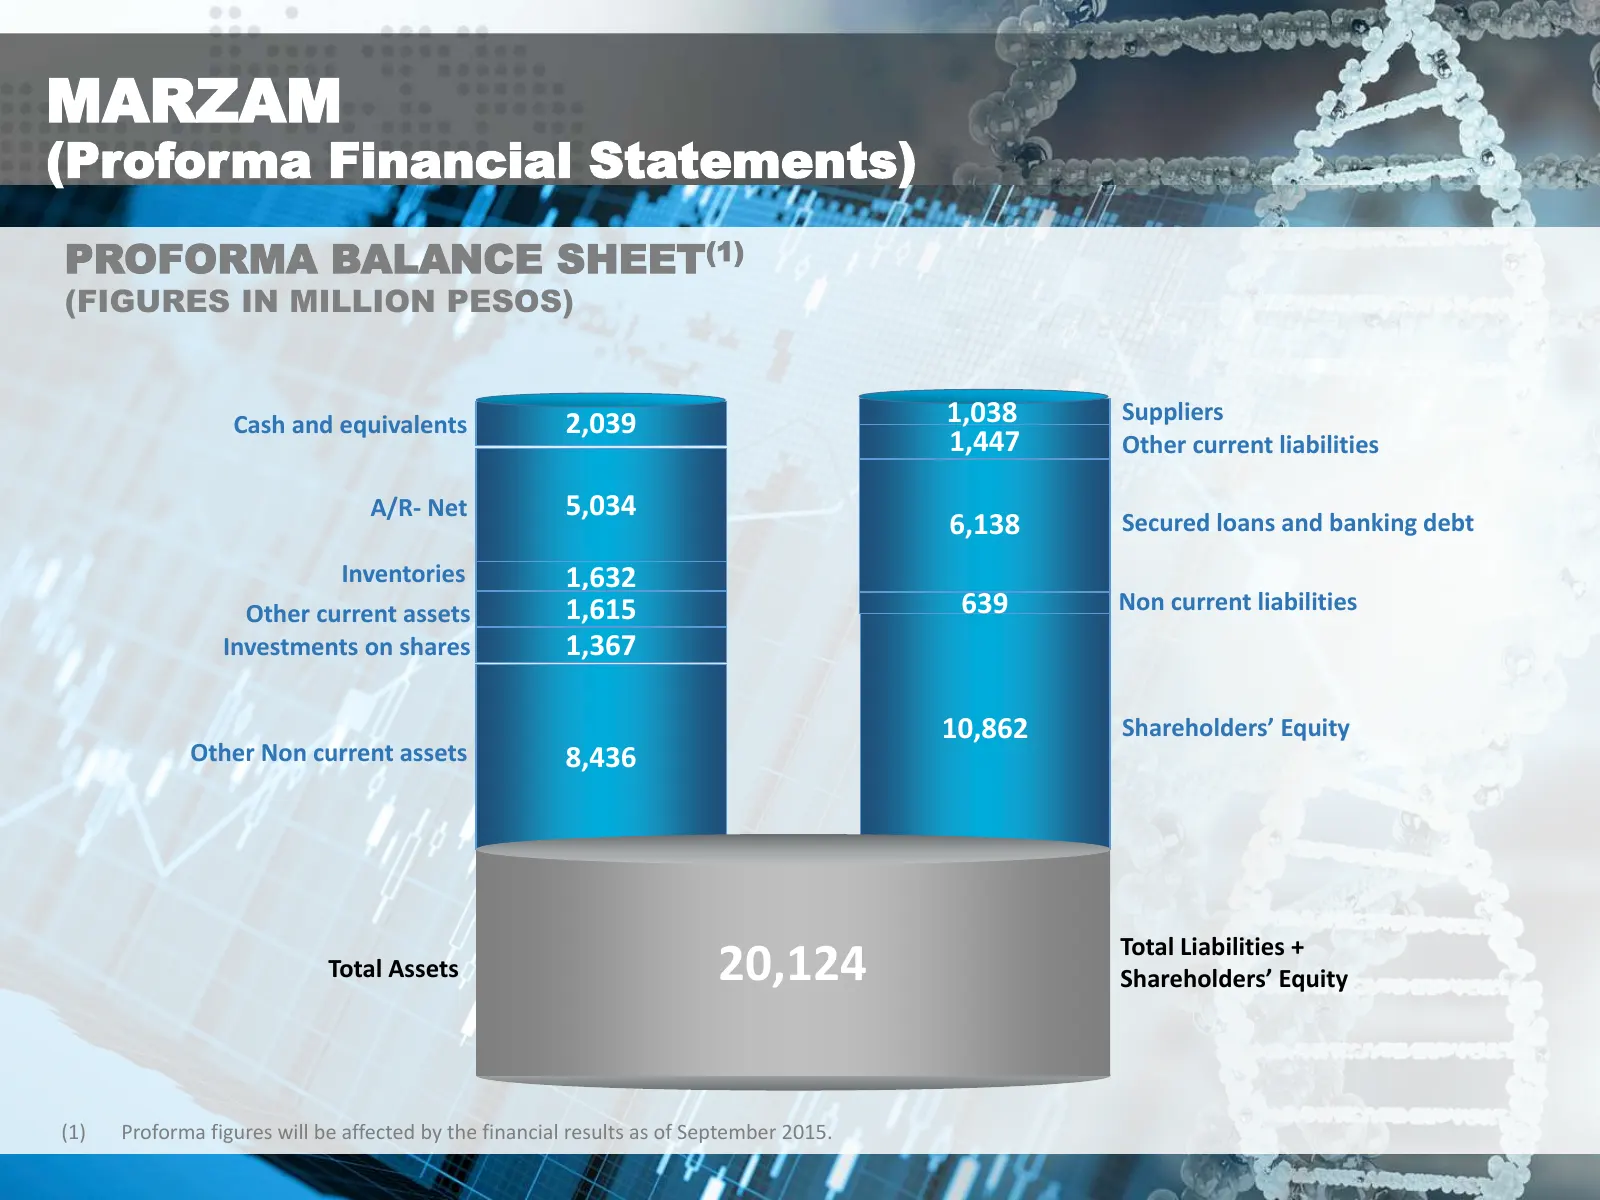
MARZAM (Proforma Financial Statements) PROFORMA BALANCE SHEET(1) (FIGURES IN MILLION PESOS) Cash and equivalents 2,039 1,038 Suppliers 1,447 Other current liabilities A/R- Net 5,034 6,138 Secured loans and banking debt Inventories 1,632 Other current assets 1,615 639 Non current liabilities Investme
Slide 45: LATAM
Genomma Lab‘ Internacional
Slide 46: New Clients
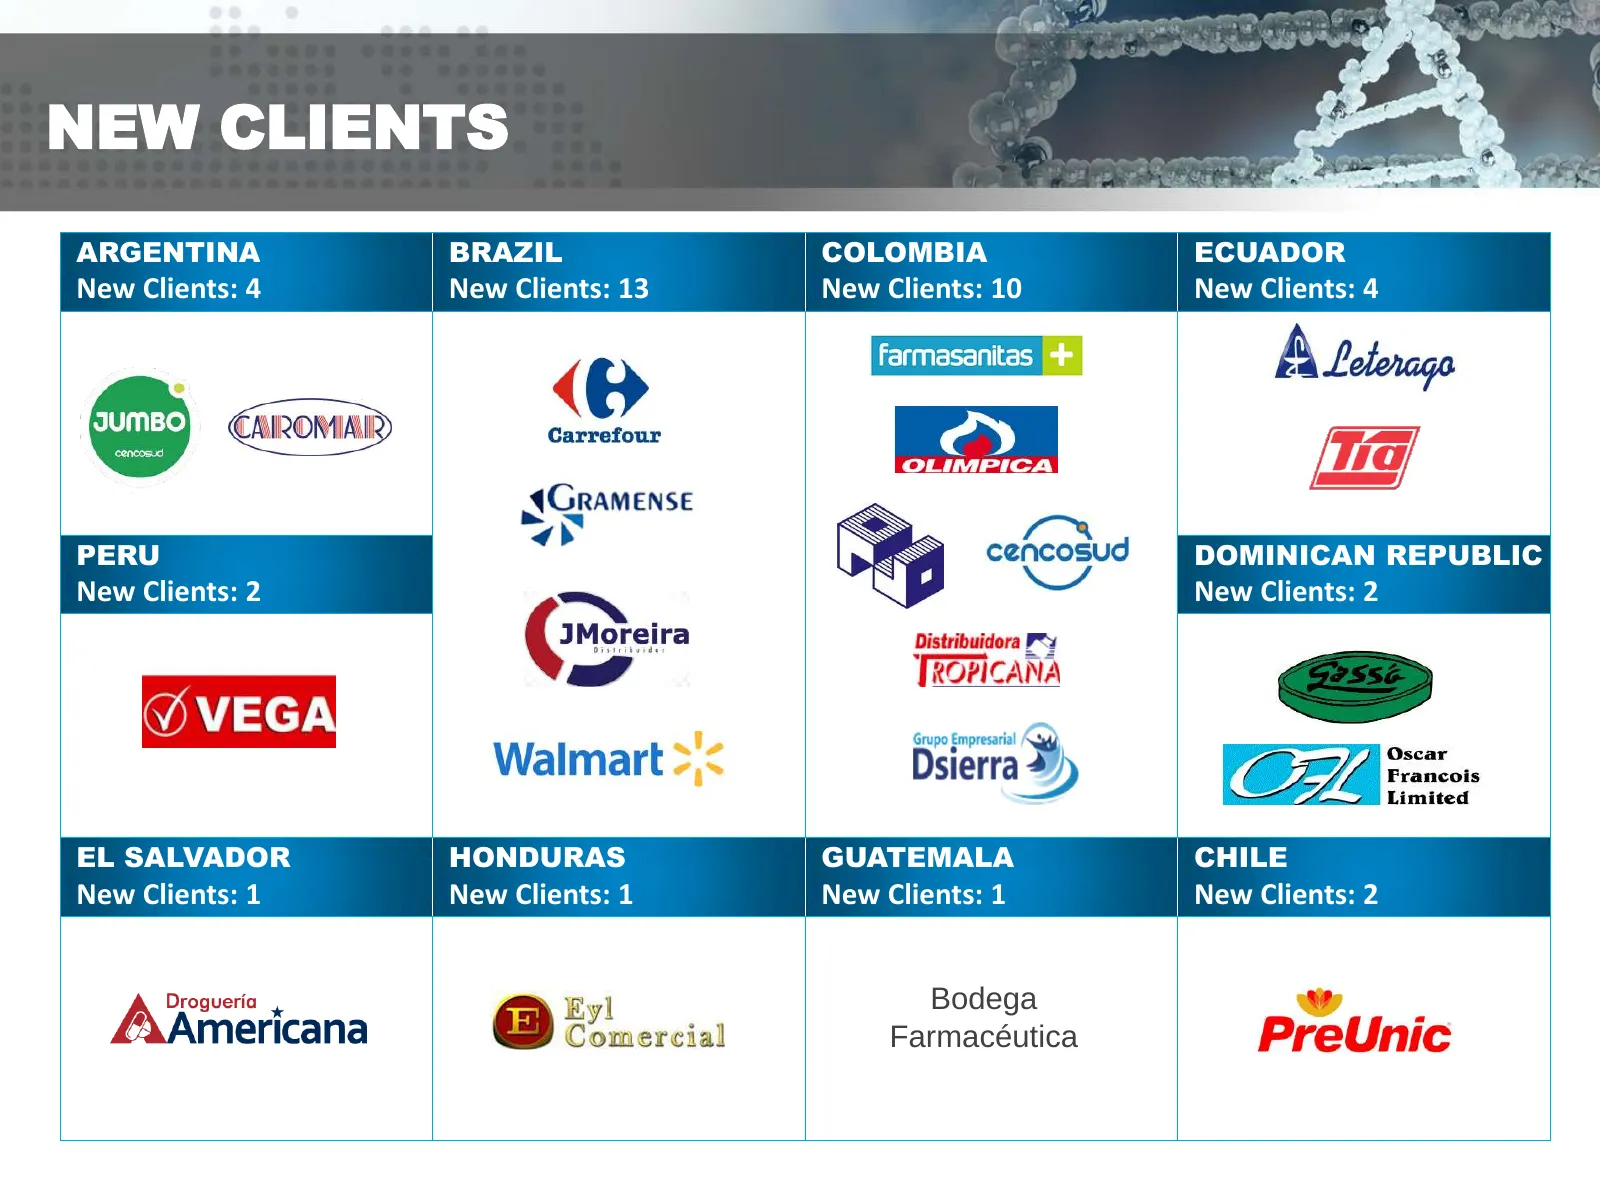
NEW CLIENTS ARGENTINA BRAZIL COLOMBIA ECUADOR New Clients: 4 New Clients: 13 New Clients: 10 New Clients: 4 PERU DOMINICAN REPUBLIC New Clients: 2 New Clients: 2 EL SALVADOR HONDURAS GUATEMALA CHILE New Clients: 1 New Clients: 1 New Clients: 1 New Clients: 2 Bodega Farmacéutica
Slide 47: Growth by Country
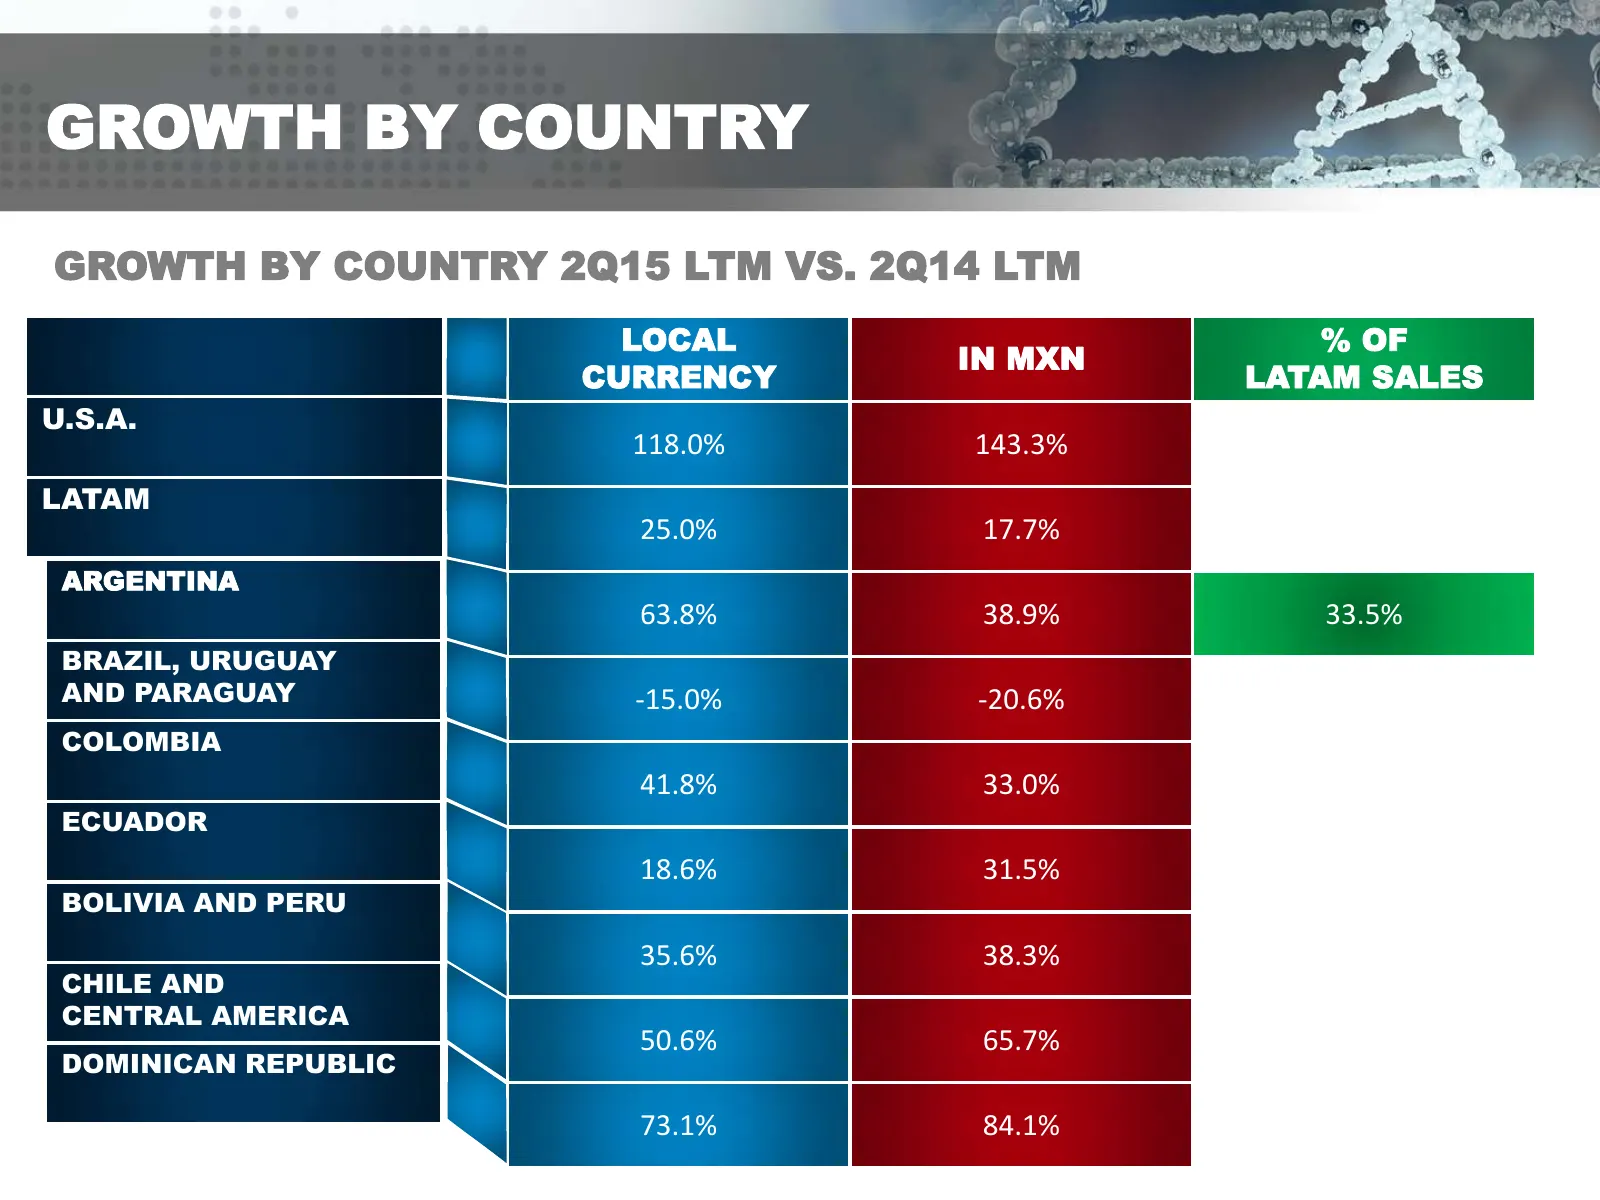
GROWTH BY COUNTRY GROWTH BY COUNTRY 2Q15 LTM VS. 2Q14 LTM LOCAL % OF IN MXN CURRENCY LATAM SALES U.S.A. 118.0% 143.3% LATAM 25.0% 17.7% ARGENTINA 63.8% 38.9% 33.5% BRAZIL, URUGUAY AND PARAGUAY -15.0% -20.6% COLOMBIA 41.8% 33.0% ECUADOR 18.6% 31.5% BOLIVIA AND PERU 35.6% 38.3% CHILE AND CENTRAL AMERI
Slide 48: Results in LATAM
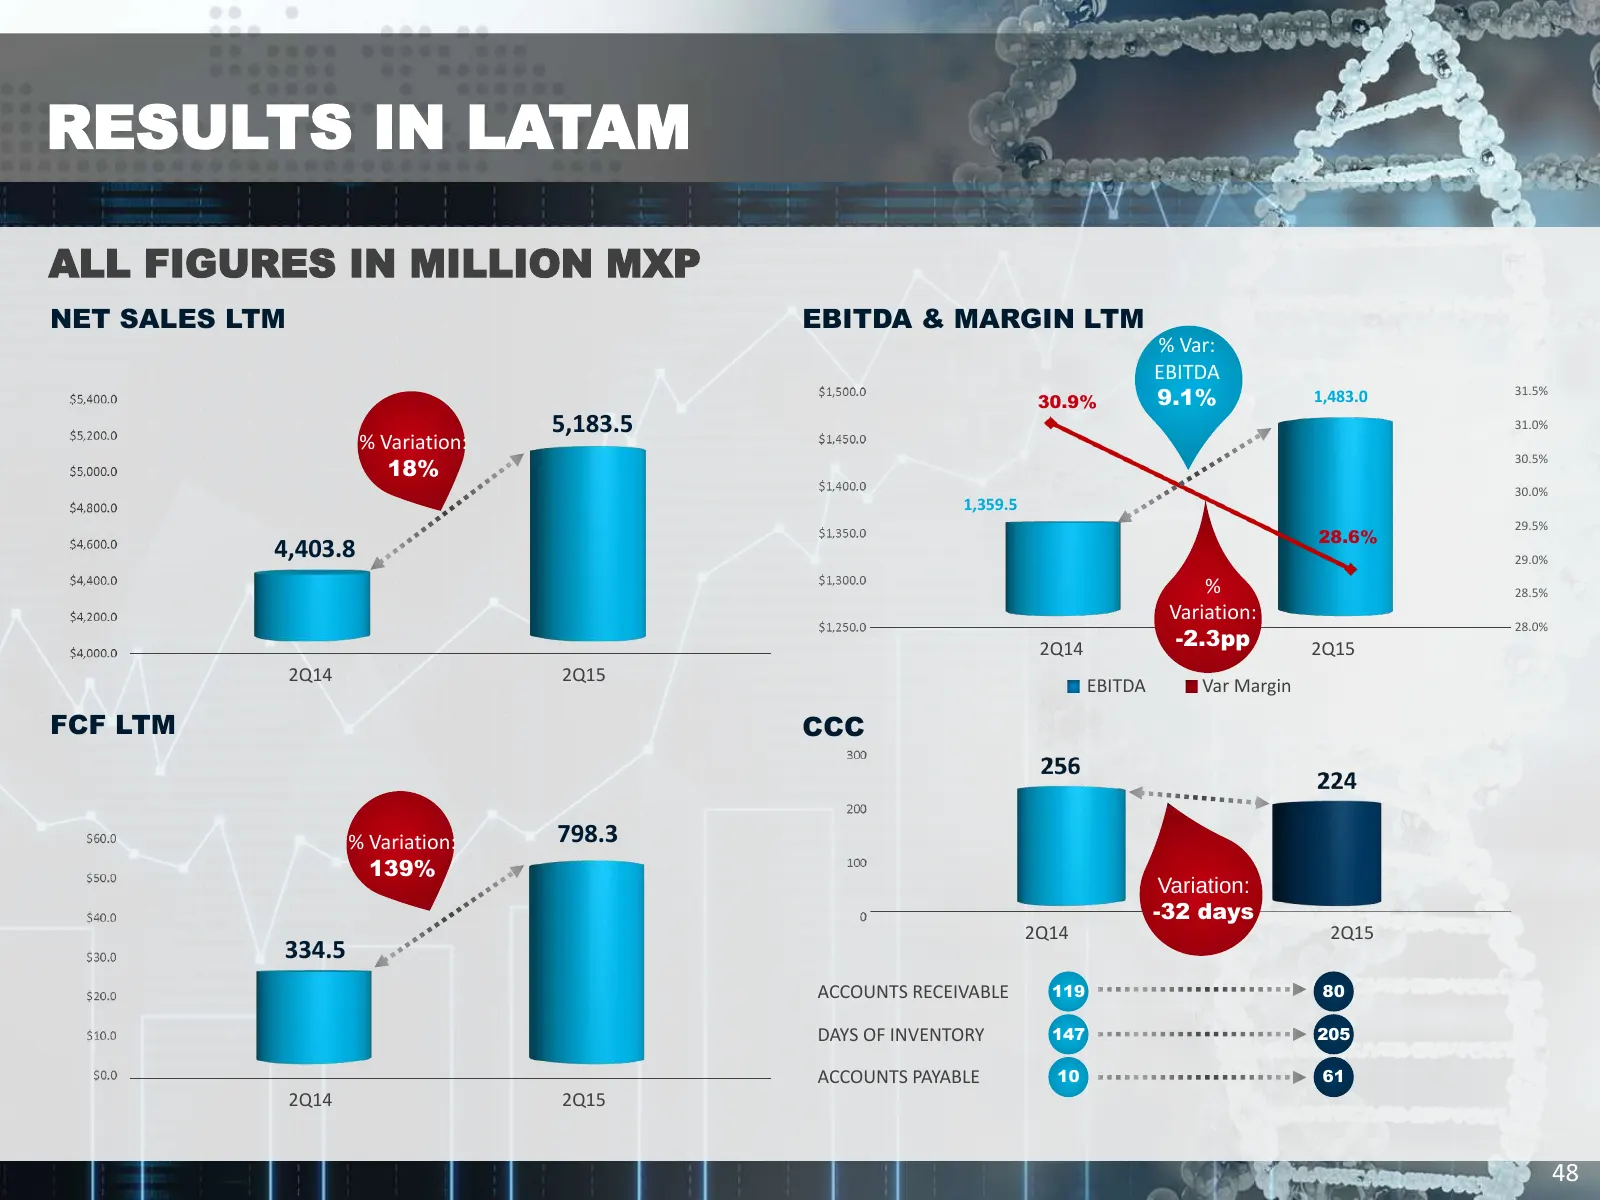
RESULTS IN LATAM ALL FIGURES IN MILLION MXP NET SALES LTM EBITDA & MARGIN LTM % Var: EBITDA 30.9% 9.1% 1,483.0 31.5% 5,183.5 31.0% % Variation: 18% 30.5% 30.0% 1,359.5 29.5% 28.6% 4,403.8 29.0% % 28.5% Variation: 28.0% 2Q14 -2.3pp 2Q15 2Q14 2Q15 EBITDA Var Margin FCF LTM CCC % Variation: 798.3 139%
Slide 49: Valuation, Core Brands and Learning from the Past
VALUATION, CORE BRANDS AND LEARNING FROM THE PAST 49
Slide 50: Valuation Hints: New Regional Disclosure
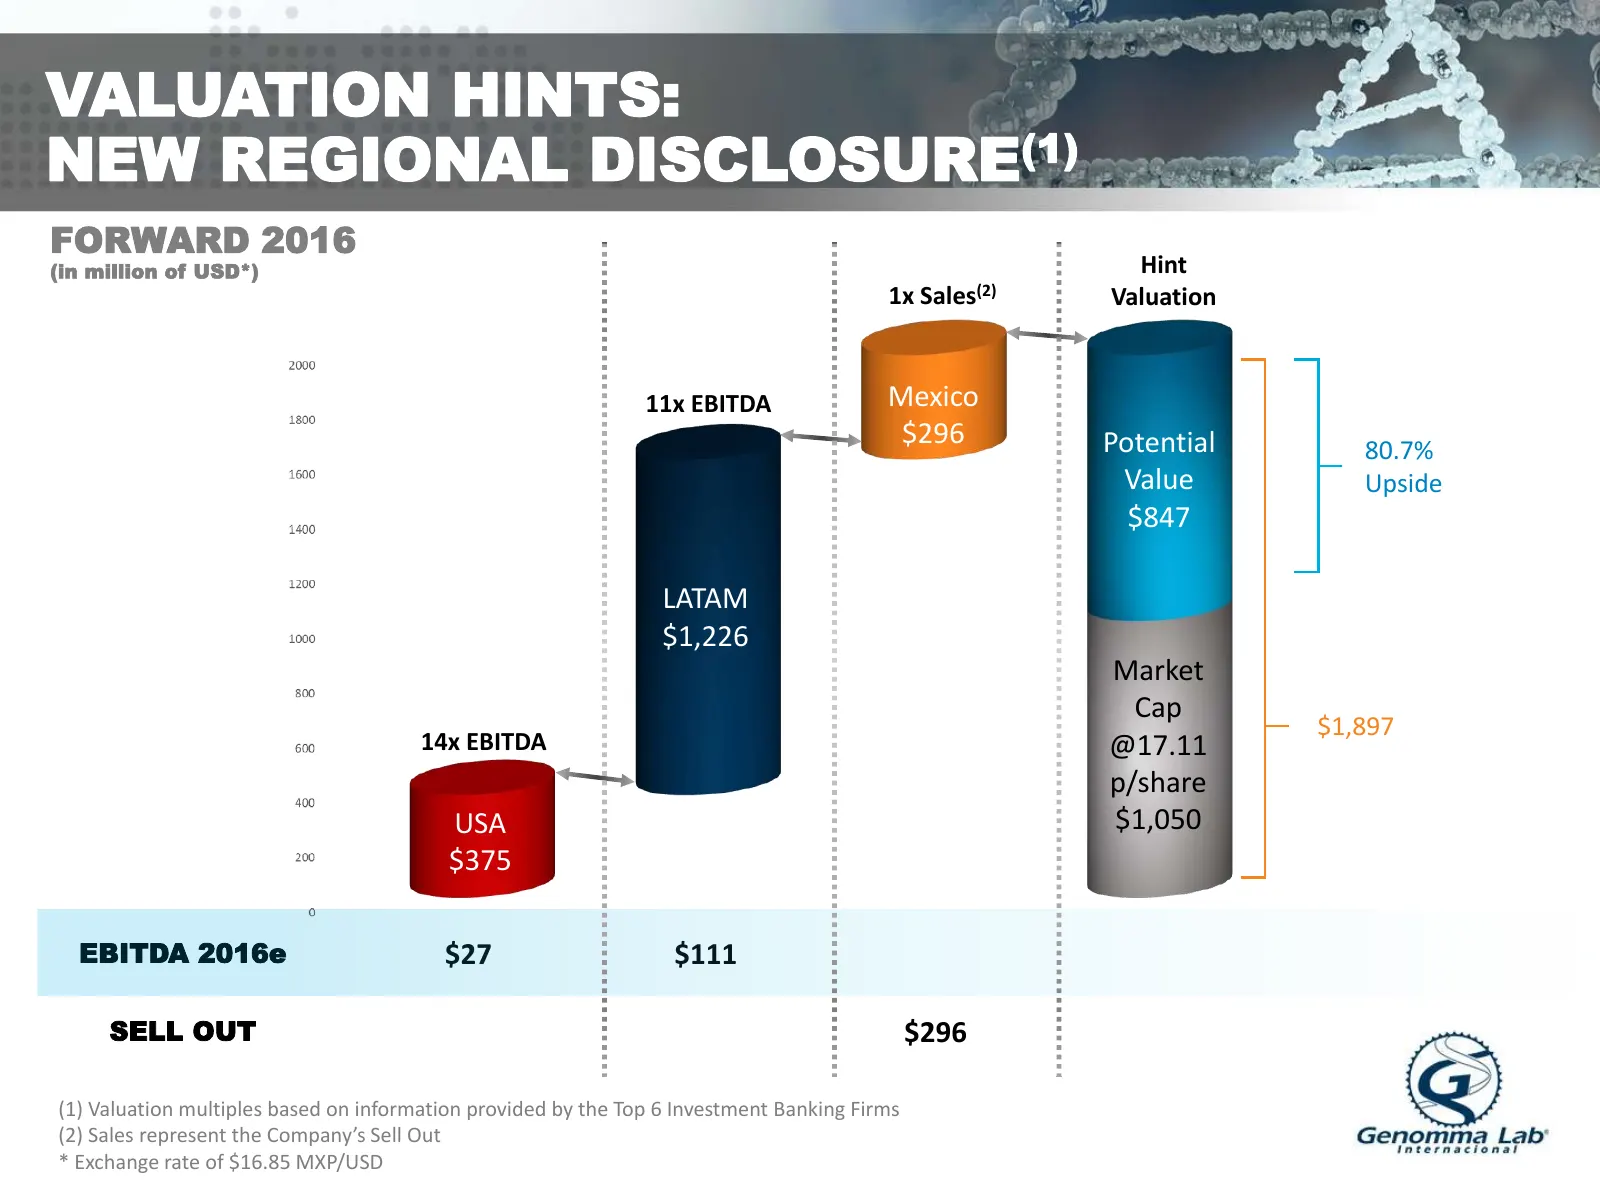
VALUATION HINTS: NEW REGIONAL DISCLOSURE (1) FORWARD 2016 (in million of USD*) Hint 1x Sales(2) Valuation 11x EBITDA Mexico $296 Potential 80.7% Value Upside $847 LATAM $1,226 Market Cap $1,897 14x EBITDA @17.11 p/share USA $1,050 $375 EBITDA 2016e $27 $111 SELL OUT $296 (1) Valuation multiples base
Slide 51: Core Brands
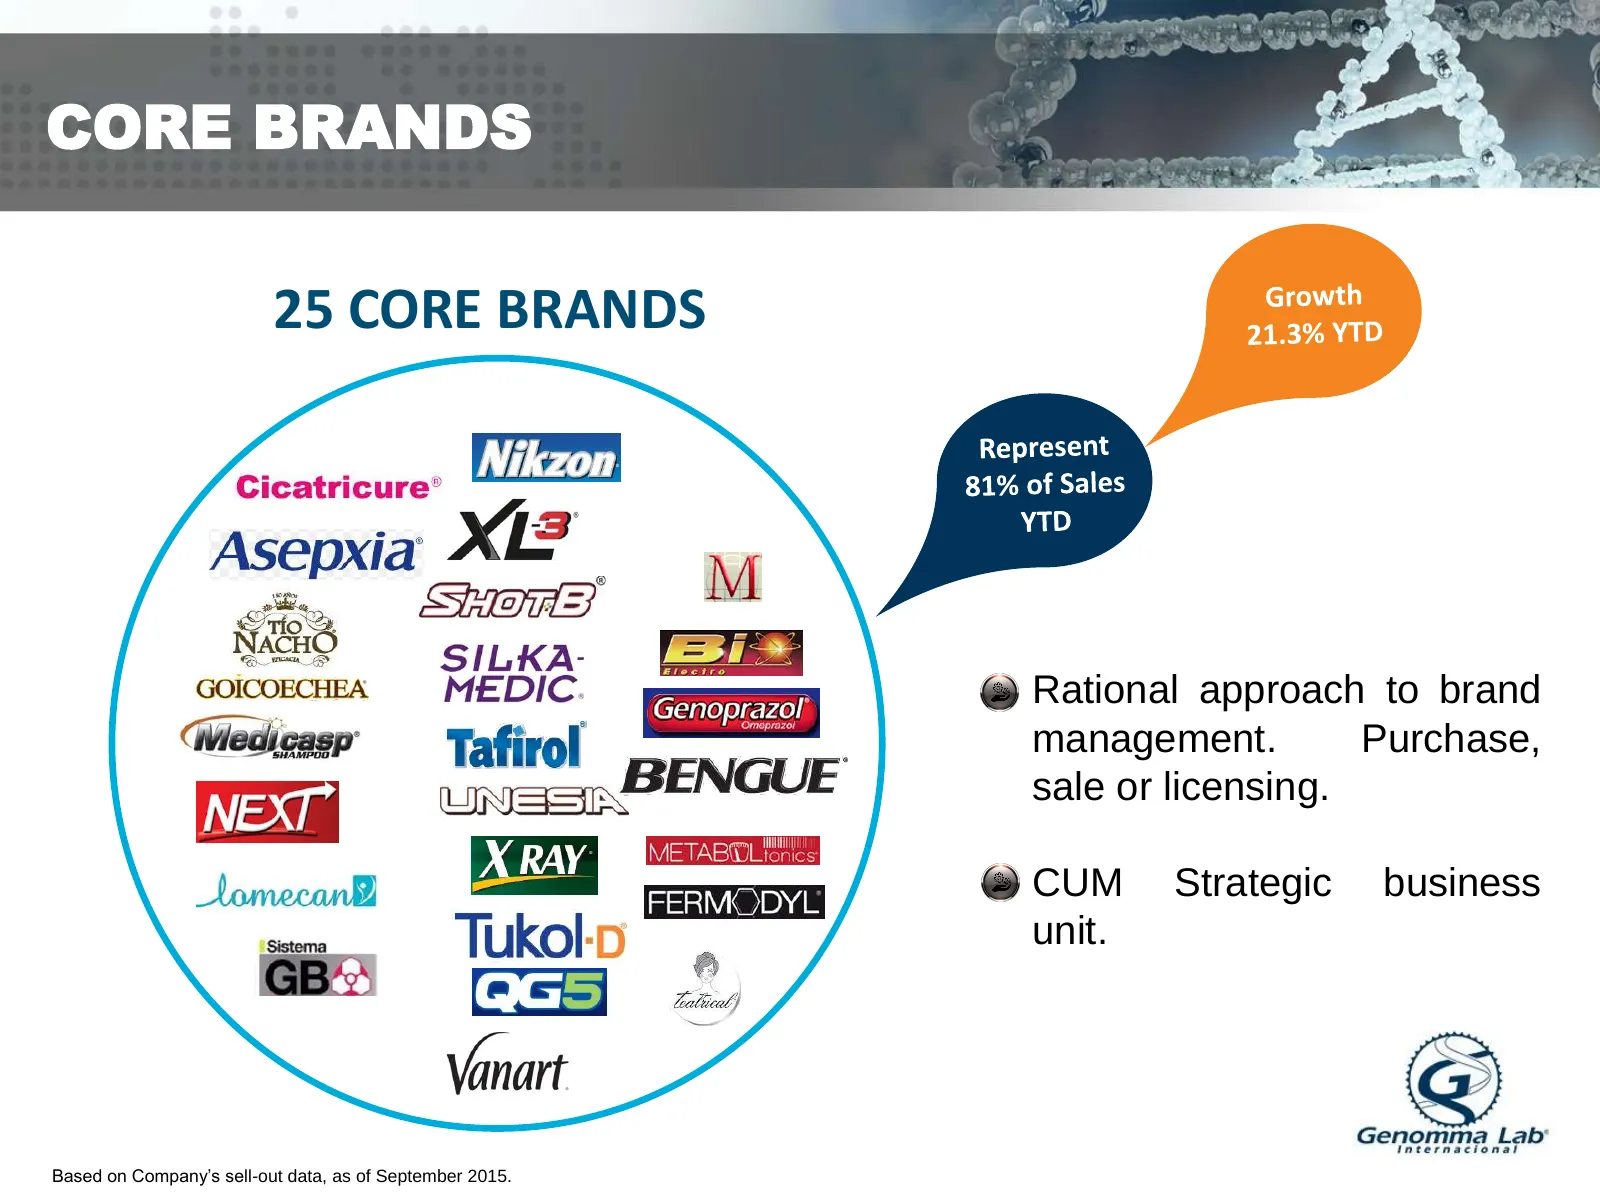
CORE BRANDS 25 CORE BRANDS • Rational approach to brand management. Purchase, sale or licensing. • CUM Strategic business unit. Based on Company’s sell-out data, as of September 2015.
Slide 52: Learning from the Past
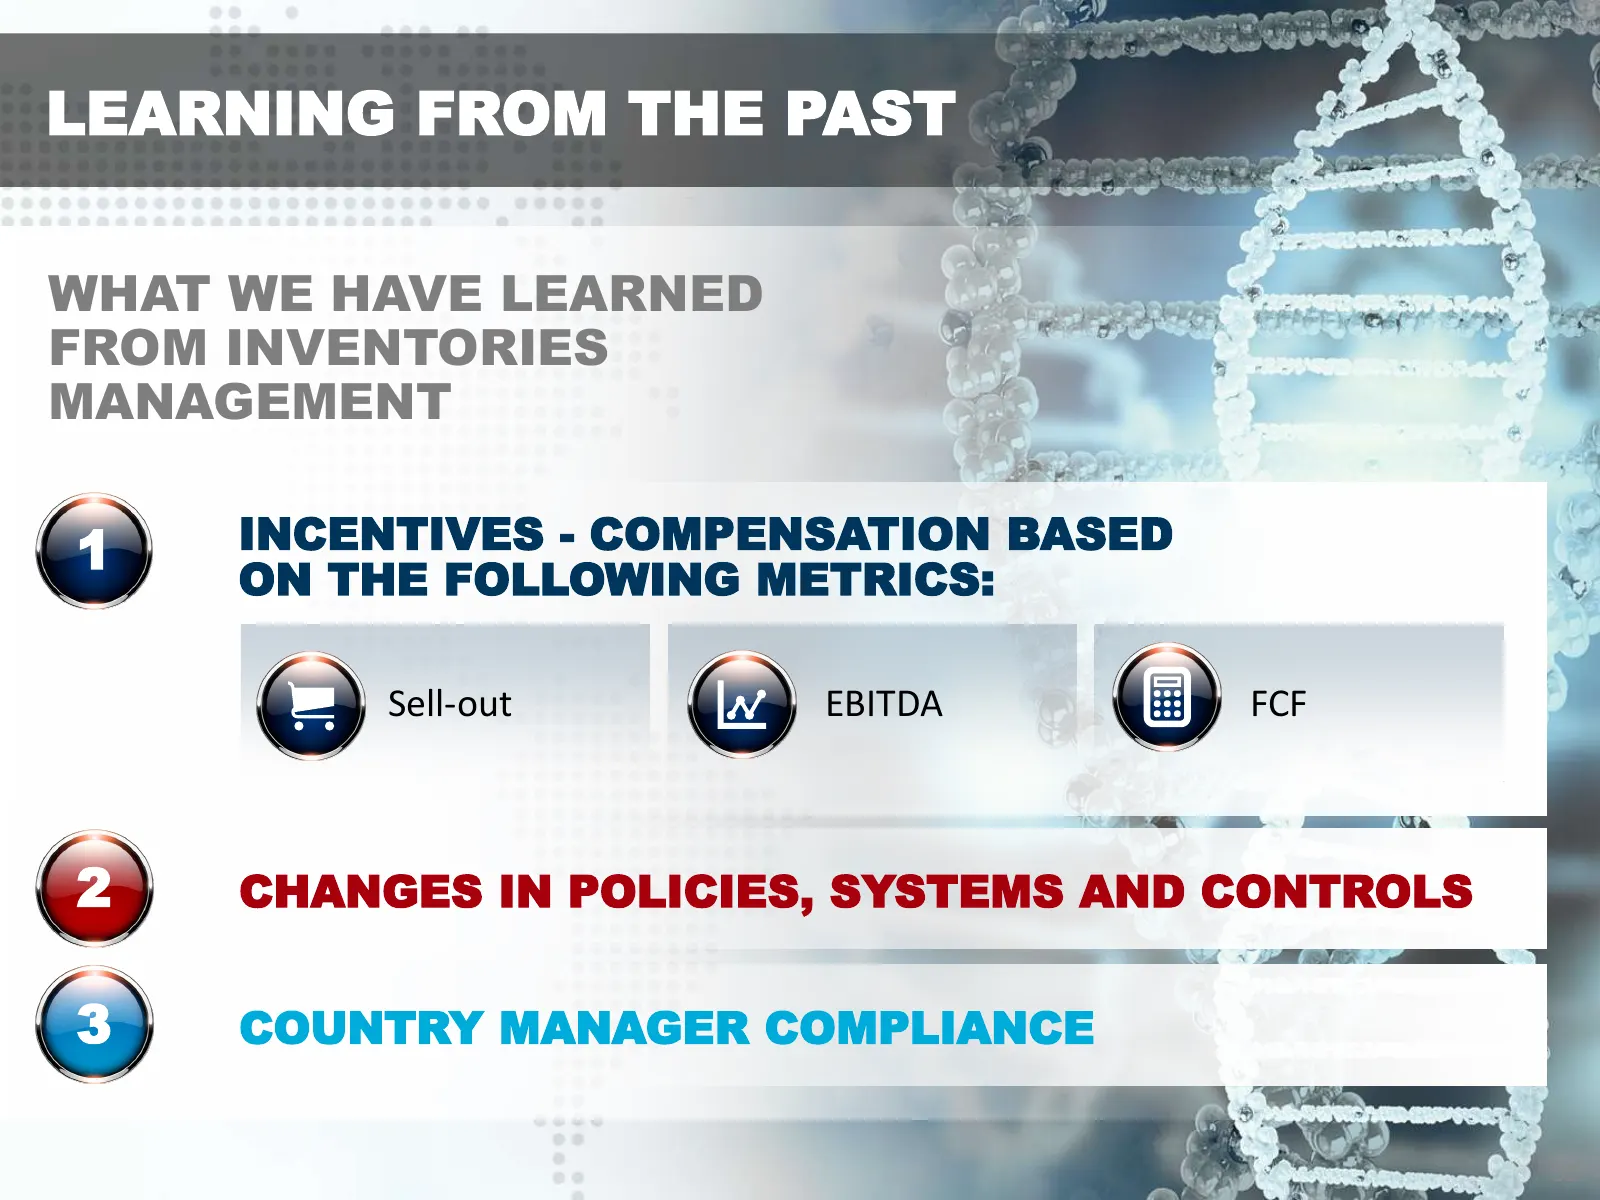
LEARNING FROM THE PAST WHAT WE HAVE LEARNED FROM INVENTORIES MANAGEMENT 1 INCENTIVES - COMPENSATION BASED ON THE FOLLOWING METRICS: Sell-out EBITDA FCF 2 CHANGES IN POLICIES, SYSTEMS AND CONTROLS 3 COUNTRY MANAGER COMPLIANCE 52
Slide 53: Guidance
Genomma Lab‘ Internacional GUIDANCE
Slide 54: Inventory Destocking at POS in Mexico
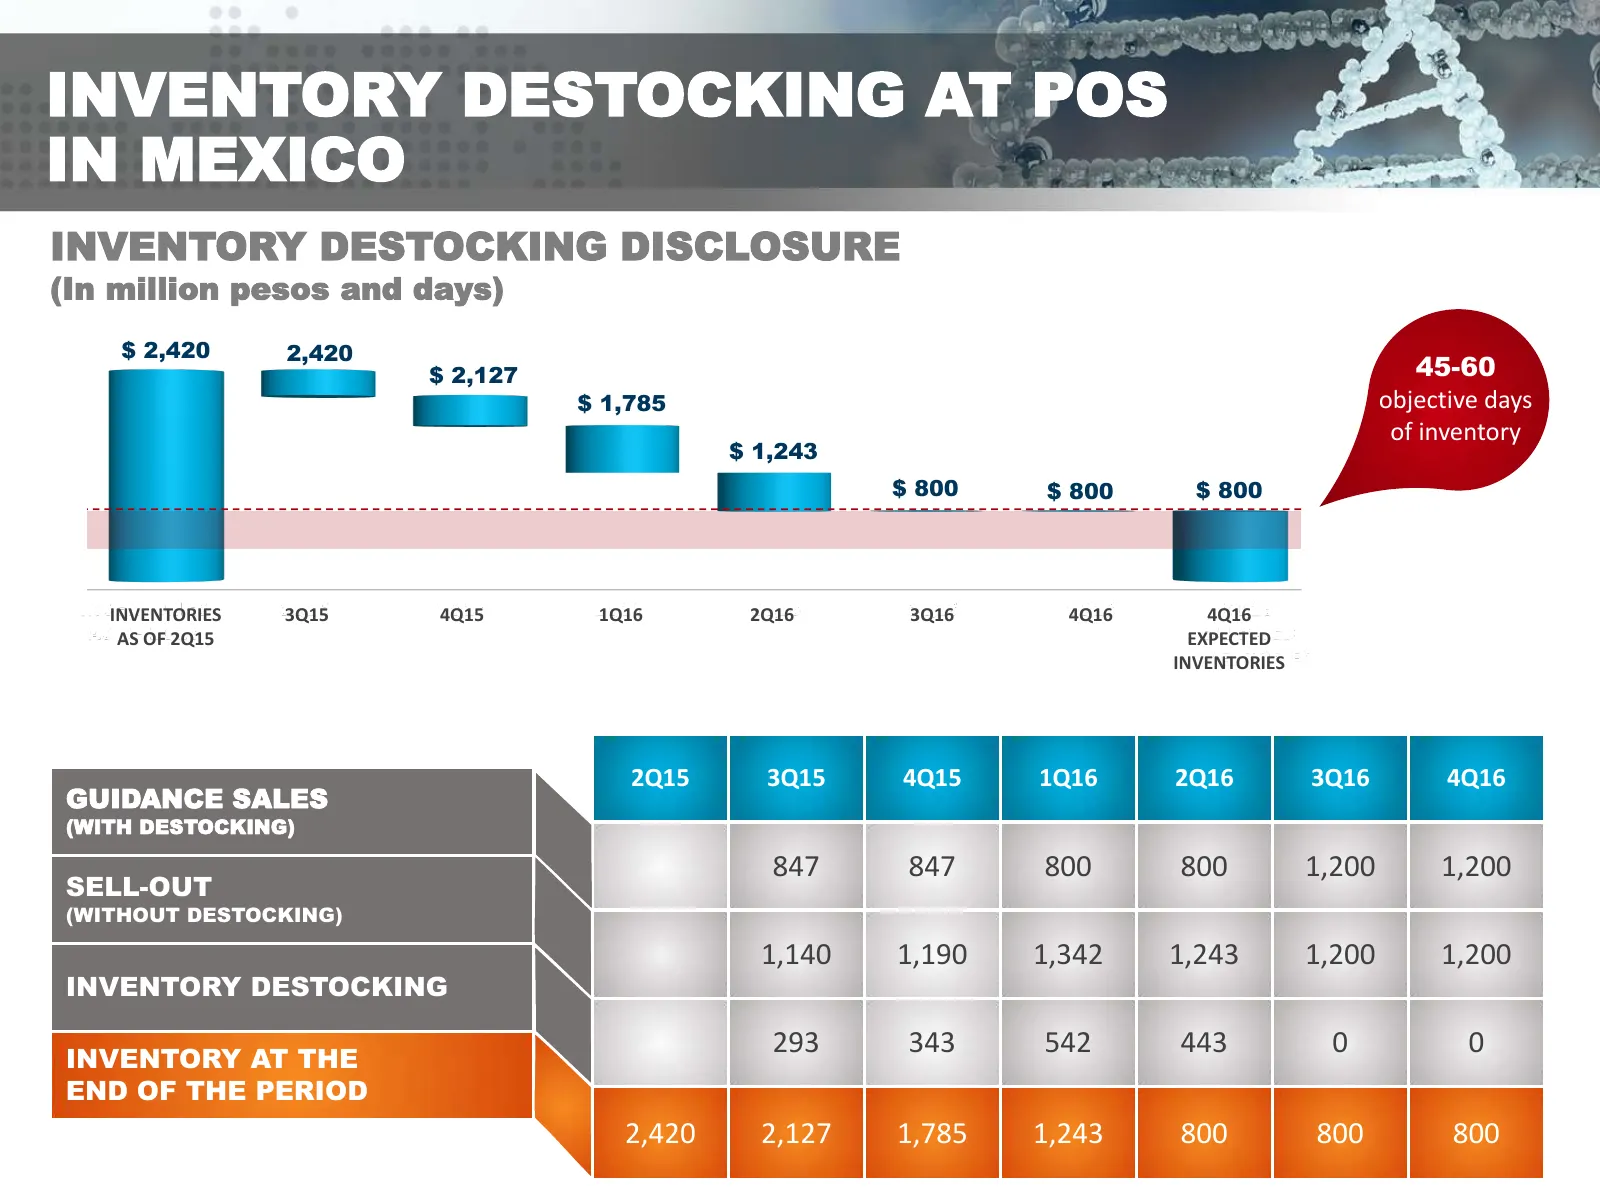
INVENTORY DESTOCKING AT POS IN MEXICO INVENTORY DESTOCKING DISCLOSURE (In million pesos and days) $ 2,420 2,420 $ 2,127 45-60 $ 1,785 objective days of inventory $ 1,243 $ 800 $ 800 $ 800 INVENTORIES 3Q15 4Q15 1Q16 2Q16 3Q16 4Q16 4Q16 AS OF 2Q15 EXPECTED INVENTORIES 2Q15 3Q15 4Q15 1Q16 2Q16 3Q16 4Q1
Slide 55: 2015 Guidance Review and 2016 Guidance
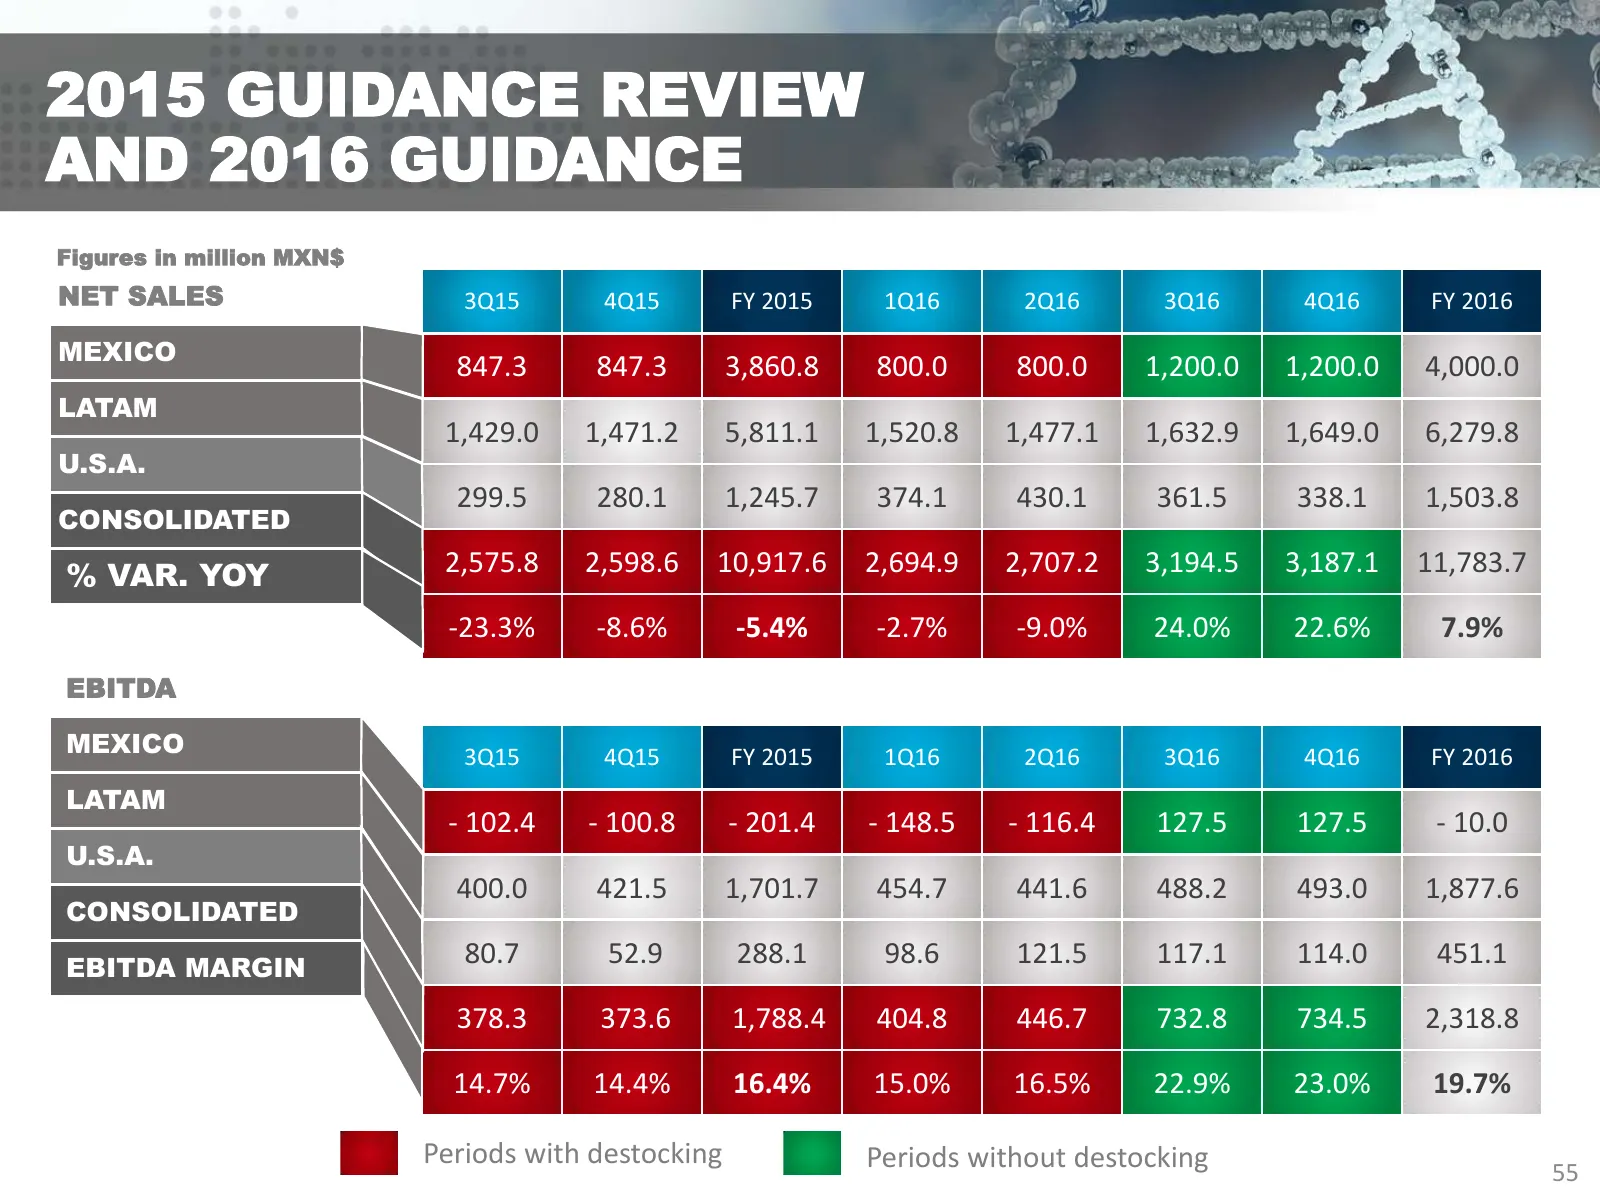
2015 GUIDANCE REVIEW AND 2016 GUIDANCE Figures in million MXN$ NET SALES 3Q15 4Q15 FY 2015 1Q16 2Q16 3Q16 4Q16 FY 2016 MEXICO 847.3 847.3 3,860.8 800.0 800.0 1,200.0 1,200.0 4,000.0 LATAM 1,429.0 1,471.2 5,811.1 1,520.8 1,477.1 1,632.9 1,649.0 6,279.8 U.S.A. 299.5 280.1 1,245.7 374.1 430.1 361.5 338
Slide 56: FCF Guidance
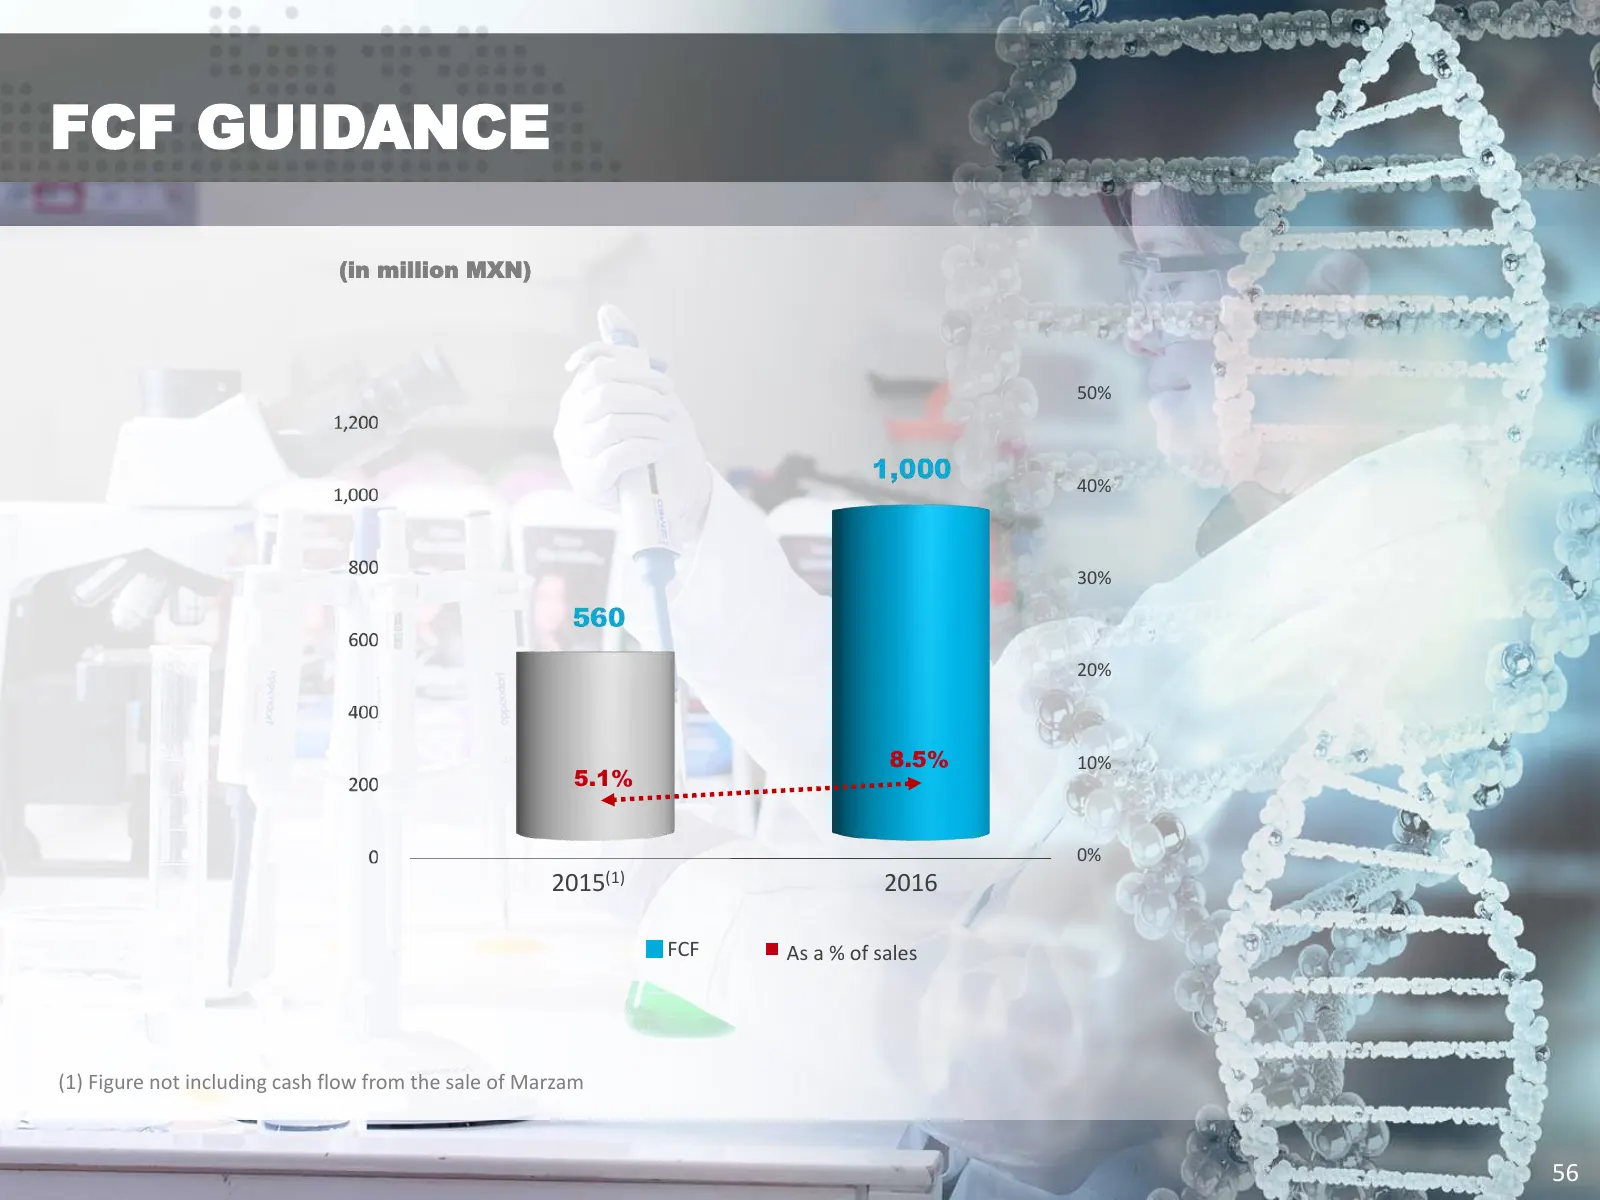
FCF GUIDANCE (in million MXN) 50% 40% 30% 20% 8.5% 10% 5.1% 0% 2015(1) 2016 FCF As a % of sales (1) Figure not including cash flow from the sale of Marzam 56
Slide 57: Final Remarks
FINAL REMARKS • ONE-YEAR TURNAROUND, FINISH INVENTORY CLEANUP BY Q2 2016. • PERFORMANCE: NEW EBITDA, NET PROFIT = FCF • TRANSPARENCY AND ACCOUNTABILITY, NO EXCUSES. • MANAGEMENT’S INVESTMENTS IN GLI. • GENOMMA DAY Q3 2016. END OF OCTOBER.
Slide 58: Investor Relations Contact
INVESTOR RELATIONS CONTACT: OSCAR VILLALOBOS – CFO ANA MARÍA YBARRA – Investor Relations inversion@genommalab.com Tel. (55) 5081-0000 ext. 5106 www.genommalab.com/inversionistas
Source: Internet Archive copy of inversionistas.genommalab.com
More decks from Genomma Lab Internacional SAB de CV Class B
 Q3 2026 Earnings Presentation27 slides · Apr 1, 2026
 Q2 2026 Earnings Presentation29 slides · Apr 1, 2026
 Investor Presentation (December 2025)32 slides · December 2025
 Q3 2025 Earnings Presentation26 slides · October 2025
 Q2 2025 Earnings Presentation33 slides · July 2025
 Q1 2025 Earnings Presentation58 slides · May 2, 2025