Omnicare — Credit Suisse conference (November 2014)
21 slides from Omnicare's conference presentation, Nov 10, 2014
Slide 1: Omnicare
Omnicare
Slide 2: Forward-Looking Statements
Forward-Looking Statements Certain of the statements made today and listed within ji ion slides are f rd-looki ‘statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-| looking statements include, but: are not limited to, all statements regarding the int
Slide 3: Agenda
Agenda Long-Term Care Pharmacy | Multi-Layered Growth Strategy
Slide 4: Omnicare Background
1} Omnicare Background
Slide 5: Company Journey: Significant Transformation Underway
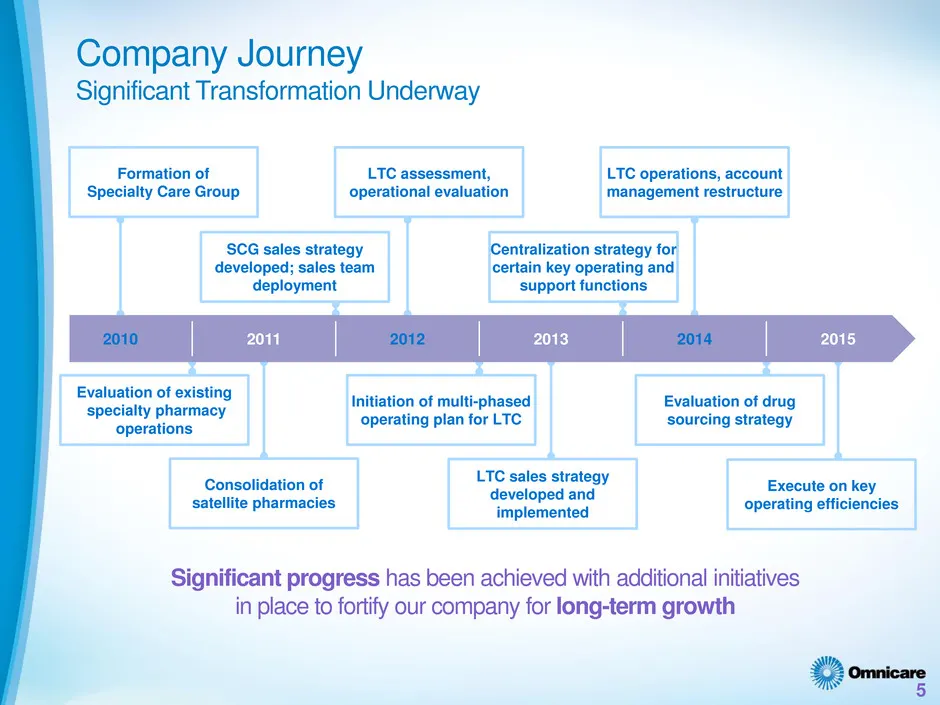
Company Journey Significant Transformation Underway mation of LTC assessment, LTC operations, account Specialty Care Group operational evaluation management restructure SCG sales strategy Centralization strategy for developed; sales team certain key operating and support functions 2011 Evaluation of
Slide 6: Company Journey: Transition to an Integrated Operating Entity
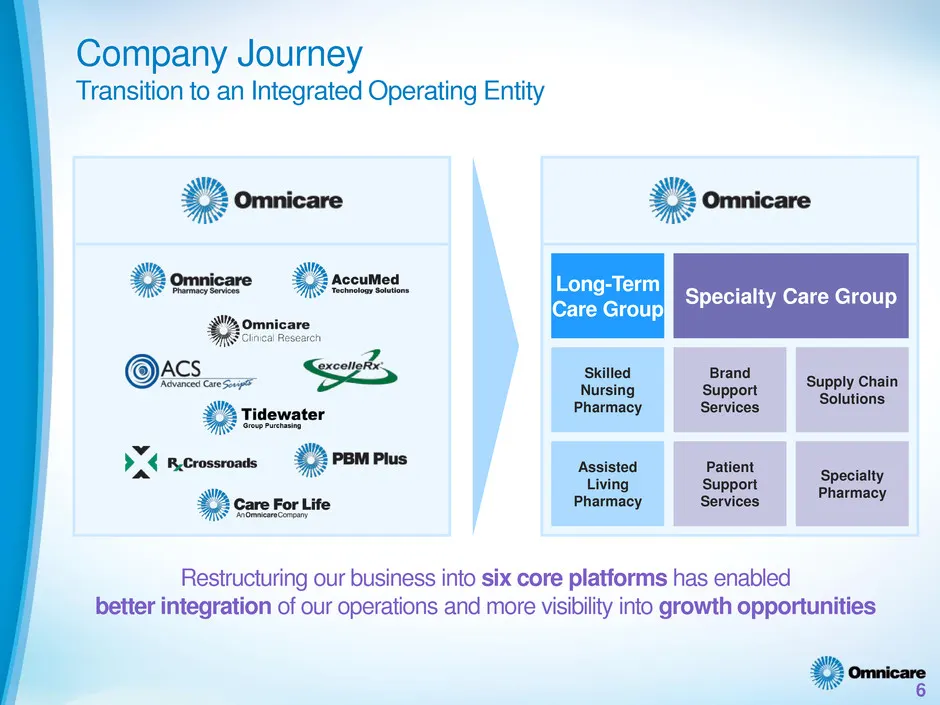
Company Journey Transition to an Integrated Operating Entity Y _ y 5 3Y) Omnicare 39} Onmicare Qminicare 7? Accumted Long-Term Perms Specialty Care Group Care Group) Omnicar jal Research ACS 3 illed Brand (Saeed eer Nursing Support Supply Chala Tidewater Pharmacy ices 3 om tt > 4 FGrossroads » rosar
Slide 7: Omnicare's Primary Businesses
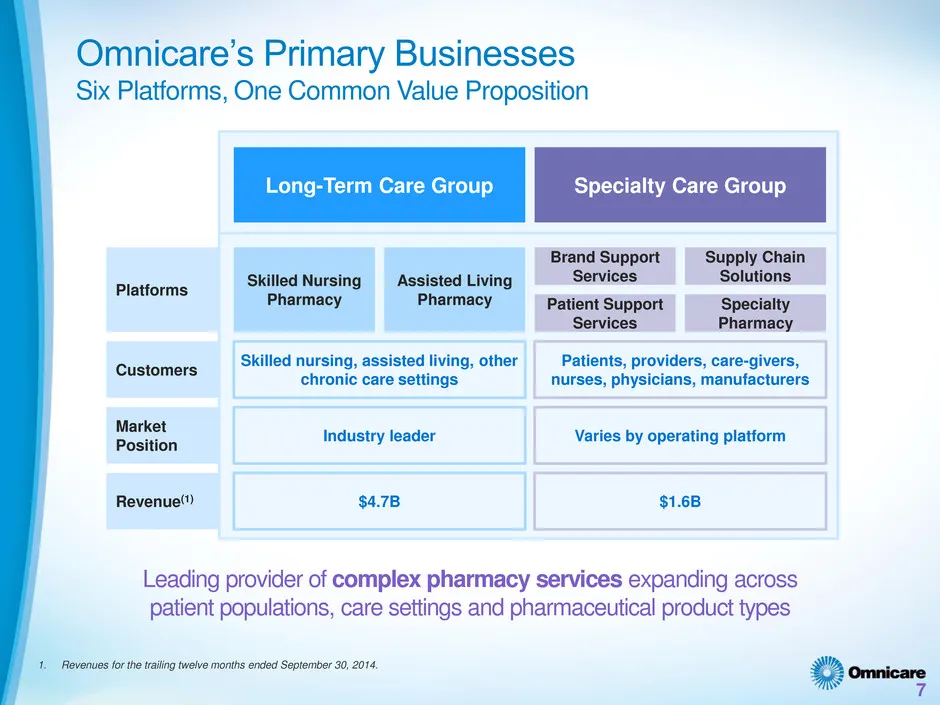
Omnicare’s Primary Businesses Six Platforms, One Common Value Proposition Long-Term Care Group Specialty Care Group Brand Support Supply Chain Services Platforms Skilled Nursing —_ Assisted Living Solutions Pharmacy Pharmacy Patient Support — Services Pharmacy Customers _ Skilled nursing, assisted l
Slide 8: Company Journey: Business Mix Reflects More Diversification
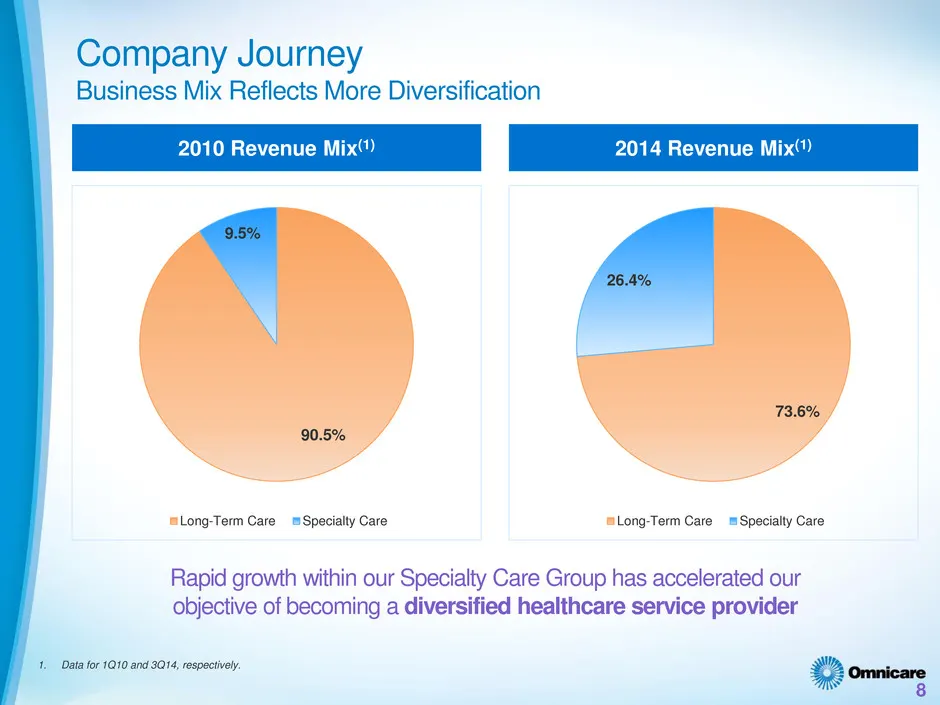
Company Journey Business Mix Reflects More Diversification 2010 Revenue Mix 2014 Revenue Mix" Long-Term Care = Specialty Care Long-Term Care = Specialty Care Rapid growth within our Specialty Care Group has accelerated our objective of becoming a diversified healthcare service provider 1, Data for 1
Slide 9: Financial Results: Quarter Trends
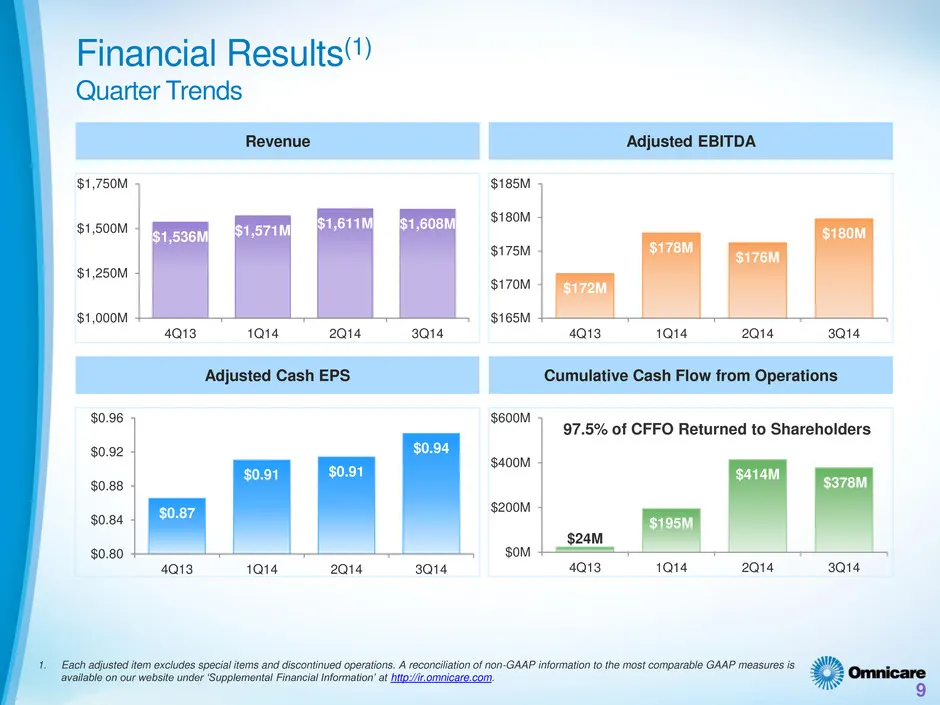
Financial Results) Quarter Trends Revenue Adjusted EBITDA 4a13 1014 2014 a4 4013 1014 2014 3014 Adjusted Cash EPS Cumulative Cash Flow from Operations M soe enn 97.5% of CFFO Returned to Shareholders $0.92 $0.88 | $0.80 | 4013 1014 2014 3014 4013 1014 2014 3014 Omnicare
Slide 10: Long-Term Care Pharmacy
(2) Long-Term Care Pharmacy;
Slide 11: Long-Term Care at a Glance
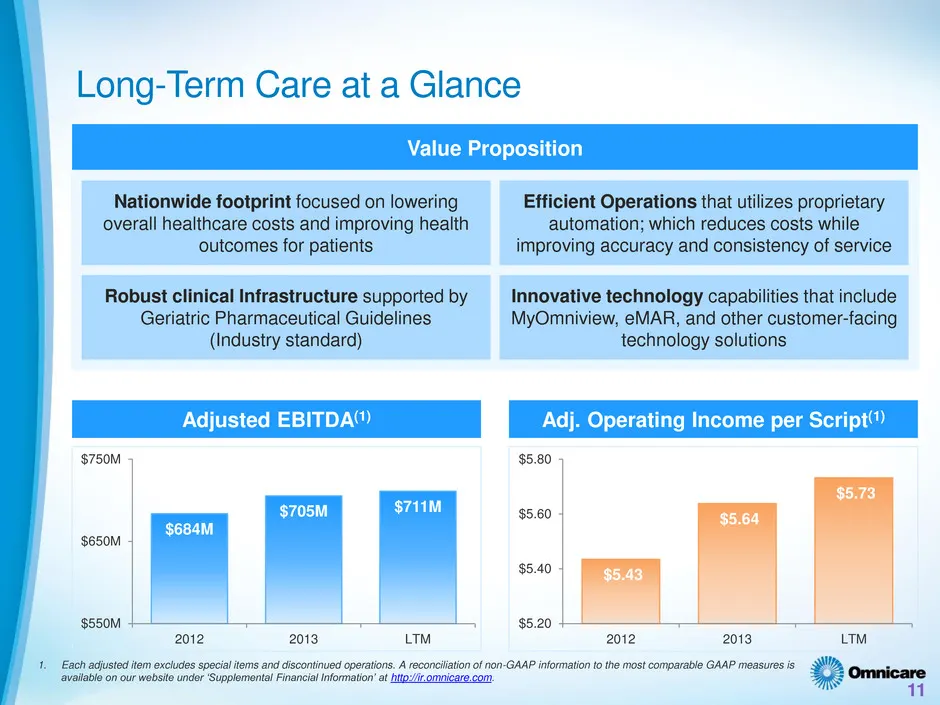
Long-Term Care at a Glance Nationwide footprint focused on lowering Efficient Operations that utilizes proprietary overall healthcare costs and improving health automation; which reduces costs while outcomes for patients improving accuracy and consistency of service Robust clinical Infrastructure su
Slide 12: Market Dynamics - Long-Term Care: Aging Population
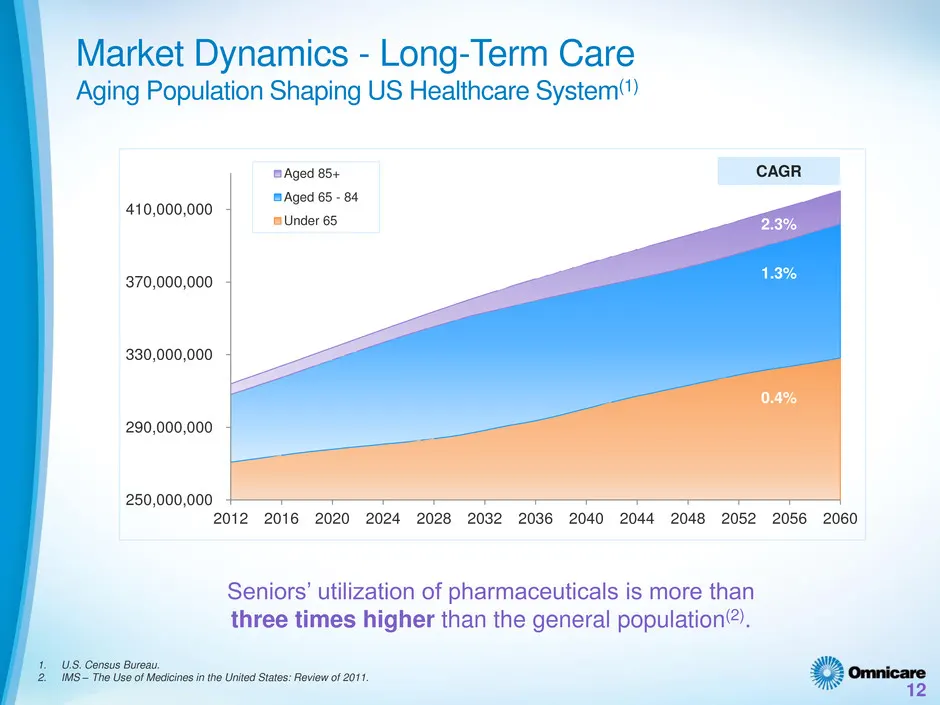
Market Dynamics - Long-Term Care Aging Population Shaping US Healthcare System") Aged 85+ CAGR Aged 65 - 84 410,000,000 mUnder 65 370,000,000 330,000,000 290,000,000 250,000,000 2012 2016 2020 2024 2028 2032 2036 2040 2044 2048 2052 2056 2060 Seniors’ utilization of pharmaceuticals is more than thre
Slide 13: Market Dynamics - Long-Term Care: Generic Volumes
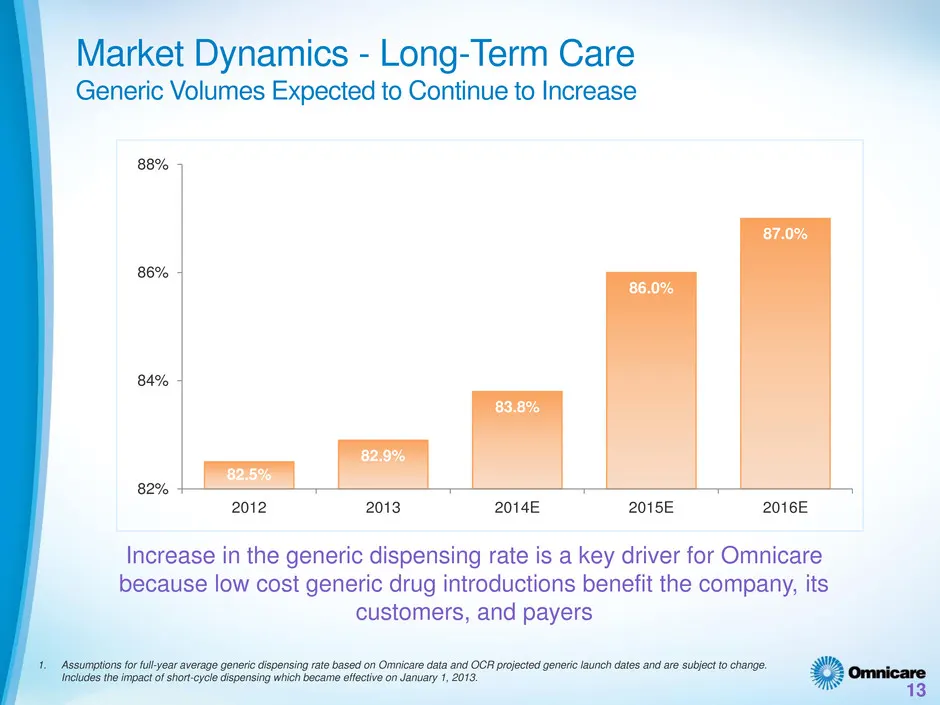
Market Dynamics - Long-Term Care Generic Volumes Expected to Continue to Increase 88% 86% 82% 2012 2013 2014E 2015E 2016E Increase in the generic dispensing rate is a key driver for Omnicare because low cost generic drug introductions benefit the company, its customers, and payers E poland i 32 omni
Slide 14: Specialty Care Group
(3) Specialty Care Group
Slide 15: Specialty Care Group at a Glance
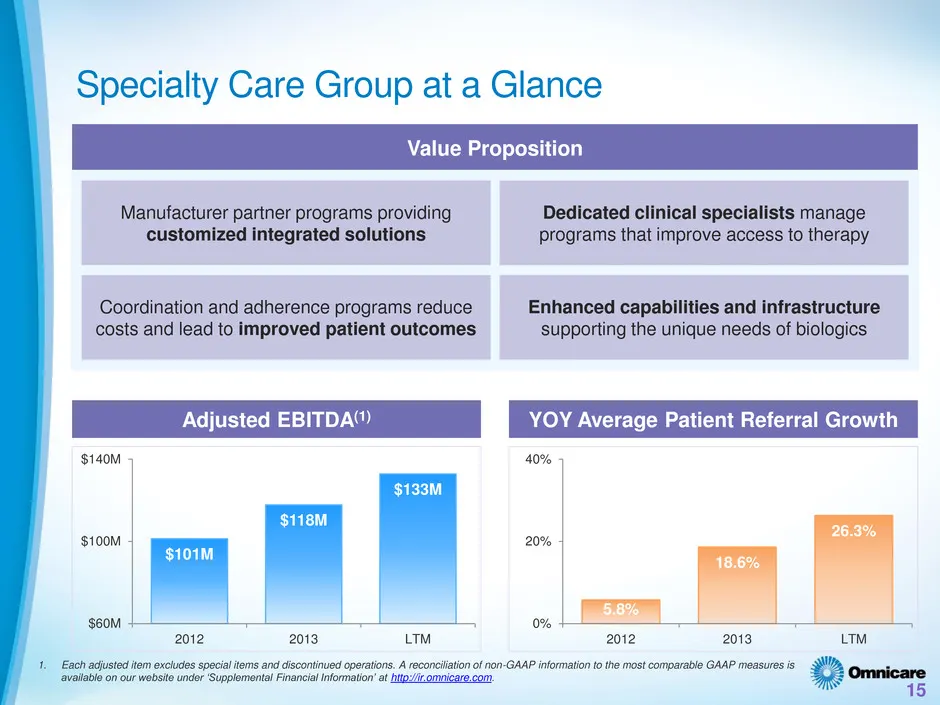
Specialty Care Group at a Glance Value Propositi Manufacturer partner programs providing Dedicated clinical specialists manage customized integrated solutions programs that improve access to therapy Coordination and adherence programs reduce Enh d id costs and lead to improved patient outcomes suppo
Slide 16: Specialty Market Overview
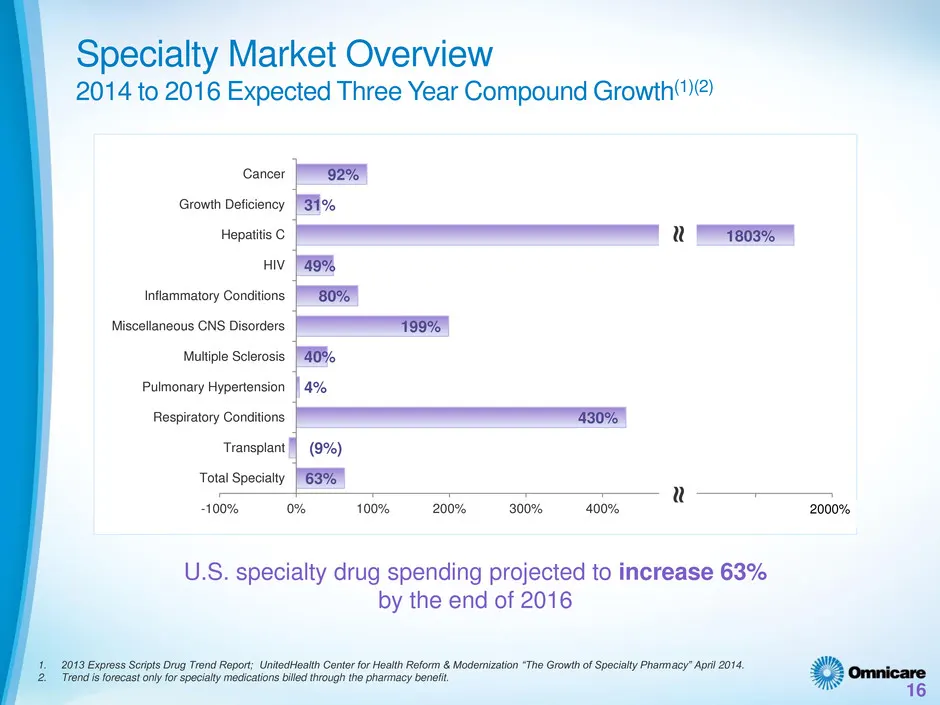
1. 2013 Expr Specialty Market Overview 2014 to 2016 Expected Three Year Compound Growth") Cancer Growth Deficiency Hepatitis © HIV Inflammatory Conditions Miscellaneous CNS Disorders Muttiple Sclerosis, Pulmonary Hypertension = Q EOS spi Transplant Total Specialty 100% U.S. speci | @% 0% 100% 200% 3
Slide 17: Growth in Specialty Market
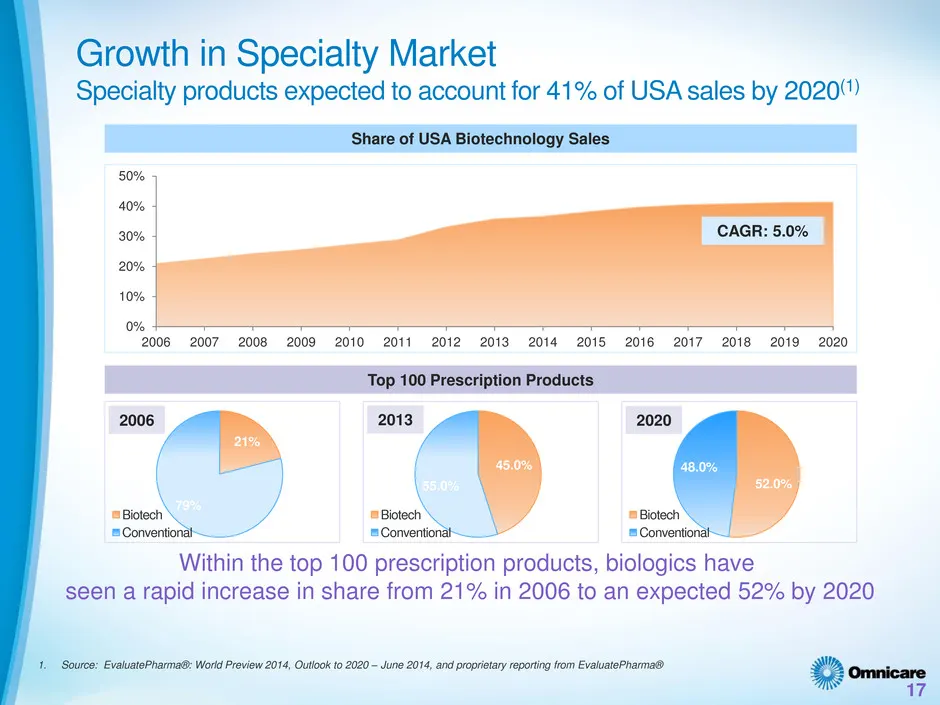
Growth in Specialty Market Specialty products expected to account for 41% of USA sales by 20201) Share of USA Biotechnology Sales 2006 2020 Biotech Biotech = Conventior cr ic 8Cor Within the top 100 prescription products, biologics have seen a rapid increase in share from 21% in 2006 to an expected
Slide 18: Multi-Layered Growth Strategy
(4) Multi-Layered Growth Strategy
Slide 19: Multi-Layered Growth Strategy
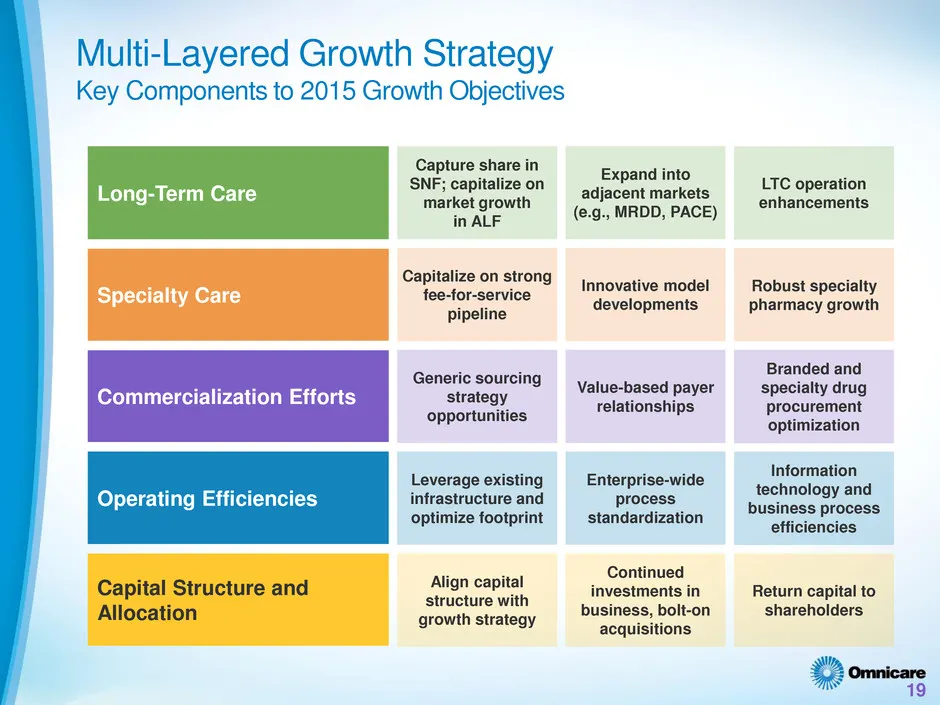
Multi-Layered Growth Strategy Key Components to 2015 Growth Objectives Capture share in SNF; capitalize on Saremelinits adjacent markets LTC operation ong-Term Care market growth enhancements ae (e.g., MRDD, PACE) Capitalize on strong , ; ; alize oni3| Innovative model Robust specialty Specialty Car
Slide 20: Value Creation
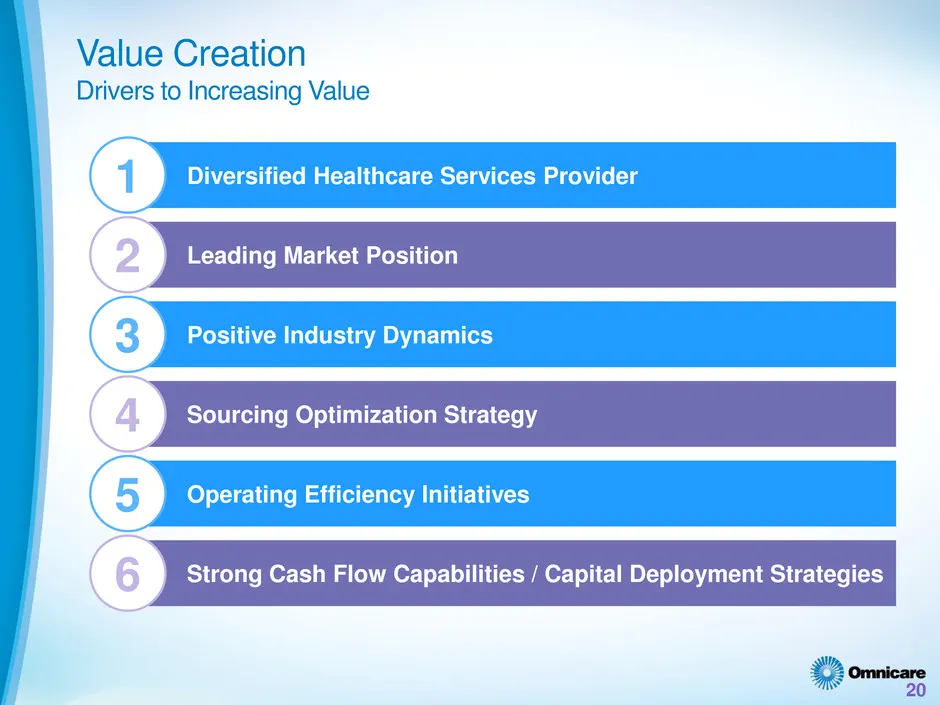
Value Creation Drivers to Increasing Value Leading Market Position Strong Cash Flow Capabilities / Capital Deployment Strategies Sourcing Optimization Strategy
Slide 21: Omnicare
Omnicare
Source: SEC EDGAR · 8-K filed Nov 10, 2014
More decks from Omnicare Inc
 Bank of America Merrill Lynch 2015 Health Care Conference20 slides · May 12, 2015
 Q1 2015 Earnings Presentation17 slides · Apr 29, 2015
 Q4 2014 Earnings Presentation18 slides · Feb 25, 2015
 33rd Annual J.P. Morgan Healthcare Conference (January 2015)34 slides · Jan 12, 2015
 Q3 2014 Earnings Presentation16 slides · Oct 24, 2014
 Q2 2014 Earnings Presentation16 slides · Jul 23, 2014