Radius Health — JP Morgan Healthcare Conference 2020
32 slides from Radius Health's conference presentation, Jan 13, 2020
Slide 1: JP Morgan Healthcare Conference
JP Morgan healthcare conference JESPER HOEILAND, CEO JANUARY 14, 2020 Exhibit 99.2
Slide 2: Safe Harbor
Safe Harbor Any statements made in this presentation relating to future financial or business performance, guidance, conditions, plans, prospects, trends or strategies and other financial or business matters, including regarding the commercialization of TYMLOS® (abaloparatide) injection in the U.S.,
Slide 3: Strategy for growth and continued leadership
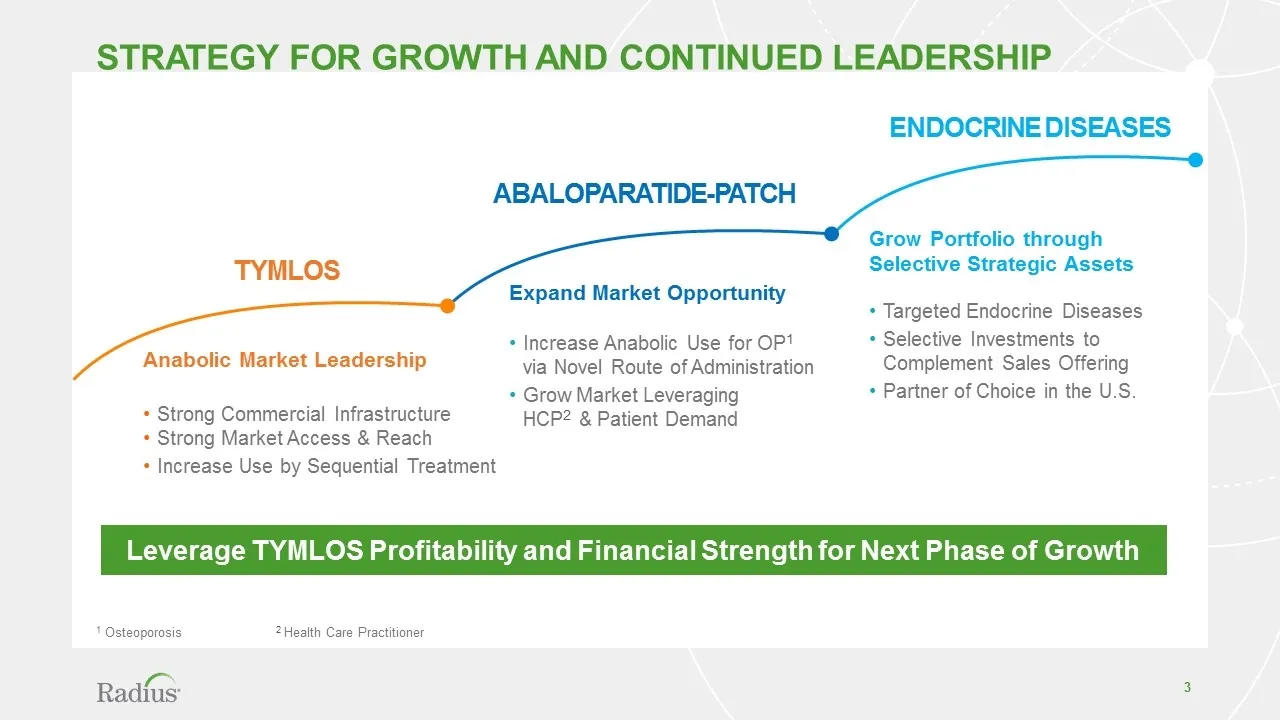
ENDOCRINE DISEASES Abaloparatide-PATCH TYMLOS Grow Portfolio through Selective Strategic Assets Targeted Endocrine Diseases Selective Investments to Complement Sales Offering Partner of Choice in the U.S. Expand Market Opportunity Increase Anabolic Use for OP1 via Novel Route of Administration Grow
Slide 4: 2019 achievements
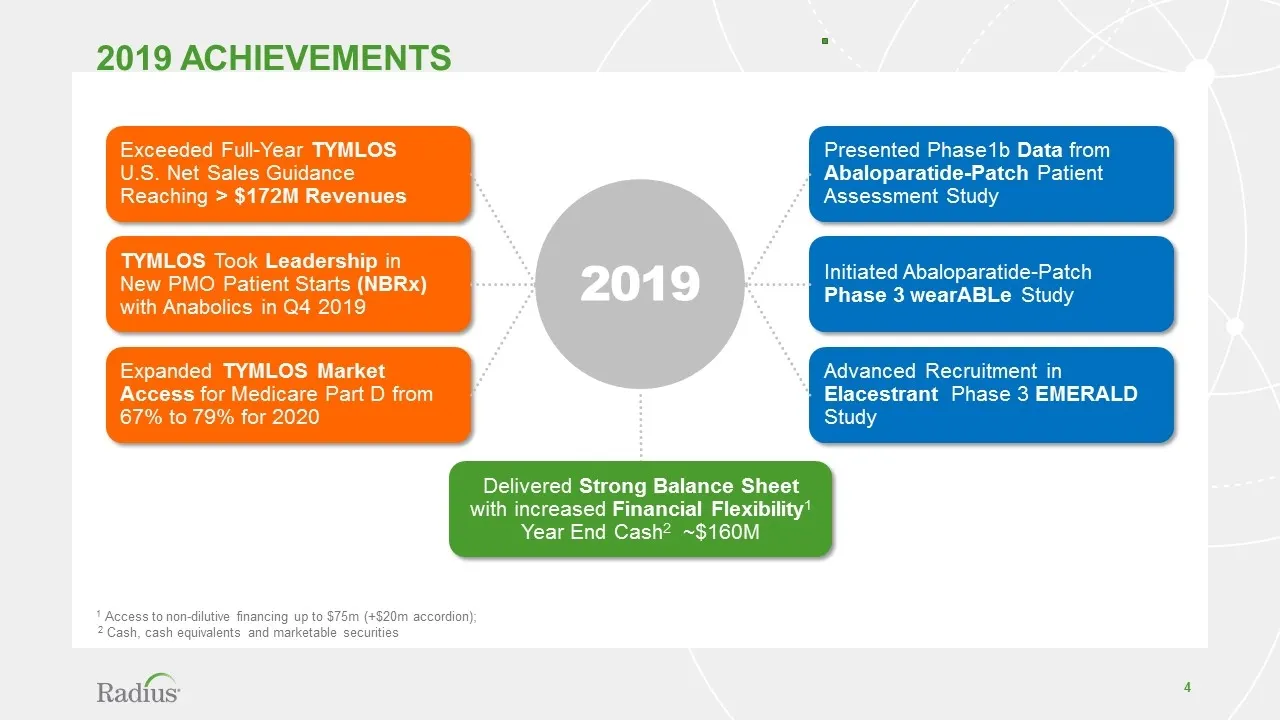
2019 achievements 1 Access to non-dilutive financing up to $75m (+$20m accordion); 2 Cash, cash equivalents and marketable securities Exceeded Full-Year TYMLOS U.S. Net Sales Guidance Reaching > $172M Revenues TYMLOS Took Leadership in New PMO Patient Starts (NBRx) with Anabolics in Q4 2019 Expanded
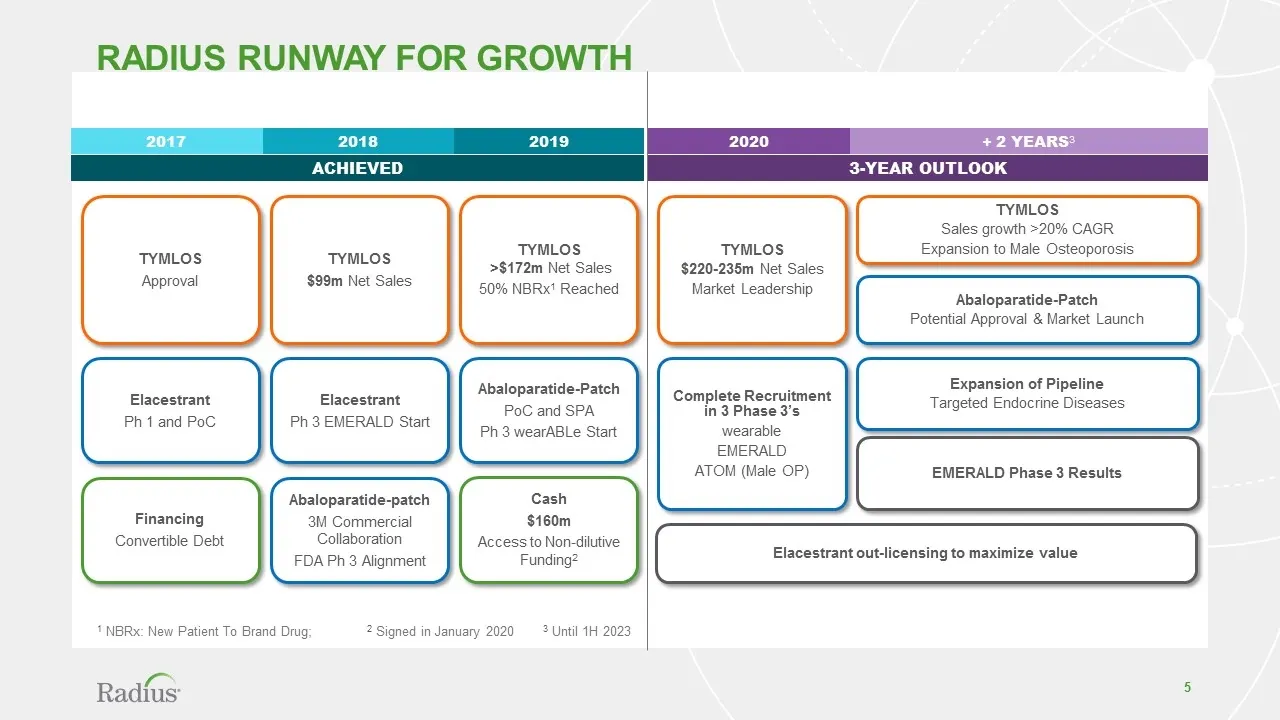
Slide 5: Radius runway for growth
Radius RUNWAY FOR GROWTH 1 NBRx: New Patient To Brand Drug; 2 Signed in January 2020 3 Until 1H 2023 2017 2018 2019 ACHIEVED 2020 + 2 YEARS3 3-YEAR OUTLOOK TYMLOS $220-235m Net Sales Market Leadership Complete Recruitment in 3 Phase 3’s wearable EMERALD ATOM (Male OP) Elacestrant out-licensing to ma
Slide 6: Pipeline Review
Pipeline Review
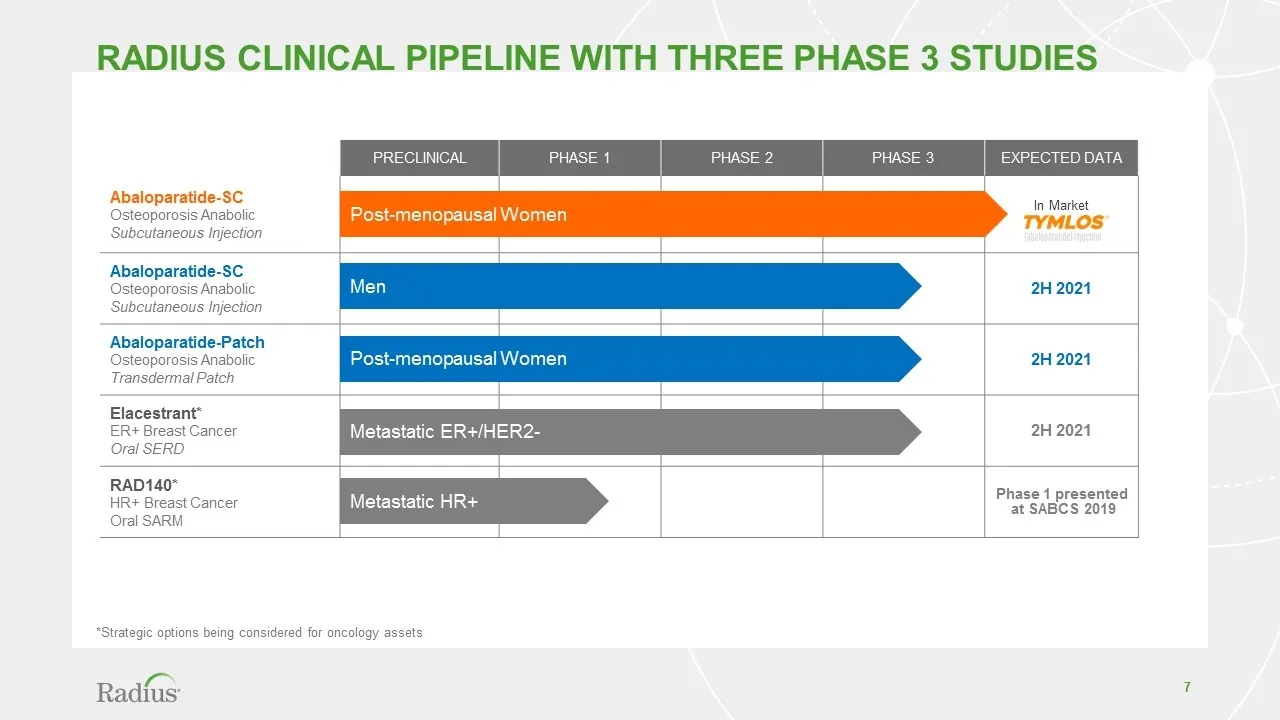
Slide 7: Radius clinical pipeline with three Phase 3 studies
Radius CLINICAL PIPELINE WITH THREE Phase 3 studies PRECLINICAL PHASE 1 PHASE 2 PHASE 3 EXPECTED DATA Abaloparatide-SC Osteoporosis Anabolic Subcutaneous Injection In Market Abaloparatide-SC Osteoporosis Anabolic Subcutaneous Injection 2H 2021 Abaloparatide-Patch Osteoporosis Anabolic Transdermal Pa
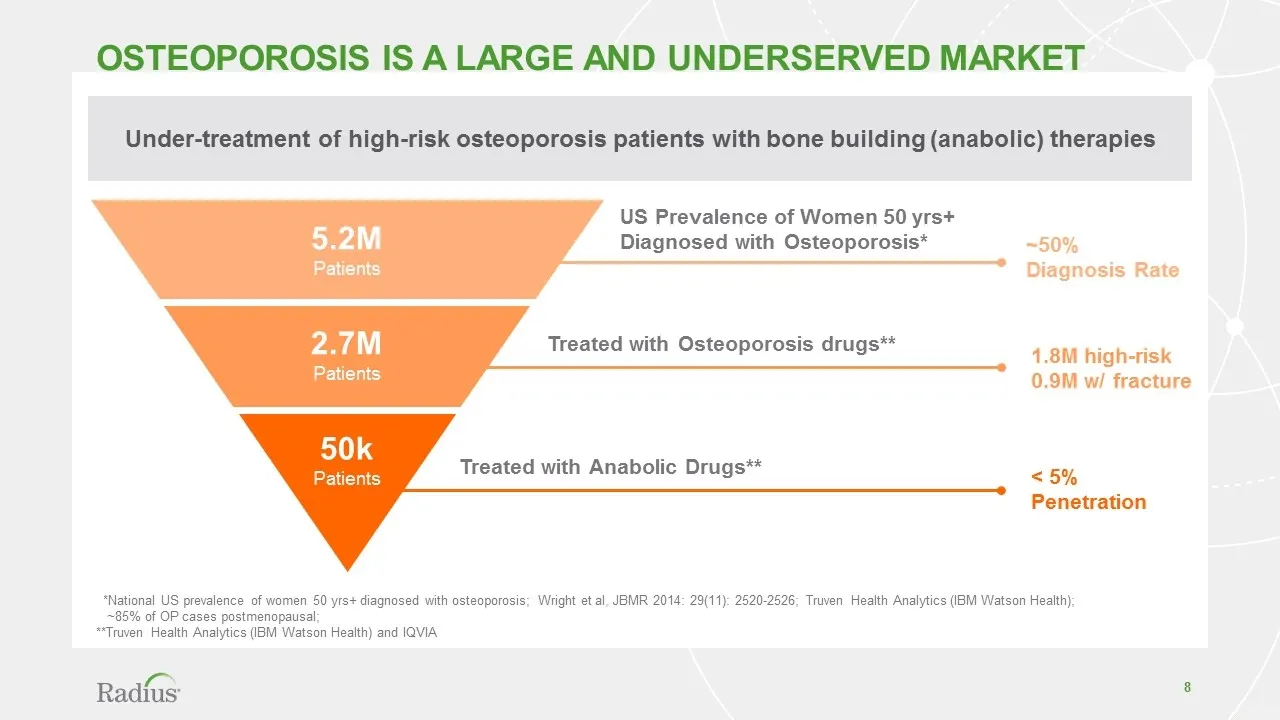
Slide 8: Osteoporosis is a Large and Underserved Market
Osteoporosis is a Large and Underserved Market 5.2M Patients 2.7M Patients 50k Patients US Prevalence of Women 50 yrs+ Diagnosed with Osteoporosis* Treated with Osteoporosis drugs** Treated with Anabolic Drugs** 1.8M high-risk 0.9M w/ fracture < 5% Penetration ~50% Diagnosis Rate Under-treatment of
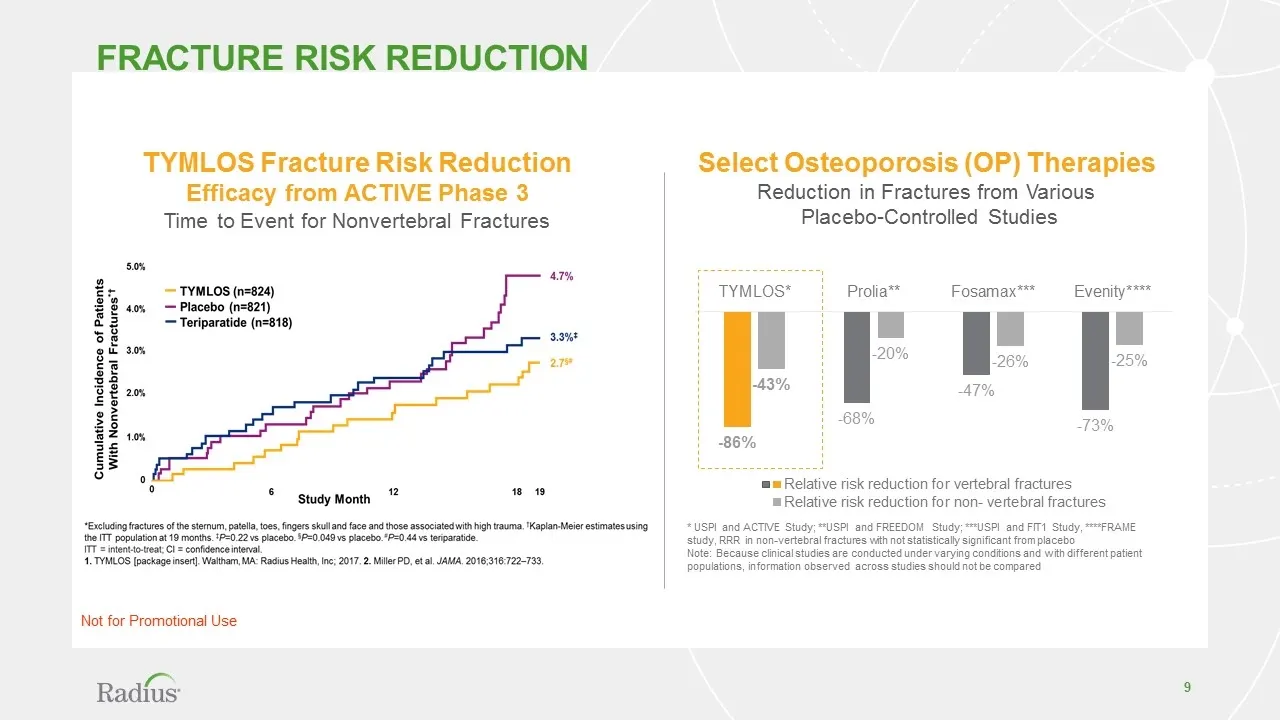
Slide 9: TYMLOS Fracture Risk Reduction Efficacy from ACTIVE Phase 3
TYMLOS Fracture Risk Reduction Efficacy from ACTIVE Phase 3 Time to Event for Nonvertebral Fractures Select Osteoporosis (OP) Therapies Reduction in Fractures from Various Placebo-Controlled Studies * USPI and ACTIVE Study; **USPI and FREEDOM Study; ***USPI and FIT1 Study, ****FRAME study, RRR in no
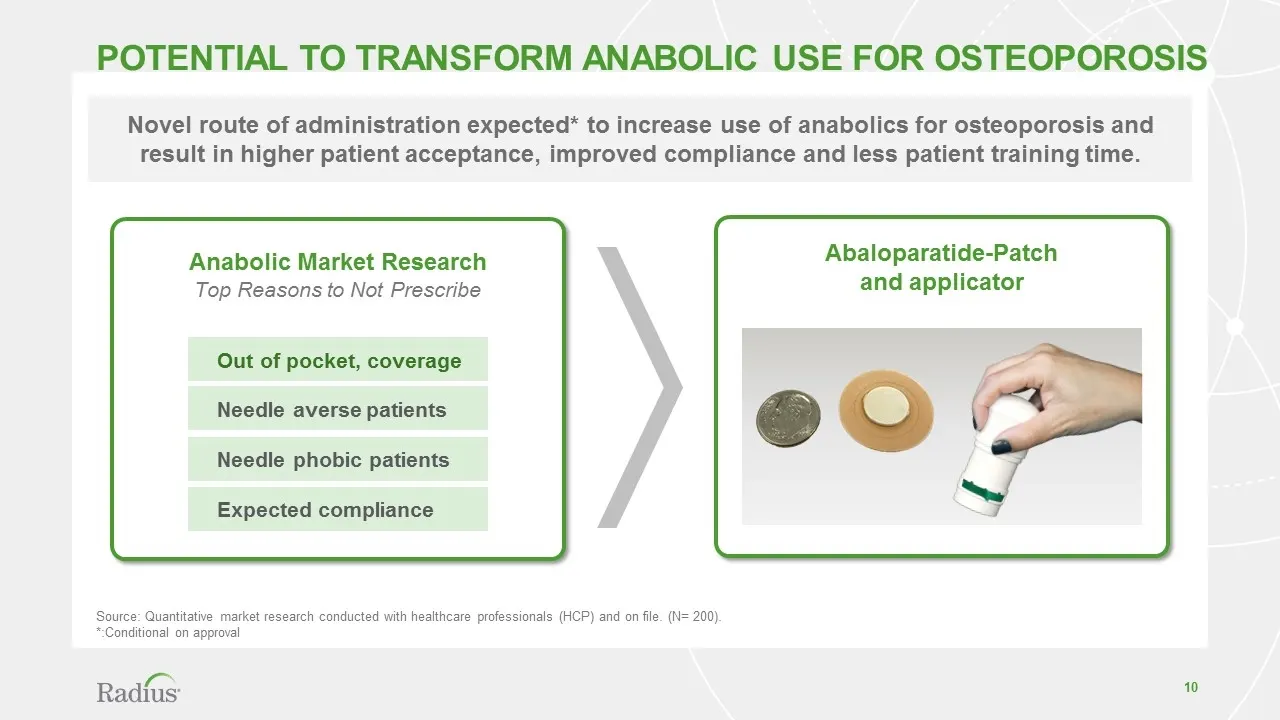
Slide 10: Potential to Transform Anabolic Use for Osteoporosis
Potential TO Transform Anabolic Use for oSTEOPOROSIS Anabolic Market Research Top Reasons to Not Prescribe Out of pocket, coverage Needle averse patients Needle phobic patients Expected compliance Novel route of administration expected* to increase use of anabolics for osteoporosis and result in hig
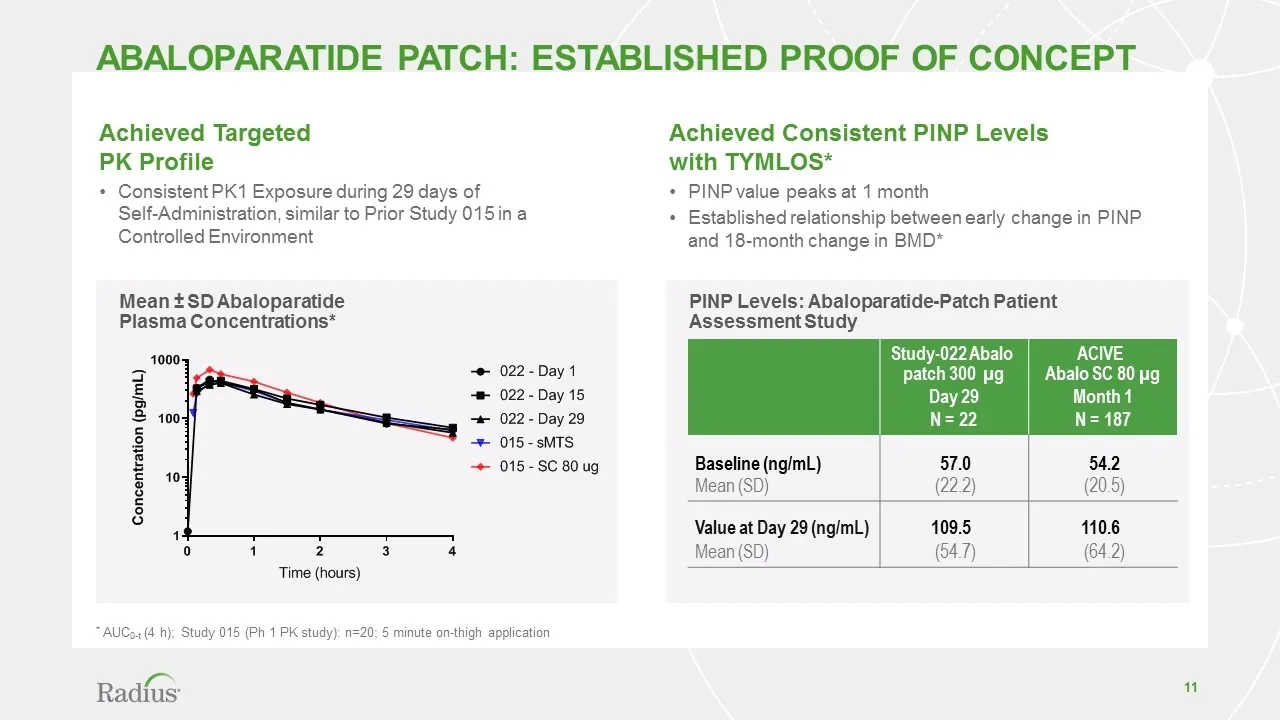
Slide 11: PINP Levels: Abaloparatide-Patch Patient Assessment Study
PINP Levels: Abaloparatide-Patch Patient Assessment Study abaloparatide patch: established Proof of concept Study-022 Abalo patch 300 µg Day 29 N = 22 ACIVE Abalo SC 80 µg Month 1 N = 187 Baseline (ng/mL) 57.0 54.2 Mean (SD) (22.2) (20.5) Value at Day 29 (ng/mL) 109.5 110.6 Mean (SD) (54.7) (64.2) A
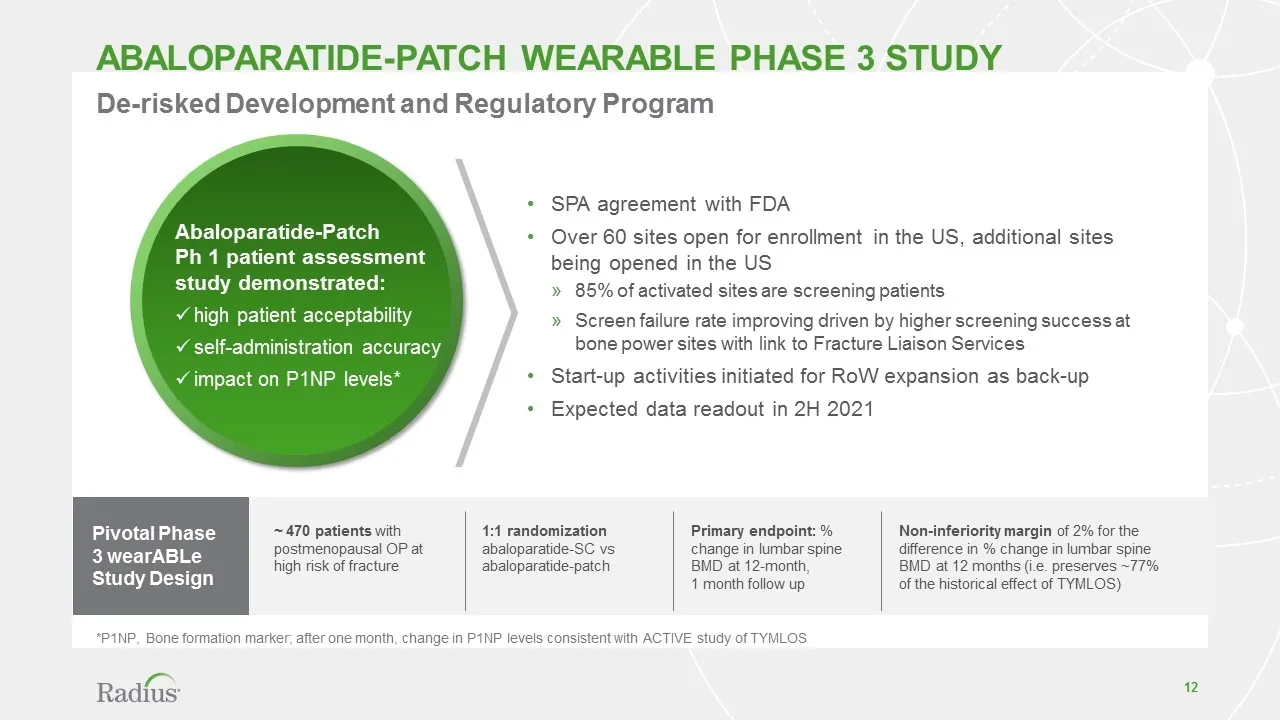
Slide 12: Abaloparatide-patch wearABLe Phase 3 study
abaloparatide-patch WEARABLE PHASE 3 STUDY SPA agreement with FDA Over 60 sites open for enrollment in the US, additional sites being opened in the US 85% of activated sites are screening patients Screen failure rate improving driven by higher screening success at bone power sites with link to Fract
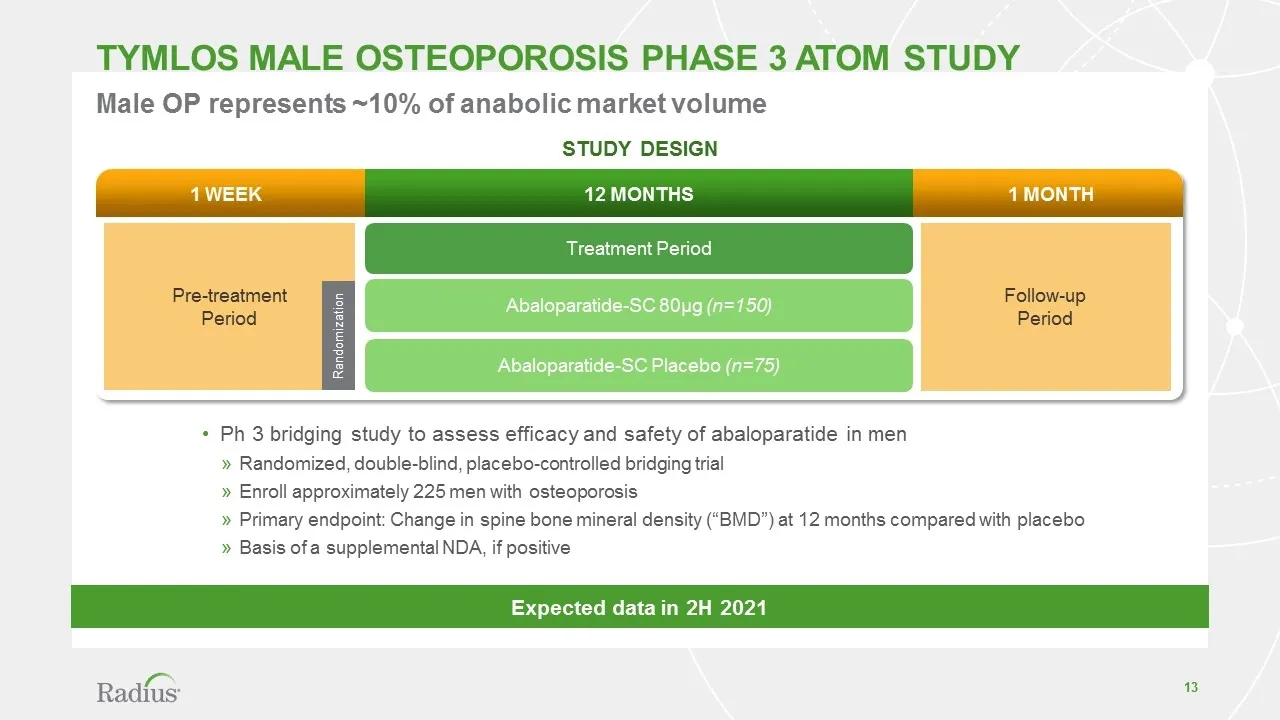
Slide 13: TYMLOS male osteoporosis Phase 3 ATOM study
TYMLOS male osteoporosis phase 3 atom STUDY 1 week 1 month 12 months Pre-treatment Period Follow-up Period Treatment Period Abaloparatide-SC 80µg (n=150) Abaloparatide-SC Placebo (n=75) Randomization Ph 3 bridging study to assess efficacy and safety of abaloparatide in men Randomized, double-blind,
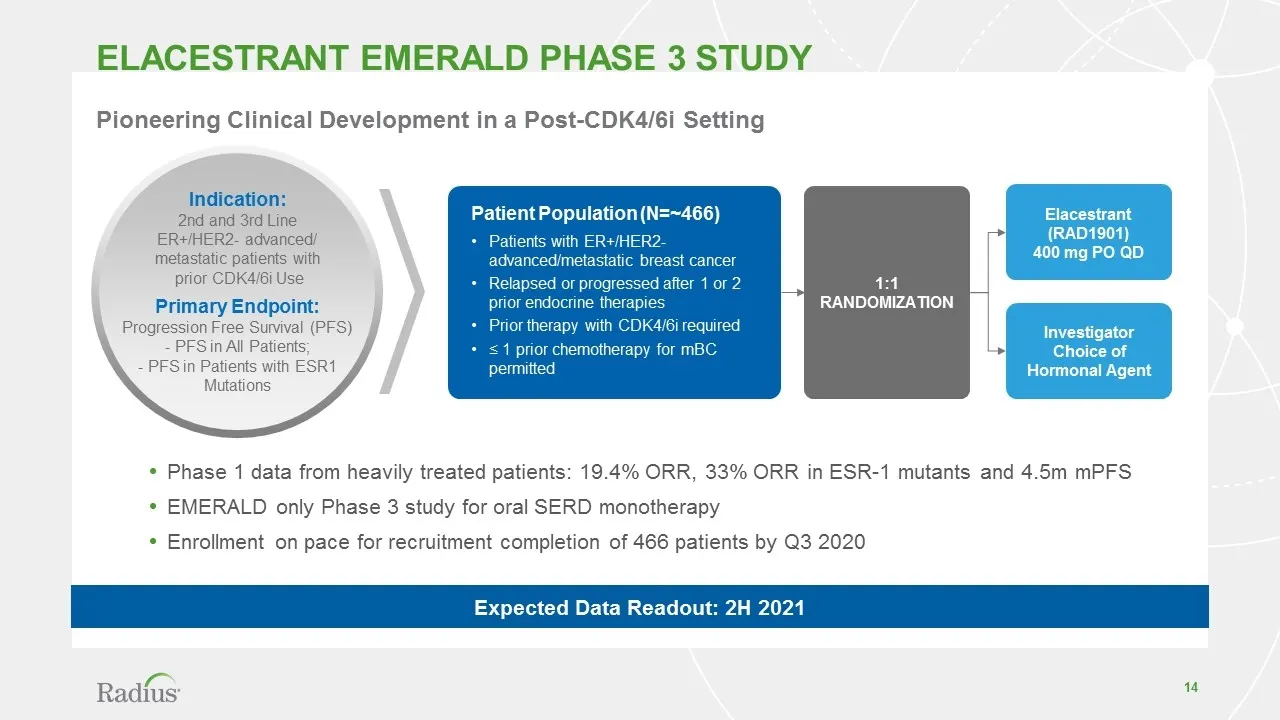
Slide 14: Elacestrant EMERALD Phase 3 study
Elacestrant EMERALD Phase 3 STUDY Phase 1 data from heavily treated patients: 19.4% ORR, 33% ORR in ESR-1 mutants and 4.5m mPFS EMERALD only Phase 3 study for oral SERD monotherapy Enrollment on pace for recruitment completion of 466 patients by Q3 2020 Elacestrant (RAD1901) 400 mg PO QD Investigato
Slide 15: Commercial Update
Commercial Update Joe Kelly SVP SALES, MARKETING & operations
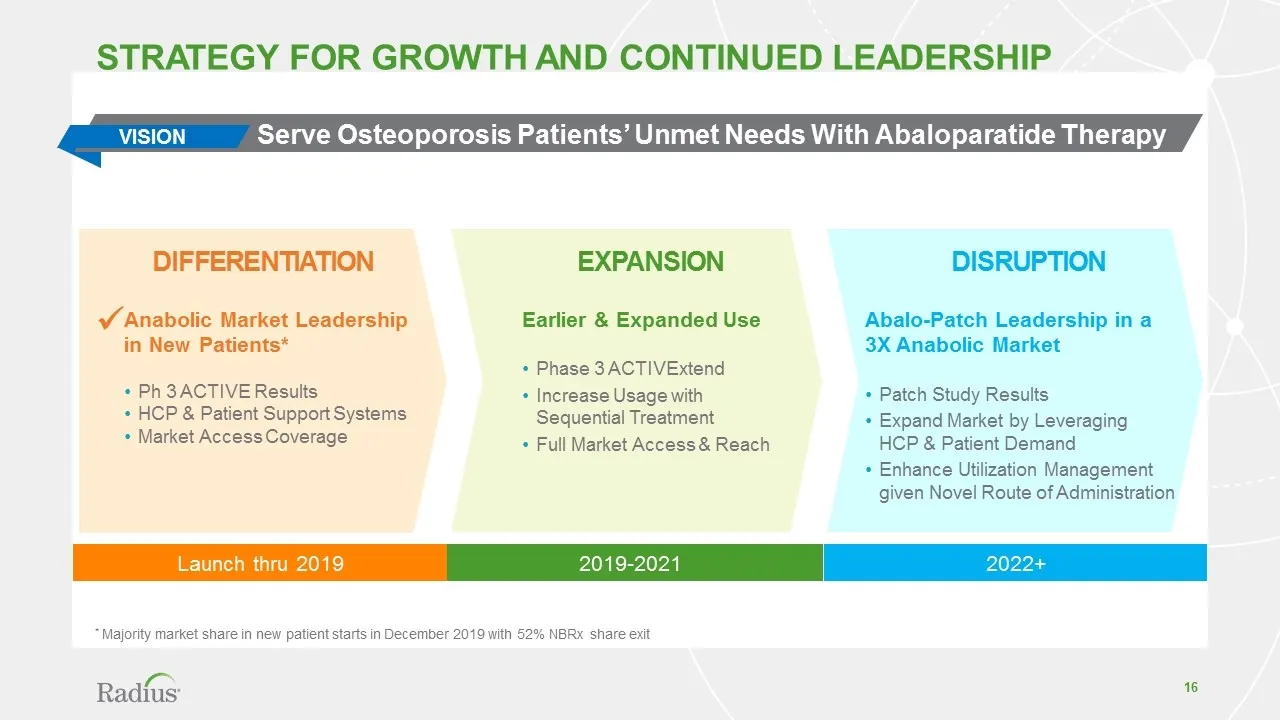
Slide 16: Abalo-Patch Leadership in an Anabolic Market
2019-2021 Disruption Expansion Differentiation Abalo-Patch Leadership in a 3X Anabolic Market Patch Study Results Expand Market by Leveraging HCP & Patient Demand Enhance Utilization Management given Novel Route of Administration Earlier & Expanded Use Phase 3 ACTIVExtend Increase Usage with Sequent
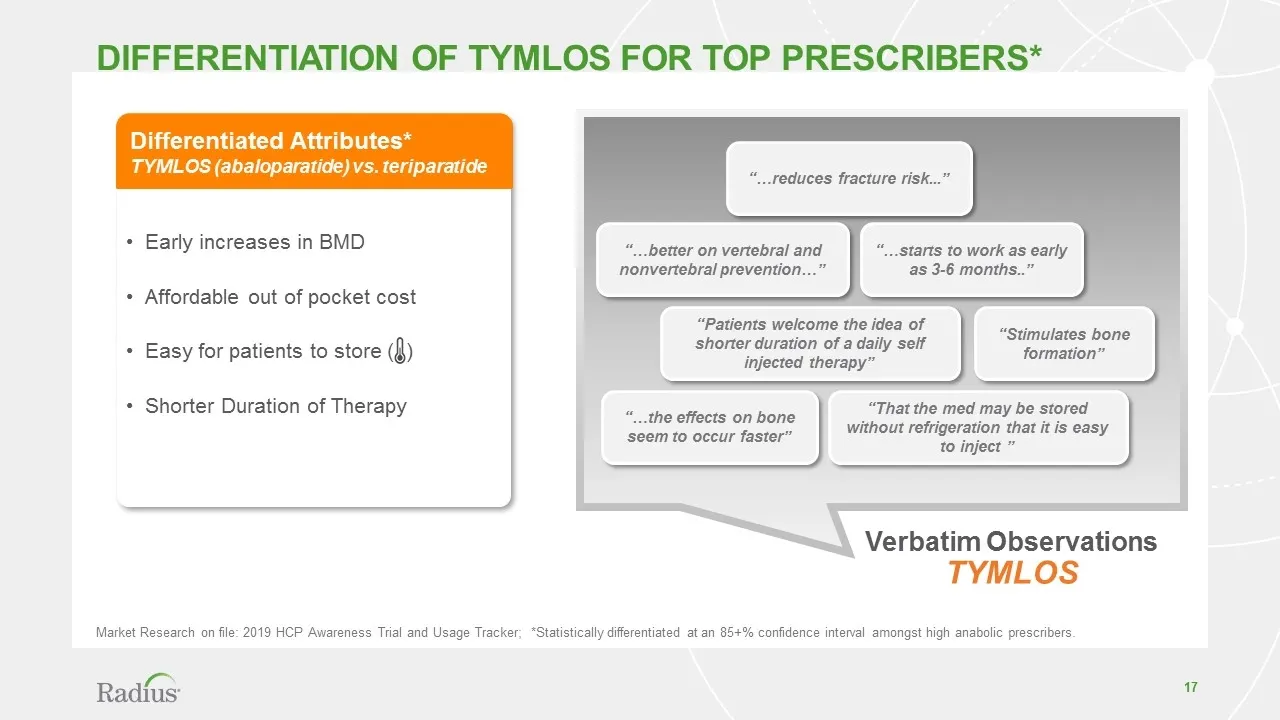
Slide 17: Differentiation of TYMLOS for top prescribers
Verbatim Observations TYMLOS “…reduces fracture risk...” “…the effects on bone seem to occur faster” “That the med may be stored without refrigeration that it is easy to inject ” “Patients welcome the idea of shorter duration of a daily self injected therapy” “Stimulates bone formation” “…better on
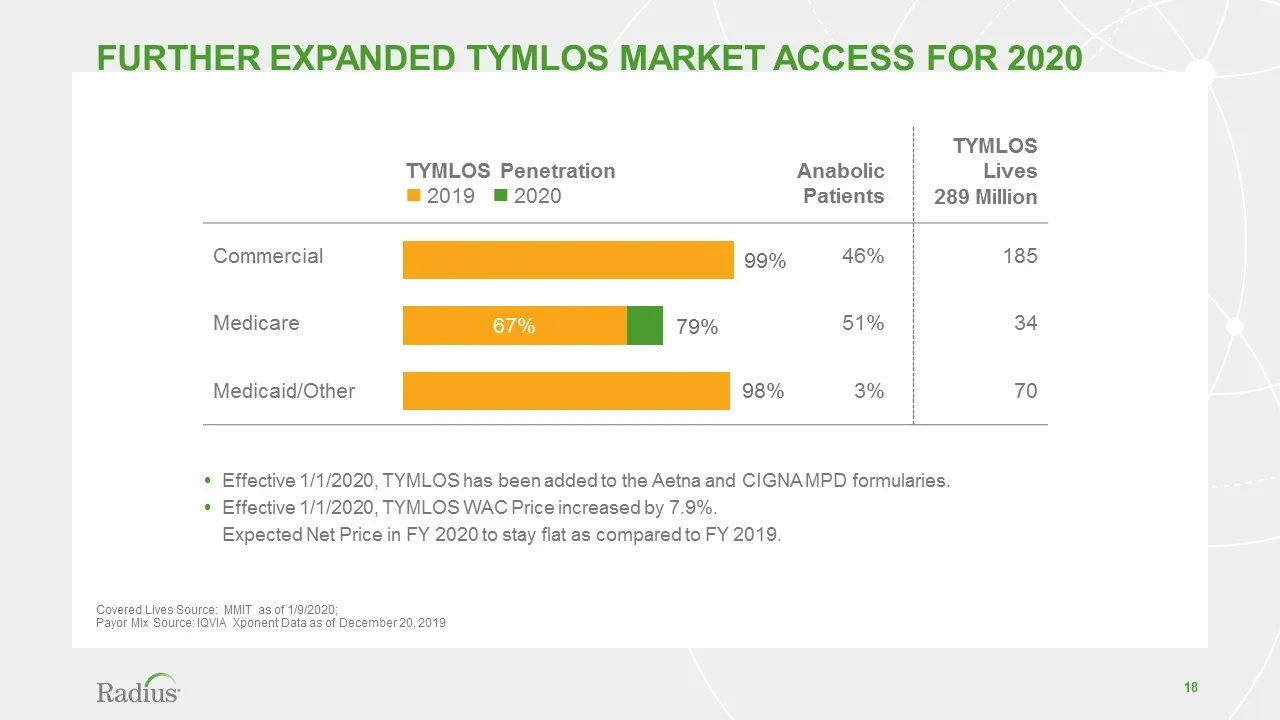
Slide 18: Further expanded TYMLOS Market Access for 2020
FURTHER expanded TYMLOS Market Access for 2020 Covered Lives Source: MMIT as of 1/9/2020; Payor Mix Source: IQVIA Xponent Data as of December 20, 2019 Effective 1/1/2020, TYMLOS has been added to the Aetna and CIGNA MPD formularies. Effective 1/1/2020, TYMLOS WAC Price increased by 7.9%. Expected Ne
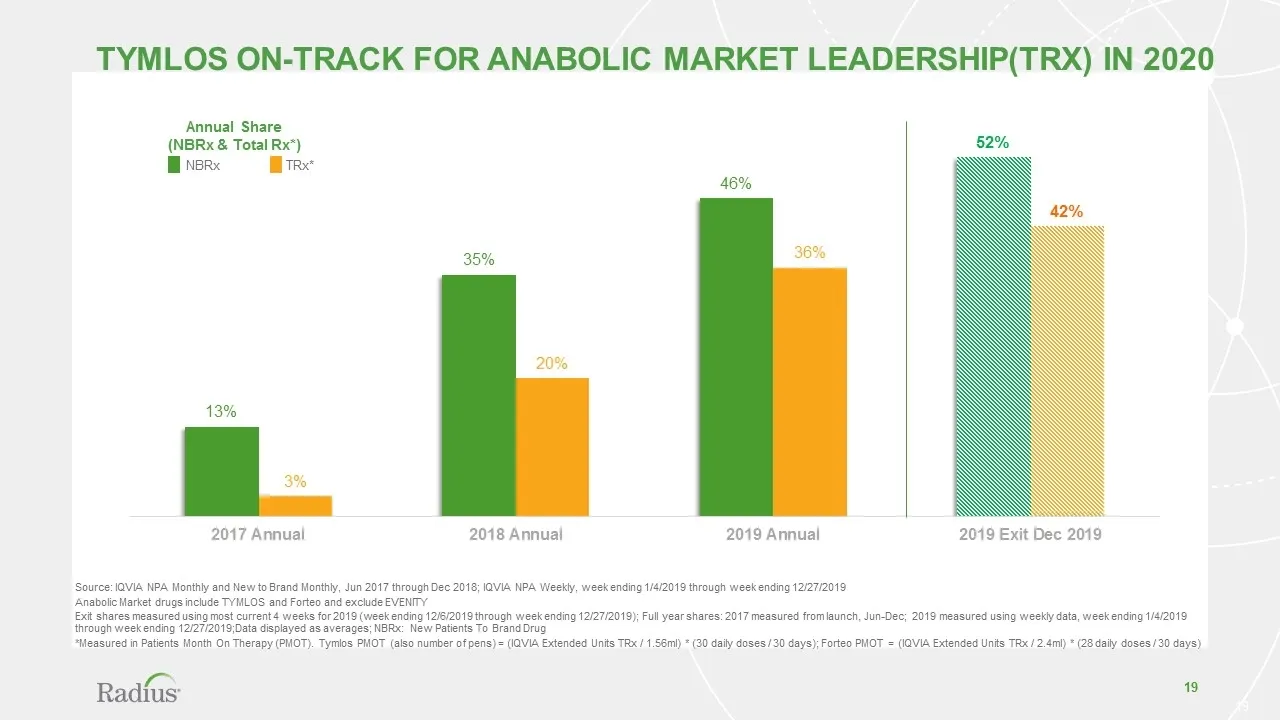
Slide 19: TYMLOS On-Track for Anabolic Market Leadership in 2020
TYMLOS On-Track for Anabolic Market Leadership(TRx) in 2020 Annual Share (NBRx & Total Rx*) Source: IQVIA NPA Monthly and New to Brand Monthly, Jun 2017 through Dec 2018; IQVIA NPA Weekly, week ending 1/4/2019 through week ending 12/27/2019 Anabolic Market drugs include TYMLOS and Forteo and exclude
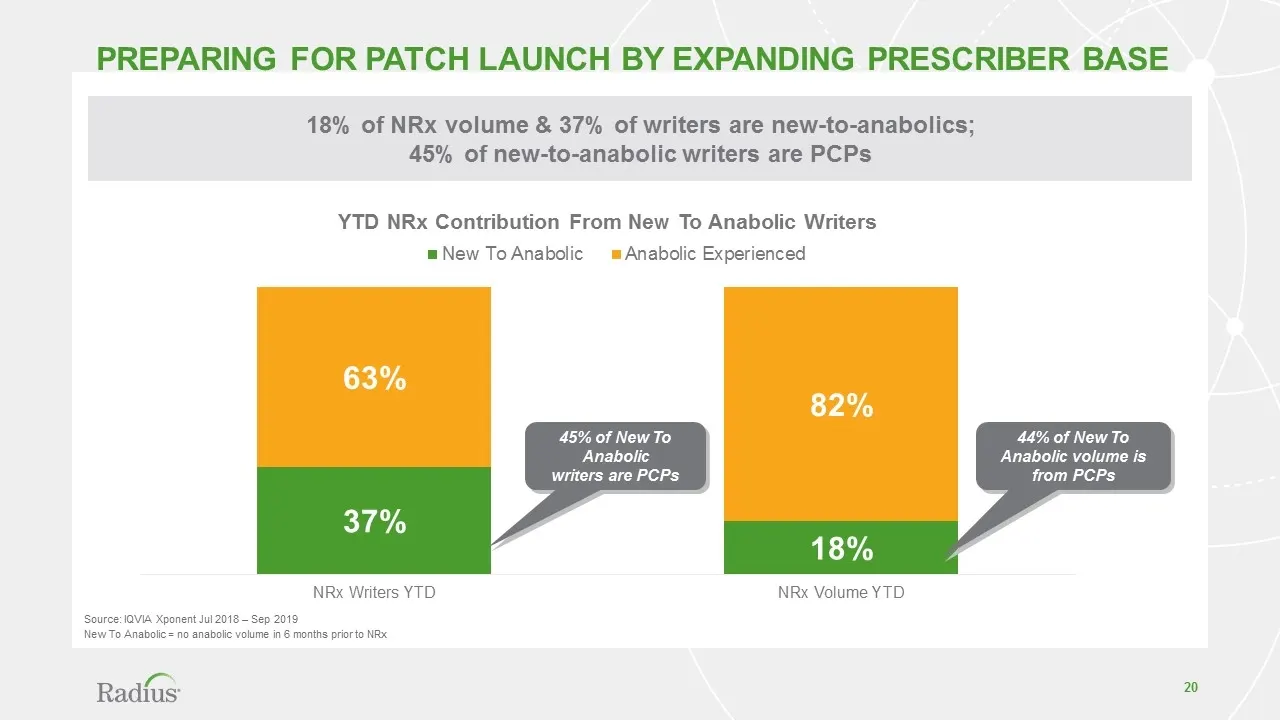
Slide 20: Preparing for Patch Launch by expanding prescriber base
18% of NRx volume & 37% of writers are new-to-anabolics; 45% of new-to-anabolic writers are PCPs Preparing FOR Patch Launch by expanding prescriber base 45% of New To Anabolic writers are PCPs 44% of New To Anabolic volume is from PCPs Source: IQVIA Xponent Jul 2018 – Sep 2019 New To Anabolic = no a
Slide 21: Financial Review
Financial Review Pepe Carmona CHIEF financial OFFICER
Slide 22: TYMLOS sales growth drives value creation
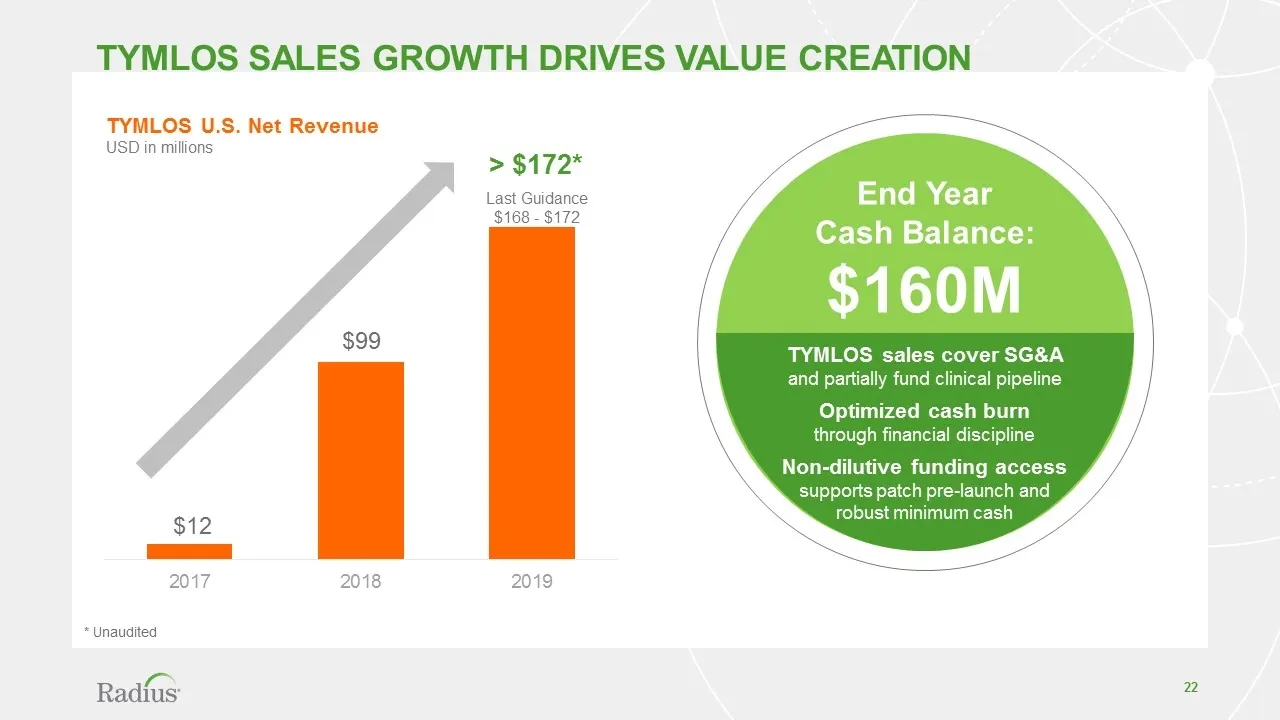
Tymlos sales growth drives value creation $12 $99 > $172* TYMLOS U.S. Net Revenue USD in millions TYMLOS sales cover SG&A and partially fund clinical pipeline Optimized cash burn through financial discipline Non-dilutive funding access supports patch pre-launch and robust minimum cash End Year Cash
Slide 23: Cash Burn
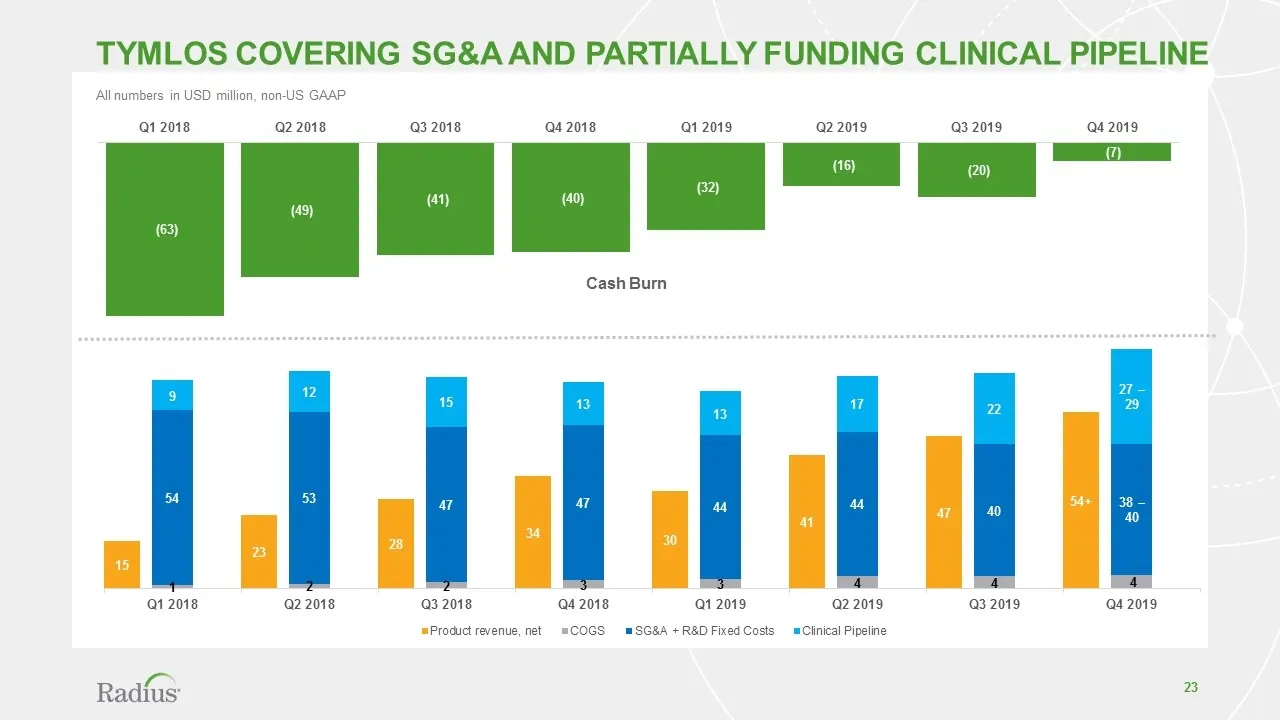
All numbers in USD million, non-US GAAP Cash Burn TYMLOS Covering SG&A and partially Funding Clinical Pipeline
Slide 24: Financial Guidance
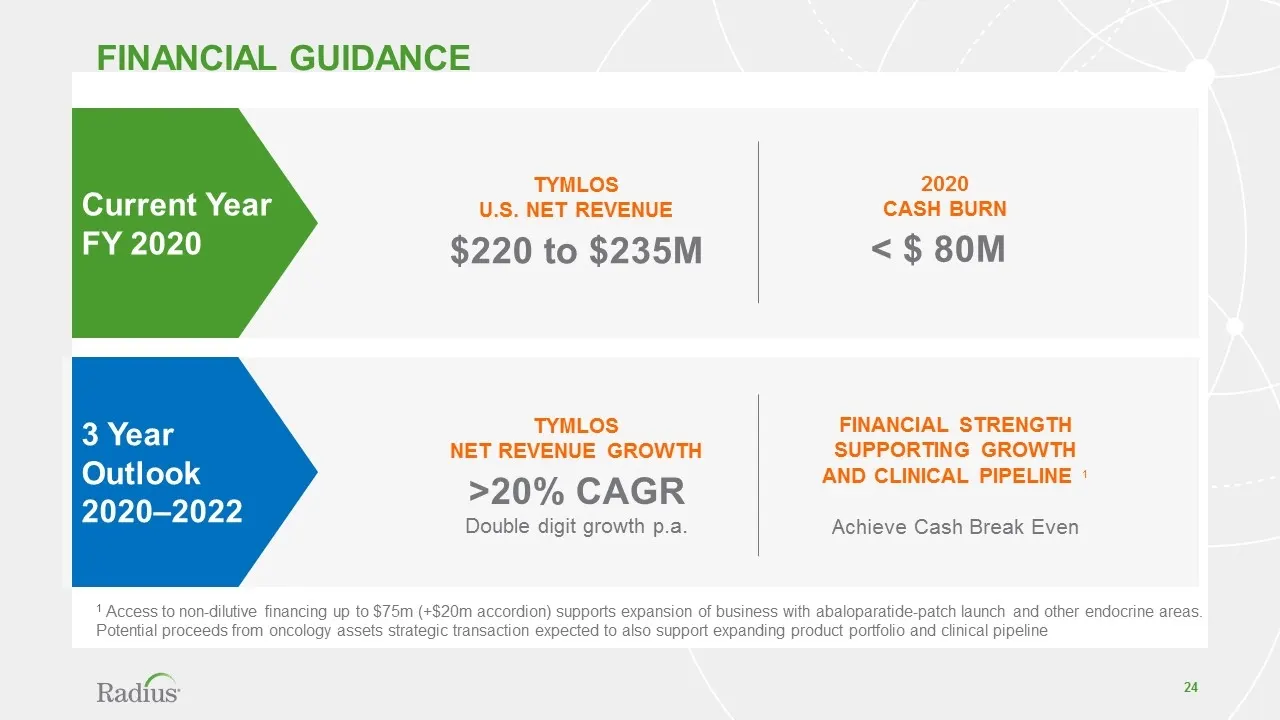
FINANCIAL GUIDANCE 1 Access to non-dilutive financing up to $75m (+$20m accordion) supports expansion of business with abaloparatide-patch launch and other endocrine areas. Potential proceeds from oncology assets strategic transaction expected to also support expanding product portfolio and clinical
Slide 25: Closing Remarks
Closing Remarks Jesper
Slide 26: 2020 Milestones
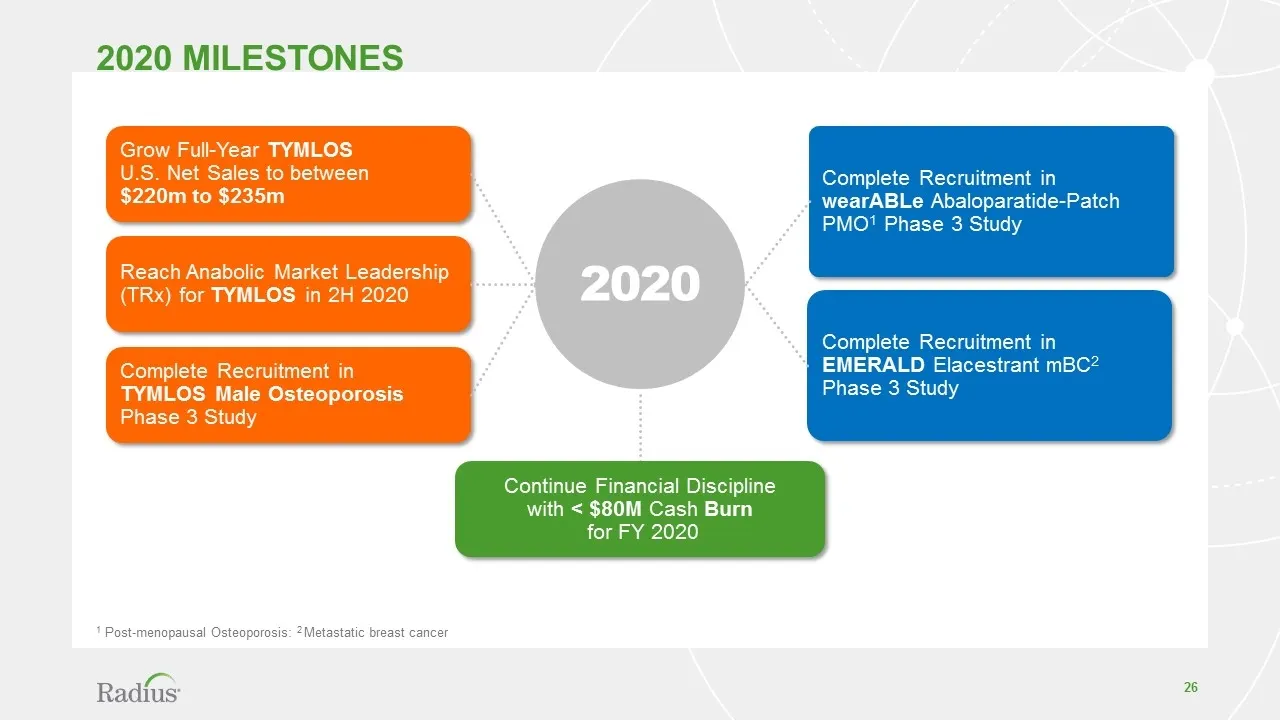
2020 Milestones 1 Post-menopausal Osteoporosis: 2 Metastatic breast cancer Grow Full-Year TYMLOS U.S. Net Sales to between $220m to $235m Reach Anabolic Market Leadership (TRx) for TYMLOS in 2H 2020 Complete Recruitment in TYMLOS Male Osteoporosis Phase 3 Study Complete Recruitment in wearABLe Abalo
Slide 27: Q&A
Q&A
Slide 28: Appendix
Appendix
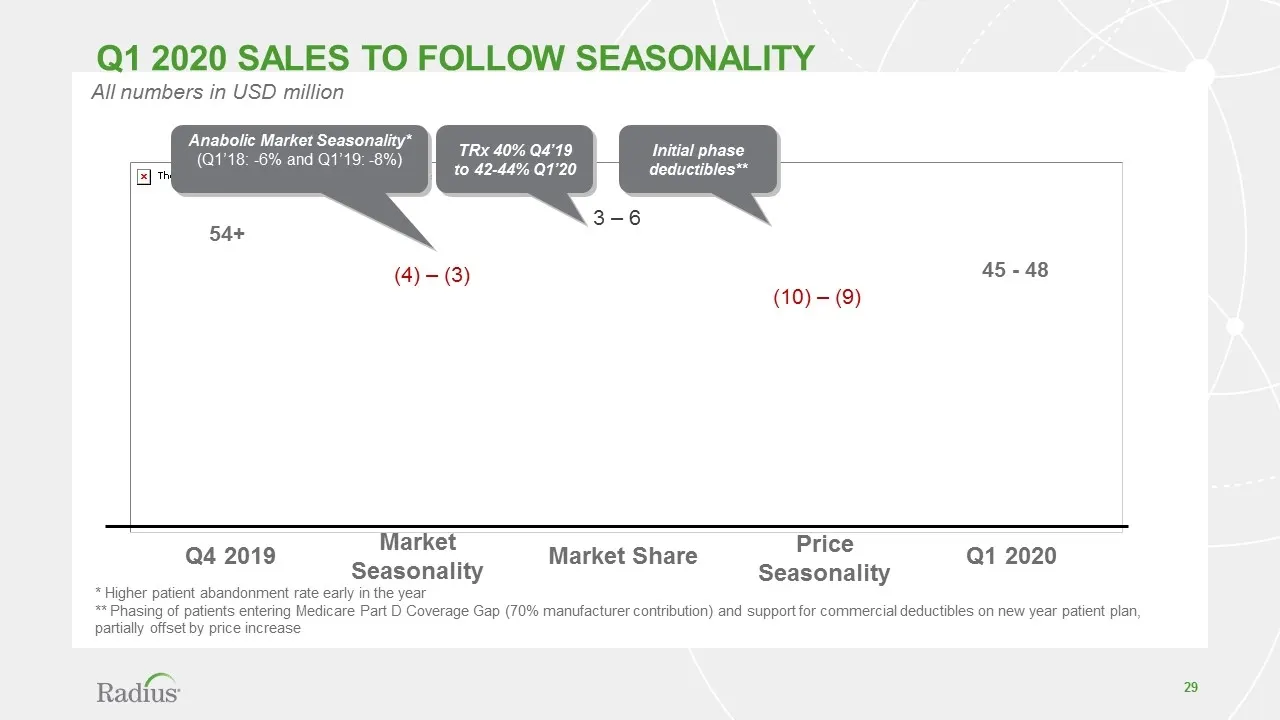
Slide 29: Q1 2020 Market Seasonality
Q4 2019 Q1 2020 Market Seasonality Market Share Price Seasonality All numbers in USD million 54+ (4) – (3) 3 – 6 (10) – (9) 45 - 48 * Higher patient abandonment rate early in the year ** Phasing of patients entering Medicare Part D Coverage Gap (70% manufacturer contribution) and support for commerc
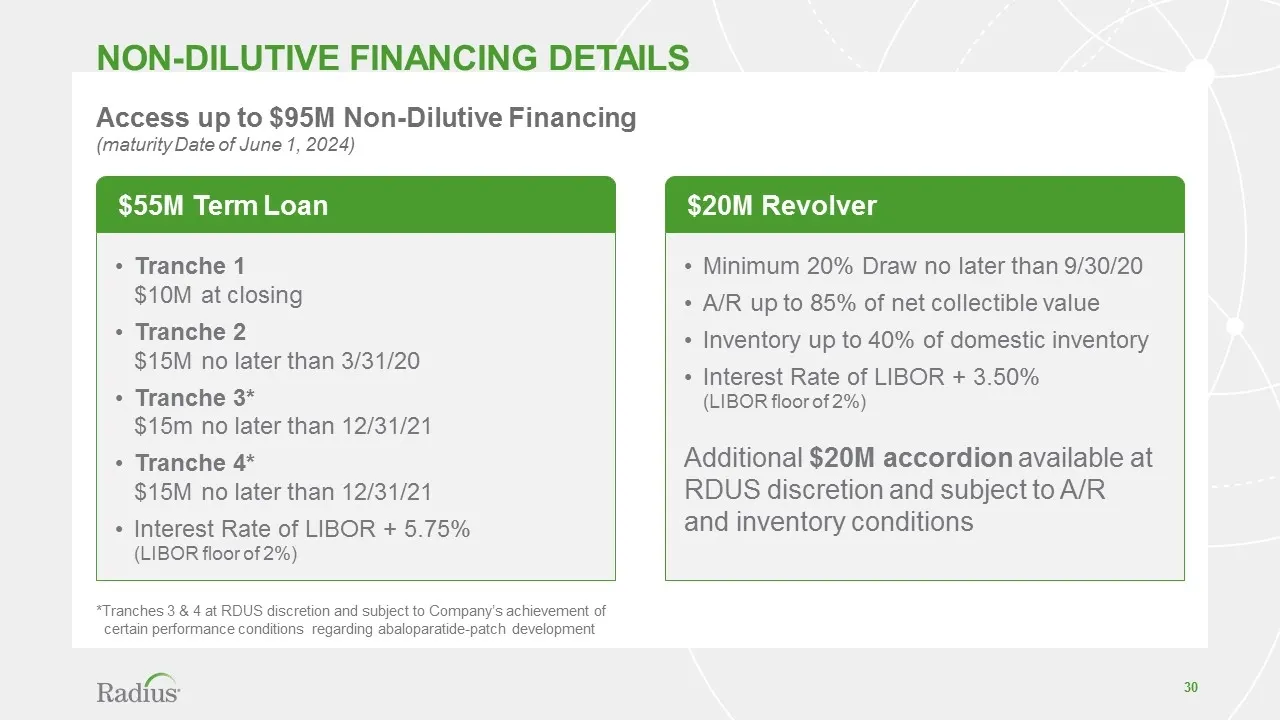
Slide 30: Non-dilutive financing details
Tranche 1 $10M at closing Tranche 2 $15M no later than 3/31/20 Tranche 3* $15m no later than 12/31/21 Tranche 4* $15M no later than 12/31/21 Interest Rate of LIBOR + 5.75% (LIBOR floor of 2%) Non-dilutive financing DETAILS Access up to $95M Non-Dilutive Financing (maturity Date of June 1, 2024) $55M
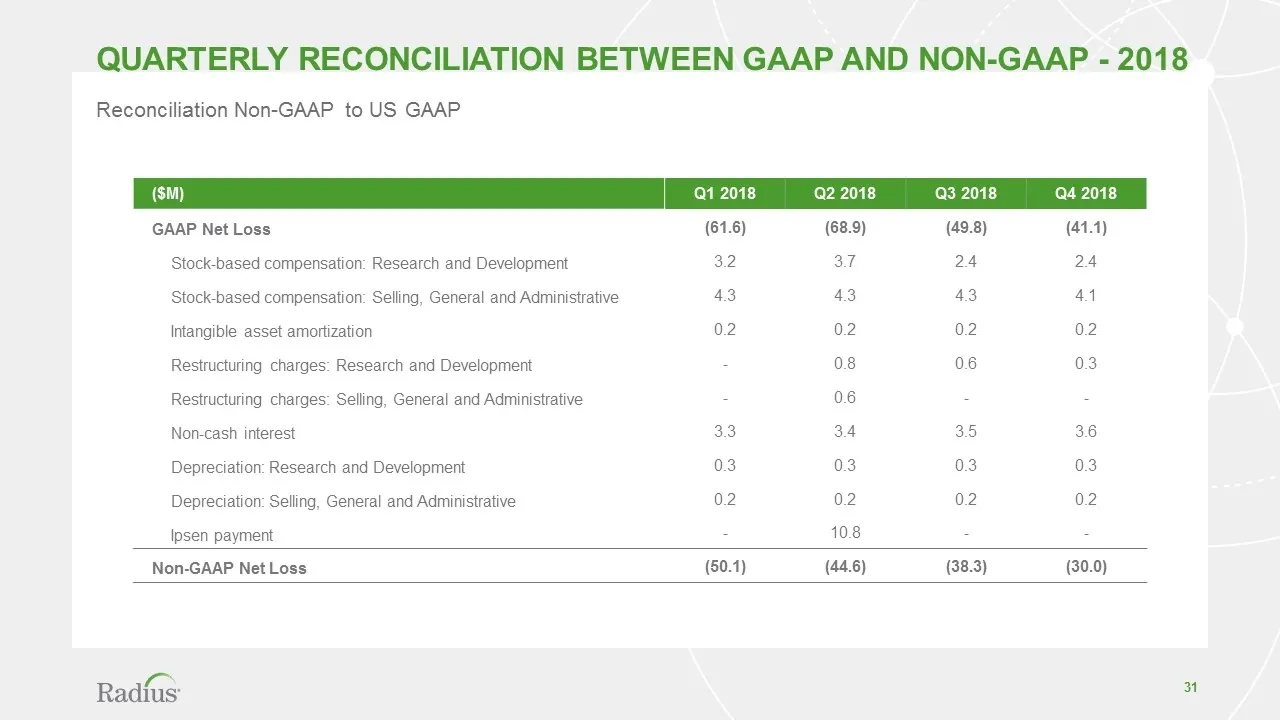
Slide 31: Reconciliation Non-GAAP to US GAAP 2018
Reconciliation Non-GAAP to US GAAP ($M) Q1 2018 Q2 2018 Q3 2018 Q4 2018 GAAP Net Loss (61.6) (68.9) (49.8) (41.1) Stock-based compensation: Research and Development 3.2 3.7 2.4 2.4 Stock-based compensation: Selling, General and Administrative 4.3 4.3 4.3 4.1 Intangible asset amortization 0.2 0.2 0.2
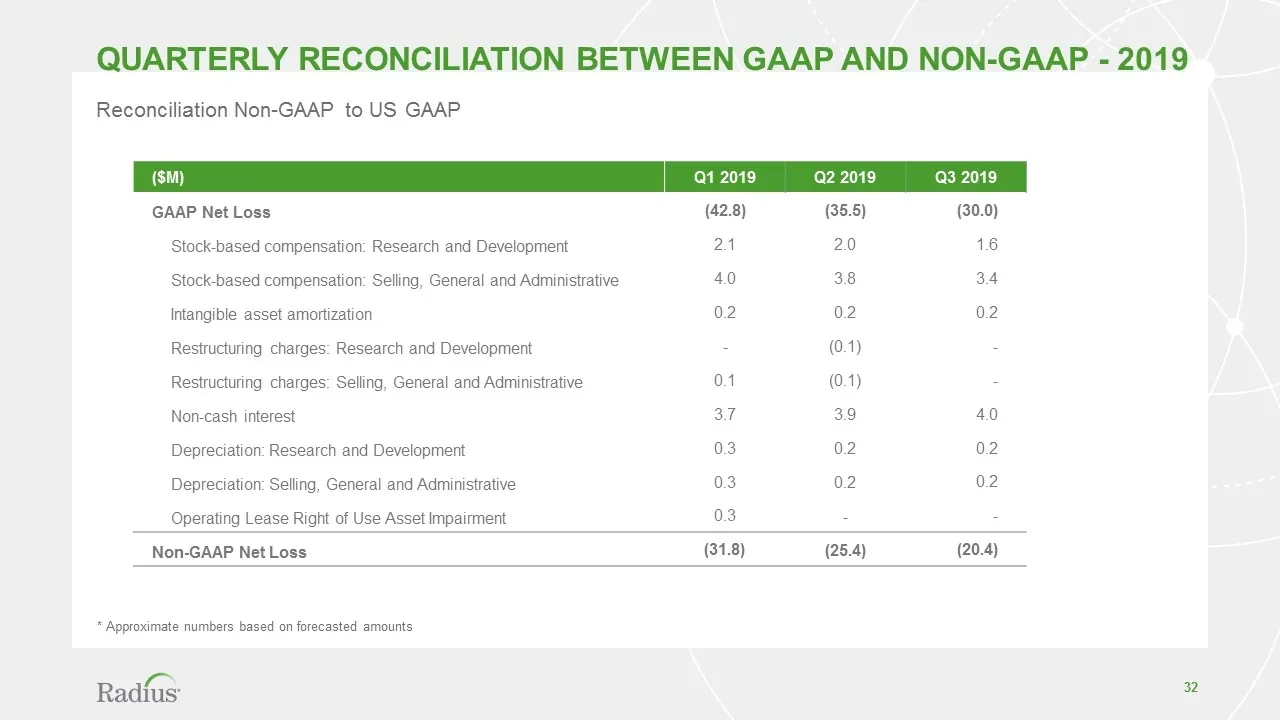
Slide 32: Reconciliation Non-GAAP to US GAAP 2019
Reconciliation Non-GAAP to US GAAP ($M) Q1 2019 Q2 2019 Q3 2019 GAAP Net Loss (42.8) (35.5) (30.0) Stock-based compensation: Research and Development 2.1 2.0 1.6 Stock-based compensation: Selling, General and Administrative 4.0 3.8 3.4 Intangible asset amortization 0.2 0.2 0.2 Restructuring charges:
Source: SEC EDGAR · 8-K filed Jan 13, 2020