SGL Carbon SE · XETR:SGL
SGL Carbon — SGL Group — Baader Investment Conference 2013
37 slides from SGL Carbon's conference presentation, Sep 26, 2013
Slide 1: Baader Investment Conference
Baader Investment Conference Jürgen Muth, CFO Munich 26 September 2013
Slide 2: Company profile
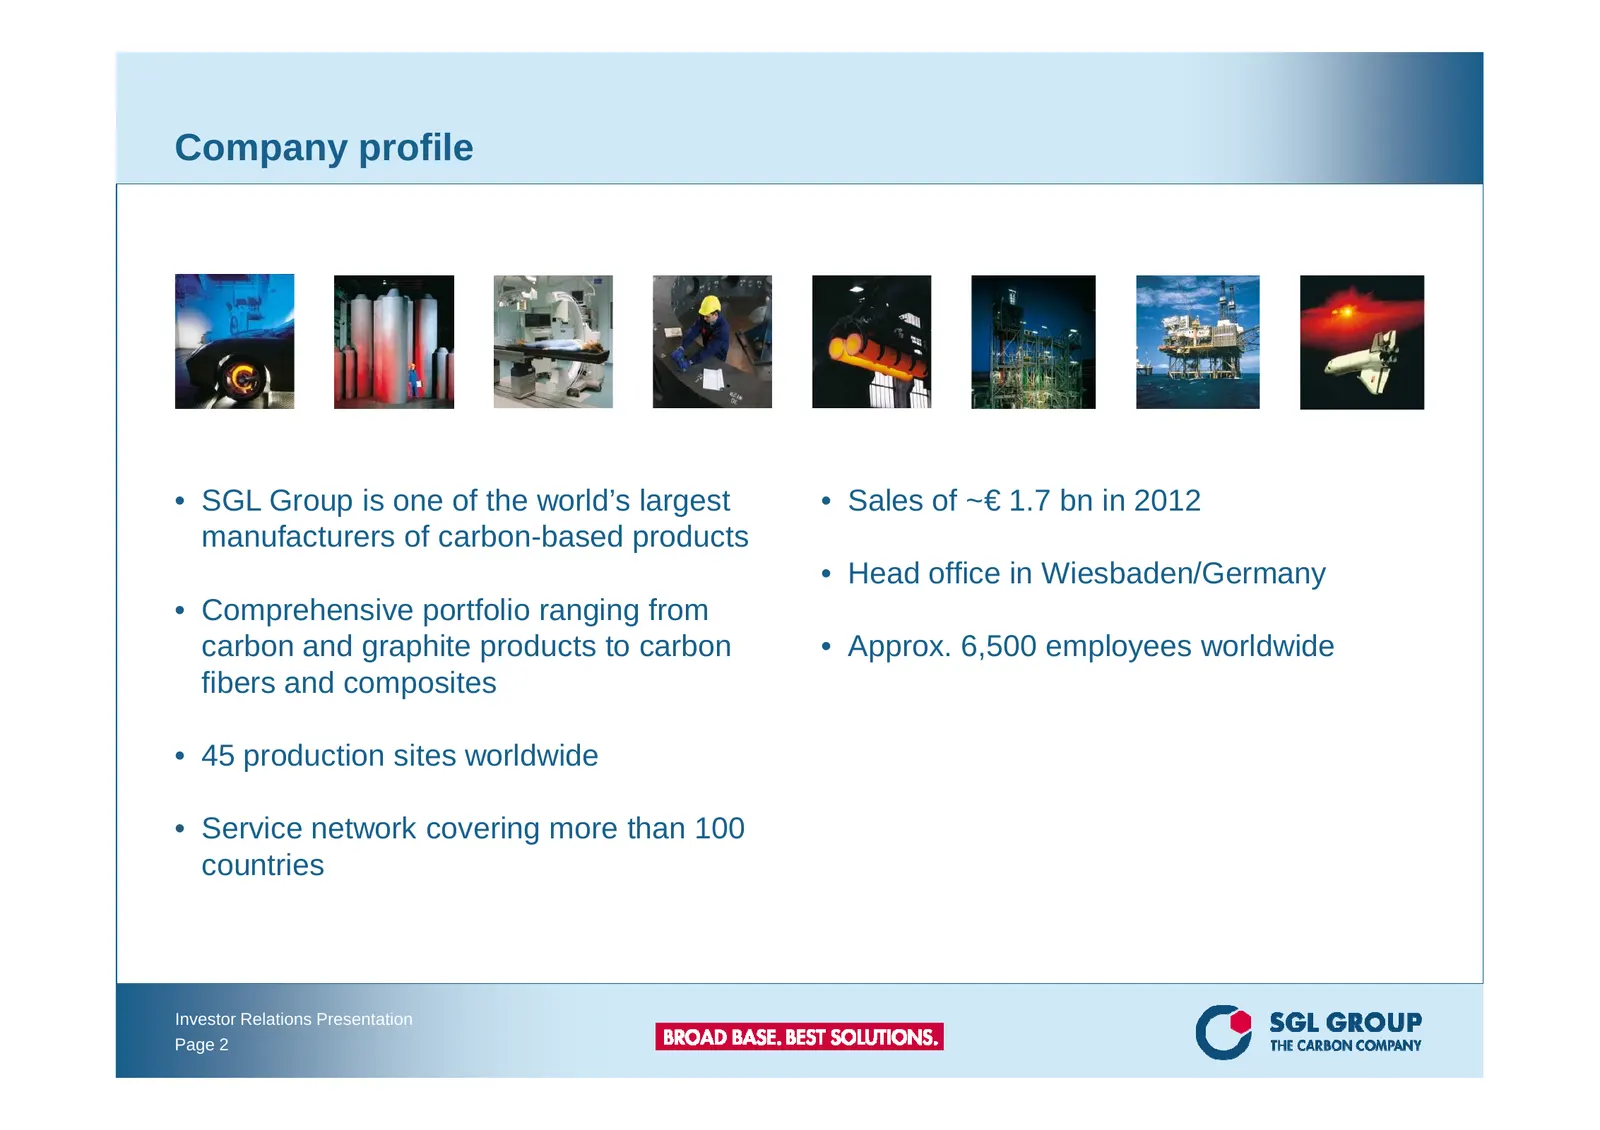
Company profile • SGL Group is one of the world’s largest • Sales of ~€ 1.7 bn in 2012 manufacturers of carbon-based products • Head office in Wiesbaden/Germany • Comprehensive portfolio ranging from carbon and graphite products to carbon • Approx. 6,500 employees worldwide fibers and composites • 4
Slide 3: Introduction to SGL Group's Businesses
Introduction to SGL Group’s Businesses Investor Relations Presentation Page 3
Slide 4: SGL Group Business structure
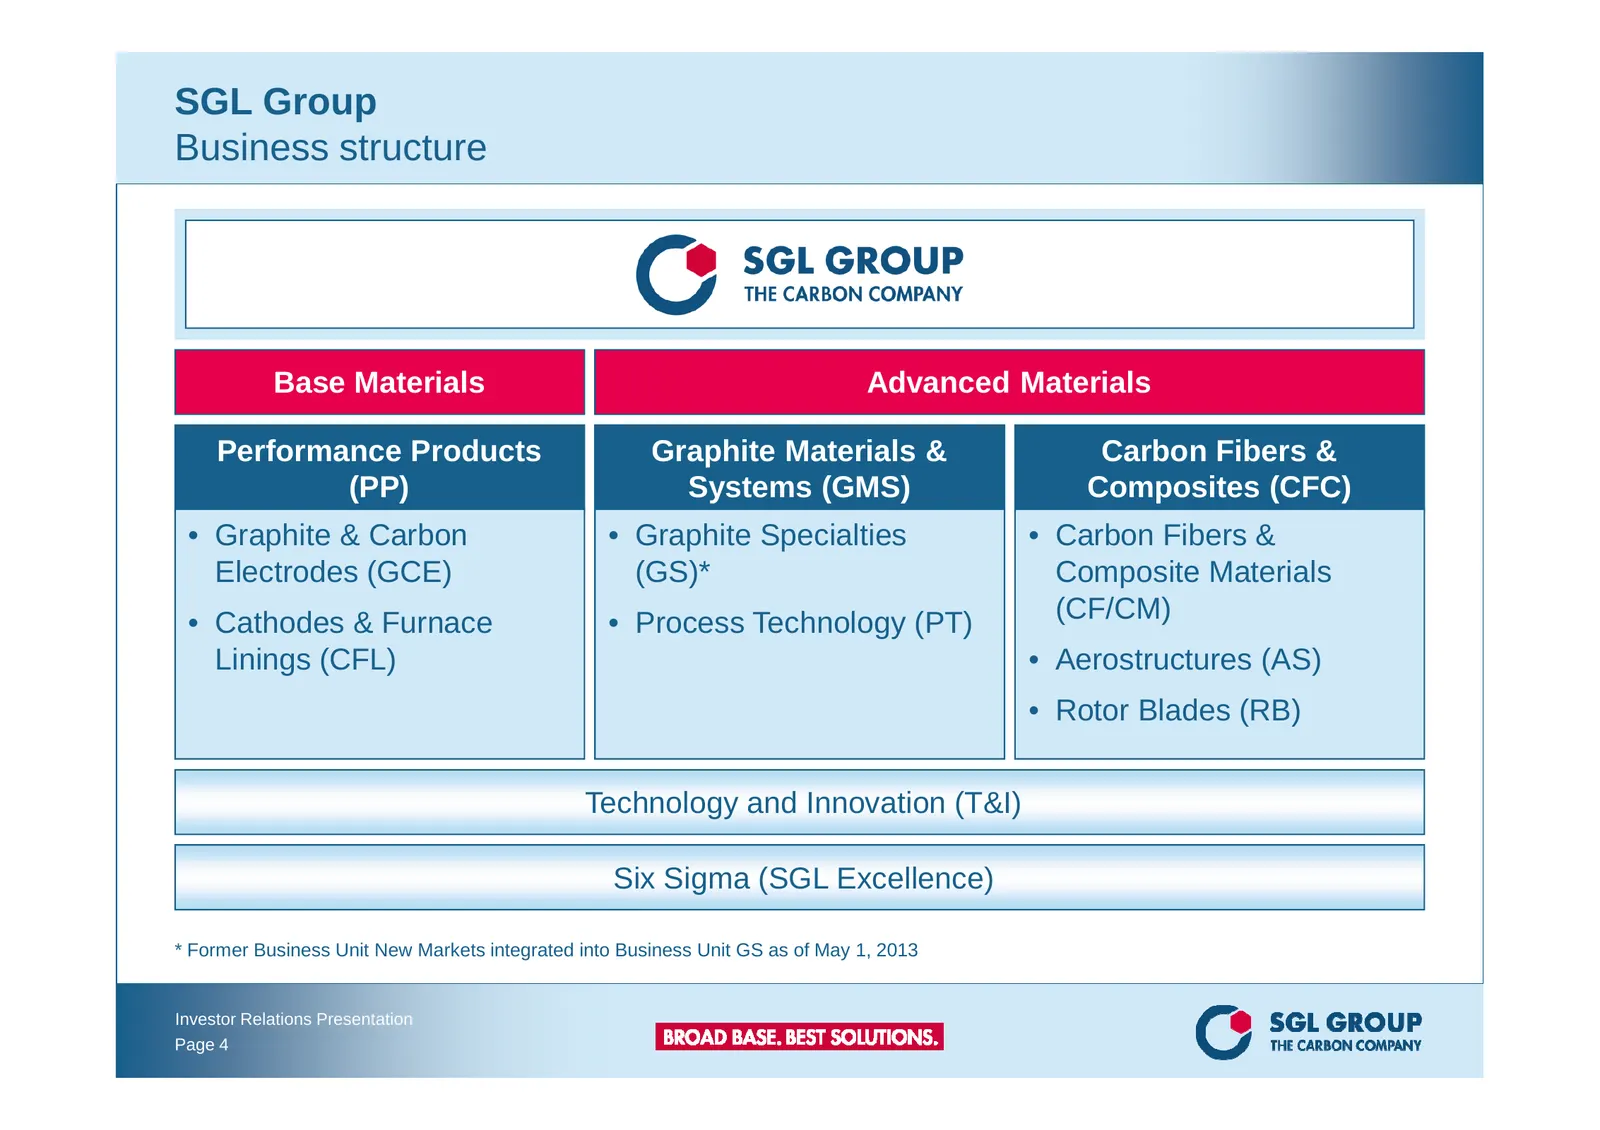
SGL Group Business structure Base Materials Advanced Materials Performance Products Graphite Materials & Carbon Fibers & (PP) Systems (GMS) Composites (CFC) • Graphite & Carbon • Graphite Specialties • Carbon Fibers & Electrodes (GCE) (GS)* Composite Materials • Cathodes & Furnace • Process Technolo
Slide 5: Performance Products (PP)
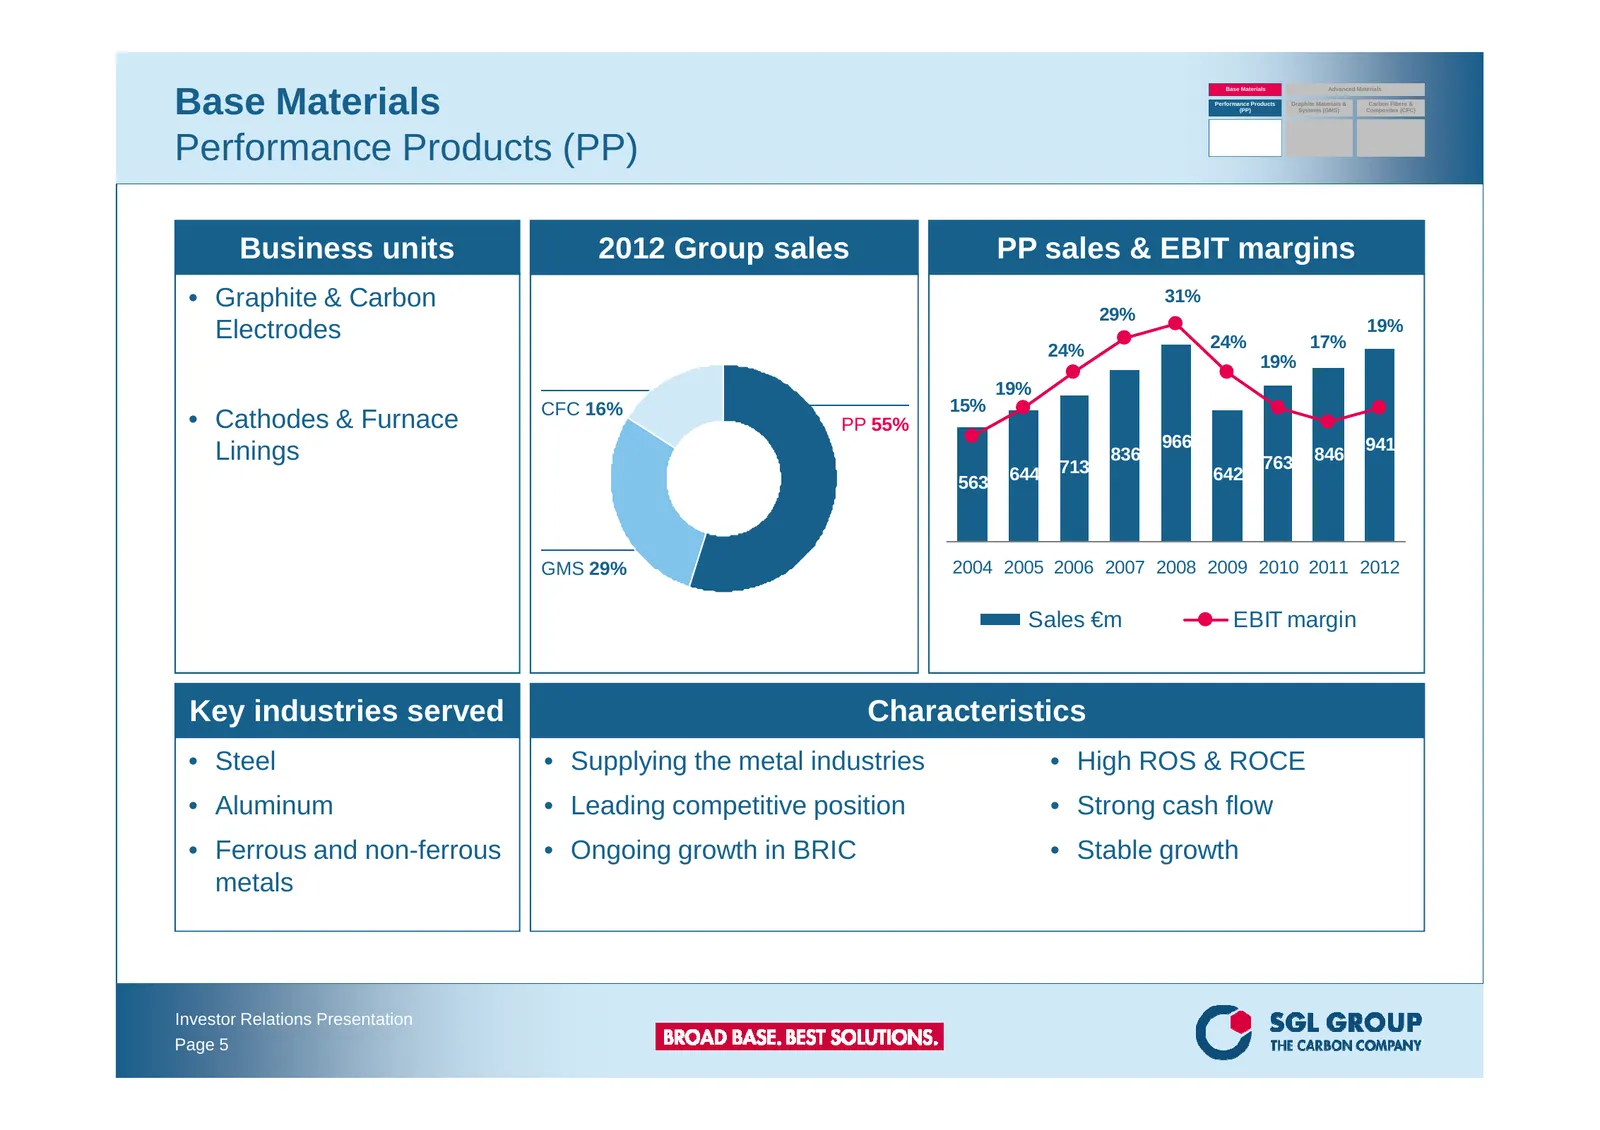
Base Materials Advanced Materials Base Materials Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Performance Products (PP) Business units 2012 Group sales PP sales & EBIT margins • Graphite & Carbon 31% 29% Electrodes 19% 24% 24% 17% 19% 19% CFC 16% 15%
Slide 6: Graphite electrodes (GE) for steel production in EAFs
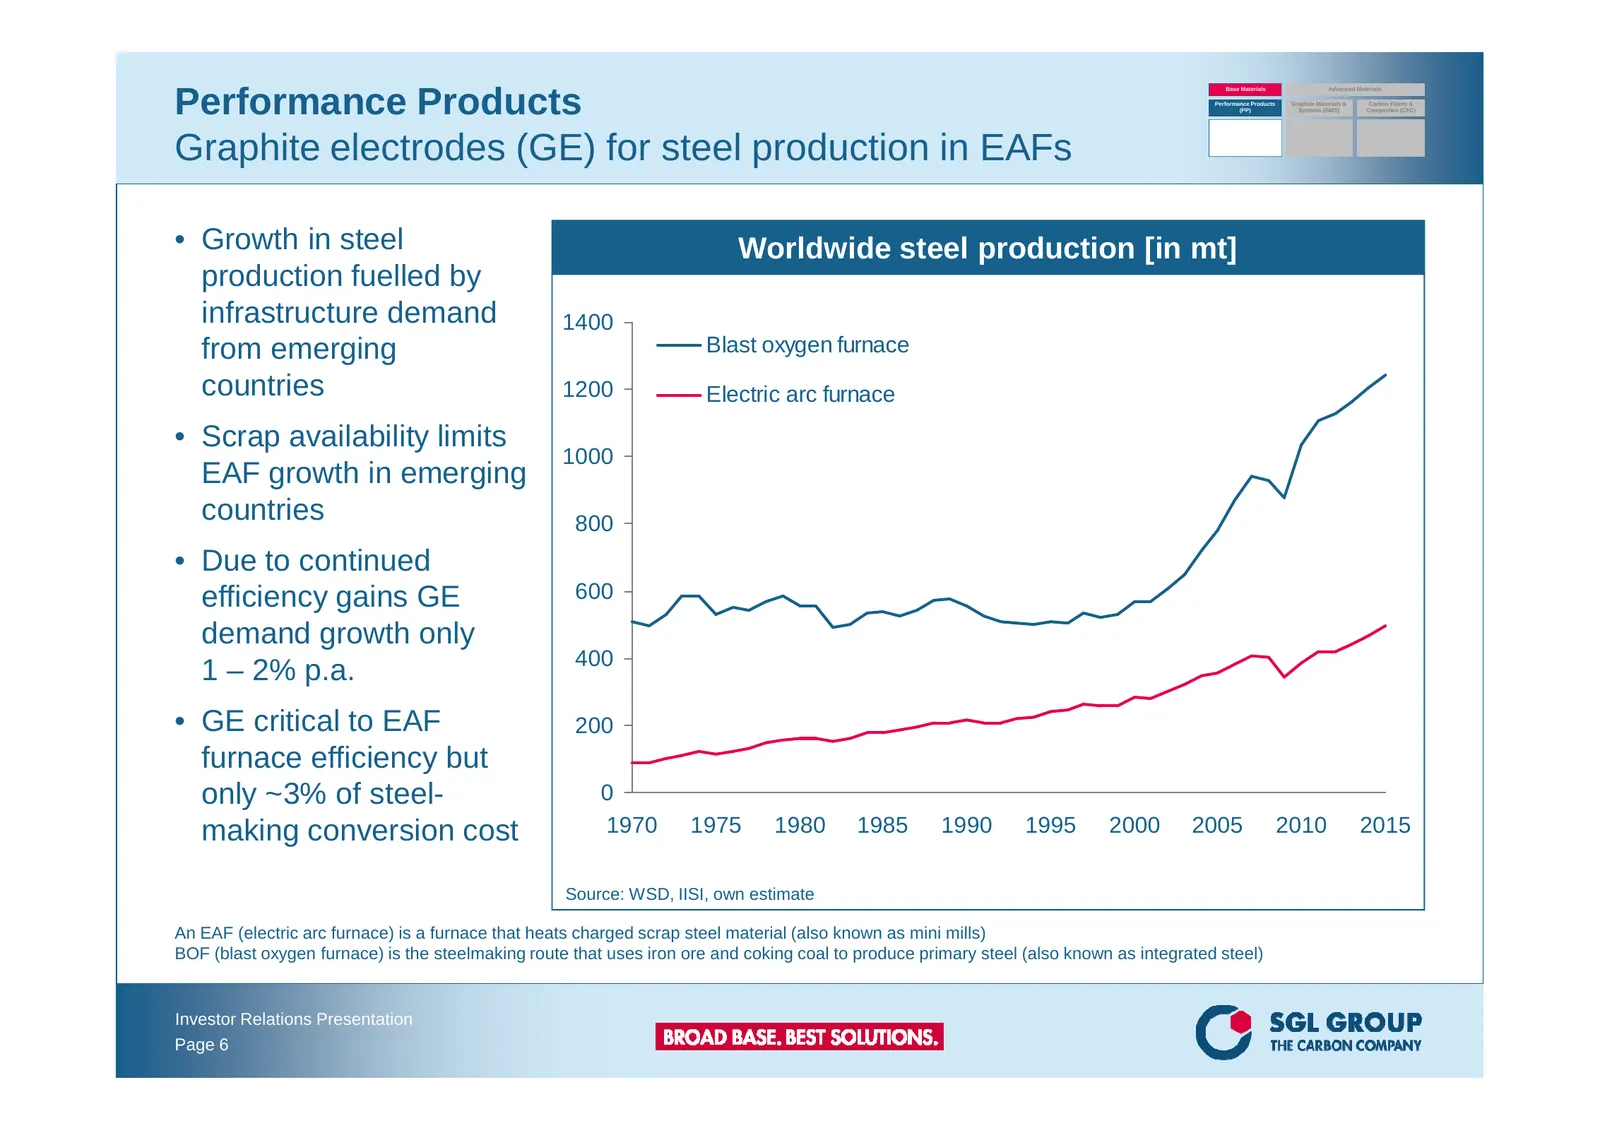
Base Materials Advanced Materials Performance Products Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Graphite electrodes (GE) for steel production in EAFs • Growth in steel Worldwide steel production [in mt] production fuelled by infrastructure demand
Slide 7: Graphite electrodes
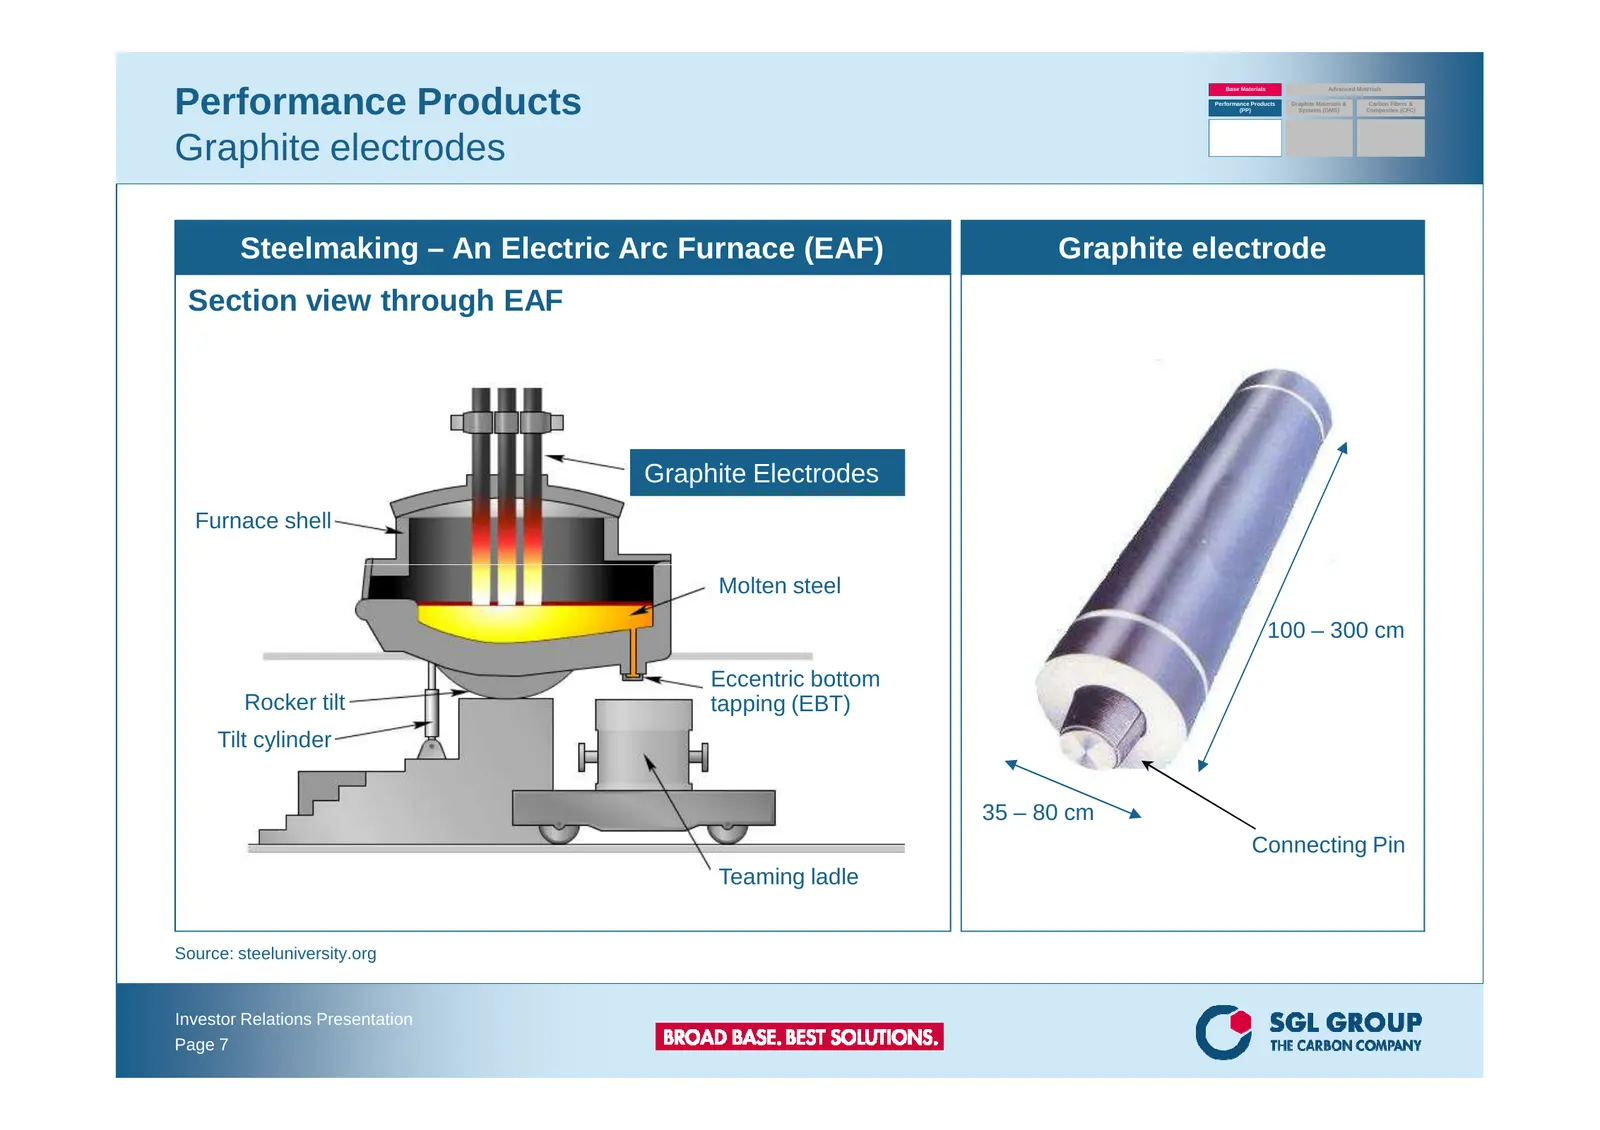
Base Materials Advanced Materials Performance Products Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Graphite electrodes Steelmaking – An Electric Arc Furnace (EAF) Graphite electrode Section view through EAF Graphite Electrodes Furnace shell Molten st
Slide 8: Graphite electrode production process
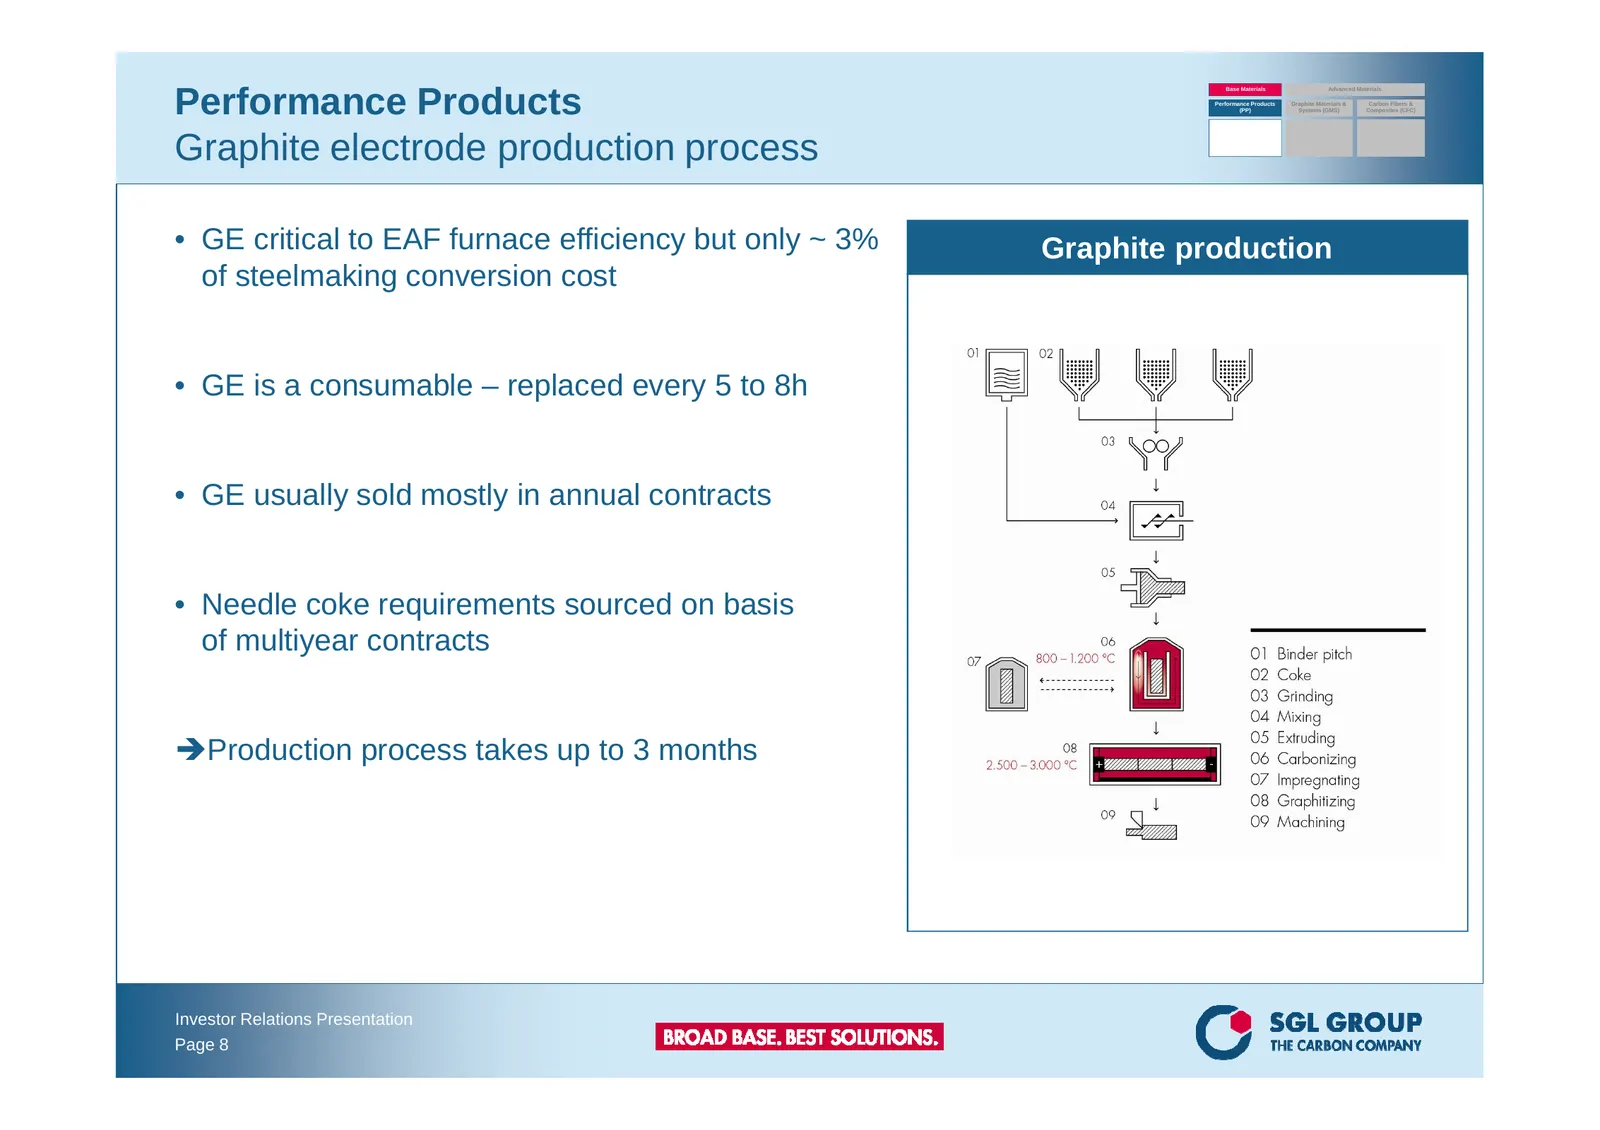
Base Materials Advanced Materials Performance Products Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Graphite electrode production process • GE critical to EAF furnace efficiency but only ~ 3% Graphite production of steelmaking conversion cost • GE is
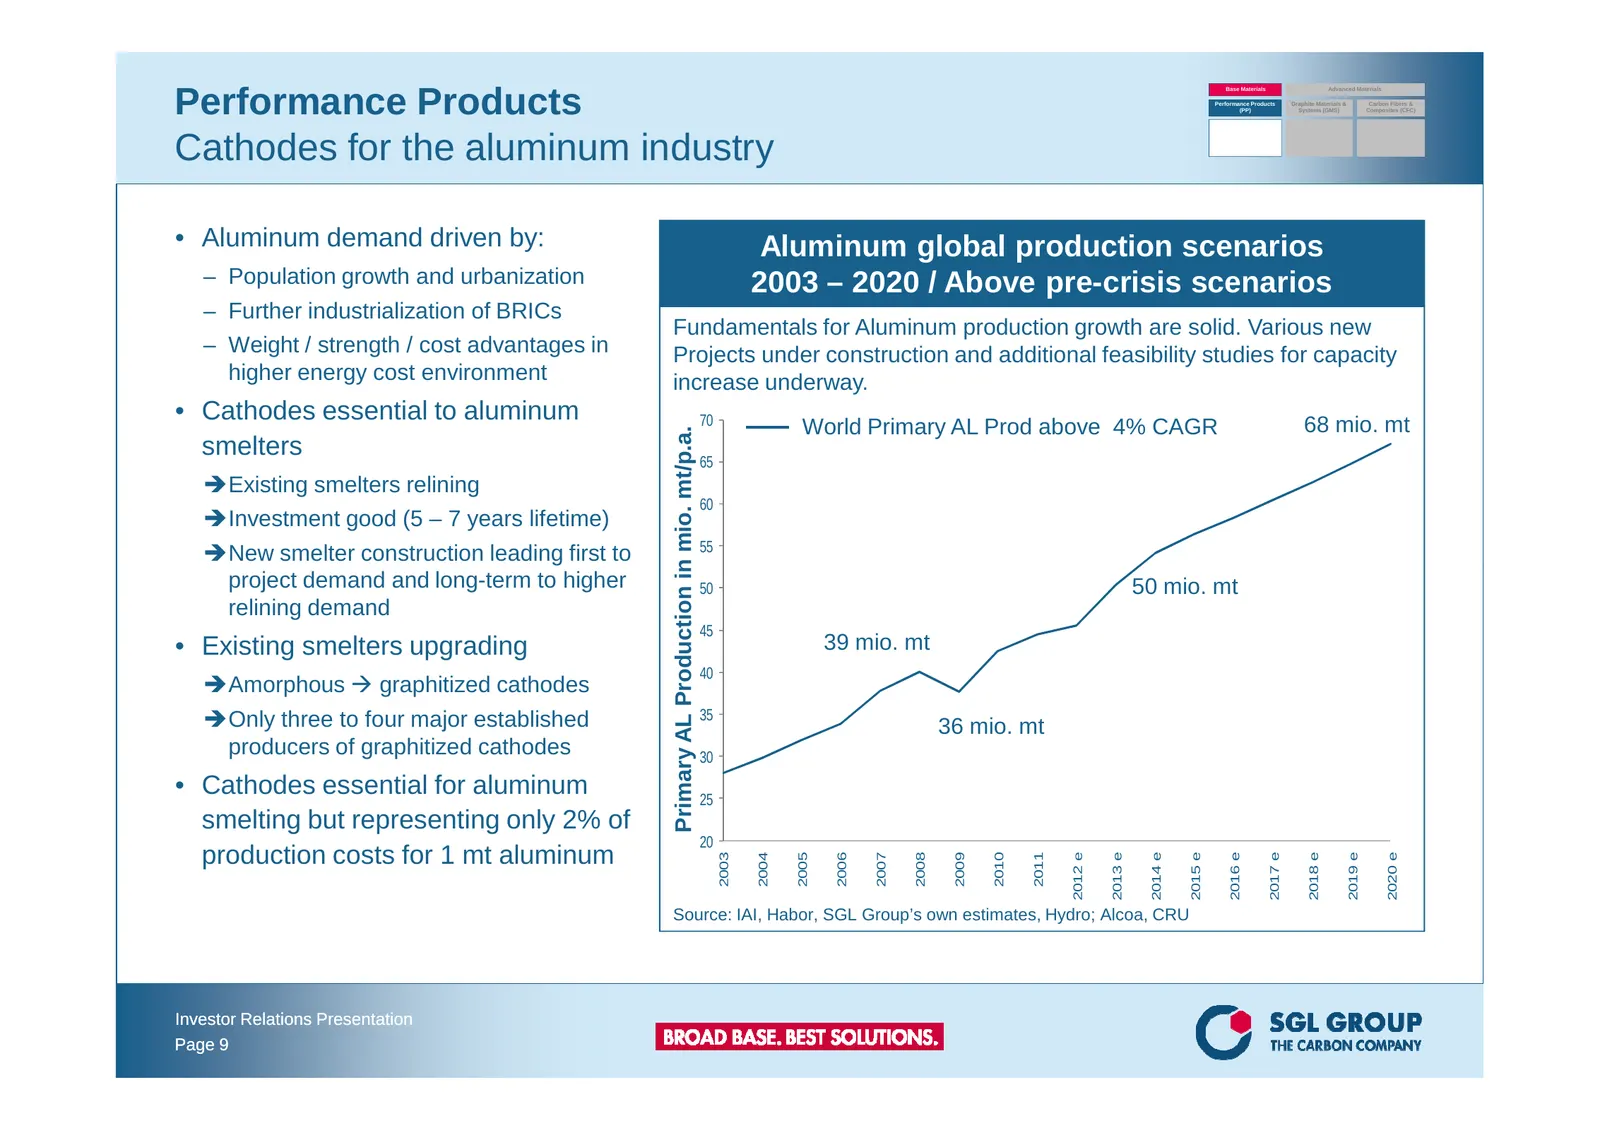
Slide 9: Cathodes for the aluminum industry
Base Materials Advanced Materials Performance Products Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Cathodes for the aluminum industry • Aluminum demand driven by: Aluminum global production scenarios – Population growth and urbanization 2003 – 2020 /
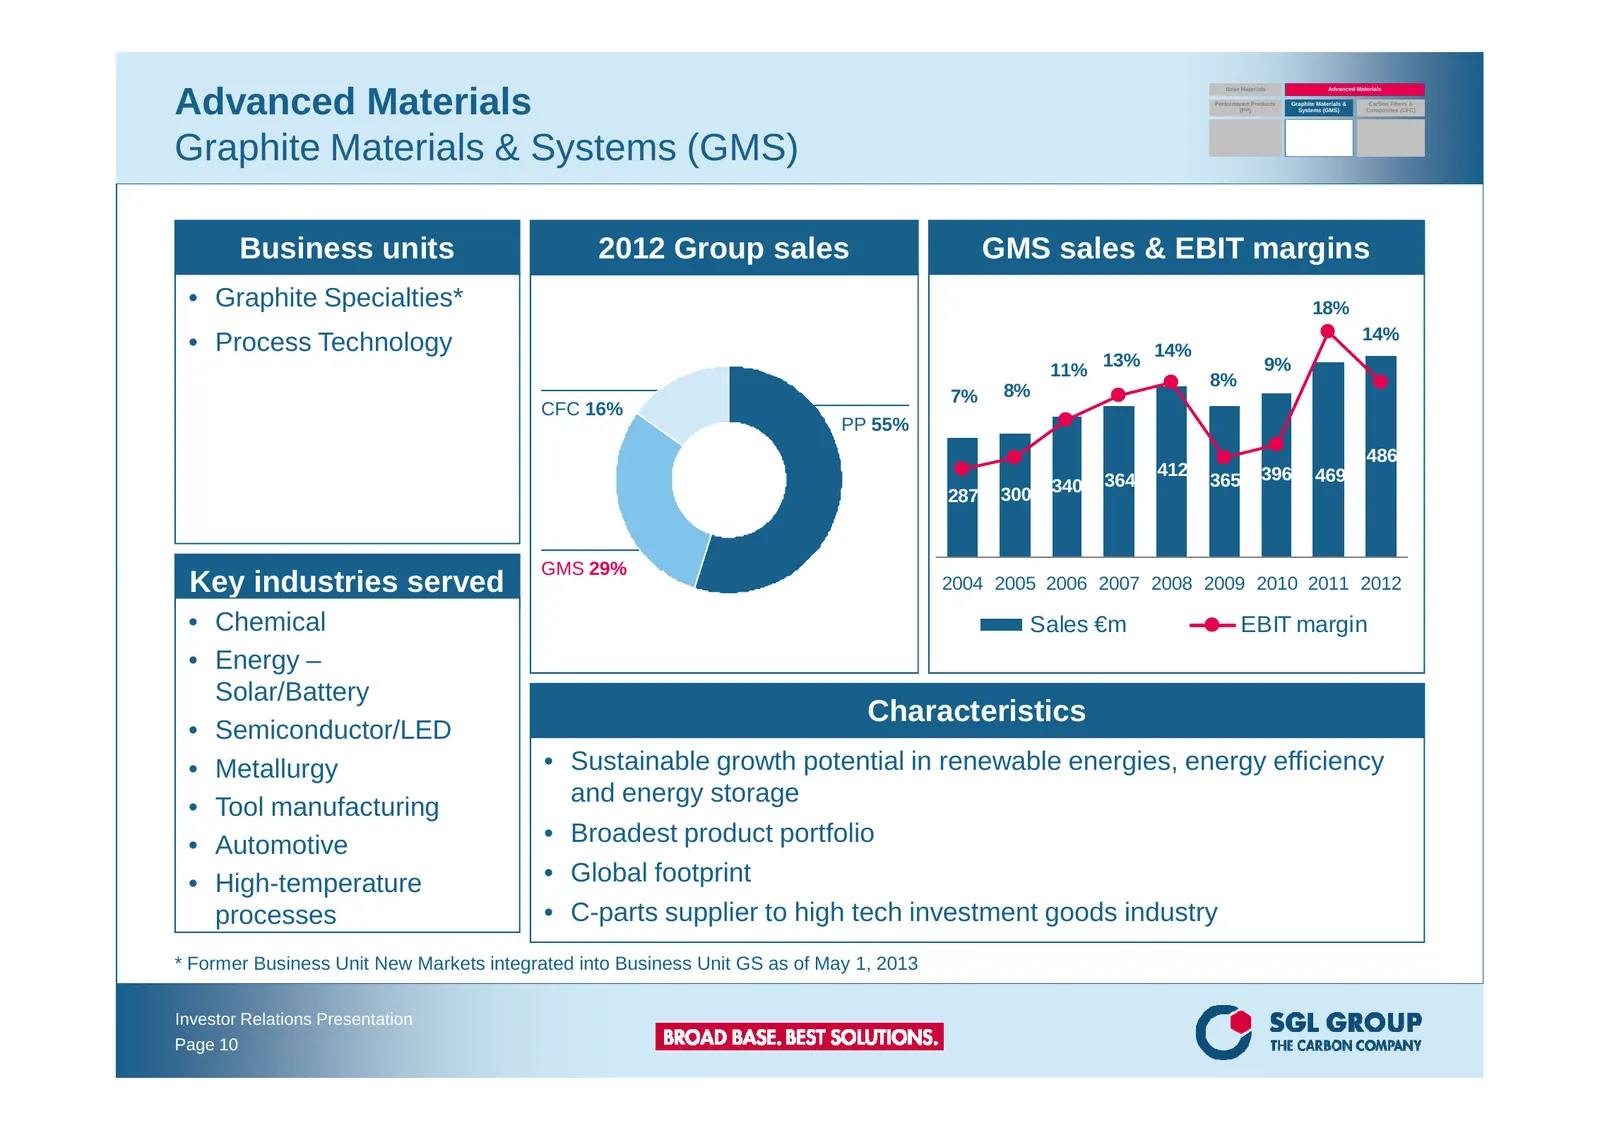
Slide 10: Graphite Materials & Systems (GMS)
Base Materials Advanced Materials Advanced Materials Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Graphite Materials & Systems (GMS) Business units 2012 Group sales GMS sales & EBIT margins • Graphite Specialties* 18% 14% • Process Technology 14% 13%
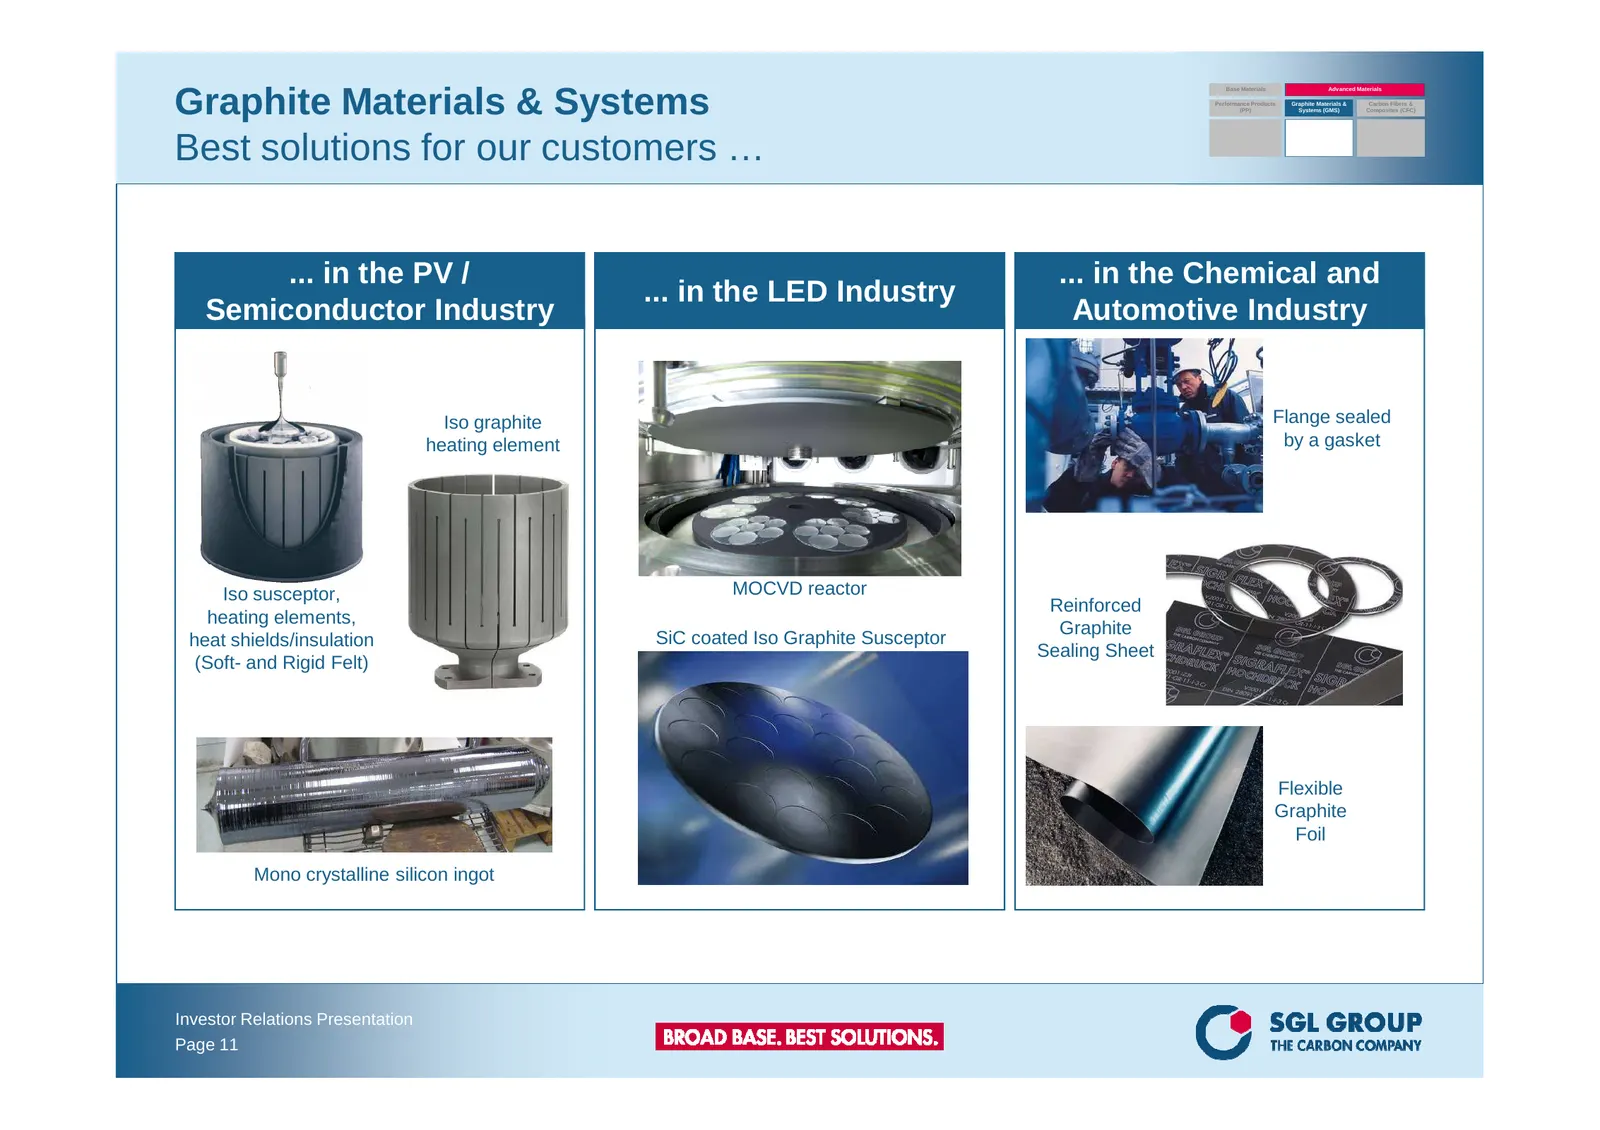
Slide 11: Best solutions for our customers
Base Materials Advanced Materials Graphite Materials & Systems Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Best solutions for our customers … ... in the PV / ... in the Chemical and ... in the LED Industry Semiconductor Industry Automotive Industry I
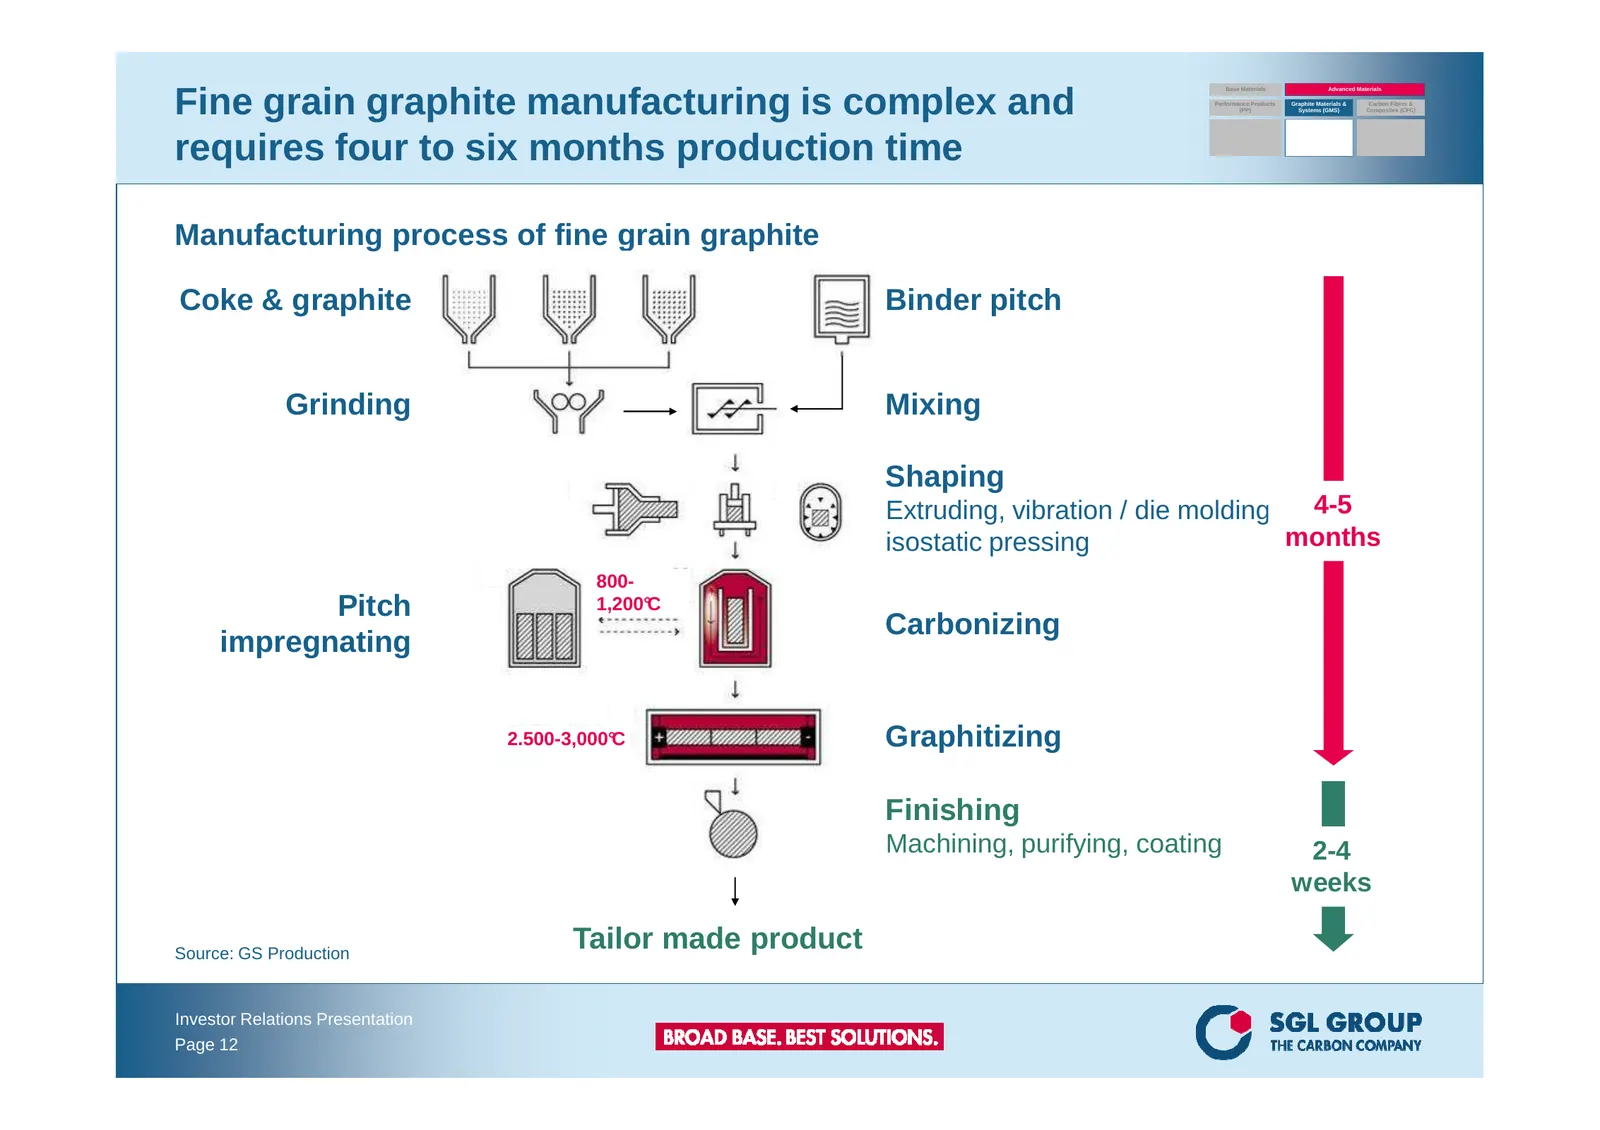
Slide 12: Fine grain graphite manufacturing is complex
Base Materials Advanced Materials Fine grain graphite manufacturing is complex and Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) requires four to six months production time Manufacturing process of fine grain graphite Coke & graphite Binder pitch Grind
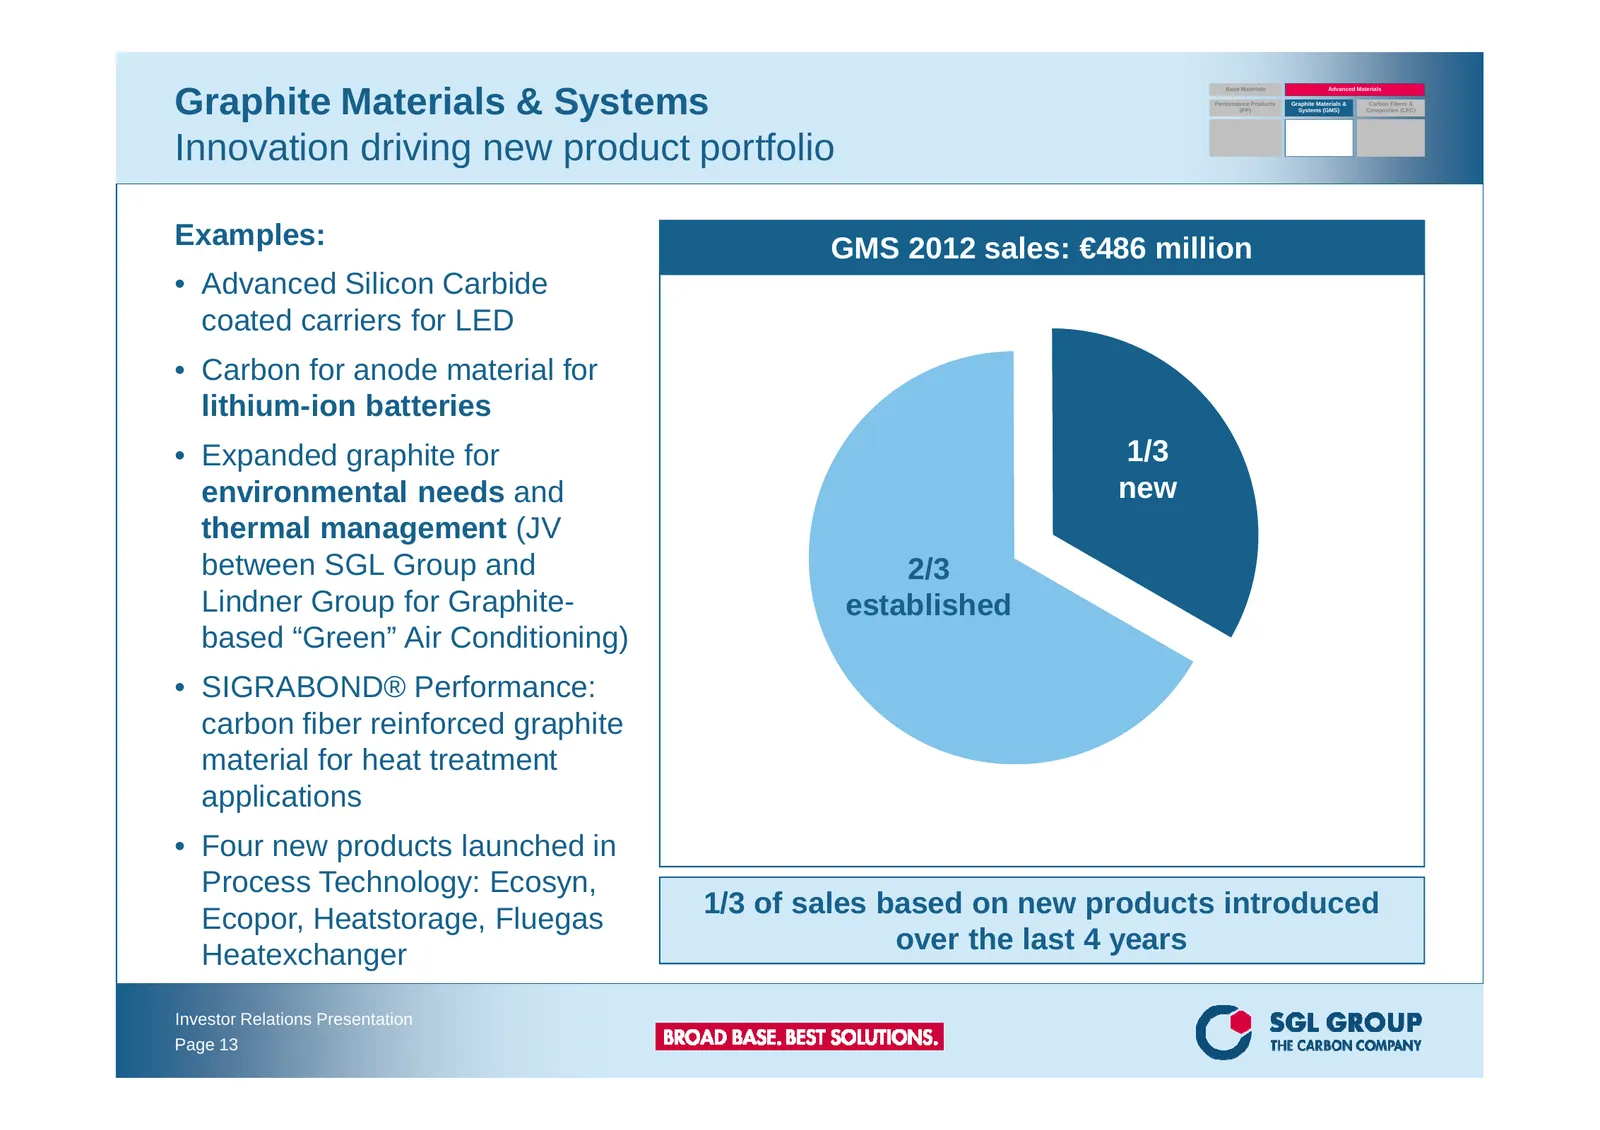
Slide 13: Innovation driving new product portfolio
Base Materials Advanced Materials Graphite Materials & Systems Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Innovation driving new product portfolio Examples: GMS 2012 sales: €486 million • Advanced Silicon Carbide coated carriers for LED • Carbon for
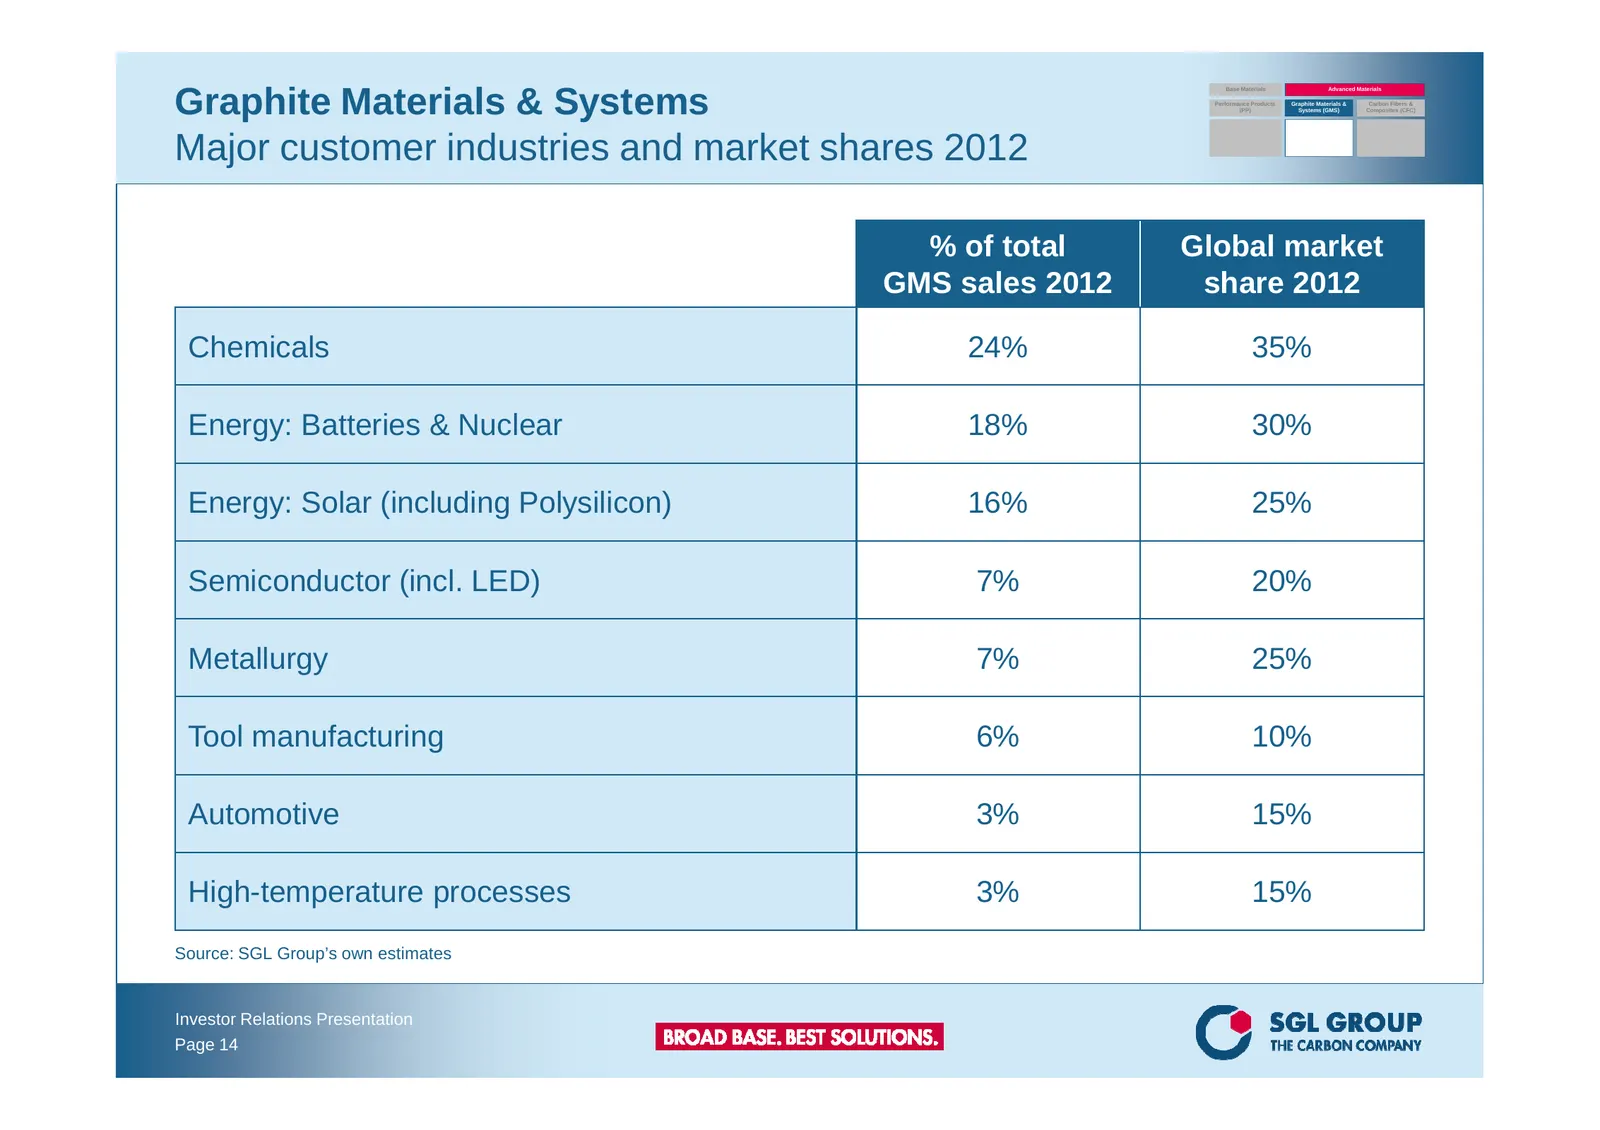
Slide 14: Major customer industries and market shares 2012
Base Materials Advanced Materials Graphite Materials & Systems Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Major customer industries and market shares 2012 % of total Global market GMS sales 2012 share 2012 Chemicals 24% 35% Energy: Batteries & Nucle
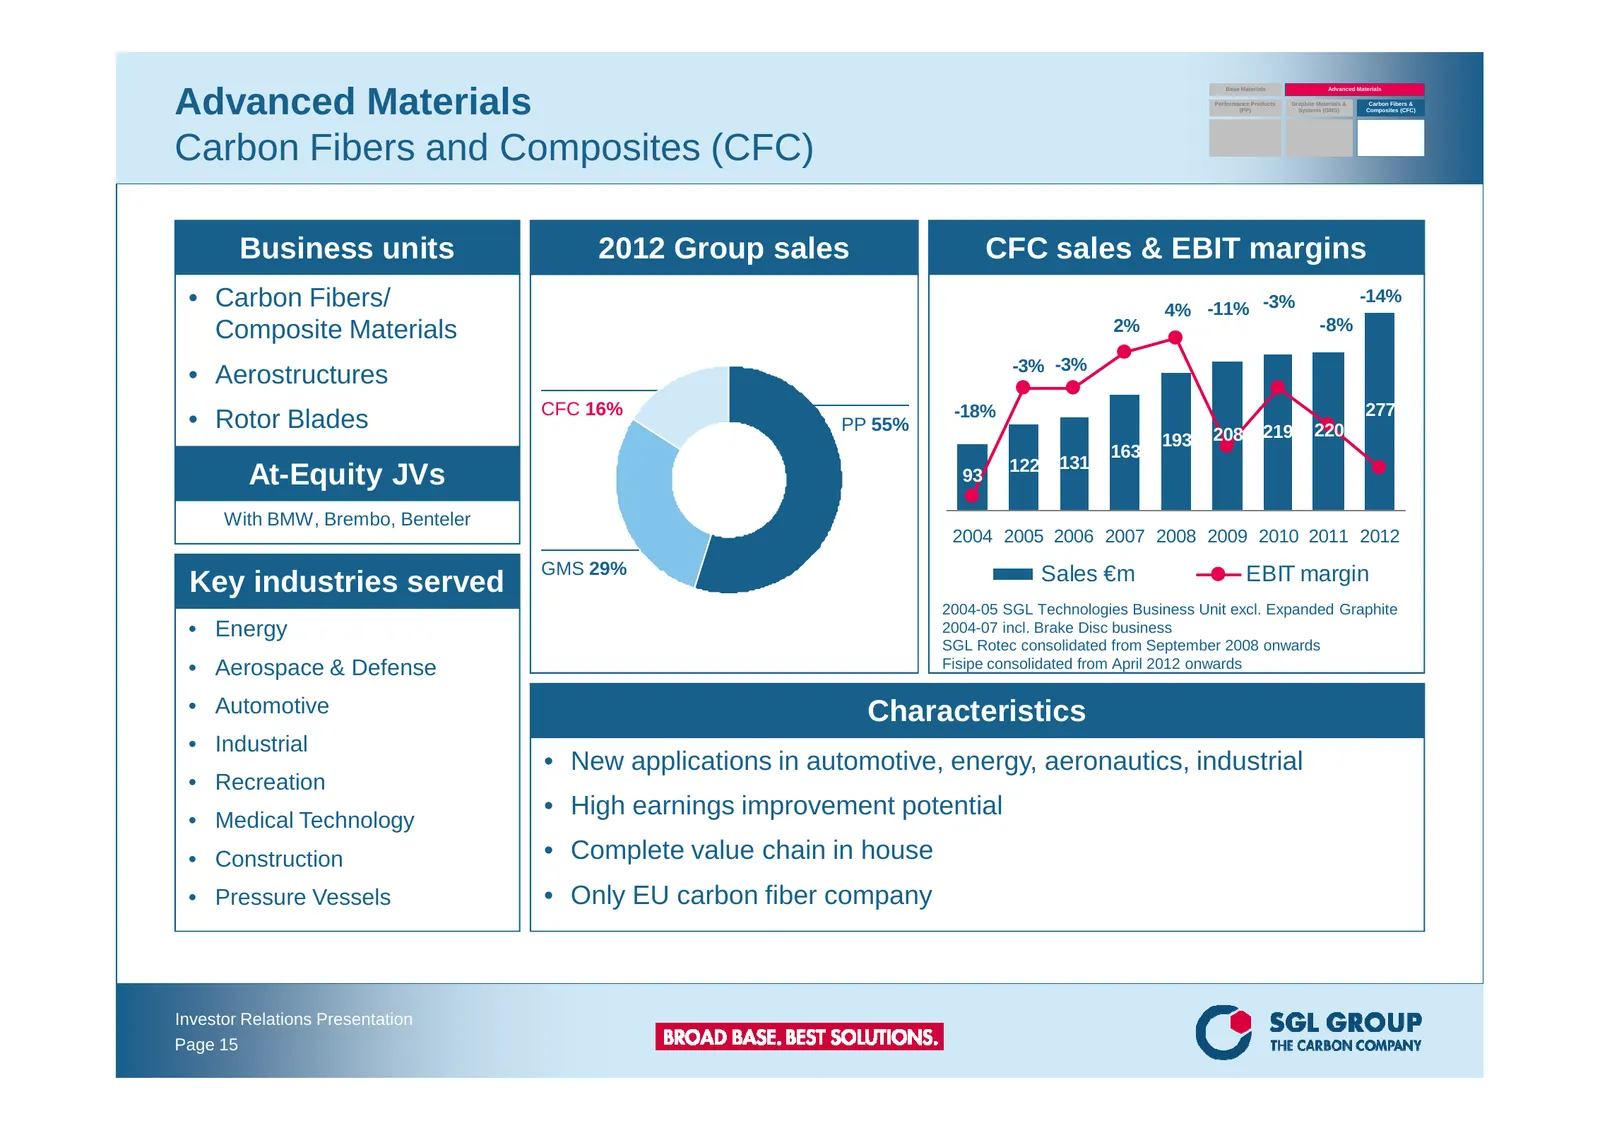
Slide 15: Carbon Fibers and Composites (CFC)
Base Materials Advanced Materials Advanced Materials Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Carbon Fibers and Composites (CFC) Business units 2012 Group sales CFC sales & EBIT margins • Carbon Fibers/ 4% -11% -3% -14% Composite Materials 2% -8%
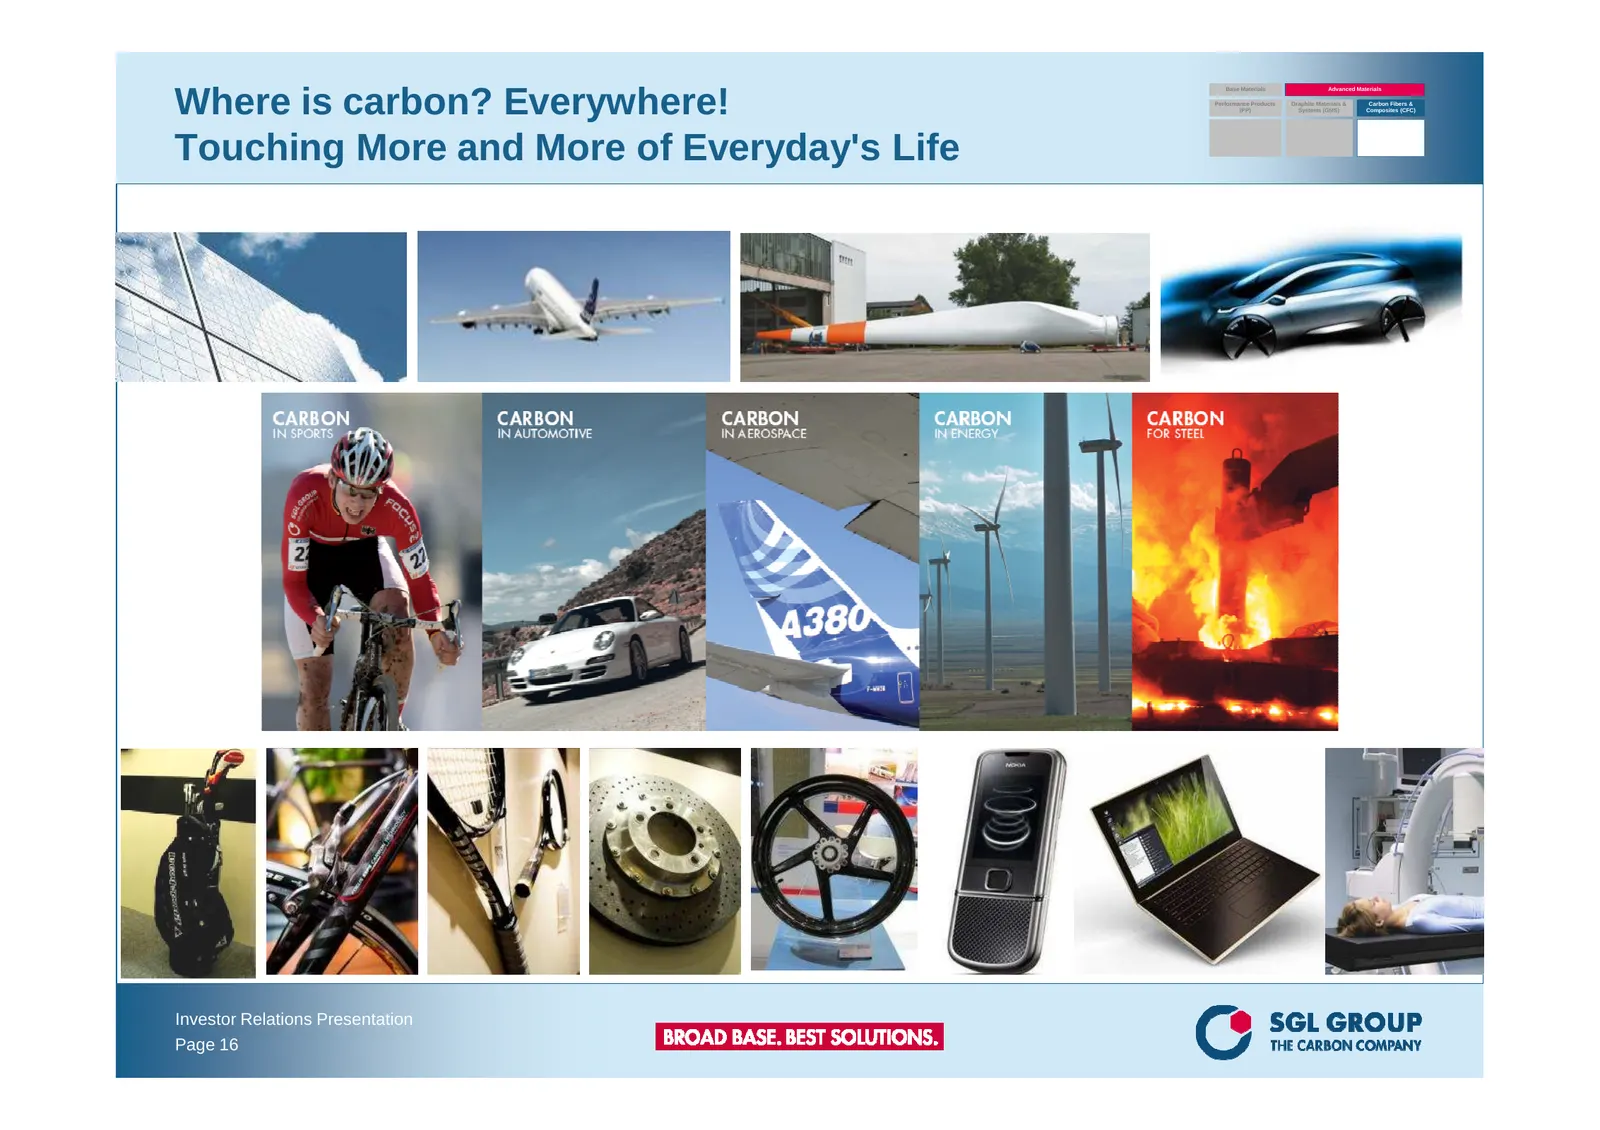
Slide 16: Where is carbon? Everywhere!
Base Materials Advanced Materials Where is carbon? Everywhere! Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Touching More and More of Everyday's Life Investor Relations Presentation Page 16
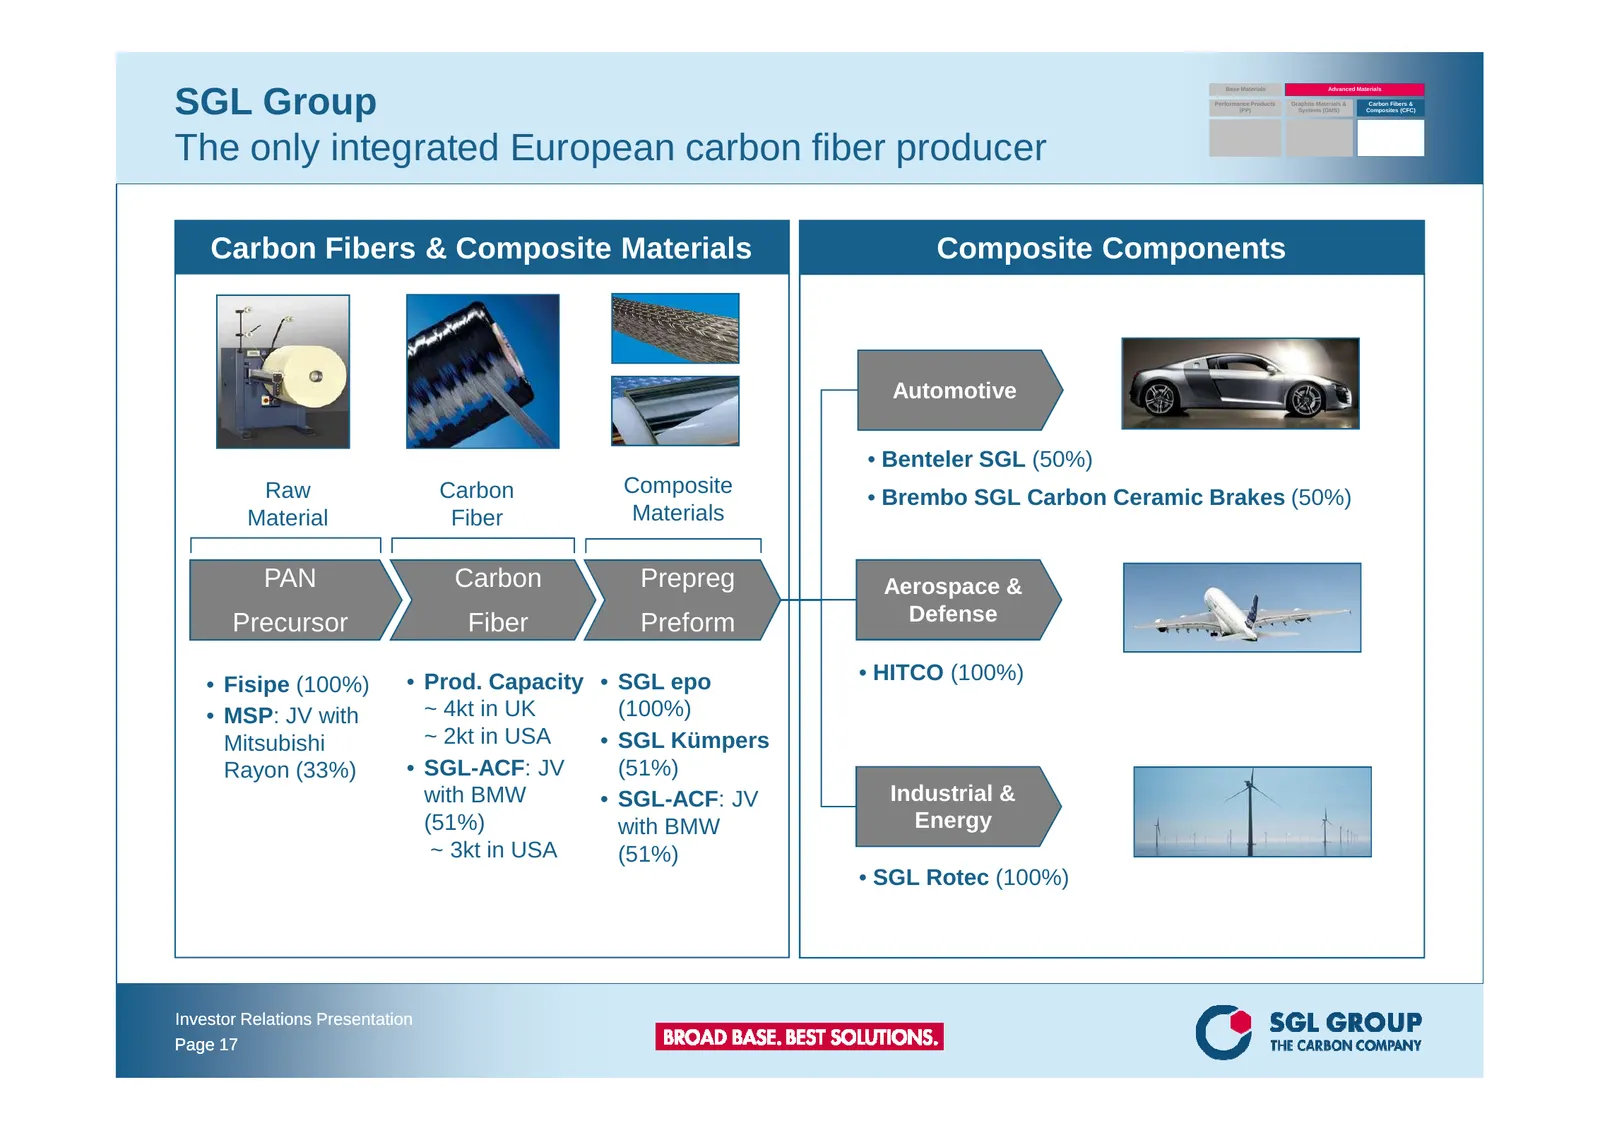
Slide 17: The only integrated European carbon fiber producer
Base Materials Advanced Materials SGL Group Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) The only integrated European carbon fiber producer Carbon Fibers & Composite Materials Composite Components Automotive • Benteler SGL (50%) Raw Carbon Composite •
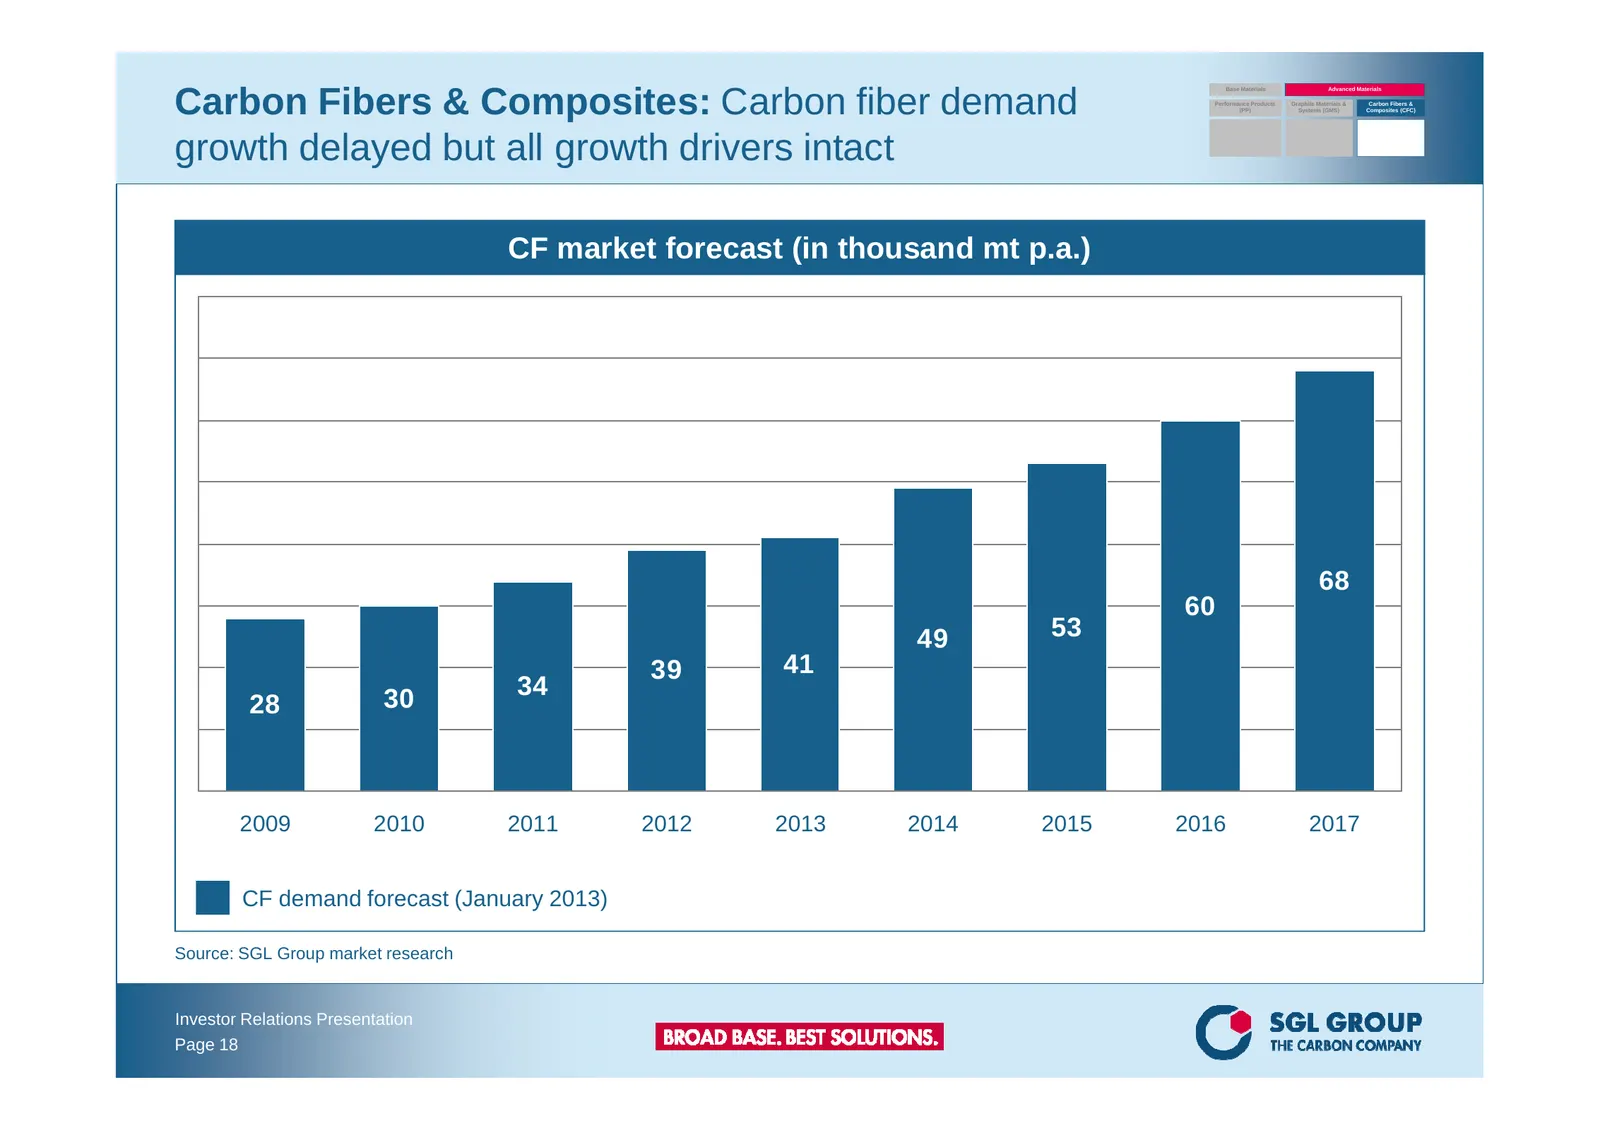
Slide 18: Carbon fiber demand growth delayed but drivers intact
Base Materials Advanced Materials Carbon Fibers & Composites: Carbon fiber demand Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) growth delayed but all growth drivers intact CF market forecast (in thousand mt p.a.) 68 60 49 53 39 41 30 34 28 2009 2010 2
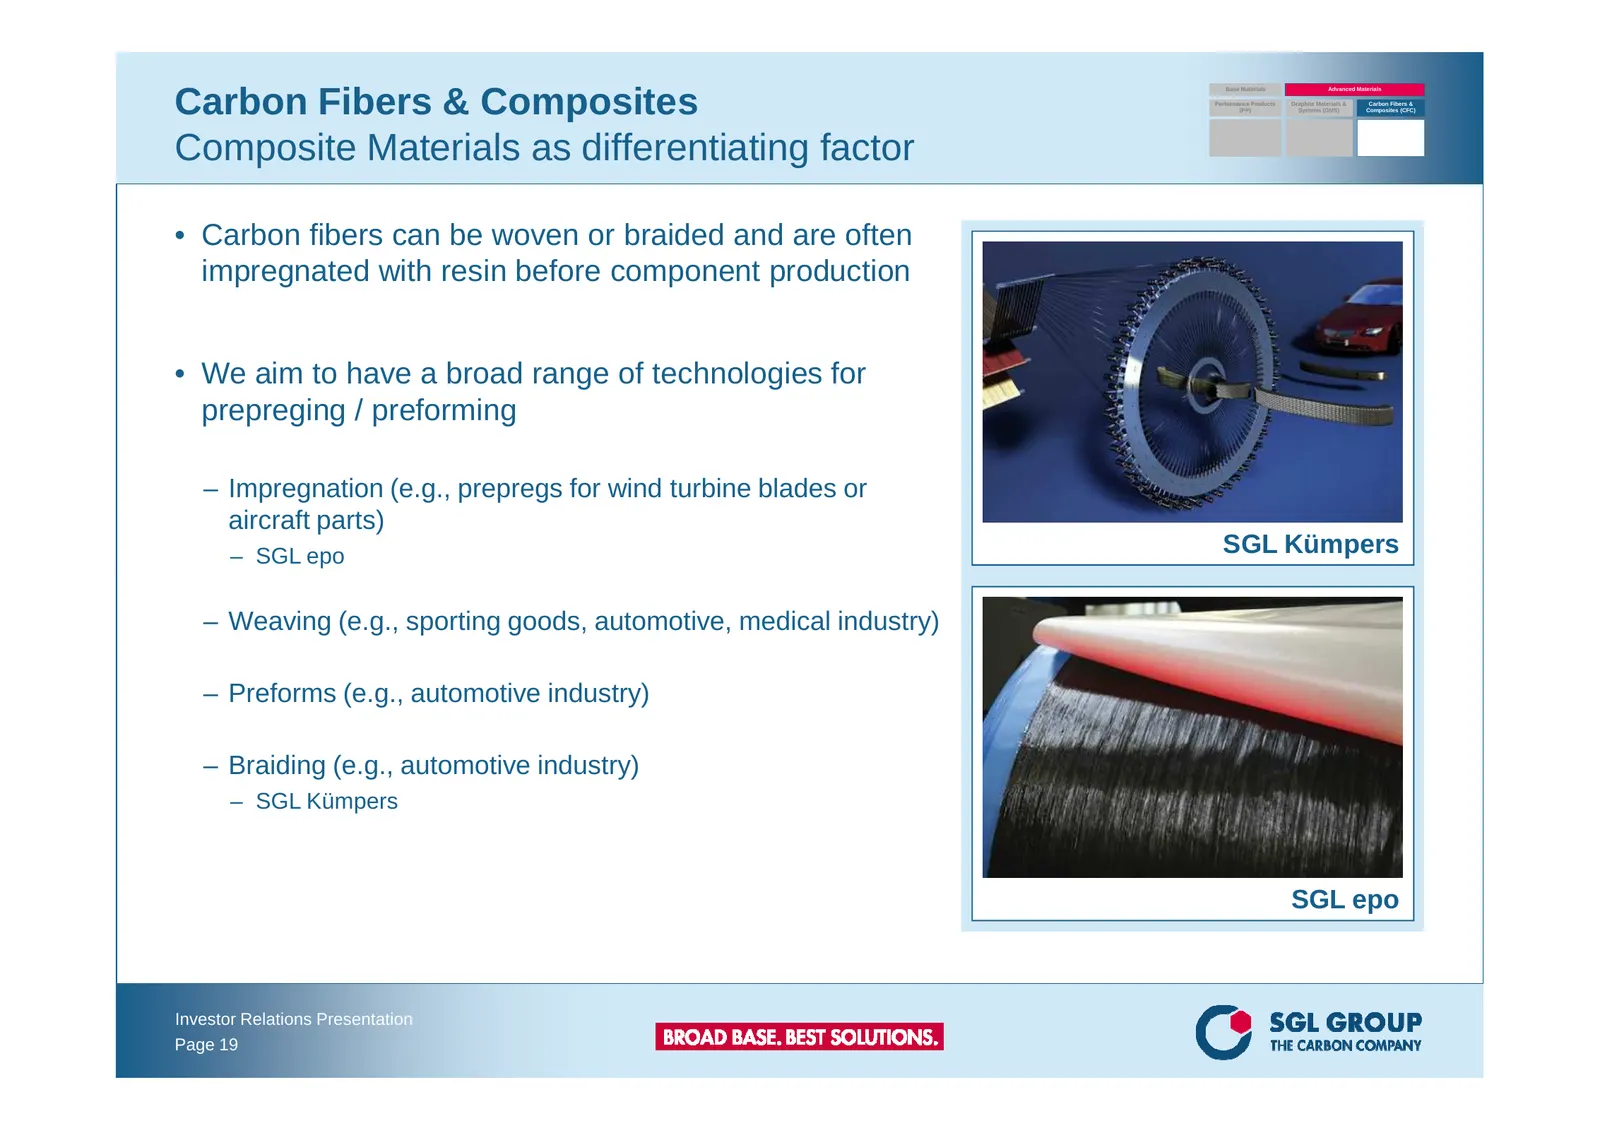
Slide 19: Composite Materials as differentiating factor
Base Materials Advanced Materials Carbon Fibers & Composites Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) Composite Materials as differentiating factor • Carbon fibers can be woven or braided and are often impregnated with resin before component produ
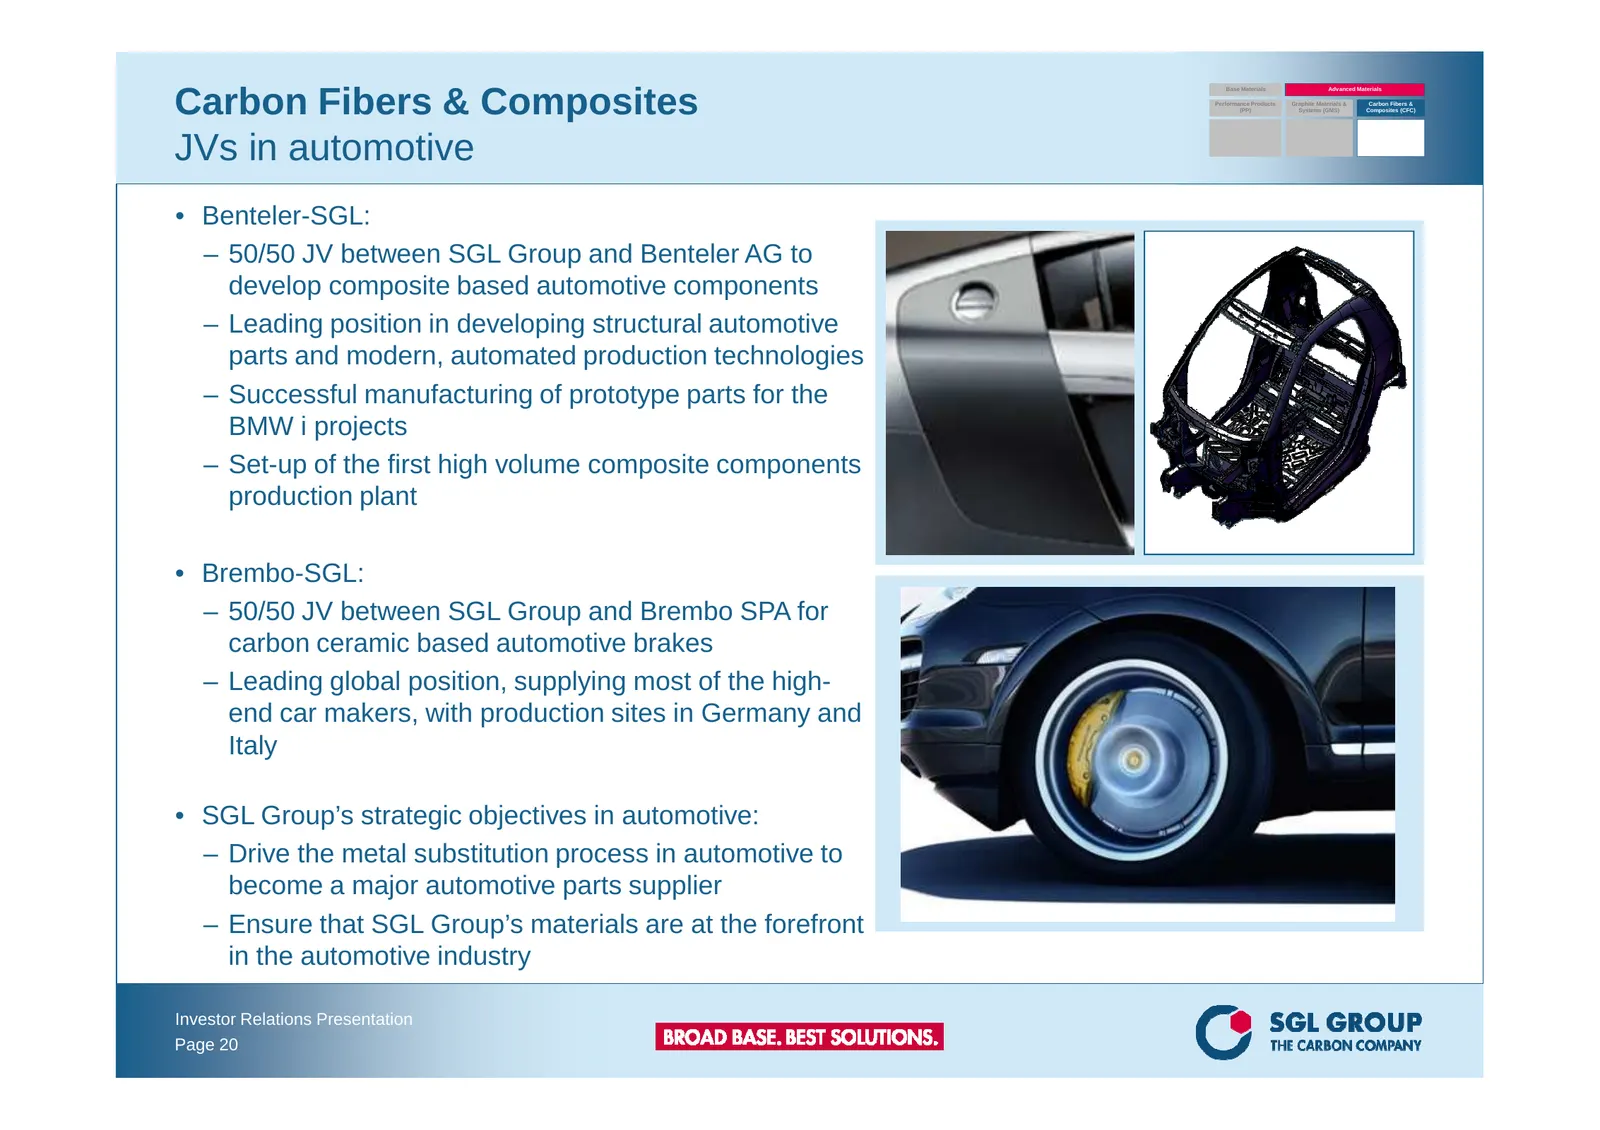
Slide 20: JVs in automotive
Base Materials Advanced Materials Carbon Fibers & Composites Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) JVs in automotive • Benteler-SGL: – 50/50 JV between SGL Group and Benteler AG to develop composite based automotive components – Leading positio
Slide 21: JVs with BMW, Mitsubishi exclusively for BMW's demand
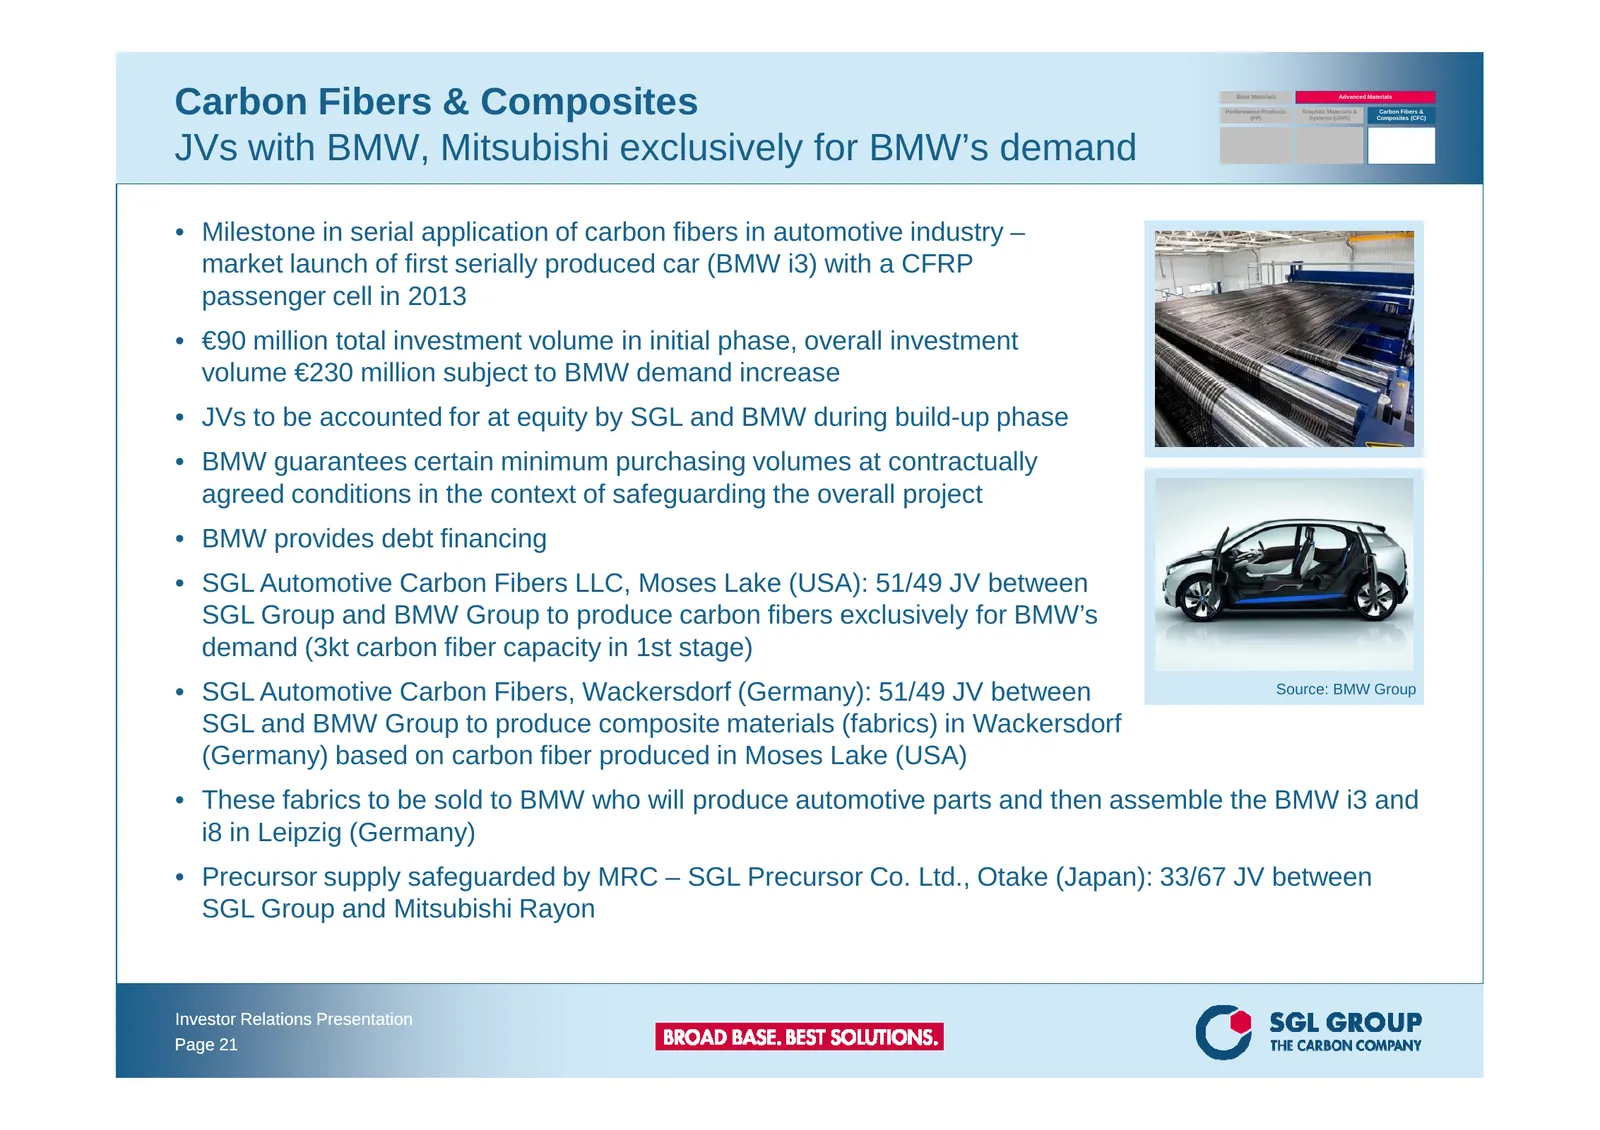
Carbon Fibers & Composites Base Materials Performance Products (PP) Advanced Materials Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) JVs with BMW, Mitsubishi exclusively for BMW’s demand • Milestone in serial application of carbon fibers in automotive industry – market launch o
Slide 22: SGL Automotive Carbon Fibers – A Truly Global Value Chain
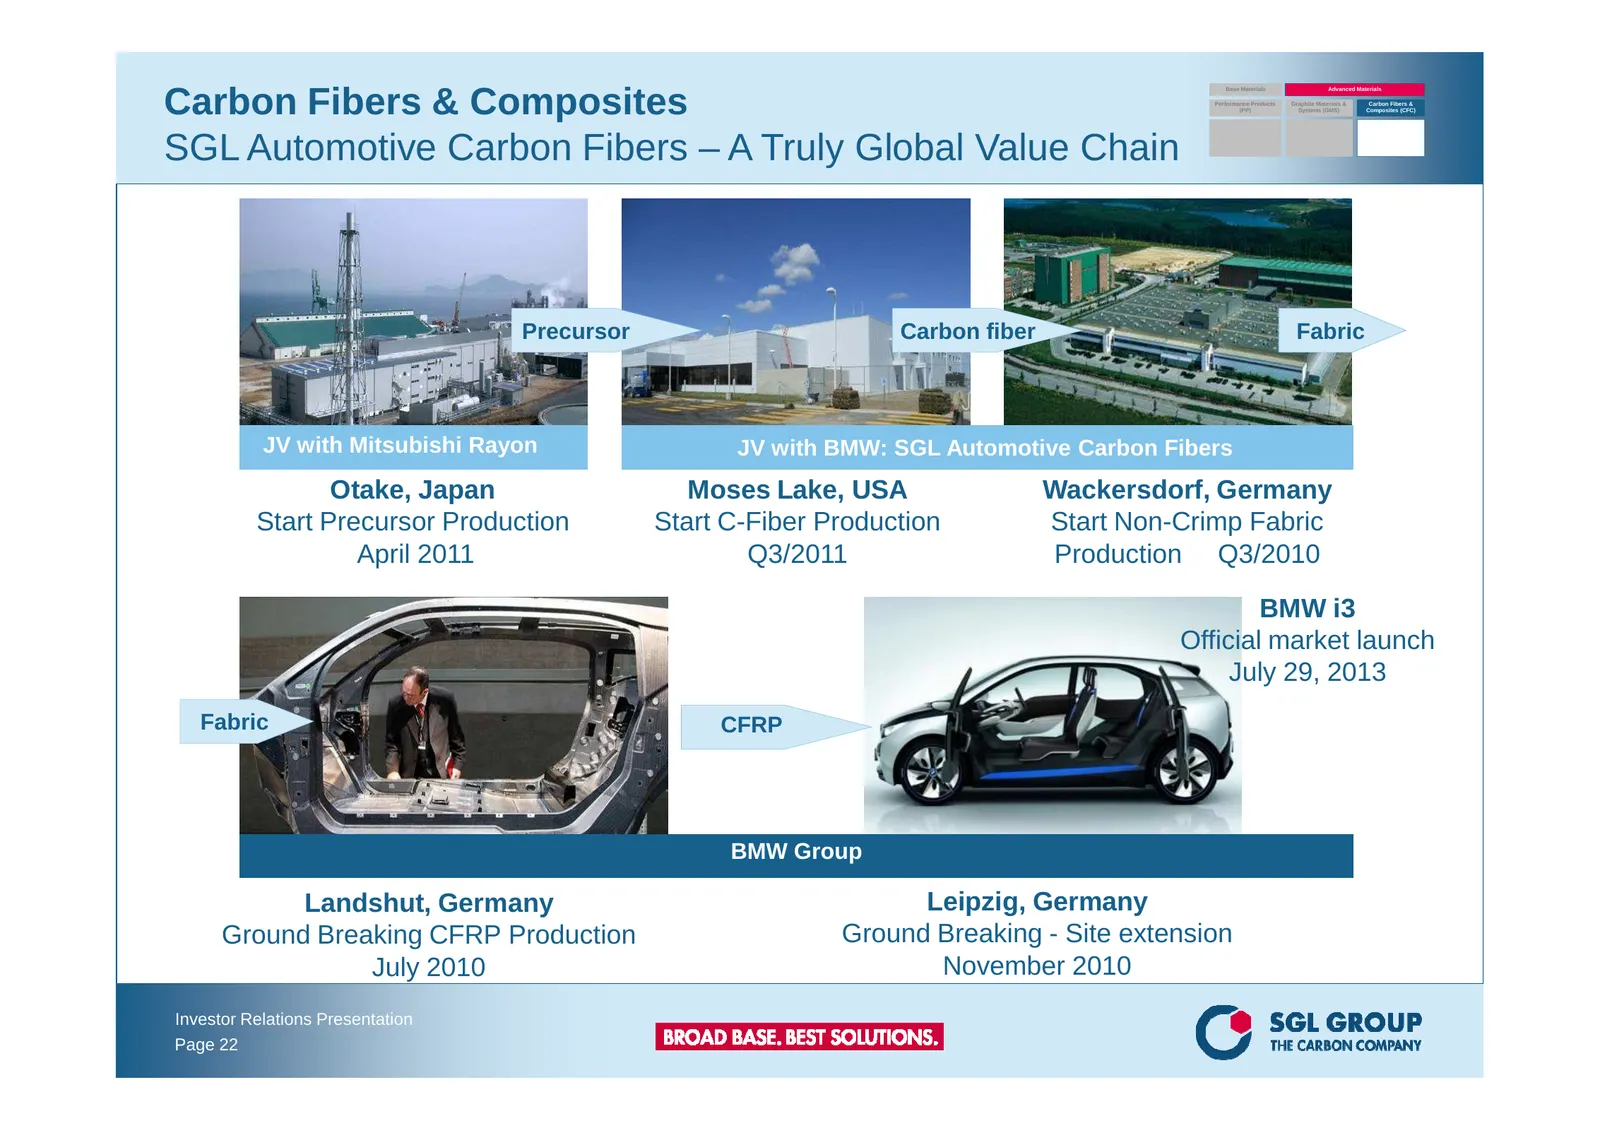
Base Materials Advanced Materials Carbon Fibers & Composites Performance Products (PP) Graphite Materials & Systems (GMS) Carbon Fibers & Composites (CFC) SGL Automotive Carbon Fibers – A Truly Global Value Chain Precursor Carbon fiber Fabric JV with Mitsubishi Rayon JV with BMW: SGL Automotive Carb
Slide 23: SGL Excellence – enables productivity and growth
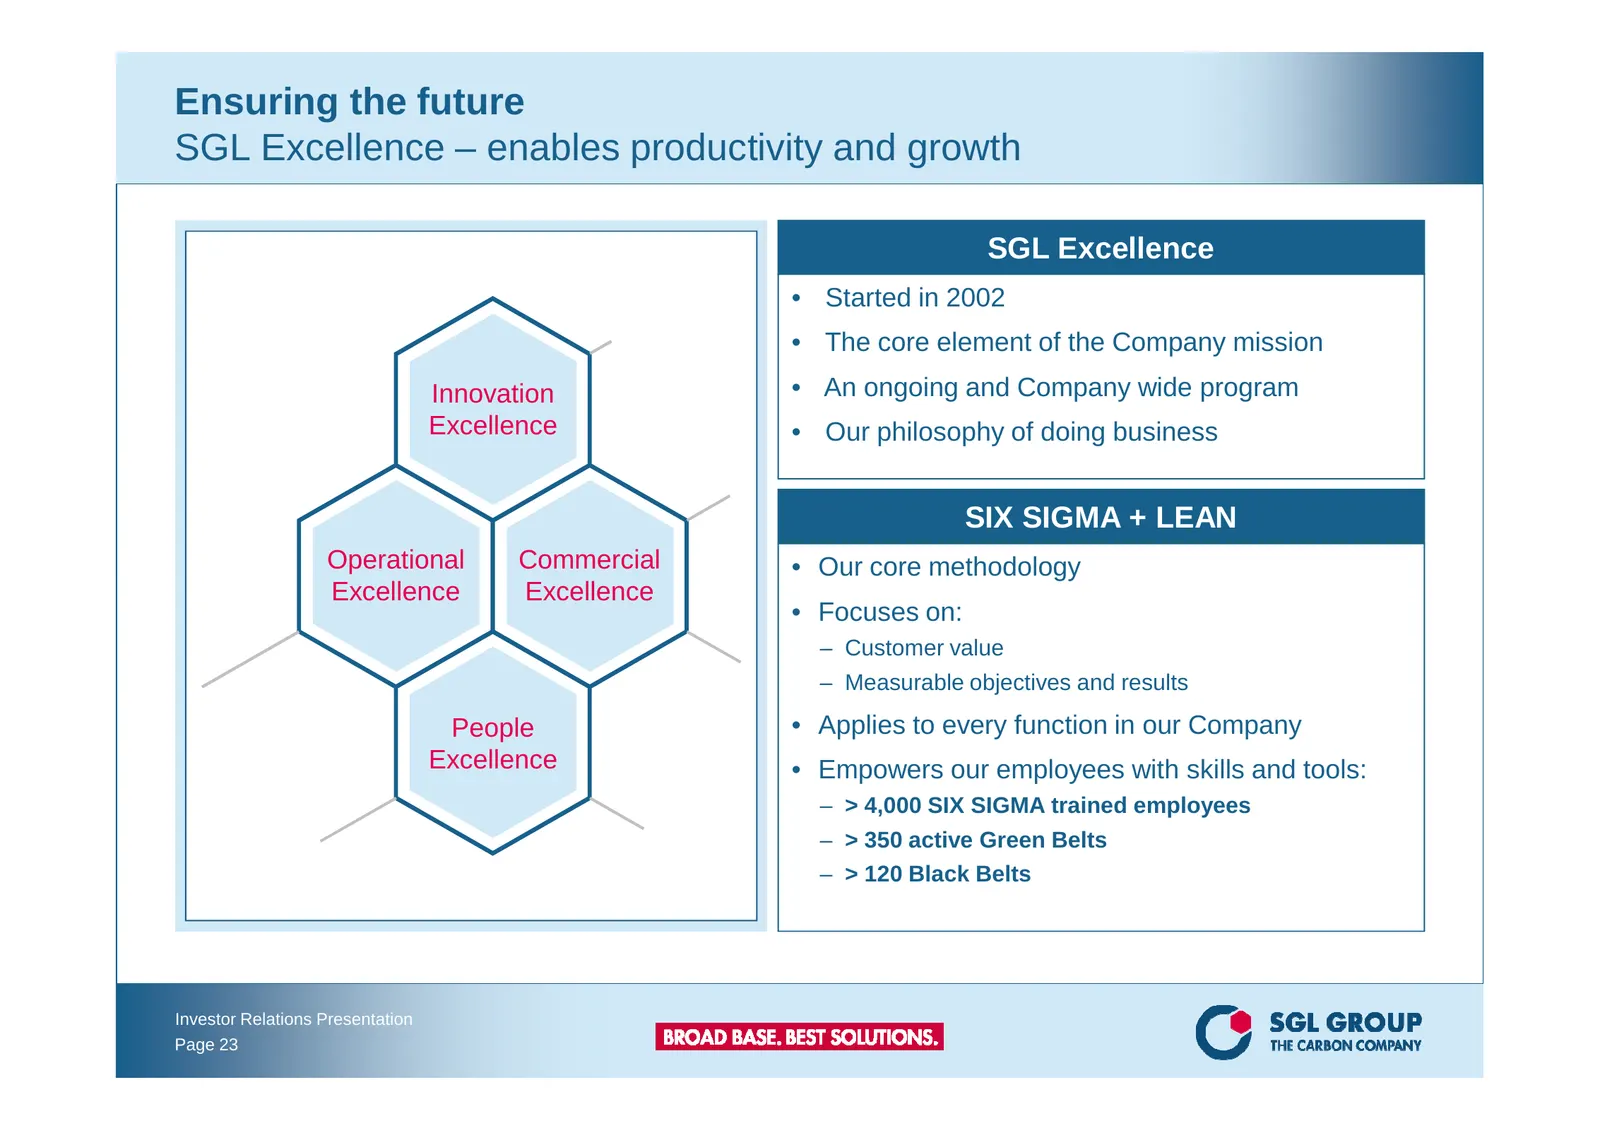
Ensuring the future SGL Excellence – enables productivity and growth SGL Excellence • Started in 2002 • The core element of the Company mission Innovation • An ongoing and Company wide program Excellence • Our philosophy of doing business SIX SIGMA + LEAN Operational Commercial • Our core methodolog
Slide 24: SGL Excellence savings
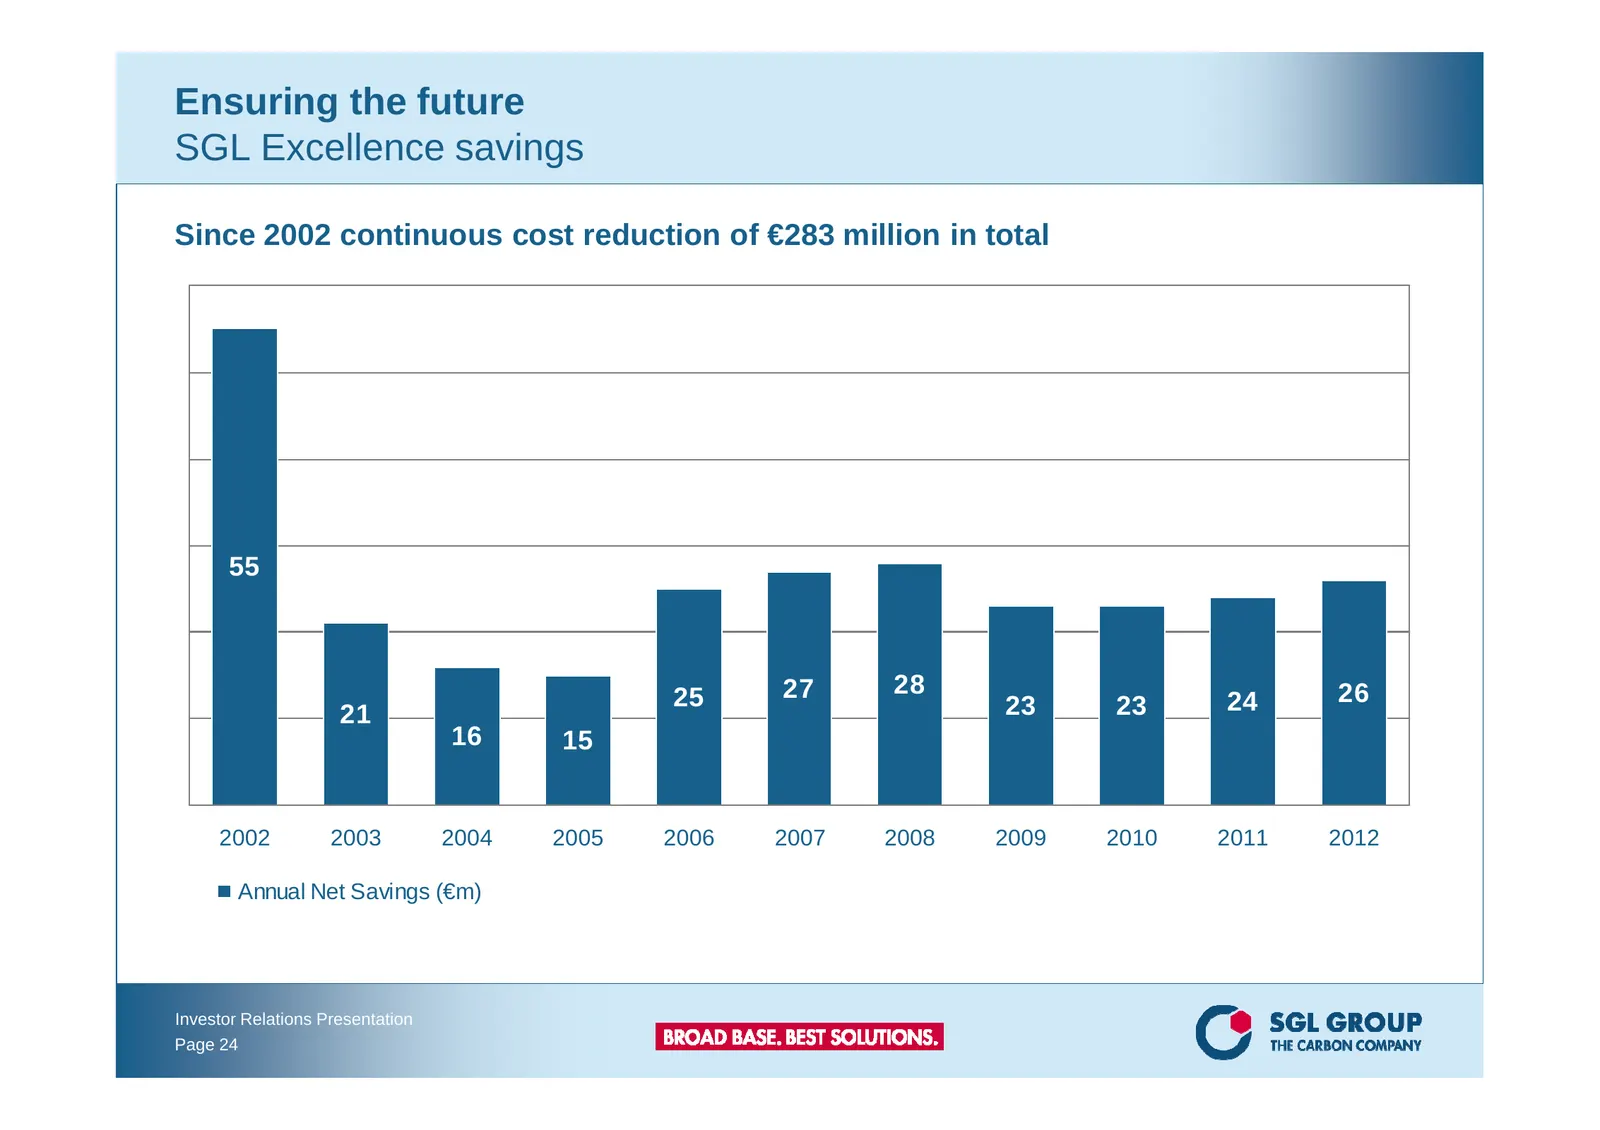
Ensuring the future SGL Excellence savings Since 2002 continuous cost reduction of €283 million in total 55 25 27 28 26 21 23 23 24 16 15 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 Annual Net Savings (€m) Investor Relations Presentation Page 24
Slide 25: Latest Financials and Outlook 2013
Latest Financials and Outlook 2013 Investor Relations Presentation Page 25
Slide 26: H1/2013 Results for the Group
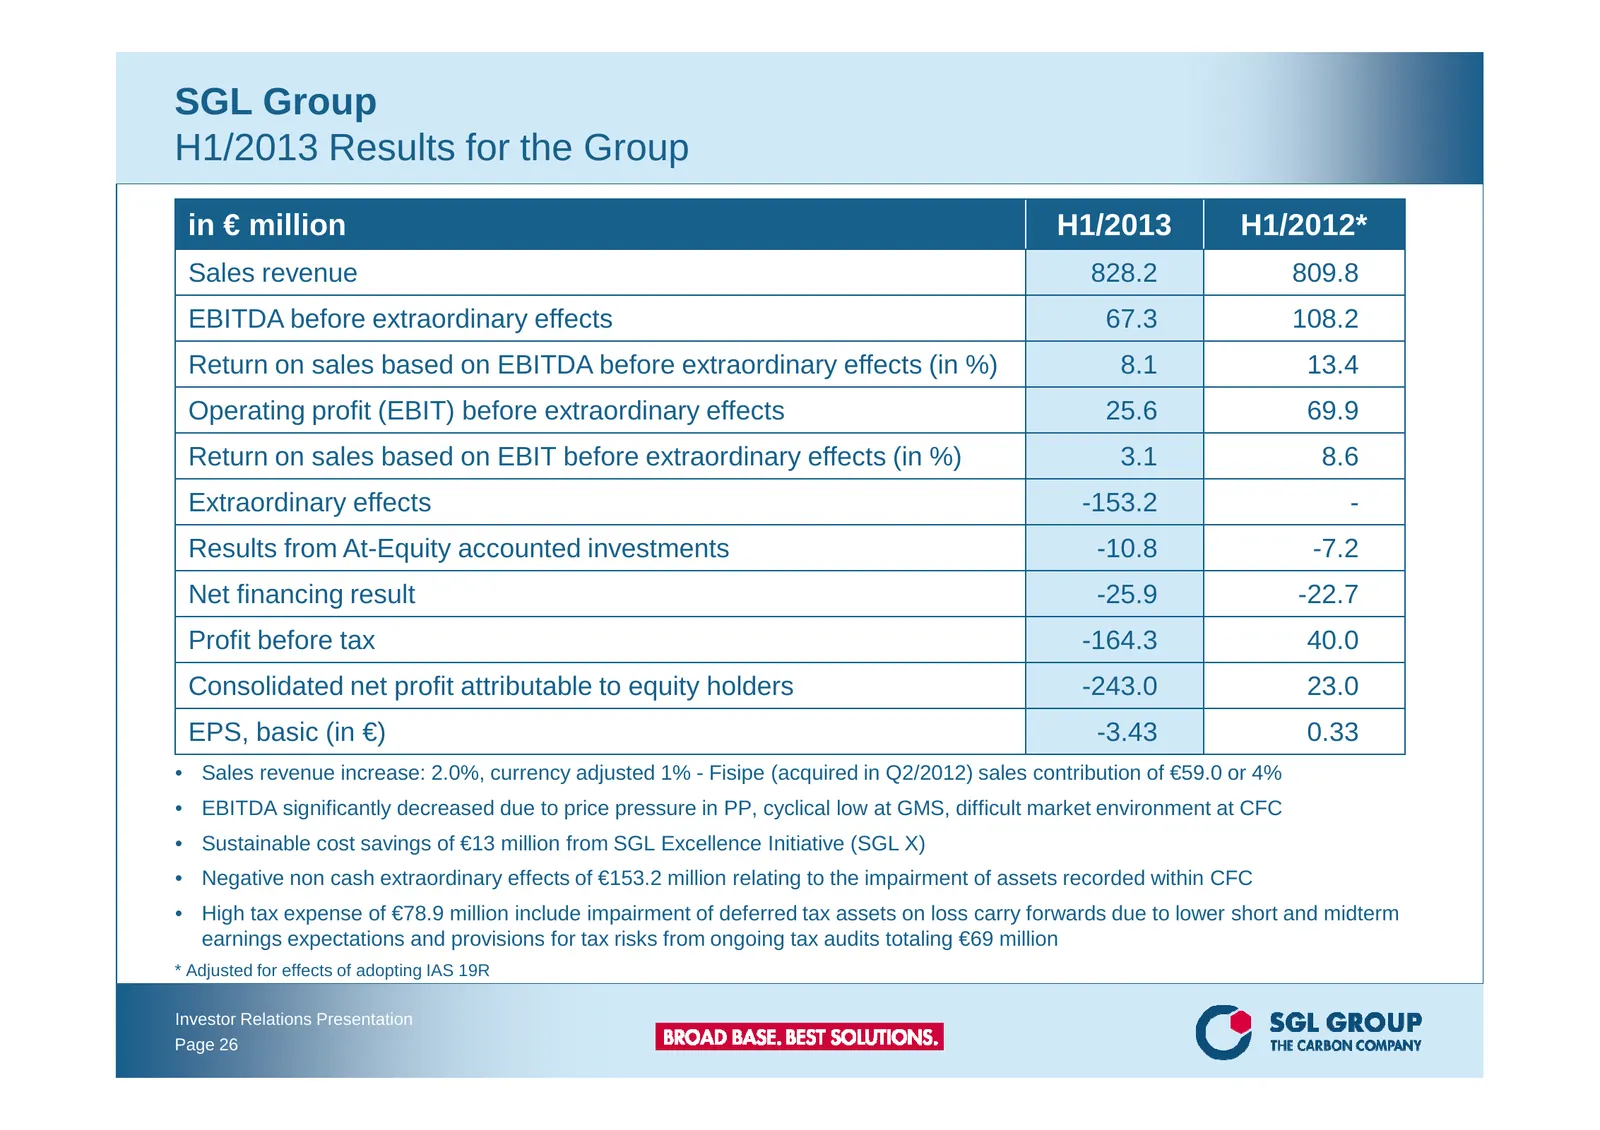
SGL Group H1/2013 Results for the Group in € million H1/2013 H1/2012* Sales revenue 828.2 809.8 EBITDA before extraordinary effects 67.3 108.2 Return on sales based on EBITDA before extraordinary effects (in %) 8.1 13.4 Operating profit (EBIT) before extraordinary effects 25.6 69.9 Return on sales b
Slide 27: H1/2013 Results for Performance Products (PP)
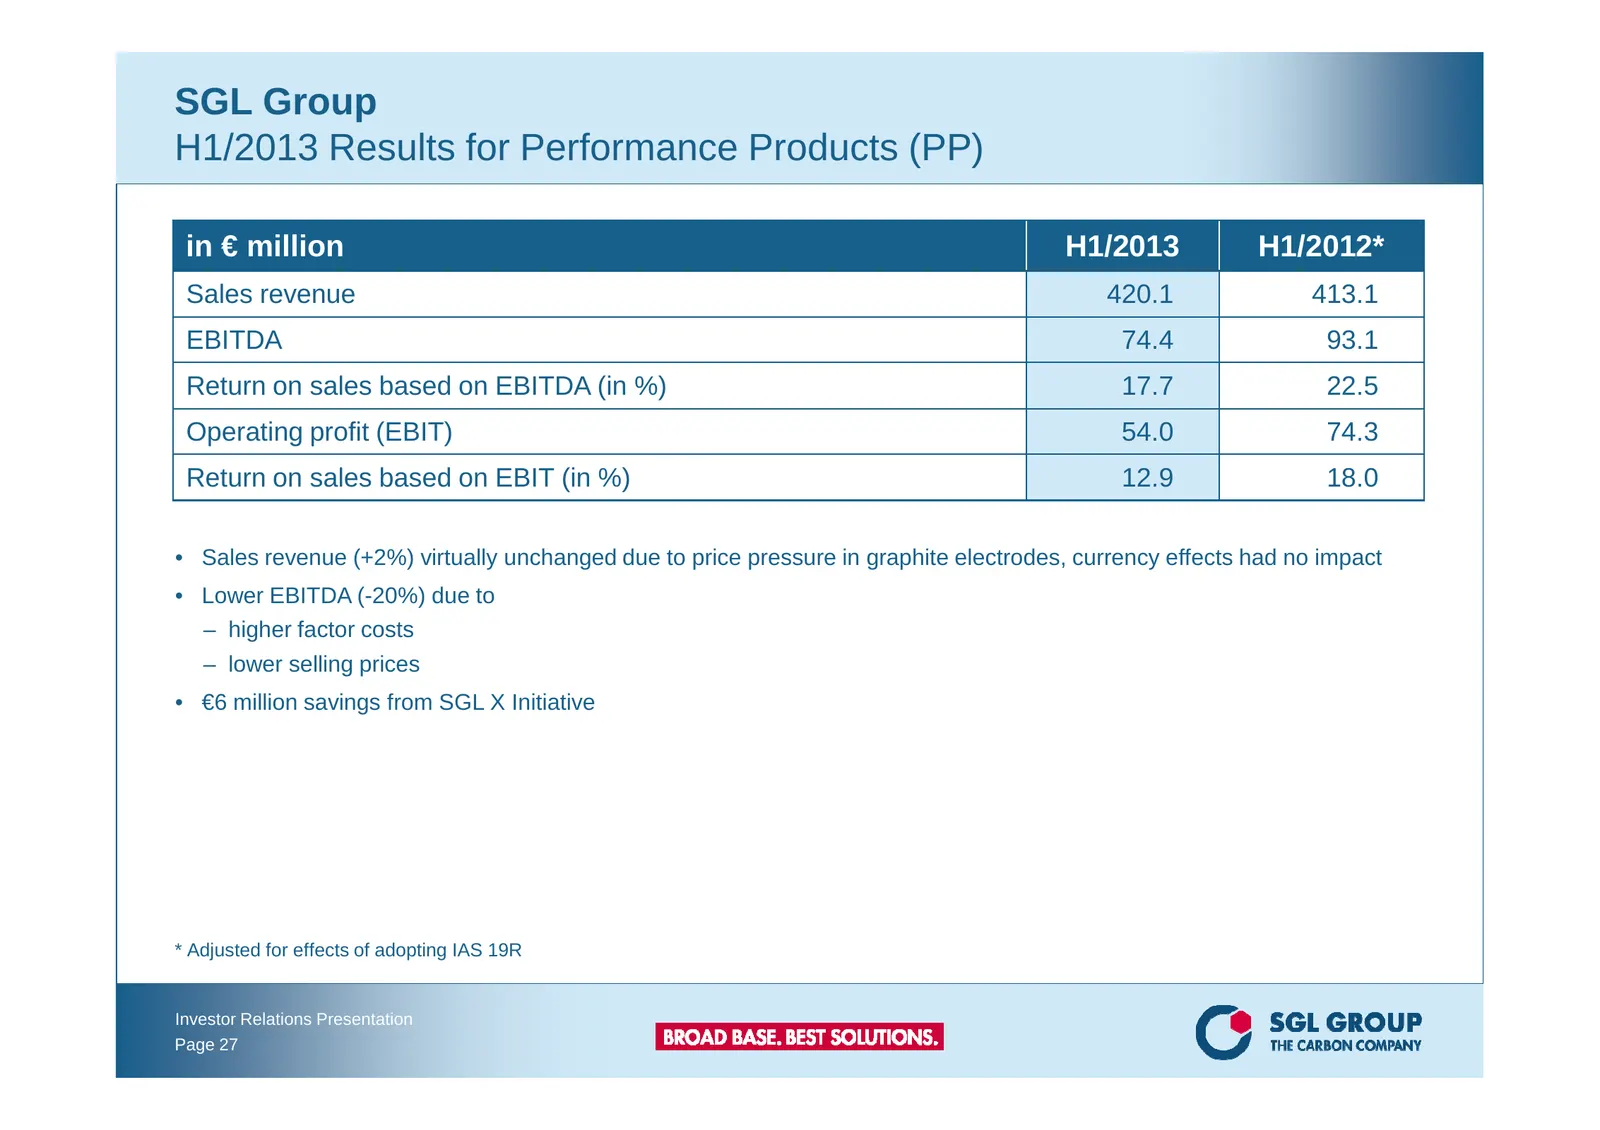
SGL Group H1/2013 Results for Performance Products (PP) in € million H1/2013 H1/2012* Sales revenue 420.1 413.1 EBITDA 74.4 93.1 Return on sales based on EBITDA (in %) 17.7 22.5 Operating profit (EBIT) 54.0 74.3 Return on sales based on EBIT (in %) 12.9 18.0 • Sales revenue (+2%) virtually unchanged
Slide 28: H1/2013 Results for Graphite Materials & Systems (GMS)
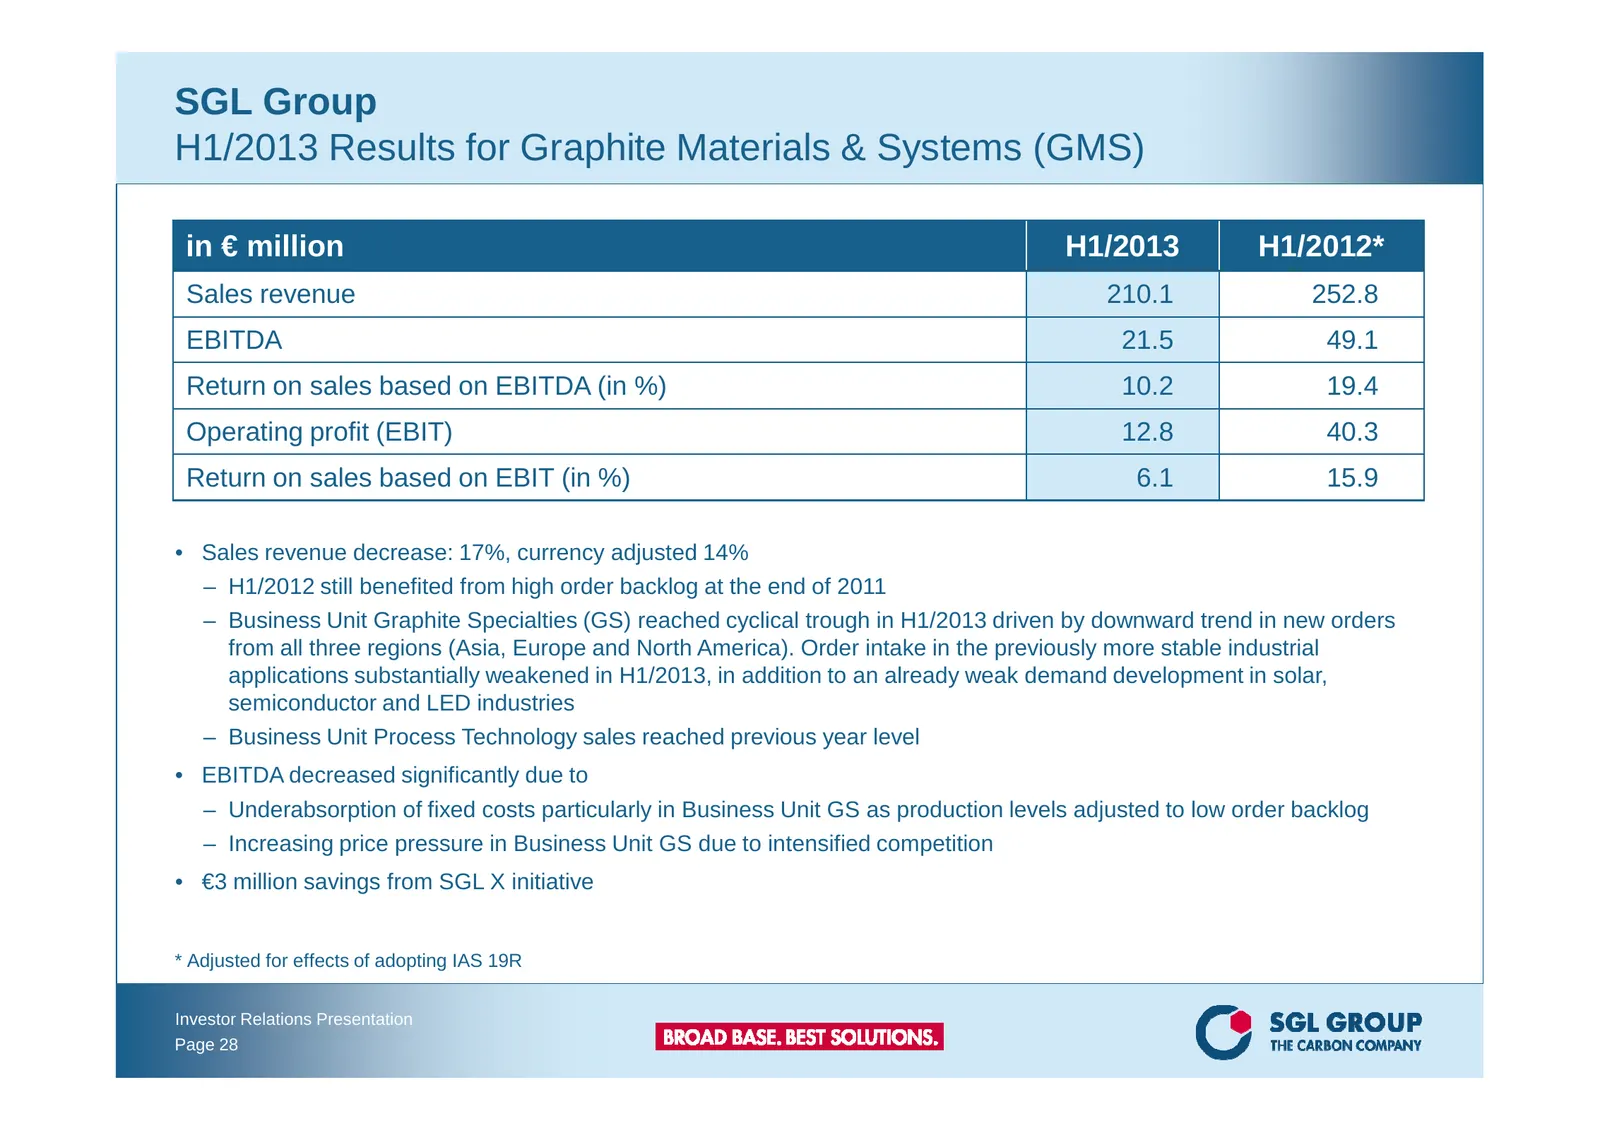
SGL Group H1/2013 Results for Graphite Materials & Systems (GMS) in € million H1/2013 H1/2012* Sales revenue 210.1 252.8 EBITDA 21.5 49.1 Return on sales based on EBITDA (in %) 10.2 19.4 Operating profit (EBIT) 12.8 40.3 Return on sales based on EBIT (in %) 6.1 15.9 • Sales revenue decrease: 17%, cu
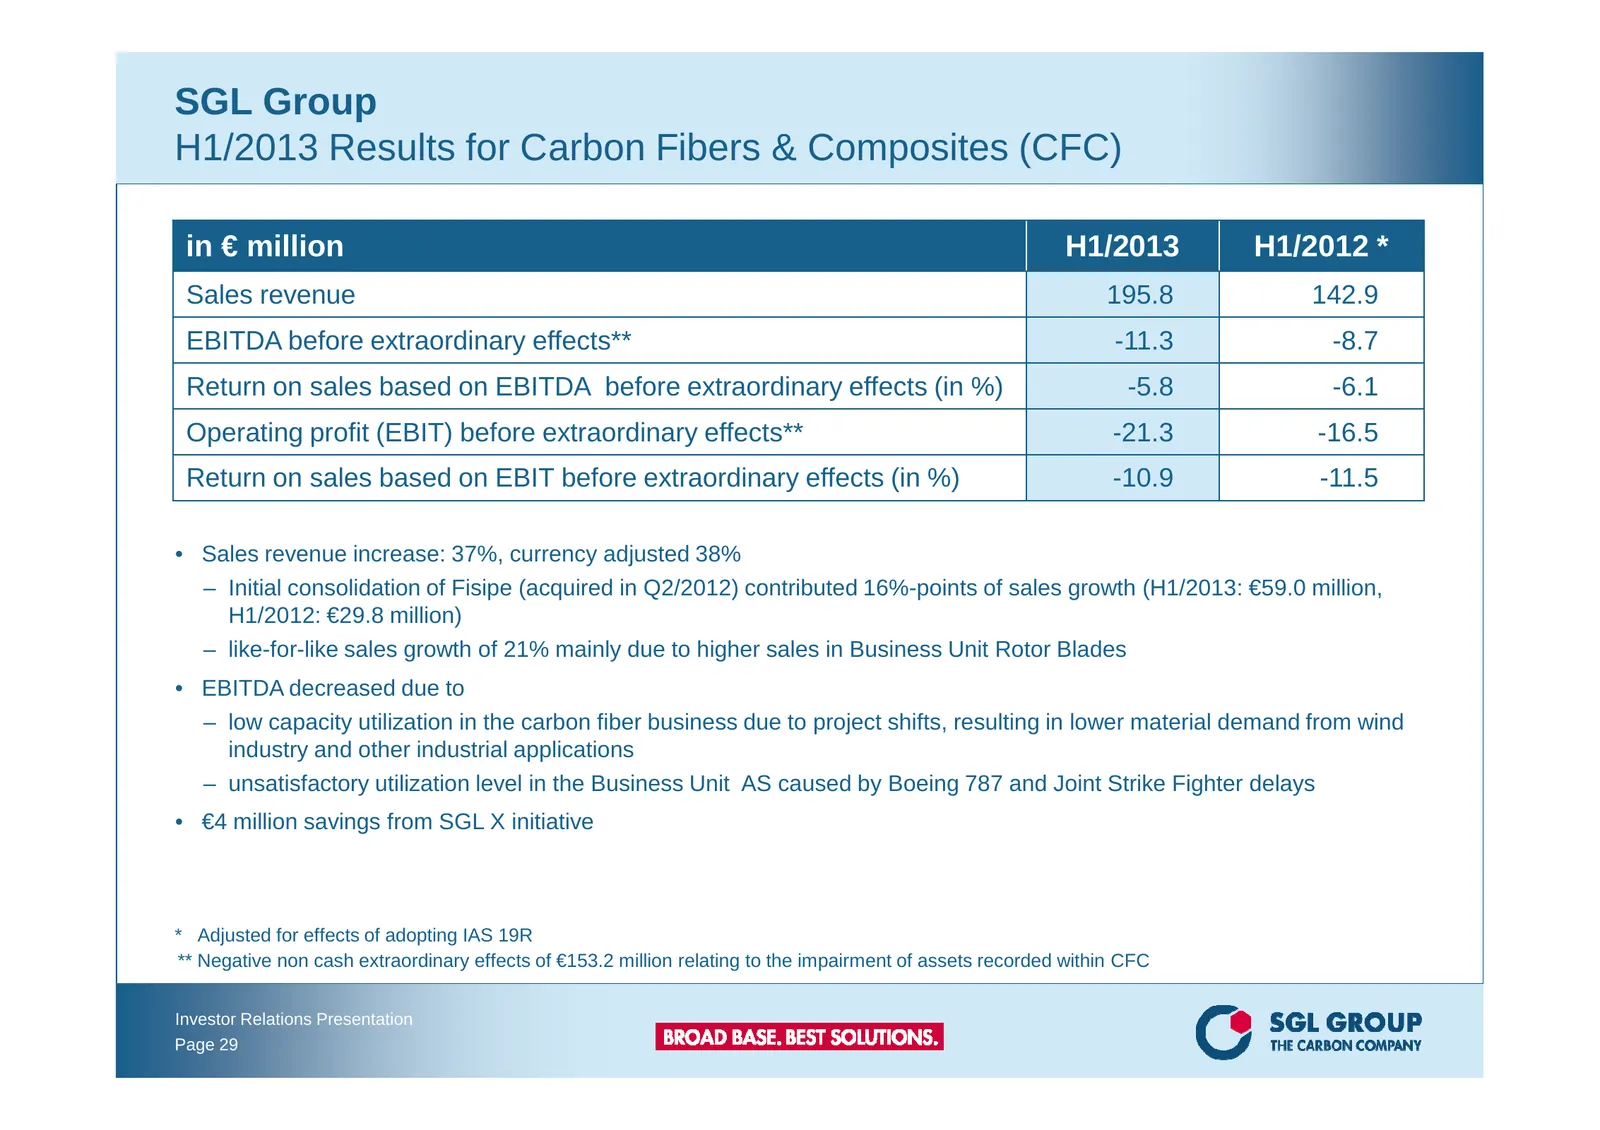
Slide 29: H1/2013 Results for Carbon Fibers & Composites (CFC)
SGL Group H1/2013 Results for Carbon Fibers & Composites (CFC) in € million H1/2013 H1/2012 * Sales revenue 195.8 142.9 EBITDA before extraordinary effects** -11.3 -8.7 Return on sales based on EBITDA before extraordinary effects (in %) -5.8 -6.1 Operating profit (EBIT) before extraordinary effects*
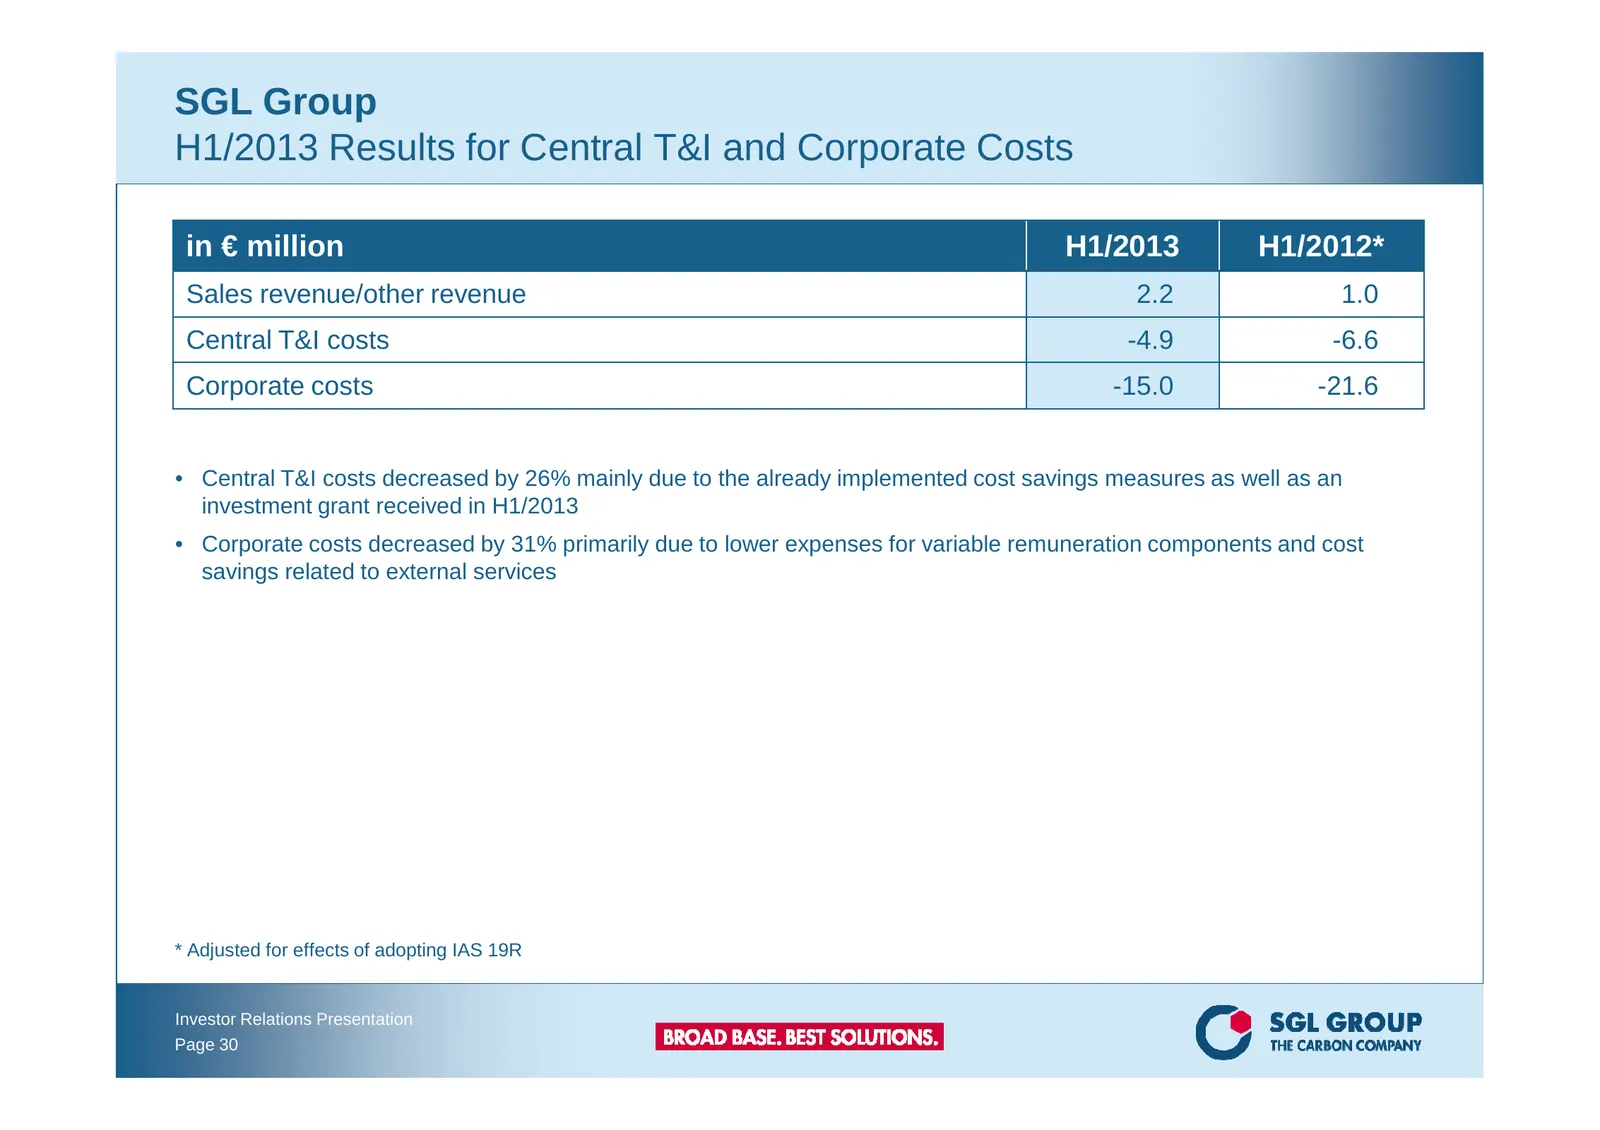
Slide 30: H1/2013 Results for Central T&I and Corporate Costs
SGL Group H1/2013 Results for Central T&I and Corporate Costs in € million H1/2013 H1/2012* Sales revenue/other revenue 2.2 1.0 Central T&I costs -4.9 -6.6 Corporate costs -15.0 -21.6 • Central T&I costs decreased by 26% mainly due to the already implemented cost savings measures as well as an inves
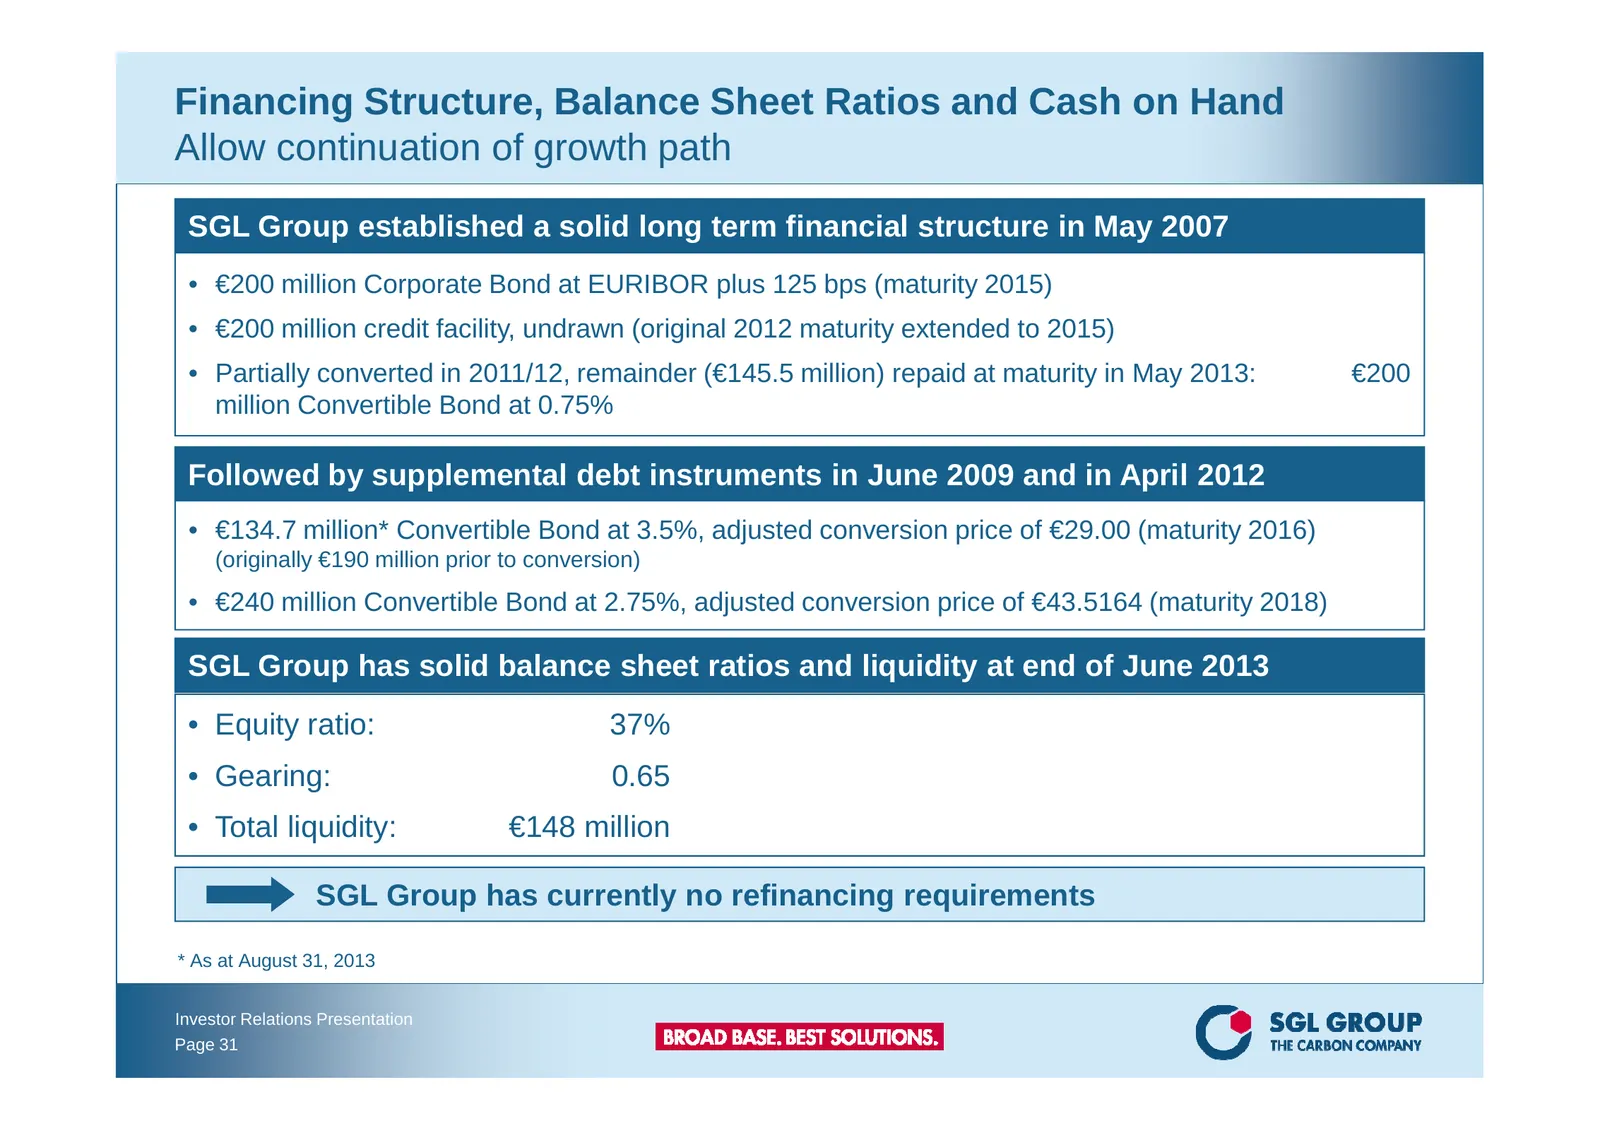
Slide 31: Financing Structure, Balance Sheet Ratios and Cash on Hand
Financing Structure, Balance Sheet Ratios and Cash on Hand Allow continuation of growth path SGL Group established a solid long term financial structure in May 2007 • €200 million Corporate Bond at EURIBOR plus 125 bps (maturity 2015) • €200 million credit facility, undrawn (original 2012 maturity e
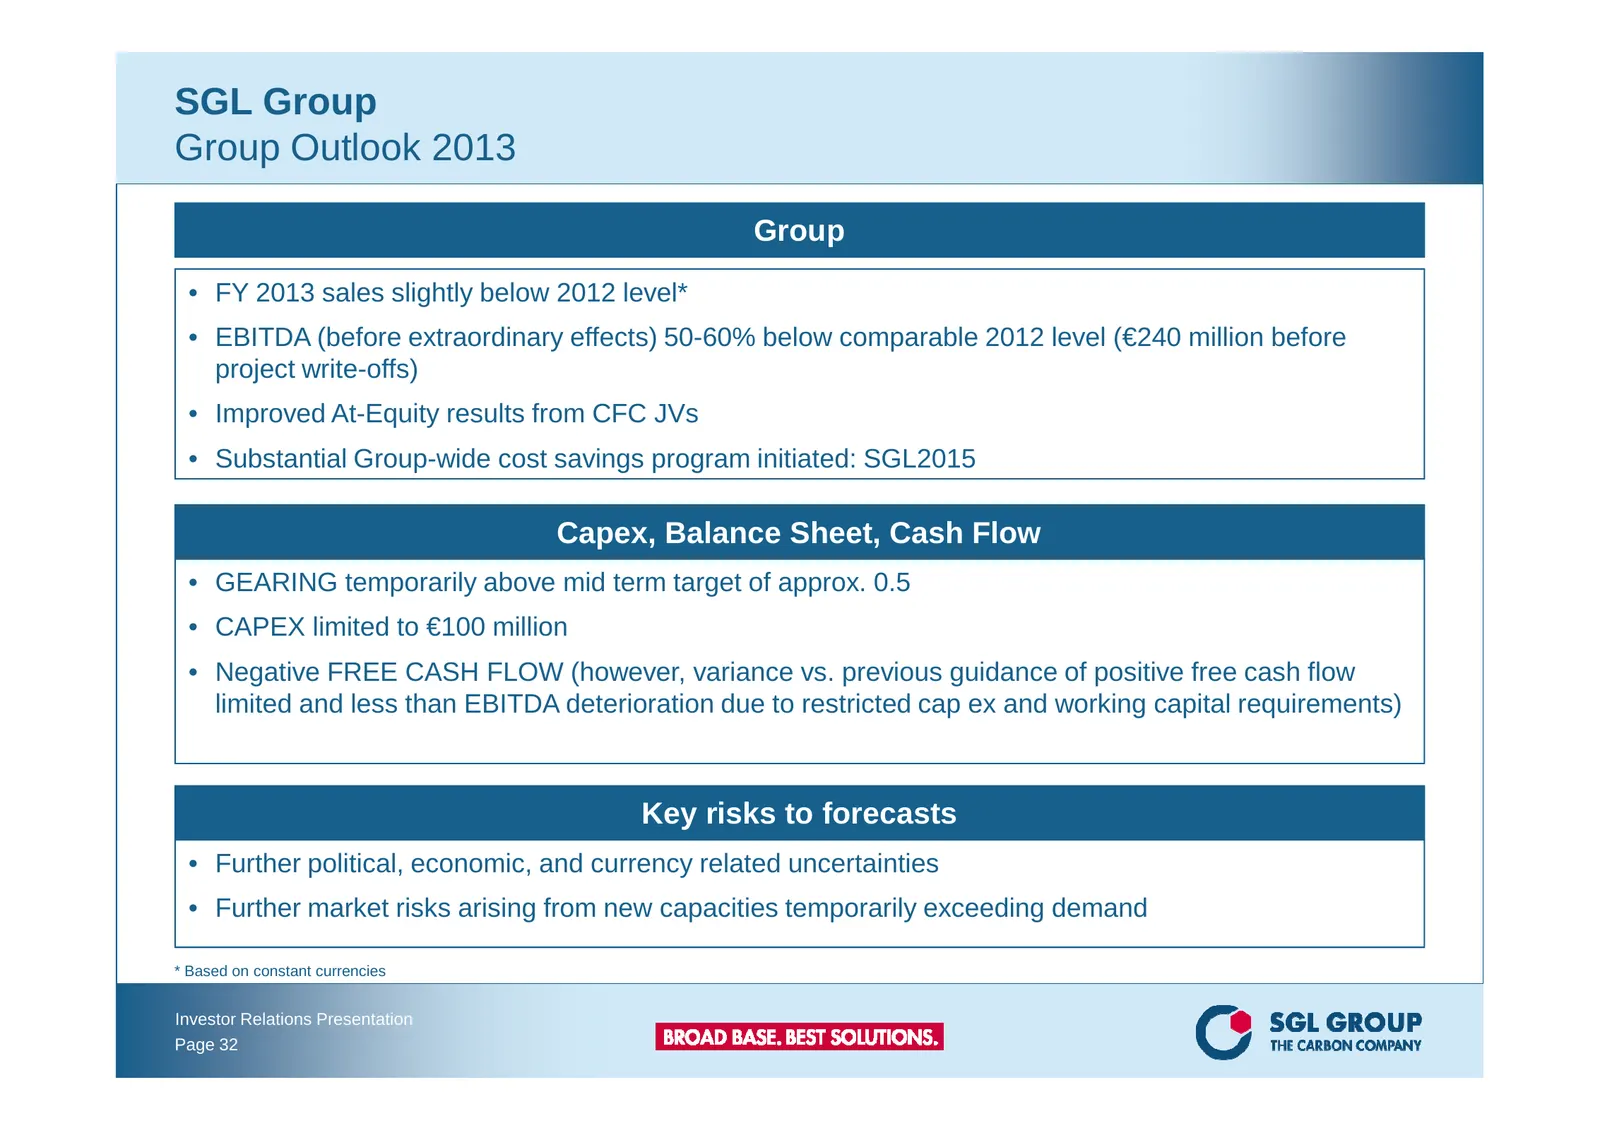
Slide 32: Group Outlook 2013
SGL Group Group Outlook 2013 Group • FY 2013 sales slightly below 2012 level* • EBITDA (before extraordinary effects) 50-60% below comparable 2012 level (€240 million before project write-offs) • Improved At-Equity results from CFC JVs • Substantial Group-wide cost savings program initiated: SGL2015
Slide 33: Business Area Outlook and Key Assumptions 2013
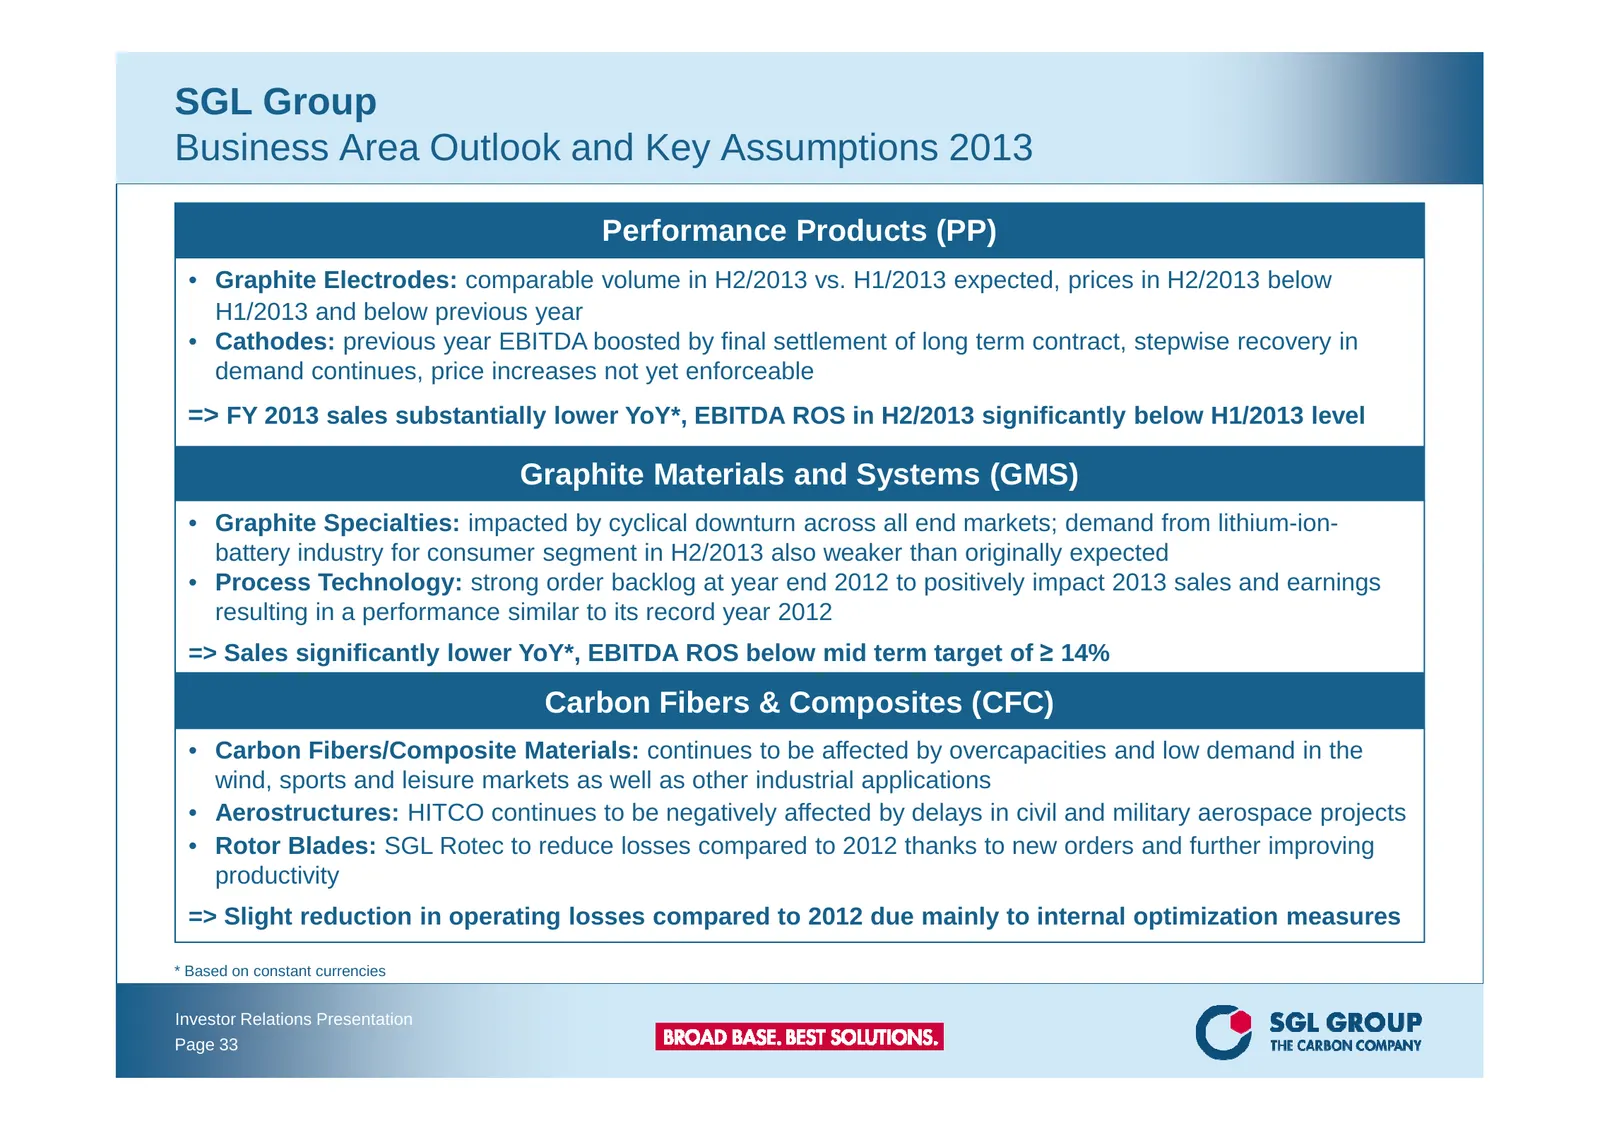
SGL Group Business Area Outlook and Key Assumptions 2013 Performance Products (PP) • Graphite Electrodes: comparable volume in H2/2013 vs. H1/2013 expected, prices in H2/2013 below H1/2013 and below previous year • Cathodes: previous year EBITDA boosted by final settlement of long term contract, ste
Slide 34: SGL2015: Comprehensive group wide cost cutting plan introduced
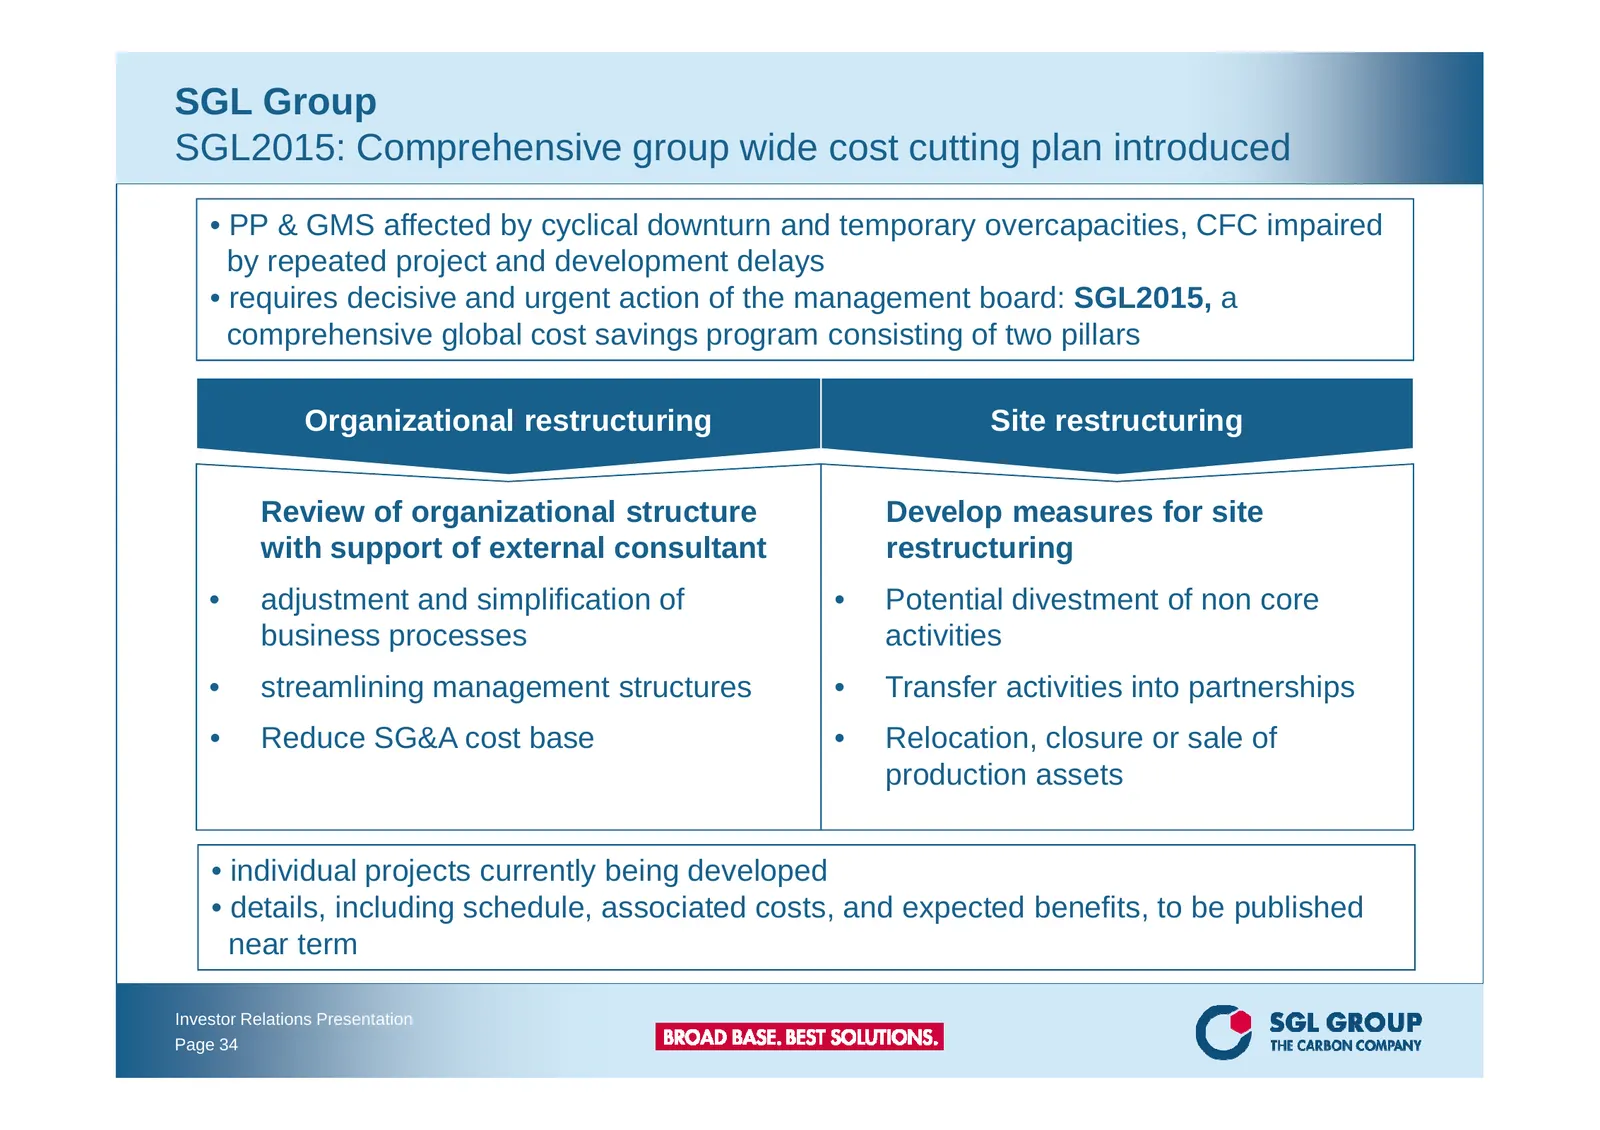
SGL Group SGL2015: Comprehensive group wide cost cutting plan introduced • PP & GMS affected by cyclical downturn and temporary overcapacities, CFC impaired by repeated project and development delays • requires decisive and urgent action of the management board: SGL2015, a comprehensive global cost
Slide 35: Fundamental long-term growth drivers for our businesses
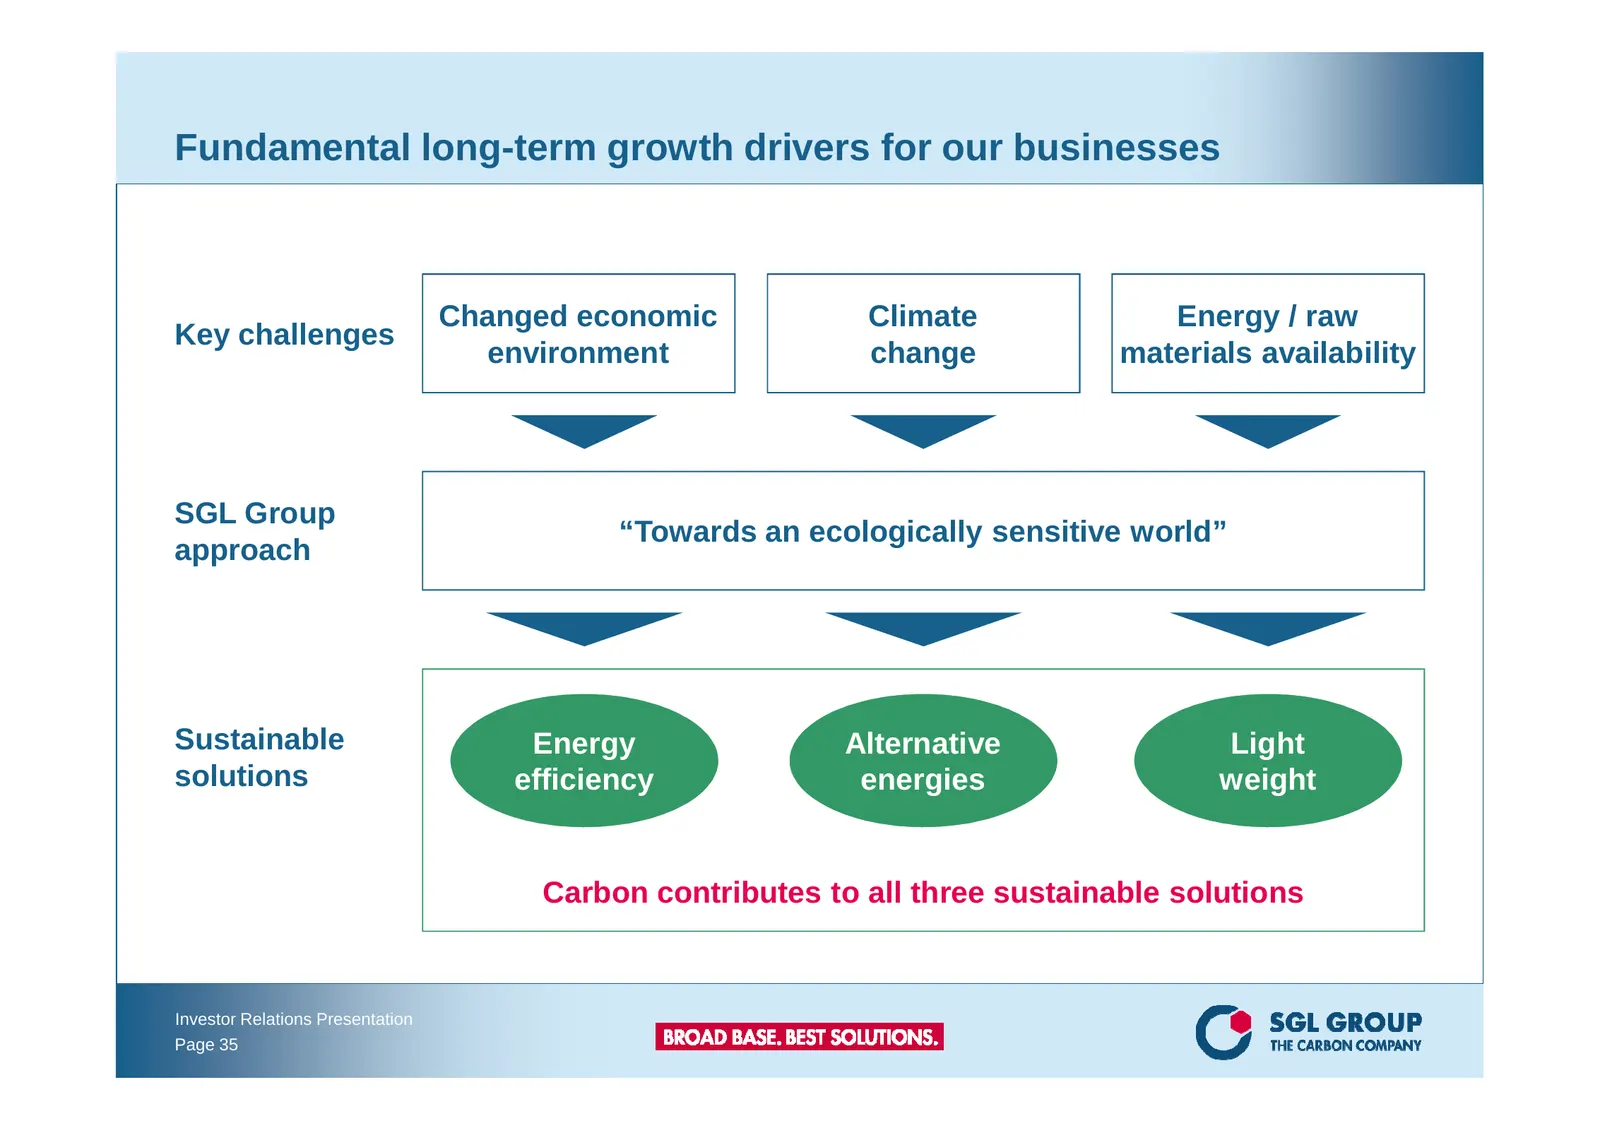
Fundamental long-term growth drivers for our businesses Changed economic Climate Energy / raw Key challenges environment change materials availability SGL Group “Towards an ecologically sensitive world” approach Sustainable Energy Alternative Light solutions efficiency energies weight Carbon contrib
Slide 36: Thank you for your attention! Any Questions?
Thank you for your attention ! Any Questions ? Investor Relations Presentation Page 36
Slide 37: Important note: forward looking statements
Important note: This presentation contains forward looking statements based on the information currently available to us and on our current projections and assumptions. By nature, forward looking statements are associated with known and unknown risks and uncertainties, as a consequence of which actu
Source: Internet Archive copy of sglgroup.com
More decks from SGL Carbon SE
 9M 2026 Earnings Presentation30 slides · Nov 5, 2026
 9M 2026 Earnings Presentation17 slides · Nov 5, 2026
 Q3 2024 Earnings Presentation28 slides · Nov 7, 2024
 H1 2024 Earnings Presentation18 slides · Aug 8, 2024
 Q1 2024 Earnings Presentation19 slides · May 8, 2024
 ESG Presentation (March 2024)7 slides · Mar 22, 2024