Ascom Holding AG · SIX:ASCN
Ascom — FY2010 Earnings Presentation
44 slides from Ascom's earnings presentation, Mar 9, 2011
Slide 1: Welcome to the Ascom Media & Analyst Conference 2010 Annual Results
WELCOME TO THE ASCOM MEDIA & ANALYST CONFERENCE 2010 ANNUAL RESULTS
Slide 2: 2011 Annual Media Conference
[ ] 2011 ANNUAL MEDIA CONFERENCE Riet Cadonau CEO (until 31 March 2011) Fritz Mumenthaler CEO (as of 1 April 2011) Martin Zwyssig CFO 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 2
Slide 3: Agenda
[ ] AGENDA 2010 RESULTS AT A GLANCE DIVISIONAL RESULTS 2010 FINANCIAL RESULTS 2011 – A FIRST STEP TOWARDS OUR GOALS QUESTIONS & ANSWERS 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 3
Slide 4: 2010 Results at a Glance
[ ] 2010 RESULTS AT A GLANCE 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 4
Slide 5: 2010: Bounce Back to Profitable Growth
[ 2010 RESULTS AT A GLANCE ] 2010: BOUNCE BACK TO PROFITABLE GROWTH Substantial growth on Group level Total revenue: CHF 571.2m (2009: CHF 537.2m) (Growth at constant exchange rates: +9.5%, in Swiss Francs: +6.3%) Organic growth: +5.3% Strong increase in incoming orders Incoming orders: CH
Slide 6: Profitability – EBITDA Increased by One Third
[ 2010 RESULTS AT A GLANCE ] PROFITABILITY – EBITDA INCREASED BY ONE THIRD EBITDA margin at remarkable level of 12.0% EBITDA: CHF 68.4m (2009: CHF 49.8m); +37.3% EBITDA margin 12.0% (2009: 9.3%) EBIT: CHF 48.4m (2009: CHF 32.8m); +47.6% EBIT margin: 8.5% Substantial increase in Group pro
Slide 7: Shareholders – Pay Out of a Dividend of 28%
[ 2010 RESULTS AT A GLANCE ] SHAREHOLDERS – PAY OUT OF A DIVIDEND OF 28% Given the marked improvement in profit, the Board of Directors proposes a dividend to the Annual General Meeting 2011 Dividend proposal Pay out of CHF 0.25 per share Pay-out ratio of 28% Dividend of CHF 9m Very posi
Slide 8: Wireless Solutions and Network Testing Show Excellent Results
[ 2010 RESULTS AT A GLANCE ] WIRELESS SOLUTIONS AND NETWORK TESTING SHOW EXCELLENT RESULTS Wireless Solutions EBITDA margin 13.1% (2009: 11.3%) Organic Growth: +11.6% Network Testing EBITDA margin 16.4% (2009: 13.6%) Organic Growth: +11.1% Security Communication EBITDA margin 1.8% (2
Slide 9: 2010 Financial Results Overview
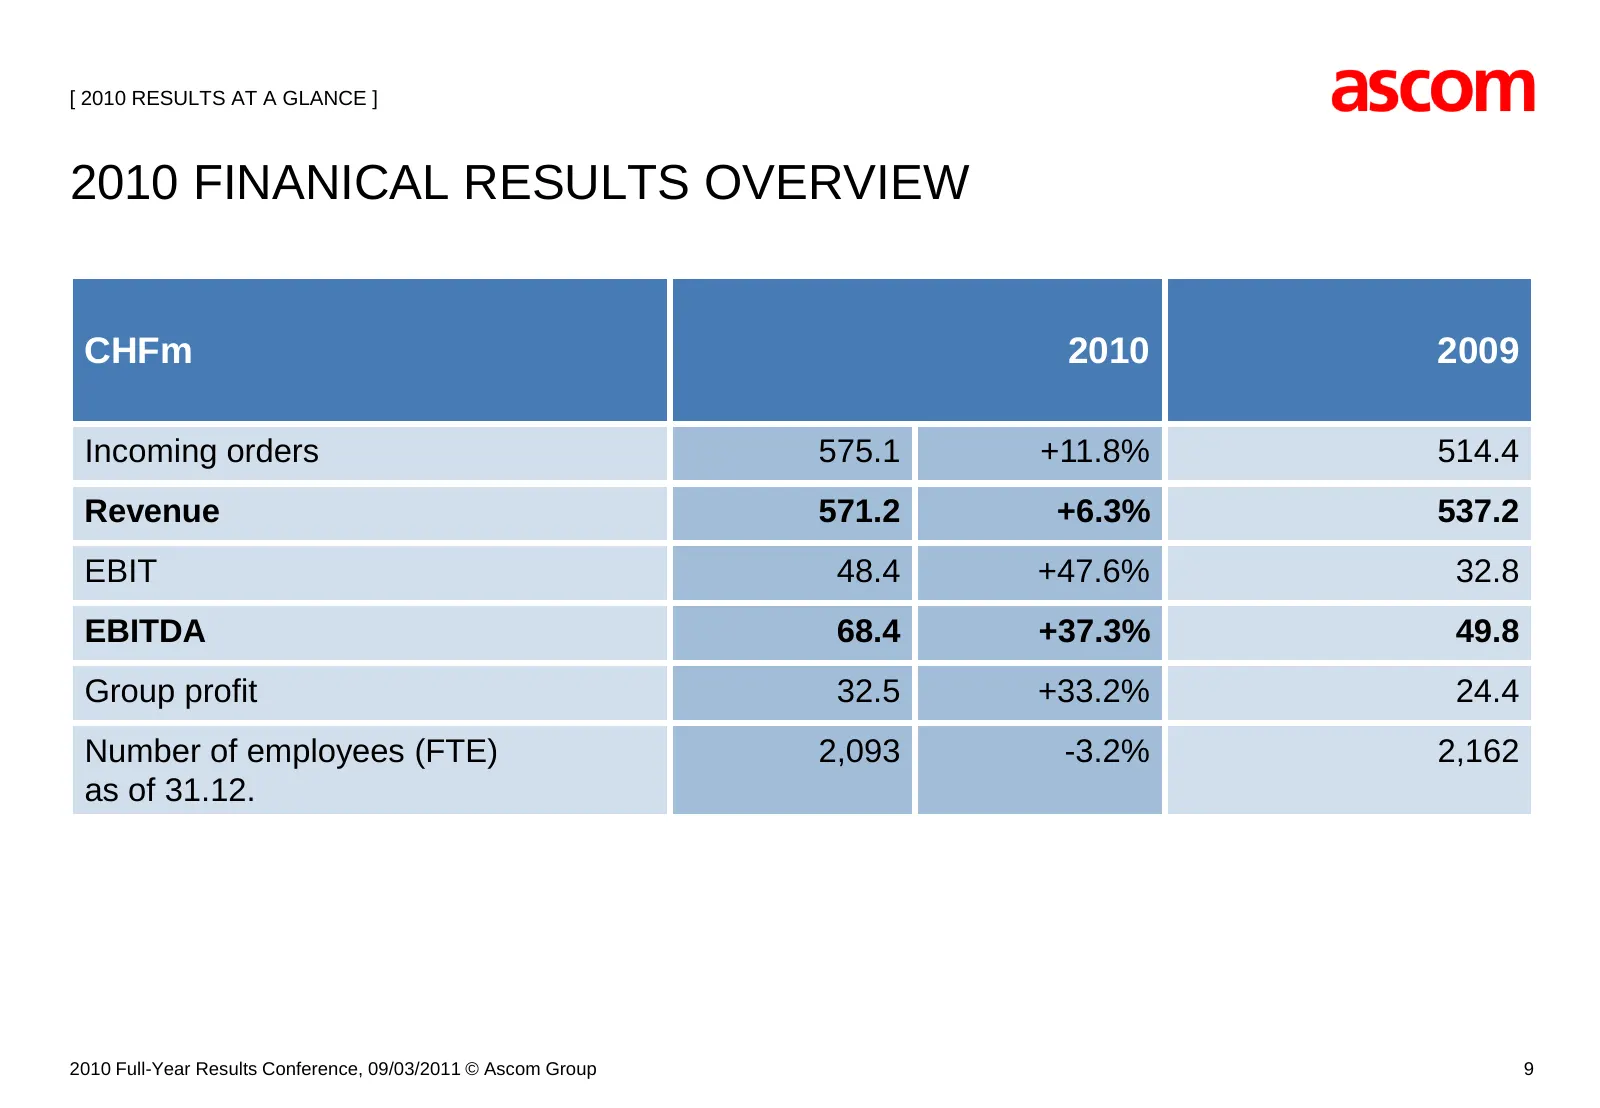
[ 2010 RESULTS AT A GLANCE ] 2010 FINANICAL RESULTS OVERVIEW CHFm 2010 2009 Incoming orders 575.1 +11.8% 514.4 Revenue 571.2 +6.3% 537.2 EBIT 48.4 +47.6% 32.8 EBITDA 68.4 +37.3% 49.8 Group profit 32.5 +33.2% 24.4 Number of employees (FTE) 2,093 -3.2% 2,162 as of 31.12. 2010 Full-Year Results Confere
Slide 10: Divisional Results
[ ] DIVISIONAL RESULTS 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 10
Slide 11: Wireless Solutions
[ ] WIRELESS SOLUTIONS LEADING WIRELESS ON-SITE COMMUNICATION COMPANY 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 11
Slide 12: Wireless Solutions – Excellent Results in 2010
[ WIRELESS SOLUTIONS ] WIRELESS SOLUTIONS – EXCELLENT RESULTS IN 2010 Revenue: CHF 282.9m (2009: CHF 265.2m) > Growth of 6.7%; at constant exchange rates +11.6% EBITDA: CHF 37.2m (2009: CHF 30.0m); > EBITDA increased by 24% > EBITDA margin: 13.1% (2009: 11.3%) Incoming orders: CHF 289.3m (2009
Slide 13: Strong Performance in All Three Channels
[ WIRELESS SOLUTIONS ] STRONG PERFORMANCE IN ALL THREE CHANNELS Direct channel shows overall substantial improvement Strong recovery in the US Health care: Good development of hospital revenues, successful launch of the new VoWiFi handset i62 Industry segment: Both public and private compani
Slide 14: Network Testing
[ ] NETWORK TESTING A GLOBAL MARKET LEADER FOR BENCHMARKING AND OPTIMIZATION OF MOBILE NETWORKS 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 14
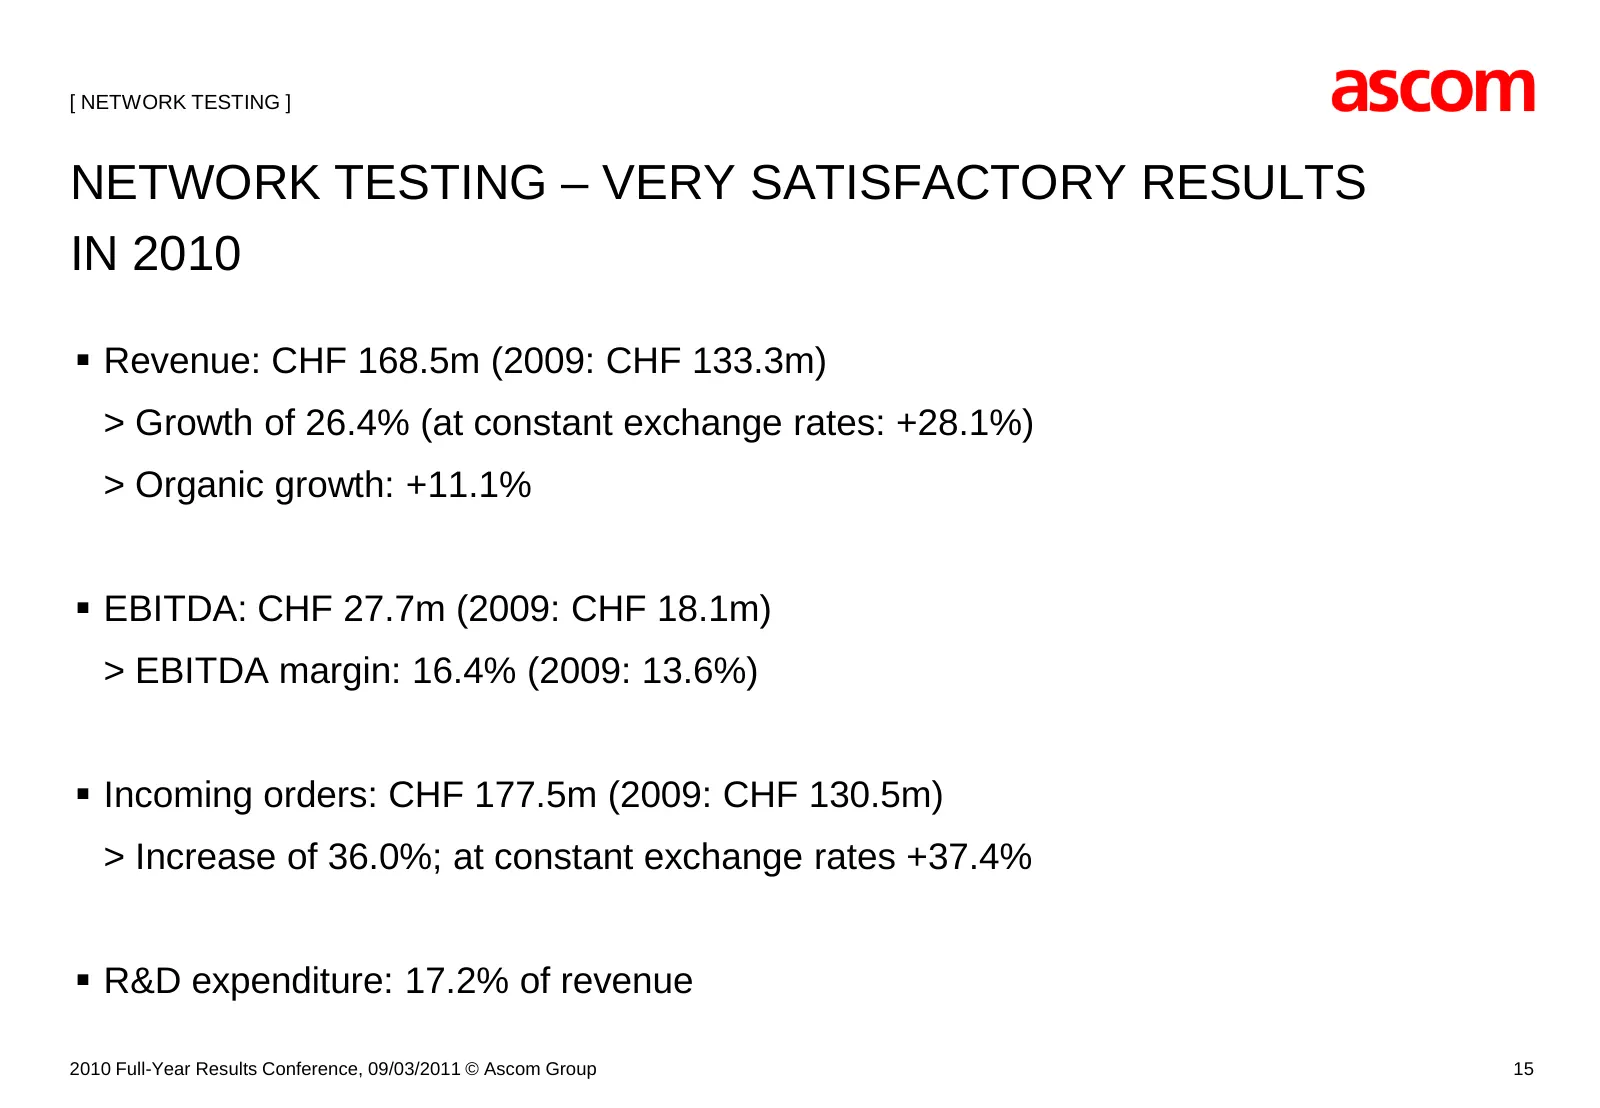
Slide 15: Network Testing – Very Satisfactory Results in 2010
[ NETWORK TESTING ] NETWORK TESTING – VERY SATISFACTORY RESULTS IN 2010 Revenue: CHF 168.5m (2009: CHF 133.3m) > Growth of 26.4% (at constant exchange rates: +28.1%) > Organic growth: +11.1% EBITDA: CHF 27.7m (2009: CHF 18.1m) > EBITDA margin: 16.4% (2009: 13.6%) Incoming orders: CHF 177.5m (2
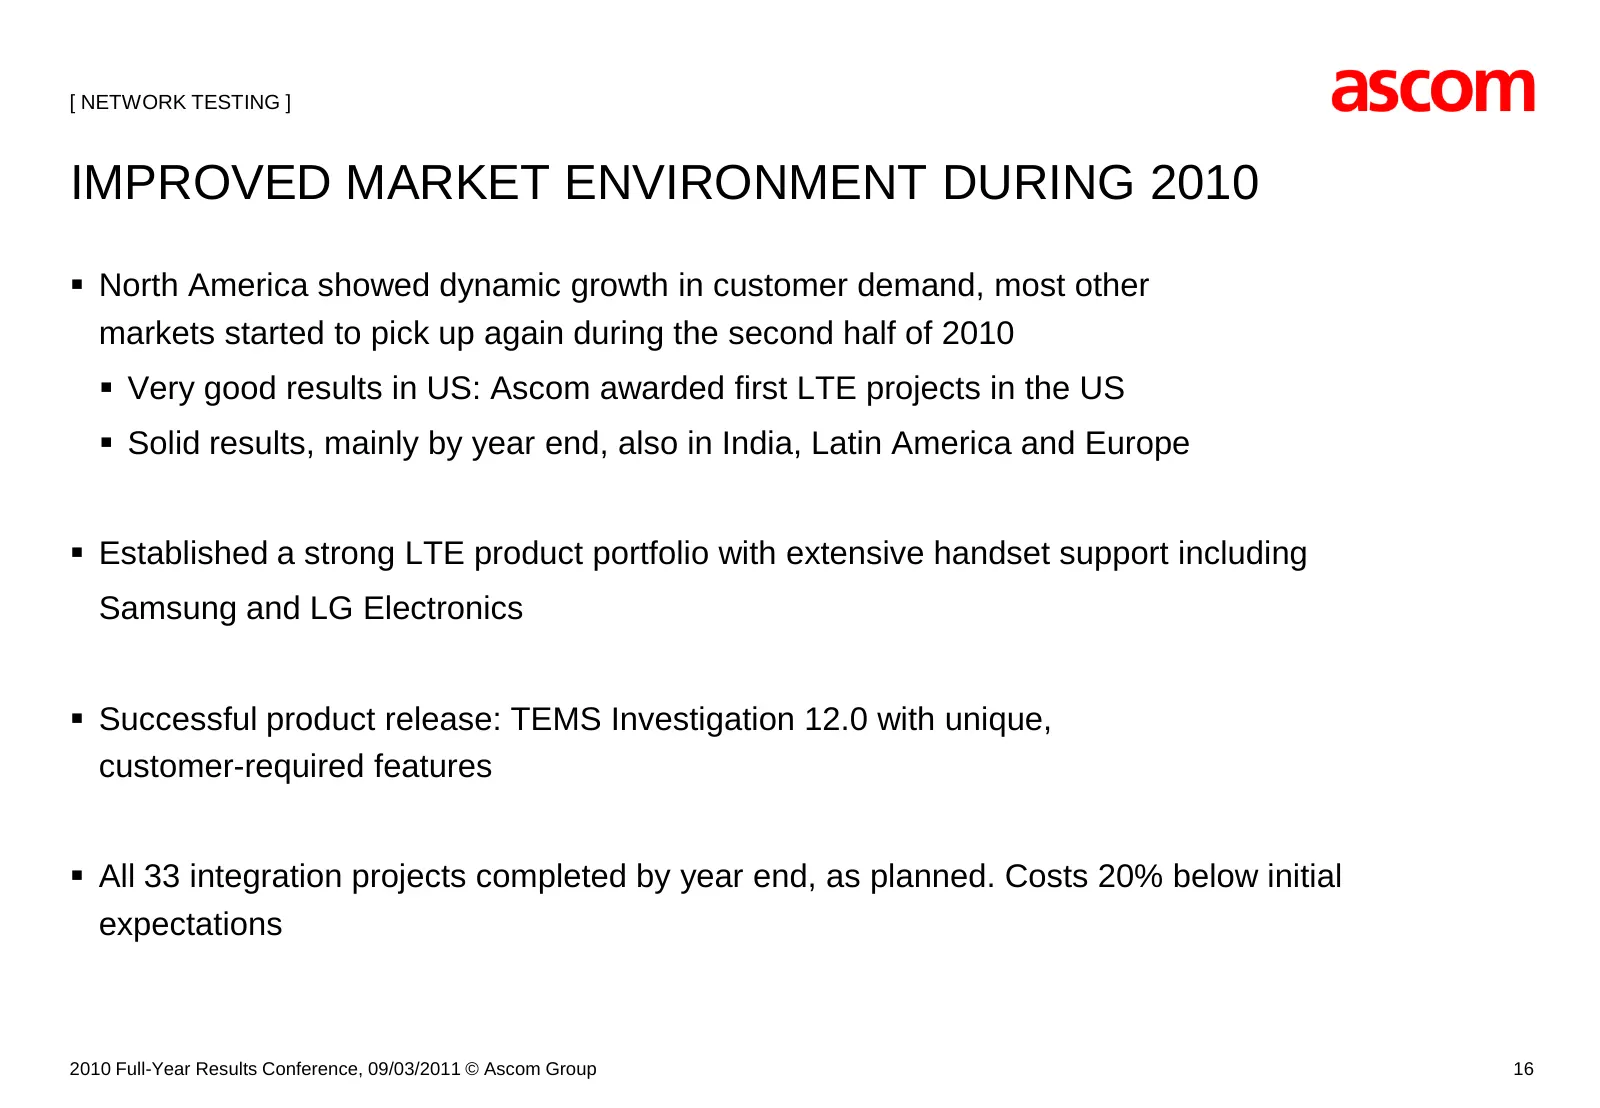
Slide 16: Improved Market Environment During 2010
[ NETWORK TESTING ] IMPROVED MARKET ENVIRONMENT DURING 2010 North America showed dynamic growth in customer demand, most other markets started to pick up again during the second half of 2010 Very good results in US: Ascom awarded first LTE projects in the US Solid results, mainly by year end,
Slide 17: Security Communication
[ ] SECURITY COMMUNICATION LEADING POSITION IN HOME MARKET SWITZERLAND 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 17
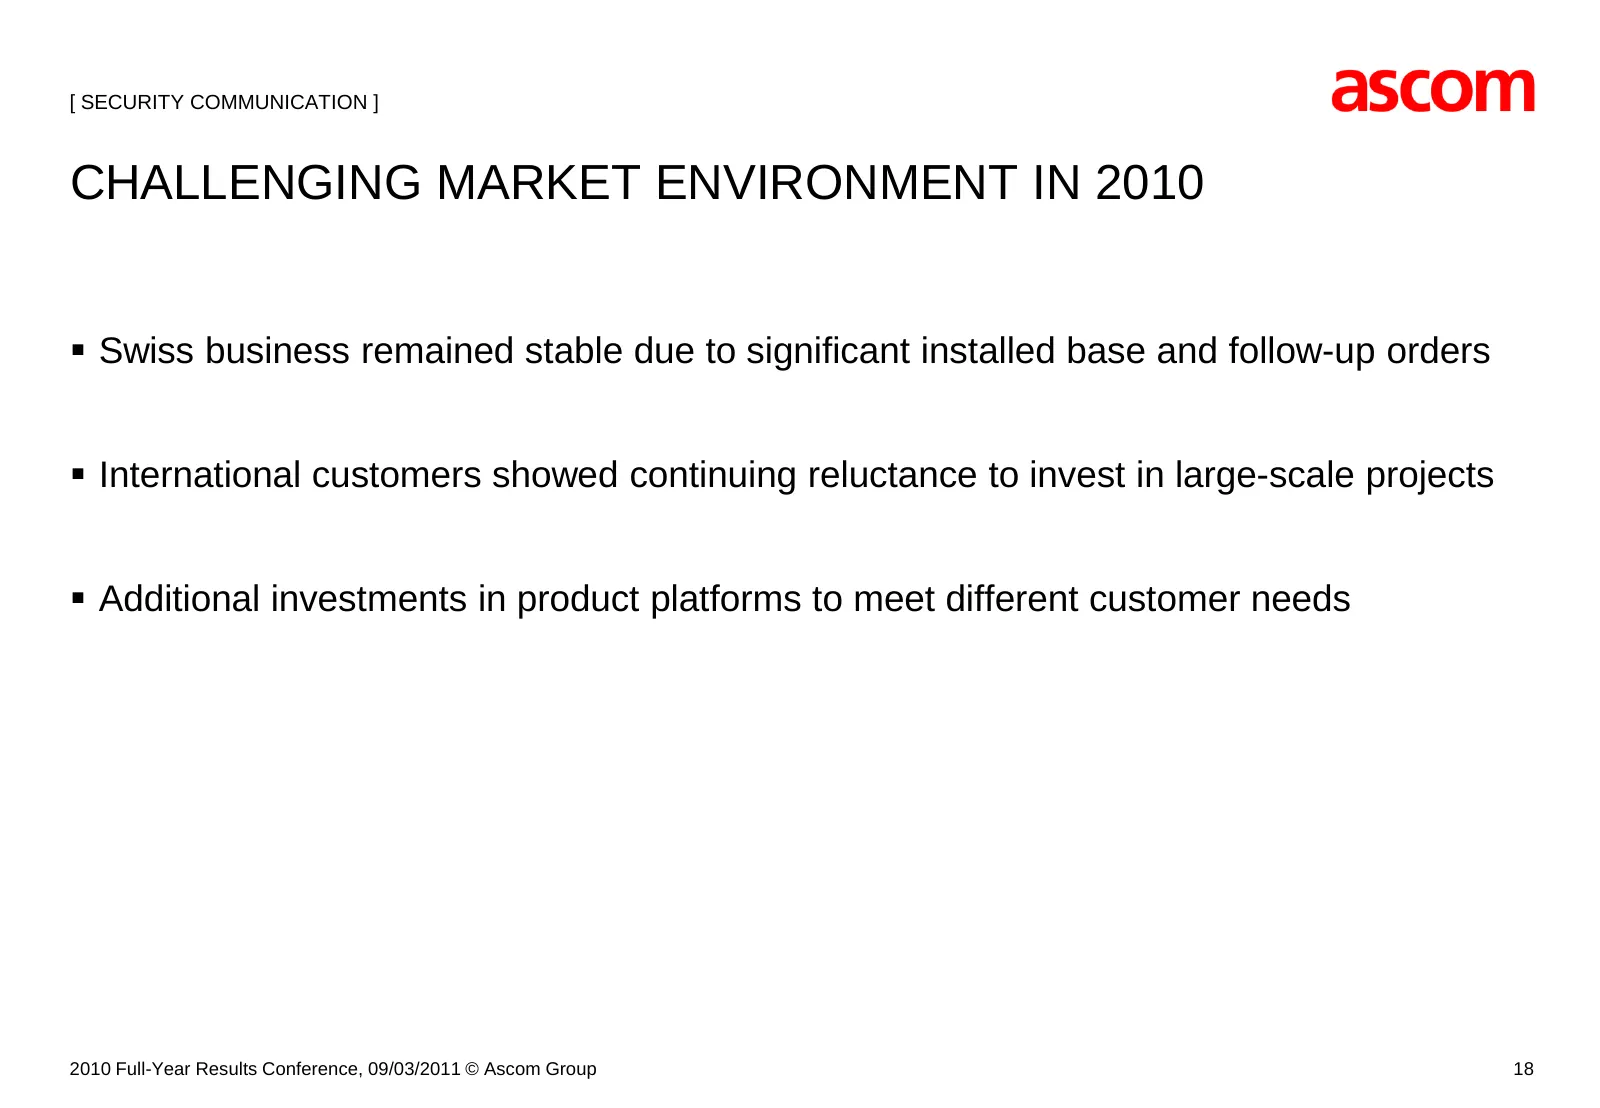
Slide 18: Challenging Market Environment in 2010
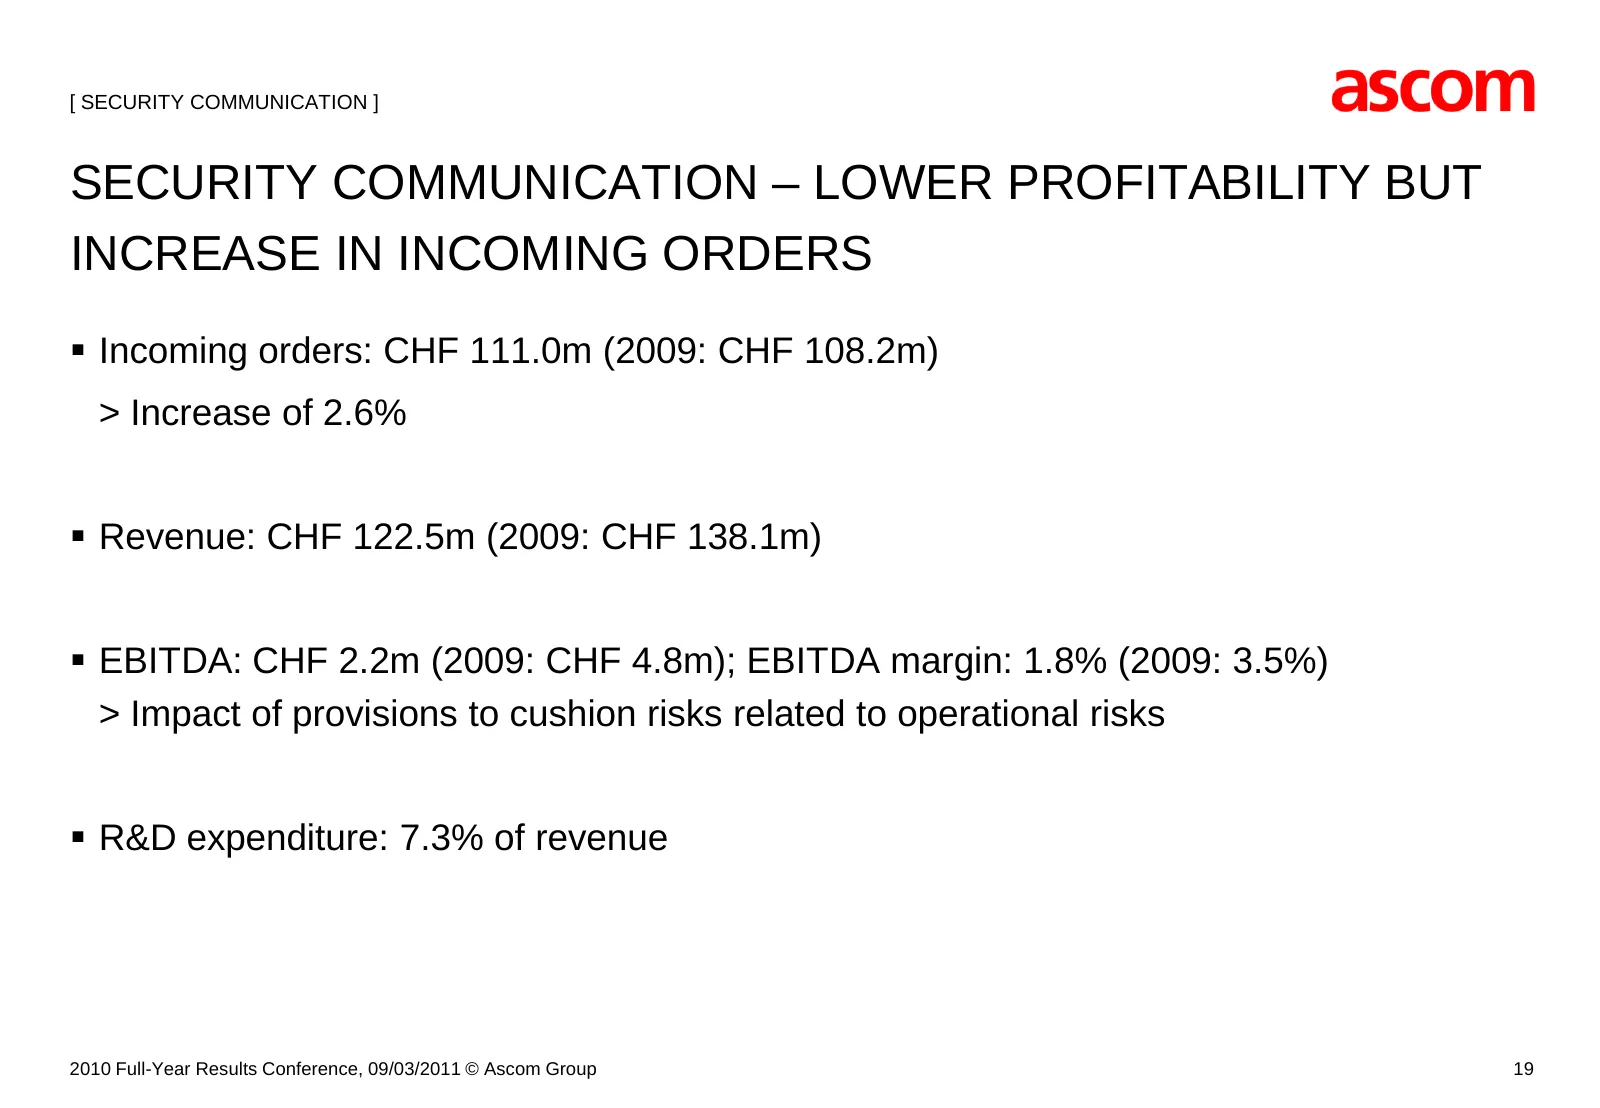
[ SECURITY COMMUNICATION ] CHALLENGING MARKET ENVIRONMENT IN 2010 Swiss business remained stable due to significant installed base and follow-up orders International customers showed continuing reluctance to invest in large-scale projects Additional investments in product platforms to meet dif
Slide 19: Security Communication – Lower Profitability but Increase in Incoming Orders
[ SECURITY COMMUNICATION ] SECURITY COMMUNICATION – LOWER PROFITABILITY BUT INCREASE IN INCOMING ORDERS Incoming orders: CHF 111.0m (2009: CHF 108.2m) > Increase of 2.6% Revenue: CHF 122.5m (2009: CHF 138.1m) EBITDA: CHF 2.2m (2009: CHF 4.8m); EBITDA margin: 1.8% (2009: 3.5%) > Impact of provi
Slide 20: 2010 Financial Results
[ ] 2010 FINANCIAL RESULTS Martin Zwyssig CFO 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 20
Slide 21: Consolidated Income Statement
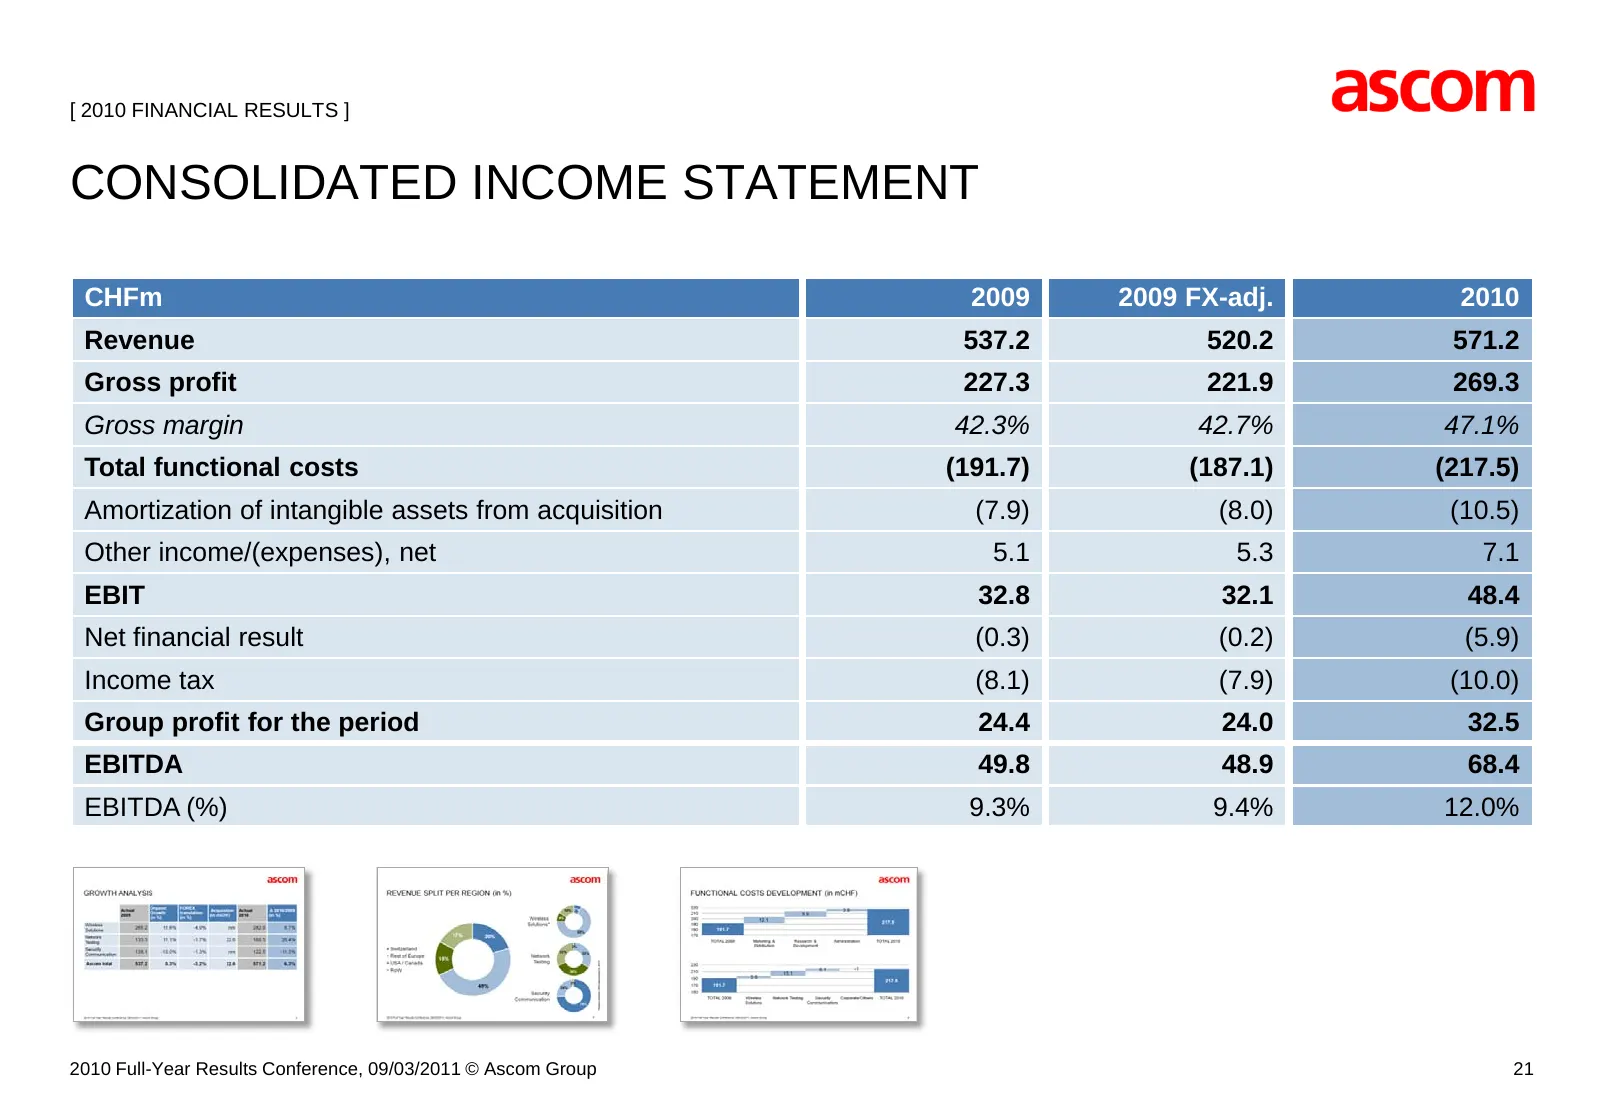
[ 2010 FINANCIAL RESULTS ] CONSOLIDATED INCOME STATEMENT CHFm 2009 2009 FX-adj. 2010 Revenue 537.2 520.2 571.2 Gross profit 227.3 221.9 269.3 Gross margin 42.3% 42.7% 47.1% Total functional costs (191.7) (187.1) (217.5) Amortization of intangible assets from acquisition (7.9) (8.0) (10.5) Other inco
Slide 22: Consolidated Balance Sheet
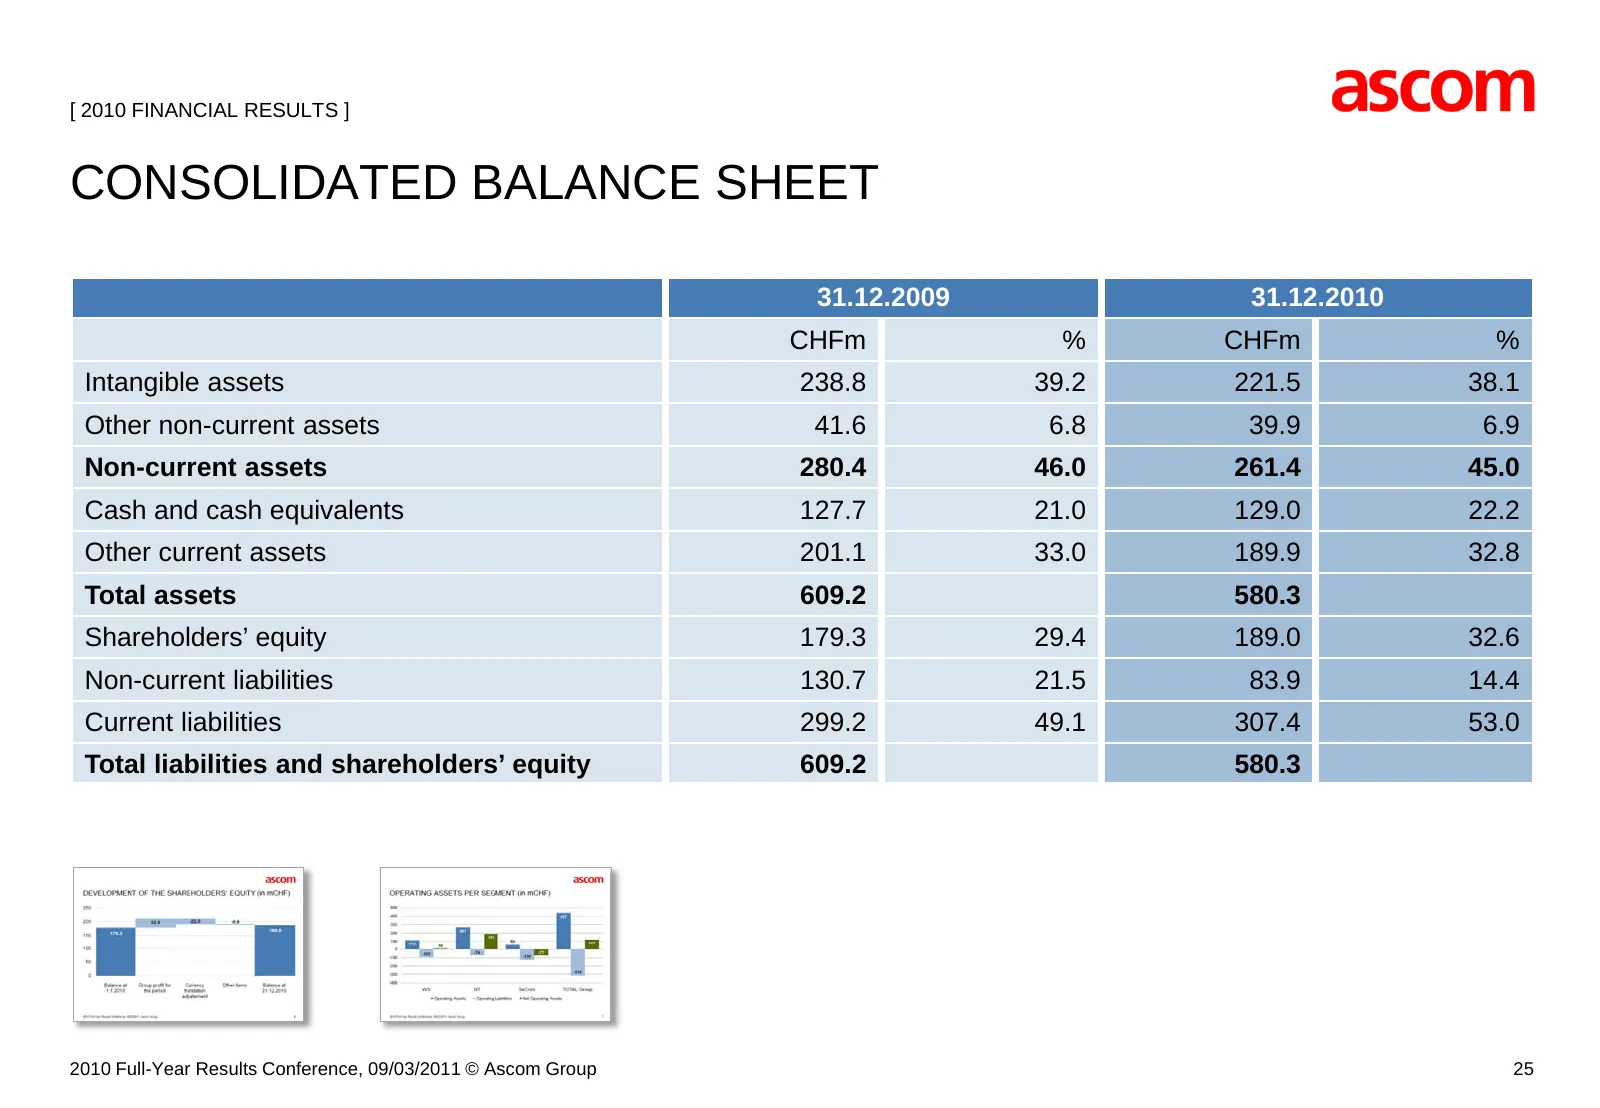
[ 2010 FINANCIAL RESULTS ] CONSOLIDATED BALANCE SHEET 31.12.2009 31.12.2010 CHFm % CHFm % Intangible assets 238.8 39.2 221.5 38.1 Other non-current assets 41.6 6.8 39.9 6.9 Non-current assets 280.4 46.0 261.4 45.0 Cash and cash equivalents 127.7 21.0 129.0 22.2 Other current assets 201.1 33.0 189.9
Slide 23: Consolidated Statement of Cash Flows
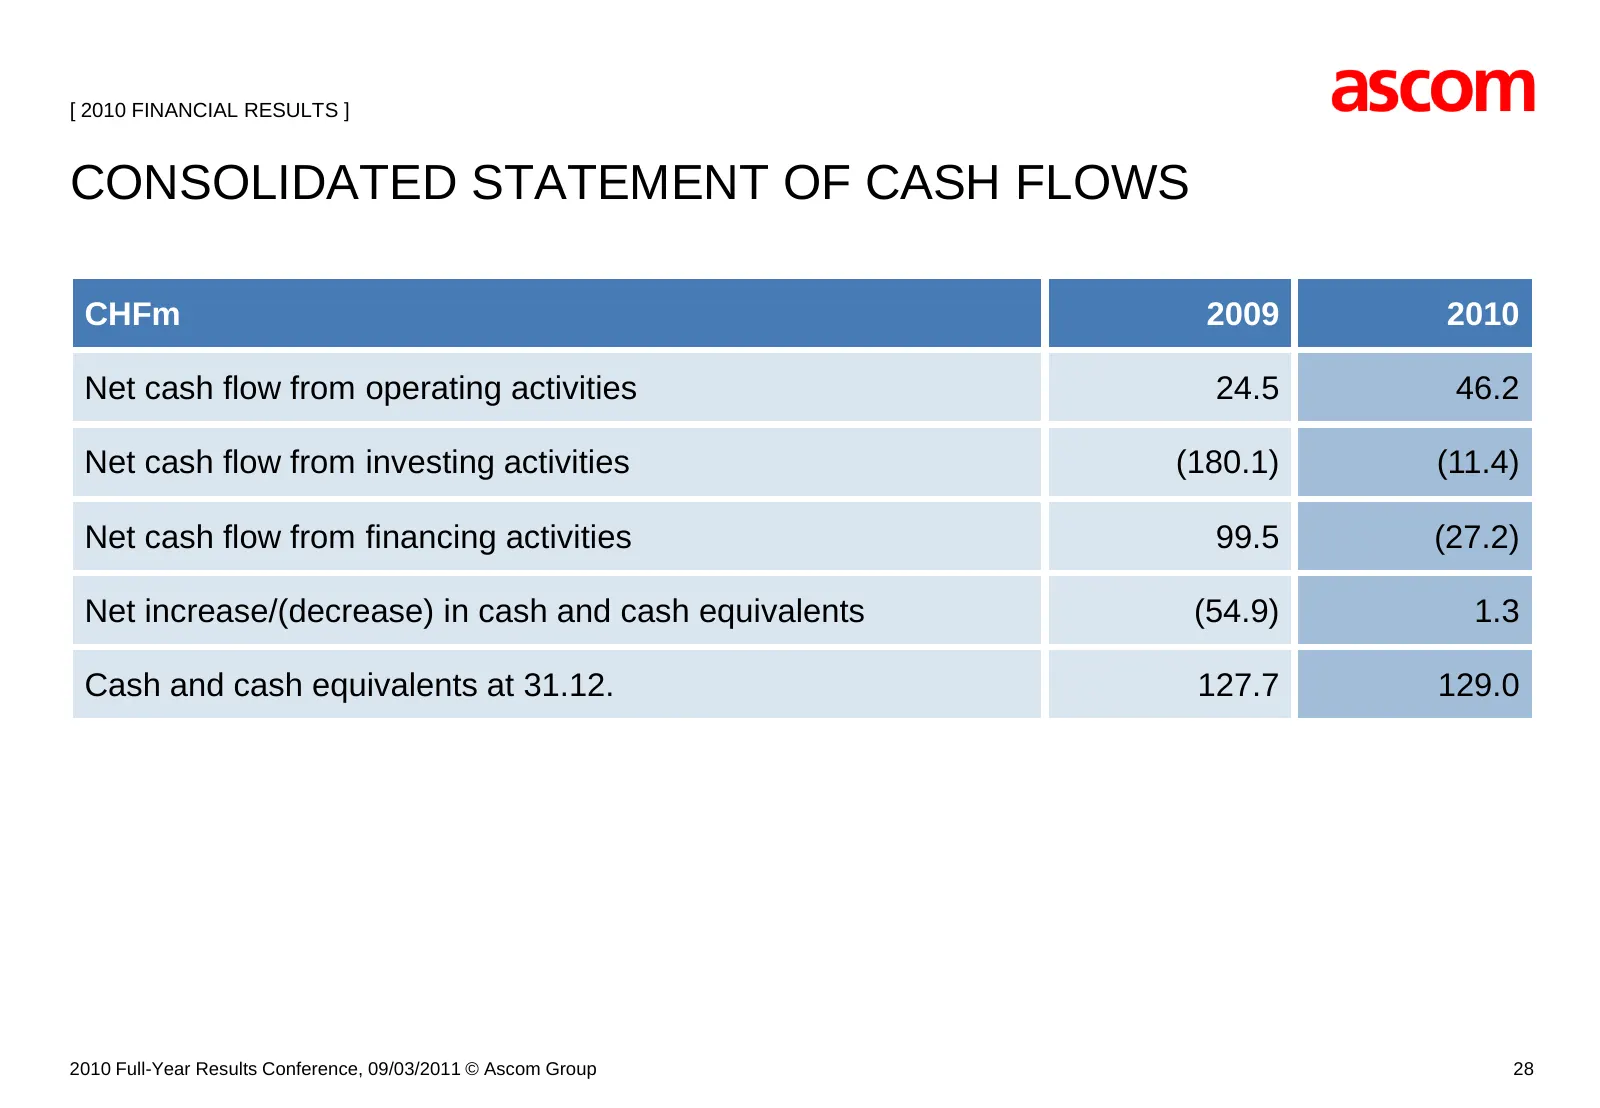
[ 2010 FINANCIAL RESULTS ] CONSOLIDATED STATEMENT OF CASH FLOWS CHFm 2009 2010 Net cash flow from operating activities 24.5 46.2 Net cash flow from investing activities (180.1) (11.4) Net cash flow from financing activities 99.5 (27.2) Net increase/(decrease) in cash and cash equivalents (54.9) 1.3
Slide 24: Transactional Currency Exposure
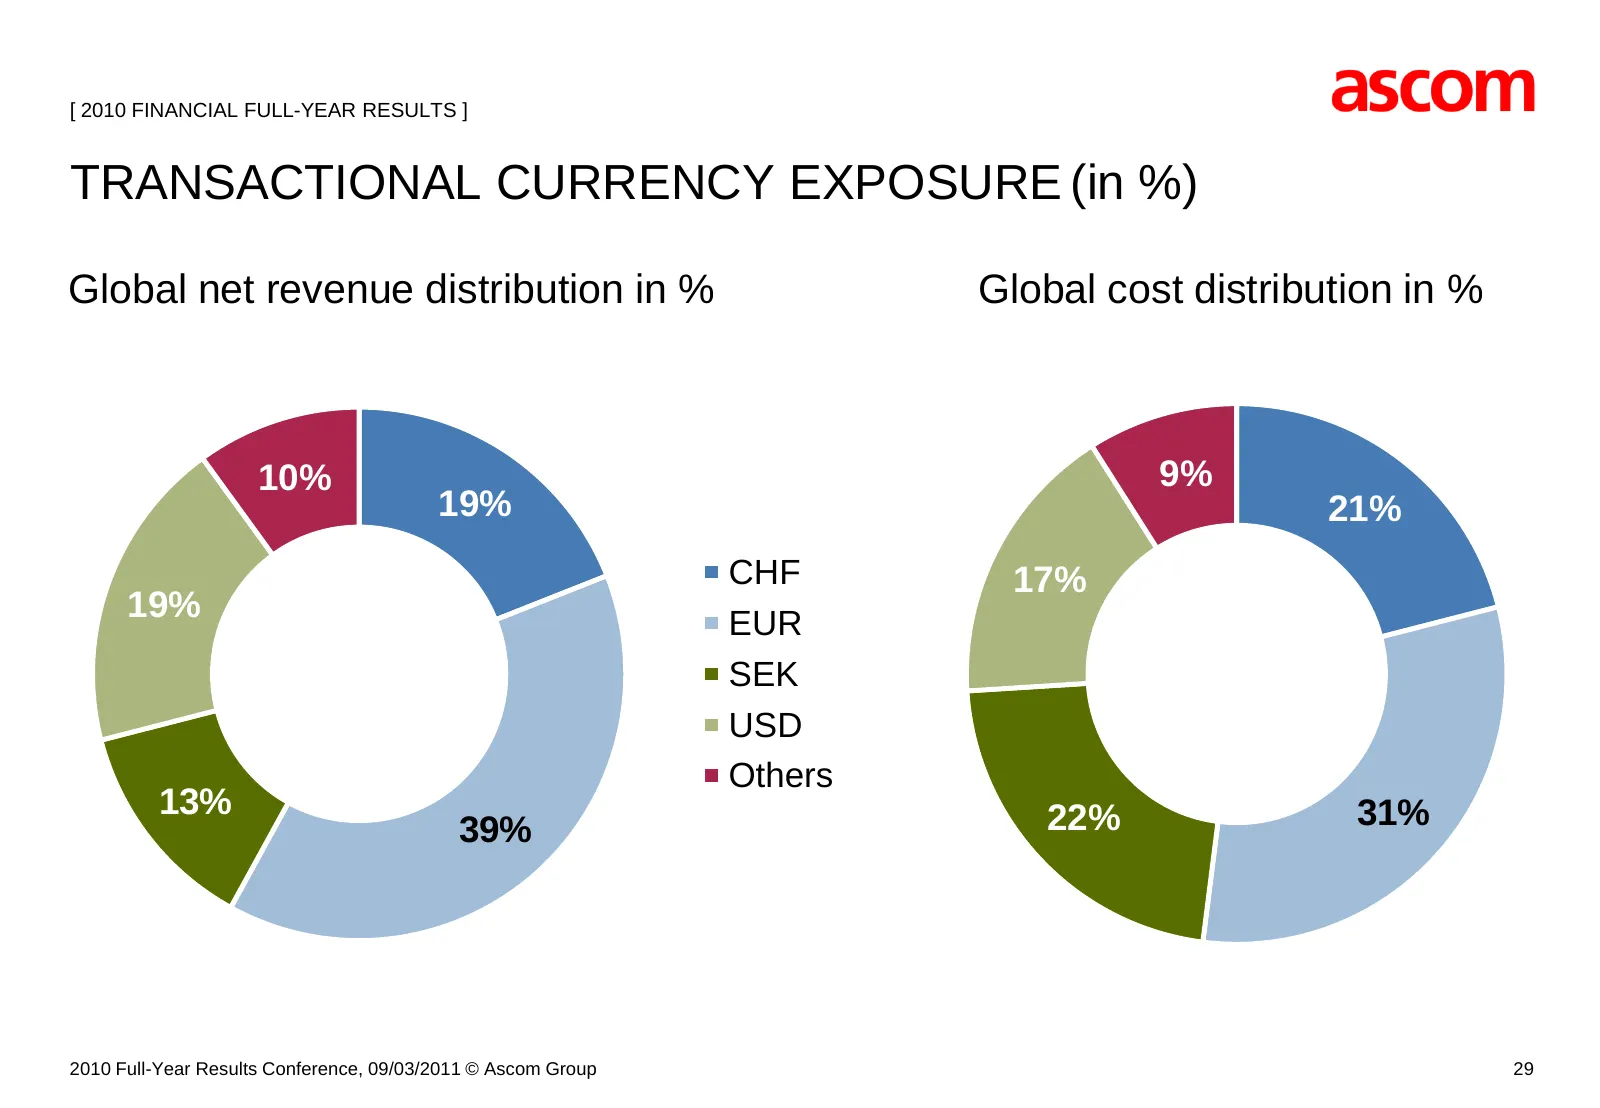
[ 2010 FINANCIAL FULL-YEAR RESULTS ] TRANSACTIONAL CURRENCY EXPOSURE (in %) Global net revenue distribution in % Global cost distribution in % 10% 9% 19% 21% CHF 17% 19% EUR SEK USD Others 13% 22% 31% 39% 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 29
Slide 25: Development of the EBIT Margin (1987-2010)
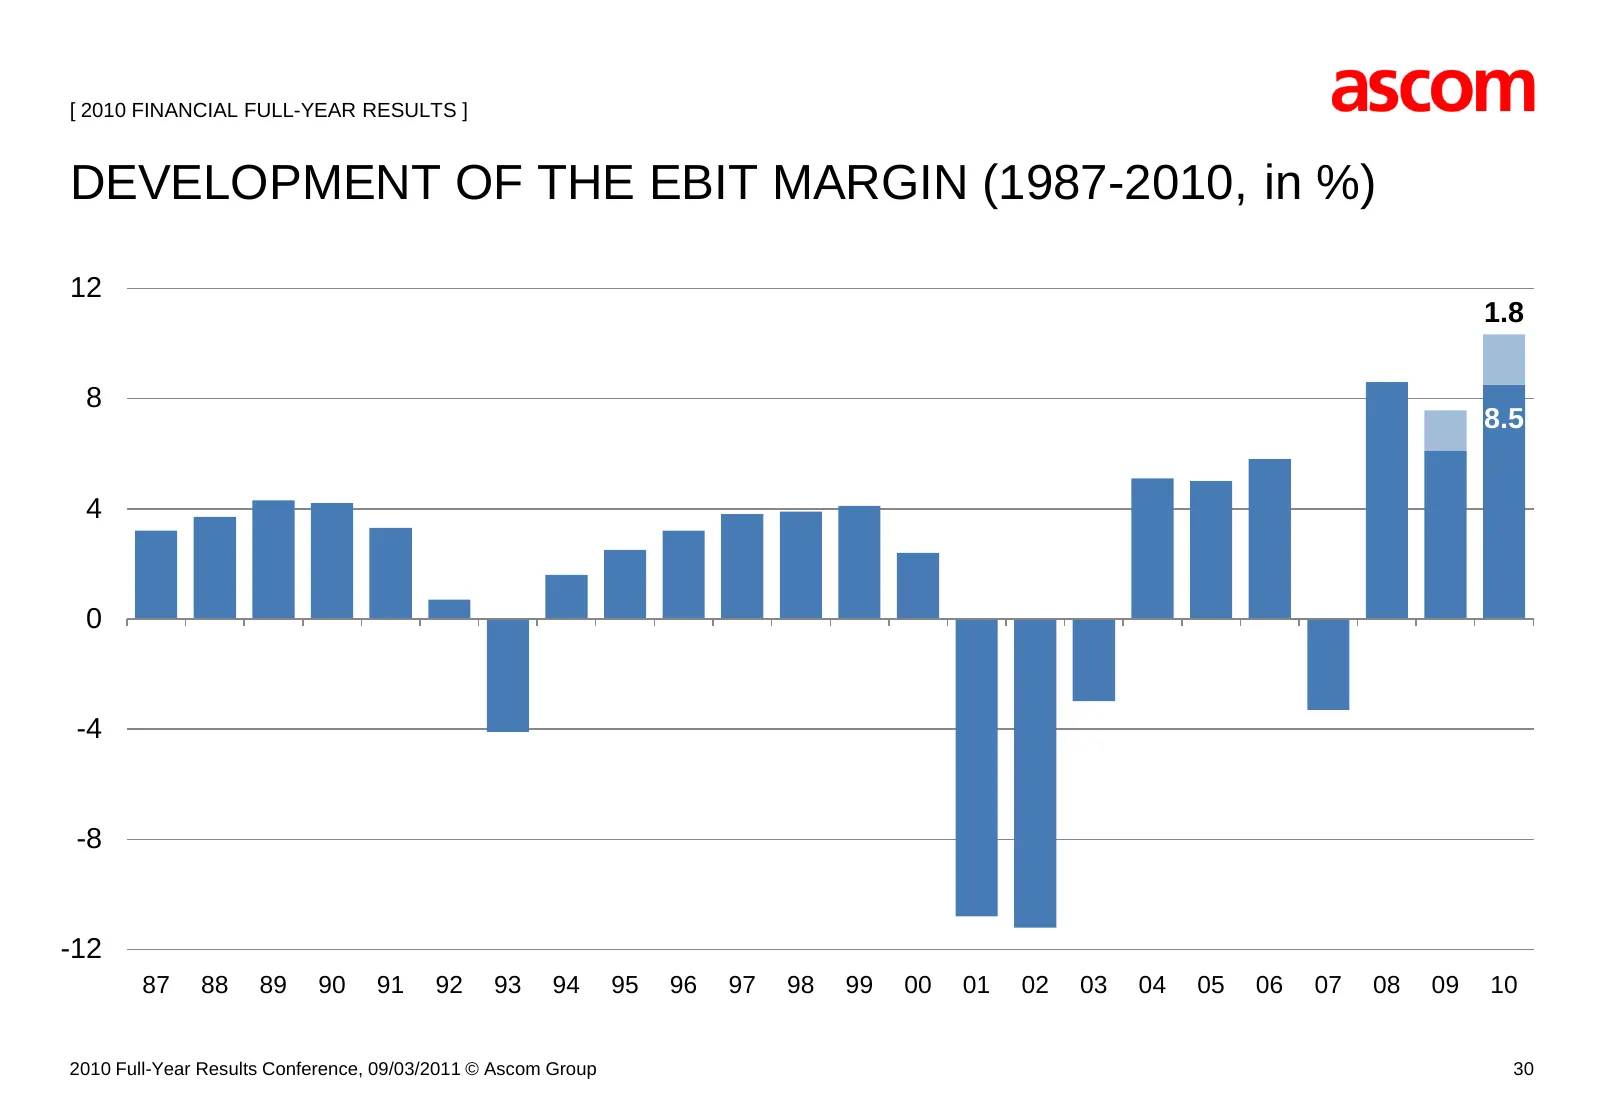
[ 2010 FINANCIAL FULL-YEAR RESULTS ] DEVELOPMENT OF THE EBIT MARGIN (1987-2010, in %) 12 1.8 8 8.5 4 0 -4 -8 -12 87 88 89 90 91 92 93 94 95 96 97 98 99 00 01 02 03 04 05 06 07 08 09 10 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 30
Slide 26: Investments in 2011 Will Enable Targeted Growth from 2012 Onwards
[ ] INVESTMENTS IN 2011 WILL ENABLE TARGETED GROWTH FROM 2012 ONWARDS Fritz Mumenthaler CEO (as of 1 April 2011) 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 31
Slide 27: Mission-Critical Communication Strategy Since 2004
[ TARGETED GROWTH ] MISSION-CRITICAL COMMUNICATION STRATEGY SINCE 2004 Customer needs: Communication systems and solutions, which enable quicker and very reliable responses, when security, safety or efficiency is mission critical Constant innovation, which ensures efficient use of customers’ inv
Slide 28: Ascom – A Mission-Critical Communication Company
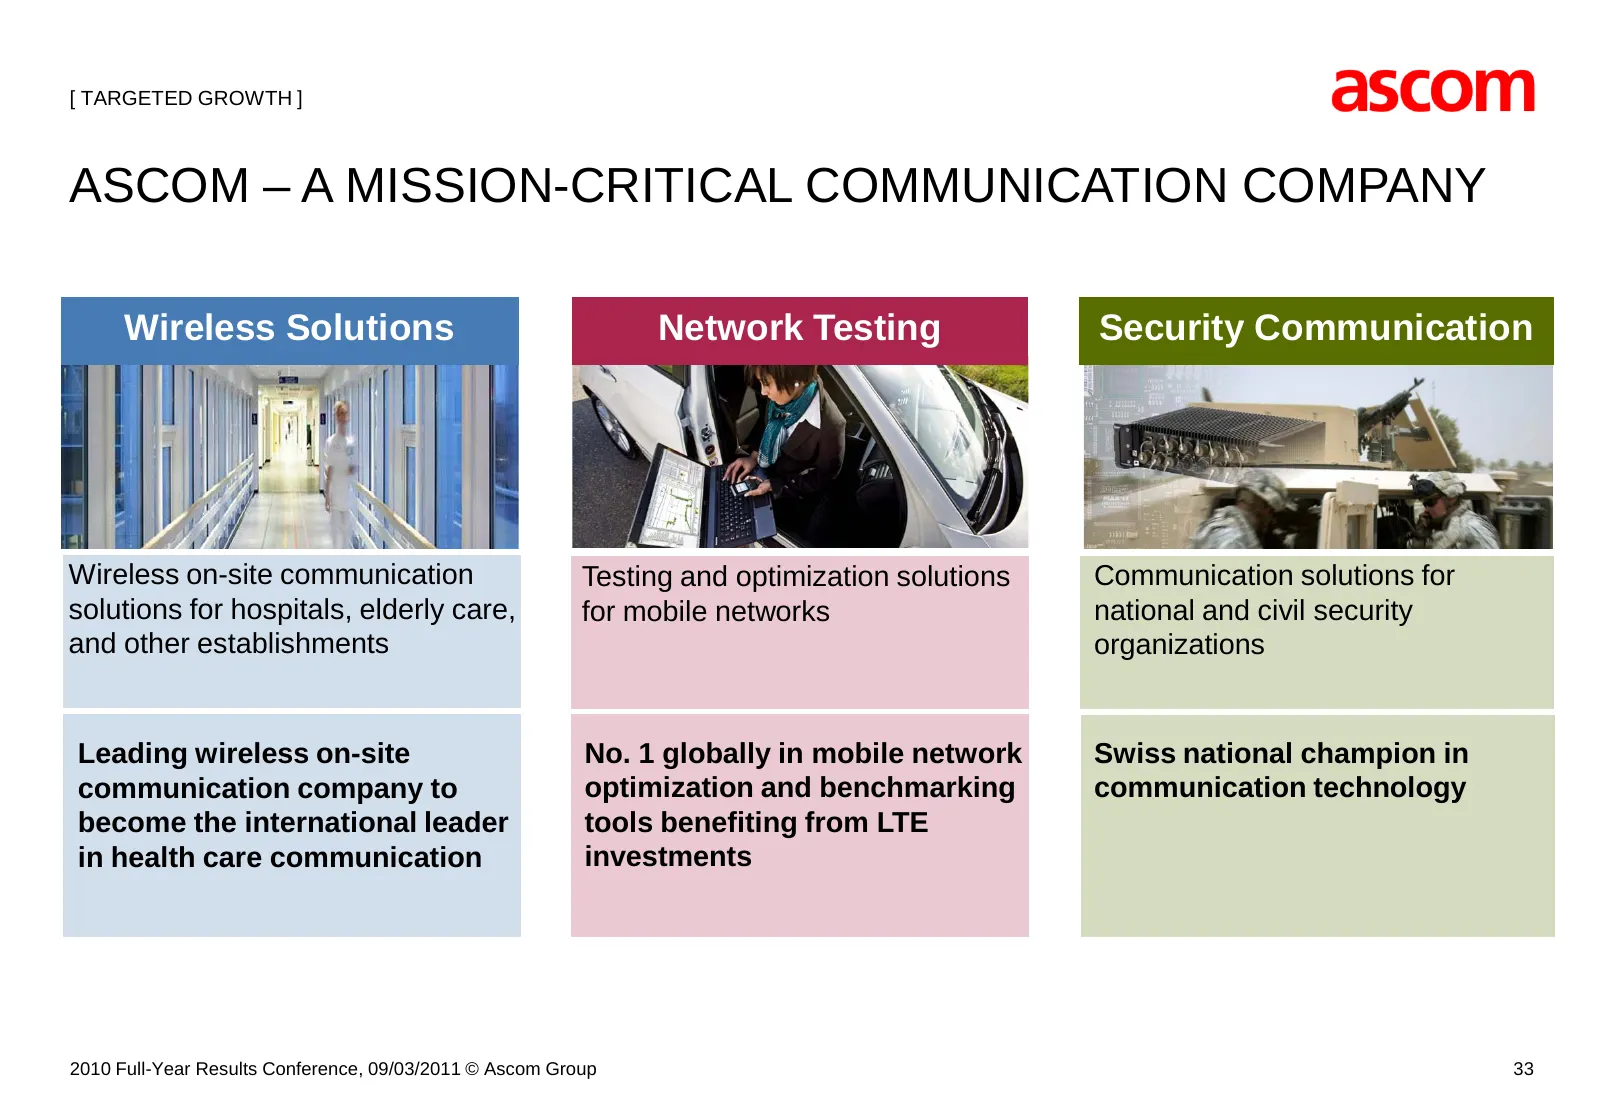
[ TARGETED GROWTH ] ASCOM – A MISSION-CRITICAL COMMUNICATION COMPANY Wireless Solutions Network Testing Security Communication Wireless on-site communication Testing and optimization solutions Communication solutions for solutions for hospitals, elderly care, for mobile networks national and civil s
Slide 29: Strategic Plan 2011-2013: 'In 13: 14 to 15'
[ TARGETED GROWTH ] STRATEGIC PLAN 2011-2013: 'IN 13: 14 TO 15' (2013: 14-15% EBITDA MARGIN) THE CONSISTENT IMPLEMENTATION OF OUR PROVEN STRATEGY 2010 Sustainable profitability achieved Leading positions in growth markets All divisions profitable and positioned to capture future growth R&D spe
Slide 30: Ascom – Global Presence
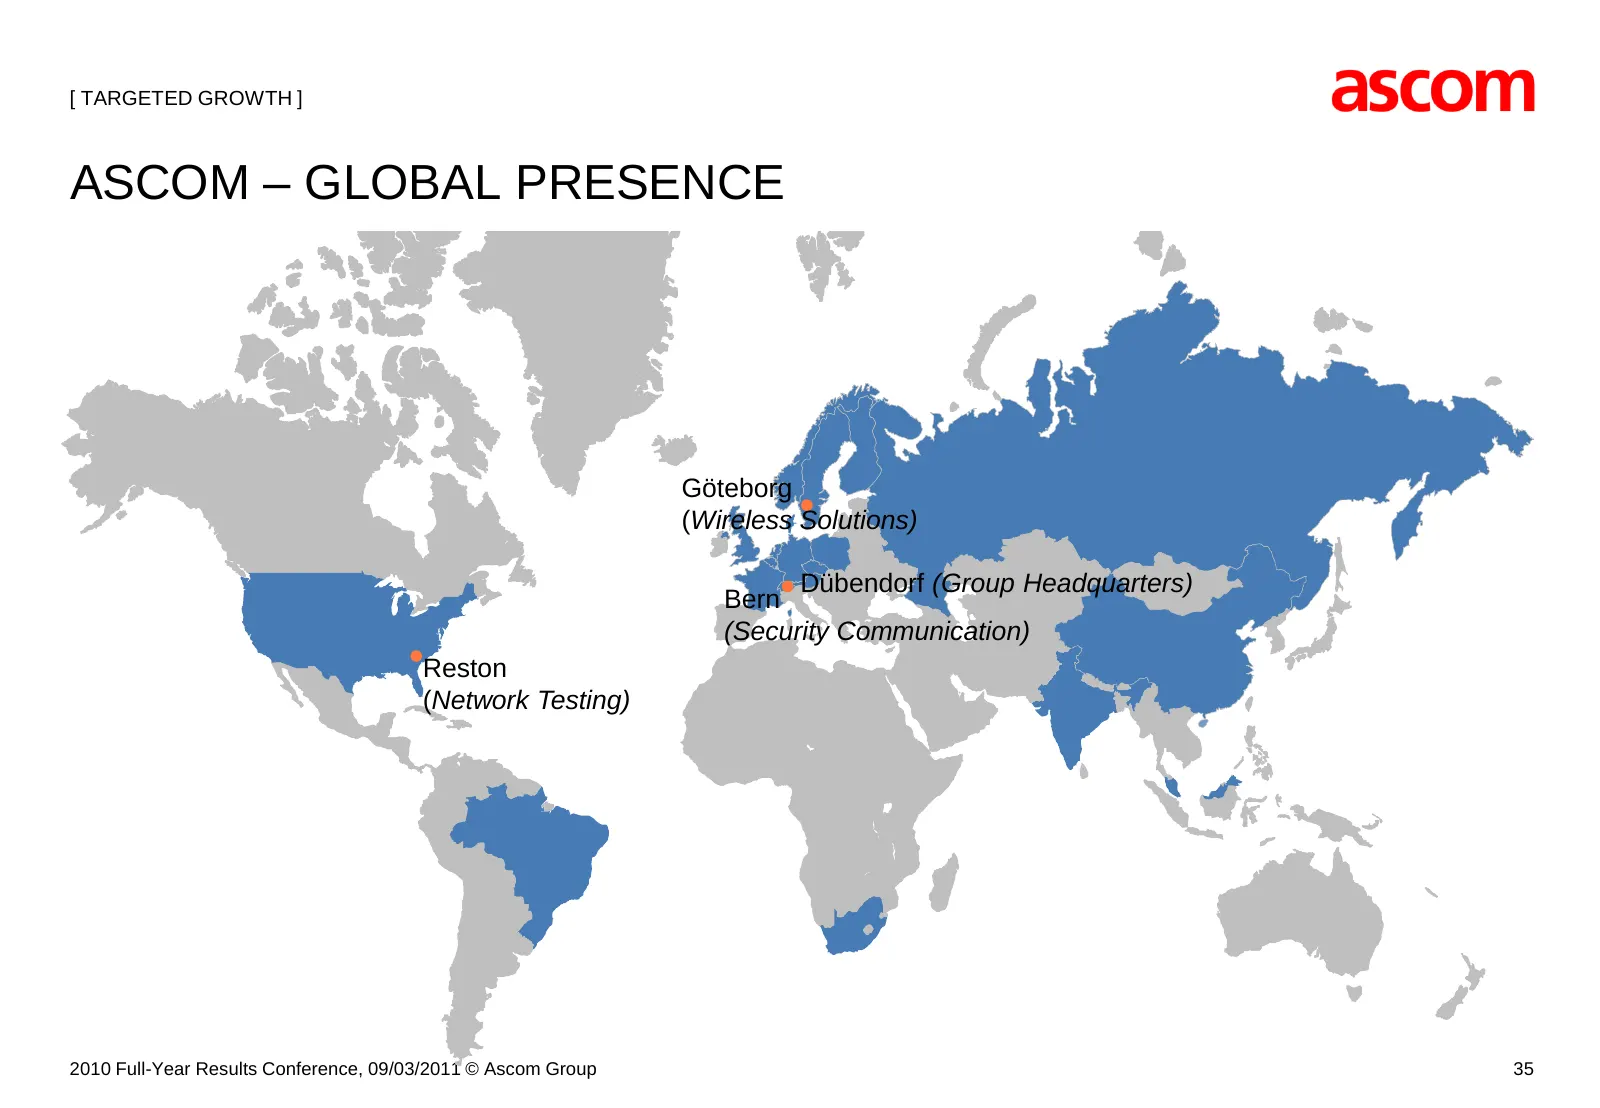
[ TARGETED GROWTH ] ASCOM – GLOBAL PRESENCE Göteborg (Wireless Solutions) Dübendorf (Group Headquarters) Bern (Security Communication) Reston (Network Testing) 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 35
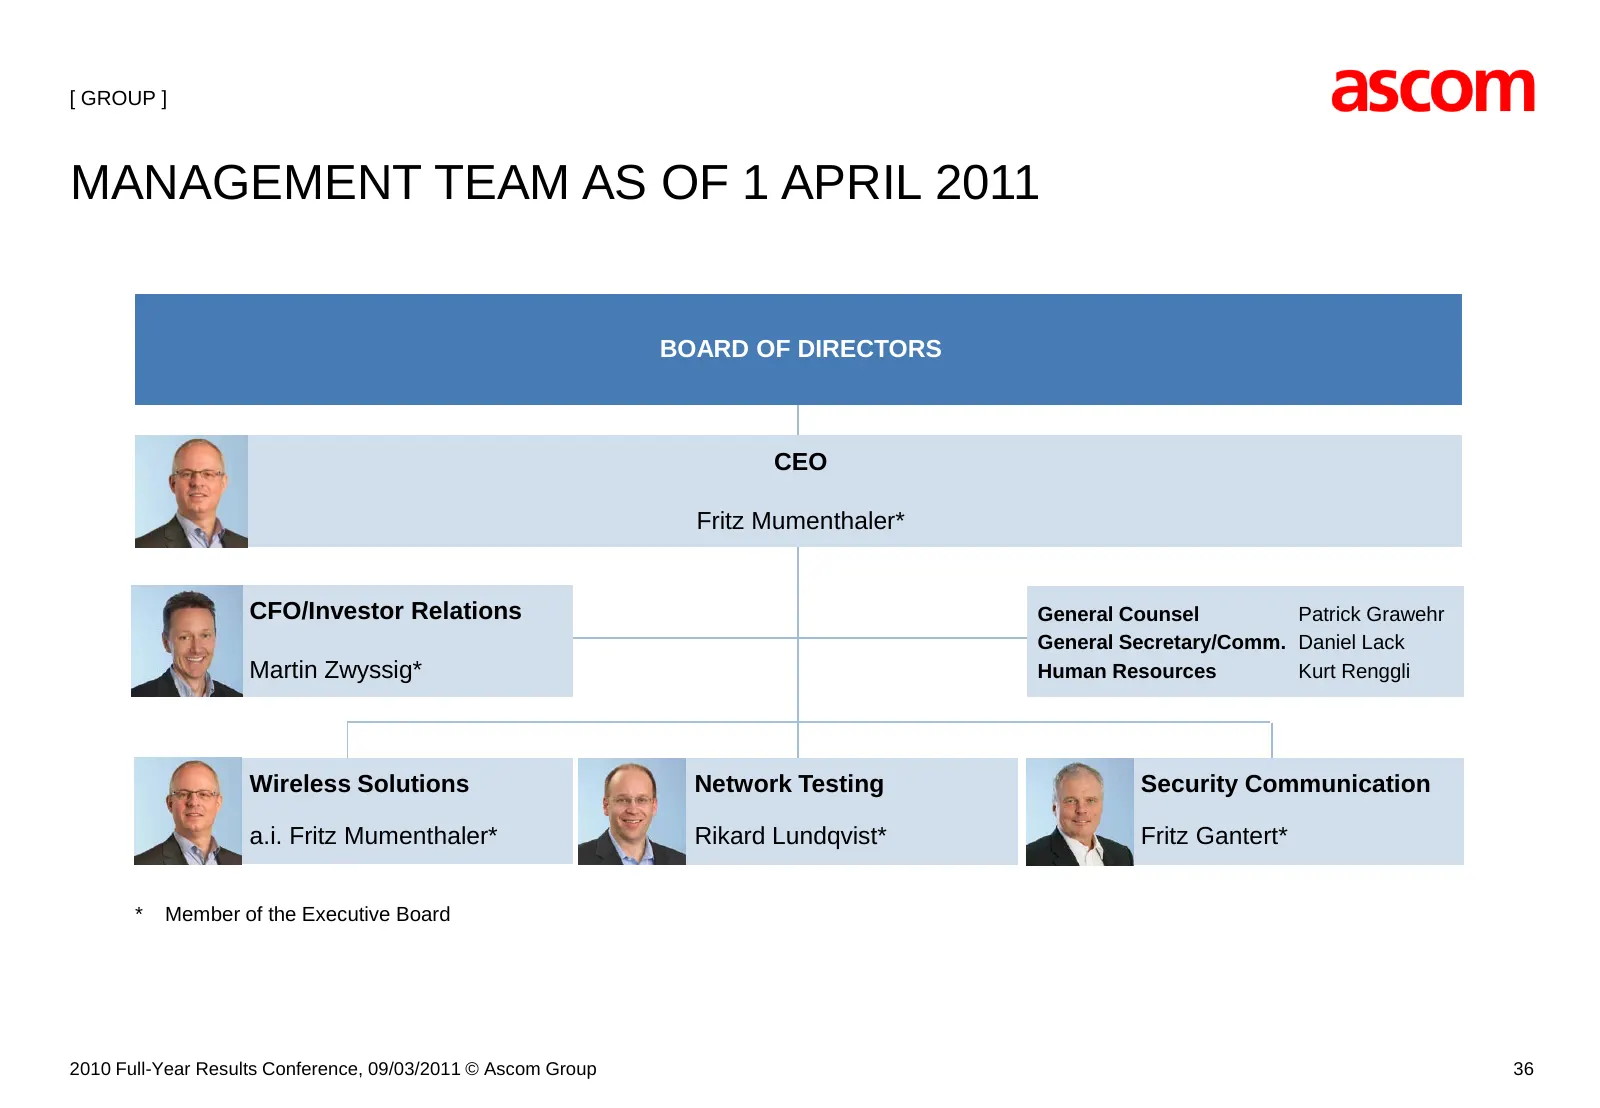
Slide 31: Management Team as of 1 April 2011
[ GROUP ] MANAGEMENT TEAM AS OF 1 APRIL 2011 BOARD OF DIRECTORS CEO Fritz Mumenthaler* CFO/Investor Relations General Counsel Patrick Grawehr General Secretary/Comm. Daniel Lack v Martin Zwyssig* Human Resources Kurt Renggli Wireless Solutions Network Testing Security Communication a.i. Fritz Mument
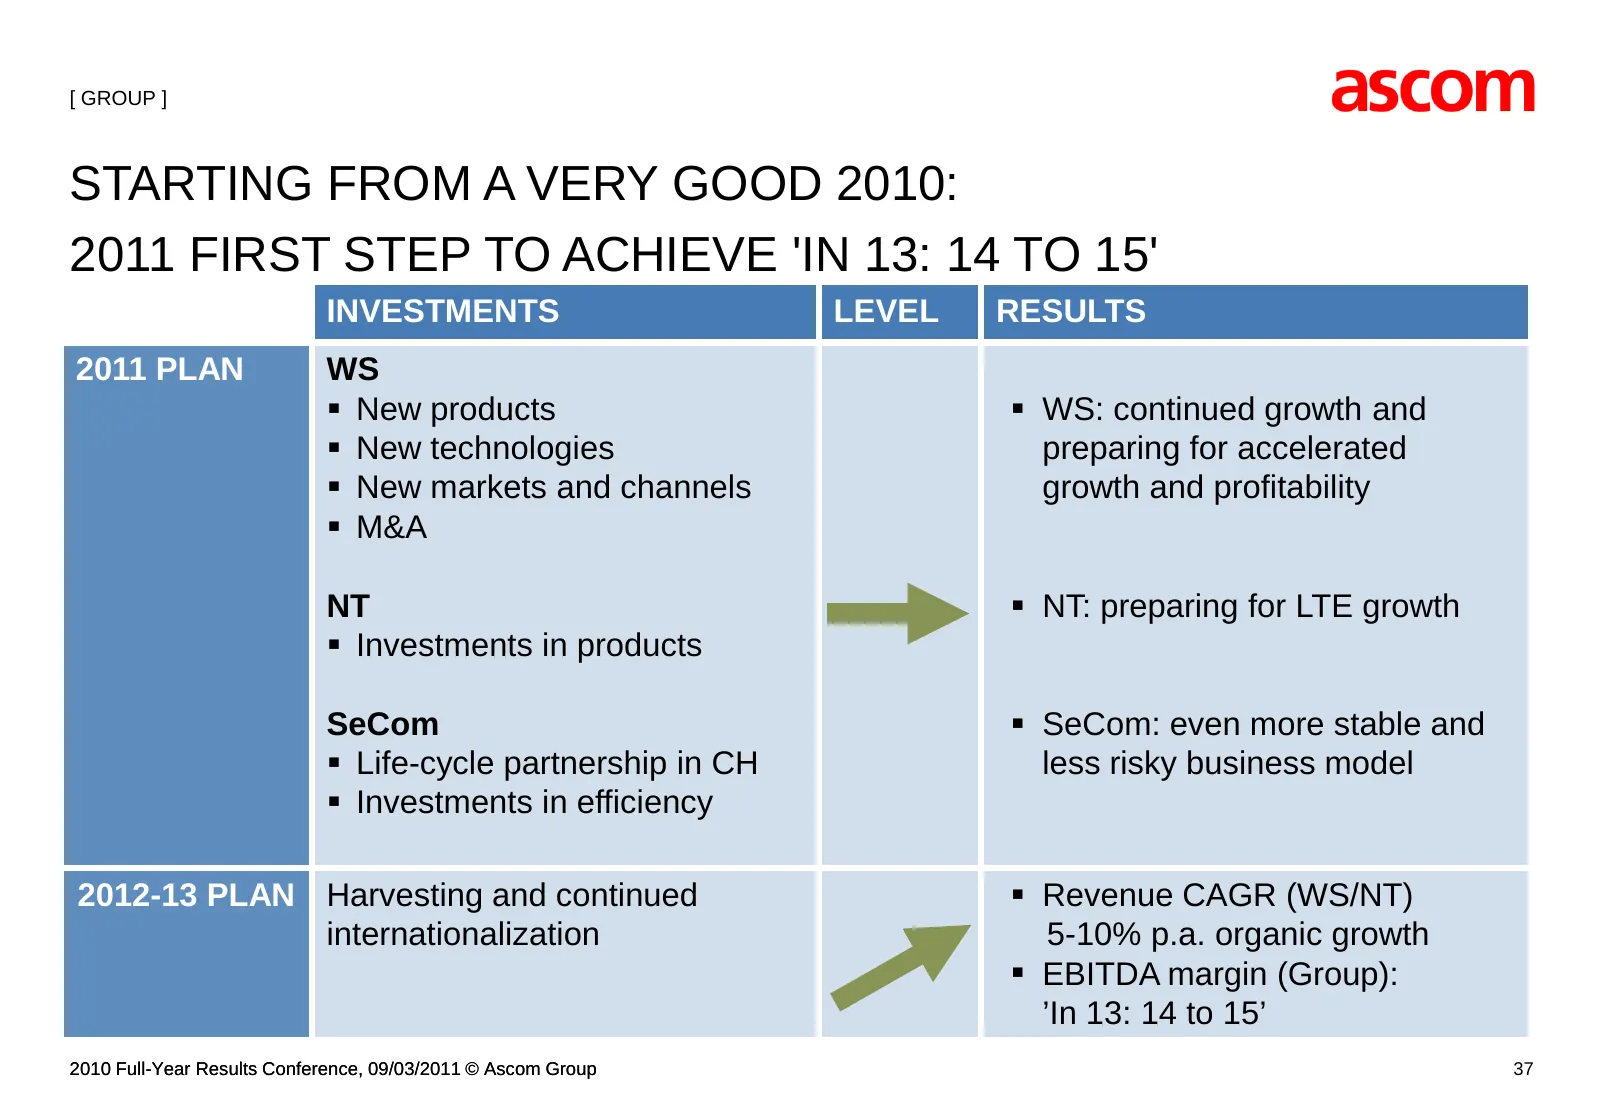
Slide 32: Starting from a Very Good 2010: 2011 First Step
[ GROUP ] STARTING FROM A VERY GOOD 2010: 2011 FIRST STEP TO ACHIEVE 'IN 13: 14 TO 15' INVESTMENTS LEVEL RESULTS 1st priority WS 2011 PLAN New products WS: continued growth and New technologies preparing for accelerated New markets and channels growth and profitability M&A NT NT: prepari
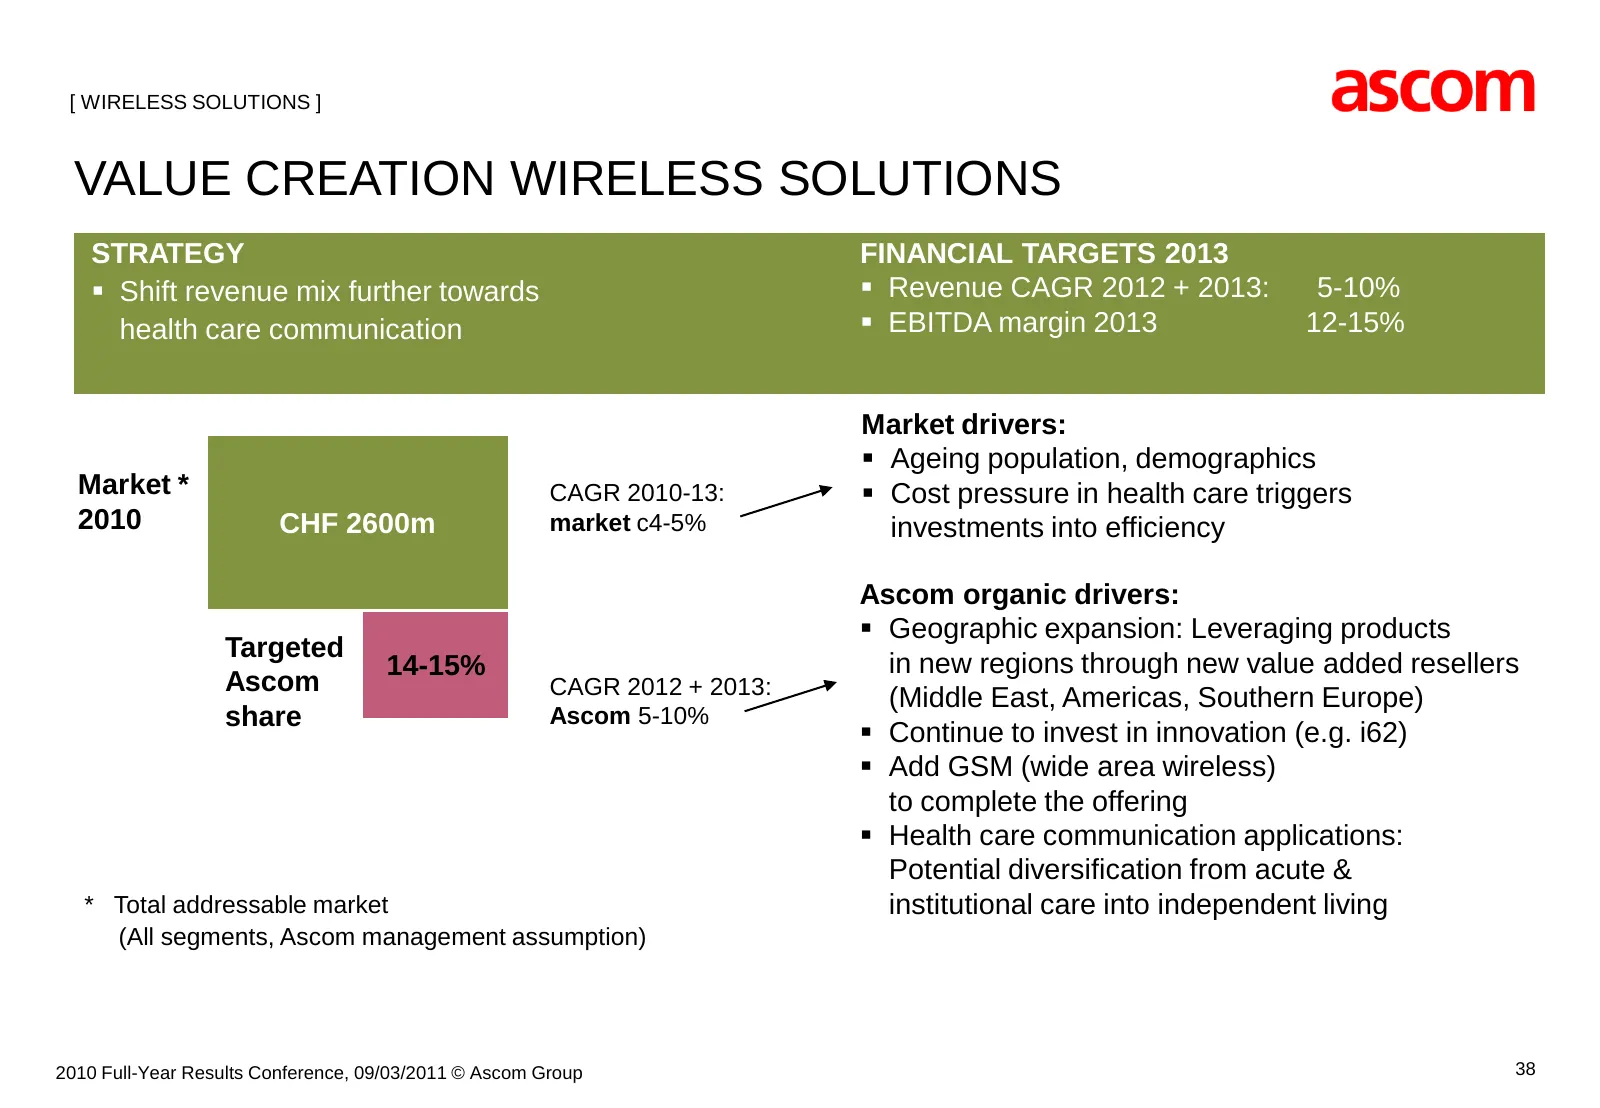
Slide 33: Value Creation Wireless Solutions
[ WIRELESS SOLUTIONS ] VALUE CREATION WIRELESS SOLUTIONS STRATEGY FINANCIAL TARGETS 2013 Shift revenue mix further towards Revenue CAGR 2012 + 2013: 5-10% health care communication EBITDA margin 2013 12-15% Market drivers: Ageing population, demographics Market * CAGR 2010-13: Cost pressur
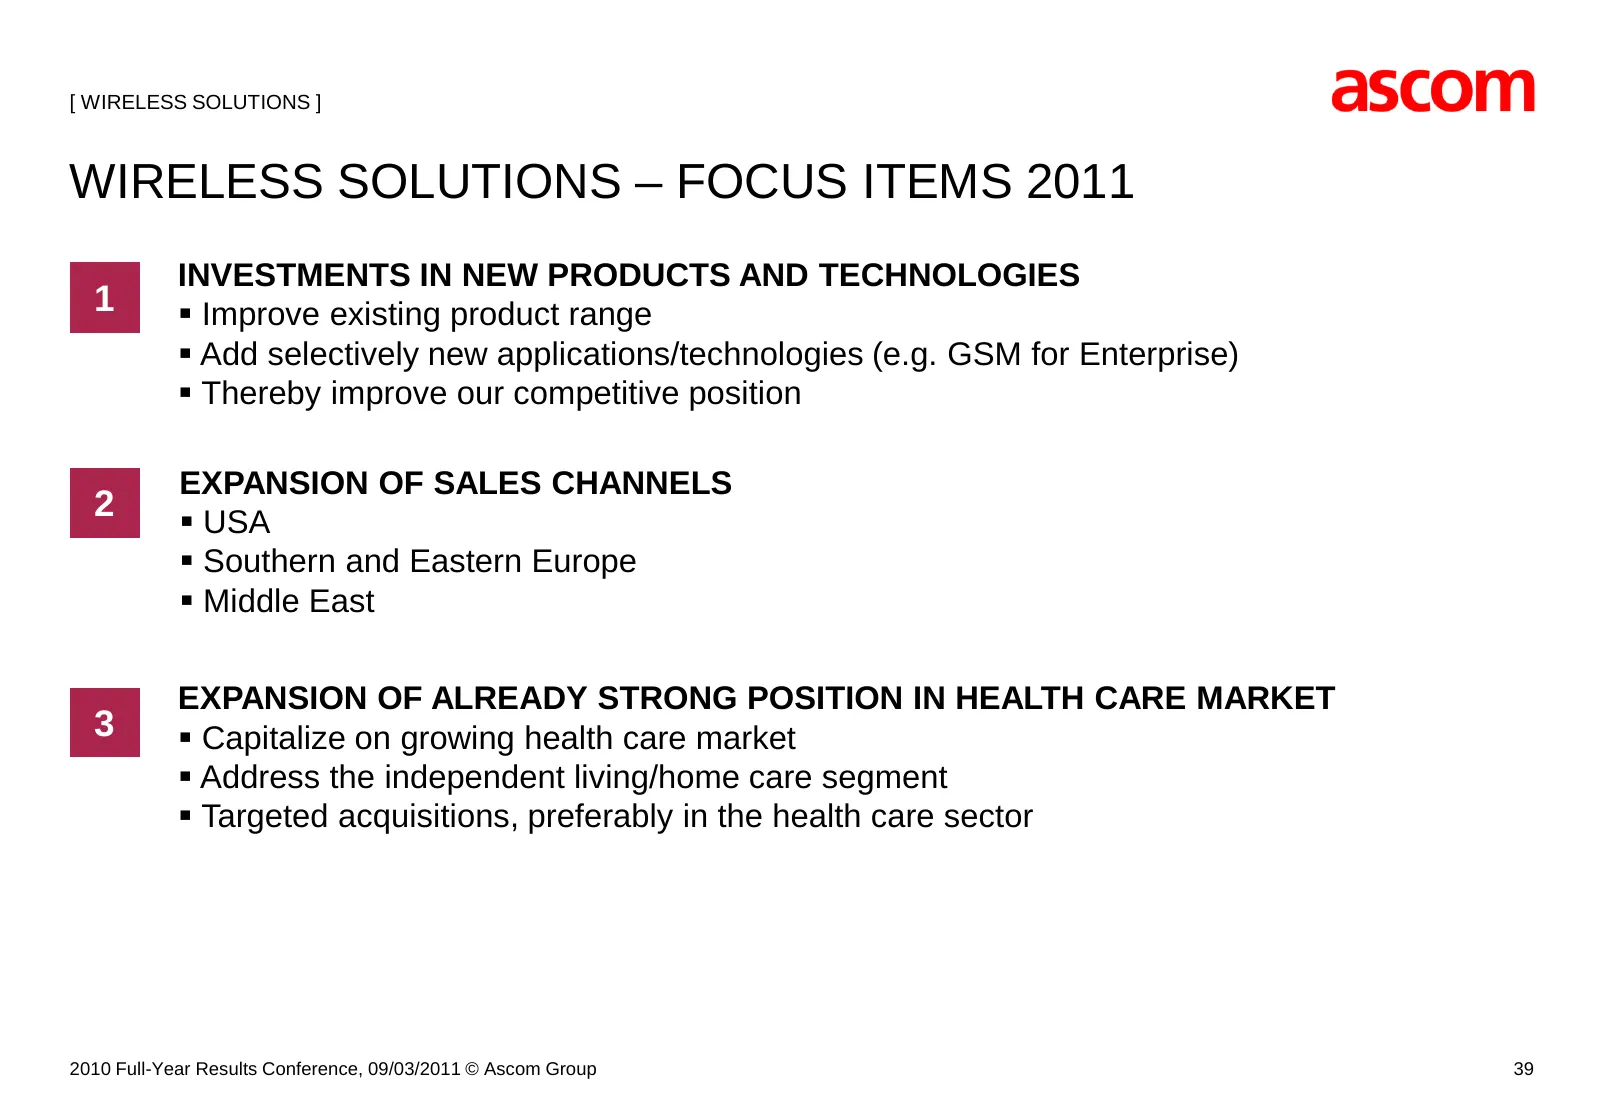
Slide 34: Wireless Solutions – Focus Items 2011
[ WIRELESS SOLUTIONS ] WIRELESS SOLUTIONS – FOCUS ITEMS 2011 INVESTMENTS IN NEW PRODUCTS AND TECHNOLOGIES 1 Improve existing product range Add selectively new applications/technologies (e.g. GSM for Enterprise) Thereby improve our competitive position EXPANSION OF SALES CHANNELS 2 USA Sout
Slide 35: Value Creation Network Testing
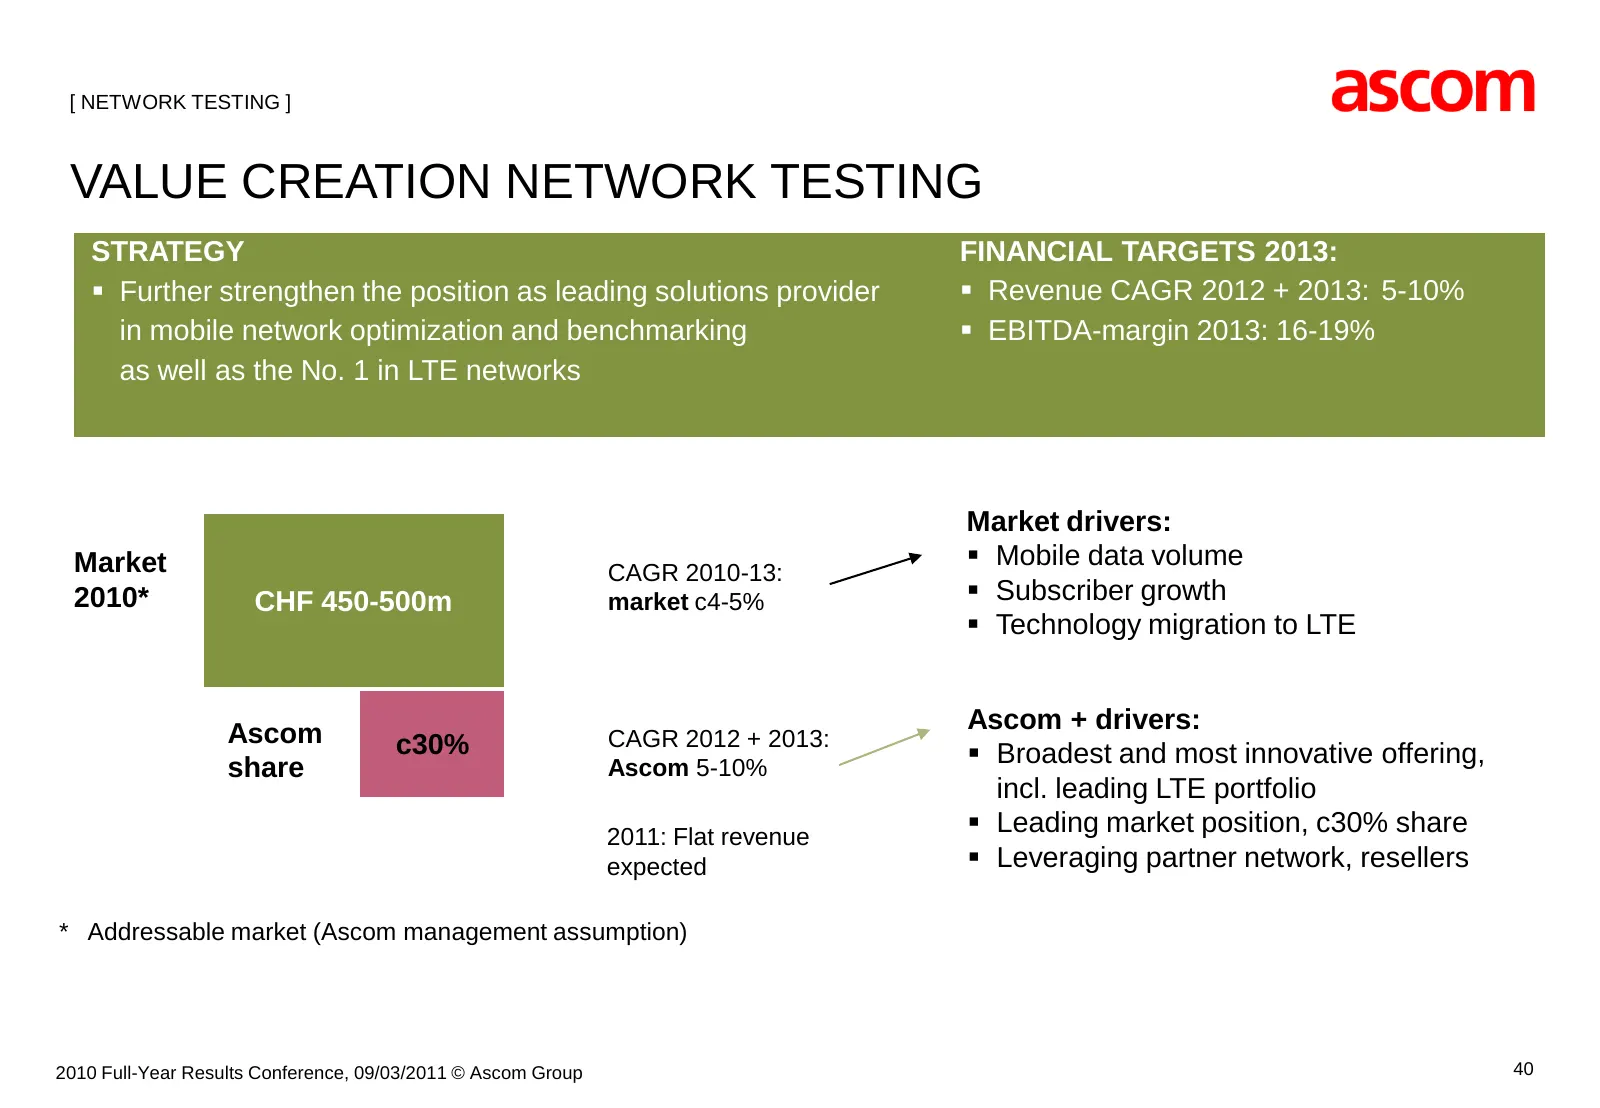
[ NETWORK TESTING ] VALUE CREATION NETWORK TESTING STRATEGY FINANCIAL TARGETS 2013: Further strengthen the position as leading solutions provider Revenue CAGR 2012 + 2013: 5-10% in mobile network optimization and benchmarking EBITDA-margin 2013: 16-19% as well as the No. 1 in LTE networks Mark
Slide 36: Network Testing – Focus Items 2011
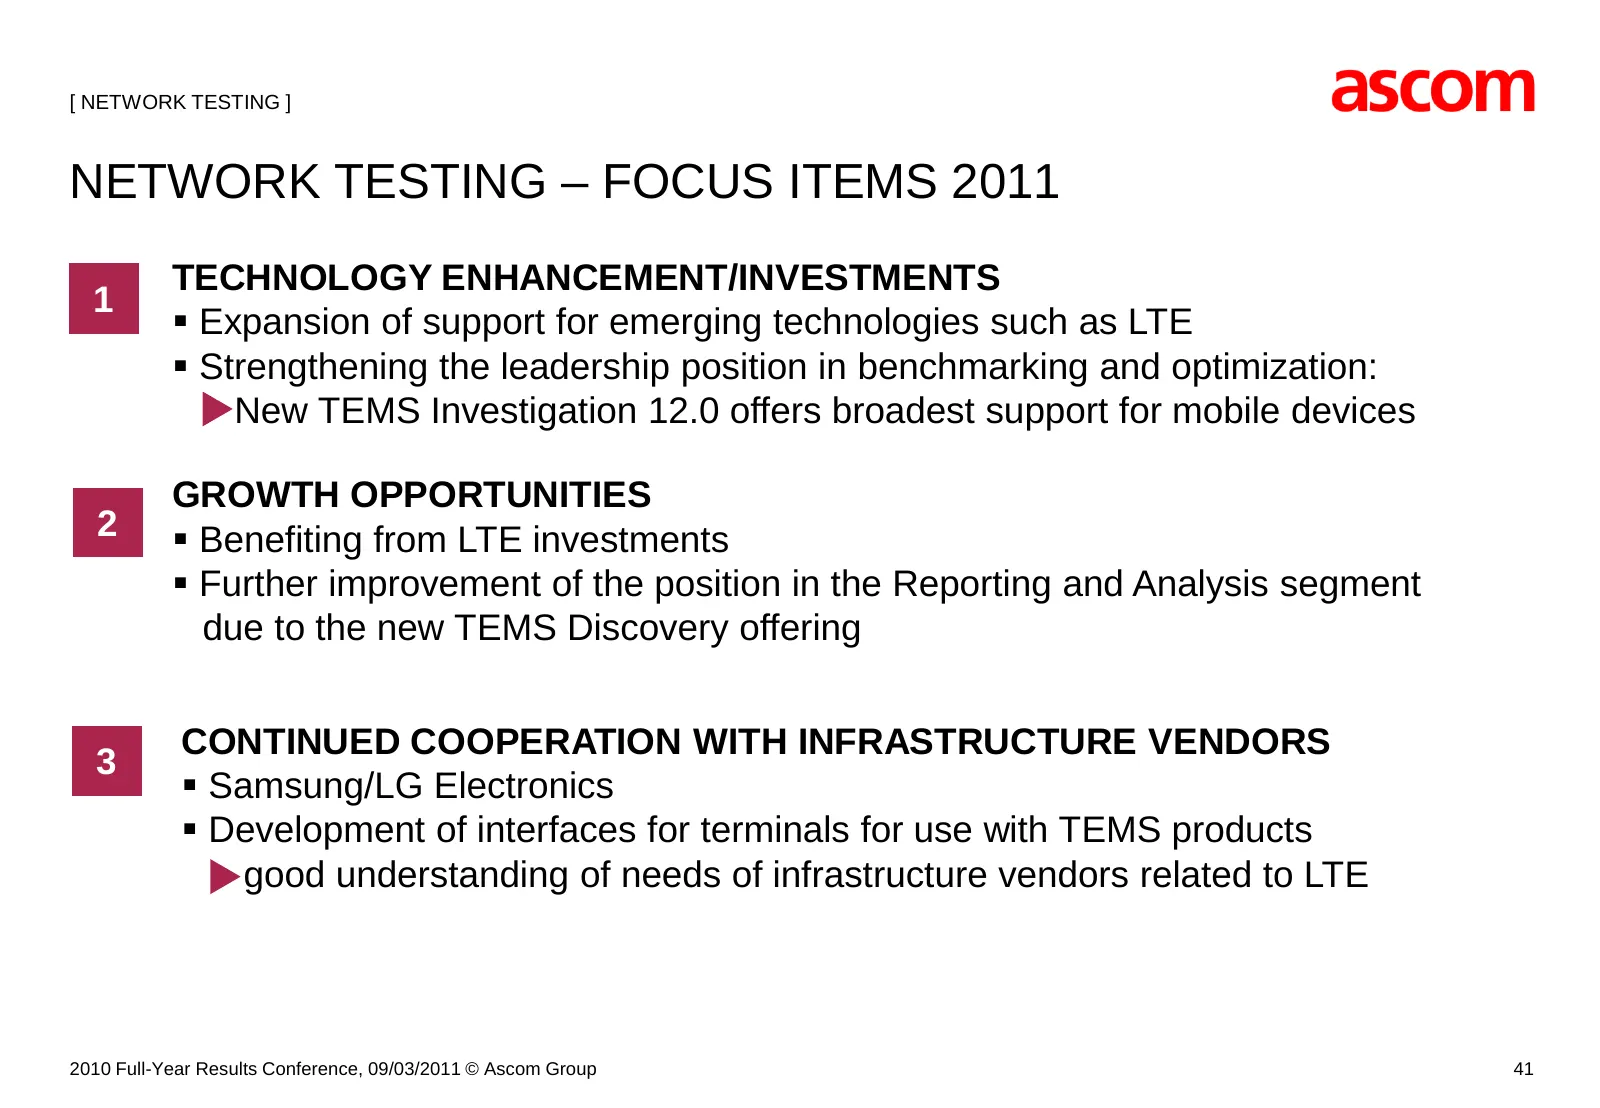
[ NETWORK TESTING ] NETWORK TESTING – FOCUS ITEMS 2011 TECHNOLOGY ENHANCEMENT/INVESTMENTS 1 Expansion of support for emerging technologies such as LTE Strengthening the leadership position in benchmarking and optimization: > New TEMS Investigation 12.0 offers broadest support for mobile devices
Slide 37: Value Creation Security Communication
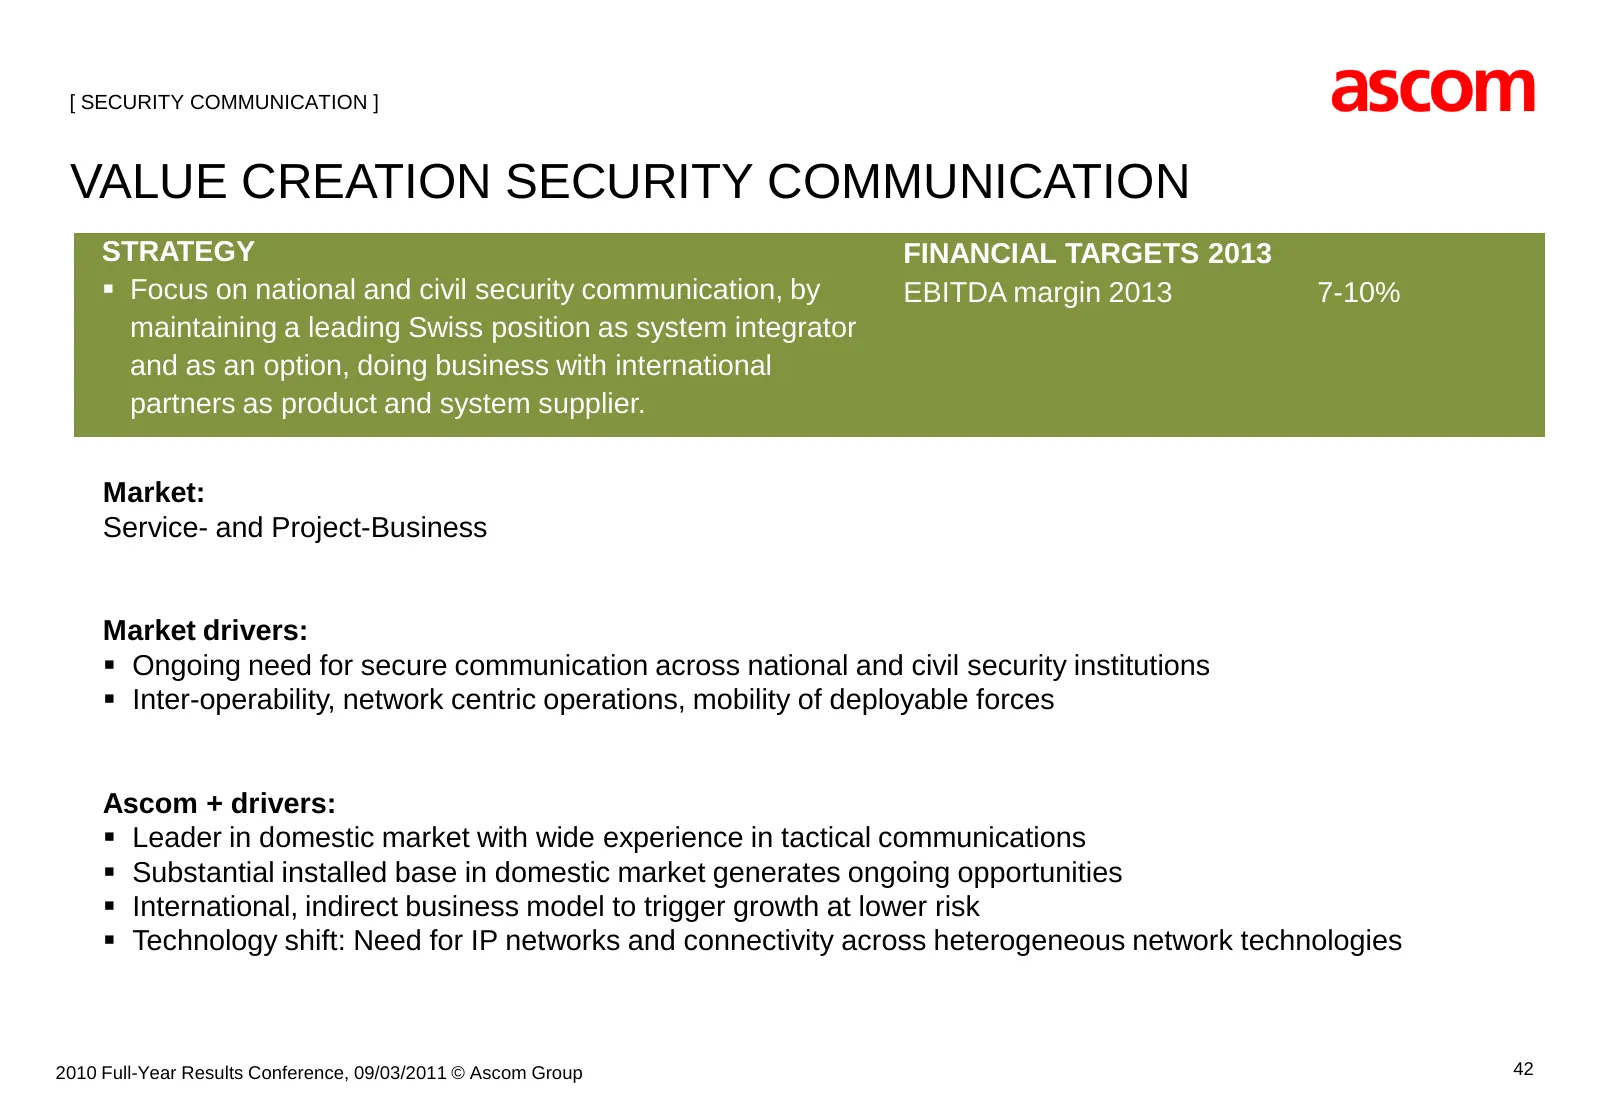
[ SECURITY COMMUNICATION ] VALUE CREATION SECURITY COMMUNICATION STRATEGY FINANCIAL TARGETS 2013 Focus on national and civil security communication, by EBITDA margin 2013 7-10% maintaining a leading Swiss position as system integrator and as an option, doing business with international partners as
Slide 38: Security Communication – Focus Items 2011
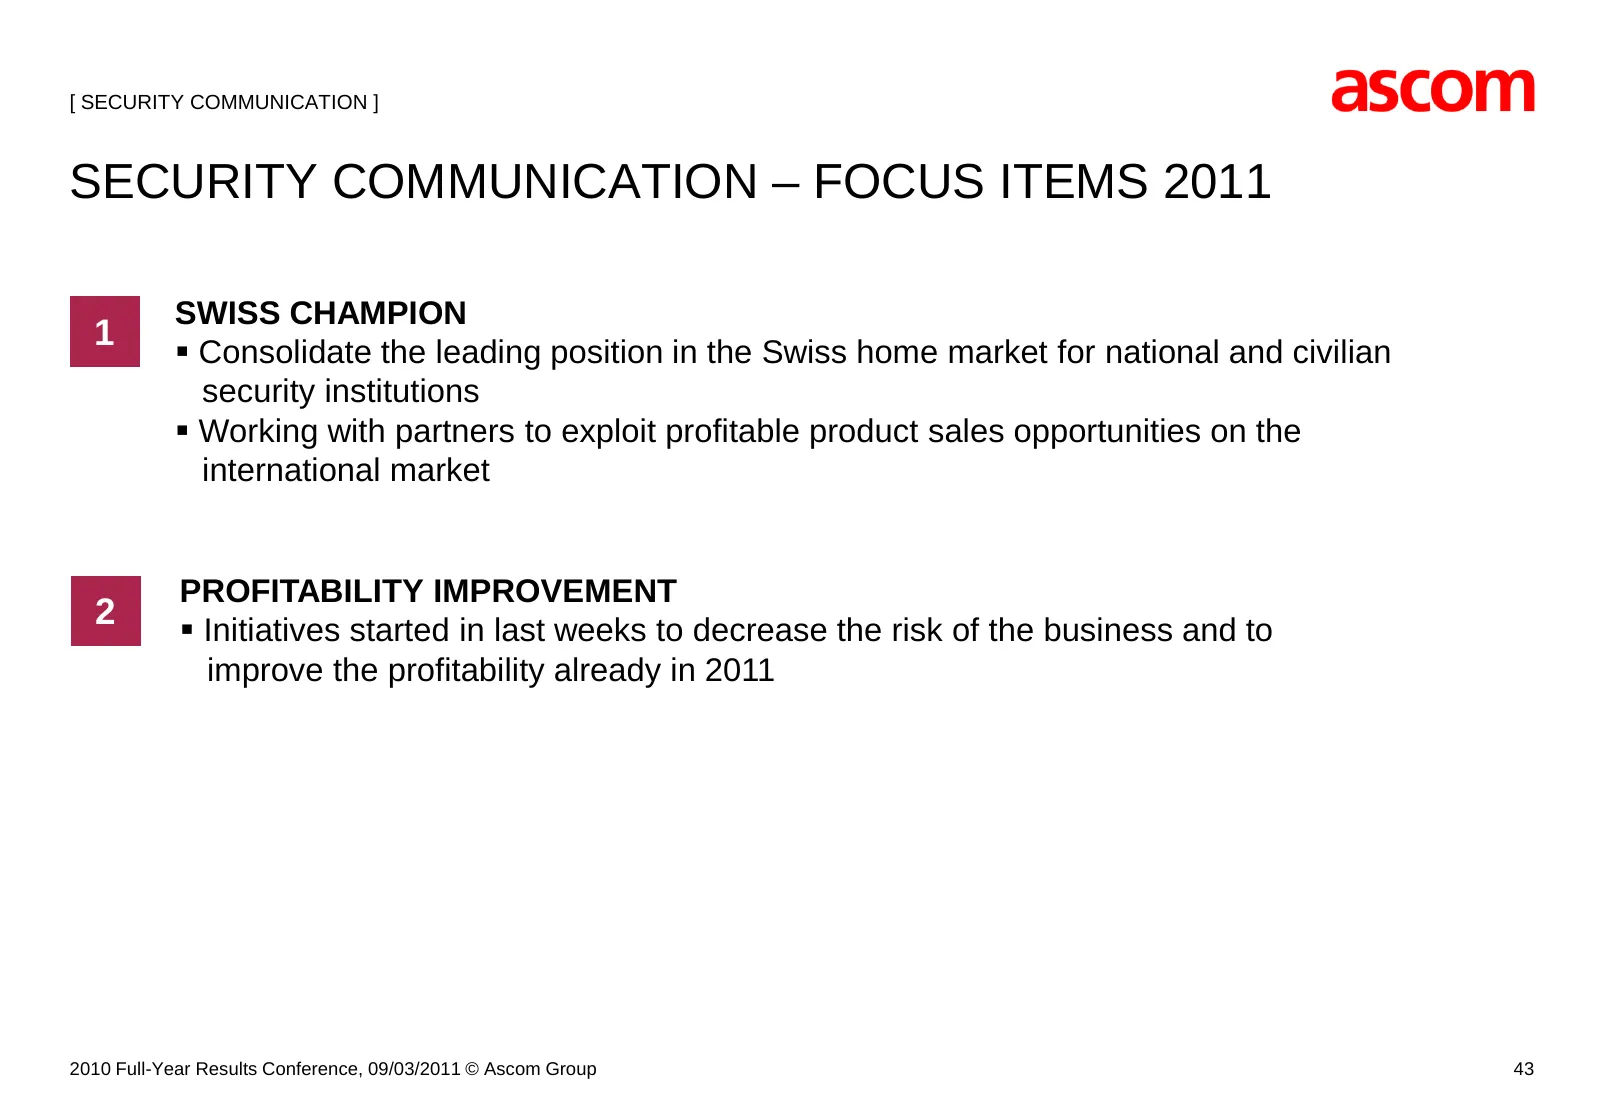
[ SECURITY COMMUNICATION ] SECURITY COMMUNICATION – FOCUS ITEMS 2011 SWISS CHAMPION 1 Consolidate the leading position in the Swiss home market for national and civilian security institutions Working with partners to exploit profitable product sales opportunities on the international market PROF
Slide 39: Outlook
[ ] OUTLOOK 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 44
Slide 40: Divisional Targets for 2012/2013 Plan
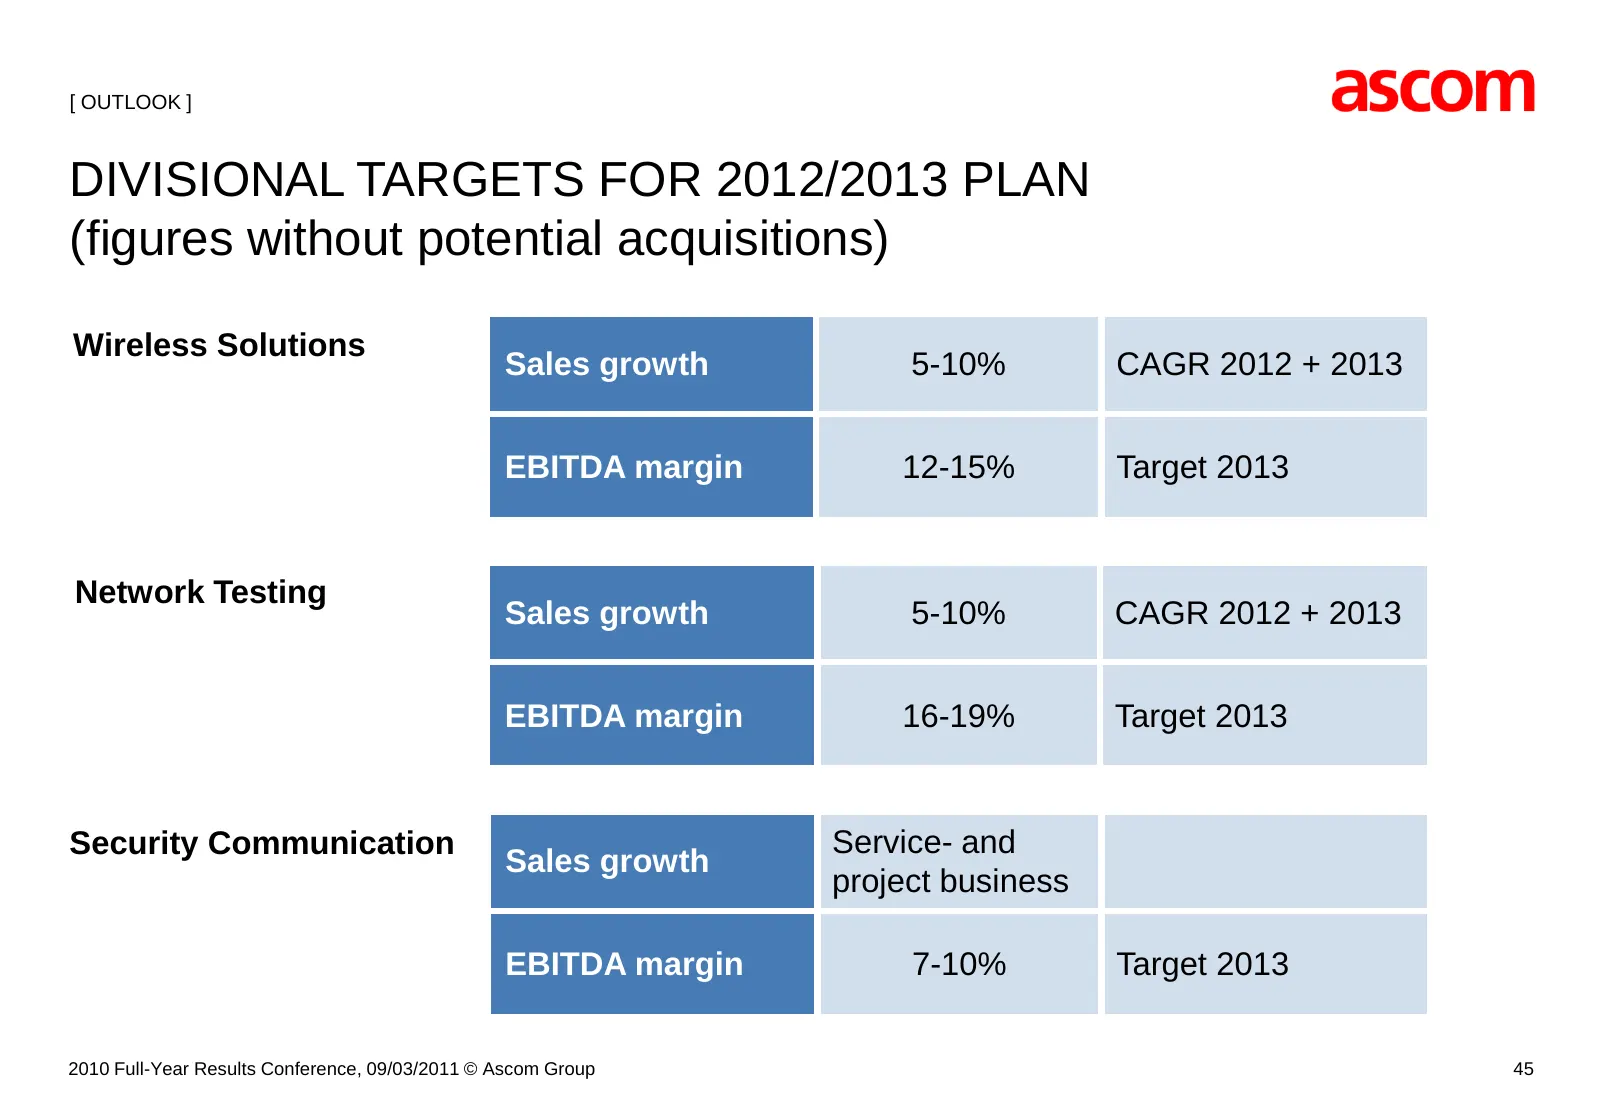
[ OUTLOOK ] DIVISIONAL TARGETS FOR 2012/2013 PLAN (figures without potential acquisitions) Wireless Solutions Sales growth 5-10% CAGR 2012 + 2013 EBITDA margin 12-15% Target 2013 Network Testing Sales growth 5-10% CAGR 2012 + 2013 EBITDA margin 16-19% Target 2013 Security Communication Service- and
Slide 41: Outlook 2011
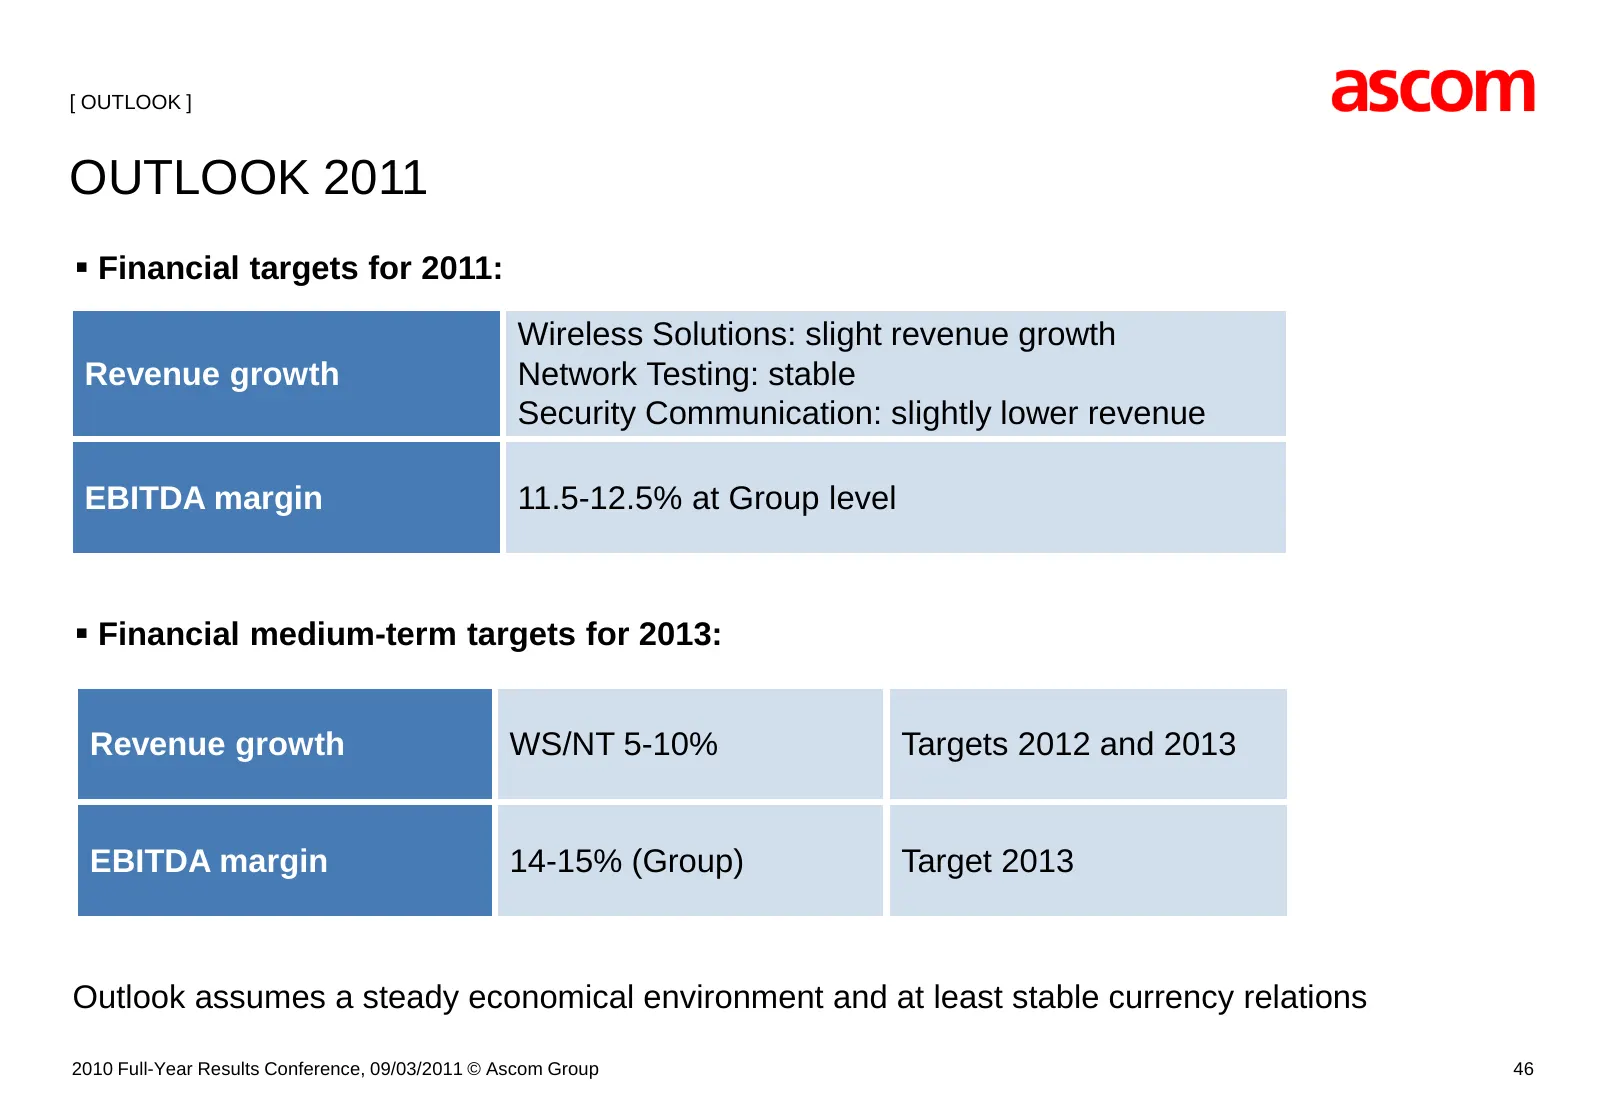
[ OUTLOOK ] OUTLOOK 2011 Financial targets for 2011: Wireless Solutions: slight revenue growth Revenue growth Network Testing: stable Security Communication: slightly lower revenue EBITDA margin 11.5-12.5% at Group level Financial medium-term targets for 2013: Revenue growth WS/NT 5-10% Targets
Slide 42: Questions & Answers
[ ] QUESTIONS & ANSWERS 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 47
Slide 43: Legal Disclaimer
LEGAL DISCLAIMER This document contains specific forward-looking statements, e.g. statements including terms like “believe”, “expect” or similar expressions. Such forward-looking statements are subject to known and unknown risks, uncertainties and other factors which may result in a substantial dive
Slide 44: Thank You!
THANK YOU! 2010 Full-Year Results Conference, 09/03/2011 © Ascom Group 49
Source: Internet Archive copy of ascom.com