CEVA, Inc. · NASDAQ:CEVA
CEVA — Investor Day (January 2019)
166 slides from CEVA's investor day presentation, Jan 14, 2019
Slide 1: Welcome to CEVA 2019 Investor and Analyst Day
Welcome to CEVA 2019 Investor and Analyst Day Richard Kingston
Slide 2: Legal Notice
Legal Notice © Forward Looking Statement This presentation contains forward-looking statements and projections about our strategy, market opportunity, customer base, product penetration and market share, stockholder returns, and our future performance and achievements, financial and otherwise. These
Slide 3: Billion CEVA-powered devices shipped worldwide
Billion CEVA-powered devices shipped worldwide
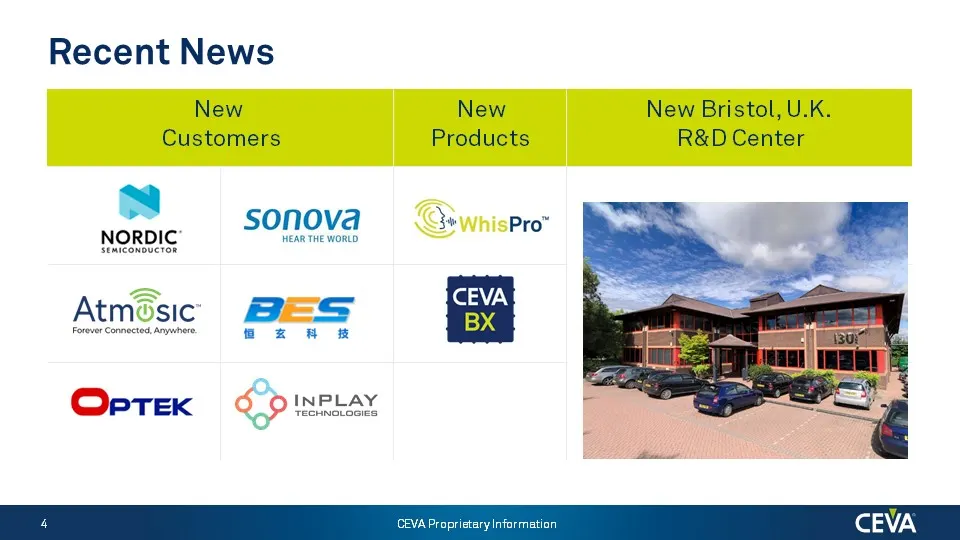
Slide 4: Recent News
Recent News New Customers nore SONOMA New Products 3» Pro™ CEVA BX CEVA Proprietary Information New Bristol, U.K. R&D Center
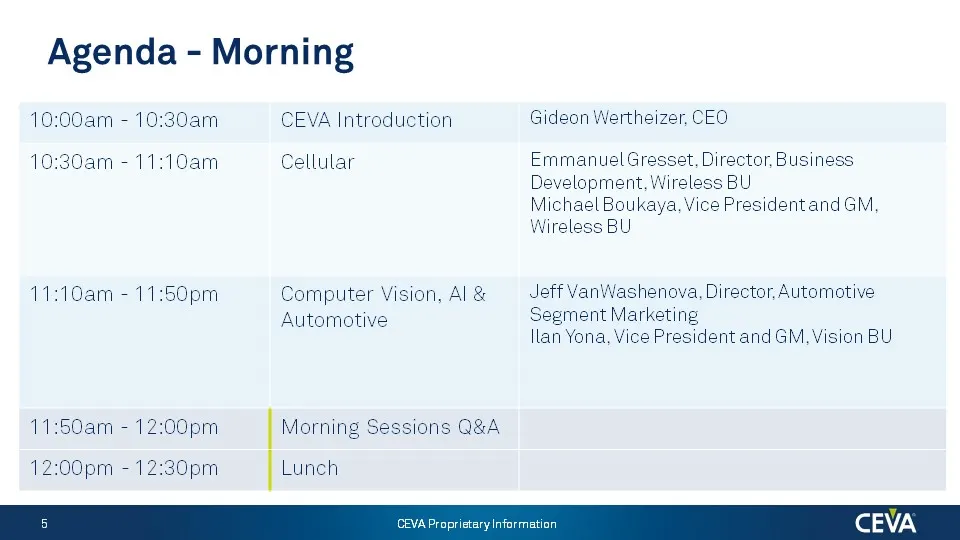
Slide 5: Agenda - Morning
Agenda - Morning 10:00am - 1 10:30am - 11: 11:10am - 11: 11:50am - 12:00pm 12:00pm - 12:30pm A Introduction Cellular Computer Vision, Al & Automotive Morning Sessions Q&A Lunch Gideon Wertheizer, CEO Emmanuel Gresset, Director, Business Development. Wireless BU Michael Boukaya. Vice President and GM
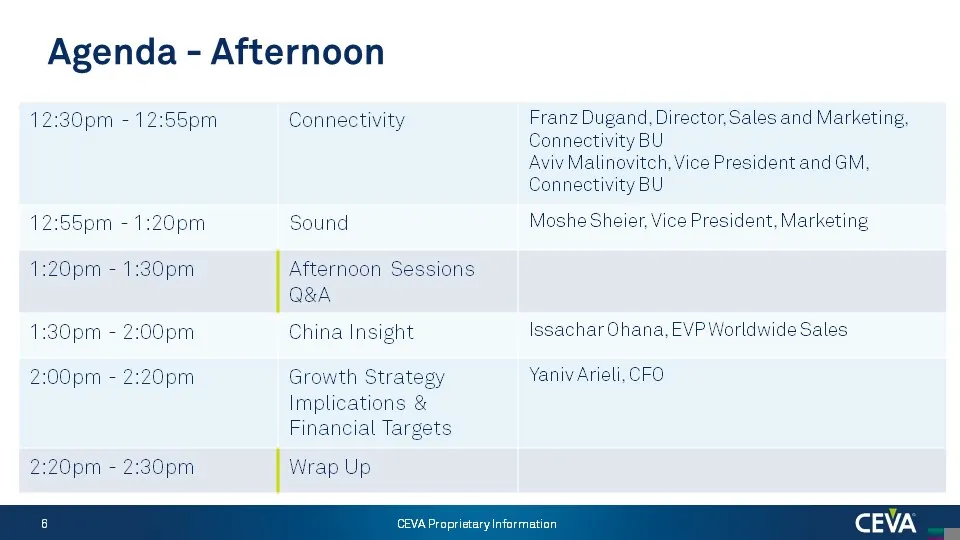
Slide 6: Agenda - Afternoon
Agenda - Afternoon 12 5pm Connectivity Franz Dugand, Director. Sales and Marketing. Connectivity BU Aviv Malinovitch, Vice President and GM Connectivity BU pm - 12: 12:55pm - 1:20pm Sound Moshe Sheier, Vice President, Marketing 1:20pm - 1:30pm Afternoon Sessions Q&A 1:30pm - Jpm China Insight Issach
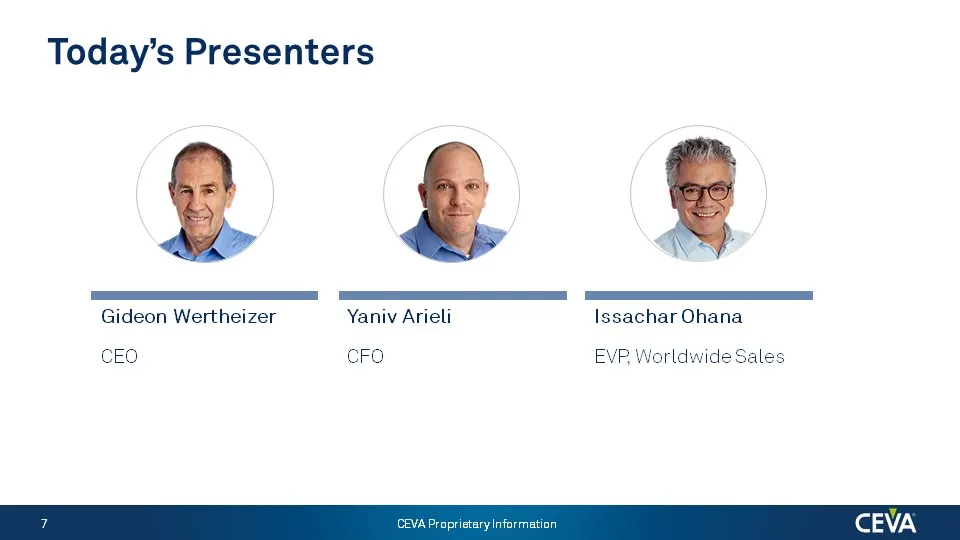
Slide 7: Today's Presenters
Today’s Presenters — EE Gideon Wertheizer Yaniv Arieli Issachar Ohana CEO CFO EVP, Worldwide Sales CEVA Proprietary Information CEVA
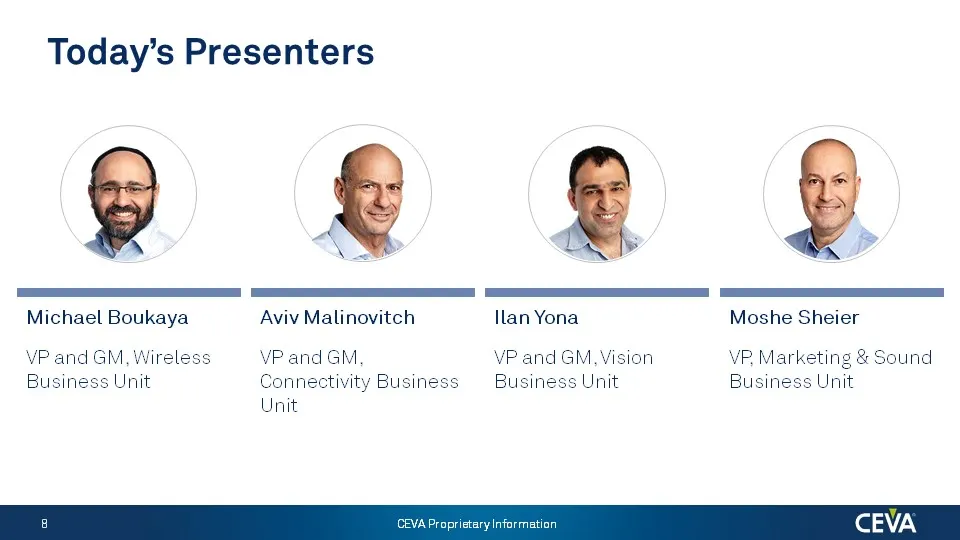
Slide 8: Today's Presenters
Today’s Presenters ‘ ) XX ¢ aw Michael Boukaya Aviv Malinovitch Ilan Yona Moshe Sheier VP and GM, Wireless VP and GM VP and GM, Vision VP, Marketing & Sound Business Unit Connectivity Business Business Unit Business Unit Unit CEVA
Slide 9: Today's Presenters
Today’s Presenters Emmanuel Gresset Jeff VanWashenova Franz Dugand Director, Business Director, Automotive Director, Sales & Development, Wireless Segment Marketing Marketing, Connectivity Business Unit Business Unit CEVA Proprietary Information CEVA
Slide 10: CEVA: Signal Processing and AI Platforms for a Smarter, Connected World
CEVA Signal Processing and Al Platforms for a Smarter, Connected World Gideon Wertheizer www.ceva-dsp.com Copyright © 2019 CEVA, Inc.
Slide 11: CEVA at a Glance
CEVA at a Glance We innovate and license technologies that process and connect data from sensors for the Internet of Things Short Range Connectivity Smart Sensing EverythingCellular CEVA Proprietary Information CEVA
Slide 12: Everything Cellular
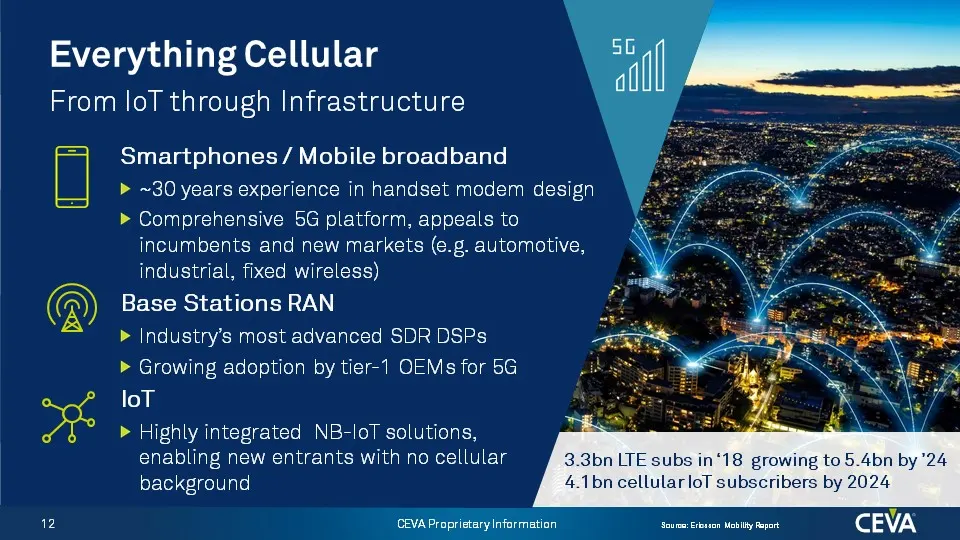
Everything Cellular From loT through Infrastructure A) iis 12 Smartphones / Mobile broadband > ~30 years experience in handset modem design > Comprehensive 5G platform, appeals to incumbents and new markets (e.g. automotive, industrial, fixed wireless) Base Stations RAN > Industry's most advanced SD
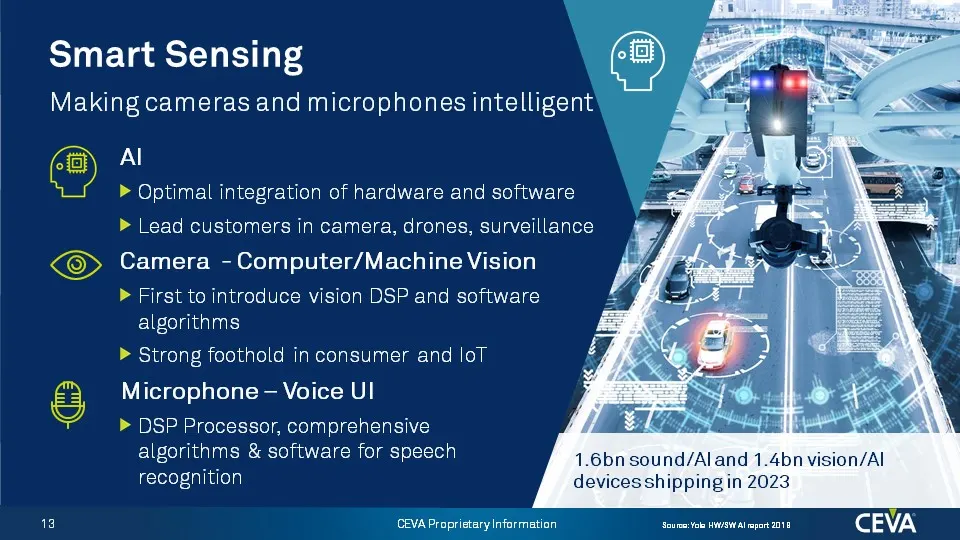
Slide 13: Smart Sensing
Smart Sensing Making cameras and microphones intelligent Al > Optimal integration of hardware and software > Lead customers in camera, drones, surveillance Camera - Computer/Machine Vision > First to introduce vision DSP and software algorithms > Strong foothold in consumer and loT = Microphone - Vo
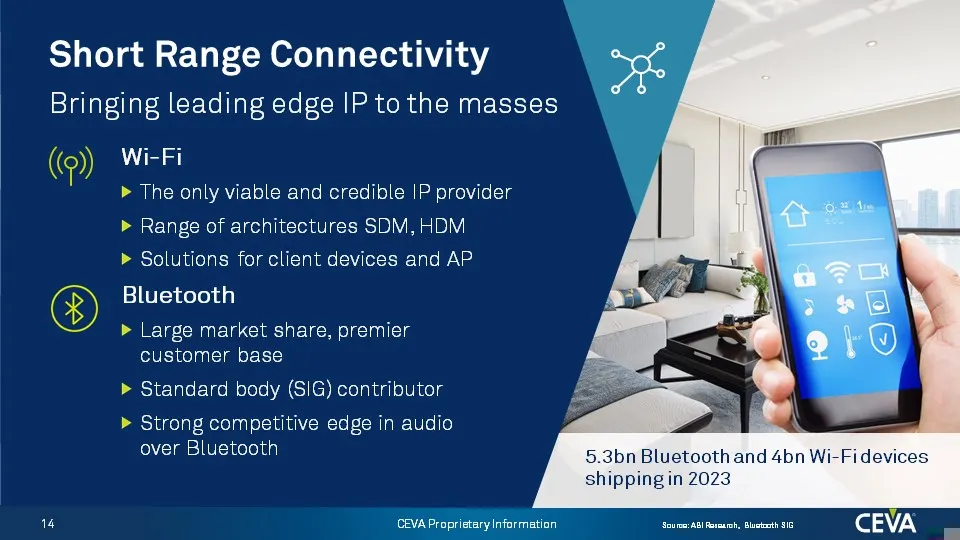
Slide 14: Short Range Connectivity
Short Range Connectivity Bringing leading edge IP to the masses KC) Wi-Fi > The only viable and credible |P provider > Range of architectures SDM, HDM > Solutions for client devices and AP Bluetooth > Large market share, premier customer base > Standard body (SIG) contributor > Strong competitive ed
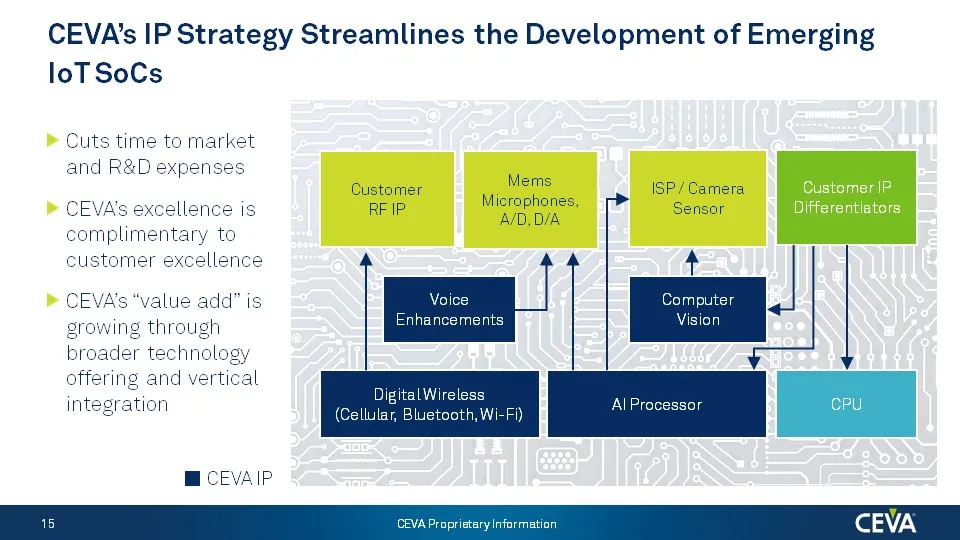
Slide 15: CEVA's IP Strategy Streamlines the Development of Emerging IoT SoCs
CEVA’s IP Strategy Streamlines the Development of Emerging loT SoCs Cuts time to market and R&D nses Mems Customer ee Customer IP icrophones, RE IP peeren Differentiators Voice Computer 4 Enhancements Vision Clie ieiesa Al Processor CPU (Cellular, Bluetooth, Wi-Fi °EVA Propristary Information CEVA
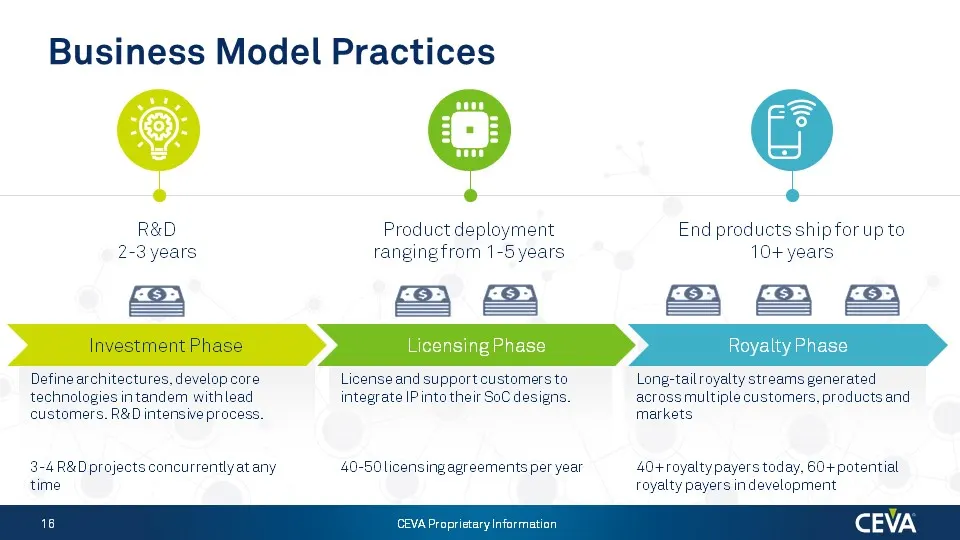
Slide 16: Business Model Practices
Business Model Practices © R&D Product dept: 2-3 years ranging fi 1 és & eH & & loyment End products ship for up to 5 years 10+ years Define architectures, develop care License and support customers to Long-tailroyalty streams generated technologies intandem withlead integrate IP into their SoC desi
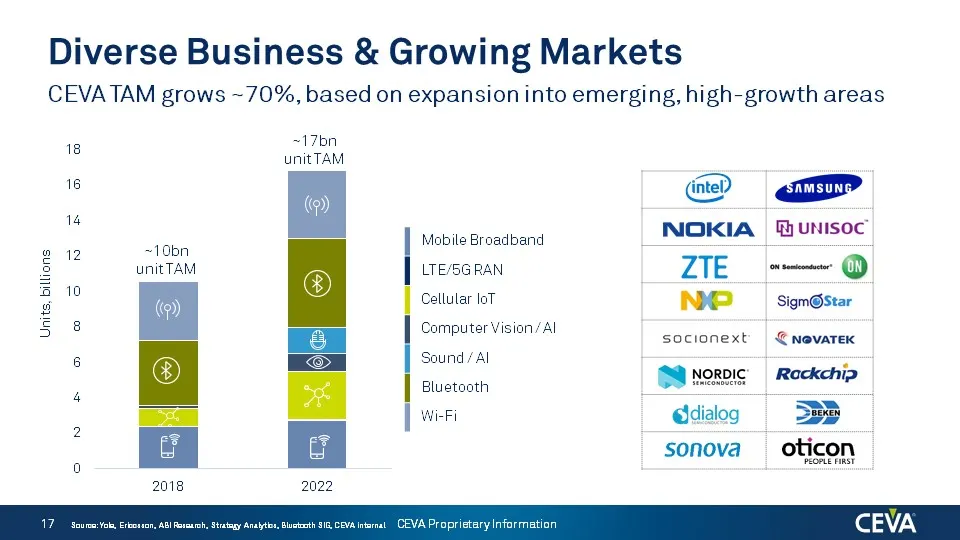
Slide 17: Diverse Business & Growing Markets
Diverse Business & Growing Markets CEVATAM grows ~70%, based on expansion into emerging, high-growth areas 18 16 14 Units. billions ~10bn unitTAM Ea 2018 ~17bn unit TAM 2022 NOKIA @unisoc | Mobite Broadband | wescran ZTE = @ | cettutar or N©@ - Sigm@star Comptenvasionwal socionext’ €NevareK Sound /A
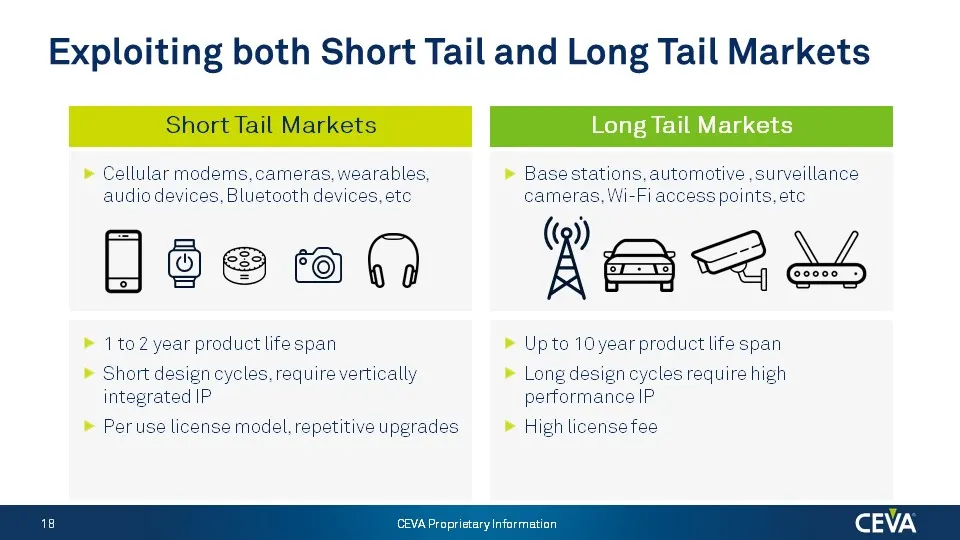
Slide 18: Exploiting both Short Tail and Long Tail Markets
Exploiting both Short Tail and Long Tail Markets ive surveillance t lifespan > r product life span » Short design cycle: integrated IP » Peruse license model, repetitive upgrades require vertically jesign cycles require high 18 CEVA
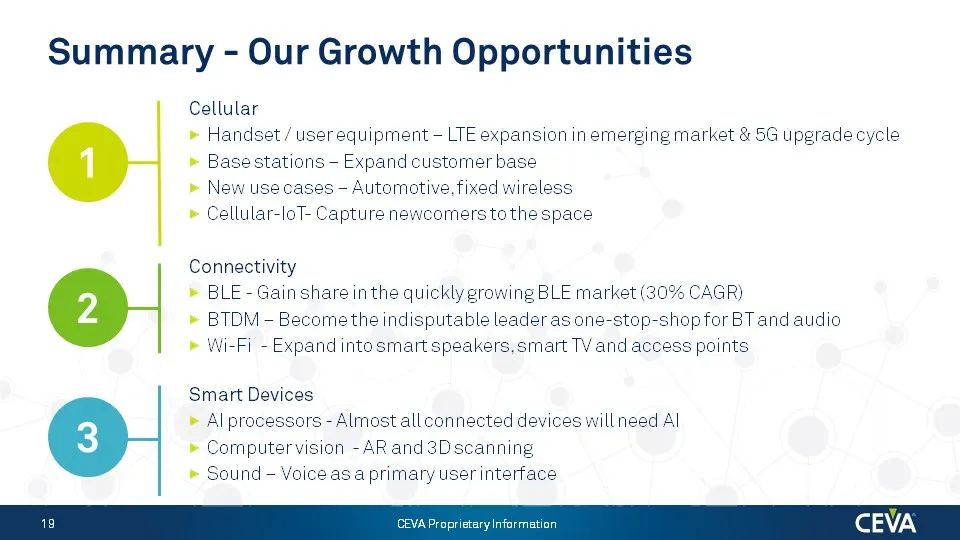
Slide 19: Summary - Our Growth Opportunities
Summary - Our Growth Opportunities Cellular » Handset / user equipment — LTE expansion in emerging rnarket & 5G upgrade cycle » Base stations - Expand customer base » New use cases - Automotive, fix » Cellular-loT- Capture newcomers tothe spi eless Connectivity » BLE - Gain share in the quickly grow
Slide 20: Thank You
Thank You
Slide 21: Cellular
CEVA Cellular Michael Boukaya Emmanuel Gresset www.ceva-dsp.com Copyright © 2019 CEVA, Inc.
Slide 22: 5G Vastly Expands Services and Use Cases
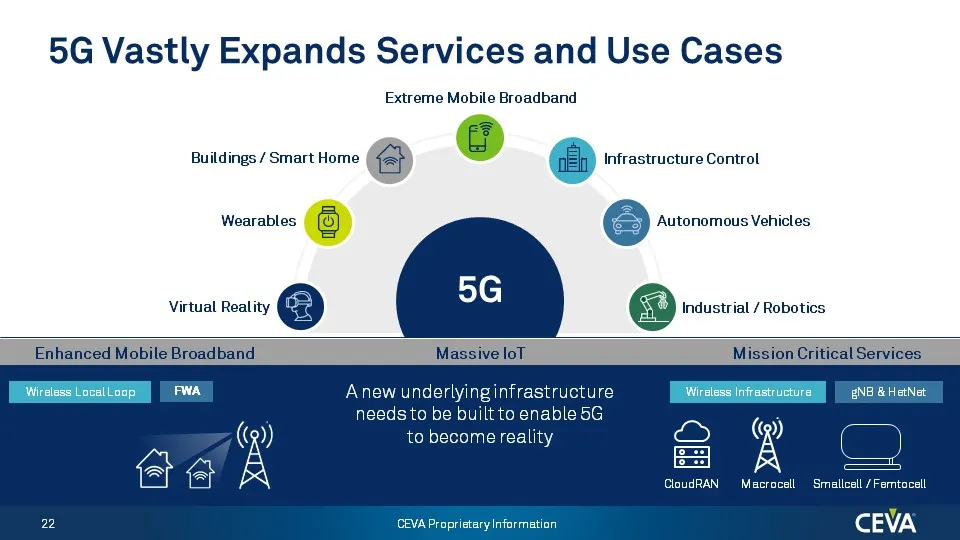
5G Vastly Expands Services and Use Cases Extreme Mobile Broadband & ‘En Infrastructure Control Buildings / Smart Home Wearables Virtual Reality @ Autonomous Vehicles Industrial / Robotics Enhanced Mobile Broadband Massive loT Mission Critical Services Anew underlyinginfrastructure gNB & HatNet needs
Slide 23: Cellular Market Dynamics & Opportunities
Cellular Market Dynamics & Opportunities CEVA Proprietary Information
Slide 24: Strong Growth of Mobile Broadband
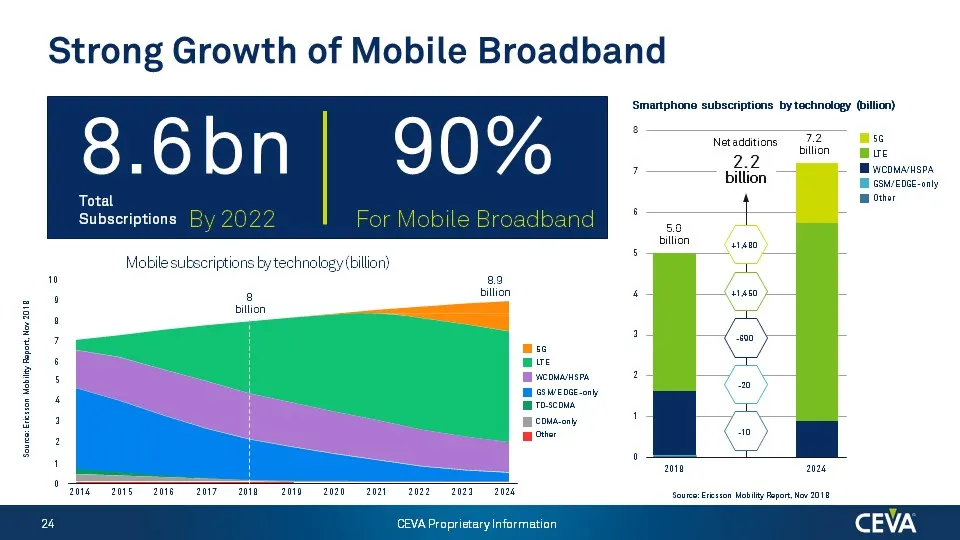
Sous: Erkston Mbit po, Ho 2018 Strong Growth of Mobile Broadband 8.6bn Total Subscriptions B) For Mobile sutscriptions by technology billion) e billion 90% Mobile Br 29 billion ——_—| 7 I wcomasna WE0GE-onl Bl cOMA.on othe: CEVA Proprietary Information ‘Smartphone subscriptions by technology (billion
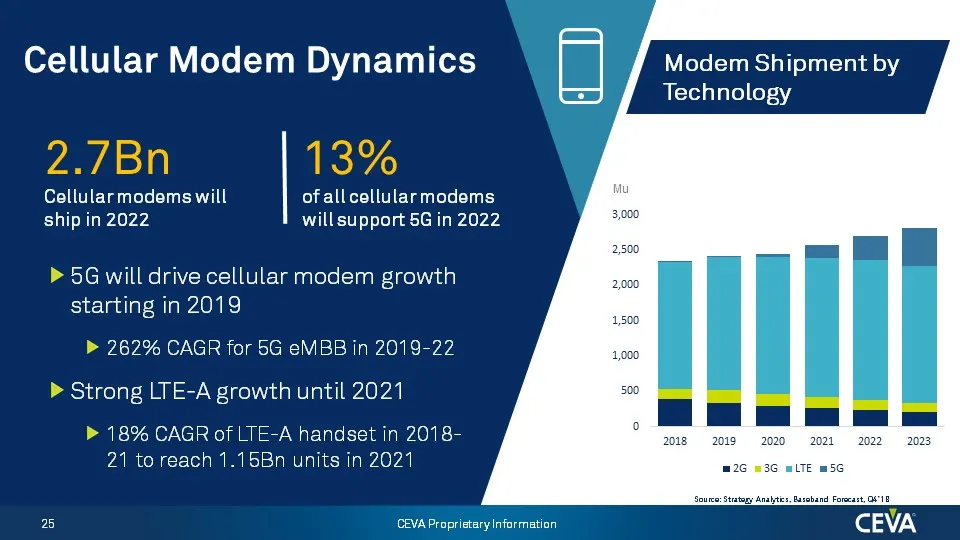
Slide 25: Cellular Modem Dynamics
Cellular Modem Dynamics Modem Shipment by oz) Technology 2.7Bn 13% Collularmodems will of allcellularmodems ship in 2022 will support 5G in 2022 > 5G will drive cellular modem growth starting in 2019 > 262% CAGR for 5G eMBB in 2019-22 > Strong LTE-A growth until 2021 > 18% CAGR of LTE-A handset in 2
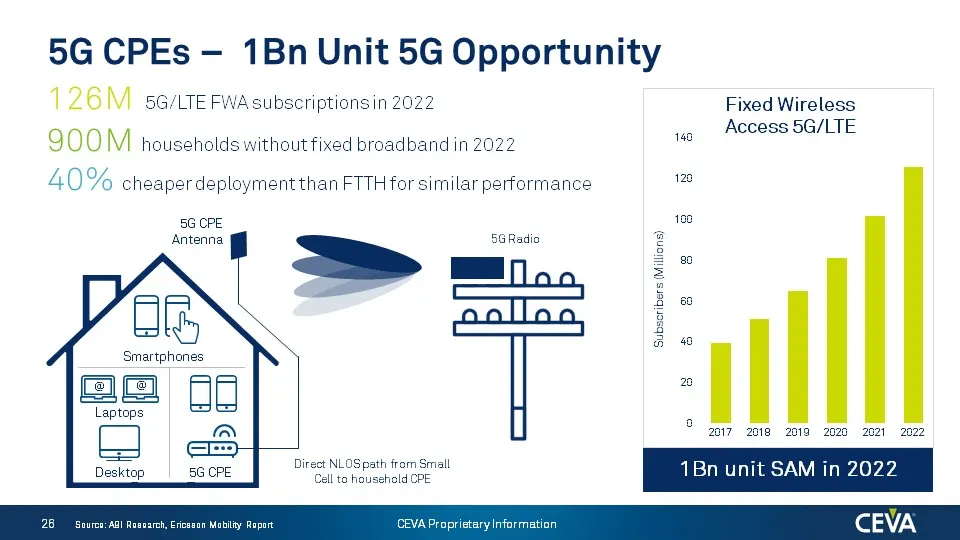
Slide 26: 5G CPEs — 1Bn Unit 5G Opportunity
5G CPEs — 1Bn Unit 5G Opportunity 126M saver 900M house subscriptionsin 2022 vithout fixed band in 2022 Fixed Wireless Access 5G/LTE 40% « oyment than FTTH for similar performance de 5G CPE Antenna 5G Radio a ie 3 tke) i « Smartphones ! 20 © por zoe 2a 2020 zo 2 Direct NLOSpath from Small | 1Bnunit
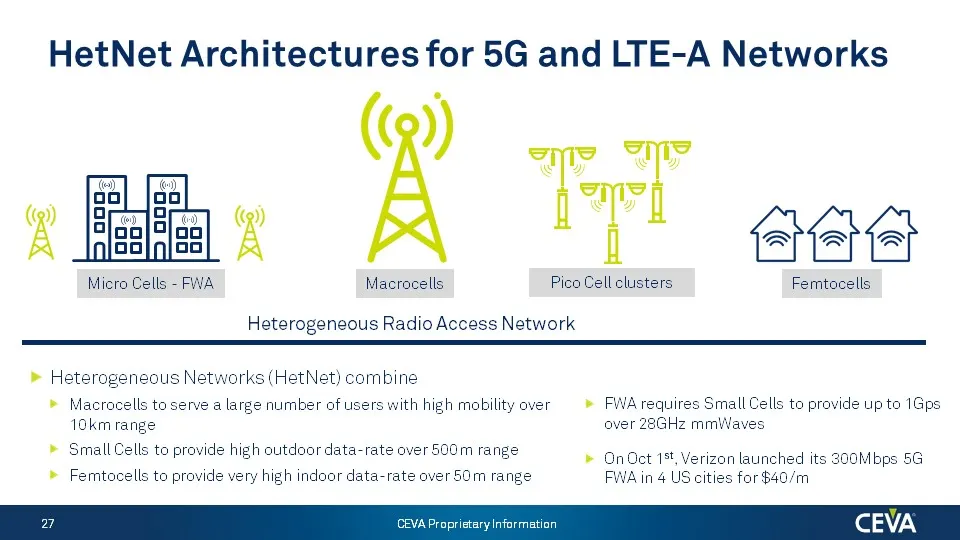
Slide 27: HetNet Architectures for 5G and LTE-A Networks
HetNet Architectures for 5G and LTE-A Networks (9) cre ex aa » Ba TH eae Pico Cell clusters Femtocells Micro Cells - FWA Macrocells Heterogeneous Radio Access Network » Heterogeneous Networks (HetNet » Macrocells to serve a large number of users with high mobility over requires Small Cells to provid
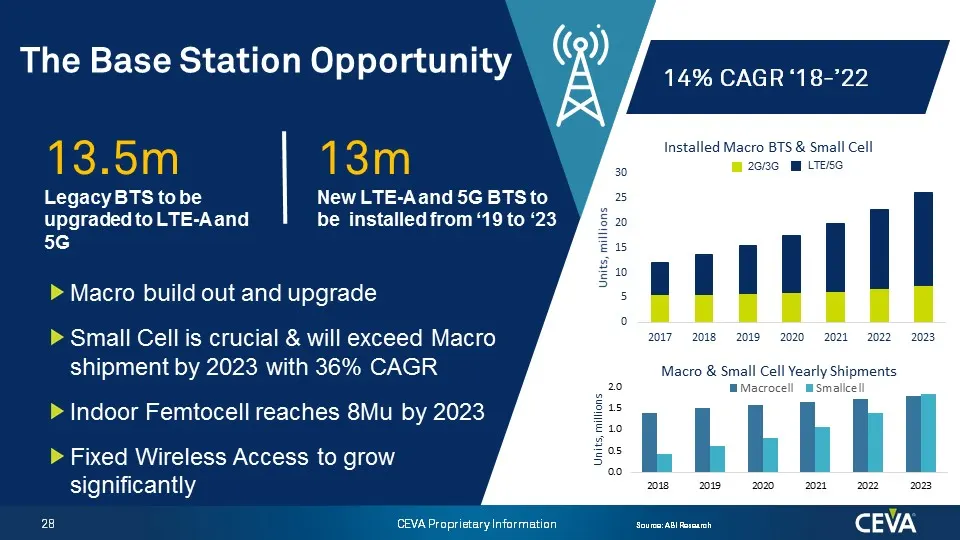
Slide 28: The Base Station Opportunity
The Base Station Opportunity 14% CAGR‘18-’22 Installed M: Cell Legacy BTS tobe New LTE-Aand 5G BTSto upgraded to LTE-Aand be installed from ‘19 to ‘23 5G Macro build out and upgrade Small Cell is crucial & will exceed Macro shipment by 2023 with 36% CAGR Indoor Femtocell reaches 8Mu by 2023 Fixed Wi
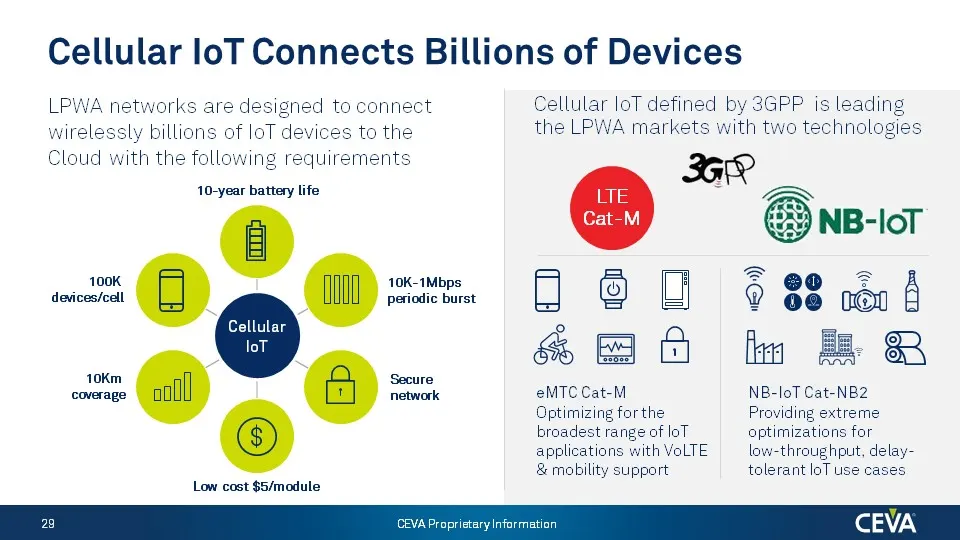
Slide 29: Cellular IoT Connects Billions of Devices
Cellular loT Connects Billions of Devices WA networks are designed to connect essly billions of Ic vices to the d with the following requirements 10-year battery life 100K 10K-1Mbps devices/cell Periodic burst Cellular loT 10Km Secure coverage network Low cost $5/module & fo eMTC Cat-M Optimizing fo
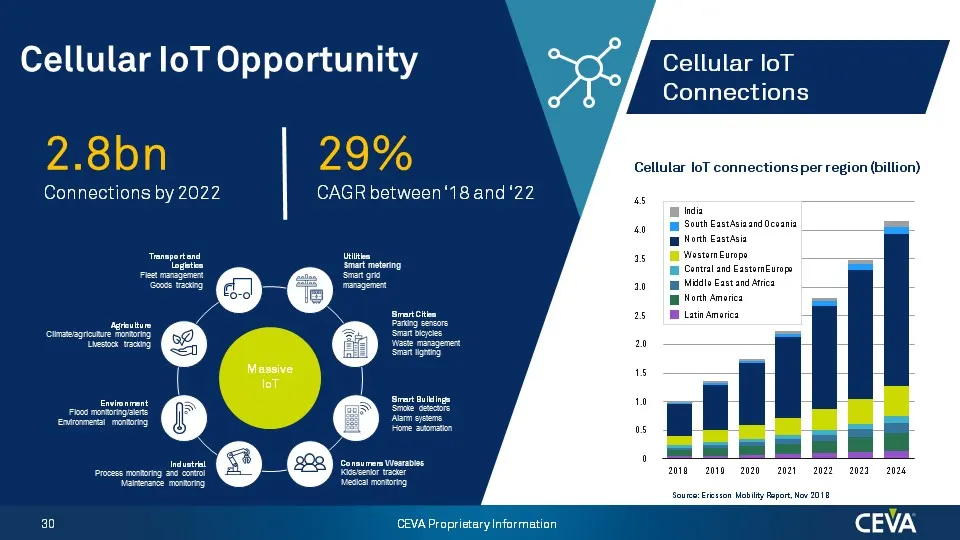
Slide 30: Cellular IoT Opportunity
Cellular loT Opportunity Cellular loT Connections Cellular loT connections per region (billion) Connections by 2022 CAGR between '18 and ‘22 4s i ida South EastAsaand Oceania Nort Eastasa Tonepartant tee as Ml WostemEuope eS seating ral and Eastom Europ rex nasgeret Sra gre one toa = aoa D lo East a
Slide 31: The Strategy
The Strategy
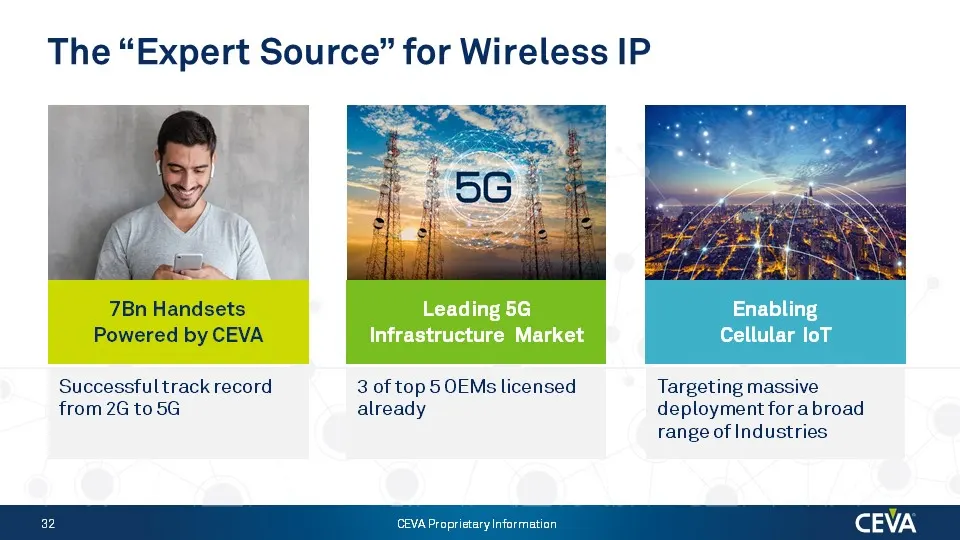
Slide 32: The "Expert Source" for Wireless IP
The “Expert Source” for Wireless IP 7Bn Handsets Powered by CEVA Successfultrack record 3 of top 5 OEMs licensed from 2G to 5G already 32 CEVA Propristaryinformation Targeting massive deployment for a broad range of Industries CEVA
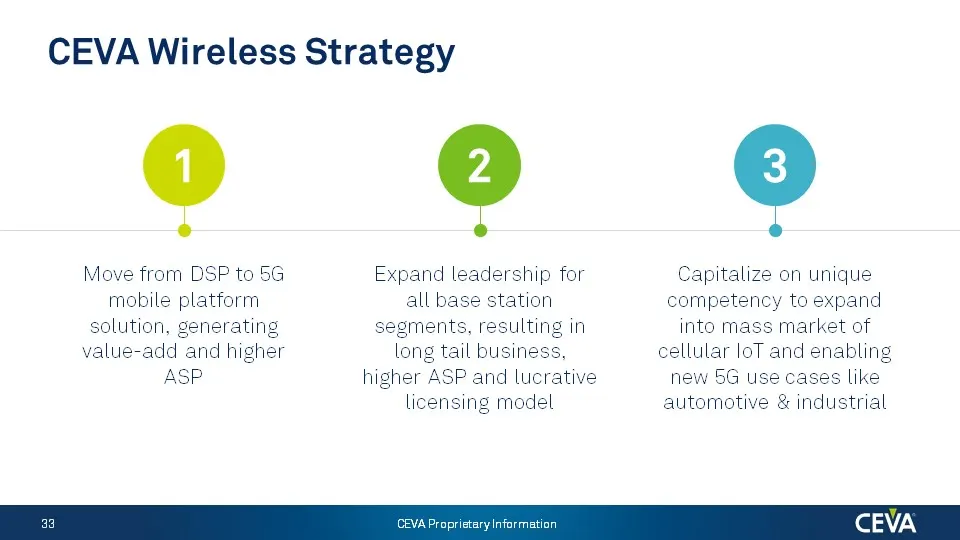
Slide 33: CEVA Wireless Strategy
CEVA Wireless Strategy o° eo 8° Move fromm DSP to 5G Expand leadership for Capitalize on unique mobile platform all base station competency to expand solution, generating segments, resulting in into mass market of value-add and higher long tail business, cellular loT and enabling ASP. higher and luc
Slide 34: Mobile Broadband
Mobile Broadband
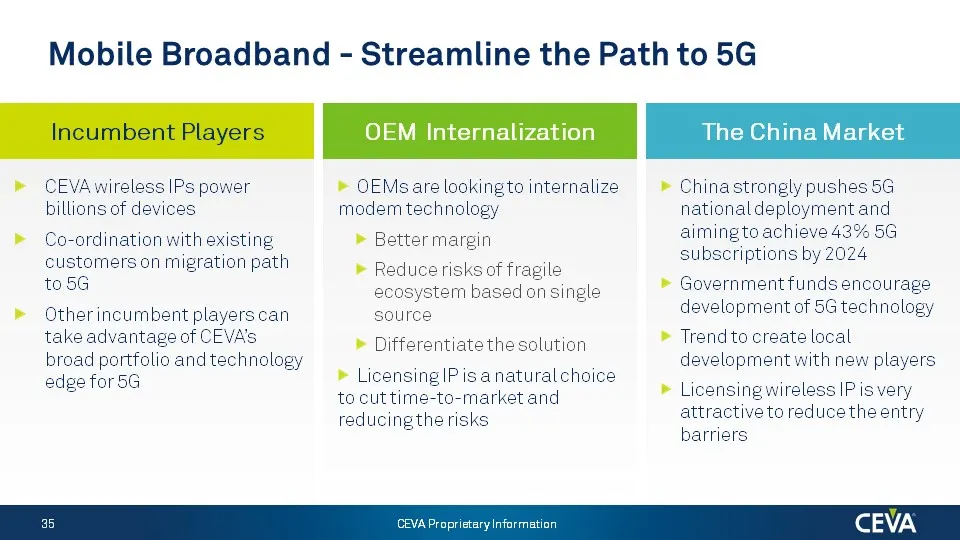
Slide 35: Mobile Broadband - Streamline the Path to 5G
Mobile Broadband - Streamline the Path to 5G —IncumbentPlayers OEM Internalization The China Market » CEVAwireless IPs power » OEMsare ingto internalize » China strongly pushes 5G billions of devices modem tech gy nationaldeployment and » Co-ordination with existing » Better margin aiming to achieve
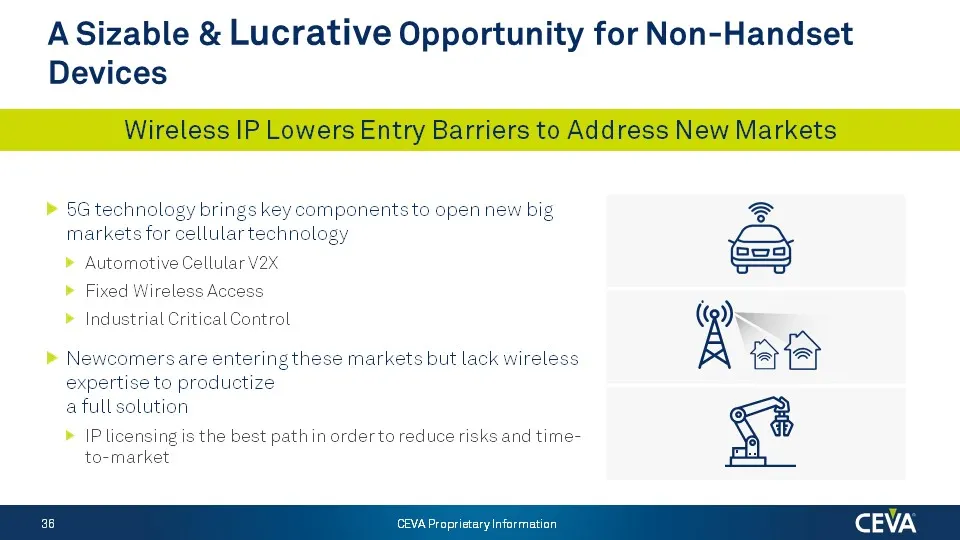
Slide 36: A Sizable & Lucrative Opportunity for Non-Handset Devices
A Sizable & Lucrative Opportunity for Non-Handset Devices hentsto open new big e Ree > 7 g i mers are entering these markets but lack wirele ‘0 producti ution @ \ fa path in orderto reduce °EVA Propristary Information CEVA
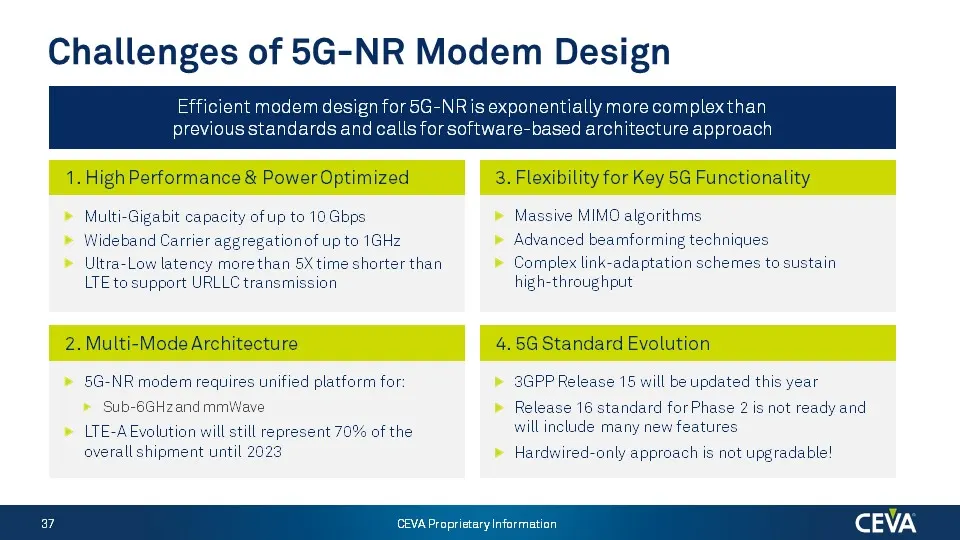
Slide 37: Challenges of 5G-NR Modem Design
Challenges of 5G-NR Modem Design Efficient modem design for 5G-NRis exponentially more complexthan previous standards and calls forsoftwa' ased architecture approach 1. High Performance & Power Optimized 3. Flexibility for Key 5G Functionality Multi-Gigabit capacity ofup to 10 Gbps Massive MIMO algo
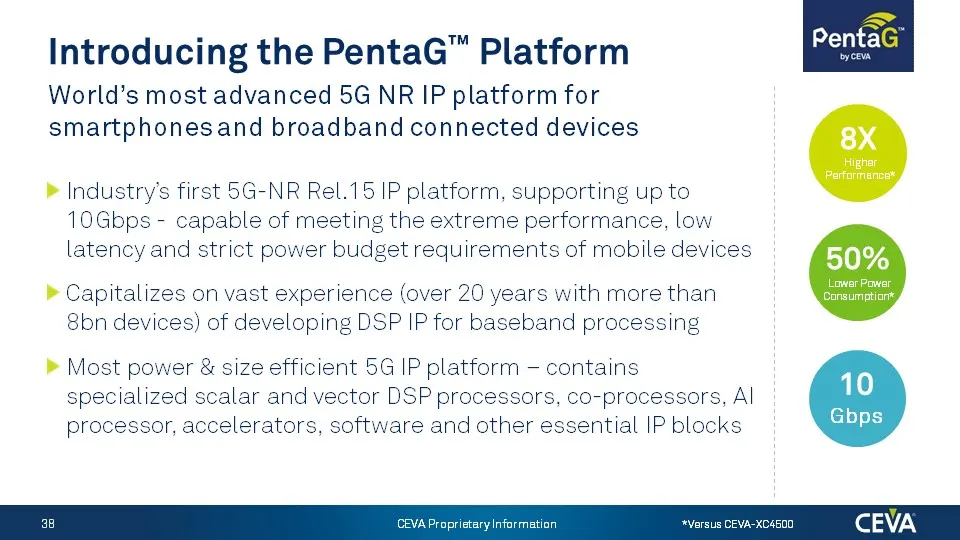
Slide 38: Introducing the PentaG Platform
Introducing the PentaG™ Platform World’s most advanced 5G NR IP platform for smartphonesand broadband connected devices » Industry's first 5G-NR Rel.15 IP platform, supporting upto: capable of mee e extreme performance and strict p r budget requirements of mobile perience (over 20 years with more th
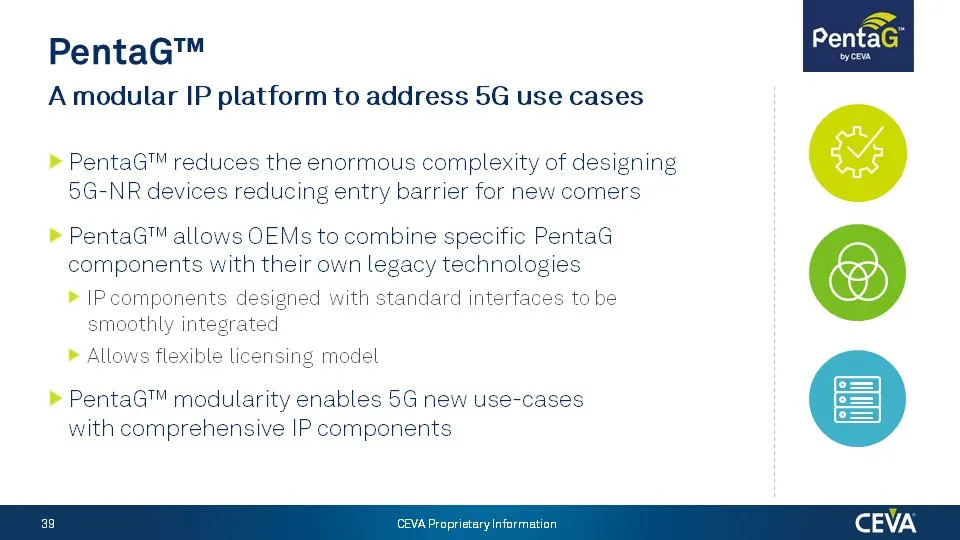
Slide 39: PentaG
PentaG™ A modular IP platform to address 5G use cases the redu >» PentaG™ redu 5G-NRd enormous complexity of designing ng entry barrier for new comers » PentaG™ all mponents » IPcormponents d smoothly integrated s OEMs toc th their ow ombine legacy t d with standard interfaces to be ® Allows flexibl
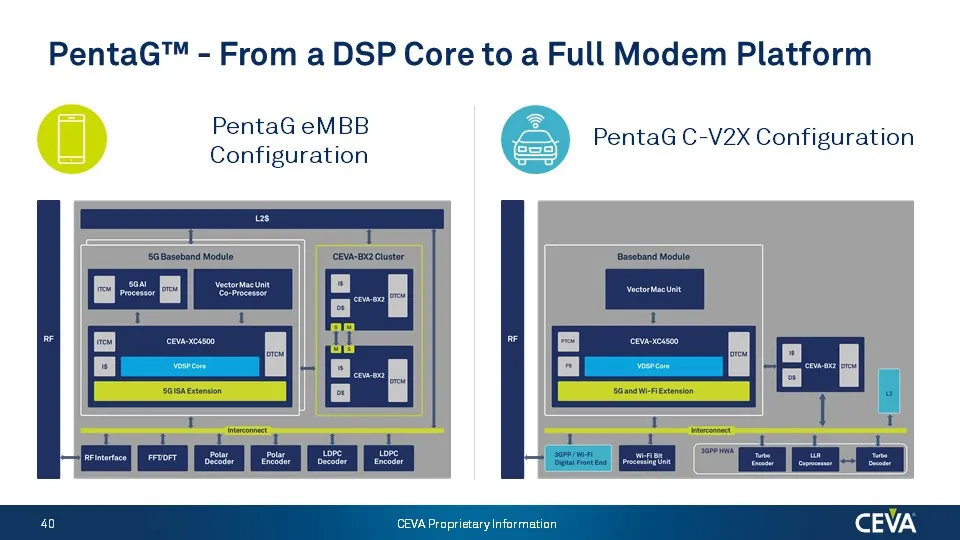
Slide 40: PentaG - From a DSP Core to a Full Modem Platform
PentaG™ - From a DSP Core to a Full Modem Platform a hentaGieM BB PentaG C-V2X Configuration Configuration SS CEVA Proprietary Information
Slide 41: Base Station
Base Station
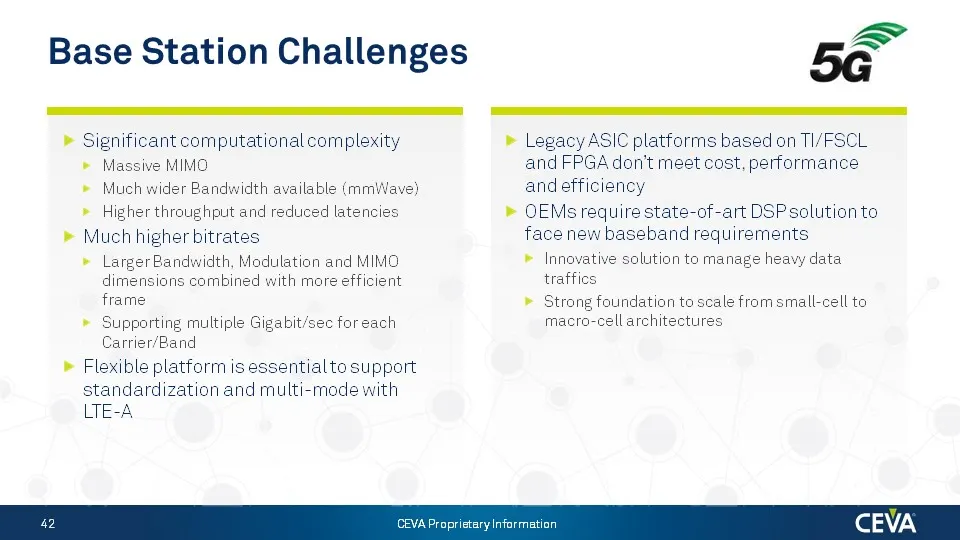
Slide 42: Base Station Challenges
Base Station Challenges 42 ® Significant computational complexity » Massive MIMO 5G » Legacy ASIC platforms based on TI/FSCL and FPGA don’t meet co » Much wider Bandwidth available (mmWave) and efficiency » Higher throughput and reduced latencies » Much higher bitrates » Larger Bandwidth, Modulation
Slide 43: Base Station — the Path to Leadership
Base Station — the Path to Leadership > Strategic investment from 2012 to design state-of-the-art vector processor for the infrastructure market from LTE to SG-NR > CEVA established a tight collaboration with 3 of the 5 Tier 1 OEMs in order to specialize the IP to address most complex eNB architectu
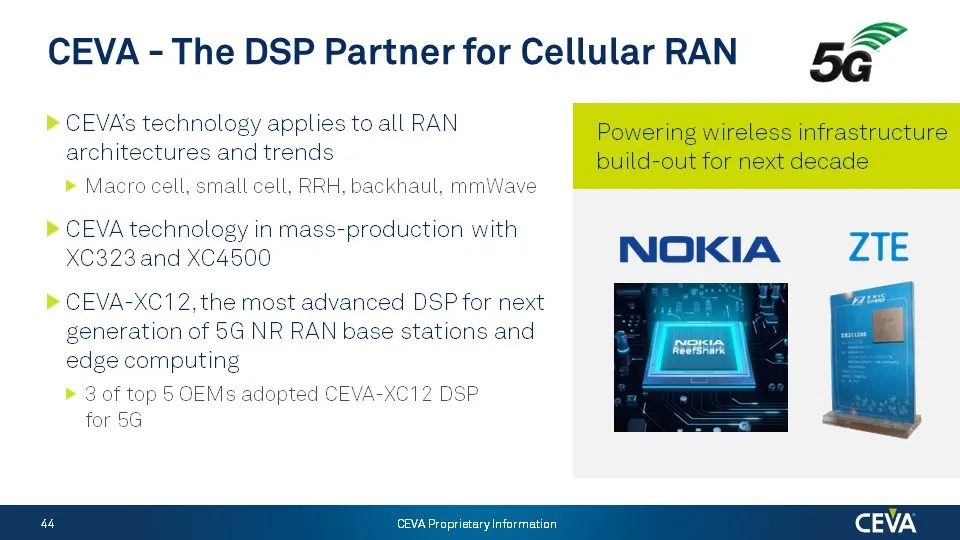
Slide 44: CEVA's technology applies to all RAN architectures
» CEVAs ti archit » Macro nology applies to all RAN ures and trends small cell, RRH, ba haul, mmWave » CEVA techno XC323 and XC4 in mass-production with » CEVA-XC12, the most advanced DSP for next generation of 5G NR RAN base stations and edg mputing > JEMs adop 44 /A Proprietary Information CEVA
Slide 45: New Infrastructure Players
New Infrastructure Players > Heterogenous nature of the 5G deployment opens the market to new small cell and femtocell companies > These companies need DSP technology designed for infrastructure > New initiatives like the OpenRAN forum will disrupt the industry landscape > Enable an open ecosystem o
Slide 46: Cellular IoT
Cellular loT
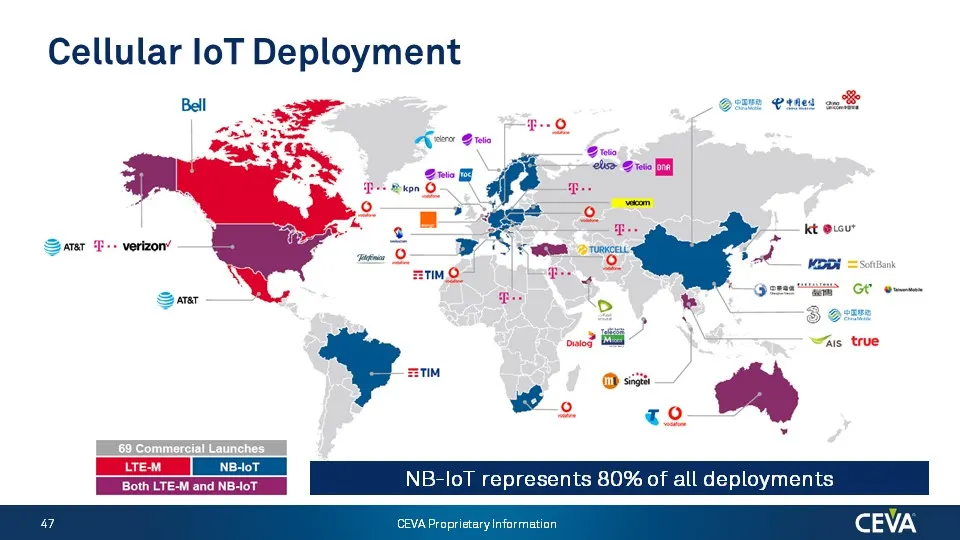
Slide 47: Cellular IoT Deployment
Cellular loT Deployment NB-loT represents 80% of all di ay /A Proprietary Information
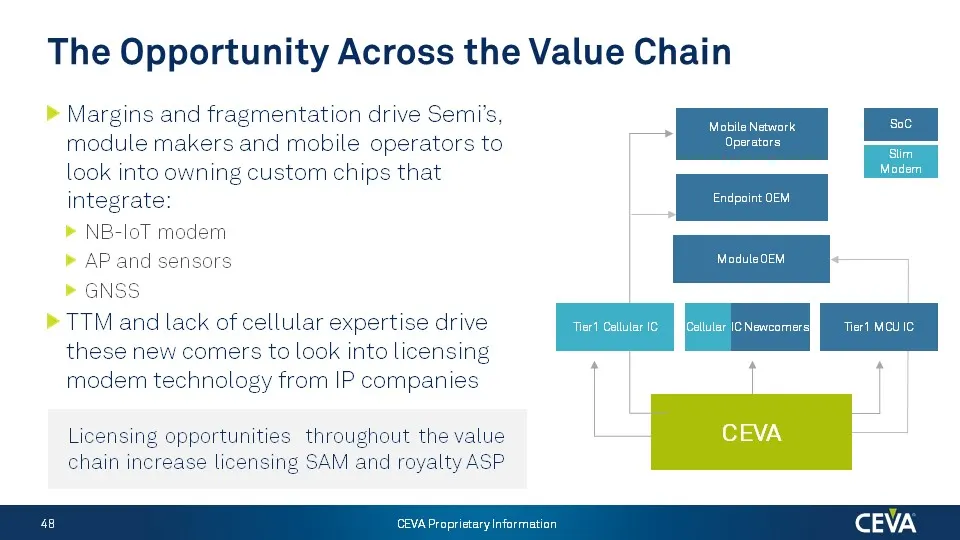
Slide 48: The Opportunity Across the Value Chain
The Opportunity Across the Value Chain » Margins and fragmentation drive Semis, module makers and mobile operators to look into owning custom chips that integrate: » NB-loT modem » AP and sensors » GNSS » TTM and lack of cellular expertise drive 43 these new comers to look into licensing modem techn
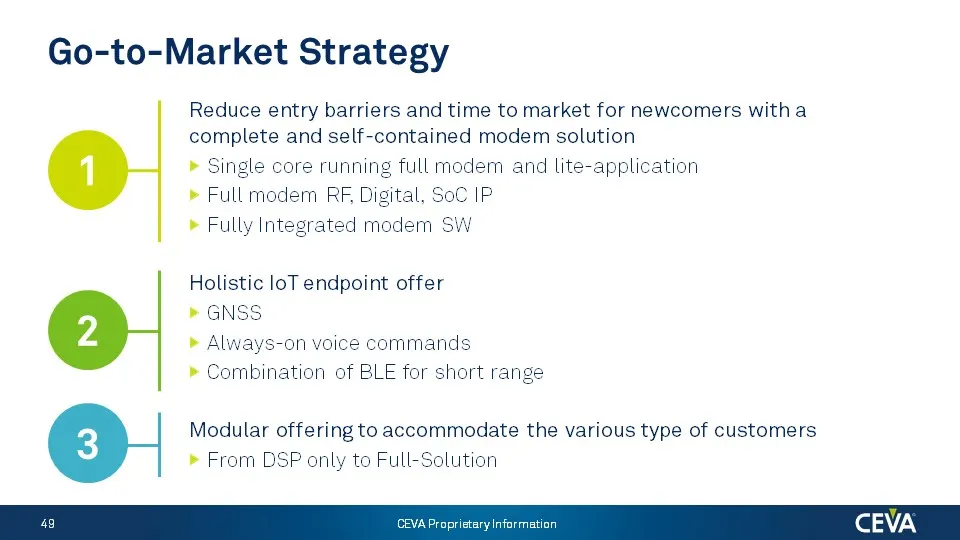
Slide 49: Go-to-Market Strategy
Go-to-Market Strategy Reduce entry barriers and time to market for newcomers witha complete and self-contained modem solution » Single core running full modem and lite-application » Full modem RF, Digital, SoC IP » Fully Integrated modem Holistic loT endpoint offer » Always-on voice cormmands Combin
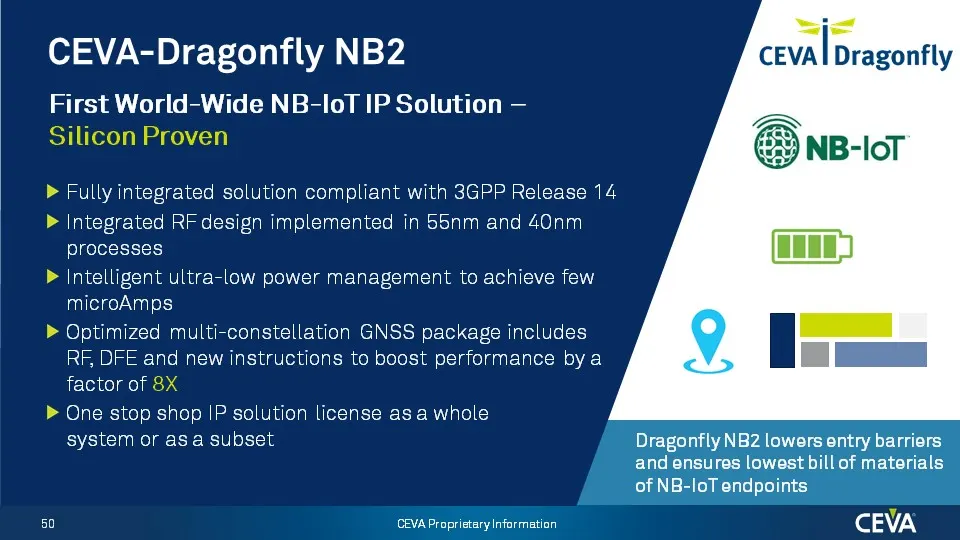
Slide 50: CEVA-Dragonfly NB2
CEVA-Dragonfly NB2 ceval Dragonfly First World-Wide NB-loT IP Solution — 50 Fully integrated solution compliant with 83GPP Release 14 Integrated RF design implemented in &5nm and 40nm processes Intelligent ultra-low power management to achieve few microAmps Optimized multi-constellation GNSS package
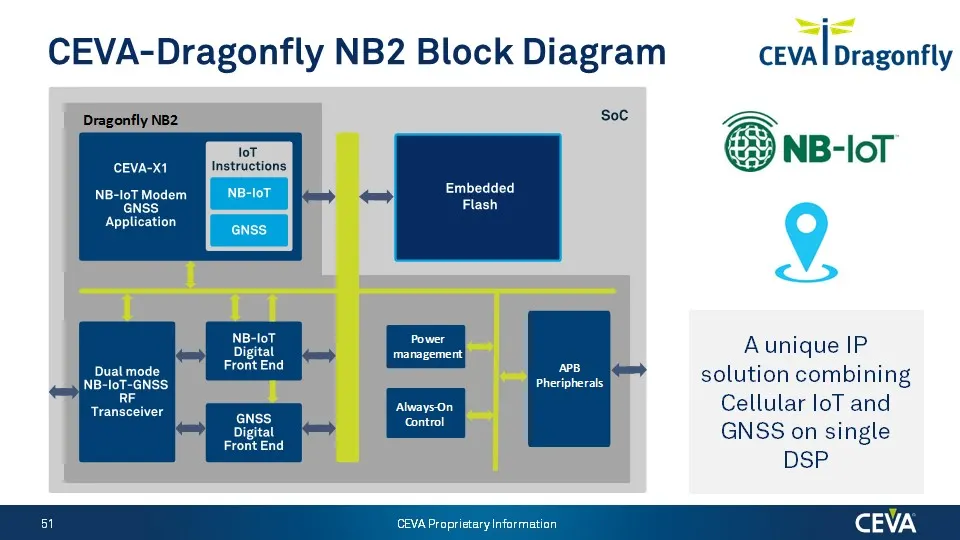
Slide 51: CEVA-Dragonfly NB2 Block Diagram
CEVA-Dragonfly NB2 Block Diagram —_ceval Dragonfly Dragonfly NB2 SoC > NB-IoT loT CEVA-X1 Instructions NB-loT Modem Embedded GNSS Application Flash ae A unique IP Fr End . ee MES eae _ ee solution combining ientiorcn Cellular loT and GNSS ‘Control ‘ Digital GNSS on single Front End DSP z CEVA Prapie
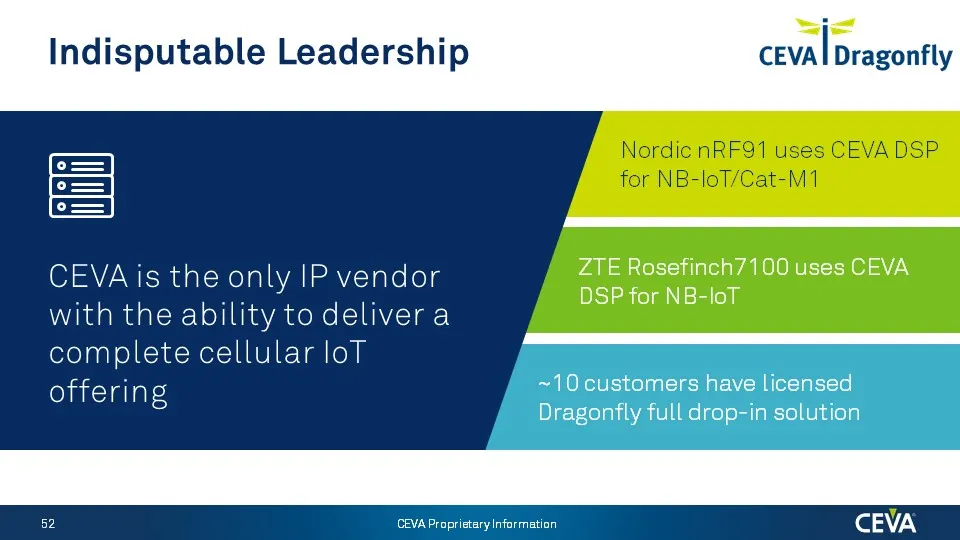
Slide 52: Indisputable Leadership
Indisputable Leadership cEVAI Dragonfly CEVA is the only IP vendor ZTE Rosefinch7100 uses CEVA with the ability to deliver a ey complete cellular loT offering ~10 customers have licensed Dragonfly full drop-in solution 52 CEVA Proprietary Information CEVA
Slide 53: Key Takeaways
Key Takeaways 5g lution CEVA Proprietary Information The de-facto wireless IP leader across all the biggest market segments CEVA
Slide 54: Thank You
Thank You
Slide 55: Computer Vision, AI and Automotive
CEVA Computer Vision, Al and Automotive Ilan Yona Jeff VanWashenova www.ceva-dsp.com Copyright © 2019 CEVA, Inc.
Slide 56: Market Trends
Market Trends
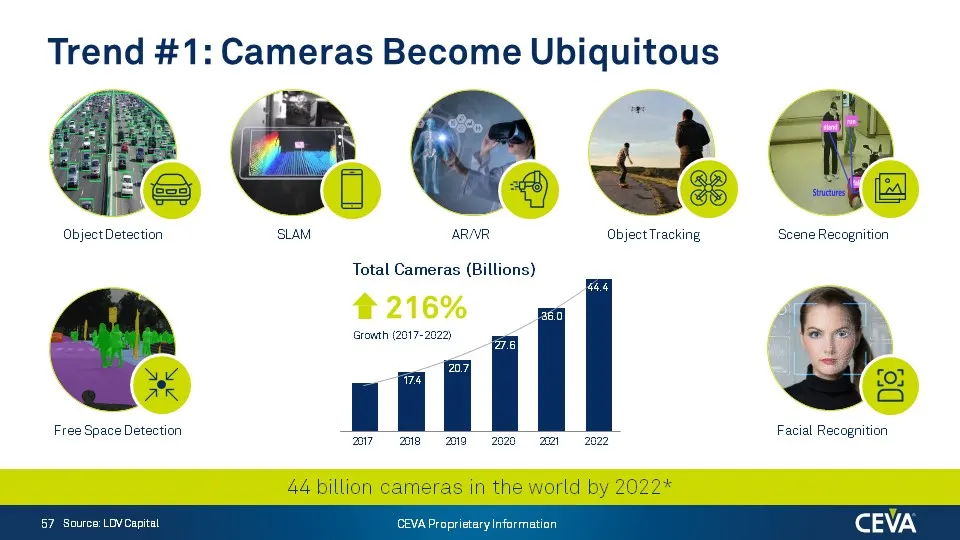
Slide 57: Trend #1: Cameras Become Ubiquitous
Trend #1: Cameras Become Ubiquitous Object Detection SLAM ARR Object Tracking Scene Recognition Total Cameras (Billions) Grovah (2017-2022) Nye 7 Free Space Detection Facial Recognition ay me ma 2020 S022 44 billion cameras in the world by 2022* Source: LOV Capital CEVA Propristaryinformation CEVA
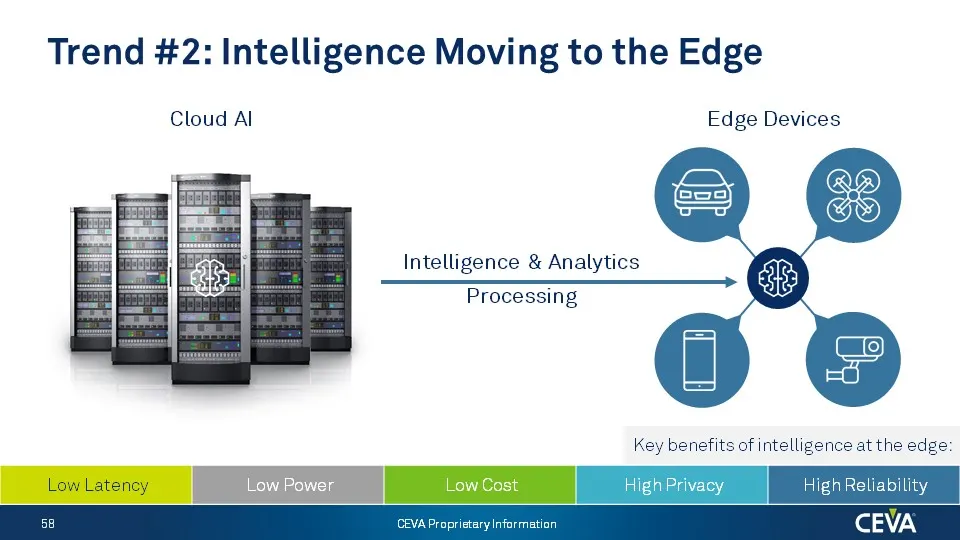
Slide 58: Trend #2: Intelligence Moving to the Edge
Trend #2: Intelligence Moving to the Edge Cloud Al Edge Devices Intelligence & Analytics Processing Key benefits of intelligence at the edge: | HighReli
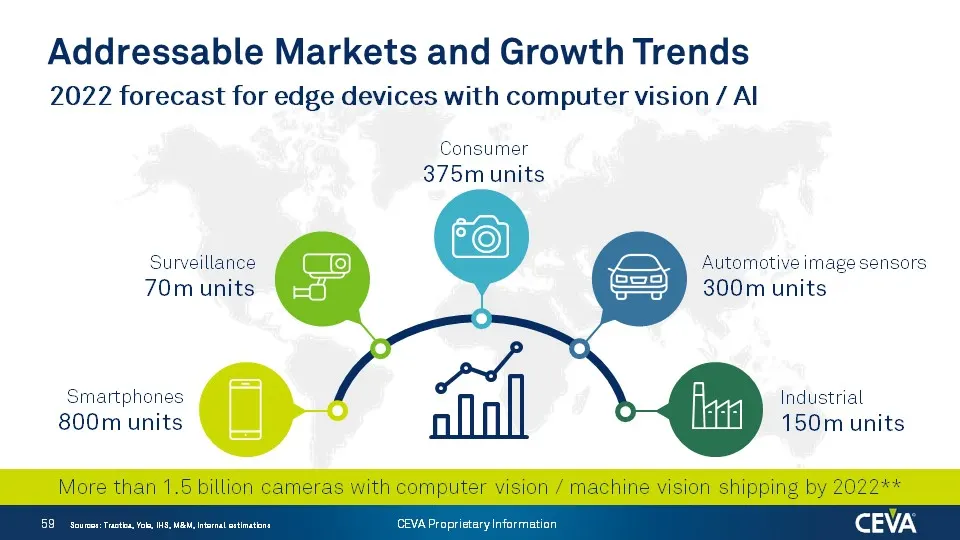
Slide 59: Addressable Markets and Growth Trends
Addressable Markets and Growth Trends 2022 forecast for edge devices with computer vision / Al Consumer 375m units Surveillance 70m units Automotive Image sensors 300m units Smartphones 800m units Industrial 150m units
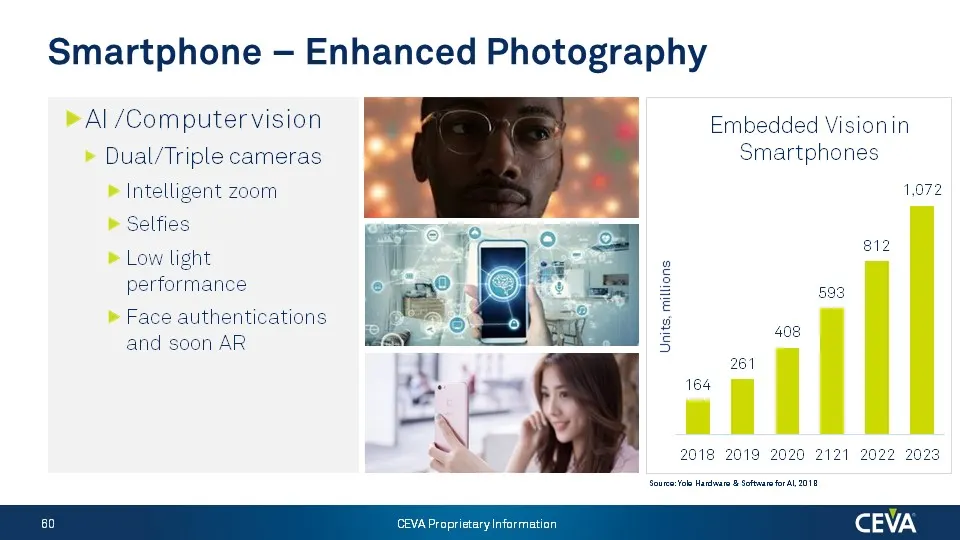
Slide 60: Smartphone — Enhanced Photography
Smartphone — Enhanced Photography » Al /Computer vision » Dual/Triple cameras ® Intelligent zoom Visionin hones > Selfies ® Low light performance » Face authentications and soon AR Units, millions 1,072 593 26 i i CEVA Proprietary Information
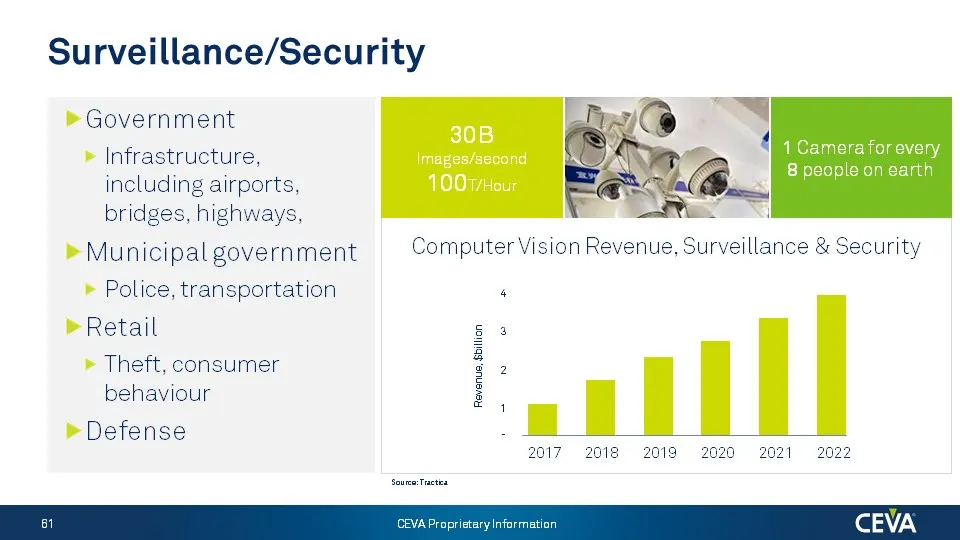
Slide 61: Surveillance/Security
Surveillance/Security » Government » Infrastructure, mages/second / 8 people on earth including airports, bridges, highways, » Municipal government Computer Vision Reven » Police, transportation n » Retail » Theft, consumer behaviour > Defense 1 Camera for every ue, Surveillance & Security a 2 Reven
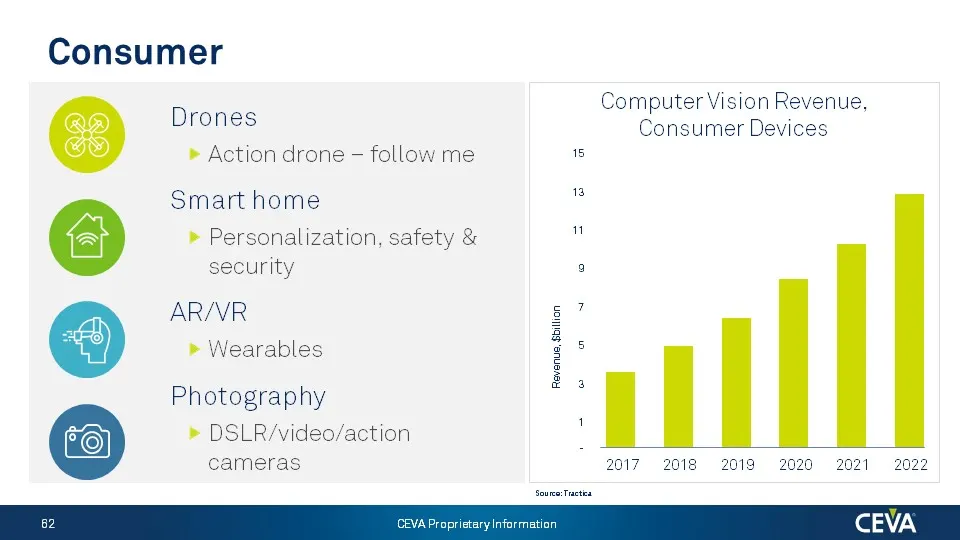
Slide 62: Consumer
Consumer Dimes Computer Vision Revenue, Consumer Devices » Action dror follow me ie Smart home ” © » Personalization, safety & a urity 9 AR/VR 7 arab g° Photography a >» DSLR ‘ cameras 2017° «2018 «82019 2020 2021 2022 /s Proprietary Information CEVA
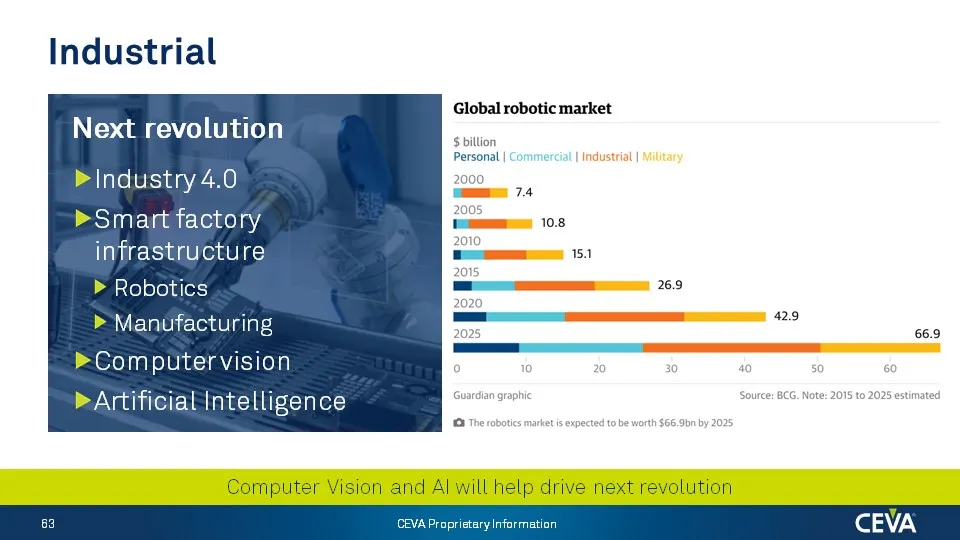
Slide 63: Industrial
Industrial Global robotic market Next revolution > Industry 4.0 >Smant factory infrastructure > Robotics > Manufacturing >Computer vision > Artificial Intelligence = 74 26.9 42.9 66.9 ° Computer Vision and Al will help drive next revolution ary Information CEVA CEVAPr
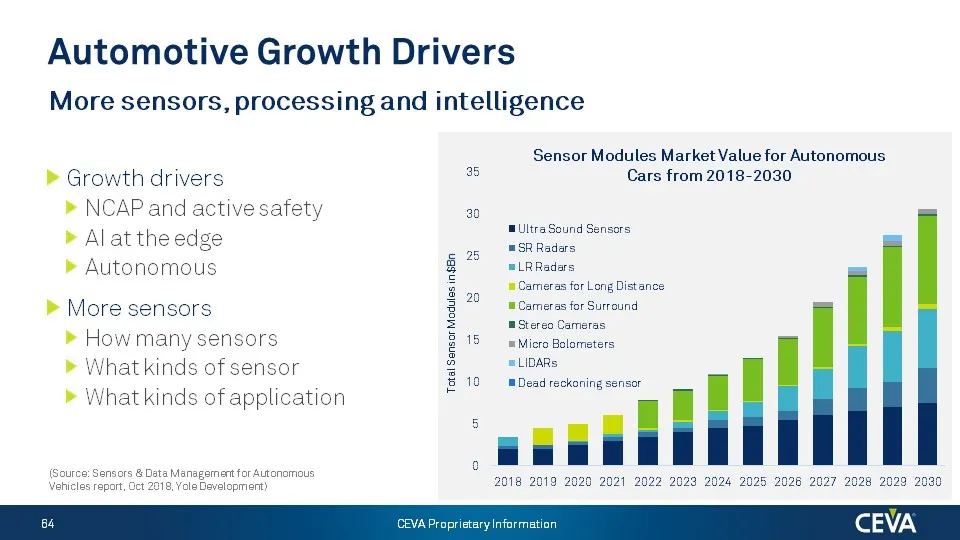
Slide 64: Automotive Growth Drivers
Automotive Growth Drivers More sensors, processing and intelligence Sensor Modules Market Value for Autonomous » Growth drivers 8 Cars from 2018-2030 » NCAP ani € € 30 Ultra Sound Sensors SR Radars ‘onl i 2018 2019 21 2022 2028 2024 2025 2026 2027 2028 2029 2030 (Source: Sensors & Data Management fo
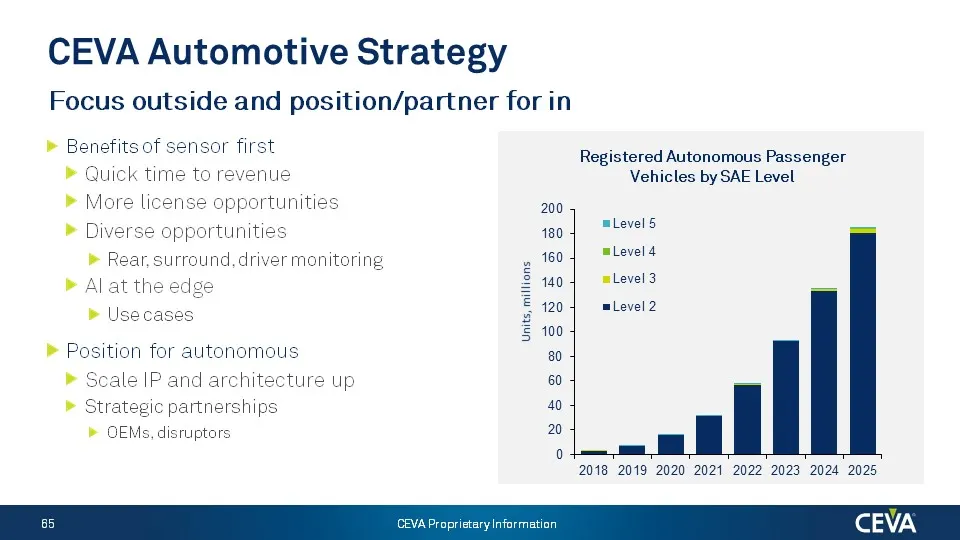
Slide 65: CEVA Automotive Strategy
CEVA Automotive Strategy Focus outside and position/partner for in » Benefits of serisor first Registered Autonomous Passenger » Quick time to revenue Vehicles by SAE Level » More license opportunities 200 » Diverse opportunities 180) eee » Rear, surround, driver monitoring 160) "Level > Alatthe 5 4
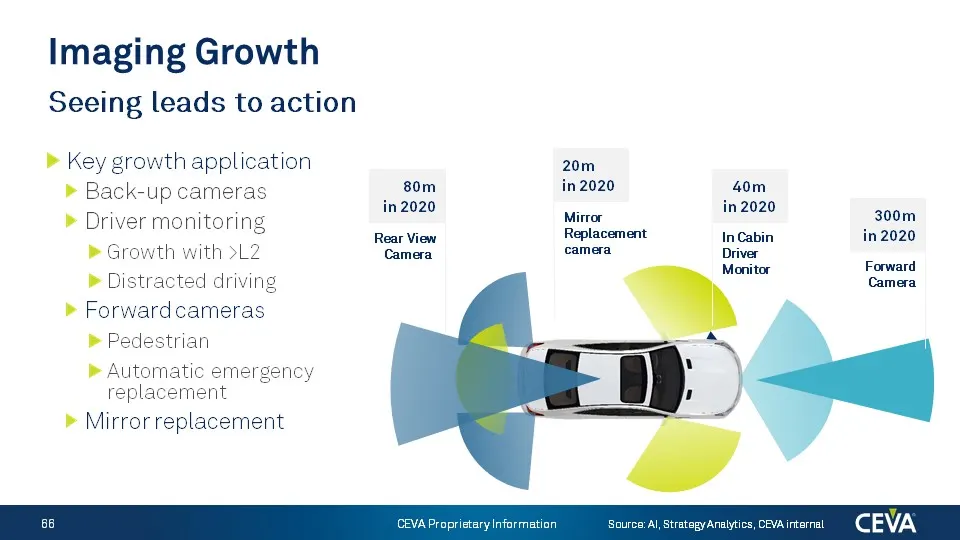
Slide 66: Imaging Growth
Imaging Growth Seeing leads to action » Key growth application 20m » Back-up cameras 80m Taiz 40m in 2020 in 2020 em » Driver monitoring Murrey pocorn = Rear View Replacement InCabin in 2020 » Growth with >L2 Camera camera’ Driver . Forward » Distracted driving Camera » Forwardcameras » Pedestrian »
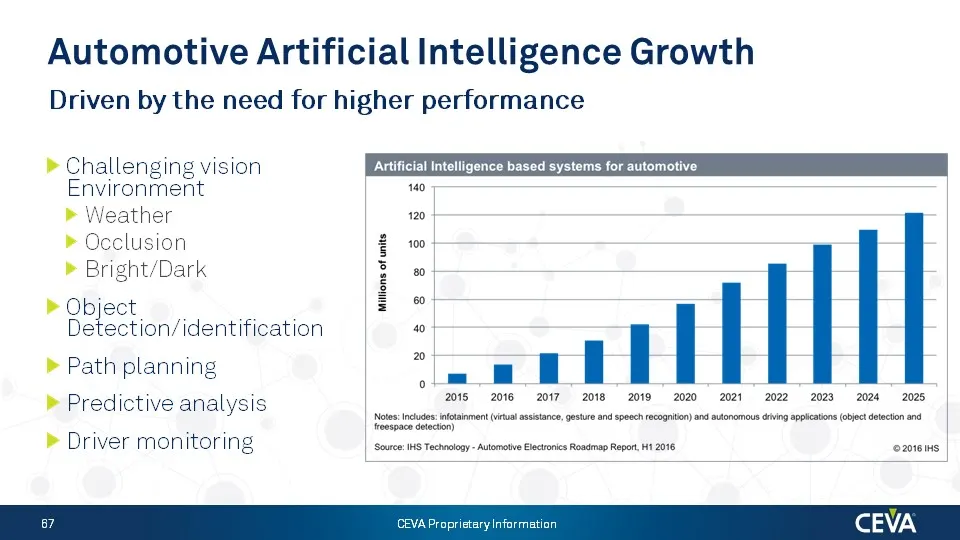
Slide 67: Automotive Artificial Intelligence Growth
Automotive Artificial Intelligence Growth Driven by the need for higher performance > Chal leng ing vis ion Artificial Intelligence based systems for automotive Environment » Weather 120 » Occlusion » Bright/Dark > Object i | j i Detection/identification ” » Path planning >a atl ERG 2015 2016 2017-2
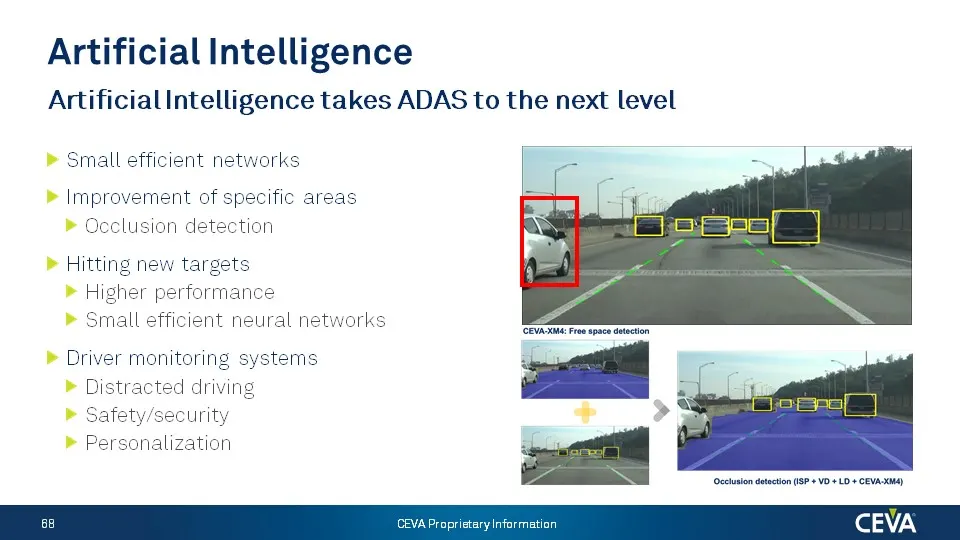
Slide 68: Artificial Intelligence
Artificial Intelligence Artificial Intelligence takes ADAS to the next level Small efficient networks Improvement of specific areas Occlusion detection w targets erformance all efficient neural networks Driver monitoring systems Distracted driving curity Personalization (cctusiondetacion (SP + VO +L
Slide 69: A Strategy for Success
A Strategy for Success Focus on growth applications > Smart cameras > Combination of CV and Al > Not all functions are Al > CV is stable and predictable > Al complements CV > CEVA-XM and NeuPro are well positioned for growth markets > Example: NextChip —- APACHE4. 69
Slide 70: Autonomous Processing Landscape
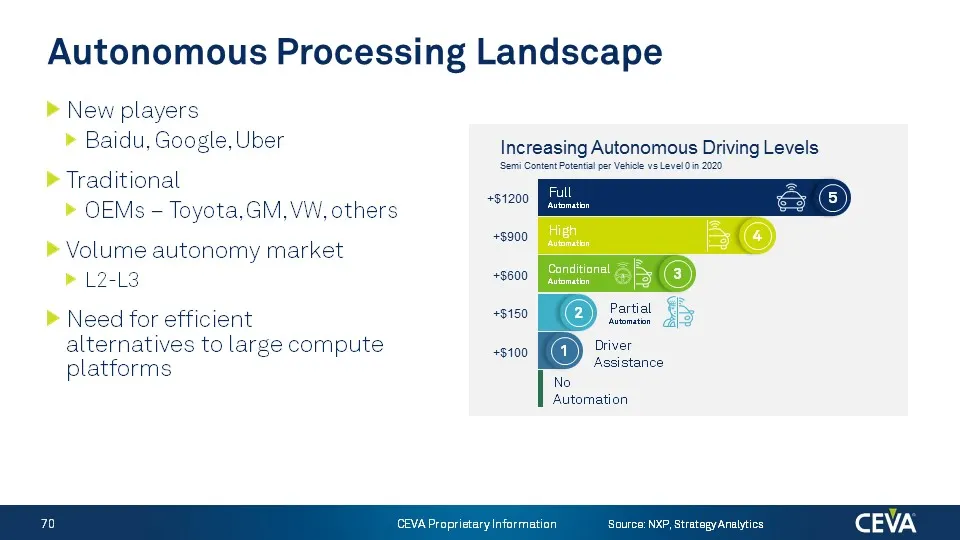
Autonomous Processing Landscape Increasing Autonomous Driving Levels ‘Semi Contant Potent a » Traditional » OEMs - vam thers +900 » Volume autonomy market > L2-13 oo 3 2 Partial § » Need for efficient Ed | eoeson alternatives to large compute +8100 ay Driver platforms Assistance No Automation CEVA /
Slide 71: CEVA's Opportunity in Autonomous Driving
CEVA’s Opportunity in Autonomous Driving Broad engagement with OEMs, Tier-1, and disruptors of the market to understand and develop IP for L4/L5 Processing requirements continue to grow quickly Solutions today not designed for mass market applications CEVA is addressing the need for new architecture
Slide 72: The Strategy
The Strategy
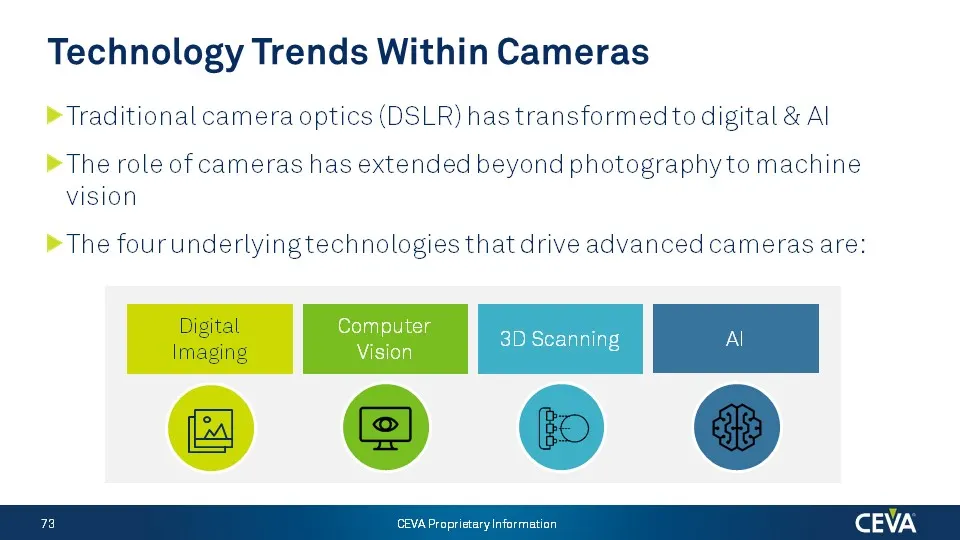
Slide 73: Technology Trends Within Cameras
Technology Trends Within Cameras » Traditional camera optics (DSLR) has transformed to digital & Al » The role of cameras has extended beyond photography to machine vision » The fourunderlying technologies that drive advanced cameras are: CEVA Proprietary Information
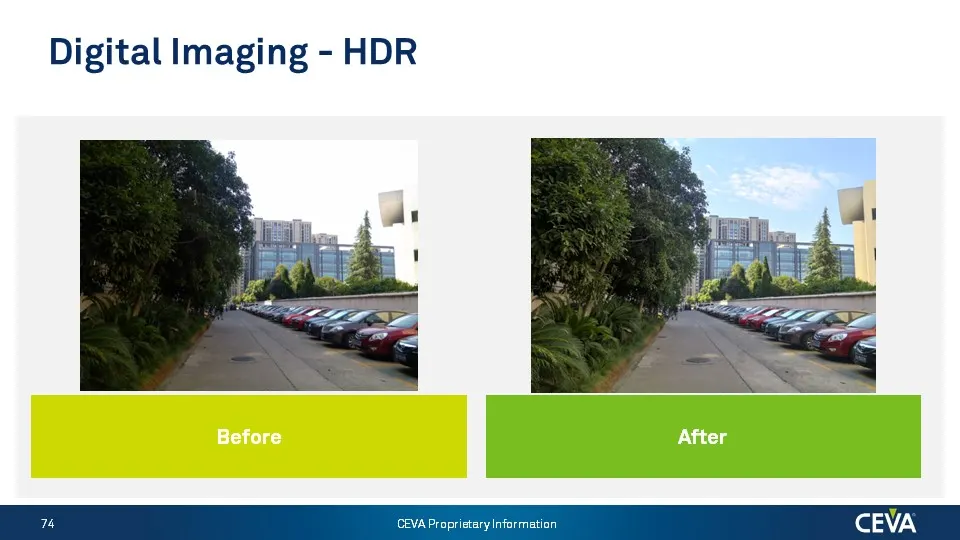
Slide 74: Digital Imaging - HDR
Digital Imaging - HDR a7 CEVA Proprietary Information CEVA
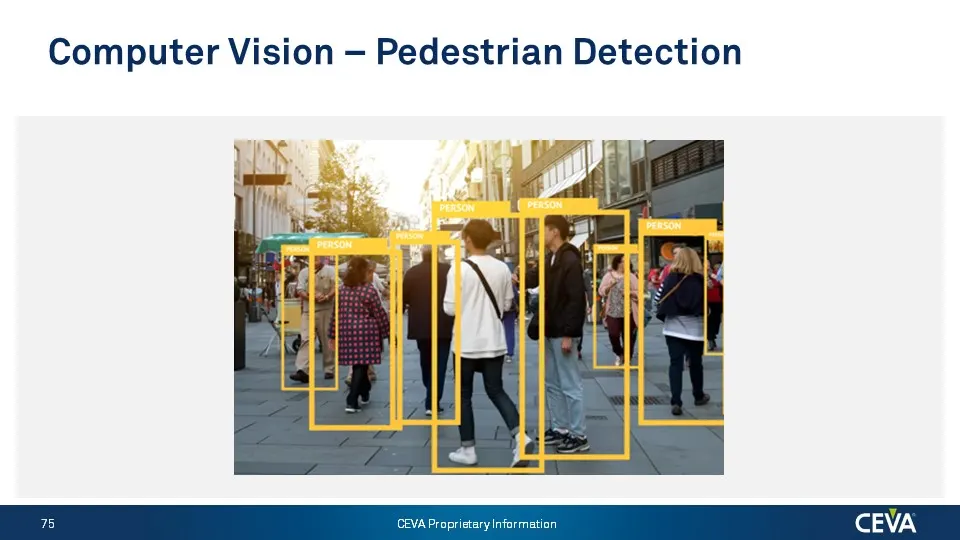
Slide 75: Computer Vision — Pedestrian Detection
Computer Vision — Pedestrian Detection
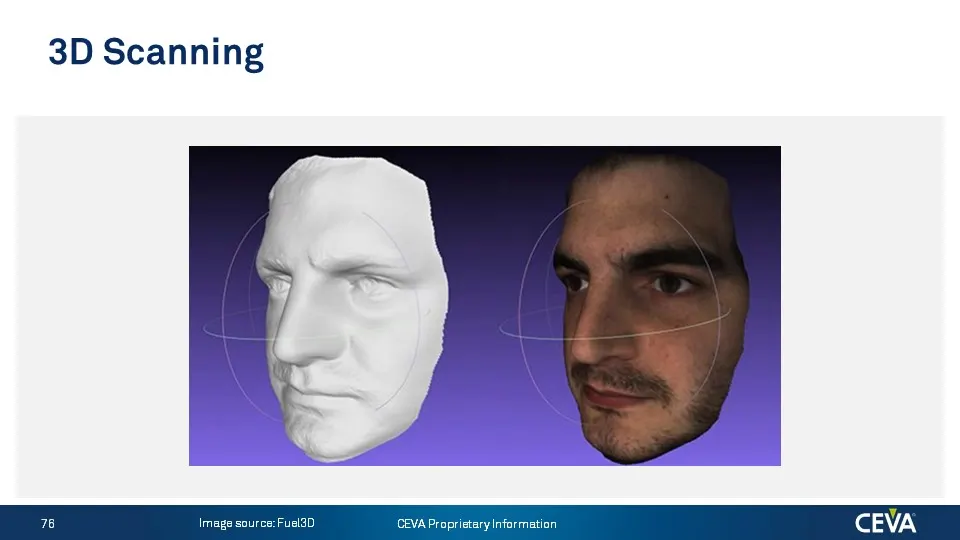
Slide 76: 3D Scanning
3D Scanning 78 Image source: FuslaD CEVA
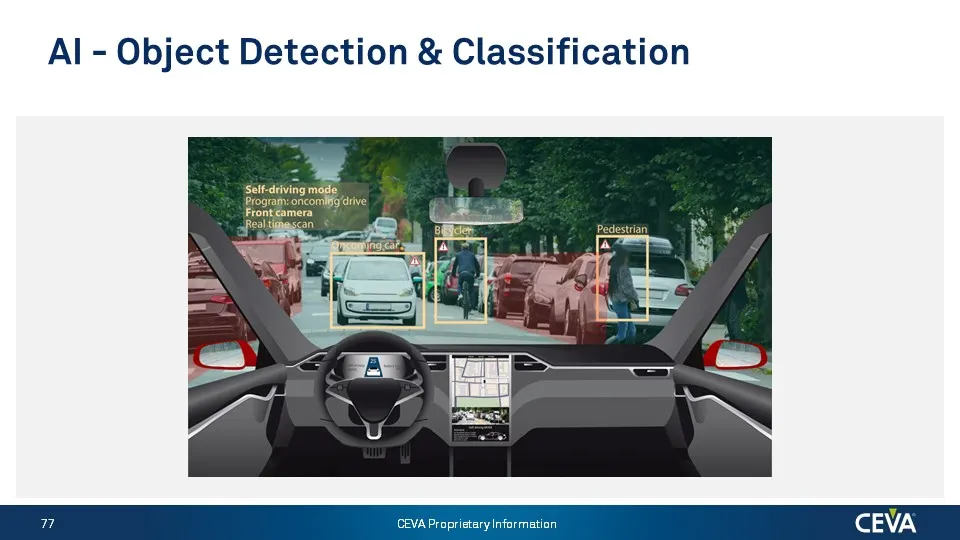
Slide 77: AI - Object Detection & Classification
Al - Object Detection & Classification
Slide 78: CV/AI - High Entry Barrier Space
CV/AI - High Entry Barrier Space > Technology competencies are scarce > Al/Machine learning space has a different domain expertise. Know how exists within the cloud, substantially less at the edge > The complexity and required performance is growing at 2X-4X in every year > A holistic view of softwa
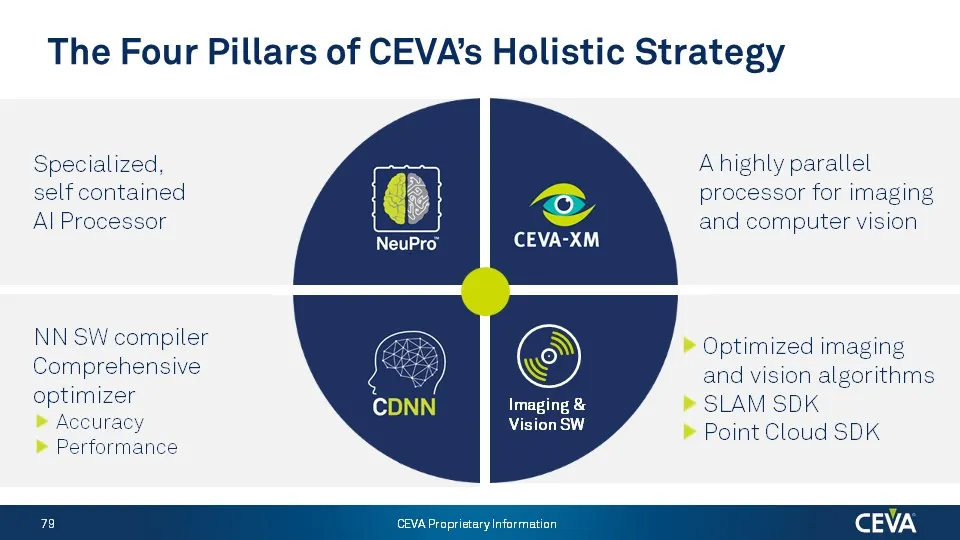
Slide 79: The Four Pillars of CEVA's Holistic Strategy
The Four Pillars of CEVA’s Holistic Strategy Imaging & Vision SW formance /s Proprietary Information CEVA
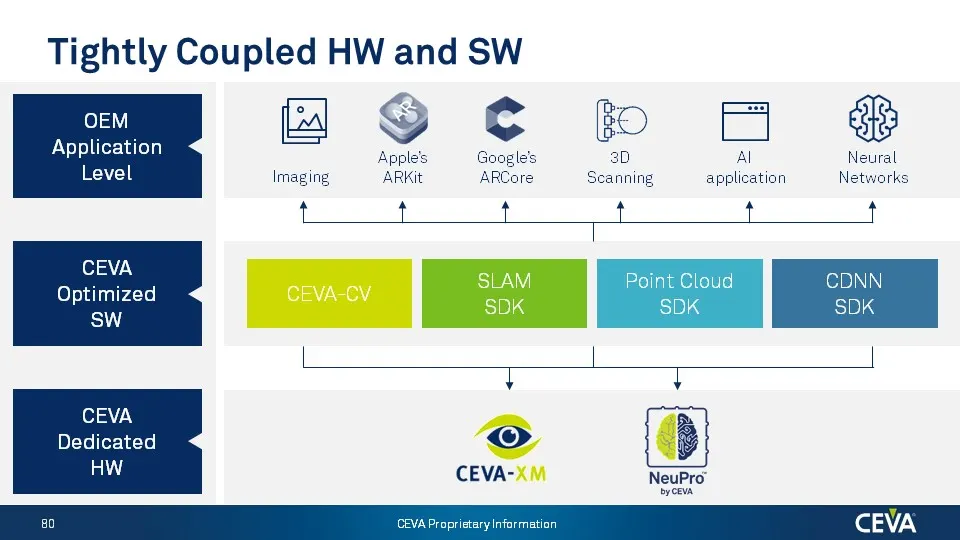
Slide 80: Tightly Coupled HW and SW
Tightly Coupled HW and SW OEM LA Application Apple's 3D Al Neural Level Imaging ARKit Scanning application Networks t t ‘3 I t i t CEVA N Optimized sw | | ; ; CEVA Dedicated oO > HW CEVA- NeuPro 80 CEVA Prapristary Information CEVA
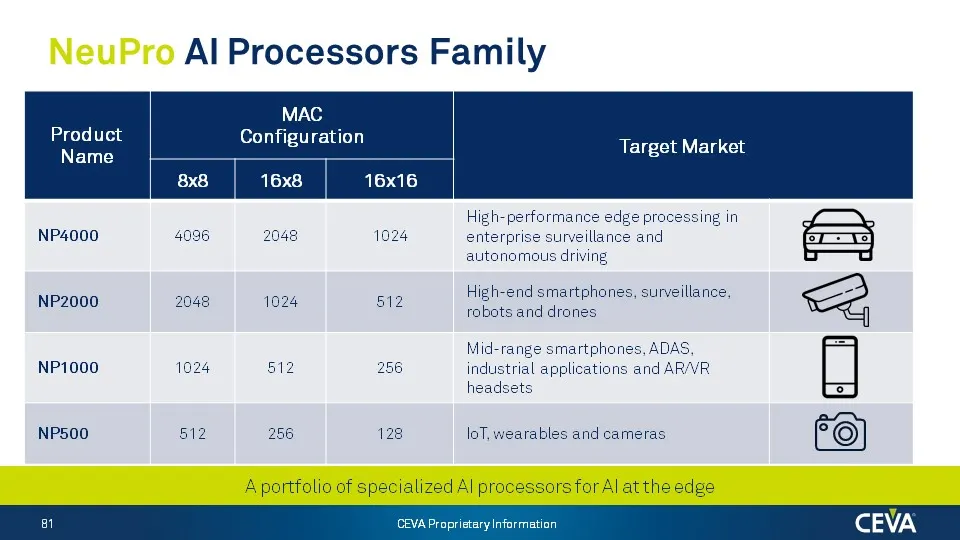
Slide 81
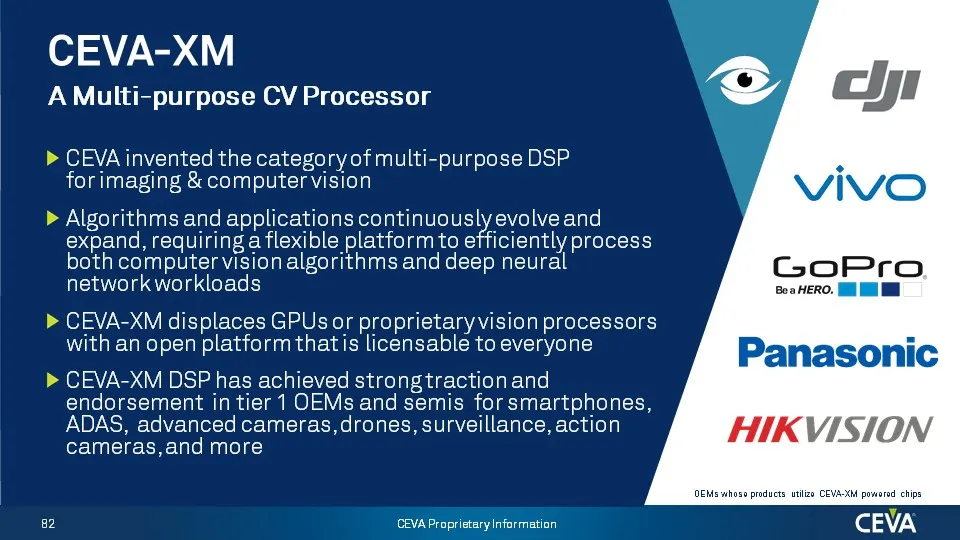
Slide 82
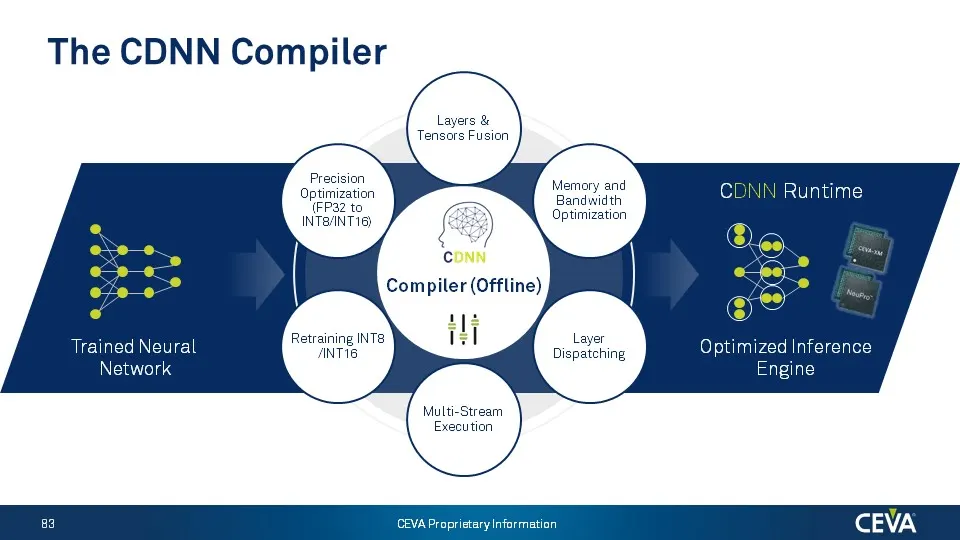
Slide 83
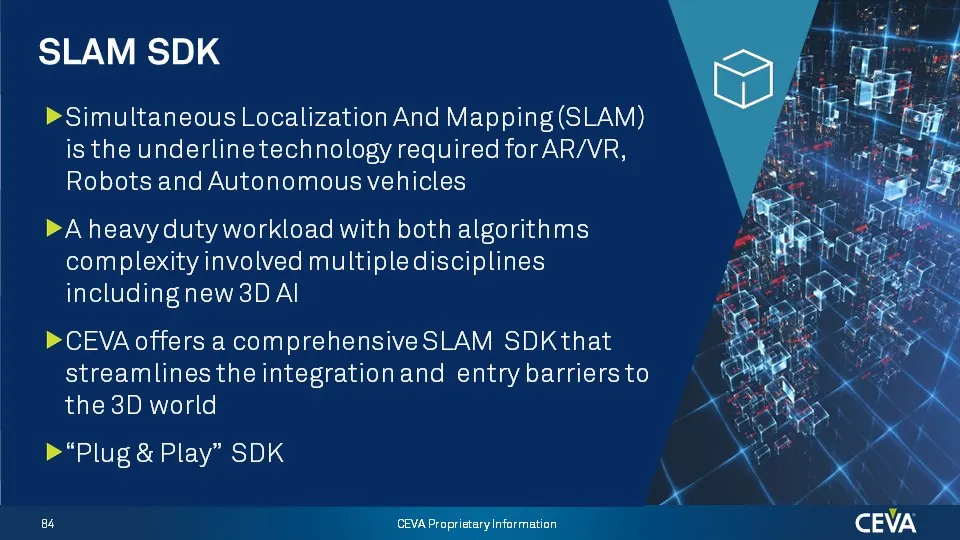
Slide 84
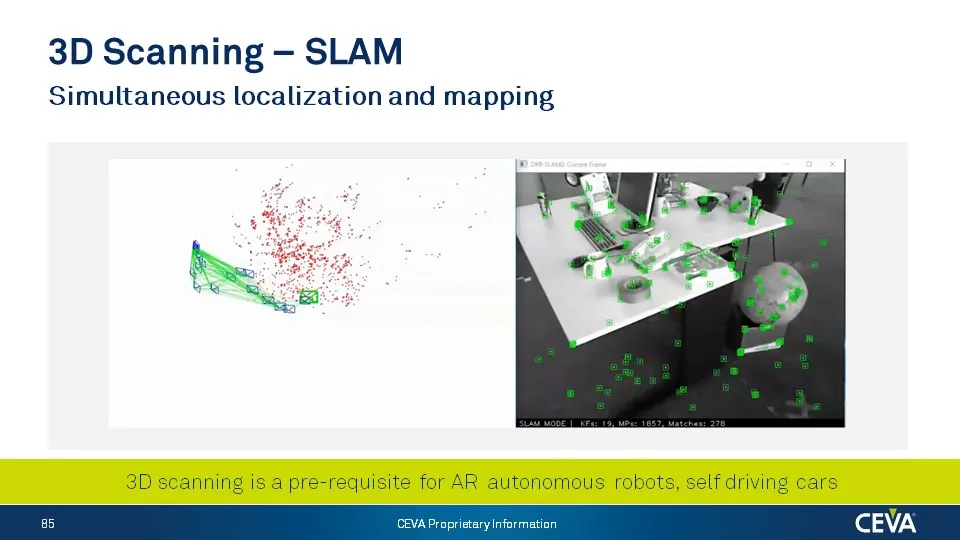
Slide 85
Slide 86
Slide 87
Slide 88
Slide 89
Slide 90
Slide 91
Slide 92
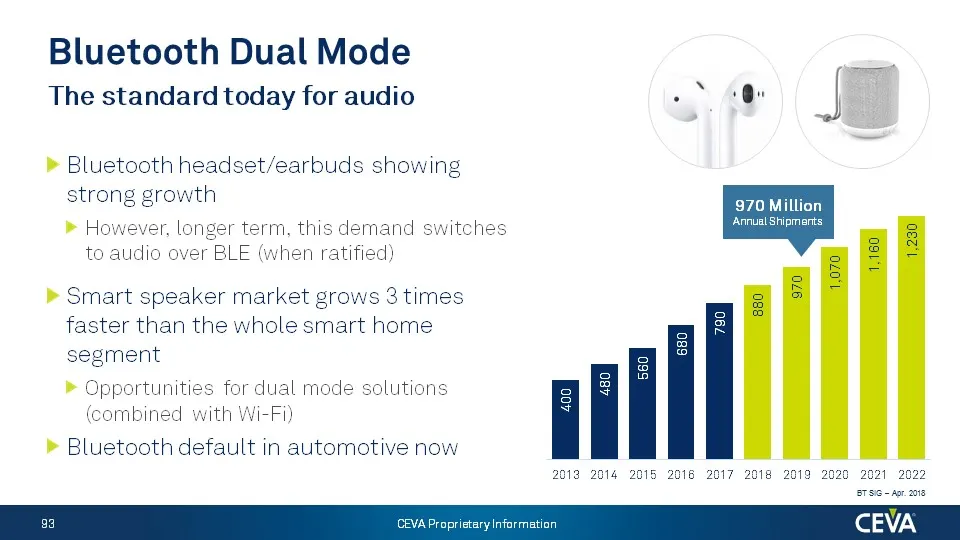
Slide 93
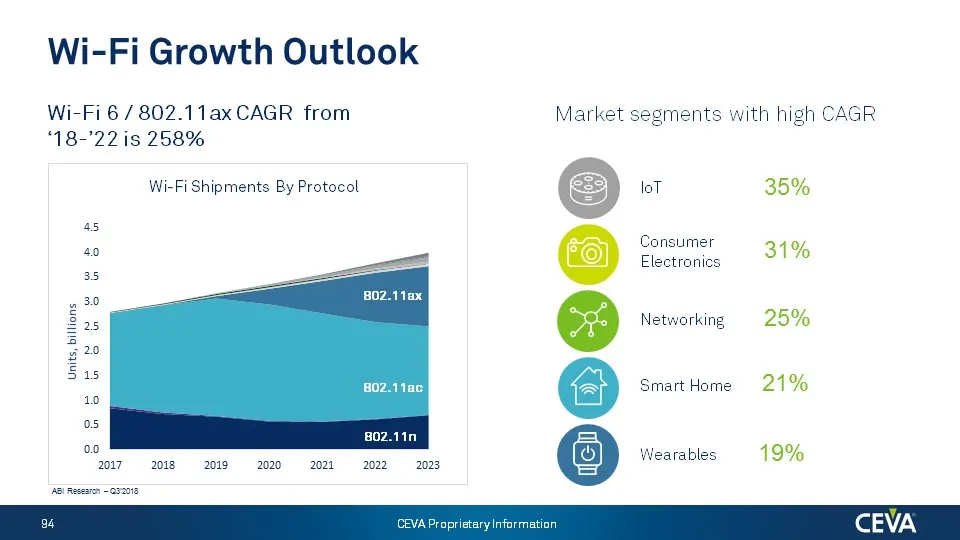
Slide 94
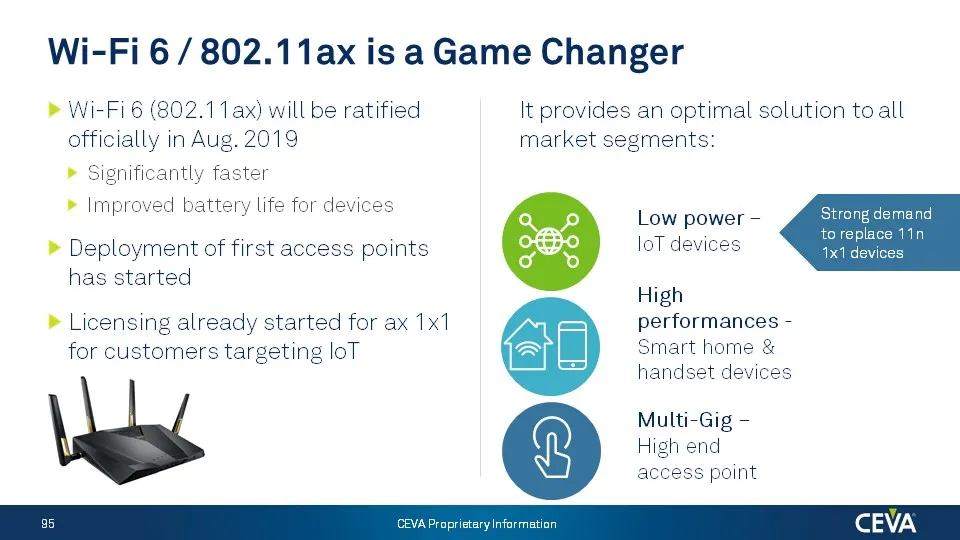
Slide 95
Slide 96
Slide 97
Slide 98
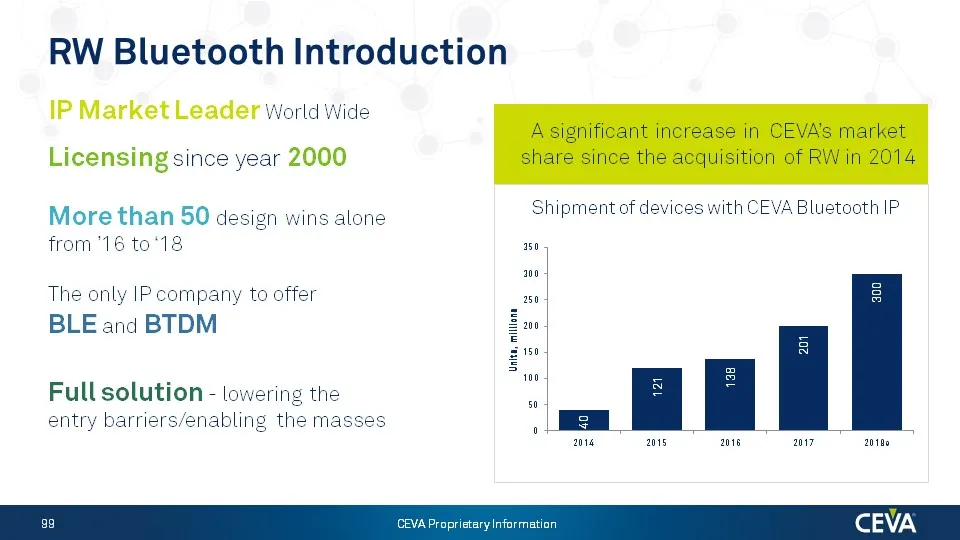
Slide 99
Slide 100
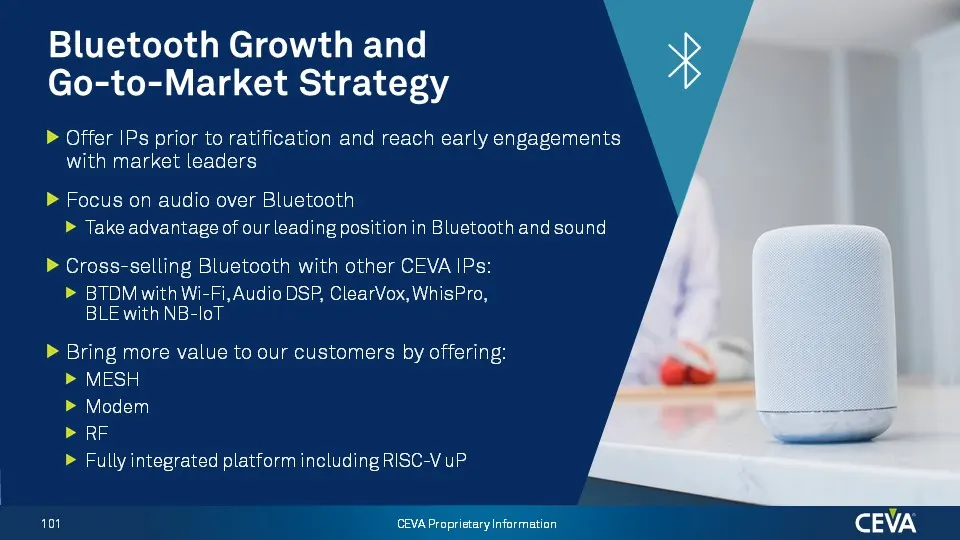
Slide 101
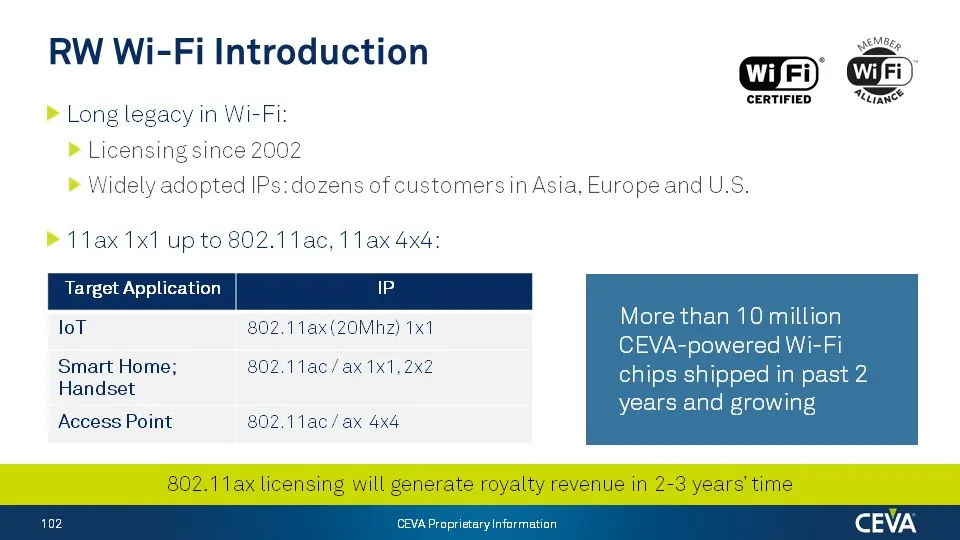
Slide 102
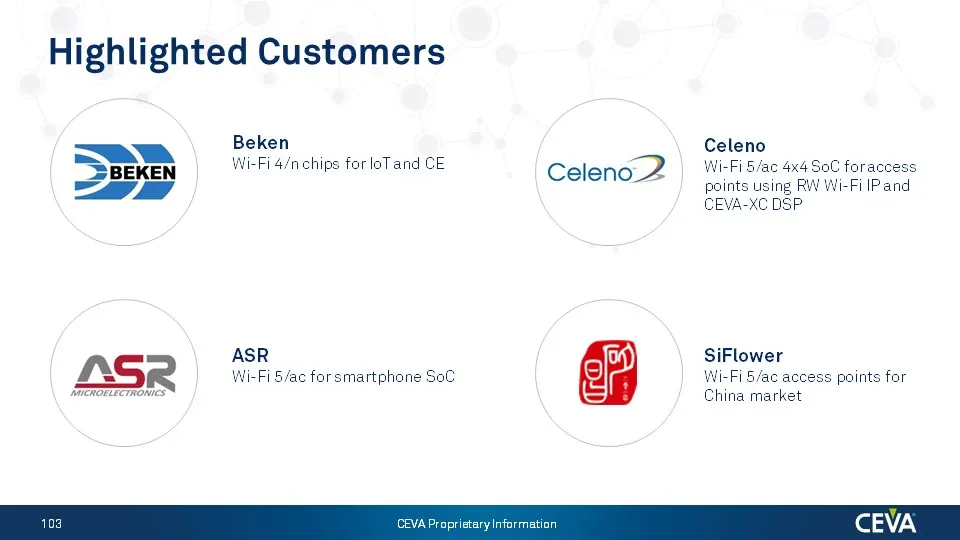
Slide 103
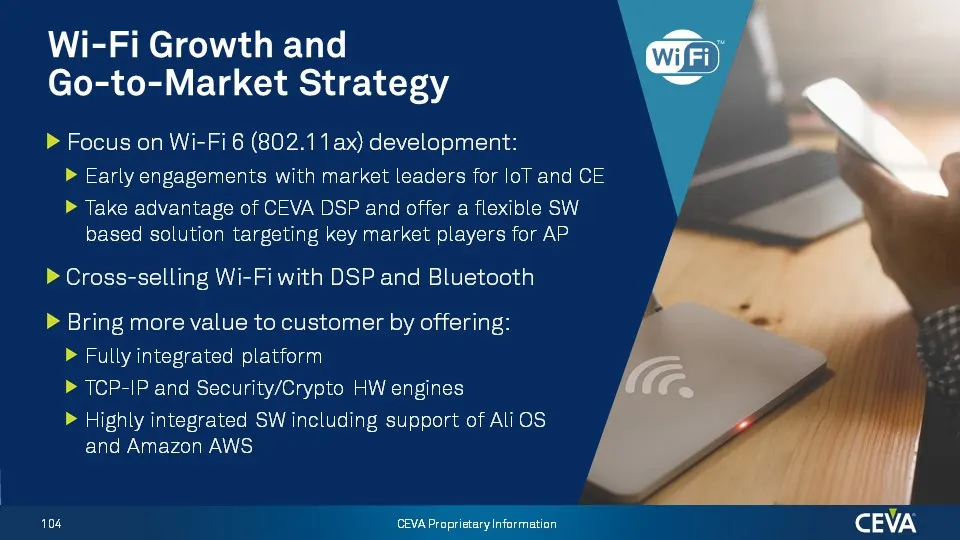
Slide 104
Slide 105
Slide 106
Slide 107
Slide 108
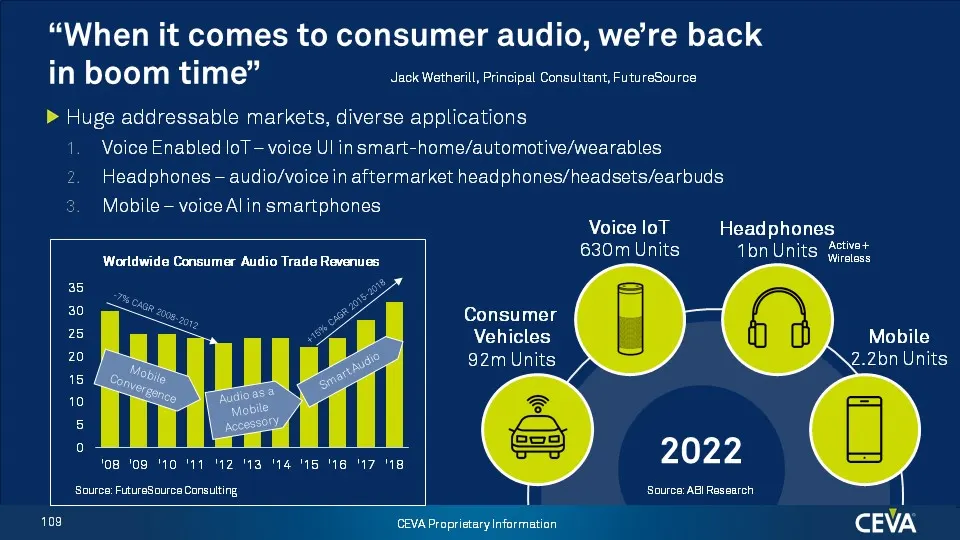
Slide 109
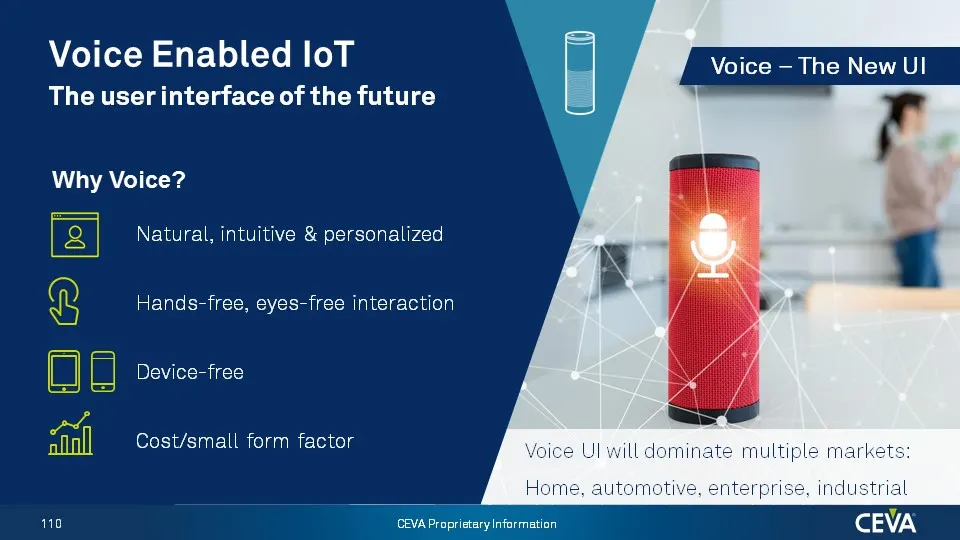
Slide 110
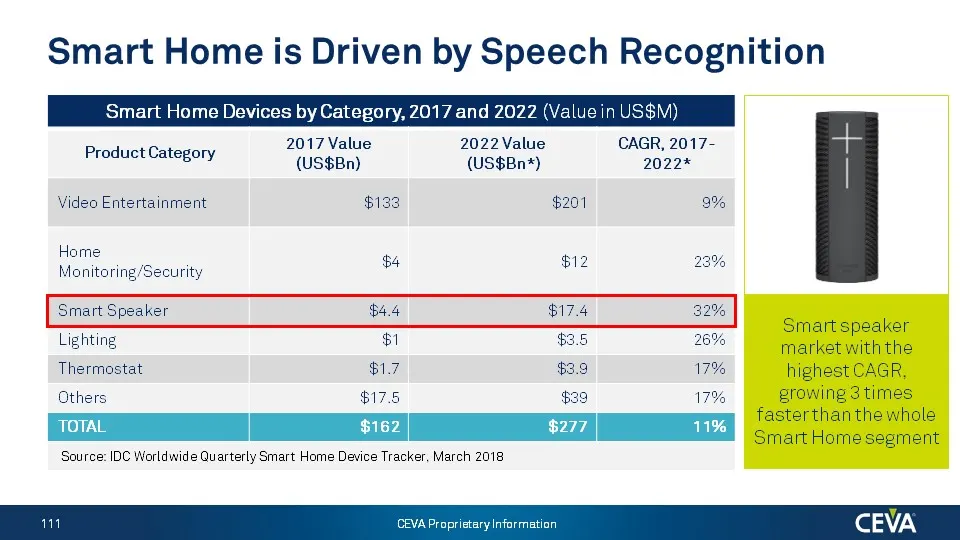
Slide 111
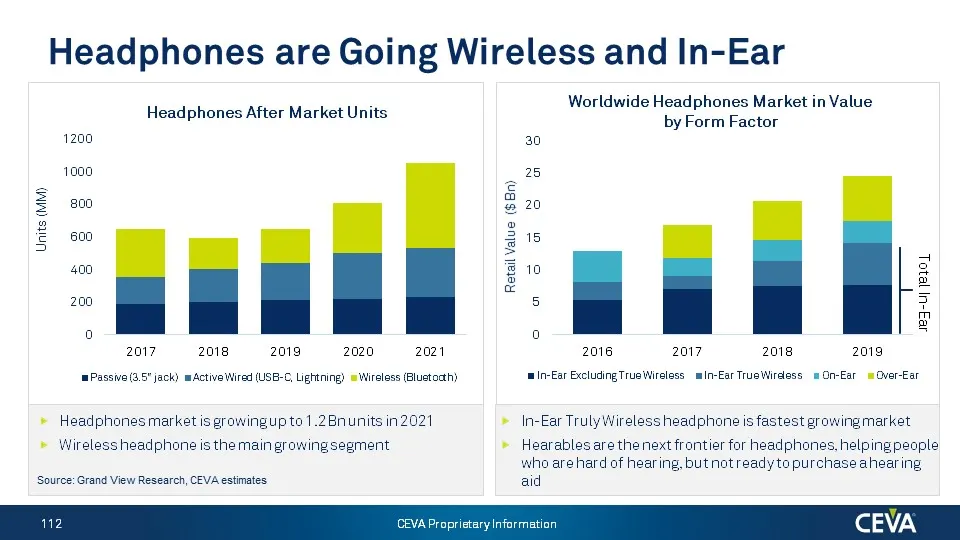
Slide 112
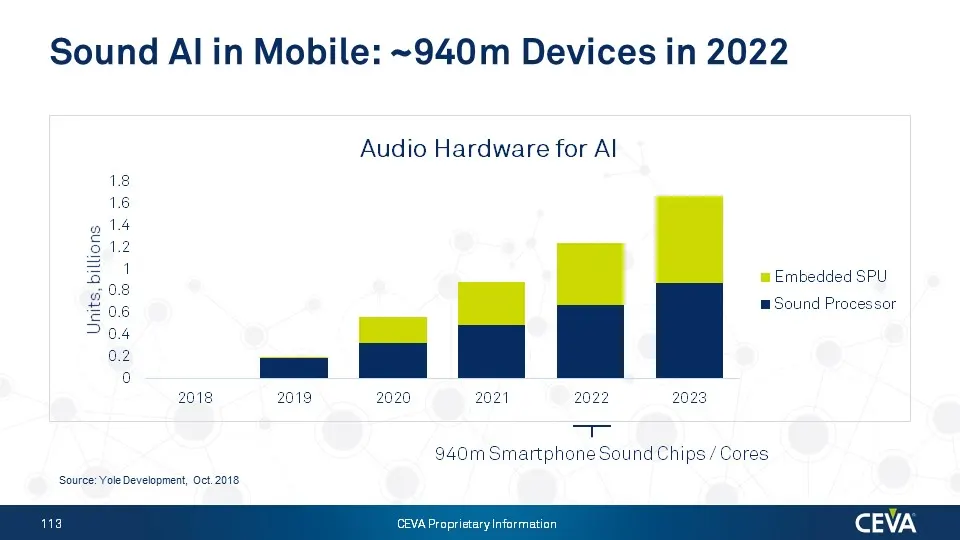
Slide 113
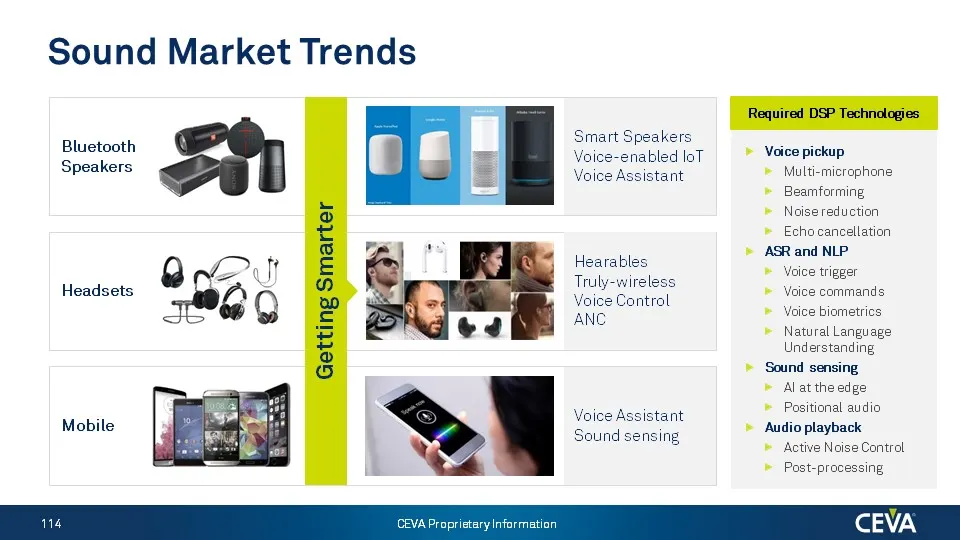
Slide 114
Slide 115
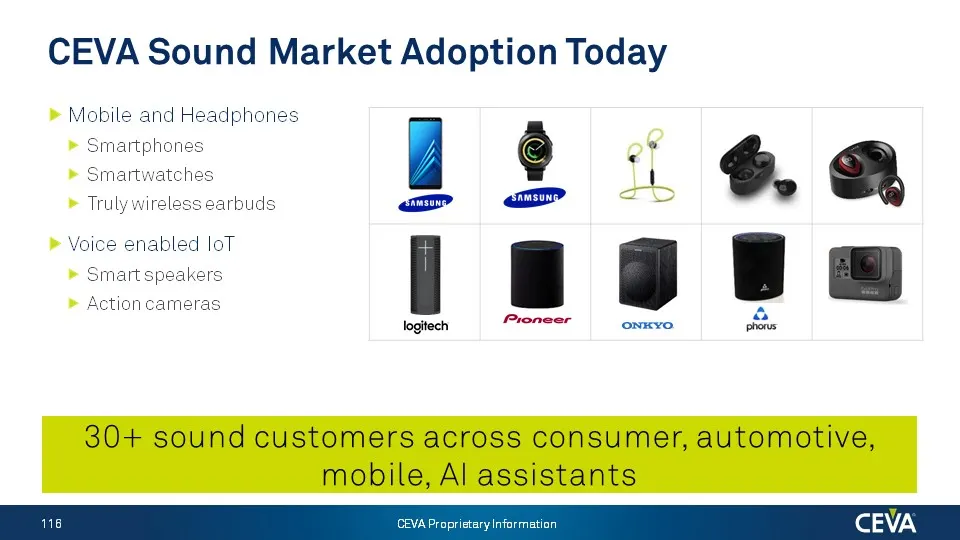
Slide 116
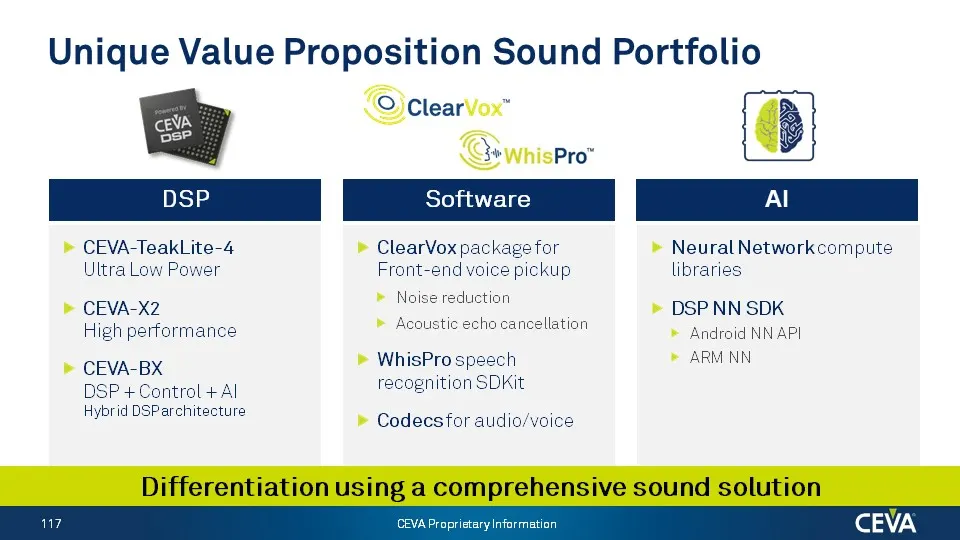
Slide 117
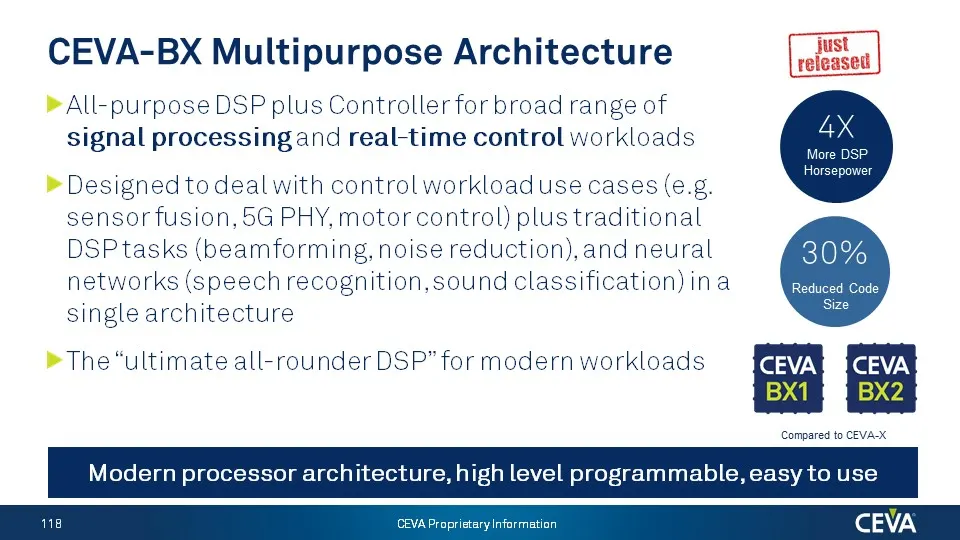
Slide 118
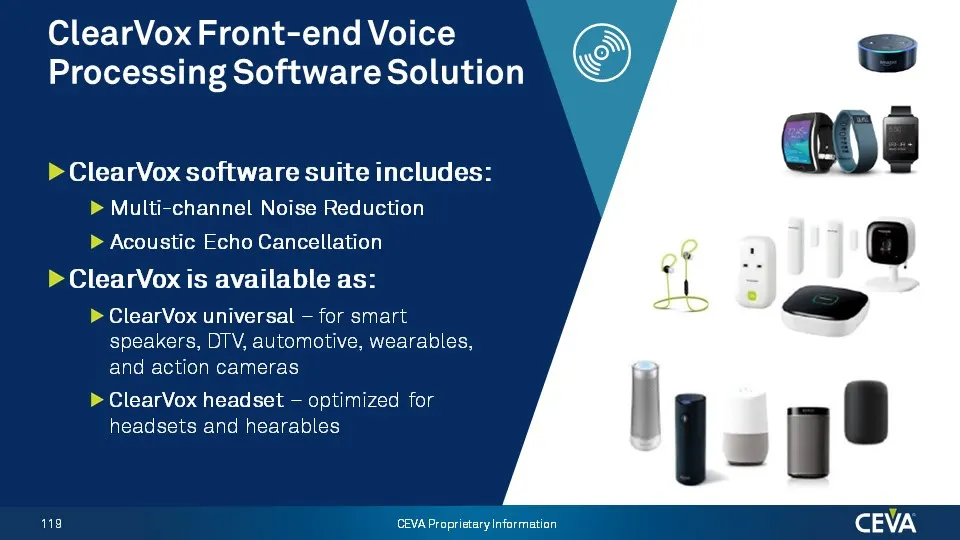
Slide 119
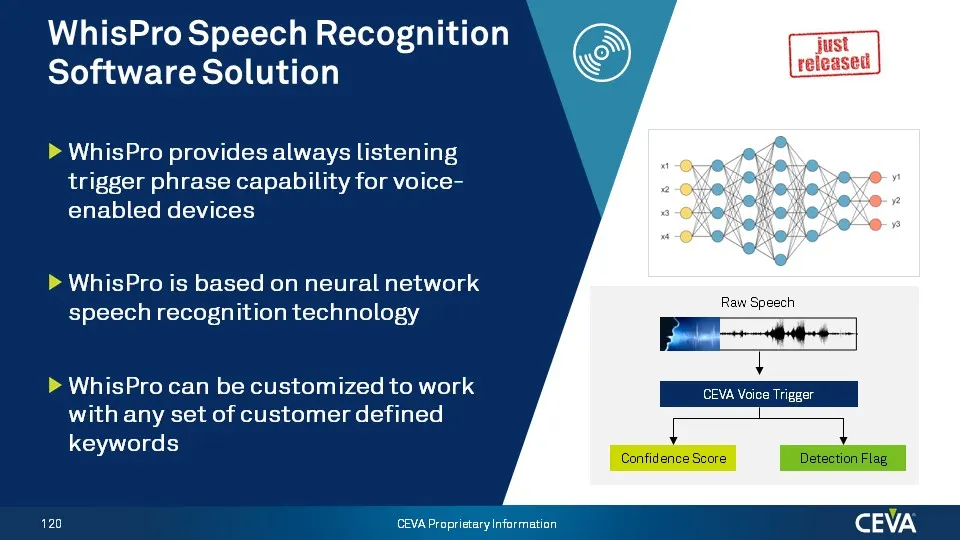
Slide 120
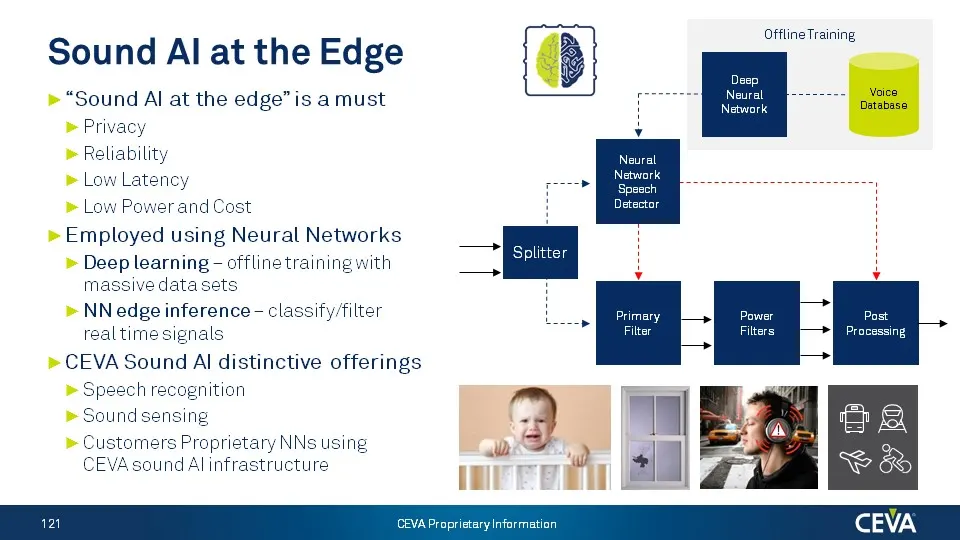
Slide 121
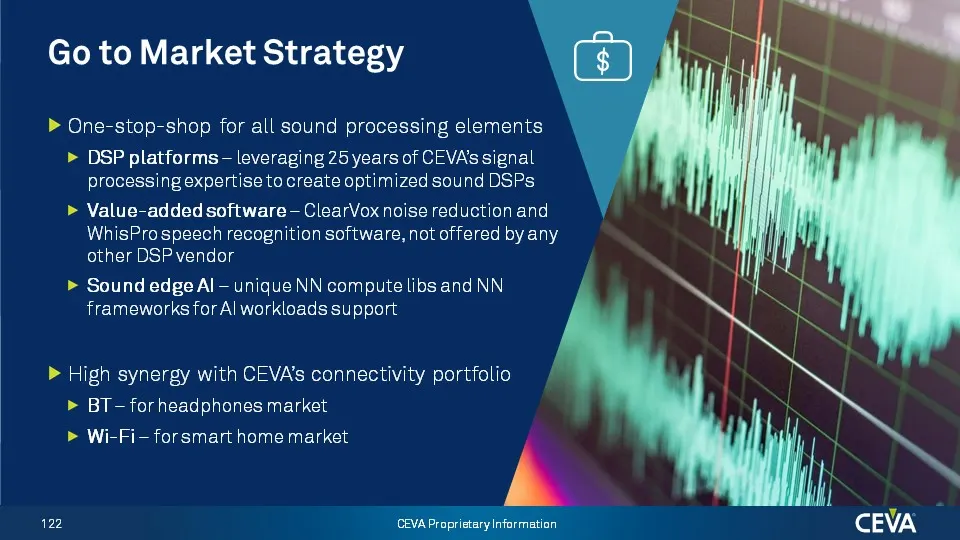
Slide 122
Slide 123
Slide 124
Slide 125
Slide 126
Slide 127
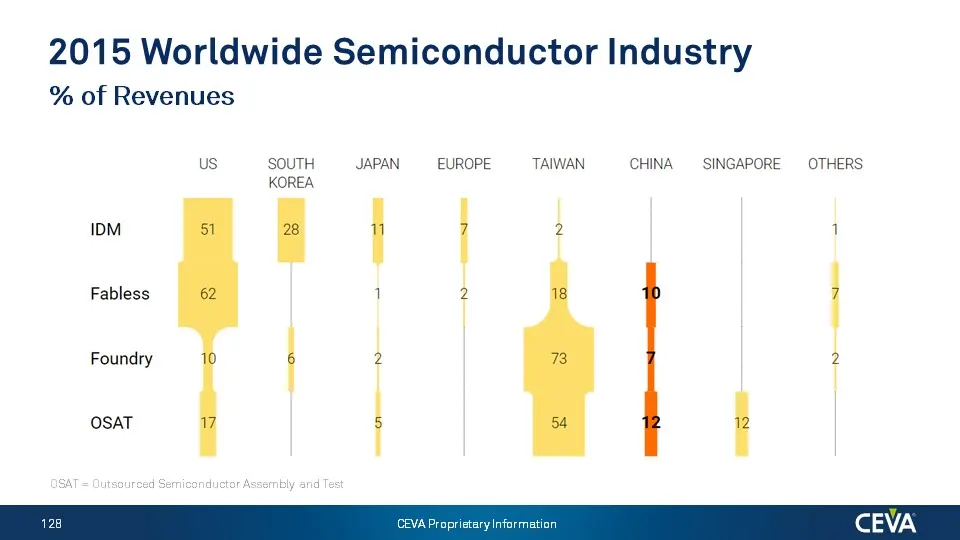
Slide 128
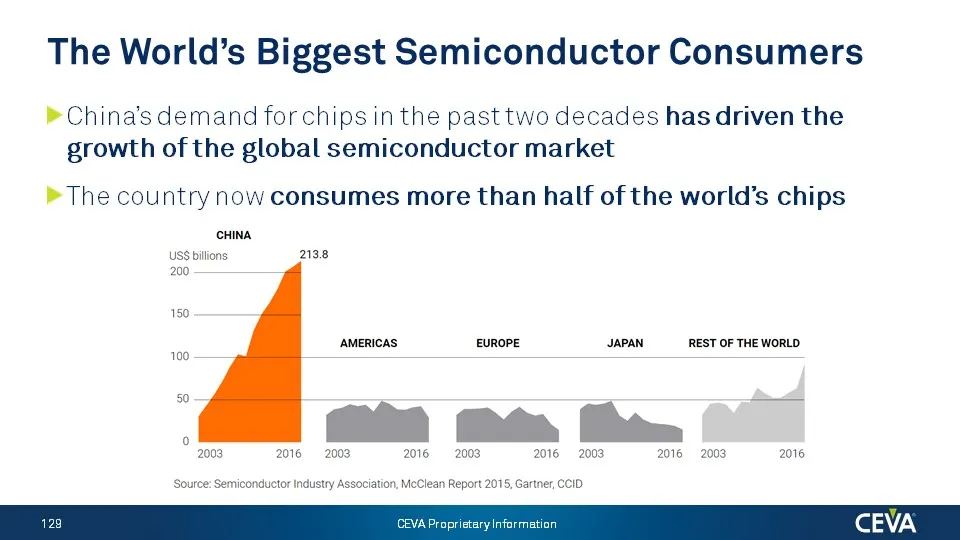
Slide 129
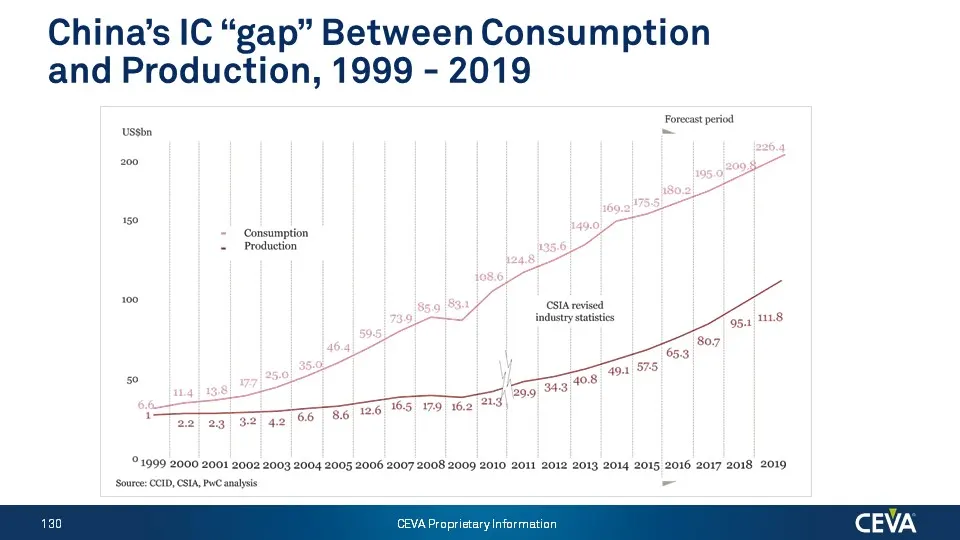
Slide 130
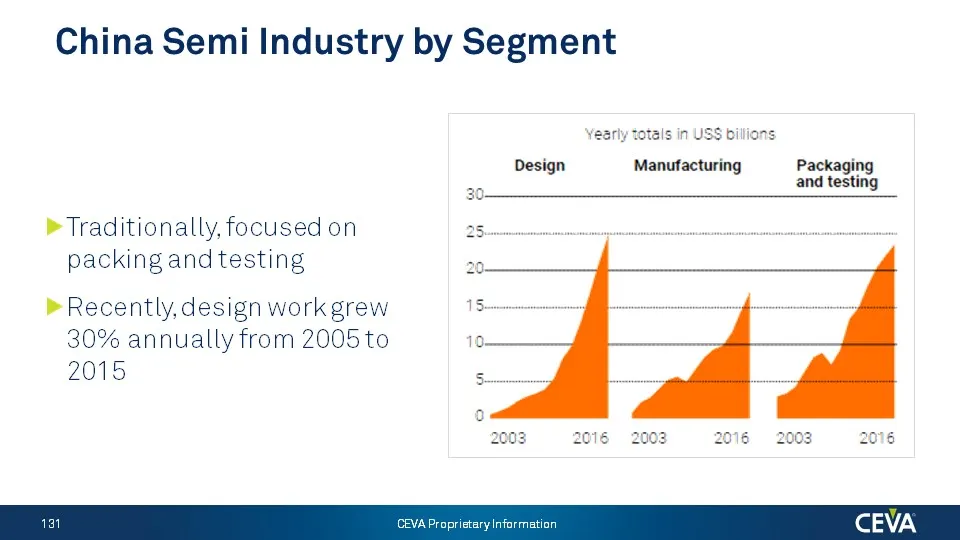
Slide 131
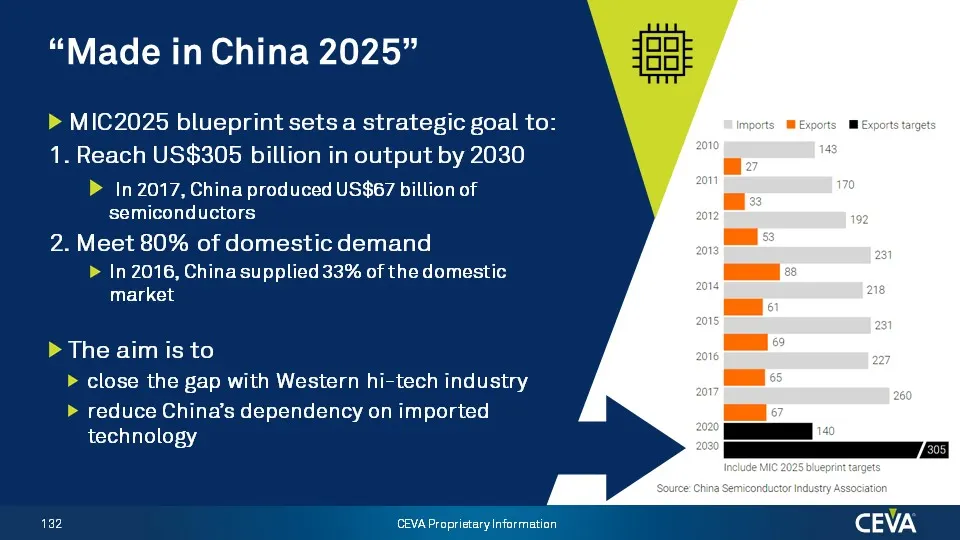
Slide 132
Slide 133
Slide 134
Slide 135
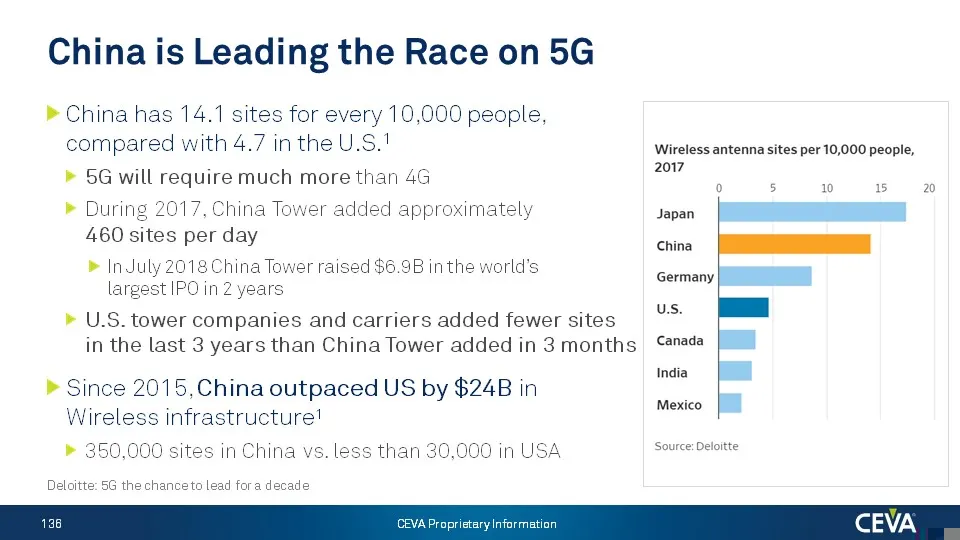
Slide 136
Slide 137
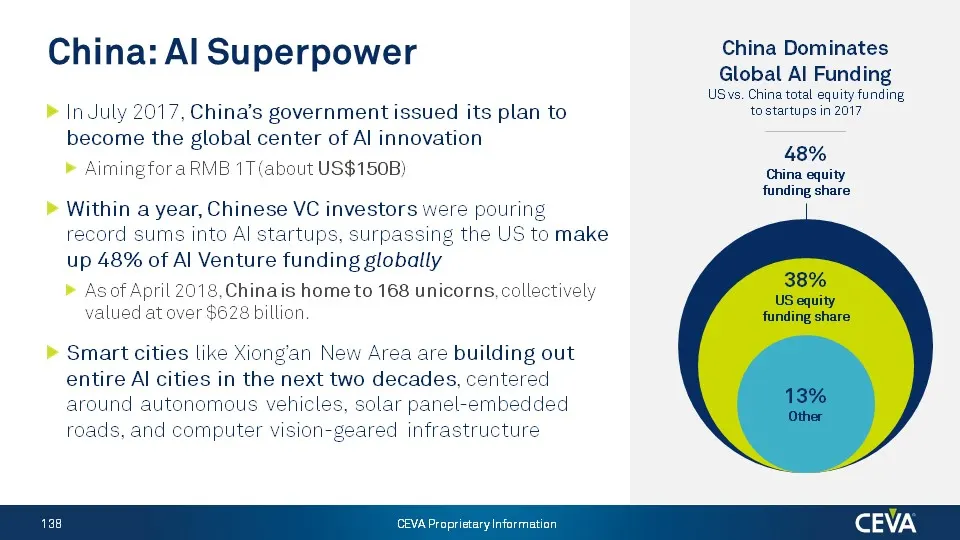
Slide 138
Slide 139
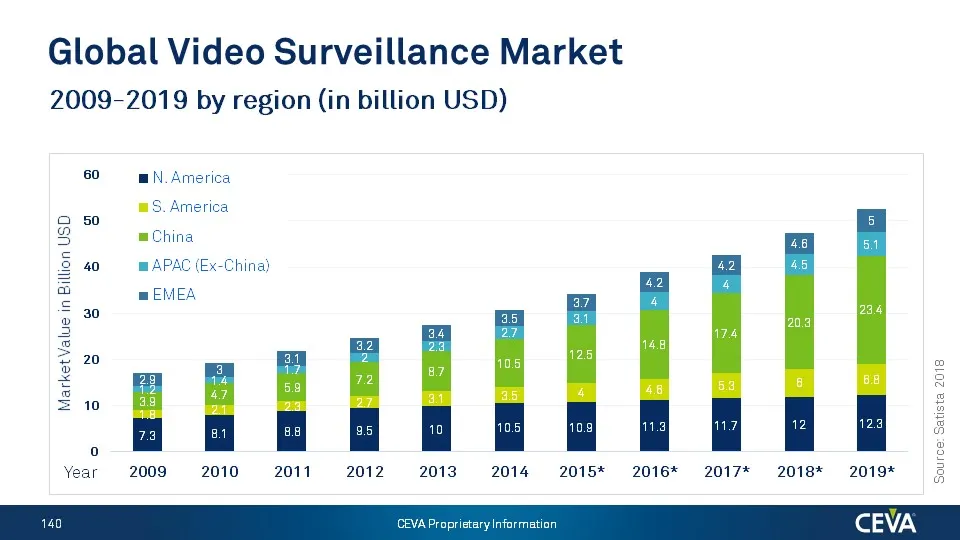
Slide 140
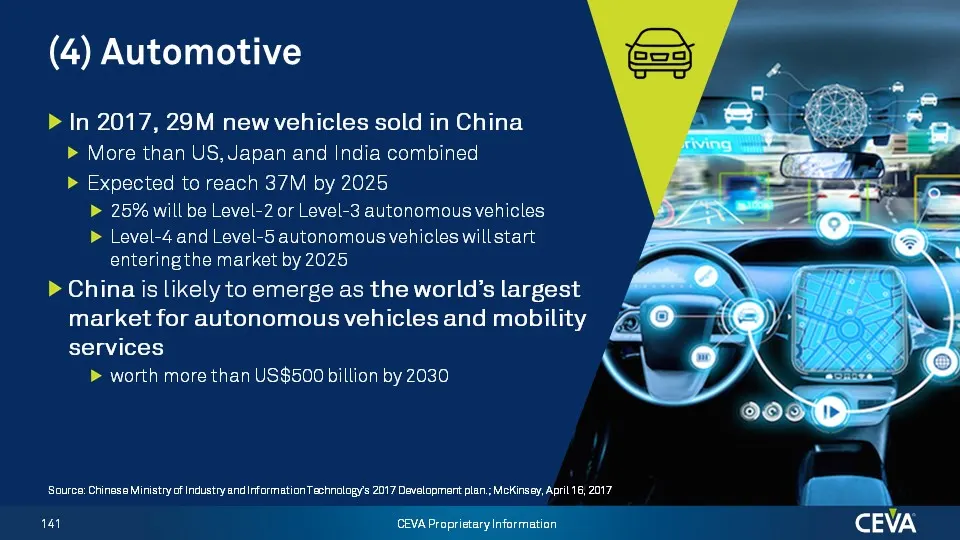
Slide 141
Slide 142
Slide 143
Slide 144
Slide 145
Slide 146
Slide 147
Slide 148
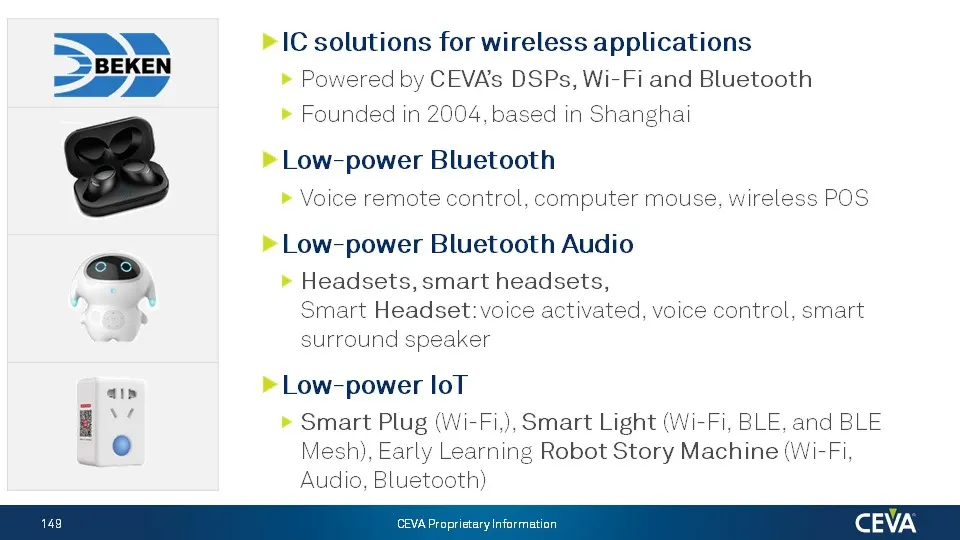
Slide 149
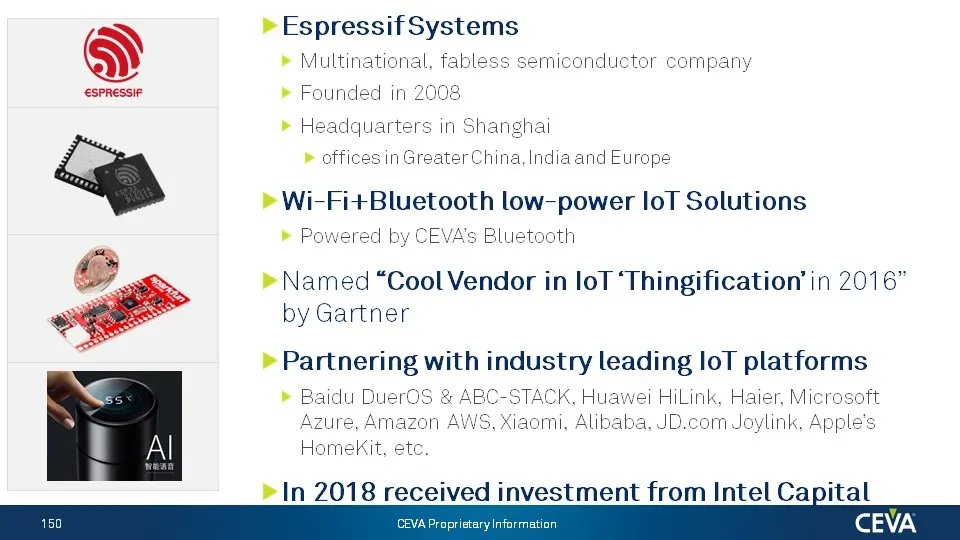
Slide 150
Slide 151
Slide 152
Slide 153
Slide 154
Slide 155
Slide 156
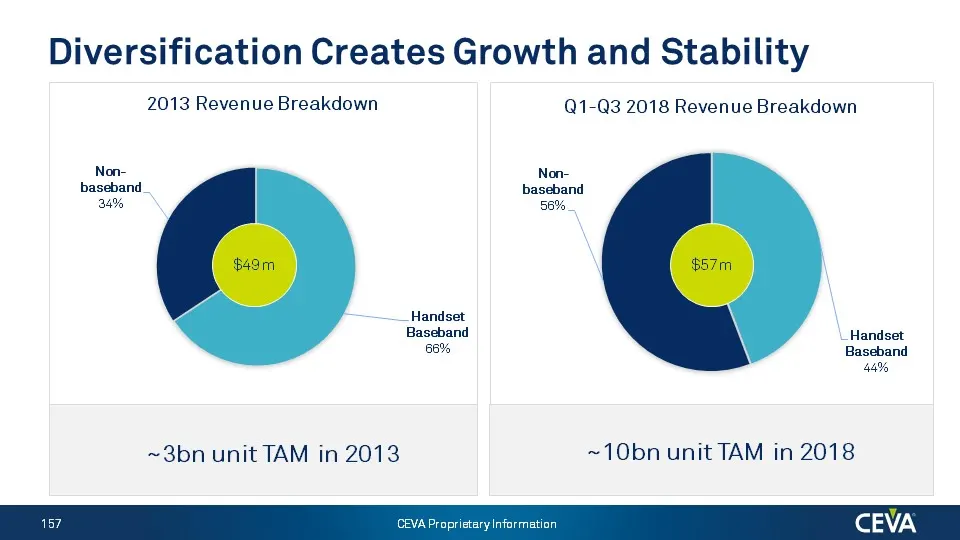
Slide 157
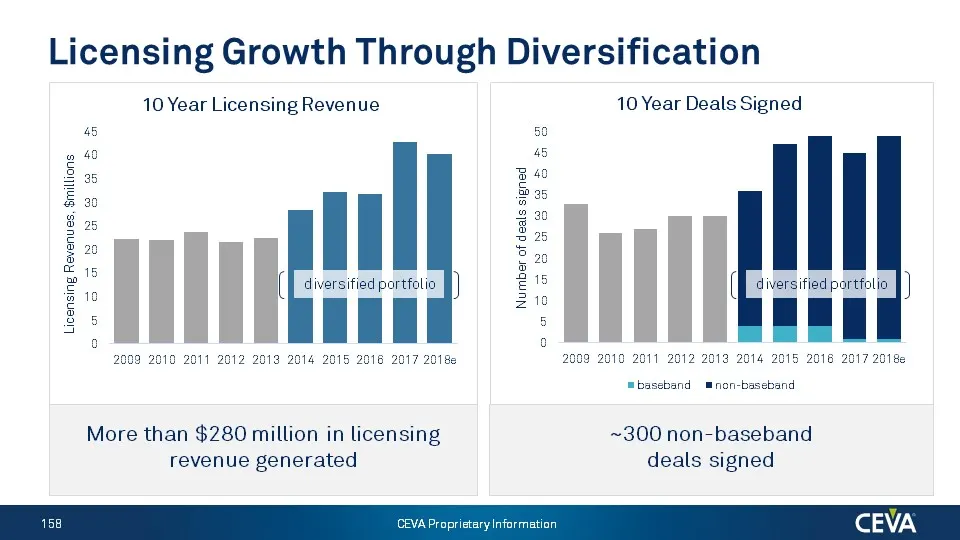
Slide 158
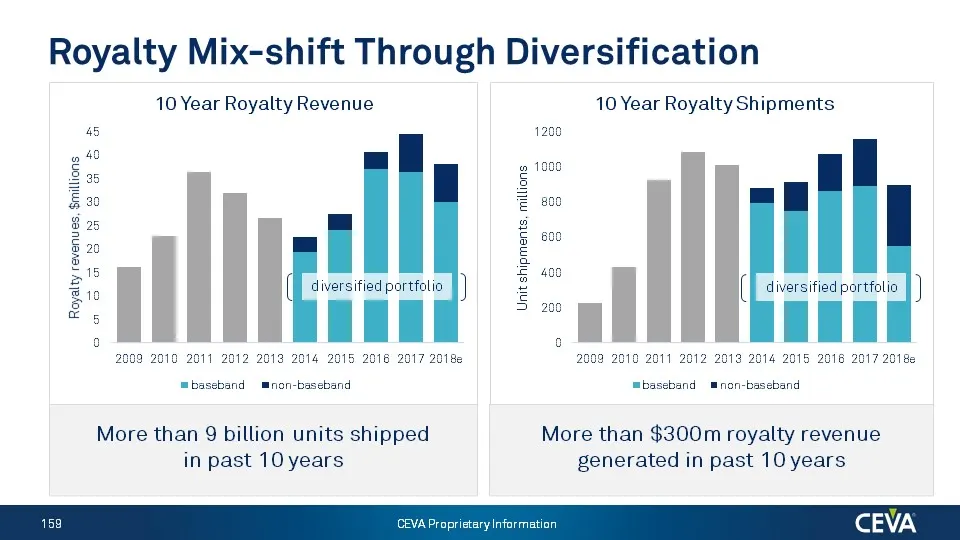
Slide 159
Slide 160
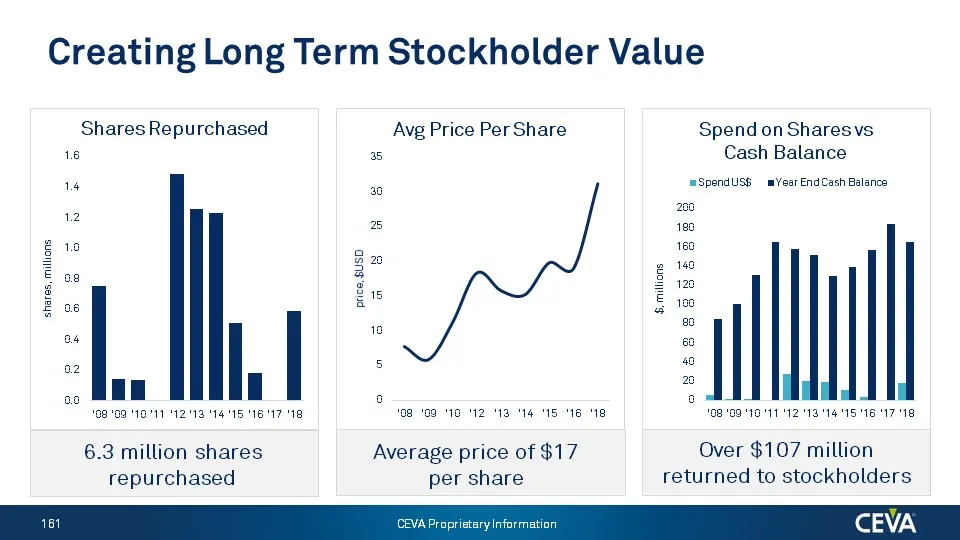
Slide 161
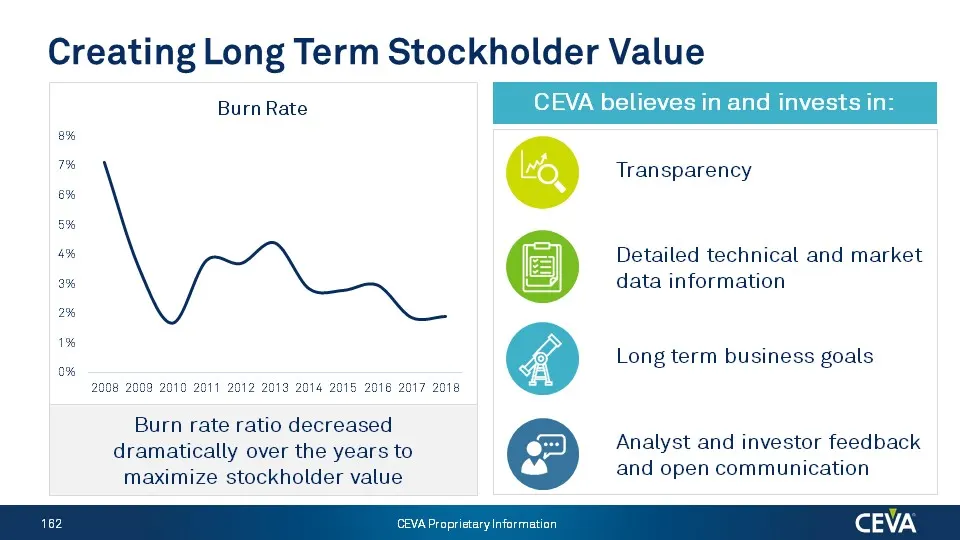
Slide 162
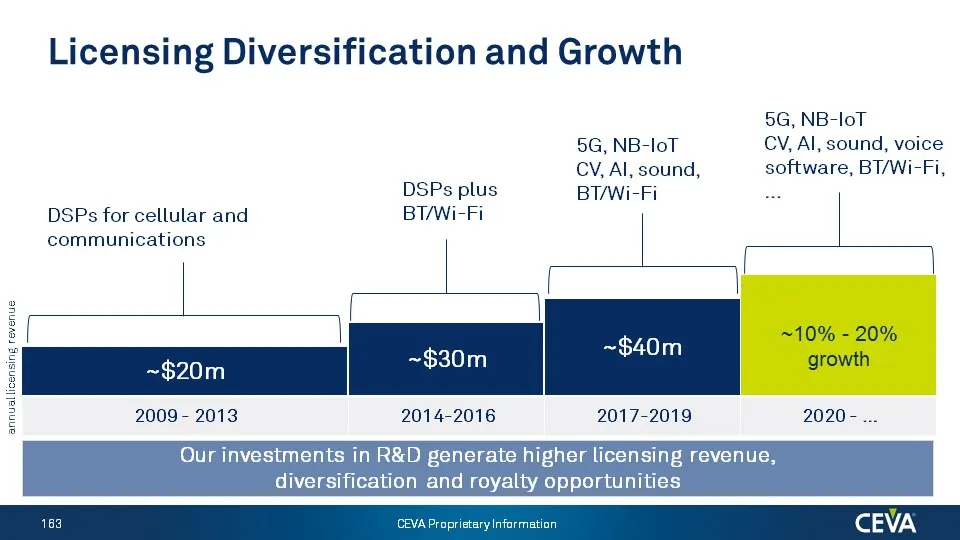
Slide 163
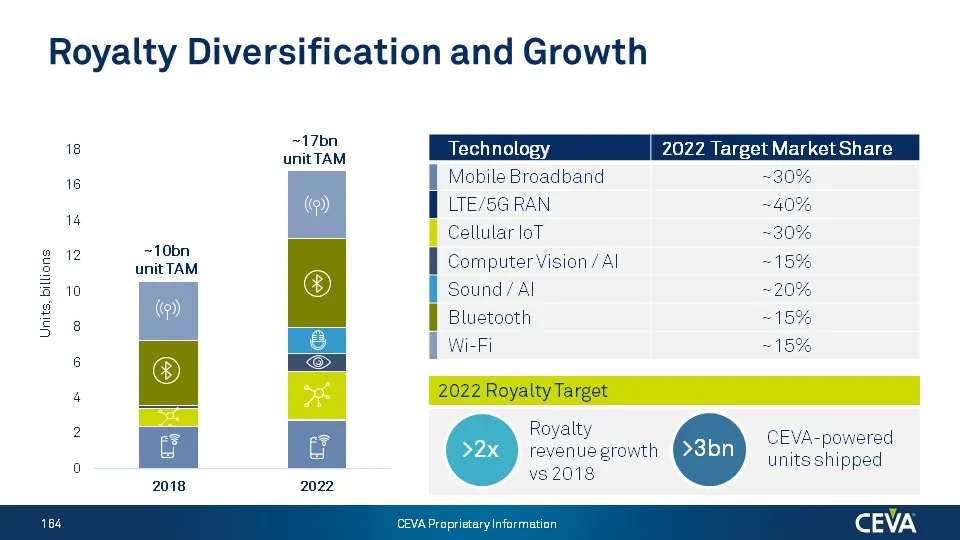
Slide 164
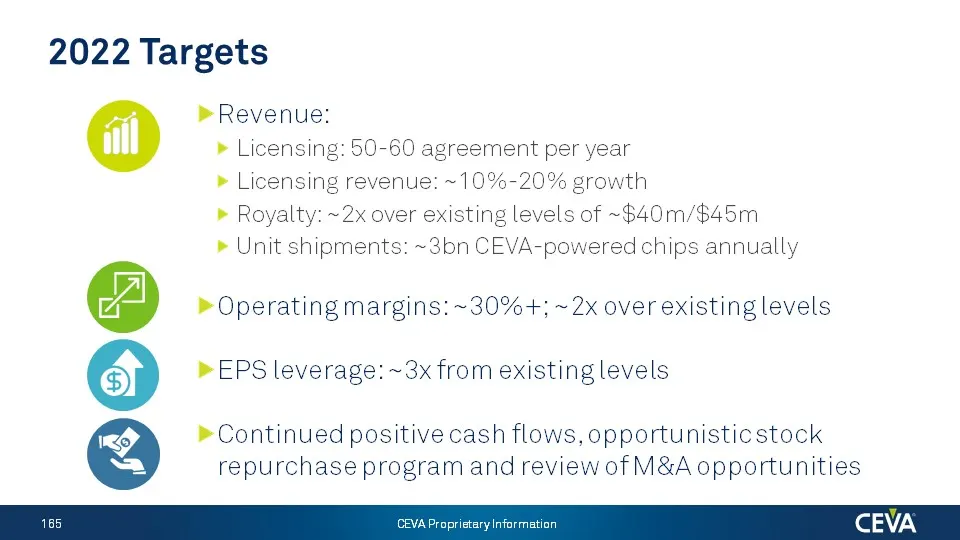
Slide 165
Slide 166
Source: SEC EDGAR · 8-K filed Jan 14, 2019
More decks from CEVA, Inc.
 Investor Day (December 2023)80 slides · December 2023
 CEVA RADAR Webinar (June 2023)28 slides · Jun 13, 2023
 Technical Presentation (June 2022)28 slides · June 2022
 Technical Presentation (December 2020)55 slides · December 2020
 Technical Presentation (November 2020)40 slides · November 2020
 Technical Presentation (September 2018)29 slides · Sep 17, 2018