Allied Capital — Merger or Acquisition (February 2010)
28 slides from Allied Capital's merger presentation, Feb 25, 2010
Slide 1: Allied Capital / Ares Capital Proposed Merger Transaction
Allied Capital Corporation (ALD) / Ares Capital Corporation (ARCC) Proposed Merger Transaction February / March 2010 Washington DC | New York www.alliedcapital.com
Slide 2: Important Notice
Important Notice FORWARD-LOOKING STATEMENTS Statements included herein and in the Joint Proxy Statement/Prospectus referred to below may constitute "forward-looking statements," which relate to future events or the future performance or financial condition of Ares Capital or Allied Capital or the co
Slide 3: Table of Contents
Strategic Rationale Strength of Ares Platform Merger Transaction Process Table of Contents Executive Summary
Slide 4: Transaction Summary
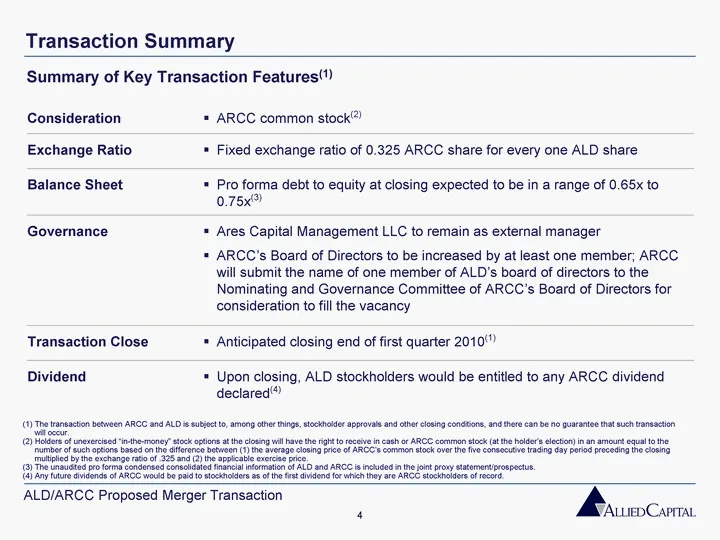
Transaction Summary Summary of Key Transaction Features(1) (1) The transaction between ARCC and ALD is subject to, among other things, stockholder approvals and other closing conditions, and there can be no guarantee that such transaction will occur. (2) Holders of unexercised "in-the-money" stock o
Slide 5: ALD Situation Overview - Stand-alone Headwinds
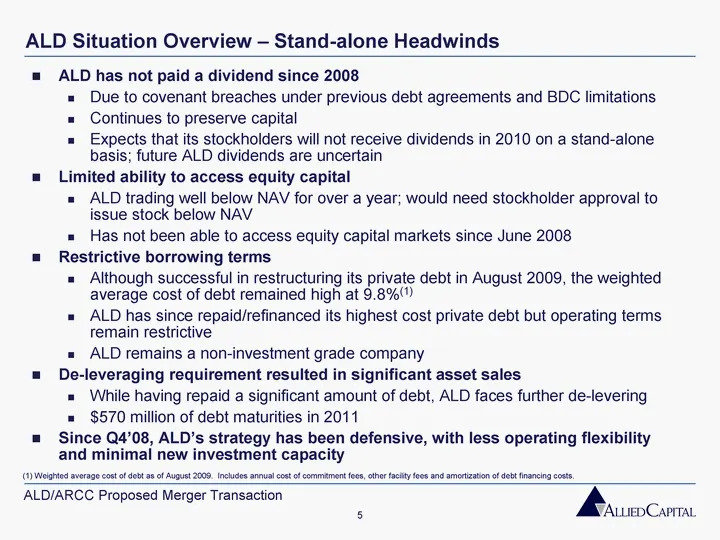
ALD Situation Overview - Stand-alone Headwinds ALD has not paid a dividend since 2008 Due to covenant breaches under previous debt agreements and BDC limitations Continues to preserve capital Expects that its stockholders will not receive dividends in 2010 on a stand-alone basis; future ALD dividend
Slide 6: Expected Benefits of Proposed Merger to ALD Stockholders
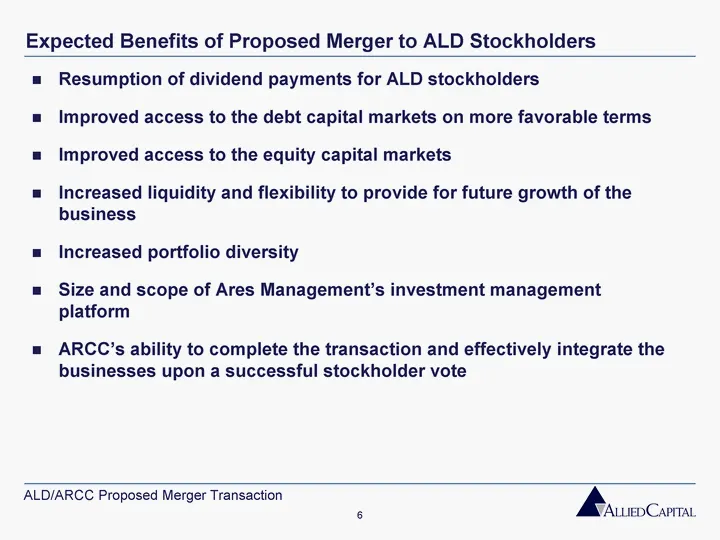
Expected Benefits of Proposed Merger to ALD Stockholders Resumption of dividend payments for ALD stockholders Improved access to the debt capital markets on more favorable terms Improved access to the equity capital markets Increased liquidity and flexibility to provide for future growth of the busi
Slide 7: Value Creation - ALD's Trading Since Announcement
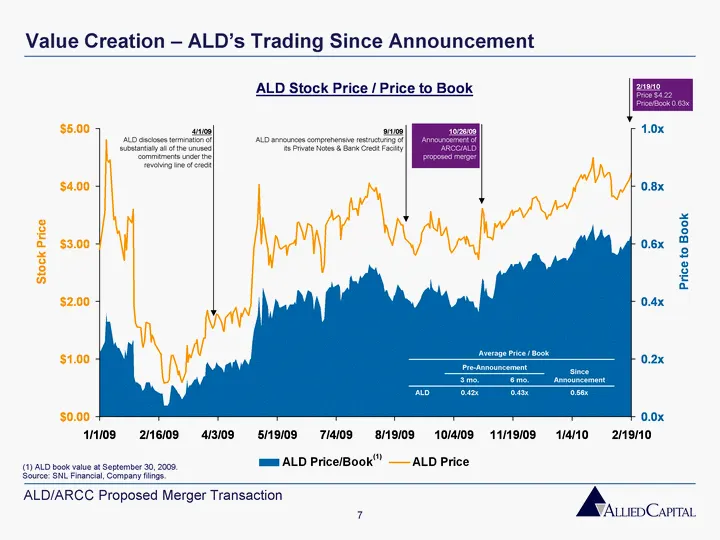
Value Creation - ALD's Trading Since Announcement ALD Price ALD Price/Book 1/1/2009 2.91 0.22 1/5/2009 3.55 0.26 1/6/2009 4.8 0.36 1/7/2009 4.47 0.33 1/8/2009 4.41 0.33 1/9/2009 4.46 0.33 1/12/2009 3.42 0.25 1/13/2009 3.47 0.26 1/14/2009 3.32 0.25 1/15/2009 3.18 0.24 1/16/2009 3.22 0.24 1/20/2009 2.
Slide 8: ARCC Price and Price/Book
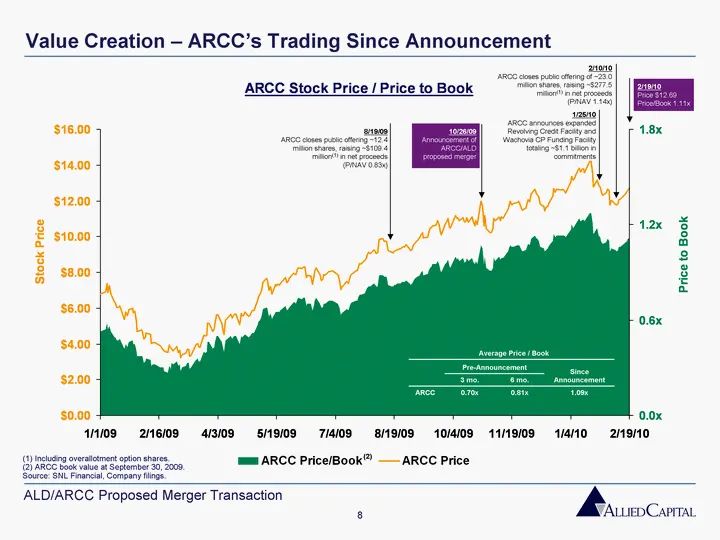
ARCC Price ARCC Price/Book 1/1/2009 6.79 0.53 1/5/2009 6.9 0.54 1/6/2009 7.39 0.58 1/7/2009 6.89 0.54 1/8/2009 7.24 0.56 1/9/2009 6.79 0.53 1/12/2009 6.34 0.49 1/13/2009 6.28 0.49 1/14/2009 6.05 0.47 1/15/2009 6.04 0.47 1/16/2009 6.13 0.48 1/20/2009 5.36 0.42 1/21/2009 5.77 0.45 1/22/2009 5.57 0.43
Slide 9: Strategic Rationale Supported By Third Party Analyst Commentary
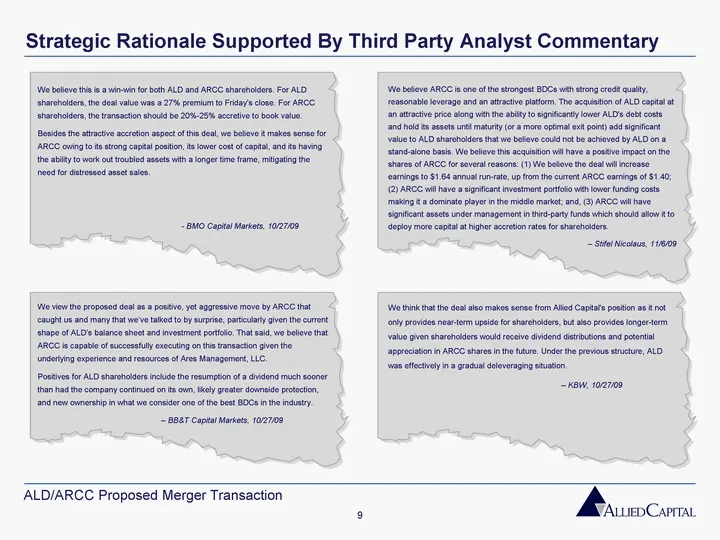
Strategic Rationale Supported By Third Party Analyst Commentary We believe this is a win-win for both ALD and ARCC shareholders. For ALD shareholders, the deal value was a 27% premium to Friday's close. For ARCC shareholders, the transaction should be 20%-25% accretive to book value. Besides the att
Slide 10: Transaction Timeline - From Announcement to Expected Close
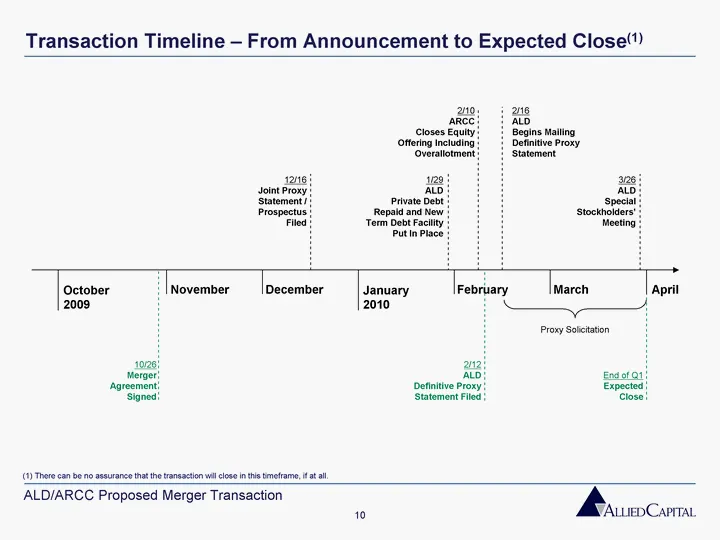
Transaction Timeline - From Announcement to Expected Close(1) 10/26 Merger Agreement Signed 12/16 Joint Proxy Statement / Prospectus Filed 1/29 ALD Private Debt Repaid and New Term Debt Facility Put In Place 2/10 ARCC Closes Equity Offering Including Overallotment 2/16 ALD Begins Mailing Definitive
Slide 11: Table of Contents
Strategic Rationale Strength of Ares Platform Merger Transaction Process Table of Contents Executive Summary
Slide 12: Resumption of Quarterly Dividends
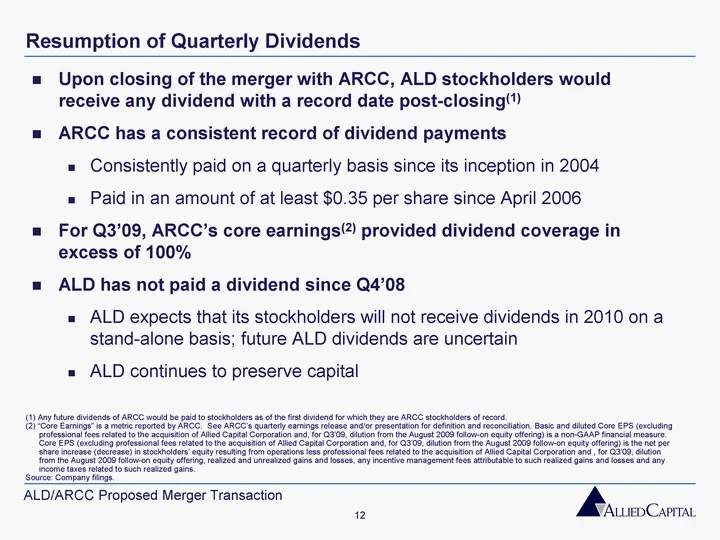
Resumption of Quarterly Dividends Upon closing of the merger with ARCC, ALD stockholders would receive any dividend with a record date post-closing(1) ARCC has a consistent record of dividend payments Consistently paid on a quarterly basis since its inception in 2004 Paid in an amount of at least $0
Slide 13: Improved Access to Debt Capital Markets at Better Terms
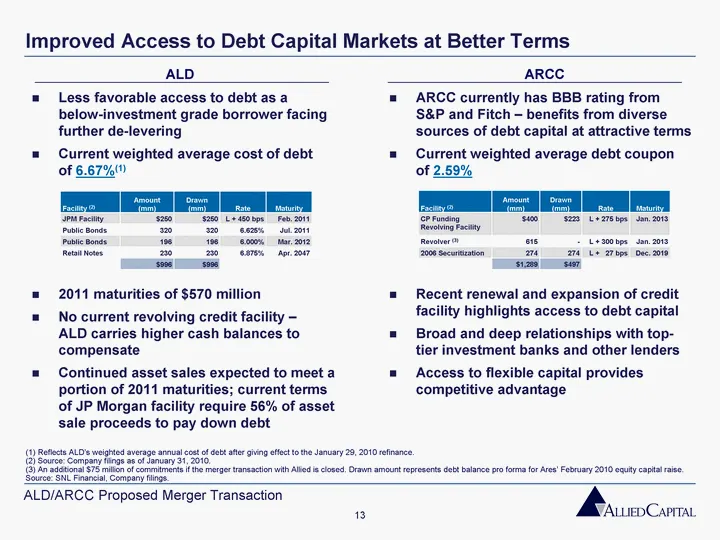
Improved Access to Debt Capital Markets at Better Terms Recent renewal and expansion of credit facility highlights access to debt capital Broad and deep relationships with top- tier investment banks and other lenders Access to flexible capital provides competitive advantage ARCC currently has BBB ra
Slide 14: Improved Access to Equity Capital Markets
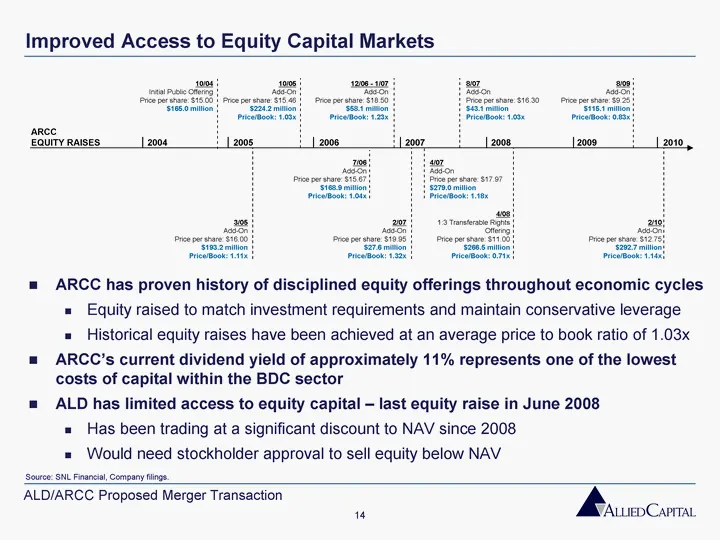
Improved Access to Equity Capital Markets ARCC has proven history of disciplined equity offerings throughout economic cycles Equity raised to match investment requirements and maintain conservative leverage Historical equity raises have been achieved at an average price to book ratio of 1.03x ARCC's
Slide 15: Creates a Larger and Better Capitalized Company
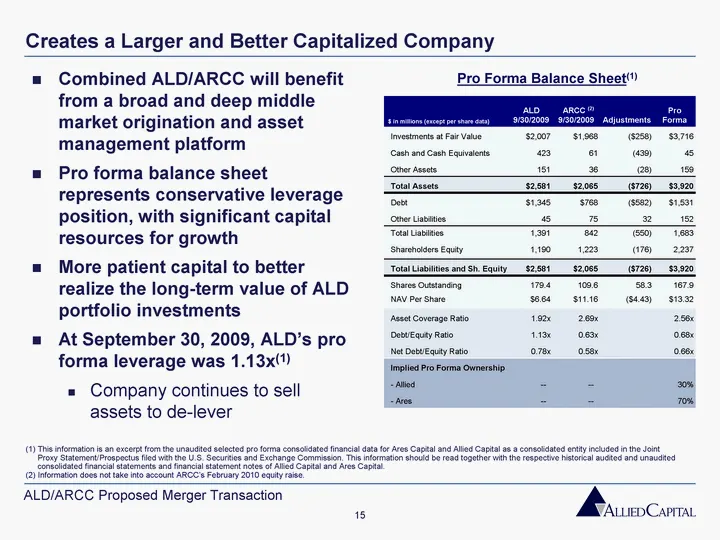
Creates a Larger and Better Capitalized Company Combined ALD/ARCC will benefit from a broad and deep middle market origination and asset management platform Pro forma balance sheet represents conservative leverage position, with significant capital resources for growth More patient capital to better
Slide 16: Improved Portfolio Diversification
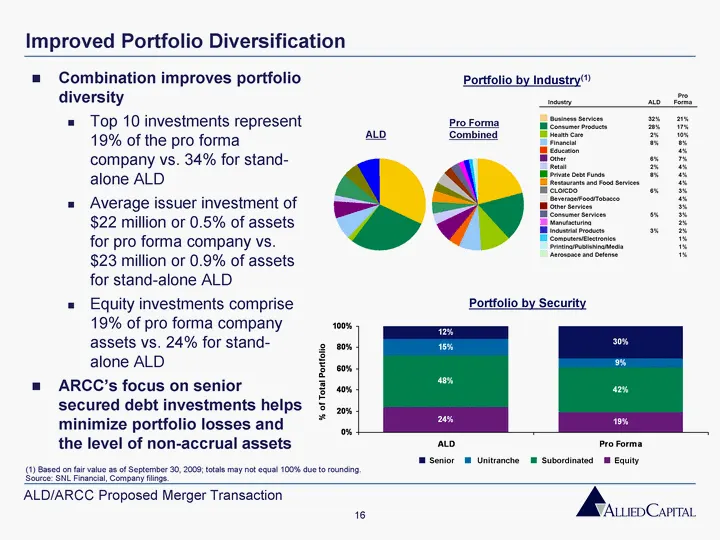
Improved Portfolio Diversification Combination improves portfolio diversity Top 10 investments represent 19% of the pro forma company vs. 34% for stand- alone ALD Average issuer investment of $22 million or 0.5% of assets for pro forma company vs. $23 million or 0.9% of assets for stand-alone ALD Eq
Slide 17: Table of Contents
Strategic Rationale Strength of Ares Platform Merger Transaction Process Table of Contents Executive Summary
Slide 18: The Ares Management Platform
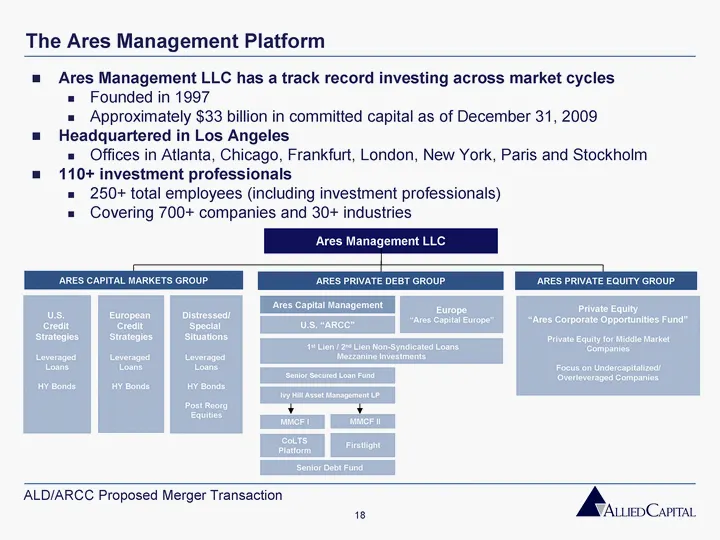
The Ares Management Platform Ares Management LLC has a track record investing across market cycles Founded in 1997 Approximately $33 billion in committed capital as of December 31, 2009 Headquartered in Los Angeles Offices in Atlanta, Chicago, Frankfurt, London, New York, Paris and Stockholm 110+ in
Slide 19: ARCC Has a Strong History of Disciplined Growth
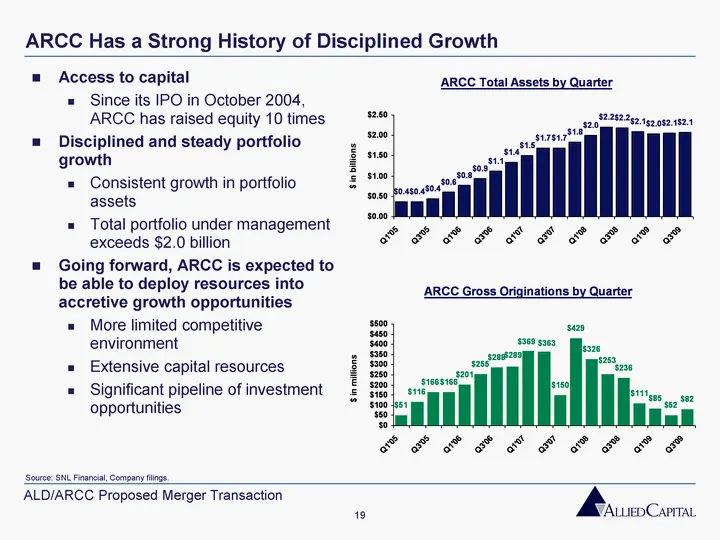
ARCC Has a Strong History of Disciplined Growth Access to capital Since its IPO in October 2004, ARCC has raised equity 10 times Disciplined and steady portfolio growth Consistent growth in portfolio assets Total portfolio under management exceeds $2.0 billion Going forward, ARCC is expected to be a
Slide 20: ARCC has a High Quality Portfolio
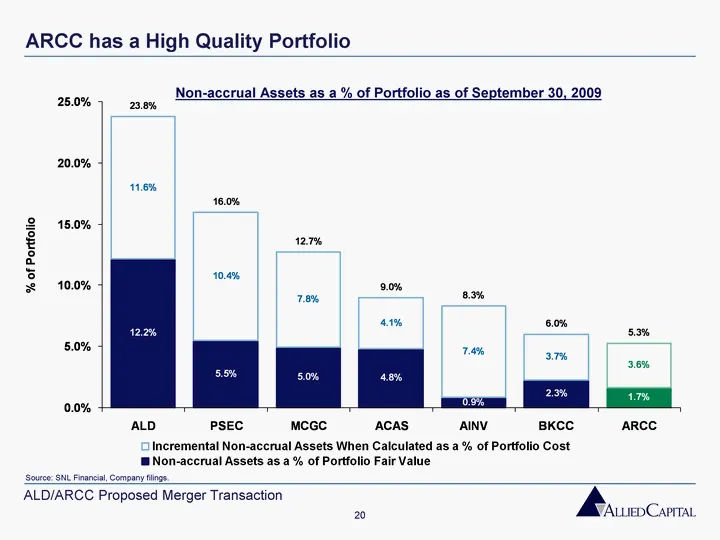
ARCC has a High Quality Portfolio Non-accrual Assets as a % of Portfolio Fair Value Incremental Non-accrual Assets When Calculated as a % of Portfolio Cost total ALD 0.1217 0.1158 0.2375 PSEC 0.0552 0.1043 0.1595 MCGC 0.0498 0.0775 0.1273 ACAS 0.0483 0.0414 0.0897 AINV 0.0087 0.0744 0.0831 BKCC 0.02
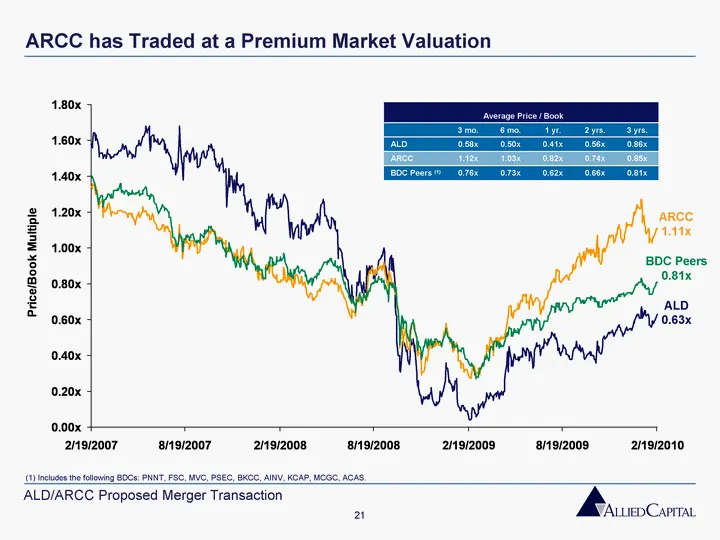
Slide 21: 2/19/2007 1.58 1.34 1.41 2/21/2007 1.56 1.33 1.39 2/22/2007 1.59 1.36 1.39 2/23/2007 1.64
2/19/2007 1.58 1.34 1.41 2/21/2007 1.56 1.33 1.39 2/22/2007 1.59 1.36 1.39 2/23/2007 1.64 1.35 1.38 2/26/2007 1.64 1.35 1.36 2/27/2007 1.6 1.3 1.32 2/28/2007 1.63 1.34 1.32 3/1/2007 1.61 1.33 1.31 3/2/2007 1.61 1.32 1.3 3/5/2007 1.57 1.22 1.24 3/6/2007 1.51 1.24 1.28 3/7/2007 1.52 1.24 1.28 3/8/2007
Slide 22: Table of Contents
Strategic Rationale Strength of Ares Platform Merger Transaction Process Table of Contents Executive Summary
Slide 23: 2008 and 2009 Were Challenging for ALD
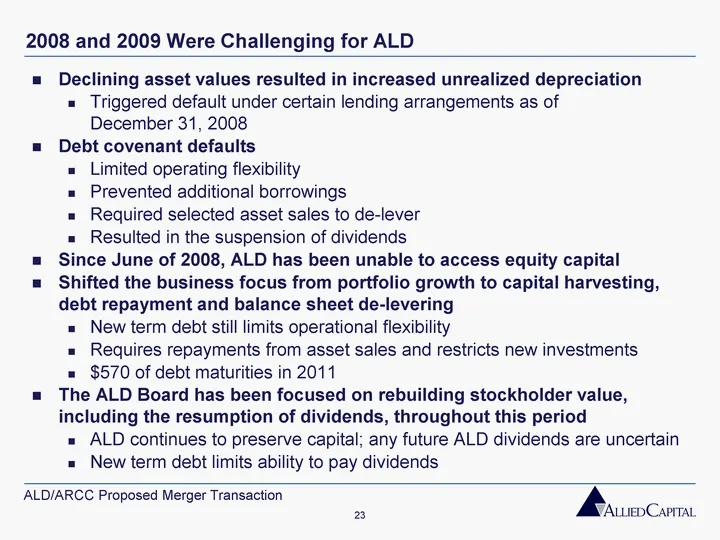
2008 and 2009 Were Challenging for ALD Declining asset values resulted in increased unrealized depreciation Triggered default under certain lending arrangements as of December 31, 2008 Debt covenant defaults Limited operating flexibility Prevented additional borrowings Required selected asset sales
Slide 24: ALD's Board Conducted a Thorough Review of Strategic Alternatives
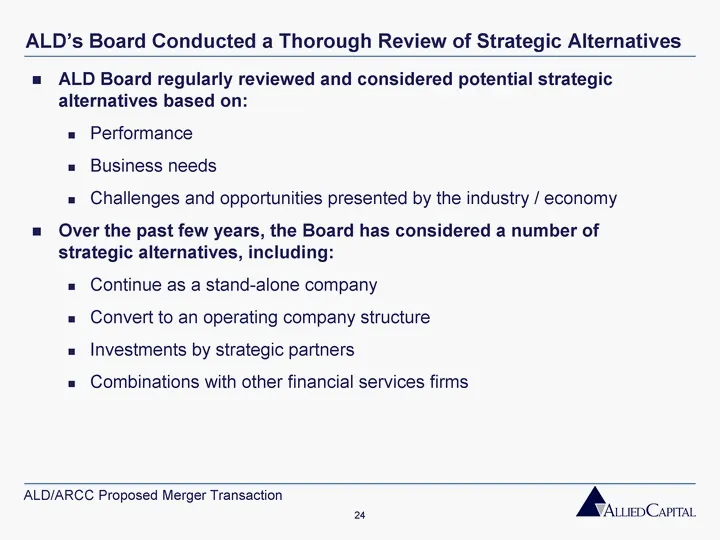
ALD's Board Conducted a Thorough Review of Strategic Alternatives ALD Board regularly reviewed and considered potential strategic alternatives based on: Performance Business needs Challenges and opportunities presented by the industry / economy Over the past few years, the Board has considered a num
Slide 25: ALD's Board Unanimously Recommended a Merger with ARCC
ALD's Board Unanimously Recommended a Merger with ARCC After consideration of other strategic alternatives and following an unsolicited approach by ARCC, ALD: Engaged Sullivan & Cromwell and Sutherland Asbill & Brennan to act as counsel Granted exclusivity to ARCC to conduct extensive diligence Cond
Slide 26: Integration Activity Update
Integration Activity Update ARCC engaged a third-party integration consultant Key targets are being communicated regularly Tracking integration milestones Established Steering and Management Committees to oversee integration process led by assigned functional group heads Weekly meetings between tran
Slide 27: ARCC's Ability to Complete Closing Upon Stockholder Vote
ARCC's Ability to Complete Closing Upon Stockholder Vote Due Diligence ARCC team of over 100 internal and external professionals conducted extensive due diligence on ALD's portfolio and business Integration Professional and institutionalized approach to integration Access to Capital ARCC recently ex
Slide 28: Expected Benefits of Proposed Merger to ALD Stockholders
Expected Benefits of Proposed Merger to ALD Stockholders Resumption of dividend payments for ALD stockholders Improved access to the debt capital markets on more favorable terms Improved access to the equity capital markets Increased liquidity and flexibility to provide for future growth of the busi
Source: SEC EDGAR · DEFA14A filed Feb 25, 2010